Western Asset Mortgage Capital
Western Asset Mortgage Capital — Q4 2012 Earnings Presentation
14 slides from Western Asset Mortgage Capital's earnings presentation, Mar 7, 2013
Slide 1: Fourth Quarter 2012 Investor Presentation
Fourth Quarter 2012 Investor Presentation March 6, 2013
Slide 2: Safe Harbor Statement
Safe Harbor Statement We make forward-looking statements in this presentation that are subject to risks and uncertainties. These forward-looking statements include information about possible or assumed future results of our business, financial condition, liquidity, results of operations, plans and o
Slide 3: Key Highlights
Key Highlights 2012 Raised over $200 million in IPO and concurrent private placements Since the IPO, generated an annualized economic return on book value in excess of 32%, comprised of: $2.35 per share in dividends $1.67 per share increase in book value Raised over $300 million of new equity in a f
Slide 4: Fourth Quarter Financial Results
Fourth Quarter Financial Results GAAP Net Income of $24.8 million, or $1.04 per share Core Net Income of $25.1 million, or $1.05 per share Net Interest Income of $28.2 million, including interest from IO securities and taking into account the full cost of hedging Net interest spread of 2.05%, includ
Slide 5: Market Update
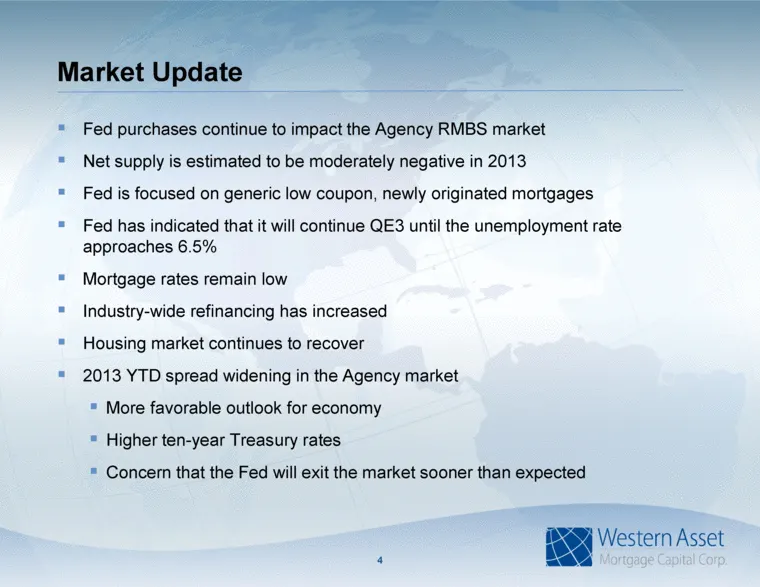
Market Update Fed purchases continue to impact the Agency RMBS market Net supply is estimated to be moderately negative in 2013 Fed is focused on generic low coupon, newly originated mortgages Fed has indicated that it will continue QE3 until the unemployment rate approaches 6.5% Mortgage rates rema
Slide 6: Portfolio Composition as of December 31, 2012
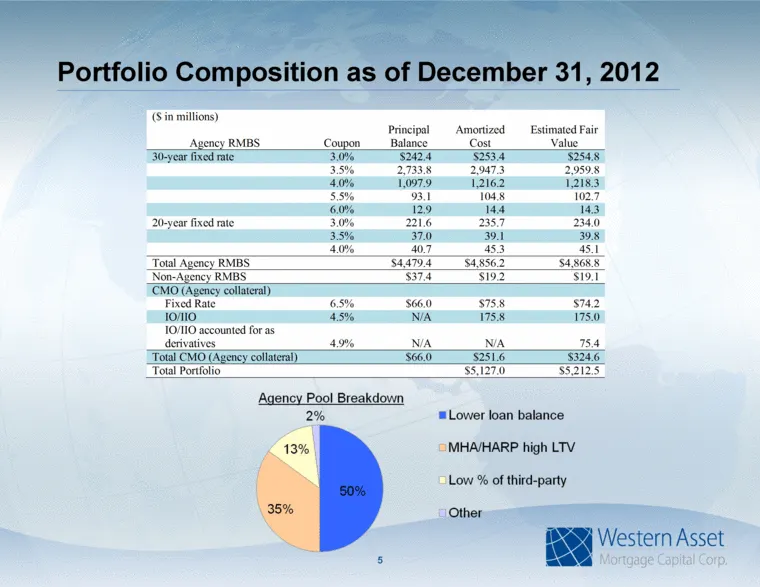
5 Portfolio Composition as of December 31, 2012 ($ in millions) Agency RMBS Coupon Principal Balance Amortized Cost Estimated Fair Value 30 - year fixed rate 3.0% $242.4 $253.4 $254.8 3.5% 2,733.8 2,947.3 2,959.8 4.0% 1,097.9 1,216.2 1,218.3 5.5% 93.1 104.8 102.7 6.0% 12.9 14.4 14.3 20 - year fixed
Slide 7: Key Portfolio Metrics as of December 31, 2012
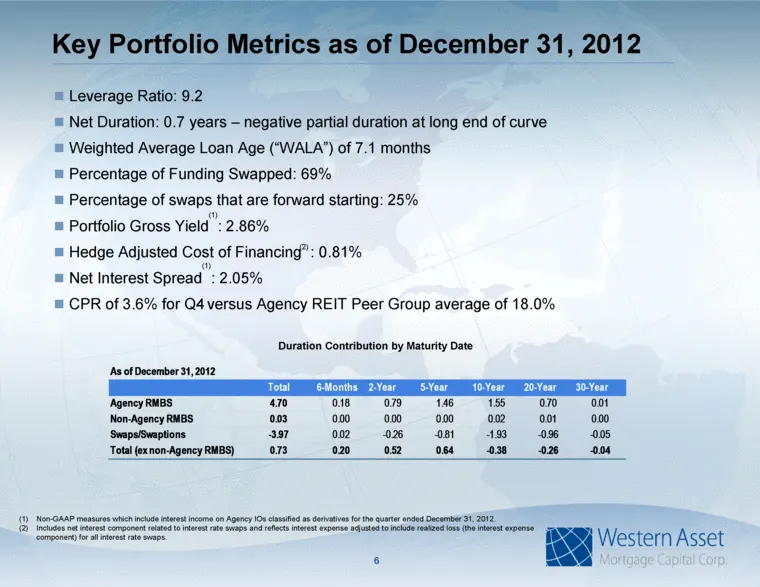
Non-GAAP measures which include interest income on Agency IOs classified as derivatives for the quarter ended December 31, 2012. Includes net interest component related to interest rate swaps and reflects interest expense adjusted to include realized loss (the interest expense component) for all int
Slide 8: Financing Summary
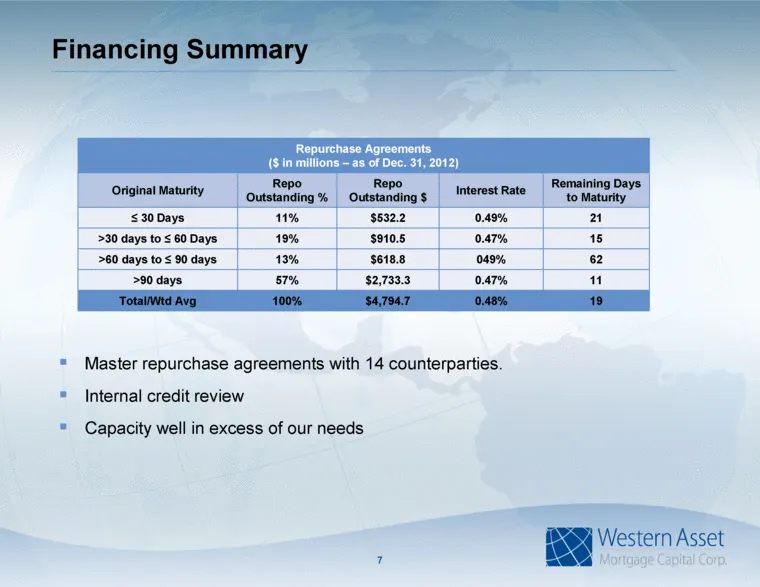
Financing Summary Repurchase Agreements ($ in millions – as of Dec. 31, 2012) Original Maturity Repo Outstanding % Repo Outstanding $ Interest Rate Remaining Days to Maturity < 30 Days 11% $532.2 0.49% 21 >30 days to < 60 Days 19% $910.5 0.47% 15 >60 days to < 90 days 13% $618.8 049% 62 >90 days 57%
Slide 9: Hedging Summary
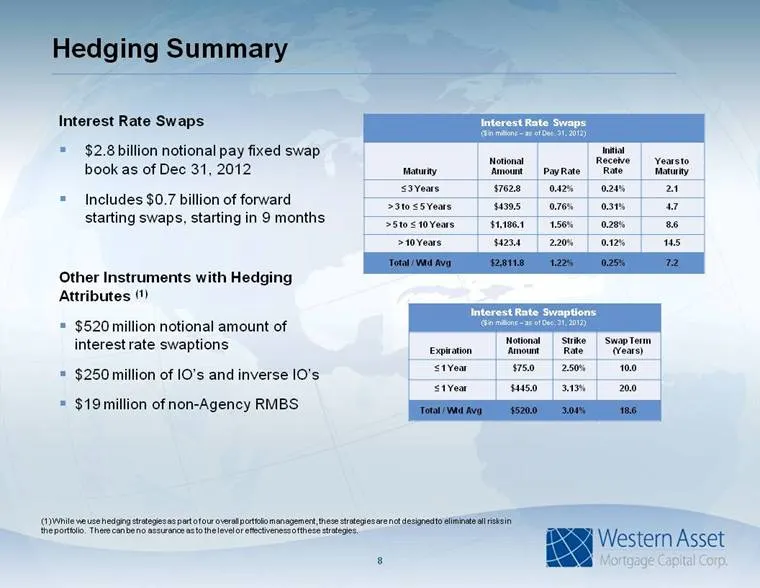
Hedging Summary Interest Rate Swaps ($ in millions – as of Dec. 31, 2012) Maturity Notional Amount Pay Rate Initial Receive Rate Years to Maturity < 3 Years $762.8 0.42% 0.24% 2.1 > 3 to < 5 Years $439.5 0.76% 0.31% 4.7 > 5 to < 10 Years $1,186.1 1.56% 0.28% 8.6 > 10 Years $423.4 2.20% 0.12% 14.5 To
Slide 10: Partial Duration Hedging Matters
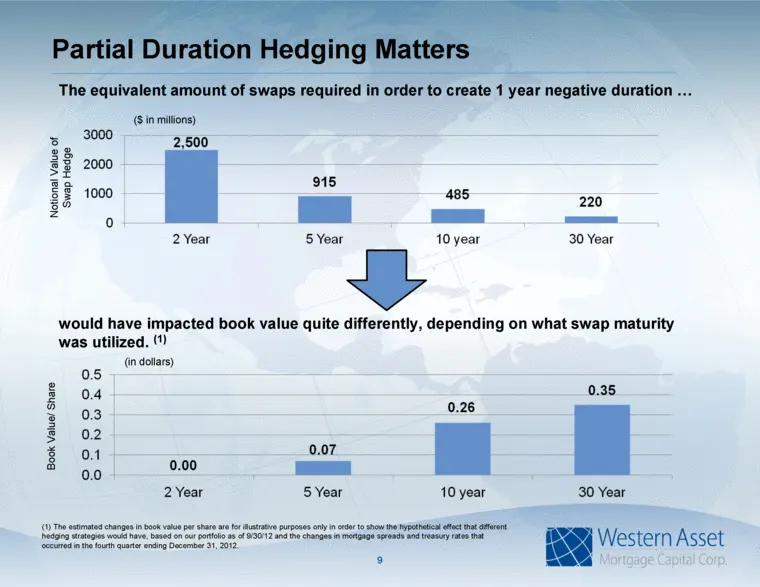
Partial Duration Hedging Matters 9 The equivalent amount of swaps required in order to create 1 year negative duration (1) The estimated changes in book value per share are for illustrative purposes only in order to show the hypothetical effect that different hedging strategies would have, based on
Slide 11: Portfolio Dynamics
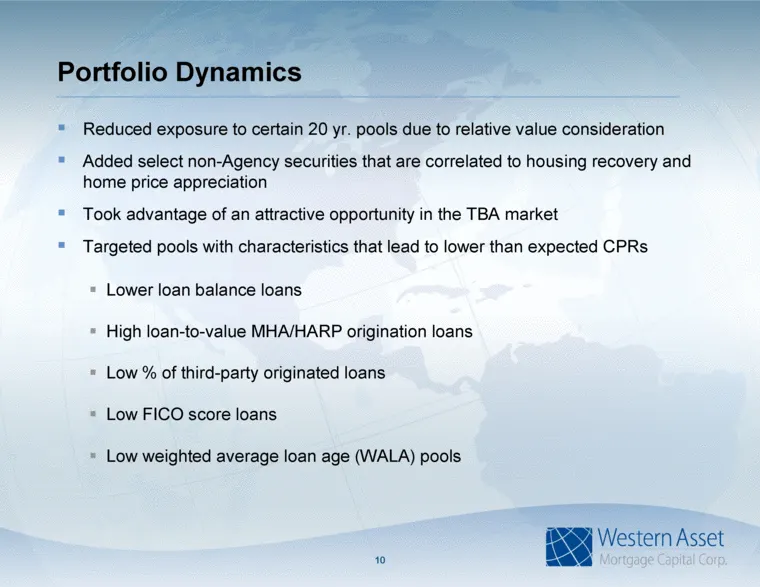
Portfolio Dynamics Reduced exposure to certain 20 yr. pools due to relative value consideration Added select non-Agency securities that are correlated to housing recovery and home price appreciation Took advantage of an attractive opportunity in the TBA market Targeted pools with characteristics tha
Slide 12: 2013 Outlook
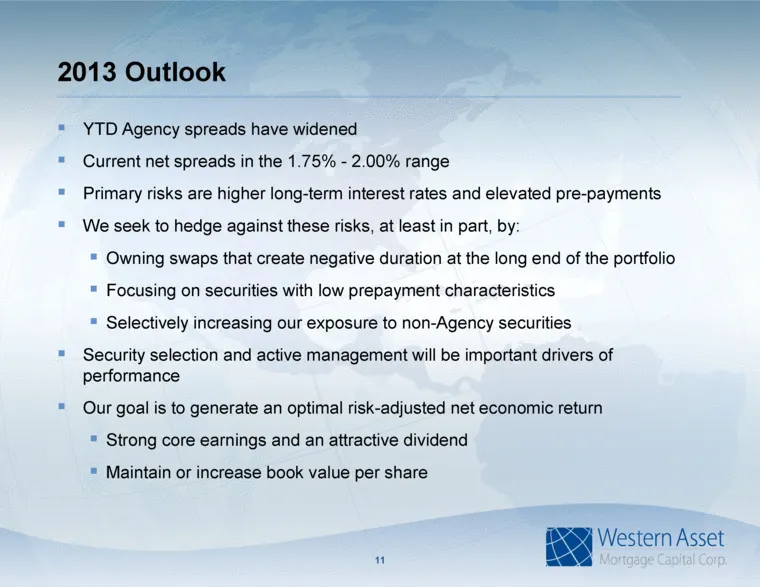
2013 Outlook YTD Agency spreads have widened Current net spreads in the 1.75% - 2.00% range Primary risks are higher long-term interest rates and elevated pre-payments We seek to hedge against these risks, at least in part, by: Owning swaps that create negative duration at the long end of the portfo
Slide 13: Investment Highlights
Investment Highlights Western Asset is one of the largest fixed income managers with extensive experience in managing RMBS since 1974 Differentiated investment approach to managing prepayment and interest rate risk We believe current net interest spreads and CPR position the Company well to seek its
Slide 14: Contact Information
Contact Information 13 Western Asset Mortgage Capital Corporation c/o Financial Profiles, Inc. 11601 Wilshire Blvd., Suite 1920 Los Angeles, CA 90025 www.westernassetmcc.com Investor Relations Contact: Larry Clark Tel: (310) 478-2700 x29 lclark@finprofiles.com
Source: SEC EDGAR · 8-K filed Mar 7, 2013
More decks from Western Asset Mortgage Capital
 Merger or Acquisition (August 2023)9 slides · Aug 9, 2023
 Q2 2023 Earnings Presentation32 slides · Aug 8, 2023
 Merger or Acquisition (July 2023)9 slides · Jul 13, 2023
 Merger or Acquisition (June 2023)16 slides · Jun 28, 2023
 Q1 2023 Earnings Presentation33 slides · May 4, 2023
 Q4 2022 Earnings Presentation34 slides · Mar 2, 2023