Bertrandt AG · XETR:BDT
Bertrandt — KPMG — Investor Presentation (June 2018)
40 slides from Bertrandt's investor presentation, Jun 14, 2018
Slide 1: KPMG's Global Automotive Executive Survey 2018
EXECUTIVE SUMMARY KPMG’s 19th consecutive Global Automotive Executive Survey 2018 There is a next in every industry – a next generation of products, services and content. See it sooner with KPMG. kpmg.com/gaes2018
Slide 2: More than 2,000,000 different views: the new look
More than 2,000,000 different views The new look This year, the concept of the Global Automotive Executive Survey received a completely new look with an interactive online platform. There you can not only dive deep into topics but also customize analyses to create your own perspectives and views – m
Slide 3: Table of contents
Table of contents KPMG.COM/GAES2018 Table of contents Foreword & our heritage 4 About the executive survey 6 Exploring the future ecosystem 8 MEGATRENDS BEYOND THE OBVIOUS 12 PRODUCT VALUE 16 CUSTOMER VALUE 24 ECOSYSTEM VALUE 28 KPMG Thought Leadership 36 Acknowledgements 38 How to use the online pl
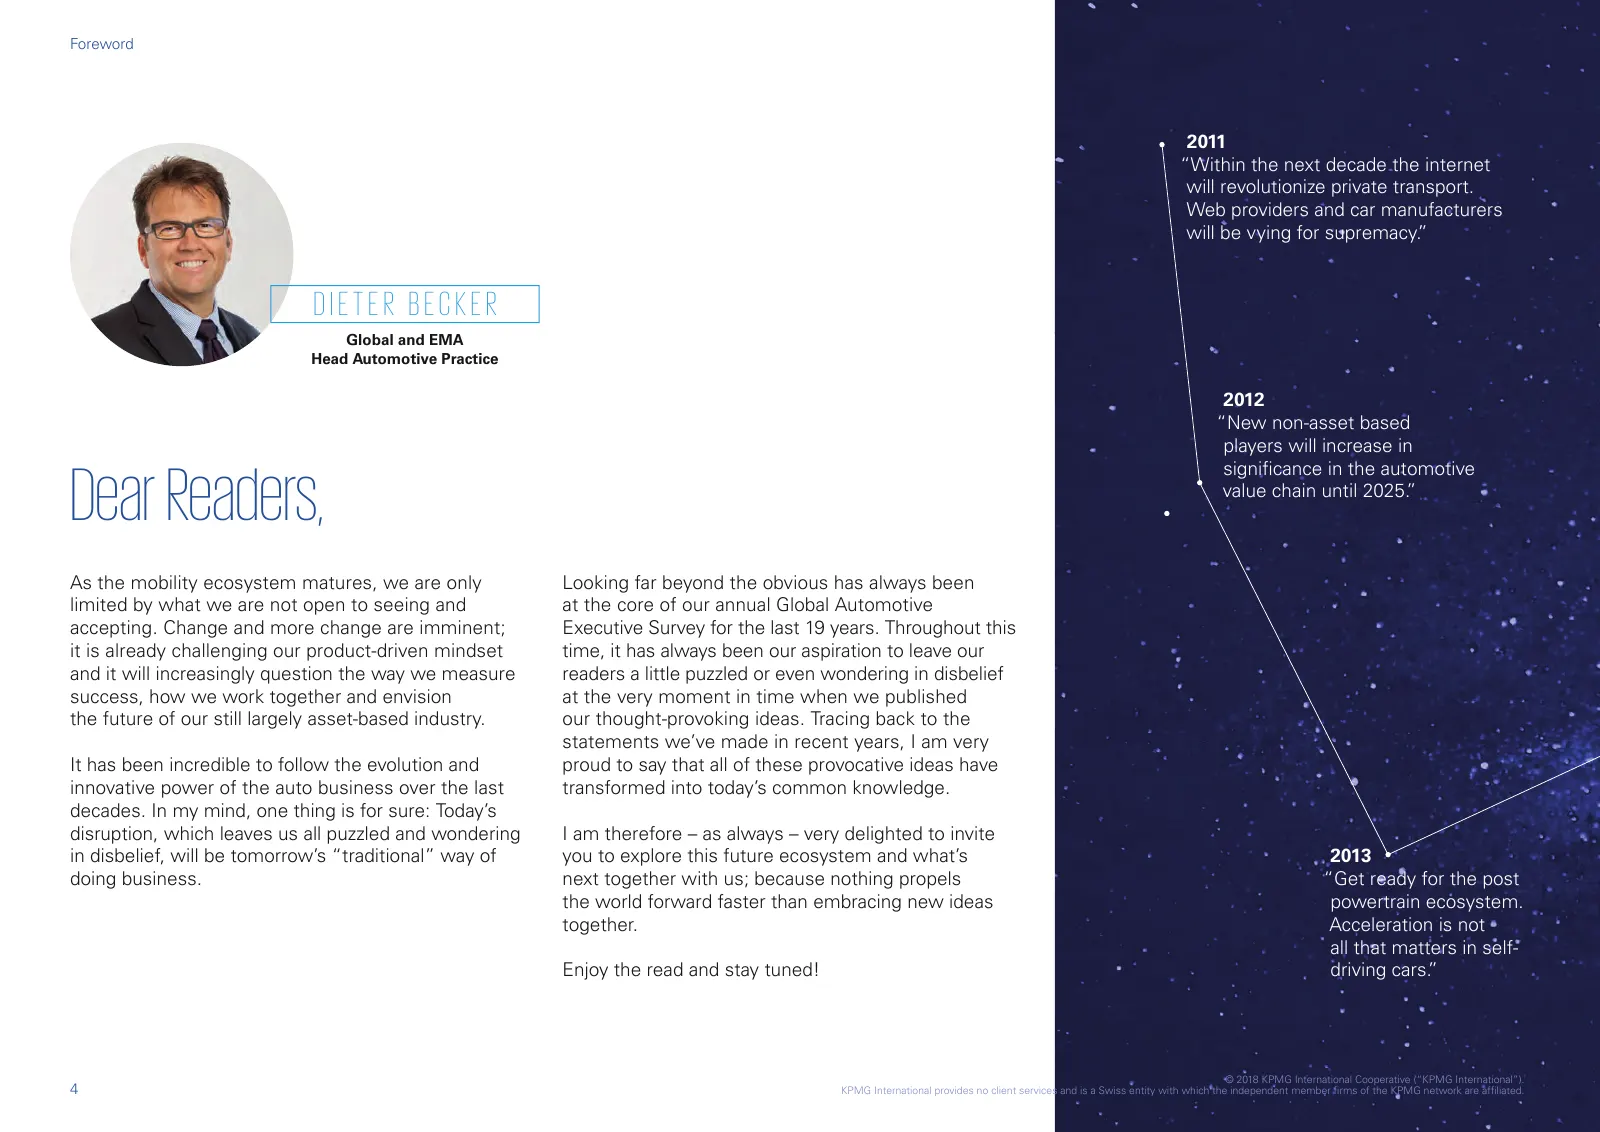
Slide 4: Foreword
Foreword 2011 “Within the next decade the internet will revolutionize private transport. Web providers and car manufacturers will be vying for supremacy.” DIETER BECKER Global and EMA Head Automotive Practice 2012 “New non-asset based players will increase in significance in the automotive Dear Read
Slide 5: Our heritage
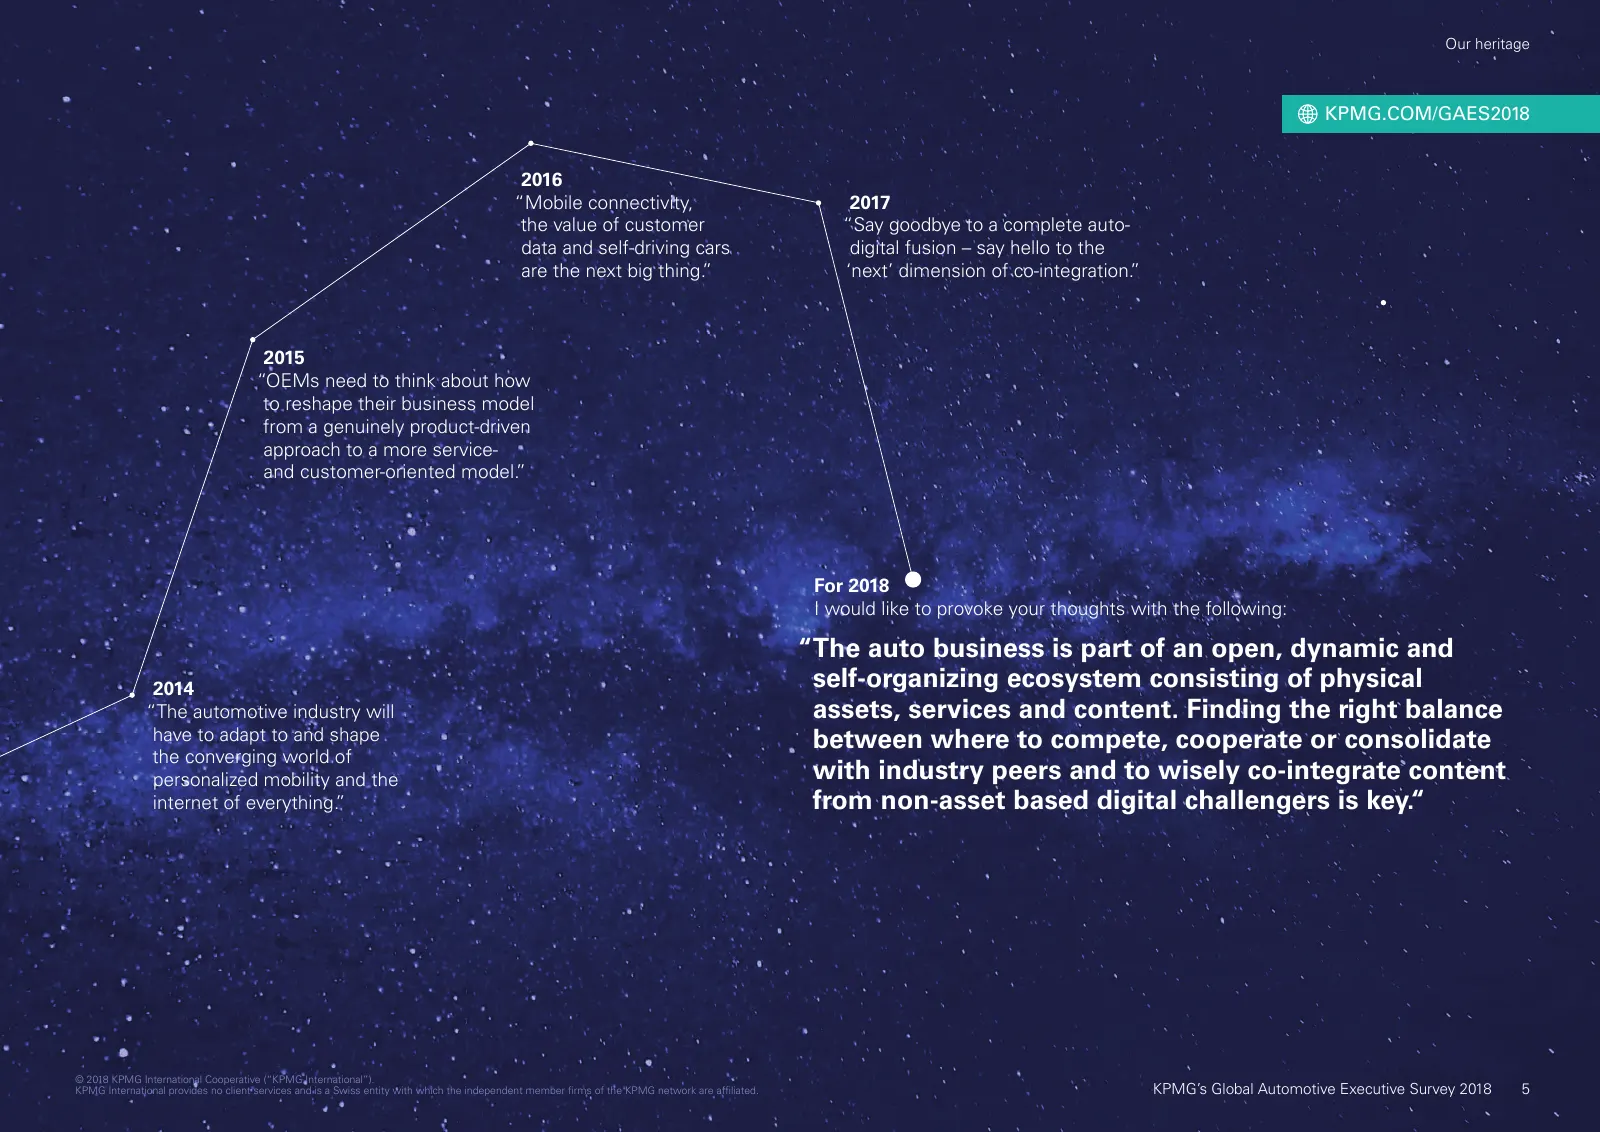
Our heritage KPMG.COM/GAES2018 2016 “Mobile connectivity, 2017 the value of customer “Say goodbye to a complete auto- data and self-driving cars digital fusion – say hello to the are the next big thing.” ‘next’ dimension of co-integration.” 2015 “OEMs need to think about how to reshape their busines
Slide 6: About the executive survey
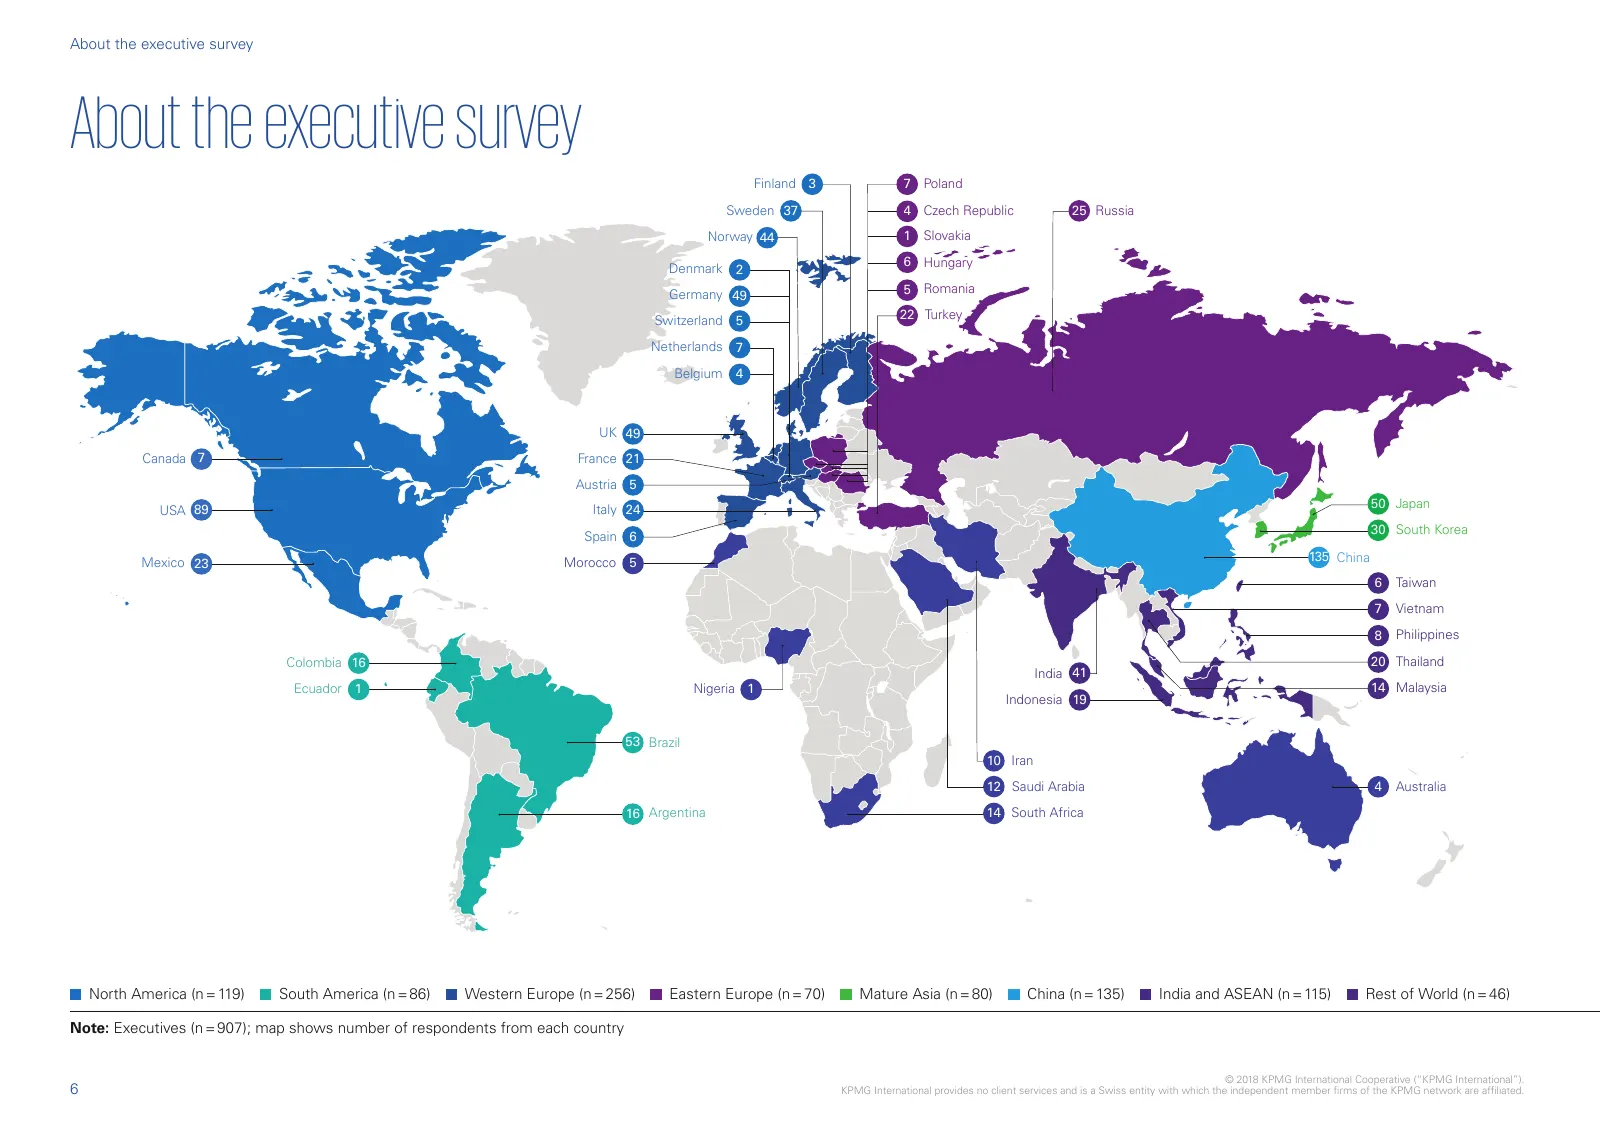
About the executive survey About the executive survey Finland 3 7 Poland Sweden 37 4 Czech Republic 25 Russia Norway 44 1 Slovakia 6 Hungary Denmark 2 Germany 49 5 Romania Switzerland 5 22 Turkey Netherlands 7 Belgium 4 UK 49 Canada 7 France 21 Austria 5 50 Japan USA 89 Italy 24 Spain 6 30 South Kor
Slide 7: 907 executives from 43 countries surveyed
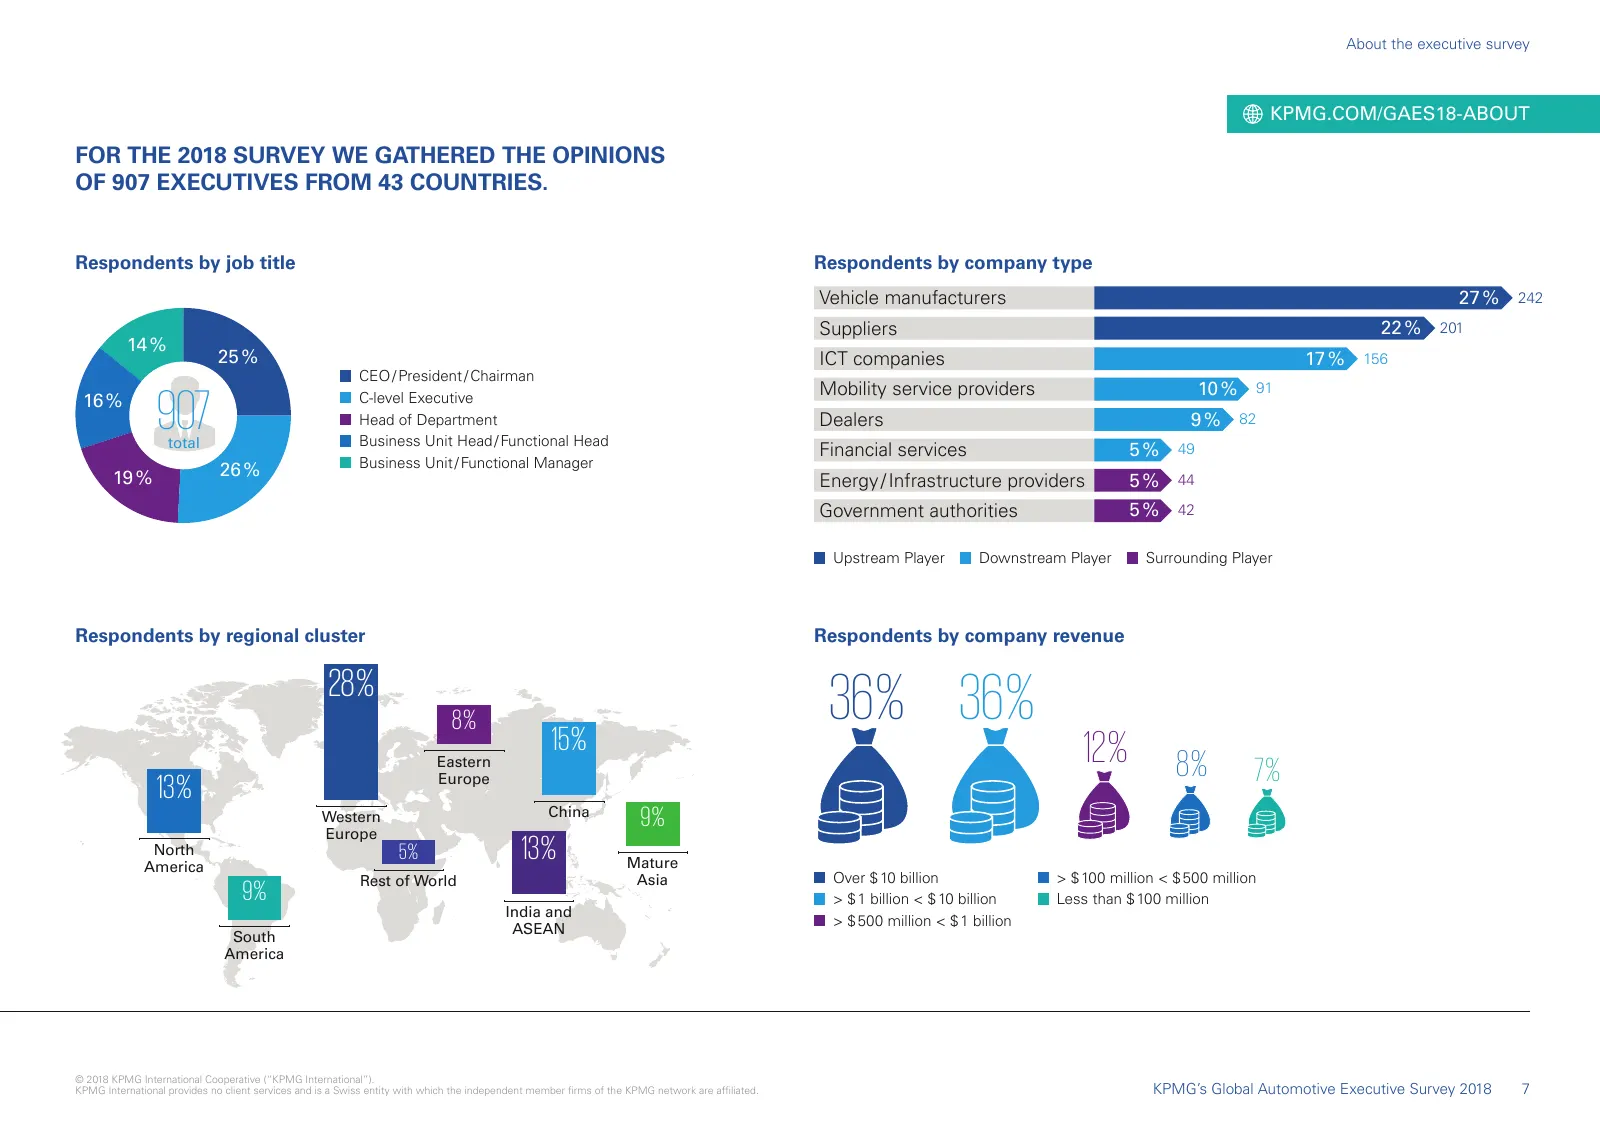
About the executive survey KPMG.COM/GAES18-ABOUT FOR THE 2018 SURVEY WE GATHERED THE OPINIONS OF 907 EXECUTIVES FROM 43 COUNTRIES. Respondents by job title Respondents by company type Vehicle manufacturers 27 % 242 Suppliers 22 % 201 14 % 25 % ICT companies 17 % 156 CEO / President / Chairman Mobili
Slide 8: The auto business is part of an open, dynamic and self-organizing ecosystem
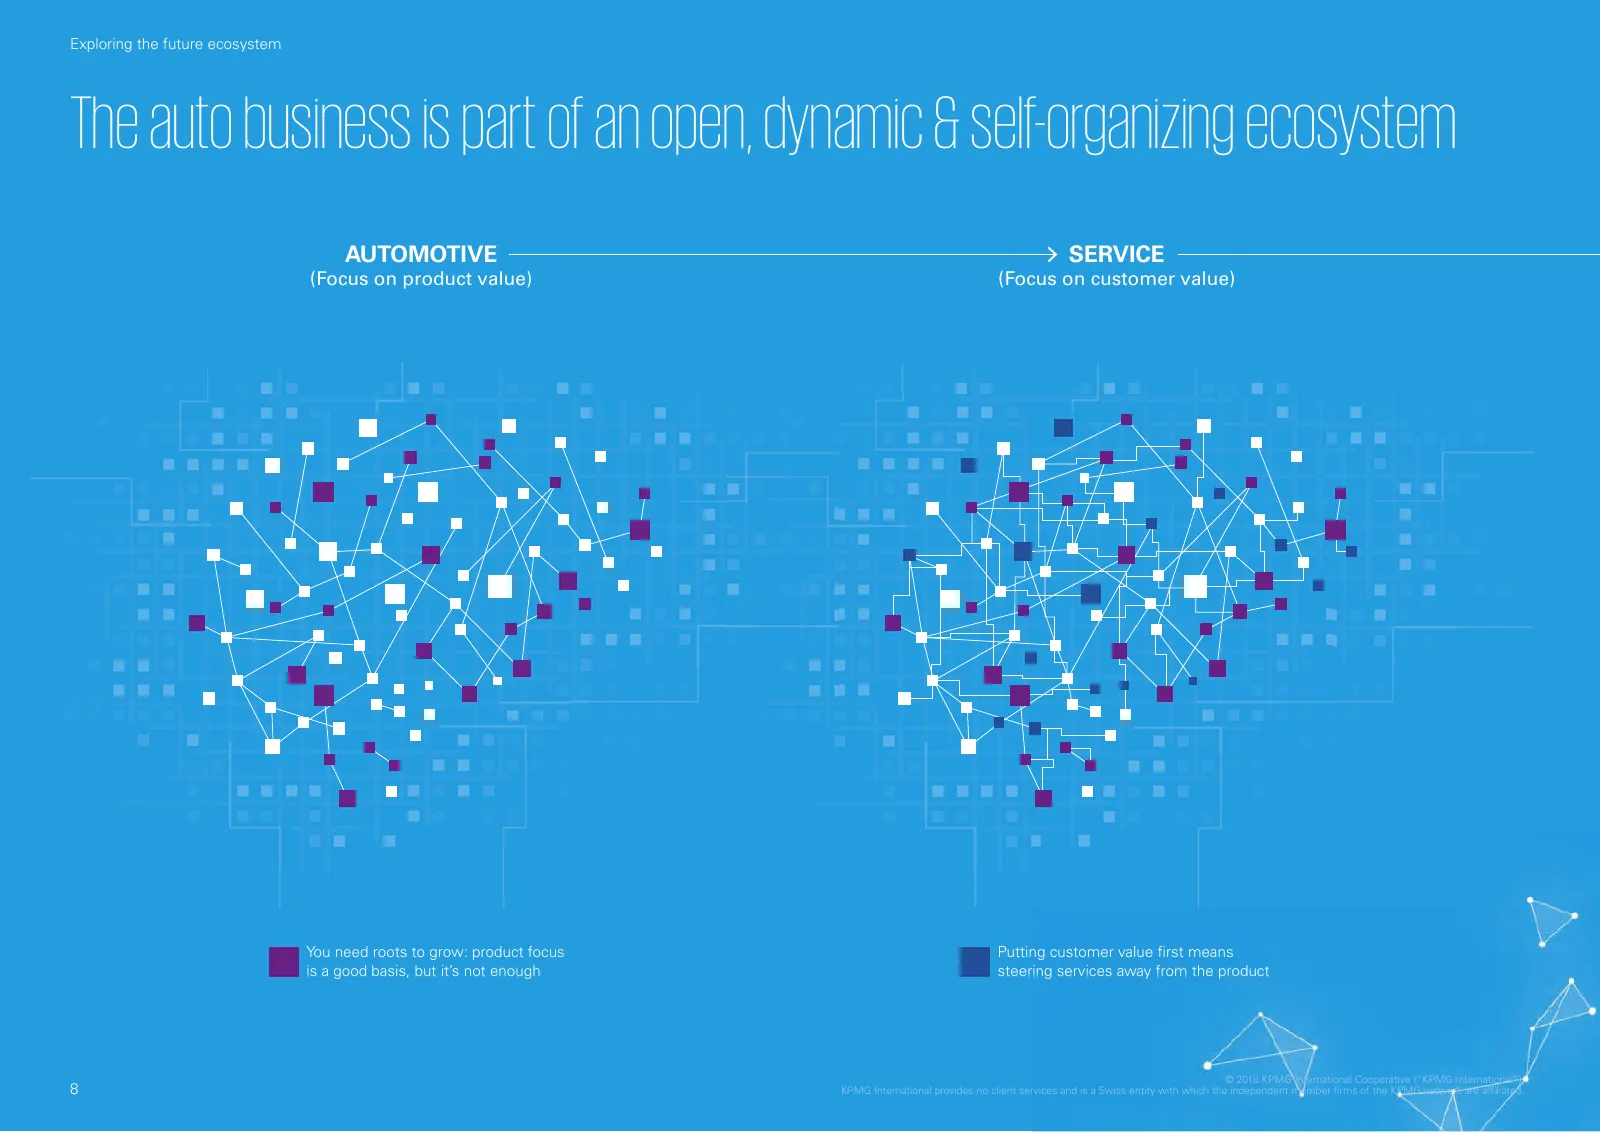
Exploring the future ecosystem The auto business is part of an open, dynamic & self-organizing ecosystem AUTOMOTIVE SERVICE (Focus on product value) (Focus on customer value) You need roots to grow: product focus Putting customer value first means is a good basis, but it’s not enough steering servic
Slide 9: Content, platform, business: focus on ecosystem value
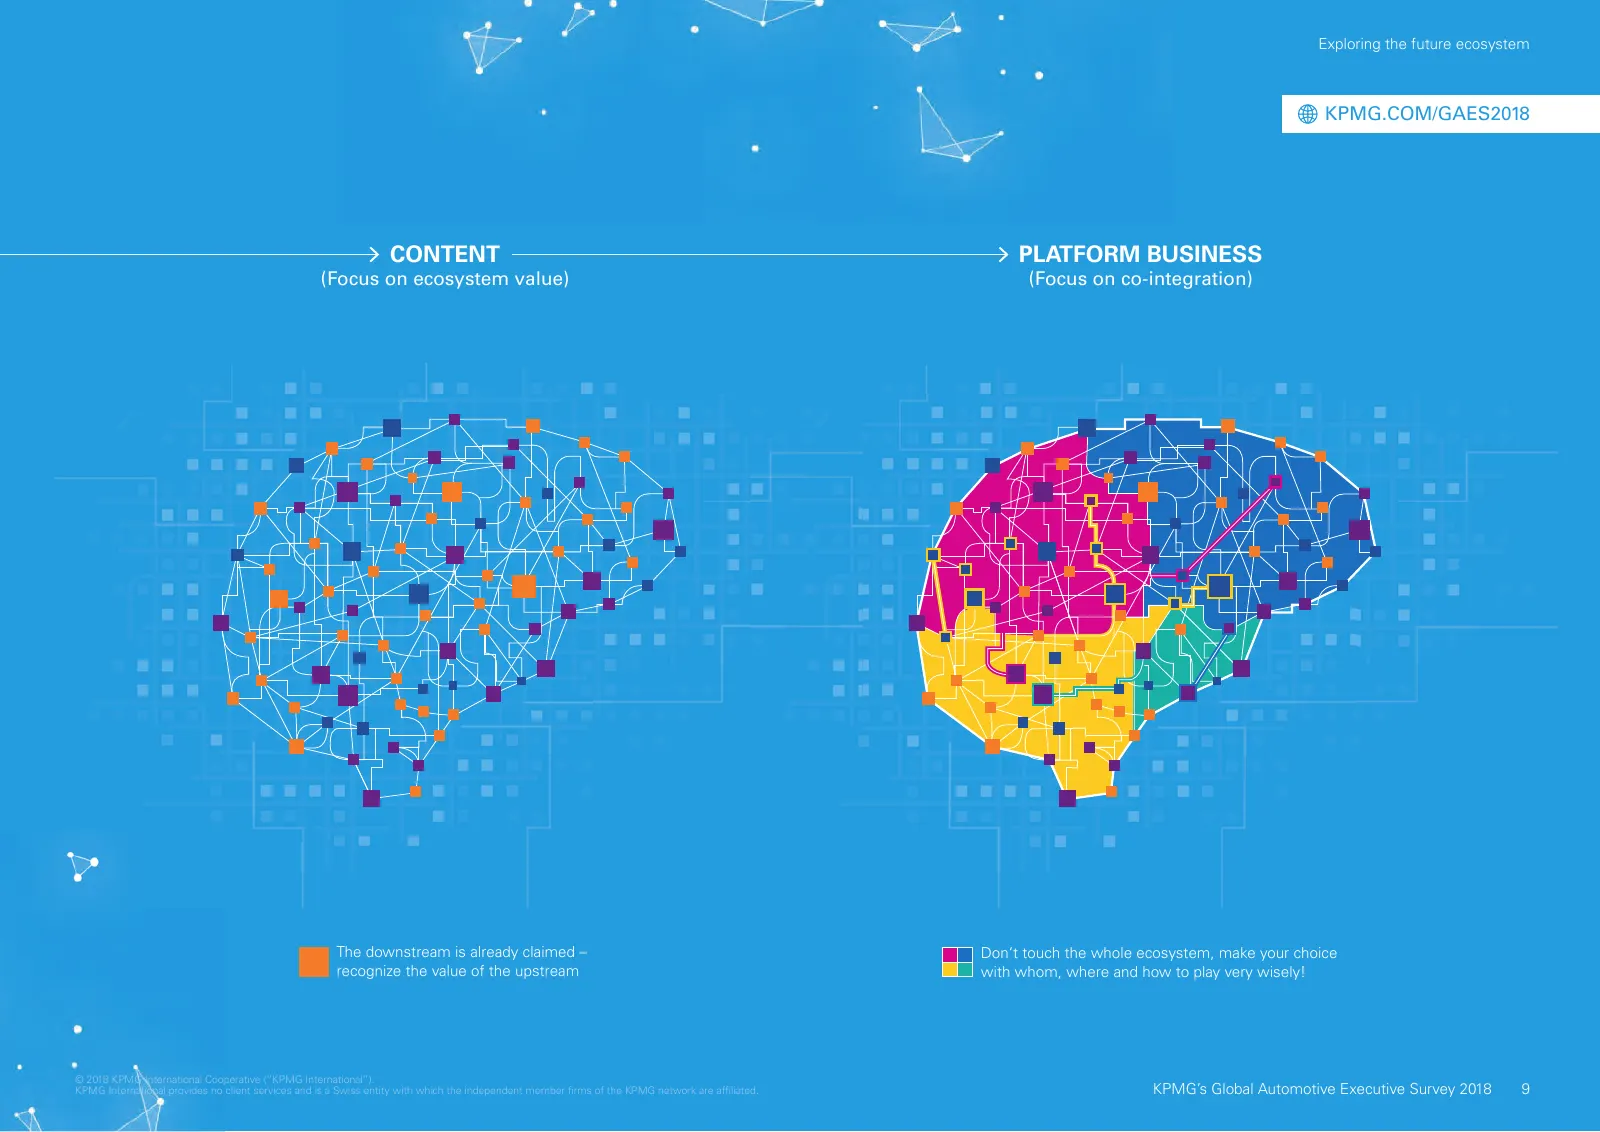
Exploring the future ecosystem KPMG.COM/GAES2018 CONTENT PLATFORM BUSINESS (Focus on ecosystem value) (Focus on co-integration) The downstream is already claimed – Don‘t touch the whole ecosystem, make your choice recognize the value of the upstream with whom, where and how to play very wisely! © 20
Slide 10: Our Global Automotive Executive Survey 2018 structure
Our GAES 2018 structure Our Global Automotive Executive Survey 2018 structure © 2018 KPMG International Cooperative (“KPMG International”). 10 KPMG International provides no client services and is a Swiss entity with which the independent member firms of the KPMG network are affiliated.
Slide 11: GAES 2018 structure
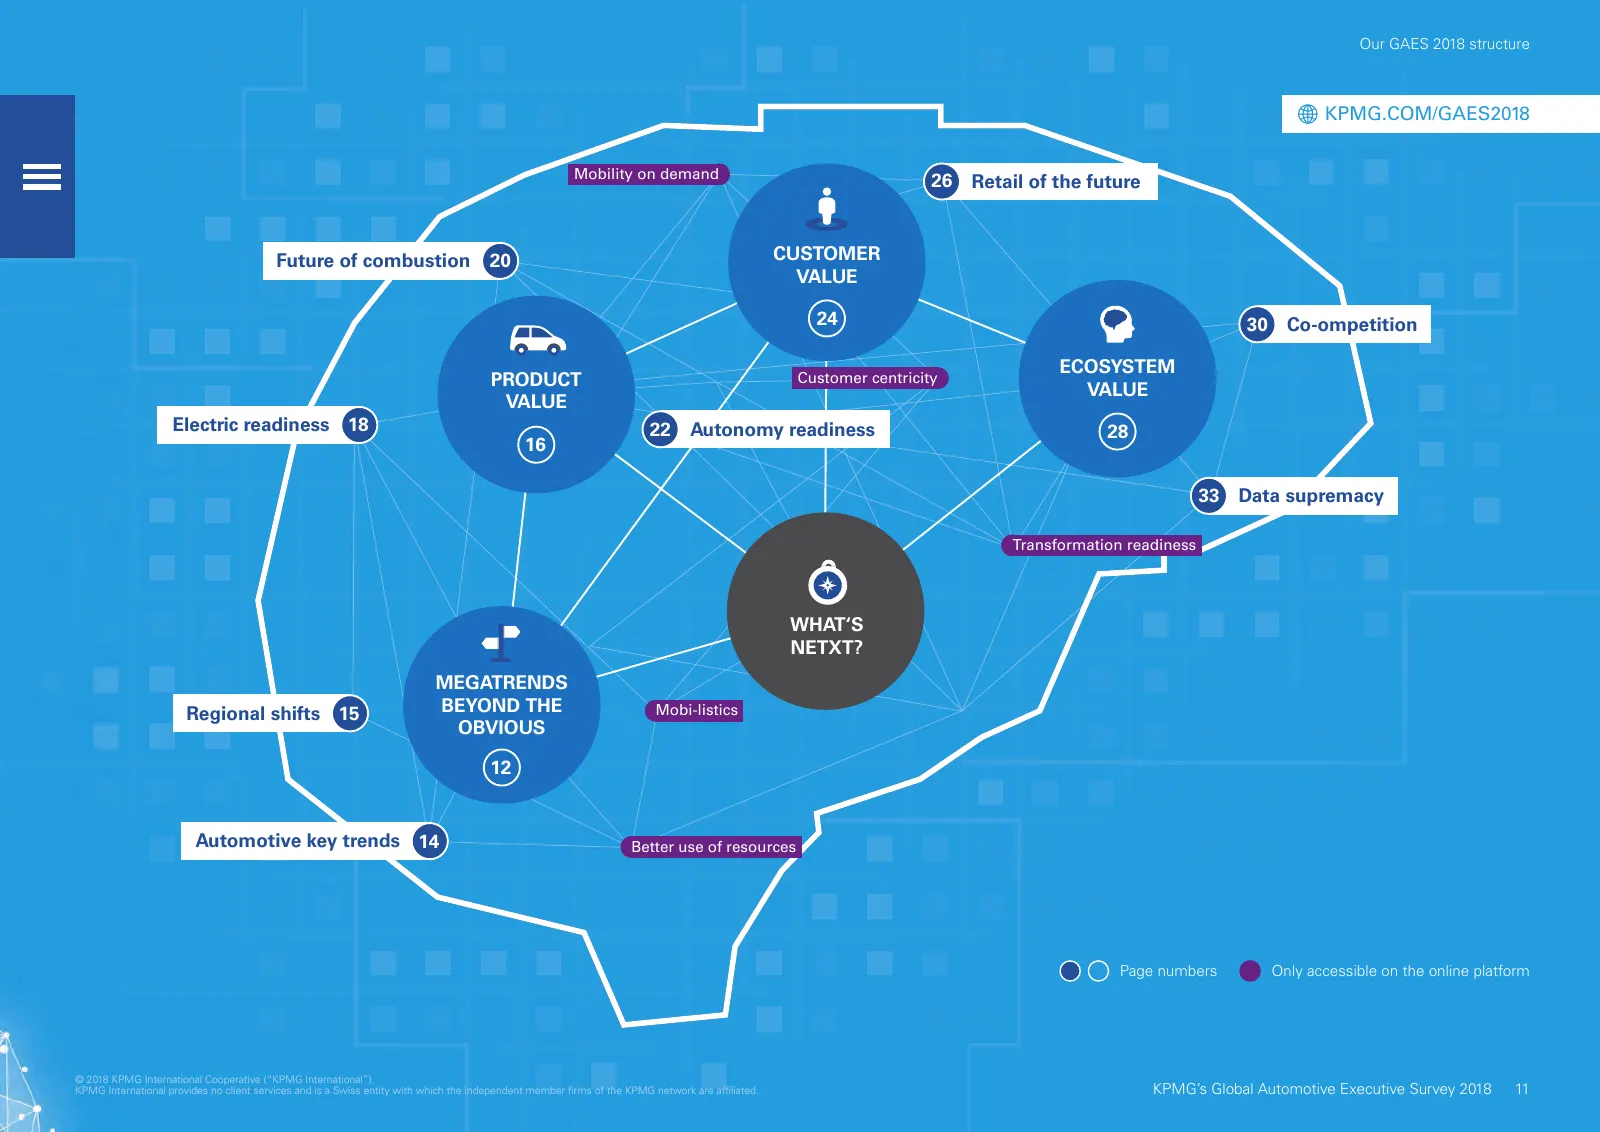
Our GAES 2018 structure KPMG.COM/GAES2018 Mobility on demand 26 Retail of the future Future of combustion 20 CUSTOMER VALUE 24 30 Co-ompetition ECOSYSTEM PRODUCT Customer centricity VALUE VALUE Electric readiness 18 22 Autonomy readiness 28 16 33 Data supremacy Transformation readiness WHAT‘S NETXT?
Slide 12: Key takeaways: Megatrends beyond the obvious
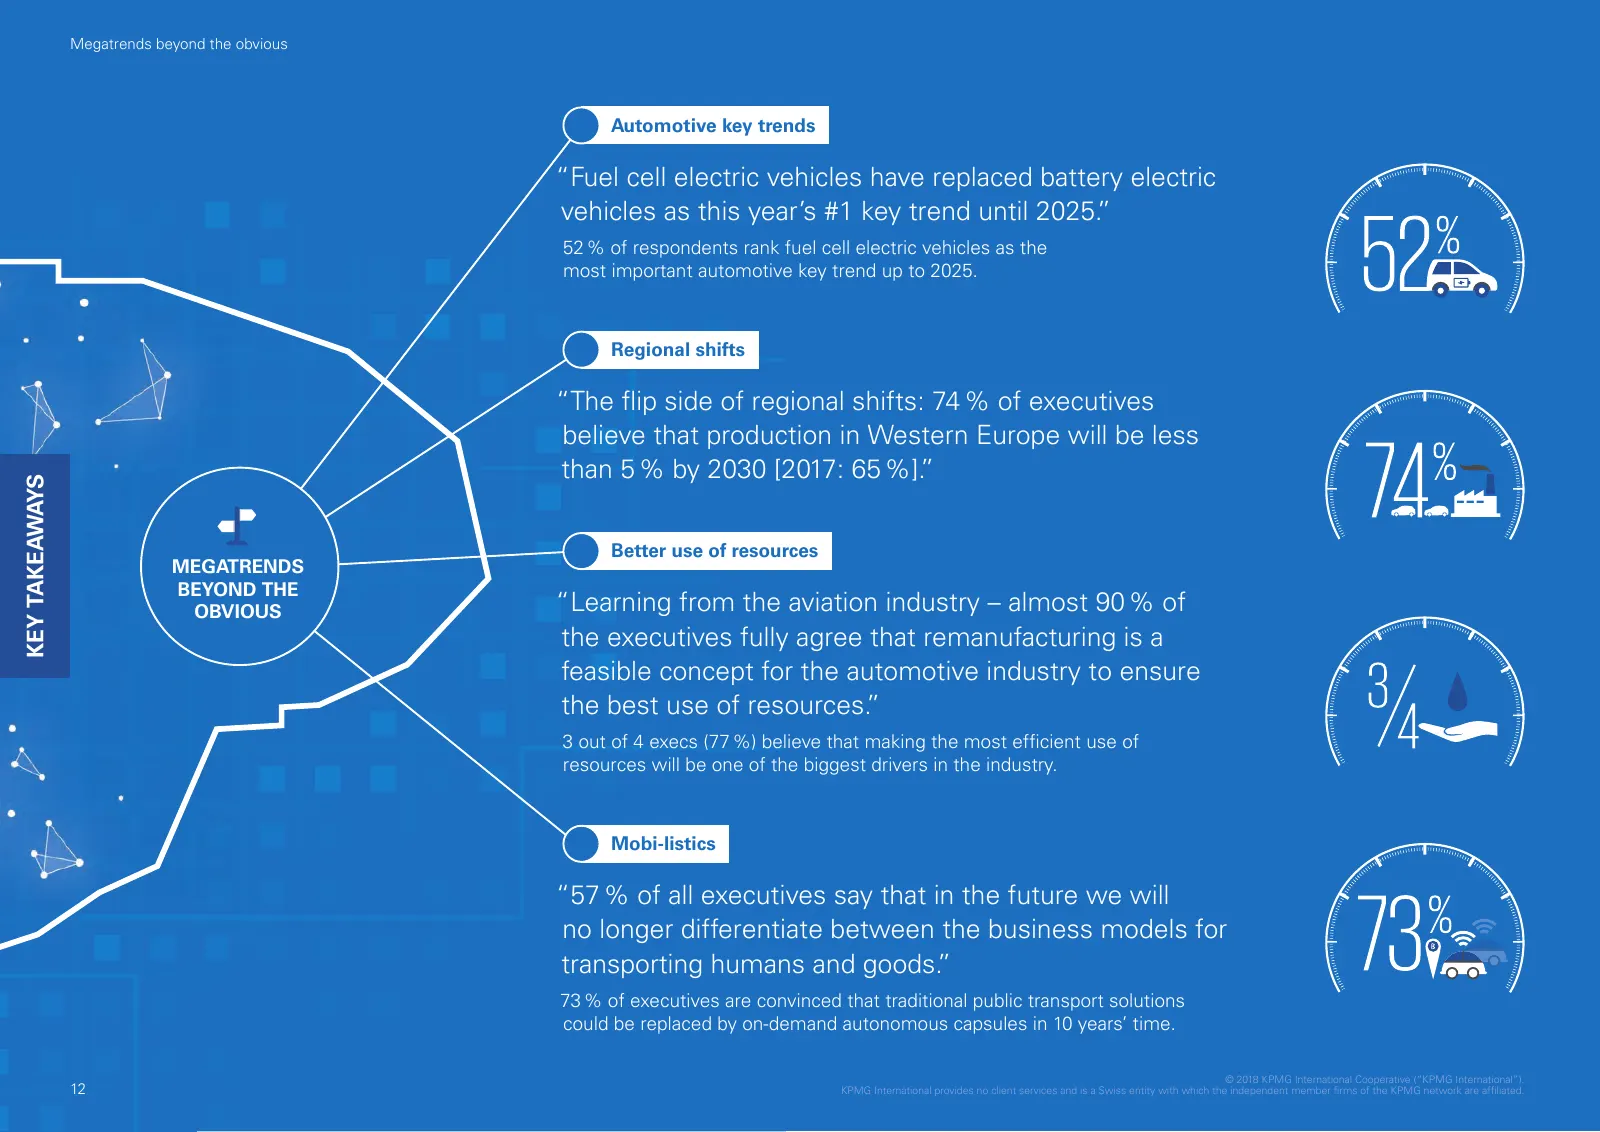
Megatrends beyond the obvious Automotive key trends “Fuel cell electric vehicles have replaced battery electric vehicles as this year’s #1 key trend until 2025.” 52 % of respondents rank fuel cell electric vehicles as the most important automotive key trend up to 2025. Regional shifts “The flip side
Slide 13: Better use of resources and mobi-listics are megatrends beyond the obvious
Megatrends beyond the obvious KPMG.COM/GAES18-MT MEGATRENDS BEYOND THE OBVIOUS Better use of resources and “mobi-listics” are megatrends beyond the obvious One thing is for sure: Although today’s Fuel cell electric vehicles have replaced battery Better use of resources is the overarching trend elect
Slide 14: Automotive key trends until 2025
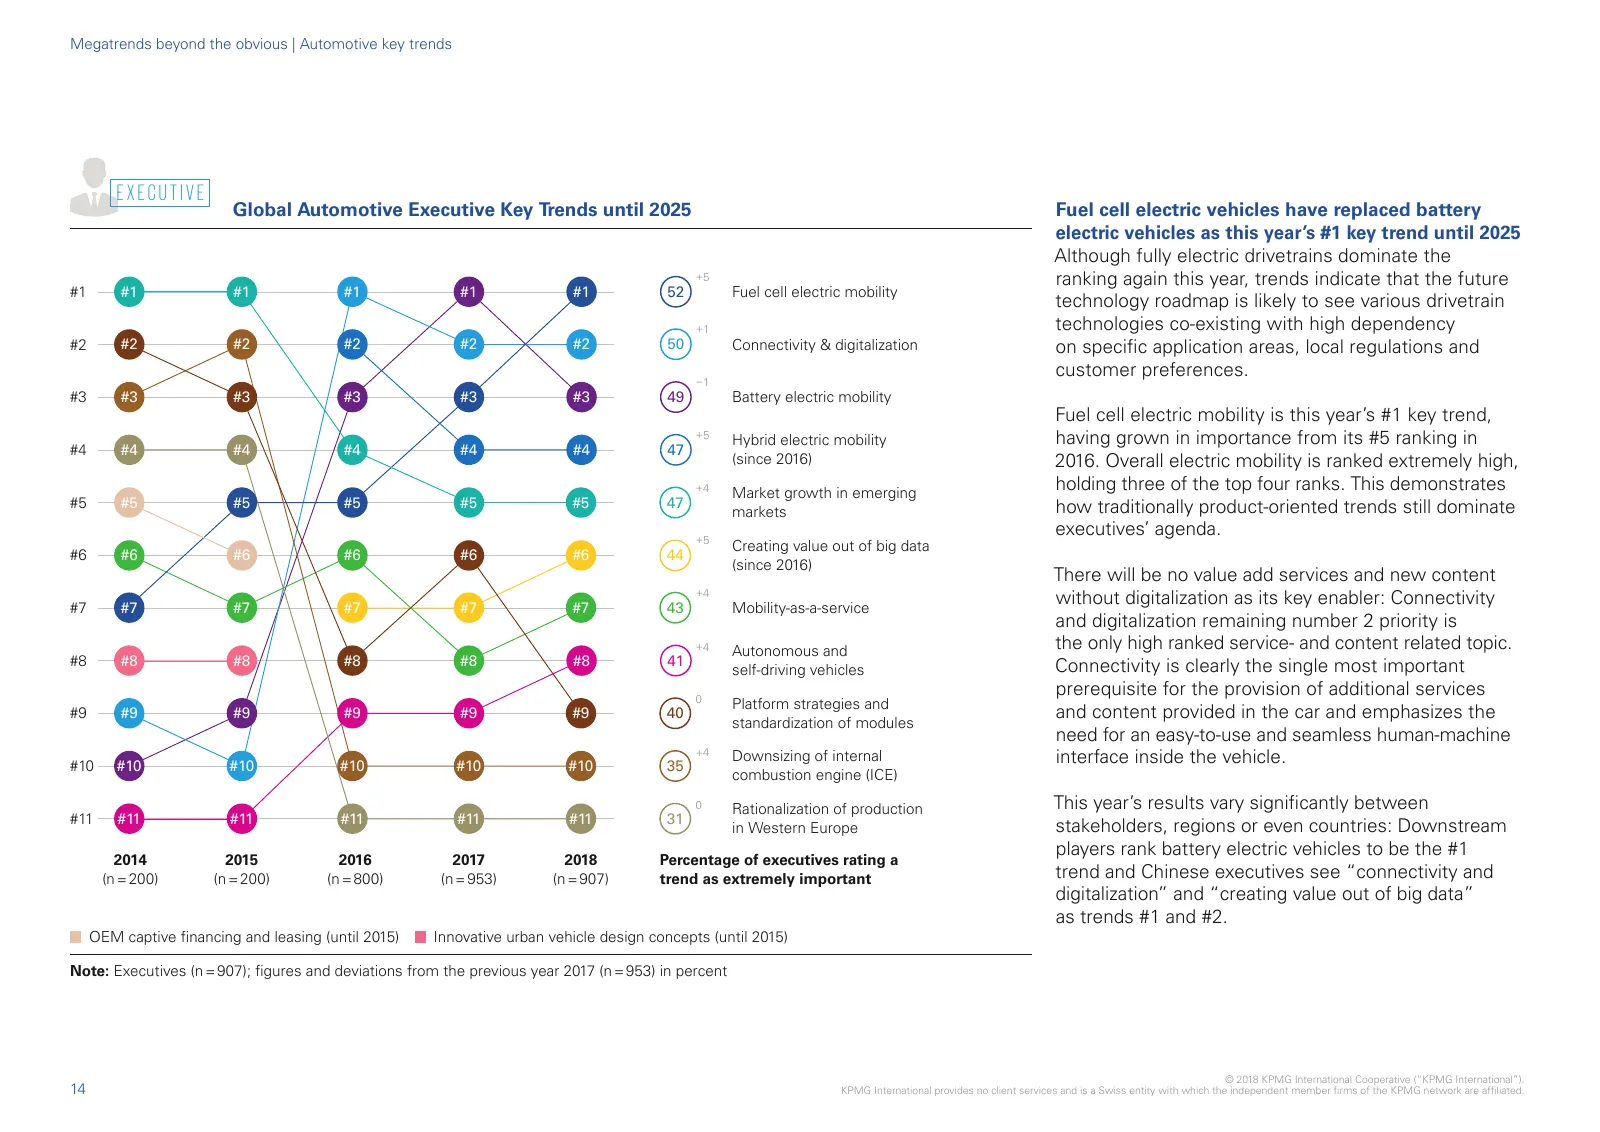
Megatrends beyond the obvious | Automotive key trends EXECUTIVE Global Automotive Executive Key Trends until 2025 Fuel cell electric vehicles have replaced battery electric vehicles as this year’s #1 key trend until 2025 Although fully electric drivetrains dominate the +5 ranking again this year, tr
Slide 15: Regional shifts
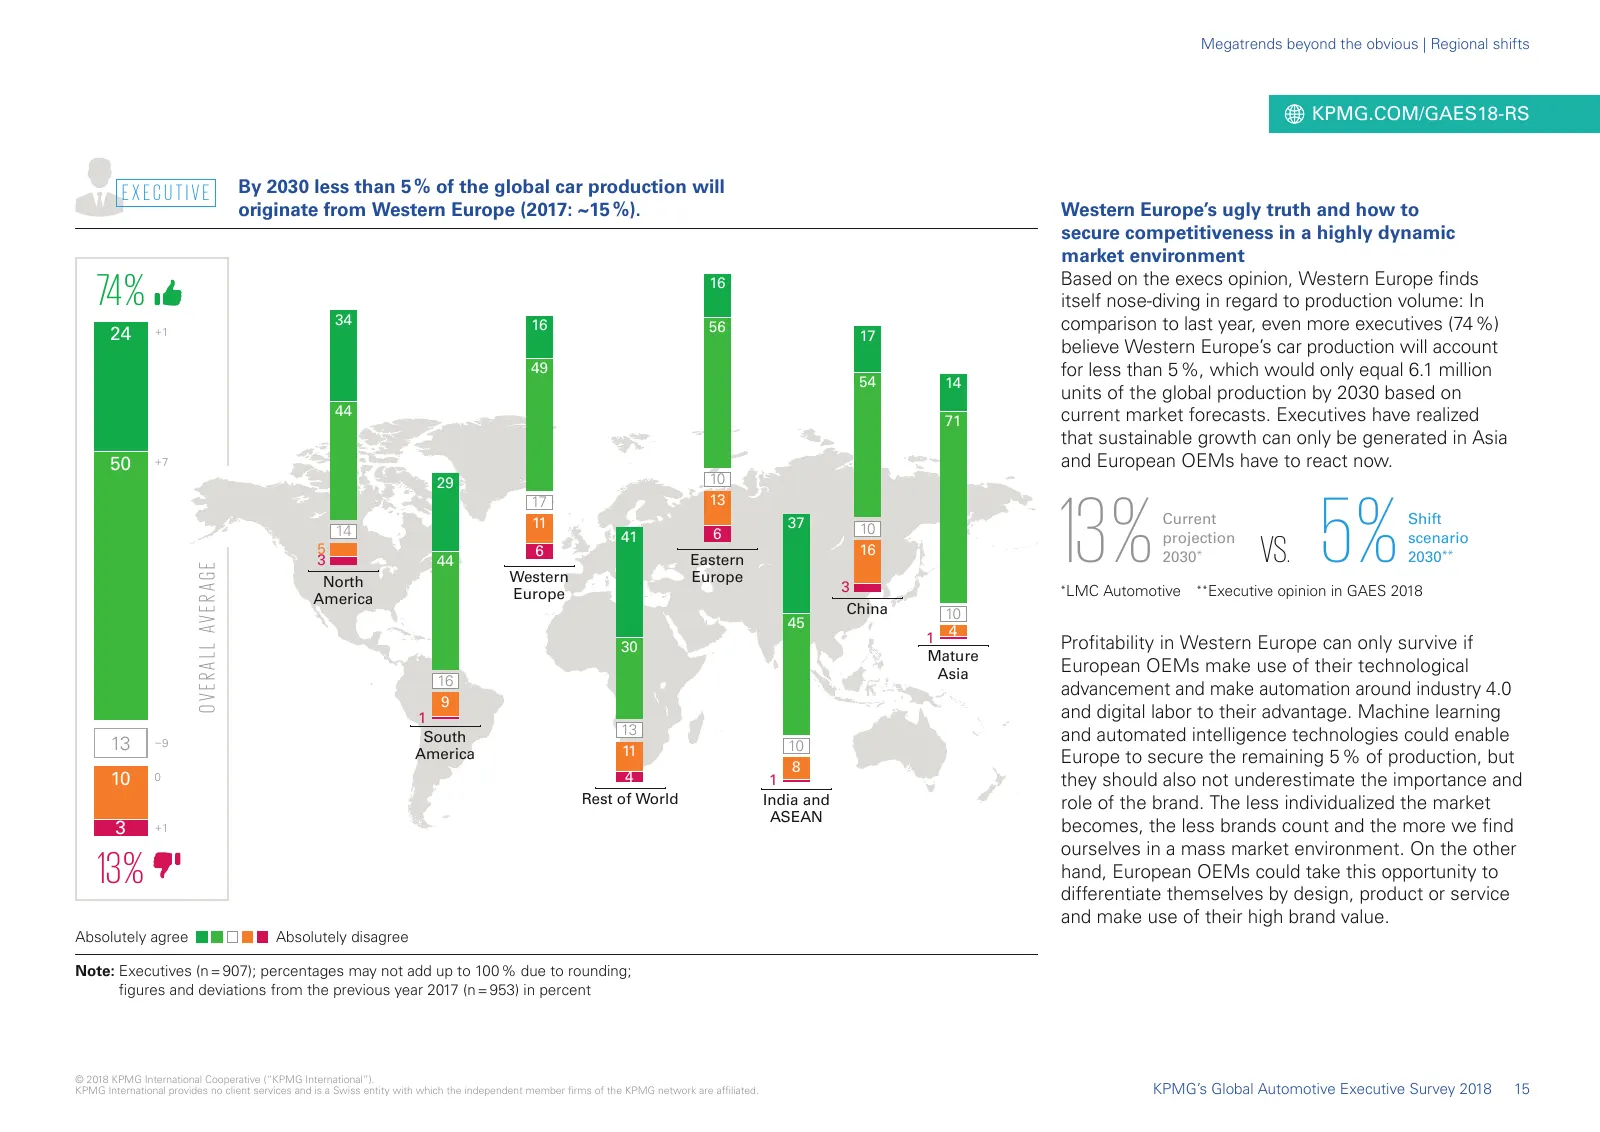
Megatrends beyond the obvious | Regional shifts KPMG.COM/GAES18-RS EXECUTIVE By 2030 less than 5 % of the global car production will originate from Western Europe (2017: ~15 %). Western Europe’s ugly truth and how to secure competitiveness in a highly dynamic market environment Based on the execs op
Slide 16: Key takeaways: Product value
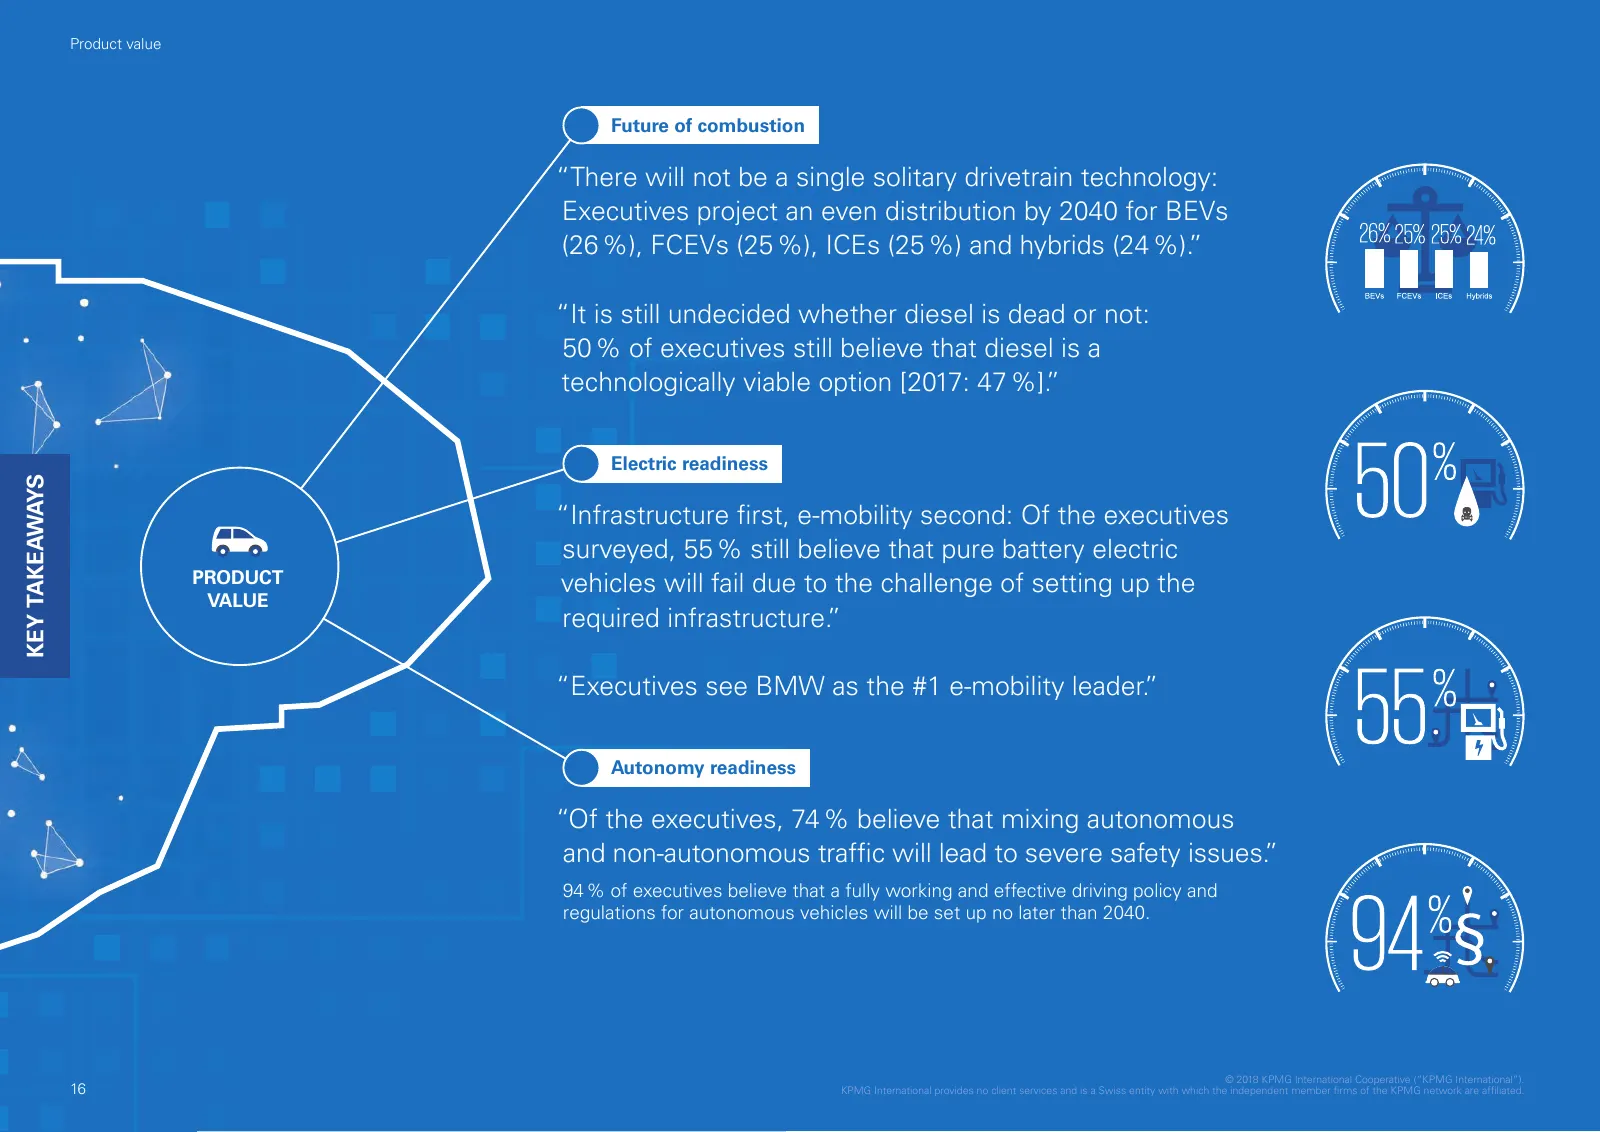
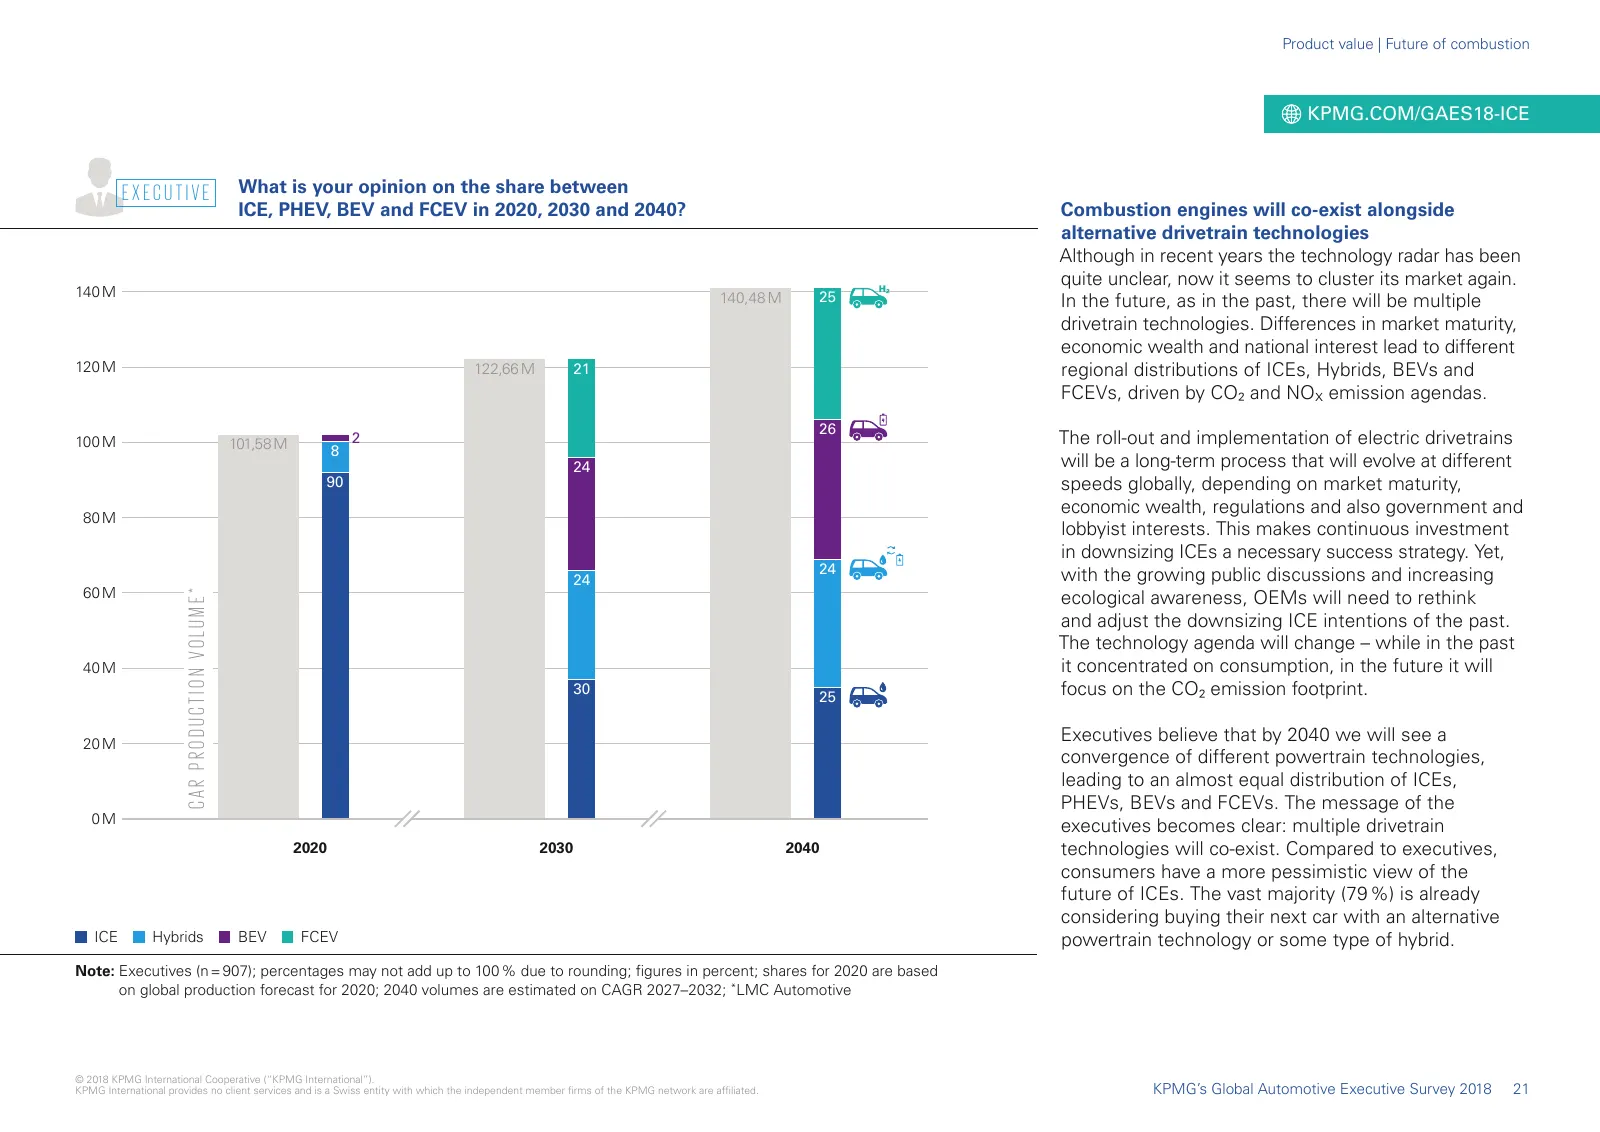
Product value Future of combustion “There will not be a single solitary drivetrain technology: Executives project an even distribution by 2040 for BEVs (26 %), FCEVs (25 %), ICEs (25 %) and hybrids (24 %).” “It is still undecided whether diesel is dead or not: 50 % of executives still believe that d
Slide 17: Going from managing products to managing the ecosystem
Product value KPMG.COM/GAES18-PV PRODUCT VALUE Going from managing a set of different products to managing the ecosystem Mobility has always relied and will Future of combustion a positive charging experience throughout the entire Even as electric drivetrain concepts advance, executives customer lif
Slide 18: Electric readiness: biggest challenge for the e-mobility ecosystem
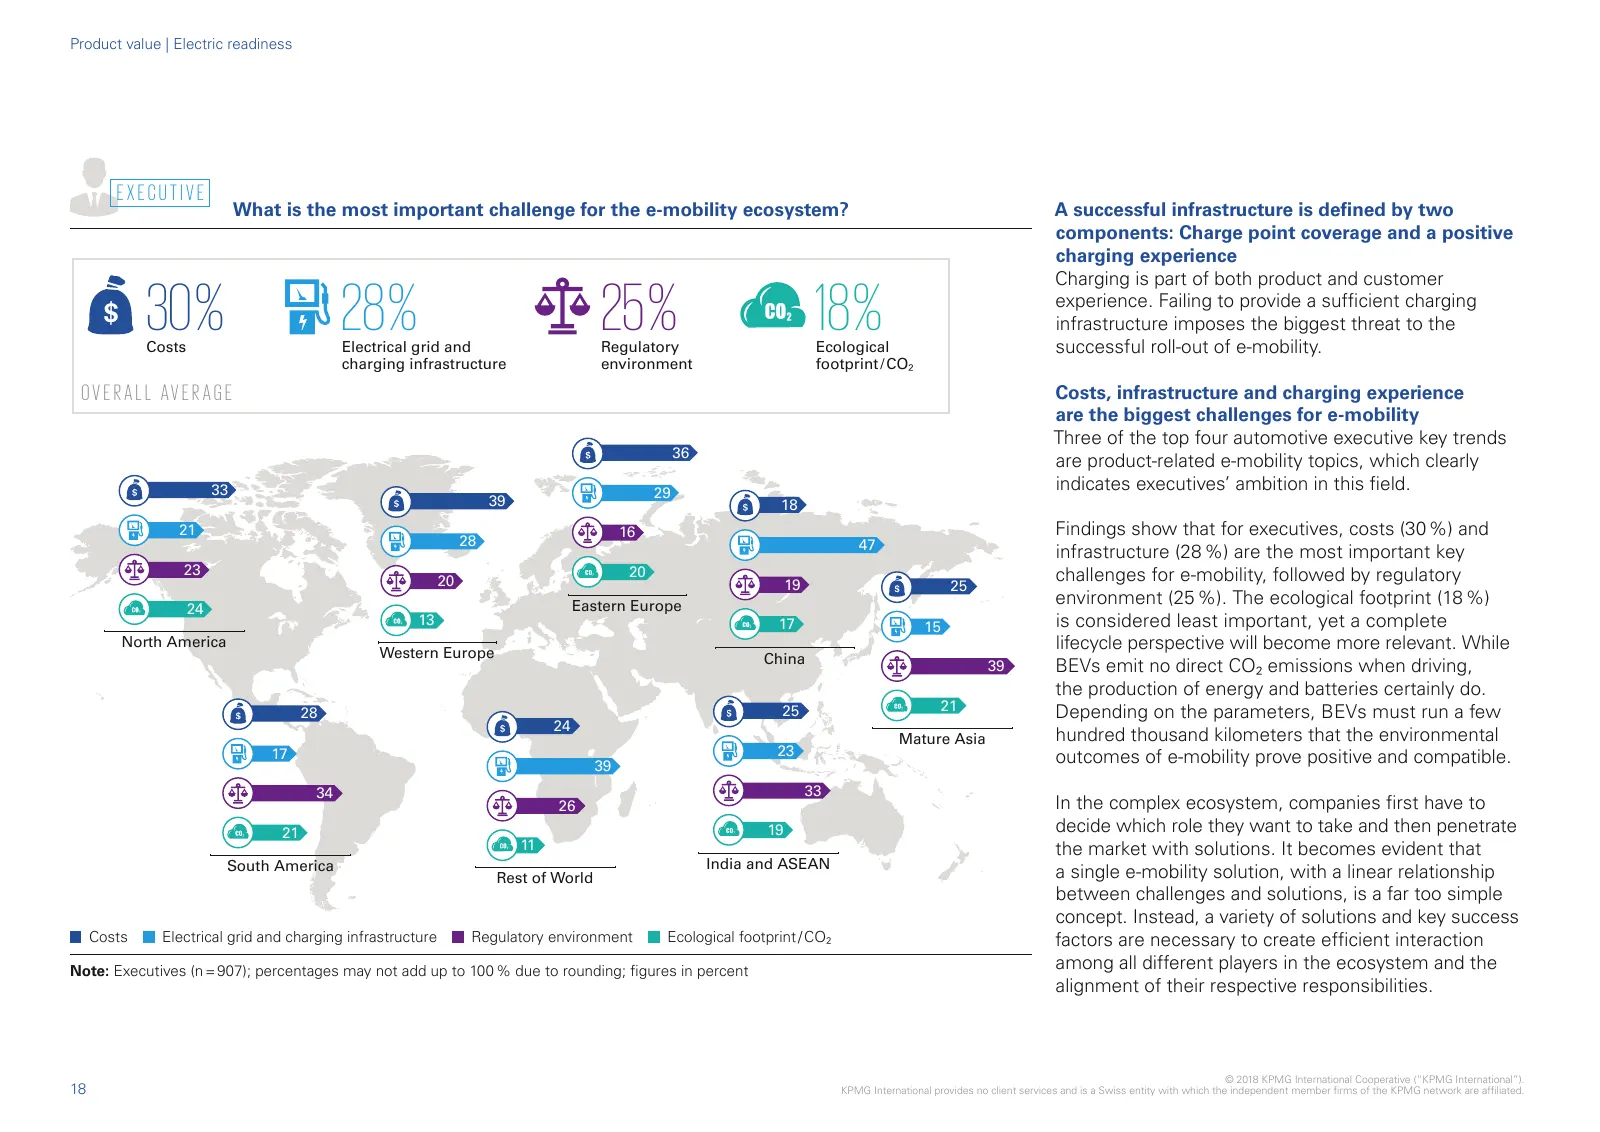
Product value | Electric readiness EXECUTIVE What is the most important challenge for the e-mobility ecosystem? A successful infrastructure is defined by two components: Charge point coverage and a positive charging experience Charging is part of both product and customer 30 % Costs 28 % Electrical
Slide 19: Infrastructure first, e-mobility second
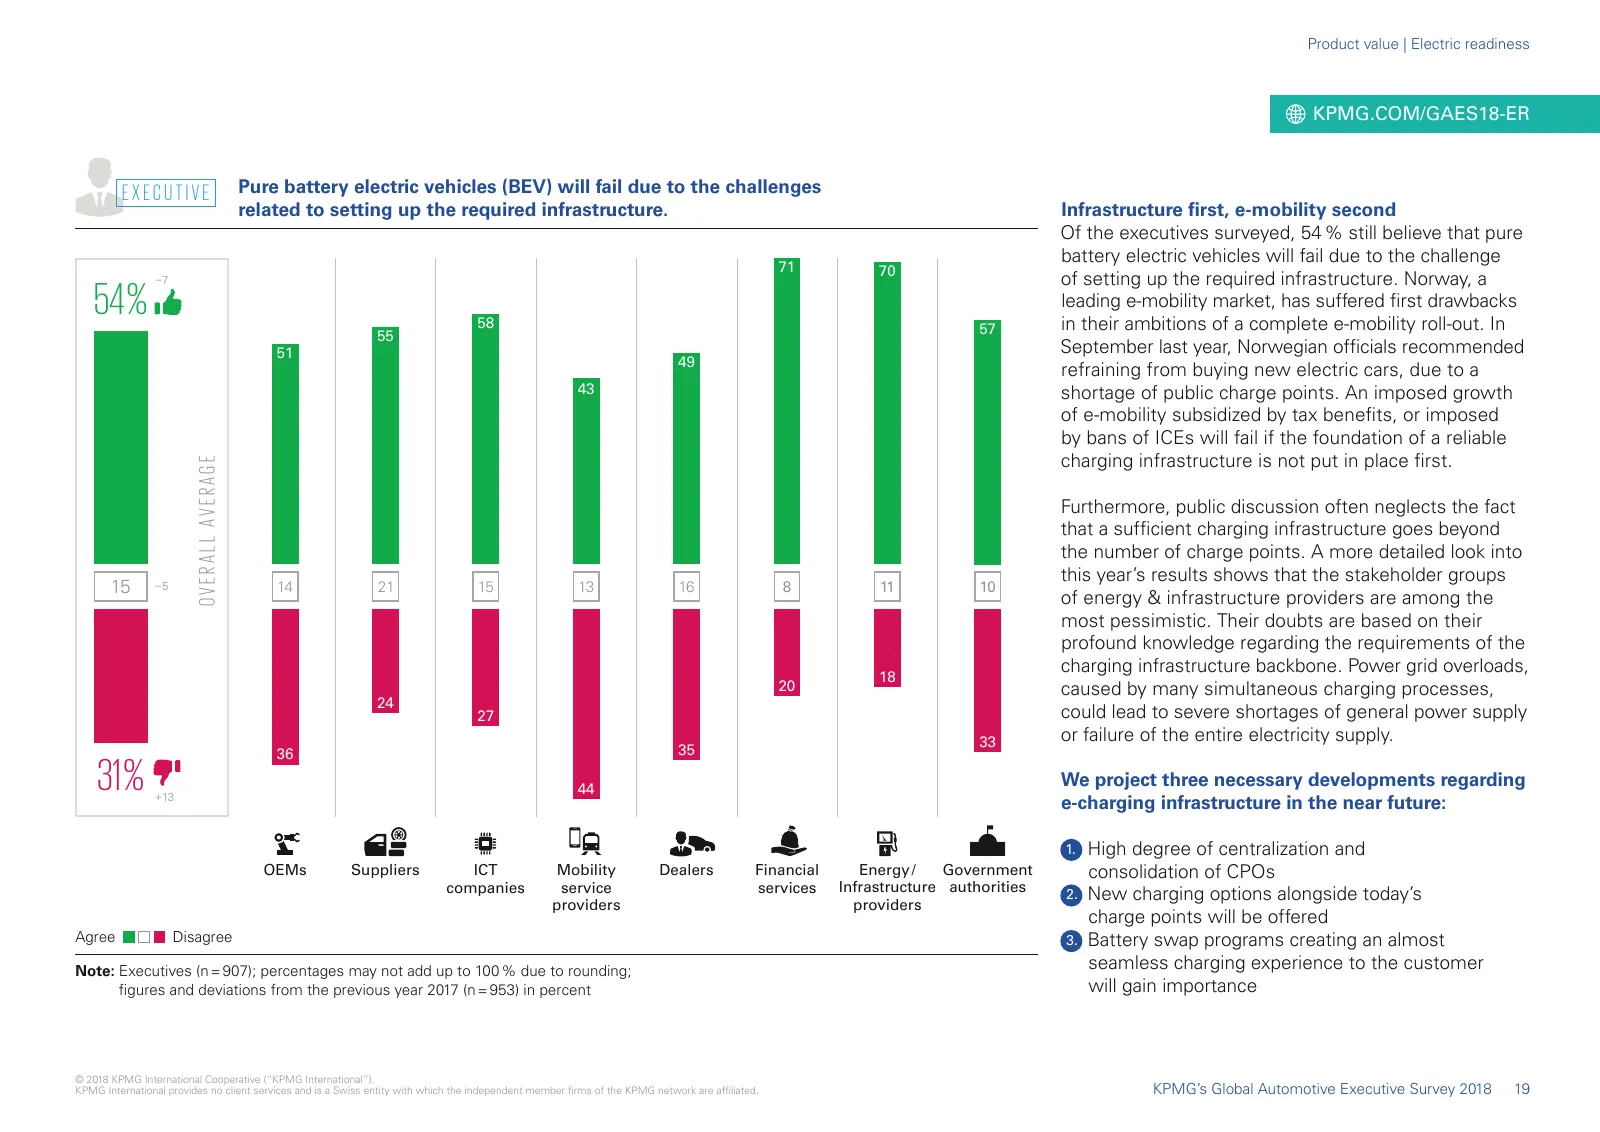
Product value | Electric readiness KPMG.COM/GAES18-ER EXECUTIVE Pure battery electric vehicles (BEV) will fail due to the challenges related to setting up the required infrastructure. Infrastructure first, e-mobility second Of the executives surveyed, 54 % still believe that pure battery electric ve
Slide 20: Consumer powertrain choice over the next 5 years
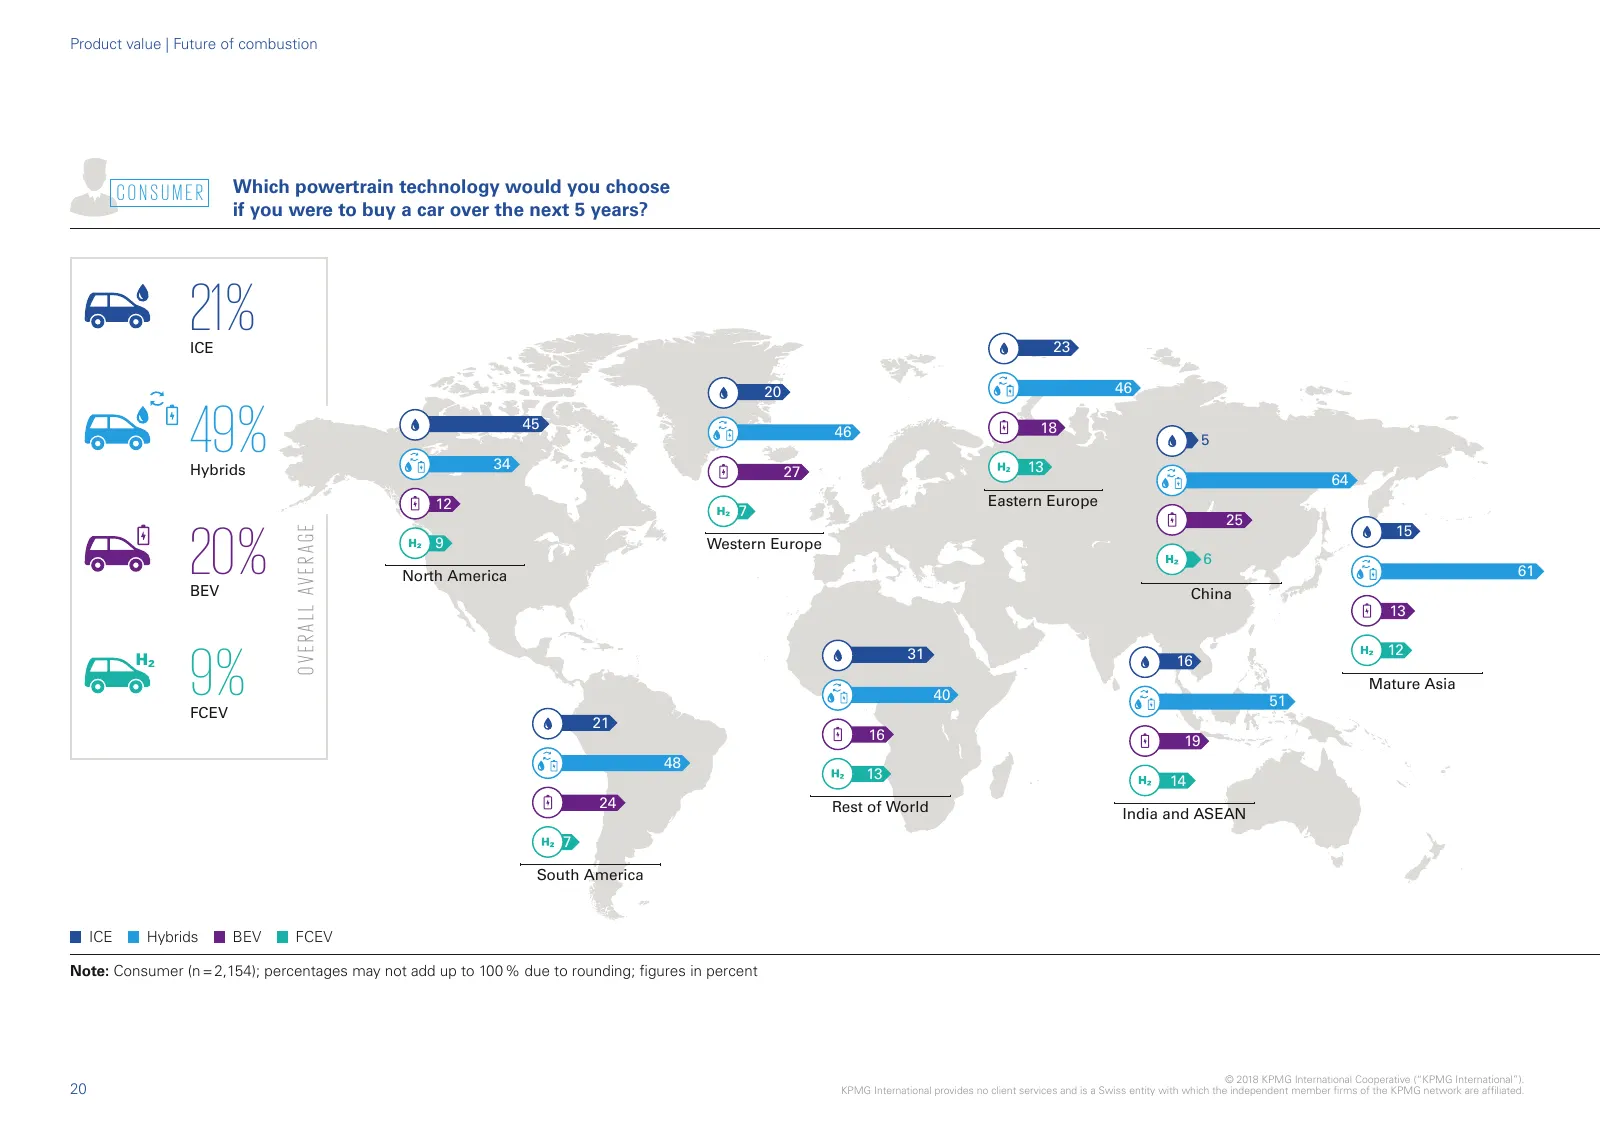
Product value | Future of combustion CONSUMER Which powertrain technology would you choose if you were to buy a car over the next 5 years? 21 % ICE 23 20 46 49 % Hybrids 34 45 27 46 13 18 5 64 12 Eastern Europe 7 25 20 % 15 O V E R A L L AV E R A G E 9 Western Europe 6 North America 61 BEV China 13
Slide 21: Combustion engines will co-exist alongside alternative drivetrains
Product value | Future of combustion KPMG.COM/GAES18-ICE EXECUTIVE What is your opinion on the share between ICE, PHEV, BEV and FCEV in 2020, 2030 and 2040? Combustion engines will co-exist alongside alternative drivetrain technologies Although in recent years the technology radar has been quite unc
Slide 22: Mixed autonomous and non-autonomous traffic will lead to safety issues
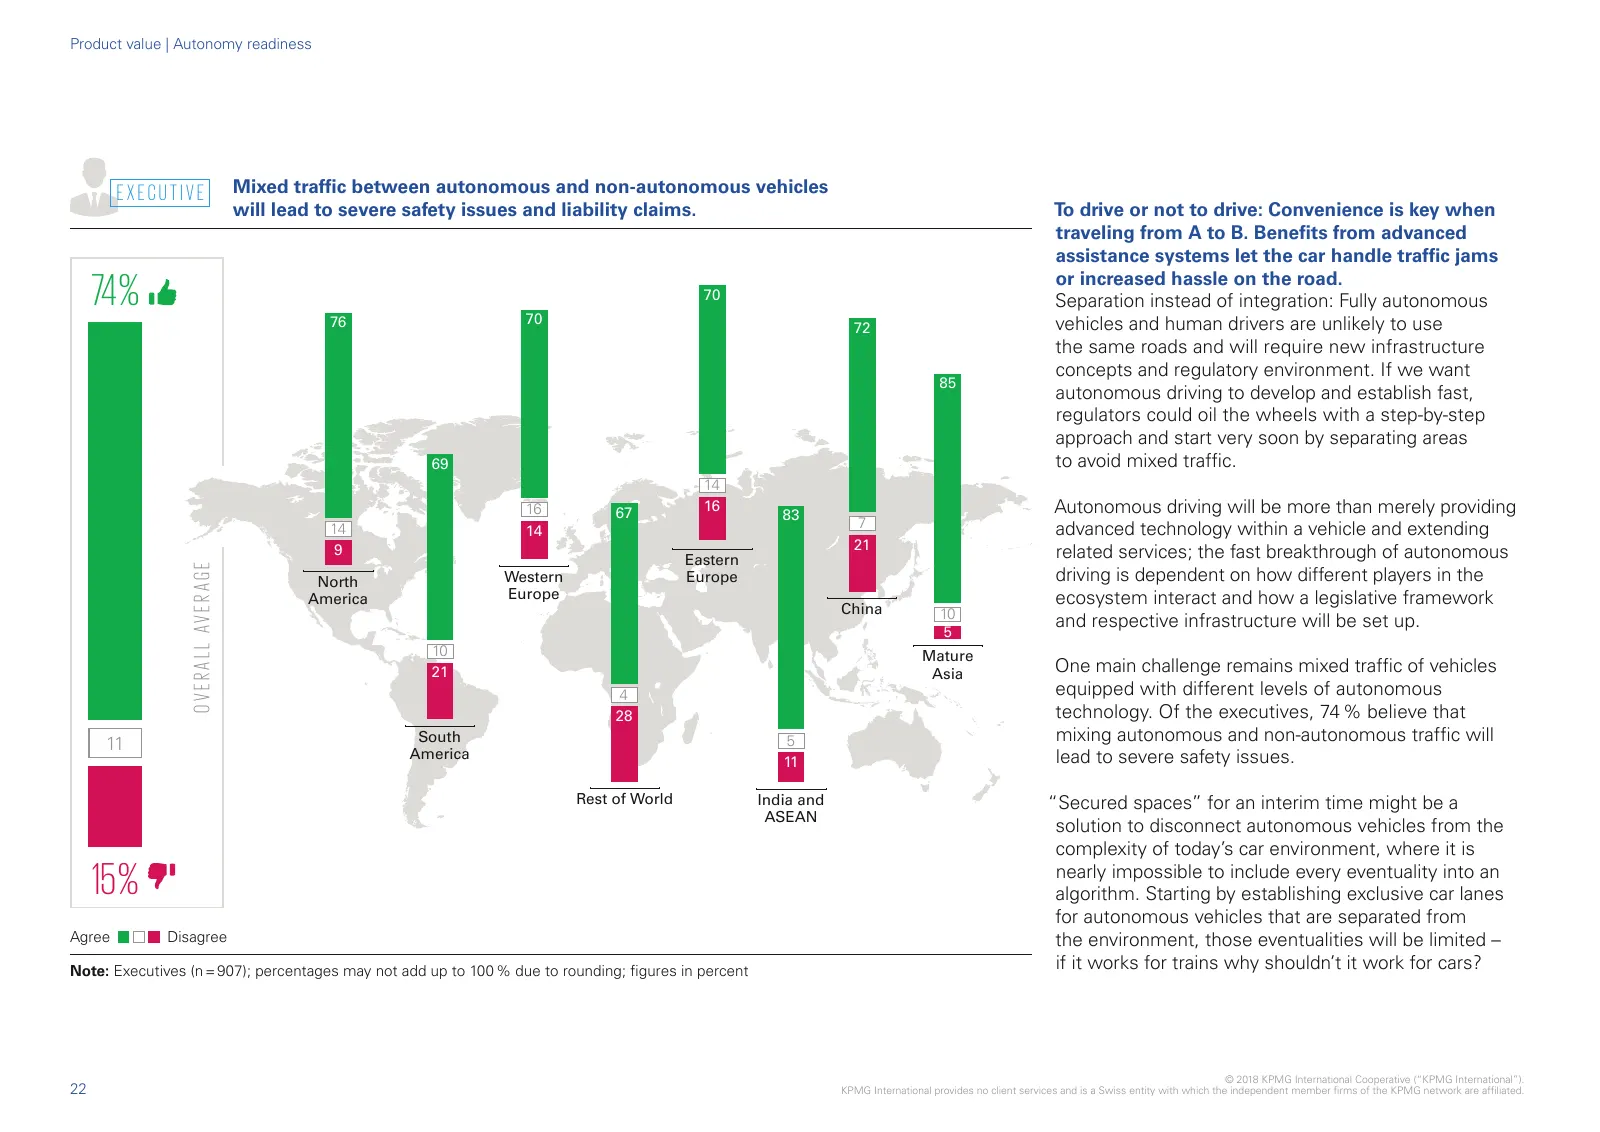
Product value | Autonomy readiness EXECUTIVE Mixed traffic between autonomous and non-autonomous vehicles will lead to severe safety issues and liability claims. To drive or not to drive: Convenience is key when traveling from A to B. Benefits from advanced assistance systems let the car handle traf
Slide 23: Mobility usage shares will evolve by asset ownership and autonomy
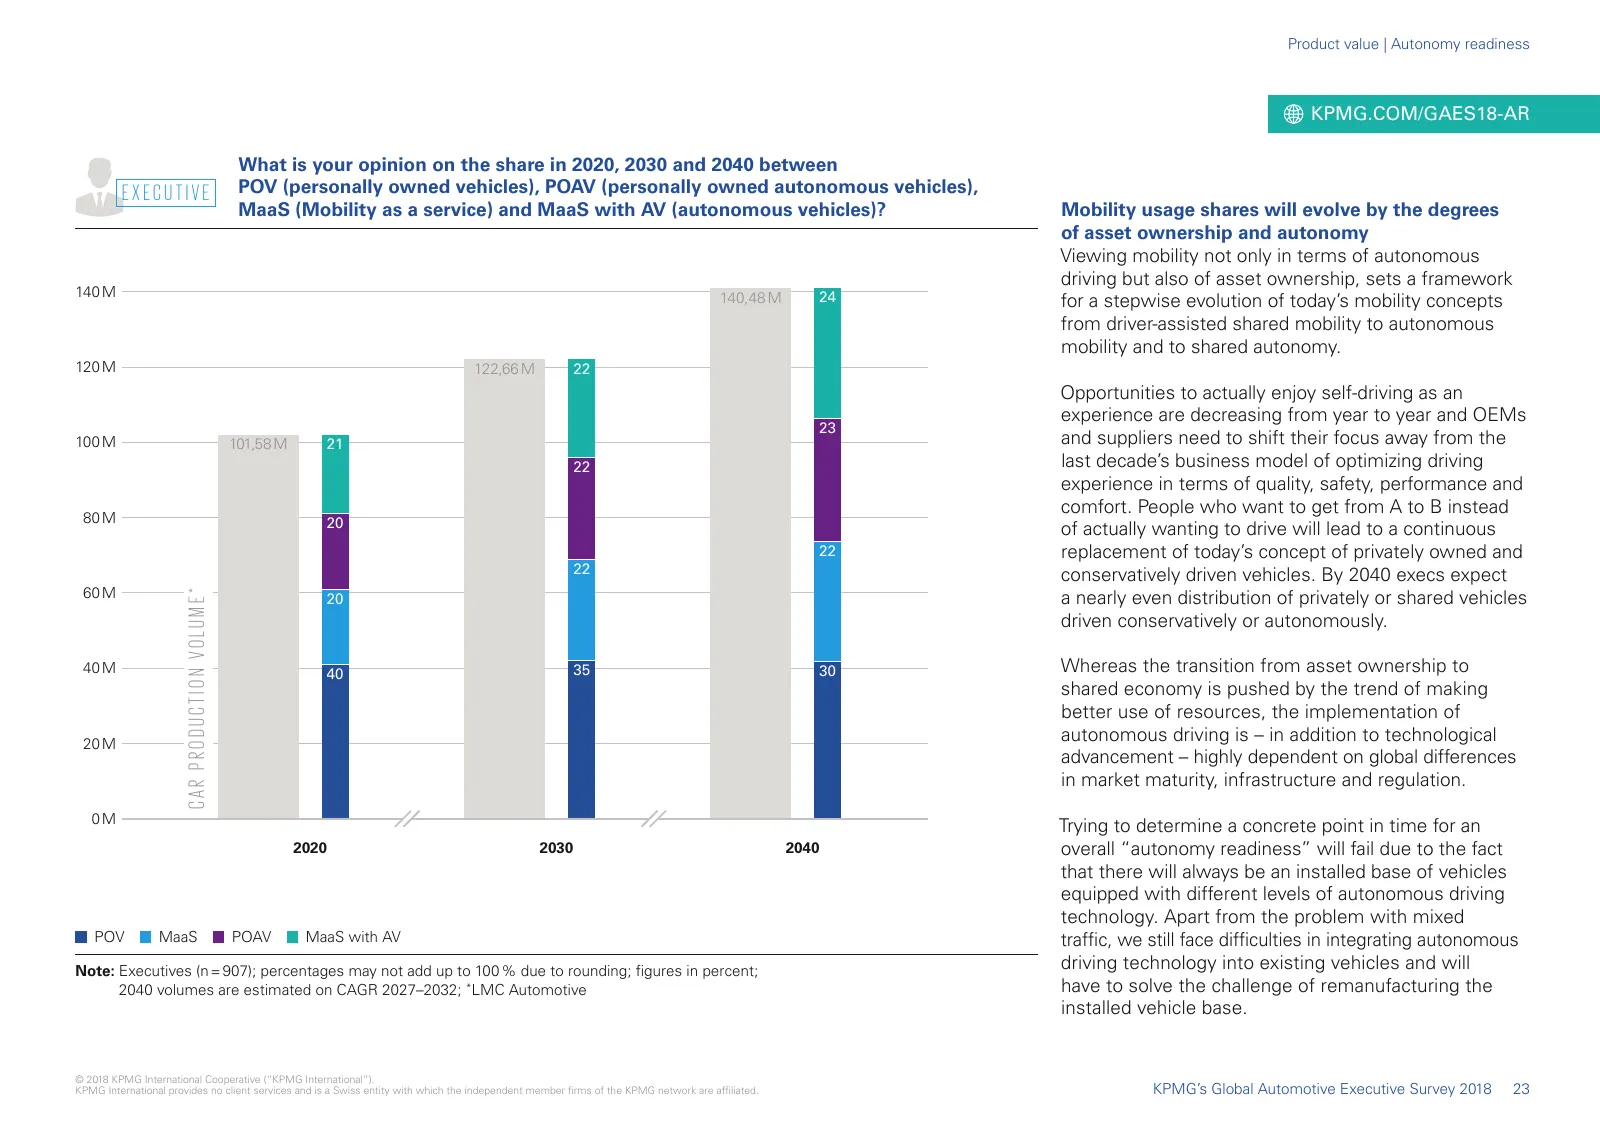
Product value | Autonomy readiness KPMG.COM/GAES18-AR What is your opinion on the share in 2020, 2030 and 2040 between EXECUTIVE POV (personally owned vehicles), POAV (personally owned autonomous vehicles), MaaS (Mobility as a service) and MaaS with AV (autonomous vehicles)? Mobility usage shares wi
Slide 24: Key takeaways: Customer value
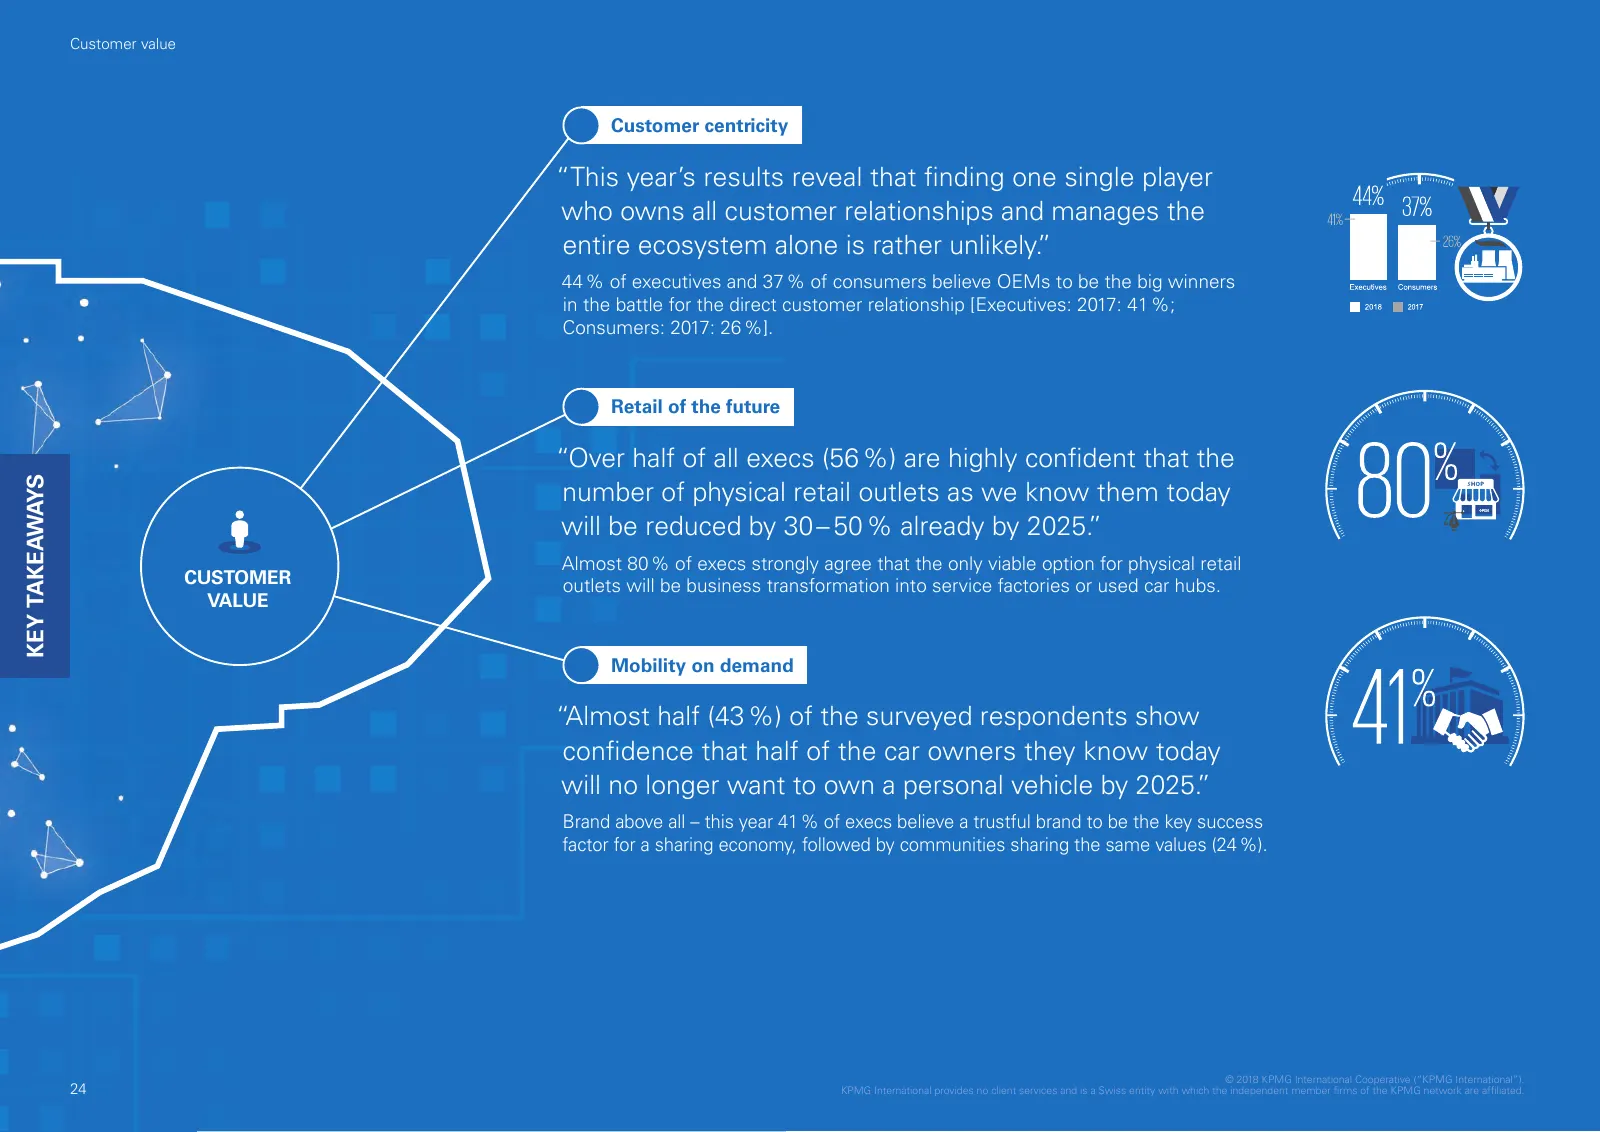
Customer value Customer centricity “This year’s results reveal that finding one single player who owns all customer relationships and manages the entire ecosystem alone is rather unlikely.” 44 % of executives and 37 % of consumers believe OEMs to be the big winners in the battle for the direct custo
Slide 25: No player can avoid defining its role within the ecosystem
Customer value KPMG.COM/GAES18-CV CUSTOMER VALUE There is not any player who can get around without defining its role within the ecosystem Agile customer touchpoint management, Customer centricity be to manage evolutionary, revolutionary and disruptive A customer-centric concept is the heart of ever
Slide 26: Number of physical retail outlets will be dramatically reduced by 2025
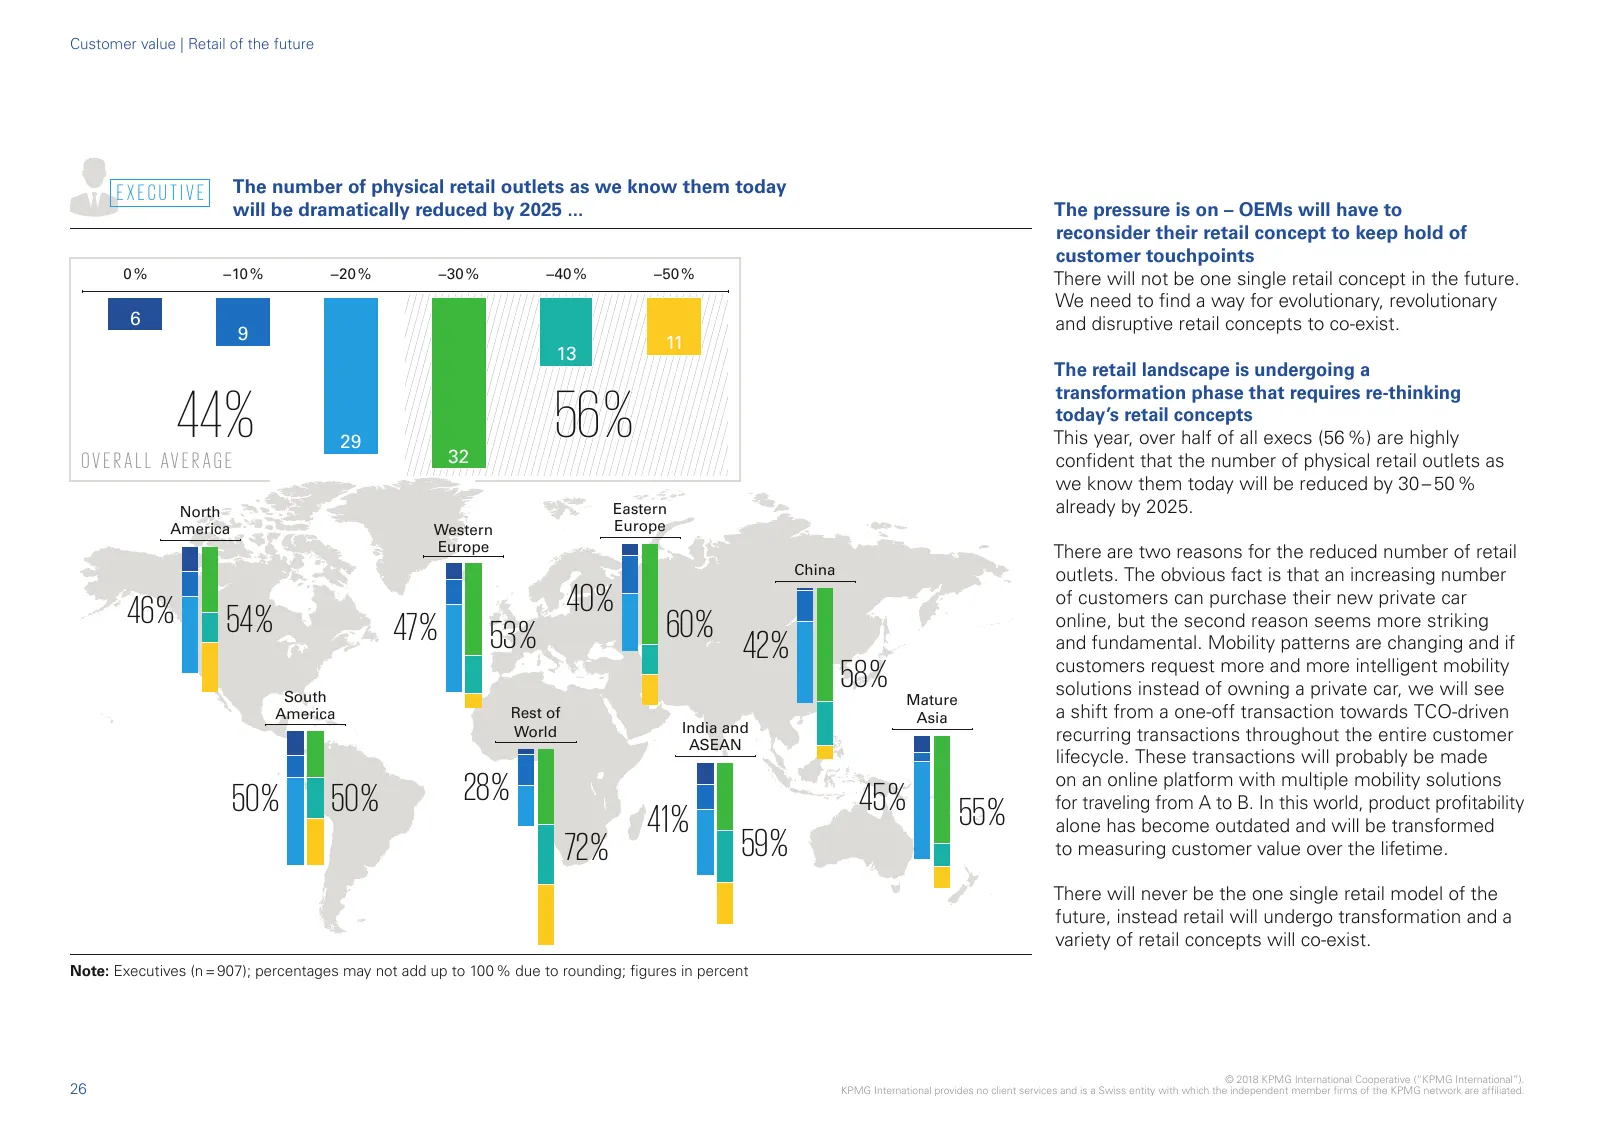
Customer value | Retail of the future EXECUTIVE The number of physical retail outlets as we know them today will be dramatically reduced by 2025 ... The pressure is on – OEMs will have to reconsider their retail concept to keep hold of customer touchpoints 0% −10 % −20 % −30 % −40 % −50 % There will
Slide 27: Retail outlets becoming service factories or used car hubs
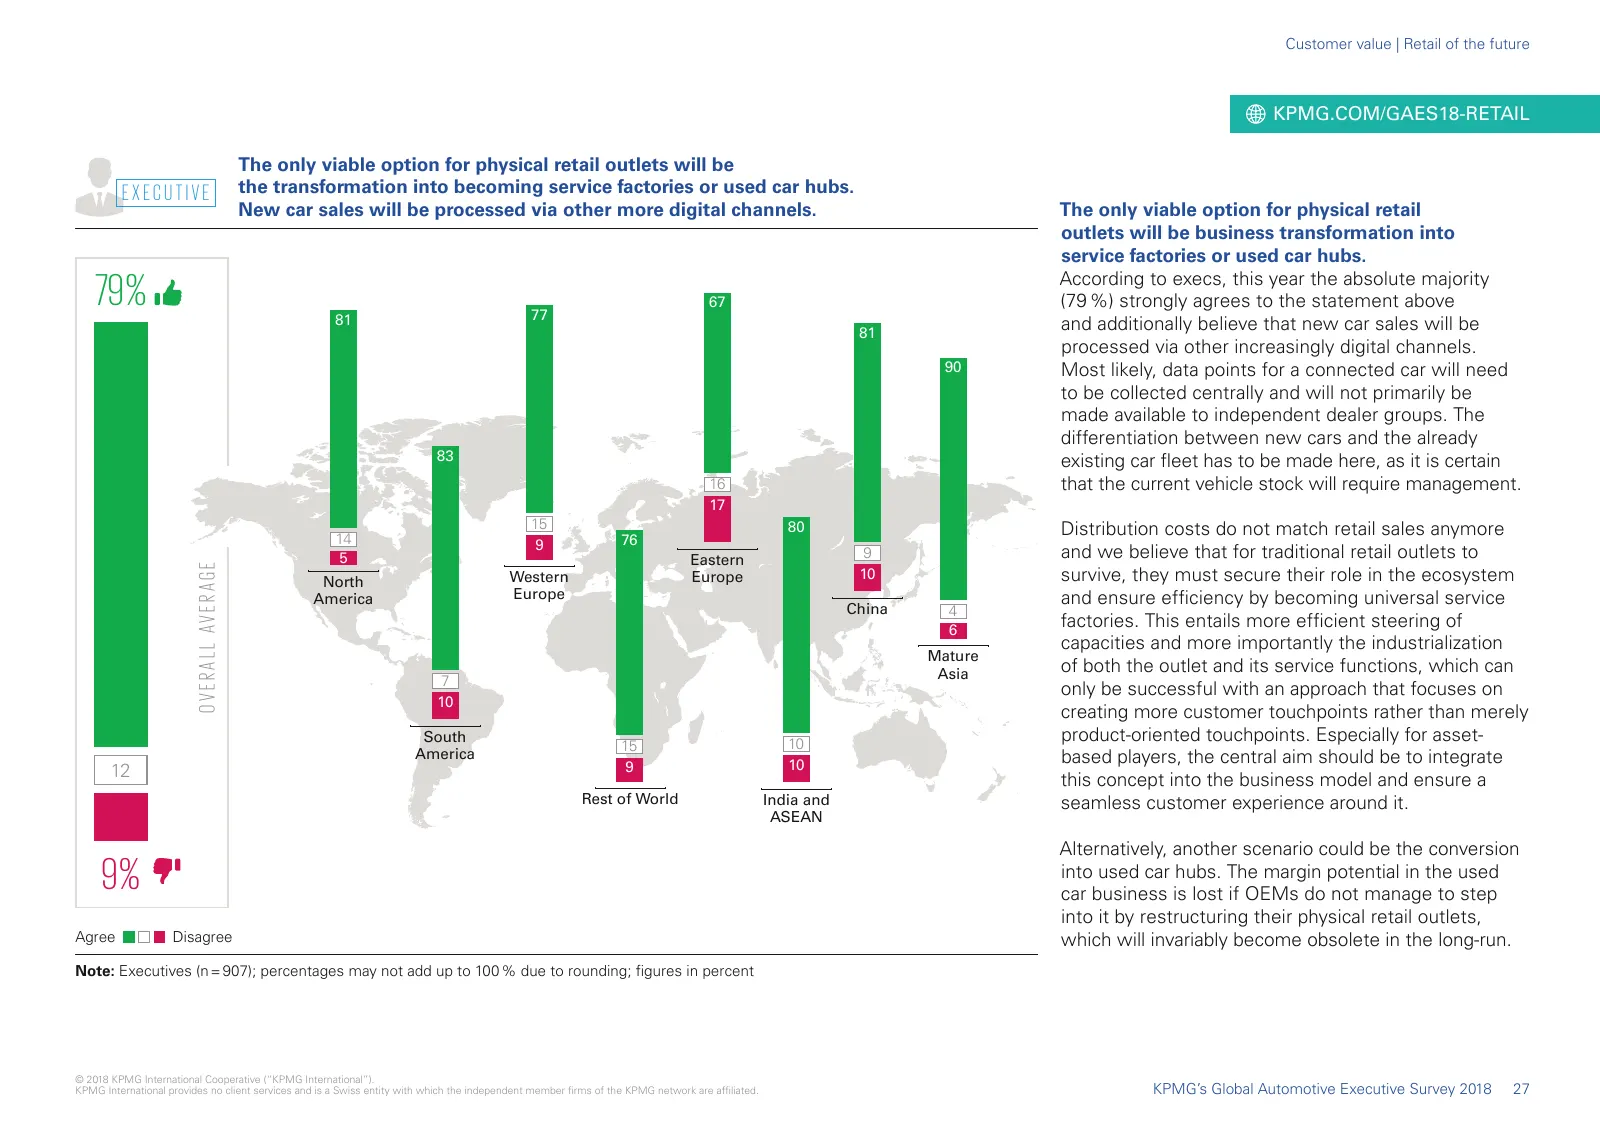
Customer value | Retail of the future KPMG.COM/GAES18-RETAIL The only viable option for physical retail outlets will be EXECUTIVE the transformation into becoming service factories or used car hubs. New car sales will be processed via other more digital channels. The only viable option for physical
Slide 28: Key takeaways: Ecosystem value
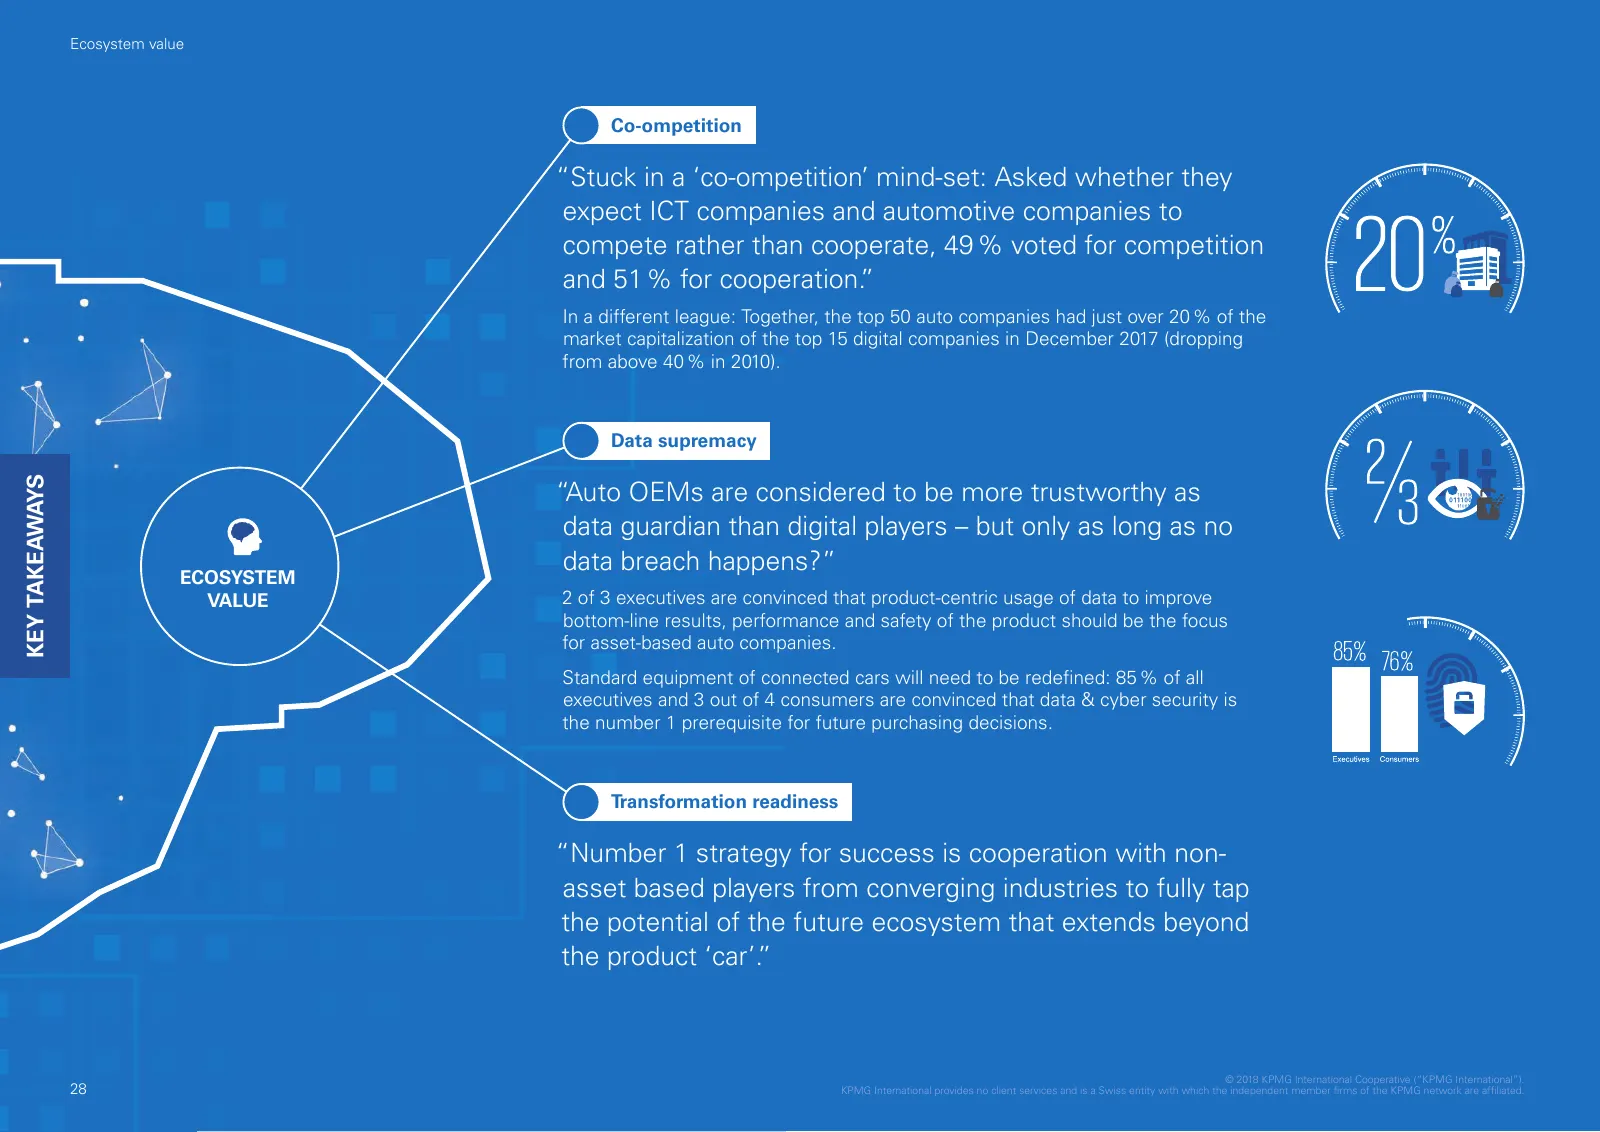
Ecosystem value Co-ompetition “Stuck in a ‘co-ompetition’ mind-set: Asked whether they expect ICT companies and automotive companies to compete rather than cooperate, 49 % voted for competition and 51 % for cooperation.” In a different league: Together, the top 50 auto companies had just over 20 % o
Slide 29: Unlocking ecosystem value is a key success factor for auto companies
Ecosystem value KPMG.COM/GAES18-ESV ECOSYSTEM VALUE Unlocking ecosystem value is a key success factor for asset-based auto companies Tapping ecosystem value demands a lot Can striking distance to digital players only be asset-based manufacturing companies is still in its early achieved by co-ompeti
Slide 30: Total market capitalization in the ecosystem
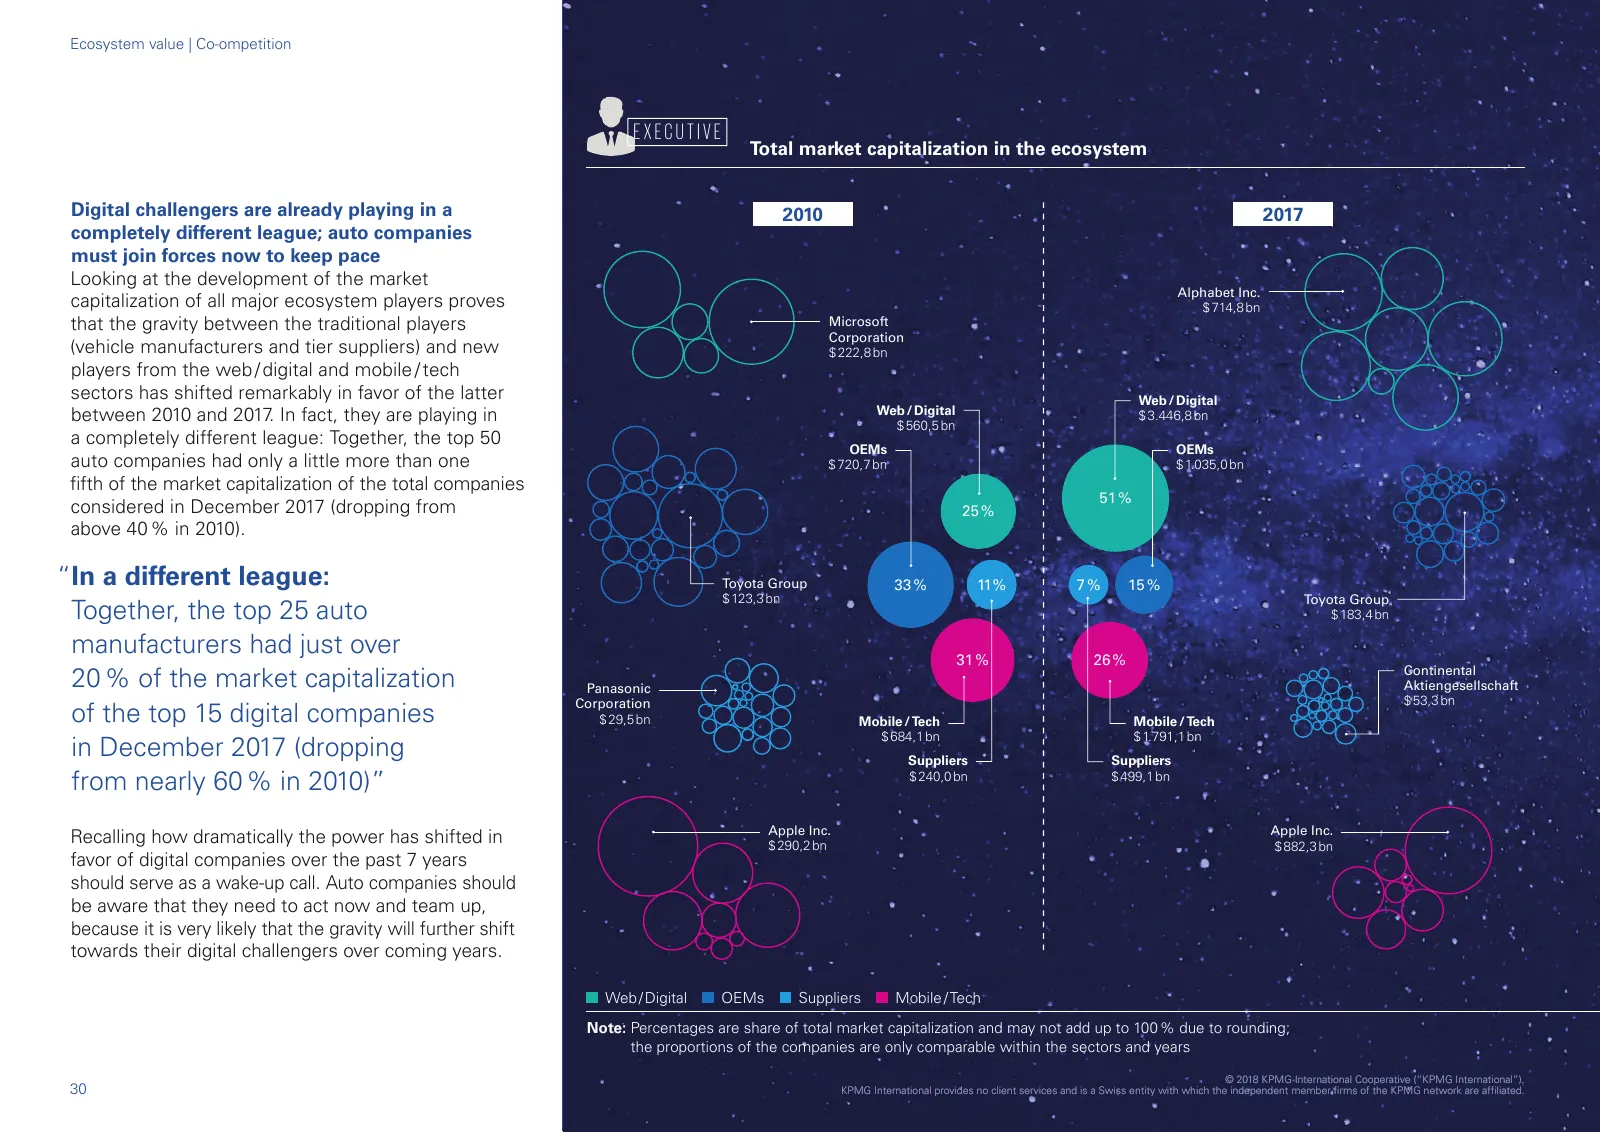
Ecosystem value | Co-ompetition EXECUTIVE Total market capitalization in the ecosystem Digital challengers are already playing in a 2010 2017 completely different league; auto companies must join forces now to keep pace Looking at the development of the market Alphabet Inc. capitalization of all maj
Slide 31: Total cash positions in the ecosystem
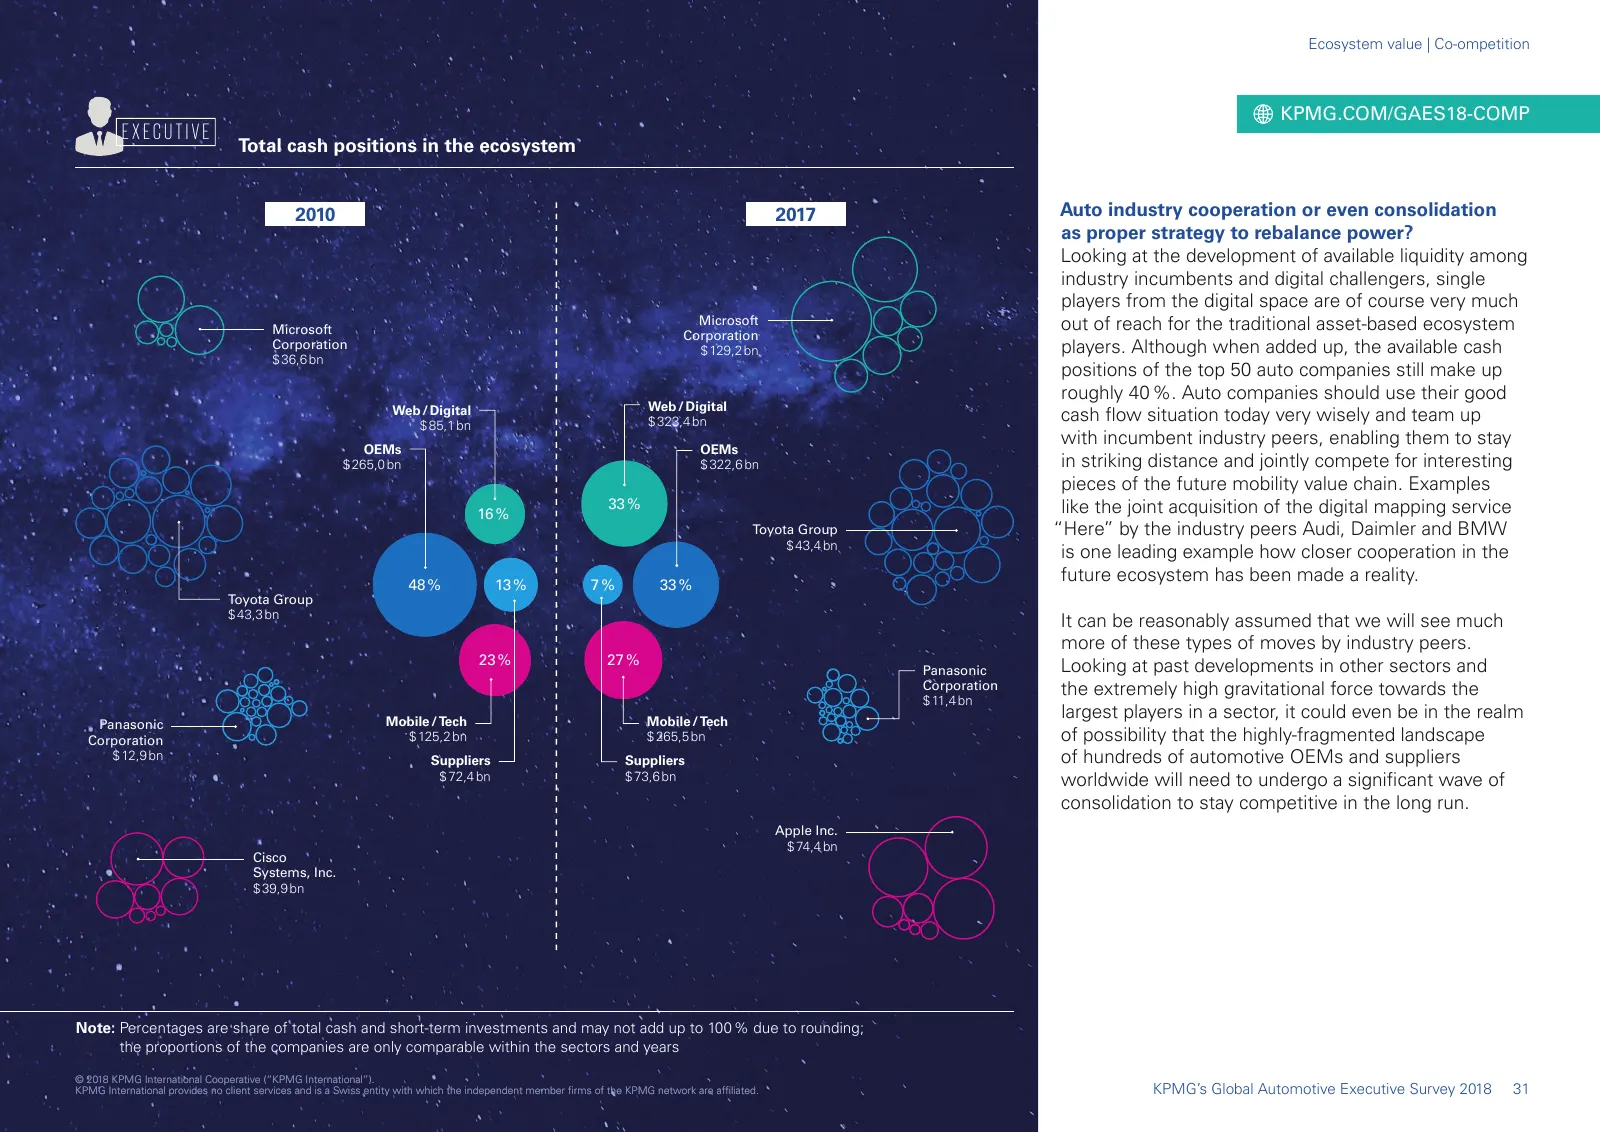
Ecosystem value | Co-ompetition KPMG.COM/GAES18-COMP EXECUTIVE Total cash positions in the ecosystem 2010 2017 Auto industry cooperation or even consolidation as proper strategy to rebalance power? Looking at the development of available liquidity among industry incumbents and digital challengers, s
Slide 32: Will ICT and automotive companies compete or cooperate?
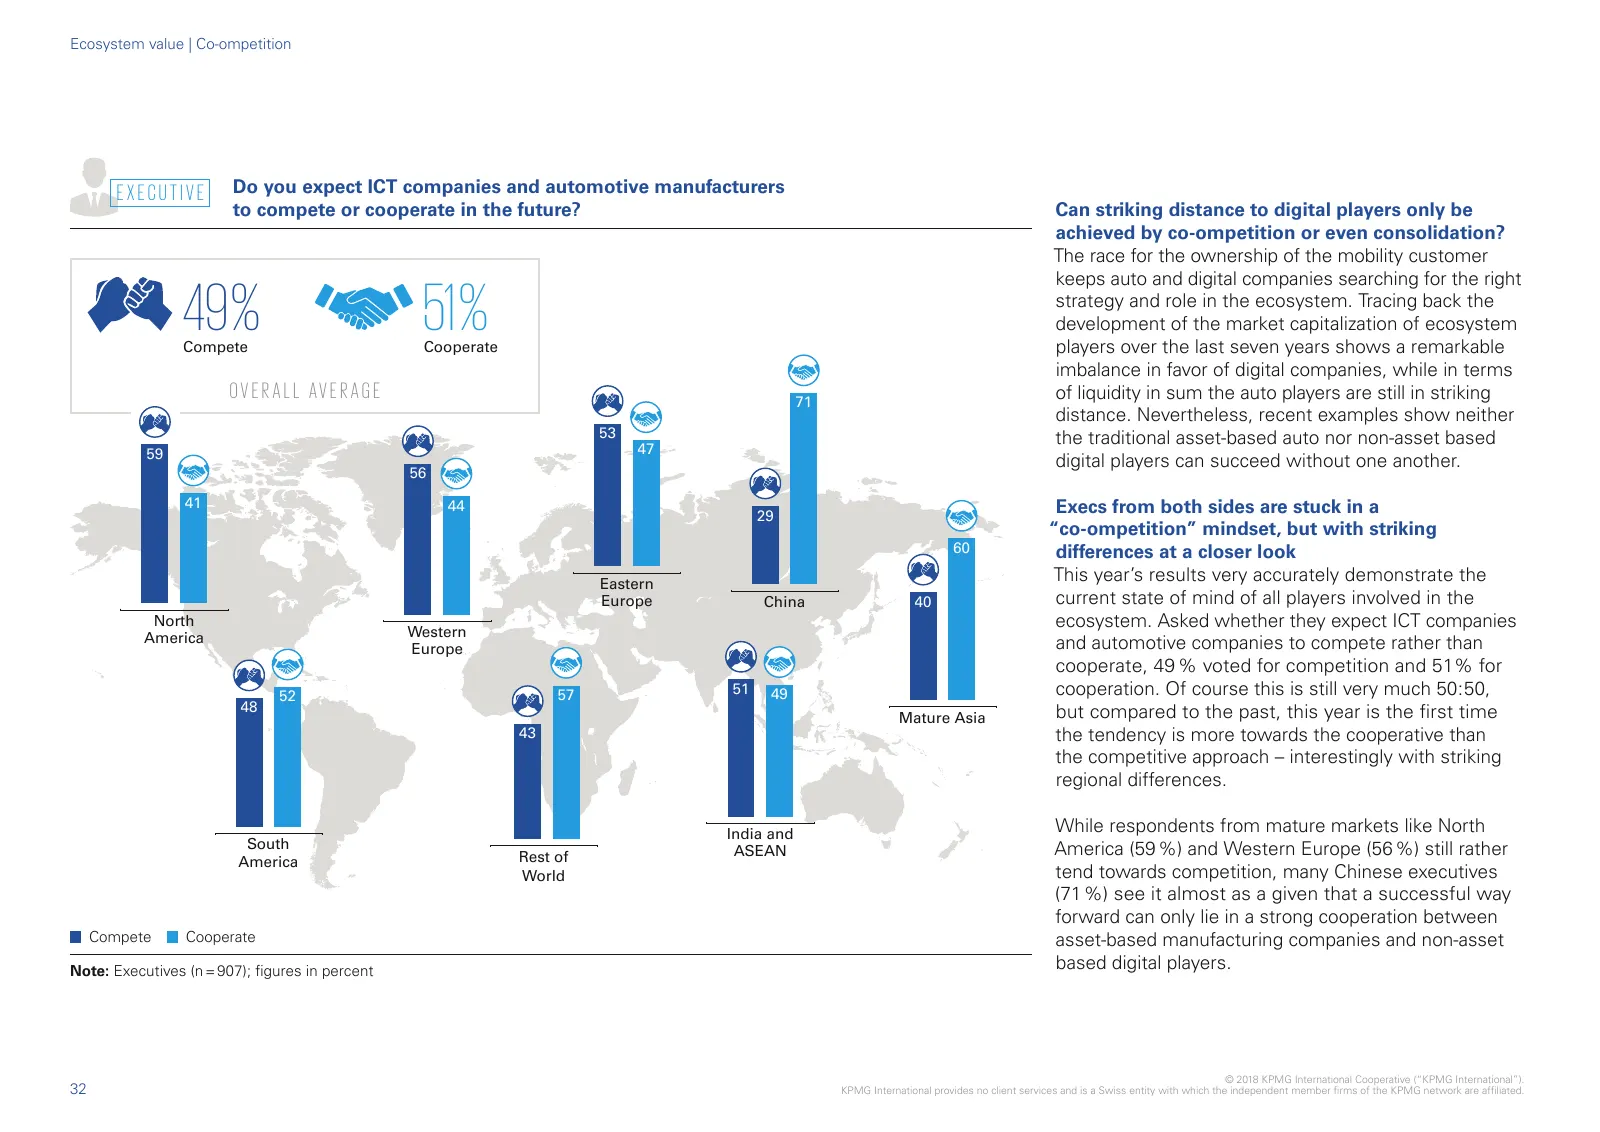
Ecosystem value | Co-ompetition EXECUTIVE Do you expect ICT companies and automotive manufacturers to compete or cooperate in the future? Can striking distance to digital players only be achieved by co-ompetition or even consolidation? The race for the ownership of the mobility customer keeps auto a
Slide 33: Where car companies can monetize data
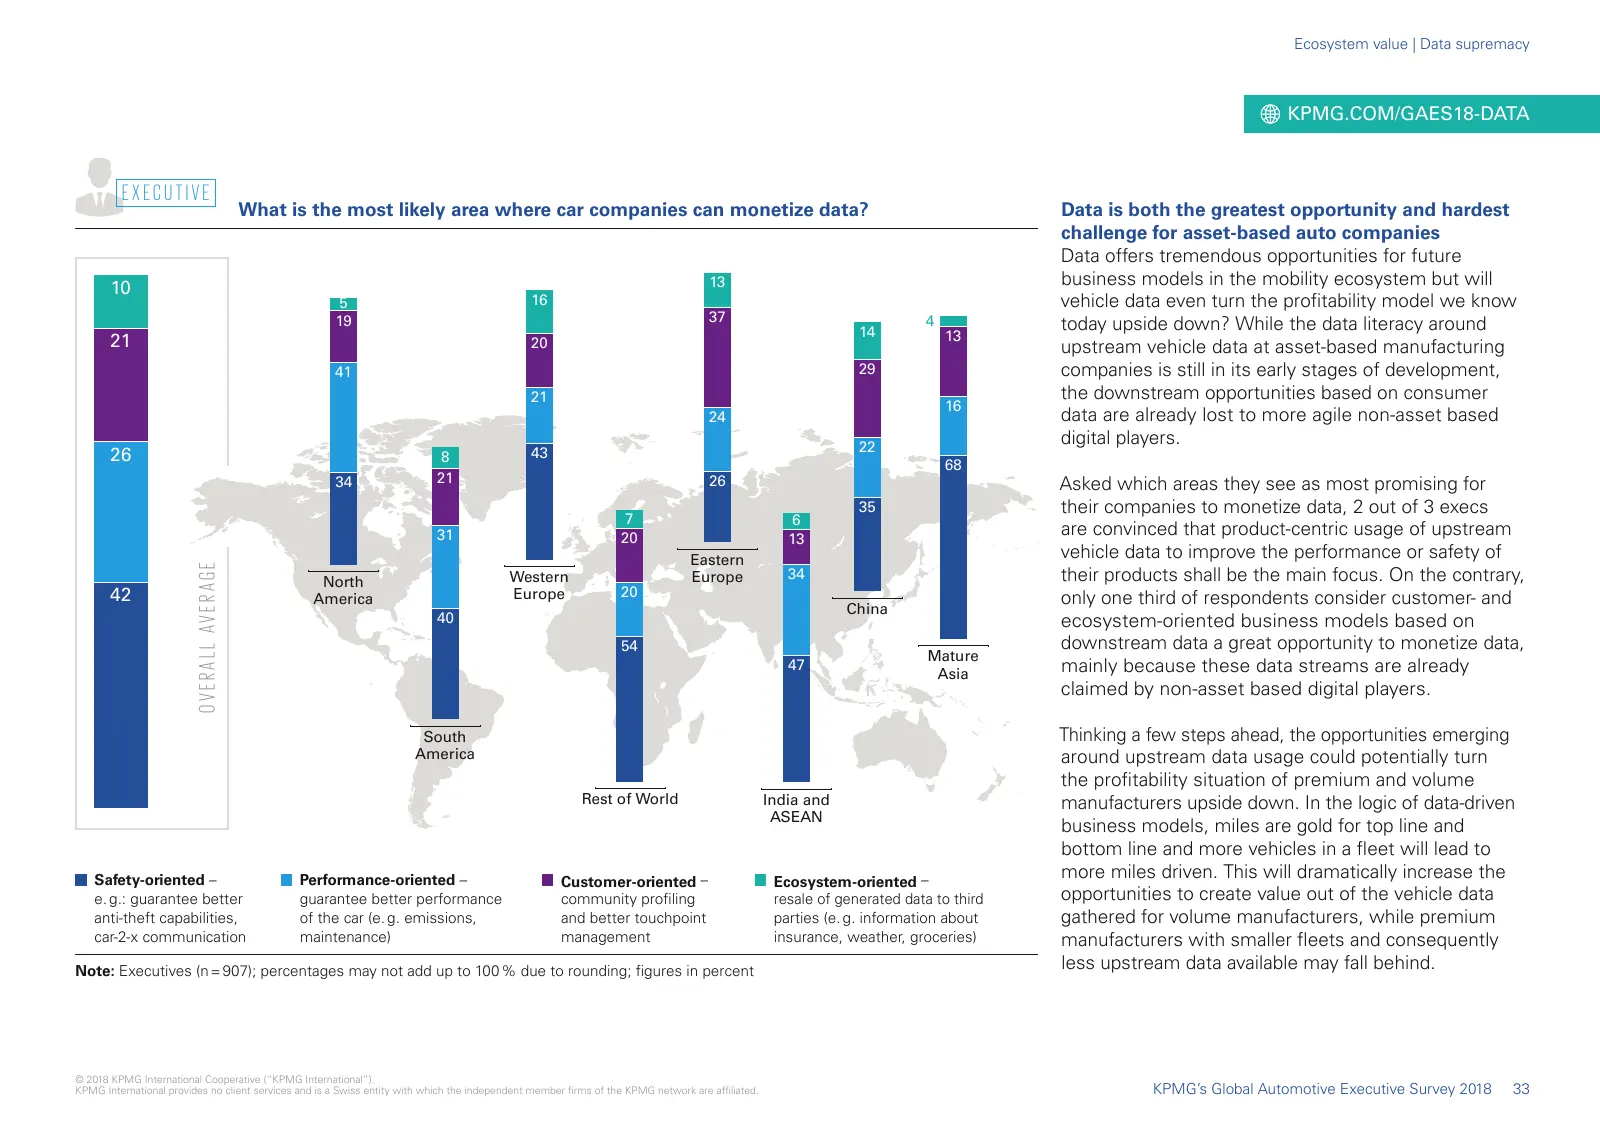
Ecosystem value | Data supremacy KPMG.COM/GAES18-DATA EXECUTIVE What is the most likely area where car companies can monetize data? Data is both the greatest opportunity and hardest challenge for asset-based auto companies Data offers tremendous opportunities for future 10 13 business models in the
Slide 34: Importance of data and cyber security in a digital business model
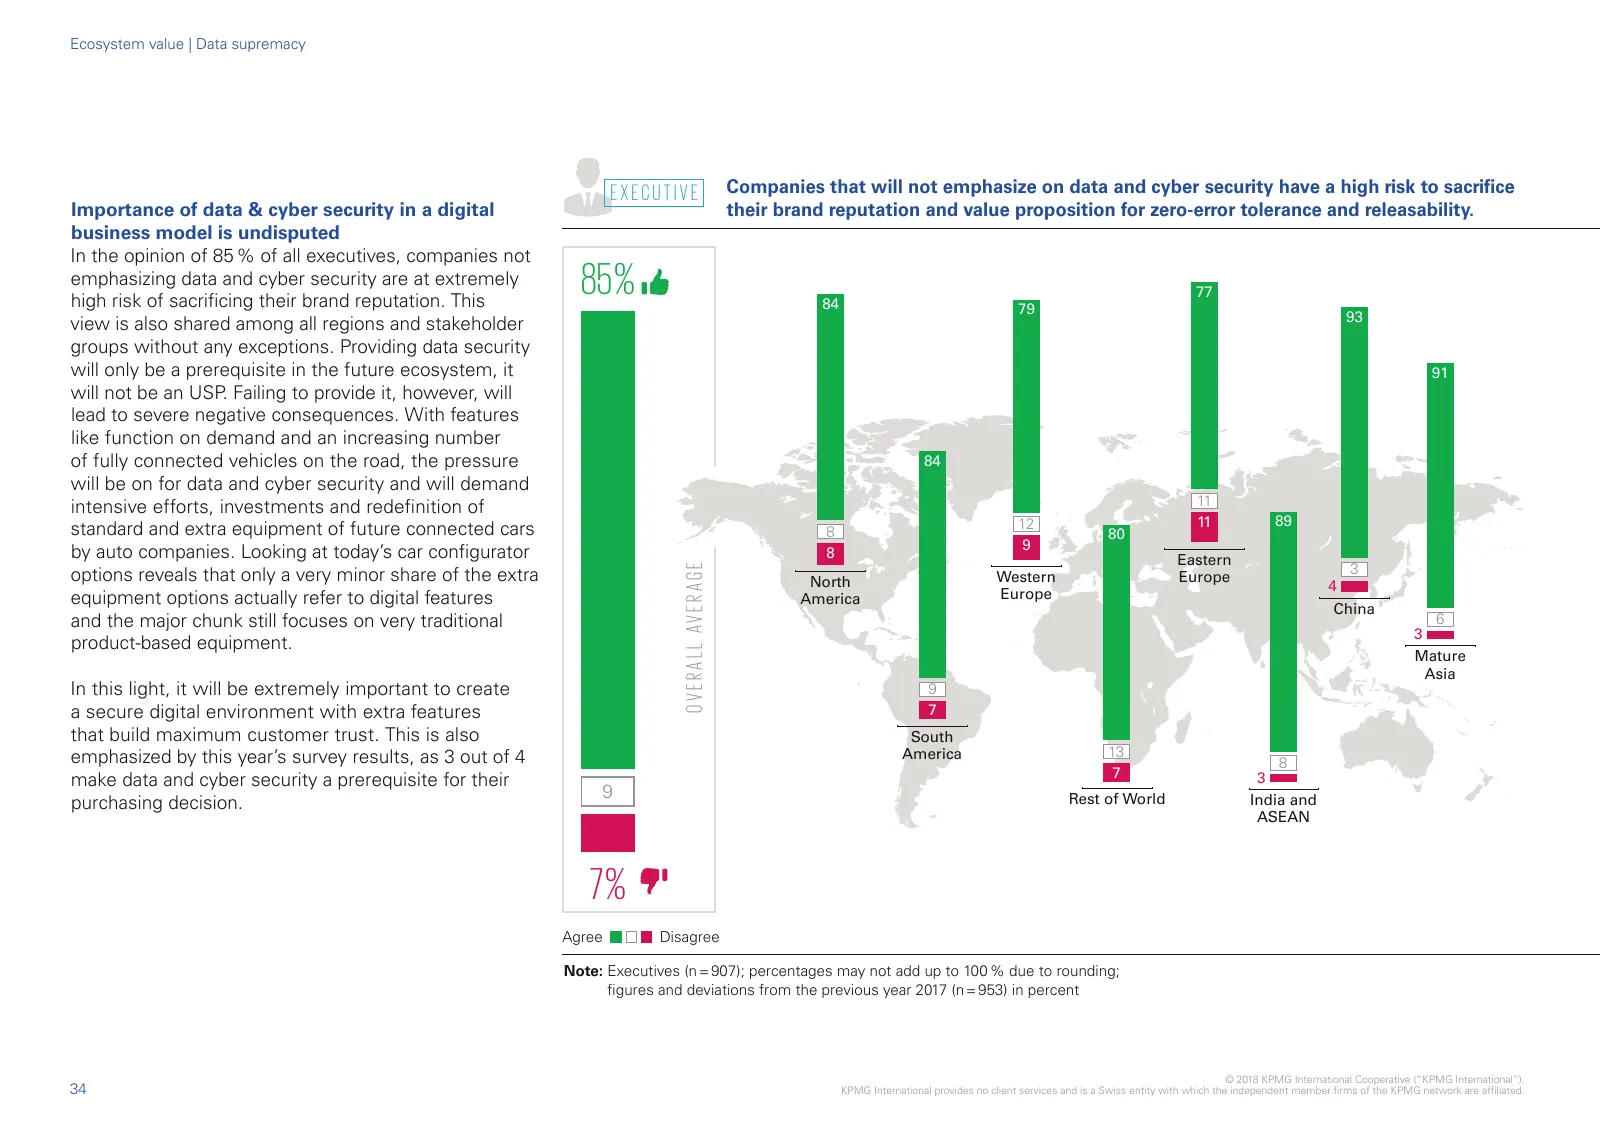
Ecosystem value | Data supremacy EXECUTIVE Companies that will not emphasize on data and cyber security have a high risk to sacrifice Importance of data & cyber security in a digital their brand reputation and value proposition for zero-error tolerance and releasability. business model is undisputed
Slide 35: Data privacy and security as a purchasing criterion
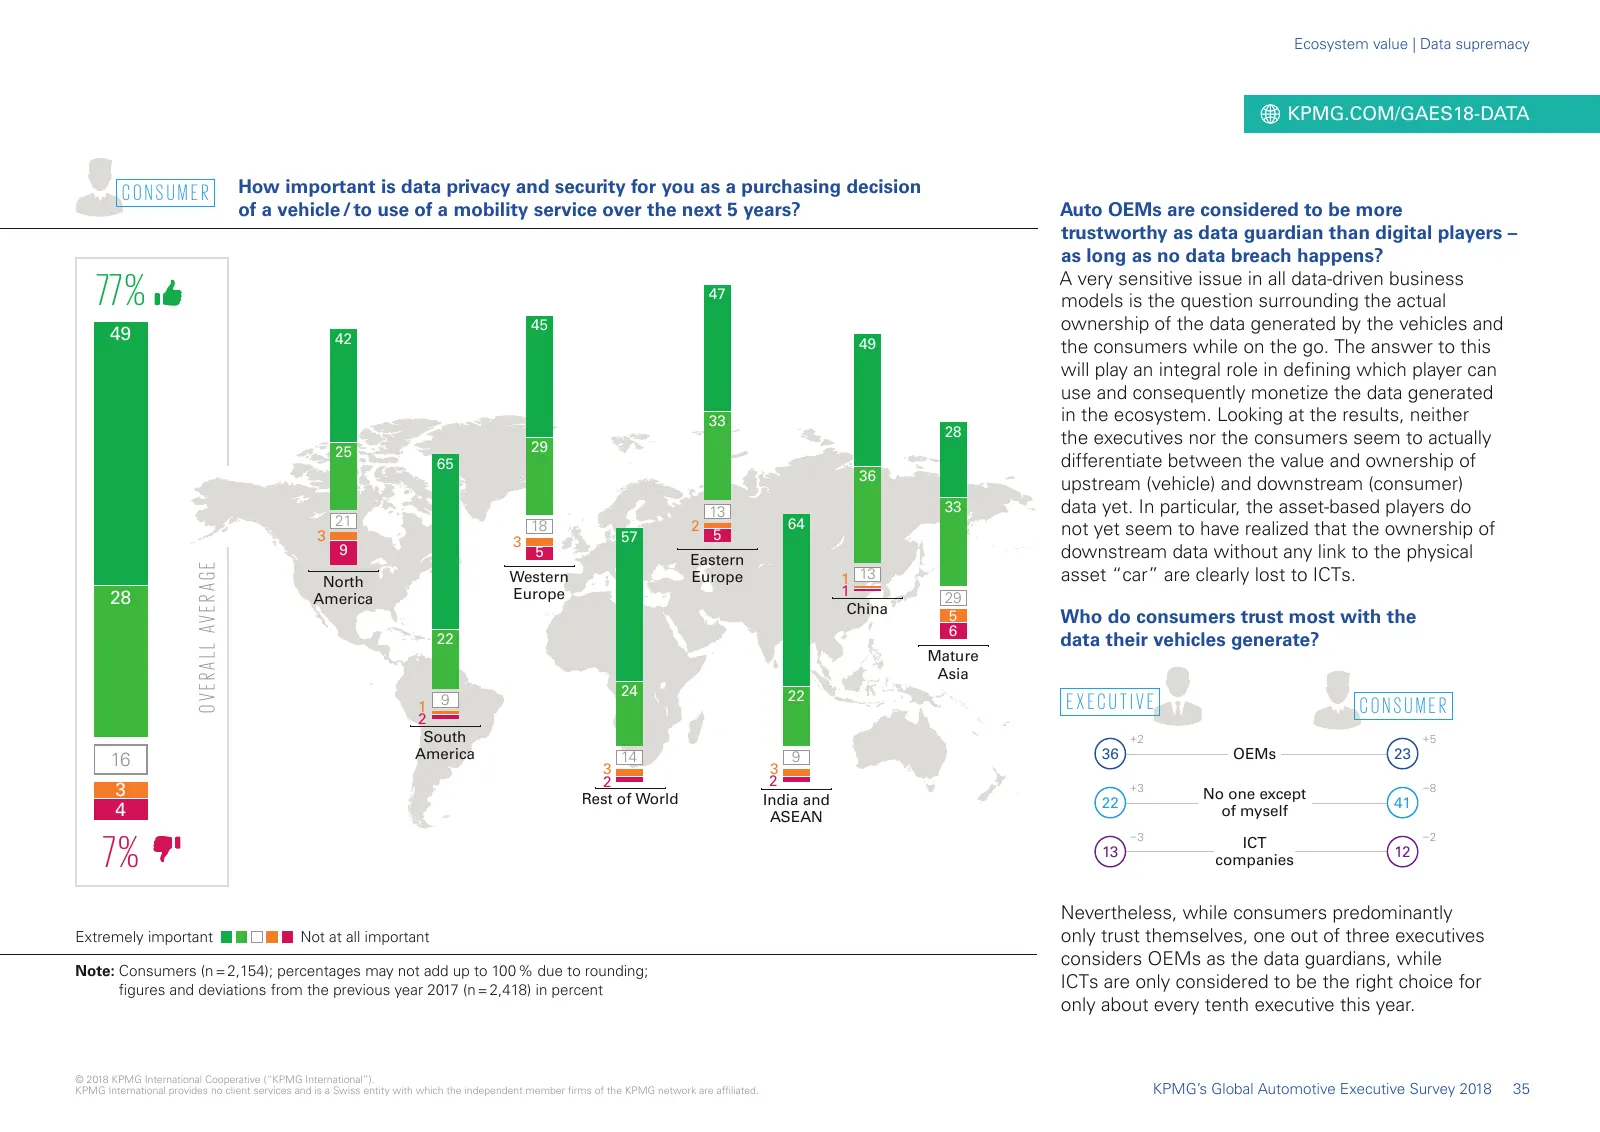
Ecosystem value | Data supremacy KPMG.COM/GAES18-DATA KPMG.COM/GAES2018 CONSUMER How important is data privacy and security for you as a purchasing decision of a vehicle / to use of a mobility service over the next 5 years? Auto OEMs are considered to be more trustworthy as data guardian than digita
Slide 36: KPMG Thought Leadership
KPMG Thought Leadership Thought Leadership JANUARY 2017 APRIL 2017 Global Automotive Executive Survey 2017 The Connected Car is her to Stay The car itself will not be the main source of profit The connected car has arrived and is here to stay! in the future! This is demonstrated by the results of Wh
Slide 37: KPMG Thought Leadership
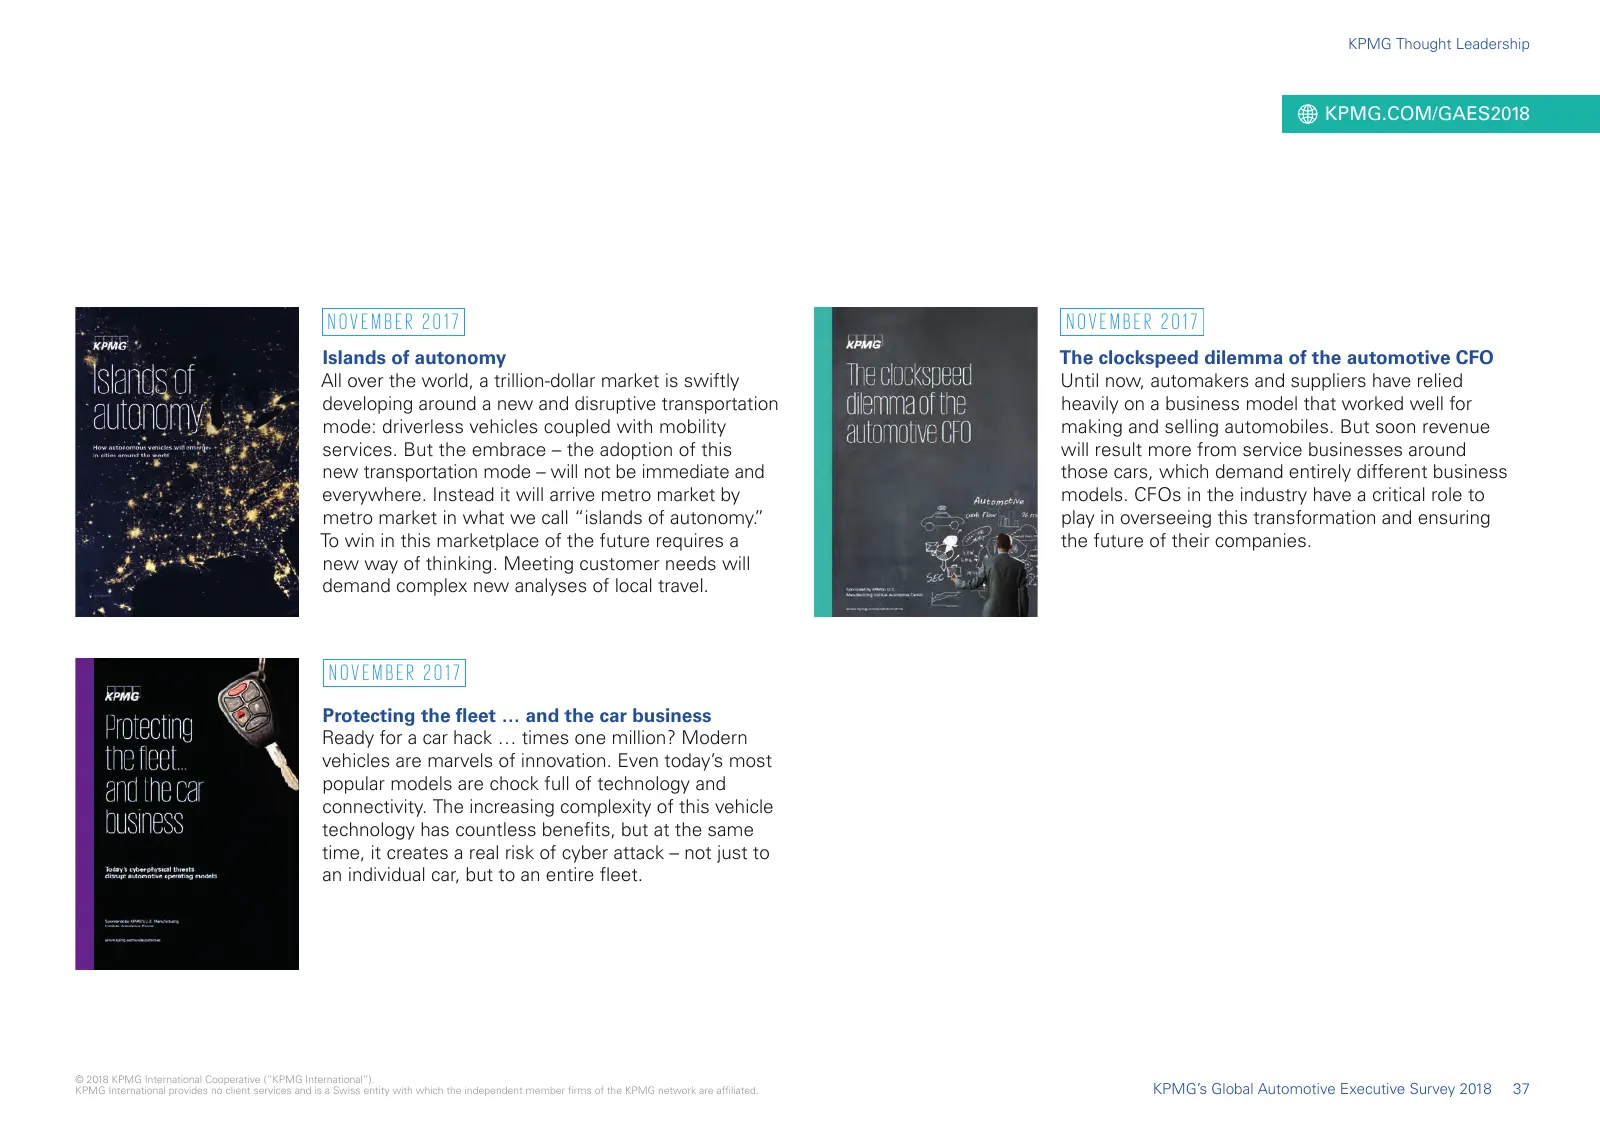
KPMG Thought Leadership KPMG.COM/GAES2018 NOVEMBER 2017 NOVEMBER 2017 Islands of autonomy The clockspeed dilemma of the automotive CFO All over the world, a trillion-dollar market is swiftly Until now, automakers and suppliers have relied developing around a new and disruptive transportation heavily
Slide 38: Acknowledgements
Acknowledgements I wish to personally thank our respondents and contributors for their involvement in this year’s survey In this year’s survey, over 900 senior Additionally, more than 2,100 consumers from around the world gave us their valuable perspectives and executives from the world’s leading
Slide 39: How to use the online platform
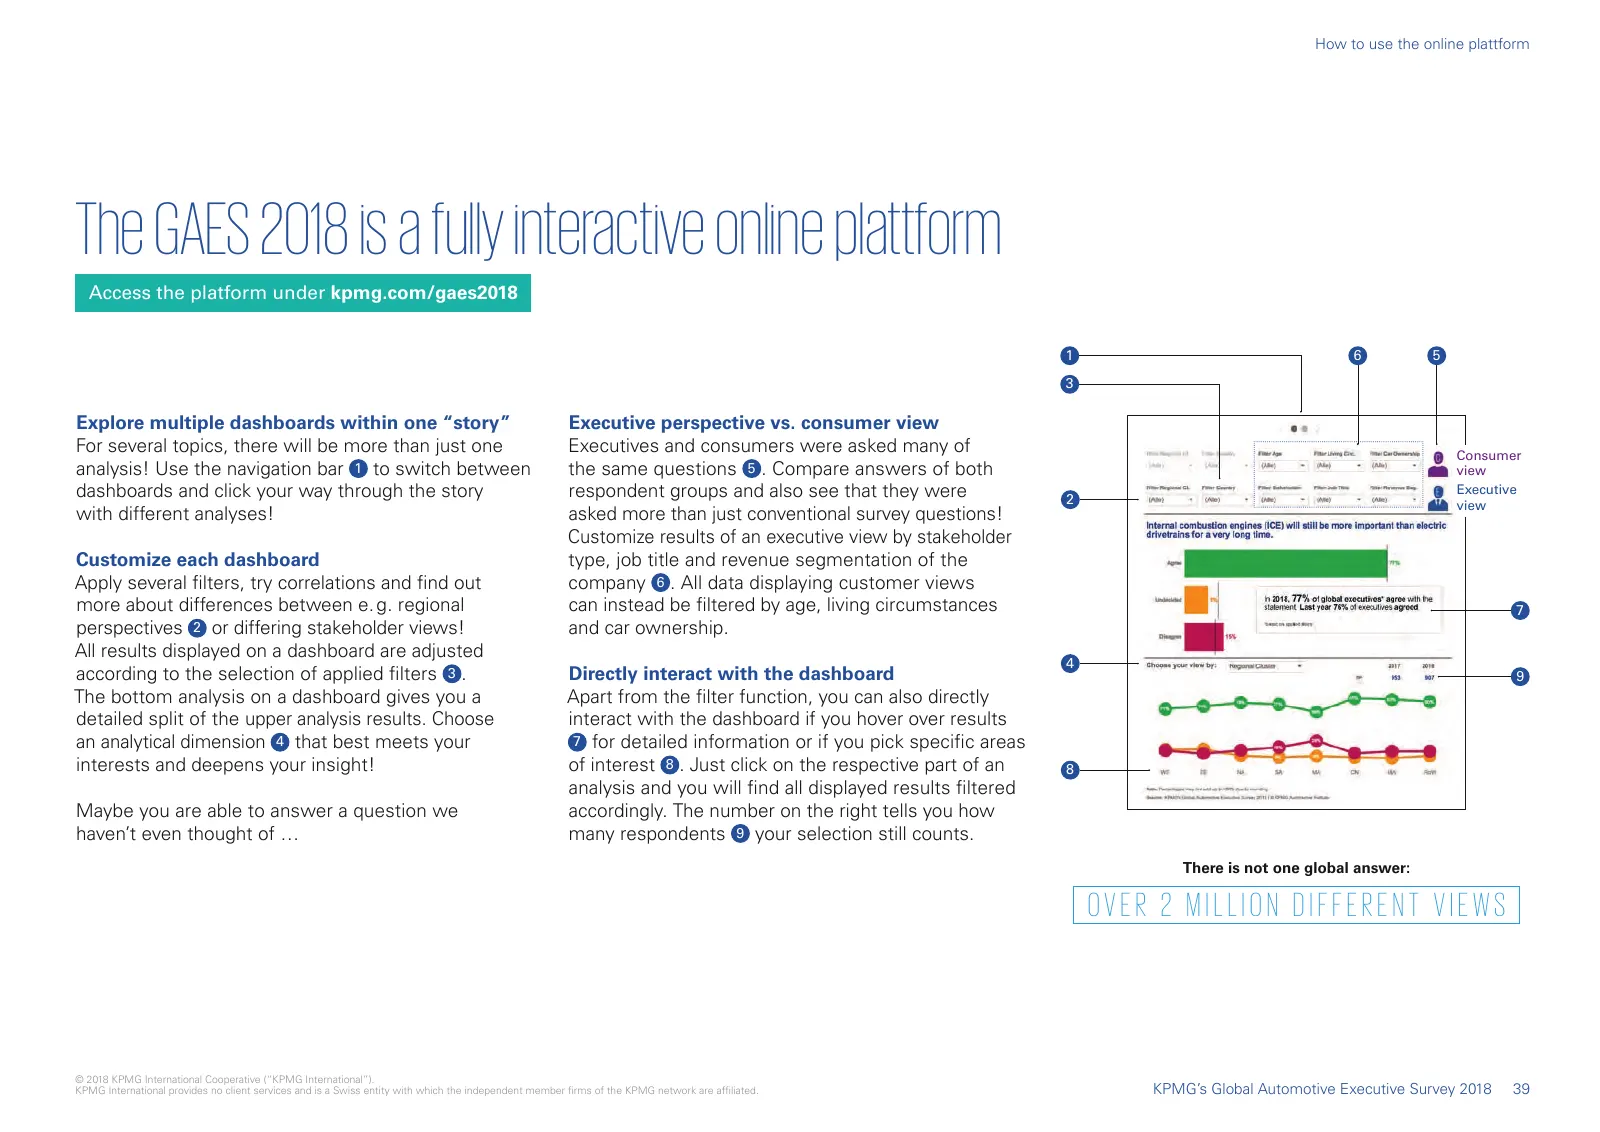
How to use the online plattform The GAES 2018 is a fully interactive online plattform Access the platform under kpmg.com/gaes2018 1 6 5 3 Explore multiple dashboards within one “story” Executive perspective vs. consumer view For several topics, there will be more than just one Executives and consume
Slide 40: Contact us
Contact us Global Americas EMA Dieter Becker Gary Silberg Dieter Becker Aline Dodd Global and EMA Head Automotive Practice The Americas Head of Automotive Global and EMA Head Automotive Practice EMA Executive for Automotive KPMG International KPMG in the US KPMG International KPMG International diet
Source: Internet Archive copy of bertrandt.com
More decks from Bertrandt AG
 9M 2025/2026 Earnings Presentation20 slides · Aug 3, 2026
 Investor Day (May 2026)82 slides · May 13, 2026
 H1 2025/2026 Earnings Presentation19 slides · May 13, 2026
 Q1 2025/2026 Earnings Presentation15 slides · Feb 12, 2026
 Investor Presentation (January 2026)61 slides · Jan 12, 2026
 FY2024/2025 Earnings Presentation41 slides · Dec 18, 2025