Whitney — Gulf South Bank Conference 2007
29 slides from Whitney's conference presentation, May 1, 2007
Slide 1: Whitney Holding Corporation Gulf South Bank Conference
Whitney Holding Corporation Gulf South Bank Conference May 1, 2007 John C. Hope III, President & Chief Operating Officer Thomas L. Callicutt, Jr., EVP and CFO
Slide 2: Welcome Back to New Orleans
Welcome Back to New Orleans
Slide 3: Thomas L. Callicutt, Jr., Chief Financial Officer
Thomas L. Callicutt, Jr. Chief Financial Officer
Slide 4: Forward-Looking Statements
Forward-Looking Statements This presentation may include forward-looking statements containing expectations about future conditions and descriptions of future plans and strategies. Whitney's ability to accurately predict the effects of future plans or strategies is inherently limited such that actua
Slide 5: A Growing, Diversified Company
A Growing, Diversified Company 123-year old name started in New Orleans Weathered many types of storms Corporate philosophy: Soundness Profitability Growth In that order of priority Over locations across 5 states Focus on Relationship Banking “It Takes a Whitney Banker”
Slide 6: A Look Back at 2006
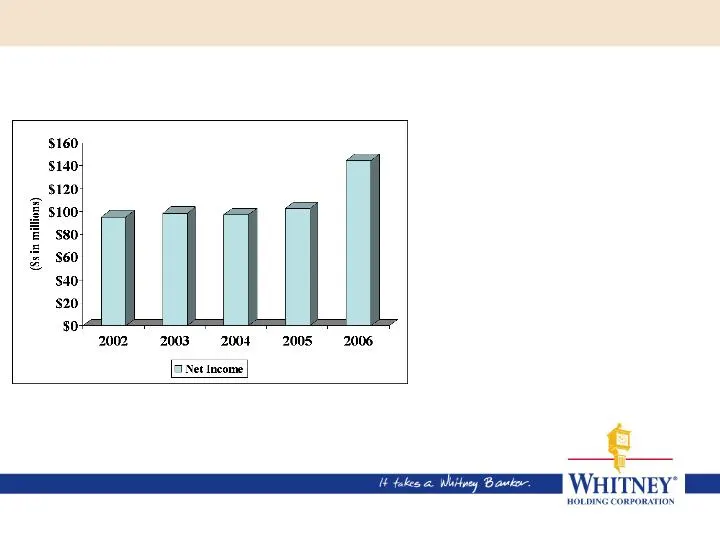
A Look Back at 2006 • 2006 was a year to return to more normal operations • Normal has a new meaning post storms • Reported record earnings in 2006 – $145 million net income – 41% higher than previous record earnings in 2005 – $2.20 per diluted share
Slide 7: 1Q'07 Earnings
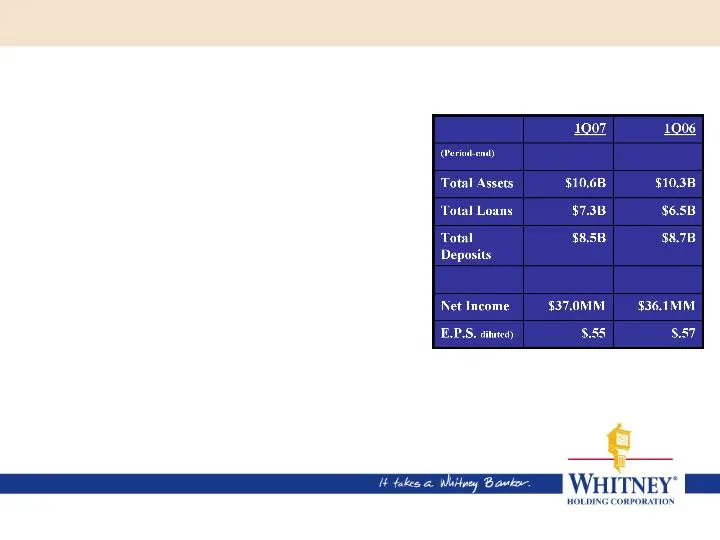
1Q’07 Earnings • Net income $37 million • Earnings per share (diluted) $.55 • Signature merger closed March 2, 2007 – Balances at merger: • $280MM in assets • $220MM in loans • $210MM in deposits • Linked-quarter organic loan growth flat from 4Q06 – Growth in Houston, Alabama, Louisiana – Florida ma
Slide 8: Louisiana Recovery Authority Additional Government Funds
Source: Louisiana Recovery Authority http://www.rememberrebirth.org/ritadocs/Ritadata091906update.pdf Additional Government Funds • Louisiana Recovery Authority – $10.4B available for Louisiana Community Development Block Grants • $8.1B available through the Road Home Program • $350MM allocated to b
Slide 9: NIM
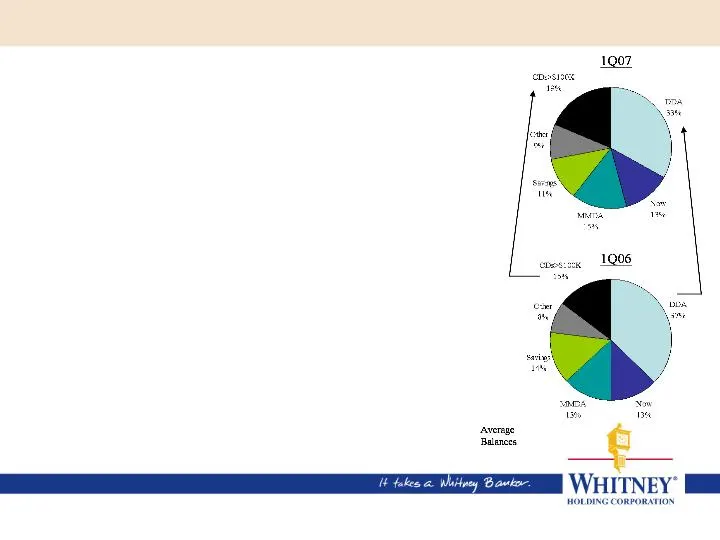
NIM 5.08% – Return to a more normal mix of deposits • Shift in funding mix from DDA to higher cost deposits • DDA 33% of total deposits at 1Q07 – Earning asset mix – Active management of loan and deposit pricing – Liquidity in the deposit base • Issued $150MM in sub-debt in late March 2007 1Q’07 Ear
Slide 10: Fee-Based Business Growth
Fee-Based Business Growth • Fees up 14% from a year ago – Net gain on sales and other revenue from foreclosed assets increased from 1Q06 • Service Charges on Deposits is the largest component of fee income – Deposit service charges up 9% from a year earlier – Fees are “seasonal” as charges are based
Slide 11: Expense Levels Higher in New Operating Environment
Expense Levels Higher in New Operating Environment • Expenses in 1Q07 increased 9% from a year earlier – Incremental operating costs from mergers • $.9MM of merger integration-related expenses from Signature – Additional amortization of intangibles – Elimination of post retirement plan – Insurance c
Slide 12: Diversified Loan Portfolio
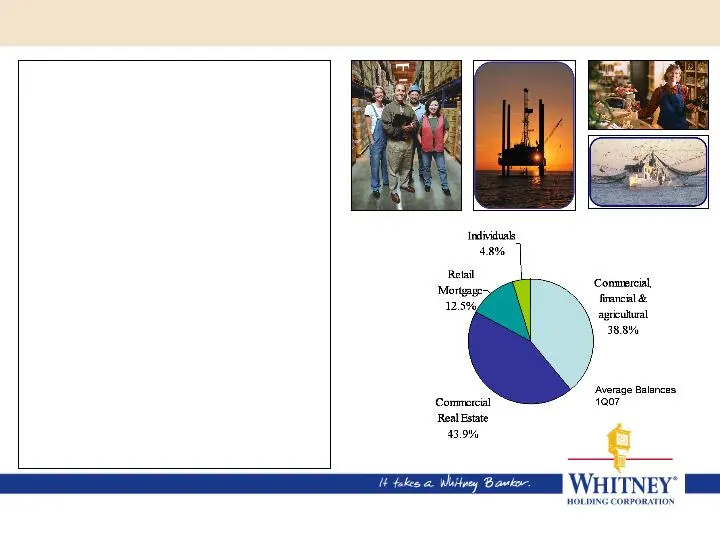
Diversified Loan Portfolio • Commercial portfolio 83% • Consumer portfolio 17% • Less diversification – But, less credit issues post-storms • No Indirect portfolio • No meaningful exposure to subprime home mortgage loans • Minimal Credit Card portfolio • Commercial customers diversified by industry
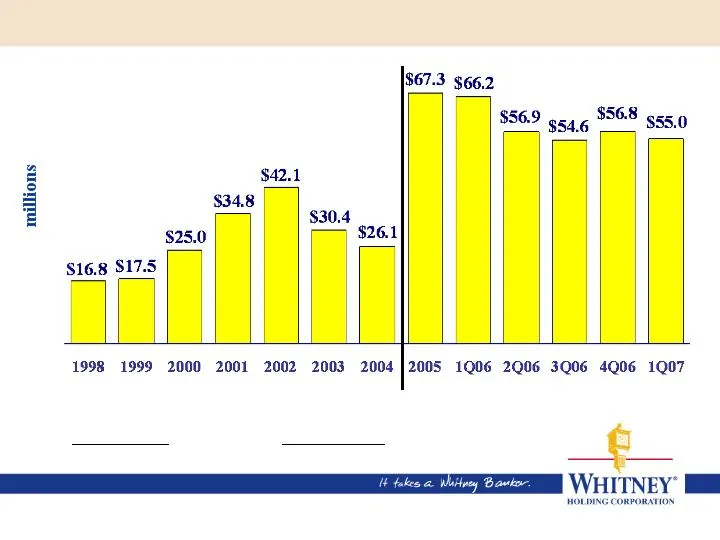
Slide 13: Working Through Nonperforming Assets Post Storms
Working Through Nonperforming Assets Post Storms NPA ratio: .48% .45% .55% .77% .95% .62% .46% 1.03% 1.02% .83% .80% .81% .76% Pre-storms
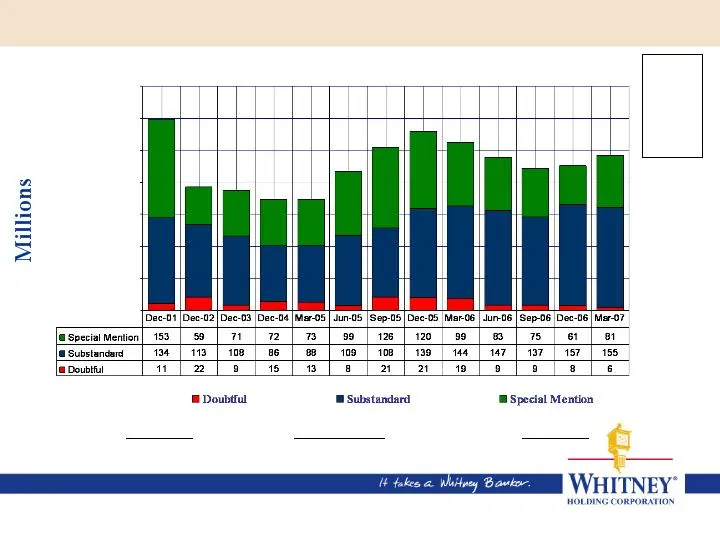
Slide 14: Loans Internally Classified as Having Above Normal Credit Risks
Loans Internally Classified as Having Above Normal Credit Risks Pre-storms Post-storms 1Q07 criticized portfolio includes $17MM from Signature merger
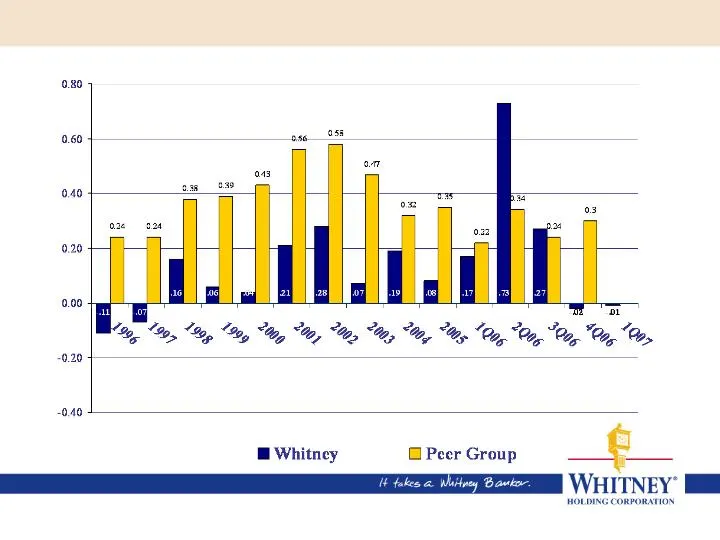
Slide 15: Net Charge-Offs At or Below Peers
Net Charge-Offs At or Below Peers Percent Net Charge-offs to Average Loans Note: Increase in 2Q’06 net charge-offs related to one storm-impacted commercial relationship. Relationship identified as impaired shortly after storms in 2005 and a substantial impairment allowance had been established.
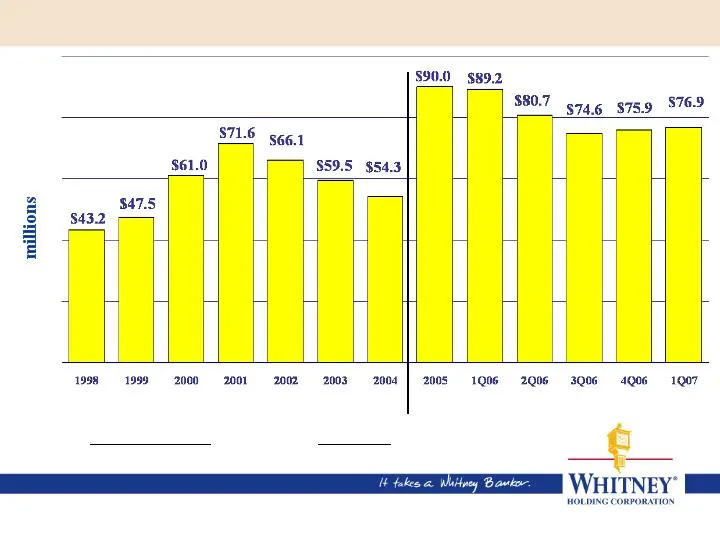
Slide 16: Allowance for Loan Losses % Loans
1.24% 1.21% 1.33% 1.59% 1.48% 1.22% ..97% 1.37% 1.37% 1.18% 1.09% 1.08% 1.06% Allowance for Loan Losses % Loans Pre-storms
Slide 17: Sound Capital Levels
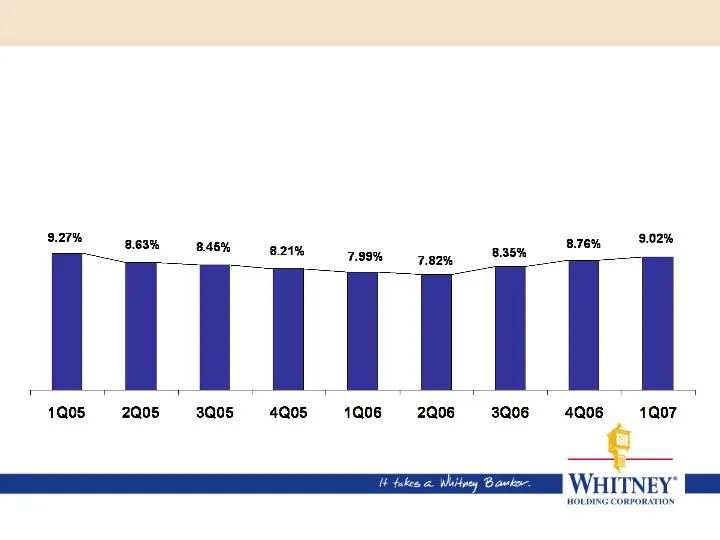
Sound Capital Levels • 1Q07 Leverage ratio --- 9.02% • Dividend payout ratio 53% (of first quarter 2007 diluted earnings per share) • Dividend yield 3.7% (based on Whitney’s April 27, 2007 closing price)
Slide 18: John C. Hope III, President and Chief Operating Officer
John C. Hope III President and Chief Operating Officer
Slide 19: Whitney Today
Whitney Today • Whitney today is a good bank • Challenging operating environment • Strong balance sheet and solid capital position • Operational resiliency • Asset quality trends are showing signs of sustained, better than anticipated performance post storms • Continuing geographic diversification t
Slide 20: Change is Needed to Ensure Continued Success
Change is Needed to Ensure Continued Success • Now is the time to focus on the next chapter in Whitney’s history • Whitney is a good bank --- with the potential to become a GREAT BANK • We will evaluate current strategies resulting in new goals and new strategies --- this may lead to change • Challe
Slide 21: An Excellent Credit Bank
An Excellent Credit Bank • Our core strength is understanding and managing credit risk • Seasoned, well understood credit culture • A track record of excellent commercial loan growth and quality
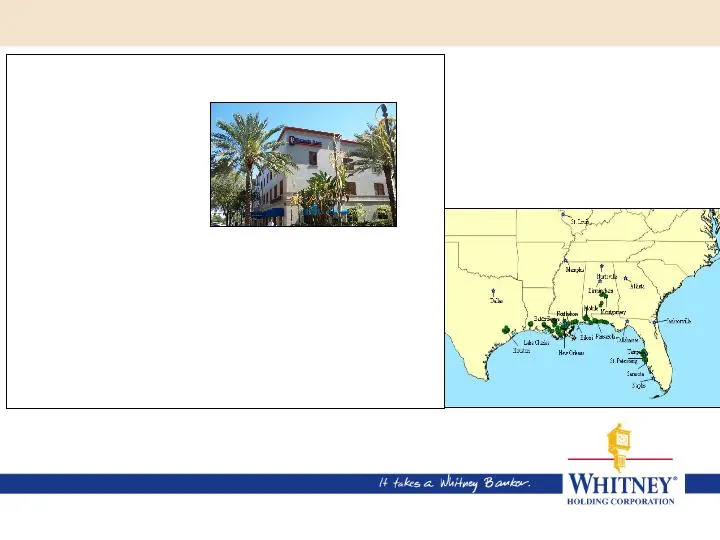
Slide 22: Acquisitions Are Important To Our Growth
Acquisitions Are Important To Our Growth • Since 1994 successfully merged banks – Assets: $3.7B – Loans: $2.3B – Deposits: $3.4B – States: – Branches: – FTE: 1,450 • Following the flow of commerce • Expand our footprint even wider • Take advantage of any opportunity
Slide 23: Focus On Growing Fee-Based Businesses
Focus On Growing Fee-Based Businesses • Acquisitions have added to fee income • Trust - (First National Bancshares) • Investment services - (Destin Bancshares) • Insurance services - (Destin Bancshares) • Treasury Management
Slide 24: Times Like These Call For A Bank Like The Whitney
TIMES LIKE THESE CALL FOR A BANK LIKE THE WHITNEY. WHITNEY" L
Slide 25: The Whitney – Uniquely Ours
The Whitney – the culture is unique; we intend to be true to it, and, that’s what our future should be built on “Uniquely Ours”
Slide 26: Focus On The Whitney Banker
Focus On The Whitney Banker
Slide 27: Heightened Level of Energy and Urgency
Heightened Level of Energy and Urgency • Success will depend on our ability to act and react quickly and decisively • Post Katrina we showed an unparalleled level of energy and urgency • Challenge now is to incorporate it in our culture
Slide 28: It's Time To Kick It Up A Notch!
It’s Time To Kick It Up A Notch!
Slide 29: Whitney Holding Corporation Gulf South Bank Conference
Whitney Holding Corporation Gulf South Bank Conference May 1, 2007 John C. Hope III, President & Chief Operating Officer Thomas L. Callicutt, Jr., EVP and CFO
Source: SEC EDGAR · 8-K filed May 1, 2007
More decks from Whitney Holding Corp
 Q4 2010 Earnings Presentation15 slides · Jan 27, 2011
 Merger or Acquisition (December 2010)18 slides · Dec 23, 2010
 Merger or Acquisition (December 2010)18 slides · Dec 22, 2010
 Stifel Nicolaus Bank & Thrift Conference 201030 slides · Nov 2, 2010
 Q3 2010 Earnings Presentation16 slides · Oct 26, 2010
 Q2 2010 Earnings Presentation18 slides · Jul 27, 2010