Kongsberg Gruppen ASA · OSL:KOG
Kongsberg Gruppen ASA — Investor Day (November 2014)
46 slides from Kongsberg Gruppen ASA's investor day presentation, Nov 4, 2014
Slide 1: Kongsberg Gruppen ASA
KONGSBERG GRUPPEN ASA Walter Qvam, President & CEO Hans-Jørgen Wibstad, CFO & Executive Vice President
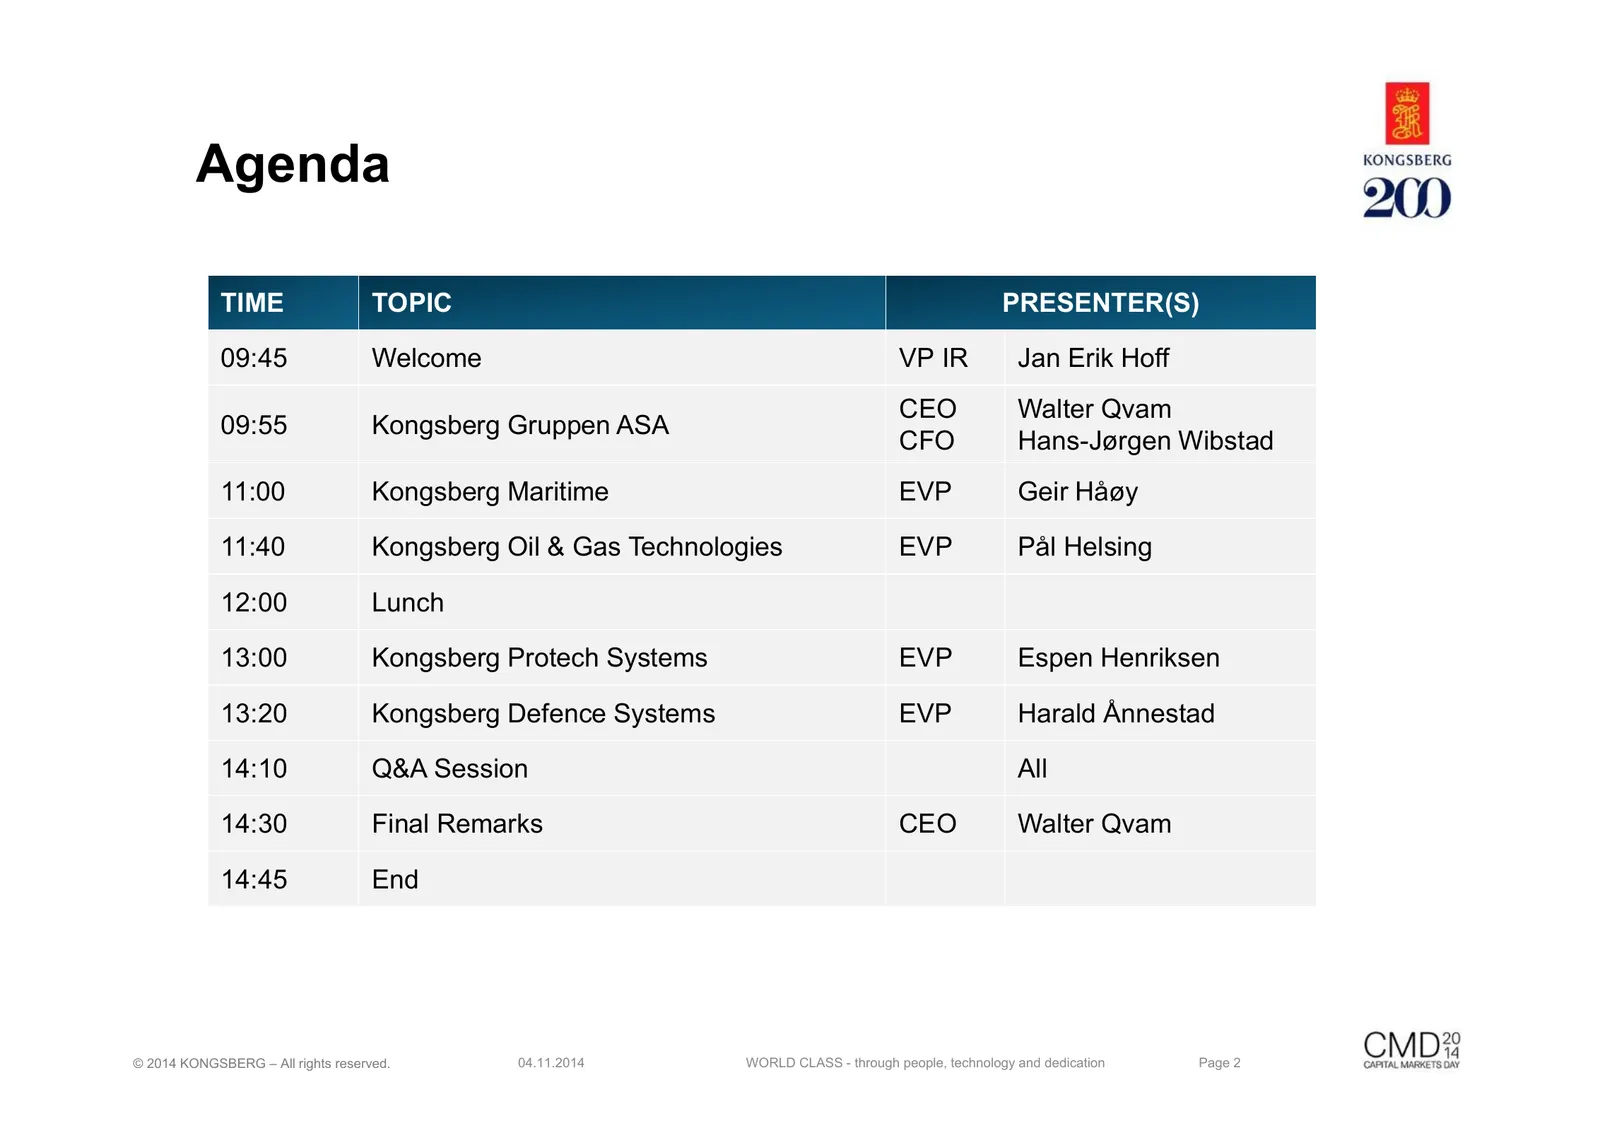
Slide 2: Agenda
Agenda TIME TOPIC PRESENTER(S) 09:45 Welcome VP IR Jan Erik Hoff CEO Walter Qvam 09:55 Kongsberg Gruppen ASA CFO Hans-Jørgen Wibstad 11:00 Kongsberg Maritime EVP Geir Håøy 11:40 Kongsberg Oil & Gas Technologies EVP Pål Helsing 12:00 Lunch 13:00 Kongsberg Protech Systems EVP Espen Henriksen 13:20 Kon
Slide 3: Extreme Performance for Extreme Conditions
EXTREME PERFORMANCE FOR EXTREME CONDITIONS We develop and deliver advanced systems and technology for people working under extreme conditions. Our solutions ensure efficiency, safety, security and high performance in operations ranging from deep sea to outer space. © 2014 KONGSBERG – All rights rese
Slide 4: Agenda
Agenda • Introduction – This is KONGSBERG • Financial status • Status ambitions from 2013 CMD • Status Delta One • Innovation • Commencing the next 200 © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 4
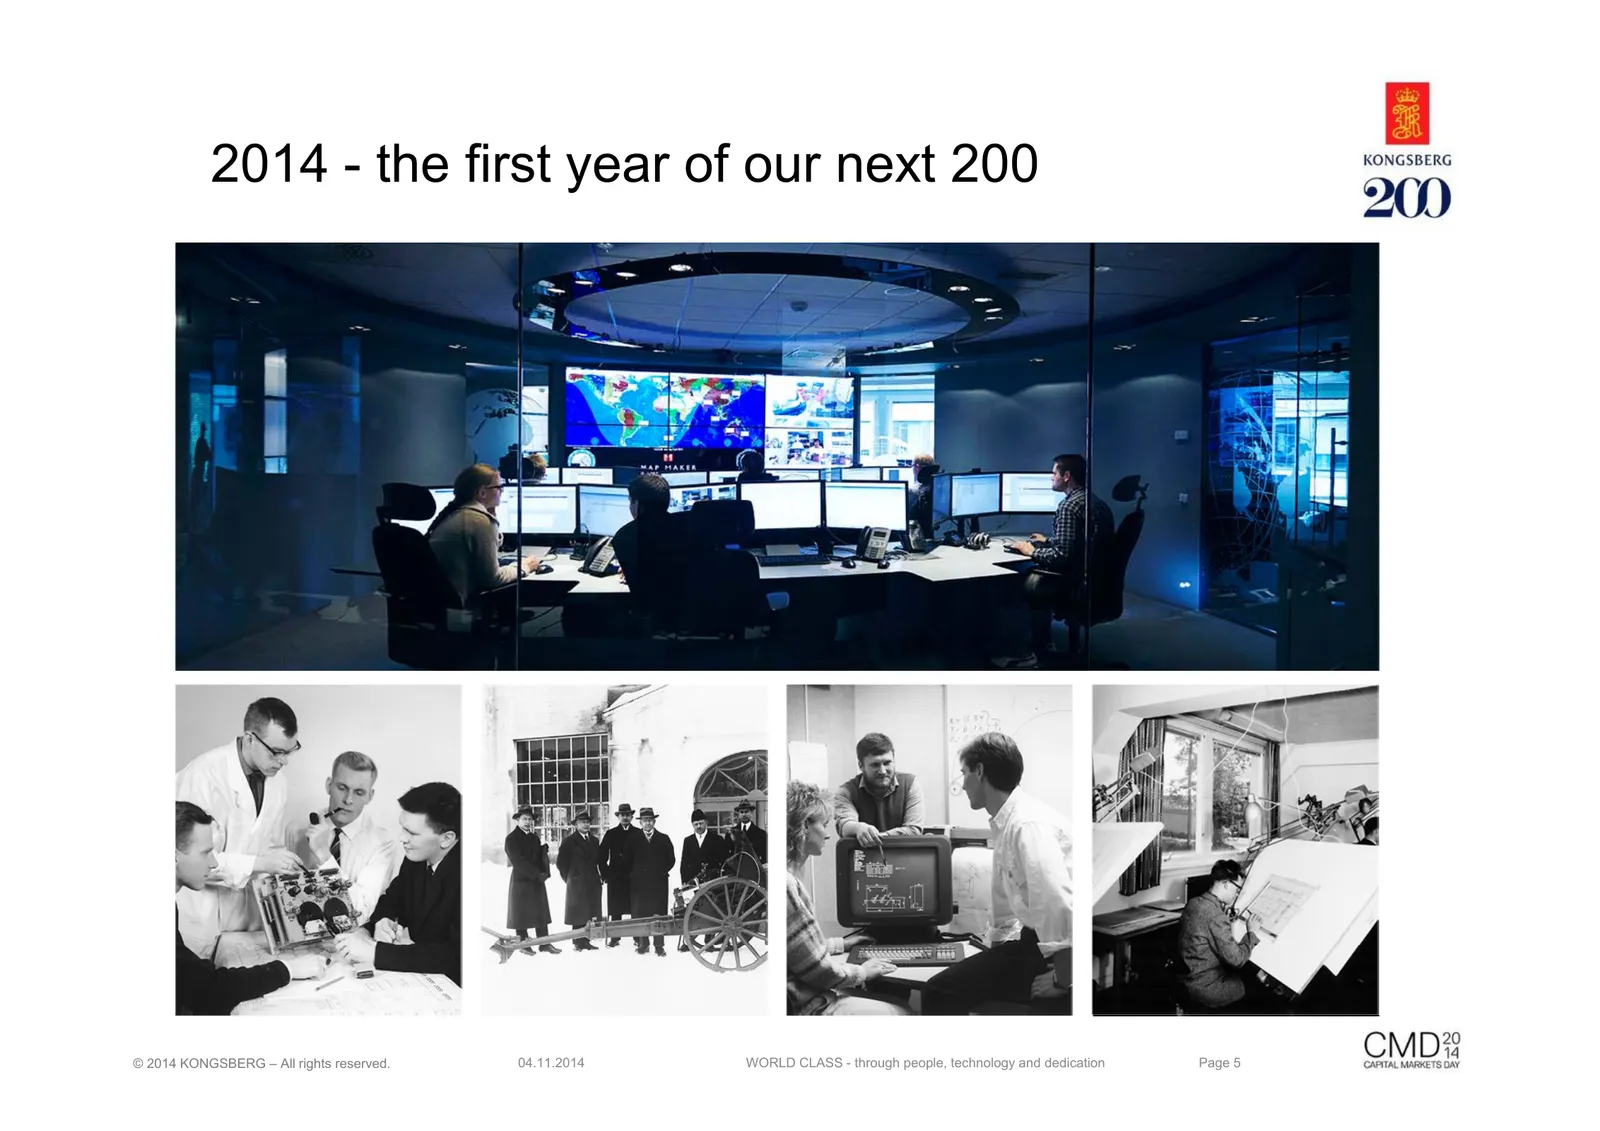
Slide 5: 2014 - the first year of our next 200
2014 - the first year of our next 200 © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 5
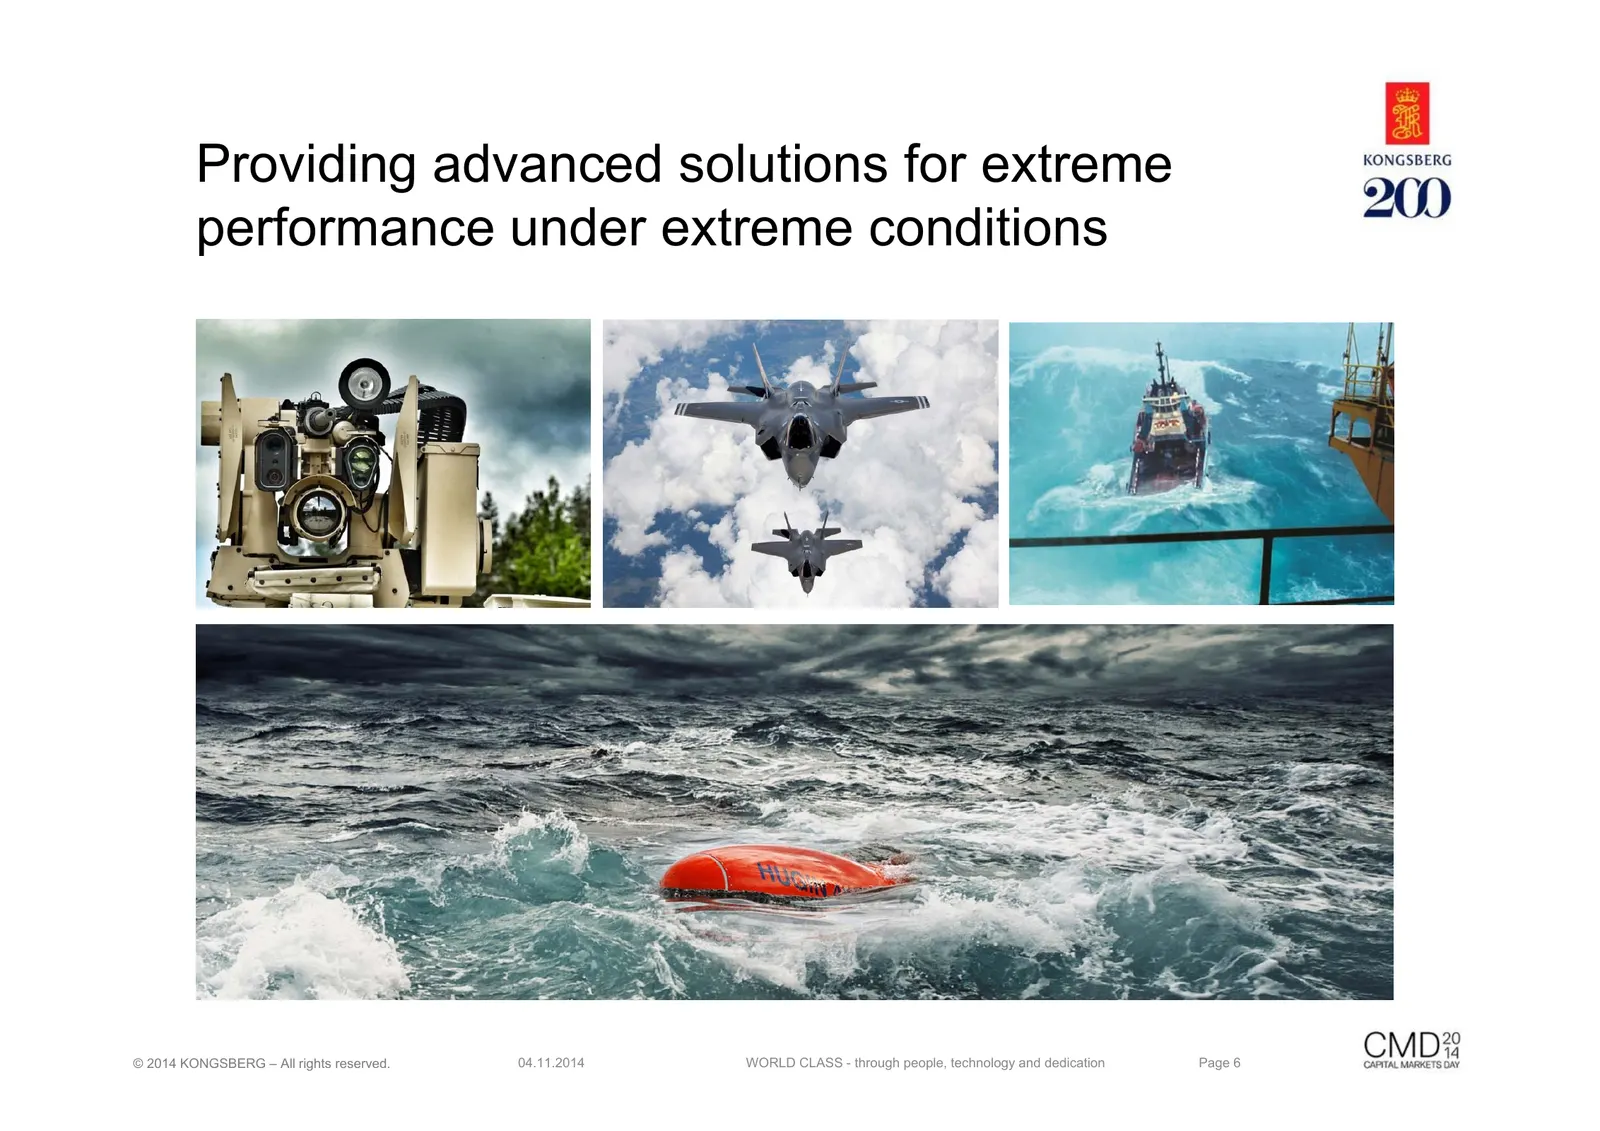
Slide 6: Providing advanced solutions for extreme performance under extreme conditions
Providing advanced solutions for extreme performance under extreme conditions © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 6
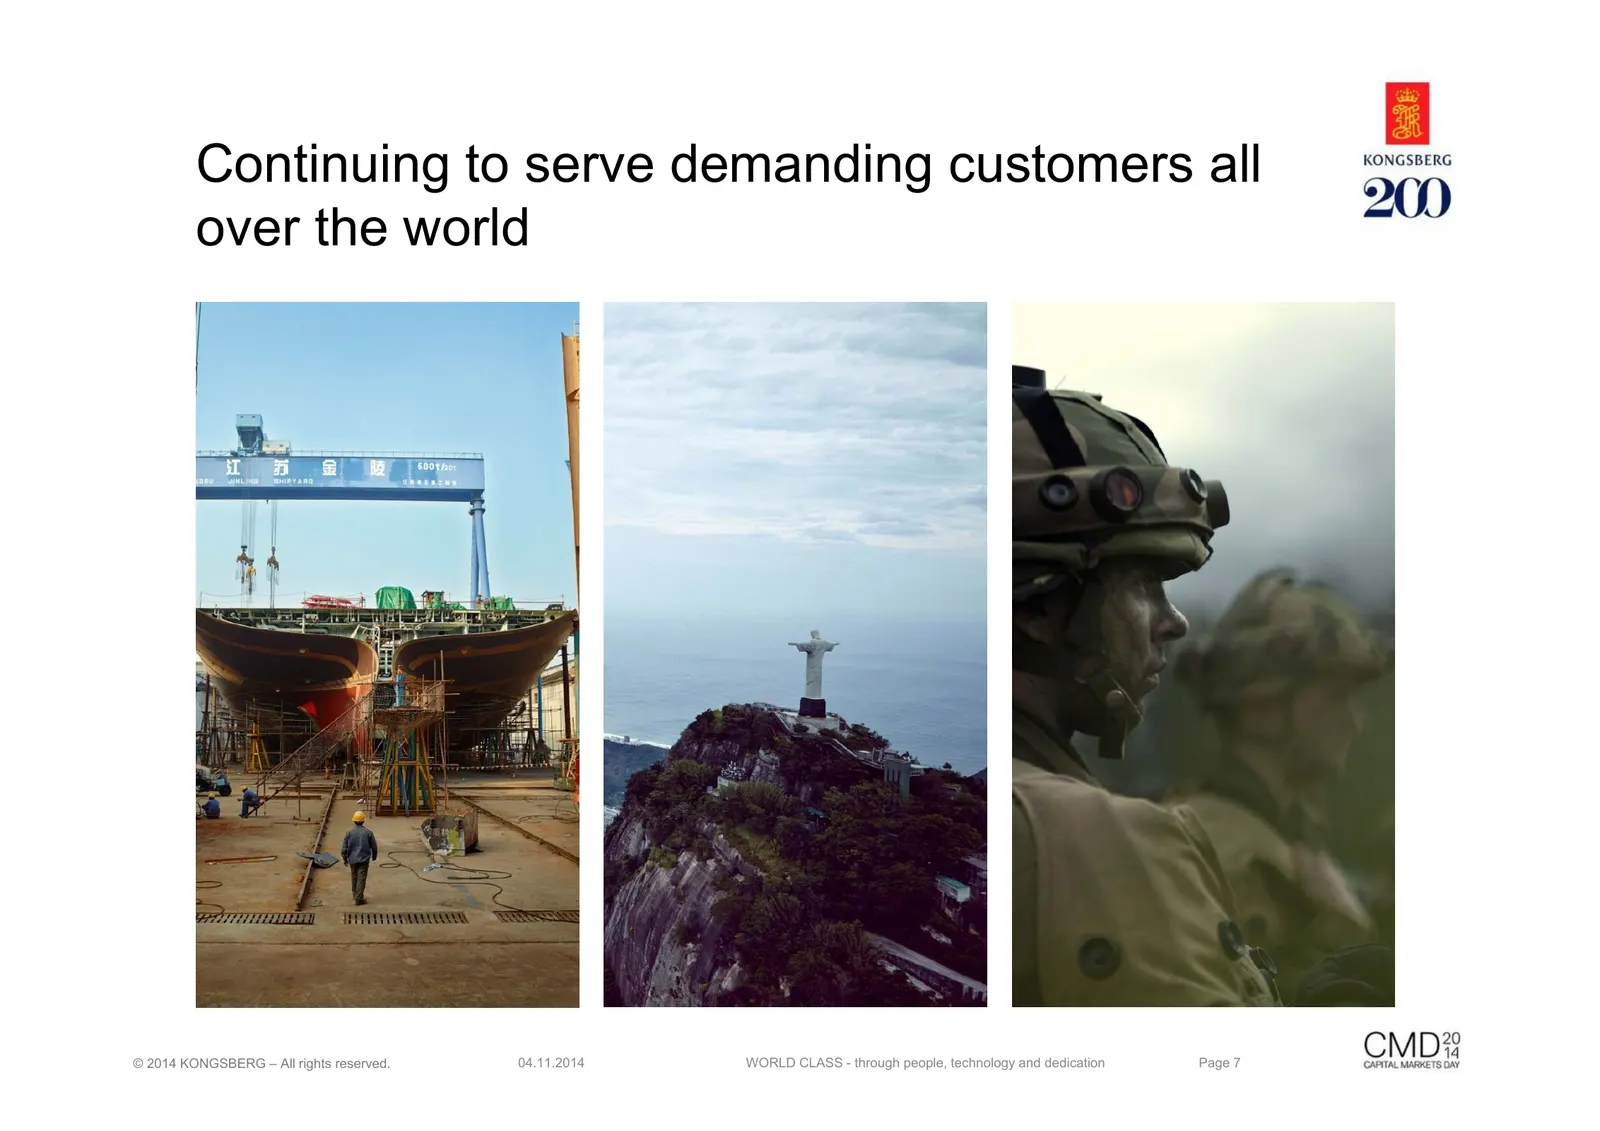
Slide 7: Continuing to serve demanding customers all over the world
Continuing to serve demanding customers all over the world © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 7
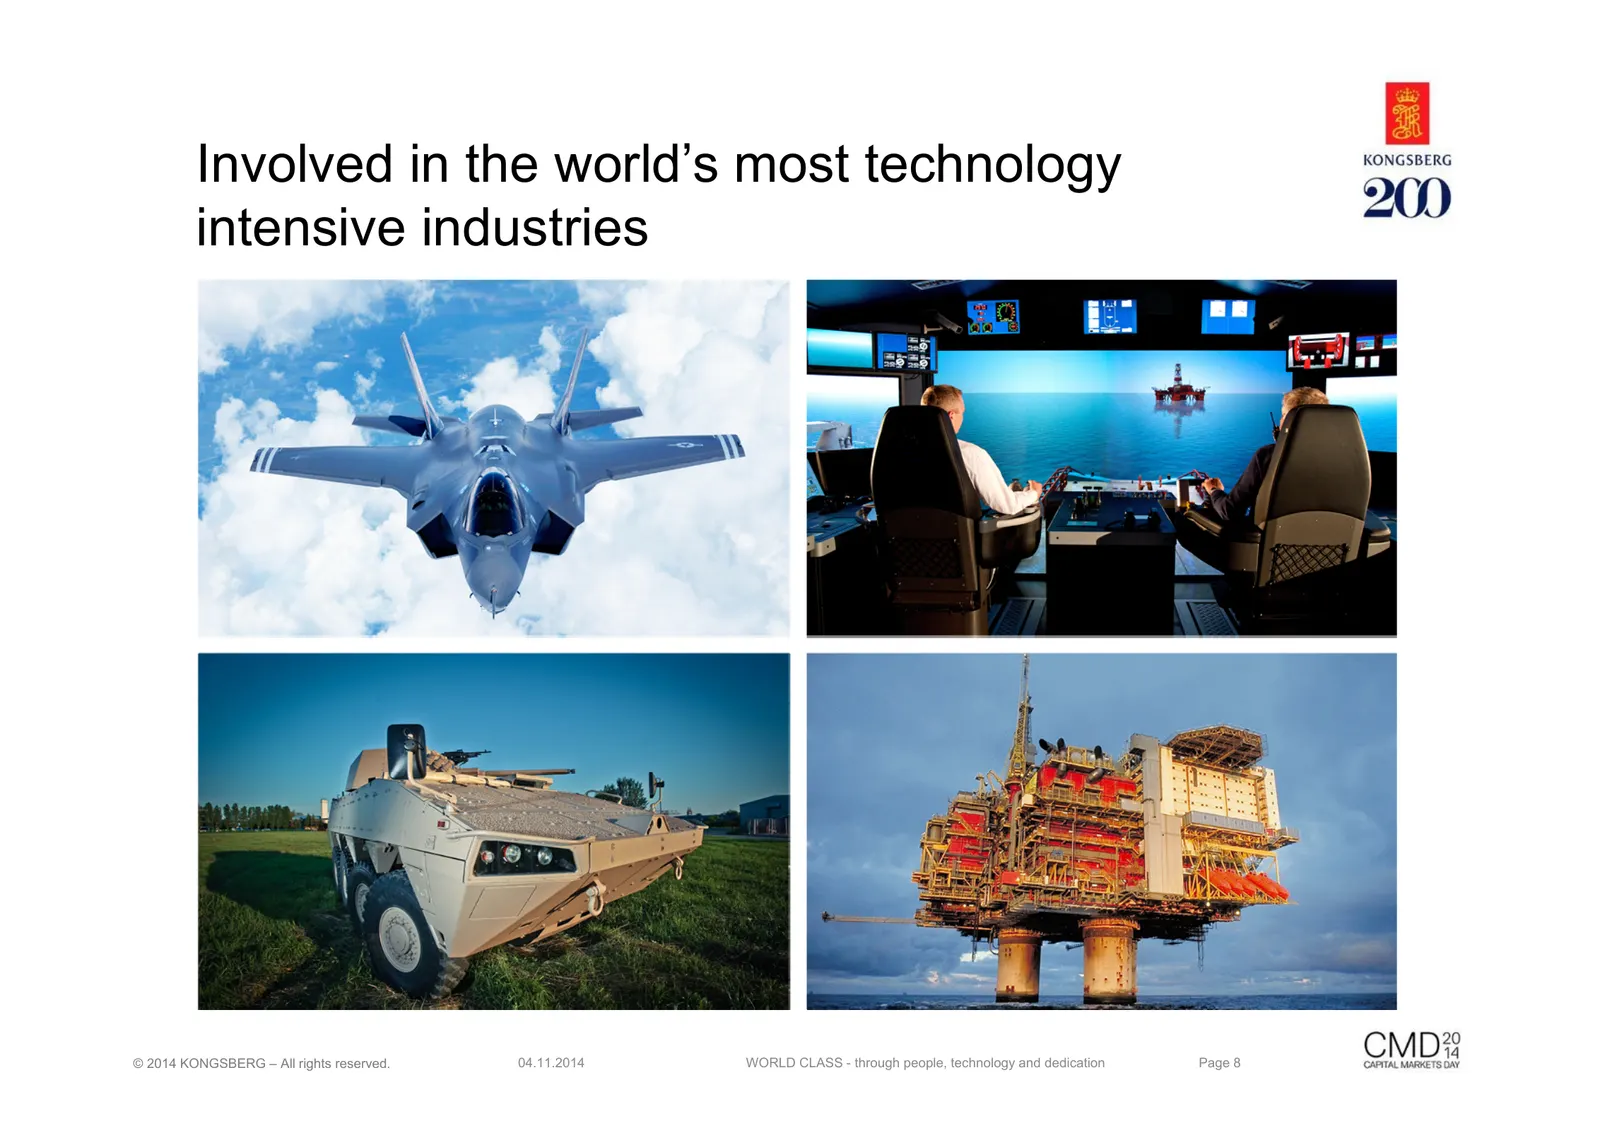
Slide 8: Involved in the world's most technology intensive industries
Involved in the world’s most technology intensive industries © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 8
Slide 9: Rapidly adapting to changes and opportunities
Rapidly adapting to changes and opportunities © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 9
Slide 10: Involved in strategic areas, often of national interest
Involved in strategic areas, often of national interest © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 10
Slide 11: Highly skilled, dedicated and hard working employees
Highly skilled, dedicated and hard working employees © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 11
Slide 12: A genuine belief in that our strong, value based culture drives our performance
A genuine belief in that our strong, value based culture drives our performance DETERMINED INNOVATIVE COLLABORATIVE RELIABLE © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 12
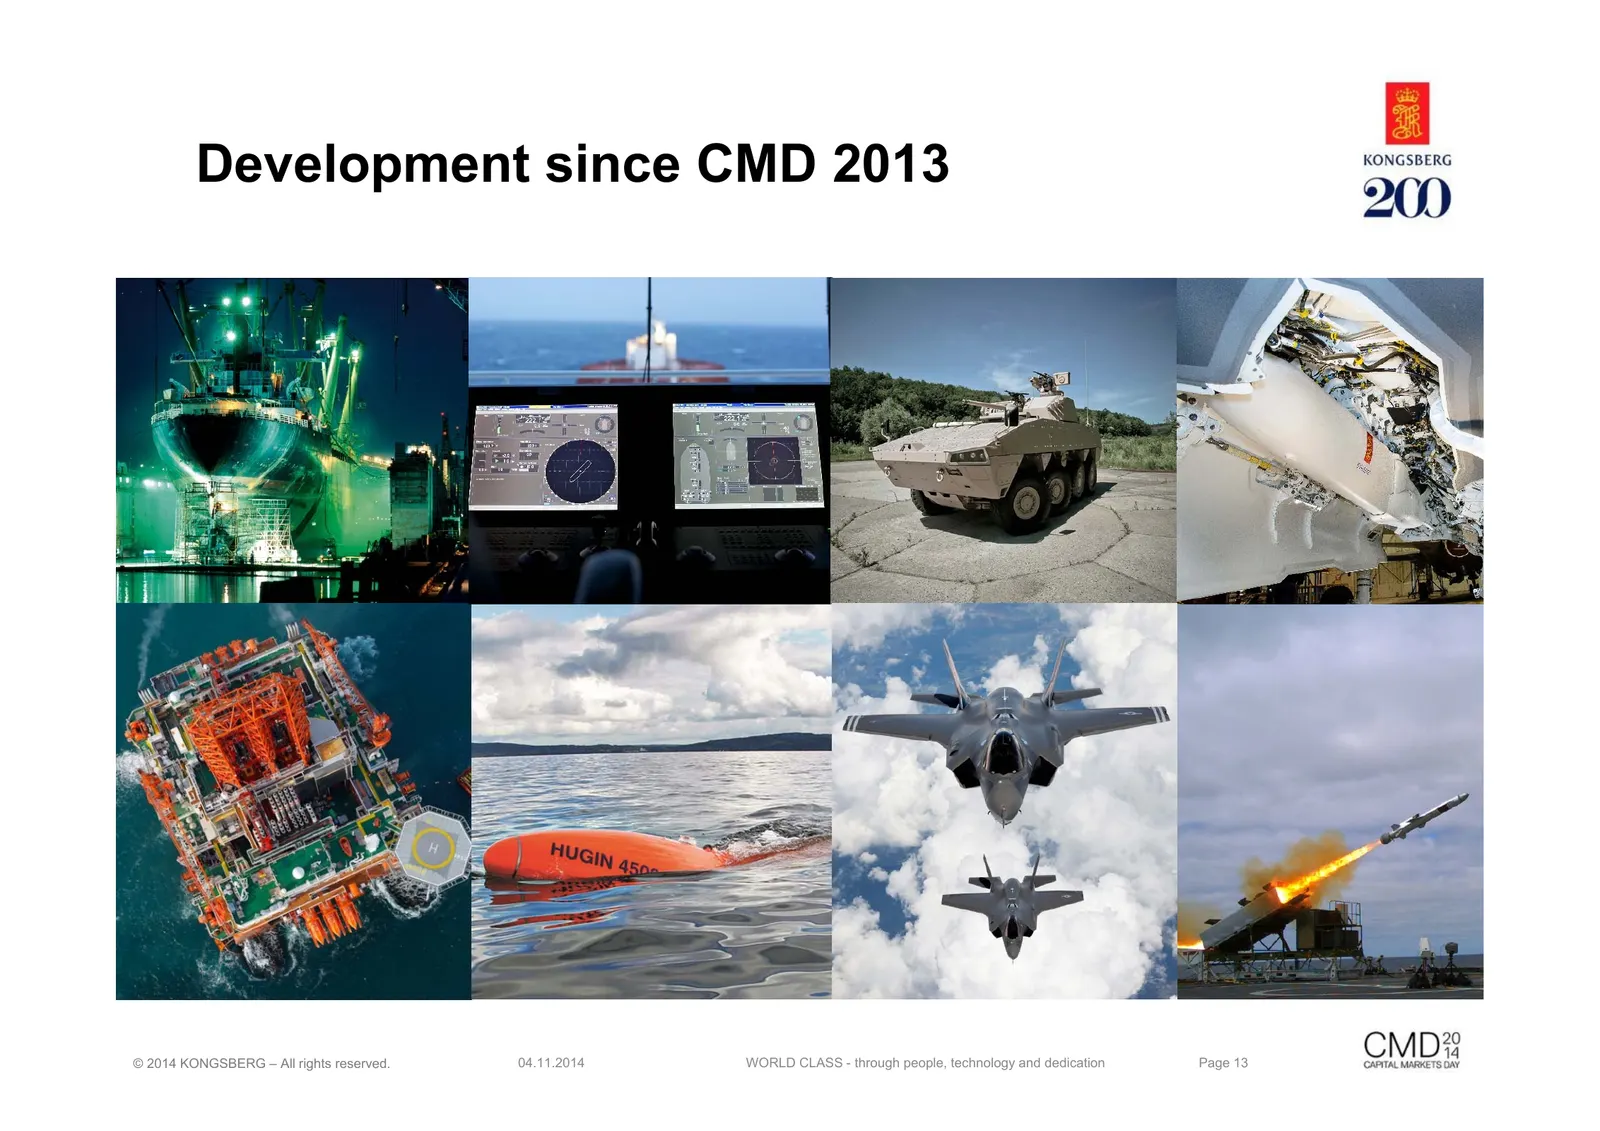
Slide 13: Development since CMD 2013
Development since CMD 2013 © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 13
Slide 14: Agenda
Agenda • Introduction – This is KONGSBERG • Financial status • Status ambitions from 2013 CMD • Status Delta One • Innovation • Commencing the next 200 © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 14
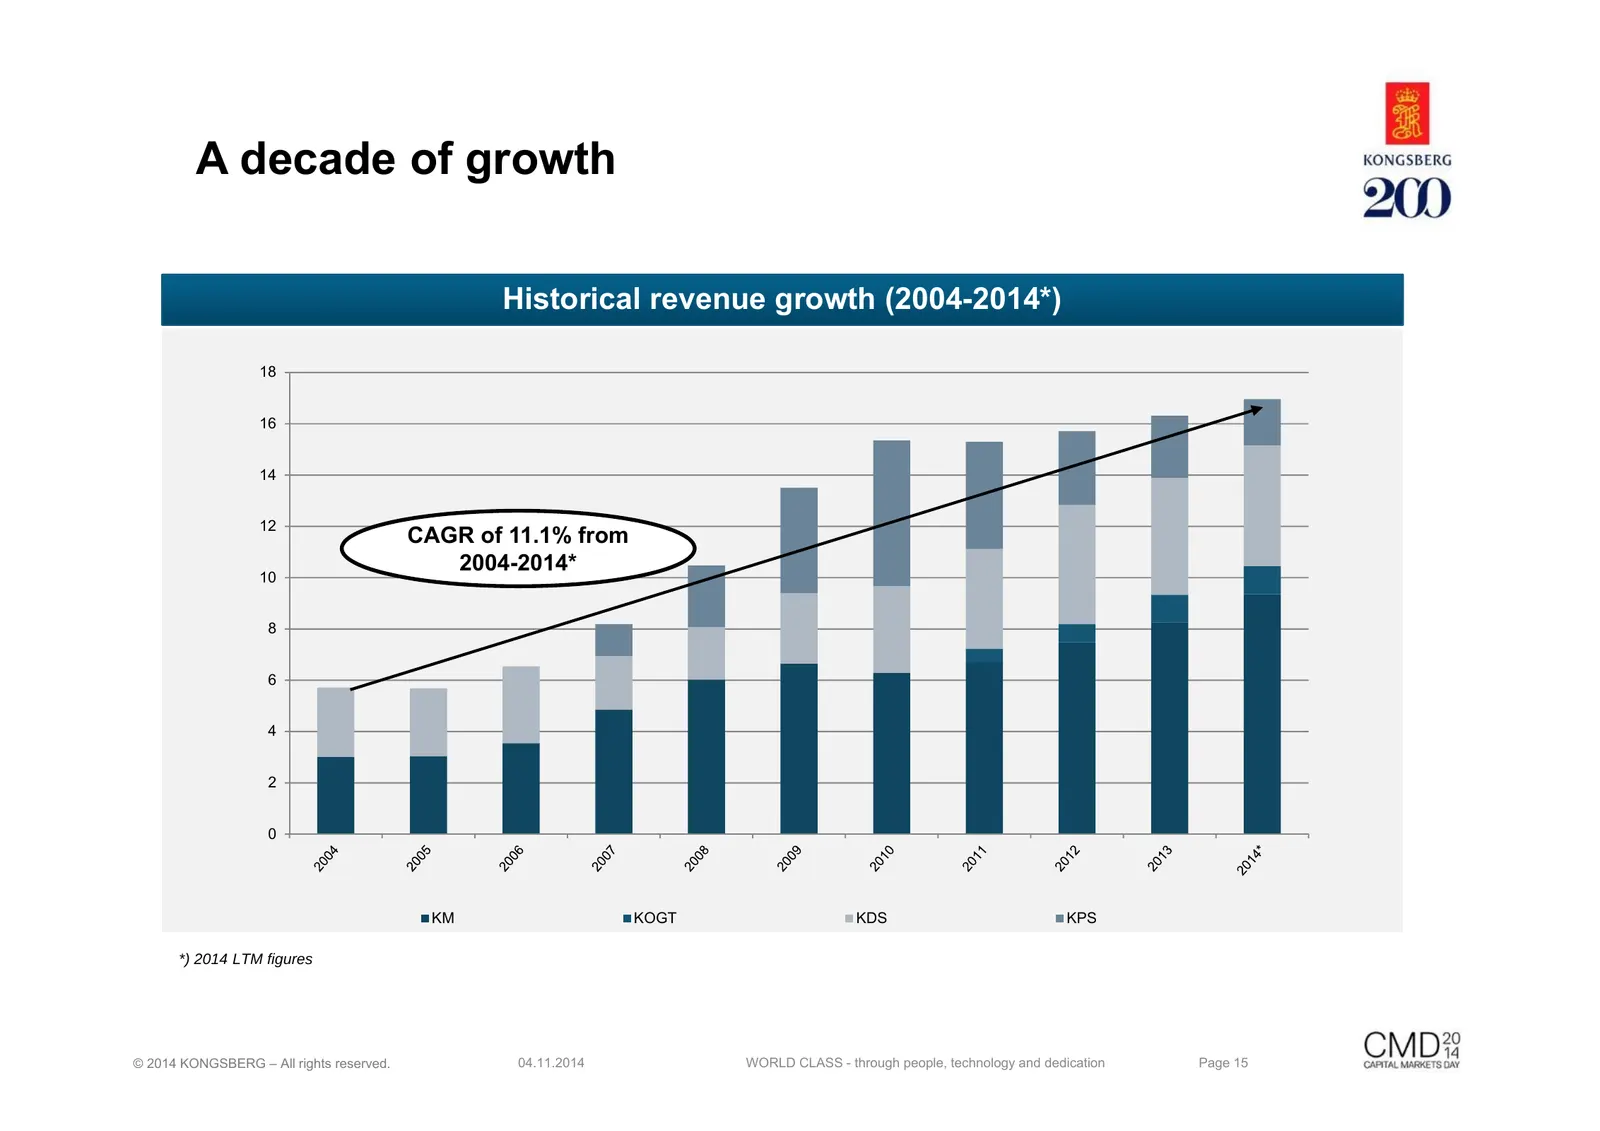
Slide 15: A decade of growth
A decade of growth Historical revenue growth (2004-2014*) 18 16 14 12 CAGR of 11.1% from 2004-2014* 10 8 6 4 2 0 KM KOGT KDS KPS *) 2014 LTM figures © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 15
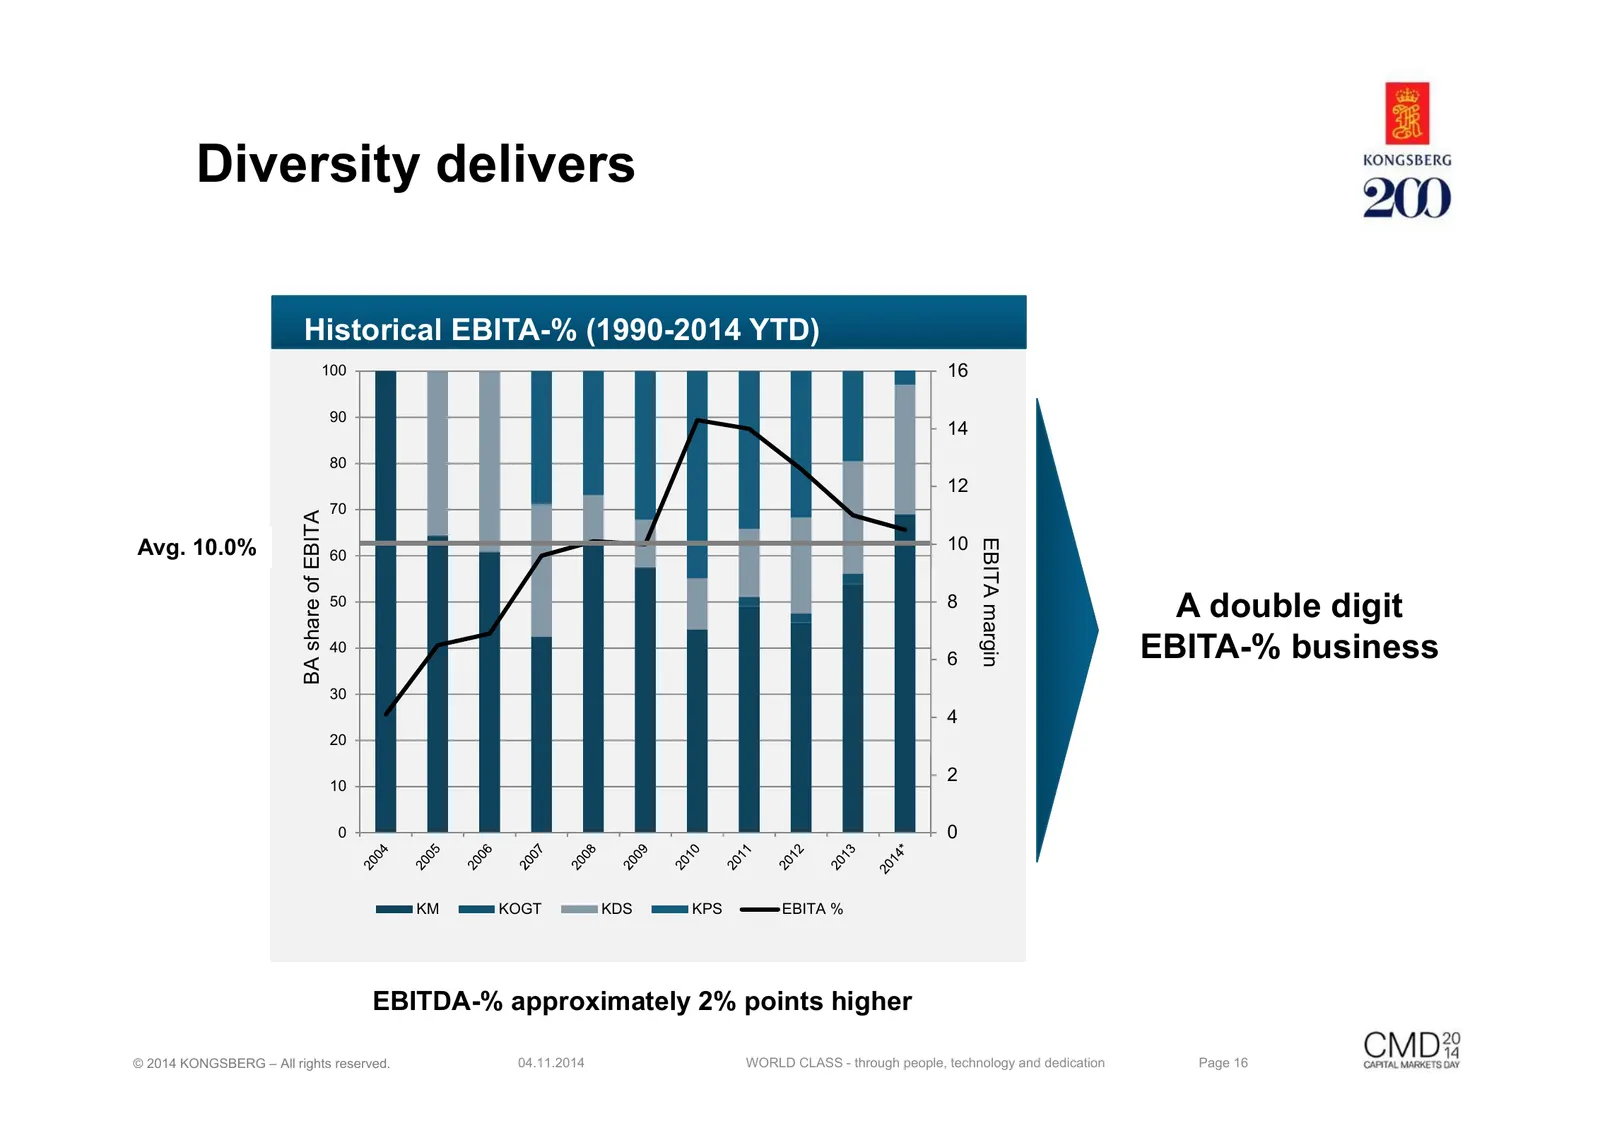
Slide 16: Diversity delivers
Diversity delivers Historical EBITA-% (1990-2014 YTD) 100 16 90 14 80 12 70 BA share of EBITA Avg. 10.0% 10 EBITA margin 60 50 8 A double digit 40 6 EBITA-% business 30 4 20 2 10 0 0 KM KOGT KDS KPS EBITA % EBITDA-% approximately 2% points higher © 2014 KONGSBERG – All rights reserved. 04.11.2014 WO
Slide 17: Increased revenues and order intake
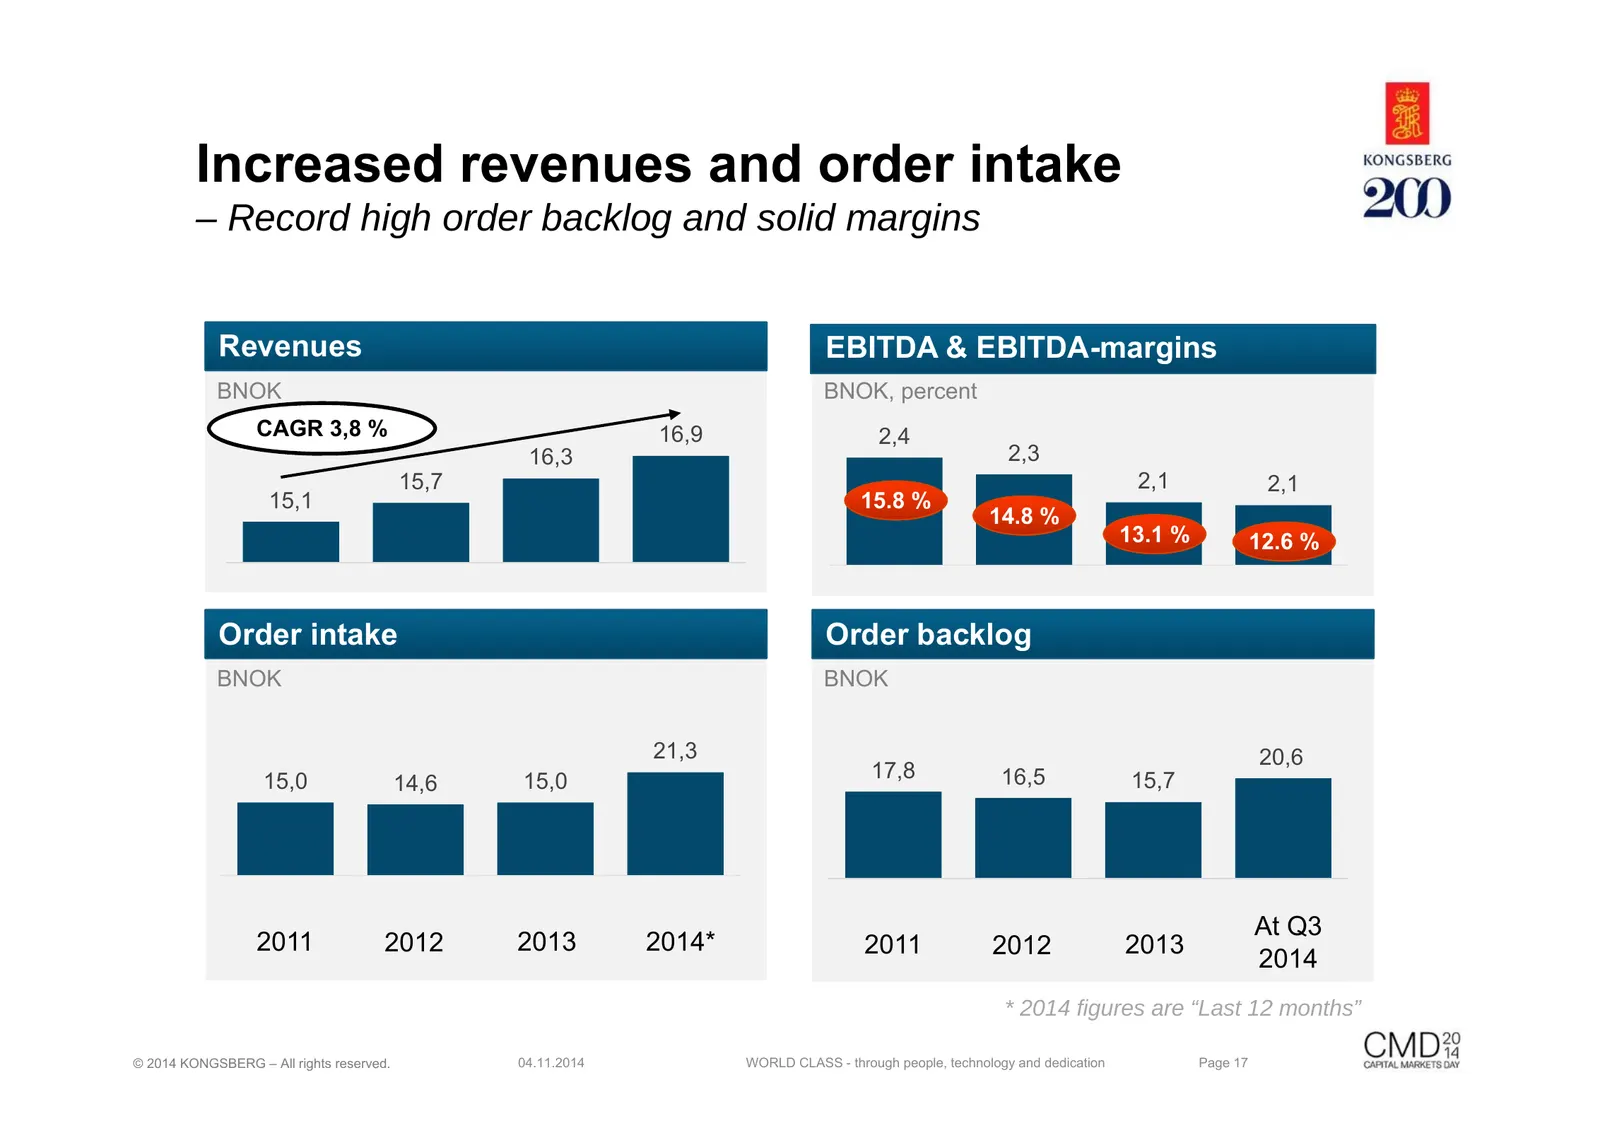
Increased revenues and order intake – Record high order backlog and solid margins Revenues EBITDA & EBITDA-margins BNOK BNOK, percent CAGR 3,8 % 16,9 2,4 16,3 2,3 15,7 2,1 2,1 15,1 15.8 % 14.8 % 13.1 % 12.6 % Order intake Order backlog BNOK BNOK 21,3 20,6 15,0 15,0 17,8 16,5 15,7 14,6 At Q3 2011 201
Slide 18: The two largest business areas are growing and improving margins
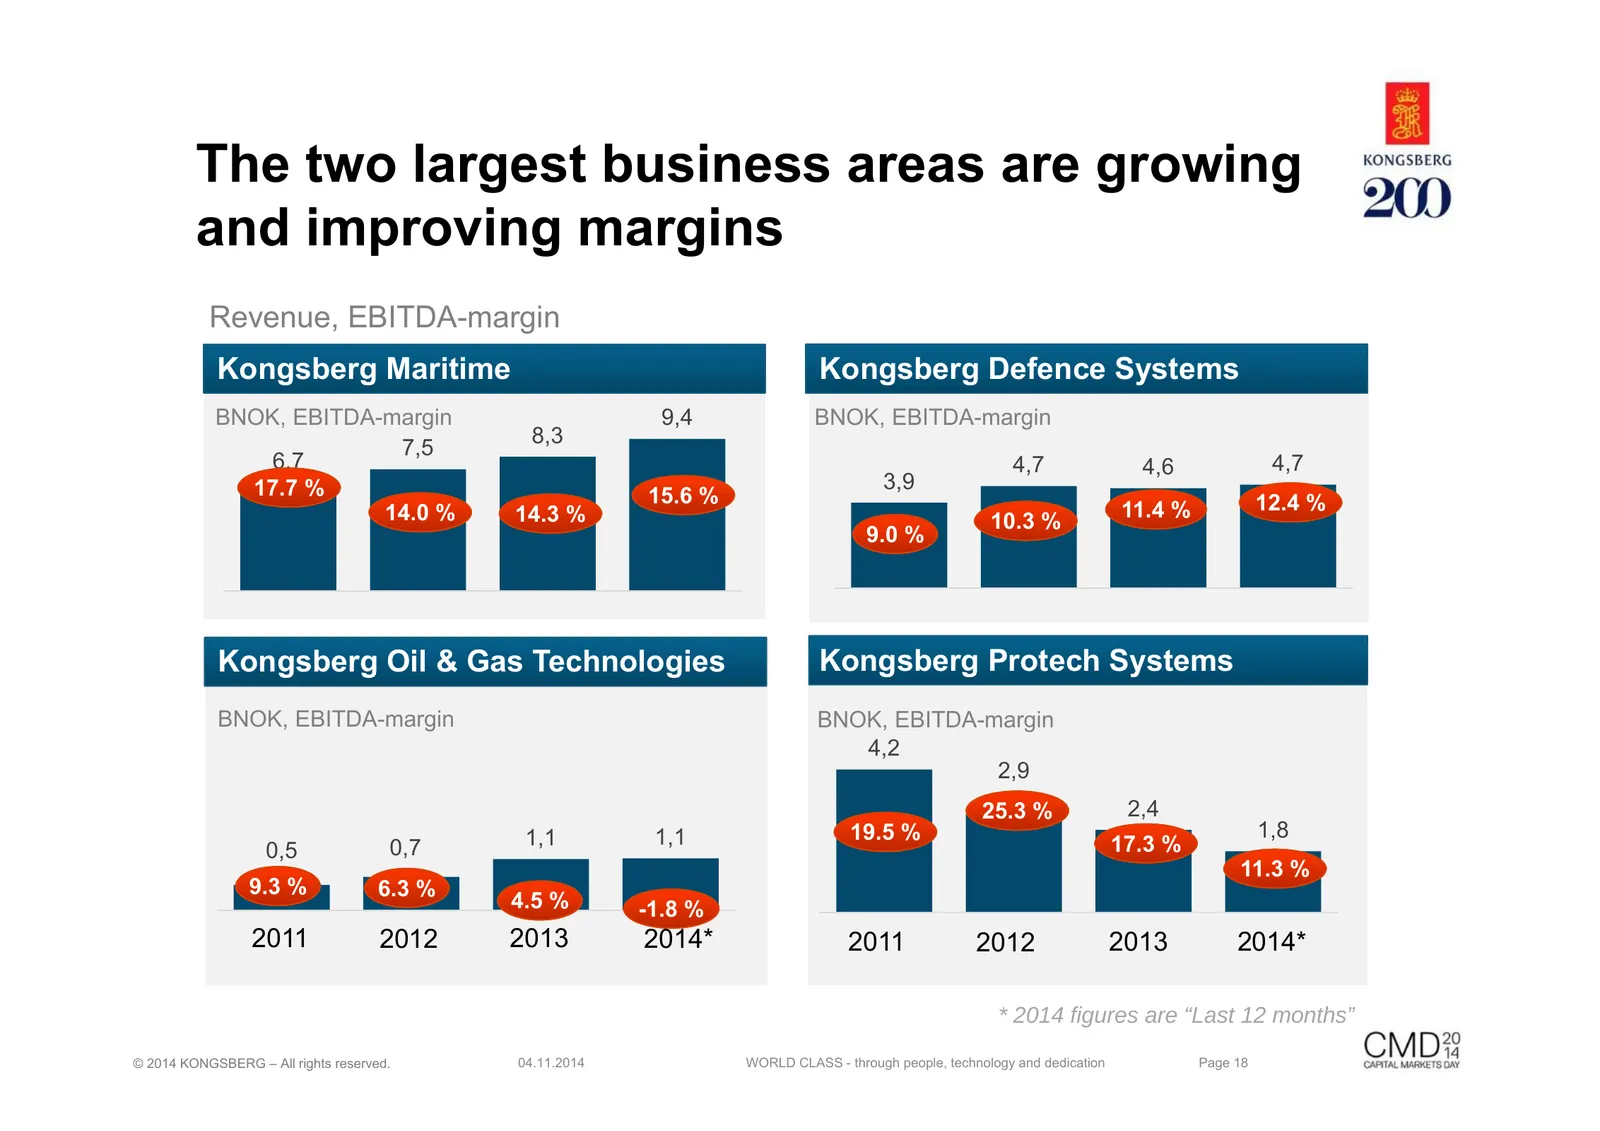
The two largest business areas are growing and improving margins Revenue, EBITDA-margin Kongsberg Maritime Kongsberg Defence Systems BNOK, EBITDA-margin 9,4 BNOK, EBITDA-margin 8,3 7,5 6,7 4,7 4,6 4,7 17.7 % 3,9 15.6 % 12.4 % 14.0 % 14.3 % 11.4 % 10.3 % 9.0 % Kongsberg Oil & Gas Technologies Kongsbe
Slide 19: Strong and improving backlog – good visibility
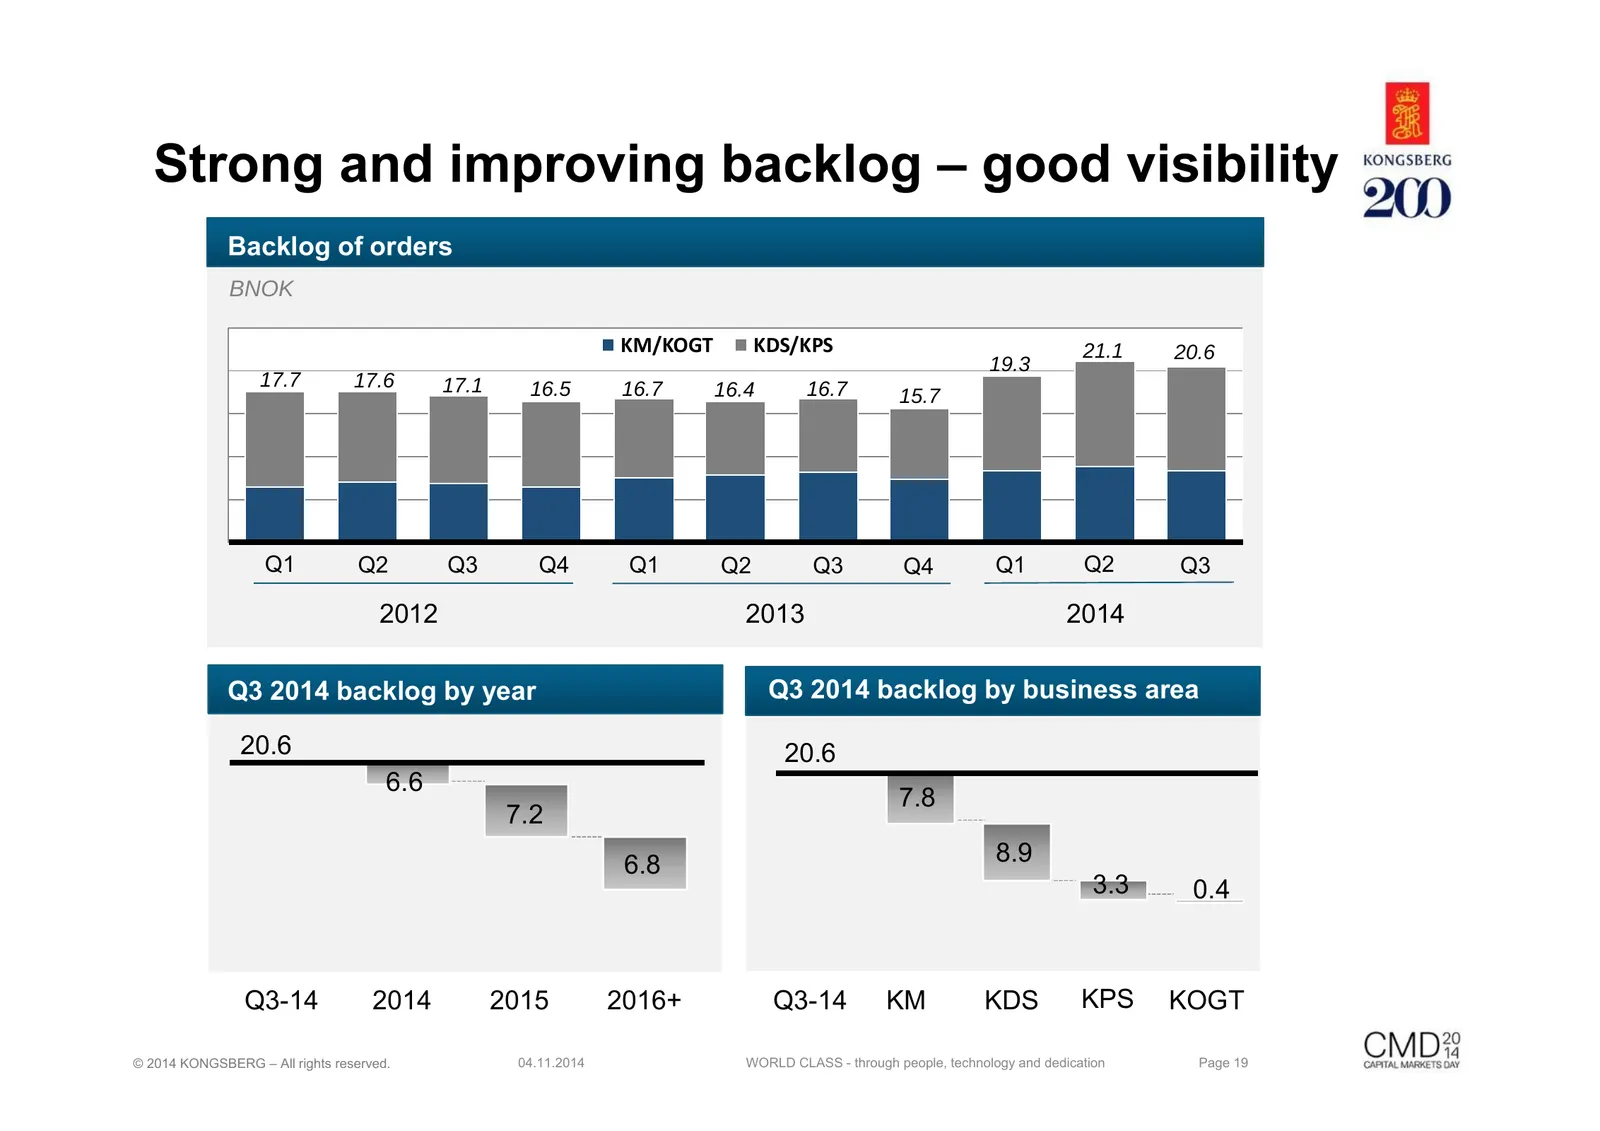
Strong and improving backlog – good visibility Backlog of orders BNOK KM/KOGT KDS/KPS 21.1 20.6 19.3 17.7 17.6 17.1 16.5 16.7 16.4 16.7 15.7 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 2012 2013 2014 Q3 2014 backlog by year Q3 2014 backlog by business area 20.6 20.6 6.6 7.8 7.2 6.8 8.9 3.3 0.4 Q3-14 2014 2015
Slide 20: Strong and improving cash flow last two years
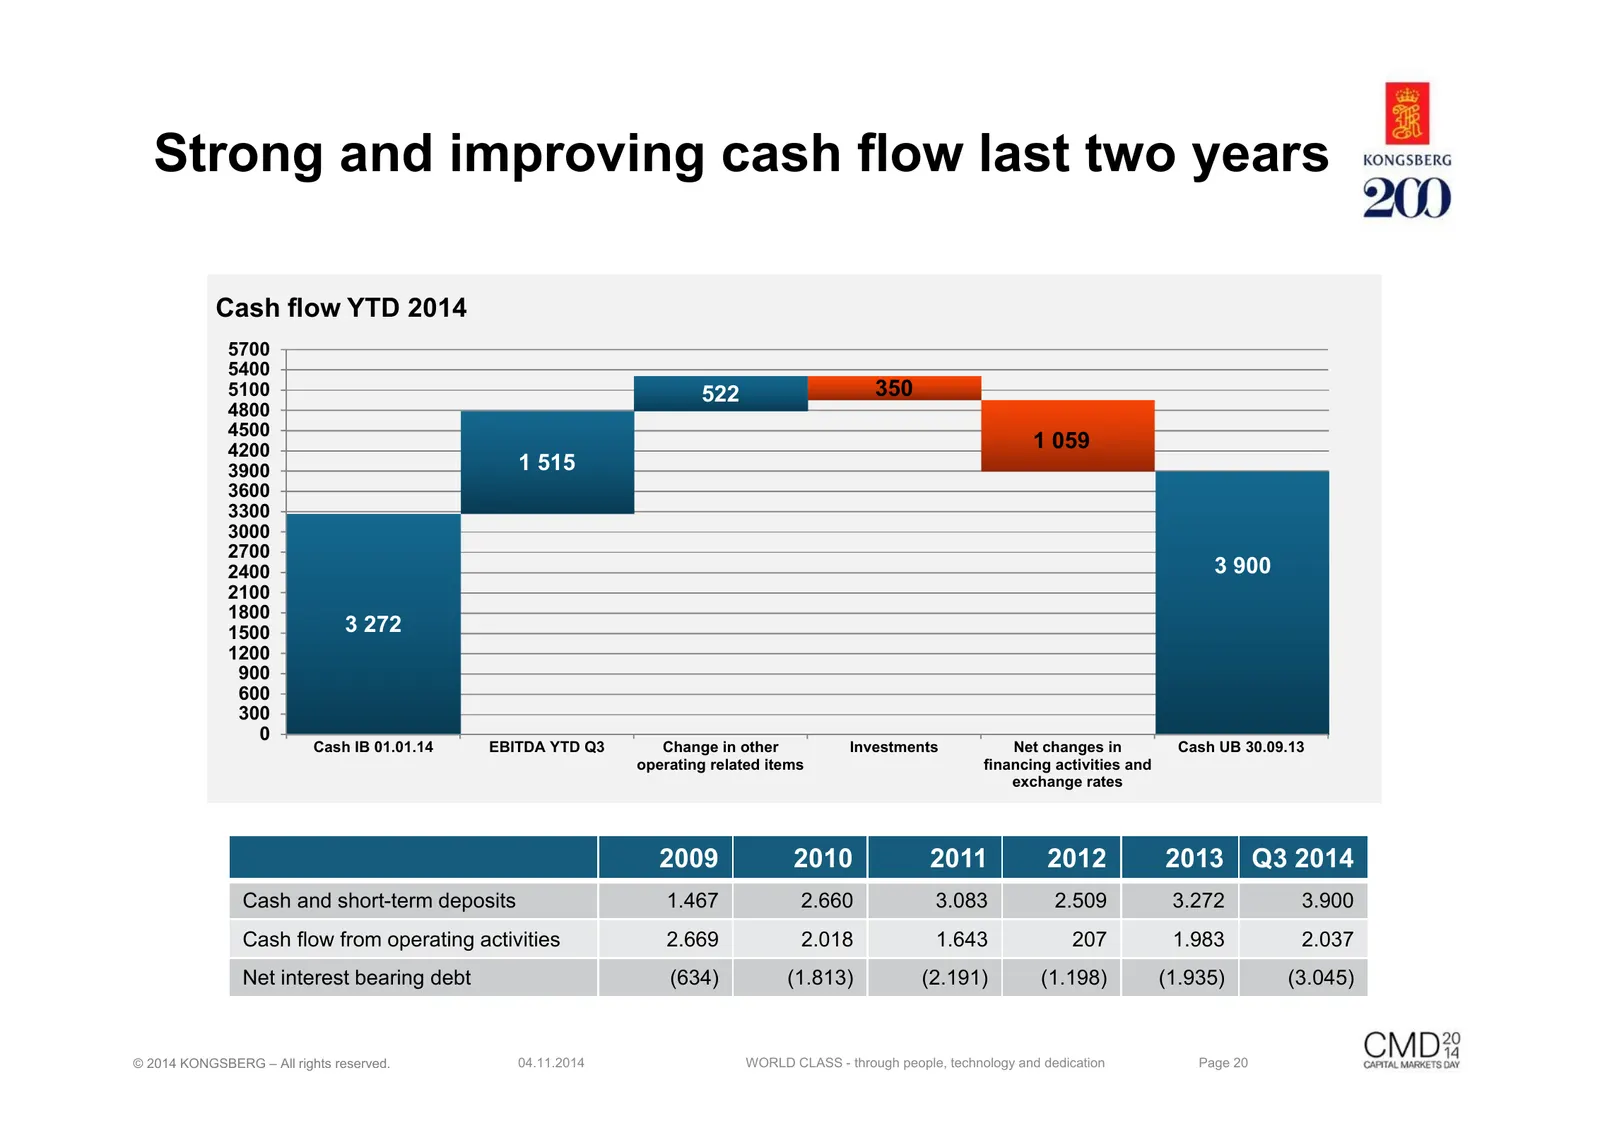
Strong and improving cash flow last two years Cash flow YTD 2014 5700 5400 5100 522 350 4800 4500 4200 1 059 3900 1 515 3600 3300 3000 2700 2400 3 900 2100 1800 1500 3 272 1200 900 600 300 0 Cash IB 01.01.14 EBITDA YTD Q3 Change in other Investments Net changes in Cash UB 30.09.13 operating related
Slide 21: Capital structure
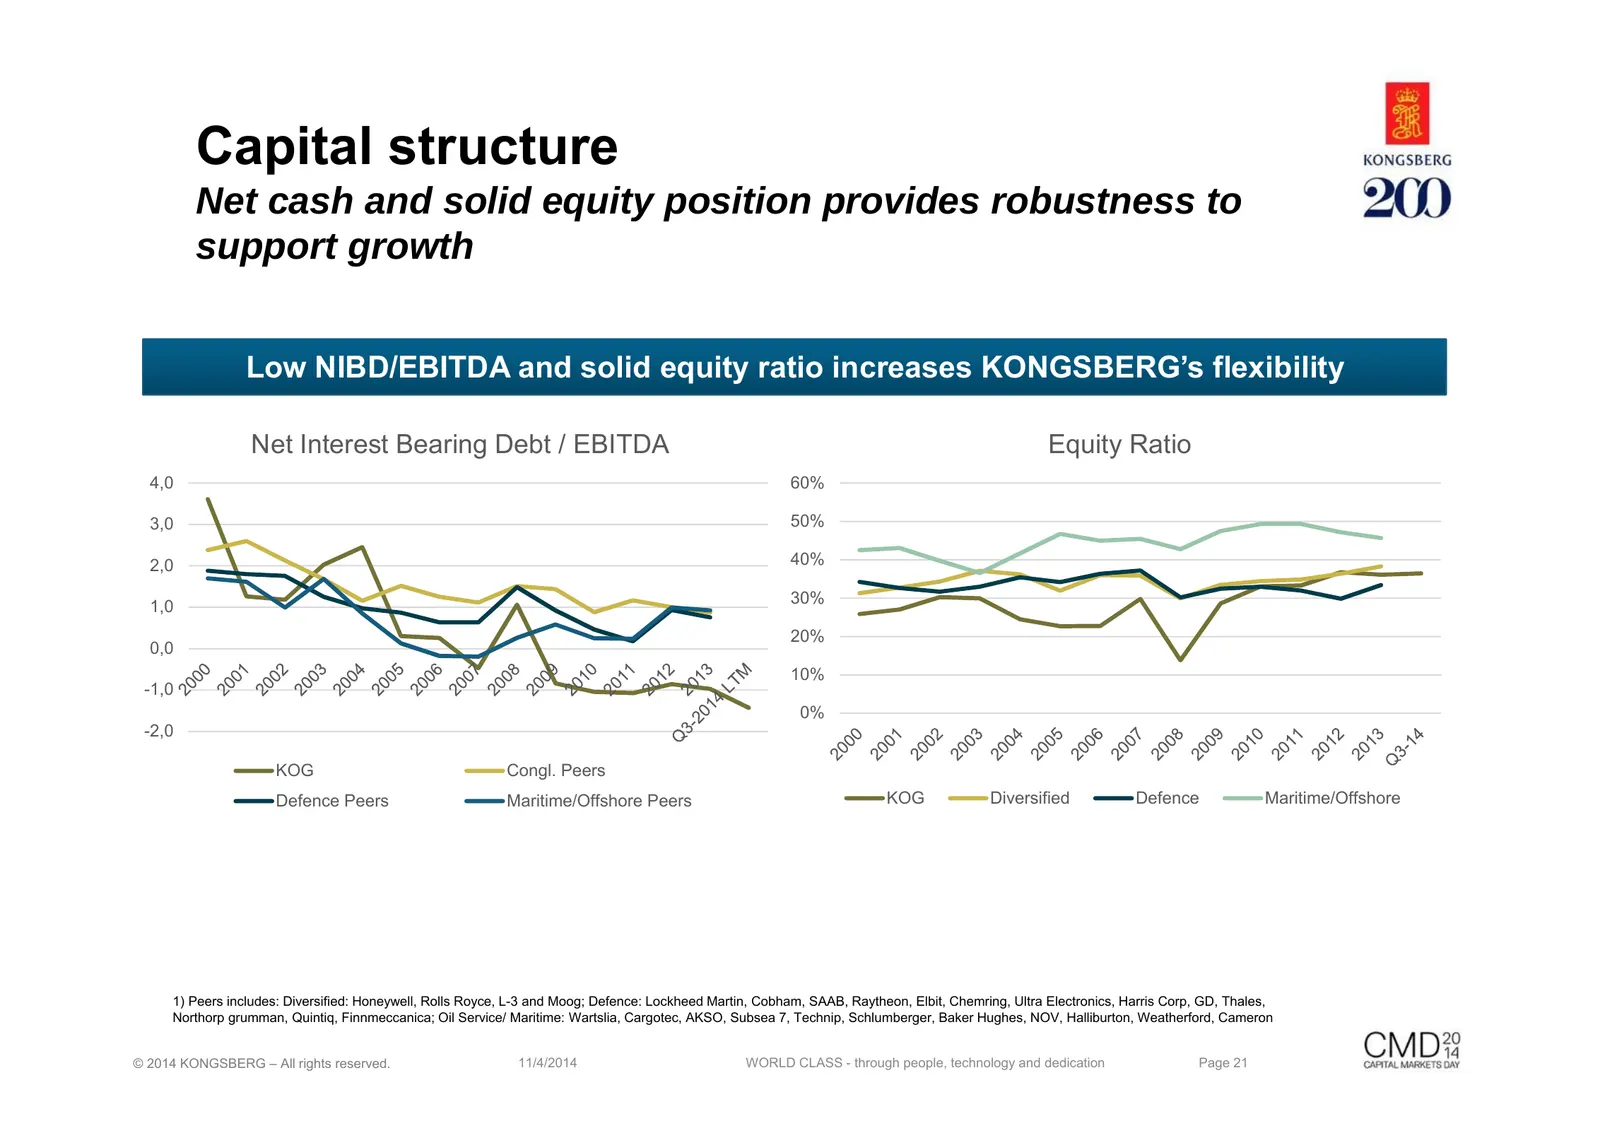
Capital structure Net cash and solid equity position provides robustness to support growth Low NIBD/EBITDA and solid equity ratio increases KONGSBERG’s flexibility Net Interest Bearing Debt / EBITDA Equity Ratio 4,0 60% 3,0 50% 2,0 40% 30% 1,0 20% 0,0 10% -1,0 0% -2,0 KOG Congl. Peers Defence Peers
Slide 22: Capital structure
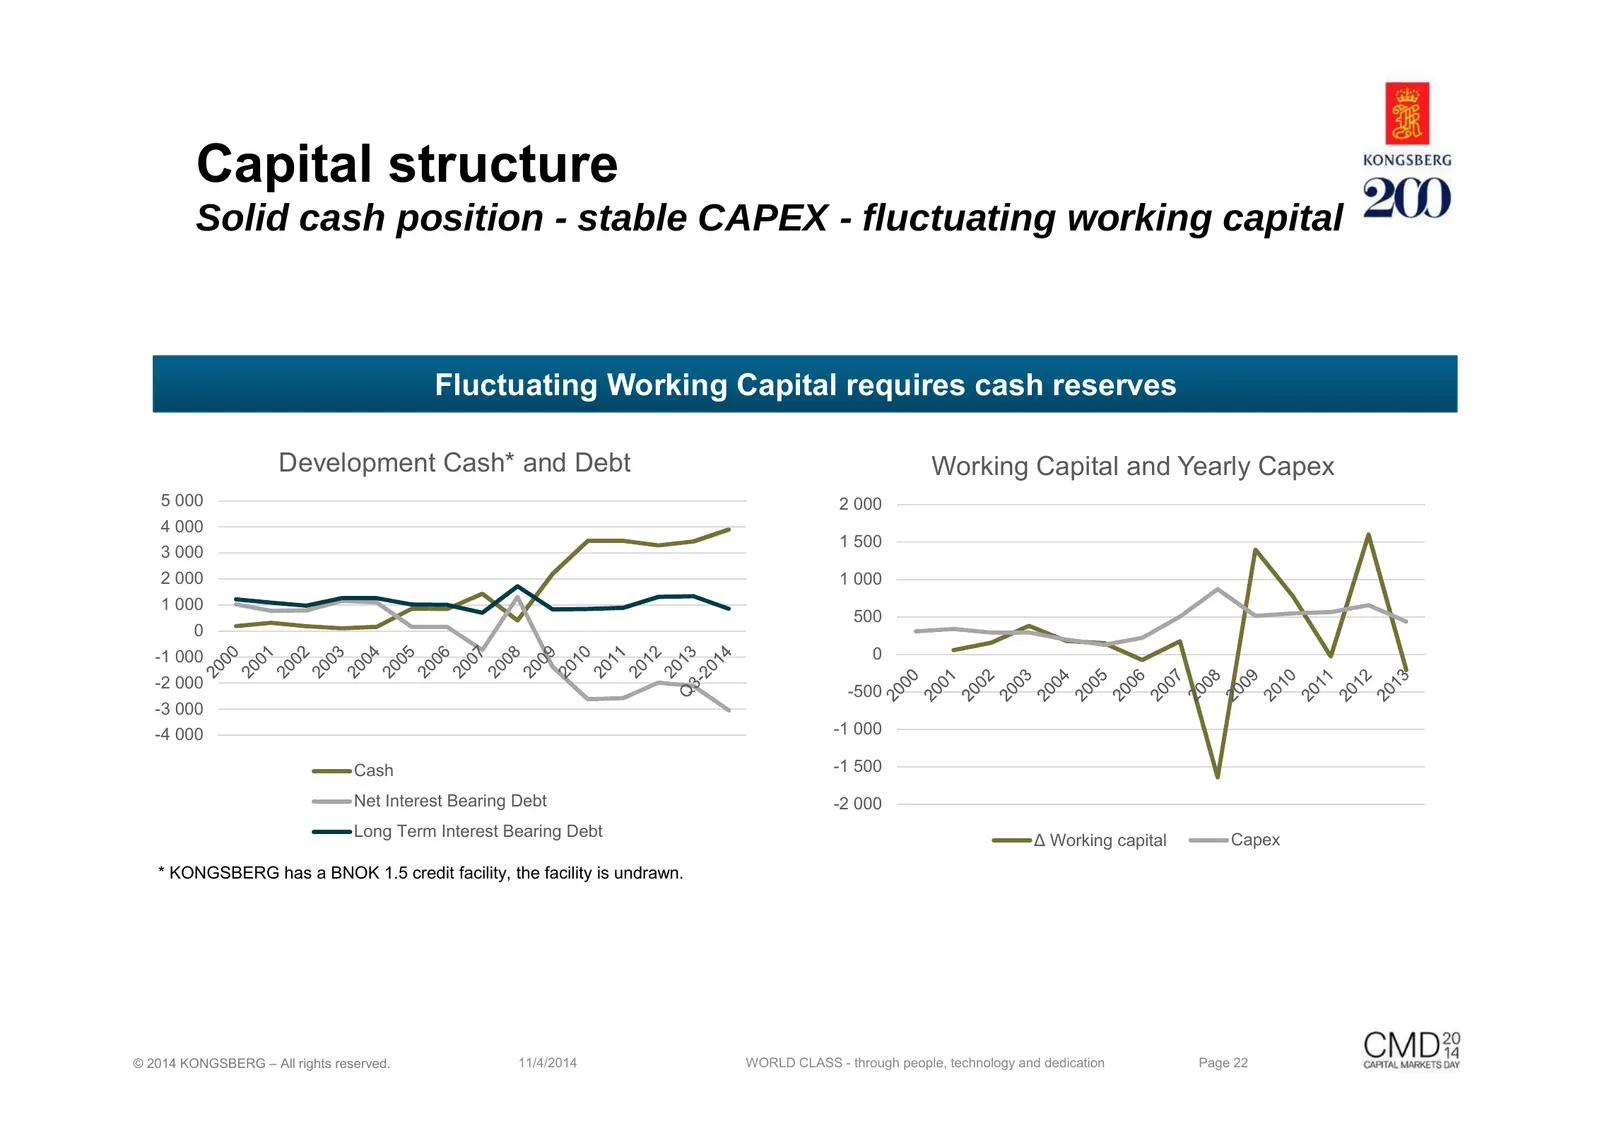
Capital structure Solid cash position - stable CAPEX - fluctuating working capital Fluctuating Working Capital requires cash reserves Development Cash* and Debt Working Capital and Yearly Capex 5 000 2 000 4 000 1 500 3 000 2 000 1 000 1 000 500 0 -1 000 0 -2 000 -500 -3 000 -4 000 -1 000 Cash -1 50
Slide 23: Capital structure
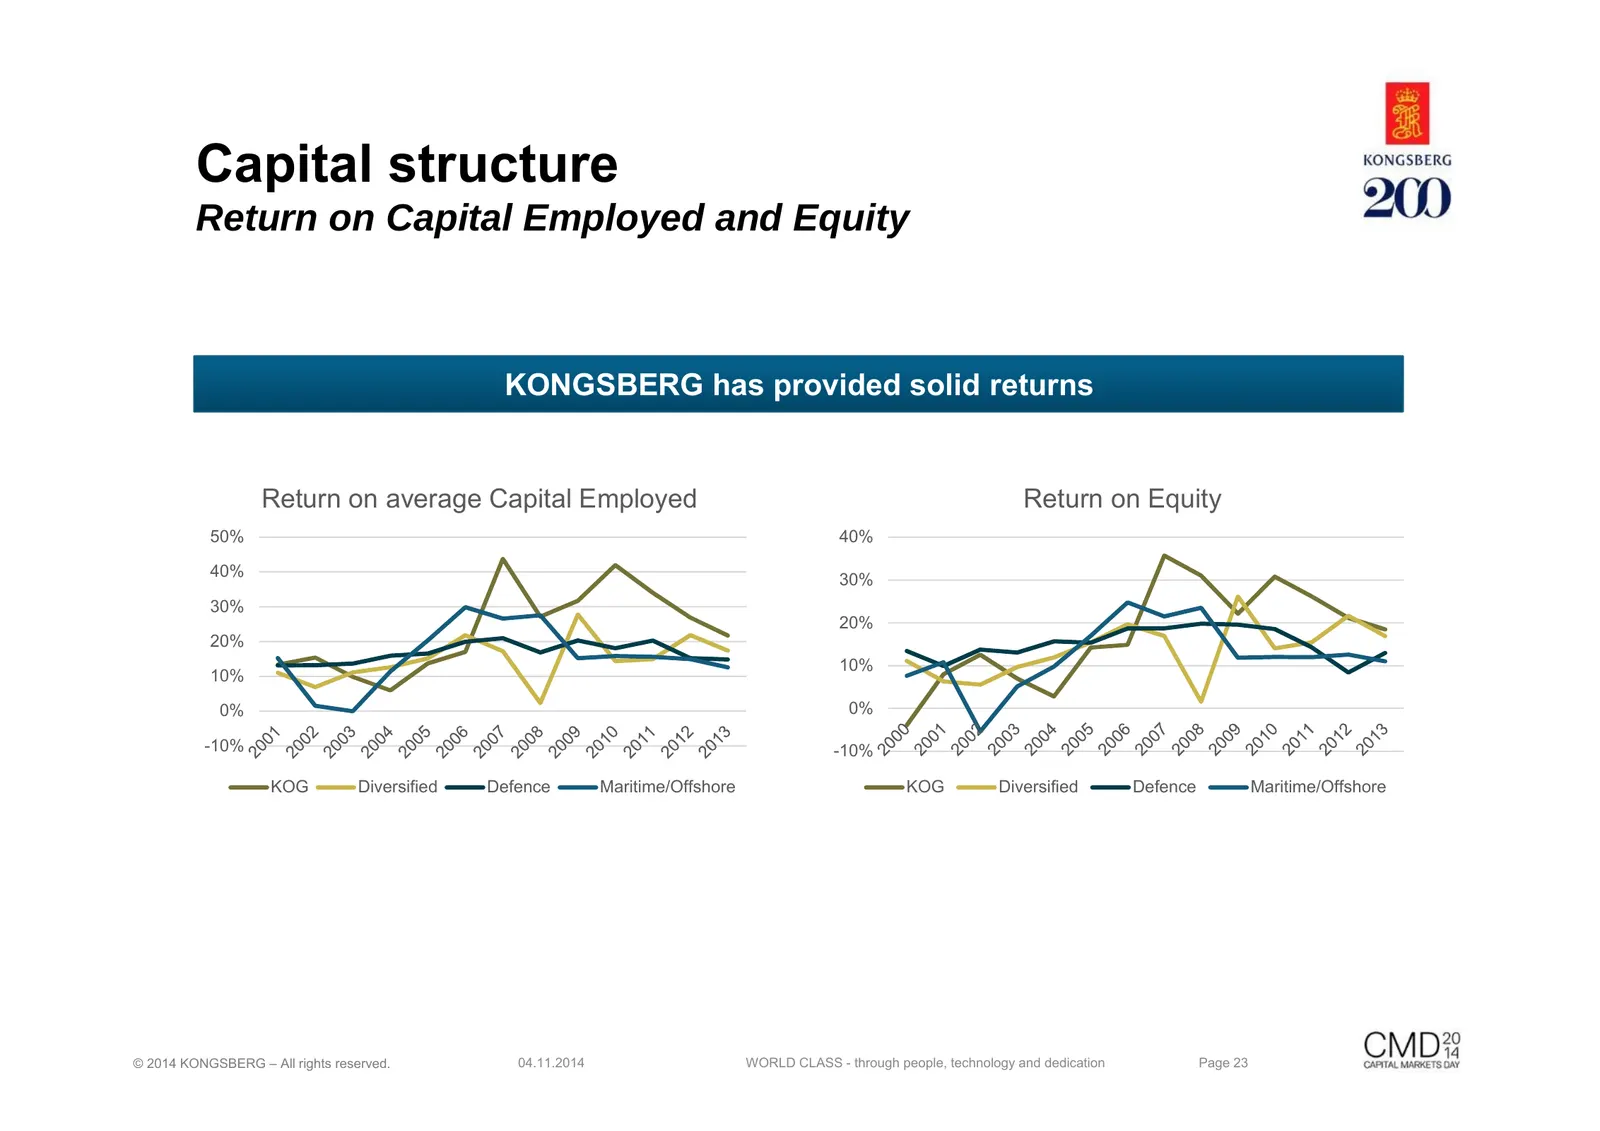
Capital structure Return on Capital Employed and Equity KONGSBERG has provided solid returns Return on average Capital Employed Return on Equity 50% 40% 40% 30% 30% 20% 20% 10% 10% 0% 0% -10% -10% KOG Diversified Defence Maritime/Offshore KOG Diversified Defence Maritime/Offshore © 2014 KONGSBERG –
Slide 24: Capital structure
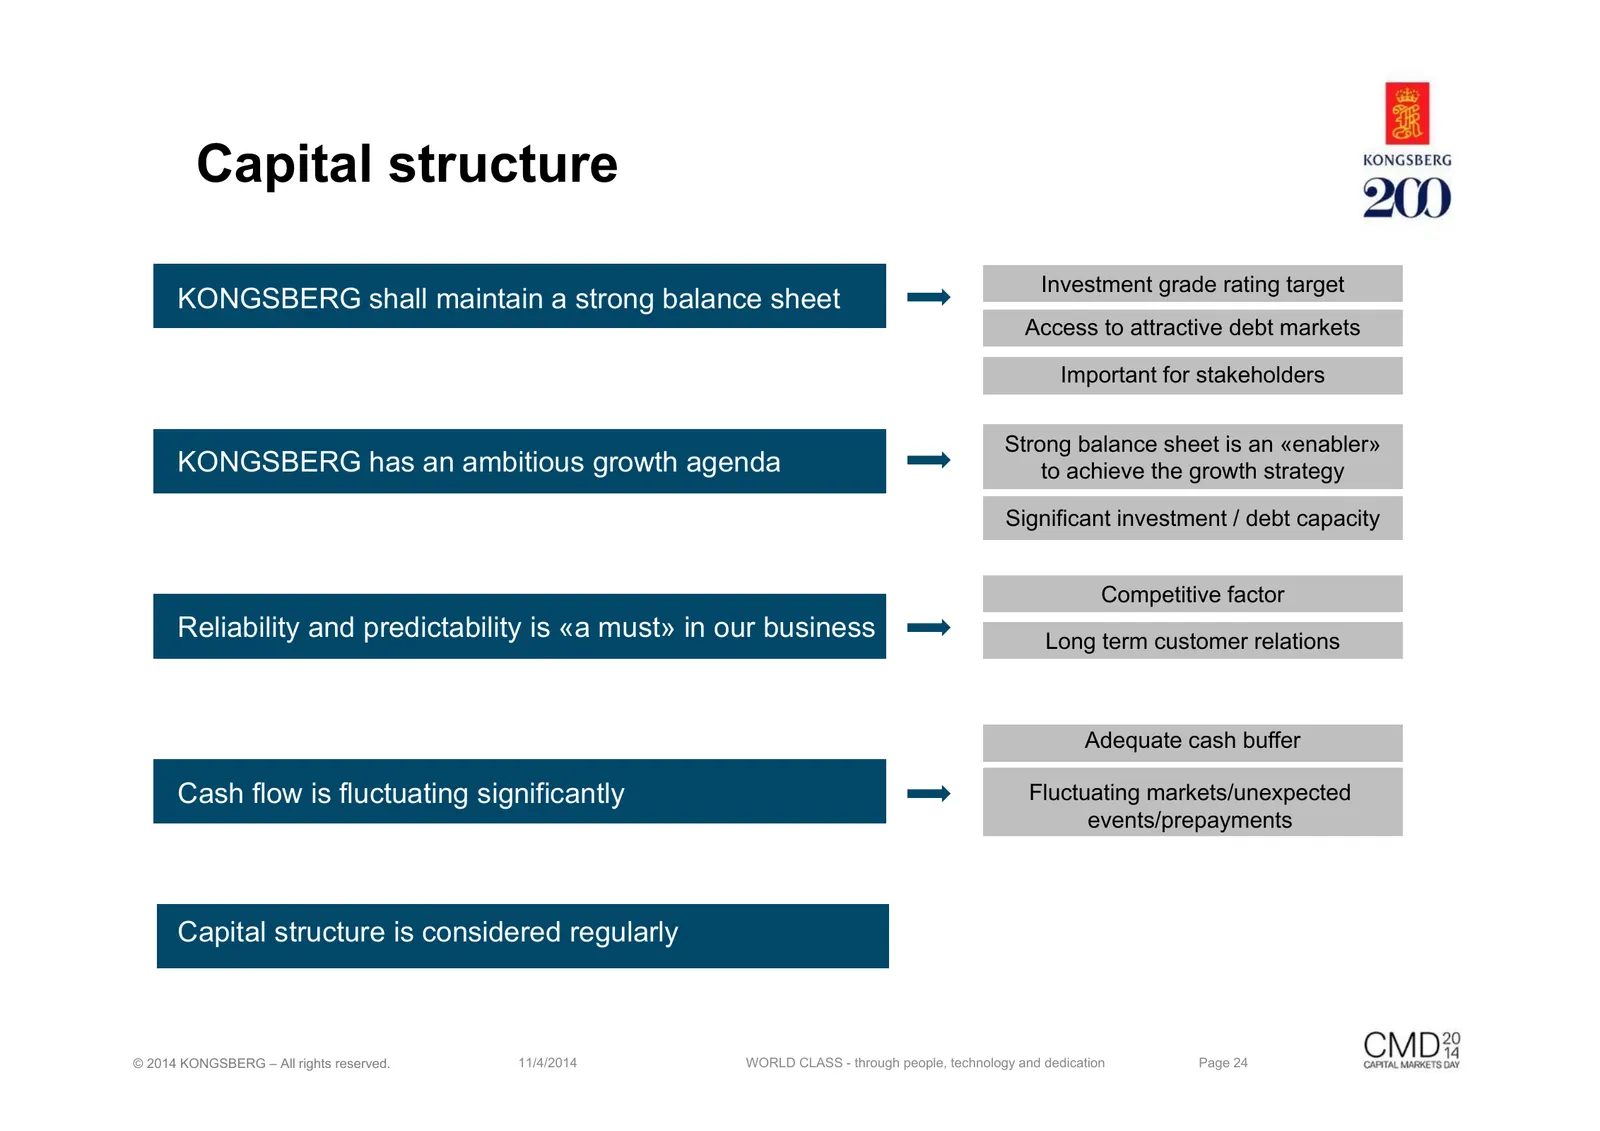
Capital structure Investment grade rating target KONGSBERG shall maintain a strong balance sheet Access to attractive debt markets Important for stakeholders Strong balance sheet is an «enabler» KONGSBERG has an ambitious growth agenda to achieve the growth strategy Significant investment / debt cap
Slide 25: Strong finances
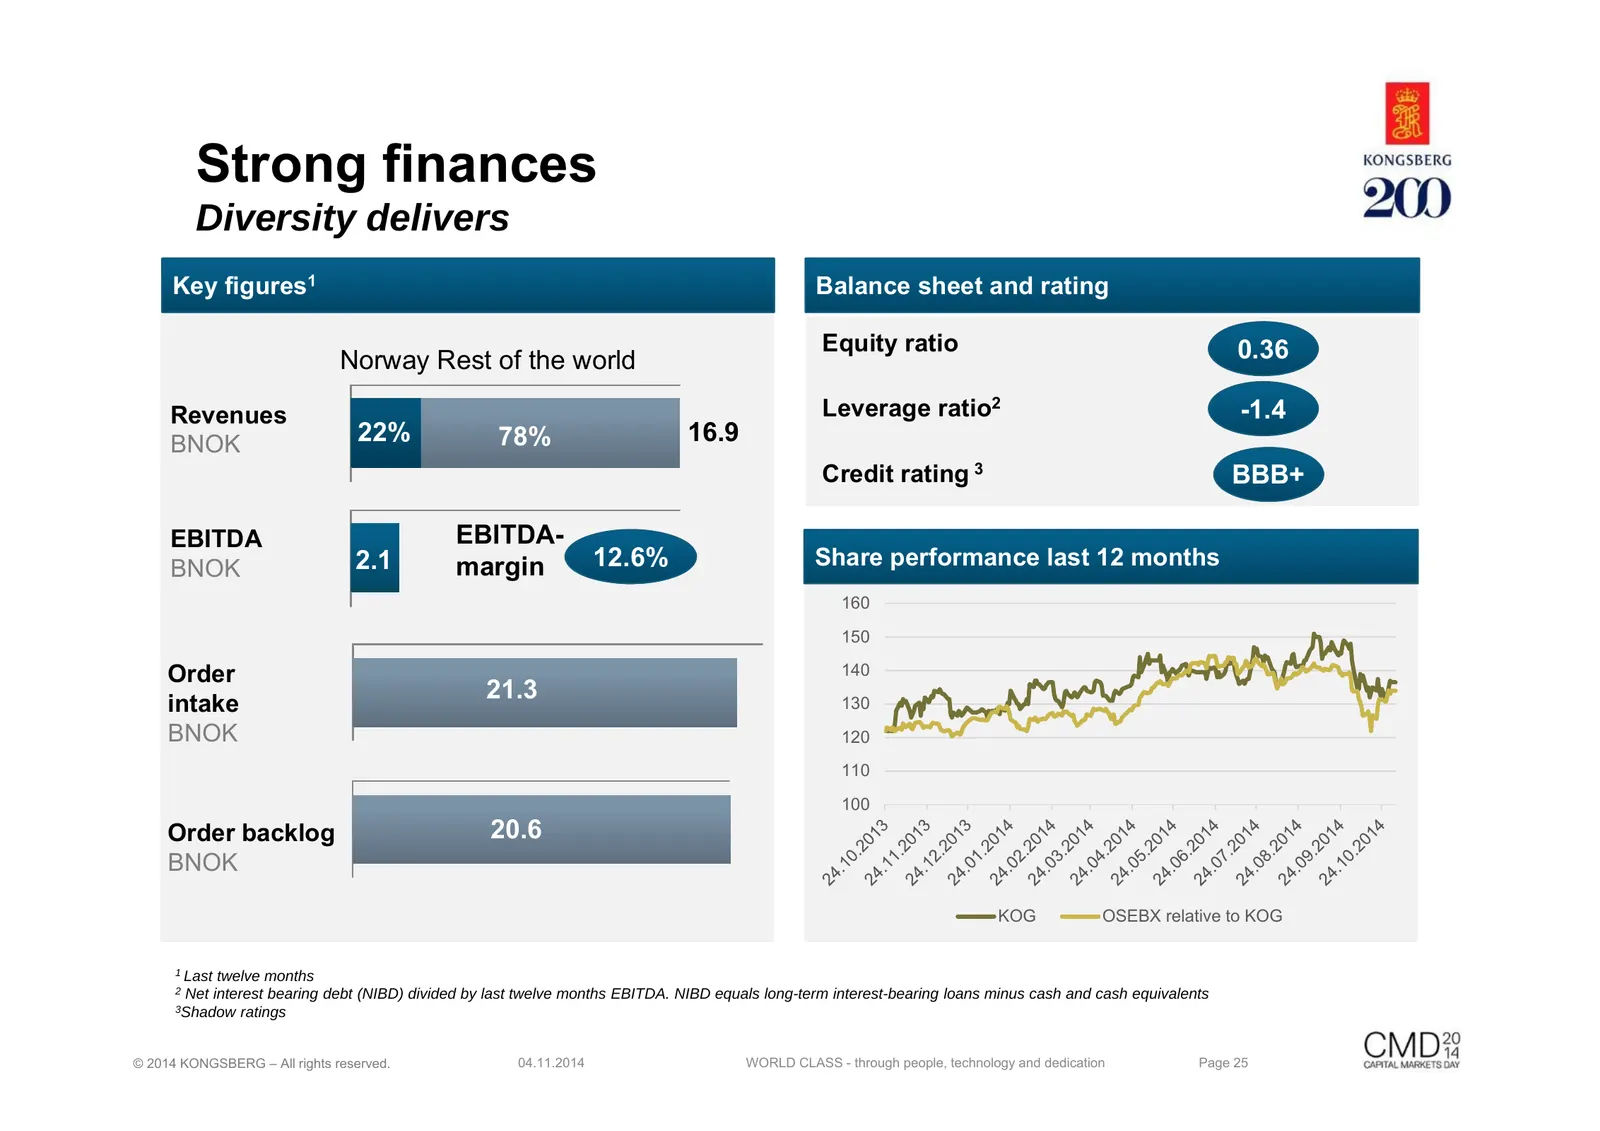
Strong finances Diversity delivers Key figures1 Balance sheet and rating Equity ratio 0.36 Norway Rest of the world Revenues Leverage ratio2 -1.4 BNOK 22% 78% 16.9 Credit rating 3 BBB+ EBITDA EBITDA- BNOK 2.1 margin 12.6% Share performance last 12 months 160 150 Order 140 21.3 intake 130 BNOK 120 11
Slide 26: Agenda
Agenda • Introduction – This is KONGSBERG • Financial status • Status ambitions from 2013 CMD • Status Delta One • Innovation • Commencing the next 200 © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 26
Slide 27: Changing markets
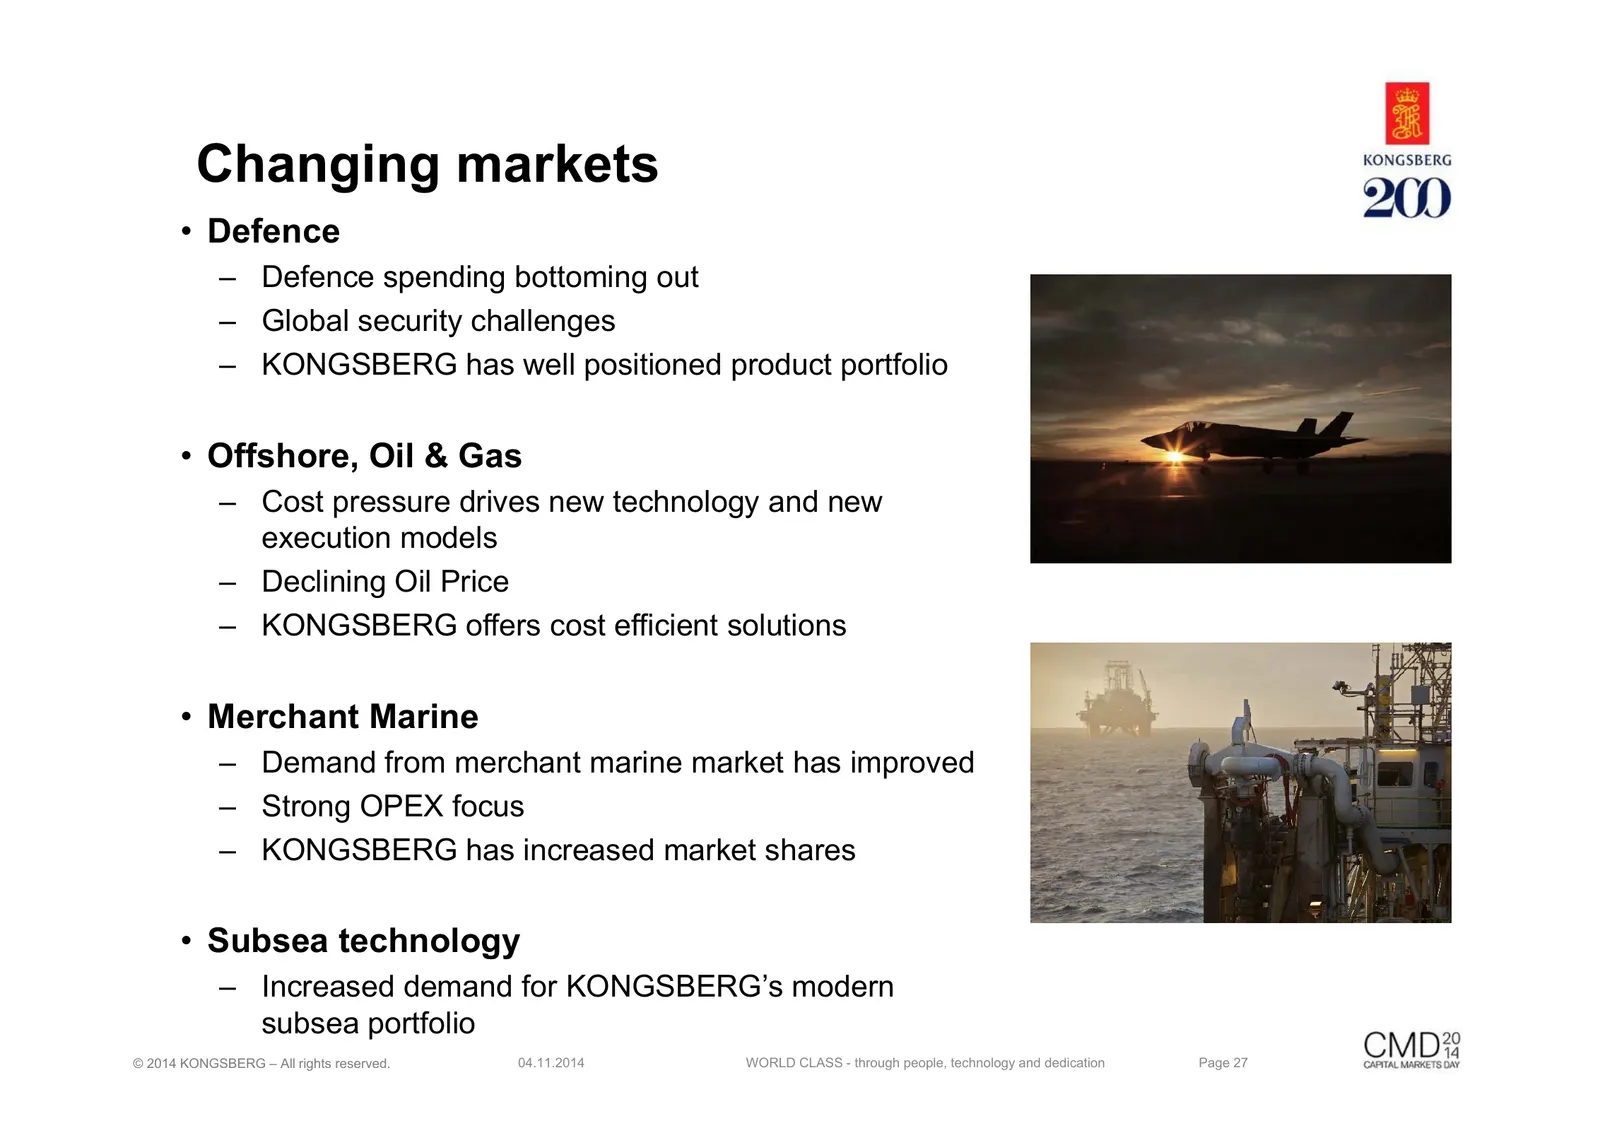
Changing markets • Defence – Defence spending bottoming out – Global security challenges – KONGSBERG has well positioned product portfolio • Offshore, Oil & Gas – Cost pressure drives new technology and new execution models – Declining Oil Price – KONGSBERG offers cost efficient solutions • Merchant
Slide 28: Taking on more systems-, solutions- and prime responsibilities
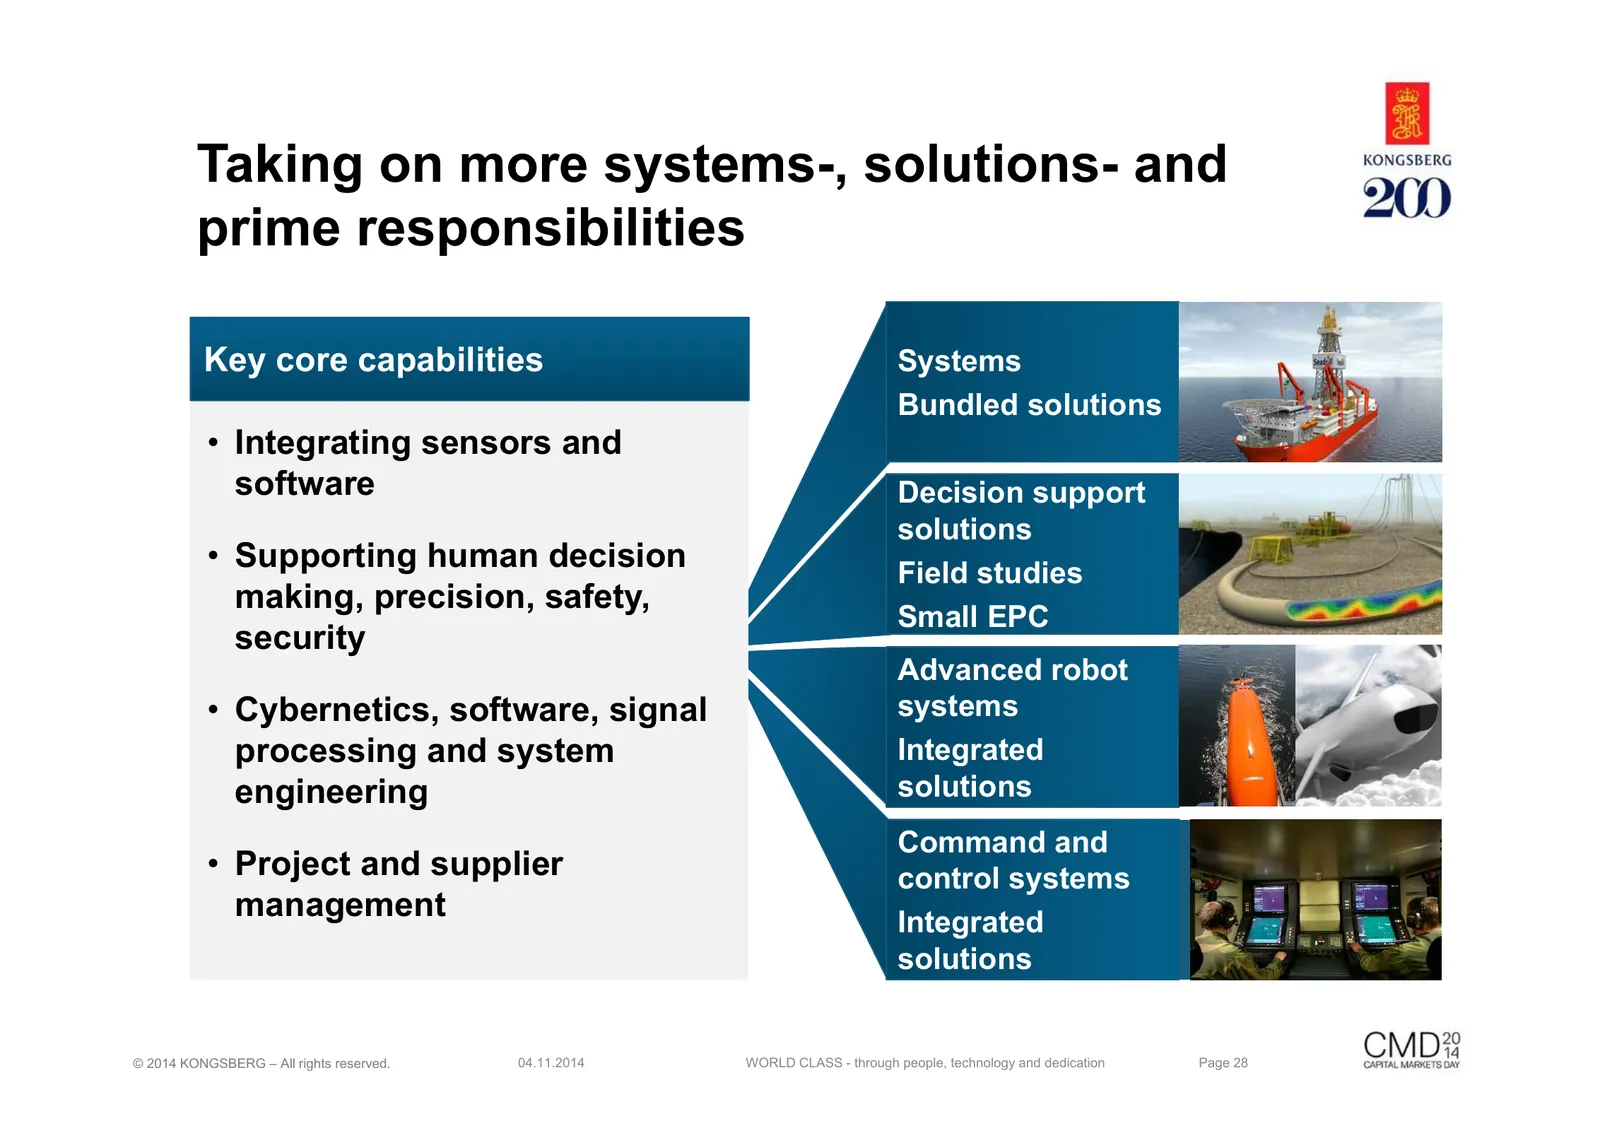
Taking on more systems-, solutions- and prime responsibilities Key core capabilities Systems Bundled solutions • Integrating sensors and software Decision support solutions • Supporting human decision Field studies making, precision, safety, Small EPC security Advanced robot • Cybernetics, software,
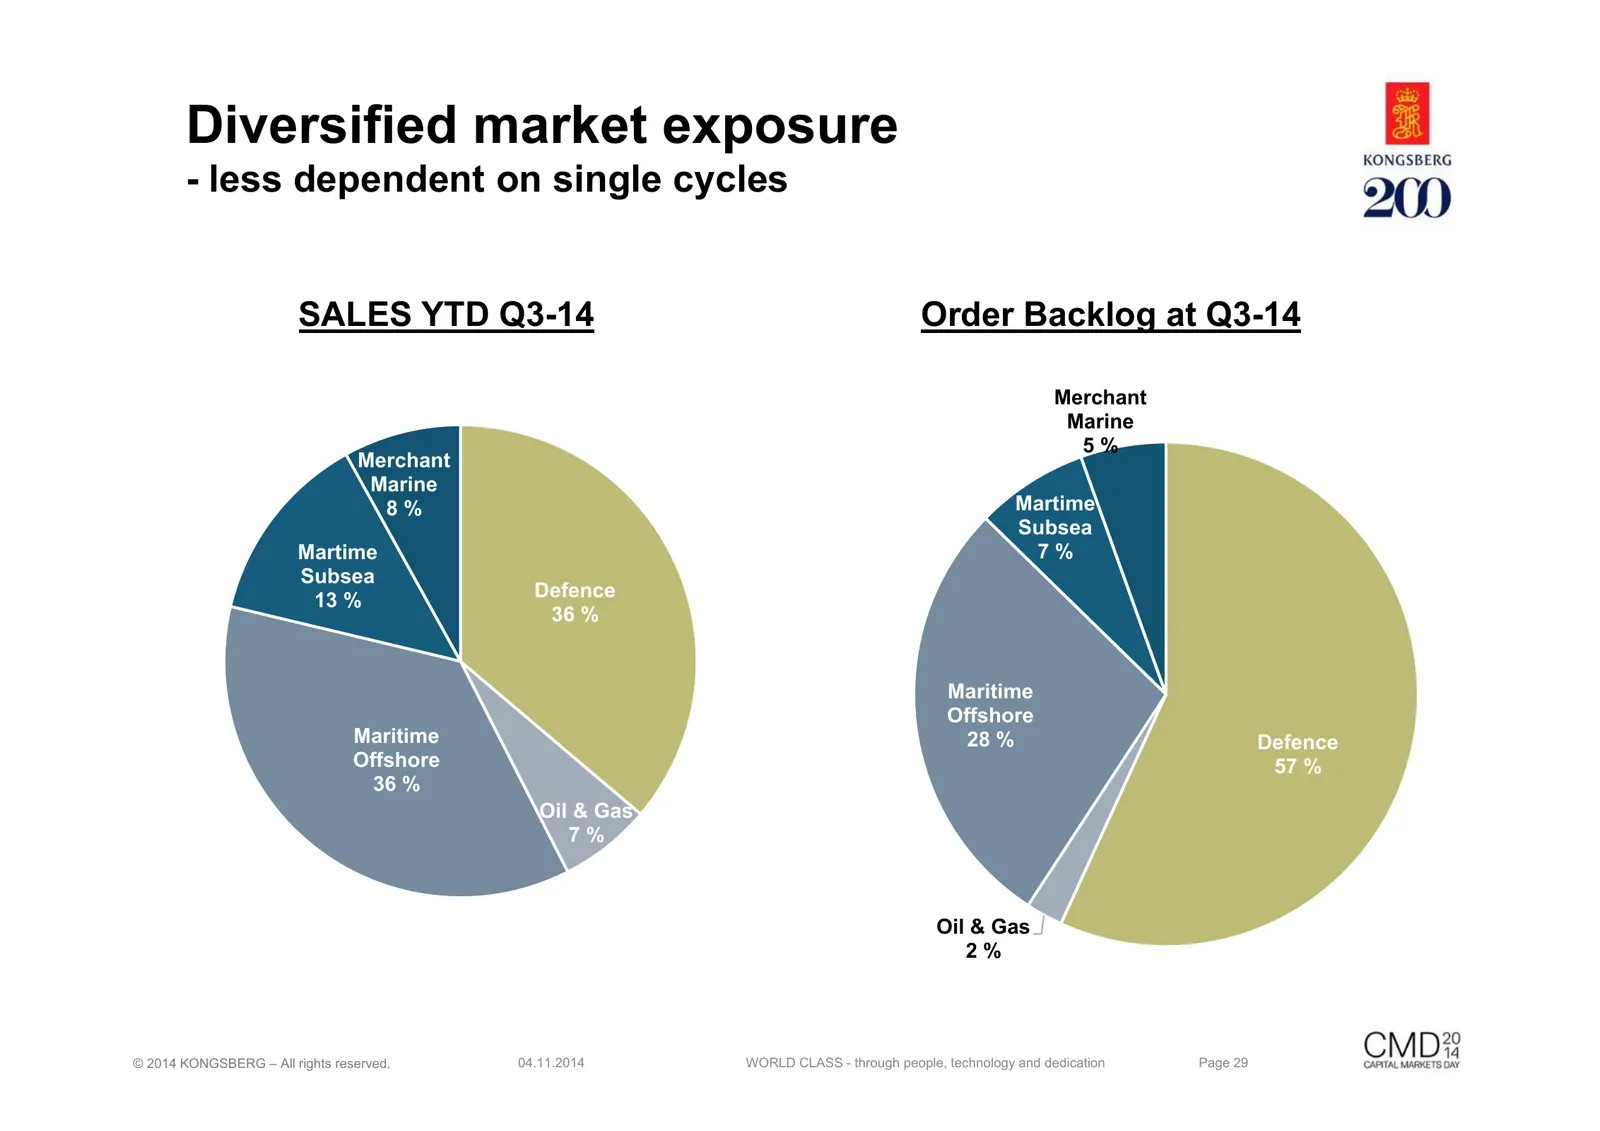
Slide 29: Diversified market exposure
Diversified market exposure - less dependent on single cycles SALES YTD Q3-14 Order Backlog at Q3-14 Merchant Marine 5% Merchant Marine 8% Martime Subsea Martime 7% Subsea 13 % Defence 36 % Maritime Offshore Maritime 28 % Defence Offshore 57 % 36 % Oil & Gas 7% Oil & Gas 2% © 2014 KONGSBERG – All ri
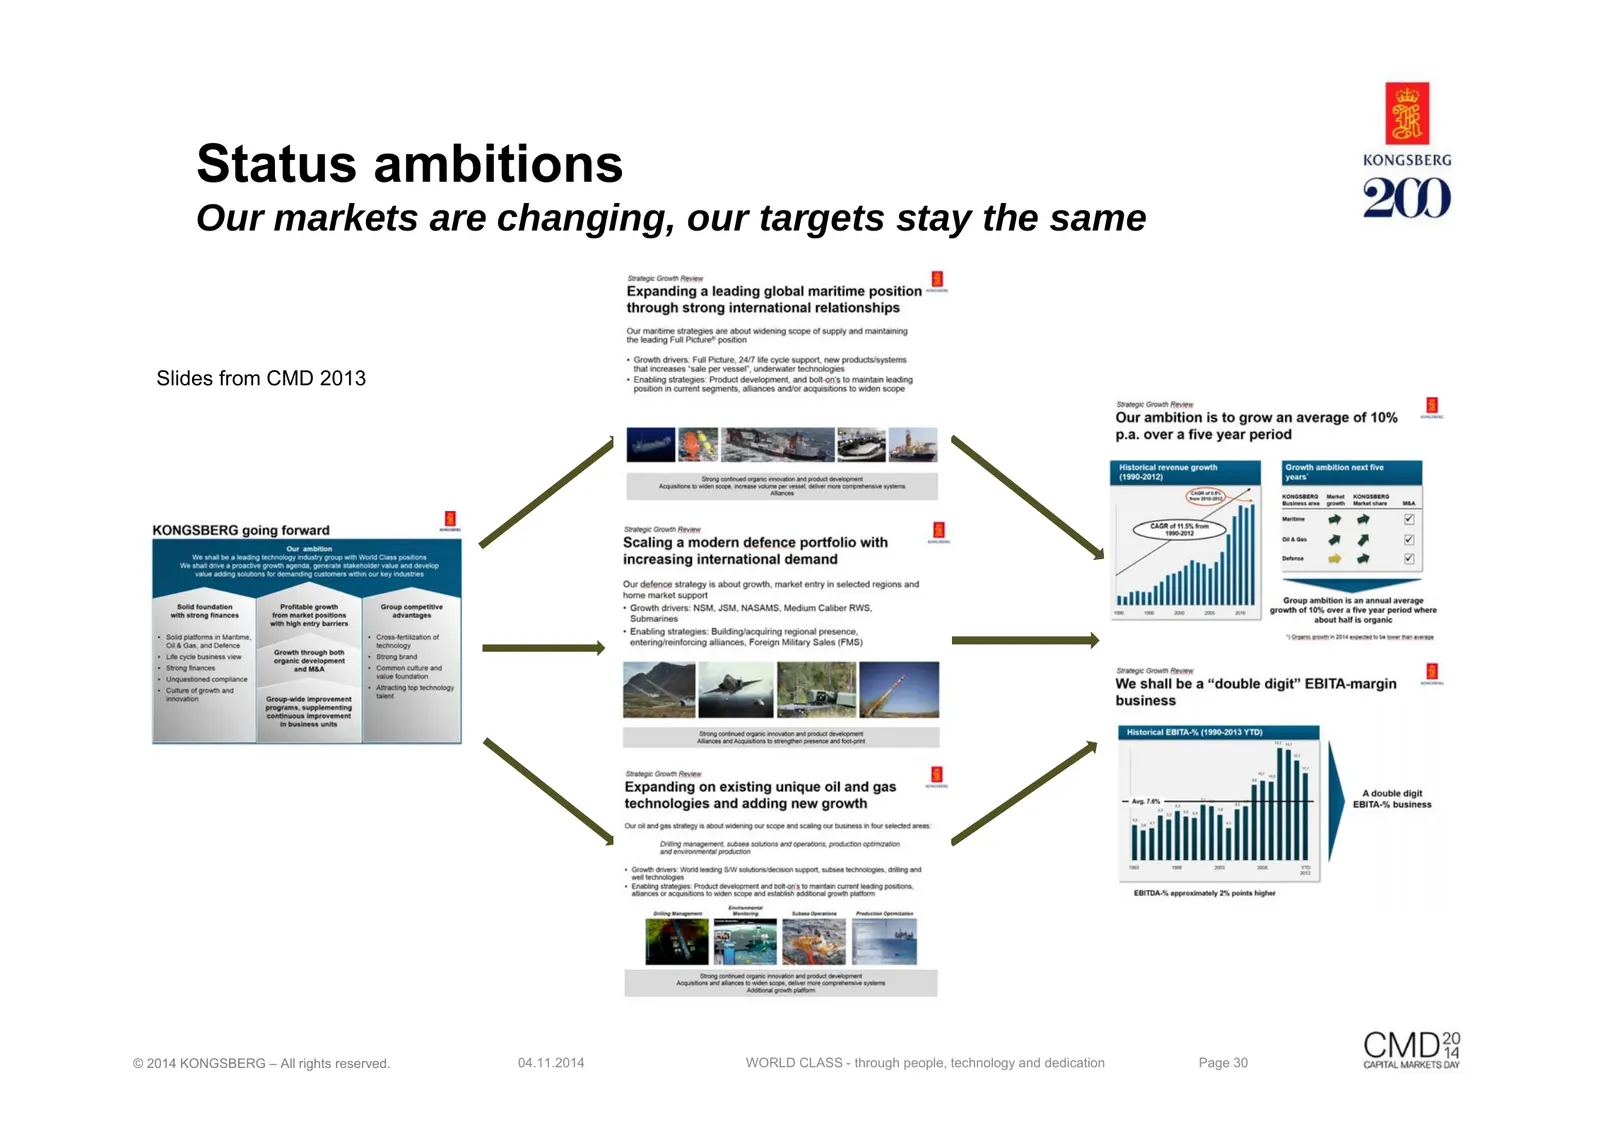
Slide 30: Status ambitions
Status ambitions Our markets are changing, our targets stay the same Slides from CMD 2013 © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 30
Slide 31: Agenda
Agenda • Introduction – This is KONGSBERG • Financial status • Status ambitions from 2013 CMD • Status Delta One • Innovation • Commencing the next 200 © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 31
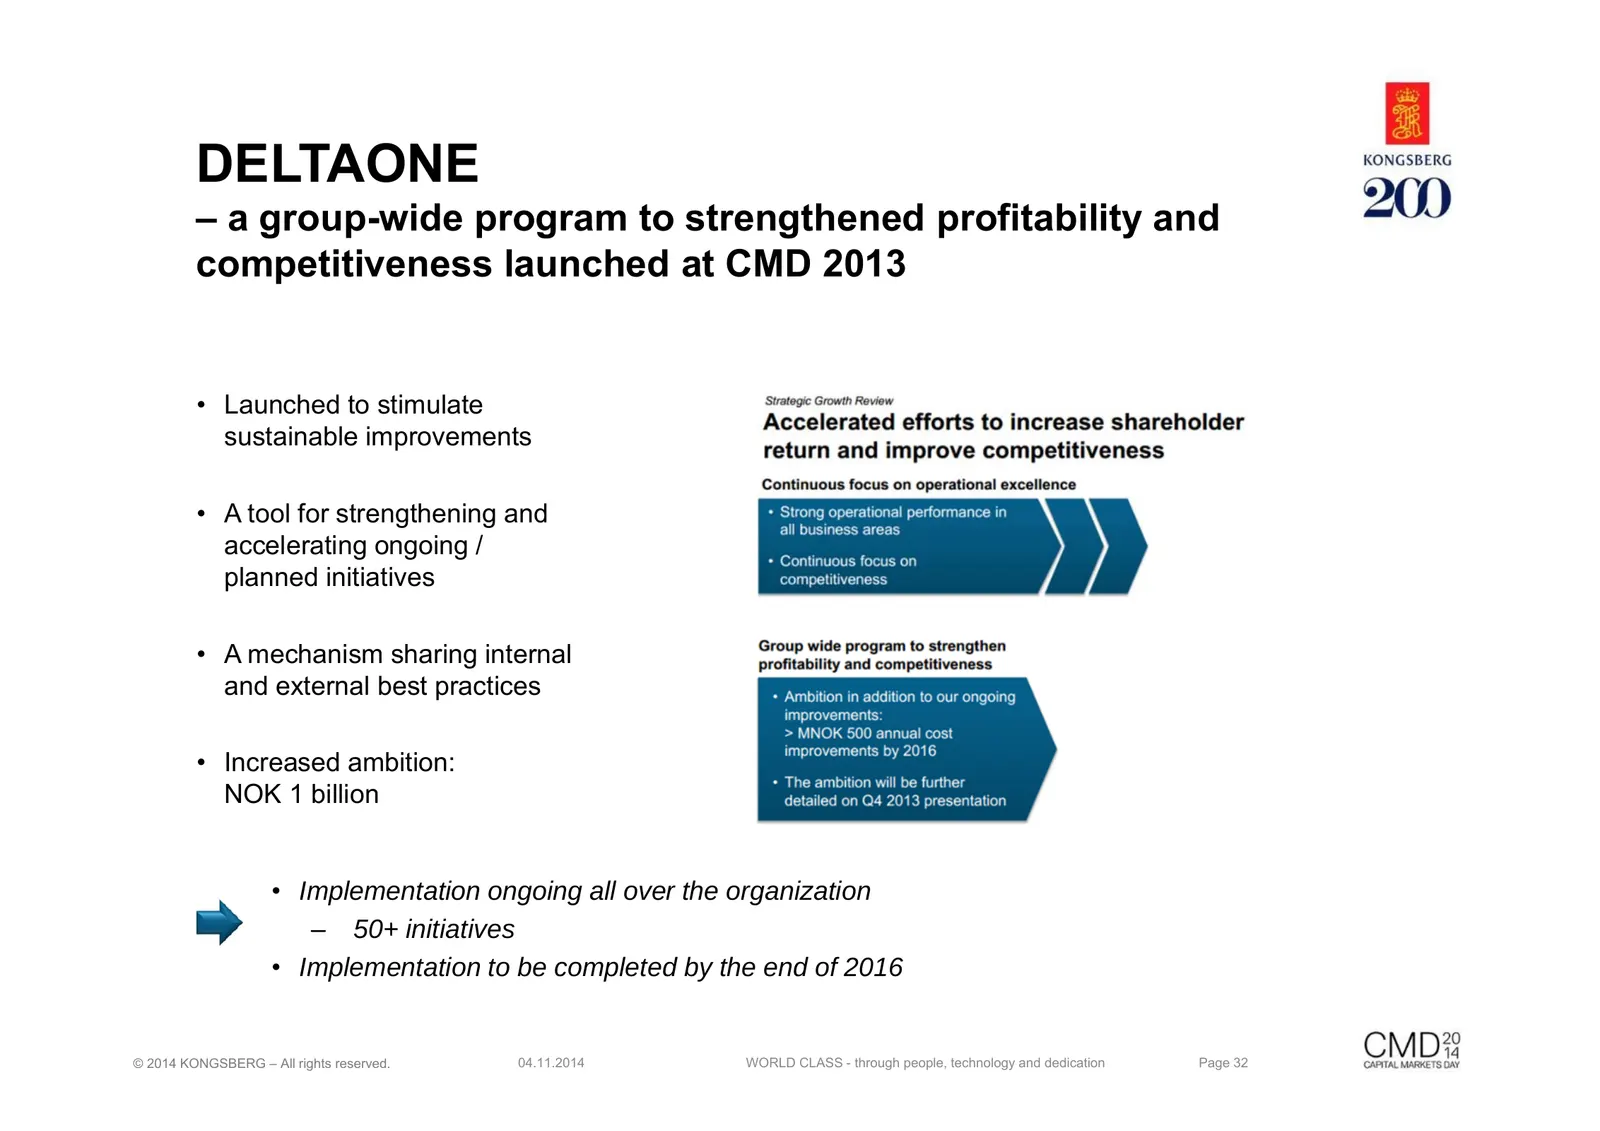
Slide 32: DeltaOne
DELTAONE – a group-wide program to strengthened profitability and competitiveness launched at CMD 2013 • Launched to stimulate sustainable improvements • A tool for strengthening and accelerating ongoing / planned initiatives • A mechanism sharing internal and external best practices • Increased amb
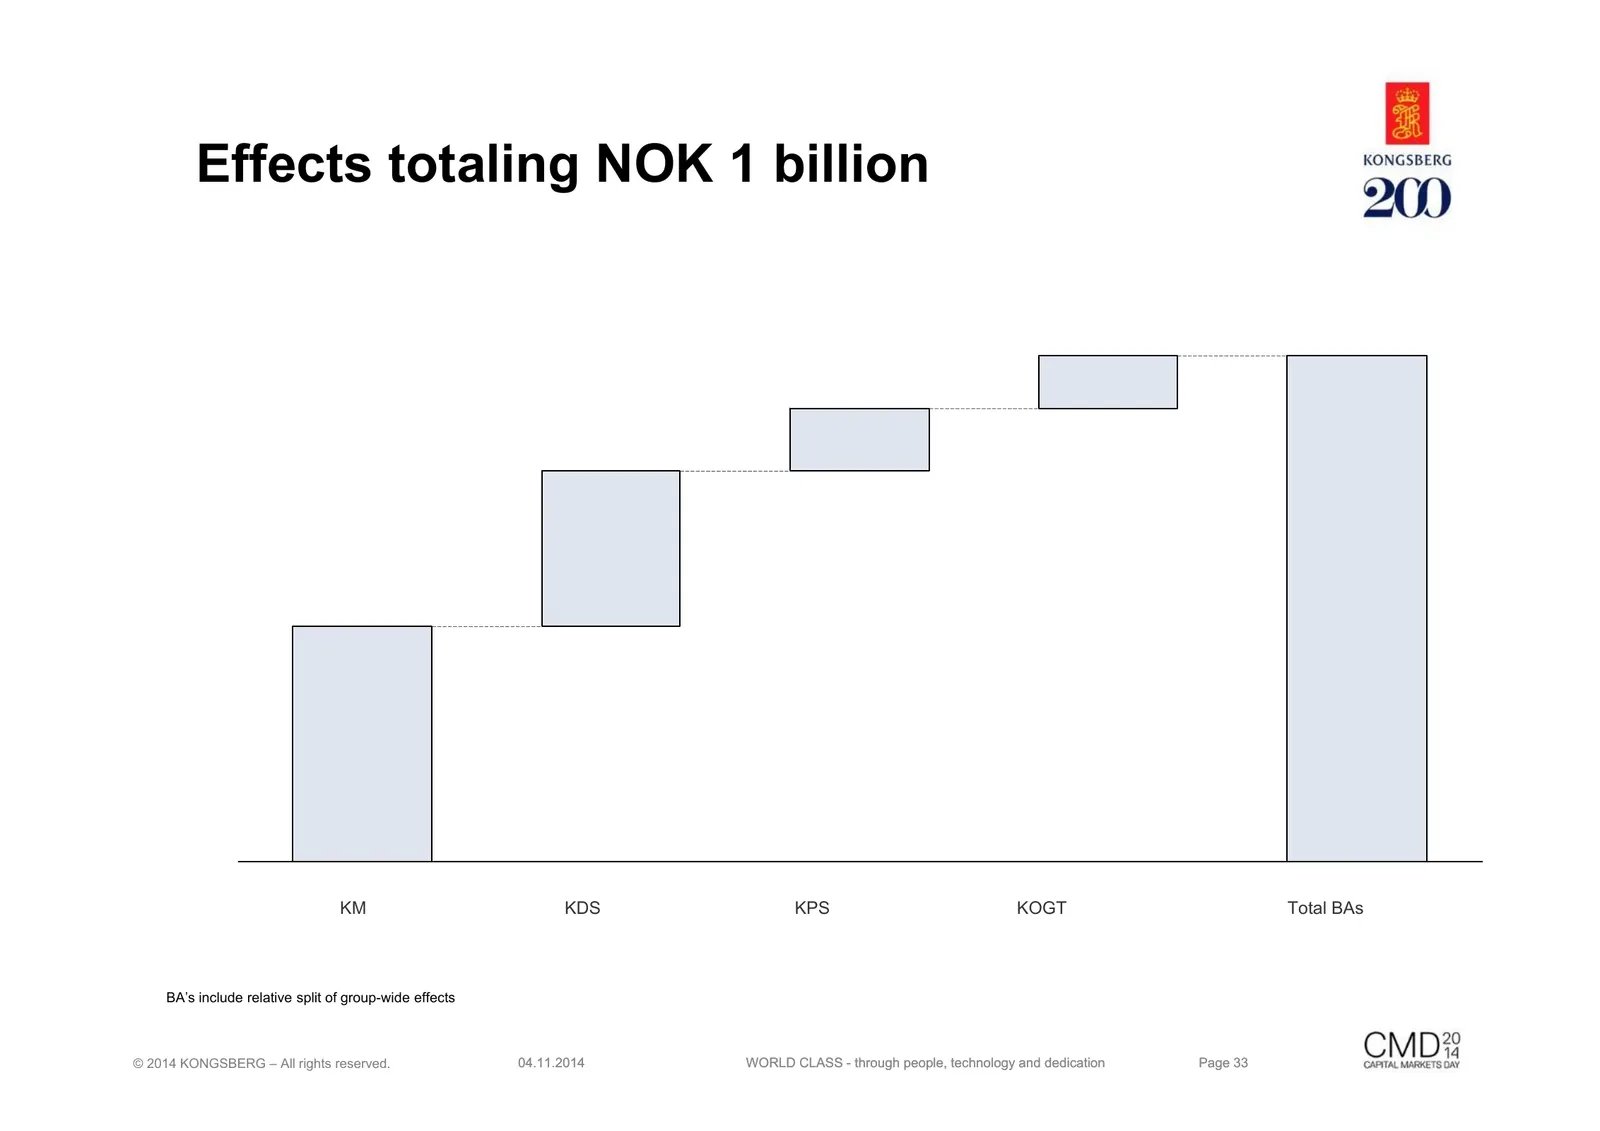
Slide 33: Effects totaling NOK 1 billion
Effects totaling NOK 1 billion KM KDS KPS KOGT Total BAs BA’s include relative split of group-wide effects © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 33
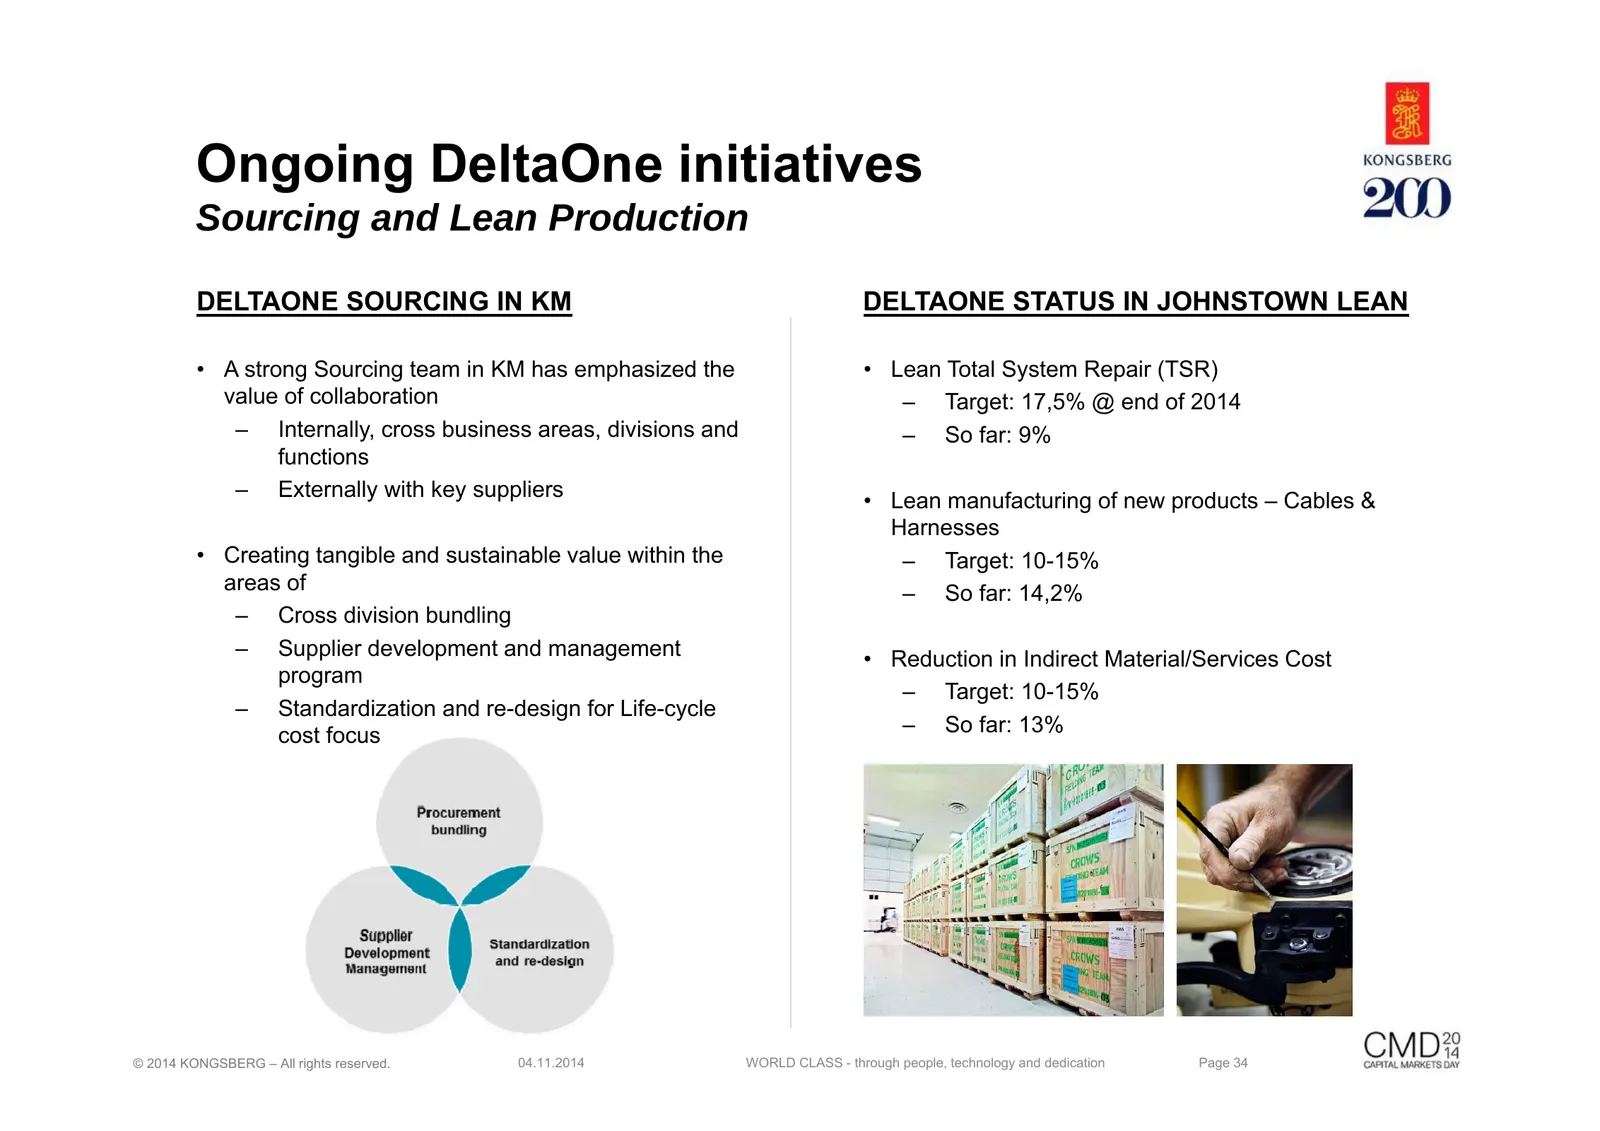
Slide 34: Ongoing DeltaOne initiatives
Ongoing DeltaOne initiatives Sourcing and Lean Production DELTAONE SOURCING IN KM DELTAONE STATUS IN JOHNSTOWN LEAN • A strong Sourcing team in KM has emphasized the • Lean Total System Repair (TSR) value of collaboration – Target: 17,5% @ end of 2014 – Internally, cross business areas, divisions an
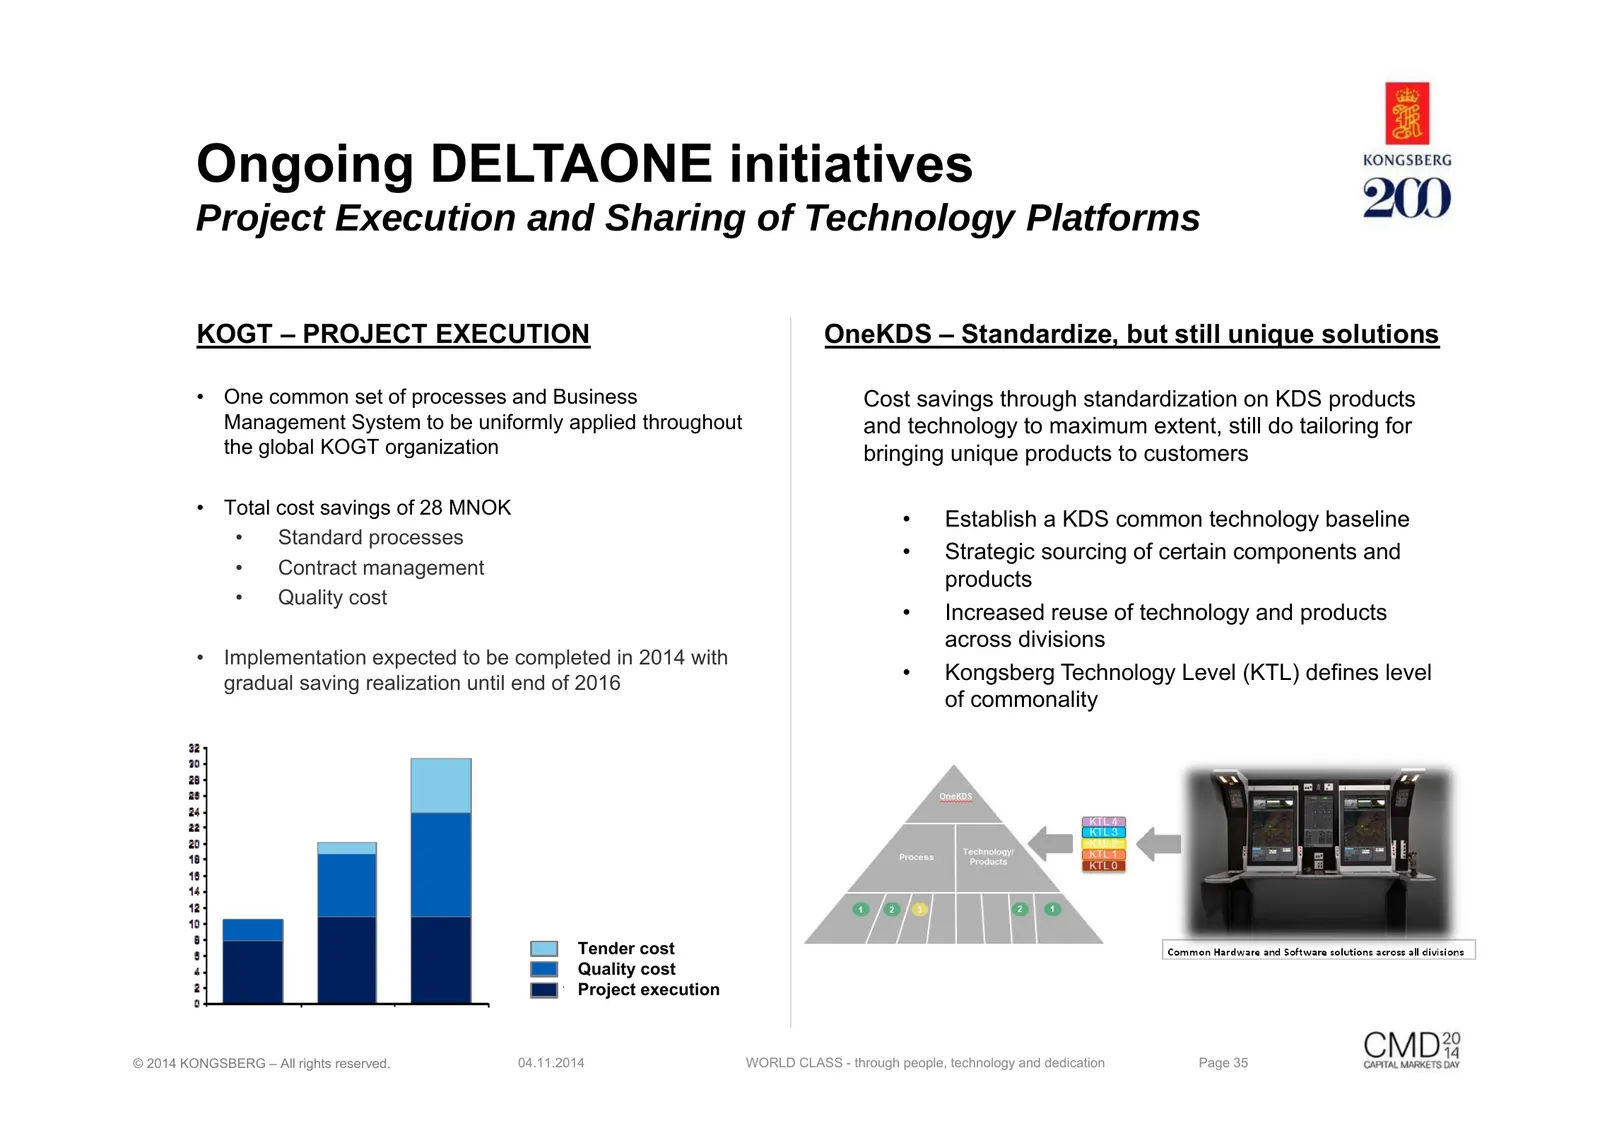
Slide 35: Ongoing DeltaOne initiatives
Ongoing DELTAONE initiatives Project Execution and Sharing of Technology Platforms KOGT – PROJECT EXECUTION OneKDS – Standardize, but still unique solutions • One common set of processes and Business Cost savings through standardization on KDS products Management System to be uniformly applied throu
Slide 36: Agenda
Agenda • Introduction – This is KONGSBERG • Financial status • Status ambitions from 2013 CMD • Status Delta One • Innovation • Commencing the next 200 © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 36
Slide 37: KONGSBERG driving innovations
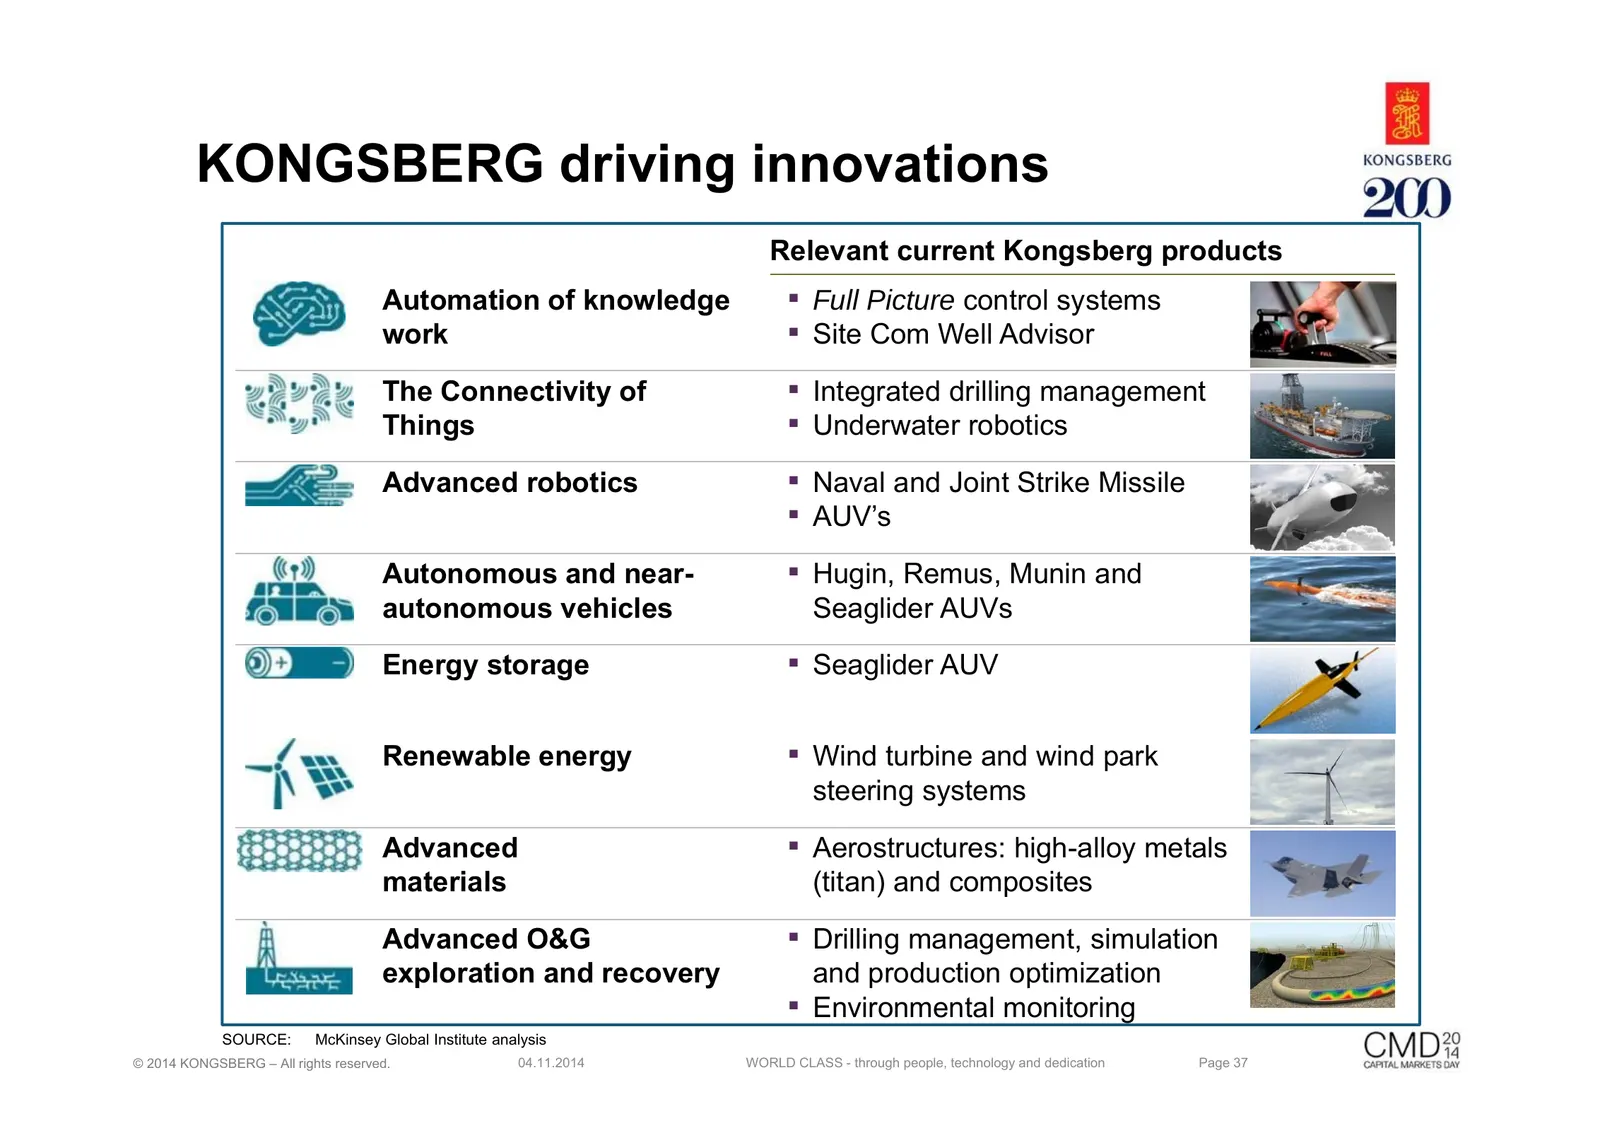
KONGSBERG driving innovations Relevant current Kongsberg products Automation of knowledge ▪ Full Picture control systems work ▪ Site Com Well Advisor The Connectivity of ▪ Integrated drilling management Things ▪ Underwater robotics Advanced robotics ▪ Naval and Joint Strike Missile ▪ AUV’s Autonomou
Slide 38: Strengthened innovation capacity through Innovate with KONGSBERG
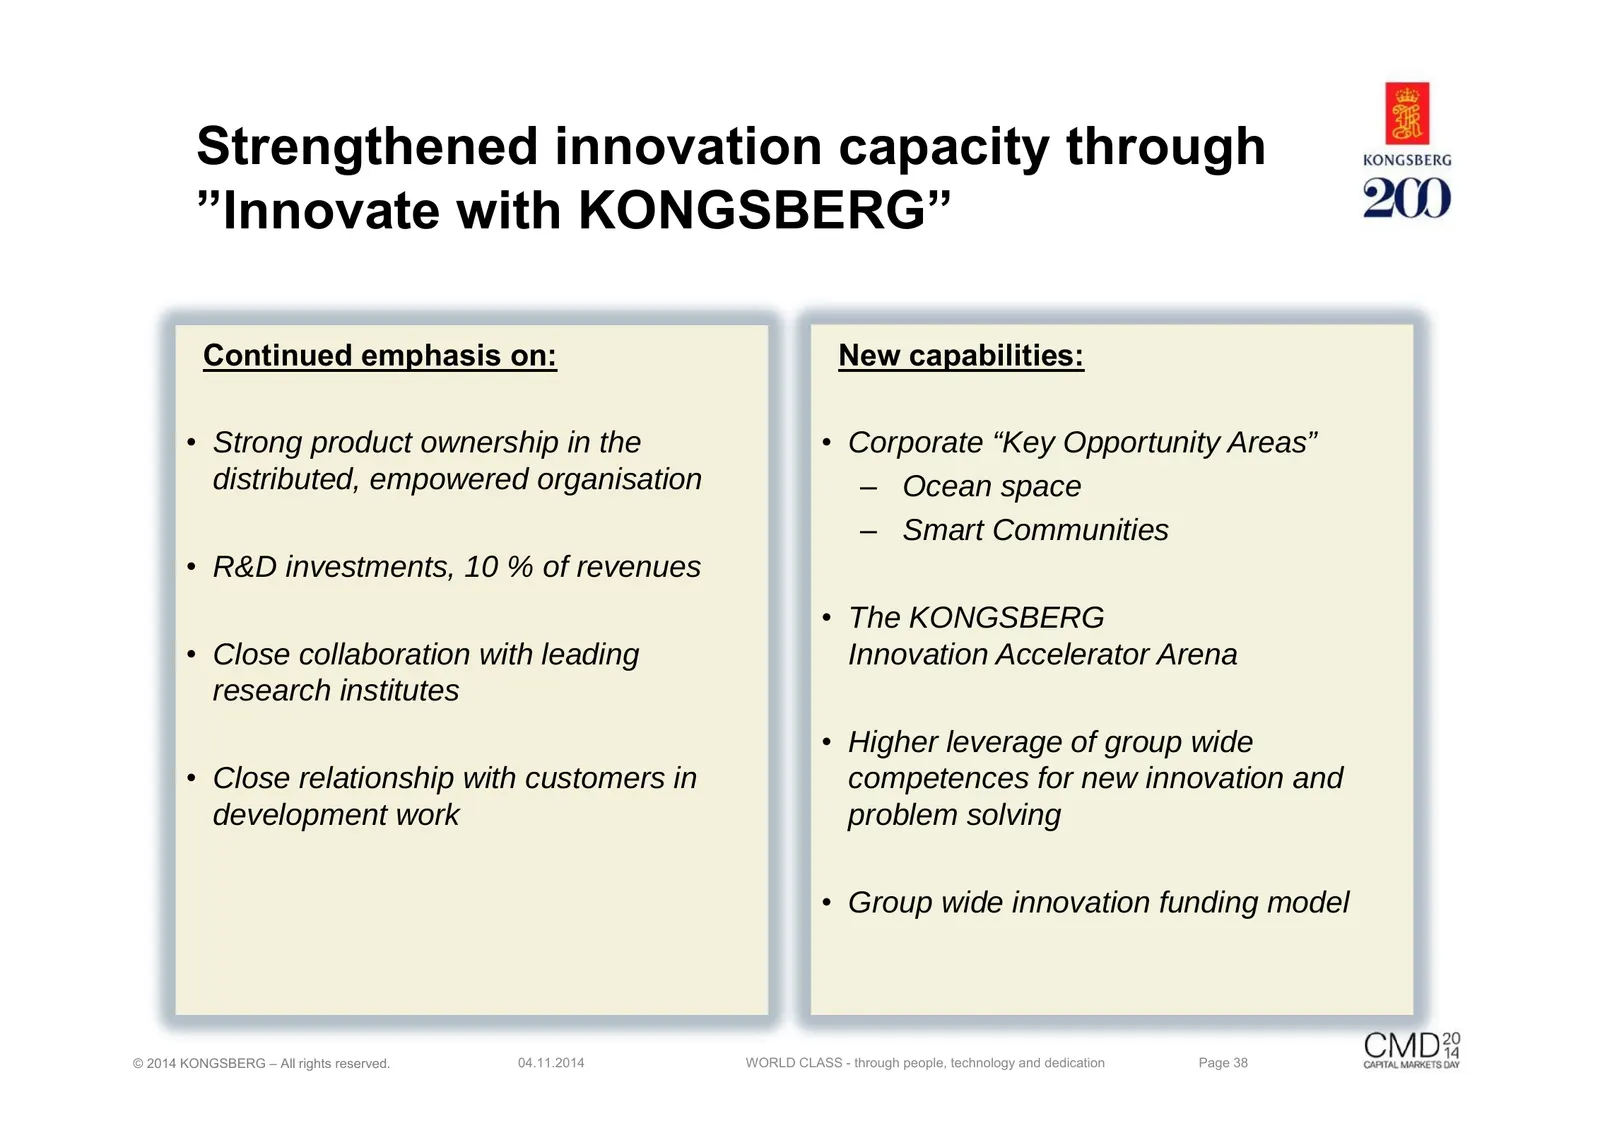
Strengthened innovation capacity through ”Innovate with KONGSBERG” Continued emphasis on: New capabilities: • Strong product ownership in the • Corporate “Key Opportunity Areas” distributed, empowered organisation – Ocean space – Smart Communities • R&D investments, 10 % of revenues • The KONGSBERG
Slide 39: The KONGSBERG Innovation model
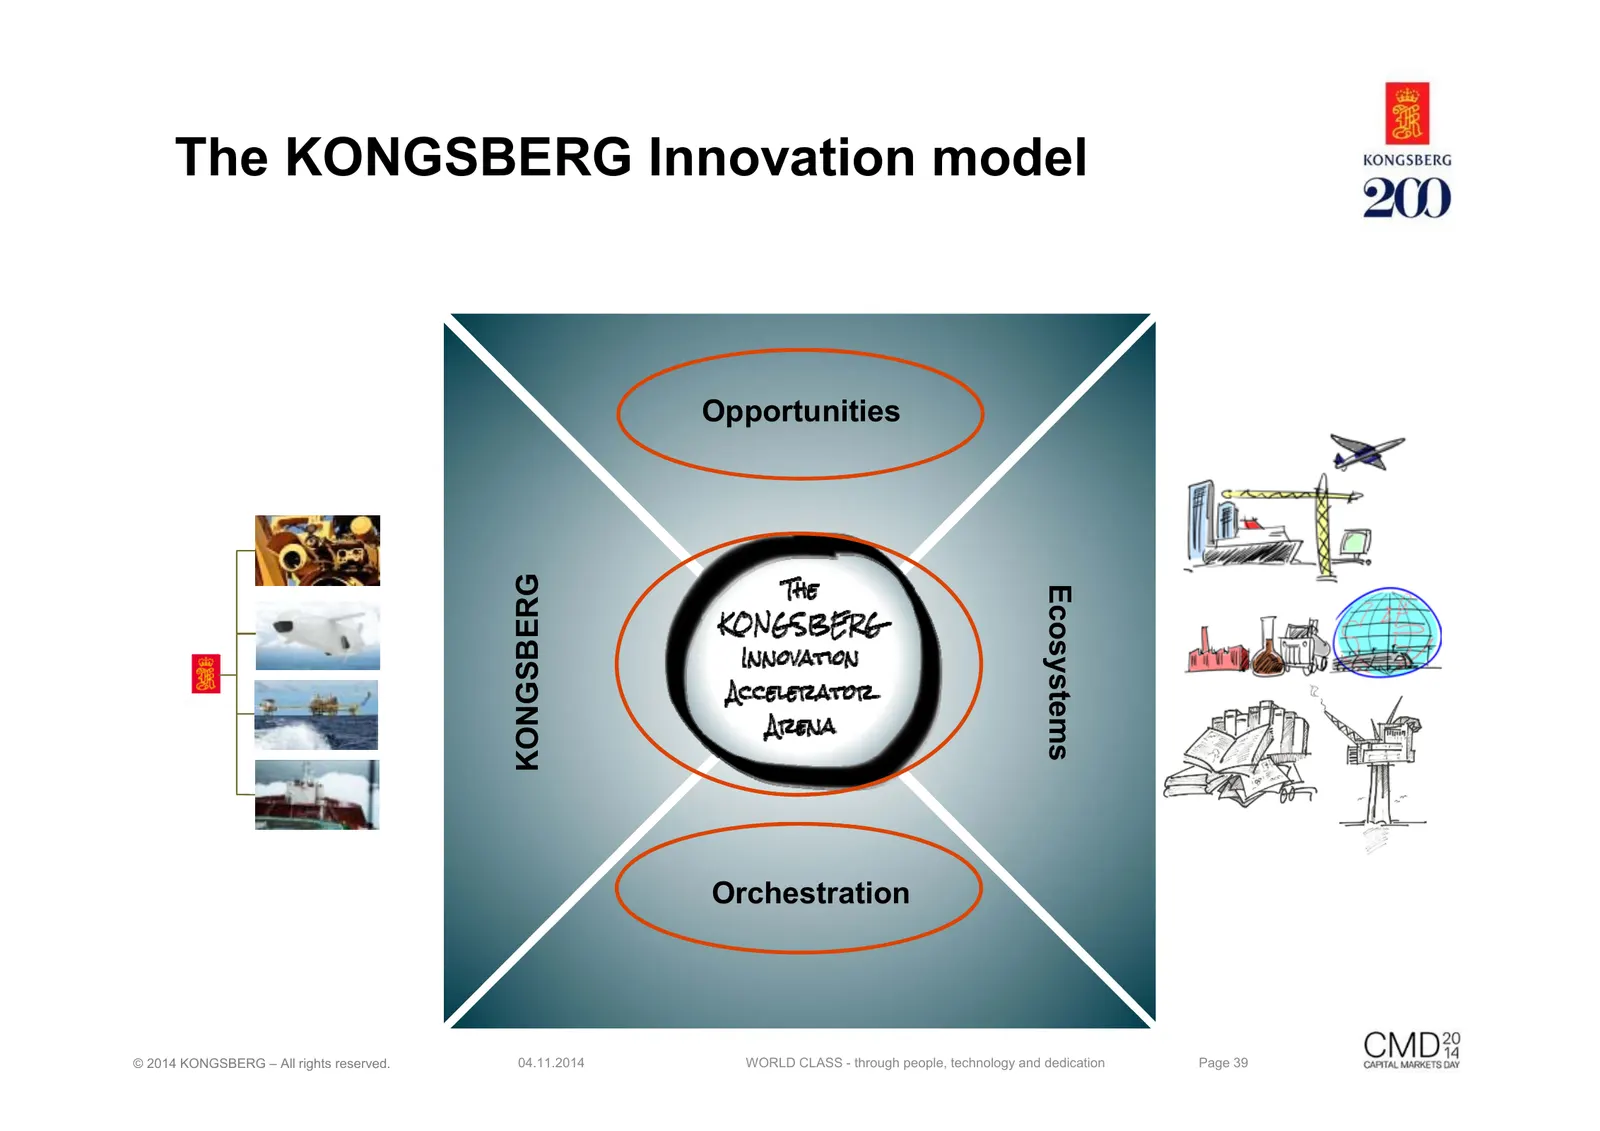
The KONGSBERG Innovation model Opportunities KONGSBERG Ecosystems Orchestration © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 39
Slide 40: Key Opportunity Areas focuses Group long term innovation efforts
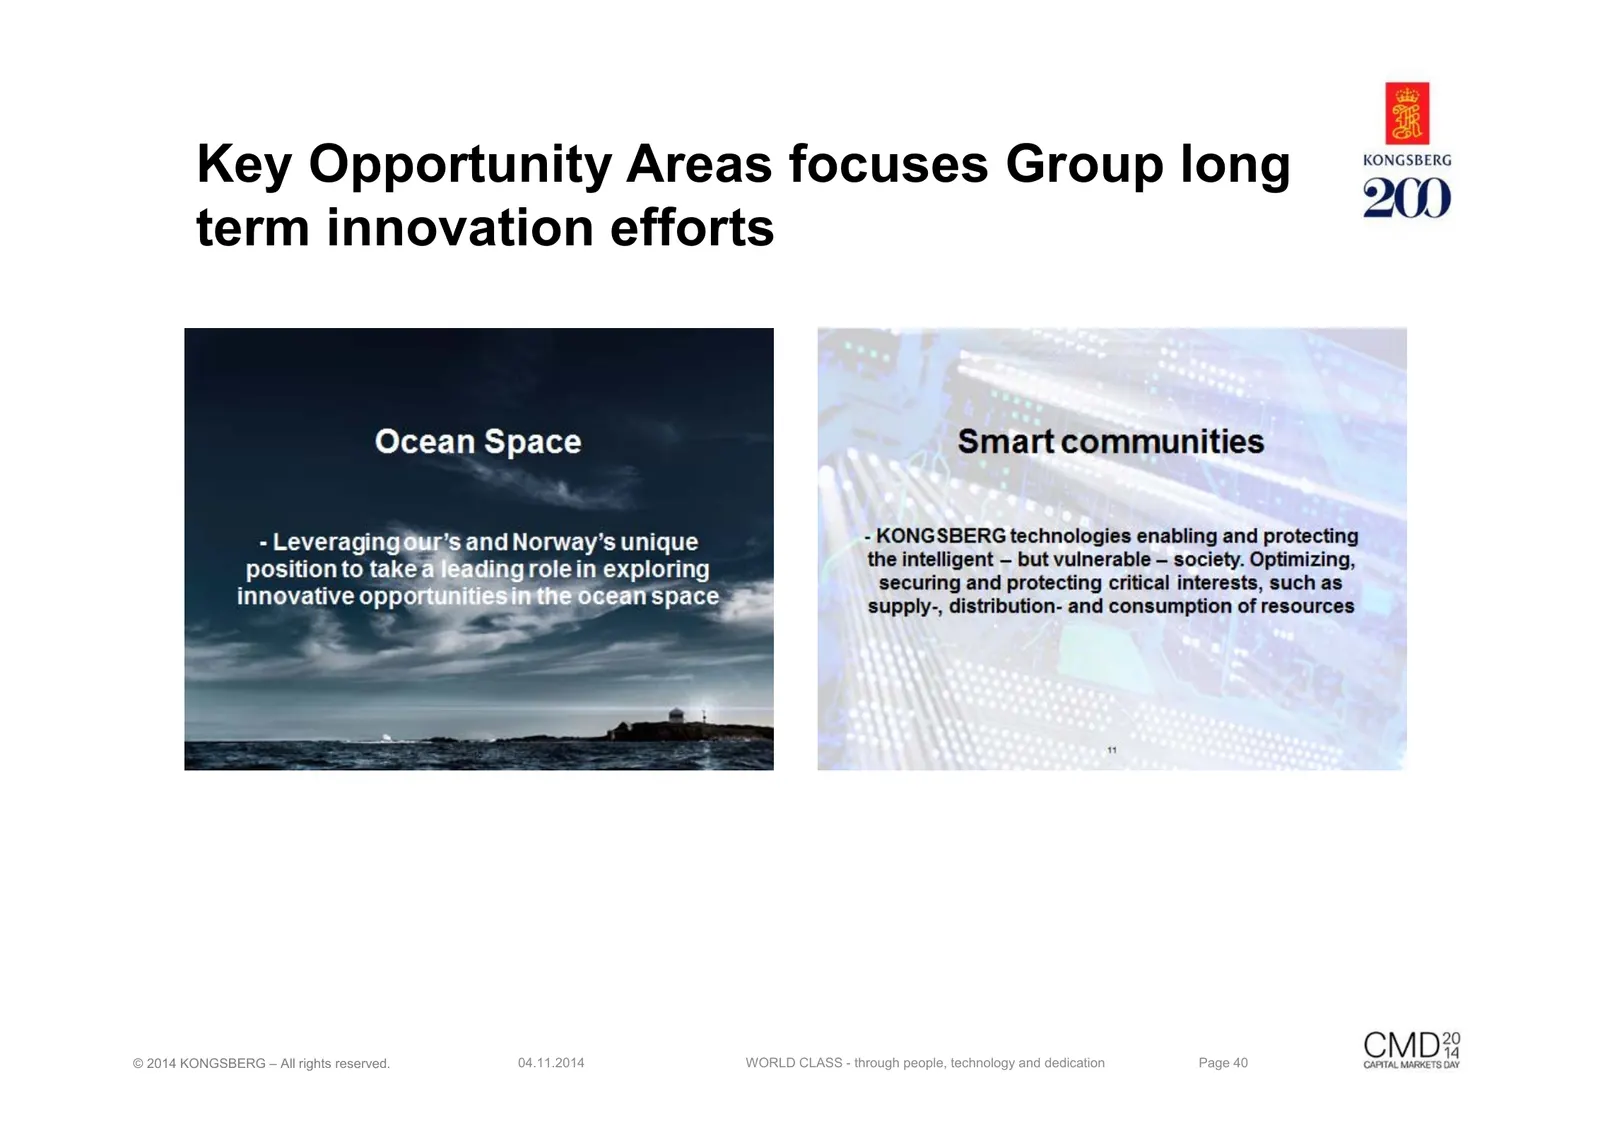
Key Opportunity Areas focuses Group long term innovation efforts © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 40
Slide 41: Agenda
Agenda • Introduction – This is KONGSBERG • Financial status • Status ambitions from 2013 CMD • Status Delta One • Innovation • Commencing the next 200 © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page 41
Slide 42: Diversity drives innovation
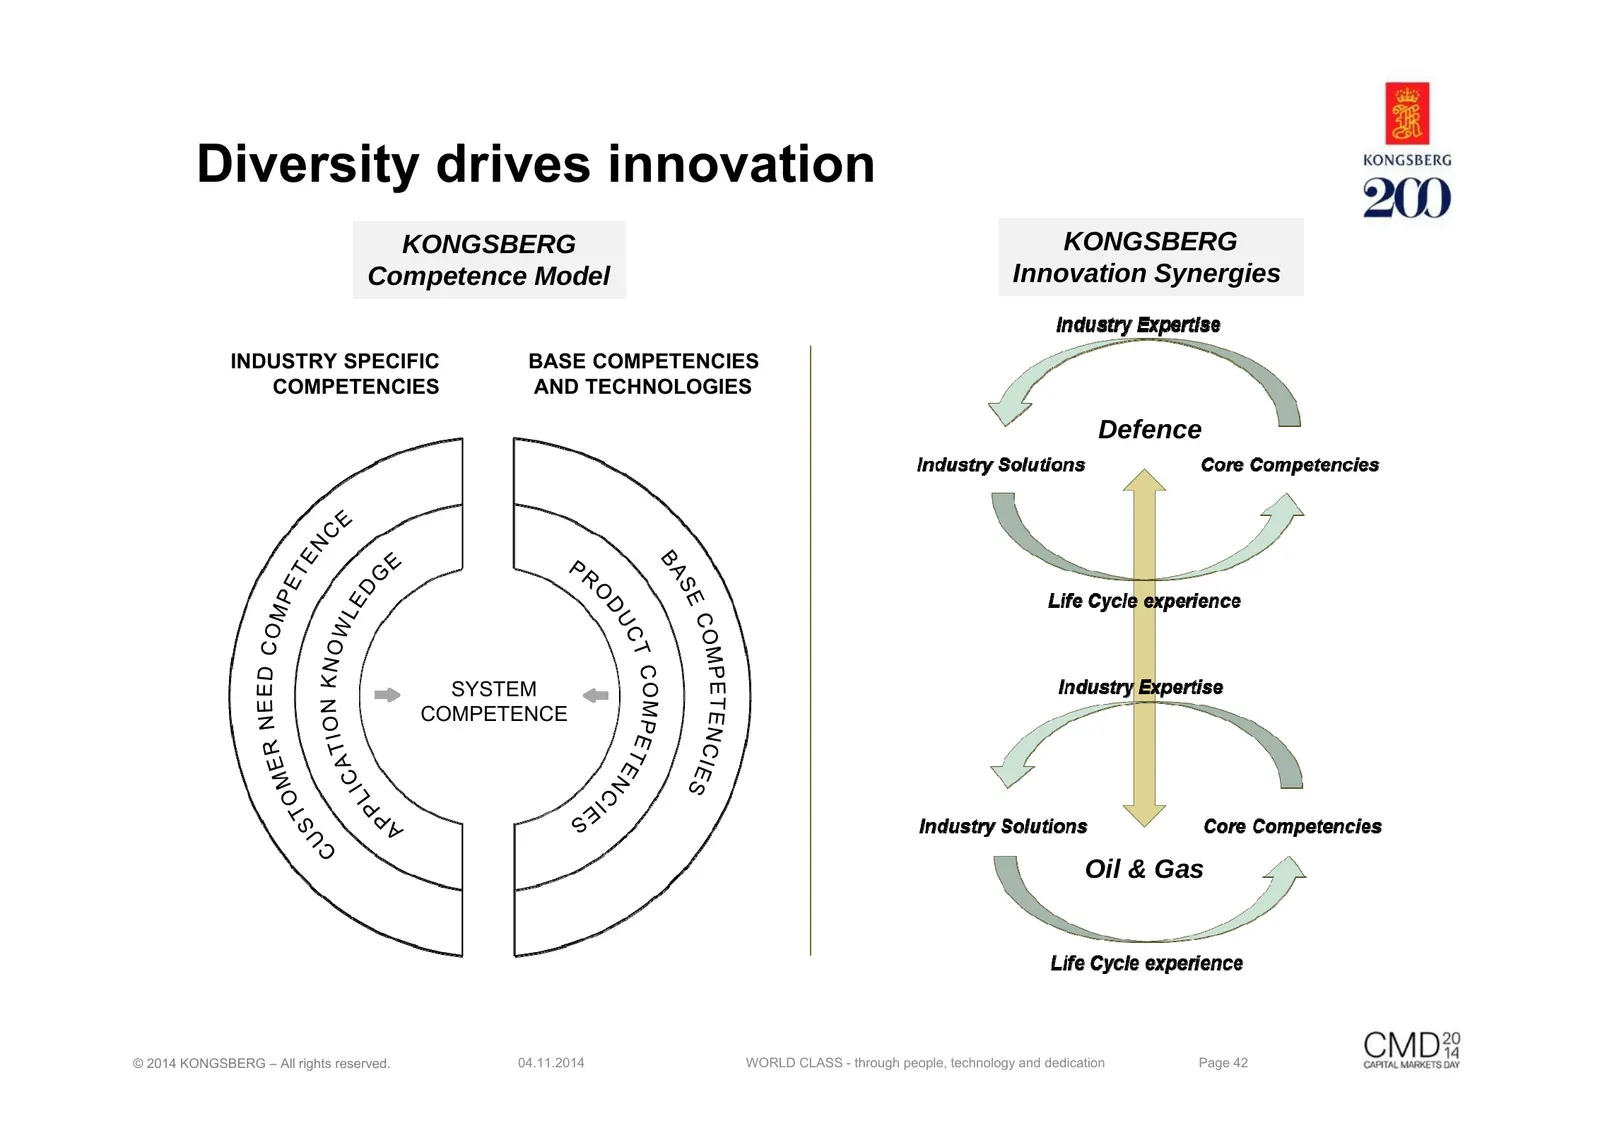
Diversity drives innovation KONGSBERG KONGSBERG Competence Model Innovation Synergies INDUSTRY SPECIFIC BASE COMPETENCIES COMPETENCIES AND TECHNOLOGIES Defence SYSTEM COMPETENCE Oil & Gas © 2014 KONGSBERG – All rights reserved. 04.11.2014 WORLD CLASS - through people, technology and dedication Page
Slide 43: Merchant Marine, Offshore and Oil & Gas
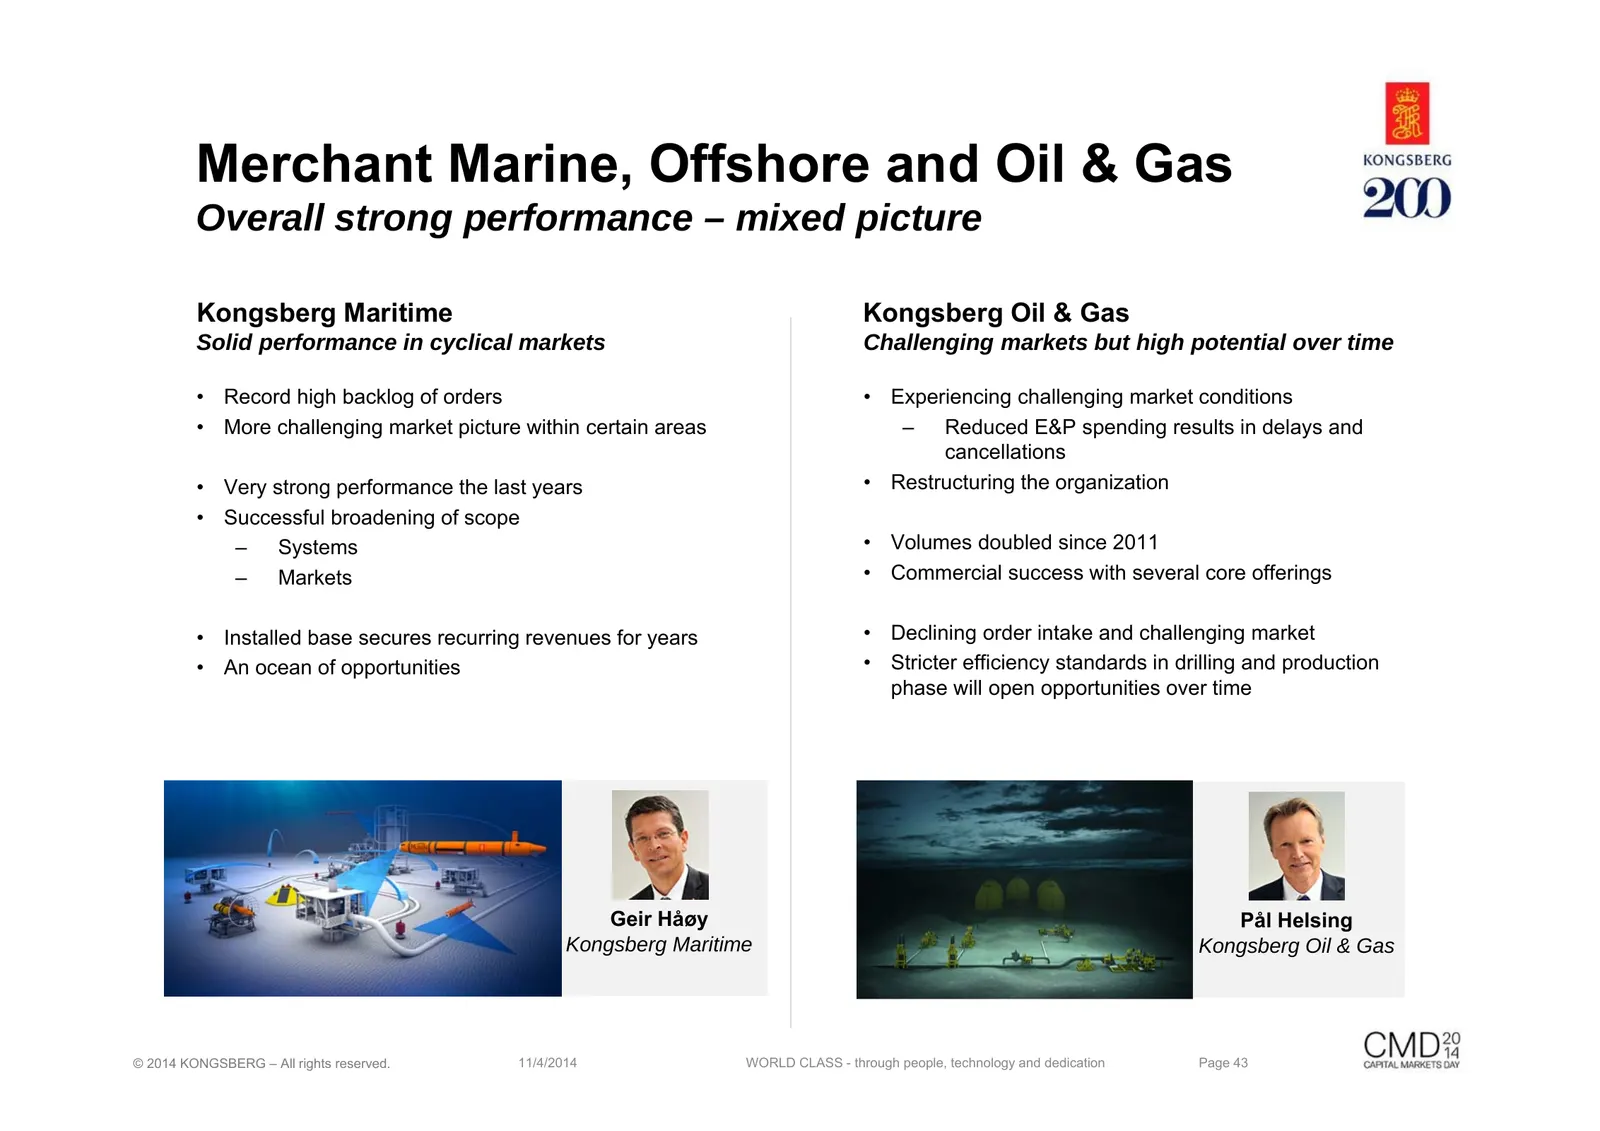
Merchant Marine, Offshore and Oil & Gas Overall strong performance – mixed picture Kongsberg Maritime Kongsberg Oil & Gas Solid performance in cyclical markets Challenging markets but high potential over time • Record high backlog of orders • Experiencing challenging market conditions • More challen
Slide 44: Defence
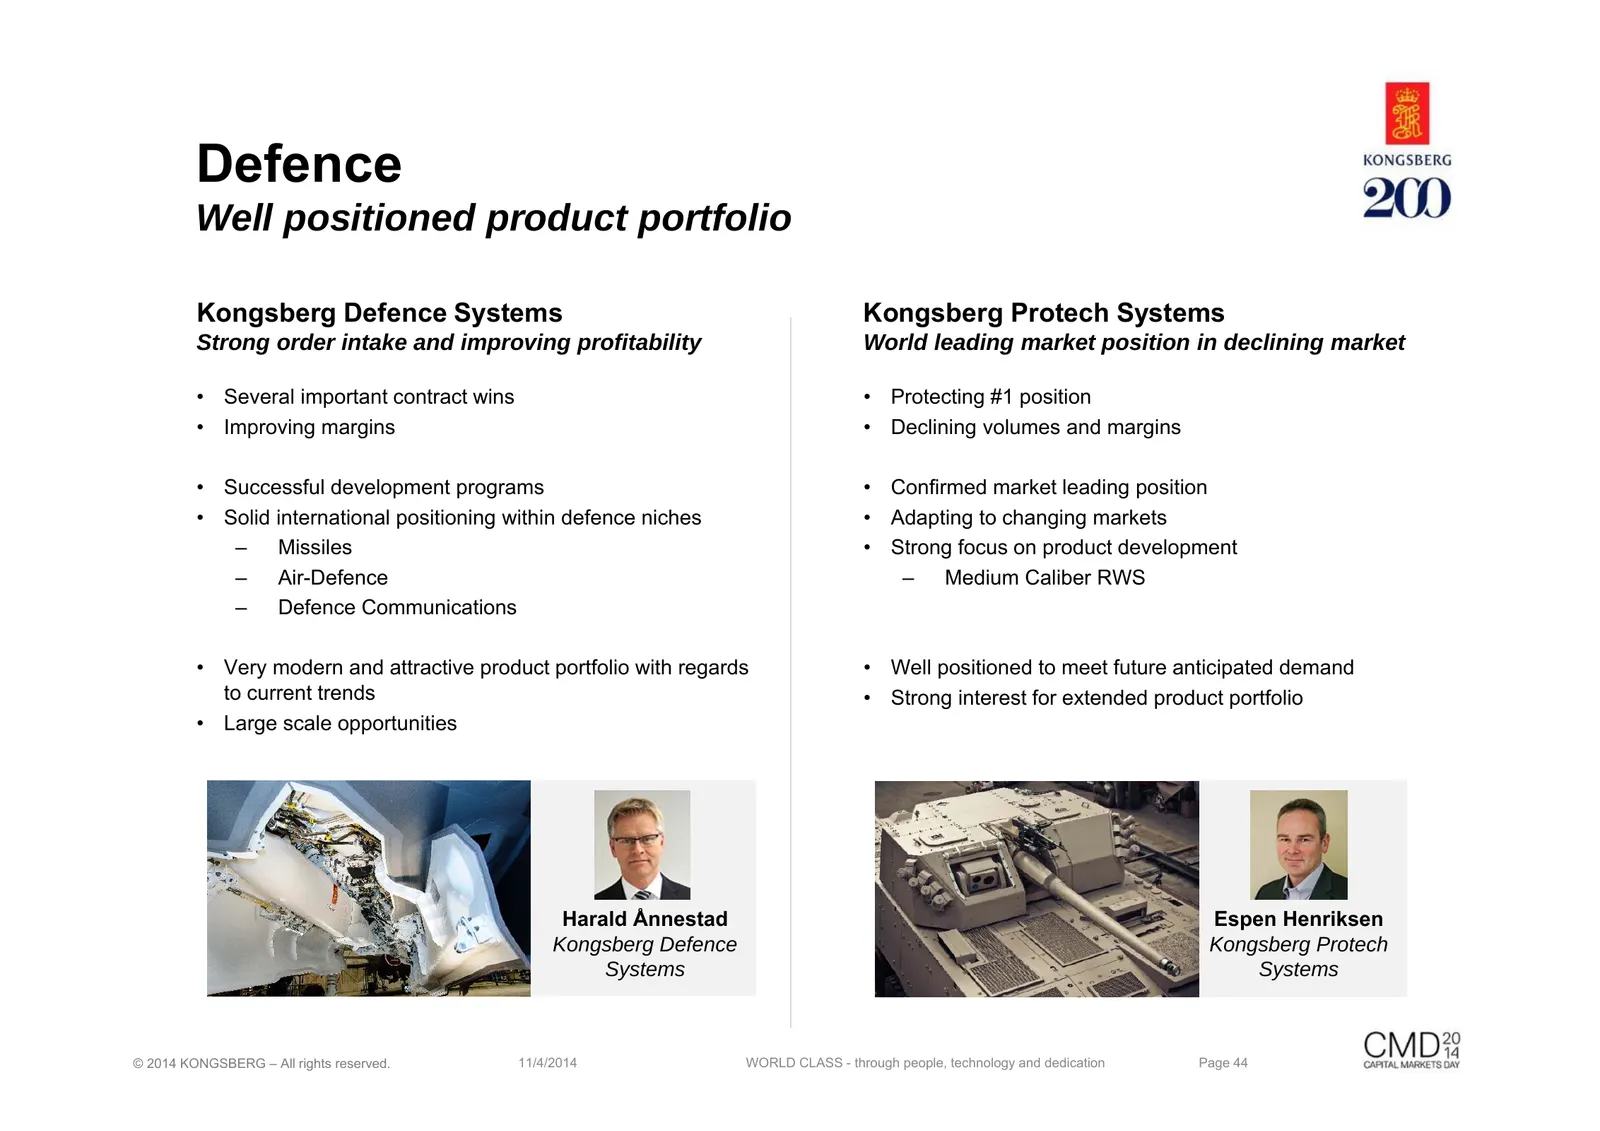
Defence Well positioned product portfolio Kongsberg Defence Systems Kongsberg Protech Systems Strong order intake and improving profitability World leading market position in declining market • Several important contract wins • Protecting #1 position • Improving margins • Declining volumes and margi
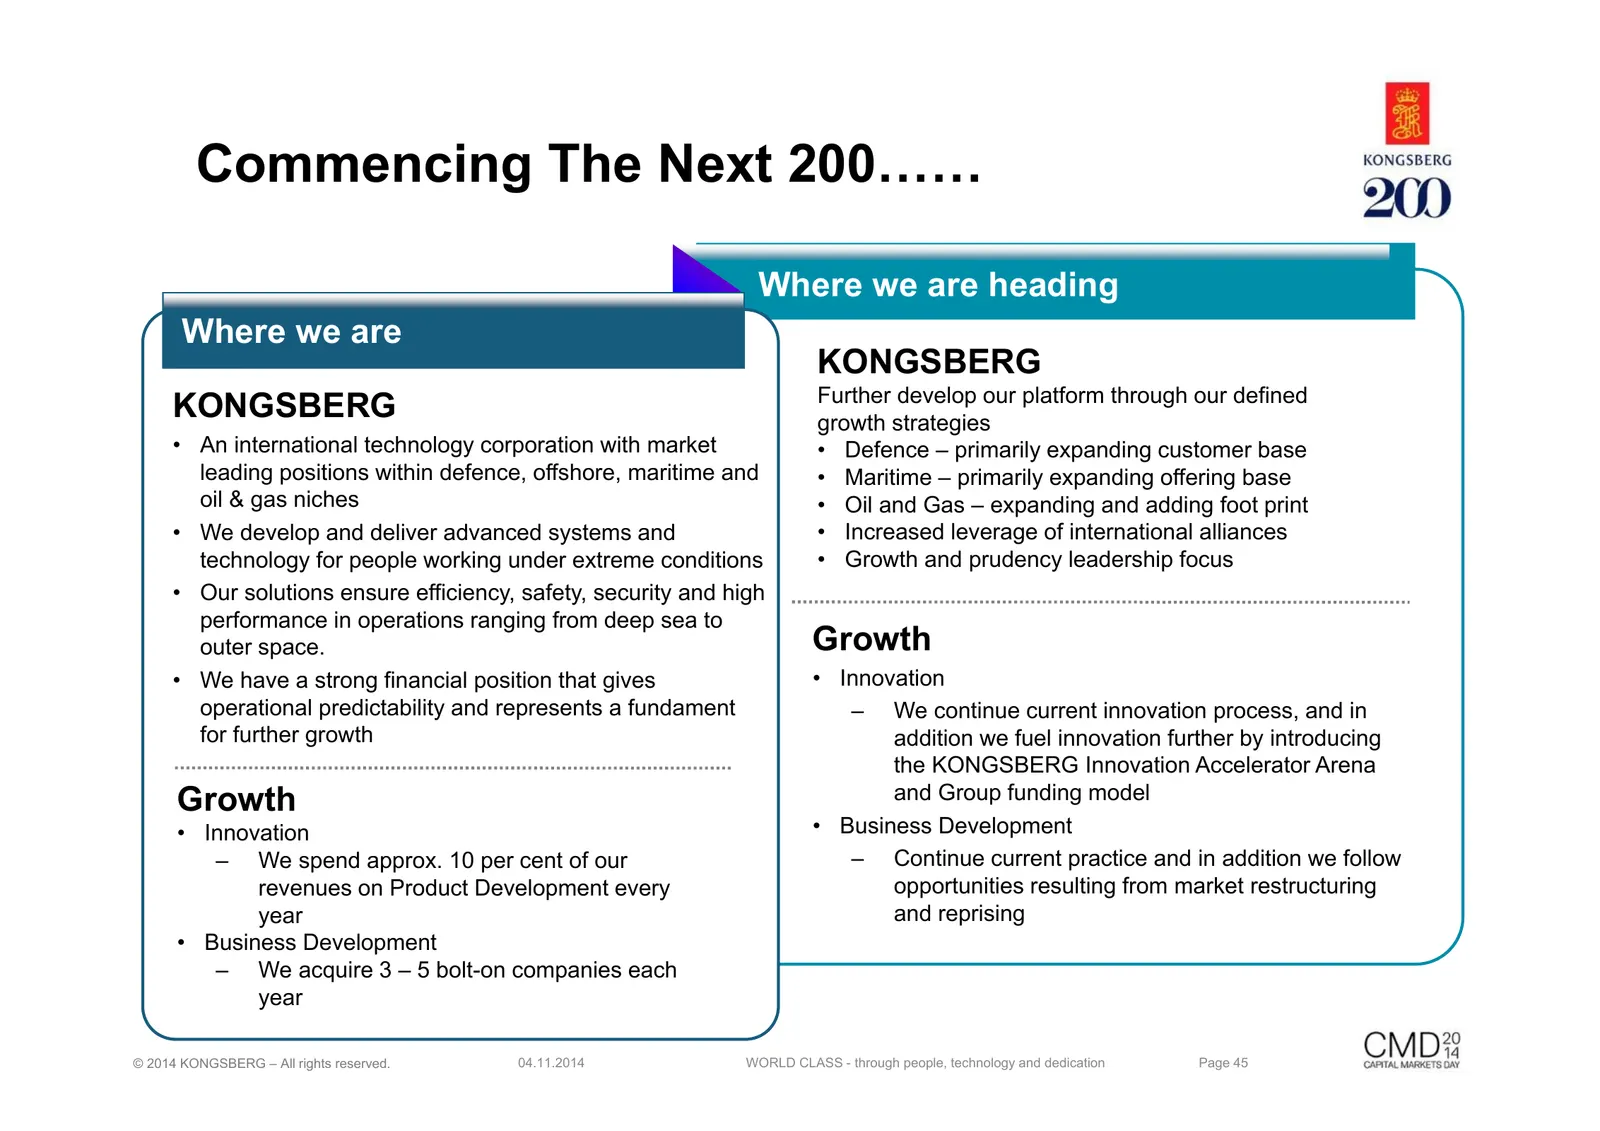
Slide 45: Commencing The Next 200
Commencing The Next 200…… Where we are heading Where we are KONGSBERG Further develop our platform through our defined KONGSBERG growth strategies • An international technology corporation with market • Defence – primarily expanding customer base leading positions within defence, offshore, maritime
Slide 46: kongsberg.com
KONGSBERG € fe} S > oO a a D Cc fe} a4
Source: company website
More decks from Kongsberg Gruppen ASA
 Q3 2026 Earnings Presentation36 slides · October 2026
 Kongsberg — Q3 2026 Earnings Presentation16 slides · October 2026
 Q2 2026 Earnings Presentation17 slides · Jul 13, 2026
 Q2 2026 Earnings Presentation32 slides · Jul 12, 2026
 Q1 2026 Earnings Presentation29 slides · May 6, 2026
 Q1 2026 Earnings Presentation28 slides · May 2026