Emaar Properties (P.J.S.C) · DFM:EMAAR
Emaar Properties (P.J.S.C) — Emaar Malls PJSC — Q3 2017 Earnings Presentation
25 slides from Emaar Properties (P.J.S.C)'s earnings presentation, Nov 15, 2017
Slide 1: Emaar Malls PJSC Q3 2017 Results
EMAAR MALLS PJSC Q3 2017 RESULTS 15 November 2017
Slide 2: Disclaimer
DISCLAIMER Emaar Malls PJSC (EM) gives notice that: The particulars of this presentation do not constitute any part of an offer or a contract. Given that the presentation contains information based on forecasts and roll outs, all statements contained in this presentation are made without responsibil
Slide 3: Table of Contents
TABLE OF CONTENTS EMAAR MALLS AT A GLANCE 4 HIGHLIGHTS 5 VISION AND STRATEGY 6 EMAAR MALLS < Financial results 7 < Rental income 8 < Portfolio results 9 < Portfolio 10 < Key strengths 11 < Lease renewal status 13 NAMSHI < Namshi at a glance 15 < Key performance indicators 16 UPCOMMING PROJECTS < Dev
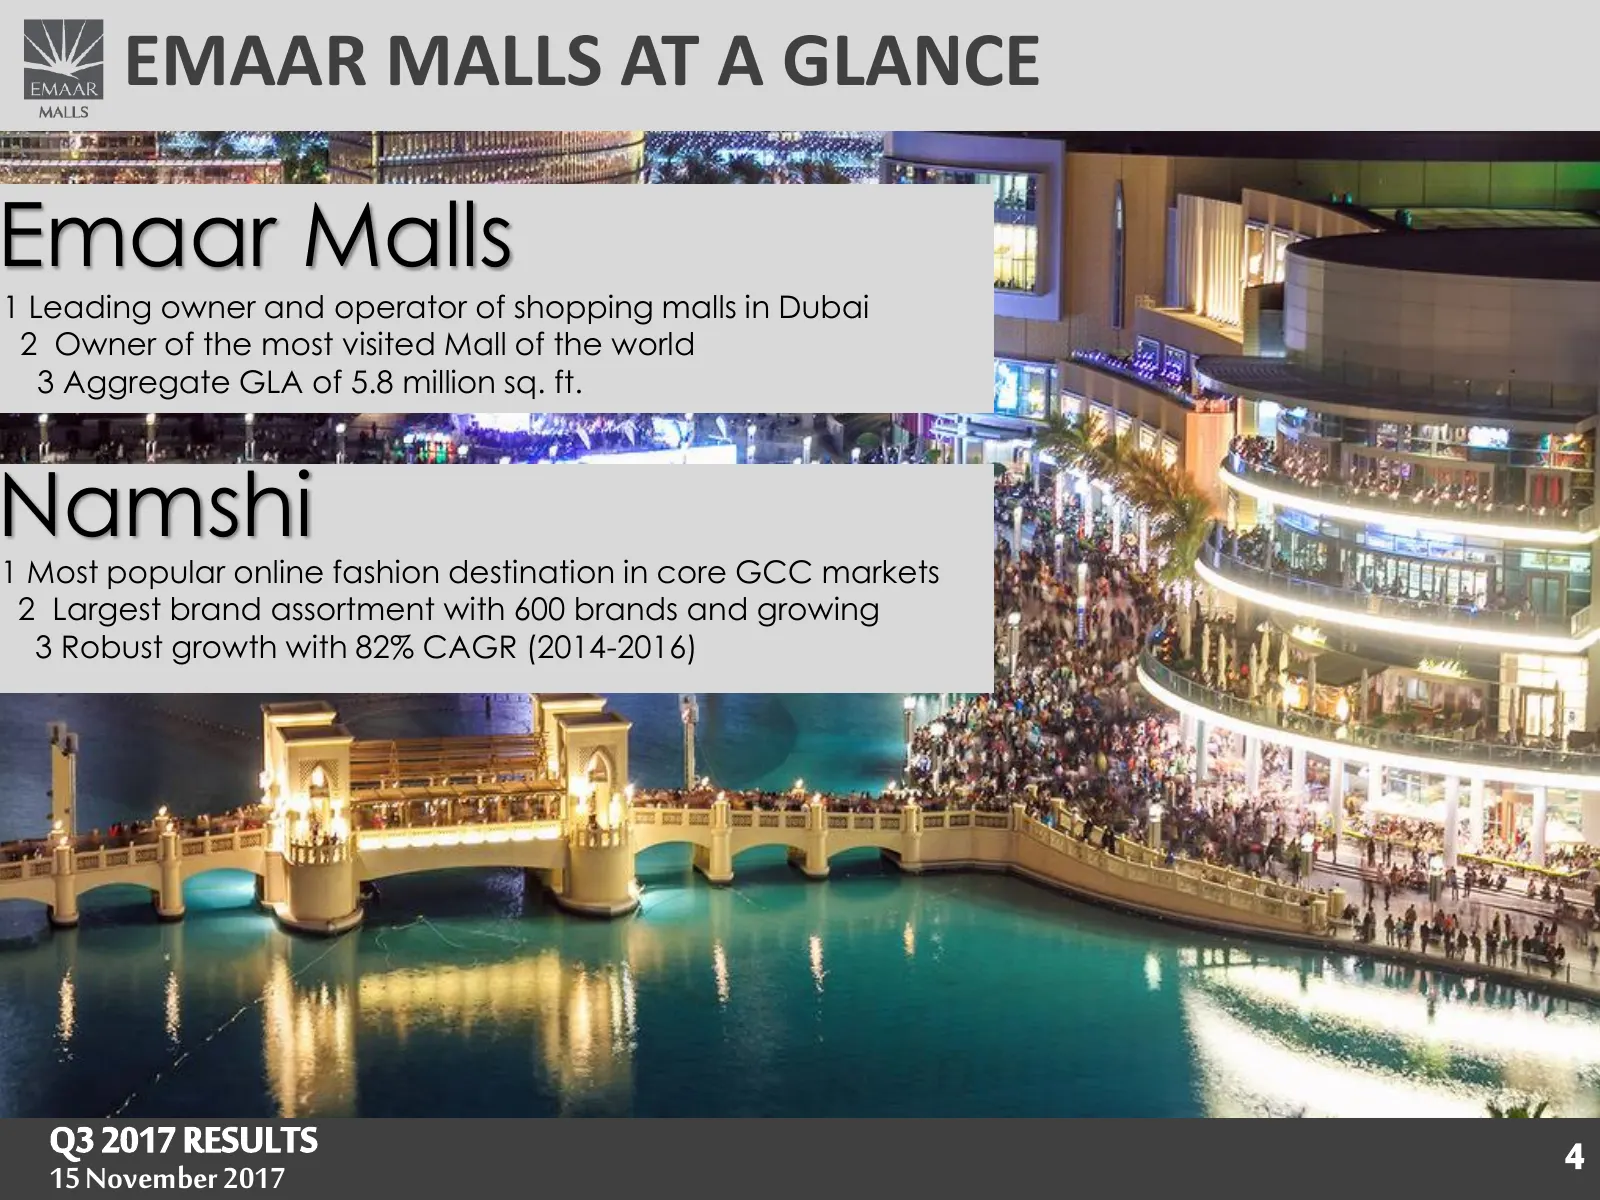
Slide 4: Emaar Malls at a Glance
EMAAR MALLS AT A GLANCE Emaar Malls 1 Leading owner and operator of shopping malls in Dubai 2 Owner of the most visited Mall of the world 3 Aggregate GLA of 5.8 million sq. ft. Namshi 1 Most popular online fashion destination in core GCC markets 2 Largest brand assortment with 600 brands and growing
Slide 5: Highlights
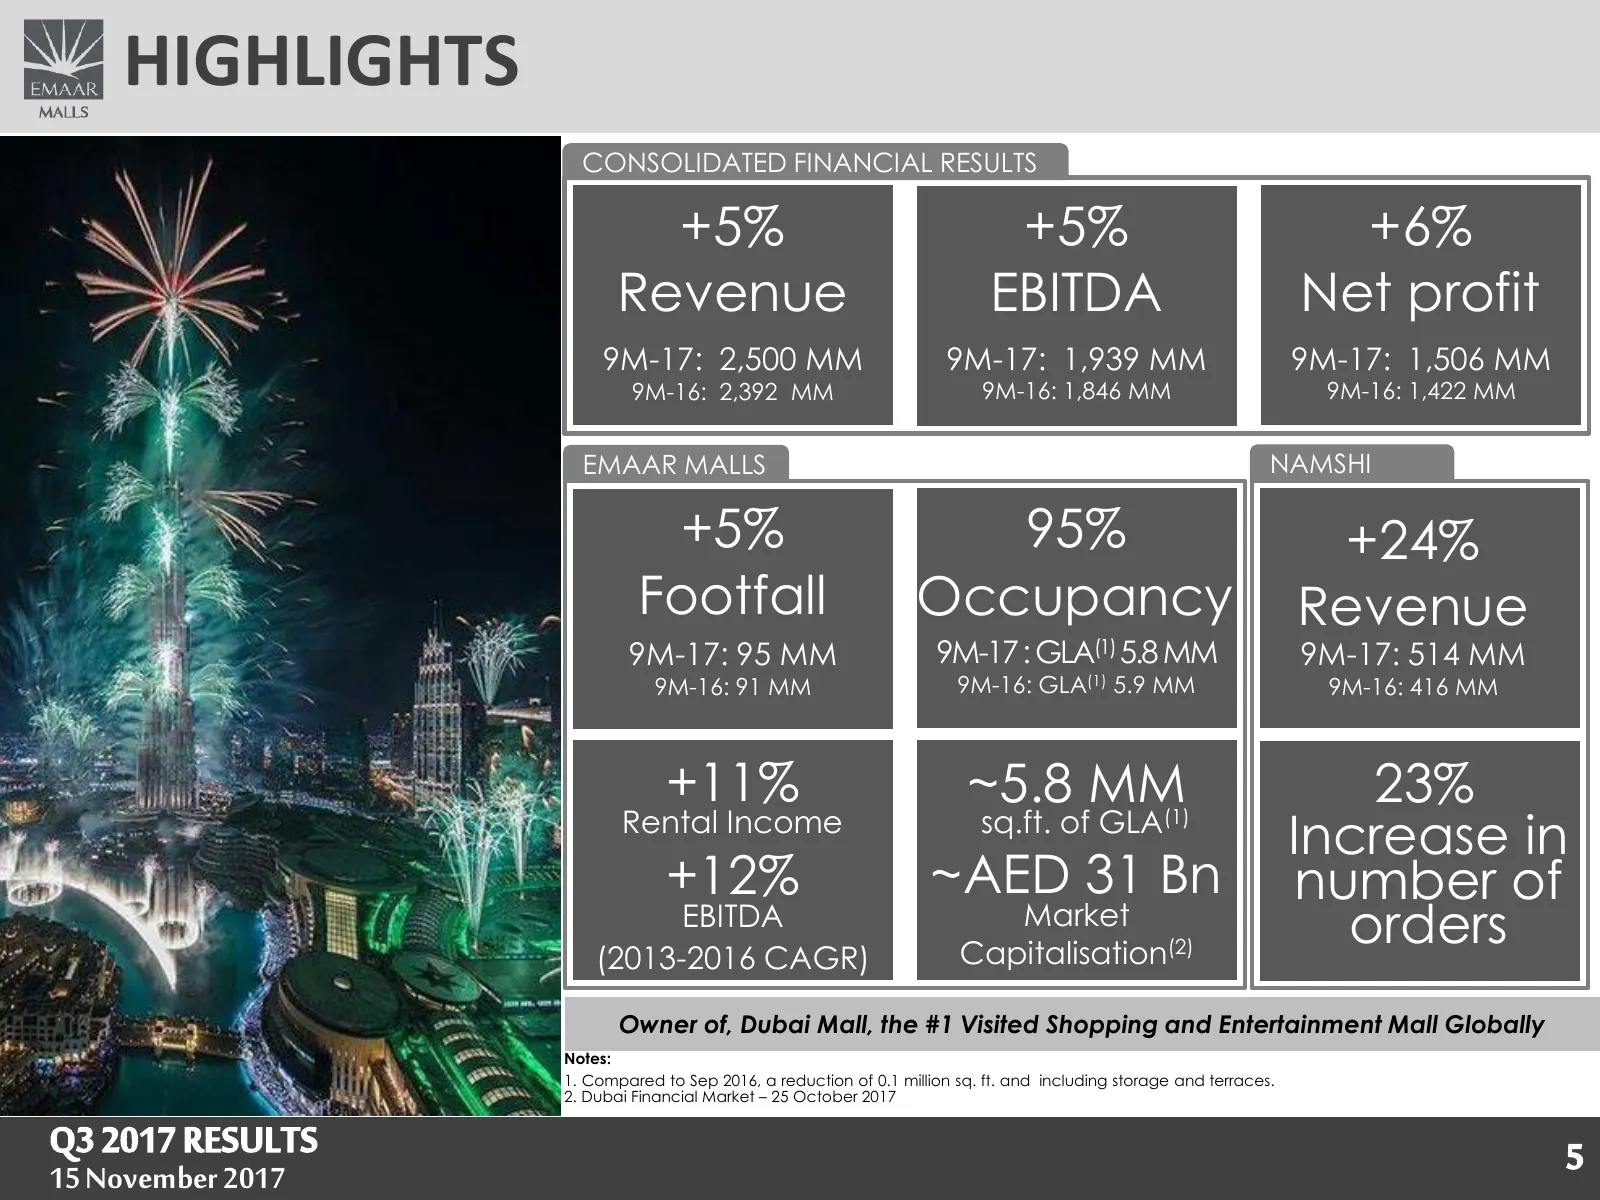
HIGHLIGHTS CONSOLIDATED FINANCIALFINANCIAL CONSOLIDATED RESULTS RESULTS +5% +5% +6% Revenue EBITDA Net profit 9M-17: 2,500 MM 9M-17: 1,939 MM 9M-17: 1,506 MM 9M-16: 2,392 MM 9M-16: 1,846 MM 9M-16: 1,422 MM EMAAR MALLS NAMSHI +5% 95% +24% Footfall Occupancy Revenue 9M-17: 95 MM 9M-17 : GLA(1) 5.8 MM
Slide 6: Vision and Strategy
OUR VISION To create world class malls delivering memorable experiences 12 Protect and Grow Portfolio in Local Market Strategy Expand Internationally 3 Innovate and Lead Transition to Next Generation Mall Q3 2017 RESULTS 66 15 November 2017
Slide 7: Financial Results Malls
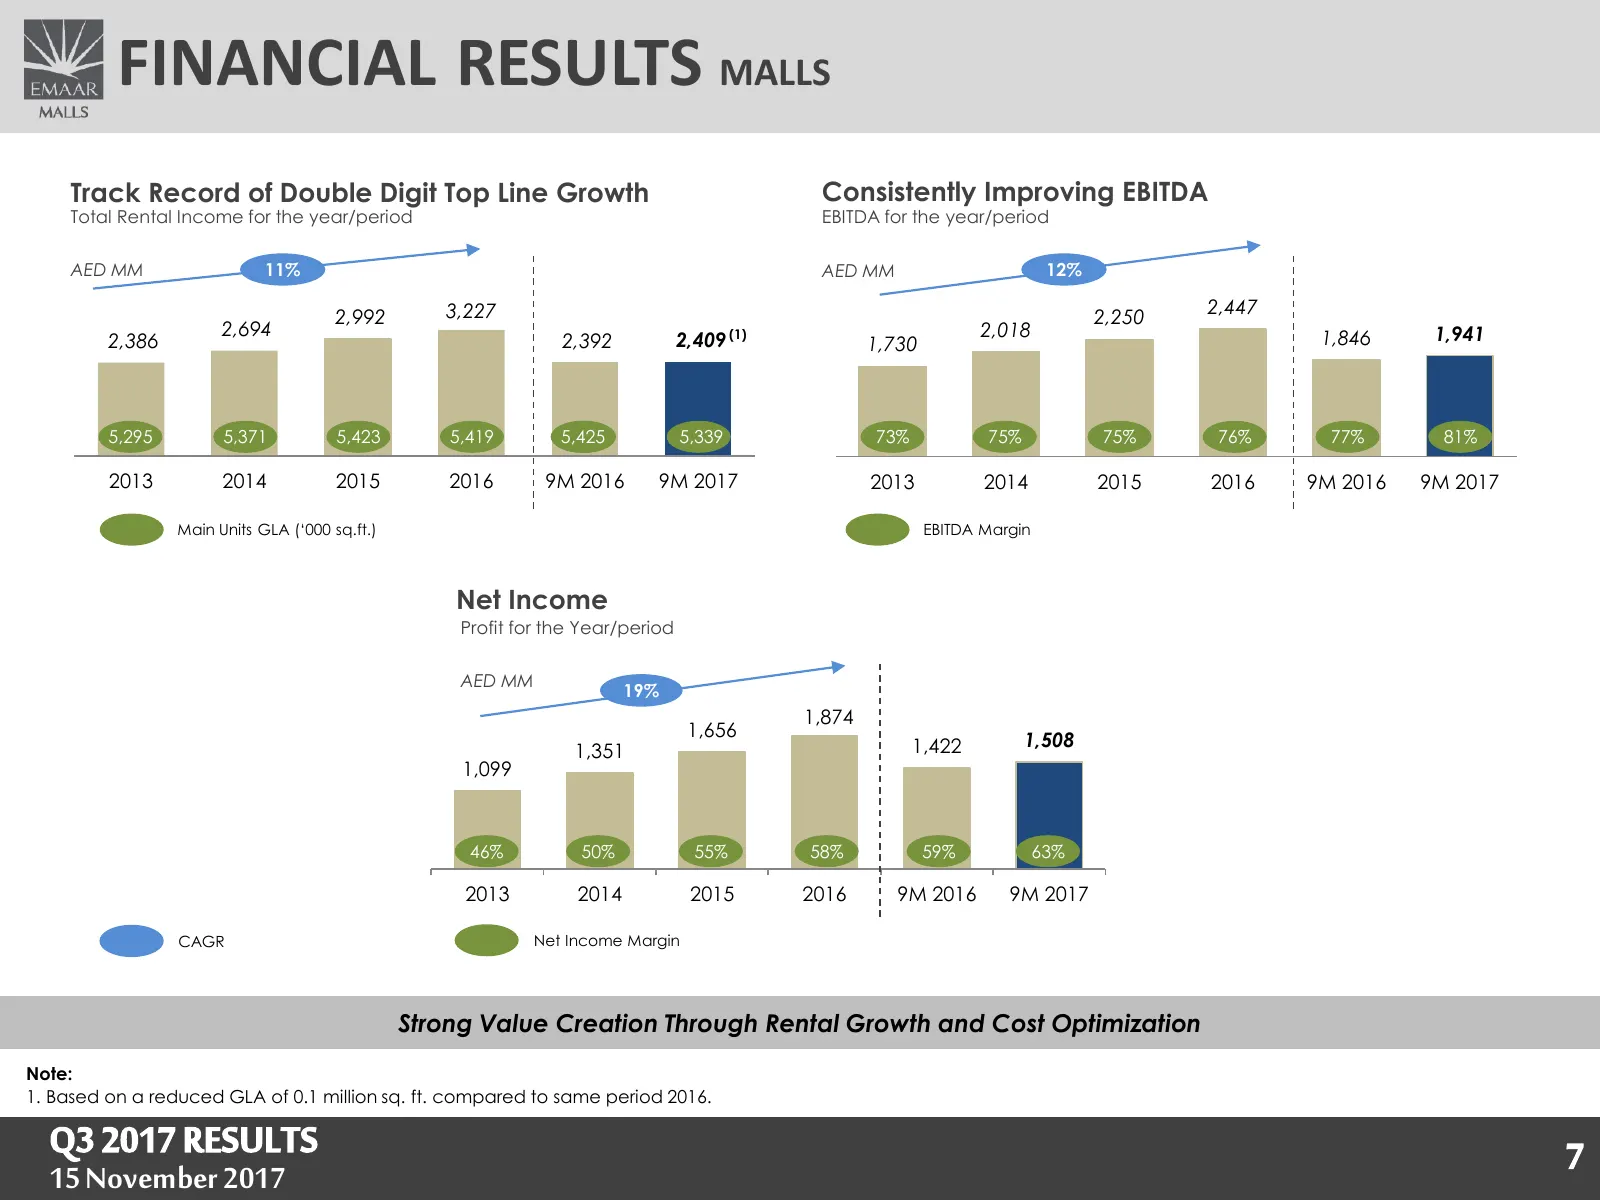
FINANCIAL RESULTS MALLS Track Record of Double Digit Top Line Growth Consistently Improving EBITDA Total Rental Income for the year/period EBITDA for the year/period AED MM 11% AED MM 12% 3,227 2,447 2,992 2,250 2,694 (1) 2,018 1,846 1,941 2,386 2,392 2,409 1,730 5,295 5,371 5,423 5,419 5,425 5,339
Slide 8: Rental Income Malls
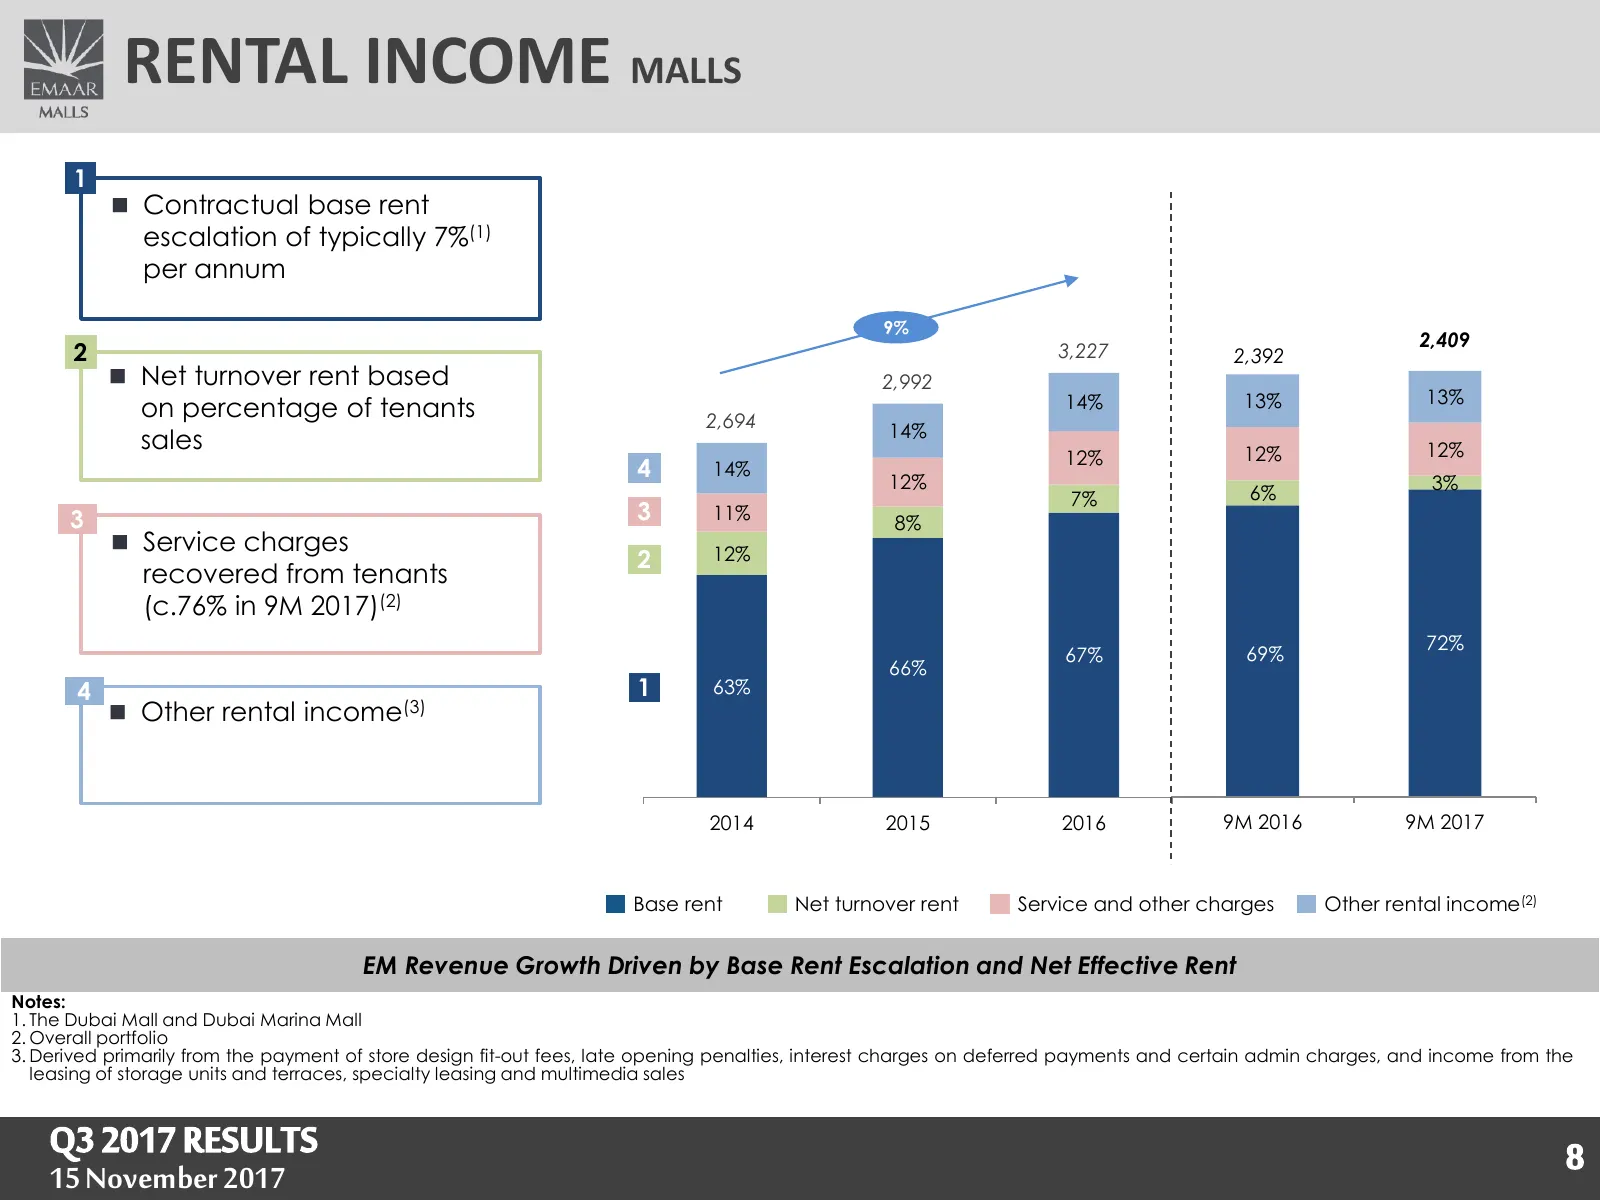
RENTAL INCOME MALLS 1 Contractual base rent escalation of typically 7%(1) per annum 9% 2,409 2 3,227 2,392 Net turnover rent based 2,992 14% 13% 13% on percentage of tenants 2,694 14% sales 12% 12% 12% 4 14% 12% 3% 7% 6% 3 3 11% 8% Service charges 12% 2 recovered from tenants (c.76% in 9M 2017
Slide 9: Portfolio Results Malls
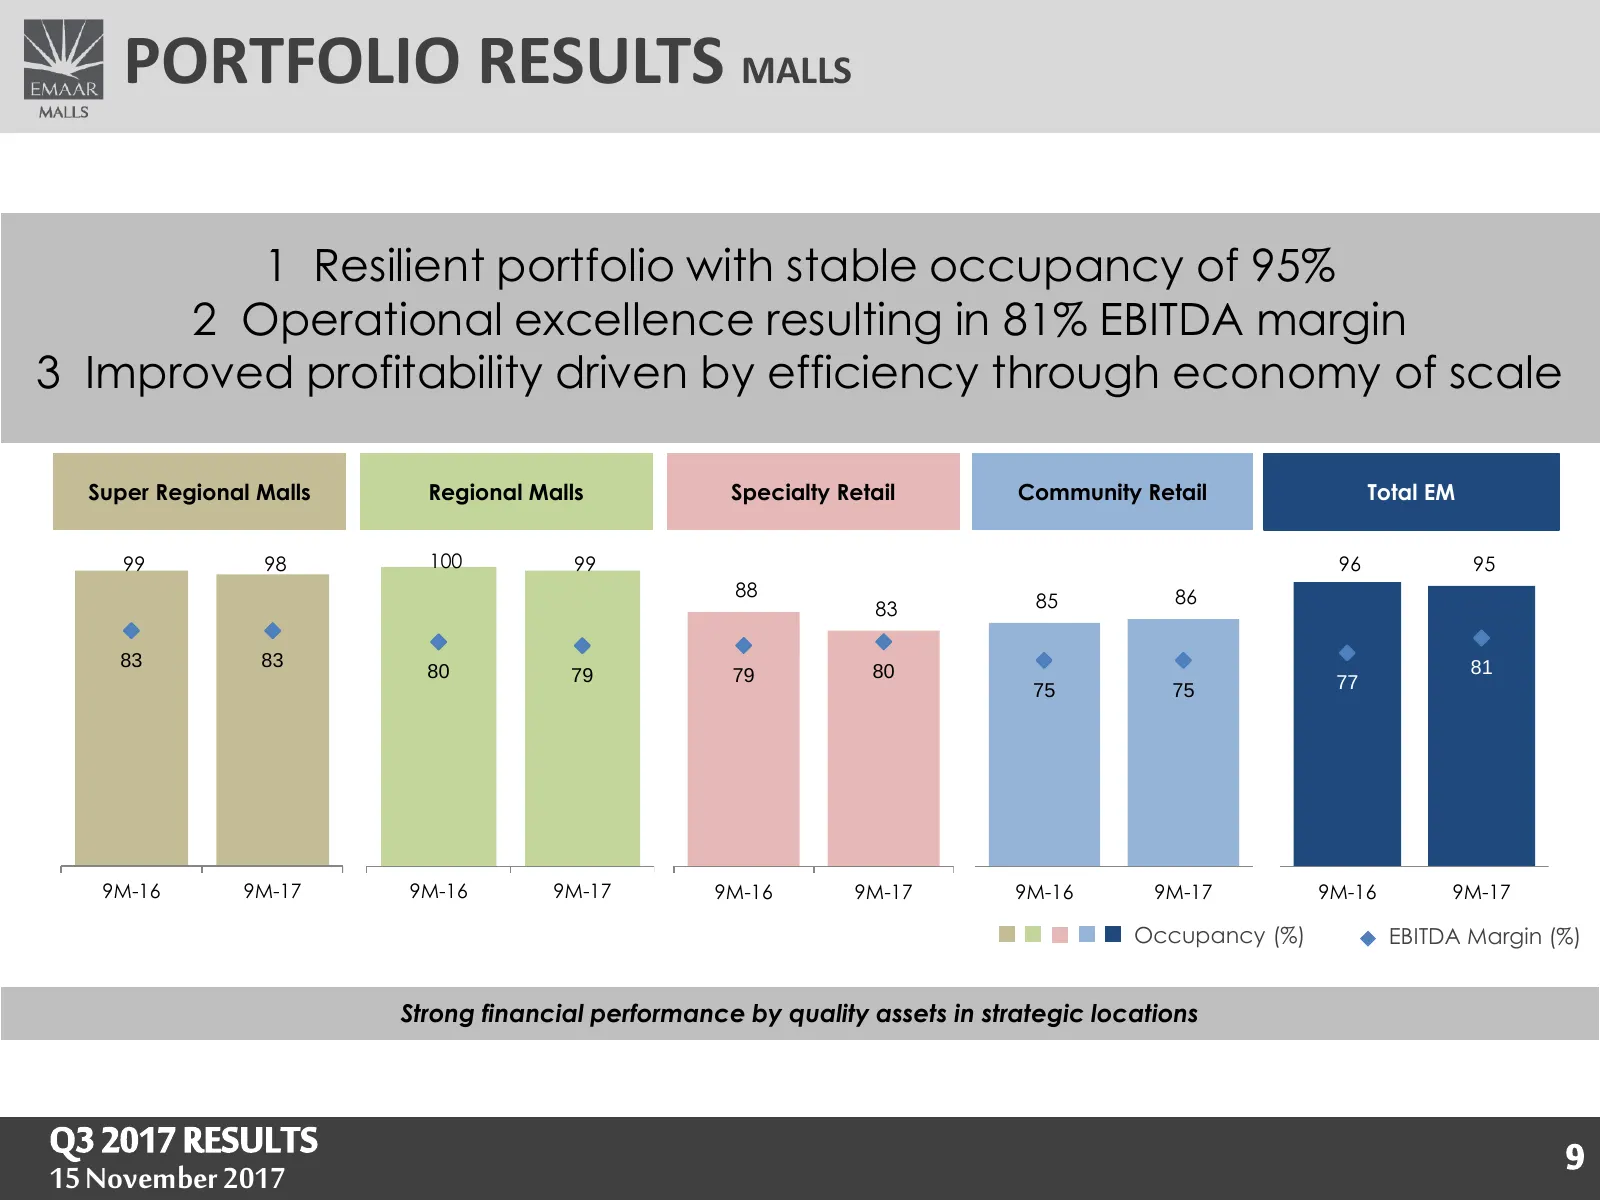
PORTFOLIO RESULTS MALLS 1 Resilient portfolio with stable occupancy of 95% 2 Operational excellence resulting in 81% EBITDA margin 3 Improved profitability driven by efficiency through economy of scale Super Regional Malls Regional Malls Specialty Retail Community Retail Total EM 99 98 100 99 96 95
Slide 10: Portfolio Malls
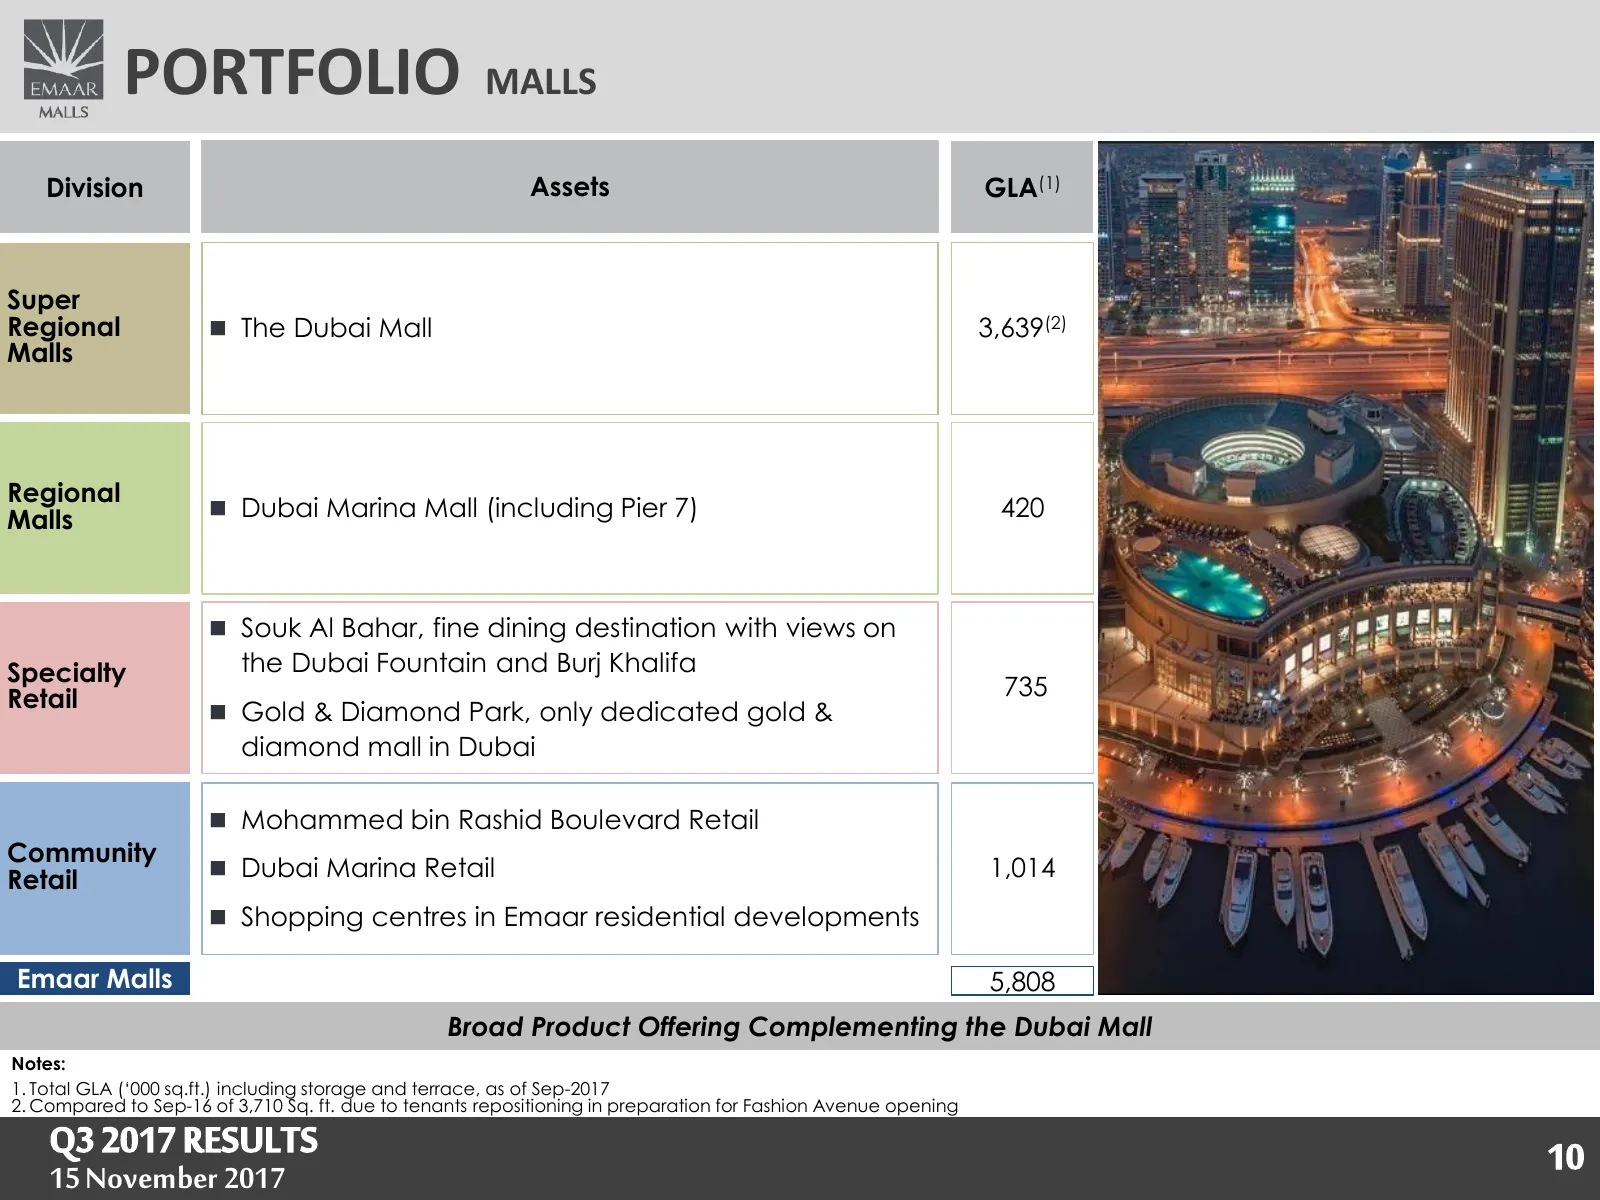
PORTFOLIO MALLS Division Assets GLA(1) Super Regional The Dubai Mall 3,639(2) Malls Regional Malls Dubai Marina Mall (including Pier 7) 420 Souk Al Bahar, fine dining destination with views on Specialty the Dubai Fountain and Burj Khalifa Retail 735 Gold & Diamond Park, only dedicated gold &
Slide 11: Key Strengths Malls
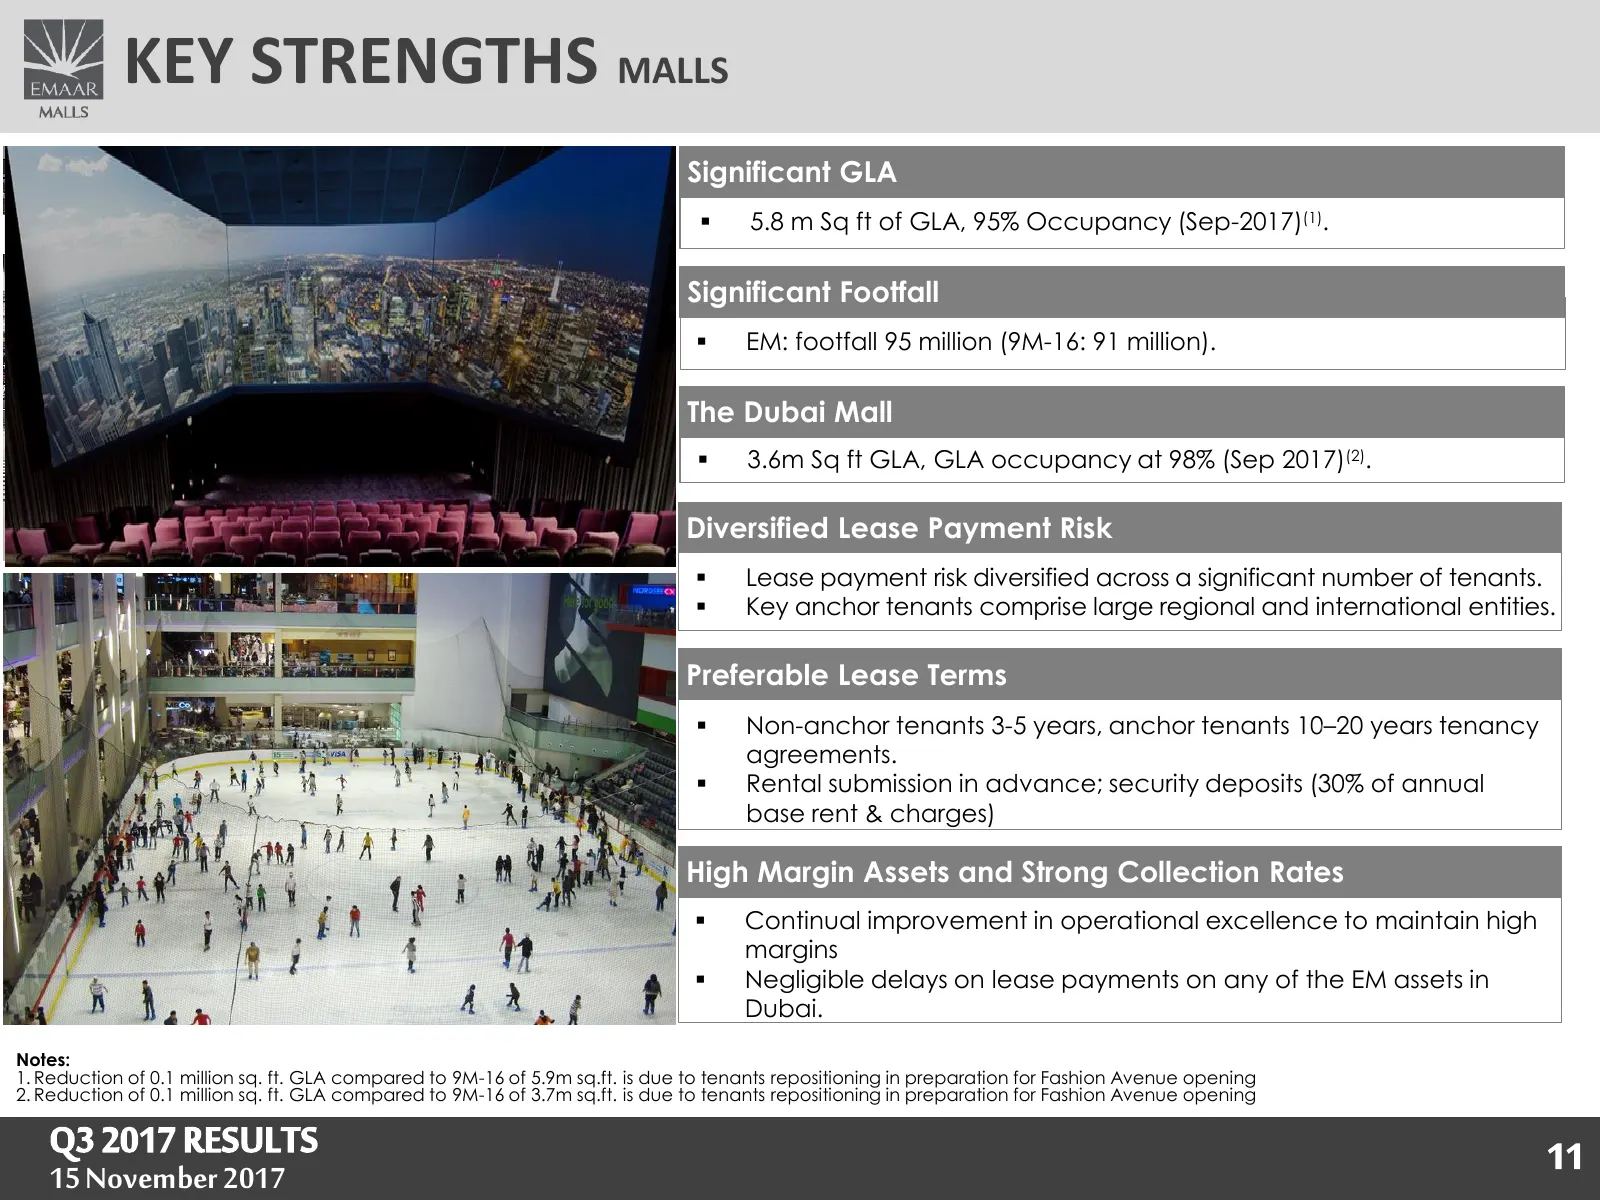
KEY STRENGTHS MALLS Significant GLA 5.8 m Sq ft of GLA, 95% Occupancy (Sep-2017)(1). Significant Footfall EM: footfall 95 million (9M-16: 91 million). The Dubai Mall 3.6m Sq ft GLA, GLA occupancy at 98% (Sep 2017)(2). Diversified Lease Payment Risk Lease payment risk diversified across a sig
Slide 12: Key Strengths (cont'd) Malls
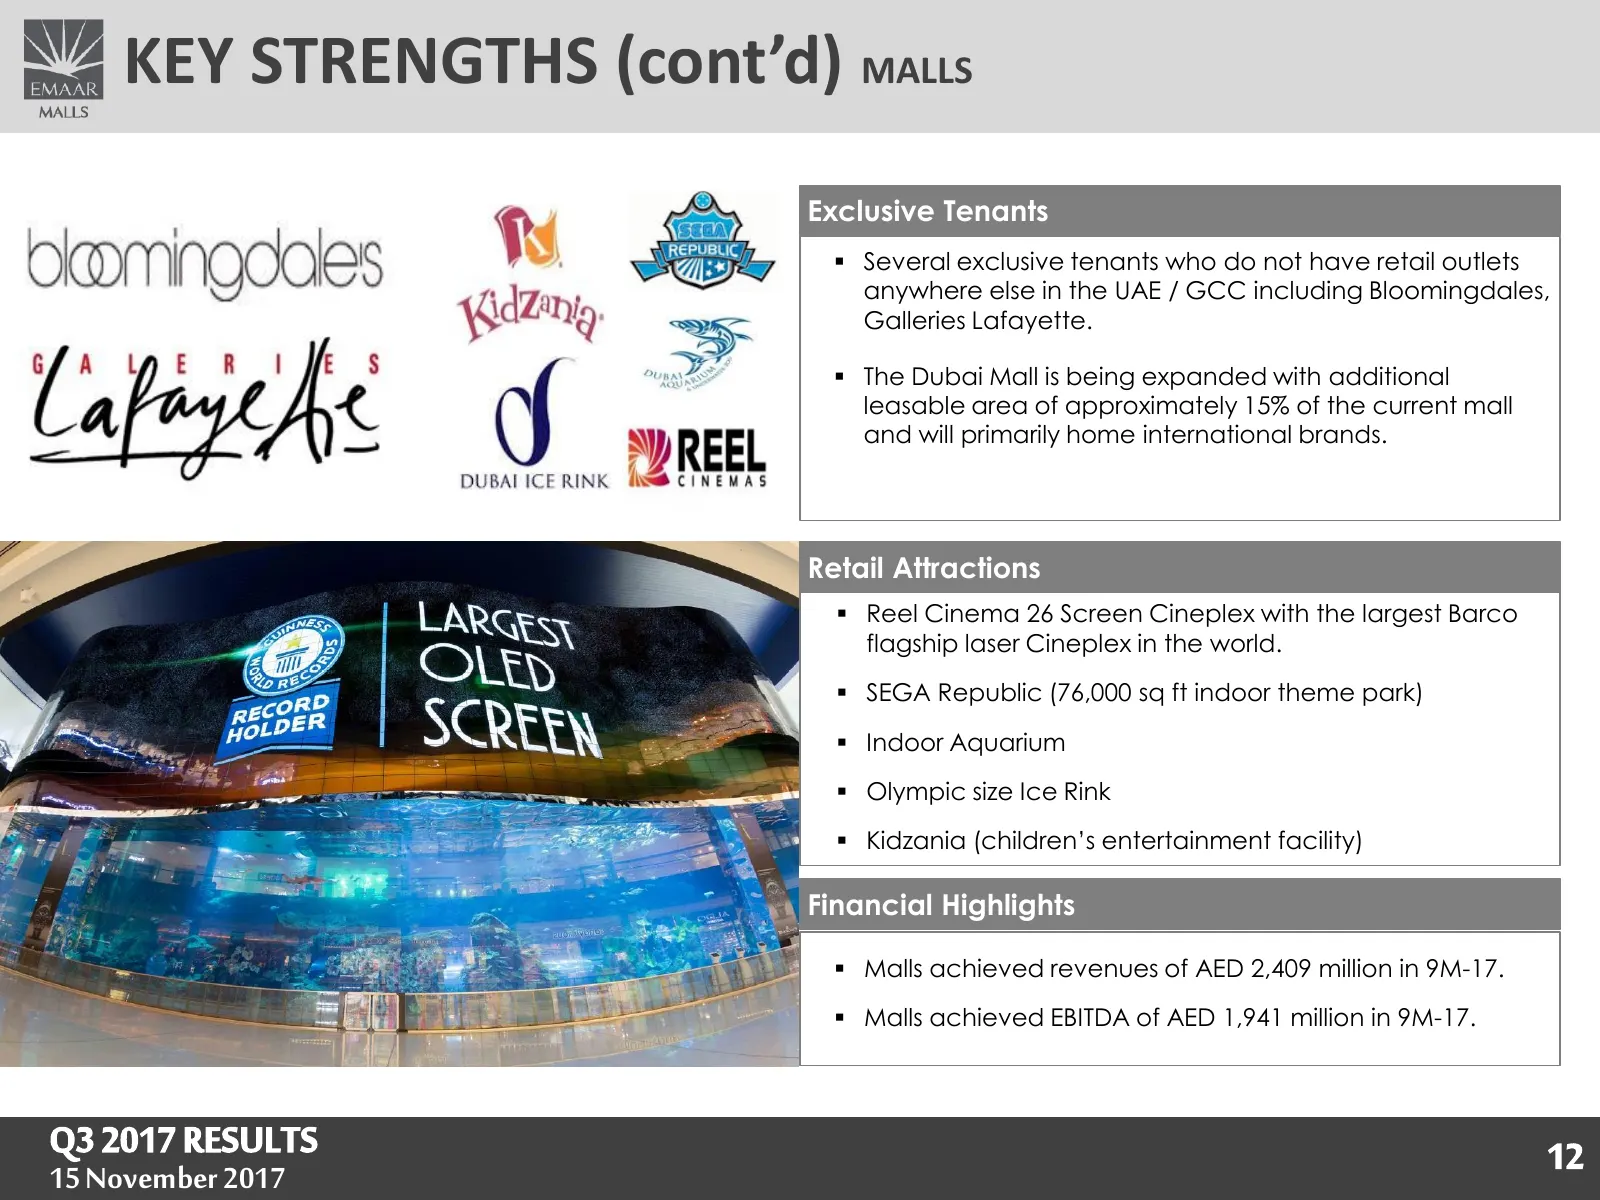
KEY STRENGTHS (cont’d) MALLS Exclusive Tenants Several exclusive tenants who do not have retail outlets anywhere else in the UAE / GCC including Bloomingdales, Galleries Lafayette. The Dubai Mall is being expanded with additional leasable area of approximately 15% of the current mall and will pr
Slide 13: Lease Renewal Status Malls
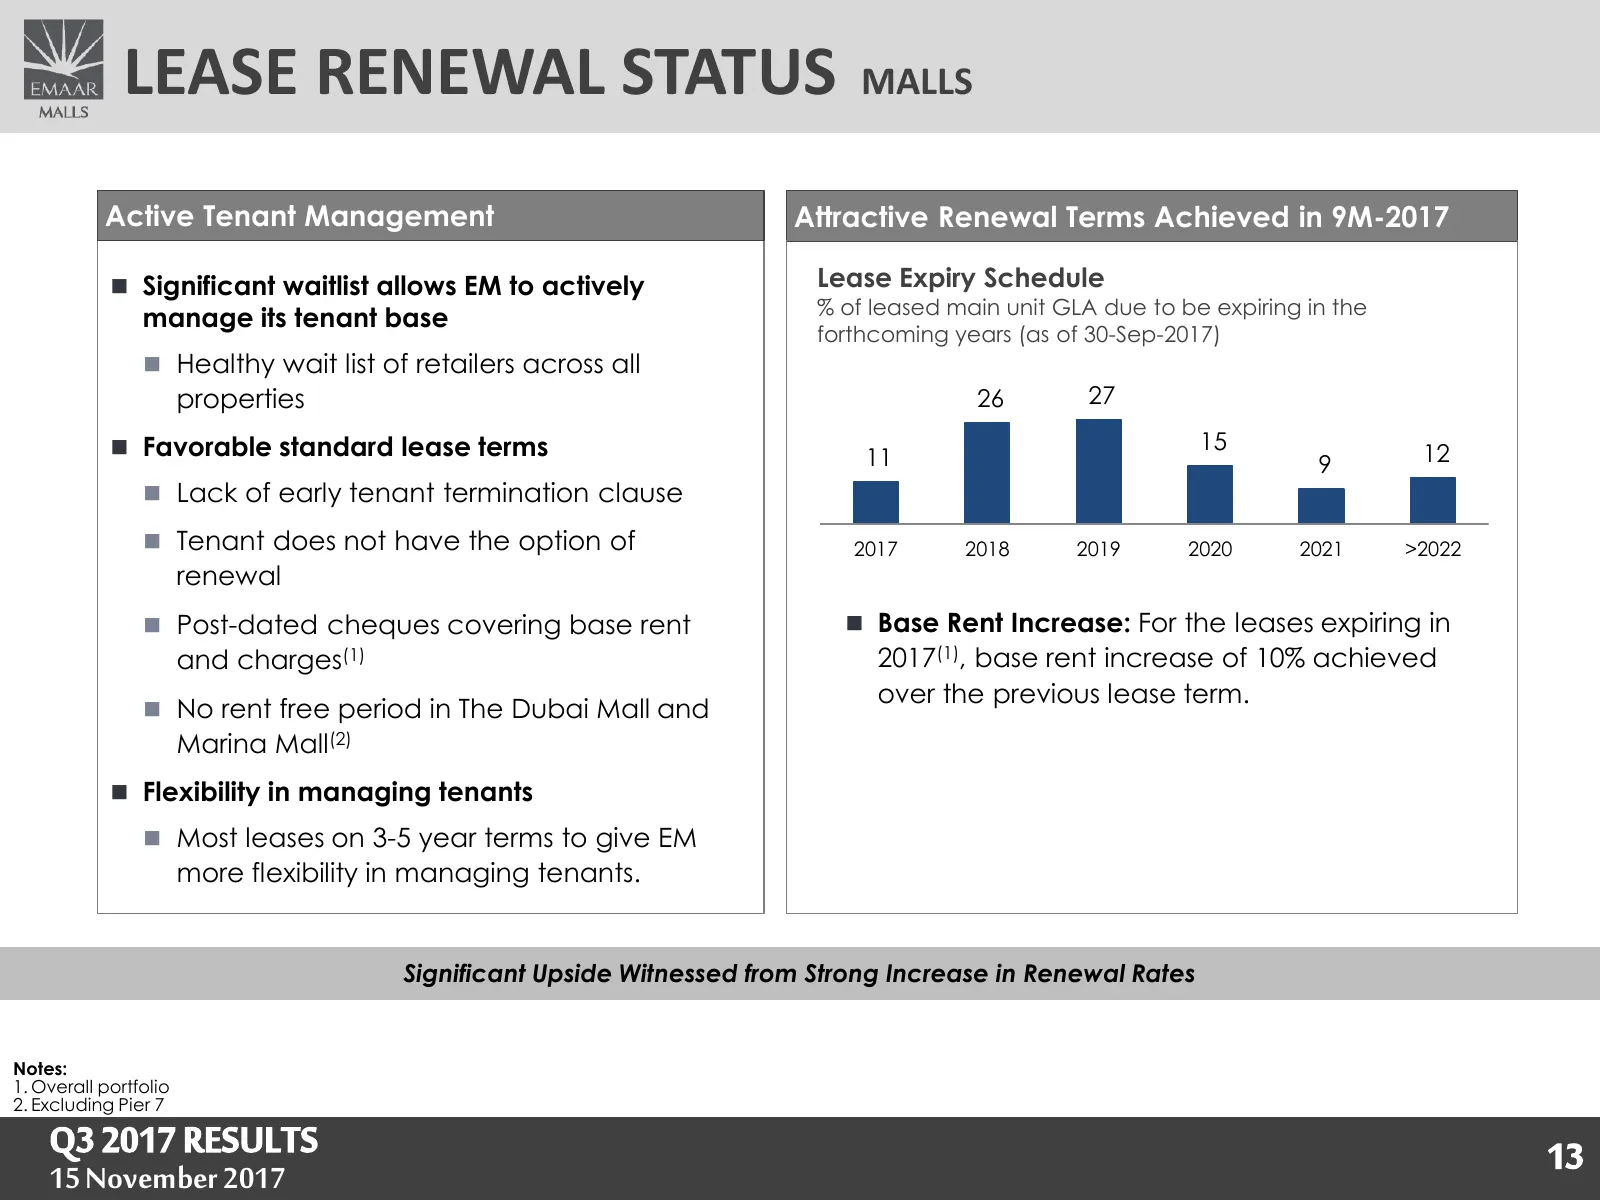
LEASE RENEWAL STATUS MALLS Active Tenant Management Attractive Renewal Terms Achieved in 9M-2017 Significant waitlist allows EM to actively Lease Expiry Schedule % of leased main unit GLA due to be expiring in the manage its tenant base forthcoming years (as of 30-Sep-2017) Healthy wait list of
Slide 14: Namshi
Q3 2017 RESULTS 1414 15 May 18 November 2017 2017
Slide 15: Namshi at a Glance
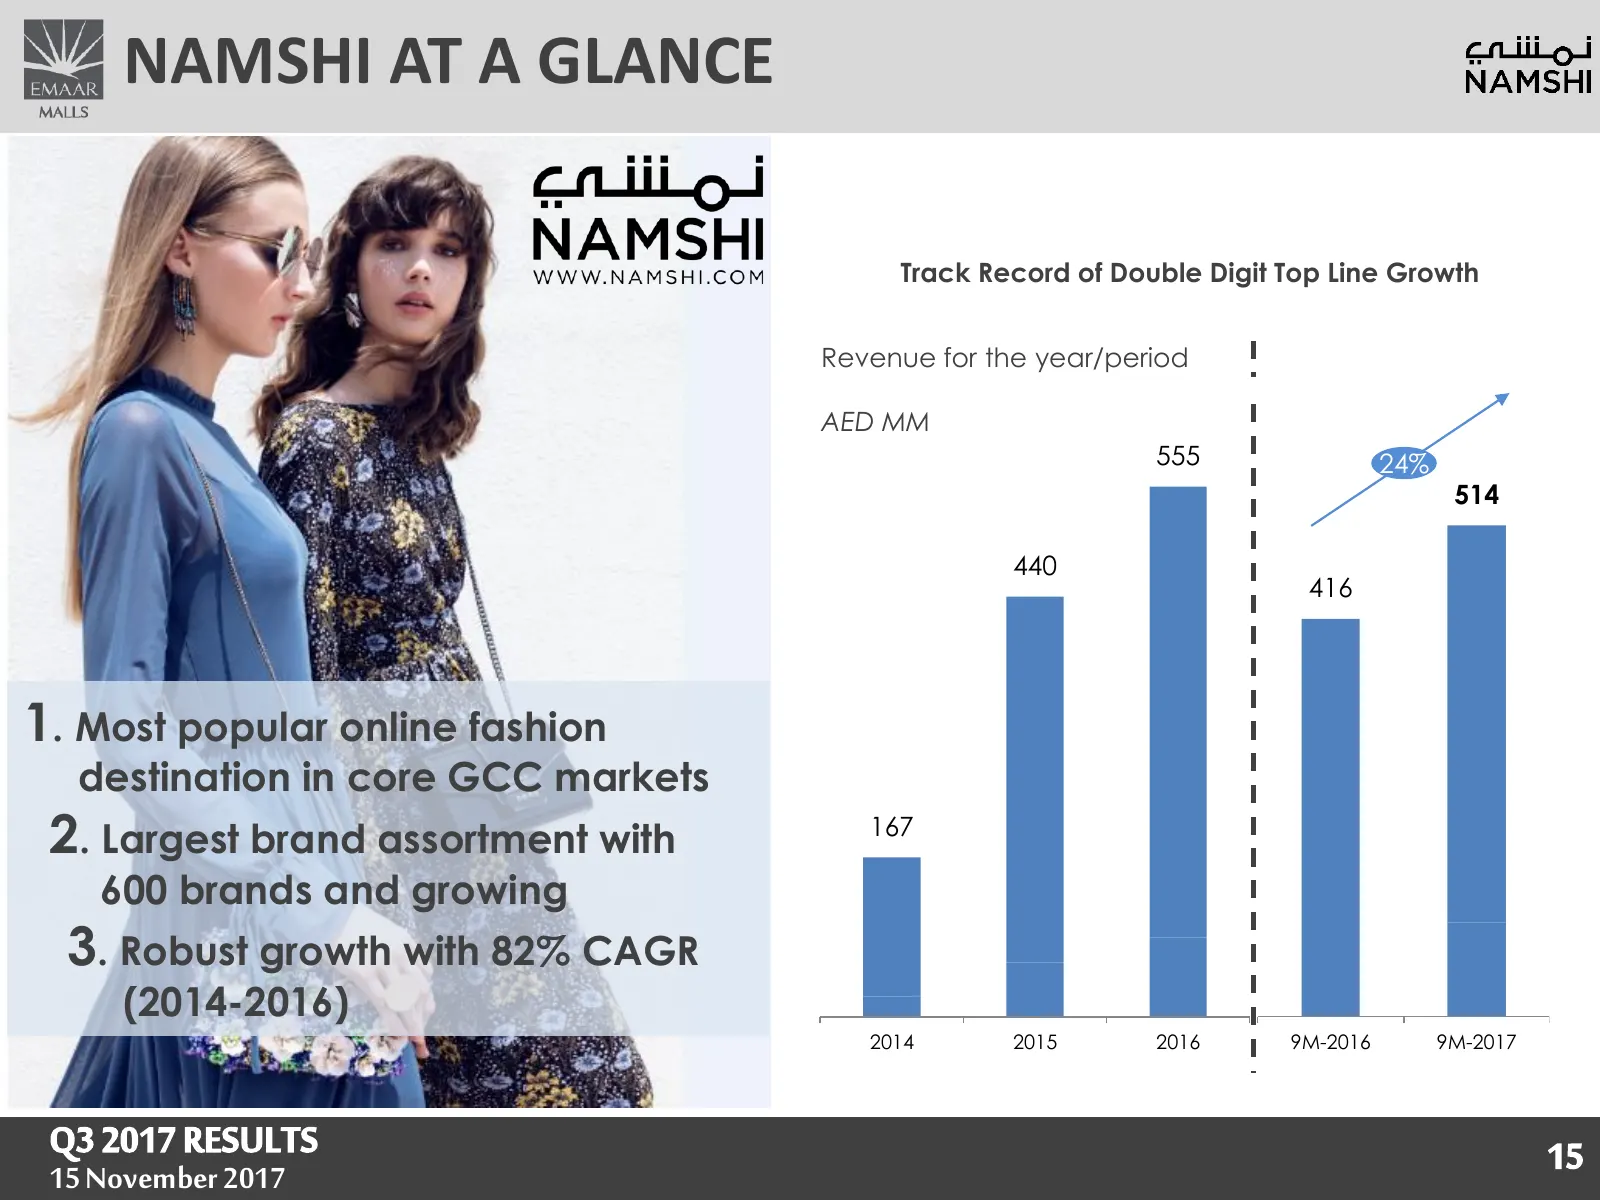
NAMSHI AT A GLANCE Track Record of Double Digit Top Line Growth Revenue for the year/period AED MM 555 24% 514 440 416 1. Most popular online fashion 472 416 destination in core GCC markets 383 358 2. Largest brand assortment with 167 600 brands and growing 3. Robust growth with 82% CAGR 145 83 98 (
Slide 16: Key Performance Indicators
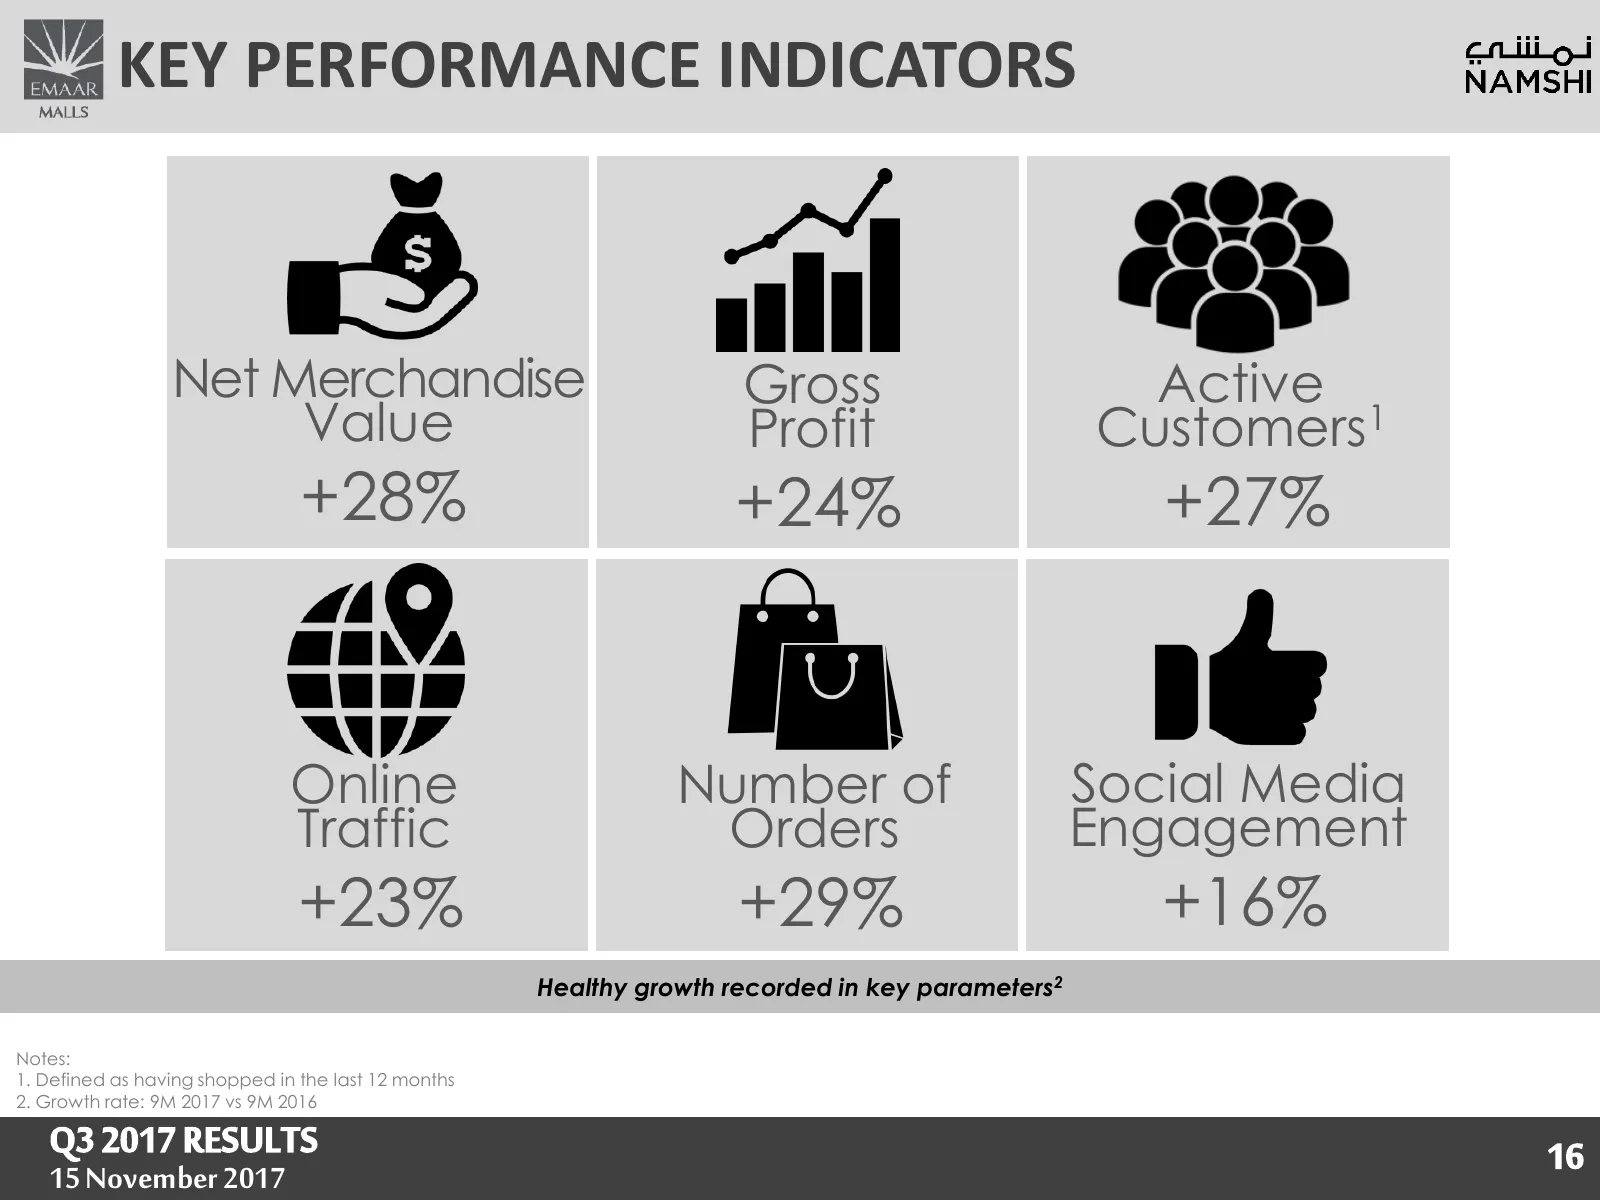
KEY PERFORMANCE INDICATORS Net Merchandise Gross Active Value Profit Customers1 +28% 29% +24% +27% Online Number of Social Media Traffic Orders Engagement +23% +29% +16% Healthy growth recorded in key parameters2 Notes: 1. Defined as having shopped in the last 12 months 2. Growth rate: 9M 2017 vs 9M
Slide 17: Upcoming Projects
UPCOMMING PROJECTS Q3 2017 RESULTS 1717 15 May 18 November 2017 2017
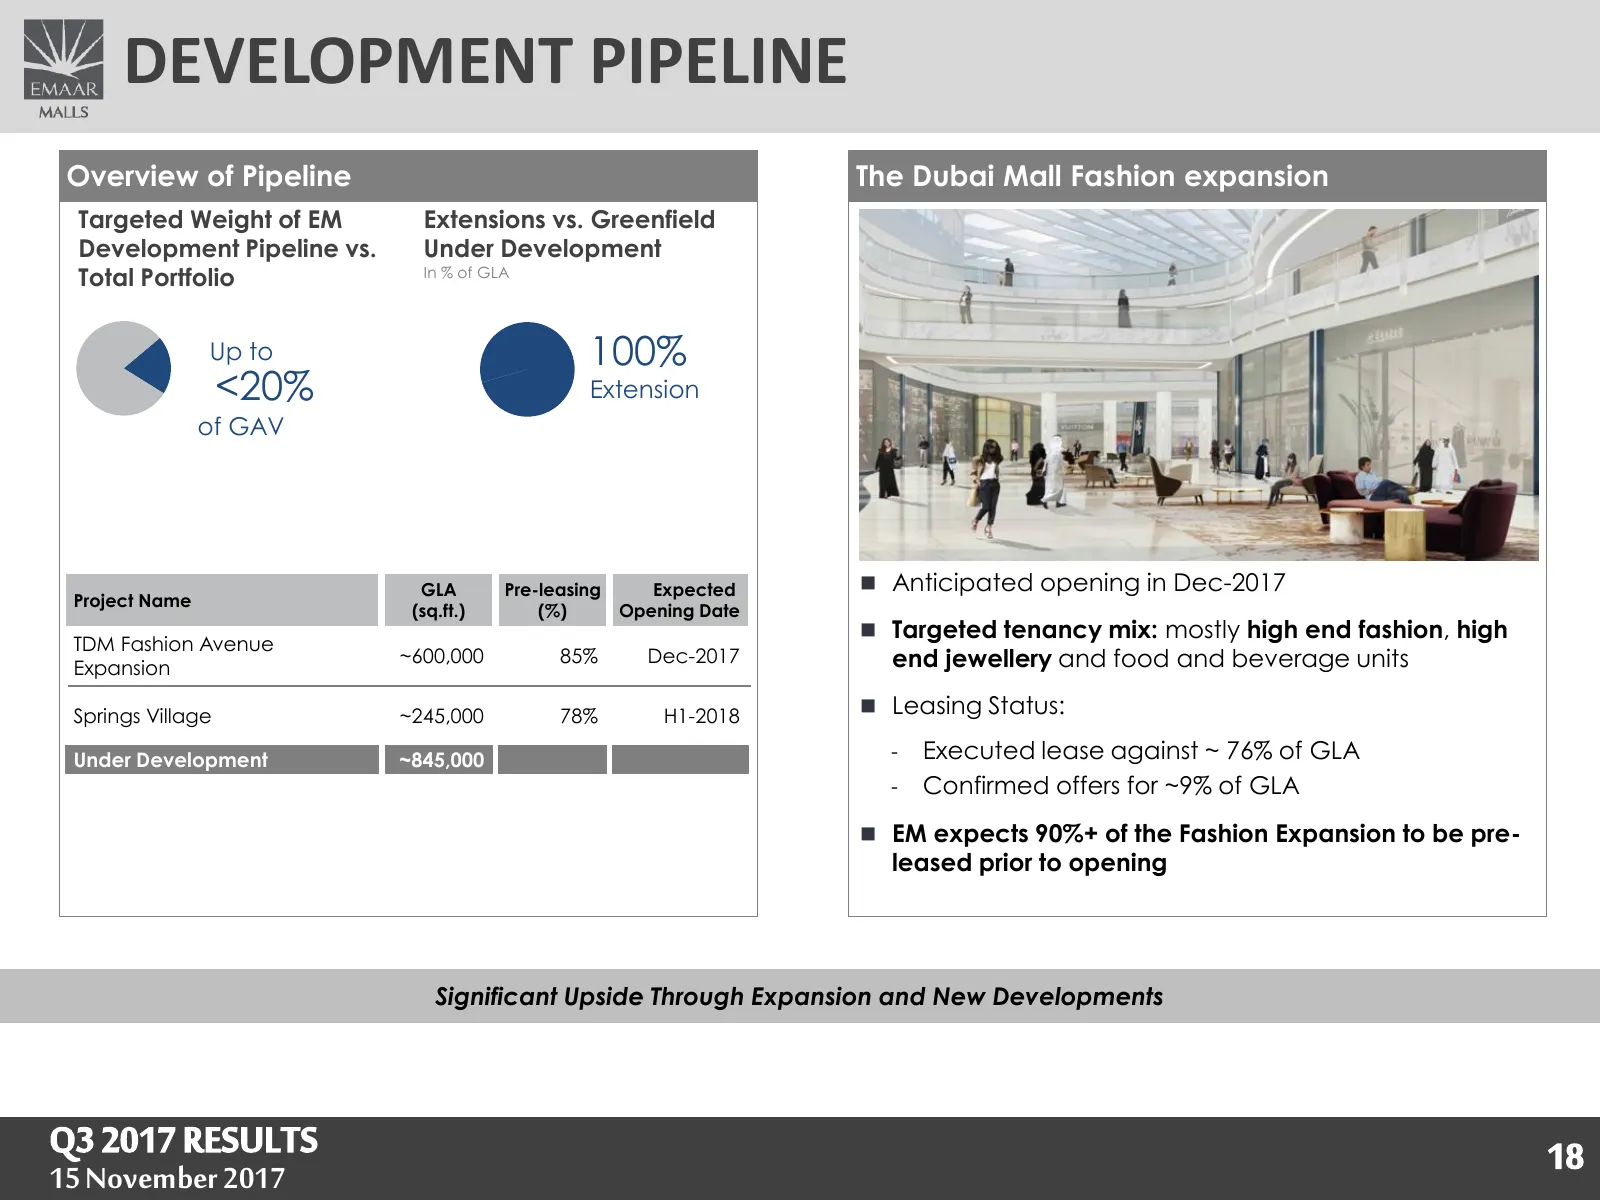
Slide 18: Development Pipeline
DEVELOPMENT PIPELINE Overview of Pipeline The Dubai Mall Fashion expansion Targeted Weight of EM Extensions vs. Greenfield Development Pipeline vs. Under Development Total Portfolio In % of GLA Up to 100% <20% Extension of GAV GLA Pre-leasing Expected Anticipated opening in Dec-2017 Project Name (
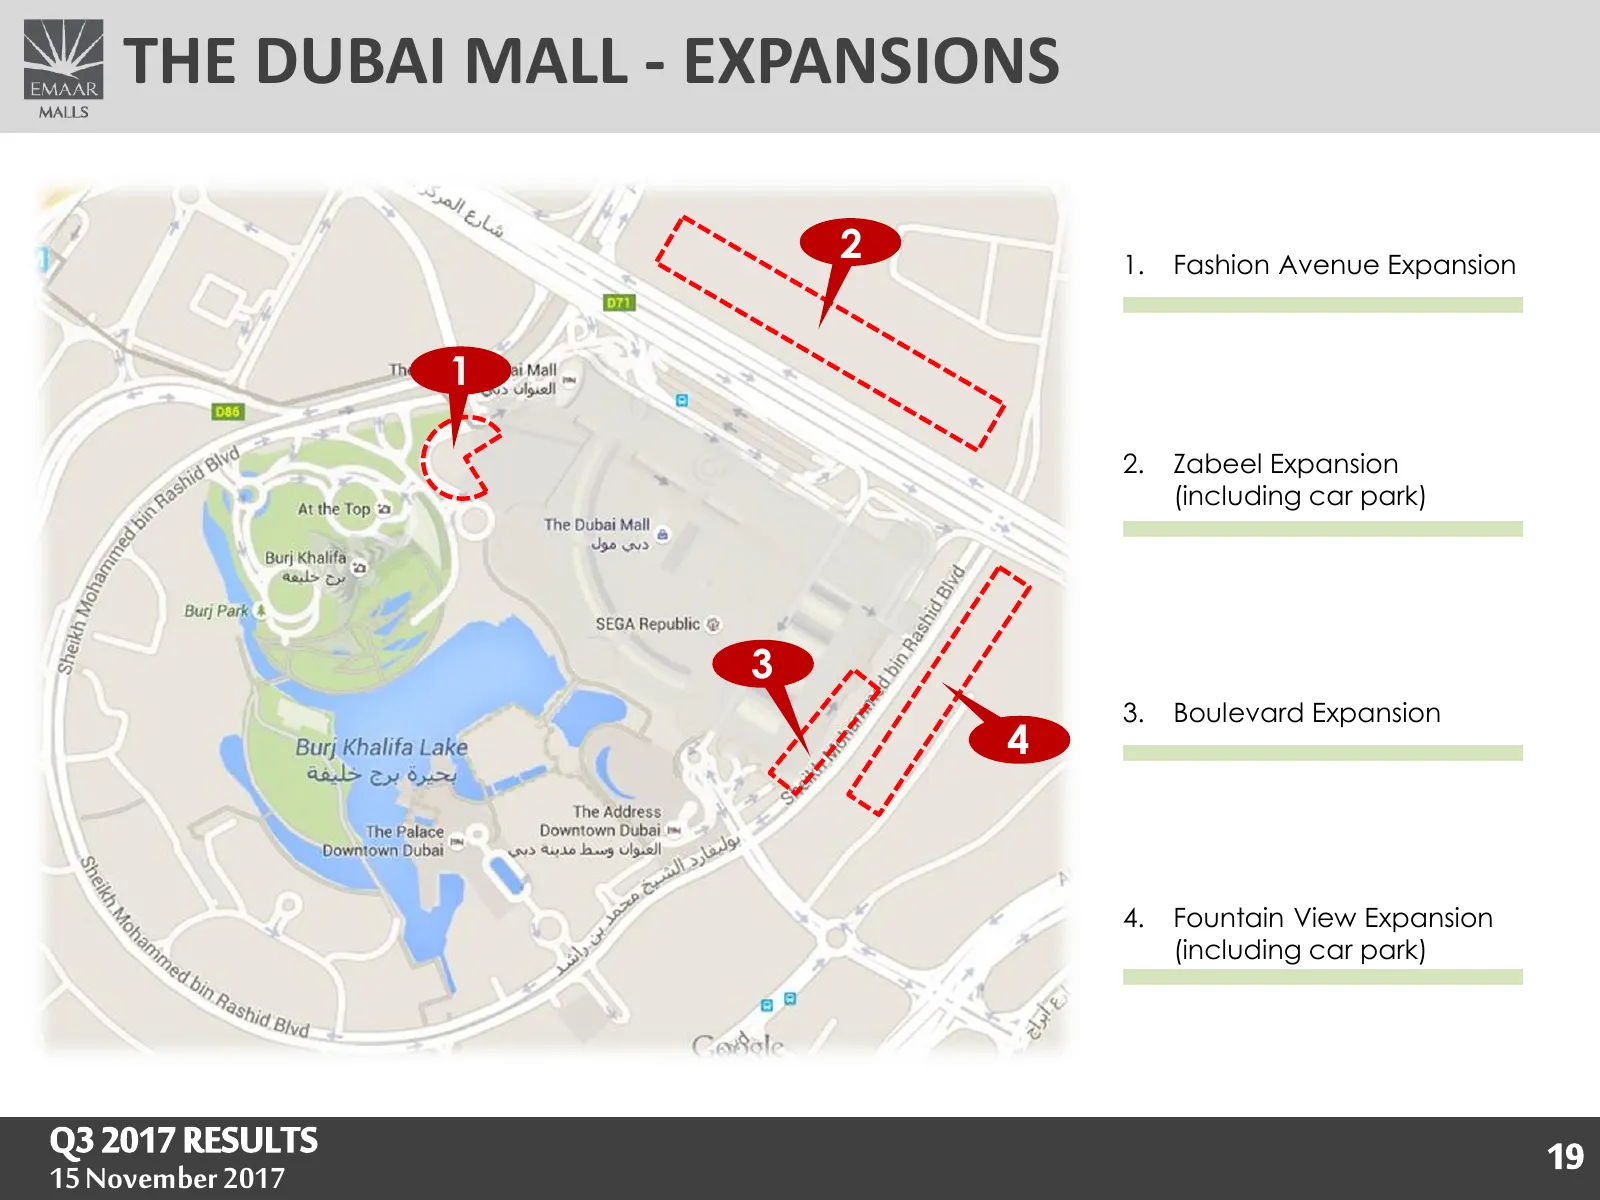
Slide 19: The Dubai Mall - Expansions
THE DUBAI MALL - EXPANSIONS 2 1. Fashion Avenue Expansion 1 2. Zabeel Expansion (including car park) 3 3. Boulevard Expansion 4 4. Fountain View Expansion (including car park) Q3 2017 RESULTS 1919 15 May 18 November 2017 2017
Slide 20: Consolidated Financial Statements
CONSOLIDATED FINANCIAL STATEMENTS Q3 2017 RESULTS 2020 15 May 18 November 2017 2017
Slide 21: Financial Highlights
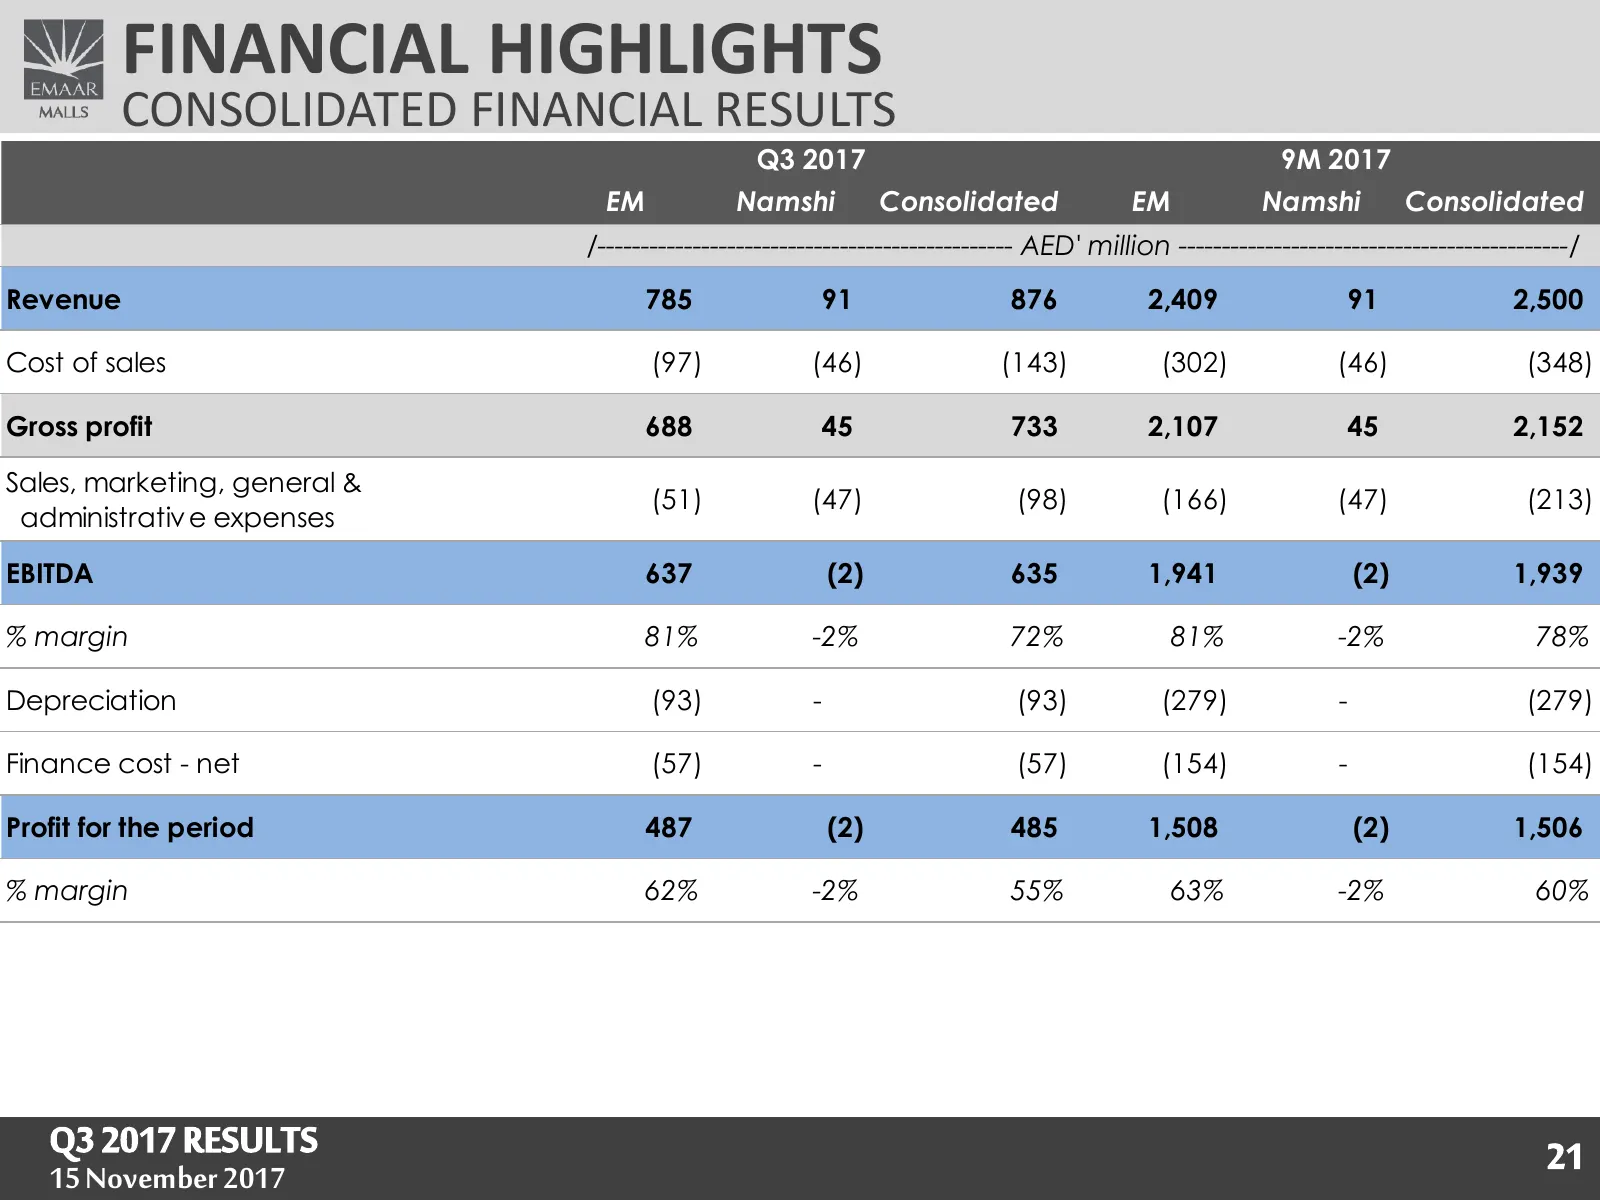
FINANCIAL HIGHLIGHTS CONSOLIDATED FINANCIAL RESULTS Q3 2017 9M 2017 EM Namshi Consolidated EM Namshi Consolidated /------------------------------------------------ AED' million ---------------------------------------------/ Revenue 785 91 876 2,409 91 2,500 Cost of sales (97) (46) (143) (302) (46) (
Slide 22: Financial Highlights
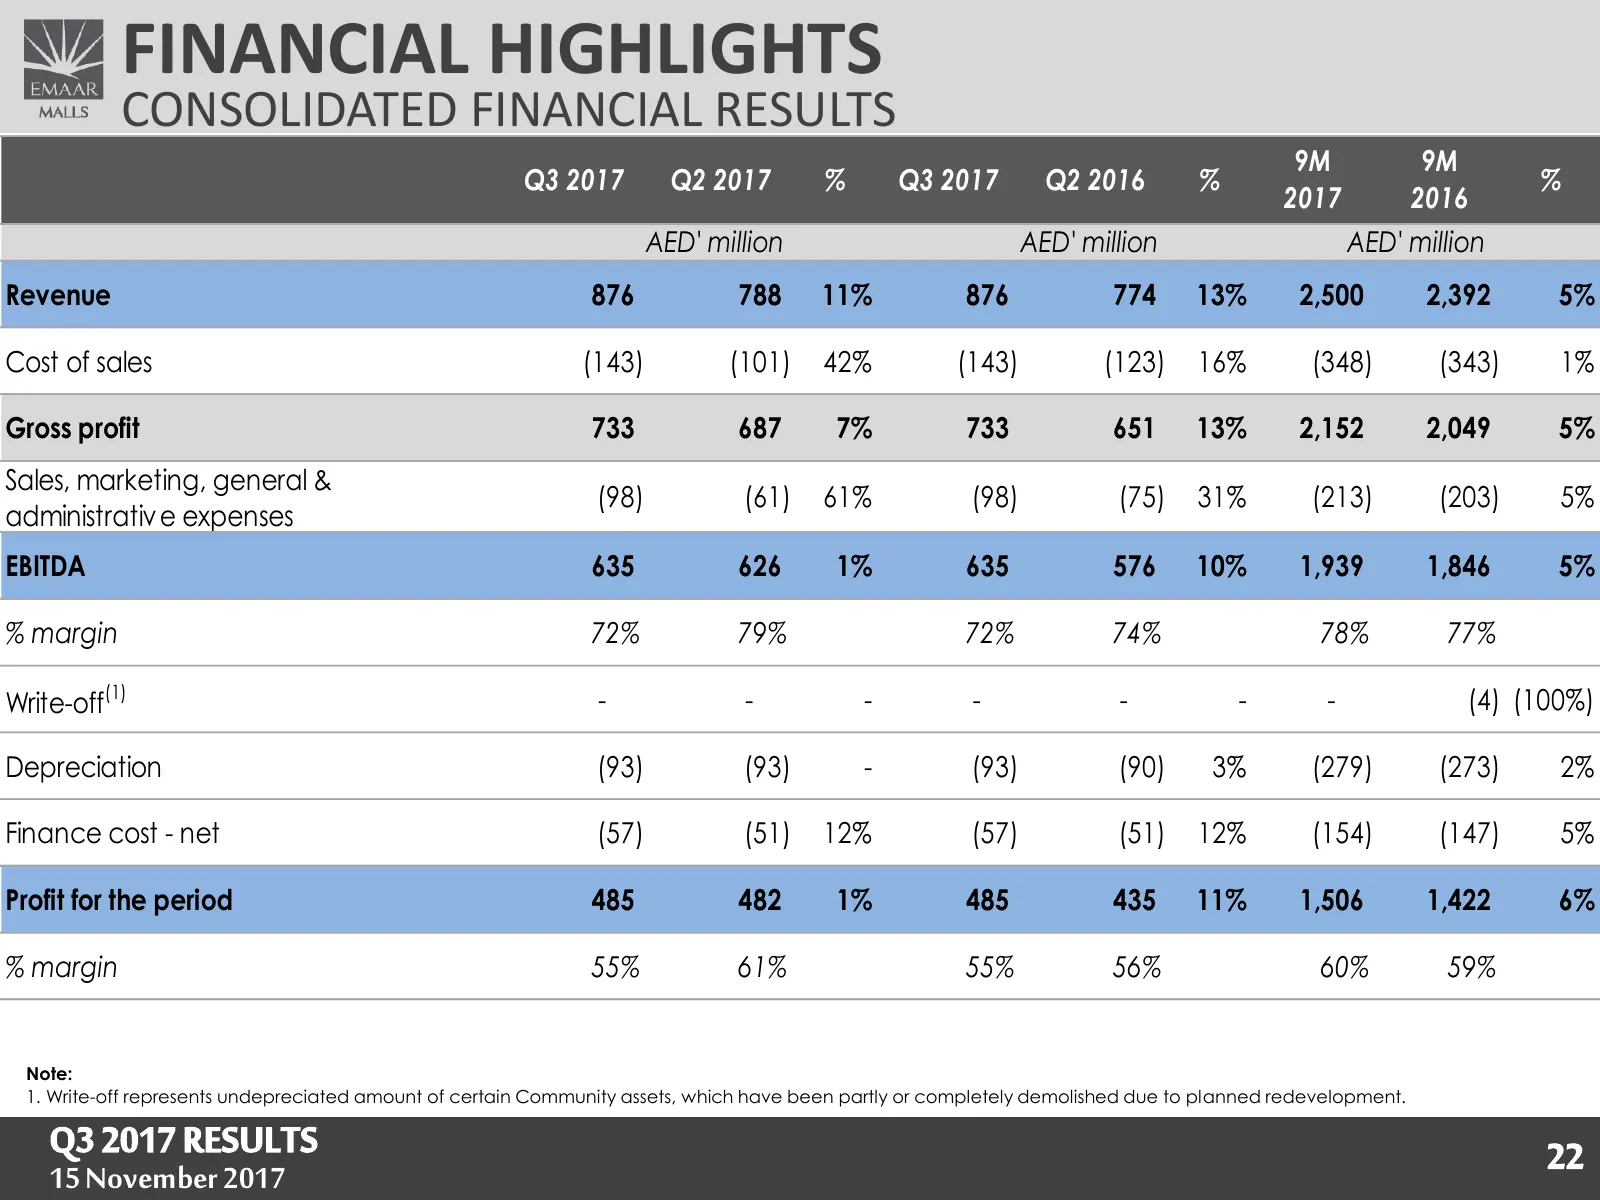
FINANCIAL HIGHLIGHTS CONSOLIDATED FINANCIAL RESULTS 9M 9M Q3 2017 Q2 2017 % Q3 2017 Q2 2016 % % 2017 2016 AED' million AED' million AED' million Revenue 876 788 11% 876 774 13% 2,500 2,392 5% Cost of sales (143) (101) 42% (143) (123) 16% (348) (343) 1% Gross profit 733 687 7% 733 651 13% 2,152 2,049
Slide 23: Financial Highlights (Ex. Namshi)
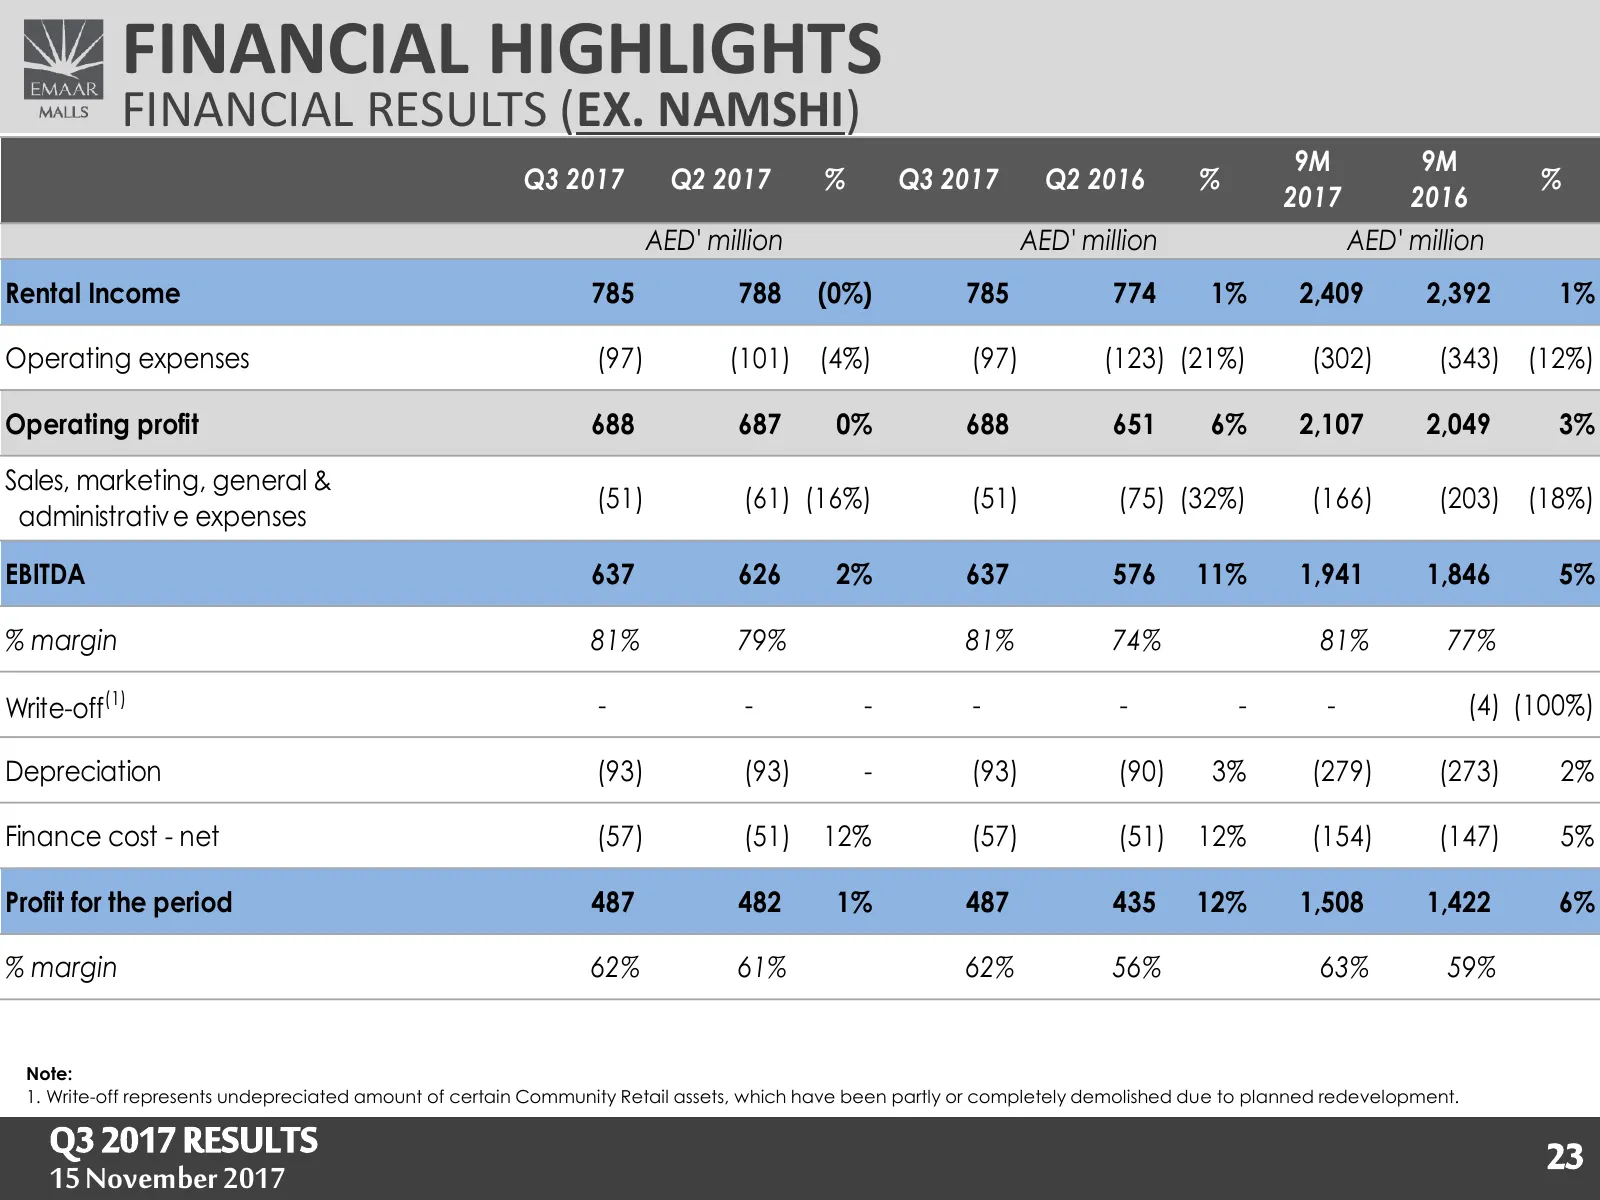
FINANCIAL HIGHLIGHTS FINANCIAL RESULTS (EX. NAMSHI) 9M 9M Q3 2017 Q2 2017 % Q3 2017 Q2 2016 % % 2017 2016 AED' million AED' million AED' million Rental Income 785 788 (0%) 785 774 1% 2,409 2,392 1% Operating expenses (97) (101) (4%) (97) (123) (21%) (302) (343) (12%) Operating profit 688 687 0% 688
Slide 24: Balance Sheet and Key Ratios
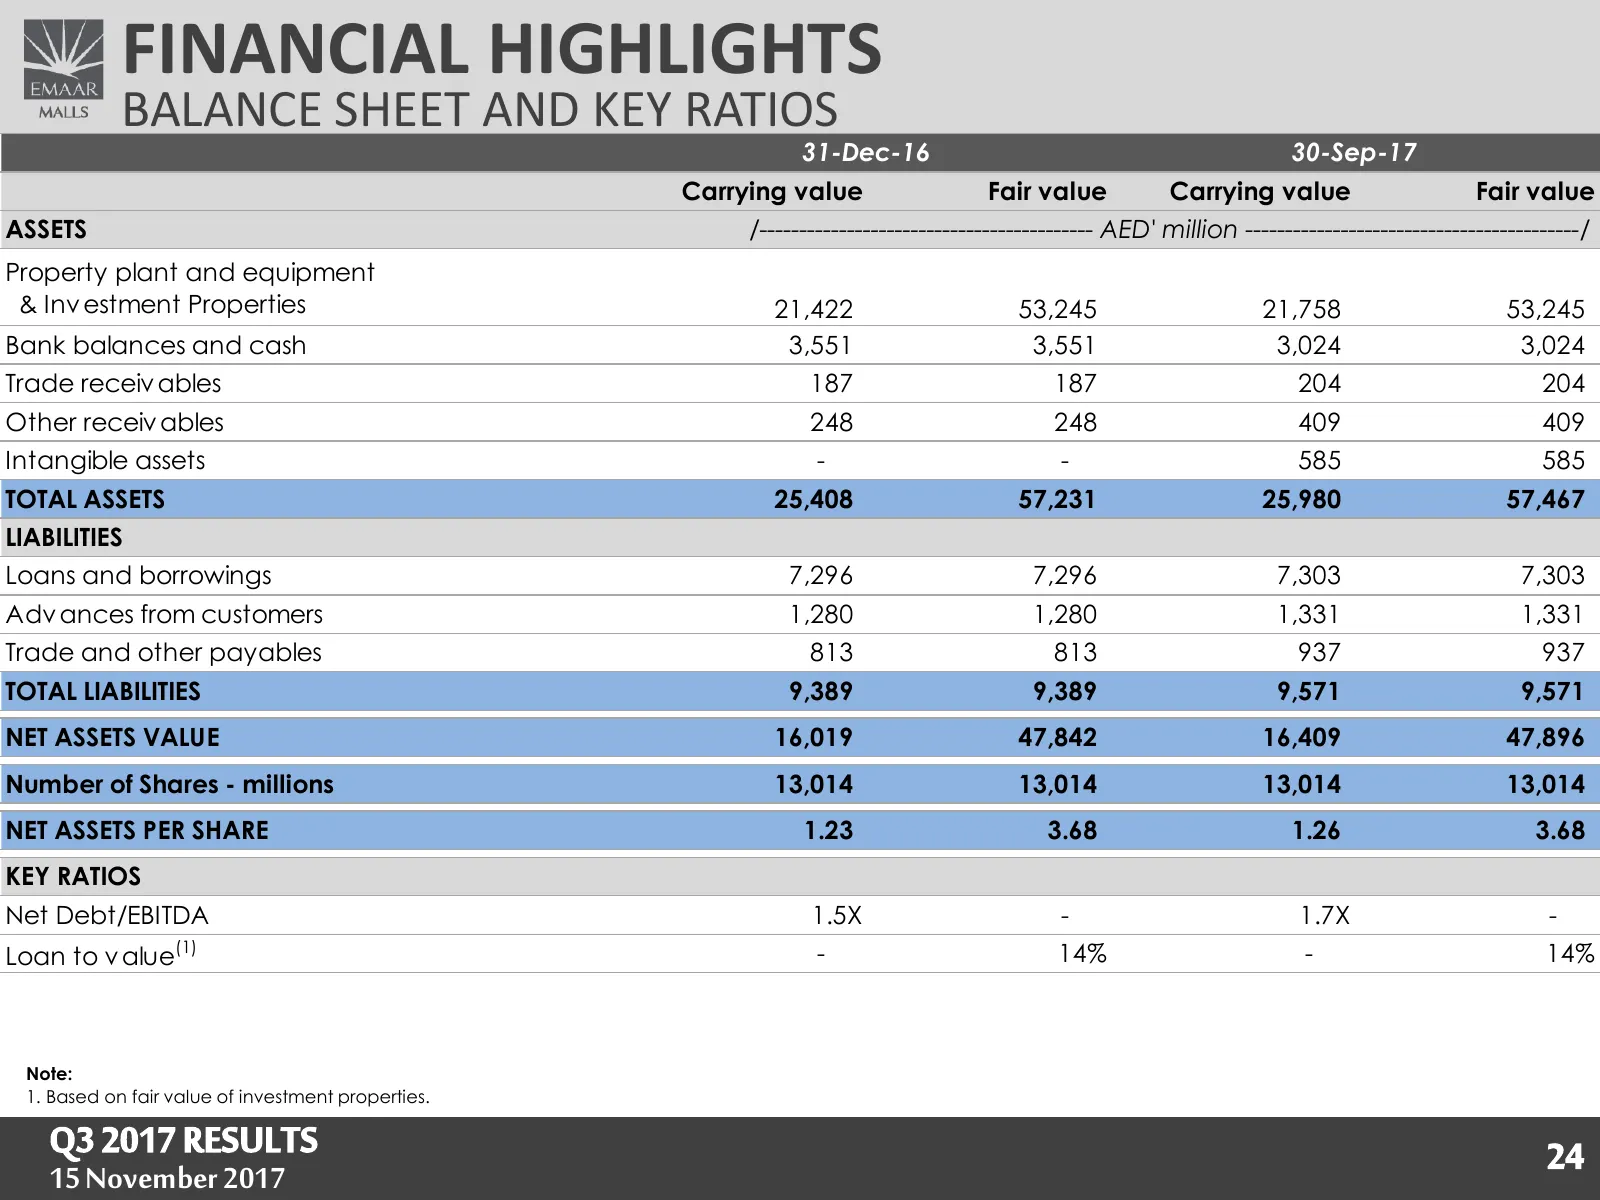
FINANCIAL HIGHLIGHTS BALANCE SHEET AND KEY RATIOS 31-Dec-16 30-Sep-17 Carrying value Fair value Carrying value Fair value ASSETS /------------------------------------------ AED' million ------------------------------------------/ Property plant and equipment & Inv estment Properties 21,422 53,245 21
Slide 25: Thank You
شكرا Q3 2017 RESULTS 25 15 November 2017
Source: Internet Archive copy of cdn.properties.emaar.com
More decks from Emaar Properties (P.J.S.C)
 H1 2026 Earnings Presentation78 slides · 2026
 Emaar Properties — 9M 2025 Earnings Presentation69 slides · November 2025
 H1 2025 Earnings Presentation69 slides · August 2025
 Emaar Properties — Q1 2025 Earnings Presentation68 slides · May 2025
 Emaar Properties — FY2025 Earnings Presentation71 slides · May 2025
 FY2024 Earnings Presentation70 slides · Feb 24, 2025