Montpelier Re — Investor Day (May 2009)
47 slides from Montpelier Re's investor day presentation, May 7, 2009
Slide 1: Montpelier Group Investor Day NYC
9 MONTPELIER GROUP Investor Day NYC May 7, 2009
Slide 2: Forward Looking Statements & Safe Harbor
Forward Looking Statements & Safe Harbor This presentation contains forward-looking statements within the meaning of the United States federal securities laws, pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995, that are not historical facts, including sta
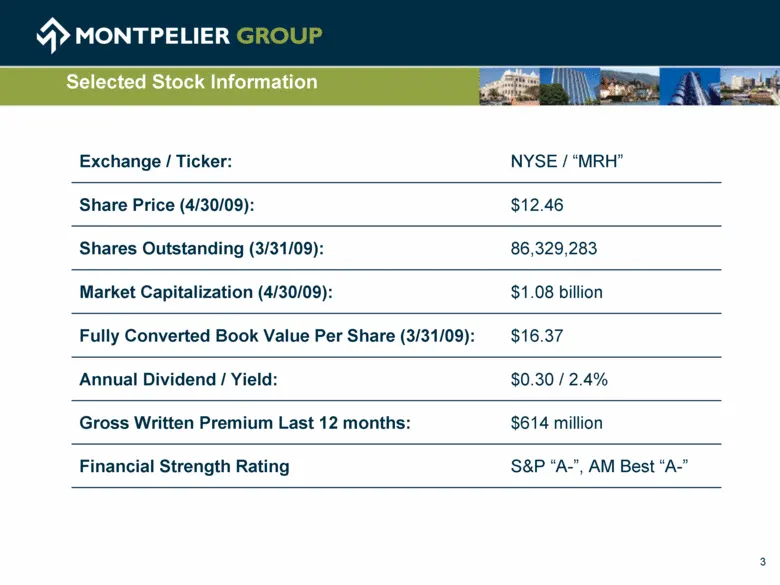
Slide 3: Selected Stock Information
Selected Stock Information Exchange / Ticker: NYSE / “MRH” Share Price (4/30/09): $12.46 Shares Outstanding (3/31/09): 86,329,283 Market Capitalization (4/30/09): $1.08 billion Fully Converted Book Value Per Share (3/31/09): $16.37 Annual Dividend / Yield: $0.30 / 2.4% Gross Written Premium Last 12
Slide 4: Introduction
Introduction Tom Busher Deputy Chairman, Chief Operating Officer Montpelier Re Holdings Ltd. 4
Slide 5: Agenda
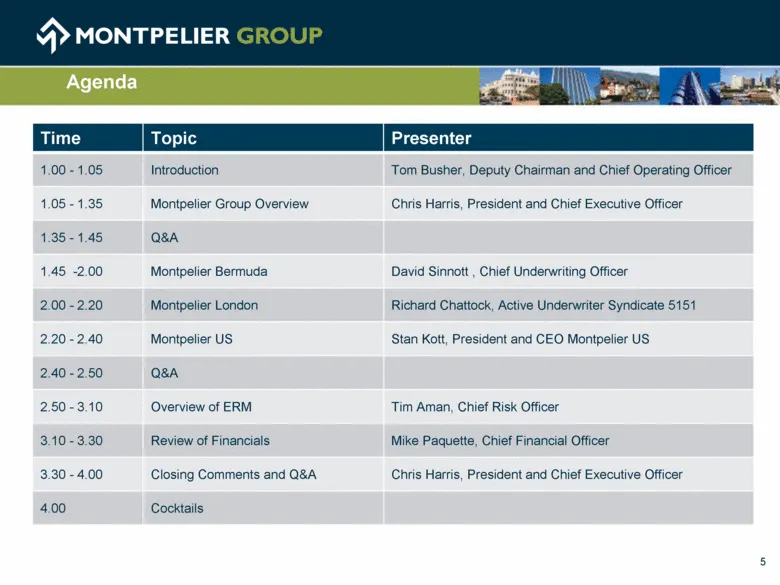
Agenda 5 Time Topic Presenter 1.00 - 1.05 Introduction Tom Busher, Deputy Chairman and Chief Operating Officer 1.05 - 1.35 Montpelier Group Overview Chris Harris, President and Chief Executive Officer 1.35 - 1.45 Q&A 1.45 -2.00 Montpelier Bermuda David Sinnott , Chief Underwriting Officer 2.00 - 2.2
Slide 6: Overview: Montpelier Group
Overview: Montpelier Group Chris Harris President & Chief Executive Officer Montpelier Re Holdings Ltd. 6
Slide 7: The Montpelier Advantage
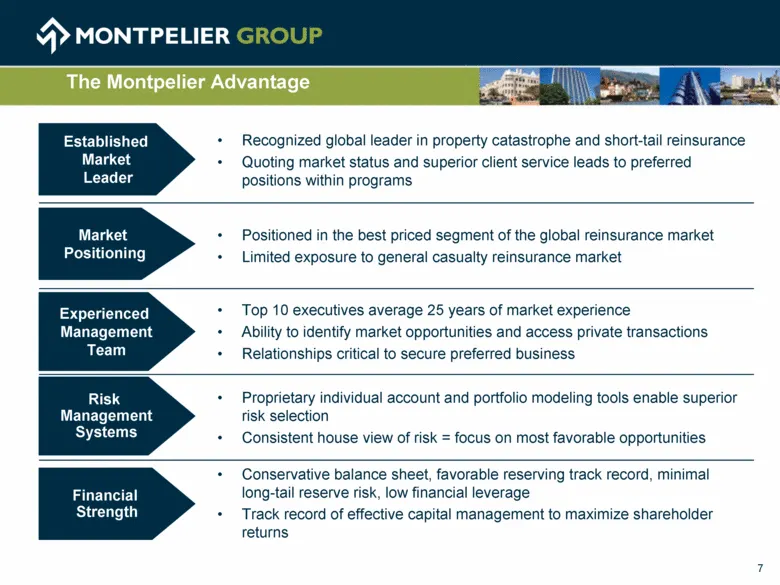
7 The Montpelier Advantage • Recognized global leader in property catastrophe and short-tail reinsurance • Quoting market status and superior client service leads to preferred positions within programs • Positioned in the best priced segment of the global reinsurance market • Limited exposure to gen
Slide 8: Organic Platform Expansion
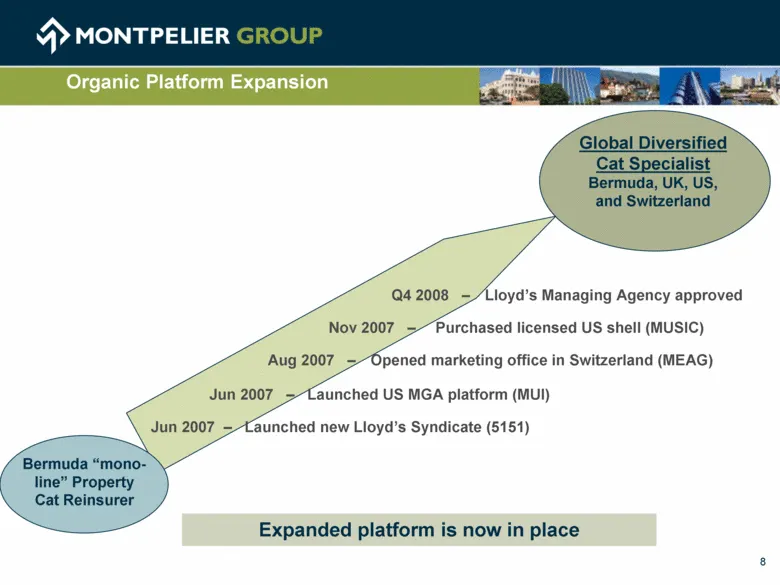
Organic Platform Expansion Bermuda “monoline” Property Cat Reinsurer Global Diversified Cat Specialist Bermuda, UK, US, and Switzerland Jun 2007 – Launched new Lloyd’s Syndicate (5151) Jun 2007 – Launched US MGA platform (MUI) Aug 2007 – Opened marketing office in Switzerland (MEAG) Nov 2007 – Purch
Slide 9: Strategic Evolution
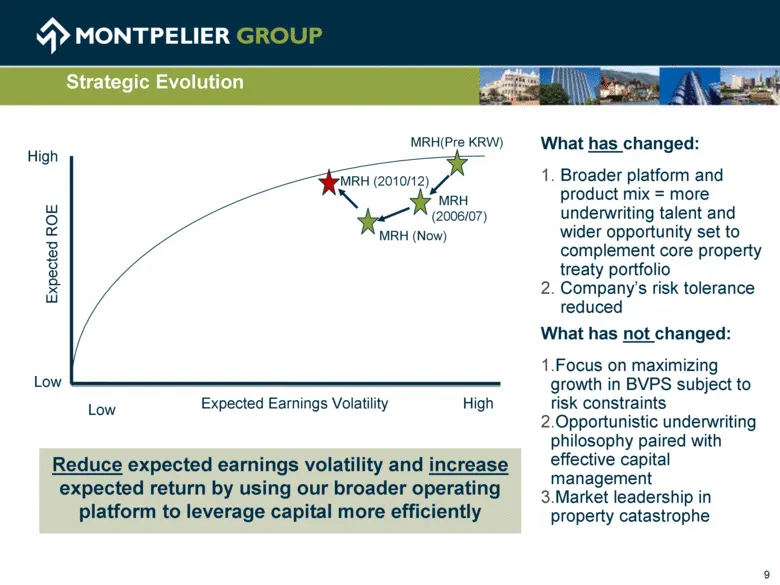
Strategic Evolution Expected ROE Expected Earnings Volatility MRH (2006/07) High High Low Low MRH (Now) MRH (2010/12) MRH(Pre KRW) 9 What has not changed: 1.Focus on maximizing growth in BVPS subject to risk constraints 2.Opportunistic underwriting philosophy paired with effective capital management
Slide 10: Book Value Per Share Growth
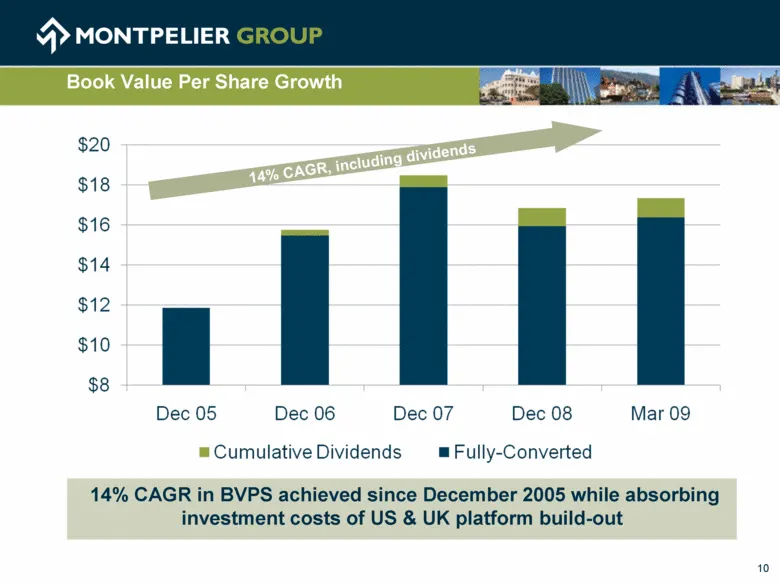
Book Value Per Share Growth 10 14% CAGR in BVPS achieved since December 2005 while absorbing investment costs of US & UK platform build-out 14 % CAGR, including dividends
Slide 11: Benefits of Organic Expansion
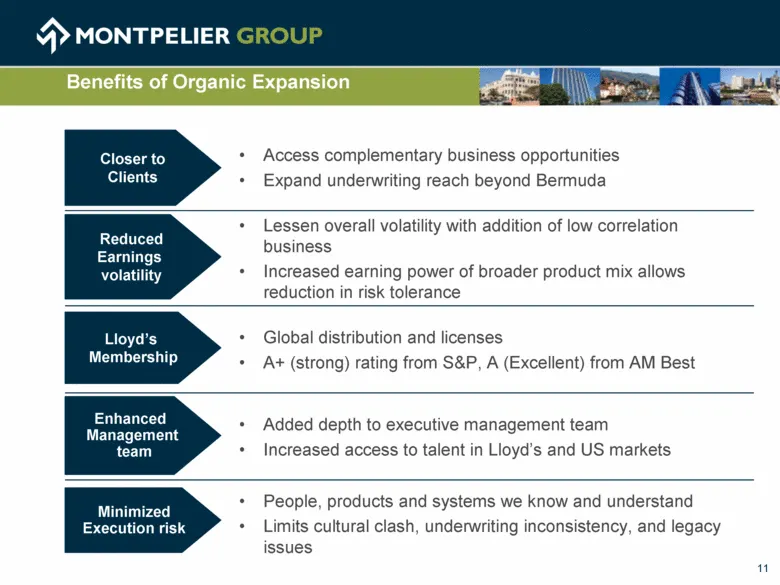
Benefits of Organic Expansion • Access complementary business opportunities • Expand underwriting reach beyond Bermuda • Lessen overall volatility with addition of low correlation business • Increased earning power of broader product mix allows reduction in risk tolerance • Global distribution and l
Slide 12: GPW Mix By Class
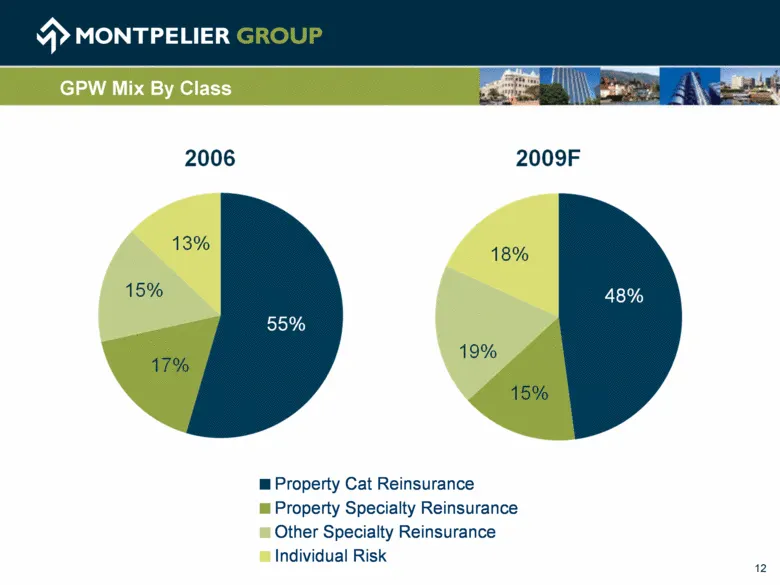
12 GPW Mix By Class Property Cat Reinsurance Property Specialty Reinsurance Other Specialty Reinsurance Individual Risk
Slide 13: GPW Mix By Segment
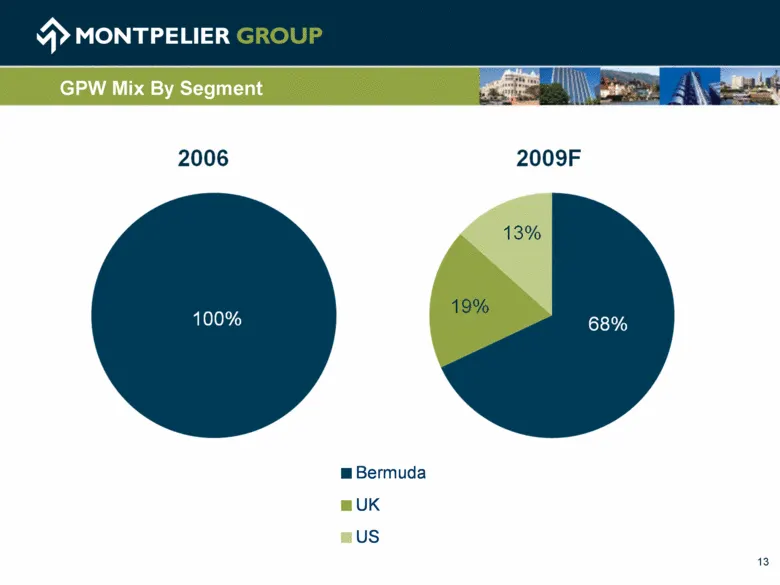
GPW Mix By Segment 13 Bermuda UK US
Slide 14: Competitive Positioning
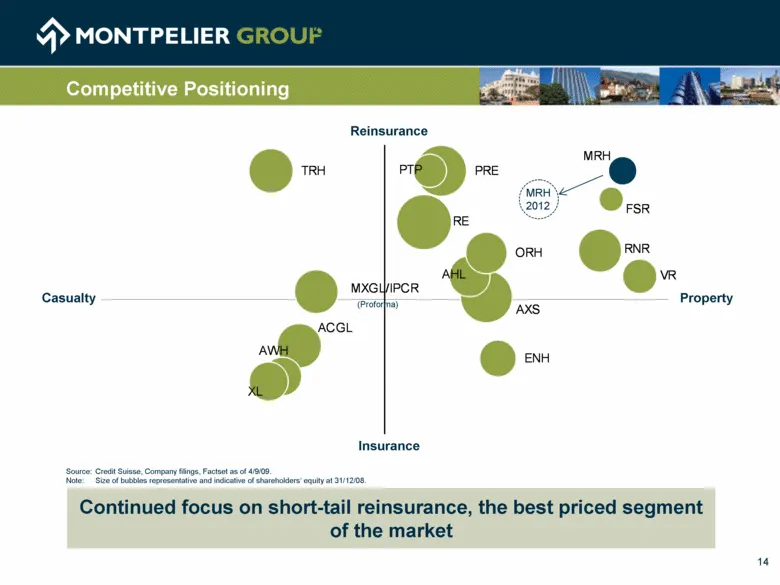
Competitive Positioning Source: Credit Suisse, Company filings, Factset as of 4/9/09. Note: Size of bubbles representative and indicative of shareholders‘ equity at 31/12/08. XL PTP PRE MRH FSR RE RNR VR ORH AHL AXS ENH MXGL/IPCR AWH ACGL TRH (Proforma) MRH 2012 Continued focus on short-tail reinsur
Slide 15: Bermuda - Montpelier Reinsurance Ltd.
Bermuda - Montpelier Reinsurance Ltd. David Sinnott Executive Vice President and Chief Underwriting Officer Montpelier Re 15
Slide 16: Overview – Montpelier Bermuda
Overview – Montpelier Bermuda Montpelier Reinsurance Ltd. • Core operating platform formed in late 2001 • Catastrophe center of excellence, recognized market leader • Superior risk selection through a combination of proprietary modeling tools and underwriting experience • 13 underwriters, 7 dedicate
Slide 17: Bermuda Operations - Lines of Business
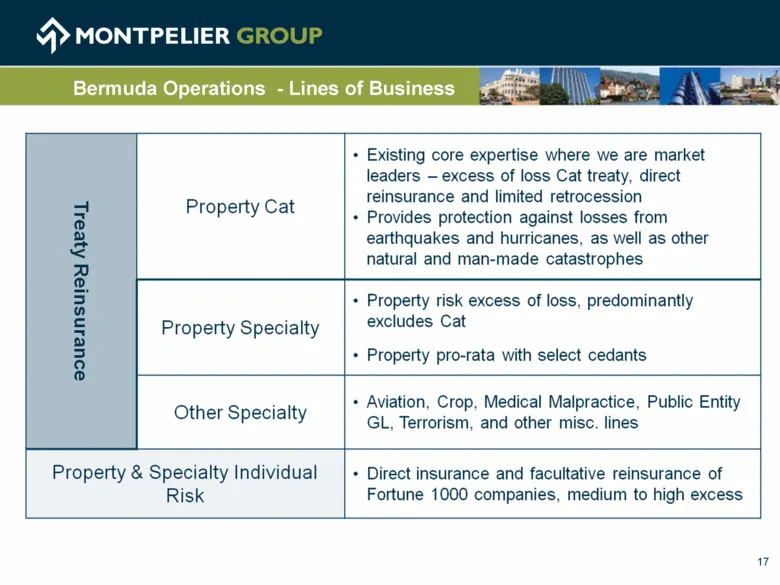
Bermuda Operations - Lines of Business 17 Treaty Reinsurance Property Cat Existing core expertise where we are market leaders – excess of loss Cat treaty, direct reinsurance and limited retrocession Provides protection against losses from earthquakes and hurricanes, as well as other natural and man-
Slide 18: GPW Mix By Class
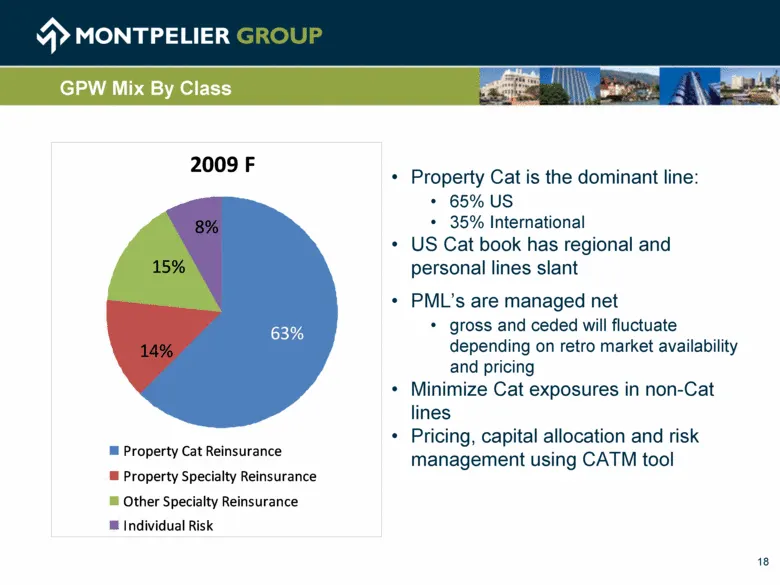
GPW Mix By Class US 52% Europe 14% 18 2009 F • Property Cat is the dominant line: • 65% US • 35% International • US Cat book has regional and personal lines slant • PML’s are managed net • gross and ceded will fluctuate depending on retro market availability and pricing • Minimize Cat exposures in n
Slide 19: Market Outlook
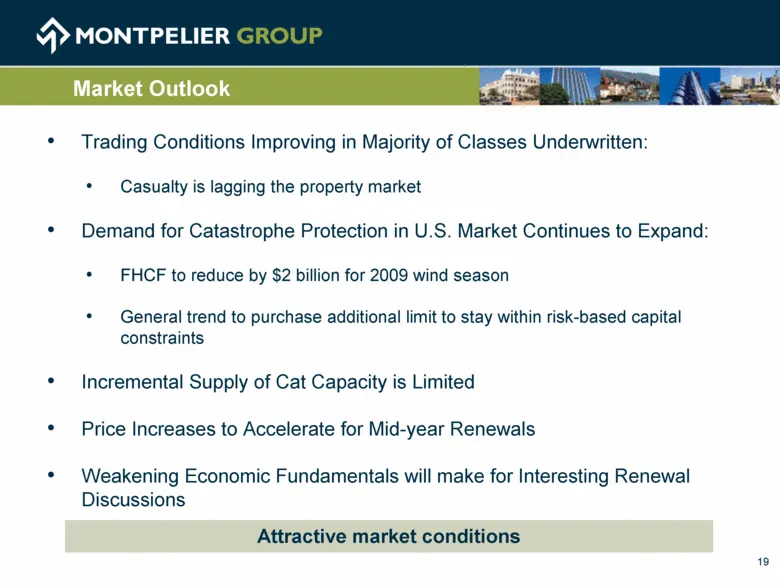
Market Outlook 19 • Trading Conditions Improving in Majority of Classes Underwritten: • Casualty is lagging the property market • Demand for Catastrophe Protection in U.S. Market Continues to Expand: • FHCF to reduce by $2 billion for 2009 wind season • General trend to purchase additional limit to
Slide 20: London - Syndicate 5151
Richard Chattock Active Underwriter Syndicate 5151 London - Syndicate 5151 20
Slide 21: Syndicate 5151 Overview
Syndicate 5151 Overview • Commenced underwriting July 1, 2007 • Launched dedicated Managing Agent (MUA) from January 2009 • Capital provided 100% via Letter of Credit by MRH • Operations in UK, Switzerland and US (MUI) • New Lines in development Building out further new underwriting lines • New Rout
Slide 22: Advantages of Lloyd's platform
Advantages of Lloyd’s platform • Global licenses • A+ ratings • Access to specialist business, closer to clients • Deep talent pool • Opportunities not seen in Bermuda • Acquisition opportunities • Flexibility (Lloyd’s trading floor, MGA Insurance, Consortiums) 22 Combination of Lloyd’s security and
Slide 23: London Operations - Lines of Business
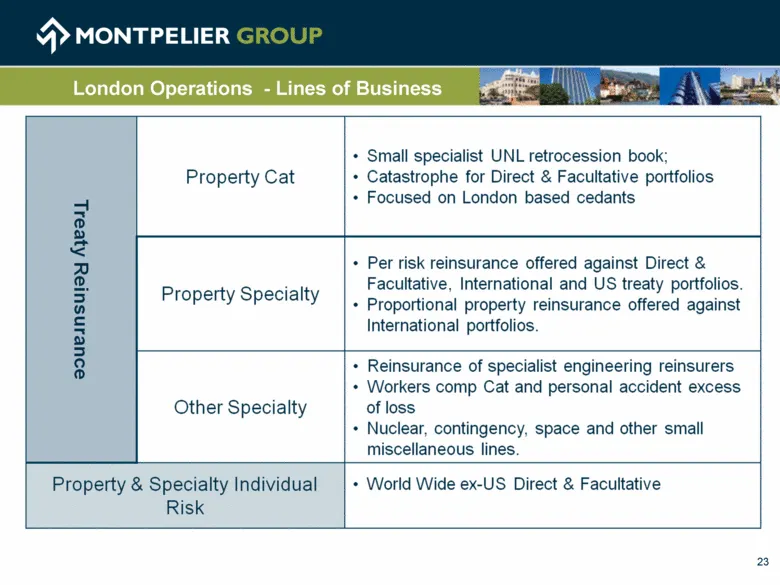
London Operations - Lines of Business 23 Treaty Reinsurance Property Cat Small specialist UNL retrocession book; Catastrophe for Direct & Facultative portfolios Focused on London based cedants Property Specialty Per risk reinsurance offered against Direct & Facultative, International and US treaty p
Slide 24: Syndicate 5151 Premium Summary
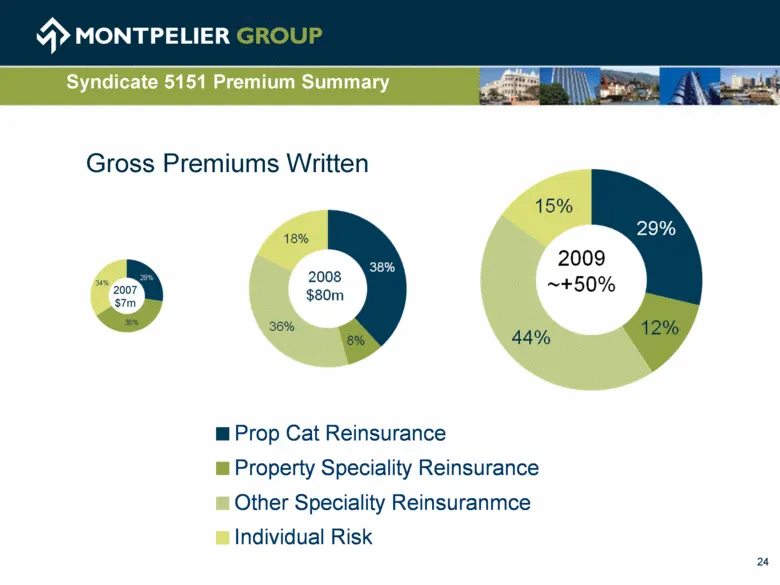
Syndicate 5151 Premium Summary 2007 $7m 24 Gross Premiums Written Prop Cat Reinsurance Property Speciality Reinsurance Other Speciality Reinsuranmce Individual Risk
Slide 25: Case Study – 5151 Engineering Treaty
Case Study – 5151 Engineering Treaty Attraction to Montpelier: Diversifying Income, global, little US cat Mix of short tail (XOL) and longer tail (Proportional) Proportional is long tail whilst maintaining the characteristics of property business Platform: Compelling Montpelier brand and Lloyd’s A+
Slide 26: Montpelier US
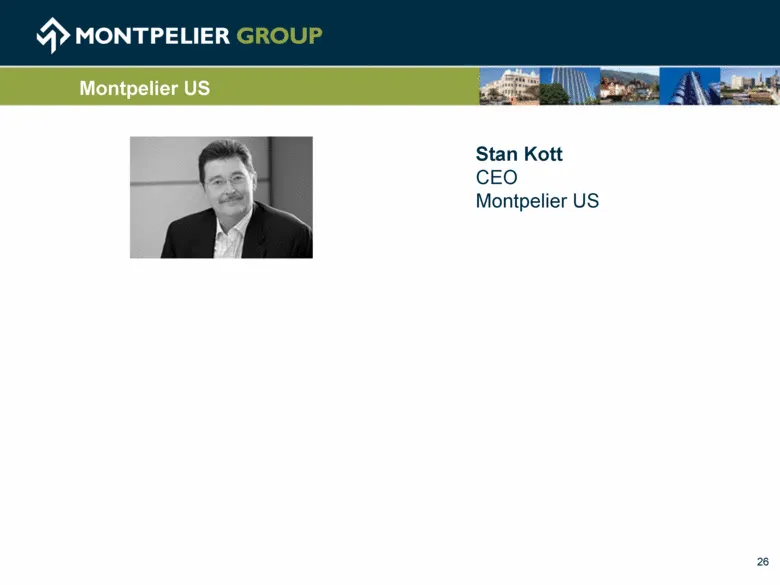
Stan Kott CEO Montpelier US Montpelier US 26
Slide 27: Montpelier US Overview
Montpelier US Overview • Establish local presence in the largest market in the world • Access business opportunities not available from Bermuda or London • Build platform to grow Group’s individual risk business • Focus primarily on lines with limited natural catastrophe exposure • Two underwriting
Slide 28: Montpelier US
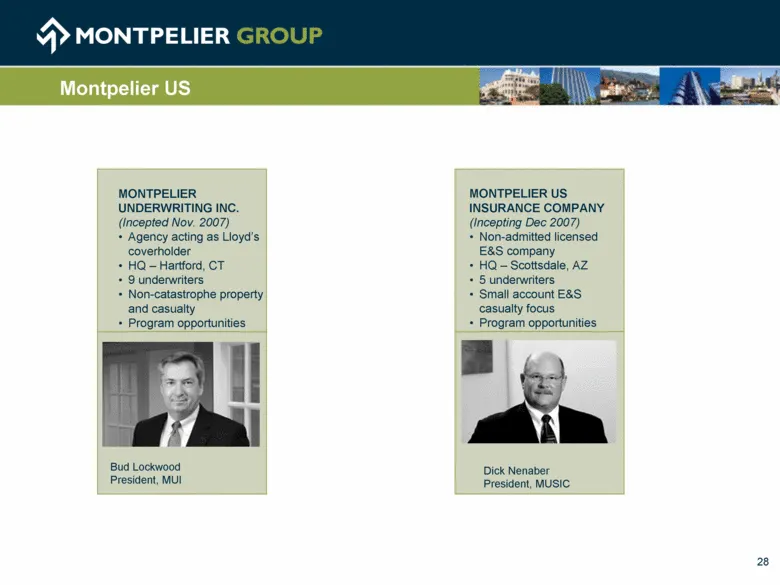
Montpelier US MONTPELIER US INSURANCE COMPANY (Incepting Dec 2007) • Non-admitted licensed E&S company • HQ – Scottsdale, AZ • 5 underwriters • Small account E&S casualty focus • Program opportunities MONTPELIER UNDERWRITING INC. (Incepted Nov. 2007) • Agency acting as Lloyd’s coverholder • HQ – Har
Slide 29: Locations & Staff - US Operation
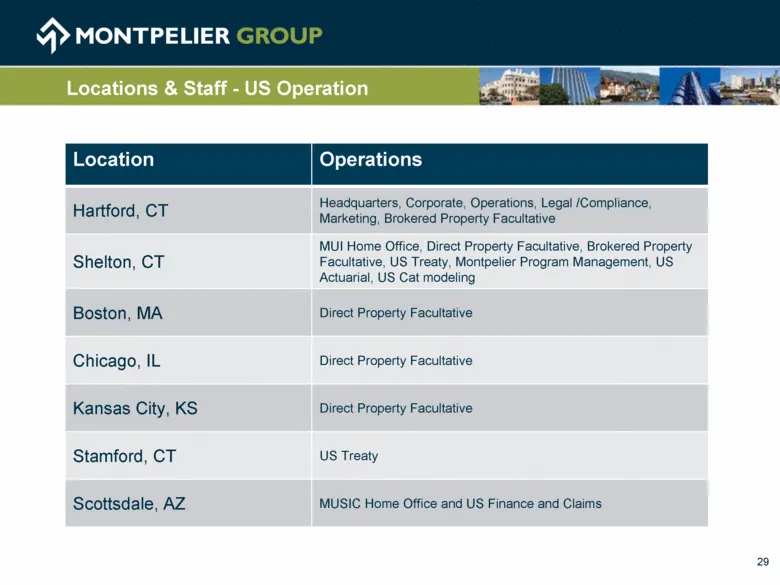
Locations & Staff - US Operation Location Operations Hartford, CT Headquarters, Corporate, Operations, Legal /Compliance, Marketing, Brokered Property Facultative Shelton, CT MUI Home Office, Direct Property Facultative, Brokered Property Facultative, US Treaty, Montpelier Program Management, US Act
Slide 30: US Operations - MUI
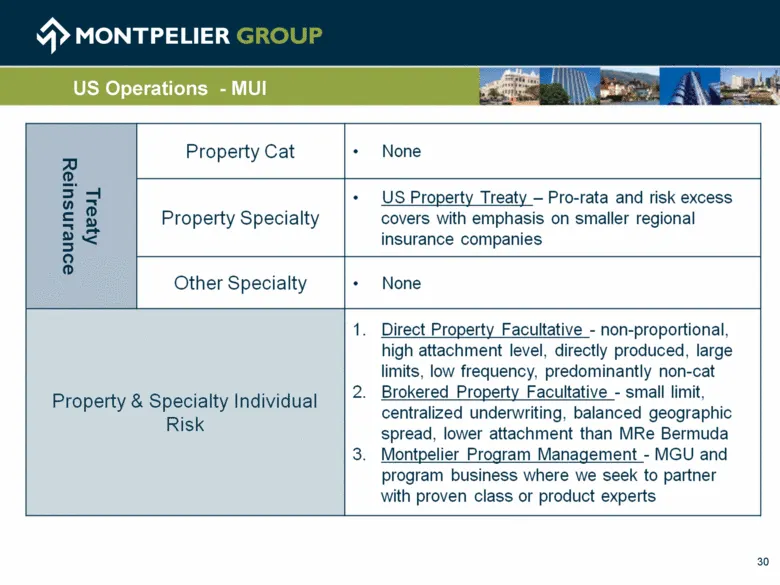
US Operations - MUI 30 Treaty Reinsurance Property Cat None Property Specialty US Property Treaty - Pro-rata and risk excess covers with emphasis on smaller regional insurance companies Other Specialty None Property & Specialty Individual Risk 1. Direct Property Facultative - non-proportional, high
Slide 31: US Operations - MUSIC
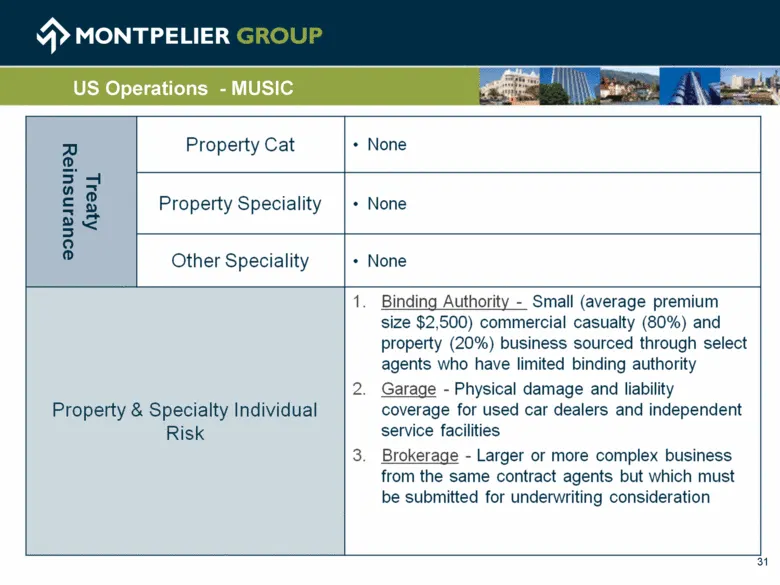
US Operations - MUSIC 31 Treaty Reinsurance Property Cat None Property Speciality None Other Speciality None Property & Specialty Individual Risk 1. Binding Authority - Small (average premium size $2,500) commercial casualty (80%) and property (20%) business sourced through select agents who have li
Slide 32: Montpelier US Premium Summary
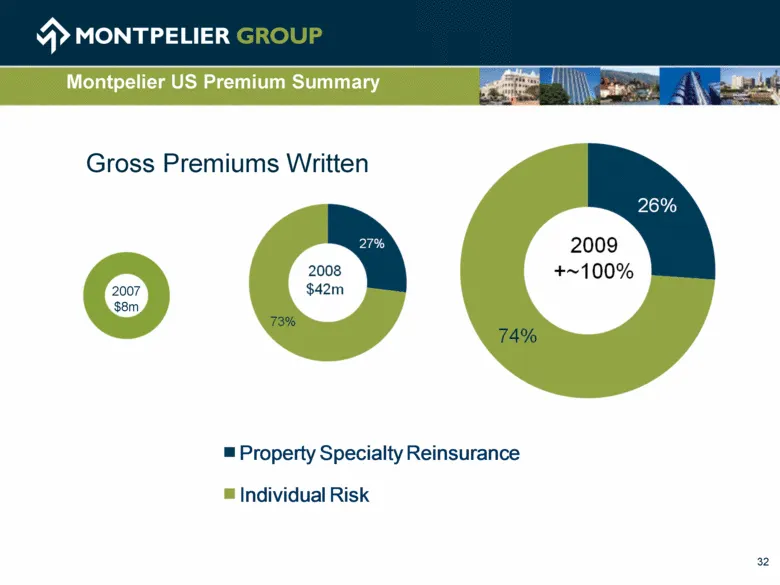
Montpelier US Premium Summary 2007 $8m 32 Gross Premiums Written Property Specialty Reinsurance Individual Risk
Slide 33: Overview: Enterprise Risk Management
Overview: Enterprise Risk Management Tim Aman Senior Vice President & Chief Risk Officer Montpelier Re Holdings Ltd. 34
Slide 34: Enterprise Risk Management Approach
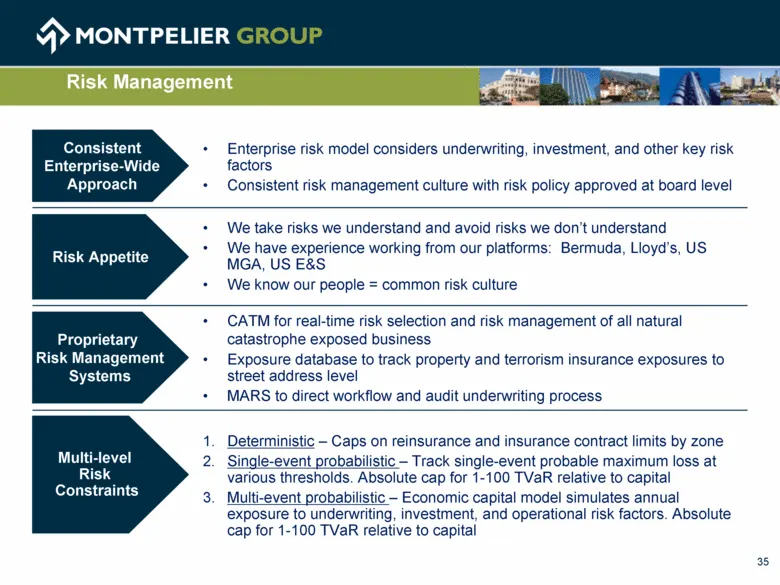
• Enterprise risk model considers underwriting, investment, and other key risk factors • Consistent risk management culture with risk policy approved at board level • We take risks we understand and avoid risks we don’t understand • We have experience working from our platforms: Bermuda, Lloyd’s, US
Slide 35: CATM
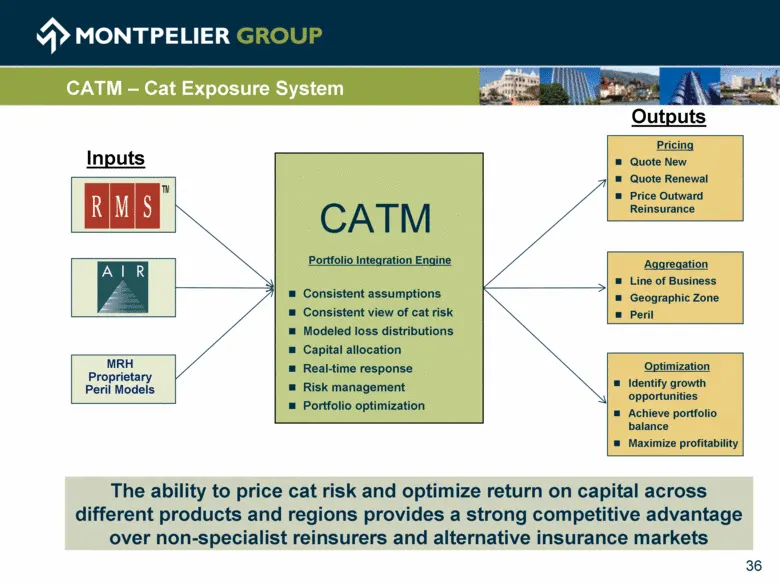
Inputs Portfolio Integration Engine Consistent assumptions Consistent view of cat risk Modeled loss distributions Capital allocation Real-time response Risk management Portfolio optimization Pricing Quote New Quote Renewal Price Outward Reinsurance Aggregation Line of Business Geographic Zone Peril
Slide 36: Exposure Management
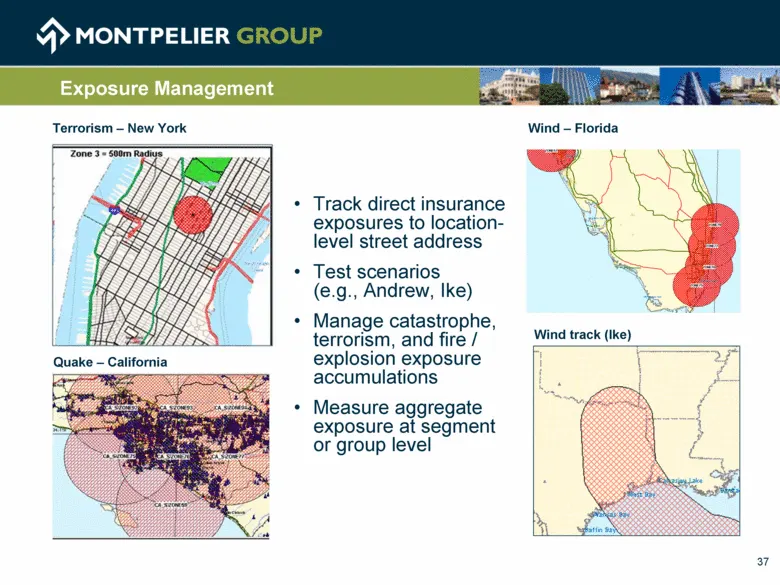
Exposure Management Terrorism – New York Wind – Florida Quake – California Wind track (Ike) • Track direct insurance exposures to location-level street address • Test scenarios (e.g., Andrew, Ike) • Manage catastrophe, terrorism, and fire / explosion exposure accumulations • Measure aggregate exposu
Slide 37: Single Event Exposure Management
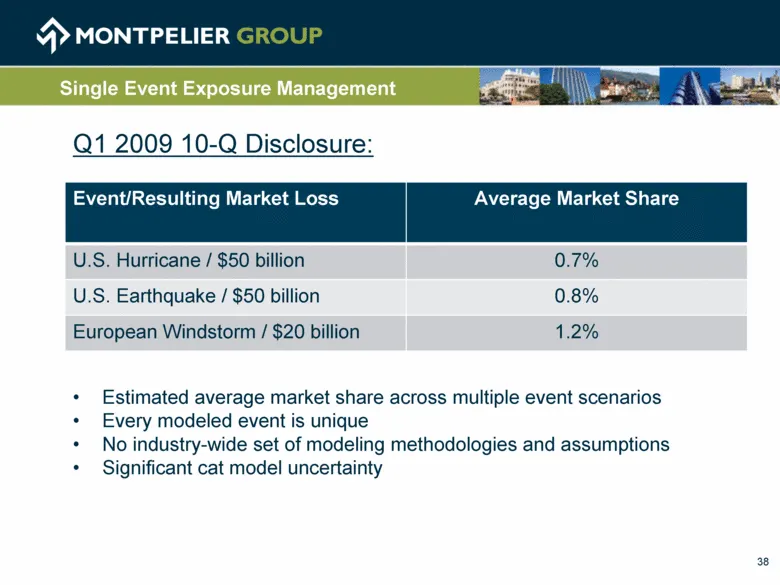
Single Event Exposure Management Q1 2009 10-Q Disclosure: • Estimated average market share across multiple event scenarios • Every modeled event is unique • No industry-wide set of modeling methodologies and assumptions • Significant cat model uncertainty 38 Event/Resulting Market Loss Average Marke
Slide 38: Peer Ike & Gustav losses
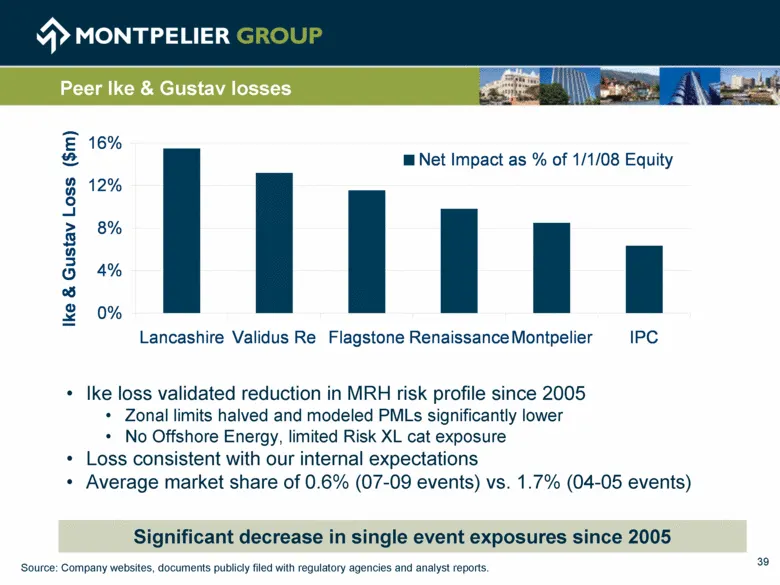
Peer Ike & Gustav losses • Ike loss validated reduction in MRH risk profile since 2005 • Zonal limits halved and modeled PMLs significantly lower • No Offshore Energy, limited Risk XL cat exposure • Loss consistent with our internal expectations • Average market share of 0.6% (07-09 events) vs. 1.7%
Slide 39: Financial Overview
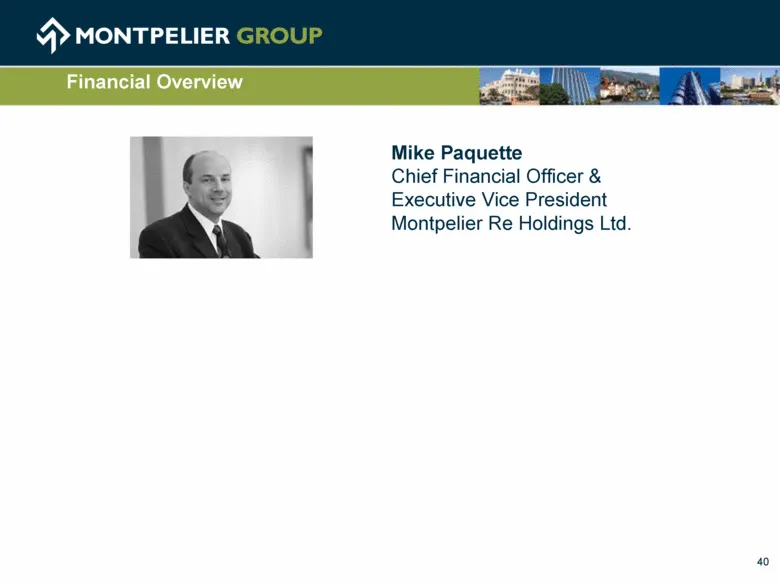
Mike Paquette Chief Financial Officer & Executive Vice President Montpelier Re Holdings Ltd. Financial Overview 40
Slide 40: Q1 2009 Update
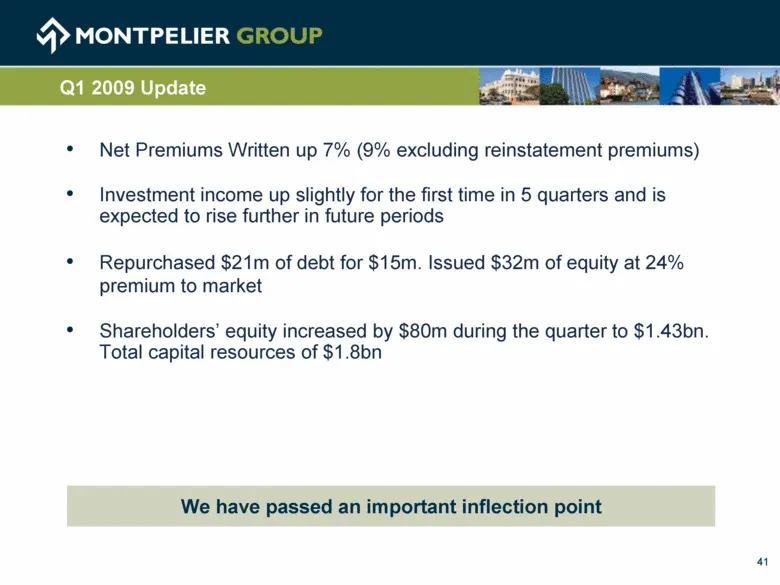
Q1 2009 Update • Net Premiums Written up 7% (9% excluding reinstatement premiums) • Investment income up slightly for the first time in 5 quarters and is expected to rise further in future periods • Repurchased $21m of debt for $15m. Issued $32m of equity at 24% premium to market • Shareholders’ equ
Slide 41: Key Financial Highlights
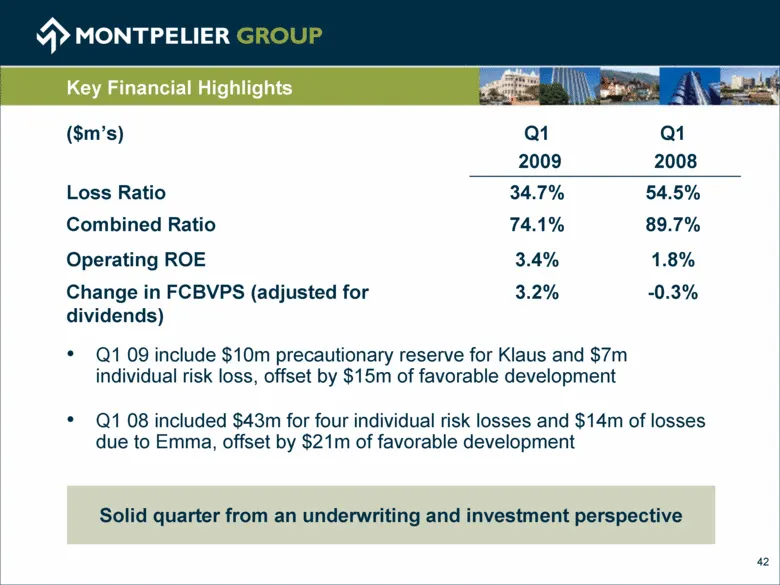
Key Financial Highlights ($m’s) Q1 2009 Q1 2008 Loss Ratio 34.7% 54.5% Combined Ratio 74.1% 89.7% Operating ROE 3.4% 1.8% Change in FCBVPS (adjusted for dividends) 3.2% -0.3% • Q1 09 include $10m precautionary reserve for Klaus and $7m individual risk loss, offset by $15m of favorable development •
Slide 42: Balance Sheet
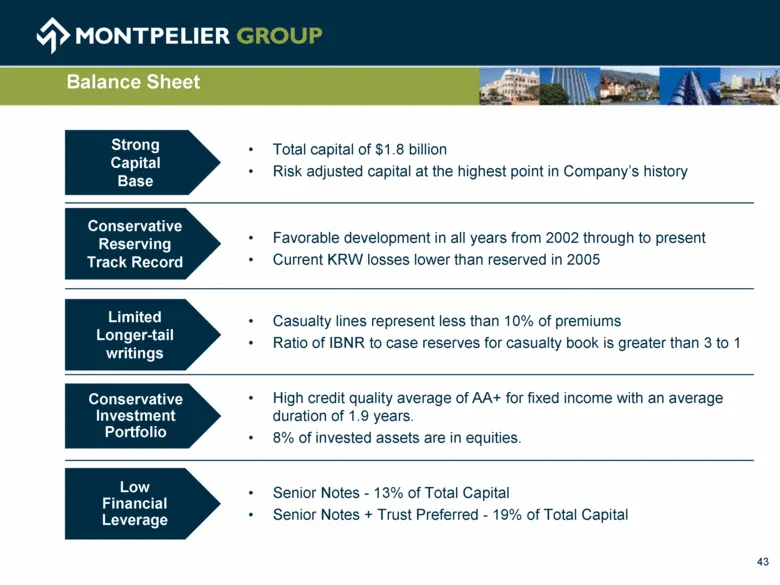
Balance Sheet • Total capital of $1.8 billion • Risk adjusted capital at the highest point in Company’s history • Favorable development in all years from 2002 through to present • Current KRW losses lower than reserved in 2005 • Casualty lines represent less than 10% of premiums • Ratio of IBNR to c
Slide 43: Balance Sheet Highlights
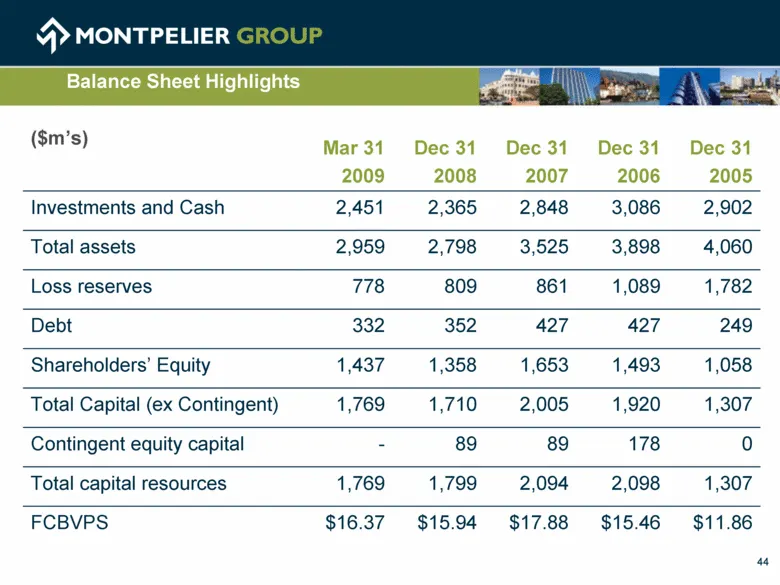
($m’s) Mar 31 2009 Dec 31 2008 Dec 31 2007 Dec 31 2006 Dec 31 2005 Investments and Cash 2,451 2,365 2,848 3,086 2,902 Total assets 2,959 2,798 3,525 3,898 4,060 Loss reserves 778 809 861 1,089 1,782 Debt 332 352 427 427 249 Shareholders’ Equity 1,437 1,358 1,653 1,493 1,058 Total Capital (ex Conting
Slide 44: Reserving Track Record
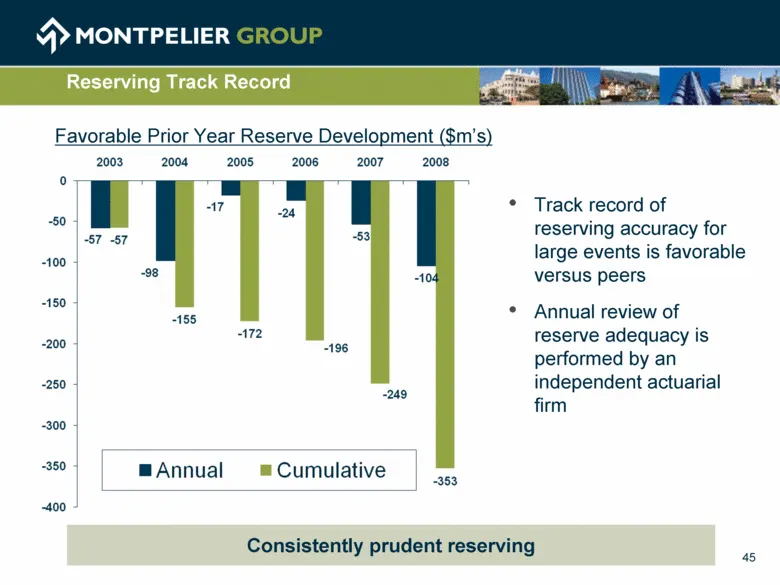
Reserving Track Record Favorable Prior Year Reserve Development ($m’s) • Track record of reserving accuracy for large events is favorable versus peers • Annual review of reserve adequacy is performed by an independent actuarial firm 45 Consistently prudent reserving
Slide 45: Investments
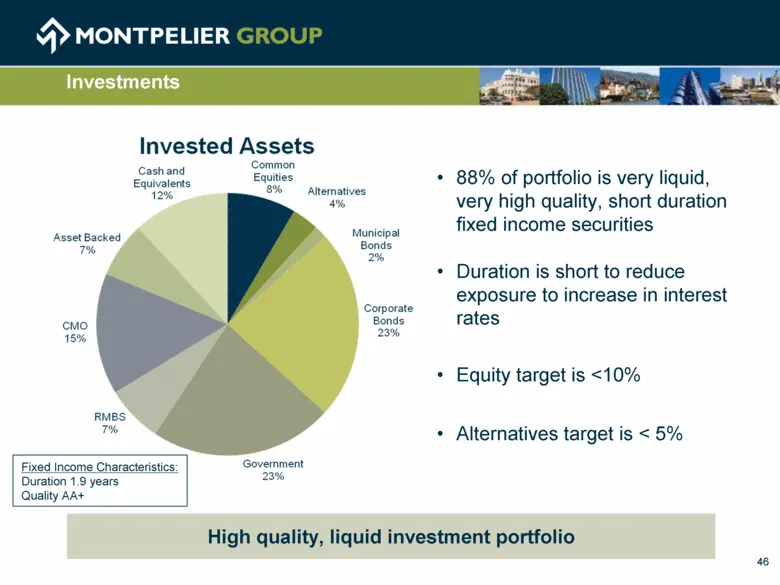
Investments Fixed Income Characteristics: Duration 1.9 years Quality AA+ • 88% of portfolio is very liquid, very high quality, short duration fixed income securities • Duration is short to reduce exposure to increase in interest rates • Equity target is <10% • Alternatives target is < 5% 46 High qua
Slide 46: Wrap-Up and Q&A
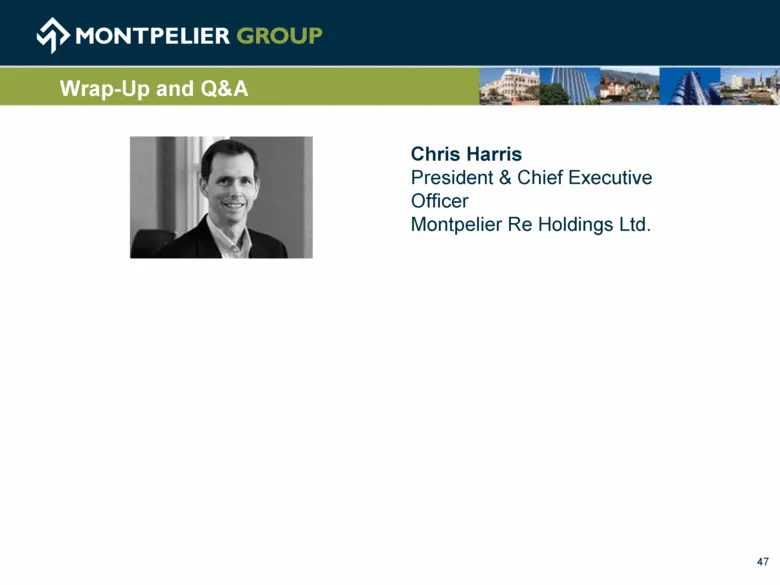
Wrap-Up and Q&A Chris Harris President & Chief Executive Officer Montpelier Re Holdings Ltd. 47
Slide 47: Website and contact information
Please visit our websites for more information on our company, products and team members: www.montpelierre.bm www.mre.bm www.montpelier5151.co.uk www.montpelierus.com www.montpeliereuropa.ch Montpelier House, 94 Pitts Bay Road, Pembroke, Bermuda PO Box HM 2079, Hamilton, Bermuda, HMHX Tel: +1 (441)
Source: SEC EDGAR · 8-K filed May 7, 2009
More decks from Montpelier Re Holdings Ltd
 Merger or Acquisition (March 2015)11 slides · Mar 31, 2015
 Merger or Acquisition (March 2015)11 slides · Mar 31, 2015
 Q4 2011 Earnings Presentation26 slides · Mar 5, 2012
 Investor Presentation (September 2011)27 slides · Sep 7, 2011
 KBW Investor Conference 201018 slides · Sep 8, 2010
 Investor Presentation (December 2007)15 slides · Dec 4, 2007