CT Automotive Group PLC · LSE:CTA
CT Automotive — H1 2024 Earnings Presentation
24 slides from CT Automotive's earnings presentation, September 2024
Slide 1: Building on a Strong Base
Innovation Defines Us Building on a Strong Base CT Automotive Group plc Interim Results 2024
Slide 2: Agenda
Agenda 1. Highlights Simon Phillips Anna Brown 2. Financial results CEO CFO Simon co-founded CT in 2000, having Anna brings substantial experience in 3. Business review identified an opportunity to disrupt the strategic and operational finance in listed automotive tooling market. companies. Prior to
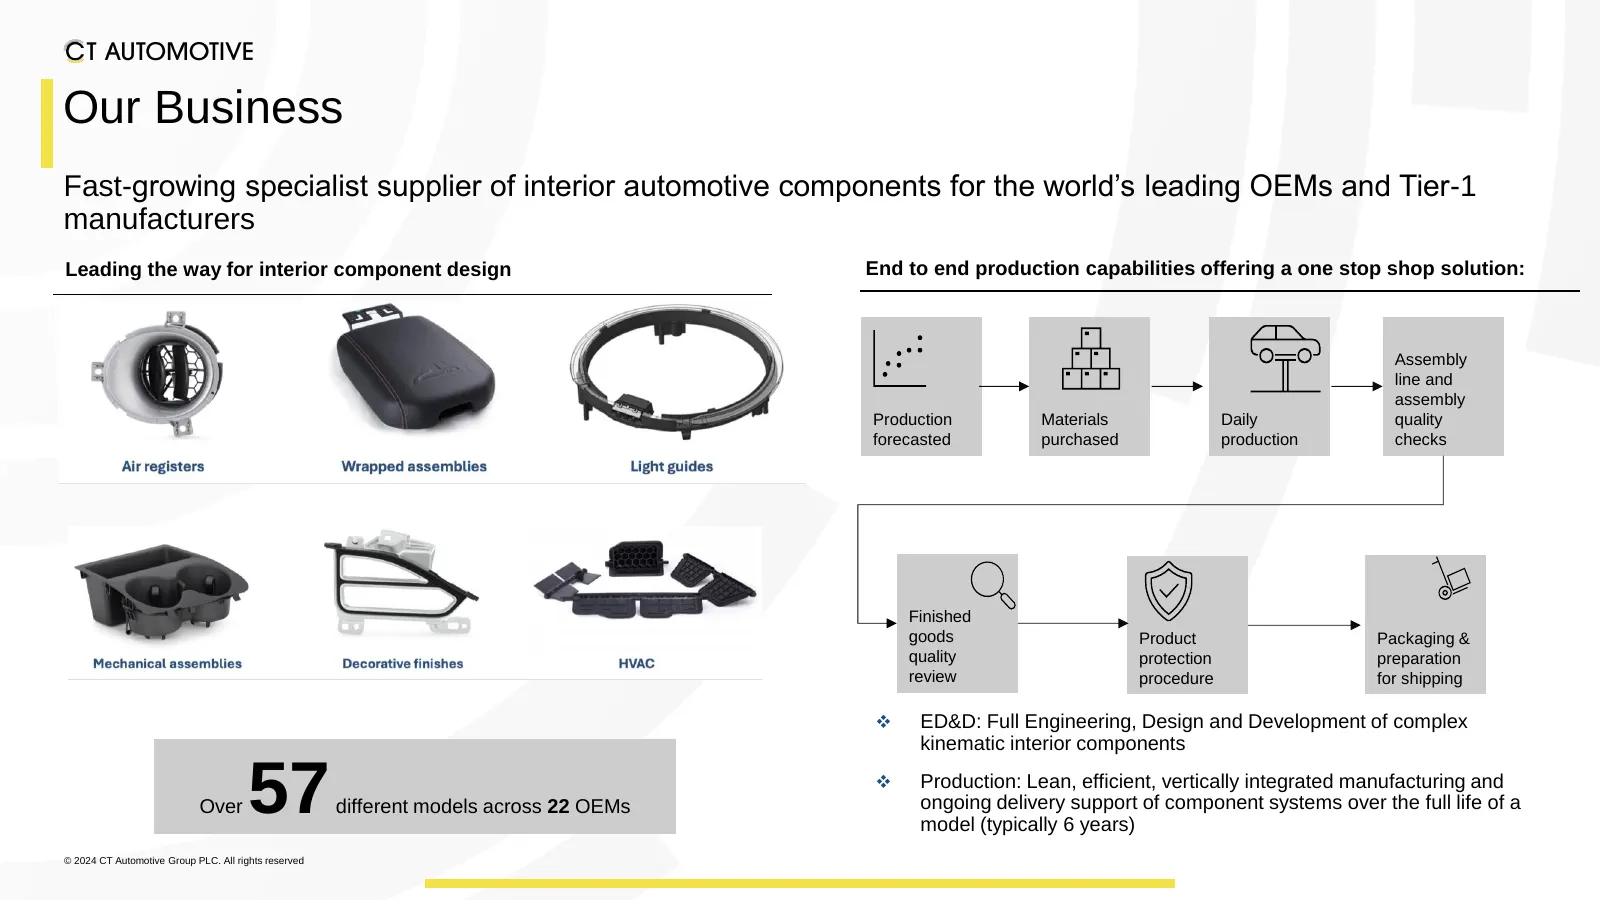
Slide 3: Our Business
Our Business Fast-growing specialist supplier of interior automotive components for the world’s leading OEMs and Tier-1 manufacturers Leading the way for interior component design End to end production capabilities offering a one stop shop solution: Assembly line and assembly Production Materials Da
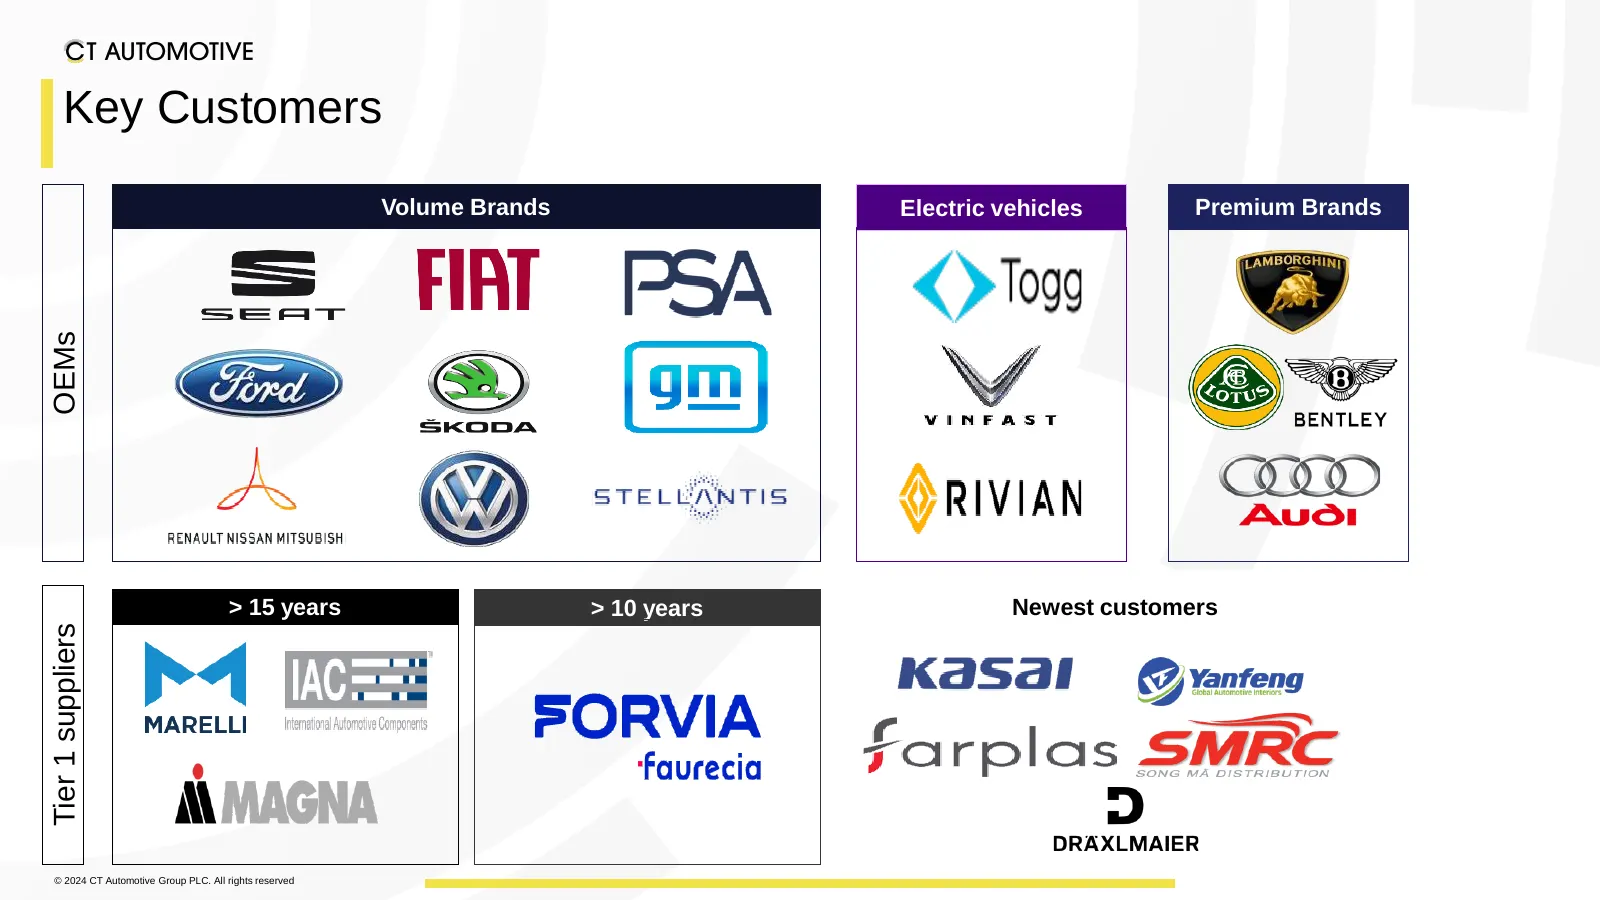
Slide 4: Key Customers
Key Customers Volume Brands Electric vehicles Premium Brands OEMs > 15 years > 10 years Newest customers Tier 1 suppliers © 2024 CT Automotive Group PLC. All rights reserved
Slide 5: Highlights
Highlights Good visibility for both 2024 and 2025 with further margin improvement © 2024 CT Automotive Group PLC. All rights reserved
Slide 6: Financial Highlights HY24
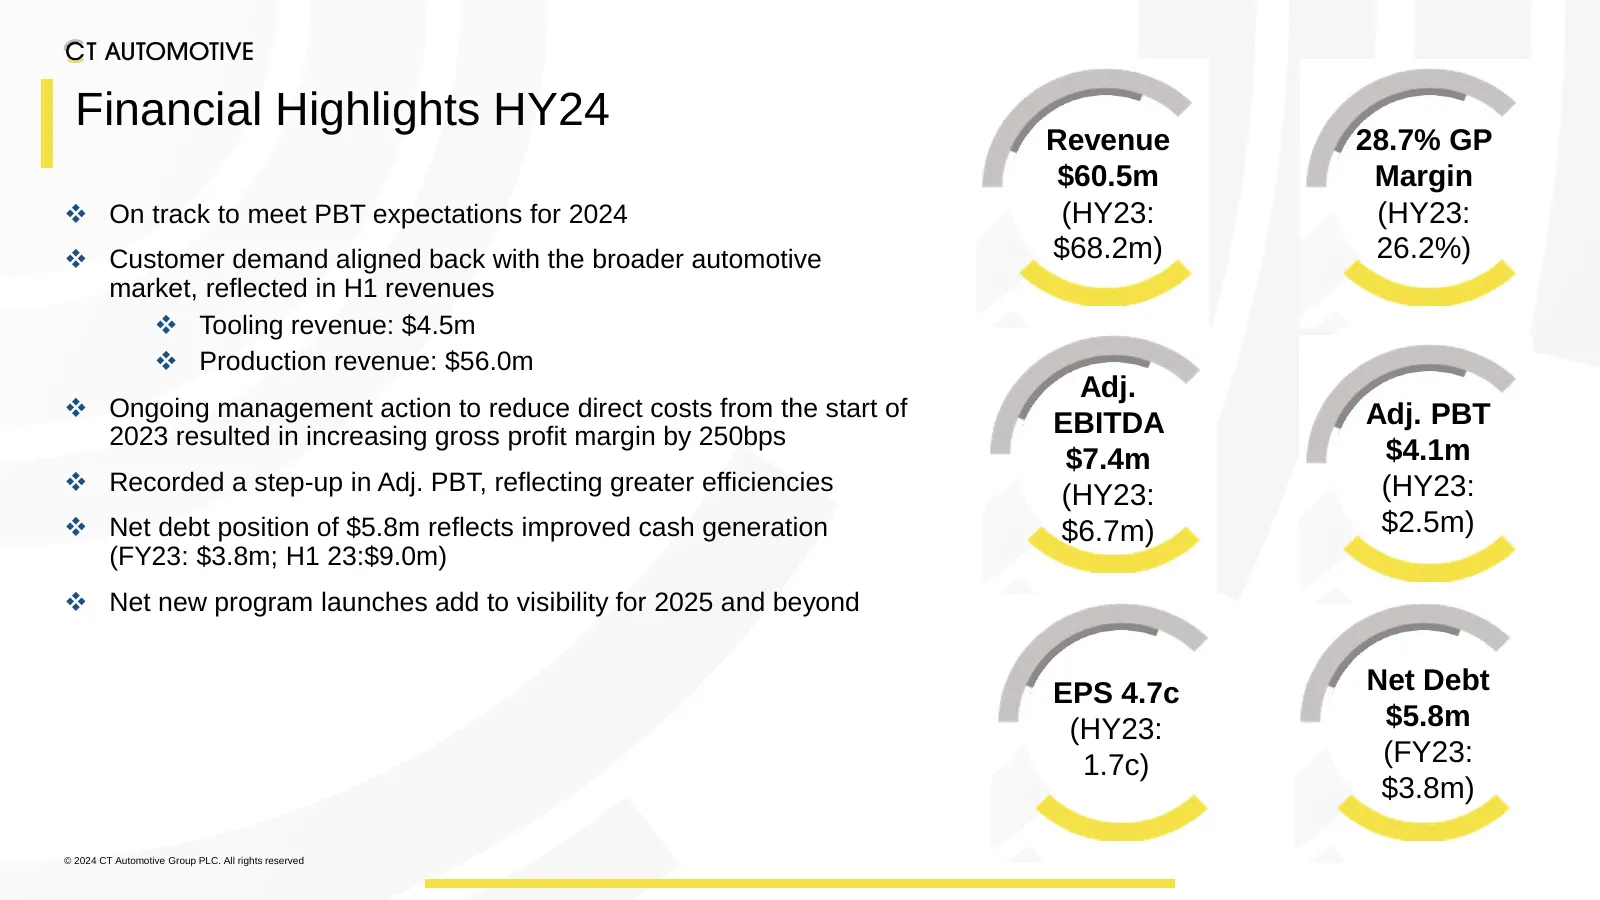
Financial Highlights HY24 Revenue 28.7% GP $60.5m Margin ❖ On track to meet PBT expectations for 2024 (HY23: (HY23: ❖ Customer demand aligned back with the broader automotive $68.2m) 26.2%) market, reflected in H1 revenues ❖ Tooling revenue: $4.5m ❖ Production revenue: $56.0m Adj. ❖ Ongoing manageme
Slide 7: Operational Highlights HY24
Operational Highlights HY24 ❖ Five contract wins in H1 with existing customers worth an Trebled estimated $27.5m Five Key Sales OEM Wins ❖ Orderbook has strengthened with new programmes Team commencing between 2025-2027 ❖ Pipeline of upcoming RFQ’s further strengthens outlook ❖ Strategic expansion o
Slide 8: Financial Results
Financial Results Improvement across all key metrics © 2024 CT Automotive Group PLC. All rights reserved
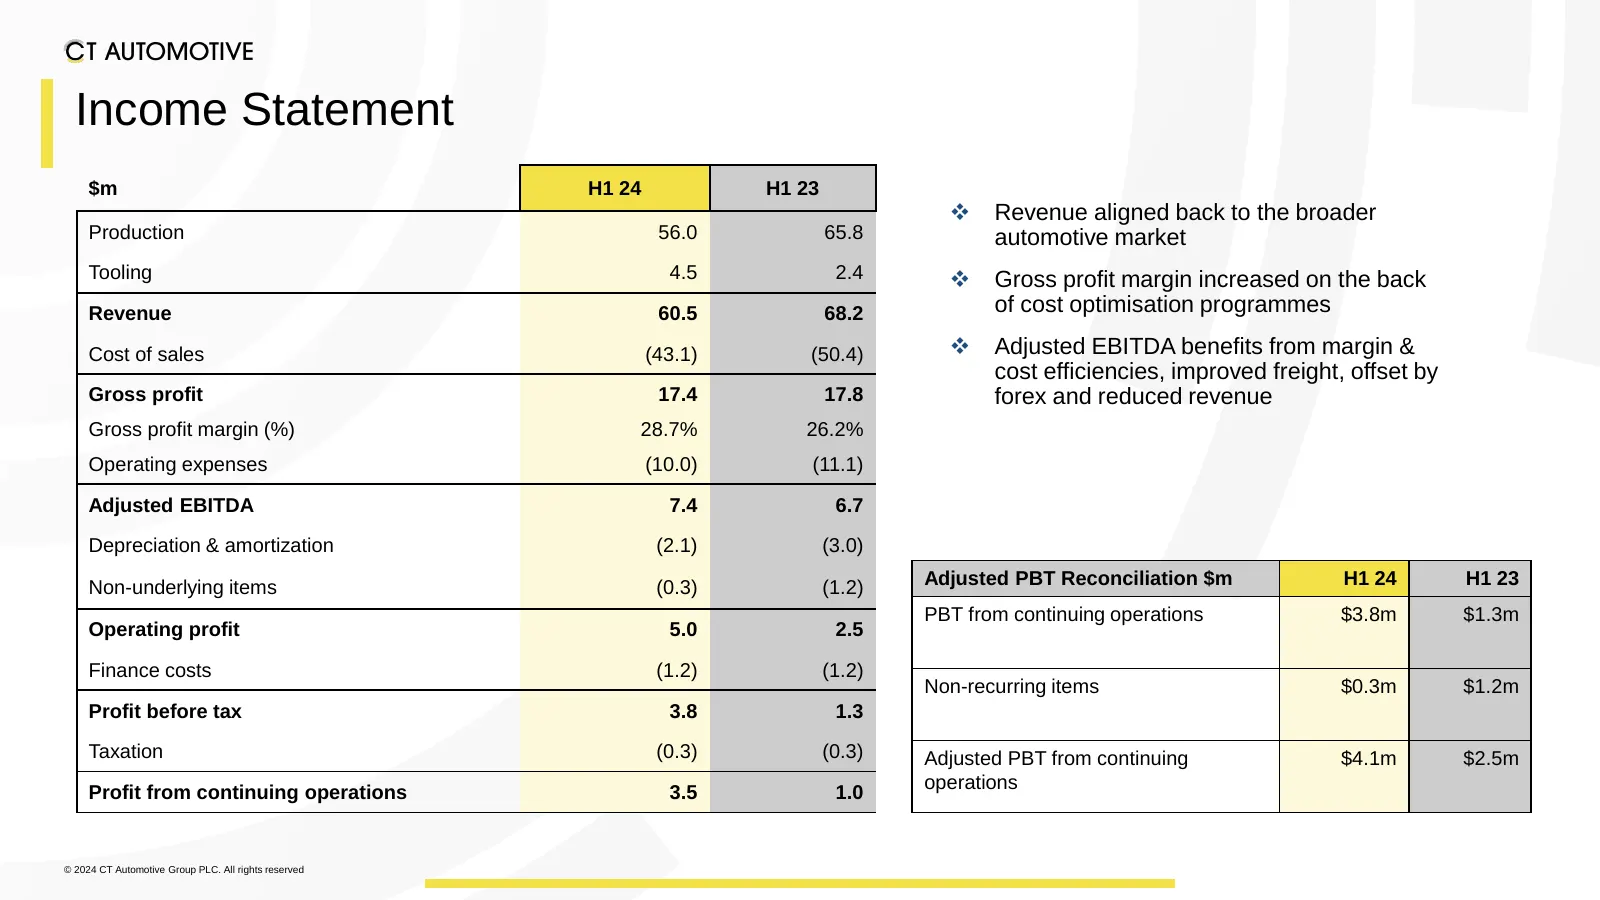
Slide 9: Income Statement
Income Statement $m H1 24 H1 23 ❖ Revenue aligned back to the broader Production 56.0 65.8 automotive market Tooling 4.5 2.4 ❖ Gross profit margin increased on the back Revenue 60.5 68.2 of cost optimisation programmes Cost of sales (43.1) (50.4) ❖ Adjusted EBITDA benefits from margin & cost efficie
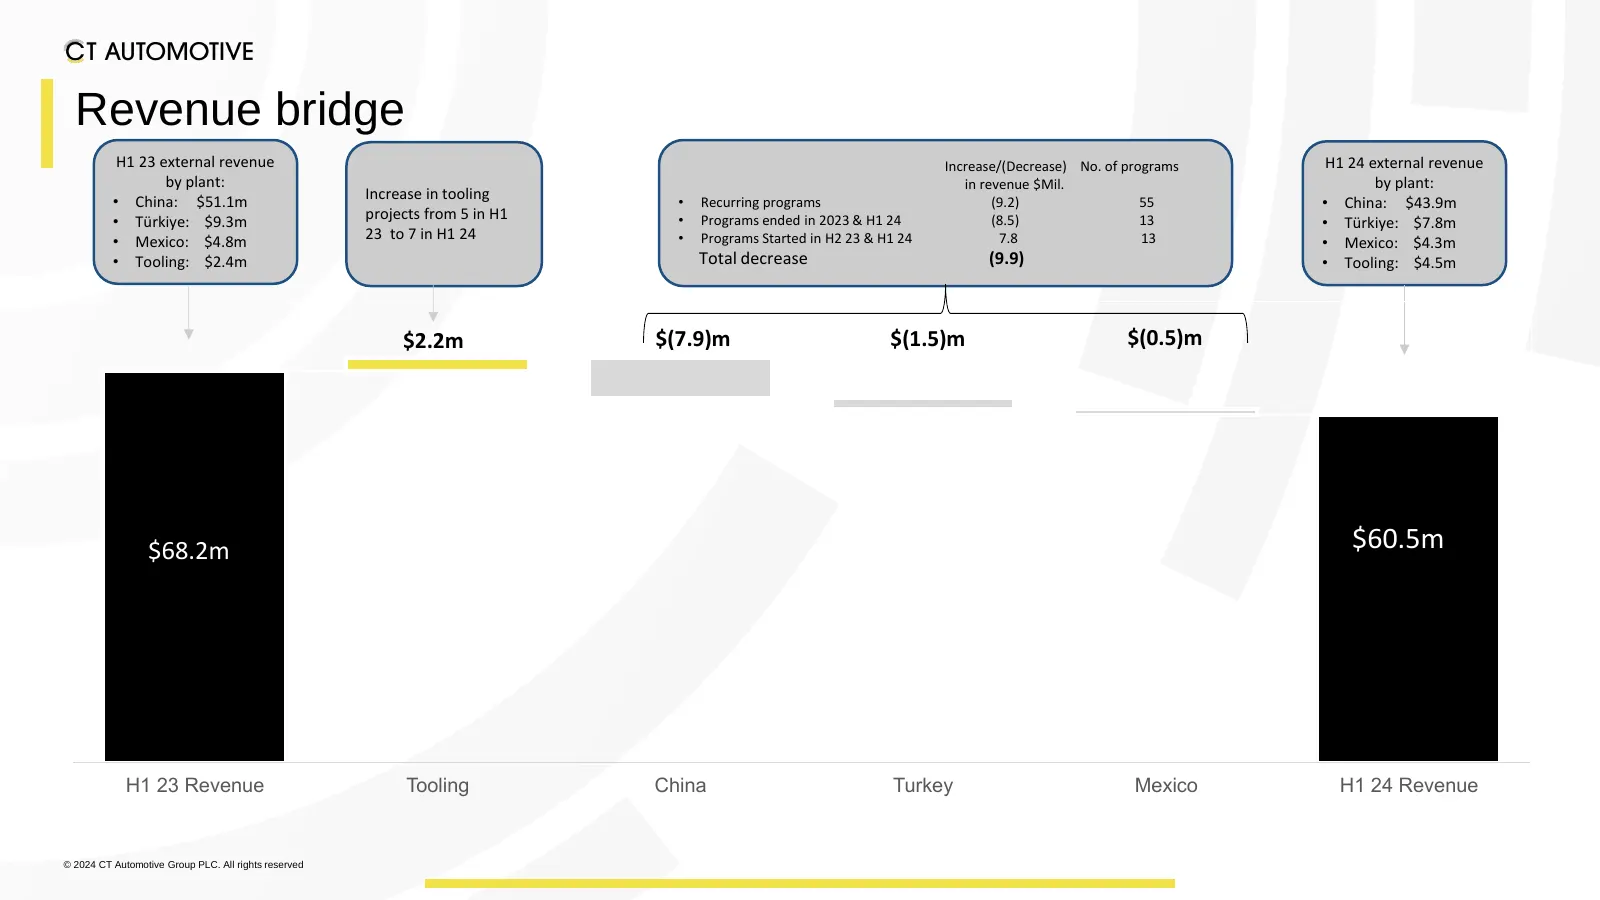
Slide 10: Revenue bridge
Revenue bridge H1 23 external revenue Increase/(Decrease) No. of programs H1 24 external revenue by plant: in revenue $Mil. by plant: • China: $51.1m Increase in tooling • Recurring programs (9.2) 55 • China: $43.9m • Türkiye: $9.3m projects from 5 in H1 • Programs ended in 2023 & H1 24 (8.5) 13 • T
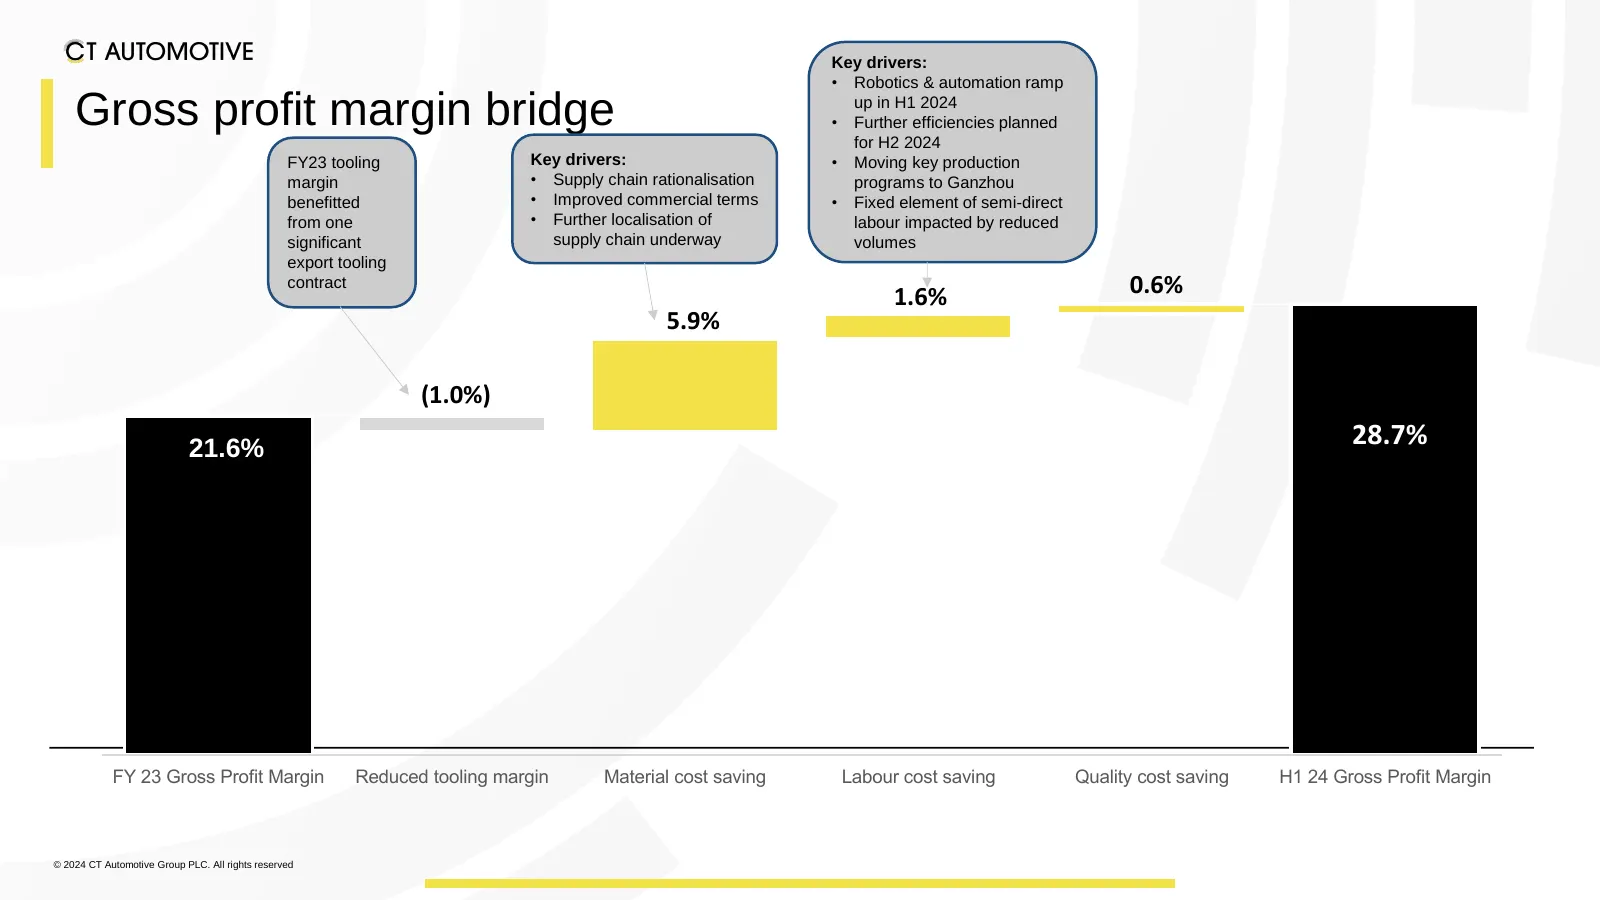
Slide 11: Gross profit margin bridge
Key drivers: • Robotics & automation ramp Gross profit margin bridge up in H1 2024 • Further efficiencies planned for H2 2024 FY23 tooling Key drivers: • Moving key production margin • Supply chain rationalisation programs to Ganzhou benefitted • Improved commercial terms • Fixed element of semi-dir
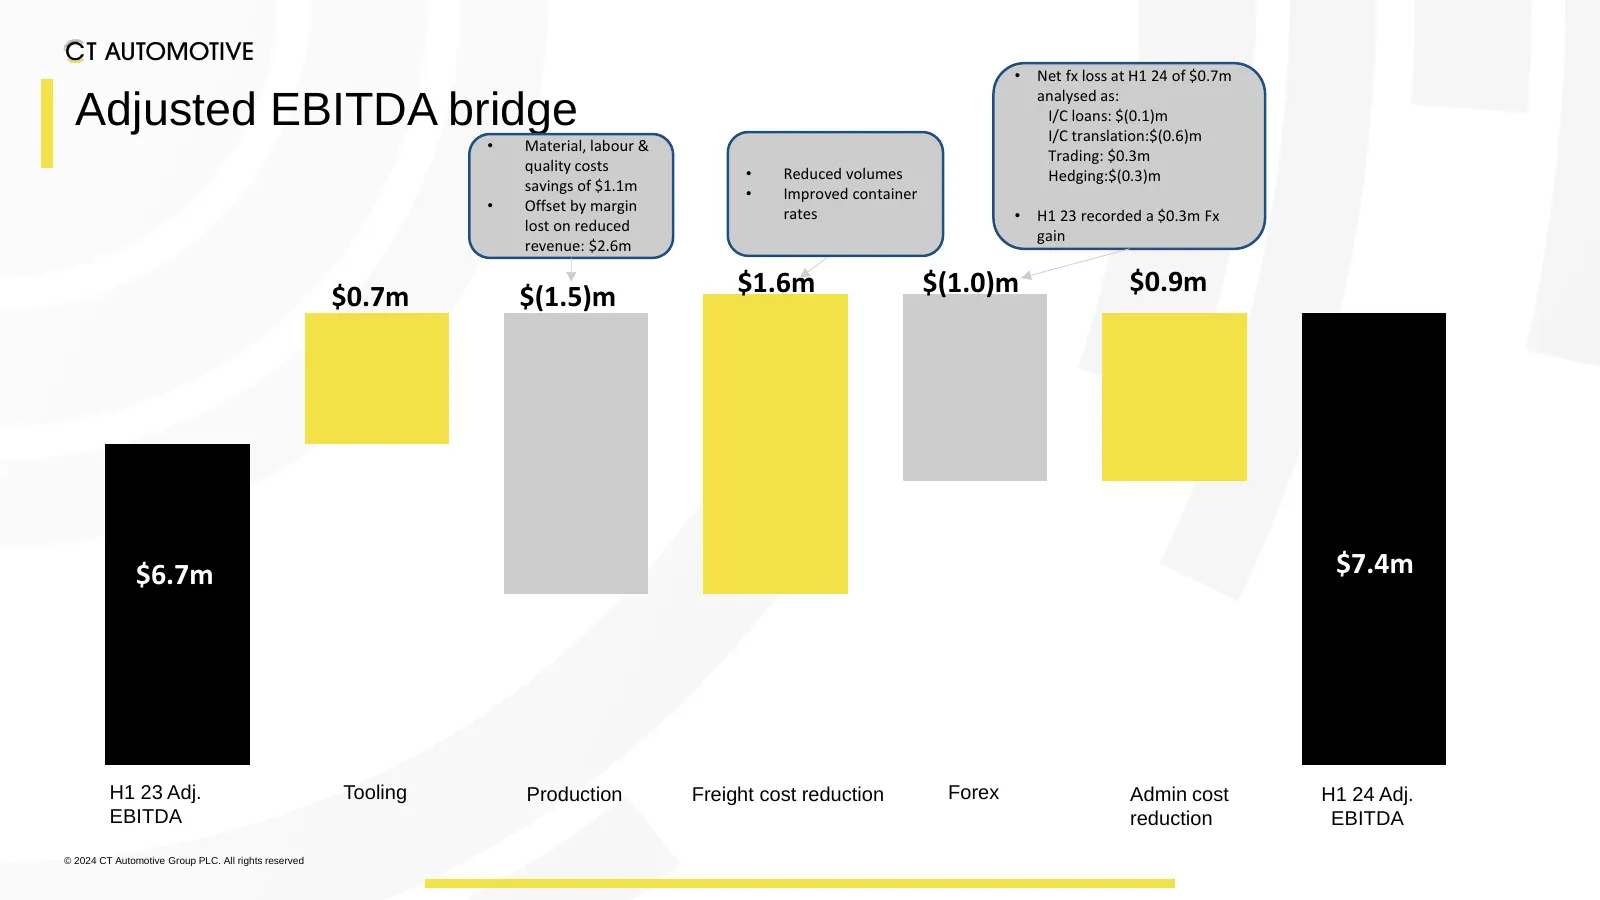
Slide 12: Adjusted EBITDA bridge
• Net fx loss at H1 24 of $0.7m analysed as: Adjusted EBITDA bridge I/C loans: $(0.1)m I/C translation:$(0.6)m • Material, labour & Trading: $0.3m quality costs • Reduced volumes Hedging:$(0.3)m savings of $1.1m • Improved container • Offset by margin rates • H1 23 recorded a $0.3m Fx lost on reduce
Slide 13: Balance sheet
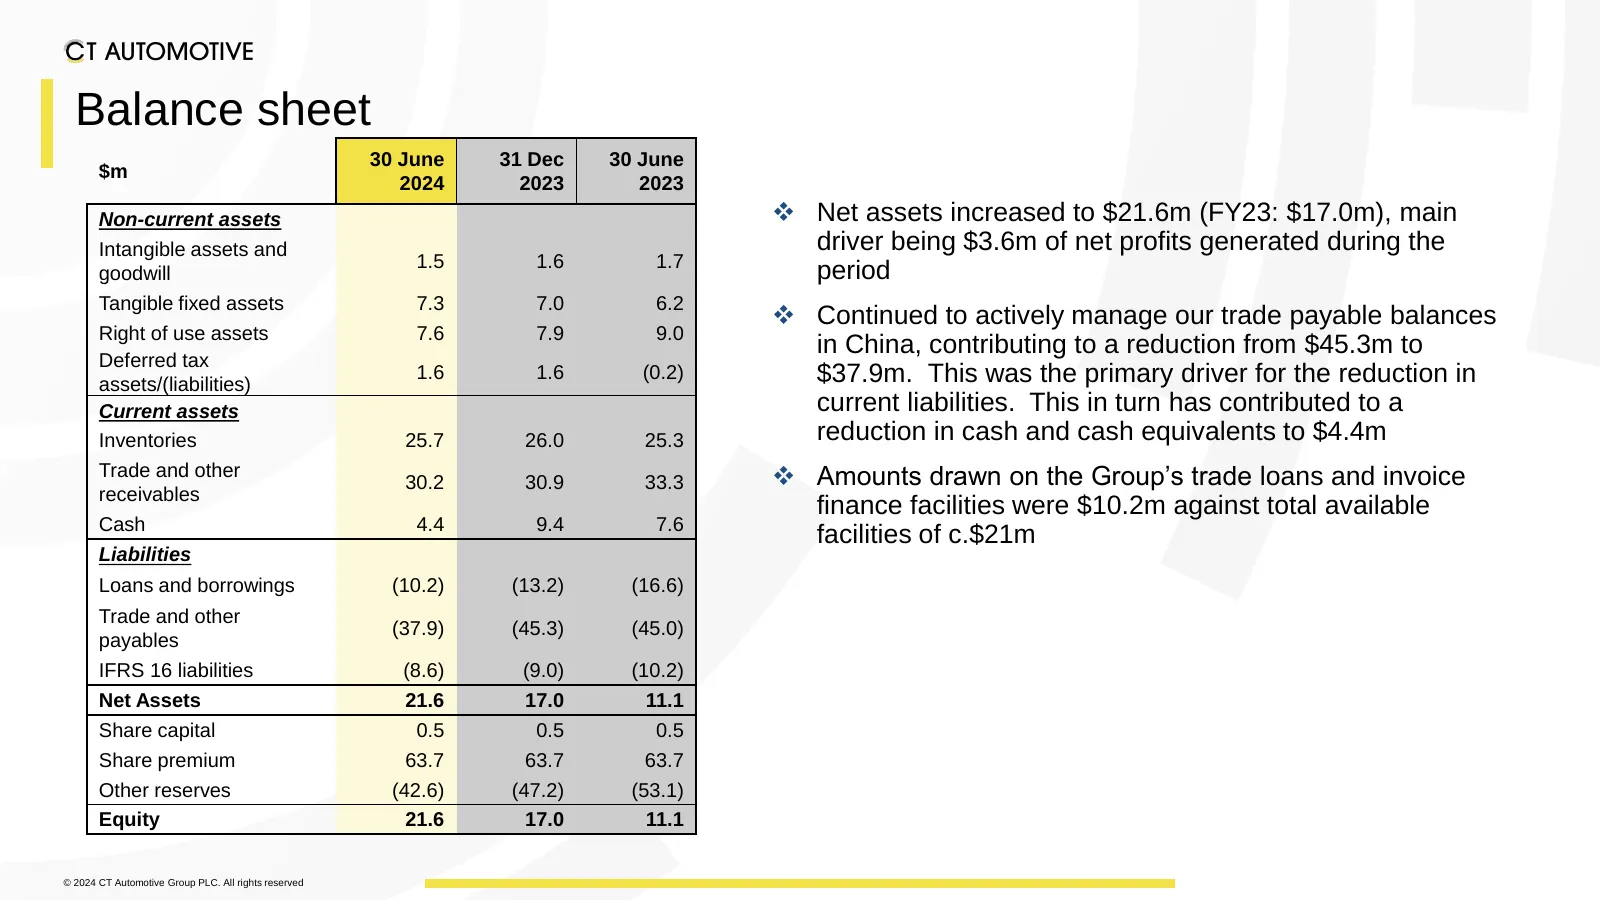
Balance sheet 30 June 31 Dec 30 June $m 2024 2023 2023 Non-current assets ❖ Net assets increased to $21.6m (FY23: $17.0m), main Intangible assets and driver being $3.6m of net profits generated during the 1.5 1.6 1.7 goodwill period Tangible fixed assets 7.3 7.0 6.2 ❖ Continued to actively manage ou
Slide 14: Net debt bridge
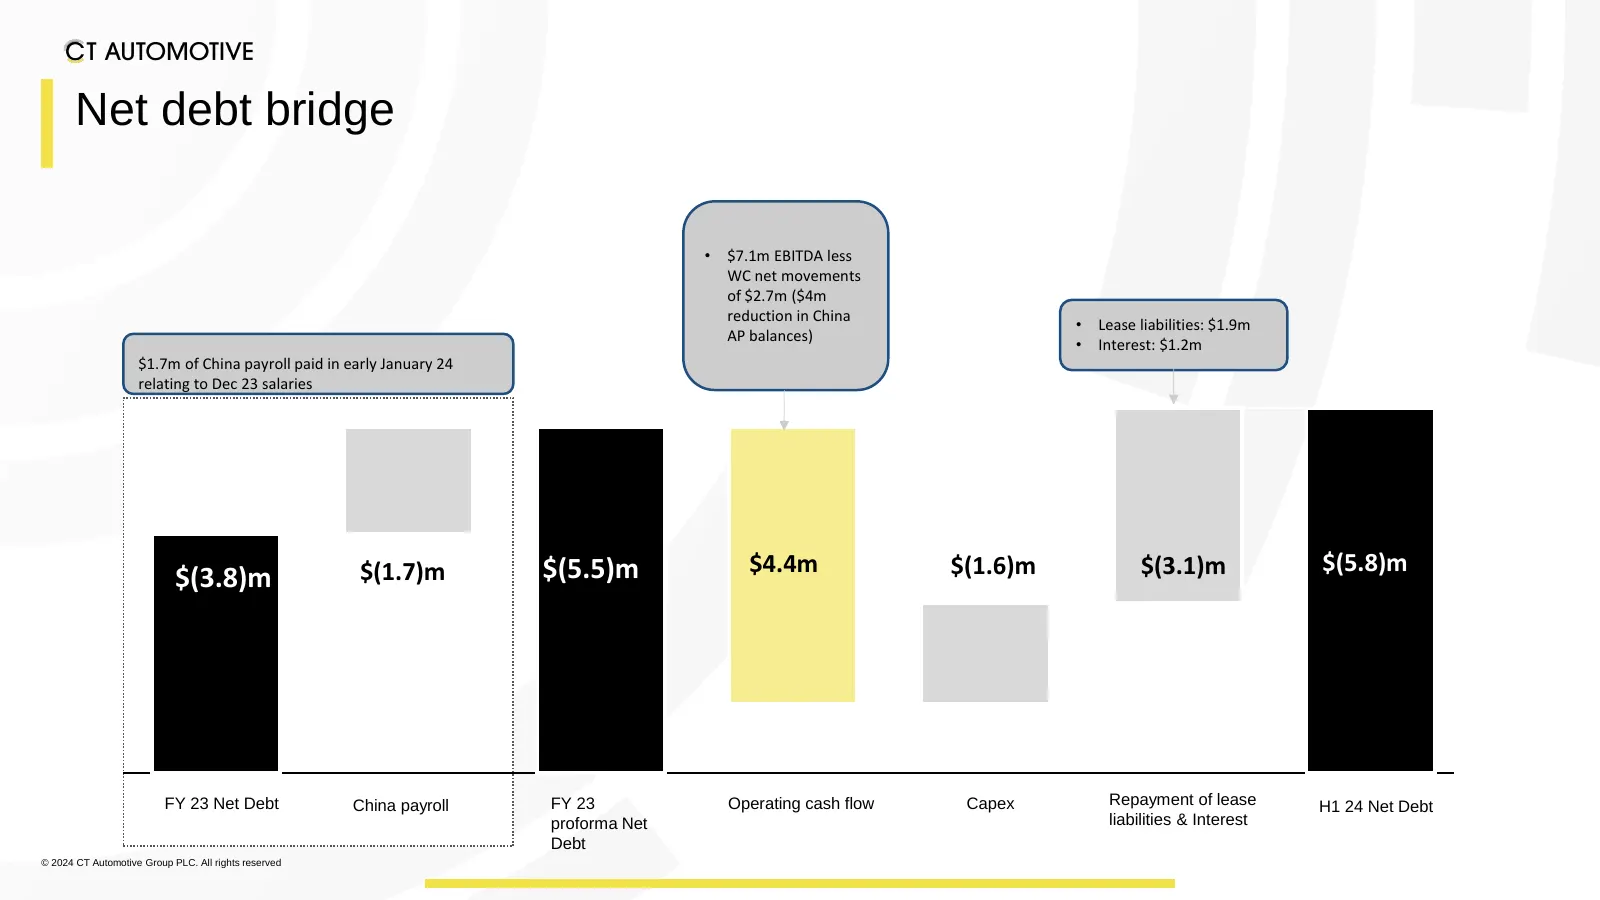
Net debt bridge • $7.1m EBITDA less WC net movements of $2.7m ($4m reduction in China • Lease liabilities: $1.9m AP balances) • Interest: $1.2m $1.7m of China payroll paid in early January 24 relating to Dec 23 salaries $(1.7)m $(5.5)m $4.4m $(1.6)m $(3.1)m $(5.8)m $(3.8)m FY 23 Net Debt China payro
Slide 15: Business review
Business review Efficiency initiatives delivering margin improvement © 2024 CT Automotive Group PLC. All rights reserved
Slide 16: Sustainability
Sustainability We are proud to work with EcoVadis who have undertaken a full sustainability report of the Group’s operations and awarded us the EcoVadis Silver Award, placing us in the top 15% of companies assessed Three key areas comprise CT Automotive’s strategy on sustainability: ❖ Reducing our c
Slide 17: Review of key operations: China
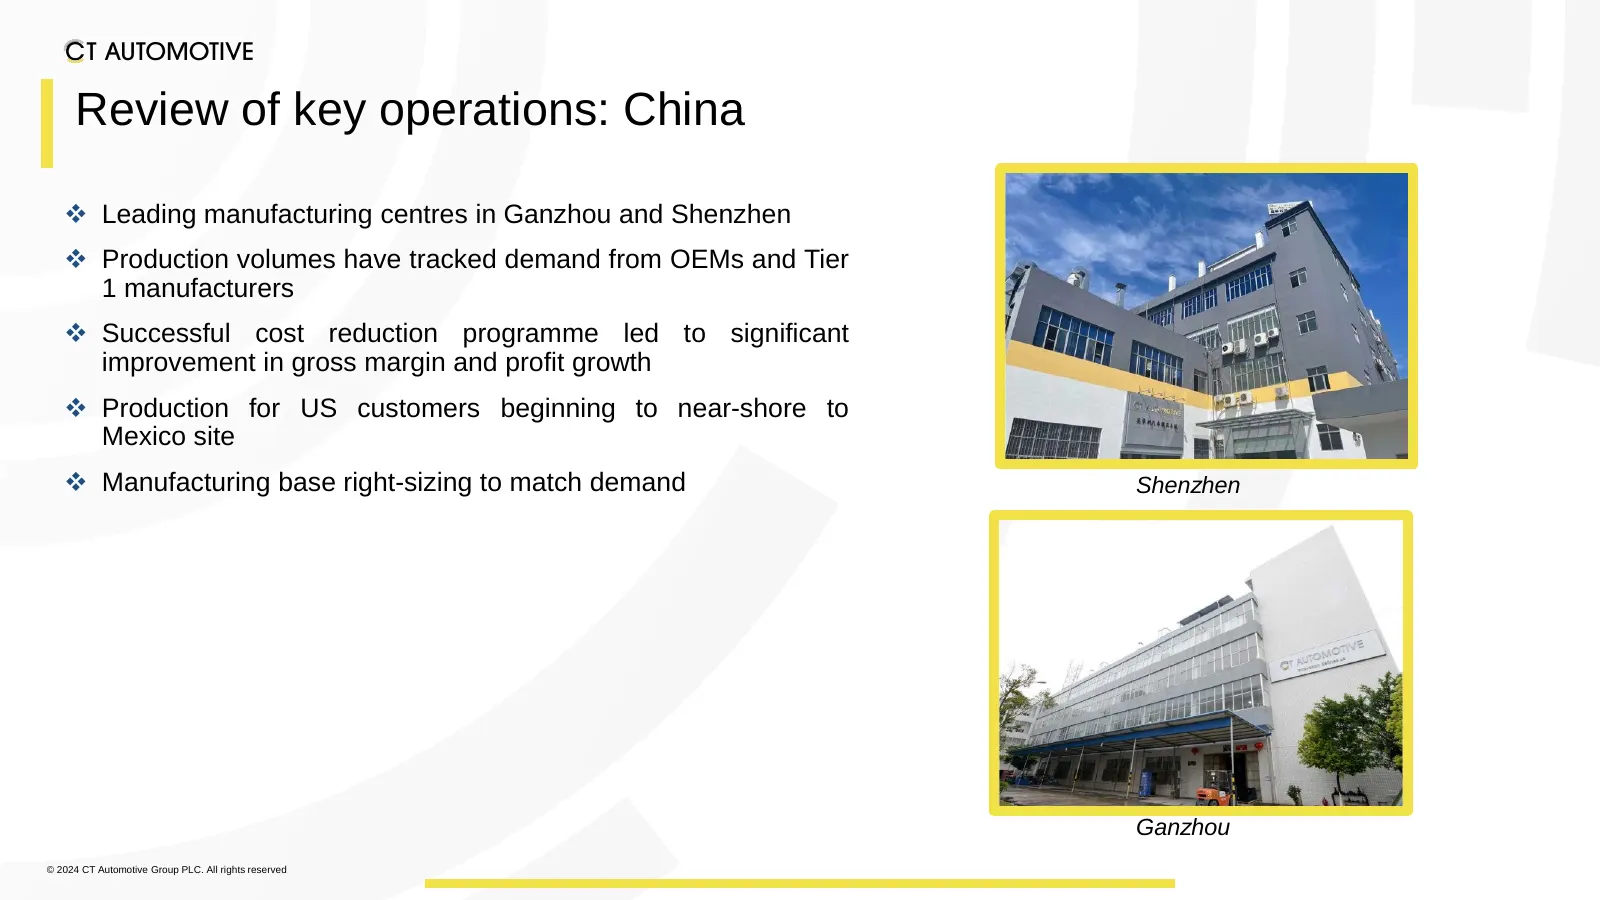
Review of key operations: China ❖ Leading manufacturing centres in Ganzhou and Shenzhen ❖ Production volumes have tracked demand from OEMs and Tier 1 manufacturers ❖ Successful cost reduction programme led to significant improvement in gross margin and profit growth ❖ Production for US customers beg
Slide 18: Review of key operations: Türkiye and Mexico
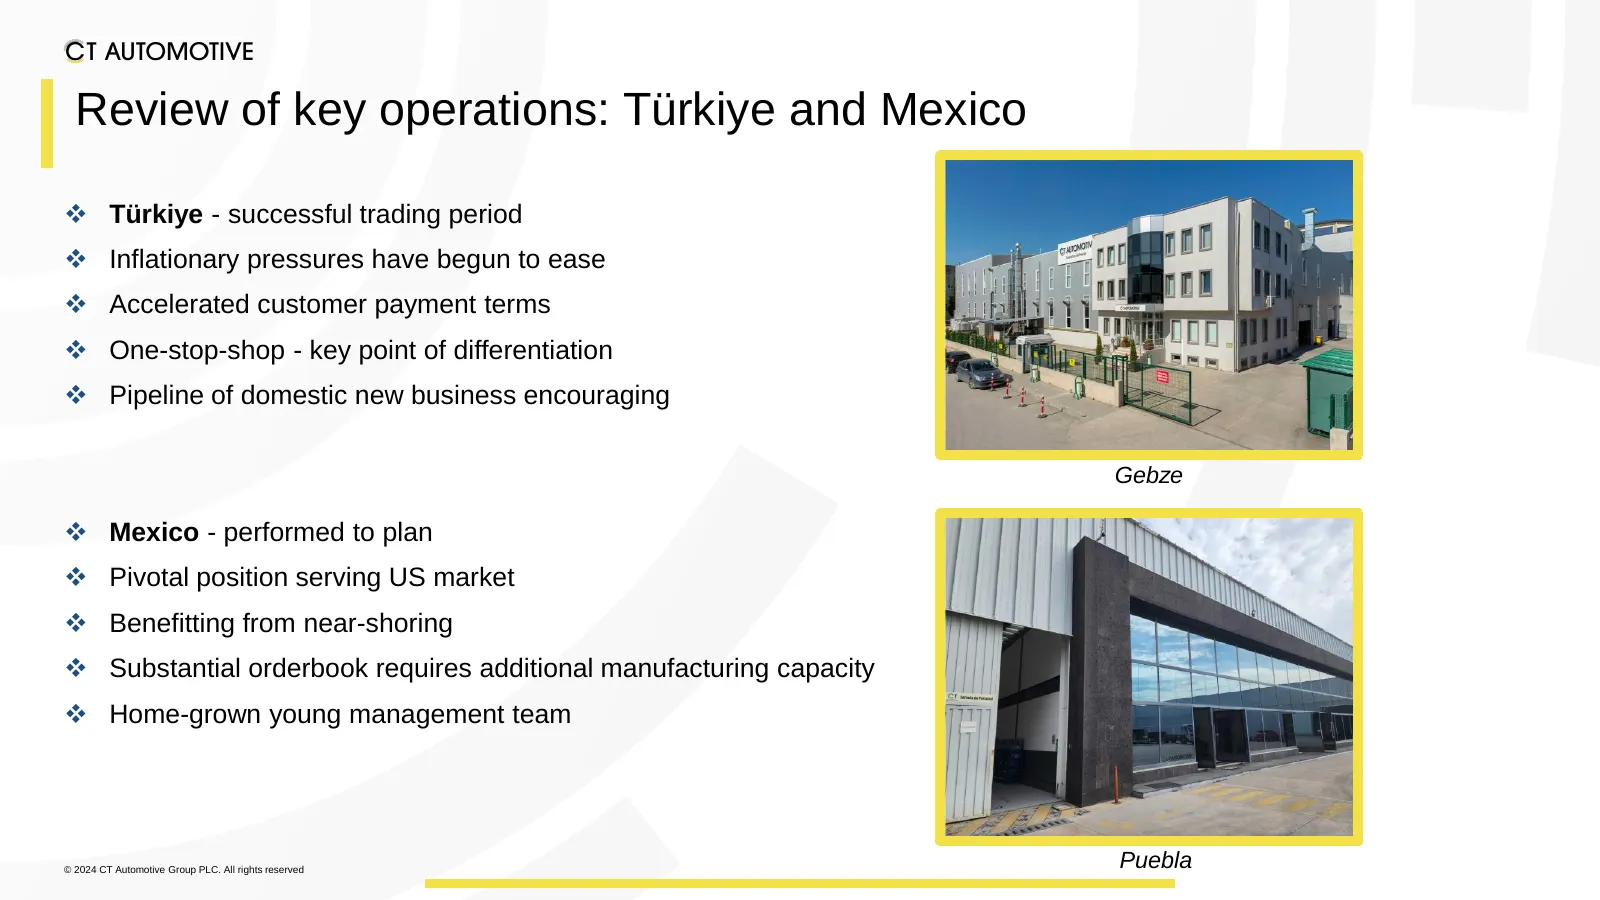
Review of key operations: Türkiye and Mexico ❖ Türkiye - successful trading period ❖ Inflationary pressures have begun to ease ❖ Accelerated customer payment terms ❖ One-stop-shop - key point of differentiation ❖ Pipeline of domestic new business encouraging Gebze ❖ Mexico - performed to plan ❖ Pivo
Slide 19: Automation Driving Future Change
Automation Driving Future Change Robotics Digitisation AI ❖ Trialling robotic options in ❖ Linking to ERP systems, China on assembly lines, ❖ Trialling AI functionality to transfer of information will injection moulding and perform administrative become entirely digital, painting tasks across manufa
Slide 20: Outlook
Outlook © 2024 CT Automotive Group PLC. All rights reserved
Slide 21: Outlook
Outlook ❖ Automotive market is navigating a transitional period ❖ CT Automotive remains well placed as a small, agile player: ❖ Good visibility for H2 2024 and 2025 ❖ Full margin benefits expected as the business scales up ❖ Expanded new business team to target market share opportunity ❖ Automation
Slide 22: Appendices
Appendices © 2024 CT Automotive Group PLC. All rights reserved
Slide 23: Global Footprint
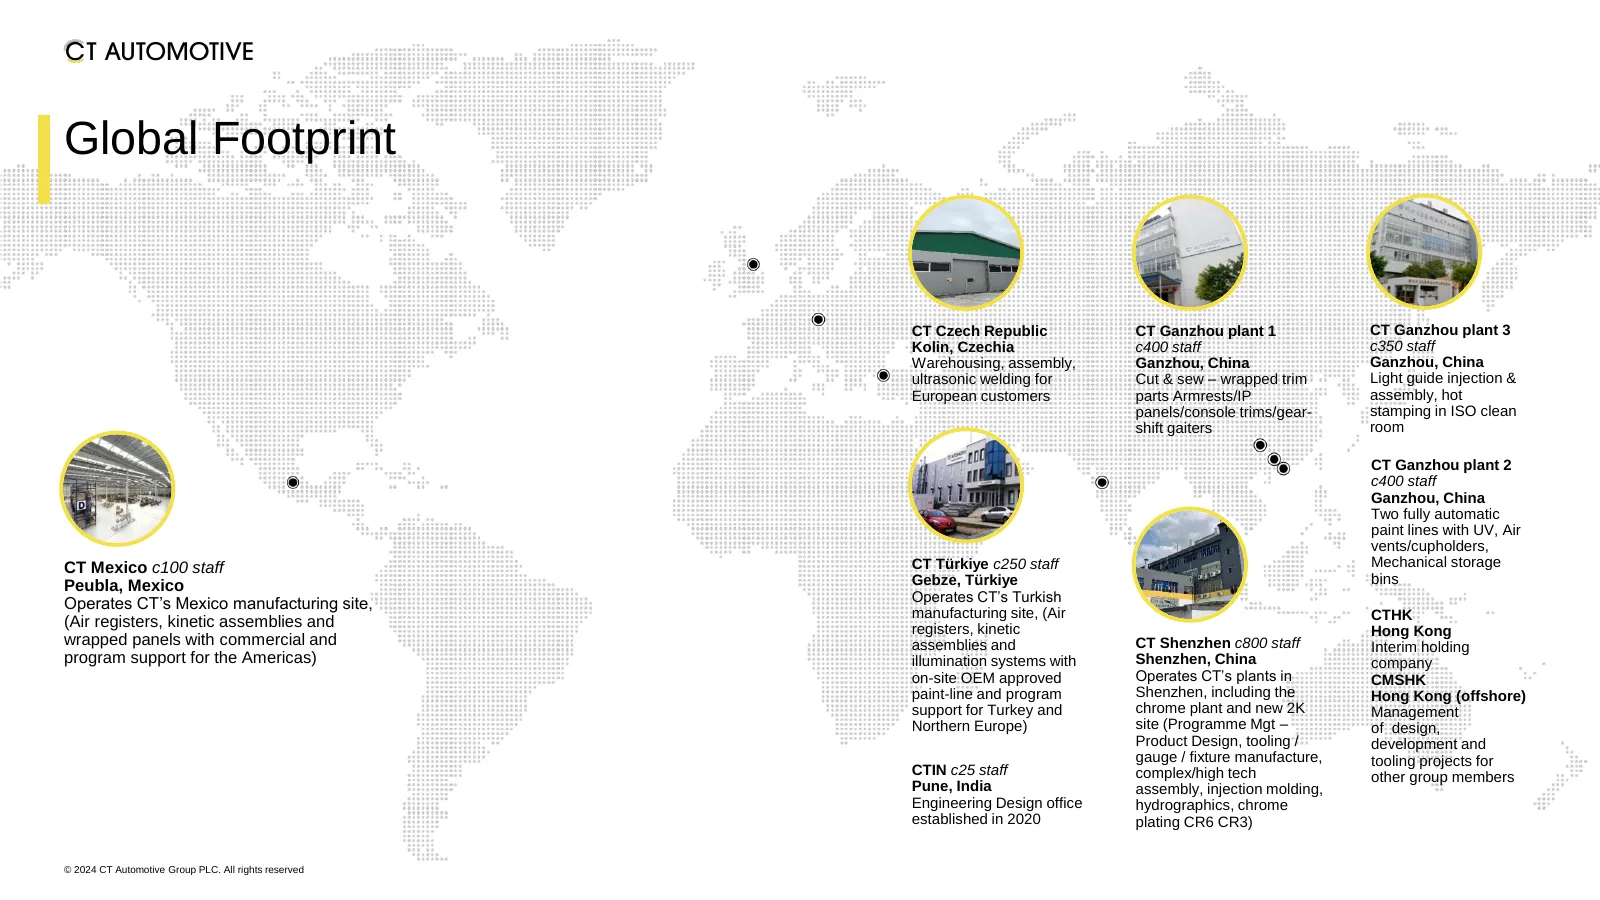
Global Footprint CT Czech Republic CT Ganzhou plant 1 CT Ganzhou plant 3 Kolin, Czechia c400 staff c350 staff Warehousing, assembly, Ganzhou, China Ganzhou, China ultrasonic welding for Cut & sew – wrapped trim Light guide injection & European customers parts Armrests/IP assembly, hot panels/console
Slide 24: Disclaimer
Disclaimer The information contained in this document (“Presentation”) has een prepared T Automotive roup This Presentation may contain forward-looking statements that involve substantial risks and uncertainties, plc (the “Company”) solel for information purposes and does not purport to e comprehens
Source: company website
More decks from CT Automotive Group PLC
 H1 2026 Earnings Presentation18 slides · Sep 16, 2026
 FY2023 Earnings Presentation24 slides · Jun 6, 2024
 H1 2023 Earnings Presentation33 slides · September 2023
 FY2022 Earnings Presentation23 slides · July 2023
 H1 2022 Earnings Presentation26 slides · September 2022
 FY2021 Earnings Presentation28 slides · May 2022