Johnson Matthey PLC · LSE:JMAT
Johnson Matthey — Investor Day (January 2013)
96 slides from Johnson Matthey's investor day presentation, Jan 31, 2013
Slide 1: Presentation to Investors / Analysts – New Business Development and Opportunities in Emission Control Technologies
Presentation to Investors / Analysts – New Business Development and Opportunities in Emission Control Technologies 31st January 2013 Follow us on Twitter: @johnson_matthey
Slide 2: Cautionary Statement
Cautionary Statement This presentation contains forward looking statements that are subject to risk factors associated with, amongst other things, the economic and business circumstances occurring from time to time in the countries and sectors in which Johnson Matthey operates. It is believed that t
Slide 3: Introduction and Welcome
Introduction and Welcome Neil Carson Chief Executive
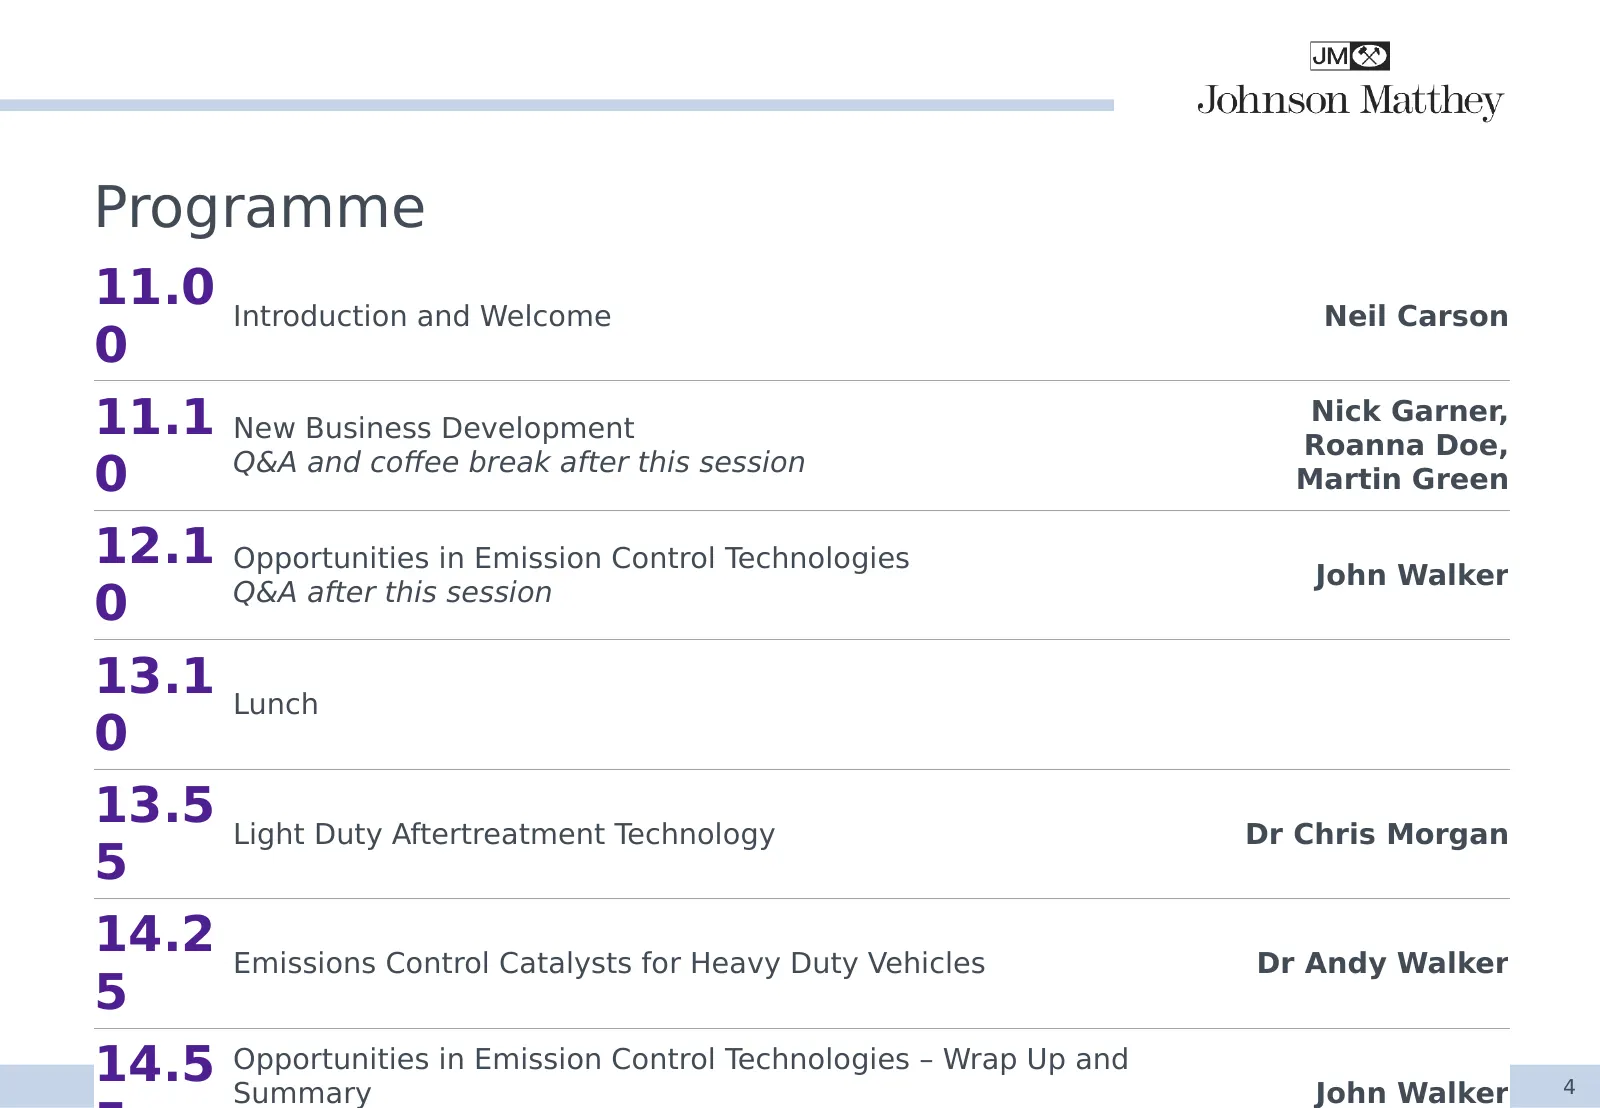
Slide 4: Programme
Programme 11.0 Introduction and Welcome Neil Carson 0 11.1 New Business Development Nick Garner, Roanna Doe, 0 Q&A and coffee break after this session Martin Green 12.1 Opportunities in Emission Control Technologies John Walker 0 Q&A after this session 13.1 Lunch 0 13.5 Light Duty Aftertreatment Tec
Slide 5: Purpose of the Day
Purpose of the Day Provid Outline Update Explain on the drivers and e our progress in four new business opportunities in How we continue to add value through an overview of areas: JM’s Emission R&D and our air purification, Control technology new business advanced Technologies to leverage developmen
Slide 6: Introduction
Introduction A world leading Success founded on Differentiation technology continued through technology company investment in R&D and product development Proven strategy in Well positioned in Delivers value place to develop growth markets new business areas 6
Slide 7: Strategy and New Business Development
Strategy and New Business Development Nick Garner Group Director, Corporate and Strategic Development
Slide 8: Introduction to Johnson Matthey New Business Development
Introduction to Johnson Matthey New Business Development Update Insight Explain Details on New Business into the New Business key growth of our work on: Development Development process opportunities Air Purification, progress Advanced Packaging, Water Purification and Battery Technology 8
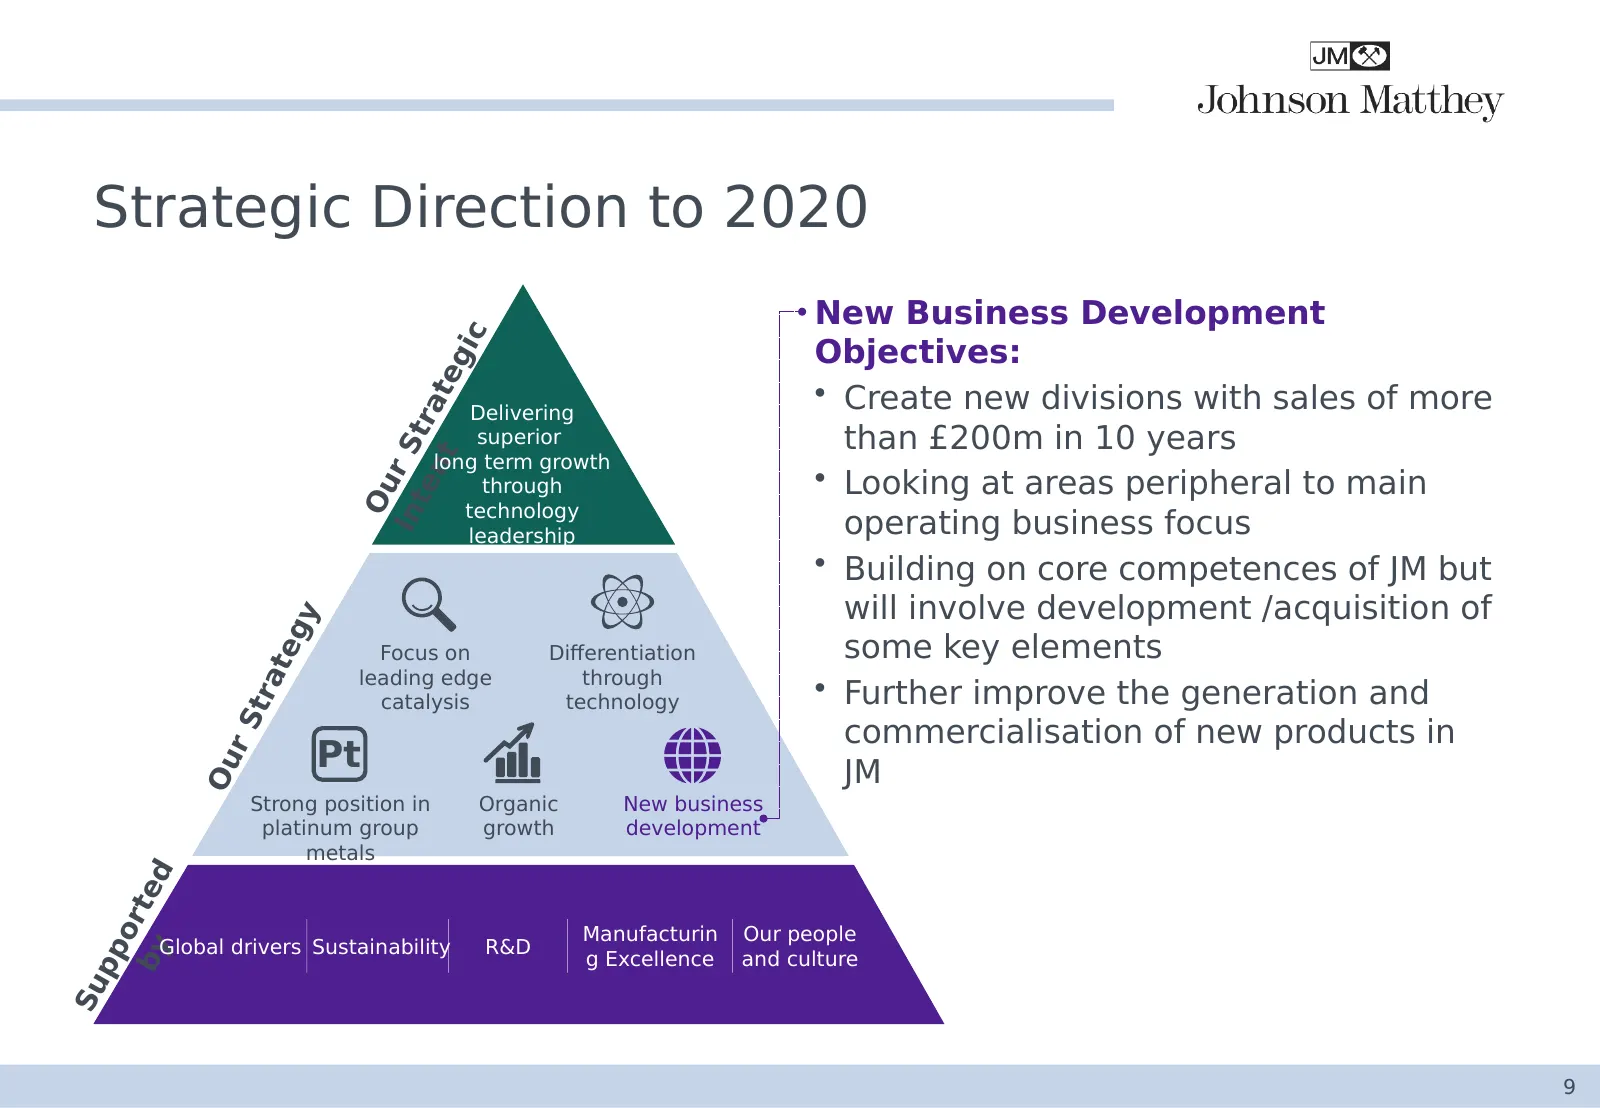
Slide 9: Strategic Direction to 2020
Strategic Direction to 2020 New Business Development ic Objectives: g nt rate Delivering • Create new divisions with sales of more superior than £200m in 10 years In r St long term growth through • Looking at areas peripheral to main Ou te technology leadership operating business focus • Building on
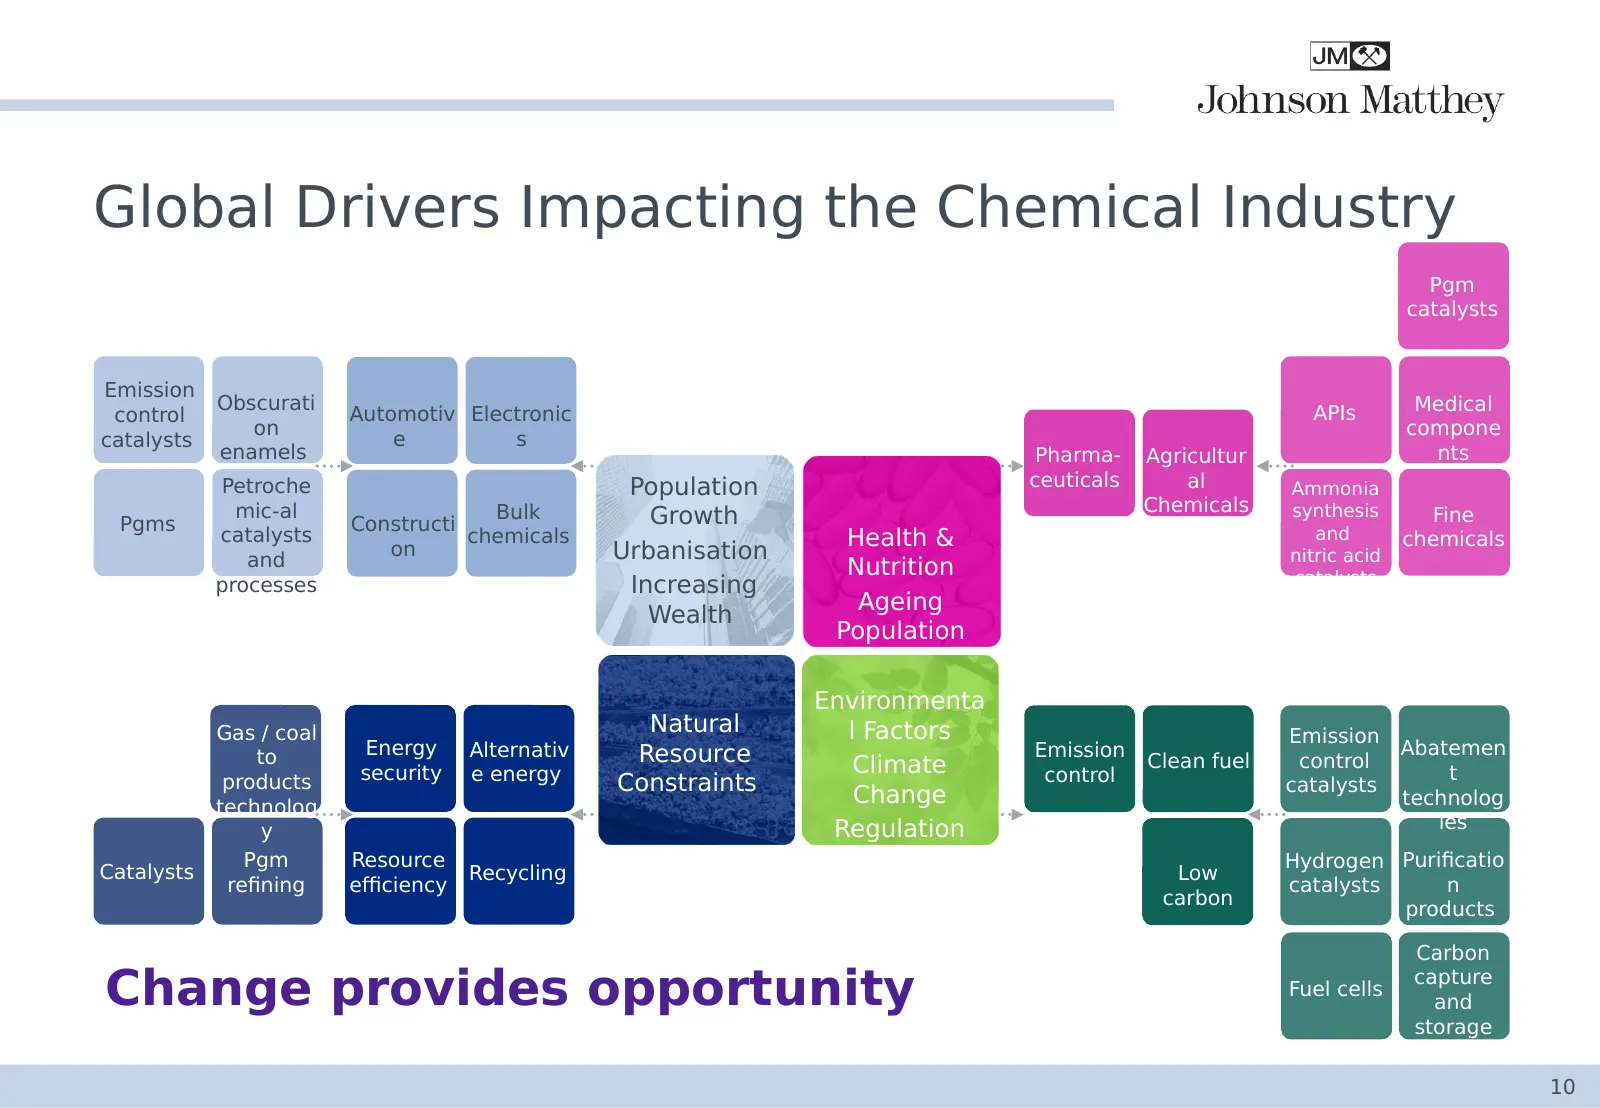
Slide 10: Global Drivers Impacting the Chemical Industry
Global Drivers Impacting the Chemical Industry Pgm catalysts Emission Obscurati APIs Medical control Automotiv Electronic on compone catalysts e s enamels Pharma- Agricultur nts Petroche Population ceuticals al Ammonia mic-al Bulk Chemicals synthesis Pgms Constructi Growth Fine catalysts chemicals H
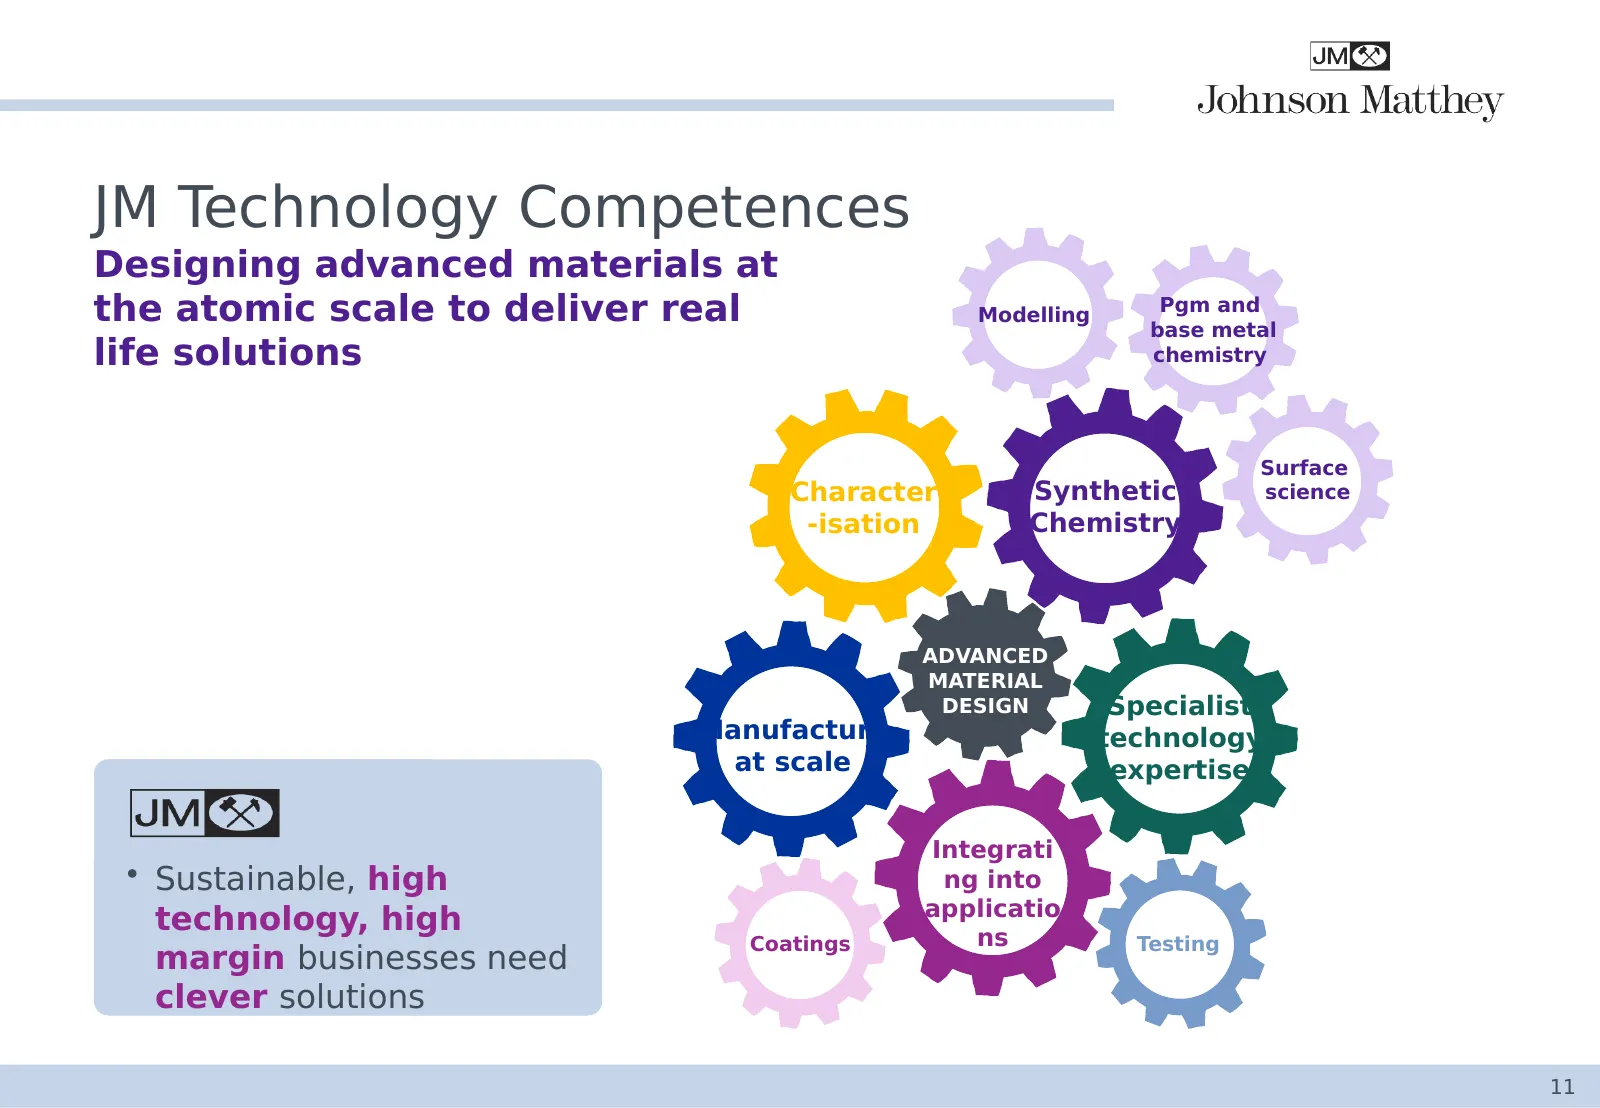
Slide 11: JM Technology Competences
JM Technology Competences Designing advanced materials at the atomic scale to deliver real Modelling Pgm and base metal life solutions chemistry Surface Character Synthetic science -isation Chemistry ADVANCED MATERIAL DESIGN Specialist Manufacture technology at scale expertise Integrati • Sustainabl
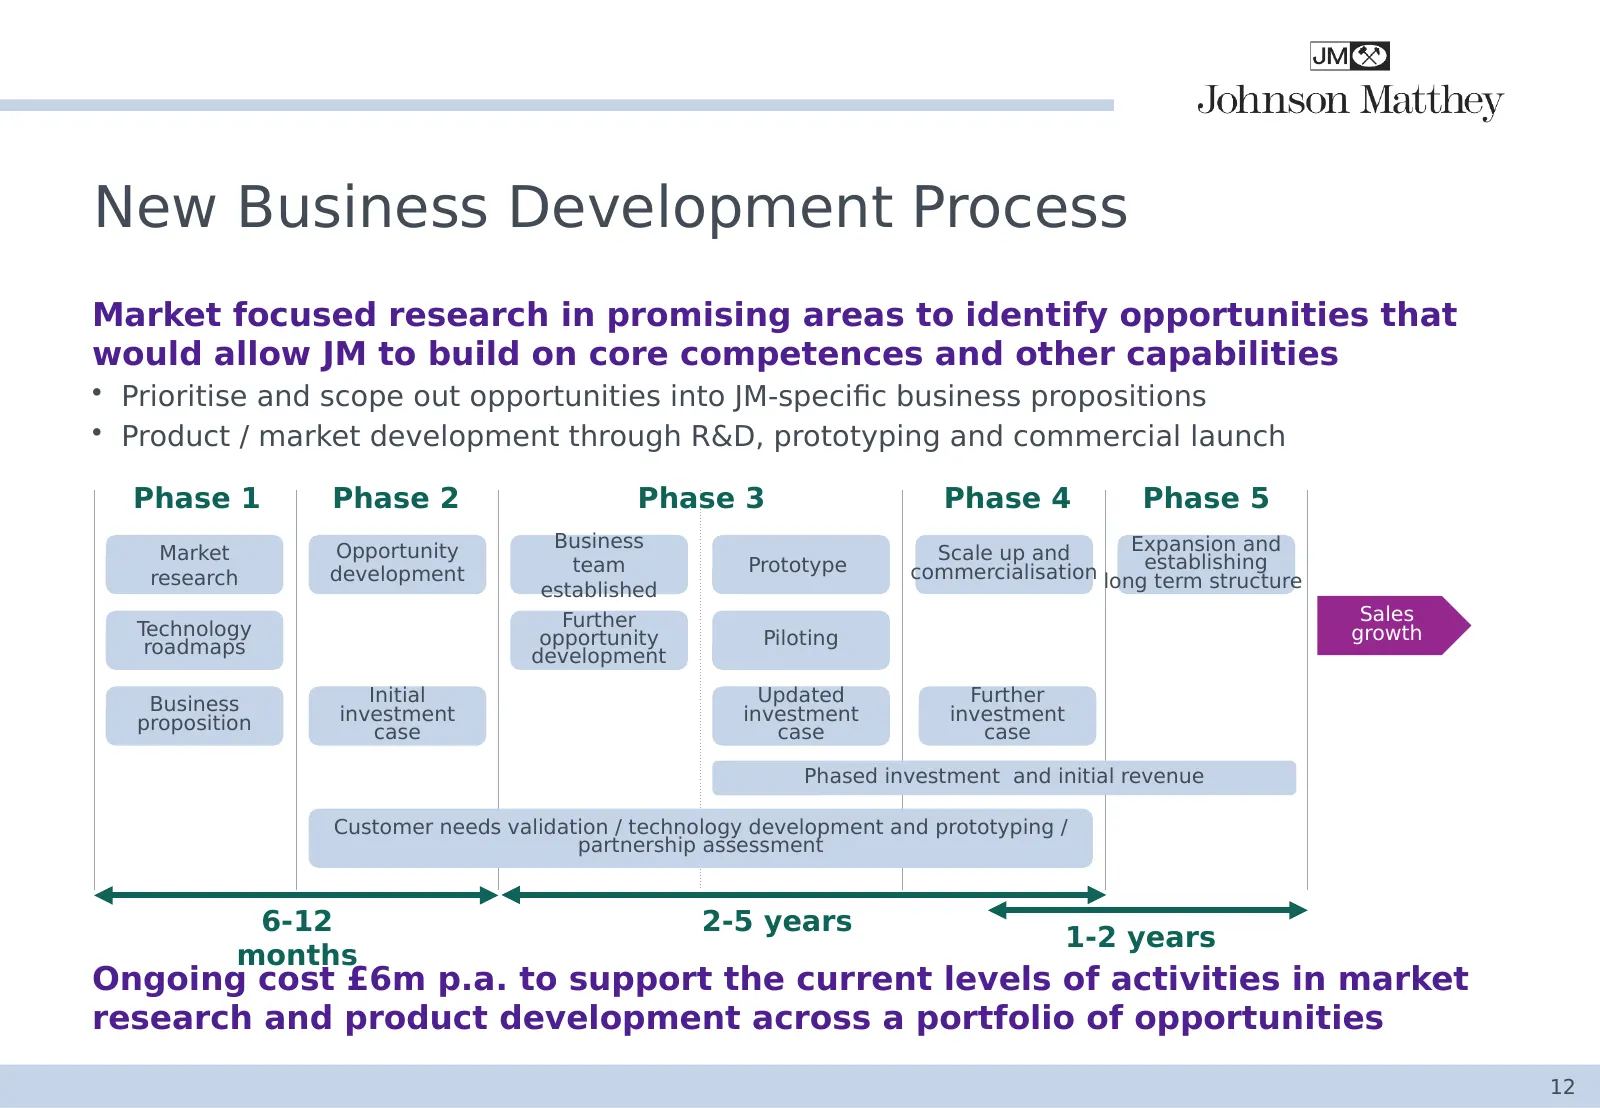
Slide 12: New Business Development Process
New Business Development Process Market focused research in promising areas to identify opportunities that would allow JM to build on core competences and other capabilities • Prioritise and scope out opportunities into JM-specific business propositions • Product / market development through R&D, pr
Slide 13: Developing a Portfolio of Opportunities
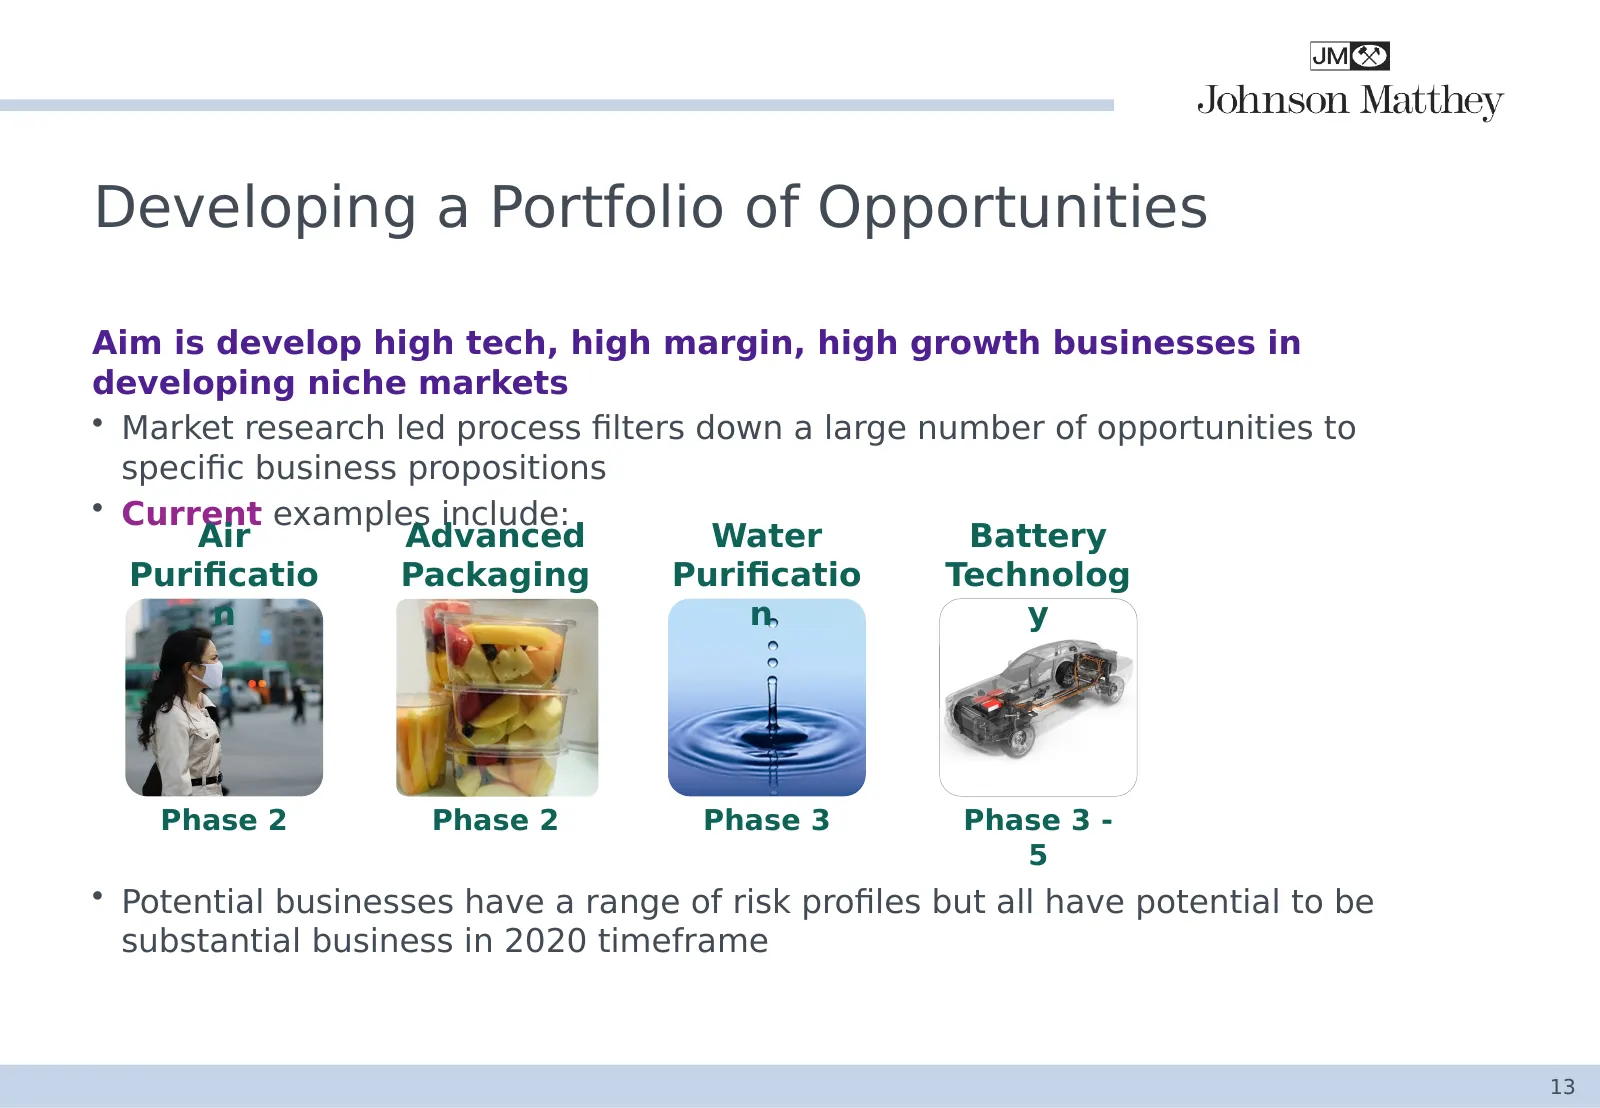
Developing a Portfolio of Opportunities Aim is develop high tech, high margin, high growth businesses in developing niche markets • Market research led process filters down a large number of opportunities to specific business propositions • Current examples include: Air Advanced Water Battery Purifi
Slide 14: Opportunities in Air Purification, Advanced Packaging and Water Purification
Opportunities in Air Purification, Advanced Packaging and Water Purification Roanna Doe Group Corporate Development Director
Slide 15: Opportunities in Air Purification
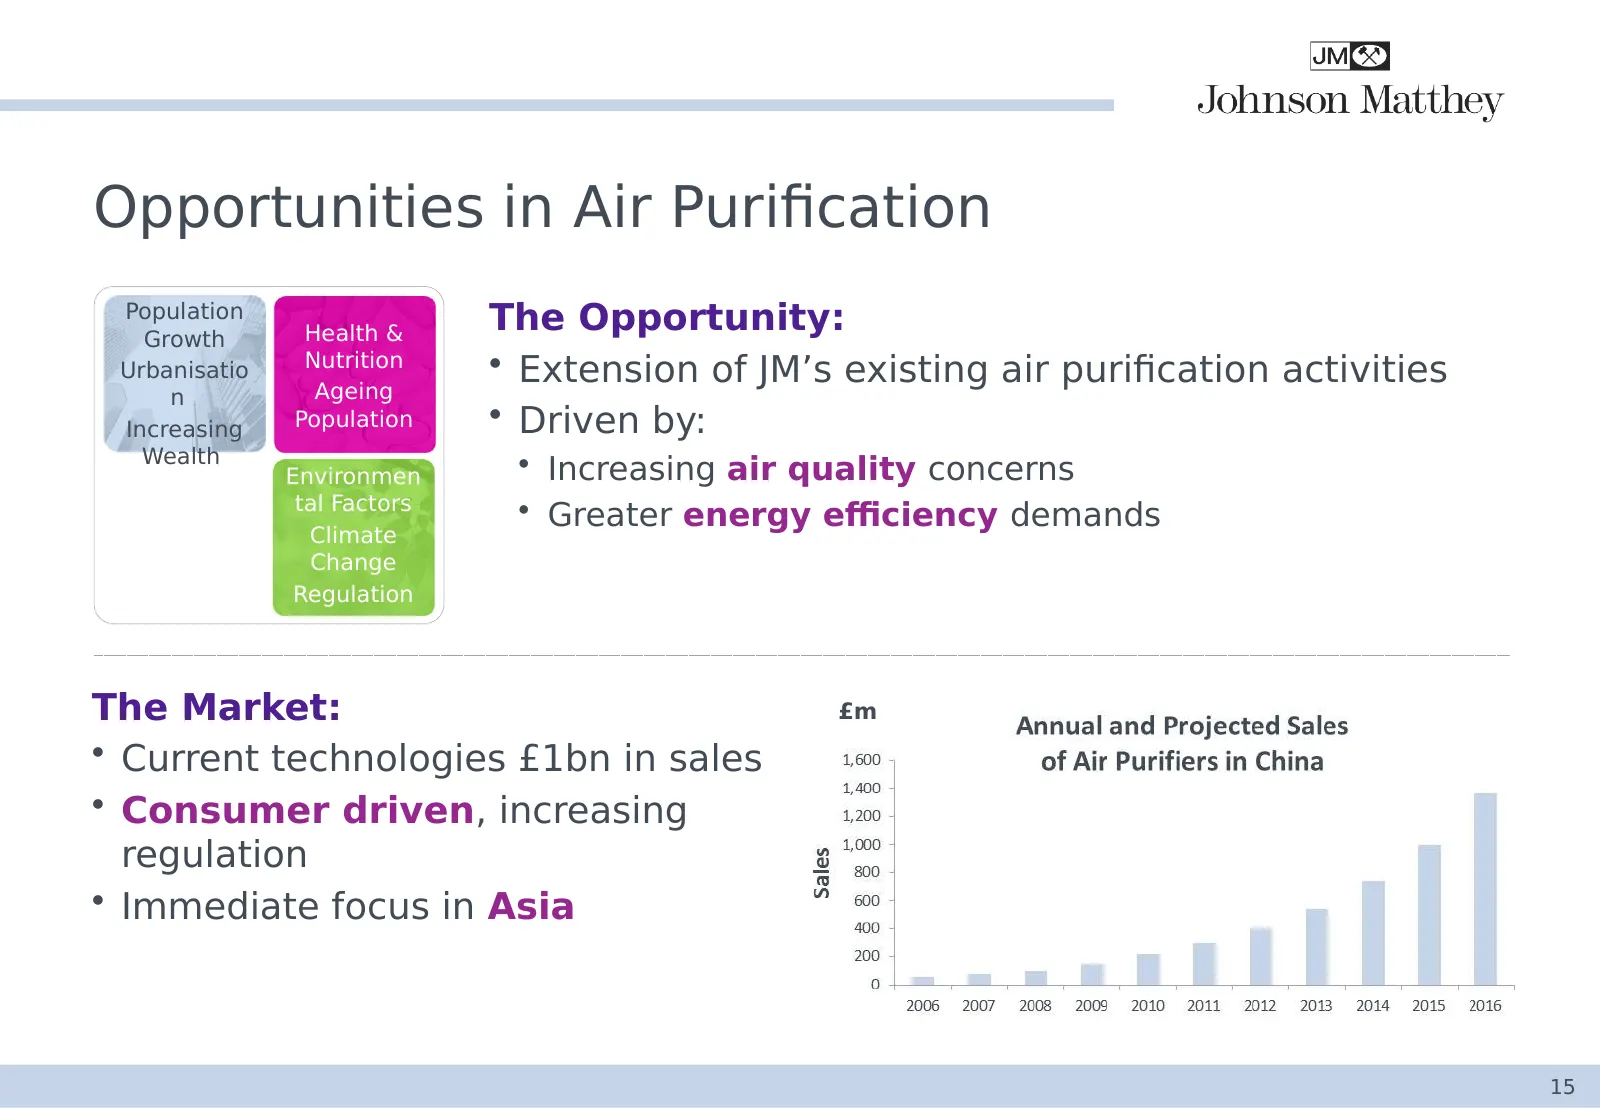
Opportunities in Air Purification Population Growth Health & The Opportunity: Urbanisatio Nutrition • Extension of JM’s existing air purification activities n Ageing Increasing Population • Driven by: Wealth • Increasing air quality concerns Environmen Natural tal Factors • Greater energy efficiency
Slide 16: Opportunities in Air Purification
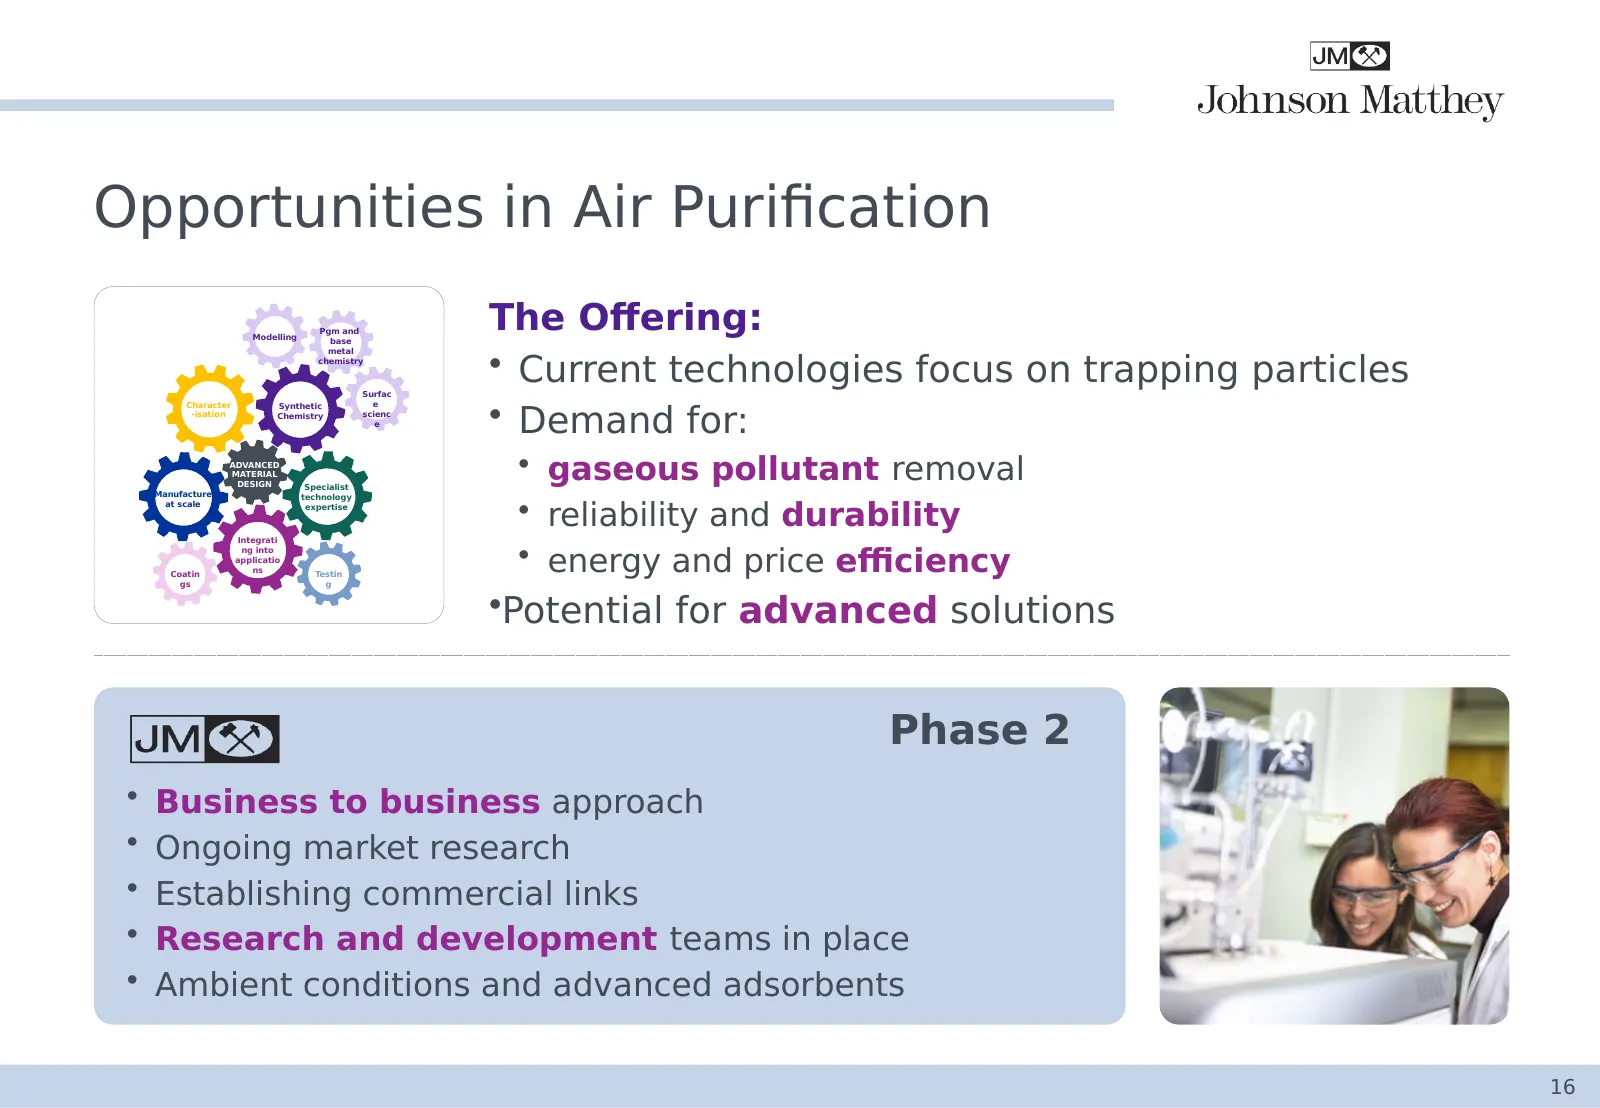
Opportunities in Air Purification Modelling Pgm and base The Offering: • Current technologies focus on trapping particles metal chemistry Surfac • Demand for: Character Synthetic e -isation Chemistry scienc e ADVANCED MATERIAL DESIGN Specialist • gaseous pollutant removal Manufacture • reliability a
Slide 17: Advanced Food Packaging
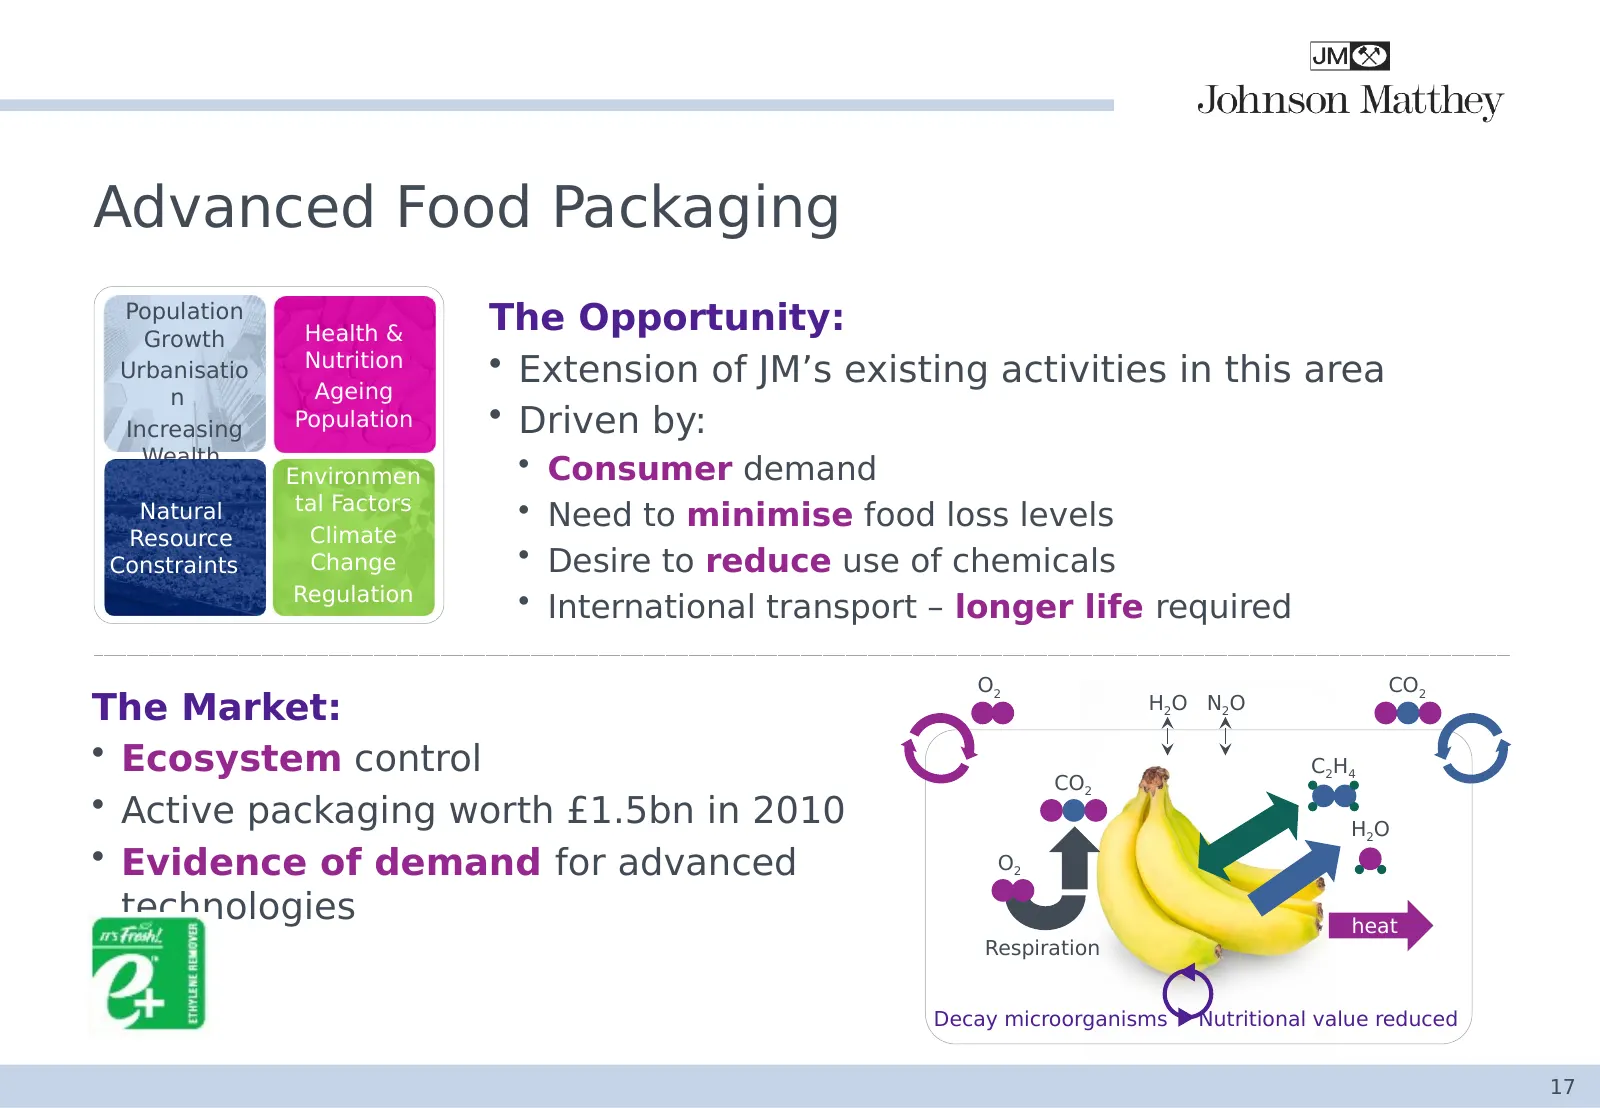
Advanced Food Packaging Population Growth Health & The Opportunity: Urbanisatio Nutrition • Extension of JM’s existing activities in this area n Ageing Increasing Population • Driven by: Wealth • Consumer demand Environmen Natural Natural tal Factors • Need to minimise food loss levels Resource Clim
Slide 18: Advanced Food Packaging
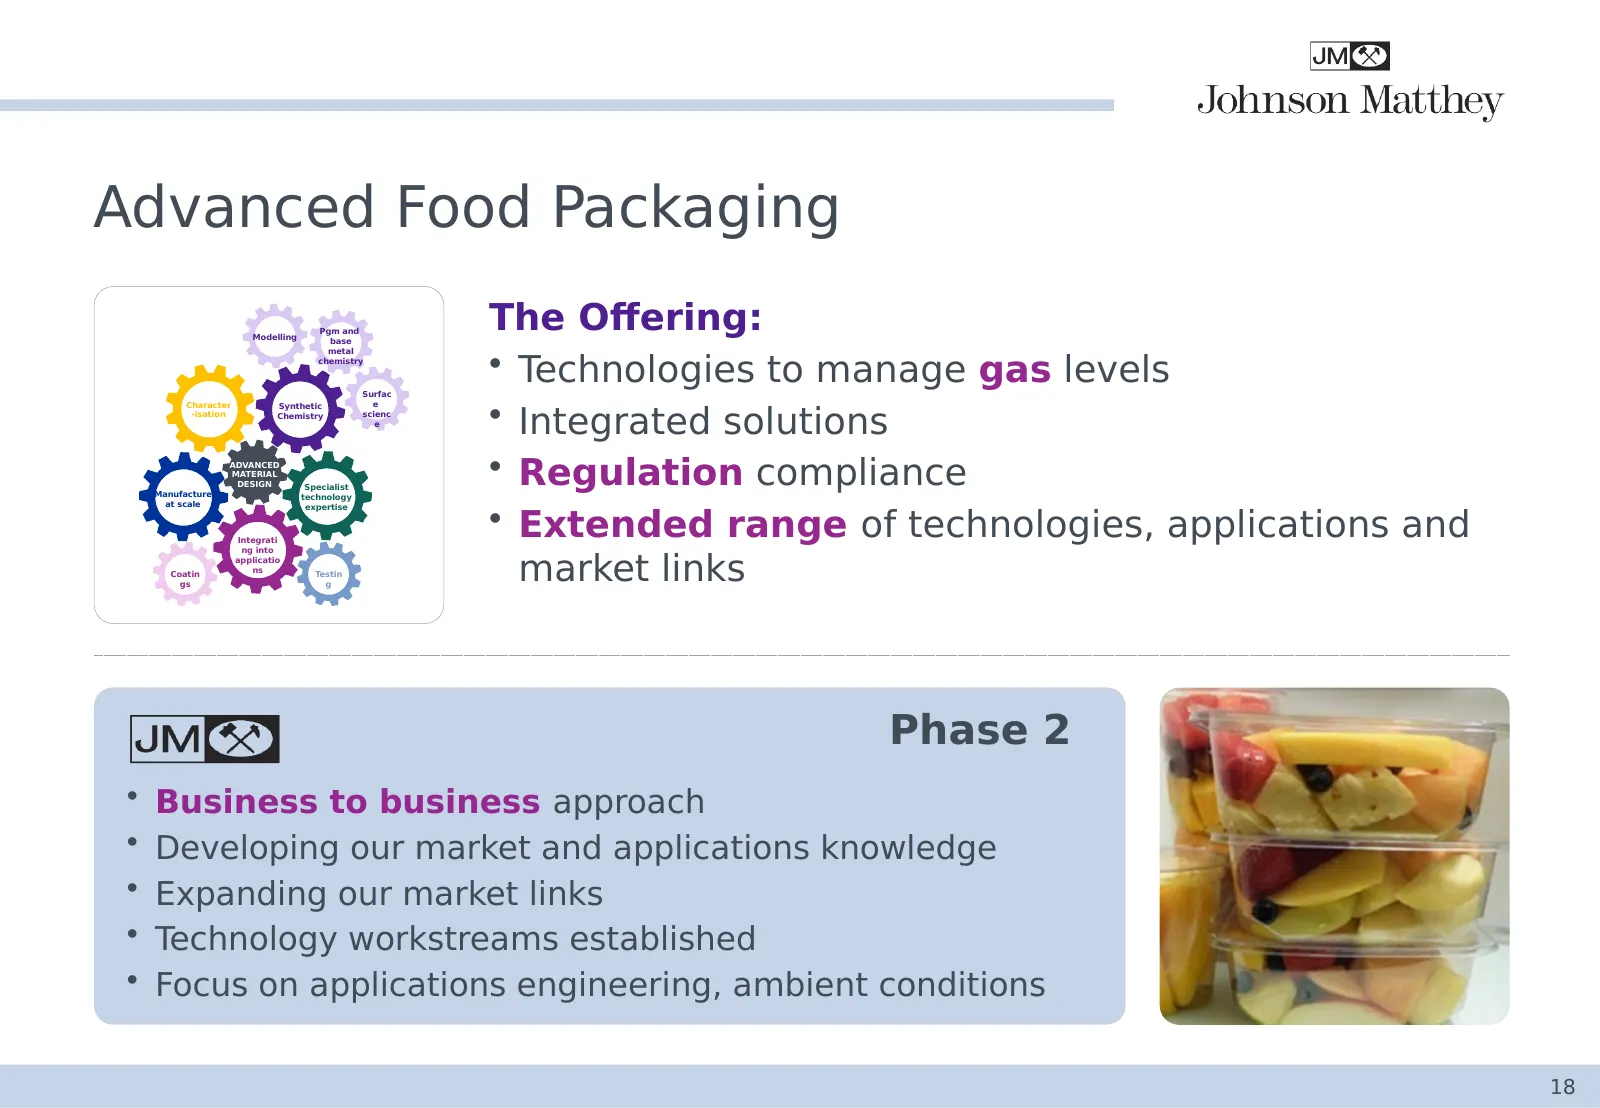
Advanced Food Packaging Modelling Pgm and base The Offering: • Technologies to manage gas levels metal chemistry Surfac • Integrated solutions Character Synthetic e -isation Chemistry scienc e v Manufacture ADVANCED MATERIAL DESIGN Specialist • Regulation compliance technology • Extended range of te
Slide 19: Water Purification
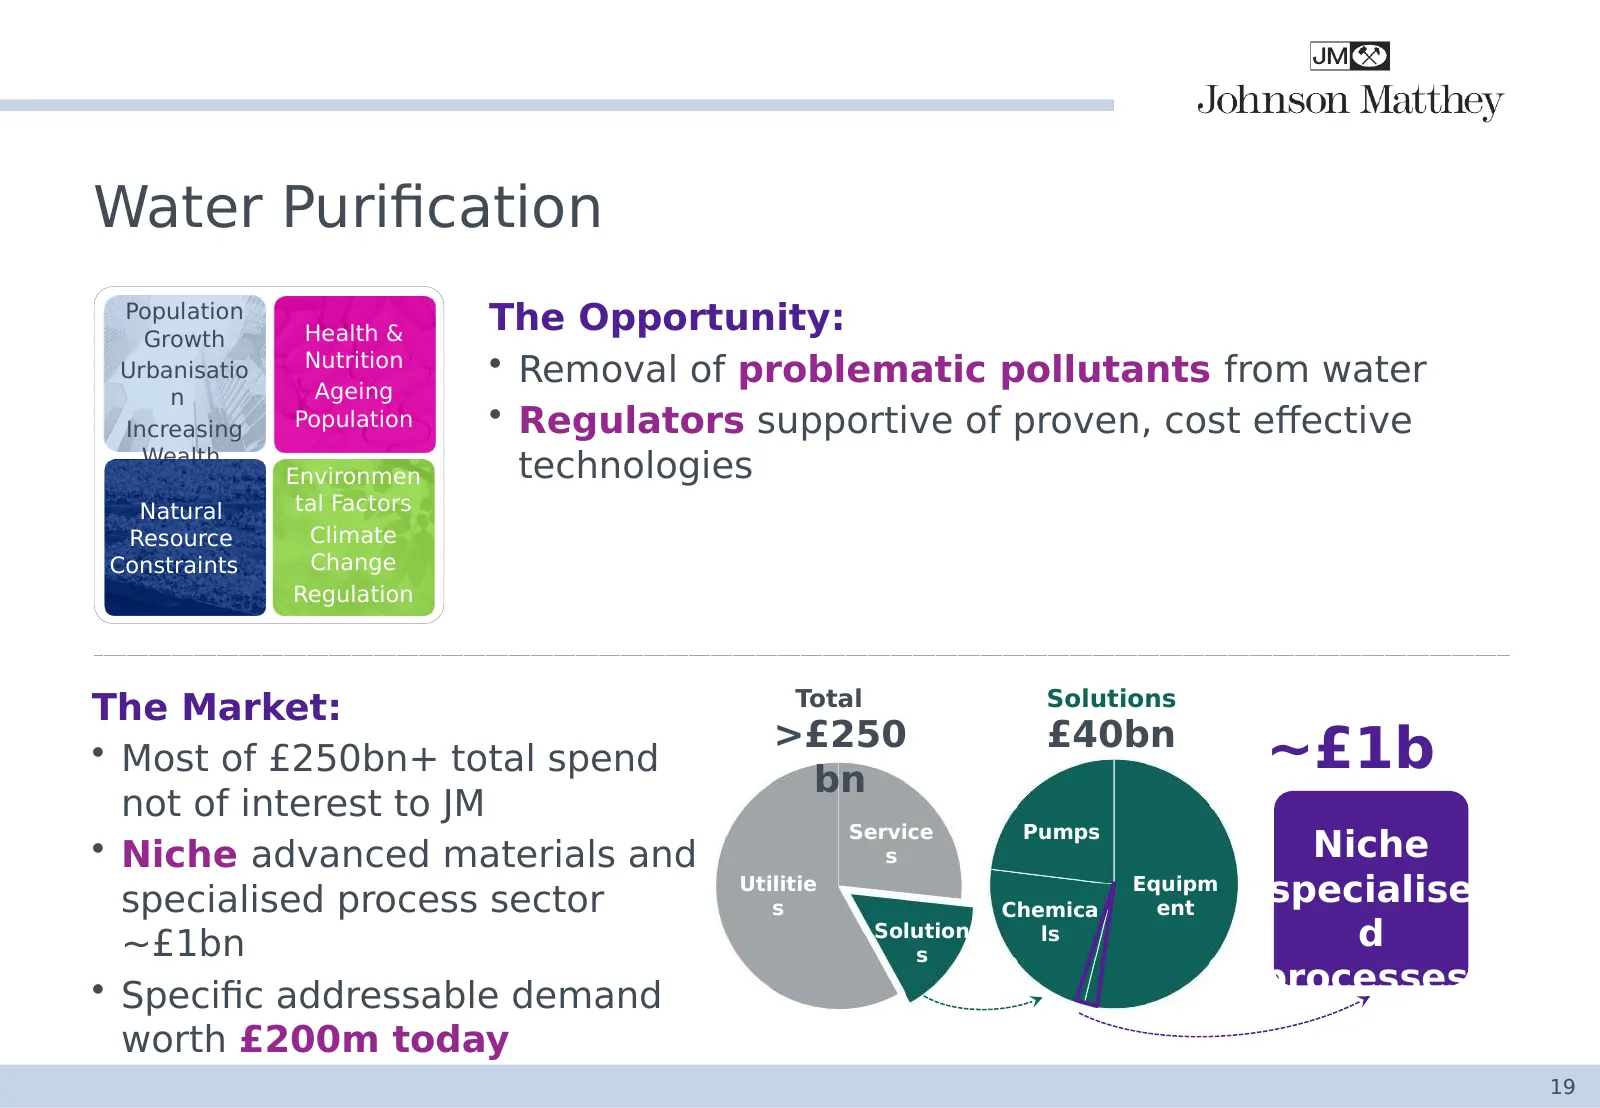
Water Purification Population Growth Health & The Opportunity: Urbanisatio Nutrition • Removal of problematic pollutants from water n Ageing Increasing Population • Regulators supportive of proven, cost effective Wealth Environmen technologies Natural tal Factors Natural Resource Climate Resource Co
Slide 20: Water Purification
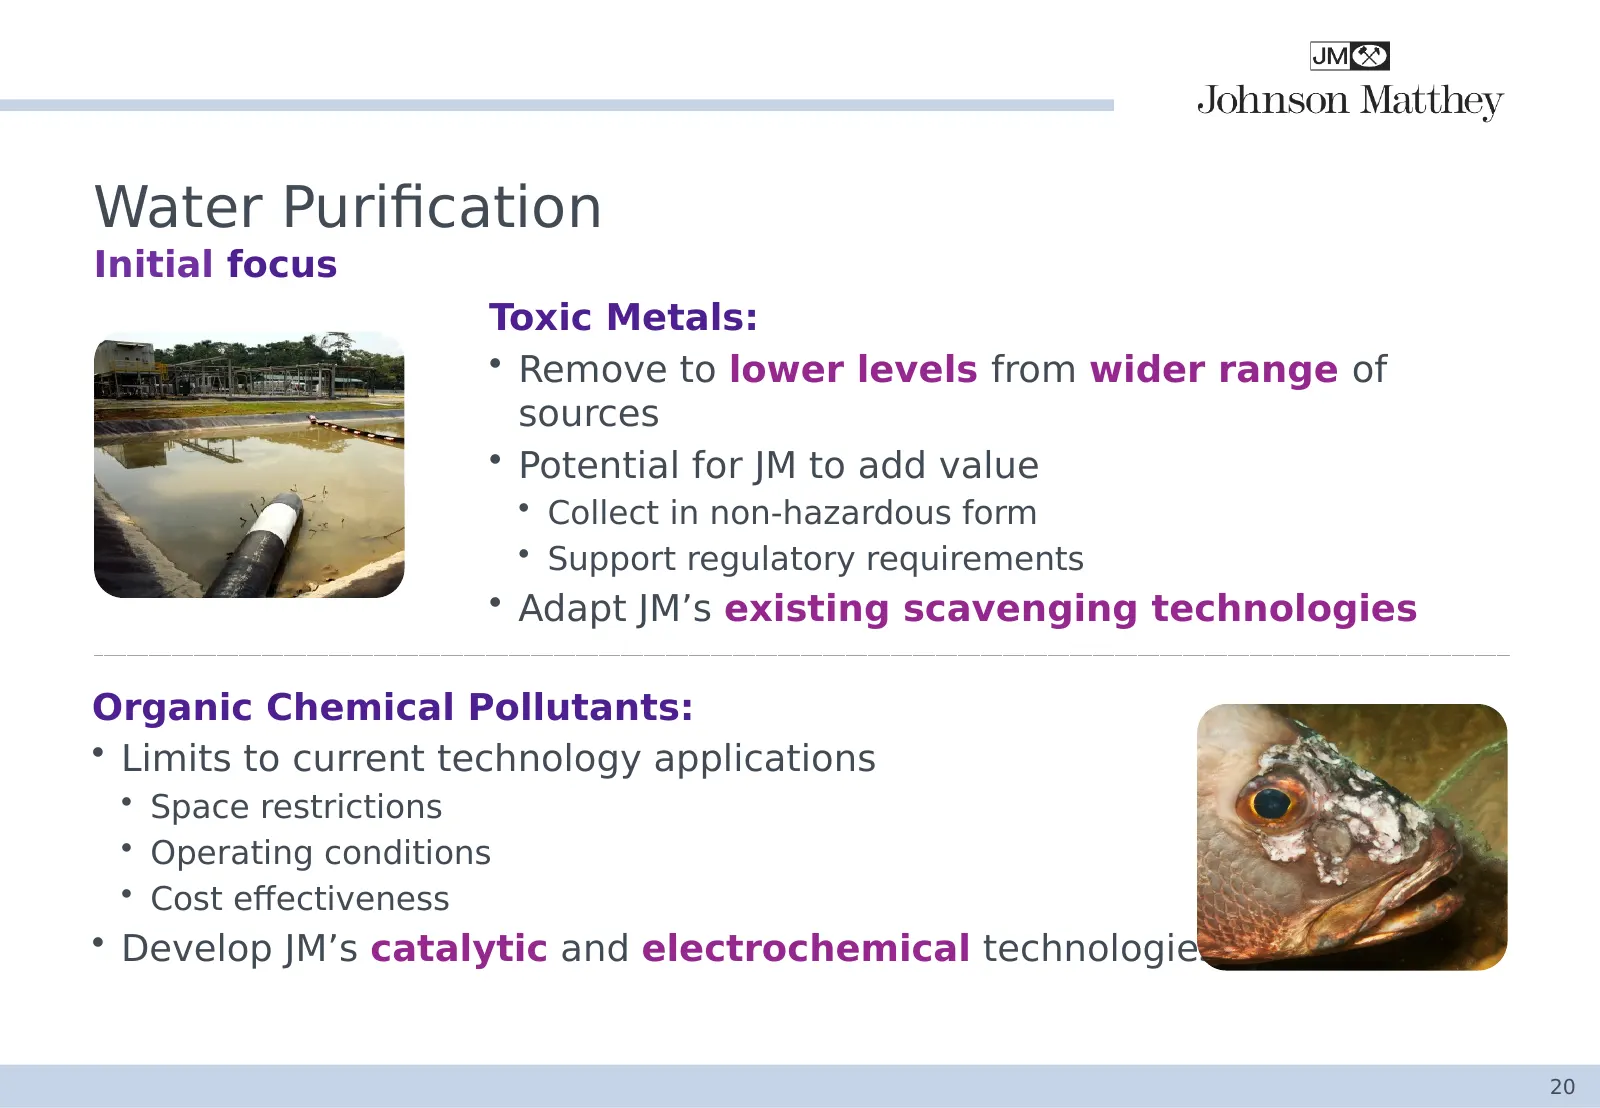
Water Purification Initial focus Toxic Metals: • Remove to lower levels from wider range of sources • Potential for JM to add value • Collect in non-hazardous form • Support regulatory requirements • Adapt JM’s existing scavenging technologies Organic Chemical Pollutants: • Limits to current technol
Slide 21: Water Purification
Water Purification Modelling Pgm and base The Offering: • Advanced material solutions for difficult to metal chemistry Surfac remove pollutants Character Synthetic e -isation Chemistry scienc e ADVANCED MATERIAL DESIGN Specialist • Initially adapt existing JM technologies • Supports high margins Man
Slide 22: Opportunities in Battery Technology
Opportunities in Battery Technology Martin Green Group Strategic Development Director
Slide 23: Batteries
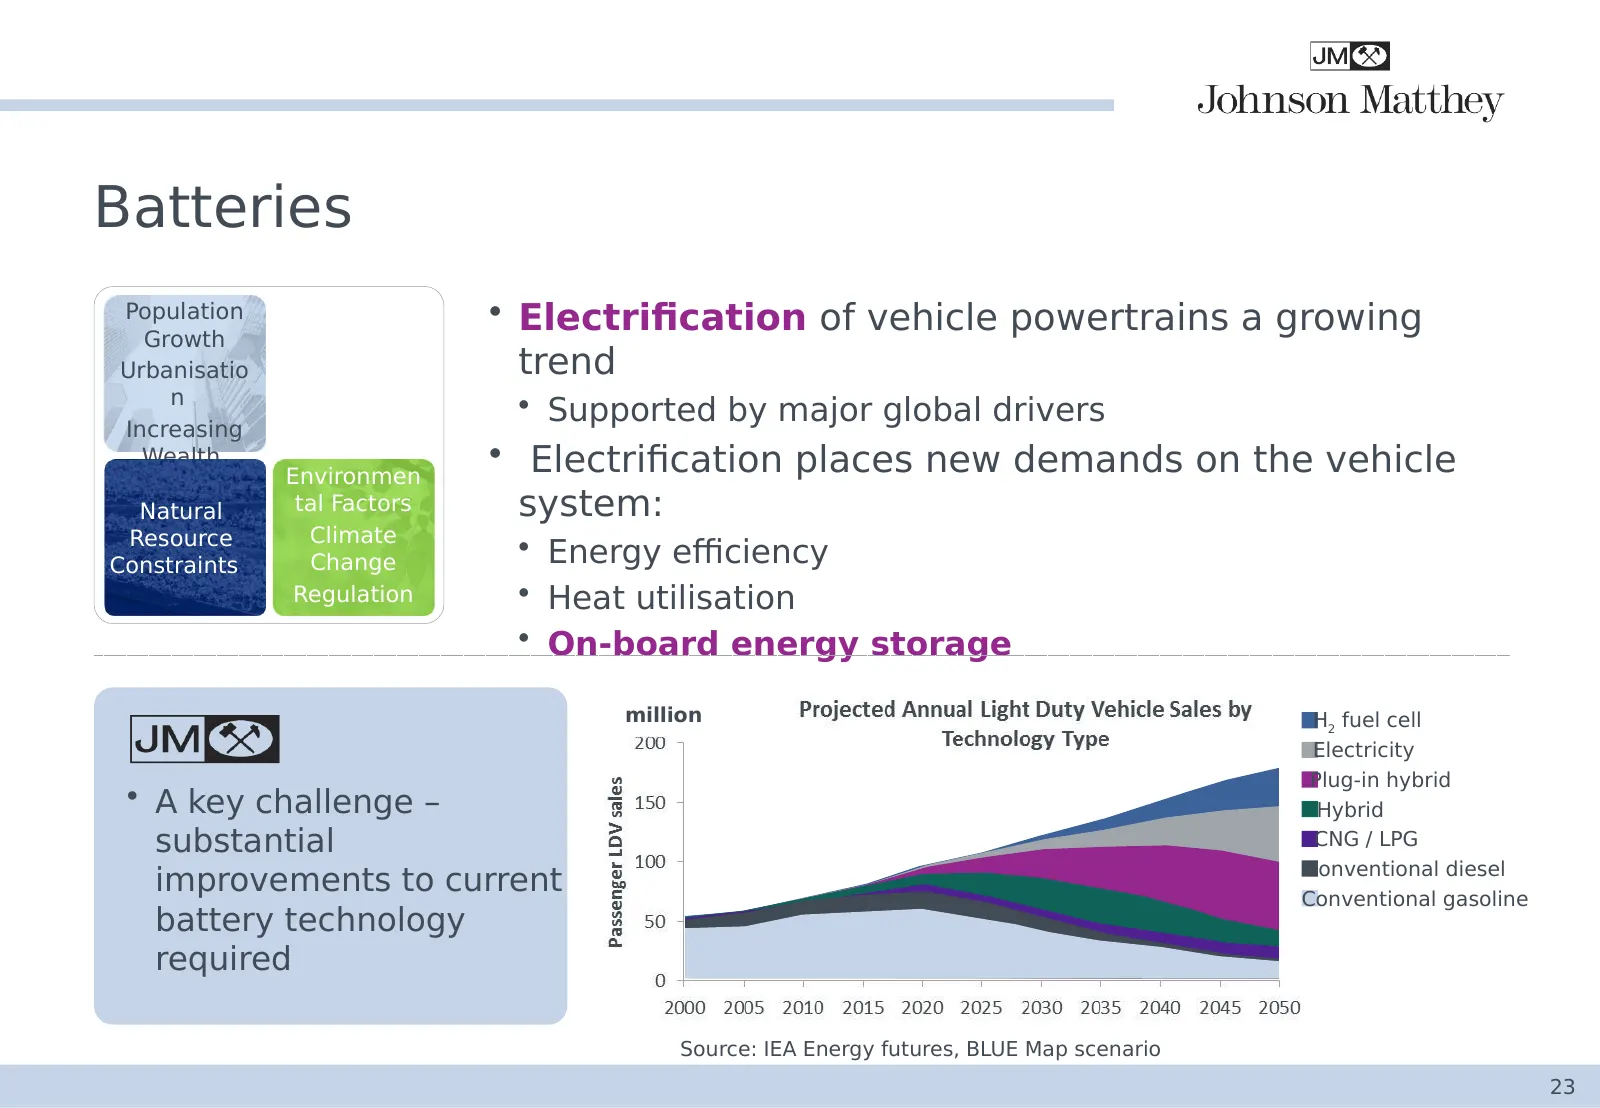
Batteries Population • Electrification of vehicle powertrains a growing Growth Urbanisatio trend n • Supported by major global drivers Increasing Wealth Environmen • Electrification places new demands on the vehicle Natural Natural tal Factors system: Resource Climate Resource Constraints Change • E
Slide 24: Battery Materials
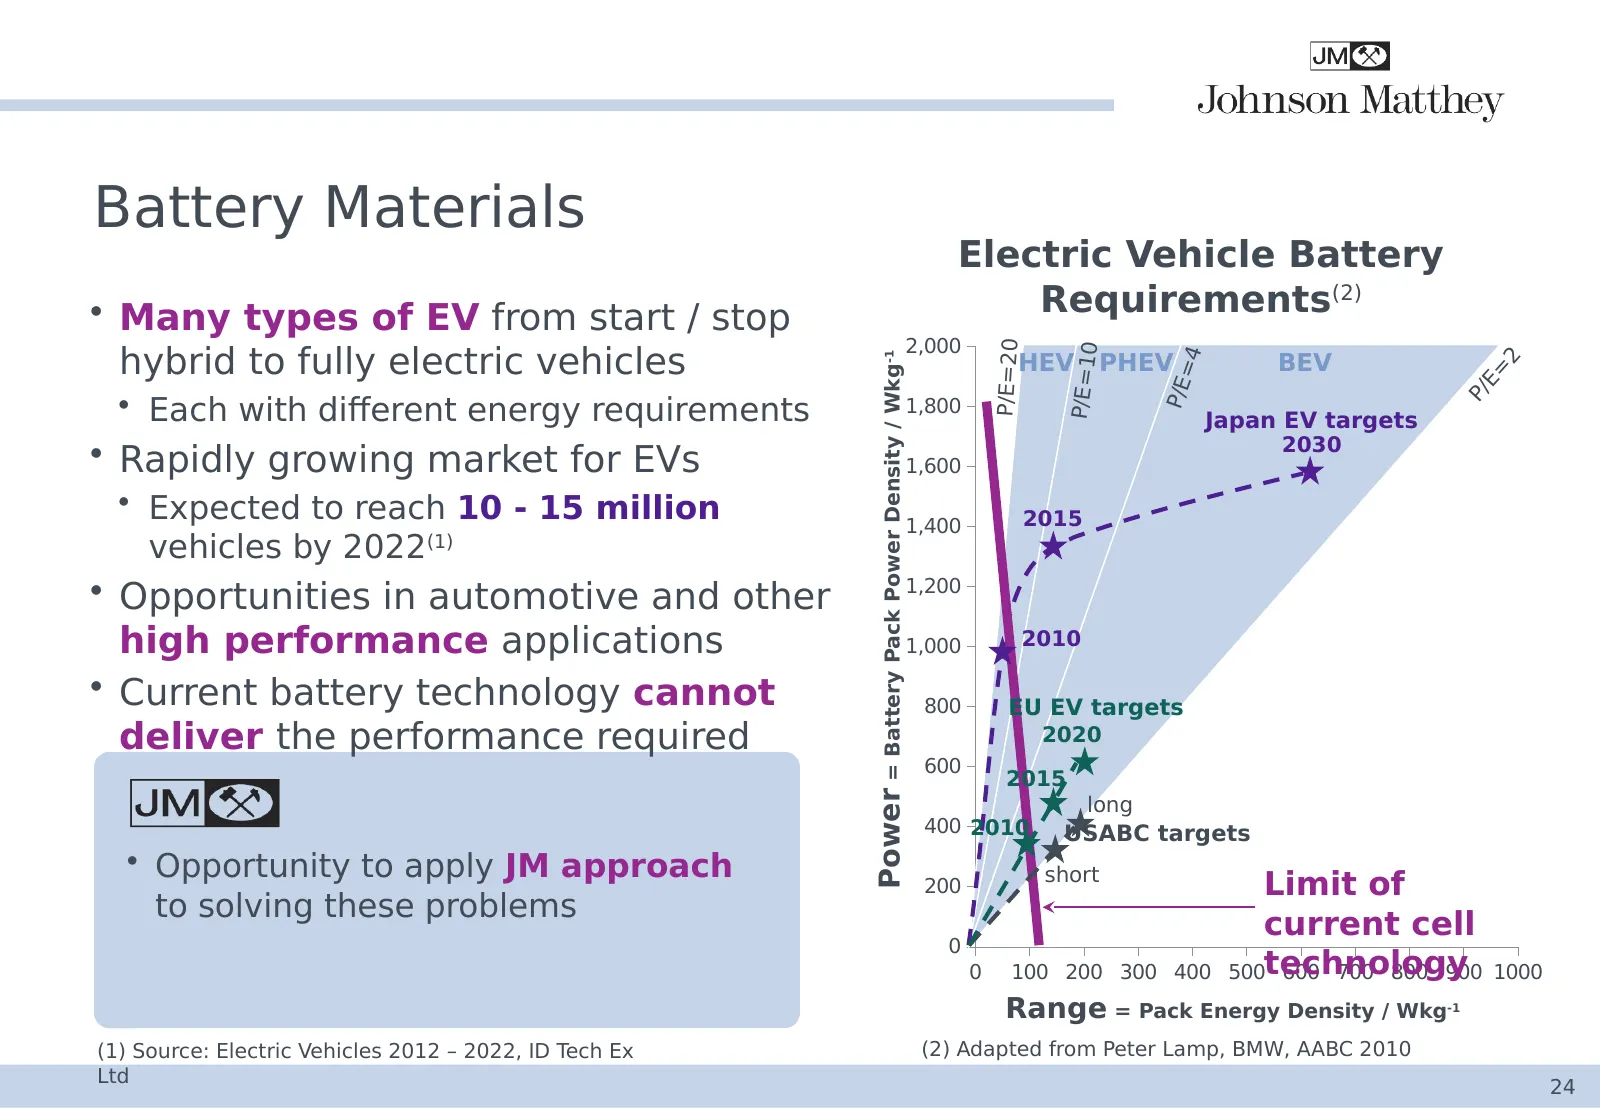
Battery Materials Electric Vehicle Battery • Many types of EV from start / stop Requirements(2) 2,000 P/E=20 hybrid to fully electric vehicles P/E=10 HEV PHEV BEV =4 Power = Battery Pack Power Density / Wkg-1 2 E= P/E • Each with different energy requirements P/ 1,800 Japan EV targets • Rapidly grow
Slide 25: What is Johnson Matthey Doing?
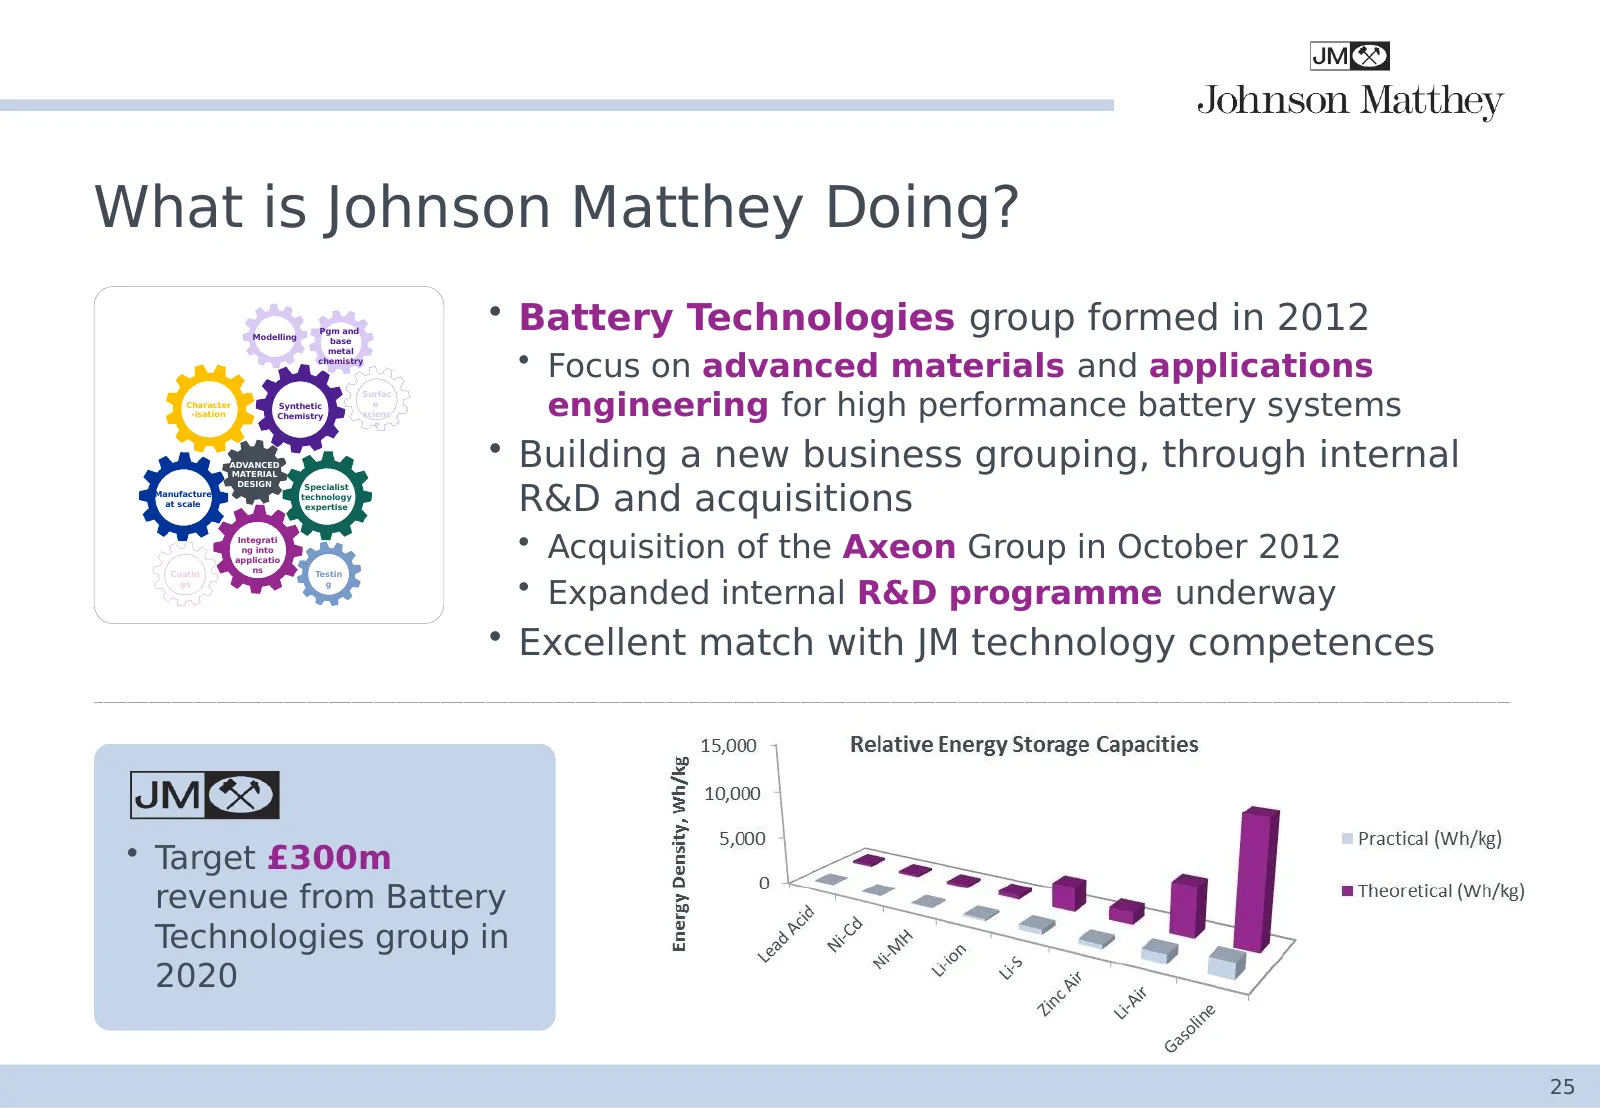
What is Johnson Matthey Doing? Modelling Pgm and • Battery Technologies group formed in 2012 base • Focus on advanced materials and applications metal chemistry engineering for high performance battery systems Surfac Character Synthetic e -isation Chemistry scienc e ADVANCED MATERIAL • Building a ne
Slide 26: Acquisition of Axeon
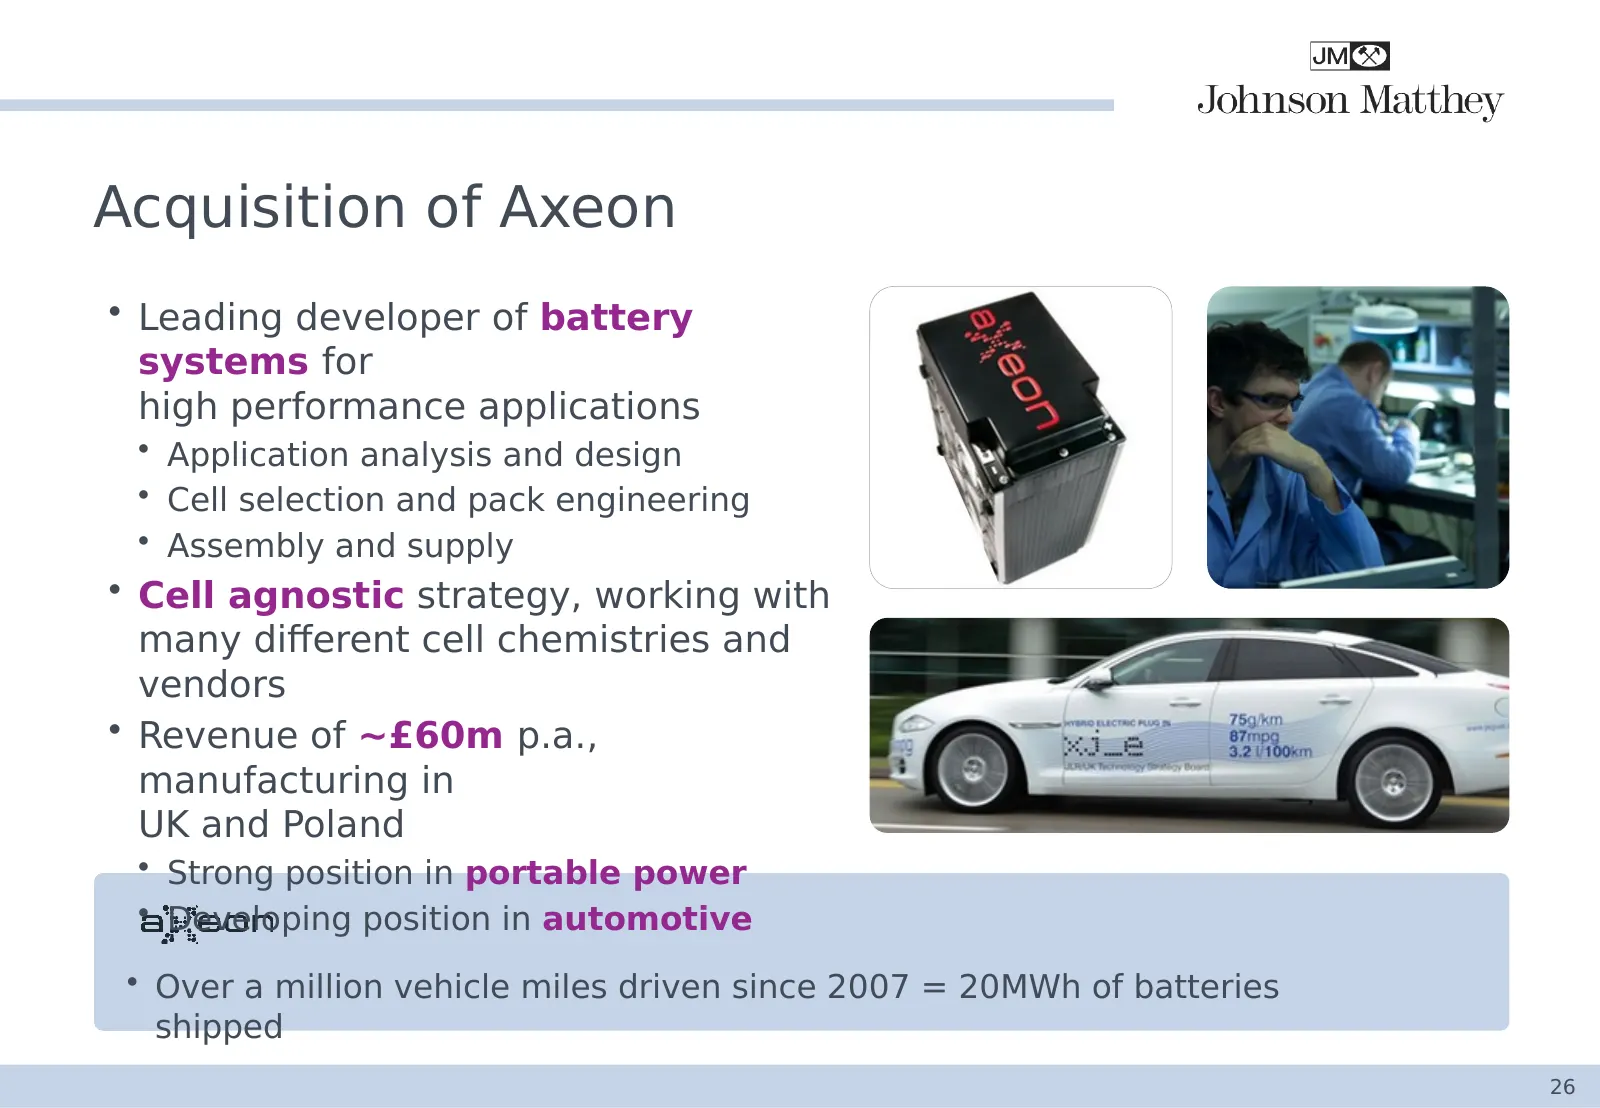
Acquisition of Axeon • Leading developer of battery systems for high performance applications • Application analysis and design • Cell selection and pack engineering • Assembly and supply • Cell agnostic strategy, working with many different cell chemistries and vendors • Revenue of ~£60m p.a., manu
Slide 27: Translating Vehicle Requirements into System Design
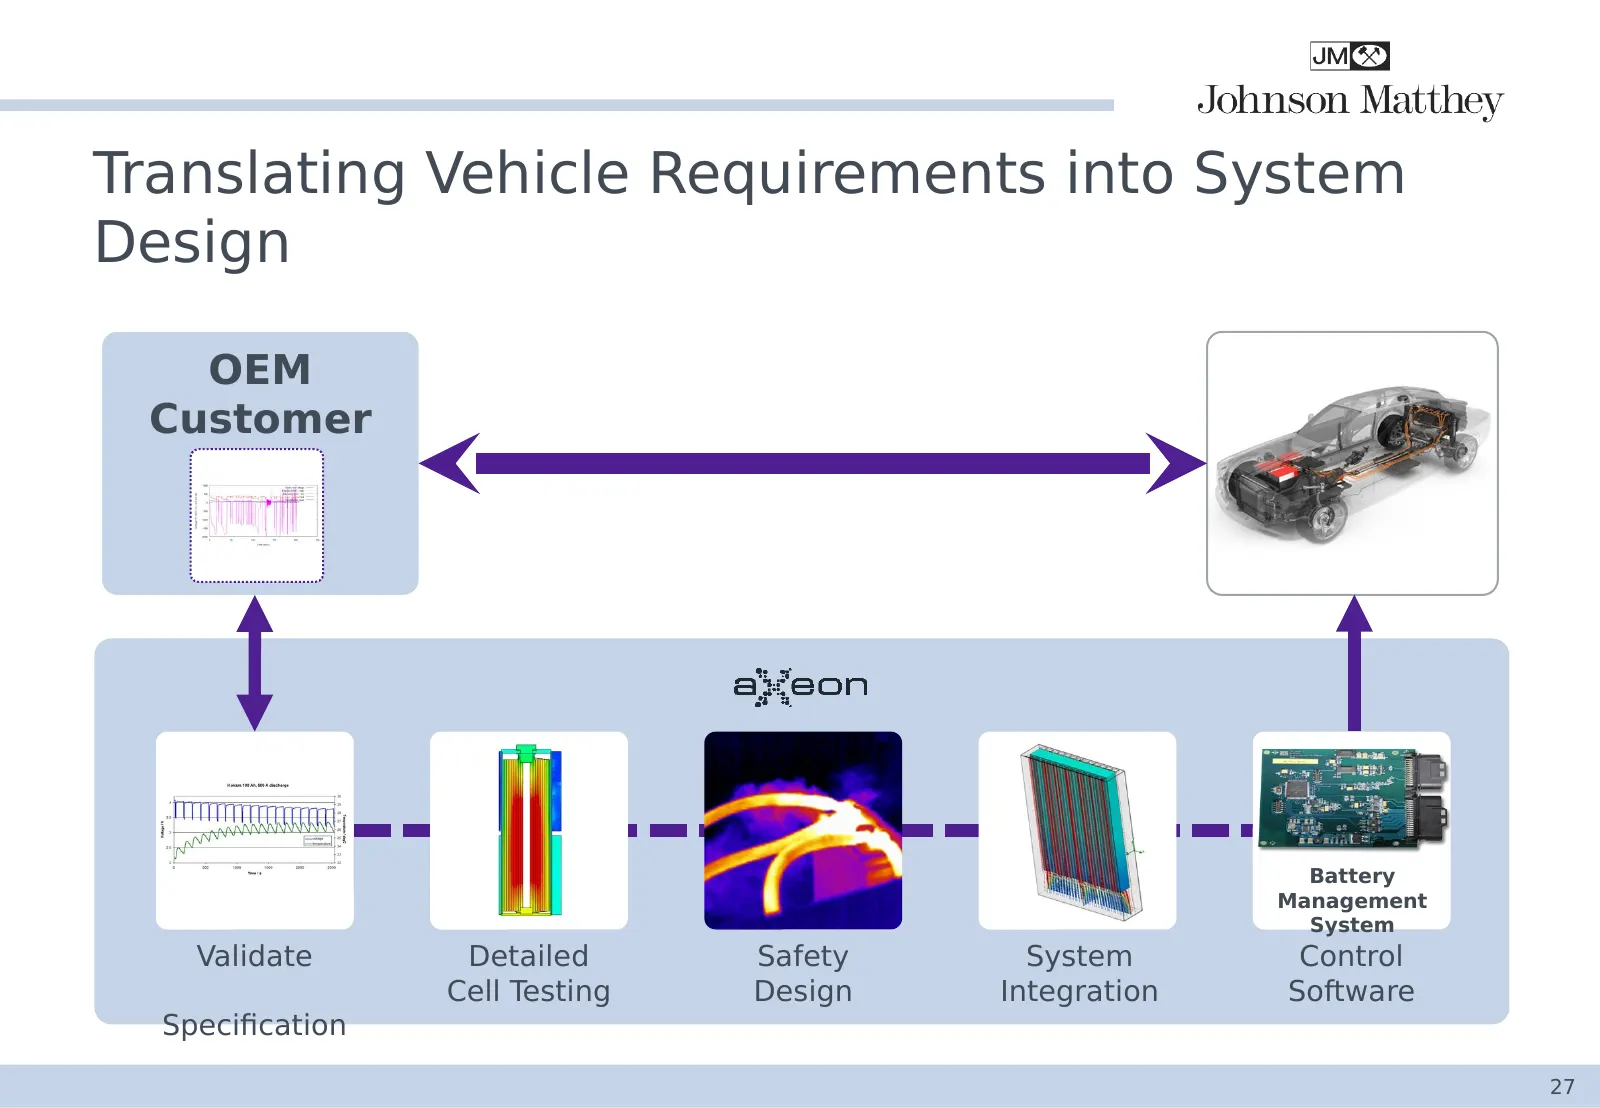
Translating Vehicle Requirements into System Design OEM Customer Battery Management System Validate Detailed Safety System Control Cell Testing Design Integration Software Specification 27
Slide 28: Axeon
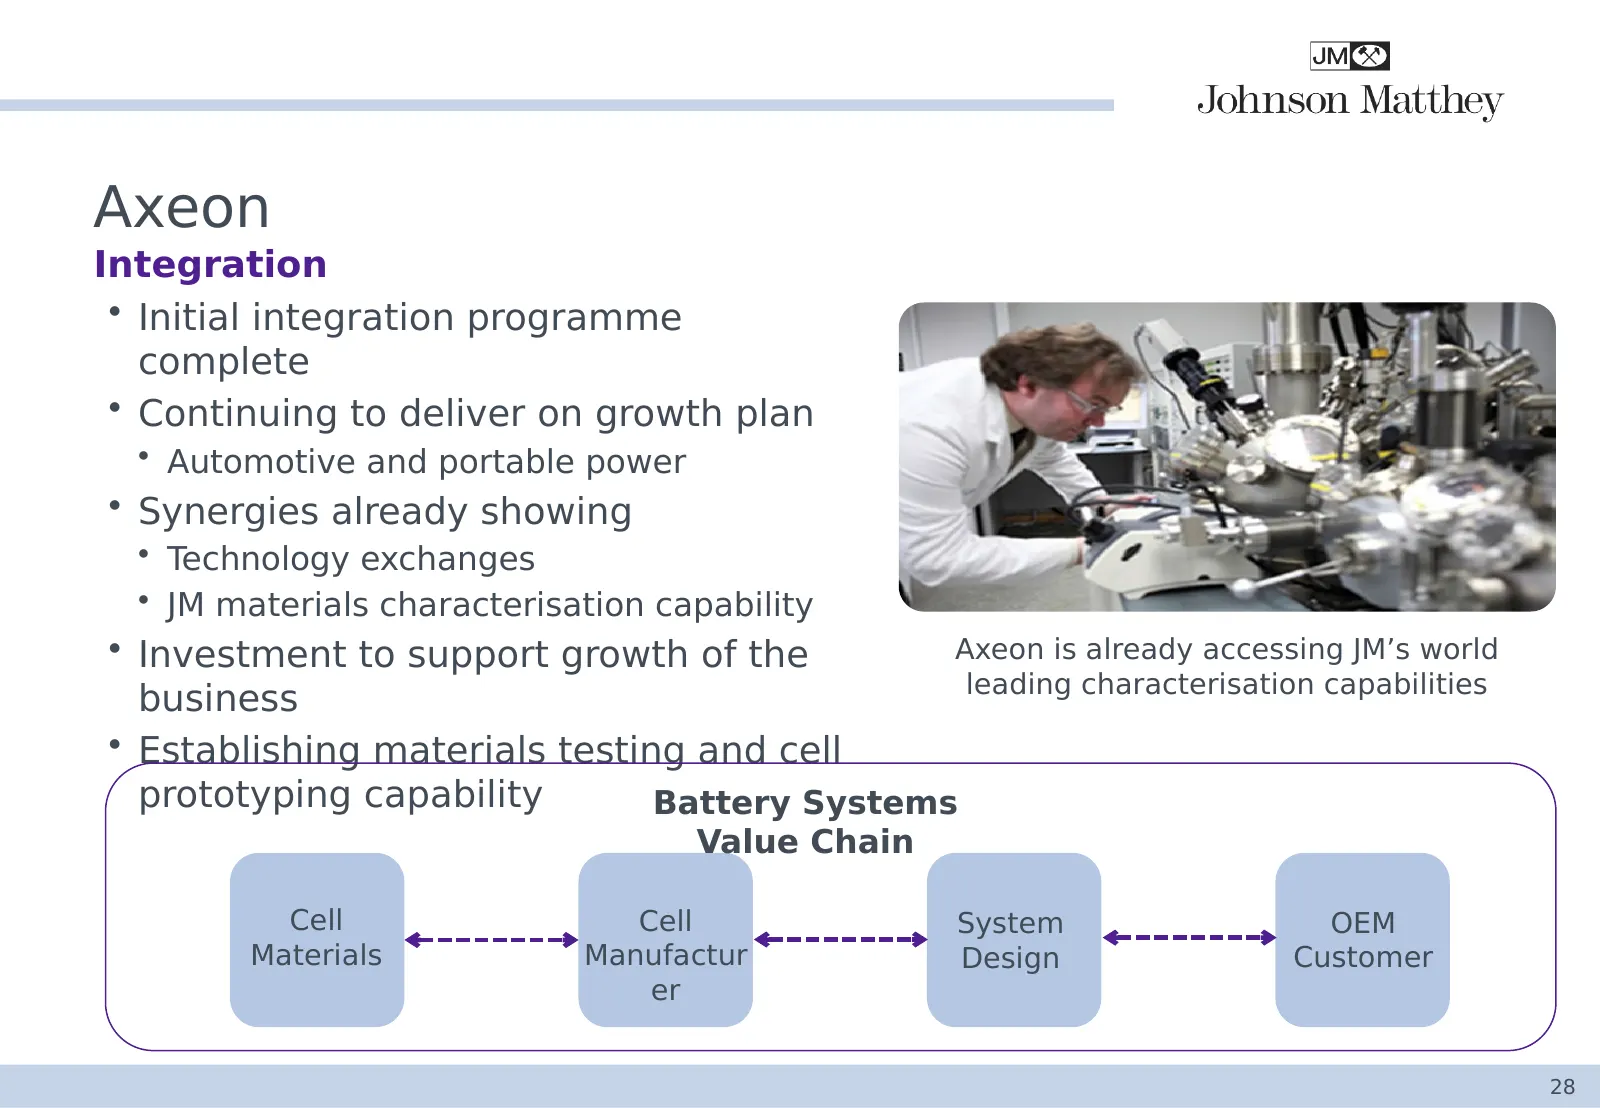
Axeon Integration • Initial integration programme complete • Continuing to deliver on growth plan • Automotive and portable power • Synergies already showing • Technology exchanges • JM materials characterisation capability • Investment to support growth of the Axeon is already accessing JM’s world
Slide 29: Battery Technology Summary
Battery Technology Summary Axeon has delivered: Next steps: • Existing revenue stream and good • Refine and developing the broader growth prospects in automotive JM materials plan for batteries • Window on Li-ion technology • Improved Li-ion technology landscape • Next generation batteries • Deep un
Slide 30: Strategy and New Business Development
Strategy and New Business Development Nick Garner Group Director, Corporate and Strategic Development
Slide 31: Developing a Portfolio of Opportunities
Developing a Portfolio of Opportunities Aim is to develop high tech, high margin, high growth businesses in developing niche markets • Market research led process filters down a large number of opportunities to specific business Air propositions. Examples discussed: Advanced Water Battery Purificati
Slide 32: JME)
JME) Johnson Matthey
Slide 33: Opportunities in Emission Control Technologies
Opportunities in Emission Control Technologies John Walker Division Director, Emission Control Technologies
Slide 34: Agenda
Agenda 0 Overview and Strategy John Walker 1 0 Introduction to Emission Control Technologies 2 (ECT) 0 Recap of Global Drivers for the Chemical 3 Industry 0 The Light Duty Catalyst Market i. Vehicle Production ii. Legislation iii. Technology and 4 Revenue Implications iv. Powertrain Trends v. Market
Slide 35: Overview
Overview Showcase Detail Highlight Explain the exciting growth the market, the expected growthhow R&D and strong opportunities in legislative in our markets customer relationships emission control and technology over the next will drive our future catalysts drivers decade growth of the business £ 35
Slide 36: Emission Control Technologies’ Strategy
Emission Control Technologies’ Strategy Maintain differentiation through A deep understanding of our technology by investing in R&D markets and customers • High performance catalysts • Materials science and manufacturing Manufacturing Excellence Deliver superior growth • Optimum efficiency • Markets
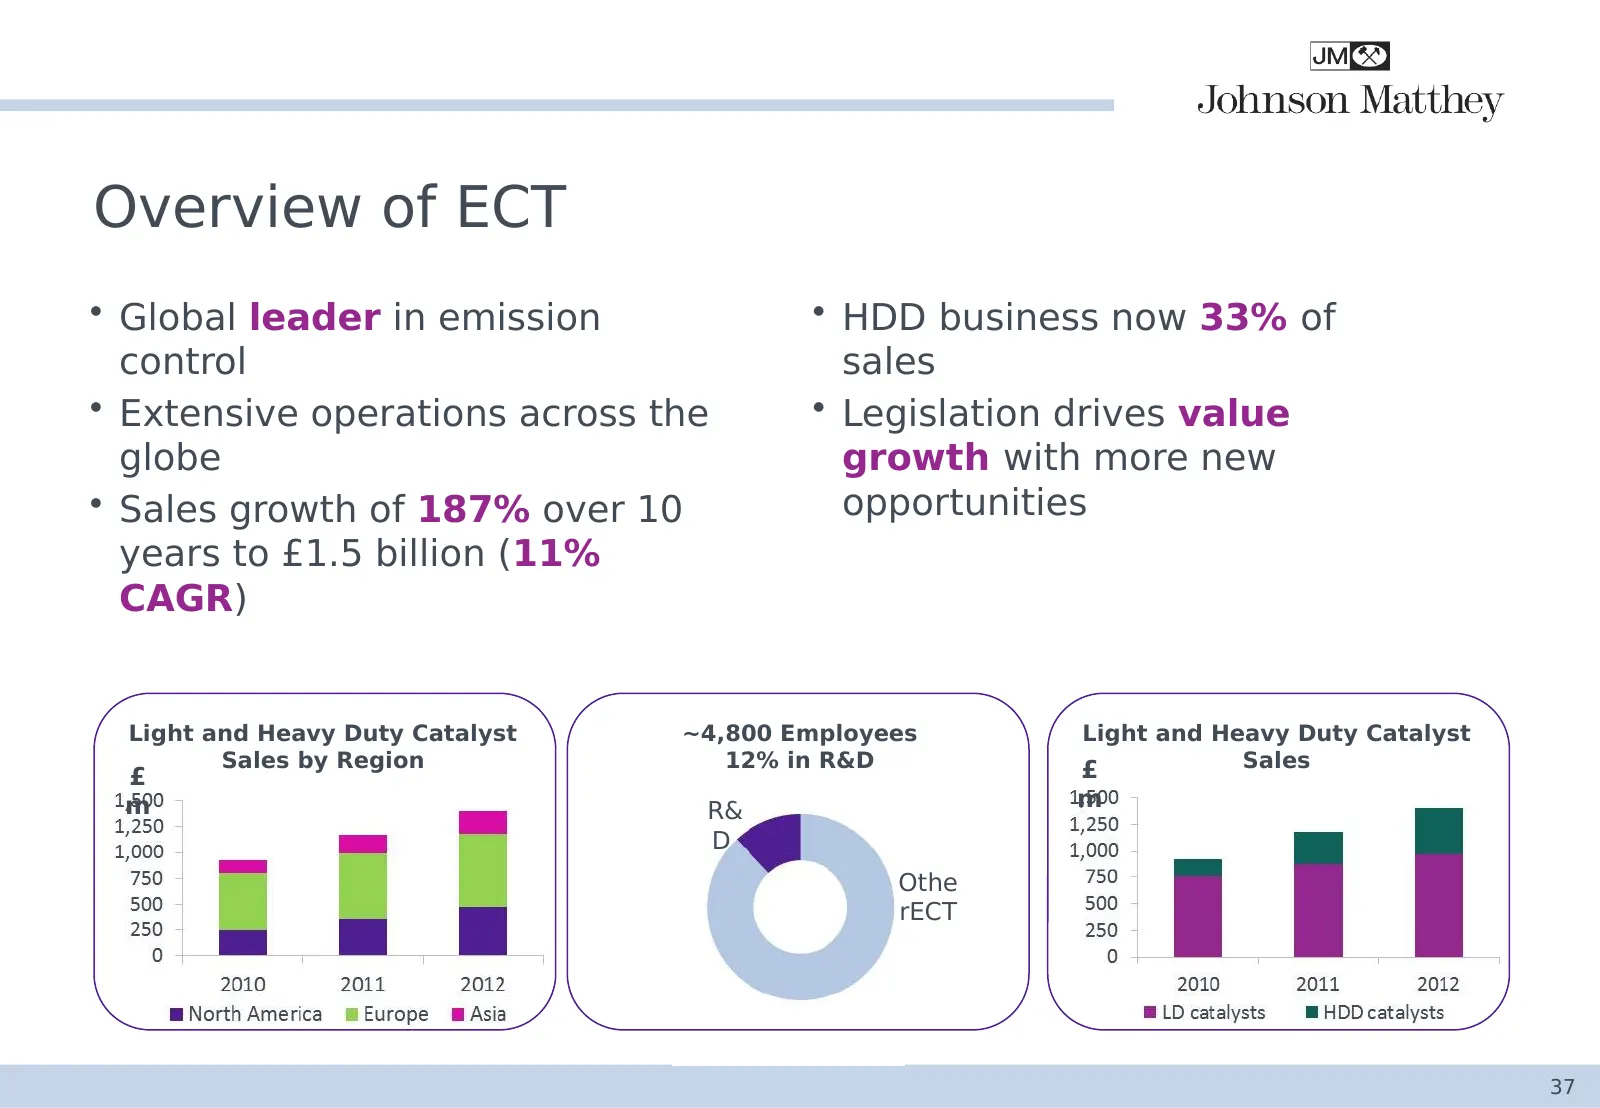
Slide 37: Overview of ECT
Overview of ECT • Global leader in emission • HDD business now 33% of control sales • Extensive operations across the • Legislation drives value globe growth with more new • Sales growth of 187% over 10 opportunities years to £1.5 billion (11% CAGR) Light and Heavy Duty Catalyst ~4,800 Employees Lig
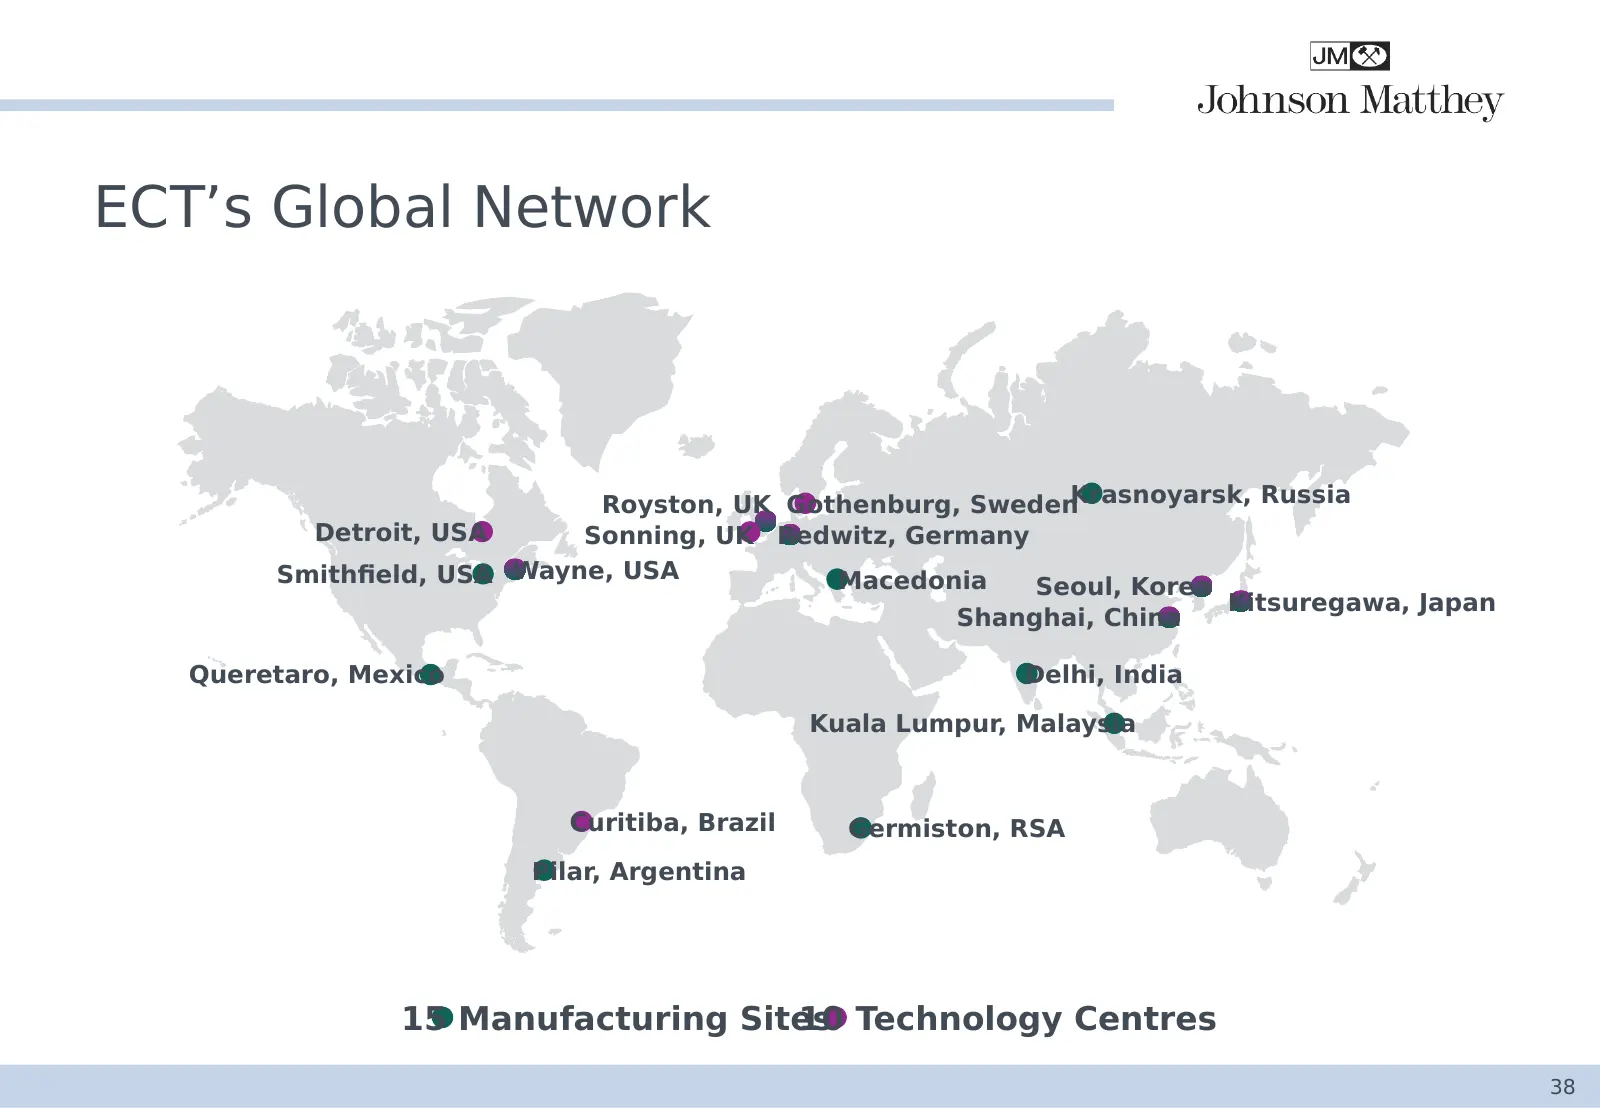
Slide 38: ECT’s Global Network
ECT’s Global Network Royston, UK Gothenburg, SwedenKrasnoyarsk, Russia Detroit, USA Sonning, UK Redwitz, Germany Smithfield, USA Wayne, USA Macedonia Seoul, Korea Kitsuregawa, Japan Shanghai, China Queretaro, Mexico Delhi, India Kuala Lumpur, Malaysia Curitiba, Brazil Germiston, RSA Pilar, Argentina
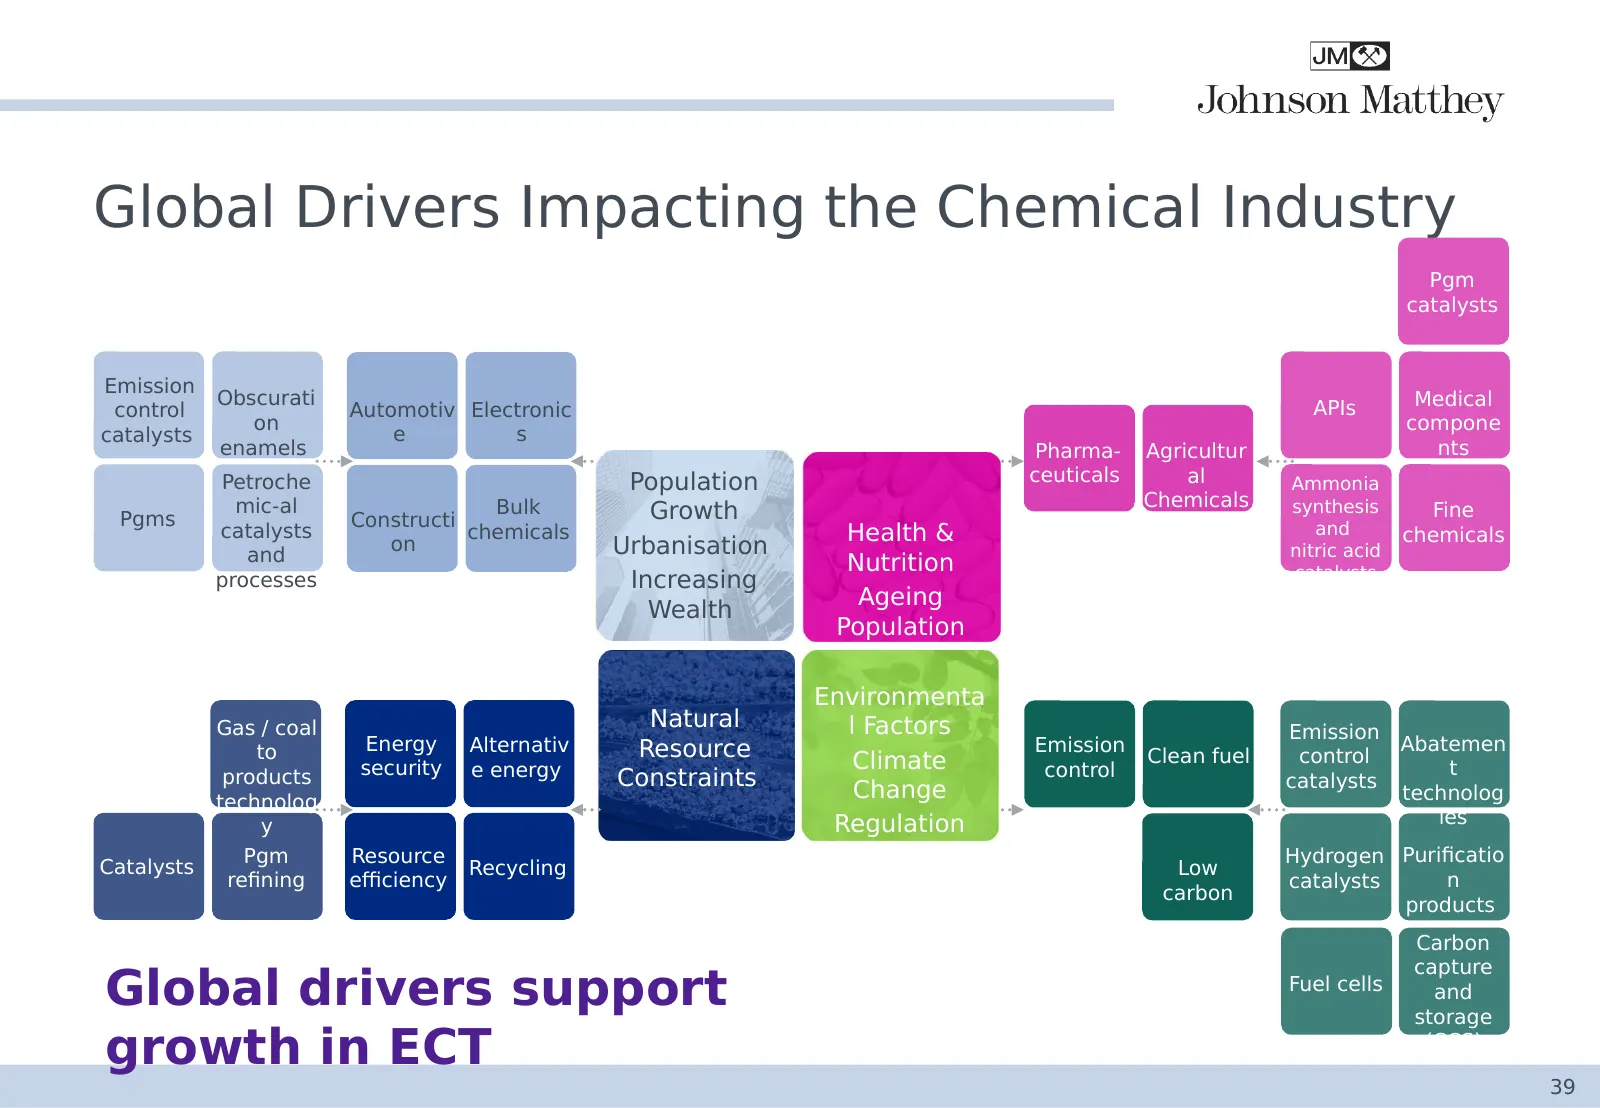
Slide 39: Global Drivers Impacting the Chemical Industry
Global Drivers Impacting the Chemical Industry Pgm catalysts Emission Obscurati APIs Medical control Automotiv Electronic on compone catalysts e s enamels Pharma- Agricultur nts Petroche Population ceuticals al Ammonia mic-al Bulk Chemicals synthesis Pgms Constructi Growth Fine catalysts chemicals H
Slide 40: The Light Duty Catalyst Market
The Light Duty Catalyst Market • Market Growth Drivers i. Vehicle Production ii. Legislation iii. Technology and Revenue Implications iv. Powertrain Trends • Market Position • Market Growth 40
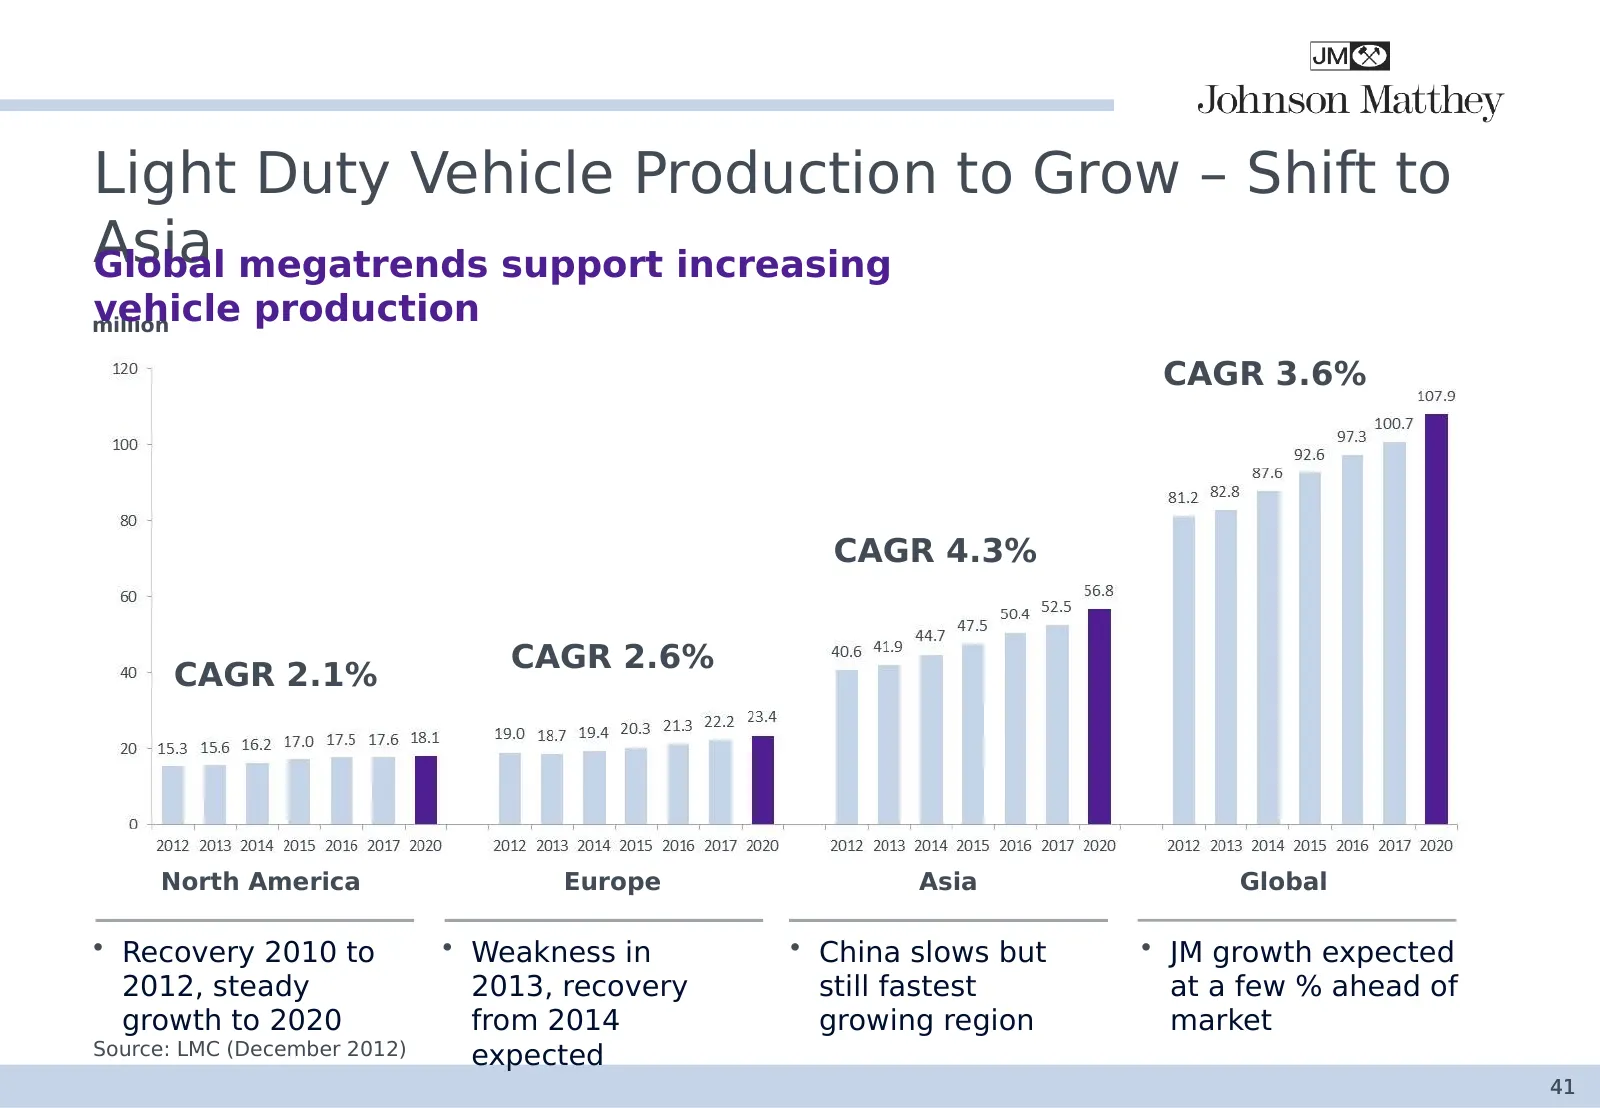
Slide 41: Light Duty Vehicle Production to Grow – Shift to Asia
Light Duty Vehicle Production to Grow – Shift to Asia Global megatrends support increasing vehicle production million CAGR 3.6% CAGR 4.3% CAGR 2.6% CAGR 2.1% North America Europe Asia Global • Recovery 2010 to • Weakness in • China slows but • JM growth expected 2012, steady 2013, recovery still fas
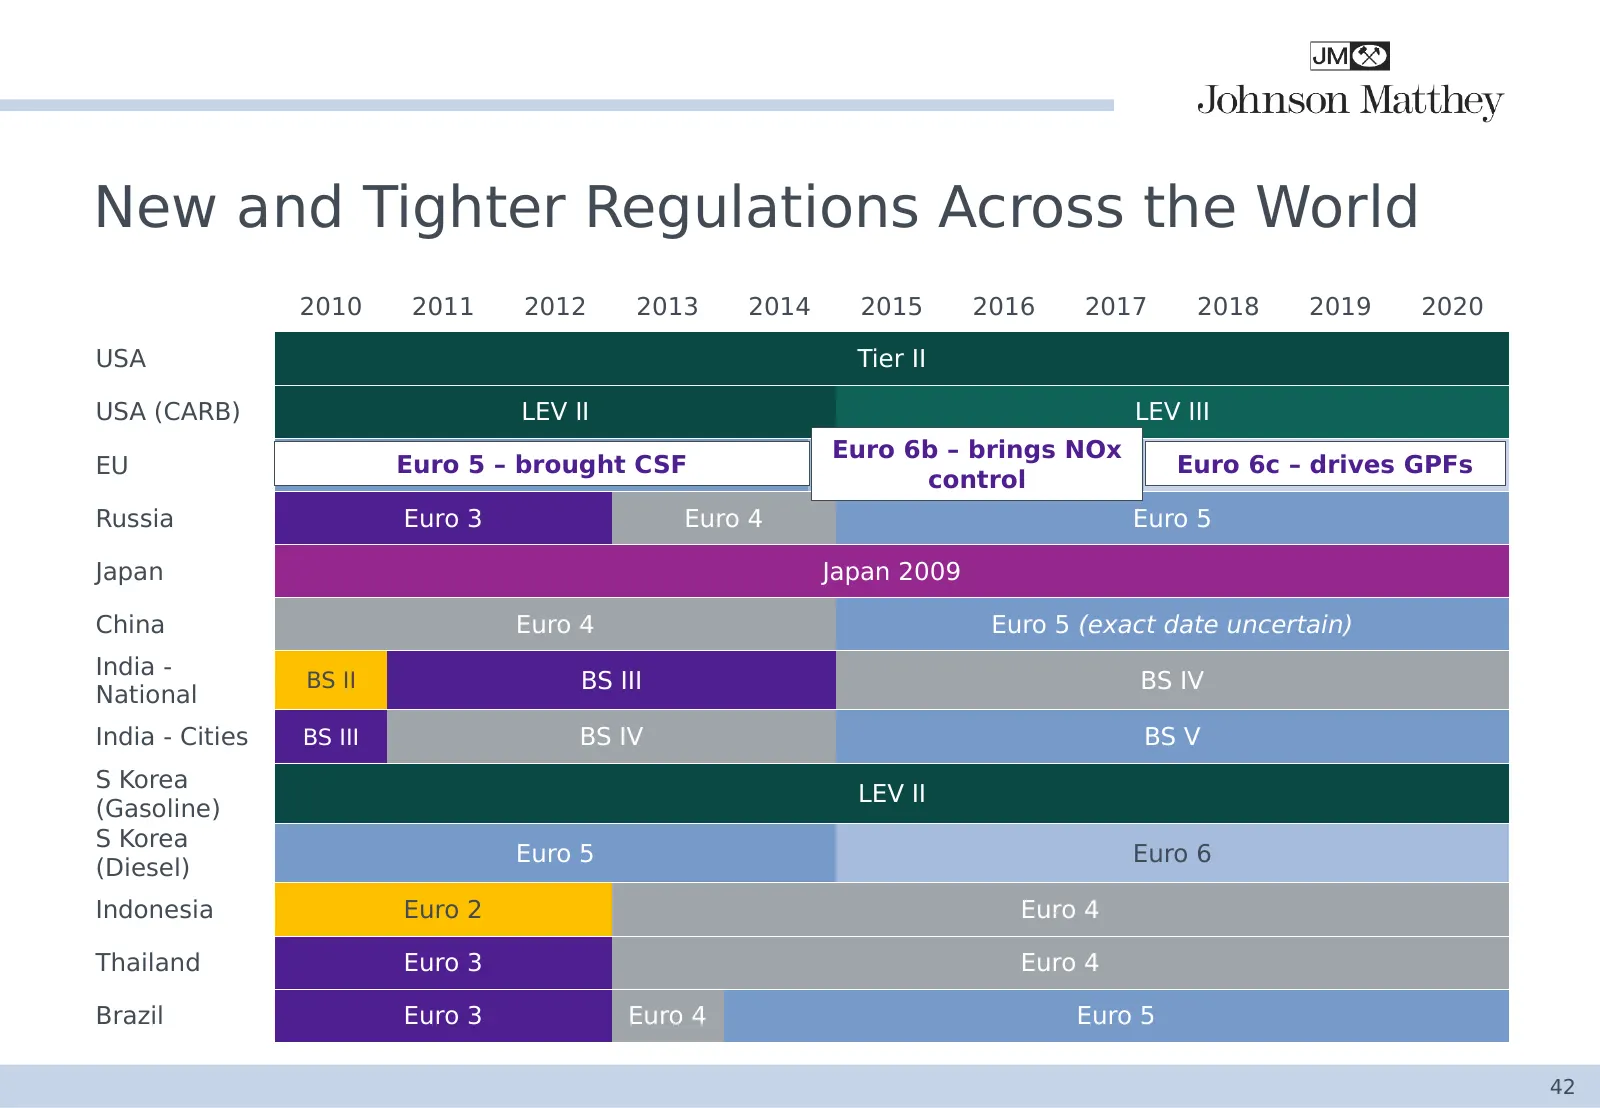
Slide 42: New and Tighter Regulations Across the World
New and Tighter Regulations Across the World 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 USA Tier II USA (CARB) LEV II LEV III Euro 6b – brings NOx EU Euro 5 –Euro brought 5 CSF Euro 6b Euro 6cEuro – drives 6c GPFs control Russia Euro 3 Euro 4 Euro 5 Japan Japan 2009 China Euro 4 Euro 5 (
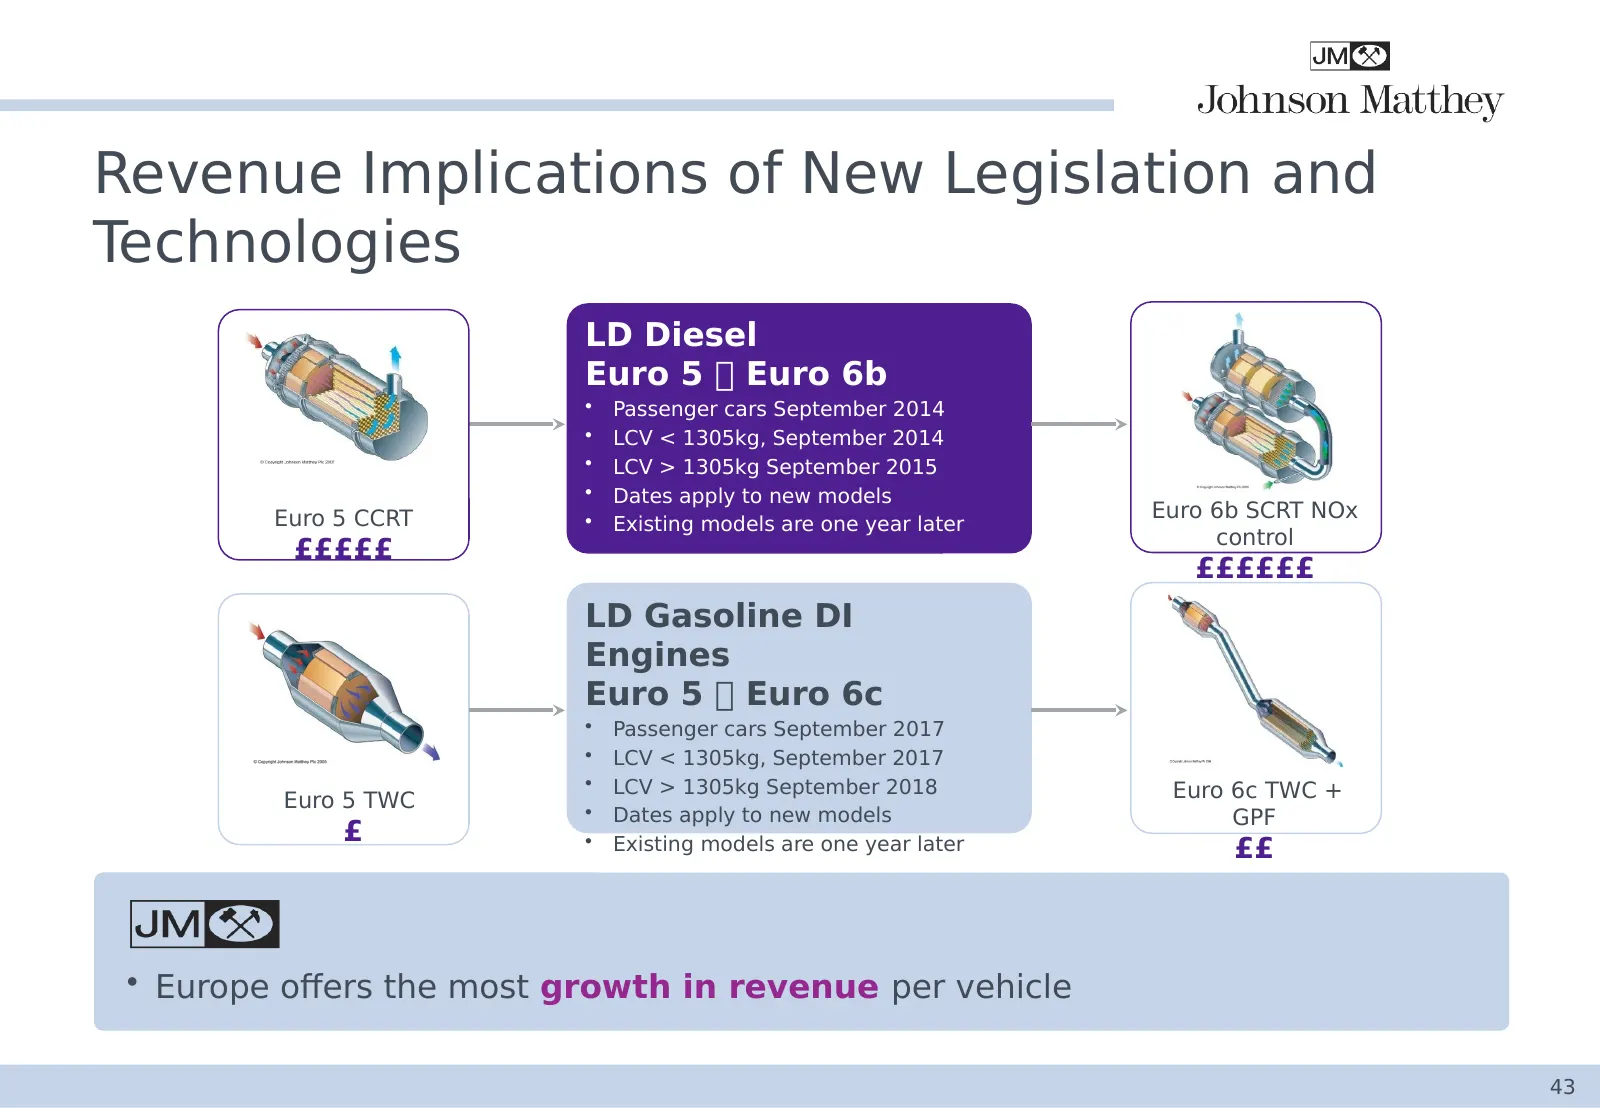
Slide 43: Revenue Implications of New Legislation and Technologies
Revenue Implications of New Legislation and Technologies LD Diesel Euro 5 Euro 6b • Passenger cars September 2014 • LCV < 1305kg, September 2014 • LCV > 1305kg September 2015 • Dates apply to new models Euro 5 CCRT • Euro 6b SCRT NOx Existing models are one year later control £££££ ££££££ LD Gasol
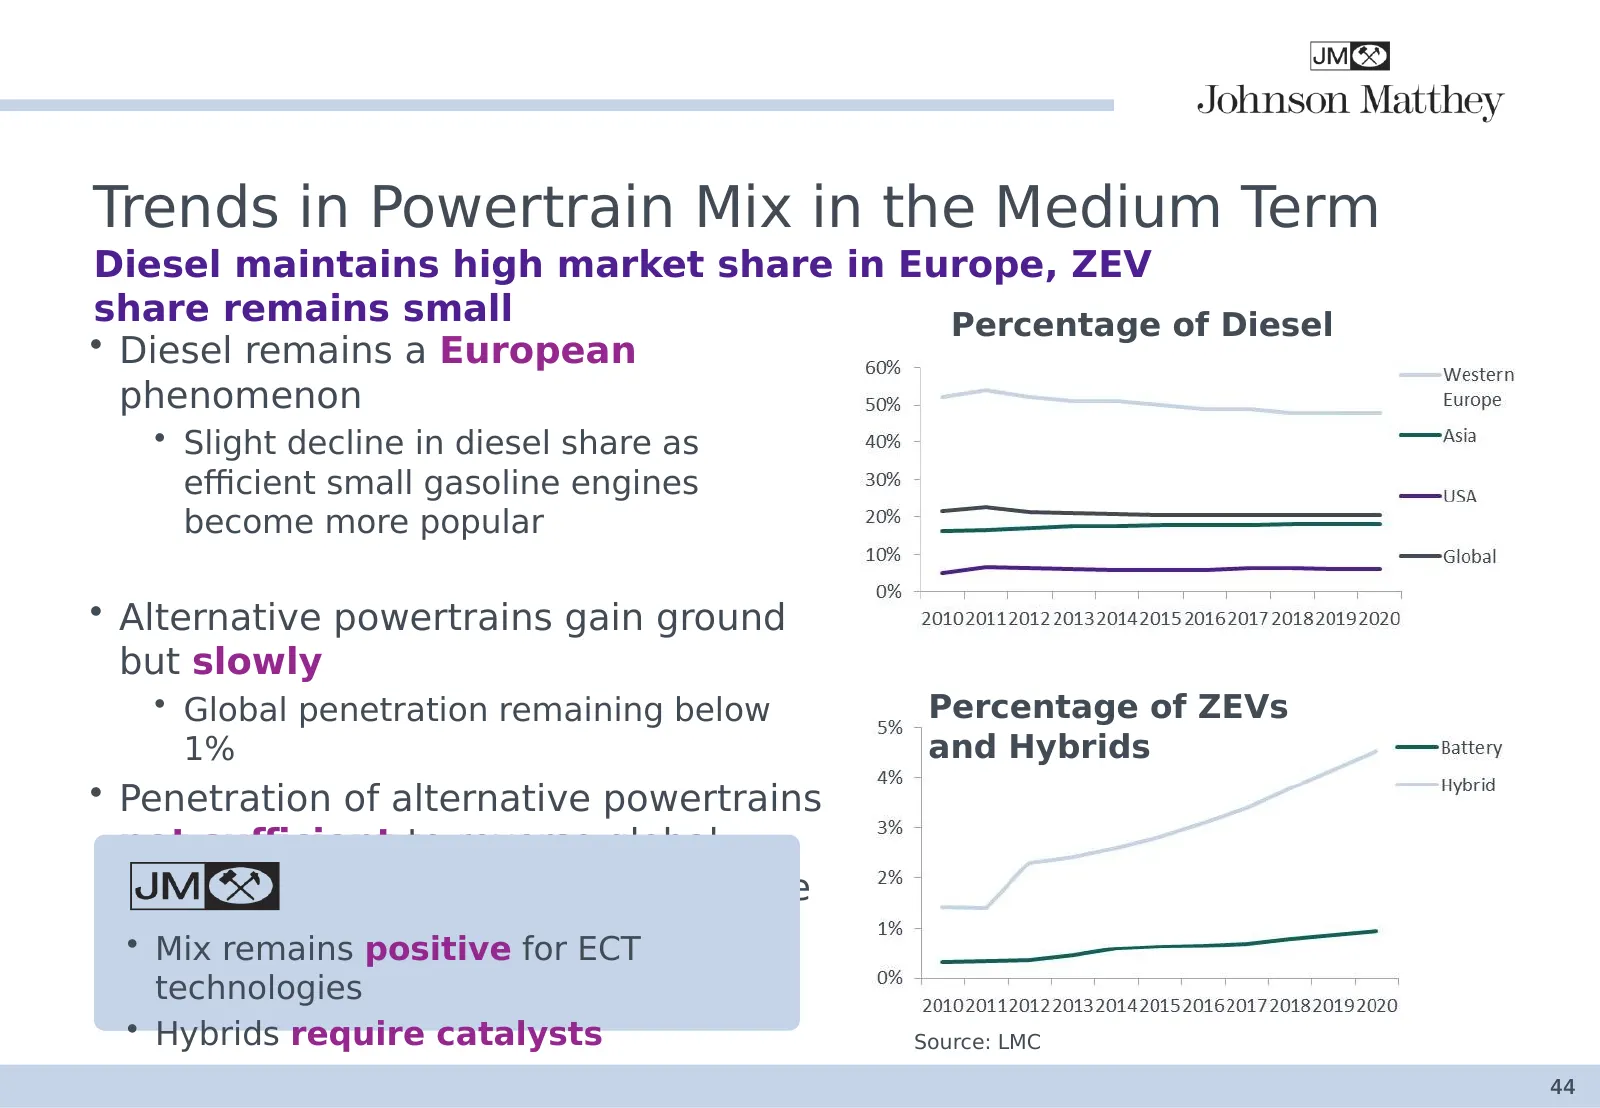
Slide 44: Trends in Powertrain Mix in the Medium Term
Trends in Powertrain Mix in the Medium Term Diesel maintains high market share in Europe, ZEV share remains small Percentage of Diesel • Diesel remains a European phenomenon • Slight decline in diesel share as efficient small gasoline engines become more popular • Alternative powertrains gain ground
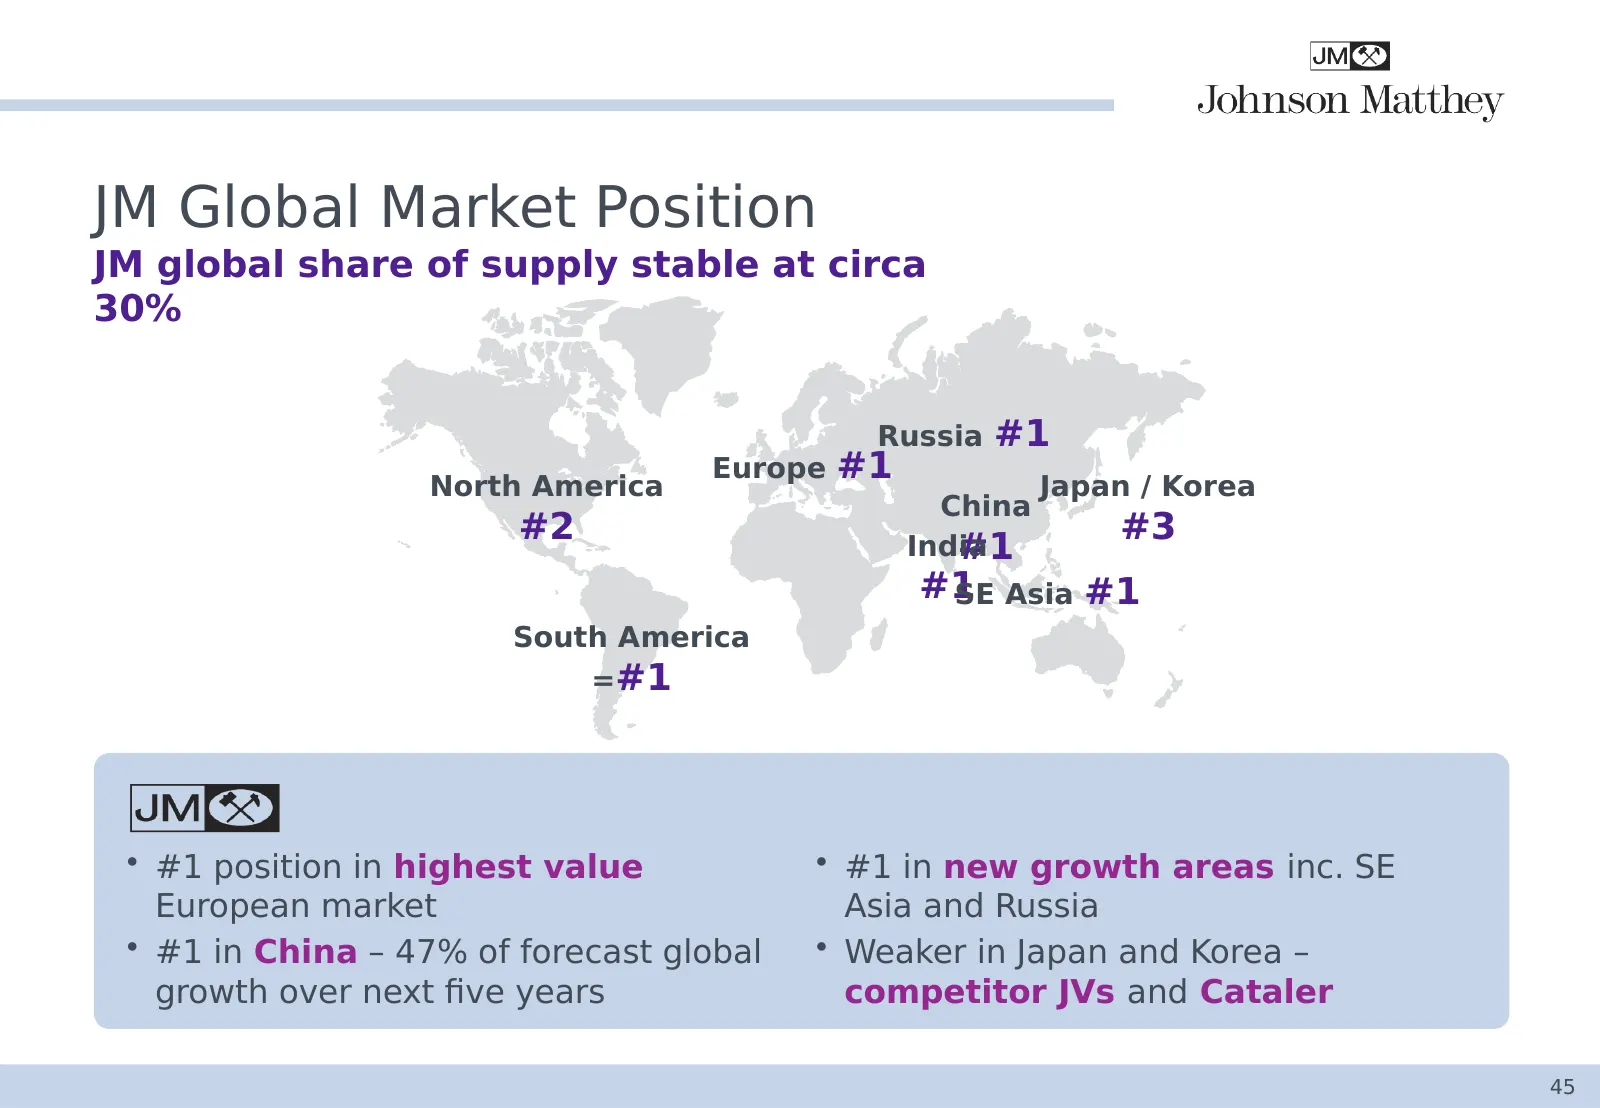
Slide 45: JM Global Market Position
JM Global Market Position JM global share of supply stable at circa 30% Russia #1 Europe #1 North America Japan / Korea China #2 #3 #1 India #1 SE Asia #1 South America =#1 • #1 position in highest value • #1 in new growth areas inc. SE European market Asia and Russia • #1 in China – 47% of forecast
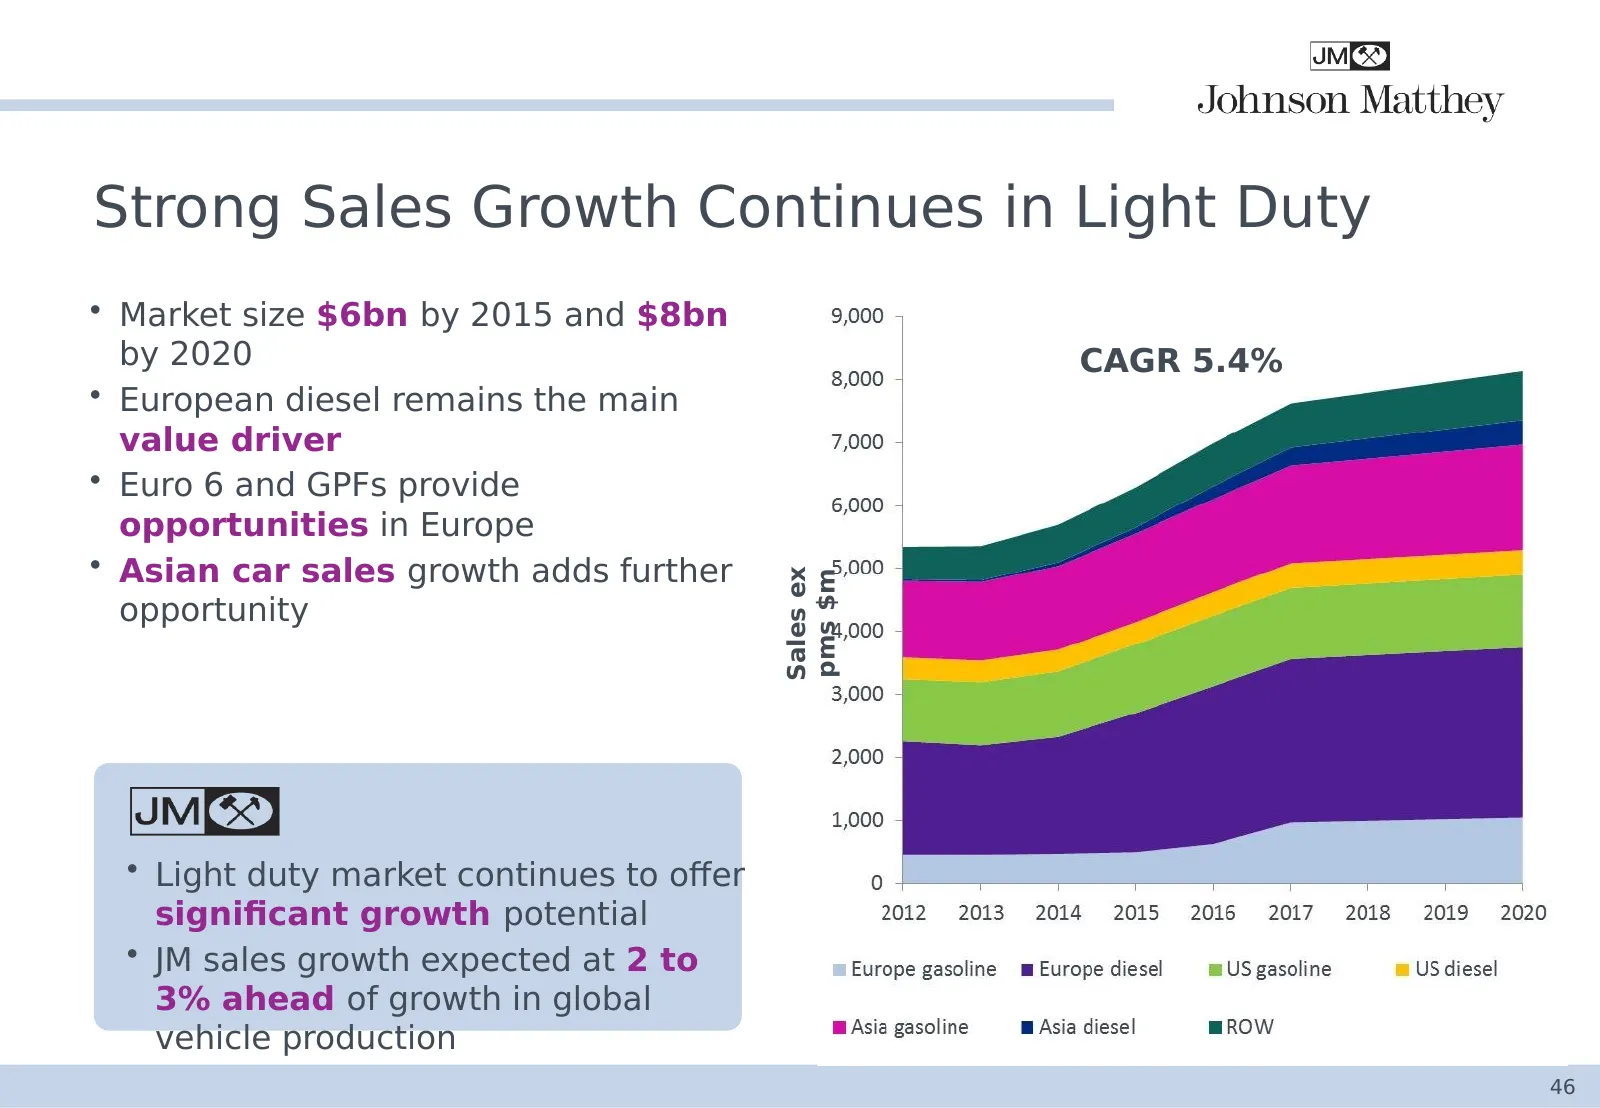
Slide 46: Strong Sales Growth Continues in Light Duty
Strong Sales Growth Continues in Light Duty • Market size $6bn by 2015 and $8bn by 2020 CAGR 5.4% • European diesel remains the main value driver • Euro 6 and GPFs provide opportunities in Europe • Asian car sales growth adds further Sales ex pms $m opportunity • Light duty market continues to offer
Slide 47: The Heavy Duty and Non-road Catalyst Market
The Heavy Duty and Non-road Catalyst Market • Market Growth Drivers i. Vehicle Production ii. Legislation iii. Technology and Revenue Implications • Market Position • Market Growth 47
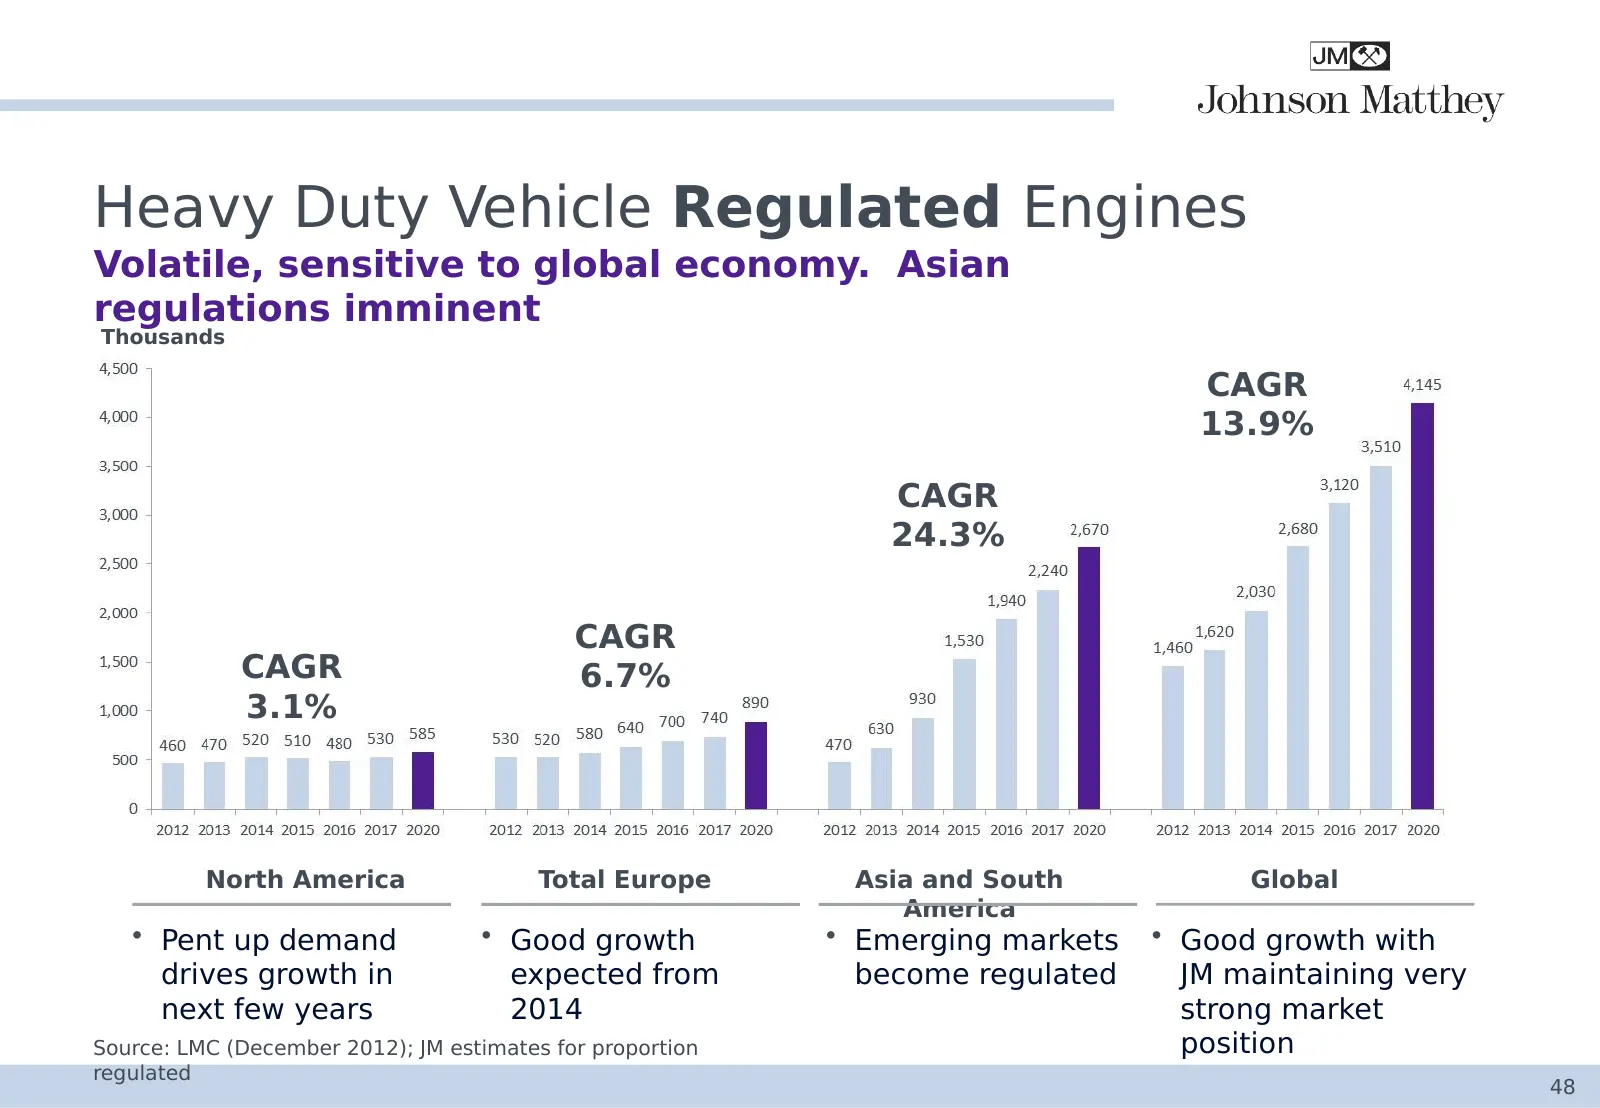
Slide 48: Heavy Duty Vehicle Regulated Engines
Heavy Duty Vehicle Regulated Engines Volatile, sensitive to global economy. Asian regulations imminent Thousands CAGR 13.9% CAGR 24.3% CAGR CAGR 6.7% 3.1% North America Total Europe Asia and South Global America • Pent up demand • Good growth • Emerging markets • Good growth with drives growth in ex
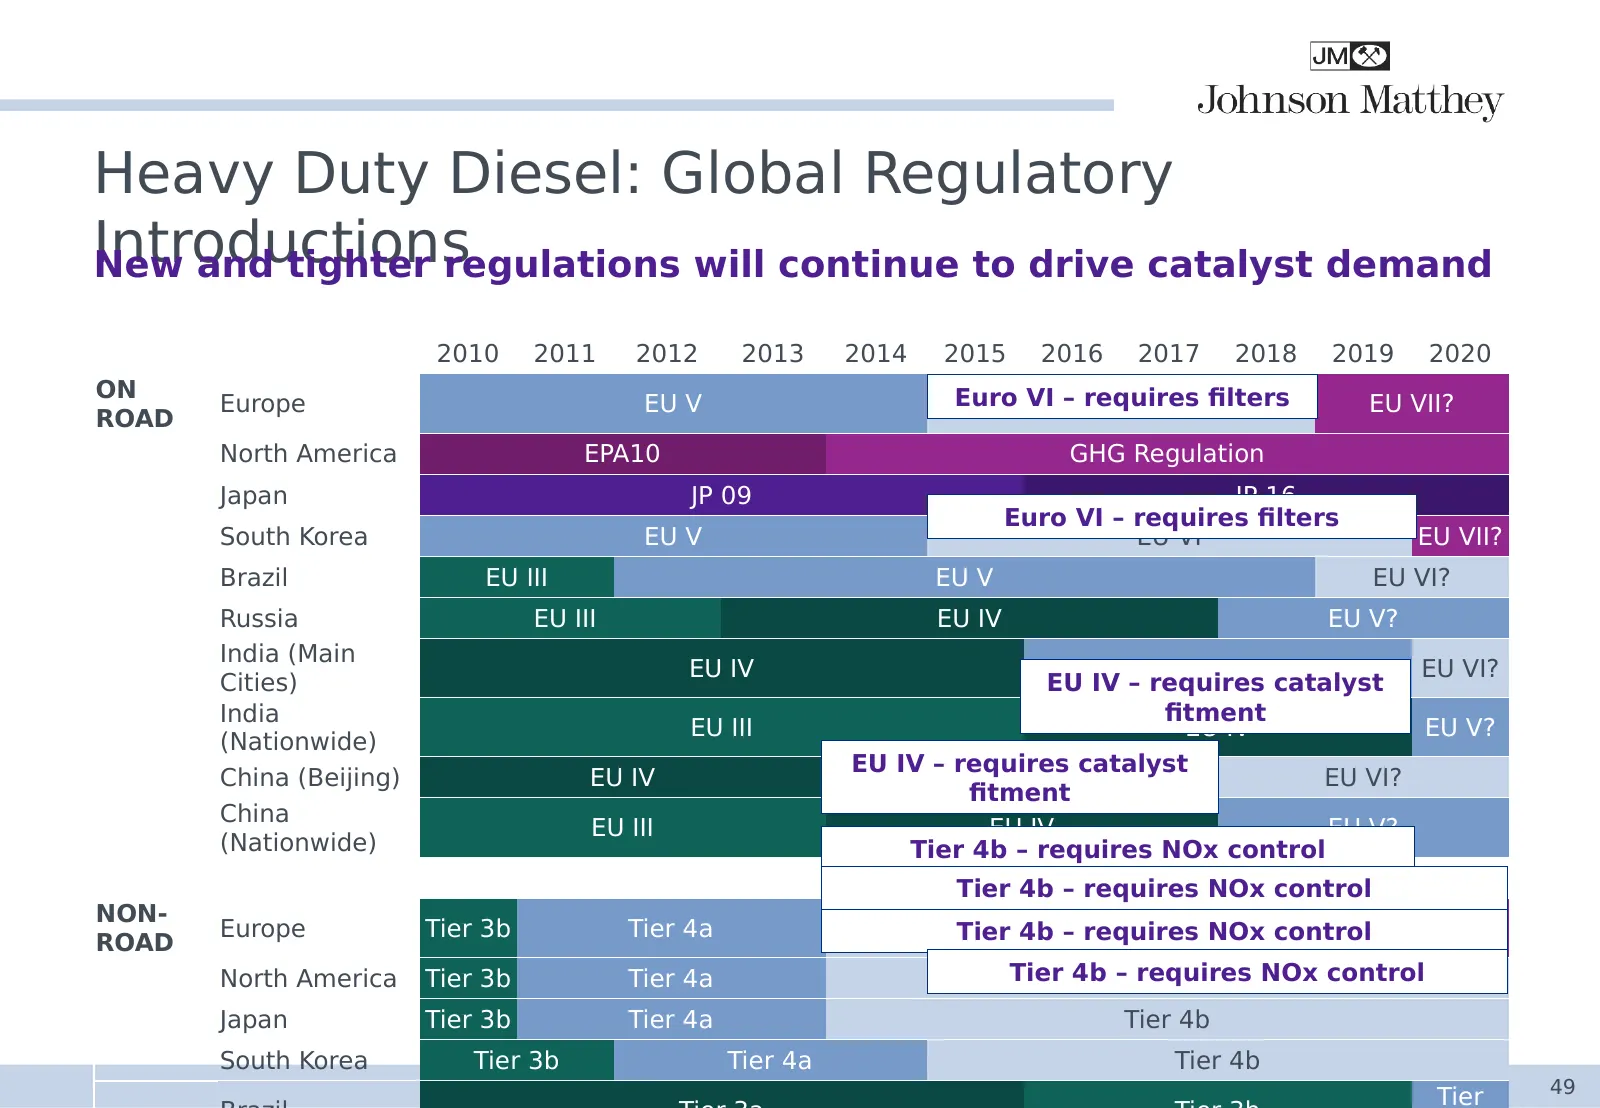
Slide 49: Heavy Duty Diesel: Global Regulatory Introductions
Heavy Duty Diesel: Global Regulatory Introductions New and tighter regulations will continue to drive catalyst demand 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 ON Euro VI – requires filters Europe EU V EU VI EU VII? ROAD North America EPA10 GHG Regulation Japan JP 09 JP 16 Euro VI – req
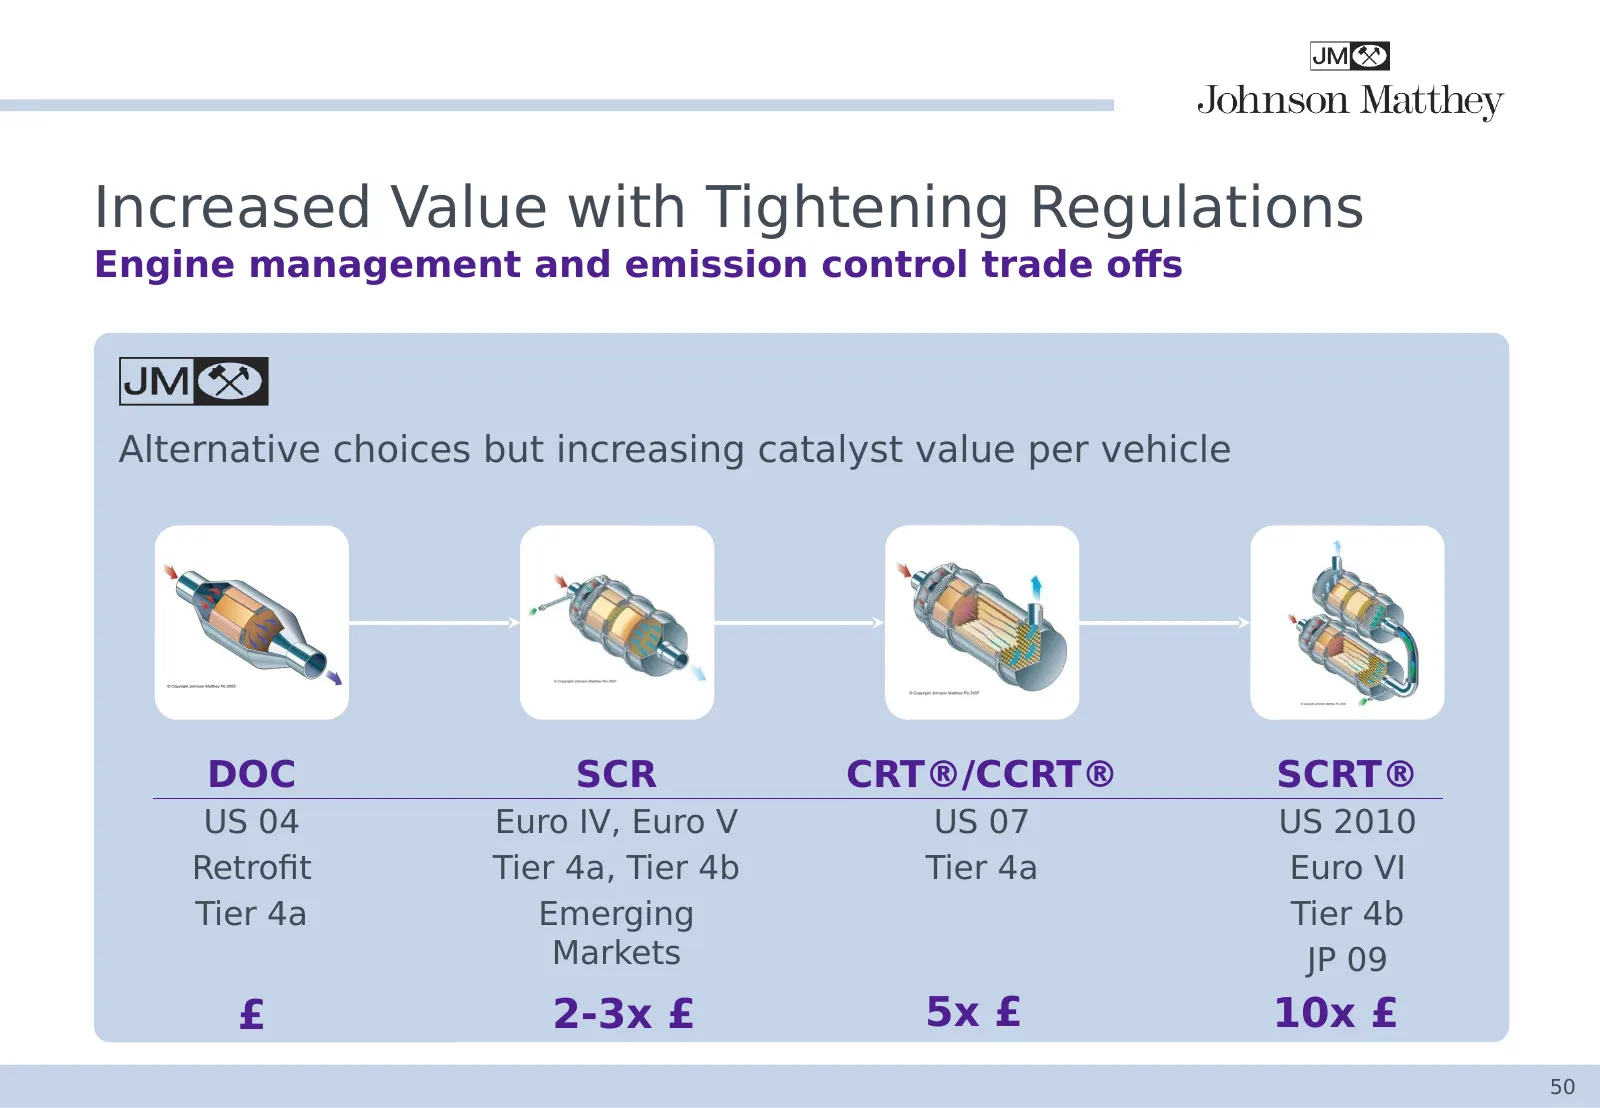
Slide 50: Increased Value with Tightening Regulations
Increased Value with Tightening Regulations Engine management and emission control trade offs Alternative choices but increasing catalyst value per vehicle DOC SCR CRT®/CCRT® SCRT® US 04 Euro IV, Euro V US 07 US 2010 Retrofit Tier 4a, Tier 4b Tier 4a Euro VI Tier 4a Emerging Tier 4b Markets JP 09 £
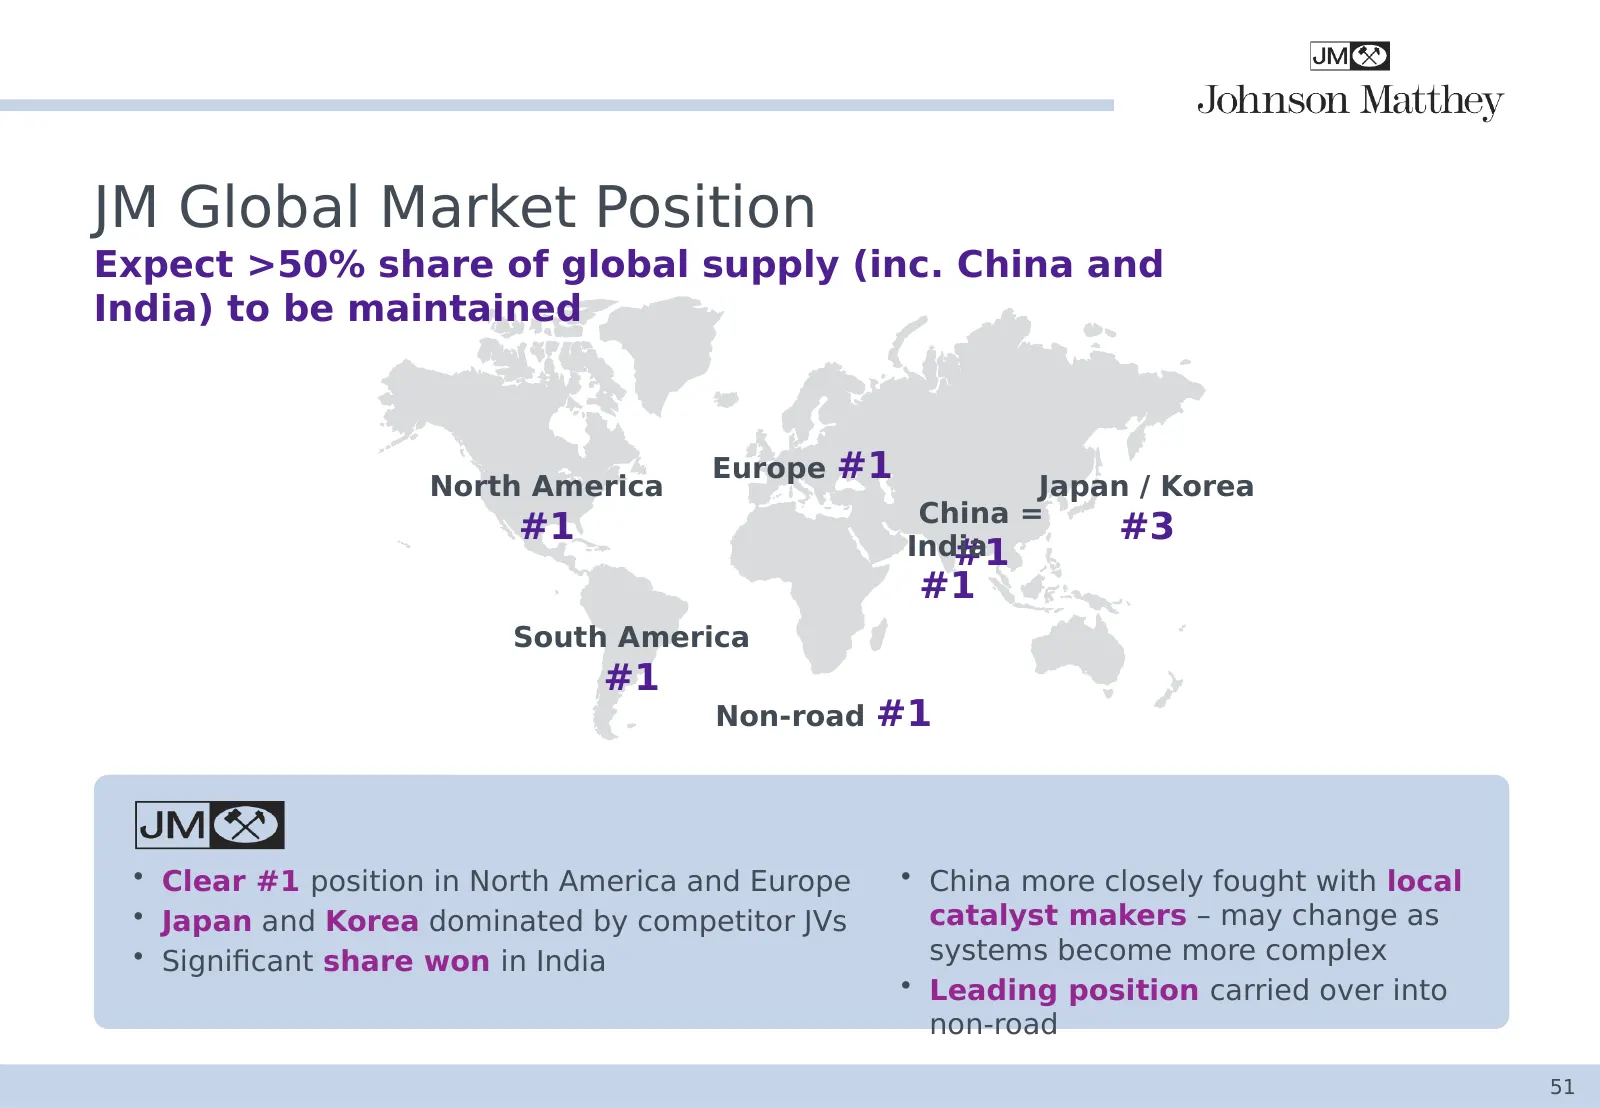
Slide 51: JM Global Market Position
JM Global Market Position Expect >50% share of global supply (inc. China and India) to be maintained Europe #1 North America Japan / Korea China = #1 India #3 #1 #1 South America #1 Non-road #1 • Clear #1 position in North America and Europe • China more closely fought with local • Japan and Korea d
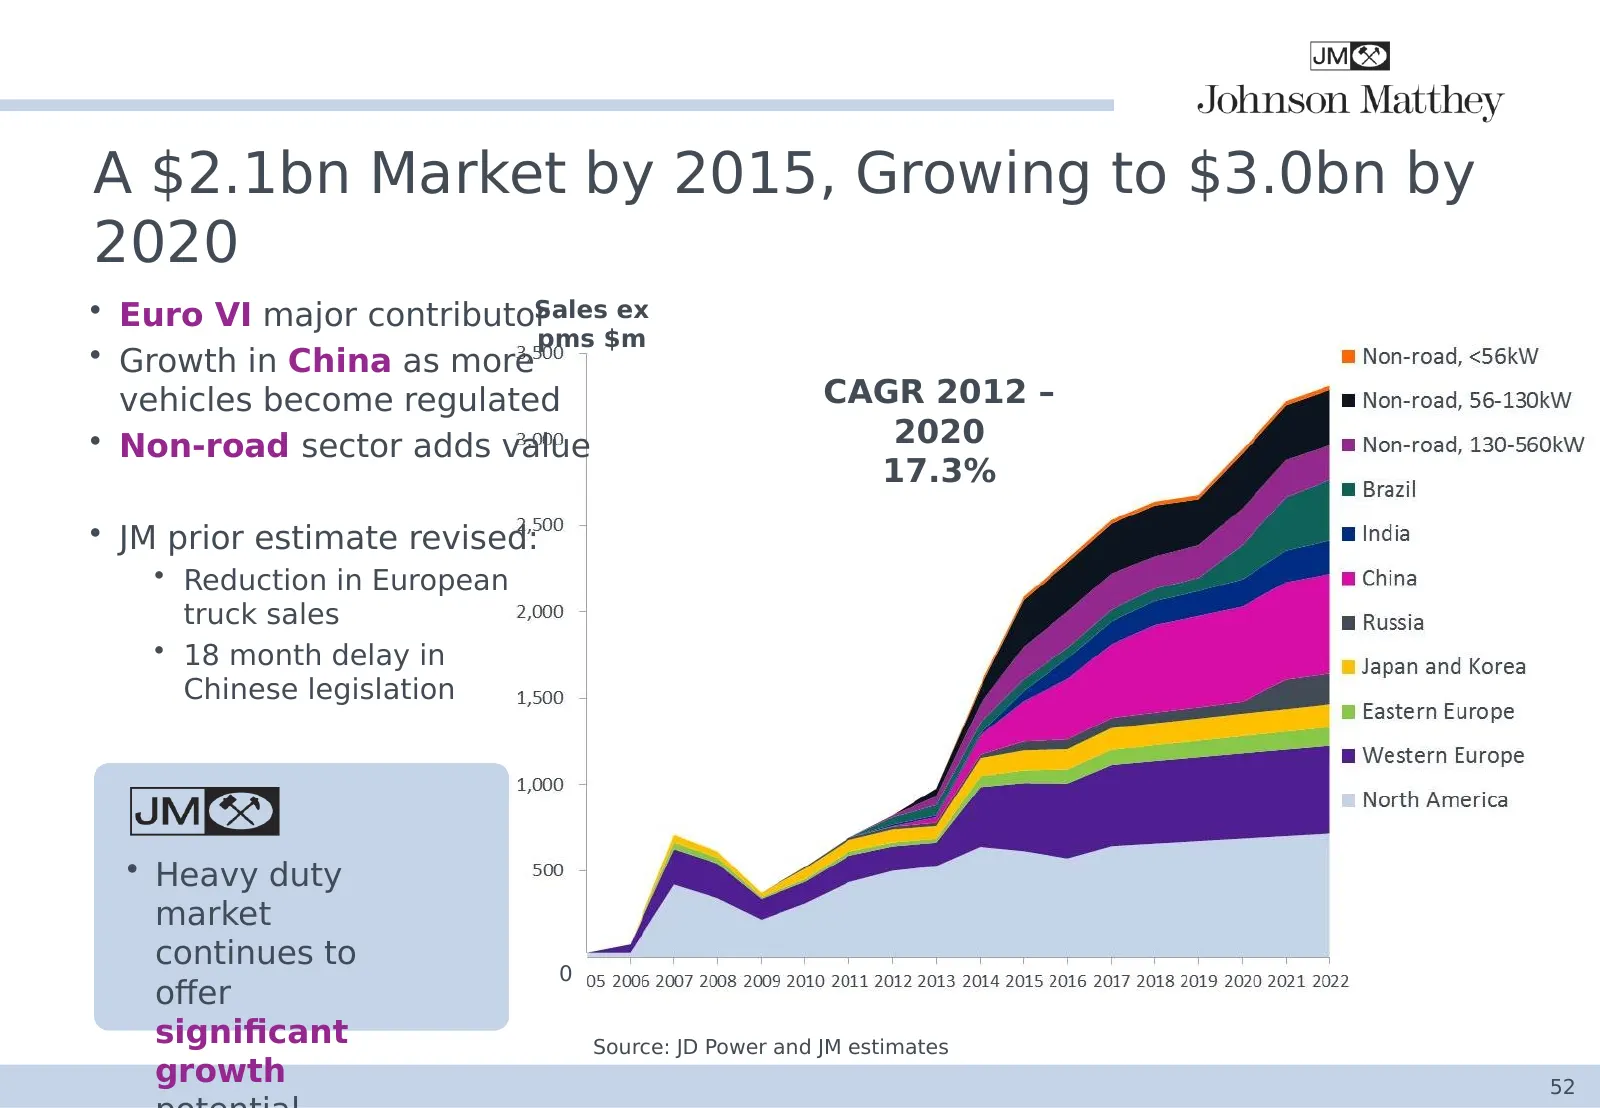
Slide 52: A $2.1bn Market by 2015, Growing to $3.0bn by 2020
A $2.1bn Market by 2015, Growing to $3.0bn by 2020 • Euro VI major contributorSales ex pms $m • Growth in China as more vehicles become regulated CAGR 2012 – • Non-road sector adds value 2020 17.3% • JM prior estimate revised: • Reduction in European truck sales • 18 month delay in Chinese legislati
Slide 53: Key Takeaways…
Key Takeaways… Growth in all Legislative Many opportunities JM continues to invest our markets tightening develop and derive ahead of growth continues to value from opportunities. ECT’s deliver value innovative capex reduces to technologies around 1x Strong position in Margins stable Double digit HD
Slide 54: Light Duty Aftertreatment Technology
Light Duty Aftertreatment Technology Dr Chris Morgan Technology Director, Emission Control Technologies, Europe
Slide 55: Agenda
Agenda Light Duty Aftertreatment Technology 0 Opportunities for New Technology 1 0 Diesel i. Selective Catalytic Reduction (SCR) 2 ii. NOx Adsorber Catalysts (NAC) iii. SCR on a Filter (SCRF®) 0 Gasoline i. Gasoline Particulate Filters (GPF) 3 ii. LEV lll 0 CO2 Regulations 4 0 Real World Emissions 5
Slide 56: Key Legislation Changes in Light Duty
Key Legislation Changes in Light Duty • Lower Diesel NOx limit for Euro 6 (2014/15) • Reduces from 180 to 80mg/km • Gasoline Particulate Number Control for Euro 6 • Limit reduces from 6x10¹² to 6x10¹¹/km in 2017/18 • Real World Driving Emissions (RDE) • Proposed to reduce off-cycle emissions in Euro
Slide 57: New Product Opportunities
New Product Opportunities Diesel NOx control • Widespread adoption of SCR and NAC • Integration onto particulate filter – SCRF® • Multifunctional filters – ammonia (NH 3) slip, hydrogen sulfide (H2S) attenuation Gasoline particulate number • Introduction of coated gasoline particulate filters – Thre
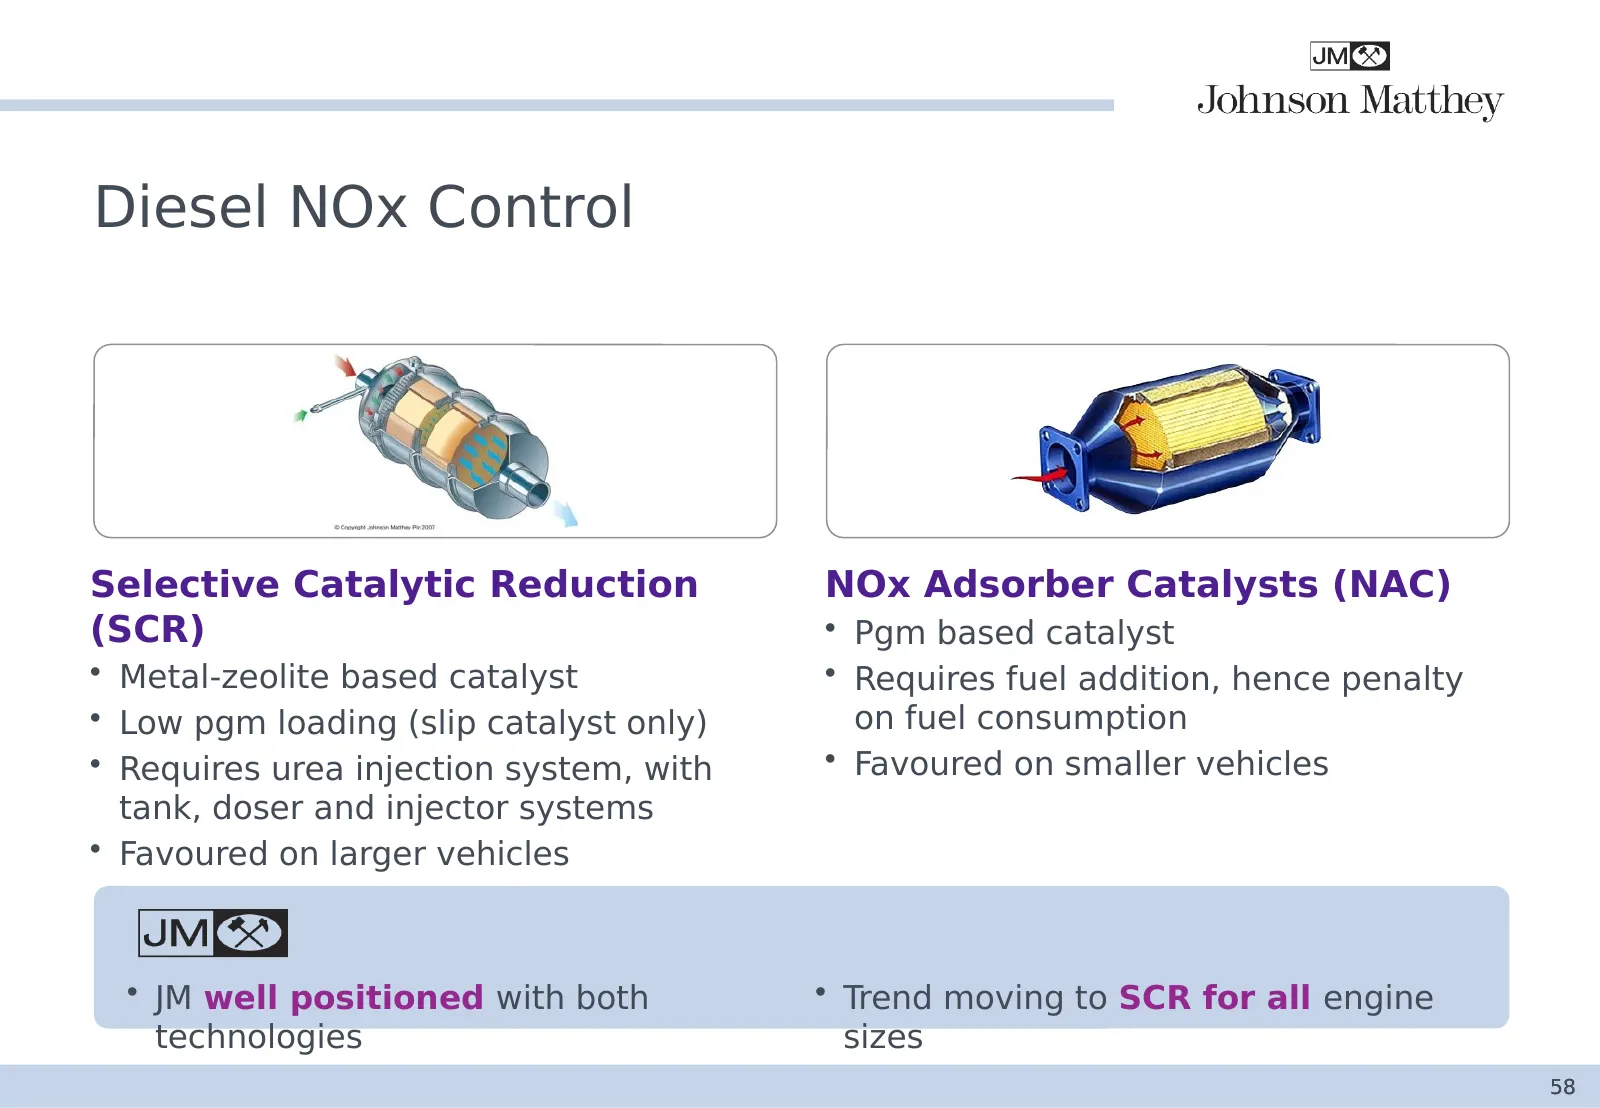
Slide 58: Diesel NOx Control
Diesel NOx Control Selective Catalytic Reduction NOx Adsorber Catalysts (NAC) (SCR) • Pgm based catalyst • Metal-zeolite based catalyst • Requires fuel addition, hence penalty • Low pgm loading (slip catalyst only) on fuel consumption • Requires urea injection system, with • Favoured on smaller vehi
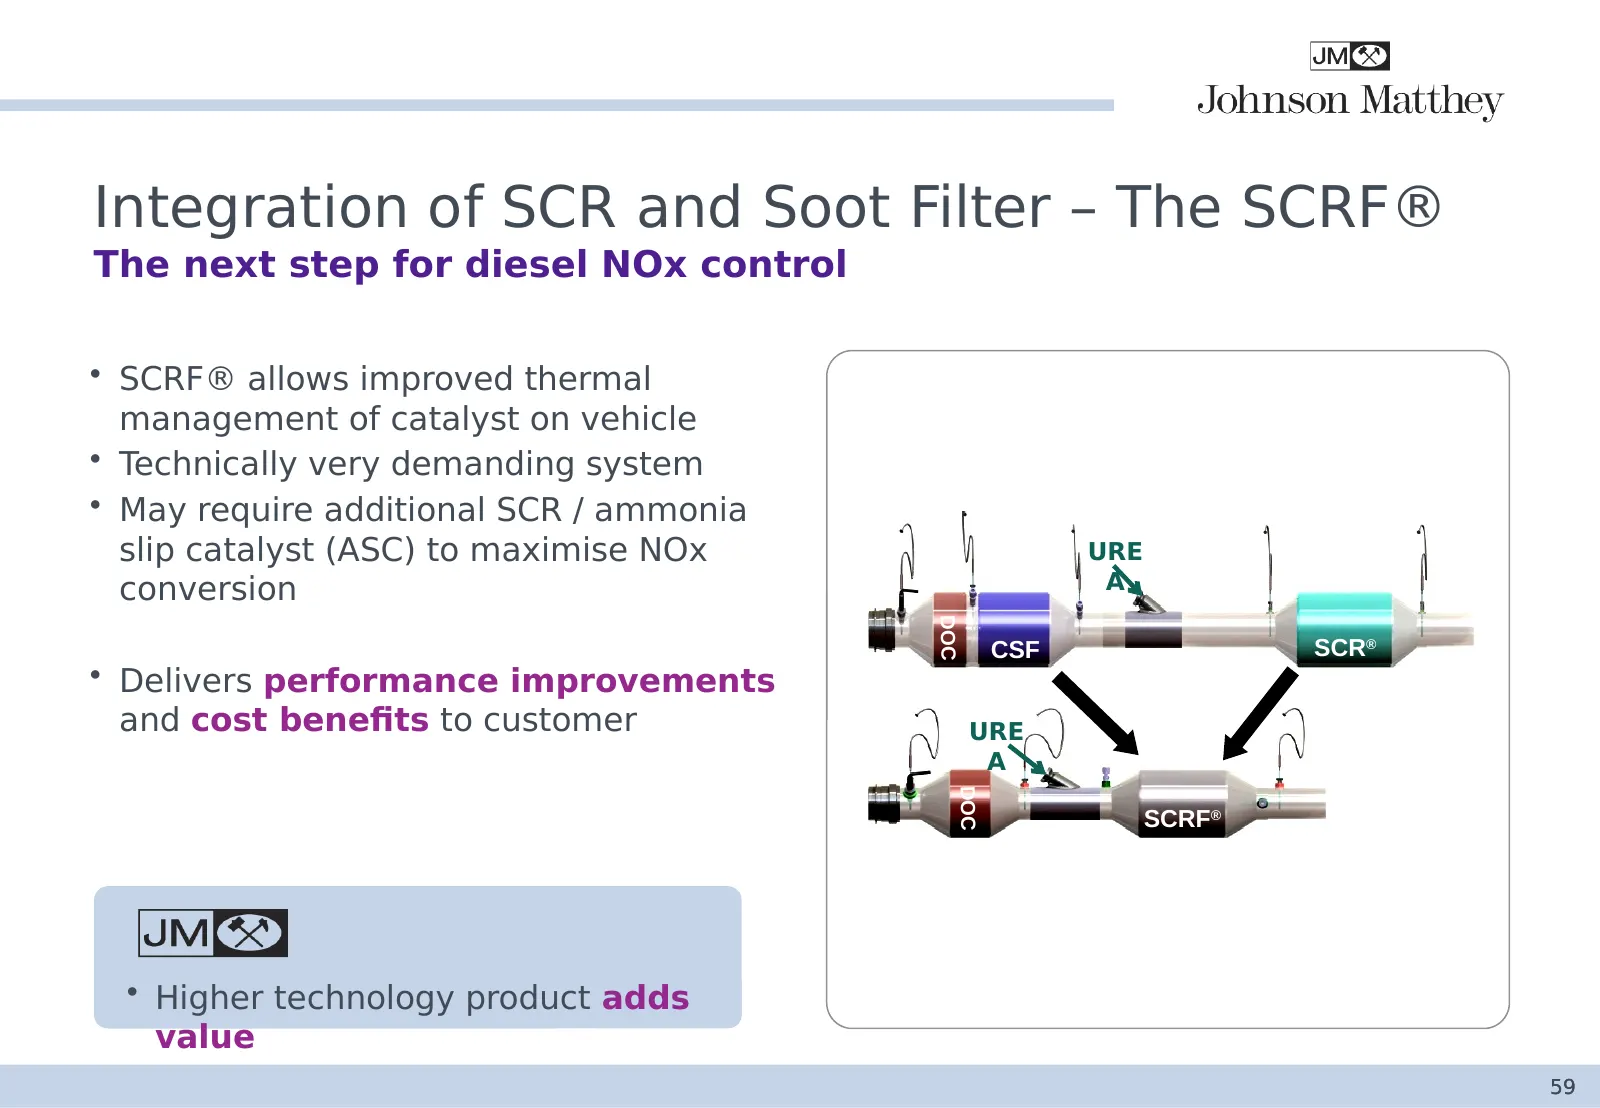
Slide 59: Integration of SCR and Soot Filter – The SCRF®
Integration of SCR and Soot Filter – The SCRF® The next step for diesel NOx control • SCRF® allows improved thermal management of catalyst on vehicle • Technically very demanding system • May require additional SCR / ammonia slip catalyst (ASC) to maximise NOx URE conversion A DOC CSF SCR® • Deliver
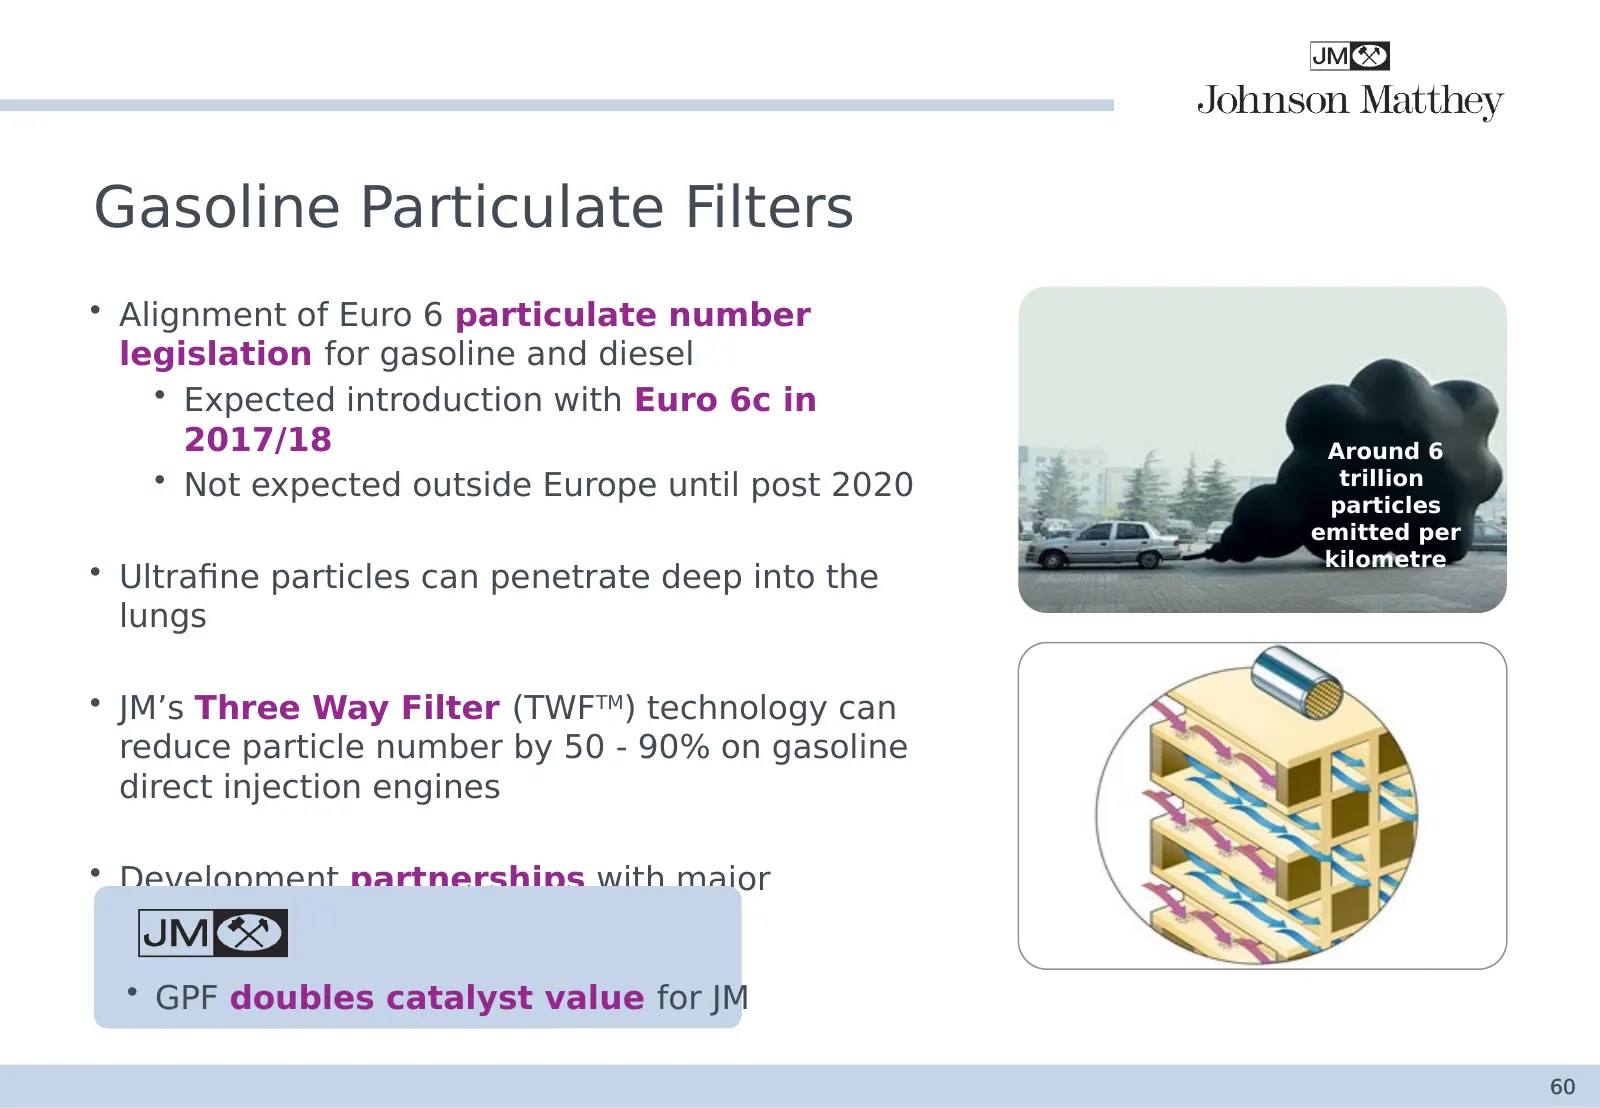
Slide 60: Gasoline Particulate Filters
Gasoline Particulate Filters • Alignment of Euro 6 particulate number legislation for gasoline and diesel • Expected introduction with Euro 6c in 2017/18 Around 6 • Not expected outside Europe until post 2020 trillion particles emitted per kilometre • Ultrafine particles can penetrate deep into the
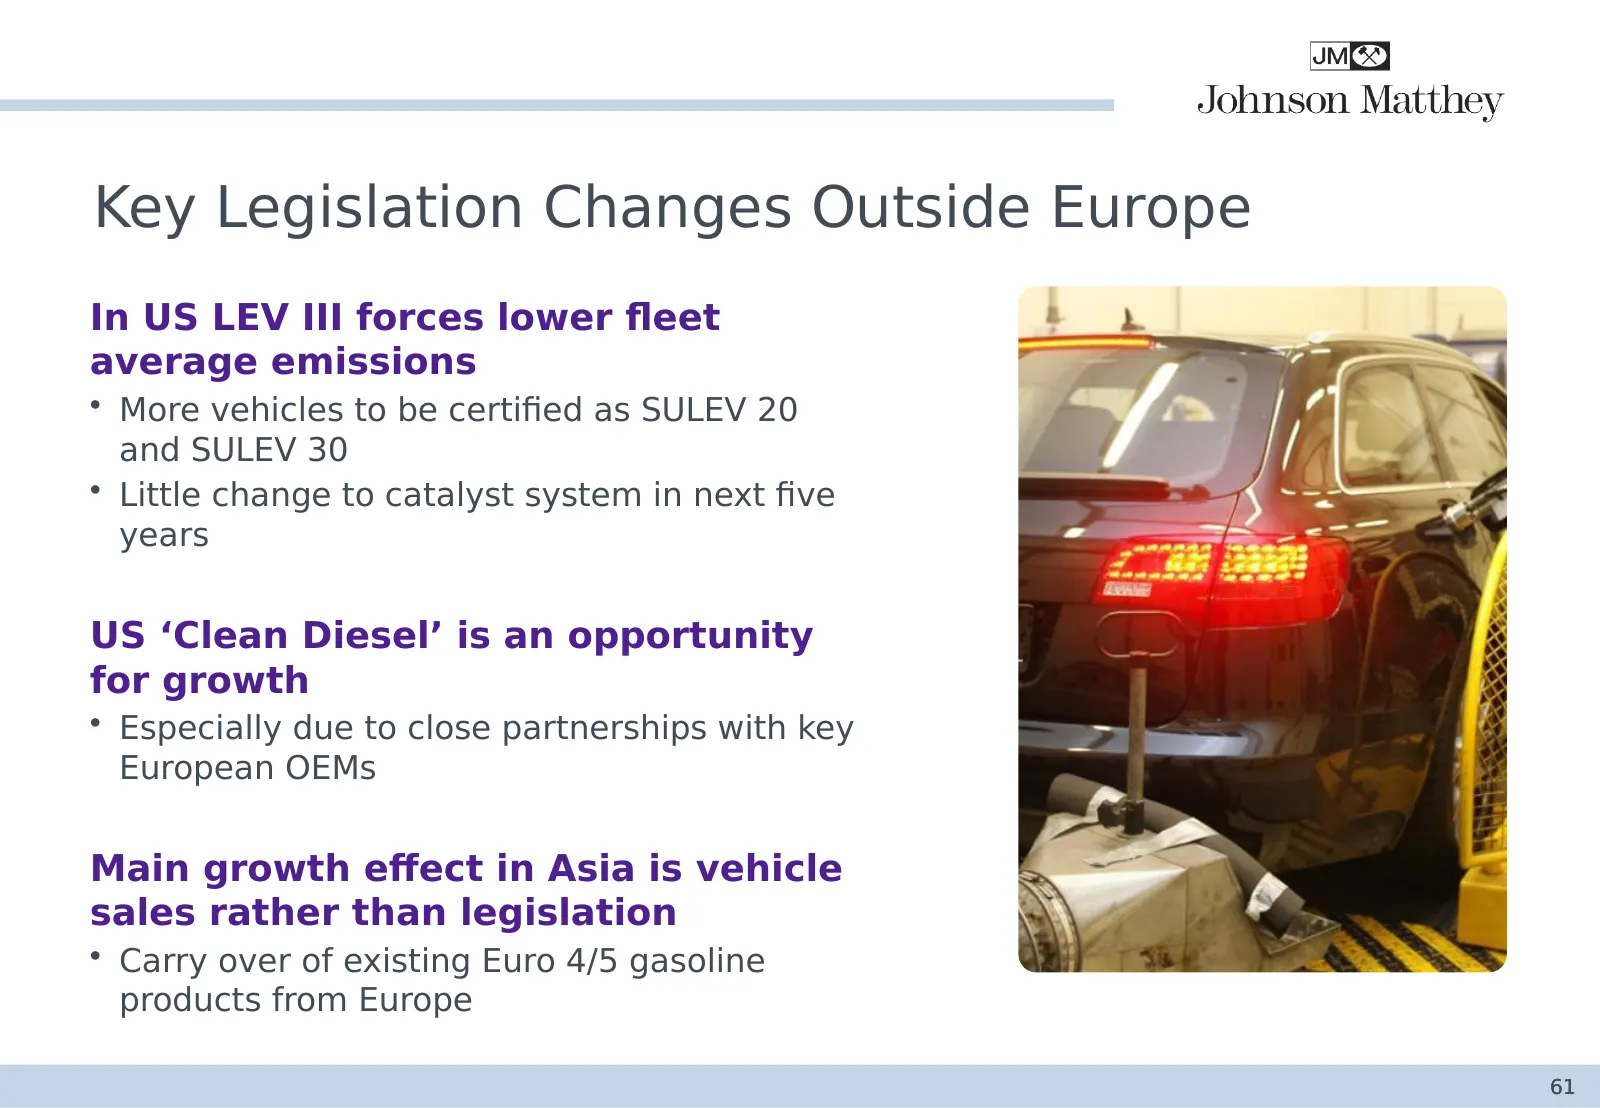
Slide 61: Key Legislation Changes Outside Europe
Key Legislation Changes Outside Europe In US LEV III forces lower fleet average emissions • More vehicles to be certified as SULEV 20 and SULEV 30 • Little change to catalyst system in next five years US ‘Clean Diesel’ is an opportunity for growth • Especially due to close partnerships with key Euro
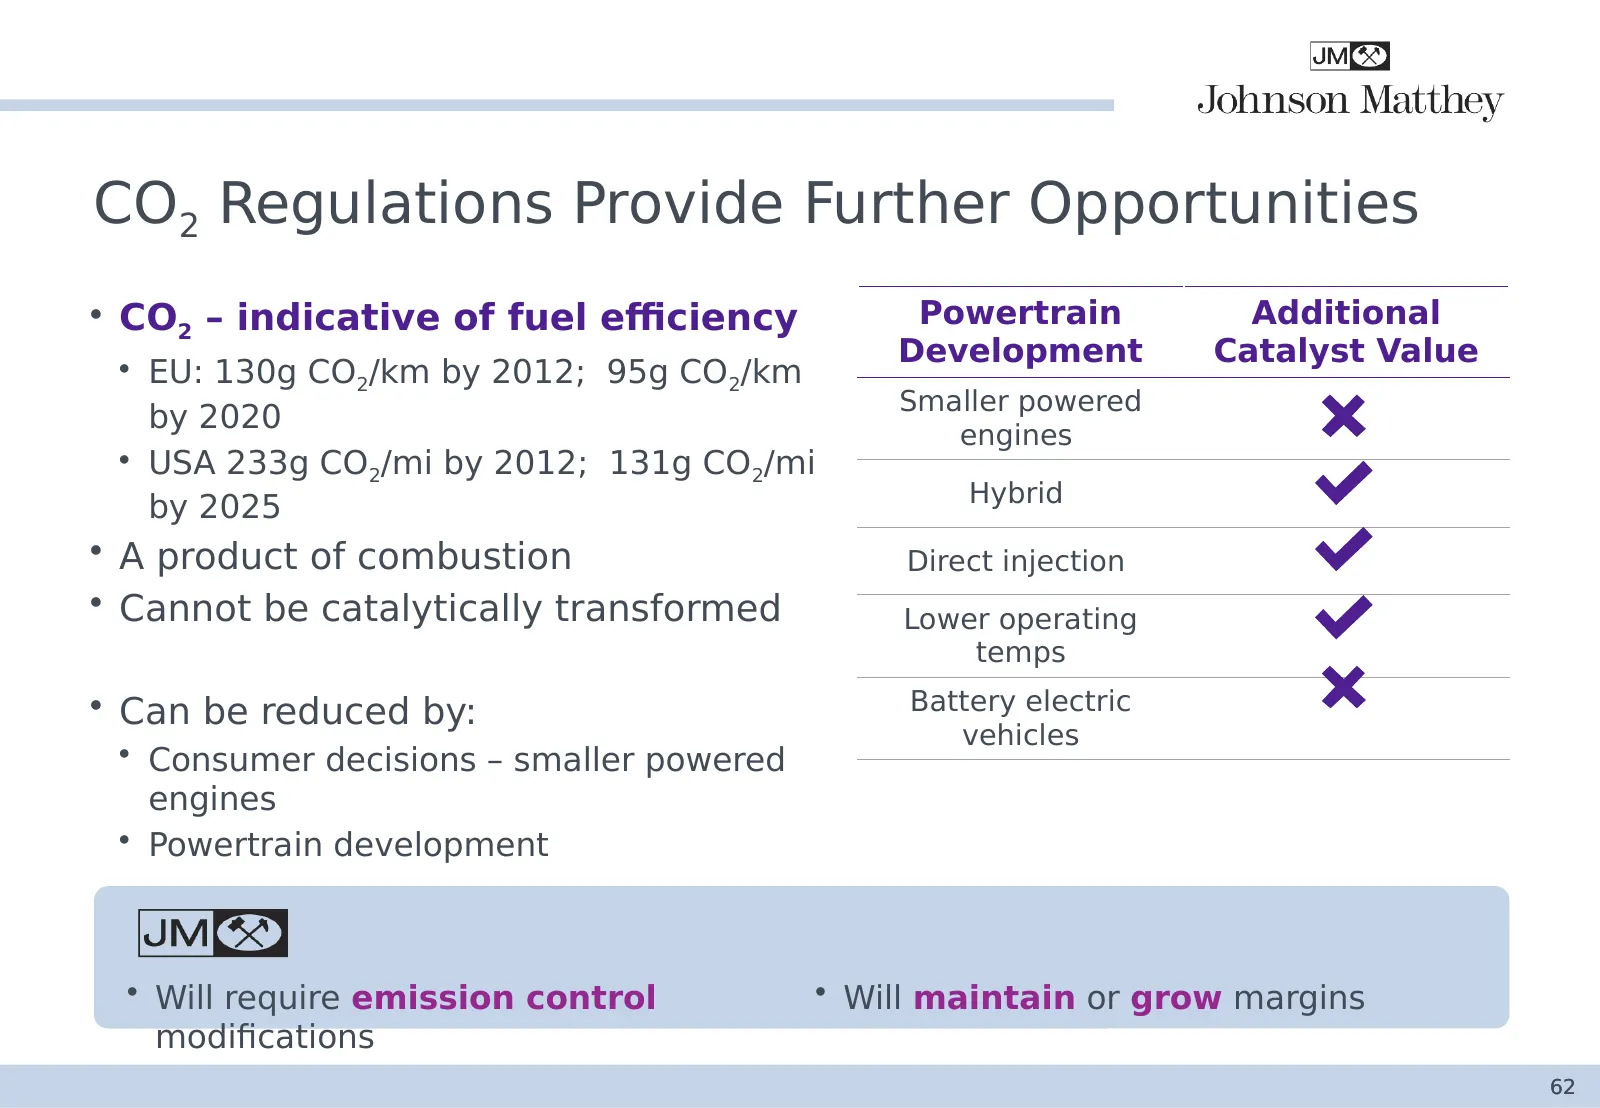
Slide 62: CO2 Regulations Provide Further Opportunities
CO2 Regulations Provide Further Opportunities • CO2 – indicative of fuel efficiency Powertrain Additional Development Catalyst Value • EU: 130g CO2/km by 2012; 95g CO2/km Smaller powered by 2020 engines • USA 233g CO2/mi by 2012; 131g CO2/mi Hybrid by 2025 • A product of combustion Direct injection
Slide 63: Real World Emissions
Real World Emissions • Confirmation of European legislation expected in 2013 • Will require more robust catalyst systems to ensure emissions compliance over wider window of operation Key challenges: • High speed diesel NOx control • Passive SCR behind NOx adsorber catalyst? • Low speed emissions • C
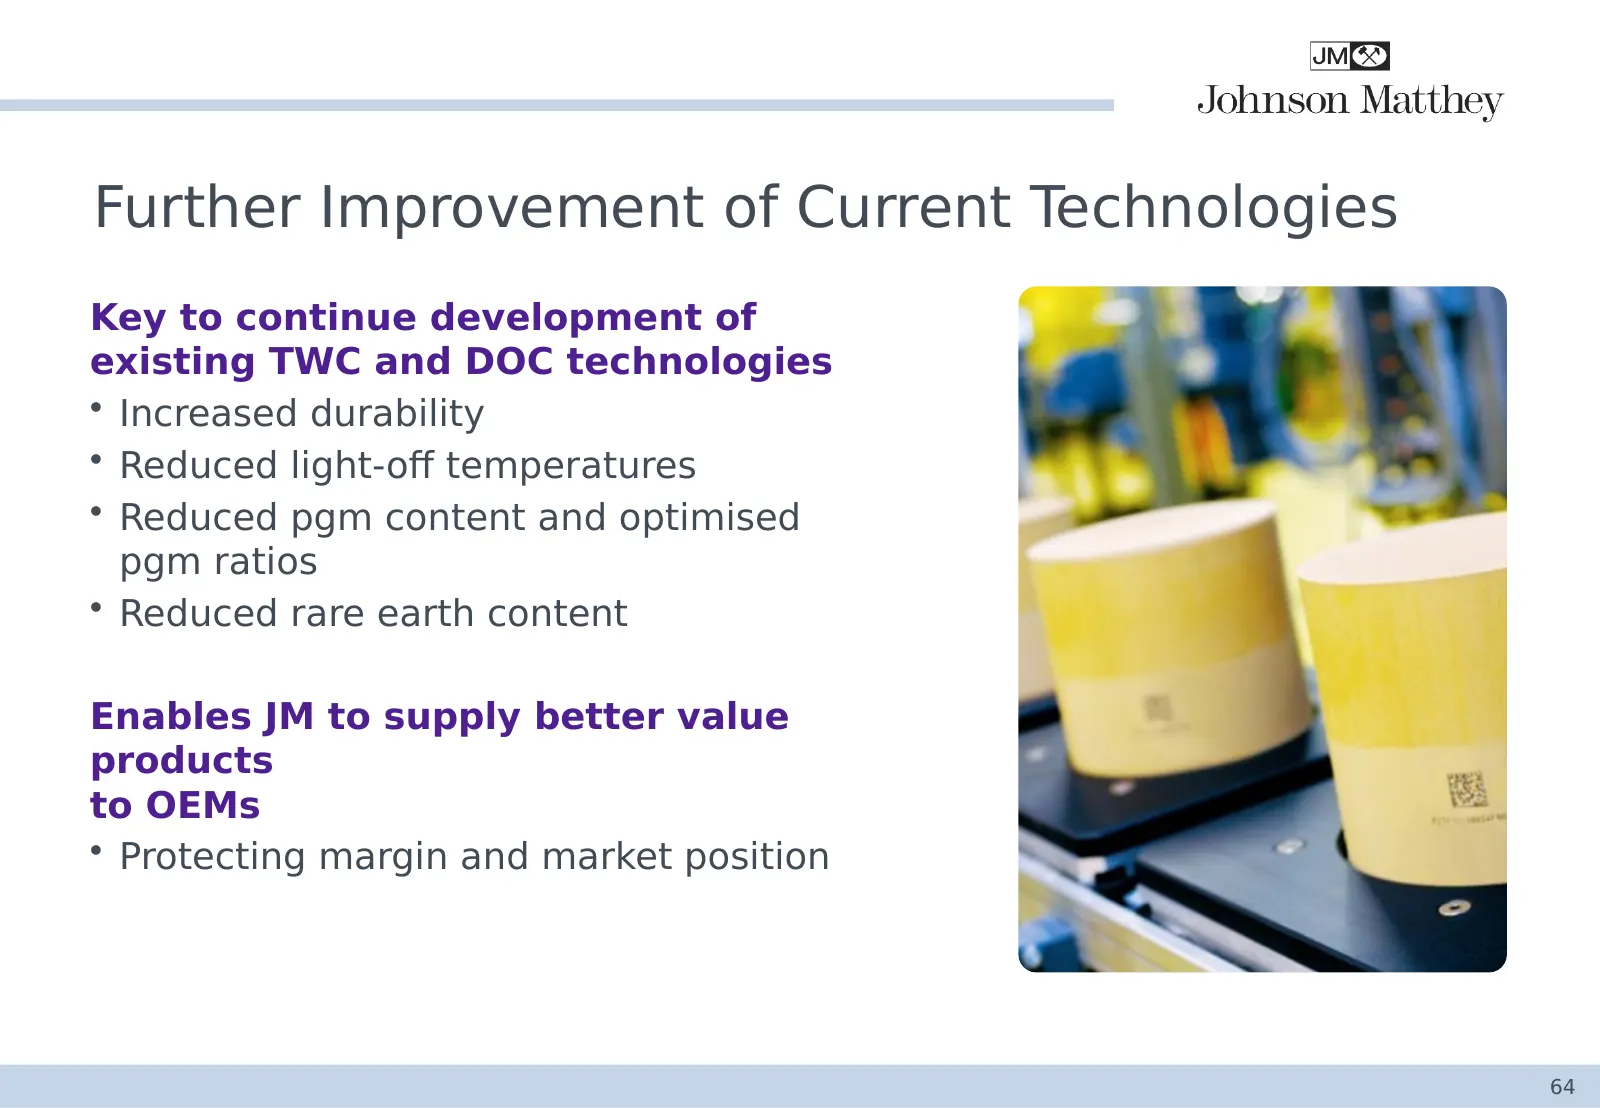
Slide 64: Further Improvement of Current Technologies
Further Improvement of Current Technologies Key to continue development of existing TWC and DOC technologies • Increased durability • Reduced light-off temperatures • Reduced pgm content and optimised pgm ratios • Reduced rare earth content Enables JM to supply better value products to OEMs • Protec
Slide 65: Emissions Control for Light Duty Vehicles
Emissions Control for Light Duty Vehicles • Vehicle production continues to grow • Exciting opportunities in diesel NOx particularly in Asia control • Tighter legislation will necessitate • SCR, NAC and SCRF® advanced and more complex catalyst • Exciting opportunities in gasoline systems particulate
Slide 66: Emissions Control for Heavy Duty Vehicles
Emissions Control for Heavy Duty Vehicles Dr Andy Walker Technology Director, HDD
Slide 67: Agenda
Agenda Emissions Control for Heavy Duty Vehicles 0 Heavy Duty Diesel (HDD) Technology Trend 1 0 Key Legislative Changes and Implications 2 0 CO2 and Fuel Economy Regulations 3 0 Potential Future Regulations 4 0 New Product Opportunities 5 0 Other Powertrains 6 67
Slide 68: HDD Technology Trend: Multifunctional Systems
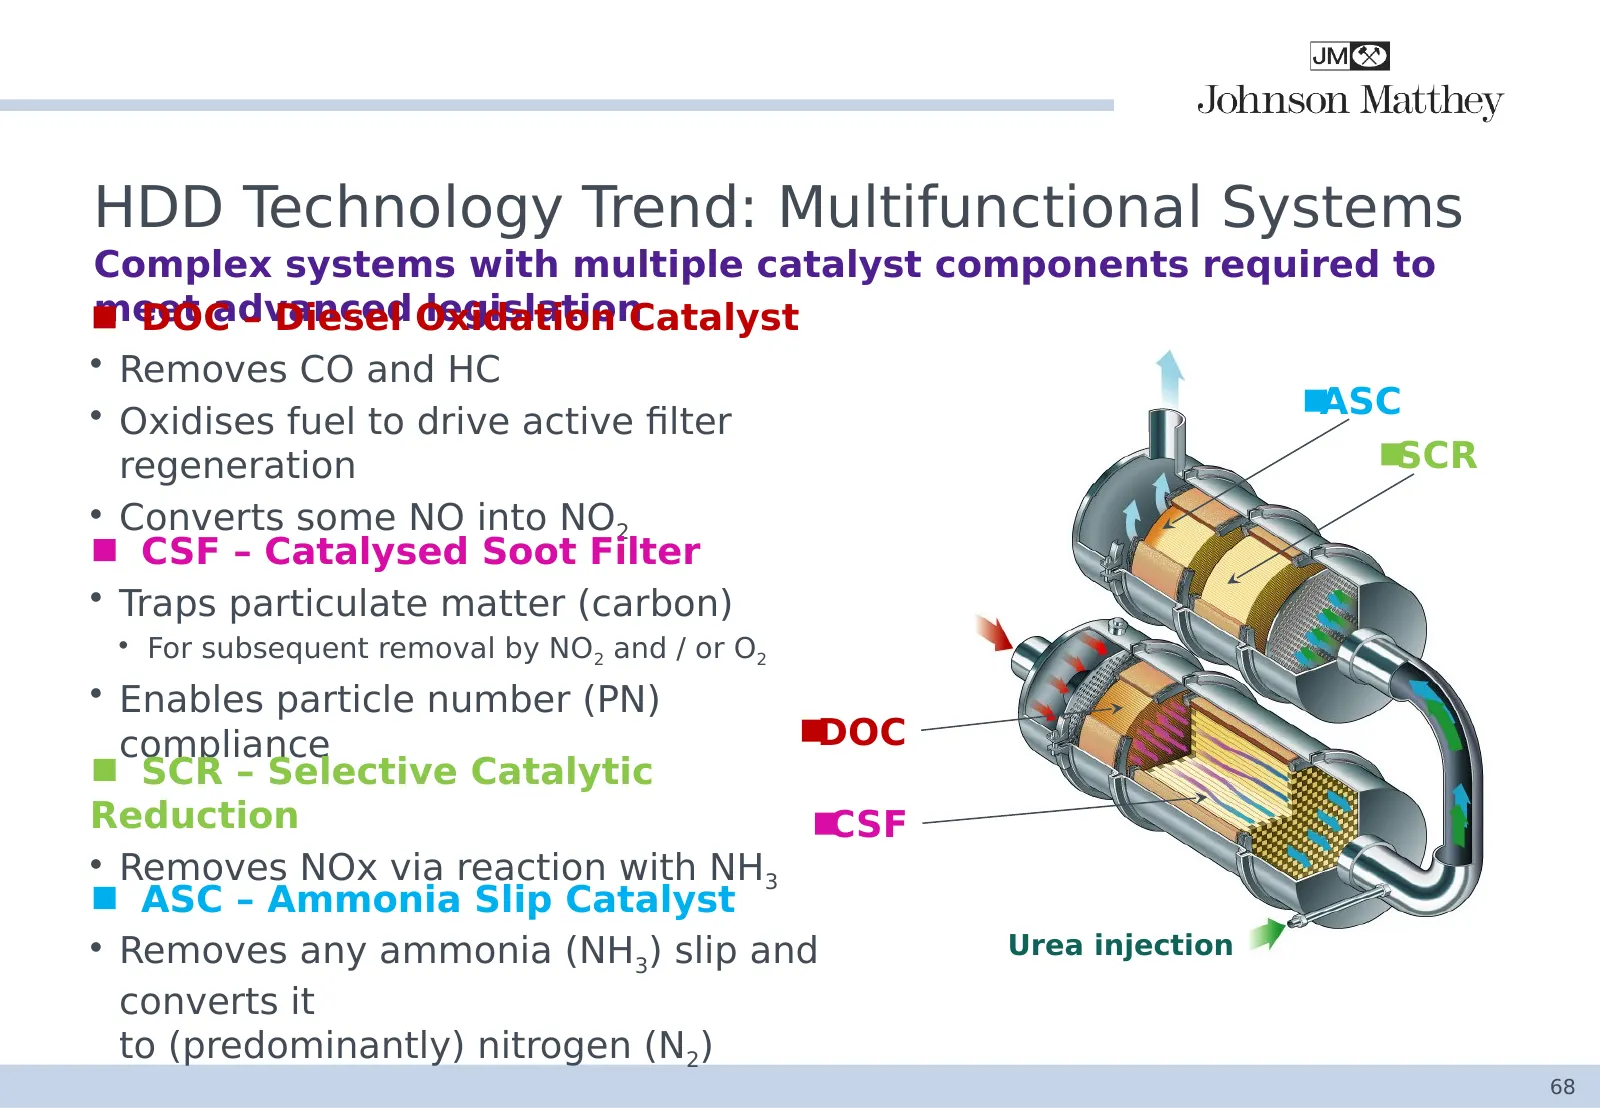
HDD Technology Trend: Multifunctional Systems Complex systems with multiple catalyst components required to meet DOCadvanced legislationCatalyst – Diesel Oxidation • Removes CO and HC • Oxidises fuel to drive active filter ASC regeneration SCR • Converts some NO into NO2 CSF – Catalysed Soot Filter
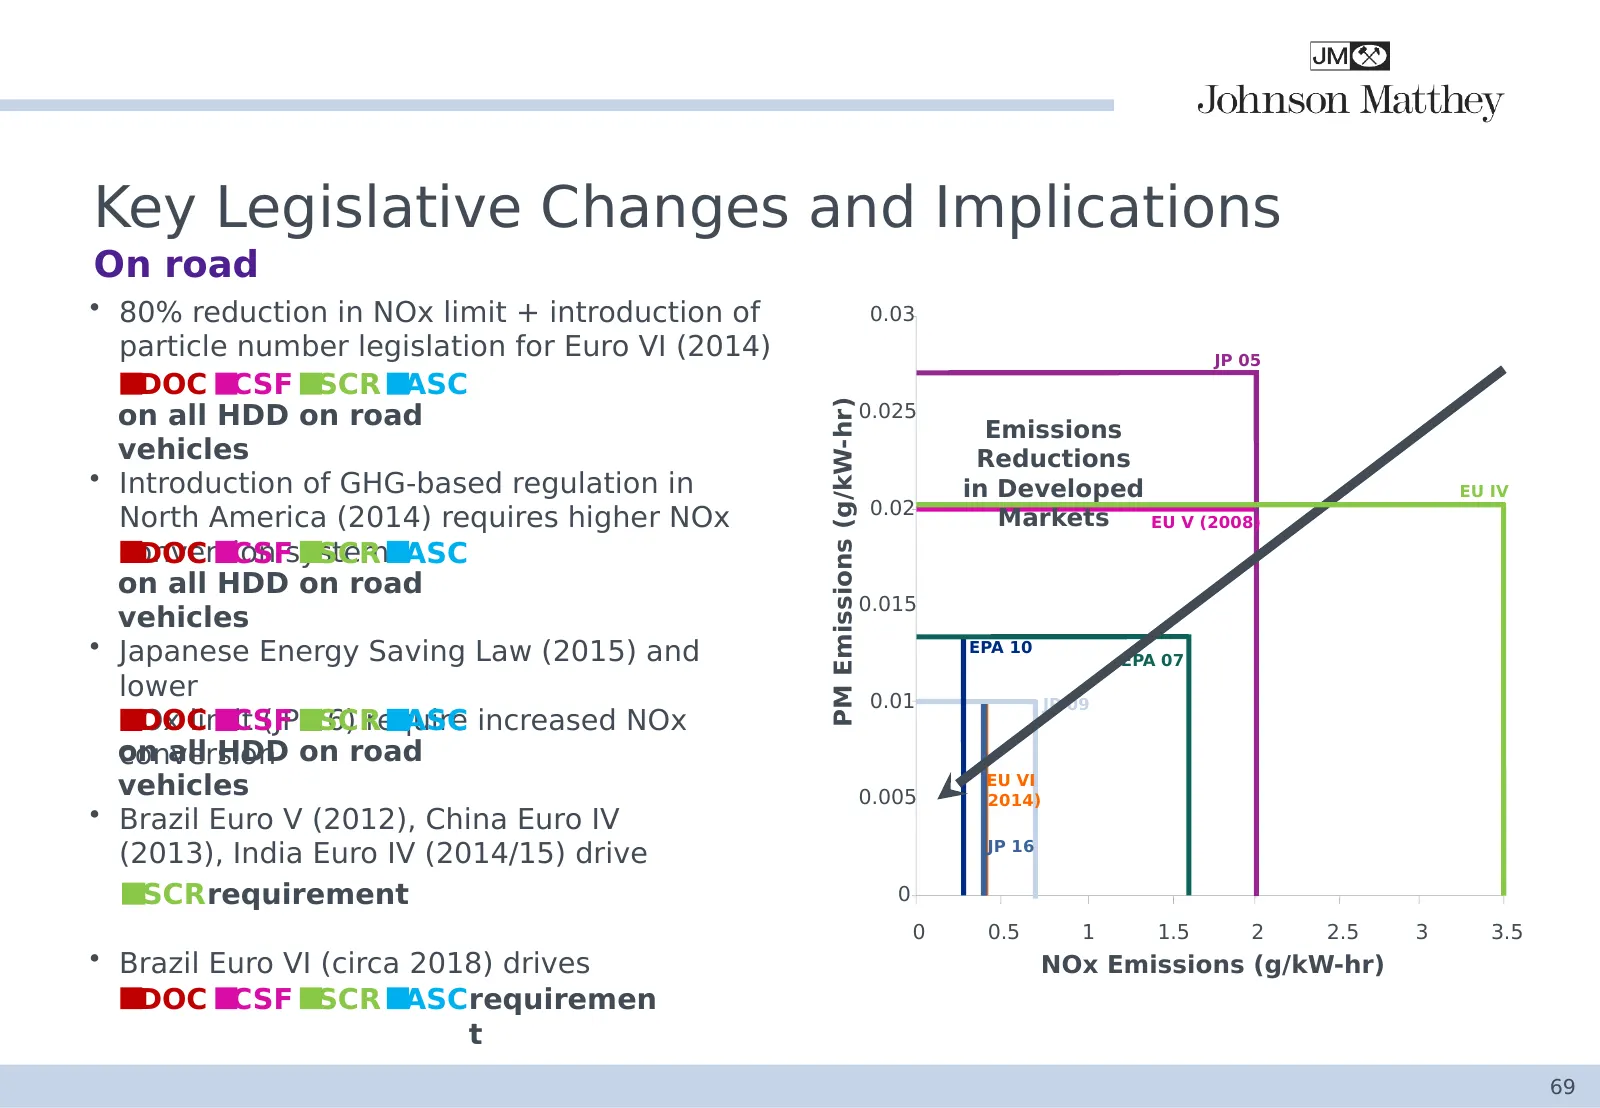
Slide 69: Key Legislative Changes and Implications
Key Legislative Changes and Implications On road • 80% reduction in NOx limit + introduction of 0.03 particle number legislation for Euro VI (2014) JP 05 DOC CSF SCR ASC on all HDD on road PM Emissions (g/kW-hr) 0.025 Emissions vehicles Reductions • Introduction of GHG-based regulation in in Develop
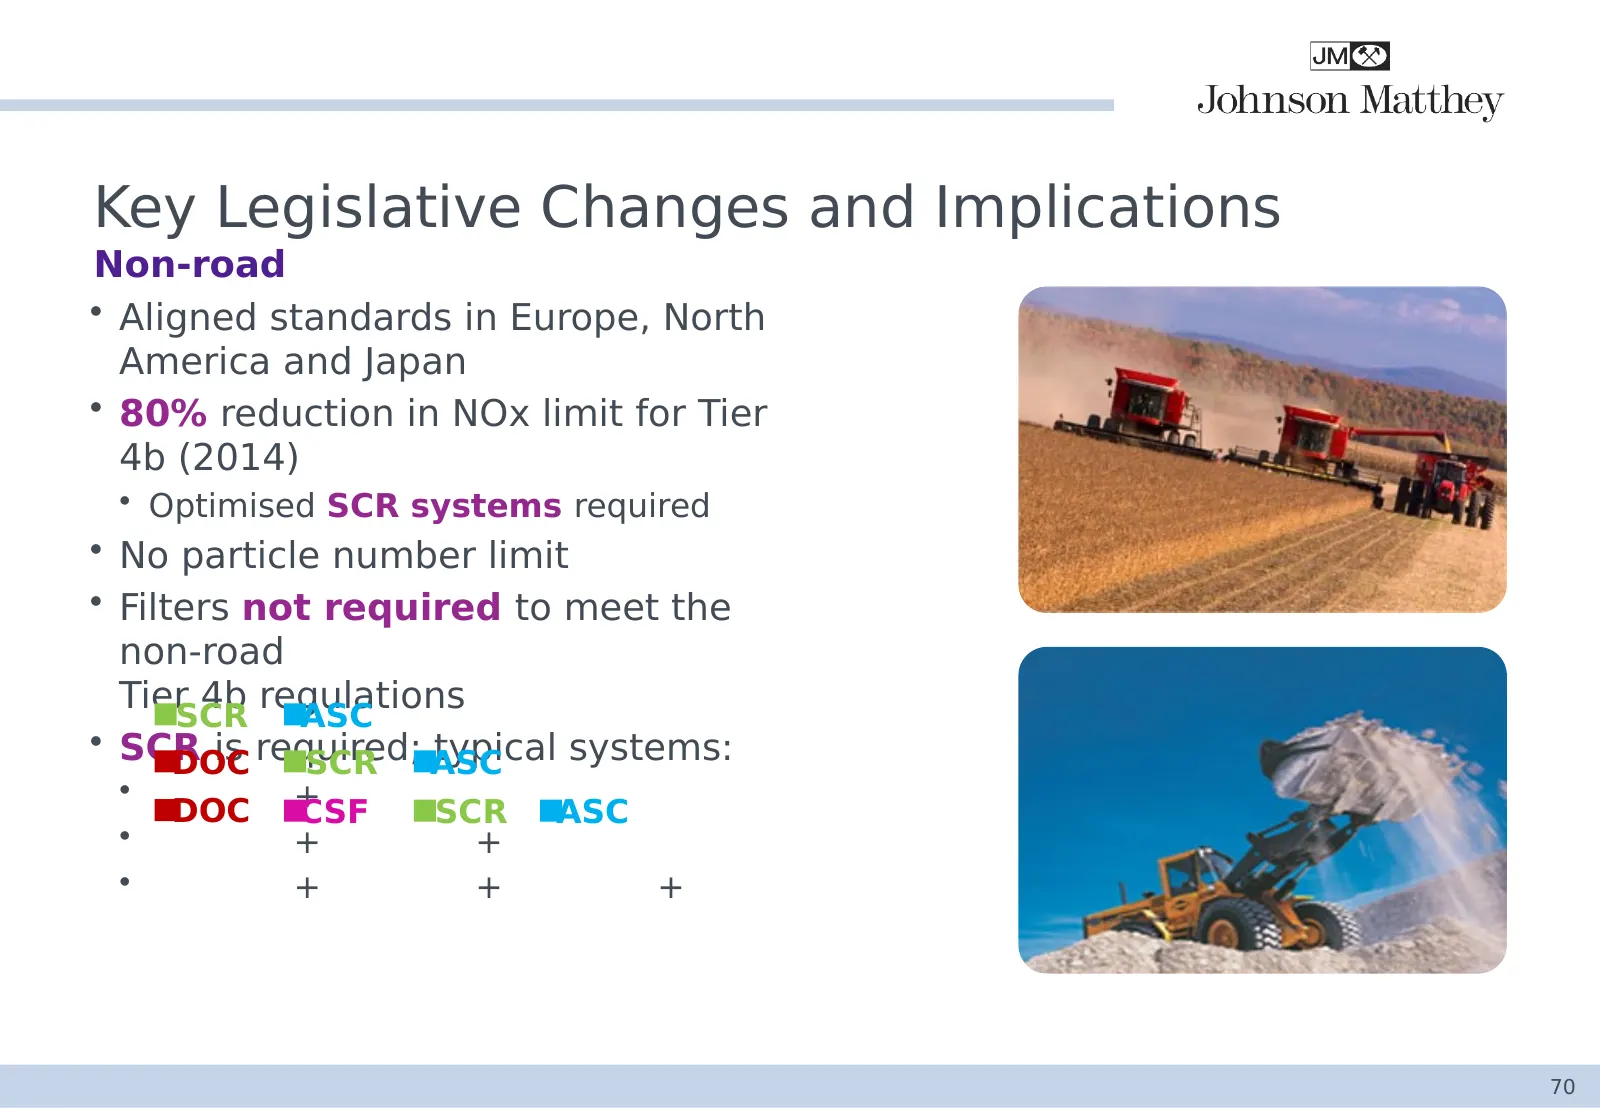
Slide 70: Key Legislative Changes and Implications
Key Legislative Changes and Implications Non-road • Aligned standards in Europe, North America and Japan • 80% reduction in NOx limit for Tier 4b (2014) • Optimised SCR systems required • No particle number limit • Filters not required to meet the non-road Tier 4b regulations SCR ASC • SCR is requir
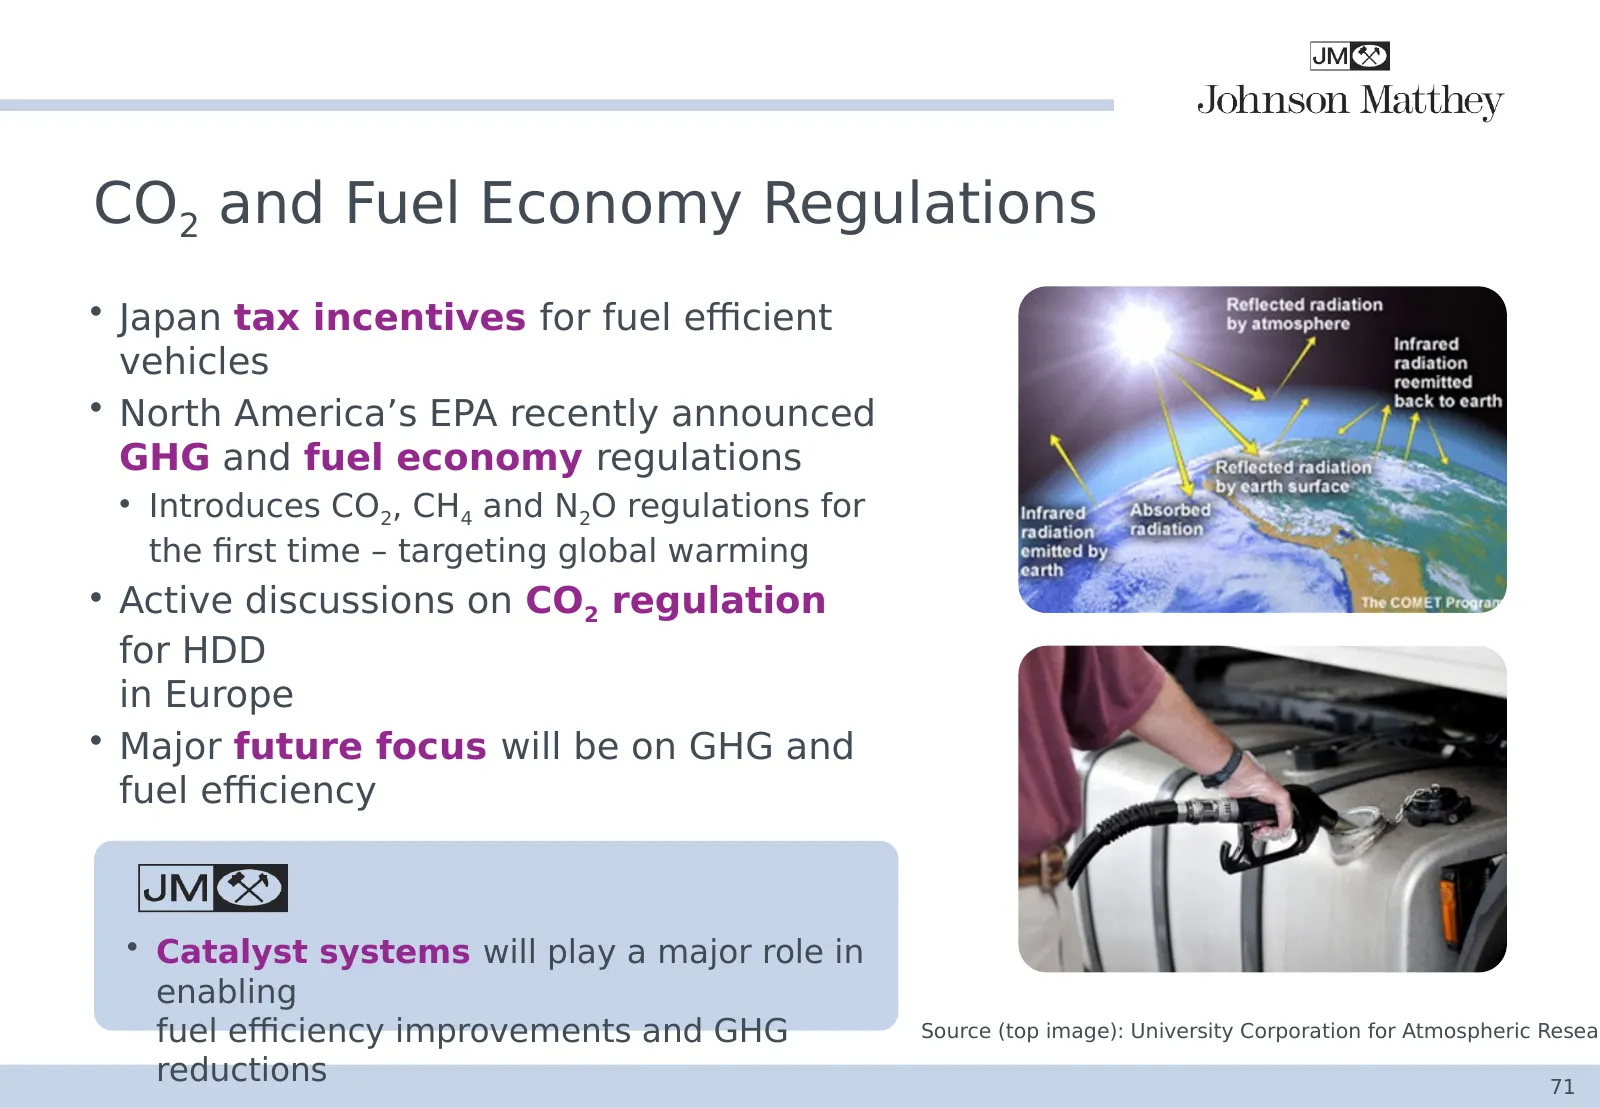
Slide 71: CO2 and Fuel Economy Regulations
CO2 and Fuel Economy Regulations • Japan tax incentives for fuel efficient vehicles • North America’s EPA recently announced GHG and fuel economy regulations • Introduces CO2, CH4 and N2O regulations for the first time – targeting global warming • Active discussions on CO2 regulation for HDD in Euro
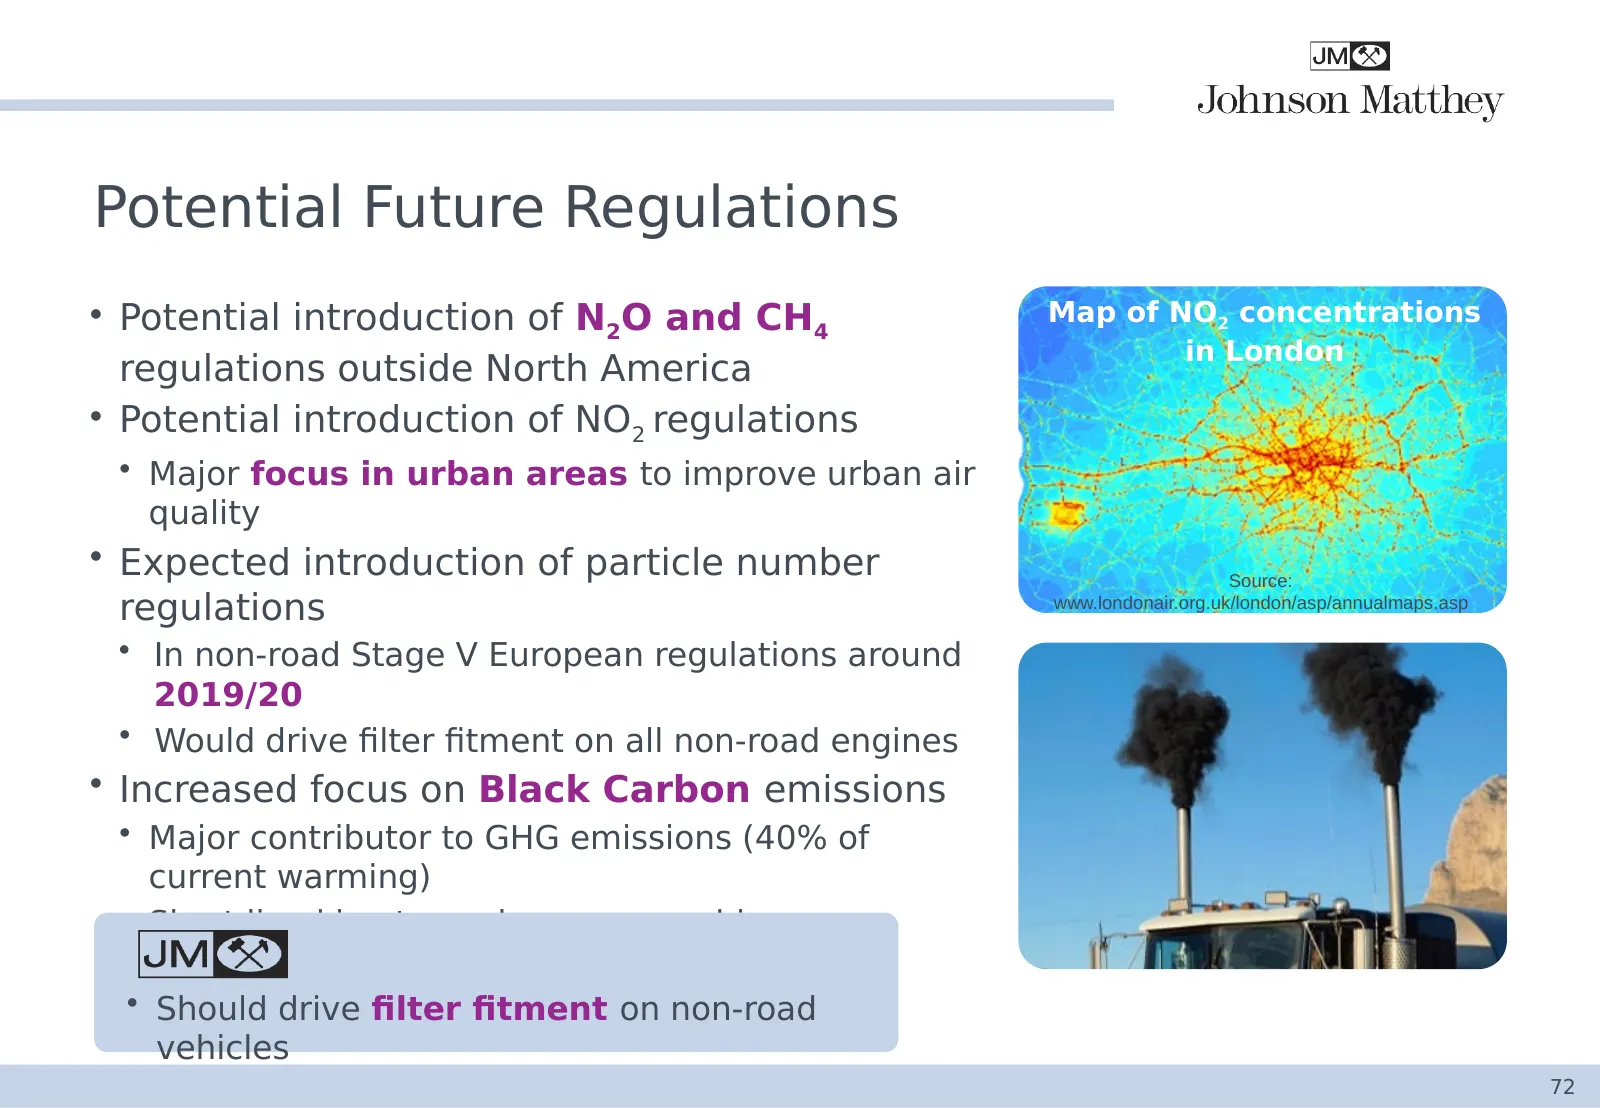
Slide 72: Potential Future Regulations
Potential Future Regulations • Potential introduction of N2O and CH4 Map of NO2 concentrations in London regulations outside North America • Potential introduction of NO2 regulations • Major focus in urban areas to improve urban air quality • Expected introduction of particle number Source: regulati
Slide 73: Current R&D Priorities and Focus
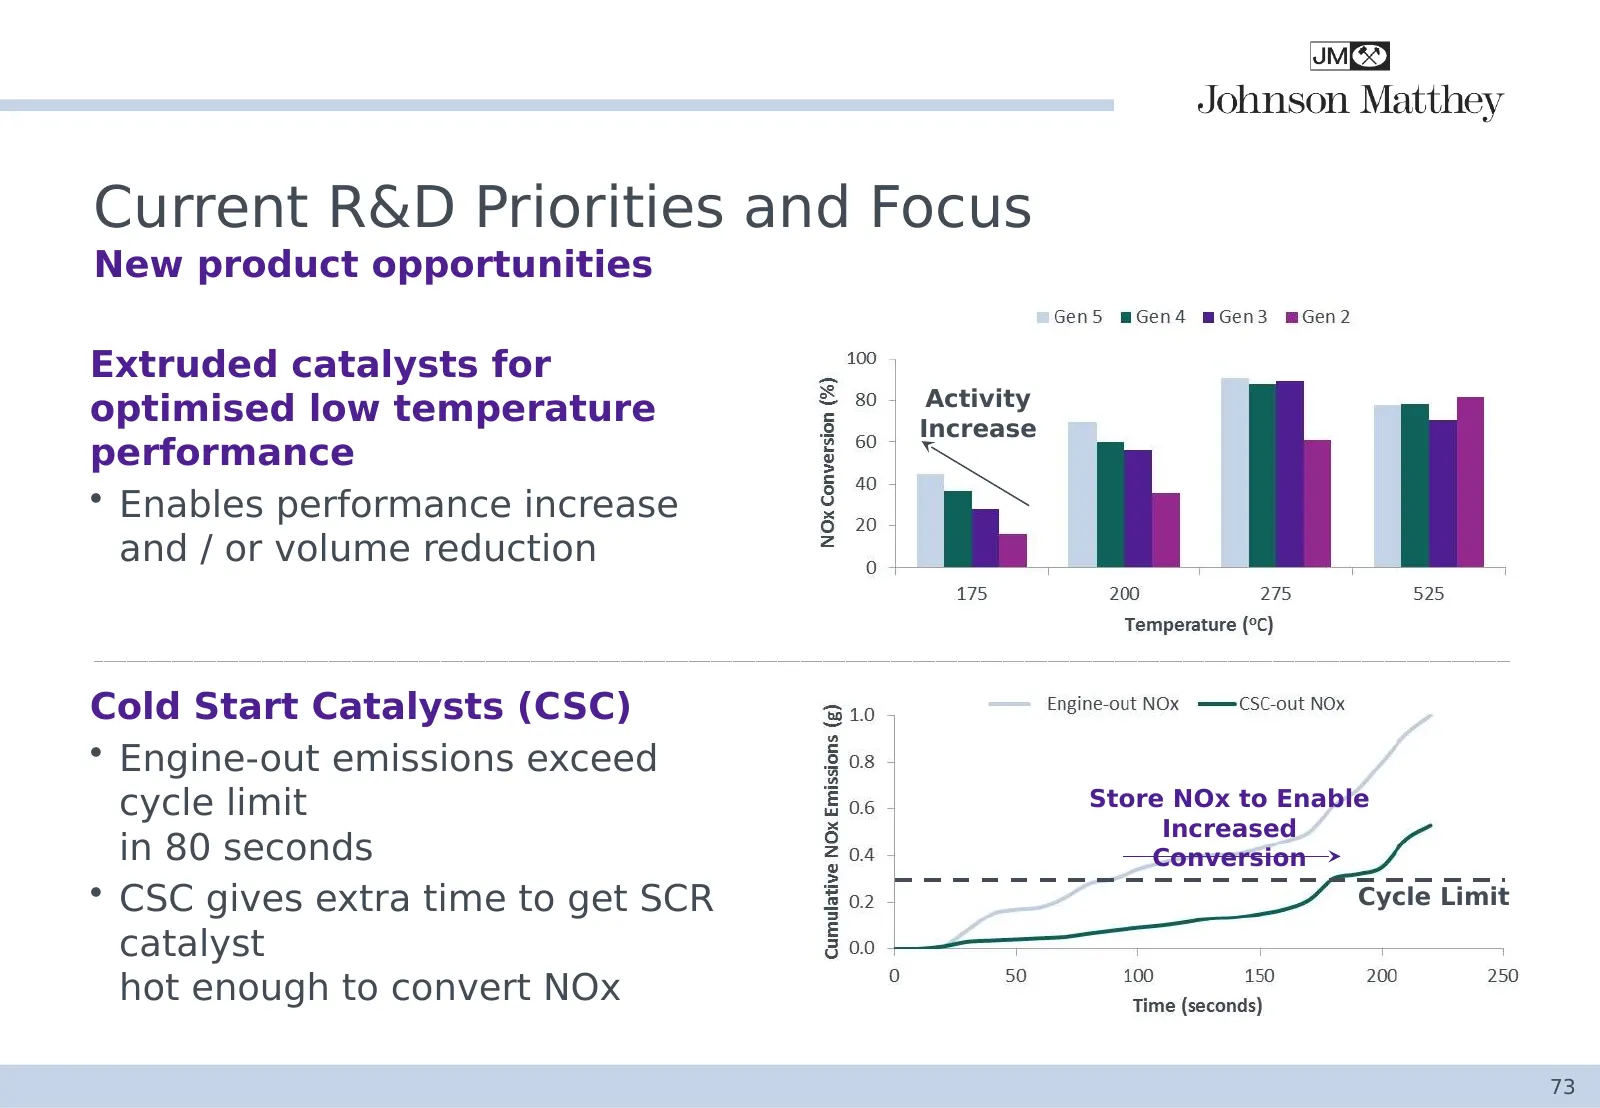
Current R&D Priorities and Focus New product opportunities Extruded catalysts for Activity optimised low temperature Increase performance • Enables performance increase and / or volume reduction Cold Start Catalysts (CSC) • Engine-out emissions exceed cycle limit Store NOx to Enable Increased in 80
Slide 74: Other Powertrains
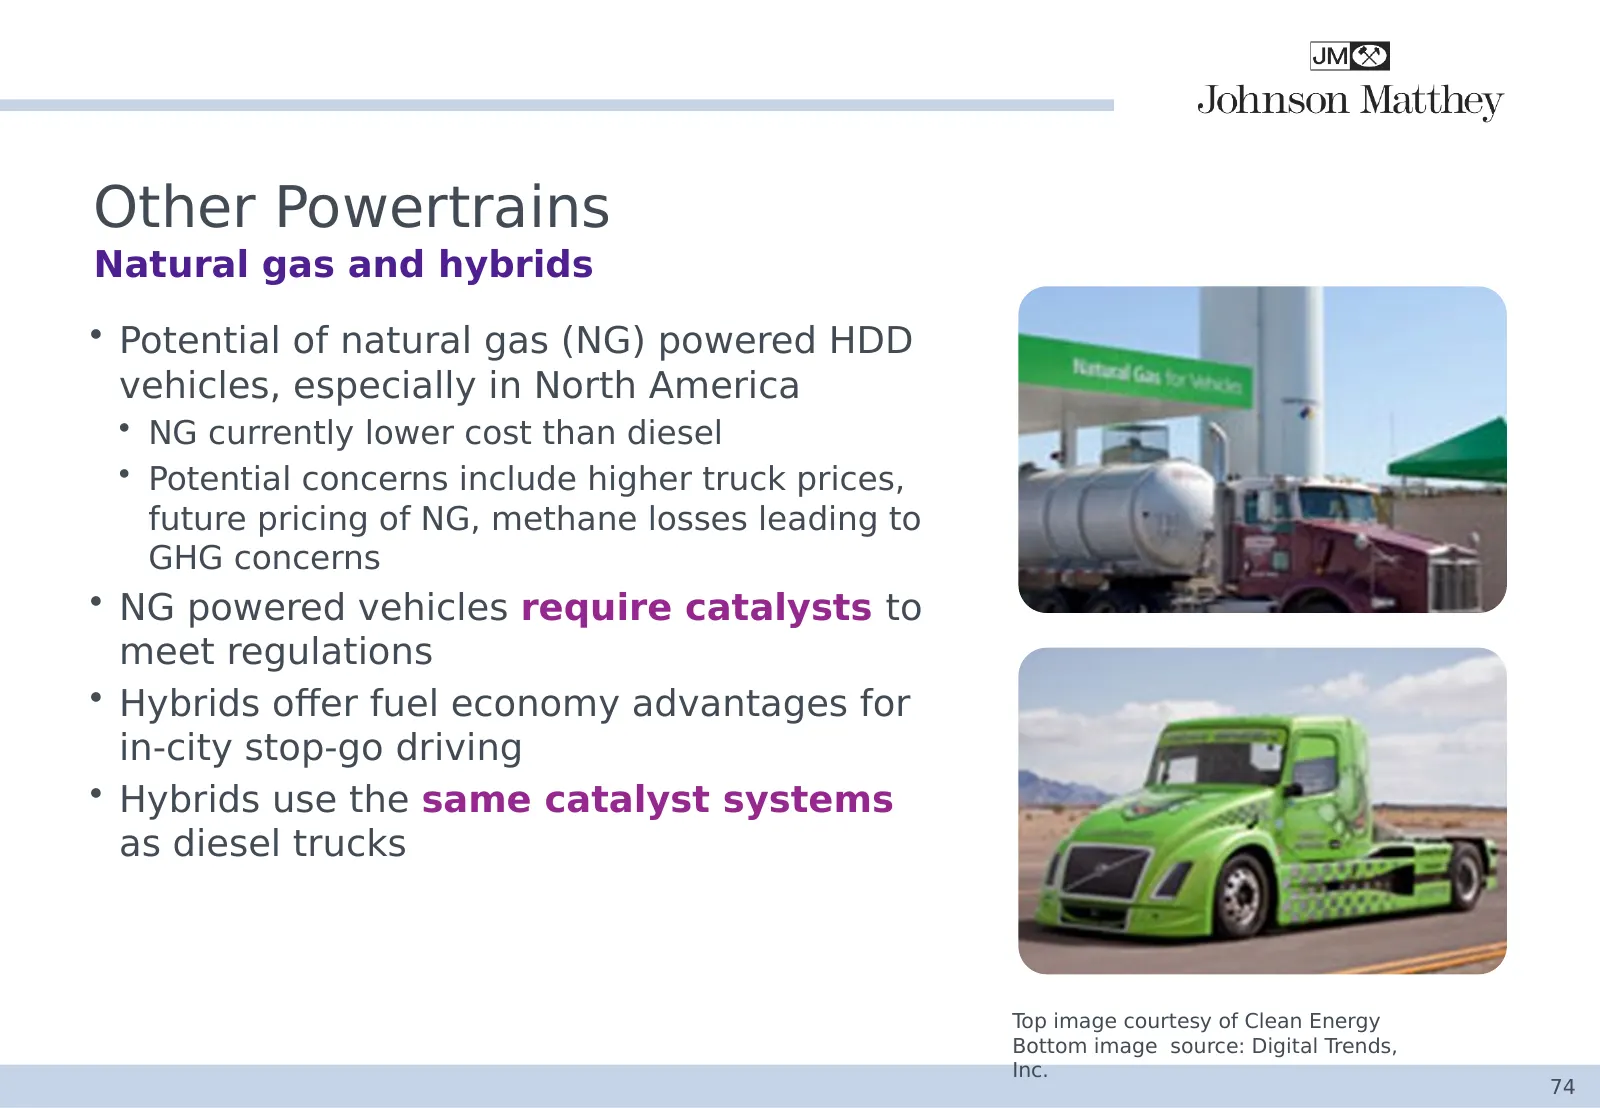
Other Powertrains Natural gas and hybrids • Potential of natural gas (NG) powered HDD vehicles, especially in North America • NG currently lower cost than diesel • Potential concerns include higher truck prices, future pricing of NG, methane losses leading to GHG concerns • NG powered vehicles requi
Slide 75: Emissions Control for Heavy Duty Vehicles
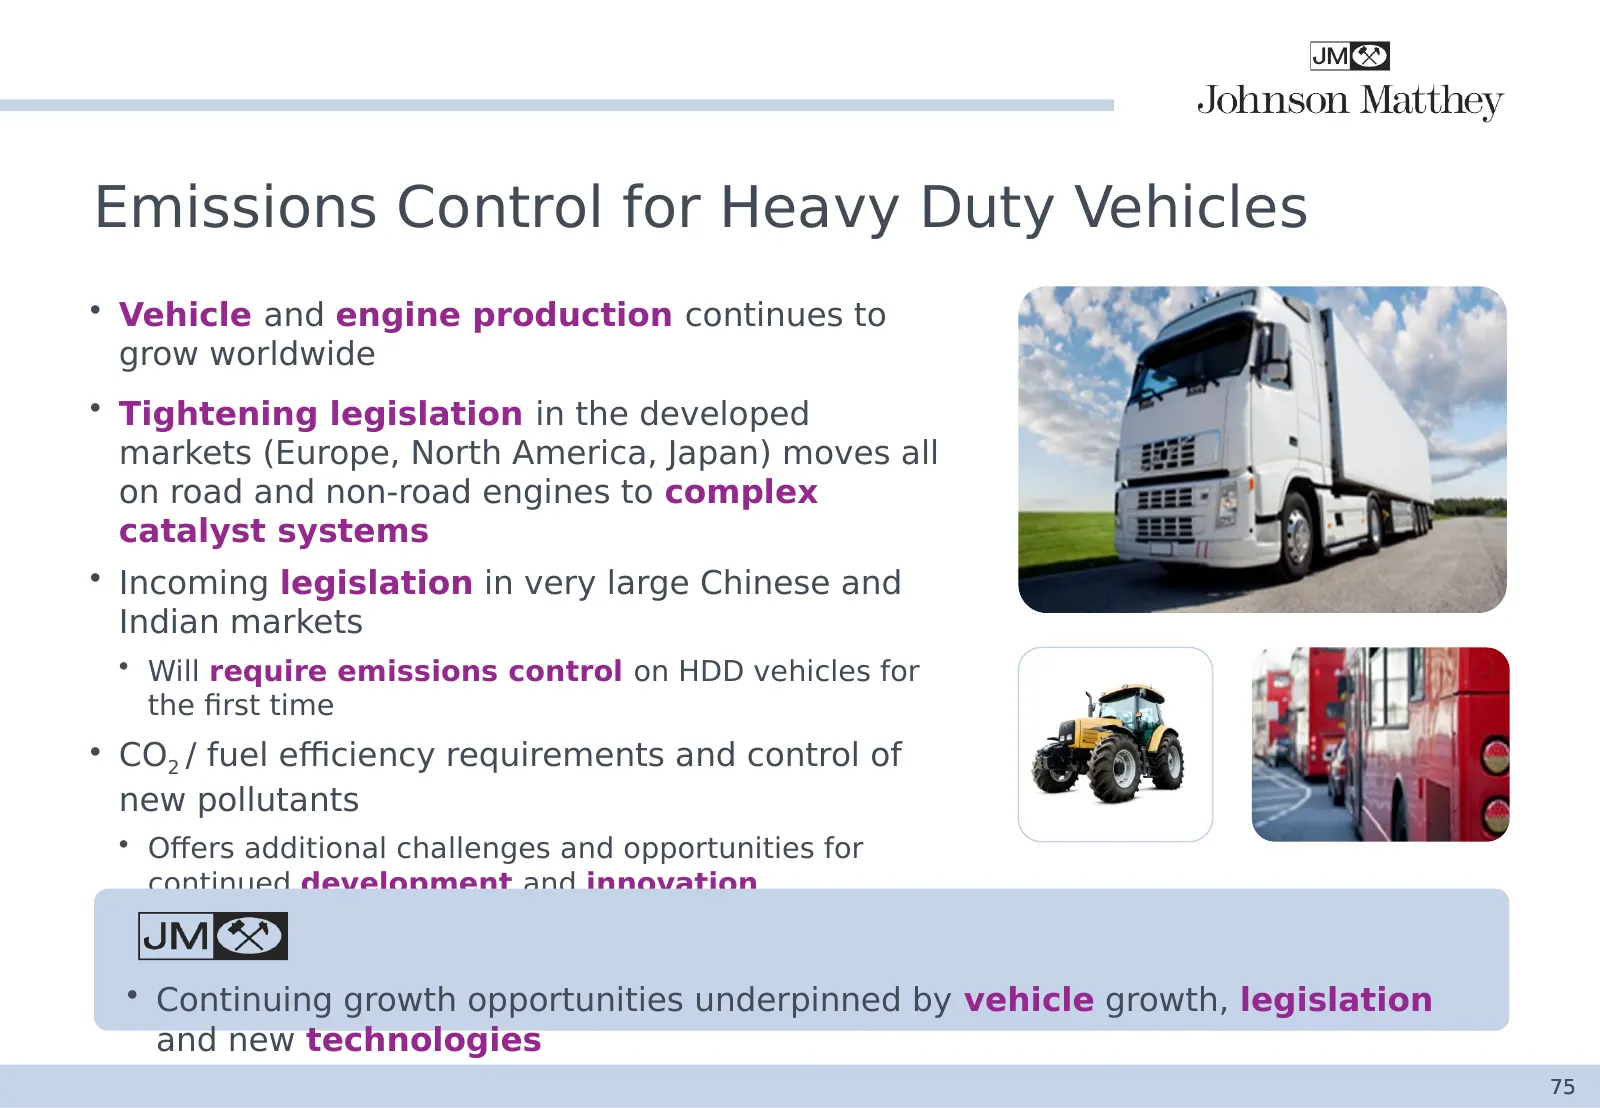
Emissions Control for Heavy Duty Vehicles • Vehicle and engine production continues to grow worldwide • Tightening legislation in the developed markets (Europe, North America, Japan) moves all on road and non-road engines to complex catalyst systems • Incoming legislation in very large Chinese and I
Slide 76: Opportunities in Emission Control Technologies
Opportunities in Emission Control Technologies John Walker Division Director, Emission Control Technologies
Slide 77: Key Takeaways…
Key Takeaways… Growth in all Legislative Many opportunities JM continues to invest our markets tightening develop and derive ahead of growth continues to value from opportunities. ECT’s deliver value innovative capex reduces to technologies around 1x Strong position in Margins stable Double digit HD
Slide 78: JME)
JME) Johnson Matthey
Slide 79: Tour of the Royston Facility
Tour of the Royston Facility Dr David Prest Managing Director, Emission Control Technologies, Europe
Slide 80: ECT Royston Operations
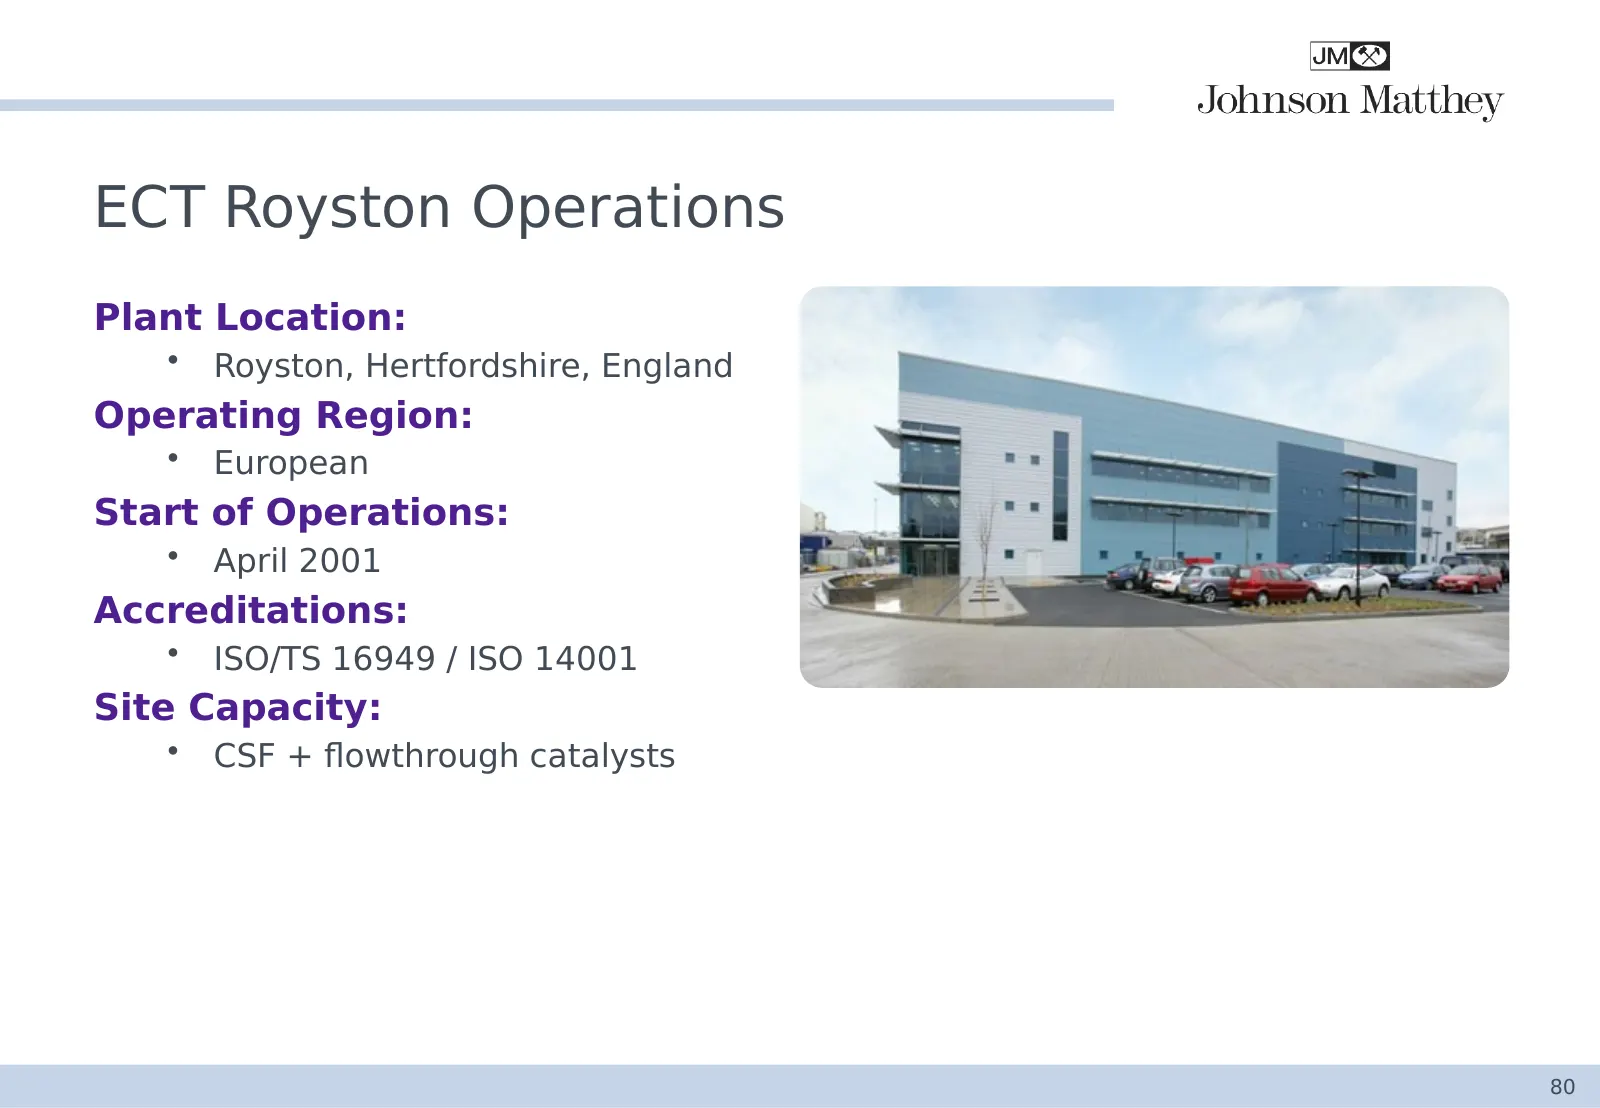
ECT Royston Operations Plant Location: • Royston, Hertfordshire, England Operating Region: • European Start of Operations: • April 2001 Accreditations: • ISO/TS 16949 / ISO 14001 Site Capacity: • CSF + flowthrough catalysts 80
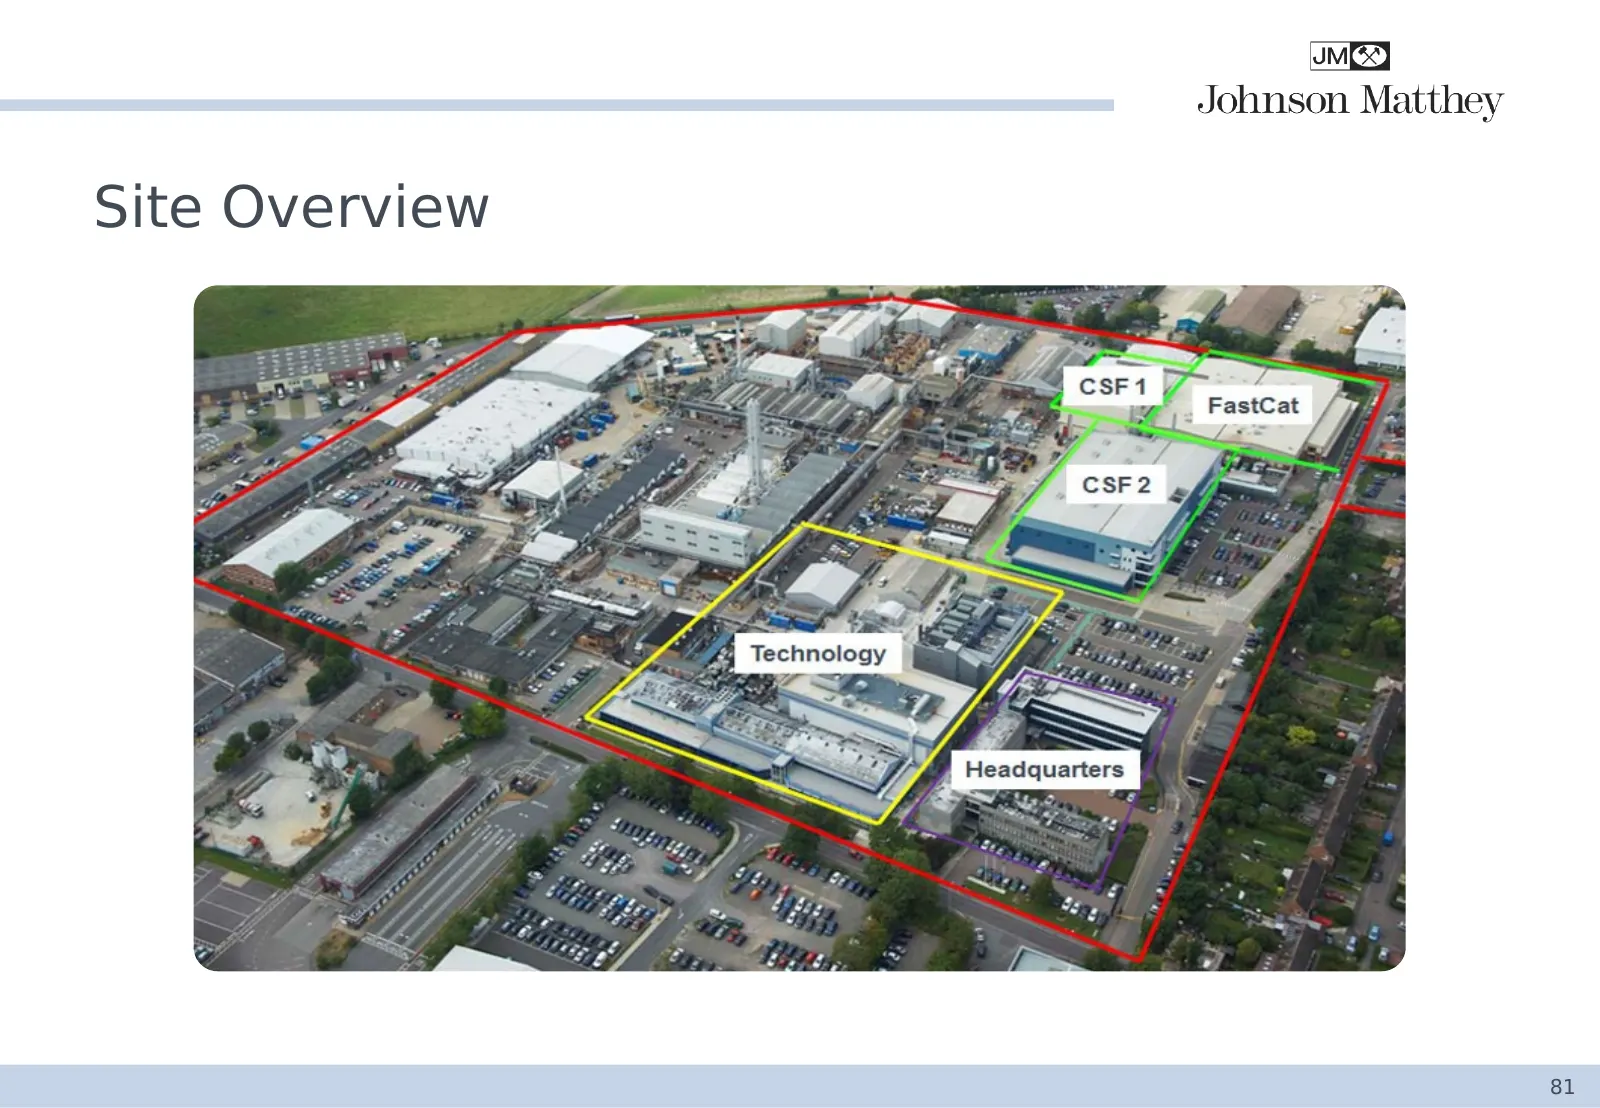
Slide 81: Site Overview
Site Overview JME) Johnson Matthey 81
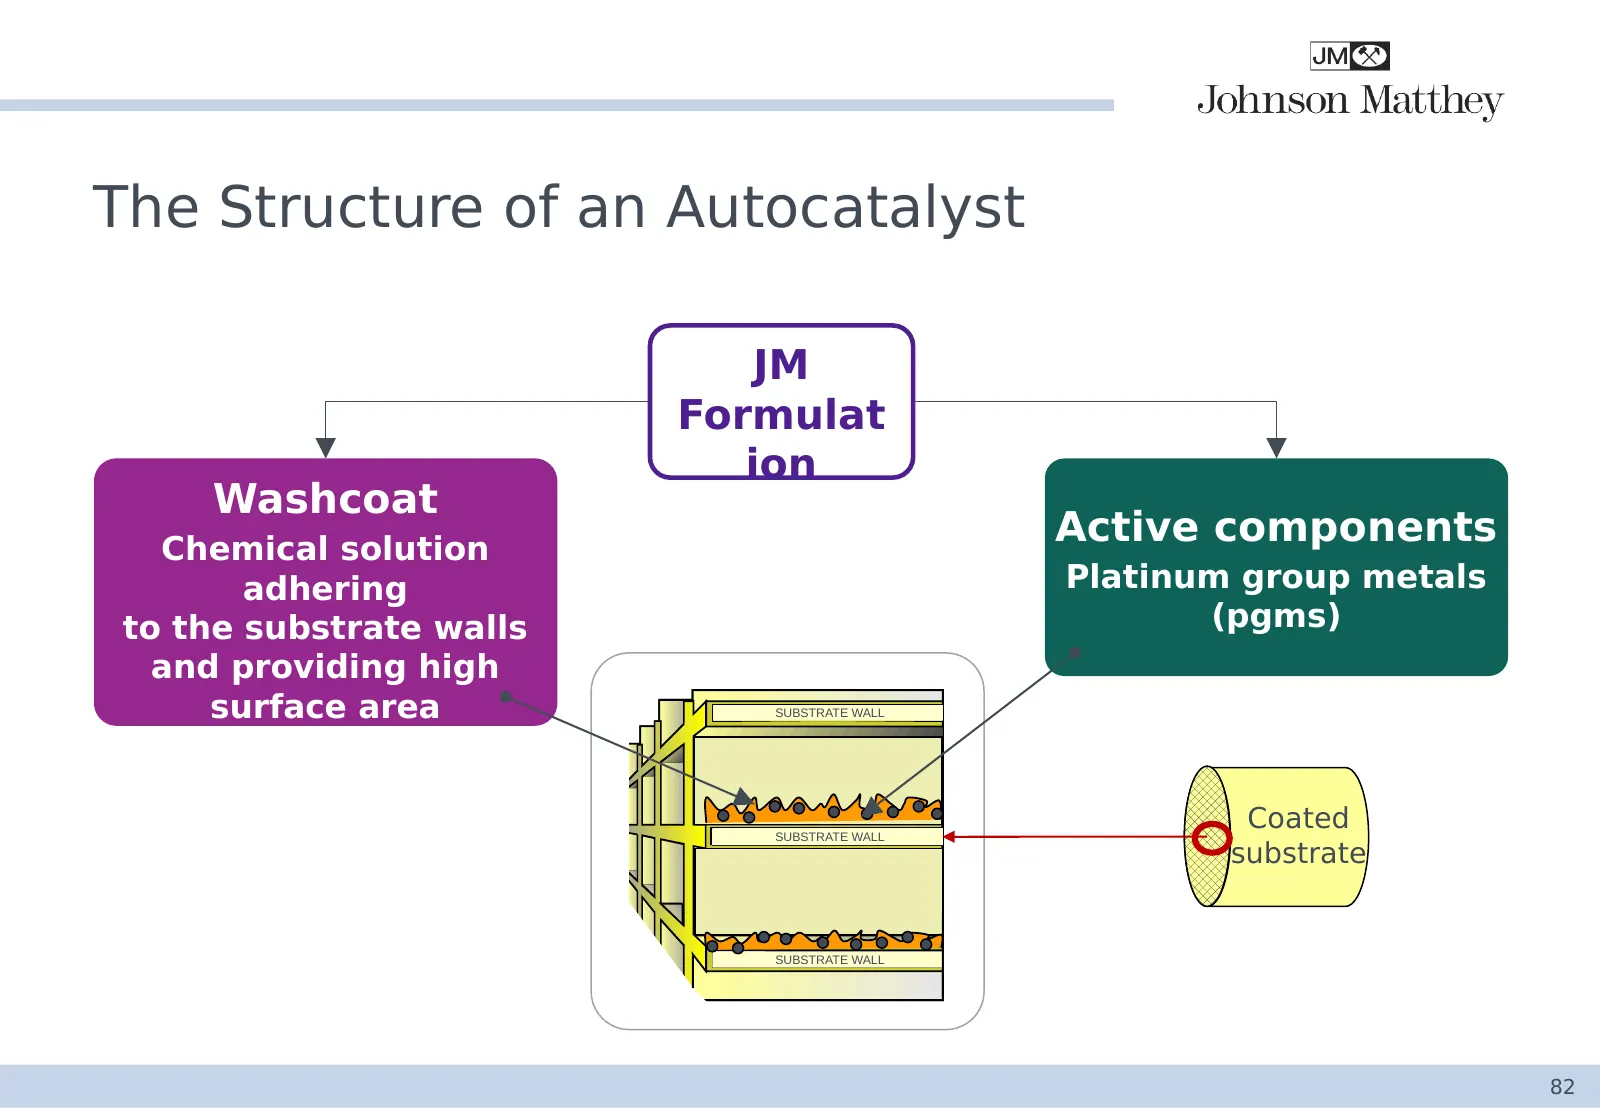
Slide 82: The Structure of an Autocatalyst
The Structure of an Autocatalyst JM Formulat ion Washcoat Chemical solution Active components adhering Platinum group metals to the substrate walls (pgms) and providing high surface area SUBSTRATE WALL to pgm Washcoat: SUBSTRATE WALL Coated substrate SUBSTRATE WALL 82
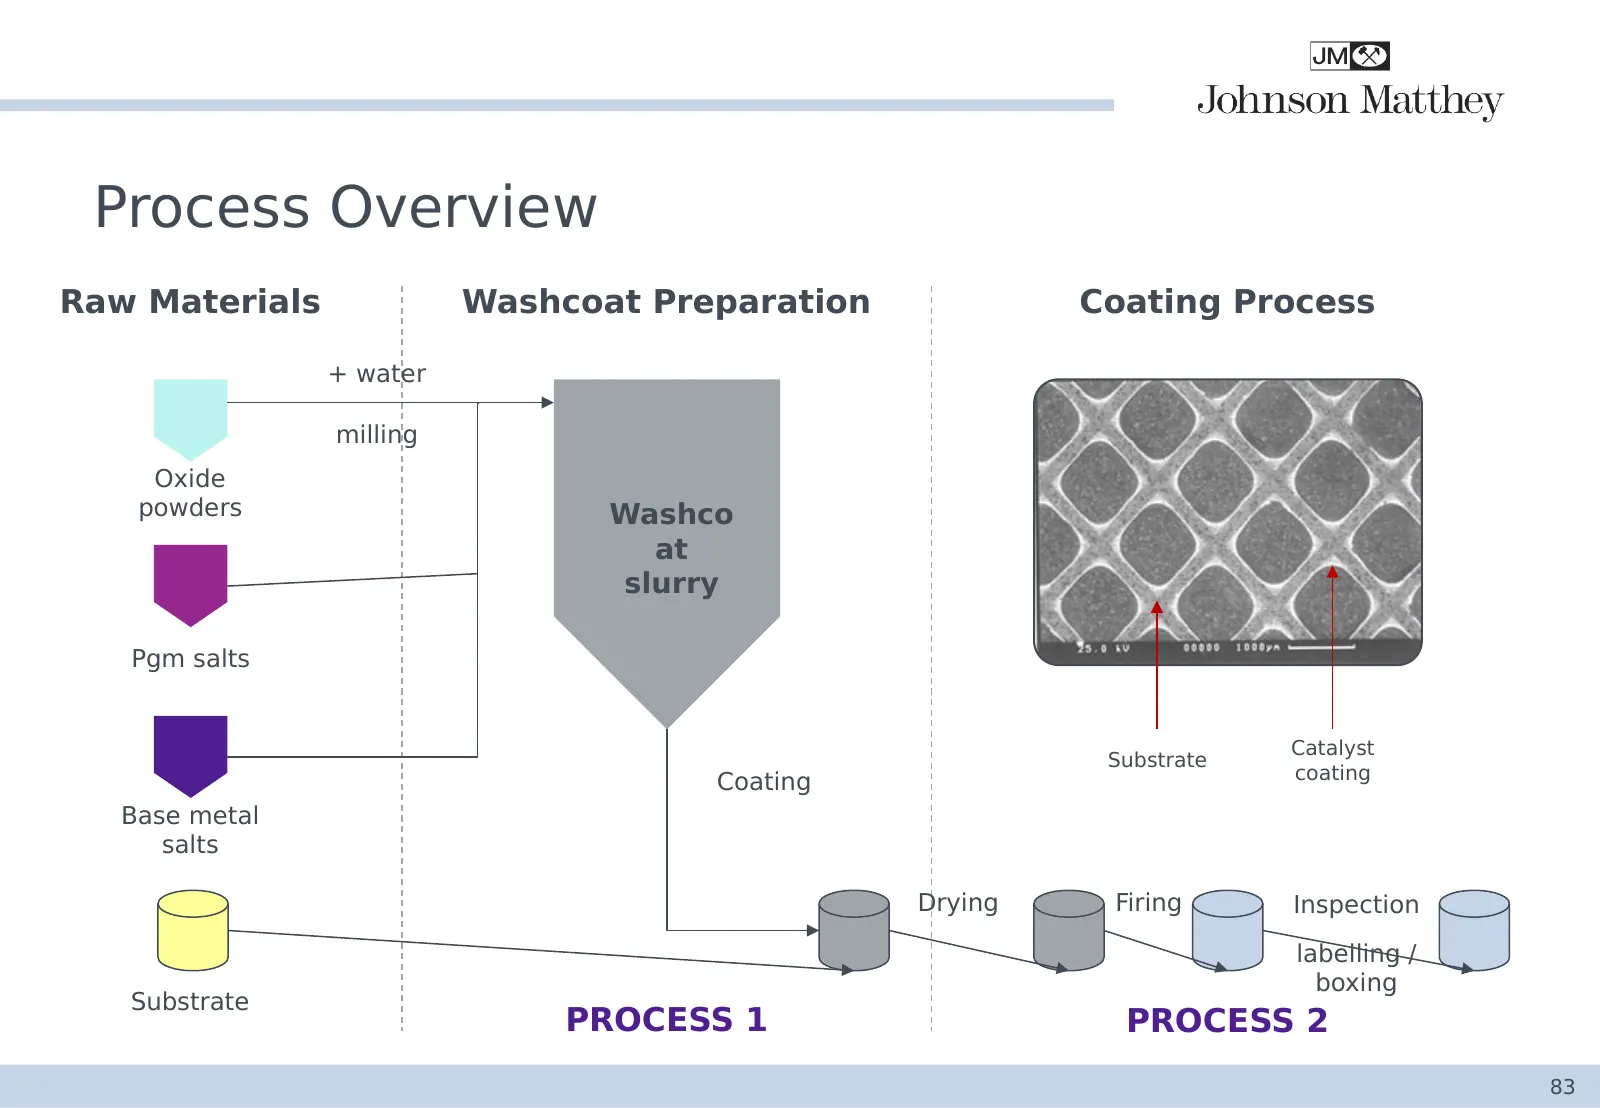
Slide 83: Process Overview
Process Overview Raw Materials Washcoat Preparation Coating Process + water milling Oxide powders Washco at slurry Pgm salts Catalyst Substrate Coating coating Base metal salts Drying Firing Inspection labelling / boxing Substrate PROCESS 1 PROCESS 2 83
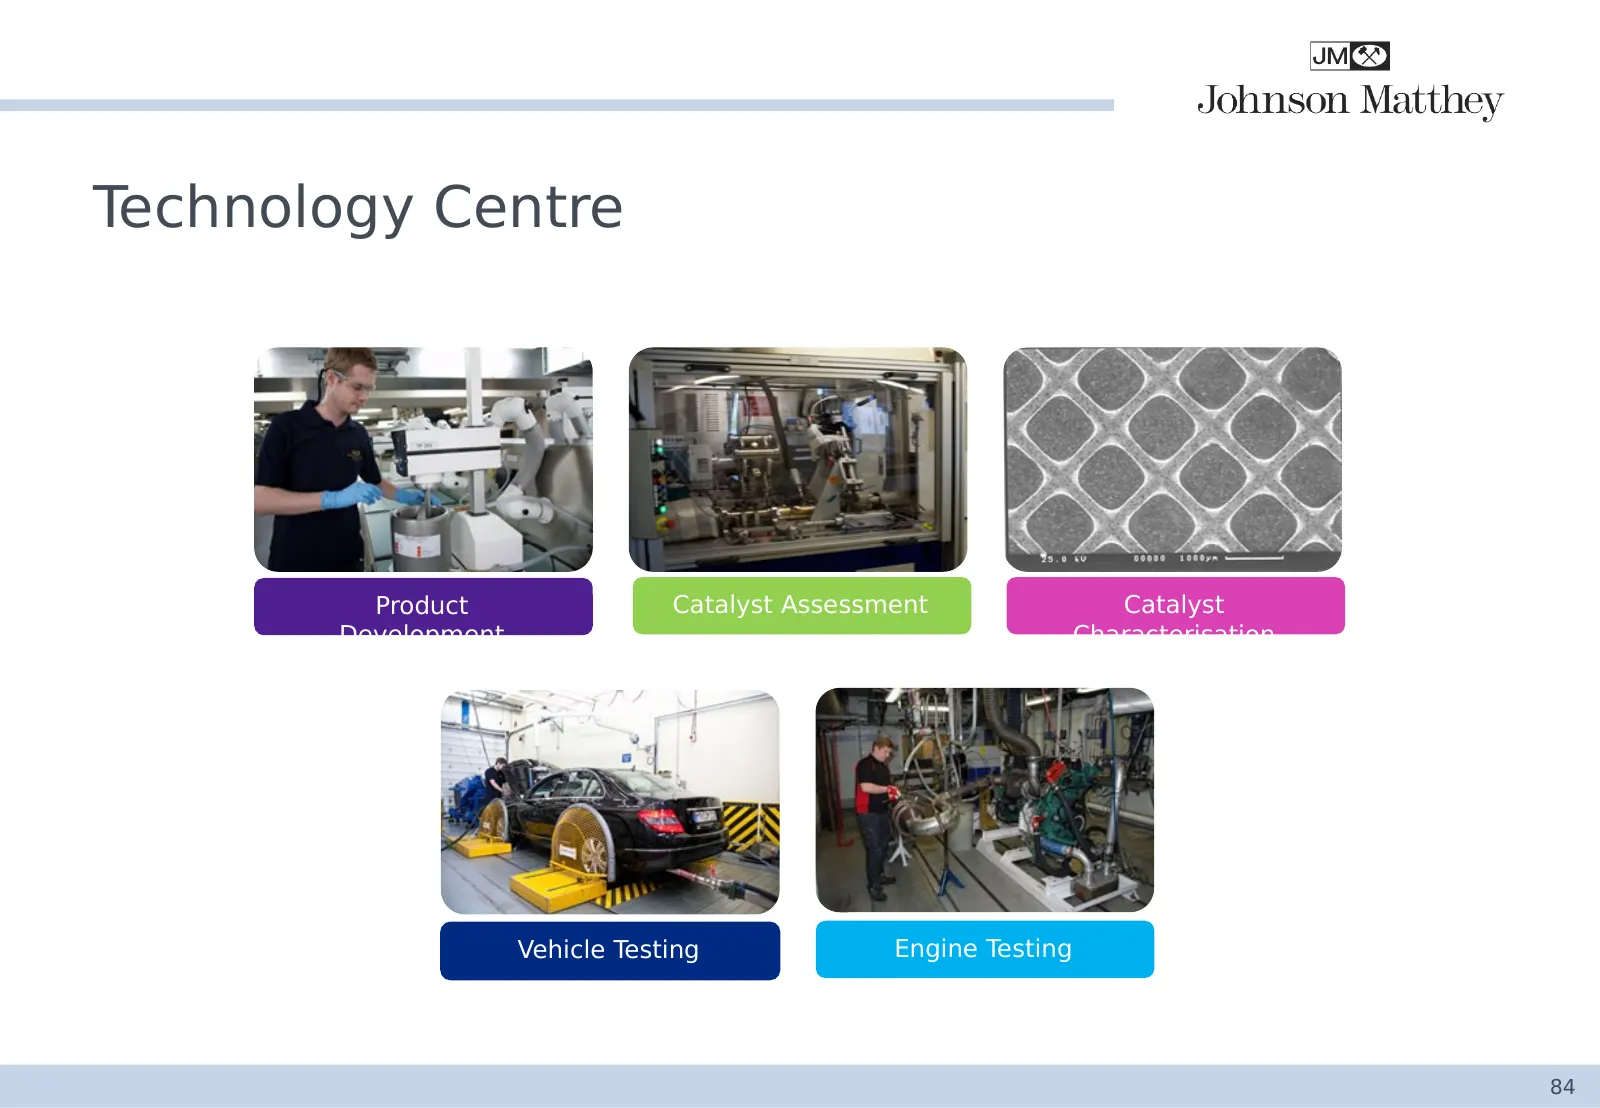
Slide 84: Technology Centre
Technology Centre Product Catalyst Assessment Catalyst Development Characterisation Vehicle Testing Engine Testing 84
Slide 85: Plant Tour
Plant Tour Safety instructions To ensure your safety please stay on the green routes when touring the factory If the fire alarm rings continuously please follow your guide to the FIRE ASSEMBLY POINT Secur ity Request that phones and other recording devices are left in the conference room 85
Slide 86: JME)
JME) Johnson Matthey
Slide 87: Closing Remarks
Closing Remarks Neil Carson Chief Executive
Slide 88: Summary
Summary A world leading Success founded on Differentiation technology continued through technology company investment in R&D and product development Proven strategy in Well positioned in Delivers value place to develop growth markets new business areas 88
Slide 89: Conclusions
Conclusions Well positioned for future growth New Business Development Emission Control Technologies • Developing a portfolio of • Good growth opportunities in all our opportunities markets • Good fit with JM technology • Legislation and technology competences, supported by global continues to drive
Slide 90: JME)
JME) Johnson Matthey
Slide 91: JM Executive Board
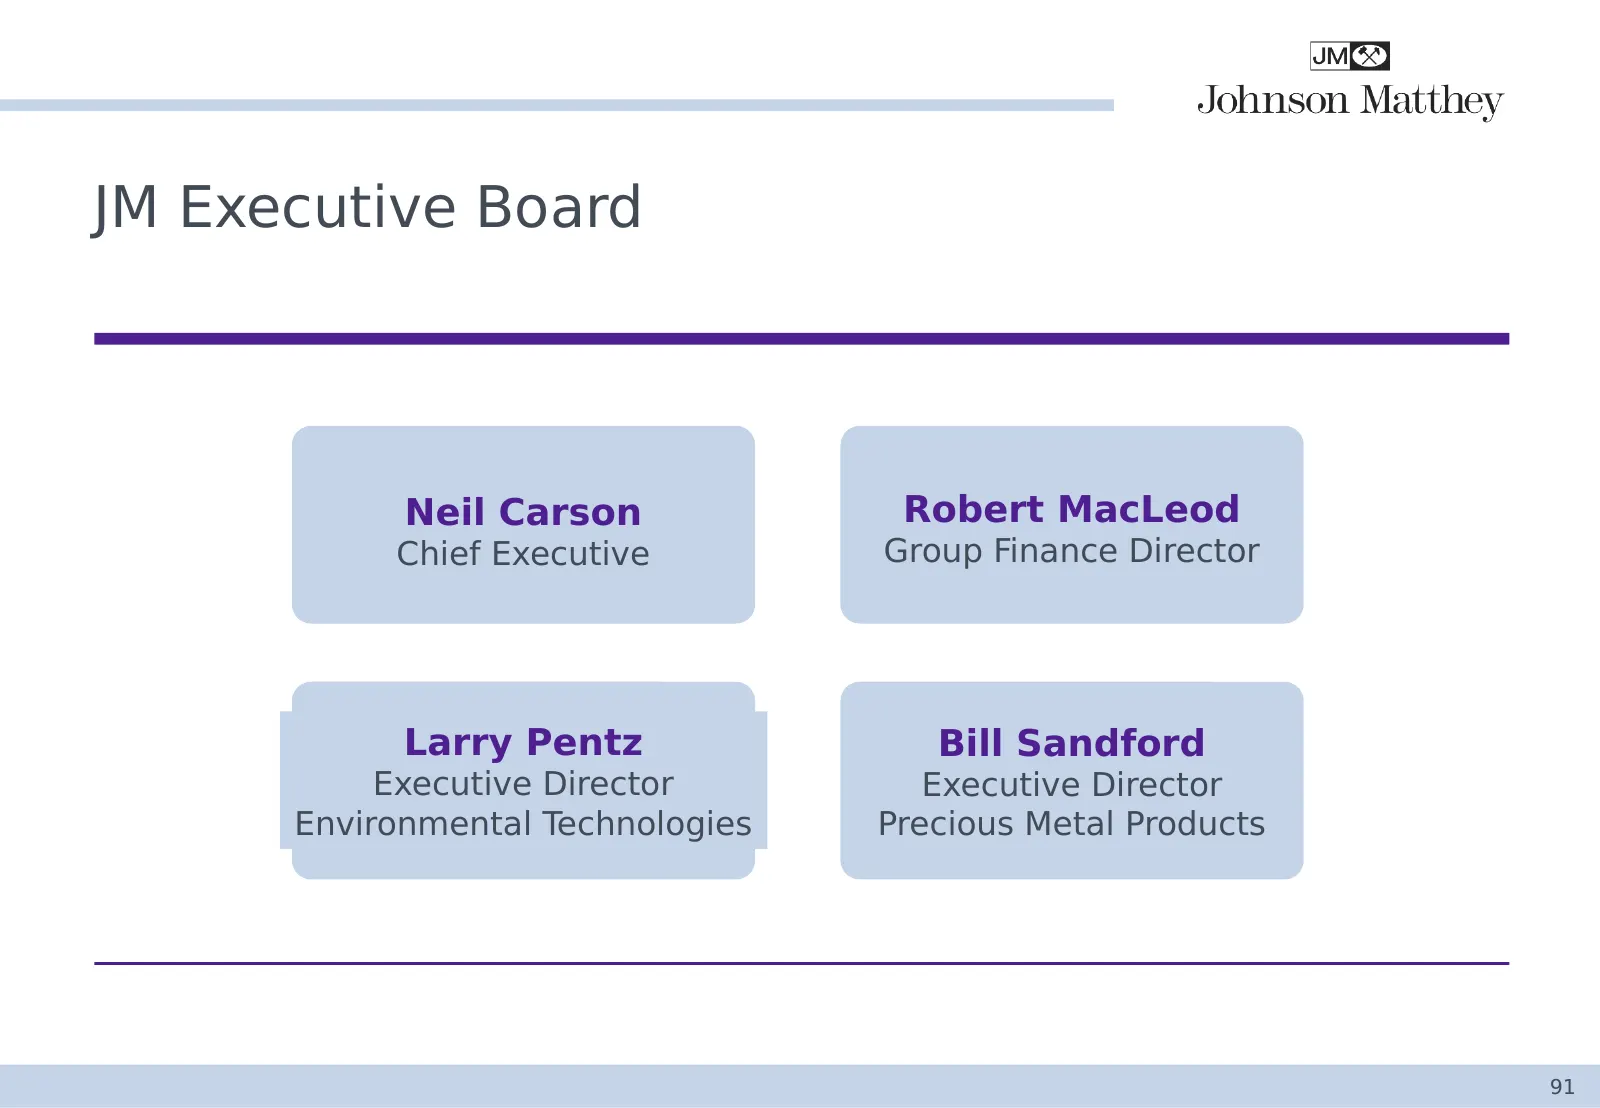
JM Executive Board Neil Carson Robert MacLeod Chief Executive Group Finance Director Larry Pentz Bill Sandford Executive Director Executive Director Environmental Technologies Precious Metal Products 91
Slide 92: Presentation Team
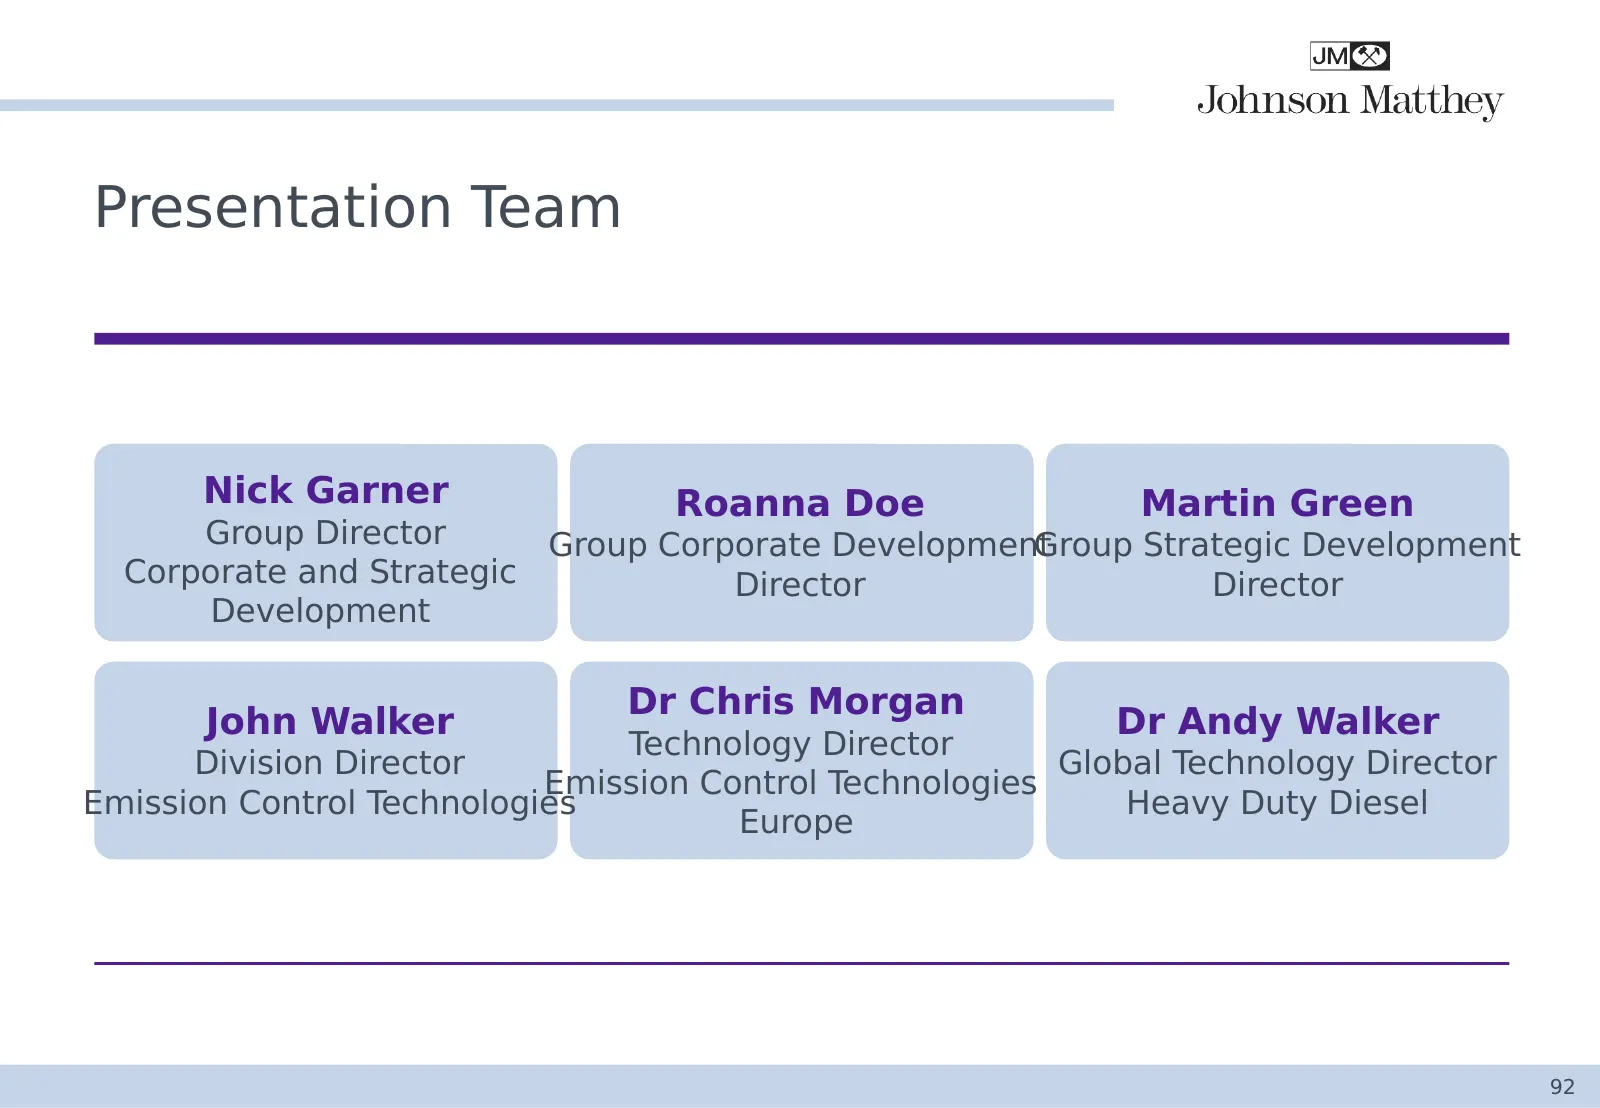
Presentation Team Nick Garner Roanna Doe Martin Green Group Director Group Corporate Development Group Strategic Development Corporate and Strategic Director Director Development Dr Chris Morgan John Walker Dr Andy Walker Technology Director Division Director Global Technology Director Emission Cont
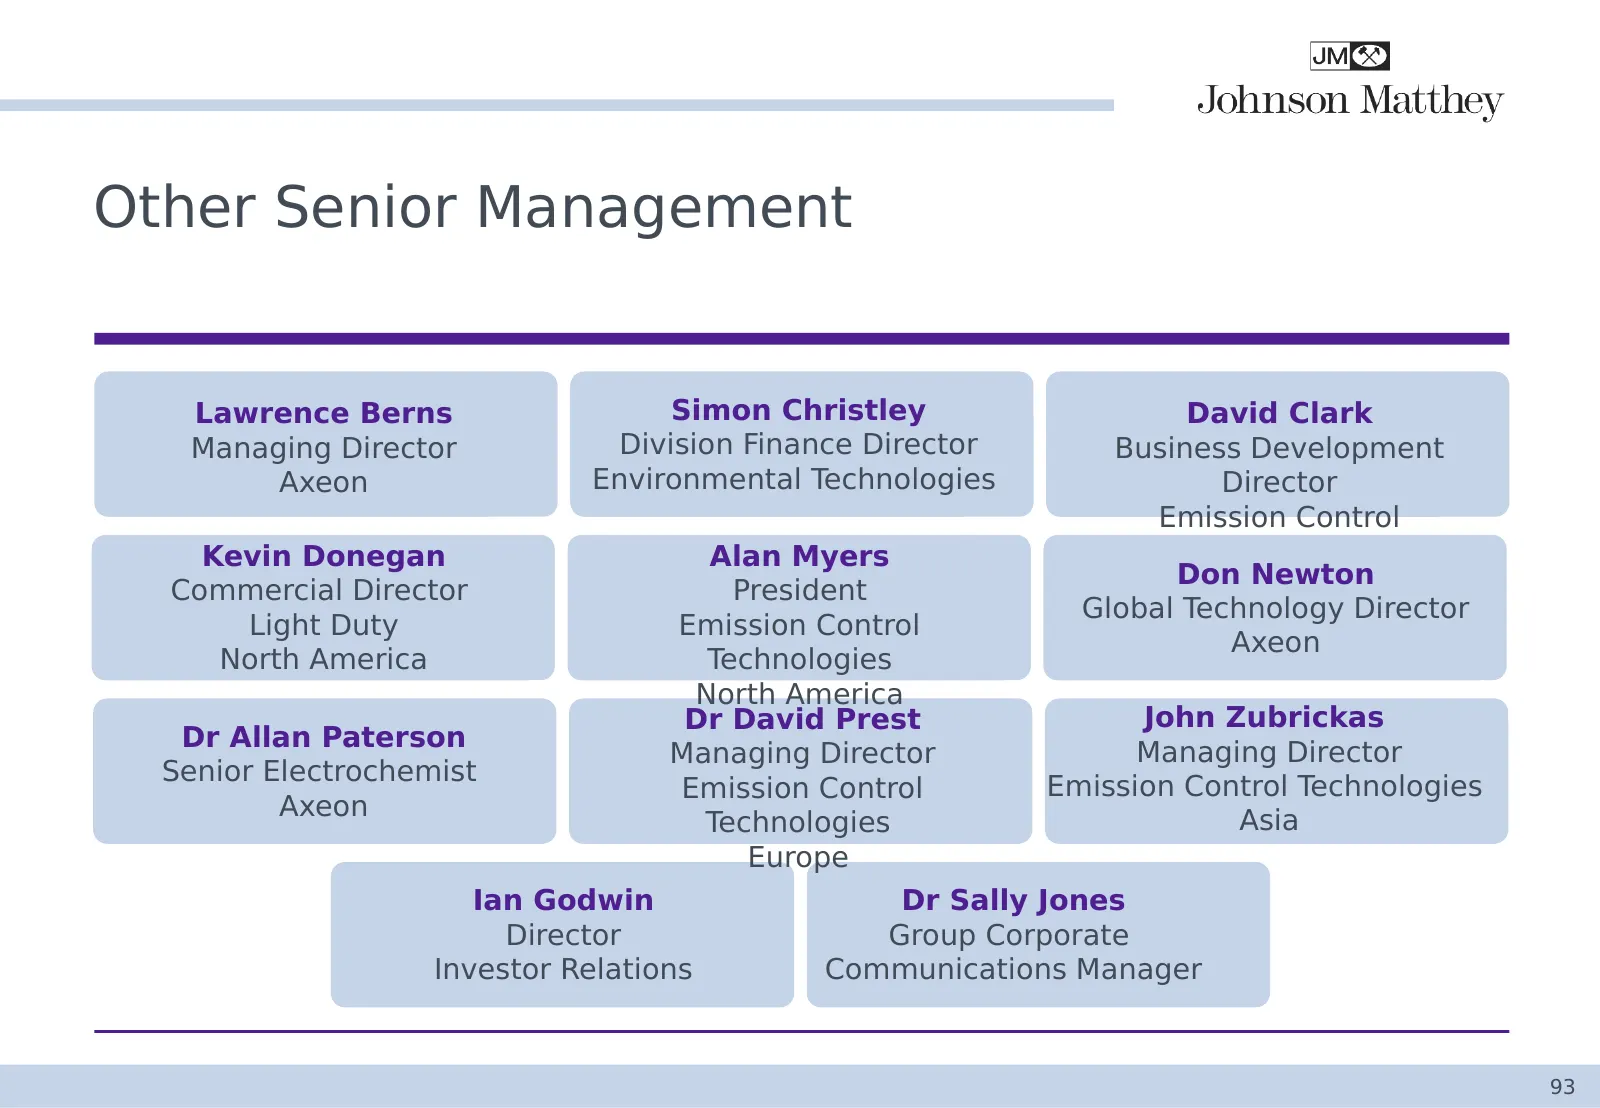
Slide 93: Other Senior Management
Other Senior Management Lawrence Berns Simon Christley David Clark Managing Director Division Finance Director Business Development Axeon Environmental Technologies Director Emission Control Kevin Donegan Alan Myers Technologies Don Newton Commercial Director President Global Technology Director Lig
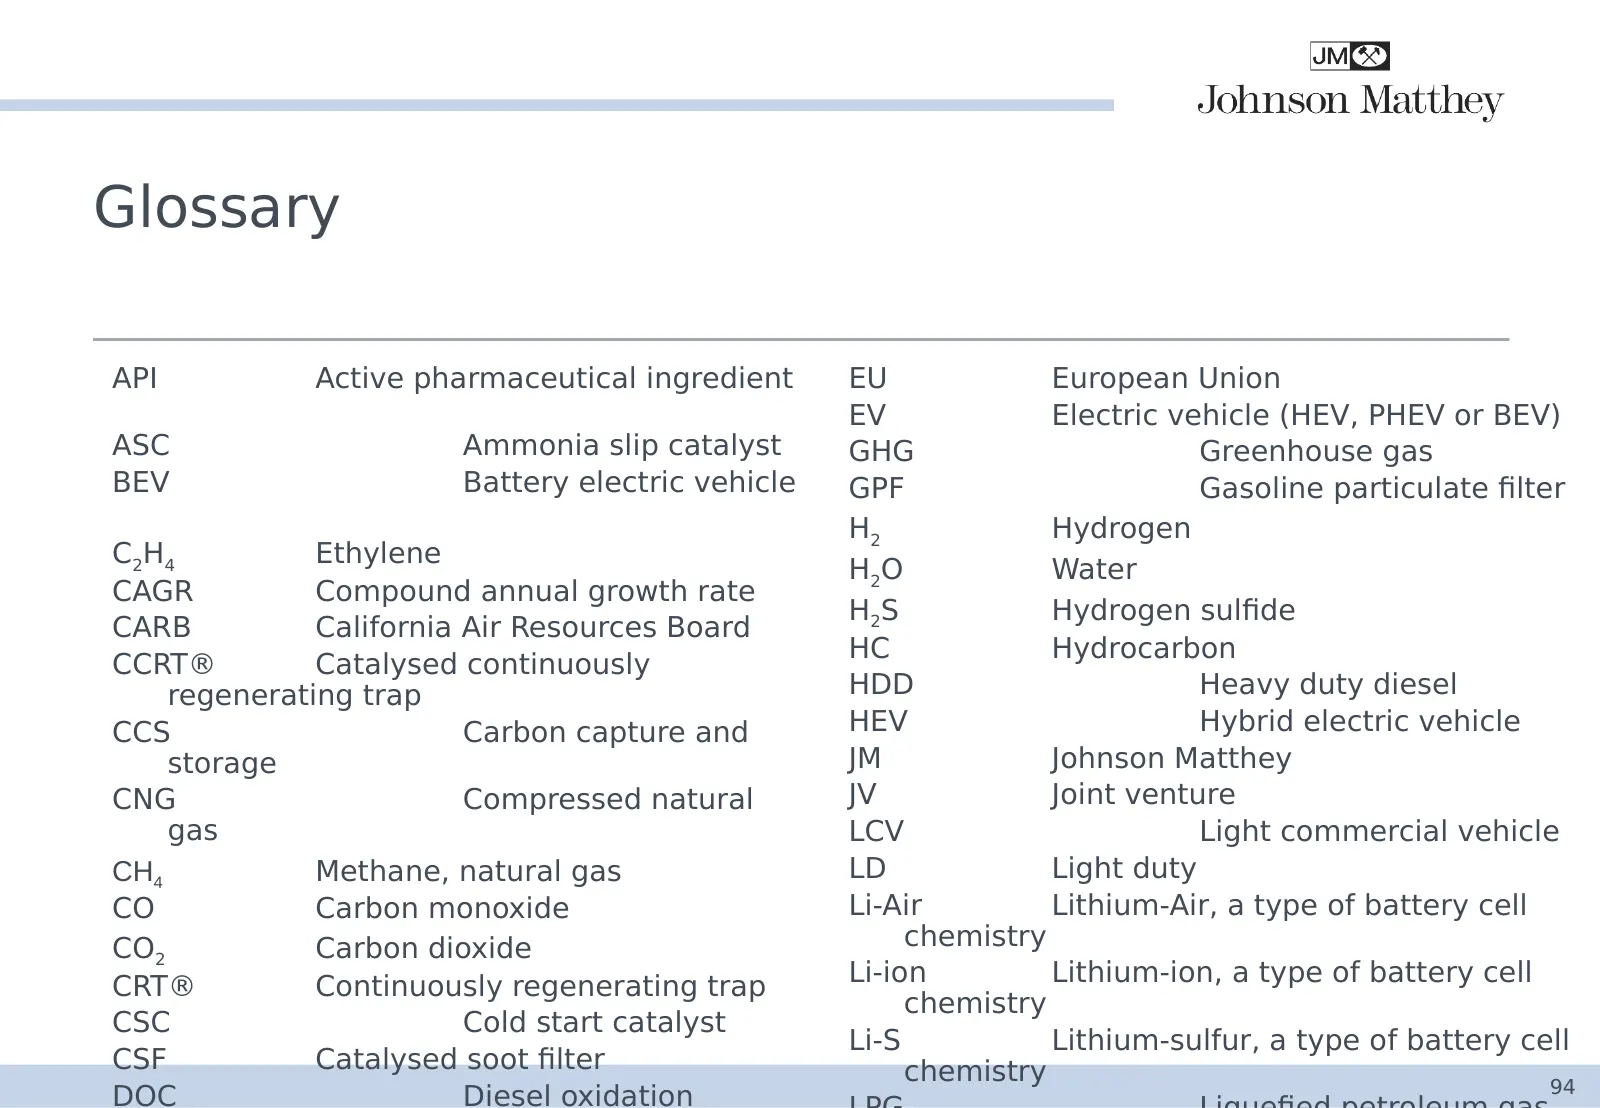
Slide 94: Glossary
Glossary API Active pharmaceutical ingredient EU European Union EV Electric vehicle (HEV, PHEV or BEV) ASC Ammonia slip catalyst GHG Greenhouse gas BEV Battery electric vehicle GPF Gasoline particulate filter H2 Hydrogen C2 H 4 Ethylene H2O Water CAGR Compound annual growth rate H2S Hydrogen sulfide
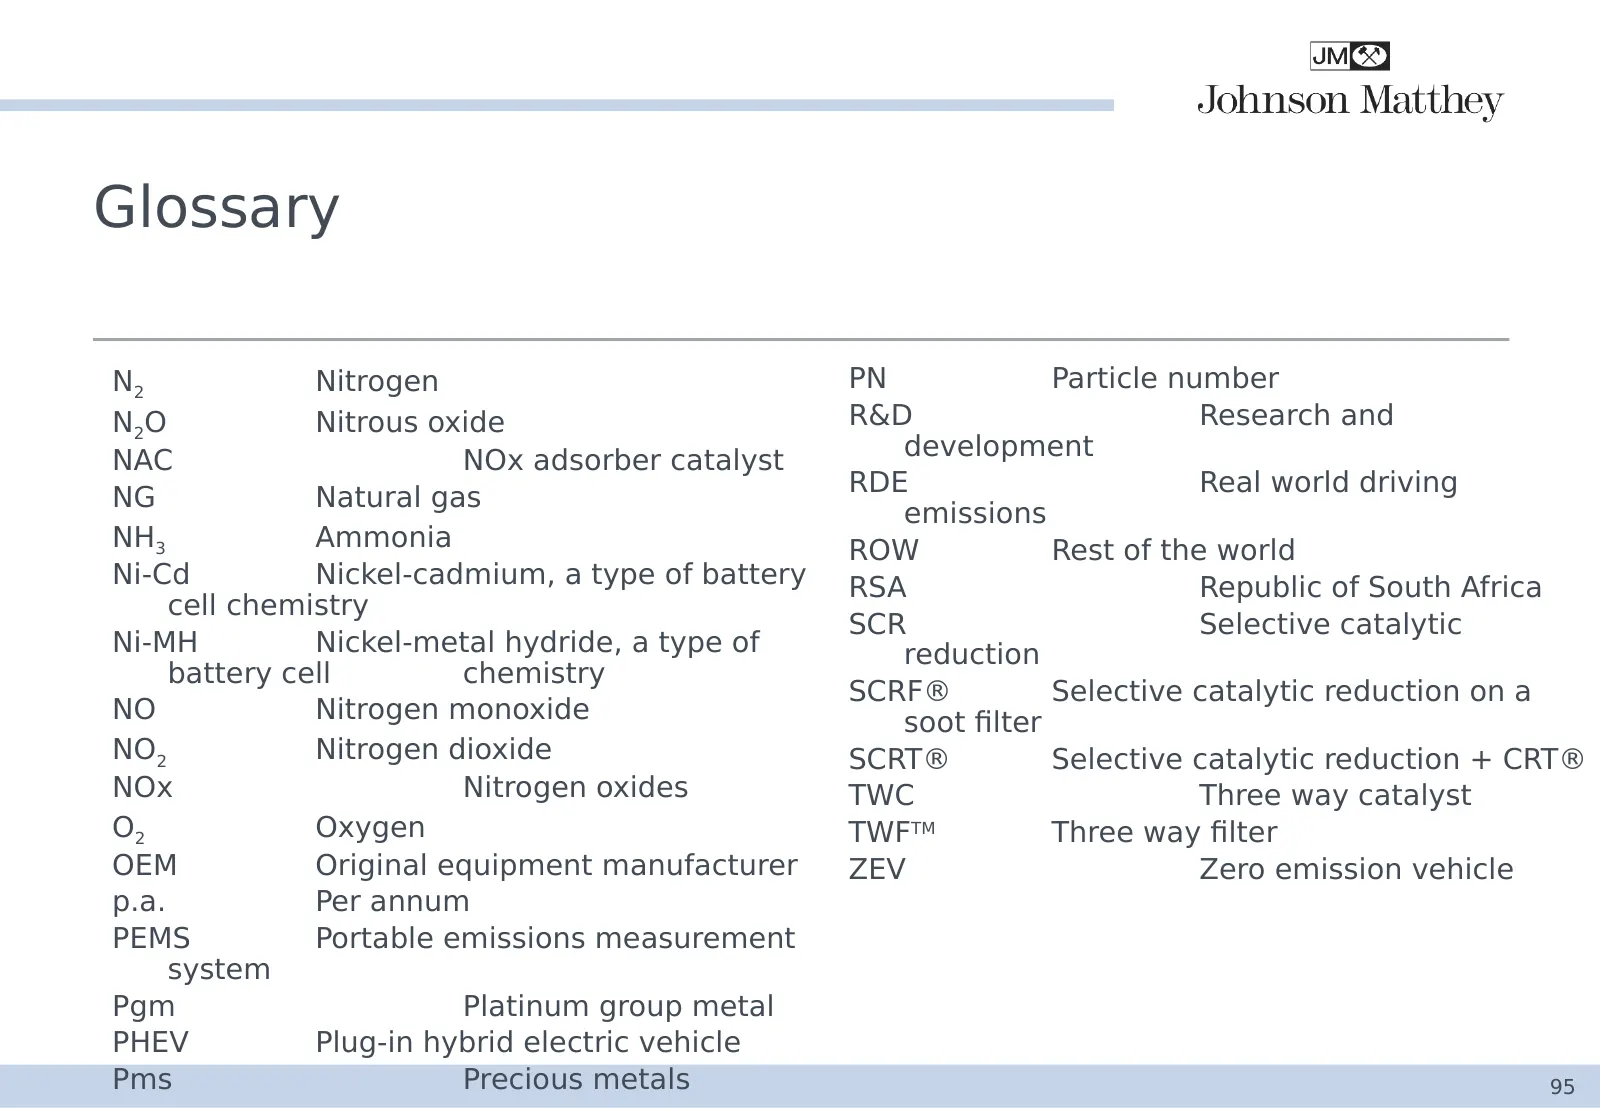
Slide 95: Glossary
Glossary N2 Nitrogen PN Particle number N2O Nitrous oxide R&D Research and NAC NOx adsorber catalyst development NG Natural gas RDE Real world driving emissions NH3 Ammonia ROW Rest of the world Ni-Cd Nickel-cadmium, a type of battery RSA Republic of South Africa cell chemistry SCR Selective catalyt
Slide 96: JME)
JME) Johnson Matthey
Source: Internet Archive copy of matthey.com
More decks from Johnson Matthey PLC
 H1 2026/27 Earnings Presentation36 slides · Nov 19, 2026
 FY2026 Earnings Presentation48 slides · May 28, 2026
 Q2 2026 Earnings Presentation42 slides · Nov 20, 2025
 FY2025 Earnings Presentation59 slides · May 22, 2025
 H1 2024/25 Earnings Presentation39 slides · Nov 27, 2024
 FY2024 Earnings Presentation45 slides · May 23, 2024