Plains Exploration & Production Company
Plains Exploration & Production — Credit Suisse 2012 Energy Summit
32 slides from Plains Exploration & Production's conference presentation, Feb 7, 2012
Slide 1: Credit Suisse 2012 Energy Summit
Credit Suisse 2012 Energy Summit February 2012 Exhibit 99.2
Slide 2: Corporate Information
Corporate Information Corporate Headquarters Contacts Plains Exploration & Production Company 700 Milam, Suite 3100 Houston, Texas 77002 Forward-Looking Statements This presentation is not for reproduction or distribution to others without PXP’s consent. James C. Flores – Chairman, President & CEO W
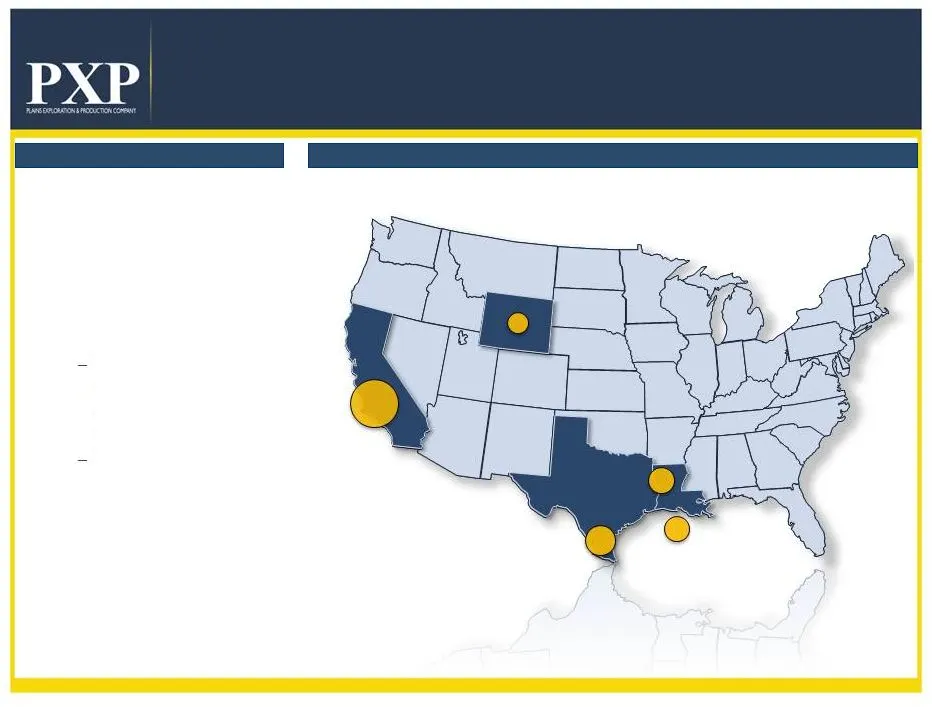
Slide 3: Core Asset Areas Overview and Background
Core Asset Areas Overview and Background Overview • PXP is an independent oil and gas company primarily engaged in acquiring, developing, exploring and producing oil and gas properties • Assets in PXP’s principal focus areas include: Mature properties with long-lived reserves and significant develop
Slide 4: 2011 Highlights
2011 Highlights • Consistently Strong Quarterly Operating Results • Exceptional Eagle Ford Development Results • Improved Eagle Ford and California Pricing Mechanisms • Improved Hedge Position Volumes and Pricing • GOM Financing and Lucius Sanctioning • Divested South Texas and Texas Panhandle Asset
Slide 5: 2011 Operational Results
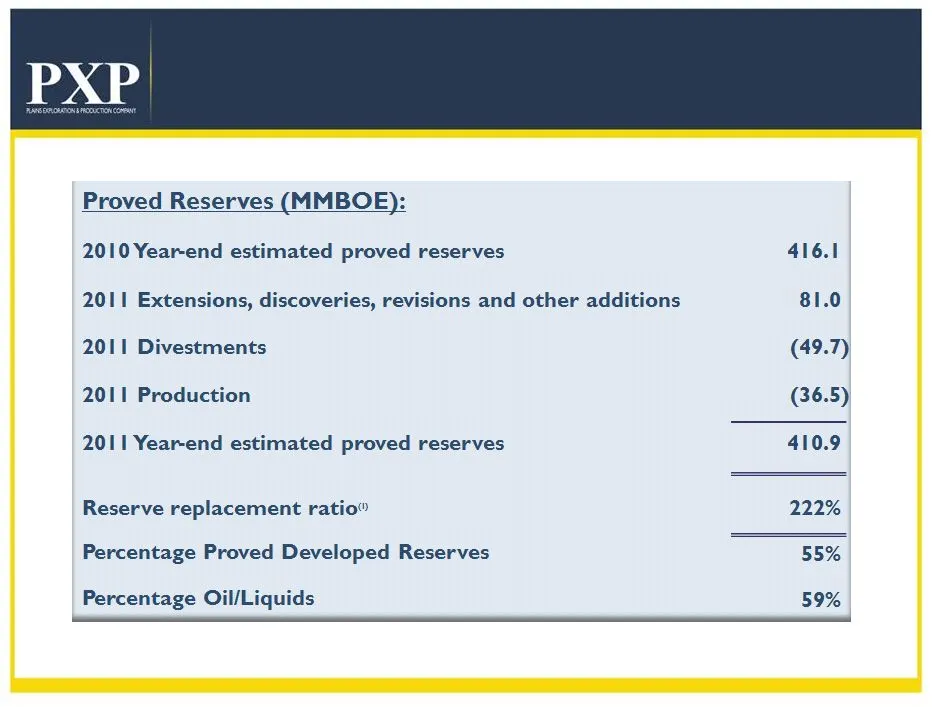
2011 Operational Results • 411 MMBOE Proved Reserves YE 2011 • Reserve Replacement Ratio of 222% • 16% Reserve Growth year-over-year pro forma for asset sales • 18% Reserve Growth in oil/liquids pro forma for asset sales • Oil/Liquids 59% of total proved, up from 54% in 2010 • 12.2 Year Proved R/P (
Slide 6: 2011 Production & Revenue Analysis
2011 Production & Revenue Analysis • 98.9 MBOE per day Production in 2011, a 12% increase over 2010 and 23% pro forma for asset sales • 82.2 MBOE per day pro forma Production in 2011, reflects 16.7 MBOE per day impact of fourth-quarter asset sales • Expect approximate 30% increase in 2012(E) oil/liq
Slide 7: 2012 Oil Hedge Program
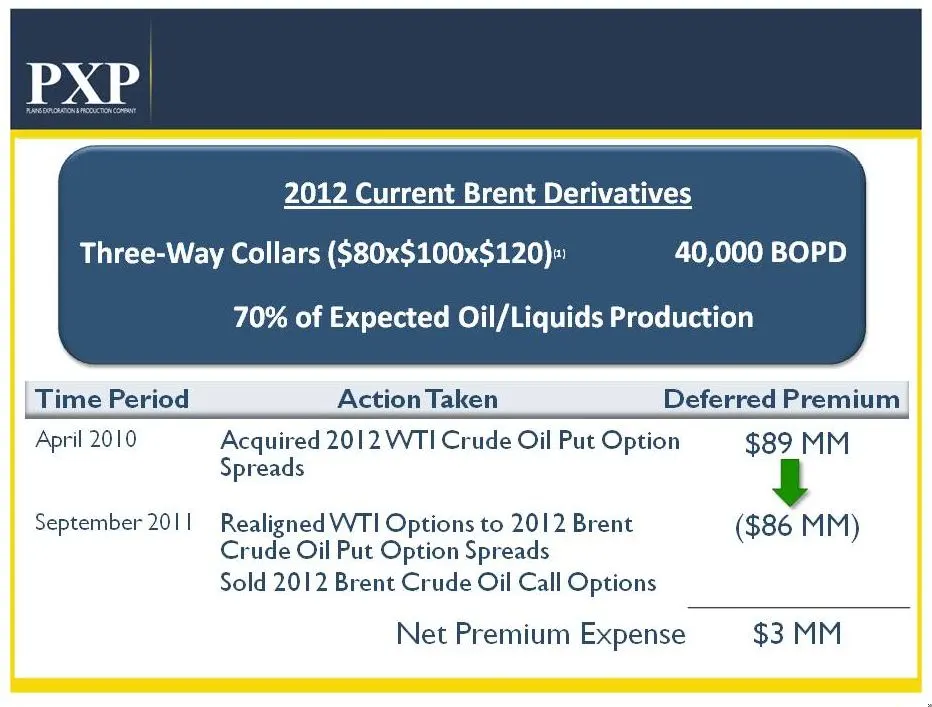
2012 Oil Hedge Program “Costless Deferred Premium Strategy” (1) Weighted average price, see detailed pricing in addendum.
Slide 8: 2013 Oil Hedge Program
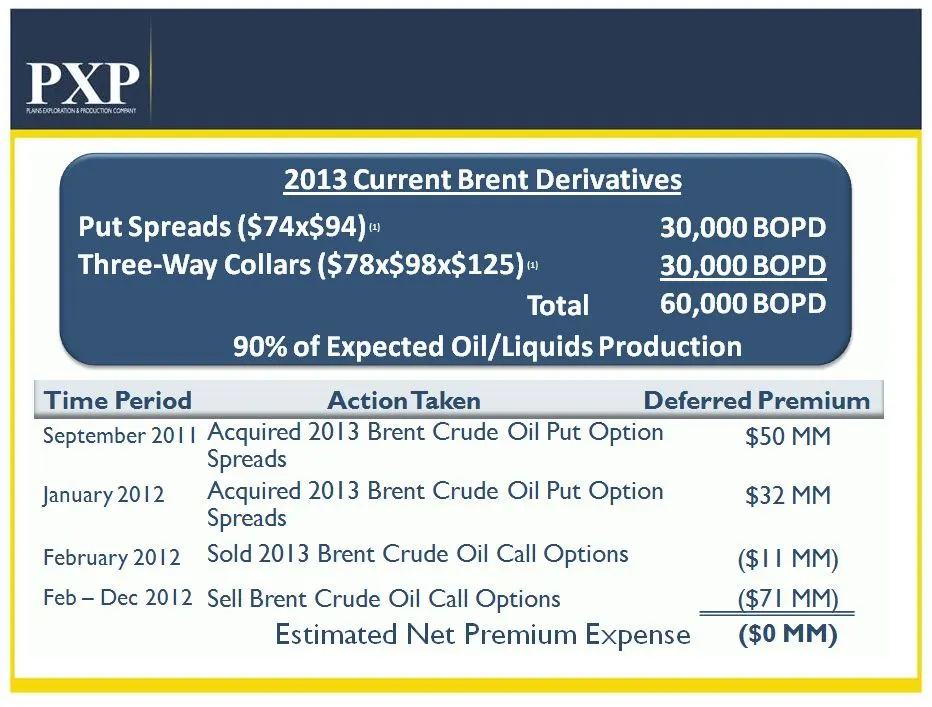
2013 Oil Hedge Program “Costless Deferred Premium Strategy” (1) Weighted average price, see detailed pricing in addendum.
Slide 9: California Oil Supply Sources
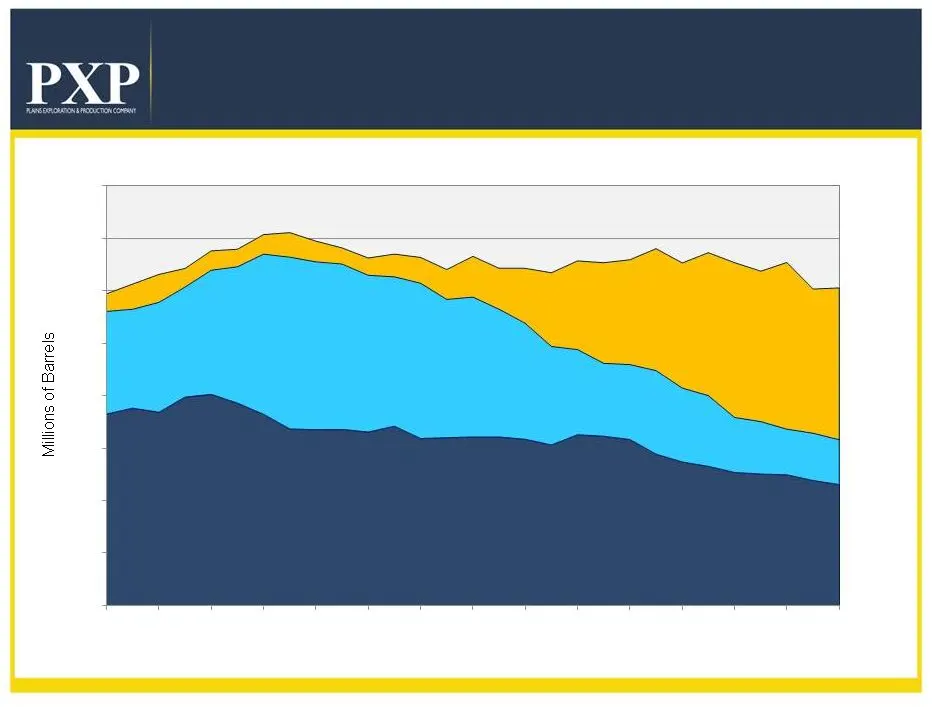
California Oil Supply Sources Source: The California Energy Commission. California Alaska Foreign
Slide 10: Operational Plan at $110 Brent Oil
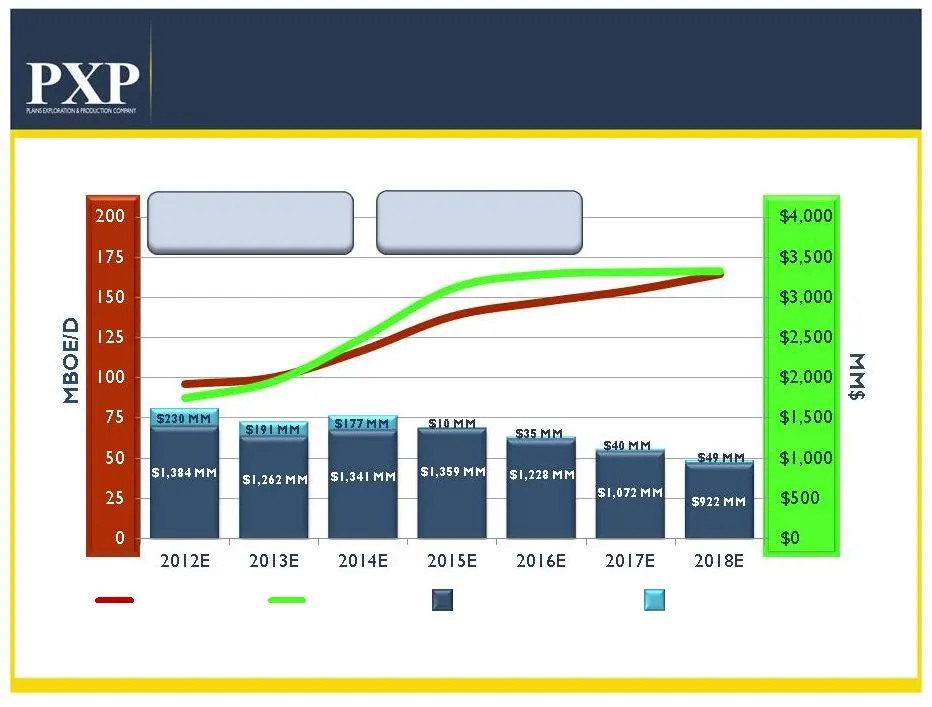
PXP Operational Plan at $110 Brent Oil Oil & Gas Capital Cash Flow Production GOM Capital PXP Net Production Oil & Gas Cash Flow (1)(2) GOM Oil Production Starts 2014 Eagle Ford Oil Growth (1) Oil and Gas revenues minus lease expenses. (2) Assumes $108/Bbl Brent based oil pricing and natural gas pri
Slide 11: Undeveloped Resource Potential
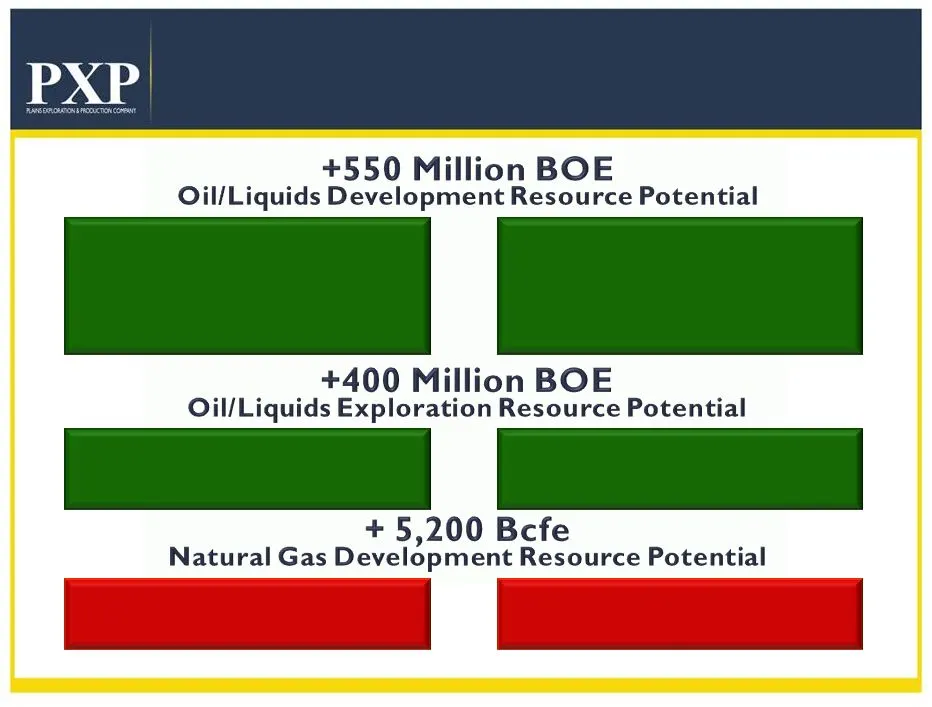
+1.8 Billion BOE 283 MMBOE 162 MMBOE 106 MMBOE California Eagle Ford Gulf of Mexico 409 MMBOE Gulf of Mexico 5,200 Bcfe 40 Bcfe Haynesville/Bossier Madden Undeveloped Resource Potential Potential Reserves Region Potential Reserves Region
Slide 12: Strong Asset Intensity
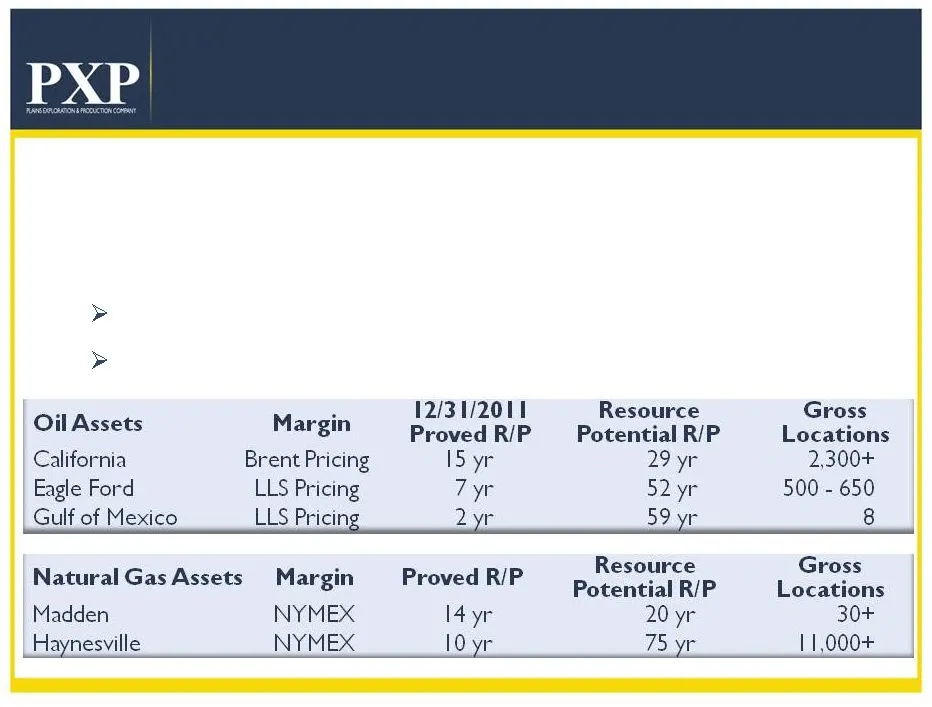
Strong Asset Intensity Asset Intensity • High Margins • Durability Proved Reserves R/P 12.2 years (1) Resource R/P 62 years (1) (1) Pro forma for 2011 asset sales.
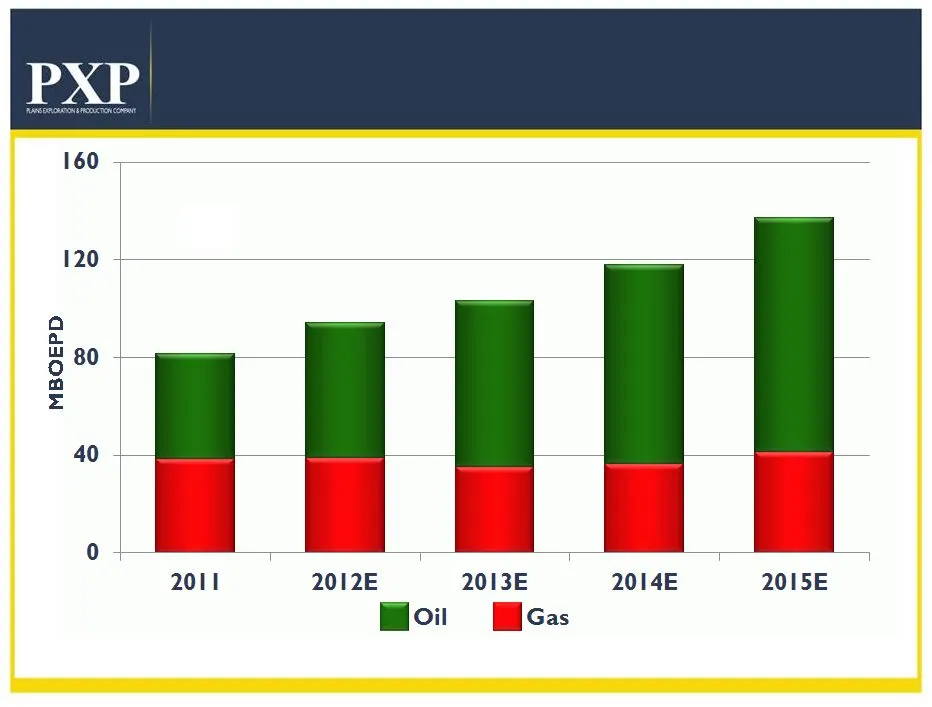
Slide 13: Multi Year Oil Growth
Multi Year Oil Growth 42% 58% 34% 66% 30% 70% 31% 69% 47% 53% Production Growth Targets 42% 58% 34% 66% 30% 70% 31% 69% 47% 53% (2) (2) (2) (2) (1) (1) Pro forma for asset sales. (2) Assumes $108/Bbl Brent based oil pricing and natural gas pricing of $3.70/MMBtu in and $110/Bbl Brent based oil prici
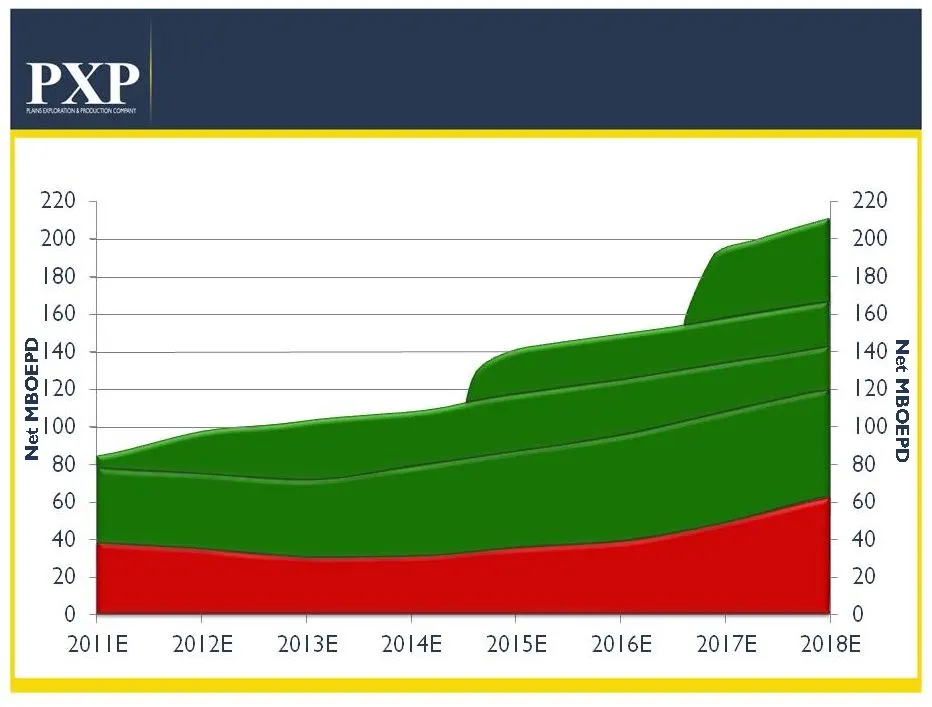
Slide 14: Asset Production Target Profile
Asset Production Target Profile Haynesville/Madden California Eagle Ford GOM-Lucius GOM Risked Exploration Success Haynesville/Madden California Eagle Ford GOM-Lucius GOM Risked Exploration Success
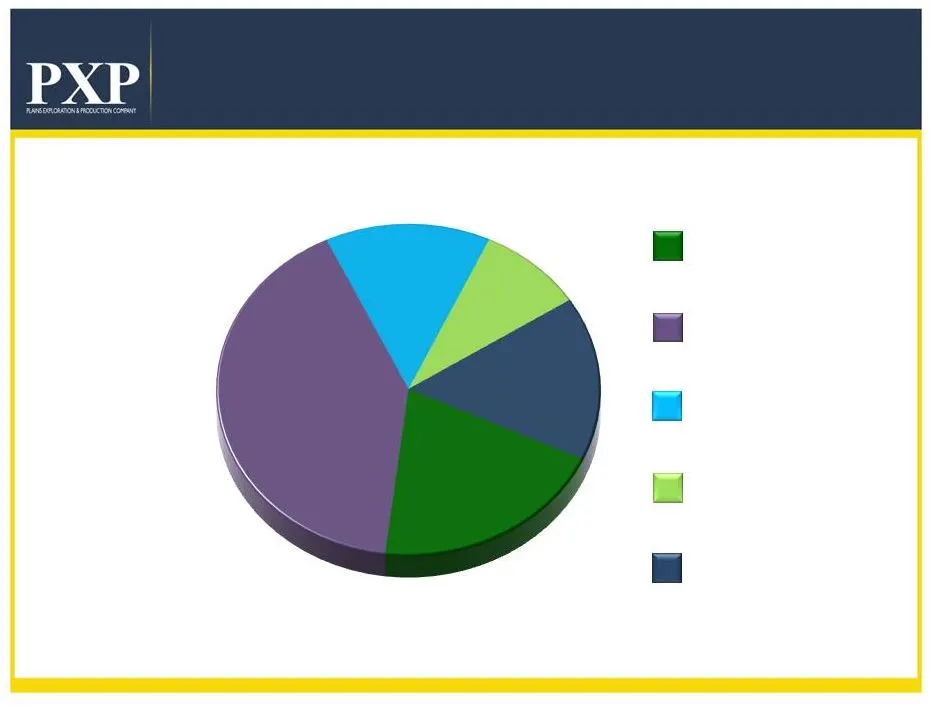
Slide 15: Capital Allocation
Capital Allocation 20% 14% 9% 16% 41% 2012 Capital Program (1) Includes development, exploitation, real estate, capitalized interest and G&A costs but does not include additional capital for exploratory successes. Exploration capital is defined as discovery and dry hole costs. 2012E $1.6 Billion (1)
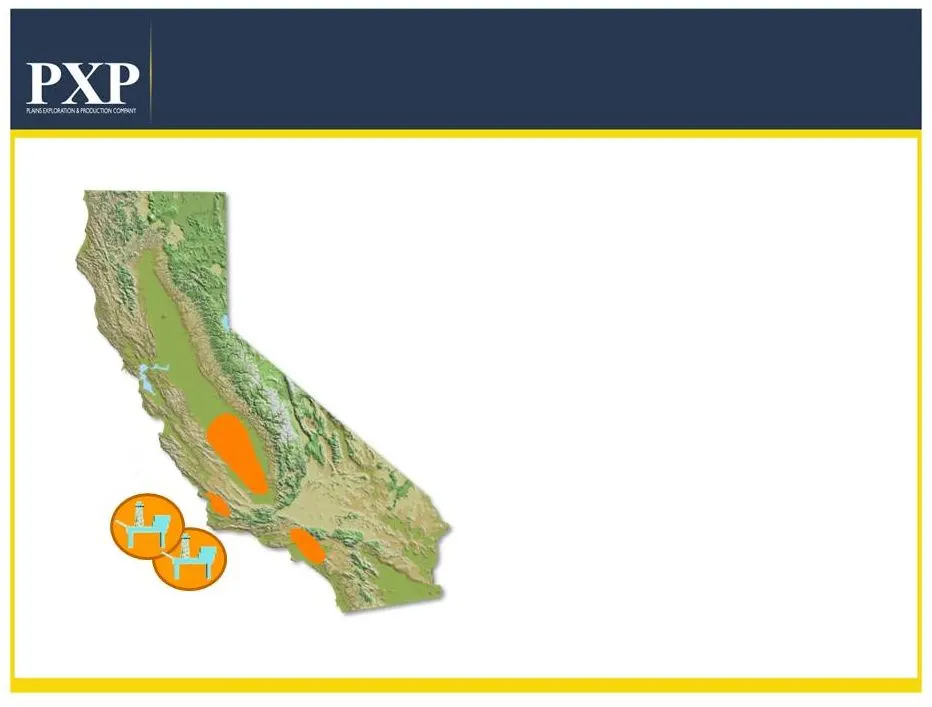
Slide 16: California Oil
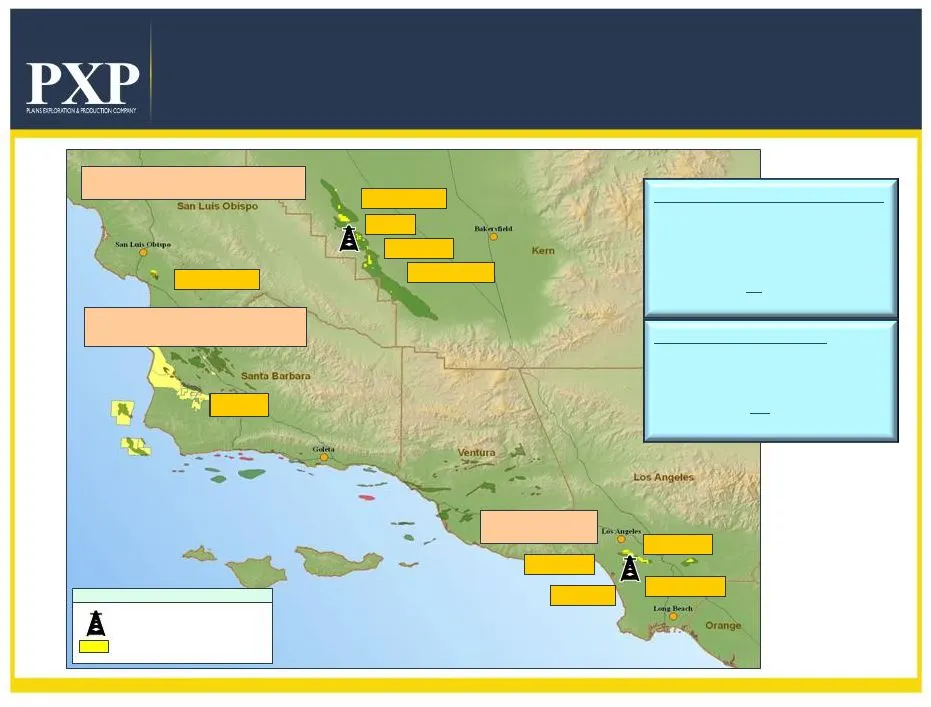
California Oil Onshore/Offshore Los Angeles Basin San Joaquin Valley Arroyo Grande Pt Pedernales Pt Arguello • 217 MMBOE Proved Reserves • 431 MMBOE Total Resource Potential • 68% Proved Developed • 14.6 yr Proved R/P, 28.9 yr Potential R/P • 2,300+ Future Well Locations The shaded areas are for ill
Slide 17: California Oil Operational Plan
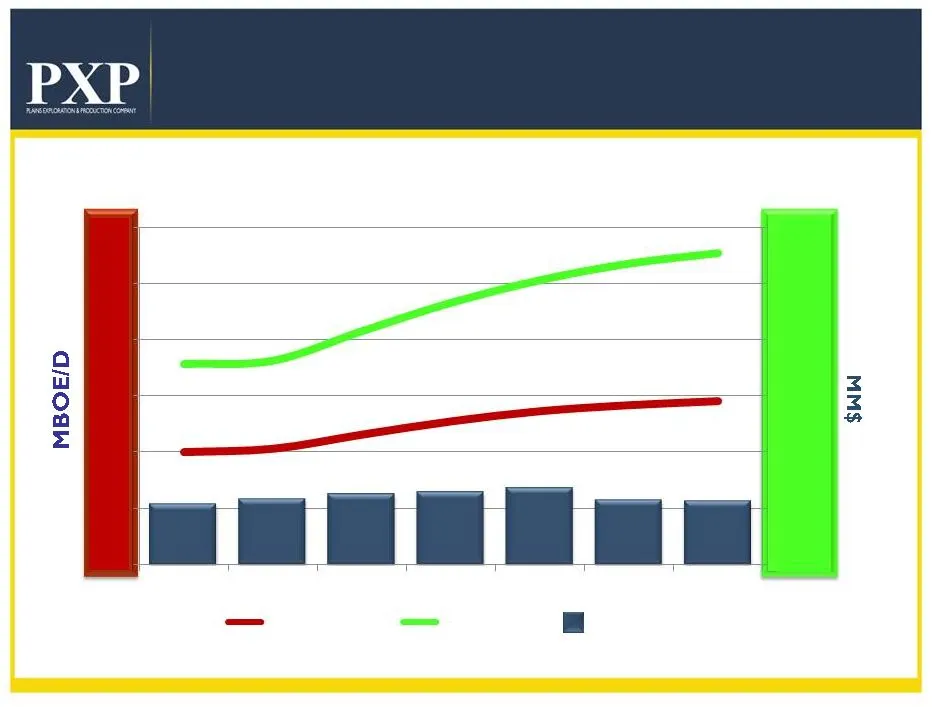
California Oil $321 MM $349 MM $371 MM $381 MM $405 MM $341 MM $334 MM 0 20 40 60 80 100 120 Operational Plan PXP Net Production Oil & Gas Cash Flow (1)(2) Capital Cash Flow Production $0 $300 $600 $900 $1,200 $1,500 $1,800 2012E 2013E 2014E 2015E 2016E 2017E 2018E (1) Oil and Gas revenues minus lea
Slide 18: Onshore California
Onshore California San Joaquin Valley Legend PXP LEASES Santa Maria Basin LA Basin Arroyo Grande Midway Sunset Cymric South Belridge McKittrick Montebello Inglewood Urban Area Las Cienegas Lompoc 2012 Activity Map PXP Gross Well Activity • Planned Wells • 3 Planned Wells • LAB Planned Wells • SMB Pl
Slide 19: Eagle Ford Horizontal Oil Play
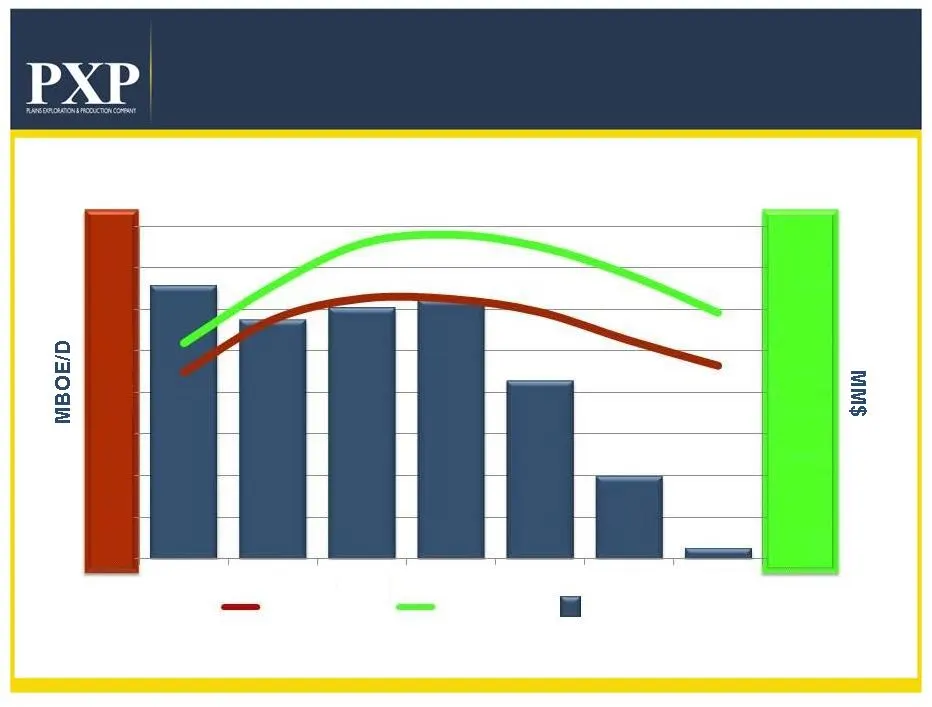
Eagle Ford Horizontal Oil Play 0 5 10 15 20 25 30 35 40 $655 MM $575 MM $602 MM $623 MM $427 MM $200 MM Operational Plan PXP Net Production Oil & Gas Cash Flow (1)(2) (1) Oil and Gas revenues minus lease expenses. (2) Assumes $108/Bbl Brent based oil pricing and natural gas pricing of $3.70/MMBtu in
Slide 20: Eagle Ford Horizontal Oil Play
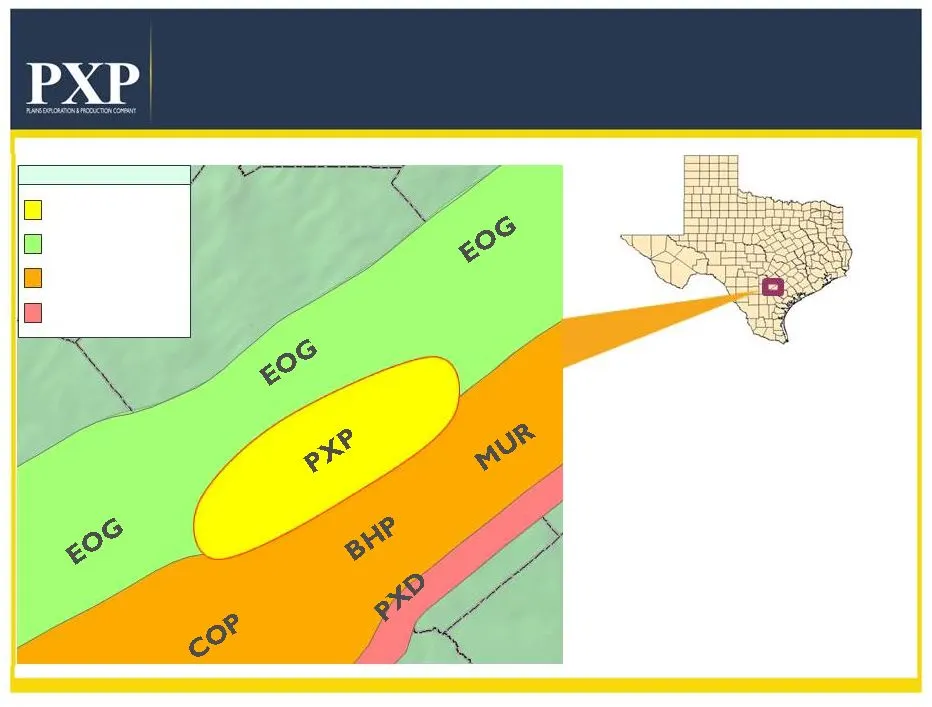
Eagle Ford Horizontal Oil Play WILSON ATASCOSA Legend PXP ACREAGE OIL WINDOW GAS CONDENSATE WINDOW DRY GAS WINDOW The shaded area is for illustrative purposes only and does not reflect actual leasehold acreage. • PXP acreage position • ~60,000 net acres • 7 to 9 rigs running in 2012 • Depth to Eagle
Slide 21: Gulf of Mexico
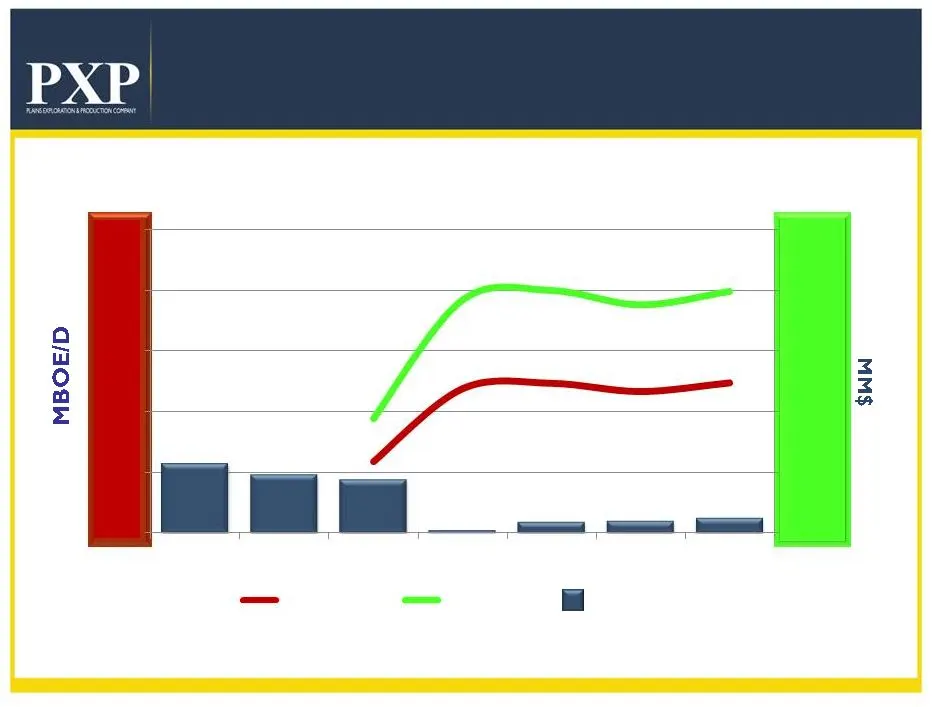
Gulf of Mexico $230 MM $191 MM $177 MM 0 10 20 30 40 50 Operational Plan Net Production Oil & Gas Cash Flow (1)(2) Capital Cash Flow Production $10 MM $35 MM $40 MM $49 MM $0 $200 $400 $600 $800 $1,000 2012E 2013E 2014E 2015E 2016E 2017E 2018E (1) Oil and Gas revenues minus lease expenses. (2) Assum
Slide 22: Gulf of Mexico Portfolio
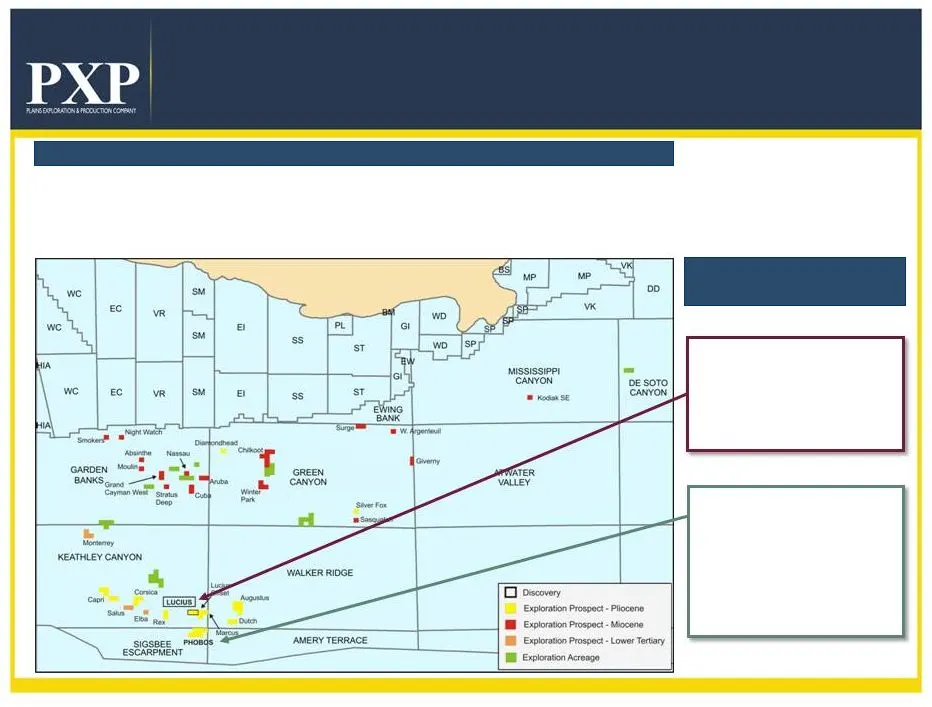
Gulf of Mexico Portfolio Deepwater Leasehold High-Quality Deepwater GOM Assets • 1 Discovery • 29 Exploration Prospects • 37 blocks of Exploration Acreage • Interest in 102 blocks • 570,000 gross acres / 191,000 net acres • Lucius discovery made PXP an early mover in Pliocene play – Acquisition of s
Slide 23: Lucius Oil Development
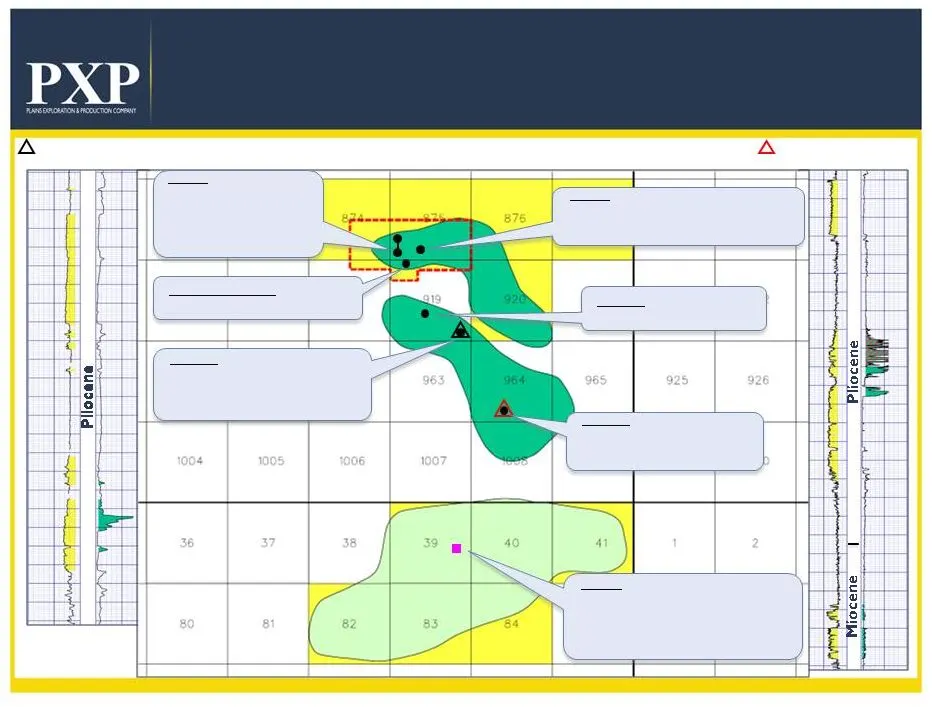
Lucius Oil Development • Lucius oil project commercial sanction announced in 2011 with additional production targeted for 2nd half 2014 • “Gross resource potential in the Lucius field is approximately 300+ MMBOE” (1) • The Hadrian 5 (KC 919-3) well, that is part of the Lucius unitization agreement,
Slide 24: Lucius / Hadrian / Phobos Oil Complex
Lucius / Hadrian / Phobos Oil Complex 500 MMBOE of Discovered Resource; 1+ BBOE Exploration Upside LUCIUS Discovery PHOBOS Prospect Lucius 1 Lucius 1ST Lucius 2 Hadrian 3 Hadrian 1 Hadrian 2 Phobos 1 • Potential 2012 drill • 25,000 acres higher than oil pay at Hadrian 2 • Pliocene, Miocene and Wilco
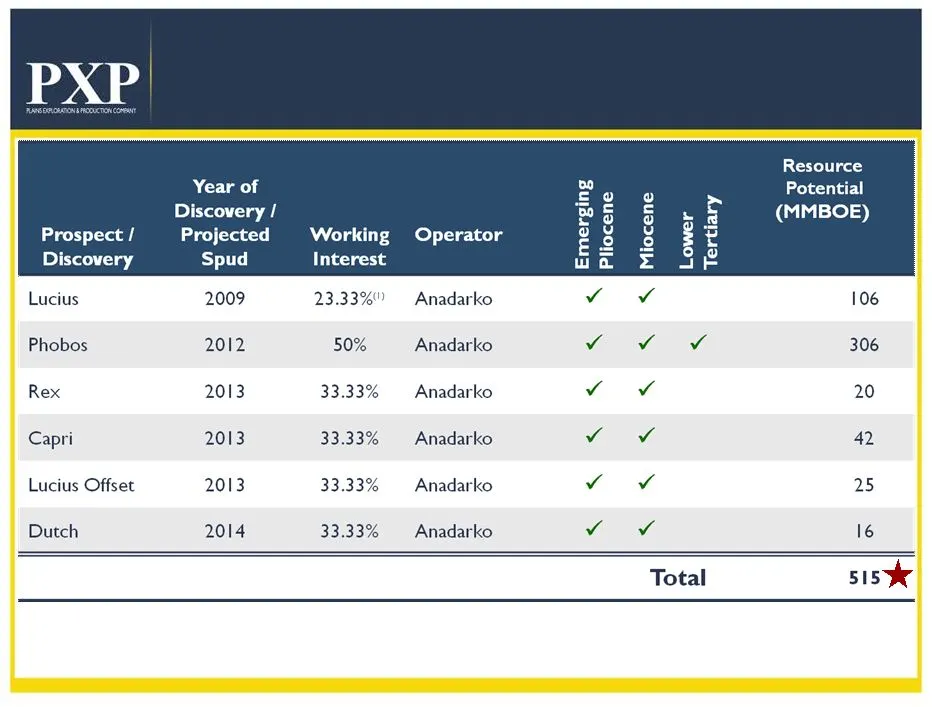
Slide 25: 2012 – 2014 Operational Plan
2012 – 2014 Operational Plan Existing Discoveries and Near-Term Exploration (1) Lucius working interest post unitization; remaining working interests reflective of existing leasehold ownership. Recent OCS Lease Sale High Bidder on Additional Inventory
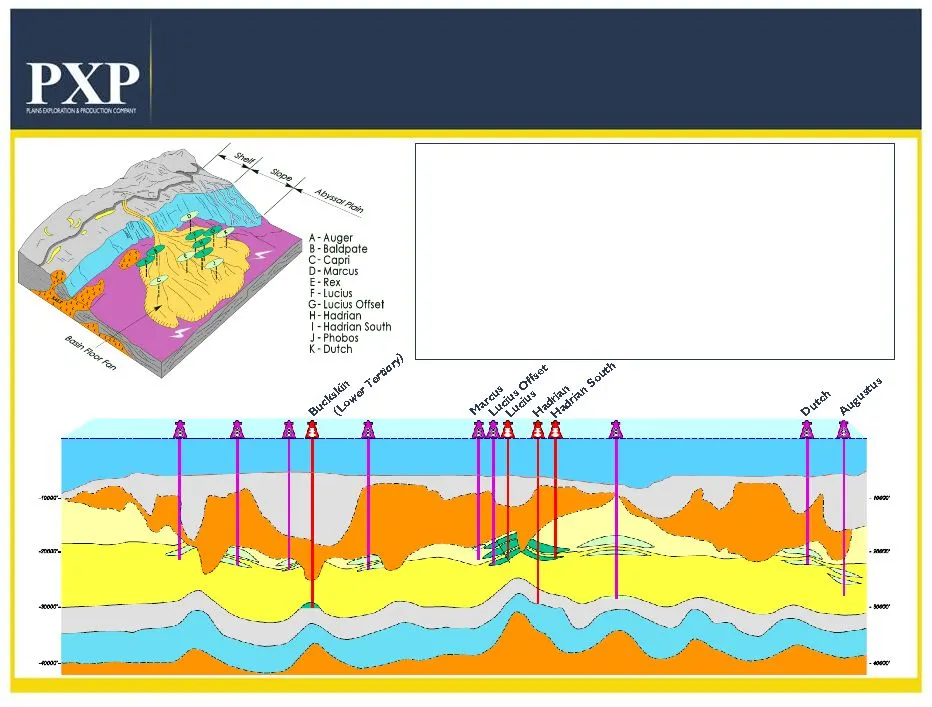
Slide 26: Premium Emerging Pliocene Position
Premium Emerging Pliocene Position Pleistocene Pliocene Miocene Lower Tertiary Cretaceous Jurassic Louann Salt Allochthonous Salt Allochthonous Salt Sea Floor Capri Elba Rex Phobos Pliocene **Figure not to scale** Corsica • Lucius discovery and derisked drilling inventory makes Plains Offshore a lea
Slide 27: Natural Gas Portfolio
Natural Gas Portfolio Projected Dry Gas Scenario at $4.00 Mcf • Closely align Natural Gas focused CapEx with Natural Gas generated operating cash flow at $4.00/Mcf 2012 Projected Operating Cash Flow at $4.00/Mcf Projected Dry Gas Cash Flow $ 143 MM 2012 Projected Capital Allocation at $4.00/Mcf Hayn
Slide 28: 2012 Objectives
2012 Objectives • Strong Quarterly Operating Results • 15%+ Production Growth • Eagle Ford Oil Development Growth Focus • Continue Lucius Oil Development Build Out with Third Party Funding • Drill Phobos Exploration Well with 300+ MMBOE Net Potential
Slide 29: Addendum
Addendum
Slide 30: Updated Hedging Position
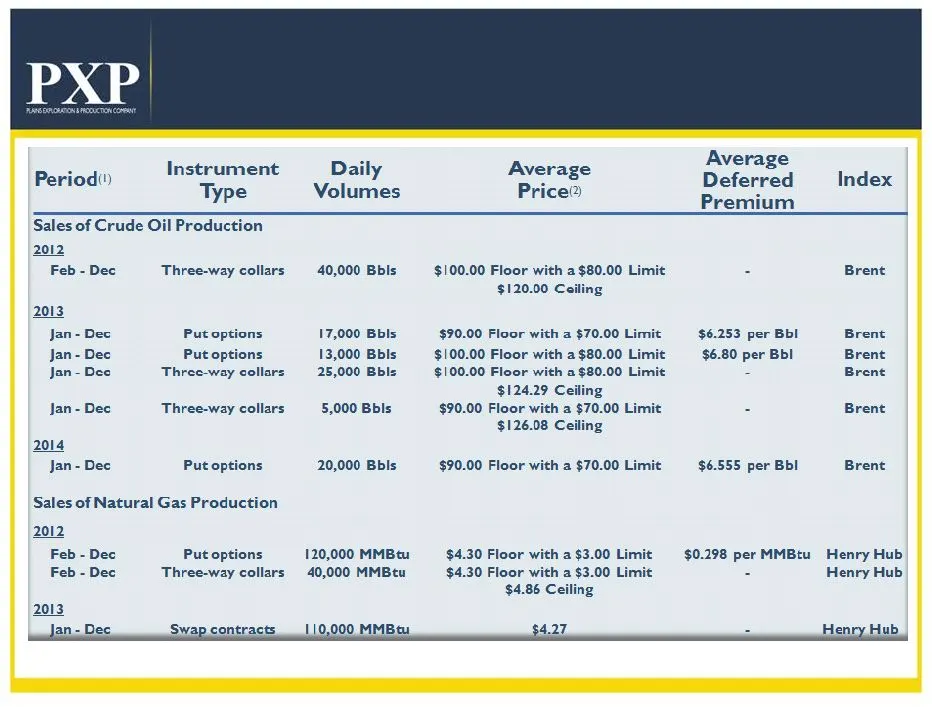
Updated Hedging Position Derivative Instruments (1) All of our derivatives are settled monthly. (2) The average strike price does not reflect the cost to purchase the put options or collars.
Slide 31: 2011 Proved Reserves Reconciliation
2011 Proved Reserves Reconciliation (1) The Reserve Replacement Ratio is an indicator of our ability to replace annual production volume and grow our reserves. It is important to economically find and develop new reserves that will offset produced volumes and provide for future production given the
Slide 32: People building value together to find and produce energy resources
“People building value together to find and produce energy resources safely, reliably and efficiently”
Source: SEC EDGAR · 8-K filed Feb 7, 2012
More decks from Plains Exploration & Production Company
 Global Metals, Mining & Steel Conference 201333 slides · May 14, 2013
 Q1 2013 Earnings Presentation46 slides · Apr 19, 2013
 Merger or Acquisition (February 2013)35 slides · Feb 25, 2013
 2013 Credit Suisse Energy Summit10 slides · Feb 5, 2013
 Merger or Acquisition (January 2013)30 slides · Jan 17, 2013
 Barclays Capital CEO Energy - Power Conference 201132 slides · Sep 6, 2011