Domino's Pizza Group plc · LSE:DOM
Domino's Pizza — Investor Day (November 2016)
132 slides from Domino's Pizza's investor day presentation, Nov 24, 2016
Slide 1: Capital Markets Day
Capital Markets Day 24th November 2016
Slide 2: Forward looking statements caution
Forward looking statements caution These 2016 Interim Results, our Annual Results, our Annual Report and the Domino’s Pizza website may contain certain "forward-looking statements" with respect to Domino’s Pizza Group plc and the Group's financial condition, results of operations and business, and c
Slide 3: Welcome
Welcome David Wild Chief Executive Officer
Slide 4: Objectives of the day
Objectives of the day • Introduce the team • UK and business potential • Technology update • International overview
Slide 5: Leadership team
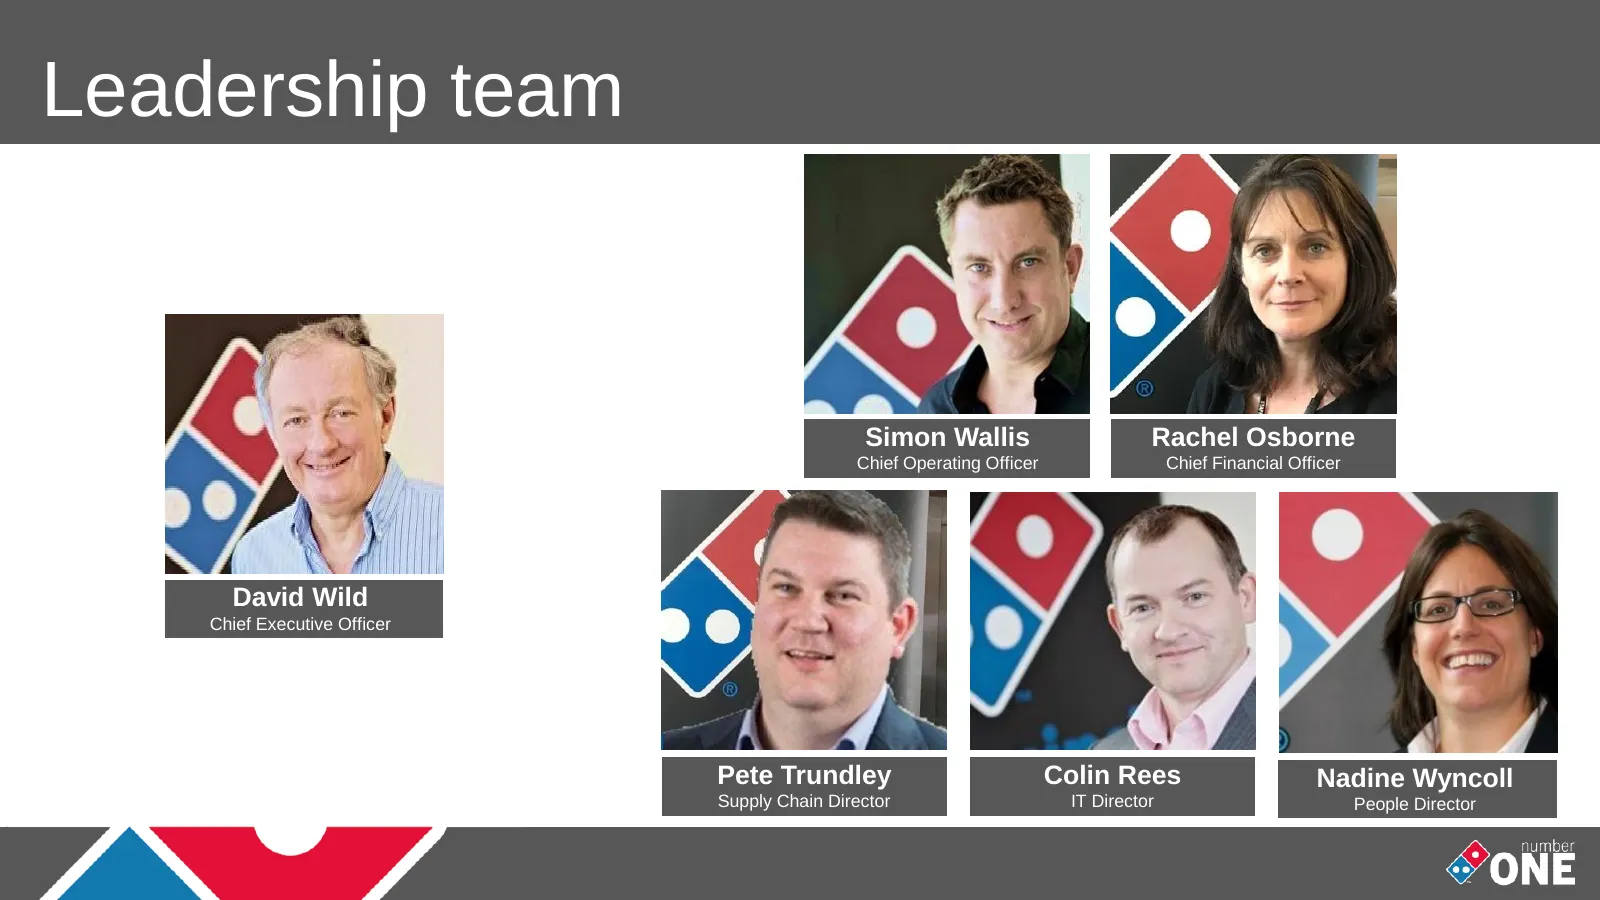
Leadership team Simon Wallis Rachel Osborne Chief Operating Officer Chief Financial Officer David Wild Chief Executive Officer Pete Trundley Colin Rees Nadine Wyncoll Supply Chain Director IT Director People Director
Slide 6: Leadership team
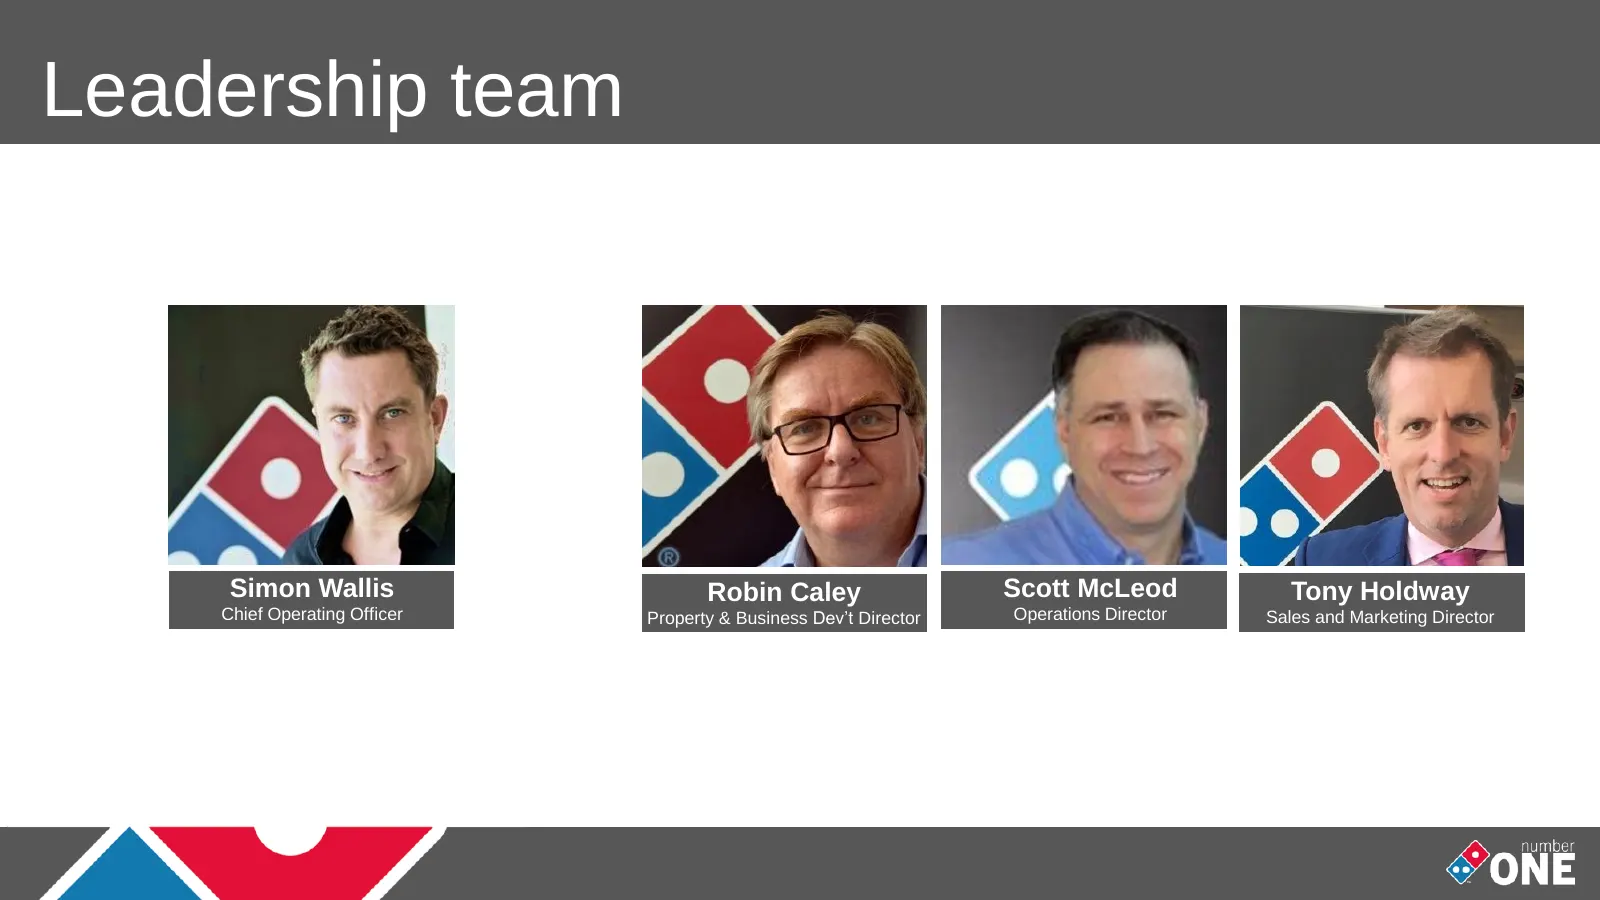
Leadership team Simon Wallis Robin Caley Scott McLeod Tony Holdway Chief Operating Officer Property & Business Dev’t Director Operations Director Sales and Marketing Director
Slide 7: Leadership team
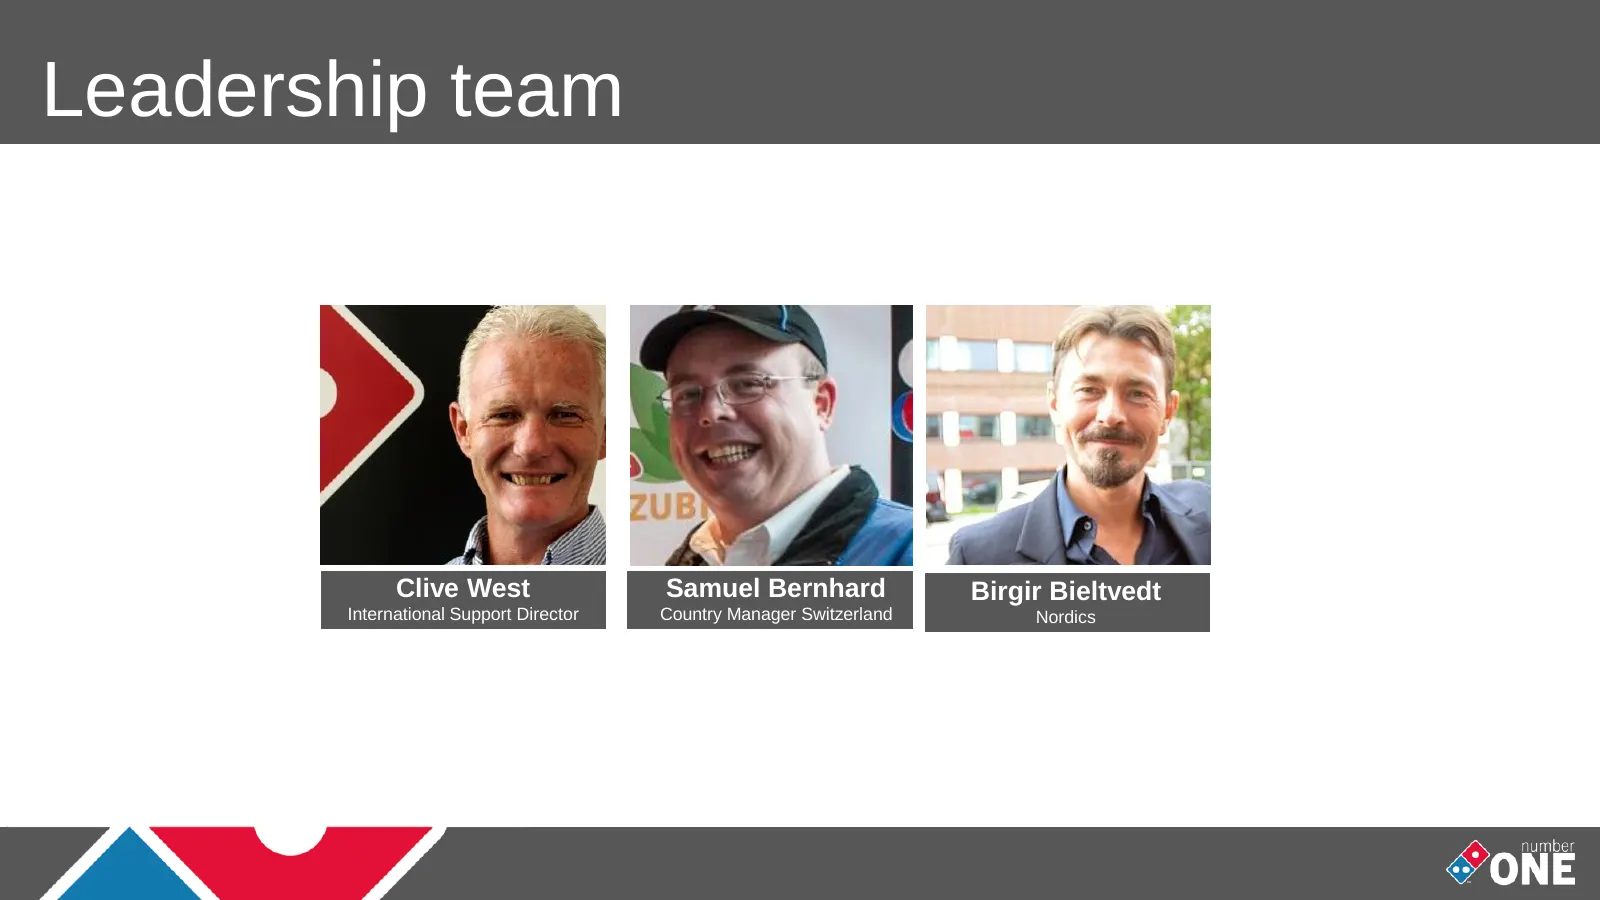
Leadership team Clive West Samuel Bernhard Birgir Bieltvedt International Support Director Country Manager Switzerland Nordics
Slide 8: Agenda
Agenda Introduction UK Business Store Growth Potential Leading Technology Break Supply Chain Franchise Model International Q&A Drinks
Slide 9: Enjoying pizza
Enjoying pizza
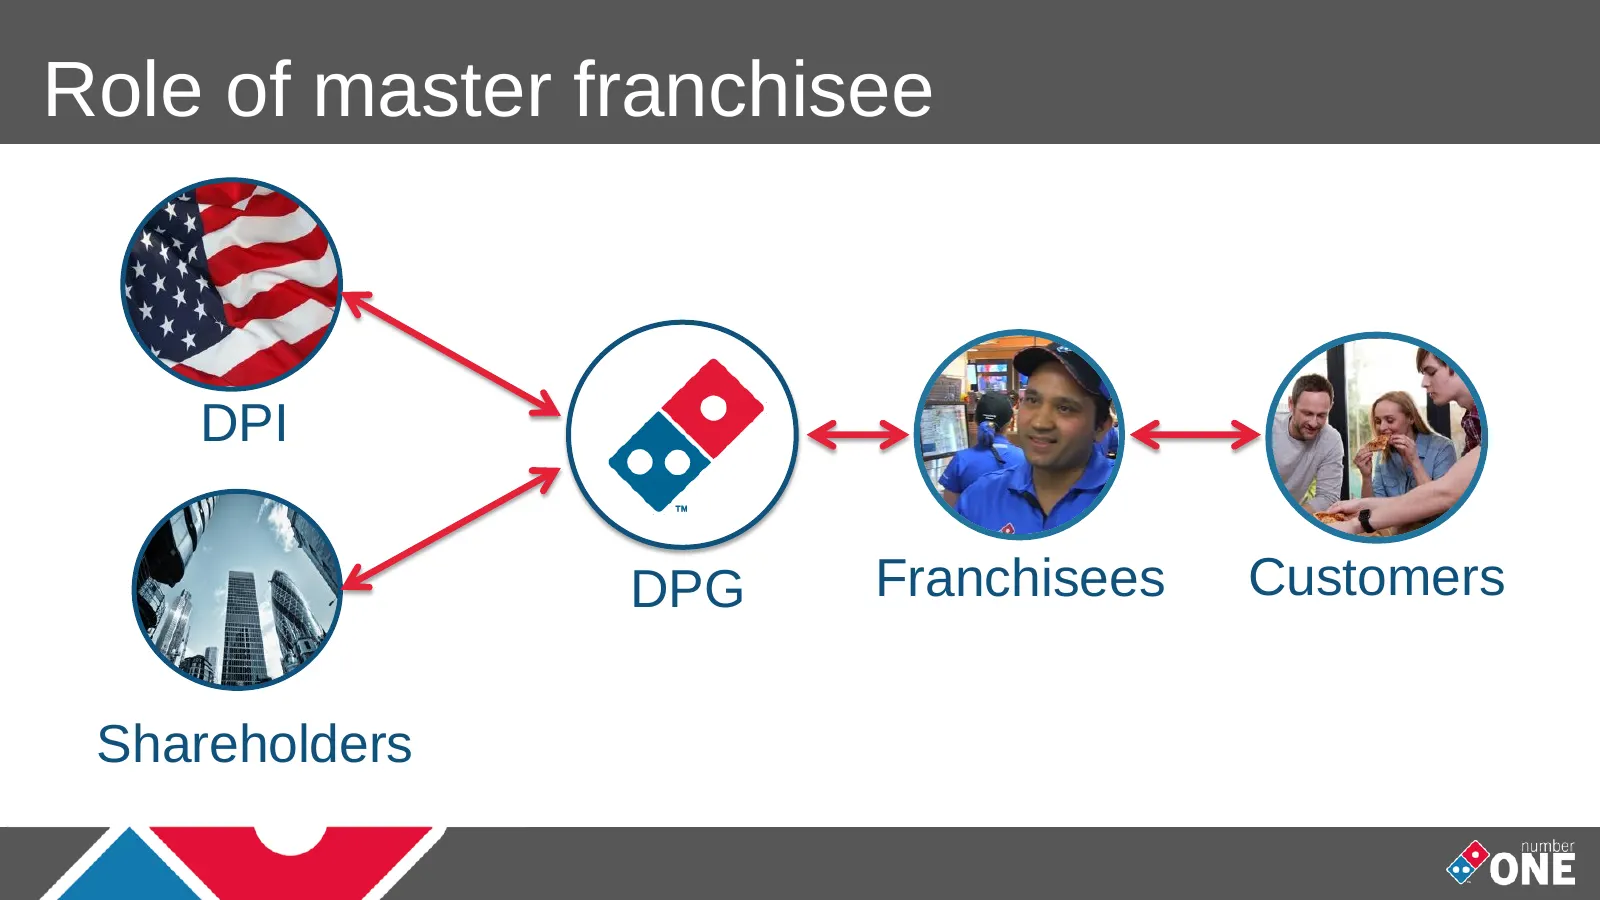
Slide 10: Role of master franchisee
Role of master franchisee DPI DPG Franchisees Customers Shareholders
Slide 11: Be the #1 pizza company
J, C BE THE #1 PIZZA COMPANY IN Tile WORLD ae IN EVERY NEIGHBOURHOOD fn” Sf
Slide 12: AN
AN
Slide 13
Slide 14: DPG | Who we are
DPG | Who we are Culture Who are we? Domino’s Pizza • Ambitious & proud What are we? • Entrepreneurial Number One • Fast-paced What’s our goal? • Dynamic Sell more pizza, have more fun!! • Fun
Slide 15: UK Business
UK Business Simon Wallis Chief Operating Officer
Slide 16: AN
AN
Slide 17
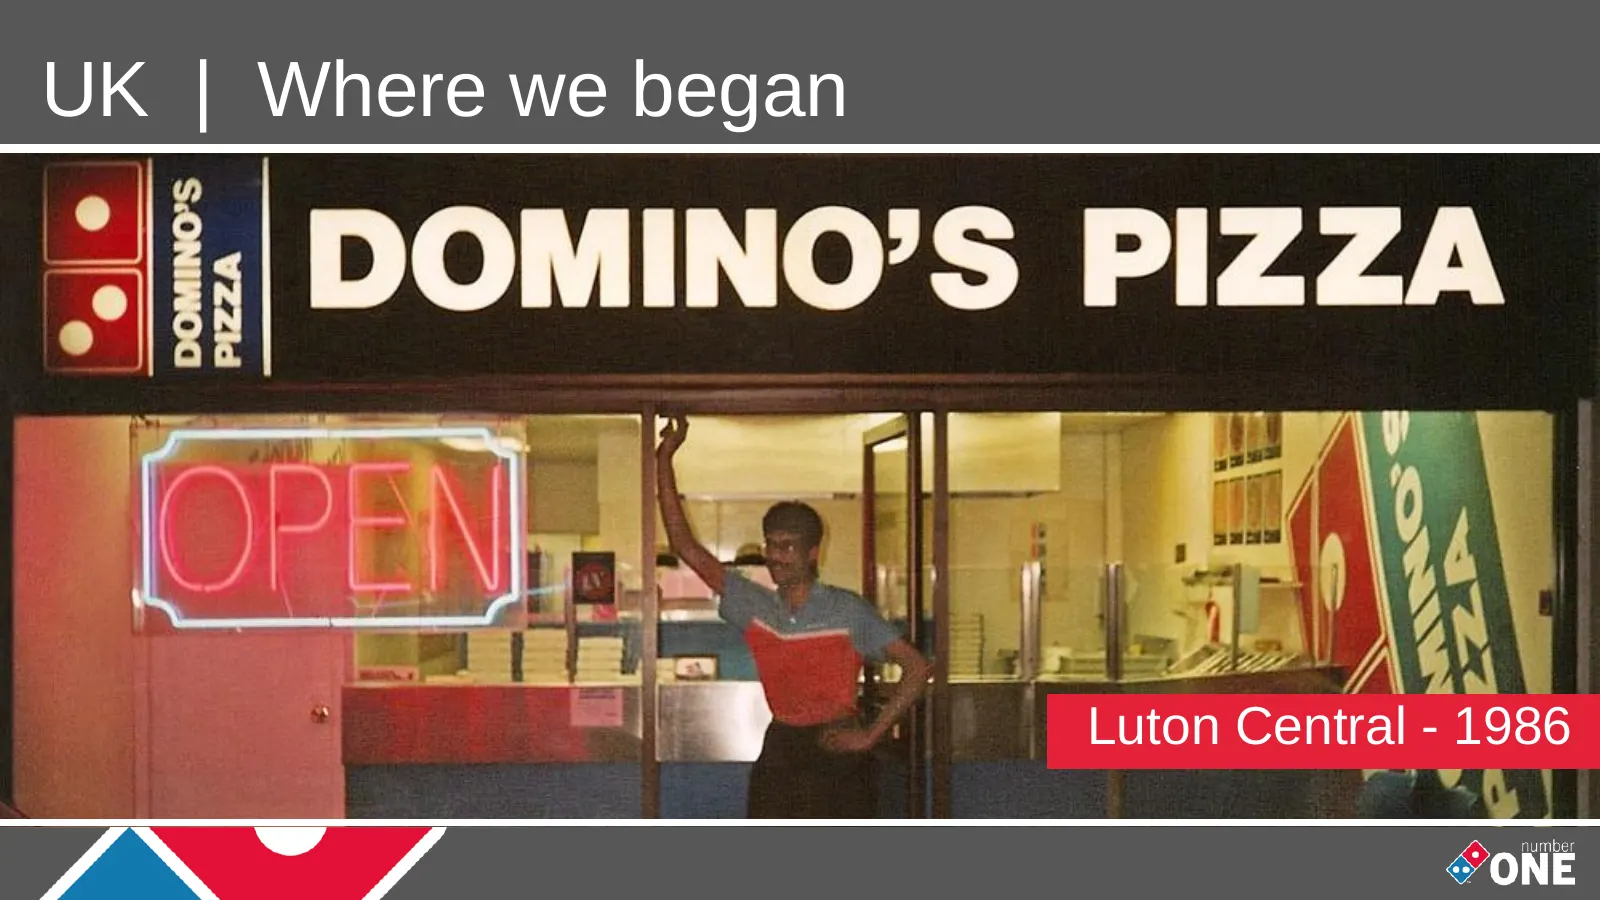
Slide 18: UK | Where we began
UK | Where we began Luton Central - 1986
Slide 19: UK | The brand that Homer built
UK | The brand that Homer built 1998 - 2008
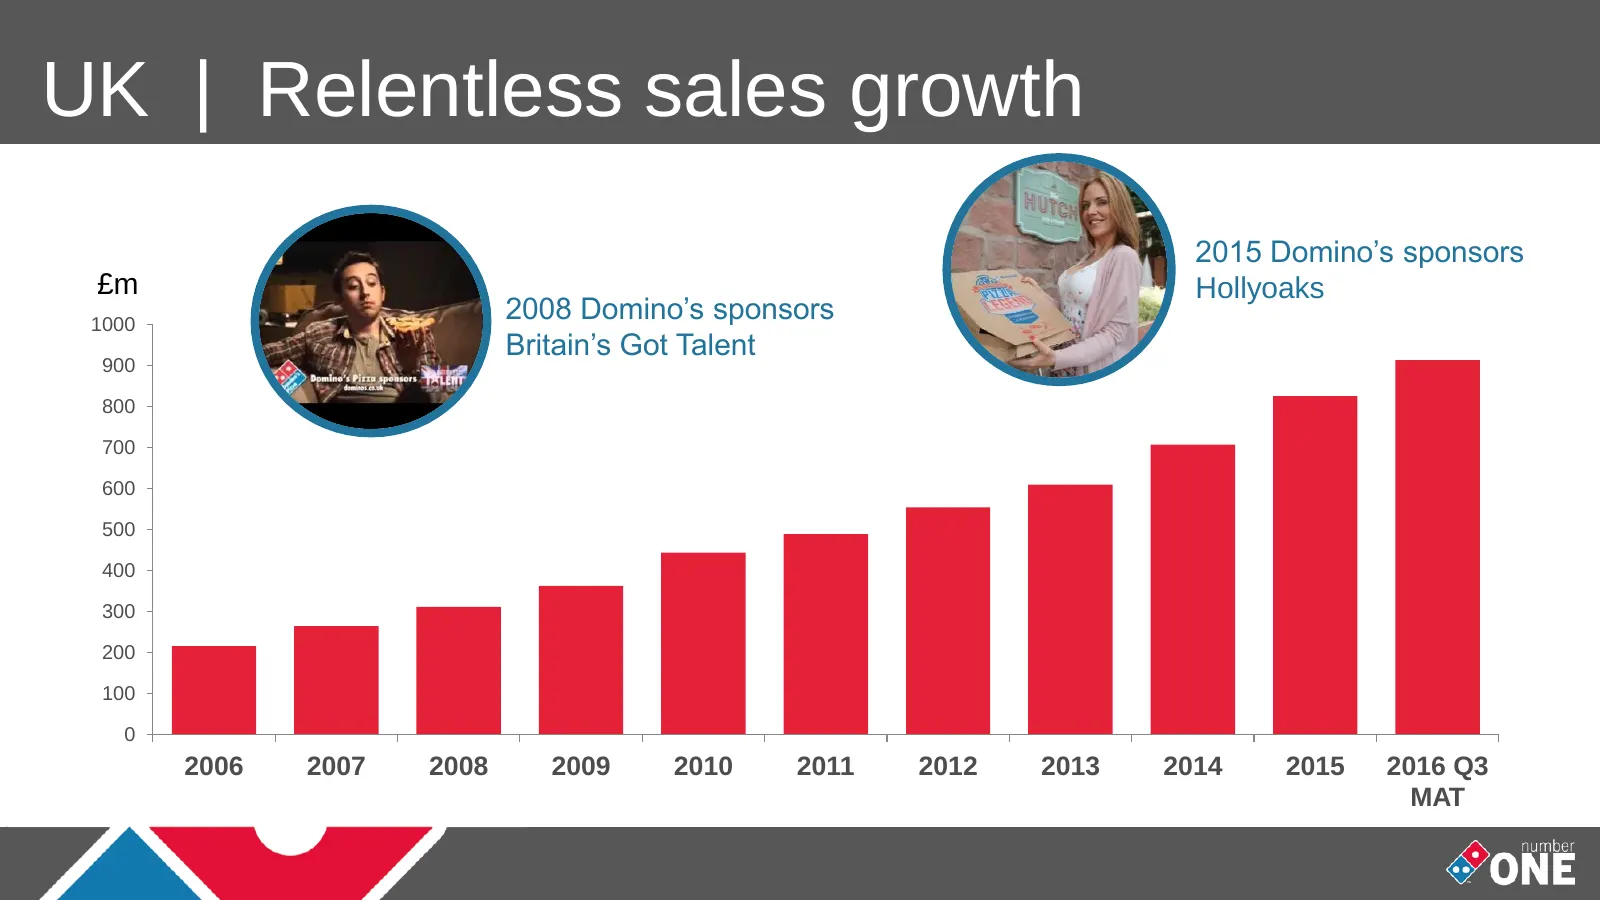
Slide 20: UK | Relentless sales growth
UK | Relentless sales growth 2015 Domino’s sponsors £m Hollyoaks 1000 2008 Domino’s sponsors Britain’s Got Talent 900 800 700 600 500 400 300 200 100 0 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Q3 MAT
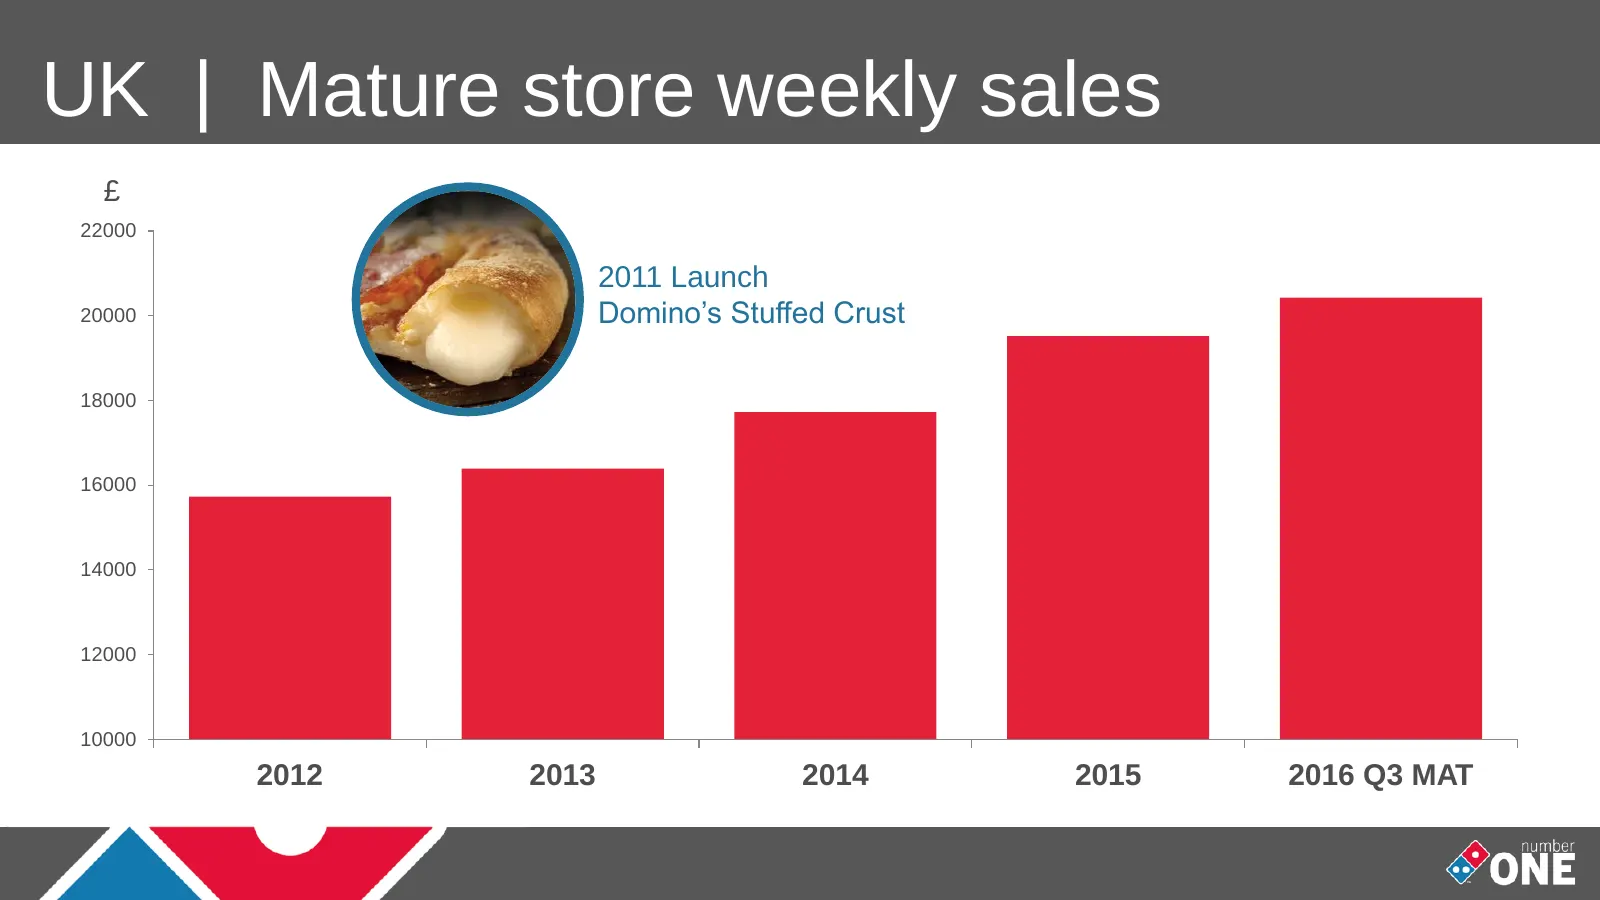
Slide 21: UK | Mature store weekly sales
UK | Mature store weekly sales £ 22000 2011 Launch 20000 Domino’s Stuffed Crust 18000 16000 14000 12000 10000 2012 2013 2014 2015 2016 Q3 MAT
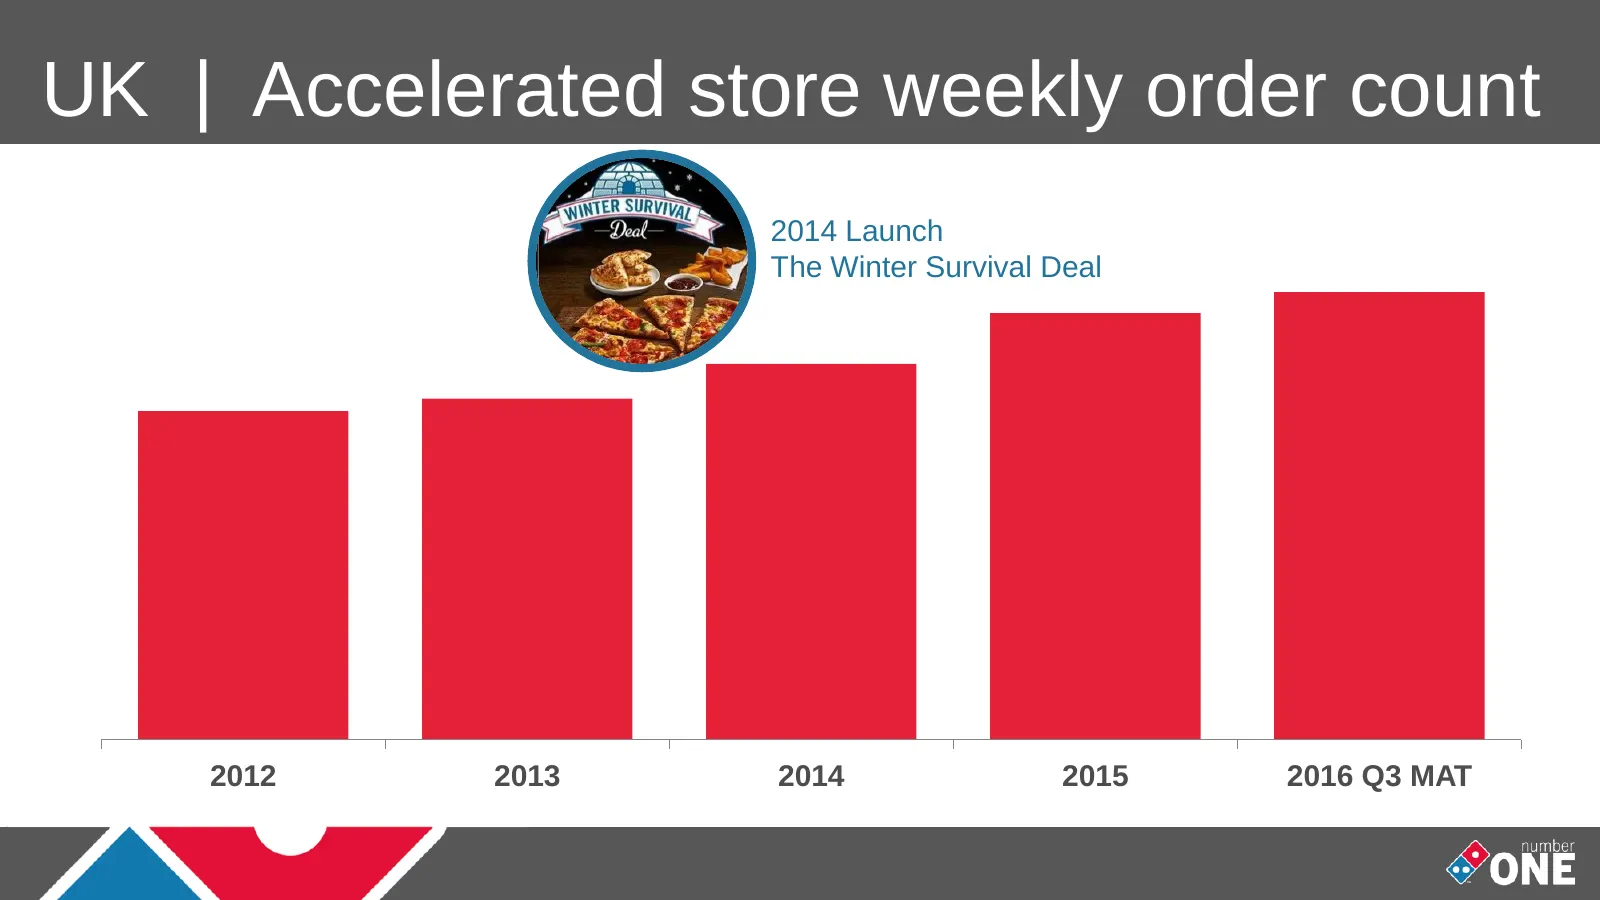
Slide 22: UK | Accelerated store weekly order count
UK | Accelerated store weekly order count 2014 Launch The Winter Survival Deal 2012 2013 2014 2015 2016 Q3 MAT
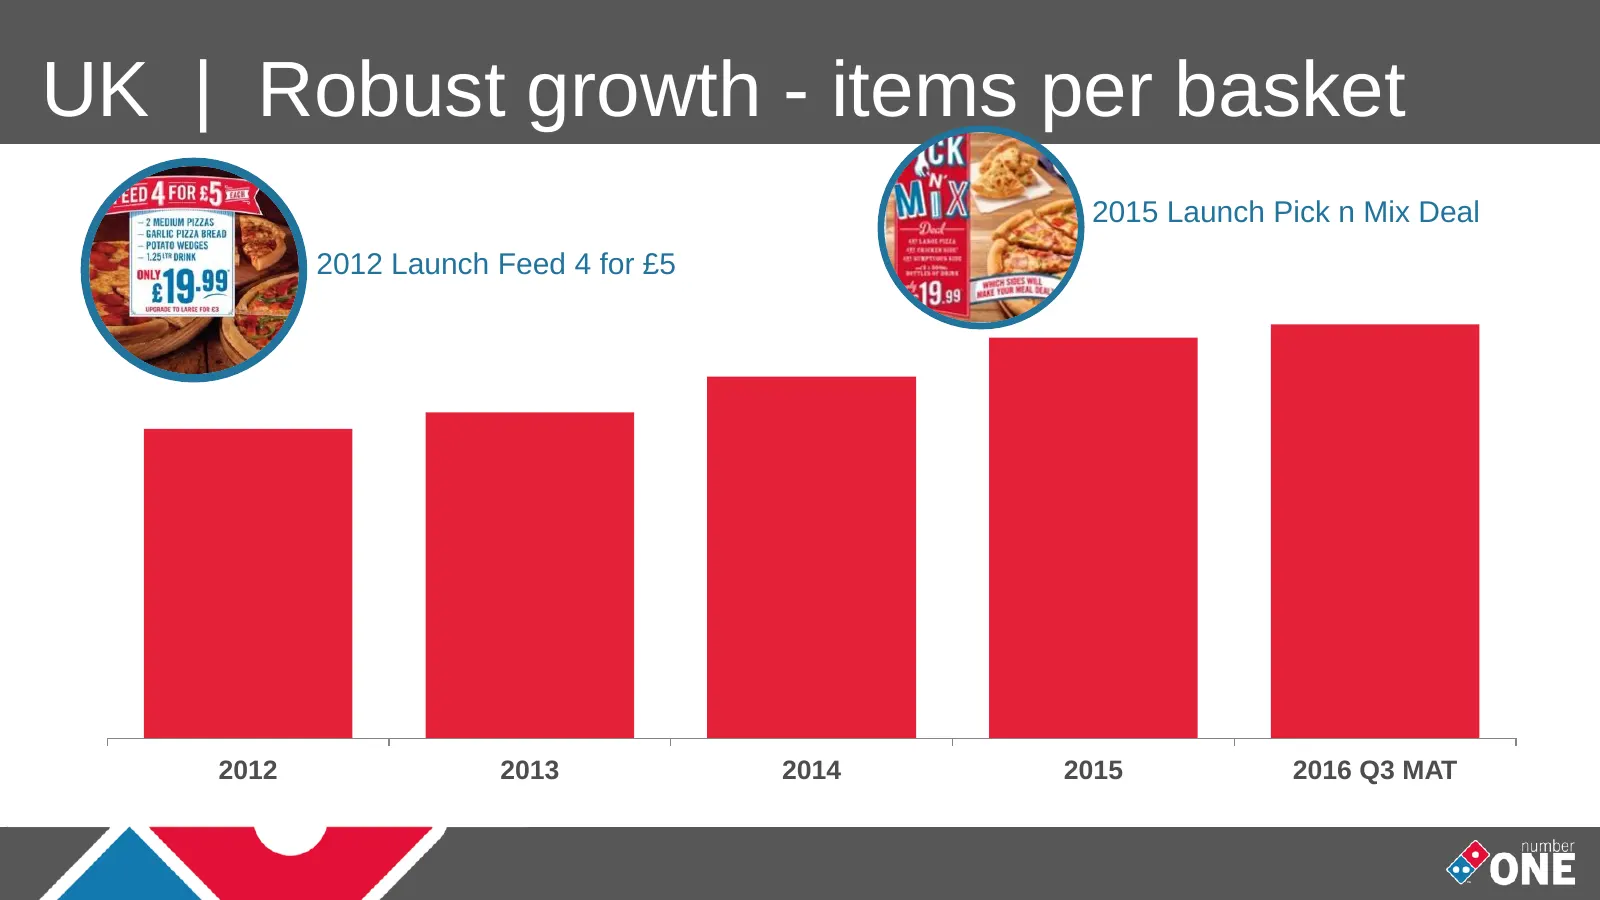
Slide 23: UK | Robust growth - items per basket
UK | Robust growth - items per basket 2015 Launch Pick n Mix Deal 2012 Launch Feed 4 for £5 2012 2013 2014 2015 2016 Q3 MAT
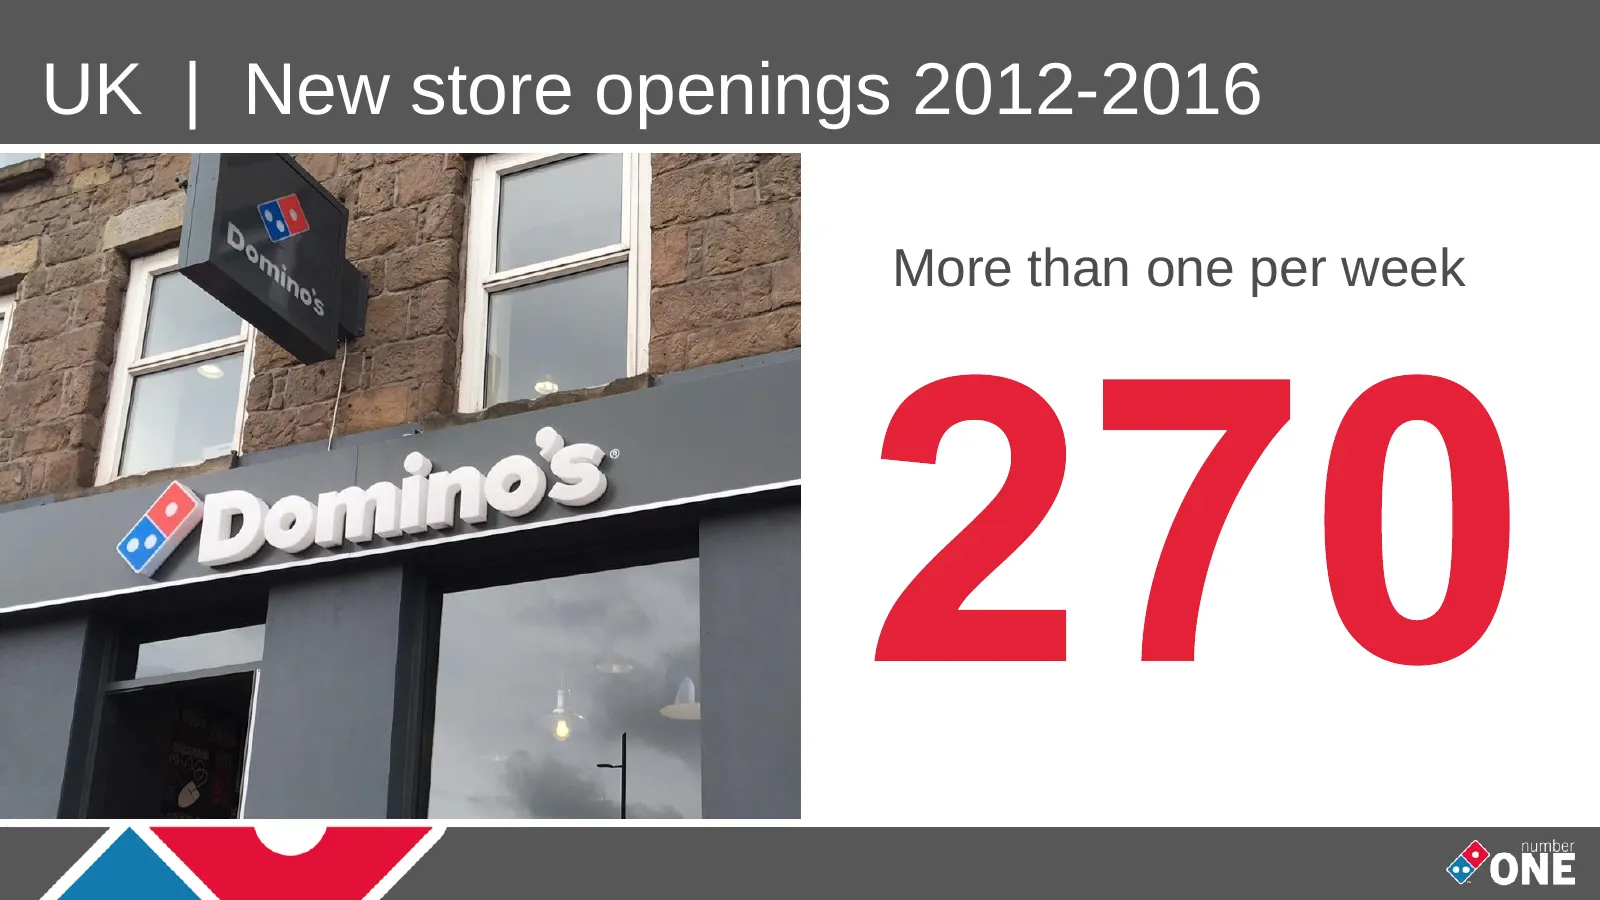
Slide 24: UK | New store openings 2012-2016
UK | New store openings 2012-2016 More than one per week
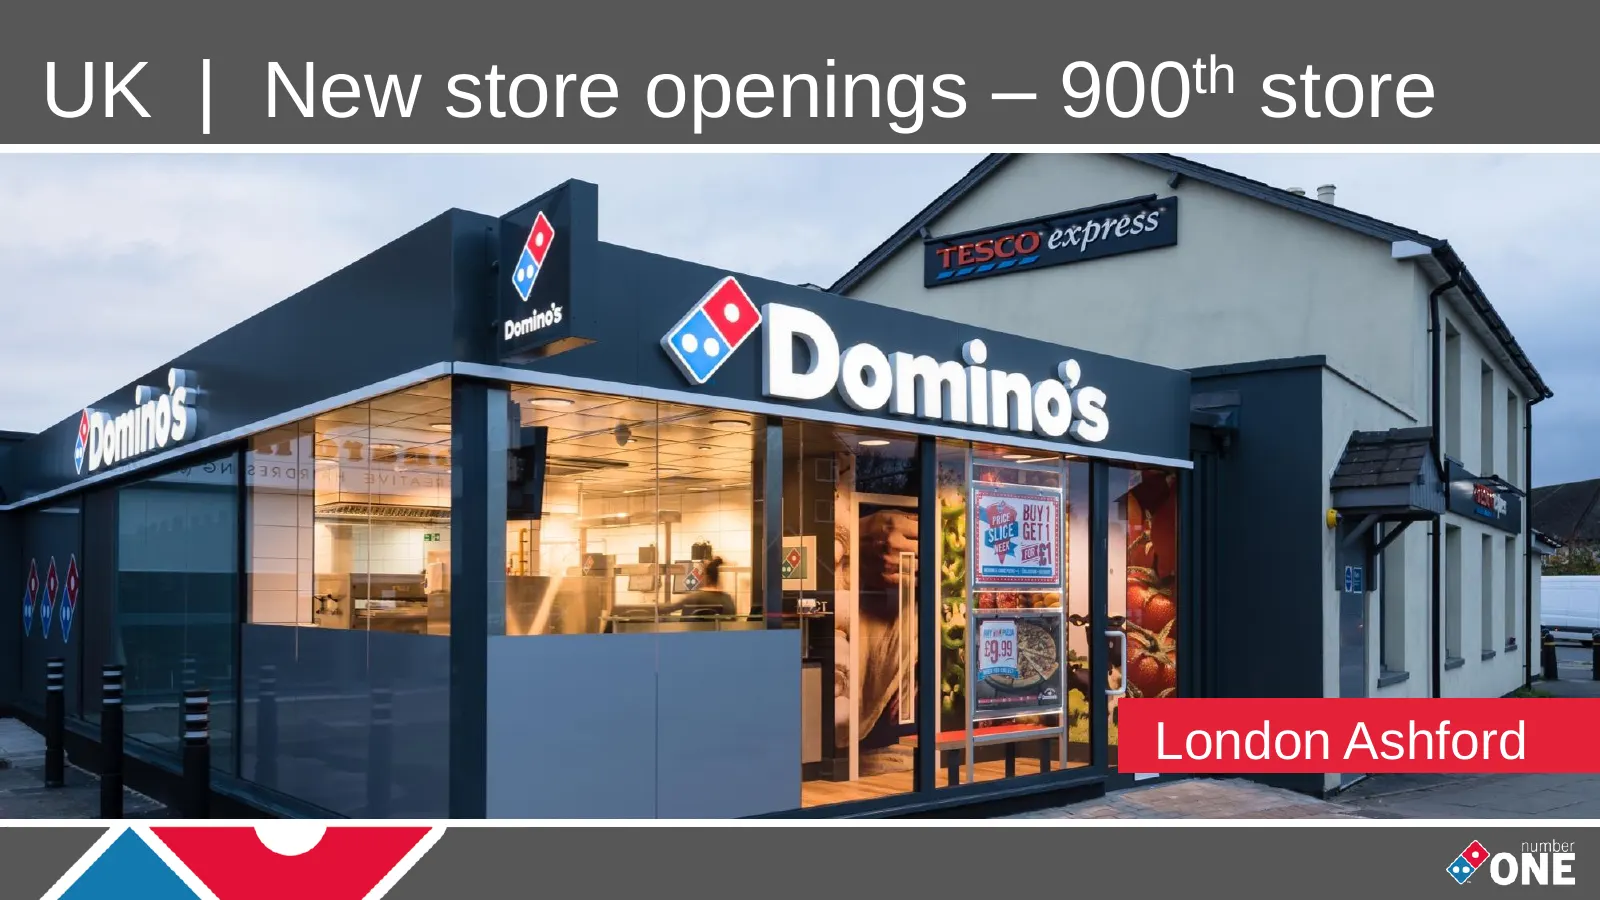
Slide 25: New store openings – 900th store
UK | New store openings – 900 store th London Ashford
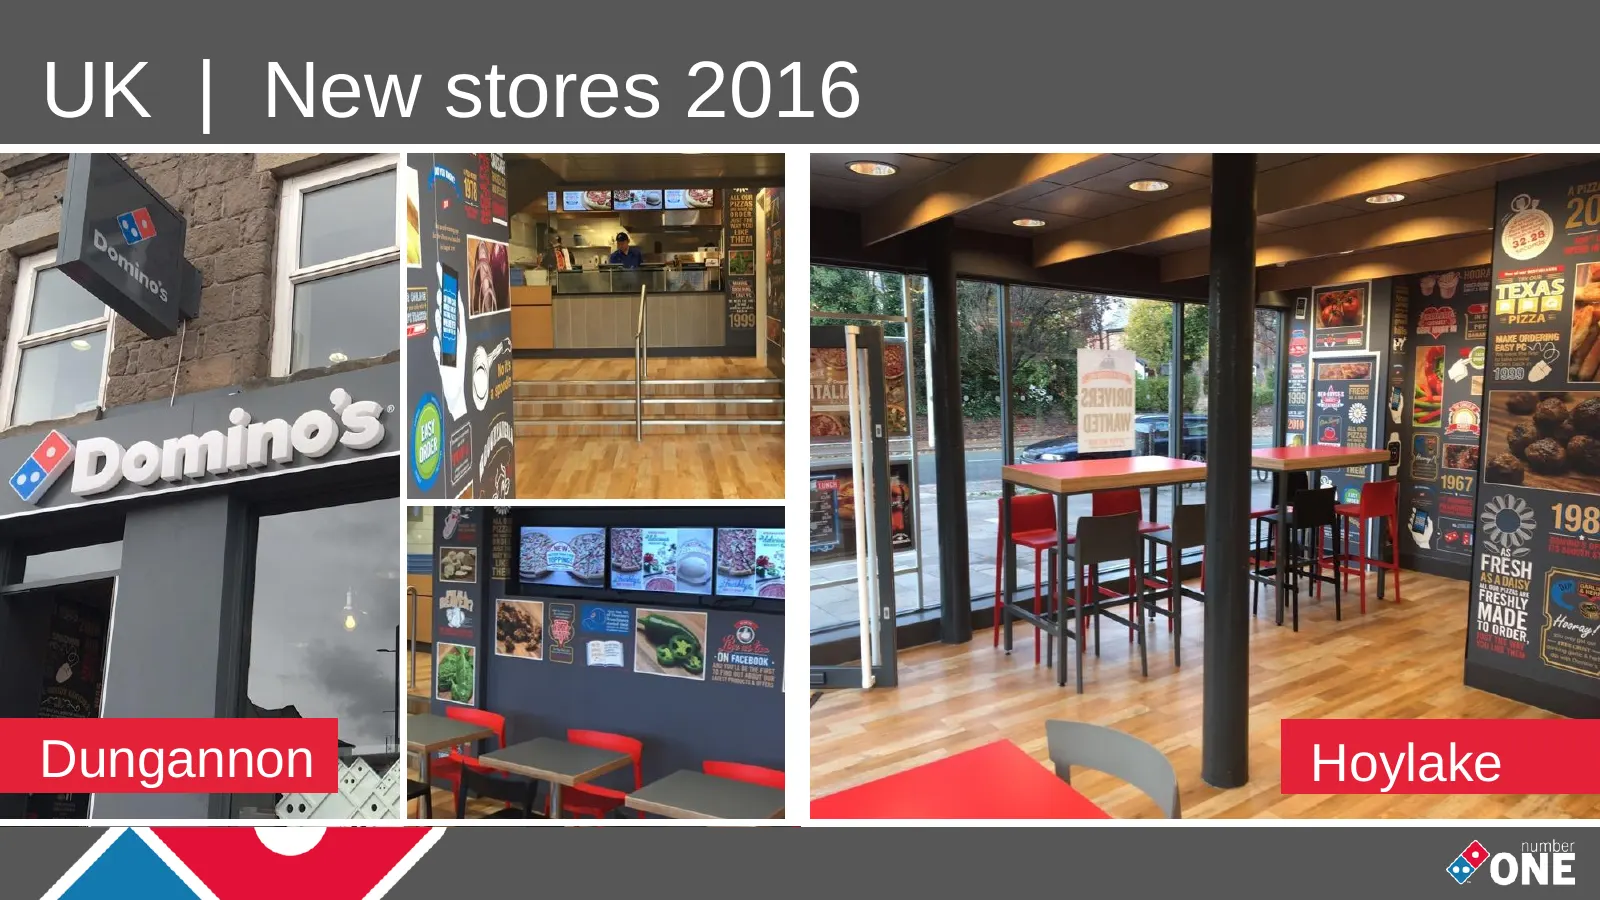
Slide 26: UK | New stores 2016
UK | New stores 2016 La 80test Delco Dungannon Hoylake
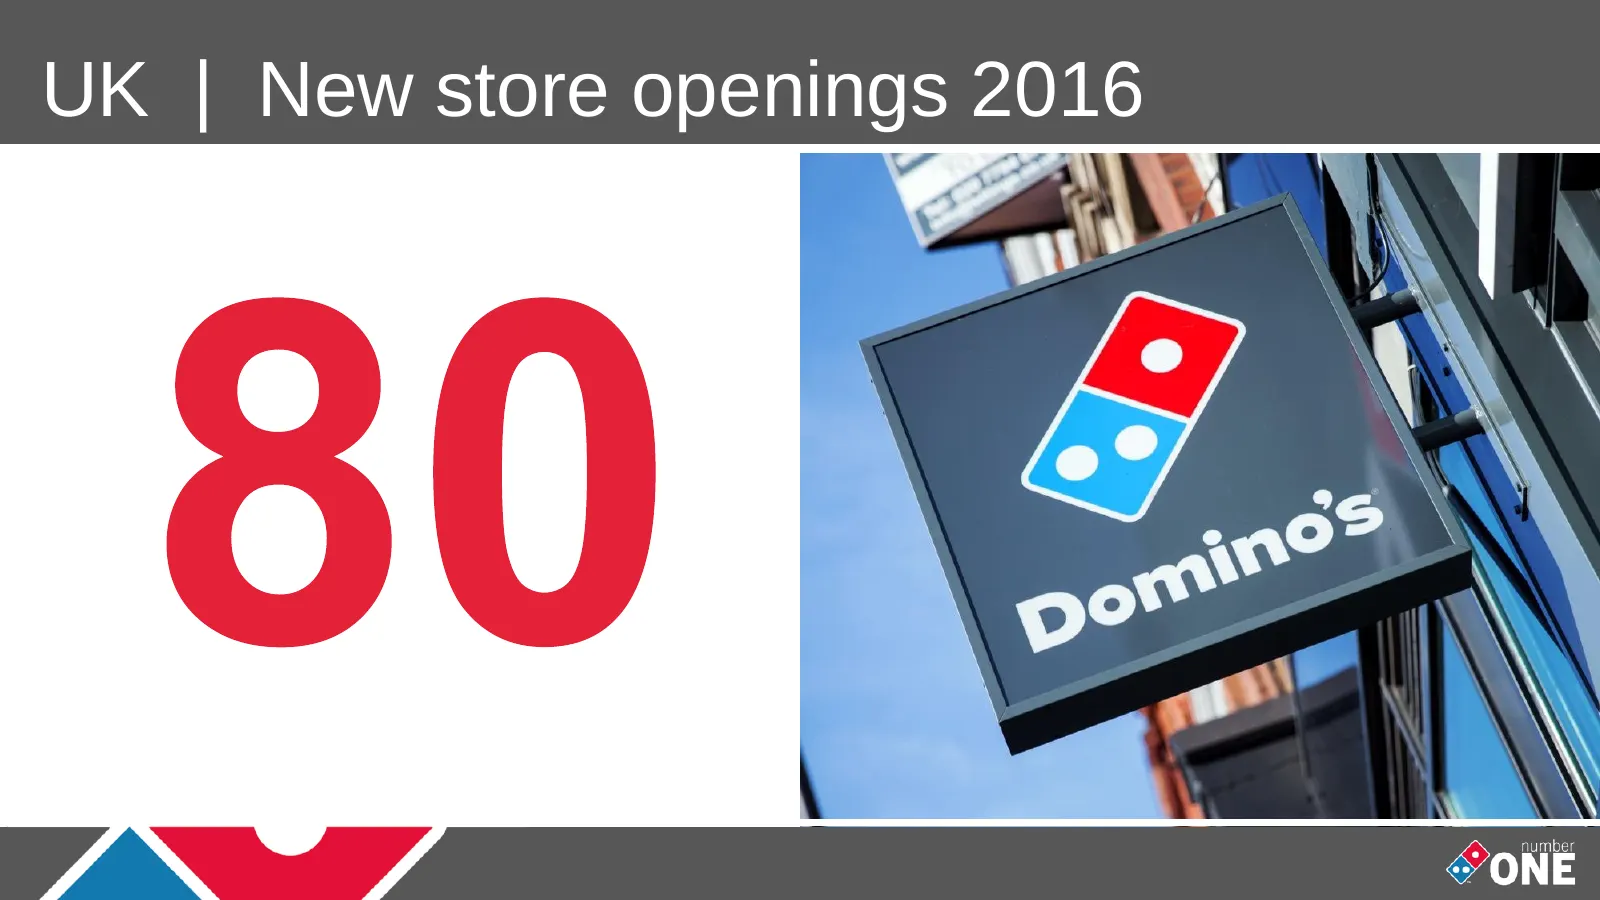
Slide 27: UK | New store openings 2016
UK | New store openings 2016
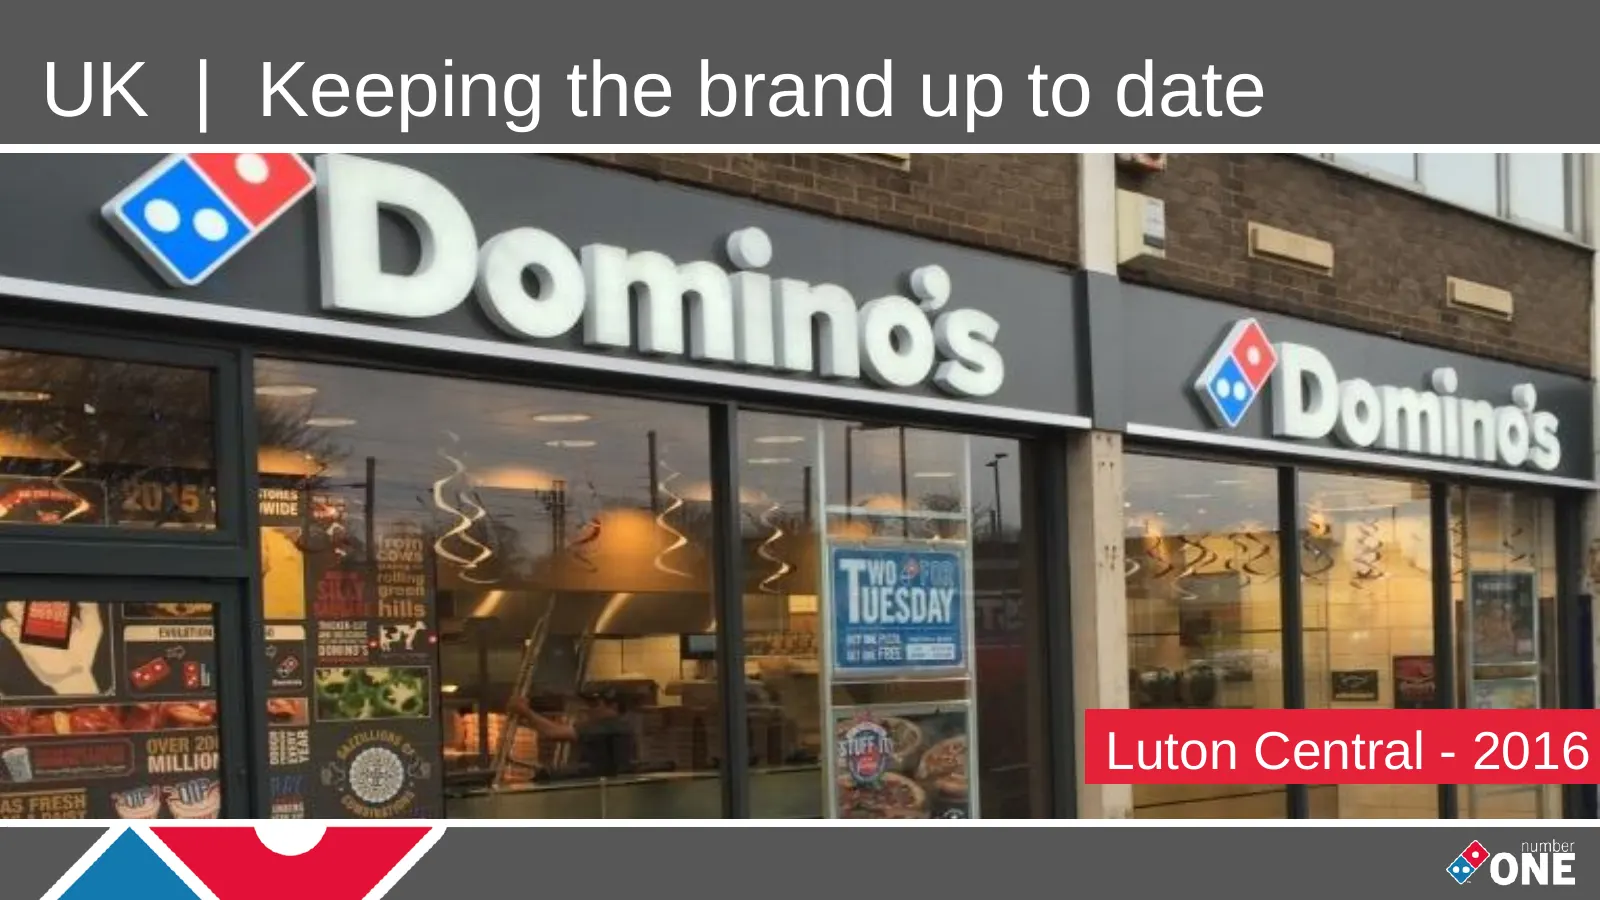
Slide 28: UK | Keeping the brand up to date
UK | Keeping the brand up to date Luton Central - 2016
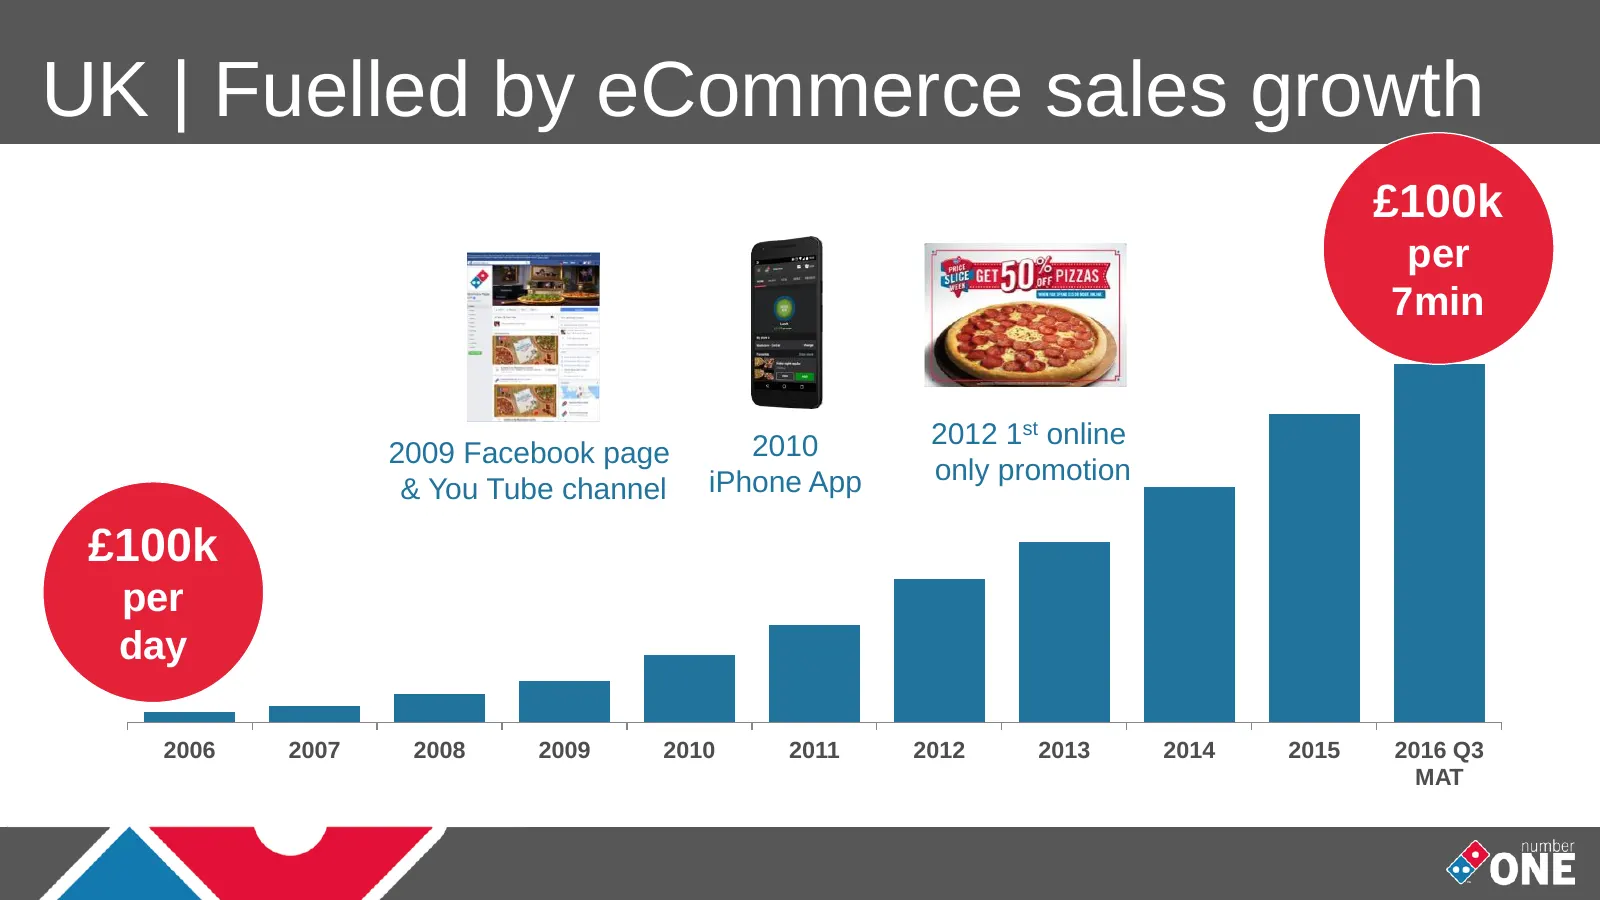
Slide 29: UK | Fuelled by eCommerce sales growth
UK | Fuelled by eCommerce sales growth £100k per 7min 2010 2012 1st online 2009 Facebook page iPhone App only promotion & You Tube channel £100k per day 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Q3 MAT
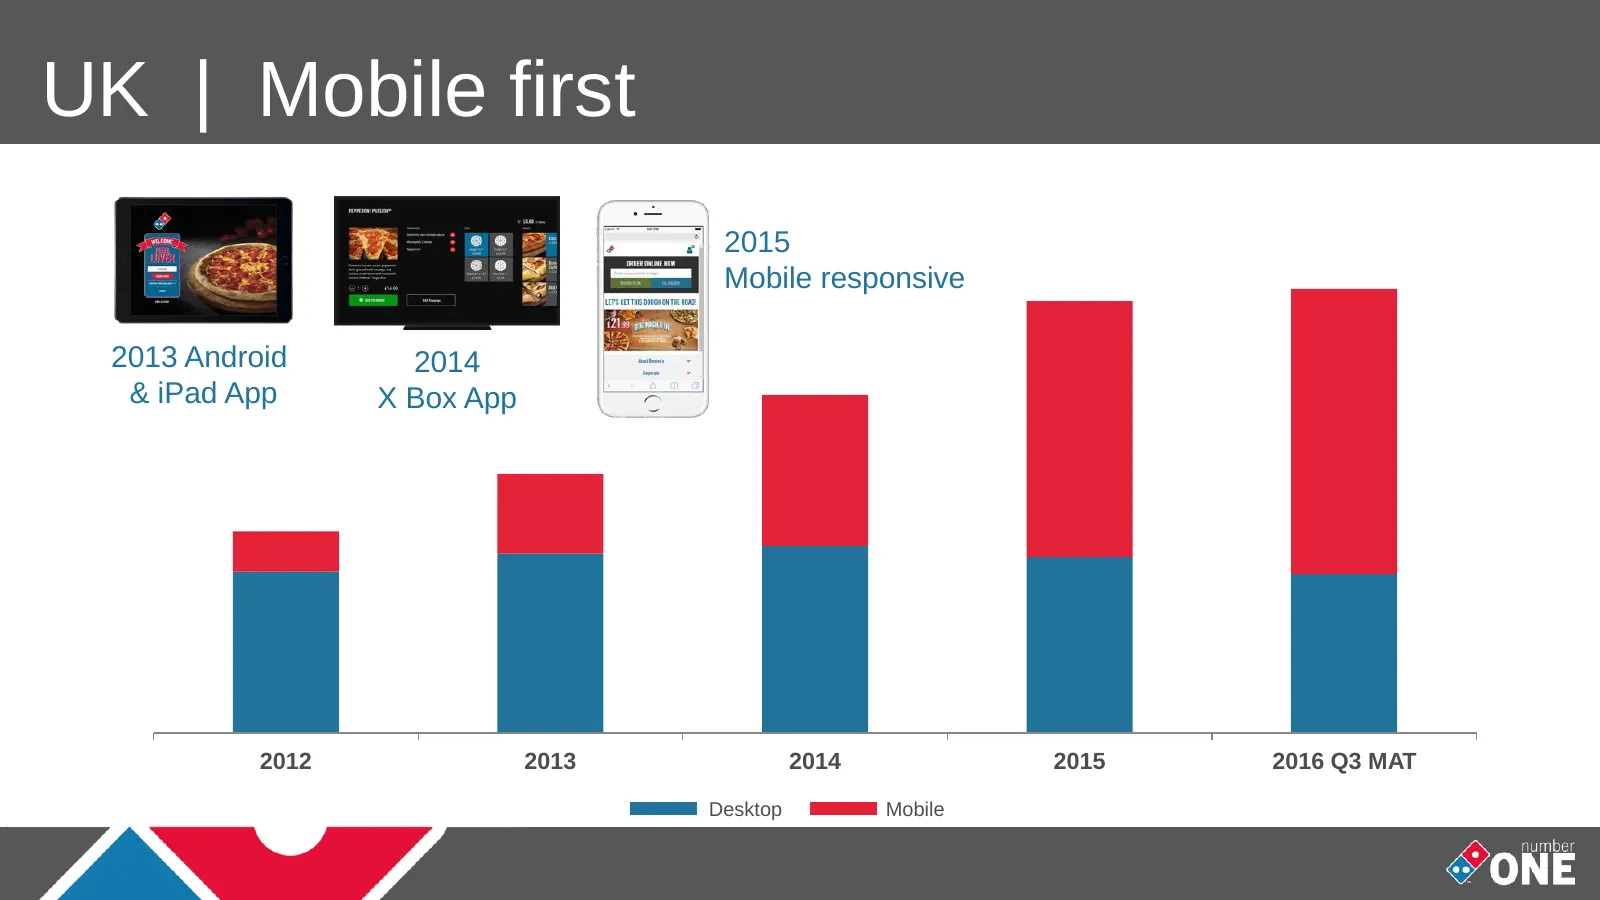
Slide 30: UK | Mobile first
UK | Mobile first 2015 Mobile responsive 2013 Android 2014 & iPad App X Box App 2012 2013 2014 2015 2016 Q3 MAT Desktop Mobile
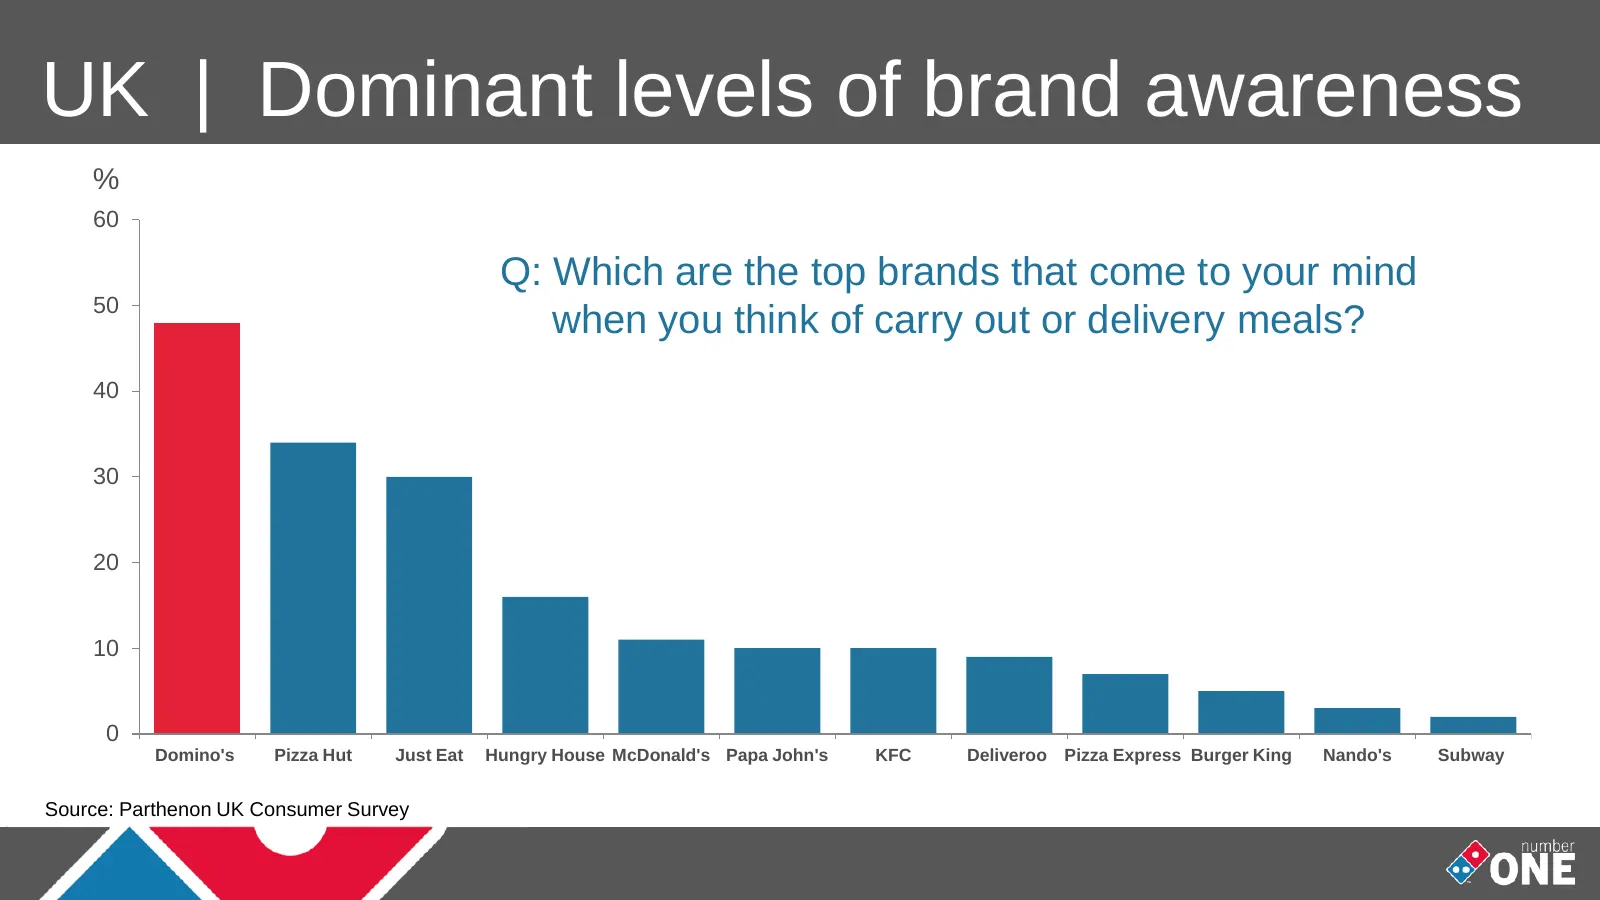
Slide 31: UK | Dominant levels of brand awareness
UK | Dominant levels of brand awareness % 60 Q: Which are the top brands that come to your mind 50 when you think of carry out or delivery meals? 40 30 20 10 0 Domino's Pizza Hut Just Eat Hungry House McDonald's Papa John's KFC Deliveroo Pizza Express Burger King Nando's Subway Source: Parthenon UK
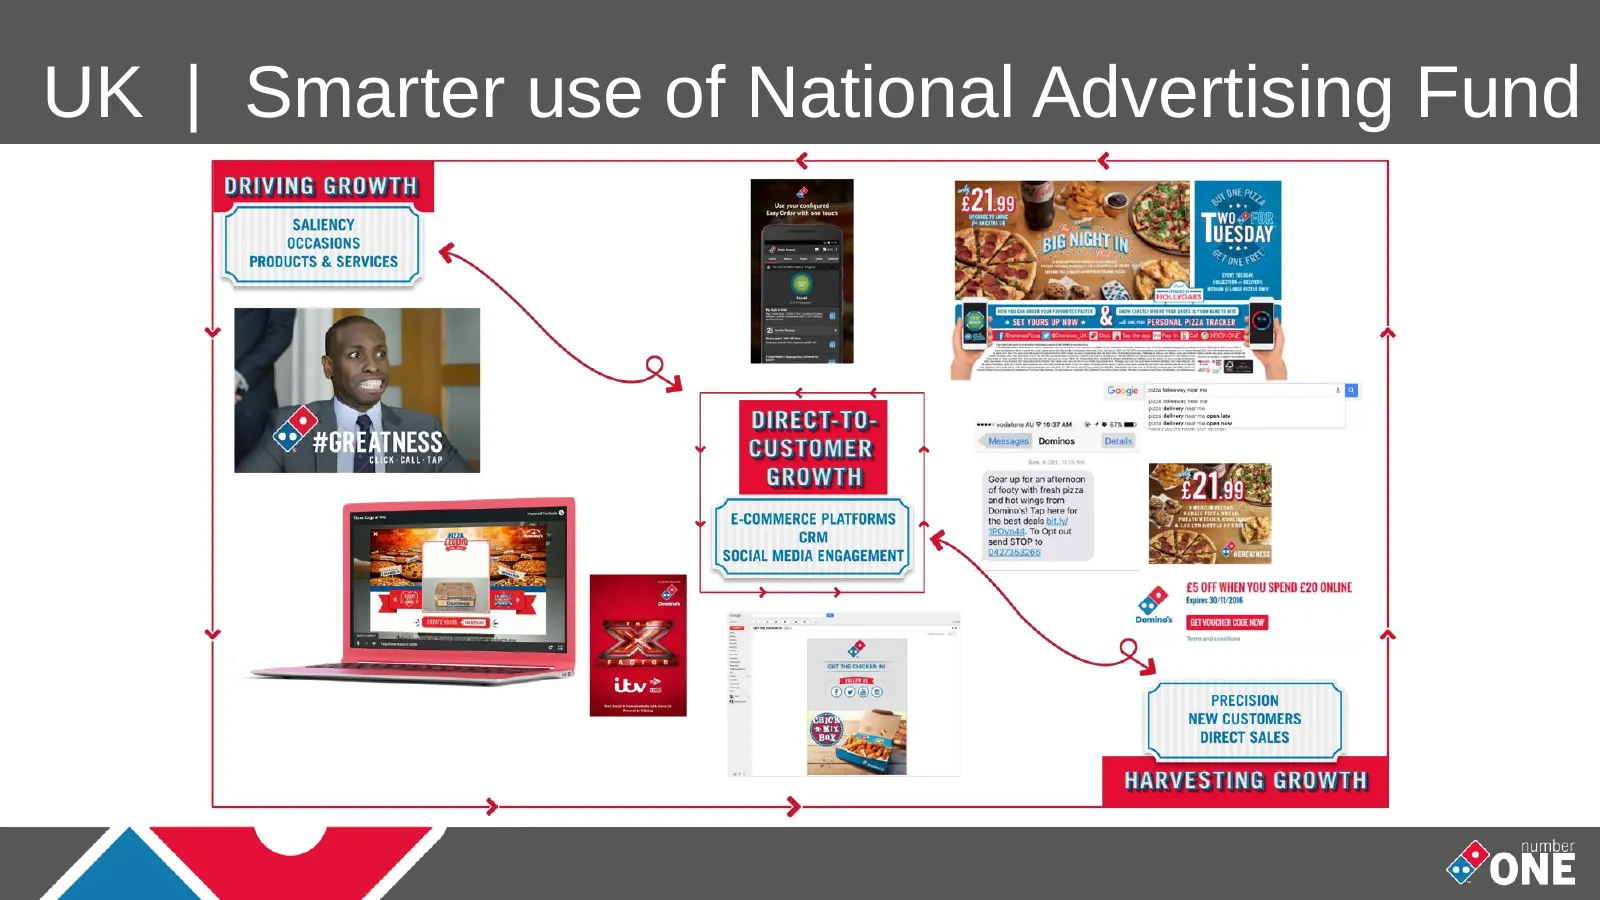
Slide 32: UK | Smarter use of National Advertising Fund
UK | Smarter use of National Advertising Fund
Slide 33: UK | Drivers of choice
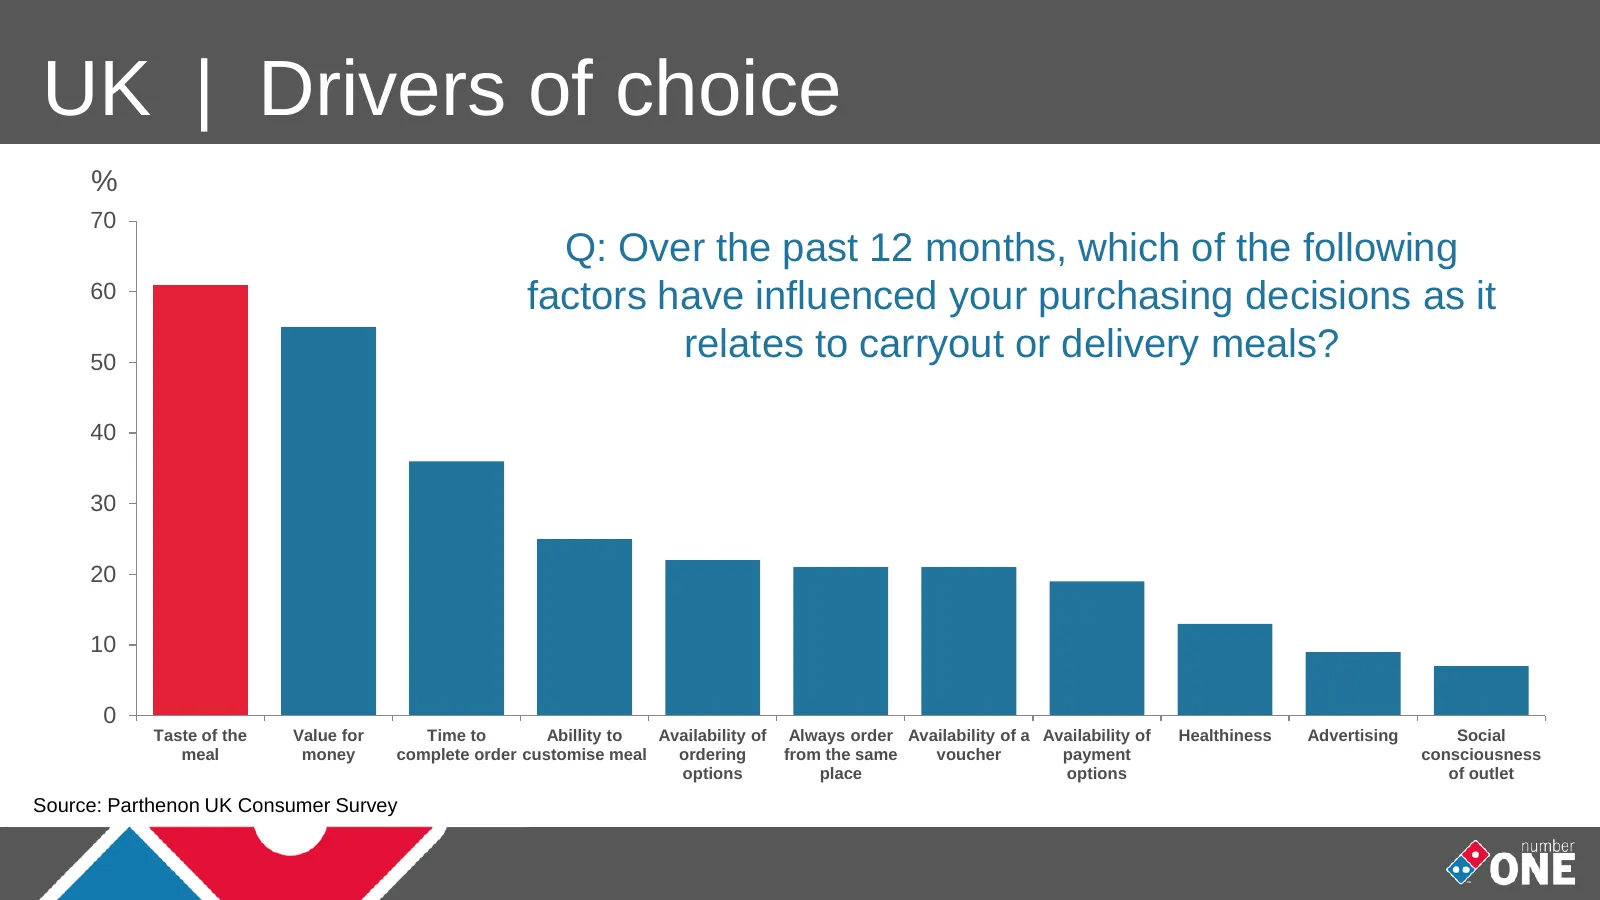
UK | Drivers of choice % 70 Q: Over the past 12 months, which of the following 60 factors have influenced your purchasing decisions as it 50 relates to carryout or delivery meals? 40 30 20 10 0 Taste of the Value for Time to Abillity to Availability of Always order Availability of a Availability of
Slide 34: UK | New product innovation
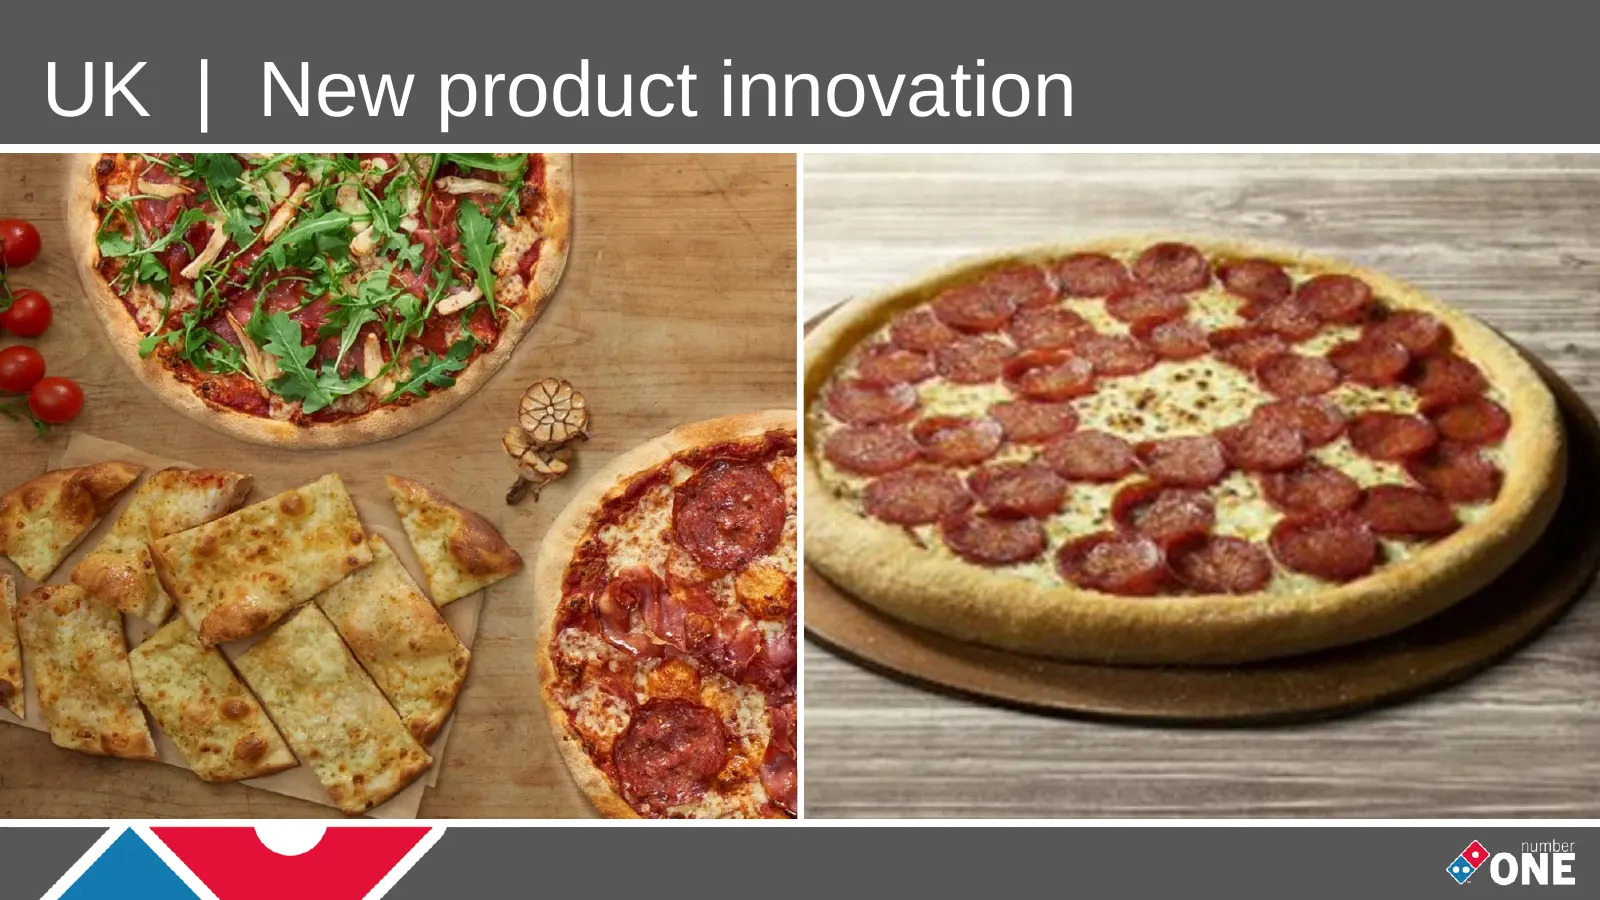
UK | New product innovation # 902. ¢ a SaBe i Spee a Fae Pe \i a aS =
Slide 35: UK | Our customer promise
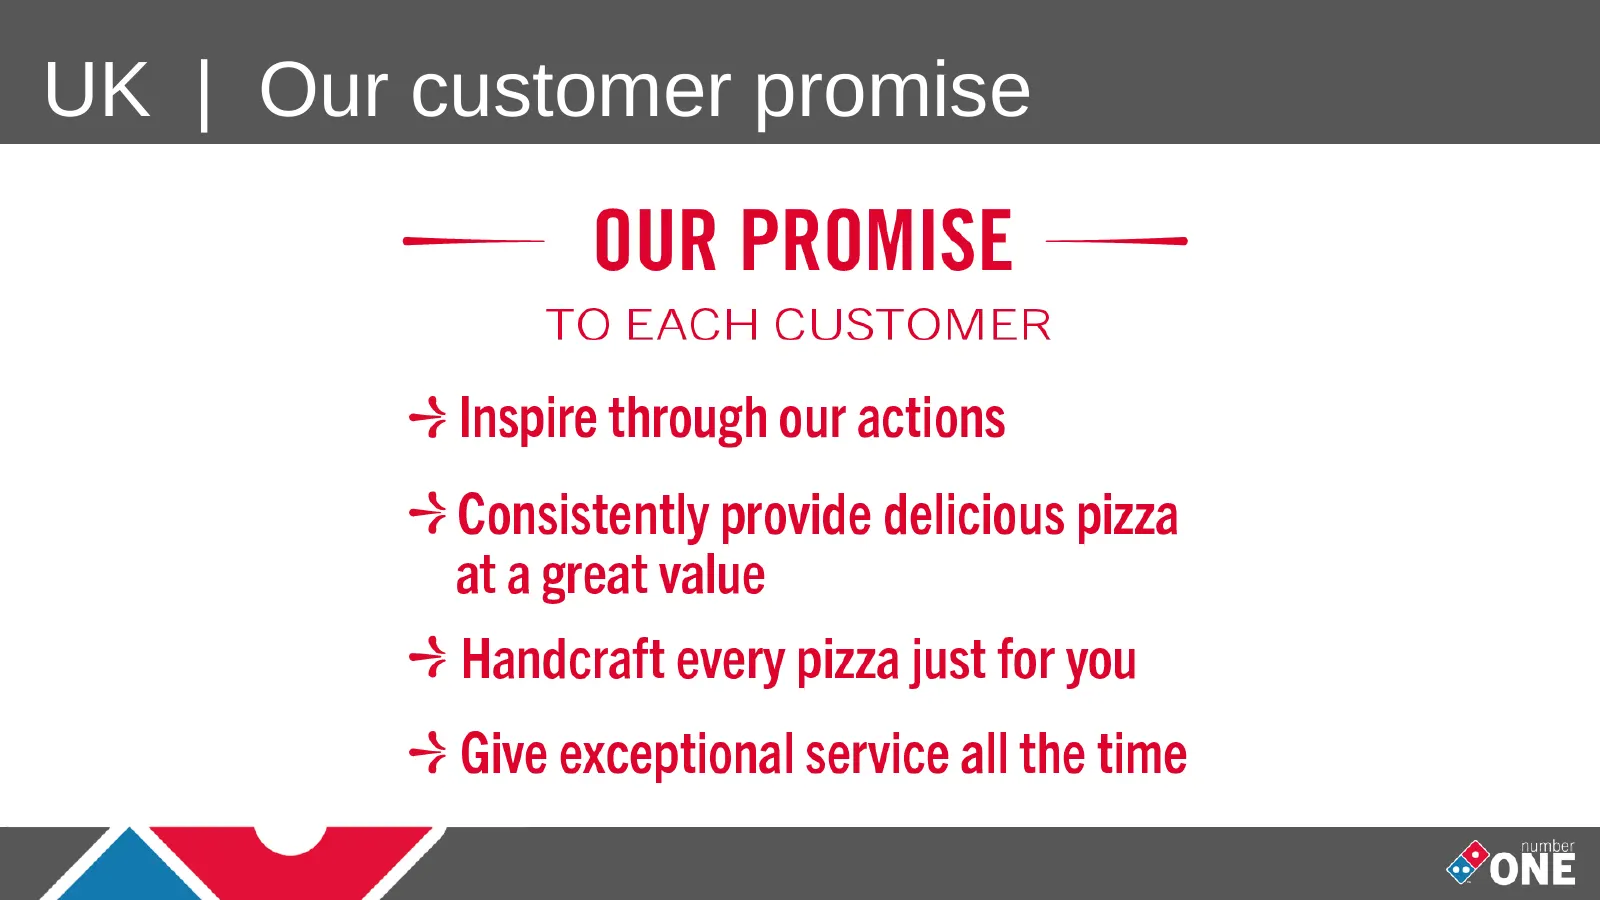
UK | Our customer promise AN
Slide 36: UK | Obsessed with operational metrics
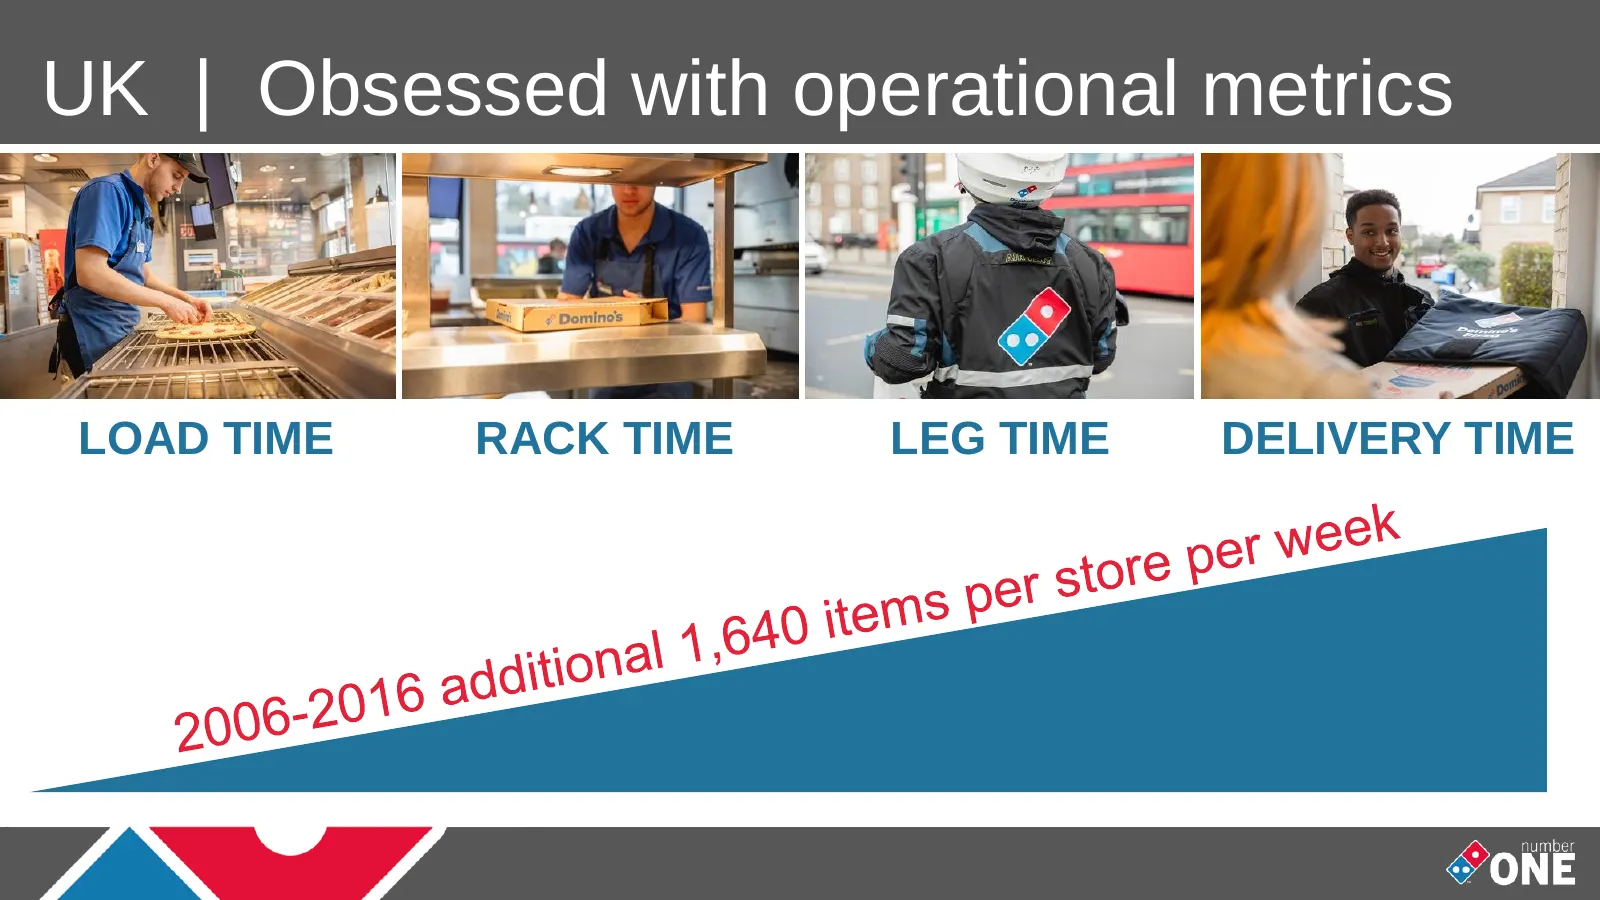
UK | Obsessed with operational metrics LOAD TIME RACK TIME LEG TIME DELIVERY TIME
Slide 37: UK | Handle the rush
UK | Handle the SS ——— rush = number
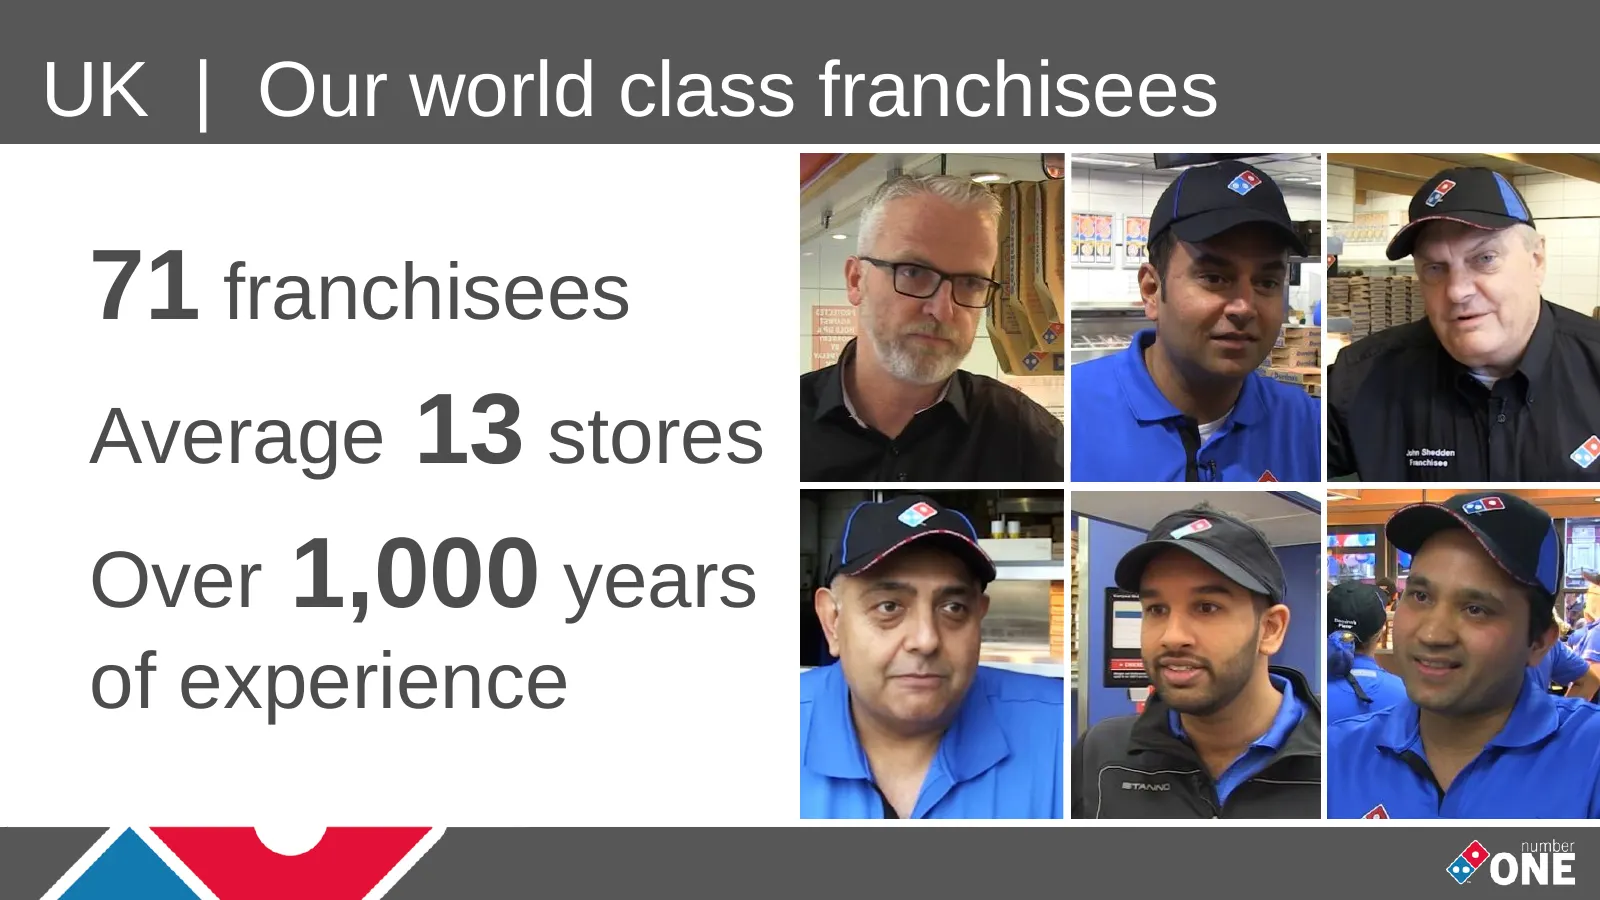
Slide 38: Our world class franchisees
UK | Our world class franchisees 71 franchisees Average 13 stores Over 1,000 years of experience
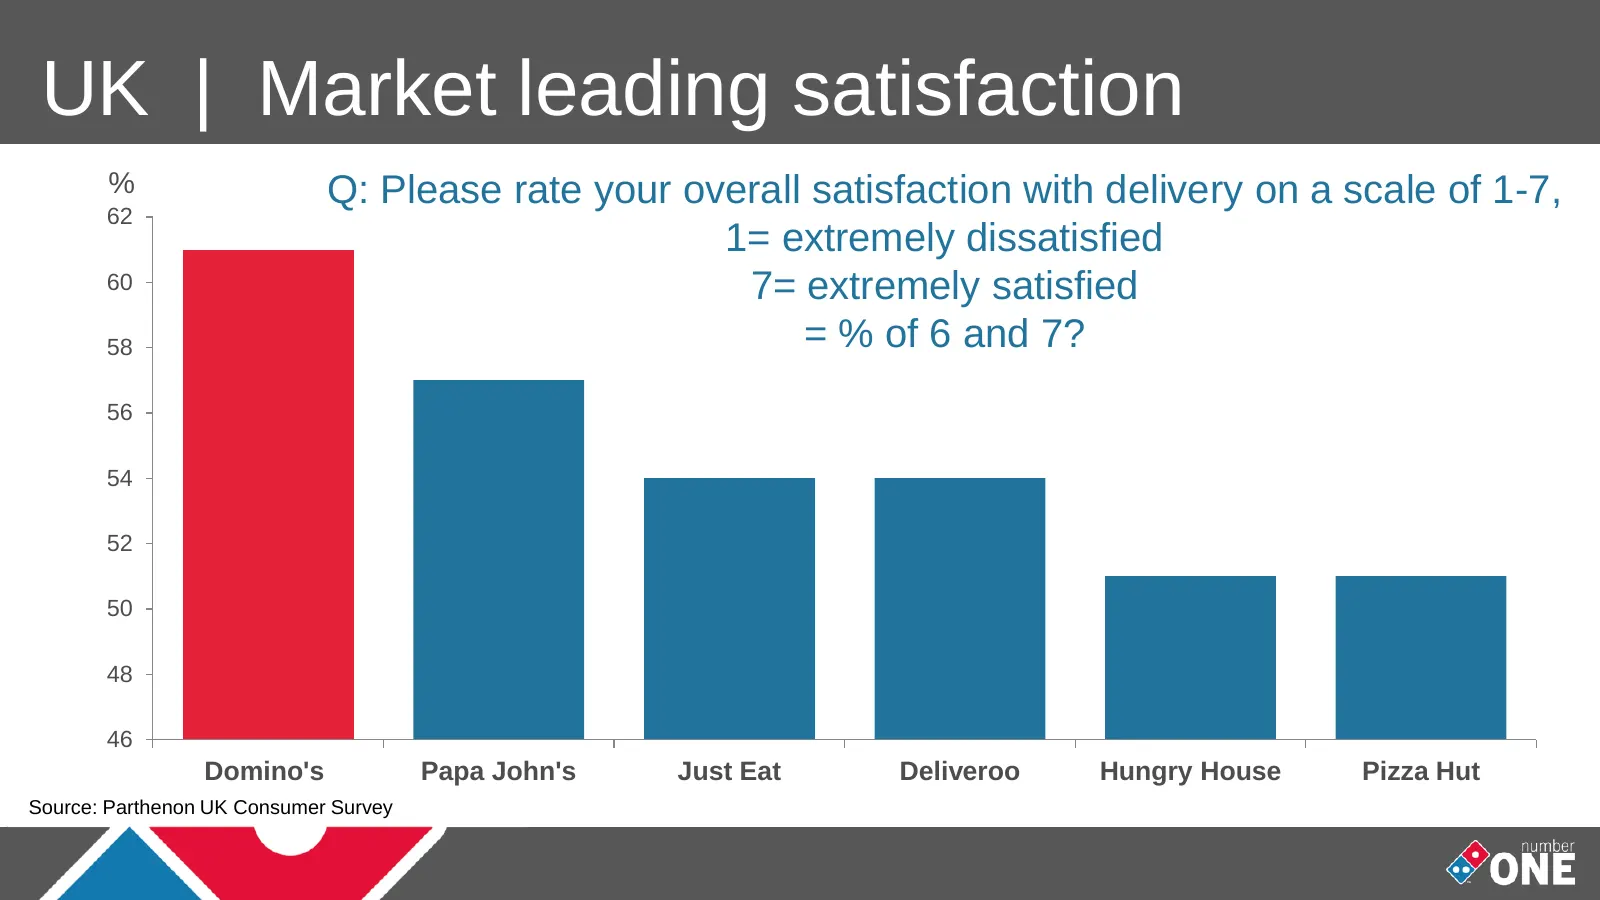
Slide 39: UK | Market leading satisfaction
UK | Market leading satisfaction % Q: Please rate your overall satisfaction with delivery on a scale of 1-7, 62 1= extremely dissatisfied 60 7= extremely satisfied 58 = % of 6 and 7? 56 54 52 50 48 46 Domino's Papa John's Just Eat Deliveroo Hungry House Pizza Hut Source: Parthenon UK Consumer Survey
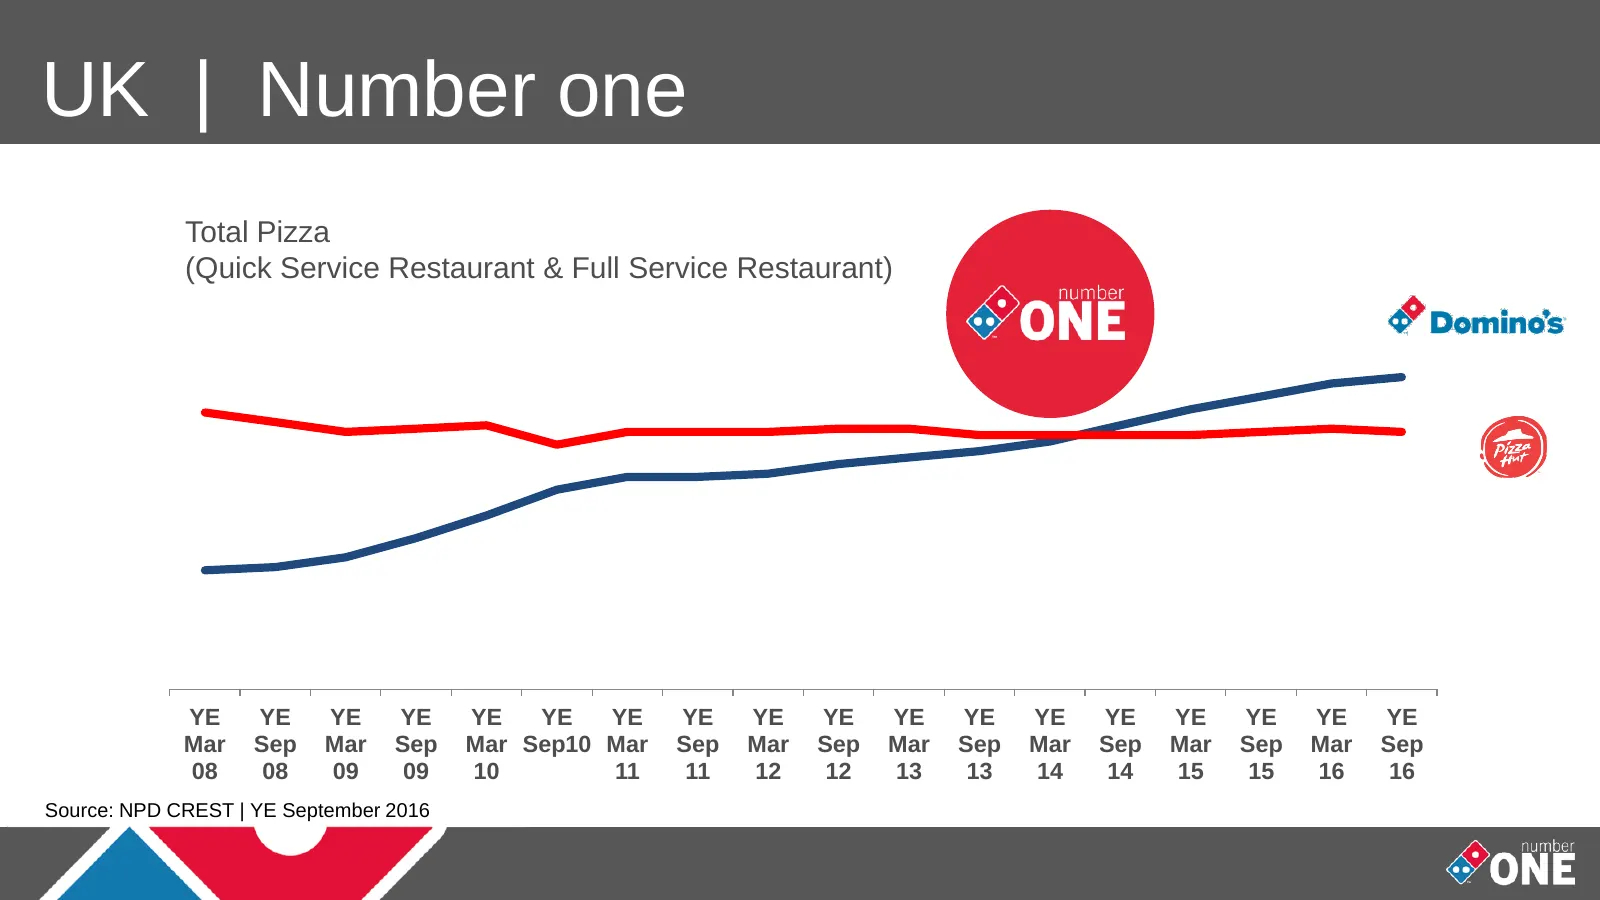
Slide 40: UK | Number one
UK | Number one Total Pizza (Quick Service Restaurant & Full Service Restaurant) YE YE YE YE YE YE YE YE YE YE YE YE YE YE YE YE YE YE Mar Sep Mar Sep Mar Sep10 Mar Sep Mar Sep Mar Sep Mar Sep Mar Sep Mar Sep 08 08 09 09 10 11 11 12 12 13 13 14 14 15 15 16 16 Source: NPD CREST | YE September 2016
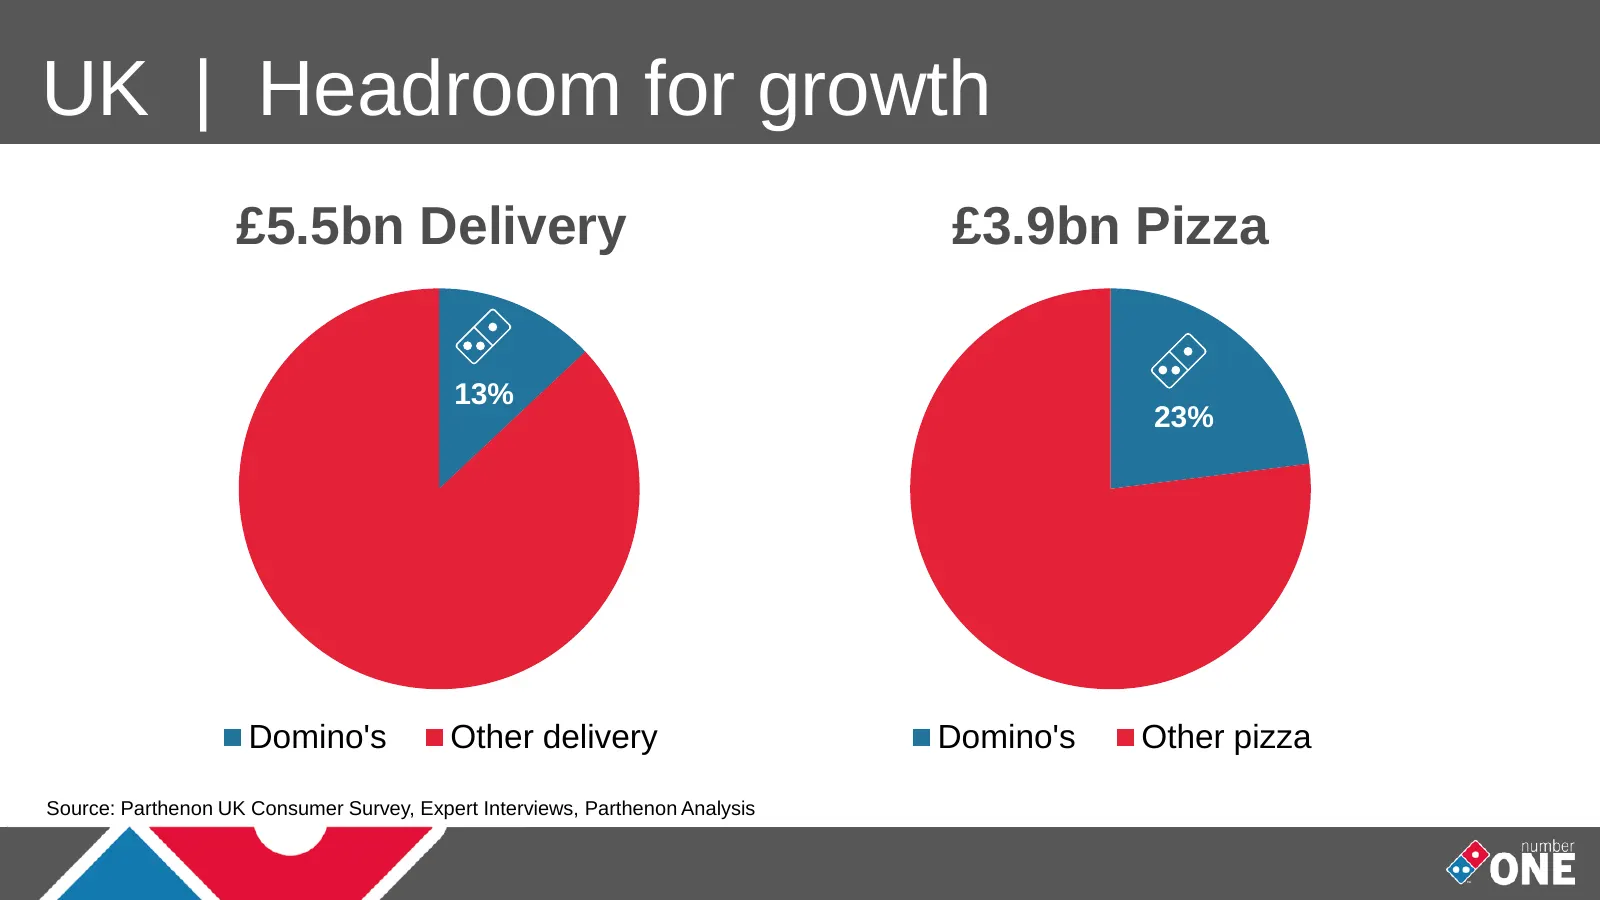
Slide 41: UK | Headroom for growth
UK | Headroom for growth £5.5bn Delivery £3.9bn Pizza 13% 23% Domino's Other delivery Domino's Other pizza Source: Parthenon UK Consumer Survey, Expert Interviews, Parthenon Analysis
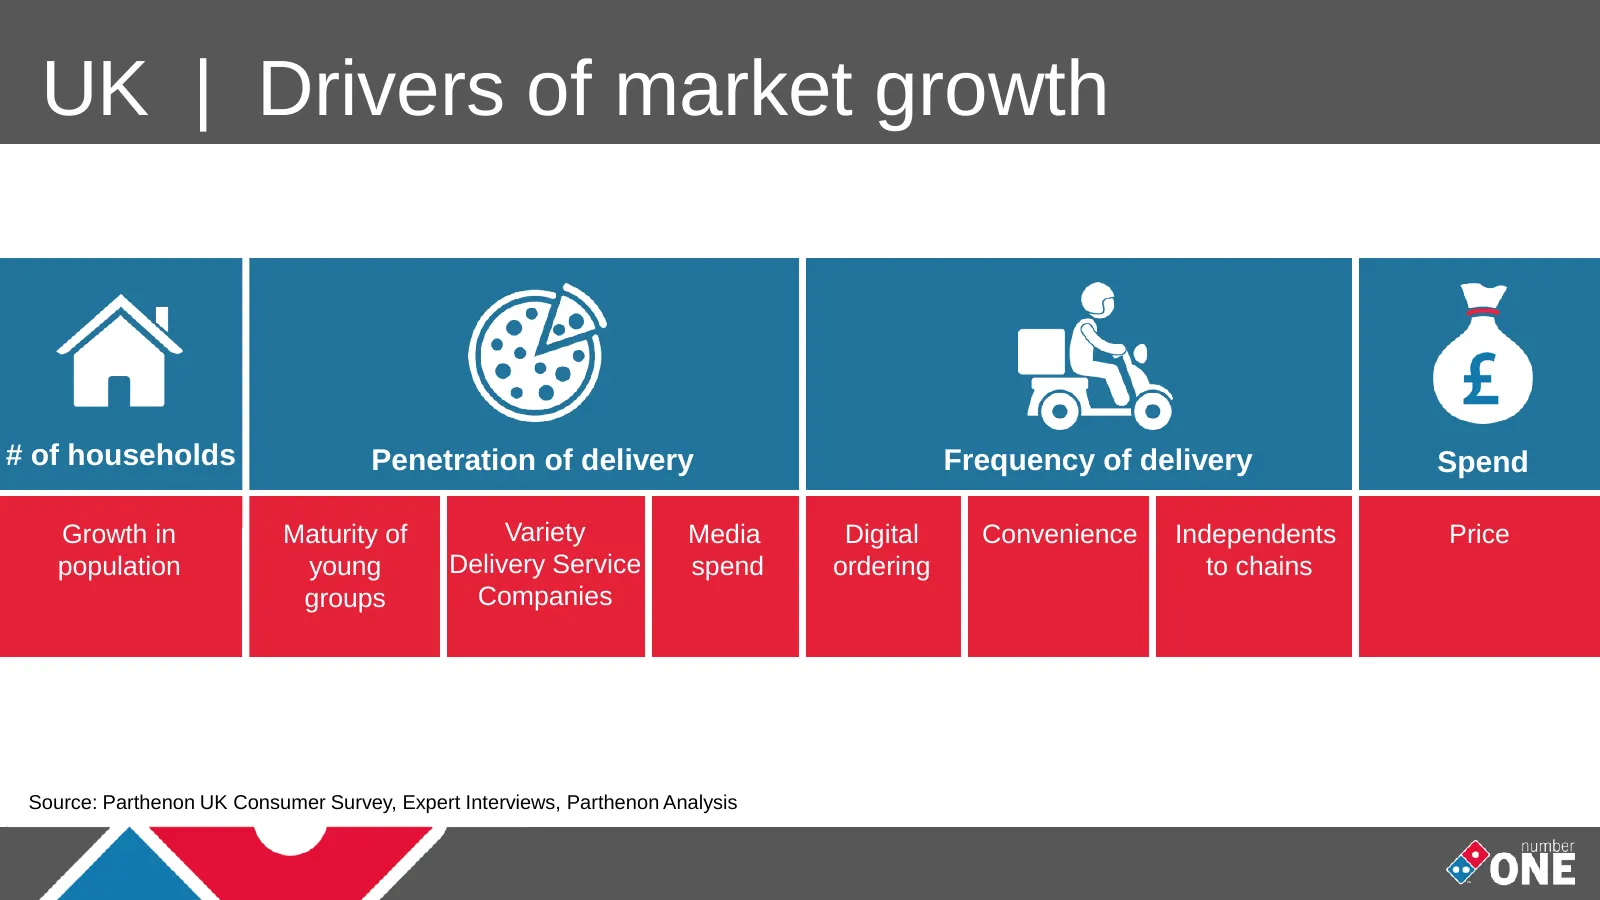
Slide 42: UK | Drivers of market growth
UK | Drivers of market growth # of households Penetration of delivery Frequency of delivery Spend Growth in Maturity of Variety Media Digital Convenience Independents Price population young Delivery Service spend ordering to chains groups Companies Source: Parthenon UK Consumer Survey, Expert Interv
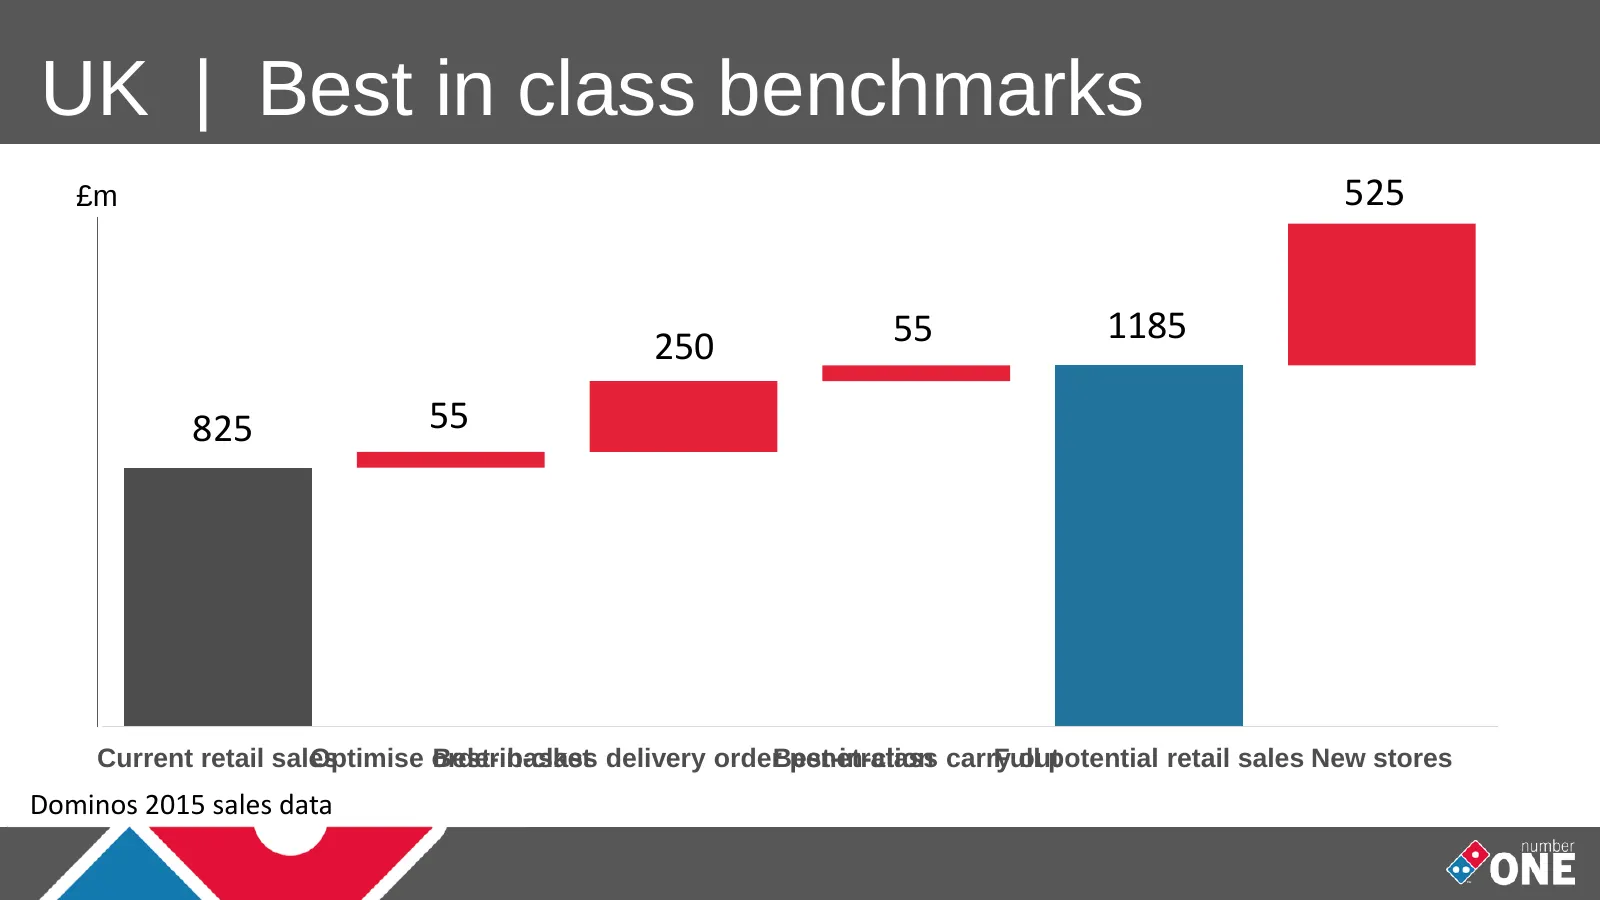
Slide 43: UK | Best in class benchmarks
UK | Best in class benchmarks £m 525 55 1185 250 825 55 Current retail sales Optimise order Best-in-class basket delivery orderBest-in-class penetration carry Full outpotential retail sales New stores Dominos 2015 sales data
Slide 44: Store Growth Potential
Store Growth Potential Robin Caley Property & Business Development Director
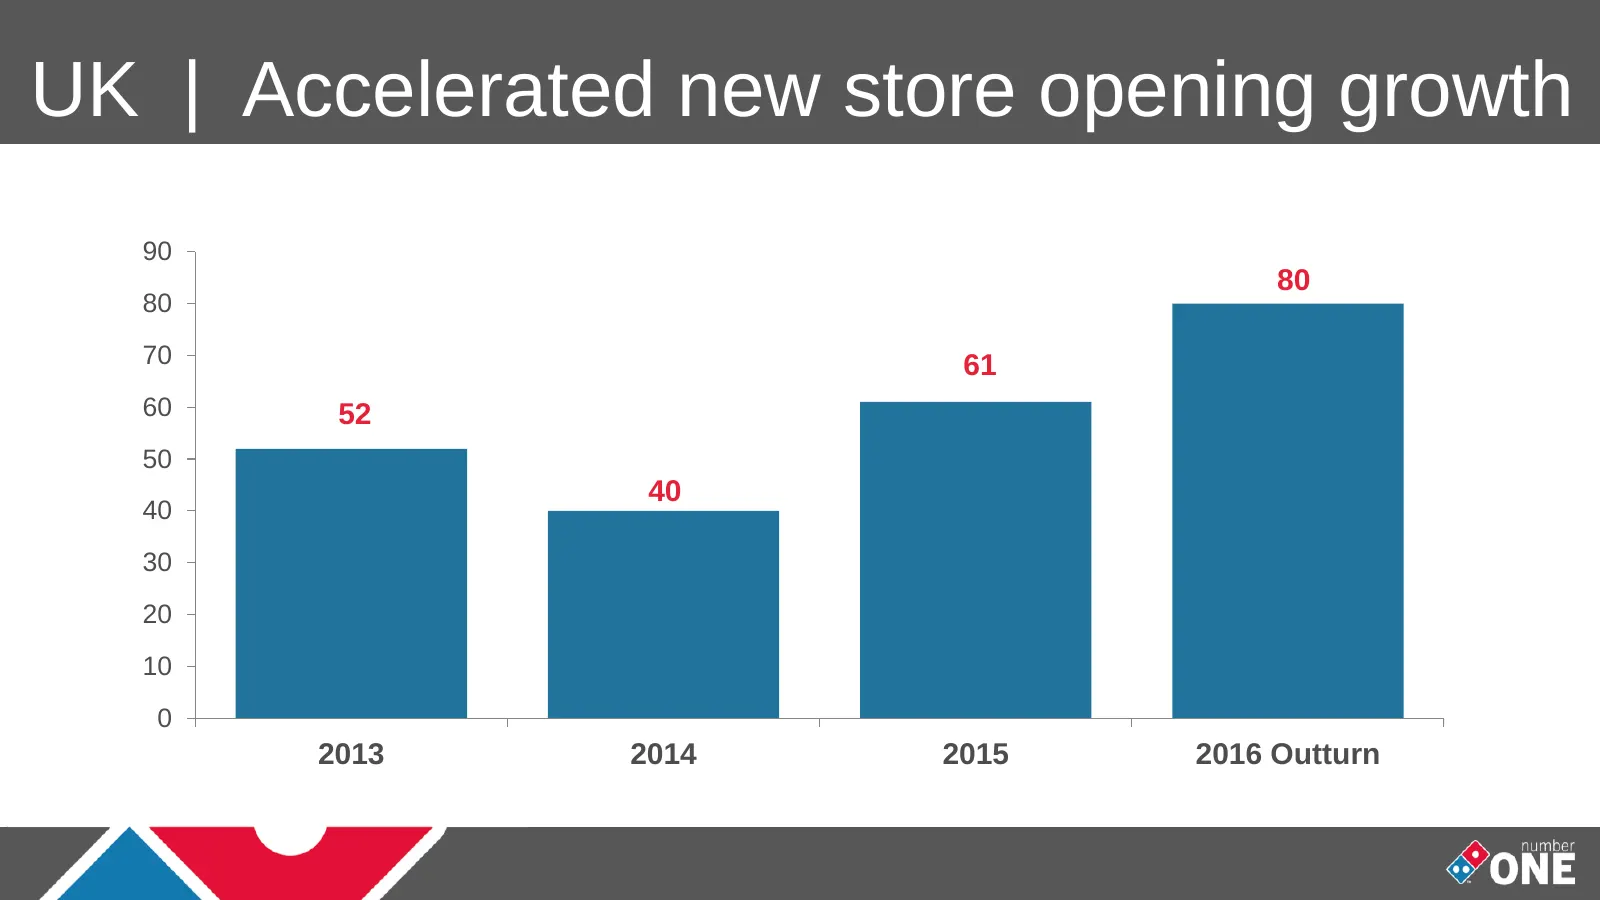
Slide 45: UK | Accelerated new store opening growth
UK | Accelerated new store opening growth 90 80 80 70 61 60 52 50 40 40 30 20 10 0 2013 2014 2015 2016 Outturn
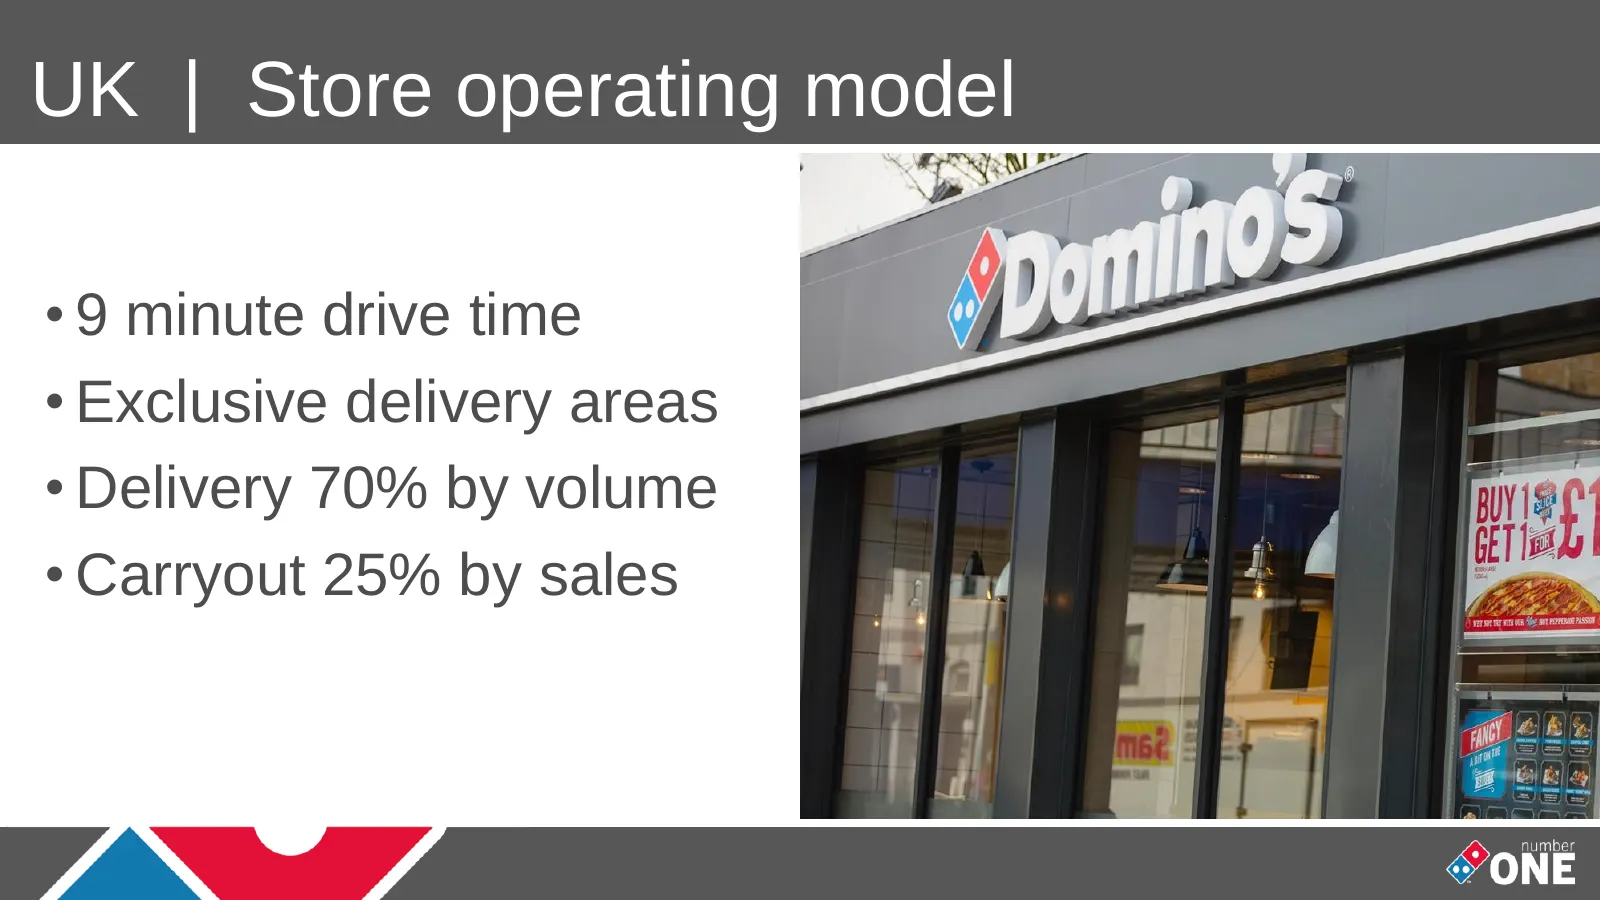
Slide 46: UK | Store operating model
UK | Store operating model • 9 minute drive time • Exclusive delivery areas • Delivery 70% by volume • Carryout 25% by sales
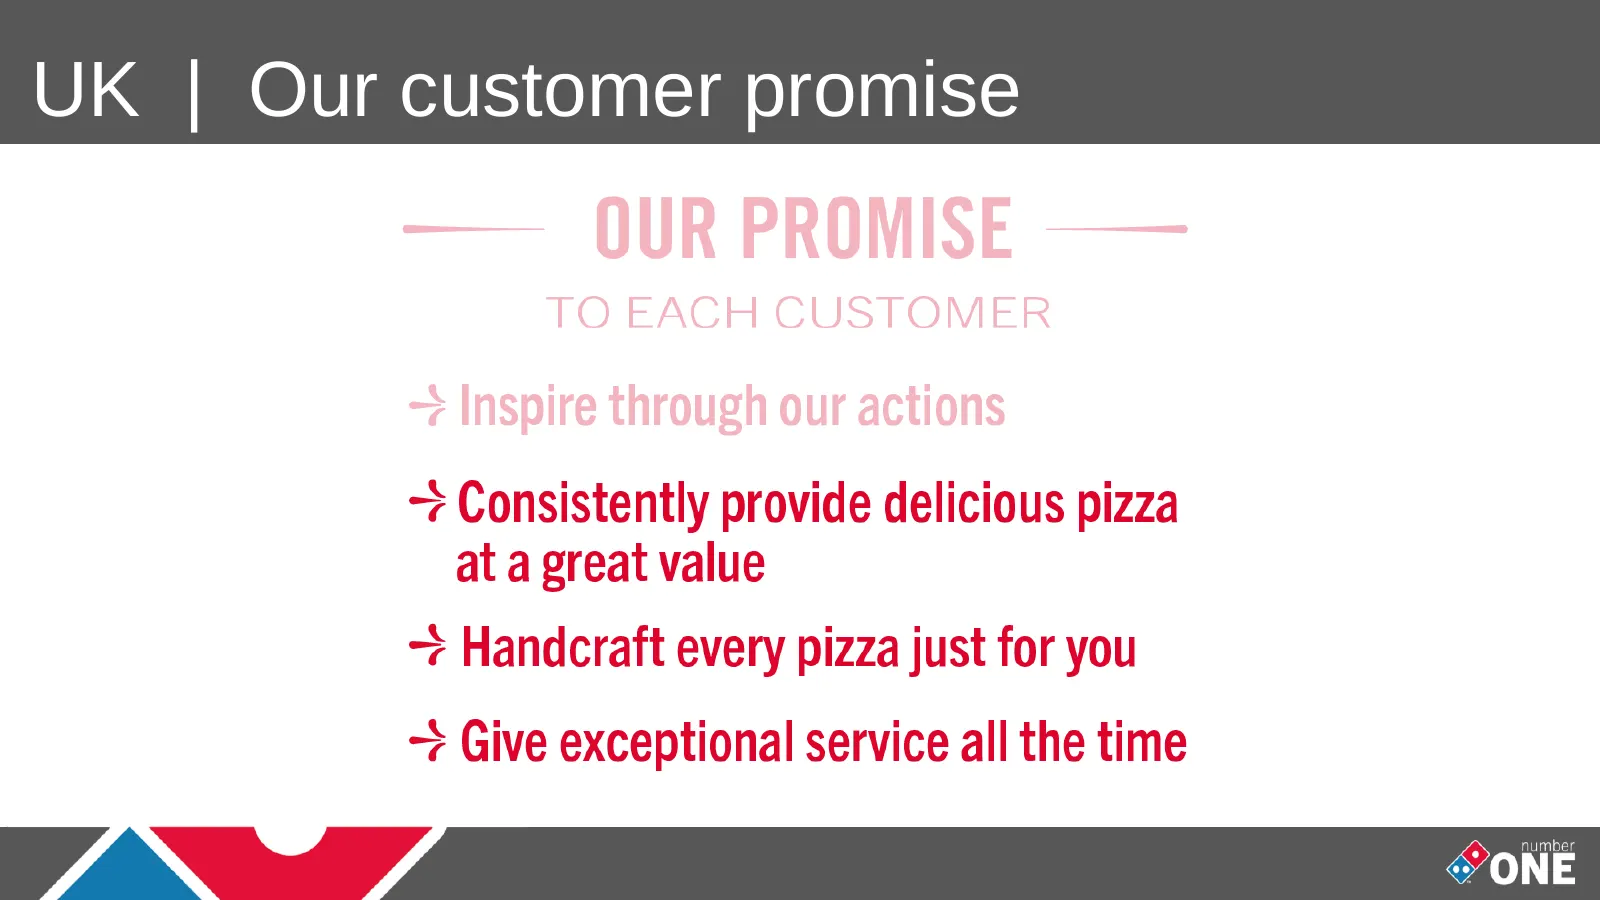
Slide 47: UK | Our customer promise
UK | Our customer promise AN
Slide 48: UK | Store growth opportunities
UK | Store growth opportunities • Dominate by splitting – Cities – Large towns pic • London • Market towns
Slide 49: UK | Store growth opportunities
UK | Store growth opportunities • Dominate by splitting – Cities – Large towns pic • London • Market towns
Slide 50: UK | Bristol - 2010
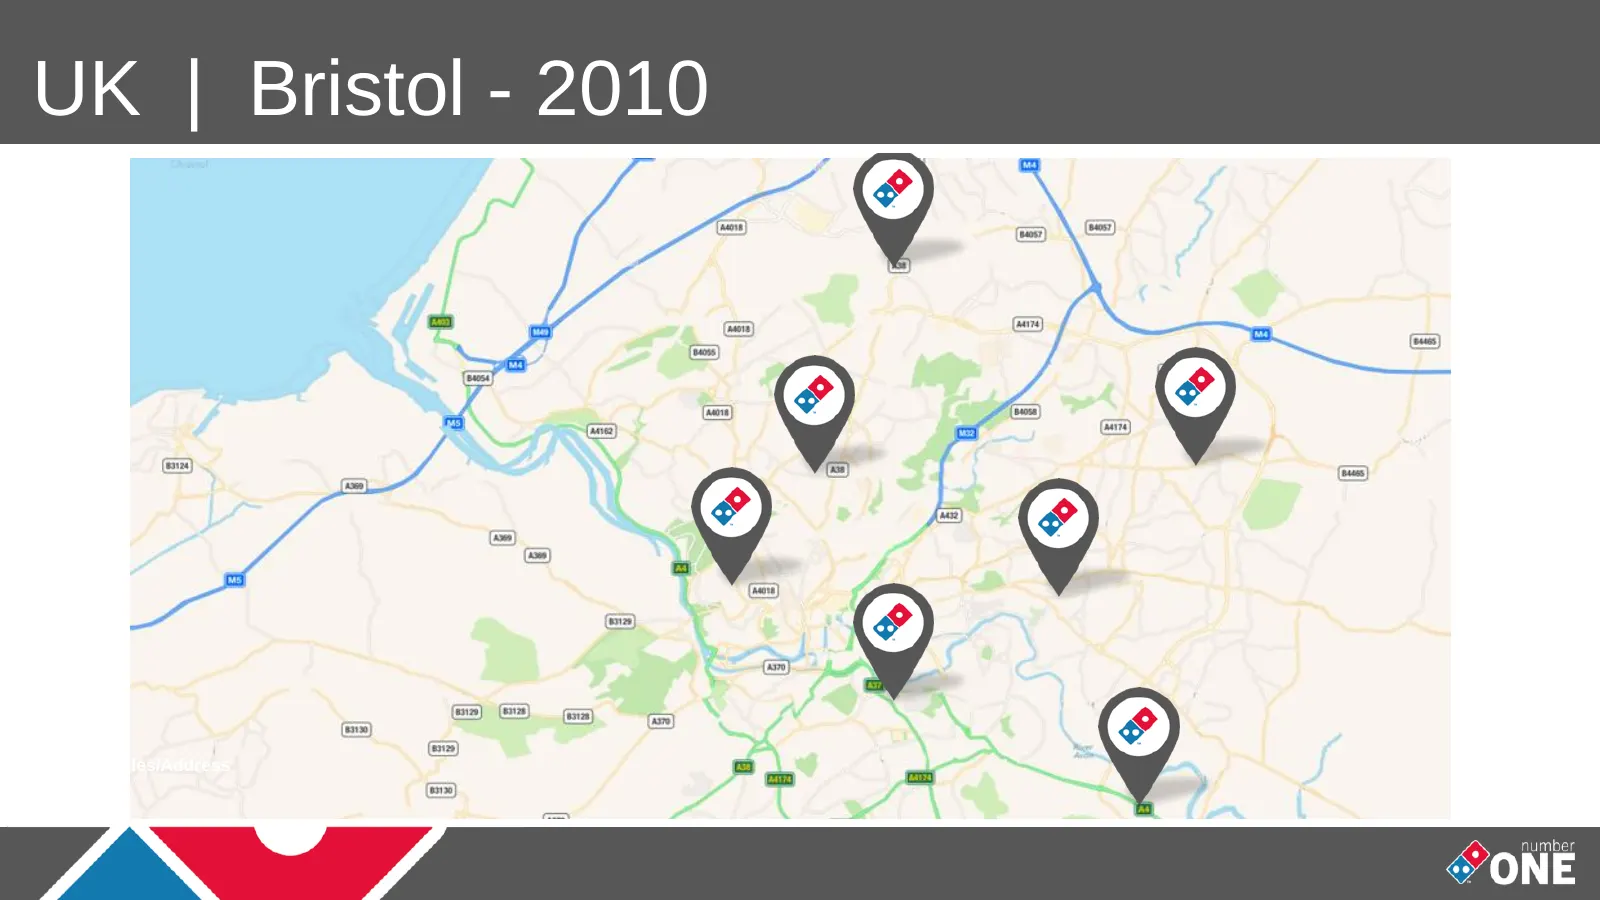
UK | Bristol - 2010 Weekly Sales/Address (£)
Slide 51: UK | Bristol - 2016
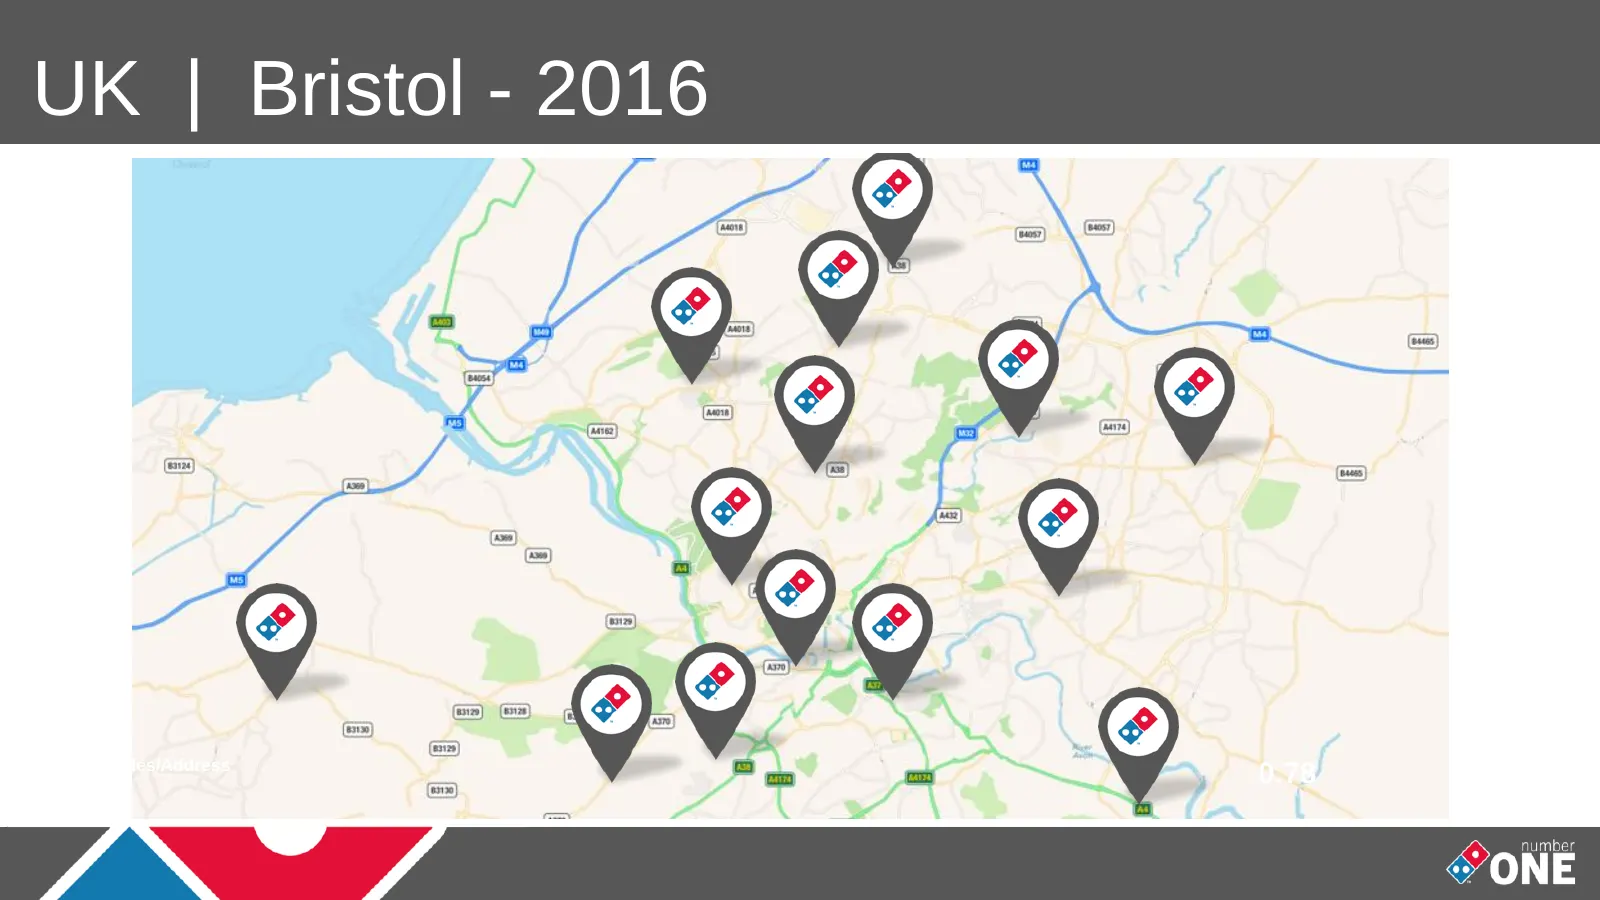
UK | Bristol - 2016 Weekly Sales/Address (£) 0.78
Slide 52: UK | Change in address count /ASPA
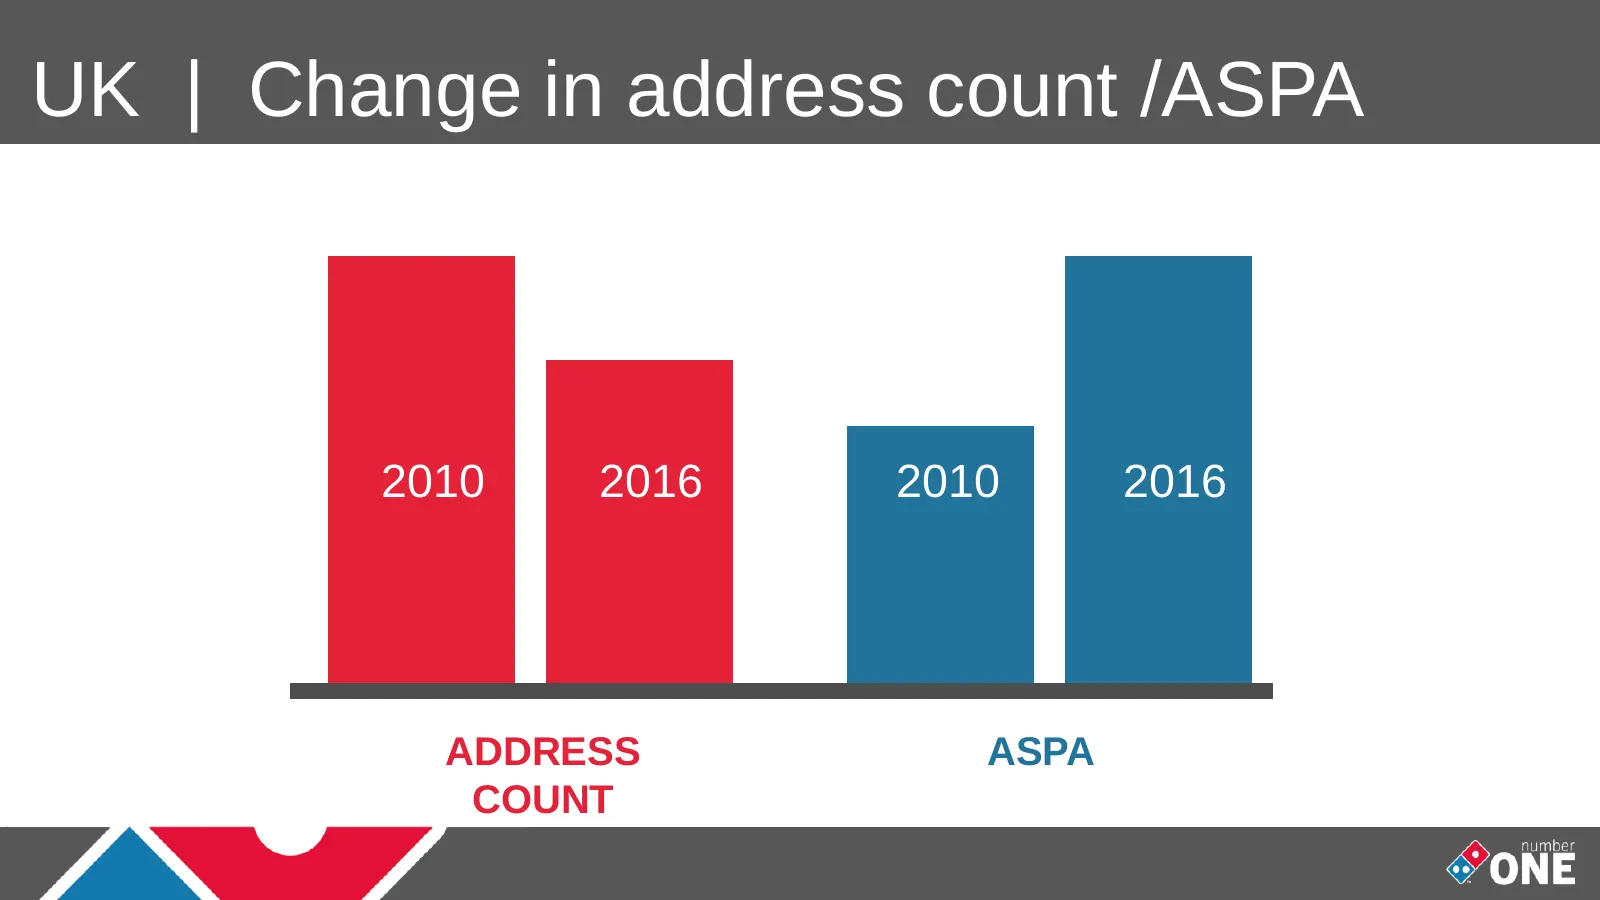
UK | Change in address count /ASPA 2010 2016 2010 2016 ADDRESS ASPA COUNT
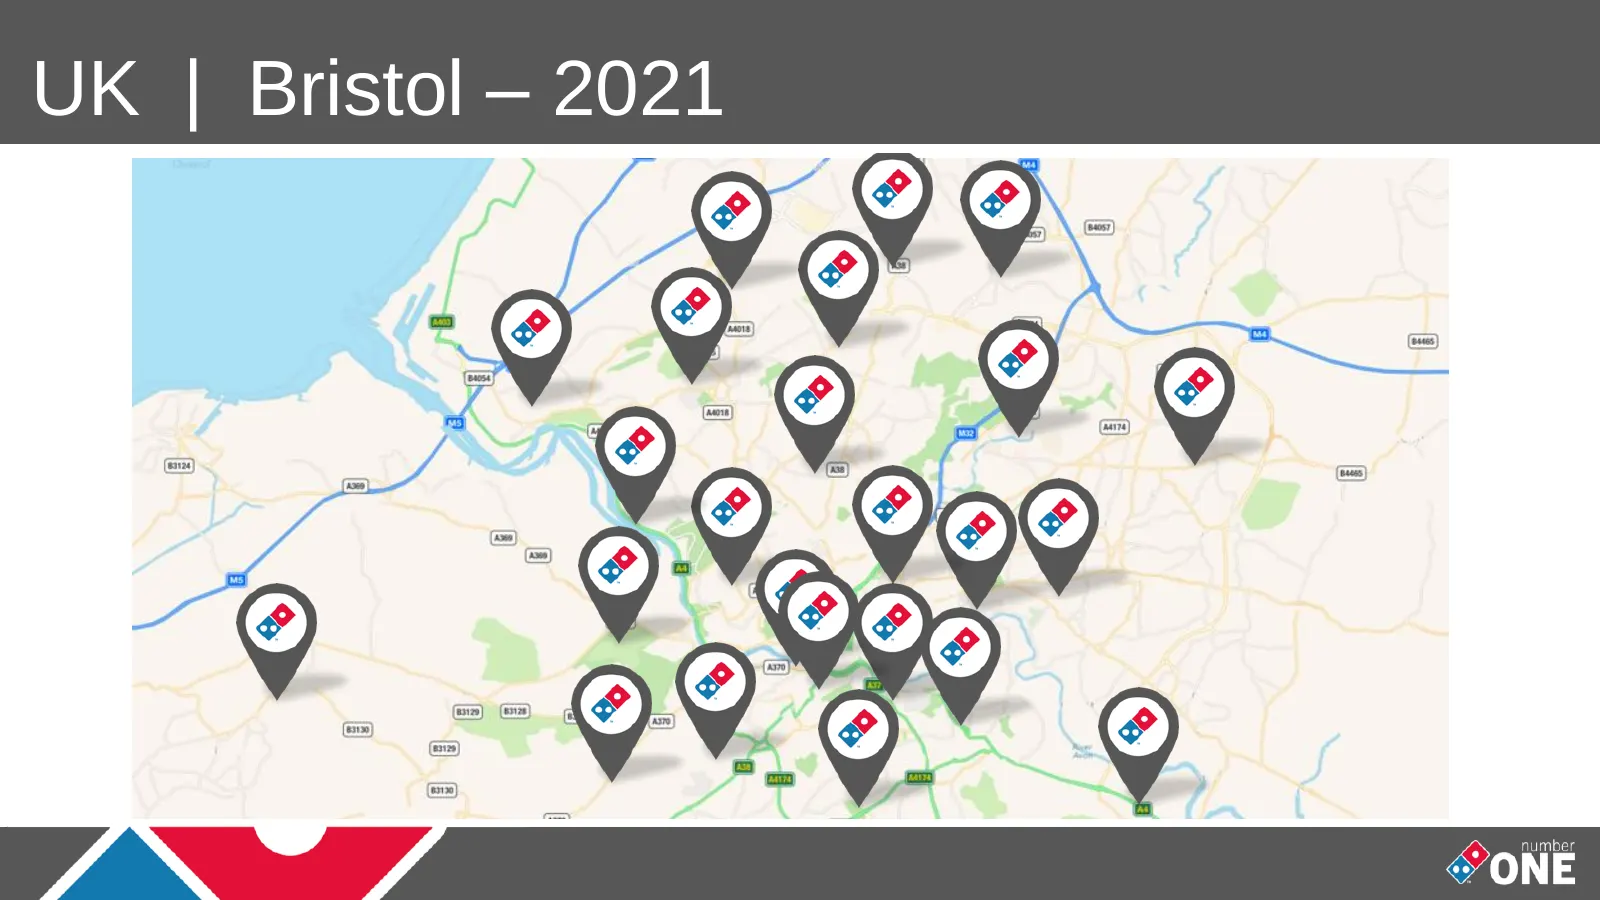
Slide 53: UK | Bristol – 2021
UK | Bristol – 2021 Weekly Sales/Address (£)
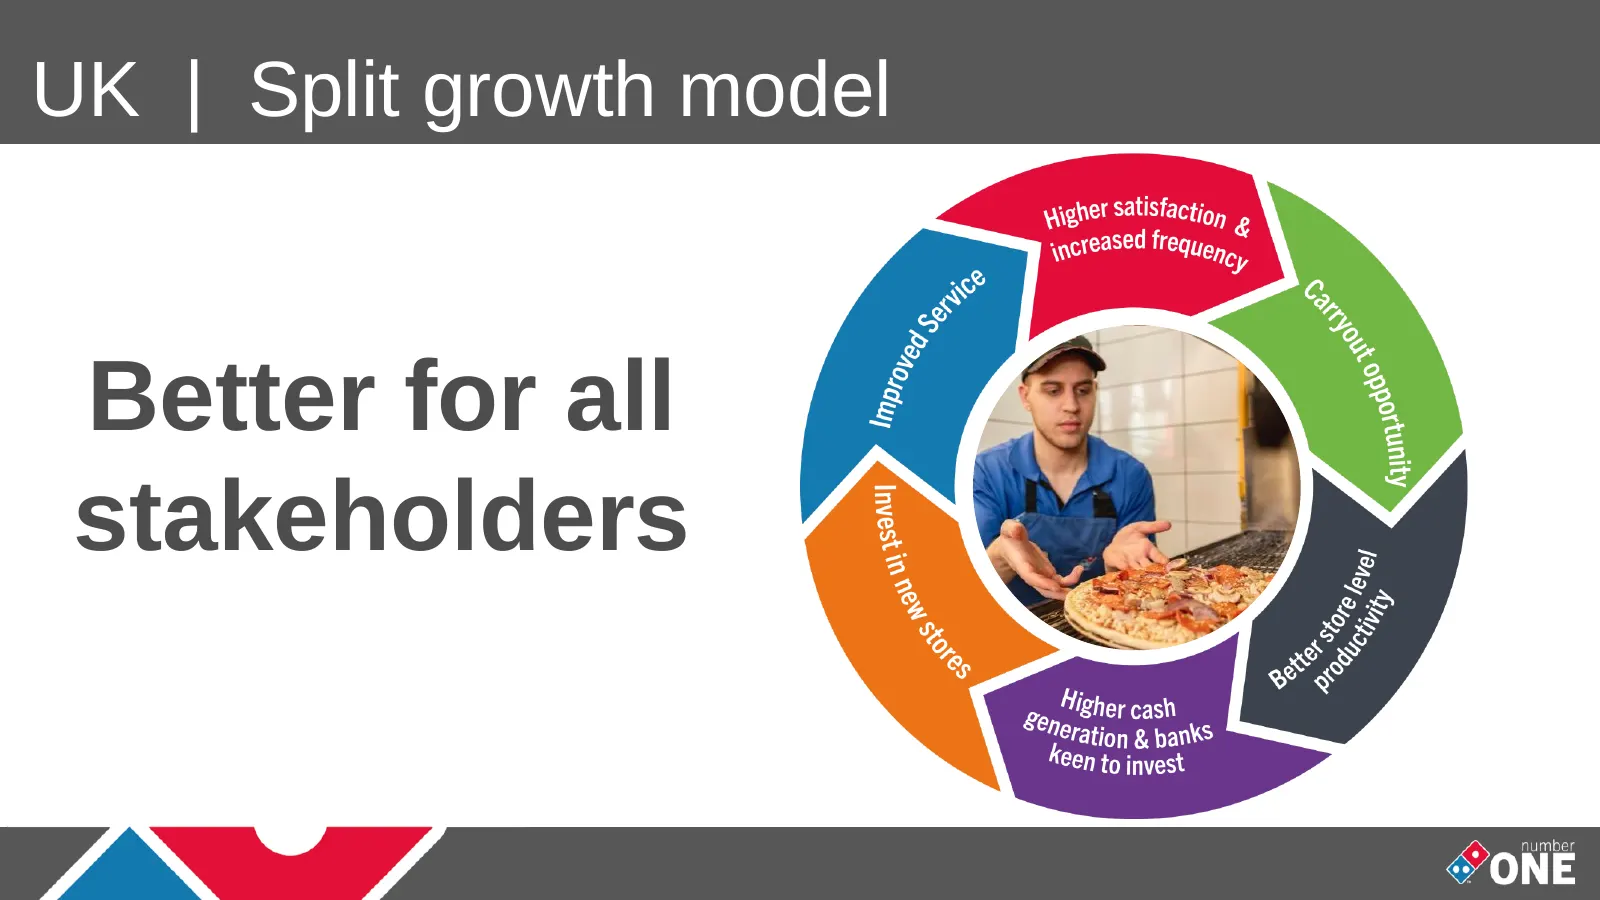
Slide 54: Better for all stakeholders
UK | Split growth model Better for all Pic stakeholders
Slide 55: UK | Store growth opportunities
UK | Store growth opportunities • Dominate by splitting – Cities – Large towns pic • London • Market towns
Slide 56: UK | Store growth opportunities
UK | Store growth opportunities • Dominate by splitting – Cities – Large towns • London • Market towns
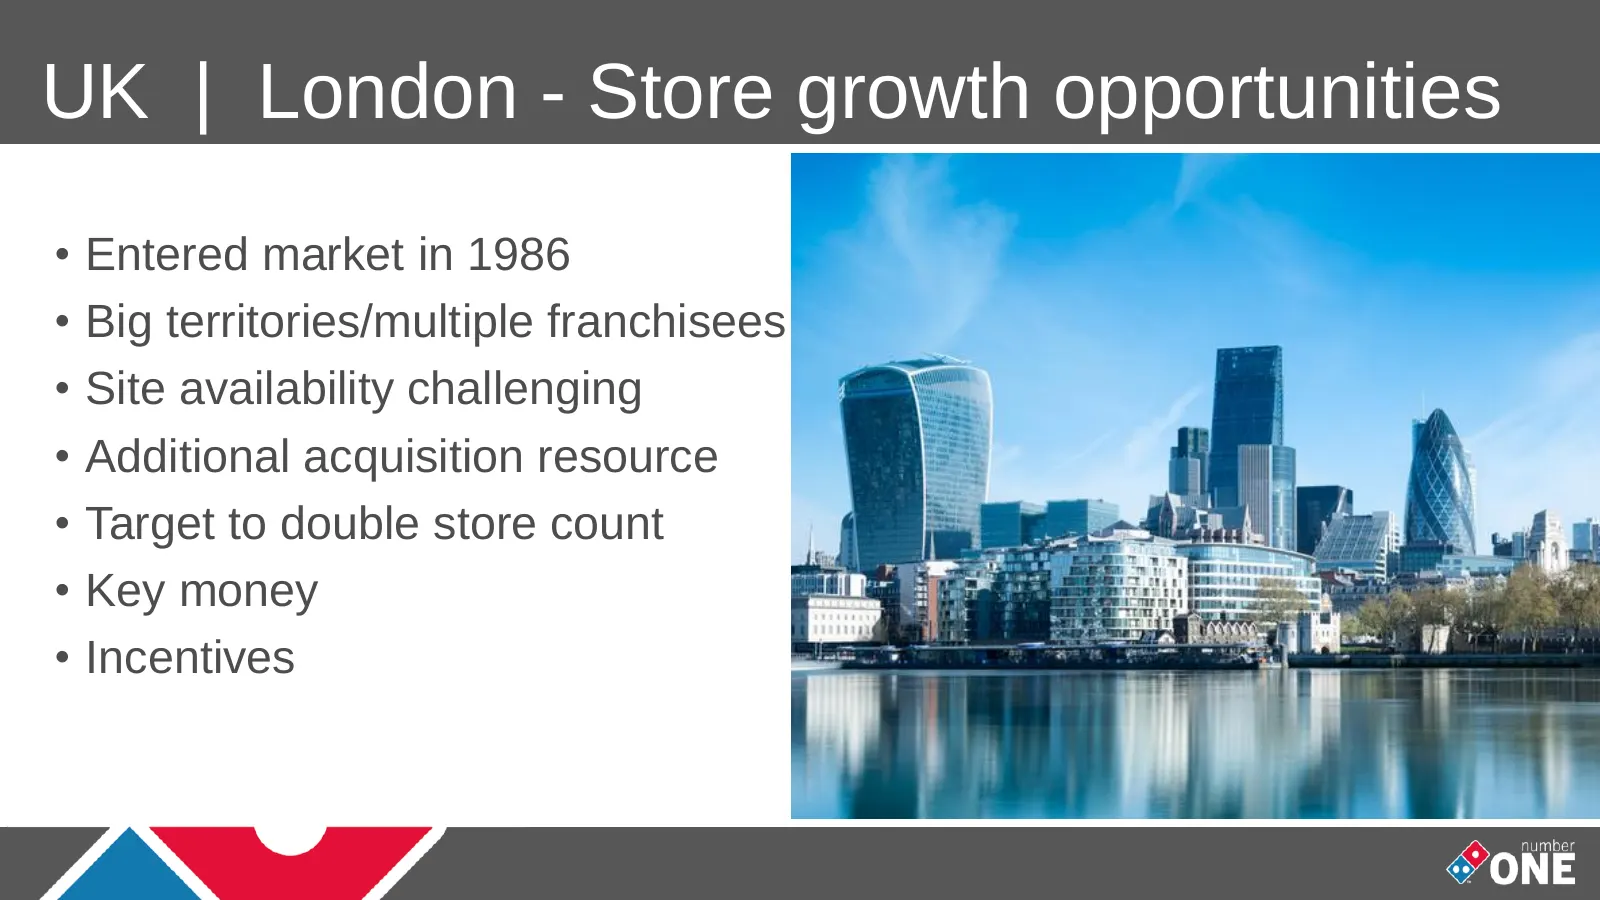
Slide 57: UK | London - Store growth opportunities
UK | London - Store growth opportunities • Entered market in 1986 • Big territories/multiple franchisees • Site availability challenging • Additional acquisition resource • Target to double store count • Key money • Incentives
Slide 58: UK | Store growth opportunities
UK | Store growth opportunities • Dominate by splitting – Cities – Large towns • London • Market towns
Slide 59: UK | Market towns - Store growth opportunities
UK | Market towns- Store growth opportunities • 1/3 of 2016 openings • AWUS > £15,000 per week • Lower capital costs v other QSR • Strong pipeline • Target c. 1/3 of openings count
Slide 60: UK | New store opportunities
UK | New store opportunities Australia Day • International benchmarks leaflet • Parthenon market sizing study Parthanon logo
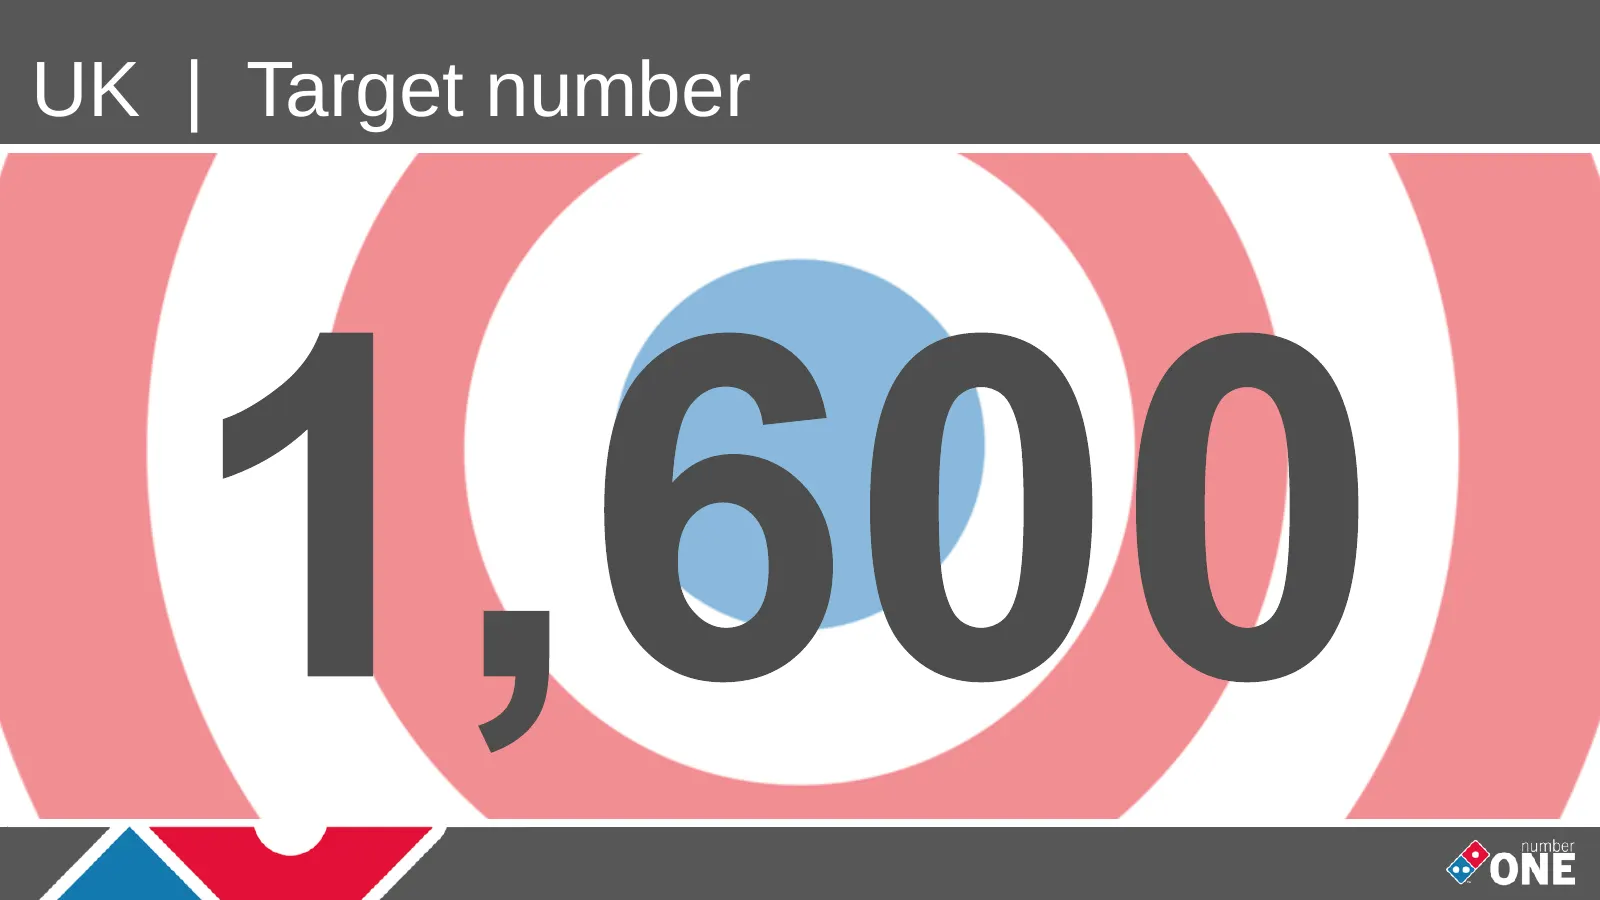
Slide 61: UK | Target number
UK | Target number
Slide 62: Leading Technology
Leading Technology Simon Wallis Chief Operating Officer
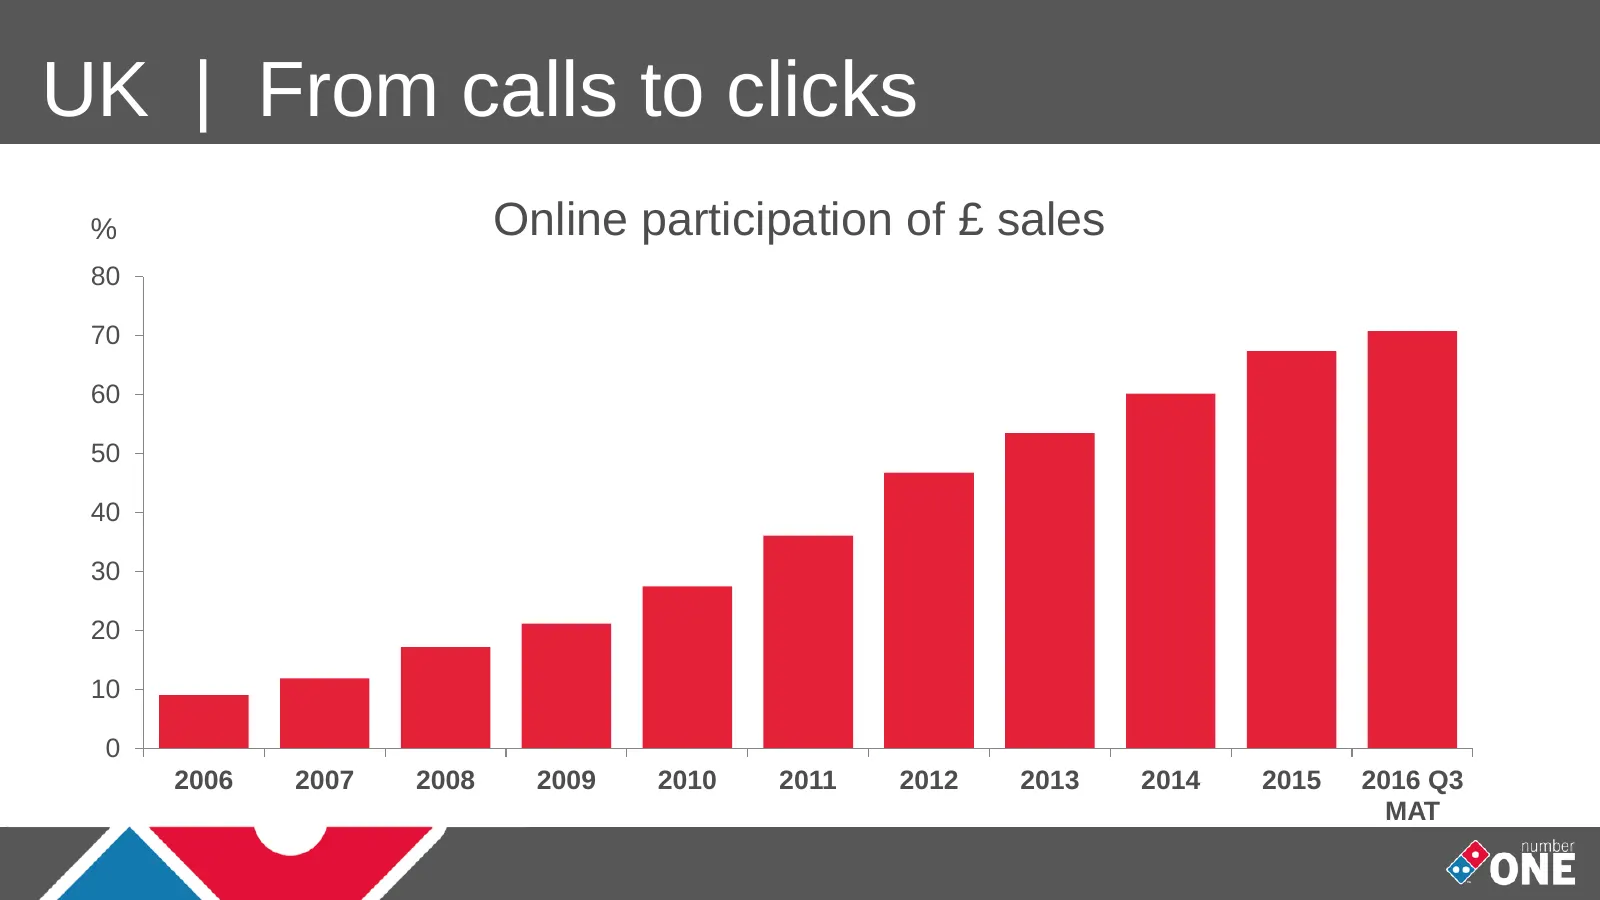
Slide 63: UK | From calls to clicks
UK | From calls to clicks % Online participation of £ sales 80 70 60 50 40 30 20 10 0 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Q3 MAT
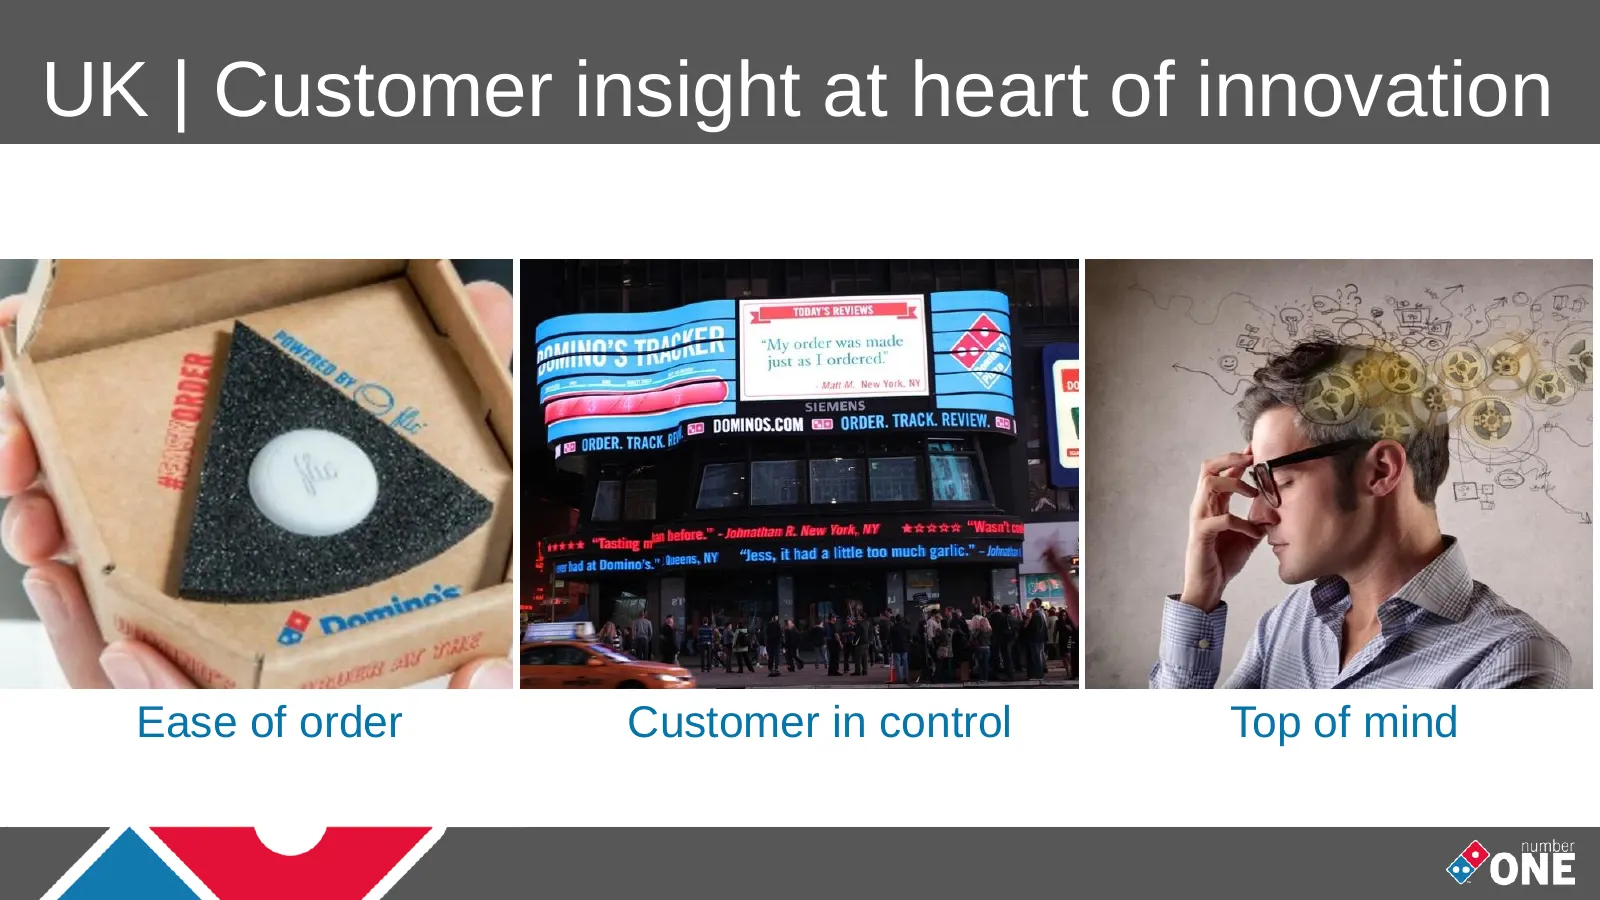
Slide 64: UK | Customer insight at heart of innovation
UK | Customer insight at heart of innovation Ease of order Customer in control Top of mind
Slide 65: UK | Mobile app
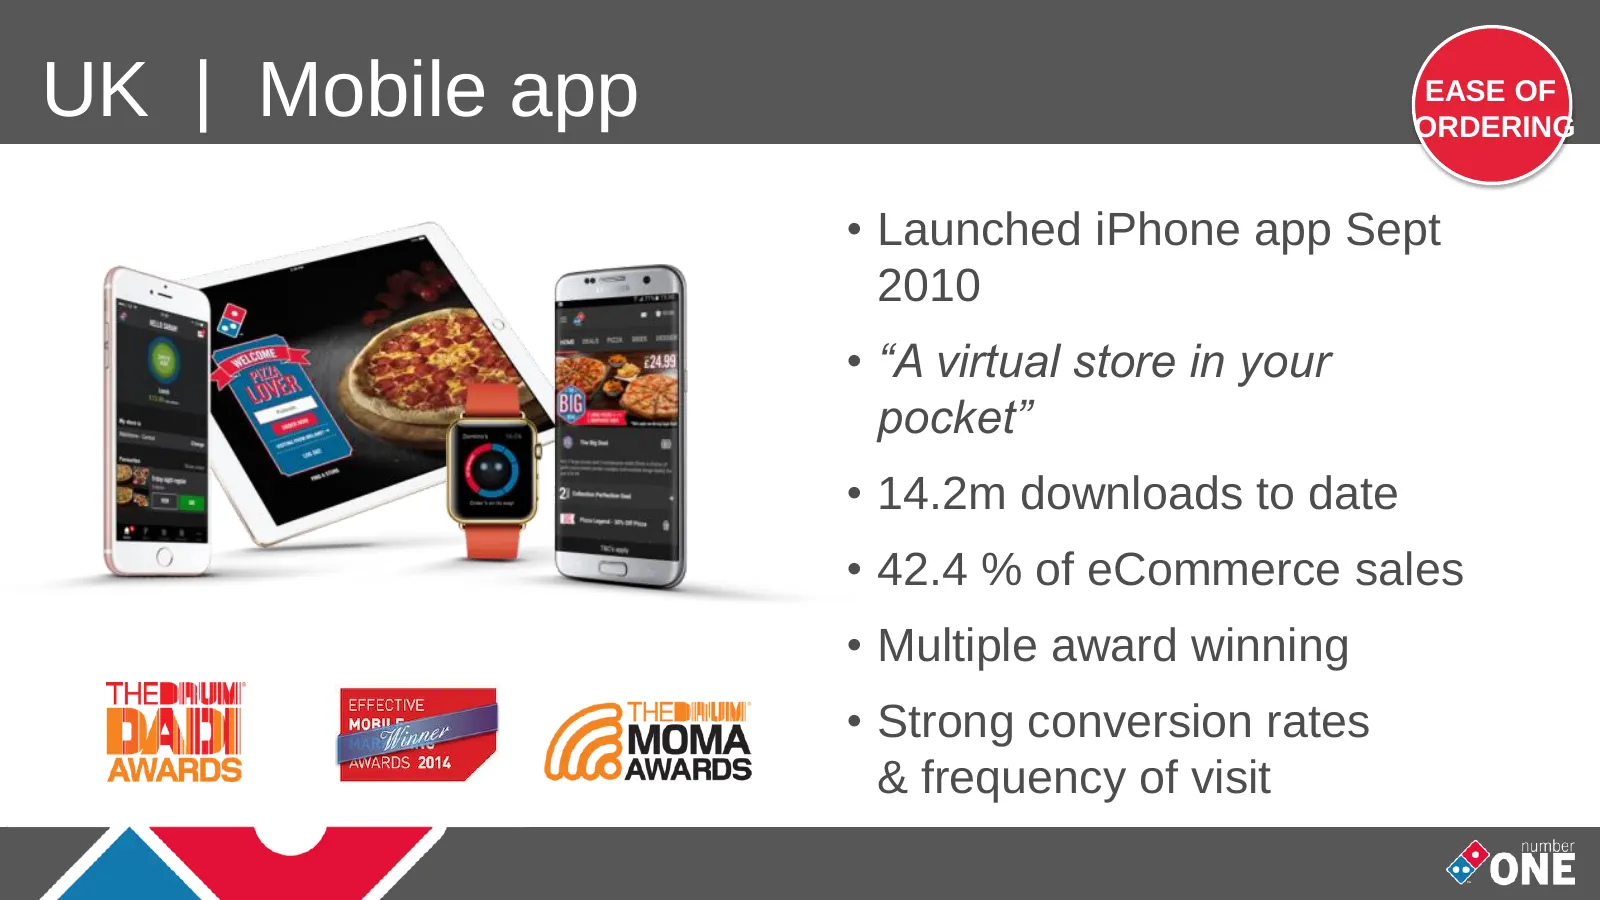
UK | Mobile app EASE OF ORDERING • Launched iPhone app Sept 2010 • “A virtual store in your pocket” • 14.2m downloads to date • 42.4 % of eCommerce sales • Multiple award winning • Strong conversion rates & frequency of visit
Slide 66: UK | Easy order
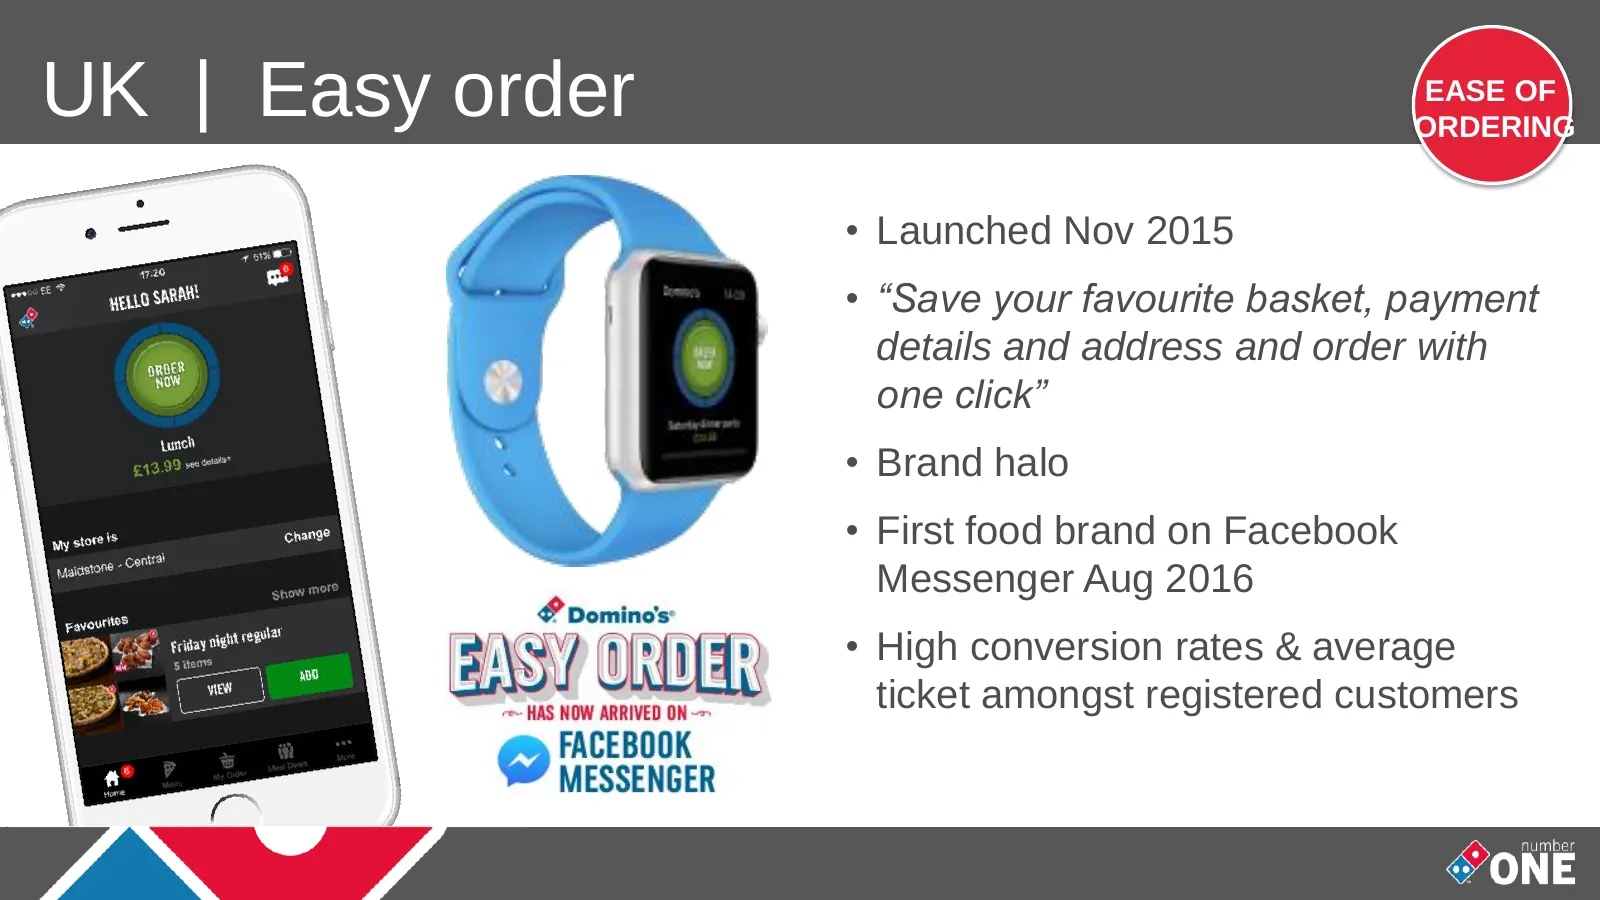
UK | Easy order EASE OF ORDERING • Launched Nov 2015 • “Save your favourite basket, payment details and address and order with one click” • Brand halo • First food brand on Facebook Messenger Aug 2016 • High conversion rates & average ticket amongst registered customers
Slide 67: UK | Pizza tracker
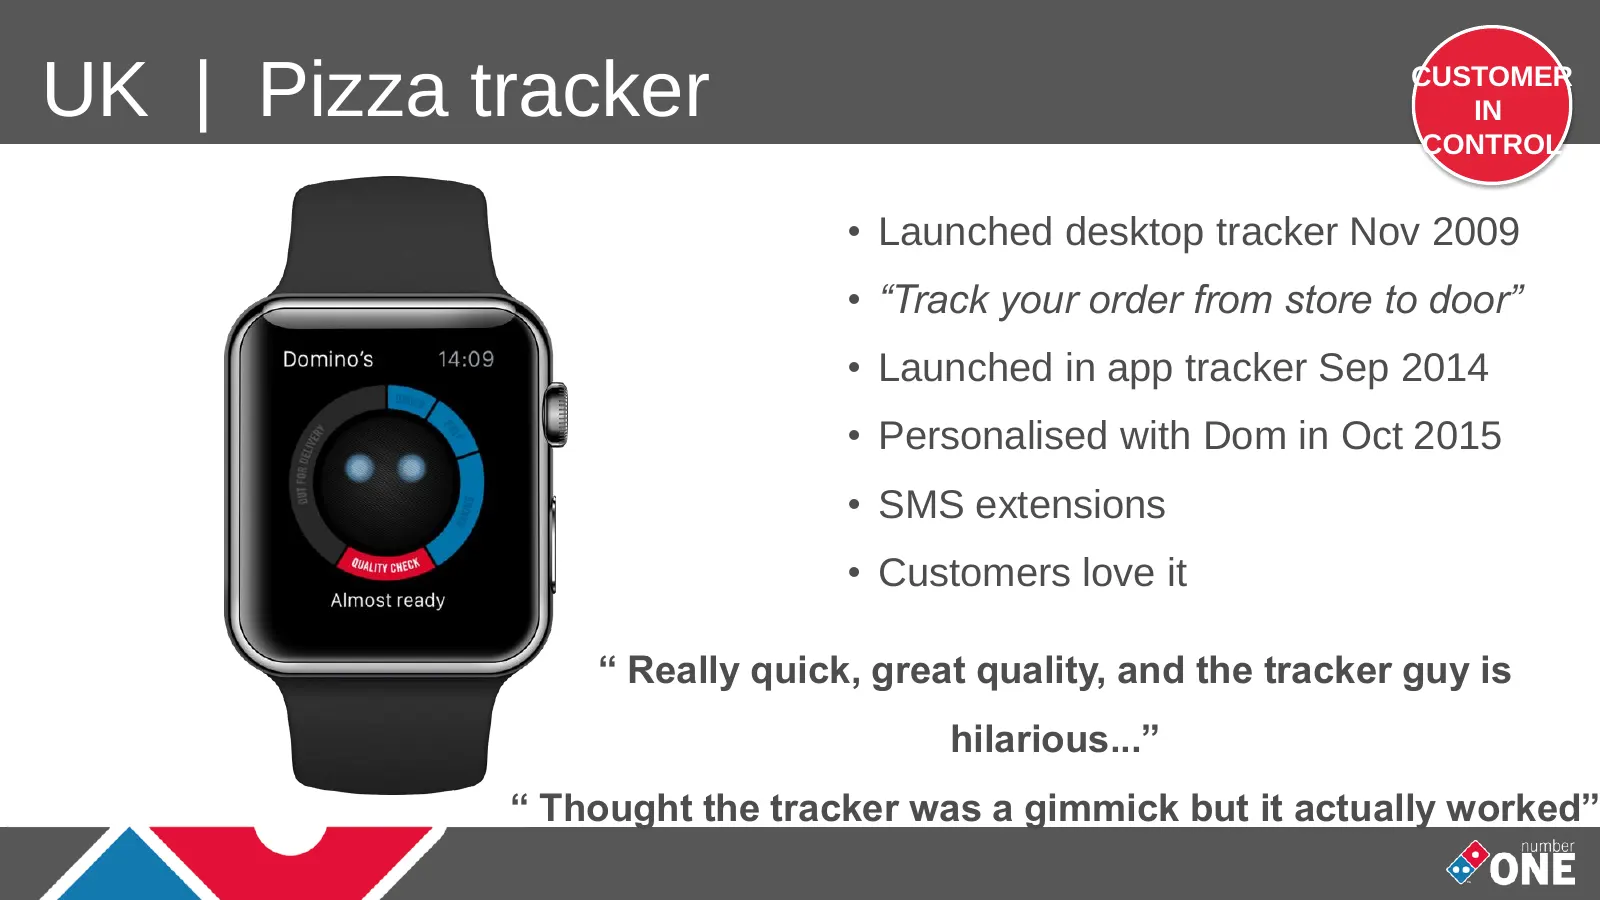
UK | Pizza tracker CUSTOMER IN CONTROL • Launched desktop tracker Nov 2009 • “Track your order from store to door” • Launched in app tracker Sep 2014 • Personalised with Dom in Oct 2015 • SMS extensions • Customers love it “ Really quick, great quality, and the tracker guy is hilarious...” “ Thought
Slide 68: UK | Legends
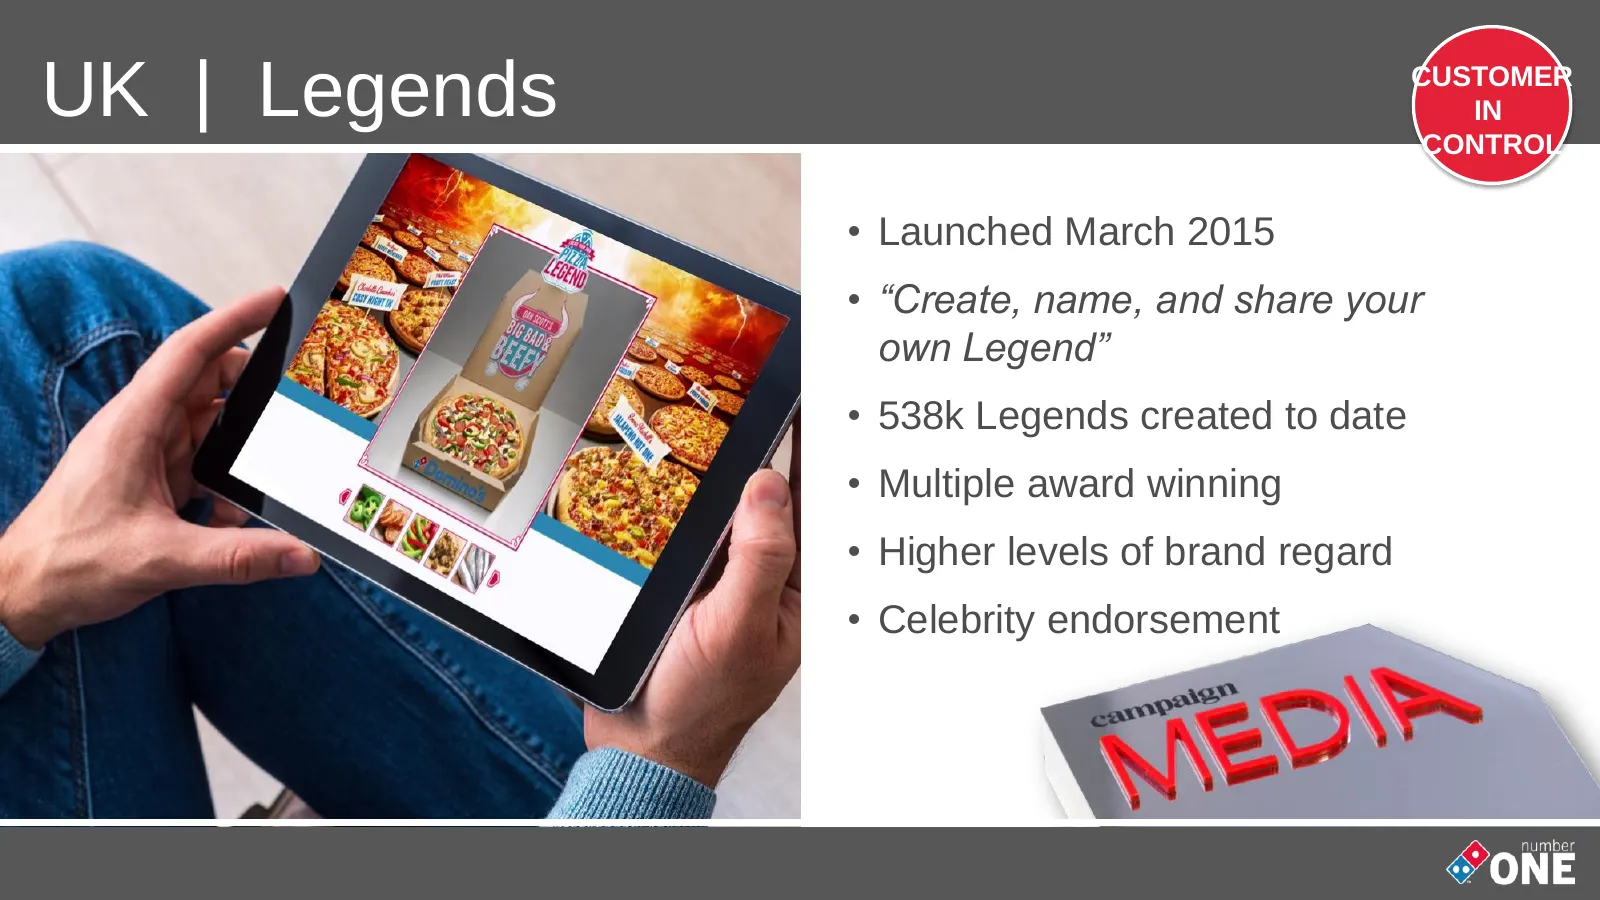
UK | Legends CUSTOMER IN CONTROL • Launched March 2015 • “Create, name, and share your own Legend” • 538k Legends created to date • Multiple award winning • Higher levels of brand regard • Celebrity endorsement
Slide 69: UK | Snapchat
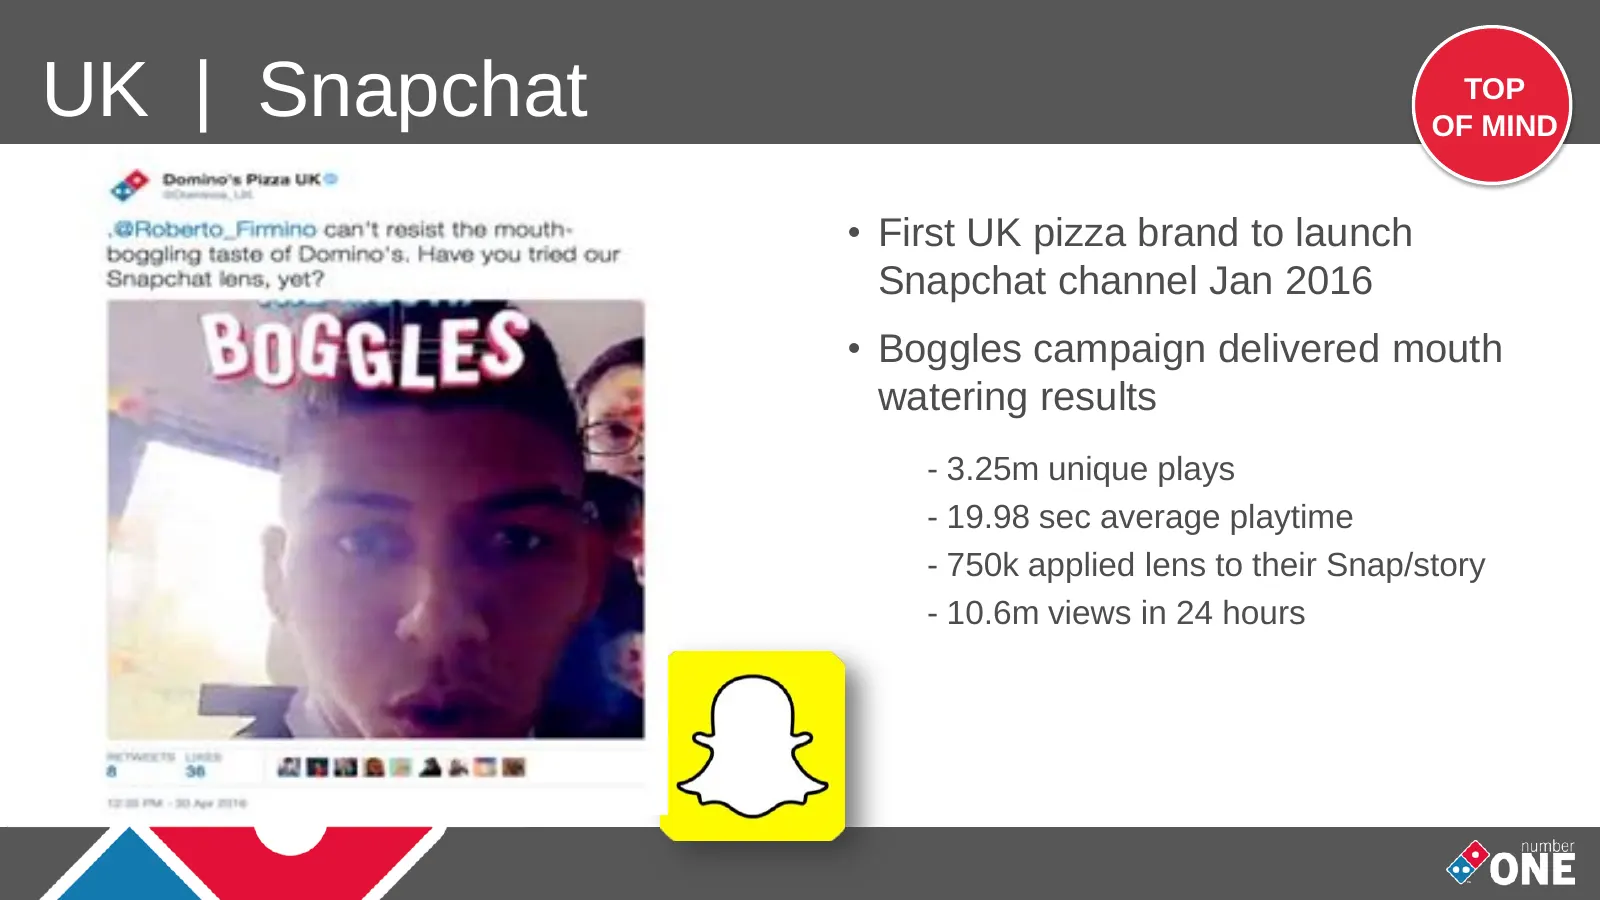
UK | Snapchat TOP OF MIND • First UK pizza brand to launch Snapchat channel Jan 2016 • Boggles campaign delivered mouth watering results - 3.25m unique plays - 19.98 sec average playtime - 750k applied lens to their Snap/story - 10.6m views in 24 hours
Slide 70: UK | Facebook Live event
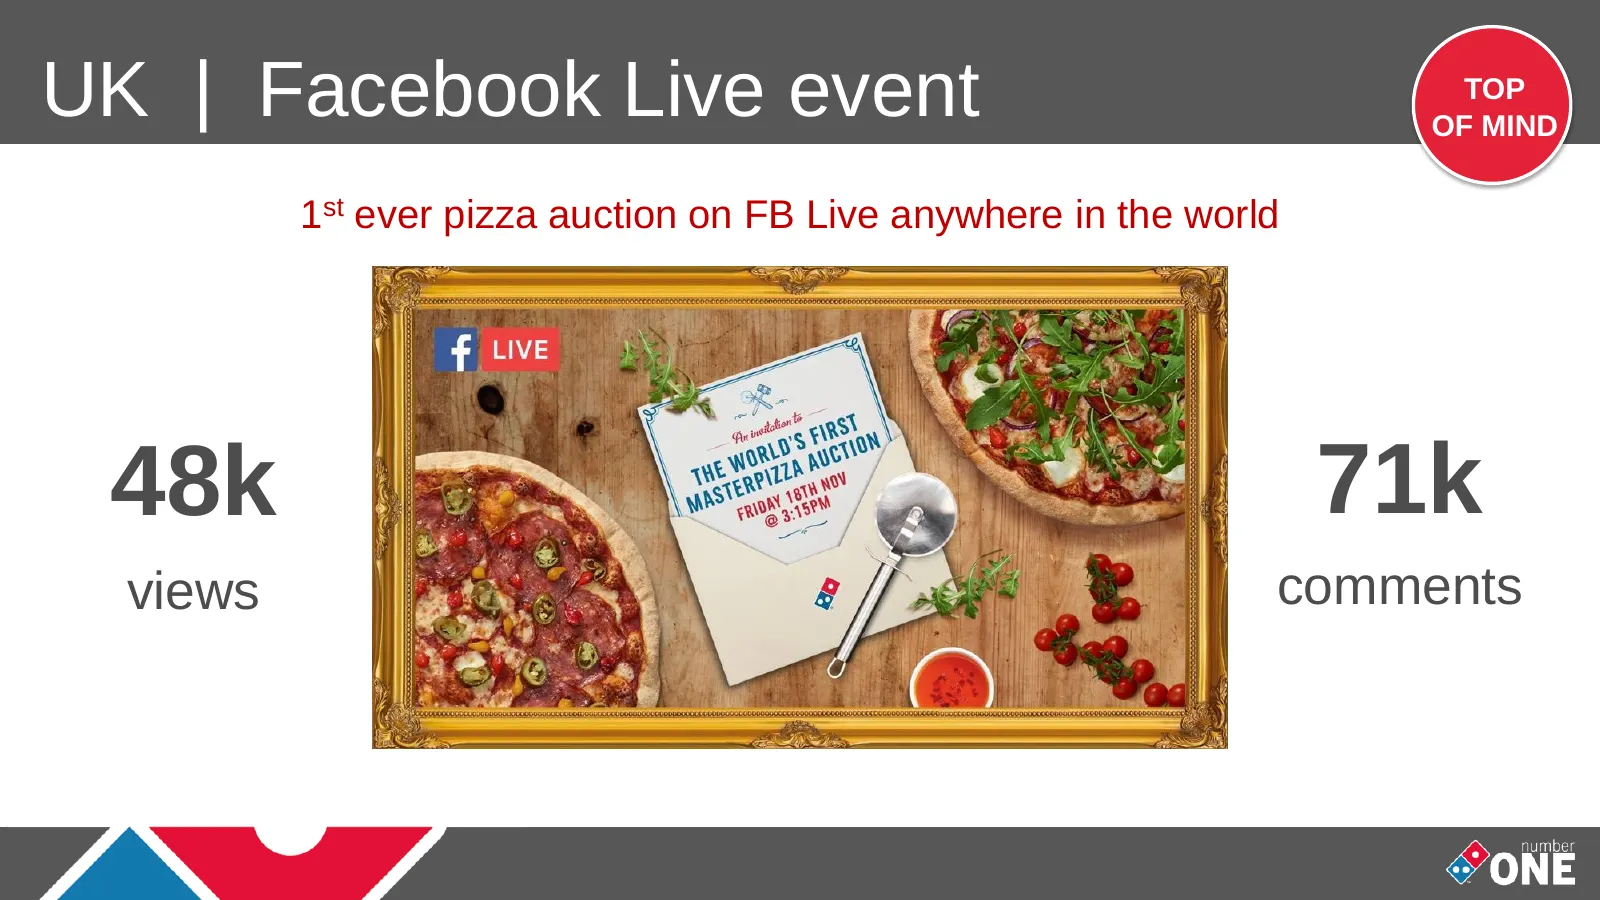
UK | Facebook Live event TOP OF MIND 1st ever pizza auction on FB Live anywhere in the world 48k 71k views comments
Slide 71: UK | Benefits of digital – fuels growth
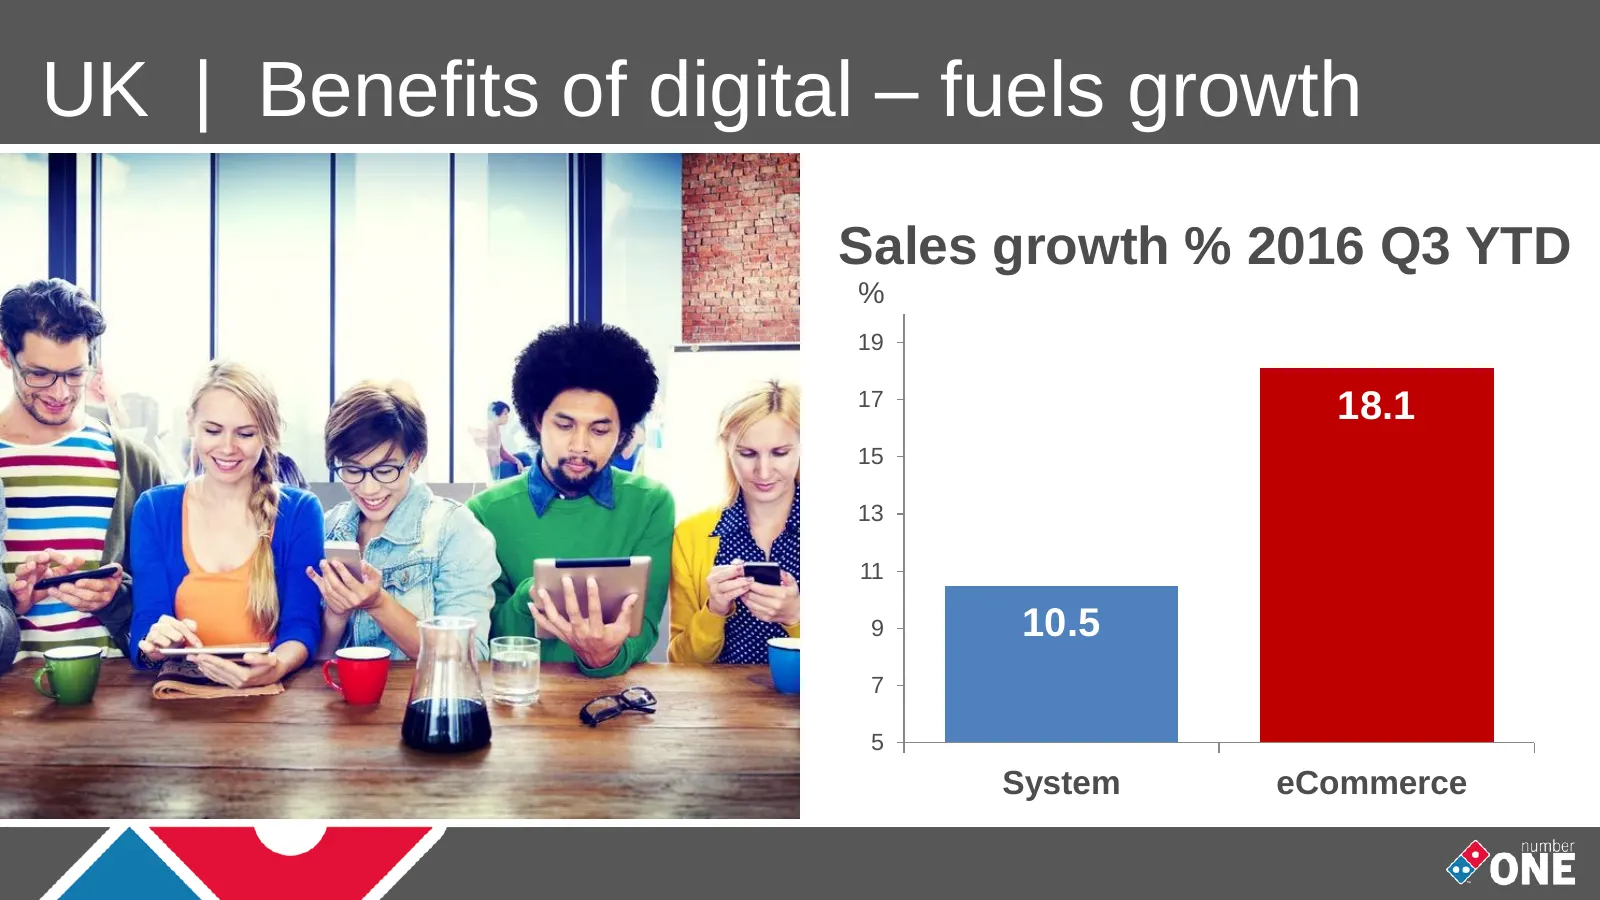
UK | Benefits of digital – fuels growth Sales growth % 2016 Q3 YTD % 19 17 18.1 15 13 11 9 10.5 7 5 System eCommerce
Slide 72: UK | Benefits of digital – increases frequency
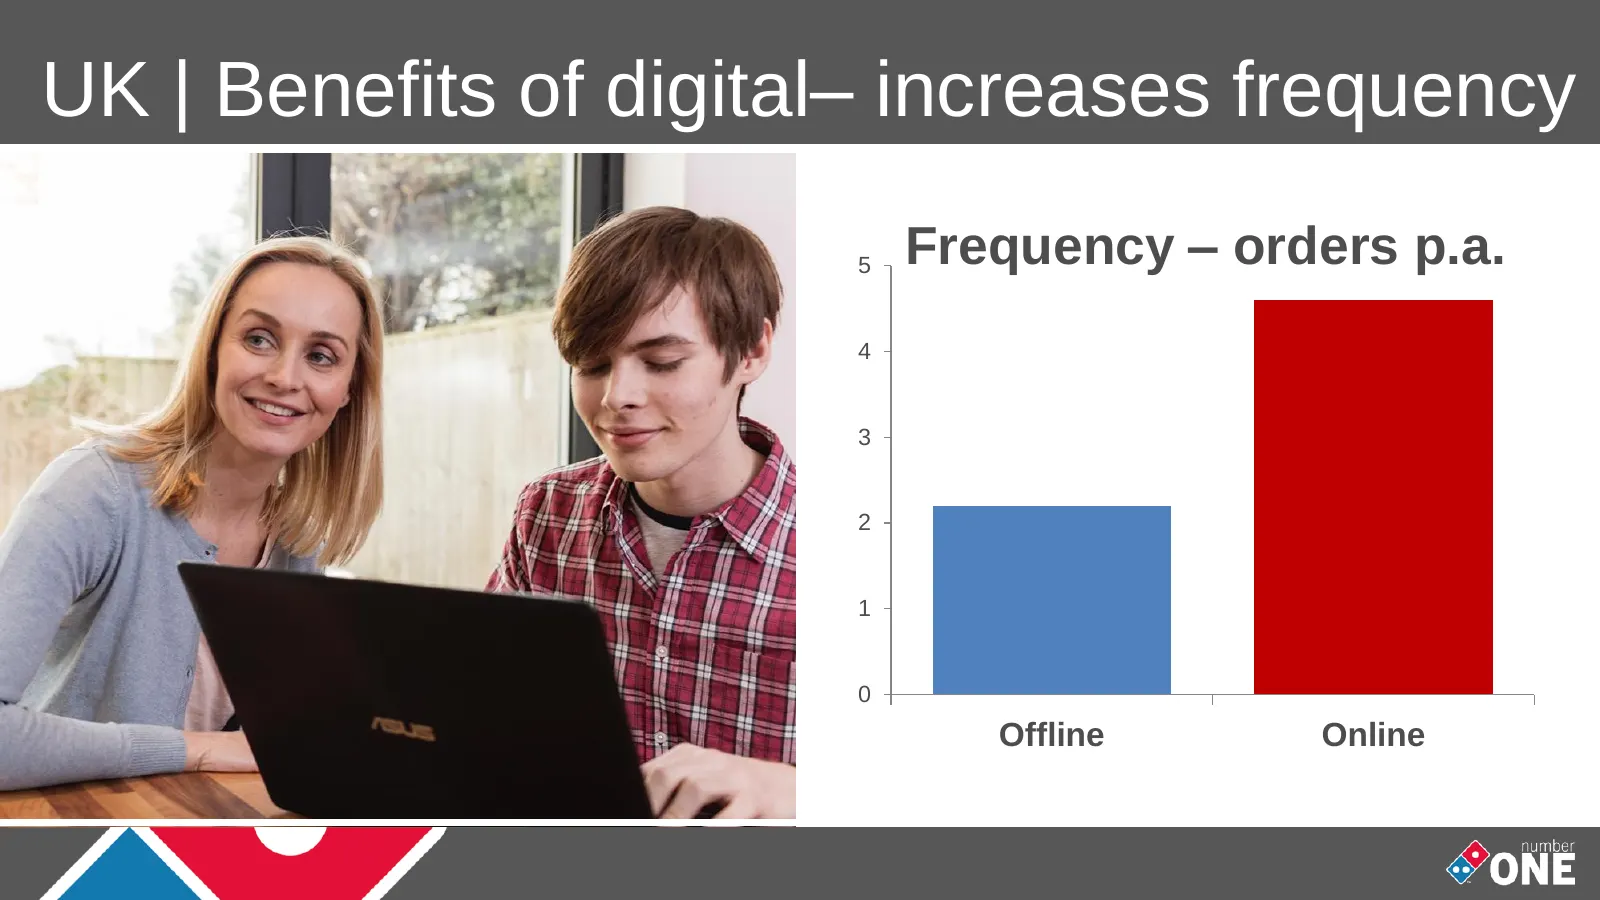
UK | Benefits of digital– increases frequency 5 Frequency – orders p.a. 4 3 2 1 0 Offline Online
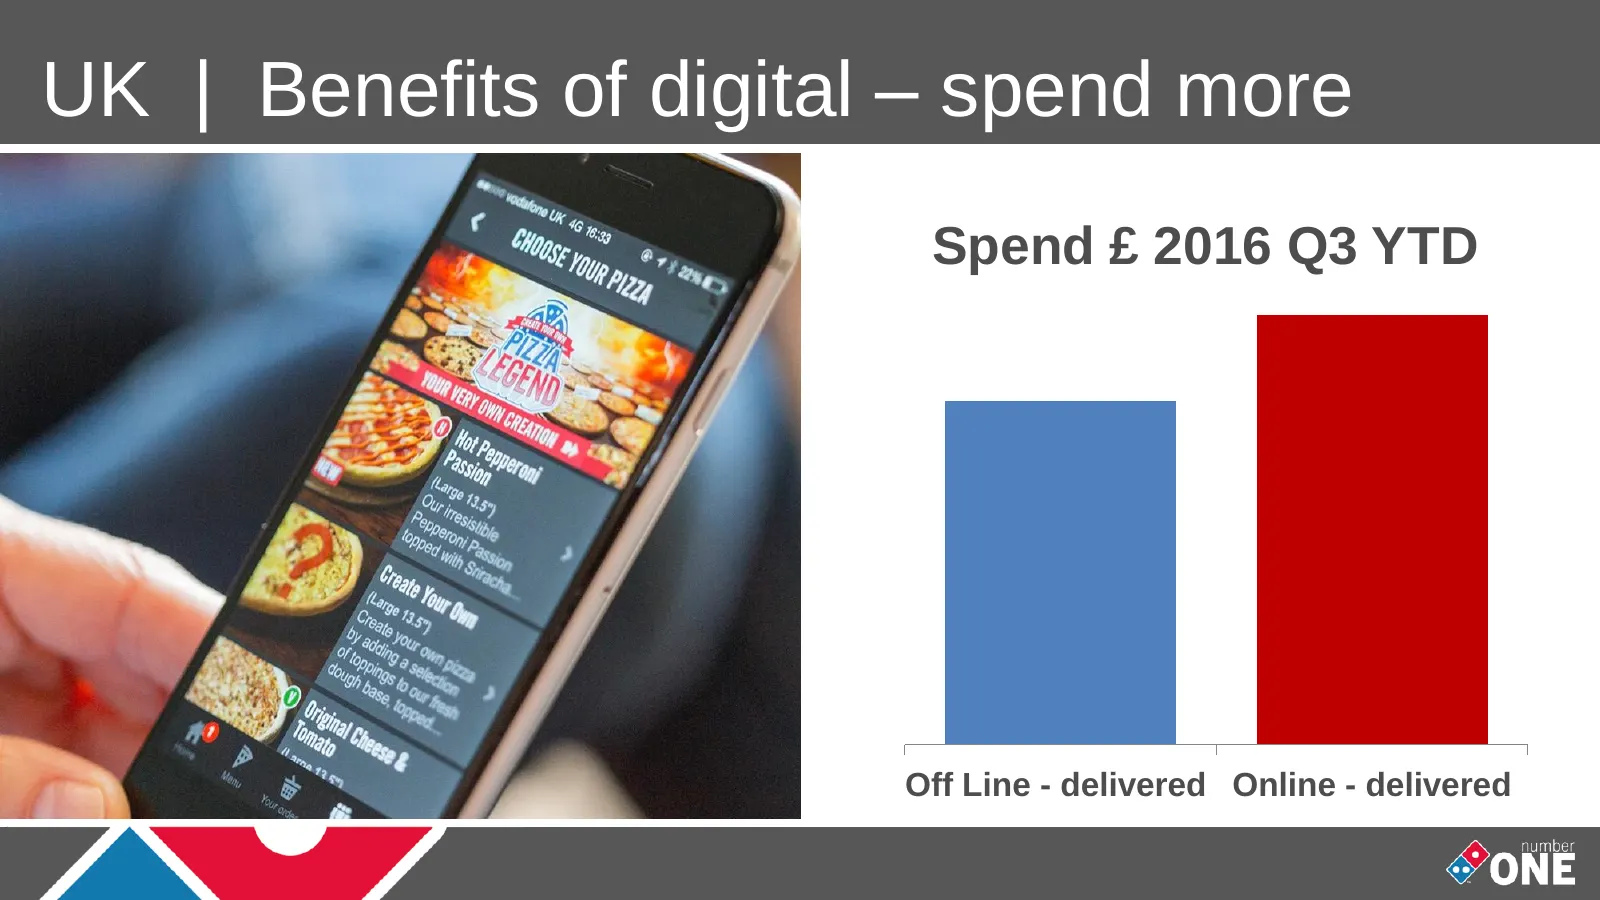
Slide 73: UK | Benefits of digital – spend more
UK | Benefits of digital – spend more Spend £ 2016 Q3 YTD Off Line - delivered Online - delivered
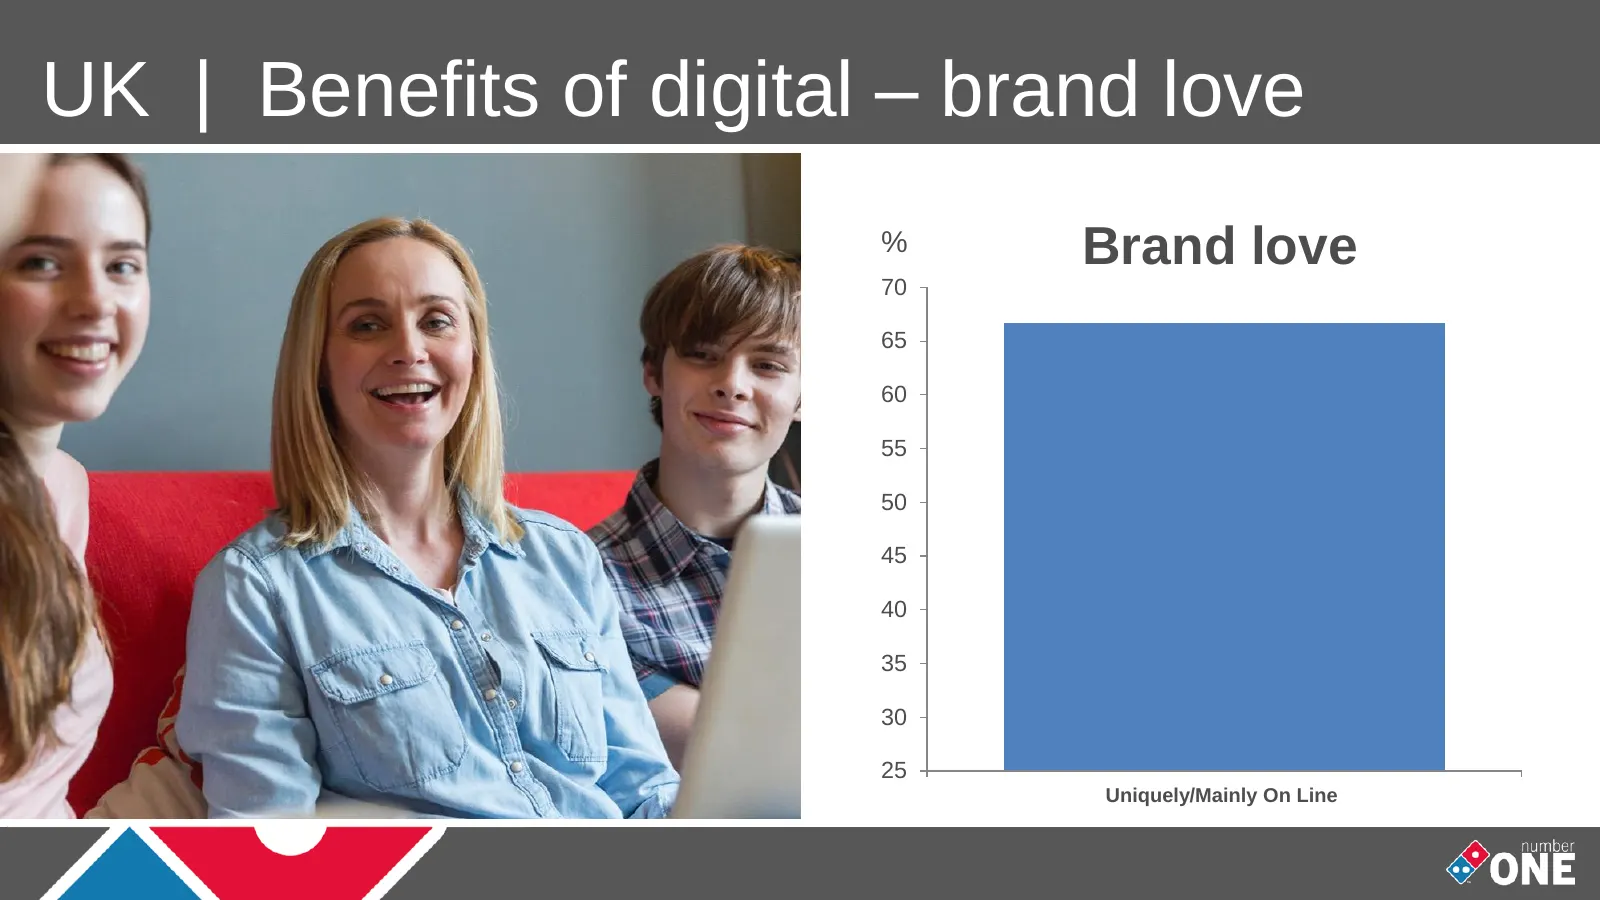
Slide 74: UK | Benefits of digital – brand love
UK | Benefits of digital – brand love % Brand love 70 65 60 55 50 45 40 35 30 25 Uniquely/Mainly On Line
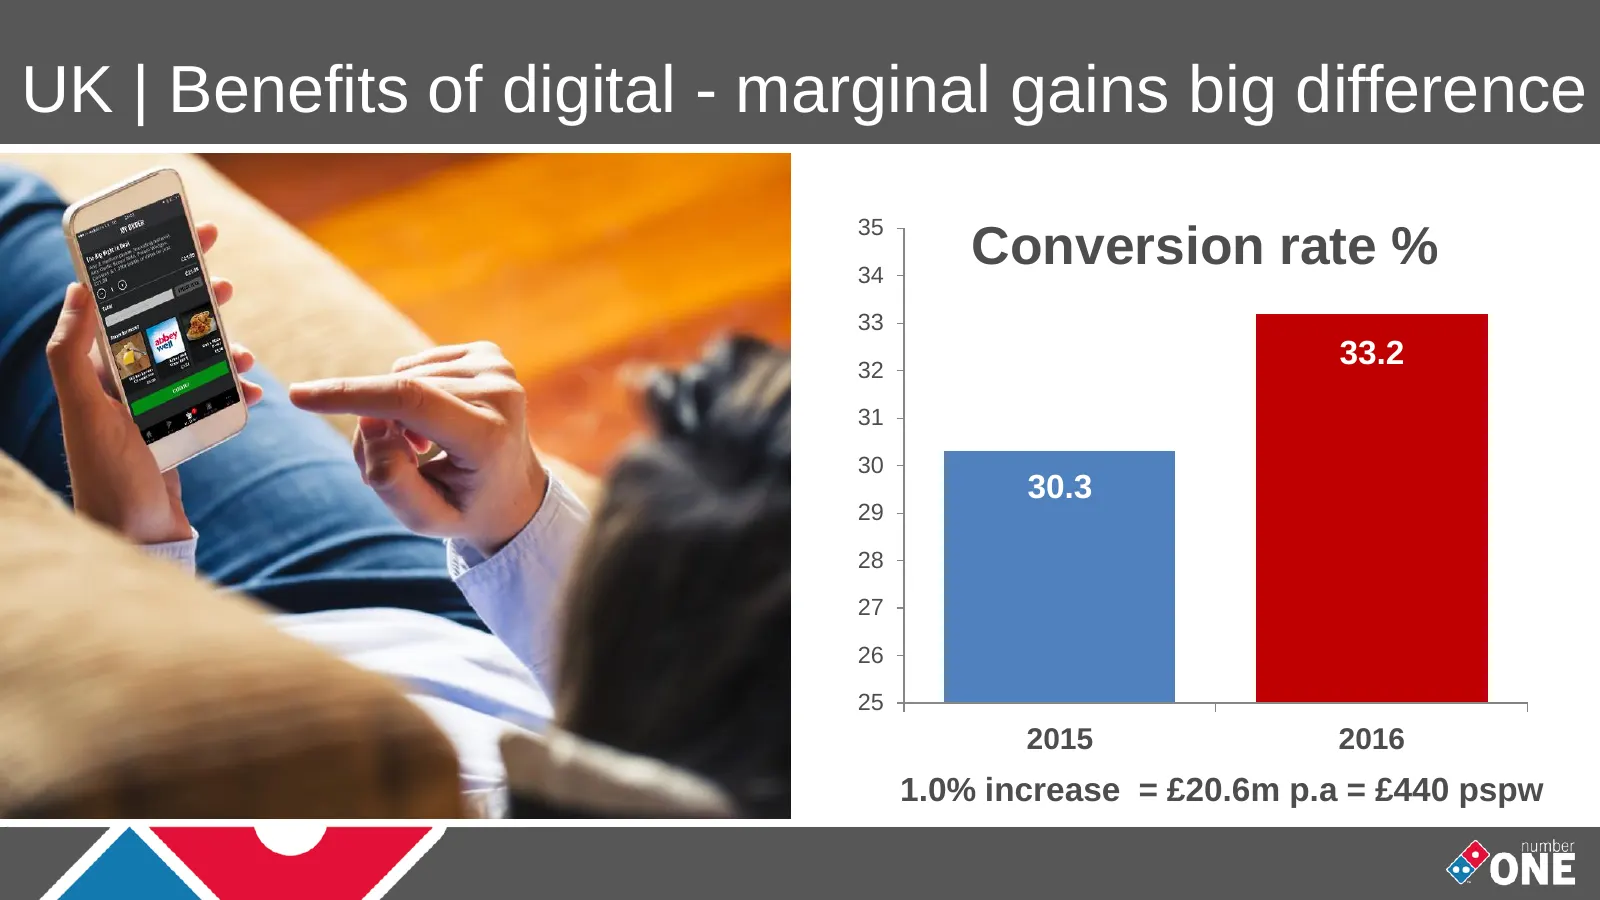
Slide 75: UK | Benefits of digital - marginal gains big difference
UK | Benefits of digital - marginal gains big difference 35 34 Conversion rate % 33 32 33.2 31 30 30.3 29 28 27 26 25 2015 2016 1.0% increase = £20.6m p.a = £440 pspw
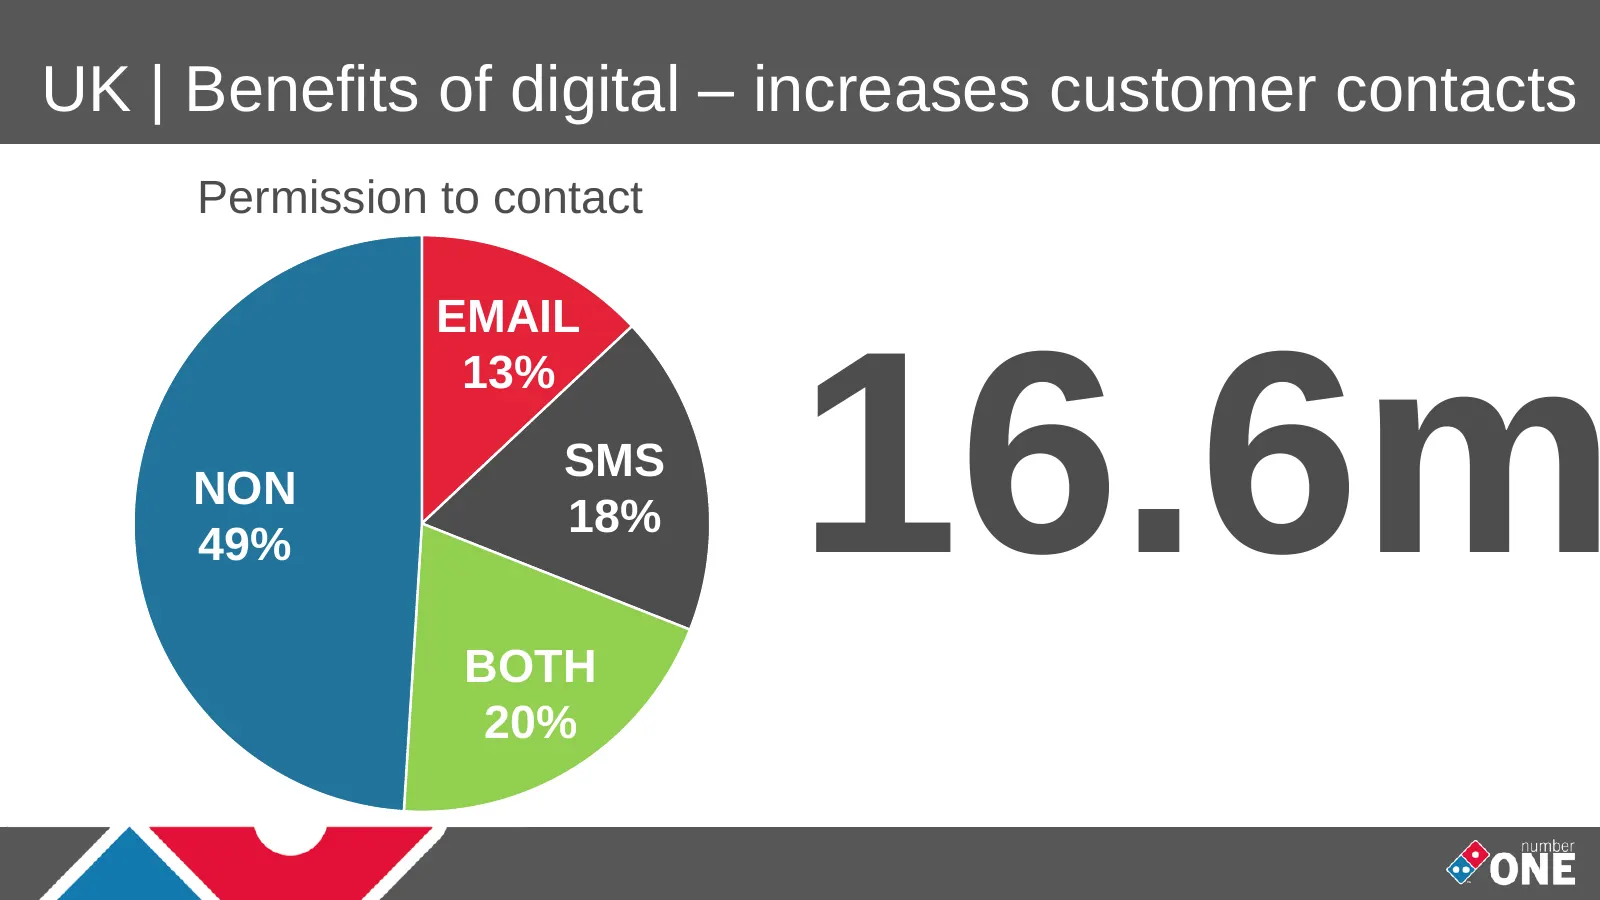
Slide 76: UK | Benefits of digital – increases customer contacts
UK | Benefits of digital – increases customer contacts Permission to contact EMAIL 16.6m 13% SMS NON 18% 49% BOTH 20%
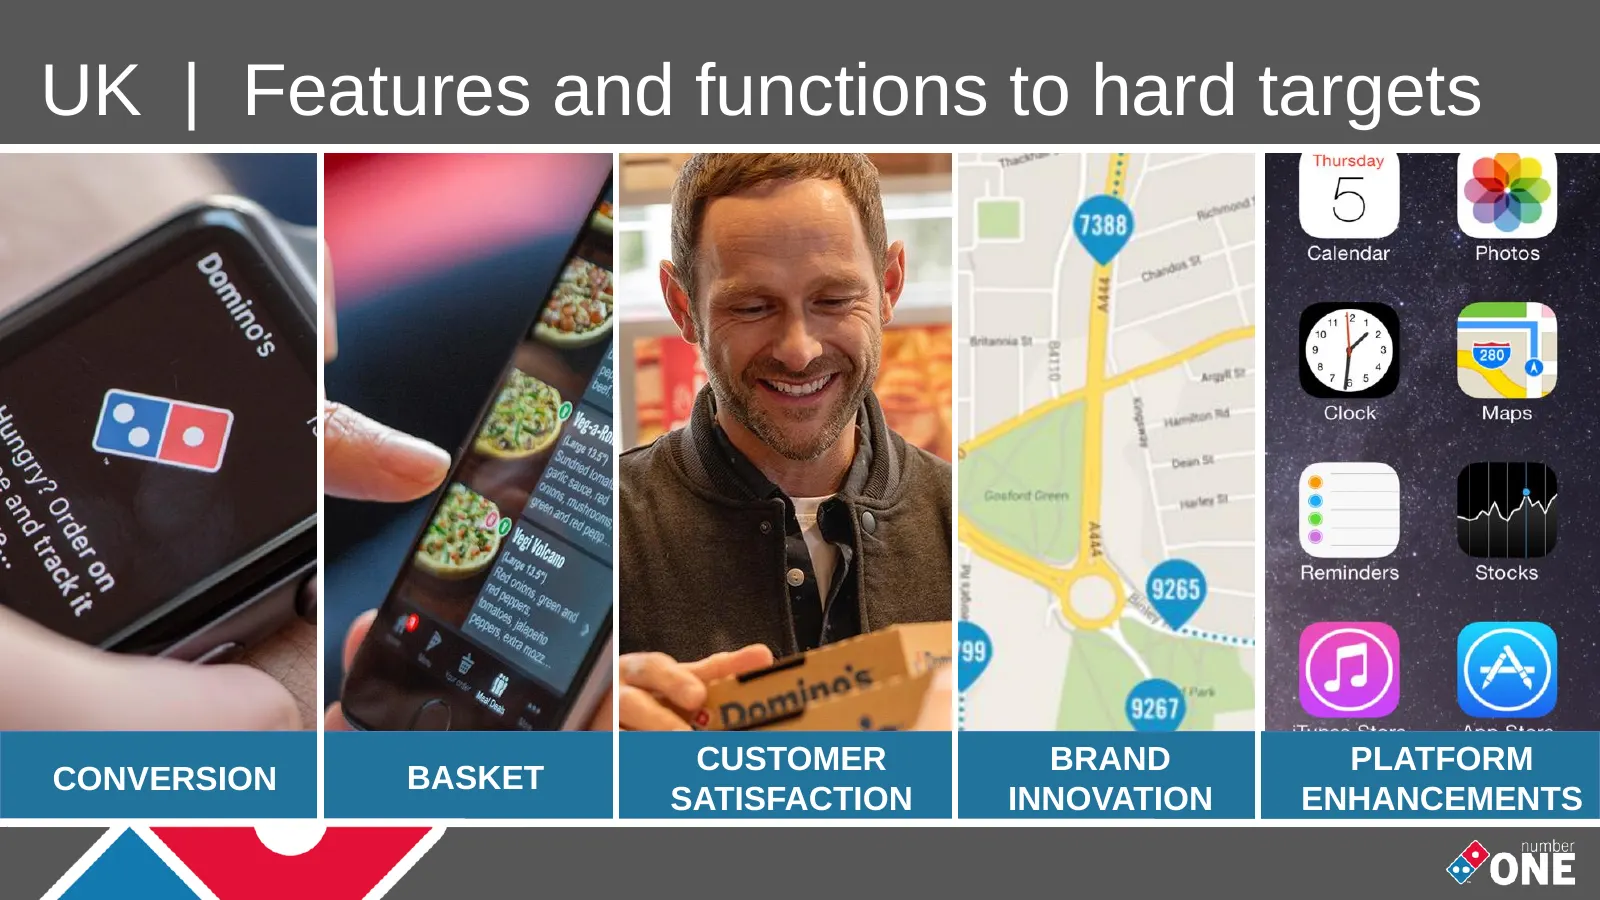
Slide 77: UK | Features and functions to hard targets
UK | Features and functions to hard targets CUSTOMER BRAND PLATFORM CONVERSION BASKET SATISFACTION INNOVATION ENHANCEMENTS
Slide 78: UK | Increased software development output
UK | Increased software development output • Consumer first • Increased investment • Special relationship between marketing and IT • More A/B testing • Agile working • Increased productivity CUSTOMER BRAND PLATFORM CONVERSION BASKET SATISFACTION INNOVATION ENHANCEMENTS
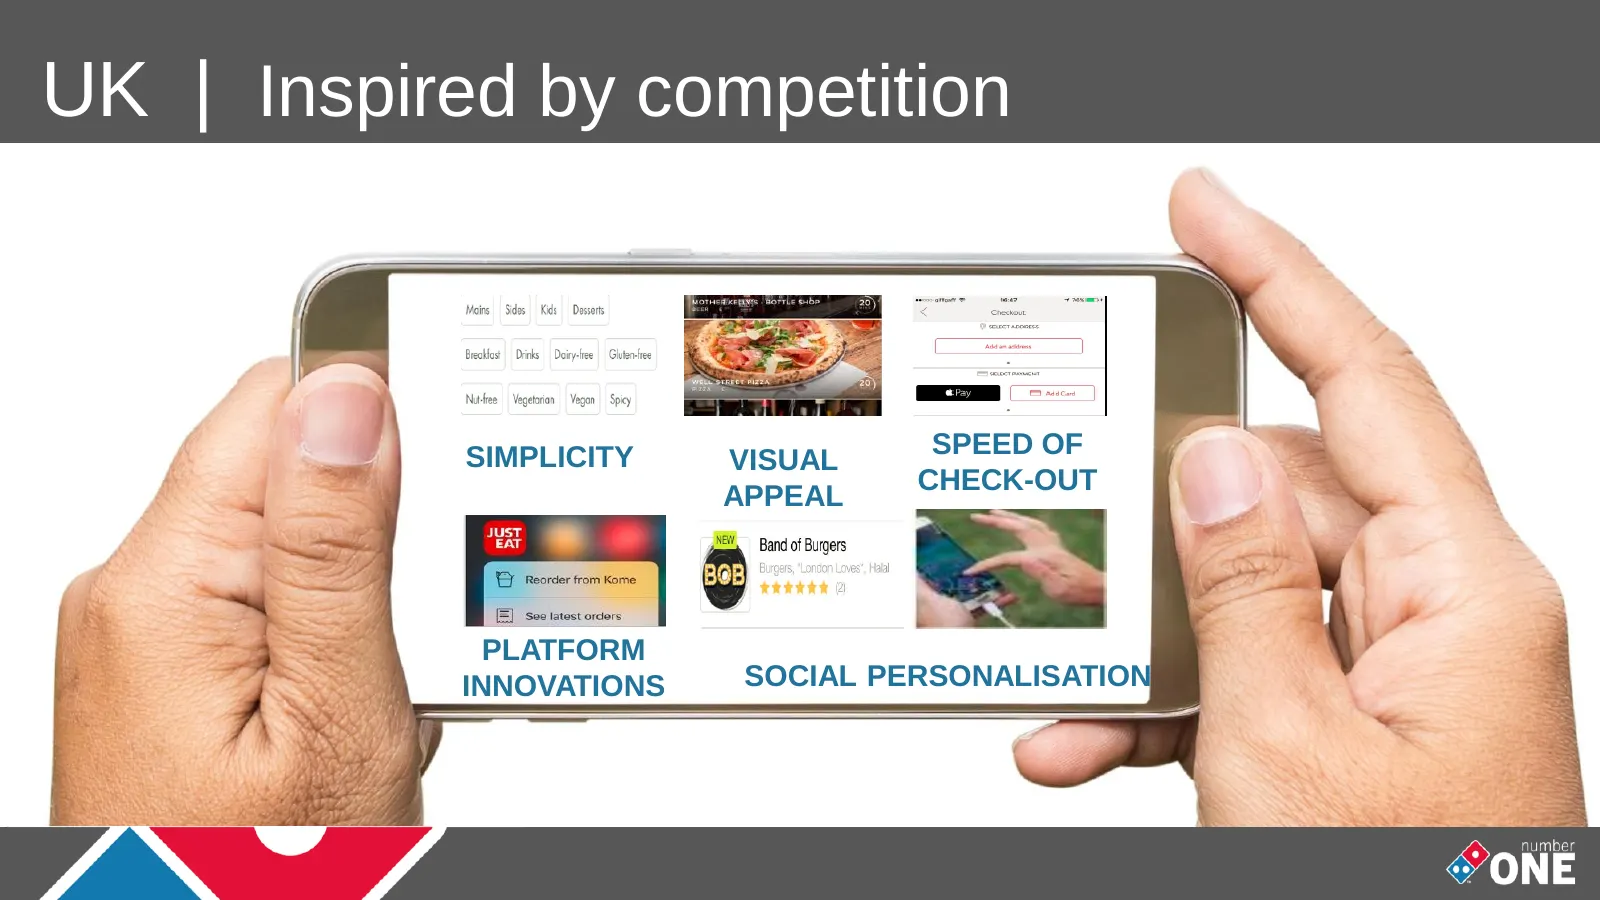
Slide 79: UK | Inspired by competition
UK | Inspired by competition SIMPLICITY SPEED OF VISUAL CHECK-OUT APPEAL PLATFORM INNOVATIONS SOCIAL PERSONALISATION
Slide 80: UK | Using technology to excite and inspire our customers
UK | Using technology to excite and inspire our customers • Launched chat-bot Aug 2016 on Facebook Messenger • Add favourite/recent orders, food imagery and pizza tracker to conversation • Extend to other social platforms • Broaden beyond eCommerce to customer service
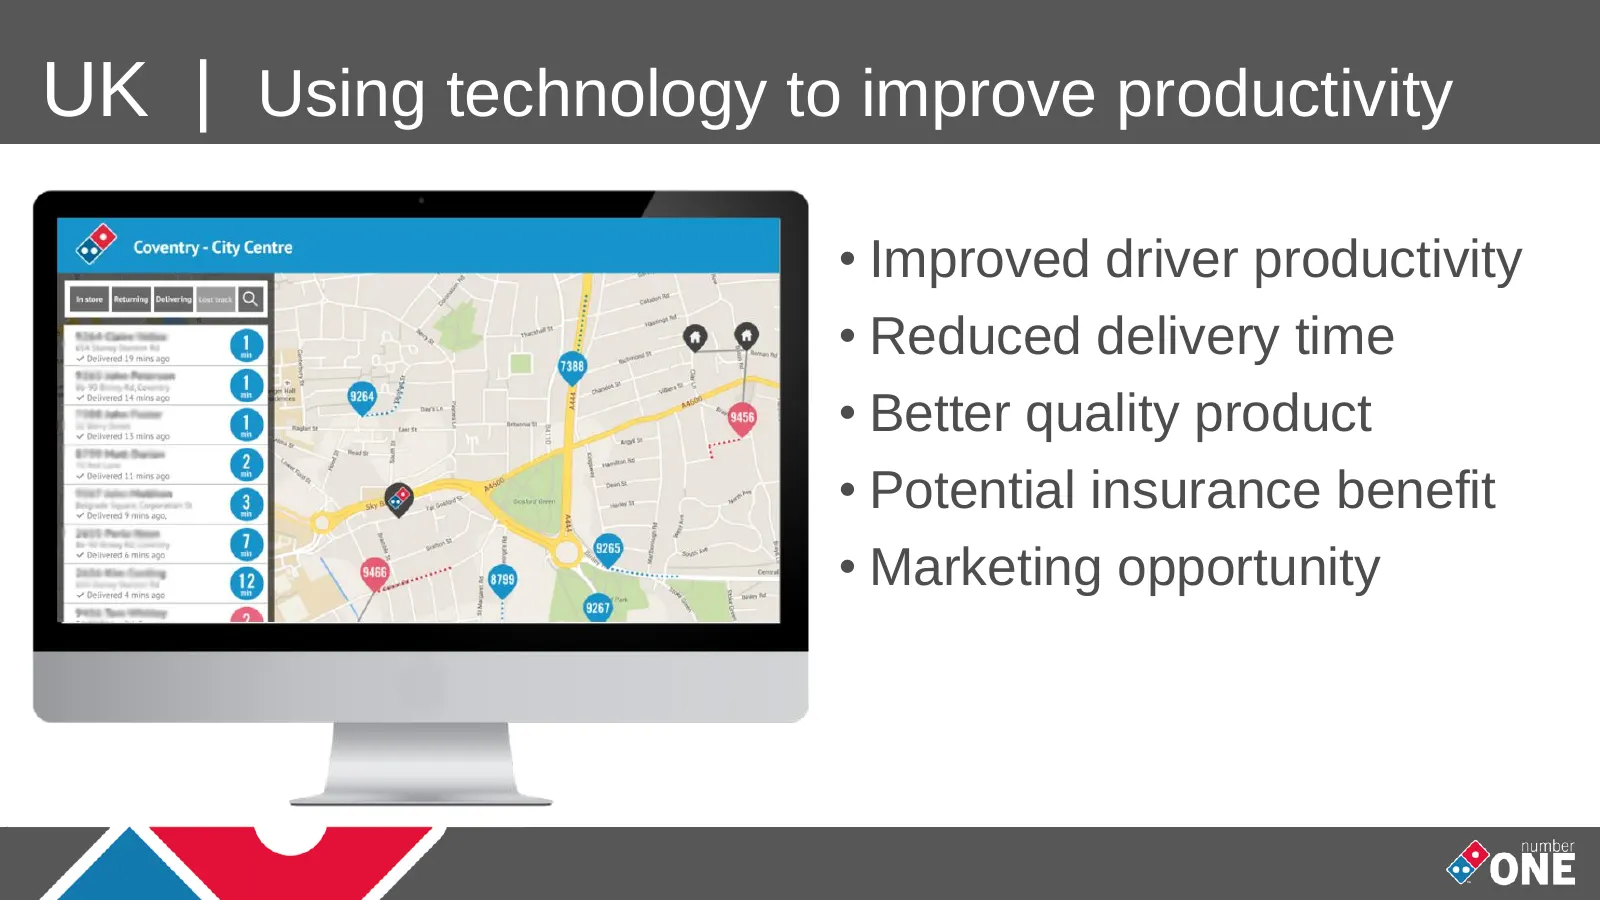
Slide 81: UK | Using technology to improve productivity
UK | Using technology to improve productivity PROOF OF CONCEPT results • Improved driver productivity • Reduced delivery time • Better quality product • Potential insurance benefit • Marketing opportunity
Slide 82: UK | Summary
UK | Summary • Consistent track record • Market leading awareness, SET A NEW regard & satisfaction STORE TARGET OF 1,600 • World class franchisees & teams • Innovative use of technology • Headroom for growth
Slide 83: Supply Chain
Supply Chain Pete Trundley Supply Chain Director
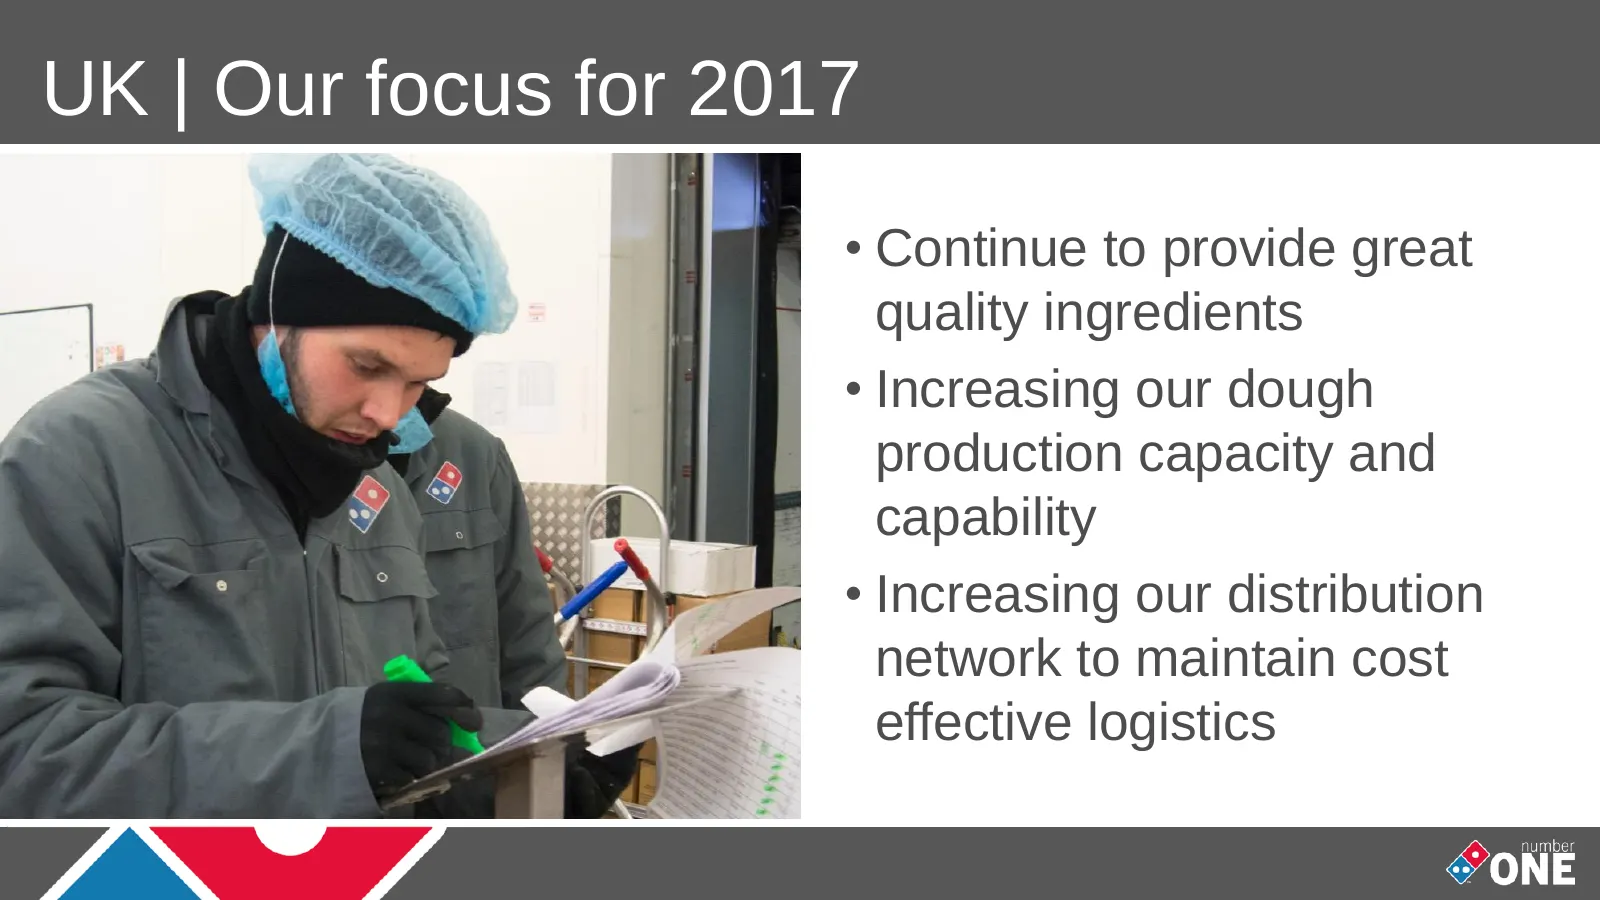
Slide 84: UK | Our focus for 2017
UK | Our focus for 2017 • Continue to provide great quality ingredients • Increasing our dough production capacity and capability • Increasing our distribution network to maintain cost effective logistics
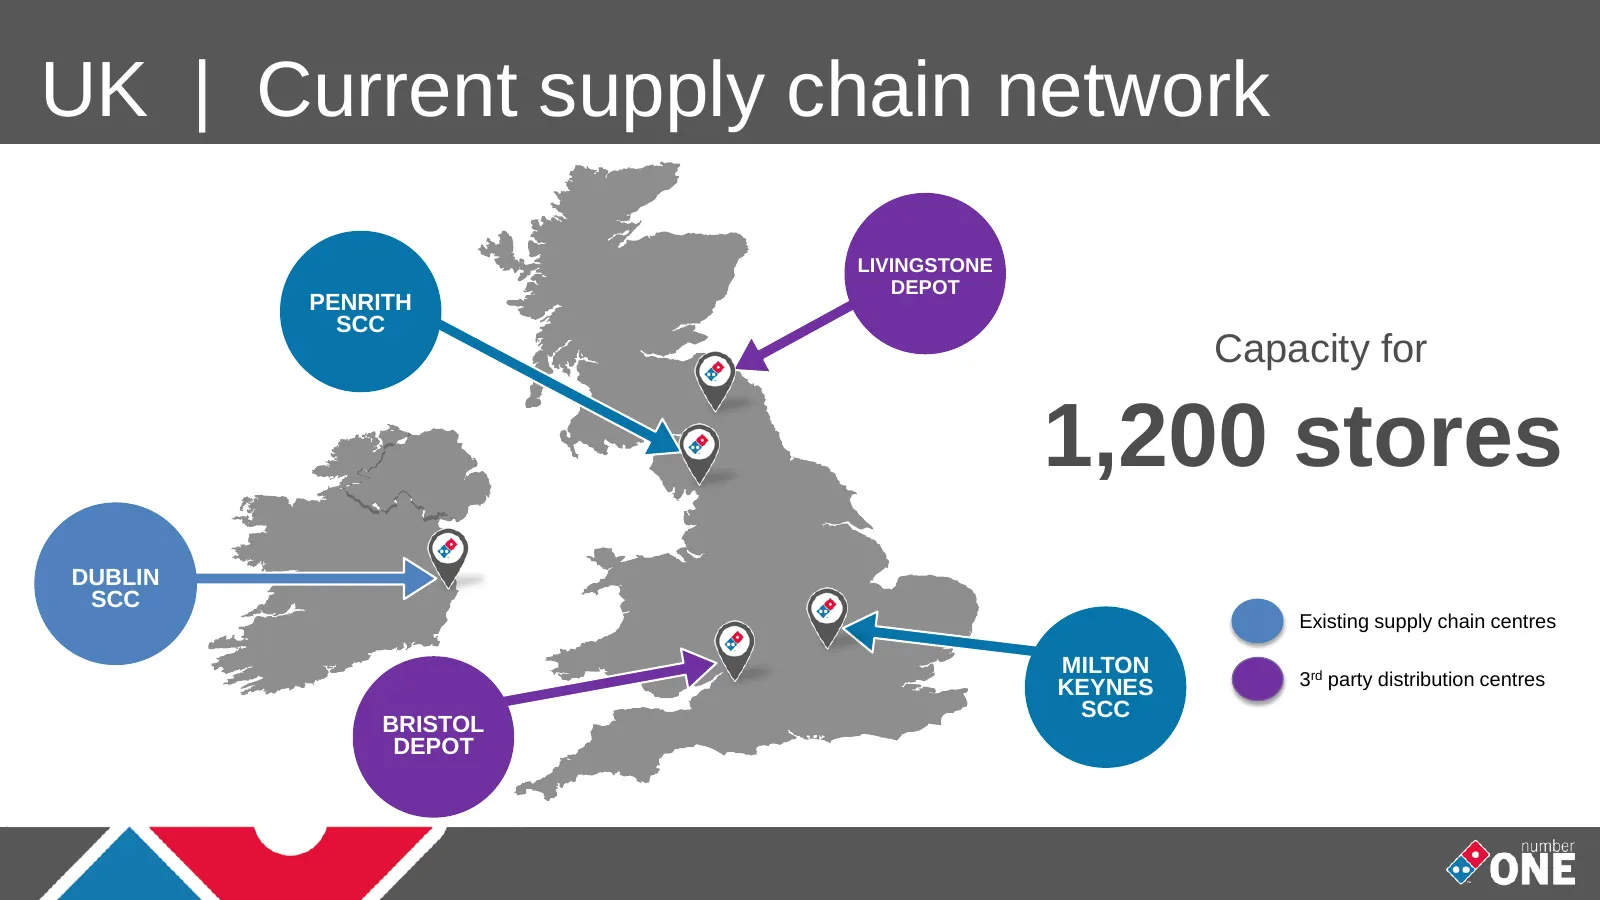
Slide 85: Current supply chain network
UK | Current supply chain network LIVINGSTONE DEPOT PENRITH SCC Capacity for WARRINGTON SCC 1,200 stores (550 stores) DUBLIN SCC Dublin Existing supply chain centres MILTON KEYNES 3rd party distribution centres SCC BRISTOL DEPOT
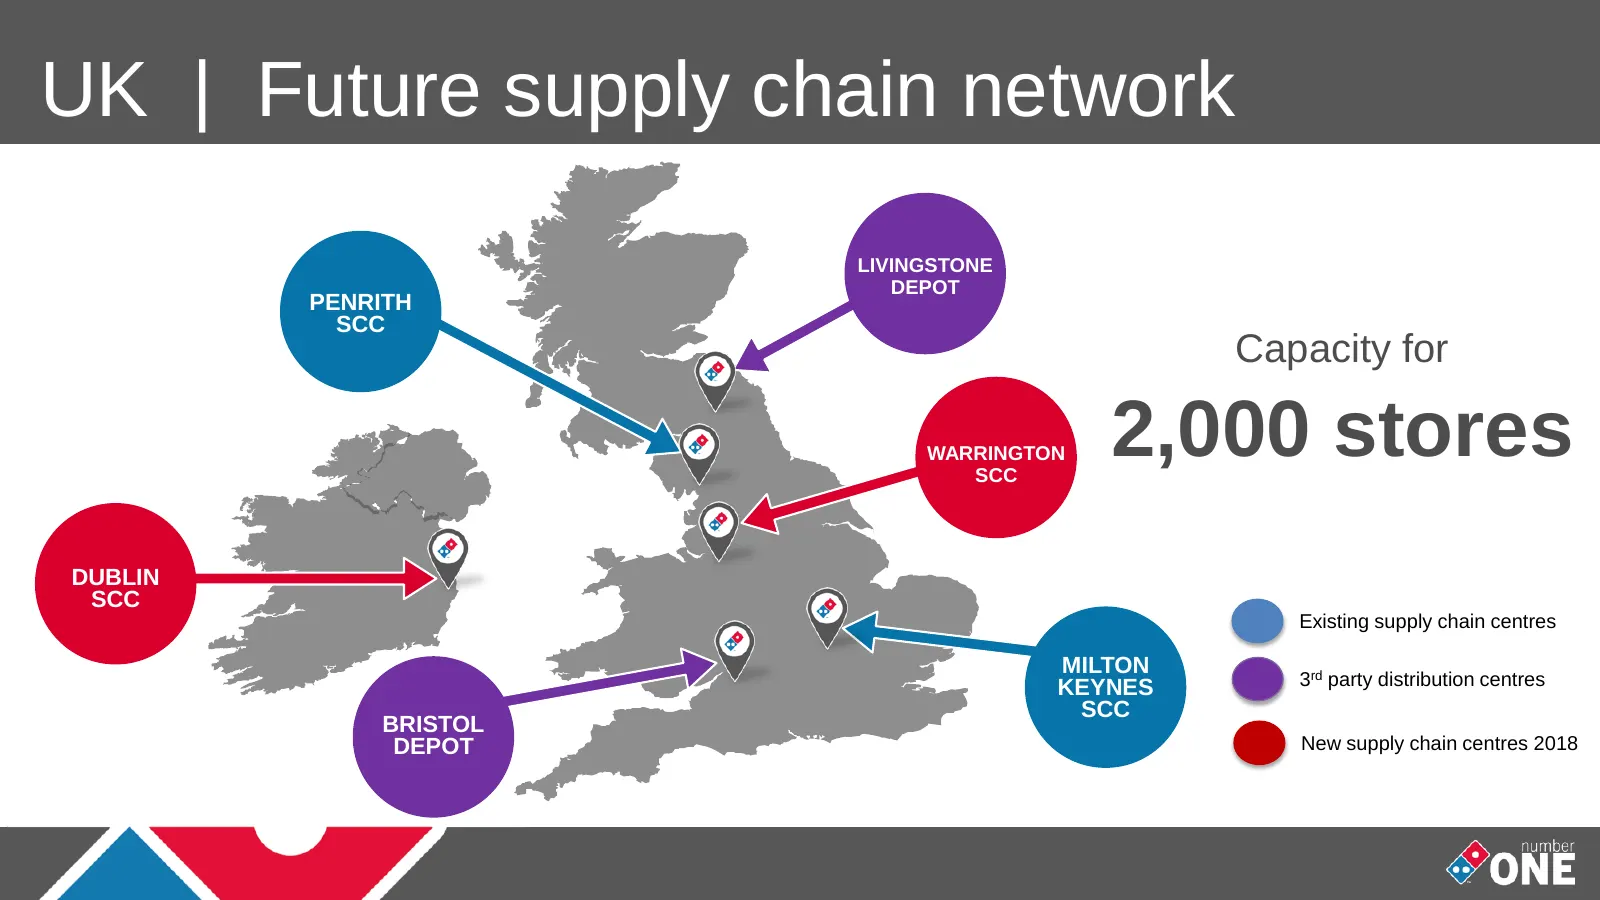
Slide 86: UK | Future supply chain network
UK | Future supply chain network LIVINGSTONE DEPOT PENRITH SCC Capacity for WARRINGTON SCC 2,000 stores DUBLIN SCC Dublin Existing supply chain centres MILTON KEYNES 3rd party distribution centres SCC BRISTOL DEPOT New supply chain centres 2018
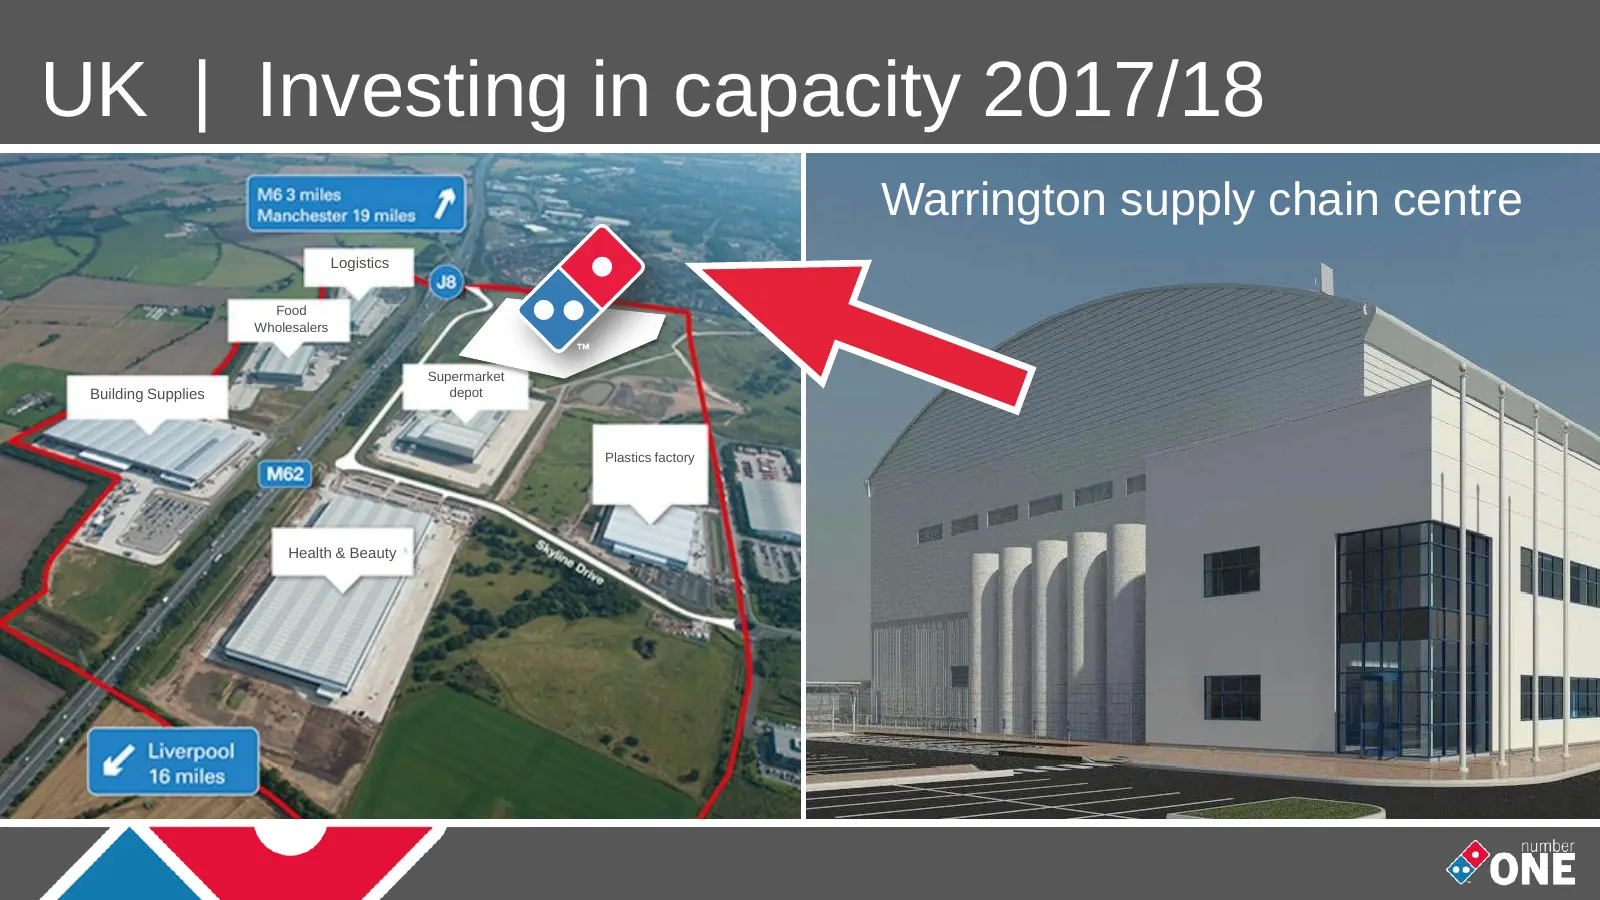
Slide 87: UK | Investing in capacity 2017/18
UK | Investing in capacity 2017/18 Warrington supply chain centre Logistics Food Wholesalers Supermarket Building Supplies depot Plastics factory Health & Beauty
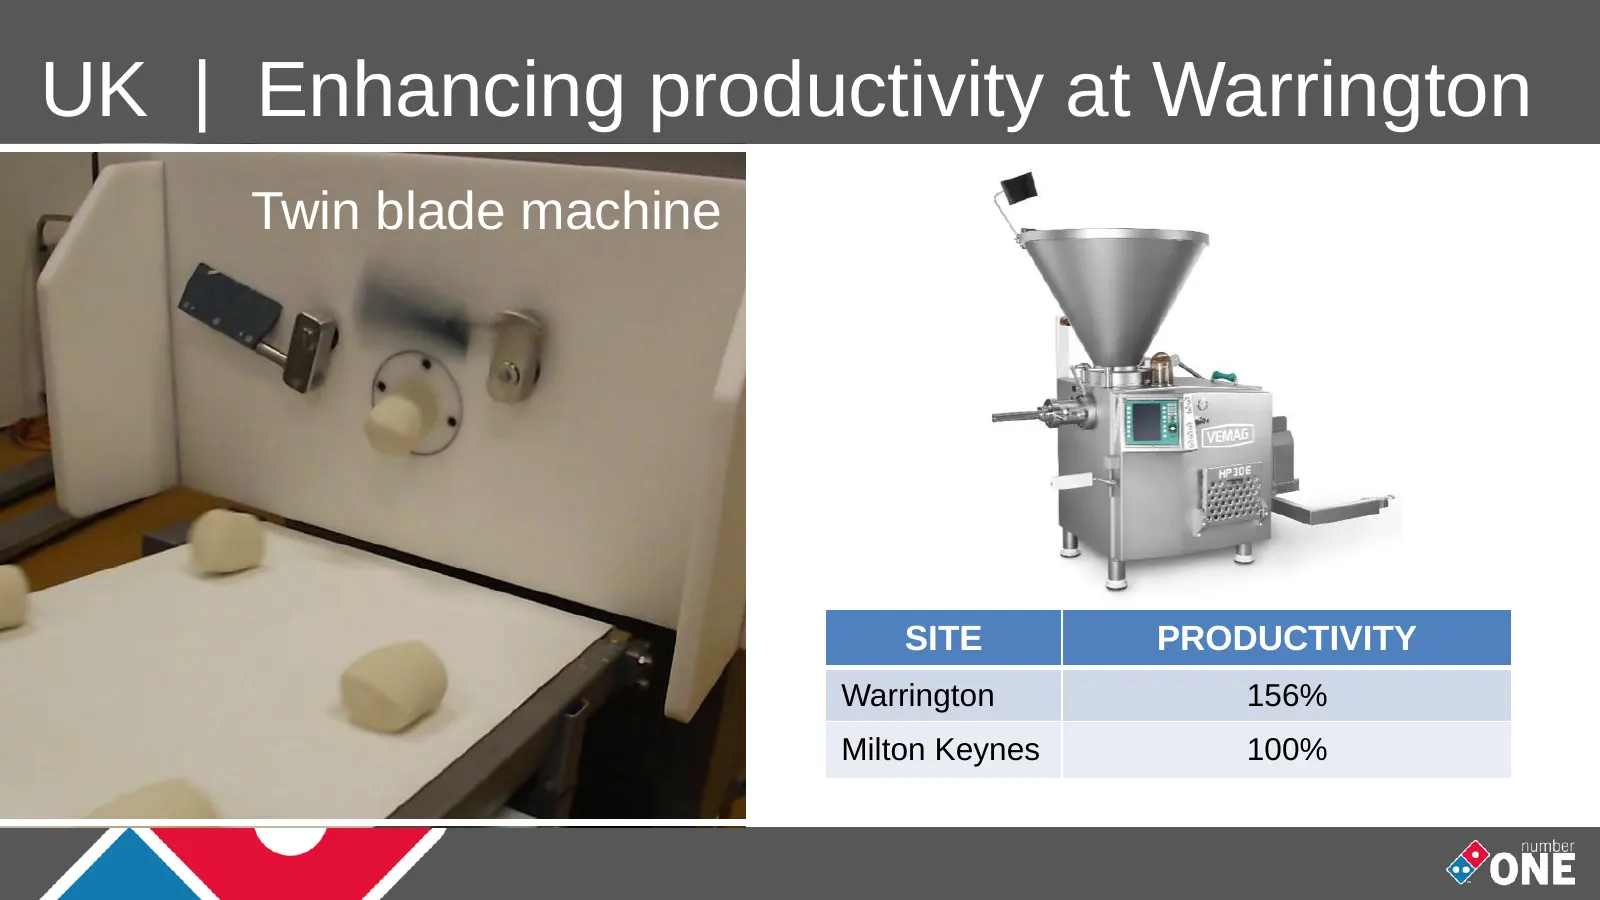
Slide 88: UK | Enhancing productivity at Warrington
UK | Enhancing productivity at Warrington Twin blade machine SITE PRODUCTIVITY Warrington 156% Milton Keynes 100%
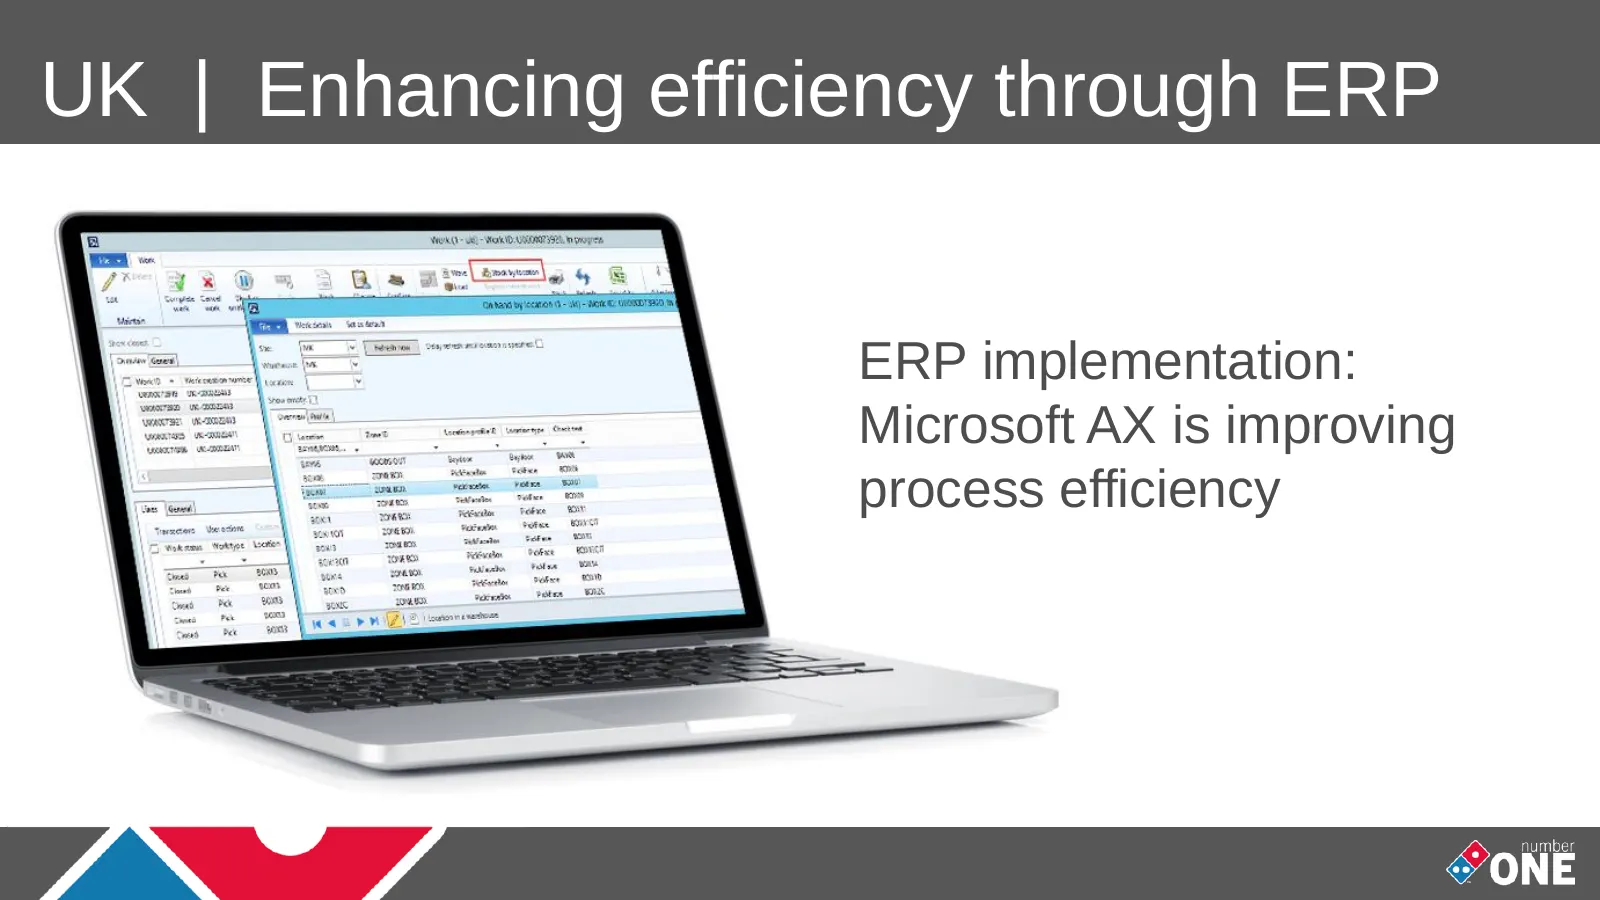
Slide 89: UK | Enhancing efficiency through ERP
UK | Enhancing efficiency through ERP ERP implementation: Microsoft AX is improving process efficiency
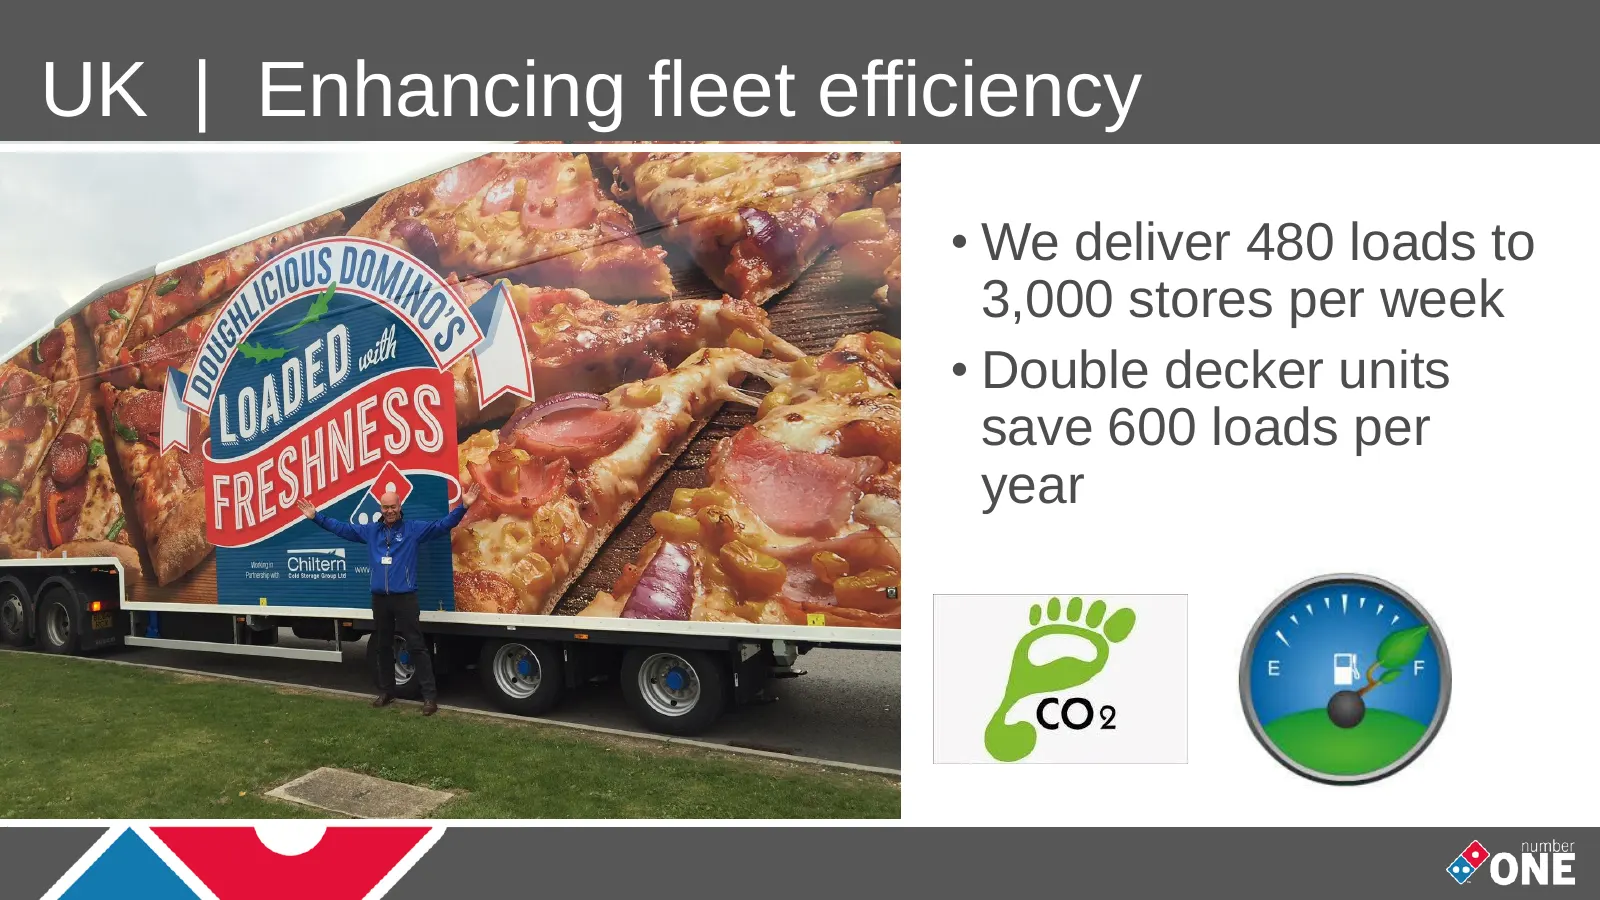
Slide 90: UK | Enhancing fleet efficiency
UK | Enhancing fleet efficiency • We deliver 480 loads to 3,000 stores per week • Double decker units save 600 loads per year
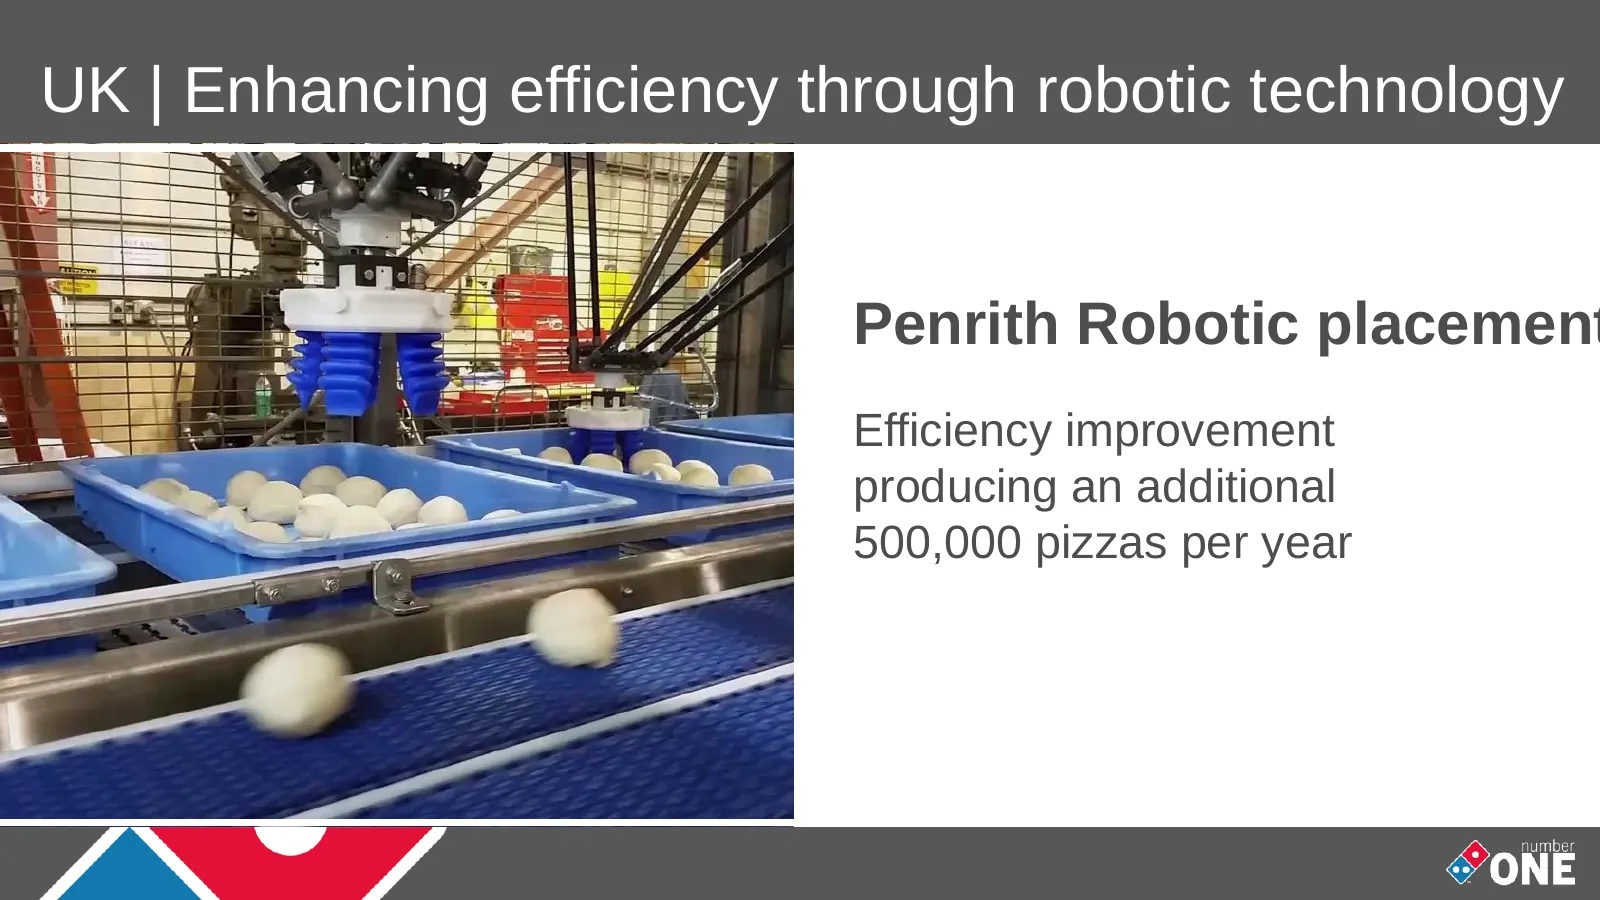
Slide 91: UK | Enhancing efficiency through robotic technology
UK | Enhancing efficiency through robotic technology Penrith Robotic placement Efficiency improvement producing an additional 500,000 pizzas per year
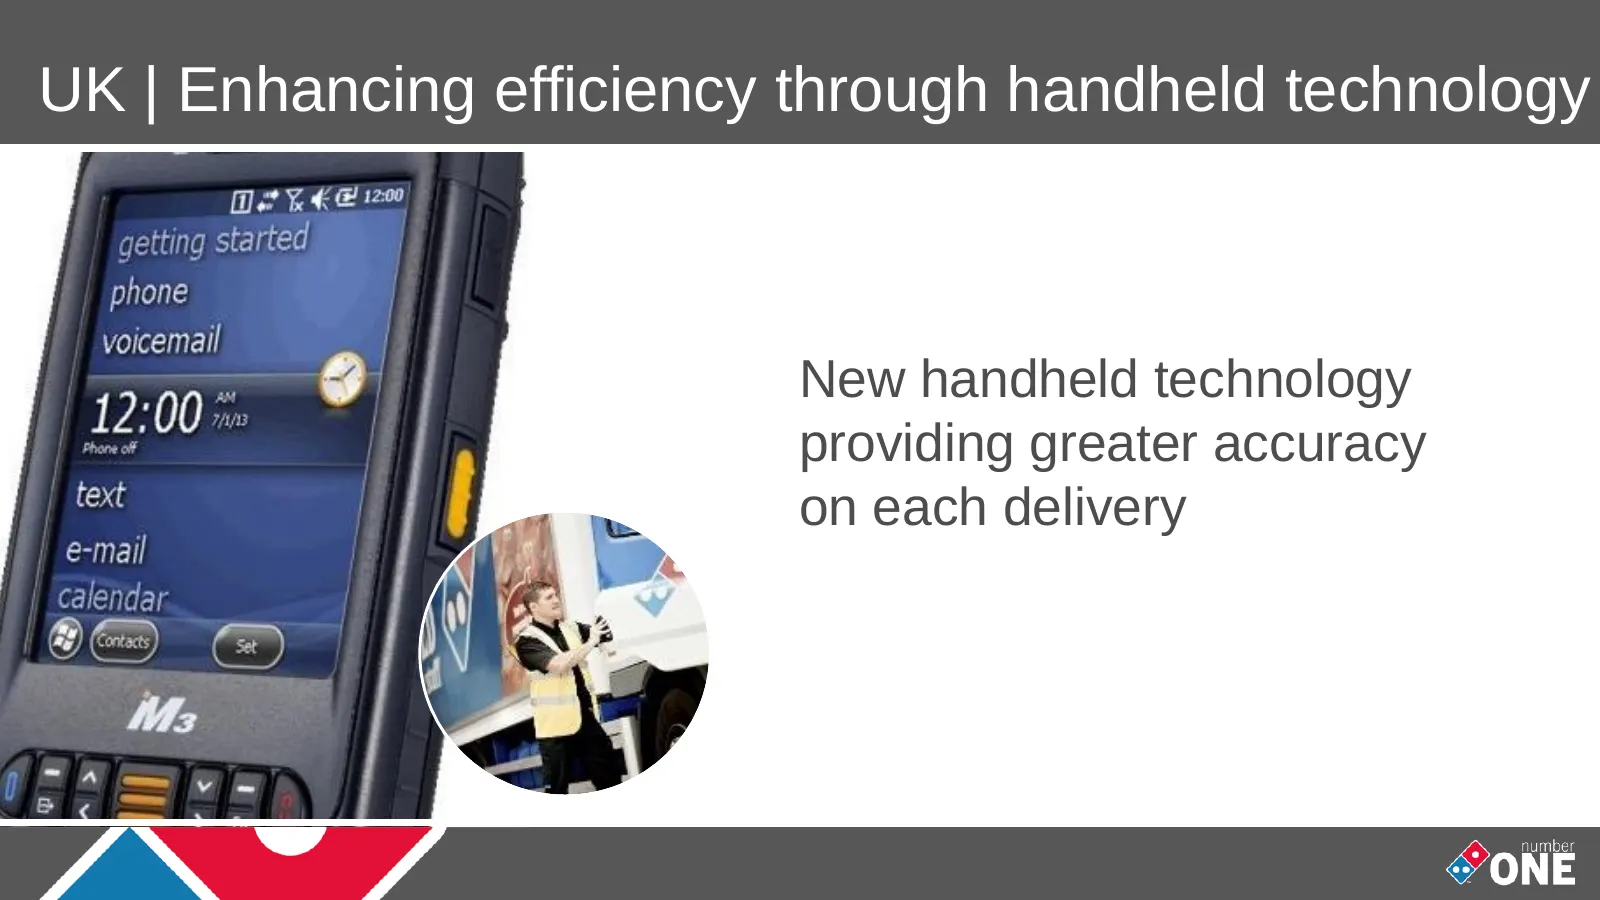
Slide 92: UK | Enhancing efficiency through handheld technology
UK | Enhancing efficiency through handheld technology New handheld technology providing greater accuracy on each delivery
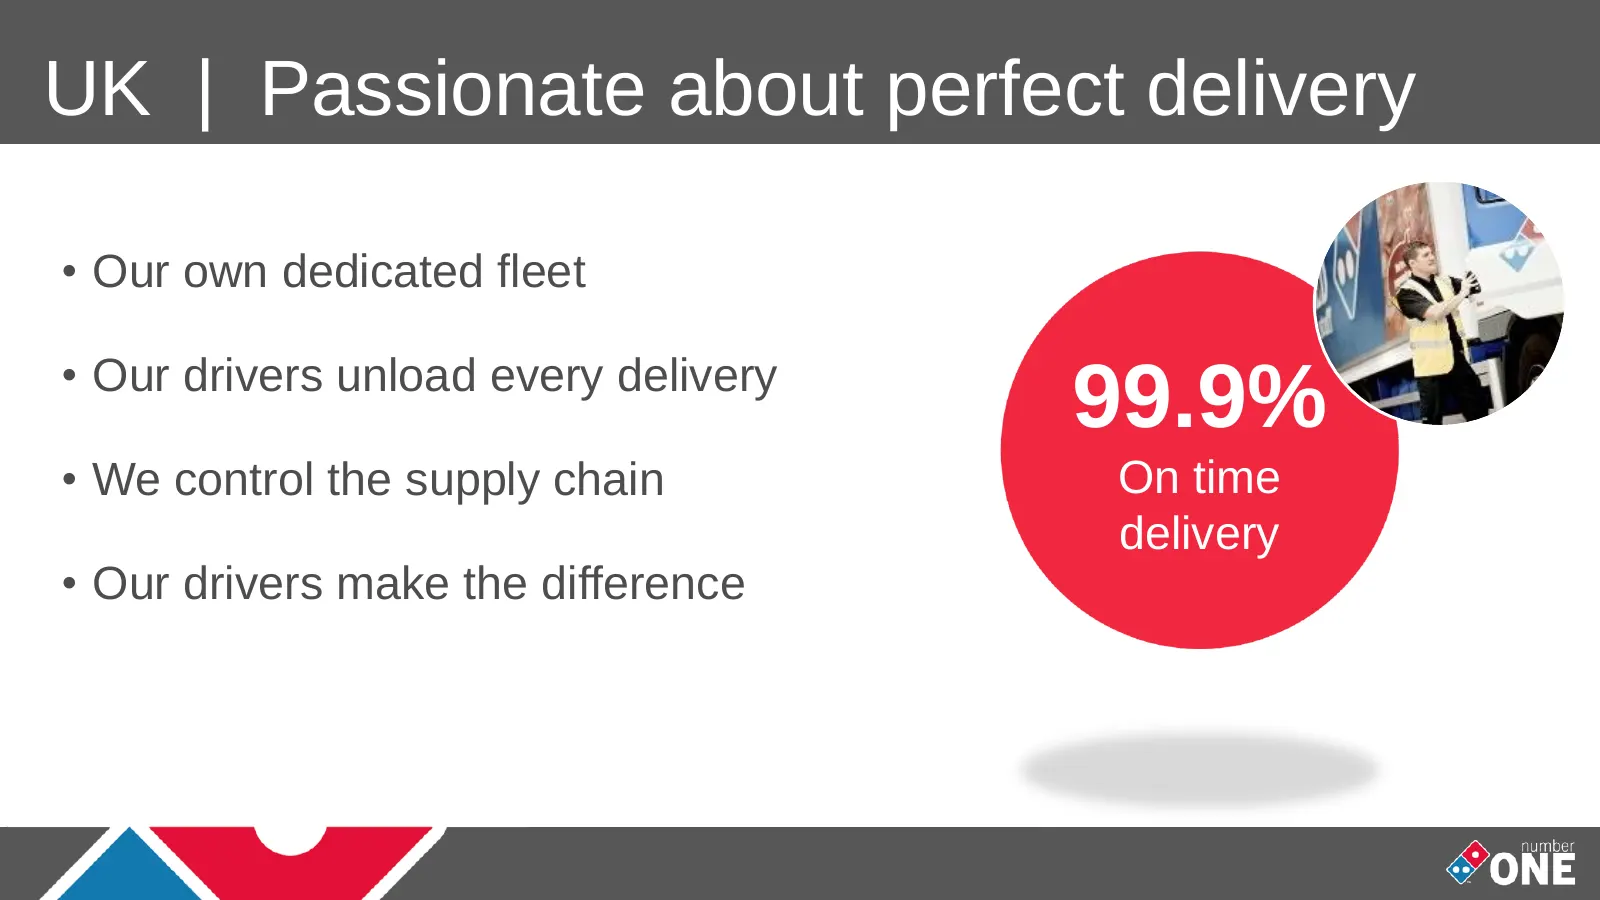
Slide 93: UK | Passionate about perfect delivery
UK | Passionate about perfect delivery • Our own dedicated fleet • Our drivers unload every delivery 99.9% • We control the supply chain On time delivery • Our drivers make the difference
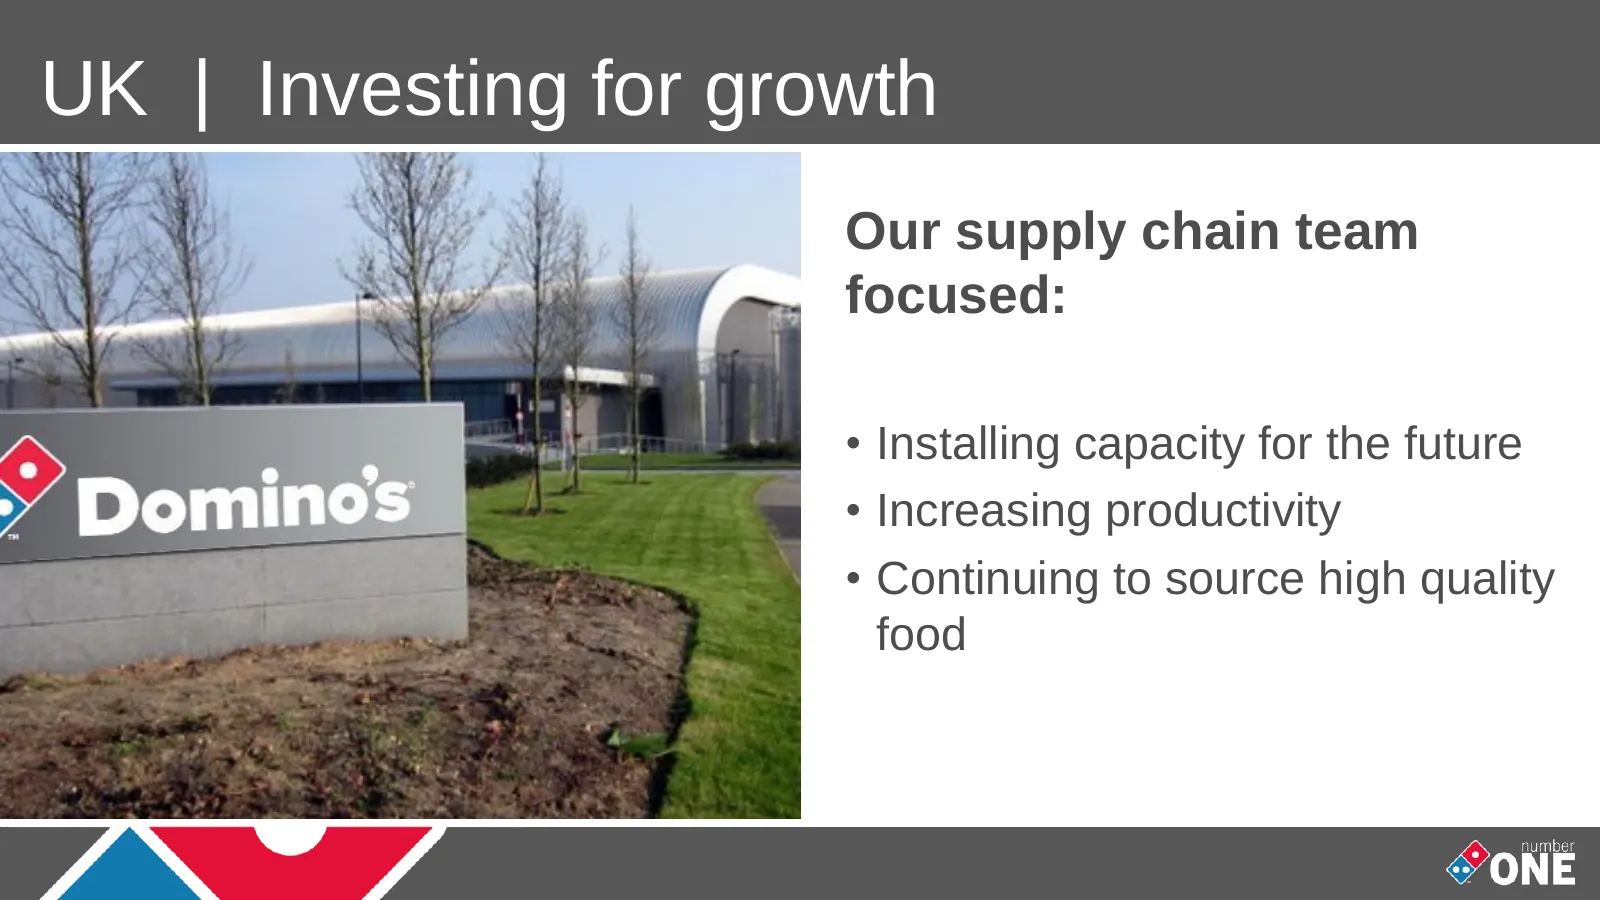
Slide 94: UK | Investing for growth
UK | Investing for growth Our supply chain team focused: • Installing capacity for the future • Increasing productivity • Continuing to source high quality food
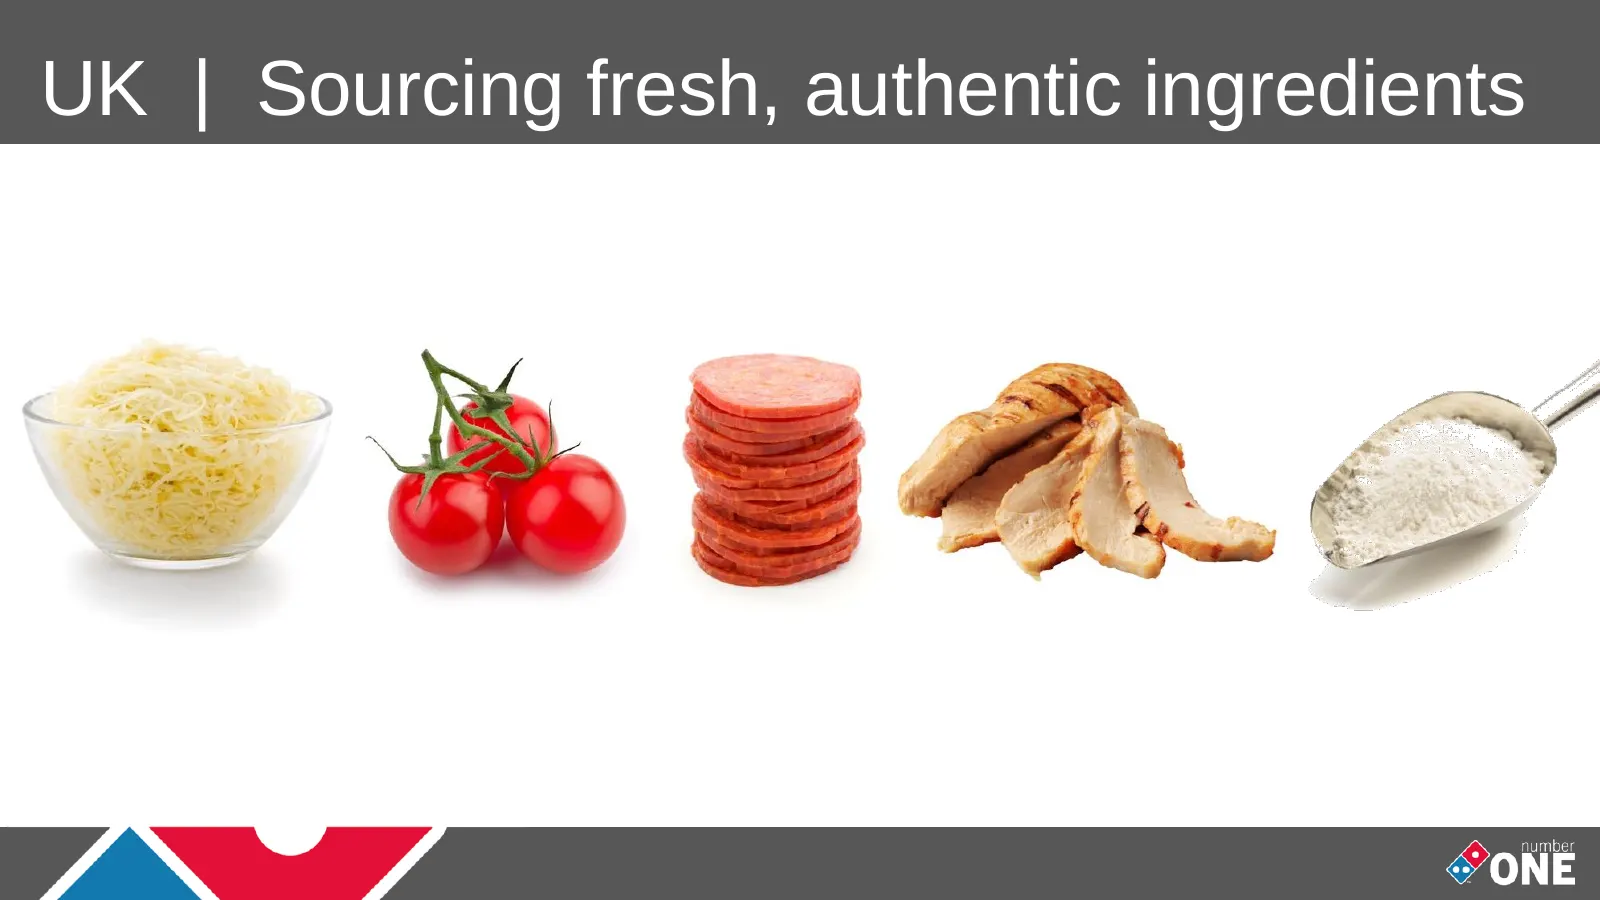
Slide 95: UK | Sourcing fresh, authentic ingredients
UK | Sourcing fresh, authentic ingredients
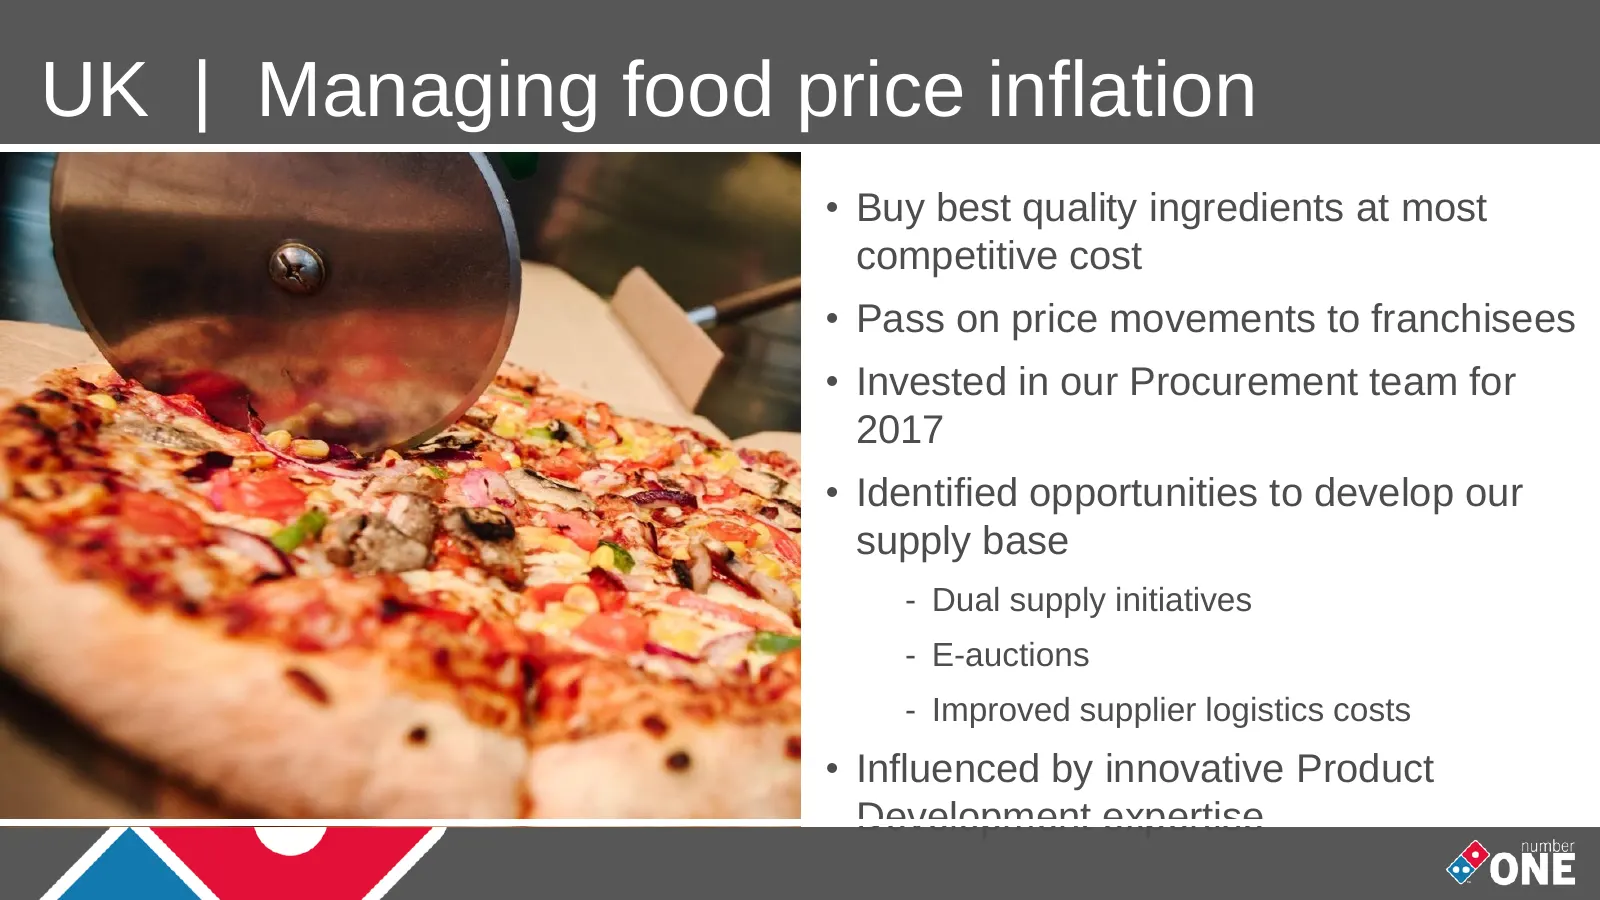
Slide 96: UK | Managing food price inflation
UK | Managing food price inflation • Buy best quality ingredients at most competitive cost • Pass on price movements to franchisees • Invested in our Procurement team for 2017 • Identified opportunities to develop our supply base - Dual supply initiatives - E-auctions - Improved supplier logistics c
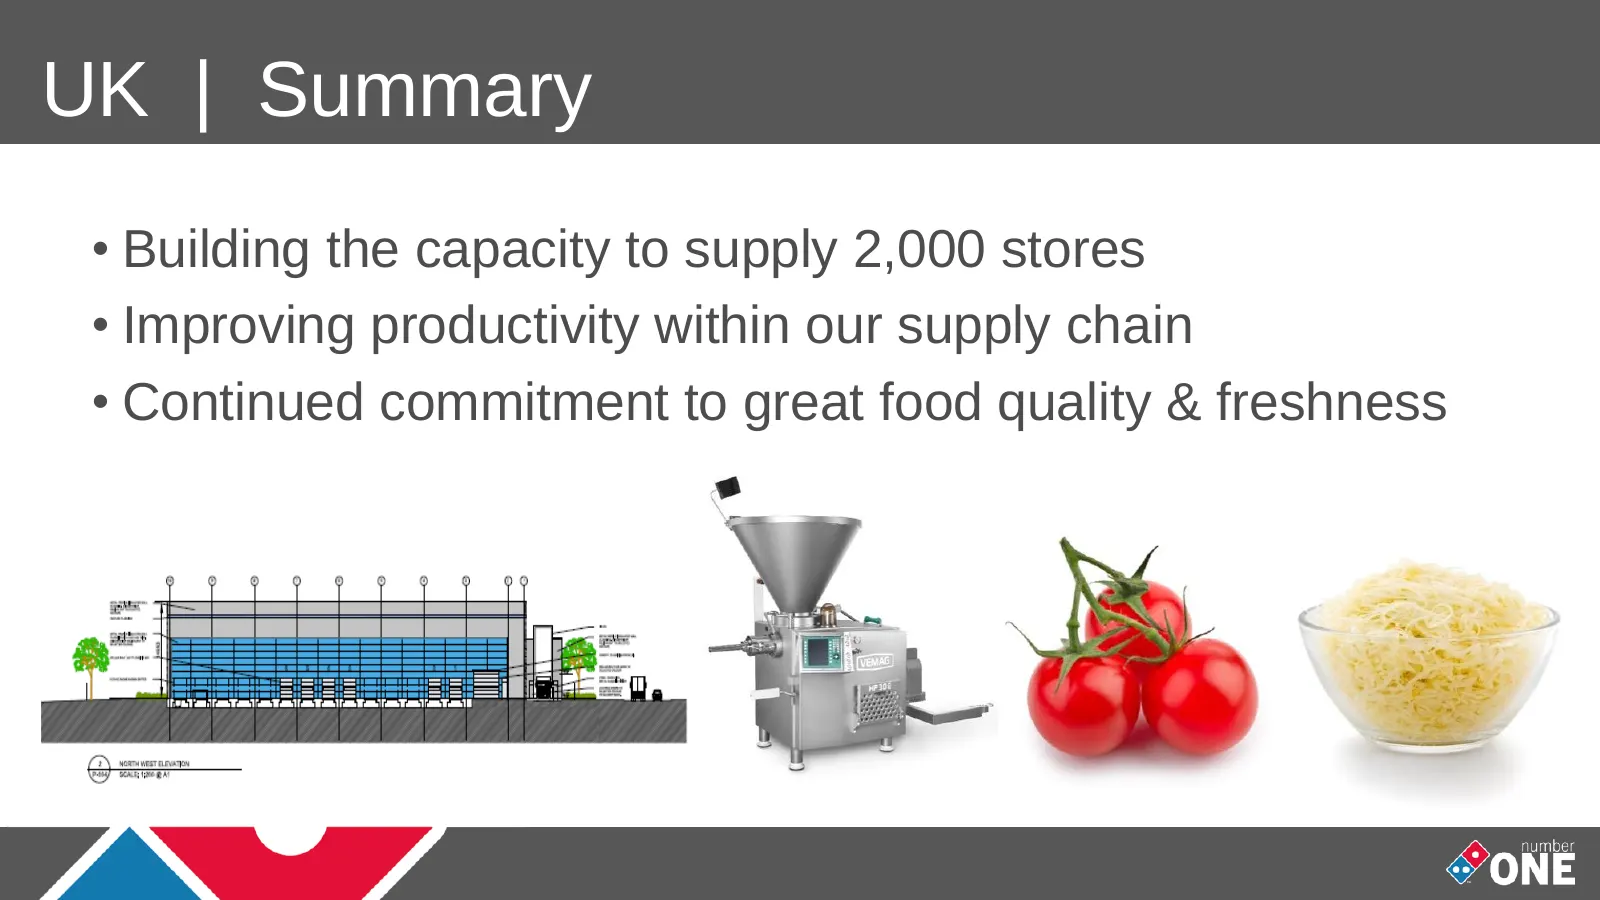
Slide 97: UK | Summary
UK | Summary • Building the capacity to supply 2,000 stores • Improving productivity within our supply chain • Continued commitment to great food quality & freshness
Slide 98: Franchise model
Franchise model Rachel Osborne Chief Financial Officer
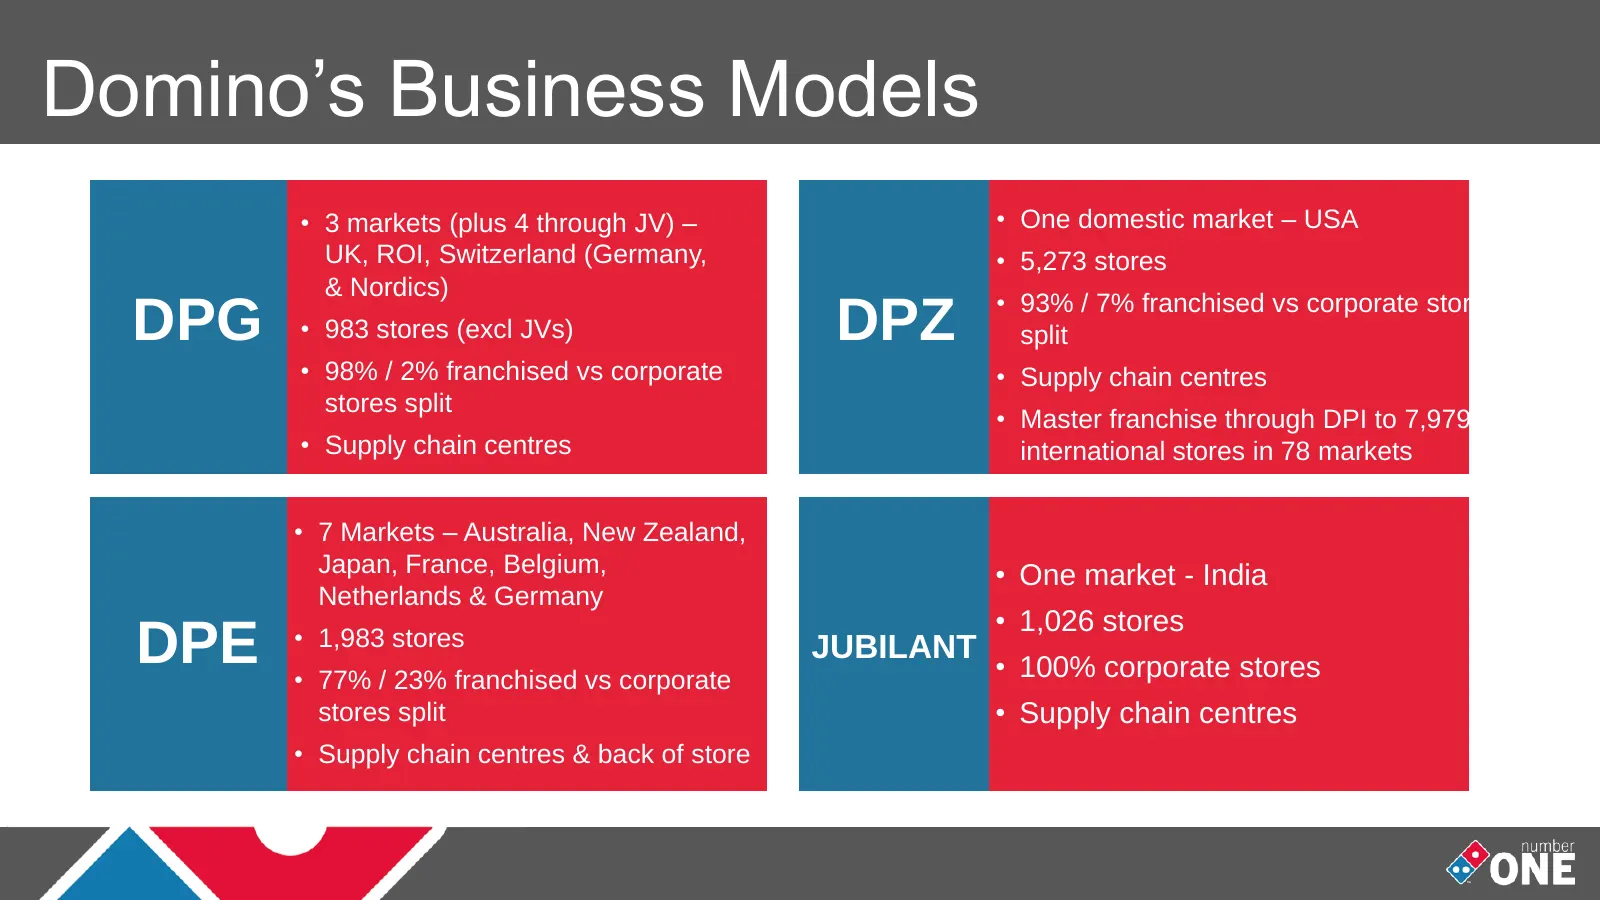
Slide 99: Domino's Business Models
Domino’s Business Models • 3 markets (plus 4 through JV) – • One domestic market – USA UK, ROI, Switzerland (Germany, • 5,273 stores & Nordics) • 93% / 7% franchised vs corporate store DPG • 983 stores (excl JVs) DPZ split • 98% / 2% franchised vs corporate • Supply chain centres stores split • Mast
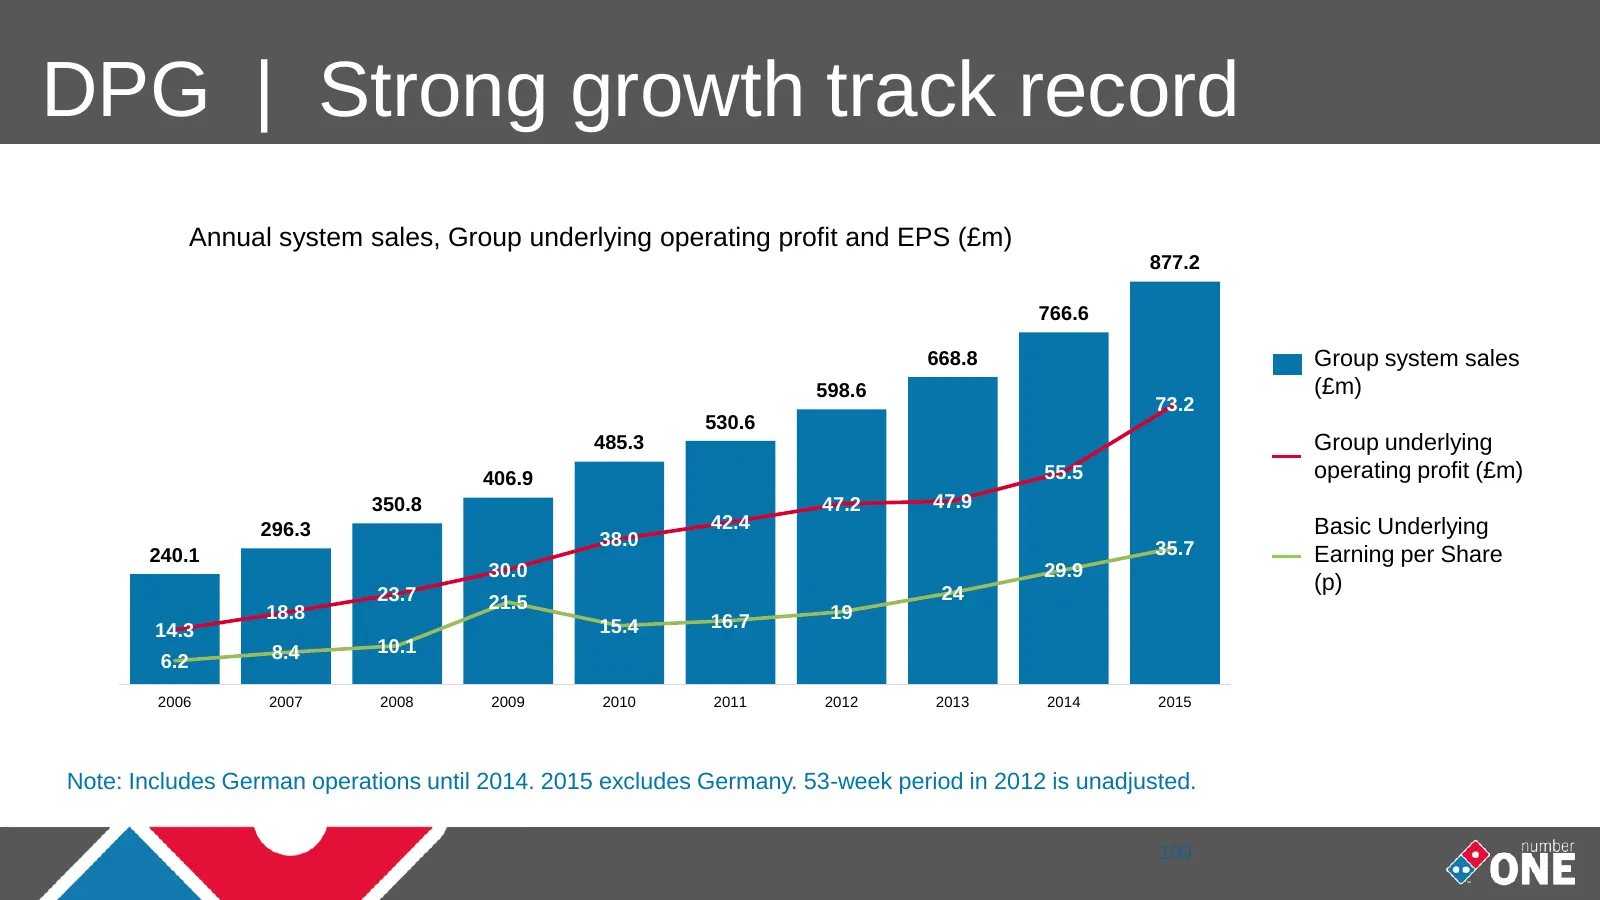
Slide 100: DPG | Strong growth track record
DPG | Strong growth track record 1,000 120 Annual system sales, Group underlying operating profit and EPS (£m) 877.2 100 800 766.6 668.8 Group system sales 80 (£m) 598.6 600 73.2 530.6 485.3 60 Group underlying 406.9 55.5 operating profit (£m) 400 350.8 47.2 47.9 296.3 42.4 40 Basic Underlying 38.0
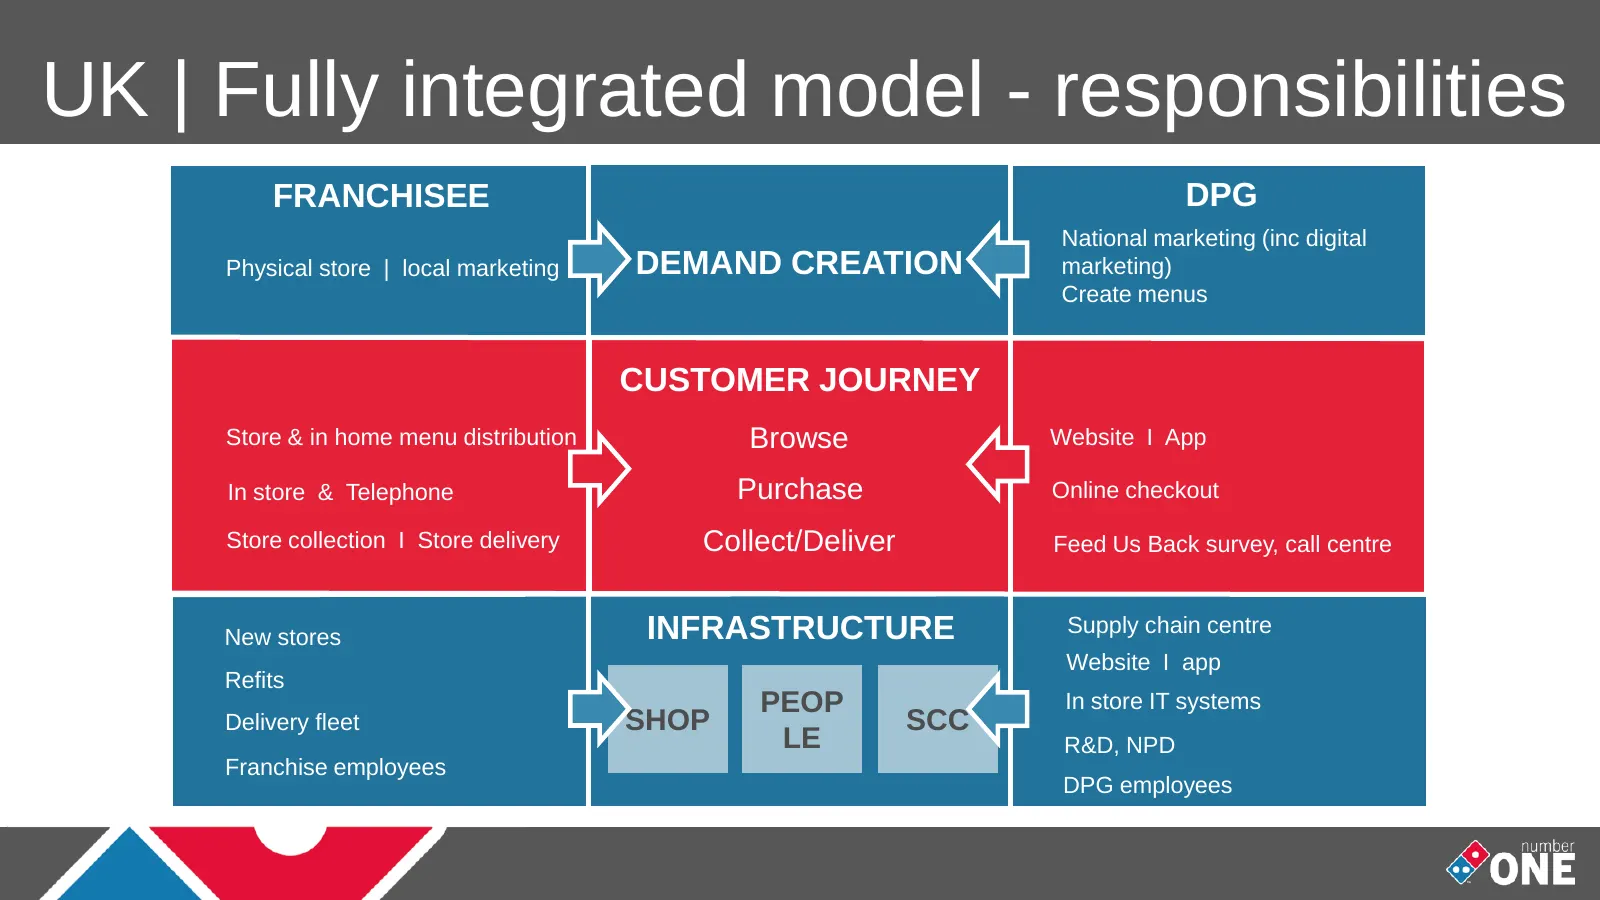
Slide 101: Fully integrated model - responsibilities
UK | Fully integrated model - responsibilities FRANCHISEE DPG National marketing (inc digital Physical store | local marketing DEMAND CREATION marketing) Create menus CUSTOMER JOURNEY Store & in home menu distribution Browse Website I App In store & Telephone Purchase Online checkout Store collectio
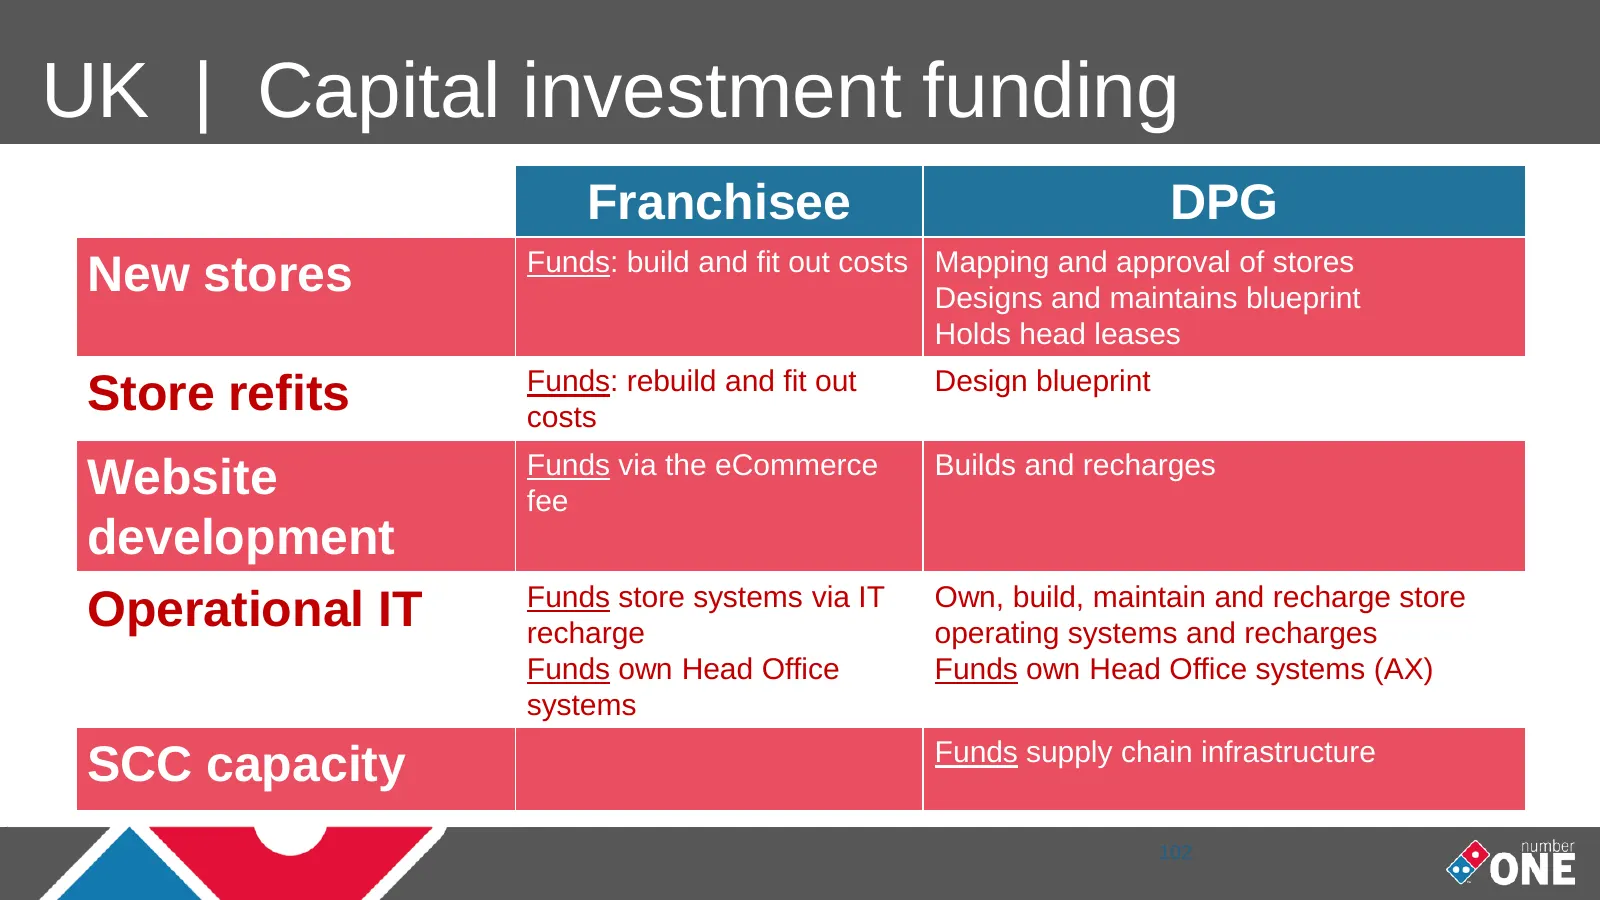
Slide 102: Capital investment funding
UK | Capital investment funding Franchisee DPG Funds: build and fit out costs Mapping and approval of stores New stores Designs and maintains blueprint Holds head leases Funds: rebuild and fit out Design blueprint Store refits costs Funds via the eCommerce Builds and recharges Website fee developmen
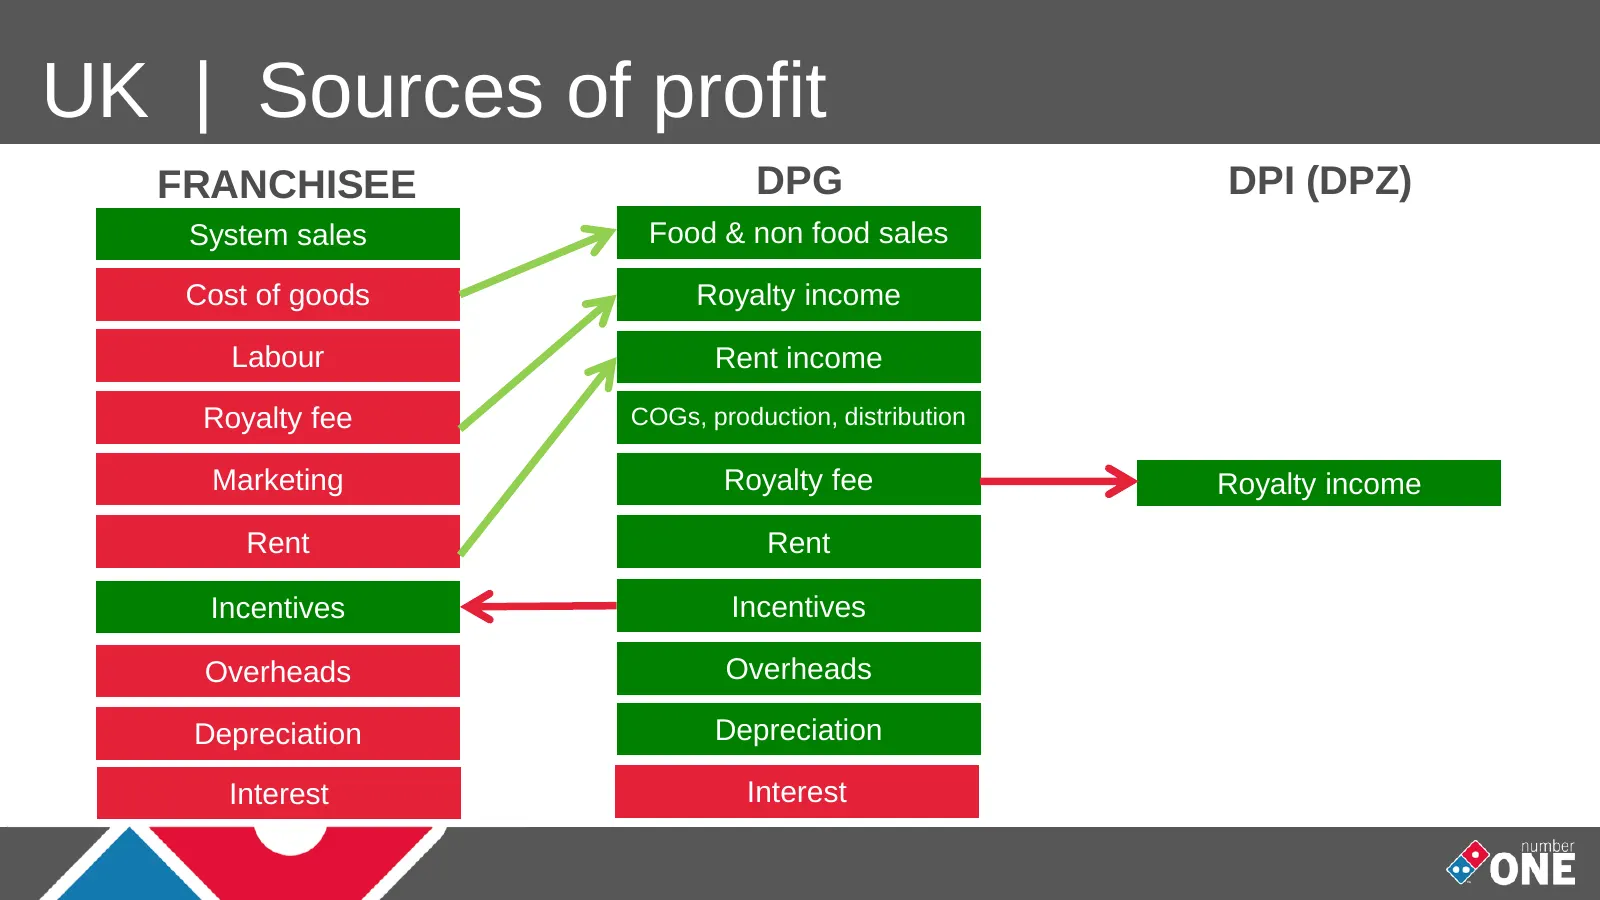
Slide 103: Sources of profit
UK | Sources of profit FRANCHISEE DPG DPI (DPZ) System sales Food & non food sales Cost of goods Royalty income Labour Rent income Royalty fee COGs, production, distribution Marketing Royalty fee Royalty income Rent Rent Incentives Incentives Overheads Overheads Depreciation Depreciation Interest In
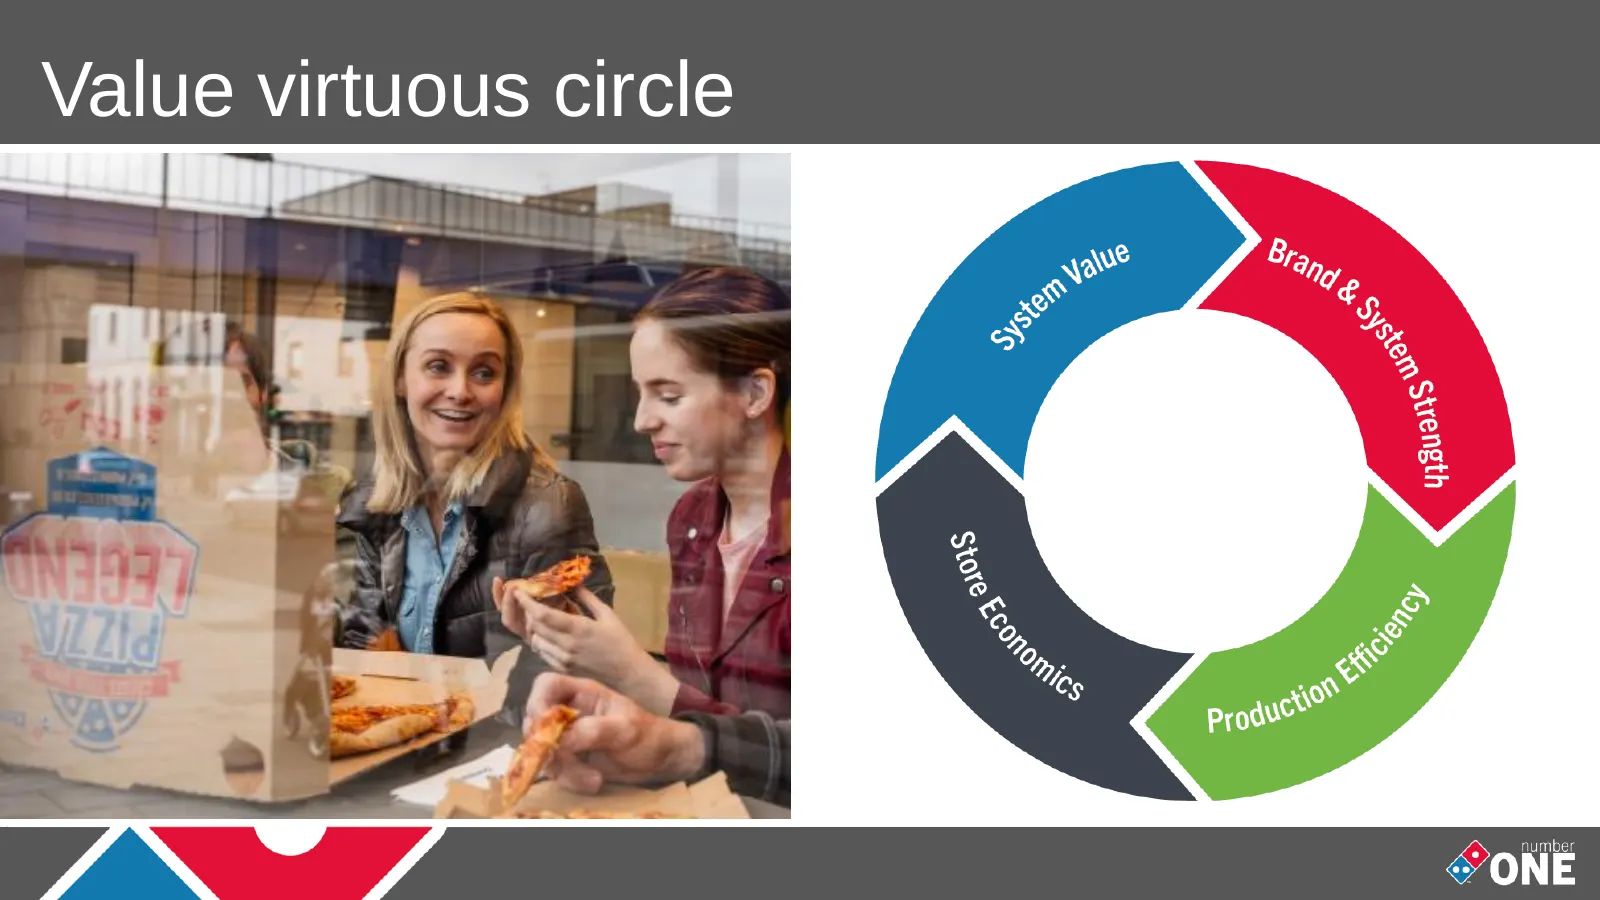
Slide 104: Value virtuous circle
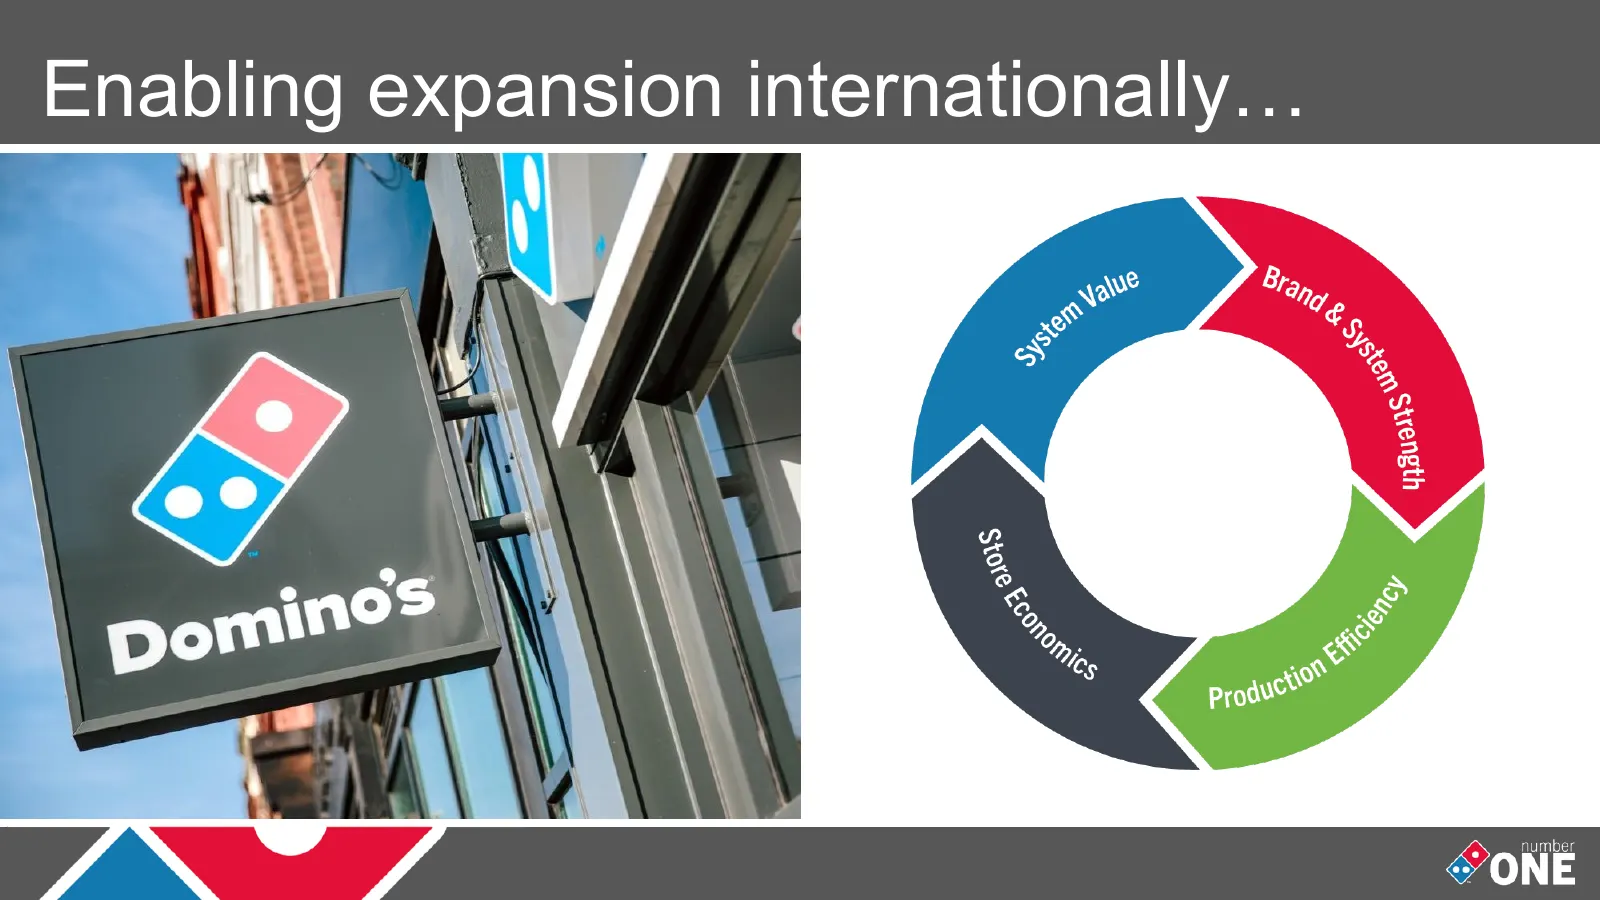
Value virtuous circle
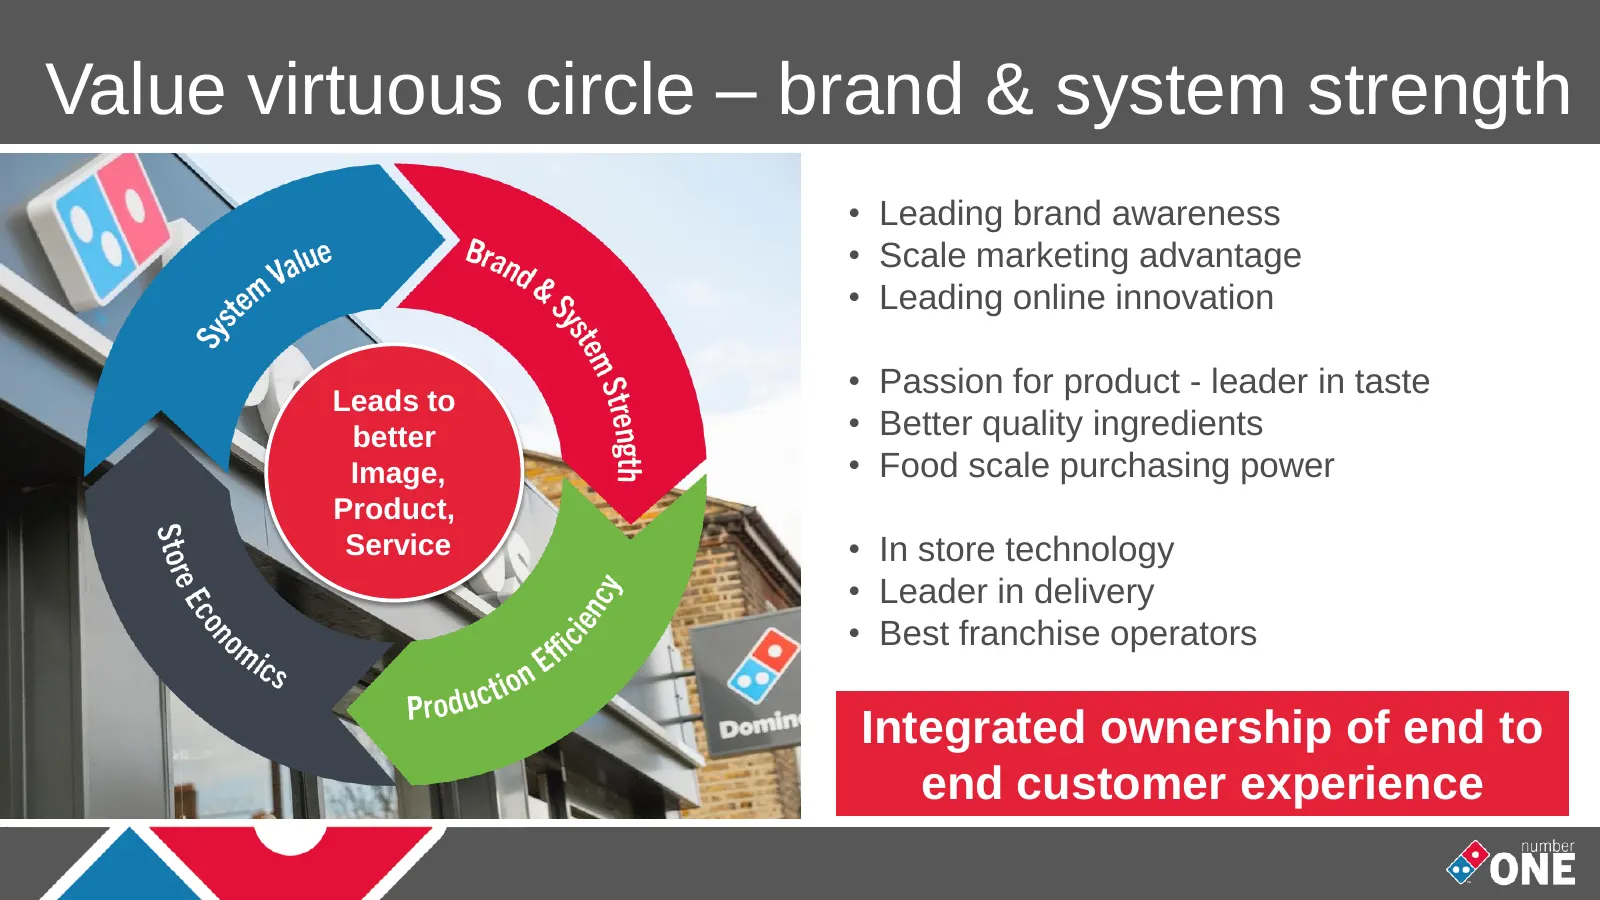
Slide 105: Value virtuous circle – brand & system strength
Value virtuous circle – brand & system strength • Leading brand awareness • Scale marketing advantage • Leading online innovation • Passion for product - leader in taste Leads to better • Better quality ingredients Image, • Food scale purchasing power Product, Service • In store technology • Leader
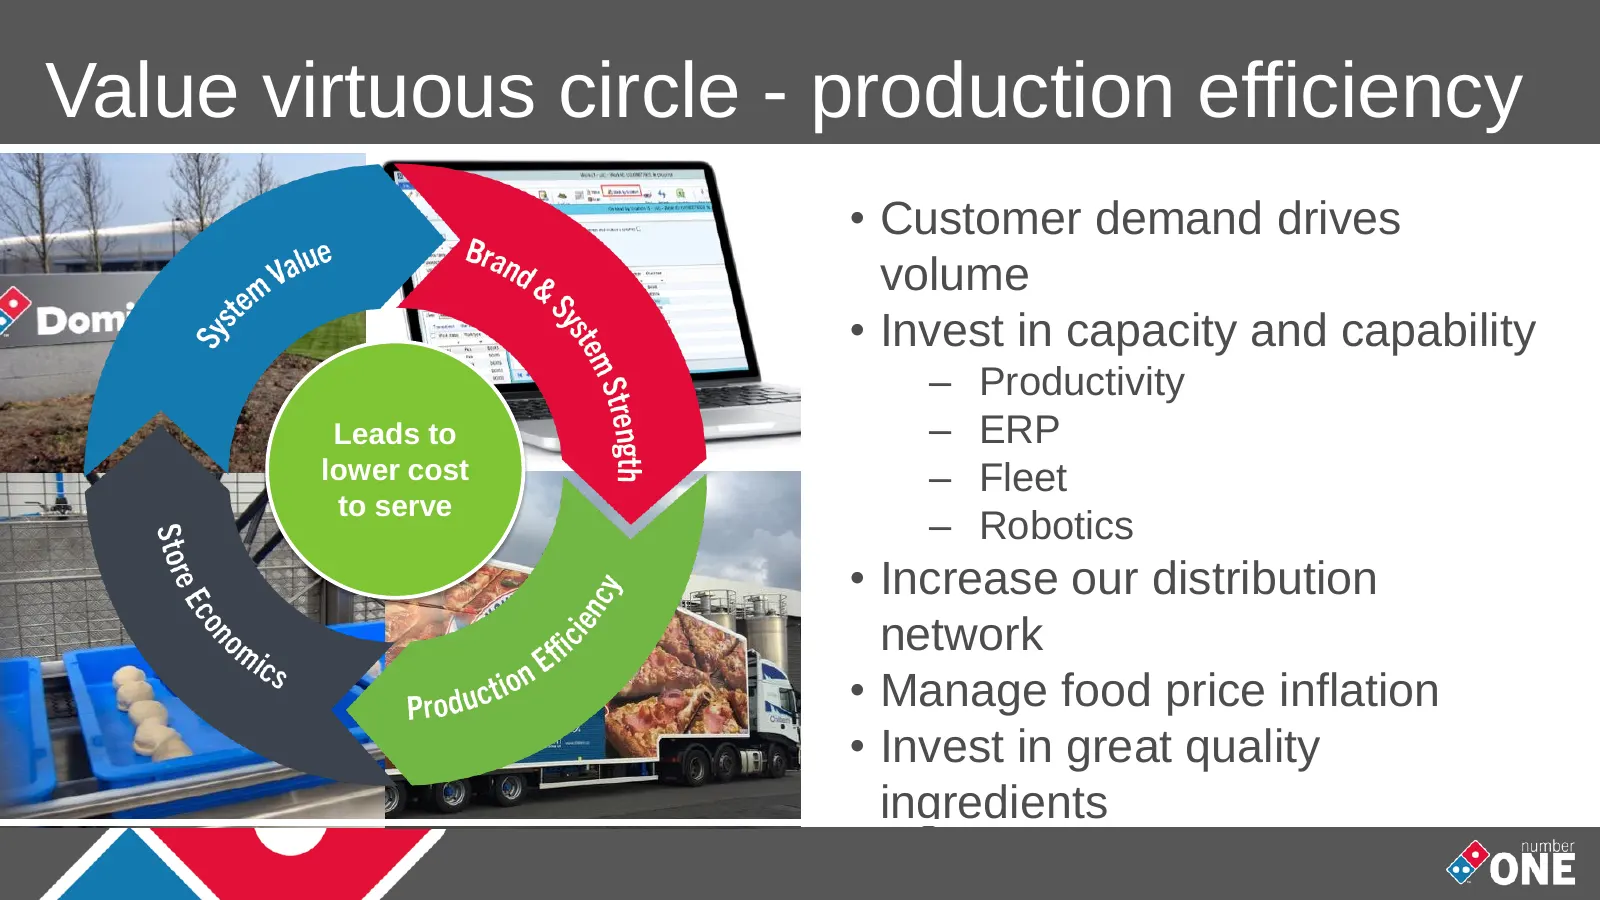
Slide 106: Value virtuous circle - production efficiency
Value virtuous circle - production efficiency • Customer demand drives volume • Invest in capacity and capability – Productivity Leads to – ERP lower cost – Fleet to serve – Robotics • Increase our distribution network • Manage food price inflation • Invest in great quality ingredients
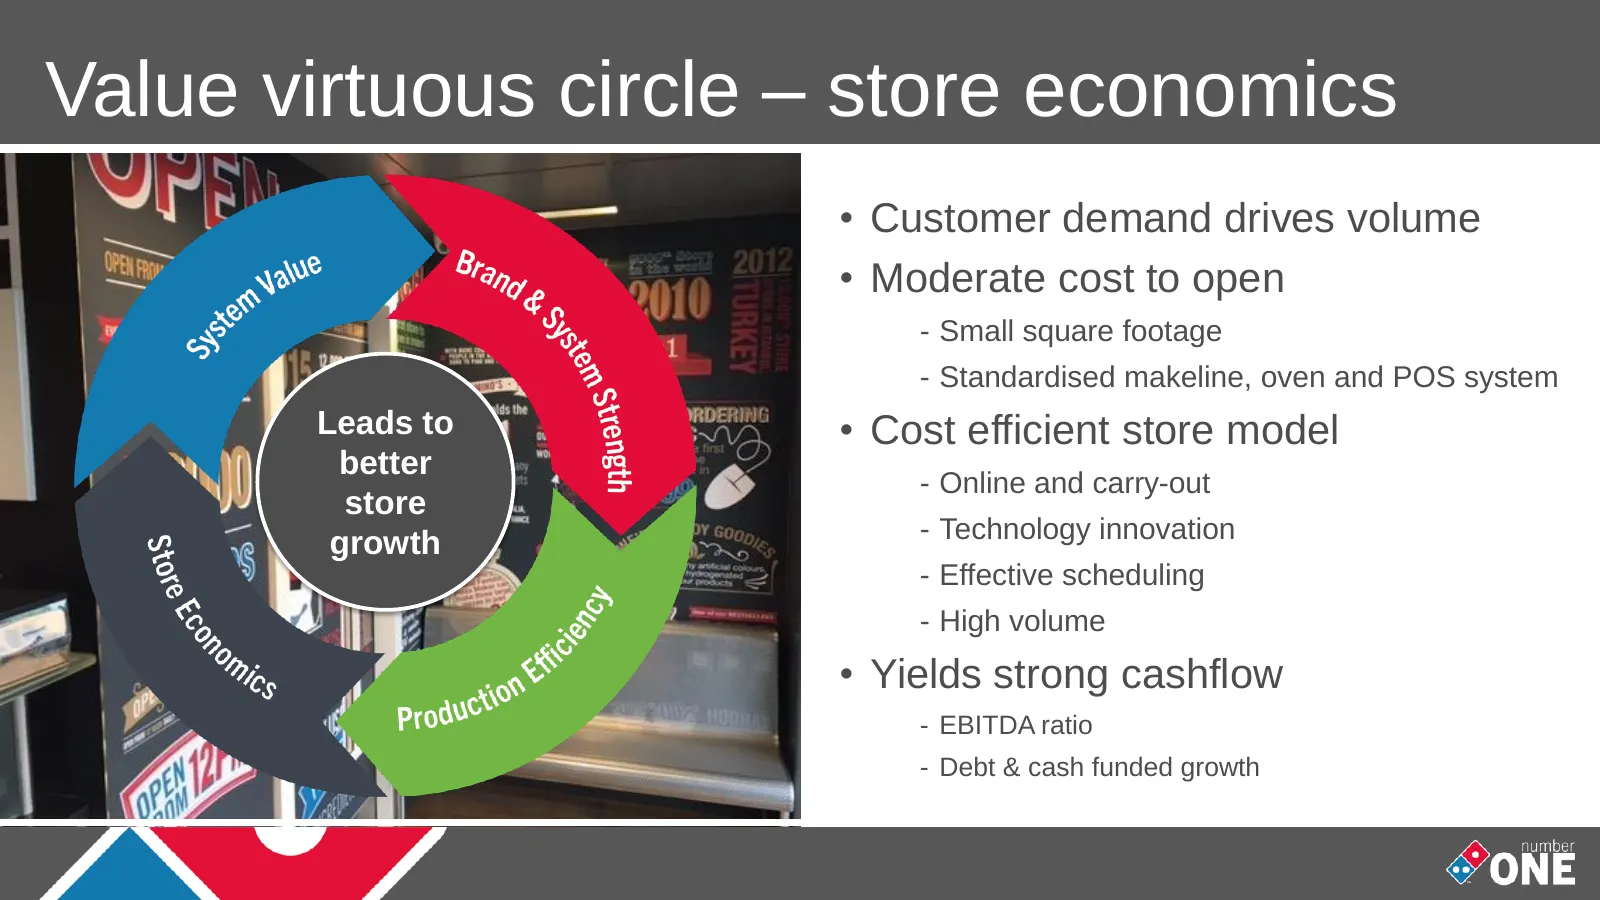
Slide 107: Value virtuous circle – store economics
Value virtuous circle – store economics • Customer demand drives volume • Moderate cost to open - Small square footage - Standardised makeline, oven and POS system Leads to • Cost efficient store model better - Online and carry-out store - Technology innovation growth - Effective scheduling - High v
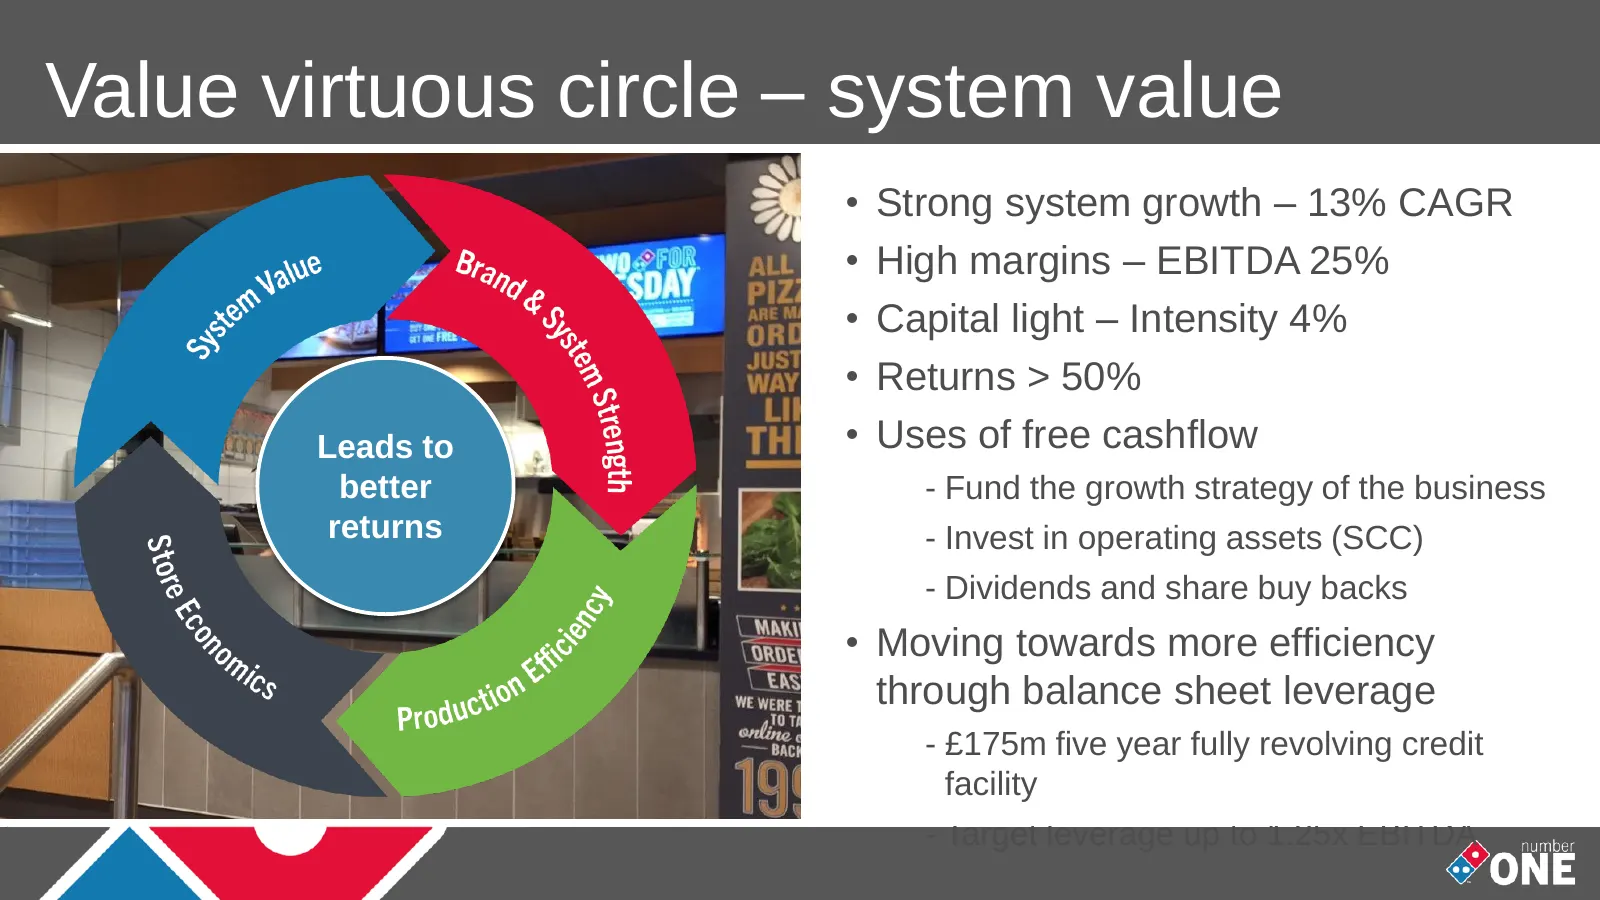
Slide 108: Value virtuous circle – system value
Value virtuous circle – system value • Strong system growth – 13% CAGR • High margins – EBITDA 25% • Capital light – Intensity 4% • Returns > 50% Leads to • Uses of free cashflow better - Fund the growth strategy of the business returns - Invest in operating assets (SCC) - Dividends and share buy ba
Slide 109: Enabling expansion internationally…
Enabling expansion internationally…
Slide 110: International
International David Wild Chief Executive Officer
Slide 111: DPG International
DPG International Objectives/rationale • Leverage UK capabilities in overseas markets • Learn from other markets to enrich UK operations • Provide development opportunities for management • Enhance long-term earnings growth
Slide 112: DPG International History
DPG International History 1991 First ROI store opened 2011 German entry 2012 Switzerland entry 2015 Joey’s acquisition & DPE JV in Germany 2016 Nordic JV
Slide 113: DPG International
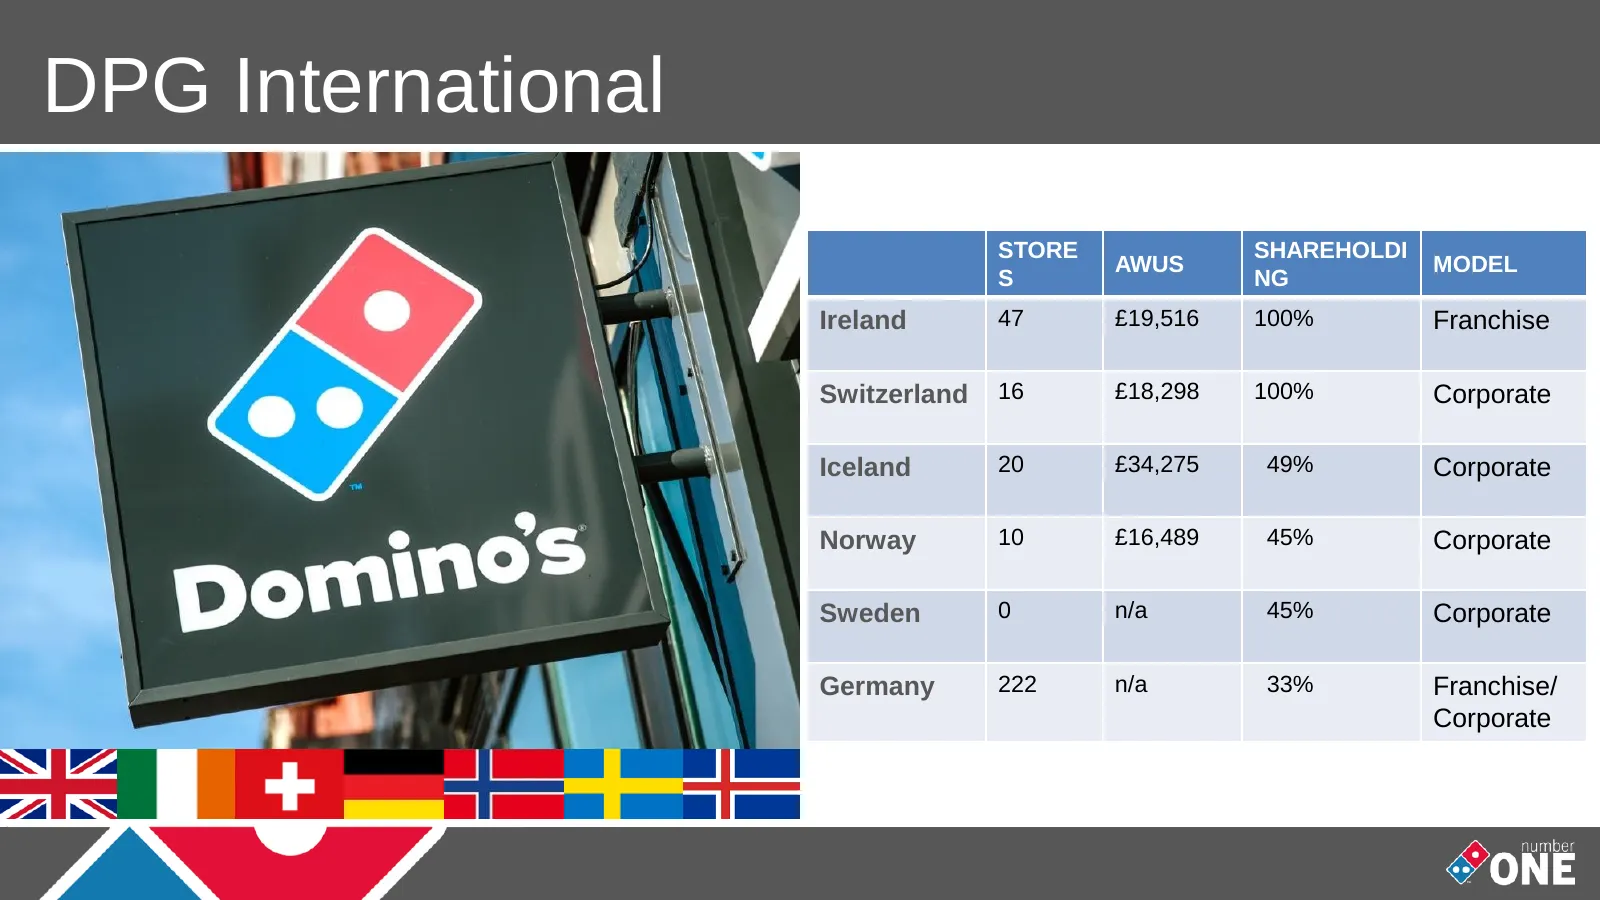
DPG International STORE SHAREHOLDI AWUS MODEL S NG Ireland 47 £19,516 100% Franchise Switzerland 16 £18,298 100% Corporate Iceland 20 £34,275 49% Corporate Norway 10 £16,489 45% Corporate Sweden 0 n/a 45% Corporate Germany 222 n/a 33% Franchise/ Corporate
Slide 114: DPG International: Shareholder agreements
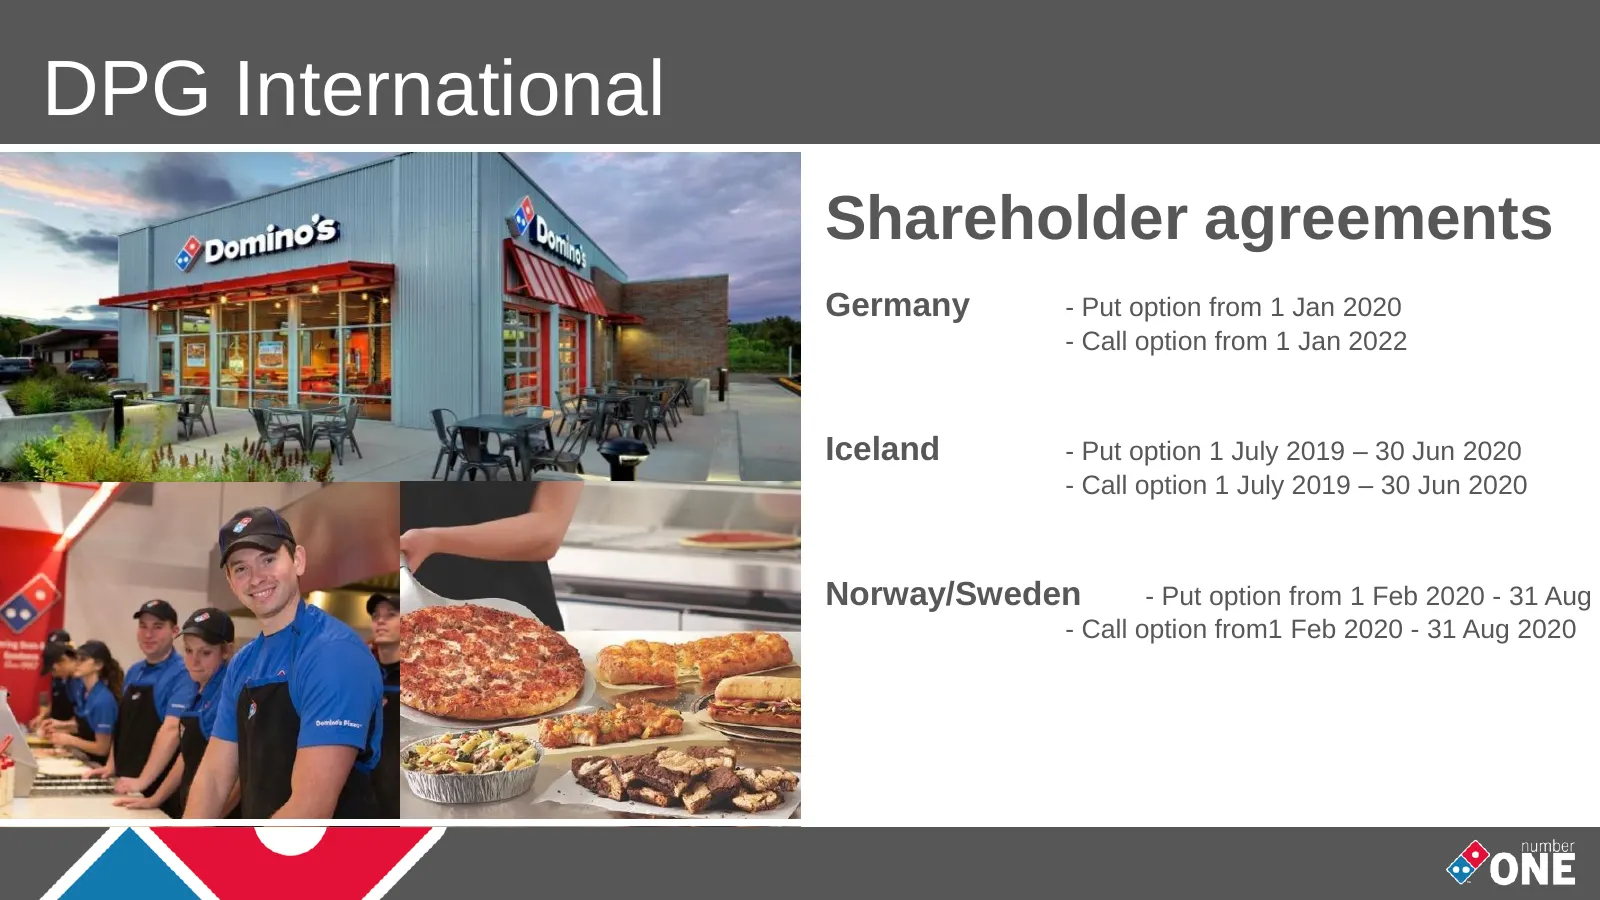
DPG International Shareholder agreements Germany - Put option from 1 Jan 2020 - Call option from 1 Jan 2022 Iceland - Put option 1 July 2019 – 30 Jun 2020 - Call option 1 July 2019 – 30 Jun 2020 Norway/Sweden - Put option from 1 Feb 2020 - 31 Aug 2 - Call option from1 Feb 2020 - 31 Aug 2020
Slide 115: DPG International: International strategy
DPG International International strategy • Leverage leadership position and open stores in Ireland • Deliver profit in Switzerland and exploit market opportunity • Work with DPE to create largest pizza chain in Germany • Develop Nordic region to its full potential • Be open to new avenues which can
Slide 116: Republic of Ireland – current situation
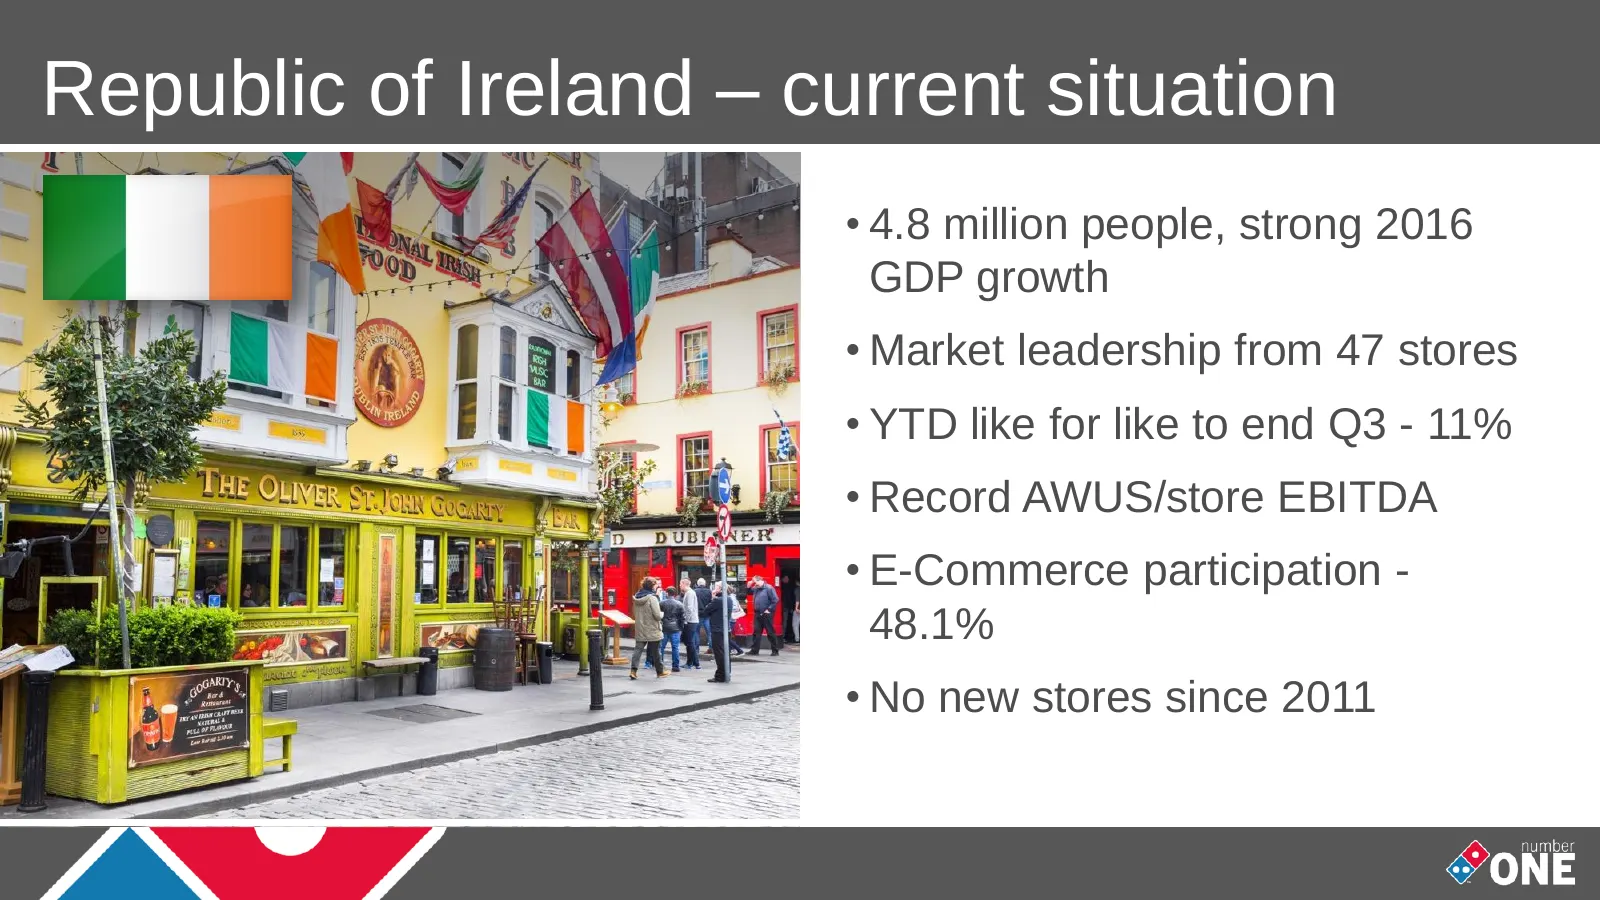
Republic of Ireland – current situation • 4.8 million people, strong 2016 GDP growth • Market leadership from 47 stores • YTD like for like to end Q3 - 11% • Record AWUS/store EBITDA • E-Commerce participation - 48.1% • No new stores since 2011
Slide 117: Republic of Ireland – future plan
Republic of Ireland – future plan • Increase e-Commerce participation • Raise collection participation • Strengthen local management • New store openings • Tailored local and national marketing • Infrastructure investment • Capacity 75 stores
Slide 118: Switzerland
Switzerland Clive West International Support Director
Slide 119: Switzerland - country background
Switzerland - country background • 8.3 Million people • Stable economy with consistent GDP growth • Non EU member with selective food import controls • High cost structure • Mixed success for global QSR brands • Market dominated by independents
Slide 120: Domino's Switzerland – current situation
Domino’s Switzerland – current situation • Domino’s entered Swiss market 2000 • DPG acquired from P/E late 2012 • 16 stores trading, six openings under DPG • YTD sales growth of 20% • eCommerce participation 46% • Mature stores cash positive • New stores slower to mature than expected • Contracted d
Slide 121: Domino's Switzerland – future plan
Domino’s Switzerland – future plan • Open six stores per annum • Reduce capital/operational costs • Balance collection and delivery at 50:50 • Introducing a Customer call centre • Drive eCommerce participation • Review dough production in 2017 • Market capacity 100 stores
Slide 122: Nordics
Nordics
Slide 123: Domino's - Iceland
Domino’s - Iceland • 332k people • One store opening in the last month bringing total stores to 21 • YTD like for likes 12.0% • E-Commerce 56% • Leverage market leadership to roll-out three stores per annum • Capacity 30 stores
Slide 124: Norway – country background
Norway – country background • 5.2 Million people • Large geographic spread • Stable economy with good natural resources • Non EU member with controlled food imports • High cost structures
Slide 125: Domino's Norway – current situation
Domino’s Norway – current situation • Market entry 2014 – all corporate stores in Oslo and Telemark • Strong incumbent pizza players – Peppe’s, Pizzabakeren, Dolly Dimple • Total sales growth 240% • E-Commerce participation 58% • Two openings in last month bringing total stores to 12 • Nine out of t
Slide 126: Domino's Norway – future plan
Domino’s Norway – future plan • Open 10 stores per annum in current region • Franchise five stores in Telemark area • Drive eCommerce share • Increase delivery participation • Open on west coast in 2018 with franchisee • Market capacity 75 stores
Slide 127: Sweden – country background
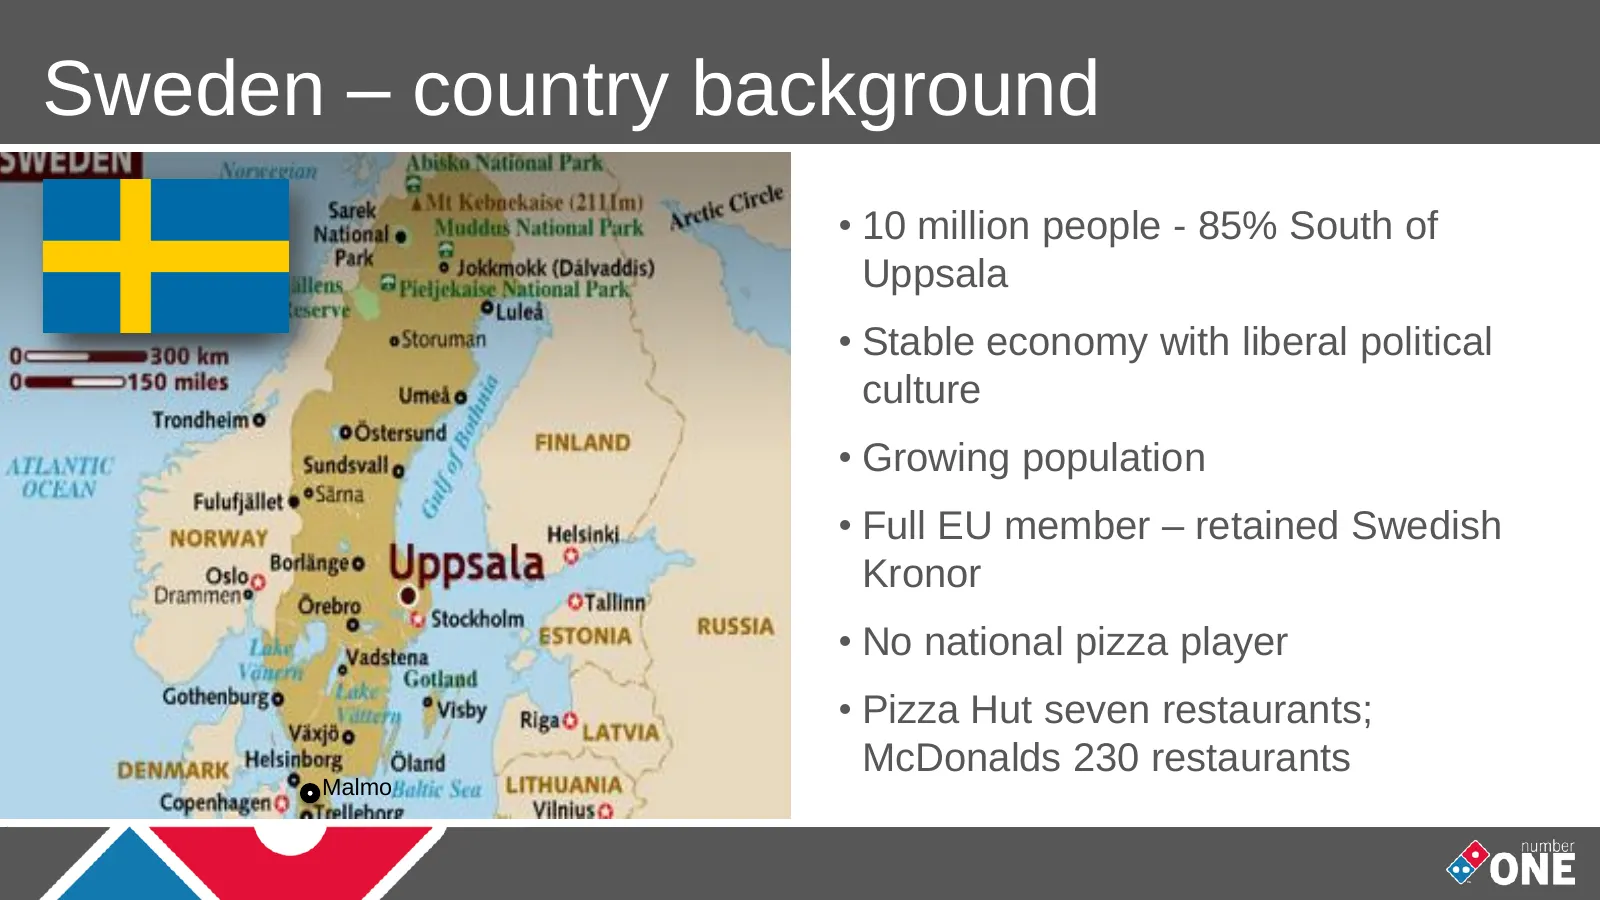
Sweden – country background • 10 million people - 85% South of Uppsala • Stable economy with liberal political culture • Growing population • Full EU member – retained Swedish Kronor • No national pizza player • Pizza Hut seven restaurants; McDonalds 230 restaurants Malmo
Slide 128: Domino's - Sweden 2016 & future plan
Domino’s - Sweden 2016 & future plan • First store opens wc 28/11 – grand opening January 2017 • Two further openings in Malmo by February 2017 • Operational management led by Birgir Bieltvedt • Back of store production capability • Strong incentives to order online • Plan Stockholm openings Q3 2017
Slide 129: Nordic Partnership
Nordic Partnership International Opportunity Birgir Bieltvedt
Slide 130: Summary of International Plan
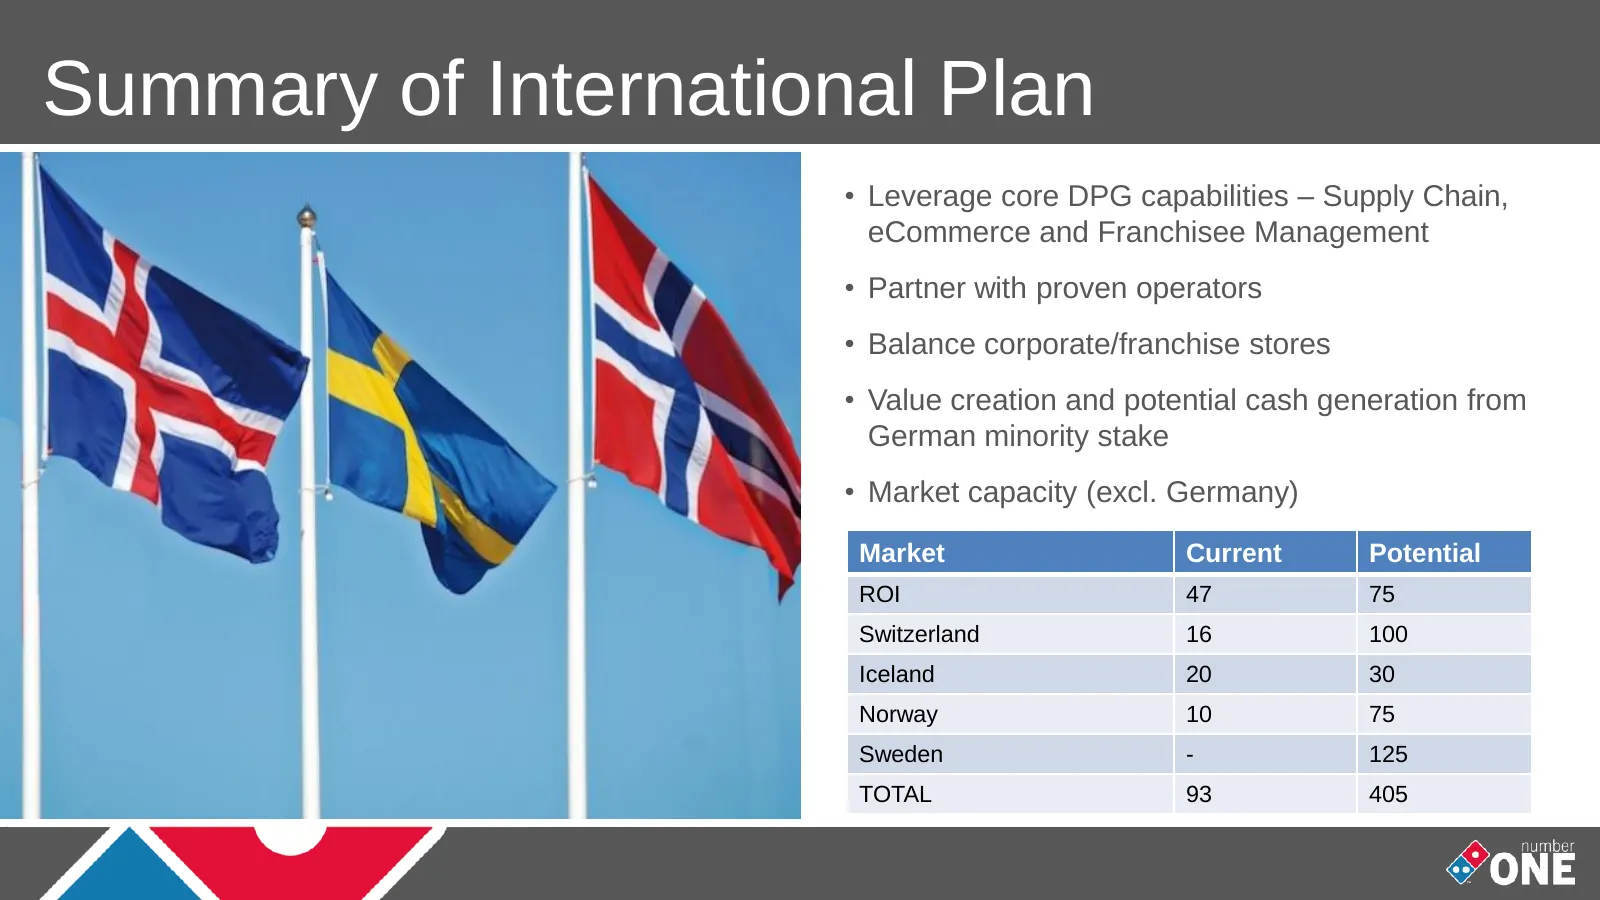
Summary of International Plan • Leverage core DPG capabilities – Supply Chain, eCommerce and Franchisee Management • Partner with proven operators • Balance corporate/franchise stores • Value creation and potential cash generation from German minority stake image • Market capacity (excl. Germany) Ma
Slide 131: DPG Summary
DPG Summary • Robust UK core with long runway ahead • Strong experienced team to build business • Significant progress in International • Double store count to > 2,000 • Cash generation and balance sheet strength COMMITTED TO GROWTH
Slide 132
Source: company website
More decks from Domino's Pizza Group plc
 H1 2026 Earnings Presentation34 slides · Aug 4, 2026
 FY2025 Earnings Presentation41 slides · Mar 10, 2026
 FY2024 Earnings Presentation42 slides · Mar 11, 2025
 H1 2024 Earnings Presentation44 slides · Aug 6, 2024
 FY2023 Earnings Presentation47 slides · Mar 12, 2024
 FY2022 Earnings Presentation39 slides · Mar 9, 2023