South Jersey Industries — Investor Presentation (September 2014)
26 slides from South Jersey Industries's investor presentation, Sep 29, 2014
Slide 1: South Jersey Industries
S\ =. iS Jersey Industries DSI
Slide 2: Forward Looking Statements
Certain statements contained in this presentation may qualify as “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. All statements other than statements of historical fact included in this Report should
Slide 3: SJI Overview
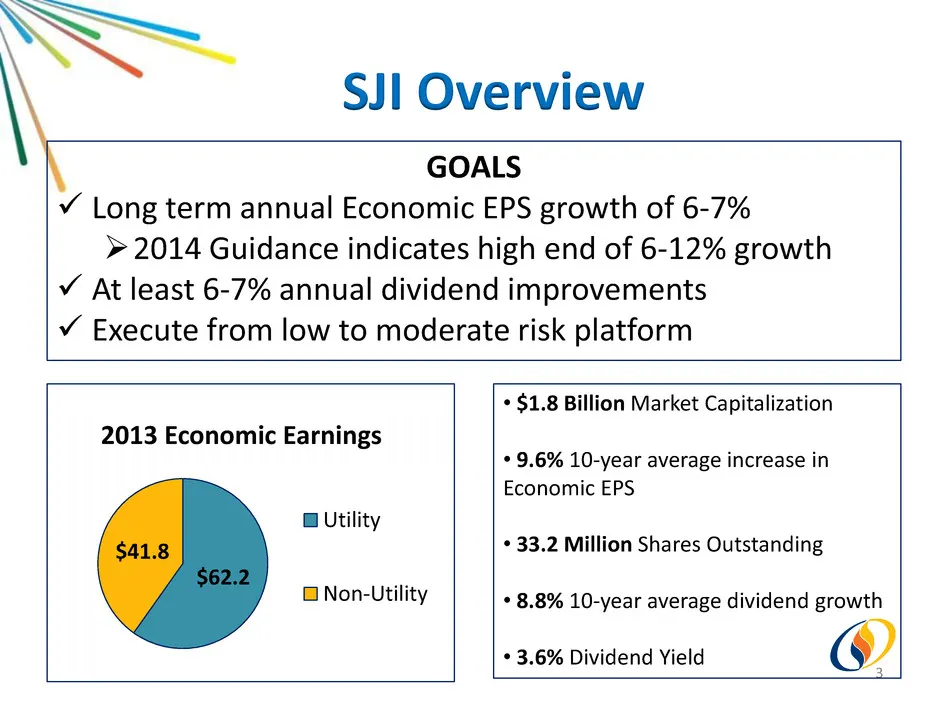
GOALS Long term annual Economic EPS growth of 6-7% 2014 Guidance indicates high end of 6-12% growth At least 6-7% annual dividend improvements Execute from low to moderate risk platform 3 SJI Overview • $1.8 Billion Market Capitalization • 9.6% 10-year average increase in Economic EPS • 33.2
Slide 4: Organization of Business
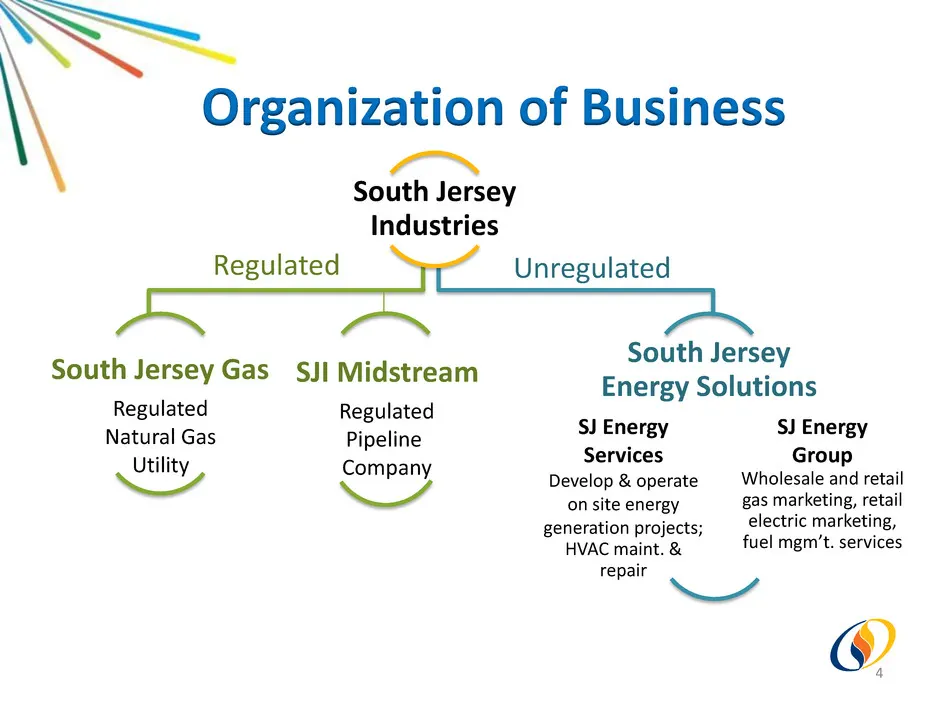
Organization of Business 4 South Jersey Industries South Jersey Gas SJI Midstream South Jersey Energy Solutions Regulated Natural Gas Utility Regulated Pipeline Company SJ Energy Services Develop & operate on site energy generation projects; HVAC maint. & repair SJ Energy Group Wholesale and retail
Slide 5: 2014 YTD Performance thru 6/30
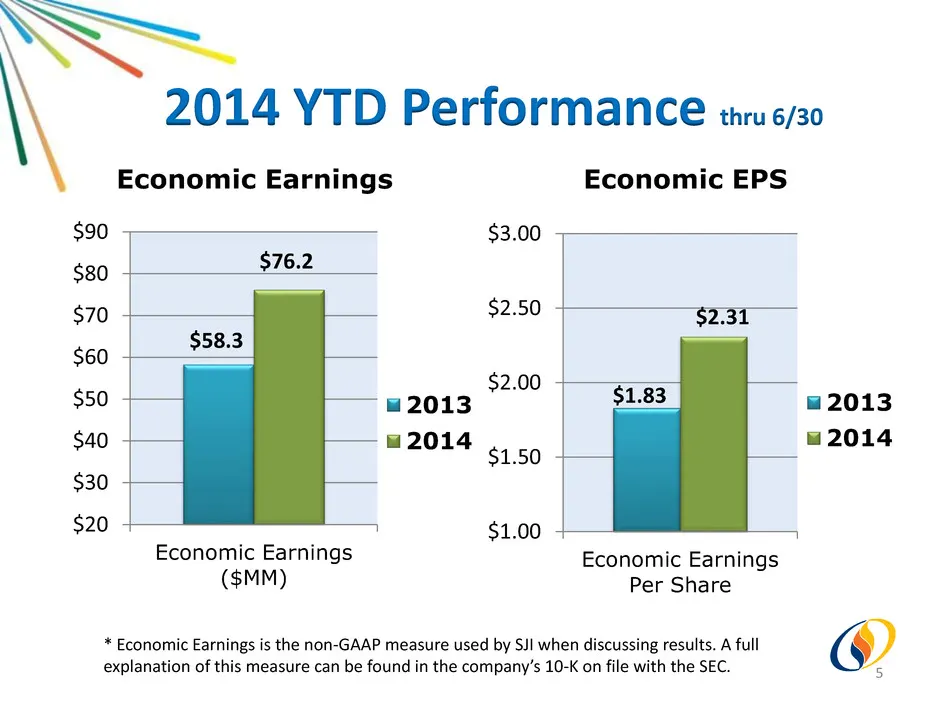
2014 YTD Performance thru 6/30 5 Economic Earnings $20 $30 $40 $50 $60 $70 $80 $90 Economic Earnings ($MM) 2013 2014 $58.3 $76.2 Economic EPS $1.00 $1.50 $2.00 $2.50 $3.00 Economic Earnings Per Share 2013 2014 $1.83 $2.31 * Economic Earnings is the non-GAAP measure used by SJI when discussing result
Slide 6: Dividend Growth
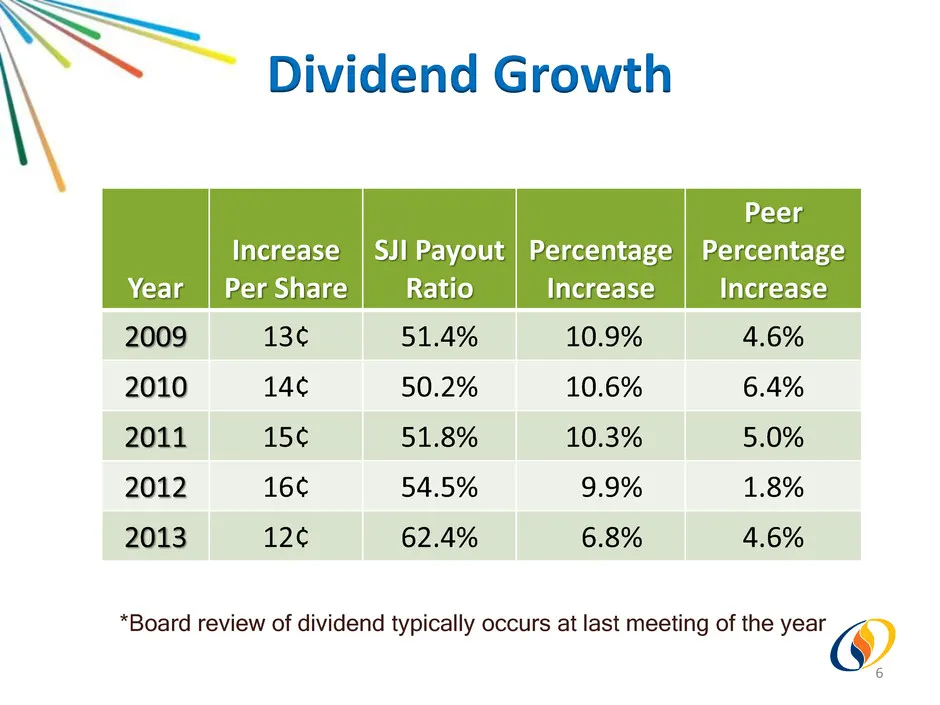
*Board review of dividend typically occurs at last meeting of the year Year Increase Per Share SJI Payout Ratio Percentage Increase Peer Percentage Increase 2009 13¢ 51.4% 10.9% 4.6% 2010 14¢ 50.2% 10.6% 6.4% 2011 15¢ 51.8% 10.3% 5.0% 2012 16¢ 54.5% 9.9% 1.8% 2013 12¢ 62.4% 6.8% 4.6% Dividend Growth
Slide 7: Regulated Businesses
Regulated Businesses 7
Slide 8: Regulated Utility - South Jersey Gas
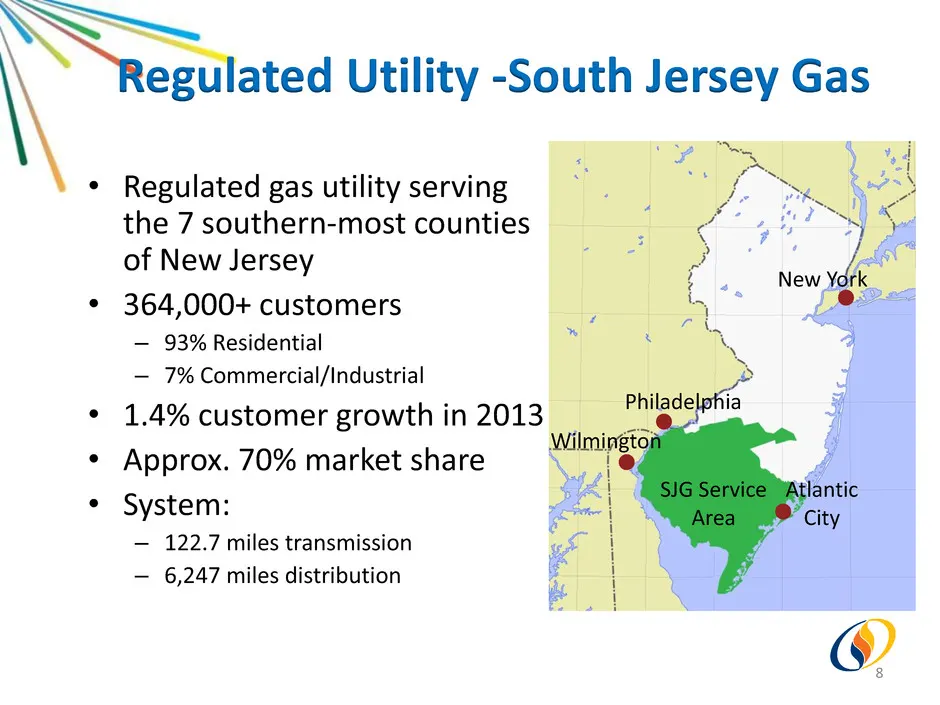
Regulated Utility -South Jersey Gas 8 • Regulated gas utility serving the 7 southern-most counties of New Jersey • 364,000+ customers – 93% Residential – 7% Commercial/Industrial • 1.4% customer growth in 2013 • Approx. 70% market share • System: – 122.7 miles transmission – 6,247 miles distribution
Slide 9: Utility Business Drivers
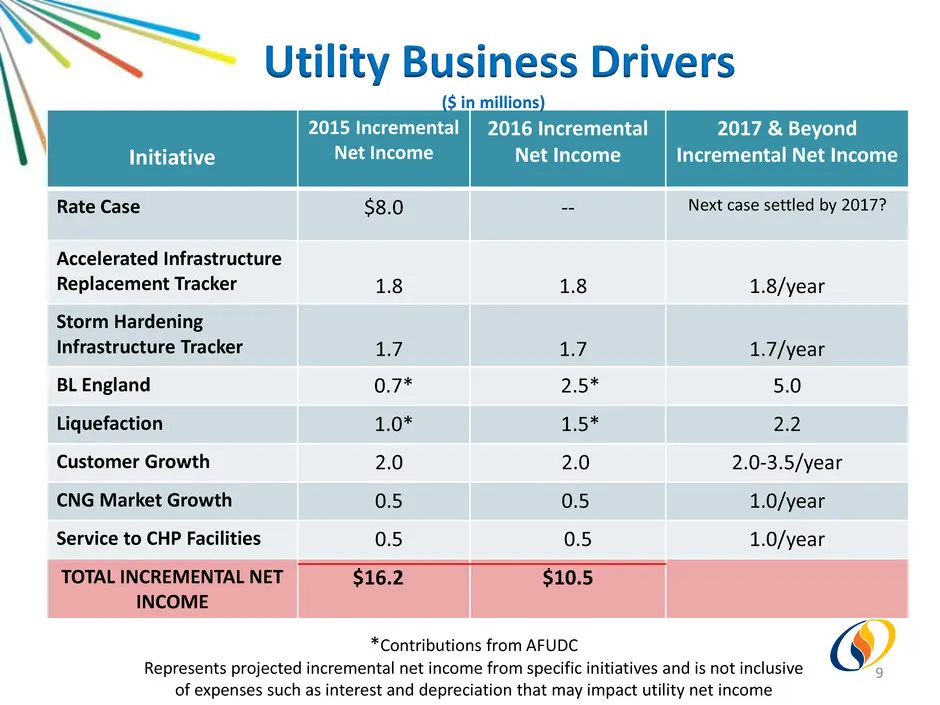
Initiative 2015 Incremental Net Income 2016 Incremental Net Income 2017 & Beyond Incremental Net Income Rate Case $8.0 -- Next case settled by 2017? Accelerated Infrastructure Replacement Tracker 1.8 1.8 1.8/year Storm Hardening Infrastructure Tracker 1.7 1.7 1.7/year BL England 0.7* 2.5* 5.0 Liquef
Slide 10: Utility Projected CAPEX
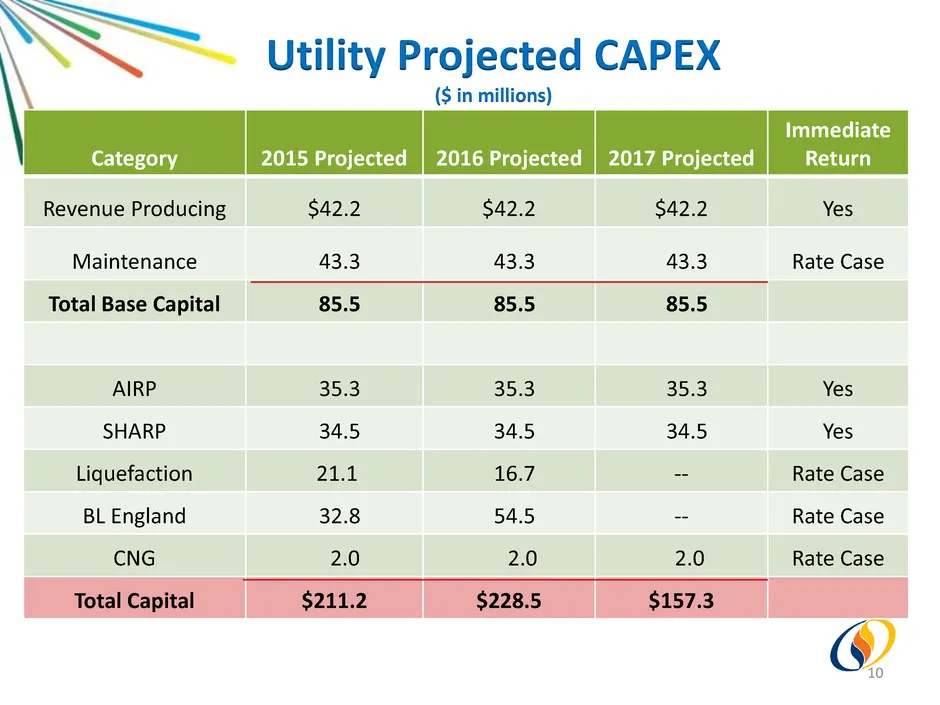
Utility Projected CAPEX ($ in millions) 10 Category 2015 Projected 2016 Projected 2017 Projected Immediate Return Revenue Producing $42.2 $42.2 $42.2 Yes Maintenance 43.3 43.3 43.3 Rate Case Total Base Capital 85.5 85.5 85.5 AIRP 35.3 35.3 35.3 Yes SHARP 34.5 34.5 34.5 Yes Liquefaction 21.1 16.7 --
Slide 11: Utility Infrastructure Growth
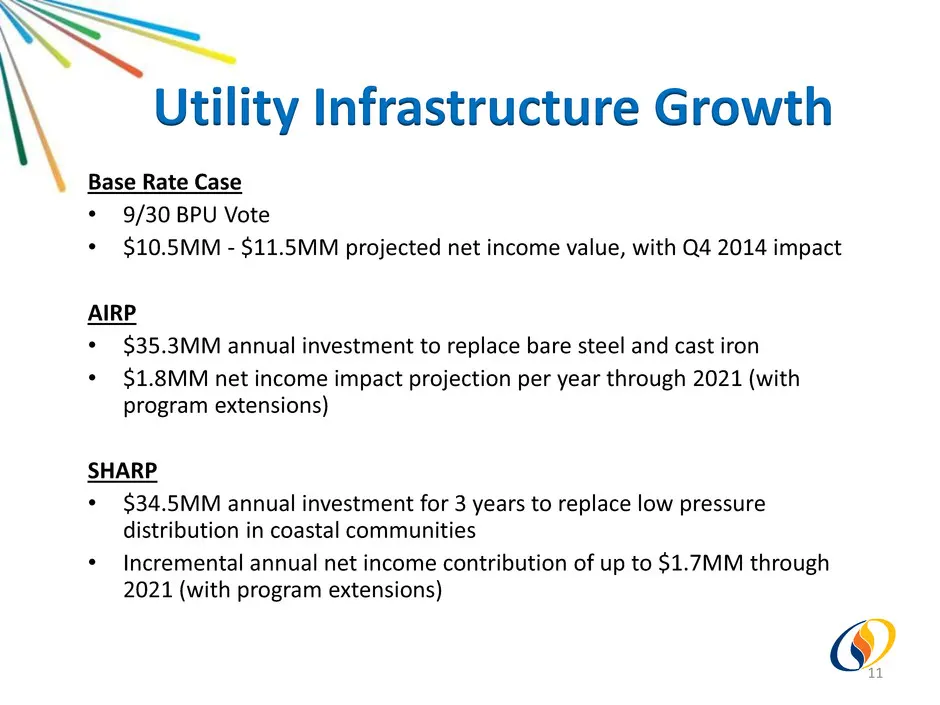
Base Rate Case • 9/30 BPU Vote • $10.5MM - $11.5MM projected net income value, with Q4 2014 impact AIRP • $35.3MM annual investment to replace bare steel and cast iron • $1.8MM net income impact projection per year through 2021 (with program extensions) SHARP • $34.5MM annual investment for 3 years
Slide 12: Utility Customer Growth
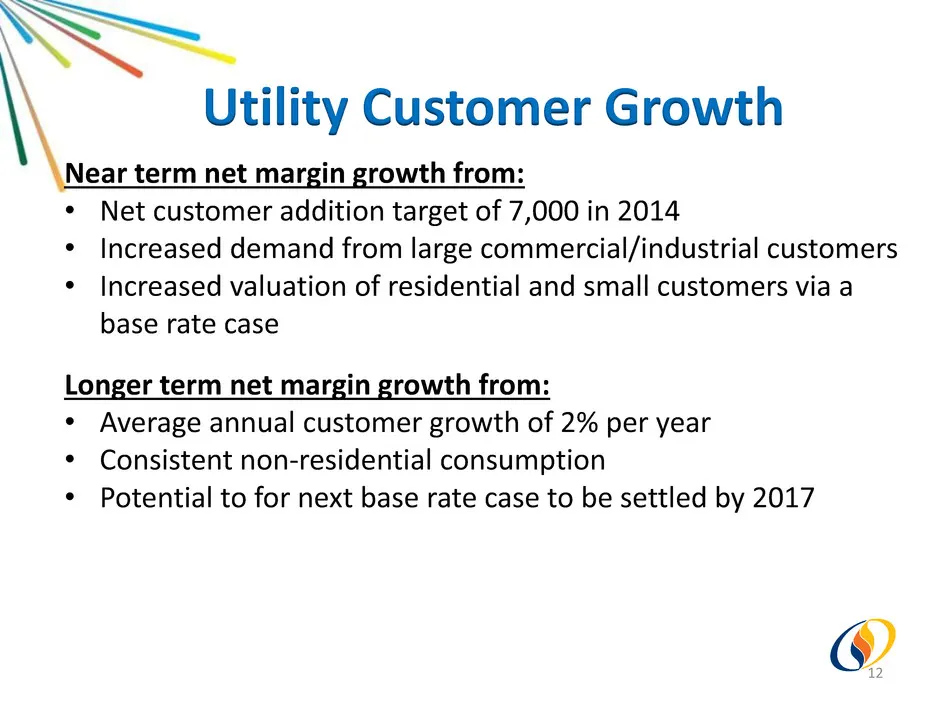
Utility Customer Growth 12 Near term net margin growth from: • Net customer addition target of 7,000 in 2014 • Increased demand from large commercial/industrial customers • Increased valuation of residential and small customers via a base rate case Longer term net margin growth from: • Average annua
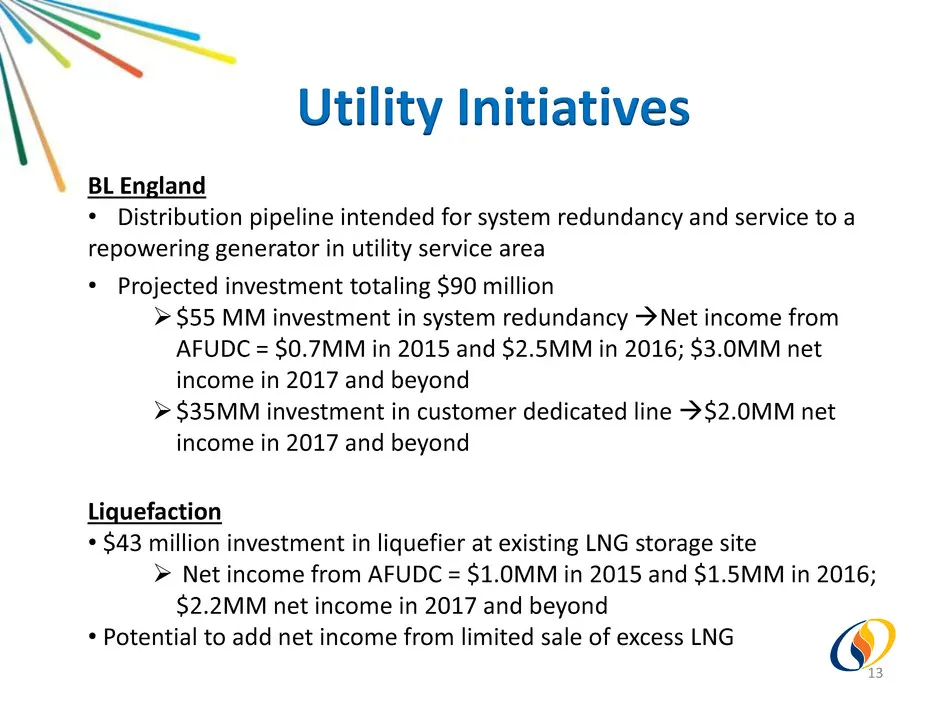
Slide 13: Utility Initiatives
BL England • Distribution pipeline intended for system redundancy and service to a repowering generator in utility service area • Projected investment totaling $90 million $55 MM investment in system redundancy Net income from AFUDC = $0.7MM in 2015 and $2.5MM in 2016; $3.0MM net income in 2017 an
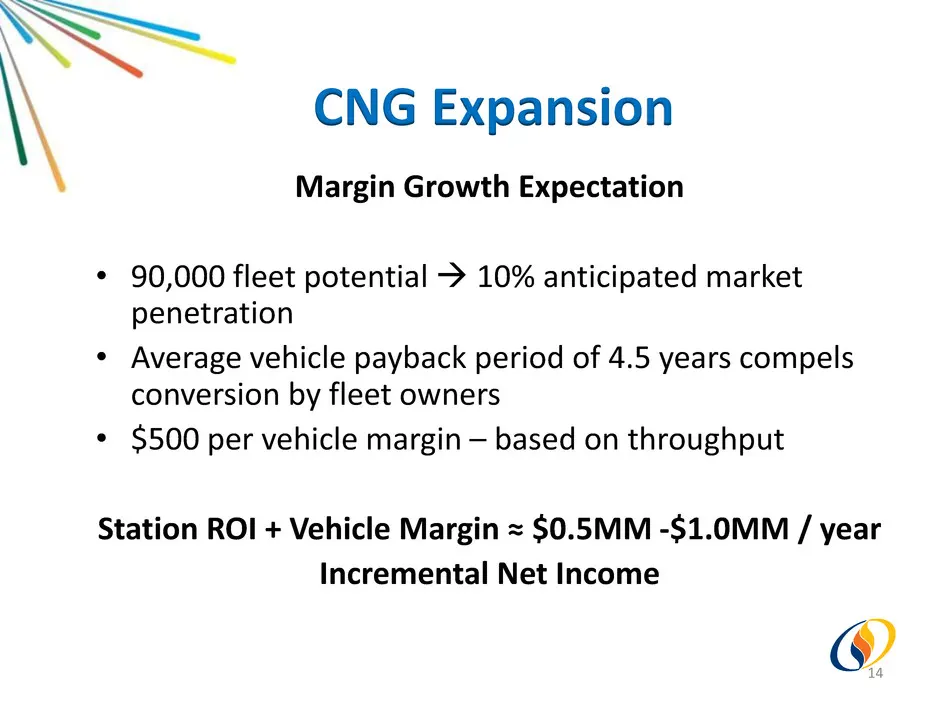
Slide 14: CNG Expansion
CNG Expansion Margin Growth Expectation • 90,000 fleet potential 10% anticipated market penetration • Average vehicle payback period of 4.5 years compels conversion by fleet owners • $500 per vehicle margin – based on throughput Station ROI + Vehicle Margin ≈ $0.5MM -$1.0MM / year Incremental Net
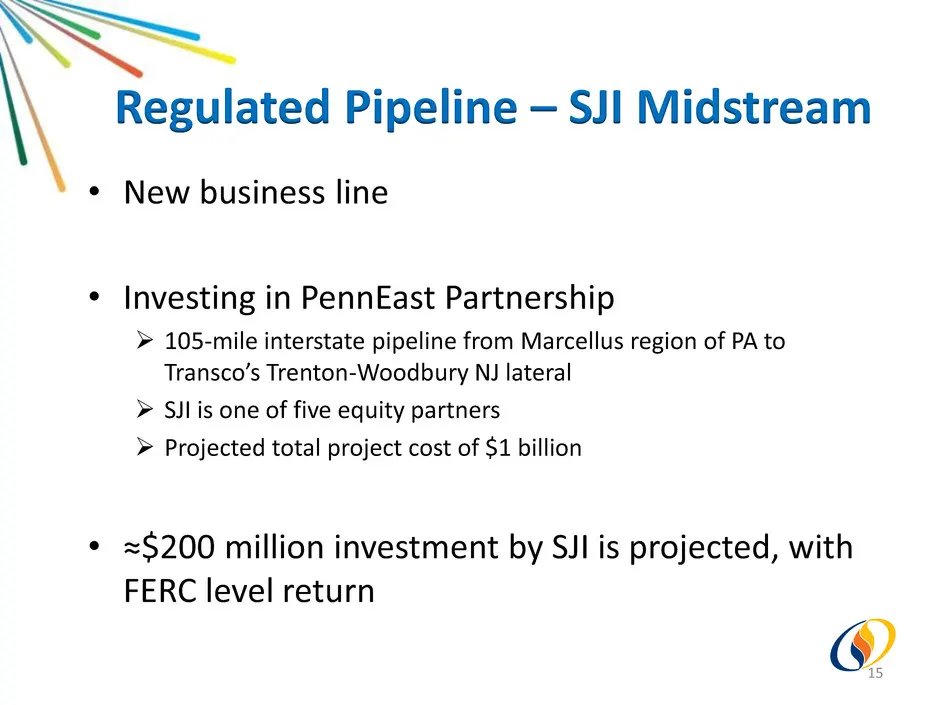
Slide 15: Regulated Pipeline – SJI Midstream
• New business line • Investing in PennEast Partnership 105-mile interstate pipeline from Marcellus region of PA to Transco’s Trenton-Woodbury NJ lateral SJI is one of five equity partners Projected total project cost of $1 billion • ≈$200 million investment by SJI is projected, with FERC leve
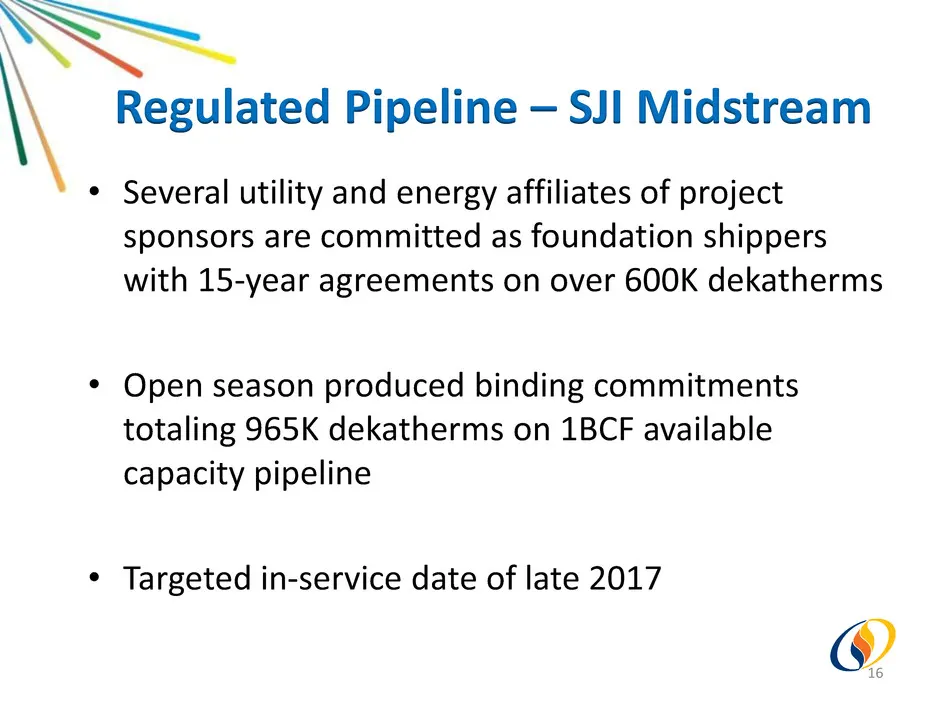
Slide 16: Regulated Pipeline – SJI Midstream
• Several utility and energy affiliates of project sponsors are committed as foundation shippers with 15-year agreements on over 600K dekatherms • Open season produced binding commitments totaling 965K dekatherms on 1BCF available capacity pipeline • Targeted in-service date of late 2017 16 Regulate
Slide 17: Unregulated Businesses
Unregulated Businesses 17
Slide 18: Unregulated Business Drivers
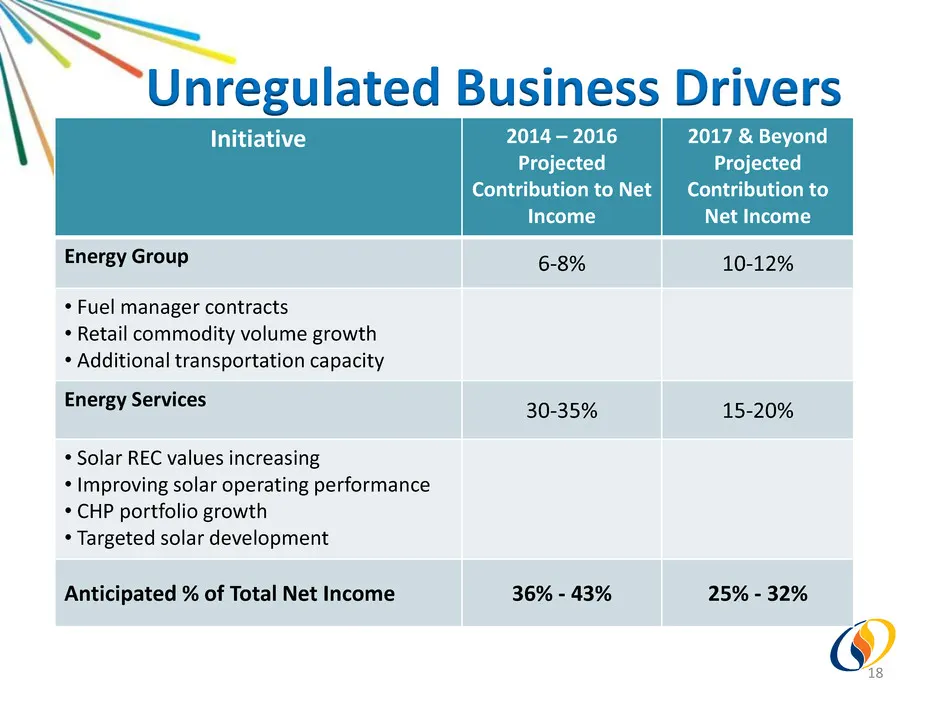
Initiative 2014 – 2016 Projected Contribution to Net Income 2017 & Beyond Projected Contribution to Net Income Energy Group 6-8% 10-12% • Fuel manager contracts • Retail commodity volume growth • Additional transportation capacity Energy Services 30-35% 15-20% • Solar REC values increasing • Improvi
Slide 19: Wholesale Commodity Marketing
Fuel Manager Contracts • Annuity-like income stream from multi-year agreements • Fixed monthly fee, with index+ based commodity price sets baseline margin • Incremental margin potential from optimizing contract loads against our assets and Marcellus position • 6 fuel manager contracts currently exec
Slide 20: Retail Commodity Marketing
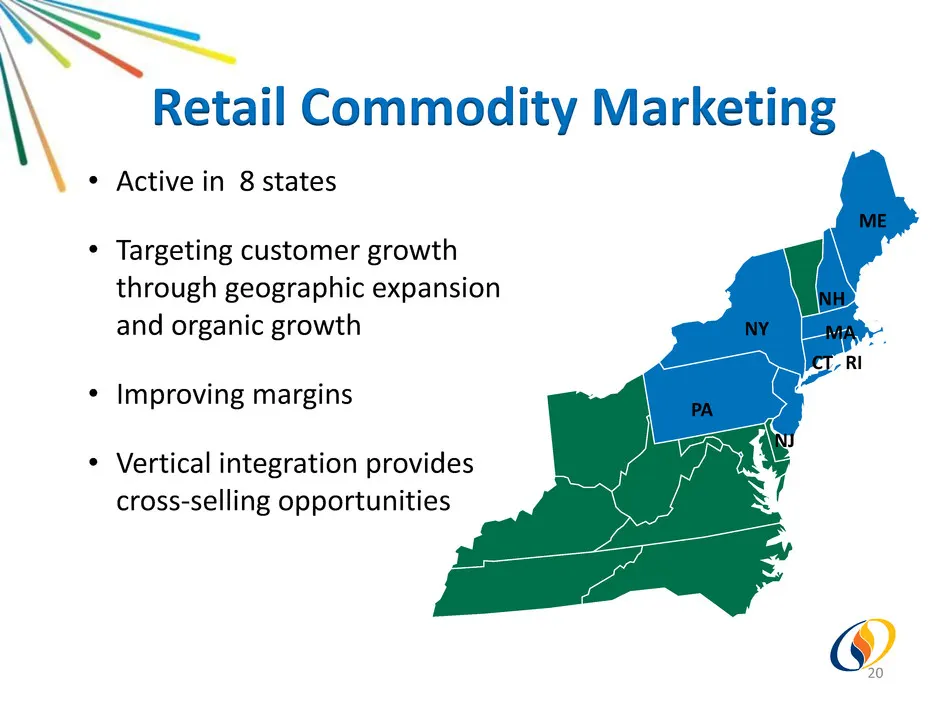
Retail Commodity Marketing NJ PA NY ME NH MA CT RI • Active in 8 states • Targeting customer growth through geographic expansion and organic growth • Improving margins • Vertical integration provides cross-selling opportunities 20
Slide 21: Combined Heat and Power (CHP)
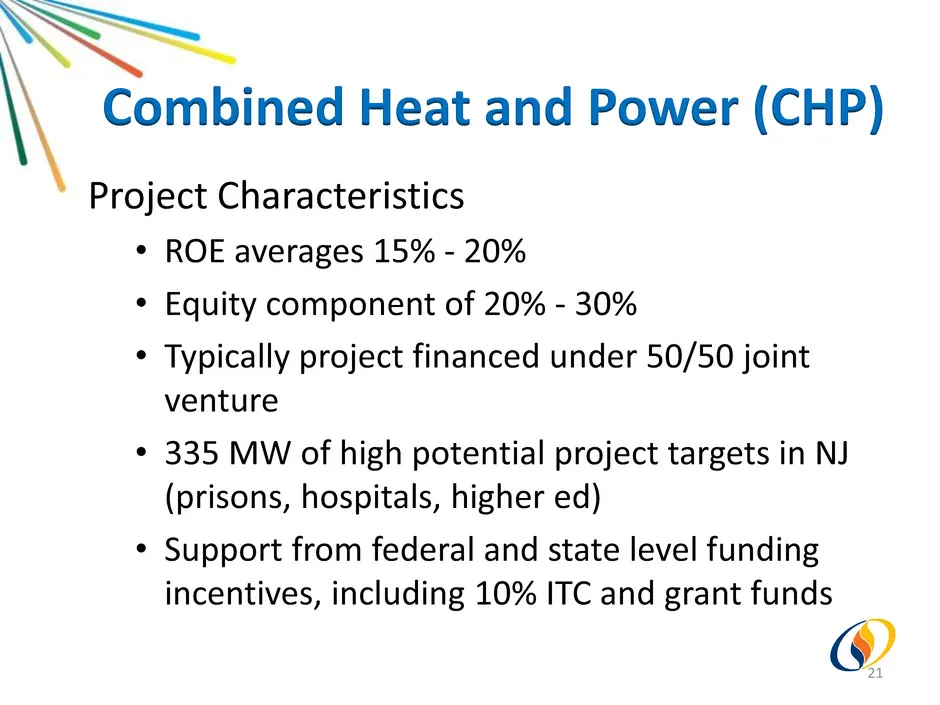
Project Characteristics • ROE averages 15% - 20% • Equity component of 20% - 30% • Typically project financed under 50/50 joint venture • 335 MW of high potential project targets in NJ (prisons, hospitals, higher ed) • Support from federal and state level funding incentives, including 10% ITC and gr
Slide 22: Solar Net Income Contribution
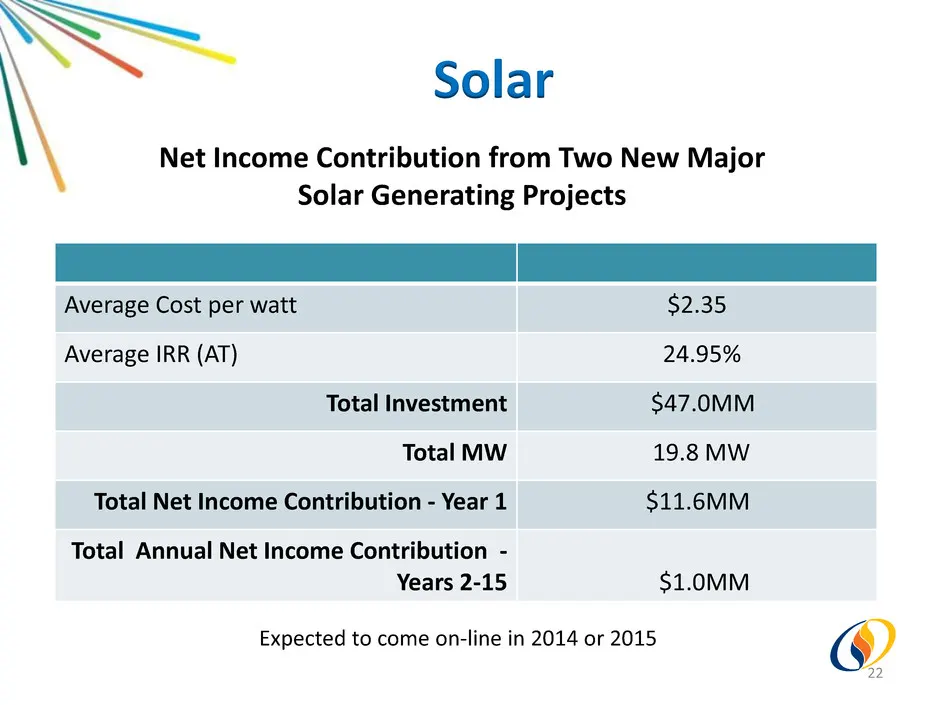
Average Cost per watt $2.35 Average IRR (AT) 24.95% Total Investment $47.0MM Total MW 19.8 MW Total Net Income Contribution - Year 1 $11.6MM Total Annual Net Income Contribution - Years 2-15 $1.0MM Solar Net Income Contribution from Two New Major Solar Generating Projects Expected to come on-line in
Slide 23: Earnings Drivers
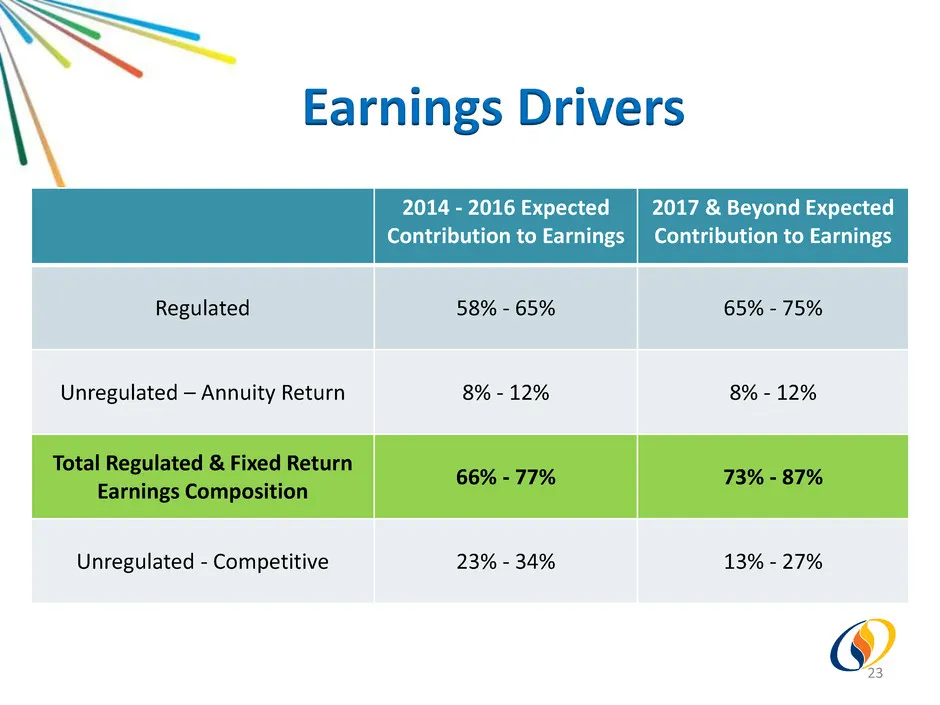
2014 - 2016 Expected Contribution to Earnings 2017 & Beyond Expected Contribution to Earnings Regulated 58% - 65% 65% - 75% Unregulated – Annuity Return 8% - 12% 8% - 12% Total Regulated & Fixed Return Earnings Composition 66% - 77% 73% - 87% Unregulated - Competitive 23% - 34% 13% - 27% Earnings Dr
Slide 24: REN fo
REN fo _—— 7 |=
Slide 25: Strategic Pipeline Capacity
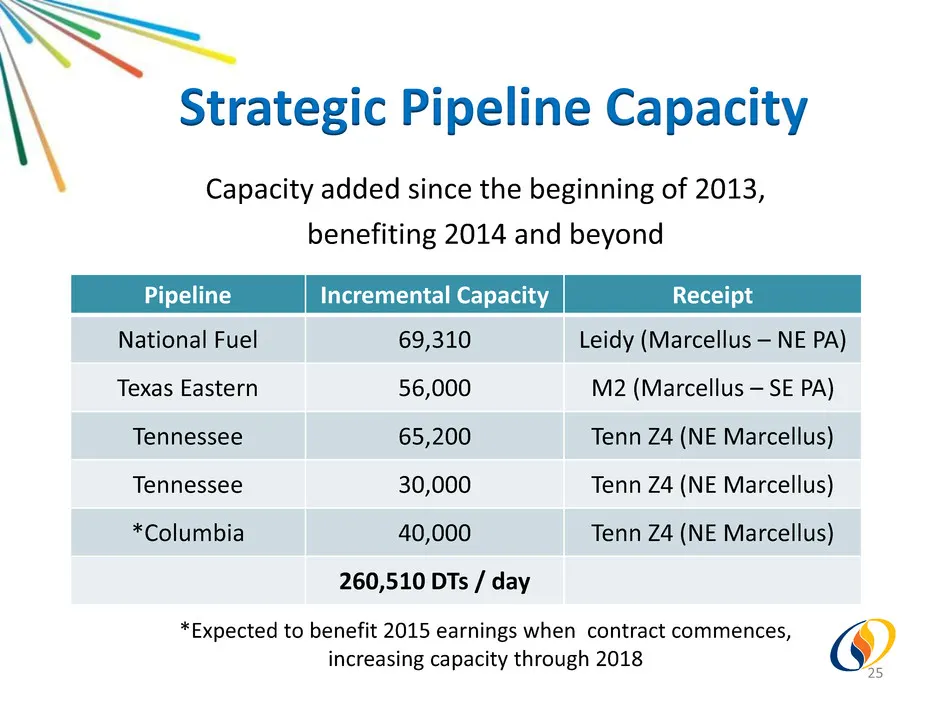
Capacity added since the beginning of 2013, benefiting 2014 and beyond Strategic Pipeline Capacity Pipeline Incremental Capacity Receipt National Fuel 69,310 Leidy (Marcellus – NE PA) Texas Eastern 56,000 M2 (Marcellus – SE PA) Tennessee 65,200 Tenn Z4 (NE Marcellus) Tennessee 30,000 Tenn Z4 (NE Mar
Slide 26: Fuel Manager Contracts
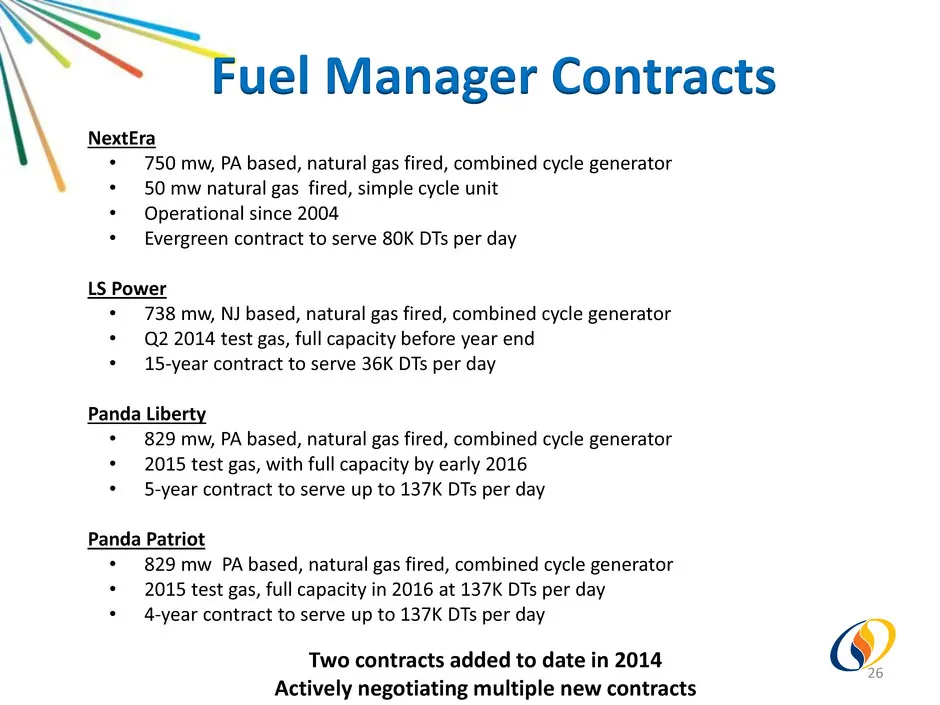
NextEra • 750 mw, PA based, natural gas fired, combined cycle generator • 50 mw natural gas fired, simple cycle unit • Operational since 2004 • Evergreen contract to serve 80K DTs per day LS Power • 738 mw, NJ based, natural gas fired, combined cycle generator • Q2 2014 test gas, full capacity befor
Source: SEC EDGAR · 8-K filed Sep 29, 2014
More decks from South Jersey Industries Inc
 FY2021 Earnings Presentation29 slides · Feb 24, 2022
 Q3 2021 Earnings Presentation31 slides · Nov 3, 2021
 Q2 2021 Earnings Presentation31 slides · Aug 4, 2021
 Investor Day (May 2021)88 slides · May 6, 2021
 FY2020 Earnings Presentation31 slides · Feb 24, 2021
 Q3 2020 Earnings Presentation37 slides · Nov 4, 2020