M&G PLC · LSE:MNG
M&G — Investor Presentation
44 slides from M&G's investor presentation
Slide 1: Bond School: Session 006 – Bits and bobs about bonds
Bond School Session 006 – Bits and bobs about bonds
Slide 2: Tax and investment disclaimer
This content is based on our understanding of current taxation, legislation and HM Revenue & Customs practice all of which are liable to change without notice. The impact of any taxation (and any tax reliefs) depends on individual circumstances. Where content includes case studies or examples thes
Slide 3: Learning objectives
Learning objectives By the end of this session, you will be able to: Understand the Identify when Describe the self- Evaluate the impact basics of why bonds chargeable events assessment Identify when it’s of exercising can be disregarded on bonds impact requirements for appropriate to use a cancella
Slide 4: Bond cancellation rights
Bond cancellation rights
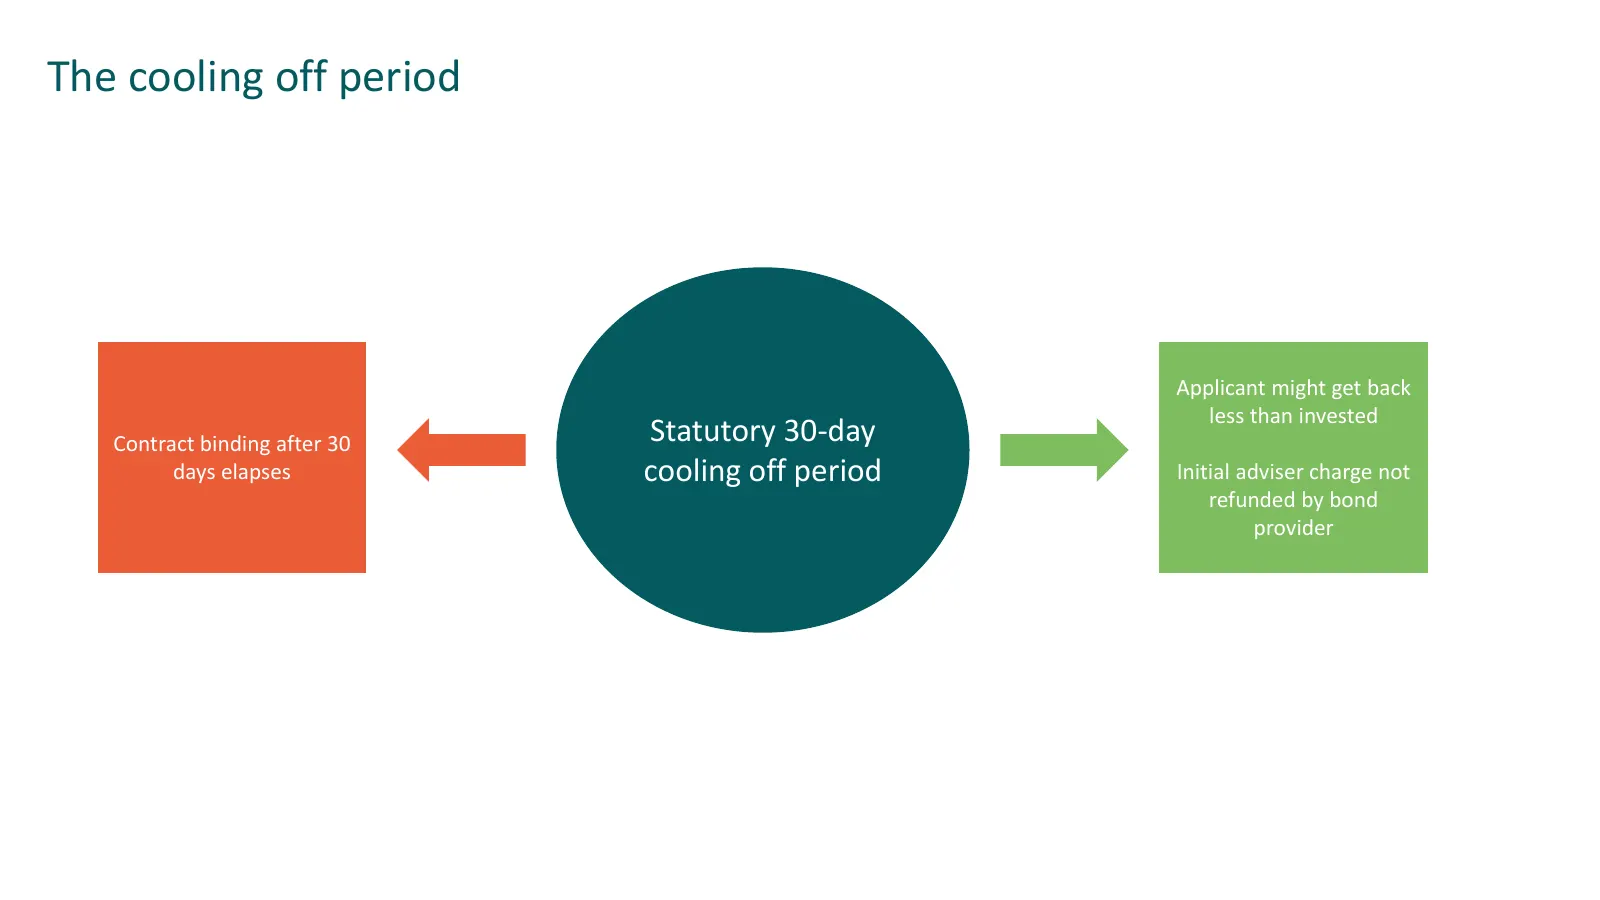
Slide 5: The cooling off period
The cooling off period Applicant might get back less than invested Contract binding after 30 Statutory 30-day days elapses cooling off period Initial adviser charge not refunded by bond provider
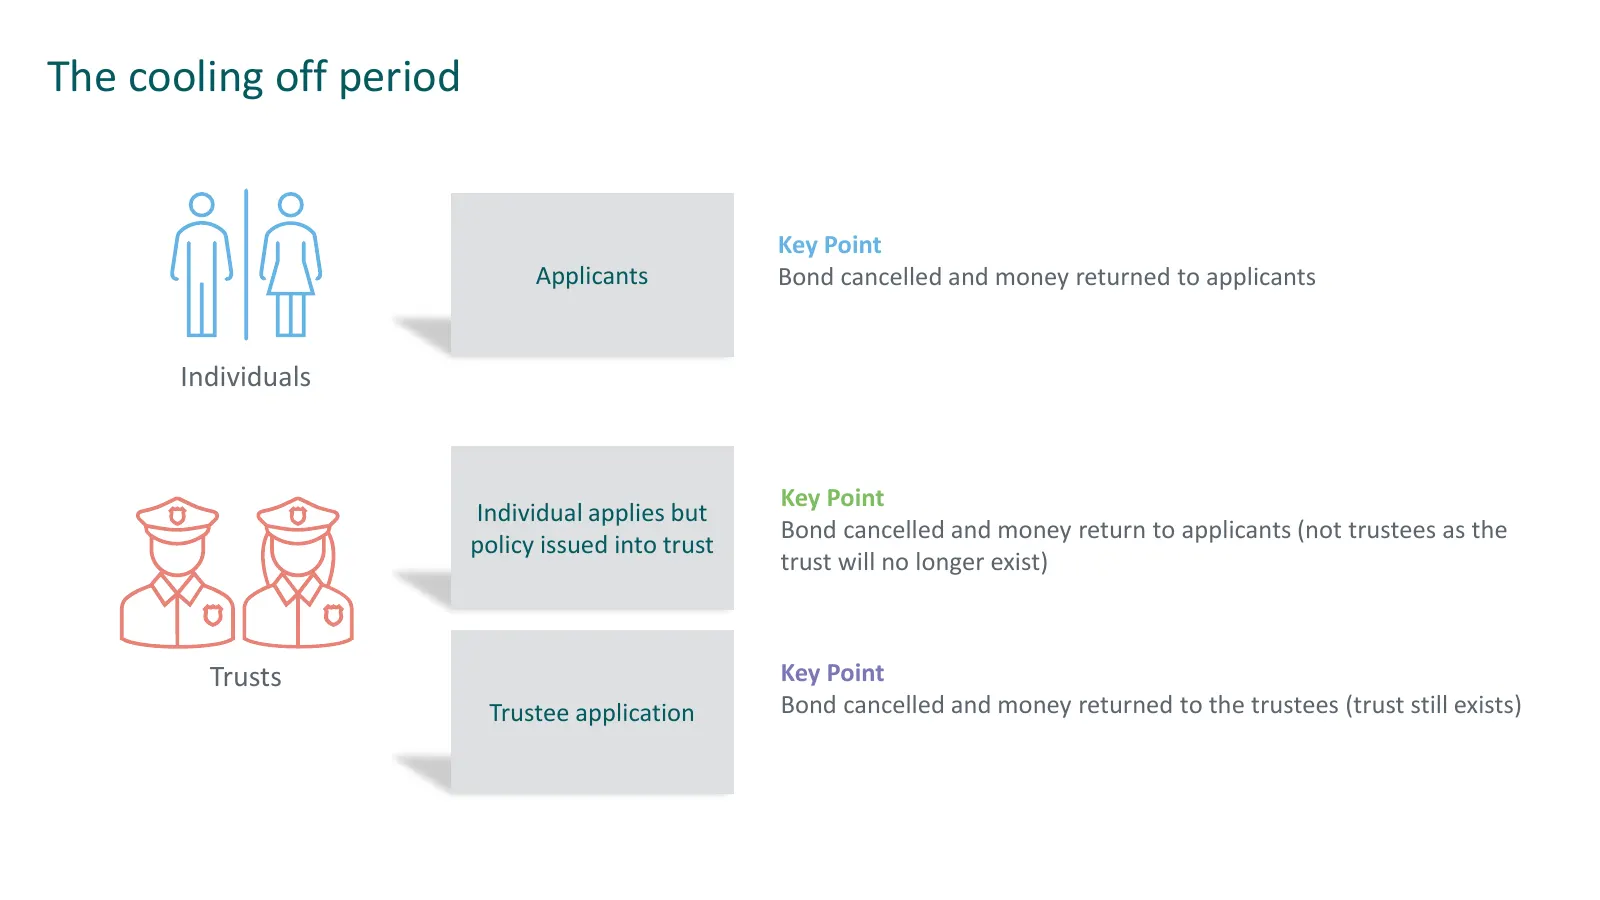
Slide 6: The cooling off period
The cooling off period Key Point Applicants Bond cancelled and money returned to applicants Individuals Key Point Individual applies but Bond cancelled and money return to applicants (not trustees as the policy issued into trust trust will no longer exist) Trusts Key Point Trustee application Bond c
Slide 7: Bond gains and Trust Registration Service
Bond gains and Trust Registration Service
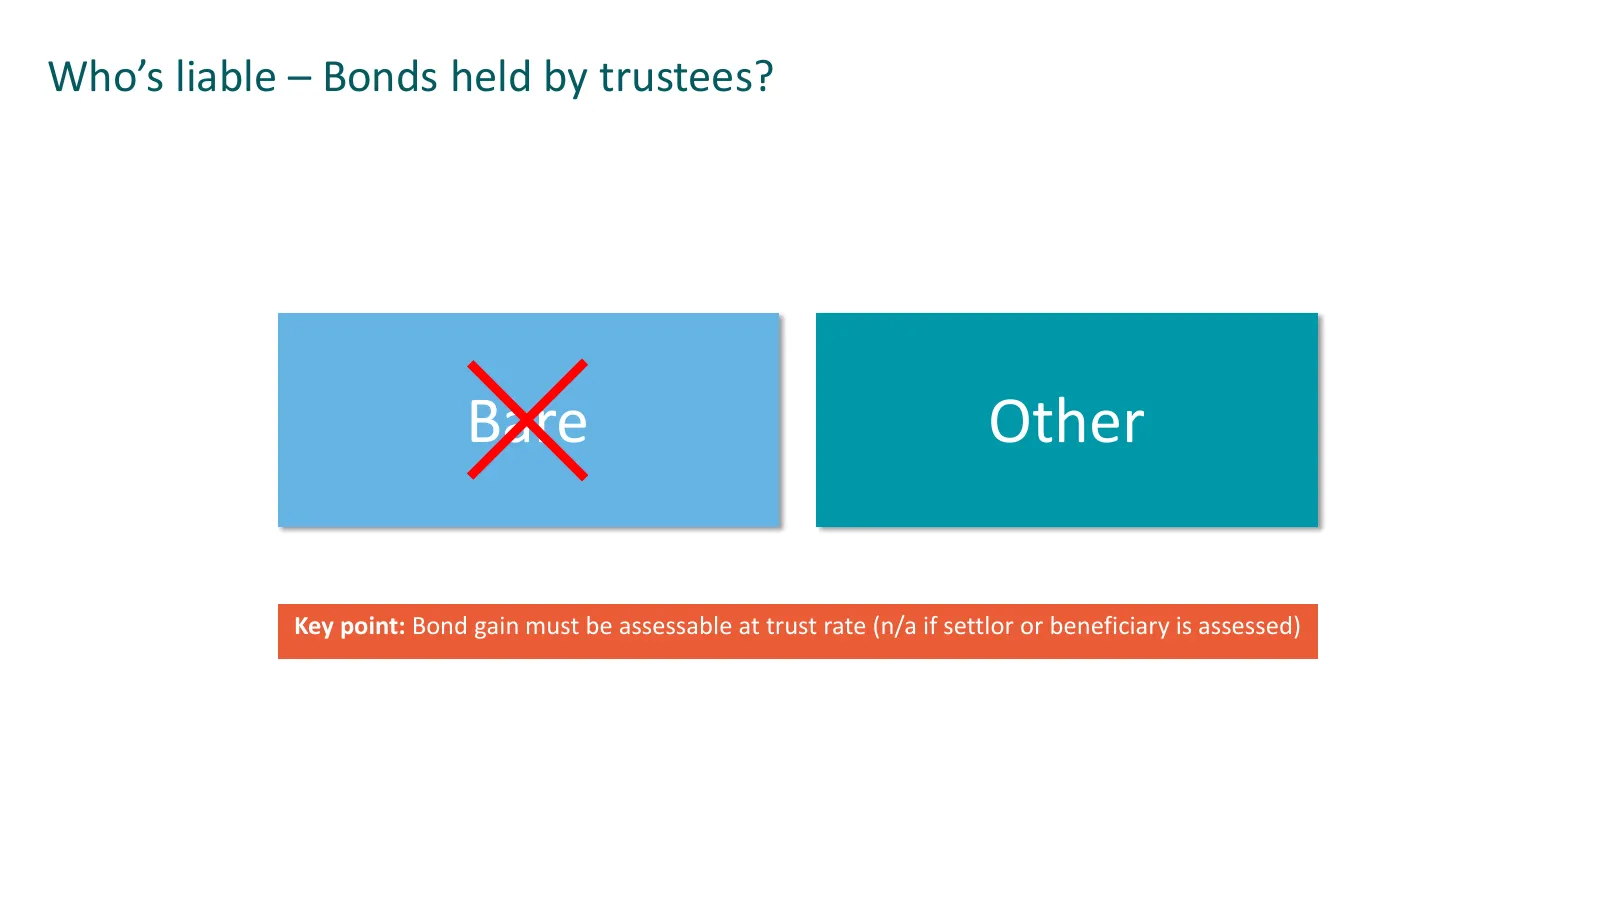
Slide 8: Who’s liable – Bonds held by trustees?
Who’s liable – Bonds held by trustees? Bare Other Key point: Bond gain must be assessable at trust rate (n/a if settlor or beneficiary is assessed)
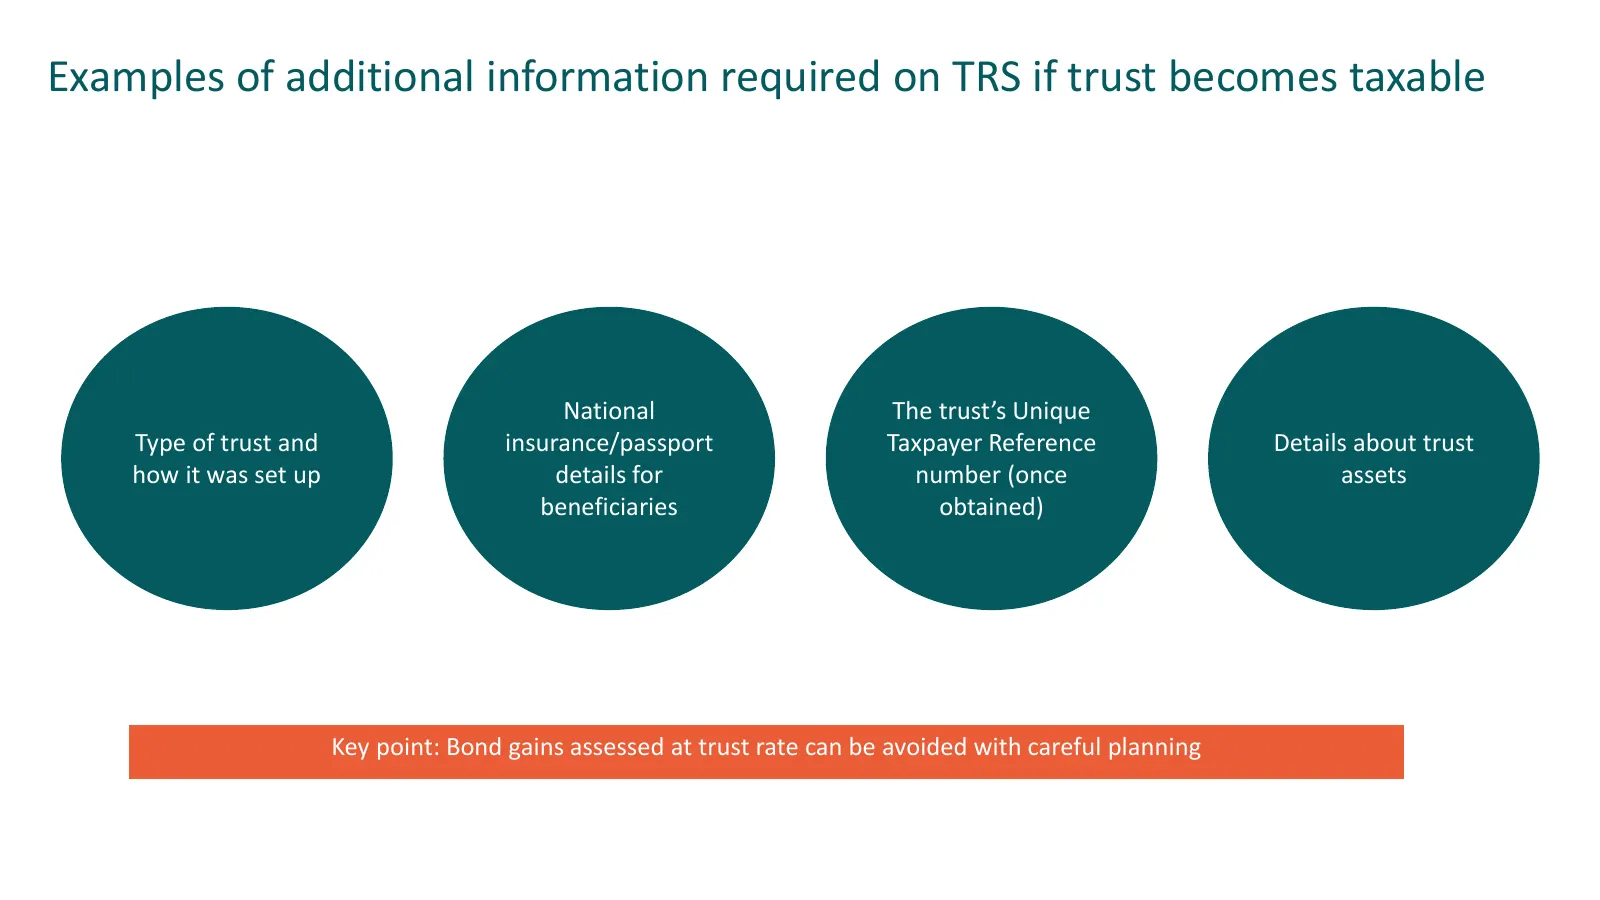
Slide 9: Additional information required on TRS if trust becomes taxable
Examples of additional information required on TRS if trust becomes taxable National The trust’s Unique Type of trust and insurance/passport Taxpayer Reference Details about trust how it was set up details for number (once assets beneficiaries obtained) Key point: Bond gains assessed at trust rate c
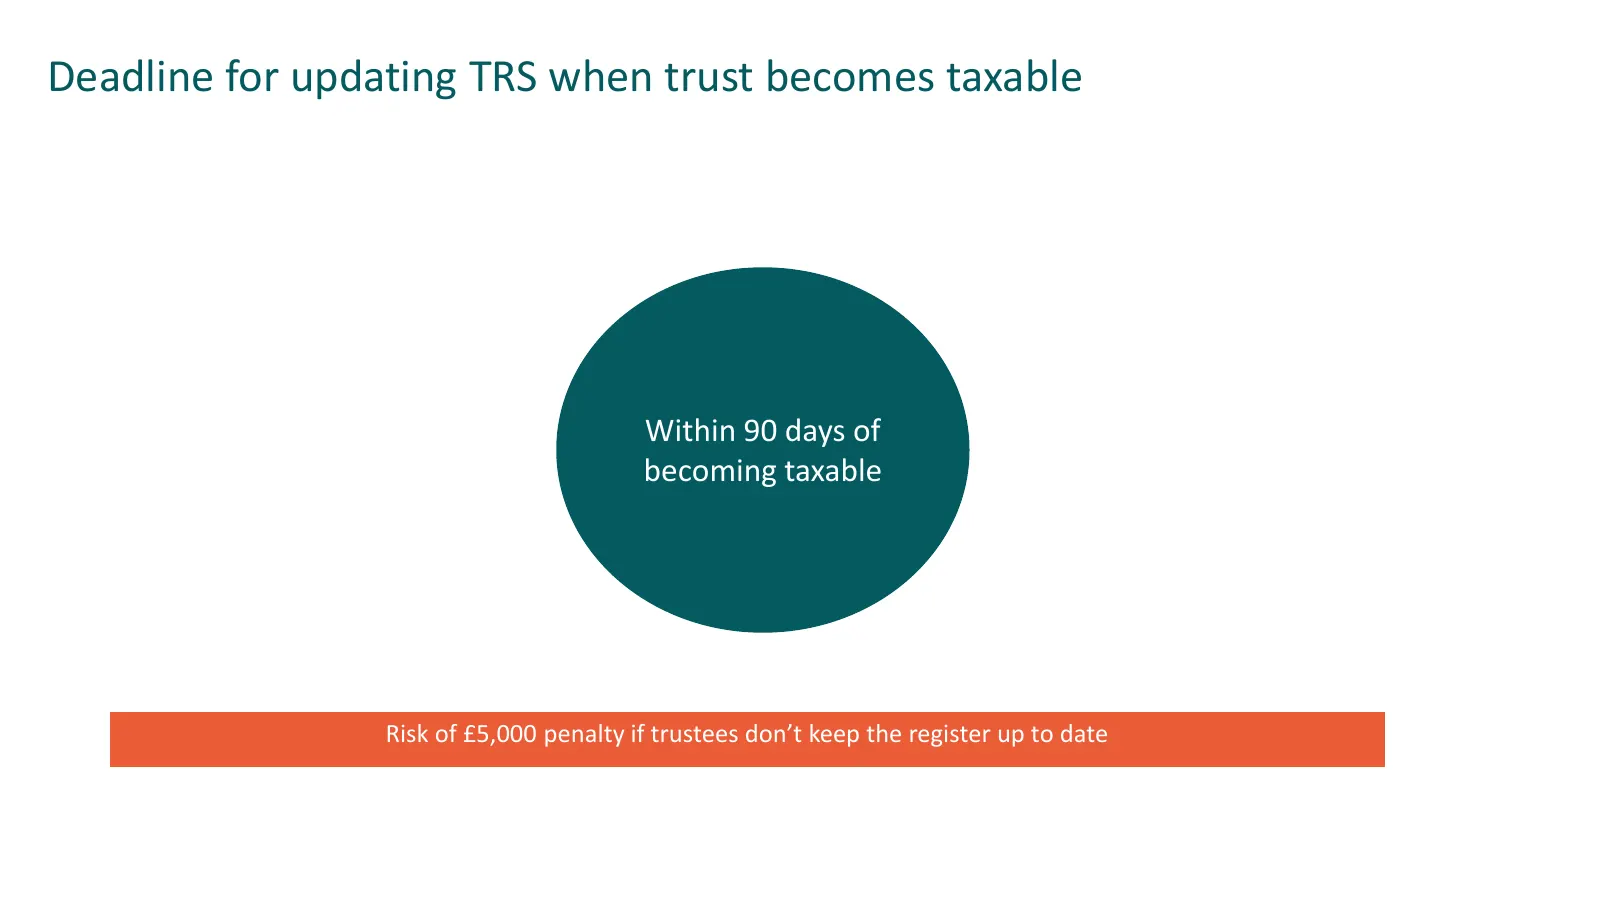
Slide 10: Deadline for updating TRS when trust becomes taxable
Deadline for updating TRS when trust becomes taxable Within 90 days of becoming taxable Risk of £5,000 penalty if trustees don’t keep the register up to date )
Slide 11: Bond gains and tax reporting (individuals)
Bond gains and tax reporting (individuals)
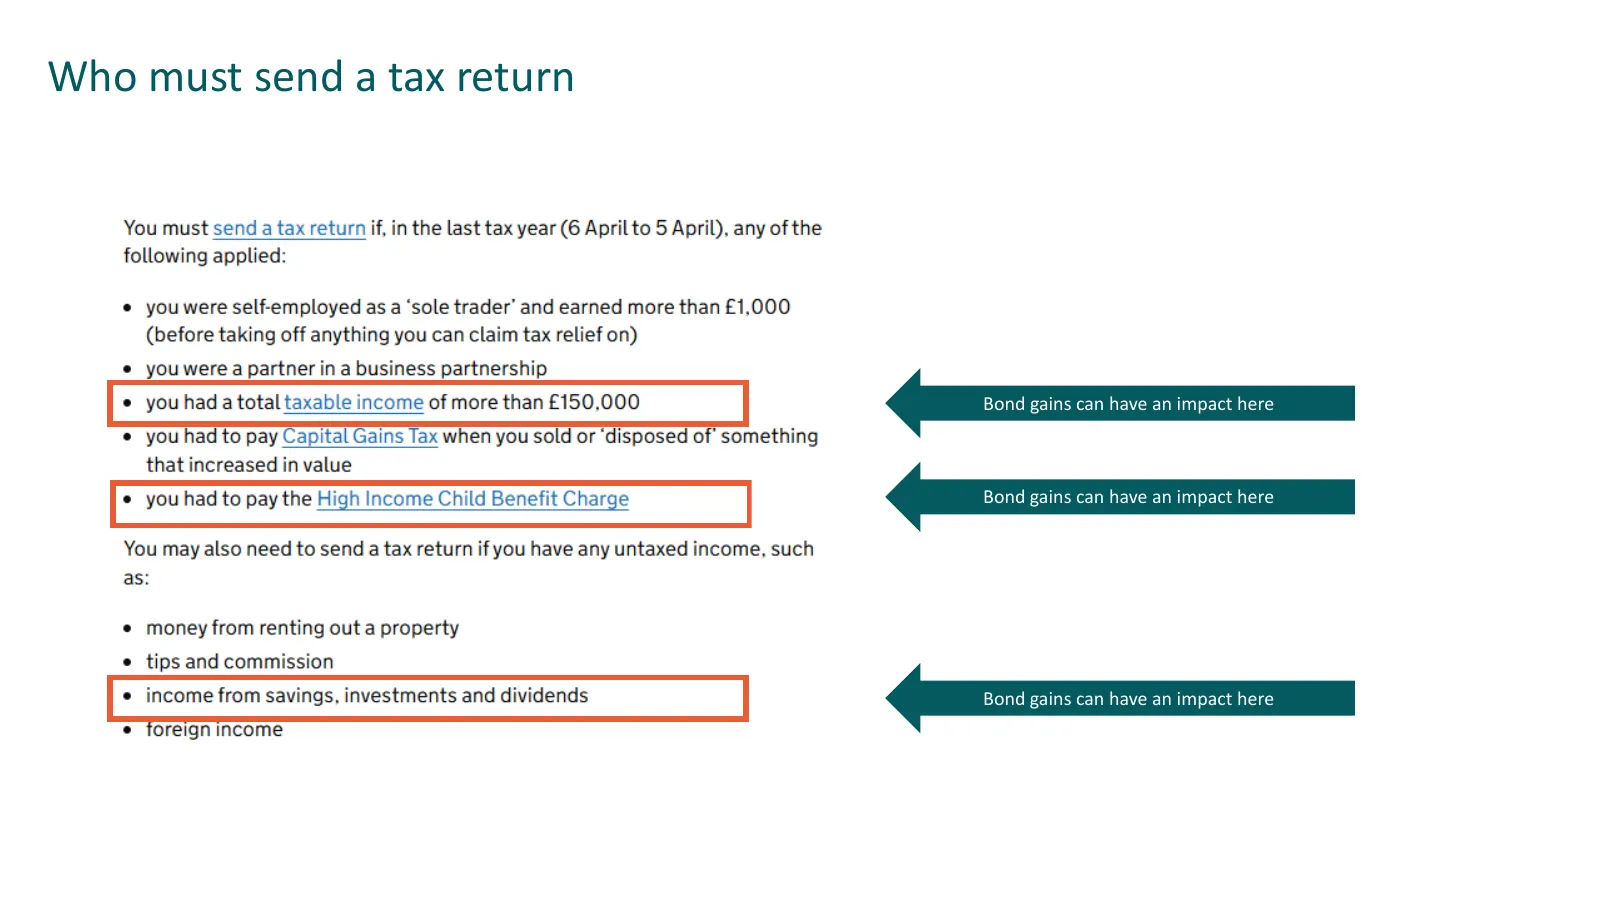
Slide 12: Who must send a tax return
Who must send a tax return Bond gains can have an impact here Bond gains can have an impact here Bond gains can have an impact here
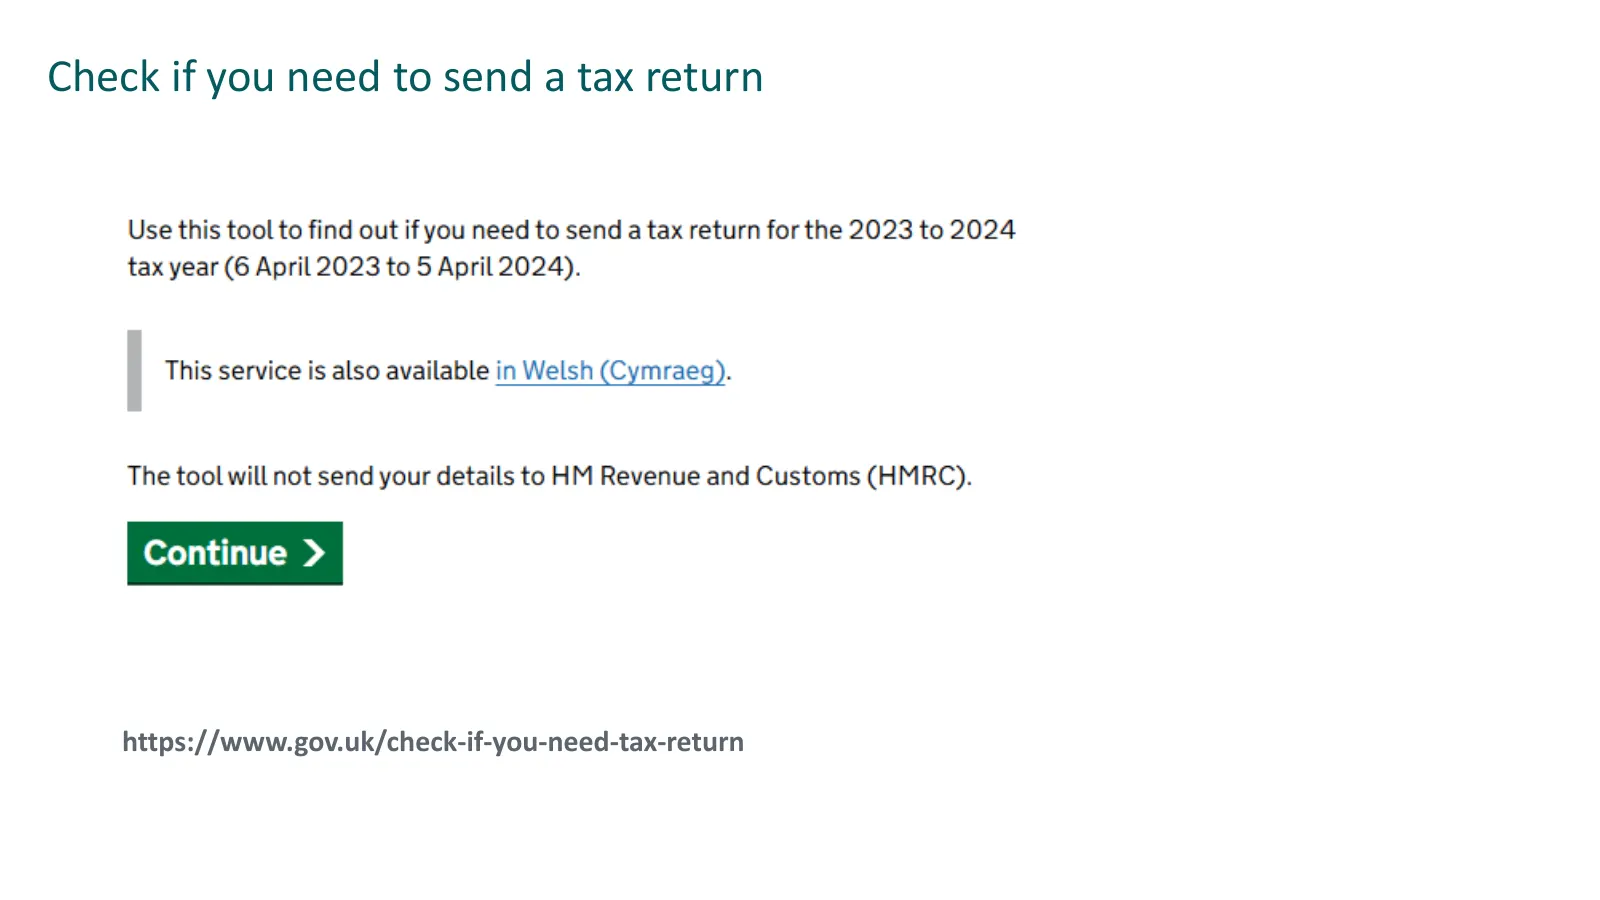
Slide 13: Check if you need to send a tax return
Check if you need to send a tax return https://www.gov.uk/check-if-you-need-tax-return
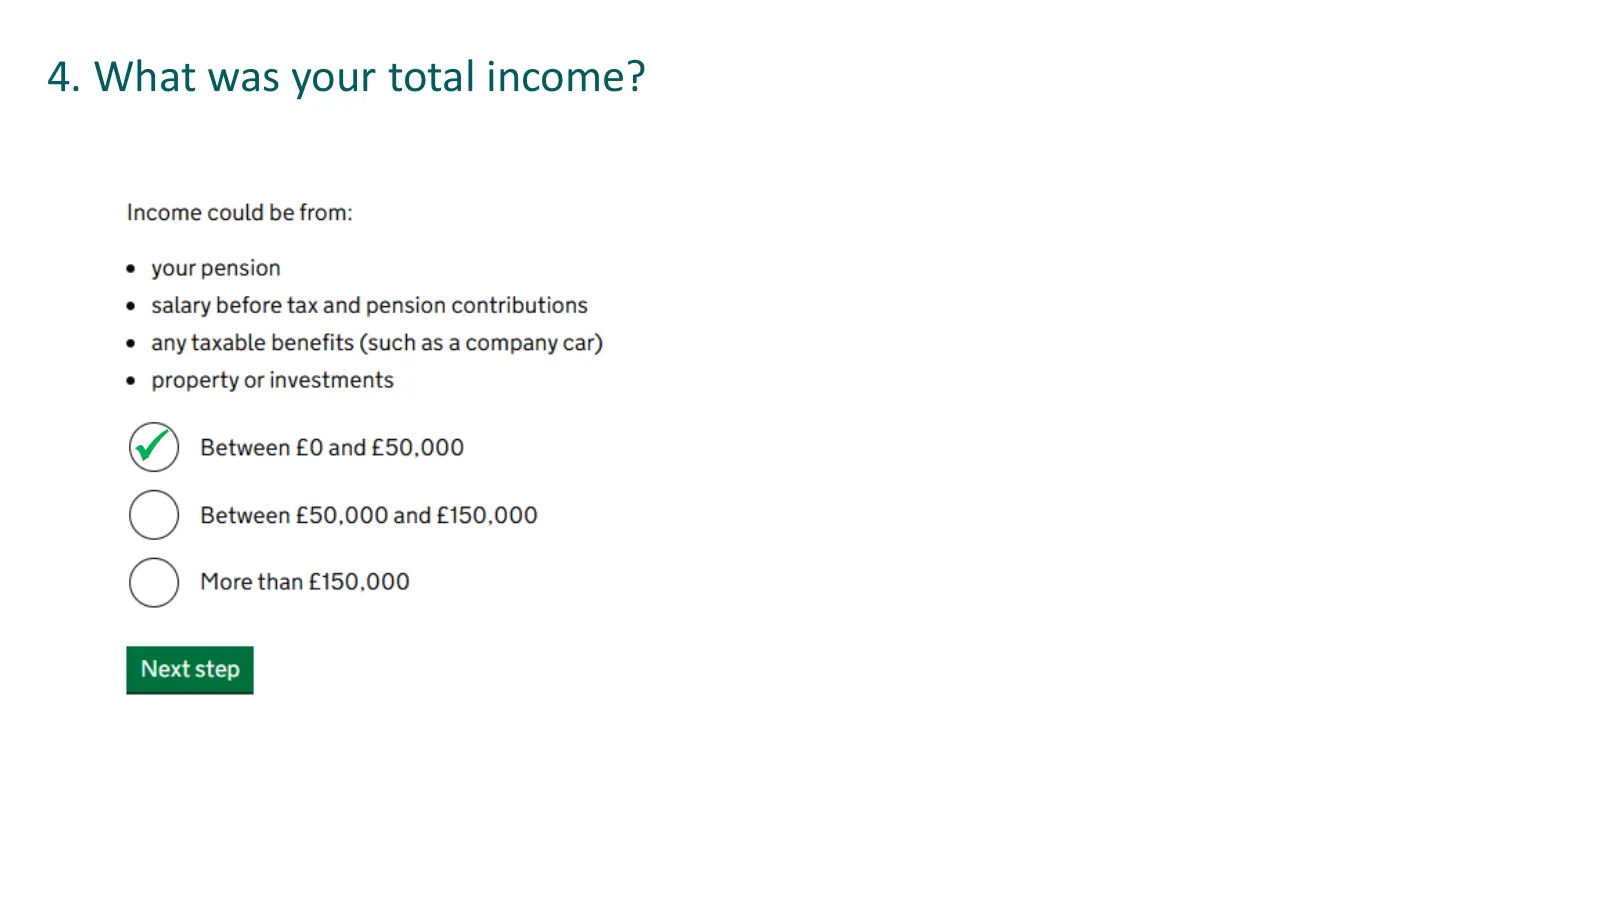
Slide 14: 4. What was your total income?
4. What was your total income? ✓
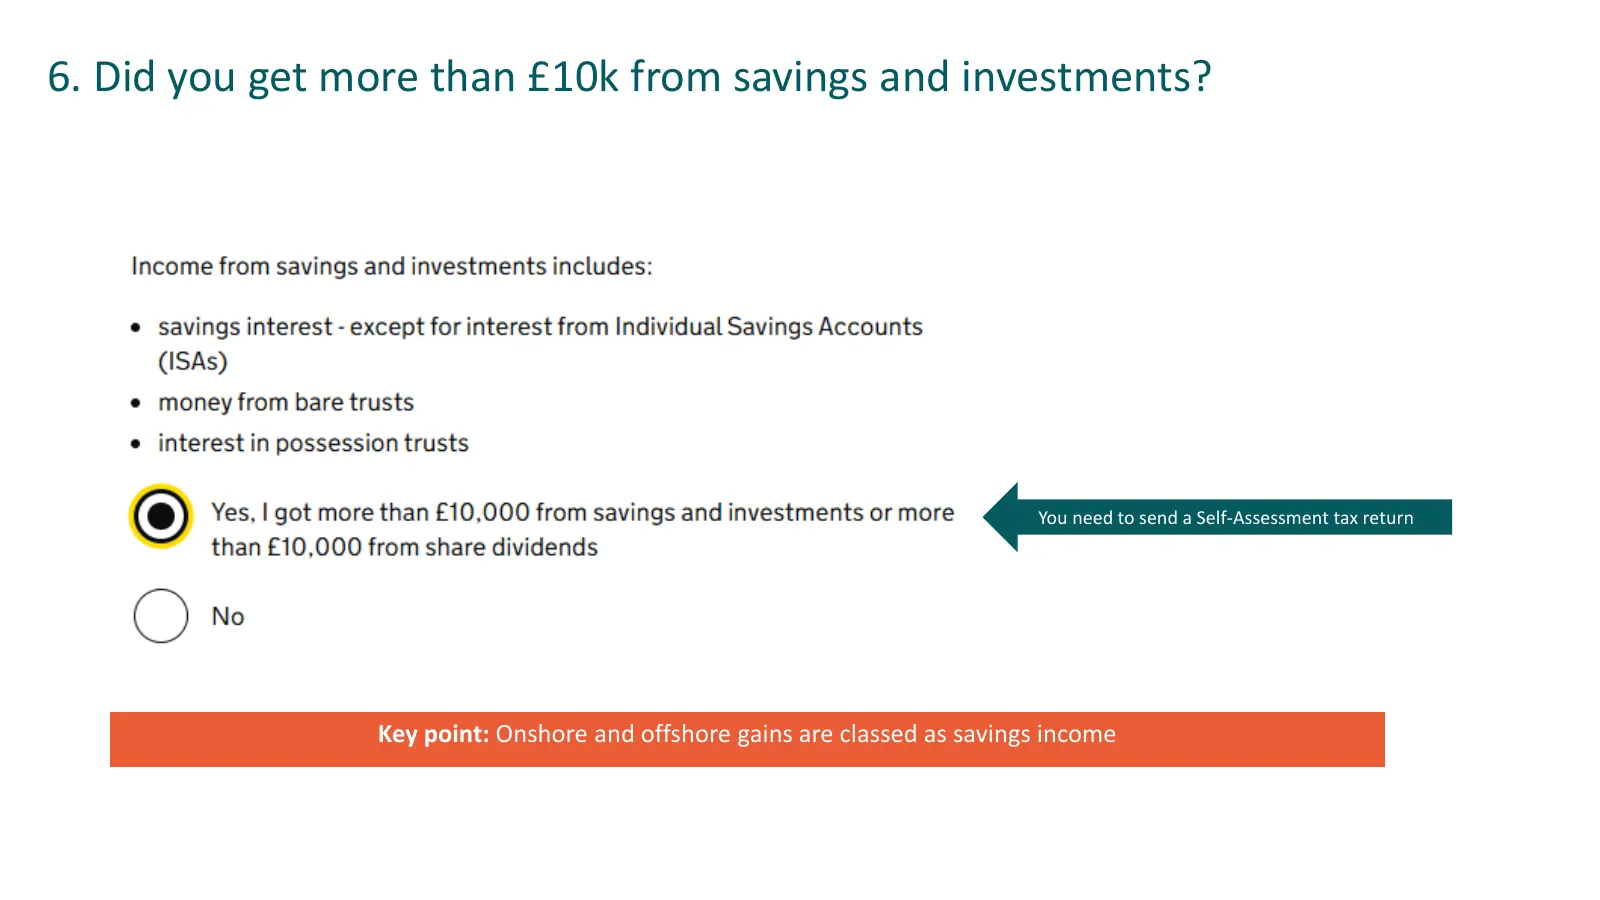
Slide 15: 6. Did you get more than £10k from savings and investments?
6. Did you get more than £10k from savings and investments? You need to send a Self-Assessment tax return Key point: Onshore and offshore gains are classed as savings income
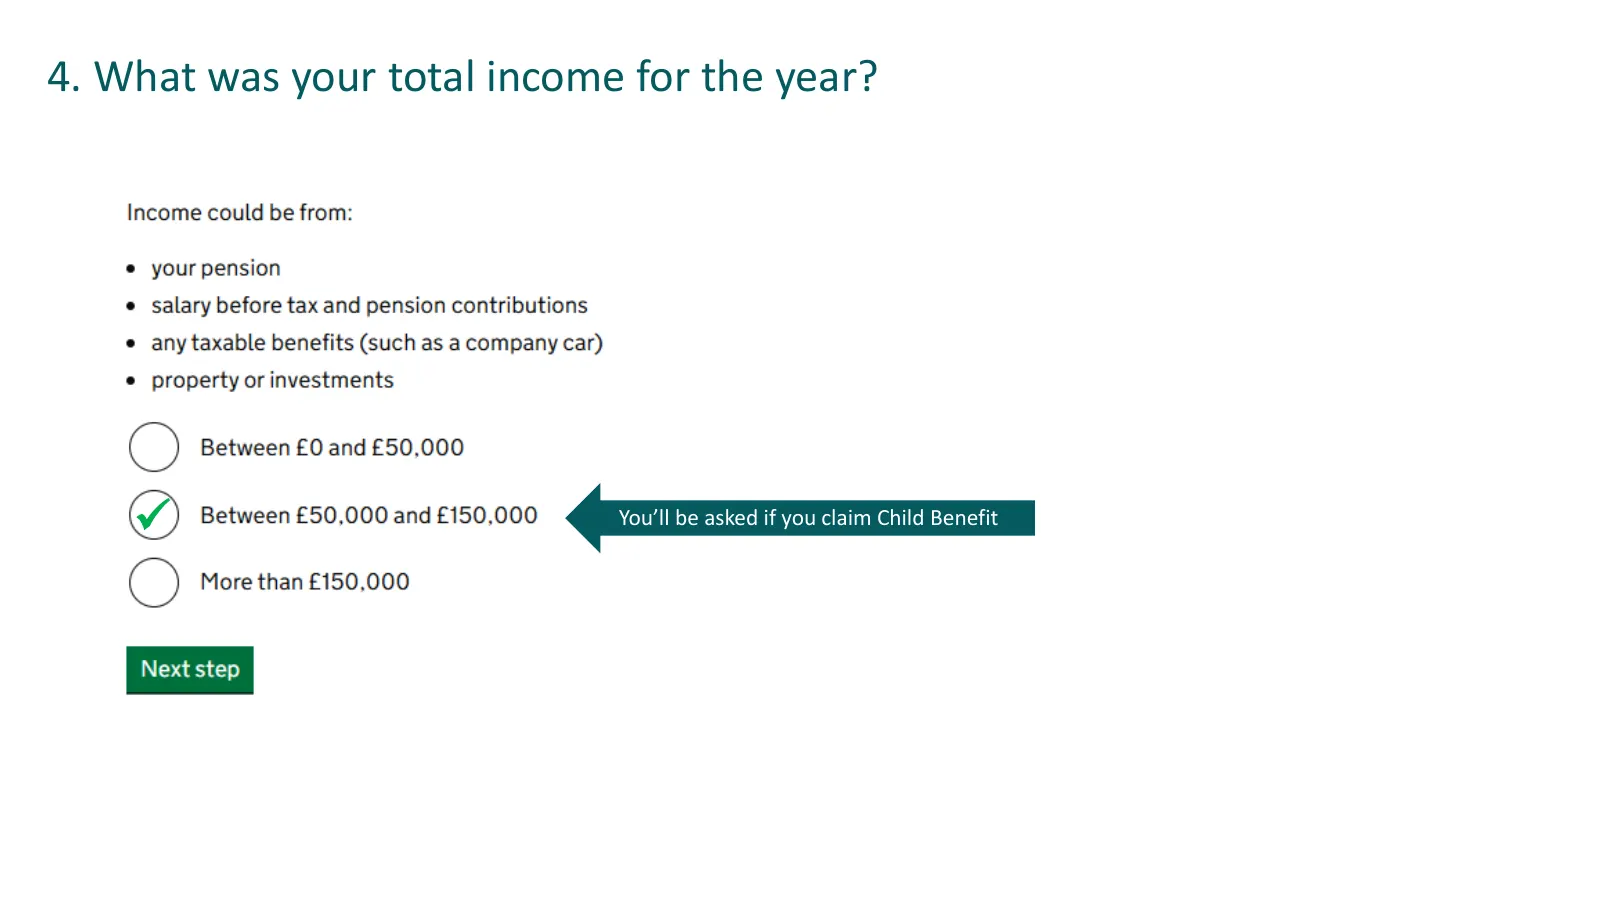
Slide 16: 4. What was your total income for the year?
4. What was your total income for the year? ✓ You’ll be asked if you claim Child Benefit
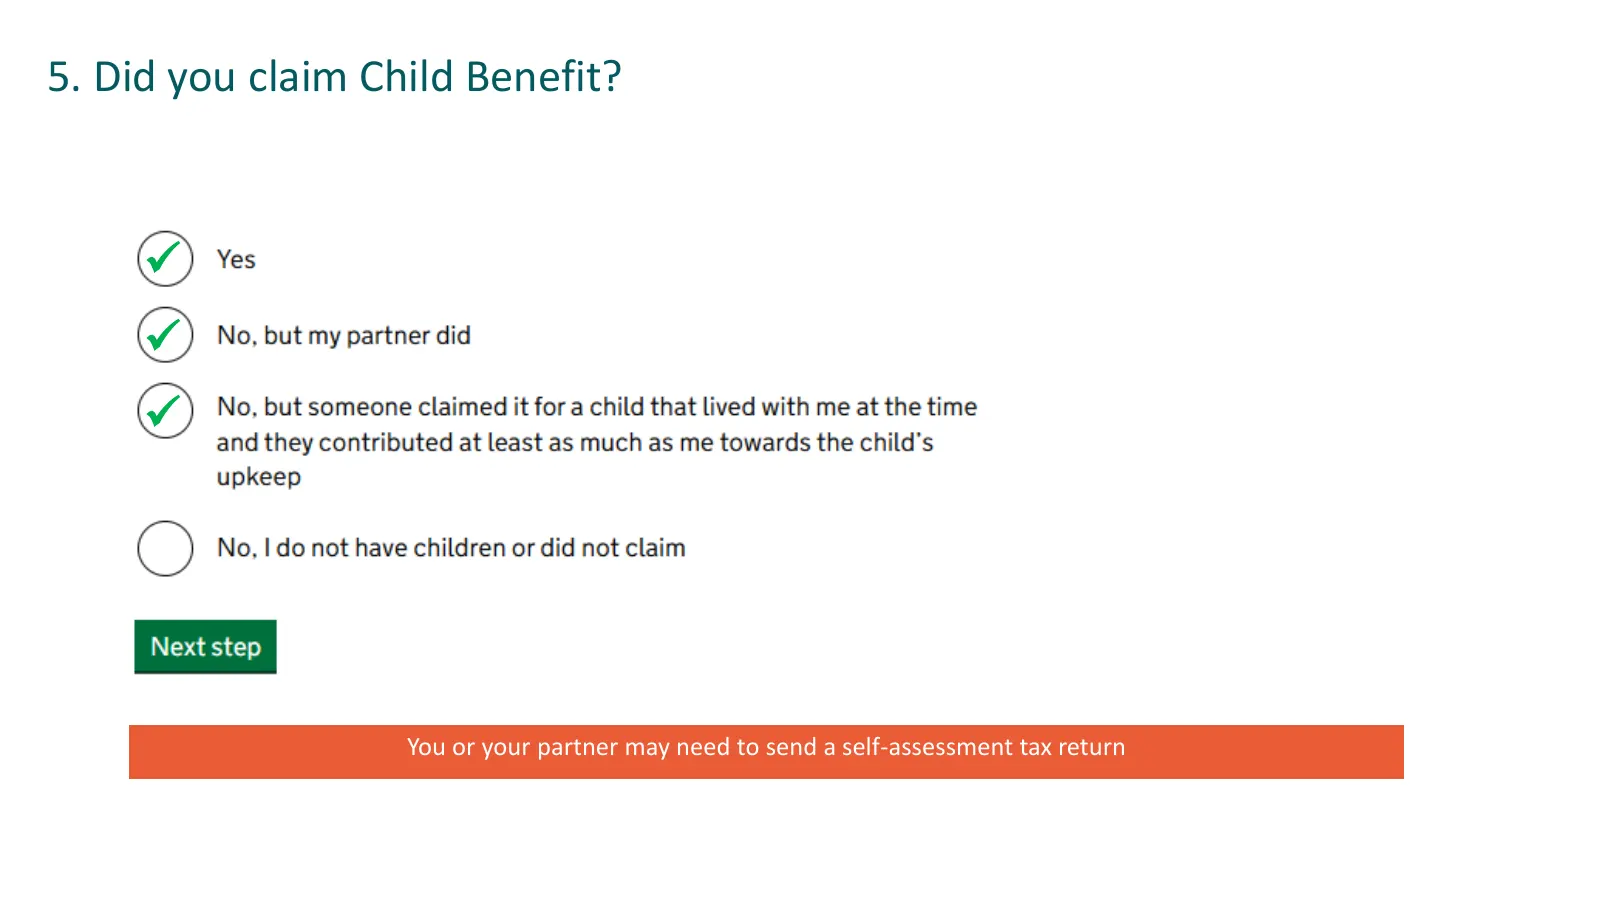
Slide 17: 5. Did you claim Child Benefit?
5. Did you claim Child Benefit? ✓ ✓ ✓ You or your partner may need to send a self-assessment tax return
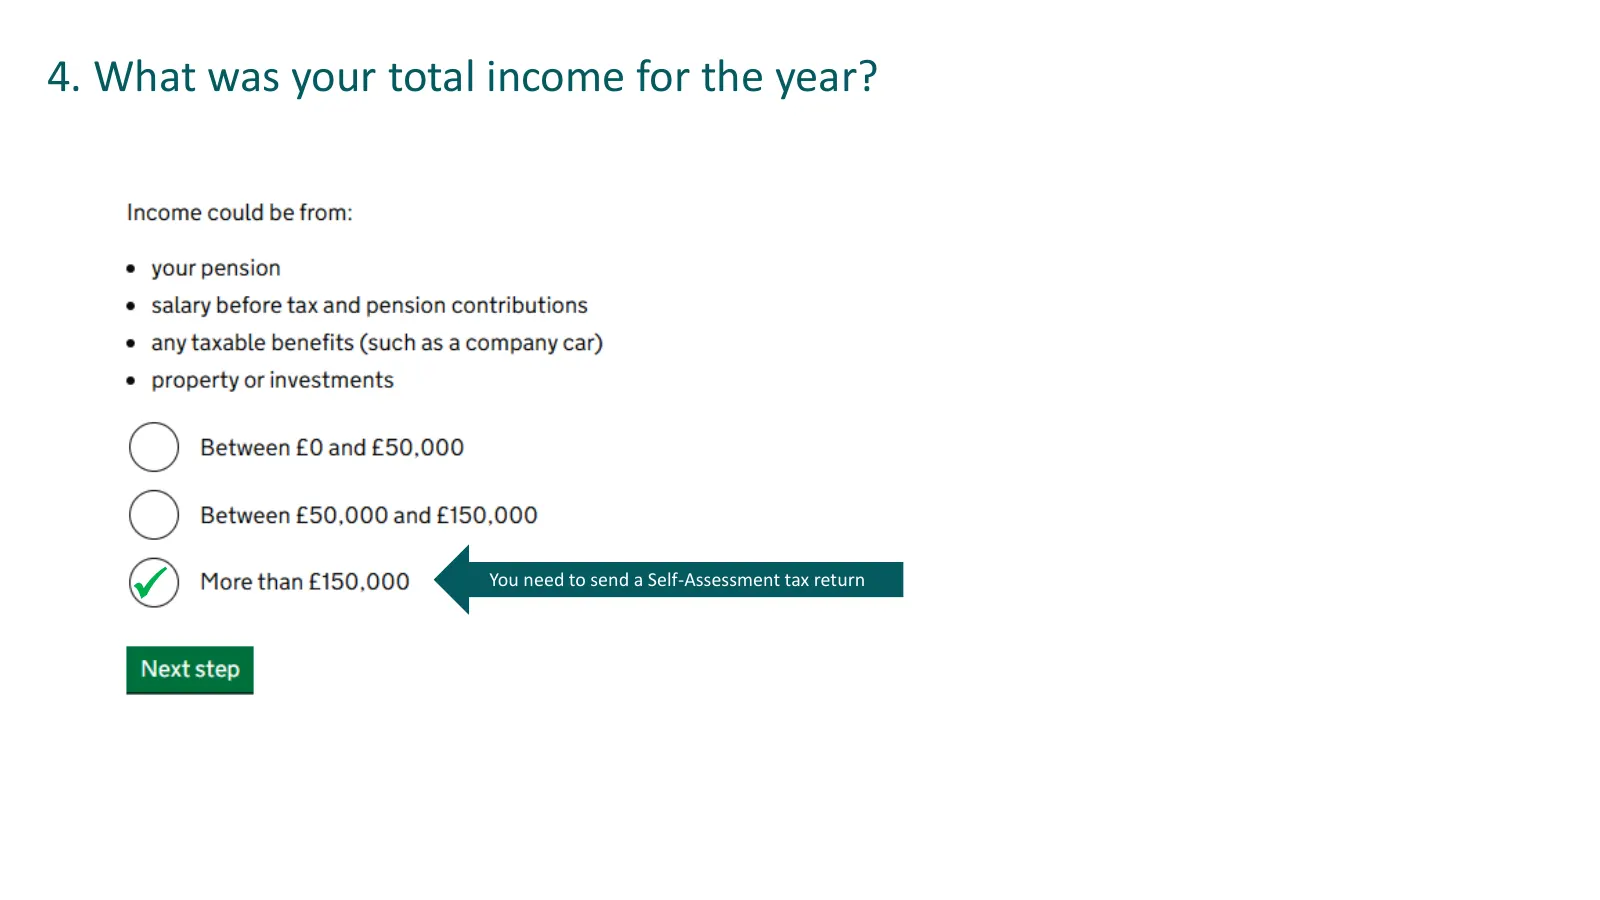
Slide 18: 4. What was your total income for the year?
4. What was your total income for the year? ✓ You need to send a Self-Assessment tax return
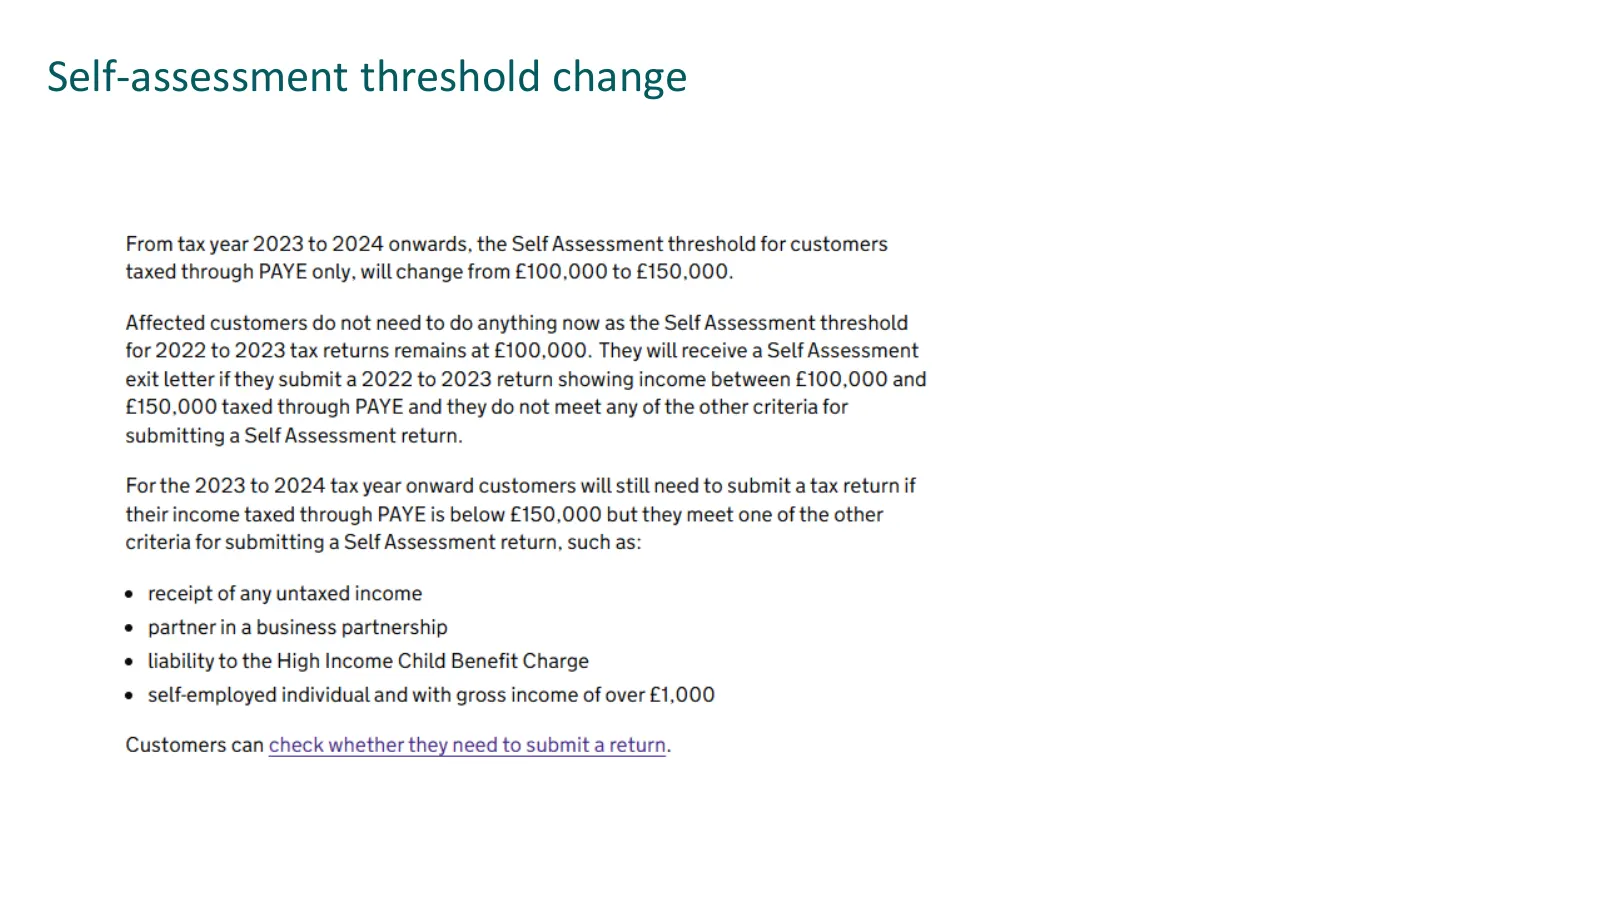
Slide 19: Self-assessment threshold change
Self-assessment threshold change
Slide 20: Self-assessment: Forms to complete if bond gain triggers self-assessment
Self-assessment: Forms to complete if bond gain triggers self-assessment Form SA100 self-assessment Guidance available in help sheets HS320 & HS321
Slide 21: Self-assessment: Additional forms required
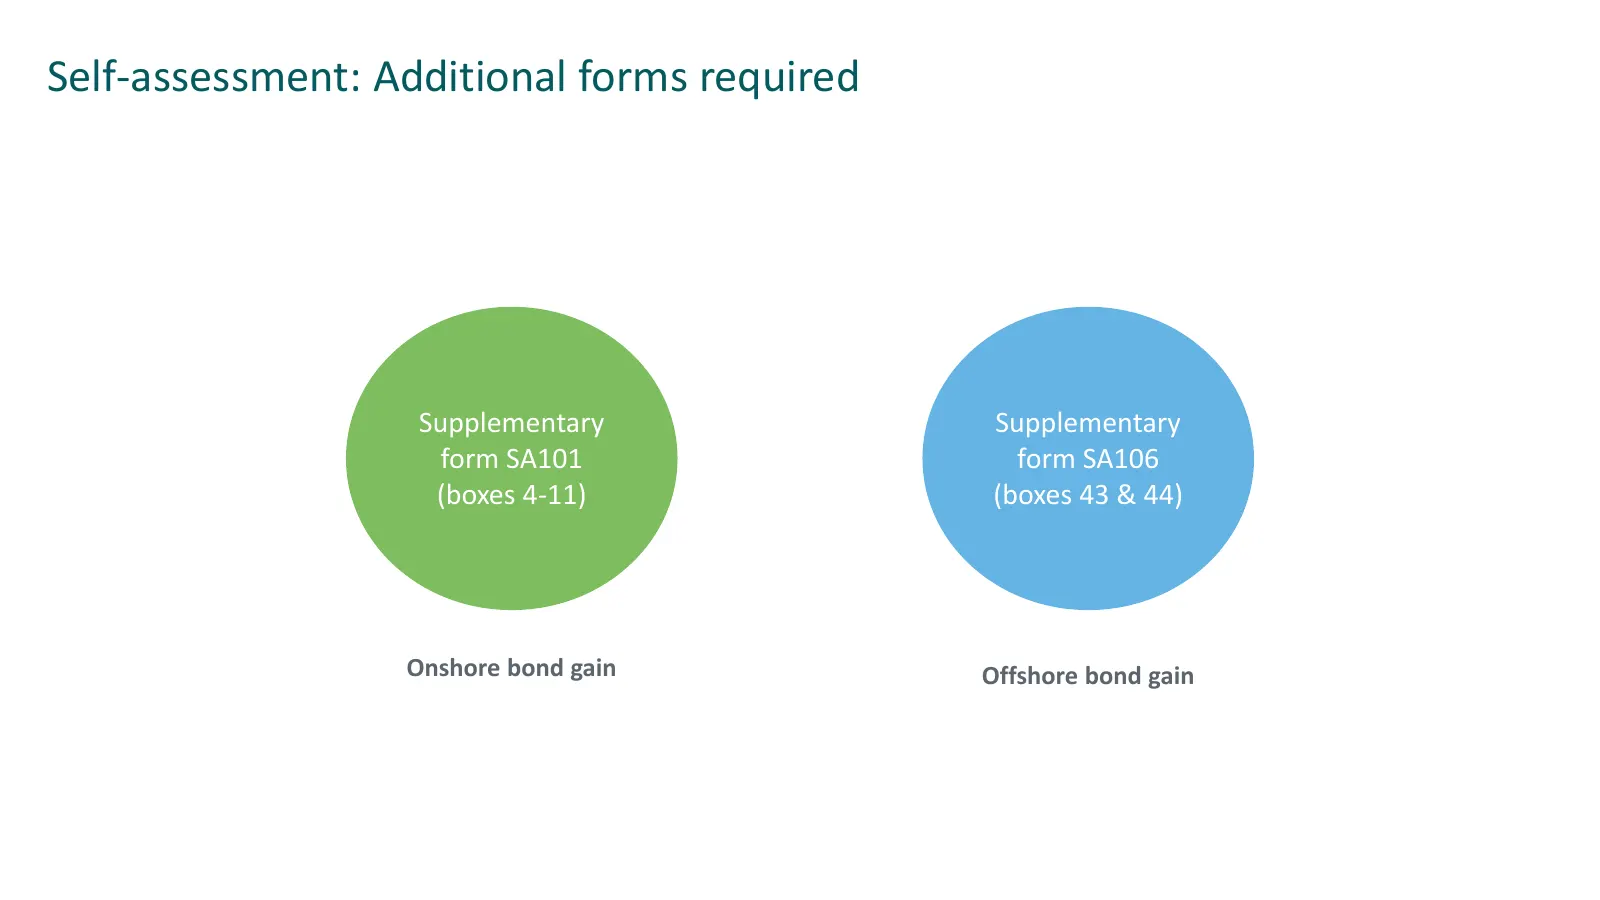
Self-assessment: Additional forms required Supplementary Supplementary form SA101 form SA106 (boxes 4-11) (boxes 43 & 44) Onshore bond gain Offshore bond gain
Slide 22: Self-assessment: Key points
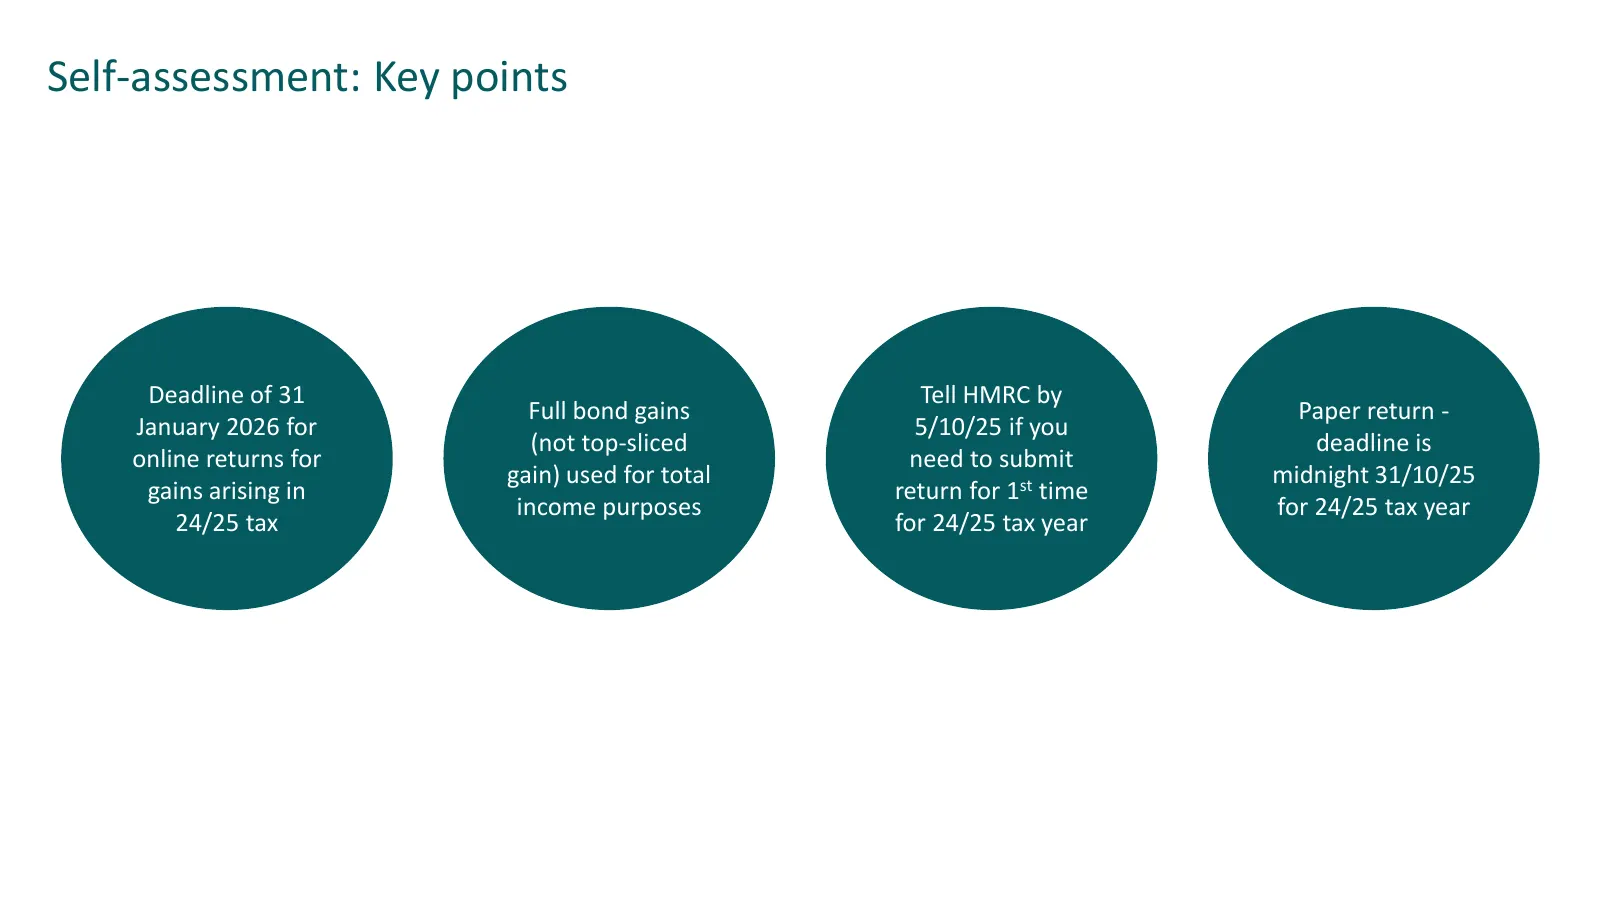
Self-assessment: Key points Deadline of 31 Tell HMRC by Full bond gains Paper return - January 2026 for 5/10/25 if you (not top-sliced deadline is online returns for need to submit gain) used for total midnight 31/10/25 gains arising in return for 1st time income purposes for 24/25 tax year 24/25 ta
Slide 23: Bond gains and tax reporting (trustees)
Bond gains and tax reporting (trustees)
Slide 24: Who’s liable – Bonds held by trustees?
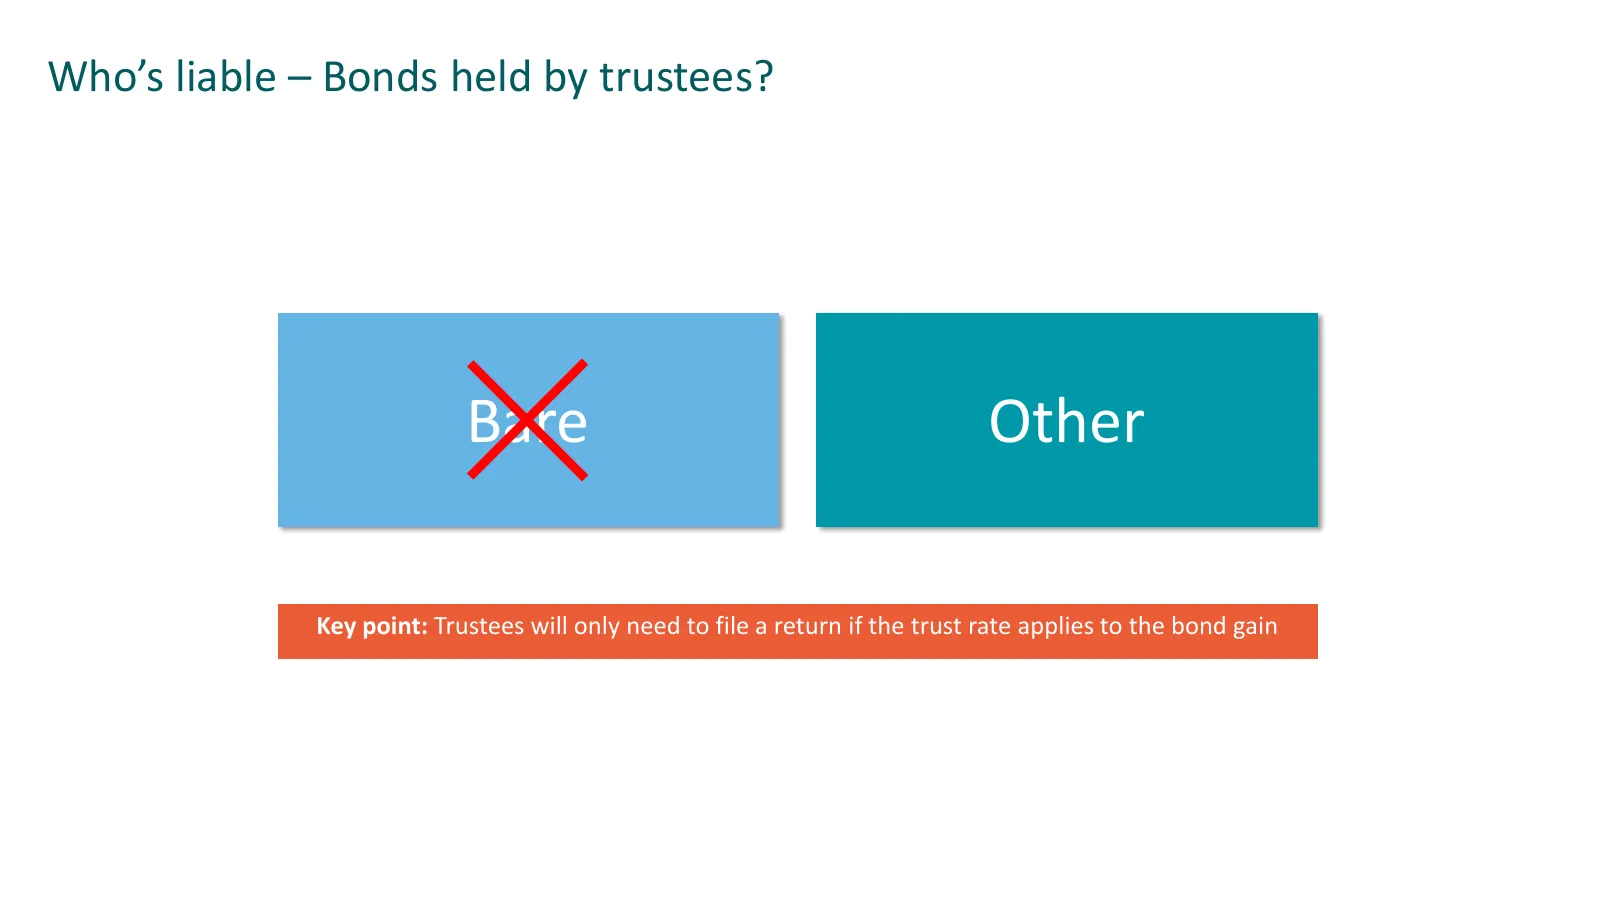
Who’s liable – Bonds held by trustees? Bare Other Key point: Trustees will only need to file a return if the trust rate applies to the bond gain
Slide 25: Tax reporting for bond gains when trustees are liable
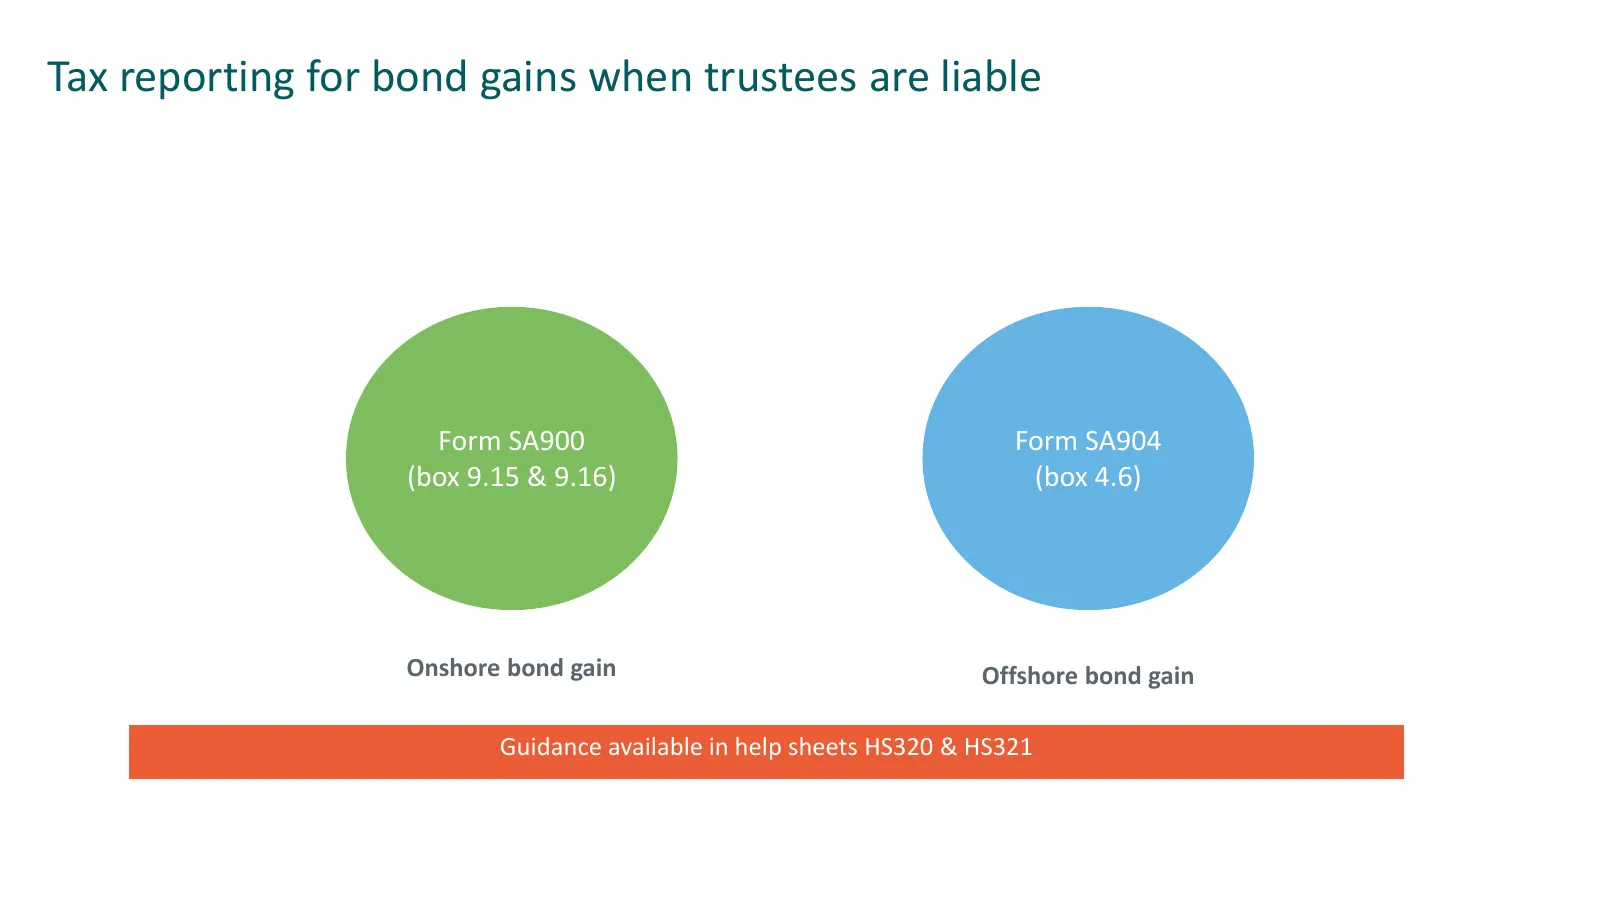
Tax reporting for bond gains when trustees are liable Form SA900 Form SA904 (box 9.15 & 9.16) (box 4.6) Onshore bond gain Offshore bond gain Guidance available in help sheets HS320 & HS321
Slide 26: Trustees: Bond gain tax reporting key points
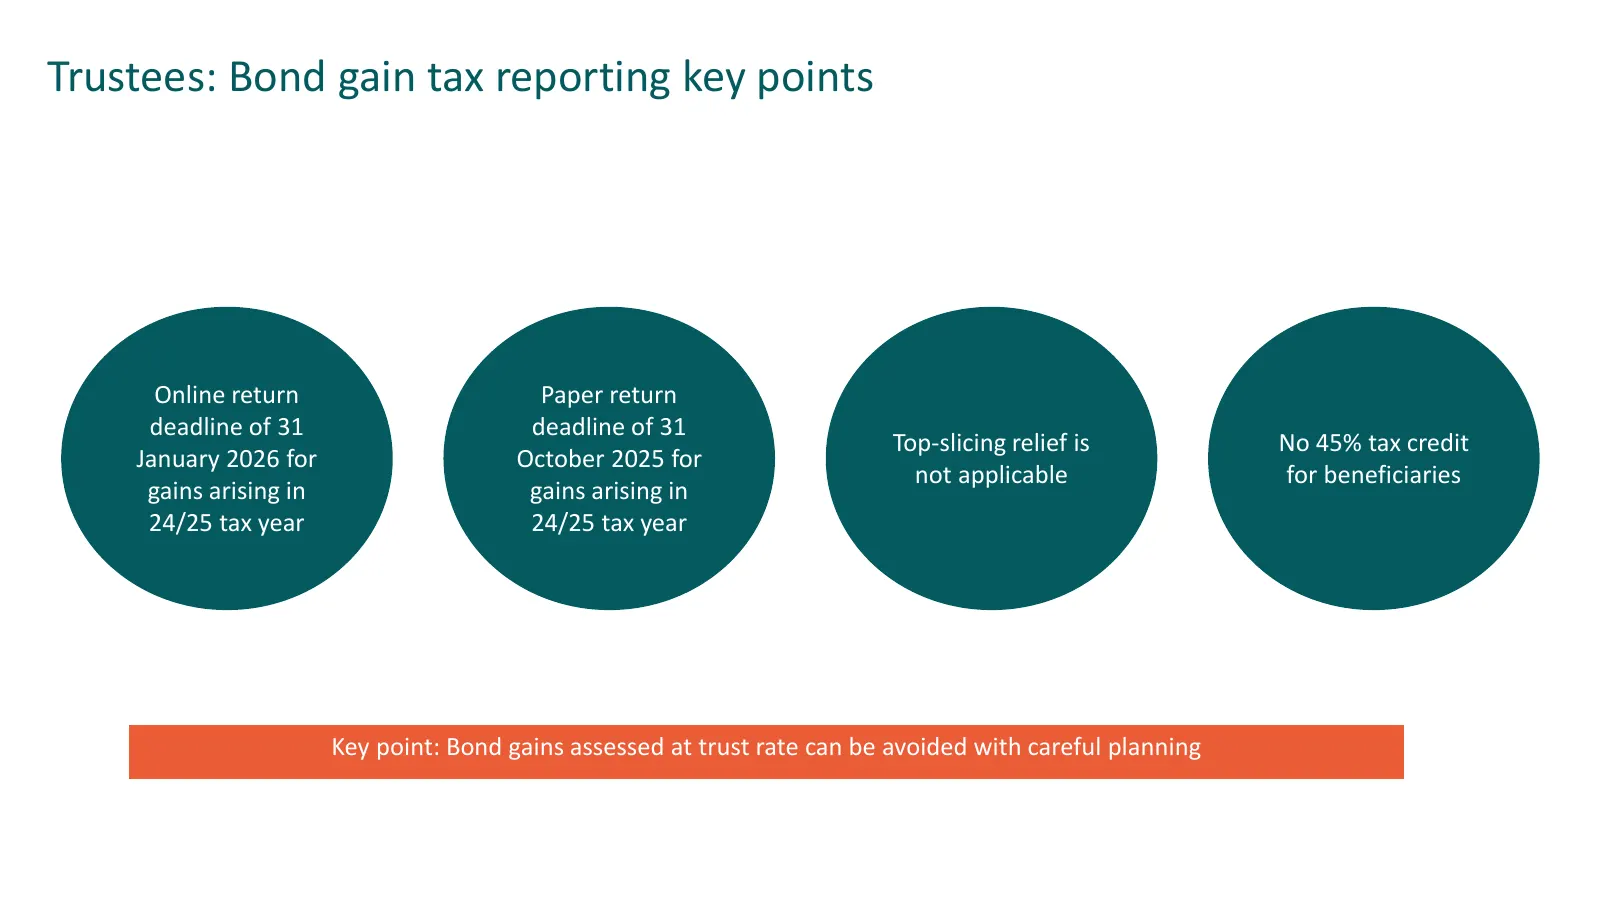
Trustees: Bond gain tax reporting key points Online return Paper return deadline of 31 deadline of 31 Top-slicing relief is No 45% tax credit January 2026 for October 2025 for not applicable for beneficiaries gains arising in gains arising in 24/25 tax year 24/25 tax year Key point: Bond gains asses
Slide 27: Gift Assignments
Gift Assignments
Slide 28: Bond assigned into a Gift Trust
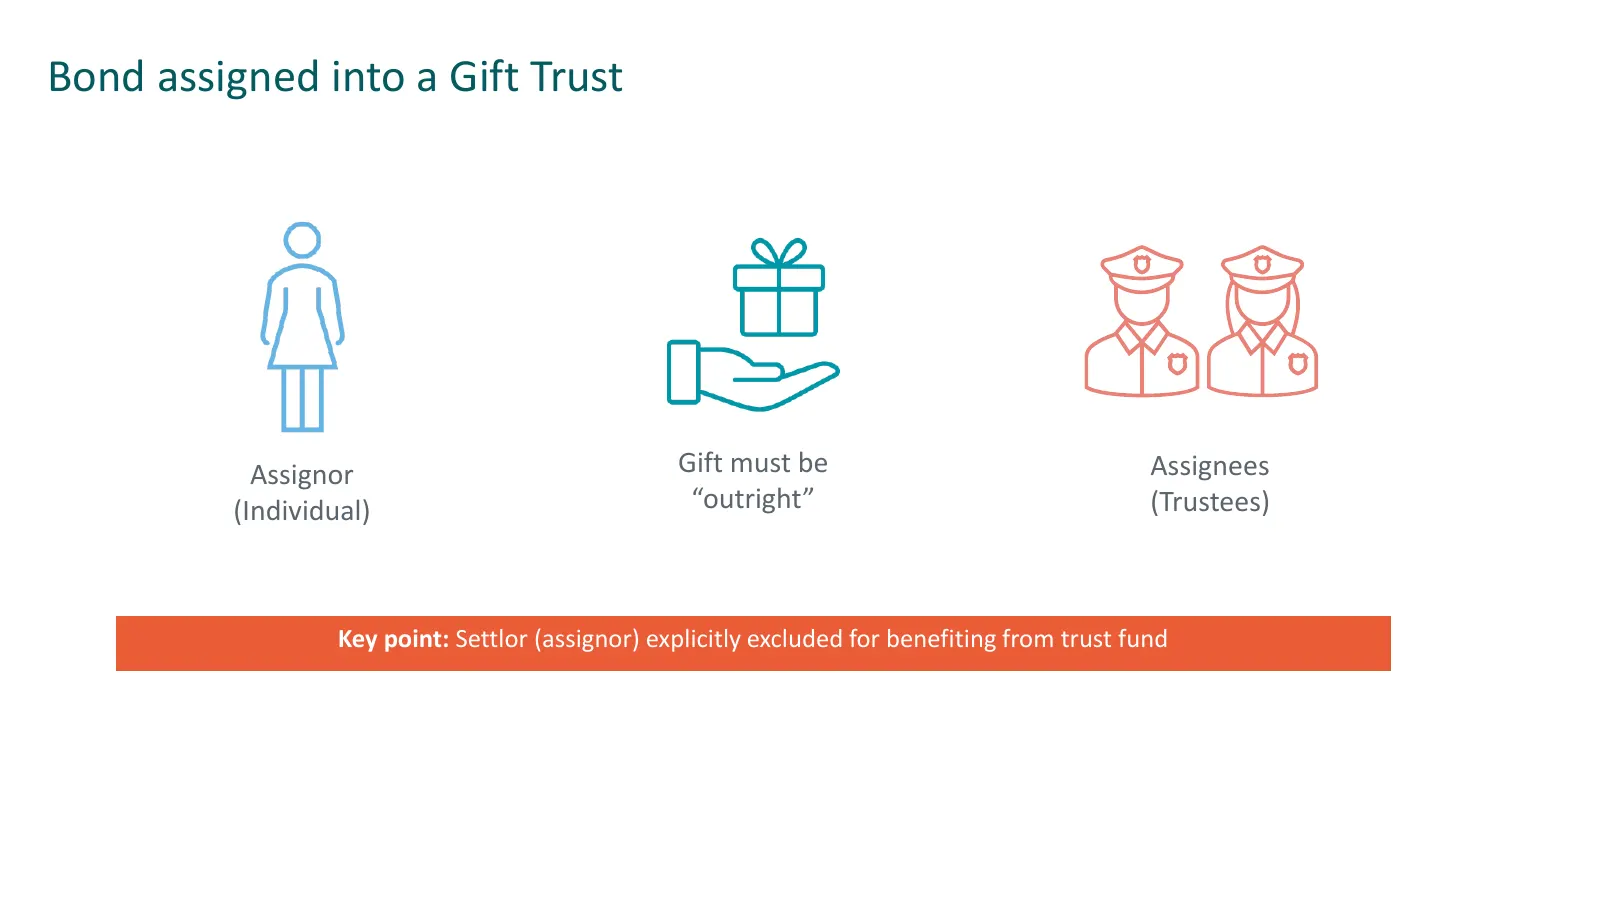
Bond assigned into a Gift Trust Assignor Gift must be Assignees (Individual) “outright” (Trustees) Key point: Settlor (assignor) explicitly excluded for benefiting from trust fund
Slide 29: Gift assignment to another individual
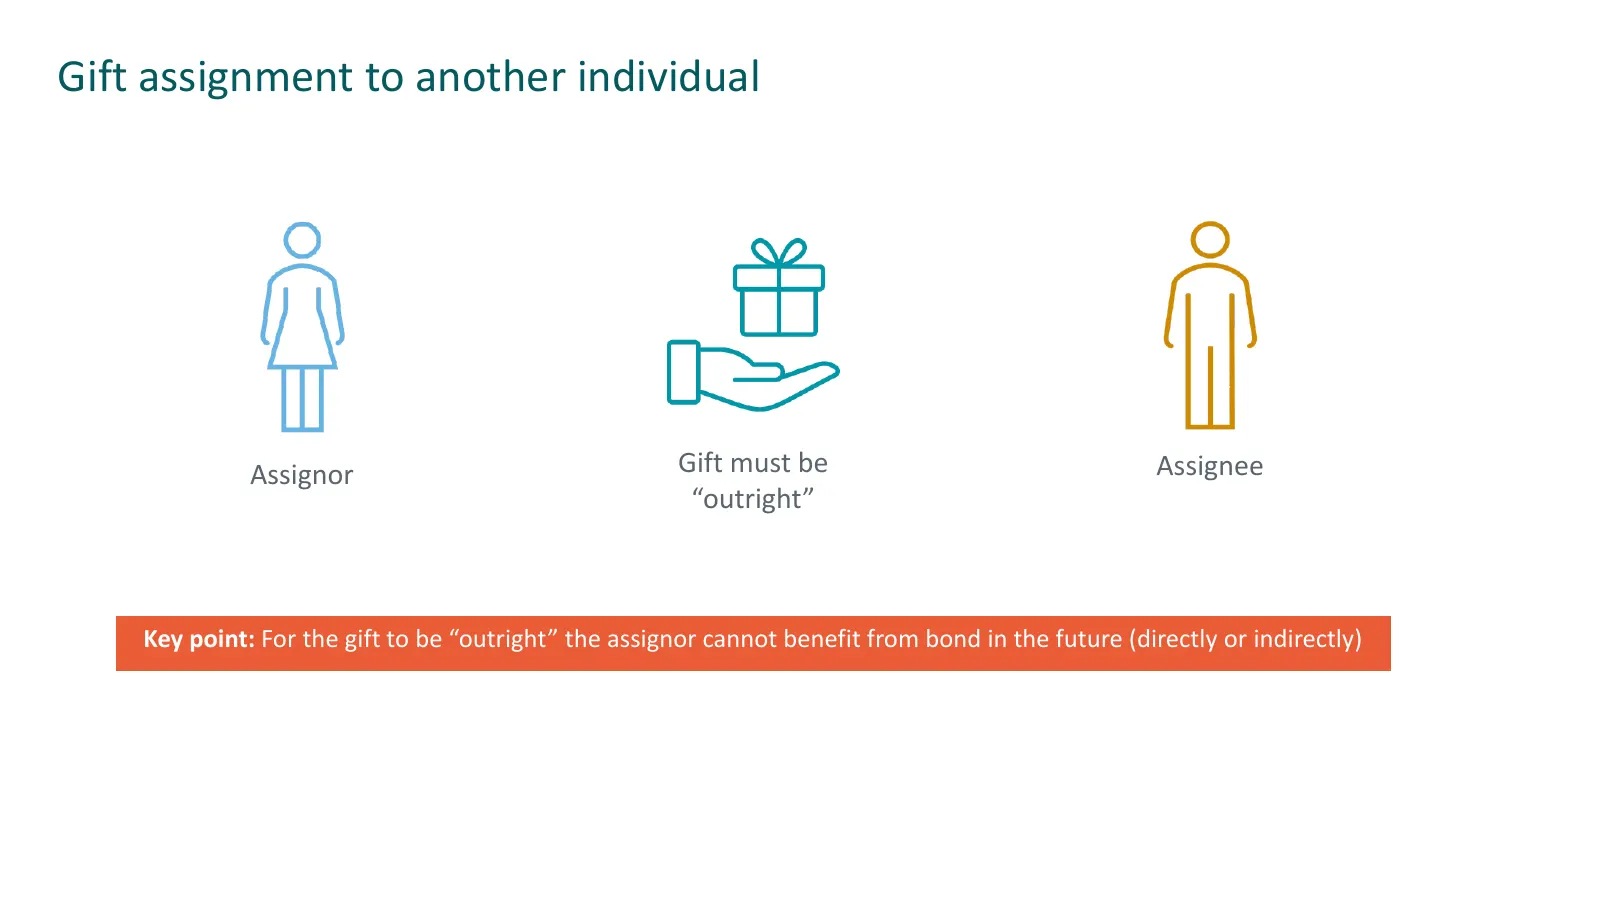
Gift assignment to another individual Assignor Gift must be Assignee “outright” Key point: For the gift to be “outright” the assignor cannot benefit from bond in the future (directly or indirectly)
Slide 30: Gift assignment to another individual
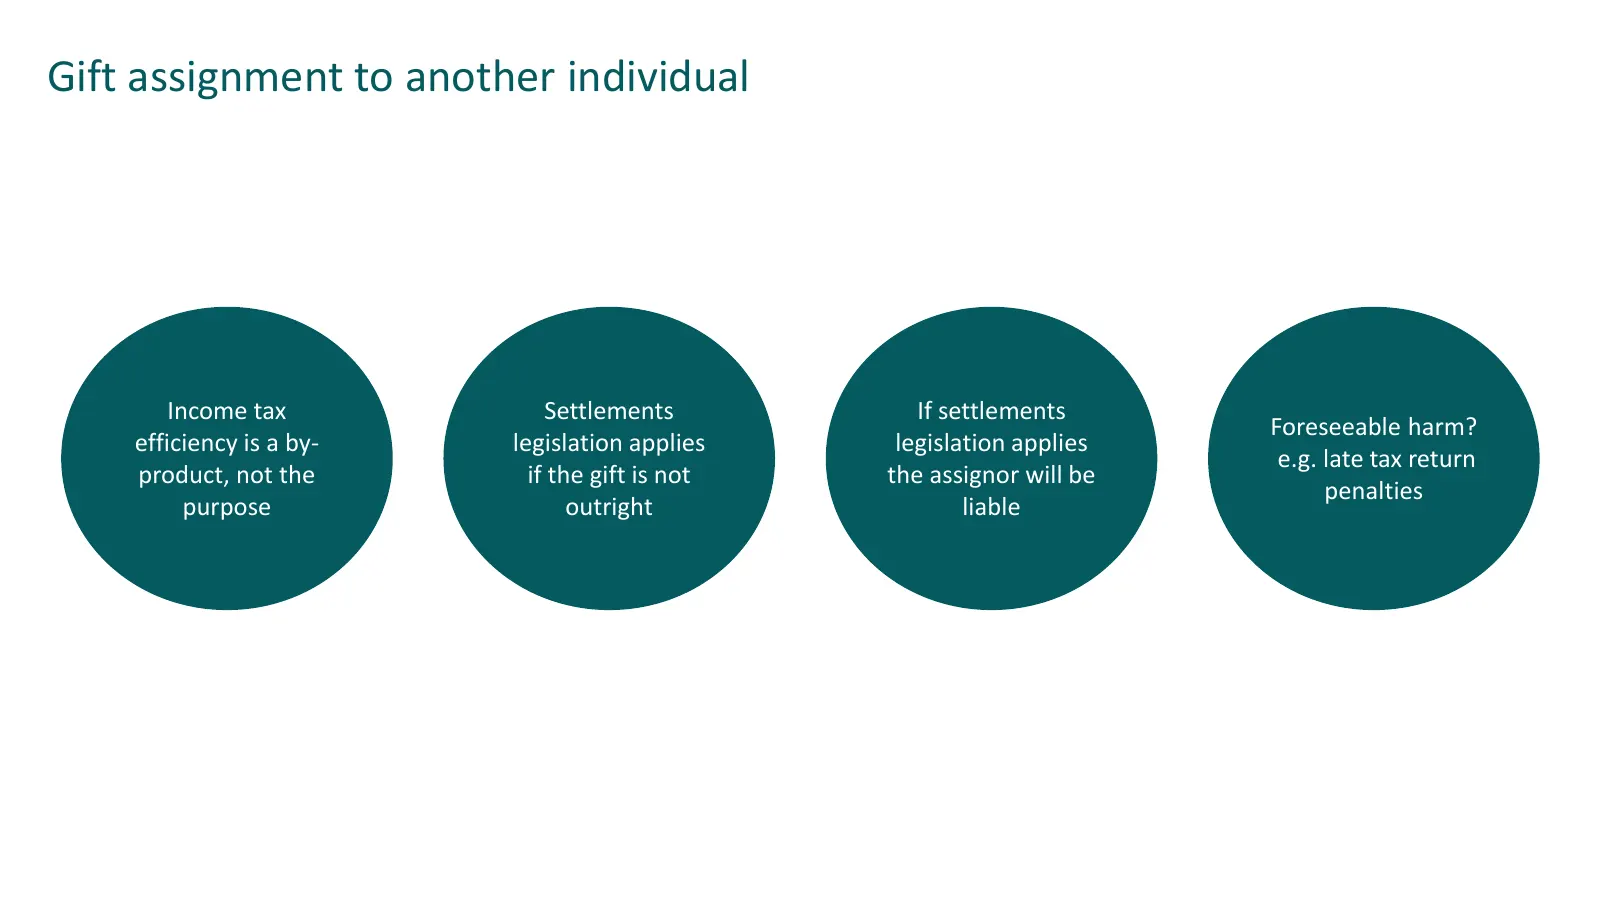
Gift assignment to another individual Income tax Settlements If settlements Foreseeable harm? efficiency is a by- legislation applies legislation applies e.g. late tax return product, not the if the gift is not the assignor will be penalties purpose outright liable
Slide 31: Is a Gift Assignment appropriate?
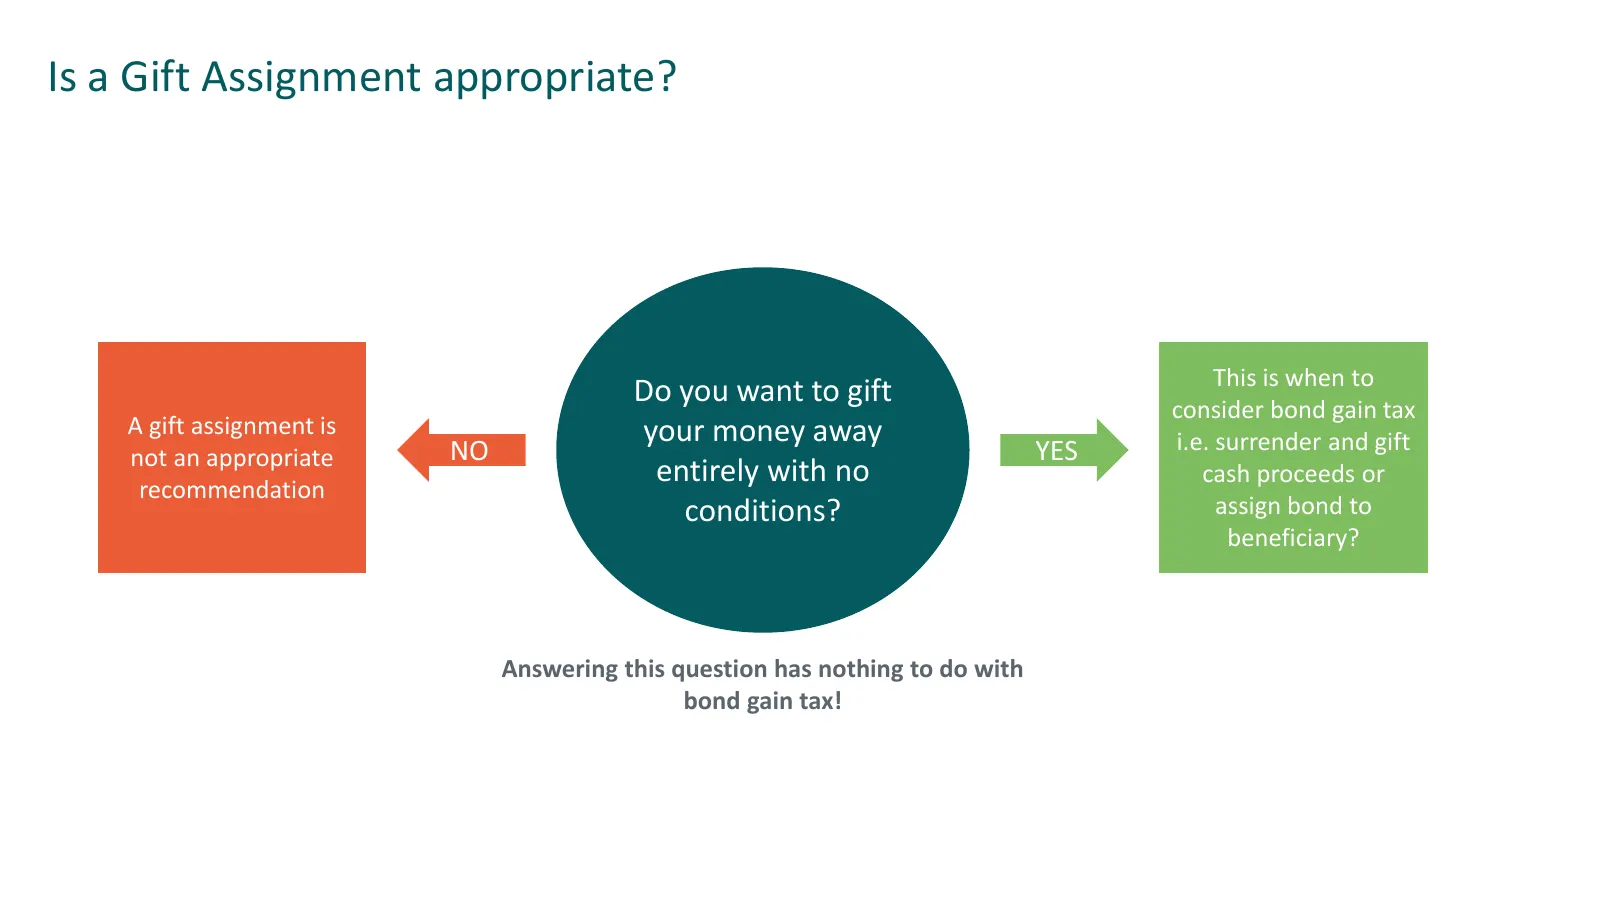
Is a Gift Assignment appropriate? This is when to Do you want to gift consider bond gain tax A gift assignment is your money away NO YES i.e. surrender and gift not an appropriate entirely with no cash proceeds or recommendation conditions? assign bond to beneficiary? Answering this question has not
Slide 32: Bonds and means tested benefits
Bonds and means tested benefits
Slide 33: Means tested benefits
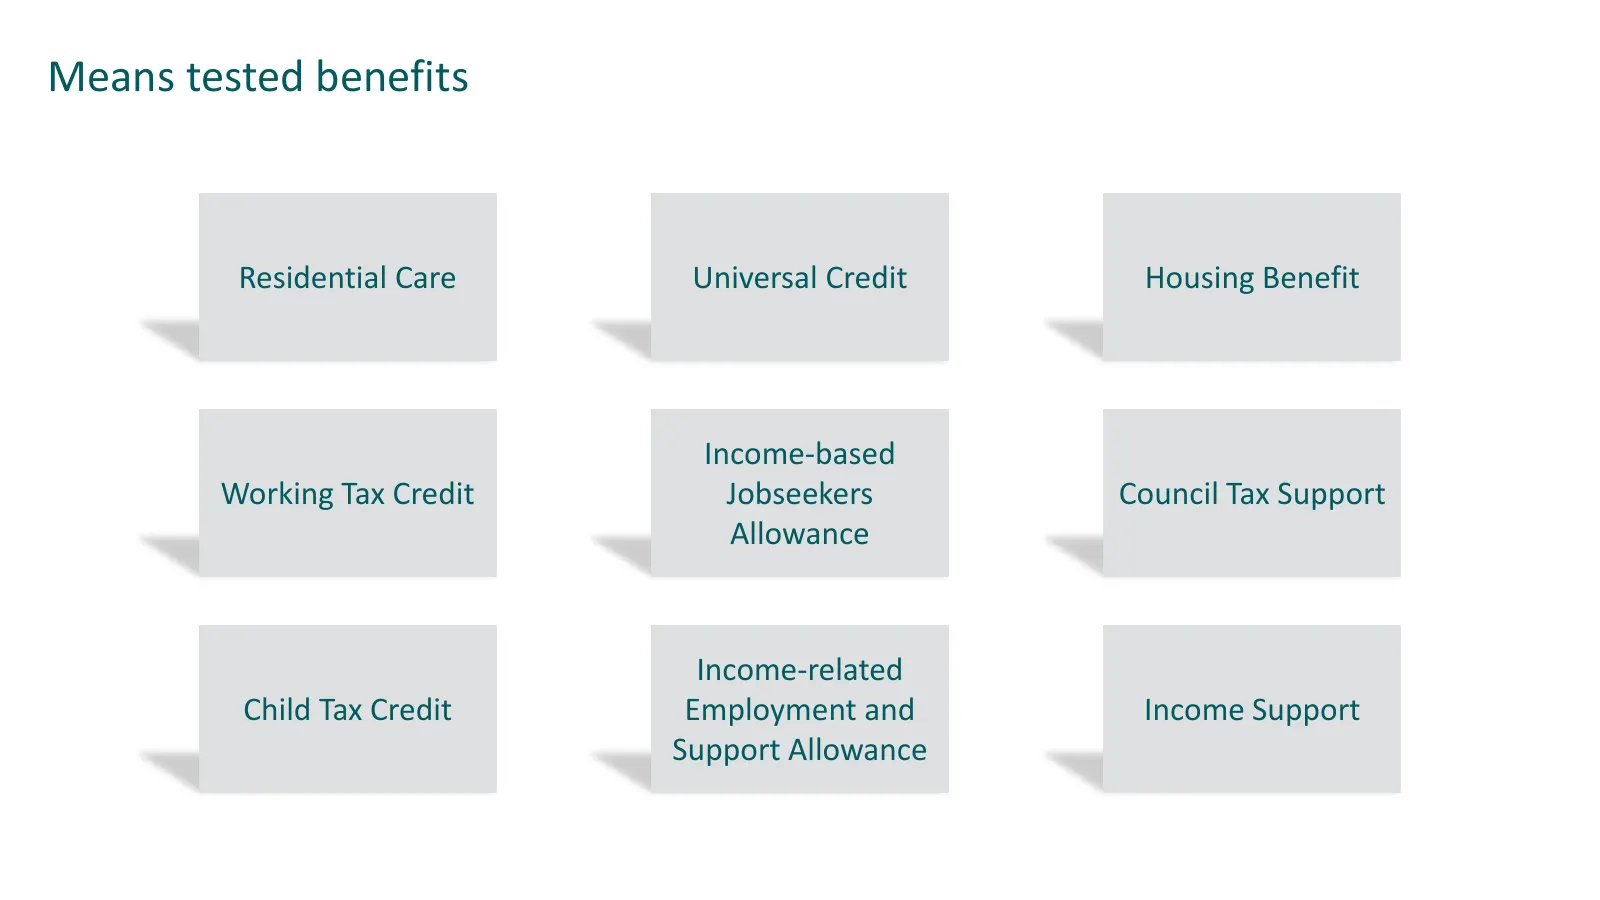
Means tested benefits Residential Care Universal Credit Housing Benefit Income-based Working Tax Credit Jobseekers Council Tax Support Allowance Income-related Child Tax Credit Employment and Income Support Support Allowance
Slide 34: The Law: Residential Care & Universal Credit
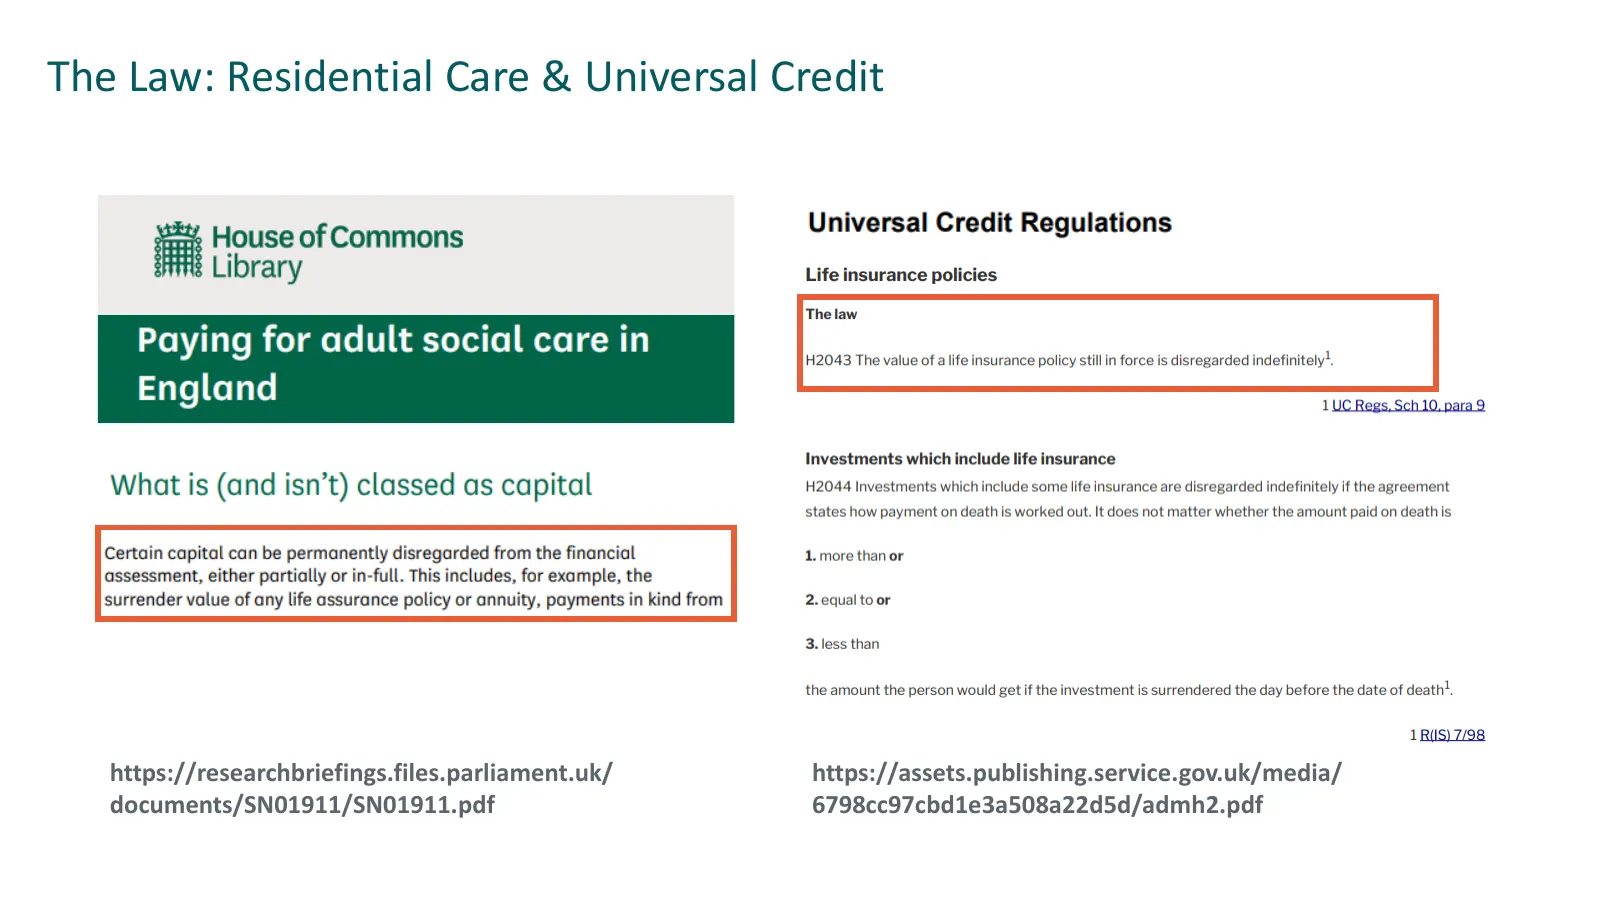
The Law: Residential Care & Universal Credit https://researchbriefings.files.parliament.uk/ https://assets.publishing.service.gov.uk/media/ documents/SN01911/SN01911.pdf 6798cc97cbd1e3a508a22d5d/admh2.pdf
Slide 35: Deprivation of assets
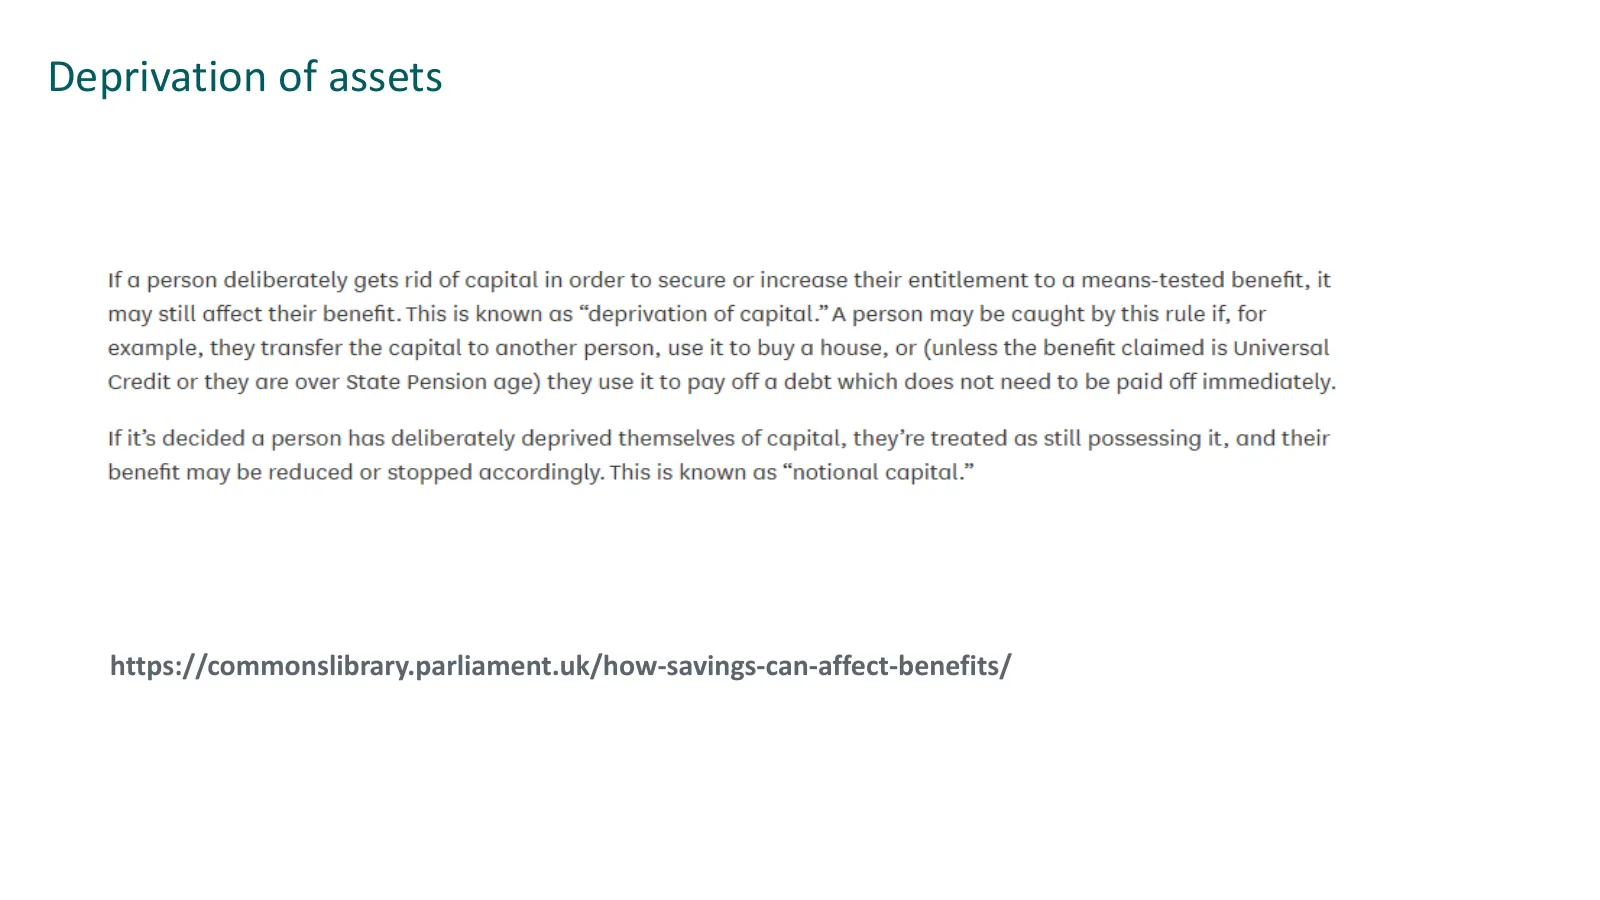
Deprivation of assets https://commonslibrary.parliament.uk/how-savings-can-affect-benefits/
Slide 36: Reasons to invest in a bond
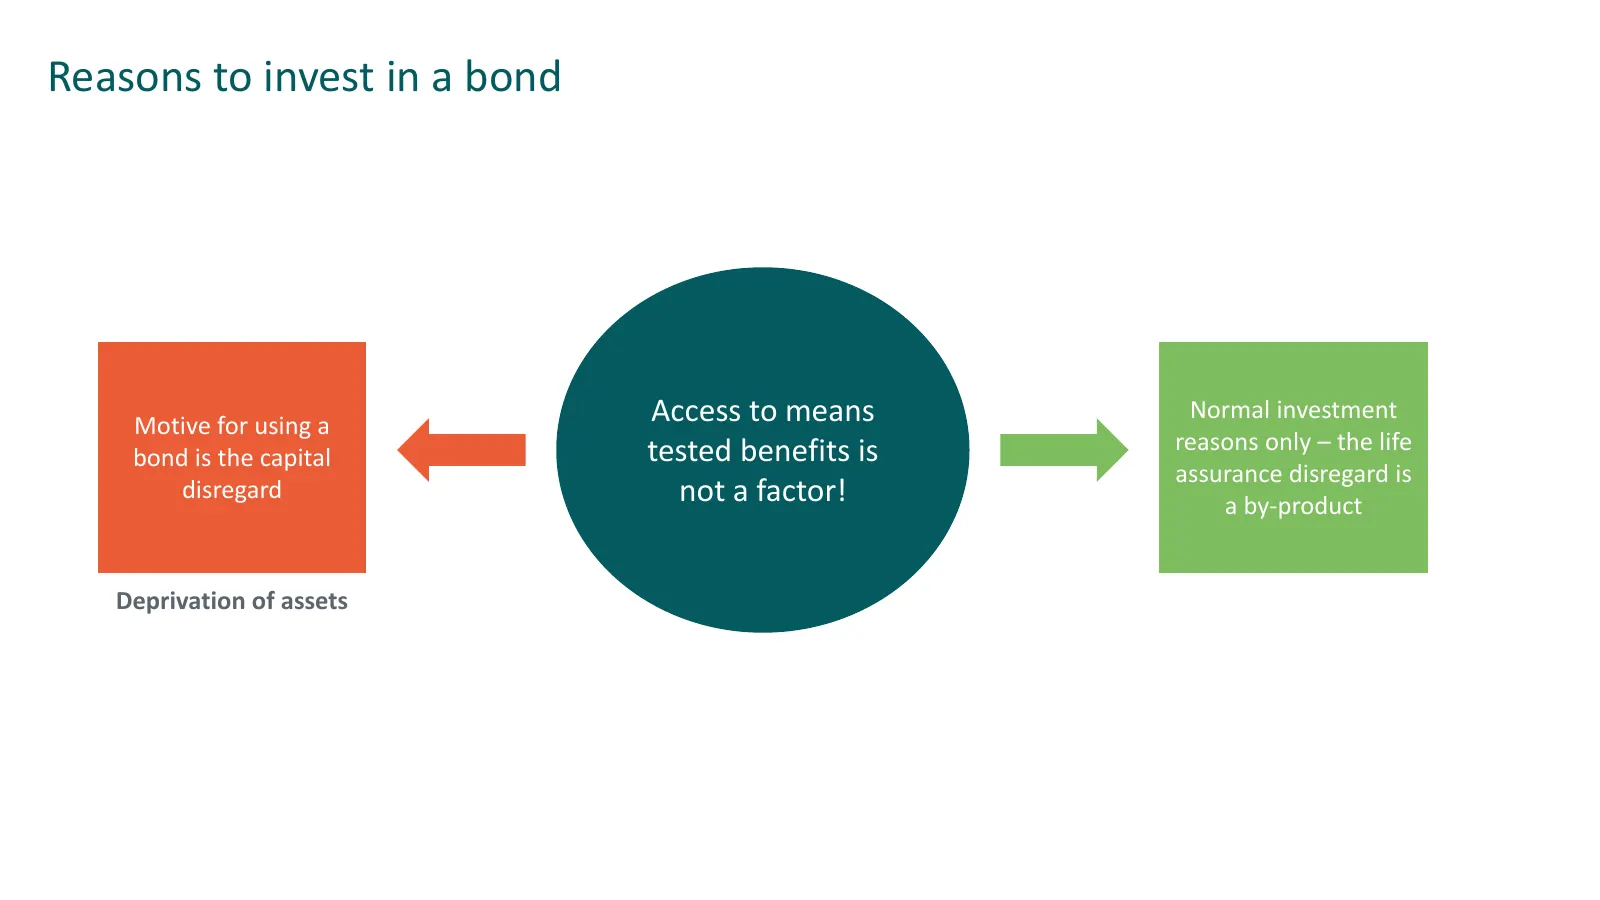
Reasons to invest in a bond Motive for using a Access to means Normal investment tested benefits is reasons only – the life bond is the capital assurance disregard is disregard not a factor! a by-product Deprivation of assets
Slide 37: Benefit Fraud examples
Benefit Fraud examples Not reporting a Providing false change in your information circumstances https://www.gov.uk/benefit-fraud
Slide 38: How to protect a gift to someone on benefits?
How to protect a gift to someone on benefits? Gift into a Create a discretionary discretionary trust during trust in your Will lifetime
Slide 39: If in doubt about impact of bonds and means tested benefits
If in doubt about impact of bonds and means tested benefits Check with the relevant benefit agency The bond provider can’t confirm
Slide 40: Learning objectives recap
Learning objectives recap By the end of this session, you will be able to: Understand the Identify when Describe the self- Evaluate the impact basics of why bonds chargeable events assessment Identify when it’s of exercising can be disregarded on bonds impact requirements for appropriate to use a ca
Slide 41: Tech Matters
Tech Matters Award winning technical support for Financial Professionals Q What are you looking for today? | Search @ si fe) x Pensions Investment & Taxation IHT & Estate Planning Tools and Calculators Events & CPD News & Views Les recommends Next event Last Updated: 30 Oct 24 | 20 min read Last Upd
Slide 42: M&G Tech Matters
Go in| Q Search for posts in this group a aa Les Cameron Manager Joined group: Feb 2023 Pending posts Requests to join Manage group Recent iti, M&G Tech Matters Home My Network Jobs ico} Messaging a = Notificatic M&G Tech Matters iti Private Listed SO View activity
Slide 43: Thank you for your time
Thank you for your time Get in touch with your usual M&G contact if you need further help
Slide 44: M&G plc registered office and regulatory information
M&G plc, incorporated and registered in England and Wales. Registered office: 10 Fenchurch Avenue, London EC3M 5AG. Registered number: 11444019. M&G plc is a holding company, some of whose subsidiaries are authorised and regulated, as applicable, by the Prudential Regulation Authority and the Financ
Source: company website
More decks from M&G PLC
 Q2 2026 Earnings Presentation54 slides · Sep 2, 2026
 M&G Wealth — M&G MPS Webinar (May 2026)24 slides · May 2026
 FY2025 Earnings Presentation59 slides · Mar 12, 2026
 H1 2025 Earnings Presentation51 slides · Sep 3, 2025
 Investor Presentation (August 2025)58 slides · August 2025
 Merger or Acquisition (May 2025)9 slides · May 30, 2025