EV Energy Partners L.P — Master Limited Partnership Investor Conference 2007
28 slides from EV Energy Partners L.P's conference presentation, Mar 13, 2007
Slide 1: Master Limited Partnership Investor Conference
Master Limited Partnership Investor Conference March 8, 2007 EV Energy Partners, L.P.
Slide 2: Risks and Forward-Looking Statements
Risks and Forward-Looking Statements This presentation includes “forward-looking statements” as defined by the Securities and Exchange Commission. All statements, other than statements of historical facts, included in this presentation that address activities, events or developments that the partner
Slide 3: EVEP Units
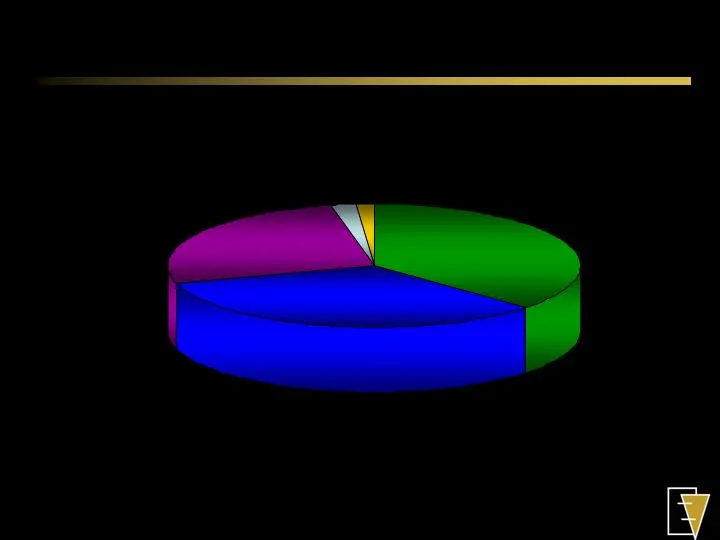
EVEP Units 3 IPO Common Units 37% Subordinated Units 26% Sponsor Common Units 1% General Partner Interest 2% Private Placement Common Units 34%
Slide 4: Unit price chart, Sept 2006 - Mar 2007
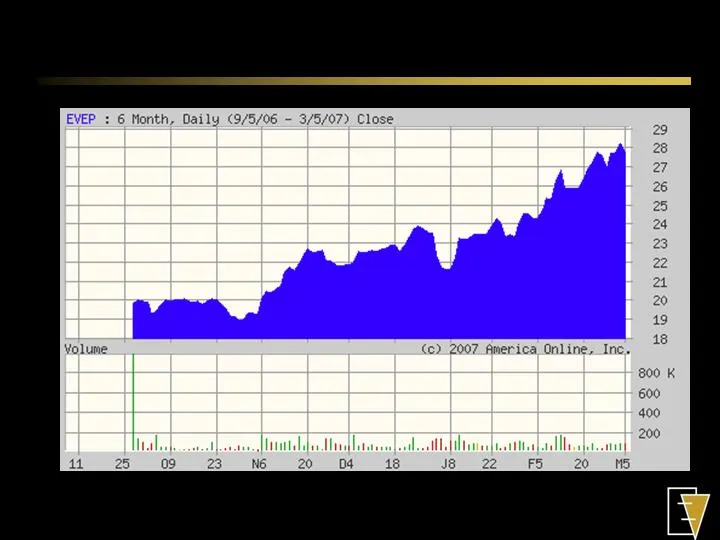
26 Month, Daily (9/5/06 - 3/5/07) Close (©) 2007 America Online, Inc. Watlesfe concot] seston Oittaban Hass fat 923 Ne 2022
Slide 5: EVEP's General Partner
EVEP’s General Partner GP Ownership EnerVest 71.25% EnCap 23.75% Management 5% EnerVest formed in 1992 EnCap formed in 1988 5
Slide 6: EnerVest Areas of Operations
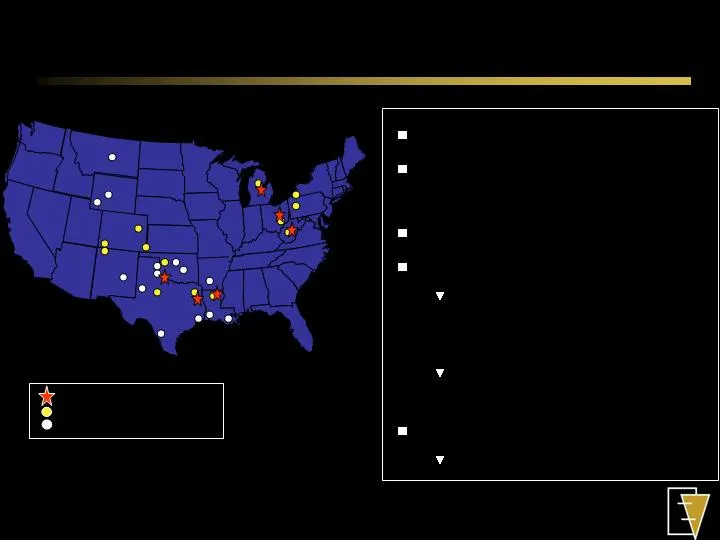
EnerVest Areas of Operations 15-year A&D Track Record Operates > 10,000 Wells in 11 States > 850 Bcfe Reserves Active in U.S. Market Acquired > $1.2 billion and divested $300 million since January 2005 Acquired > $250 million in 2006 ~ 360 Employees > 50 technical professionals EVEP Assets EnerVest
Slide 7: Complementary Business Lines
Complementary Business Lines Combined Ability to maintain large presence in key basins over the long term Economies of Scale Drilling services, marketing Scale to maintain employee base more effectively Maintain Basin expertise MLP Business - EVEP Focus on mostly producing reserves >80% PDP Buy and
Slide 8: EVEP Business Strategy and Philosophy
EVEP Business Strategy and Philosophy Increase reserves and production through accretive acquisitions Maintain conservative debt levels to reduce risk and facilitate acquisitions Reduce exposure to commodity price risk through hedging Keep inventory of PUD drilling locations sufficient to maintain p
Slide 9: Activity Since IPO (Sept 2006 - Jan 2007)
Activity Since IPO September 2006EV Energy Partners prices IPO December 2006 Closed two acquisitions for $28 MM Negotiated transactions with Five States Energy January 2007 Closed $71.6 MM Mich acquisition Drop down acquisition from EnerVest Fund IX Management anticipates recommending increase in di
Slide 10: Activity Since IPO (Feb-Mar 2007)
Activity Since IPO February 2007 Paid initial distribution of $0.40/unit for 4Q 2006 February 2007 Completed $100 MM equity private placement Proceeds to repay existing debt Significant financing capacity to continue to capitalize on future growth opportunities March 2007 Announced $96 MM acquisitio
Slide 11: Attractive Acquisition Metrics
Attractive Acquisition Metrics Acquisition Price Reserves Rate $/mcfe $/mcfepd ($mm) (Bcfe) (Mcfepd) Five States 28 14.8 3,100 1.90 9,032 Michigan 72 56.3 6,850 1.27 10,453 Monroe 96 65.4 7,600 1.47 12,631 Total/Average 196 136.4 17,550 1.43 11,166 Further Diversification All transactions are negoti
Slide 12: Dramatic Growth Since IPO
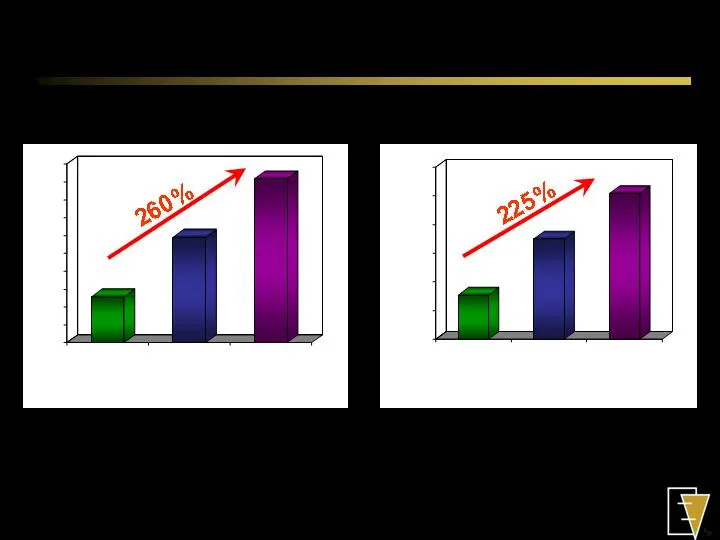
Dramatic Growth Since IPO Proved Reserves - BCFE Production – MCFE/D 12 12/31/2005 12/31/06 Pro forma Michigan 12/31/06 Pro forma Monroe 51 bcfe 183 bcfe 118 bcfe 5,000 10,000 15,000 20,000 25,000 30,000 IPO Current Pro forma Michigan Current Pro forma Monroe 7,700 mcfe/d 17,500 mcfe/d 25,100 mcfe/d
Slide 13: Asset Overview
Asset Overview EV Energy Partners, L.P.
Slide 14: EVEP Areas of Operations
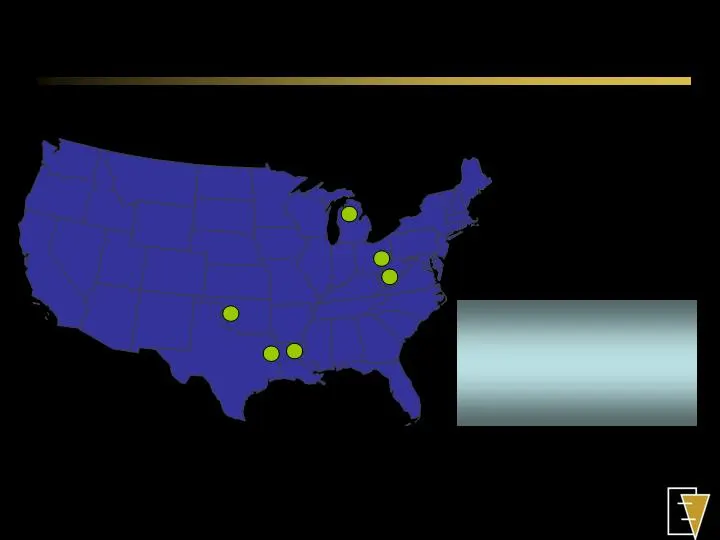
EVEP Areas of Operations * Pro forma for Michigan and Monroe acquisitions 14 EVEP Total Assets * Proved Reserves: 183.4 Bcfe Current Net Prod.: 25.1 mmcfe/d Natural Gas: 93% PDP: 94% PDP Decline Rate (2007-2008): 7.1%
Slide 15: Appalachia/Michigan Assets
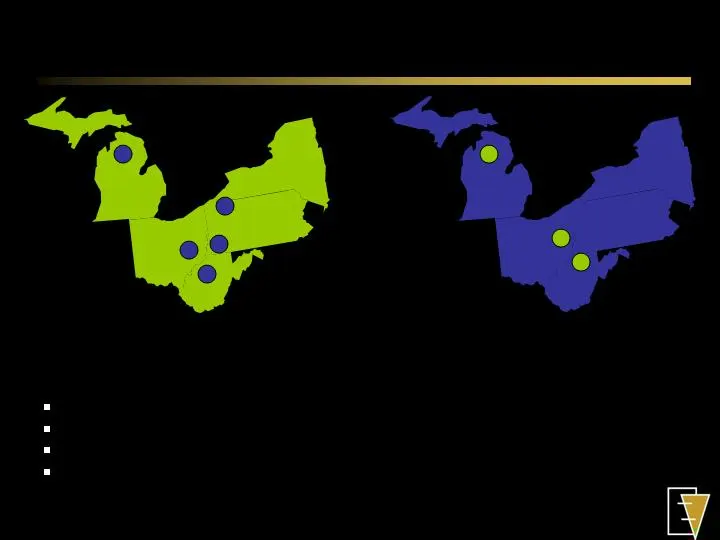
Appalachia/Michigan Assets EnerVest Proved Reserves 395 BCFE 69 MMCFE/D Attractive Characteristics Long-lived reserves, predictable decline rates Premium pricing High drilling success rates, low maintenance capital requirements Significant consolidation opportunities EVEP Proved Reserves 88.7 BCFE 1
Slide 16: EVEP Appalachia Assets
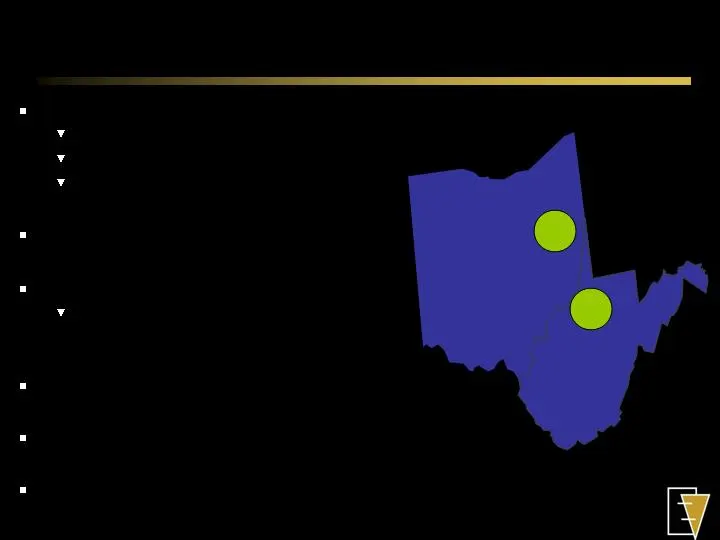
EVEP Appalachia Assets Proved Reserves (12/31/06): 32.4 Bcfe 81% Gas 87% PDP Average working interest >90% Premium Pricing Average premium to NYMEX of over $1.00 Drilling targets: 1,000 to 6,000 feet Current Net Rate ~ 5,300 Mcfed R/P ratio 17 years 16
Slide 17: Michigan Acquisition
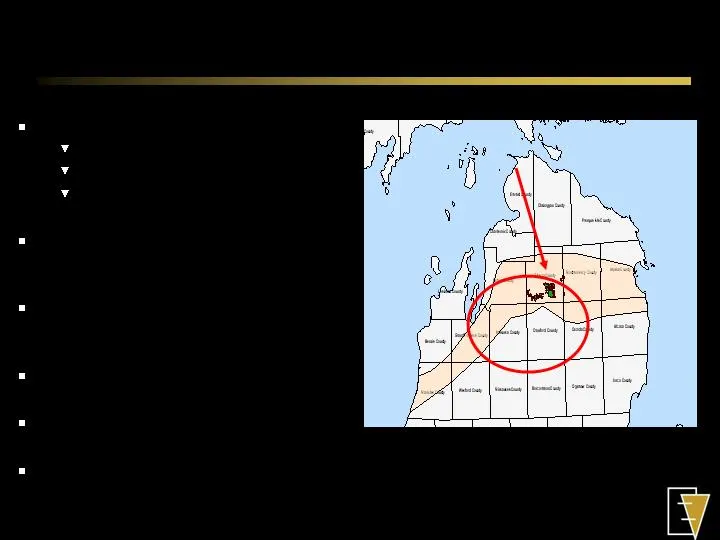
Michigan Acquisition Proved Reserves (12/31/06): 56.3 Bcfe 100% Gas 89% PDP 100% operated, 91% average working interest Otsego & Montmorency Counties, Michigan, 341 producing wells Reservoir: Antrim Shale Current Net Rate ~ 6,850 Mcfed R/P ratio >20 years Note: Michigan acquisition closed 1/31/07. 1
Slide 18: Mid-Continent Acquisitions
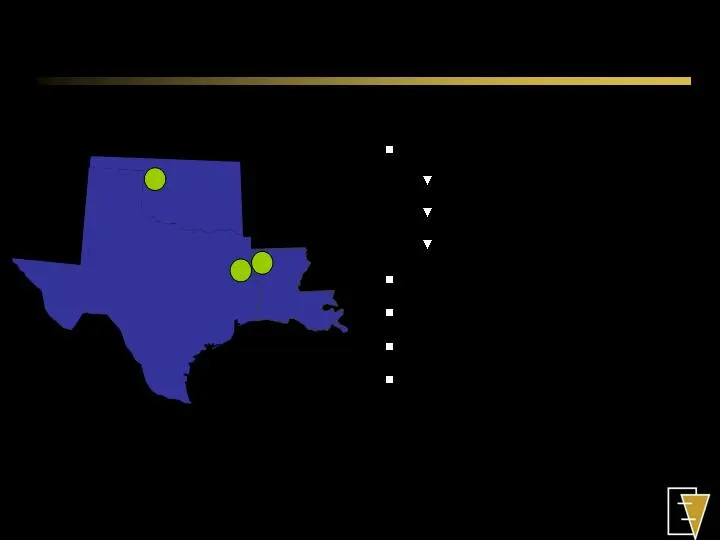
Mid-Continent Acquisitions Proved Reserves (12/31/06) 14.7 Bcfe 60% gas 97% PDP ~9% Average working interest 100% Outside Operated Current Net Rate ~ 3,100 Mcfed R/P Ratio 13 Years 18
Slide 19: Monroe Field Acquisition
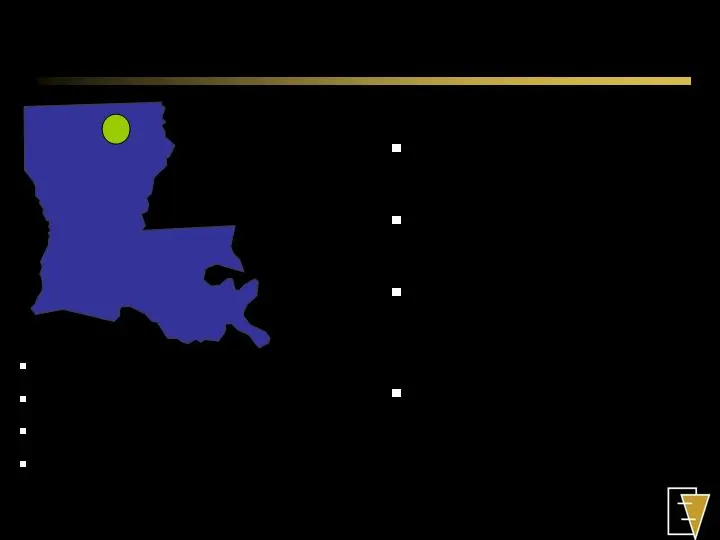
Monroe Field Acquisition Substantially increases presence in field 65.4 Bcfe increase in reserves to 80.2 Bcfe 7,600 mcfed increase in current production rate to 9,850 mcfed Significant increase in transportation and marketing Discovered in 1916 Produced > 7 Tcf Covers 460 miles in 3 parishes EnerVe
Slide 20: Monroe Field Acquisition
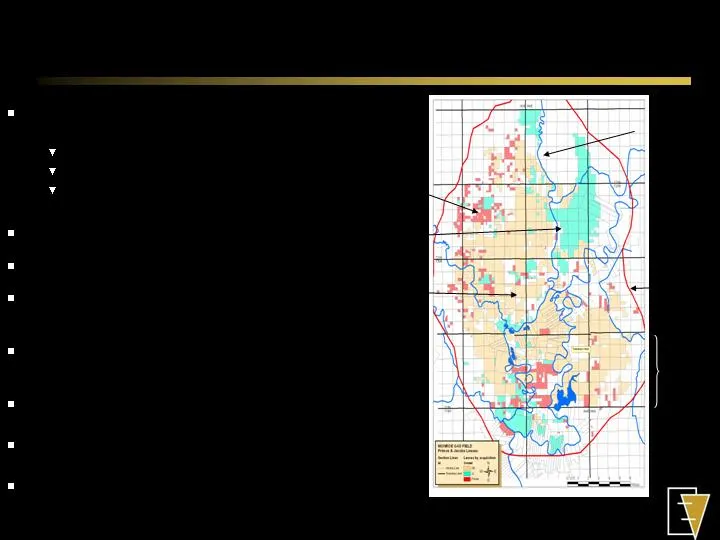
Monroe Field Acquisition EVEP - Jacobs EVEP - Primos Approximate field limits EnerVest Monroe, LP Six miles Ouachita river Pro forma Proved Reserves (12/31/06) 80.2 Bcfe 100% gas 99% PDP 100% working interest 160,000 gross acres Gas transportation and marketing ~ $2.1 MM per year Additional unbooked
Slide 21: Financial Overview
Financial Overview EV Energy Partners, L.P.
Slide 22: Commodity Price Hedging
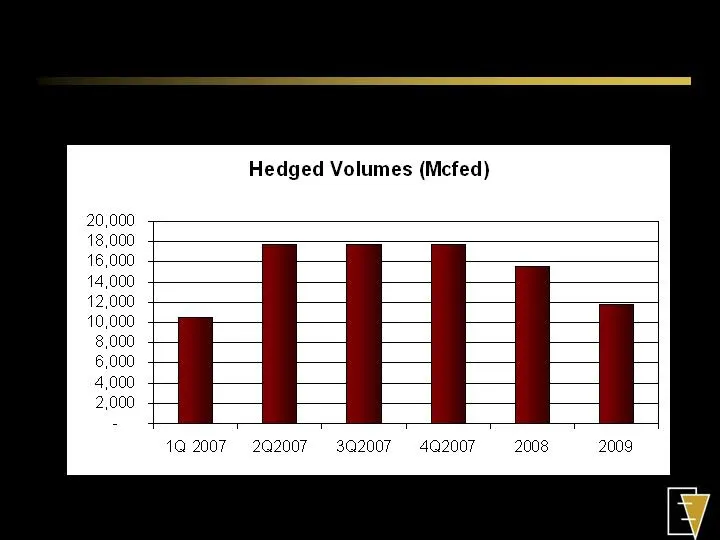
Commodity Price Hedging 22
Slide 23: Hedge positions 2007
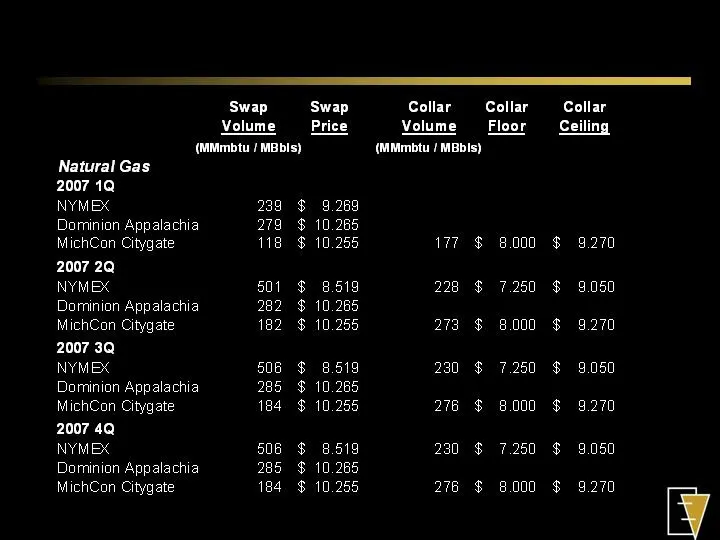
Swap Swap Collar Collar Collar Volume Price Volume Floor Ceiling (MMmbtu / MBbIs) (MMmbtu / MBbis) Natural Gas 2007 19 NYMEX 239 $ 9.269 Darninion Appalachia 279 $ 10.266 MichCon Citygate 118 $ 10.255 177 $ 8.000 $ 9270 2007 29 NYMEX sul $ g.sig 228 $ 7.250 $ 9.050 Darninian Appalachia 282 $ 10.265
Slide 24: Hedge positions 2008-2009
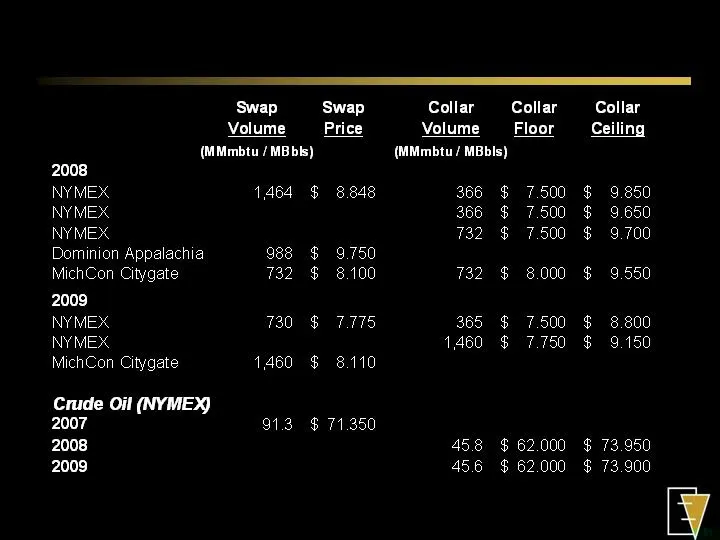
Swap Swap Collar Collar. Collar Volume Price Volume Floor —_Geiling (MMmbtu / MBbis) (MMmbtu / MBbIs) 2008 NYMEX 1464 $ 8848 366 $ 7.500 $ 9.850 NYMEX 366 $ 7.500 $ 9.650 NYMEX 732 $ 7.500 $ 9.700 Dominion Appalachia 988 $ 9.750 MichCon Citygate 732 $ 8.100 732 $ 8.000 $ 9.550 2009 NYMEX 730 $ 7.775
Slide 25: Attractive Distribution Yield
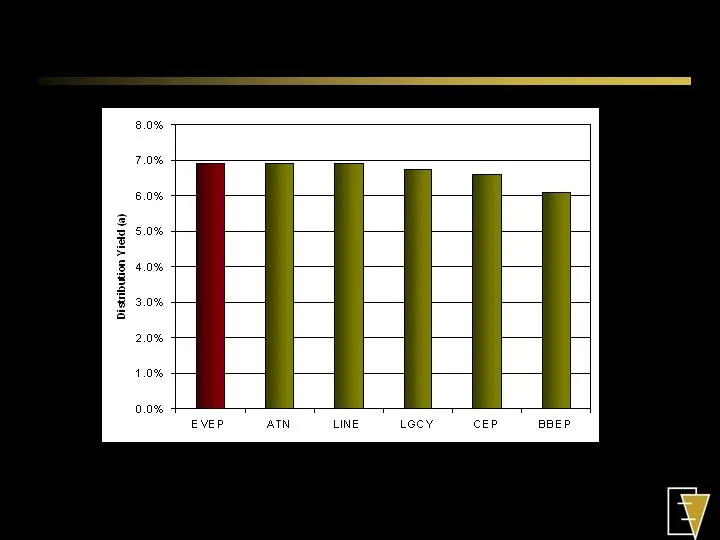
Attractive Distribution Yield (a) Source: Company filings and announcements. Distribution Yield calculated based on 1) closing unit prices at 02/27/07 and 2) recent announcements regarding expected distribution rates for EVEP ($1.84 annualized beginning 1Q 2007) and Linn Energy ($2.28 annualized beg
Slide 26: Significant Cushion Over Distributions
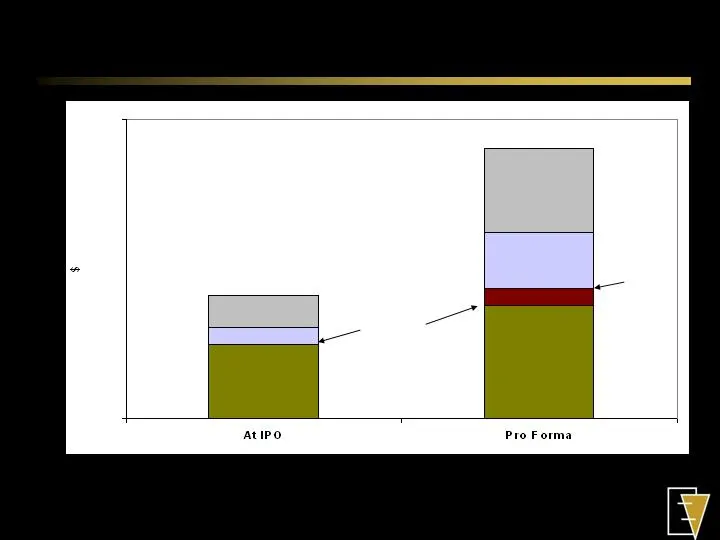
Significant Cushion Over Distributions Note: At IPO based on forecasted operating surplus in prospectus dated 9/26/06. Pro Forma is based on midpoint of 2007 Guidance estimates, assumed 2007 NYMEX prices of $7.50 for natural gas and $60.00 for crude oil, $100 million equity issuance in February, 200
Slide 27: Summary Highlights
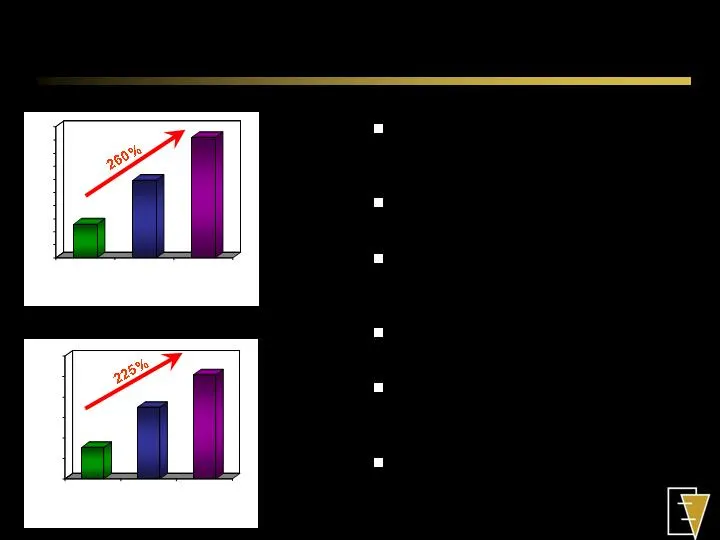
Summary Highlights Proved Reserves - BCFE 51 bcfe 183 bcfe 118 bcfe Production – MCFE/D Long reserve life with low annual decline rates Low-risk PUD locations Experienced management team Strong financial position Relationship with EnerVest and EnCap Attractive yield with strong cash distribution cov
Slide 28: Master Limited Partnership Investor Conference
Master Limited Partnership Investor Conference EV Energy Partners, L.P.
Source: SEC EDGAR · 8-K filed Mar 13, 2007