Old Mutual Ltd. · JSE:OMU
Old Mutual — Merger or Acquisition (October 2014)
22 slides from Old Mutual's merger presentation, Oct 17, 2014
Slide 1: Acquisition of Quilter Cheviot
OLD MUTUAL PLC ACQUISITION OF QUILTER CHEVIOT Julian Roberts, Group Chief Executive Officer 17 October 2014 INVESTMENT | SAVINGS | INSURANCE | BANKING
Slide 2: Disclaimer
DISCLAIMER This presentation may contain certain forward-looking statements with respect to certain of Old Mutual plc’s plans and its current goals and expectations relating to its future financial condition, performance and results. By their nature, all forward-looking statements involve risk and u
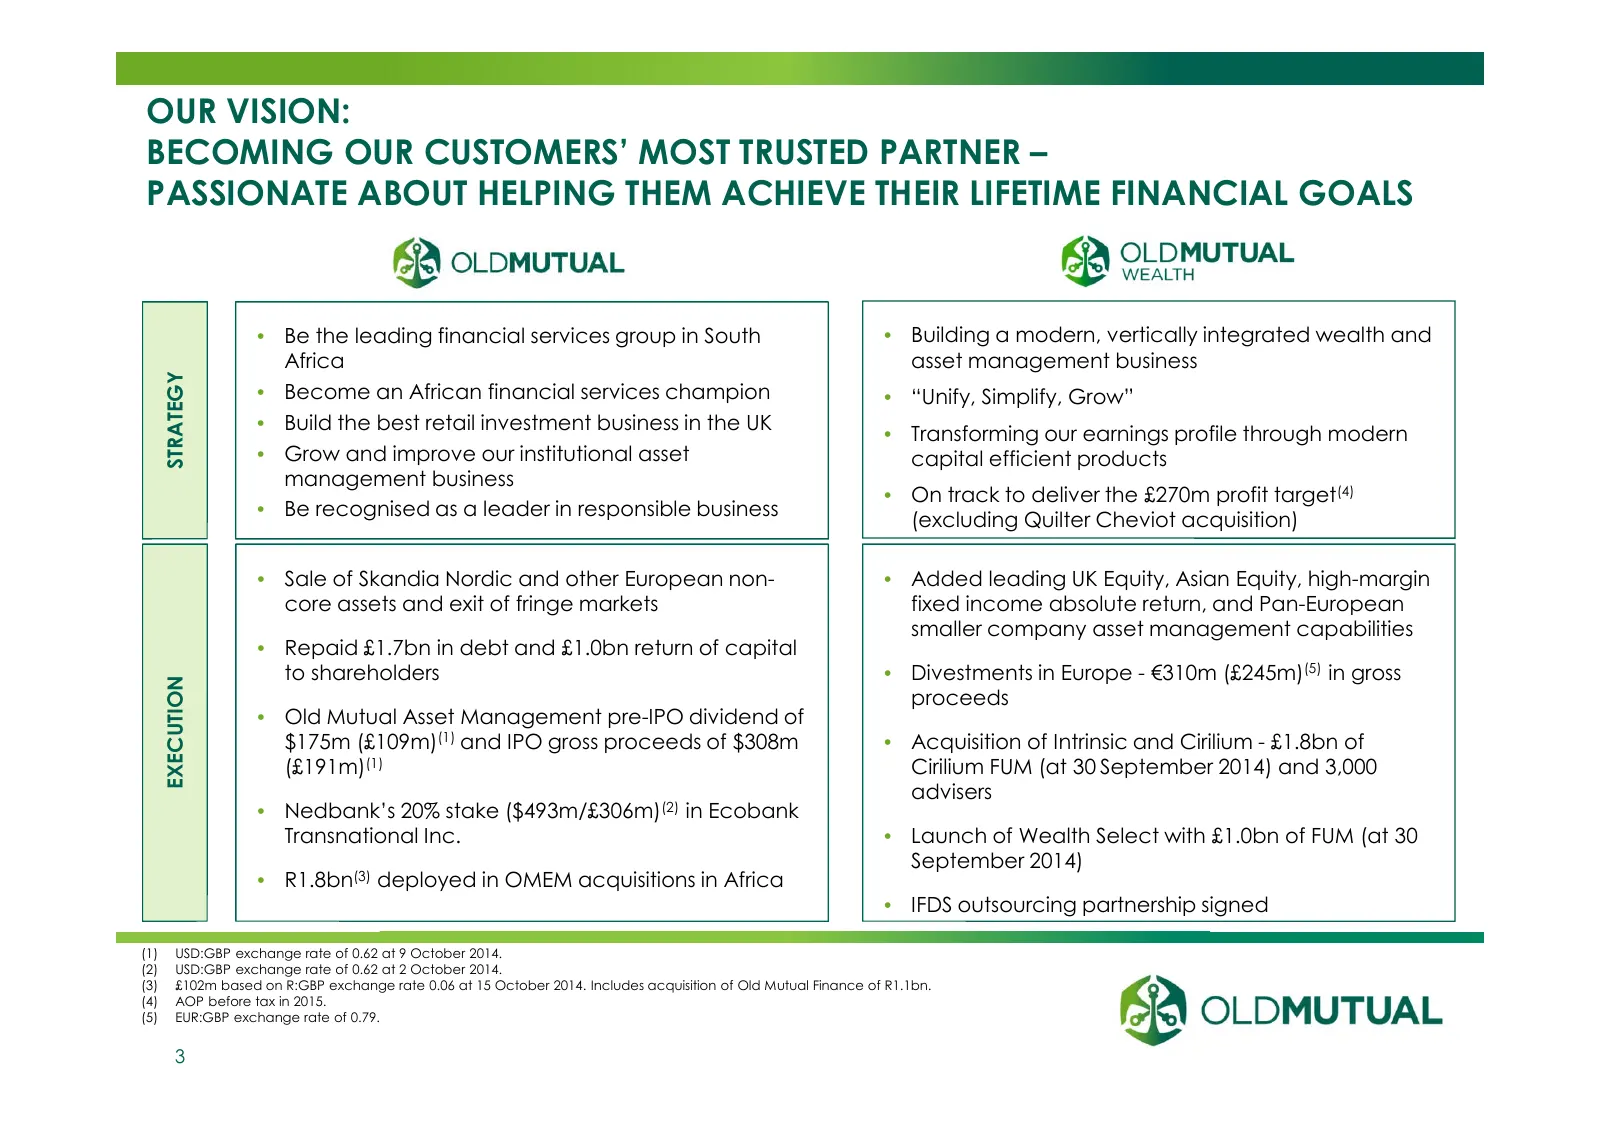
Slide 3: Our Vision: Becoming Our Customers' Most Trusted Partner
OUR VISION: BECOMING OUR CUSTOMERS’ MOST TRUSTED PARTNER – PASSIONATE ABOUT HELPING THEM ACHIEVE THEIR LIFETIME FINANCIAL GOALS • Be the leading financial services group in South • Building a modern, vertically integrated wealth and Africa asset management business STRATEGY • Become an African finan
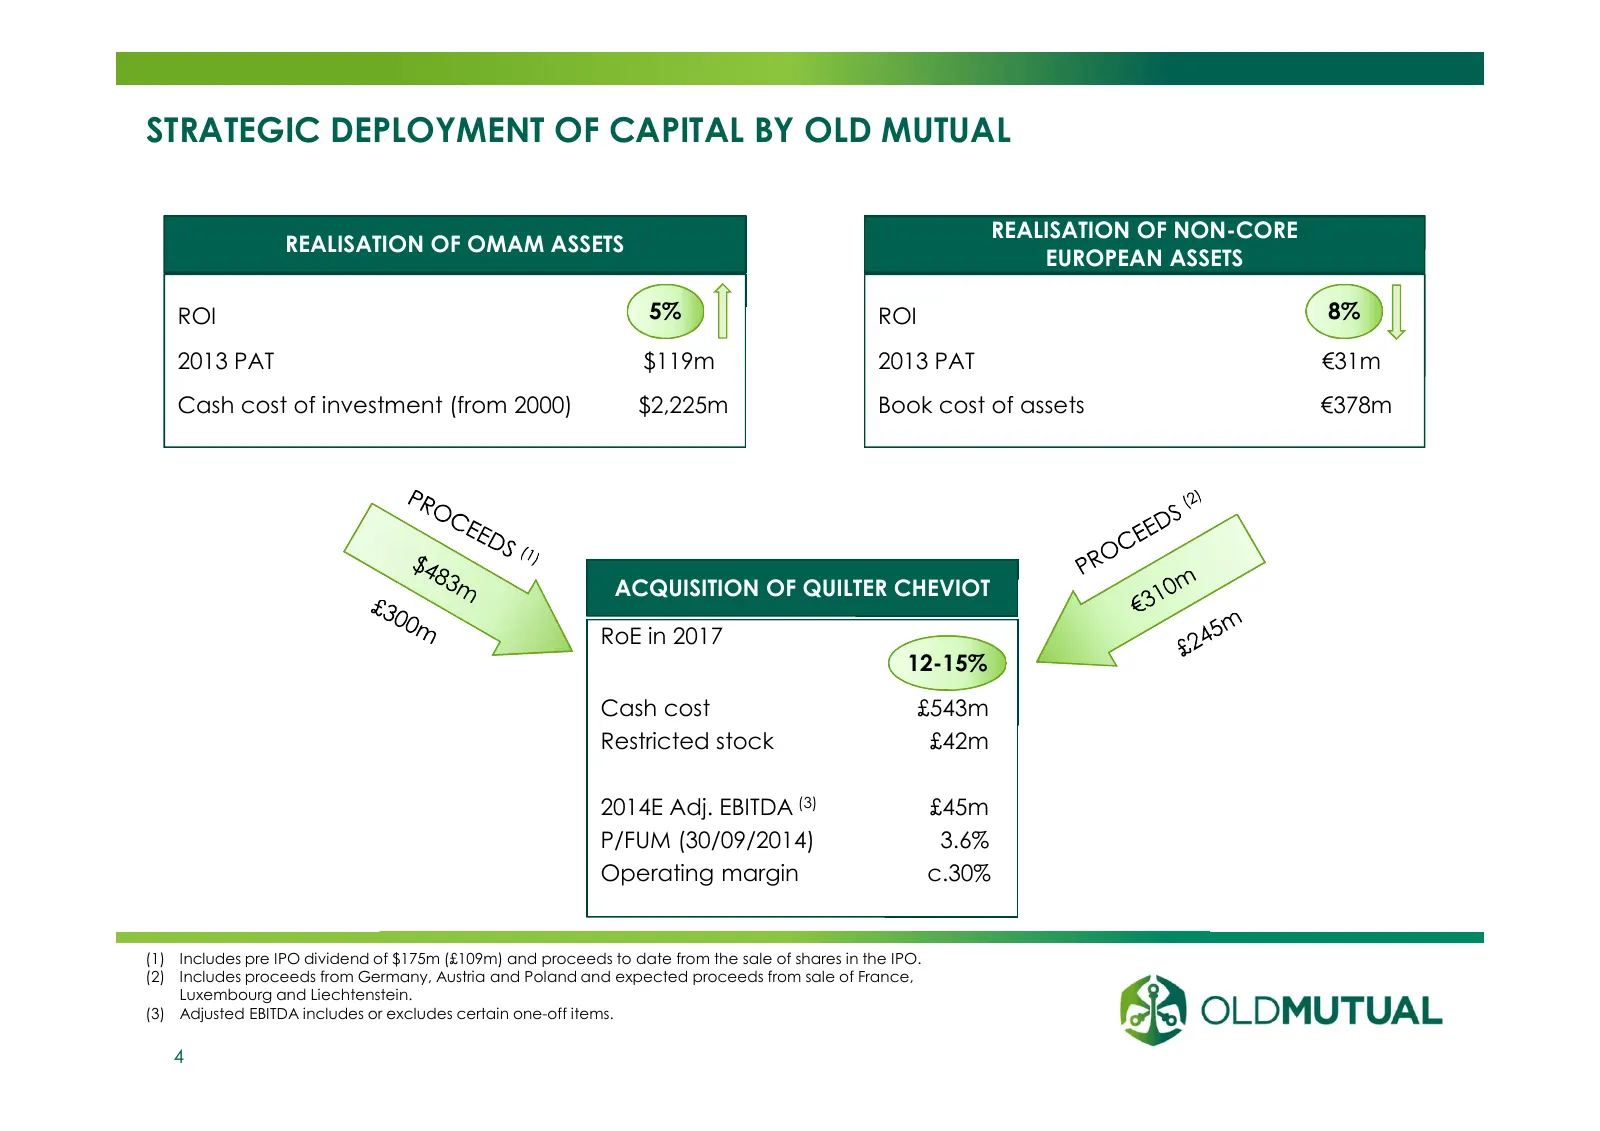
Slide 4: Strategic Deployment of Capital by Old Mutual
STRATEGIC DEPLOYMENT OF CAPITAL BY OLD MUTUAL REALISATION OF NON-CORE REALISATION OF OMAM ASSETS EUROPEAN ASSETS ROI 5% ROI 8% 2013 PAT $119m 2013 PAT €31m Cash cost of investment (from 2000) $2,225m Book cost of assets €378m ACQUISITION OF QUILTER CHEVIOT RoE in 2017 12-15% Cash cost £543m Restrict
Slide 5: Quilter Cheviot Transaction Rationale
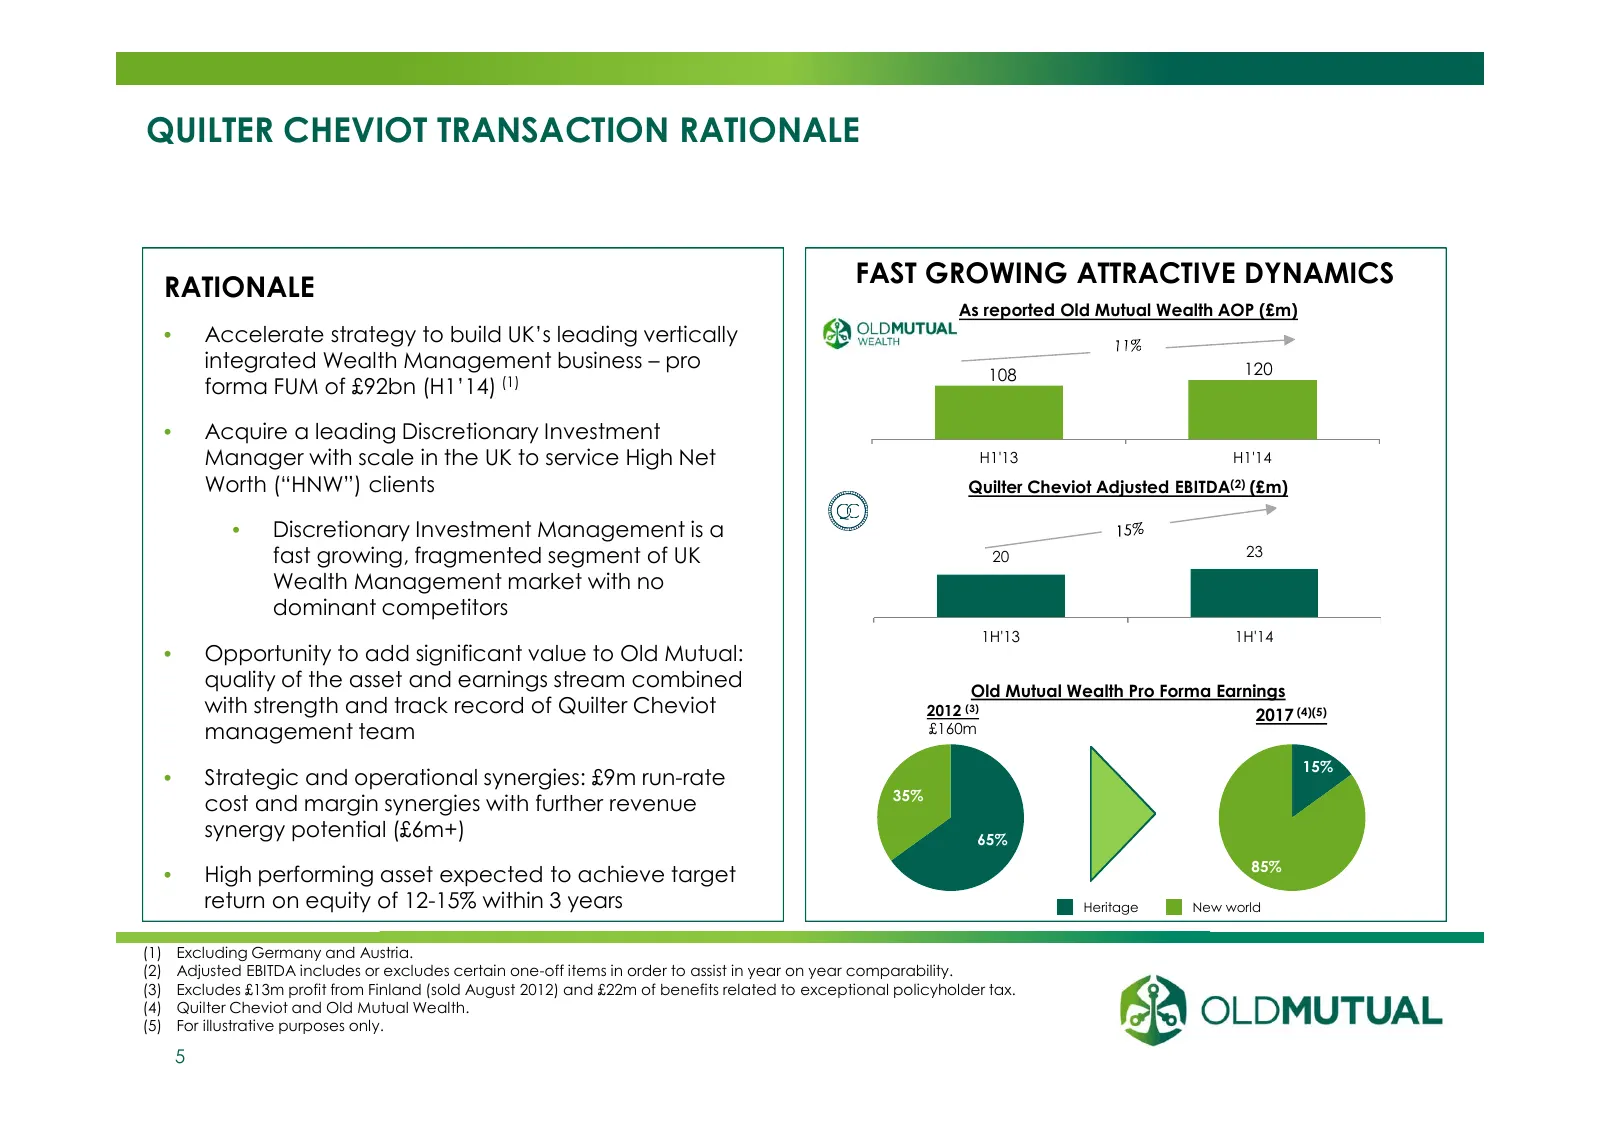
QUILTER CHEVIOT TRANSACTION RATIONALE RATIONALE FAST GROWING ATTRACTIVE DYNAMICS As reported Old Mutual Wealth AOP (£m) • Accelerate strategy to build UK’s leading vertically integrated Wealth Management business – pro 120 108 forma FUM of £92bn (H1’14) (1) • Acquire a leading Discretionary Investme
Slide 6: Transaction Terms
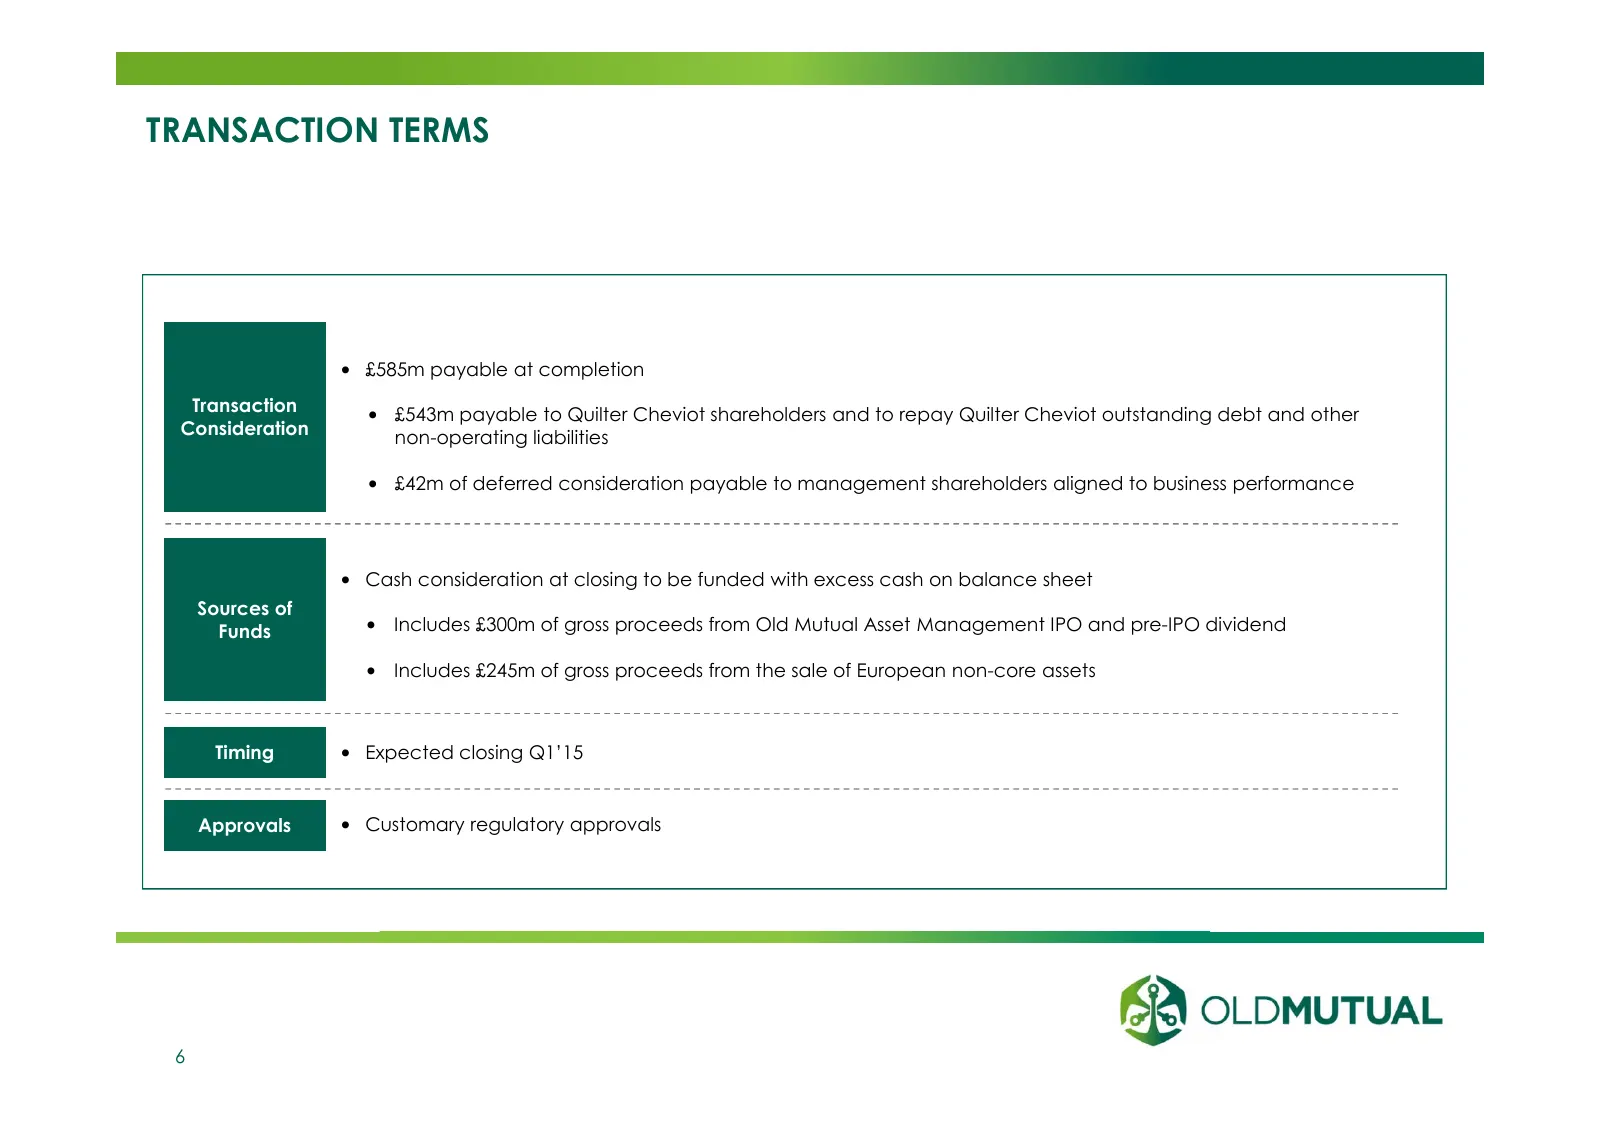
TRANSACTION TERMS • £585m payable at completion Transaction • £543m payable to Quilter Cheviot shareholders and to repay Quilter Cheviot outstanding debt and other Consideration non-operating liabilities • £42m of deferred consideration payable to management shareholders aligned to business performa
Slide 7: Acquiring Scale in Attractive Affluent / HNW Segment
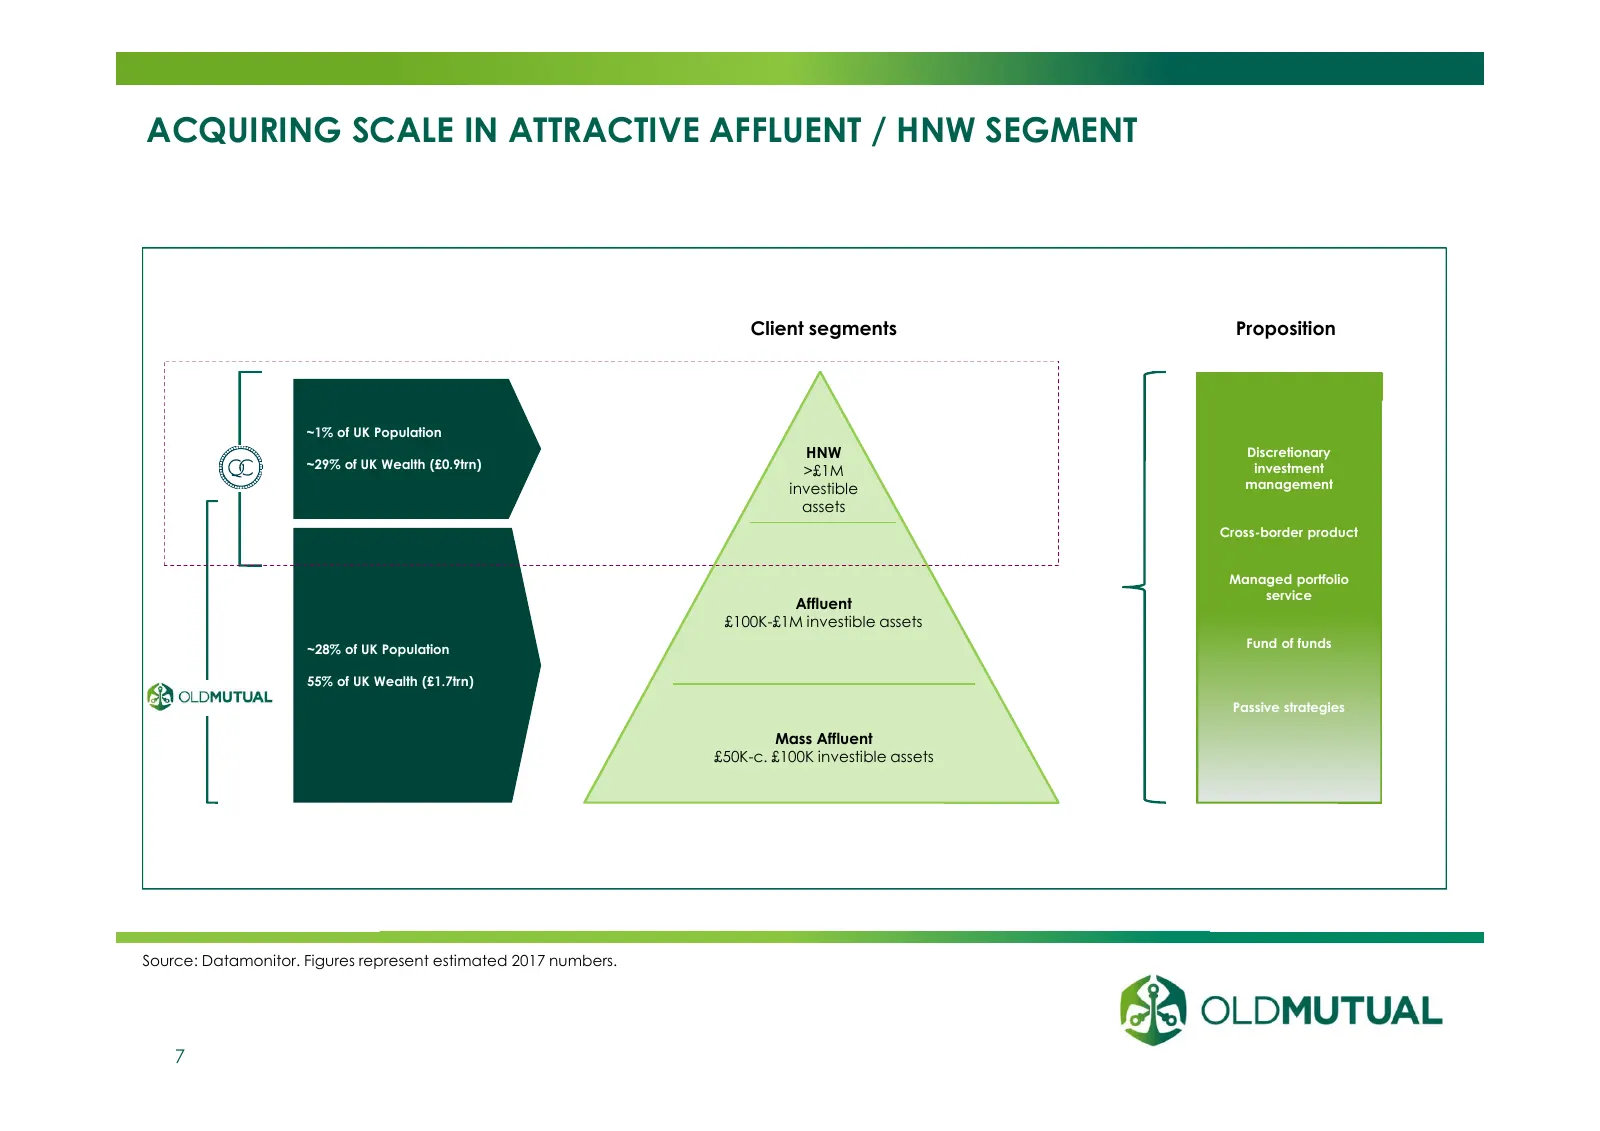
ACQUIRING SCALE IN ATTRACTIVE AFFLUENT / HNW SEGMENT Client segments Proposition ~1% of UK Population HNW Discretionary ~29% of UK Wealth (£0.9trn) >£1M investment investible management assets Cross-border product Managed portfolio service Affluent £100K-£1M investible assets ~28% of UK Population F
Slide 8: UK Discretionary Market Is Large and Growing
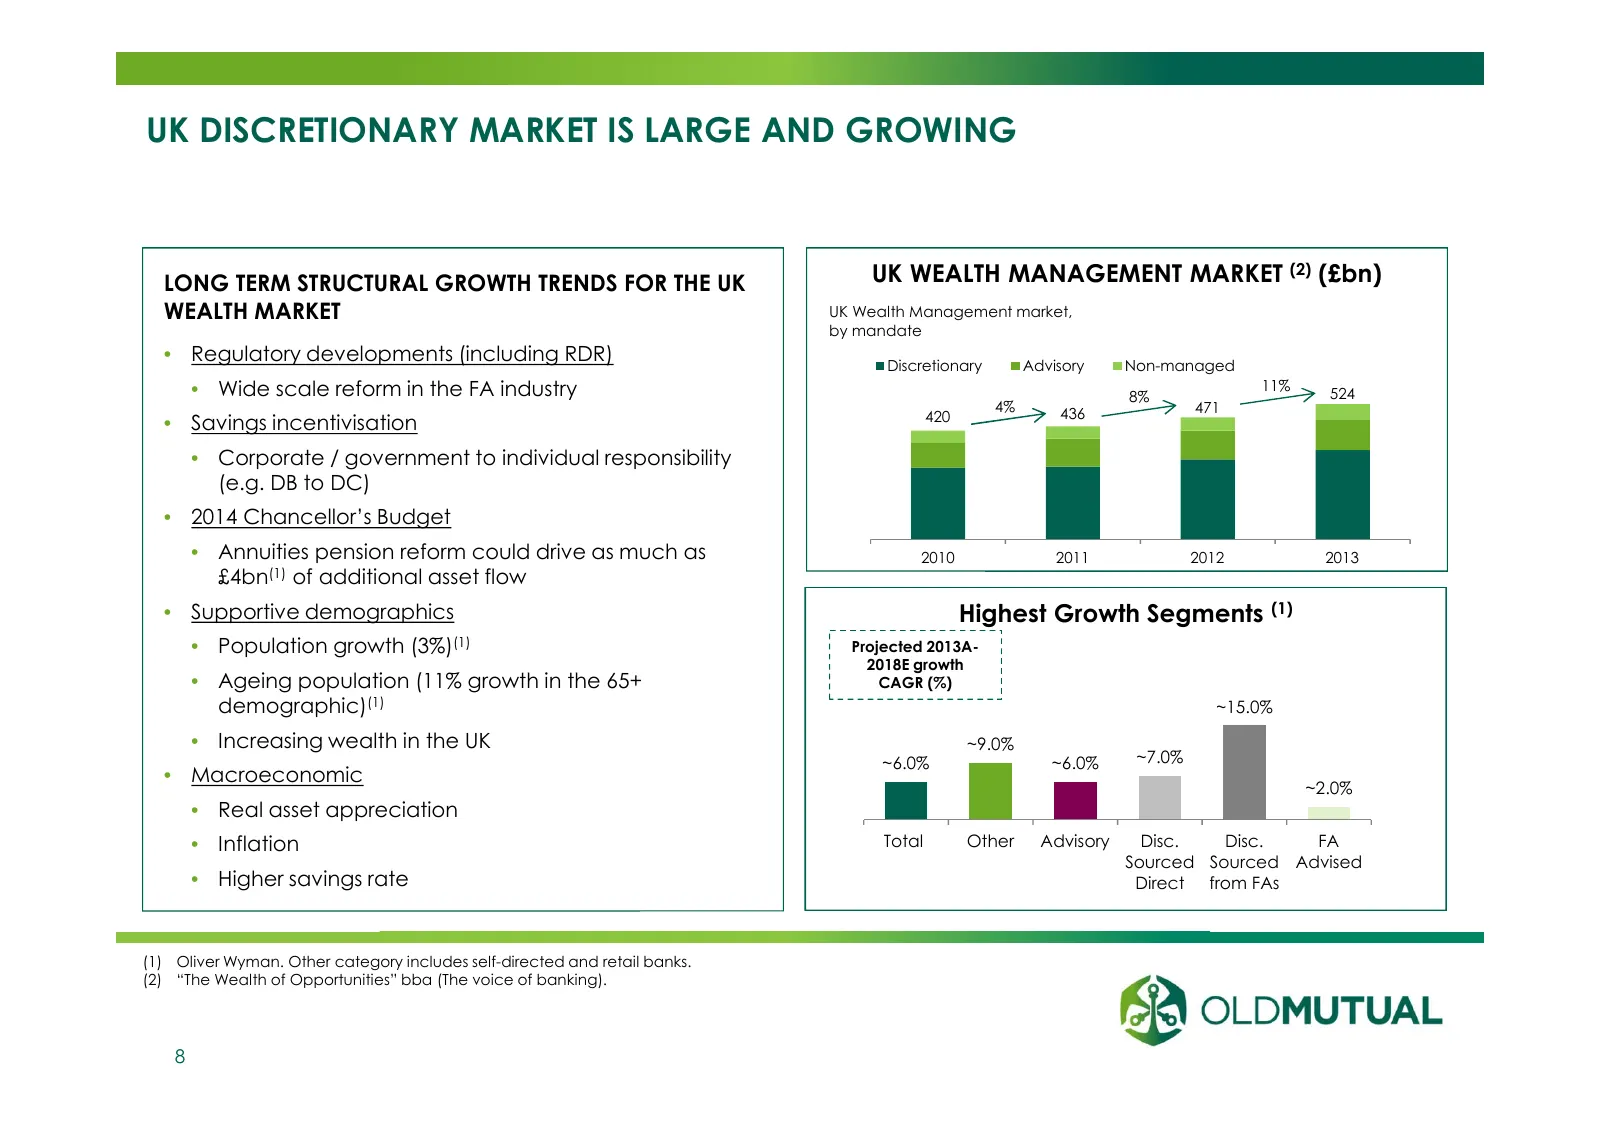
UK DISCRETIONARY MARKET IS LARGE AND GROWING LONG TERM STRUCTURAL GROWTH TRENDS FOR THE UK UK WEALTH MANAGEMENT MARKET (2) (£bn) WEALTH MARKET UK Wealth Management market, by mandate • Regulatory developments (including RDR) Discretionary Advisory Non-managed • Wide scale reform in the FA industry 8
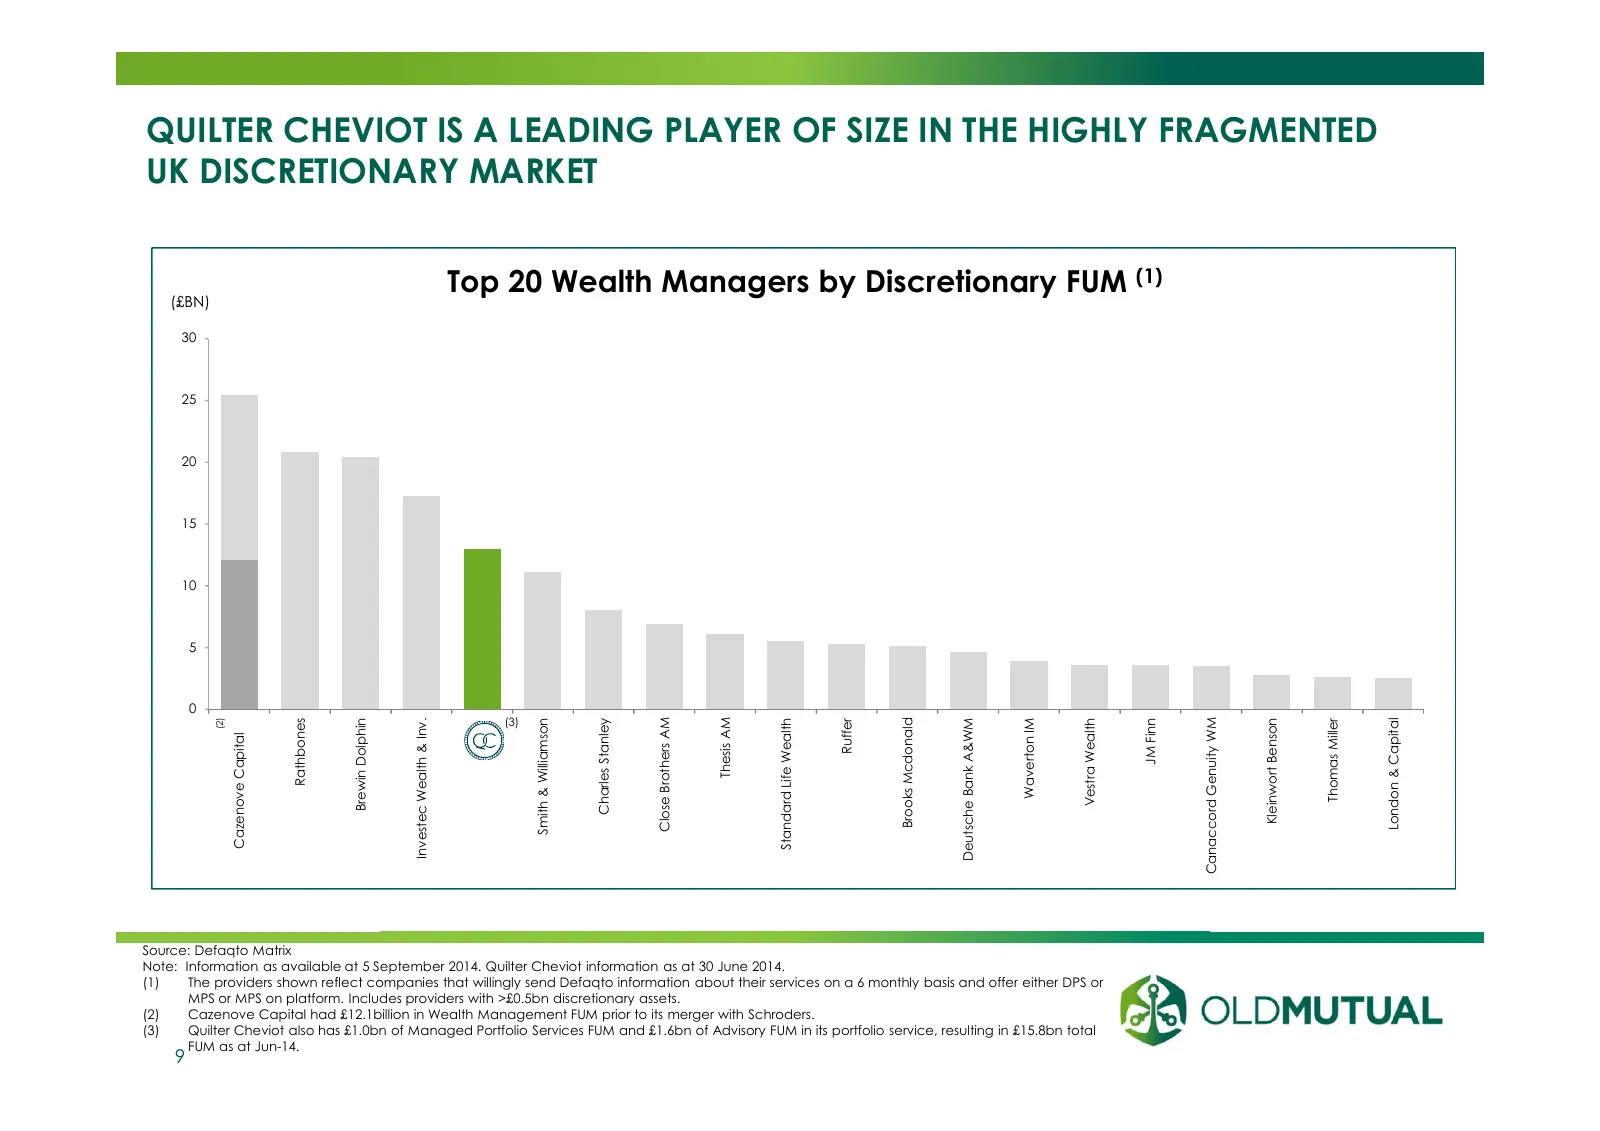
Slide 9: Quilter Cheviot Is a Leading Player in Fragmented UK Discretionary Market
QUILTER CHEVIOT IS A LEADING PLAYER OF SIZE IN THE HIGHLY FRAGMENTED UK DISCRETIONARY MARKET (£BN) Top 20 Wealth Managers by Discretionary FUM (1) 30 25 20 15 10 5 0 (3) (2) Close Brothers AM Thesis AM Canaccord Genuity WM Brooks Mcdonald Rathbones Brewin Dolphin Smith & Williamson Standard Life Wea
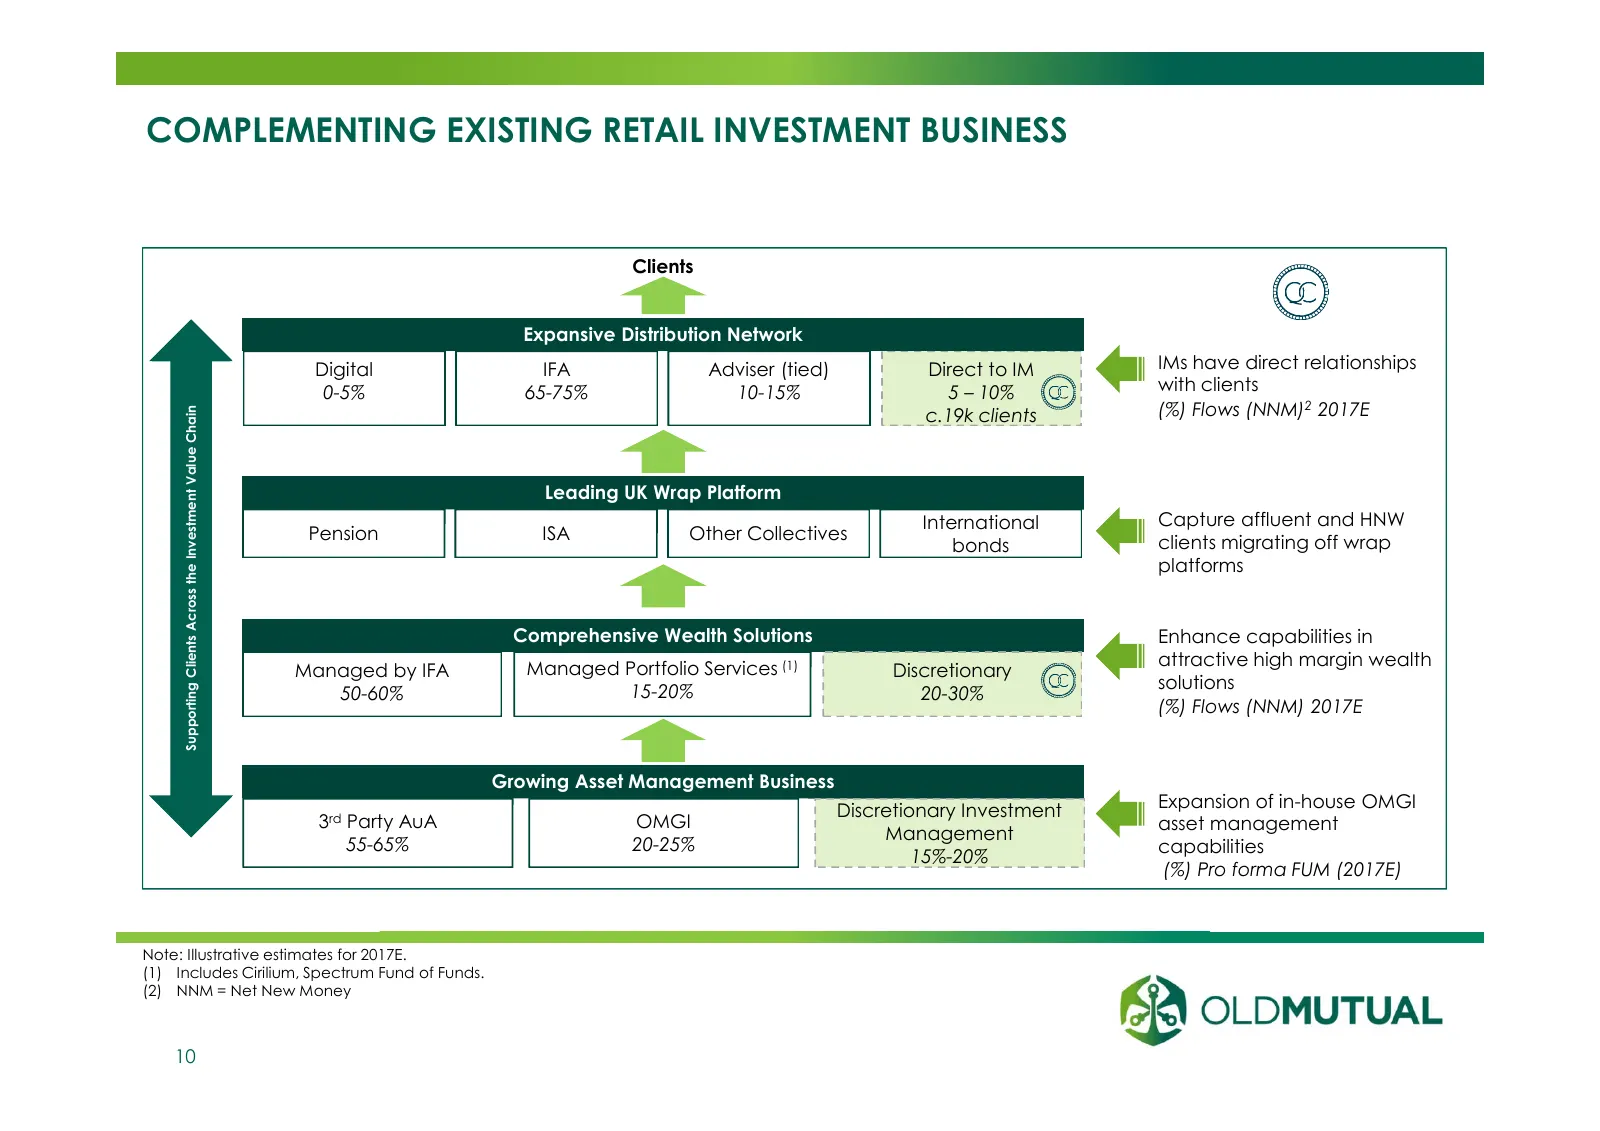
Slide 10: Complementing Existing Retail Investment Business
COMPLEMENTING EXISTING RETAIL INVESTMENT BUSINESS Clients Expansive Distribution Network Digital IFA Adviser (tied) Direct to IM IMs have direct relationships 0-5% 65-75% 10-15% 5 – 10% with clients c.19k clients (%) Flows (NNM)2 2017E Supporting Clients Across the Investment Value Chain Leading UK
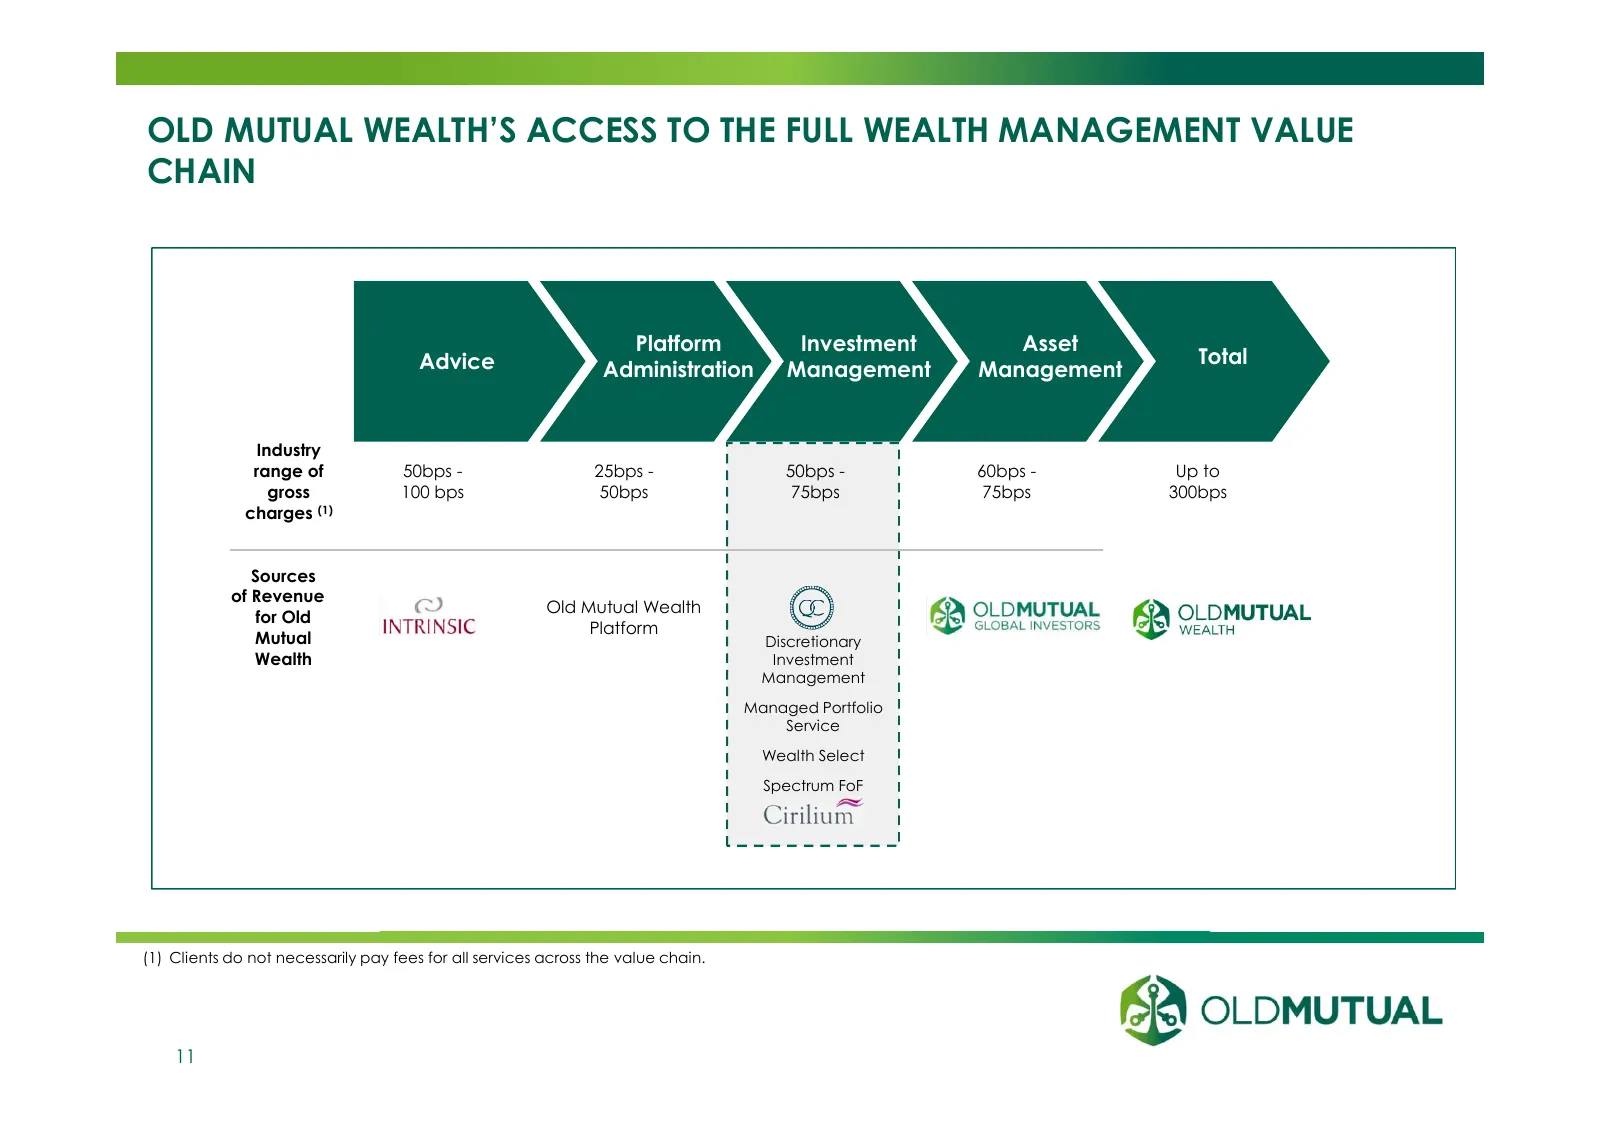
Slide 11: Old Mutual Wealth's Access to Full Wealth Management Value Chain
OLD MUTUAL WEALTH’S ACCESS TO THE FULL WEALTH MANAGEMENT VALUE CHAIN Platform Investment Asset Advice Total Administration Management Management Industry range of 50bps - 25bps - 50bps - 60bps - Up to gross 100 bps 50bps 75bps 75bps 300bps charges (1) Sources of Revenue Old Mutual Wealth for Old Pla
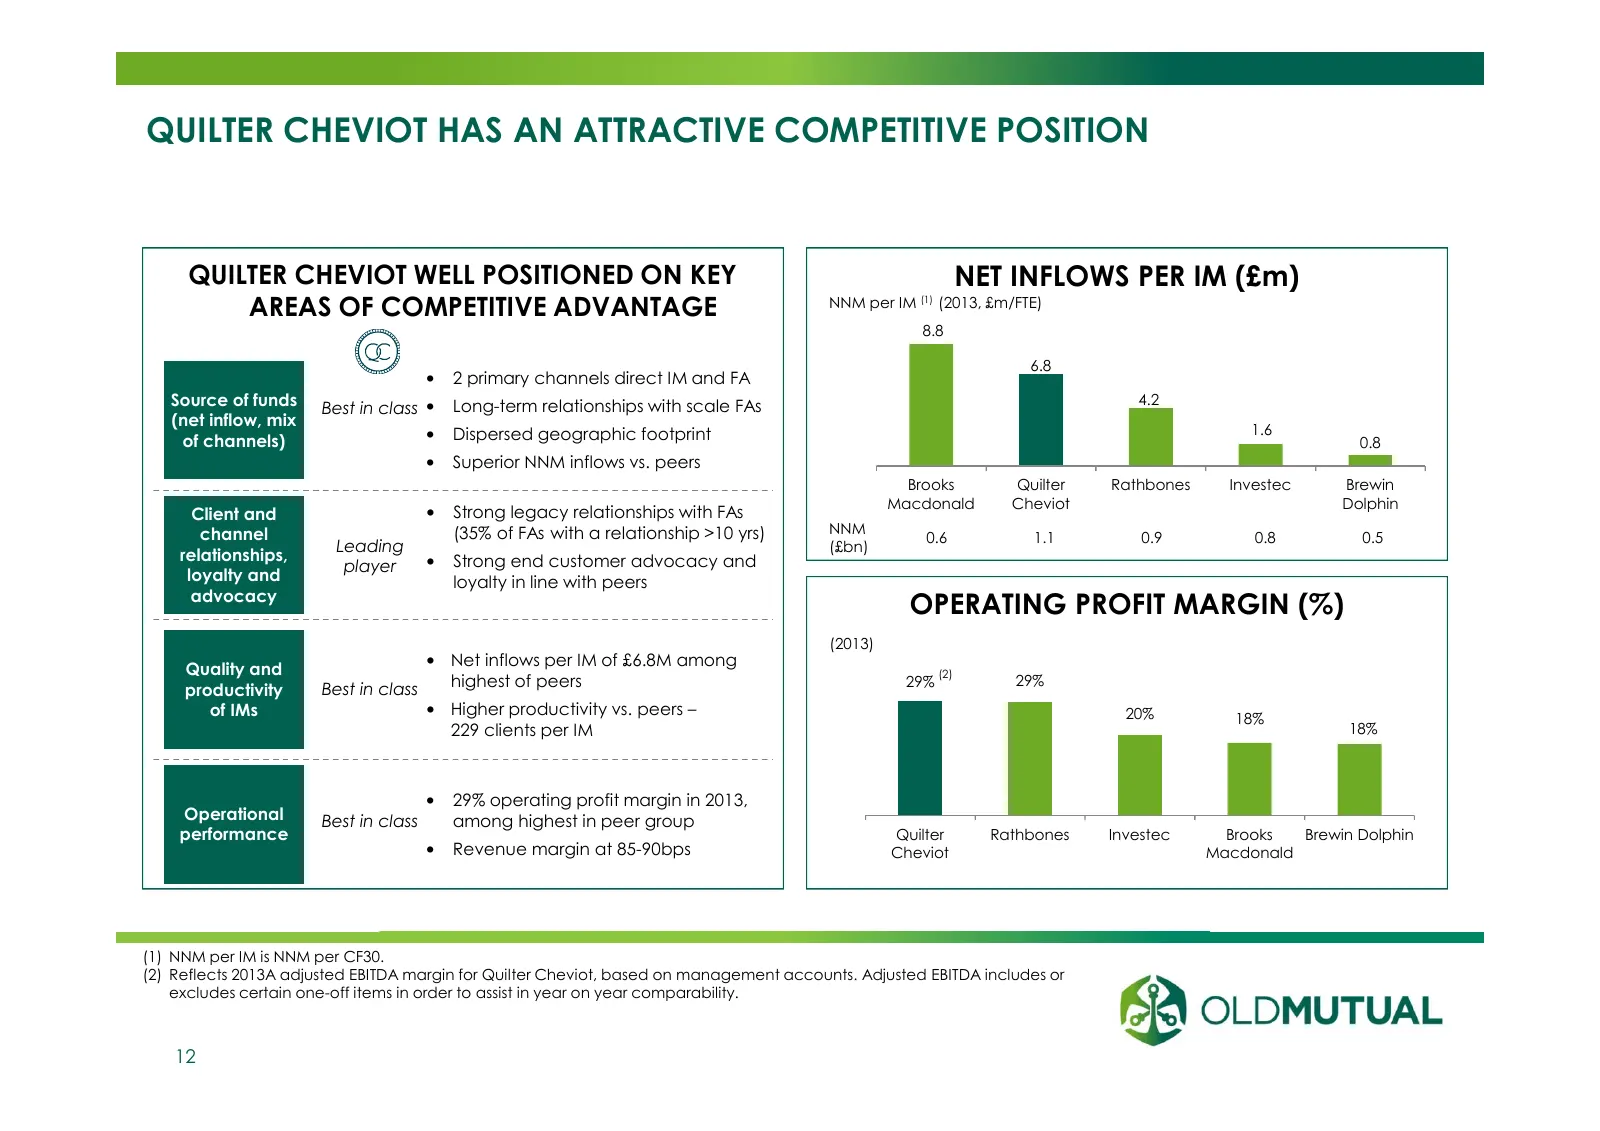
Slide 12: Quilter Cheviot Has an Attractive Competitive Position
QUILTER CHEVIOT HAS AN ATTRACTIVE COMPETITIVE POSITION QUILTER CHEVIOT WELL POSITIONED ON KEY NET INFLOWS PER IM (£m) AREAS OF COMPETITIVE ADVANTAGE NNM per IM (1) (2013, £m/FTE) 8.8 6.8 • 2 primary channels direct IM and FA Source of funds Best in class • Long-term relationships with scale FAs 4.2
Slide 13: Quilter Cheviot Has a Track Record of Strong Financial Performance
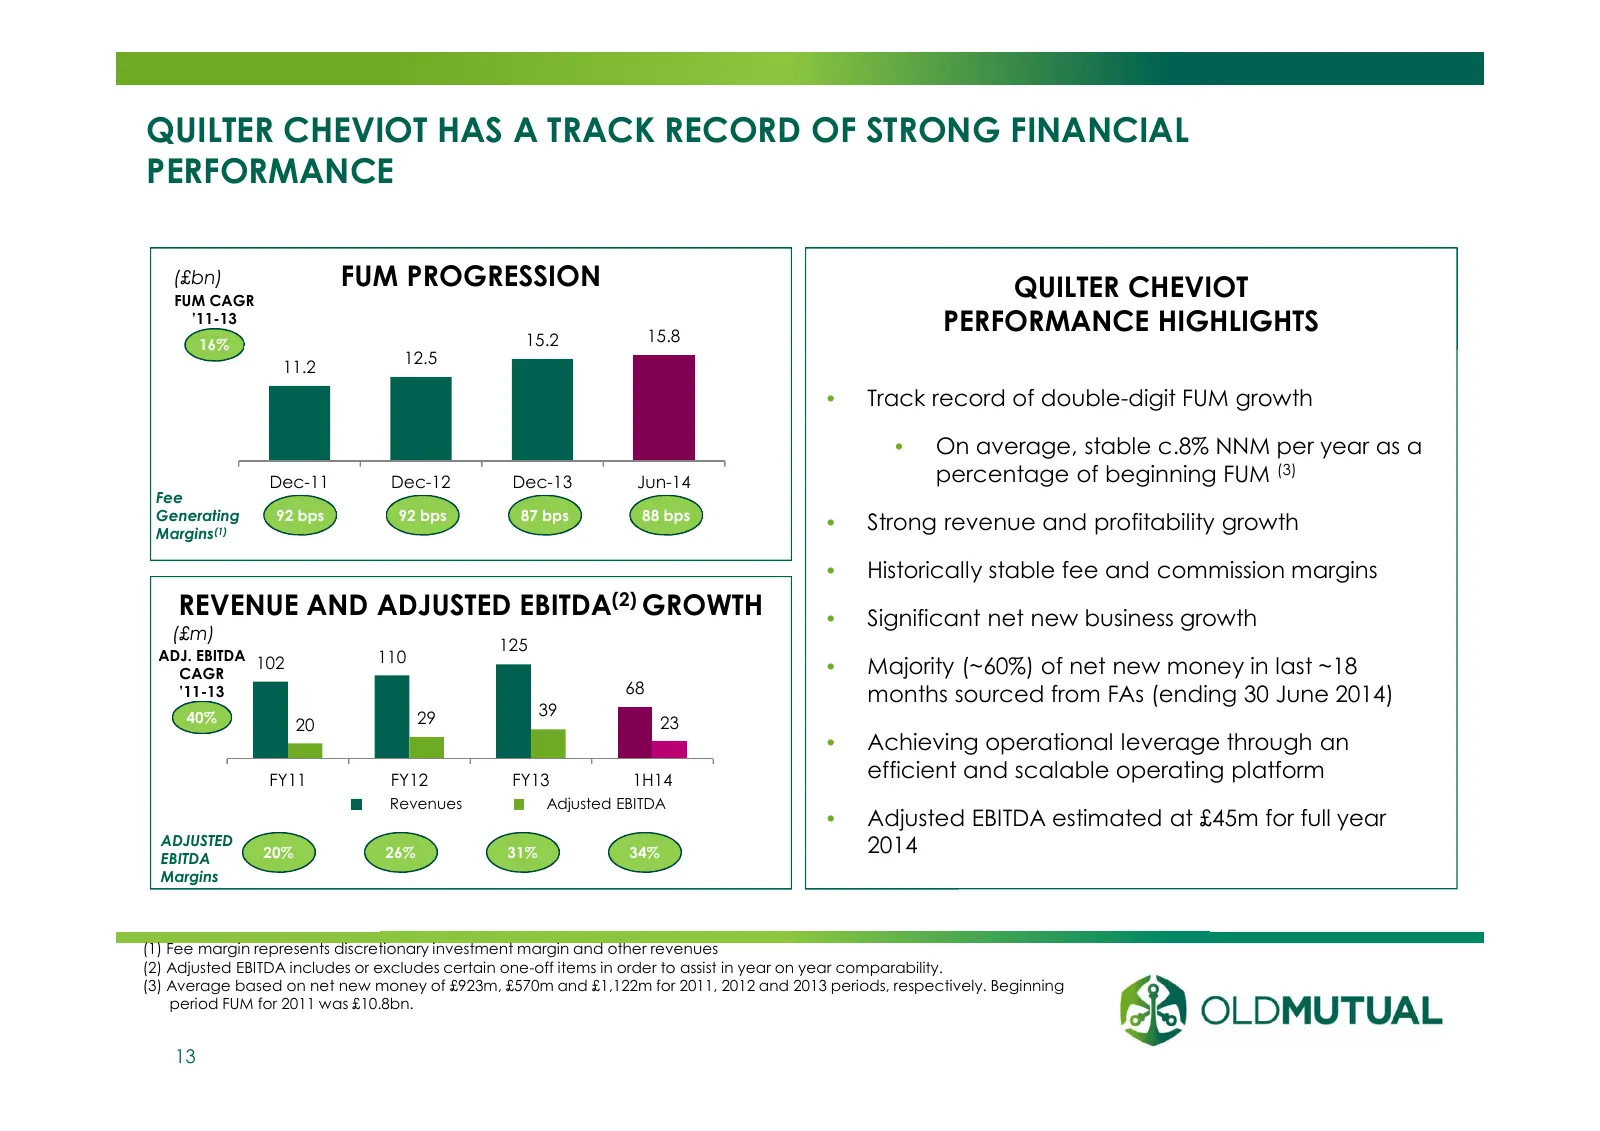
QUILTER CHEVIOT HAS A TRACK RECORD OF STRONG FINANCIAL PERFORMANCE (£bn) FUM PROGRESSION QUILTER CHEVIOT FUM CAGR ’11-13 15.8 PERFORMANCE HIGHLIGHTS 16% 15.2 12.5 11.2 • Track record of double-digit FUM growth • On average, stable c.8% NNM per year as a Dec-11 Dec-12 Dec-13 Jun-14 percentage of begi
Slide 14: Attractive Opportunities to Enhance Value
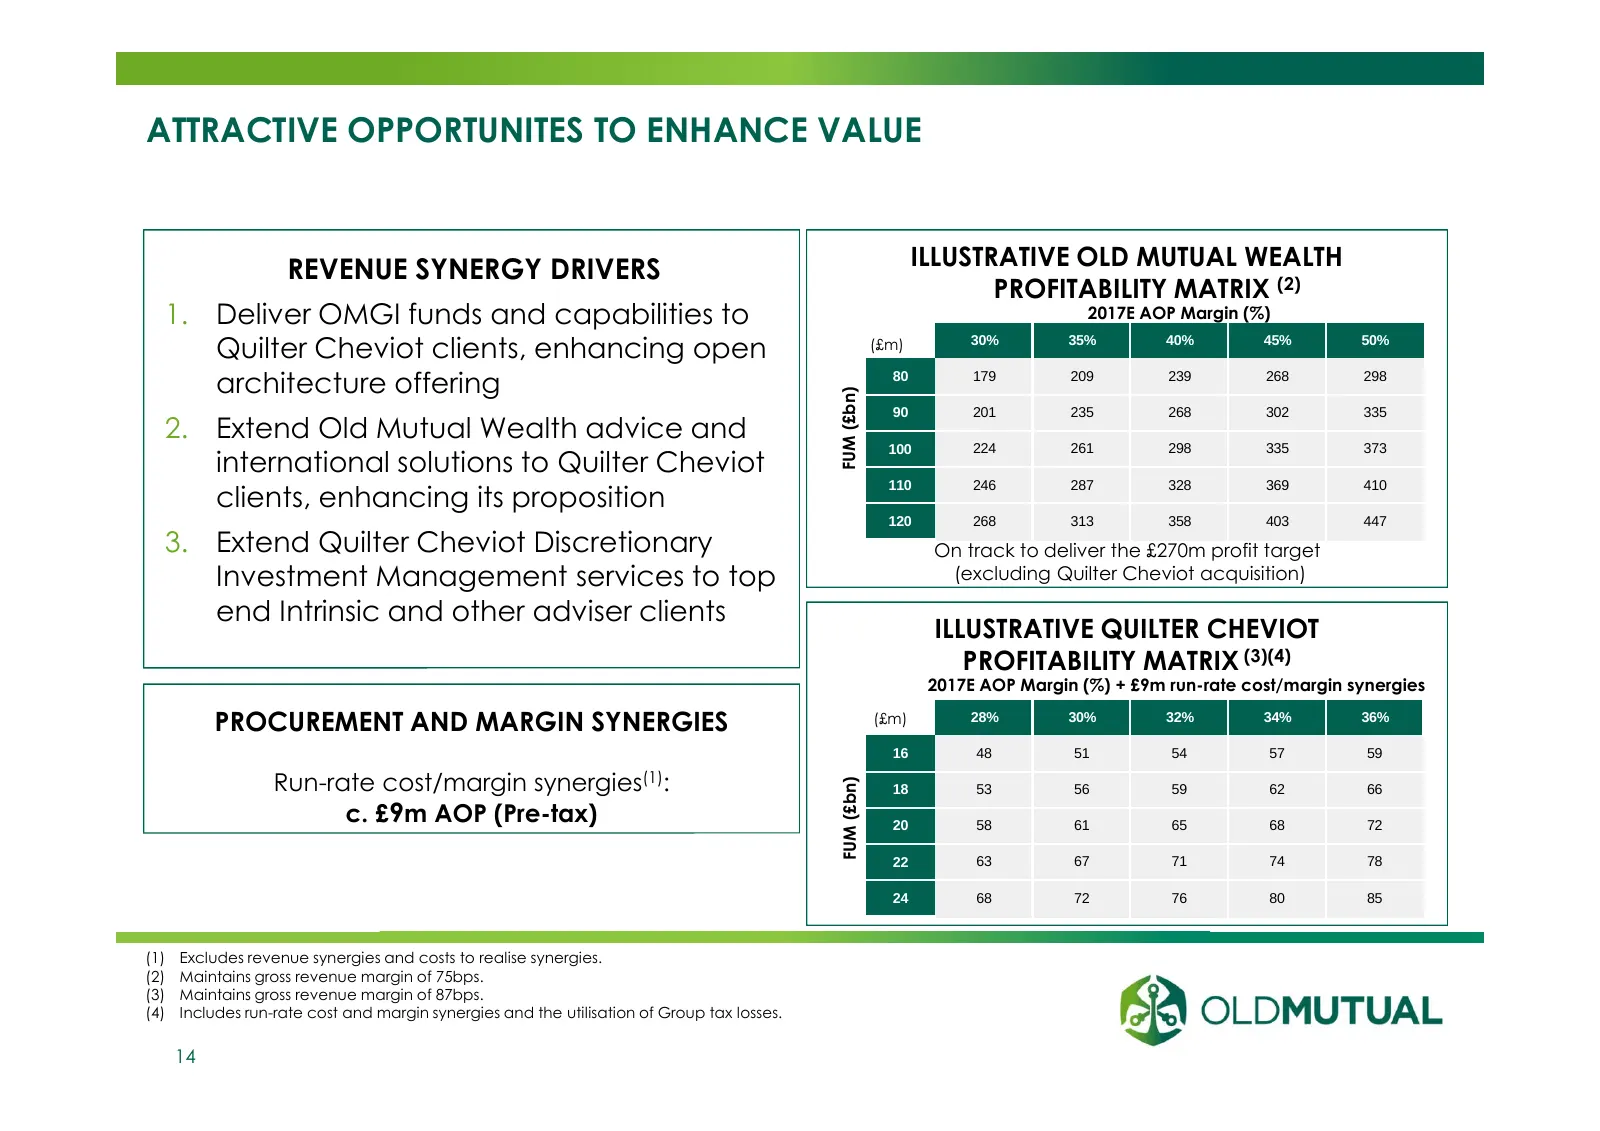
ATTRACTIVE OPPORTUNITES TO ENHANCE VALUE REVENUE SYNERGY DRIVERS ILLUSTRATIVE OLD MUTUAL WEALTH PROFITABILITY MATRIX (2) 1. Deliver OMGI funds and capabilities to 2017E AOP Margin (%) Quilter Cheviot clients, enhancing open (£m) 30% 35% 40% 45% 50% architecture offering 80 179 209 239 268 298 FUM (£
Slide 15: Summary
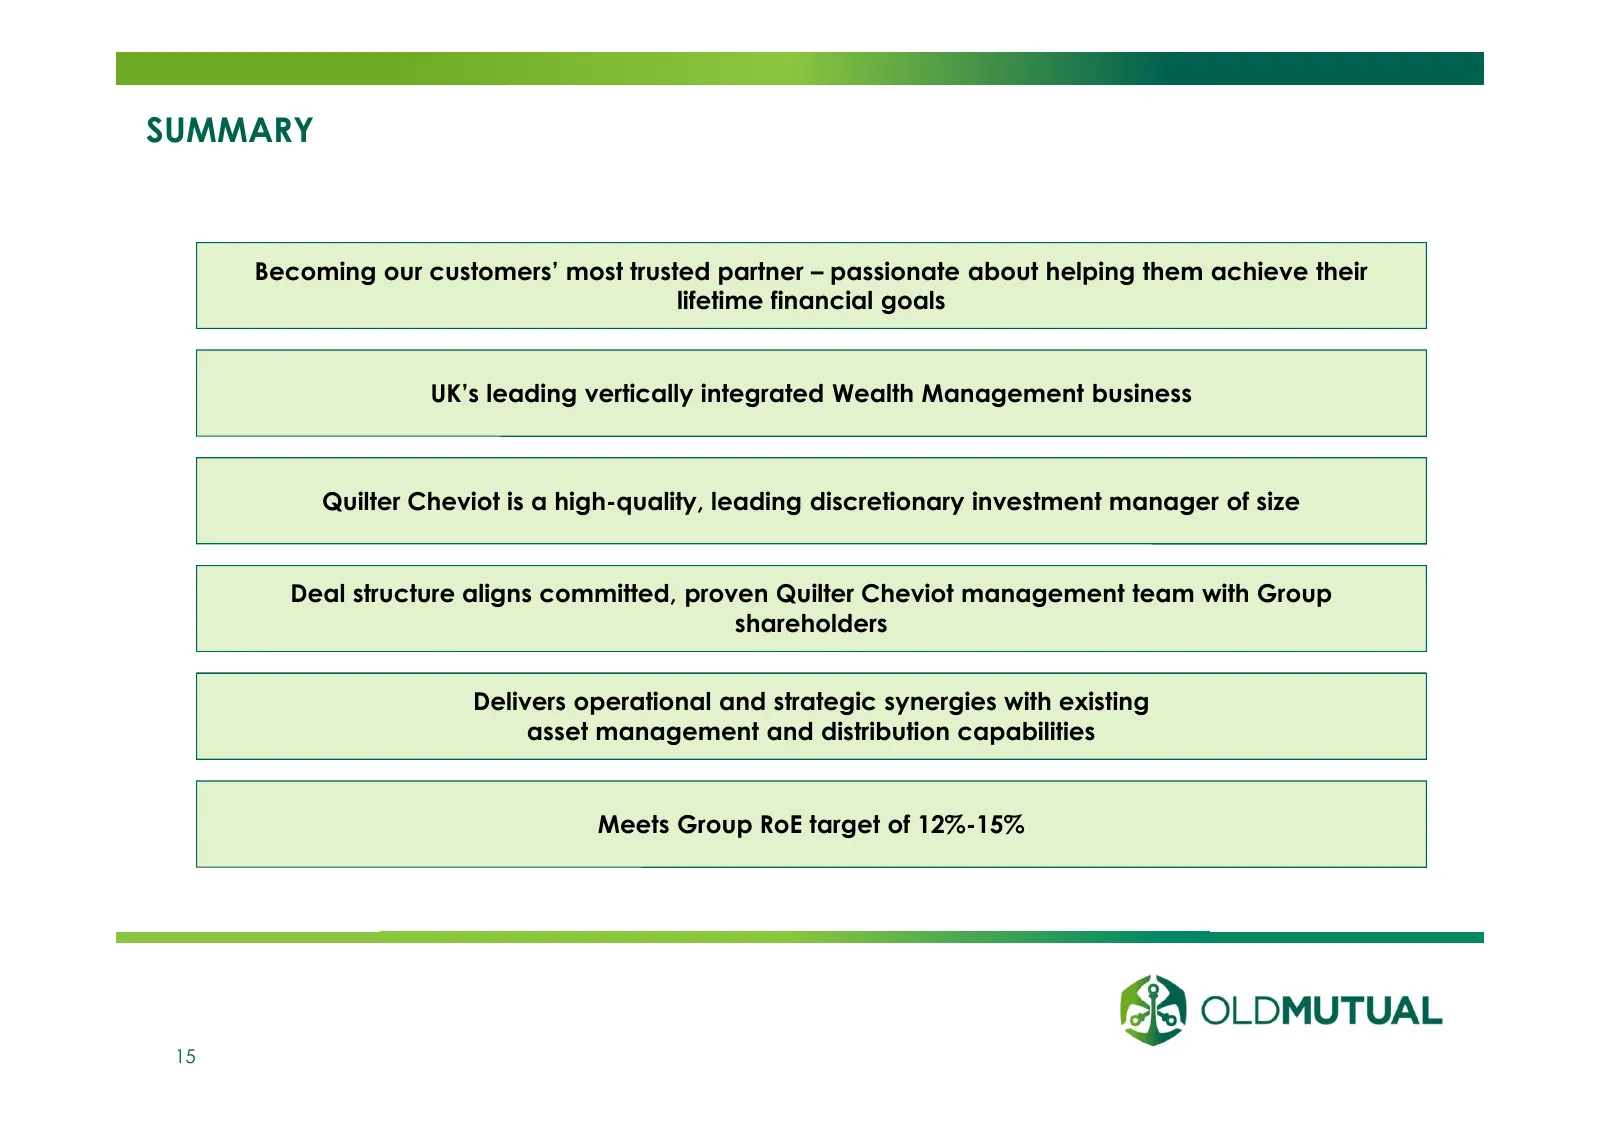
SUMMARY Becoming our customers’ most trusted partner – passionate about helping them achieve their lifetime financial goals UK’s leading vertically integrated Wealth Management business Quilter Cheviot is a high-quality, leading discretionary investment manager of size Deal structure aligns committe
Slide 16: Appendix
DDD ee APPENDIX i BQ OLDMUTUAL
Slide 17: Overview of Quilter Cheviot
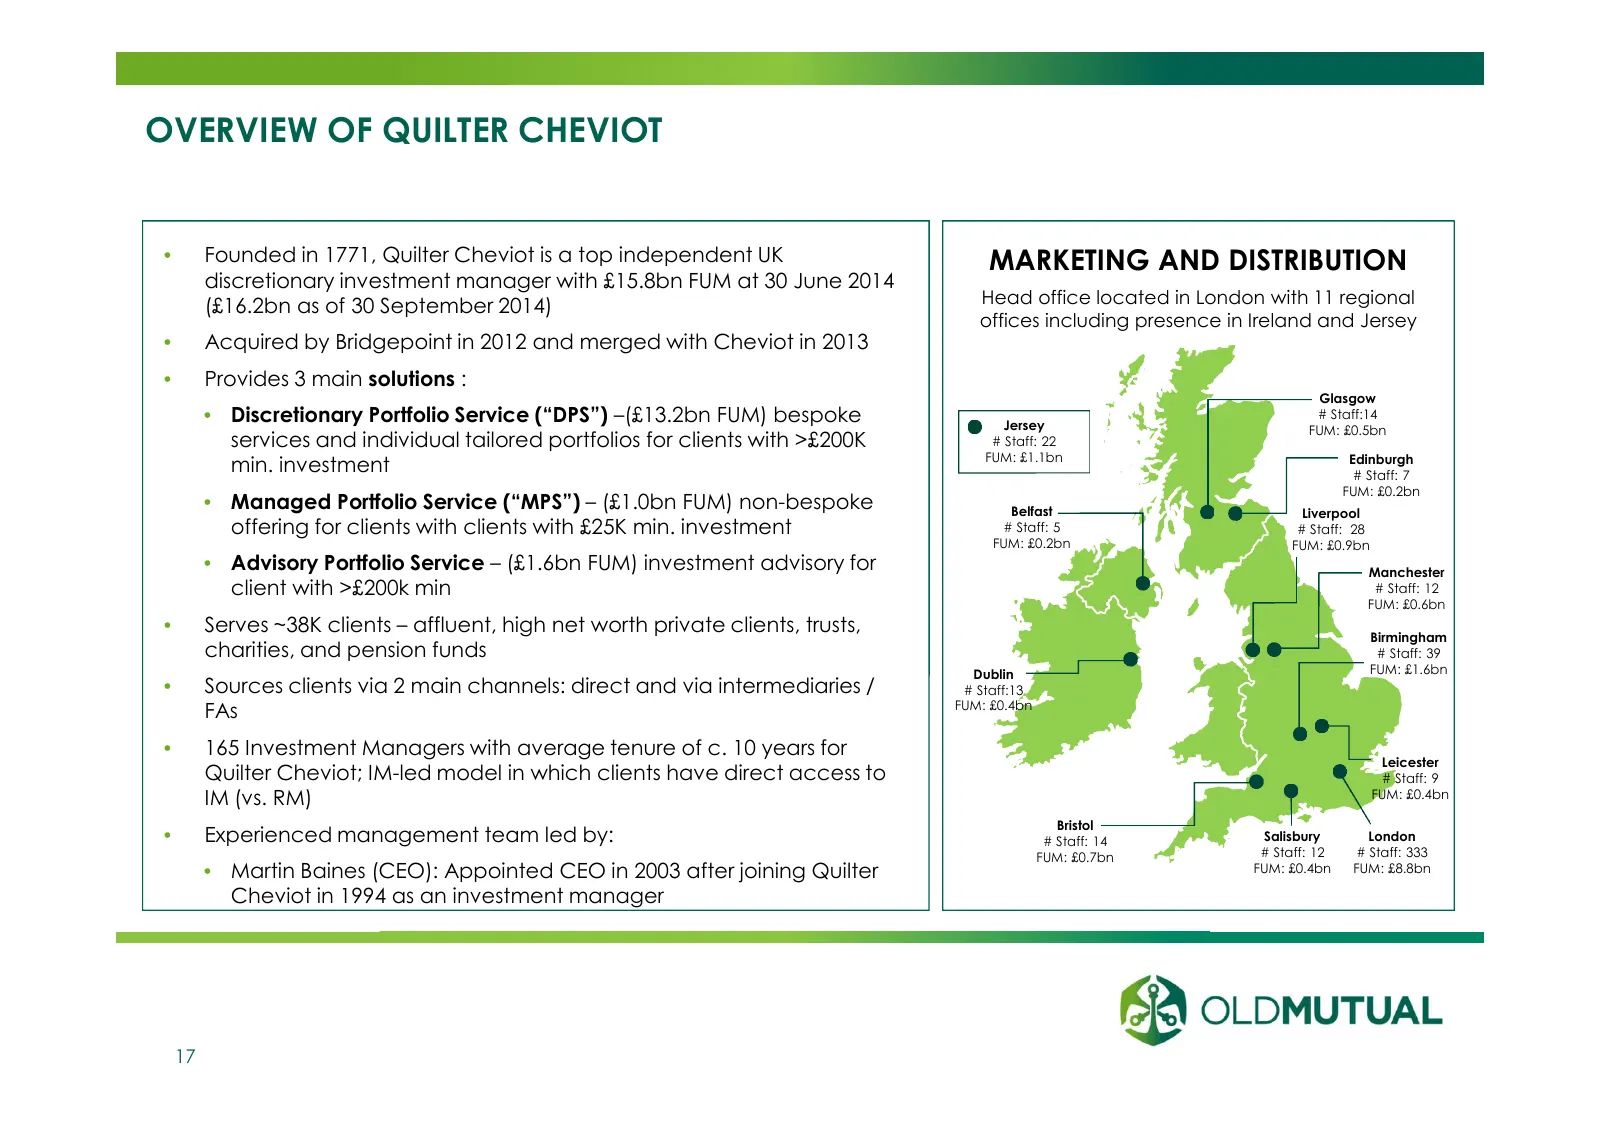
OVERVIEW OF QUILTER CHEVIOT • Founded in 1771, Quilter Cheviot is a top independent UK MARKETING AND DISTRIBUTION discretionary investment manager with £15.8bn FUM at 30 June 2014 (£16.2bn as of 30 September 2014) Head office located in London with 11 regional offices including presence in Ireland a
Slide 18: Evolving Economics for Client Investment Solutions for Affluent & HNW Markets
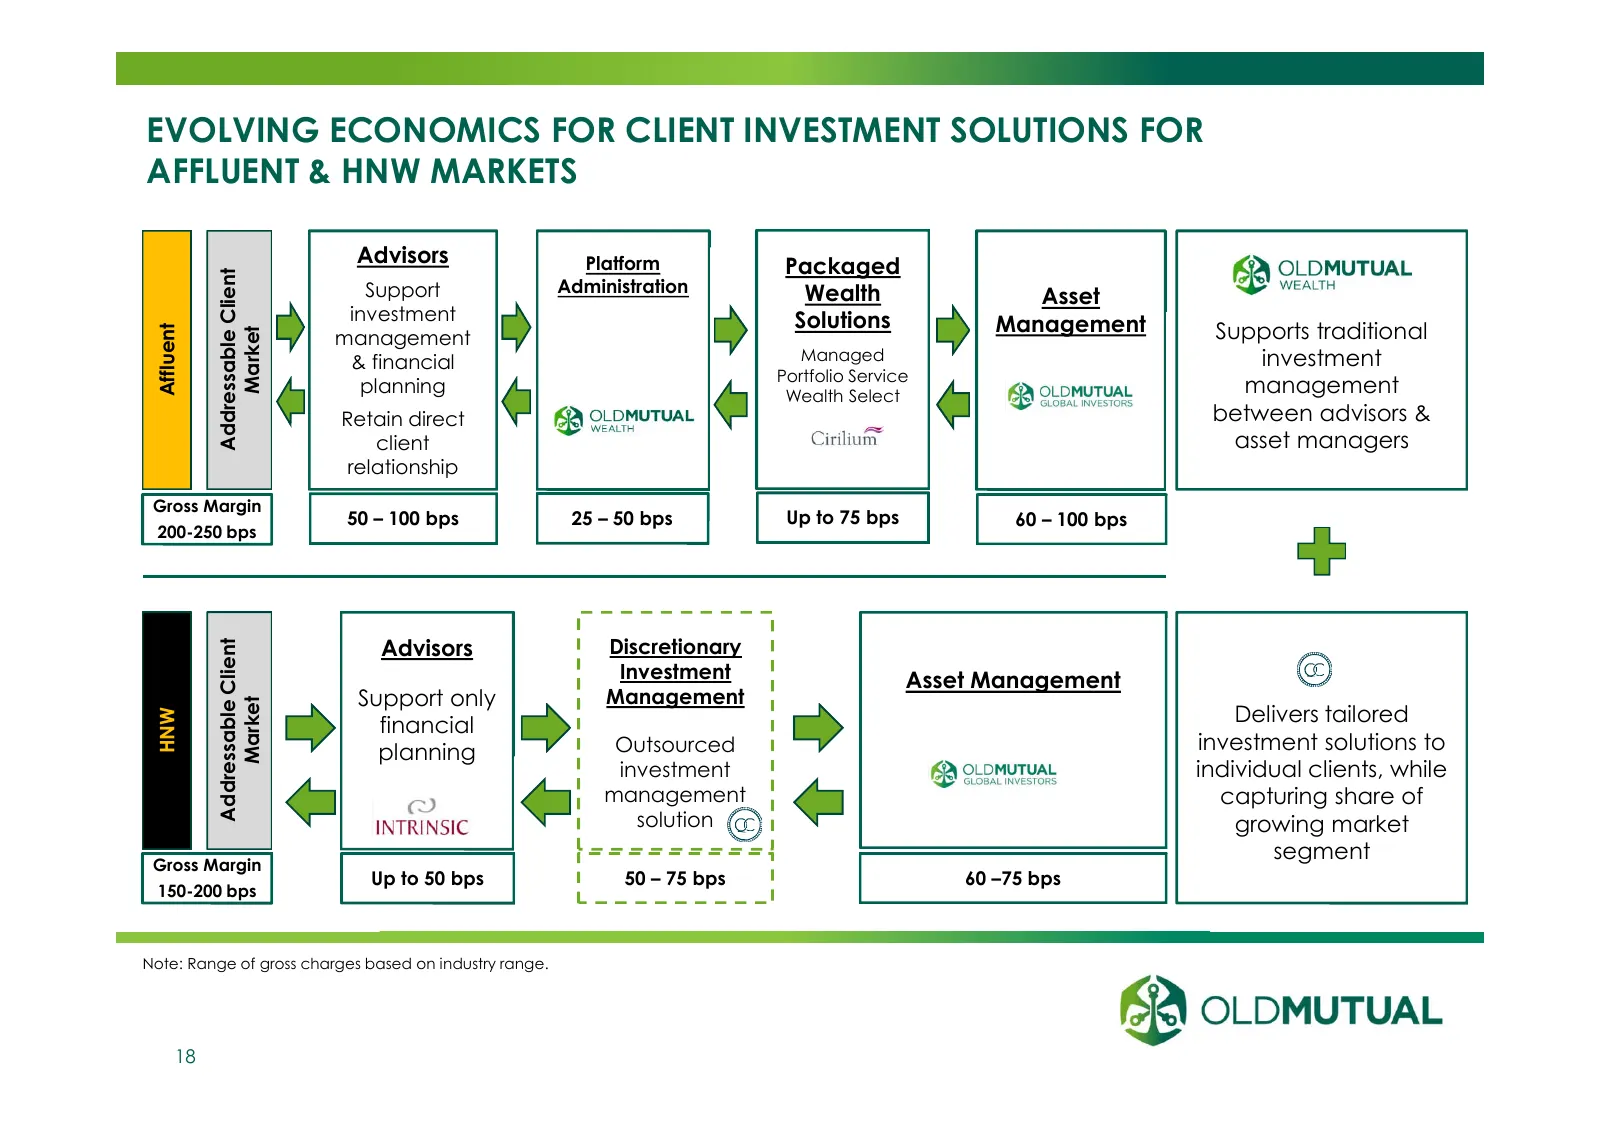
EVOLVING ECONOMICS FOR CLIENT INVESTMENT SOLUTIONS FOR AFFLUENT & HNW MARKETS Advisors Platform Packaged Addressable Client Support Administration Wealth Asset investment Solutions Management Supports traditional Affluent management Market & financial Managed investment Portfolio Service planning We
Slide 19: Integration of Quilter Cheviot into Old Mutual Wealth
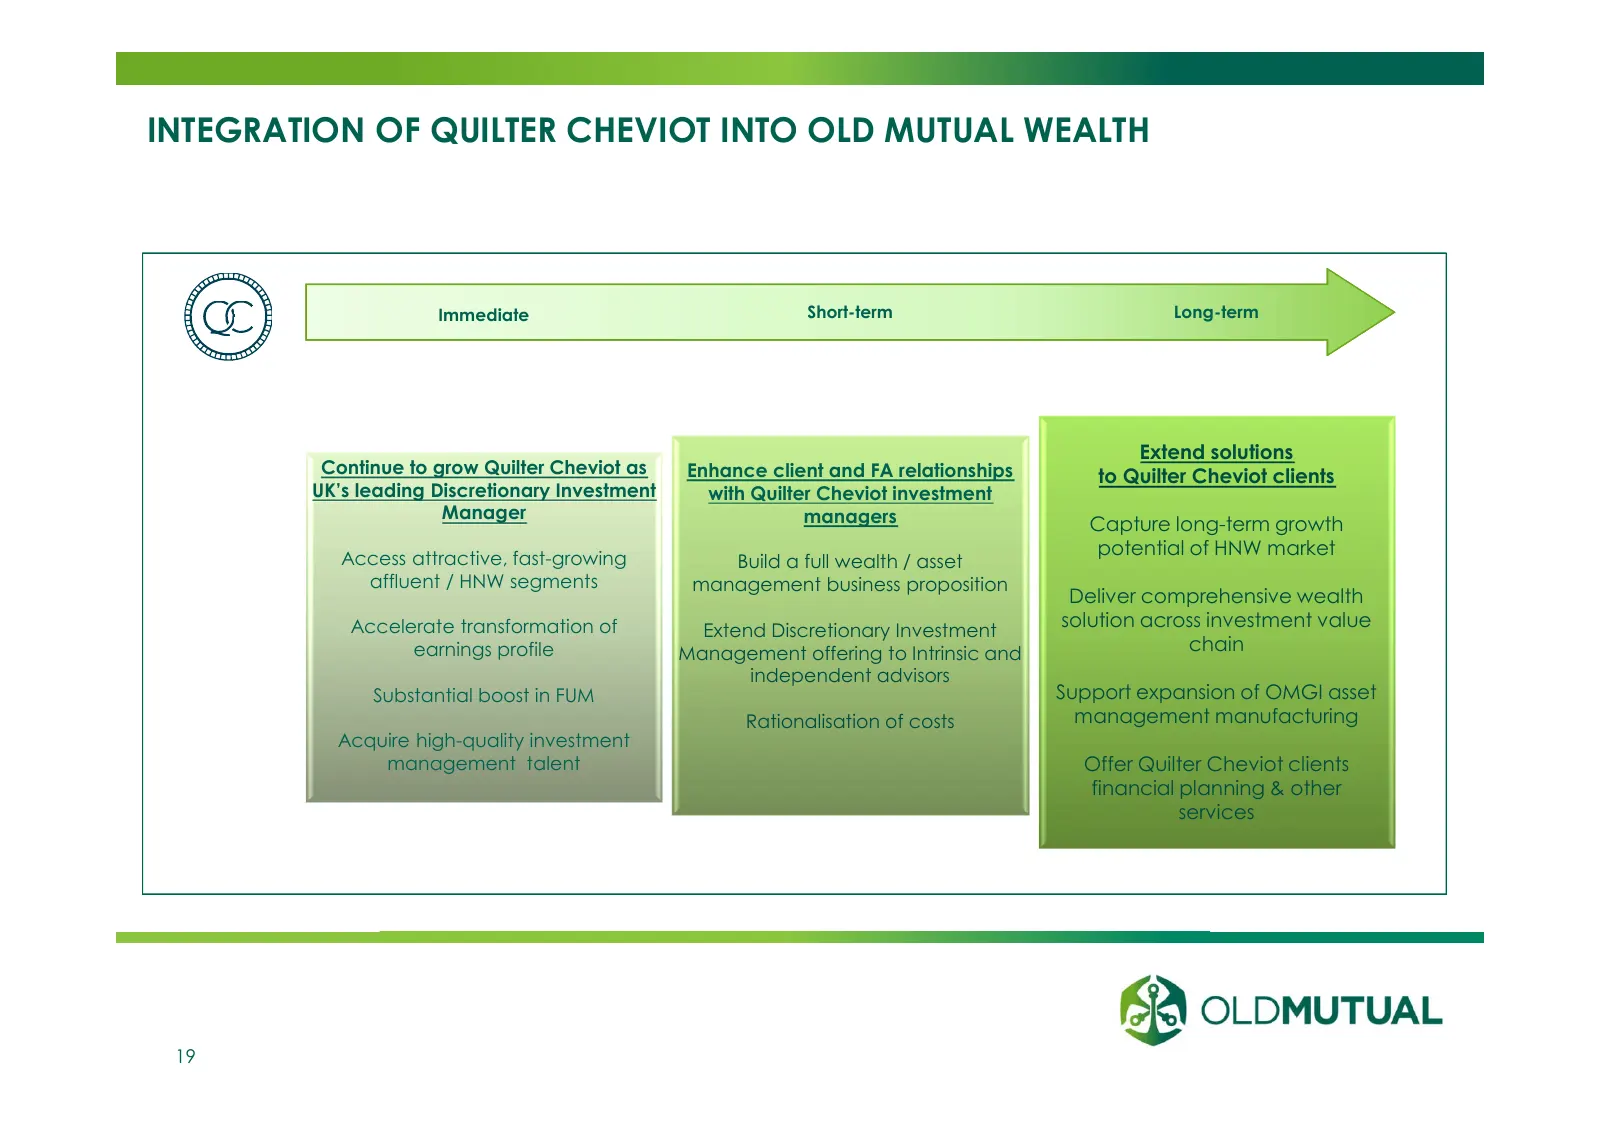
INTEGRATION OF QUILTER CHEVIOT INTO OLD MUTUAL WEALTH Immediate Short-term Long-term Extend solutions Continue to grow Quilter Cheviot as Enhance client and FA relationships to Quilter Cheviot clients UK’s leading Discretionary Investment with Quilter Cheviot investment Manager managers Capture long
Slide 20: Pro Forma Cash and Capital Impact
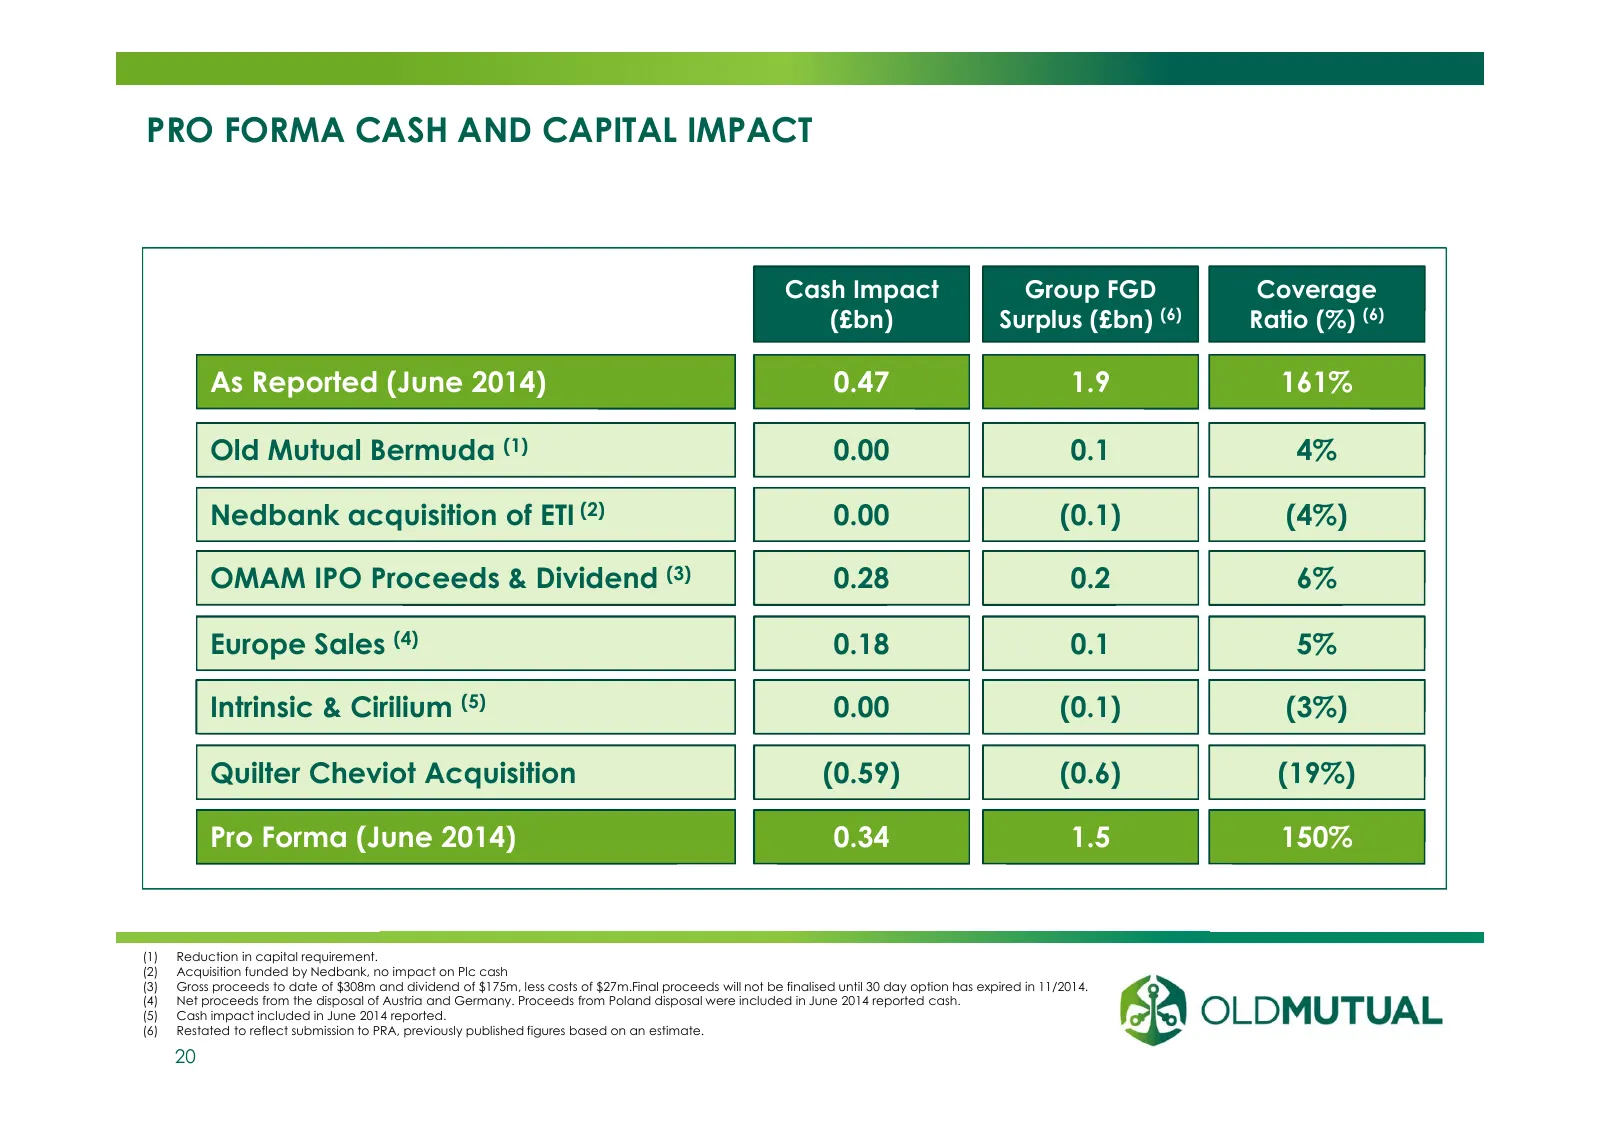
PRO FORMA CASH AND CAPITAL IMPACT Cash Impact Group FGD Coverage (£bn) Surplus (£bn) (6) Ratio (%) (6) As Reported (June 2014) 0.47 1.9 161% Old Mutual Bermuda (1) 0.00 0.1 4% Nedbank acquisition of ETI (2) 0.00 (0.1) (4%) OMAM IPO Proceeds & Dividend (3) 0.28 0.2 6% Europe Sales (4) 0.18 0.1 5% Int
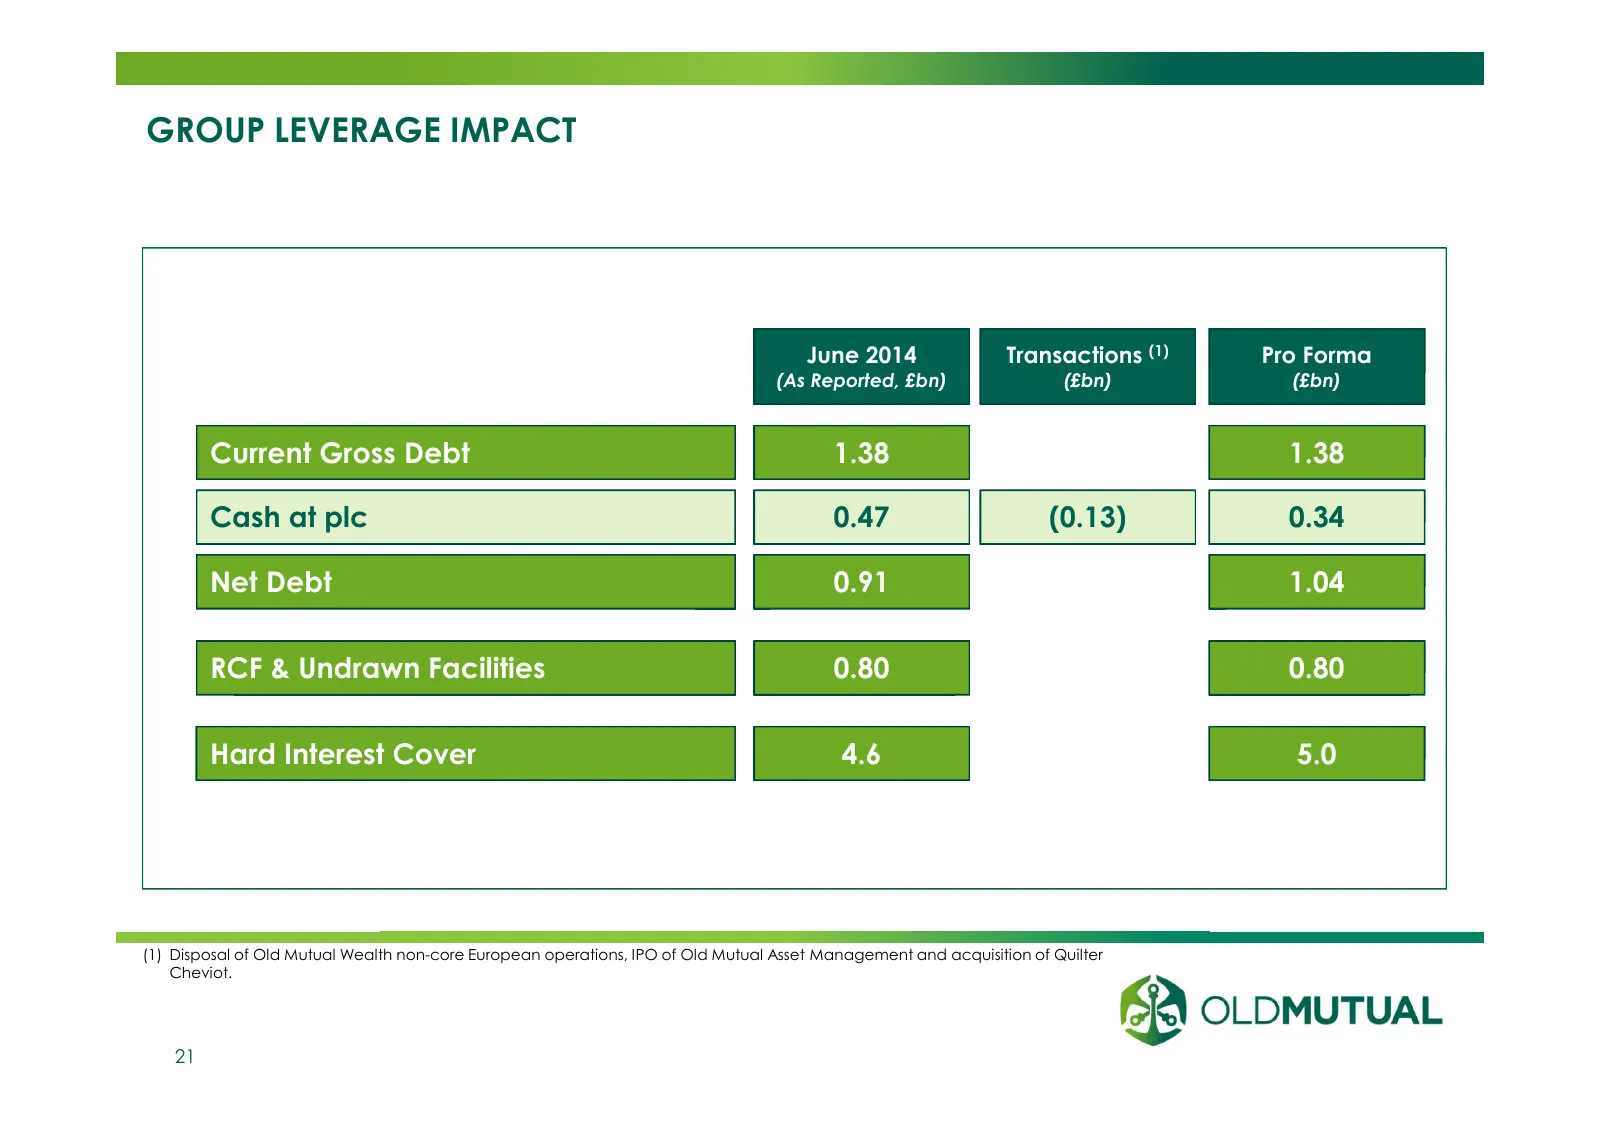
Slide 21: Group Leverage Impact
GROUP LEVERAGE IMPACT June 2014 Transactions (1) Pro Forma (As Reported, £bn) (£bn) (£bn) Current Gross Debt 1.38 1.38 Cash at plc 0.47 (0.13) 0.34 Net Debt 0.91 1.04 RCF & Undrawn Facilities 0.80 0.80 Hard Interest Cover 4.6 5.0 (1) Disposal of Old Mutual Wealth non-core European operations, IPO of
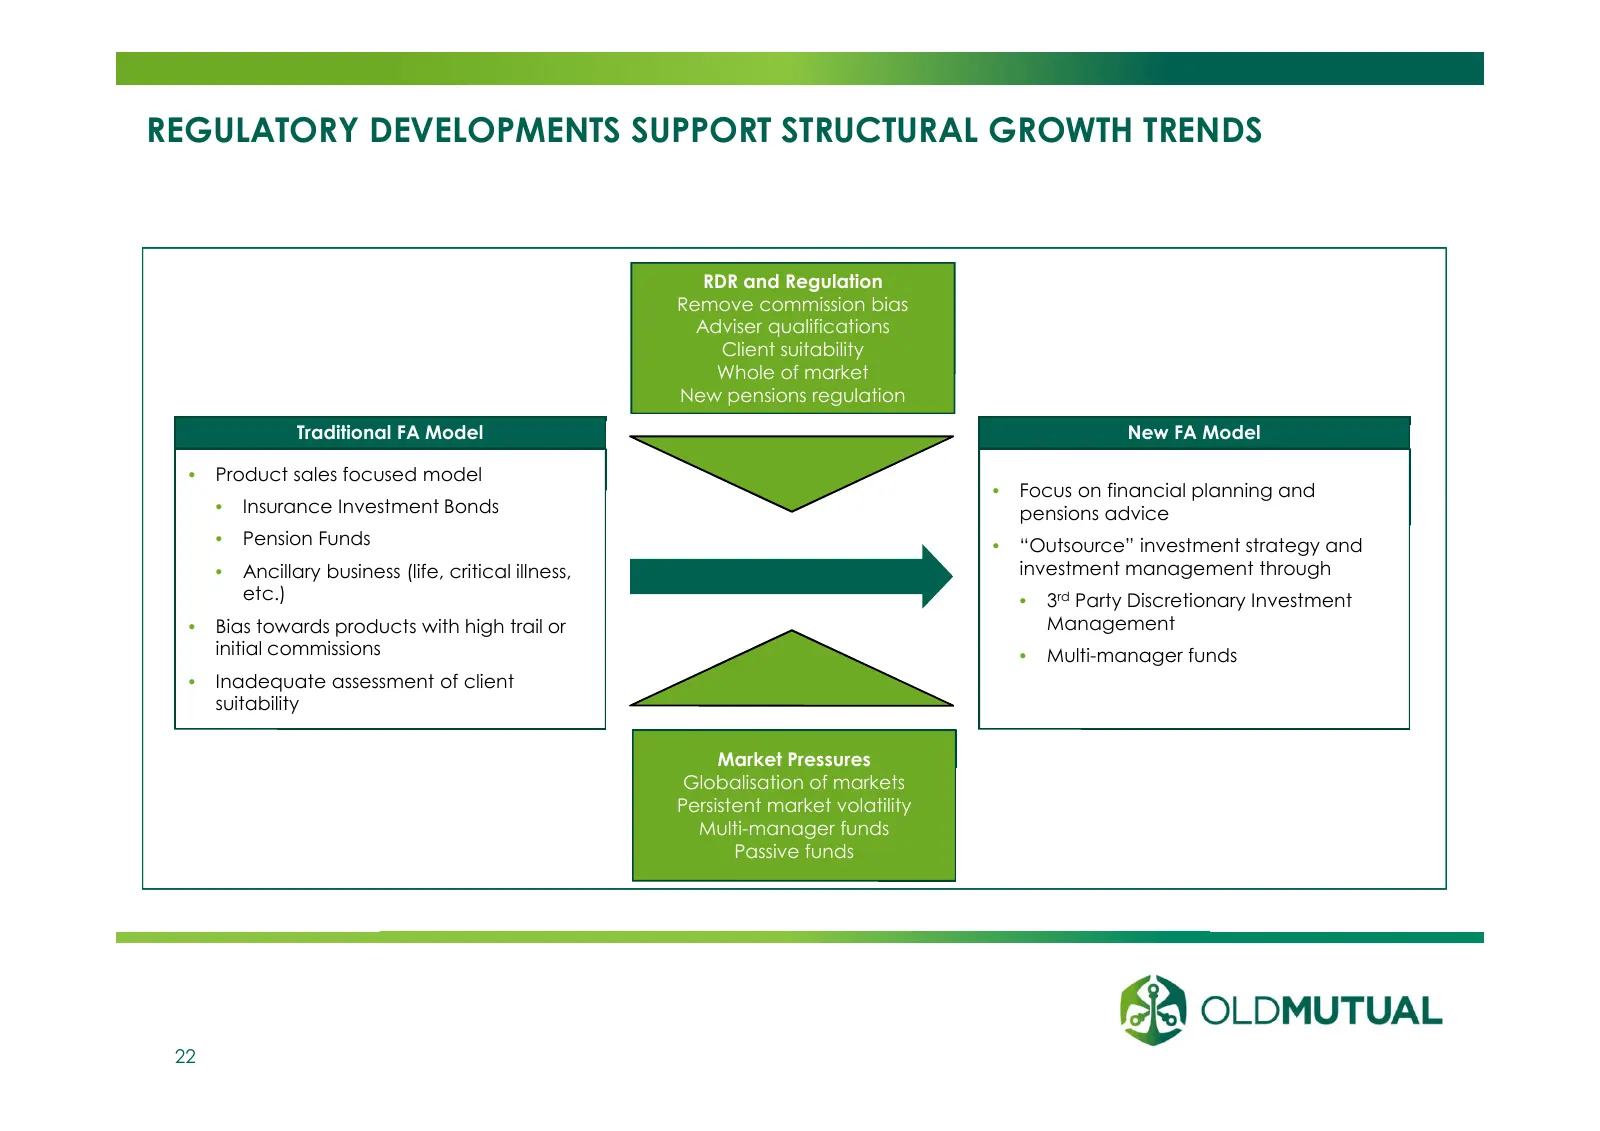
Slide 22: Regulatory Developments Support Structural Growth Trends
REGULATORY DEVELOPMENTS SUPPORT STRUCTURAL GROWTH TRENDS RDR and Regulation Remove commission bias Adviser qualifications Client suitability Whole of market New pensions regulation Traditional FA Model New FA Model • Product sales focused model • Focus on financial planning and • Insurance Investmen
Source: Internet Archive copy of oldmutual.com
More decks from Old Mutual Ltd.
 FY2025 Earnings Presentation46 slides · Oct 12, 2026
 Q2 2026 Earnings Presentation48 slides · Sep 8, 2026
 H1 2025 Earnings Presentation45 slides · Sep 10, 2025
 FY2024 Earnings Presentation40 slides · Mar 18, 2025
 FY2023 Earnings Presentation39 slides · Mar 27, 2024
 H1 2024 Earnings Presentation33 slides · 2024