Ascom Holding AG · SIX:ASCN
Ascom — H1 2014 Earnings Presentation
39 slides from Ascom's earnings presentation, Aug 20, 2014
Slide 1: SPLIT ATLTAA LE |
SPLIT ATLTAA LE | LLL EG Aa HE SIM ITATILLL TT MIL LLTA- DT bef bel Lee Vila \ ee er
Slide 2: PE, EE, DRC i
PE, EE, DRC i WA KA Vv MEET iid Hi CREM hh & TT 177i LEE EUTEN VeutE A: il Li ie ALT LT Pe | CPHTHECEETVNENSAN
Slide 3: Agenda 20 August 2014
[ ] AGENDA 20 AUGUST 2014 Review H1/2014 Financial Statements H1/2014 Outlook Ascom Half-Year Media Conference 2014 3
Slide 4: Strong H2 expected after slow start in H1/2014
STRONG H2 EXPECTED AFTER SLOW START IN H1/2014 Ascom Group Slow start mainly due to fewer large projects and delays of project decisions Positive book-to-bill ratio in both divisions resulting in build-up of order backlog Based on backlog and healthy pipeline much stronger second half-year exp
Slide 5: H2 with much stronger EBITDA anticipated
H2 WITH MUCH STRONGER EBITDA ANTICIPATED Wireless Solutions Division Mixed business performance On-going investments in important growth initiatives such as Ascom Myco and UNITE software suite WS anticipates stronger second half-year with a much stronger EBITDA margin Ascom Half-Year Media Con
Slide 6: Recovery expected after weak H1/2014
RECOVERY EXPECTED AFTER WEAK H1/2014 Network Testing Division Large orders received in H1/2013 could only be partially compensated Asia Pacific: new organization / investments in market recovery NT targets to deliver profitability for the full year 2014 in line with the previous year Ascom Hal
Slide 7: H1 below expectations but market potential intact
H1 BELOW EXPECTATIONS BUT MARKET POTENTIAL INTACT WEAK TOP LINE BUT GOOD ORDER BACKLOG Overall we see neither major fundamental changes nor structural issues in our markets. The good potential in our markets was confirmed. Weaknesses in certain regions have been addressed. Historically Ascom h
Slide 8: Strong second half-year anticipated
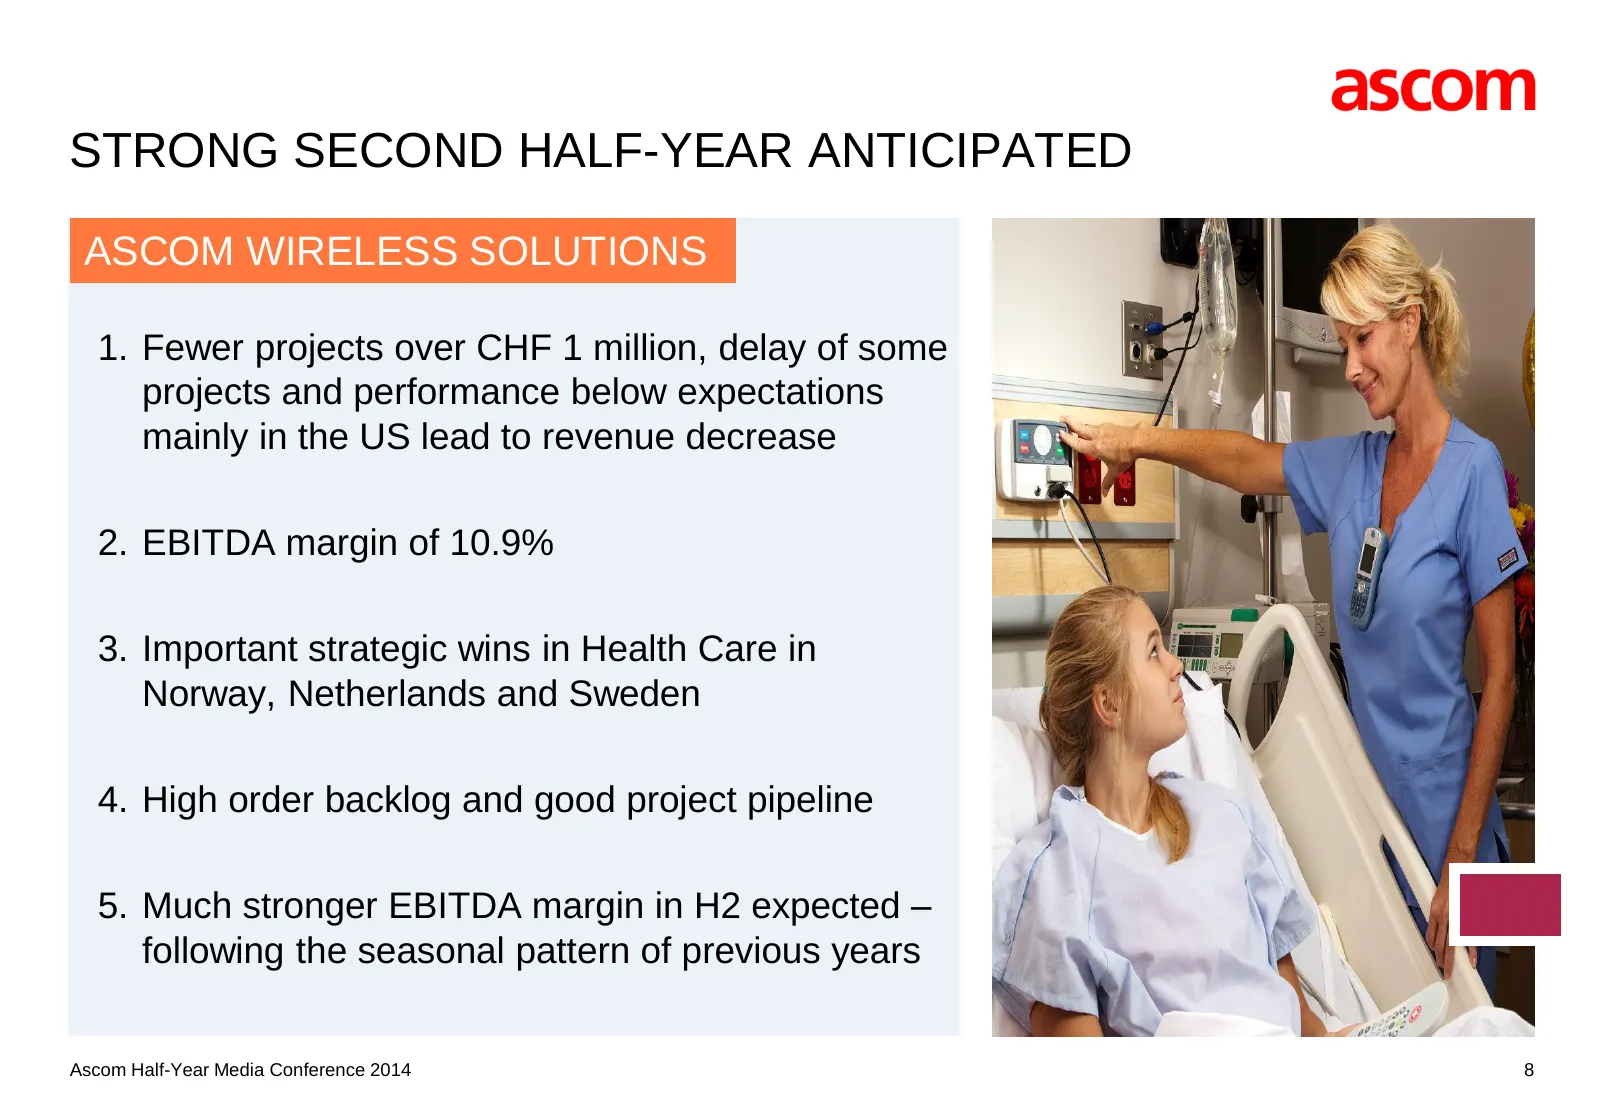
STRONG SECOND HALF-YEAR ANTICIPATED ASCOM WIRELESS SOLUTIONS 1. Fewer projects over CHF 1 million, delay of some projects and performance below expectations mainly in the US lead to revenue decrease 2. EBITDA margin of 10.9% 3. Important strategic wins in Health Care in Norway, Netherlands and Swede
Slide 9: Further investments in growth initiatives
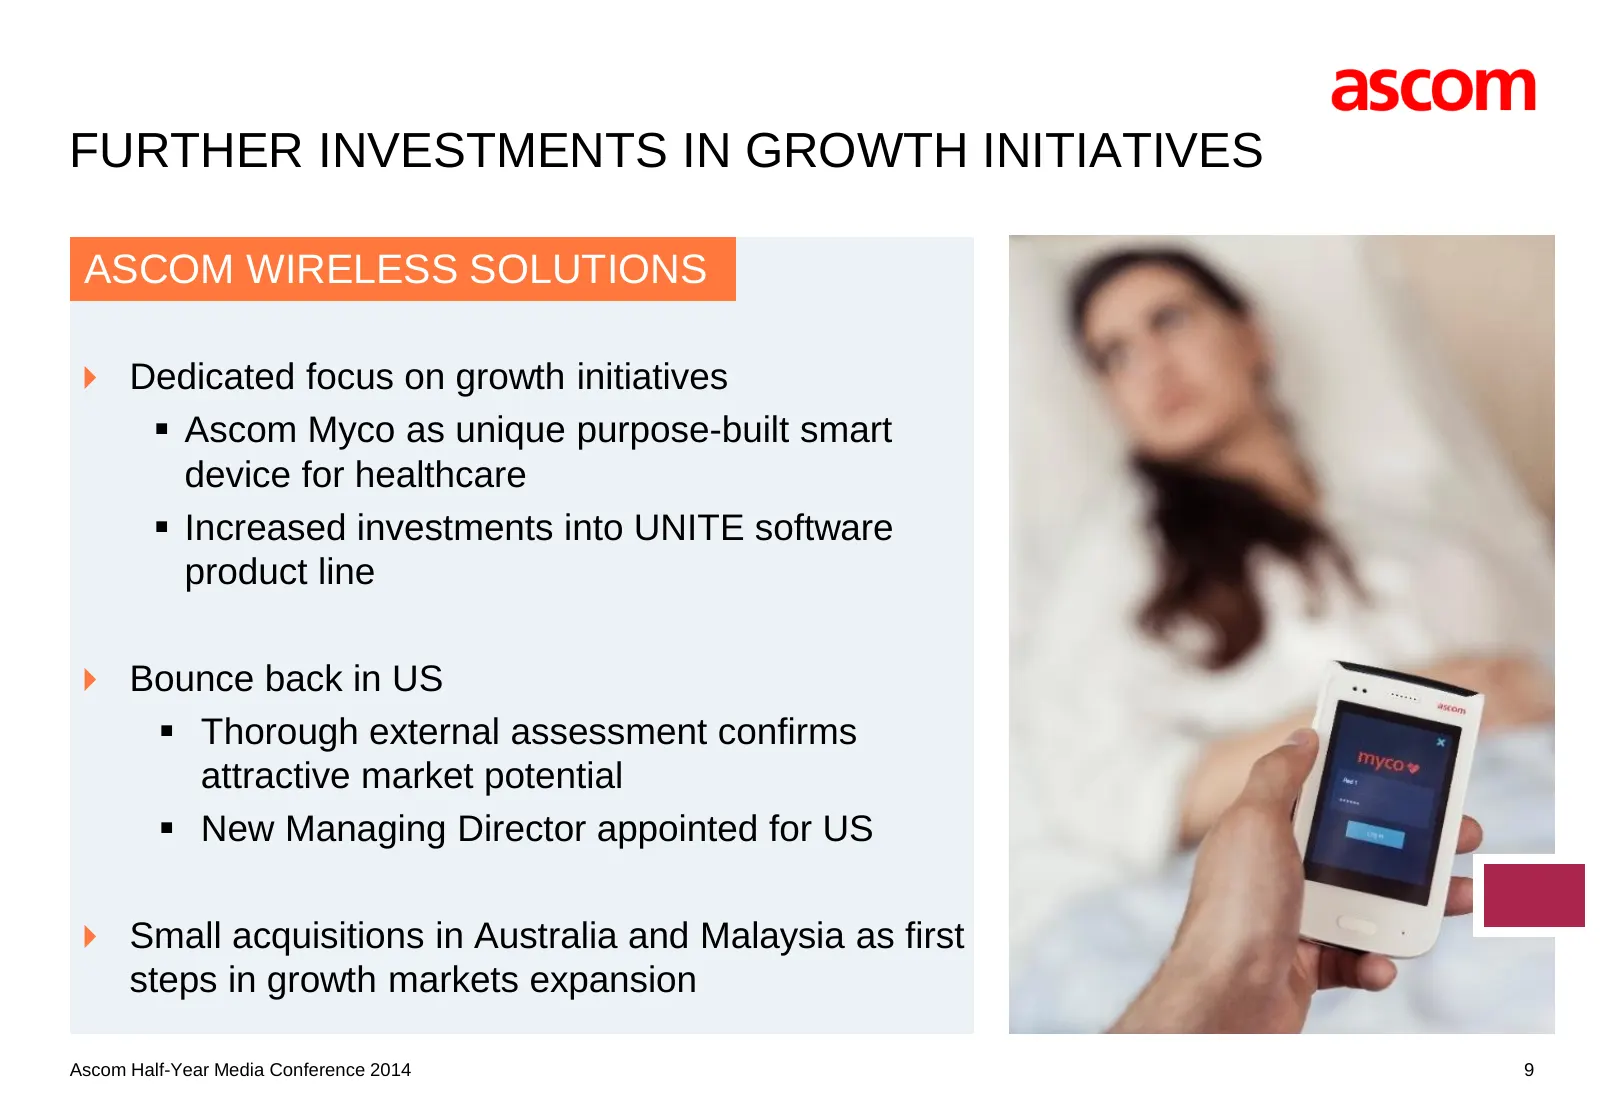
FURTHER INVESTMENTS IN GROWTH INITIATIVES ASCOM WIRELESS SOLUTIONS Dedicated focus on growth initiatives Ascom Myco as unique purpose-built smart device for healthcare Increased investments into UNITE software product line Bounce back in US Thorough external assessment confirms attractive
Slide 10: Challenging first half year
CHALLENGING FIRST HALF YEAR ASCOM NETWORK TESTING 1. Large orders received in H1/2013 could only partially be compensated 2. Large US operators returning to seasonal purchasing pattern 3. EMEA overall on track, but APAC and Latin America below expectations 4. Stable gross margin, but overall lower p
Slide 11: Well positioned to bounce back in H2/2014
WELL POSITIONED TO BOUNCE BACK IN H2/2014 ASCOM NETWORK TESTING Focus on recovery in APAC Assessment confirms capability of Network Testing to recover in APAC Appointment of new Managing Director Dedicated plan to recover implemented Investments in growth initiatives: Development of Capa
Slide 12: Financial Statements H1/2014
[ ] FINANCIAL STATEMENTS H1/2014 BIANKA WILSON Ascom Half-Year Media Conference 2014 12
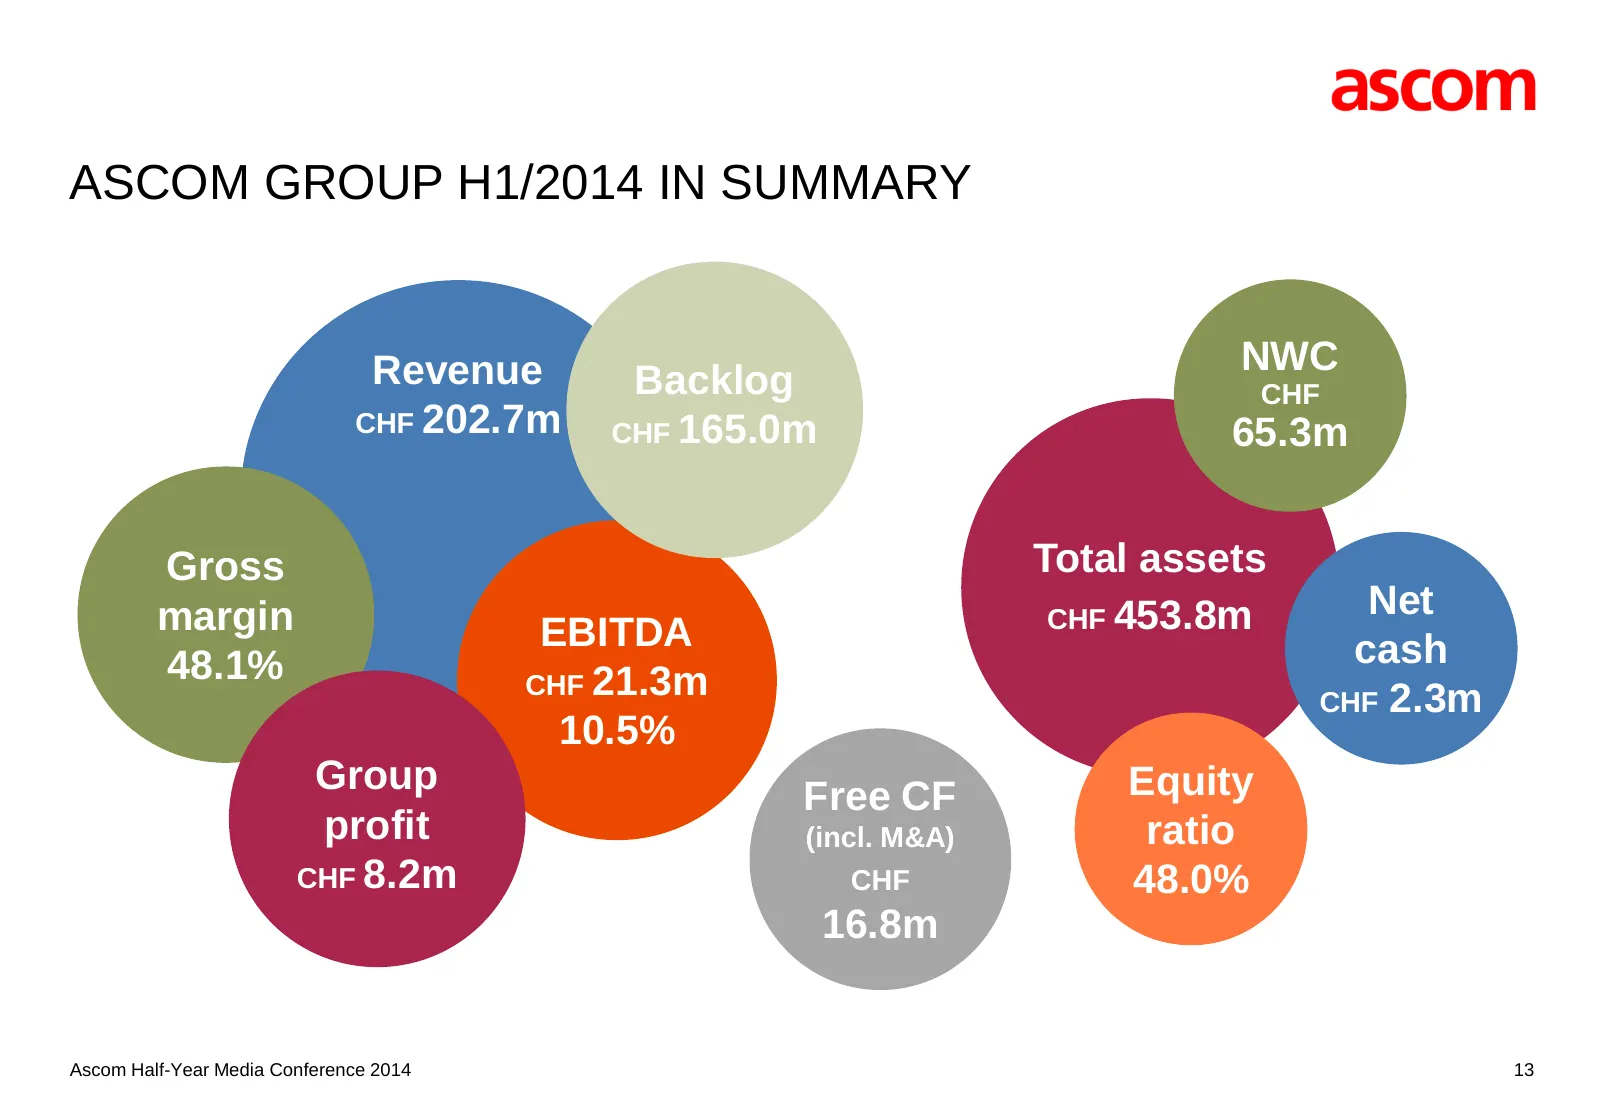
Slide 13: Ascom Group H1/2014 in summary
ASCOM GROUP H1/2014 IN SUMMARY Revenue NWC Backlog CHF CHF 202.7m CHF 165.0m 65.3m Gross Total assets margin CHF 453.8m Net EBITDA cash 48.1% CHF 21.3m CHF 2.3m 10.5% Group Equity Free CF profit (incl. M&A) ratio CHF 8.2m CHF 48.0% 16.8m Ascom Half-Year Media Conference 2014 13
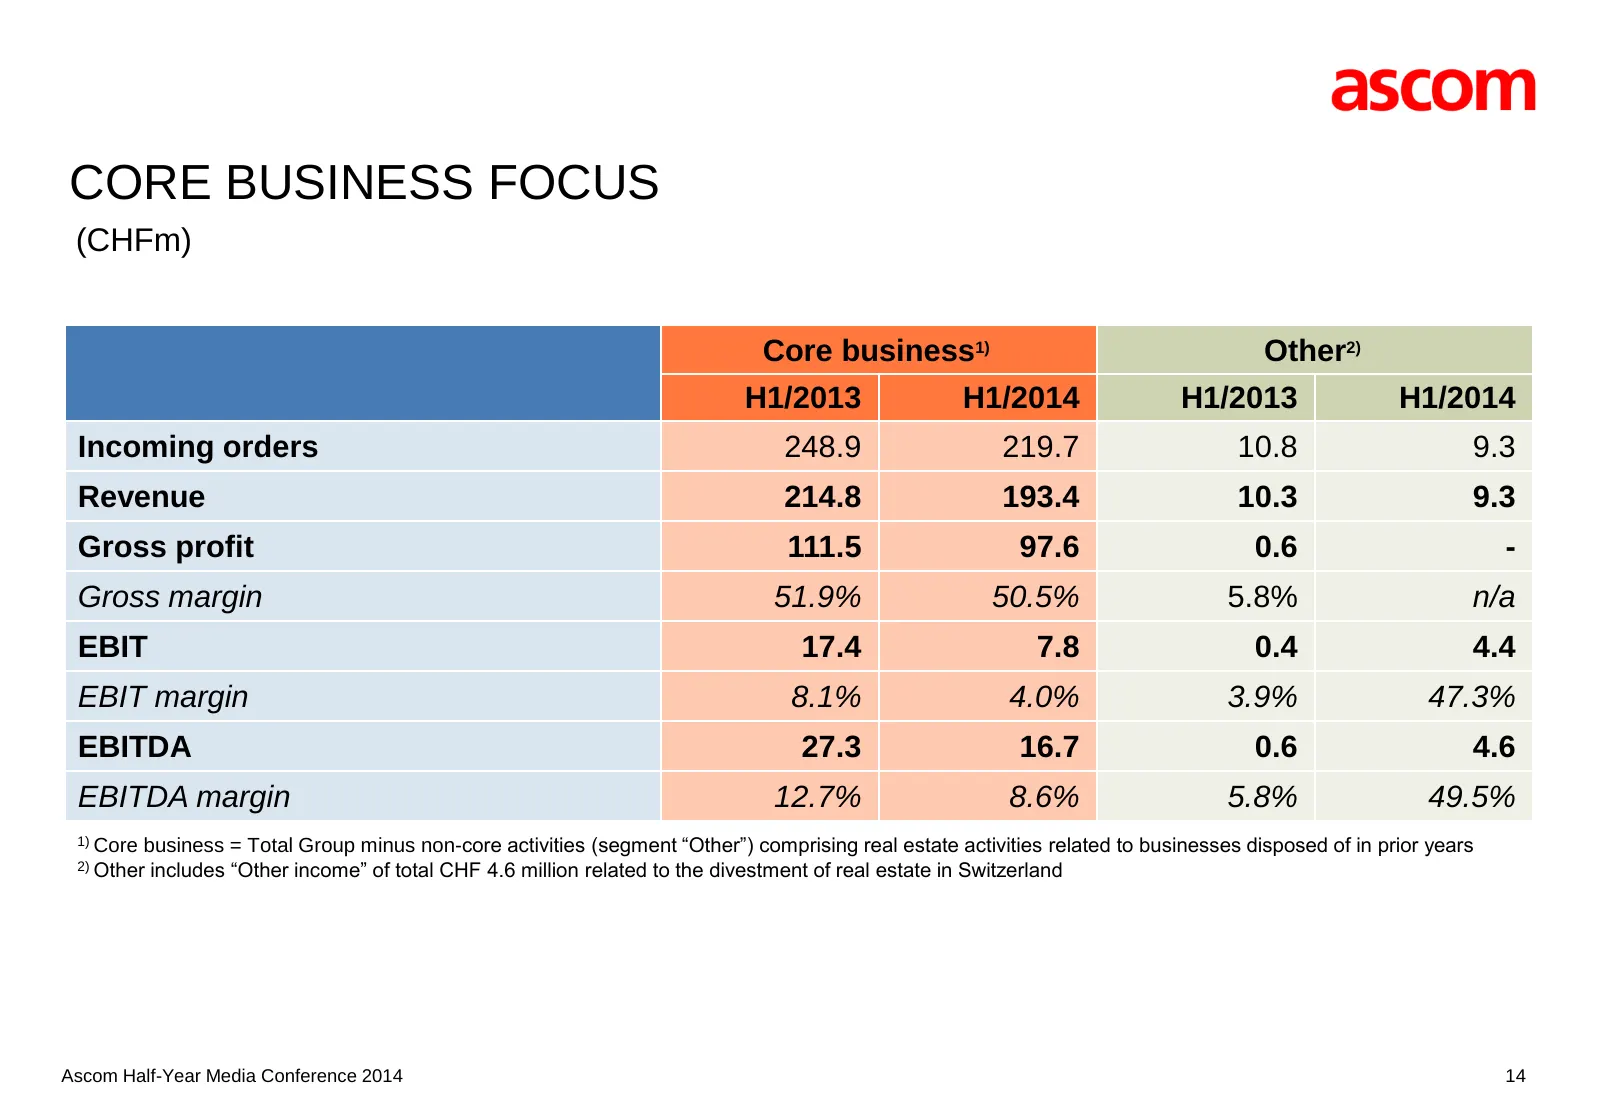
Slide 14: Core business focus
CORE BUSINESS FOCUS (CHFm) Core business1) Other2) H1/2013 H1/2014 H1/2013 H1/2014 Incoming orders 248.9 219.7 10.8 9.3 Revenue 214.8 193.4 10.3 9.3 Gross profit 111.5 97.6 0.6 - Gross margin 51.9% 50.5% 5.8% n/a EBIT 17.4 7.8 0.4 4.4 EBIT margin 8.1% 4.0% 3.9% 47.3% EBITDA 27.3 16.7 0.6 4.6 EBITDA
Slide 15: Wireless Solutions H1/2014 performance overview
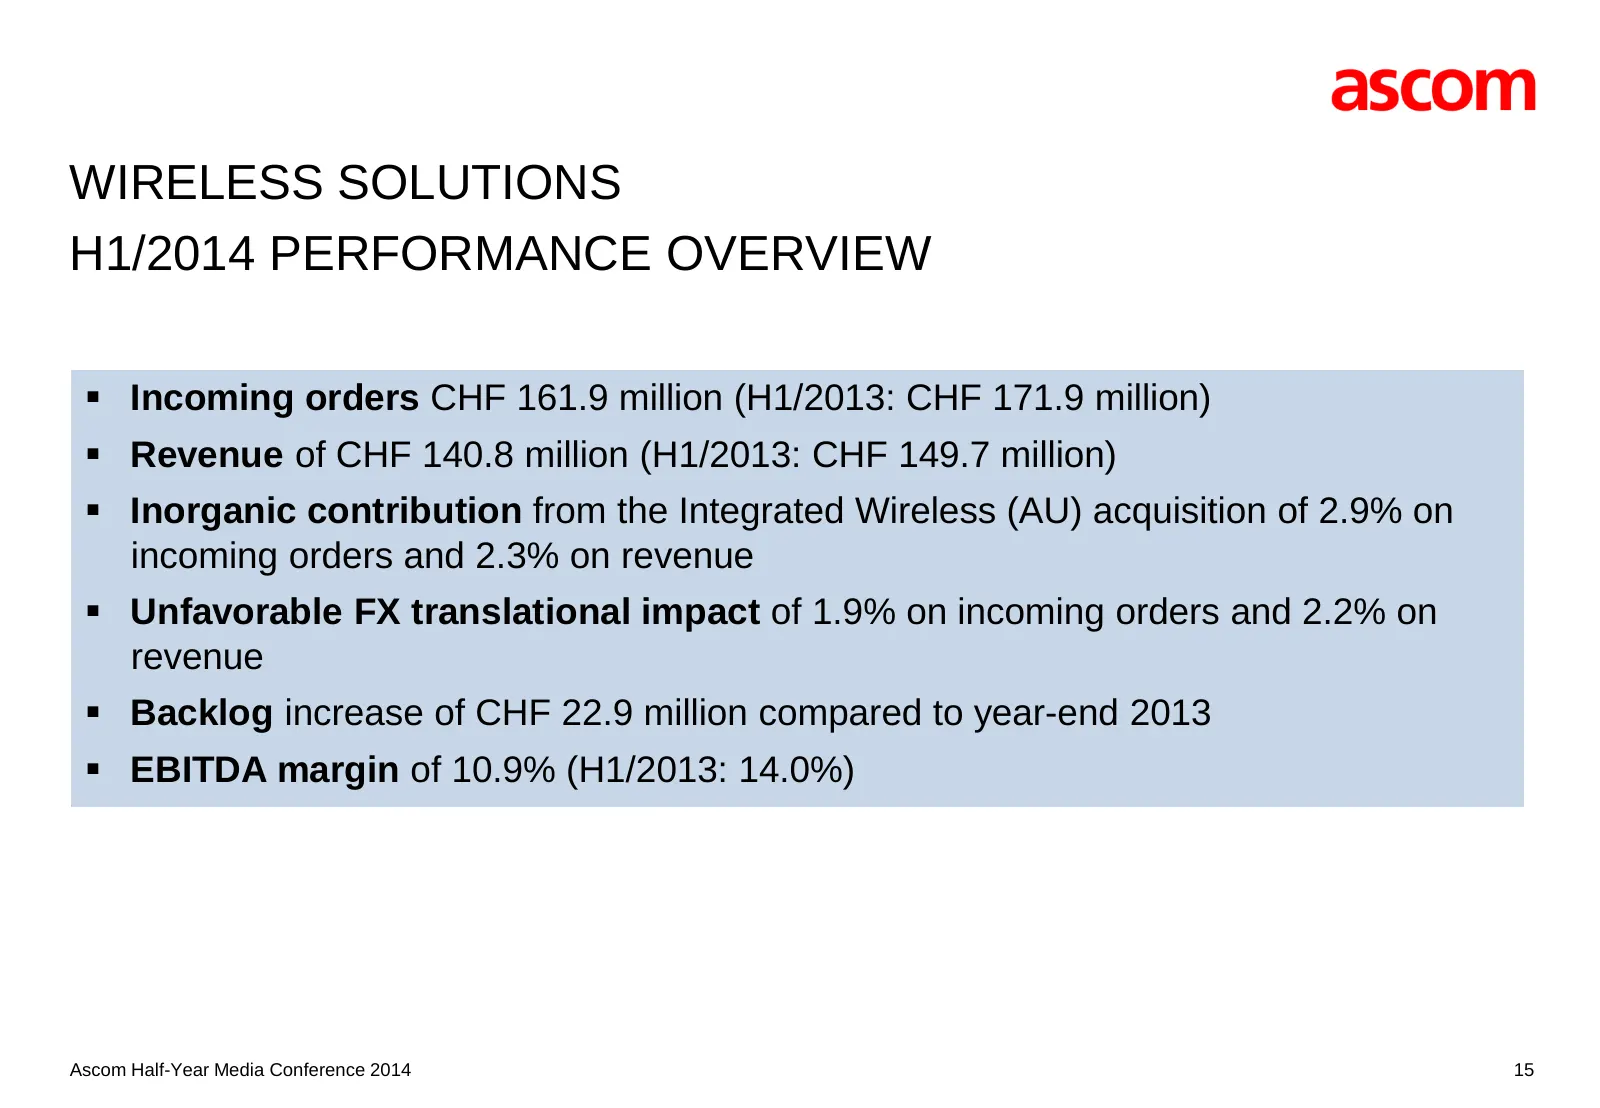
WIRELESS SOLUTIONS H1/2014 PERFORMANCE OVERVIEW Incoming orders CHF 161.9 million (H1/2013: CHF 171.9 million) Revenue of CHF 140.8 million (H1/2013: CHF 149.7 million) Inorganic contribution from the Integrated Wireless (AU) acquisition of 2.9% on incoming orders and 2.3% on revenue Unfavor
Slide 16: Network Testing H1/2014 performance overview
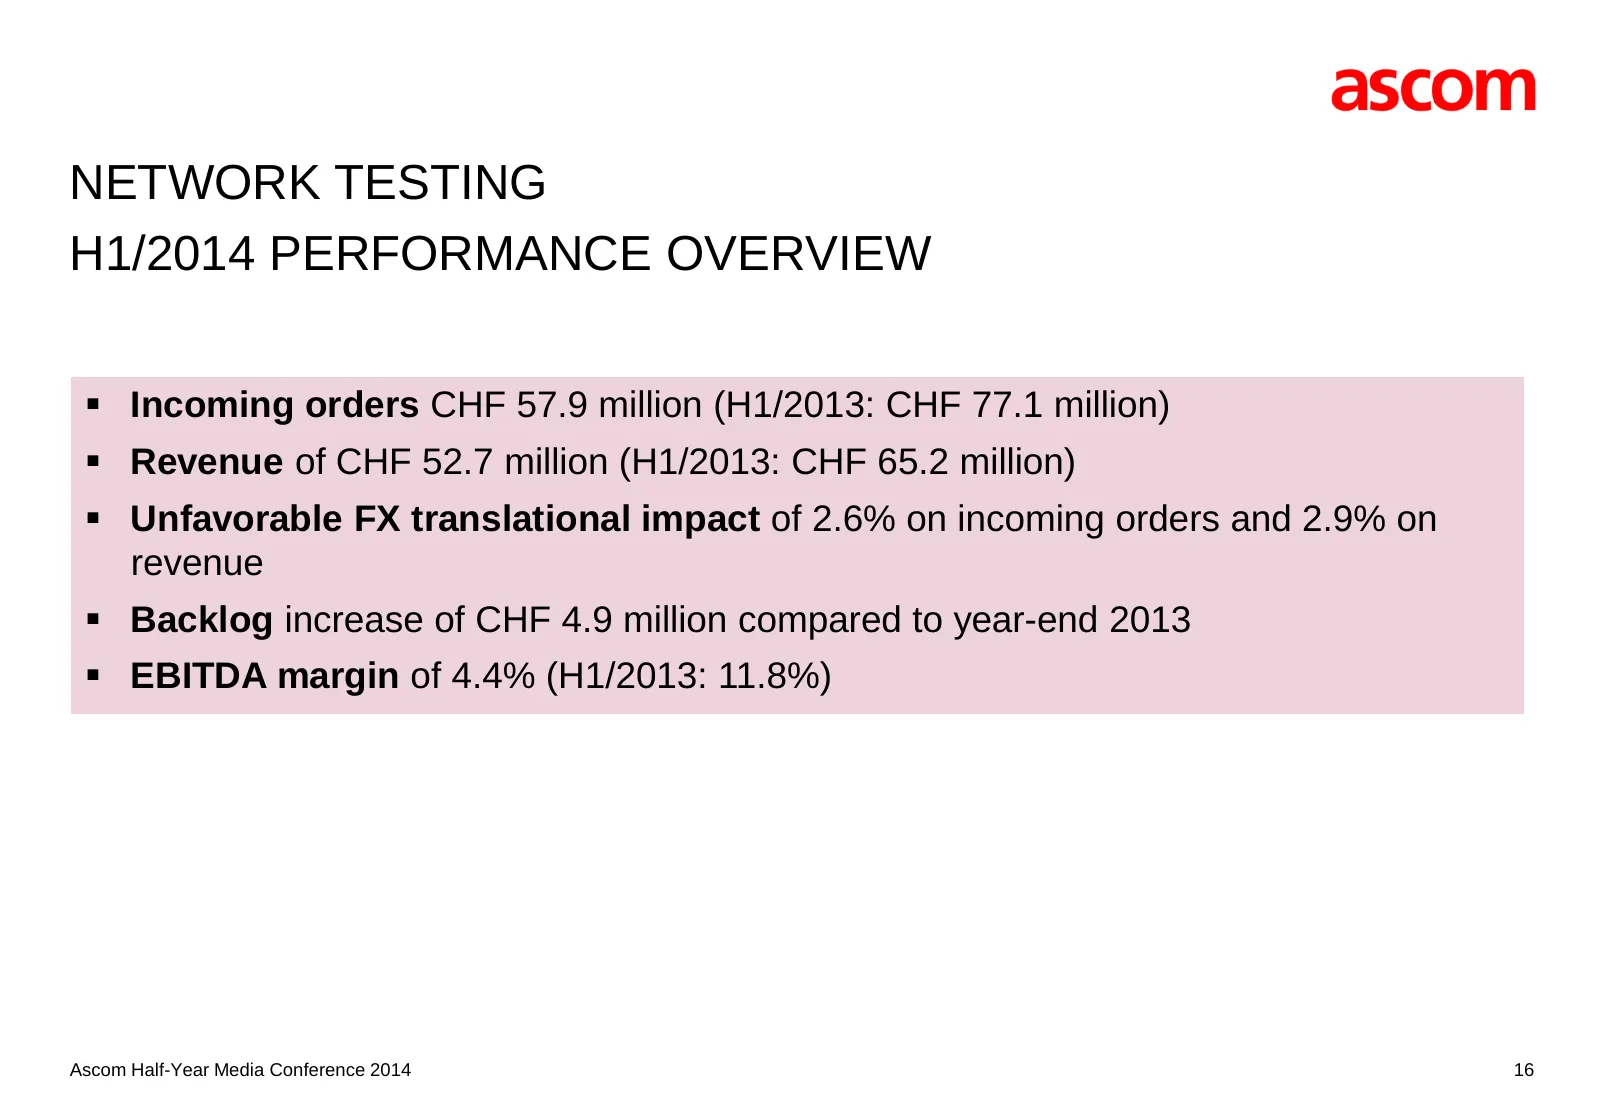
NETWORK TESTING H1/2014 PERFORMANCE OVERVIEW Incoming orders CHF 57.9 million (H1/2013: CHF 77.1 million) Revenue of CHF 52.7 million (H1/2013: CHF 65.2 million) Unfavorable FX translational impact of 2.6% on incoming orders and 2.9% on revenue Backlog increase of CHF 4.9 million compared to
Slide 17: Continued backlog build
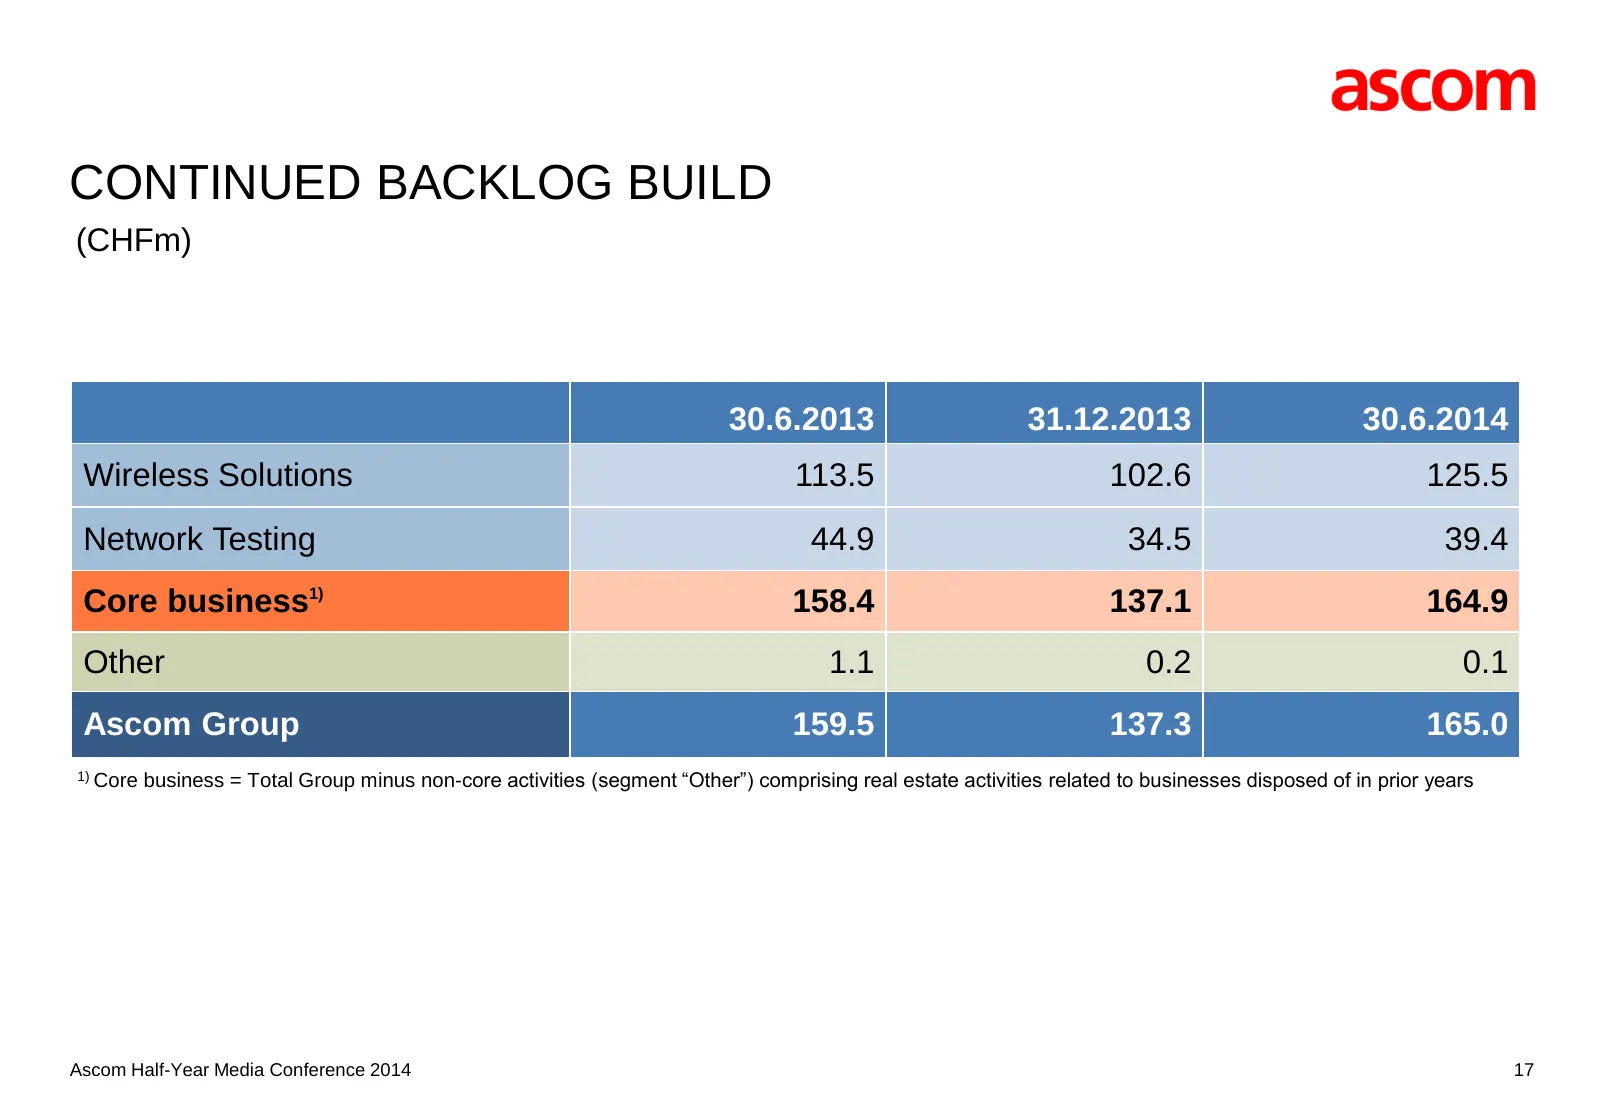
CONTINUED BACKLOG BUILD (CHFm) 30.6.2013 31.12.2013 30.6.2014 Wireless Solutions 113.5 102.6 125.5 Network Testing 44.9 34.5 39.4 Core business1) 158.4 137.1 164.9 Other 1.1 0.2 0.1 Ascom Group 159.5 137.3 165.0 1) Core business = Total Group minus non-core activities (segment “Other”) comprising re
Slide 18: EBITDA reflects volume decrease and cost savings
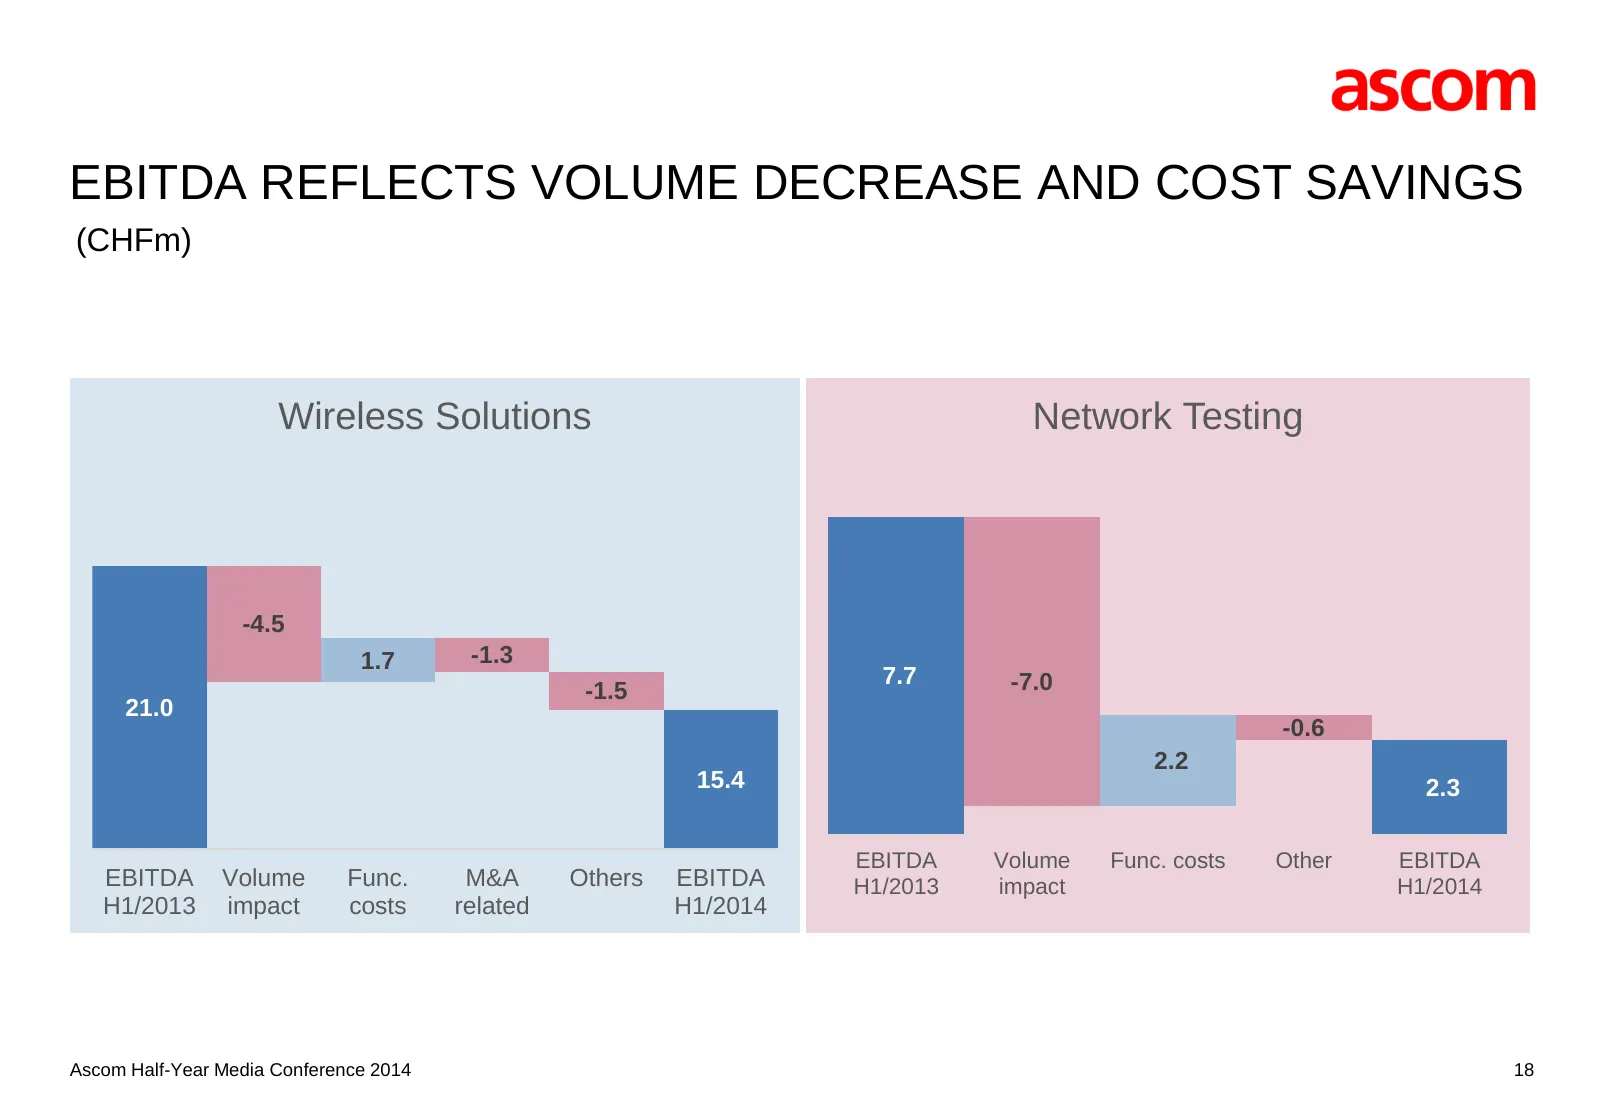
EBITDA REFLECTS VOLUME DECREASE AND COST SAVINGS (CHFm) Wireless Solutions Network Testing -4.5 1.7 -1.3 7.7 -7.0 -1.5 21.0 -0.6 2.2 15.4 2.3 EBITDA Volume Func. costs Other EBITDA EBITDA Volume Func. M&A Others EBITDA H1/2013 impact H1/2014 H1/2013 impact costs related H1/2014 Ascom Half-Year Media
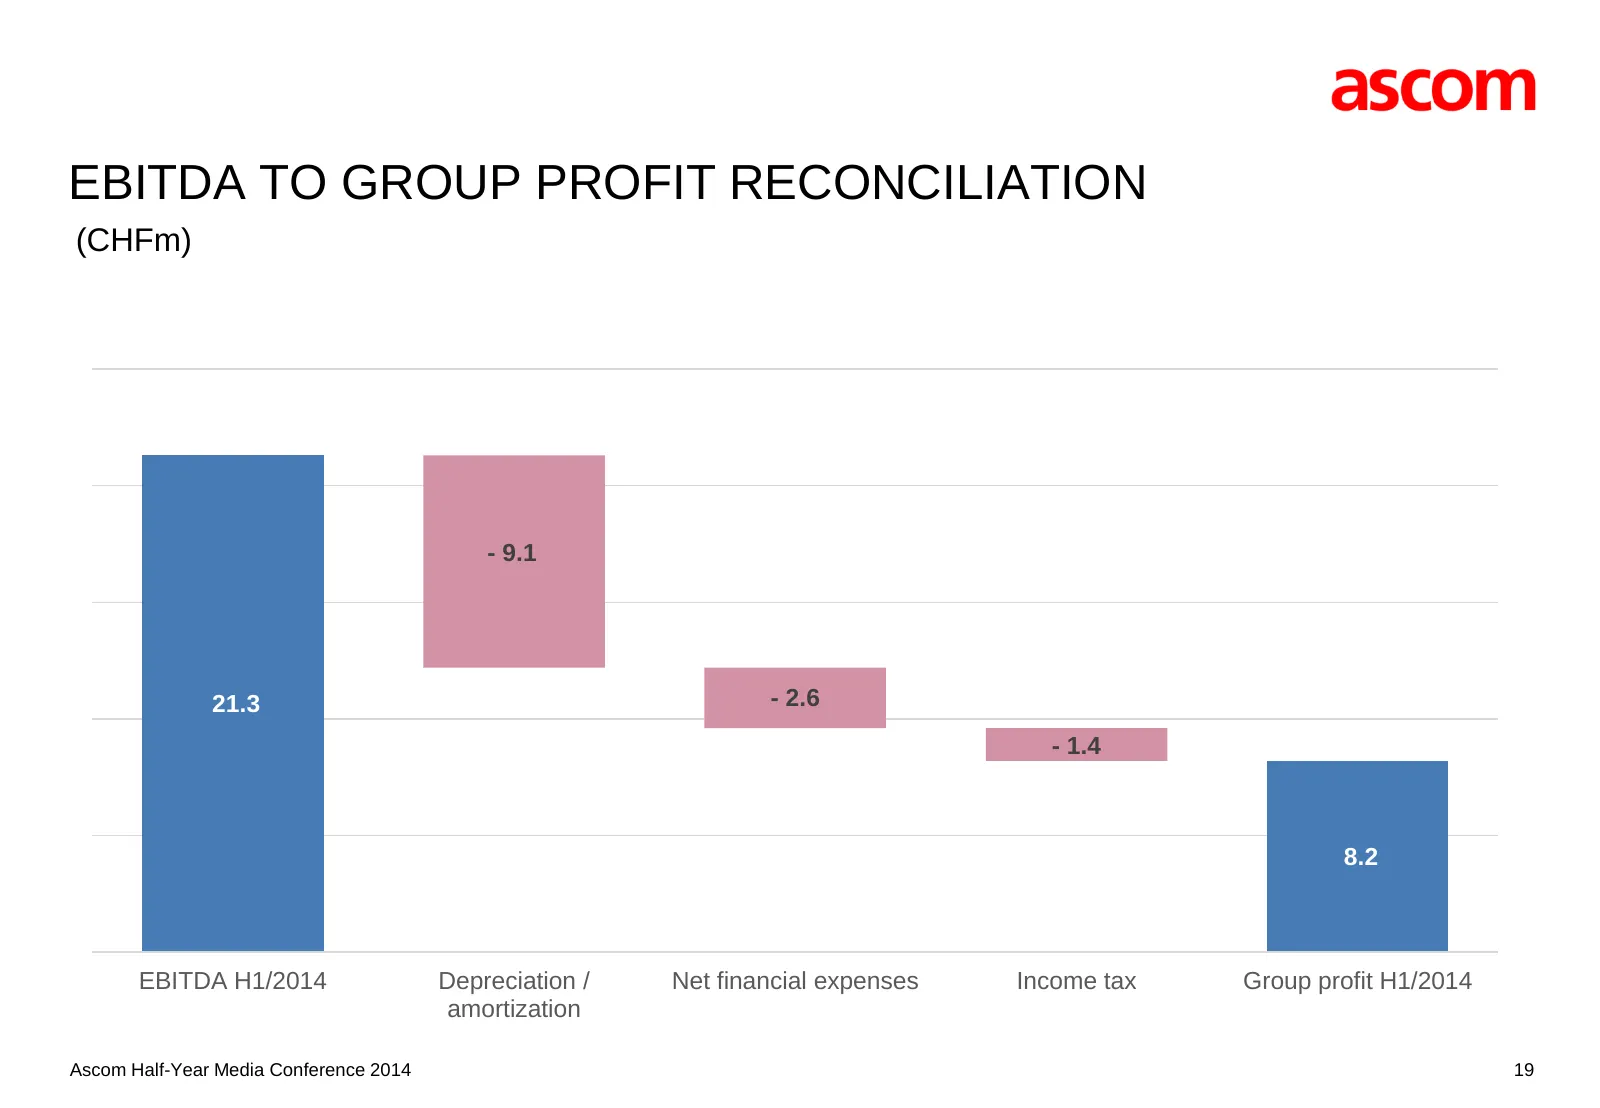
Slide 19: EBITDA to group profit reconciliation
EBITDA TO GROUP PROFIT RECONCILIATION (CHFm) - 9.1 21.3 - 2.6 - 1.4 8.2 EBITDA H1/2014 Depreciation / Net financial expenses Income tax Group profit H1/2014 amortization Ascom Half-Year Media Conference 2014 19
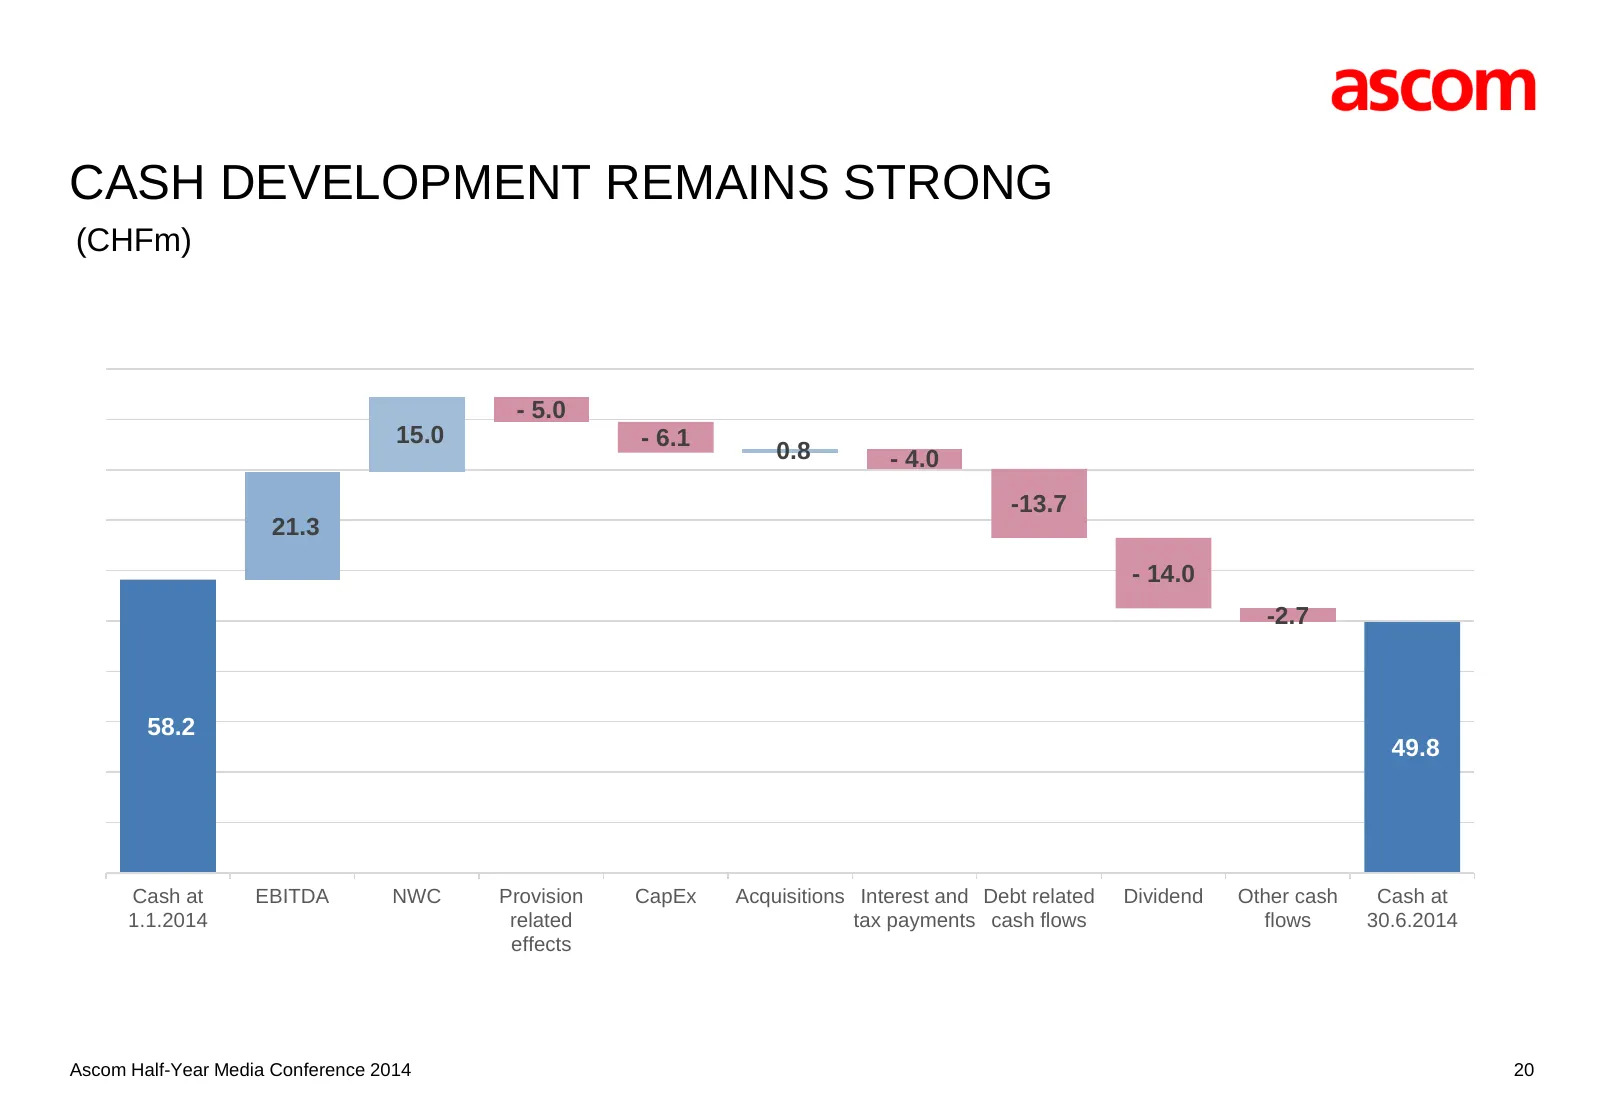
Slide 20: Cash development remains strong
CASH DEVELOPMENT REMAINS STRONG (CHFm) - 5.0 15.0 - 6.1 0.8 - 4.0 -13.7 21.3 - 14.0 -2.7 58.2 49.8 Cash at EBITDA NWC Provision CapEx Acquisitions Interest and Debt related Dividend Other cash Cash at 1.1.2014 related tax payments cash flows flows 30.6.2014 effects Ascom Half-Year Media Conference 2
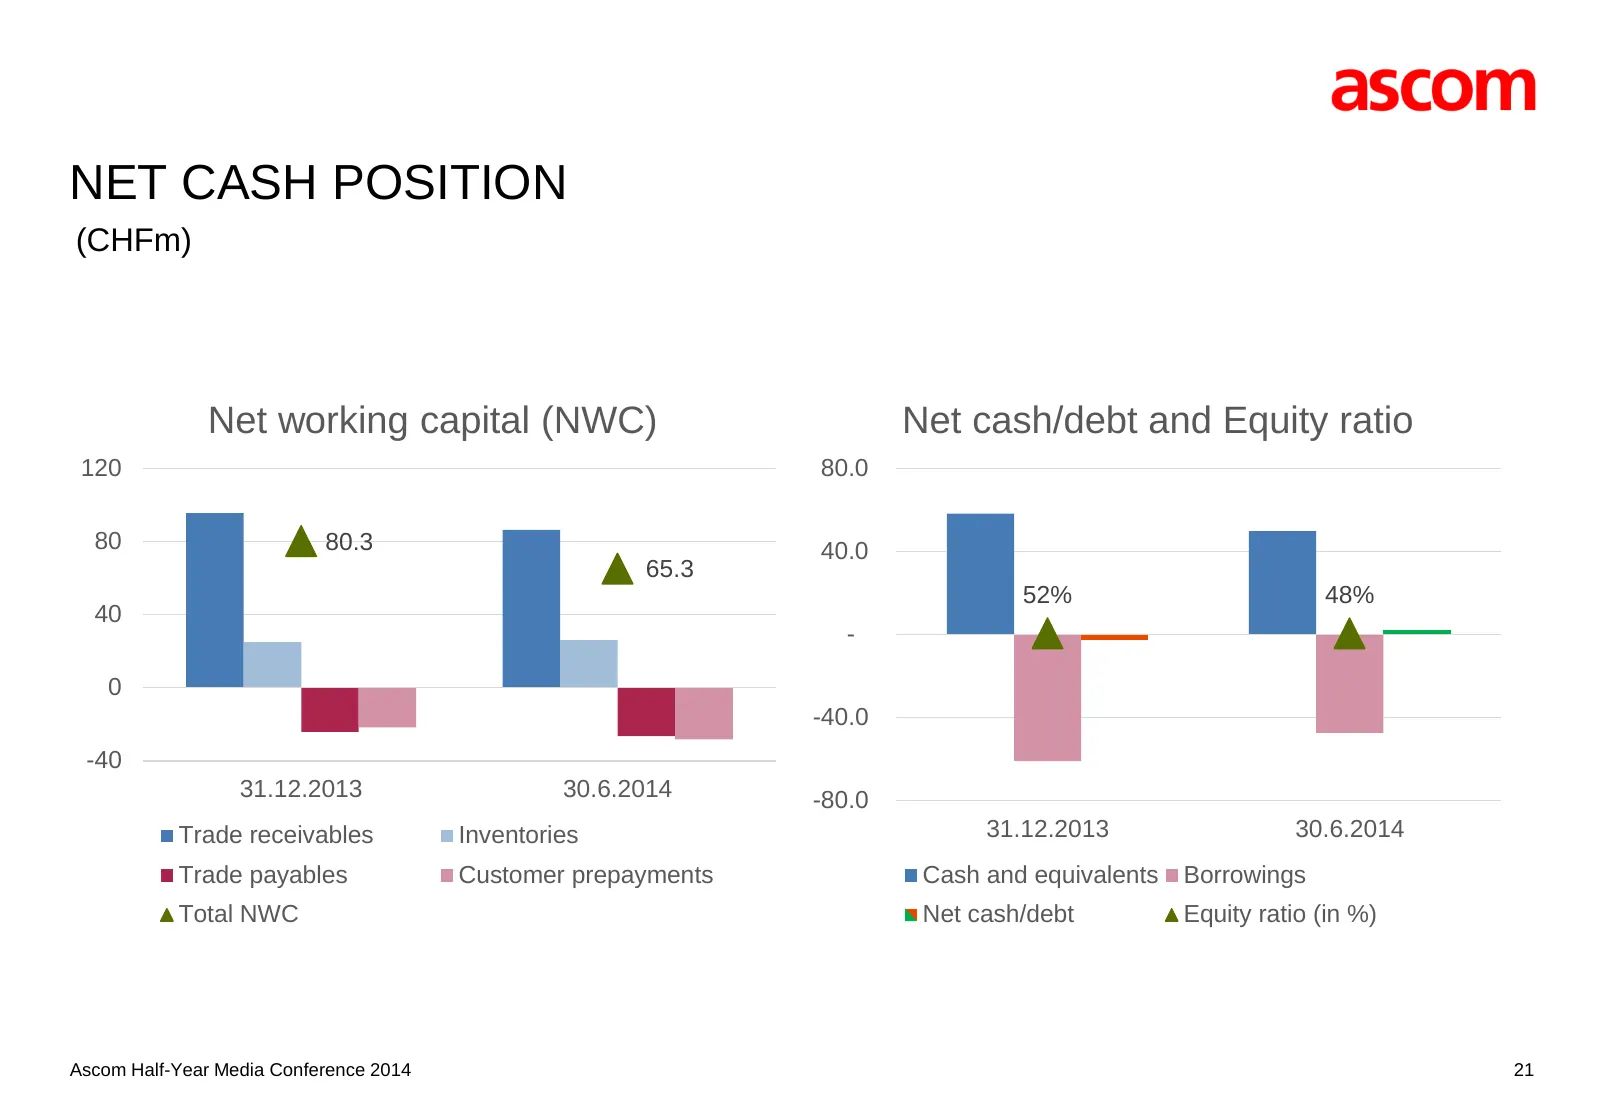
Slide 21: Net cash position
NET CASH POSITION (CHFm) Net working capital (NWC) Net cash/debt and Equity ratio 120 80.0 80 80.3 40.0 65.3 52% 48% 40 - 0 -40.0 -40 31.12.2013 30.6.2014 -80.0 Trade receivables Inventories 31.12.2013 30.6.2014 Trade payables Customer prepayments Cash and equivalents Borrowings Total NWC Net cash/d
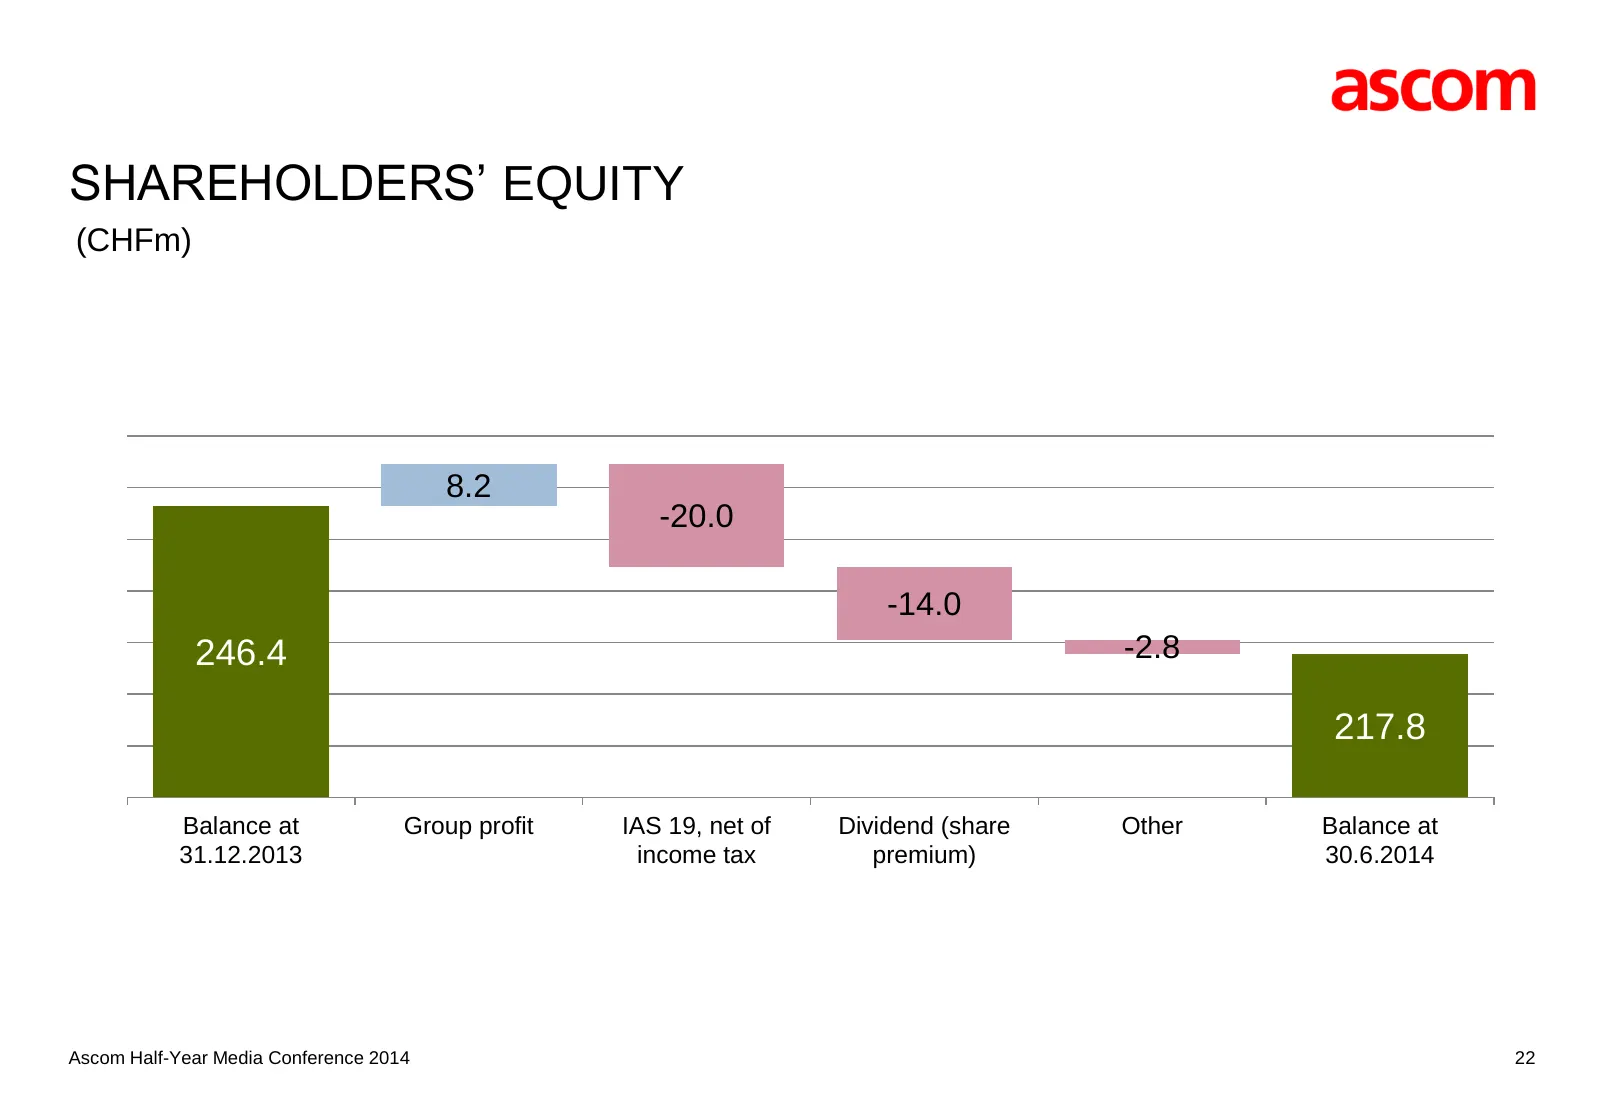
Slide 22: Shareholders' equity
SHAREHOLDERS’ EQUITY (CHFm) 8.2 -20.0 234.6 -14.0 246.4 -2.8 217.8 Balance at Group profit IAS 19, net of Dividend (share Other Balance at 31.12.2013 income tax premium) 30.6.2014 Ascom Half-Year Media Conference 2014 22
Slide 23: Outlook
[ ] OUTLOOK FRITZ MUMENTHALER Ascom Half-Year Media Conference 2014 23
Slide 24: Ascom Wireless Solutions
[ ] ASCOM WIRELESS SOLUTIONS Ascom Half-Year Media Conference 2014 24
Slide 25: The power of one – improving workflow management
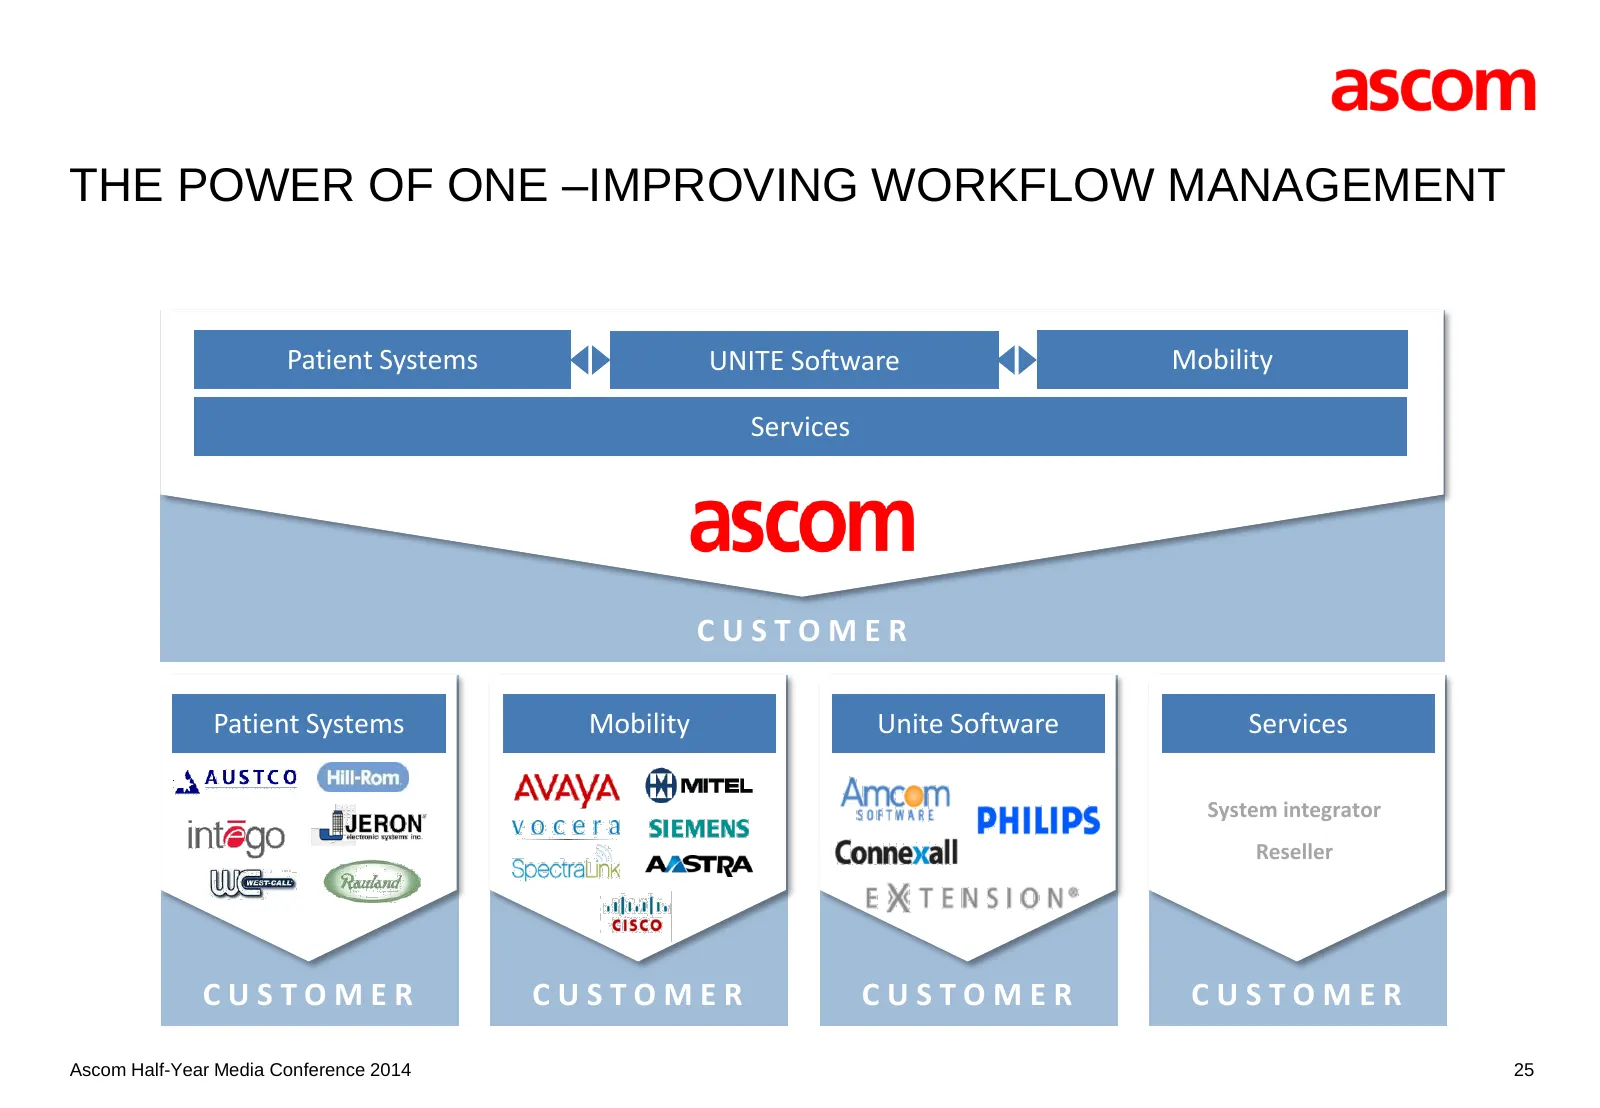
THE POWER OF ONE –IMPROVING WORKFLOW MANAGEMENT Patient Systems UNITE Software Mobility Services CUSTOMER Patient Systems Mobility Unite Software Services System integrator Reseller CUSTOMER CUSTOMER CUSTOMER CUSTOMER Ascom Half-Year Media Conference 2014 25
Slide 26: Ascom UNITE – the core of integrated workflow
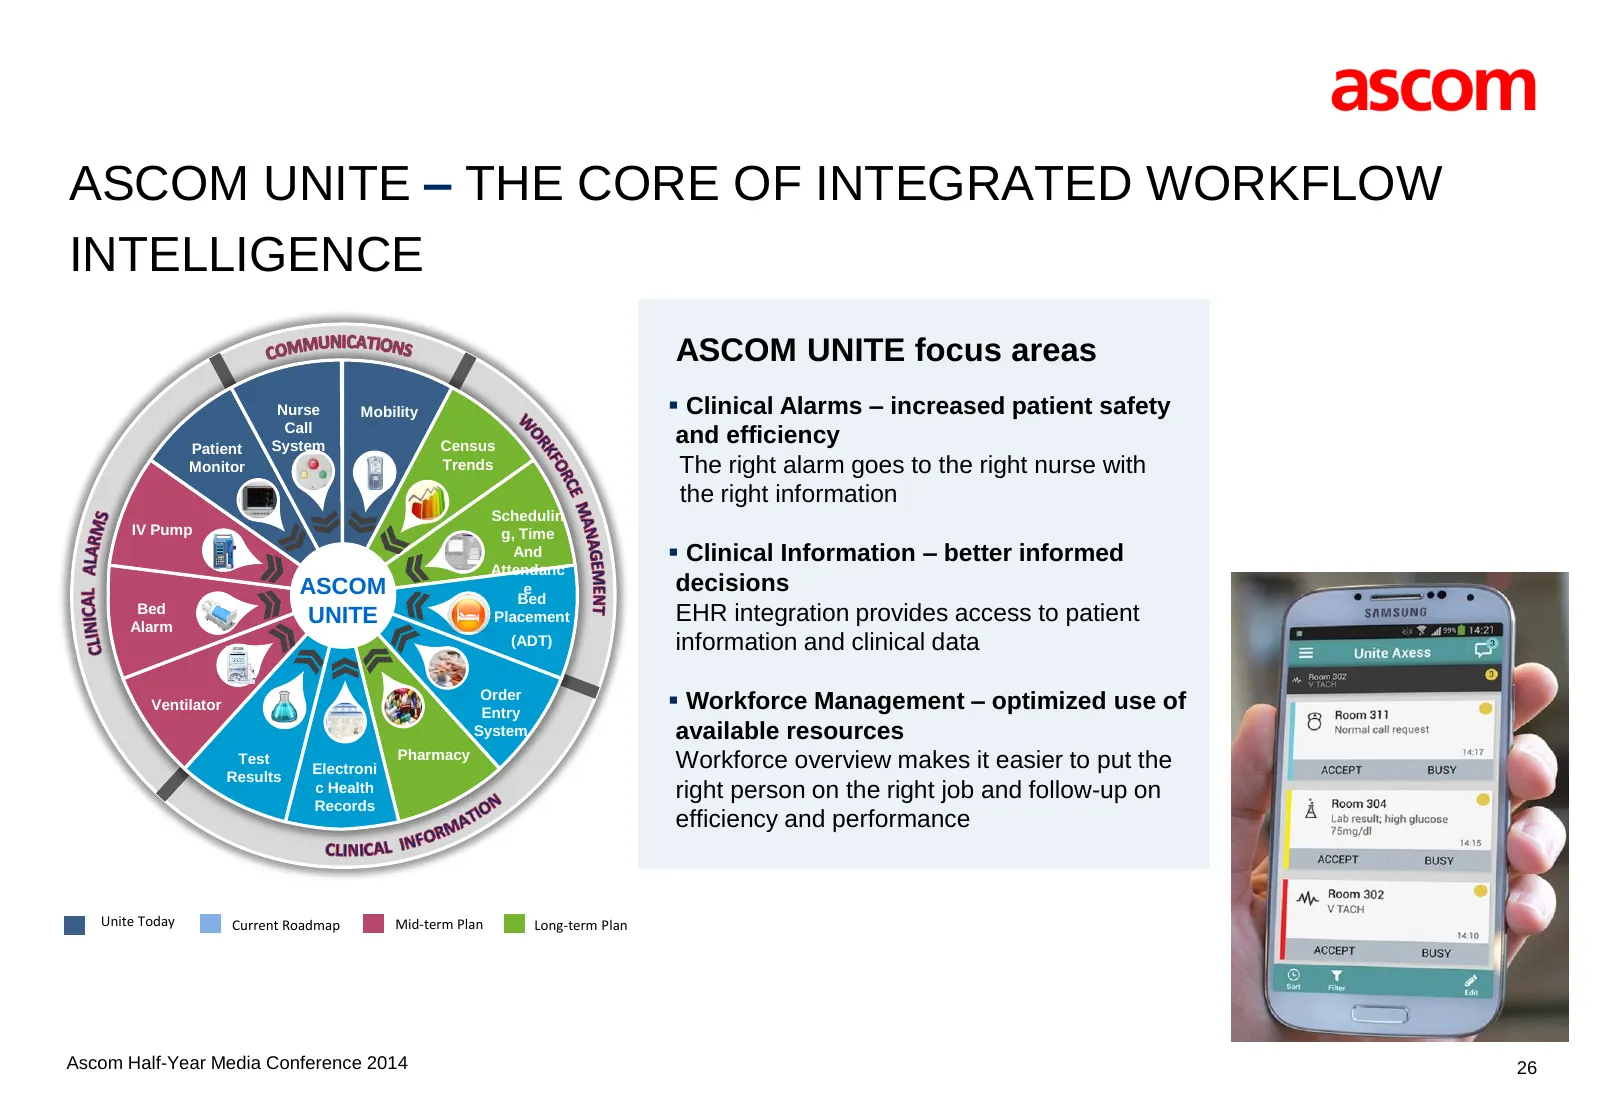
ASCOM UNITE – THE CORE OF INTEGRATED WORKFLOW INTELLIGENCE ASCOM UNITE focus areas Nurse Mobility Clinical Alarms – increased patient safety Call Patient System Census and efficiency Monitor Trends The right alarm goes to the right nurse with the right information Schedulin IV Pump g, Time And C
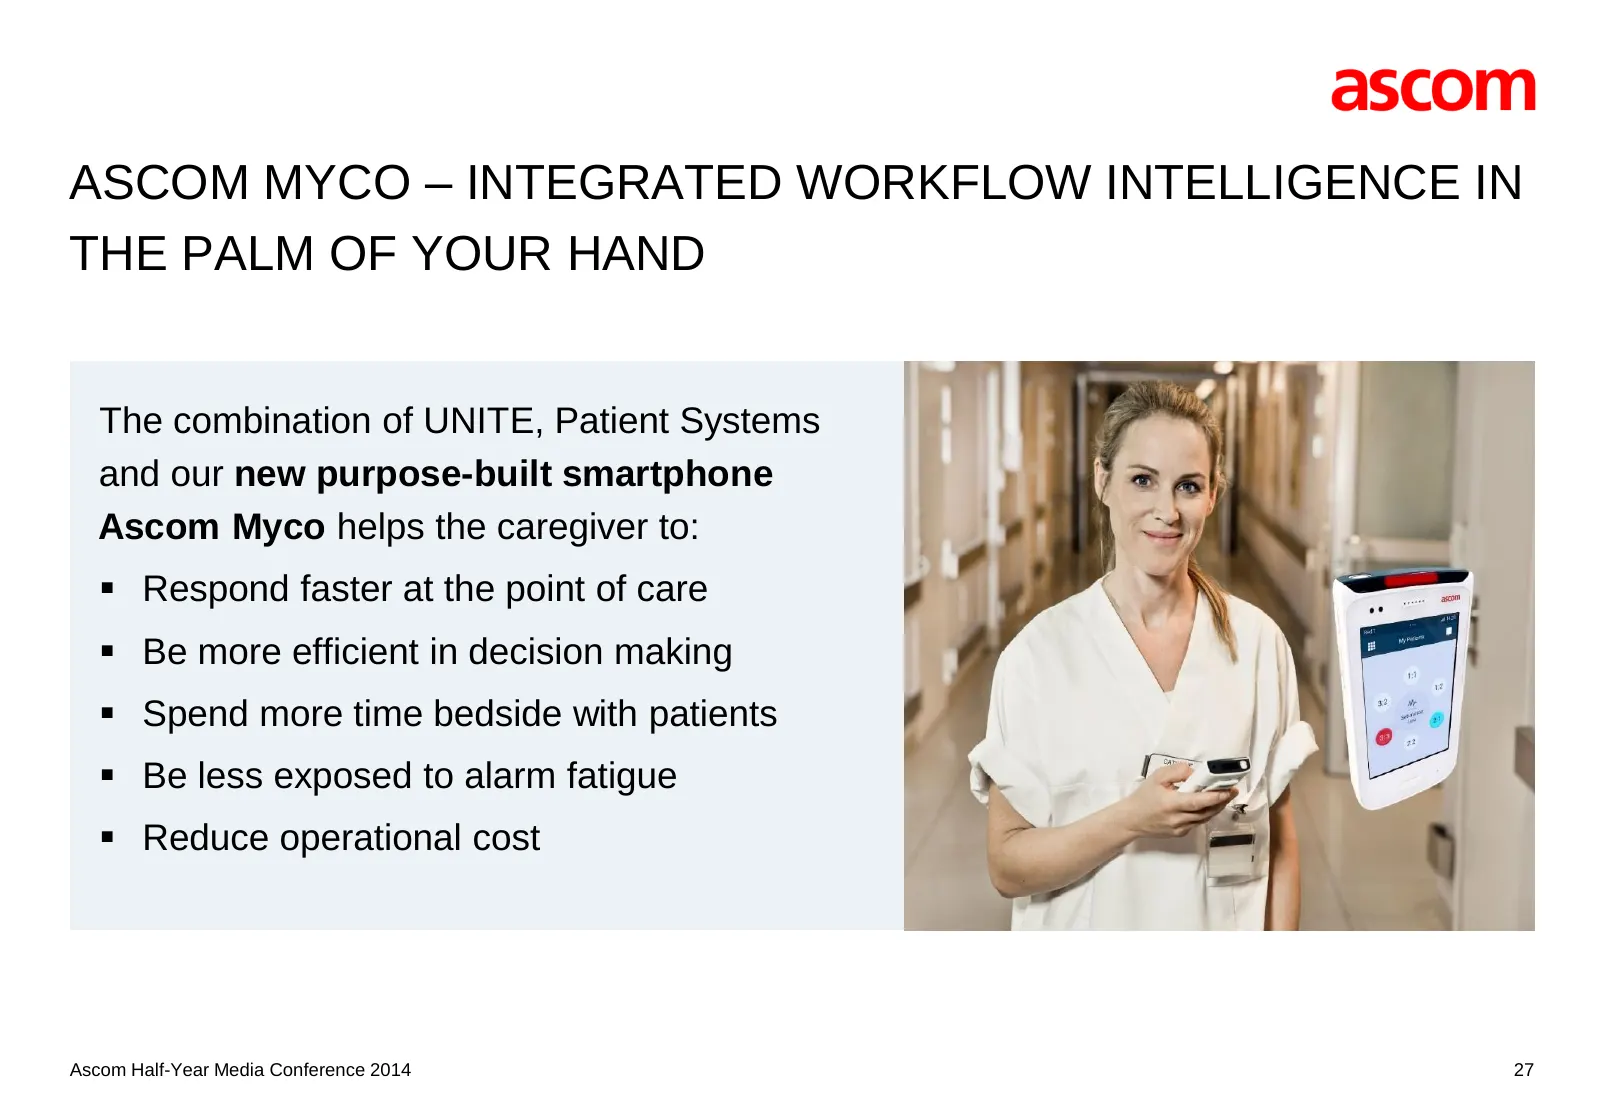
Slide 27: Ascom Myco – integrated workflow intelligence in the palm of your hand
ASCOM MYCO – INTEGRATED WORKFLOW INTELLIGENCE IN THE PALM OF YOUR HAND The combination of UNITE, Patient Systems and our new purpose-built smartphone Ascom Myco helps the caregiver to: Respond faster at the point of care Be more efficient in decision making Spend more time bedside with patient
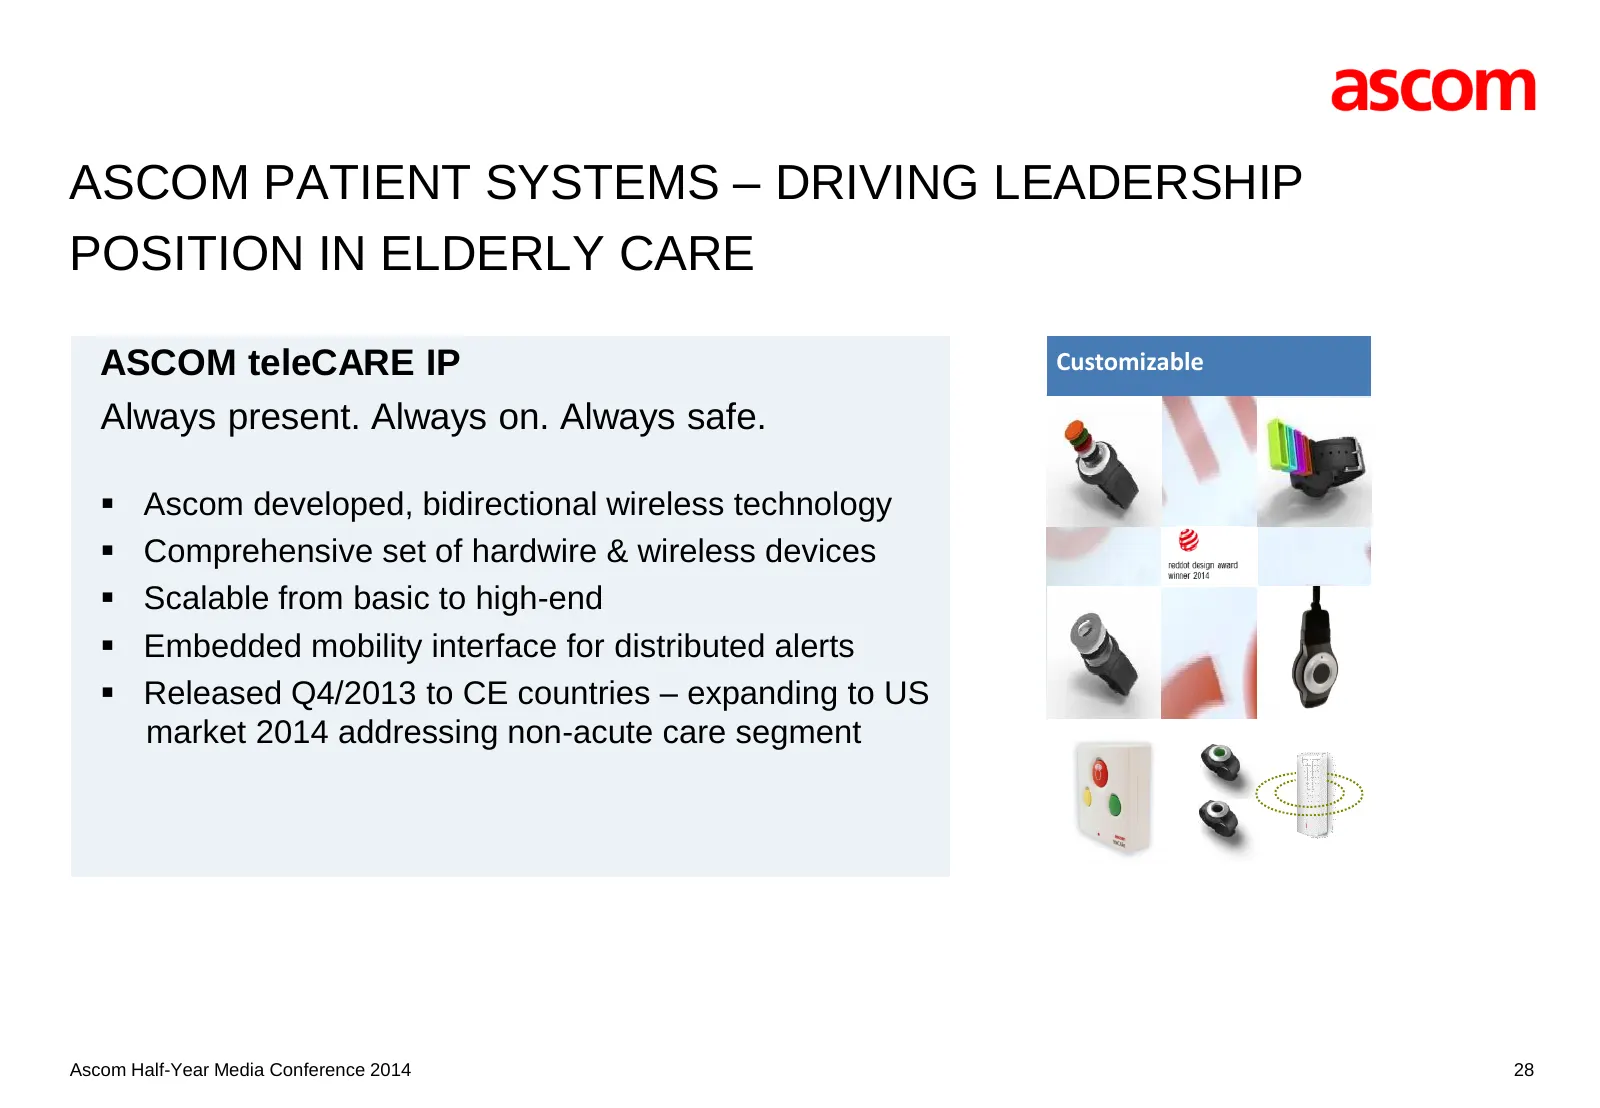
Slide 28: Ascom Patient Systems – driving leadership
ASCOM PATIENT SYSTEMS – DRIVING LEADERSHIP POSITION IN ELDERLY CARE ASCOM teleCARE IP Customizable Always present. Always on. Always safe. Ascom developed, bidirectional wireless technology Comprehensive set of hardwire & wireless devices reddot design Scalable from basic to high-end award win
Slide 29: Ascom Network Testing
[ ] ASCOM NETWORK TESTING Ascom Half-Year Media Conference 2014 29
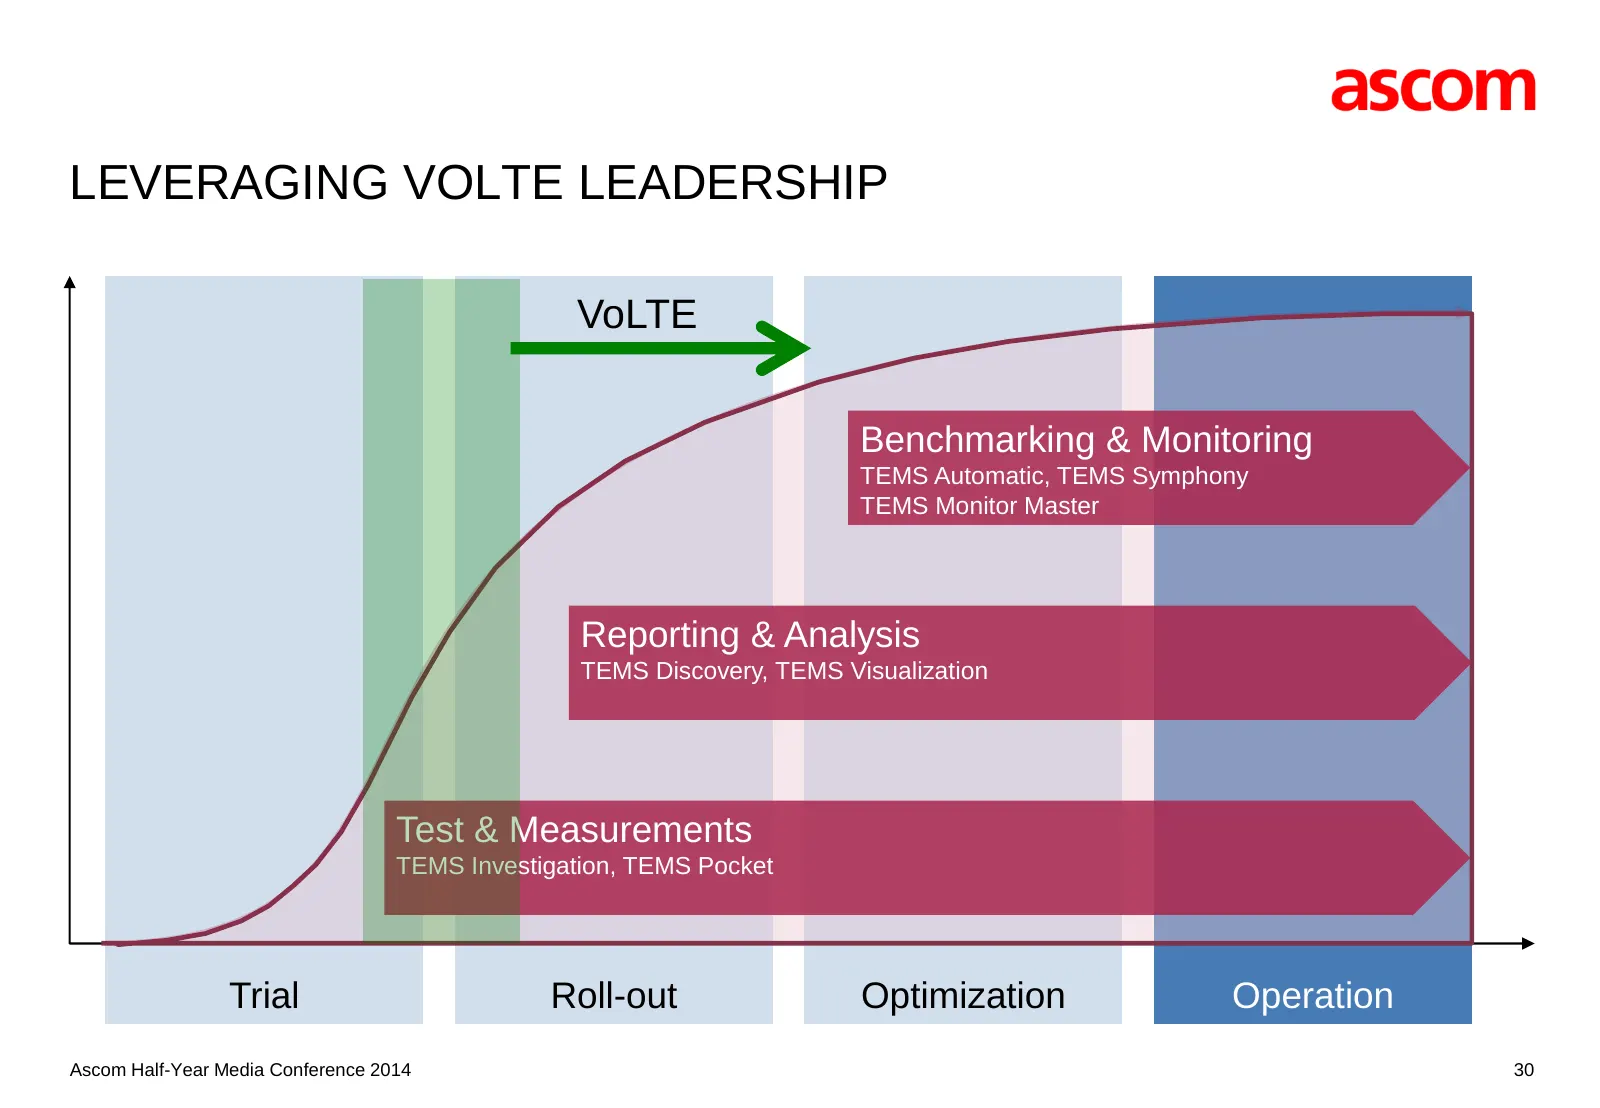
Slide 30: Leveraging VoLTE leadership
LEVERAGING VOLTE LEADERSHIP VoLTE Benchmarking & Monitoring TEMS Automatic, TEMS Symphony TEMS Monitor Master Reporting & Analysis TEMS Discovery, TEMS Visualization Test & Measurements TEMS Investigation, TEMS Pocket Trial Roll-out Optimization Operation Ascom Half-Year Media Conference 2014 30
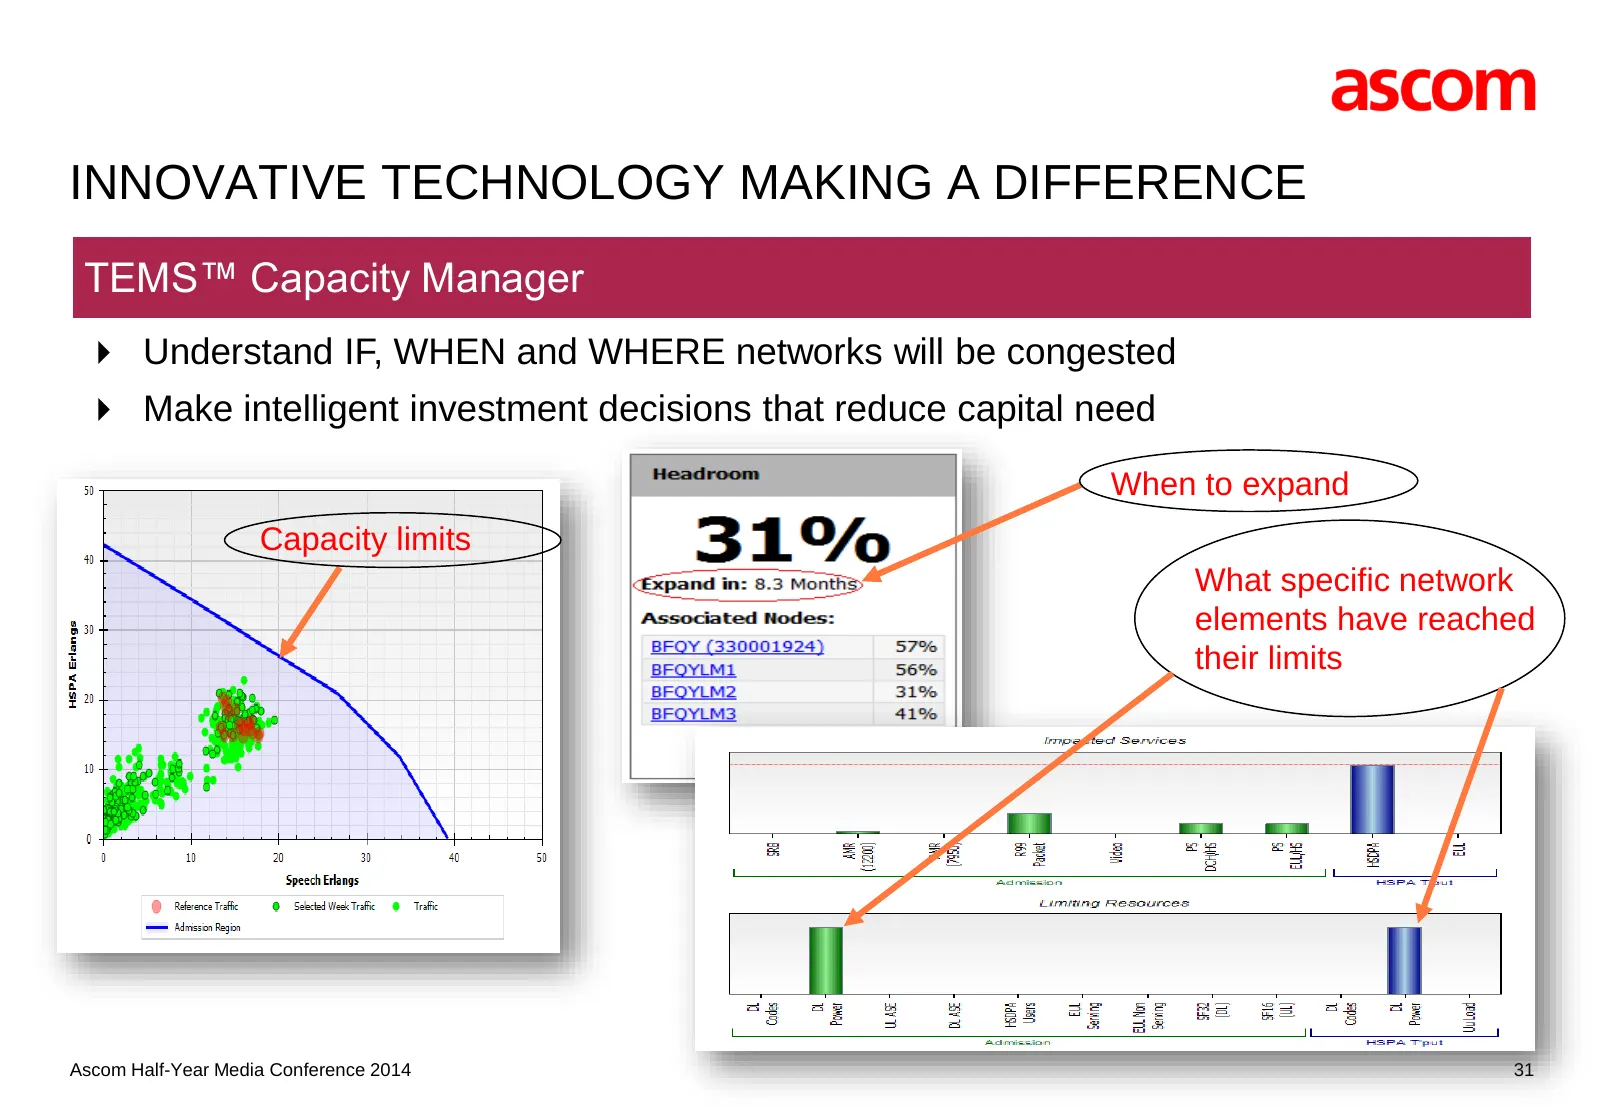
Slide 31: Innovative technology making a difference
INNOVATIVE TECHNOLOGY MAKING A DIFFERENCE TEMS™ Capacity Manager Understand IF, WHEN and WHERE networks will be congested Make intelligent investment decisions that reduce capital need When to expand Capacity limits What specific network elements have reached their limits Ascom Half-Year Media C
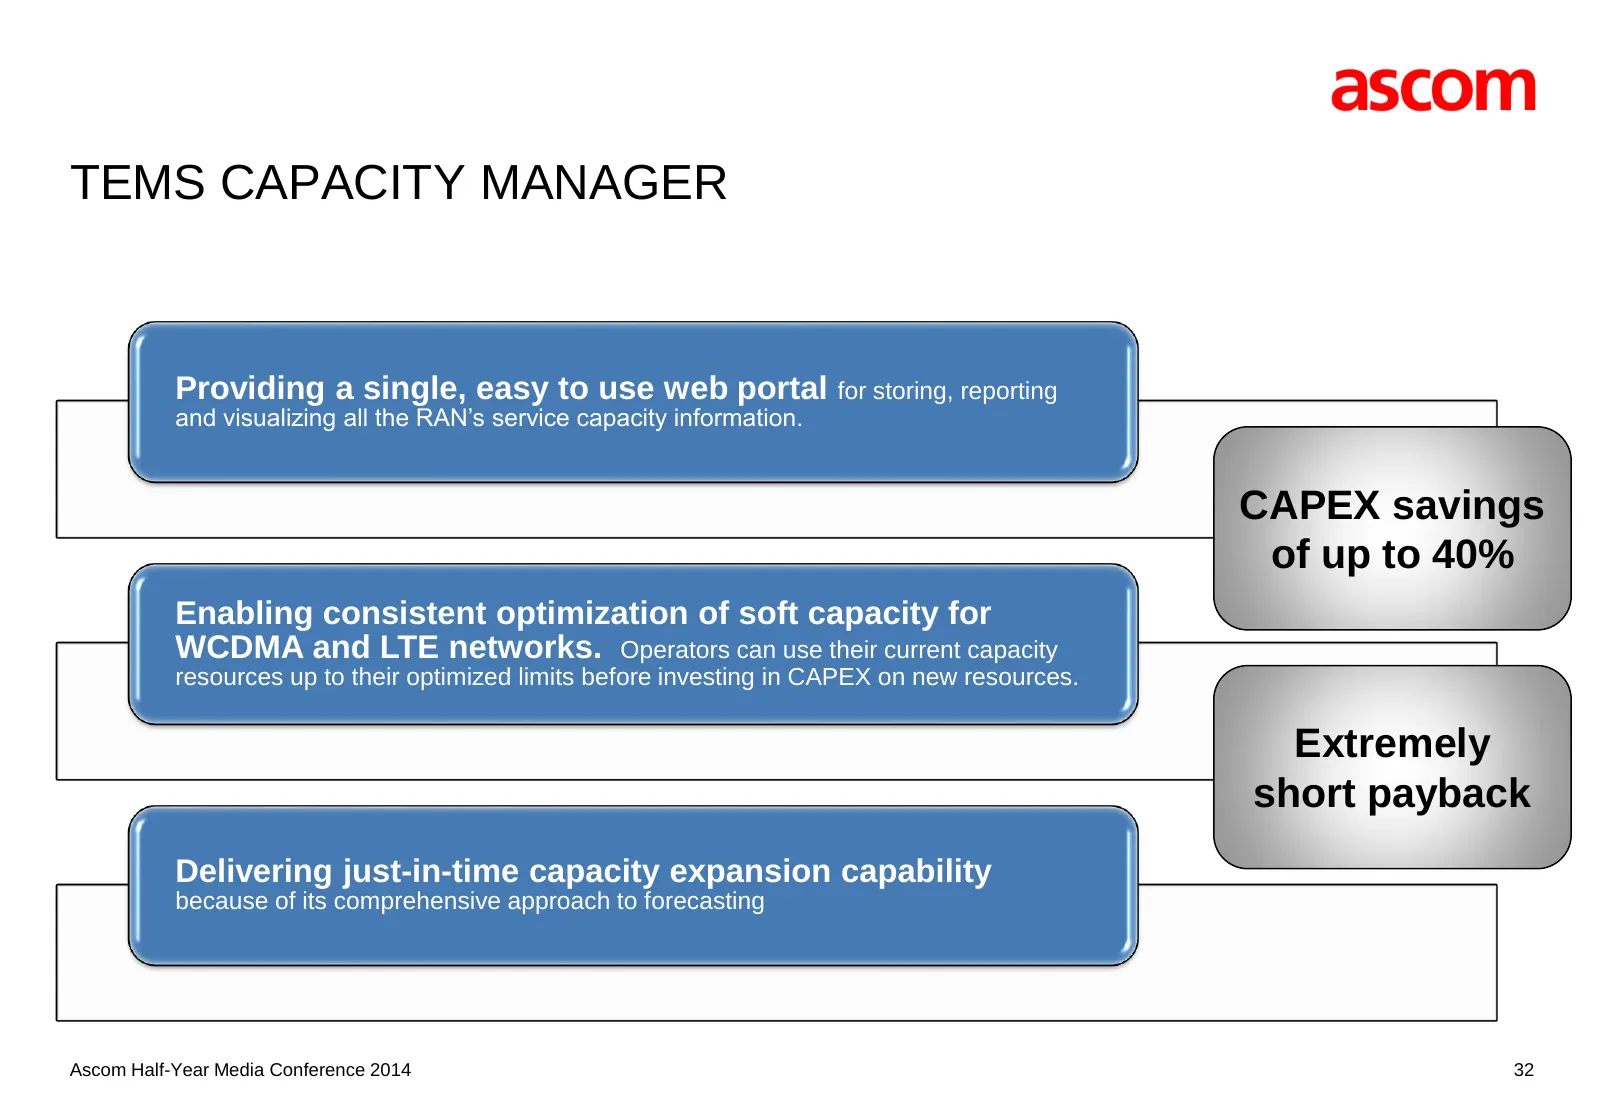
Slide 32: TEMS Capacity Manager
TEMS CAPACITY MANAGER Providing a single, easy to use web portal for storing, reporting and visualizing all the RAN’s service capacity information. CAPEX savings of up to 40% Enabling consistent optimization of soft capacity for WCDMA and LTE networks. Operators can use their current capacity resour
Slide 33: Complex bilateral contracts made simple
COMPLEX BILATERAL CONTRACTS MADE SIMPLE New solution automates eContract Exchange between carriers Replaces expensive, time-consuming manual processes Provides user tools to monitor & measure contract performance Provides carriers cost savings & interconnect efficiencies: Reduces risk, legal i
Slide 34: Outlook FY 2014 starting point
OUTLOOK FY 2014 STARTING POINT Ascom historically has a stronger second half-year High order backlog and strong project pipeline in both divisions Tight cost management in place Strengthened management team with appointment of new key people Ascom Half-Year Media Conference 2014 34
Slide 35: Two important orders already received in H2/2014
OUTLOOK TWO IMPORTANT ORDERS ALREADY RECEIVED IN H2/2014 Wireless Solutions wins CHF 4.7 million order from OEM customer for DECT wireless network solution and handsets. Network Testing receives a lower single digit CHF million order from Swisscom for products and solutions to expand, improve, a
Slide 36: Outlook: targets 2014 for the core business
OUTLOOK Targets 2014* for the Core Business Revenue at previous year’s level EBITDA margin in the range of 14–16% Net Profit 2014* Ascom anticipates net profit to be at around the previous year’s level (2013: CHF 36.9 million) * Outlook assumes a steady economical environment and at least stab
Slide 37: Group contact
[ ] GROUP CONTACT Ascom Holding AG Corp. Communications / IR Tel: + 41 41 544 78 00 Zugerstrasse 32 Fax: + 41 41 761 97 25 6340 Baar investor@ascom.com Ascom Half-Year Media Conference 2014 37
Slide 38: Legal disclaimer
LEGAL DISCLAIMER This document contains specific forward-looking statements, e.g. statements including terms like “believe”, “expect” or similar expressions. Such forward-looking statements are subject to known and unknown risks, uncertainties and other factors which may result in a substantial dive
Slide 39: eZ ie
eZ ie
Source: Internet Archive copy of ascom.com