Applied Biosystems — Applera — Merger or Acquisition (June 2008)
31 slides from Applied Biosystems's merger presentation, Jun 12, 2008
Slide 1: Creating the Premier Provider of Biotechnology Reagents and Systems
Creating the Premier Provider of Biotechnology Reagents and Systems June 12, 2008 Filed by Invitrogen Corporation Pursuant to Rule 425 under the Securities Act of 1933 and Deemed Filed Pursuant to Rule 14a-12 Under the Securities Exchange Act of 1934 Subject Company: Applera Corporation Commission F
Slide 2: Forward-Looking Statements
2 Certain statements contained in this presentations are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, and Invitrogen and Applera intend that such forward-looking statements be subject to the safe harbor created thereby. Forward-looking stat
Slide 3: Non-GAAP Measurements and Additional Information
3 Non-GAAP Measurements This presentation and discussion includes certain financial information which constitute “non-GAAP financial measures” as defined by the SEC. The GAAP measures which are most directly comparable to these measures, as well as a reconciliation of these measures with the most di
Slide 4: Participants in the Solicitation
4 Invitrogen and Applera and their respective directors, executive officers and certain other members of their management and employees may be deemed to be participants in the solicitation of proxies in connection with the proposed transaction. Information concerning all of the participants in the s
Slide 5: Agenda
5 Agenda Transaction Overview Strategic Rationale Financial Highlights Next Steps
Slide 6: Transaction Overview
6 Transaction Structure Consideration and Relative Ownership Approvals Company Name Headquarters Closing Employees Transaction Overview • Invitrogen will acquire all of the outstanding shares of Applied Biosystems for $38 per share in a combination of cash and stock, for a total value of $6.7 billio
Slide 7: Board Composition and Executive Management
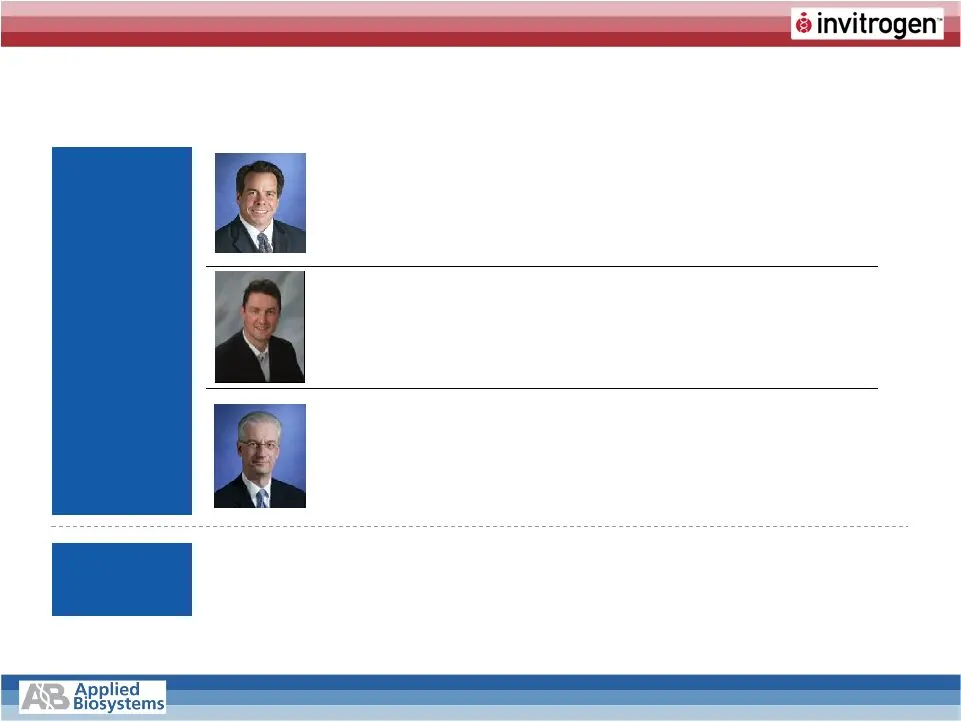
7 Board Composition Executive Management • 9 Invitrogen and 3 Applera board members Greg Lucier Chairman, President and CEO • Invitrogen CEO and Board Member since May 2003 • Invitrogen Chairman since April 2004 • Former Corporate Officer of General Electric Corporation David Hoffmeister Senior VP,
Slide 8: Combining Industry Leaders
8 Combining Industry Leaders • Founded: 1987 • Premier provider of consumable kits and reagents • Annual revenue of $1.3 billion • Leading positions in: – Cell Culture (GIBCO) – Labeling and Detection – Molecular Biology Kits • ~4,700 employees • 1,200 patents & licenses • Carlsbad, CA (HQ) • Founde
Slide 9: Shared Vision
9 Advance Science to Improve the Human Condition Innovate to Solve Customer Workflow Challenges Deliver Superior Quality and Reliability Differentiate the Customer Experience Win Together Shared Vision
Slide 10: Newco Competitive Advantages and Industry Dynamics
10 Newco Competitive Advantages Industry Dynamics New Company Well-Positioned to Benefit From Macrotrends Genomics and cell biology convergence Translation of technologies to applied markets Race to understand human genome and genetic variations Growth in emerging geographies Positioned to capture m
Slide 11: Agenda
11 Agenda Transaction Overview Strategic Rationale Financial Highlights Next Steps
Slide 12: Strategic Rationale
12 • Highly complementary, best-in-class product offerings • Broad and extensive commercial network • Strong platform for expansion into high-growth markets • Significant value creation opportunities for shareholders • Strong financial profile Strategic Rationale Merger combines the industry's premi
Slide 13: Best in Class Product Offerings Across All Major Biological Disciplines
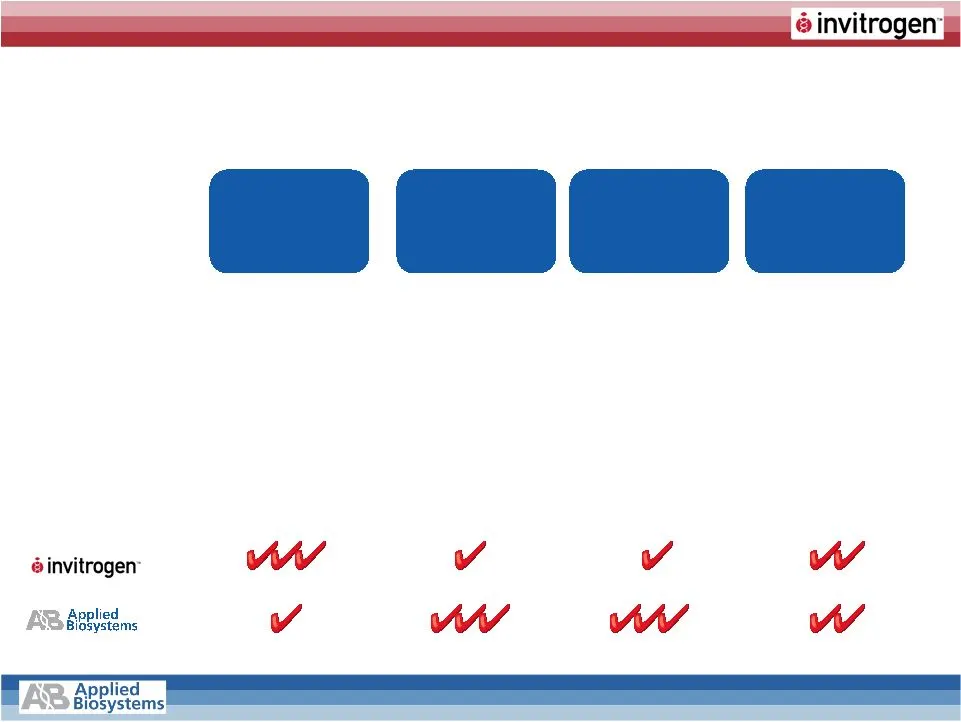
13 Gene Regulation Proteomics Cell Biology Genomics Best in Class Product Offerings Across All Major Biological Disciplines… • ChargeSwitch® nucleic acid prep • SYBR ® Green • Gateway ® & TOPO ® cloning • SuperScript ® reverse transcription • Lipofectamine ® transfection • Novex ® gels, stains, stan
Slide 14: Highly Complementary Revenue Streams
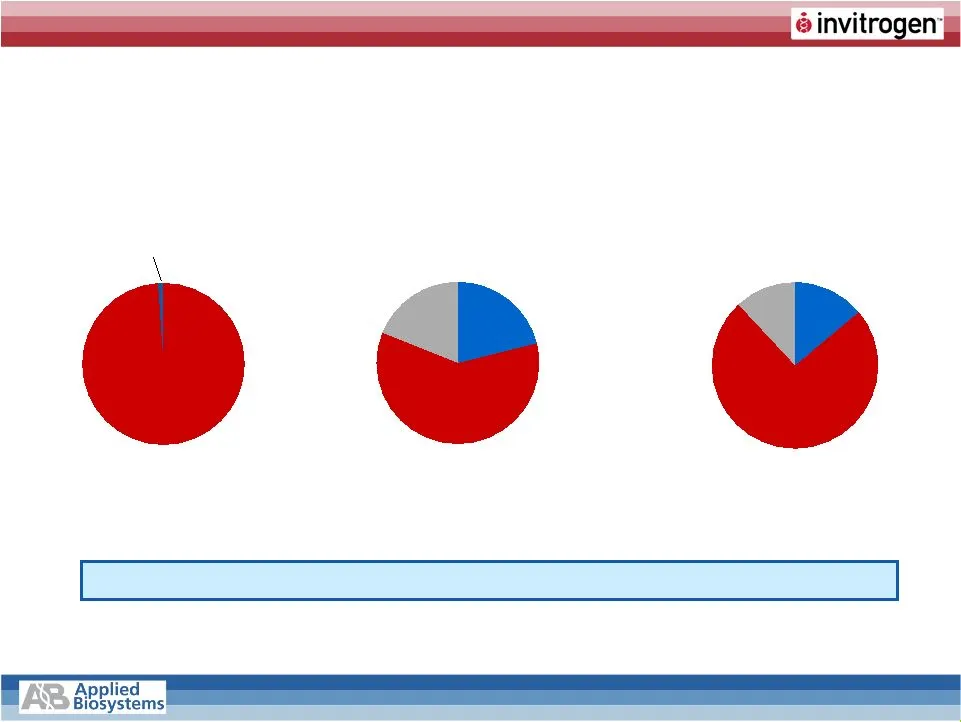
14 …With Highly Complementary Revenue Streams… Consumables & Services* 60% Mass Spec Instruments 19% Instrument Reagent Systems 21% Consumables & Services* 74% Mass Spec Instruments 12% Instrument Reagent Systems 14% Consumables & Services* 99% Instrument Reagent Systems 1% IVGN Revenues ABI Revenue
Slide 15: Invitrogen and Applied Biosystems logos
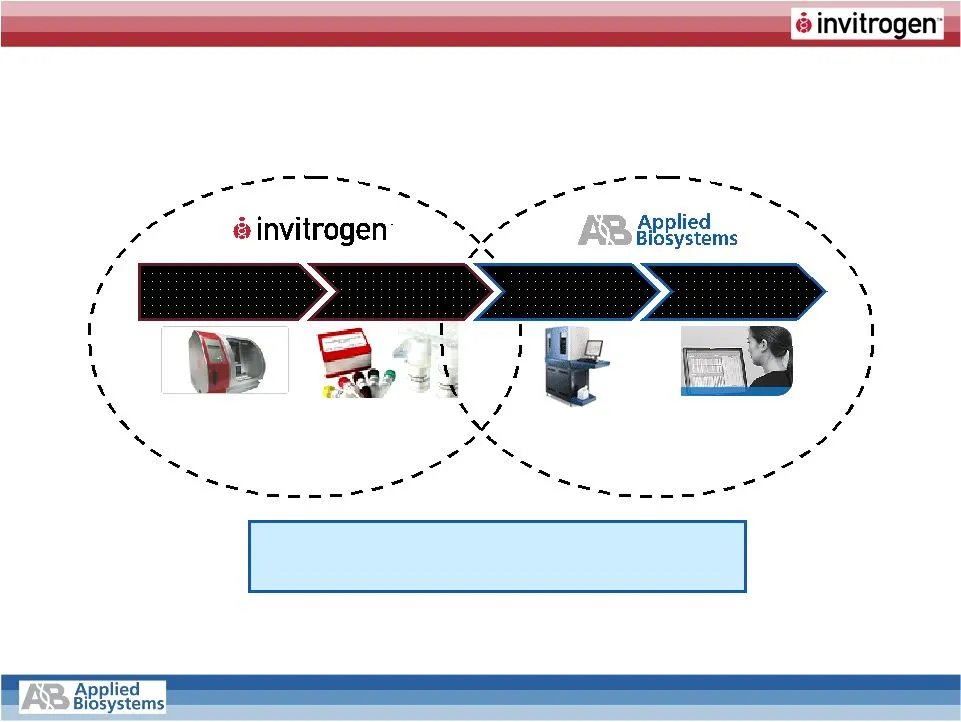
®invitrogen’ Yo éinvitrogen aval S Applied as aN ‘Applied Bibbystems
Slide 16: Innovation Engine Supported by Significant Scale
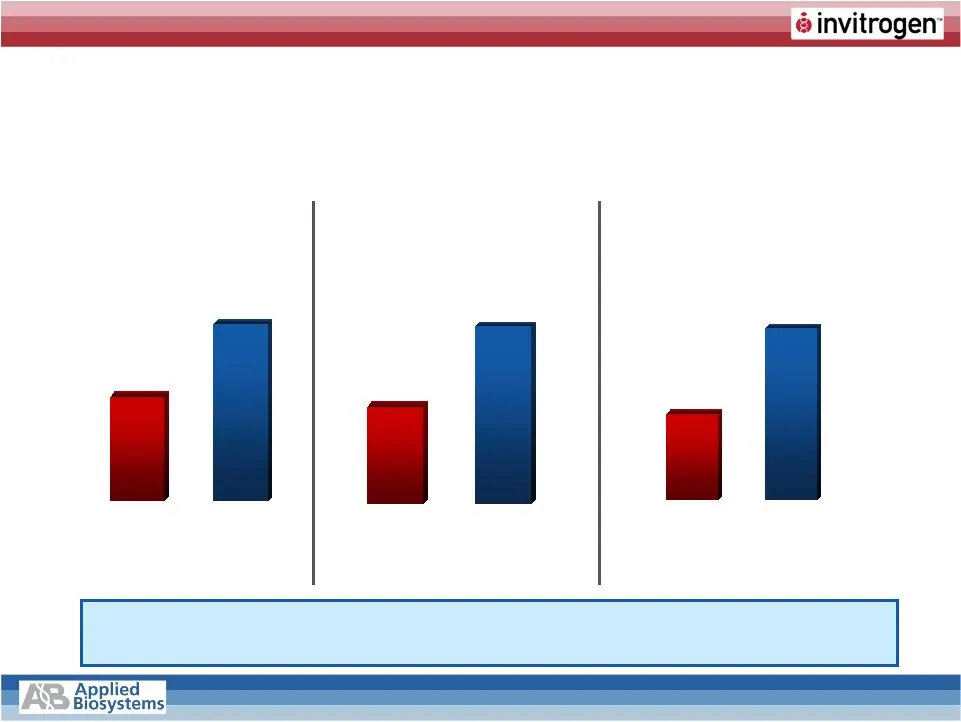
16 $112 $190 IVGN (1) ABI (2) Patents & Licenses 1,200 2,400 IVGN ABI R&D Investment (in millions) R&D Investment (% of revenue) 8.5% 11.4% IVGN ABI (2,3) (2) FY2008 Estimate (3) excludes mass spec revenue Leading investment in R&D provides significant scale for developing breakthrough innovations I
Slide 17: Broad and Extensive Commercial Network with Complementary Skills
17 • Excels at repeat business • e-Commerce expertise • 1,000+ supply centers • Strong relationships with bench scientists • Excels at systems sales • Global service infrastructure • Presence beyond life sciences • High level customer relationships • Approximately 3,000 sales & service personnel • F
Slide 18: Strong Platform for Expansion Into High Growth Markets
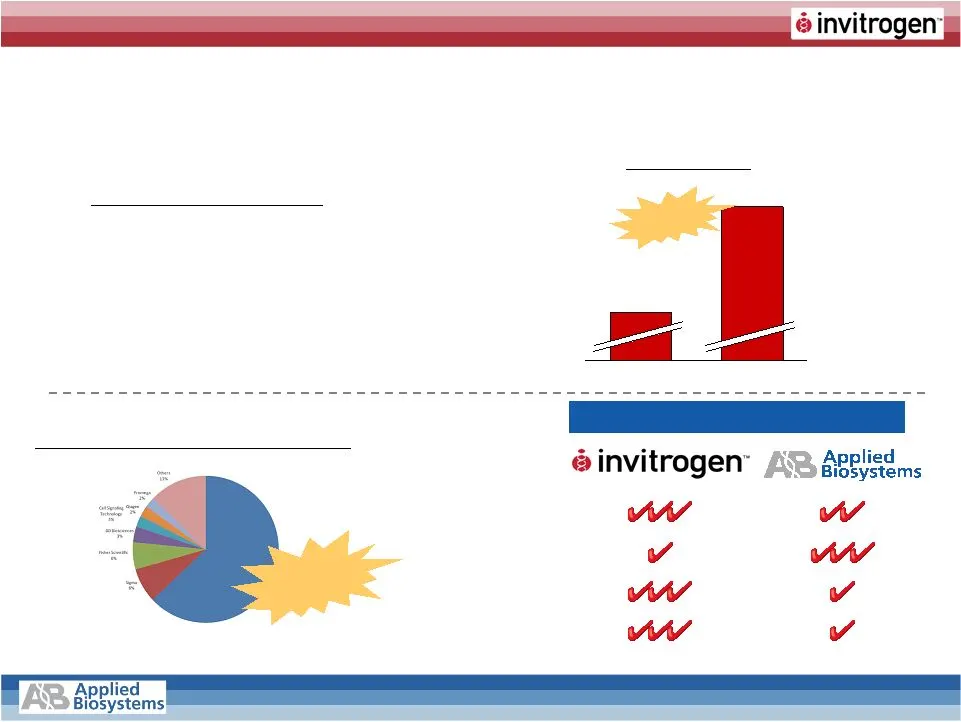
18 Applied Markets Emerging Geographies Cell Biology Next Gen Sequencing Market Size Market Growth Capabilities: $9B Low double digits $1B Midteen’s $6B High single digits >35% $200M Strong Platform for Expansion Into High Growth Markets
Slide 19: Complete Solutions in Key Cell Biology Workflows
19 Capabilities/Presence: New Company Will Have Capabilities to Offer Complete Solutions in Key Cell Biology Workflows $8.2B $6.3B 2010 2007 Key Growth Points: •Disease relevant cells and cell inputs •Stem cells and cell therapy •Multiplexing and bench top instrumentation 9% CAGR IVGN 63% Best Cell
Slide 20: Applied Markets Represent Attractive Growth Opportunity
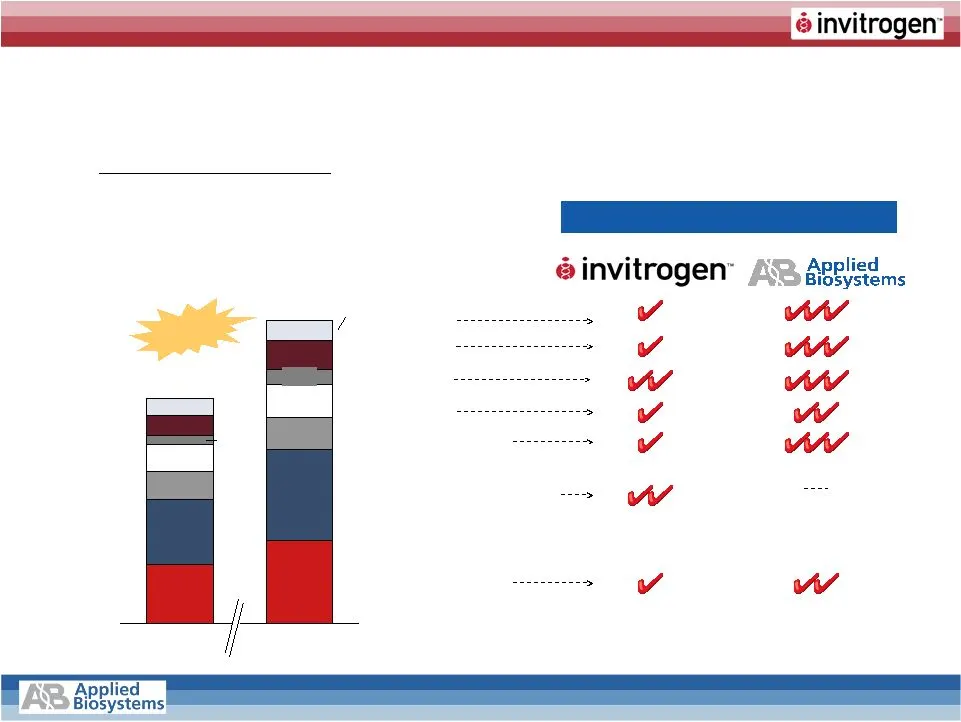
20 800 2,700 2,400 1,200 600 3,700 3,400 Capabilities/Presence: Applied Markets Represent Attractive Growth Opportunity 1,100 1,100 $9.2B 1,400 1,300 $12.4B 2010 Other Forensics QA / QC AgBio Food Safety Histology/Cytology Molecular Dx 2007 Source: Kalorama, Global Strategic Business, Frost and Sull
Slide 21: Next Generation Sequencing Driving New Discoveries
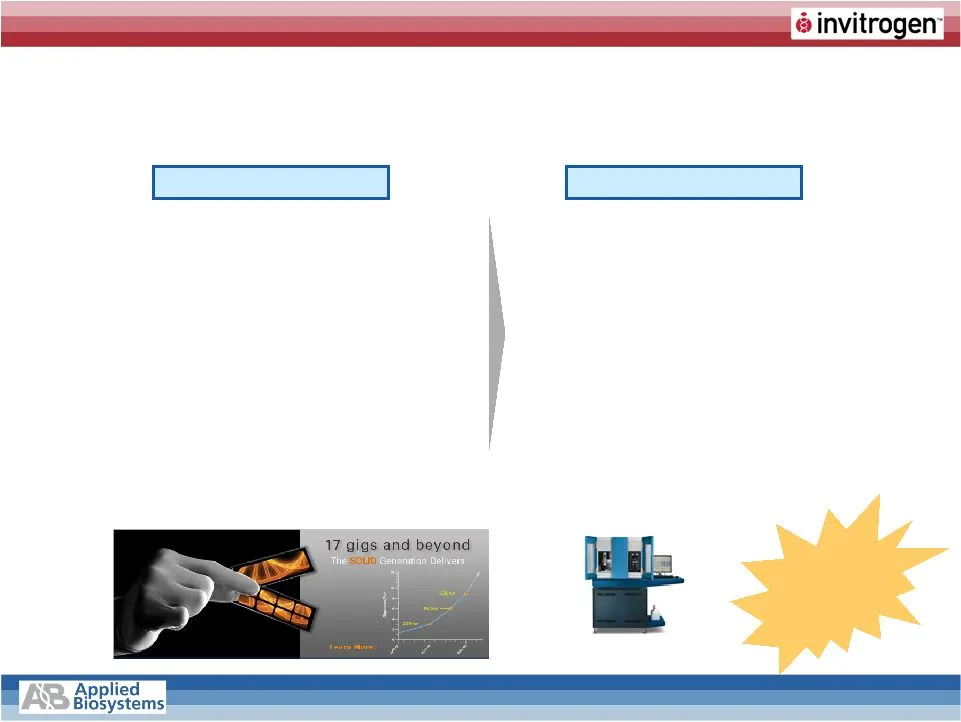
21 “Genomic Revolution” • Improved diagnostics & disease management • Transformed clinical trials … right treatments for right patients • Genomic baseline at birth … educated consumer and lifestyle choices improve human condition Next Generation Sequencing Driving New Discoveries… SOLiD Platform • H
Slide 22: Genomic Analysis Drives Downstream Revenue
22 Application to therapeutics /diagnostics Increased validation by RT-PCR Genomic Analysis Drives Downstream Revenue SOLiD™ drives down the cost of rare SNP /expressor discovery Increase in cell biology research to understand gene products in context More questions
Slide 23: Agenda
23 Agenda Transaction Overview Strategic Rationale Financial Highlights Next Steps
Slide 24: Significant Opportunities for Value Creation
24 • At least $125 million annual cost savings by rd year – Raw material synergies – Overhead redundancies – Facility rationalizaton – R&D scale • At least $50 million annual Operating Income from revenue synergies by 3 rd year – Cross selling/channel synergies – Penetration of new markets – New joi
Slide 25: Strong Financial Profile
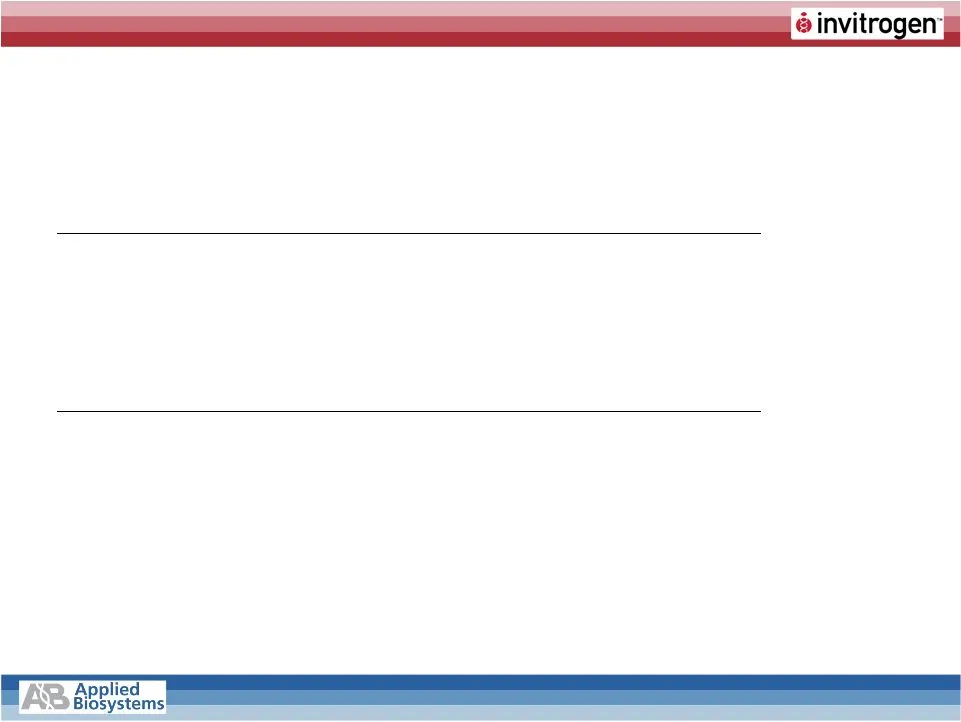
25 • ~$3.5 billion in combined LTM revenue • Strong EBITDA and operating cash flow contribution • Intent to quickly repay debt LTM March 31, 2008 $803 23% $480 22% $323 24% Operating Cash Flow as % of Revenue $859 25% $490 23% $369 28% EBITDA (1) as % of Revenue $3,496 $2,173 $1,323 Revenue ProForma
Slide 26: Revenue Diversified Across Segments
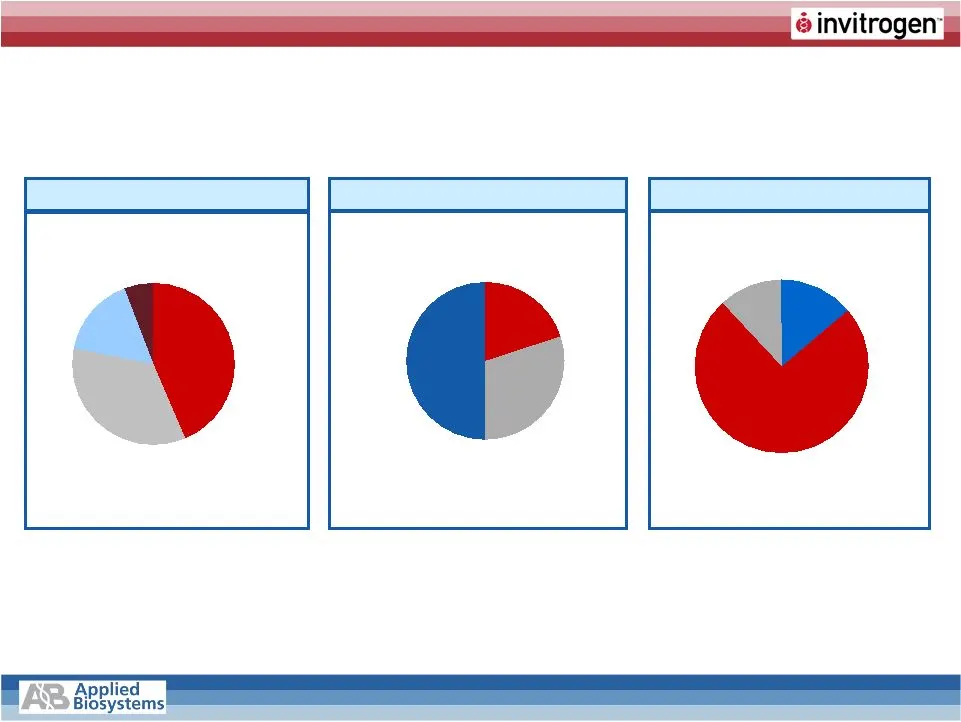
26 Revenue Diversified Across Segments… …with a significant contribution from high-margin consumables Rev. By End Markets Rev. By Product Mix Industry & Other 20% Pharma & Biotech 30% Academic & Govt 50% Rev. By Geography United States 44% Europe 34% APAC 16% Other 6% Consumables & Services 74% Mass
Slide 27: 2009 Financial Goals
27 2009 Financial Goals $2.60+ (2) Non-GAAP EPS (1) Mid single digits Organic Revenue Growth 2009E Notes: (1) Non-GAAP EPS excludes certain acquisition related costs, including amortization of intangible assets, business integration and other expenses. (2) Neutral to slightly accretive to 2009 Stree
Slide 28: Agenda
28 Agenda Transaction Overview Strategic Rationale Financial Highlights Next Steps
Slide 29: Next Steps
29 Next Steps • Approvals – Invitrogen and ABI shareholder approval – HSR, ECMR and other regulatory approval – Expected close: Fall of 2008 • Integration Roadmap – Project management team put in place immediately – Upon closing: • Reagent businesses combined quickly and smoothly • Instrument busine
Slide 30: Experienced Management Teams Will Deliver on Deal Promise
30 Experienced Management Teams Will Deliver on Deal Promise • Invitrogen team: – Executed upon significant improvements to financial profile in <2 years – >30% shareholder returns in last 5 years – Integrated 15 acquisitions in 3 years – On track to deliver consecutive quarter of strong organic gro
Slide 31: Strategic Rationale
31 • Highly complementary, best-in-class product offerings • Broad and extensive commercial network • Strong platform for expansion into high-growth markets • Significant opportunities for value creation for shareholders • Strong financial profile Strategic Rationale Merger combines the industry's p
Source: SEC EDGAR · 425 filed Jun 12, 2008