NewBridge Bancorp — Raymond James Financial, Inc. Institutional Investors Conference (May 2011)
30 slides from NewBridge Bancorp's conference presentation, May 24, 2011
Slide 1: Raymond James Financial, Inc. Chicago, Illinois May 25, 2011
Raymond James Financial, Inc. Chicago, Illinois May 25, 2011
Slide 2: Forward Looking Statements
Forward Looking Statements Information in this presentation may contain forward looking statements. Such statements involve known and unknown risks, uncertainties and other factors that may cause actual results to differ materially. Forward looking statements are often characterized by the use of qu
Slide 3: NBBC Overview
NBBC Overview Recent Performance Loan Portfolio Analysis Outlook and Summary
Slide 4: Corporate Profile
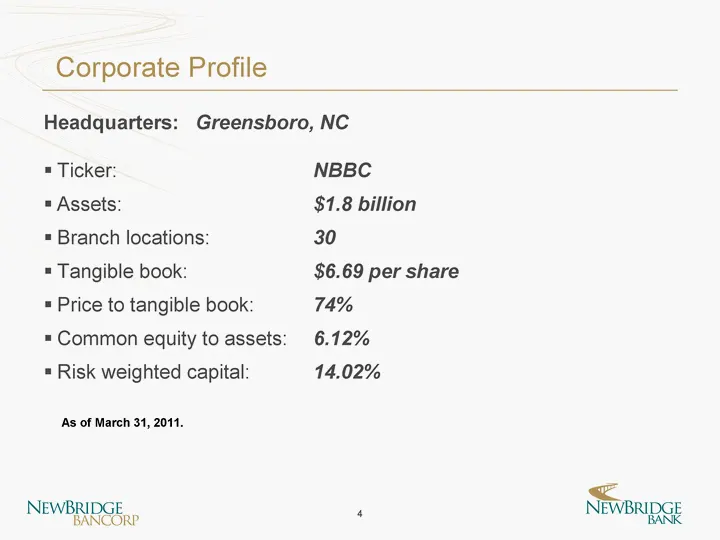
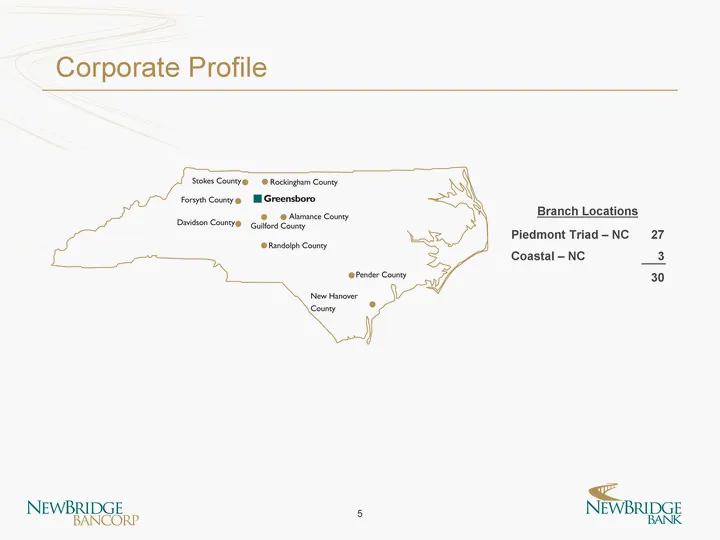
Headquarters: Greensboro, NC Ticker: NBBC Assets: $1.8 billion Branch locations: 30 Tangible book: $6.69 per share Price to tangible book: 74% Common equity to assets: 6.12% Risk weighted capital: 14.02% Corporate Profile As of March 31, 2011.
Slide 5: Branch Locations
Corporate Profile Branch Locations Branch Locations Piedmont Triad - NC 27 Coastal - NC 3 30
Slide 6: Background
NewBridge Bancorp Formed July 2007 from a merger of equals Two mature franchises in NC's third largest MSA Strong core deposits with an opportunity to expand market share New management team overcoming challenges Legacy organizations lacked uniform credit culture and defined performance culture Bank
Slide 7: Leadership
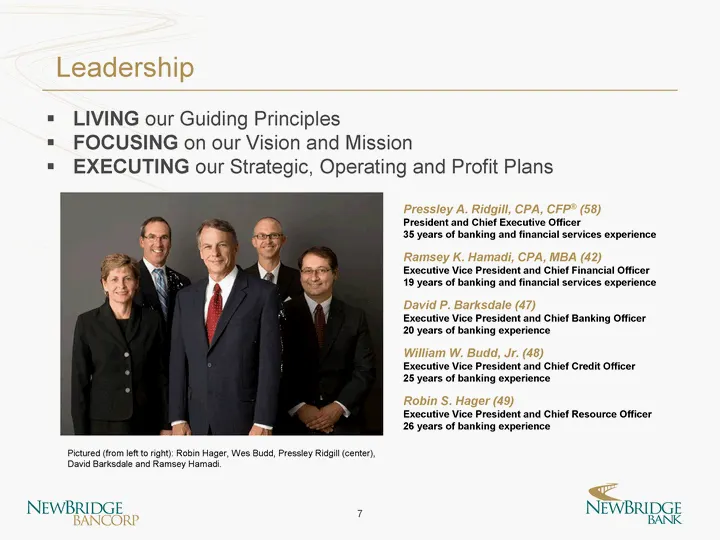
LIVING our Guiding Principles FOCUSING on our Vision and Mission EXECUTING our Strategic, Operating and Profit Plans Pressley A. Ridgill, CPA, CFP(r) (58) President and Chief Executive Officer 35 years of banking and financial services experience Ramsey K. Hamadi, CPA, MBA (42) Executive Vice Presid
Slide 8: Significant Accomplishments
Profitable in each of the last six quarters Charged off $123 million, or 7.6%, of loans and OREO since 2007 Reduced branches from 42 to 30 Reduced staff from 690 to 488 Improved core efficiency from 84% to 65% Increased core deposits from 55% to 68% Improved asset liability management practices Deve
Slide 9: Recent Performance
NBBC Overview Recent Performance Loan Portfolio Analysis Outlook and Summary
Slide 10: Full Year 2010 Results
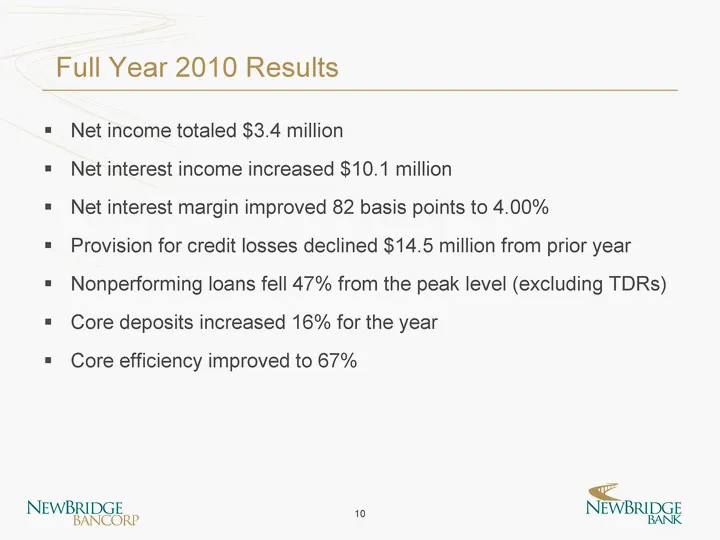
Net income totaled $3.4 million Net interest income increased $10.1 million Net interest margin improved 82 basis points to 4.00% Provision for credit losses declined $14.5 million from prior year Nonperforming loans fell 47% from the peak level (excluding TDRs) Core deposits increased 16% for the y
Slide 11: Trends
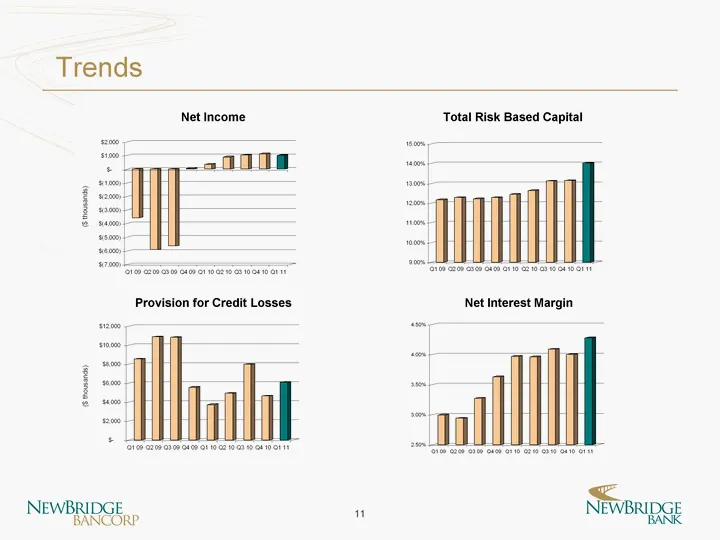
Trends Net Income Total Risk Based Capital Provision for Credit Losses Net Interest Margin
Slide 12: Managing Net Interest Margin
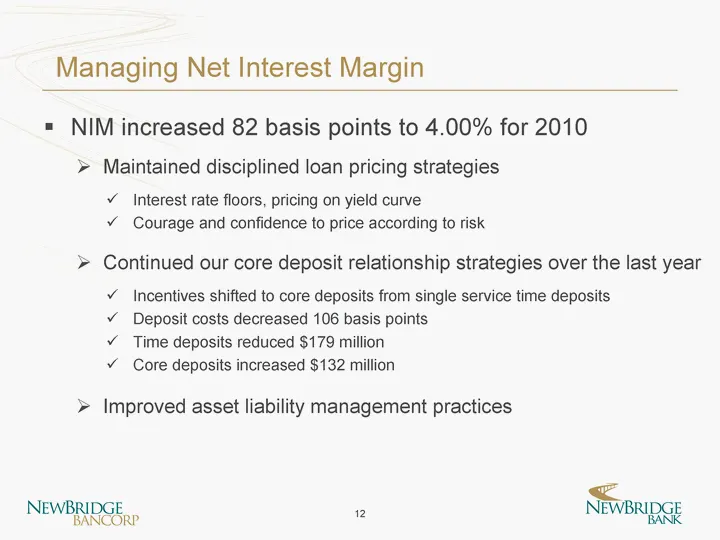
NIM increased 82 basis points to 4.00% for 2010 Maintained disciplined loan pricing strategies Interest rate floors, pricing on yield curve Courage and confidence to price according to risk Continued our core deposit relationship strategies over the last year Incentives shifted to core deposits from
Slide 13: Growing Core Deposits
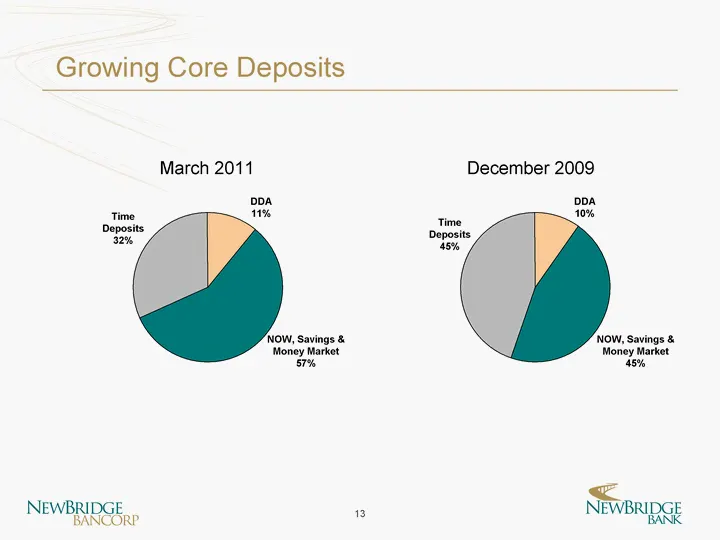
Growing Core Deposits December 2009 March 2011 Time Deposits 32% DDA 11% NOW, Savings & Money Market 57% Time Deposits 45% DDA 10% NOW, Savings & Money Market 45%
Slide 14: Non-Interest Income Growth
Investment Services, Trust, Mortgage Banking and Private Banking Investment and Trust Services restructured to become Wealth Management Private Banking initiative launched (late 2009) Bradford Mortgage acquisition (December 2009) resulting in a 262% increase in mortgage revenues over prior year Non-
Slide 15: Controlling Non-Interest Expense
Implemented disciplined Profit Plan accountability Lowered 2010 non-interest expense $5.0 million August 2010 core processing system conversion Significant expense savings Increased functionality Franchise Validation Plan developed and implemented Investing in sales staff Efficiency, net of OREO rel
Slide 16: Reduce Non-Interest Expense
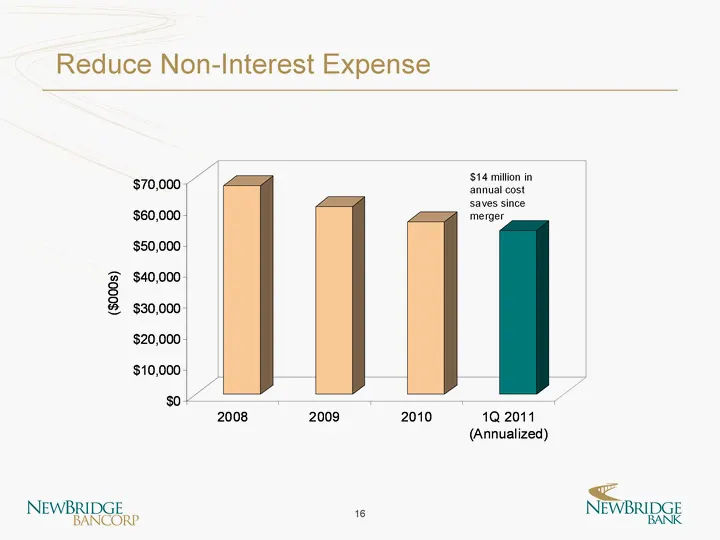
Reduce Non-Interest Expense
Slide 17: Loan Portfolio Analysis
NBBC Overview Recent Performance Loan Portfolio Analysis Outlook and Summary
Slide 18: Improving Asset Quality
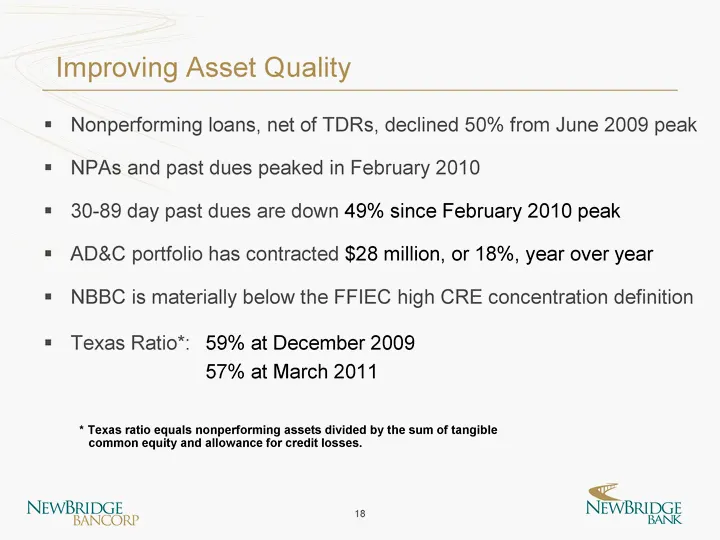
Nonperforming loans, net of TDRs, declined 50% from June 2009 peak NPAs and past dues peaked in February 2010 30-89 day past dues are down 49% since February 2010 peak AD&C portfolio has contracted $28 million, or 18%, year over year NBBC is materially below the FFIEC high CRE concentration definiti
Slide 19: Loan Composition
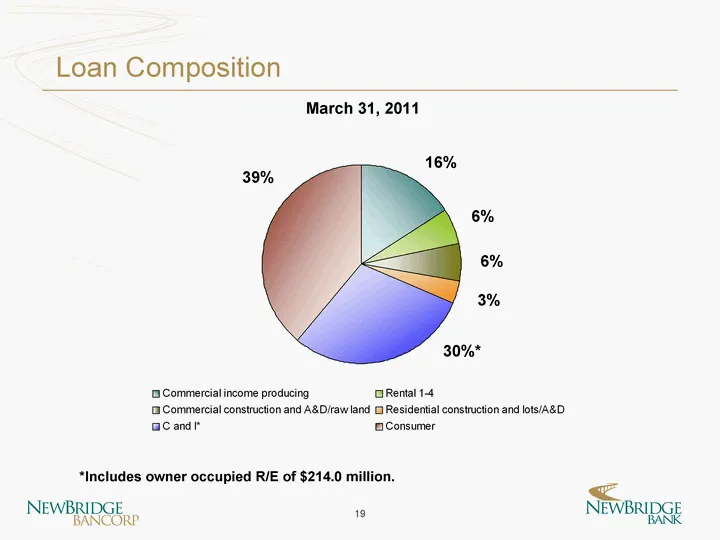
Loan Composition *Includes owner occupied R/E of $214.0 million. March 31, 2011 39% 16% 6% 6% 3% 30%*
Slide 20: AD&C Portfolio Mix
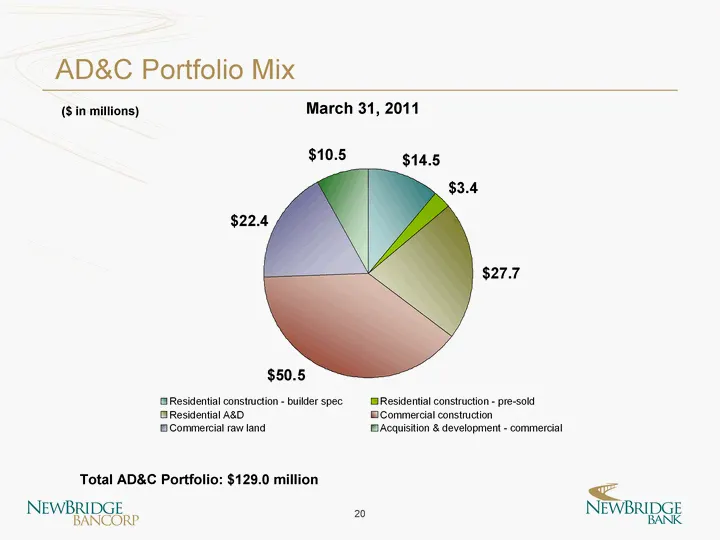
AD&C Portfolio Mix ($ in millions) Total AD&C Portfolio: $129.0 million March 31, 2011
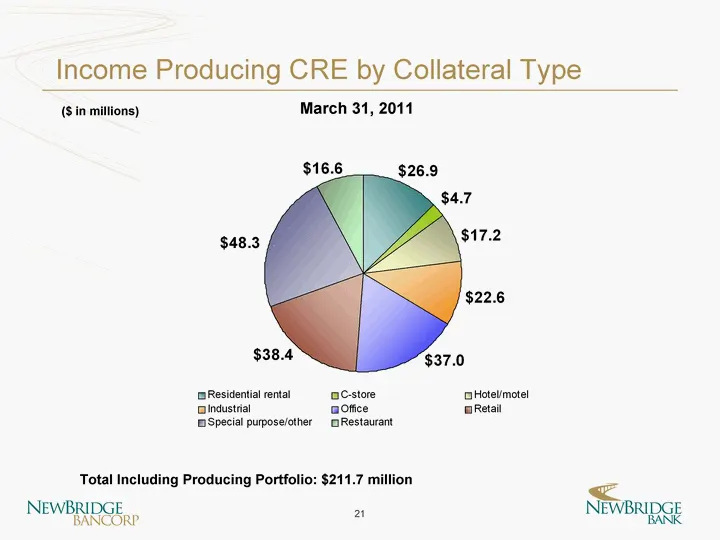
Slide 21: Income Producing CRE by Collateral Type
Income Producing CRE by Collateral Type ($ in millions) Total Including Producing Portfolio: $211.7 million March 31, 2011
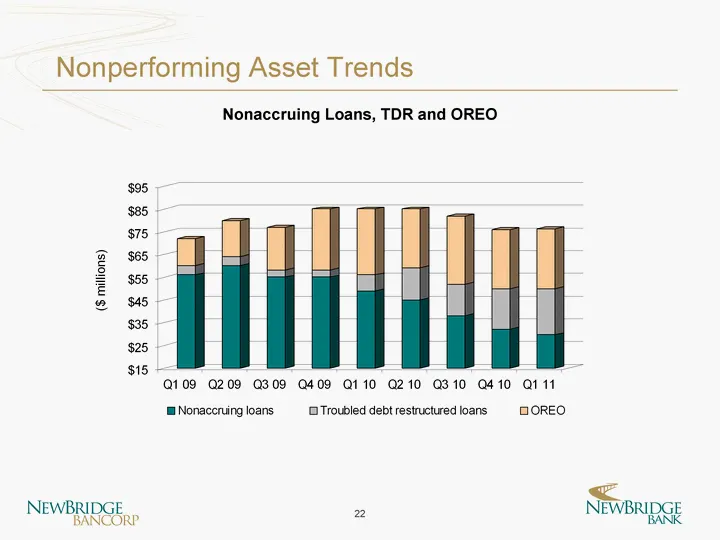
Slide 22: Nonperforming Asset Trends
Nonperforming Asset Trends Nonaccruing Loans, TDR and OREO
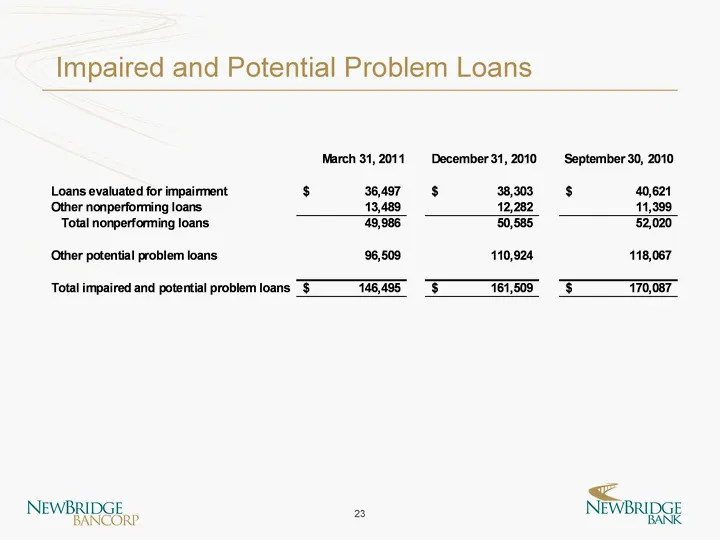
Slide 23: Impaired and Potential Problem Loans
Impaired and Potential Problem Loans
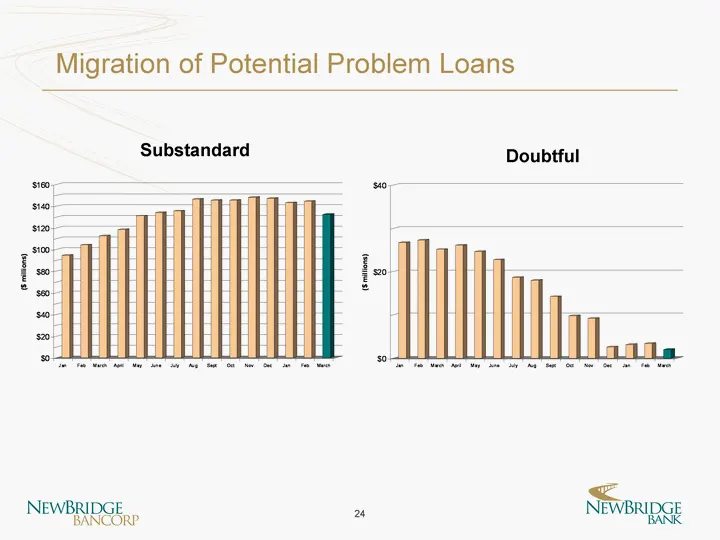
Slide 24: Migration of Potential Problem Loans
Migration of Potential Problem Loans Substandard Doubtful
Slide 25: ALLL Analysis
ALLL Analysis Charged off $123 million of loans and OREO since 2007 Impaired loans have been written down 21% as of Q1 2011 ALLL to retained loans is 2.32% as of Q1 2011 UBPR Peer percentage - 2.15% 93% of ALLL is in general reserves $29.1 million ALLL covers projected charge-offs by 1.50x
Slide 26: Risk Management Infrastructure
Risk Management Infrastructure Internal loan review reports to Board Credit Committee External loan review engaged by Board Credit Committee Appraisal/valuation function is independent from production Centralized construction administration Centralized retail and small business underwriting Fully au
Slide 27: Outlook and Summary
NBBC Overview Recent Performance Loan Portfolio Analysis Outlook and Summary
Slide 28: Outlook
Remain profitable as credit related costs expected to decline Net interest margin stable above 4% Credit improvement has relieved pressure to raise capital Measured investment in profitable business lines Continued focus on cost management culture Prepared to be an opportunistic/strategic acquirer T
Slide 29: Summary
Thriving community bank with critical mass Improving asset quality Gaining core deposit share in an attractive MSA Experienced management team No immediate capital needs Pursuing organic growth and expansion through LPO's/acquisition Trading at a discount to tangible book value Summary
Slide 30: Raymond James Financial, Inc. Chicago, Illinois May 25, 2011
Raymond James Financial, Inc. Chicago, Illinois May 25, 2011
Source: SEC EDGAR · 8-K filed May 24, 2011
More decks from NewBridge Bancorp
 Q4 2015 Earnings Presentation27 slides · Feb 11, 2016
 Merger or Acquisition (October 2015)18 slides · Oct 13, 2015
 Shareholder Meeting (May 2015)24 slides · May 13, 2015
 Merger or Acquisition (October 2014)14 slides · Oct 9, 2014
 Investor Presentation (August 2014)32 slides · Aug 6, 2014
 Shareholder Meeting (May 2014)17 slides · May 16, 2014