Southern Union — Howard Weil Energy Conference 2007
30 slides from Southern Union's conference presentation, Apr 2, 2007
Slide 1: Howard Weil Energy Conference
Howard Weil Energy Conference New Orleans April 1-5, 2007 www.sug.com
Slide 2: Forward-Looking Statements
Forward-Looking Statements Statements contained in this presentation that include company expectations or predictions of the future are forward-looking statements intended to be covered by the safe harbor provisions of the Securities Act of 1933 and the Securities Exchange Act of 1934. It is importa
Slide 3: Table of Contents
Table of Contents 9 Southern Union Company Overview 9 Strategic plan 9 Organic growth projects 9 Strategic initiatives 9 Financial information 9 Conclusion 9 Appendix 3
Slide 4: Southern Union Company Overview
Southern Union Company Overview
Slide 5: Map of Operations
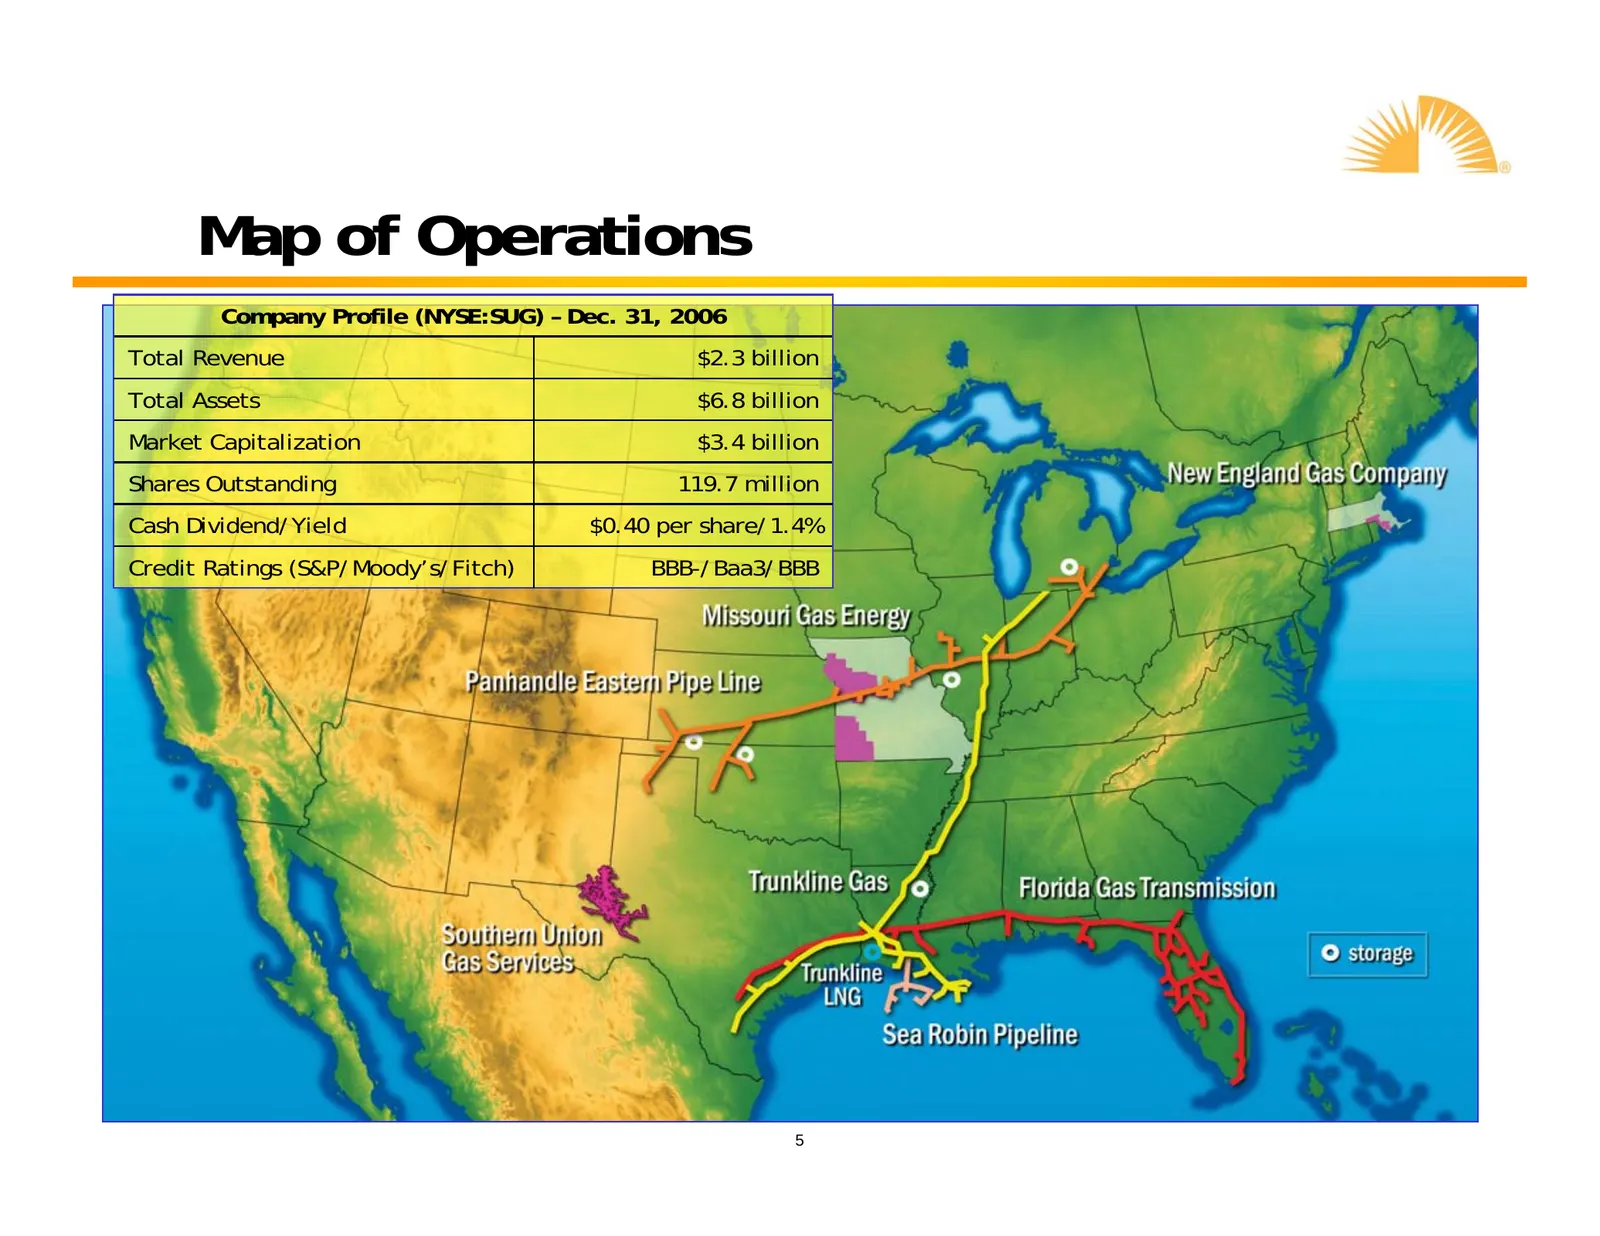
Map of Operations Company Profile (NYSE:SUG) – Dec. 31, 2006 Total Revenue $2.3 billion Total Assets $6.8 billion Market Capitalization $3.4 billion Shares Outstanding 119.7 million Cash Dividend/Yield $0.40 per share/1.4% Credit Ratings (S&P/Moody’s/Fitch) BBB-/Baa3/BBB 5
Slide 6: Value Through Transformation
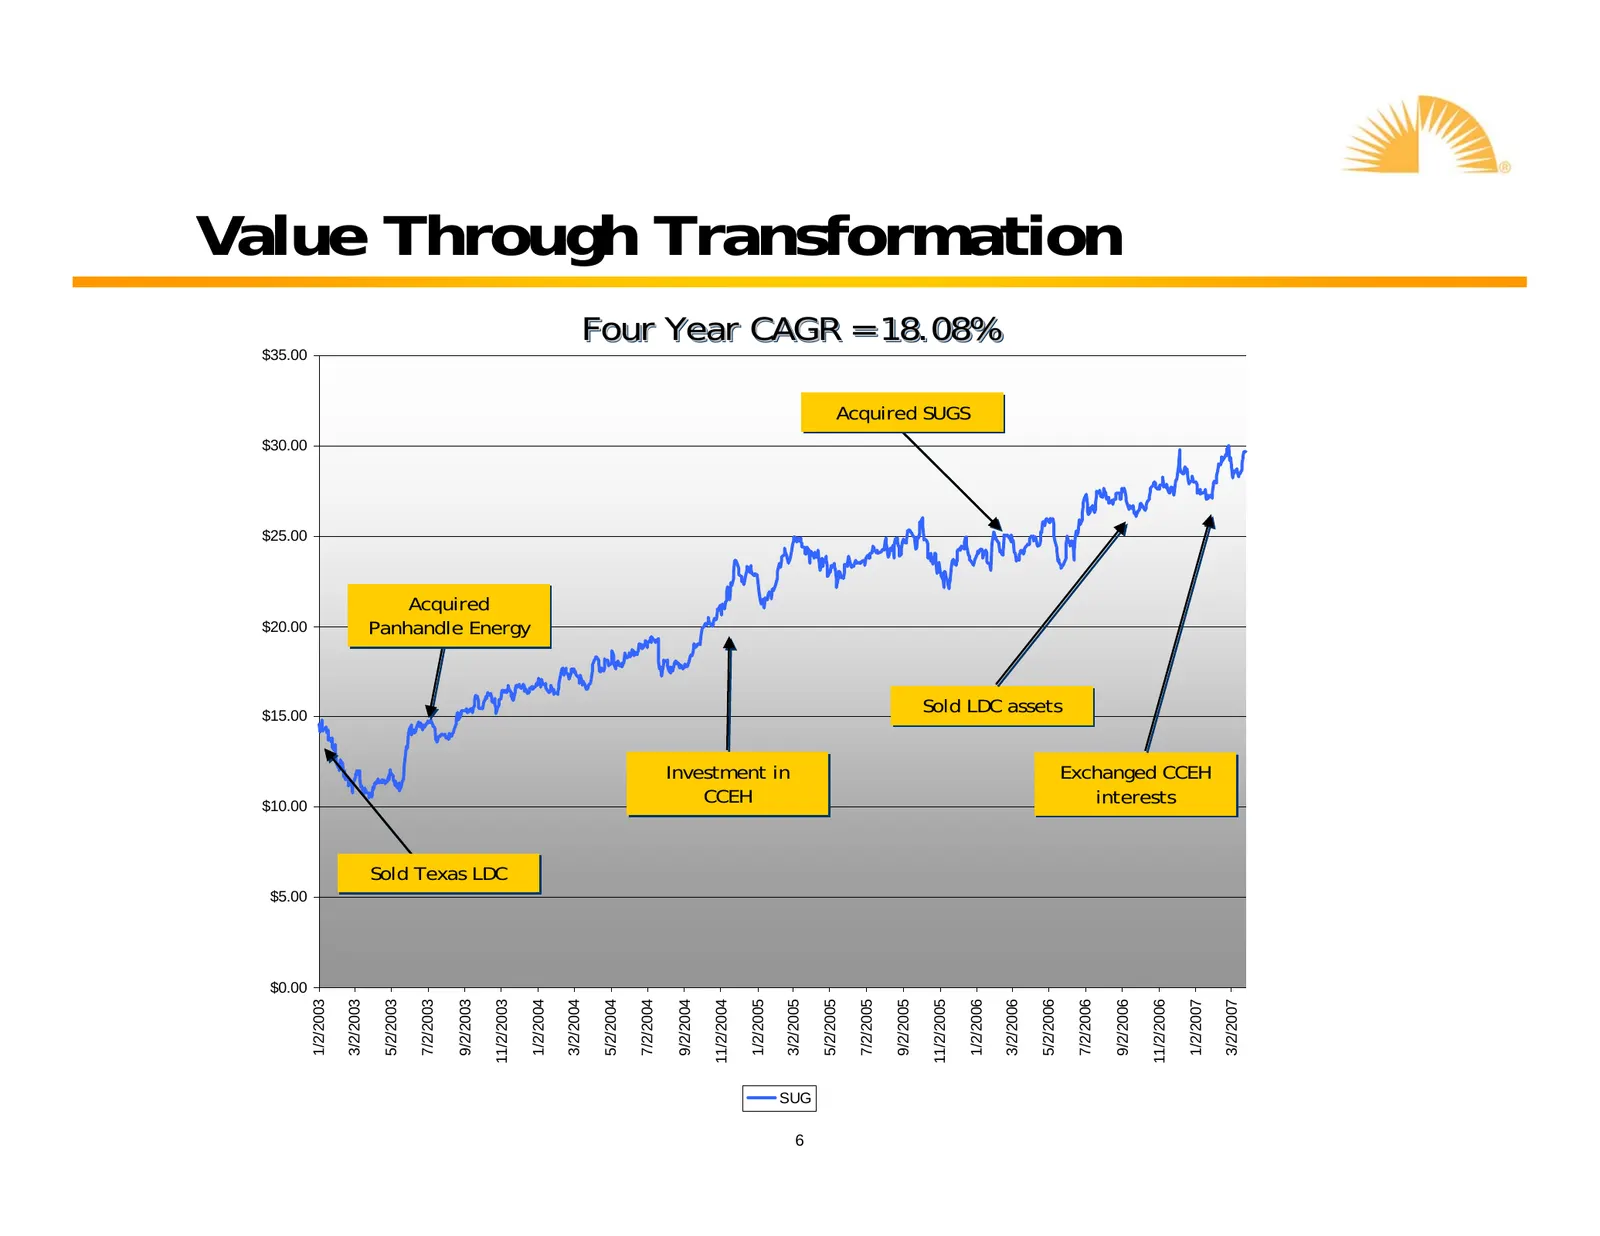
Value Through Transformation Four Year CAGR = 18.08% $35.00 Acquired Acquired SUGS SUGS $30.00 $25.00 Acquired Acquired $20.00 Panhandle Panhandle Energy Energy $15.00 Sold Sold LDC LDC assets assets Investment Investment in in Exchanged Exchanged CCEH CCEH $10.00 CCEH CCEH interests interests Sold
Slide 7: Significant Events - 2006
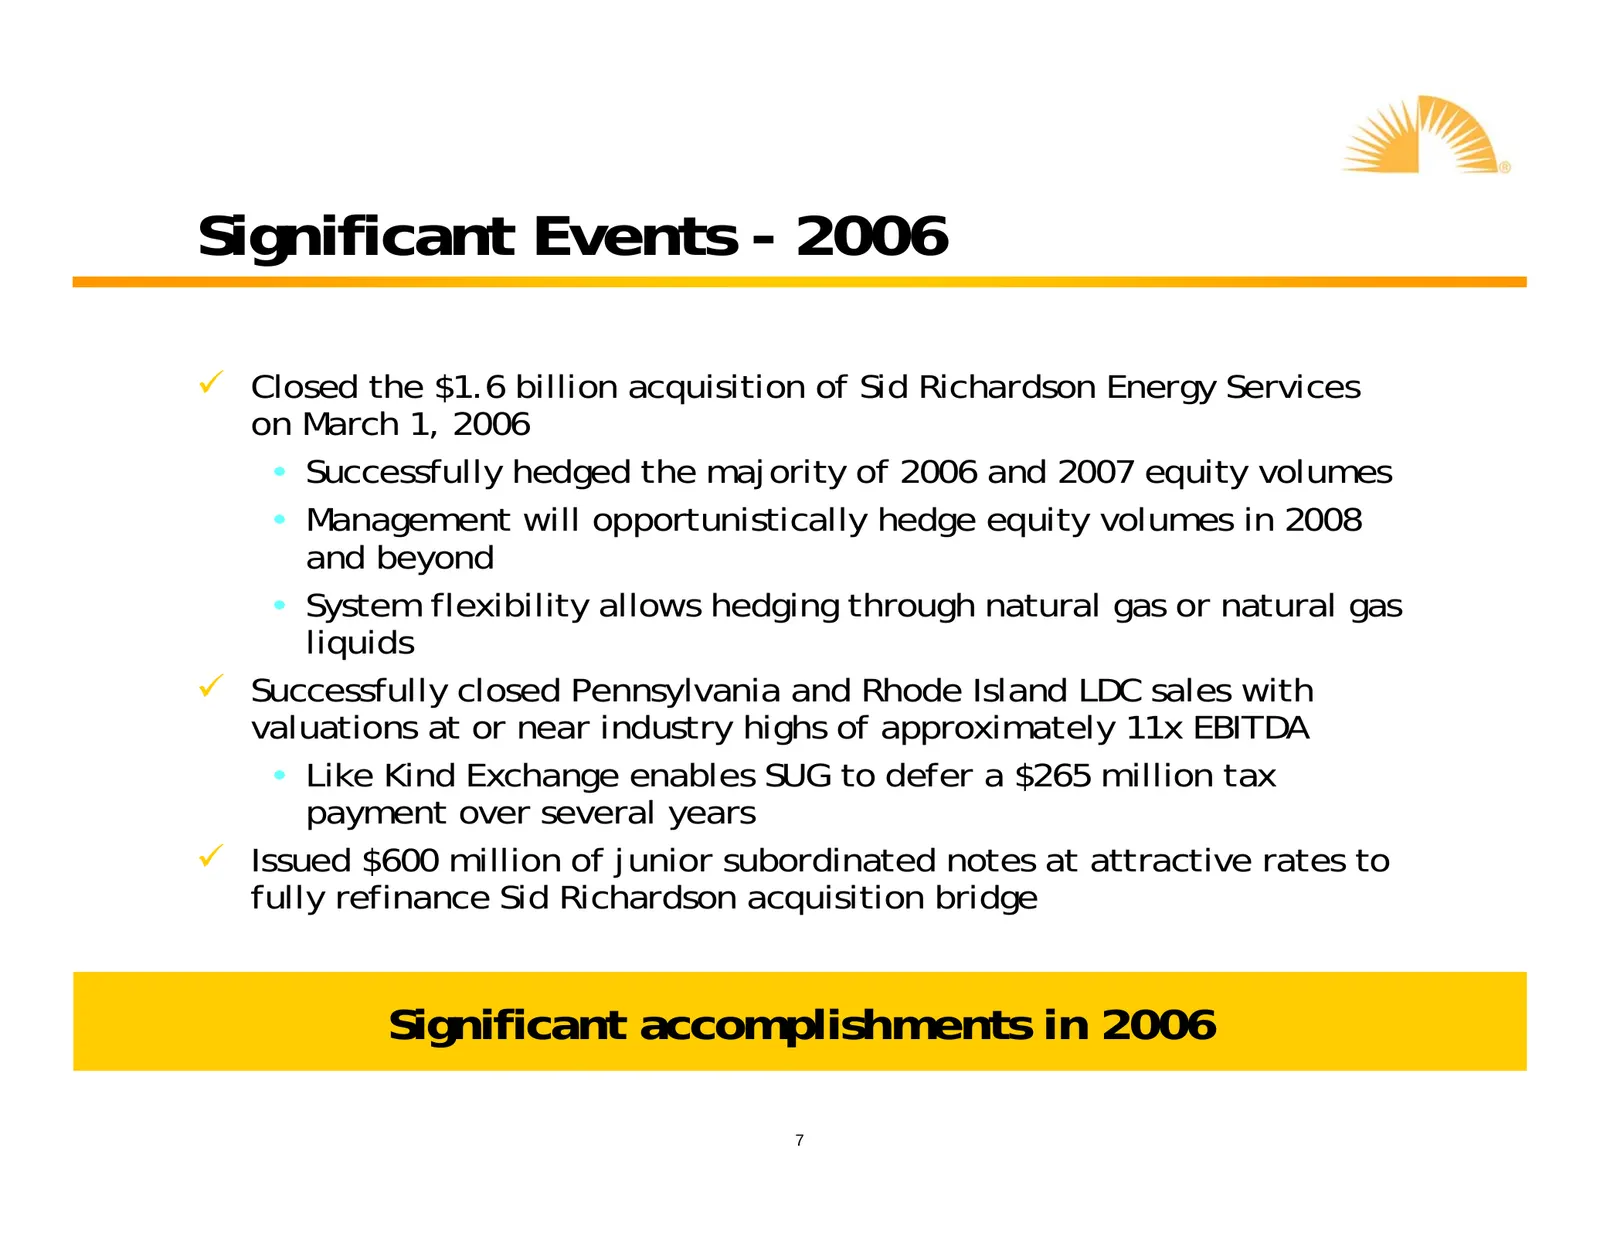
Significant Events - 2006 9 Closed the $1.6 billion acquisition of Sid Richardson Energy Services on March 1, 2006 • Successfully hedged the majority of 2006 and 2007 equity volumes • Management will opportunistically hedge equity volumes in 2008 and beyond • System flexibility allows hedging throug
Slide 8: Significant Events – 2006 (cont.)
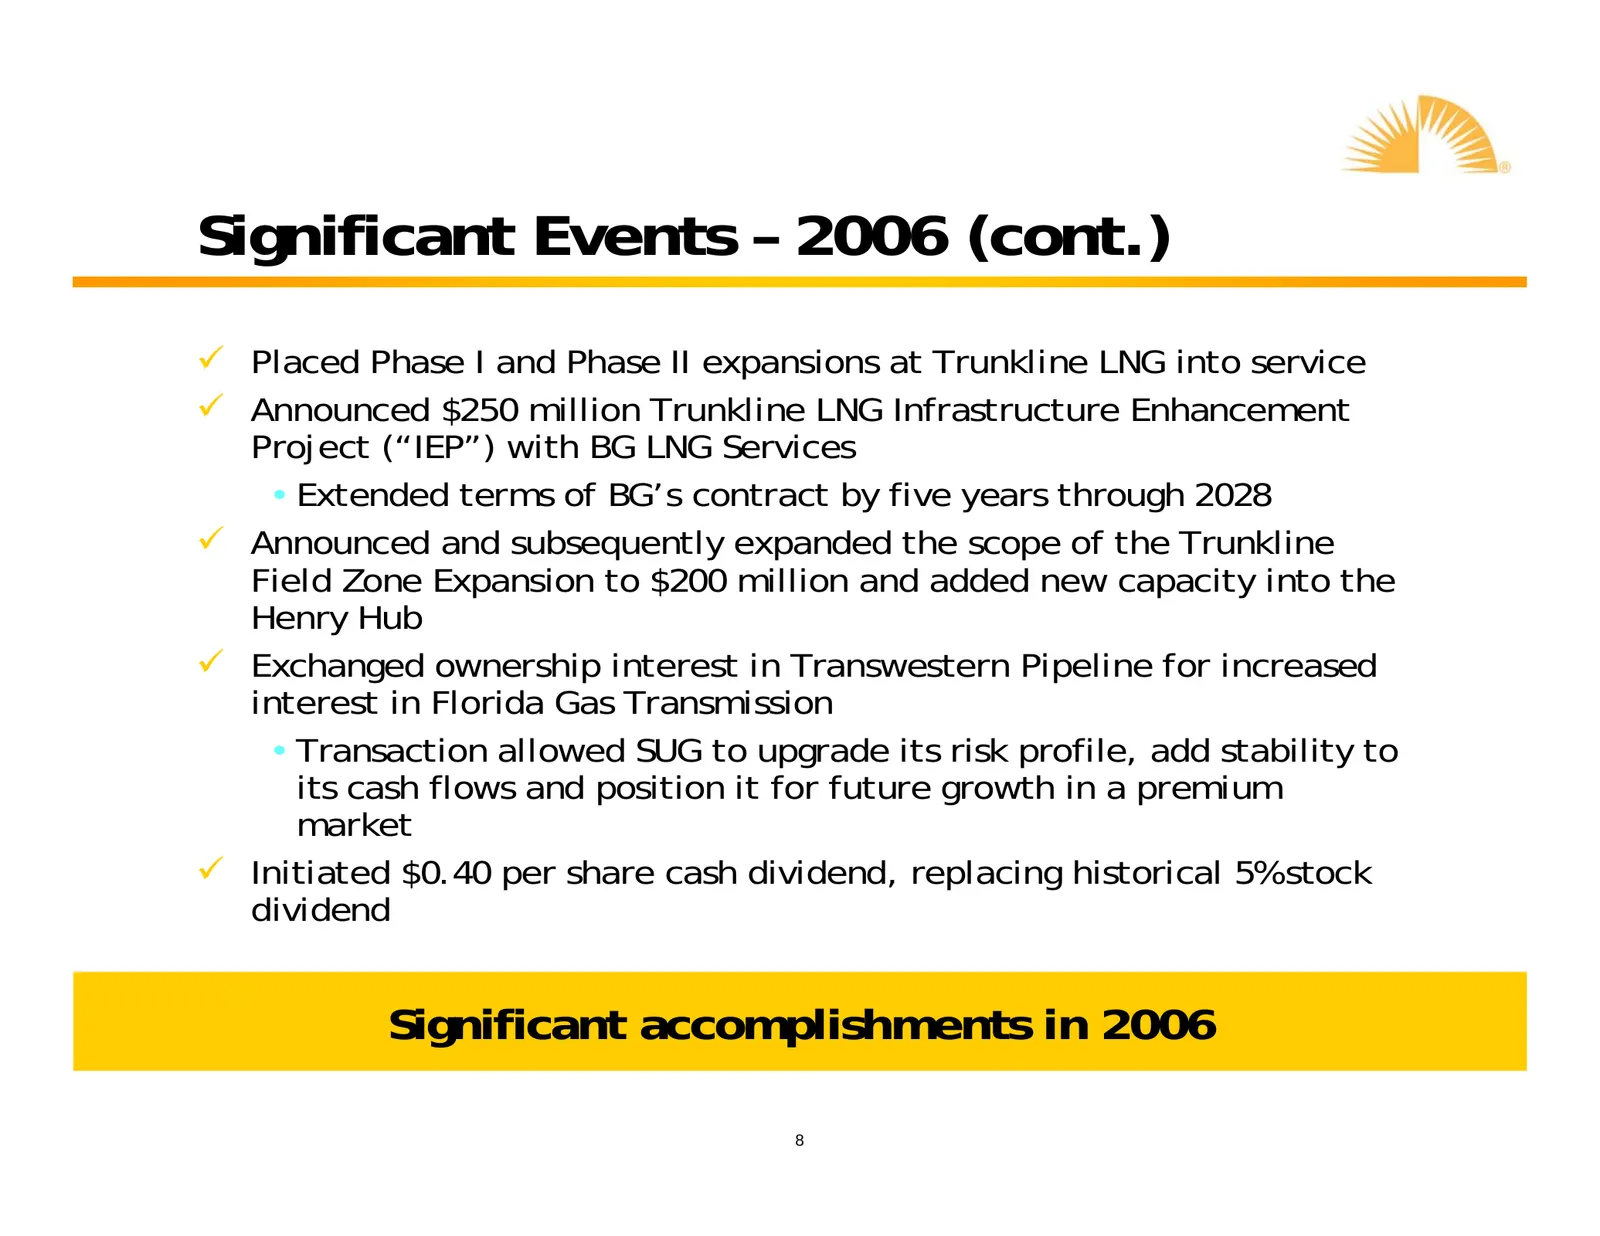
Significant Events – 2006 (cont.) 9 Placed Phase I and Phase II expansions at Trunkline LNG into service 9 Announced $250 million Trunkline LNG Infrastructure Enhancement Project (“IEP”) with BG LNG Services • Extended terms of BG’s contract by five years through 2028 9 Announced and subsequently ex
Slide 9: Strategic Plan
Strategic Plan yl”,
Slide 10: Strategic Plan Summary
Strategic Plan Summary 9 Southern Union Company’s entrepreneurial focus and strong work ethic has transformed it from a state-regulated natural gas utility to one of the nation’s largest diversified natural gas companies 9 Future value creation will come from: • Organic growth projects 9 Trunkline G
Slide 11: Organic Growth Projects
Organic Growth Projects yl”,
Slide 12: Trunkline Field Zone Expansion
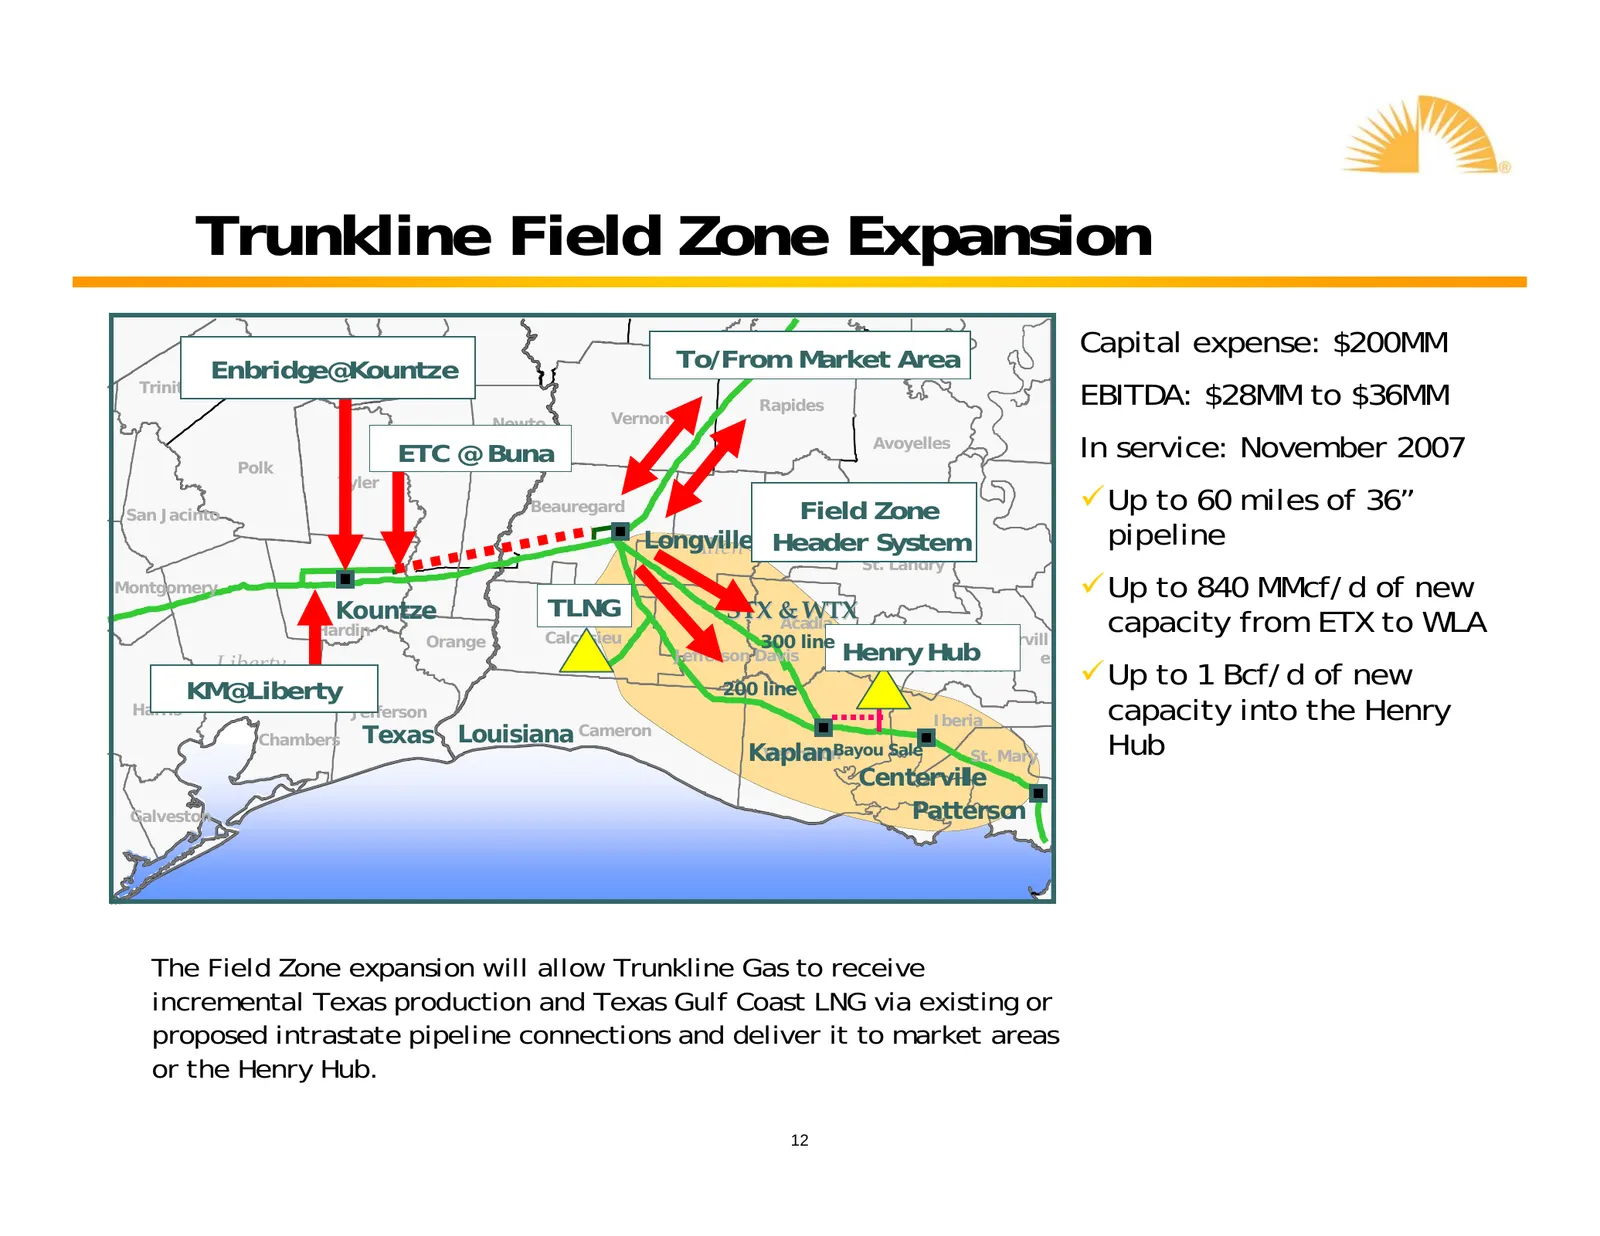
Trunkline Field Zone Expansion To/From Market Area Capital expense: $200MM Enbridge@Kountze Angelina Trinity Rapides EBITDA: $28MM to $36MM Newto Vernon ETC @ Buna Jasper n Avoyelles In service: November 2007 Polk Tyler San Jacinto Beauregard Field Zone 9Up to 60 miles of 36” Evangeline Allen Header
Slide 13: Trunkline LNG: Infrastructure Enhancement Project
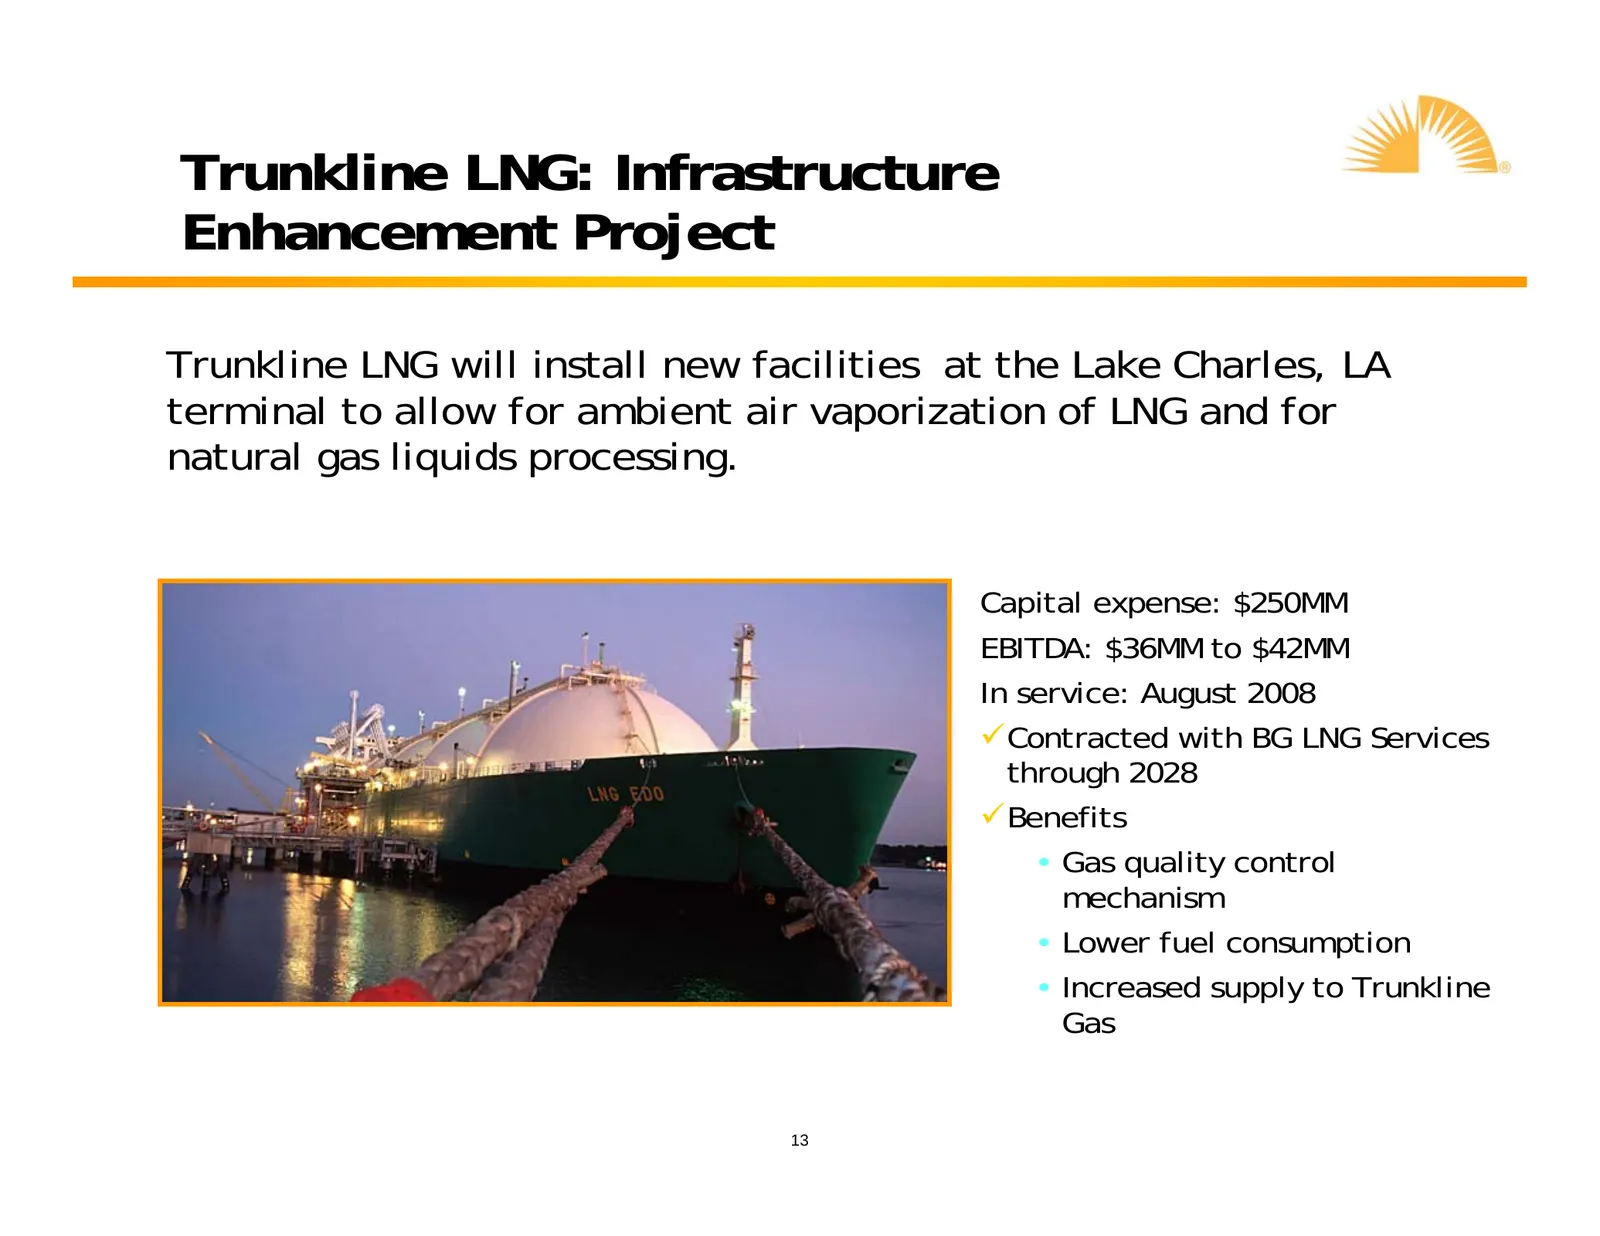
Trunkline LNG: Infrastructure Enhancement Project Trunkline LNG will install new facilities at the Lake Charles, LA terminal to allow for ambient air vaporization of LNG and for natural gas liquids processing. Capital expense: $250MM EBITDA: $36MM to $42MM In service: August 2008 9Contracted with BG
Slide 14: FGT Phase VII
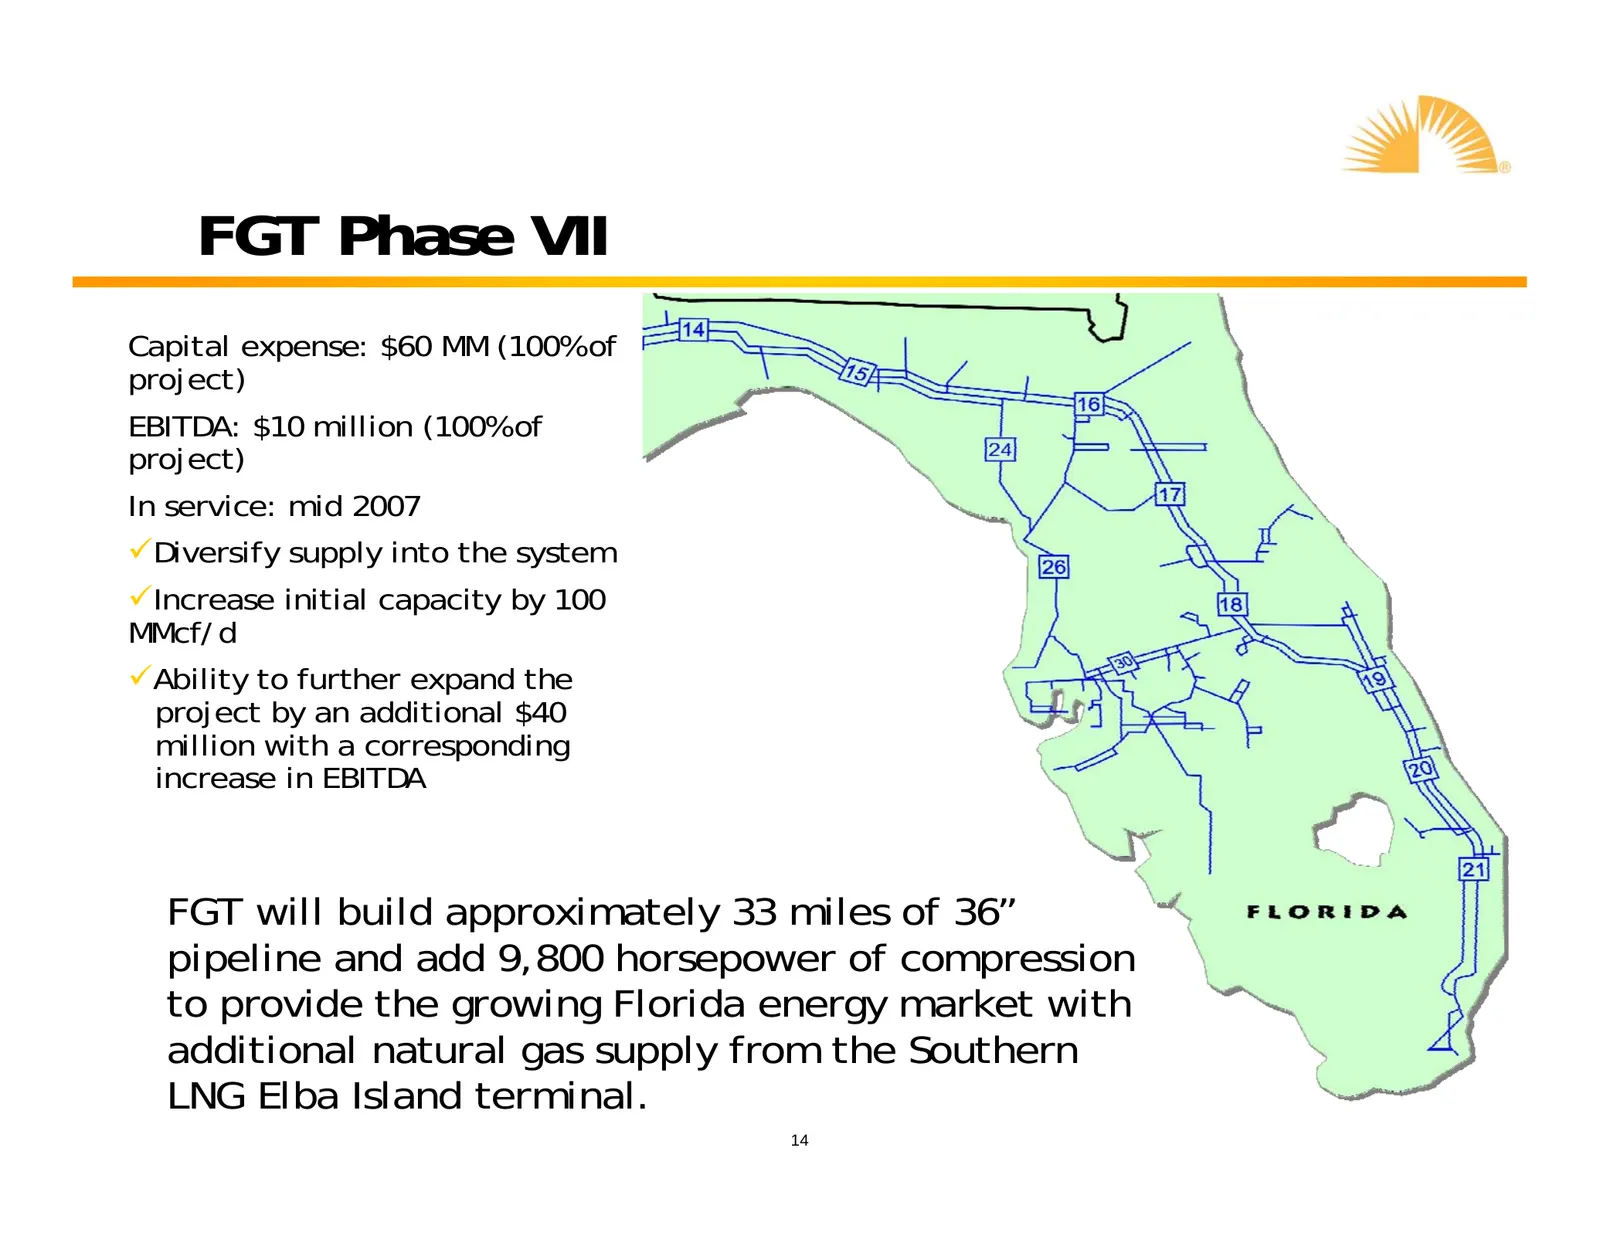
FGT Phase VII Capital expense: $60 MM (100% of project) EBITDA: $10 million (100% of project) In service: mid 2007 9Diversify supply into the system 9Increase initial capacity by 100 MMcf/d 9Ability to further expand the project by an additional $40 million with a corresponding increase in EBITDA FG
Slide 15: SUGS 2007 Project Summary
SUGS 2007 Project Summary 9 More than fifteen organic growth and system enhancement projects across the system 9 Up to $28MM of organic growth projects that will add incremental volumes to the system 9 Up to $23MM of system enhancement projects that will generate operating efficiencies and allow fur
Slide 16: SUGS Growth Projects
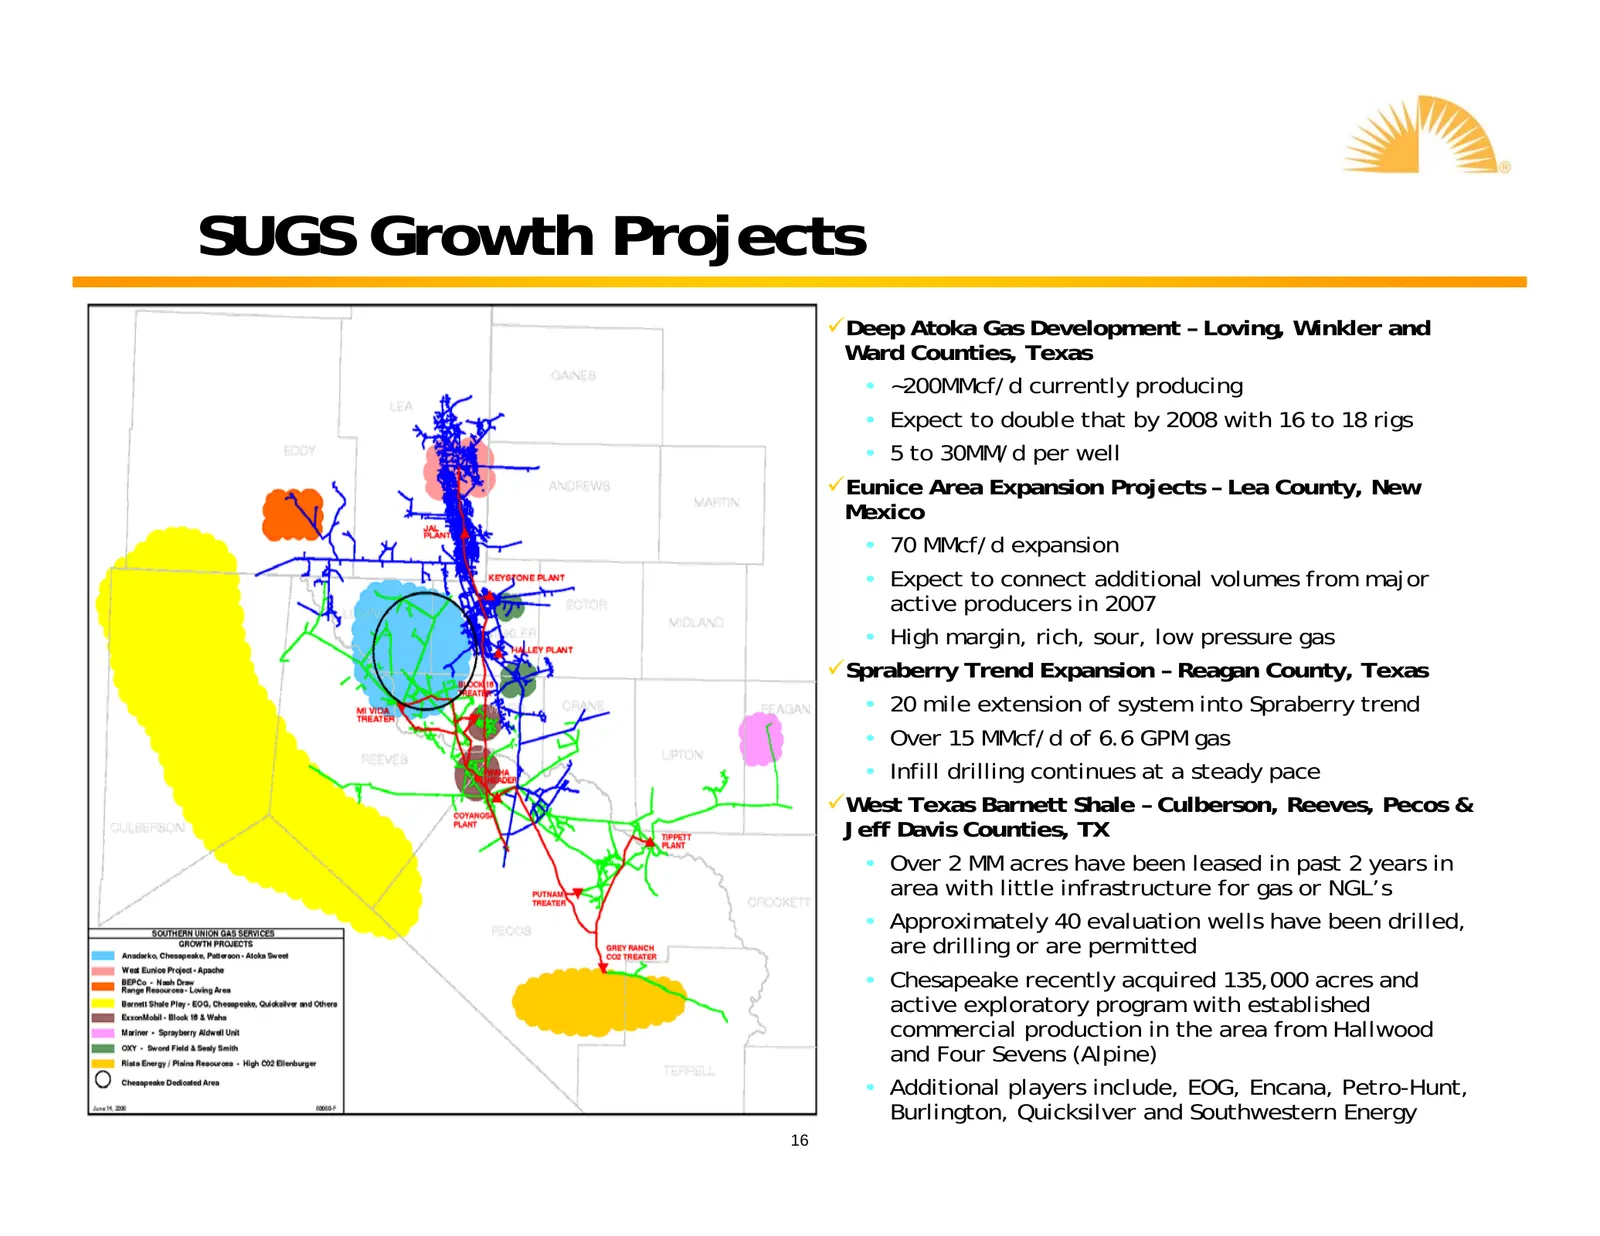
SUGS Growth Projects 9Deep Atoka Gas Development – Loving, Winkler and Ward Counties, Texas • ~200MMcf/d currently producing • Expect to double that by 2008 with 16 to 18 rigs • 5 to 30MM/d per well 9Eunice Area Expansion Projects – Lea County, New Mexico • 70 MMcf/d expansion • Expect to connect ad
Slide 17: Distribution Business Summary
Distribution Business Summary 9 Missouri Gas Energy • MGE is currently involved in a rate proceeding before the Missouri Public Service Commission • MGE is seeking a $41.7MM annual rate increase • MGE is seeking a straight fixed-variable rate design to mitigate weather and conservation impact on mar
Slide 18: Strategic Initiatives
Strategic Initiatives yl”,
Slide 19: MLP Structure
MLP Structure 9 SUG currently intends to create an MLP by the end of 3Q2007 with Southwest Gas Storage assets • MLP would seek to develop additional storage projects • MLP would seek market-based rates for Southwest Gas Storage and additional projects • Offering would be moderately sized to fit the
Slide 20: Market Opportunities
Market Opportunities 9 Southern Union to continue to evaluate opportunities in the market • Strategic acquisitions for SUG or potential MLP • Partnership or joint venture opportunities with other strategic investors 9 Southern Union Gas Services is well positioned to capture potential opportunities
Slide 21: Financial Information
Financial Information yl”,
Slide 22: Guidance and Outlook
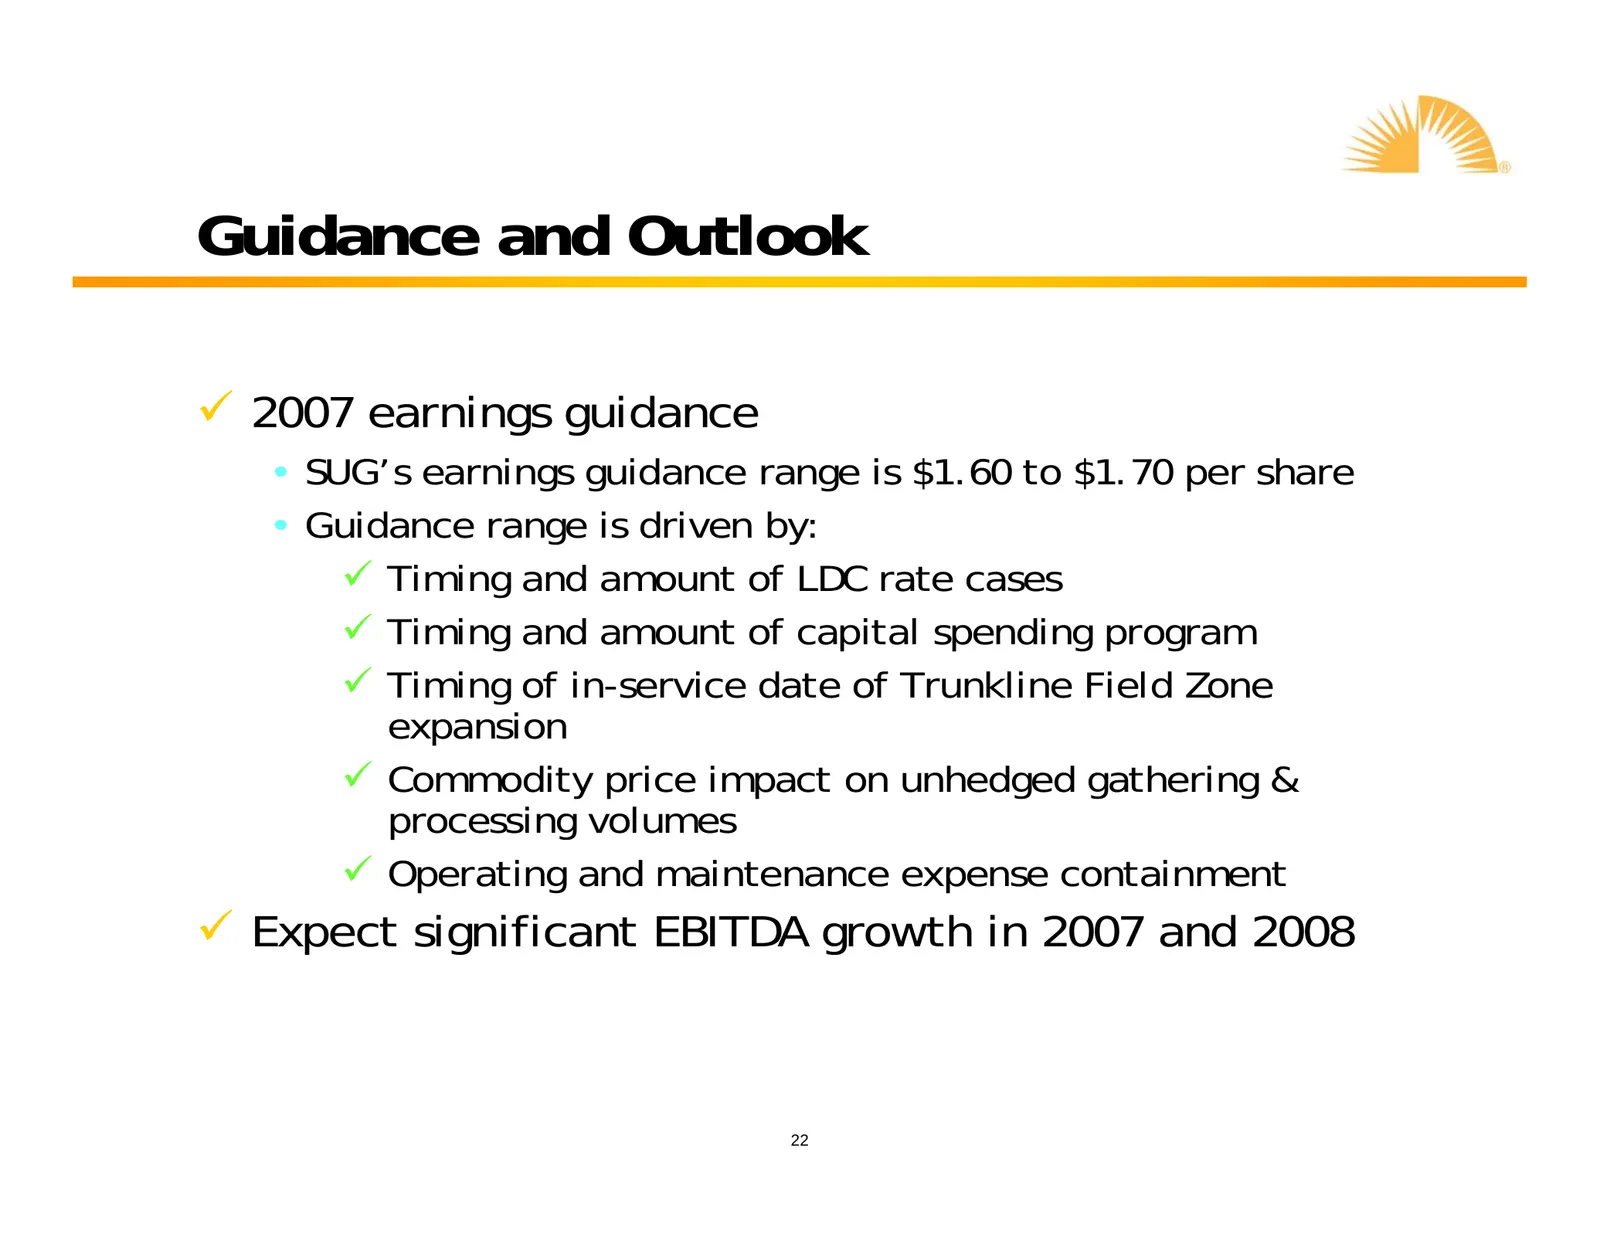
Guidance and Outlook 9 2007 earnings guidance • SUG’s earnings guidance range is $1.60 to $1.70 per share • Guidance range is driven by: 9 Timing and amount of LDC rate cases 9 Timing and amount of capital spending program 9 Timing of in-service date of Trunkline Field Zone expansion 9 Commodity pri
Slide 23: Pro Forma EBITDA
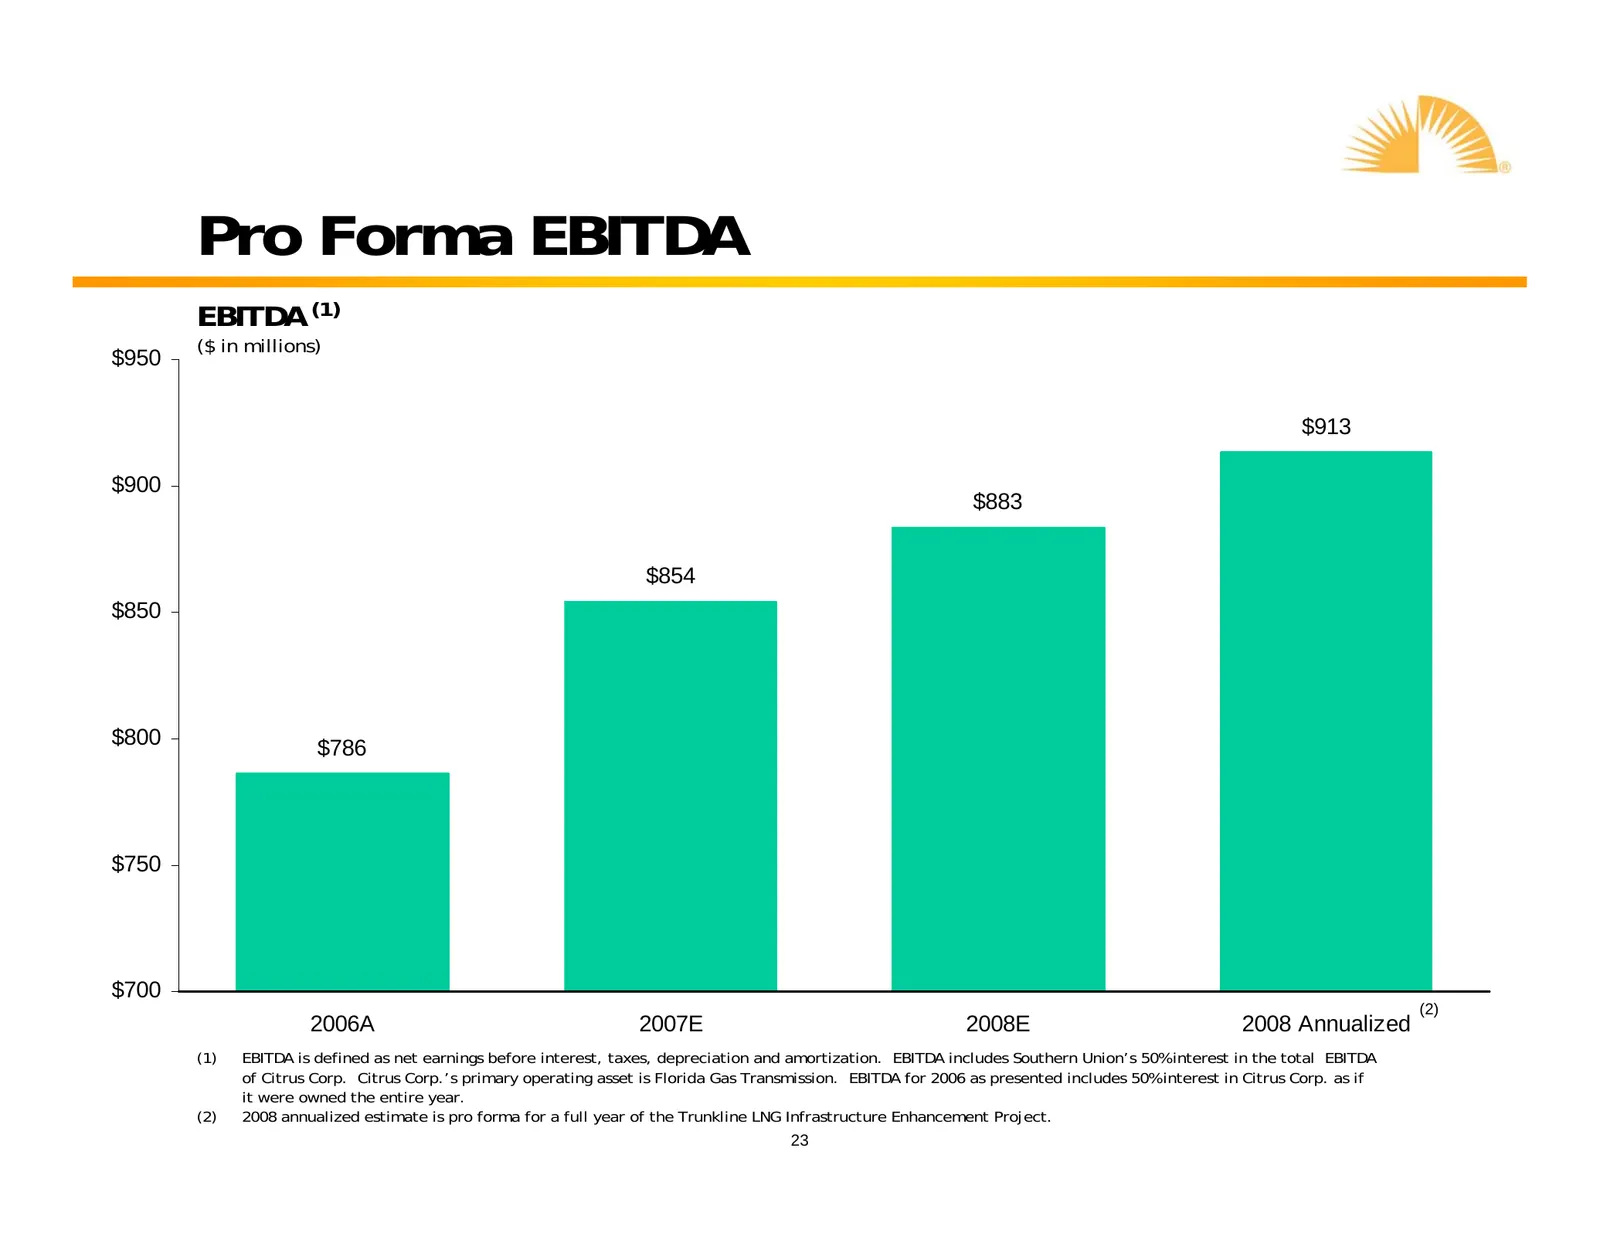
Pro Forma EBITDA EBITDA (1) ($ in millions) $950 $913 $900 $883 $854 $850 $800 $786 $750 $700 (2) 2006A 2007E 2008E 2008 Annualized (1) EBITDA is defined as net earnings before interest, taxes, depreciation and amortization. EBITDA includes Southern Union’s 50% interest in the total EBITDA of Citrus
Slide 24: Pro Forma EBITDA – Segments
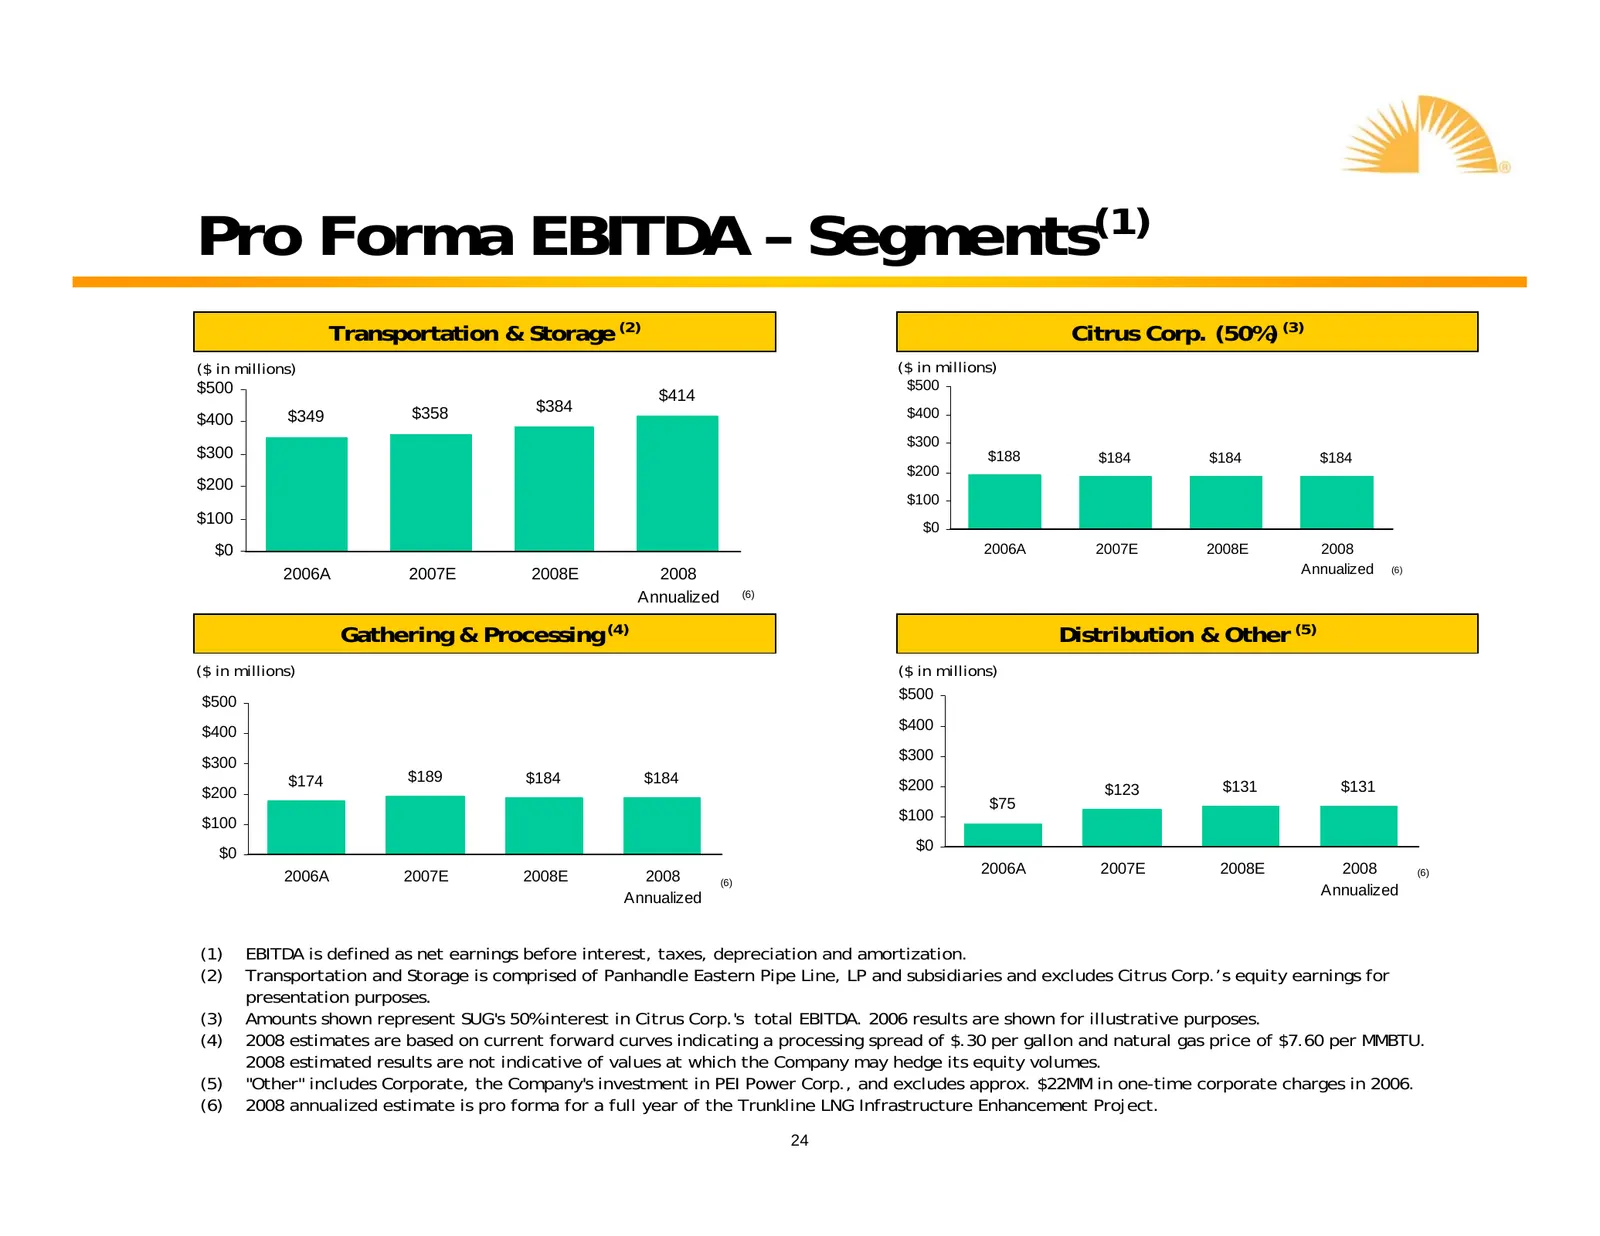
Pro Forma EBITDA – Segments(1) Transportation & Storage (2) Citrus Corp. (50%) (3) ($ in millions) ($ in millions) $500 $500 $414 $358 $384 $400 $400 $349 $300 $300 $188 $184 $184 $184 $200 $200 $100 $100 $0 $0 2006A 2007E 2008E 2008 2006A 2007E 2008E 2008 Annualized (6) Annualized (6) Gathering & P
Slide 25: Investment Grade Focus
Investment Grade Focus 9 Preservation of investment grade ratings is important for: • Lower financing costs while accessing capital markets • Rate making and reduced regulatory scrutiny • Mitigates the need to post collateral in gathering & processing and distribution segments • Park and loan busine
Slide 26: Conclusion
Conclusion yl”,
Slide 27: Summary
Summary 9 Compelling vision and clear strategic plan going forward • Strategic transformation and value creation achieved • Organic growth projects well advanced with clear visibility for value creation • MLP structure as a growth vehicle providing a lower cost of capital and strategic flexibility •
Slide 28: Appendix
Appendix yl”,
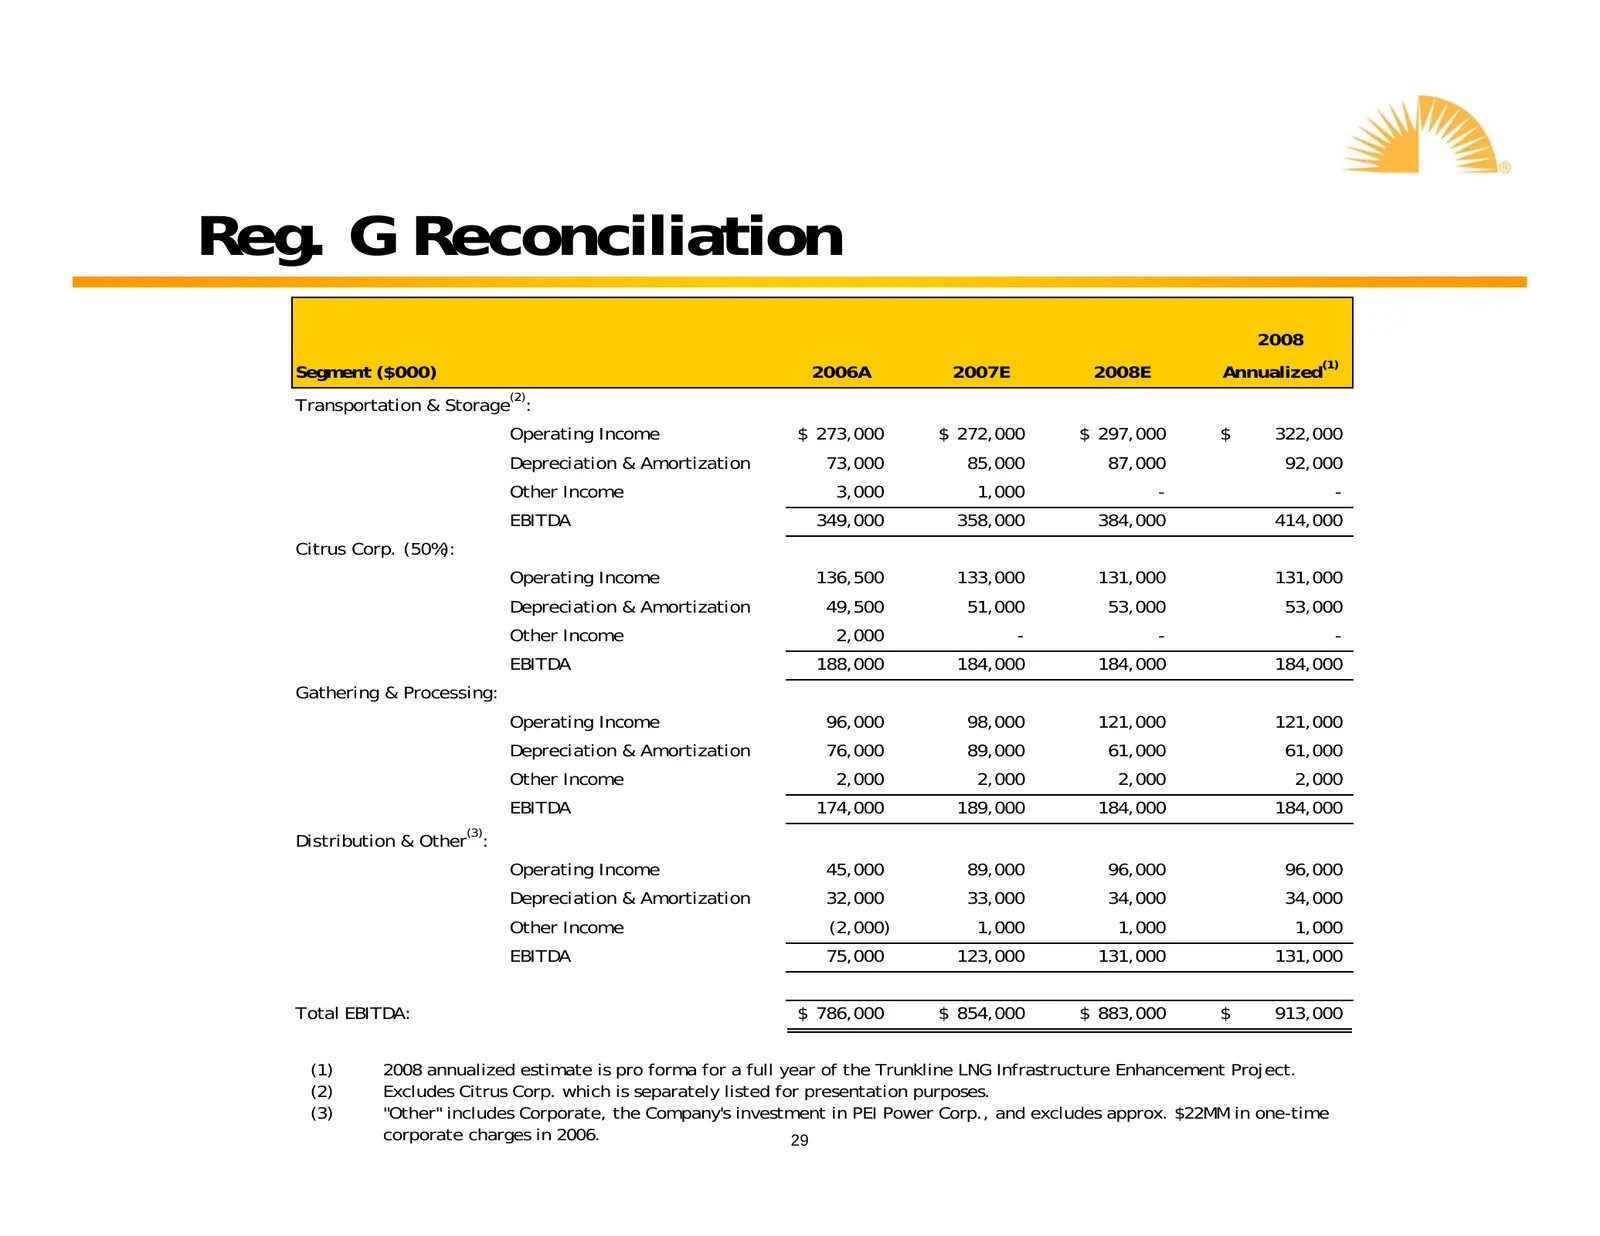
Slide 29: Reg. G Reconciliation
Reg. G Reconciliation 2008 (1) Segment ($000) 2006A 2007E 2008E Annualized (2) Transportation & Storage : Operating Income $ 273,000 $ 272,000 $ 297,000 $ 322,000 Depreciation & Amortization 73,000 85,000 87,000 92,000 Other Income 3,000 1,000 - - EBITDA 349,000 358,000 384,000 414,000 Citrus Corp.
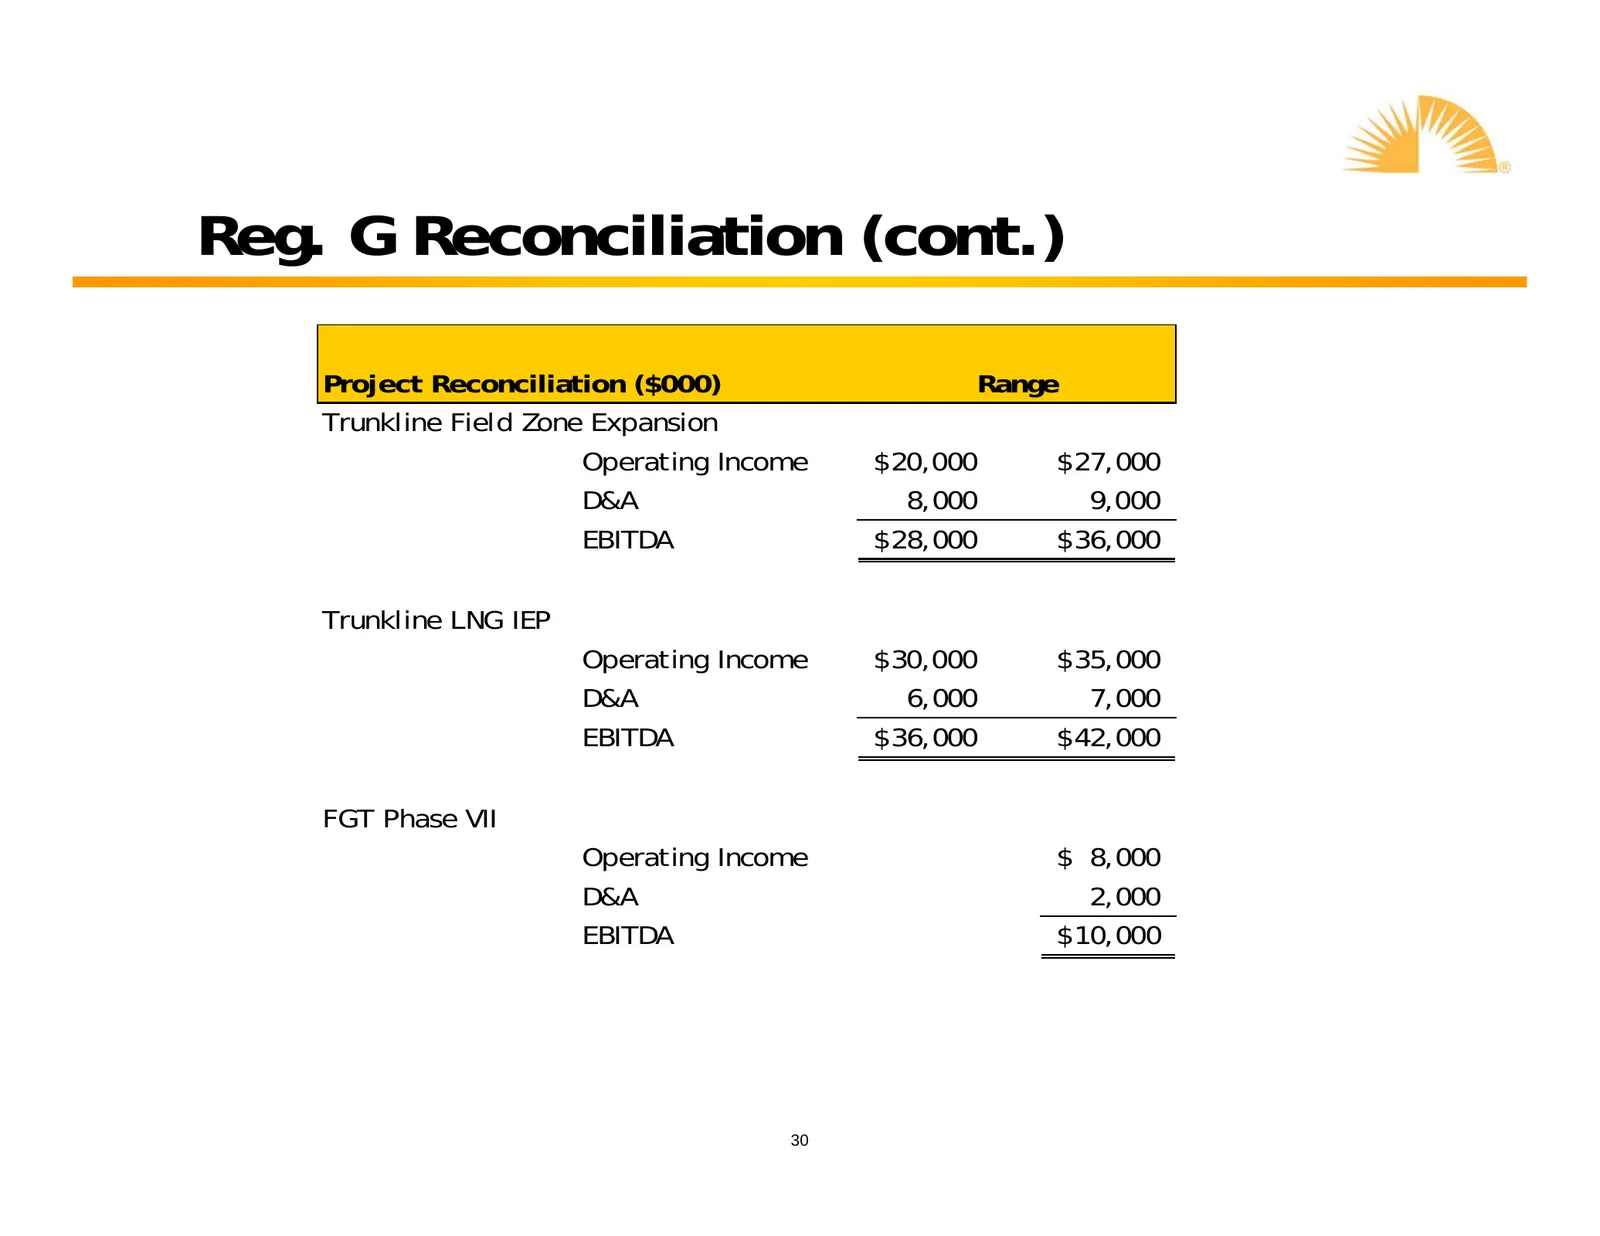
Slide 30: Reg. G Reconciliation (cont.)
Reg. G Reconciliation (cont.) Project Reconciliation ($000) Range Trunkline Field Zone Expansion Operating Income $ 20,000 $ 27,000 D&A 8,000 9,000 EBITDA $ 28,000 $ 36,000 Trunkline LNG IEP Operating Income $ 30,000 $ 35,000 D&A 6,000 7,000 EBITDA $ 36,000 $ 42,000 FGT Phase VII Operating Income $
Source: SEC EDGAR · 8-K filed Apr 2, 2007
More decks from Southern Union Co
 Barclays Capital Investment Grade Energy and Pipeline Conference 201232 slides · Mar 8, 2012
 Debt Investor Presentation (February 2012)33 slides · Feb 22, 2012
 Merger or Acquisition (July 2011)11 slides · Jul 5, 2011
 Merger or Acquisition (June 2011)22 slides · Jun 16, 2011
 Investor Presentation (February 2011)37 slides · Feb 25, 2011
 BMO Capital Markets 2010 Utilities and Pipelines Day23 slides · Nov 30, 2010