Carramerica Realty — Investor Day (September 2005)
91 slides from Carramerica Realty's investor day presentation, Sep 20, 2005
Slide 1: Investor Day Program
Investor Day Program September 20, 2005
Slide 2: Agenda: Safe Harbor and Overview
Agenda Safe Harbor Agenda Overview Steve Walsh, Senior VP, Capital Markets
Slide 3: Forward-Looking Statements
Forward-Looking Statements Certain statements in this package may constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Such forward-looking statements involve known and unknown risks, uncertainties and other factors that may cause the ac
Slide 4: Agenda: Operating Strategy
Agenda Operating Strategy Presented by: Phil Hawkins, President & COO
Slide 5: Agenda: Washington, DC Market Review
Agenda Washington, DC Market Review Presented by: Phillip Thomas, Managing Director
Slide 6: Agenda: Chicago Market Review
Agenda Chicago Market Review Presented by: Jerry O’Malley, Managing Director
Slide 7: Agenda: Texas and Denver/Salt Lake Market Review
Agenda Texas and Denver/Salt Lake Market Review Presented by: Jeff Pace, Managing Director
Slide 8: Break
BREAK
Slide 9: Agenda: Seattle Market Review
Agenda Seattle Market Review Presented by: Clete Casper, Managing Director
Slide 10: Agenda: Southern California Market Review
Agenda Southern California Market Review Presented by: Malcolm O’Donnell, Managing Director
Slide 11: Agenda: San Francisco Bay Area Market Review
Agenda San Francisco Bay Area Market Review Presented by: Christopher Peatross, Managing Director
Slide 12: Agenda: The Future, Wrap Up and Q&A
Agenda The Future Wrap Up and Q&A Presented by: Tom Carr, CEO
Slide 13: Agenda
Agenda Overview and Operating Strategy: Phil Hawkins, President Market Reviews: Washington—Phillip Thomas Chicago—Jerry O’Malley Texas and Denver/SLC—Jeff Pace Seattle—Clete Casper Southern California—Malcolm O’Donnell San Francisco Bay Area—Chris Peatross The Future and Wrap Up: Tom Carr, CEO
Slide 14: National Real Estate Company Today
National Real Estate Company Today National company; strong market focus A high-quality office portfolio 43 years of real estate experience 27 million SF in 290 operating properties $4.2 billion enterprise value
Slide 15: Key Messages
CarrAmerica Investor Conference Key Messages Strong execution through the market downturn Market improvement is accelerating CarrAmerica is very well positioned to benefit from the recovery
Slide 16: Strong Execution Through the Market Downturn
Operating Strategy Strong Execution Through the Market Downturn (2002—2004) Averaged approximately 2.9 million SF of leasing and maintained occupancy above market averages Dramatically upgraded portfolio Maintained financial flexibility Completely upgraded back-of-house while cutting overhead
Slide 17: Dramatically Upgraded the Portfolio
Operating Strategy Dramatically Upgraded the Portfolio (2002 to Today) Acquired $1.1 billion of high-quality assets Sold $709 million of non-core assets Concentrated capital into infill locations and out of commodity, suburban office
Slide 18: Recent Additions of High Quality Assets
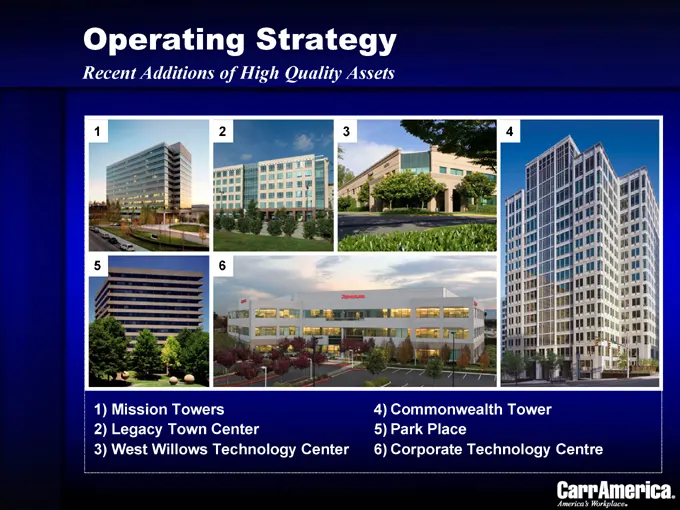
Operating Strategy Recent Additions of High Quality Assets 1 2 3 4 5 6 1) Mission Towers 2) Legacy Town Center 3) West Willows Technology Center 4) Commonwealth Tower 5) Park Place 6) Corporate Technology Centre
Slide 19: Focused Portfolio: Property Operating Income
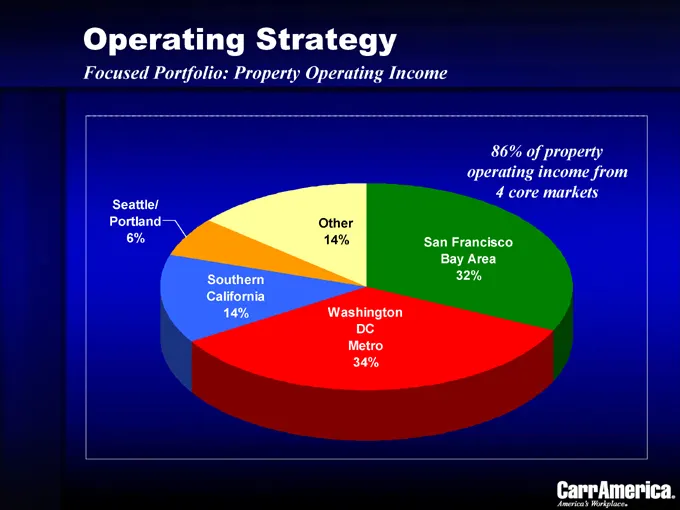
Operating Strategy Focused Portfolio: Property Operating Income 86% of property operating income from 4 core markets Seattle/Portland 6% Other 14% San Francisco Bay Area 32% Washington DC Metro 34% Southern California 14%
Slide 20: Improved Operations and Strengthened Balance Sheet
Operating Strategy Improved Operations and Strengthened Balance Sheet Created the Shared Service Center and cut approximately $8 million from G&A costs Maintained investment grade ratings at mid BBB Created financial flexibility with asset sales and equity offering
Slide 21: Broad Based Market Improvement Creates Opportunity
Operating Strategy Broad Based Market Improvement Creates Opportunity Vacancy rates have dropped in all markets, but CarrAmerica’s key submarkets have improved more significantly Key submarkets in DC, close-in Virginia, Orange County, San Diego, Austin and Eastside Seattle are experiencing: Strong r
Slide 22: Strong Local Player Well Positioned in the Markets
Operating Strategy Strong Local Player that is Well Positioned in the Markets Seasoned local teams with strong experience and great relationships Highly decentralized decision making Strong submarket focus Ready to take advantage of all opportunities
Slide 23: Key Focus Areas to Improve Results
Operating Strategy Key Focus Areas to Improve Results Leasing Increase occupancy and push rental economics Investments Continued focus on quality assets Development Active developer in strong submarkets Service Successful 3rd party service business leverages local team’s capabilities and increases R
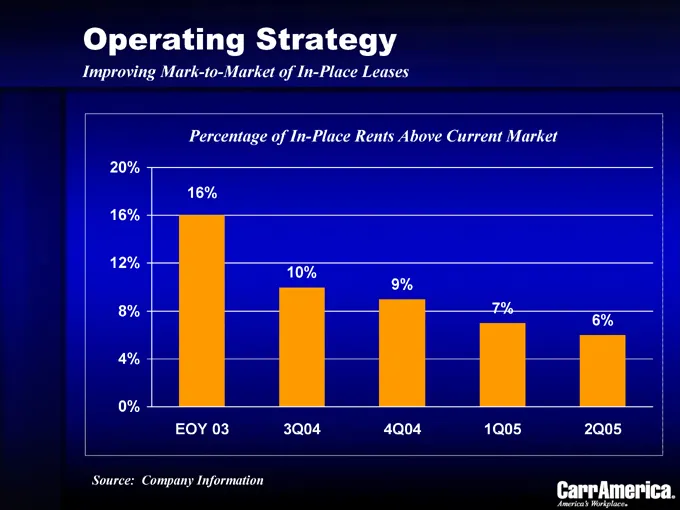
Slide 24: Improving Mark-to-Market of In-Place Leases
Operating Strategy Improving Mark-to-Market of In-Place Leases Percentage of In-Place Rents Above Current Market 20% 16% 12% 8% 4% 0% 16% 10% 9% 7% 6% EOY 03 3Q04 4Q04 1Q05 2Q05 Source: Company Information
Slide 25: Improving Portfolio Operating Dynamics
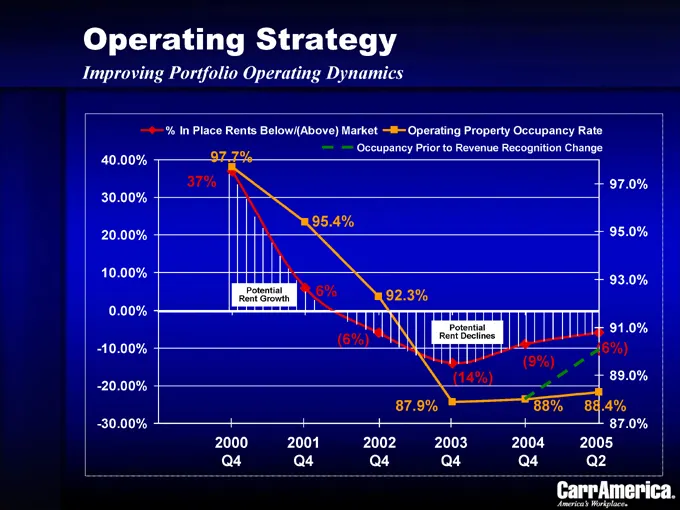
Operating Strategy Improving Portfolio Operating Dynamics % In Place Rents Below/(Above) Market Operating Property Occupancy Rate Occupancy Prior to Revenue Recognition Change 40.00% 30.00% 20.00% 10.00% 0.00% -10.00% -20.00% -30.00% 97.7% 37% 95.4% 6% Potential Rent Growth (6%) 92.3% Potential Rent
Slide 26: Acquisitions and Dispositions Recycling
Operating Strategy Acquisitions and Dispositions – Recycling has Improved our Position Reduced exposure to underperforming markets, submarkets and assets Provided reinvestment dollars to upgrade the portfolio and improve submarket presence Generated significant gains
Slide 27: Agenda
Agenda Overview and Operating Strategy: Phil Hawkins, President Market Reviews: Washington—Phillip Thomas Chicago—Jerry O’Malley Texas and Denver/SLC—Jeff Pace Seattle—Clete Casper Southern California—Malcolm O’Donnell San Francisco Bay Area—Chris Peatross The Future and Wrap Up: Tom Carr, CEO
Slide 28: Washington, DC Market Scorecard
Washington, DC Market Market Scorecard 98% portfolio occupancy Approximately 90% of IMF vacancy committed Diverse value added transactions Terrell Place trophy JV development Douglas Development relationship: Atlantic Building and 1199 F Street Third party service IMF, Newseum, Shakespeare Theatre S
Slide 29: Washington, D.C. Office Inventory
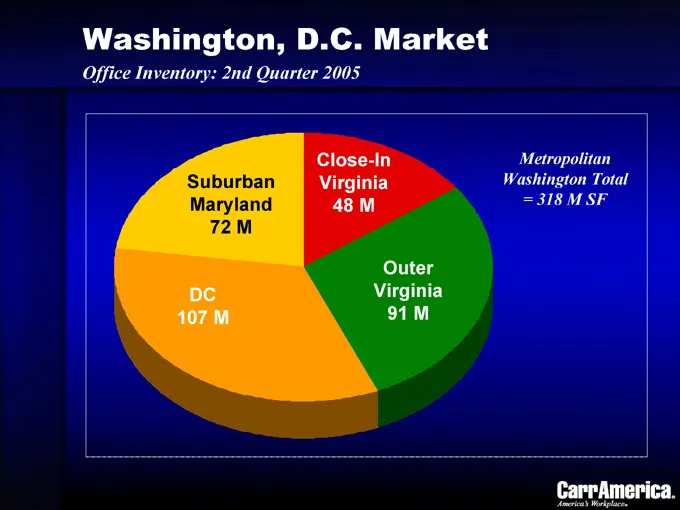
Washington, D.C. Market Office Inventory: 2nd Quarter 2005 Metropolitan Washington Total = 318 M SF Close-In Virginia 48 M Outer Virginia 91 M DC 107 M Suburban Maryland 72 M
Slide 30: Washington, D.C. Total Vacancy
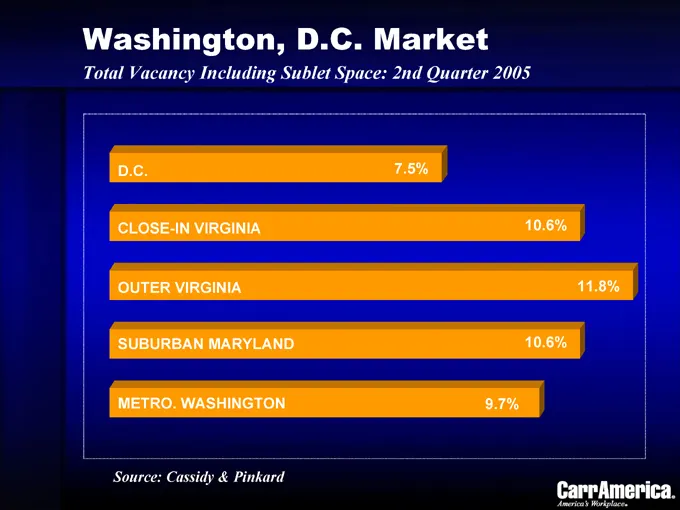
Washington, D.C. Market Total Vacancy Including Sublet Space: 2nd Quarter 2005 D.C. 7.5% CLOSE-IN VIRGINIA 10.6% OUTER VIRGINIA 11.8% SUBURBAN MARYLAND 10.6% METRO. WASHINGTON 9.7% Source: Cassidy & Pinkard
Slide 31: Washington, D.C. Market Dynamics
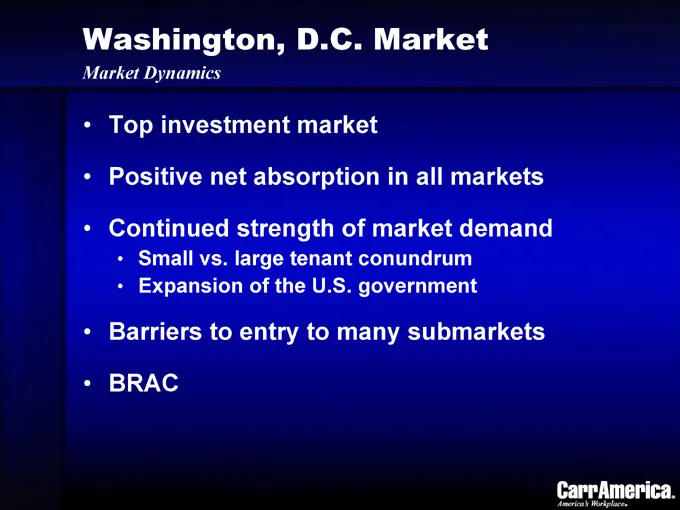
Washington, D.C. Market Market Dynamics Top investment market Positive net absorption in all markets Continued strength of market demand Small vs. large tenant conundrum Expansion of the U.S. government Barriers to entry to many submarkets BRAC
Slide 32: CarrAmerica's Presence in Washington
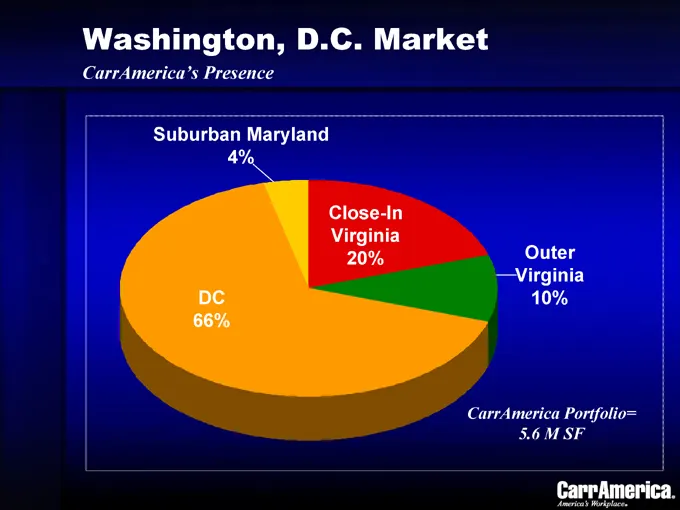
Washington, D.C. Market CarrAmerica’s Presence Suburban Maryland 4% Close-In Virginia 20% Outer Virginia 10% DC 66% CarrAmerica Portfolio= 5.6 M SF
Slide 33: Washington Current Market Strategy
Washington, D.C. Market Current Market Strategy Leverage strong market presence into new transactions Opportunistically invest to outperform market returns Invested $481 million from 1/1/02 to present Increase control of land sites in downtown Washington and key suburban submarkets
Slide 34: Recent Investments: Park Place
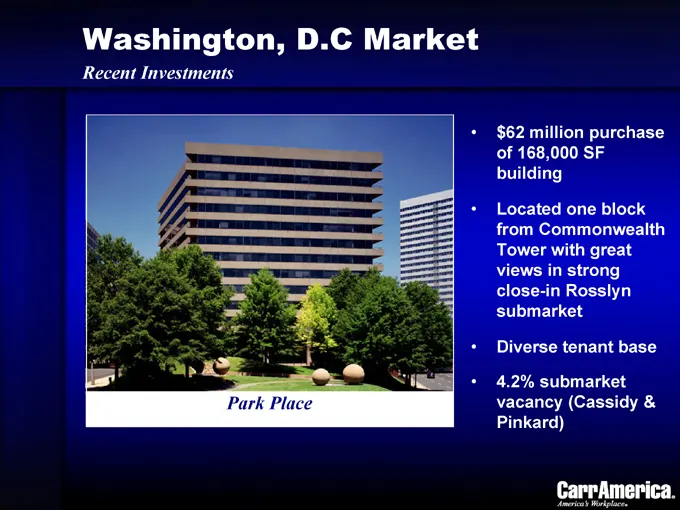
Washington, D.C Market Recent Investments $62 million purchase of 168,000 SF building Located one block from Commonwealth Tower with great views in strong close-in Rosslyn submarket Diverse tenant base 4.2% submarket vacancy (Cassidy & Pinkard) Park Place
Slide 35: Development Opportunities and Mezzanine Investing
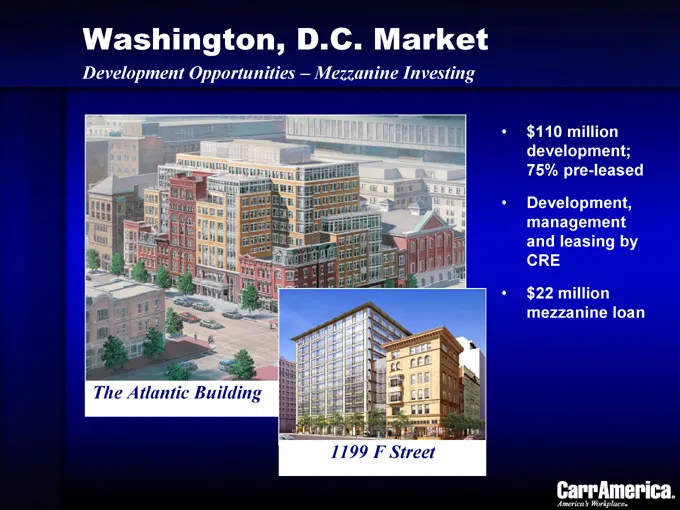
Washington, D.C. Market Development Opportunities – Mezzanine Investing $110 million development; 75% pre-leased Development, management and leasing by CRE $22 million mezzanine loan The Atlantic Building 1199 F Street
Slide 36: Washington Development Pipeline
Washington, D.C. Market Development Pipeline Need to have many projects in different stages due to long lead times for delivery Existing relationships provide link to pipeline Existing portfolio will provide opportunities on Pennsylvania Avenue 1775 Pennsylvania Avenue 1919 Pennsylvania Avenue
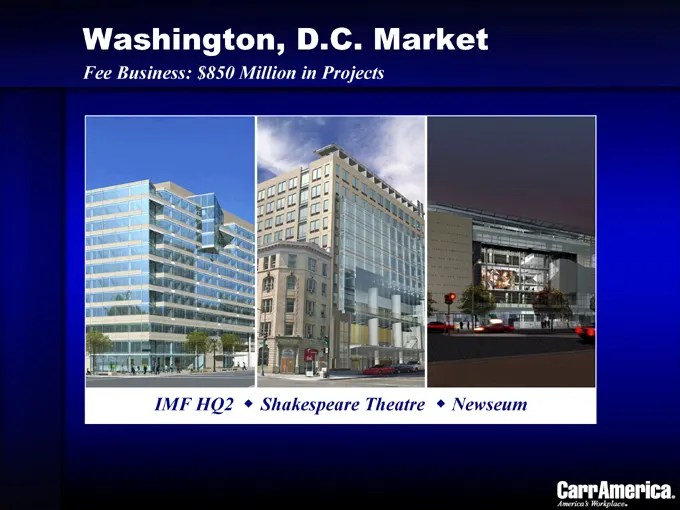
Slide 37: Fee Business: $850 Million in Projects
Washington, D.C. Market Fee Business: $850 Million in Projects IMF HQ2 Shakespeare Theatre Newseum
Slide 38: Agenda
Agenda Overview and Operating Strategy: Phil Hawkins, President Market Reviews: Washington—Phillip Thomas Chicago—Jerry O’Malley Texas and Denver/SLC—Jeff Pace Seattle—Clete Casper Southern California—Malcolm O’Donnell San Francisco Bay Area—Chris Peatross The Future and Wrap Up: Tom Carr, CEO
Slide 39: Chicago Market Scorecard
The Chicago Market Market Scorecard Portfolio is 87% committed with United Stationers lease Largest deal (+200,000 SF) done two years in a row Leased 375,000 SF YTD Portfolio is 40% in JV structure with NYSTRS
Slide 40: Chicago Metro Market
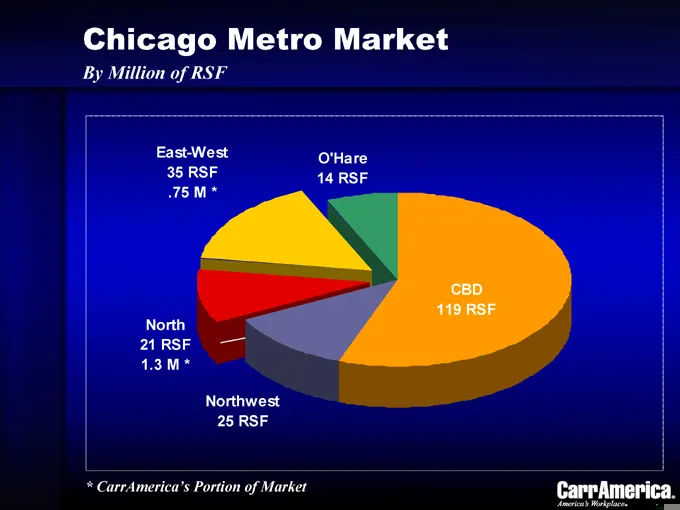
Chicago Metro Market By Million of RSF East-West 35 RSF .75 M * O’Hare 14 RSF CBD 119 RSF Northwest 25 RSF North 21 RSF 1.3 M * * CarrAmerica’s Portion of Market
Slide 41: Chicago Market Dynamics
The Chicago Market Market Dynamics Continued overall weak market characterized by corporate retrenchment Downtown is expensive; $14 to $17 operating expenses; bias toward “new” towers; Class A 1980’s vintage suffering Suburbs have slow but steady leasing recovery Large block availability is in East-
Slide 42: Investment Strategy: Passing on Downtown Market
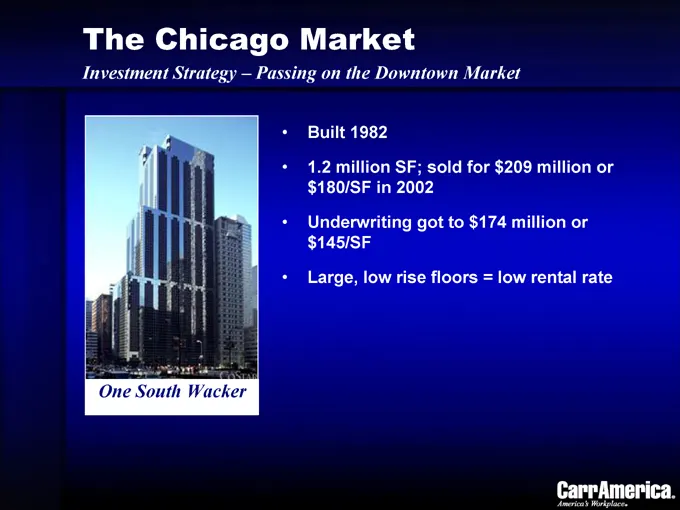
The Chicago Market Investment Strategy – Passing on the Downtown Market Built 1982 1.2 million SF; sold for $209 million or $180/SF in 2002 Underwriting got to $174 million or $145/SF Large, low rise floors = low rental rate One South Wacker
Slide 43: Parkway North in the North Suburbs
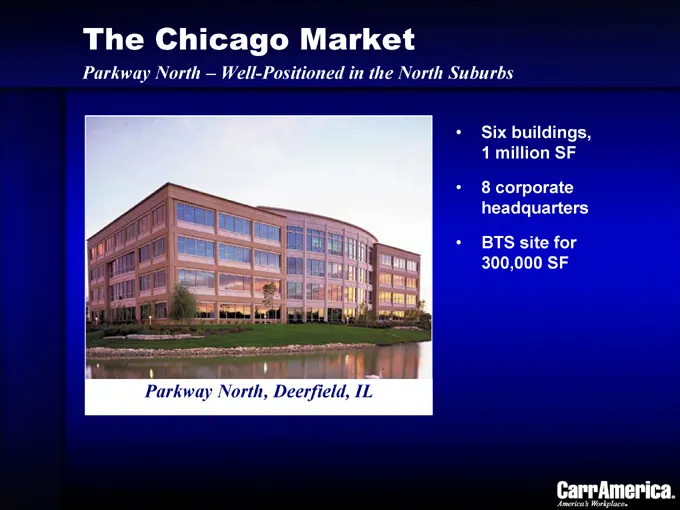
The Chicago Market Parkway North – Well-Positioned in the North Suburbs Six buildings, 1 million SF 8 corporate headquarters BTS site for 300,000 SF Parkway North, Deerfield, IL
Slide 44: Agenda
Agenda Overview and Operating Strategy: Phil Hawkins, President Market Reviews: Washington—Phillip Thomas Chicago—Jerry O’Malley Texas and Denver/SLC—Jeff Pace Seattle—Clete Casper Southern California—Malcolm O’Donnell San Francisco Bay Area—Chris Peatross The Future and Wrap Up: Tom Carr, CEO
Slide 45: Texas and Denver/Salt Lake Market Strategy
Texas and Denver/Salt Lake Markets Market Strategy Opportunistic strategy reflecting low barrier markets Extensive use of joint ventures to leverage equity capital and spread risk Significant fee revenue increases returns
Slide 46: Dallas Market Scorecard
The Dallas Market Market Scorecard 90+% portfolio occupancy 70% of portfolio is in JV structure $50 million in BTS deals over the last three years Capital recycling will result in ownership of only “A” properties
Slide 47: Dallas Market Dynamics
The Dallas Market Market Dynamics Strong submarket recoveries in Preston Center, Legacy and Uptown Traditionally high job growth with concentration of corporate offices Liquid capital market; rewards for having a nimble investment strategy
Slide 48: Royal Ridge Joint Venture
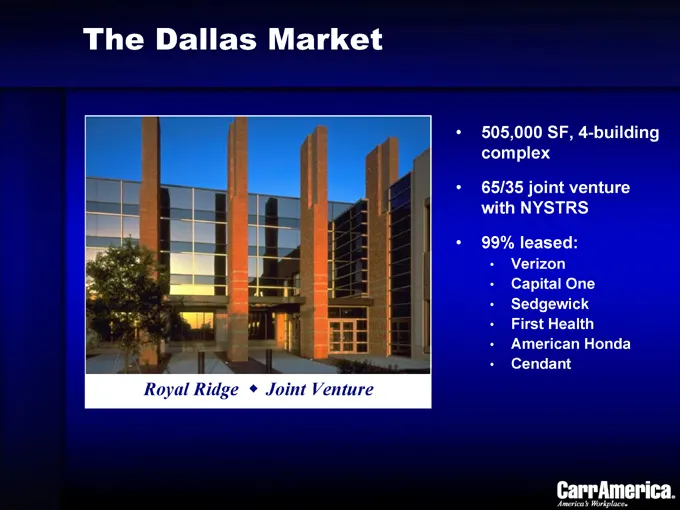
The Dallas Market 505,000 SF, 4-building complex 65/35 joint venture with NYSTRS 99% leased: Verizon Capital One Sedgewick First Health American Honda Cendant Royal Ridge Joint Venture
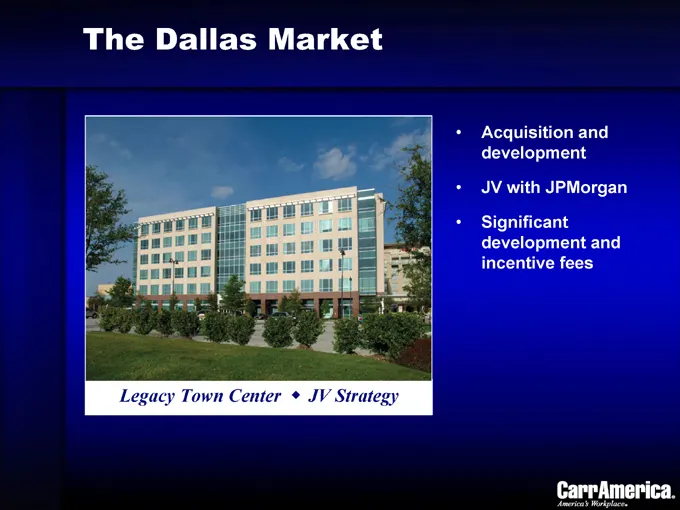
Slide 49: Legacy Town Center JV Strategy
The Dallas Market Acquisition and development JV with JPMorgan Significant development and incentive fees Legacy Town Center JV Strategy
Slide 50: Austin Current Market Strategy
The Austin Market Current Market Strategy 1.7 million SF – mostly CarrAmerica development 85% of portfolio is in JV structure Recycled out of 1 million SF Stay in the deal flow for acquisitions and development Additional opportunity to develop positions in Riata
Slide 51: Austin Market Dynamics
The Austin Market Market Dynamics Suburban recovery well underway Leasing velocity is high in many submarkets and rents are beginning to push upward Limited development opportunities in the strongest submarkets Due to its smaller size, the market moves directionally very quickly
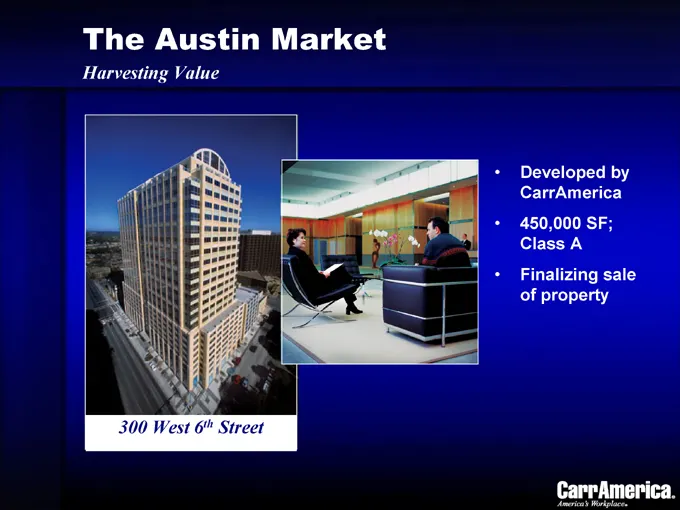
Slide 52: Austin: Harvesting Value
The Austin Market Harvesting Value Developed by CarrAmerica 450,000 SF; Class A Finalizing sale of property 300 West 6th Street
Slide 53: Austin: Market Success
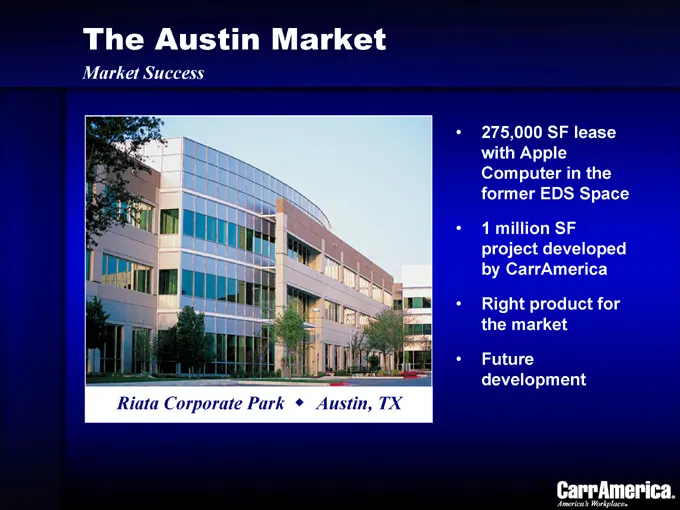
The Austin Market Market Success 275,000 SF lease with Apple Computer in the former EDS Space 1 million SF project developed by CarrAmerica Right product for the market Future development Riata Corporate Park Austin, TX
Slide 54: Denver and Salt Lake Markets Scorecard
Denver and Salt Lake Markets Market Scorecard Denver: 94% leased 1.7 million SF Mainly JV portfolio; Panorama is a market leader Salt Lake City: 97% leased 627,000 SF Strong suburban recovery BTS and development activity
Slide 55: Break
BREAK
Slide 56: Agenda
Agenda Overview and Operating Strategy: Phil Hawkins, President Market Reviews: Washington—Phillip Thomas Chicago—Jerry O’Malley Texas and Denver/SLC—Jeff Pace Seattle—Clete Casper Southern California—Malcolm O’Donnell San Francisco Bay Area—Chris Peatross The Future and Wrap Up: Tom Carr, CEO
Slide 57: Seattle Market Scorecard
The Seattle Market Market Scorecard Portfolio is 89% committed $51 million invested year to date Repositioning portfolio
Slide 58: Seattle Market Dynamics
The Seattle Market Market Dynamics Dynamic market with good barriers to entry Microsoft, Boeing, Nordstrom and WAMU –strong local companies headquartered in the market Bellevue submarket has leased up –development and spillover to the other East End markets
Slide 59: Eastside Office Market Vacancy Percentage
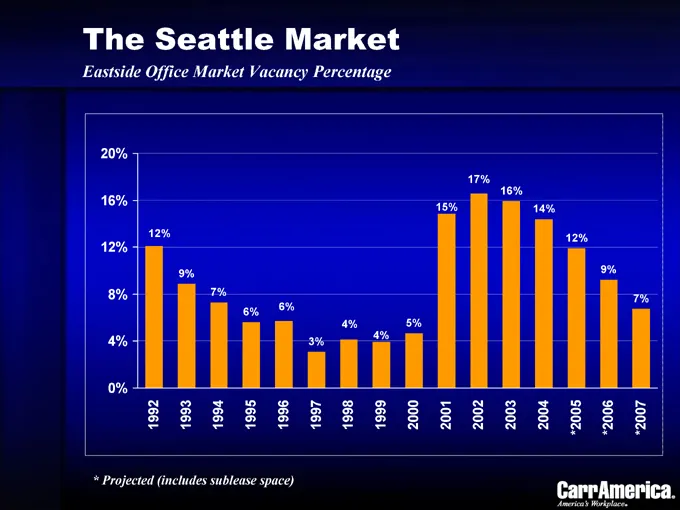
The Seattle Market Eastside Office Market Vacancy Percentage 20% 16% 12% 8% 4% 0% 1992 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 *2005 *2006 *2007 12% 9% 7% 6% 6% 3% 4% 4% 5% 15% 17% 16% 14% 12% 9% 7% * Projected (includes sublease space)
Slide 60: Leasing Successes: Willow Creek
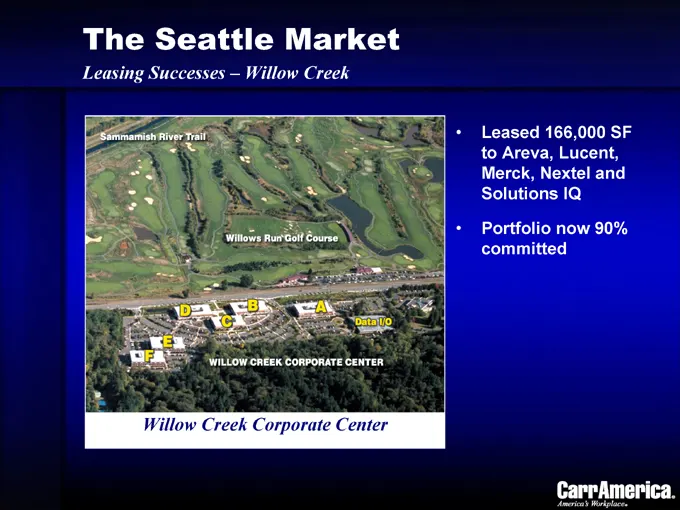
The Seattle Market Leasing Successes – Willow Creek Leased 166,000 SF to Areva, Lucent, Merck, Nextel and Solutions IQ Portfolio now 90% committed Willow Creek Corporate Center
Slide 61: Seattle Recent Portfolio Additions
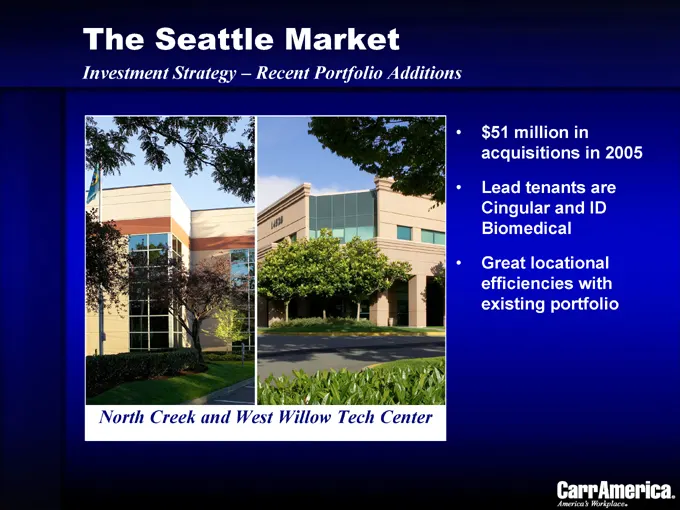
The Seattle Market Investment Strategy – Recent Portfolio Additions $51 million in acquisitions in 2005 Lead tenants are Cingular and ID Biomedical Great locational efficiencies with existing portfolio North Creek and West Willow Tech Center
Slide 62: Seattle Development Pipeline
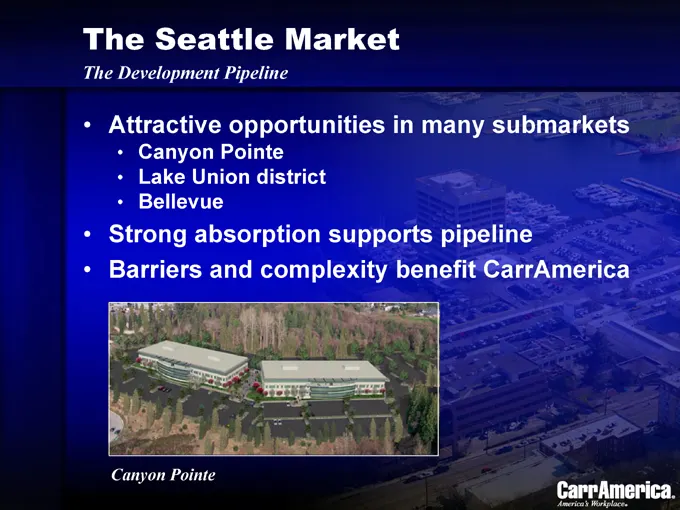
The Seattle Market The Development Pipeline Attractive opportunities in many submarkets Canyon Pointe Lake Union district Bellevue Strong absorption supports pipeline Barriers and complexity benefit CarrAmerica Canyon Pointe
Slide 63: Agenda
Agenda Overview and Operating Strategy: Phil Hawkins, President Market Reviews: Washington—Phillip Thomas Chicago—Jerry O’Malley Texas and Denver/SLC—Jeff Pace Seattle—Clete Casper Southern California—Malcolm O’Donnell San Francisco Bay Area—Chris Peatross The Future and Wrap Up: Tom Carr, CEO
Slide 64: Southern California Market Scorecard
Southern California Region Market Scorecard - 2003 through 2005 Operations Summary 2003 Higher vacancy with little business expansion Leased 500,000 SF 2004 Market rebounded quickly Leased 1 million SF (107 transactions) 2005 Portfolio has “filled up” 98% committed wholly owned properties* 94% commi
Slide 65: Southern California Commercial Market Base
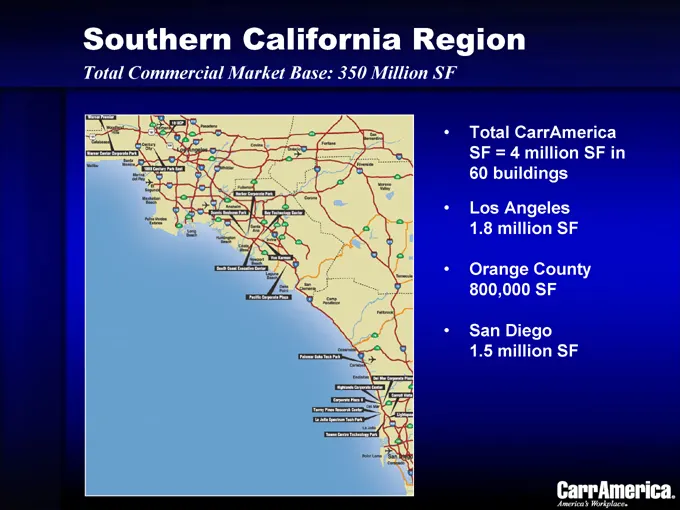
Southern California Region Total Commercial Market Base: 350 Million SF Total CarrAmerica SF = 4 million SF in 60 buildings Los Angeles 1.8 million SF Orange County 800,000 SF San Diego 1.5 million SF
Slide 66: Southern California Market Dynamics
Southern California Region Market Dynamics Large and dynamic market with good barriers to entry Large concentration of entertainment/media/ defense/technology Highly skilled workforce Strong life science cluster in San Diego
Slide 67: Southern California Market Strategy
Southern California Region Market Strategy Pushing rates Focus on development opportunities Start San Diego biotech building early 2006 Opportunistic acquisitions
Slide 68: High Profile Acquisitions in LA
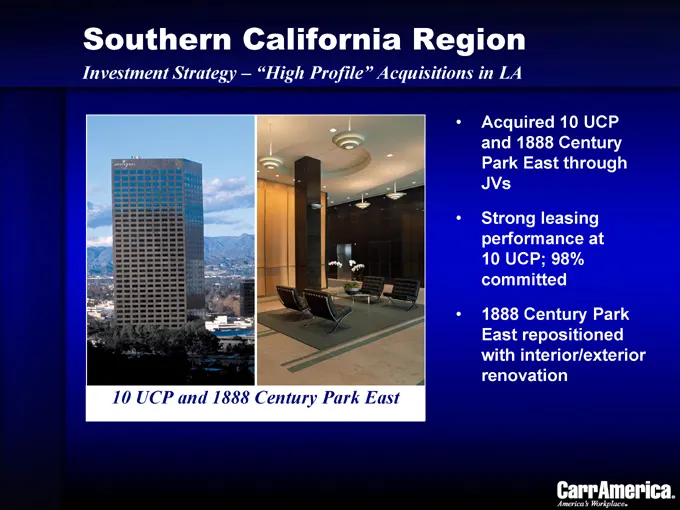
Southern California Region Investment Strategy – “High Profile” Acquisitions in LA Acquired 10 UCP and 1888 Century Park East through JVs Strong leasing performance at 10 UCP; 98% committed 1888 Century Park East repositioned with interior/exterior renovation 10 UCP and 1888 Century Park East
Slide 69: Investment Strategy: Why We Passed
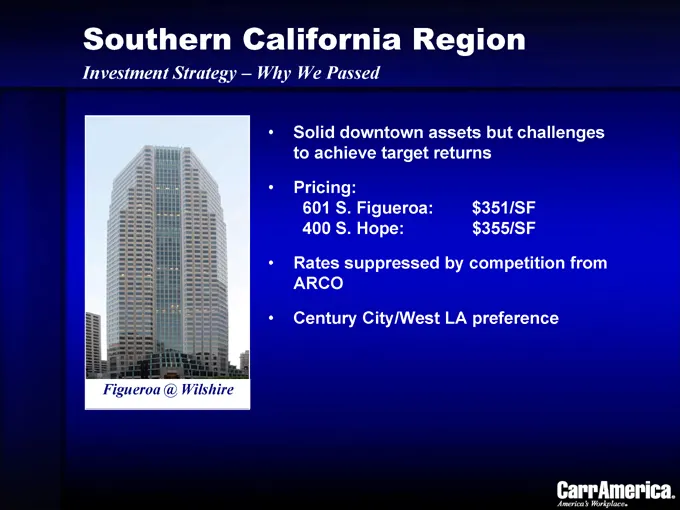
Southern California Region Investment Strategy – Why We Passed Solid downtown assets but challenges to achieve target returns Pricing: S. Figueroa: $351/SF 400 S. Hope: $355/SF Rates suppressed by competition from ARCO Century City/West LA preference Figueroa @ Wilshire
Slide 70: Investment Strategy: Selling into Strength
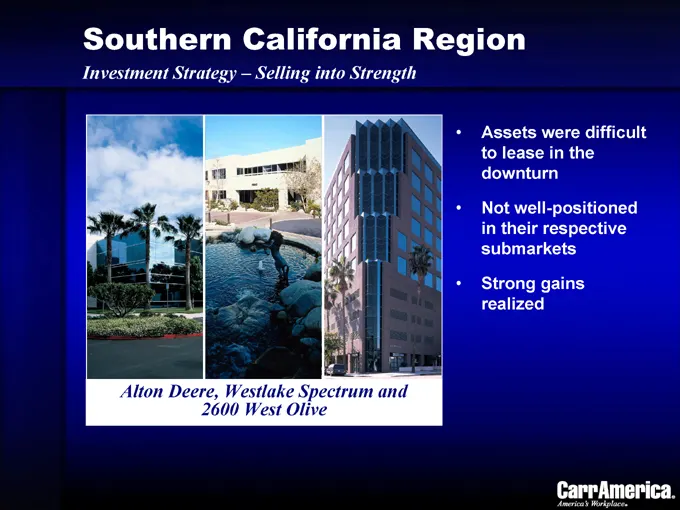
Southern California Region Investment Strategy – Selling into Strength Assets were difficult to lease in the downturn Not well-positioned in their respective submarkets Strong gains realized Alton Deere, Westlake Spectrum and 2600 West Olive
Slide 71: Re-invest in High Quality Assets
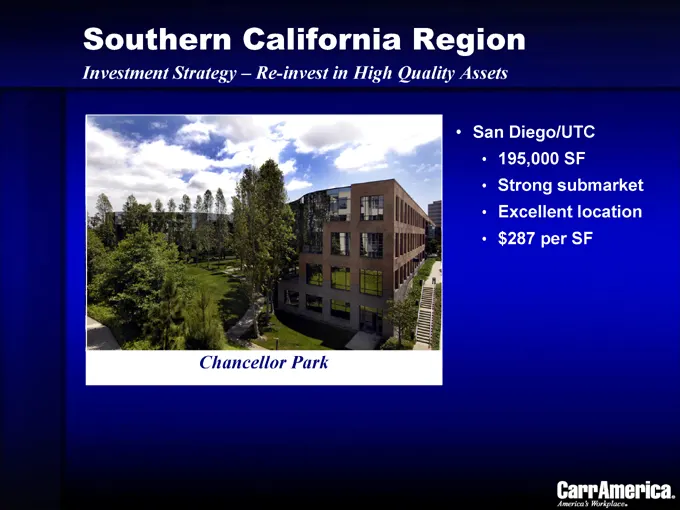
Southern California Region Investment Strategy – Re-invest in High Quality Assets San Diego/UTC 195,000 SF Strong submarket Excellent location $287 per SF Chancellor Park
Slide 72: Agenda
Agenda Overview and Operating Strategy: Phil Hawkins, President Market Reviews: Washington—Phillip Thomas Chicago—Jerry O’Malley Texas and Denver/SLC—Jeff Pace Seattle—Clete Casper Southern California—Malcolm O’Donnell San Francisco Bay Area—Chris Peatross The Future and Wrap Up: Tom Carr, CEO
Slide 73: San Francisco Bay Area Market Scorecard
San Francisco Bay Area Market Market Scorecard 90% committed Approximately 750,000 SF of leases completed YTD 2005 (72 transactions) Strategically acquiring buildings and sites for future development opportunities
Slide 74: San Francisco Bay Area Market Dynamics
San Francisco Bay Area Market Market Dynamics Large and dynamic market with good barriers to entry Large concentration of Fortune 500 companies Highly skilled workforce Easy access to capital for industry and technology = venture capital firms
Slide 75: CarrAmerica vs. Market Occupancy
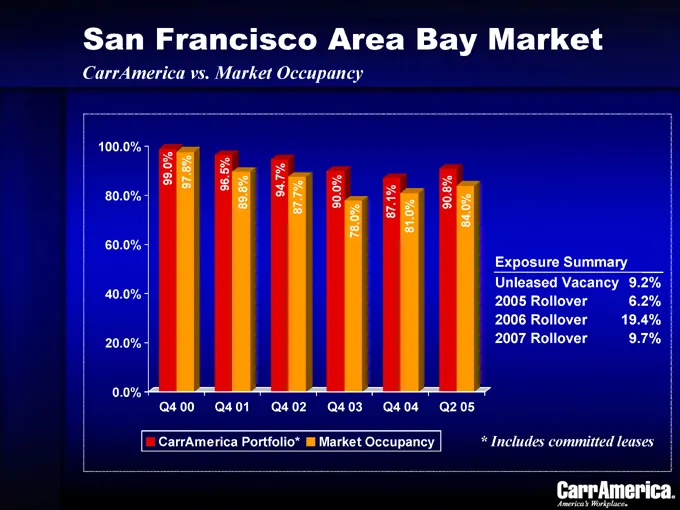
San Francisco Area Bay Market CarrAmerica vs. Market Occupancy 100.0% 80.0% 60.0% 40.0% 20.0% 0.0% 99.0% 97.8% 96.5% 89.8% 94.7% 87.7% 90.0% 78.0% 87.1% 81.0% 90.8% 84.0% Q4 00 Q4 01 Q4 02 Q4 03 Q4 04 Q2 05 Exposure Summary Unleased Vacancy 9.2% 2005 Rollover 6.2% 2006 Rollover 19.4% 2007 Rollover 9
Slide 76: Bay Area Vacancy and Average Rental Rates
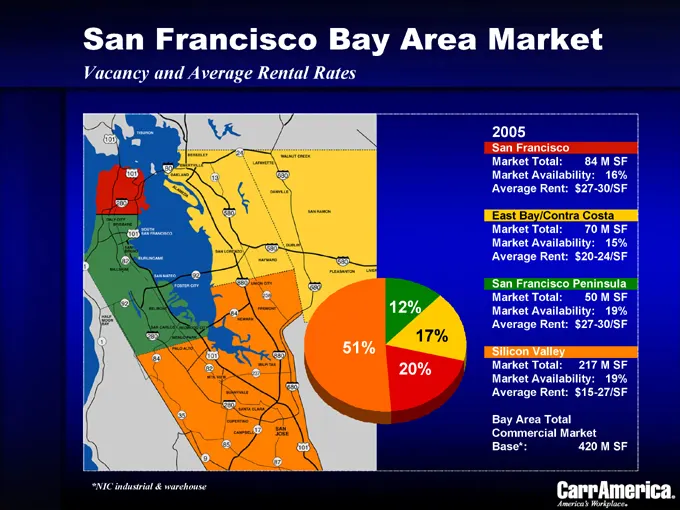
San Francisco Bay Area Market Vacancy and Average Rental Rates 12% 17% 20% 51% 2005 San Francisco Market Total: 84 M SF Market Availability: 16% Average Rent: $27-30/SF East Bay/Contra Costa Market Total: 70 M SF Market Availability: 15% Average Rent: $20-24/SF San Francisco Peninsula Market Total:
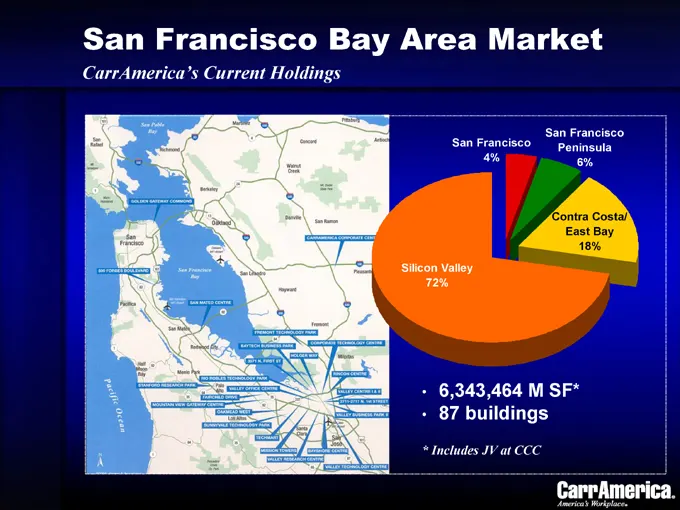
Slide 77: CarrAmerica's Current Holdings
San Francisco Bay Area Market CarrAmerica’s Current Holdings San Francisco 4% San Francisco Peninsula 6% Contra Costa/ East Bay 18% Silicon Valley 72% 6,343,464 M SF* 87 buildings * Includes JV at CCC
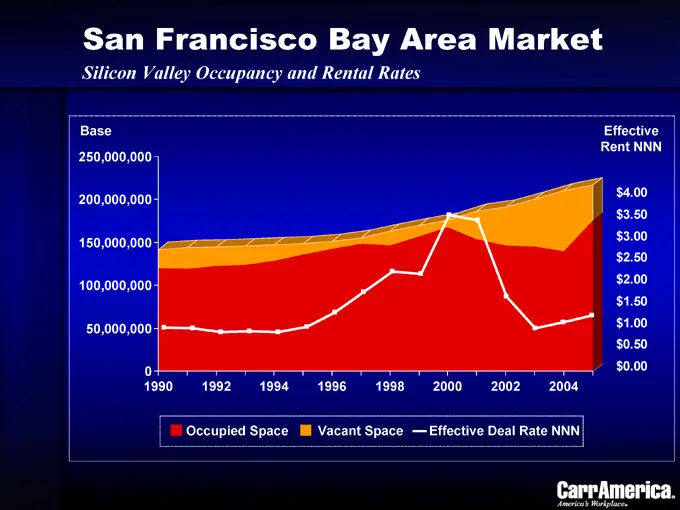
Slide 78: Silicon Valley Occupancy and Rental Rates
San Francisco Bay Area Market Silicon Valley Occupancy and Rental Rates Base 250,000,000 200,000,000 150,000,000 100,000,000 50,000,000 0 Effective Rent NNN $4.00 $3.50 $3.00 $2.50 $2.00 $1.50 $1.00 $0.50 $0.00 1990 1992 1994 1996 1998 2000 2002 2004 Occupied Space Vacant Space Effective Deal Rate N
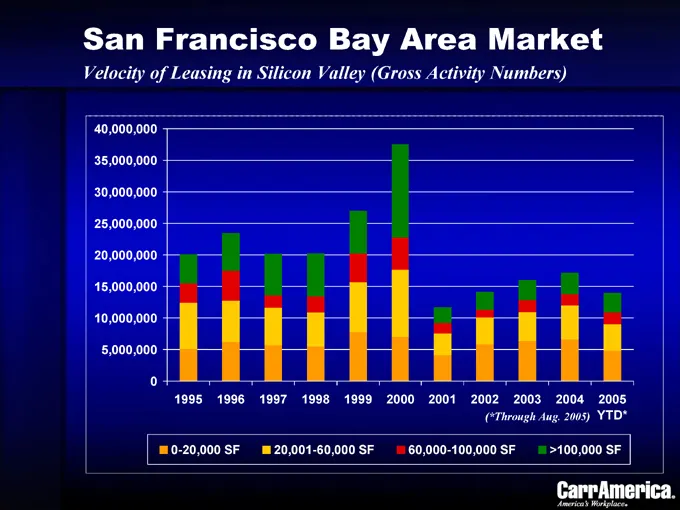
Slide 79: Velocity of Leasing in Silicon Valley
San Francisco Bay Area Market Velocity of Leasing in Silicon Valley (Gross Activity Numbers) 40,000,000 35,000,000 30,000,000 25,000,000 20,000,000 15,000,000 10,000,000 5,000,000 0 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 (*Through Aug. 2005) YTD* 0-20,000 SF 20,001-60,000 SF 60,000-1
Slide 80: Market Strategy: Responding to Changing Conditions
San Francisco Bay Area Market Market Strategy: Responding to Rapidly Changing Market Conditions Lease strategy Push rental rates for Class A assets Occupancy-driven for lower quality assets Focus on tenant’s credit and expansion capability Less emphasis on early renewal Investment strategy Acquire C
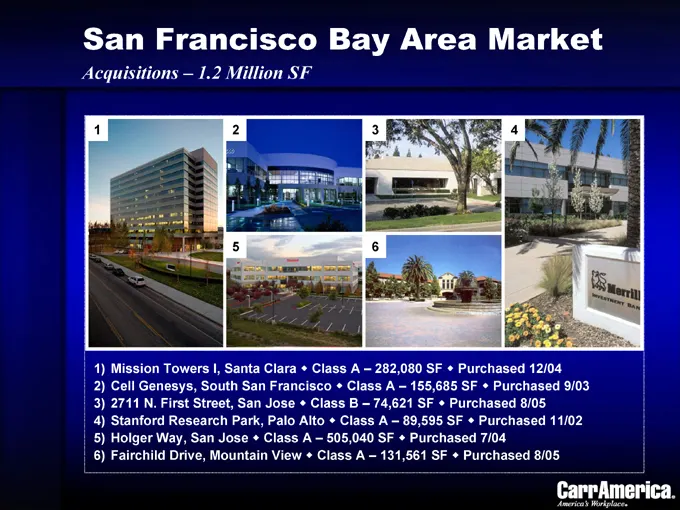
Slide 81: Acquisitions - 1.2 Million SF
San Francisco Bay Area Market Acquisitions – 1.2 Million SF 1 2 3 4 5 6 1) Mission Towers I, Santa Clara Class A – 282,080 SF Purchased 12/04 2) Cell Genesys, South San Francisco Class A – 155,685 SF Purchased 9/03 3) 2711 N. First Street, San Jose Class B – 74,621 SF Purchased 4) Stanford Research
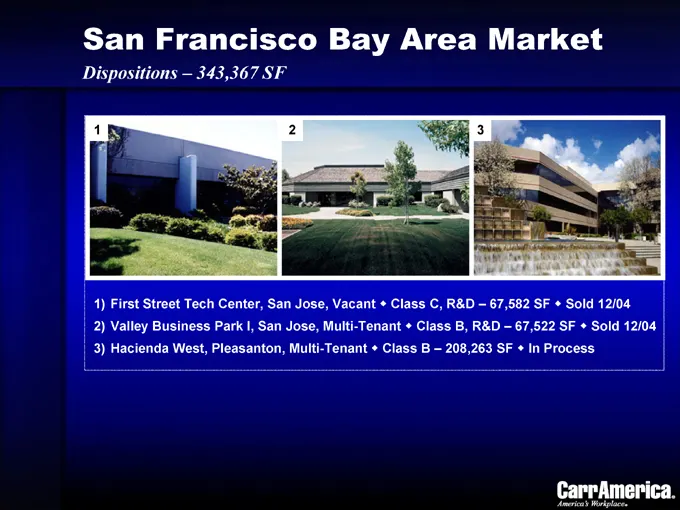
Slide 82: Dispositions - 343,367 SF
San Francisco Bay Area Market Dispositions – 343,367 SF 1 2 3 1) First Street Tech Center, San Jose, Vacant Class C, R&D – 67,582 SF Sold 12/04 2) Valley Business Park I, San Jose, Multi-Tenant Class B, R&D – 67,522 SF Sold 12/04 3) Hacienda West, Pleasanton, Multi-Tenant Class B – 208,263 SF In Pro
Slide 83: Agenda
Agenda Overview and Operating Strategy: Phil Hawkins, President Market Reviews: Washington—Phillip Thomas Chicago—Jerry O’Malley Texas and Denver/SLC—Jeff Pace Seattle—Clete Casper Southern California—Malcolm O’Donnell San Francisco Bay Area—Chris Peatross The Future and Wrap Up: Tom Carr, CEO
Slide 84: CarrAmerica is Well Positioned: The Future
CarrAmerica is Well Positioned The Future Improving portfolio dynamics A strong balance sheet Shifting external growth opportunities The right operating model
Slide 85: Improving Portfolio Dynamics
CarrAmerica is Well Positioned Improving Portfolio Dynamics Improving mark-to-market from leasing, dispositions and acquisitions Improving occupancy to date More submarkets experiencing rent increases
Slide 86: A Strong Balance Sheet
CarrAmerica is Well Positioned A Strong Balance Sheet Moderate leverage Strong line capacity Investment grade rating
Slide 87: Shifting External Growth Opportunities
CarrAmerica is Well Positioned Shifting External Growth Opportunities Opportunistic purchases and/or investments in completed buildings Development window is open or fast approaching in good submarkets
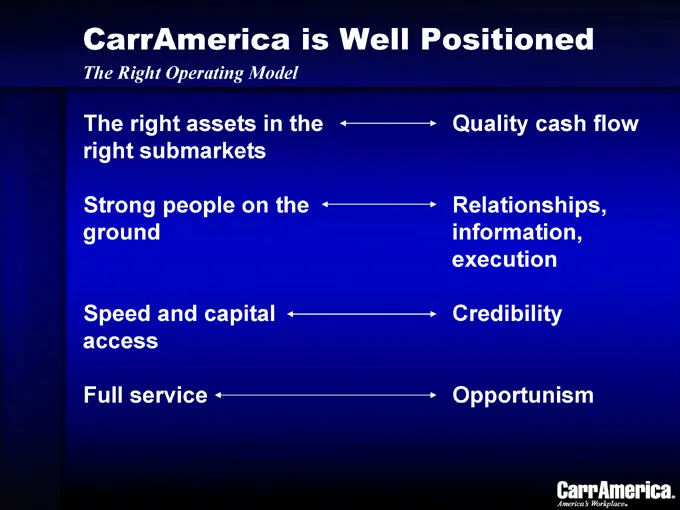
Slide 88: The Right Operating Model
CarrAmerica is Well Positioned The Right Operating Model The right assets in the right submarkets Quality cash flow Strong people on the ground Relationships, information, execution Speed and capital access Credibility Full service Opportunism
Slide 89: Key Messages
CarrAmerica Investor Conference Key Messages Strong execution through the market downturn Market improvement is accelerating CarrAmerica is very well positioned to benefit from the recovery
Slide 90: Q & A
Q & A
Slide 91: Investor Day Program
Investor Day Program September 20, 2005
Source: SEC EDGAR · 8-K filed Sep 20, 2005