Layne Christensen — Investor Day (April 2016)
110 slides from Layne Christensen's investor day presentation, Apr 14, 2016
Slide 1: Investor Day Presentation April 14, 2016
Investor Day Presentation April 14, 2016 Exhibit 99.1
Slide 2: Safe harbor
Safe harbor This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements may include, but are not limited to, statements of plans and objectives, statements of future economic performance and statements of assumptio
Slide 3: Today's agenda
Today’s agenda Layne Strategy Division Presentations Inliner Mineral Services Heavy Civil Water Resources Financial Overview Closing and Outlook
Slide 4: Safety is a core value at Layne
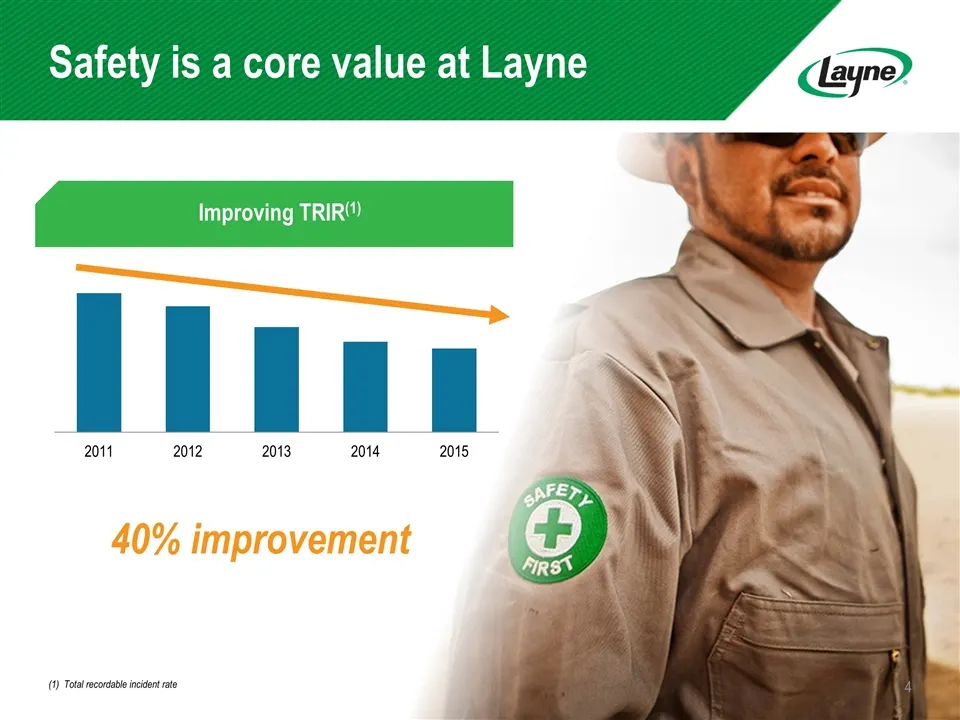
Safety is a core value at Layne (1) Total recordable incident rate Improving TRIR(1) 40% improvement
Slide 5: Management team
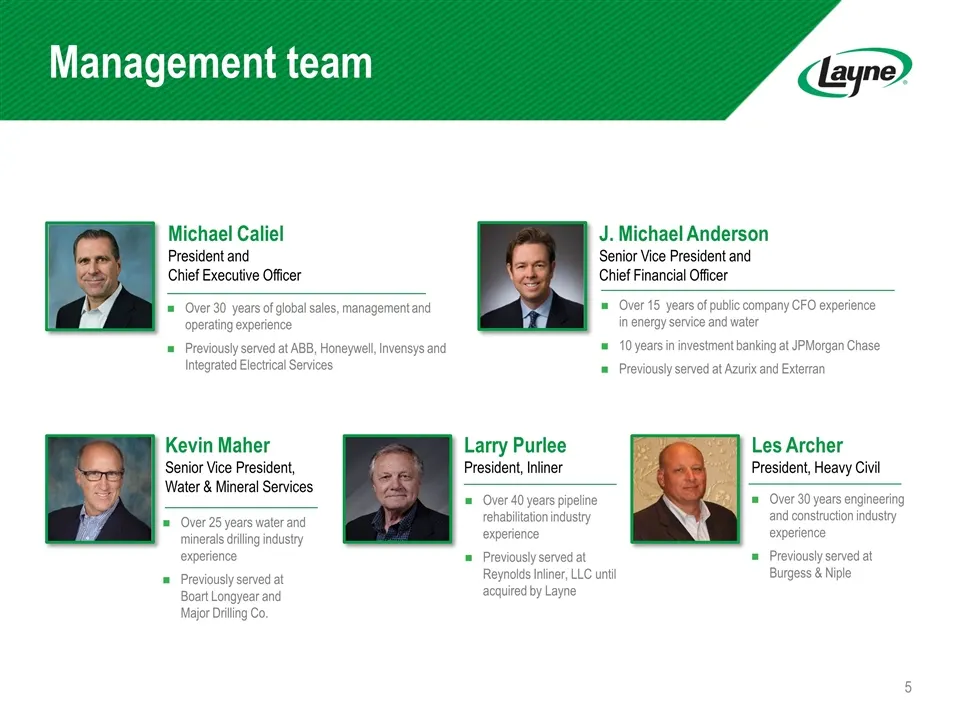
Management team Michael Caliel President and Chief Executive Officer J. Michael Anderson Senior Vice President and Chief Financial Officer Kevin Maher Senior Vice President, Water & Mineral Services Larry Purlee President, Inliner Les Archer President, Heavy Civil Over 30 years of global sales, mana
Slide 6: What you will hear today
What you will hear today Why now 1 2 3 5 What we do Unlocking value Who we are 4 Why water Track record of leadership and innovation since 1882 Business units with leading positions in attractive growth markets New management team intensely focused on profitability and creating shareholder value Pos
Slide 7: Who we are: overview
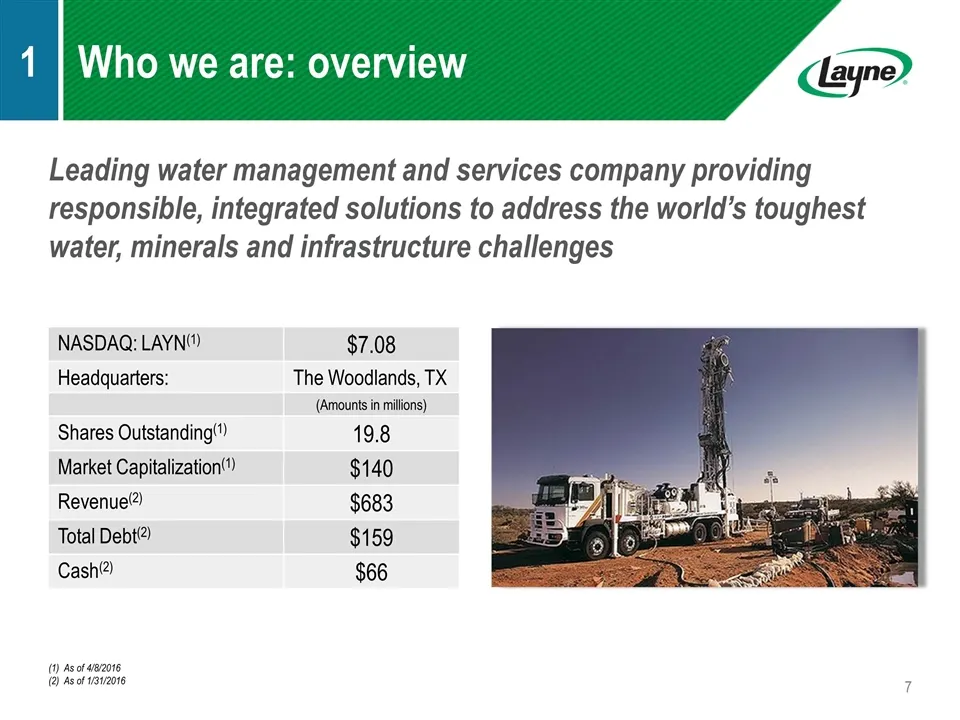
Leading water management and services company providing responsible, integrated solutions to address the world’s toughest water, minerals and infrastructure challenges 1 Who we are: overview (1) As of 4/8/2016 (2) As of 1/31/2016 NASDAQ: LAYN(1) $7.08 Headquarters: The Woodlands, TX (Amounts in mill
Slide 8: Innovator of water solutions since 1882
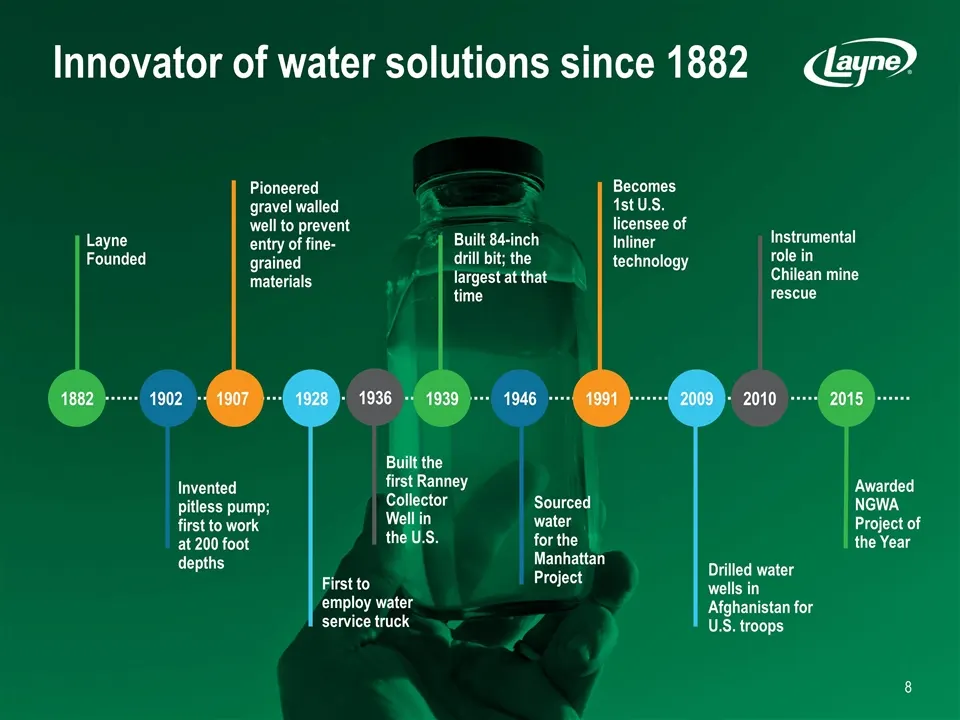
Innovator of water solutions since 1882 2015 2009 2010 1991 1946 1939 1907 1882 1902 1928 Layne Founded Pioneered gravel walled well to prevent entry of fine-grained materials Built 84-inch drill bit; the largest at that time Instrumental role in Chilean mine rescue Becomes 1st U.S. licensee of Inli
Slide 9: What we do
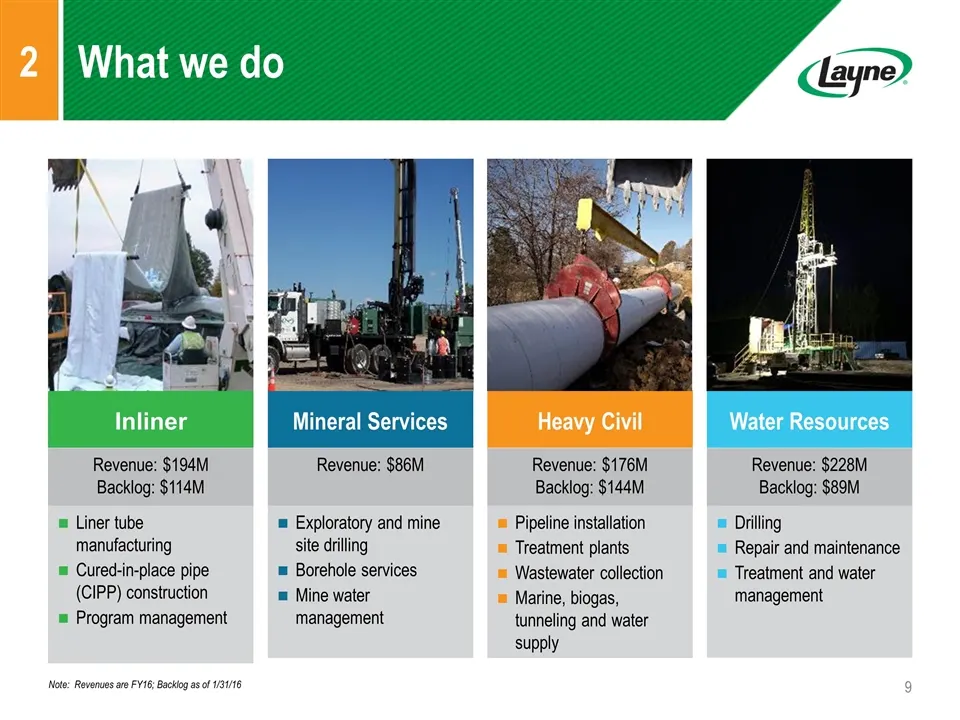
2 What we do Note: Revenues are FY16; Backlog as of 1/31/16 Water Resources Revenue: $228M Backlog: $89M Drilling Repair and maintenance Treatment and water management Heavy Civil Revenue: $176M Backlog: $144M Pipeline installation Treatment plants Wastewater collection Marine, biogas, tunneling and
Slide 10: All of Layne's business units are leaders in their space
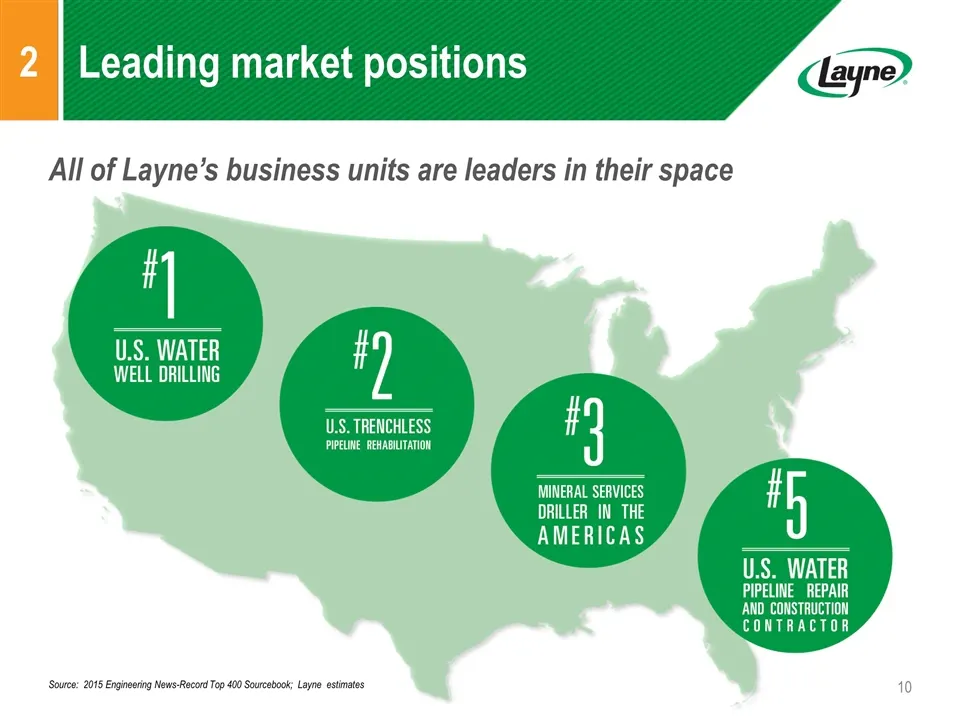
All of Layne’s business units are leaders in their space 2 Leading market positions Source: 2015 Engineering News-Record Top 400 Sourcebook; Layne estimates
Slide 11: Broad portfolio with diverse and growing customer base
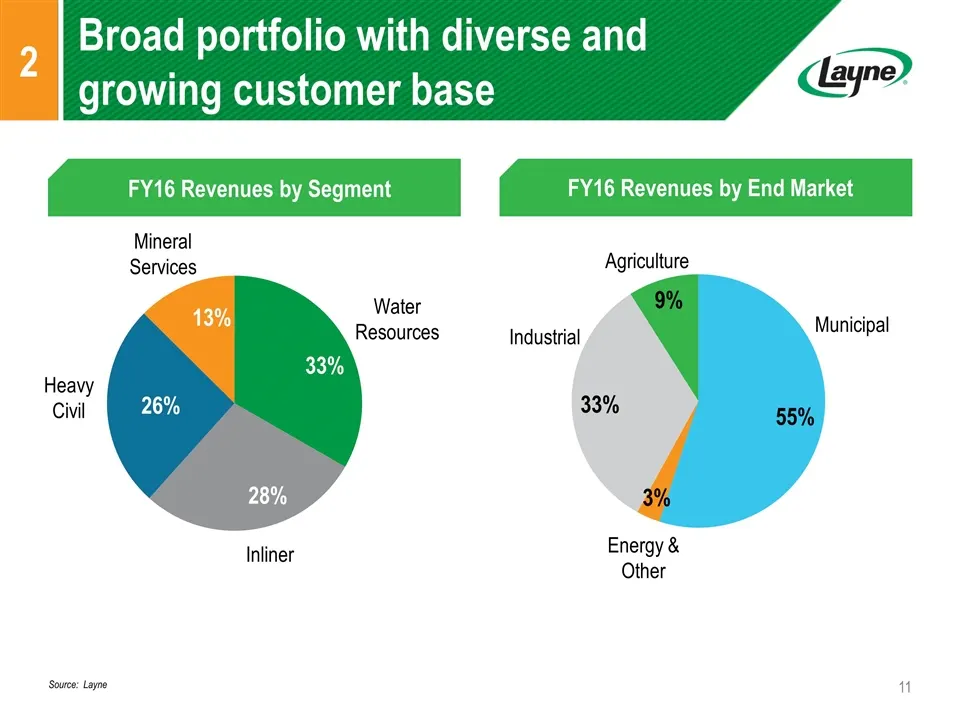
2 Broad portfolio with diverse and growing customer base FY16 Revenues by Segment FY16 Revenues by End Market Source: Layne
Slide 12: Inliner Market Dynamics
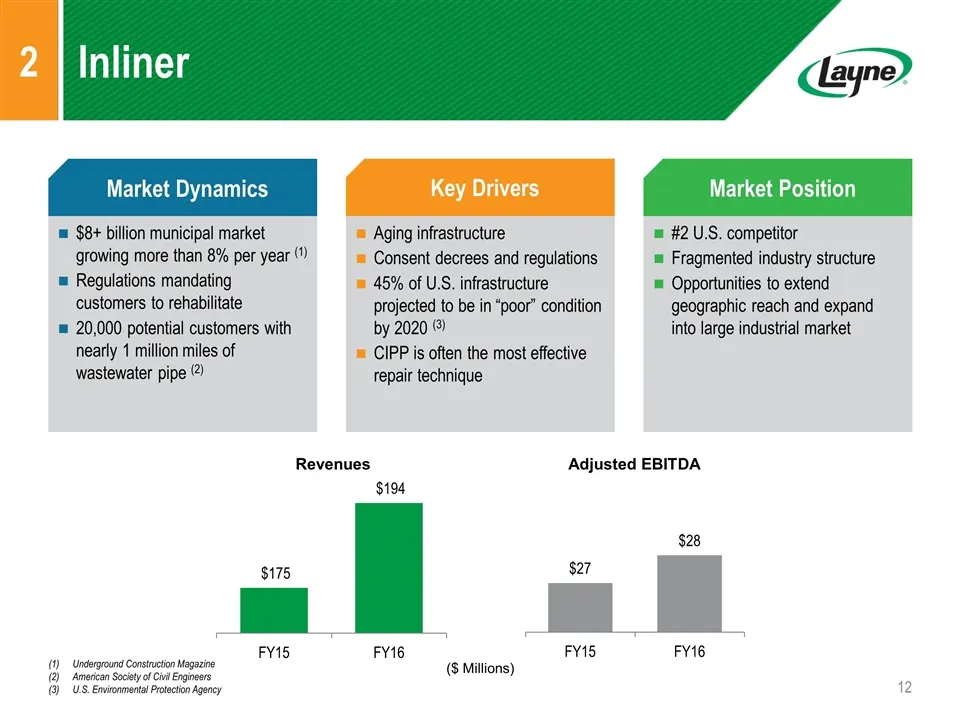
2 Inliner Market Dynamics $8+ billion municipal market growing more than 8% per year (1) Regulations mandating customers to rehabilitate 20,000 potential customers with nearly 1 million miles of wastewater pipe (2) Market Position Key Drivers #2 U.S. competitor Fragmented industry structure Opportun
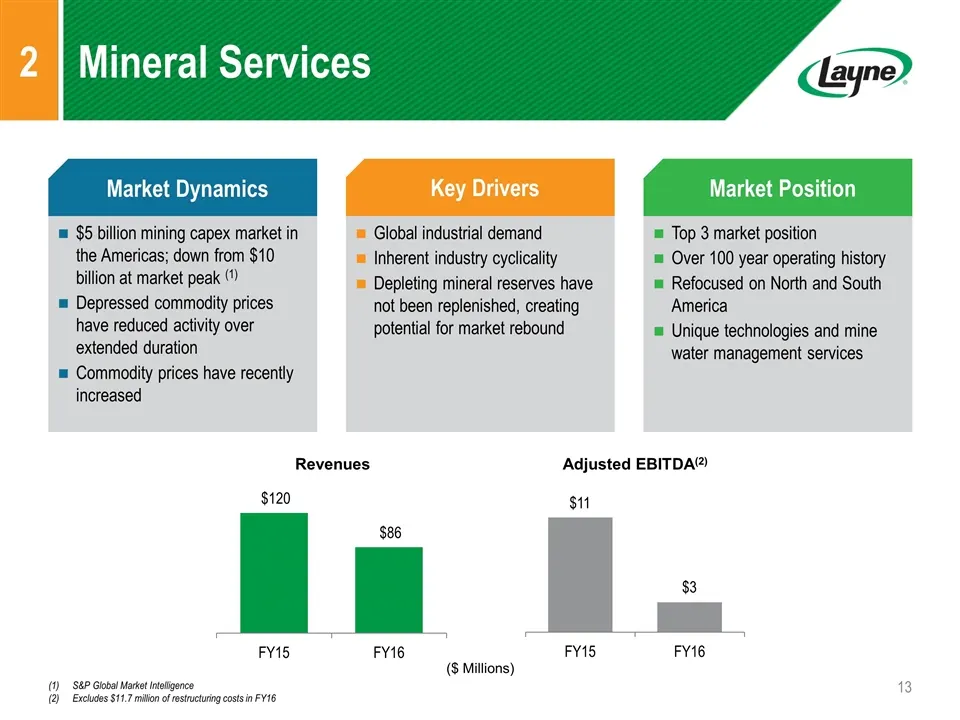
Slide 13: Mineral Services Market Dynamics
2 Mineral Services S&P Global Market Intelligence Excludes $11.7 million of restructuring costs in FY16 Market Dynamics $5 billion mining capex market in the Americas; down from $10 billion at market peak (1) Depressed commodity prices have reduced activity over extended duration Commodity prices ha
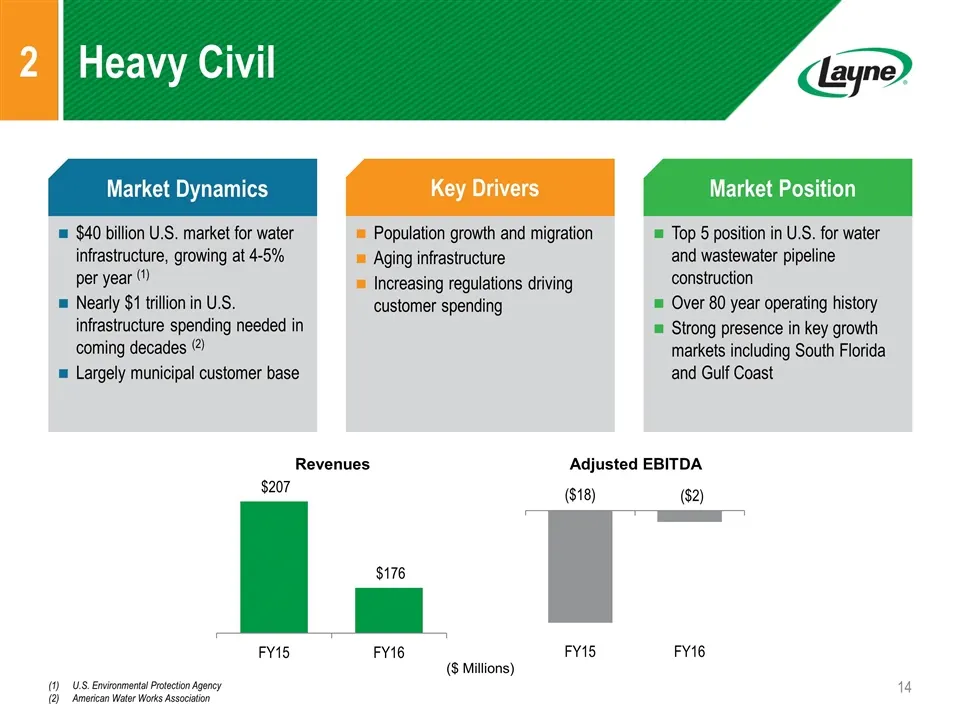
Slide 14: Heavy Civil Market Dynamics
2 Heavy Civil Market Dynamics $40 billion U.S. market for water infrastructure, growing at 4-5% per year (1) Nearly $1 trillion in U.S. infrastructure spending needed in coming decades (2) Largely municipal customer base Market Position Key Drivers Top 5 position in U.S. for water and wastewater pip
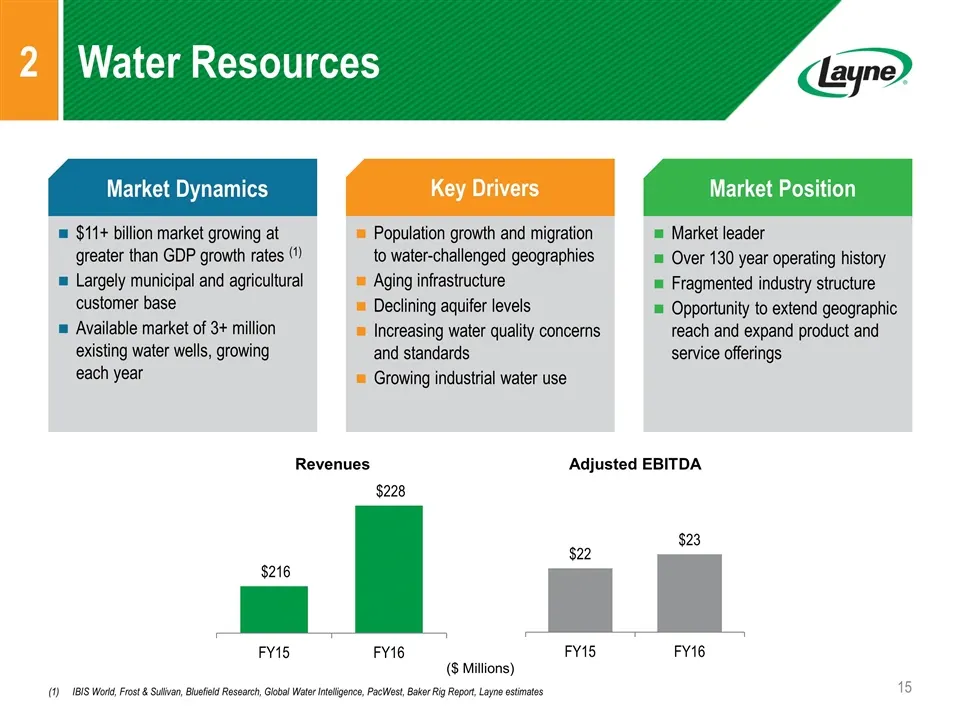
Slide 15: Water Resources Market Dynamics
2 Water Resources Market Dynamics $11+ billion market growing at greater than GDP growth rates (1) Largely municipal and agricultural customer base Available market of 3+ million existing water wells, growing each year Market Position Key Drivers Market leader Over 130 year operating history Fragmen
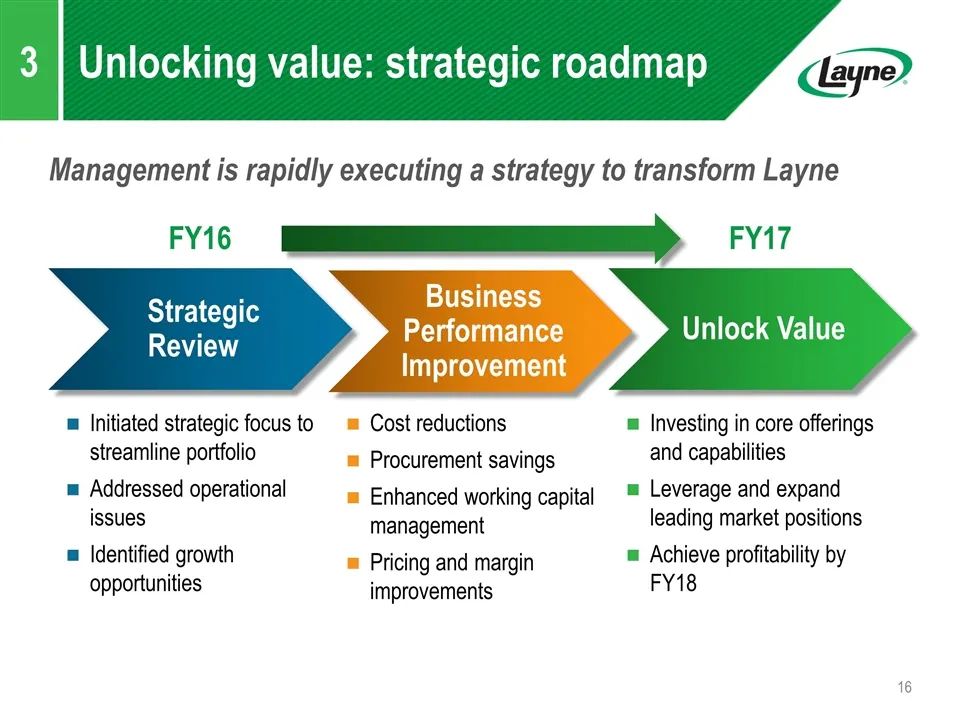
Slide 16: Unlocking value: strategic roadmap
Management is rapidly executing a strategy to transform Layne 3 Unlocking value: strategic roadmap Strategic Review Business Performance Improvement Unlock Value Initiated strategic focus to streamline portfolio Addressed operational issues Identified growth opportunities Investing in core offerings
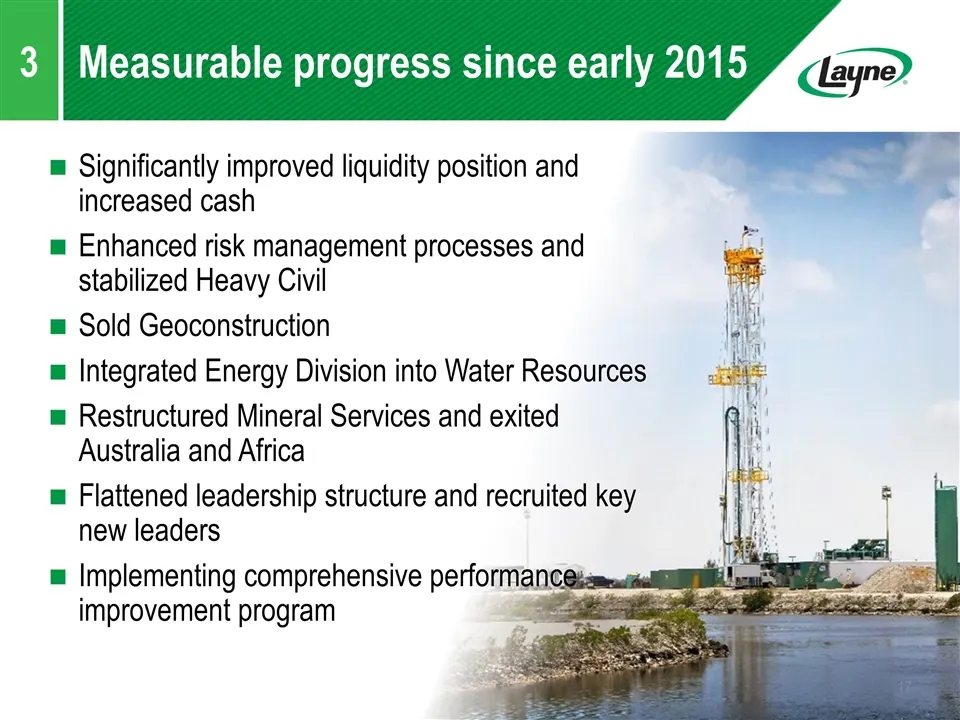
Slide 17: Measurable progress since early 2015
Significantly improved liquidity position and increased cash Enhanced risk management processes and stabilized Heavy Civil Sold Geoconstruction Integrated Energy Division into Water Resources Restructured Mineral Services and exited Australia and Africa Flattened leadership structure and recruited k
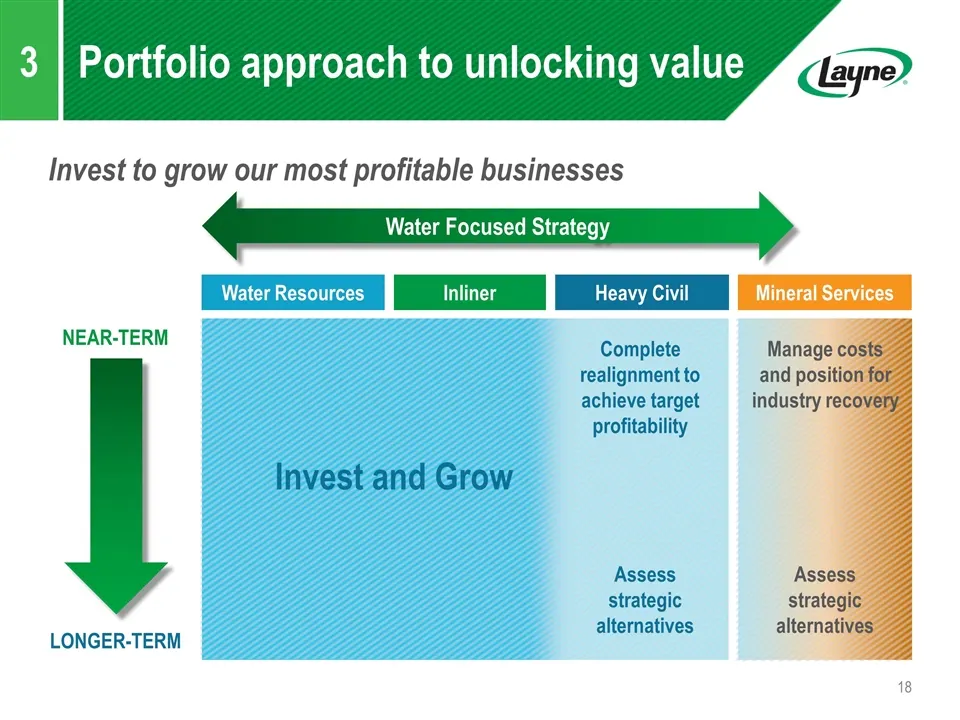
Slide 18: Portfolio approach to unlocking value
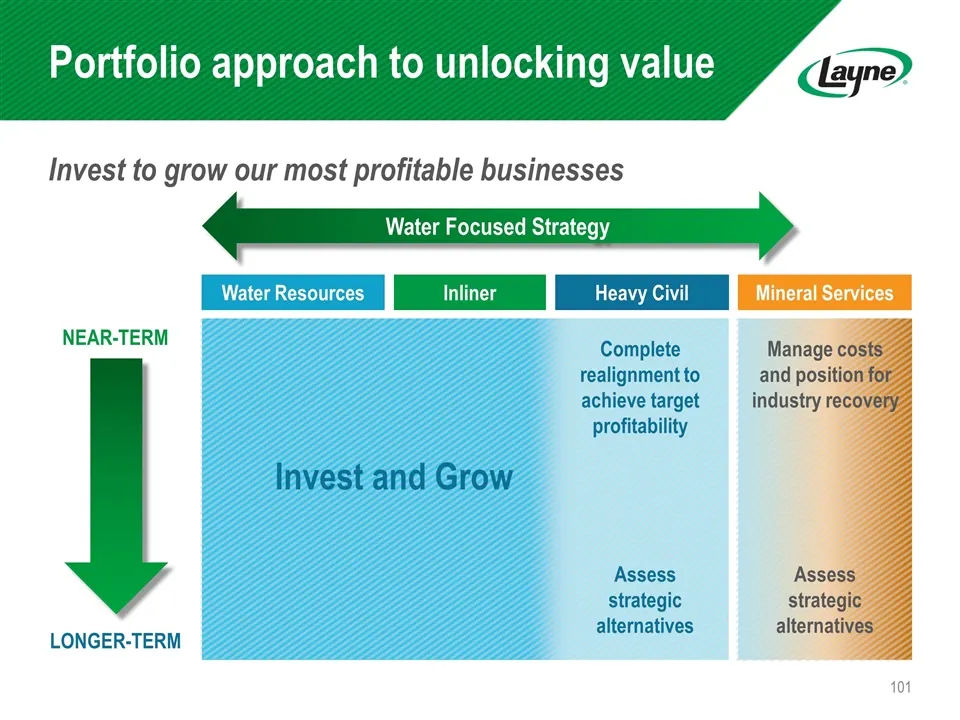
3 Portfolio approach to unlocking value Water Focused Strategy Water Resources Inliner Heavy Civil Mineral Services NEAR-TERM LONGER-TERM Invest and Grow Complete realignment to achieve target profitability Assess strategic alternatives Manage costs and position for industry recovery Assess strategi
Slide 19: Why water
Stressed water supplies and water quality issues, magnified by drought, declining aquifer levels and increasing water demand are severely stressing infrastructure and water supplies Aging and inefficient infrastructure compounded by historical under underinvestment, is driving the need for significa
Slide 20: Investing in the water industry quote
“Investing in the water industry is one of the great opportunities for the coming decades. Water is the scarce resource that will define the 21st century, much like plentiful oil defined the last century.” Matthew Diserio, Water Asset Management “Investors Are Mining for Water, the Next Hot Commodit
Slide 21: Investment highlights – why now
Capitalizing on long history of success and solid brand equity Leveraging leading market positions Refined strategy focused on water New management team driving financial, operational and strategic restructuring Operating in large, fragmented and attractive growth markets 5 Investment highlights – w
Slide 22: Inliner
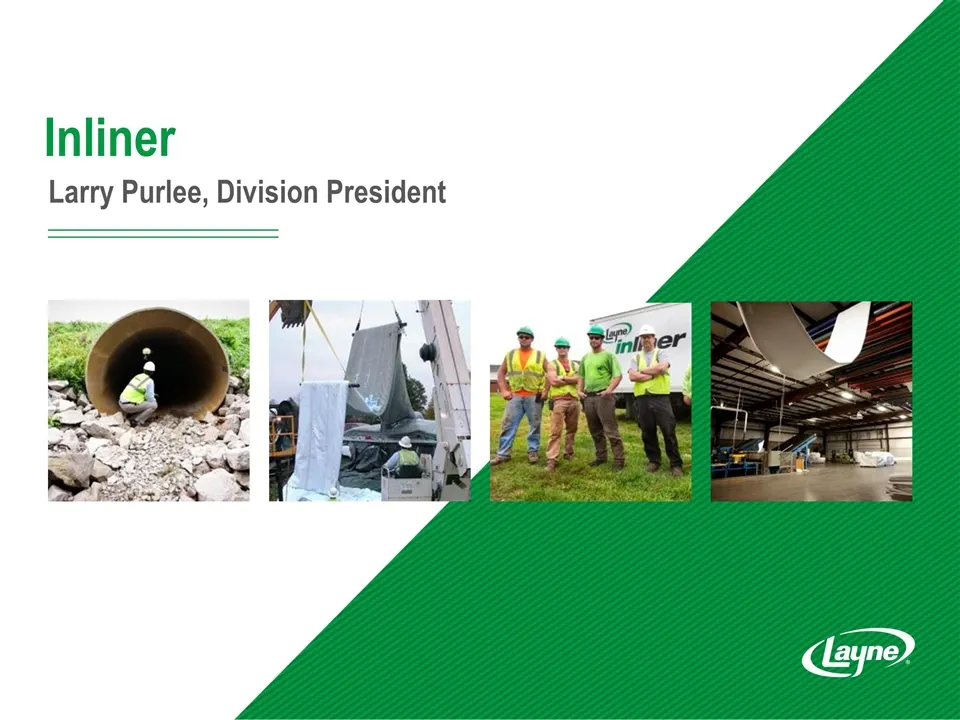
Inliner Larry Purlee, Division President
Slide 23: What you will hear today: Inliner
What you will hear today Leader and innovator in pipe rehabilitation with enviable record of success and additional expansion opportunities 1 2 3 Where we compete Why pipe rehabilitation What we do 4 Why Layne #2 U.S. CIPP rehabilitation provider Early pioneer in CIPP industry Attractive growth busi
Slide 24: What we do: overview
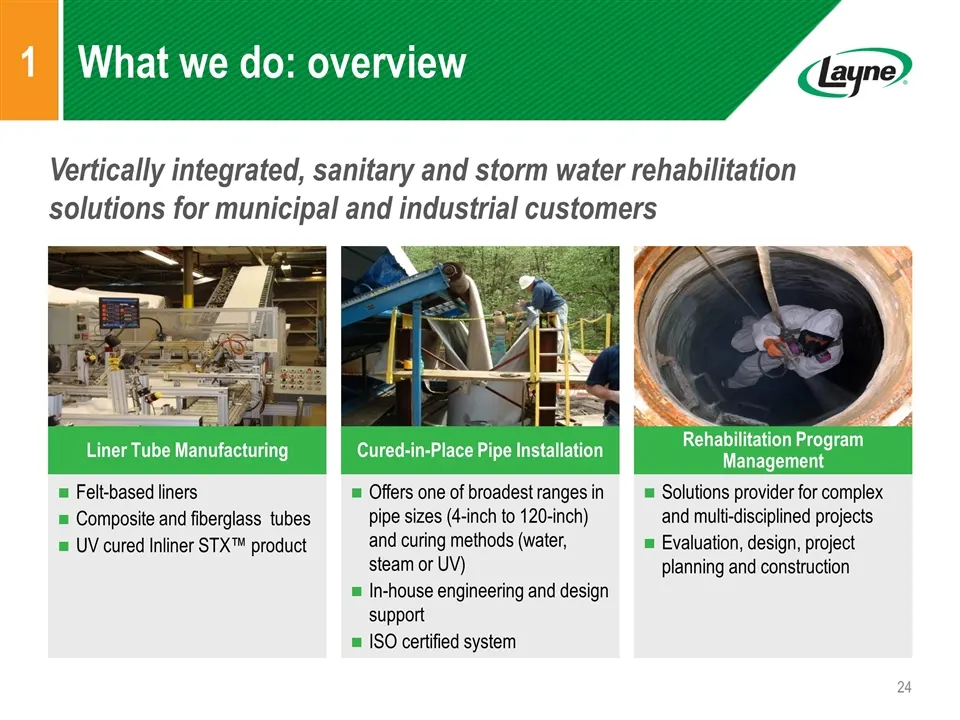
Vertically integrated, sanitary and storm water rehabilitation solutions for municipal and industrial customers 1 What we do: overview Rehabilitation Program Management Solutions provider for complex and multi-disciplined projects Evaluation, design, project planning and construction Cured-in-Place
Slide 25: Inliner by the numbers
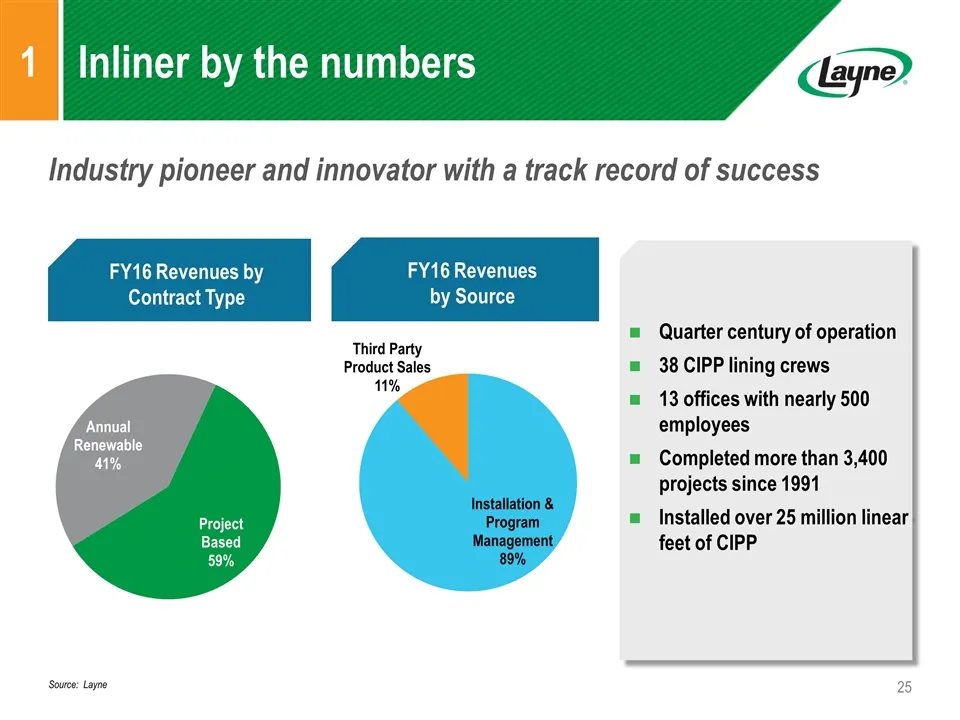
Industry pioneer and innovator with a track record of success 1 Inliner by the numbers FY16 Revenues by Contract Type Quarter century of operation 38 CIPP lining crews 13 offices with nearly 500 employees Completed more than 3,400 projects since 1991 Installed over 25 million linear feet of CIPP FY1
Slide 26: Cured-in-Place Pipe process
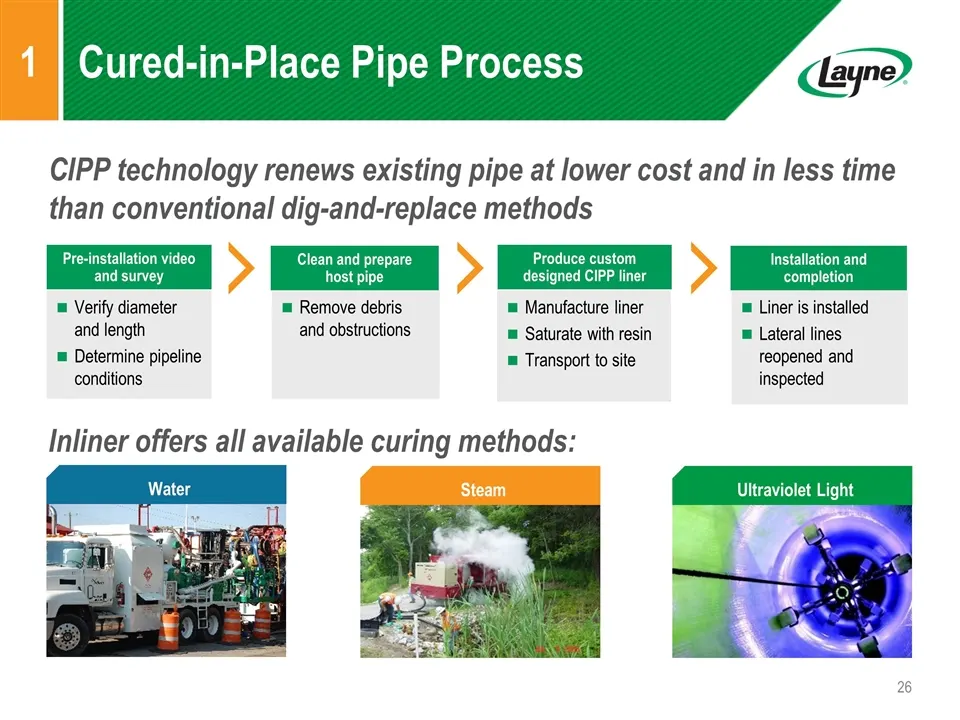
CIPP technology renews existing pipe at lower cost and in less time than conventional dig-and-replace methods 1 Cured-in-Place Pipe Process Water Steam Ultraviolet Light Inliner offers all available curing methods: Pre-installation video and survey Clean and prepare host pipe Produce custom designed
Slide 27: Liner manufacturing
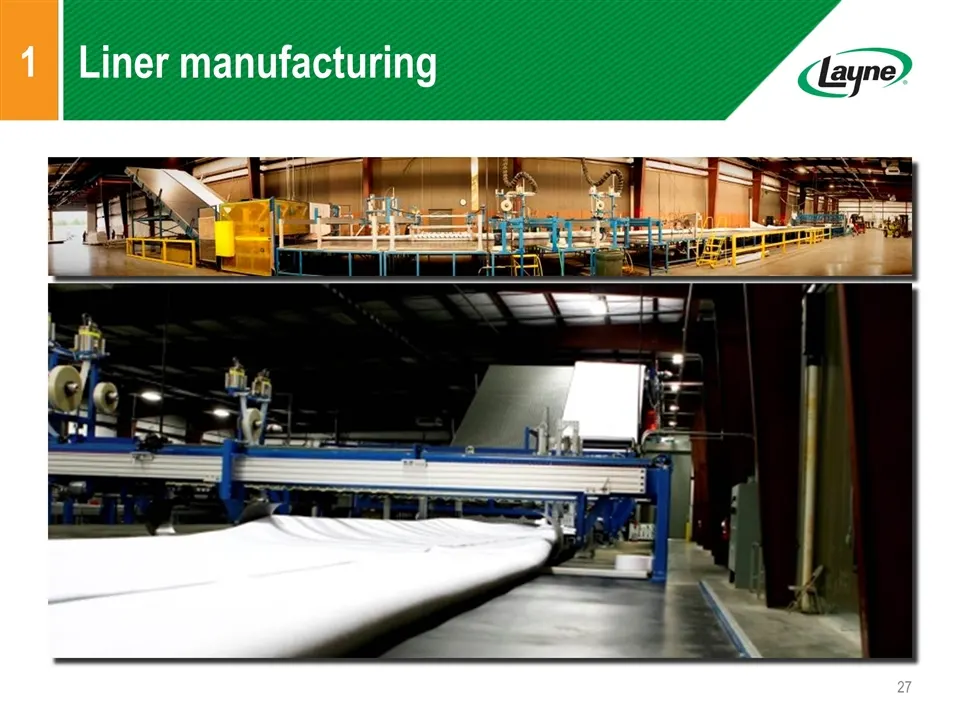
1 Liner manufacturing
Slide 28: Liner saturation
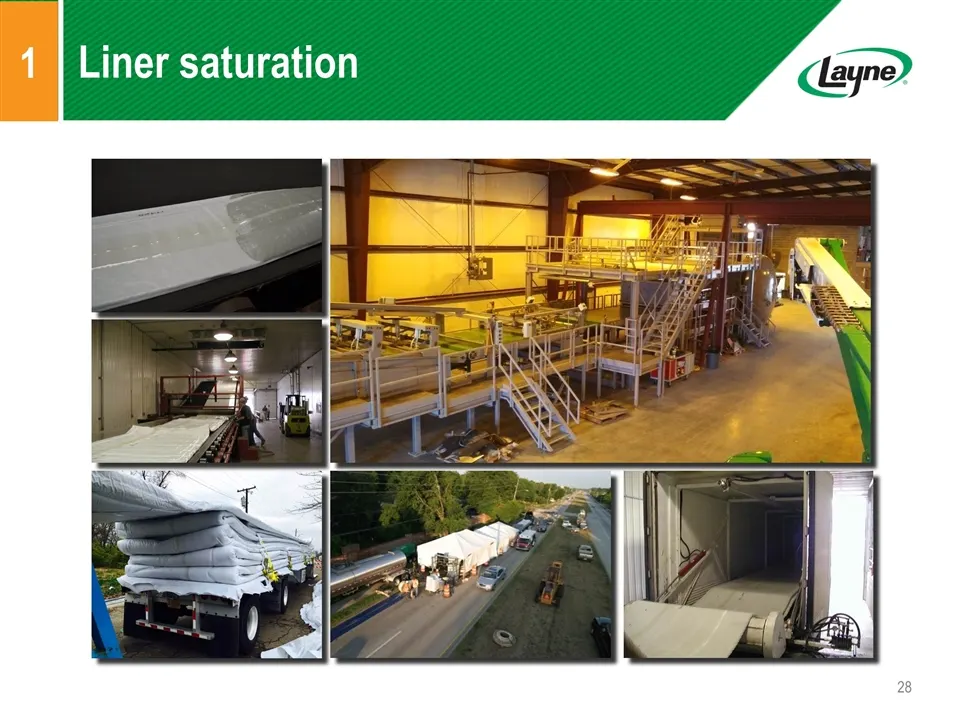
1 Liner saturation
Slide 29: Finished product
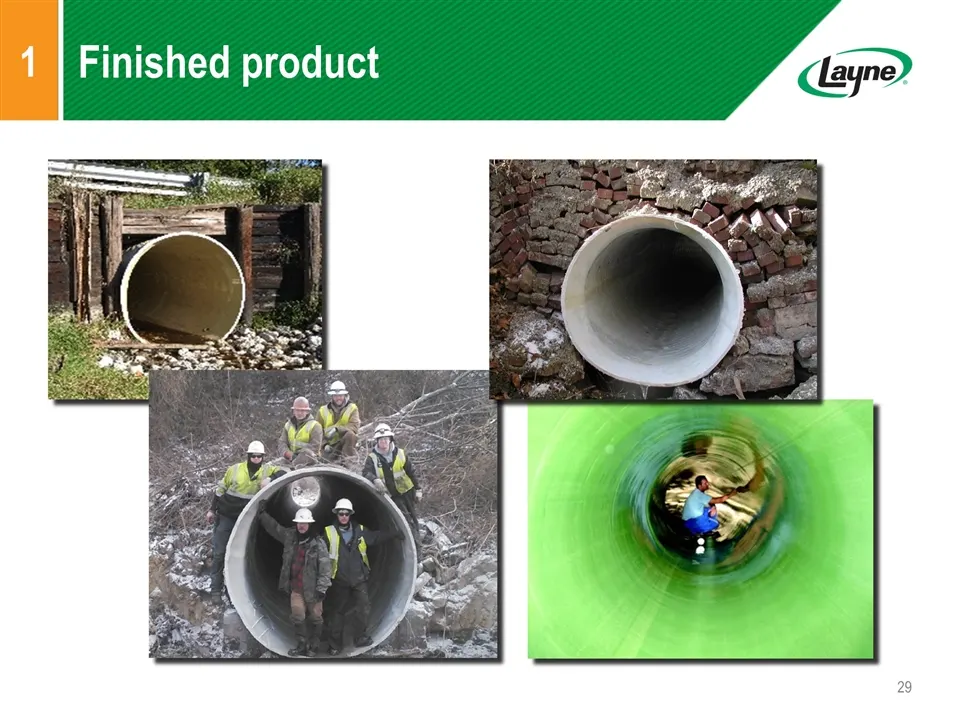
1 Finished product
Slide 30: Critical project execution
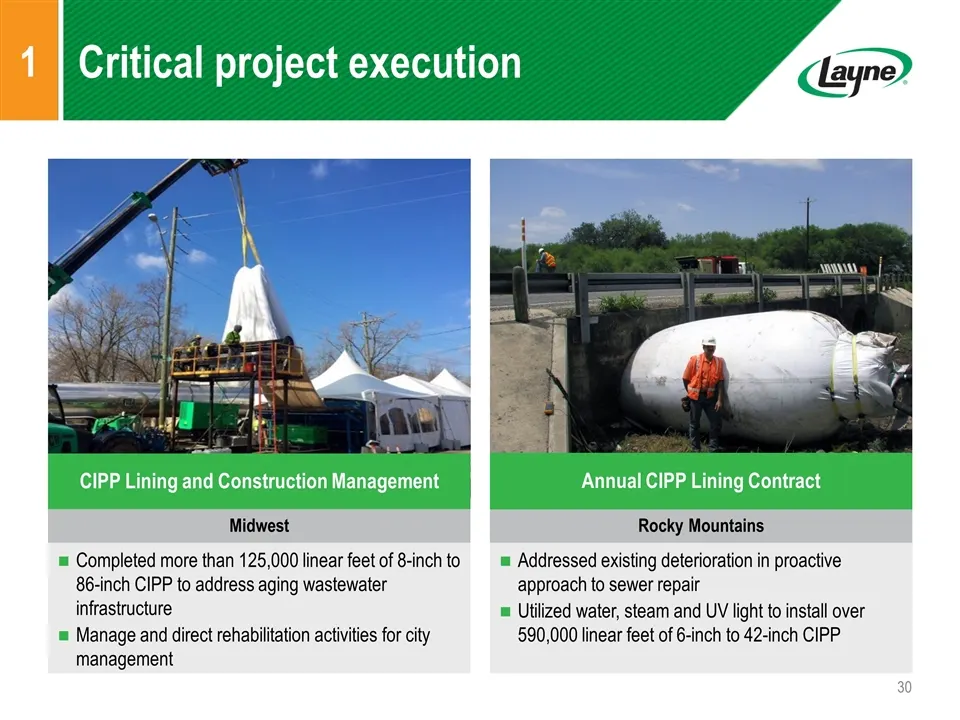
1 Critical project execution CIPP Lining and Construction Management Completed more than 125,000 linear feet of 8-inch to 86-inch CIPP to address aging wastewater infrastructure Manage and direct rehabilitation activities for city management Midwest Addressed existing deterioration in proactive appr
Slide 31: Critical project execution
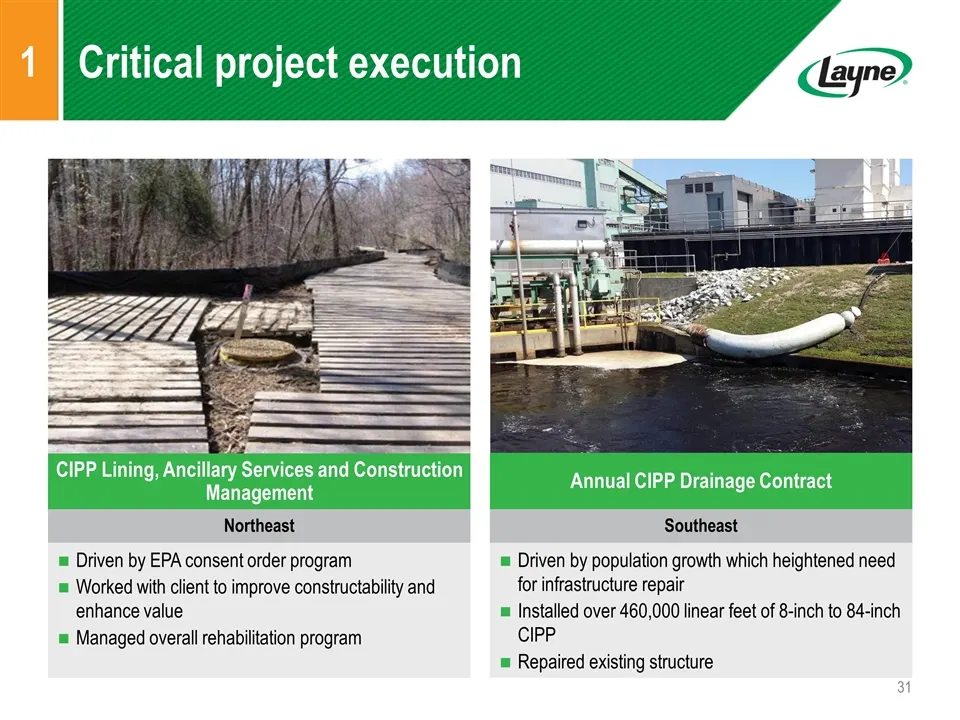
1 Critical project execution CIPP Lining, Ancillary Services and Construction Management Driven by EPA consent order program Worked with client to improve constructability and enhance value Managed overall rehabilitation program Northeast Annual CIPP Drainage Contract Driven by population growth whi
Slide 32: Where we compete: population-dense regions
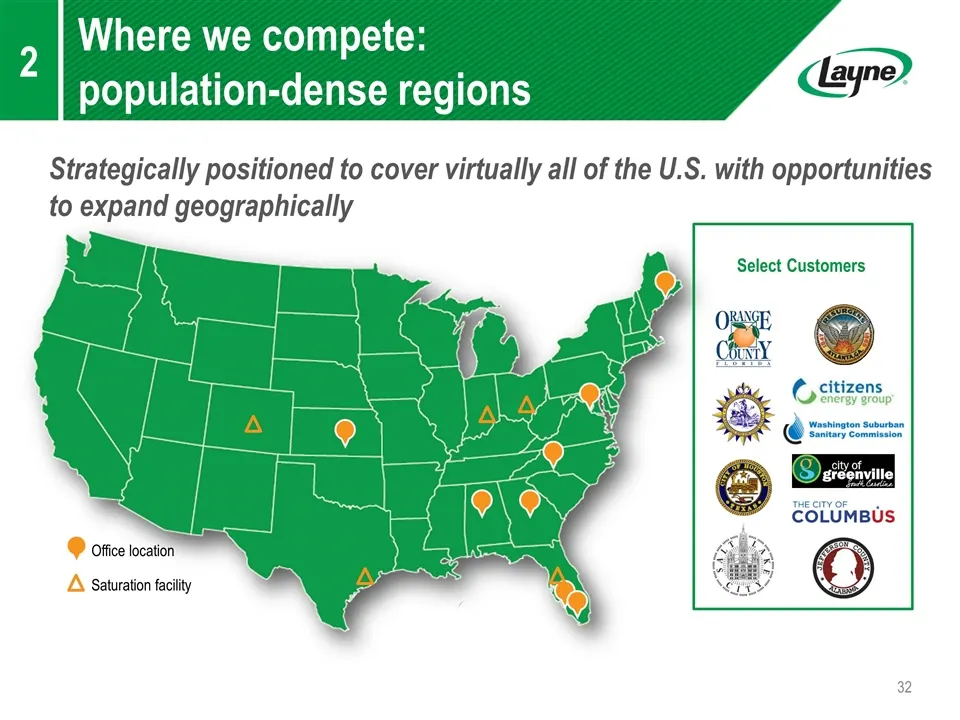
Strategically positioned to cover virtually all of the U.S. with opportunities to expand geographically 2 Where we compete: population-dense regions Office location Saturation facility Select Customers
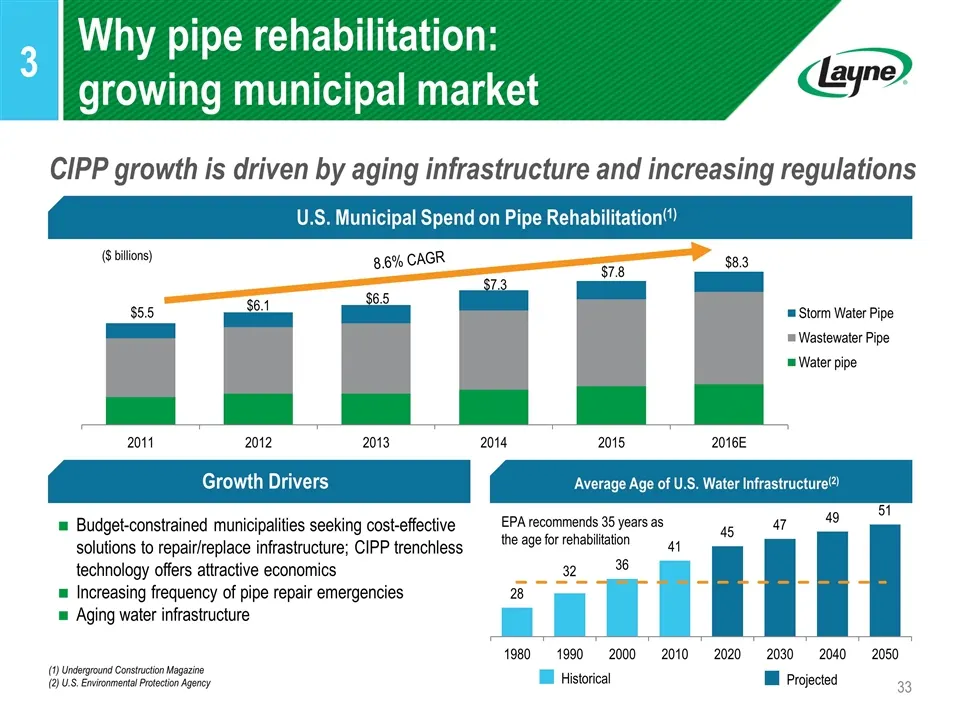
Slide 33: Why pipe rehabilitation: growing municipal market
CIPP growth is driven by aging infrastructure and increasing regulations 3 Why pipe rehabilitation: growing municipal market U.S. Municipal Spend on Pipe Rehabilitation(1) (1) Underground Construction Magazine (2) U.S. Environmental Protection Agency ($ billions) 8.6% CAGR Budget-constrained municip
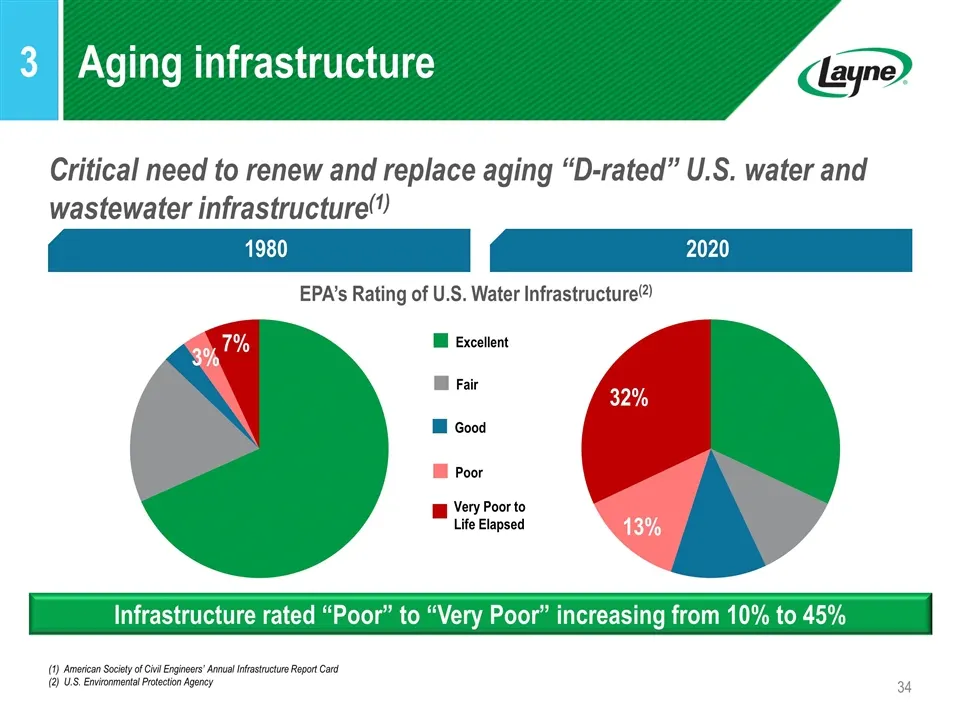
Slide 34: Aging infrastructure
Critical need to renew and replace aging “D-rated” U.S. water and wastewater infrastructure(1) 3 Aging infrastructure (1) American Society of Civil Engineers’ Annual Infrastructure Report Card (2) U.S. Environmental Protection Agency Excellent Good Very Poor to Life Elapsed Fair Poor 1980 2020 Infra
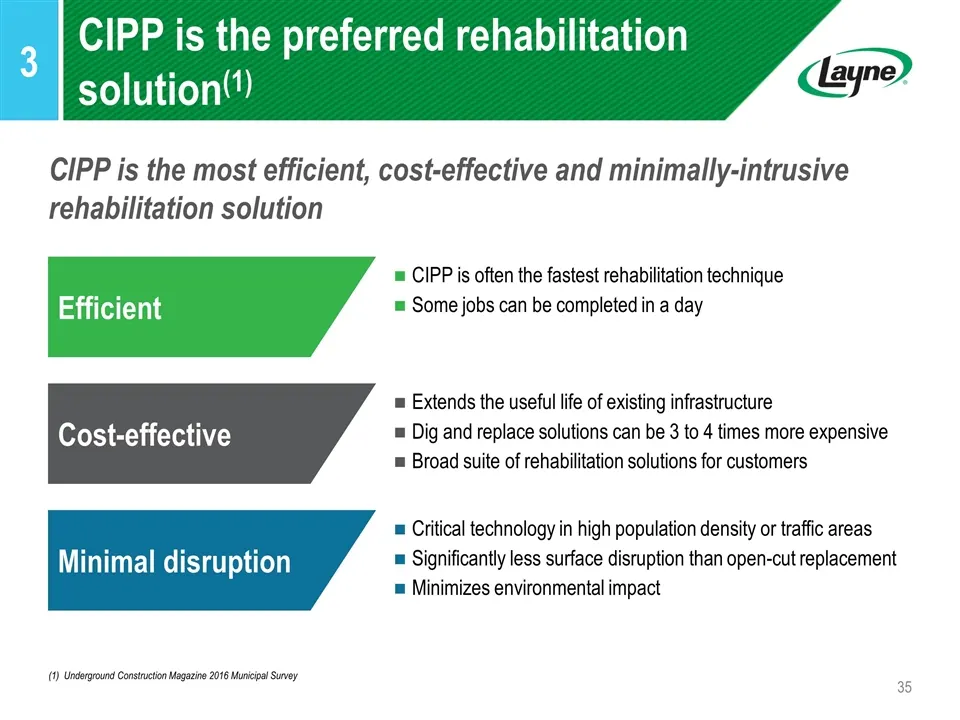
Slide 35: CIPP is the most efficient rehabilitation solution
CIPP is the most efficient, cost-effective and minimally-intrusive rehabilitation solution 3 CIPP is the preferred rehabilitation solution(1) Critical technology in high population density or traffic areas Significantly less surface disruption than open-cut replacement Minimizes environmental impact
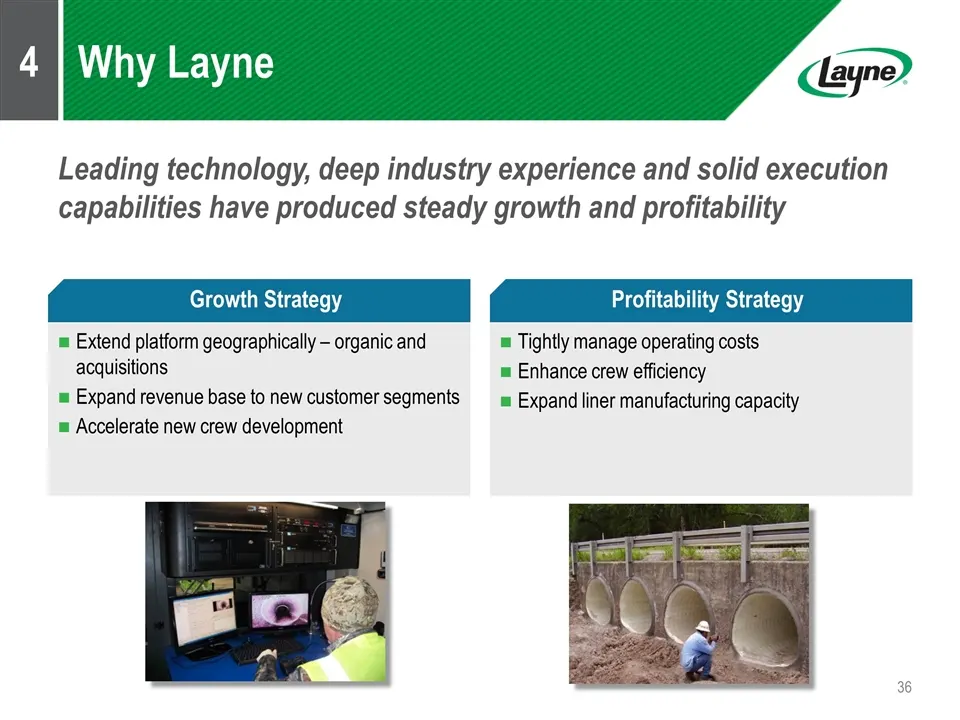
Slide 36: Why Layne: growth and profitability strategy
Leading technology, deep industry experience and solid execution capabilities have produced steady growth and profitability 4 Why Layne Tightly manage operating costs Enhance crew efficiency Expand liner manufacturing capacity Extend platform geographically – organic and acquisitions Expand revenue
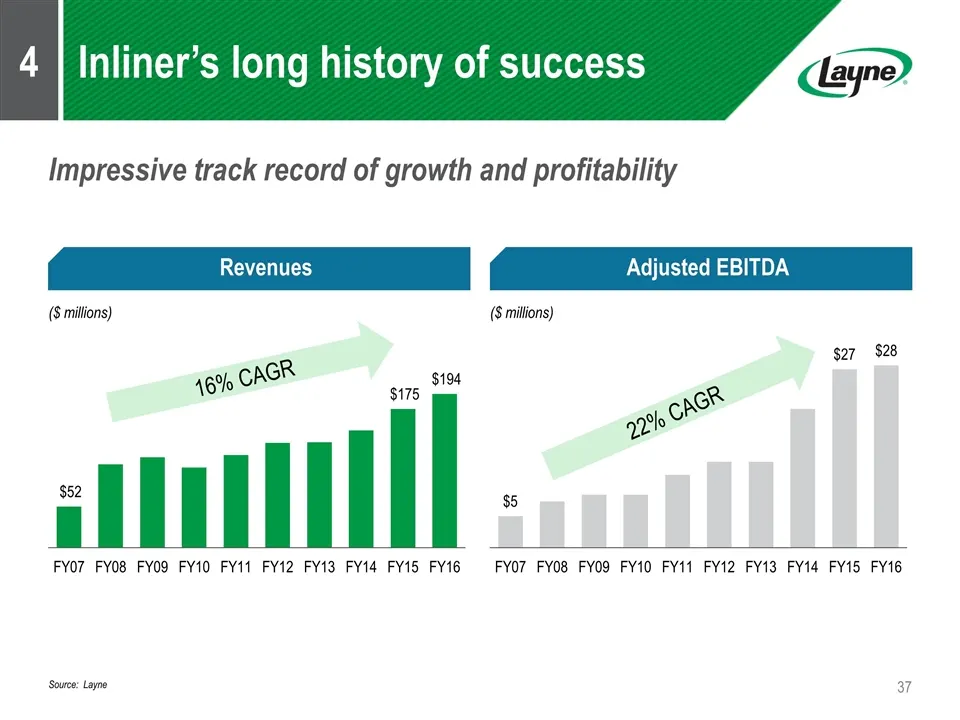
Slide 37: Impressive track record of growth and profitability
Impressive track record of growth and profitability Inliner’s long history of success ($ millions) ($ millions) Revenues Adjusted EBITDA 16% CAGR 22% CAGR 4 Source: Layne
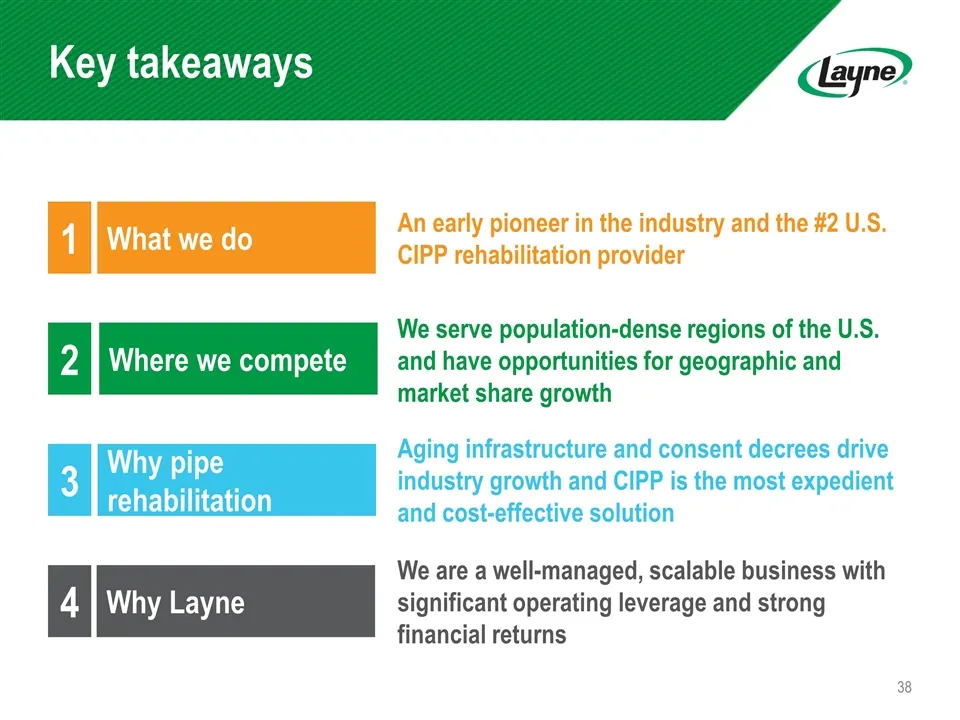
Slide 38: Key takeaways
Key takeaways 1 2 3 Where we compete Why pipe rehabilitation What we do 4 Why Layne Aging infrastructure and consent decrees drive industry growth and CIPP is the most expedient and cost-effective solution We are a well-managed, scalable business with significant operating leverage and strong financ
Slide 39: Mineral Services Division
Mineral Services Division Kevin Maher, Senior Vice President
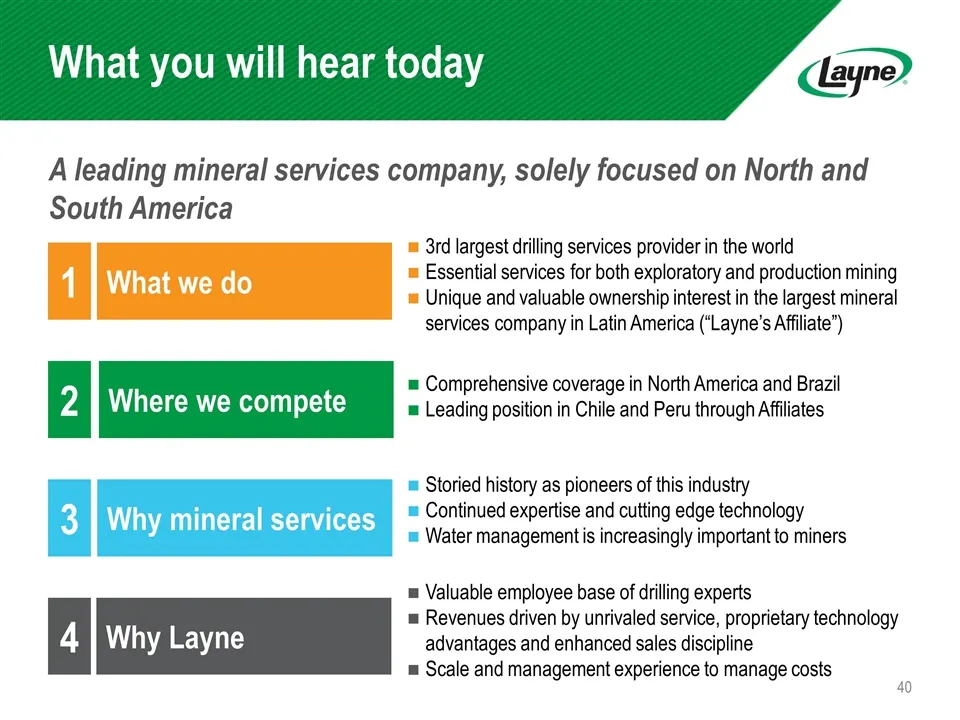
Slide 40: What you will hear today: Mineral Services
What you will hear today A leading mineral services company, solely focused on North and South America 1 2 3 Where we compete Why mineral services What we do 4 Why Layne 3rd largest drilling services provider in the world Essential services for both exploratory and production mining Unique and valua
Slide 41: What we do: overview
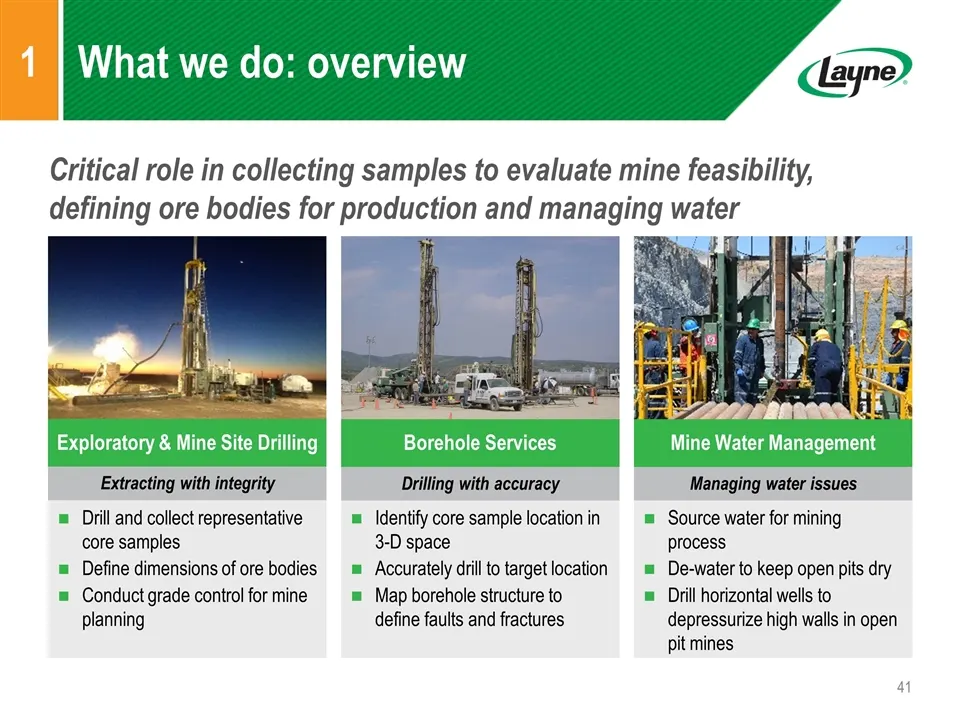
Critical role in collecting samples to evaluate mine feasibility, defining ore bodies for production and managing water 1 What we do: overview Exploratory & Mine Site Drilling Borehole Services Mine Water Management Drill and collect representative core samples Define dimensions of ore bodies Conduc
Slide 42: Mineral Services by the numbers
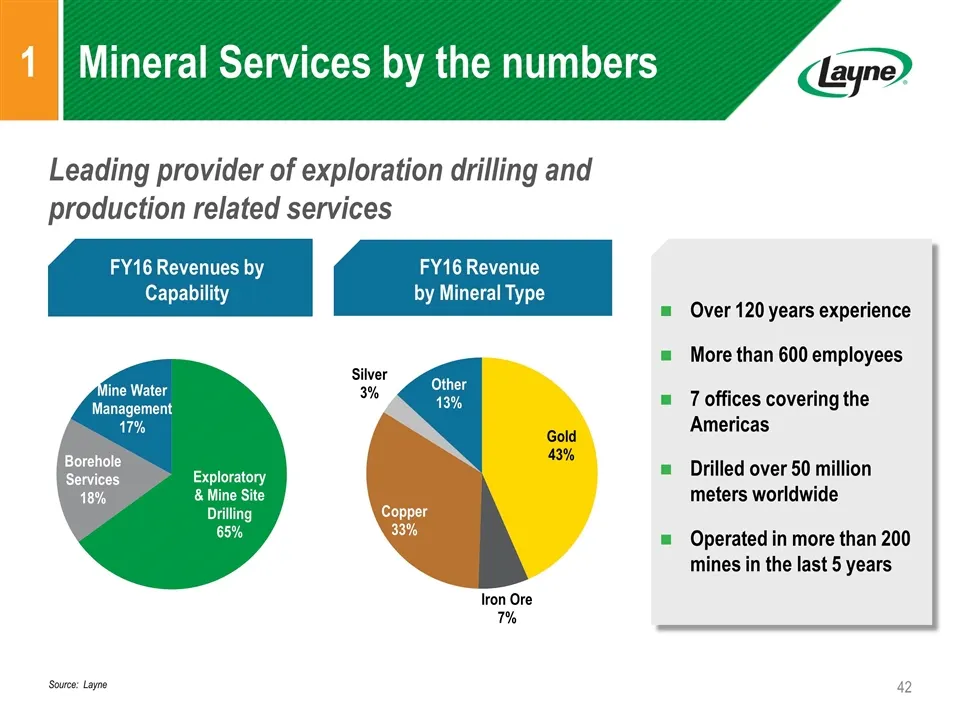
Leading provider of exploration drilling and production related services 1 Mineral Services by the numbers FY16 Revenues by Capability Over 120 years experience More than 600 employees 7 offices covering the Americas Drilled over 50 million meters worldwide Operated in more than 200 mines in the las
Slide 43: Layne's Latin America Affiliate: a unique asset
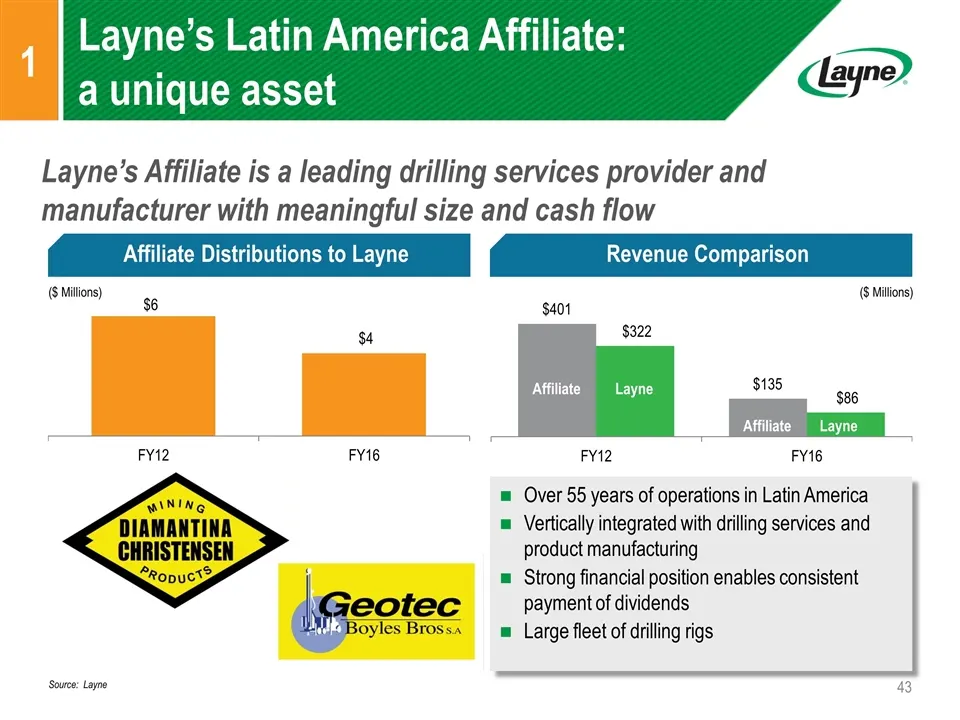
Layne’s Affiliate is a leading drilling services provider and manufacturer with meaningful size and cash flow 1 Layne’s Latin America Affiliate: a unique asset Over 55 years of operations in Latin America Vertically integrated with drilling services and product manufacturing Strong financial positio
Slide 44: Expert capabilities: diamond drilling and borehole surveys
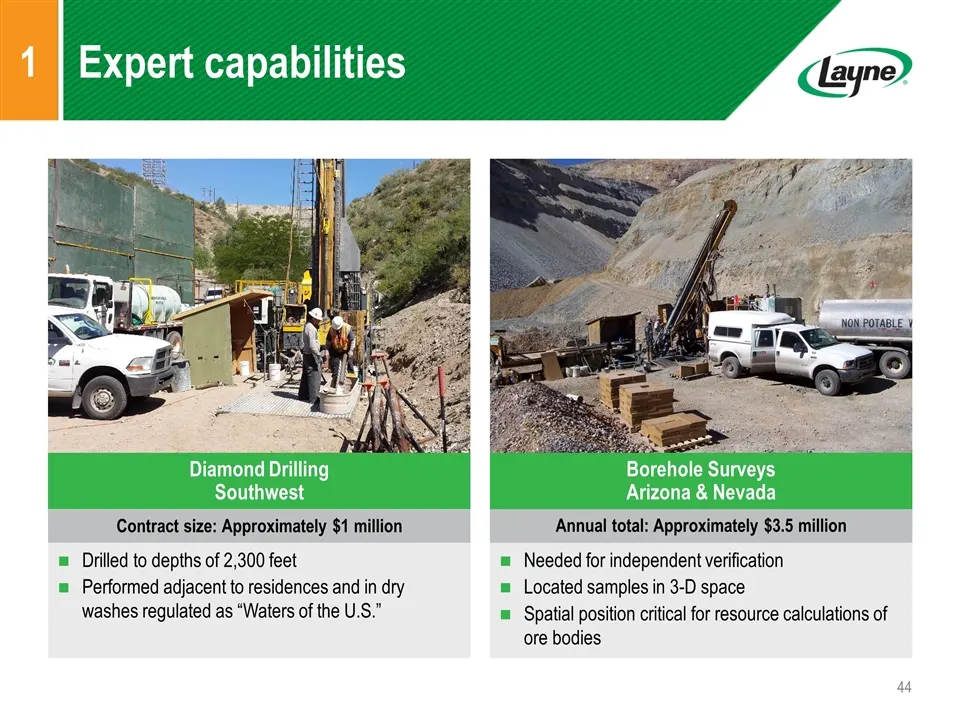
Borehole Surveys Arizona & Nevada 1 Expert capabilities Diamond Drilling Southwest Contract size: Approximately $1 million Drilled to depths of 2,300 feet Performed adjacent to residences and in dry washes regulated as “Waters of the U.S.” Annual total: Approximately $3.5 million Needed for independ
Slide 45: Expert capabilities: exploration drilling and mine water
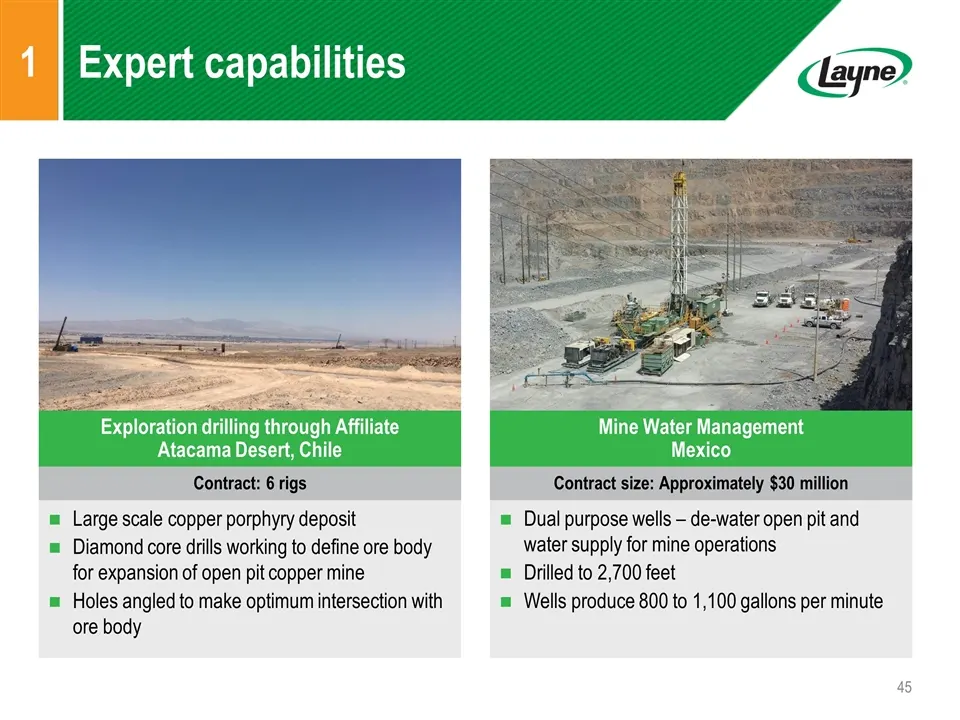
1 Expert capabilities Exploration drilling through Affiliate Atacama Desert, Chile Large scale copper porphyry deposit Diamond core drills working to define ore body for expansion of open pit copper mine Holes angled to make optimum intersection with ore body Contract: 6 rigs Mine Water Management M
Slide 46: Expert capabilities: mine water management
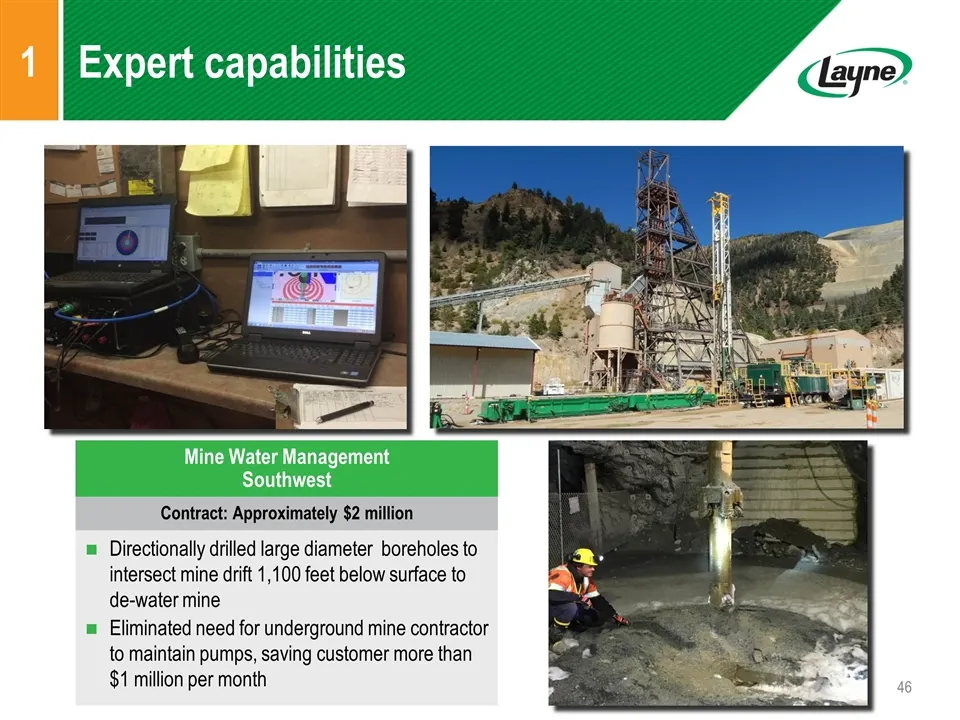
1 Expert capabilities Mine Water Management Southwest Contract: Approximately $2 million Directionally drilled large diameter boreholes to intersect mine drift 1,100 feet below surface to de-water mine Eliminated need for underground mine contractor to maintain pumps, saving customer more than $1 mi
Slide 47: Where we compete: North and South America
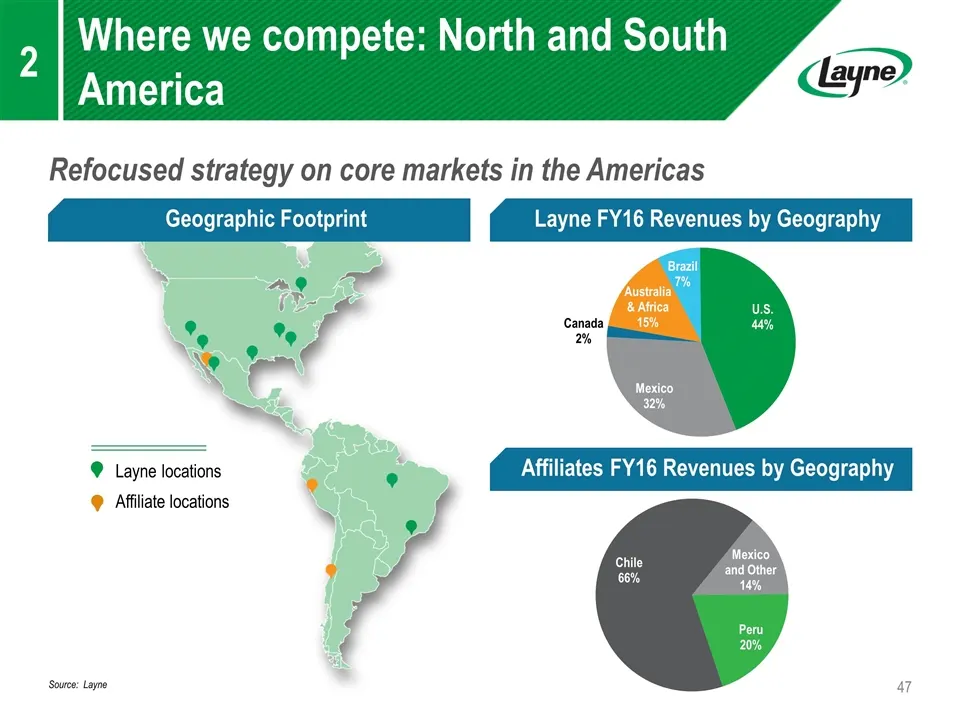
Layne locations Affiliate locations Refocused strategy on core markets in the Americas 2 Where we compete: North and South America Layne FY16 Revenues by Geography Affiliates FY16 Revenues by Geography Source: Layne Geographic Footprint
Slide 48: Managing the downturn
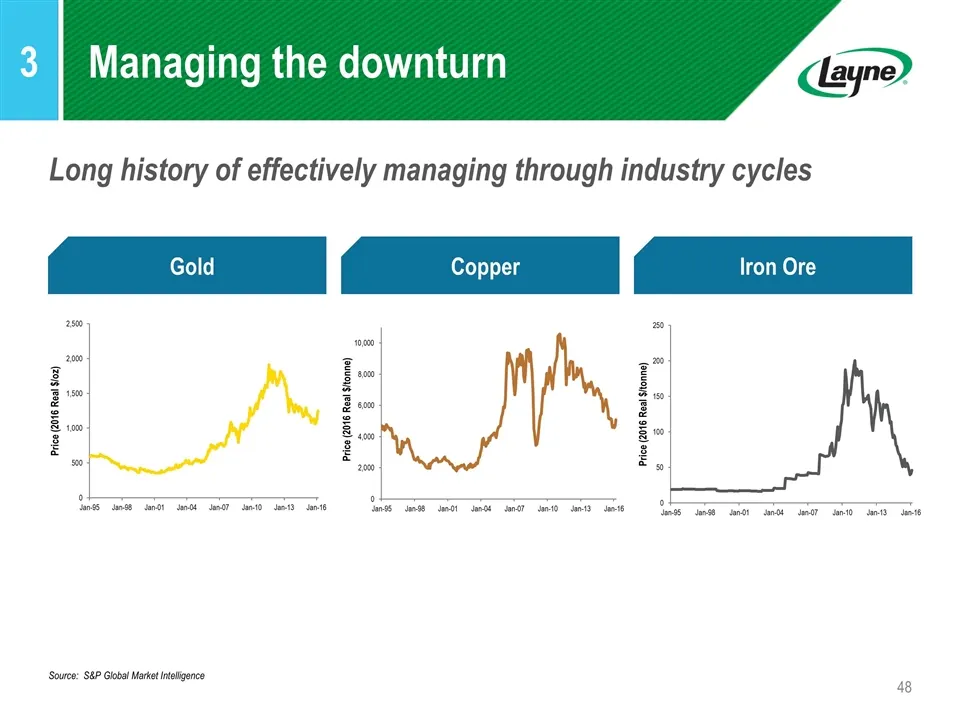
Long history of effectively managing through industry cycles 3 Managing the downturn Gold Copper Iron Ore Source: S&P Global Market Intelligence
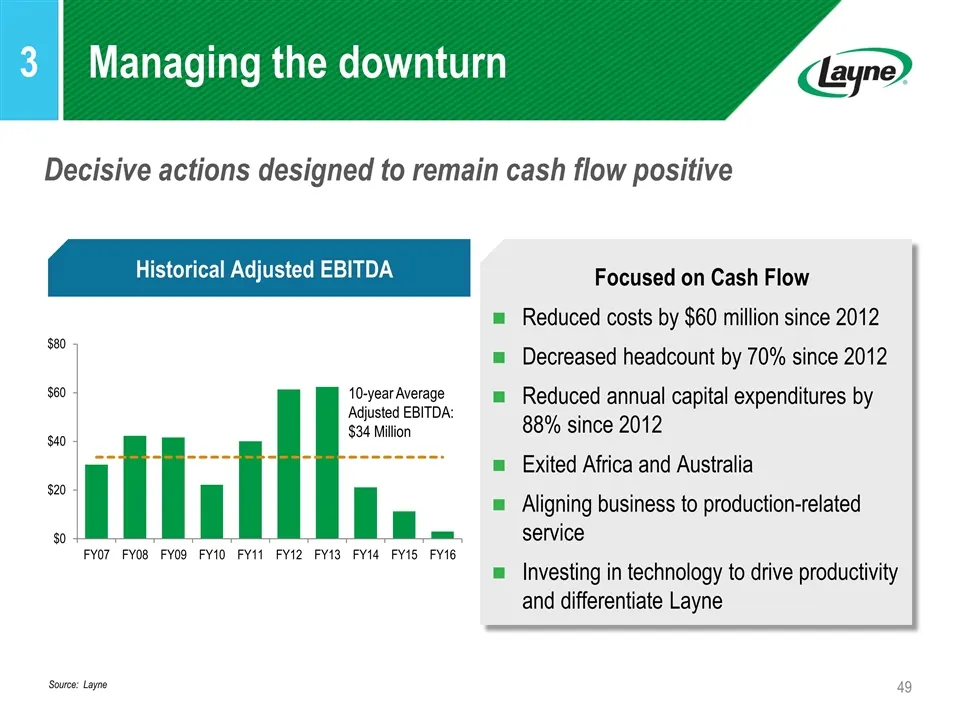
Slide 49: Decisive actions designed to remain cash flow positive
Decisive actions designed to remain cash flow positive 3 Managing the downturn 10-year Average Adjusted EBITDA: $34 Million Historical Adjusted EBITDA Focused on Cash Flow Reduced costs by $60 million since 2012 Decreased headcount by 70% since 2012 Reduced annual capital expenditures by 88% since 2
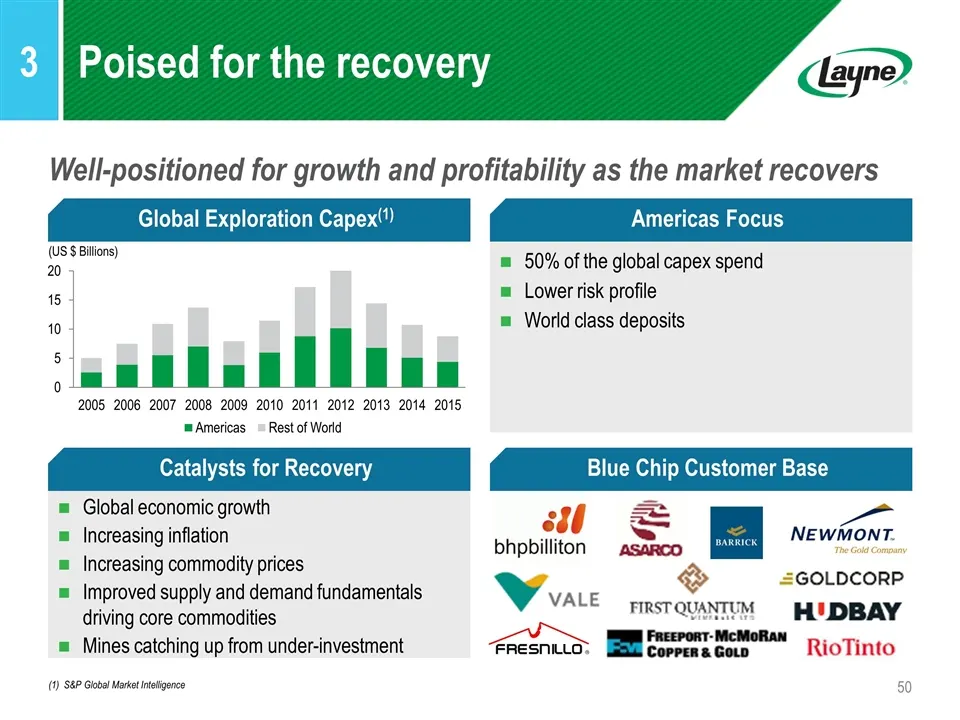
Slide 50: Poised for the recovery
(1) S&P Global Market Intelligence Well-positioned for growth and profitability as the market recovers 3 Poised for the recovery Global economic growth Increasing inflation Increasing commodity prices Improved supply and demand fundamentals driving core commodities Mines catching up from under-inves
Slide 51: Top mineral services provider focused on the Americas
Layne is a top 3 mineral services provider globally and the only one focused solely on the Americas
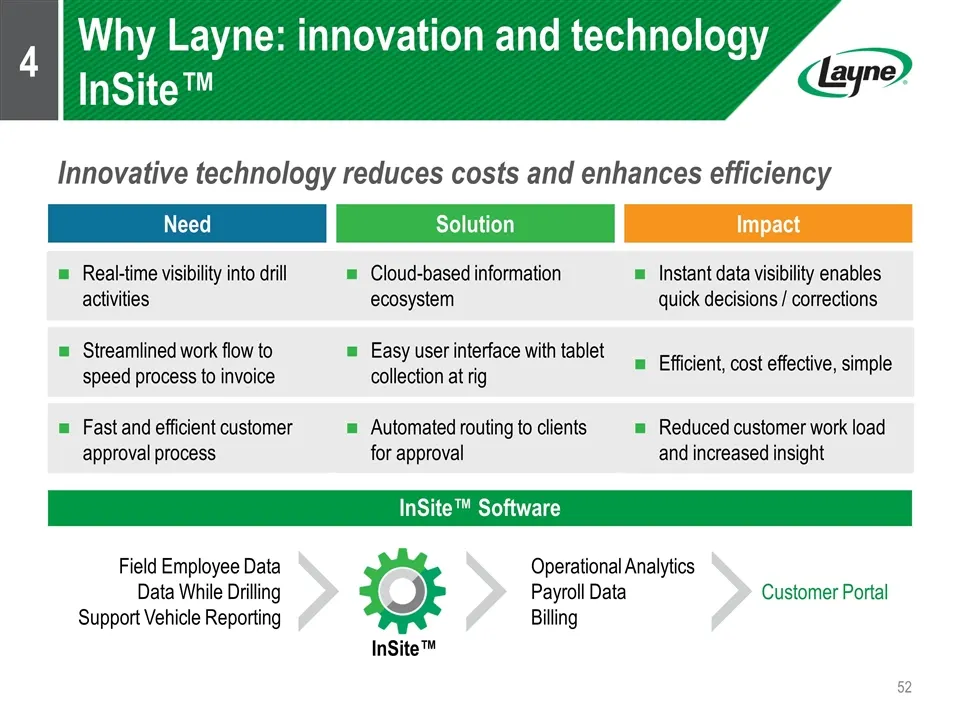
Slide 52: Innovation and technology: InSite
Innovative technology reduces costs and enhances efficiency 4 Why Layne: innovation and technology InSite™ InSite™ Software Operational Analytics Payroll Data Billing Need Solution Impact Real-time visibility into drill activities Streamlined work flow to speed process to invoice Fast and efficient
Slide 53: Innovation and technology: Automated Rod Manipulator
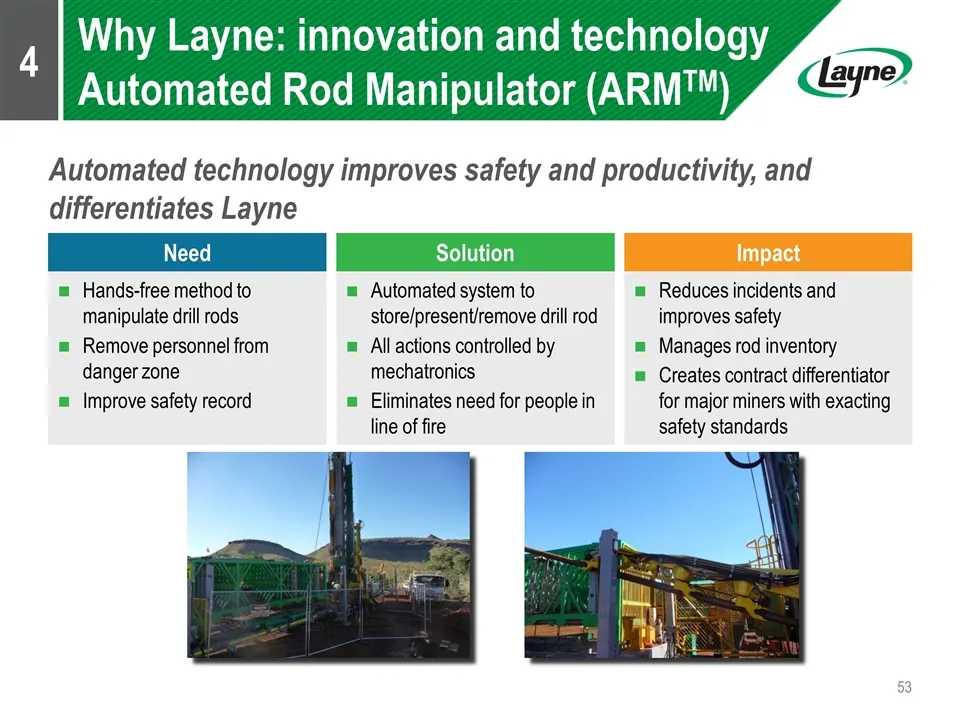
Automated technology improves safety and productivity, and differentiates Layne 4 Why Layne: innovation and technology Automated Rod Manipulator (ARMTM) Hands-free method to manipulate drill rods Remove personnel from danger zone Improve safety record Automated system to store/present/remove drill r
Slide 54: Focused on cost management and technology
Focused on cost management and technology to drive efficiency 4 Why Layne Utilize more focused platform in the Americas to drive further cost efficiencies Collaborate with Affiliates to reduce costs and leverage best practices and technology Grow mine water management solutions, capitalizing on Layn
Slide 55: Key takeaways
Key takeaways Concentrated focus and leadership position in geographies representing half of the industry’s capital expenditures 3rd largest global mineral services provider with 100 year history Strategically focused on core markets in the Americas: U.S., Mexico, Brazil, Chile and Peru We provide e
Slide 56: Heavy Civil
Heavy Civil Les Archer, Division President
Slide 57: What you will hear today: Heavy Civil
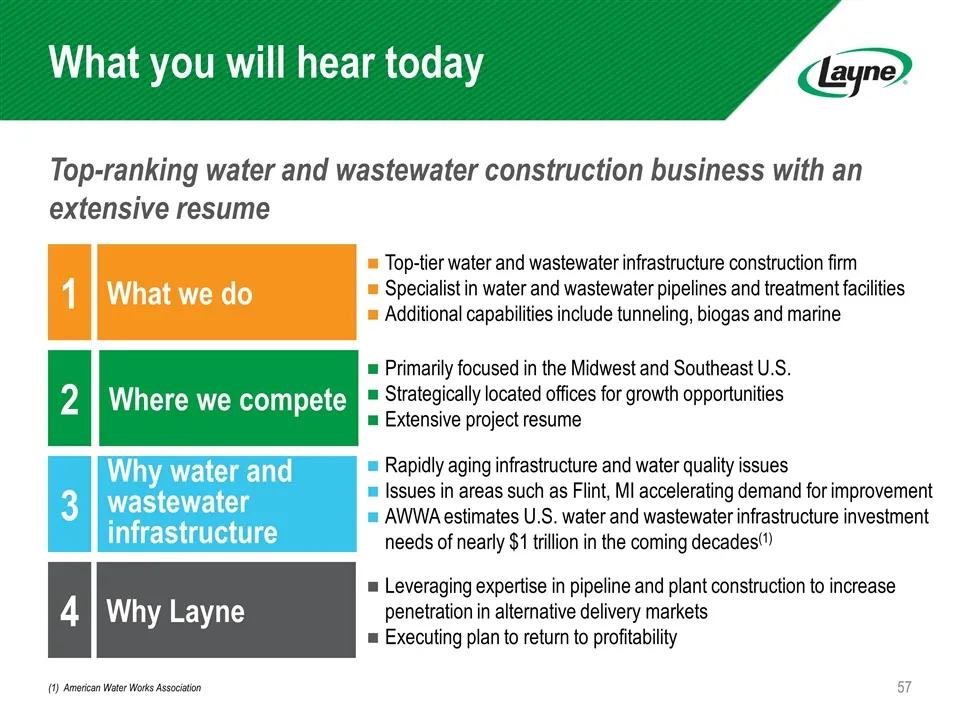
What you will hear today Top-ranking water and wastewater construction business with an extensive resume 1 2 3 Where we compete Why water and wastewater infrastructure What we do 4 Why Layne Top-tier water and wastewater infrastructure construction firm Specialist in water and wastewater pipelines a
Slide 58: What we do: overview
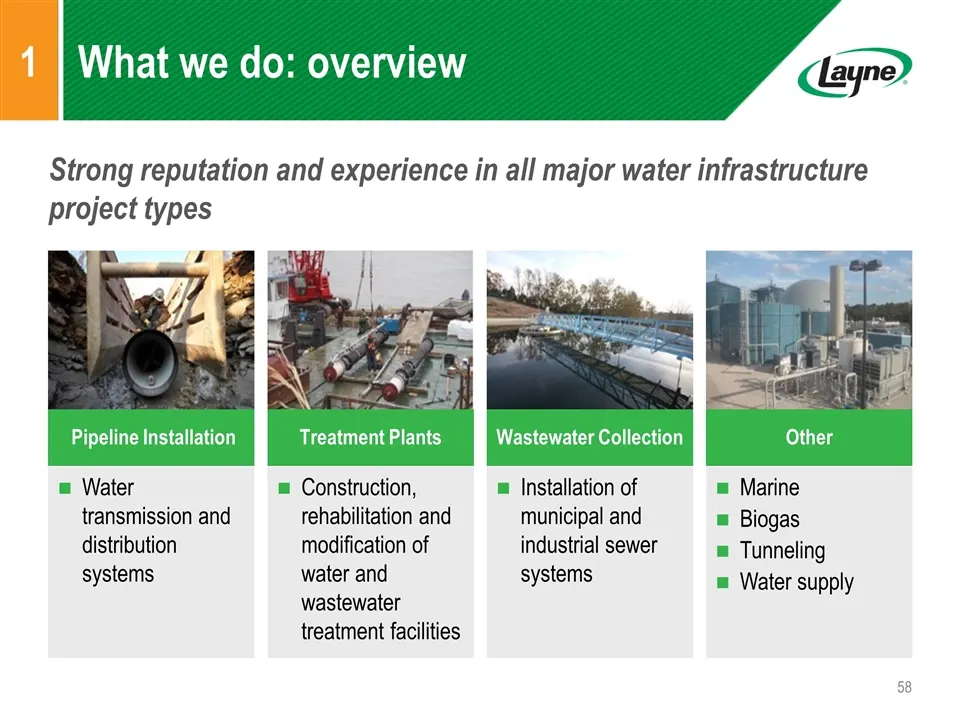
Strong reputation and experience in all major water infrastructure project types 1 What we do: overview Pipeline Installation Treatment Plants Water transmission and distribution systems Construction, rehabilitation and modification of water and wastewater treatment facilities Installation of munici
Slide 59: Heavy Civil by the numbers
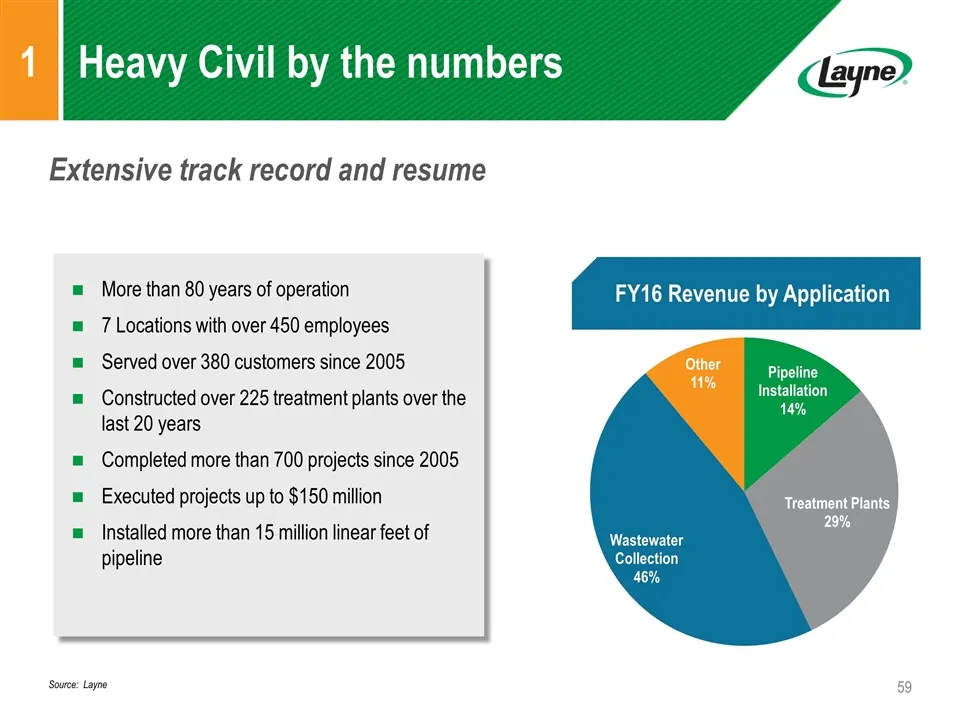
1 Heavy Civil by the numbers FY16 Revenue by Application More than 80 years of operation 7 Locations with over 450 employees Served over 380 customers since 2005 Constructed over 225 treatment plants over the last 20 years Completed more than 700 projects since 2005 Executed projects up to $150 mill
Slide 60: Traditional vs alternative delivery
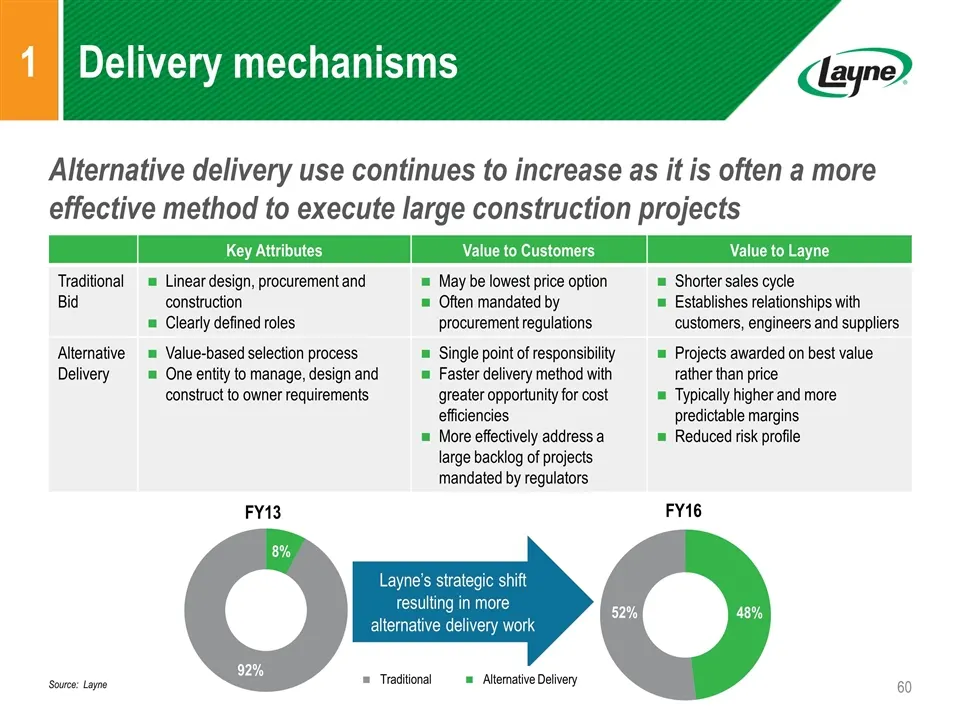
Traditional Layne’s strategic shift resulting in more alternative delivery work Alternative Delivery Alternative delivery use continues to increase as it is often a more effective method to execute large construction projects 1 Delivery mechanisms Key Attributes Value to Customers Value to Layne Tra
Slide 61: Critical project execution
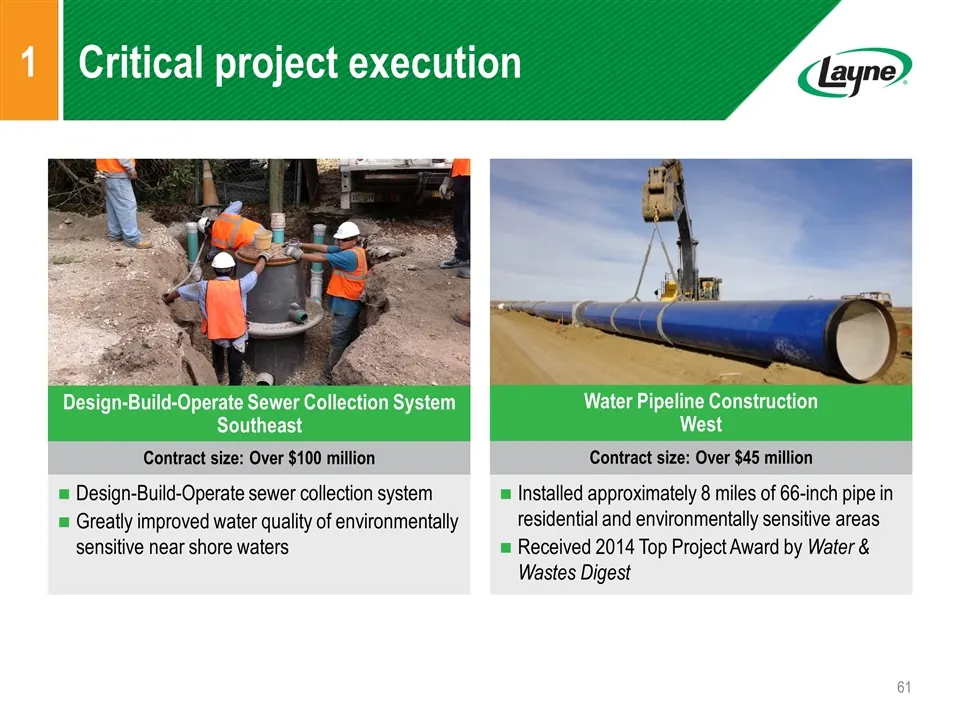
1 Critical project execution Design-Build-Operate Sewer Collection System Southeast Contract size: Over $100 million Design-Build-Operate sewer collection system Greatly improved water quality of environmentally sensitive near shore waters Water Pipeline Construction West Contract size: Over $45 mil
Slide 62: Critical project execution
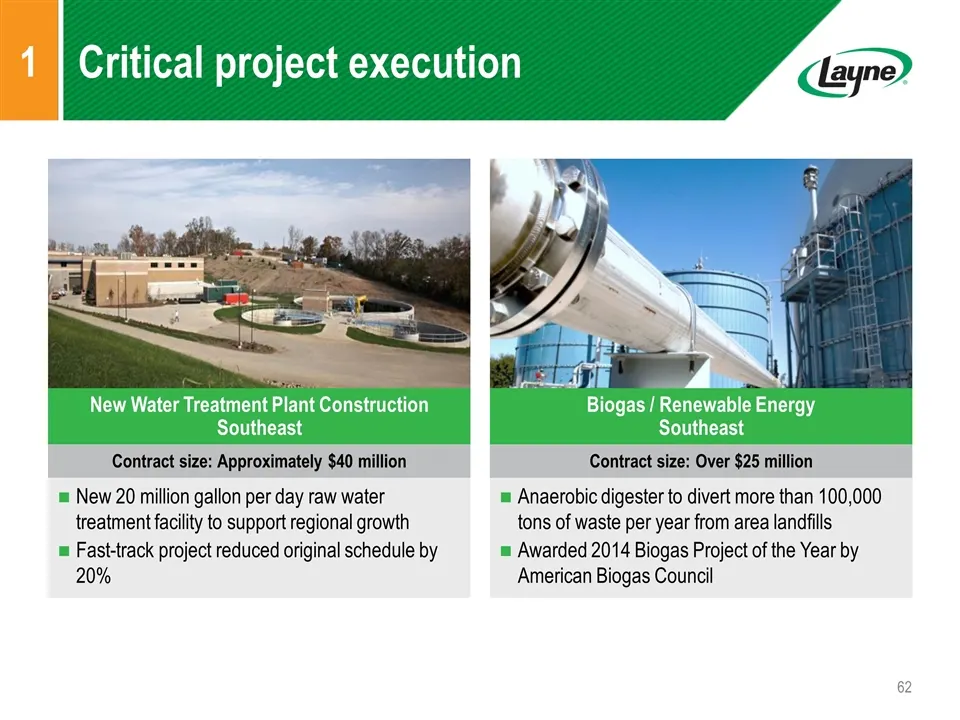
1 Critical project execution Biogas / Renewable Energy Southeast Contract size: Over $25 million Anaerobic digester to divert more than 100,000 tons of waste per year from area landfills Awarded 2014 Biogas Project of the Year by American Biogas Council New Water Treatment Plant Construction Southea
Slide 63: Where we compete: national player with local knowledge
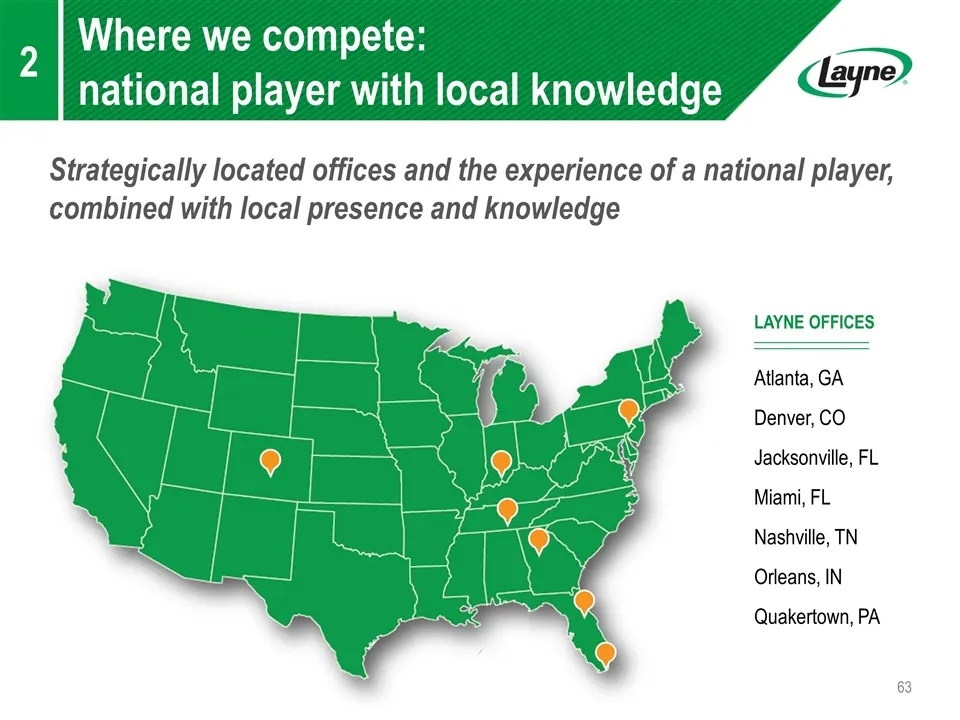
Miami, FL Jacksonville, FL Atlanta, GA Nashville, TN Orleans, IN Quakertown, PA Denver, CO Strategically located offices and the experience of a national player, combined with local presence and knowledge 2 Where we compete: national player with local knowledge LAYNE OFFICES
Slide 64: Top ranked contractor with high quality customer base
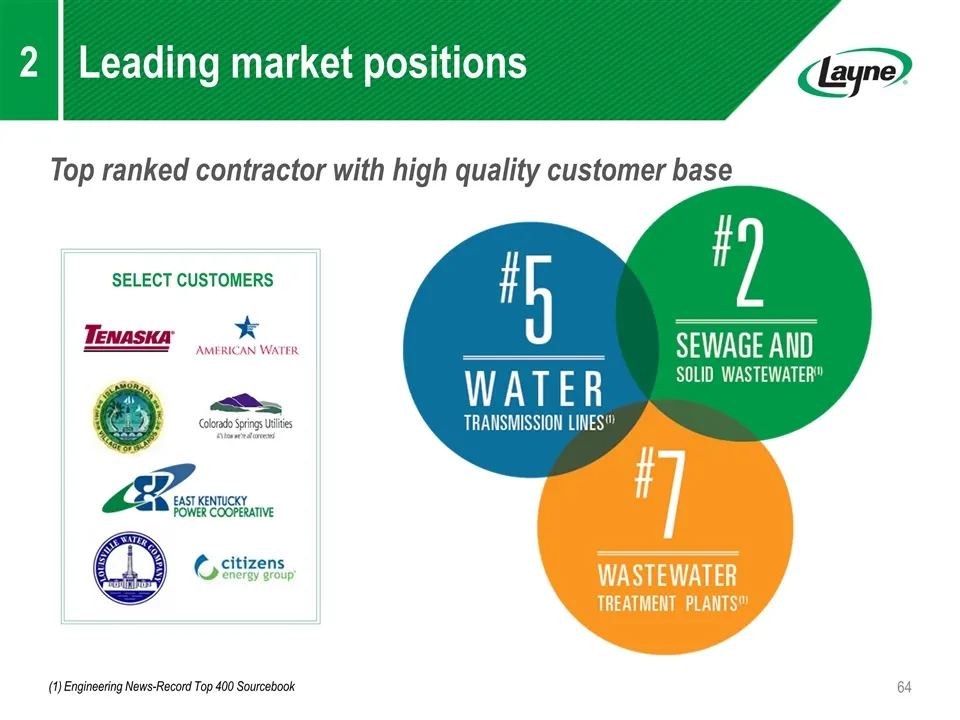
Top ranked contractor with high quality customer base 2 Leading market positions (1) Engineering News-Record Top 400 Sourcebook SELECT CUSTOMERS
Slide 65: Right Turn Plan: strategic realignment
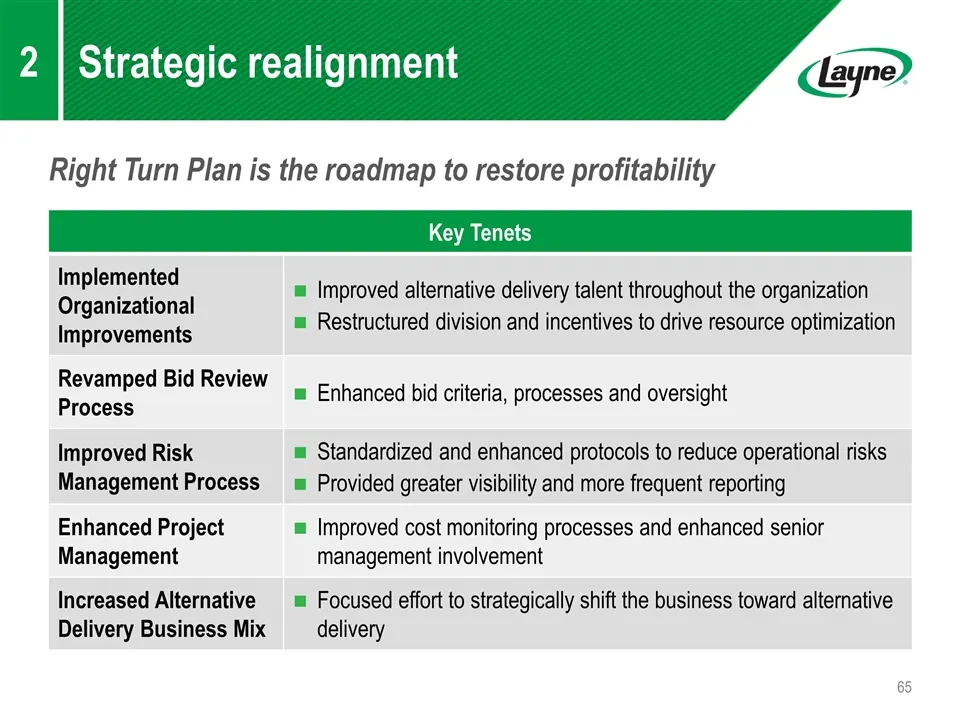
Key Tenets Implemented Organizational Improvements Improved alternative delivery talent throughout the organization Restructured division and incentives to drive resource optimization Revamped Bid Review Process Enhanced bid criteria, processes and oversight Improved Risk Management Process Standard
Slide 66: Why water infrastructure: increasing spend
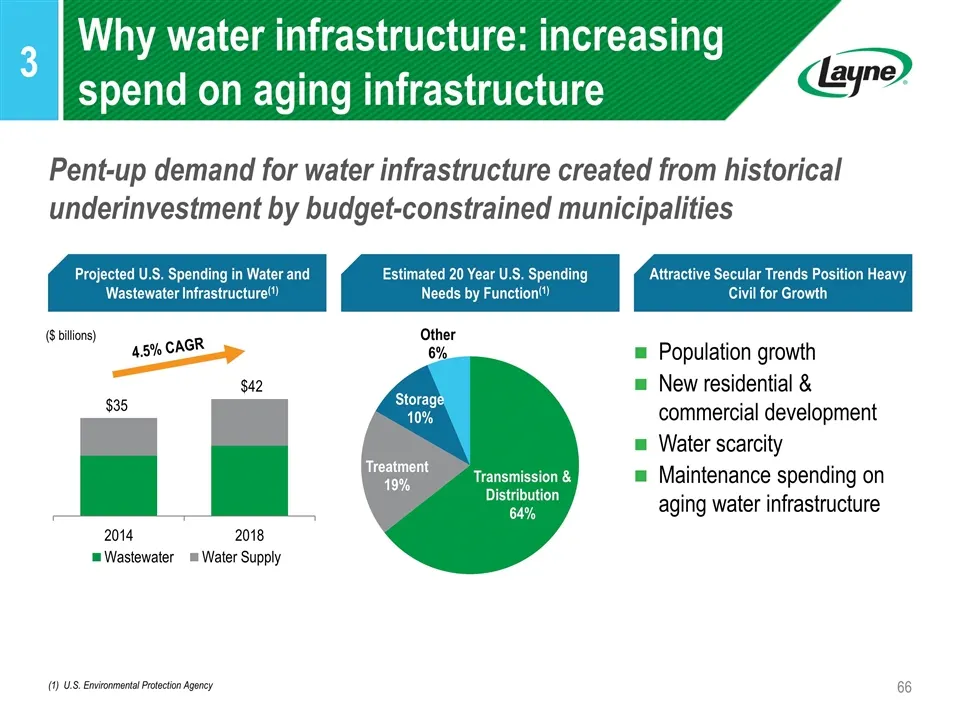
Pent-up demand for water infrastructure created from historical underinvestment by budget-constrained municipalities 3 Why water infrastructure: increasing spend on aging infrastructure (1) U.S. Environmental Protection Agency $35 $42 Projected U.S. Spending in Water and Wastewater Infrastructure(1)
Slide 67: Miami-Dade infrastructure investment quote
“During the next two decades, Miami-Dade will invest approximately $12.6 billion to enhance and upgrade our infrastructure” Miami-Dade Water and Sewer Department, September 2014
Slide 68: Why Layne: growth and profitability strategy
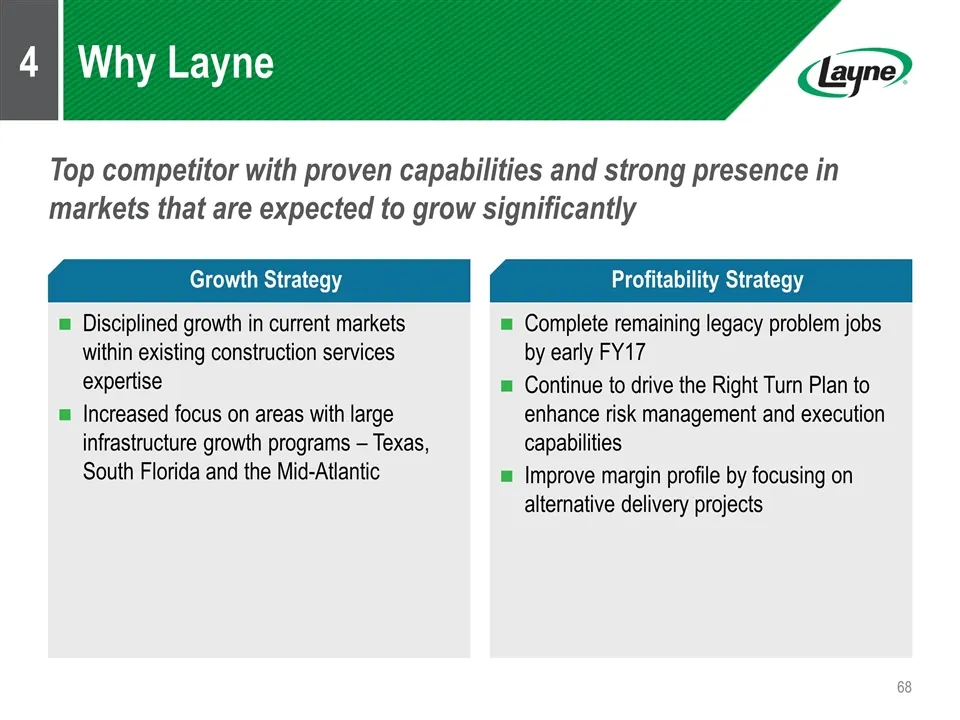
Top competitor with proven capabilities and strong presence in markets that are expected to grow significantly 4 Why Layne Complete remaining legacy problem jobs by early FY17 Continue to drive the Right Turn Plan to enhance risk management and execution capabilities Improve margin profile by focusi
Slide 69: Key takeaways
Aging infrastructure, population growth and increasing regulation drive demand for project investment We are executing a comprehensive plan to return to profitability and establish a foundation for long-term growth We are a top 5 U.S. competitor for pipeline construction, leveraging our proven track
Slide 70: Water Resources Division
Water Resources Division Kevin Maher, Senior Vice President
Slide 71: What you will hear today: Water Resources
What you will hear today The leader in a large water services industry benefiting from positive secular trends with decades of growth potential 1 2 3 Where we compete Why water What we do 4 Why Layne #1 U.S. water well driller and pump repair company Over 130 years leading the water industry Strong
Slide 72: What we do: overview
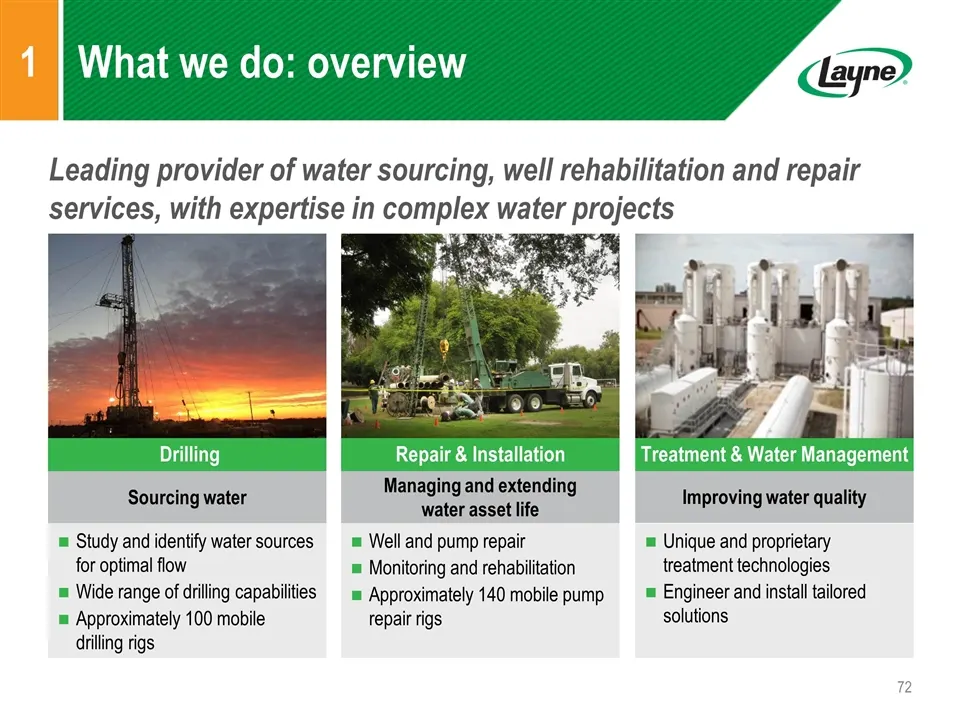
Leading provider of water sourcing, well rehabilitation and repair services, with expertise in complex water projects 1 What we do: overview Study and identify water sources for optimal flow Wide range of drilling capabilities Approximately 100 mobile drilling rigs Sourcing water Drilling Well and p
Slide 73: Water Resources by the numbers
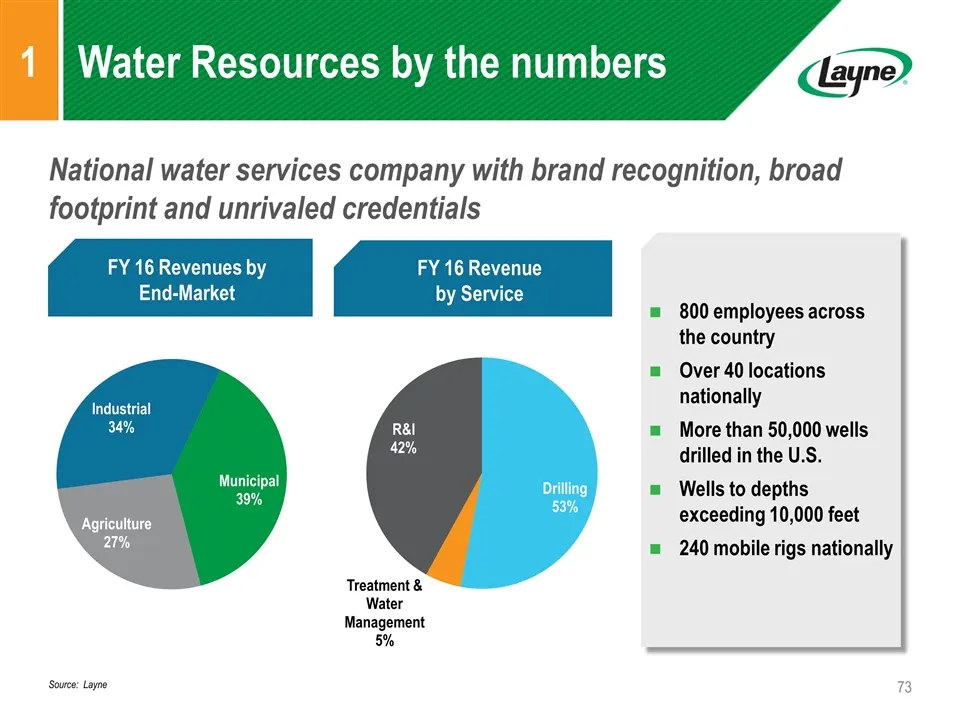
National water services company with brand recognition, broad footprint and unrivaled credentials 1 Water Resources by the numbers FY 16 Revenues by End-Market 800 employees across the country Over 40 locations nationally More than 50,000 wells drilled in the U.S. Wells to depths exceeding 10,000 fe
Slide 74: Expert capabilities in water wells
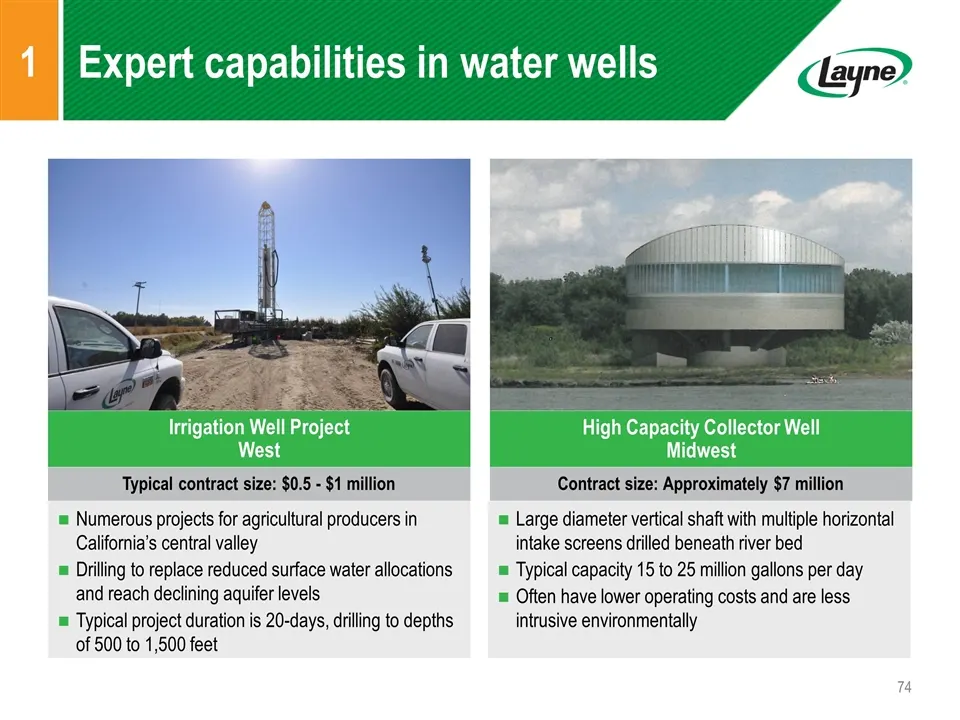
Expert capabilities in water wells Typical contract size: $0.5 - $1 million Numerous projects for agricultural producers in California’s central valley Drilling to replace reduced surface water allocations and reach declining aquifer levels Typical project duration is 20-days, drilling to depths of
Slide 75: Expert capabilities: injection wells and LayneOx
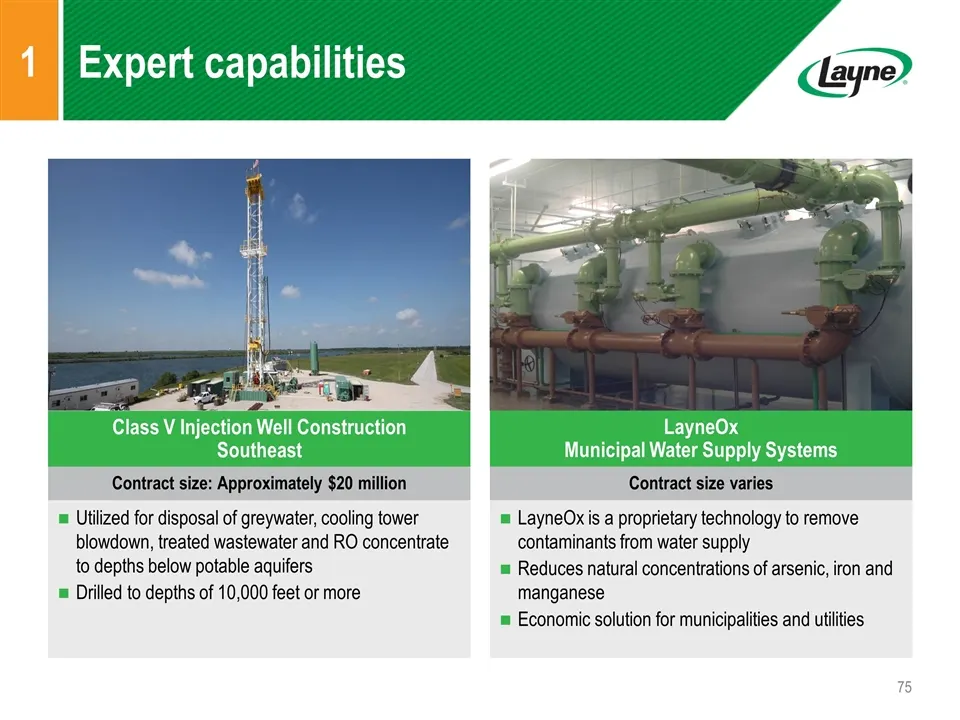
1 Expert capabilities Class V Injection Well Construction Southeast Utilized for disposal of greywater, cooling tower blowdown, treated wastewater and RO concentrate to depths below potable aquifers Drilled to depths of 10,000 feet or more Contract size: Approximately $20 million LayneOx Municipal W
Slide 76: Expert capabilities in water filtration
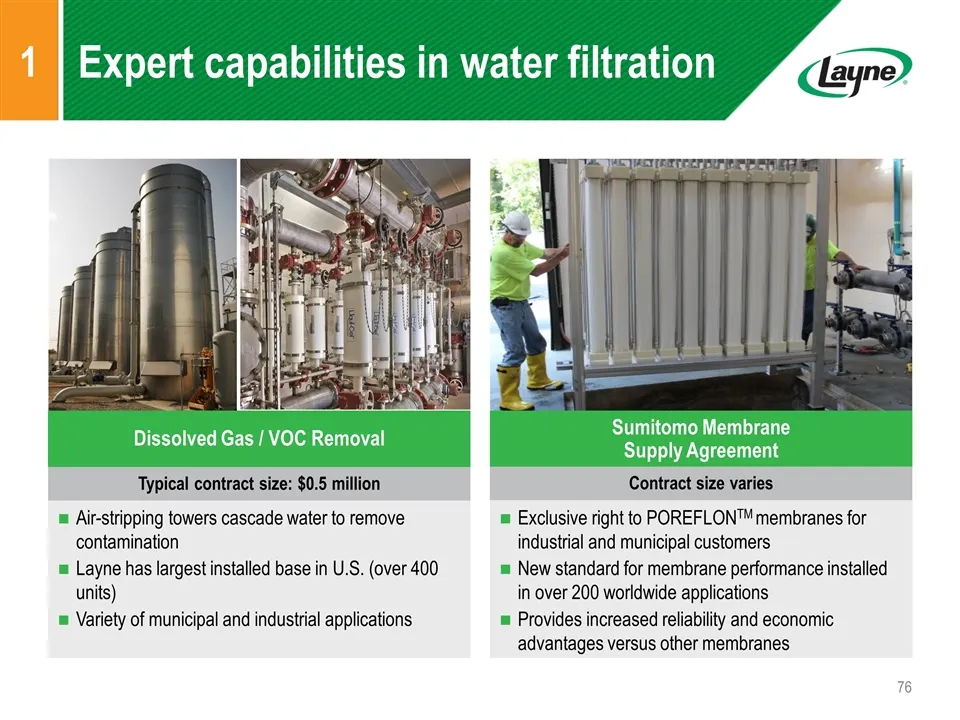
1 Expert capabilities in water filtration Sumitomo Membrane Supply Agreement Contract size varies Exclusive right to POREFLONTM membranes for industrial and municipal customers New standard for membrane performance installed in over 200 worldwide applications Provides increased reliability and econo
Slide 77: Award winning capabilities with unique solutions
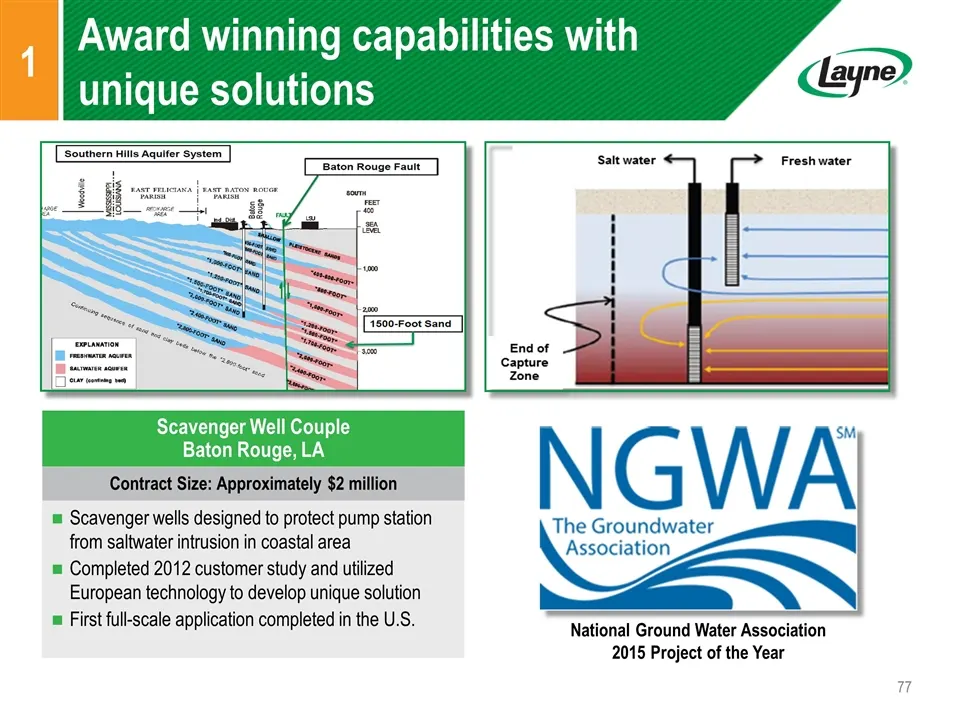
1 Award winning capabilities with unique solutions Scavenger Well Couple Baton Rouge, LA Scavenger wells designed to protect pump station from saltwater intrusion in coastal area Completed 2012 customer study and utilized European technology to develop unique solution First full-scale application co
Slide 78: Where we compete: operations nationwide
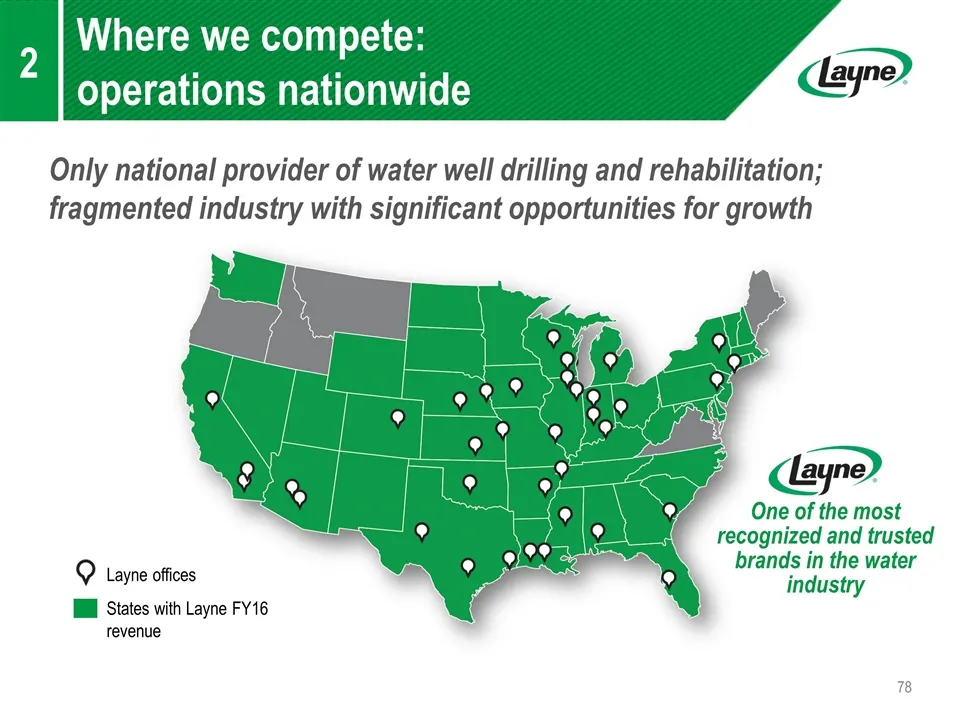
Only national provider of water well drilling and rehabilitation; fragmented industry with significant opportunities for growth Where we compete: operations nationwide Layne offices States with Layne FY16 revenue One of the most recognized and trusted brands in the water industry 2
Slide 79: Why water
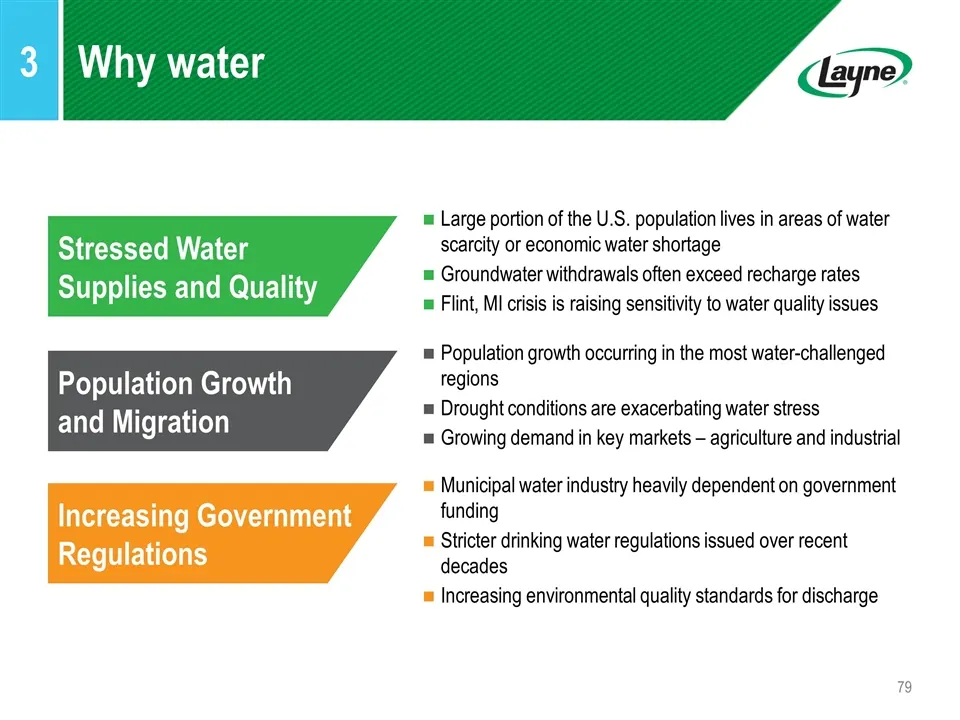
3 Why water Large portion of the U.S. population lives in areas of water scarcity or economic water shortage Groundwater withdrawals often exceed recharge rates Flint, MI crisis is raising sensitivity to water quality issues Stressed Water Supplies and Quality Population growth occurring in the most
Slide 80: California water crisis
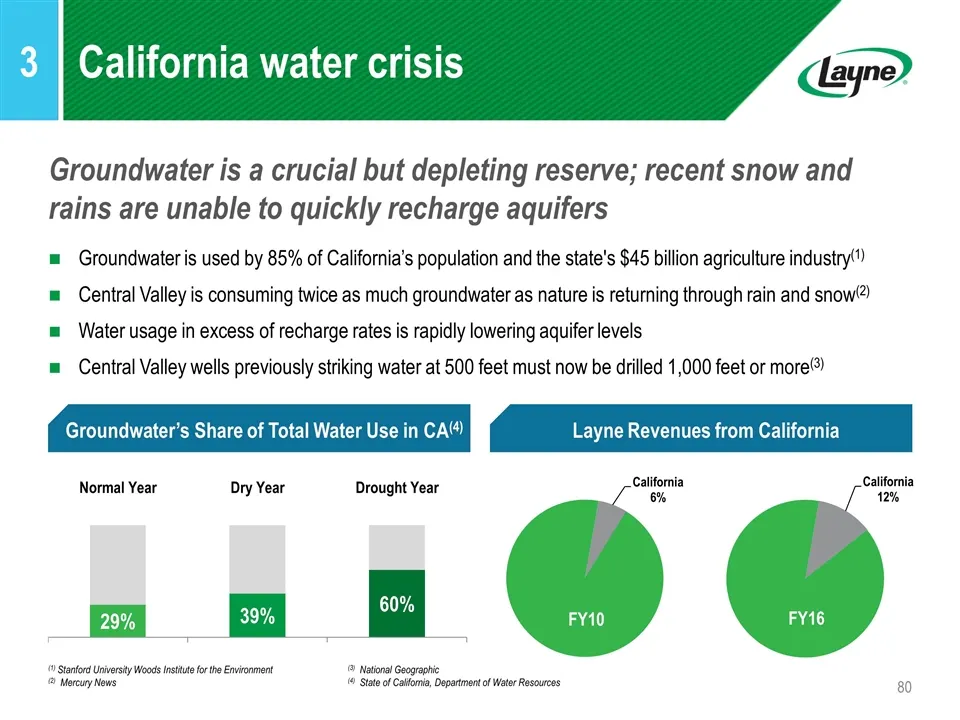
Groundwater is a crucial but depleting reserve; recent snow and rains are unable to quickly recharge aquifers Groundwater is used by 85% of California’s population and the state's $45 billion agriculture industry(1) Central Valley is consuming twice as much groundwater as nature is returning through
Slide 81: Groundwater depletion trends across the U.S.
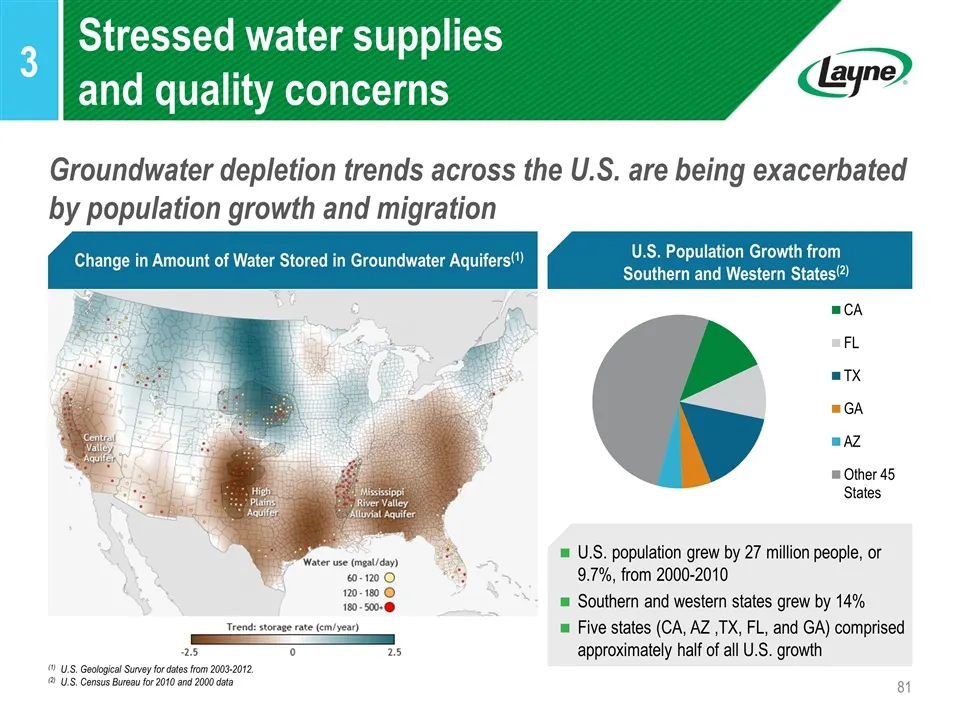
Groundwater depletion trends across the U.S. are being exacerbated by population growth and migration 3 Stressed water supplies and quality concerns (1)U.S. Geological Survey for dates from 2003-2012. (2)U.S. Census Bureau for 2010 and 2000 data U.S. population grew by 27 million people, or 9.7%, fr
Slide 82: Increasing regulation
Increasing regulation is expected to create more opportunities through tighter water quality standards and required infrastructure improvements 2015 Green Infrastructure for Clean Water Act 2014 California Sustainable Groundwater Management Act 2014 Water Resources Reform and Development Act 1996 Sa
Slide 83: Market estimated at over $11 billion
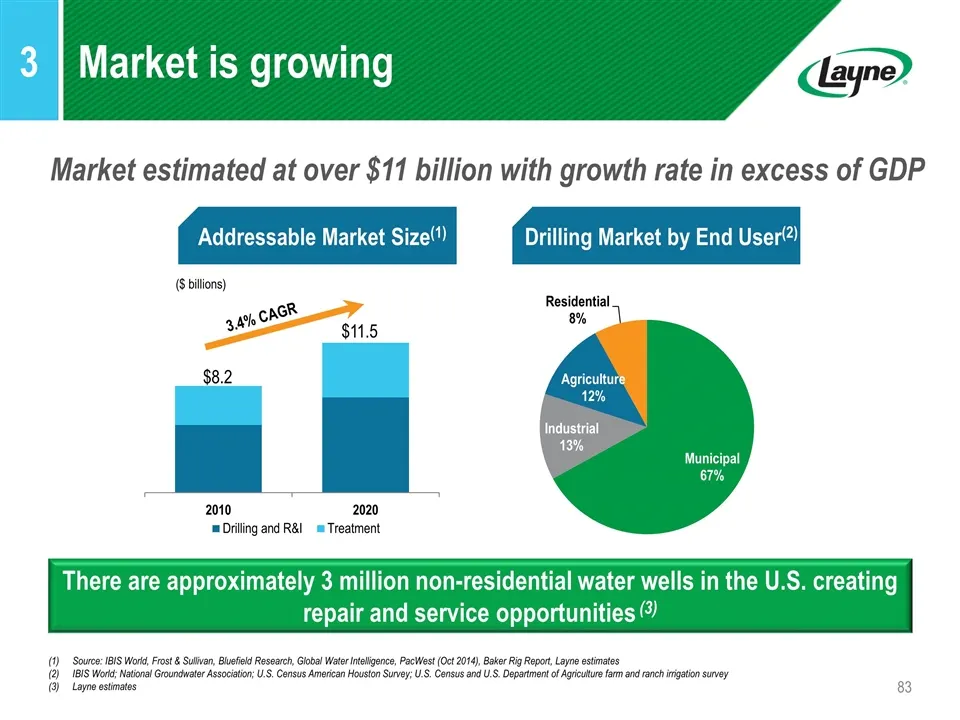
Market estimated at over $11 billion with growth rate in excess of GDP 3 Market is growing ($ billions) Source: IBIS World, Frost & Sullivan, Bluefield Research, Global Water Intelligence, PacWest (Oct 2014), Baker Rig Report, Layne estimates IBIS World; National Groundwater Association; U.S. Census
Slide 84: Executing plan to grow profitably
Grow service and repair by leveraging existing installed base Extend platform geographically – organic and acquisitions Expand portfolio of products and services with focus on recurring revenue streams Drive best operating practices to improve margins Streamline cost structure through back office re
Slide 85: Key takeaways
Key takeaways The leader in a large water services industry that is benefiting from positive secular trends with decades of growth potential 1 2 3 Where we compete Why water What we do 4 Why Layne Largest water well driller and pump repair company in the country with over 130 years of experience lea
Slide 86: Financial Overview
Financial Overview Michael Anderson, Chief Financial Officer
Slide 87: Financial strategy
Financial strategy New management has improved our financial position and is focused on enhancing profitability to increase Layne’s stock price Clarify Value of Layne Stock Improve Returns and Cash Flow Complete Business Performance Improvement (“BPI”) Plan Enhance Financial Position
Slide 88: Enhance financial position
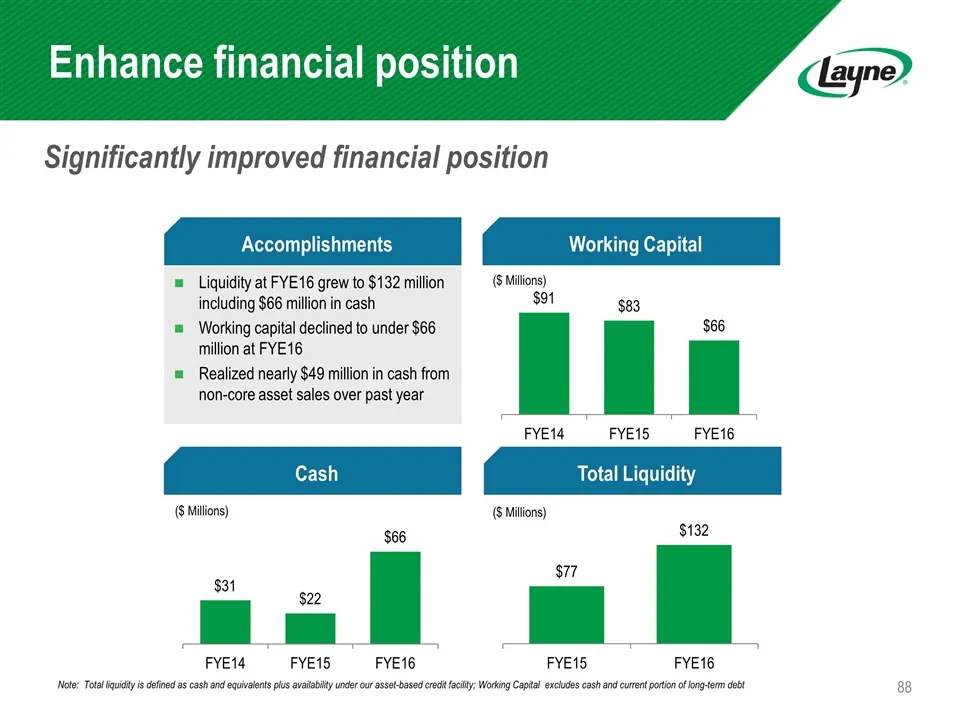
Enhance financial position Significantly improved financial position Liquidity at FYE16 grew to $132 million including $66 million in cash Working capital declined to under $66 million at FYE16 Realized nearly $49 million in cash from non-core asset sales over past year Note: Total liquidity is defi
Slide 89: Enhance financial position: debt maturities
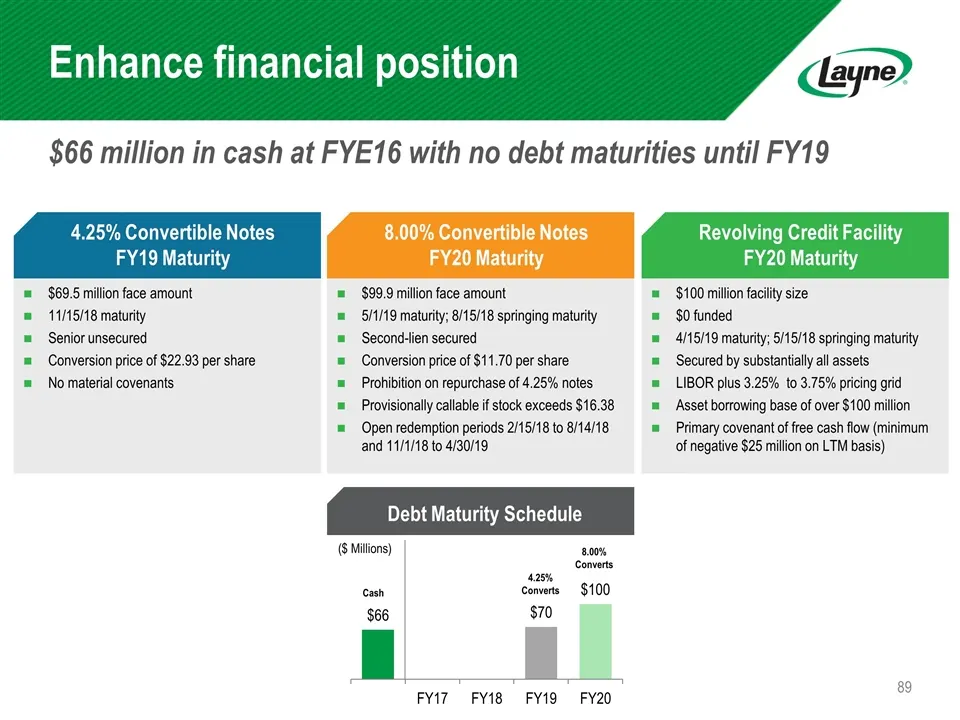
Enhance financial position $66 million in cash at FYE16 with no debt maturities until FY19 4.25% Convertible Notes FY19 Maturity 8.00% Convertible Notes FY20 Maturity Revolving Credit Facility FY20 Maturity $100 million facility size $0 funded 4/15/19 maturity; 5/15/18 springing maturity Secured by
Slide 90: Complete BPI plan
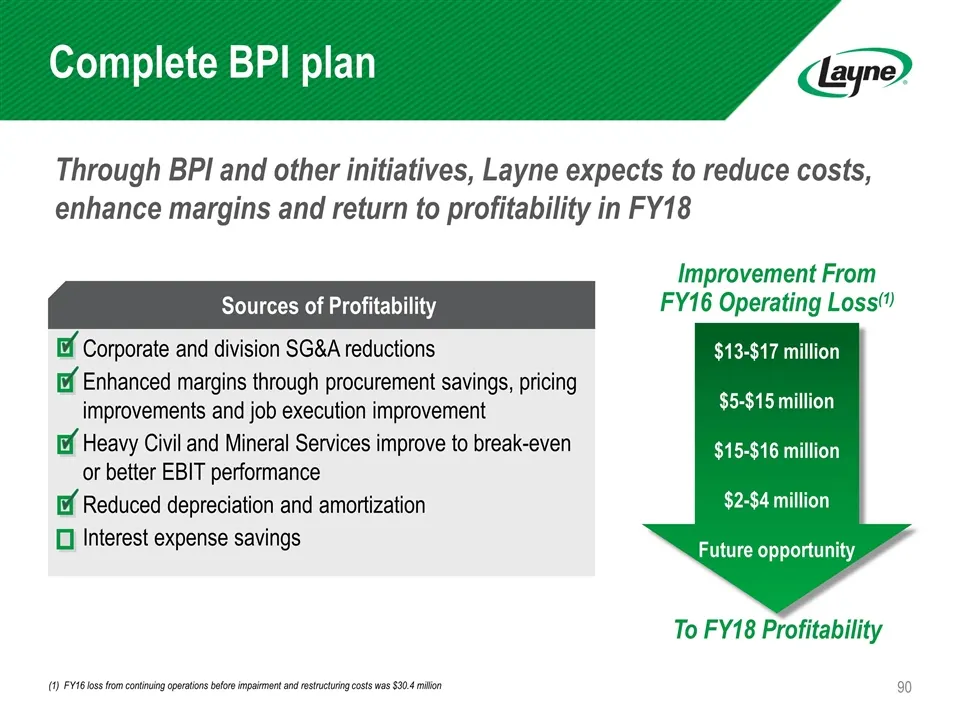
Complete BPI plan Through BPI and other initiatives, Layne expects to reduce costs, enhance margins and return to profitability in FY18 Corporate and division SG&A reductions Enhanced margins through procurement savings, pricing improvements and job execution improvement Heavy Civil and Mineral Serv
Slide 91: Complete BPI plan: SG&A savings
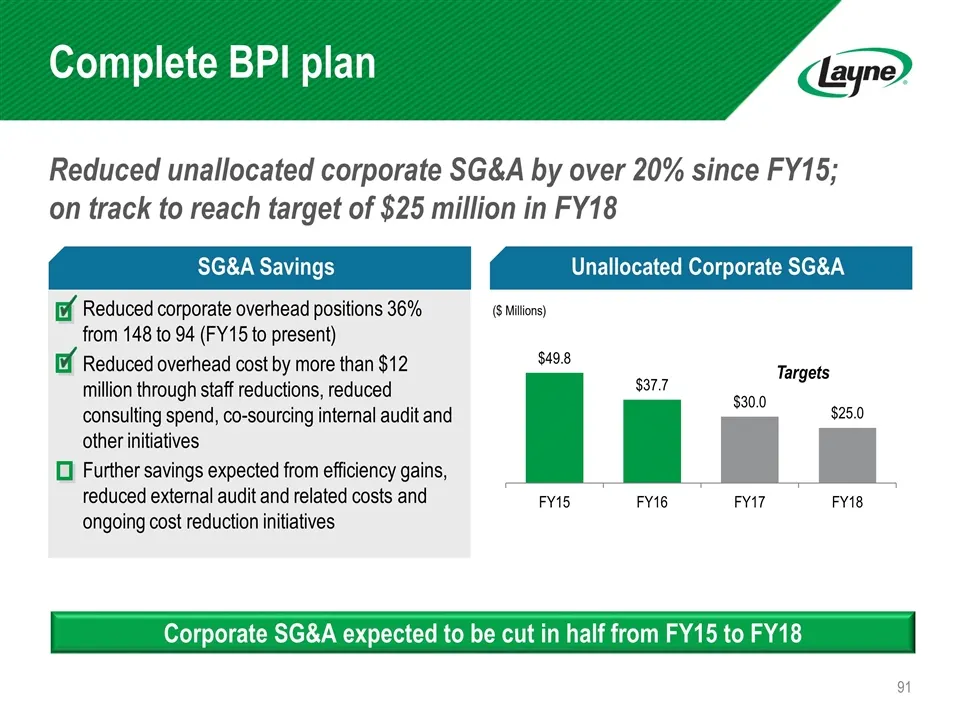
Complete BPI plan Reduced unallocated corporate SG&A by over 20% since FY15; on track to reach target of $25 million in FY18 Reduced corporate overhead positions 36% from 148 to 94 (FY15 to present) Reduced overhead cost by more than $12 million through staff reductions, reduced consulting spend, co
Slide 92: BPI initiatives and targeted savings
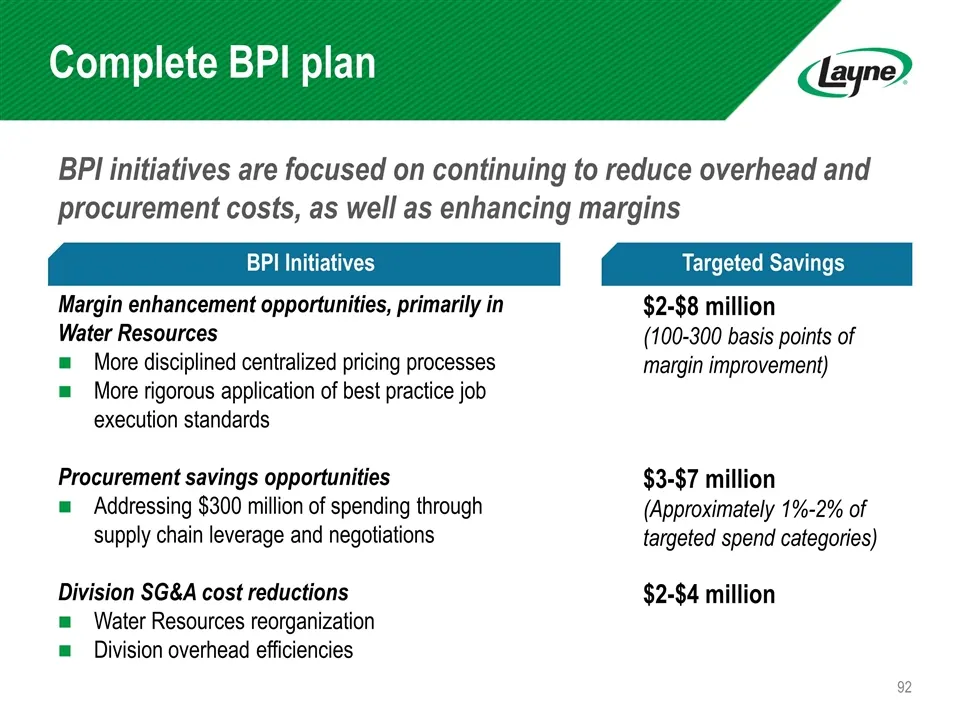
BPI initiatives are focused on continuing to reduce overhead and procurement costs, as well as enhancing margins Margin enhancement opportunities, primarily in Water Resources More disciplined centralized pricing processes More rigorous application of best practice job execution standards Procuremen
Slide 93: Improve returns and cash flow: capital investment
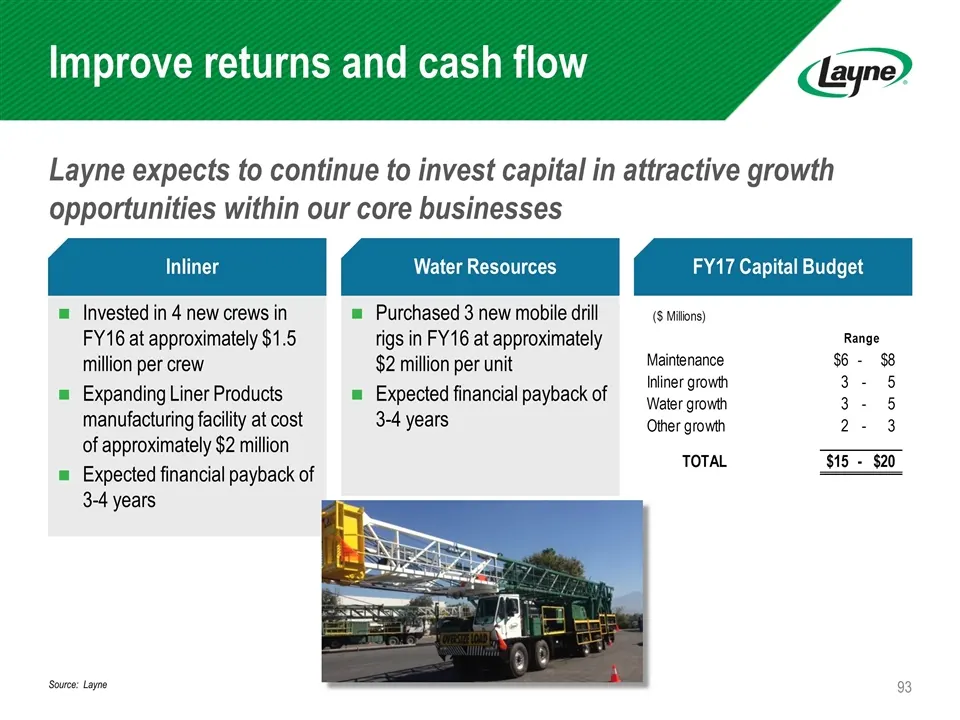
Improve returns and cash flow Layne expects to continue to invest capital in attractive growth opportunities within our core businesses Purchased 3 new mobile drill rigs in FY16 at approximately $2 million per unit Expected financial payback of 3-4 years Invested in 4 new crews in FY16 at approximat
Slide 94: Improve returns and cash flow: acquisition criteria
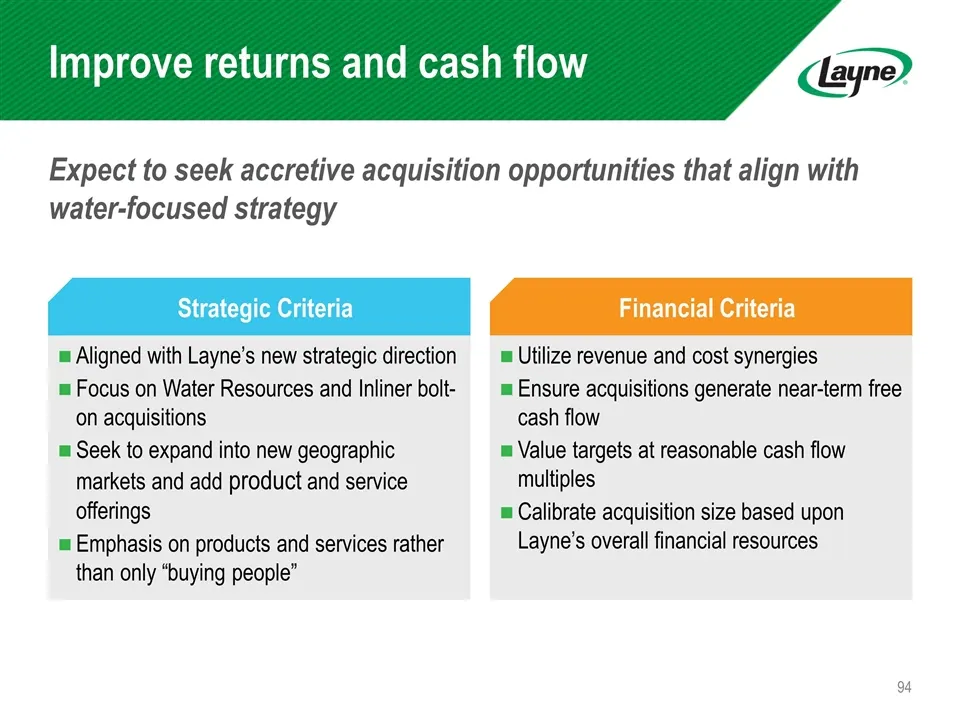
Improve returns and cash flow Expect to seek accretive acquisition opportunities that align with water-focused strategy Strategic Criteria Aligned with Layne’s new strategic direction Focus on Water Resources and Inliner bolt-on acquisitions Seek to expand into new geographic markets and add product
Slide 95: Improve returns and cash flow: outlook by division
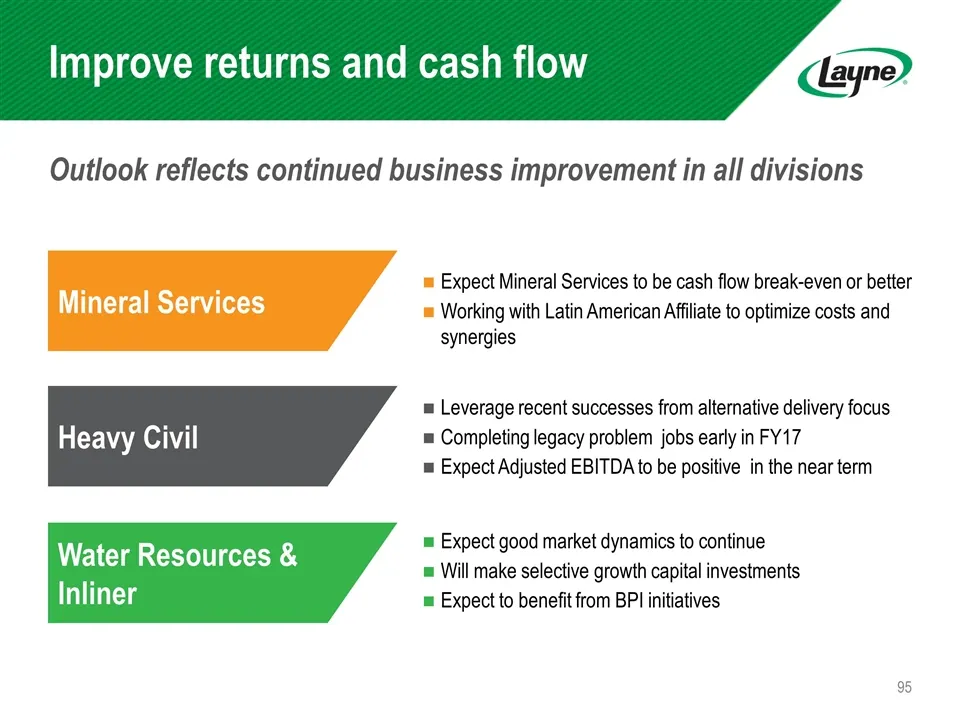
Improve returns and cash flow Leverage recent successes from alternative delivery focus Completing legacy problem jobs early in FY17 Expect Adjusted EBITDA to be positive in the near term Heavy Civil Expect Mineral Services to be cash flow break-even or better Working with Latin American Affiliate t
Slide 96: Clarify value of Layne stock
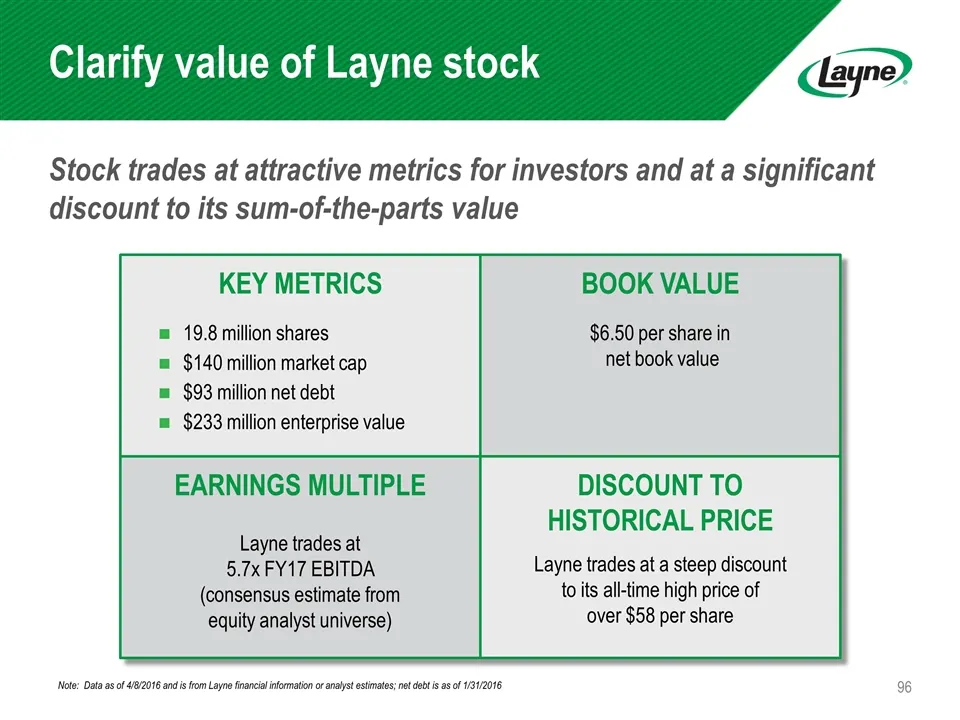
Clarify value of Layne stock Stock trades at attractive metrics for investors and at a significant discount to its sum-of-the-parts value Note: Data as of 4/8/2016 and is from Layne financial information or analyst estimates; net debt is as of 1/31/2016 19.8 million shares $140 million market cap $9
Slide 97: Sum-of-the-parts valuation
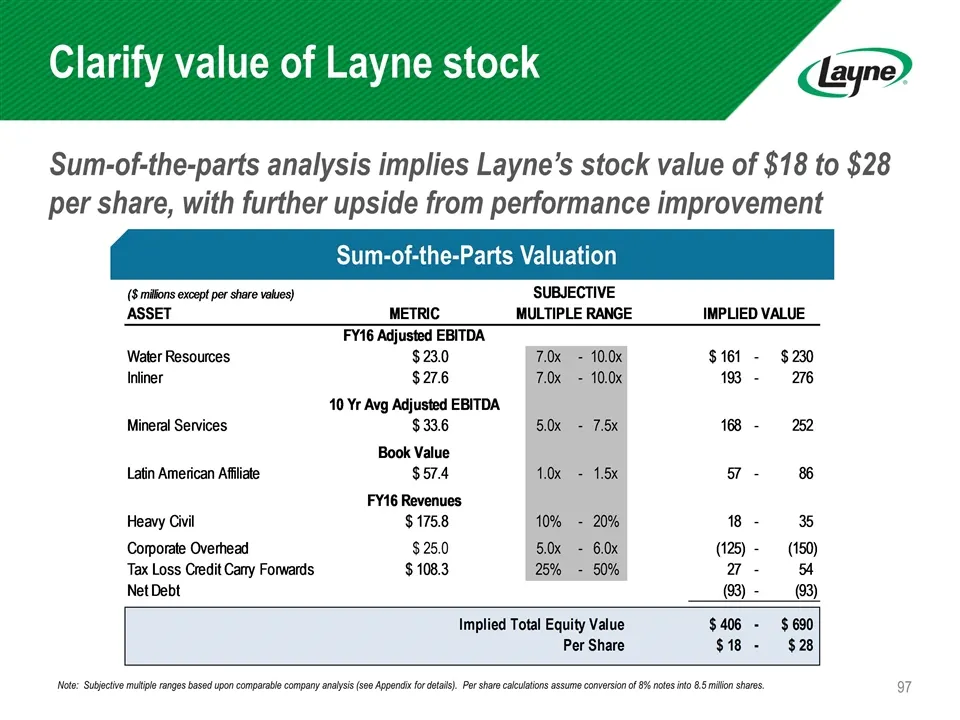
Clarify value of Layne stock Sum-of-the-parts analysis implies Layne’s stock value of $18 to $28 per share, with further upside from performance improvement Note: Subjective multiple ranges based upon comparable company analysis (see Appendix for details). Per share calculations assume conversion of
Slide 98: Committed to generate value for all stakeholders
Layne is committed to generate value for all stakeholders through: Cost savings and enhanced efficiencies Free cash flow generation Attractive growth capital investments Value accretive bolt-on acquisitions
Slide 99: Closing & Outlook
Closing & Outlook Michael Caliel, President & CEO
Slide 100: What you heard today
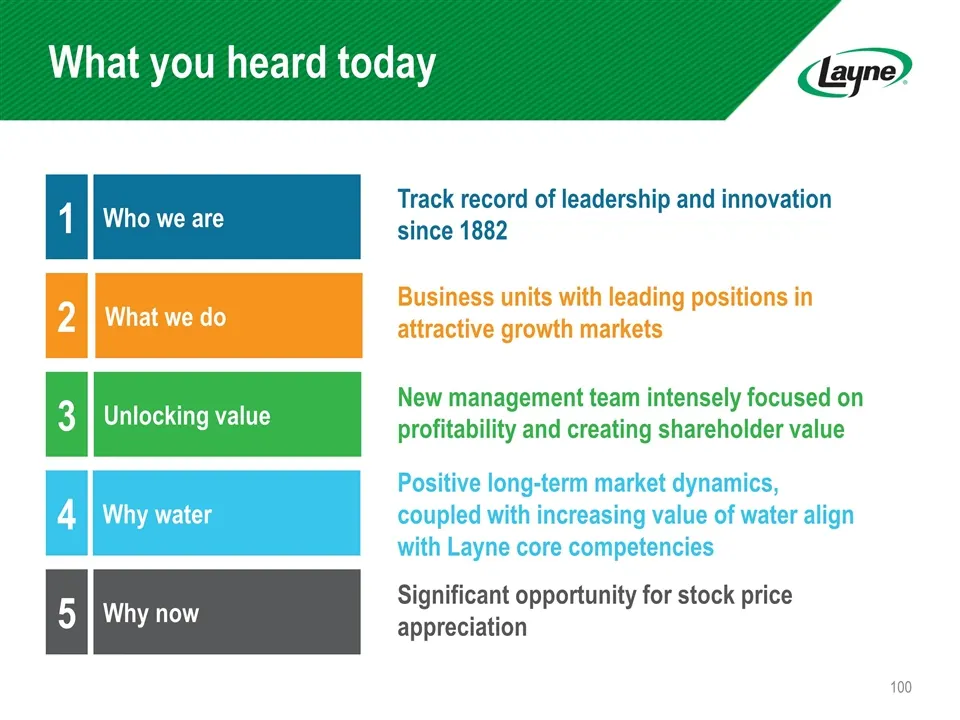
What you heard today Why now 1 2 3 5 What we do Unlocking value Who we are 4 Why water Track record of leadership and innovation since 1882 Business units with leading positions in attractive growth markets New management team intensely focused on profitability and creating shareholder value Signifi
Slide 101: Portfolio approach to unlocking value
Portfolio approach to unlocking value Invest to grow our most profitable businesses Water Focused Strategy Water Resources Inliner Heavy Civil Mineral Services NEAR-TERM LONGER-TERM Invest and Grow Complete realignment to achieve target profitability Assess strategic alternatives Manage costs and po
Slide 102: Investment highlights – why now
Investment highlights – why now Leading water management services company with a clear strategy focused on water Capitalizing on long history of success and solid brand equity Leveraging leading market positions New management team driving financial, operational and strategic restructuring Operating
Slide 103: Layne logo
Slide 104: Appendix
Appendix
Slide 105: Non-GAAP disclosure
Non-GAAP disclosure Use of Non- GAAP Financial Information We use Adjusted EBITDA to assess performance which is not defined in generally accepted accounting principles (GAAP). Adjusted EBITDA represents income or loss from continuing operations before interest, taxes, depreciation and amortization,
Slide 106: Non-GAAP reconciliation: Inliner, Minerals
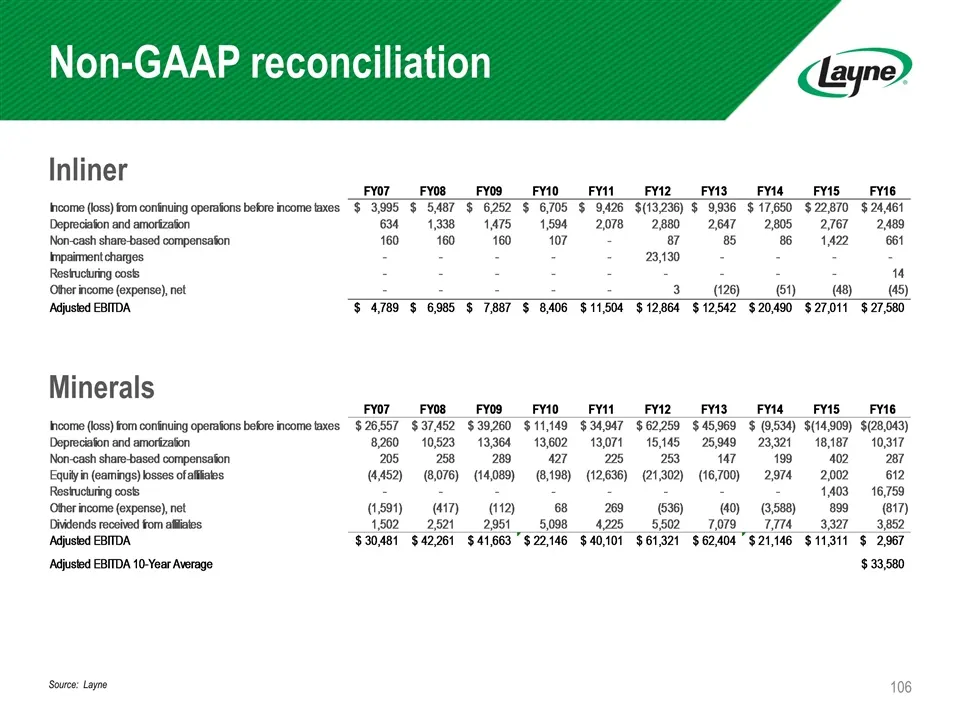
Non-GAAP reconciliation Inliner Minerals Source: Layne
Slide 107: Non-GAAP reconciliation: Water Resources, Heavy Civil
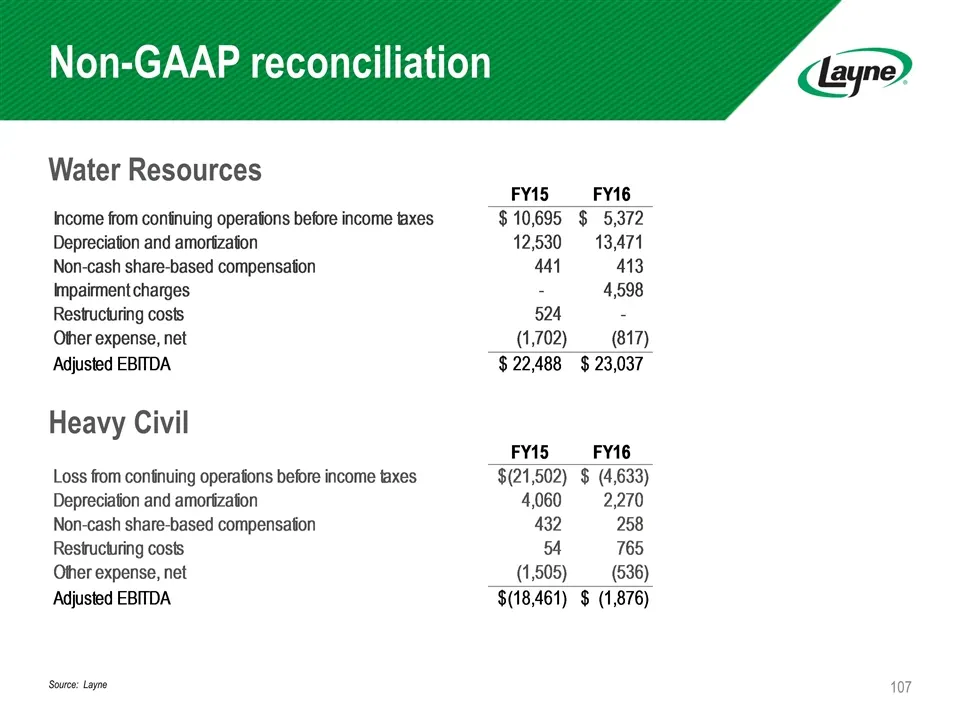
Non-GAAP reconciliation Water Resources Heavy Civil Source: Layne
Slide 108: Trading comparable information: Drilling
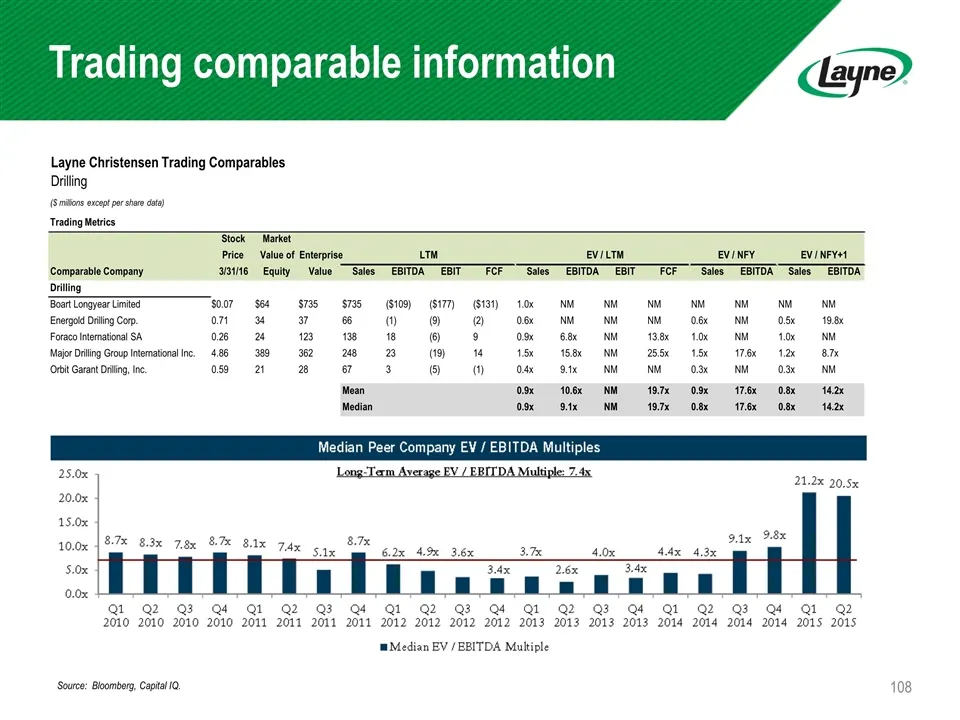
Trading comparable information Source: Bloomberg, Capital IQ. Layne Christensen Trading Comparables Drilling ($ millions except per share data) Trading Metrics Stock Market Price Value of Enterprise LTM EV / LTM EV / NFY EV / NFY+1 Comparable Company 3/31/16 Equity Value Sales EBITDA EBIT FCF Sales
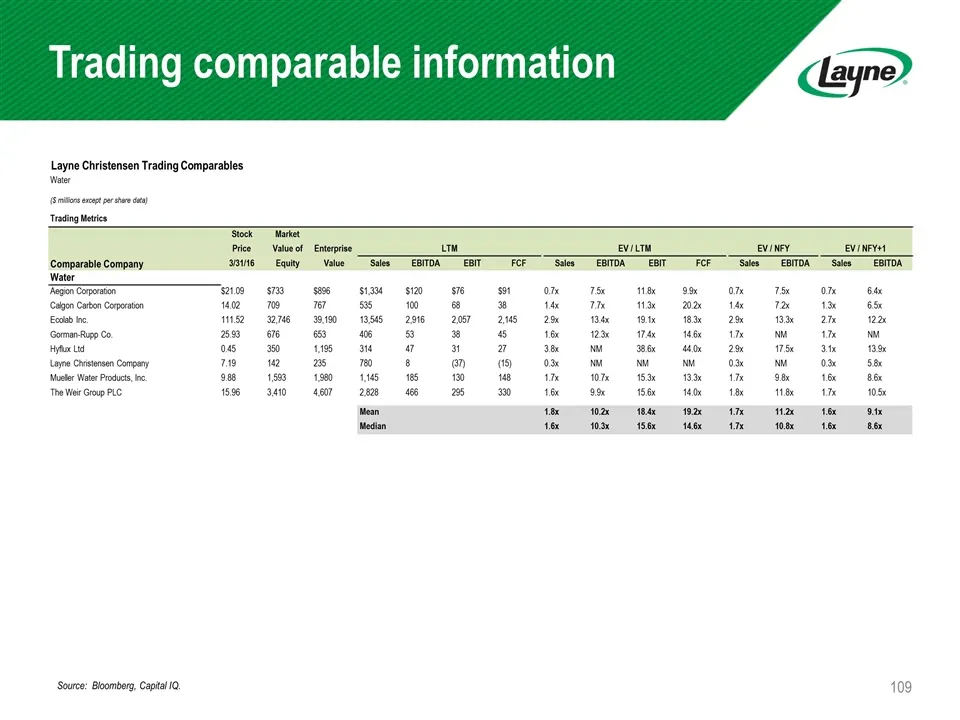
Slide 109: Trading comparable information: Water
Trading comparable information Source: Bloomberg, Capital IQ. Layne Christensen Trading Comparables Water ($ millions except per share data) Trading Metrics Stock Market Price Value of Enterprise LTM EV / LTM EV / NFY EV / NFY+1 Comparable Company 3/31/16 Equity Value Sales EBITDA EBIT FCF Sales EBI
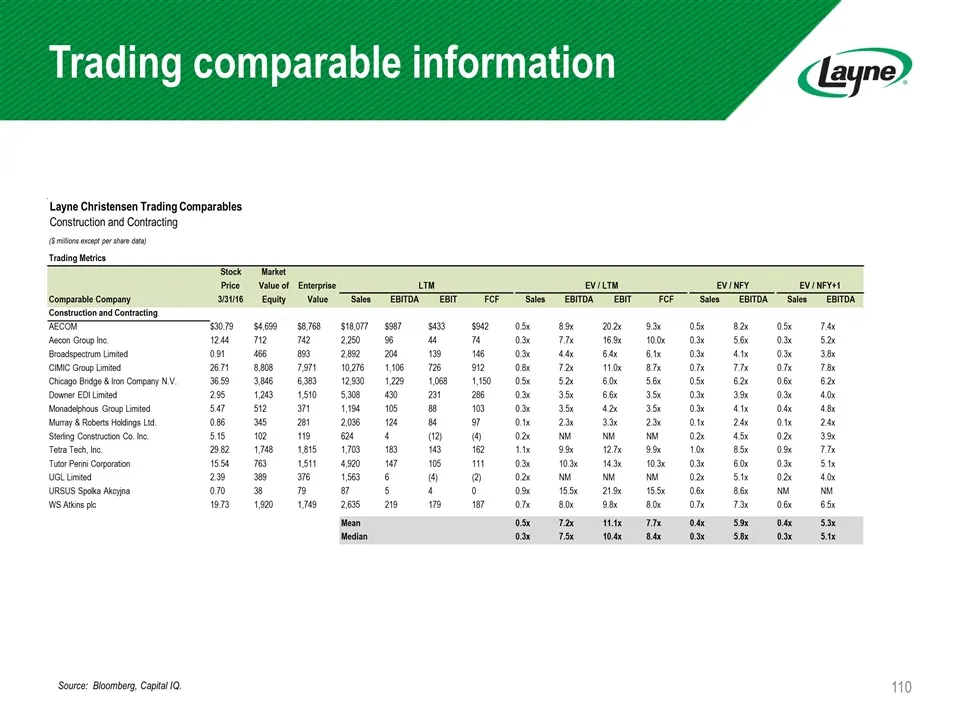
Slide 110: Trading comparable information: Construction and Contracting
Trading comparable information Source: Bloomberg, Capital IQ. Layne Christensen Trading Comparables Construction and Contracting ($ millions except per share data) Trading Metrics Stock Market Price Value of Enterprise LTM EV / LTM EV / NFY EV / NFY+1 Comparable Company 3/31/16 Equity Value Sales EB
Source: SEC EDGAR · 8-K filed Apr 14, 2016
More decks from Layne Christensen Company
 Southwest IDEAS Investor Conference November 201730 slides · Nov 16, 2017
 D.A. Davidson 16th Annual Engineering & Construction Conference 201729 slides · Sep 20, 2017
 Jefferies 2017 Industrials Conference29 slides · Aug 7, 2017
 Gabelli & Company's 27th Annual Pump, Valve, & Water Systems Symposium (March 2017)29 slides · Mar 1, 2017
 D.A. Davidson Engineering & Construction Conference 201627 slides · Sep 8, 2016
 Jefferies Industrials Conference 201623 slides · Aug 10, 2016