Ellaktor SA · ATHEX:ELLAKTOR
Ellaktor SA — El.Tech. Anemos — 9M 2018 Earnings Presentation
14 slides from Ellaktor SA's earnings presentation, December 2018
Slide 1: 9m 2018 Results
9m 2018 Results December 2018
Slide 2: Calendar of main events (01 – 09/2018)
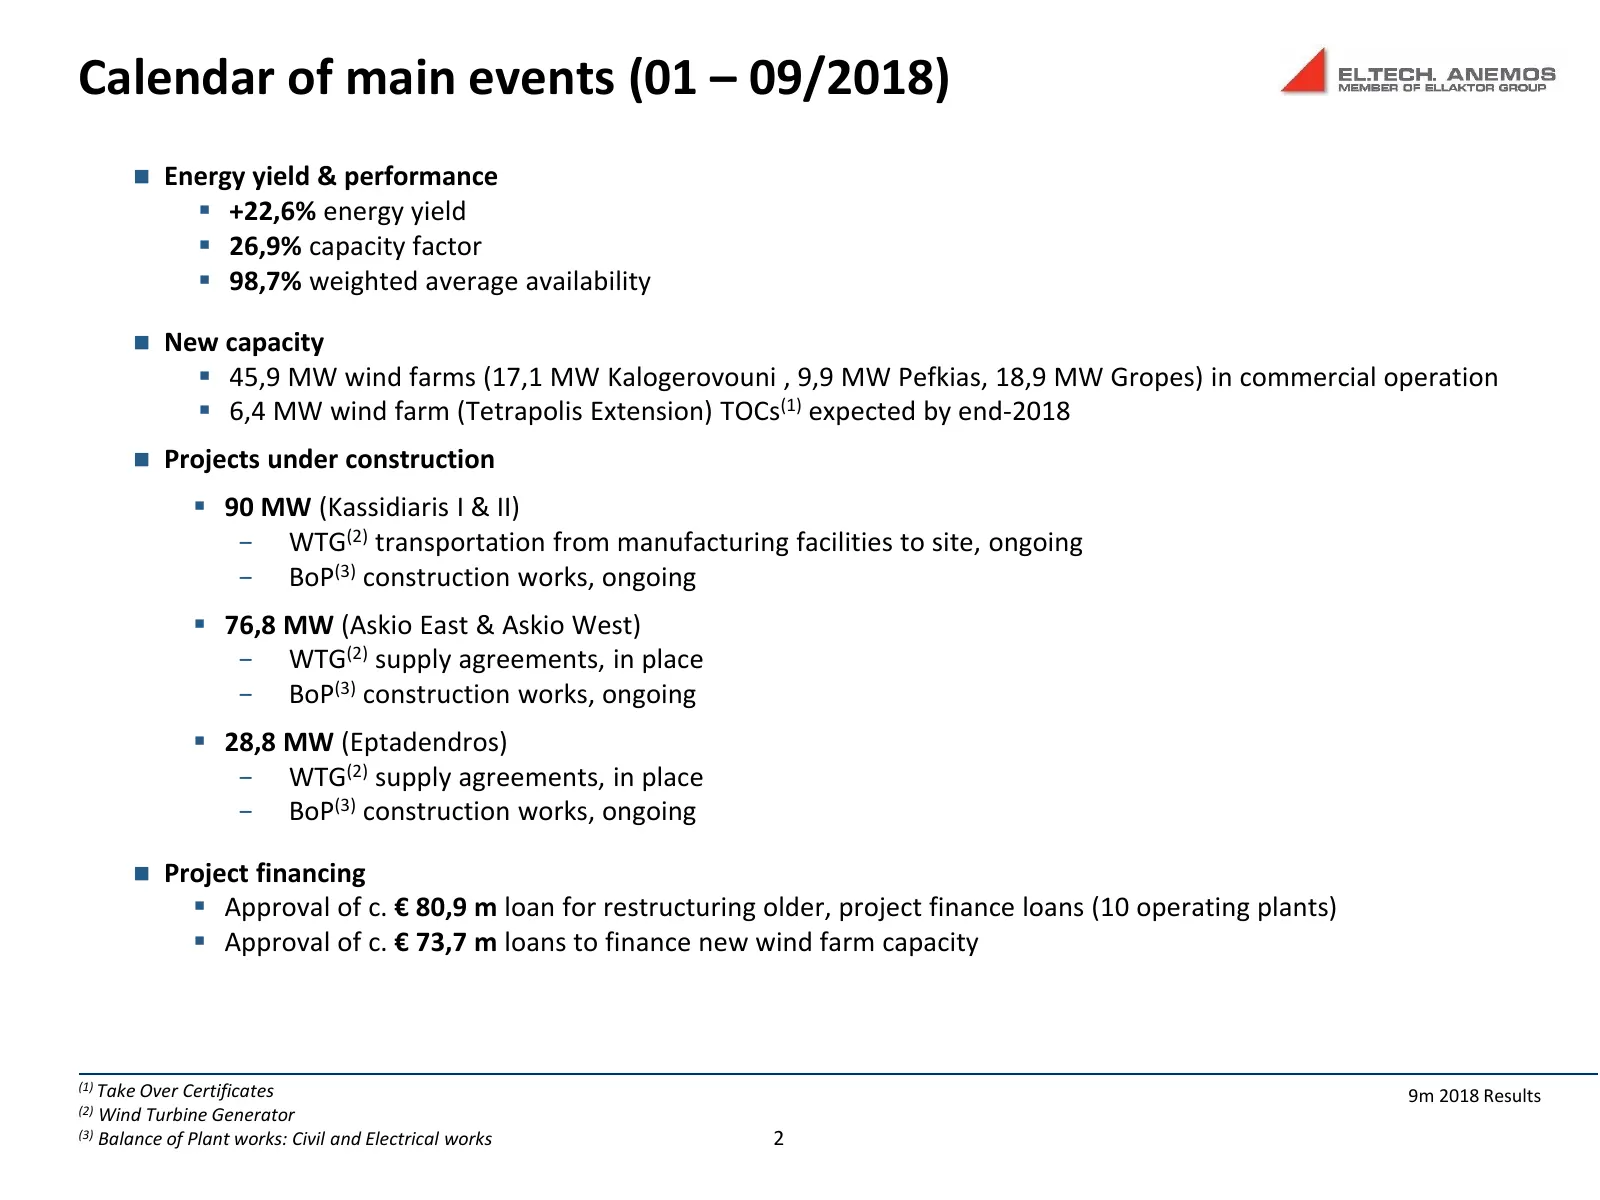
Calendar of main events (01 – 09/2018) Energy yield & performance +22,6% energy yield 26,9% capacity factor 98,7% weighted average availability New capacity 45,9 MW wind farms (17,1 MW Kalogerovouni , 9,9 MW Pefkias, 18,9 MW Gropes) in commercial operation 6,4 MW wind farm (Tetrapolis
Slide 3: Financial highlights
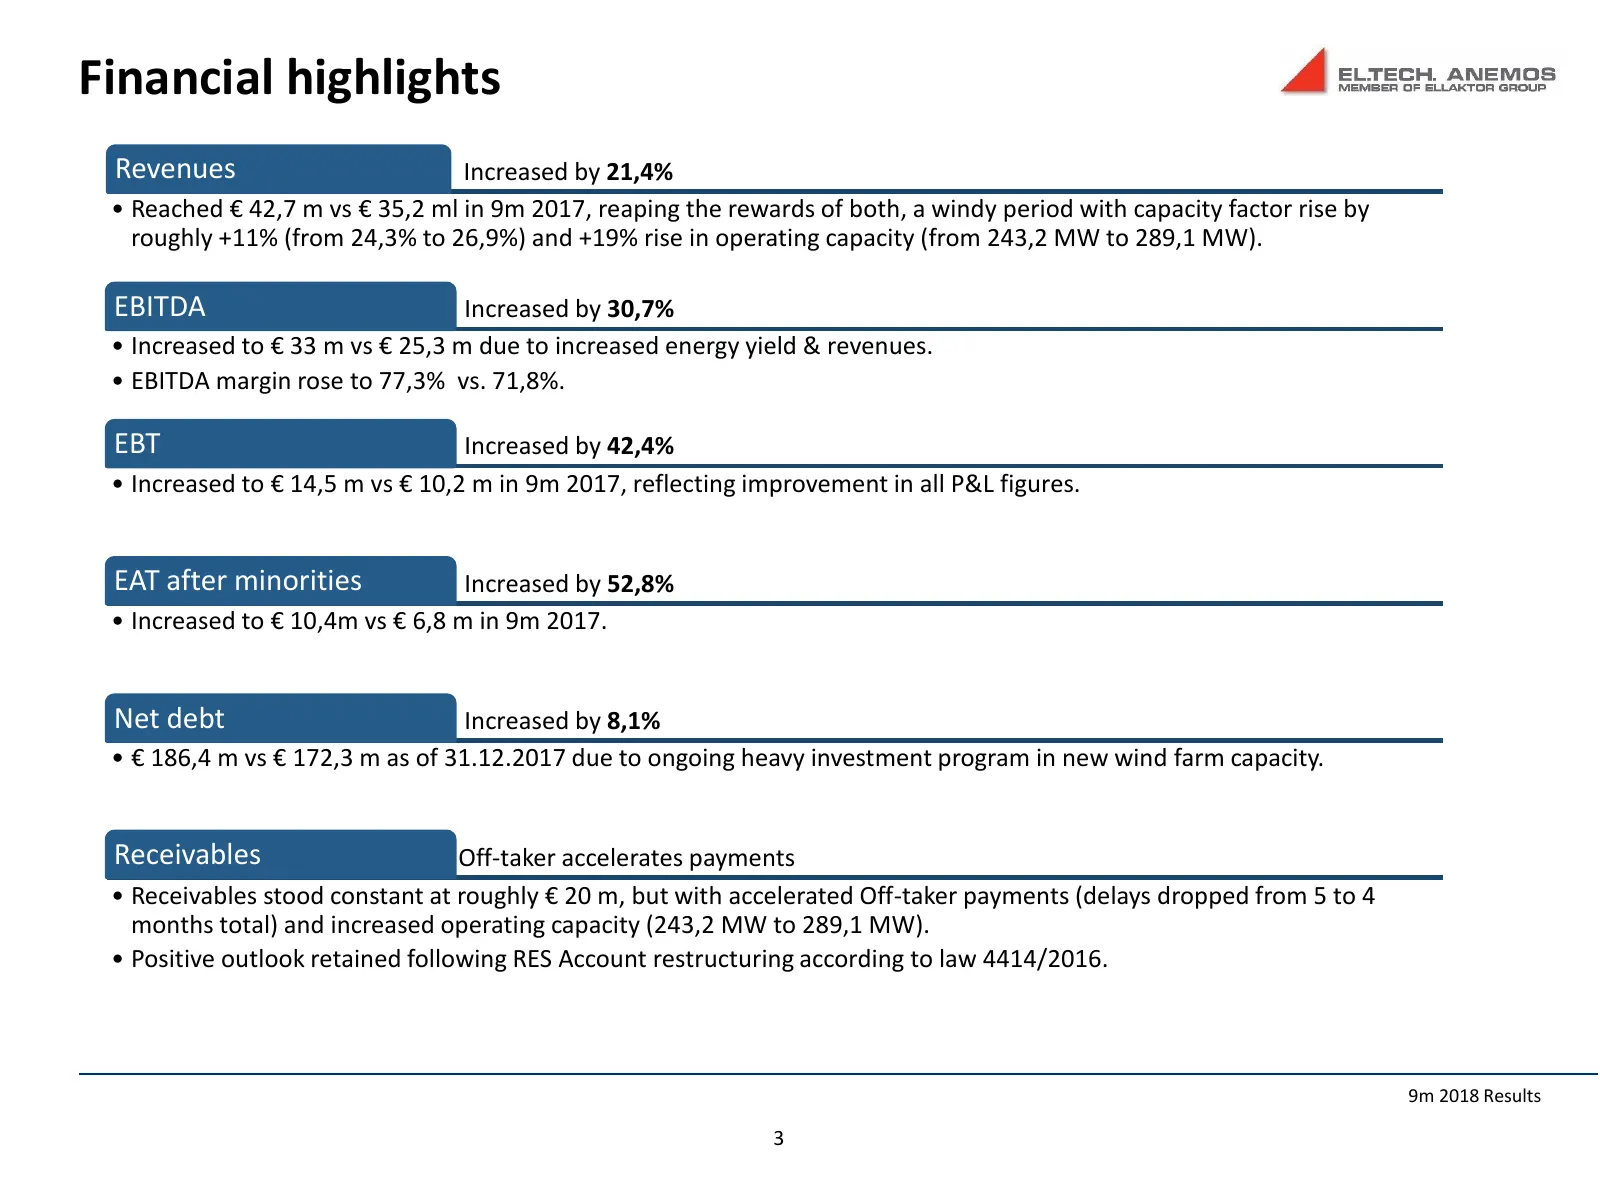
Financial highlights Revenues Increased by 21,4% • Reached € 42,7 m vs € 35,2 ml in 9m 2017, reaping the rewards of both, a windy period with capacity factor rise by roughly +11% (from 24,3% to 26,9%) and +19% rise in operating capacity (from 243,2 MW to 289,1 MW). EBITDA Increased by 30,7% • Increa
Slide 4: Evolution of key P&L figures (IFRS in € m)
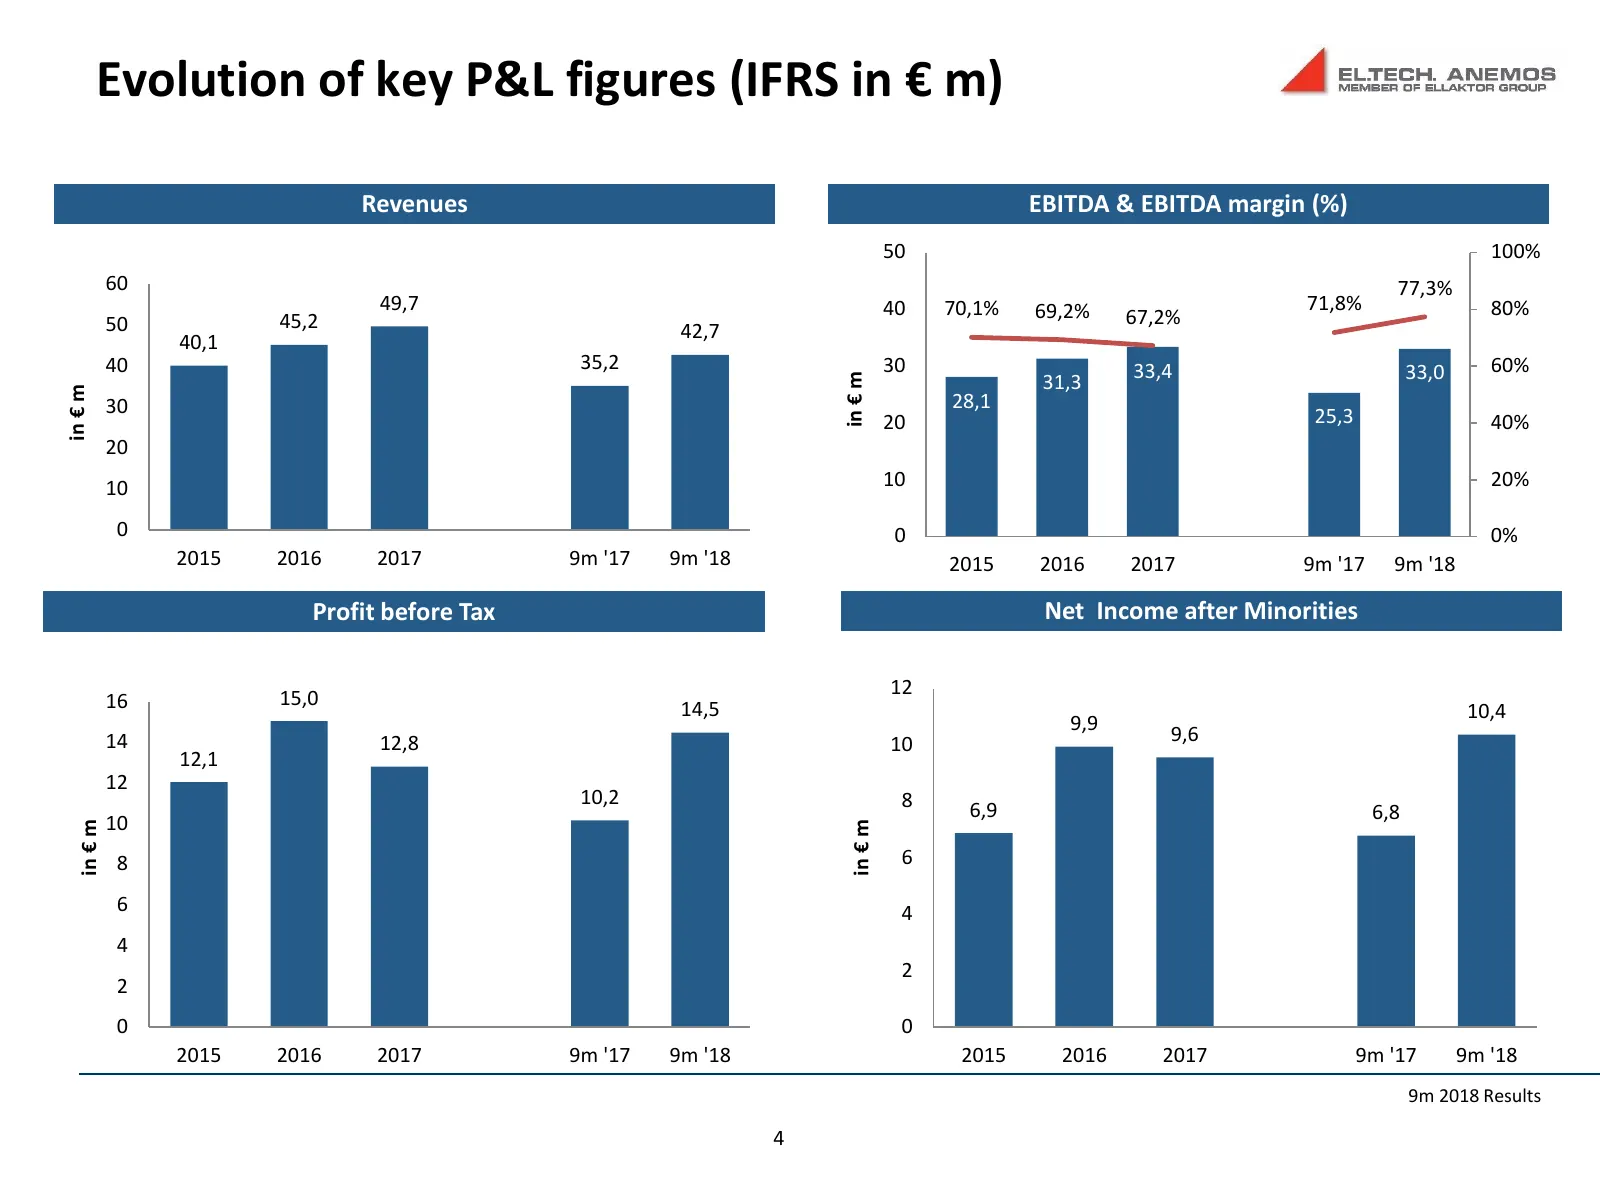
Evolution of key P&L figures (IFRS in € m) Revenues EBITDA & EBITDA margin (%) 50 100% 60 77,3% 49,7 40 70,1% 69,2% 71,8% 80% 50 45,2 67,2% 40,1 42,7 40 35,2 30 33,4 33,0 60% in € m 31,3 in € m 30 28,1 20 25,3 40% 20 10 10 20% 0 0 0% 2015 2016 2017 9m '17 9m '18 2015 2016 2017 9m '17 9m '18 Profit b
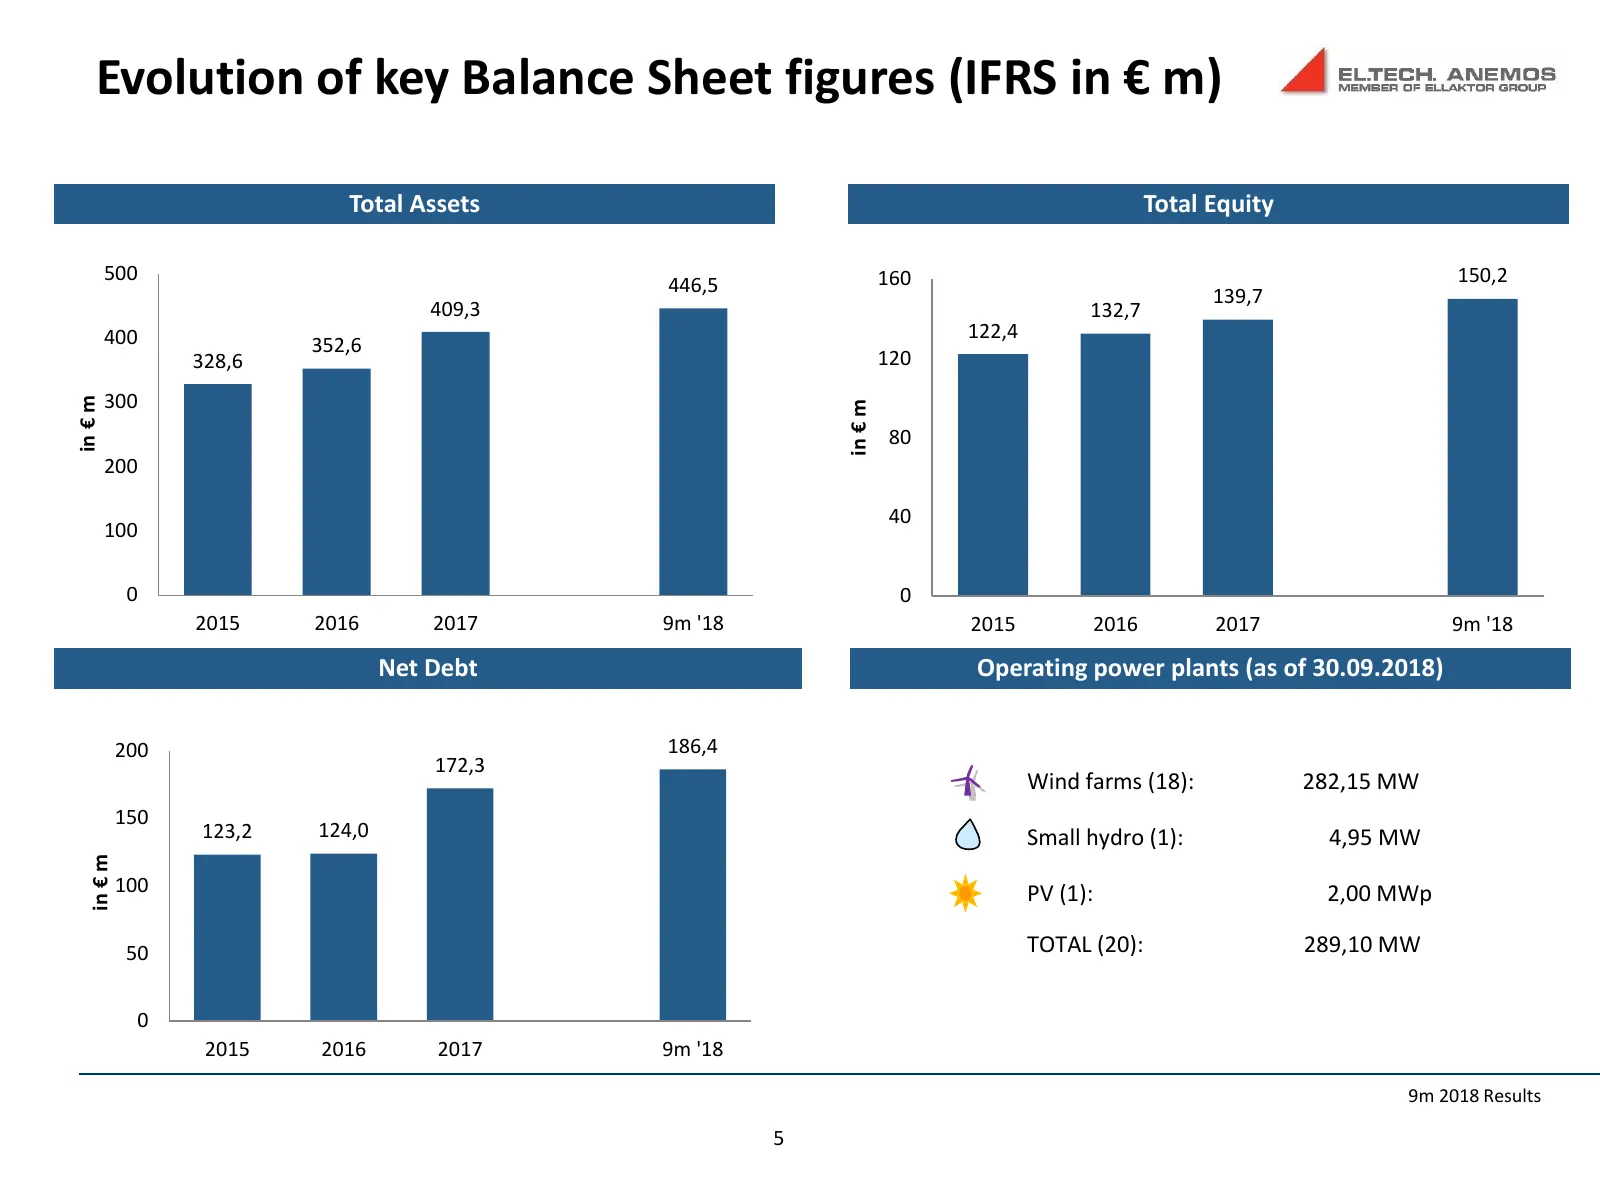
Slide 5: Evolution of key Balance Sheet figures (IFRS in € m)
Evolution of key Balance Sheet figures (IFRS in € m) Total Assets Total Equity 500 160 150,2 446,5 139,7 409,3 132,7 400 122,4 352,6 328,6 120 300 in € m in € m 80 200 40 100 0 0 2015 2016 2017 9m '18 2015 2016 2017 9m '18 Net Debt Operating power plants (as of 30.09.2018) 200 186,4 172,3 Wind farms
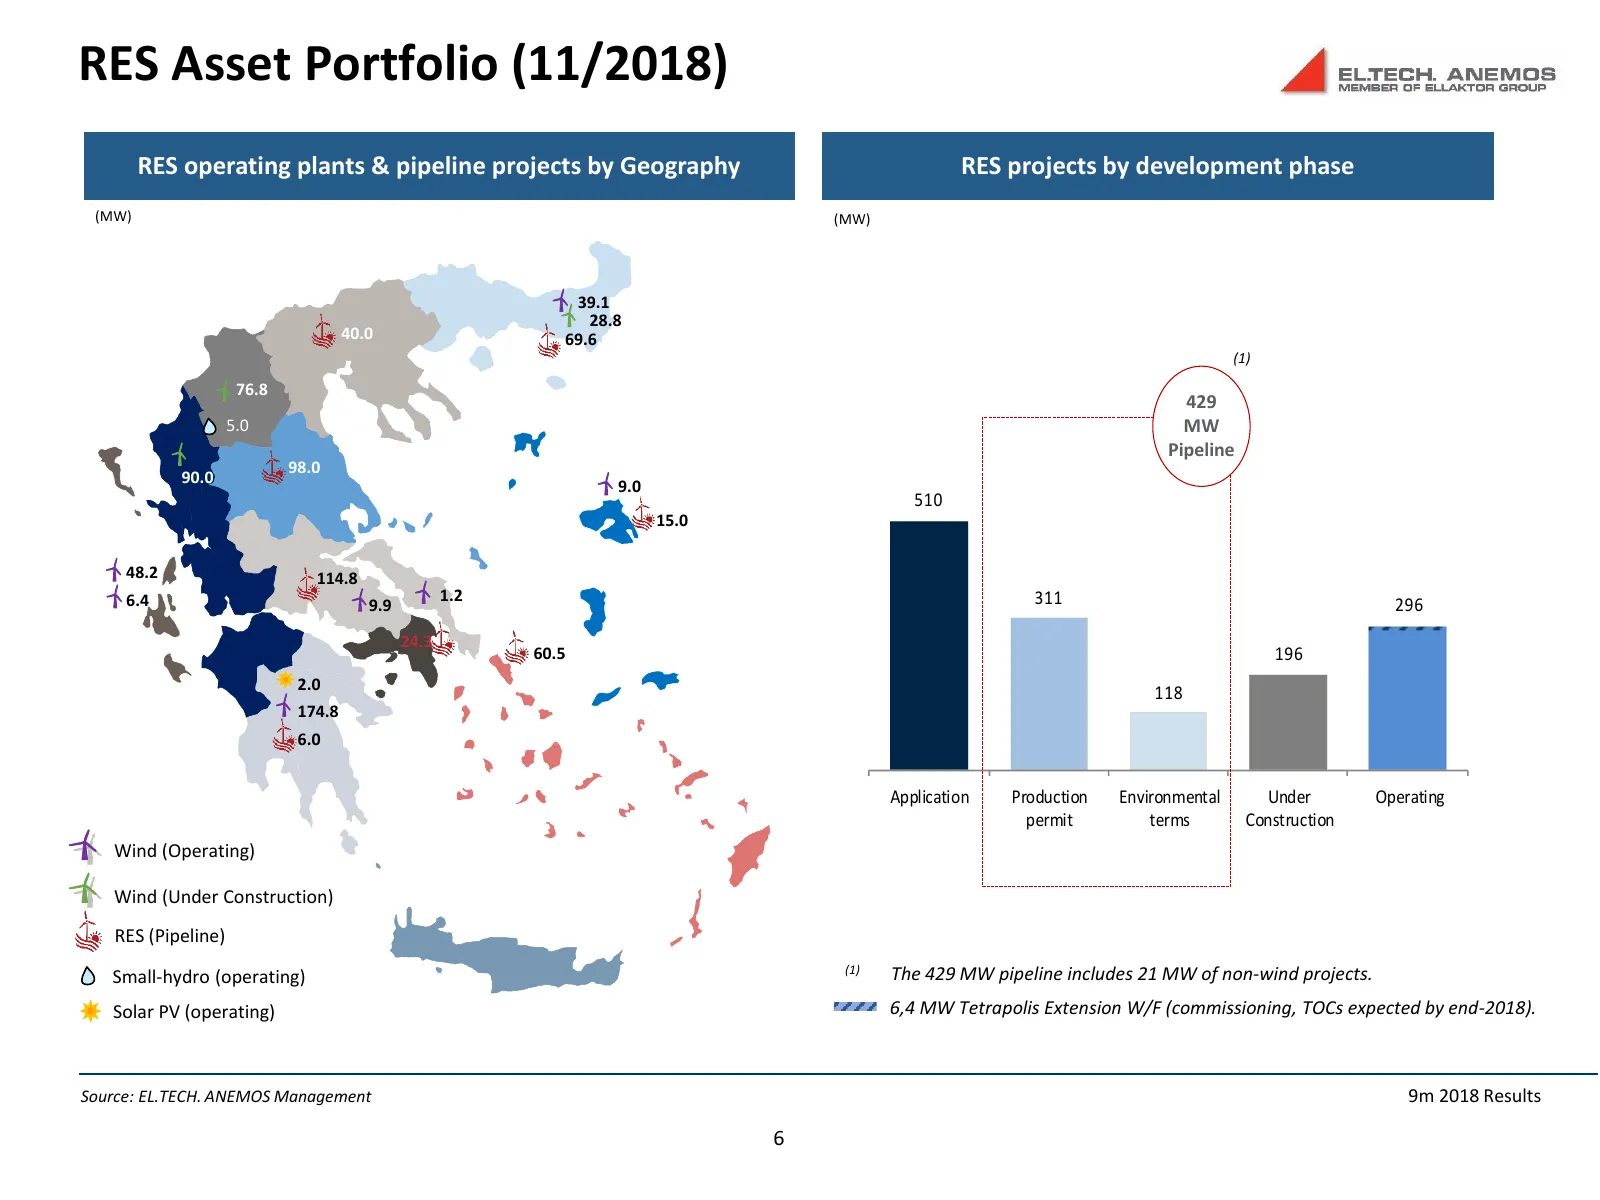
Slide 6: RES Asset Portfolio (11/2018)
RES Asset Portfolio (11/2018) RES operating plants & pipeline projects by Geography RES projects by development phase (MW) (MW) 39.1 28.8 40.0 69.6 (1) 76.8 429 5.0 MW Pipeline 98.0 90.0 9.0 510 15.0 48.2 114.8 6.4 1.2 311 9.9 296 24.3 60.5 196 2.0 118 174.8 6.0 Application Production Environmental
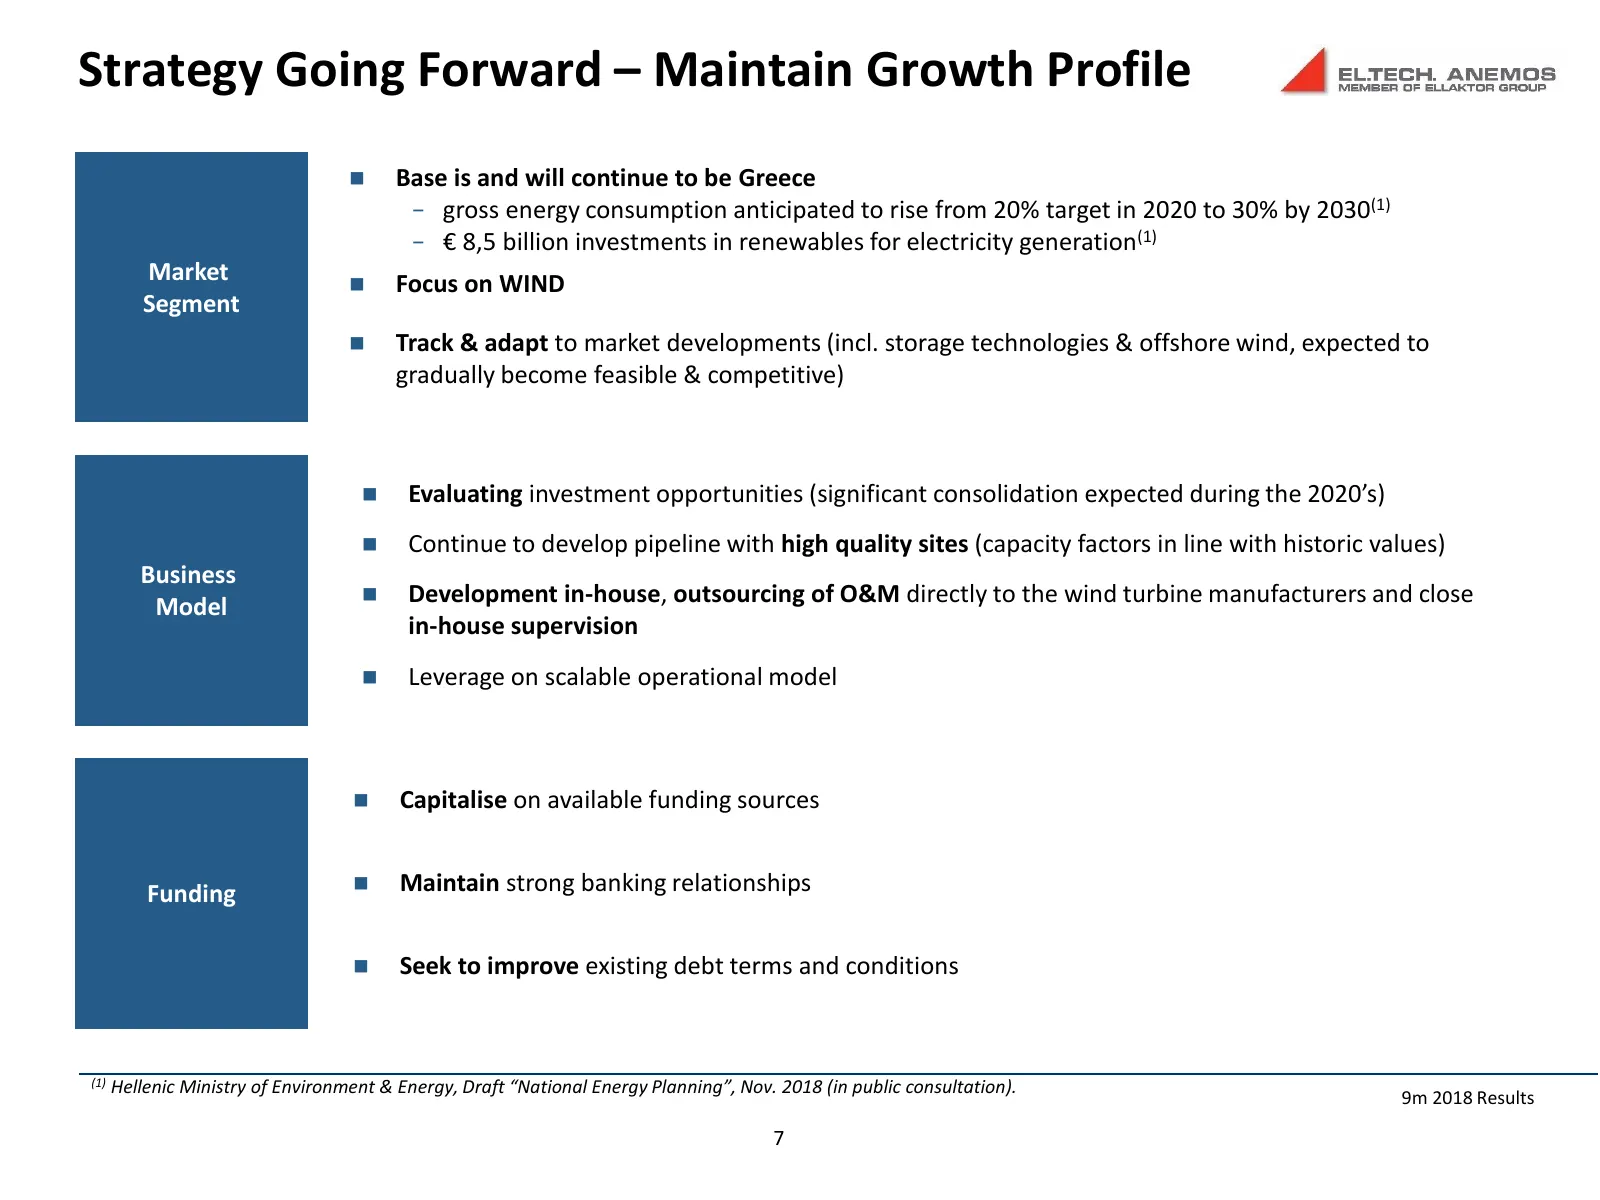
Slide 7: Strategy Going Forward – Maintain Growth Profile
Strategy Going Forward – Maintain Growth Profile Base is and will continue to be Greece − gross energy consumption anticipated to rise from 20% target in 2020 to 30% by 2030(1) − € 8,5 billion investments in renewables for electricity generation(1) Market Focus on WIND Segment Track & adapt to
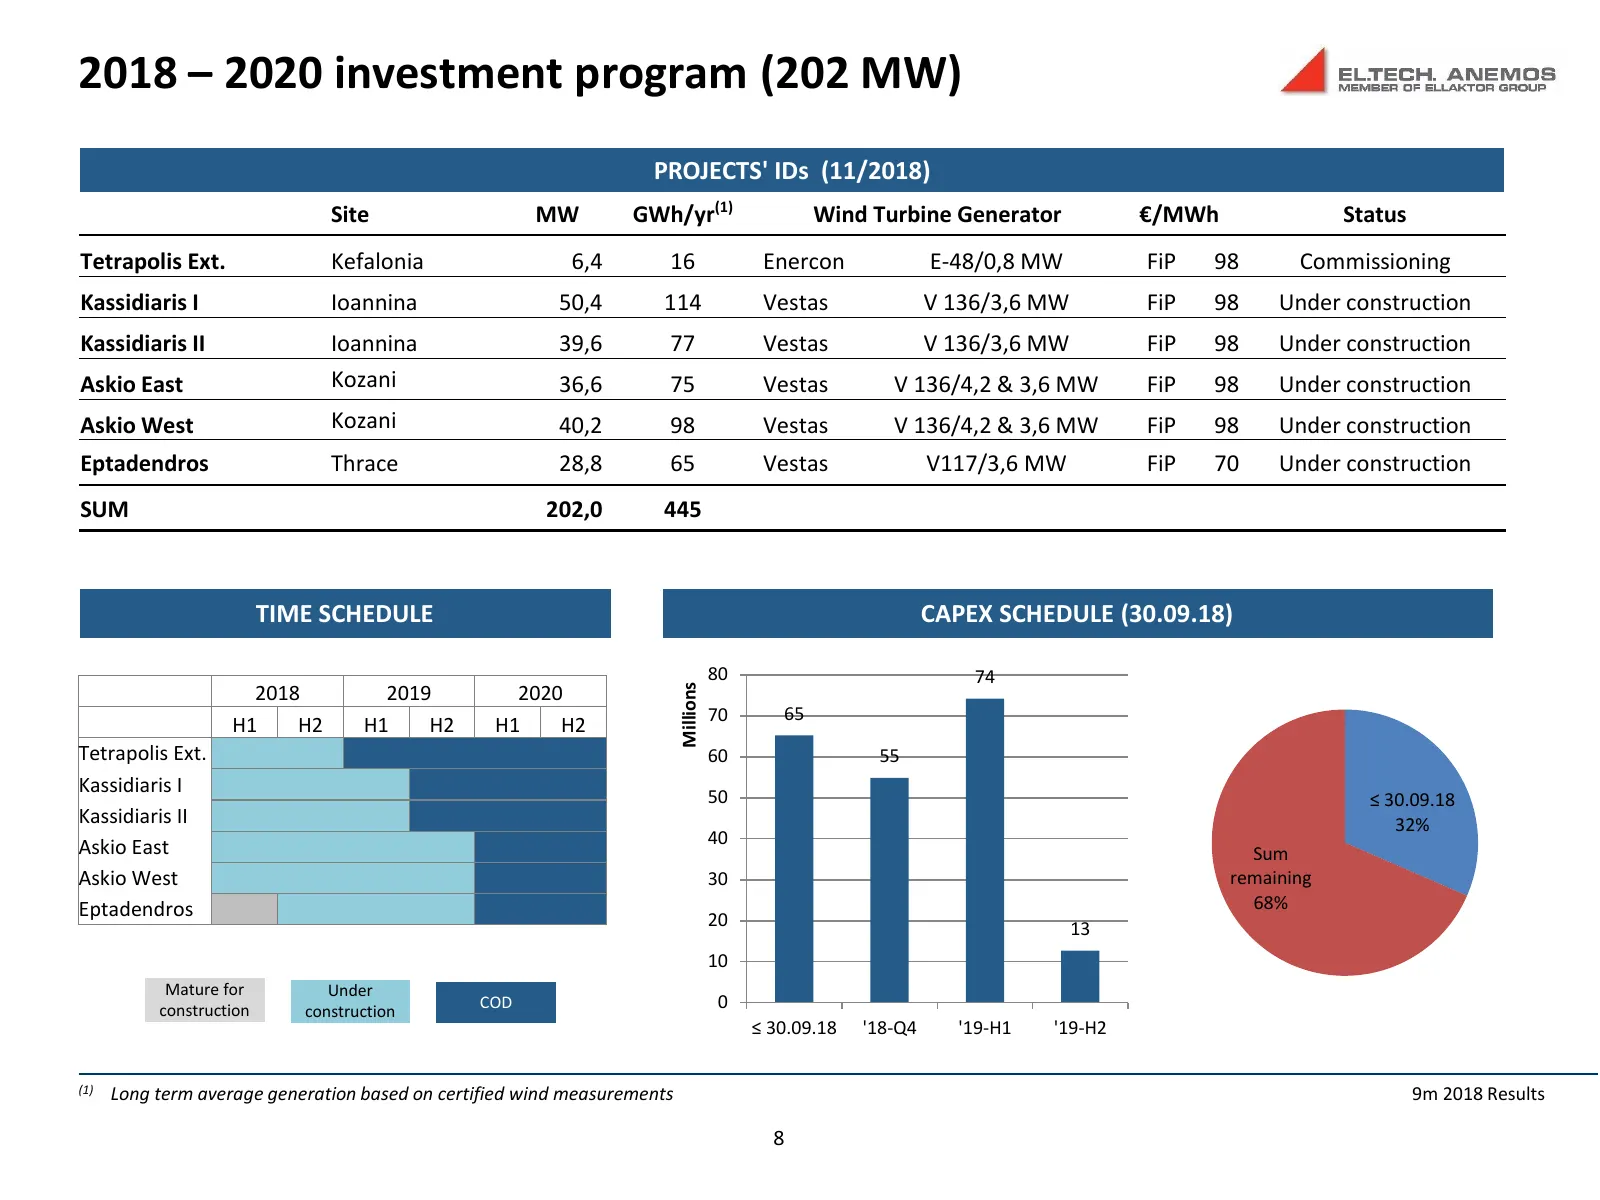
Slide 8: 2018 – 2020 investment program (202 MW)
2018 – 2020 investment program (202 MW) PROJECTS' IDs (11/2018) Site MW GWh/yr(1) Wind Turbine Generator €/ΜWh Status Tetrapolis Ext. Kefalonia 6,4 16 Enercon E-48/0,8 MW FiP 98 Commissioning Kassidiaris I Ioannina 50,4 114 Vestas V 136/3,6 MW FiP 98 Under construction Kassidiaris II Ioannina 39,6 7
Slide 9: Performance
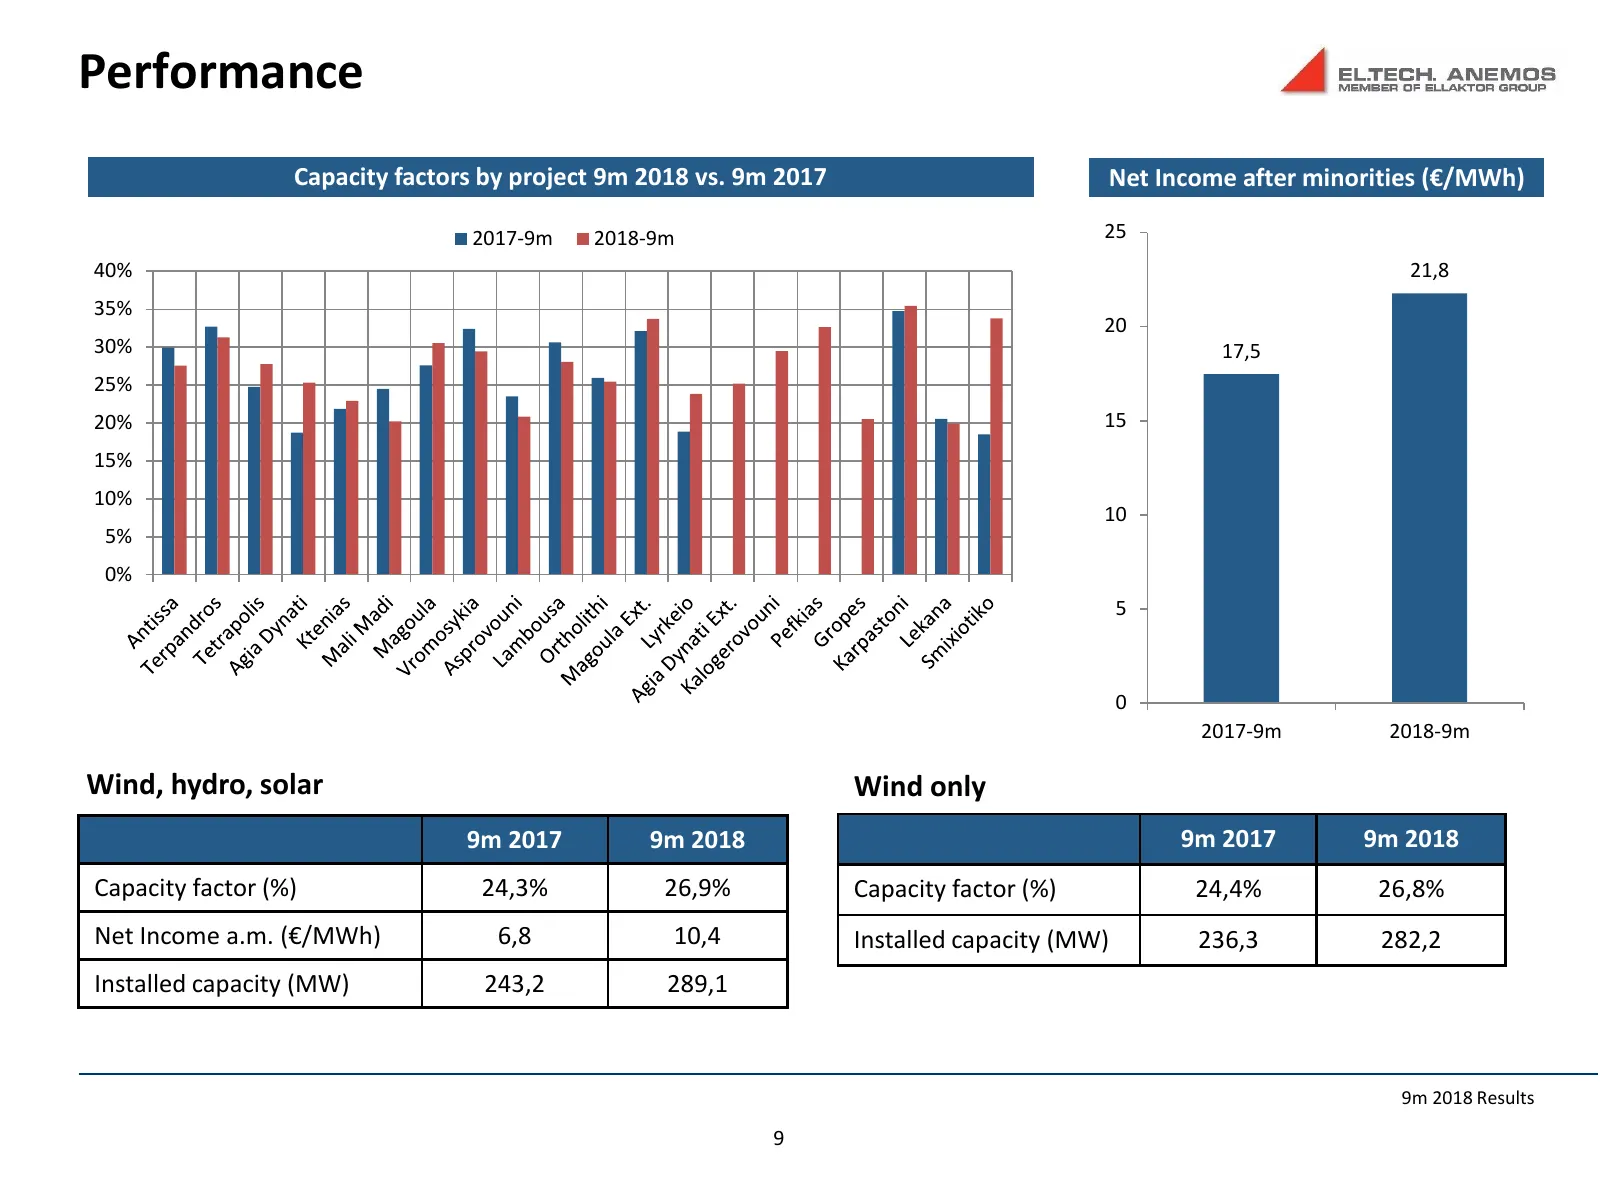
Performance Capacity factors by project 9m 2018 vs. 9m 2017 Net Income after minorities (€/MWh) 2017-9m 2018-9m 25 40% 21,8 35% 20 30% 17,5 25% 20% 15 15% 10% 10 5% 0% 5 0 2017-9m 2018-9m Wind, hydro, solar Wind only 9m 2017 9m 2018 9m 2017 9m 2018 Capacity factor (%) 24,3% 26,9% Capacity factor (%)
Slide 10: Group Asset Performance Details (11/2018)
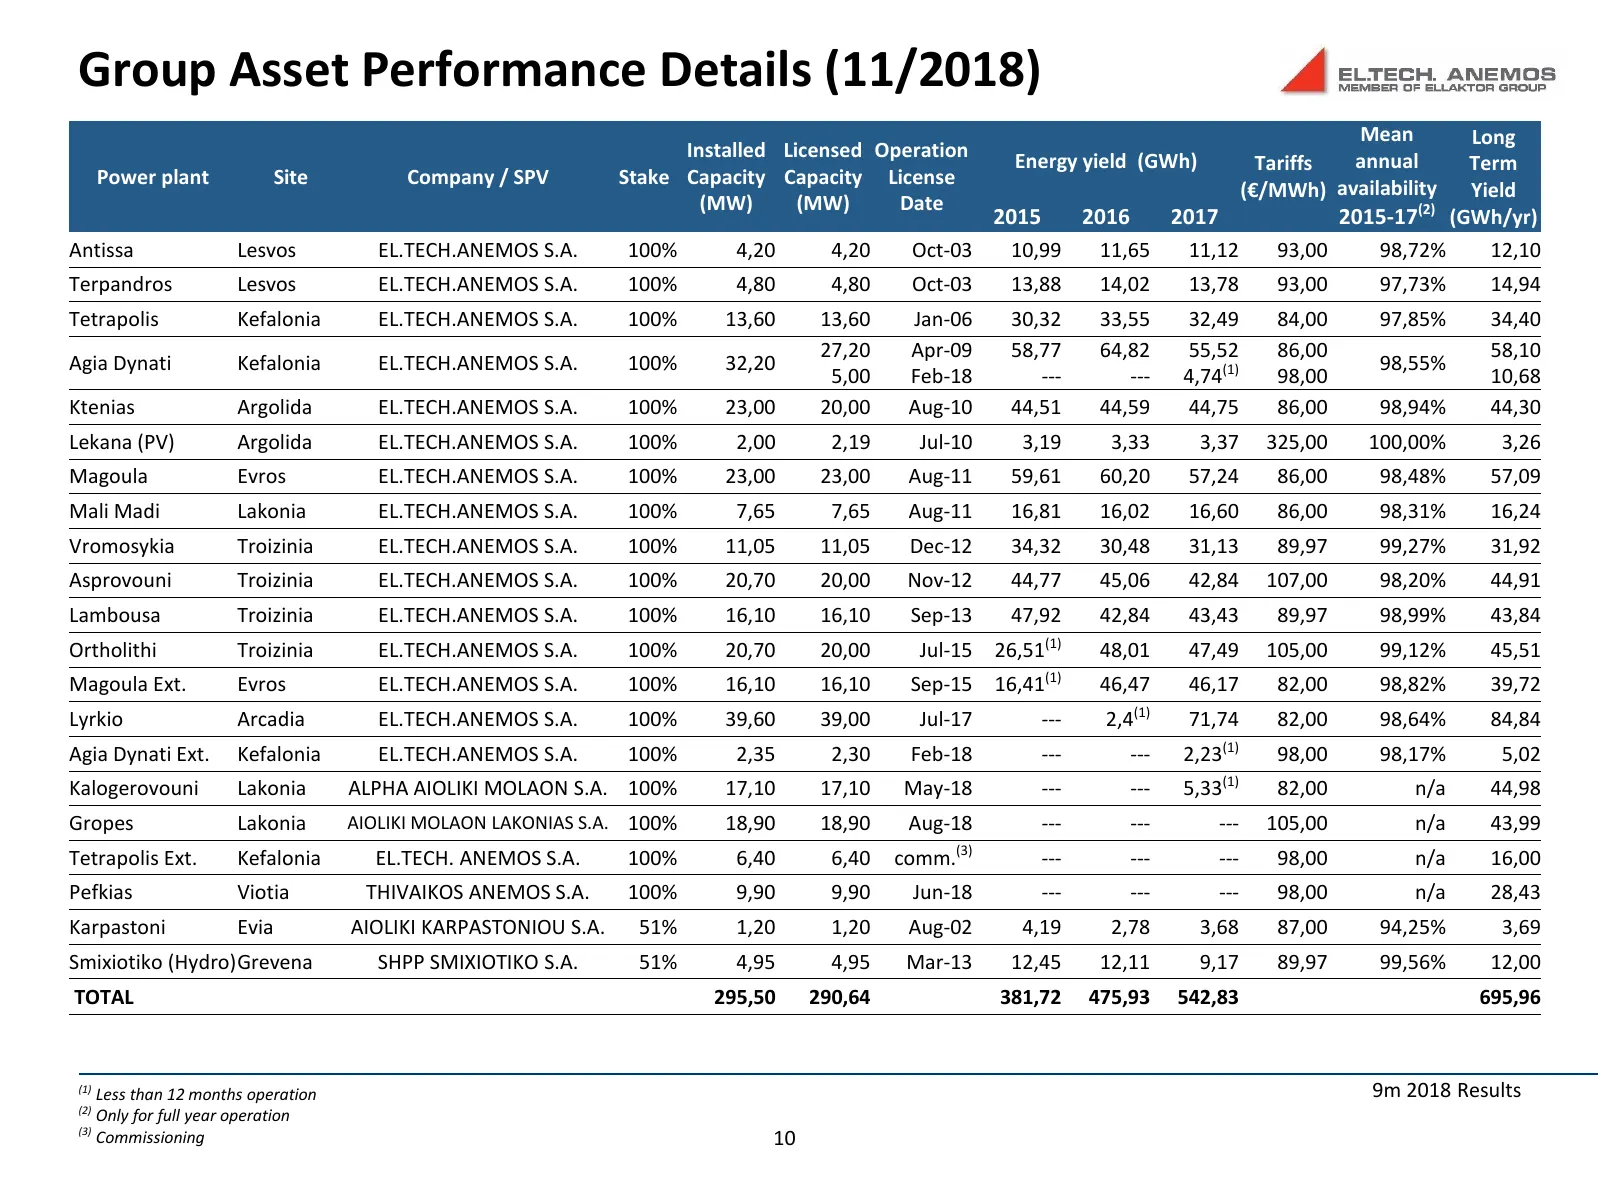
Group Asset Performance Details (11/2018) Mean Long Installed Licensed Operation Energy yield (GWh) annual Tariffs Term Power plant Site Company / SPV Stake Capacity Capacity License (€/MWh) availability Yield (MW) (MW) Date 2015 2016 2017 2015-17(2) (GWh/yr) Antissa Lesvos EL.TECH.ANEMOS S.A. 100%
Slide 11: Consolidated P&L
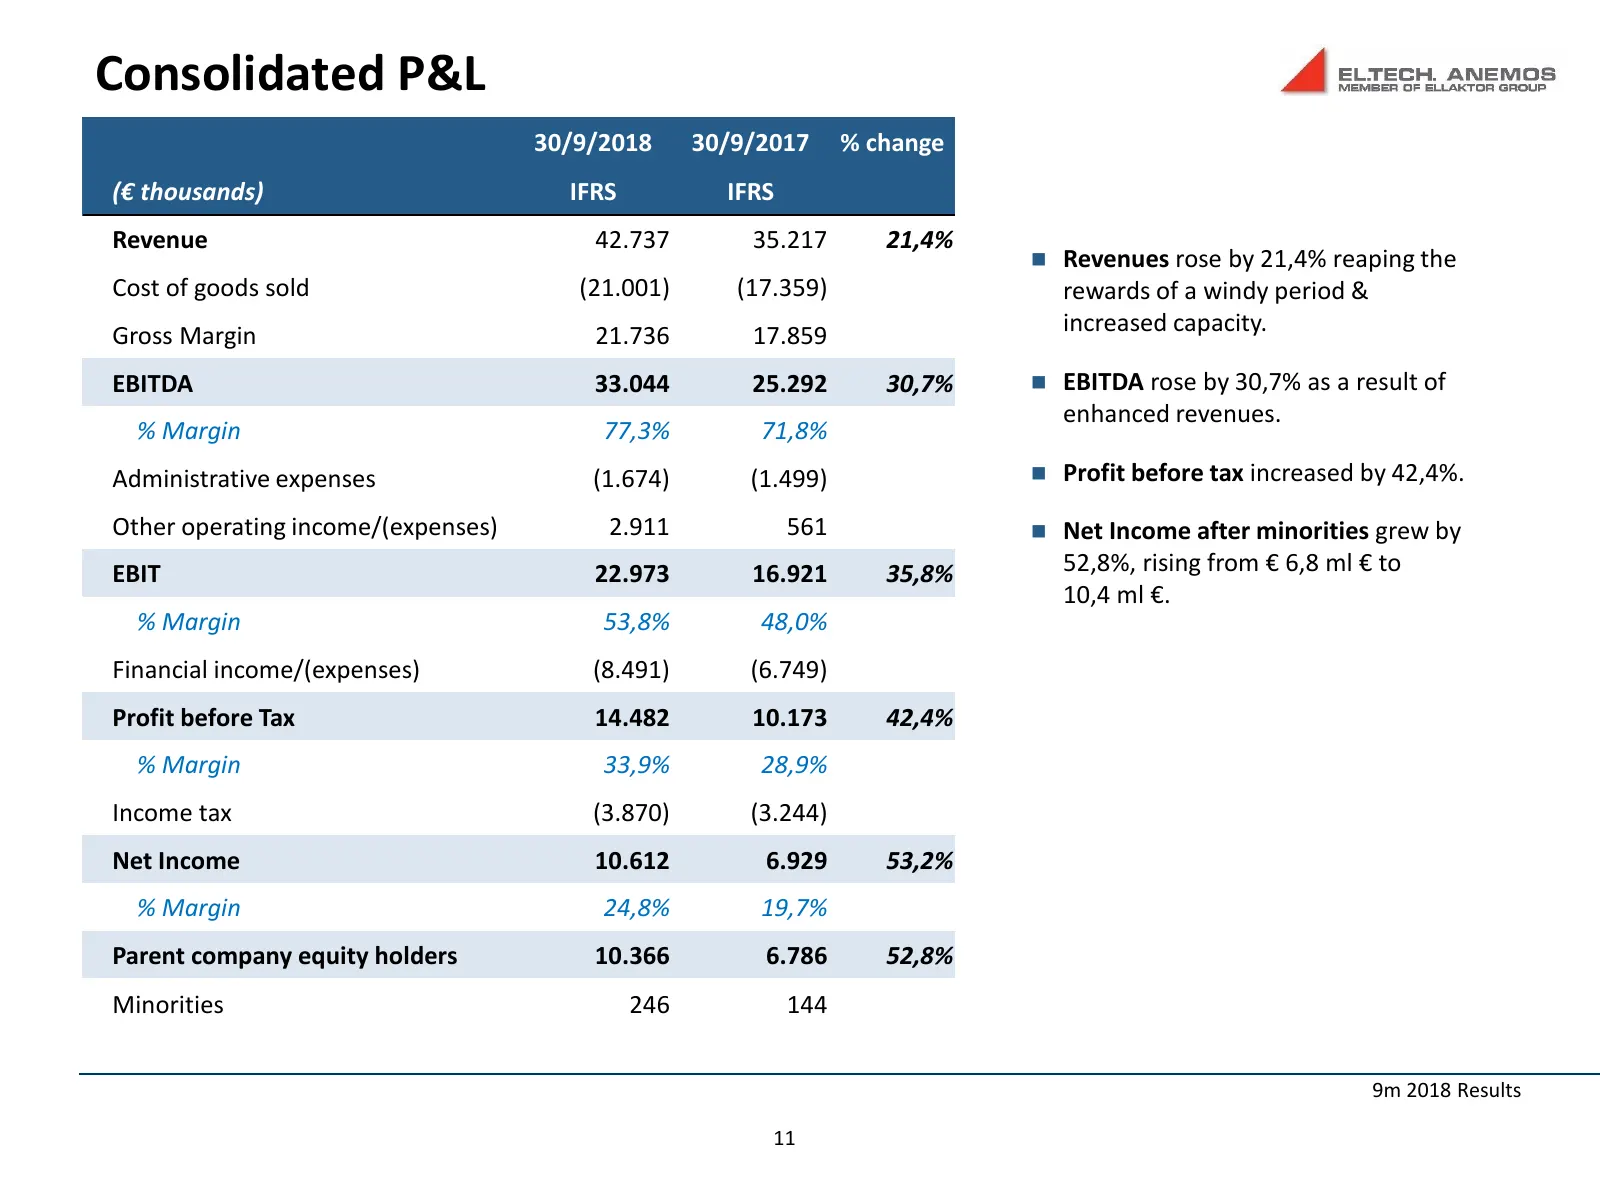
Consolidated P&L 30/9/2018 30/9/2017 % change (€ thousands) IFRS IFRS Revenue 42.737 35.217 21,4% Revenues rose by 21,4% reaping the Cost of goods sold (21.001) (17.359) rewards of a windy period & Gross Margin 21.736 17.859 increased capacity. EBITDA 33.044 25.292 30,7% EBITDA rose by 30,7% as
Slide 12: Consolidated Balance Sheet
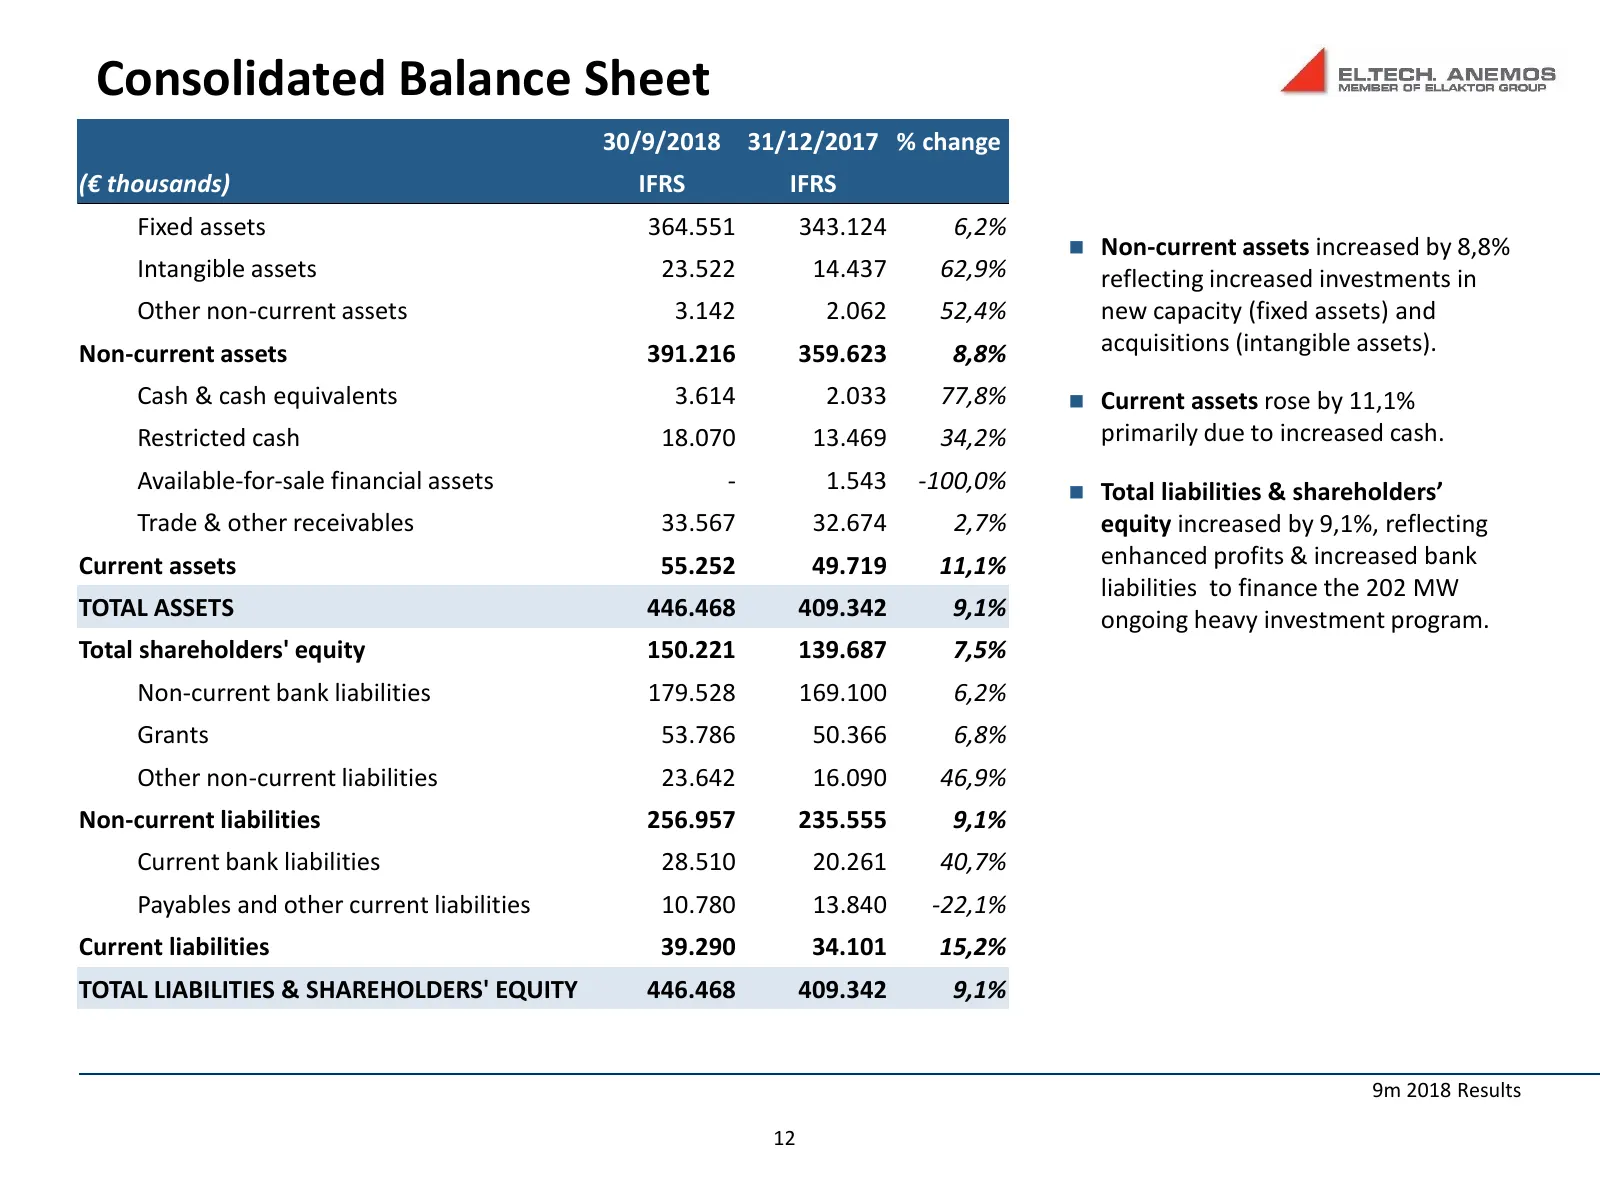
Consolidated Balance Sheet 30/9/2018 31/12/2017 % change (€ thousands) IFRS IFRS Fixed assets 364.551 343.124 6,2% Non-current assets increased by 8,8% Intangible assets 23.522 14.437 62,9% reflecting increased investments in Other non-current assets 3.142 2.062 52,4% new capacity (fixed assets) a
Slide 13: Consolidated Cash Flows
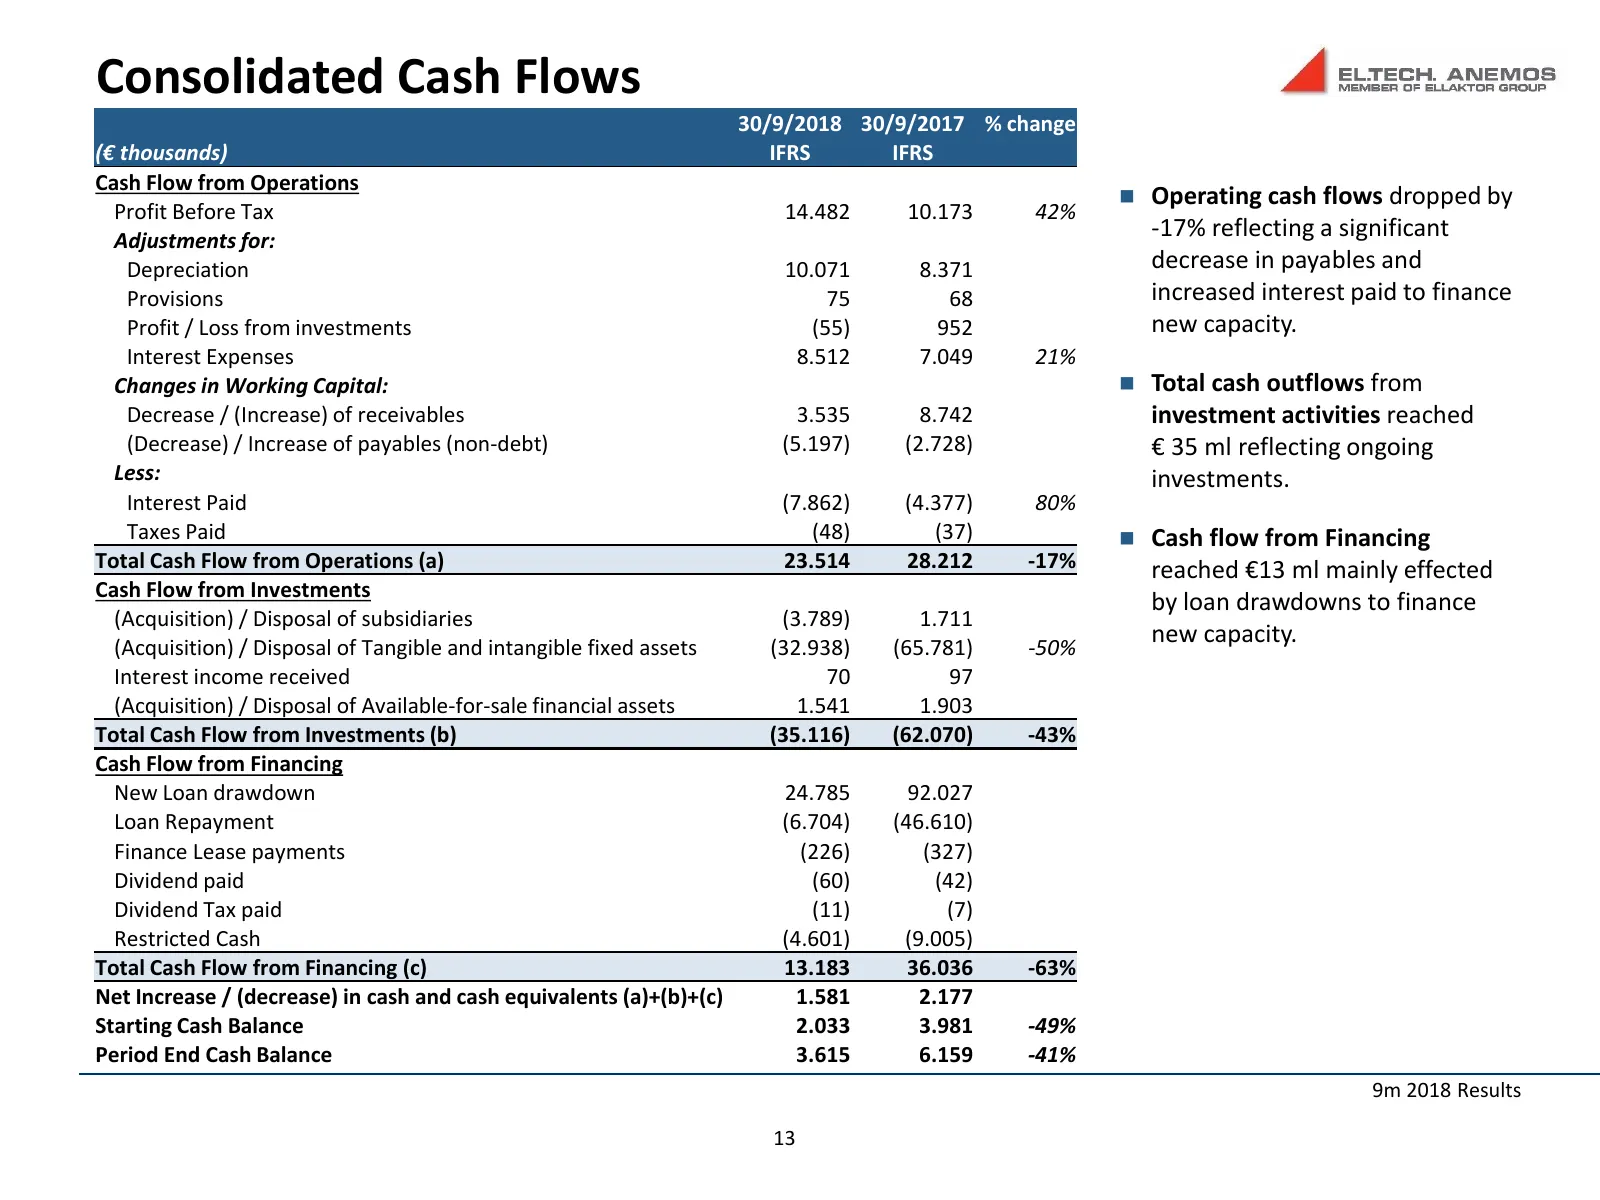
Consolidated Cash Flows 30/9/2018 30/9/2017 % change (€ thousands) IFRS IFRS Cash Flow from Operations Operating cash flows dropped by Profit Before Tax 14.482 10.173 42% Adjustments for: -17% reflecting a significant Depreciation 10.071 8.371 decrease in payables and Provisions 75 68 increased in
Slide 14: Disclaimer
Disclaimer This presentation has been prepared by EL.TECH. ANEMOS S.A. (the “Company”). The information contained in this presentation has not been independently verified and no representation or warranty, express or implied, is made as to, and no reliance should be placed on, the fairness, accuracy
Source: Internet Archive copy of ellaktor.com
More decks from Ellaktor SA
 FY2025 Earnings Presentation23 slides · Apr 17, 2026
 FY2024 Earnings Presentation30 slides · Apr 24, 2025
 H1 2024 Earnings Presentation30 slides · Sep 12, 2024
 FY2023 Earnings Presentation32 slides · Apr 18, 2024
 9M 2023 Earnings Presentation31 slides · Nov 23, 2023
 9M 2023 Earnings Presentation48 slides · November 2023