Mead Johnson Nutrition — Deutsche Bank Conference 2014
33 slides from Mead Johnson Nutrition's conference presentation, Jun 16, 2014
Slide 1: Deutsche Bank Conference, 18 June 2014, Paris
Deutsche Bank Conference 18 June 2014 Paris Kasper Jakobsen President and CEO Pete Leemputte Executive VP and CFO
Slide 2: Safe Harbor Statement
Safe Harbor Statement Forward-Looking Statements Certain statements in this presentation are forward-looking as defined in the Private Securities Litigation Reform Act of 1995. These forward-looking statements may be identified by the fact they use words such as “should,” “expect,” “anticipate,” “es
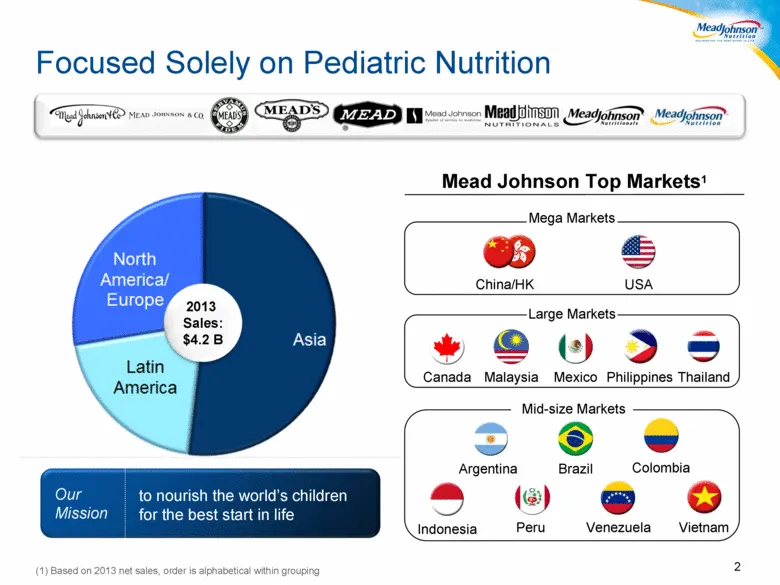
Slide 3: Focused Solely on Pediatric Nutrition
Focused Solely on Pediatric Nutrition Our Mission to nourish the world’s children for the best start in life 2013 Sales: $4.2 B (1) Based on 2013 net sales, order is alphabetical within grouping 2 Mead Johnson Top Markets1 Our Vision Mega Markets Mexico Canada Large Markets Malaysia Philippines Thai
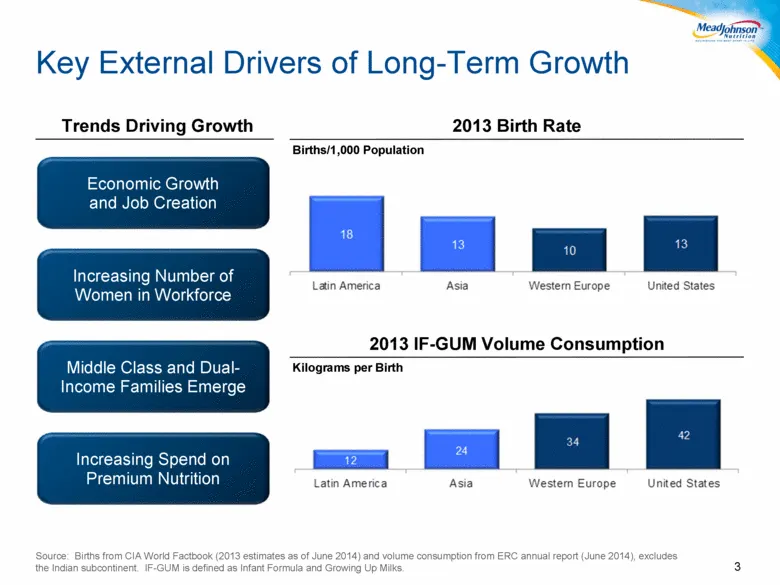
Slide 4: Key External Drivers of Long-Term Growth
Key External Drivers of Long-Term Growth 3 Source: Births from CIA World Factbook (2013 estimates as of June 2014) and volume consumption from ERC annual report (June 2014), excludes the Indian subcontinent. IF-GUM is defined as Infant Formula and Growing Up Milks. Economic Growth and Job Creation I
Slide 5: Strategy Reflects Strong Category Prospects
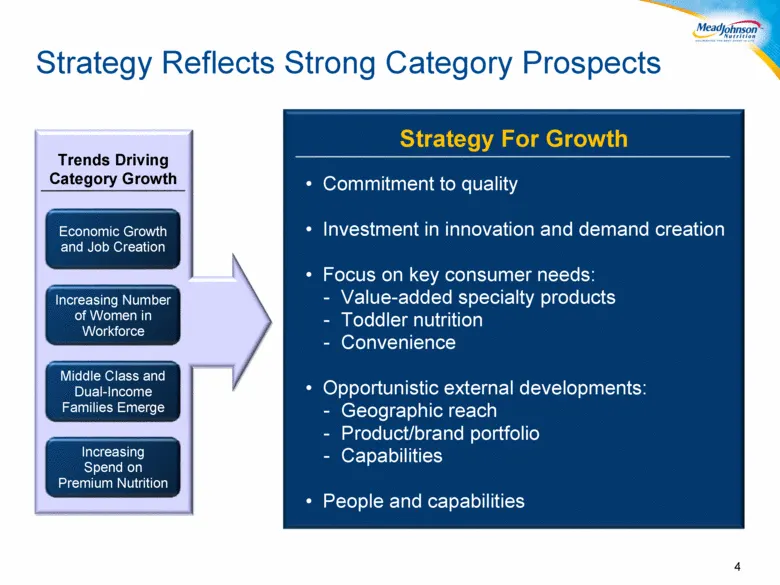
Strategy Reflects Strong Category Prospects 4 Economic Growth and Job Creation Increasing Spend on Premium Nutrition Increasing Number of Women in Workforce Middle Class and Dual-Income Families Emerge Trends Driving Category Growth Commitment to quality Investment in innovation and demand creation
Slide 6: Strong Revenue Growth and Improving Consumer Affordability
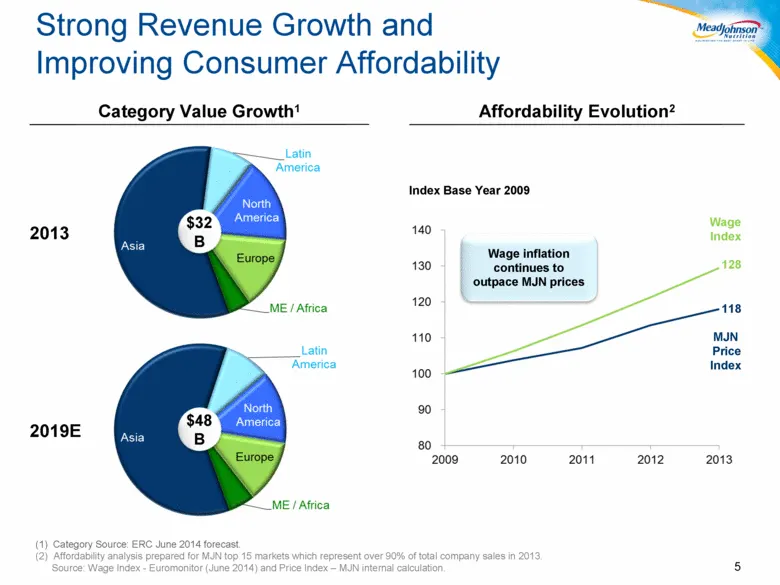
5 (1) Category Source: ERC June 2014 forecast. Affordability analysis prepared for MJN top 15 markets which represent over 90% of total company sales in 2013. Source: Wage Index - Euromonitor (June 2014) and Price Index – MJN internal calculation. Wage Index 128 118 MJN Price Index Wage inflation co
Slide 7: MJN Evolution
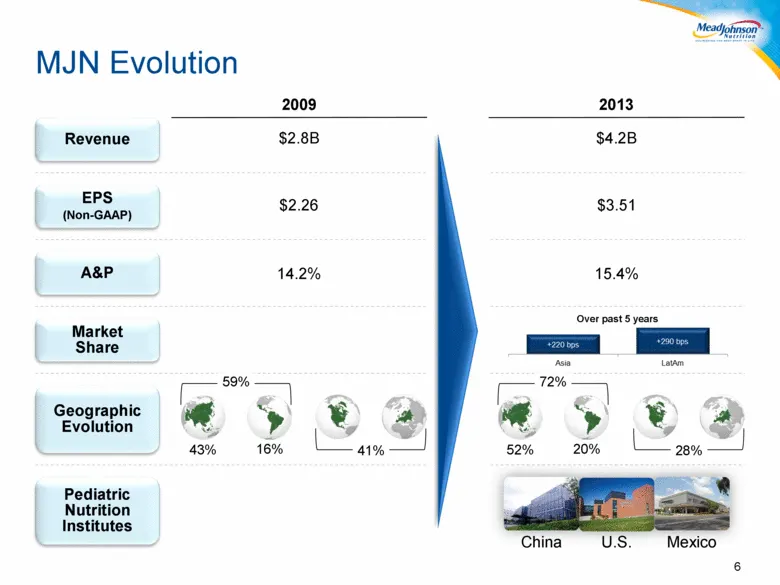
MJN Evolution 6 Revenue EPS (Non-GAAP) Geographic Evolution Pediatric Nutrition Institutes $2.8B $2.26 2009 2013 $4.2B $3.51 16% 43% 59% 20% 52% 72% A&P Market Share 14.2% 15.4% Over past 5 years China U.S. Mexico 41% 28%
Slide 8: Scientific Excellence
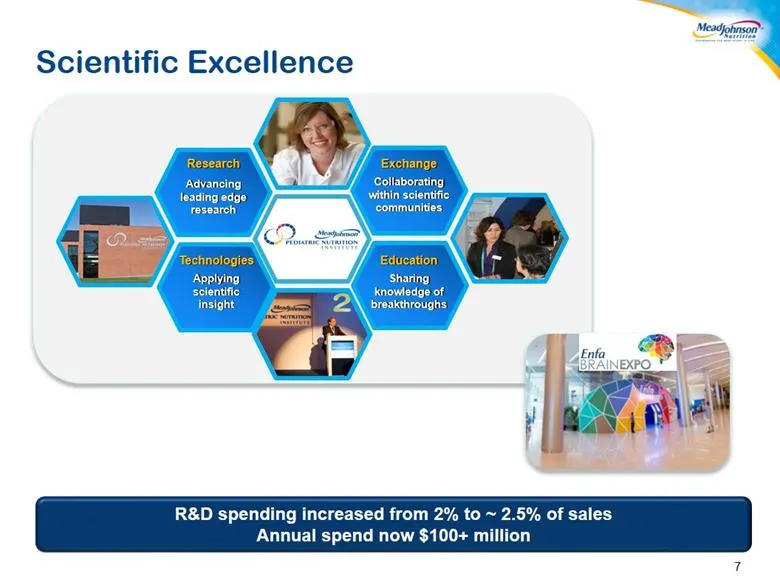
Scientific Excellence 7 R&D spending increased from 2% to ~ 2.5% of sales Annual spend now $100+ million Technologies Applying scientific insight Research Advancing leading edge research Exchange Collaborating within scientific communities Education Sharing knowledge of breakthroughs
Slide 9: Translating Insights into Nutrition Solutions
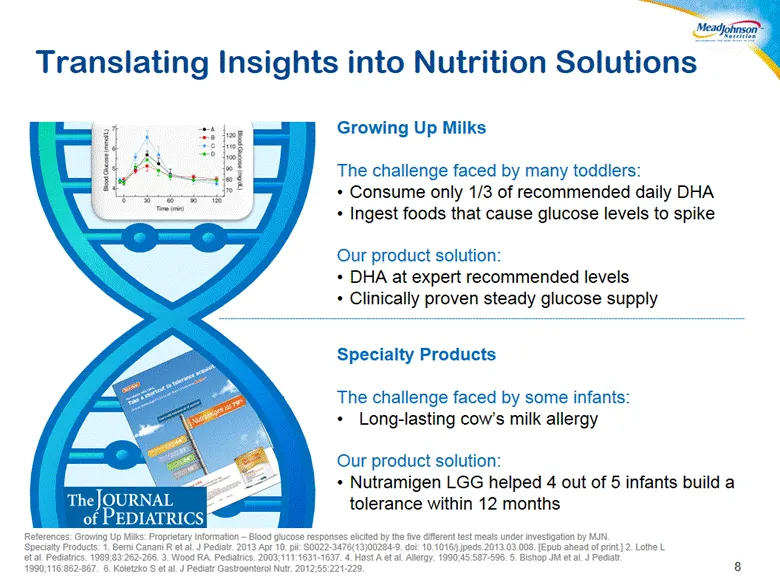
Translating Insights into Nutrition Solutions 8 Growing Up Milks The challenge faced by many toddlers: Consume only 1/3 of recommended daily DHA Ingest foods that cause glucose levels to spike Our product solution: DHA at expert recommended levels Clinically proven steady glucose supply Formulations
Slide 10: Case Studies Exemplifying Global Footprint
9 Brazil: Premiumization United States: Category Extension China: Expanding Reach Case Studies Exemplifying Global Footprint
Slide 11: Case Study #1: Brazil Premium Infant Formula Development
Case Study # 1:Brazil 10 Premium Infant Formula Development
Slide 12: Attractive Market Conditions
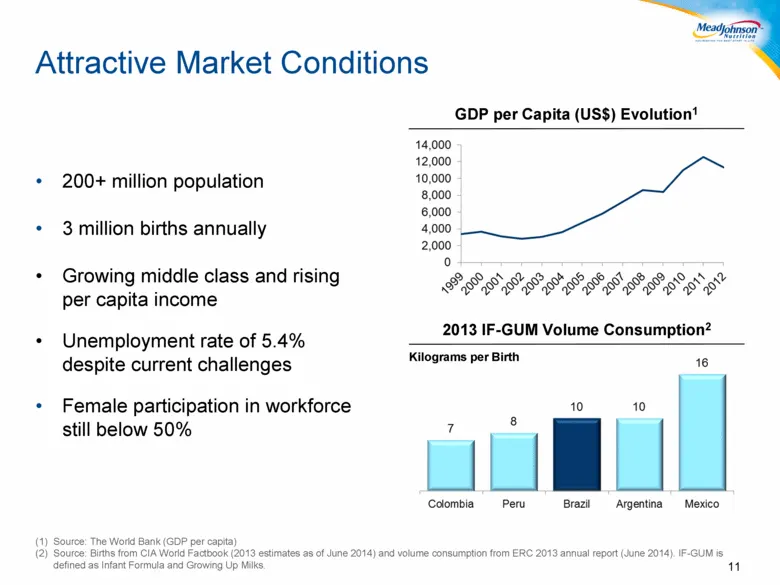
Attractive Market Conditions 11 200+ million population 3 million births annually Growing middle class and rising per capita income Unemployment rate of 5.4% despite current challenges Female participation in workforce still below 50% GDP per Capita (US$) Evolution1 2013 IF-GUM Volume Consumption2 S
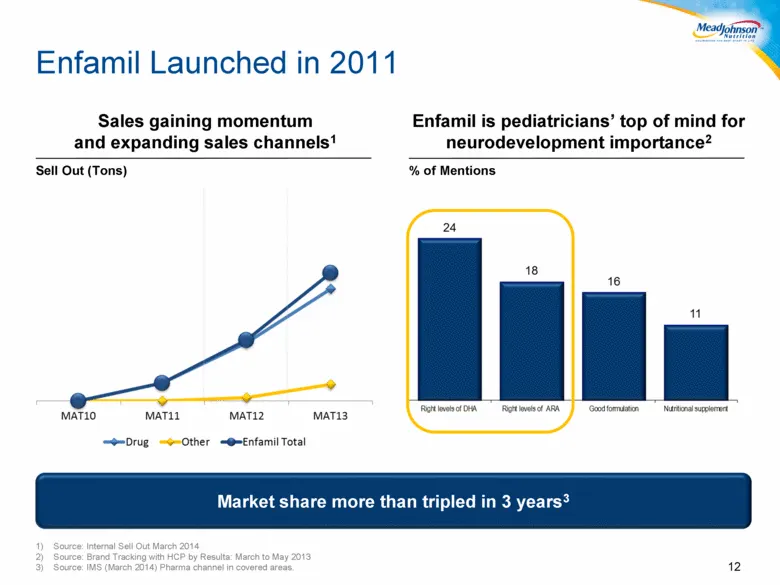
Slide 13: Sales gaining momentum and expanding sales channels
Sales gaining momentum and expanding sales channels1 Enfamil Launched in 2011 12 Enfamil is pediatricians’ top of mind for neurodevelopment importance2 Source: Internal Sell Out March 2014 Source: Brand Tracking with HCP by Resulta: March to May 2013 Source: IMS (March 2014) Pharma channel in covere
Slide 14: Case Study #2: China City and Channel Development
City and Channel Development Case Study # 2: China 13
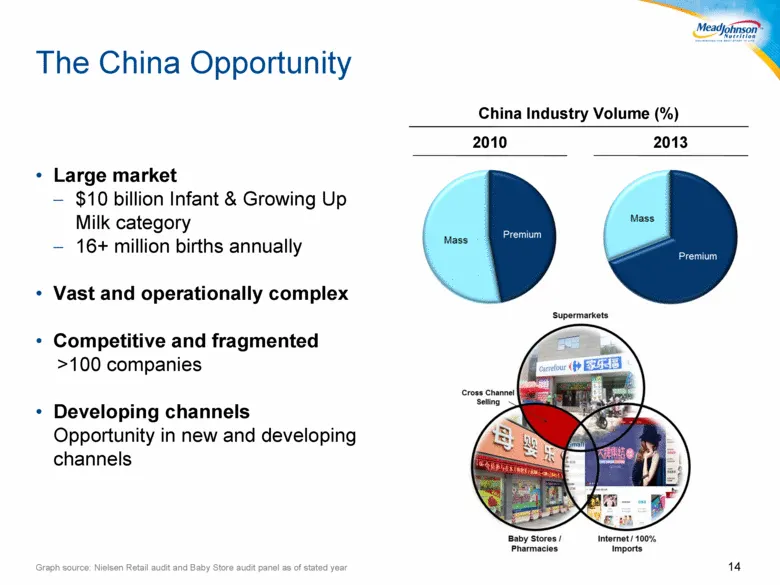
Slide 15: The China Opportunity
The China Opportunity Large market $10 billion Infant & Growing Up Milk category 16+ million births annually Vast and operationally complex Competitive and fragmented >100 companies Developing channels Opportunity in new and developing channels Graph source: Nielsen Retail audit and Baby Store audit
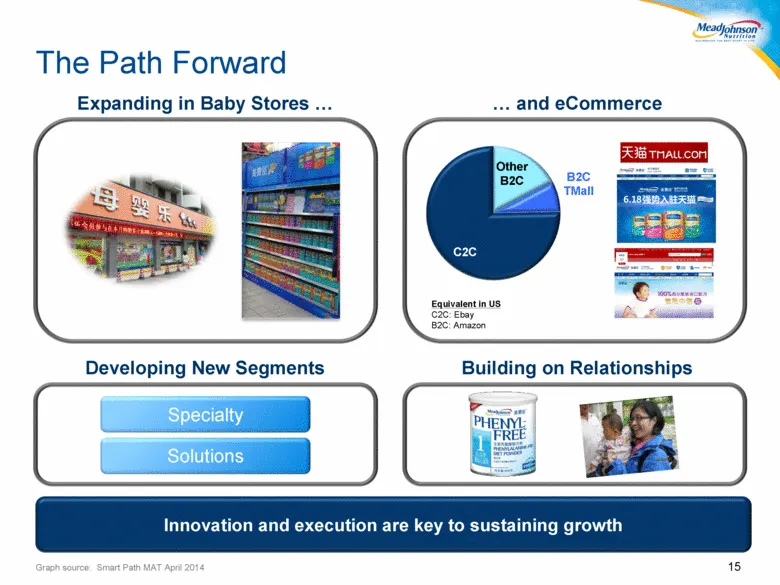
Slide 16: The Path Forward
The Path Forward Developing New Segments Building on Relationships Expanding in Baby Stores and eCommerce Specialty Solutions 15 Innovation and execution are key to sustaining growth Equivalent in US C2C: Ebay B2C: Amazon C2C Other B2C B2C TMall Graph source: Smart Path MAT April 2014
Slide 17: Case Study #3: United States
Case Study # 3: United States 16 Investing in Innovation and Children’s Category
Slide 18: United States Near Term Challenges But Reason for Future Optimism
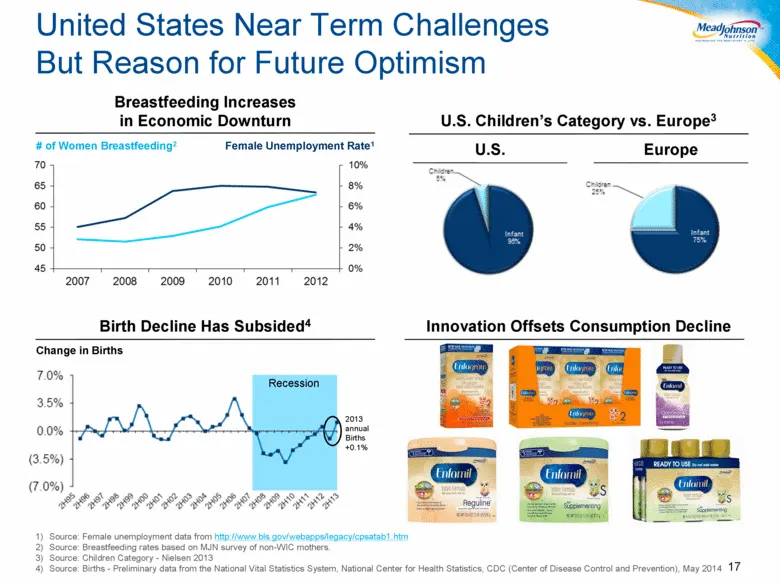
United States Near Term Challenges But Reason for Future Optimism 17 Source: Female unemployment data from http://www.bls.gov/webapps/legacy/cpsatab1.htm Source: Breastfeeding rates based on MJN survey of non-WIC mothers. Source: Children Category - Nielsen 2013 Source: Births - Preliminary data fro
Slide 19: Strong Commitment to Corporate Social Responsibility
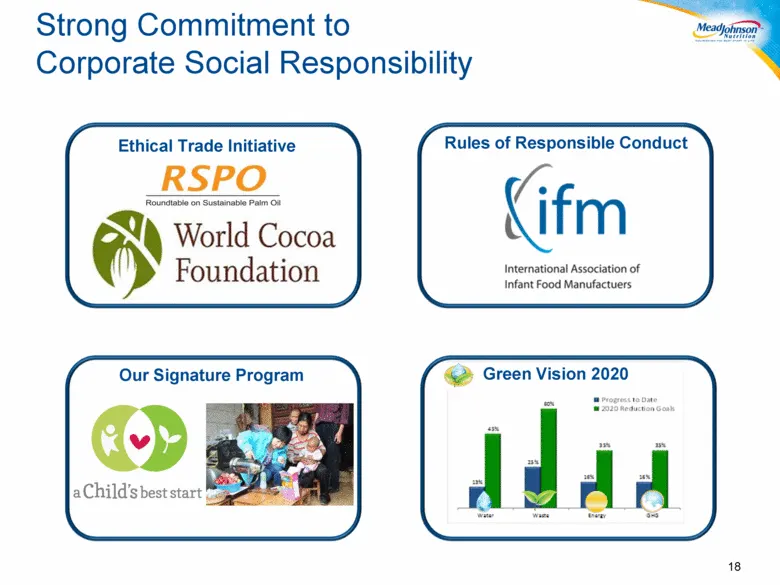
Strong Commitment to Corporate Social Responsibility 18 Ethical Trade Initiative Green Vision 2020 Our Signature Program Rules of Responsible Conduct
Slide 20: Our Commitment To Our Shareholders
19 Our Commitment To Our Shareholders Trends Driving Growth MJN Ambition Economic Growth and Job Creation Increasing Number of Women in Workforce Middle Class and Dual-Income Families Emerge Increasing Spend on Premium Nutrition Our Ambition is to deliver superior revenue and earnings growth within
Slide 21: Financial Highlights
19 Financial Highlights
Slide 22: Strong Financial Performance
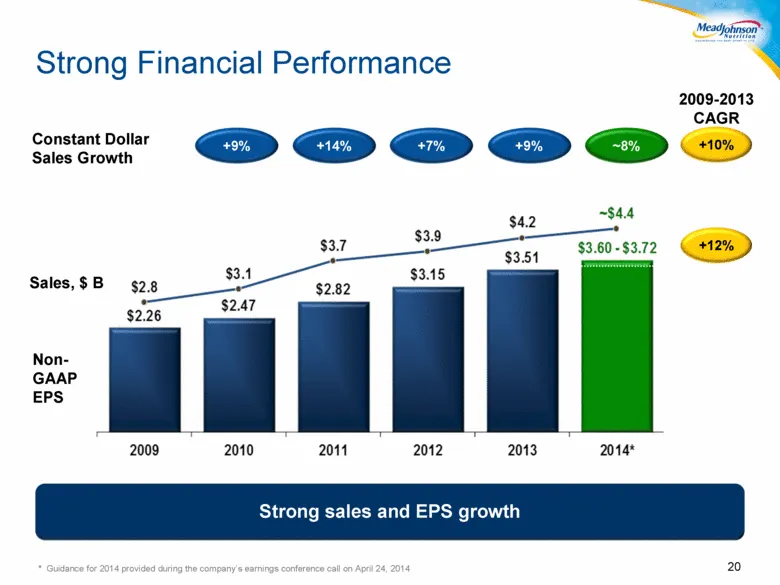
Strong Financial Performance 20 * Guidance for 2014 provided during the company’s earnings conference call on April 24, 2014 Strong sales and EPS growth +10% 2009-2013 CAGR +12% Sales, $ B Non-GAAP EPS Constant Dollar Sales Growth ~8% +9% +14% +9% +7%
Slide 23: Gross Margin: Inflation vs. Price & Productivity
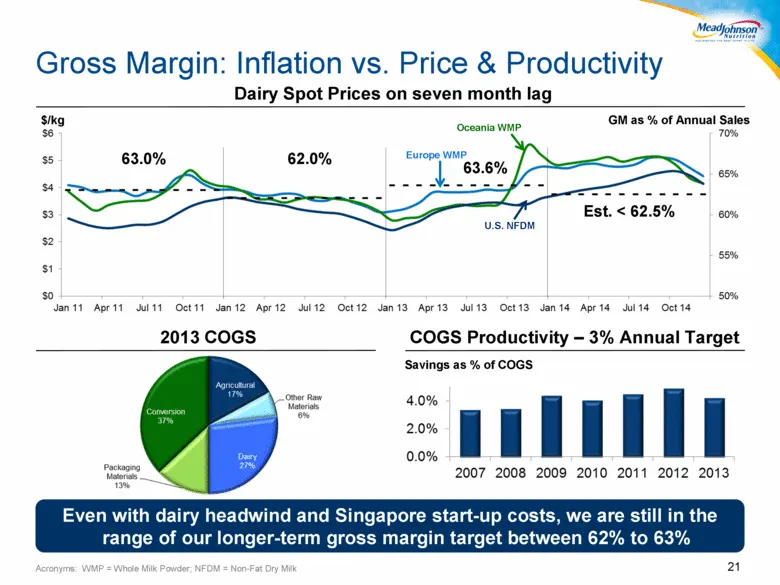
Gross Margin: Inflation vs. Price & Productivity Acronyms: WMP = Whole Milk Powder; NFDM = Non-Fat Dry Milk Savings as % of COGS 2013 COGS 21 Dairy Spot Prices on seven month lag $/kg Oceania WMP GM as % of Annual Sales Europe WMP U.S. NFDM 63.0% 62.0% Est. < 62.5% 63.6% Even with dairy headwind and
Slide 24: Asia Investment: Ensuring Capacity for Growth
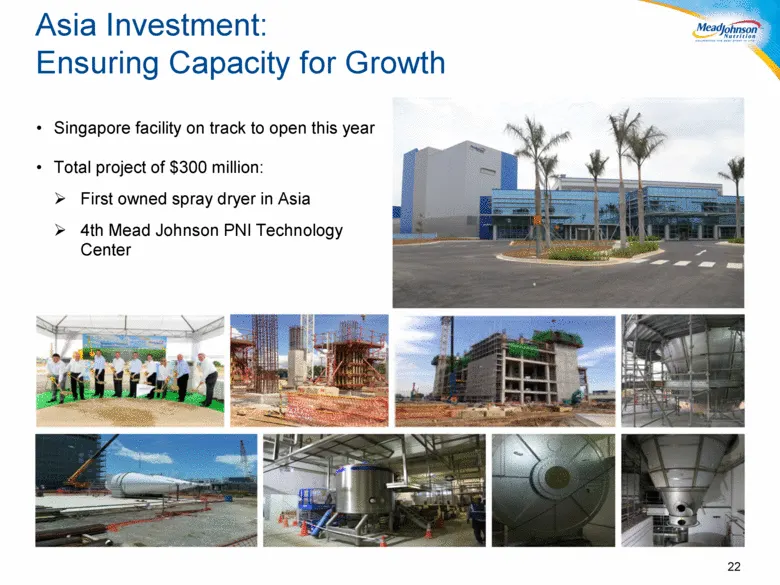
Asia Investment: Ensuring Capacity for Growth 22 Singapore facility on track to open this year Total project of $300 million: First owned spray dryer in Asia 4th Mead Johnson PNI Technology Center
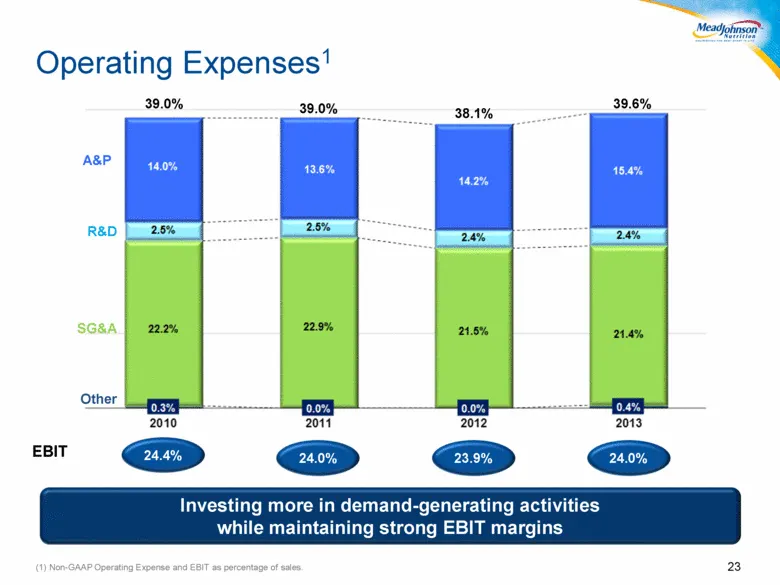
Slide 25: Operating Expenses
Operating Expenses1 (1) Non-GAAP Operating Expense and EBIT as percentage of sales. 23 39.0% 39.0% 38.1% 39.6% A&P R&D SG&A Other Investing more in demand-generating activities while maintaining strong EBIT margins EBIT 24.0% 23.9% 24.0% 24.4%
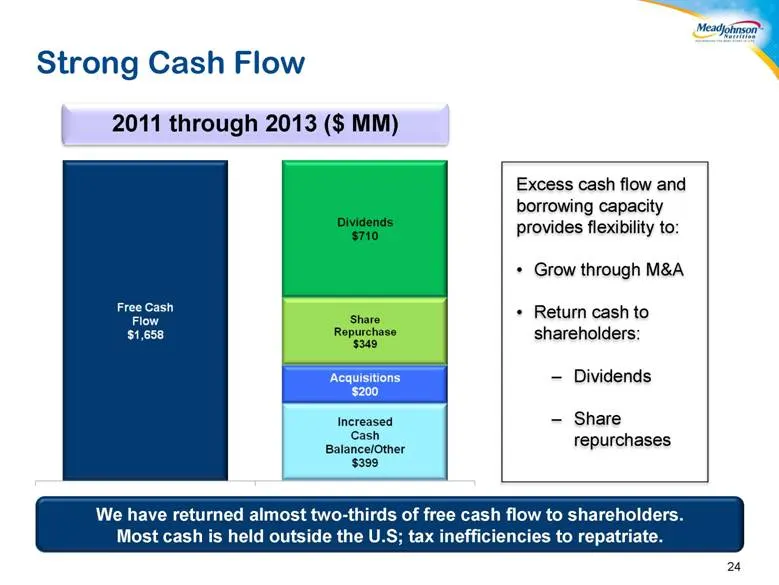
Slide 26: Strong Cash Flow
Strong Cash Flow 24 Excess cash flow and borrowing capacity provides flexibility to: Grow through M&A Return cash to shareholders: Dividends Share repurchases 2011 through 2013 ($ MM) We have returned almost two-thirds of free cash flow to shareholders. Most cash is held outside the U.S; tax ineffic
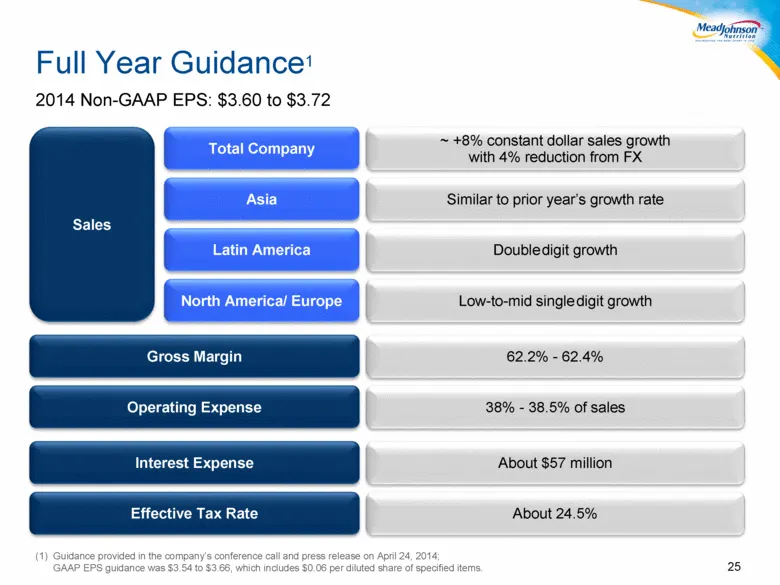
Slide 27: Full Year Guidance
Full Year Guidance1 2014 Non-GAAP EPS: $3.60 to $3.72 25 Guidance provided in the company’s conference call and press release on April 24, 2014; GAAP EPS guidance was $3.54 to $3.66, which includes $0.06 per diluted share of specified items. ~ +8% constant dollar sales growth with 4% reduction from
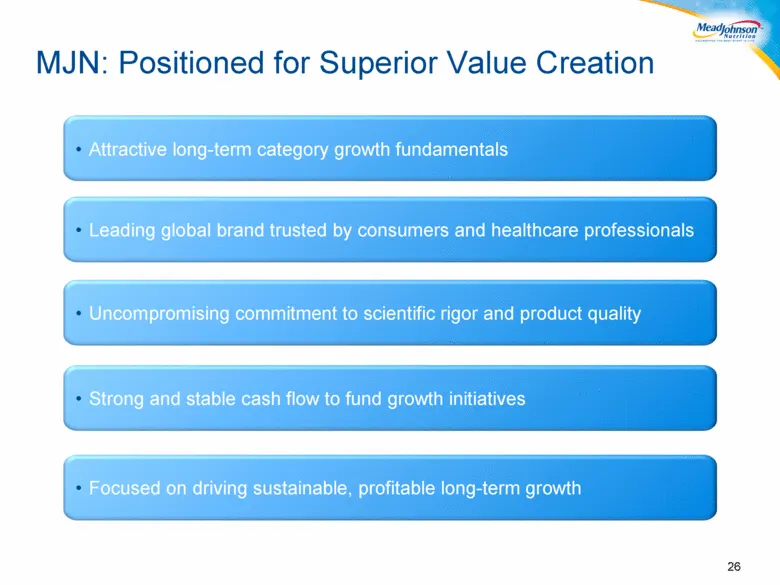
Slide 28: MJN: Positioned for Superior Value Creation
Attractive long-term category growth fundamentals Strong and stable cash flow to fund growth initiatives MJN: Positioned for Superior Value Creation 26 Leading global brand trusted by consumers and healthcare professionals Uncompromising commitment to scientific rigor and product quality Focused on
Slide 29: Appendix
27 Appendix
Slide 30: Reconciliation of non-GAAP to GAAP
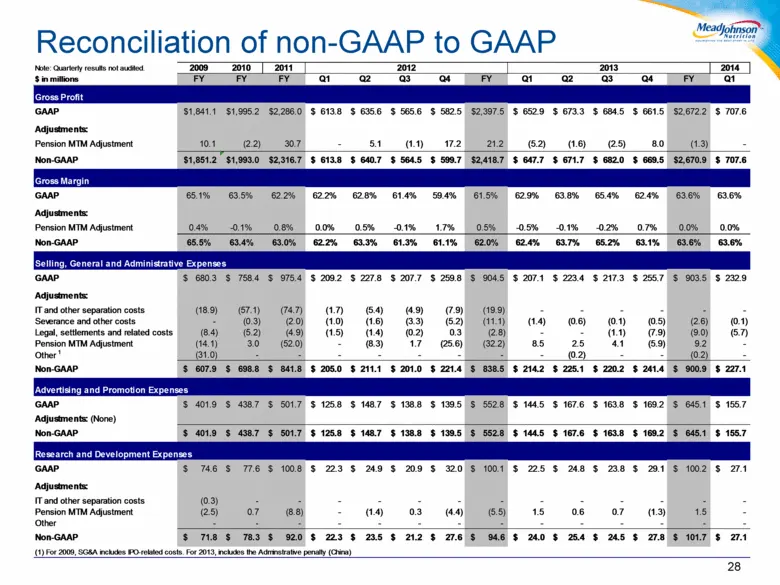
28 Reconciliation of non-GAAP to GAAP Note: Quarterly results not audited. 2014 $ in millions FY FY FY Q1 Q2 Q3 Q4 FY Q1 Q2 Q3 Q4 FY Q1 Gross Profit GAAP $1,841.1 $1,995.2 $2,286.0 $ 613.8 $ 635.6 $ 565.6 $ 582.5 $2,397.5 $ 652.9 $ 673.3 $ 684.5 $ 661.5 $2,672.2 $ 707.6 Adjustments: Pension MTM Adju
Slide 31: Reconciliation of non-GAAP to GAAP
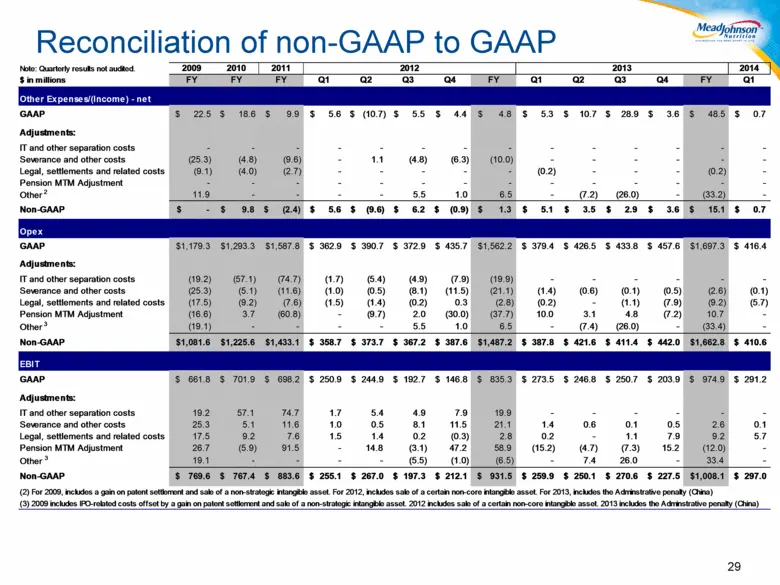
Reconciliation of non-GAAP to GAAP 29 Note: Quarterly results not audited. 2014 $ in millions FY FY FY Q1 Q2 Q3 Q4 FY Q1 Q2 Q3 Q4 FY Q1 Other Expenses/(Income) - net GAAP $ 22.5 $ 18.6 $ 9.9 $ 5.6 $ (10.7) $ 5.5 $ 4.4 $ 4.8 $ 5.3 $ 10.7 $ 28.9 $ 3.6 $ 48.5 $ 0.7 Adjustments: IT and other separation
Slide 32: Reconciliation of non-GAAP to GAAP
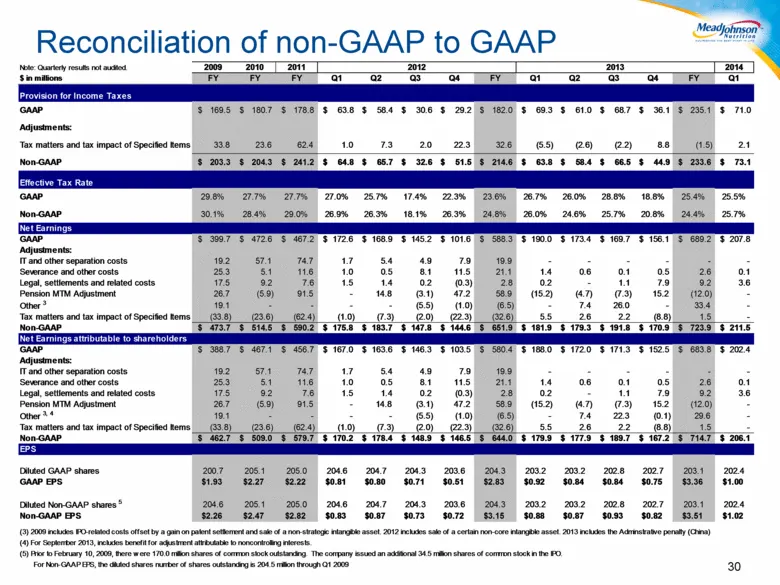
Reconciliation of non-GAAP to GAAP 30 Note: Quarterly results not audited. 2014 $ in millions FY FY FY Q1 Q2 Q3 Q4 FY Q1 Q2 Q3 Q4 FY Q1 GAAP $ 169.5 $ 180.7 $ 178.8 $ 63.8 $ 58.4 $ 30.6 $ 29.2 $ 182.0 $ 69.3 $ 61.0 $ 68.7 $ 36.1 $ 235.1 $ 71.0 Adjustments: Tax matters and tax impact of Specified Ite
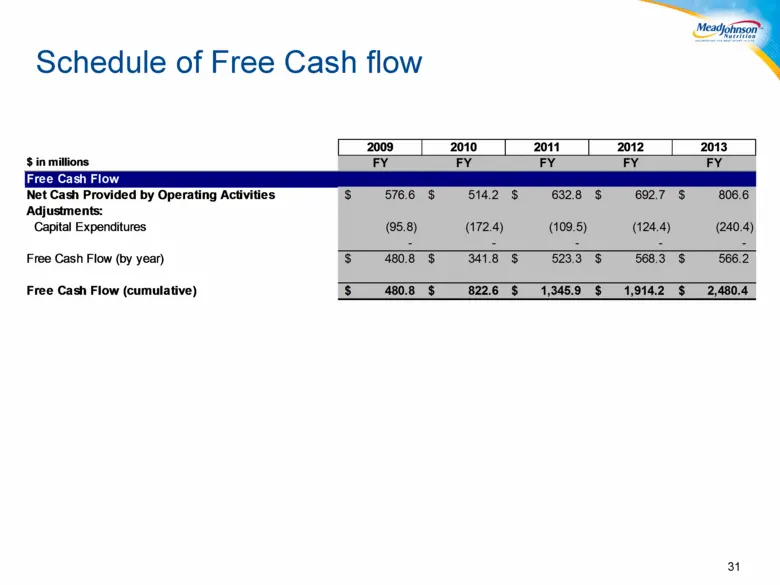
Slide 33: Schedule of Free Cash Flow
Schedule of Free Cash flow 31 2009 2010 2011 2012 2013 $ in millions FY FY FY FY FY Free Cash Flow Net Cash Provided by Operating Activities $ 576.6 $ 514.2 $ 632.8 $ 692.7 $ 806.6 Adjustments: Capital Expenditures (95.8) (172.4) (109.5) (124.4) (240.4) - - - - - Free Cash Flow (by year) $ 480.8 $ 3
Source: SEC EDGAR · 8-K filed Jun 16, 2014
More decks from Mead Johnson Nutrition CO
 Morgan Stanley Global Consumer & Retail Conference 201616 slides · Nov 15, 2016
 Barclays Global Consumer Staples Conference 201618 slides · Sep 7, 2016
 Q1 2016 Earnings Presentation20 slides · Apr 28, 2016
 FY2015 Earnings Presentation23 slides · Jan 28, 2016
 Q3 2015 Earnings Presentation26 slides · Oct 22, 2015
 Investor Day (October 2015)15 slides · Oct 22, 2015