Andeavor — Tesoro Corp /New/ — ISI Bermuda Energy Conference 2013
32 slides from Andeavor's conference presentation, May 8, 2013
Slide 1: ISI Bermuda Energy Conference May 2013
ISI Bermuda Energy Conference May 2013 Greg Goff President and CEO Exhibit 99.1
Slide 2: Forward Looking Statements
Forward Looking Statements This Presentation includes forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements relate to, among other things: • Tesoro's competitive position and competitive advantages; • The implementation and anticipate
Slide 3: Tesoro Today
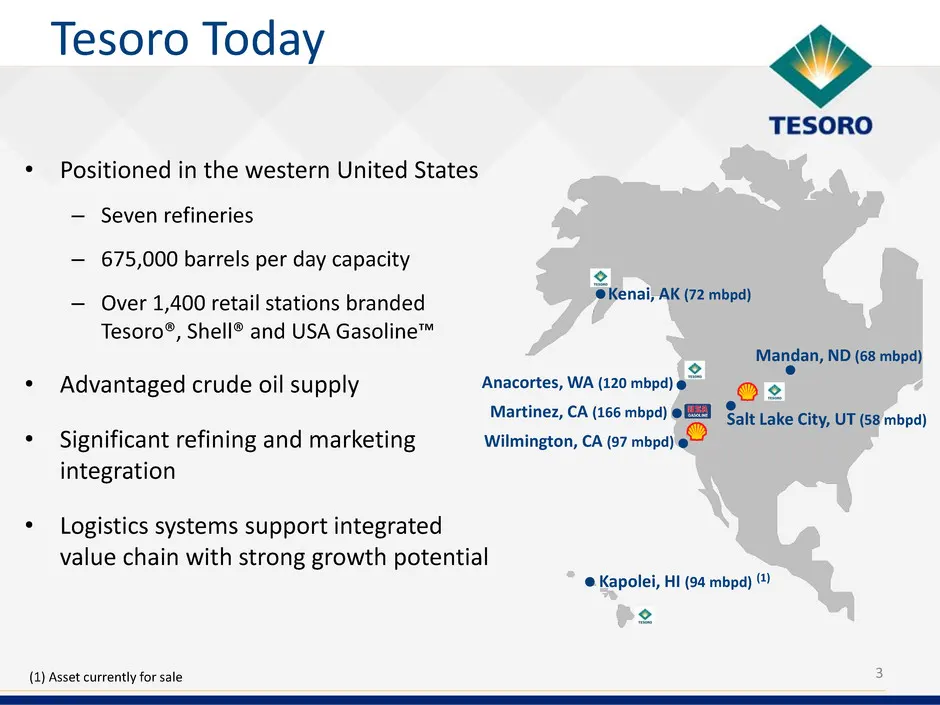
• Positioned in the western United States – Seven refineries – 675,000 barrels per day capacity – Over 1,400 retail stations branded Tesoro®, Shell® and USA Gasoline™ • Advantaged crude oil supply • Significant refining and marketing integration • Logistics systems support integrated value chain wit
Slide 4: Key Messages
4 Key Messages • Delivering key strategic initiatives and driving significant shareholder value • Strengthening our West Coast business • Advantaged position in the Mid-Continent • Driving feedstock advantage to PADD5 refineries • Tesoro Logistics (TLLP) creating significant value as a strategic gro
Slide 5: Strategic Priorities
• Operational efficiency and effectiveness – Safety and reliability – System improvements – Cost leadership • Commercial excellence • Financial discipline • Value-driven growth • High-performing culture Strategic Priorities 5
Slide 6: Large Capital Program
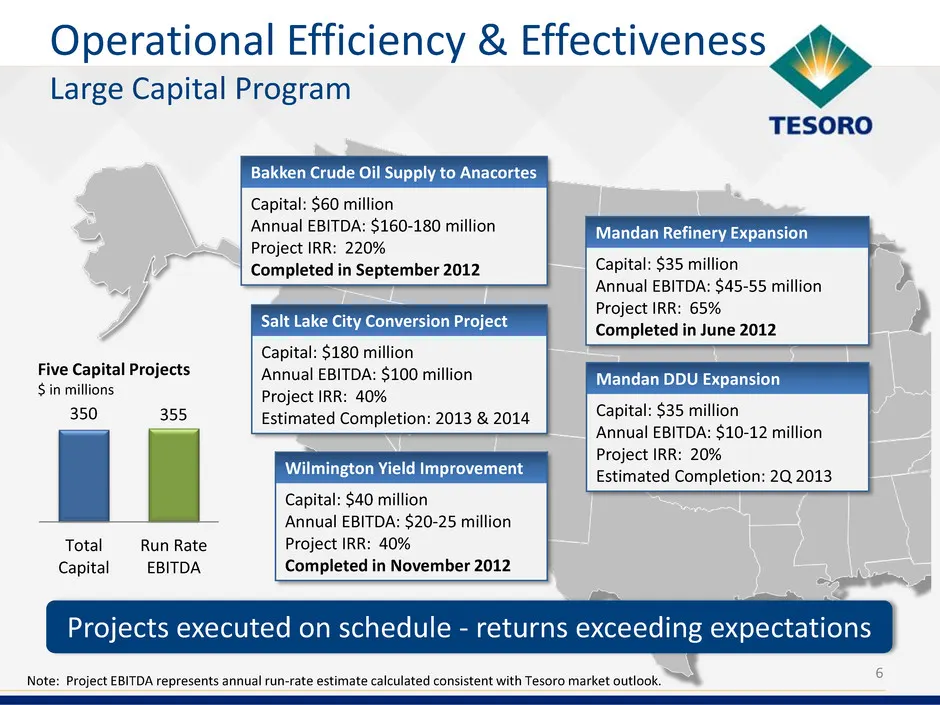
6 Mandan Refinery Expansion Capital: $35 million Annual EBITDA: $45-55 million Project IRR: 65% Completed in June 2012 Mandan DDU Expansion Capital: $35 million Annual EBITDA: $10-12 million Project IRR: 20% Estimated Completion: 2Q 2013 Bakken Crude Oil Supply to Anacortes Capital: $60 million Annu
Slide 7: Small Capital Program, 2012 Completed Projects
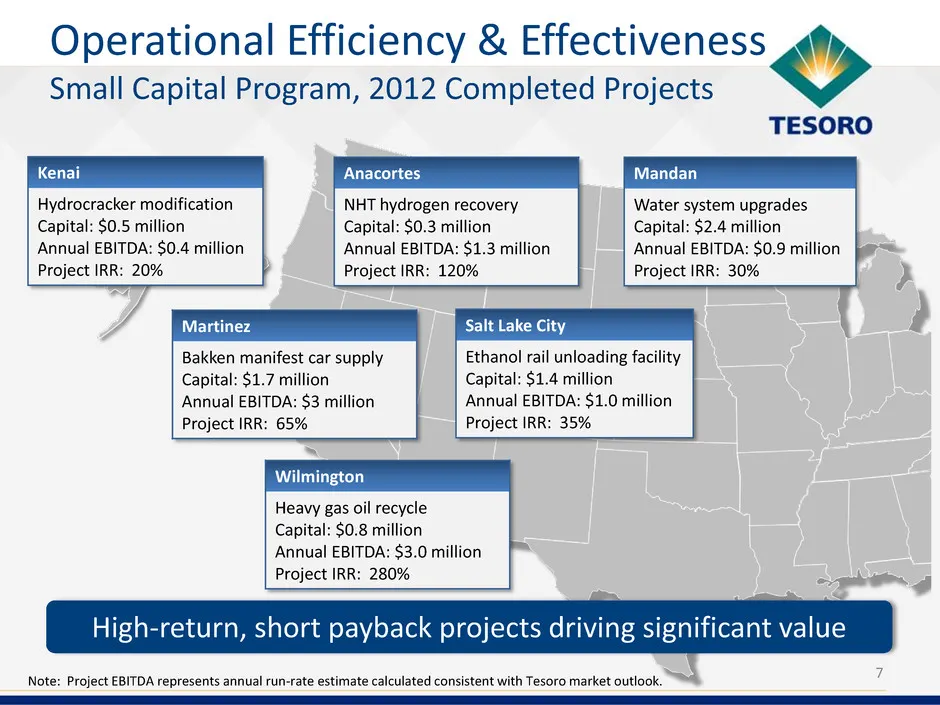
7 Operational Efficiency & Effectiveness Small Capital Program, 2012 Completed Projects Mandan Water system upgrades Capital: $2.4 million Annual EBITDA: $0.9 million Project IRR: 30% Anacortes NHT hydrogen recovery Capital: $0.3 million Annual EBITDA: $1.3 million Project IRR: 120% Salt Lake City E
Slide 8: High-Return Capital Investments
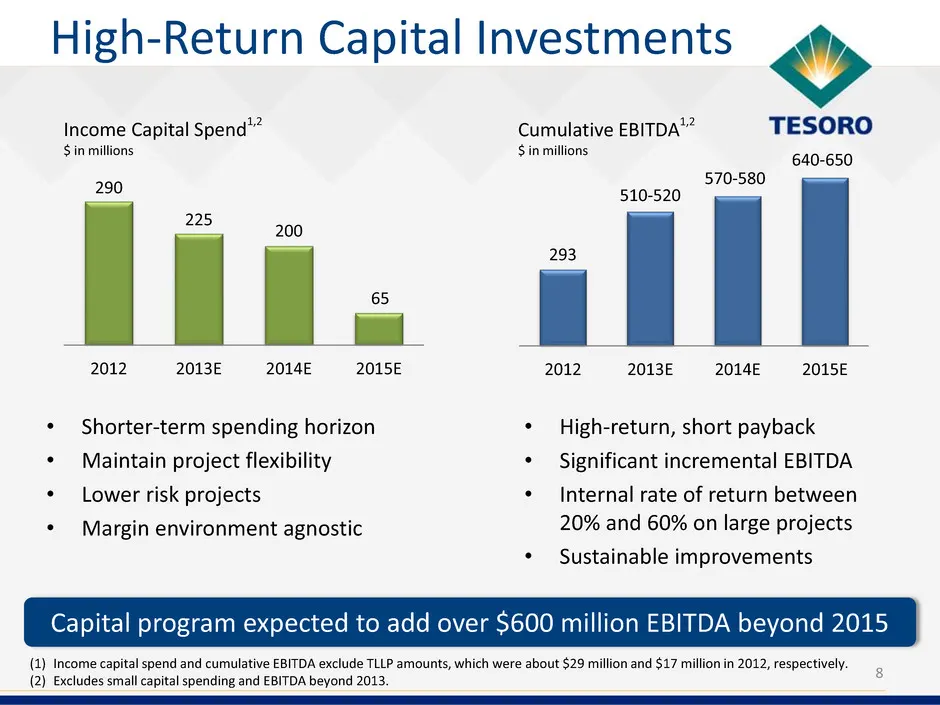
290 225 200 65 2012 2013E 2014E 2015E Income Capital Spend 1,2 $ in millions • High-return, short payback • Significant incremental EBITDA • Internal rate of return between 20% and 60% on large projects • Sustainable improvements • Shorter-term spending horizon • Maintain project flexibility • Lower
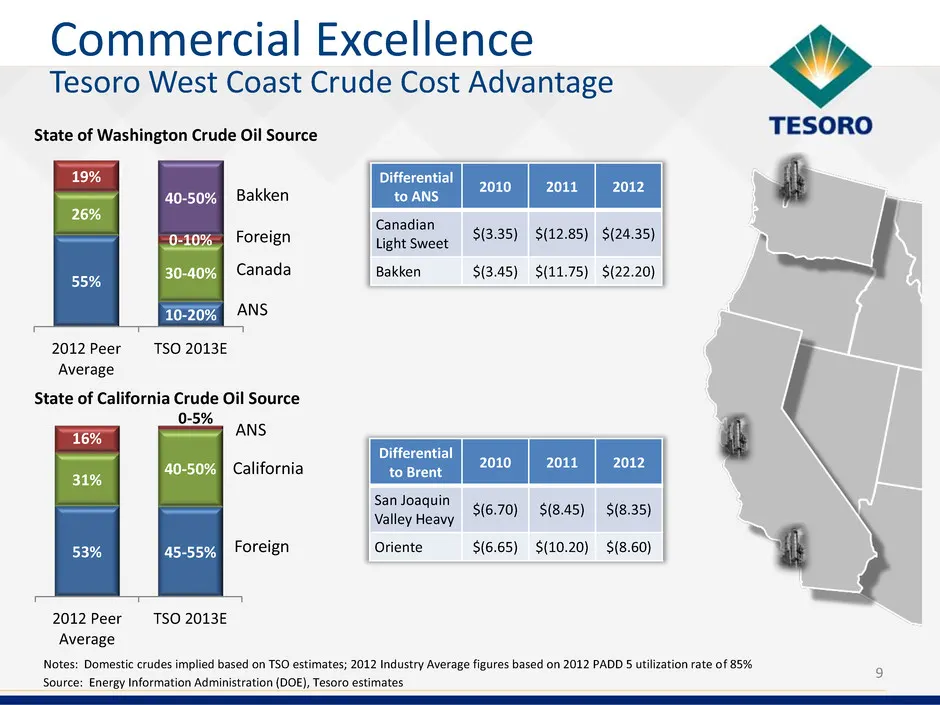
Slide 9: Tesoro West Coast Crude Cost Advantage
9 Source: Energy Information Administration (DOE), Tesoro estimates Notes: Domestic crudes implied based on TSO estimates; 2012 Industry Average figures based on 2012 PADD 5 utilization rate of 85% State of Washington Crude Oil Source State of California Crude Oil Source Commercial Excellence Tesoro
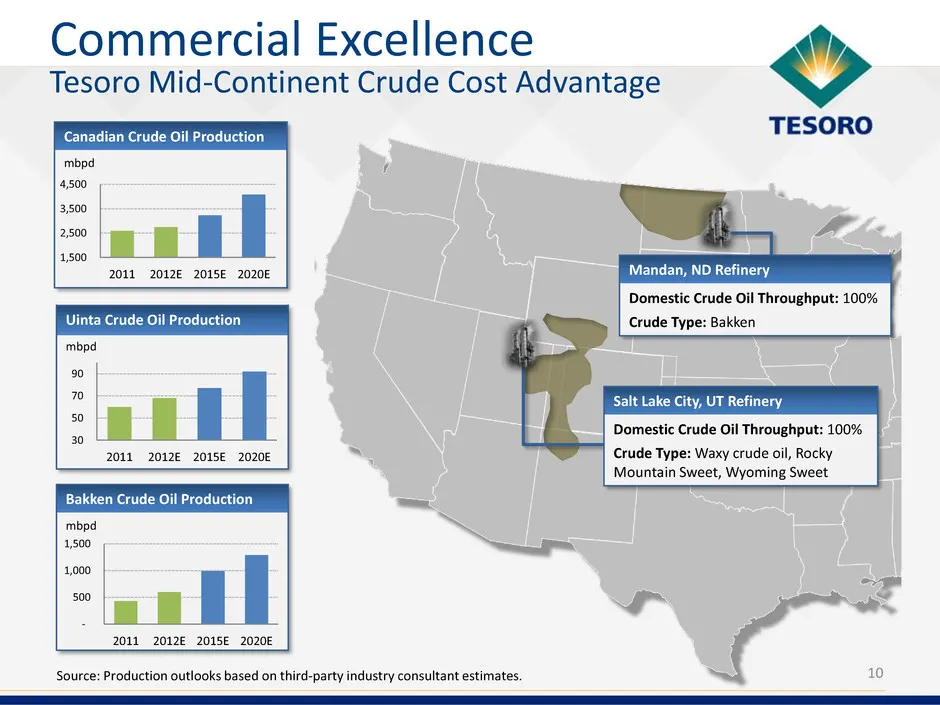
Slide 10: Tesoro Mid-Continent Crude Cost Advantage
Uinta Crude Oil Production mbpd Bakken Crude Oil Production mbpd - 500 1,000 1,500 2011 2012E 2015E 2020E Canadian Crude Oil Production mbpd 30 50 70 90 2011 2012E 2015E 2020E 10 Mandan, ND Refinery Domestic Crude Oil Throughput: 100% Crude Type: Bakken Salt Lake City, UT Refinery Domestic Crude Oil
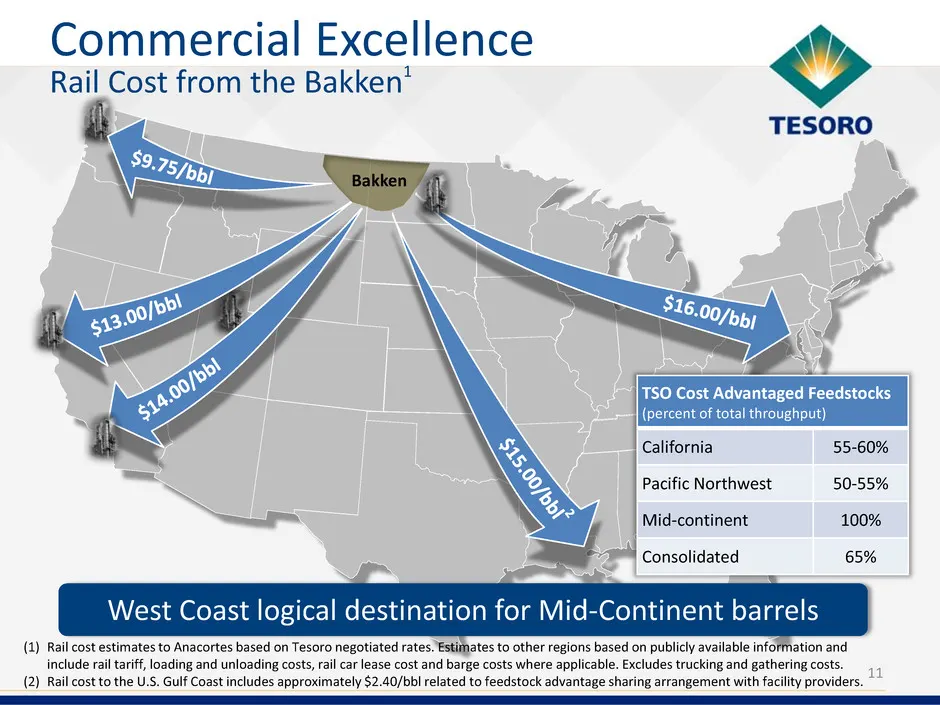
Slide 11: Bakken Rail Cost
Bakken Commercial Excellence Rail Cost from the Bakken1 West Coast logical destination for Mid-Continent barrels 11 (1) Rail cost estimates to Anacortes based on Tesoro negotiated rates. Estimates to other regions based on publicly available information and include rail tariff, loading and unloading
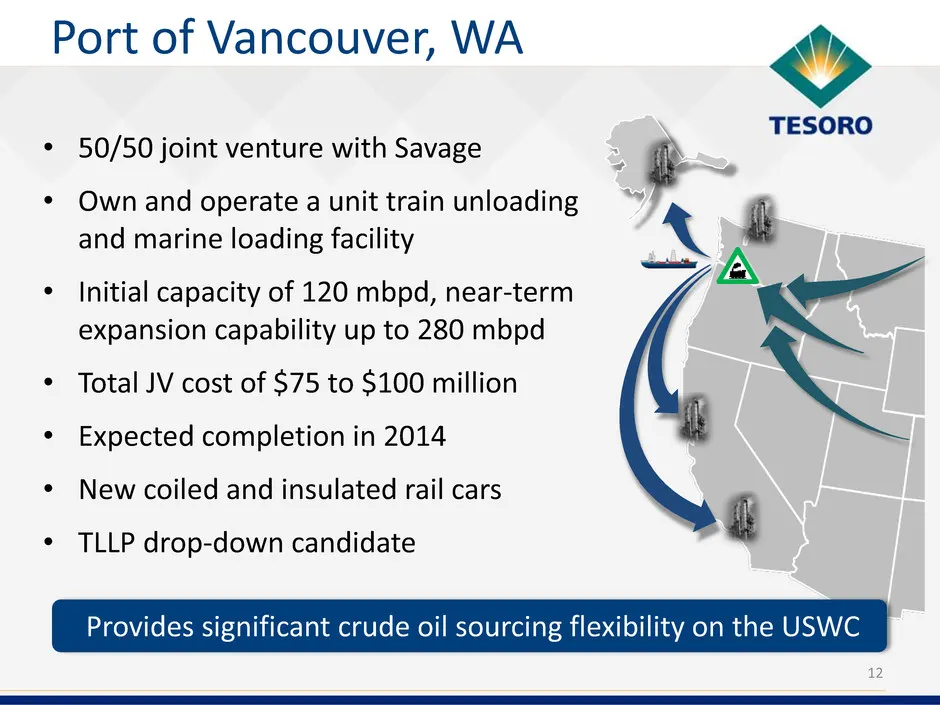
Slide 12: Port of Vancouver, WA
12 Port of Vancouver, WA • 50/50 joint venture with Savage • Own and operate a unit train unloading and marine loading facility • Initial capacity of 120 mbpd, near-term expansion capability up to 280 mbpd • Total JV cost of $75 to $100 million • Expected completion in 2014 • New coiled and insulate
Slide 13: Carson Acquisition
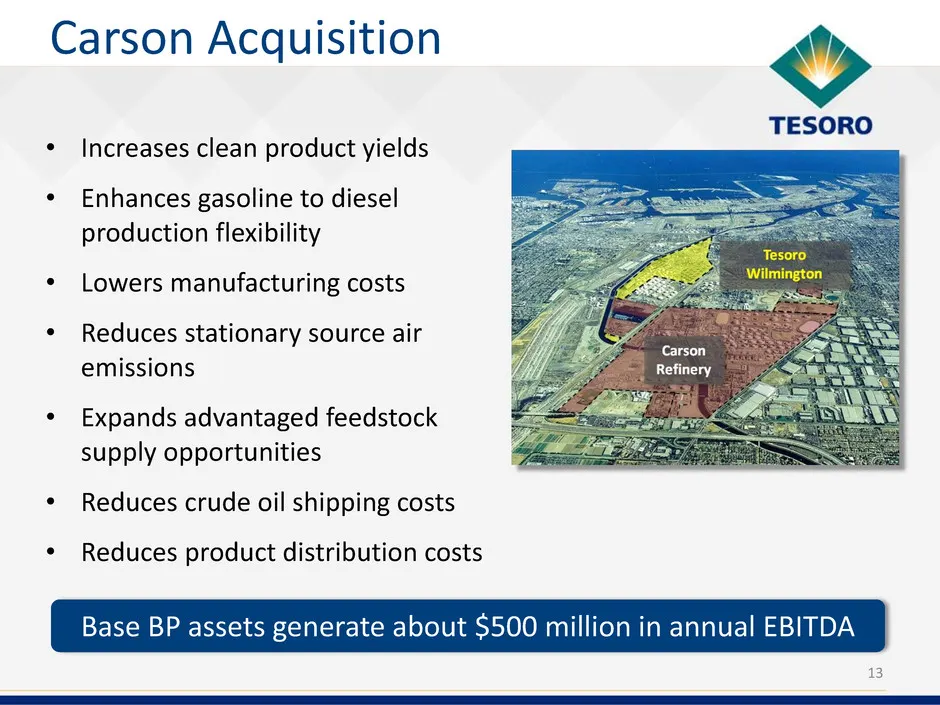
13 Carson Acquisition • Increases clean product yields • Enhances gasoline to diesel production flexibility • Lowers manufacturing costs • Reduces stationary source air emissions • Expands advantaged feedstock supply opportunities • Reduces crude oil shipping costs • Reduces product distribution cos
Slide 14: Carson Synergy Overview
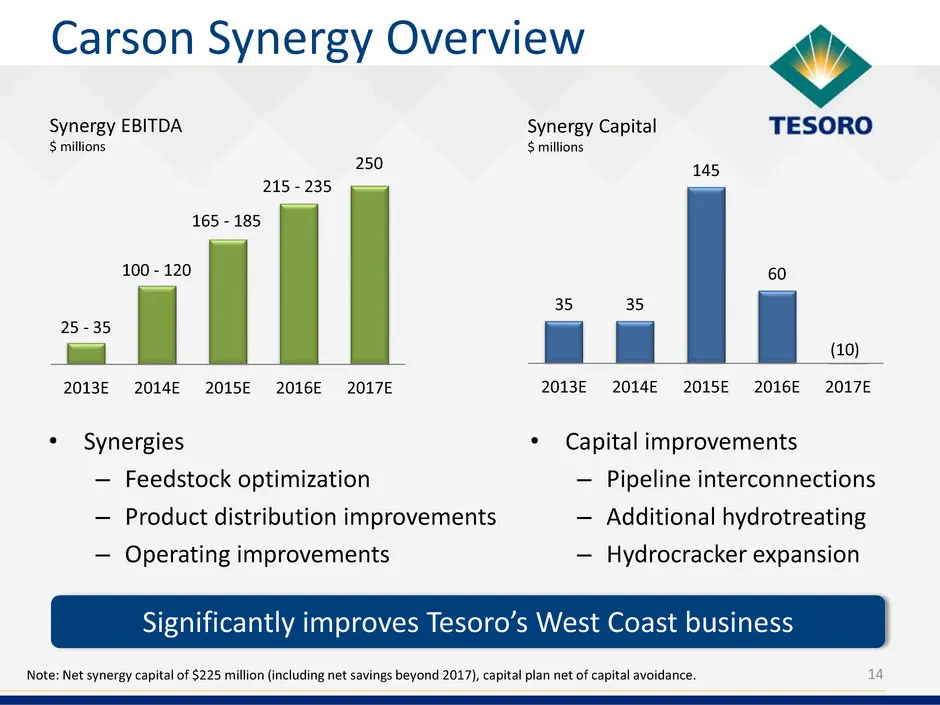
250 2013E 2014E 2015E 2016E 2017E Synergy EBITDA $ millions • Capital improvements – Pipeline interconnections – Additional hydrotreating – Hydrocracker expansion Synergy Capital $ millions 35 35 145 60 2013E 2014E 2015E 2016E 2017E Note: Net synergy capital of $225 million (including net savings be
Slide 15: California Regulatory Environment
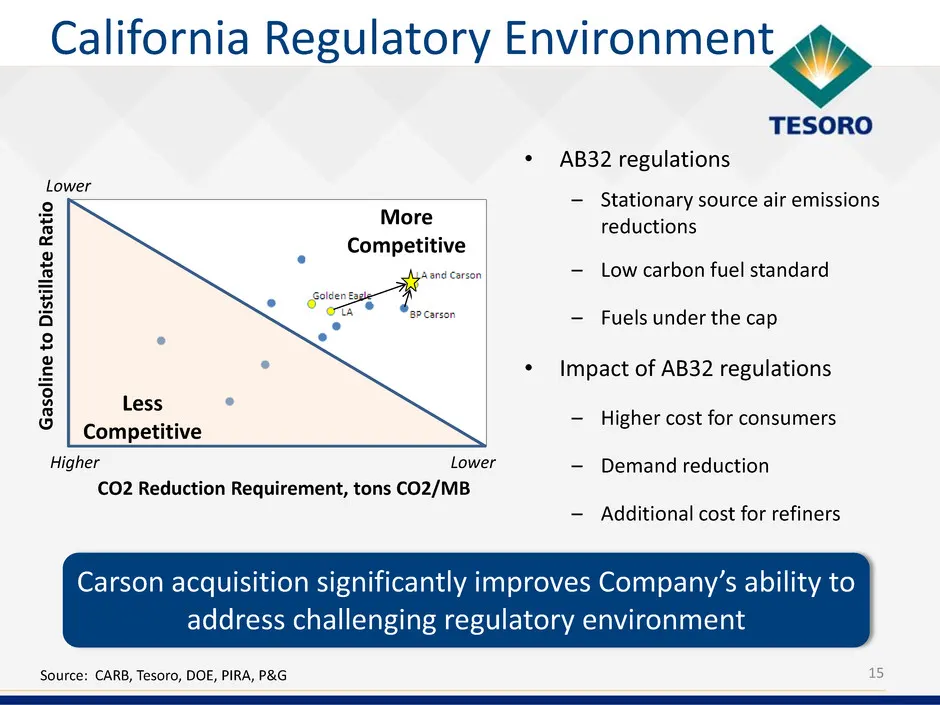
CO2 Reduction Requirement, tons CO2/MB Higher Lower G as o line t o D is ti lla te Rati o Lower More Competitive Less Competitive • AB32 regulations – Stationary source air emissions reductions – Low carbon fuel standard – Fuels under the cap • Impact of AB32 regulations – Higher cost for consumers
Slide 16: Success of Tesoro Logistics
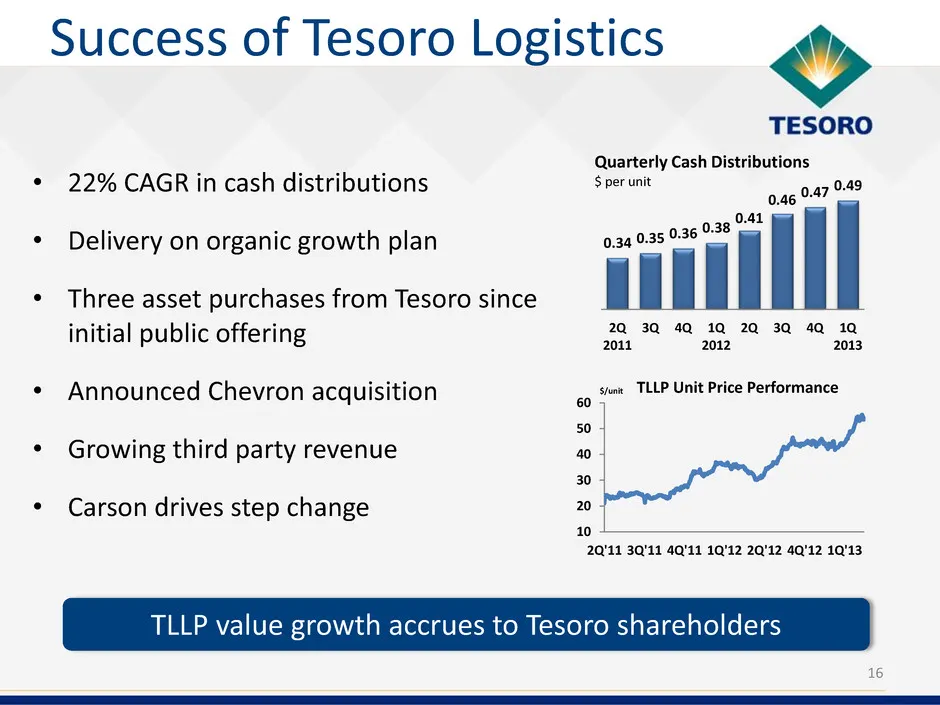
• 22% CAGR in cash distributions • Delivery on organic growth plan • Three asset purchases from Tesoro since initial public offering • Announced Chevron acquisition • Growing third party revenue • Carson drives step change 16 TLLP value growth accrues to Tesoro shareholders Success of Tesoro Logisti
Slide 17: Chevron Northwest Products System
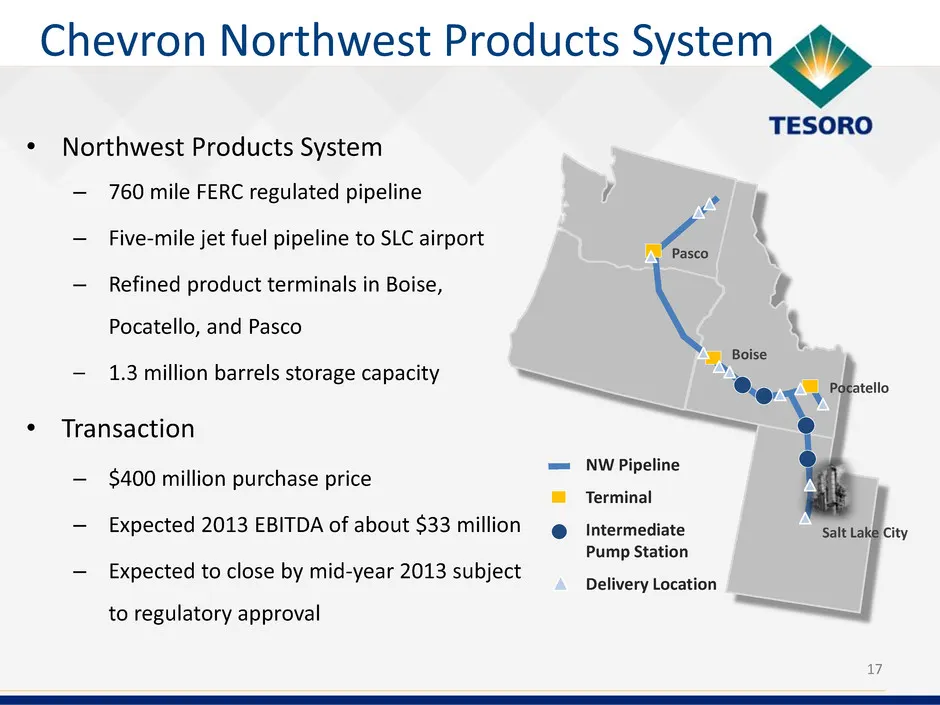
• Northwest Products System – 760 mile FERC regulated pipeline – Five-mile jet fuel pipeline to SLC airport – Refined product terminals in Boise, Pocatello, and Pasco – 1.3 million barrels storage capacity • Transaction – $400 million purchase price – Expected 2013 EBITDA of about $33 million – Expe
Slide 18: TLLP and Carson Logistics
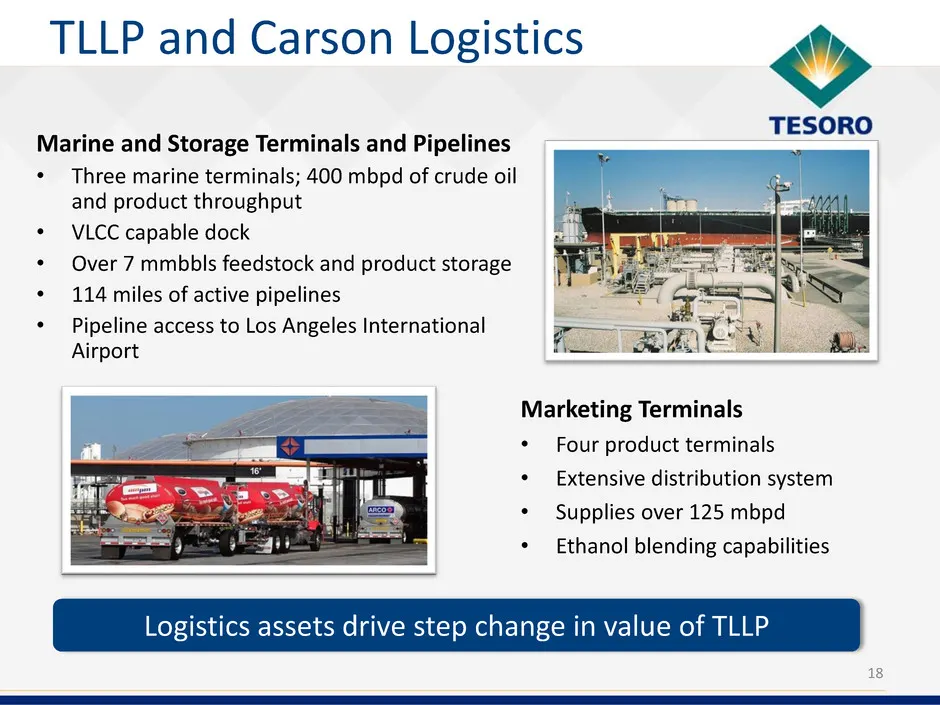
Marine and Storage Terminals and Pipelines • Three marine terminals; 400 mbpd of crude oil and product throughput • VLCC capable dock • Over 7 mmbbls feedstock and product storage • 114 miles of active pipelines • Pipeline access to Los Angeles International Airport Marketing Terminals • Four produc
Slide 19: Tesoro Benefits From TLLP's Growth
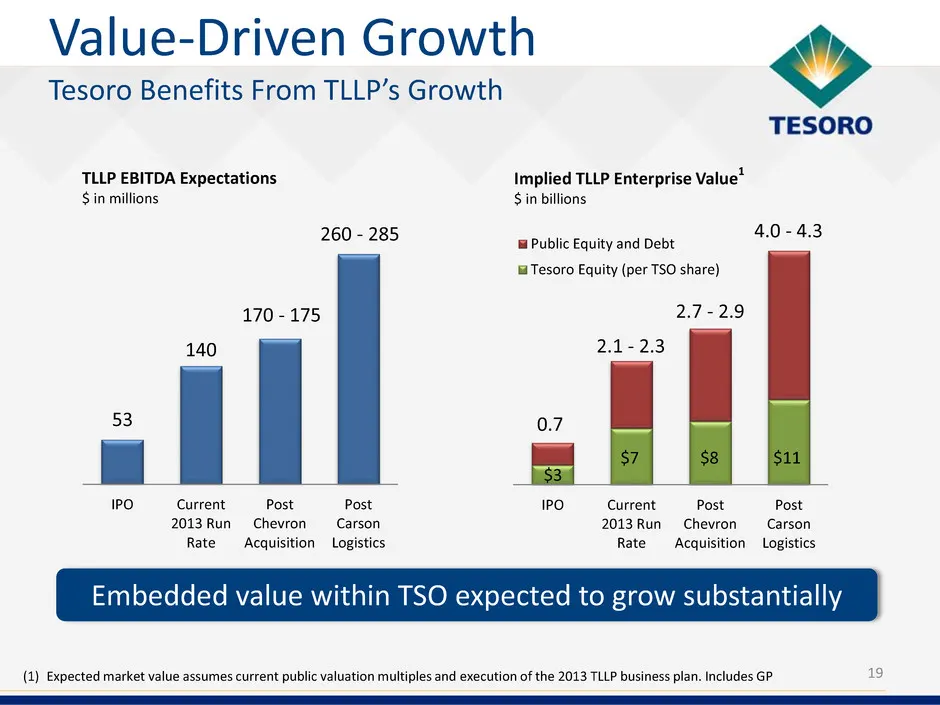
19 Embedded value within TSO expected to grow substantially Value-Driven Growth Tesoro Benefits From TLLP’s Growth Implied TLLP Enterprise Value1 $ in billions (1) Expected market value assumes current public valuation multiples and execution of the 2013 TLLP business plan. Includes GP TLLP EBITDA E
Slide 20: Financial Priorities
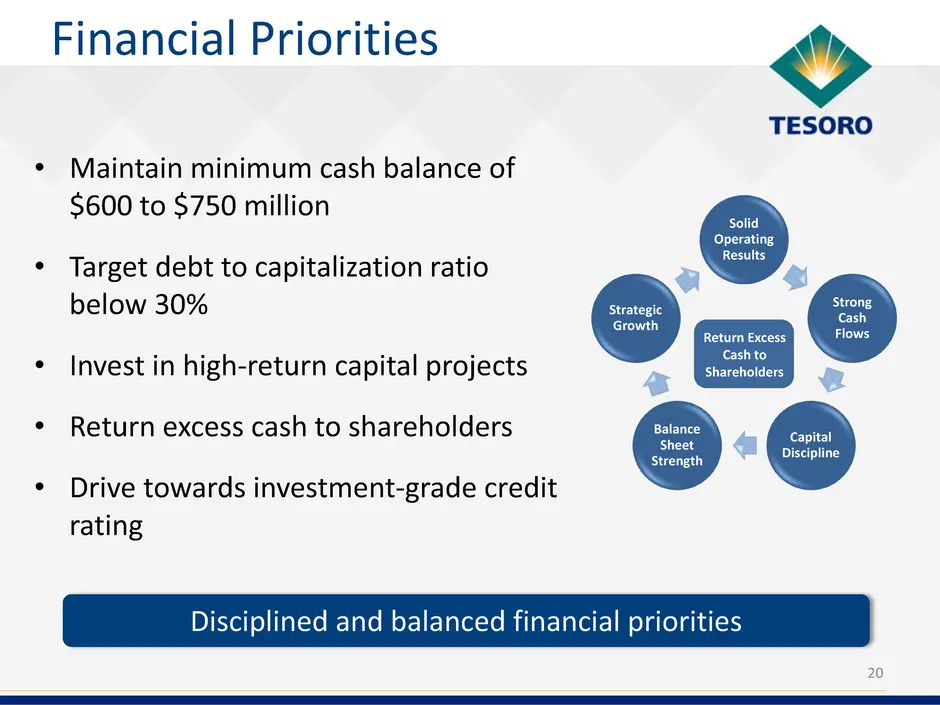
Solid Operating Results Strong Cash Flows Capital Discipline Balance Sheet Strength Strategic Growth • Maintain minimum cash balance of $600 to $750 million • Target debt to capitalization ratio below 30% • Invest in high-return capital projects • Return excess cash to shareholders • Drive towards i
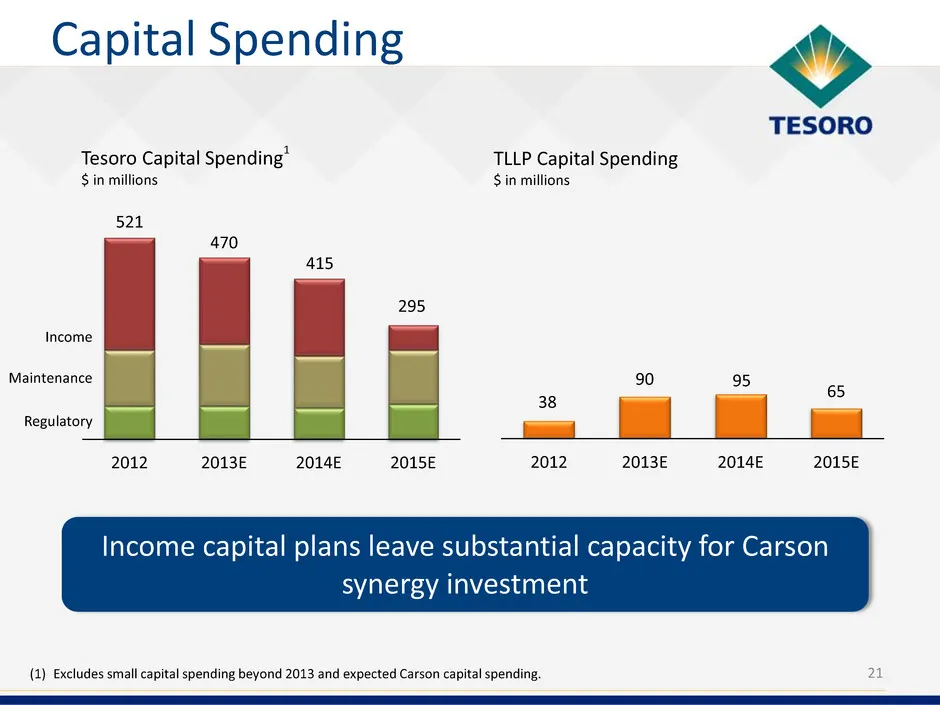
Slide 21: Capital Spending
2012 2013E 2014E 2015E Capital Spending 21 Tesoro Capital Spending 1 $ in millions 521 470 415 295 Regulatory Maintenance Income 38 90 95 65 2012 2013E 2014E 2015E TLLP Capital Spending $ in millions Income capital plans leave substantial capacity for Carson synergy investment (1) Excludes small cap
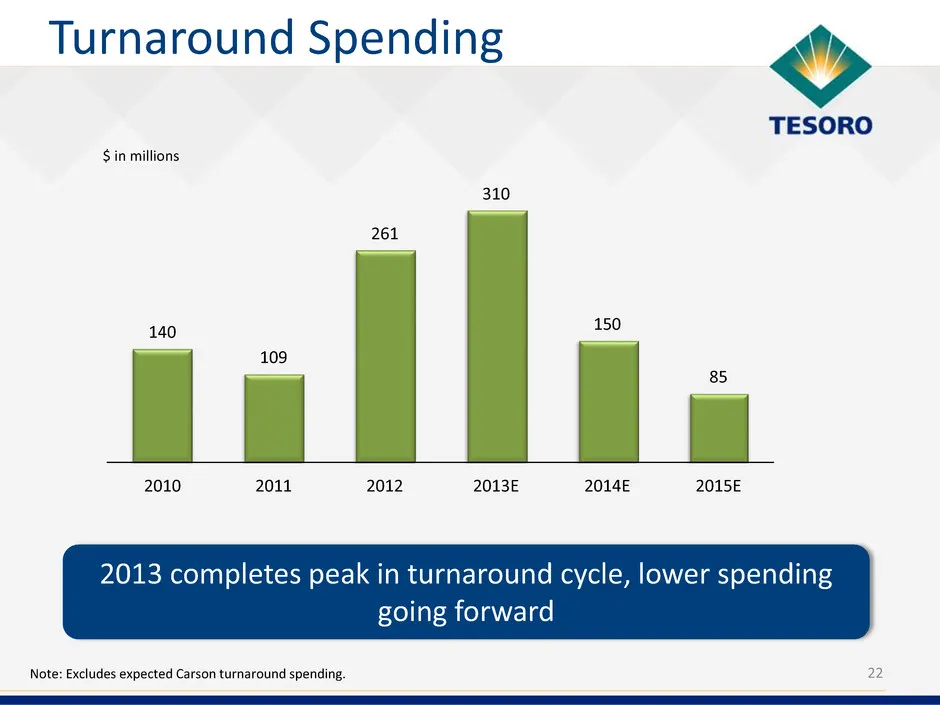
Slide 22: Turnaround Spending
140 109 261 310 150 85 2010 2011 2012 2013E 2014E 2015E Turnaround Spending 22 $ in millions 2013 completes peak in turnaround cycle, lower spending going forward Note: Excludes expected Carson turnaround spending.
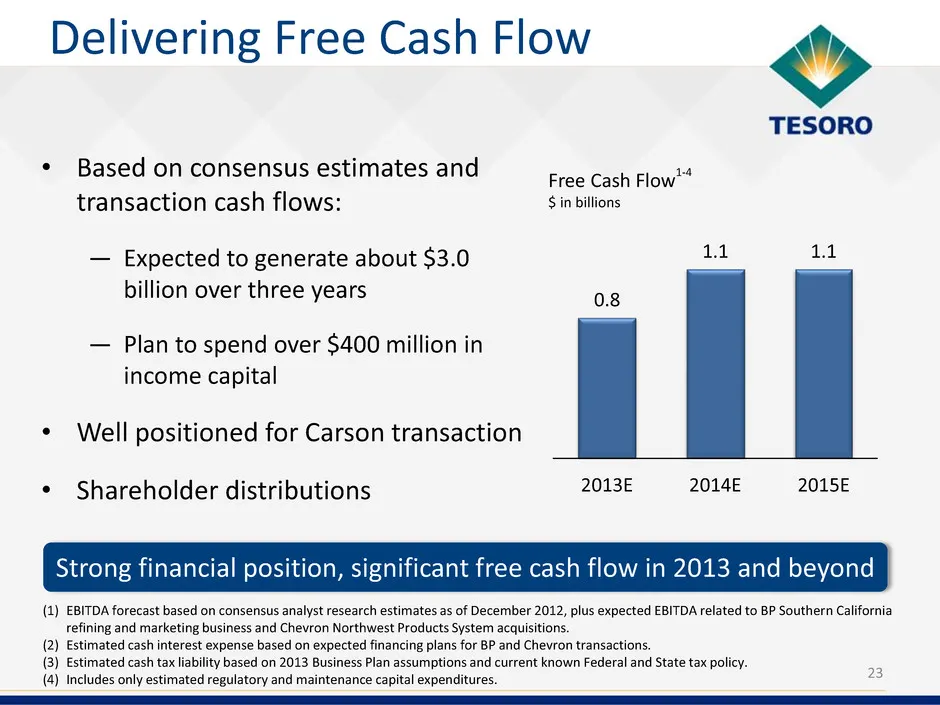
Slide 23: Delivering Free Cash Flow
0.8 1.1 1.1 2013E 2014E 2015E 23 Free Cash Flow 1-4 $ in billions • Based on consensus estimates and transaction cash flows: — Expected to generate about $3.0 billion over three years — Plan to spend over $400 million in income capital • Well positioned for Carson transaction • Shareholder distribut
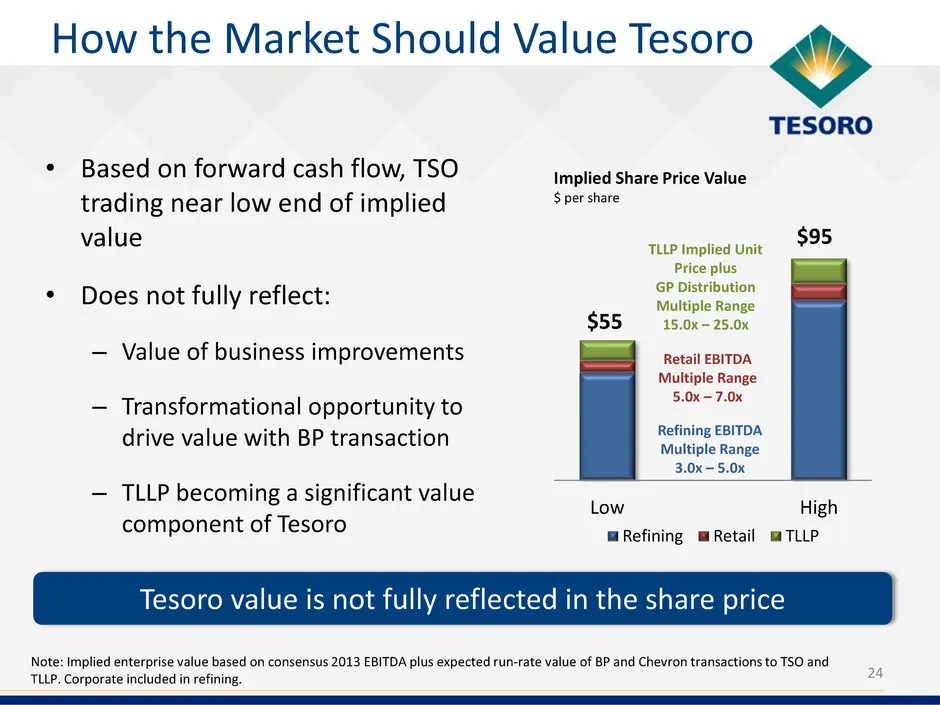
Slide 24: How the Market Should Value Tesoro
24 Tesoro value is not fully reflected in the share price How the Market Should Value Tesoro Note: Implied enterprise value based on consensus 2013 EBITDA plus expected run-rate value of BP and Chevron transactions to TSO and TLLP. Corporate included in refining. • Based on forward cash flow, TSO tr
Slide 25: Appendix
TESORO Appendix
Slide 26: Mandan Refinery Expansion
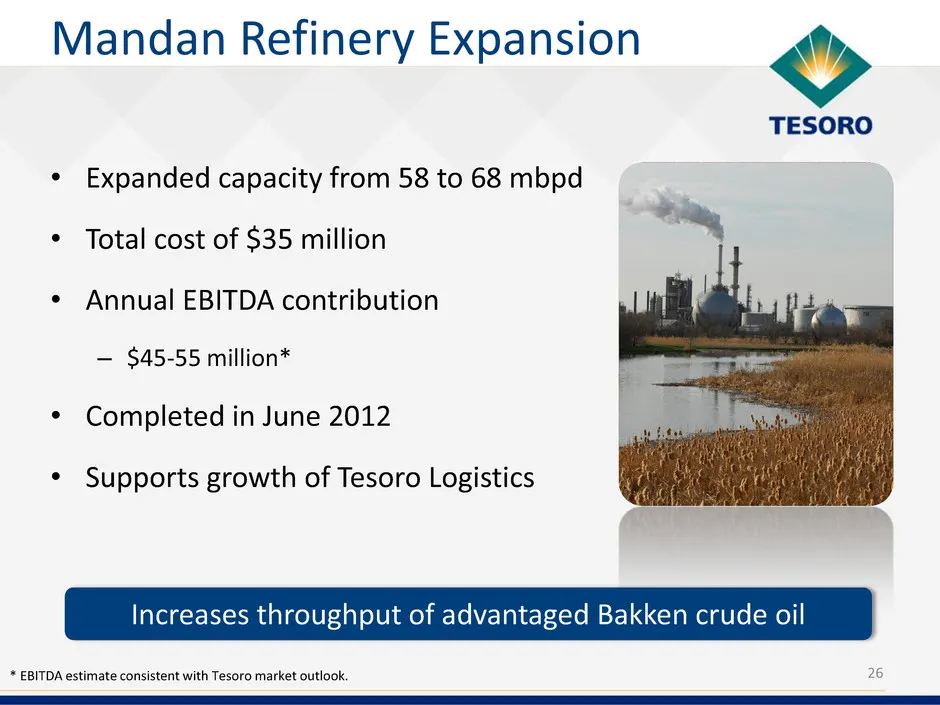
• Expanded capacity from 58 to 68 mbpd • Total cost of $35 million • Annual EBITDA contribution – $45-55 million* • Completed in June 2012 • Supports growth of Tesoro Logistics 26 Mandan Refinery Expansion Increases throughput of advantaged Bakken crude oil * EBITDA estimate consistent with Tesoro m
Slide 27: Bakken Crude Oil Supply to Anacortes
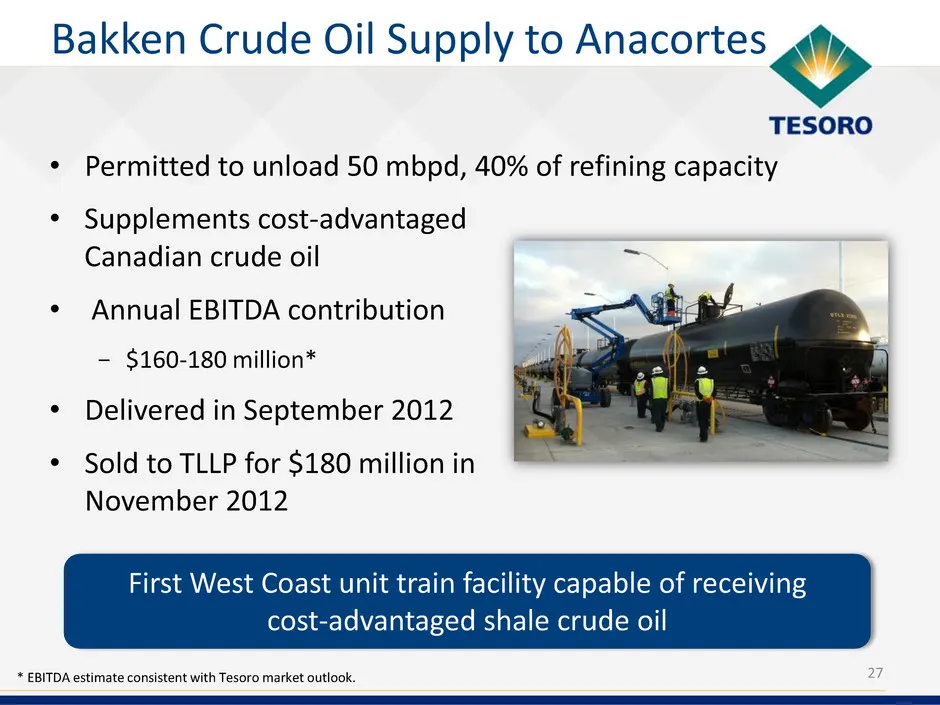
• Permitted to unload 50 mbpd, 40% of refining capacity 27 Bakken Crude Oil Supply to Anacortes • Supplements cost-advantaged Canadian crude oil • Annual EBITDA contribution - $160-180 million* • Delivered in September 2012 • Sold to TLLP for $180 million in November 2012 First West Coast unit train
Slide 28: Wilmington Yield Improvement
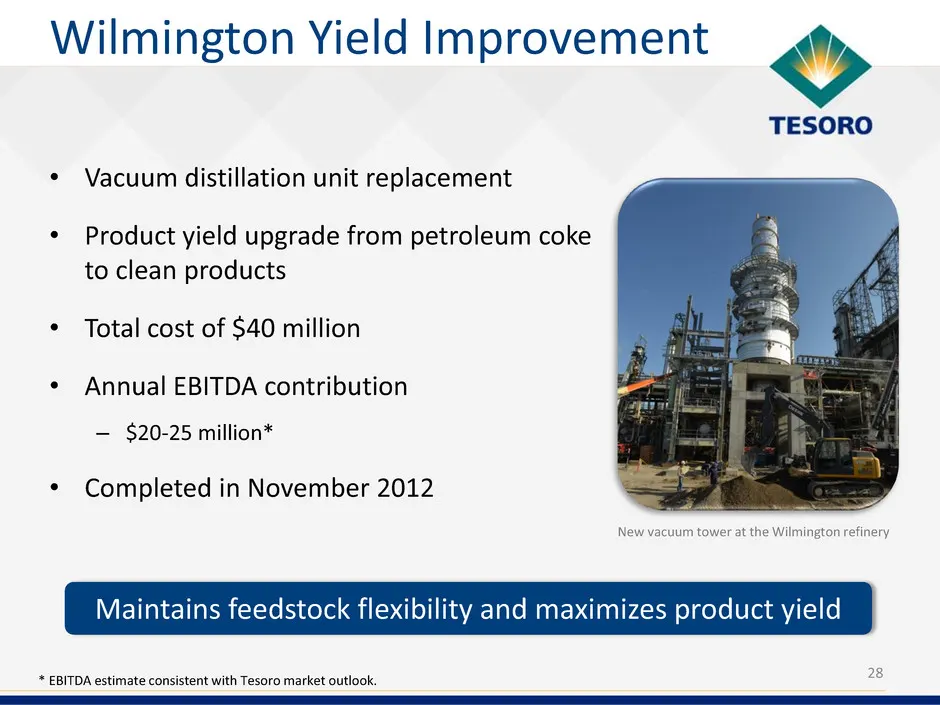
• Vacuum distillation unit replacement • Product yield upgrade from petroleum coke to clean products • Total cost of $40 million • Annual EBITDA contribution – $20-25 million* • Completed in November 2012 28 Wilmington Yield Improvement Maintains feedstock flexibility and maximizes product yield * E
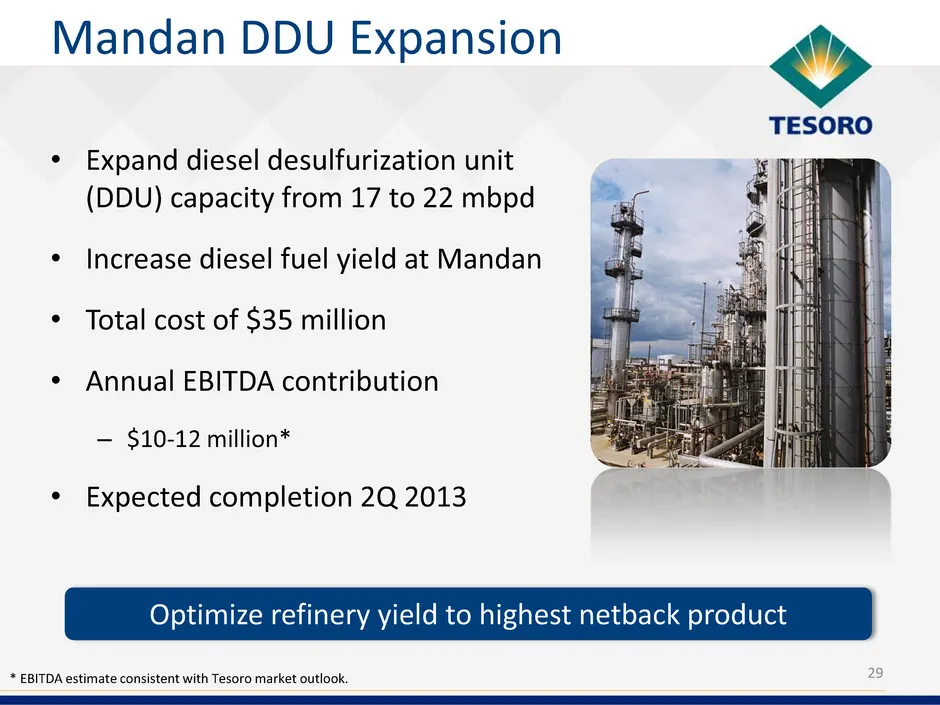
Slide 29: Mandan DDU Expansion
• Expand diesel desulfurization unit (DDU) capacity from 17 to 22 mbpd • Increase diesel fuel yield at Mandan • Total cost of $35 million • Annual EBITDA contribution – $10-12 million* • Expected completion 2Q 2013 29 Mandan DDU Expansion Optimize refinery yield to highest netback product * EBITDA e
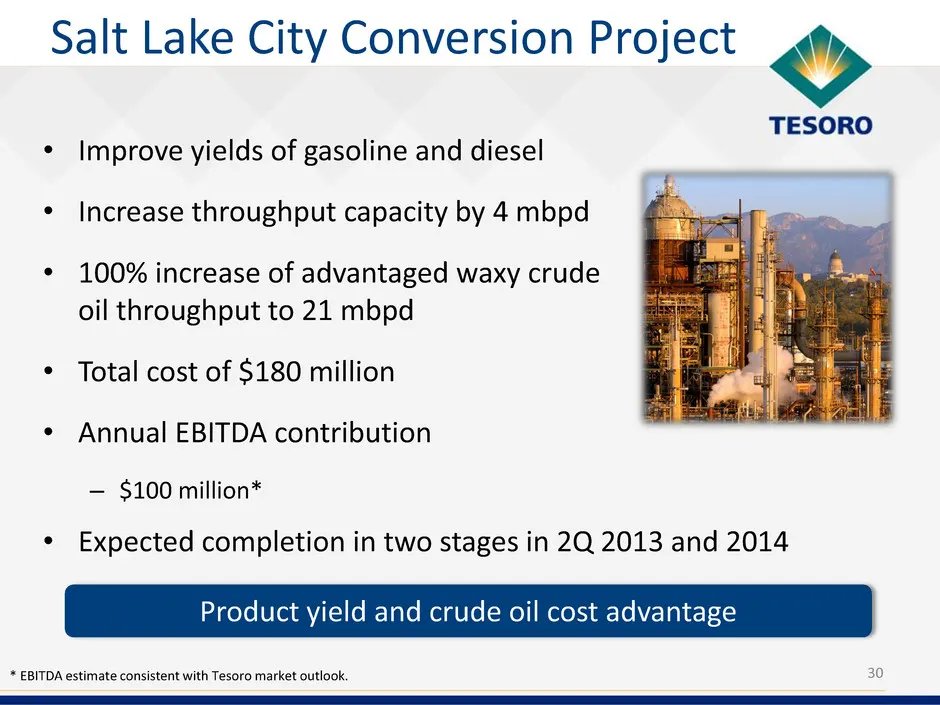
Slide 30: Salt Lake City Conversion Project
30 Salt Lake City Conversion Project • Improve yields of gasoline and diesel • Increase throughput capacity by 4 mbpd • 100% increase of advantaged waxy crude oil throughput to 21 mbpd • Total cost of $180 million • Annual EBITDA contribution – $100 million* Product yield and crude oil cost advantag
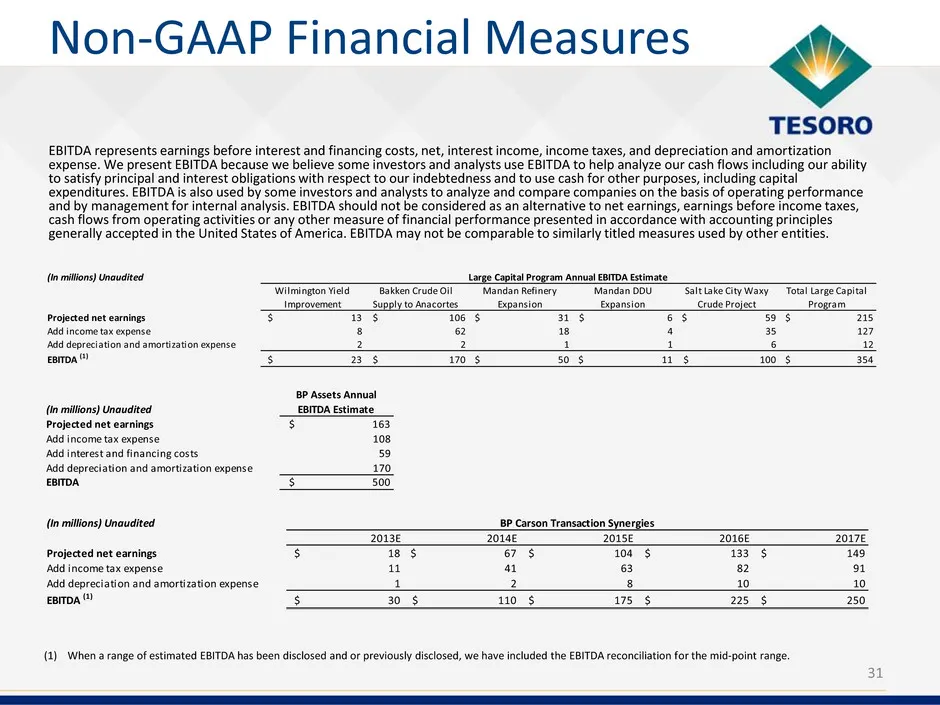
Slide 31: Non-GAAP Financial Measures
31 Non-GAAP Financial Measures EBITDA represents earnings before interest and financing costs, net, interest income, income taxes, and depreciation and amortization expense. We present EBITDA because we believe some investors and analysts use EBITDA to help analyze our cash flows including our abili
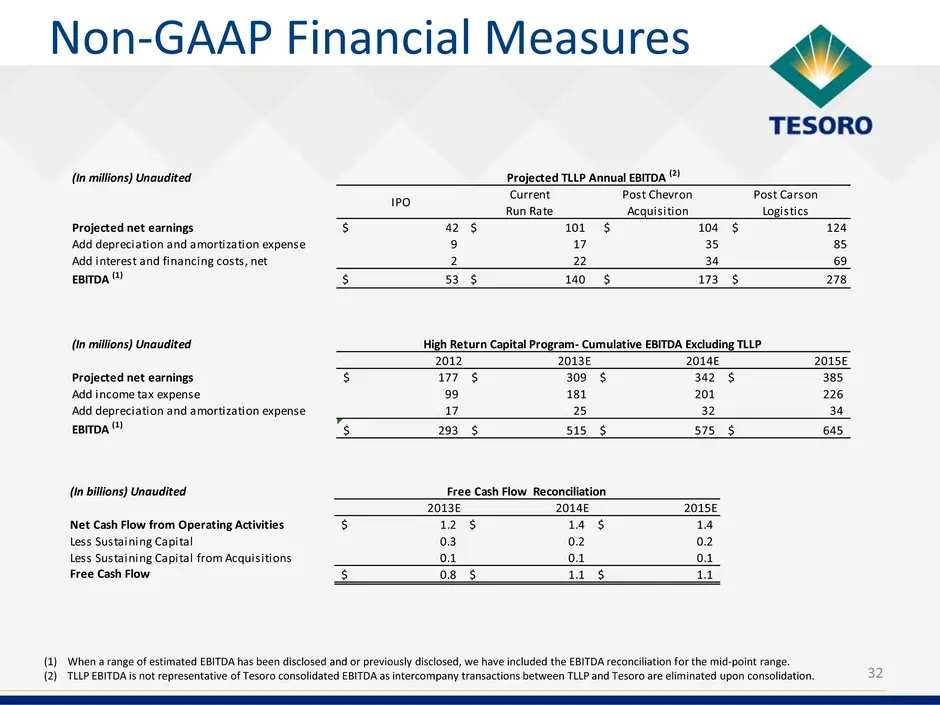
Slide 32: Non-GAAP Financial Measures
32 Non-GAAP Financial Measures (1) When a range of estimated EBITDA has been disclosed and or previously disclosed, we have included the EBITDA reconciliation for the mid-point range. (2) TLLP EBITDA is not representative of Tesoro consolidated EBITDA as intercompany transactions between TLLP and Te
Source: SEC EDGAR · 8-K filed May 8, 2013
More decks from Andeavor
 Barclays CEO Energy-Power Conference 201896 slides · Sep 5, 2018
 Merger or Acquisition (June 2018)34 slides · Jun 6, 2018
 Merger or Acquisition (May 2018)10 slides · May 10, 2018
 Merger or Acquisition (April 2018)25 slides · Apr 30, 2018
 2018 Wolfe Research 4th Annual Refiners Conference37 slides · Jan 3, 2018
 Tesoro Corp /New/ — Investor Day (December 2015)84 slides · Dec 9, 2015