Kingfisher PLC · LSE:KGF
Kingfisher — H1 2013/14 Earnings Presentation
56 slides from Kingfisher's earnings presentation, September 2013
Slide 1: Kingfisher plc Interim Results
Kingfisher plc Interim Results Half year ended 3 August 2013
Slide 2: Disclaimer
Disclaimer THE FOLLOWING PRESENTATION IS BEING MADE ONLY TO, AND IS ONLY DIRECTED AT, PERSONS TO WHOM SUCH PRESENTATION MAY LAWFULLY BE COMMUNICATED (‘RELEVANT PERSONS’). ANY PERSON WHO IS NOT A RELEVANT PERSON SHOULD NOT ACT OR RELY ON THIS PRESENTATION OR ANY OF ITS CONTENTS. THIS PRESENTATION DOE
Slide 3: Ian Cheshire, Group Chief Executive
Ian Cheshire Group Chief Executive
Slide 4: Agenda
Agenda Introduction Ian Cheshire Chief Executive Financial review Karen Witts Finance Director Creating the Leader Ian Cheshire Chief Executive Steve Willett CEO Group Productivity & Development Guy Colleau CEO Group Sourcing & Offer Questions 4
Slide 5: 2013/14 H1 Summary
2013/14 H1 Summary H1 a challenging and volatile 6 months ● On-going weak consumer confidence in our major markets ● Q1/Q2 weather patterns – Sales of outdoor products down 10% in Q1; up 9% in Q2 – Retail profit down 29.2% in Q1; up 10.8% in Q2 £145m provision release from resolution of French tax c
Slide 6: UK and France – two different stories over the last 5 years
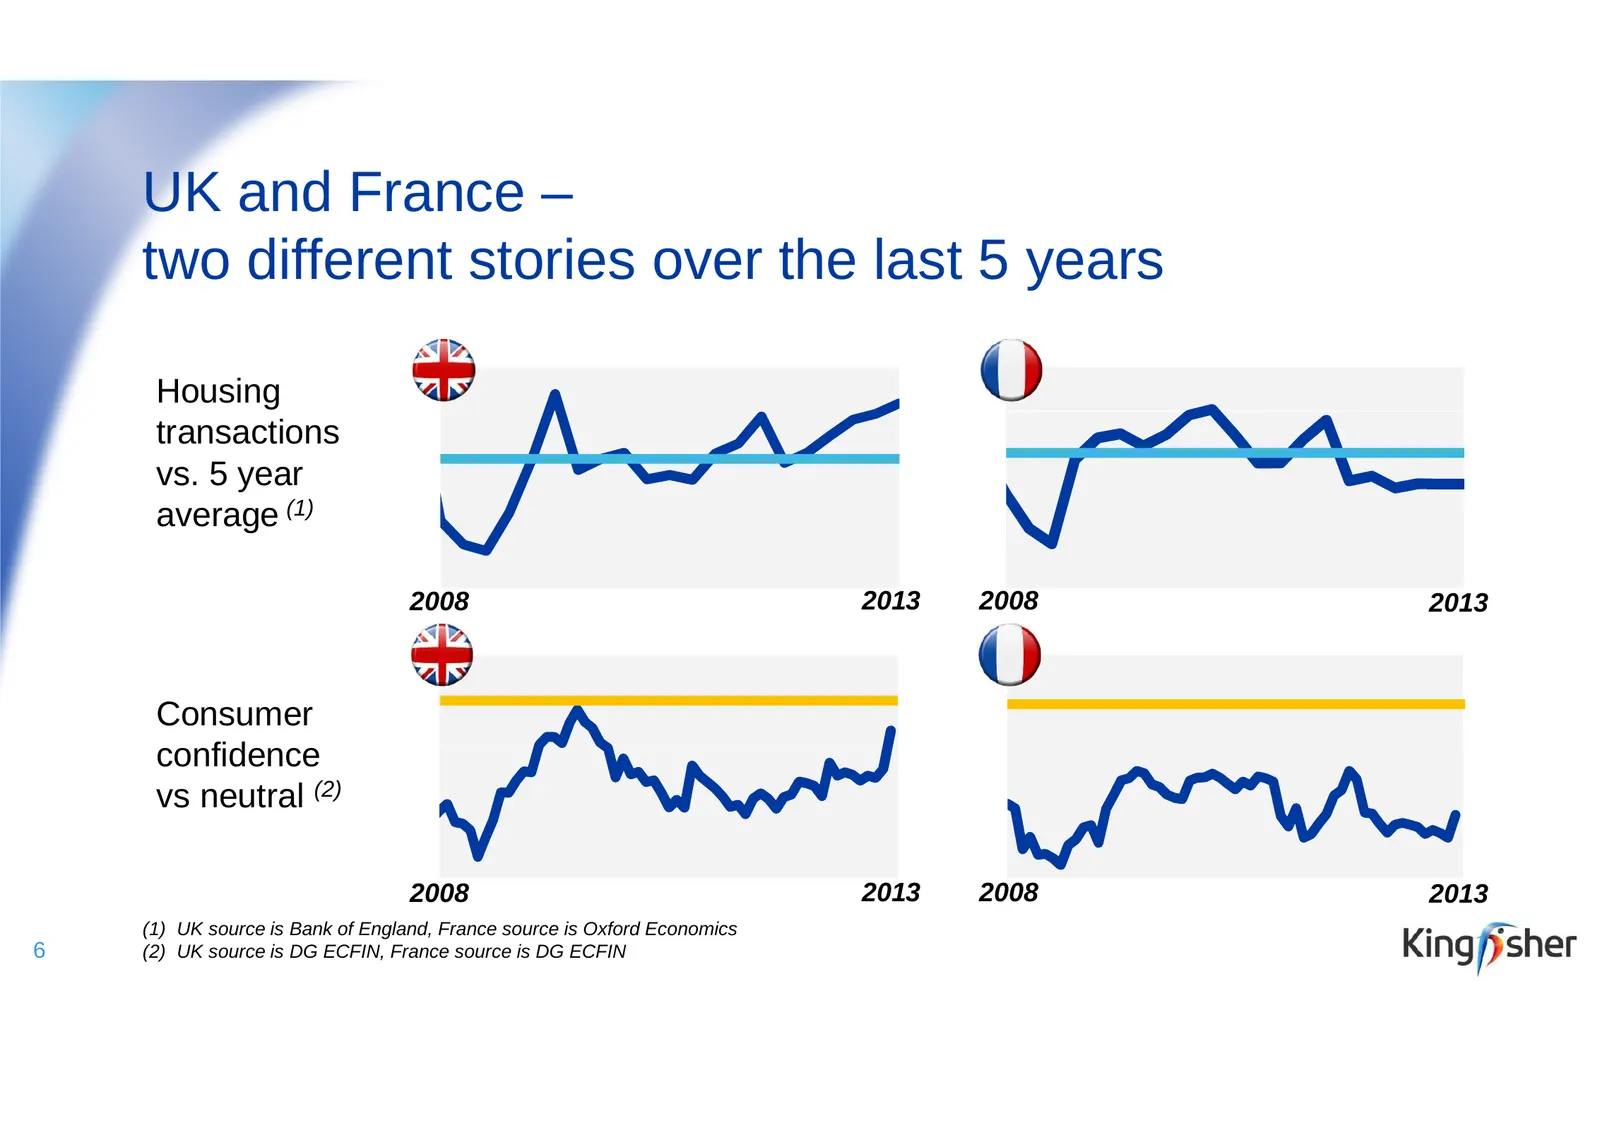
UK and France – two different stories over the last 5 years Housing transactions vs. 5 year average (1) 2008 2013 2008 2013 Consumer confidence vs neutral (2) 2008 2013 2008 2013 (1) UK source is Bank of England, France source is Oxford Economics 6 (2) UK source is DG ECFIN, France source is DG ECFI
Slide 7: Karen Witts, Group Finance Director
Karen Witts Group Finance Director
Slide 8: Financial summary
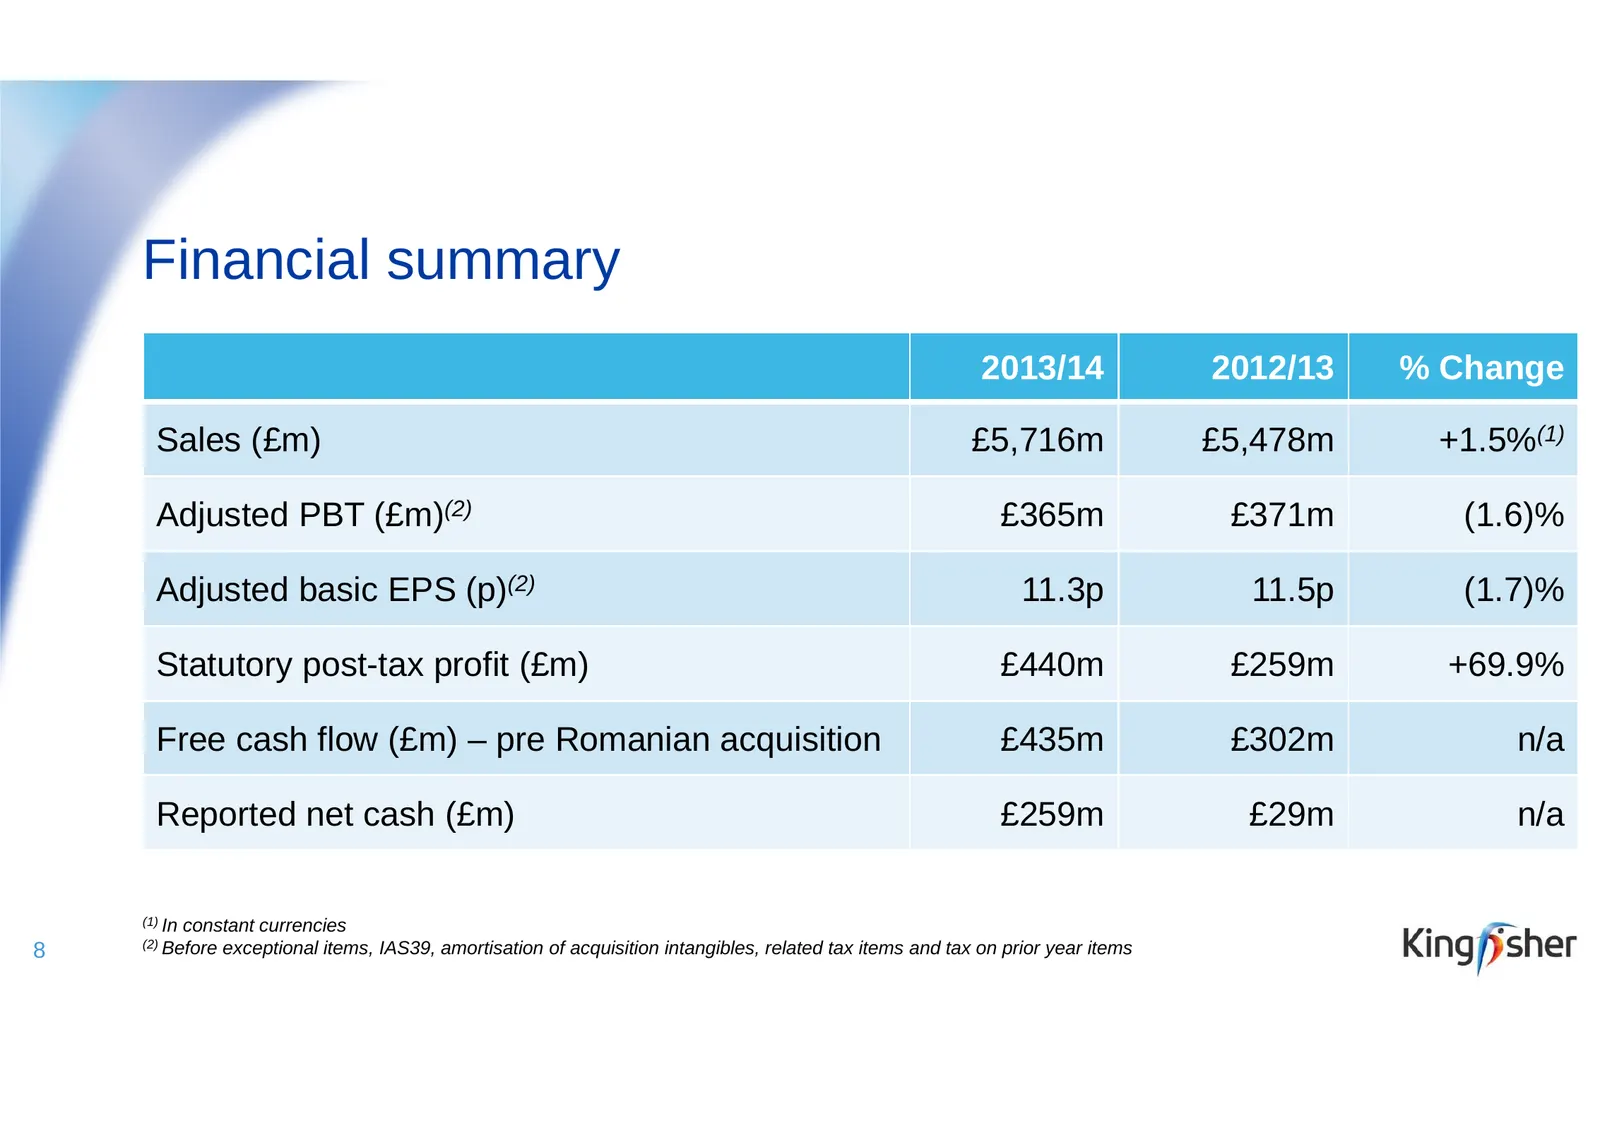
Financial summary 2013/14 2012/13 % Change Sales (£m) £5,716m £5,478m +1.5%(1) Adjusted PBT (£m)(2) £365m £371m (1.6)% Adjusted basic EPS (p)(2) 11.3p 11.5p (1.7)% Statutory post-tax profit (£m) £440m £259m +69.9% Free cash flow (£m) – pre Romanian acquisition £435m £302m n/a Reported net cash (£m)
Slide 9: Financial summary continued
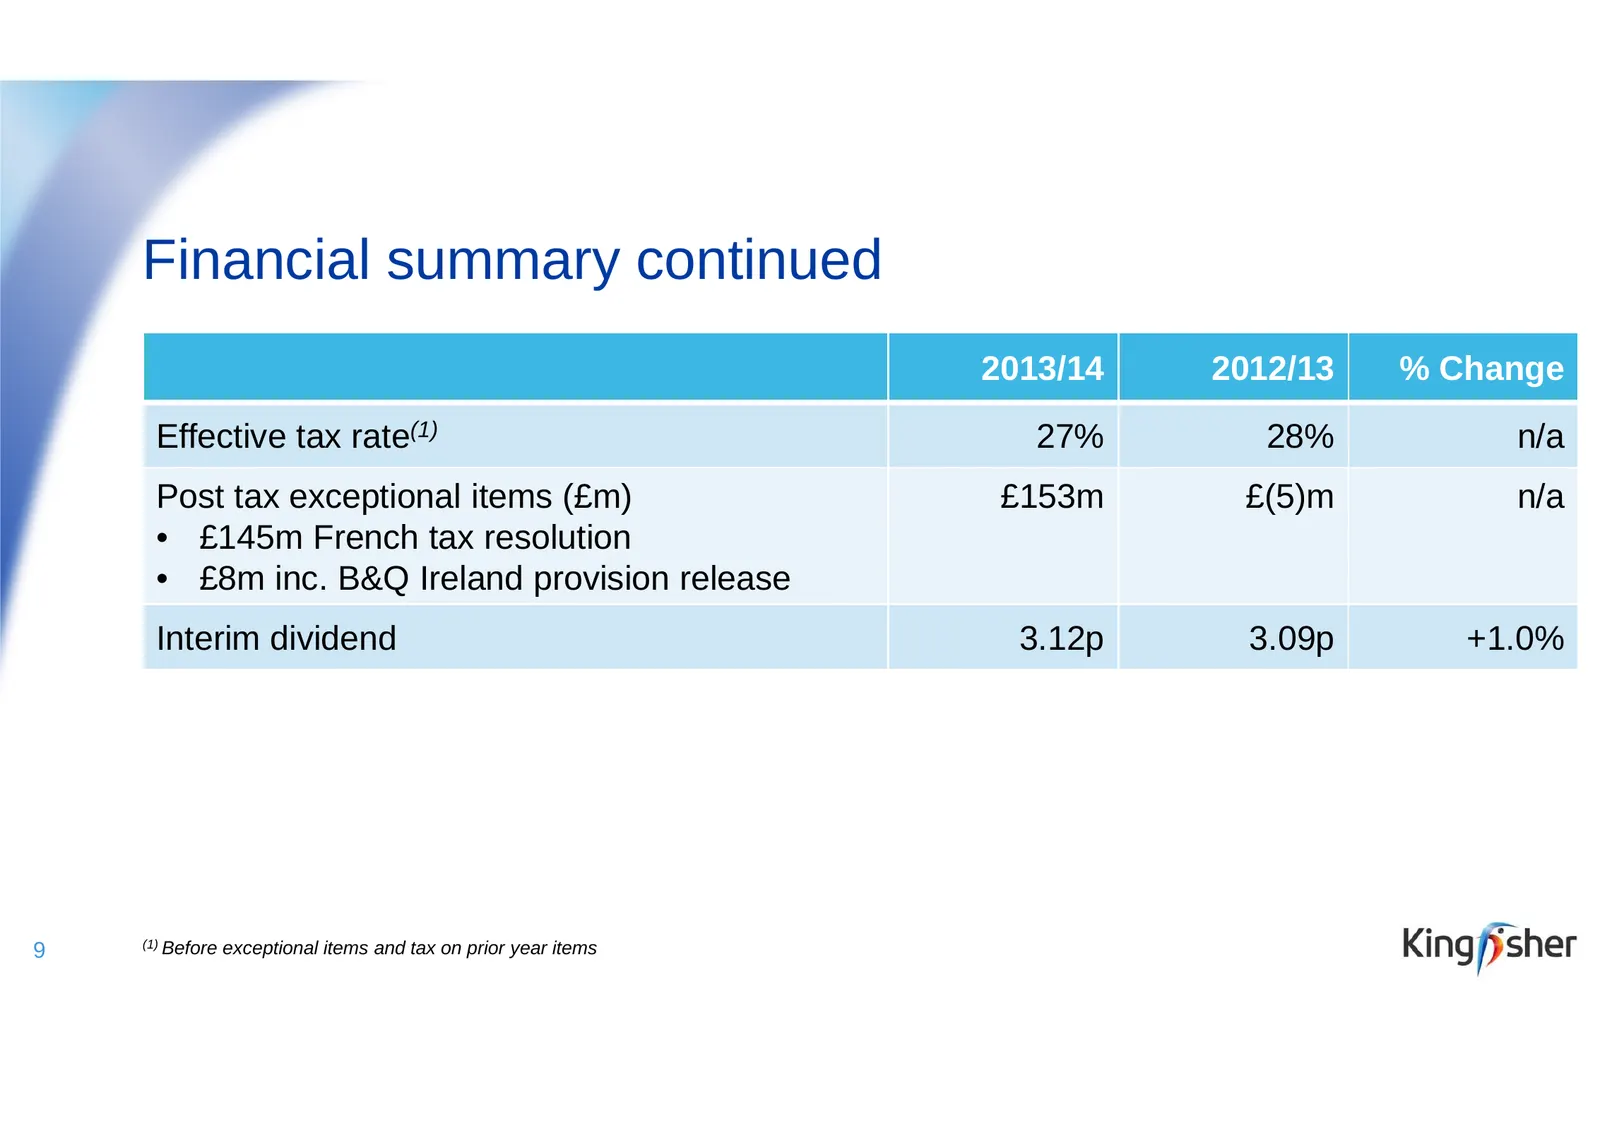
Financial summary continued 2013/14 2012/13 % Change Effective tax rate(1) 27% 28% n/a Post tax exceptional items (£m) £153m £(5)m n/a • £145m French tax resolution • £8m inc. B&Q Ireland provision release Interim dividend 3.12p 3.09p +1.0% (1) Before exceptional items and tax on prior year items 9
Slide 10: France – performing well in soft markets
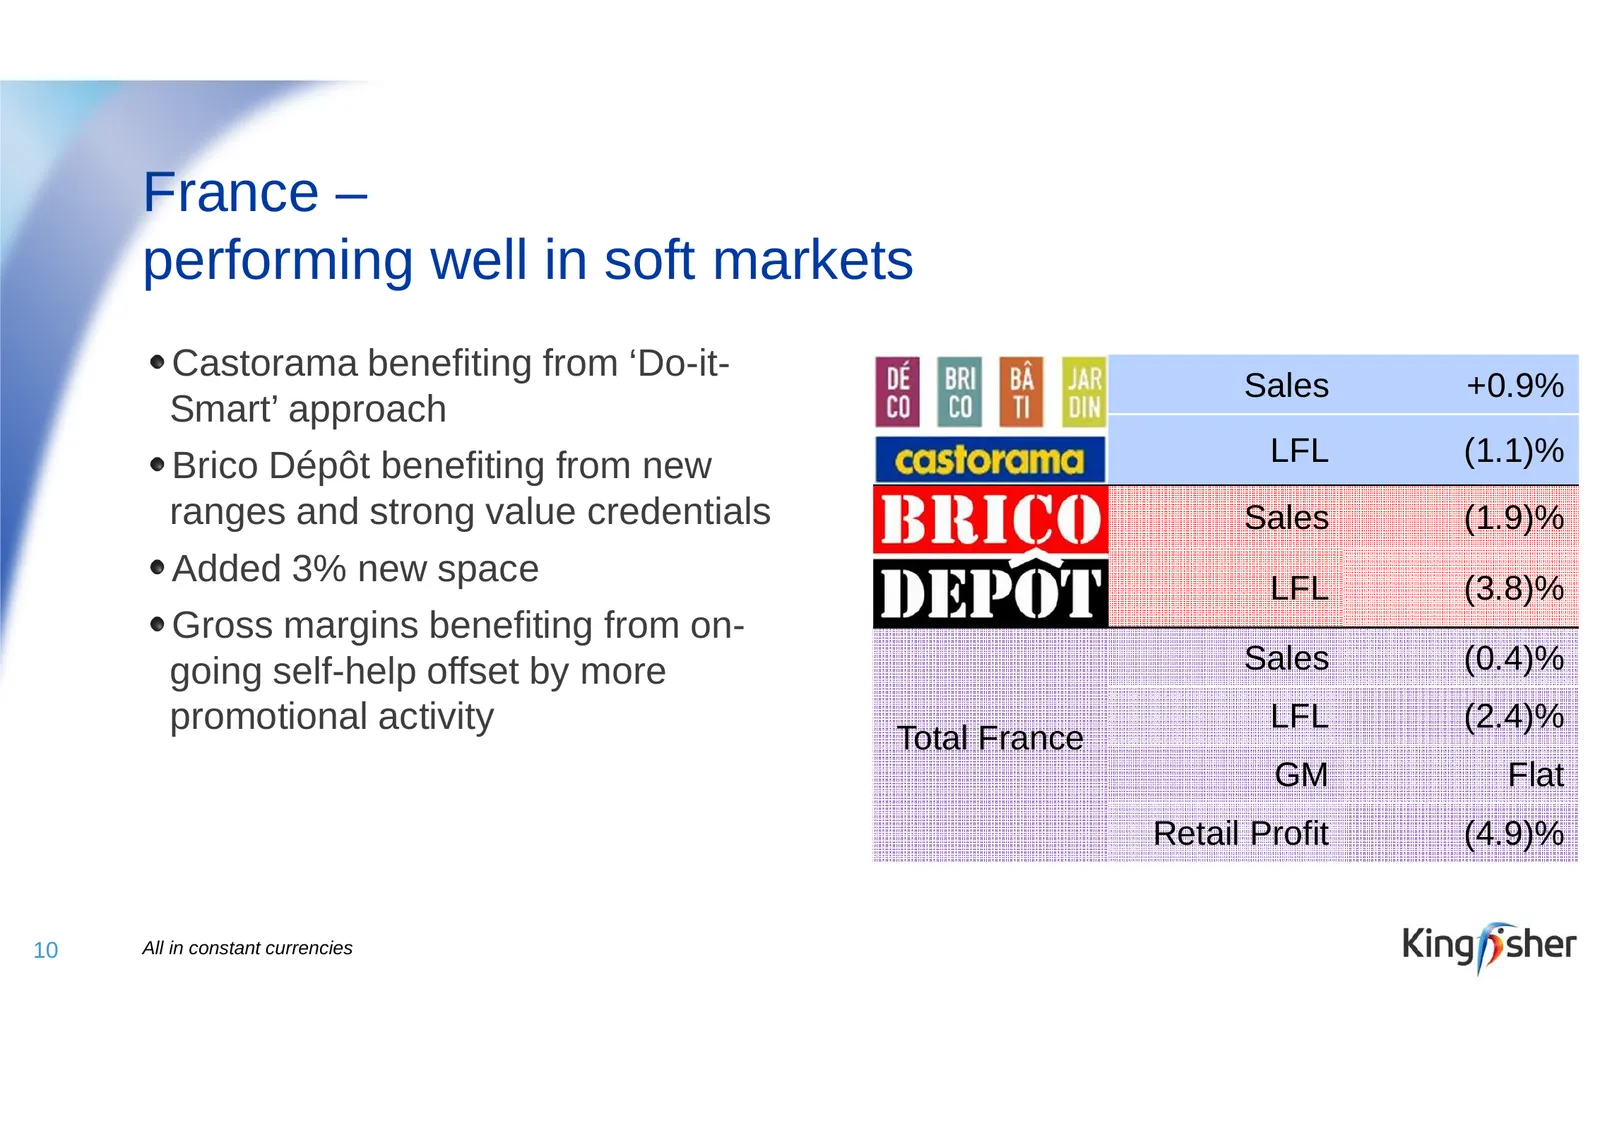
France – performing well in soft markets Castorama benefiting from ‘Do-it- Sales +0.9% Smart’ approach Brico Dépôt benefiting from new LFL (1.1)% ranges and strong value credentials Sales (1.9)% Added 3% new space LFL (3.8)% Gross margins benefiting from on- going self-help offset by more Sales (0.4
Slide 11: UK & Ireland – H1 profits broadly flat despite challenging Q1
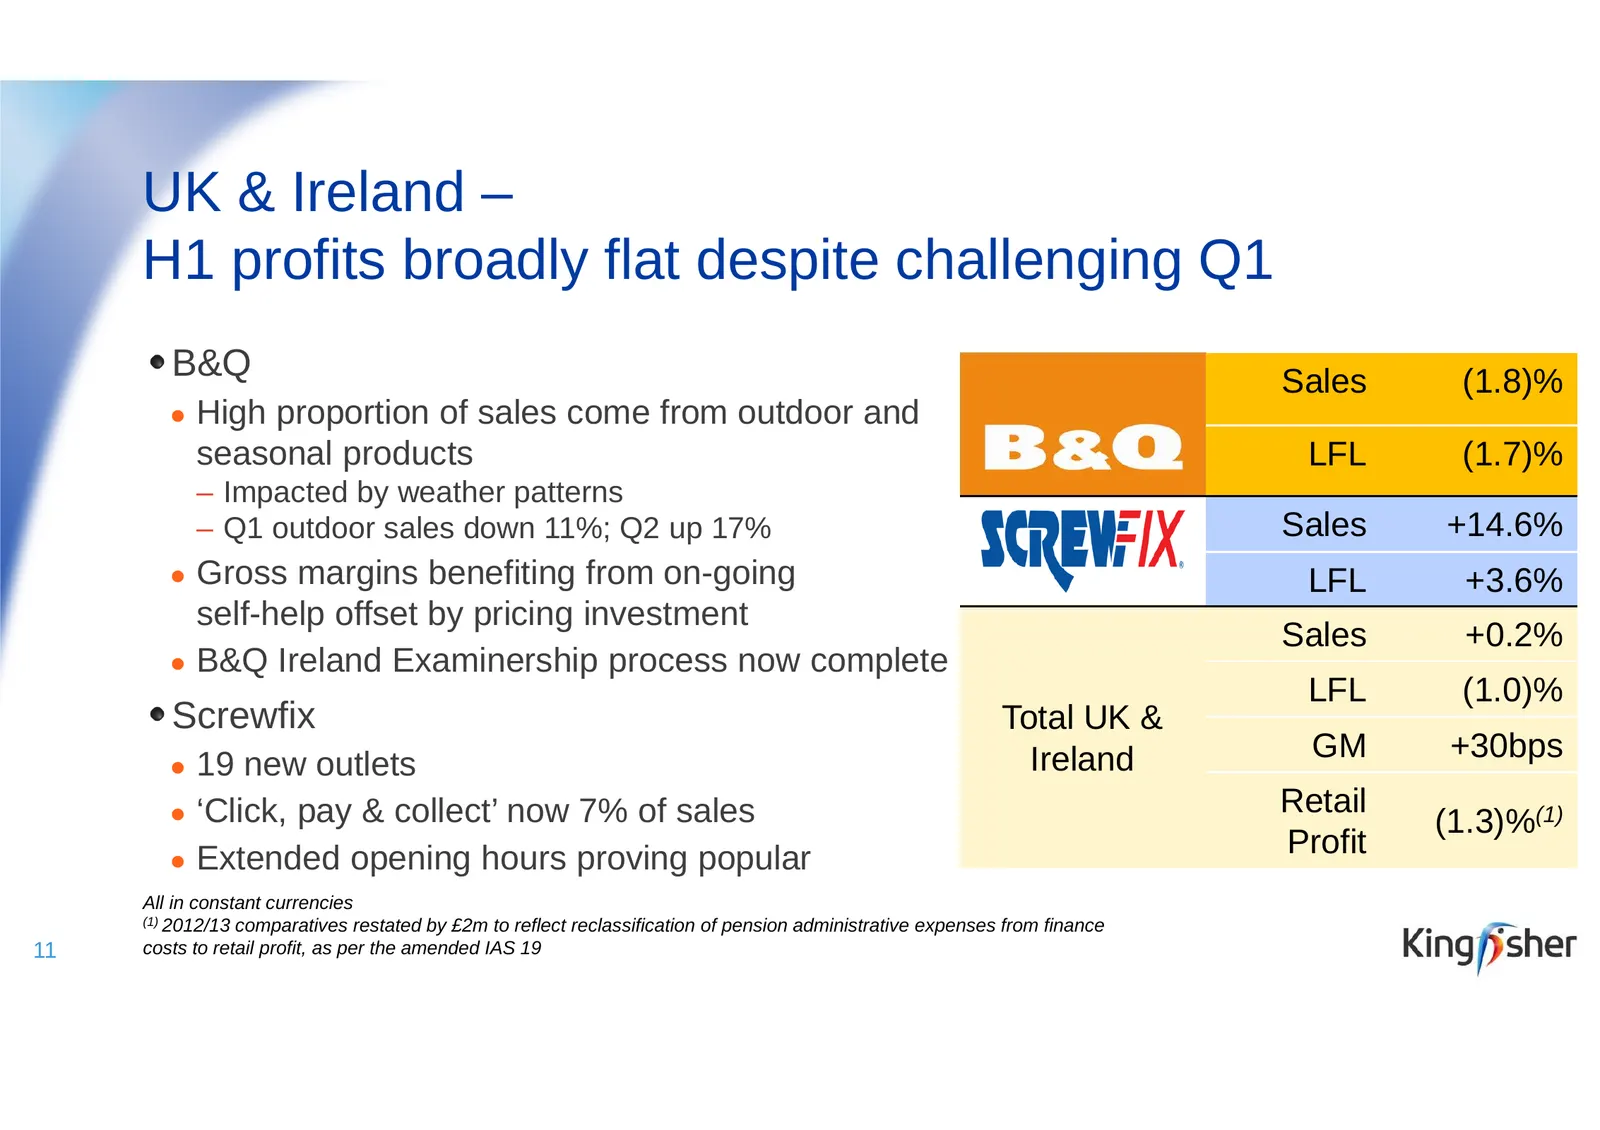
UK & Ireland – H1 profits broadly flat despite challenging Q1 B&Q Sales (1.8)% ● High proportion of sales come from outdoor and seasonal products LFL (1.7)% – Impacted by weather patterns – Q1 outdoor sales down 11%; Q2 up 17% Sales +14.6% ● Gross margins benefiting from on-going LFL +3.6% self-help
Slide 12: Other International – profit decline largely due to lower contribution from Hornbach
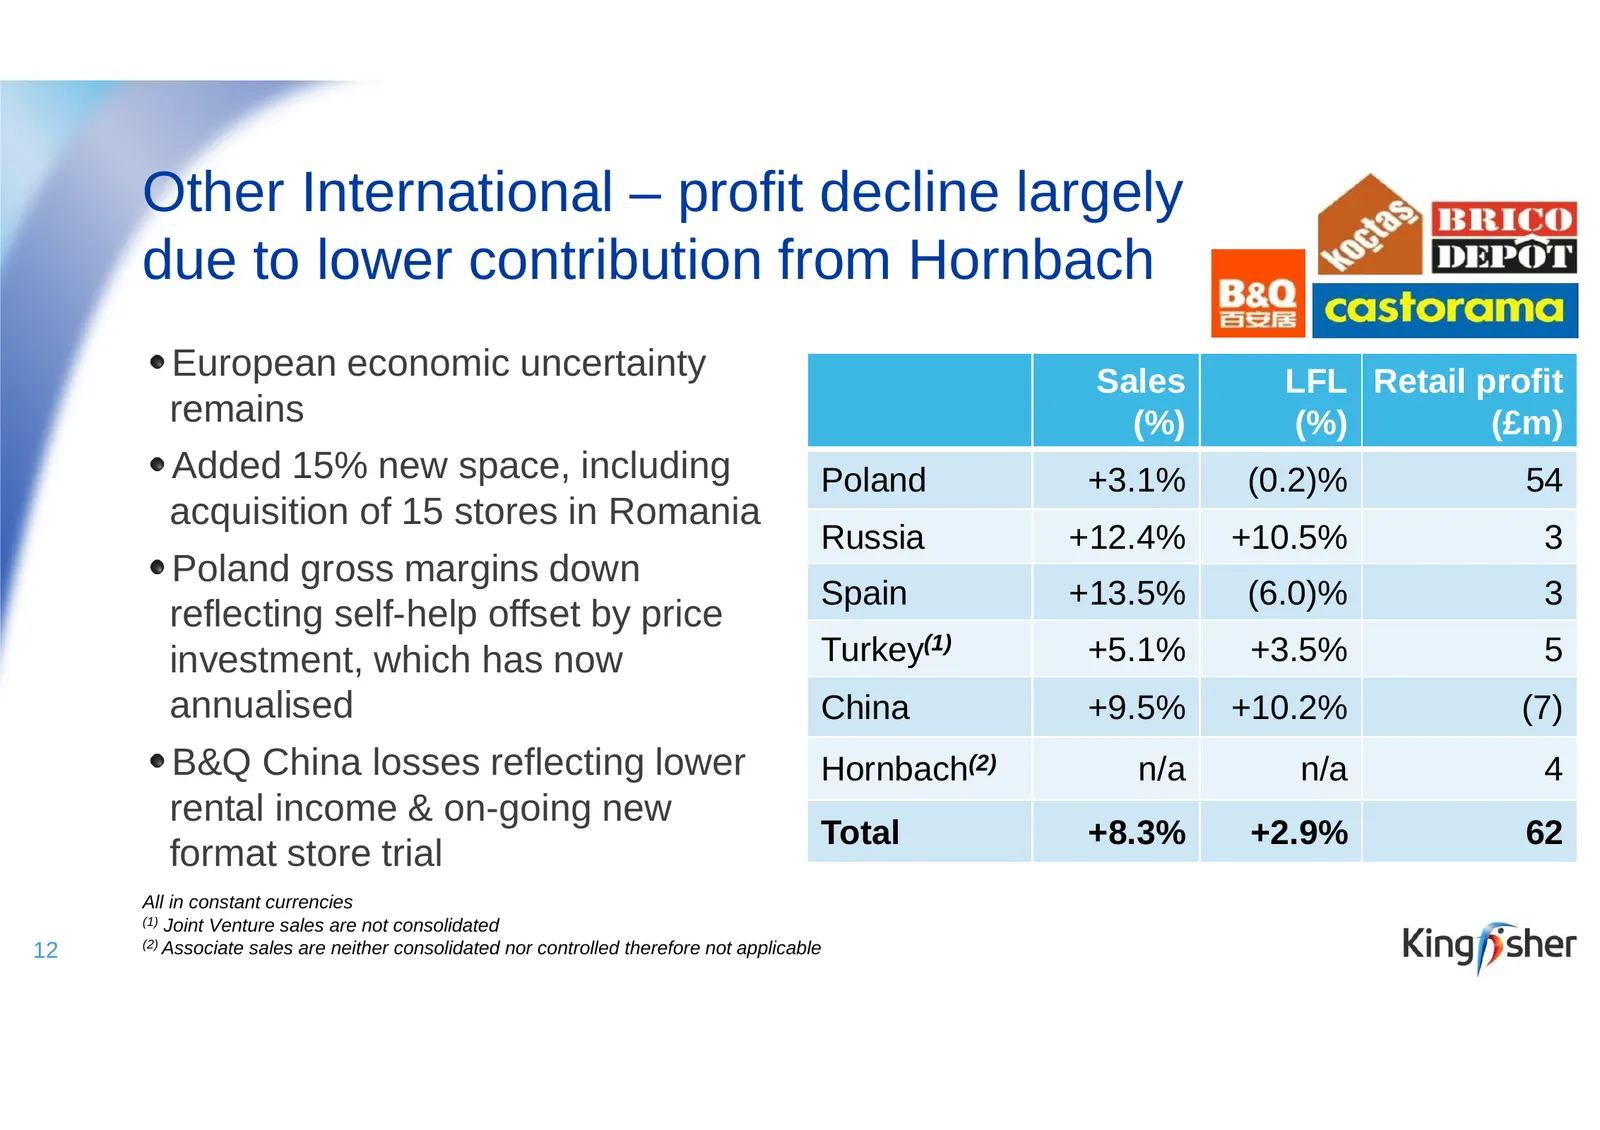
Other International – profit decline largely due to lower contribution from Hornbach European economic uncertainty Sales LFL Retail profit remains (%) (%) (£m) Added 15% new space, including Poland +3.1% (0.2)% 54 acquisition of 15 stores in Romania Russia +12.4% +10.5% 3 Poland gross margins down S
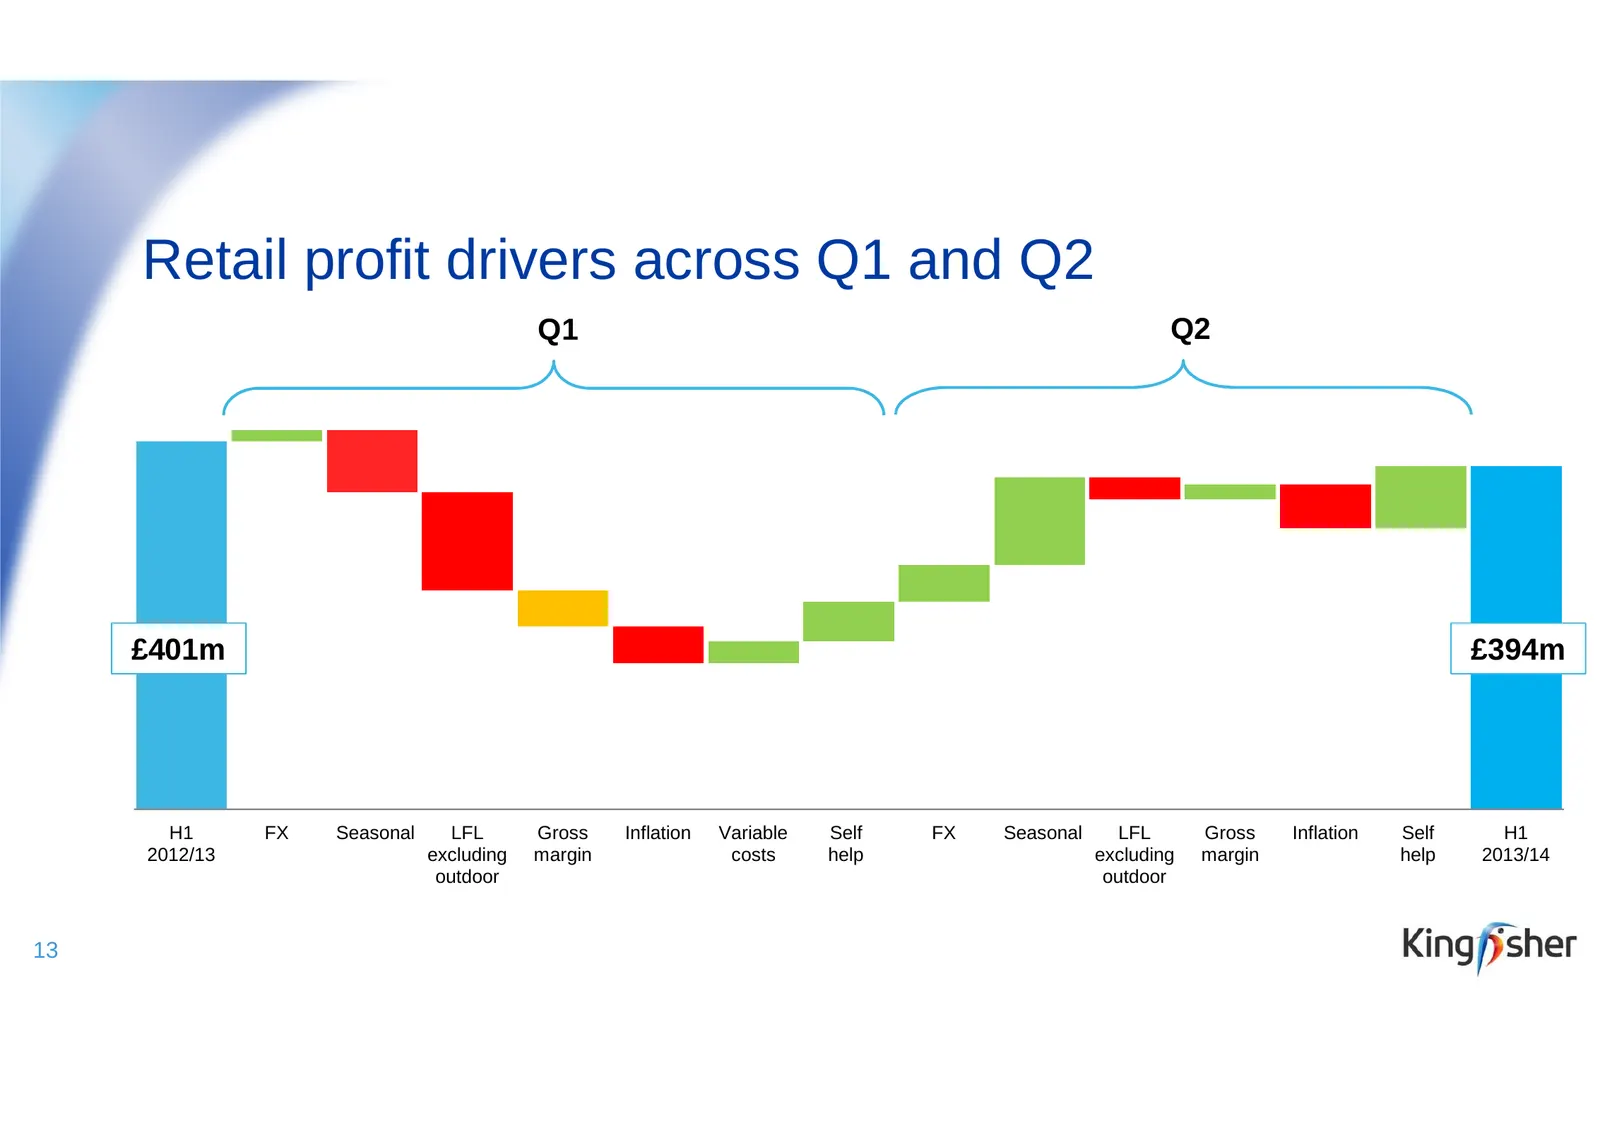
Slide 13: Retail profit drivers across Q1 and Q2
Retail profit drivers across Q1 and Q2 Q1 Q2 £401m £394m H1 FX Seasonal LFL Gross Inflation Variable Self FX Seasonal LFL Gross Inflation Self H1 2012/13 excluding margin costs help excluding margin help 2013/14 outdoor outdoor 13
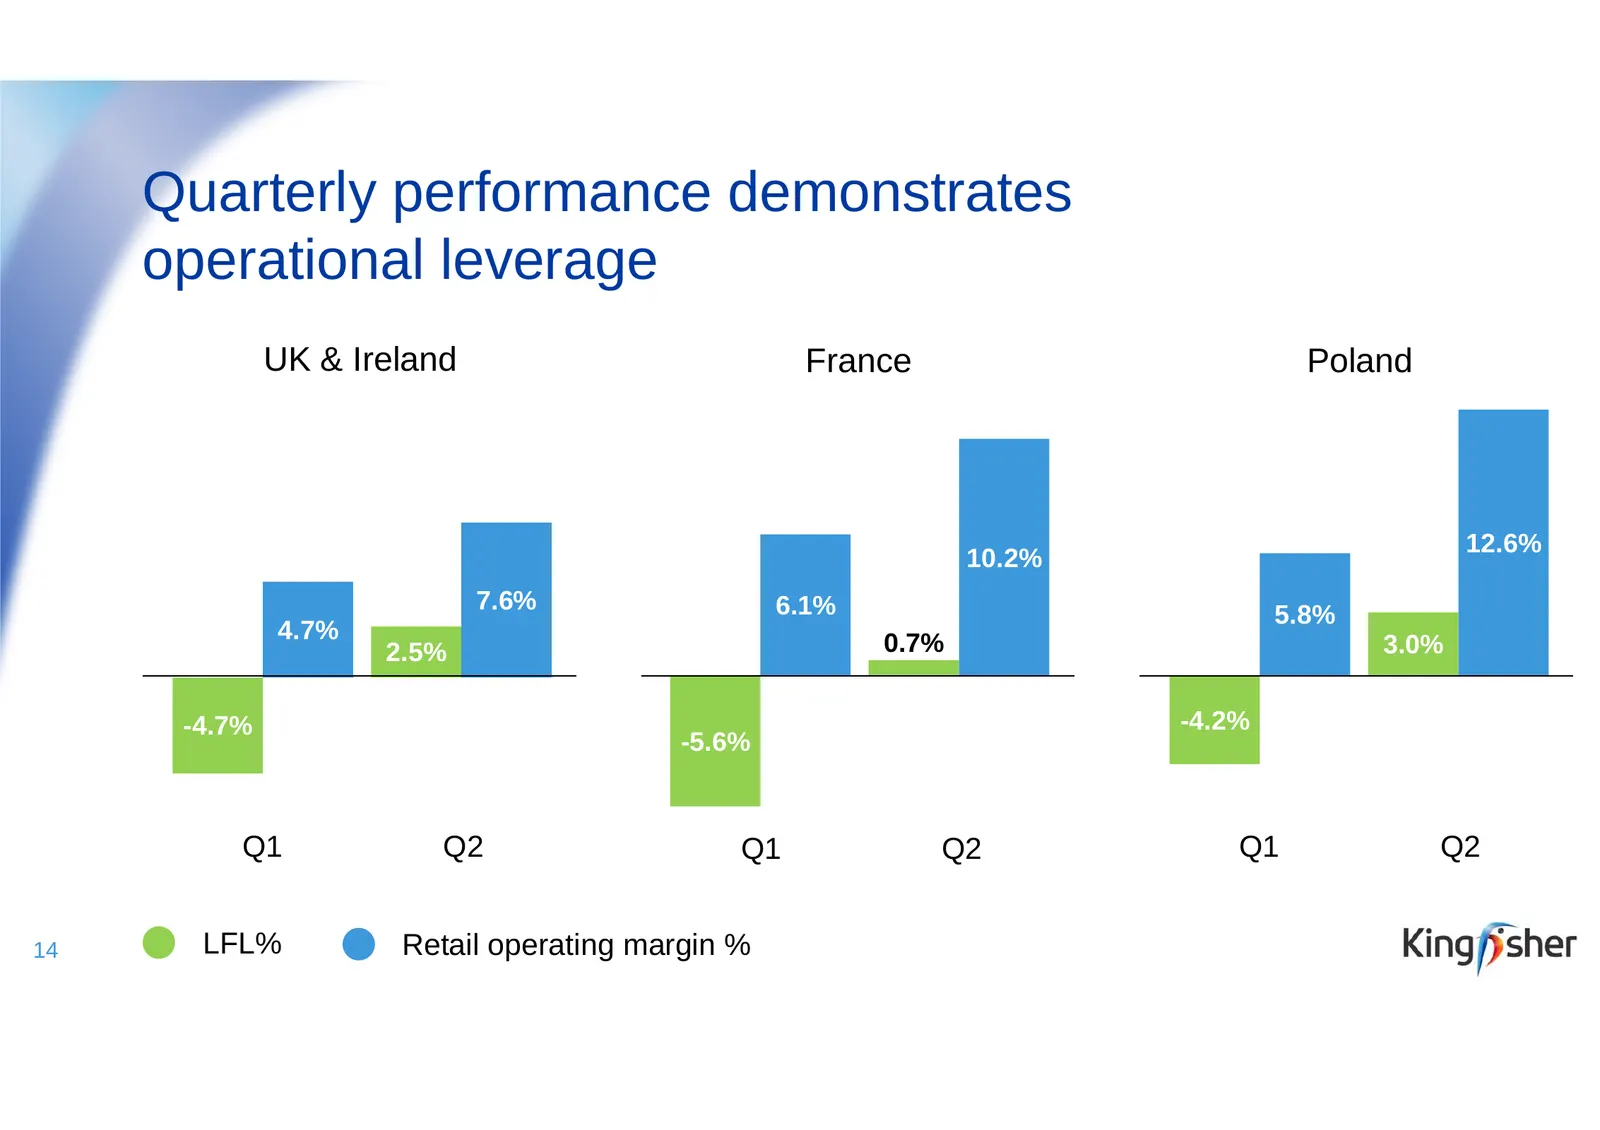
Slide 14: Quarterly performance demonstrates operational leverage
Quarterly performance demonstrates operational leverage UK & Ireland France Poland 12.6% 10.2% 7.6% 6.1% 5.8% 4.7% 0.7% 2.5% 3.0% -4.7% -4.2% -5.6% Q1 Q2 Q1 Q2 Q1 Q2 14 LFL% Retail operating margin %
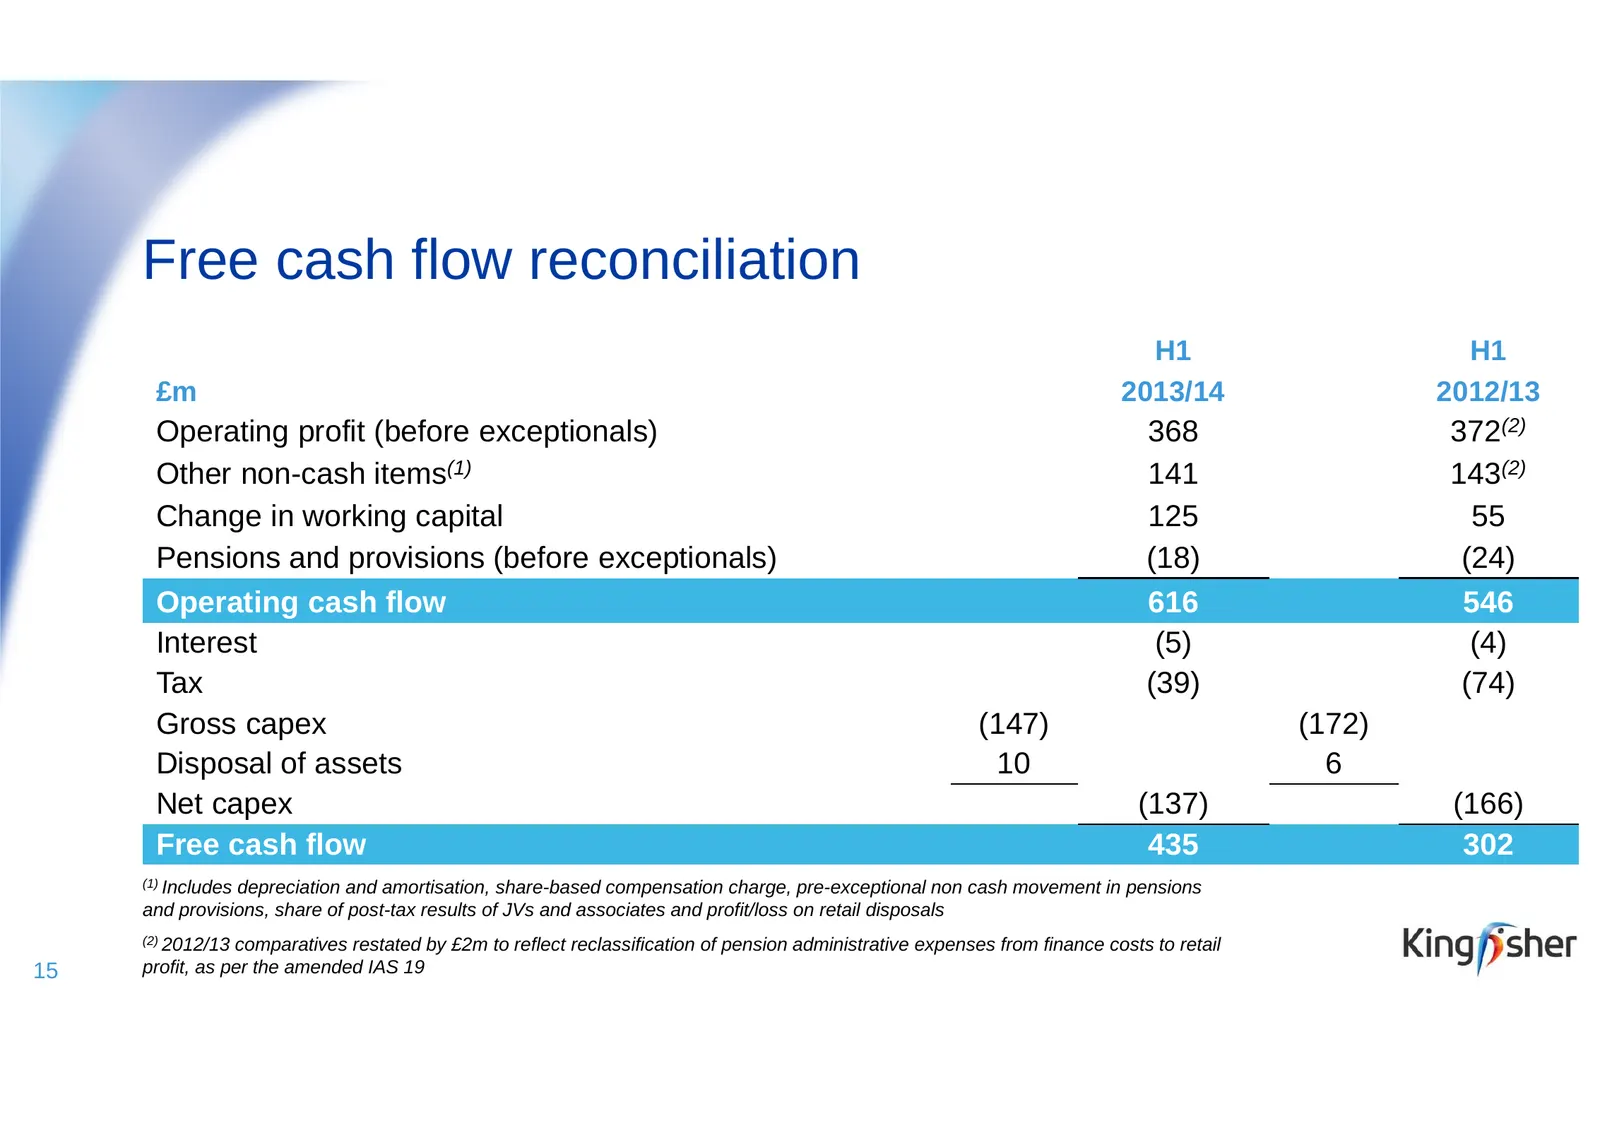
Slide 15: Free cash flow reconciliation
Free cash flow reconciliation H1 H1 £m 2013/14 2012/13 Operating profit (before exceptionals) 368 372(2) Other non-cash items(1) 141 143(2) Change in working capital 125 55 Pensions and provisions (before exceptionals) (18) (24) Operating cash flow 616 546 Interest (5) (4) Tax (39) (74) Gross capex
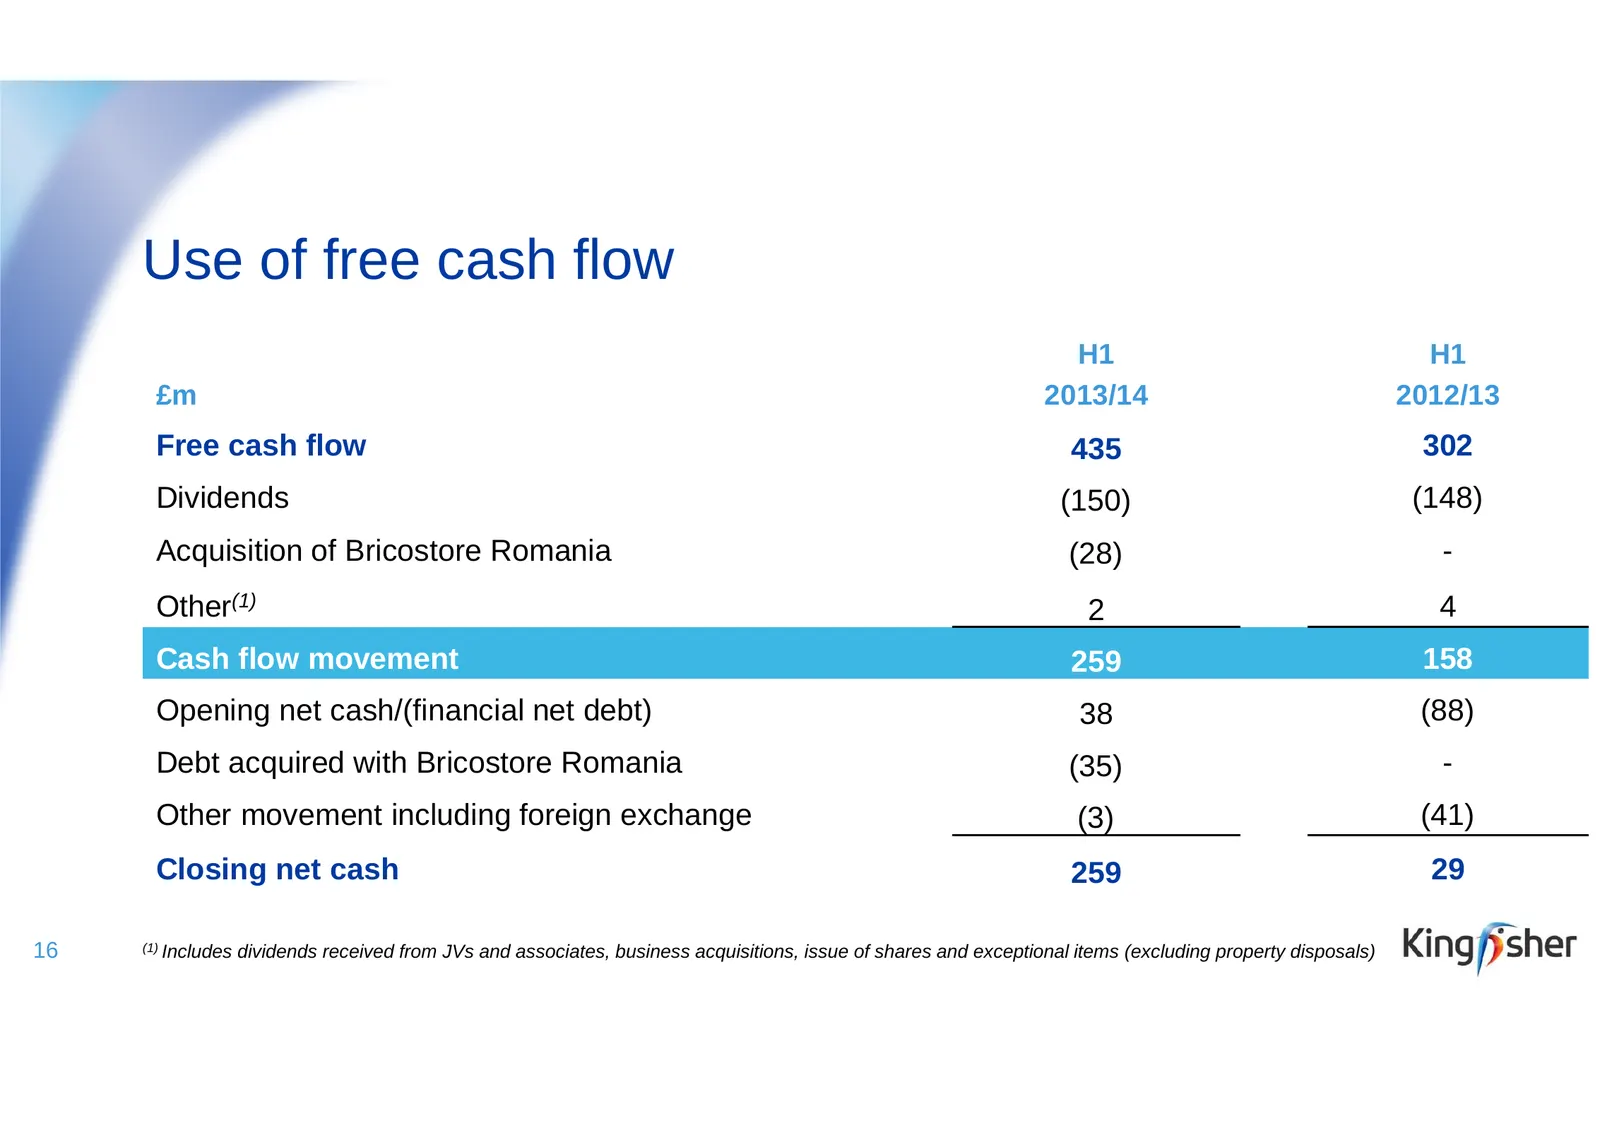
Slide 16: Use of free cash flow
Use of free cash flow H1 H1 £m 2013/14 2012/13 Free cash flow 435 302 Dividends (150) (148) Acquisition of Bricostore Romania (28) - Other(1) 2 4 Cash flow movement 259 158 Opening net cash/(financial net debt) 38 (88) Debt acquired with Bricostore Romania (35) - Other movement including foreign exc
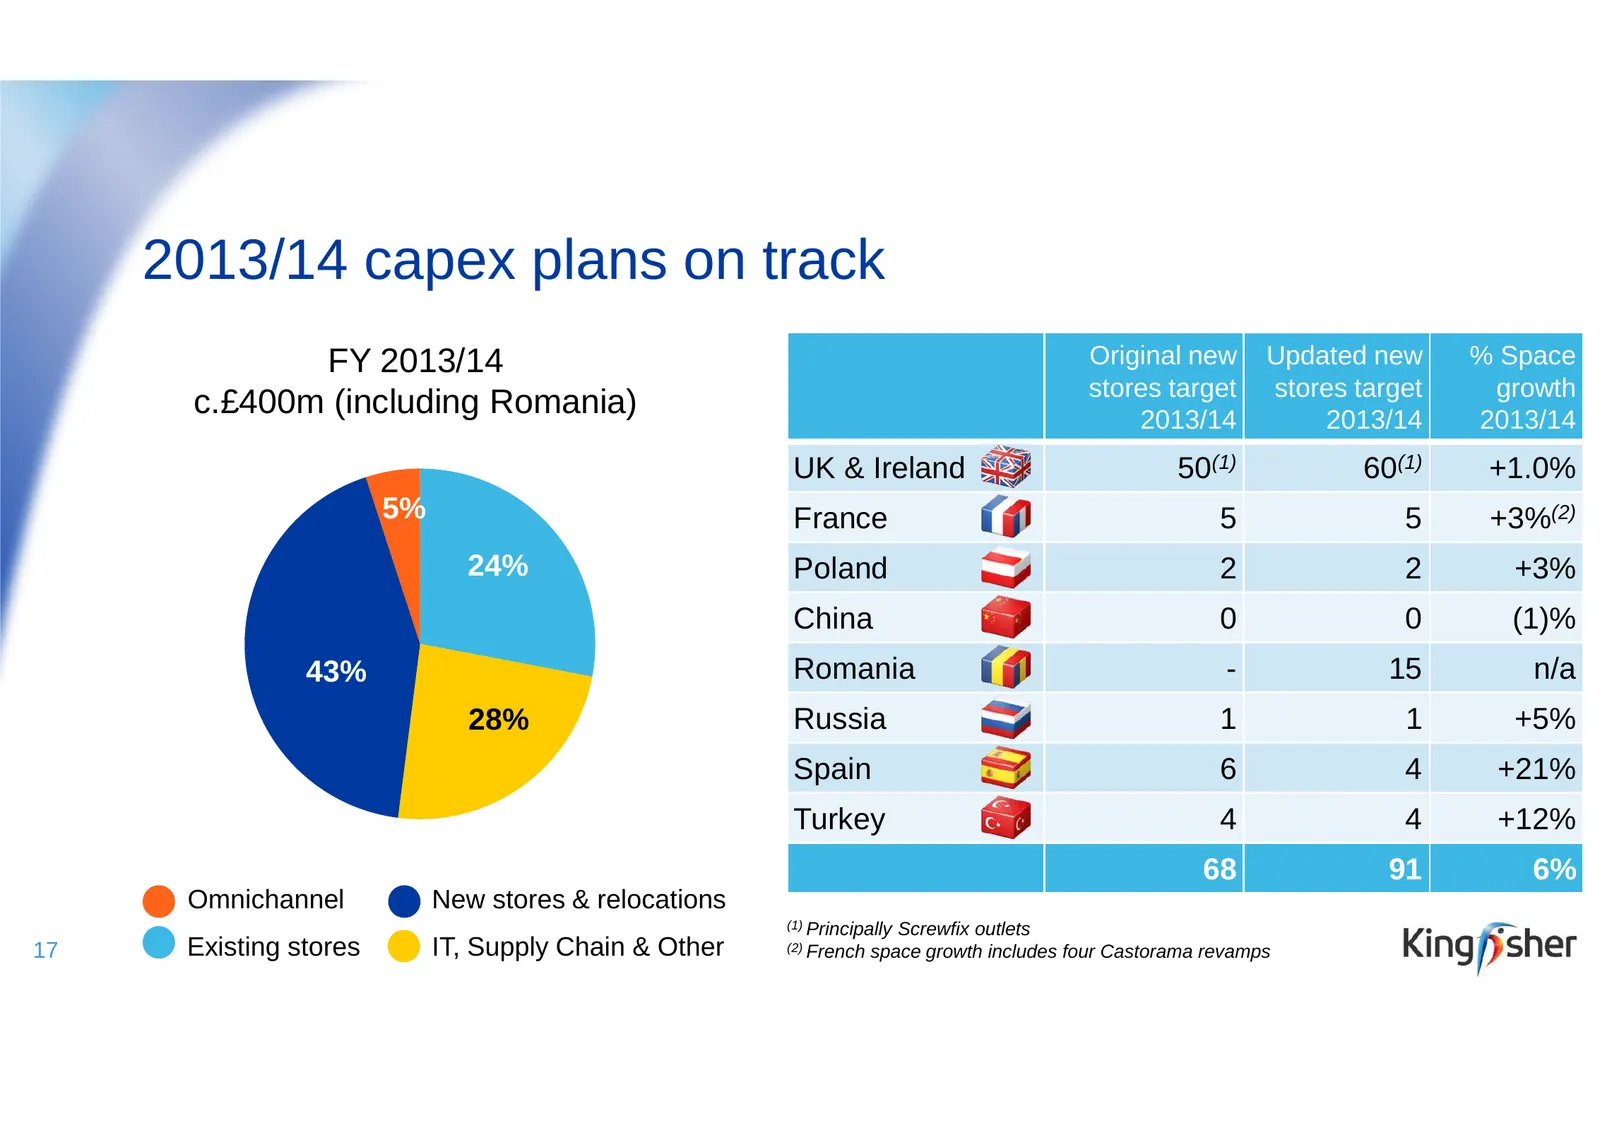
Slide 17: 2013/14 capex plans on track
2013/14 capex plans on track FY 2013/14 Original new Updated new % Space stores target stores target growth c.£400m (including Romania) 2013/14 2013/14 2013/14 UK & Ireland 50(1) 60(1) +1.0% 5% France 5 5 +3%(2) 24% Poland 2 2 +3% China 0 0 (1)% 43% Romania - 15 n/a 28% Russia 1 1 +5% Spain 6 4 +21%
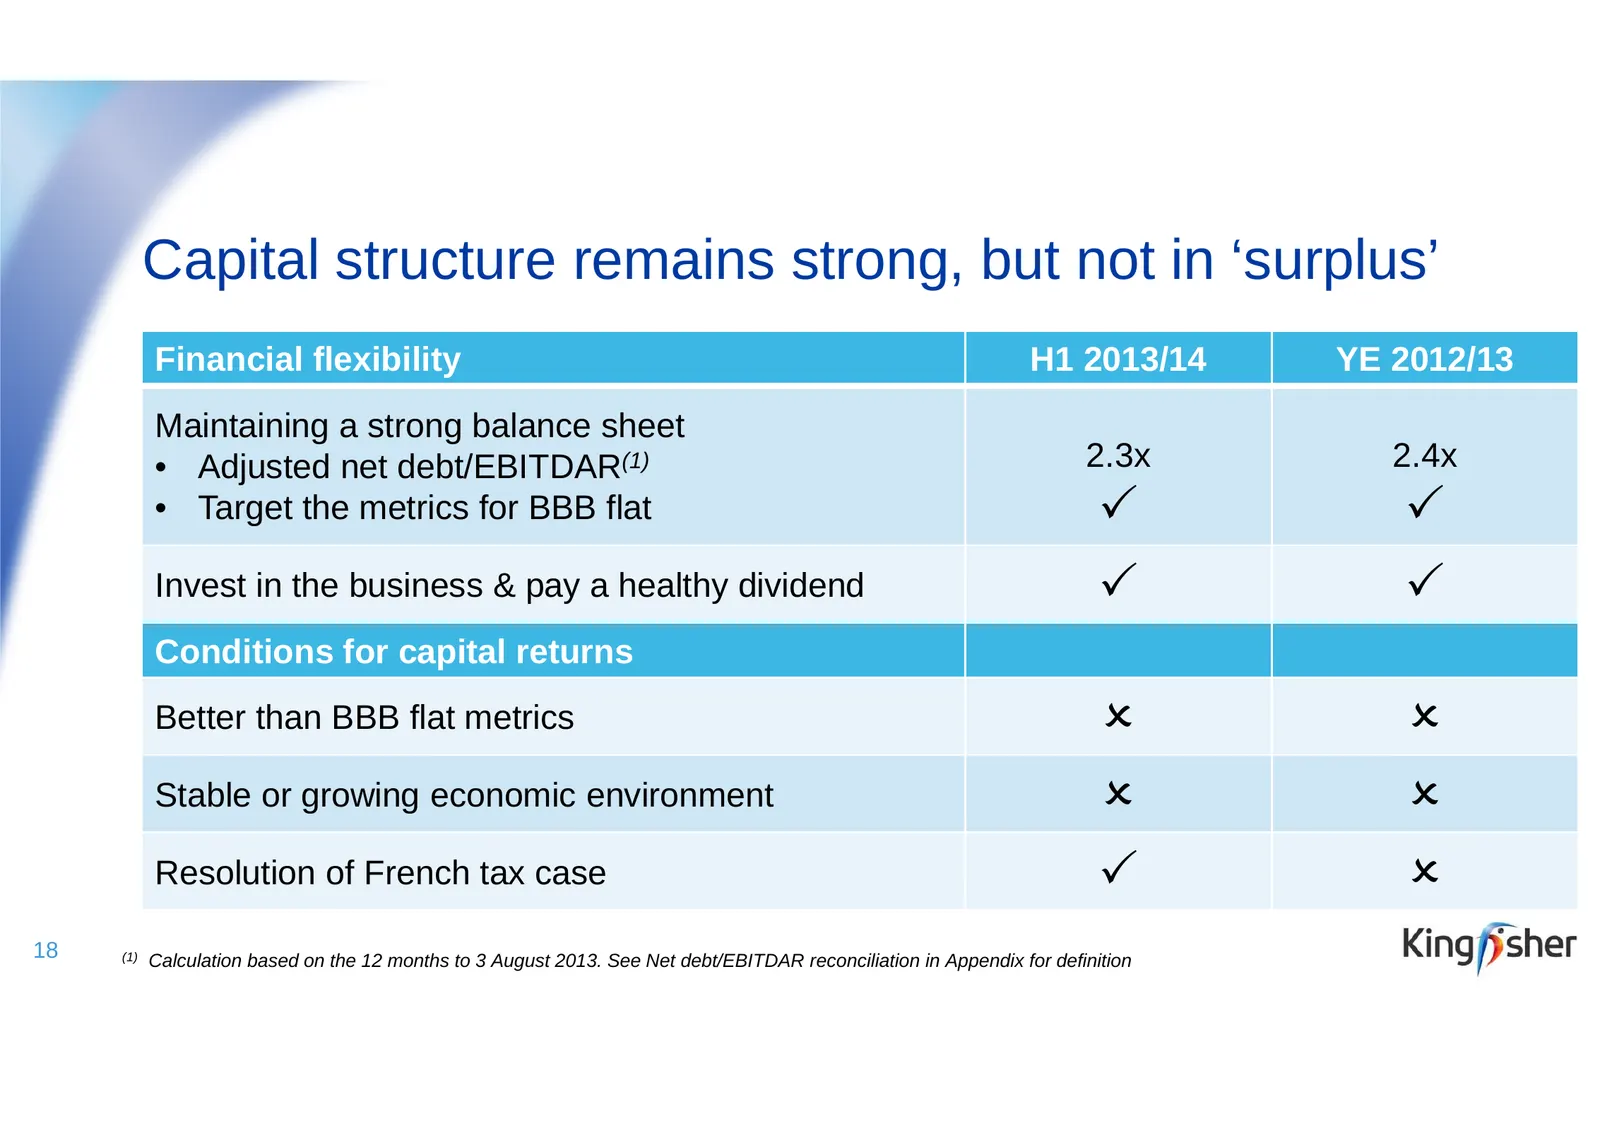
Slide 18: Capital structure remains strong, but not in 'surplus'
Capital structure remains strong, but not in ‘surplus’ Financial flexibility H1 2013/14 YE 2012/13 Maintaining a strong balance sheet • Adjusted net debt/EBITDAR(1) 2.3x 2.4x • Target the metrics for BBB flat Invest in the business & pay a healthy dividend Conditions for capital returns Better than
Slide 19: 2013/14 H1 summary
2013/14 H1 summary Broadly flat in a challenging first half ● Q2 upturn mostly weather driven ● Q2 performance demonstrates operational leverage ● Self-help continuing to support short-term performance Balance sheet remains strong, not in capital ‘surplus’ ● Continue to invest for growth ● Focus on
Slide 20: Ian Cheshire, Group Chief Executive
Ian Cheshire Group Chief Executive
Slide 21: 'Creating the Leader'
BETTER HOMES, DE! TER LIVES
Slide 22: 'Creating the Leader'
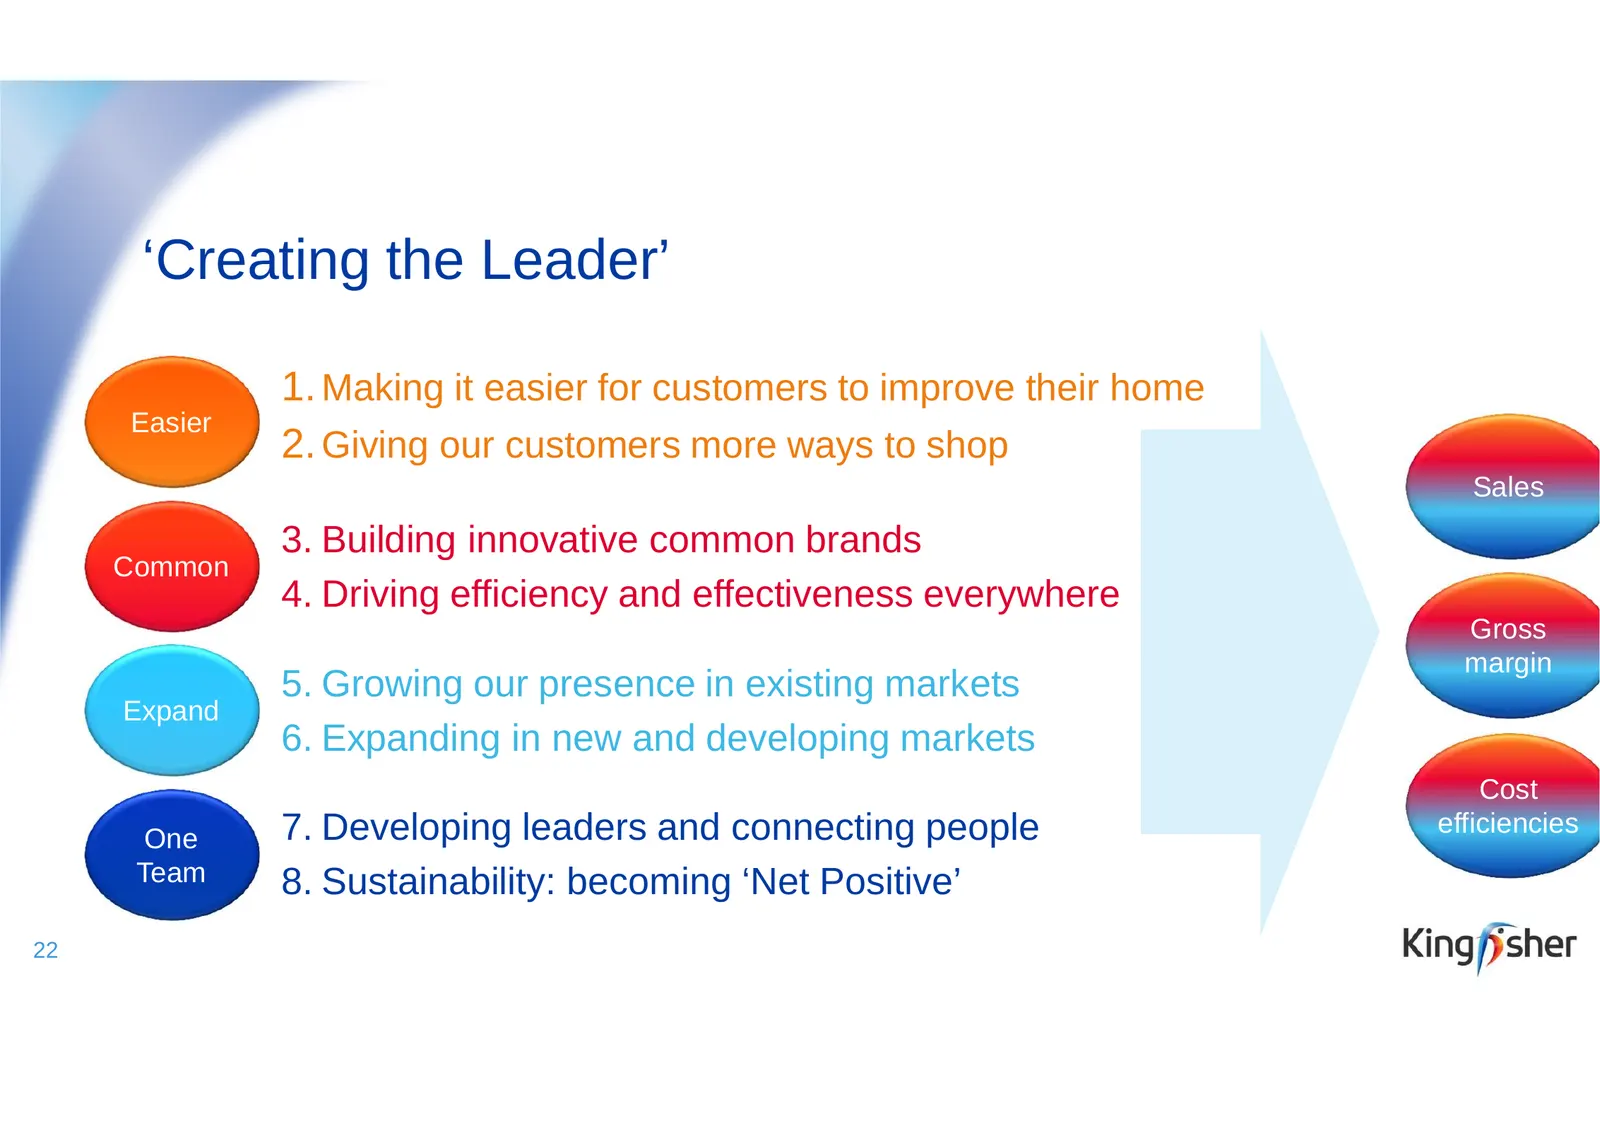
‘Creating the Leader’ 1. Making it easier for customers to improve their home Easier 2. Giving our customers more ways to shop Sales 3. Building innovative common brands Common 4. Driving efficiency and effectiveness everywhere Gross margin 5. Growing our presence in existing markets Expand 6. Expan
Slide 23: Kingfisher
23 King/sher
Slide 24: 2013/14 milestones H1 update – Affordability
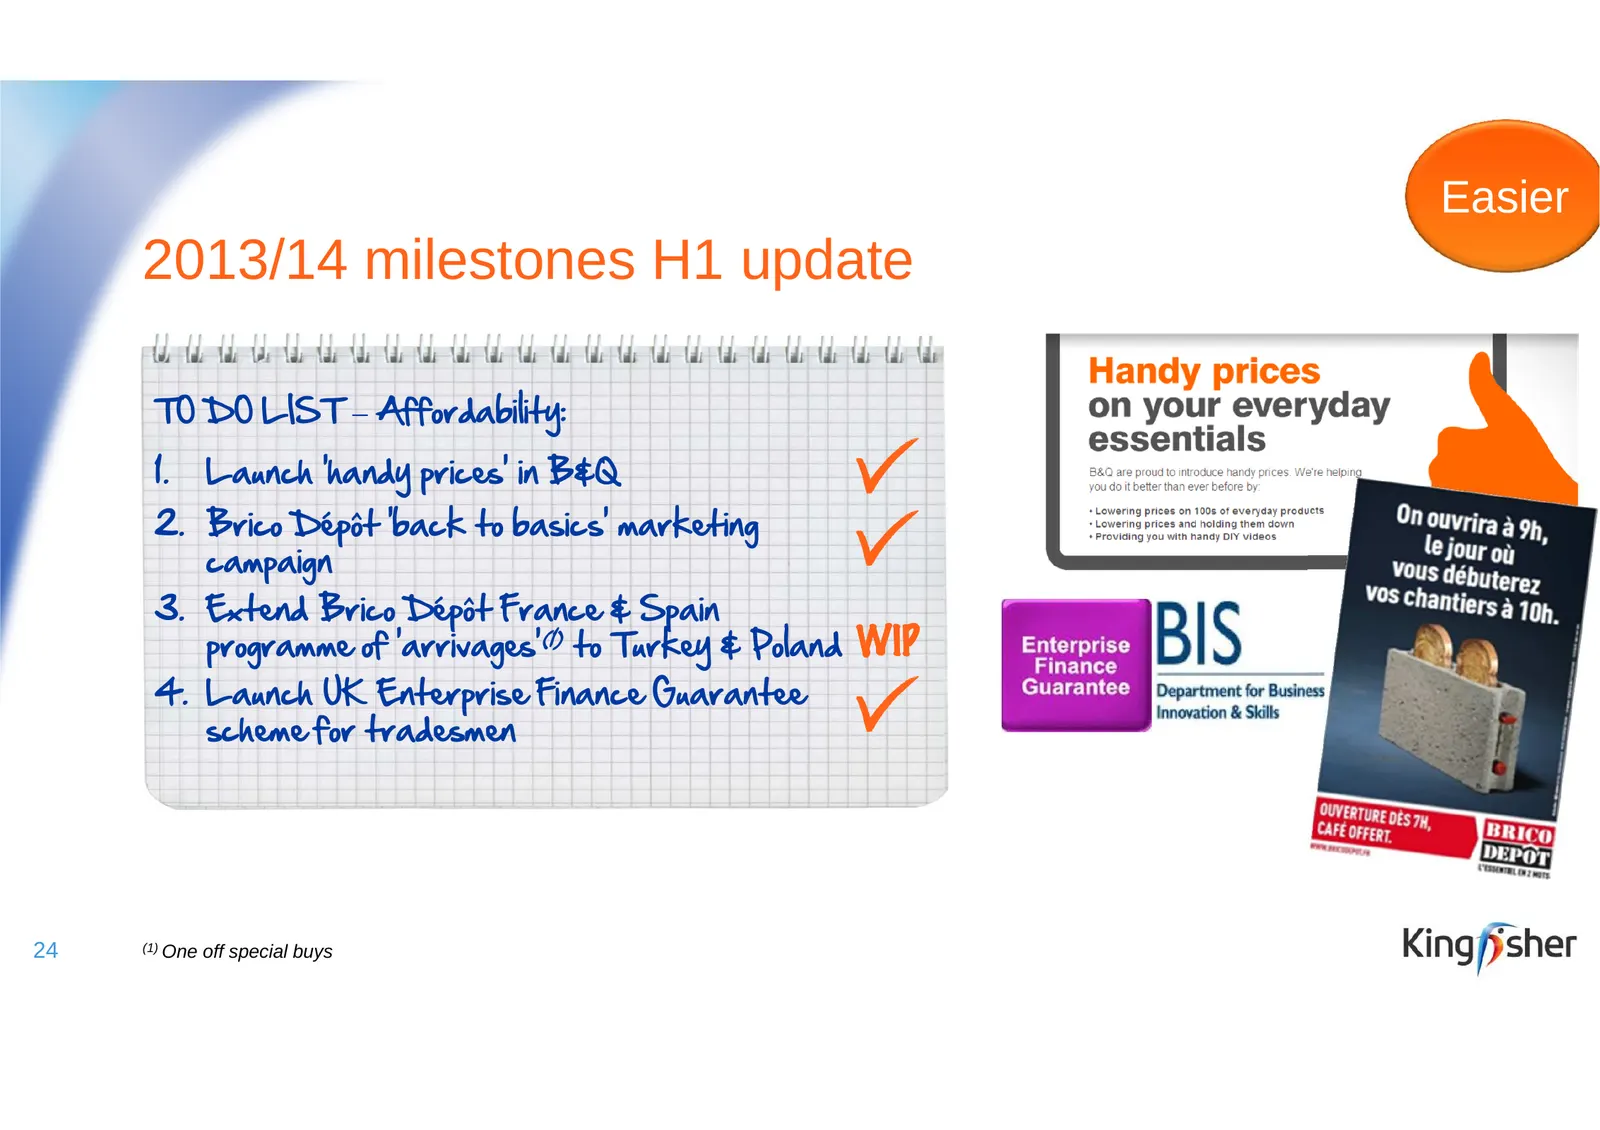
Easier 2013/14 milestones H1 update TO DO LIST – Affordability: 1. Launch ‘handy prices’ in B&Q 2. Brico Dépôt ‘back to basics’ marketing campaign 3. Extend Brico Dépôt France & Spain programme of ‘arrivages’(1) to Turkey & Poland XJQ 4. Launch UK Enterprise Finance Guarantee scheme for tradesmen 24
Slide 25: 2013/14 milestones H1 update – Omnichannel
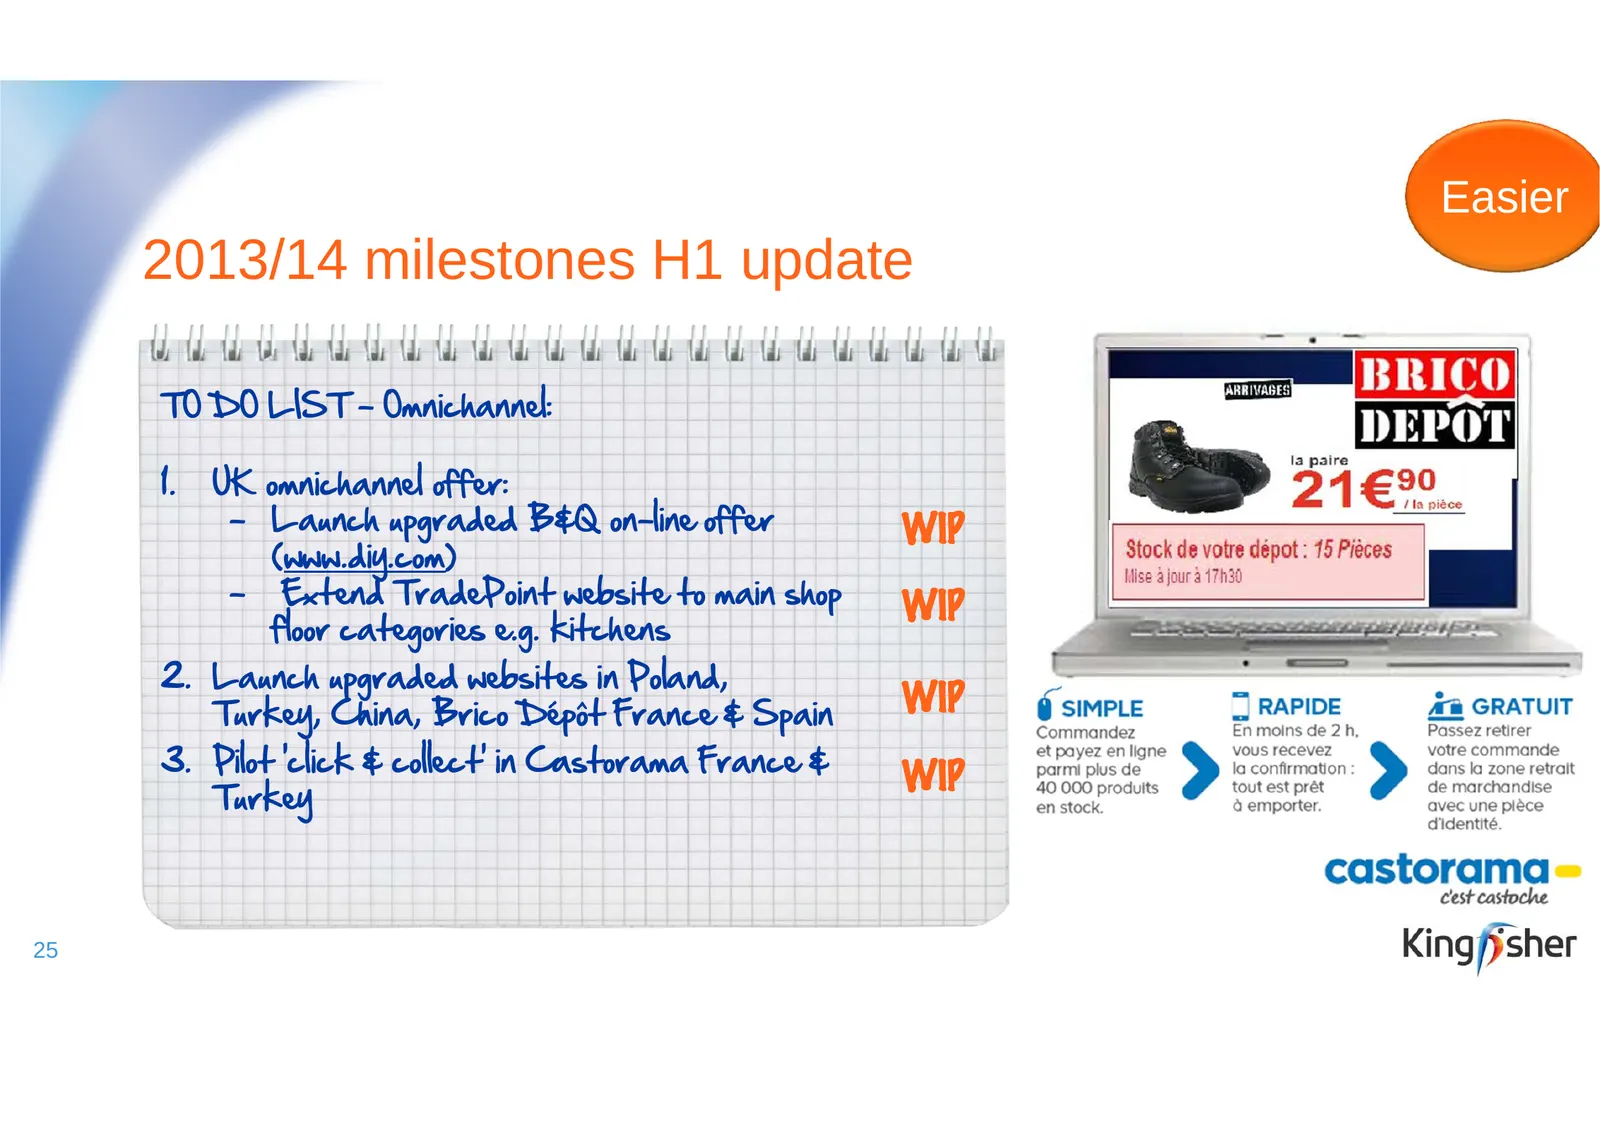
Easier 2013/14 milestones H1 update TO DO LIST - Omnichannel: 1. UK omnichannel offer: - Launch upgraded B&Q on-line offer XJQ (www.diy.com) - Extend TradePoint website to main shop XJQ floor categories e.g. kitchens 2. Launch upgraded websites in Poland, Turkey, China, Brico Dépôt France & Spain XJ
Slide 26: Steve Willett, CEO Group Productivity & Development
Steve Willett CEO Group Productivity & Development
Slide 27: Developing UK omnichannel offer
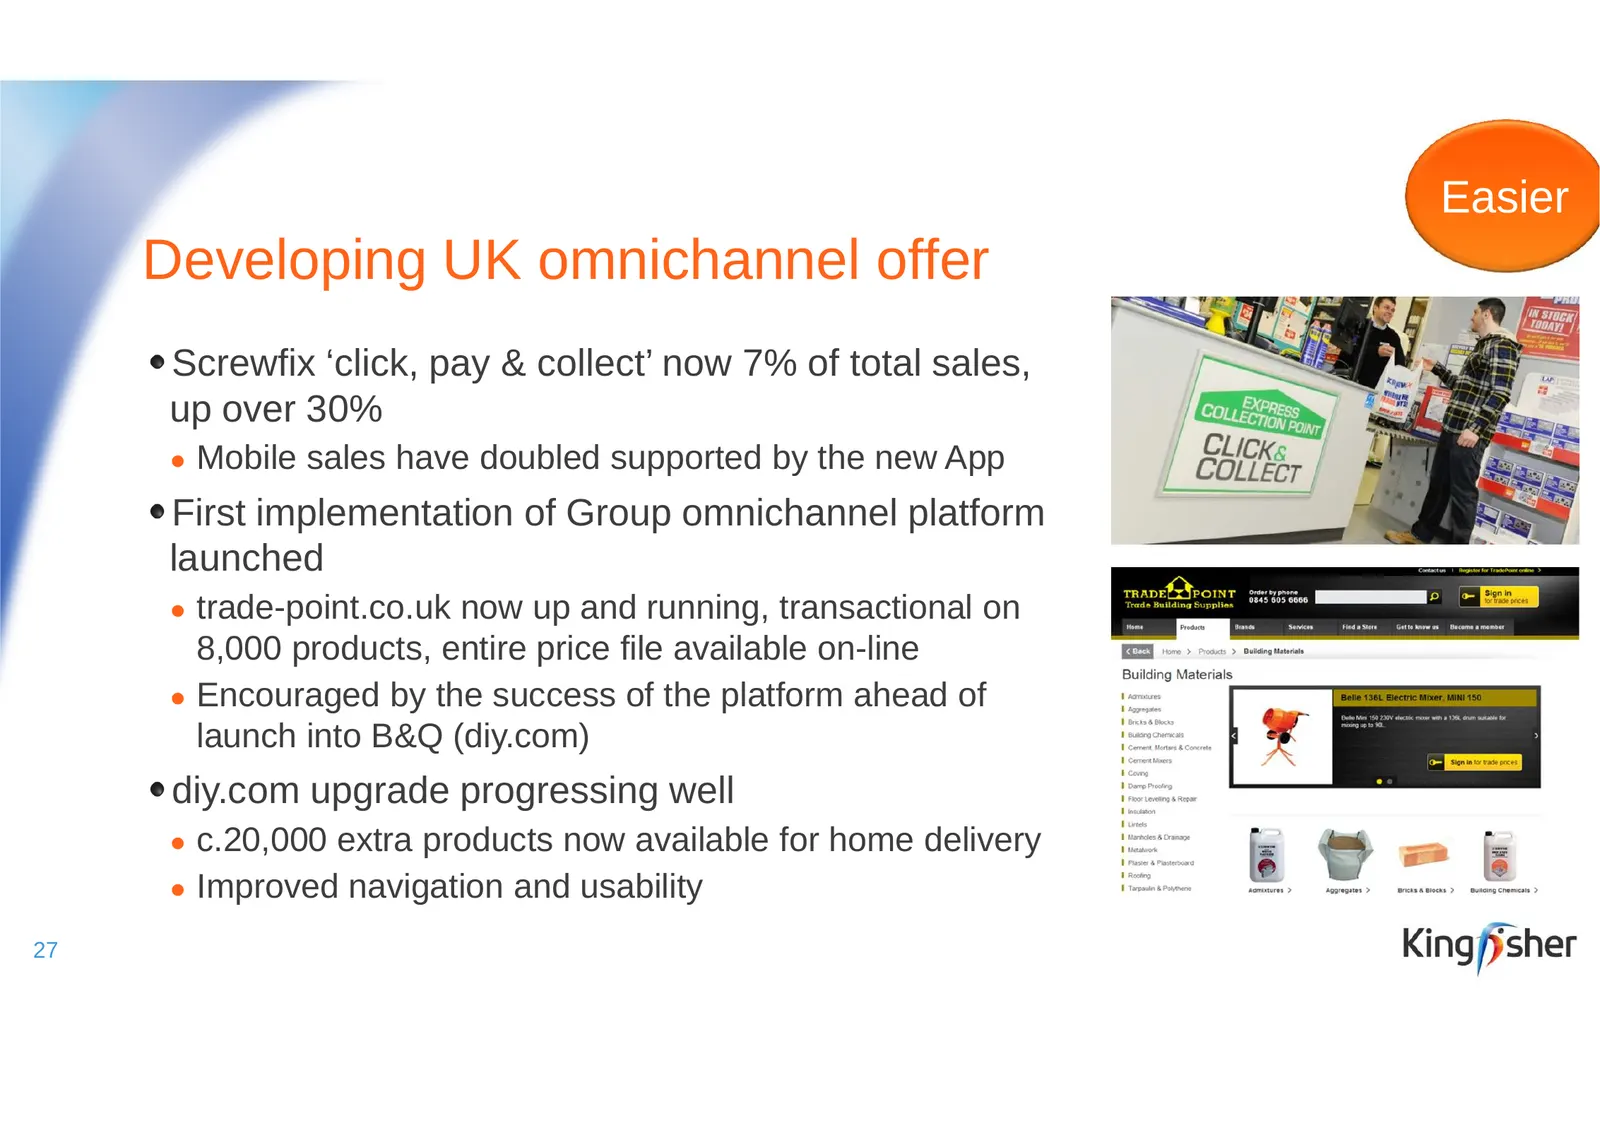
Easier Developing UK omnichannel offer Screwfix ‘click, pay & collect’ now 7% of total sales, up over 30% ● Mobile sales have doubled supported by the new App First implementation of Group omnichannel platform launched ● trade-point.co.uk now up and running, transactional on 8,000 products, entire p
Slide 28: B&Q UK omnichannel – encouraging signs on doors
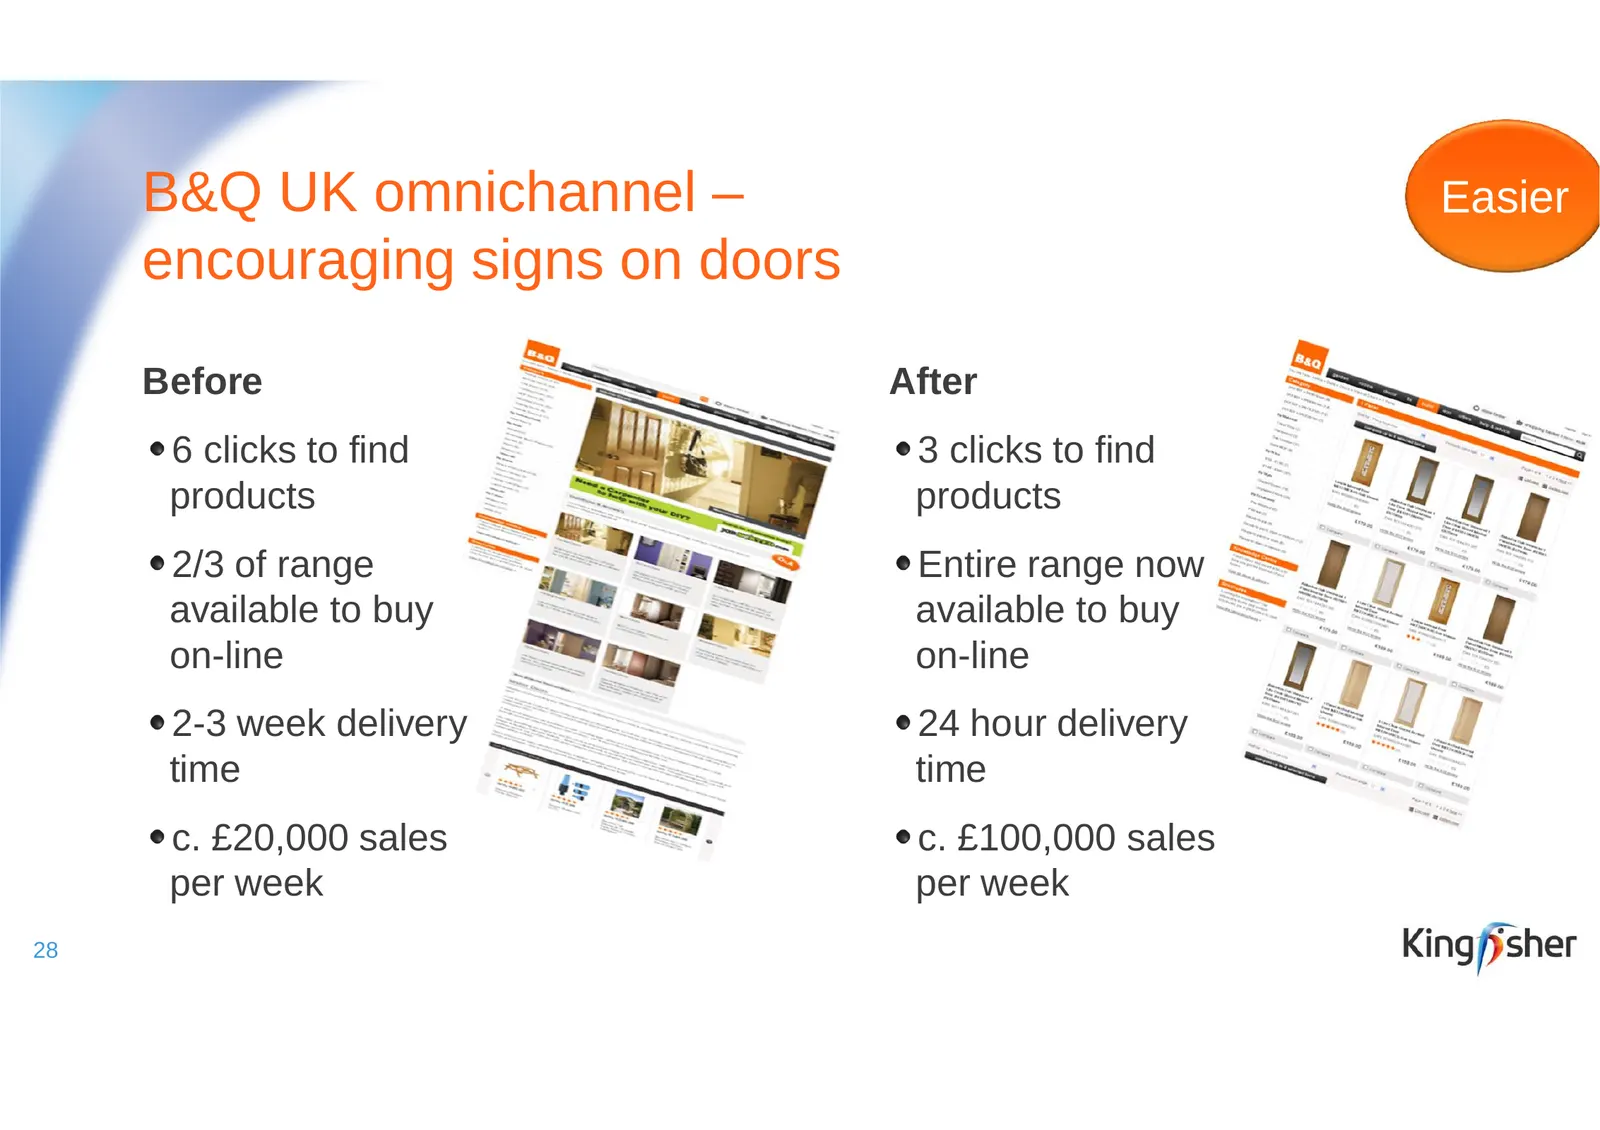
B&Q UK omnichannel – Easier encouraging signs on doors Before After 6 clicks to find 3 clicks to find products products 2/3 of range Entire range now available to buy available to buy on-line on-line 2-3 week delivery 24 hour delivery time time c. £20,000 sales c. £100,000 sales per week per week 28
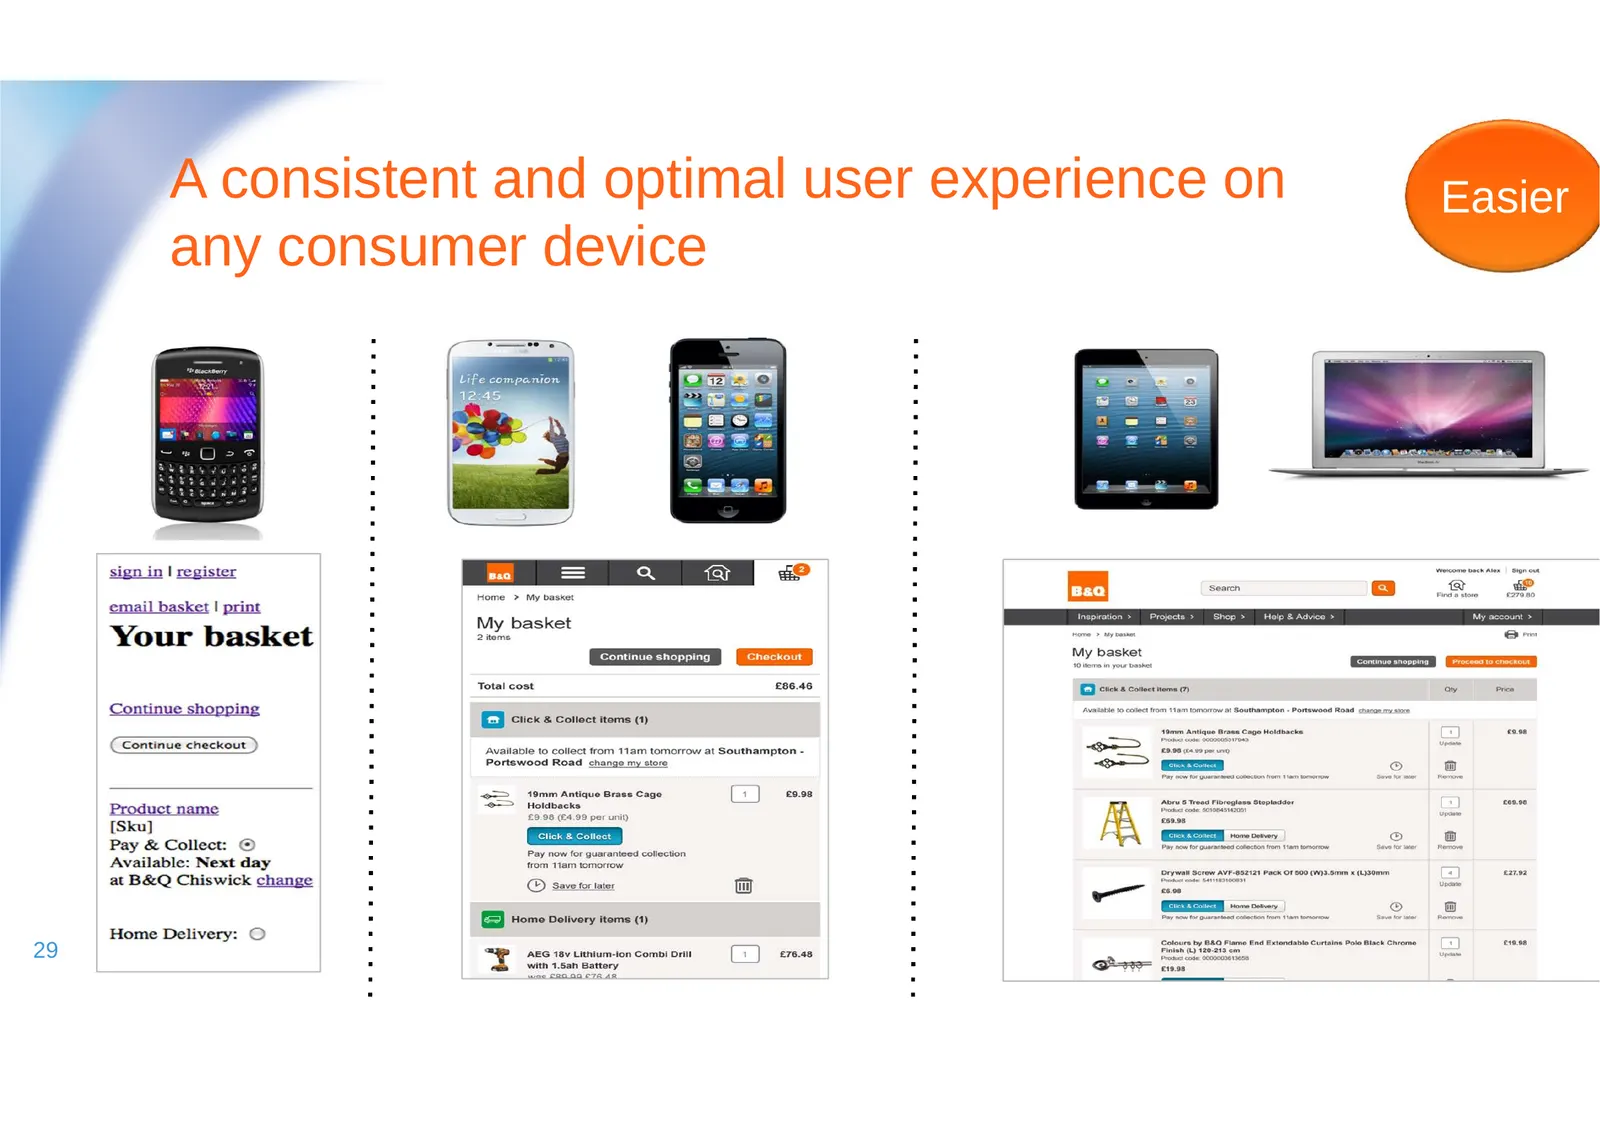
Slide 29: A consistent and optimal user experience on any consumer device
A consistent and optimal user experience on Easier any consumer device 29
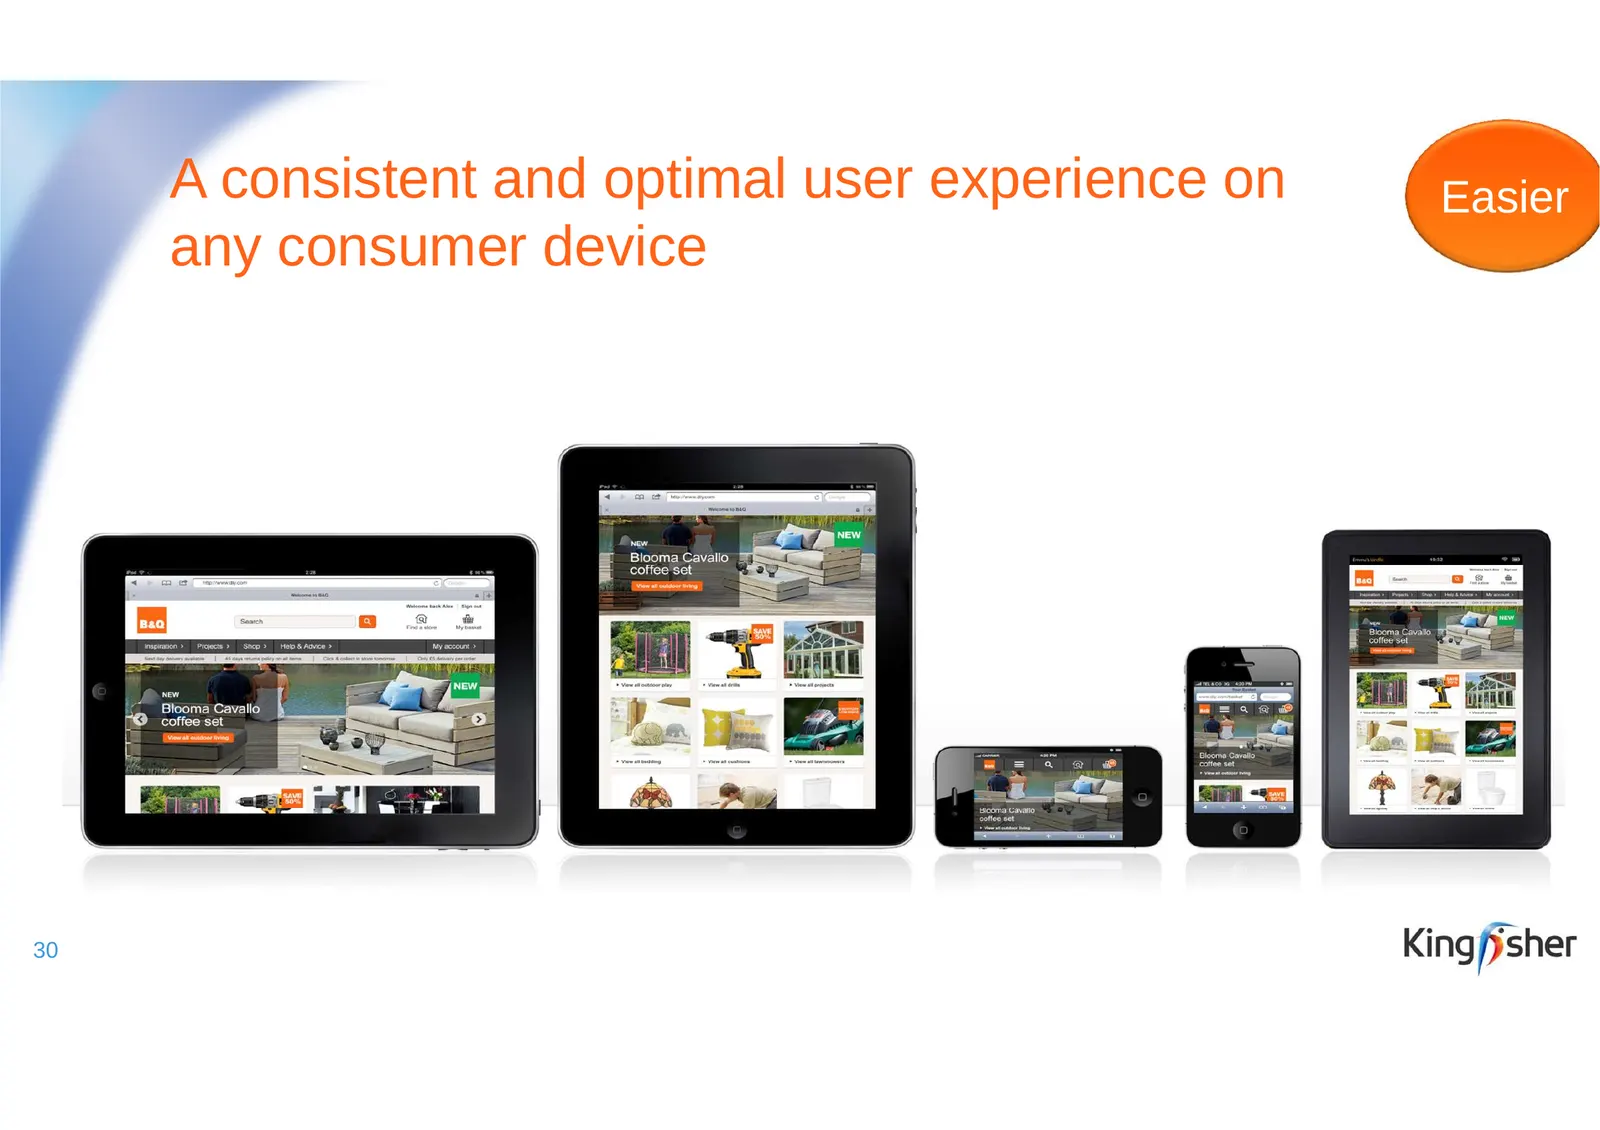
Slide 30: A consistent and optimal user experience on any consumer device
A consistent and optimal user experience on Easier any consumer device 30
Slide 31: Ian Cheshire, Group Chief Executive
Ian Cheshire Group Chief Executive
Slide 32: Easier
CC EDIVERSE O) A SSInternavionaL EXCLUSIVE | FE DIRECT — S T =z) SOENGINE A = oO OW King/psher
Slide 33: 2013/14 milestones H1 update – Product
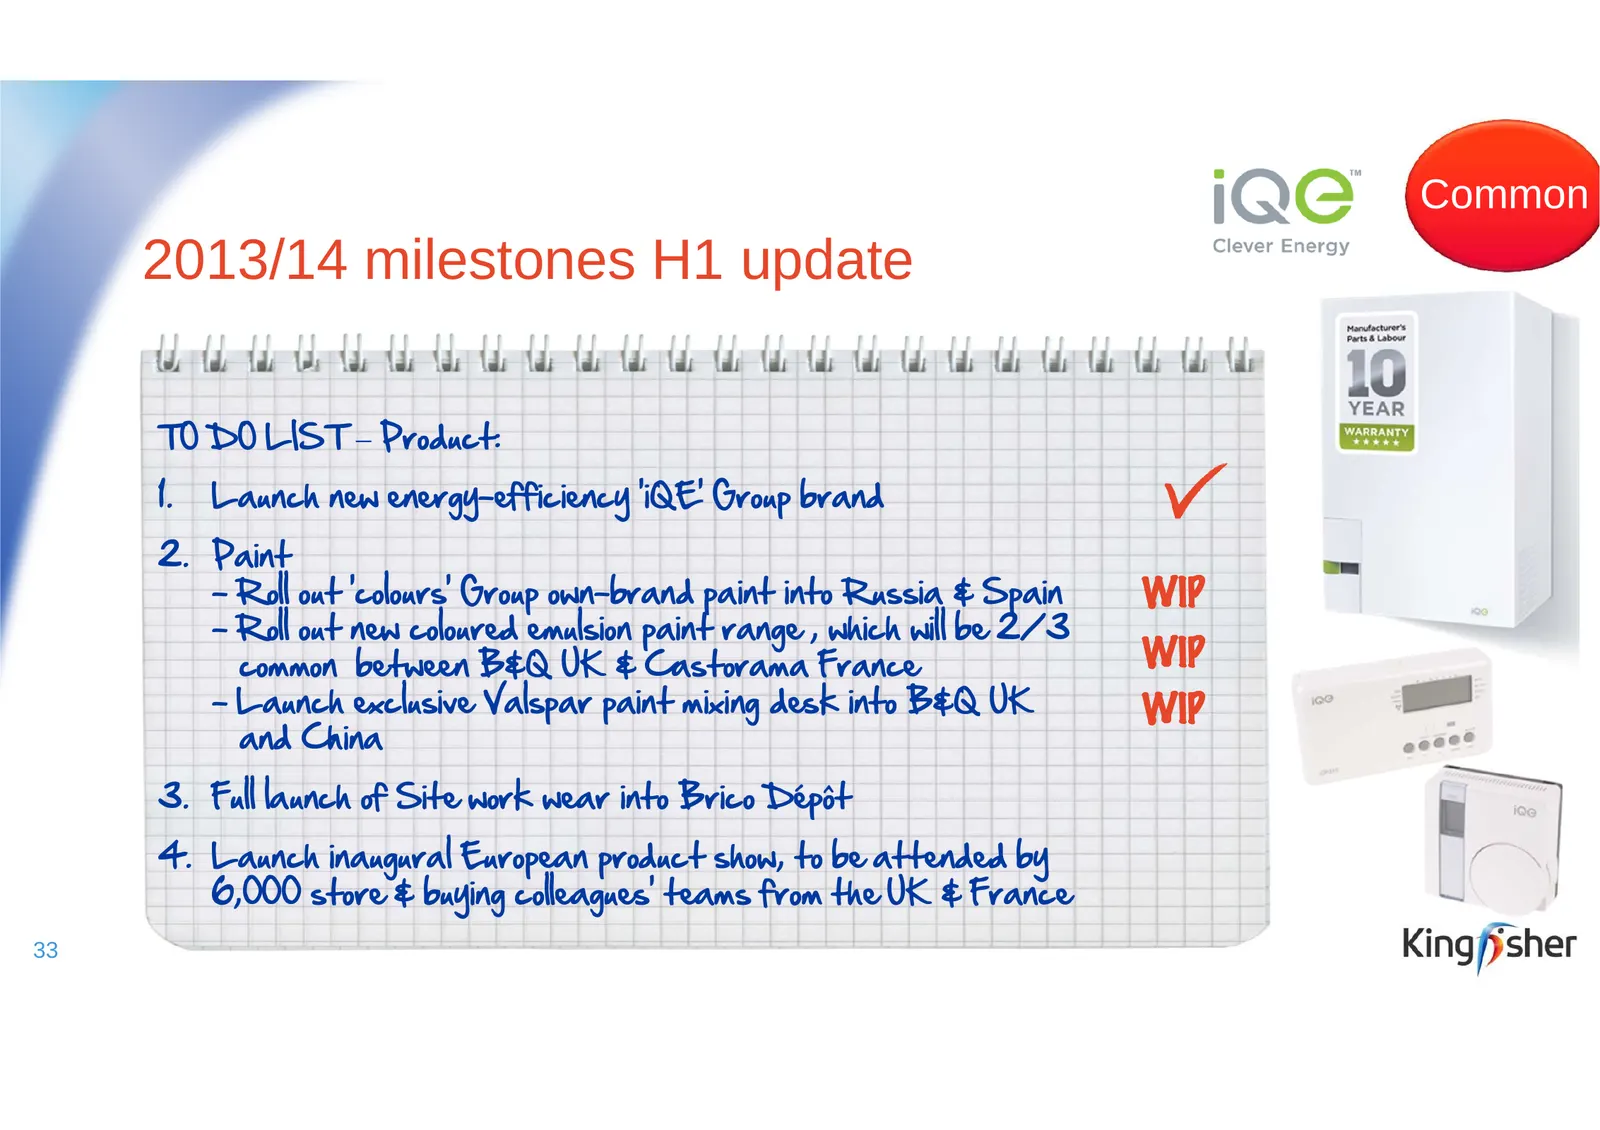
EASIER Common 2013/14 milestones H1 update TO DO LIST – Product: 1. Launch new energy-efficiency ‘iQE’ Group brand 2. Paint - Roll out ‘colours’ Group own-brand paint into Russia & Spain XJQ - Roll out new coloured emulsion paint range , which will be 2/3 common between B&Q UK & Castorama France XJQ
Slide 34: Our global sourcing capability evolving towards a more integrated group
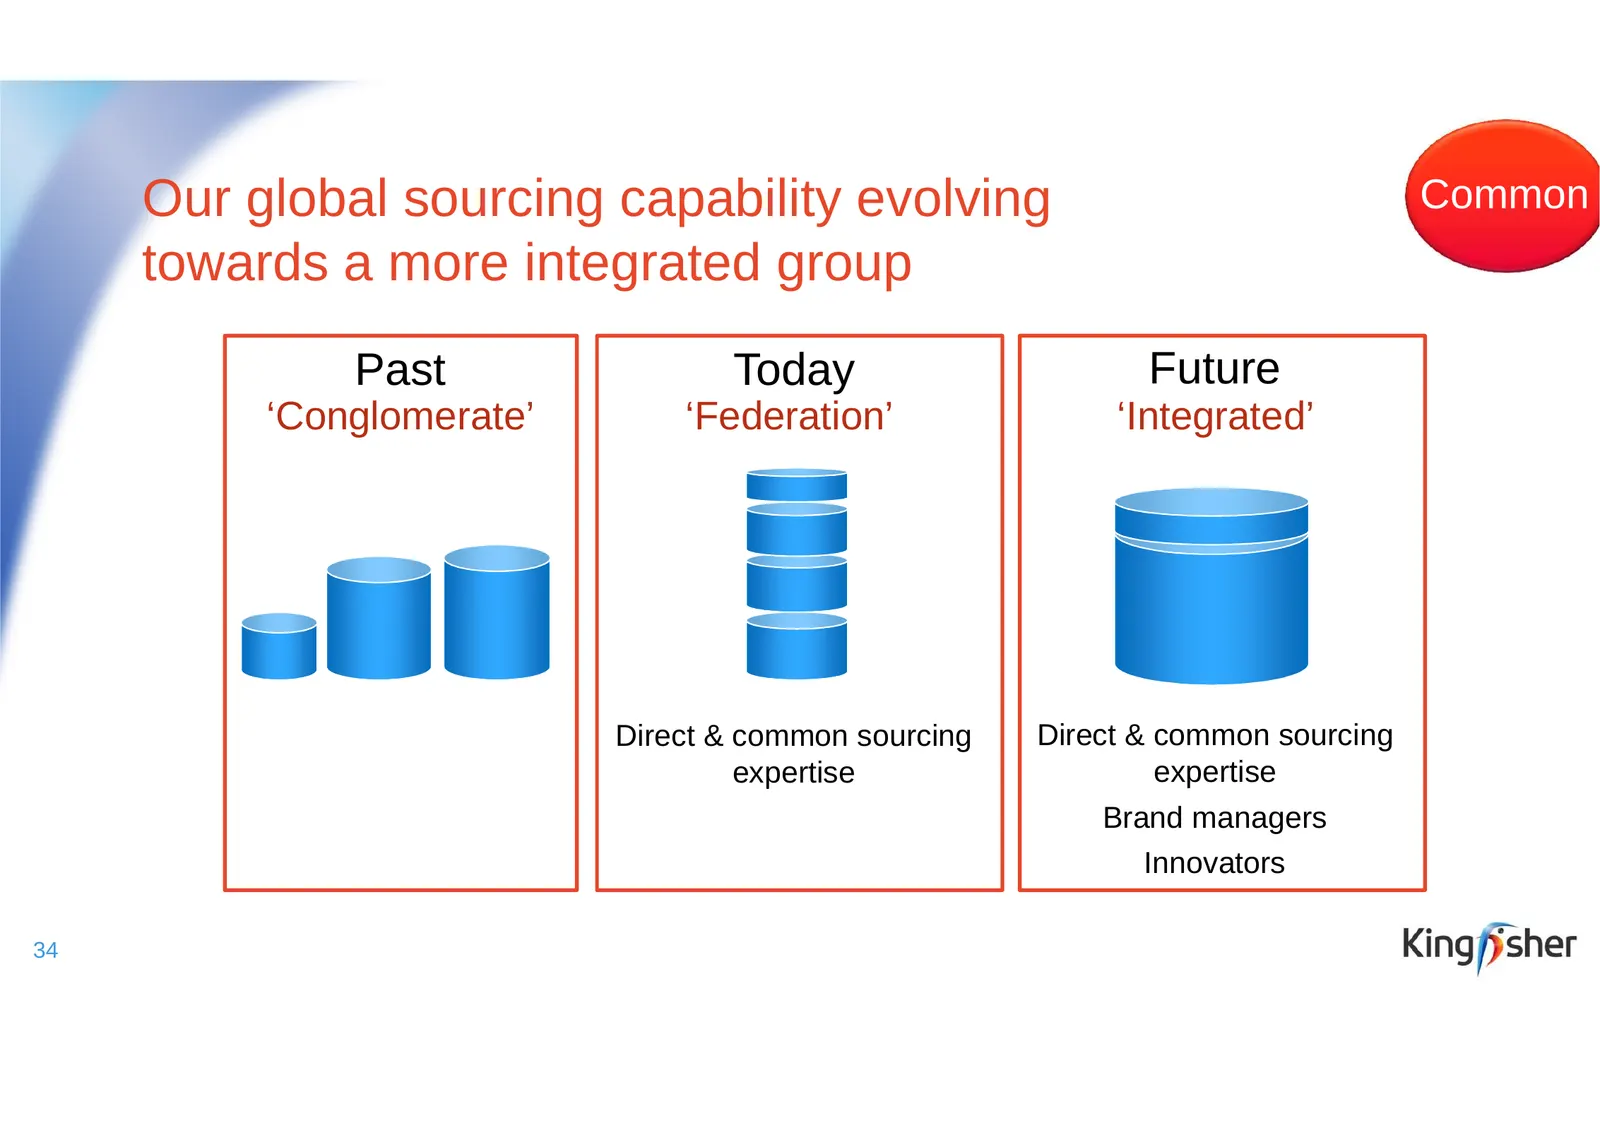
Our global sourcing capability evolving Common towards a more integrated group Past Today Future ‘Conglomerate’ ‘Federation’ ‘Integrated’ Direct & common sourcing Direct & common sourcing expertise expertise Brand managers Innovators 34
Slide 35: Guy Colleau, CEO Group Sourcing & Offer
Guy Colleau CEO Group Sourcing & Offer
Slide 36: The journey so far since 2008
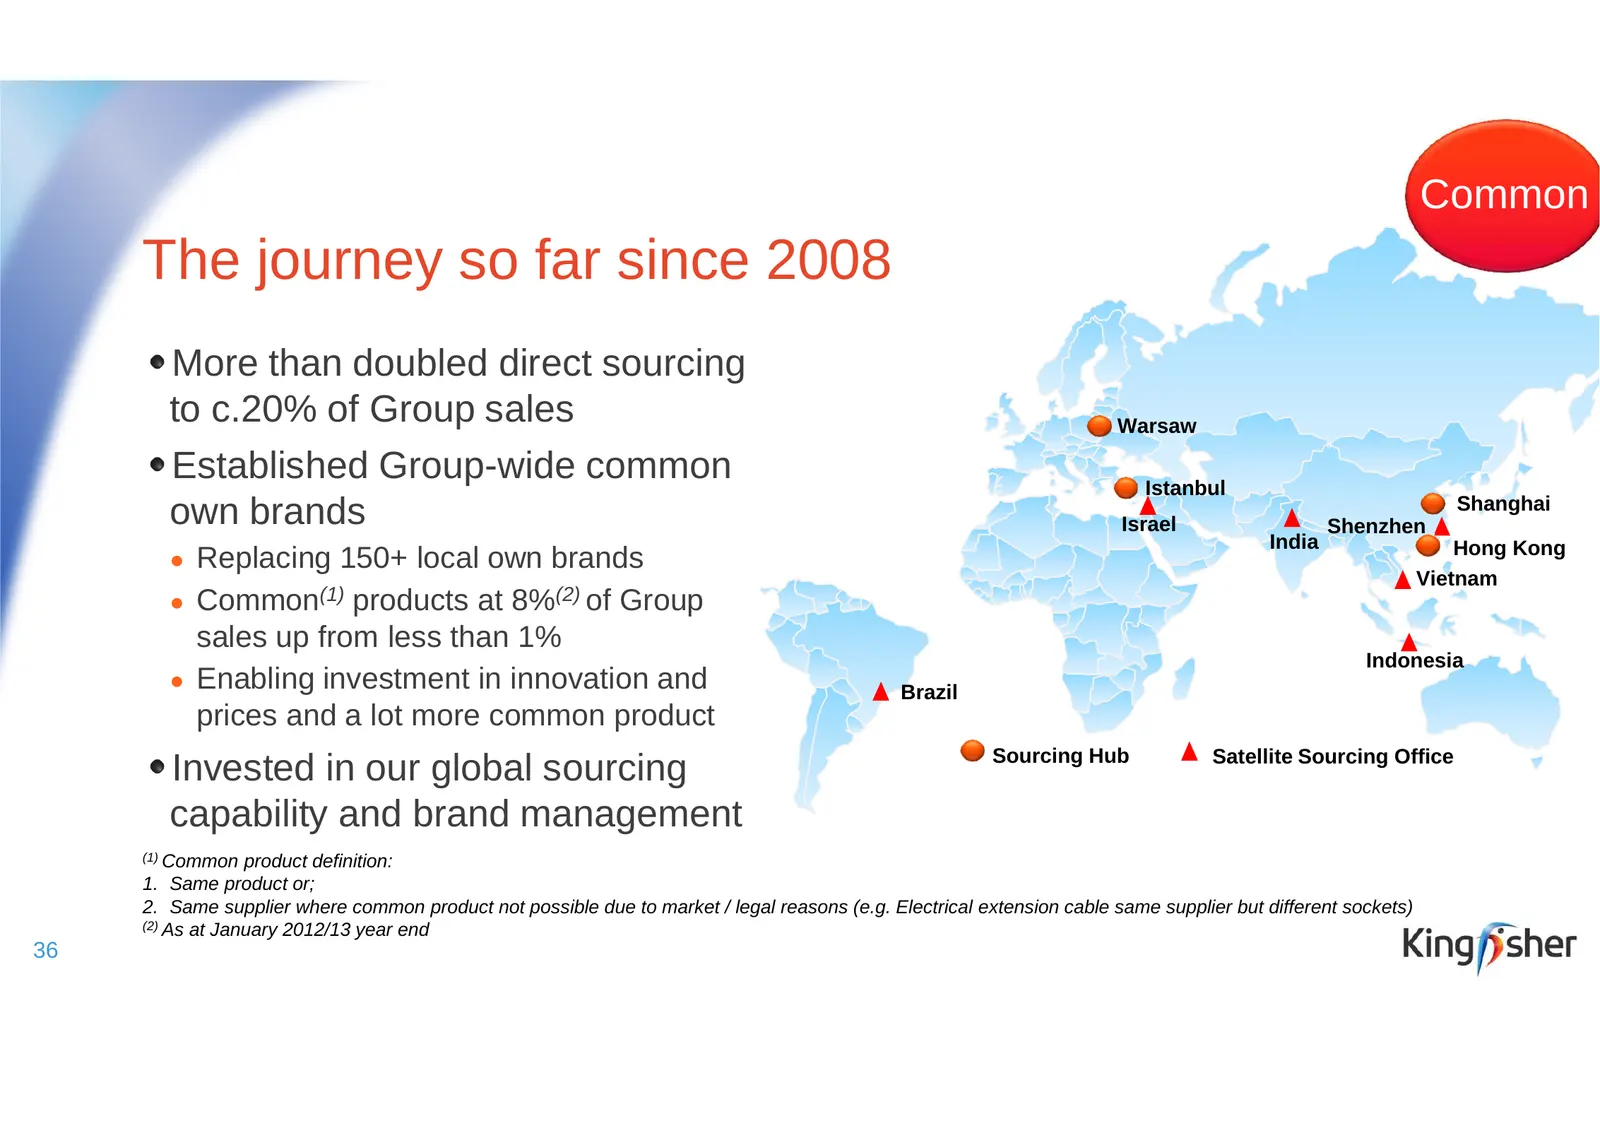
Common The journey so far since 2008 More than doubled direct sourcing to c.20% of Group sales Warsaw Established Group-wide common Istanbul Shanghai own brands Israel Shenzhen India Hong Kong ● Replacing 150+ local own brands Vietnam ● Common(1) products at 8%(2) of Group sales up from less than 1%
Slide 37: More to go for, approach evolving
Common More to go for, approach evolving Sourcing together across operating companies is increasingly ‘business as usual’ ● Increasingly driven and owned by commercial operators ‘on the ground’ ● 3 layers of opportunity – own label, direct & common ● Inaugural European product show Oct 2013 across t
Slide 38: Expanding successful own brand 'SITE' brand
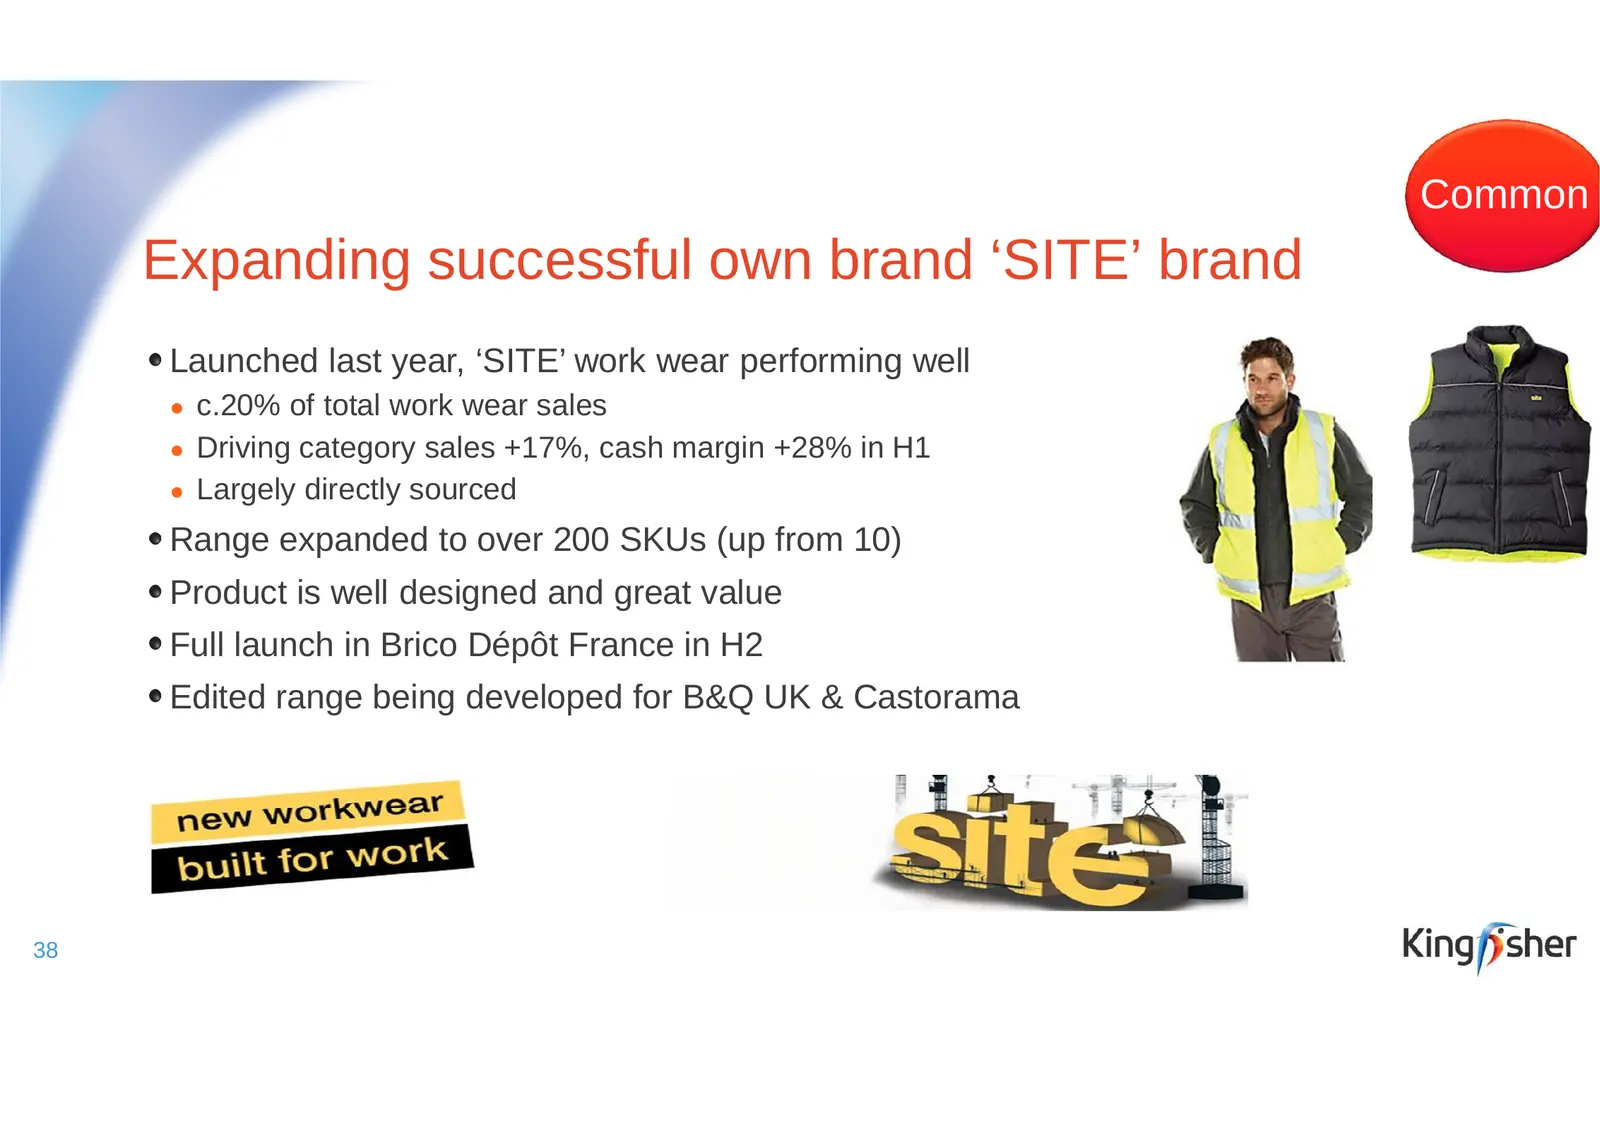
EASIER Common Expanding successful own brand ‘SITE’ brand Launched last year, ‘SITE’ work wear performing well ● c.20% of total work wear sales ● Driving category sales +17%, cash margin +28% in H1 ● Largely directly sourced Range expanded to over 200 SKUs (up from 10) Product is well designed and g
Slide 39: Ian Cheshire, Group Chief Executive
Ian Cheshire Group Chief Executive
Slide 40: 2013/14 milestones H1 update – Efficiency
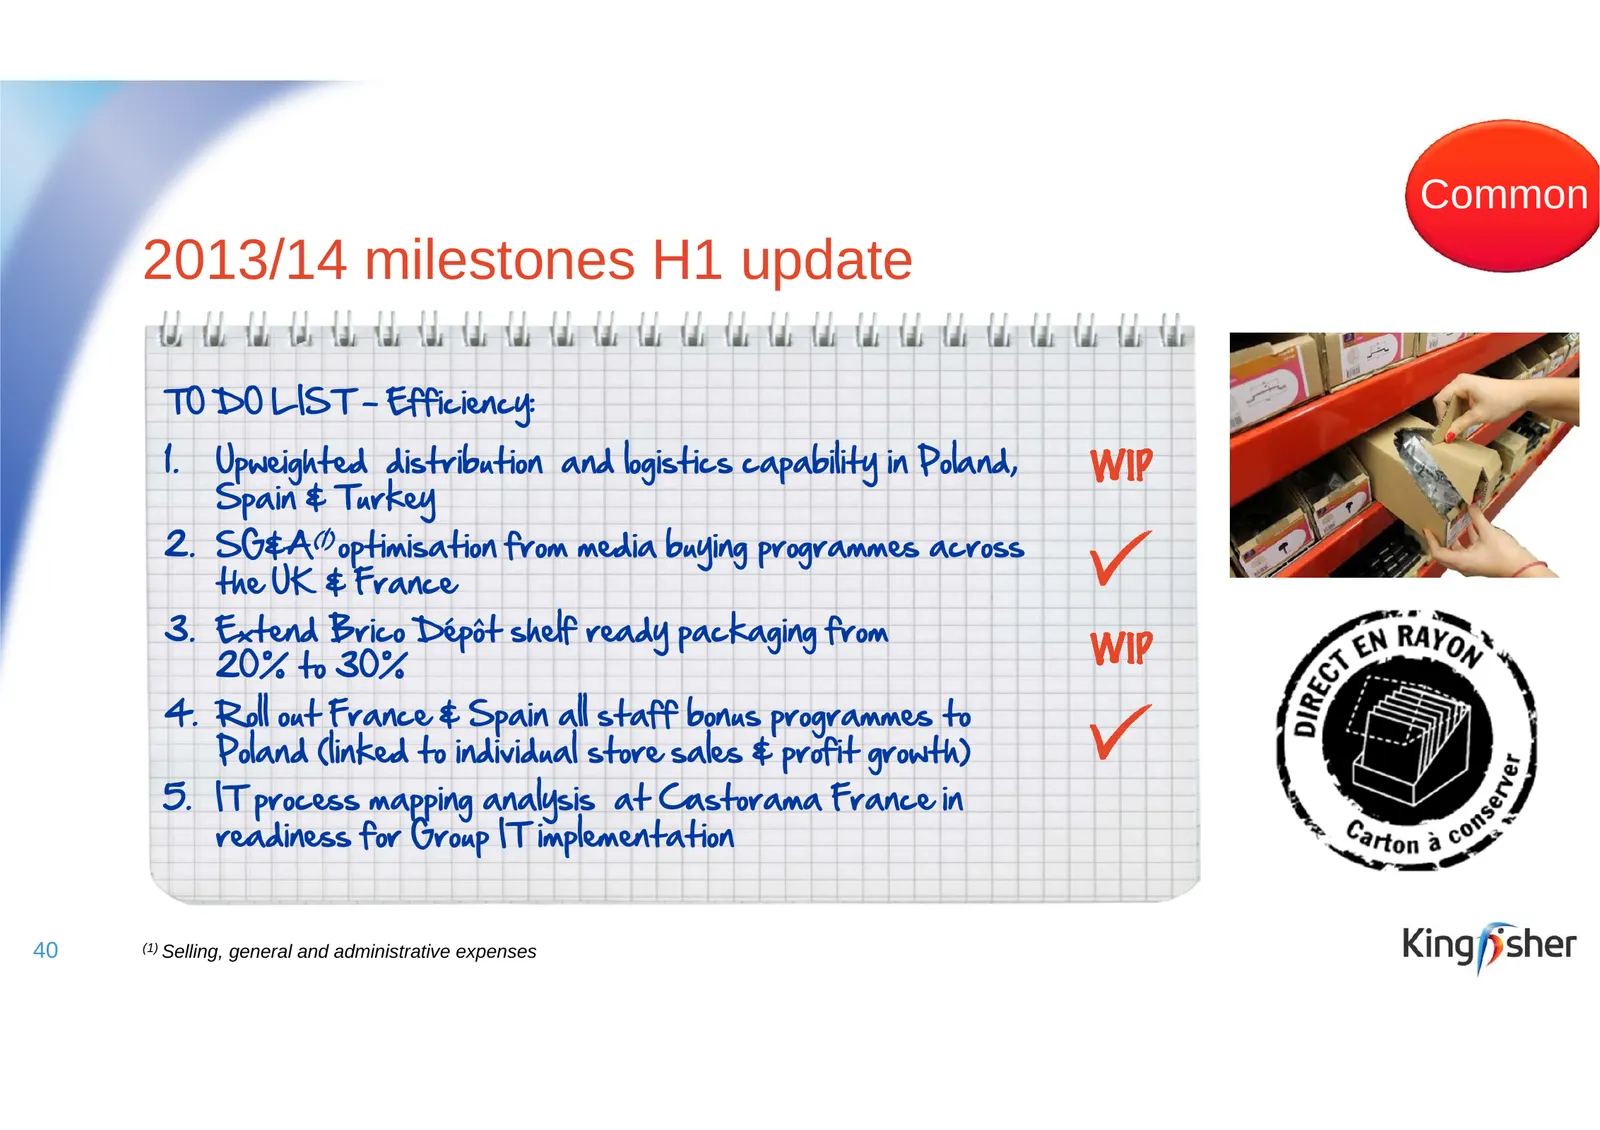
EASIER Common 2013/14 milestones H1 update TO DO LIST - Efficiency: 1. Upweighted distribution and logistics capability in Poland, XJQ Spain & Turkey 2. SG&A(1) optimisation from media buying programmes across the UK & France 3. Extend Brico Dépôt shelf ready packaging from 20% to 30% XJQ 4. Roll ou
Slide 41: Efficiency initiatives progressing well
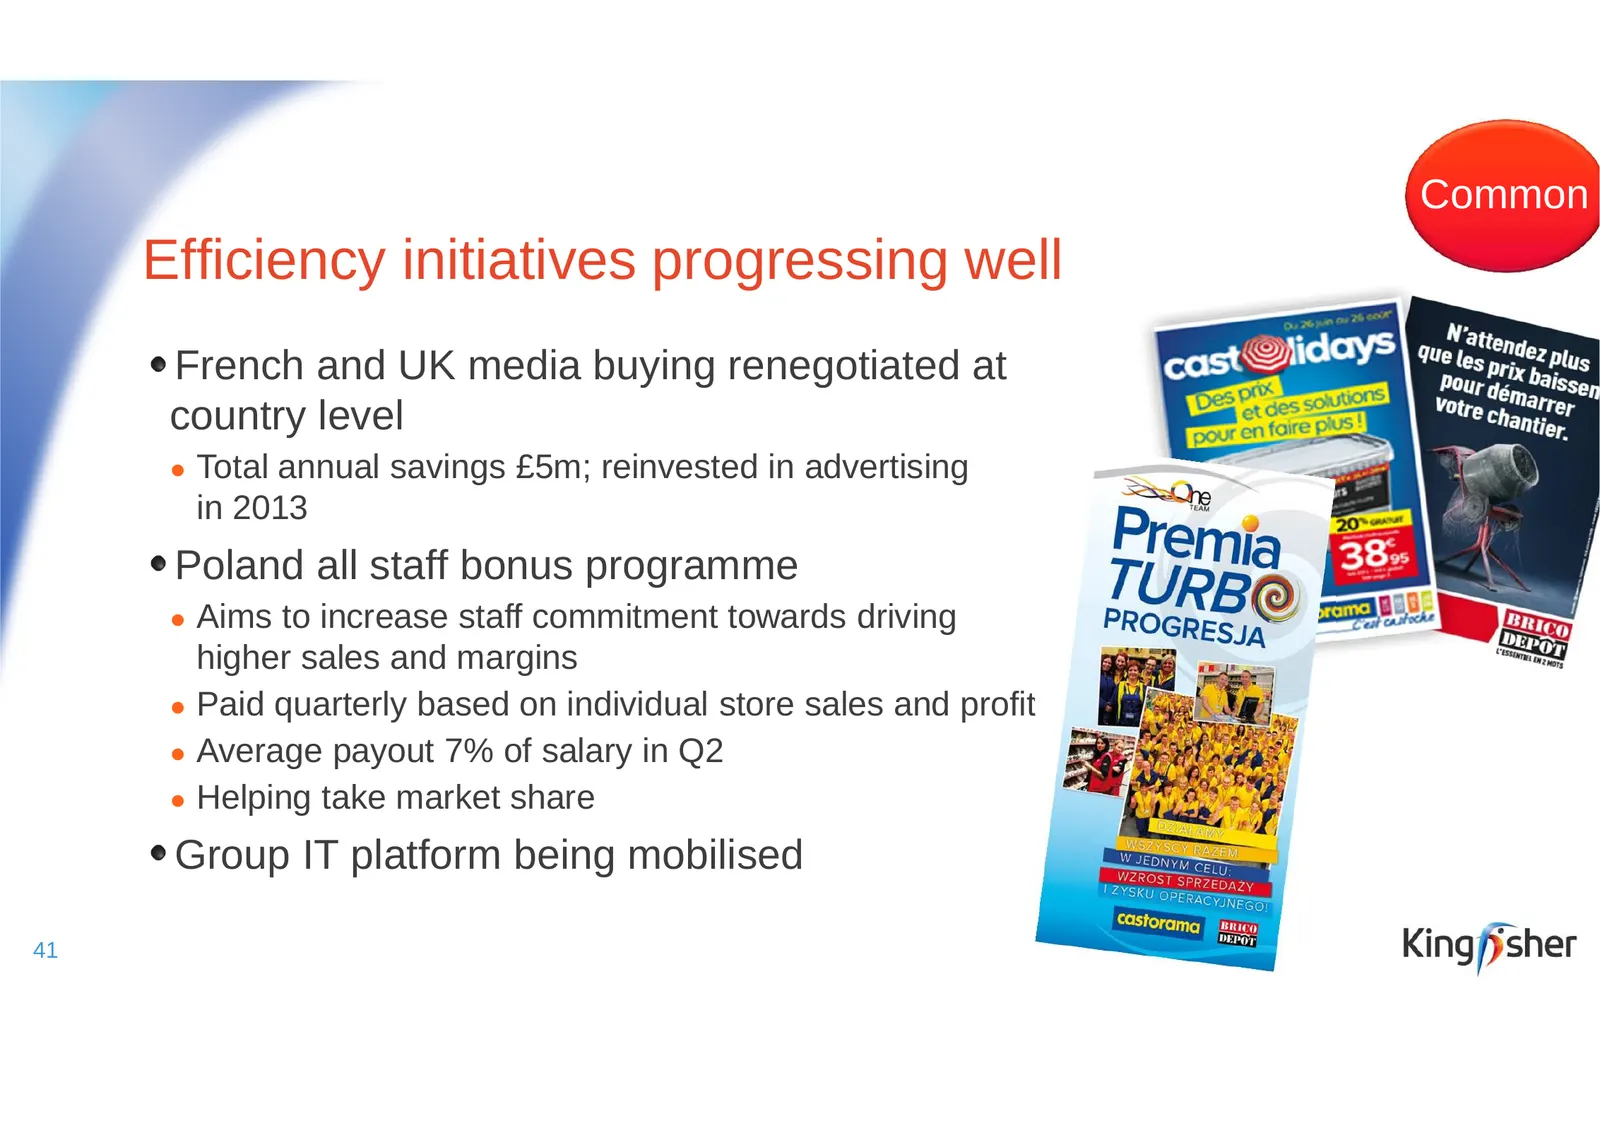
Common Efficiency initiatives progressing well French and UK media buying renegotiated at country level ● Total annual savings £5m; reinvested in advertising in 2013 Poland all staff bonus programme ● Aims to increase staff commitment towards driving higher sales and margins ● Paid quarterly based o
Slide 42: Growth
GROWTH HIGHER RETURNS ANI-CHANNEL FLEXIBILITY NEW TERRITORIE AMBITION INTERNATIONAL CAPABILITY = in 42 King/jsher
Slide 43: 2013/14 milestones H1 update – Space growth
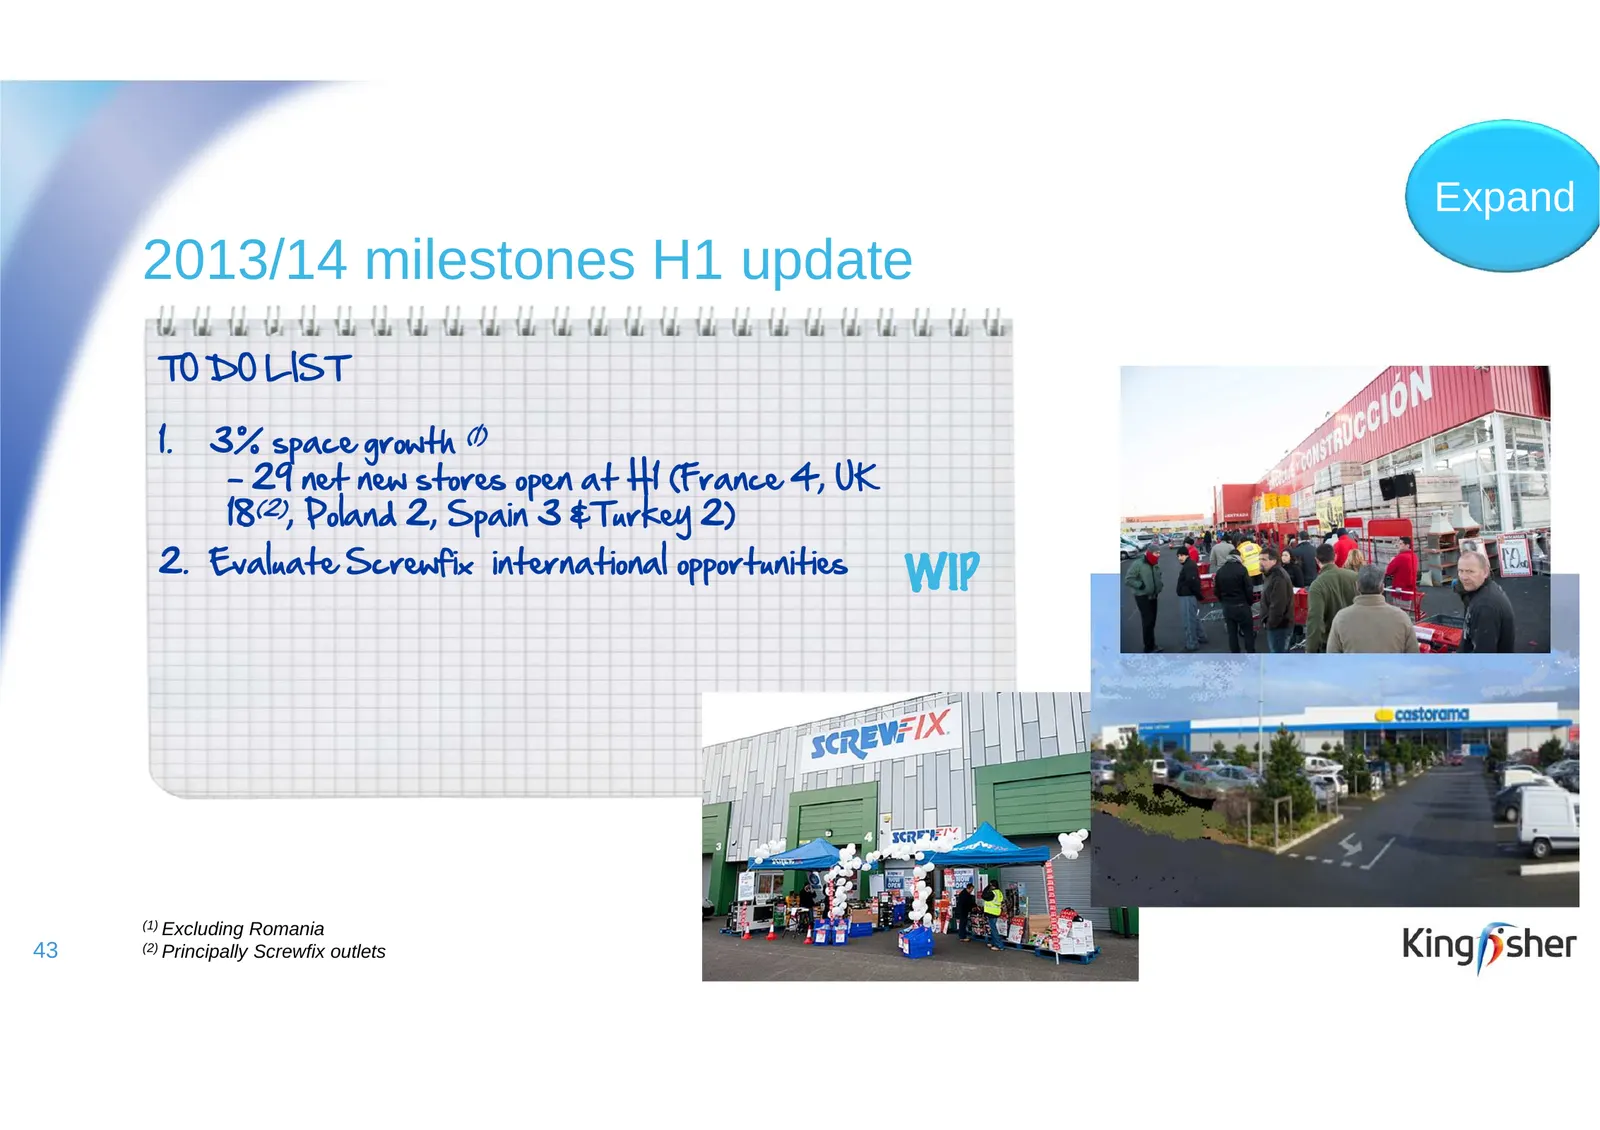
Expand 2013/14 milestones H1 update TO DO LIST 1. 3% space growth (1) - 29 net new stores open at H1 (France 4, UK 18(2), Poland 2, Spain 3 &Turkey 2) 2. Evaluate Screwfix international opportunities XJQ (1) Excluding Romania 43 (2) Principally Screwfix outlets
Slide 44: Capitalising on consolidation opportunities
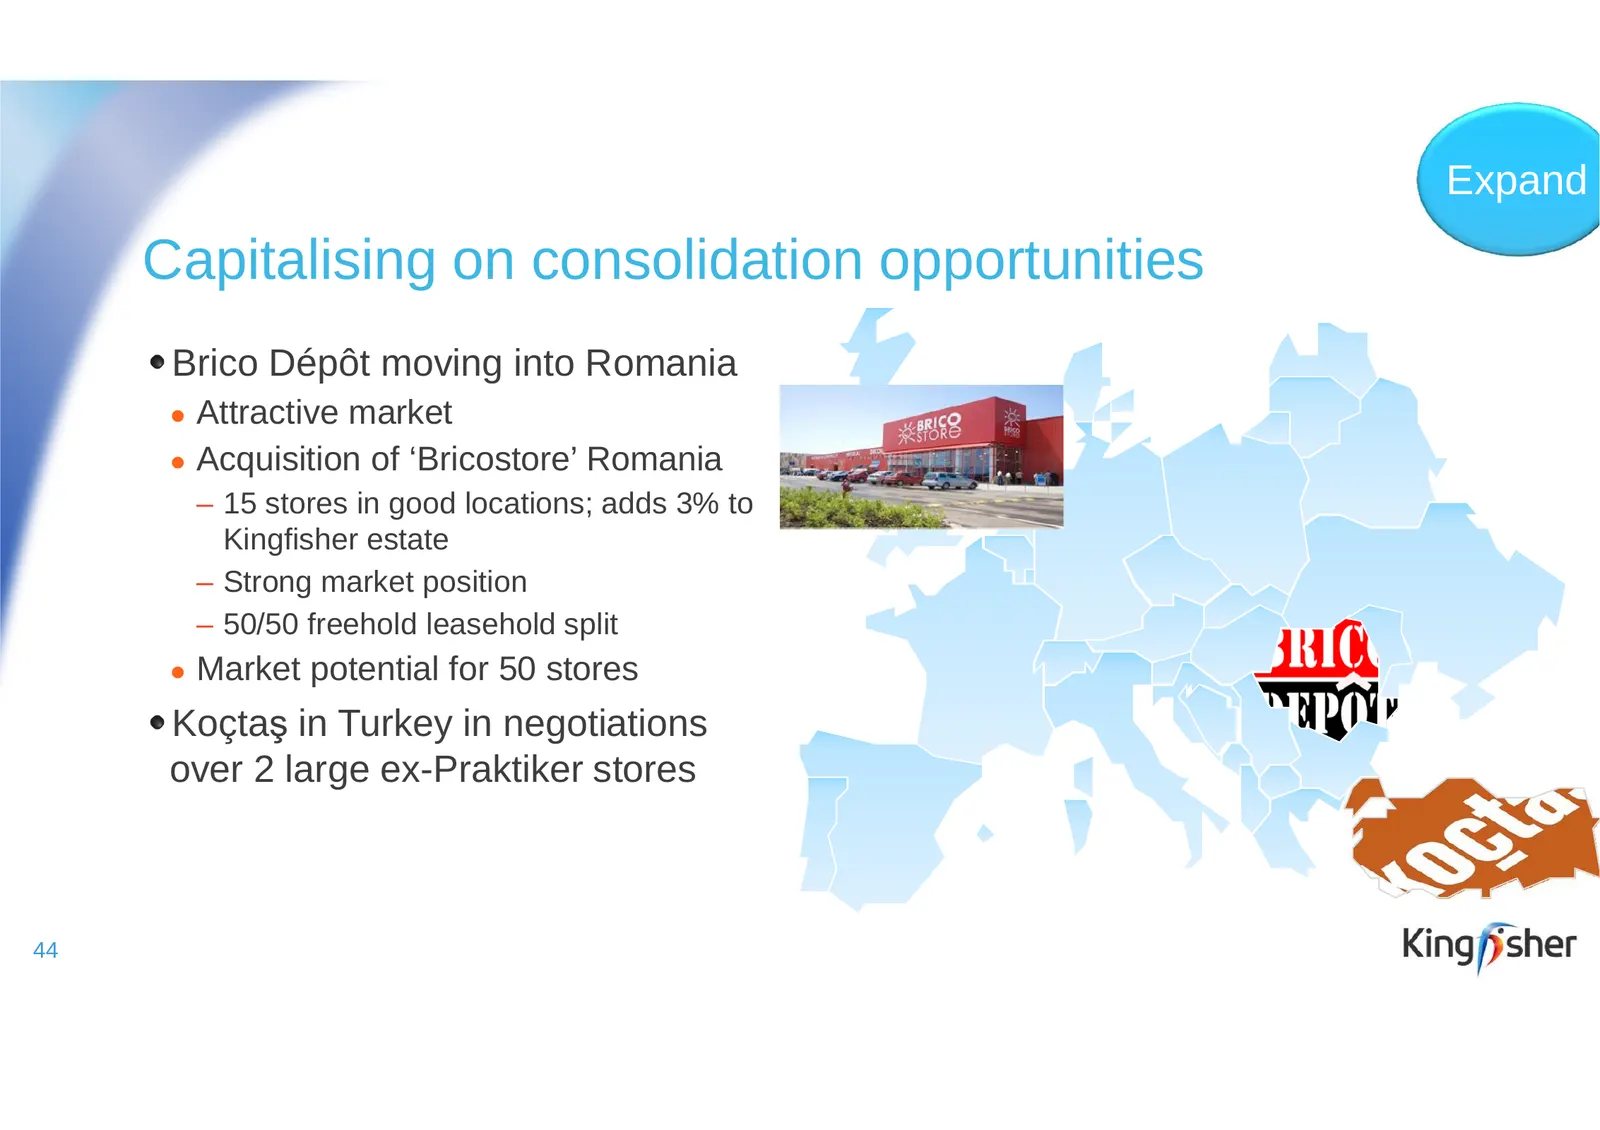
Expand Capitalising on consolidation opportunities Brico Dépôt moving into Romania ● Attractive market ● Acquisition of ‘Bricostore’ Romania – 15 stores in good locations; adds 3% to Kingfisher estate – Strong market position – 50/50 freehold leasehold split ● Market potential for 50 stores Koçtaş i
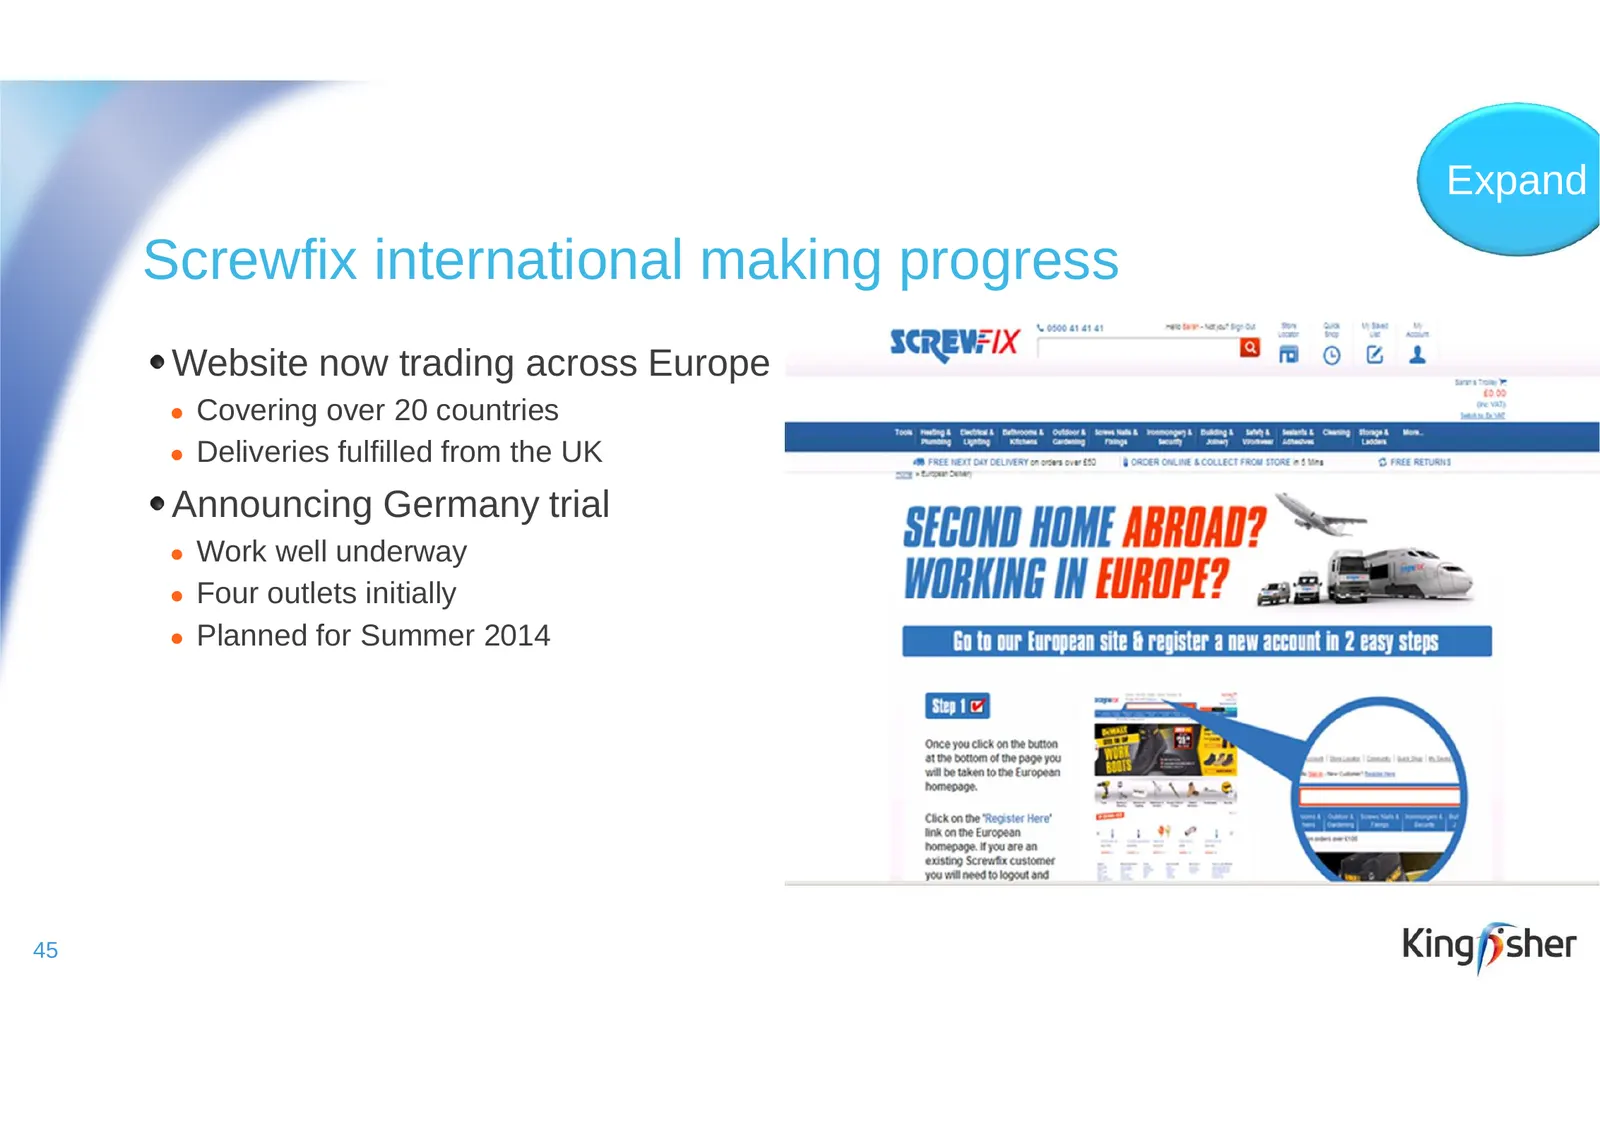
Slide 45: Screwfix international making progress
Expand Screwfix international making progress Website now trading across Europe ● Covering over 20 countries ● Deliveries fulfilled from the UK Announcing Germany trial ● Work well underway ● Four outlets initially ● Planned for Summer 2014 45
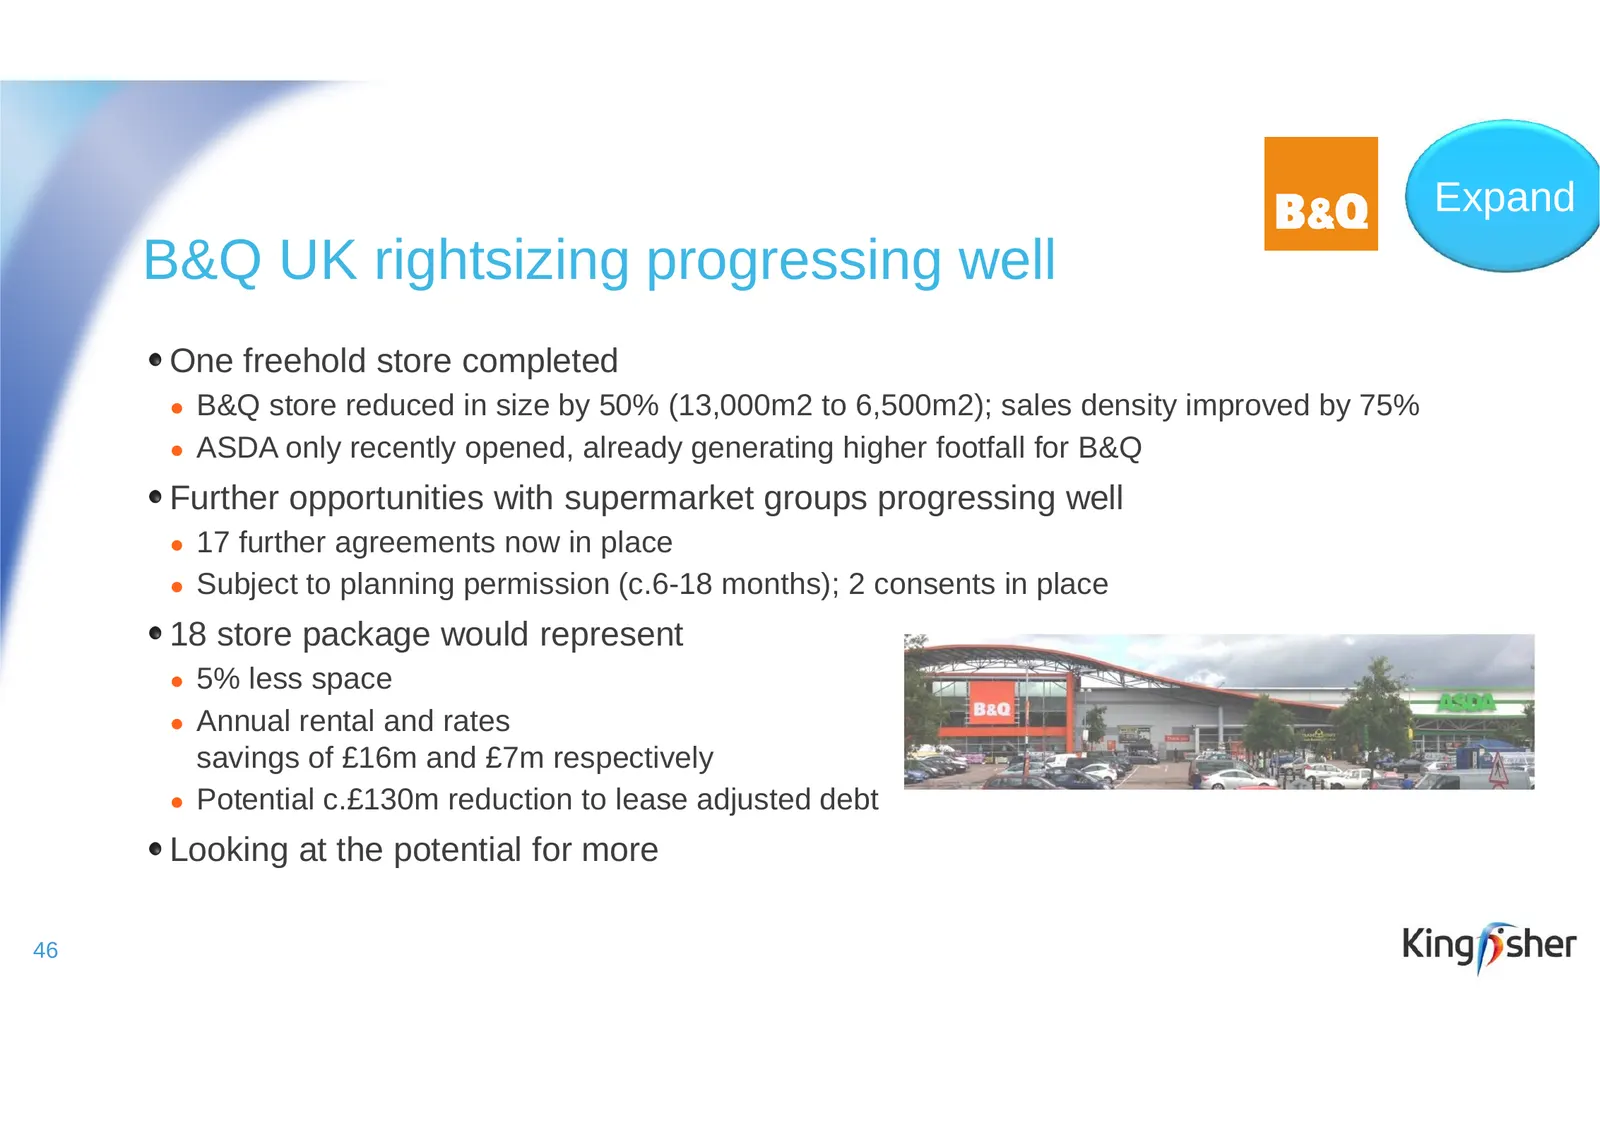
Slide 46: B&Q UK rightsizing progressing well
Expand B&Q UK rightsizing progressing well One freehold store completed ● B&Q store reduced in size by 50% (13,000m2 to 6,500m2); sales density improved by 75% ● ASDA only recently opened, already generating higher footfall for B&Q Further opportunities with supermarket groups progressing well ● 17
Slide 47: One Team
ACADEMY DEVELOPING LEADERS RECRUITMENT CONNECTINGH ata = FORCE Val FOR GOOD ROSIE Nae 2 King/ysher
Slide 48: One Team 2013/14 H1 progress
One Team One Team 2013/14 H1 progress Recently appointed Richard Gillies from M&S as Group Sustainability Director, to lead ‘Net Positive’ agenda Increase in cross-Group people moves Continued to develop ‘Kingfisher One Academy’ Launched B&Q UK & Ireland ‘Good Woods’ woodland stewardship initiative
Slide 49: 2013/14 H1 Summary
2013/14 H1 Summary H1 a challenging and volatile 6 months ● On-going weak consumer confidence in our major markets ● Q1/Q2 weather patterns ‘Creating the Leader’ programme progressing well ● 8 steps, 2013/14 milestones for future growth on track ● On-going self-help initiatives continuing to support
Slide 50: Cautionary note regarding forward-looking statements
Cautionary note regarding forward-looking statements THIS PRESENTATION CONTAINS FORWARD-LOOKING STATEMENTS, WHICH SHOULD BE CONSIDERED, AMONGST OTHER STATUTORY PROVISIONS, IN LIGHT OF THE SAFE HARBOUR PROVISIONS OF THE UNITED STATES PRIVATE SECURITIES LITIGATION REFORM ACT OF 1995. ALL STATEMENTS OT
Slide 51: Appendices
Appendices
Slide 52: Statutory financial reconciliation
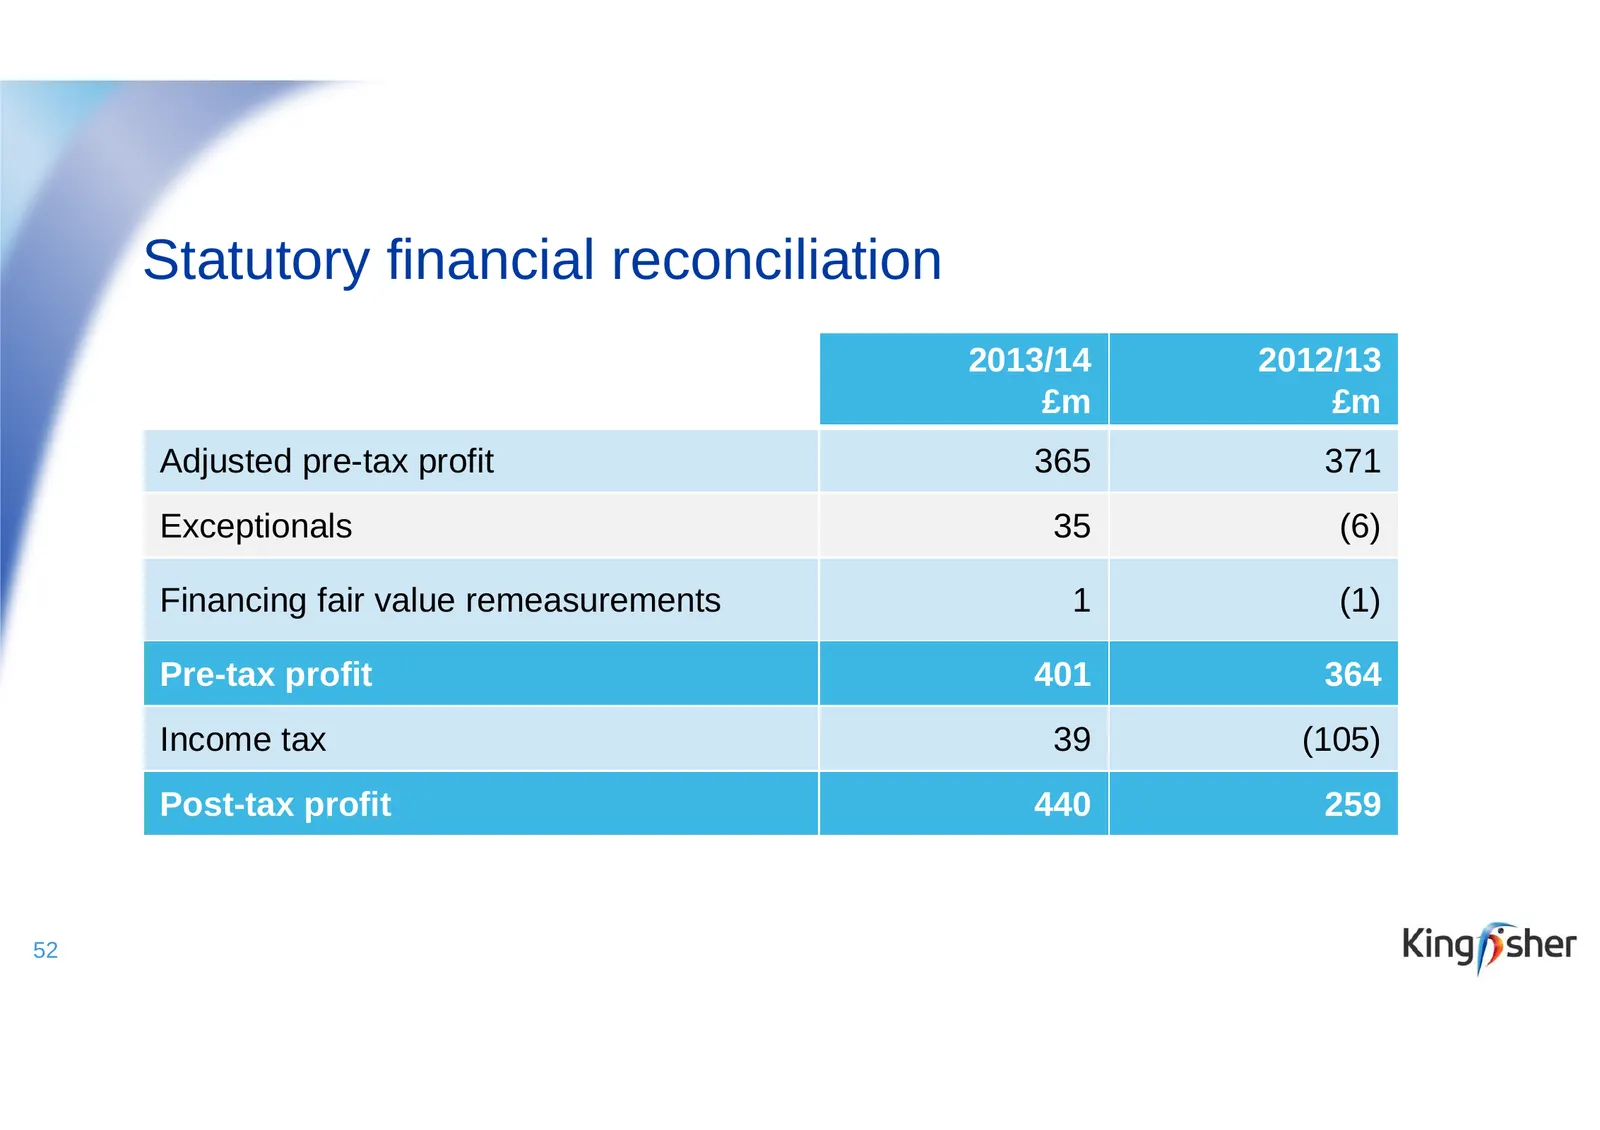
Statutory financial reconciliation 2013/14 2012/13 £m £m Adjusted pre-tax profit 365 371 Exceptionals 35 (6) Financing fair value remeasurements 1 (1) Pre-tax profit 401 364 Income tax 39 (105) Post-tax profit 440 259 52
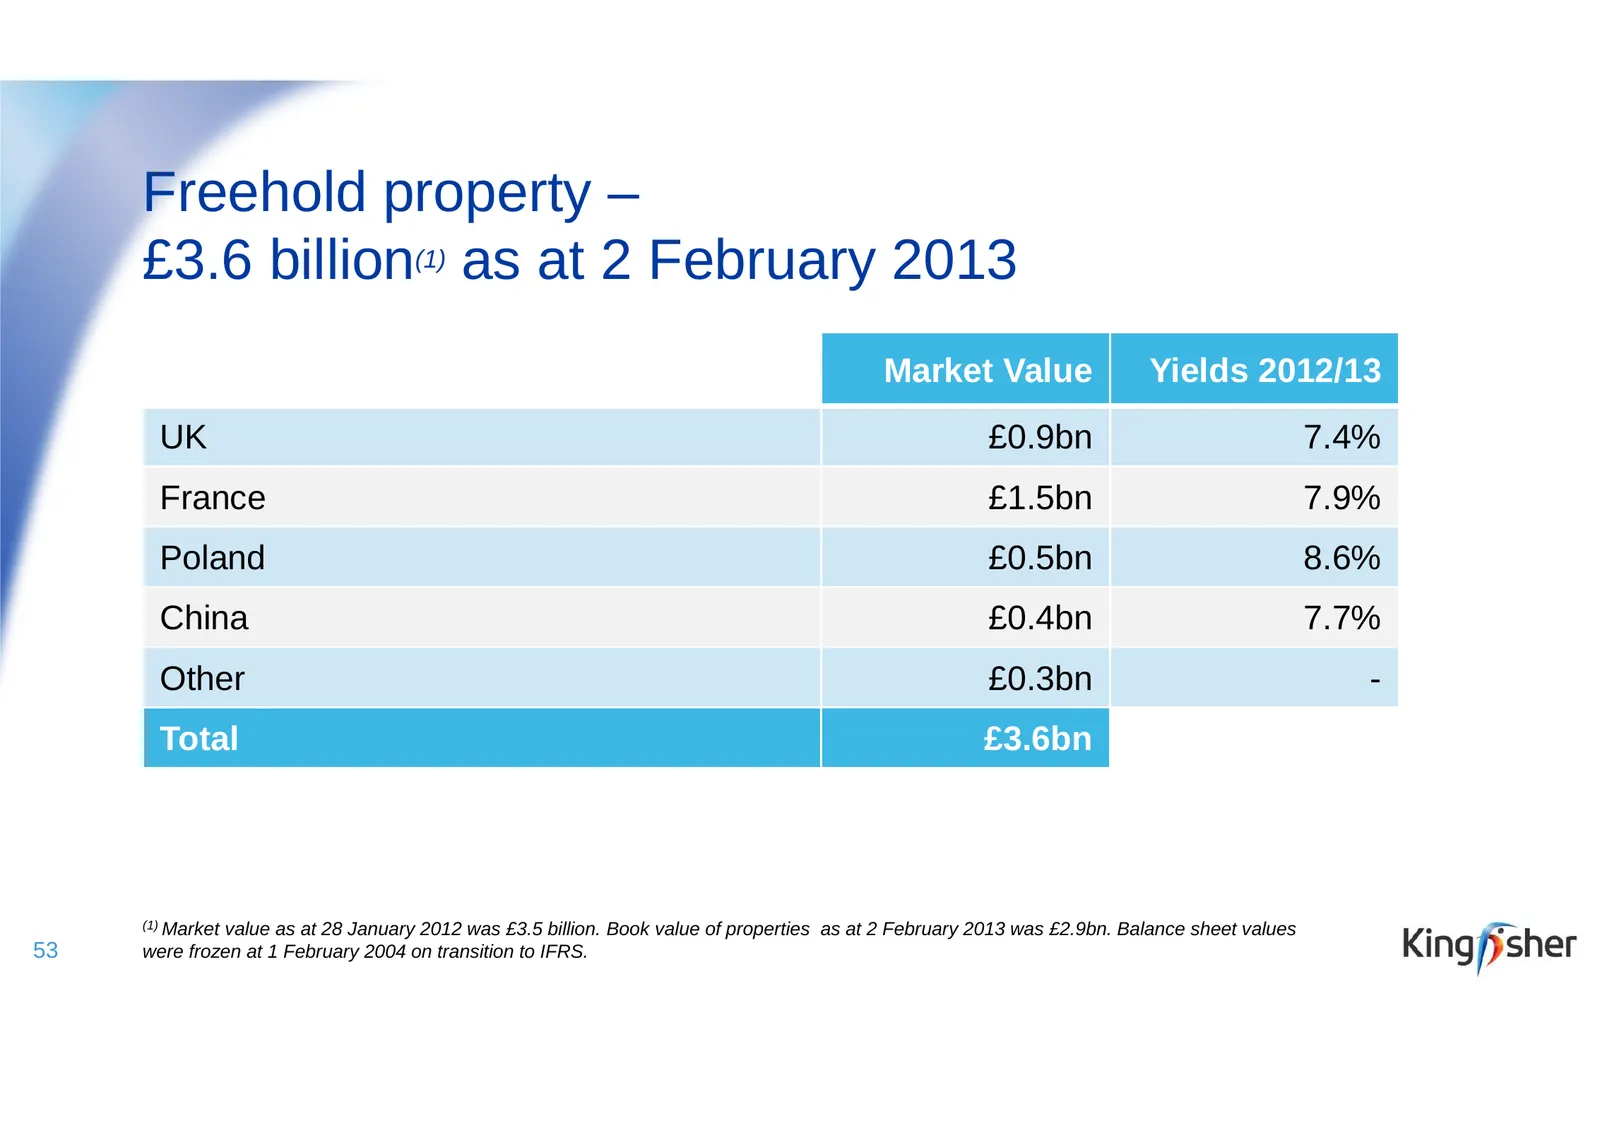
Slide 53: Freehold property – £3.6 billion as at 2 February 2013
Freehold property – £3.6 billion(1) as at 2 February 2013 Market Value Yields 2012/13 UK £0.9bn 7.4% France £1.5bn 7.9% Poland £0.5bn 8.6% China £0.4bn 7.7% Other £0.3bn - Total £3.6bn (1) Market value as at 28 January 2012 was £3.5 billion. Book value of properties as at 2 February 2013 was £2.9bn.
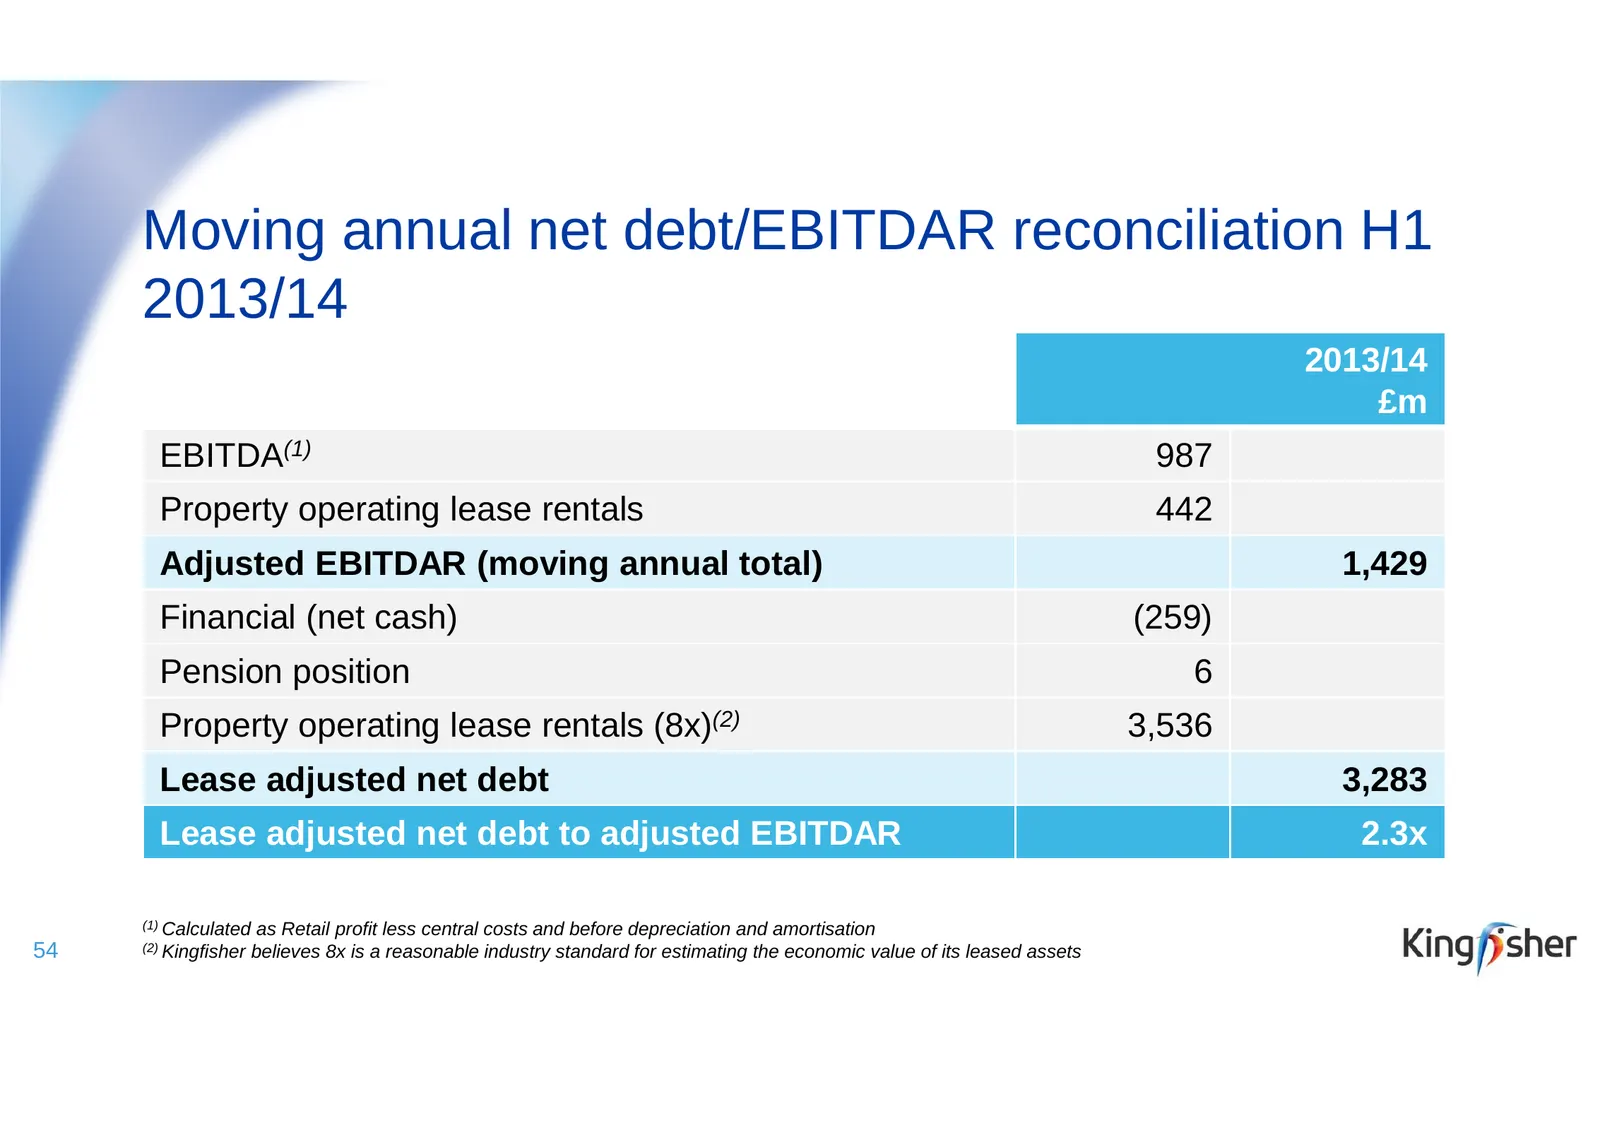
Slide 54: Moving annual net debt/EBITDAR reconciliation H1
Moving annual net debt/EBITDAR reconciliation H1 2013/14 2013/14 £m EBITDA(1) 987 Property operating lease rentals 442 Adjusted EBITDAR (moving annual total) 1,429 Financial (net cash) (259) Pension position 6 Property operating lease rentals (8x)(2) 3,536 Lease adjusted net debt 3,283 Lease adjuste
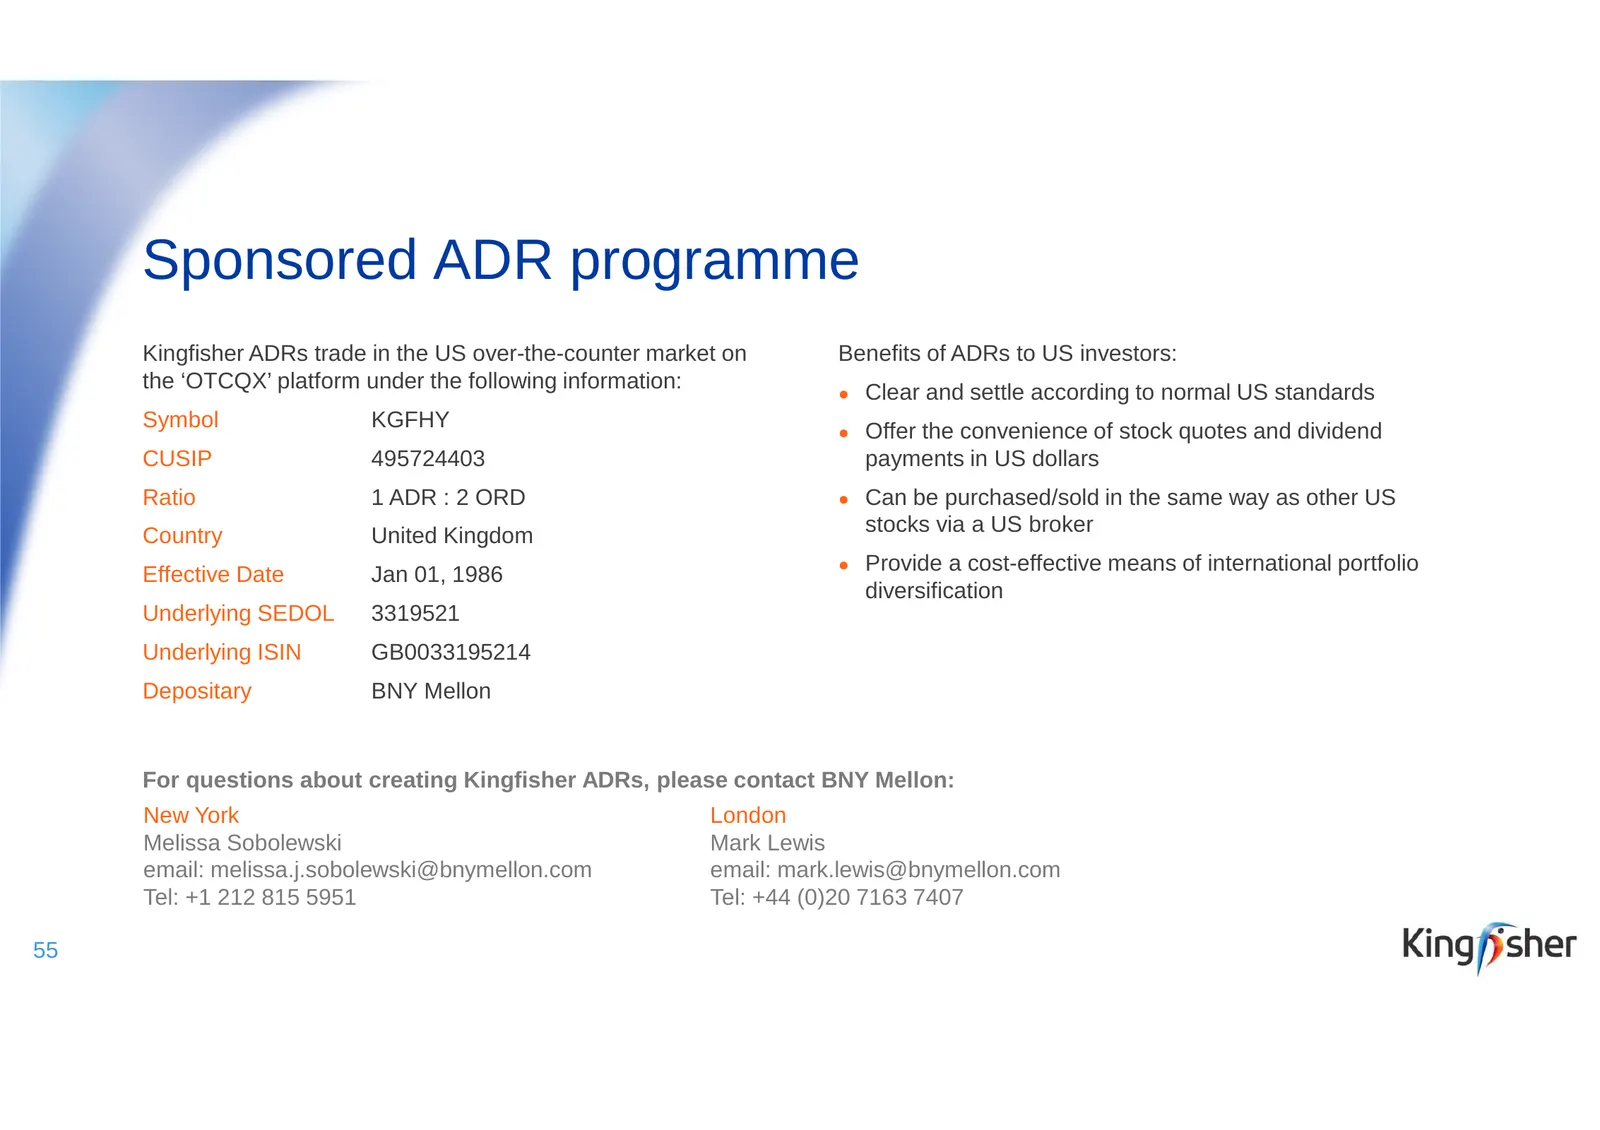
Slide 55: Sponsored ADR programme
Sponsored ADR programme Kingfisher ADRs trade in the US over-the-counter market on Benefits of ADRs to US investors: the ‘OTCQX’ platform under the following information: ● Clear and settle according to normal US standards Symbol KGFHY ● Offer the convenience of stock quotes and dividend CUSIP 49572
Slide 56: Contacts
Contacts Ian Harding, Group Communications Director +44 (0)20 7644 1029 Sarah Levy, Head of Investor Relations +44 (0)20 7644 1032 Nigel Cope, Head of Media Relations +44 (0)20 7644 1030 Matt Duffy, Investor Relations Manager +44 (0)20 7644 1082 Clare Haines, Media Relations Manager +44 (0)20 7644 1
Source: Internet Archive copy of kingfisher.com
More decks from Kingfisher PLC
 H1 2026/27 Earnings Presentation33 slides · Sep 22, 2026
 FY2025/26 Earnings Presentation39 slides · Mar 24, 2026
 H1 2025/26 Earnings Presentation38 slides · Sep 23, 2025
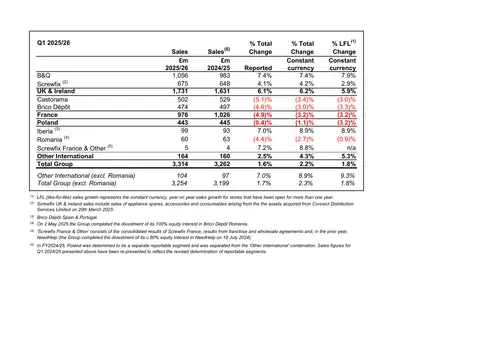 H1 2025/26 Earnings Presentation6 slides · September 2025
 FY2024/25 Earnings Presentation35 slides · Apr 8, 2025
 FY2024/25 Earnings Presentation40 slides · Mar 25, 2025