M&G PLC · LSE:MNG
M&G — M&G Wealth — Investor Presentation
36 slides from M&G's investor presentation
Slide 1: Techy Tuesday Tax Tools: Tax Relief Modeller and Bond Gain Tool
Techy Tuesday Tax Tools Tax Relief Modeller and Bond Gain Tool The information that follows is based on our understanding of current taxation, legislation and HM Revenue & Customs practice all of which are liable to change without notice. This is just for UK advisers – it’s not for use with clients
Slide 2: Important information on taxation and legislation
This content is based on our understanding of current taxation, legislation and HM Revenue & Customs practice all of which are liable to change without notice. The impact of any taxation (and any tax reliefs) depends on individual circumstances. Where content includes case studies or examples these
Slide 3: Learning Objectives
Learning Objectives By the end of this session you will be able to: Demonstrate the Understand the inputs required for theory for using the using the Tax Tax Relief Modeller Relief Modeller Bond Gain and Tax Bond Gain and Tax Wrapper Wrapper Comparison Tools Comparison Tools
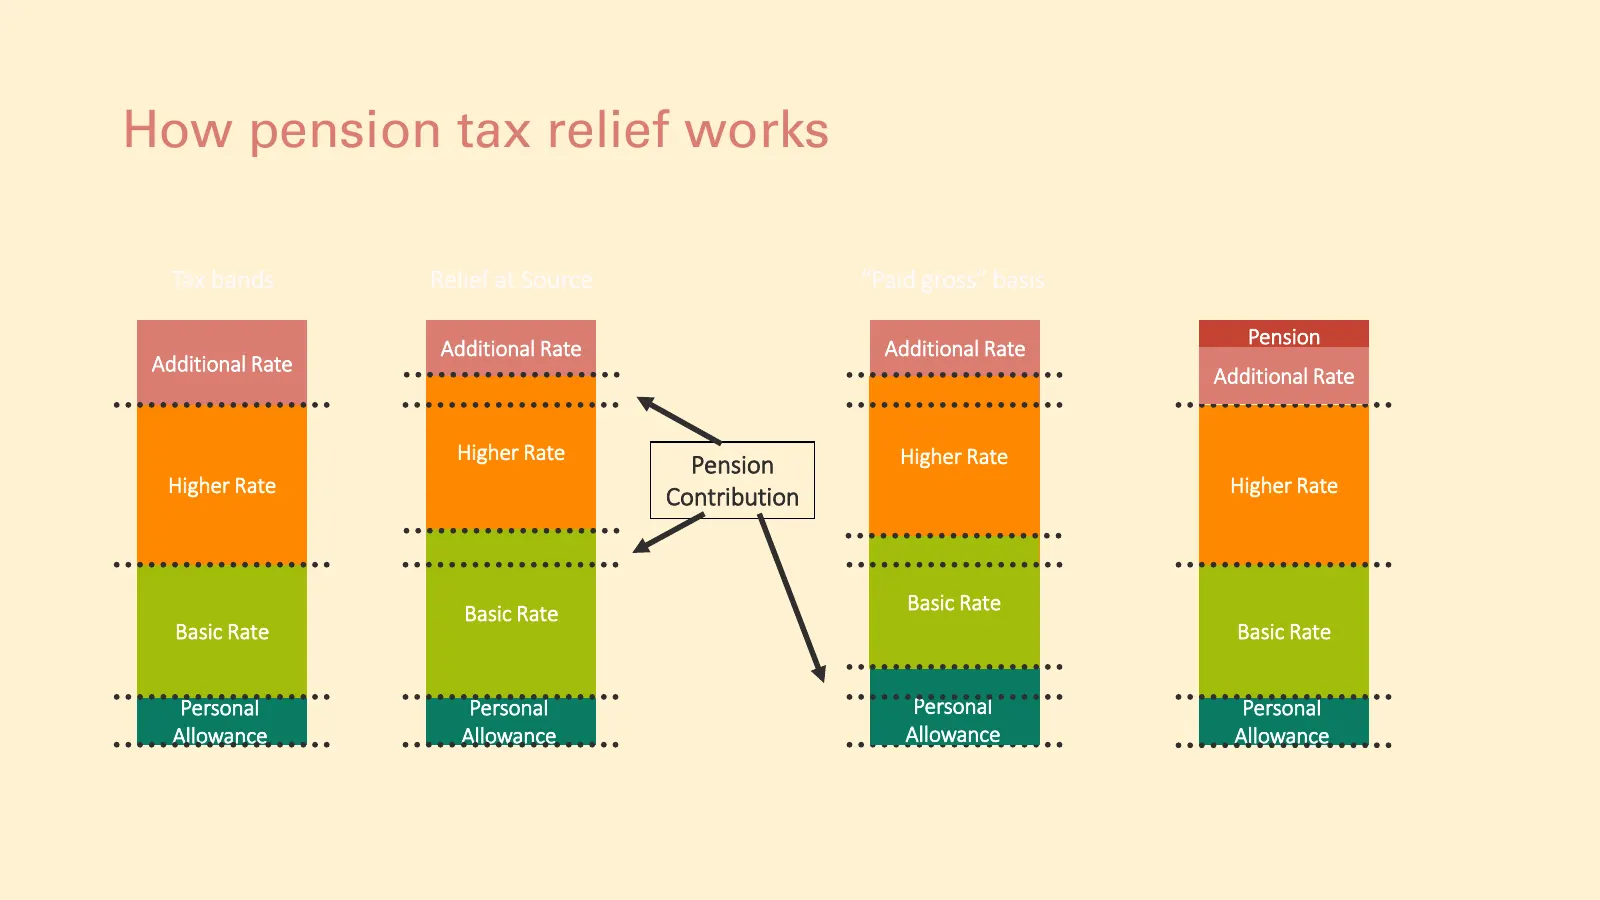
Slide 4: How pension tax relief works
How pension tax relief works Tax bands Relief at Source “Paid gross” basis Pension Additional Rate Additional Rate Additional Rate Additional Rate Additional Rate Additional Rate Higher Rate Higher Rate Pension Higher Rate Higher Rate Higher Rate Higher Rate Contribution Basic Rate Basic Rate Basic
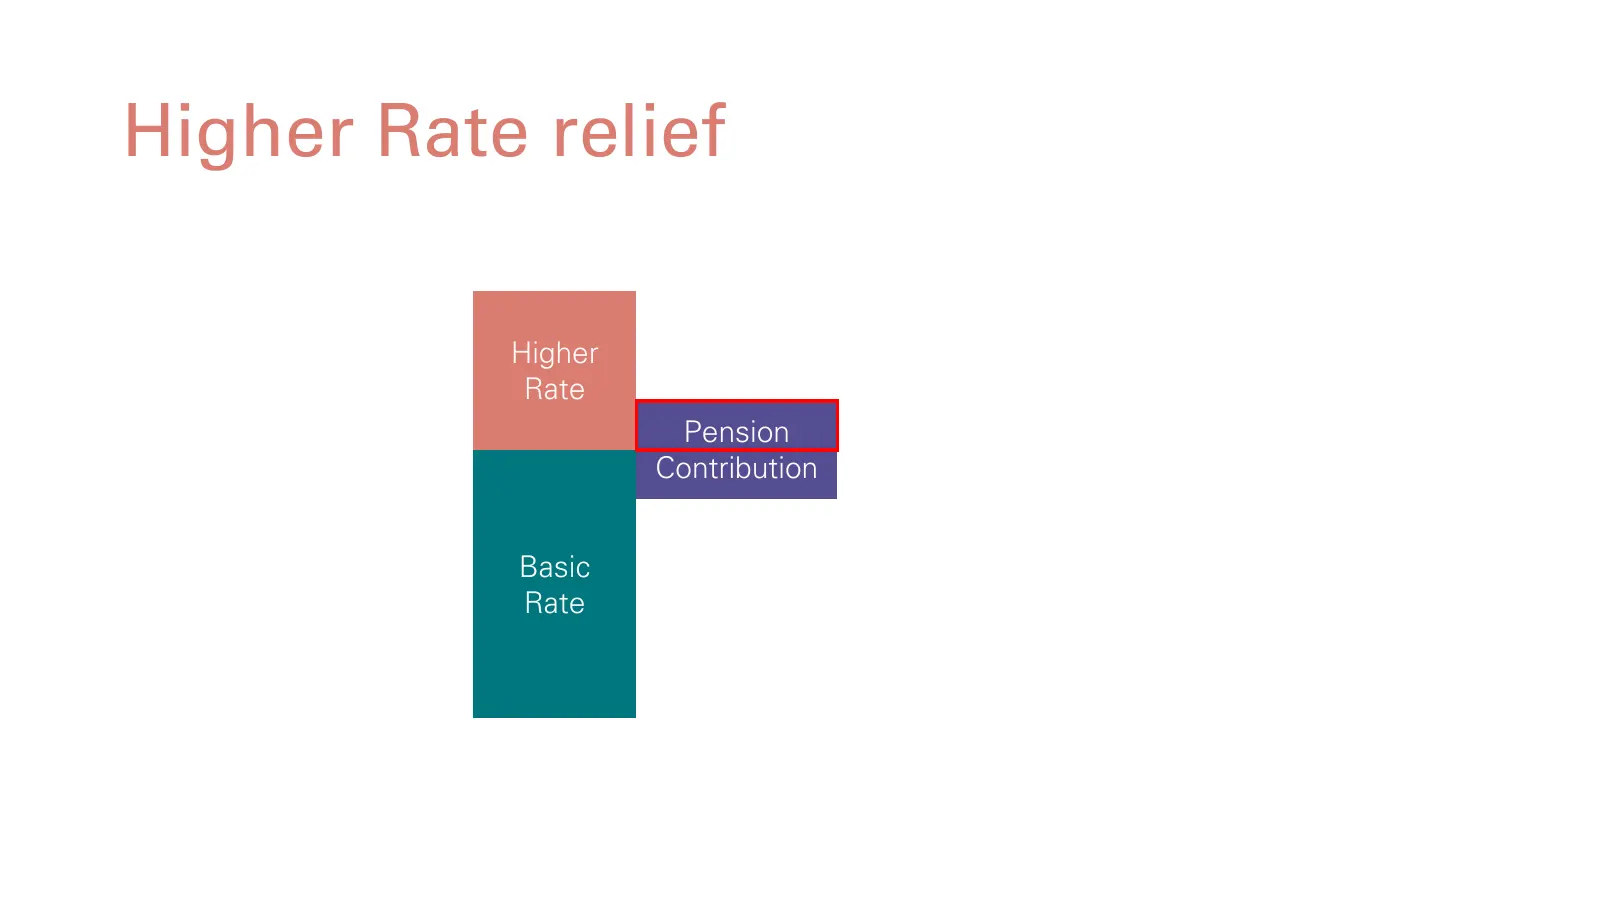
Slide 5: Higher Rate relief
Higher Rate relief Higher Rate Pension Contribution Basic Rate
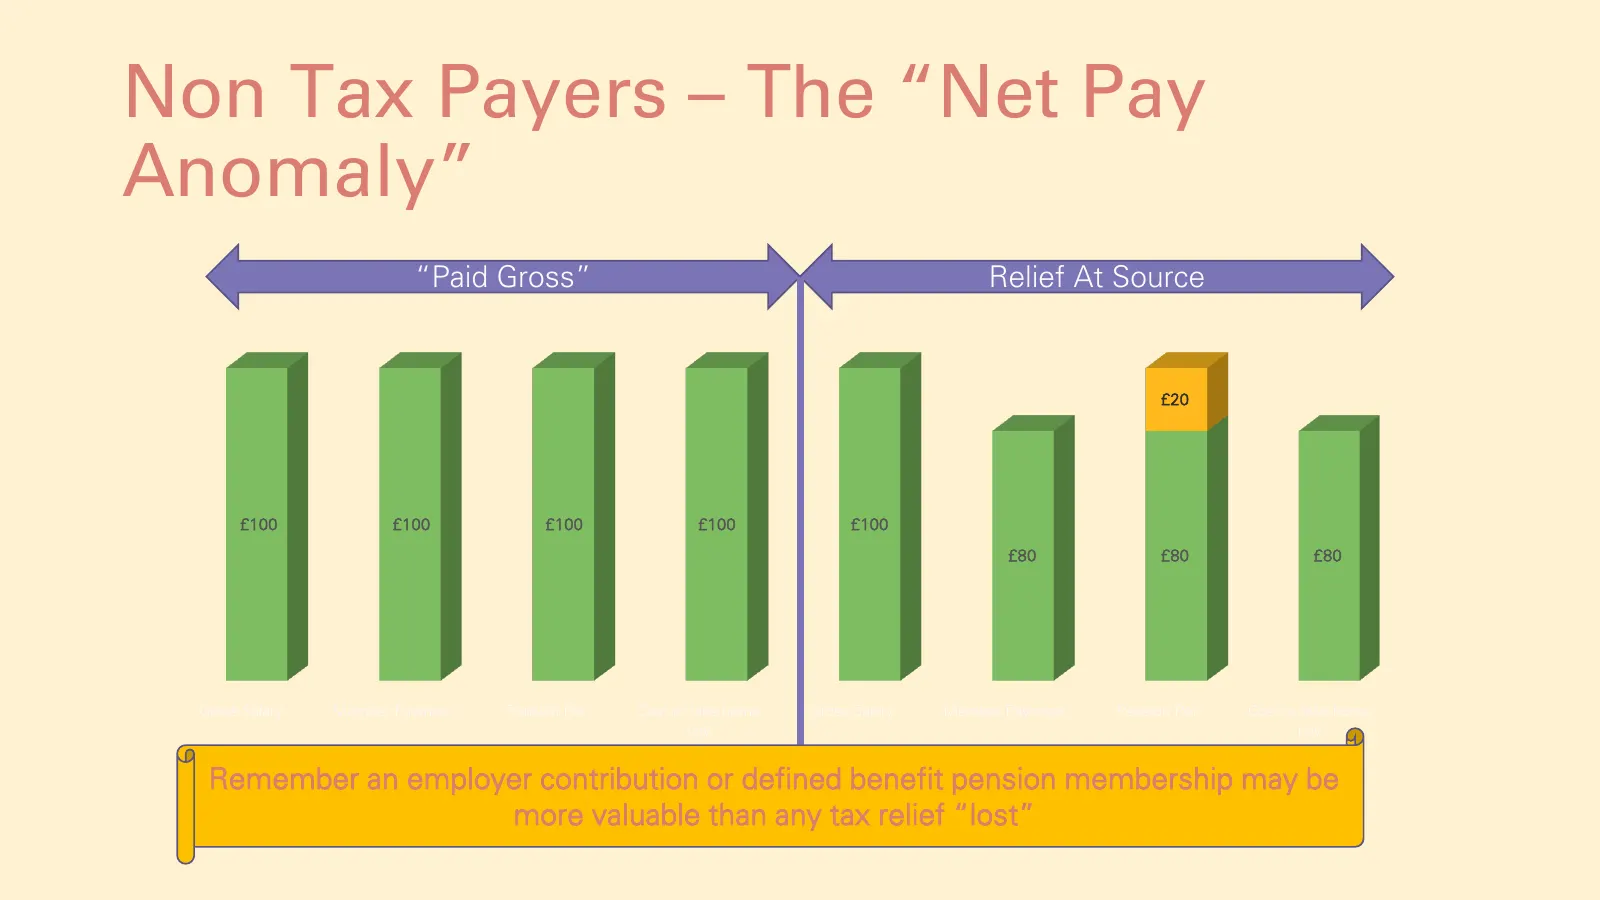
Slide 6: Non Tax Payers – The "Net Pay Anomaly"
Non Tax Payers – The “Net Pay Anomaly” “Paid Gross” Relief At Source £20 £100 £100 £100 £100 £100 £80 £80 £80 Gross Salary Member Payment Pension Pot Cost to take home Gross Salary Member Payment Pension Pot Cost to take home pay pay Remember an employer contribution or defined benefit pension membe
Slide 7: The Steps of Income Tax
The 7 Steps of Income Tax
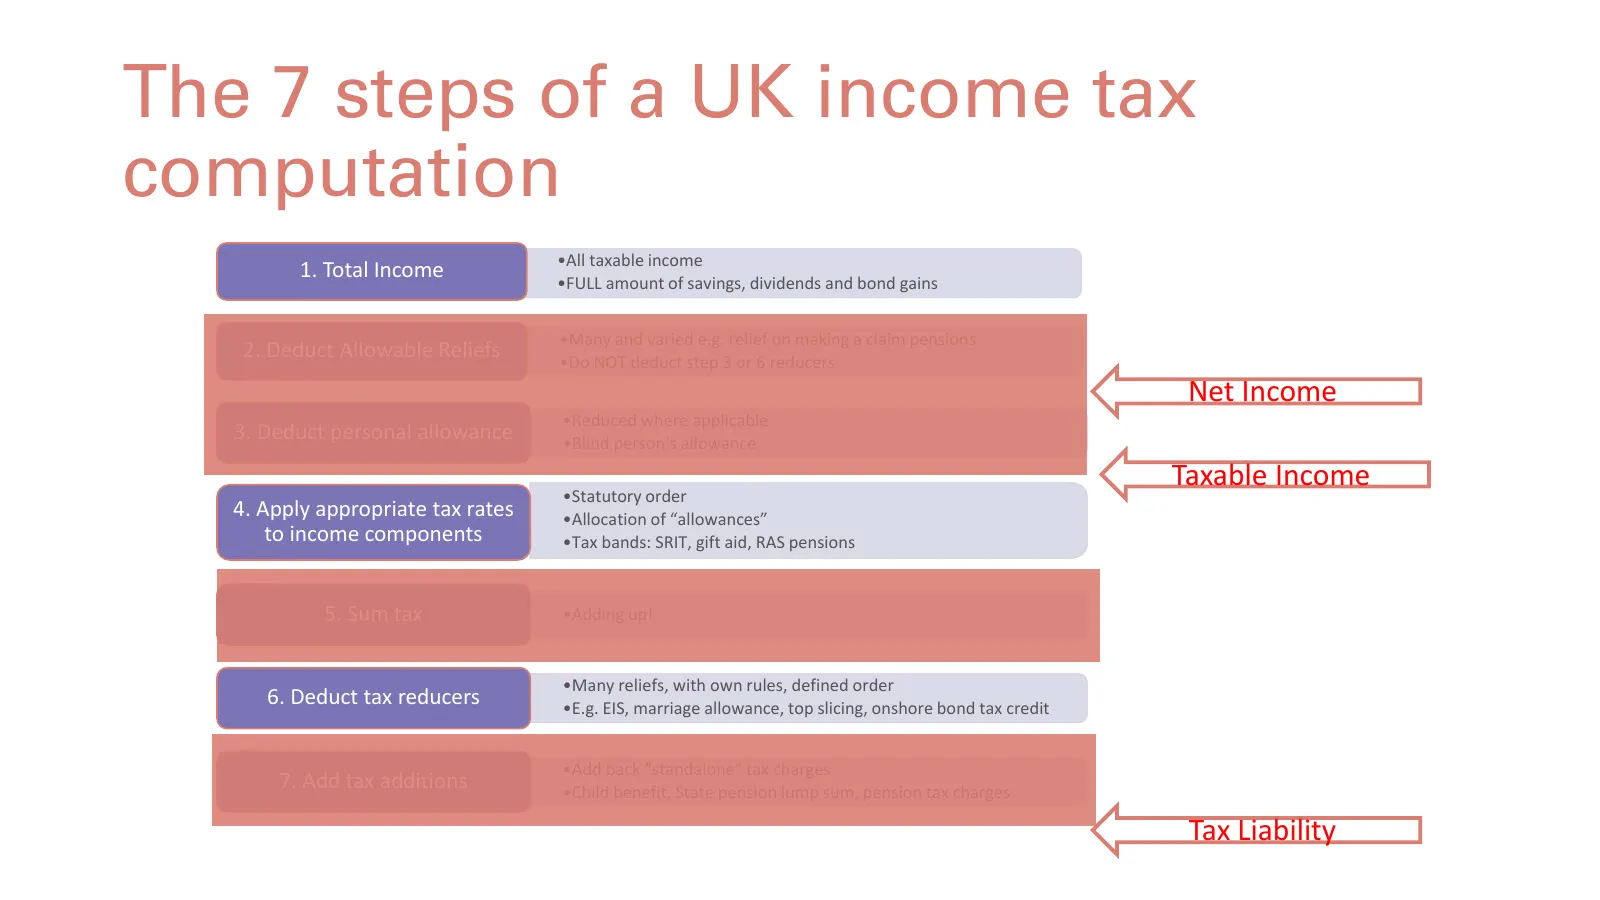
Slide 8: The steps of a UK income tax computation
The 7 steps of a UK income tax computation •All taxable income 1. Total Income •FULL amount of savings, dividends and bond gains •Many and varied e.g. relief on making a claim pensions 2. Deduct Allowable Reliefs •Do NOT deduct step 3 or 6 reducers Net Income •Reduced where applicable 3. Deduct pers
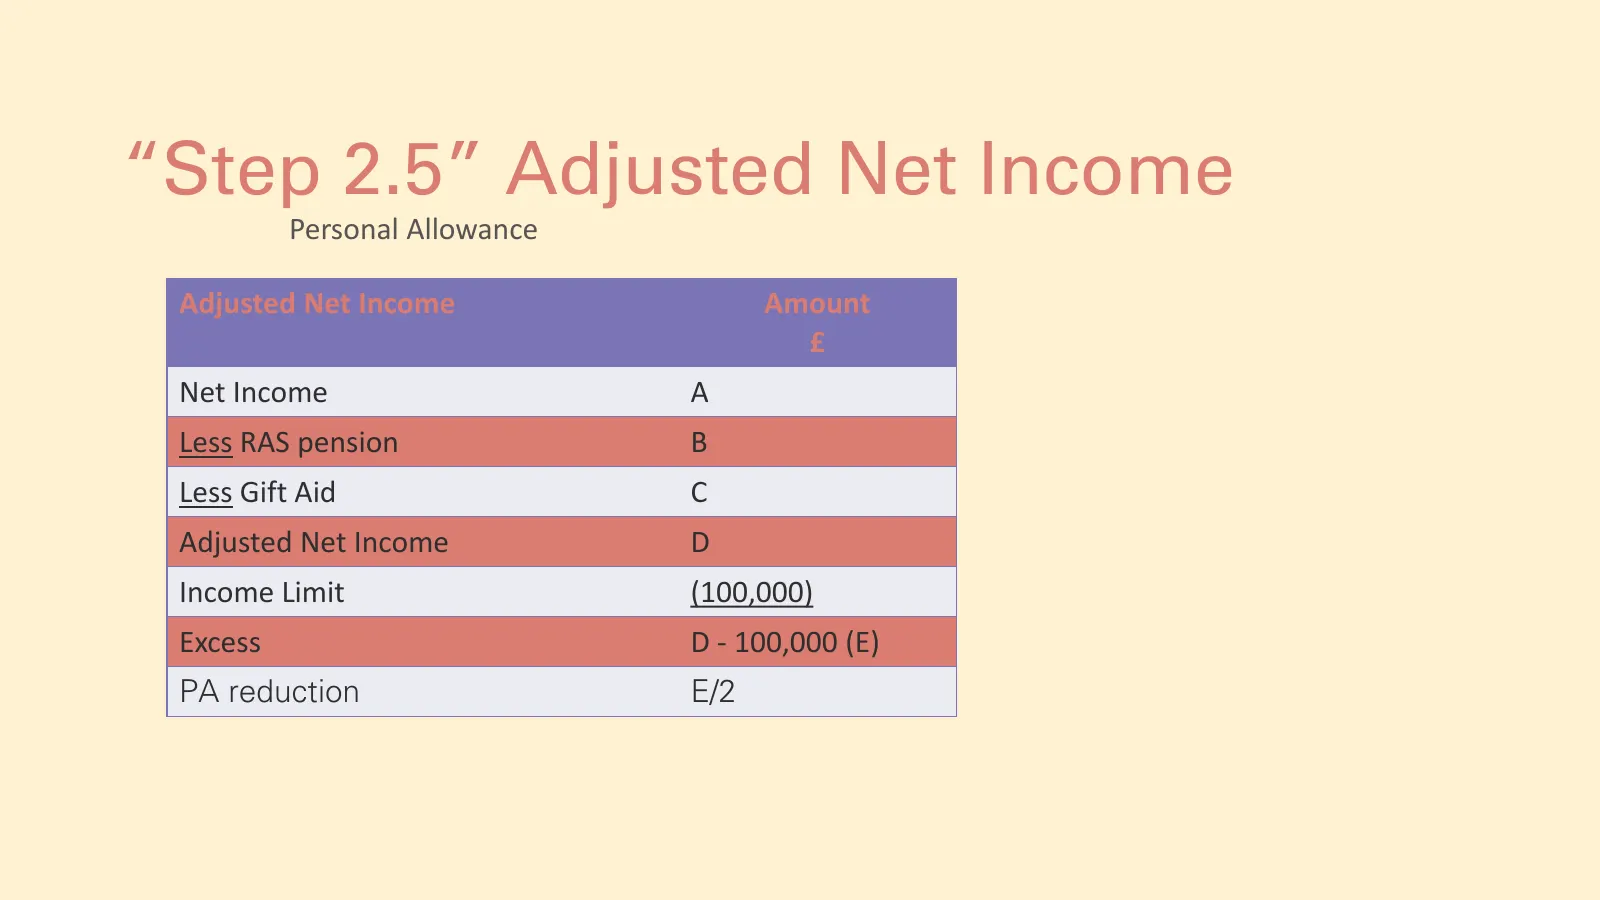
Slide 9: "Step 2.5" Adjusted Net Income
“Step 2.5” Adjusted Net Income Personal Allowance Adjusted Net Income Amount £ Net Income A Less RAS pension B Less Gift Aid C Adjusted Net Income D Income Limit (100,000) Excess D - 100,000 (E) PA reduction E/2
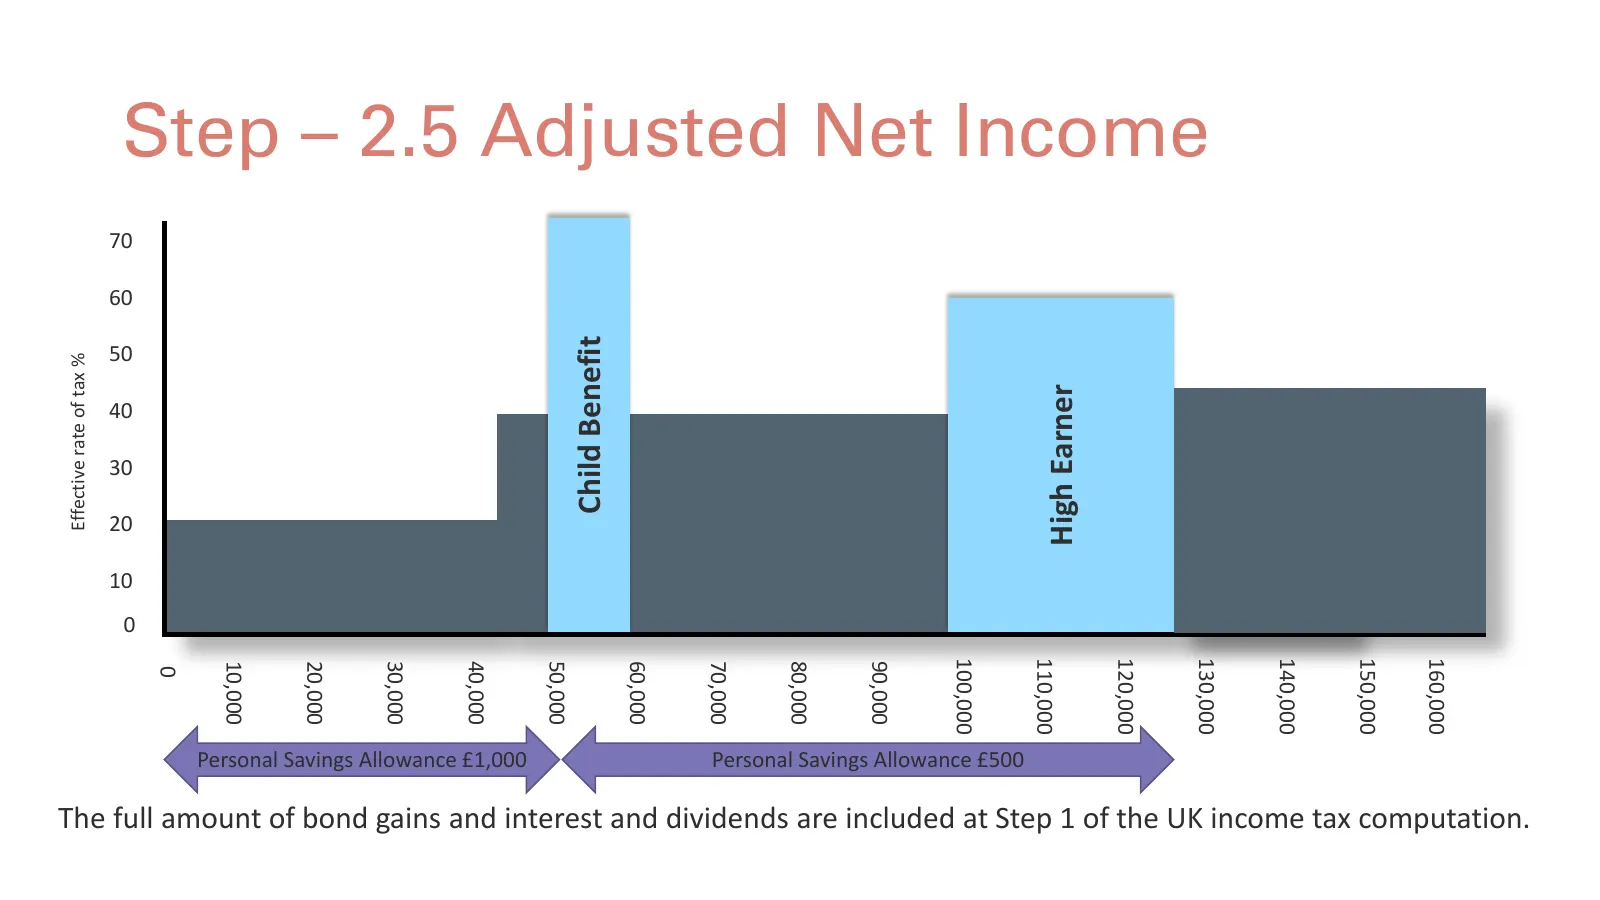
Slide 10: High Earner Child Benefit
Step – 2.5 Adjusted Net Income 70 60 Child Benefit 50 Effective rate of tax % High Earner 40 30 20 10 0 100,000 110,000 120,000 130,000 140,000 150,000 160,000 10,000 20,000 30,000 40,000 50,000 60,000 70,000 80,000 90,000 0 Personal Savings Allowance £1,000 PersonalIncome £ Allowance £500 Savings T
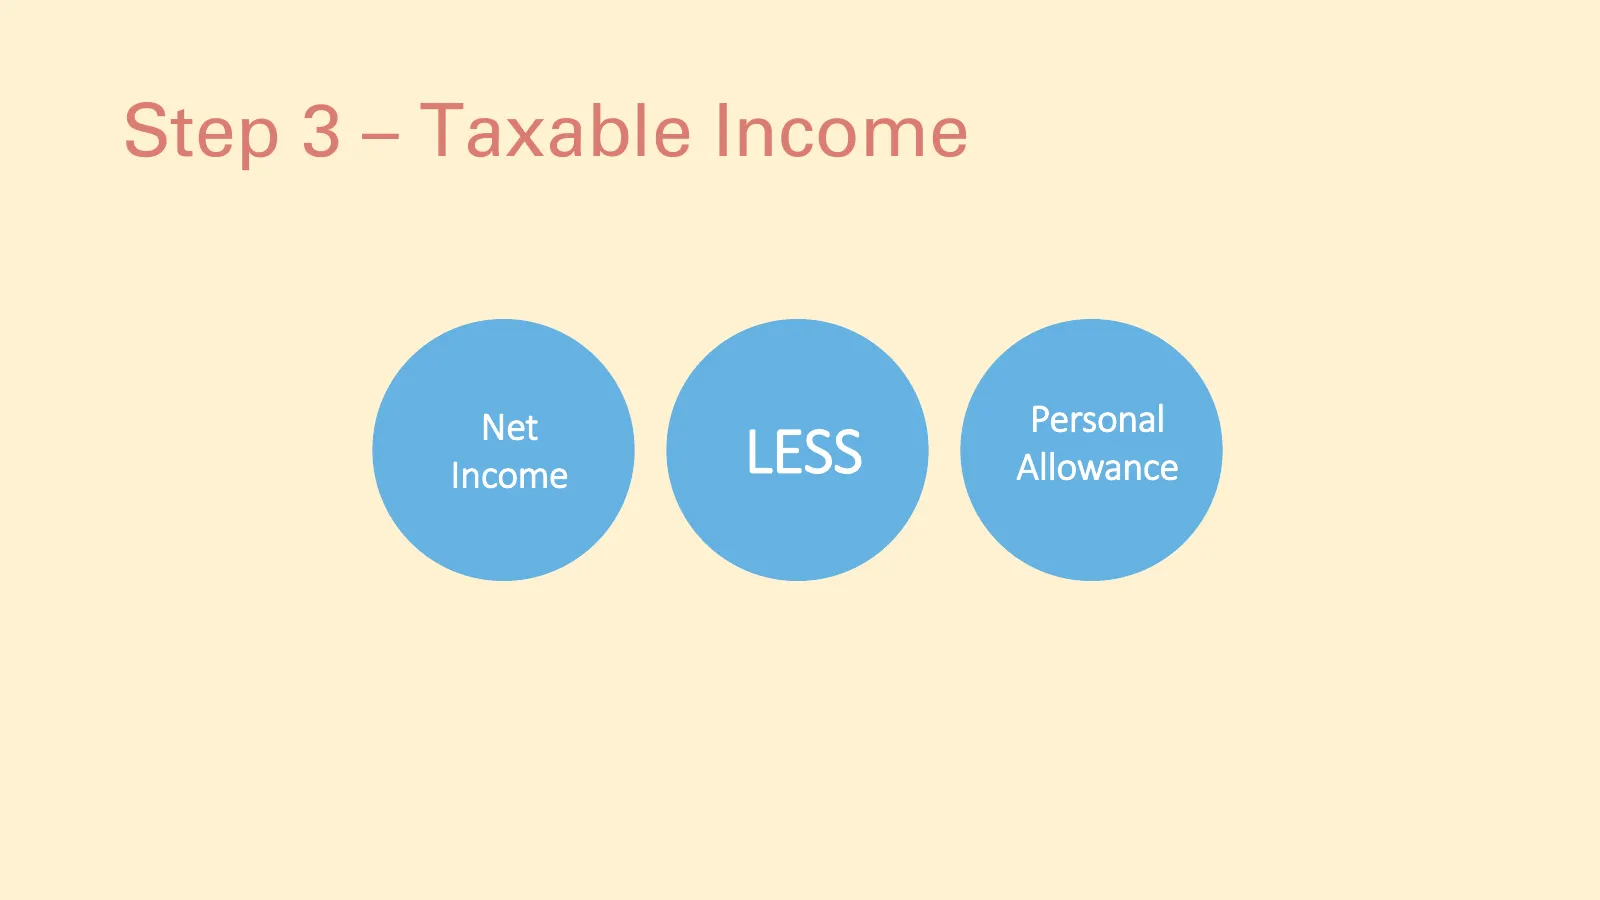
Slide 11: Step 3 – Taxable Income
Step 3 – Taxable Income Net Personal Income LESS Allowance
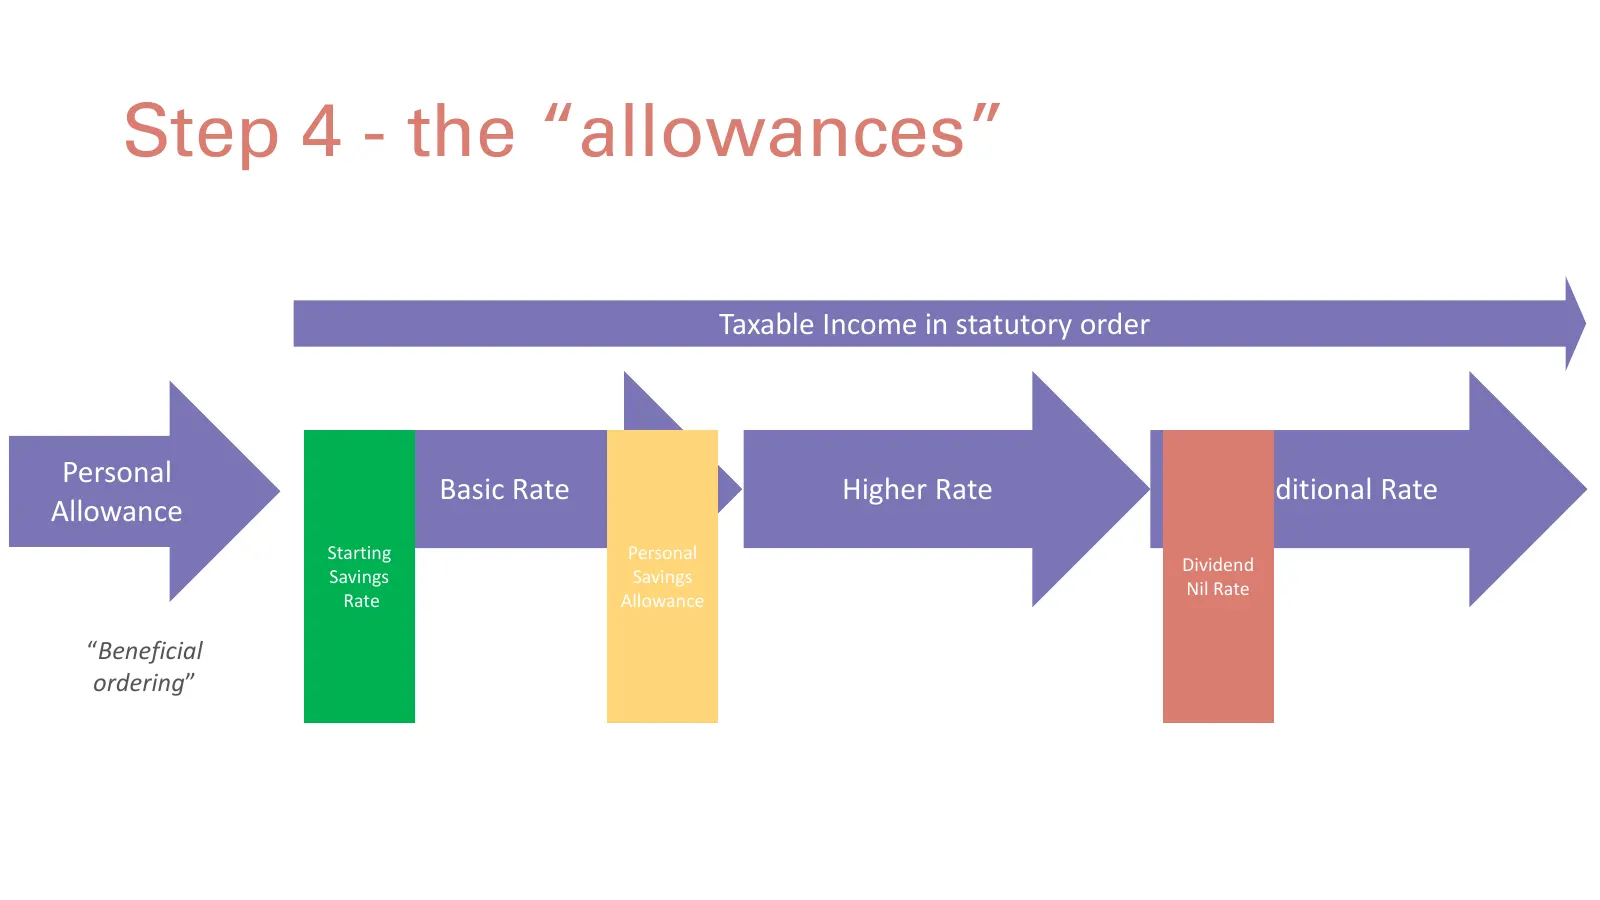
Slide 12: Step 4 - the "allowances"
Step 4 - the “allowances” Taxable Income in statutory order Personal Basic Rate Higher Rate Additional Rate Allowance Starting Personal Dividend Savings Savings Nil Rate Rate Allowance “Beneficial ordering”
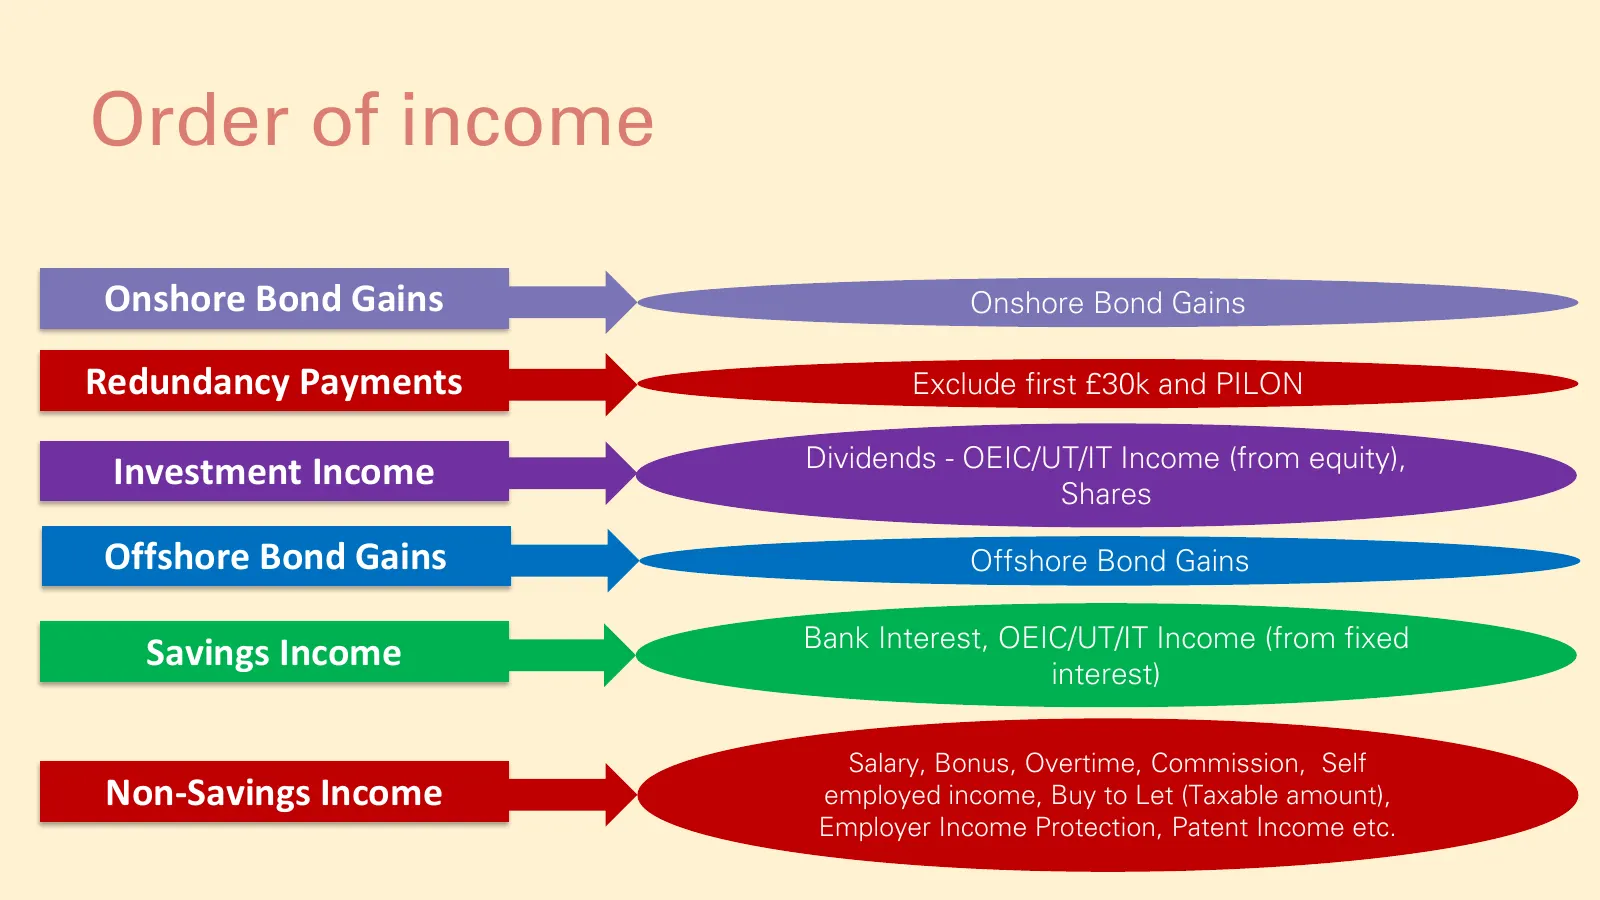
Slide 13: Order of income
Order of income Onshore Bond Gains Onshore Bond Gains Redundancy Payments Exclude first £30k and PILON Dividends - OEIC/UT/IT Income (from equity), Investment Income Shares Offshore Bond Gains Offshore Bond Gains Bank Interest, OEIC/UT/IT Income (from fixed Savings Income interest) Salary, Bonus, Ov
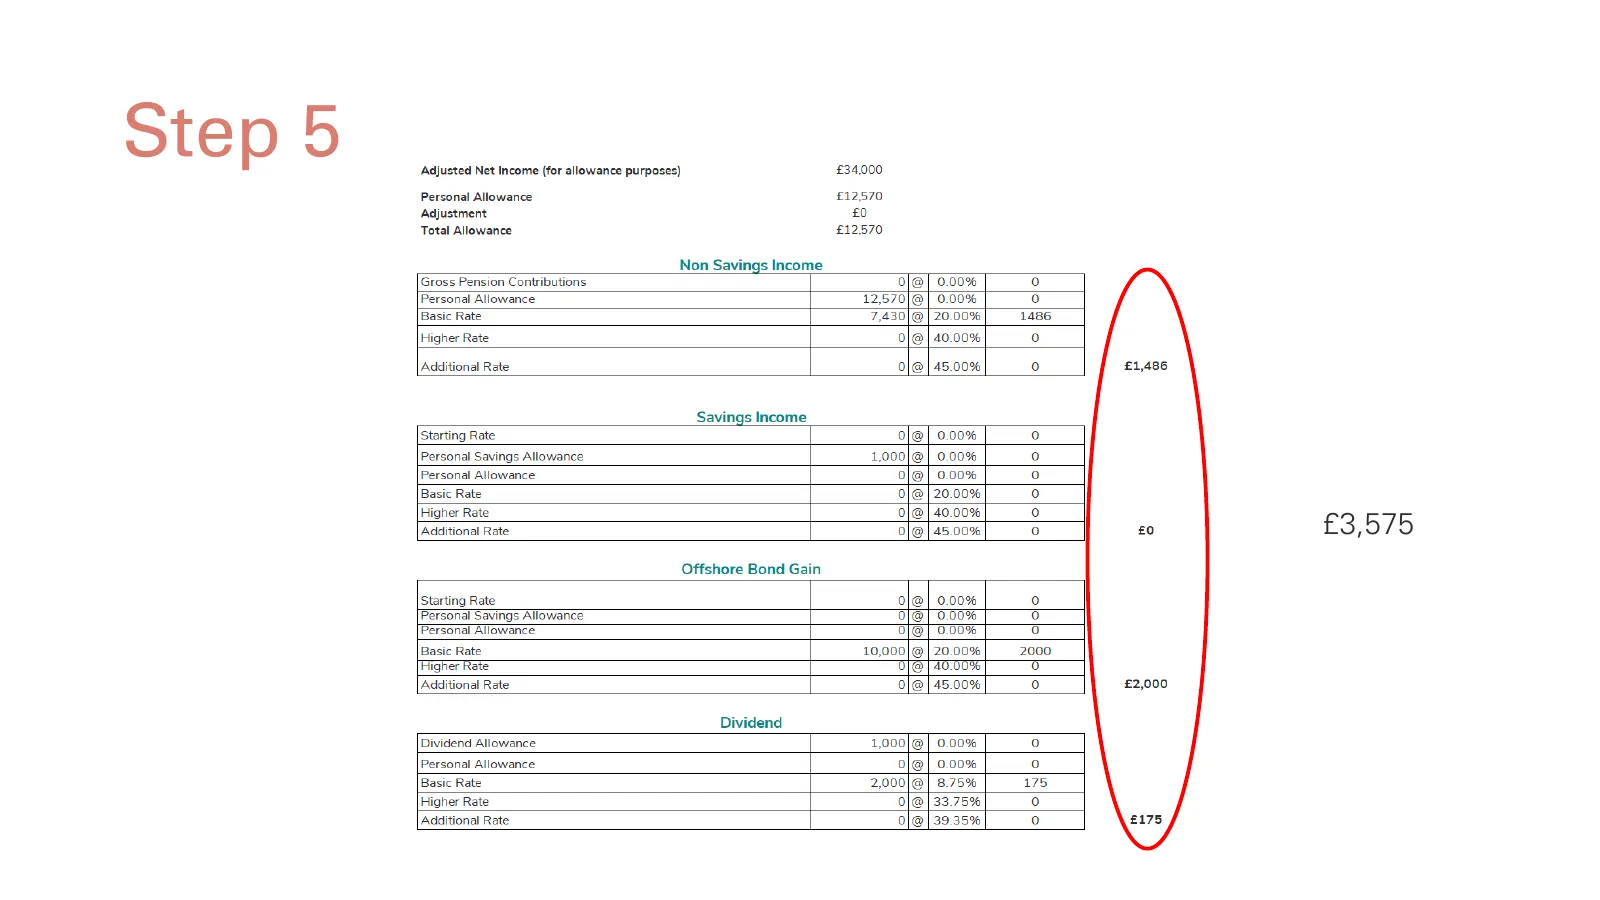
Slide 14: Step 5
Step 5 Adjusted Net Income (for allowance purposes) ‘£34,000 Personal Allowance £12570 Adjustment £0 Total Allowance £12570 Non Savings Income [Gross Pension Contributions 0/@| 0.00% oO Personal Aliowance 12,570|@ | 0.00% 0 Basic Rate 7,430[@|20.00%| 1486 Higher Rate ol@| 40.00% ° Additional Rate 0}
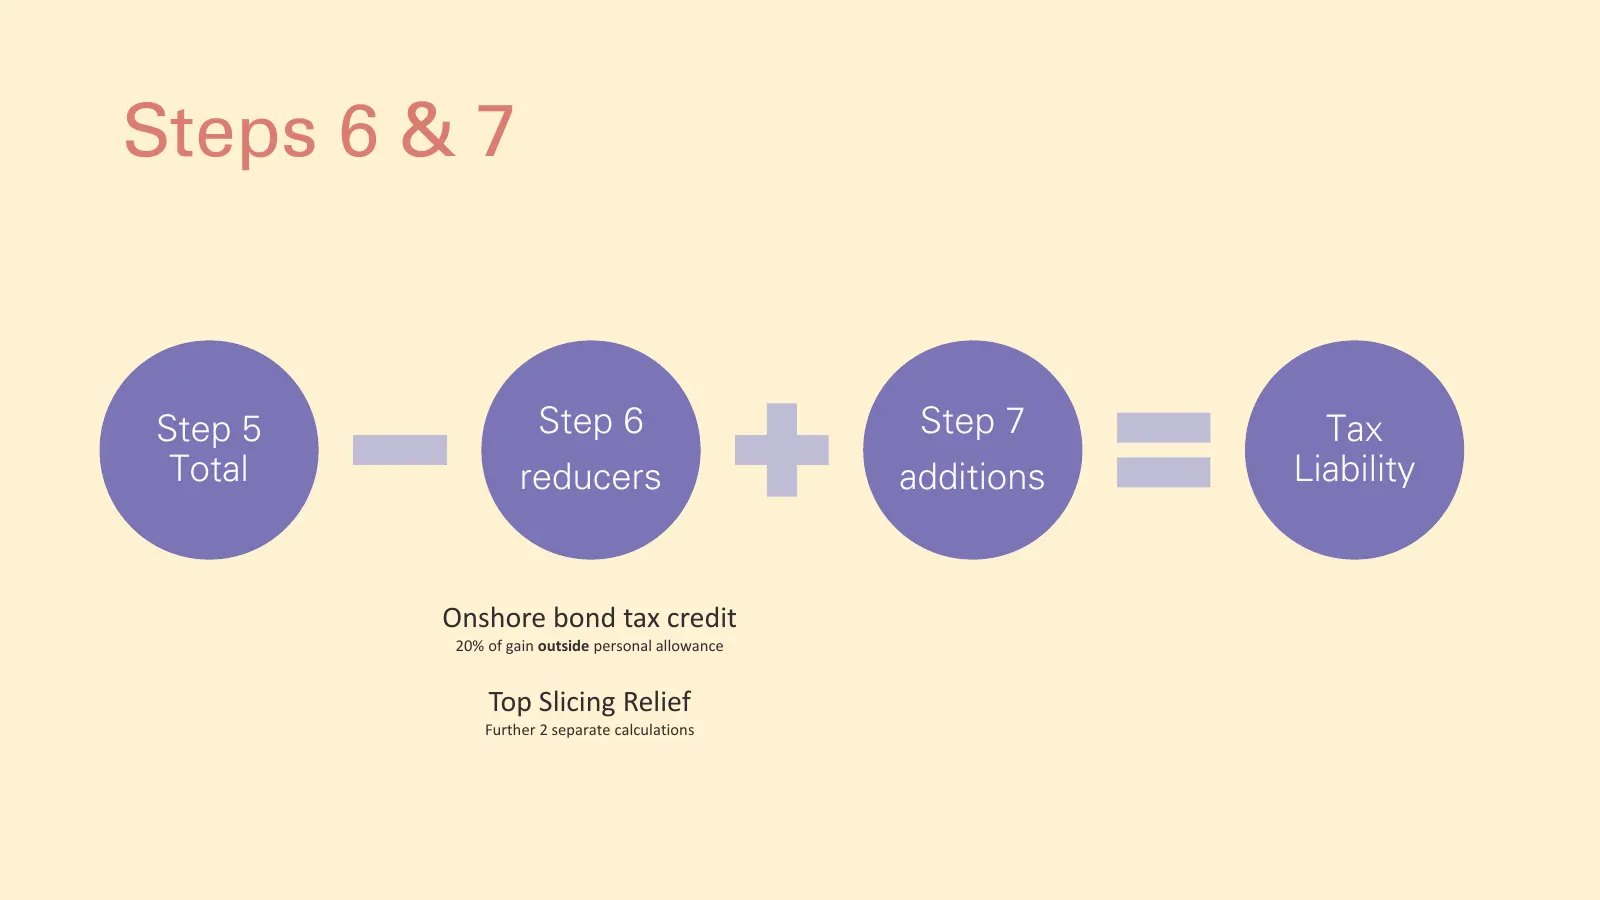
Slide 15: Steps 6 & 7
Steps 6 & 7 Step 5 Step 6 Step 7 Tax Total reducers additions Liability Onshore bond tax credit 20% of gain outside personal allowance Top Slicing Relief Further 2 separate calculations
Slide 16: Taxable gains computation
Taxable gains computation Total Gains tax year Losses accruing in tax year Adjusted Net Gains Annual Exempt Amount Losses brought forward (restricted)
Slide 17: Top slicing
Top slicing
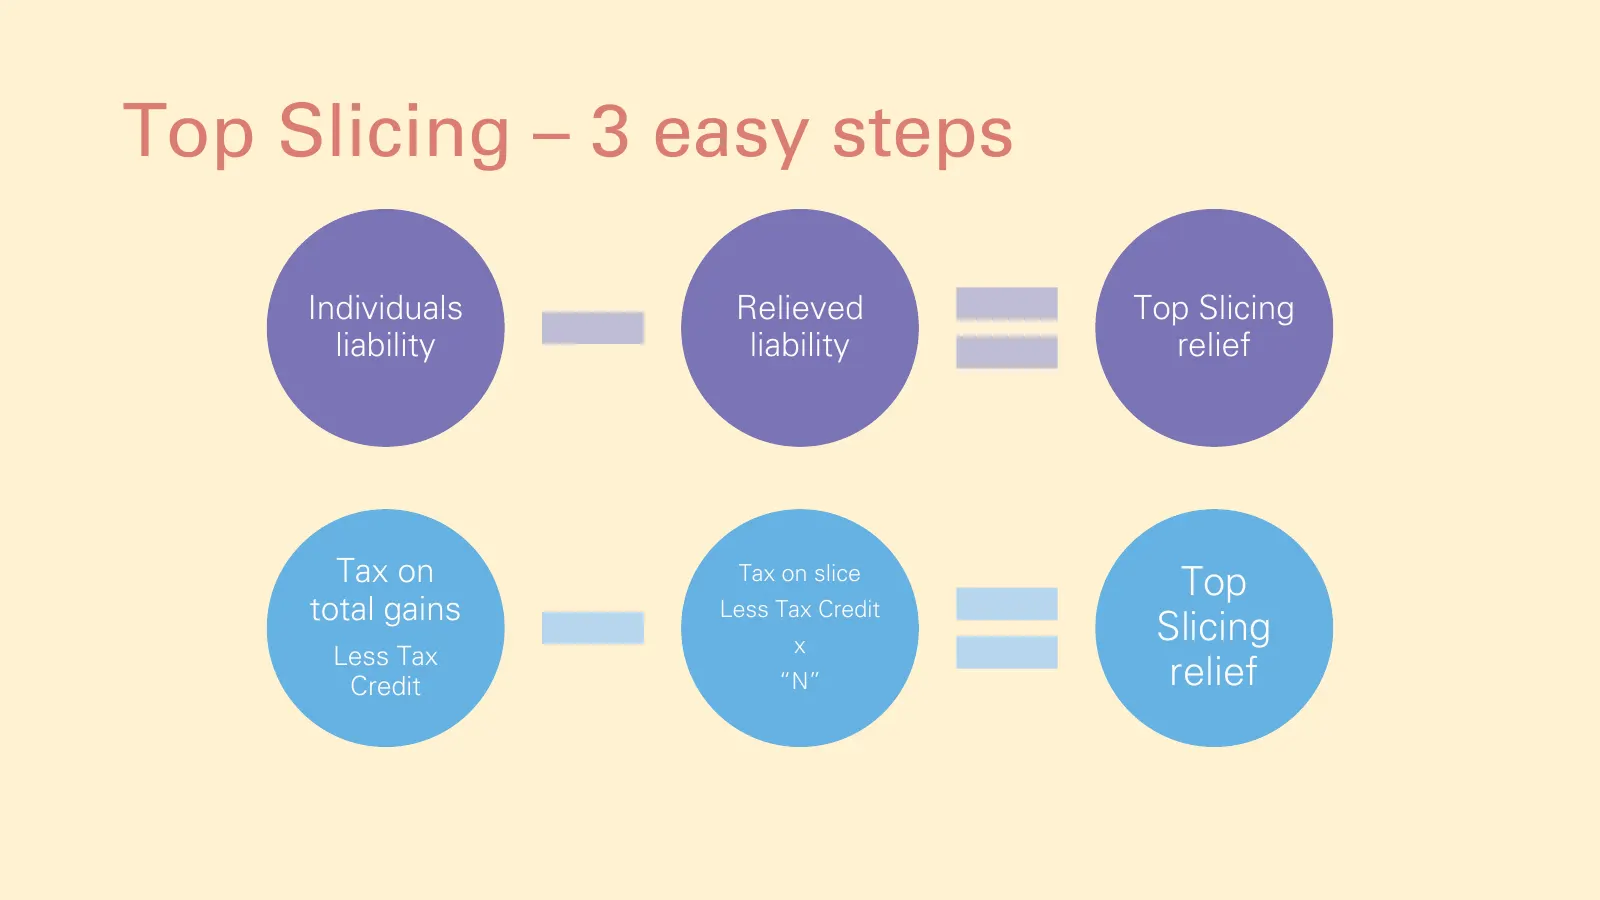
Slide 18: Top Slicing – 3 easy steps
Top Slicing – 3 easy steps Individuals Relieved Top Slicing liability liability relief Tax on Tax on slice Top total gains Less Tax Credit x Slicing Less Tax Credit “N” relief
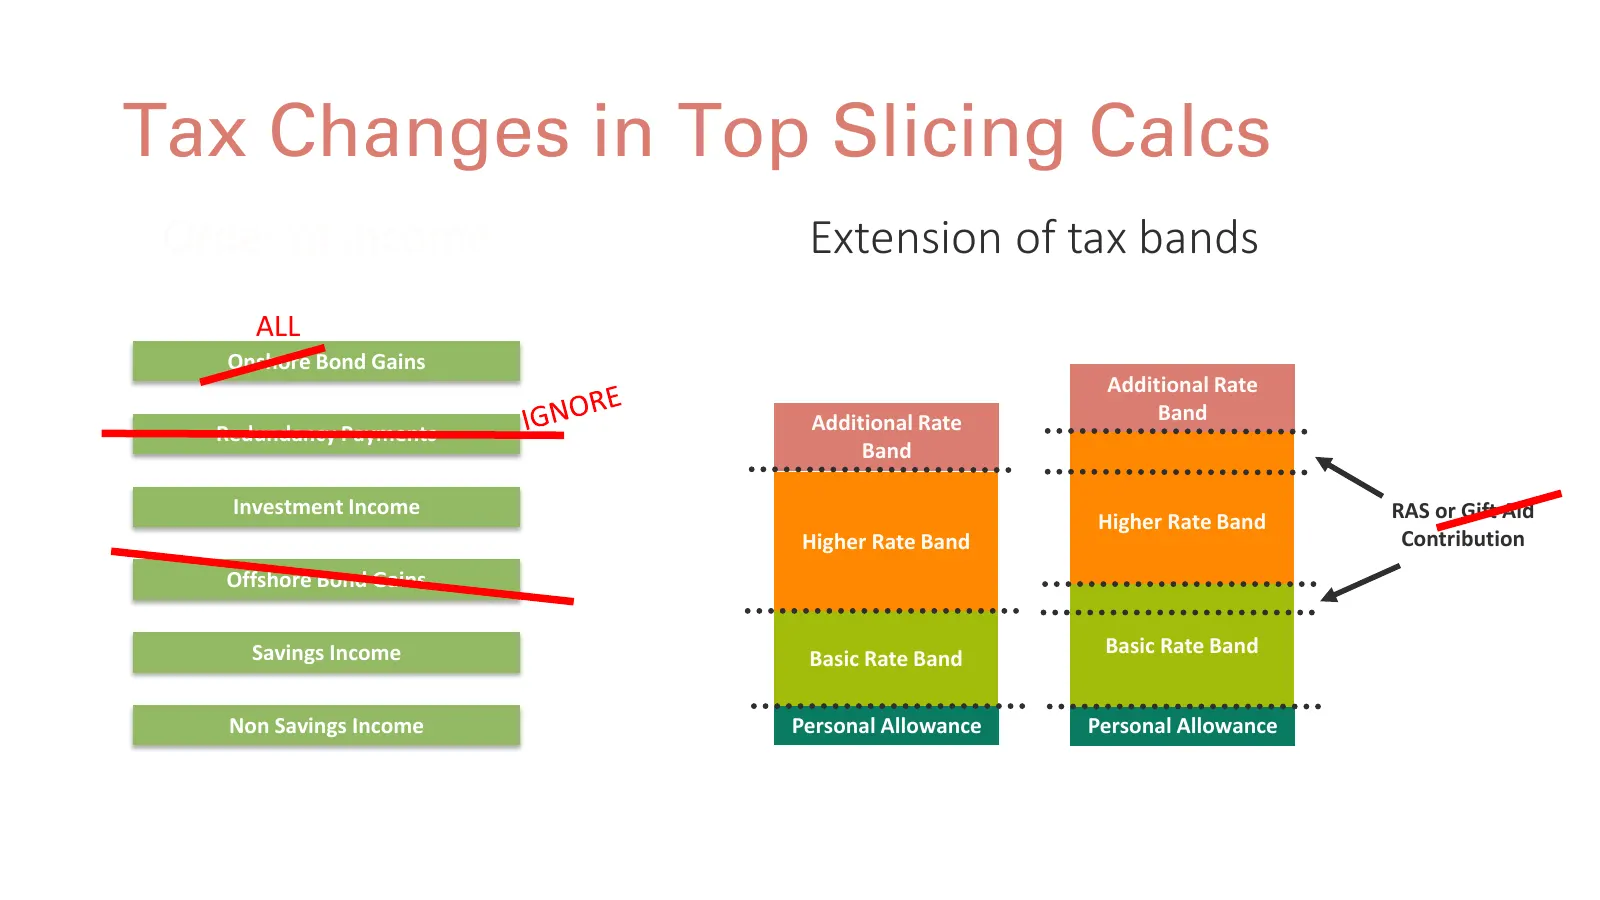
Slide 19: Tax Changes in Top Slicing Calcs
Tax Changes in Top Slicing Calcs Order of income Extension of tax bands ALL Onshore Bond Gains Additional Rate Additional Rate Band Redundancy Payments Band Investment Income RAS or Gift Aid Higher Rate Band Higher Rate Band Contribution Offshore Bond Gains Savings Income Basic Rate Band Basic Rate
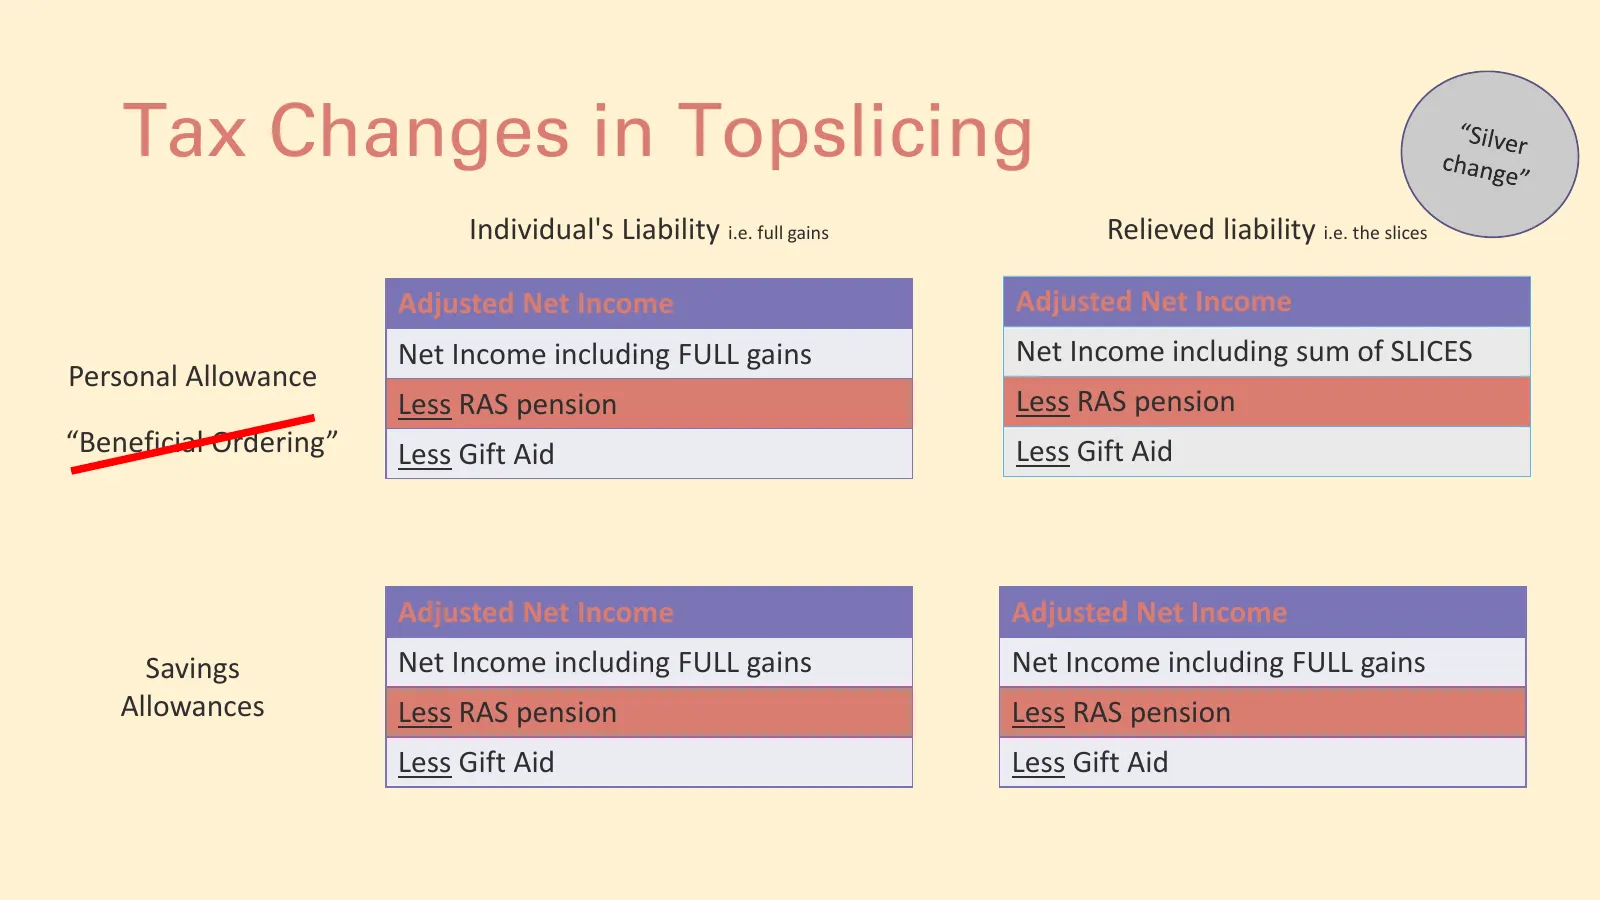
Slide 20: Tax Changes in Topslicing
Tax Changes in Topslicing Individual's Liability i.e. full gains Relieved liability i.e. the slices Adjusted Net Income Adjusted Net Income Net Income including FULL gains Net Income including sum of SLICES Personal Allowance Less RAS pension Less RAS pension “Beneficial Ordering” Less Gift Aid Less
Slide 21: LET'S GO LIVE.
LET'S GO LIVE.
Slide 22: Key points about the 5% TDA
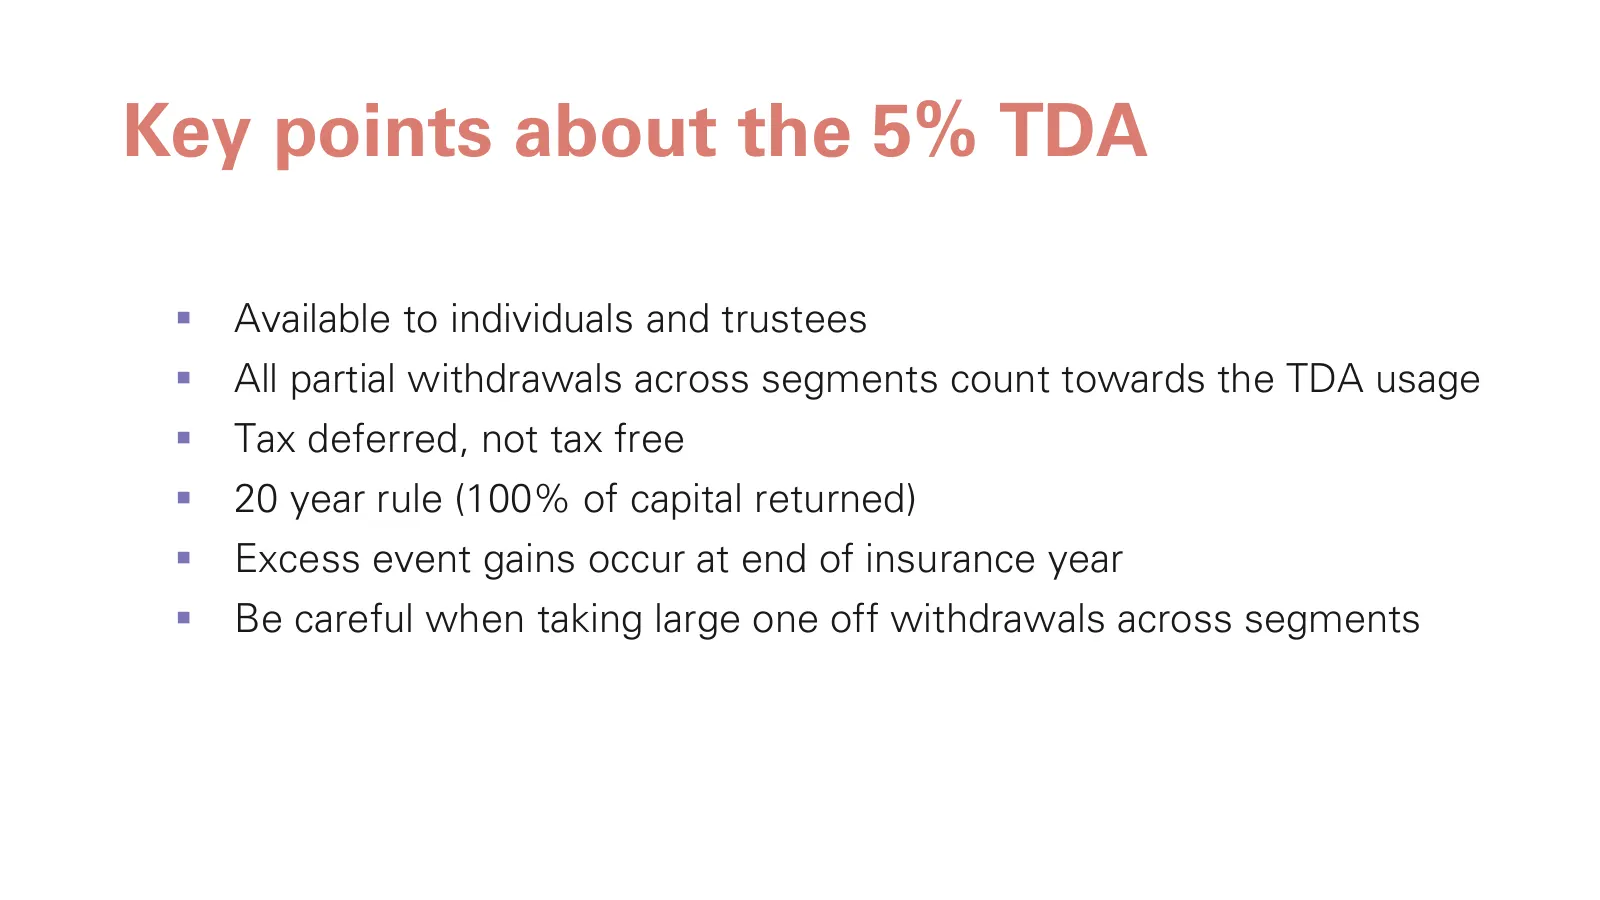
Key points about the 5% TDA ▪ Available to individuals and trustees ▪ All partial withdrawals across segments count towards the TDA usage ▪ Tax deferred, not tax free ▪ 20 year rule (100% of capital returned) ▪ Excess event gains occur at end of insurance year ▪ Be careful when taking large one off
Slide 23: 5% TDA Worksheet: Excess events
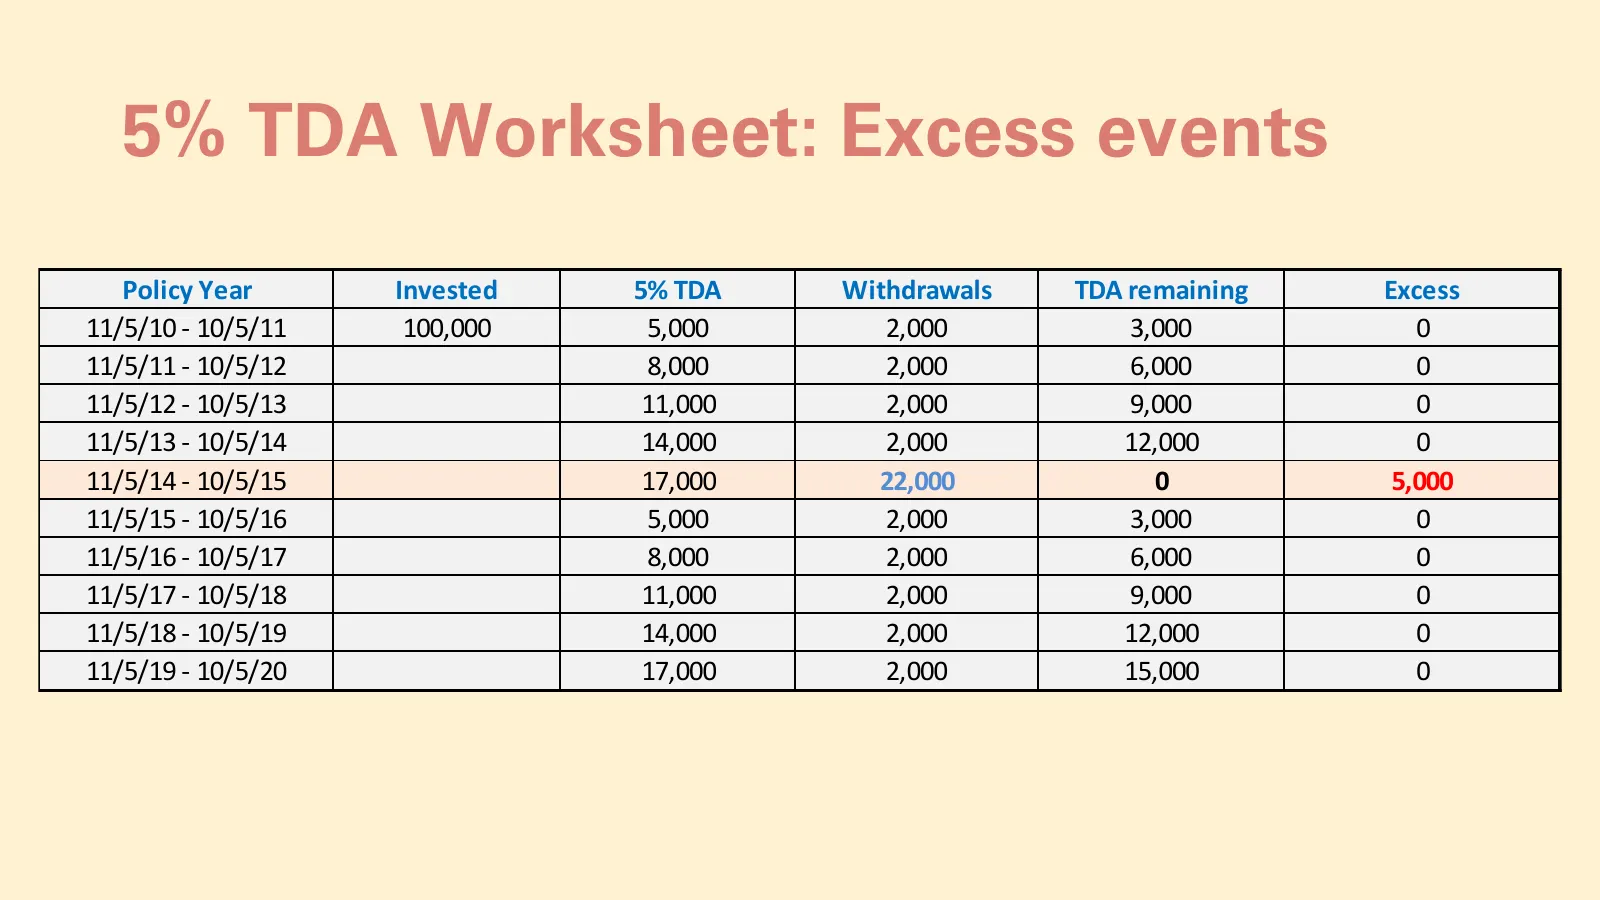
5% TDA Worksheet: Excess events Policy Year Invested 5% TDA Withdrawals TDA remaining Excess 11/5/10 - 10/5/11 100,000 5,000 2,000 3,000 0 11/5/11 - 10/5/12 8,000 2,000 6,000 0 11/5/12 - 10/5/13 11,000 2,000 9,000 0 11/5/13 - 10/5/14 14,000 2,000 12,000 0 11/5/14 - 10/5/15 17,000 22,000 0 5,000 11/5
Slide 24: Gain calculation (not partials!)
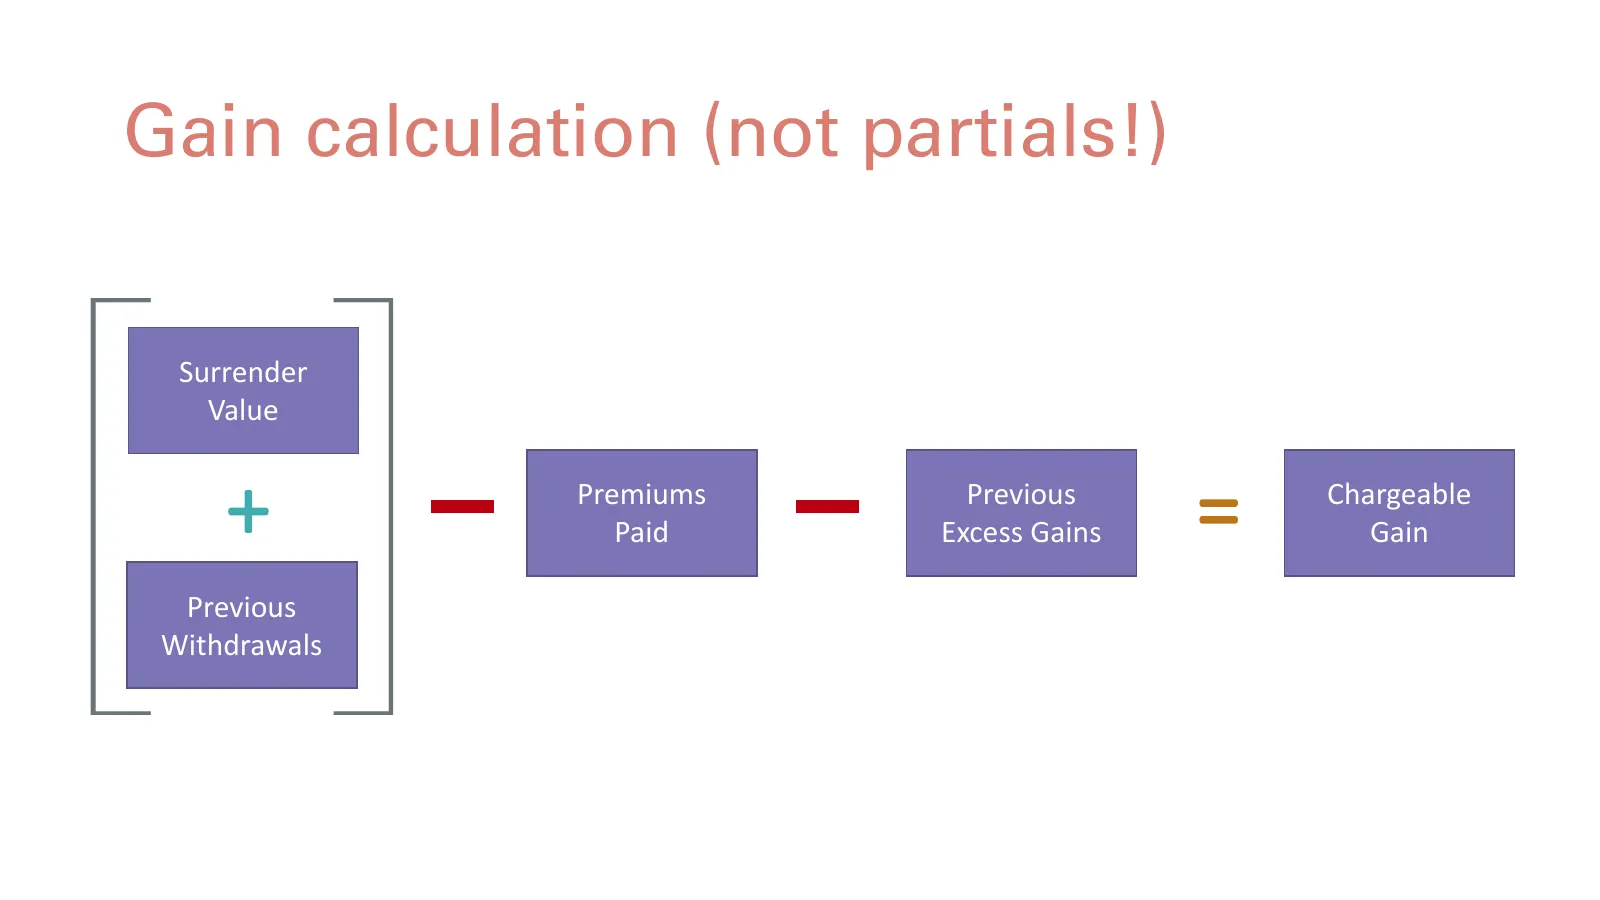
Gain calculation (not partials!) Surrender Value + Premiums Paid Previous Excess Gains = Chargeable Gain Previous Withdrawals
Slide 25: Calculating "N" – post 5 April 13 policies or policies treated as such
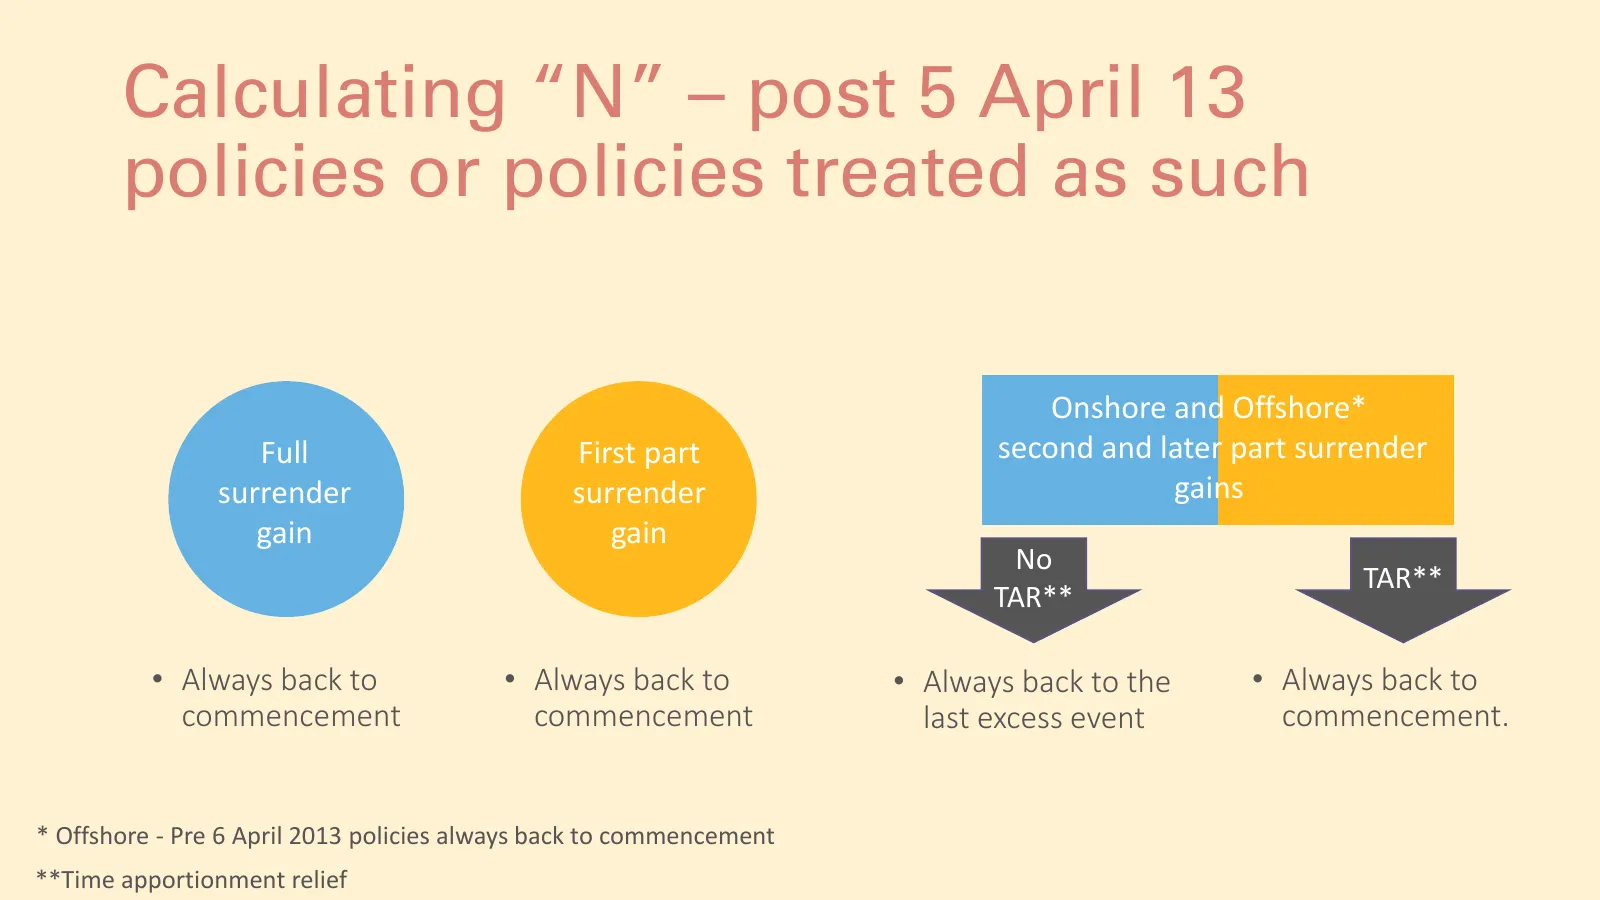
Calculating “N” – post 5 April 13 policies or policies treated as such Onshore and Offshore* Full First part second and later part surrender surrender surrender gains gain gain No TAR** TAR** • Always back to • Always back to • Always back to the • Always back to commencement commencement last exces
Slide 26: Insurance Year v Tax Year
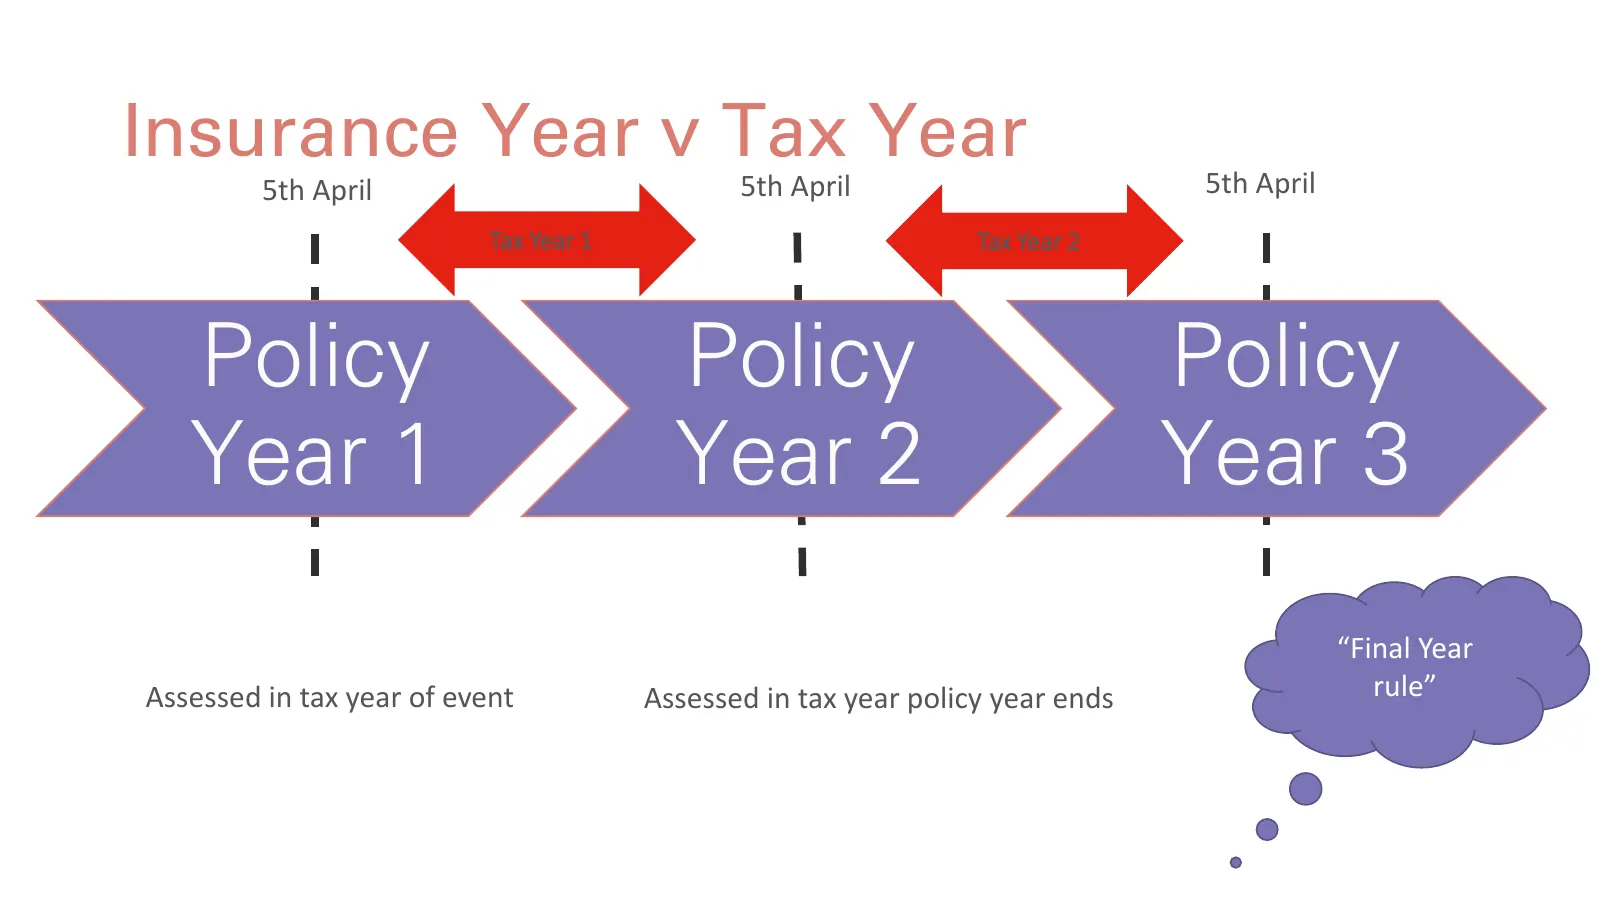
Insurance Year v Tax Year 5th April 5th April 5th April Tax Year 1 Tax Year 2 Policy Policy Policy Year 1 Year 2 Year 3 “Final Year Assessed in tax year of event Assessed in tax year policy year ends rule”
Slide 27: Final Year rules
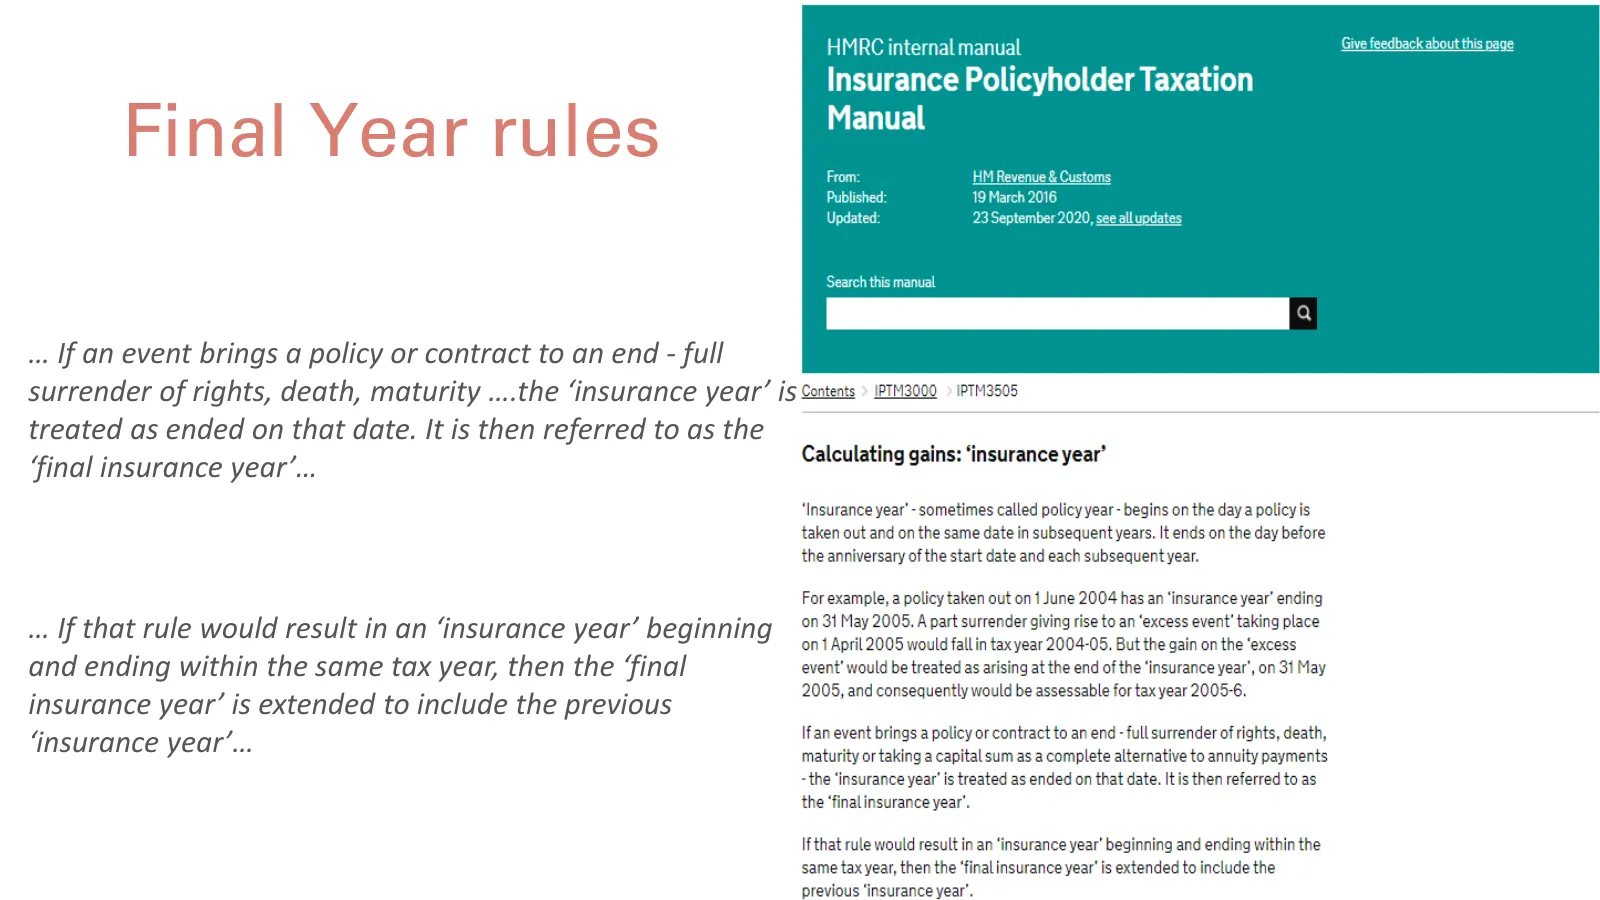
Final Year rules … If an event brings a policy or contract to an end - full surrender of rights, death, maturity ….the ‘insurance year’ is treated as ended on that date. It is then referred to as the ‘final insurance year’… … If that rule would result in an ‘insurance year’ beginning and ending with
Slide 28: LET'S GO LIVE.
LET'S GO LIVE.
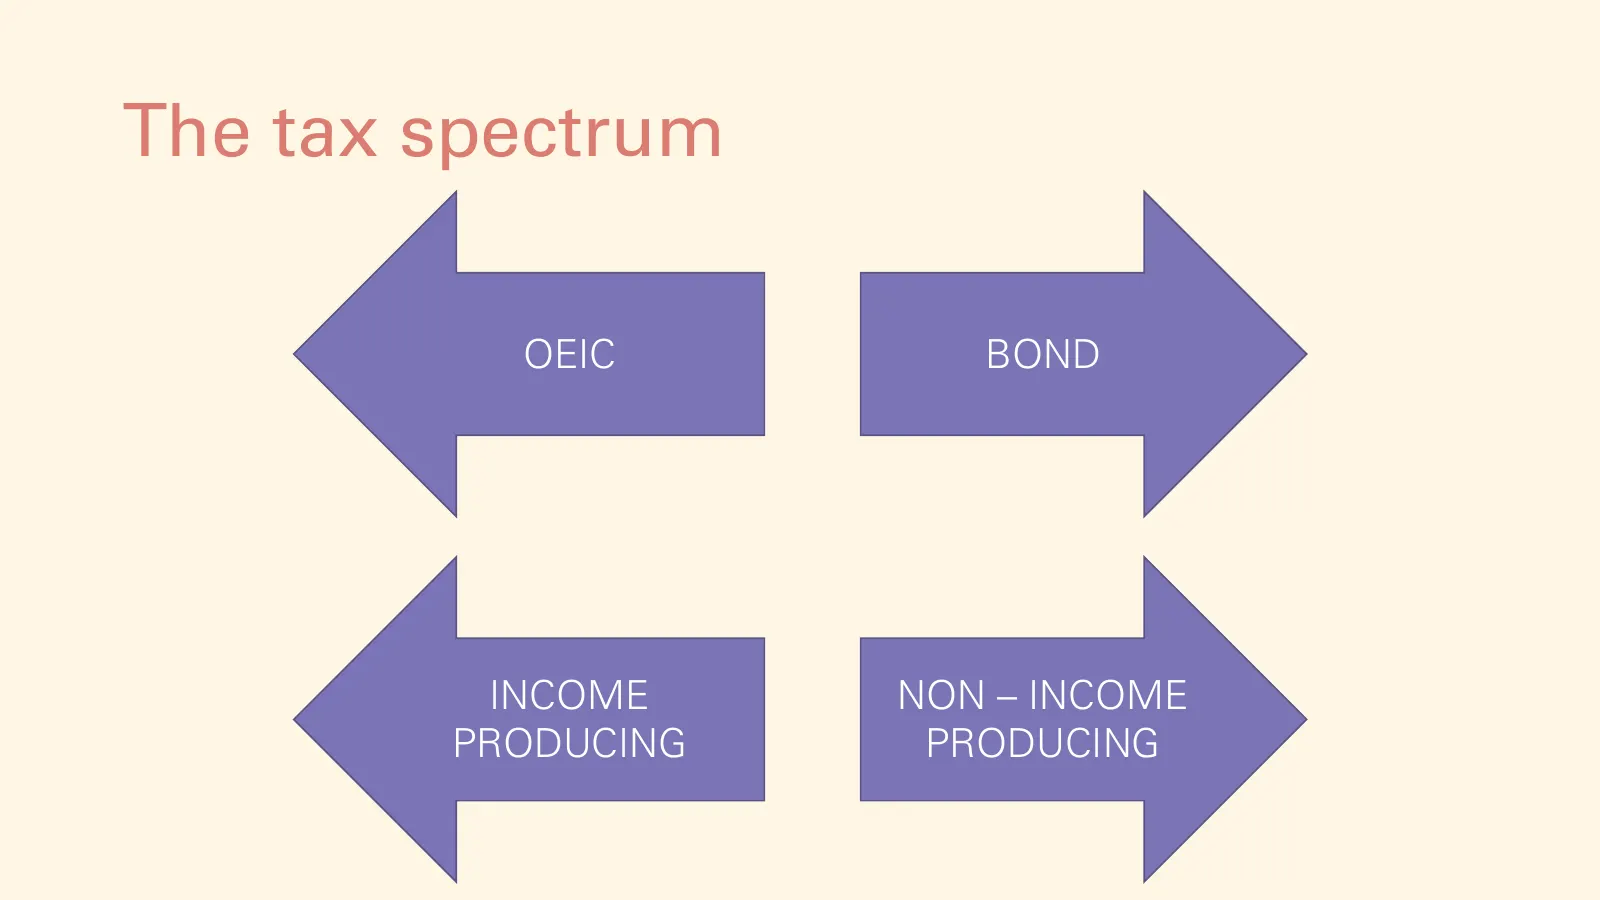
Slide 29: The tax spectrum
The tax spectrum OEIC BOND INCOME NON – INCOME PRODUCING PRODUCING
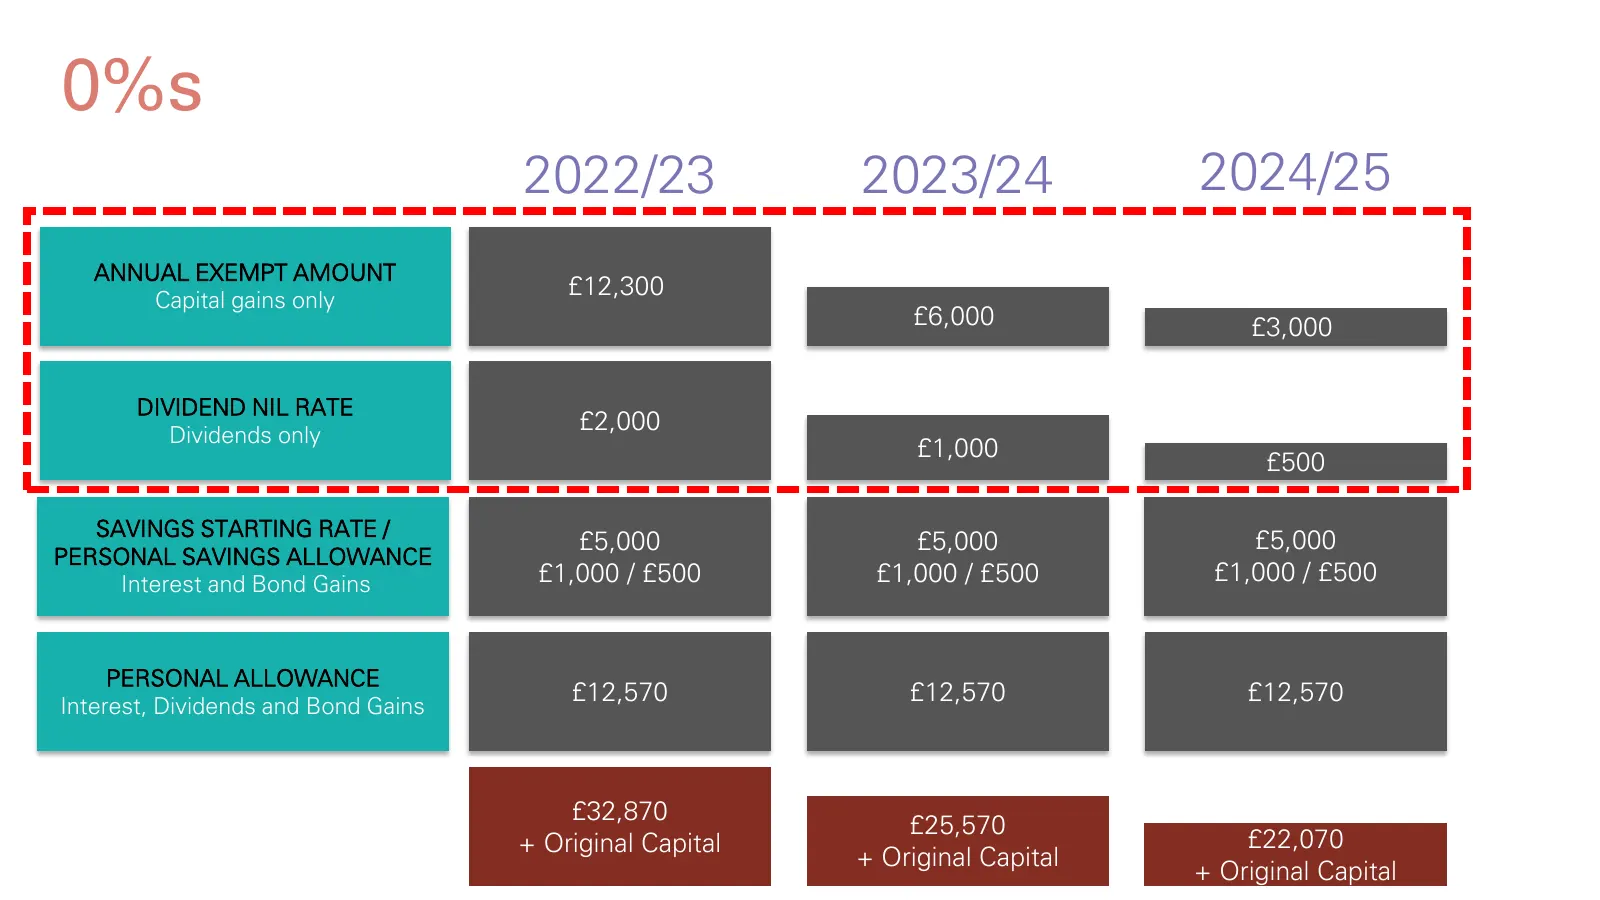
Slide 30: 0%s
0%s 2022/23 2023/24 2024/25 ANNUAL EXEMPT AMOUNT Capital gains only £12,300 £6,000 £3,000 DIVIDEND NIL RATE Dividends only £2,000 £1,000 £500 SAVINGS STARTING RATE / £5,000 £5,000 £5,000 PERSONAL SAVINGS ALLOWANCE Interest and Bond Gains £1,000 / £500 £1,000 / £500 £1,000 / £500 PERSONAL ALLOWANCE I
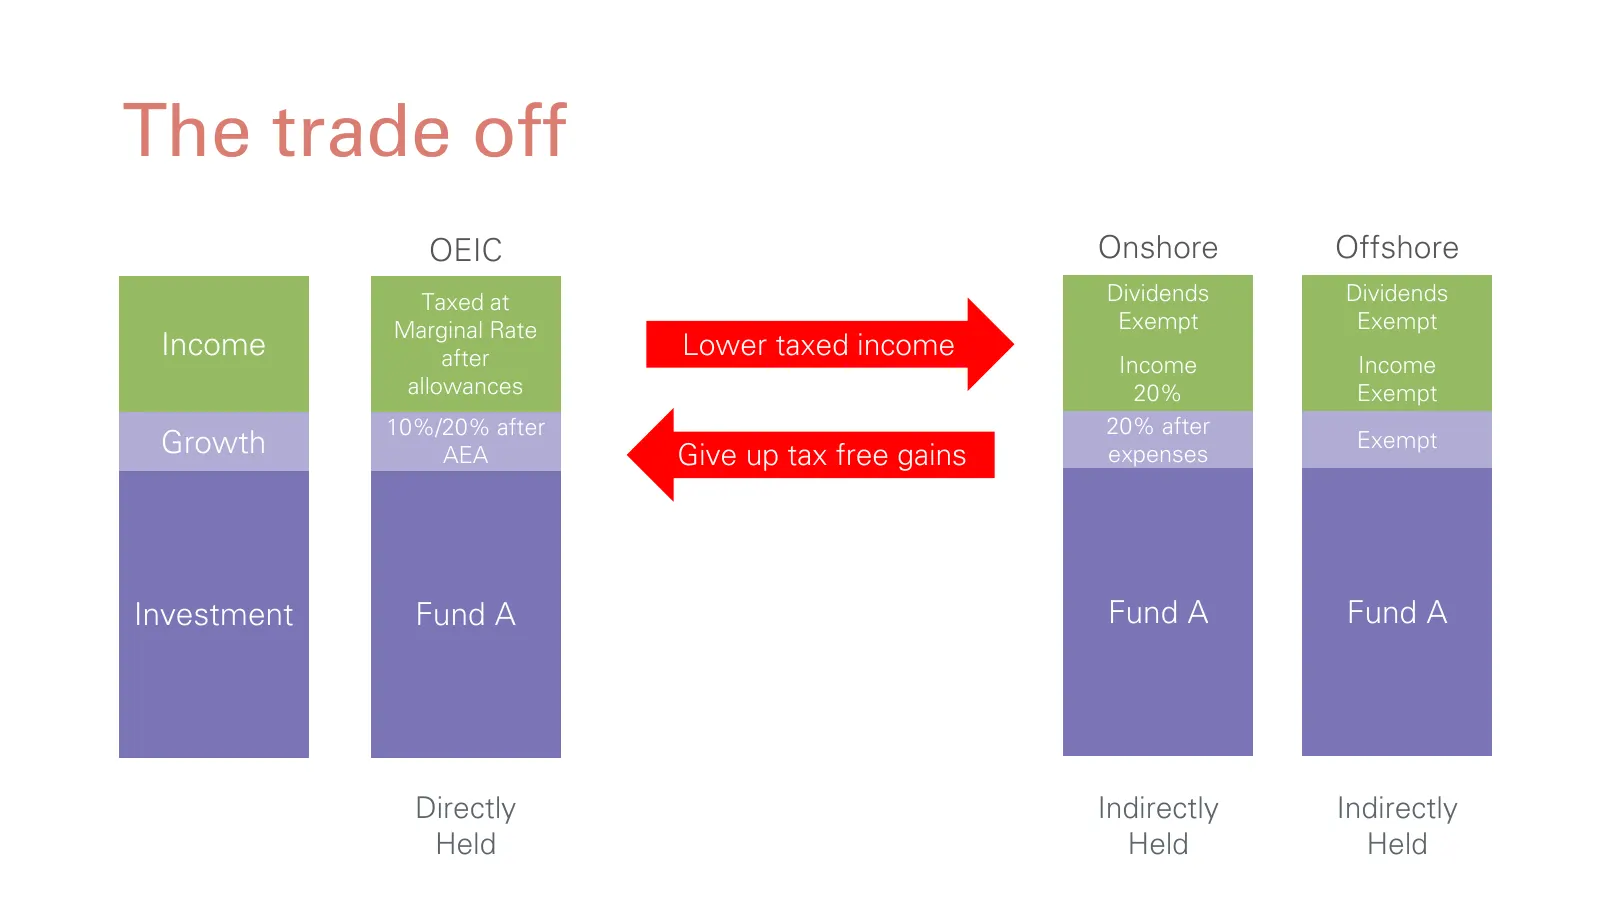
Slide 31: The trade off
The trade off OEIC Onshore Offshore Taxed at Dividends Dividends Marginal Rate Exempt Exempt Income after Lower taxed income Income Income allowances 20% Exempt 10%/20% after 20% after Growth AEA Give up tax free gains expenses Exempt Investment Fund A Fund A Fund A Directly Indirectly Indirectly He
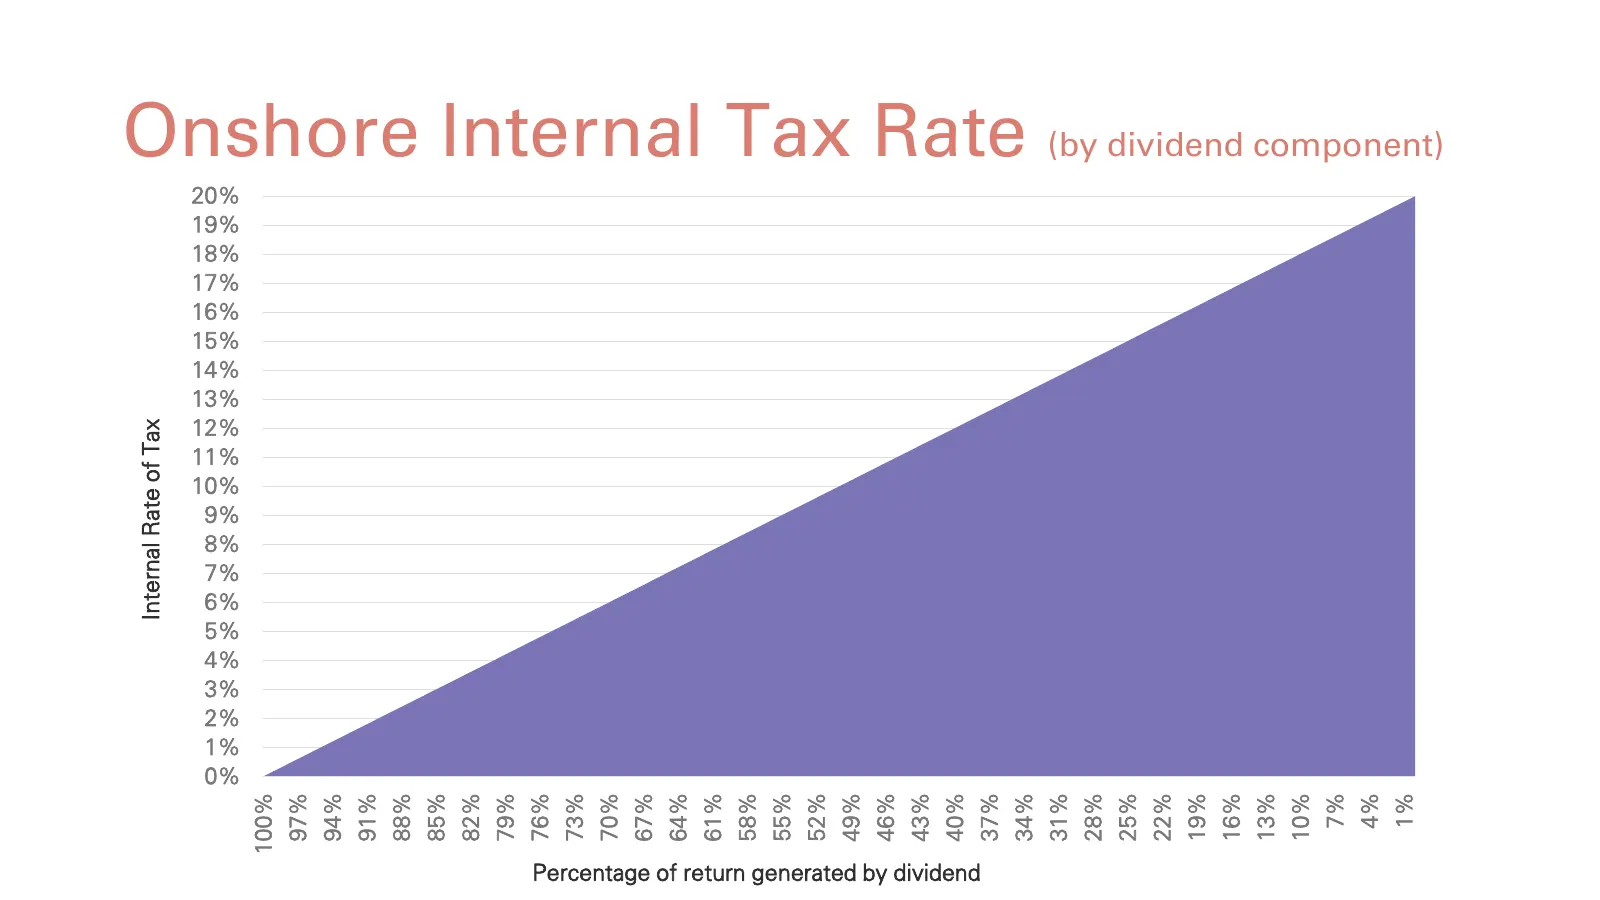
Slide 32: Onshore Internal Tax Rate (by dividend component)
Onshore Internal Tax Rate (by dividend component) 20% 19% 18% 17% 16% 15% 14% 13% 12% Internal Rate of Tax 11% 10% 9% 8% 7% 6% 5% 4% 3% 2% 1% 0% 64% 43% 100% 97% 94% 91% 88% 85% 82% 79% 76% 73% 70% 67% 61% 58% 55% 52% 49% 46% 40% 37% 34% 31% 28% 25% 22% 19% 16% 13% 10% 7% 4% 1% Percentage of return
Slide 33: LET'S GO LIVE.
LET'S GO LIVE.
Slide 34: Learning Objectives
Learning Objectives By the end of this session you will be able to: Demonstrate the Understand the inputs required for theory for using the using the Tax Tax Relief Modeller Relief Modeller Bond Gain and Tax Bond Gain and Tax Wrapper Wrapper Comparison Tools Comparison Tools
Slide 35: Thanks for your time
Thanks for your time Get in touch with your usual contact if you need further help.
Slide 36: M&G Wealth brand and regulatory information
M&G Wealth is a trademarked brand of the M&G plc group, which includes 3 business divisions as follows: M&G Wealth Advice, provided by M&G Wealth Advice Limited, registered number: 08022795. Model Portfolio Services, provided by M&G Wealth Investments LLP, registered number: 0C305442. M&G Wealth Pla
Source: company website
More decks from M&G PLC
 Q2 2026 Earnings Presentation54 slides · Sep 2, 2026
 M&G Wealth — M&G MPS Webinar (May 2026)24 slides · May 2026
 FY2025 Earnings Presentation59 slides · Mar 12, 2026
 H1 2025 Earnings Presentation51 slides · Sep 3, 2025
 Investor Presentation (August 2025)58 slides · August 2025
 Merger or Acquisition (May 2025)9 slides · May 30, 2025