Easylink Services International Corp
Easylink Services International — Investor Presentation (October 2011)
26 slides from Easylink Services International's investor presentation, Oct 18, 2011
Slide 1: Investor Presentation
Investor Presentation Tom Stallings, Chief Executive Officer Glen Shipley, Chief Financial Officer October 18-19, 2011
Slide 2: Safe Harbor
Safe Harbor Statements included that are not historical facts (including any statements concerning plans and objectives of management for future operations or economic performance, or assumptions or forecasts related thereto), are forward-looking statements. These statements can be identified by the
Slide 3: Agenda
Agenda Overview EasyLink Services International Corporation The Opportunity Delivering Enterprise Communications Applications Over the Cloud Solutions, Customers, and Growth Strategy Team Financials Summary Questions and Answers 3 Agenda:
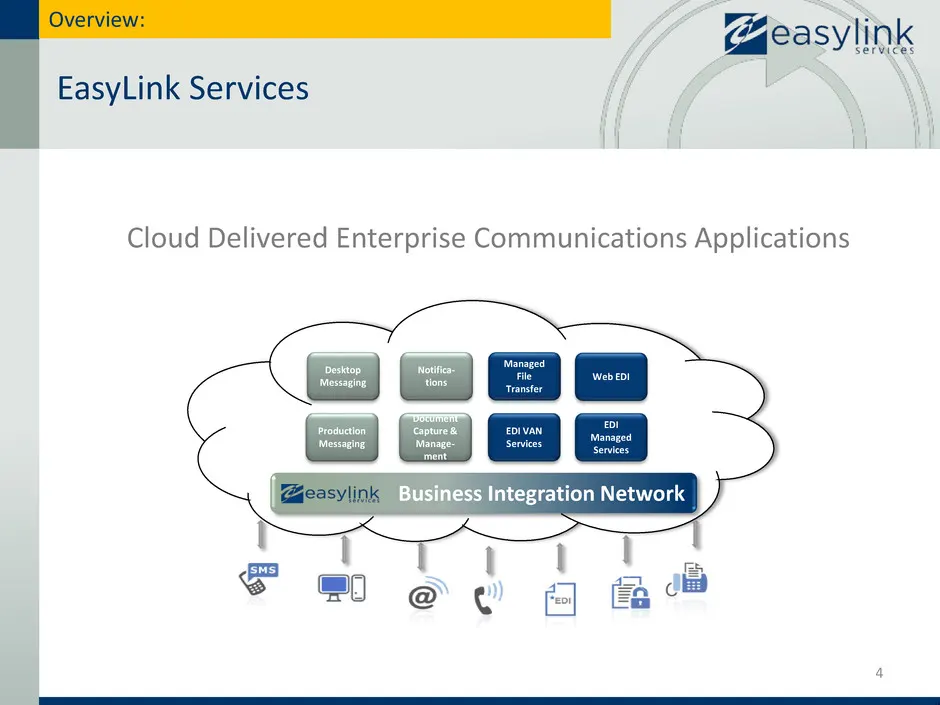
Slide 4: EasyLink Services Overview: Cloud Delivered Enterprise Communications Applications
EasyLink Services 4 Overview: Cloud Delivered Enterprise Communications Applications Business Integration Network EDI VAN Services EDI Managed Services Managed File Transfer Web EDI Desktop Messaging Notifica- tions Production Messaging Document Capture & Manage- ment
Slide 5: Investor Snapshot
Investor Snapshot 5 Overview (continued): Exchange: NASDAQ Capital Markets Ticker: ESIC Headquarters: Atlanta, GA International Headquarters: London and Tokyo Employees: 540+ Shares Outstanding: 31.75M Market Cap1: $169.9M Enterprise Value2: $244.7M 1 Market Cap is calculated using s
Slide 6: EasyLink Services Overview: Cloud Delivered Applications AaaS
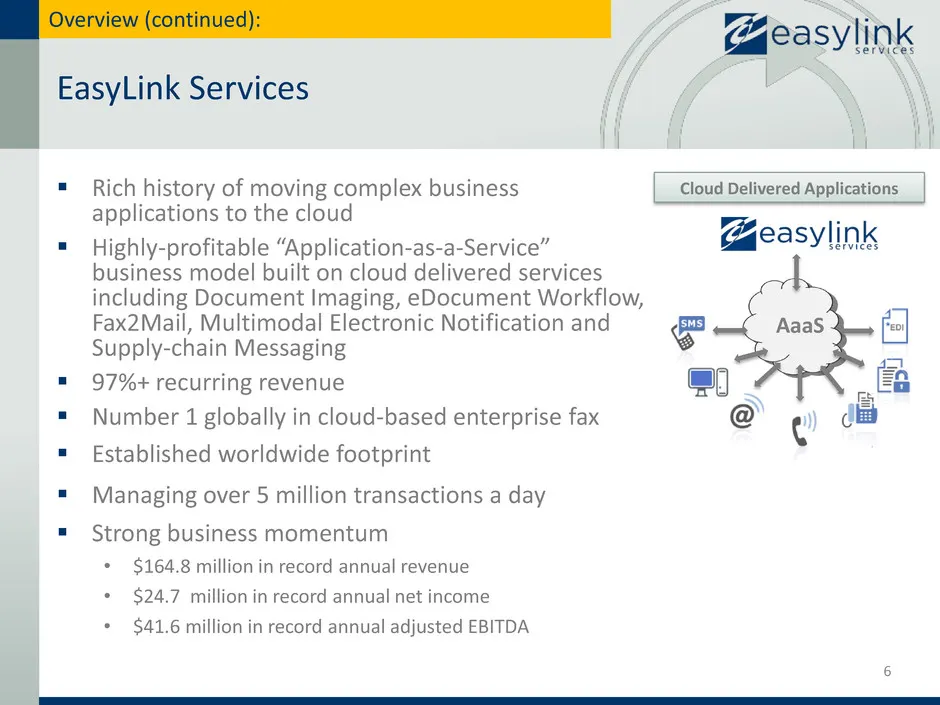
Rich history of moving complex business applications to the cloud Highly-profitable “Application-as-a-Service” business model built on cloud delivered services including Document Imaging, eDocument Workflow, Fax2Mail, Multimodal Electronic Notification and Supply-chain Messaging 97%+ recurring
Slide 7: Enterprise Cloud-based AaaS = High Growth Market
Enterprise Cloud-based AaaS = High Growth Market The total market for enterprise cloud- based services will grow from $12.1 billion in 2010 to $35.6 billion in 2015 Spending on enterprise communications applications is expected to grow to $17.7 billion in 2015 Our addressable market for cloud
Slide 8: Market Disrupting Transition to The Cloud
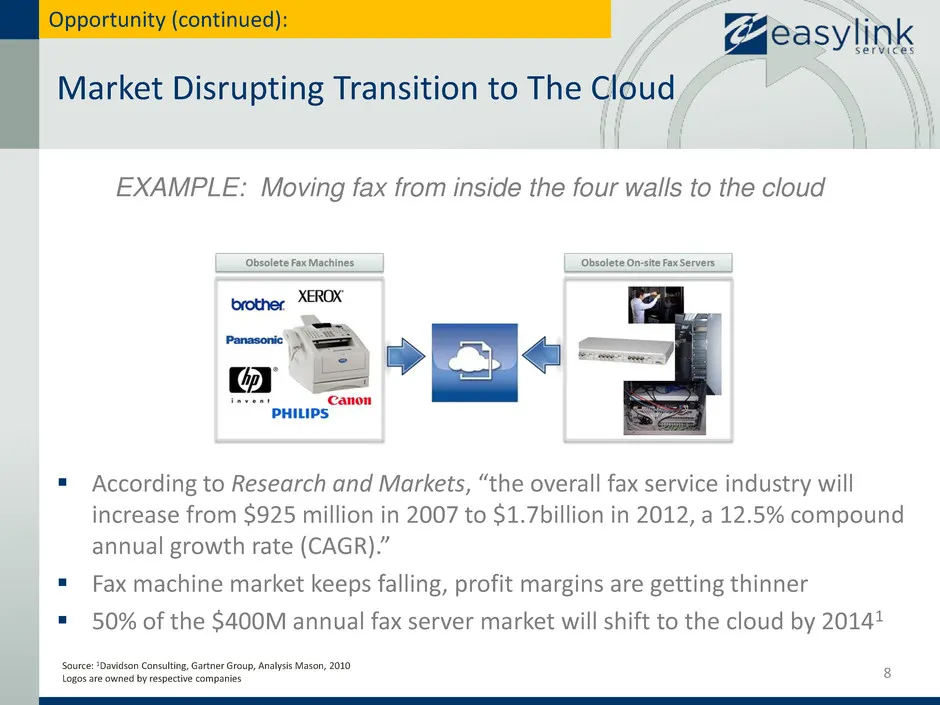
Market Disrupting Transition to The Cloud According to Research and Markets, “the overall fax service industry will increase from $925 million in 2007 to $1.7billion in 2012, a 12.5% compound annual growth rate (CAGR).” Fax machine market keeps falling, profit margins are getting thinner 50% o
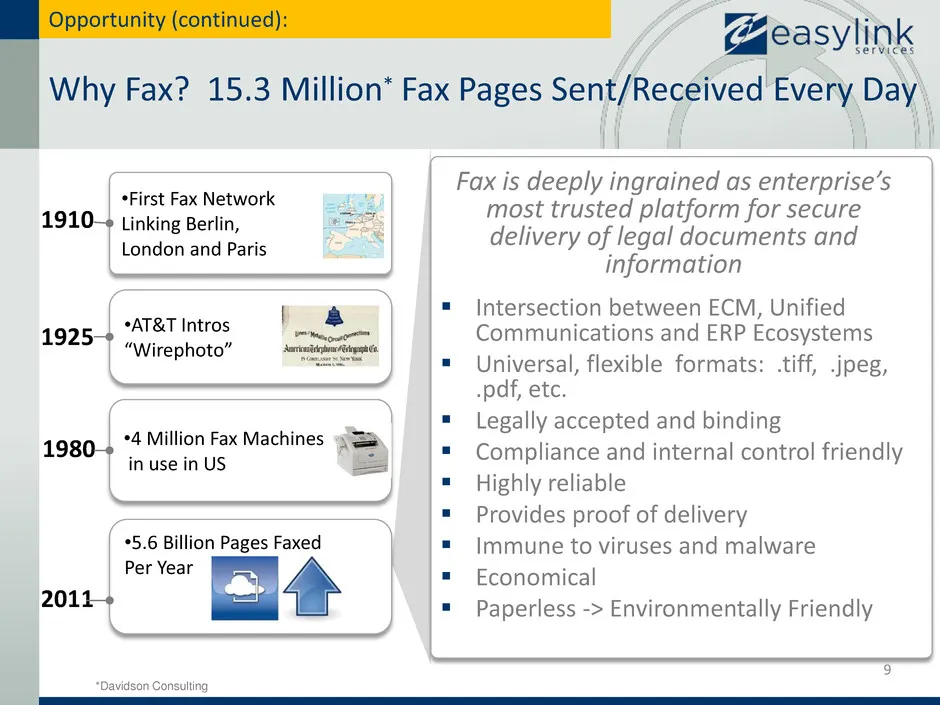
Slide 9: Why Fax?
Why Fax? 15.3 Million* Fax Pages Sent/Received Every Day Fax is deeply ingrained as enterprise’s most trusted platform for secure delivery of legal documents and information Intersection between ECM, Unified Communications and ERP Ecosystems Universal, flexible formats: .tiff, .jpeg, .pdf, etc.
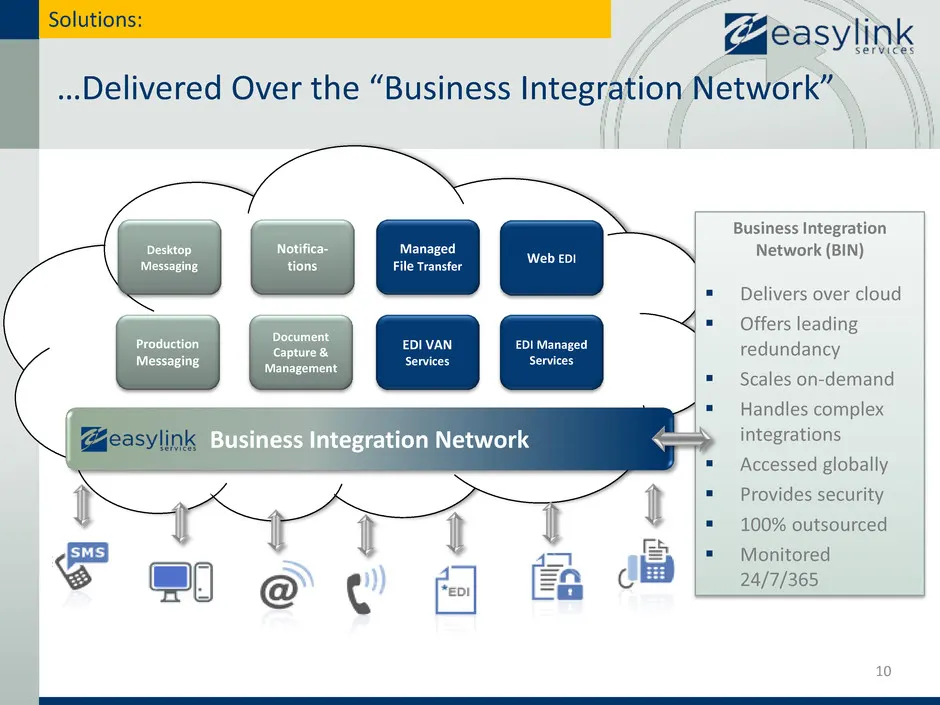
Slide 10: Delivered Over the Business Integration Network
Business Integration Network EDI VAN Services EDI Managed Services Managed File Transfer Web EDI Desktop Messaging Notifica- tions Production Messaging Document Capture & Management 10 …Delivered Over the “Business Integration Network” Solutions: Business Integration Network (BIN) Delivers over cl
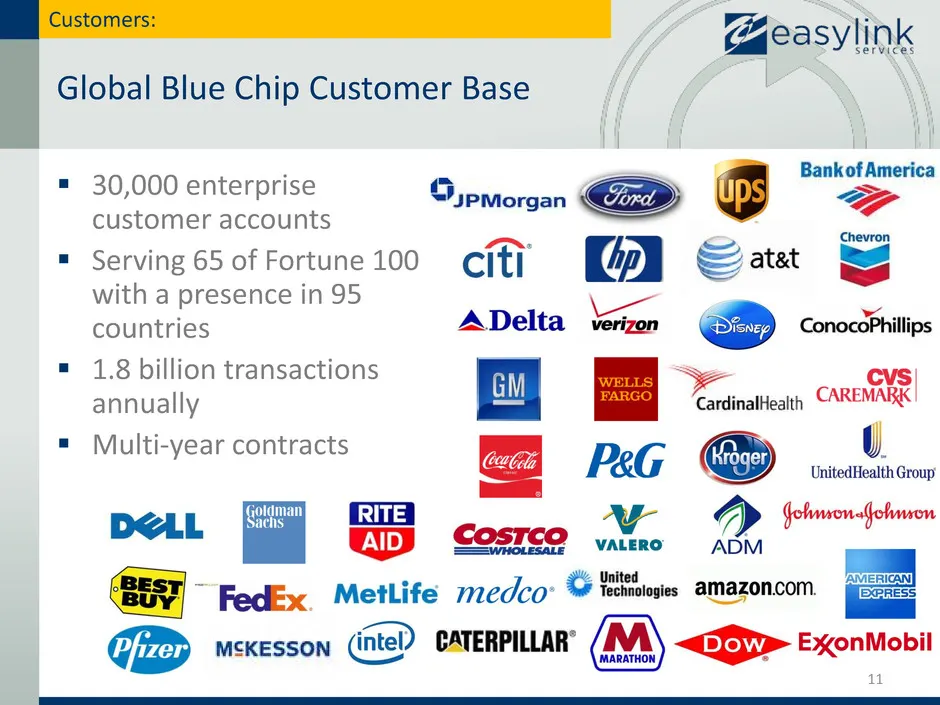
Slide 11: Global Blue Chip Customer Base
Global Blue Chip Customer Base 30,000 enterprise customer accounts Serving 65 of Fortune 100 with a presence in 95 countries 1.8 billion transactions annually Multi-year contracts Customers: 11
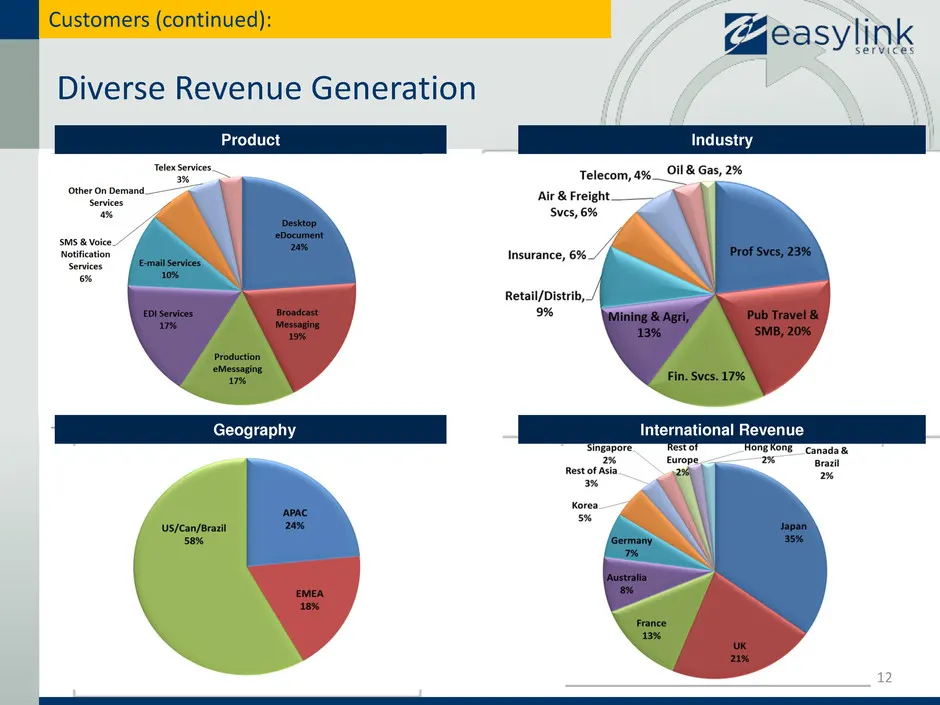
Slide 12: Diverse Revenue Generation
Product Diverse Revenue Generation Customers (continued): Industry Geography International Revenue 12
Slide 13: Competitive Differentiators
Competitive Differentiators 100% outsourced and managed risk Global scale and leadership Broader portfolio of applications Complex integration experience Low total cost of ownership 13 Customers (continued):
Slide 14: Organic Growth and Through M&A
Organic Growth and Through M&A Organic Growth • Desktop Messaging is growing double digits • Capture new enterprise accounts transitioning to the cloud • Cross-sell broader portfolio of applications into existing 30,000 customer accounts maximizing the number of services per customer • Expand glob
Slide 15: Proven Ability to Drive EBITDA Through M&A
Proven Ability to Drive EBITDA Through M&A Six acquisitions in six years Strong integration track record with focus on driving synergies Produced results • Significant cash flow from new businesses • More diverse industry base • Expanded application portfolio • Increased geographic, customer a
Slide 16: Strong, Experienced Leadership Team
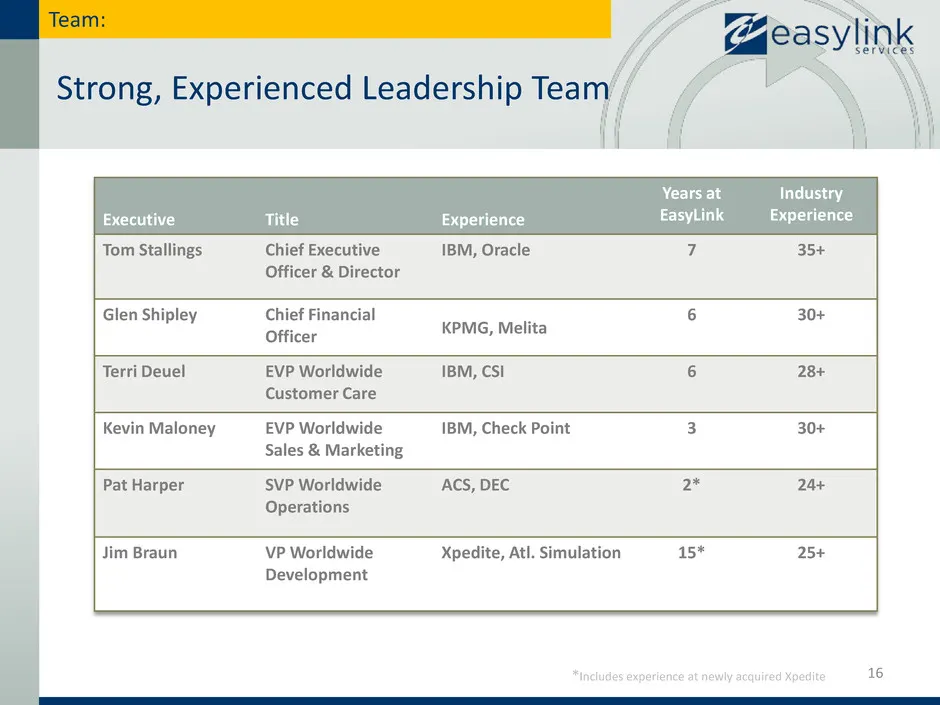
Strong, Experienced Leadership Team 16 Executive Title Experience Years at EasyLink Industry Experience Tom Stallings Chief Executive Officer & Director IBM, Oracle 7 35+ Glen Shipley Chief Financial Officer KPMG, Melita 6 30+ Terri Deuel EVP Worldwide Customer Care IBM, CSI 6 28+ Kevin Maloney EVP
Slide 17: Financial Overview
Financial Overview 17 Financial Overview: Glen Shipley, Chief Financial Officer
Slide 18: Financial Overview
Financial Overview Fiscal Year: August 1 – July 31 FY 2011 Results reflect approximately 9 months of contribution from the Xpedite acquisition Integration synergies are taking effect • At or near record revenues, cash flow and gross profit forecasted Continuing integration efforts • Data cen
Slide 19: Q4 and Annual FY 2011 Highlights
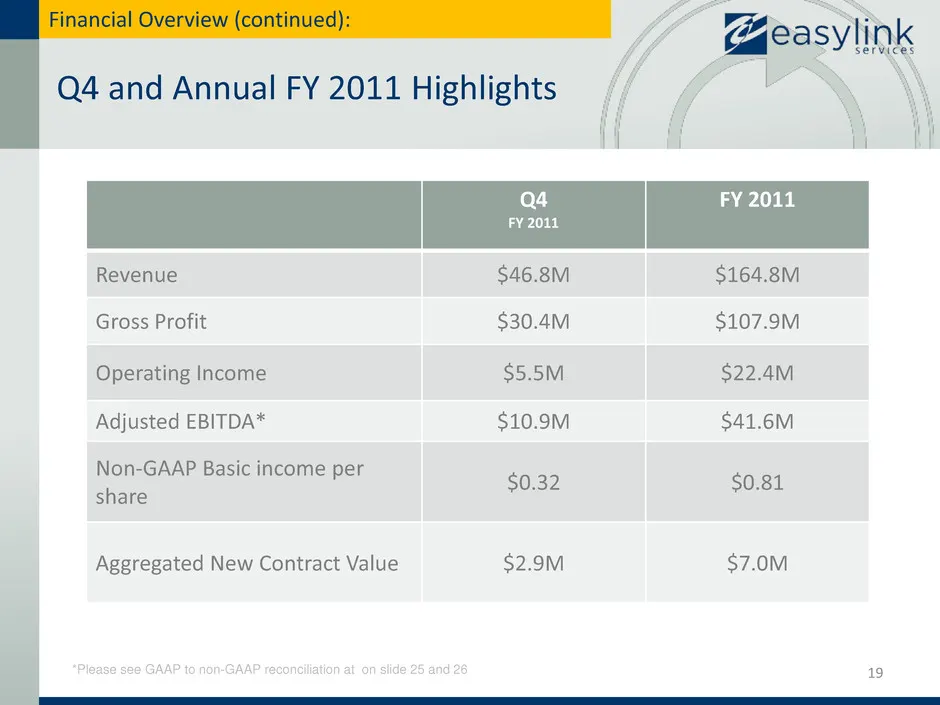
Q4 and Annual FY 2011 Highlights 19 Financial Overview (continued): Q4 FY 2011 FY 2011 Revenue $46.8M $164.8M Gross Profit $30.4M $107.9M Operating Income $5.5M $22.4M Adjusted EBITDA* $10.9M $41.6M Non-GAAP Basic income per share $0.32 $0.81 Aggregated New Contract Value $2.9M $7.0M *Please see GAA
Slide 20: Balance Sheet Highlights
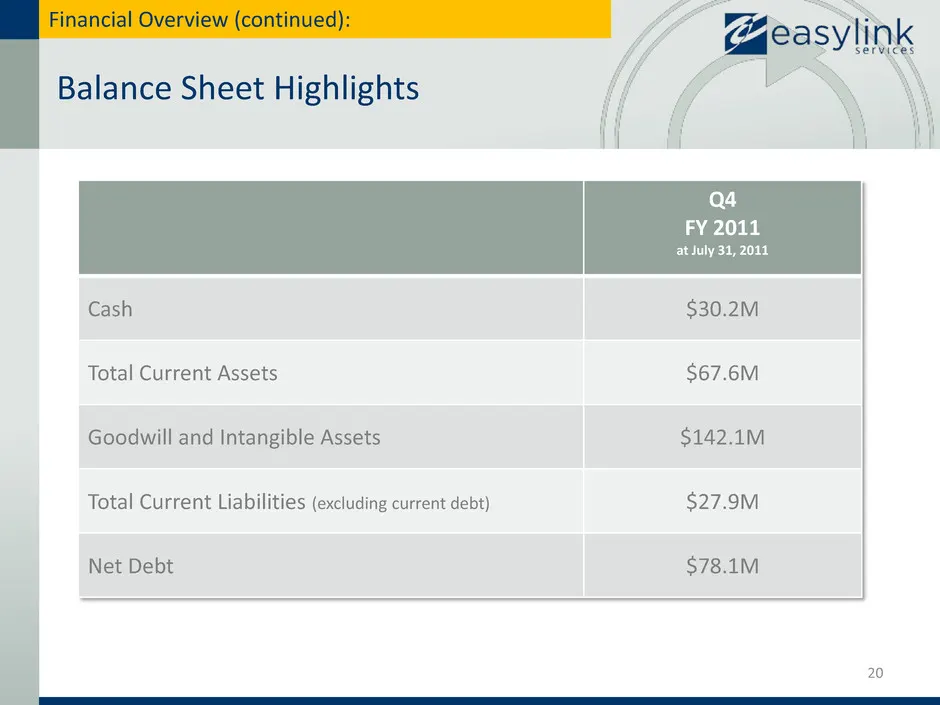
Balance Sheet Highlights 20 Financial Overview (continued): Q4 FY 2011 at July 31, 2011 Cash $30.2M Total Current Assets $67.6M Goodwill and Intangible Assets $142.1M Total Current Liabilities (excluding current debt) $27.9M Net Debt $78.1M
Slide 21: Cash Available to Pay Down Debt
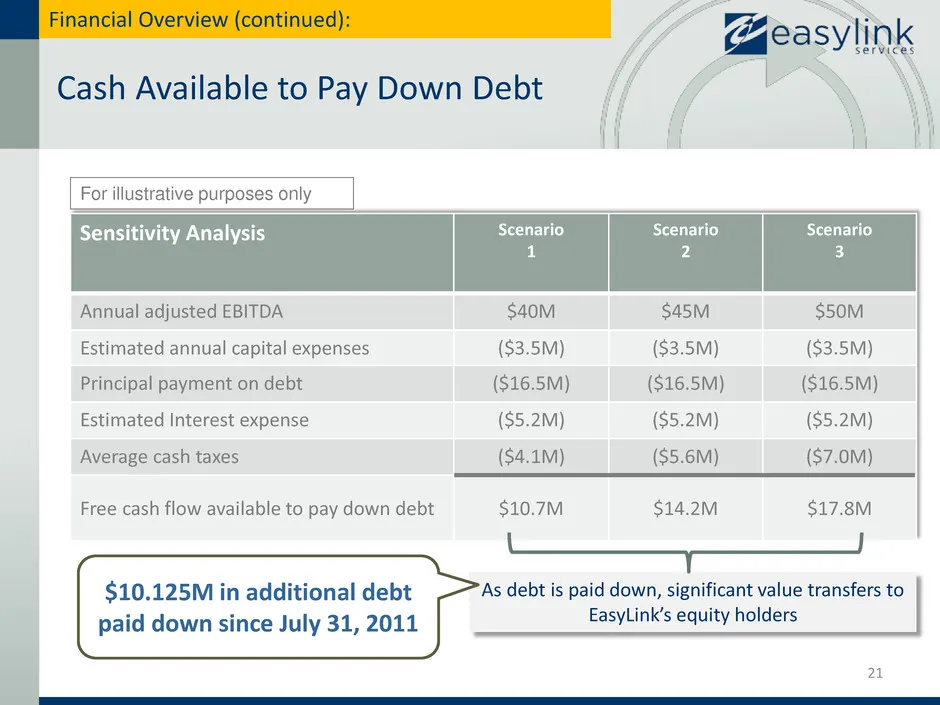
Cash Available to Pay Down Debt 21 Financial Overview (continued): Sensitivity Analysis Scenario 1 Scenario 2 Scenario 3 Annual adjusted EBITDA $40M $45M $50M Estimated annual capital expenses ($3.5M) ($3.5M) ($3.5M) Principal payment on debt ($16.5M) ($16.5M) ($16.5M) Estimated Interest expense ($5
Slide 22: Guidance for Fiscal Year Ending July 31, 2012
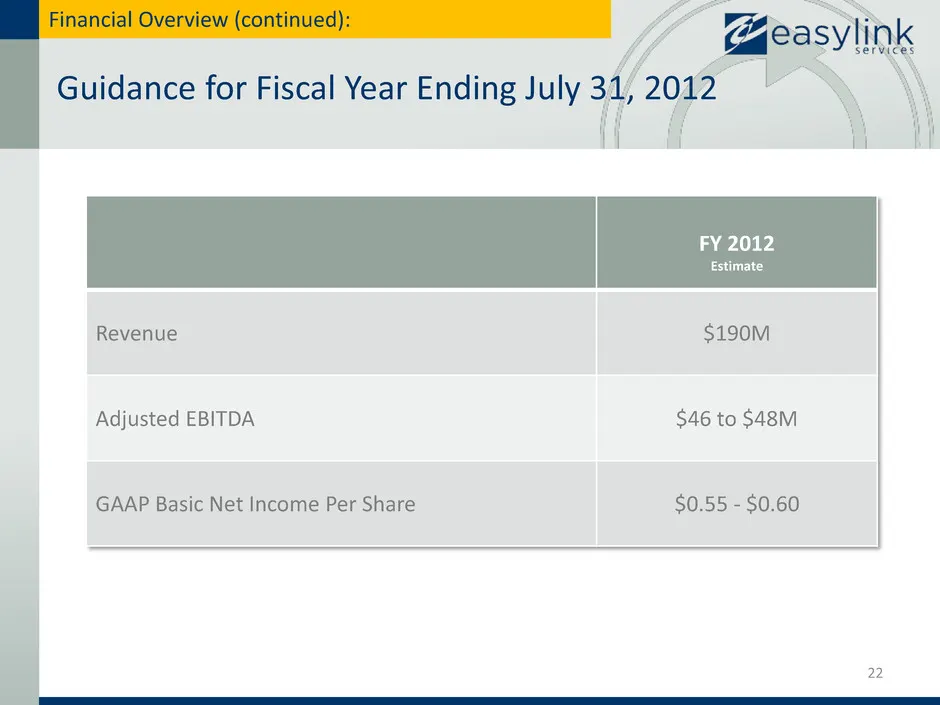
Guidance for Fiscal Year Ending July 31, 2012 22 Financial Overview (continued): FY 2012 Estimate Revenue $190M Adjusted EBITDA $46 to $48M GAAP Basic Net Income Per Share $0.55 - $0.60
Slide 23: Summary
Summary Our success is based on a cloud computing business model which includes 97%+ recurring revenue and fixed-cost leverage We have a large, diverse customer base with a global footprint and top market position We have an excellent track record of generating significant cash flow for which
Slide 24: Questions and Answers
Questions and Answers 24 Questions and Answers:
Slide 25: EBITDA Reconciliation
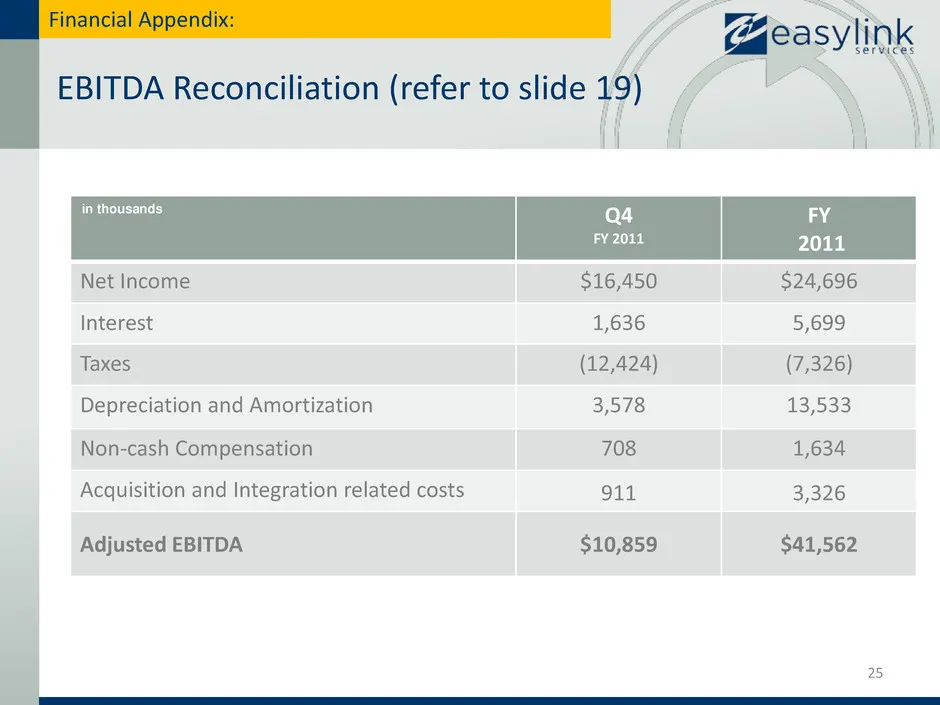
EBITDA Reconciliation (refer to slide 19) 25 Financial Appendix: Q4 FY 2011 FY 2011 Net Income $16,450 $24,696 Interest 1,636 5,699 Taxes (12,424) (7,326) Depreciation and Amortization 3,578 13,533 Non-cash Compensation 708 1,634 Acquisition and Integration related costs 911 3,326 Adjusted EBITDA $1
Slide 26: Non-GAAP Basic Net Income Per Common Share Reconciliation
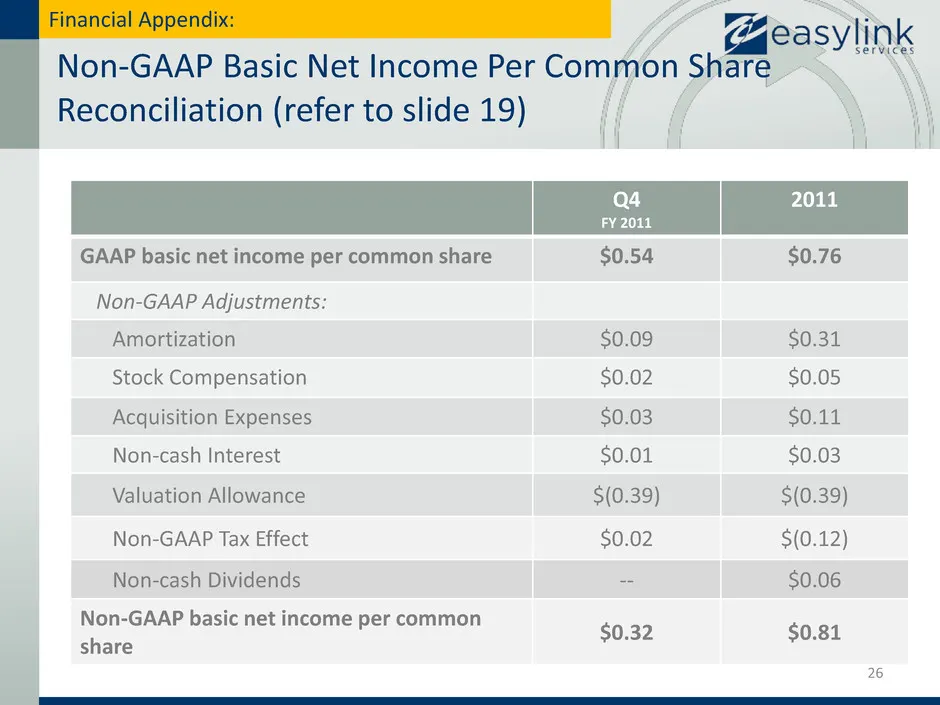
Non-GAAP Basic Net Income Per Common Share Reconciliation (refer to slide 19) 26 Financial Appendix: Q4 FY 2011 2011 GAAP basic net income per common share $0.54 $0.76 Non-GAAP Adjustments: Amortization $0.09 $0.31 Stock Compensation $0.02 $0.05 Acquisition Expenses $0.03 $0.11 Non-cash Interest $0.
Source: SEC EDGAR · 8-K filed Oct 18, 2011
More decks from Easylink Services International Corp
 Investor Presentation (July 2011)25 slides · Jul 20, 2011
 Investor Presentation (June 2011)25 slides · Jun 29, 2011
 Investor Presentation (May 2011)26 slides · May 16, 2011
 Investor Presentation (April 2011)26 slides · Apr 27, 2011
 Investor Presentation (June 2010)23 slides · Jun 7, 2010
 22nd Annual ROTH OC Growth Stock Conference 201022 slides · Mar 15, 2010