Pacific Mercantile Bancorp — Investor Presentation (November 2018)
22 slides from Pacific Mercantile Bancorp's investor presentation, Nov 5, 2018
Slide 1: November 2018 Investor Presentation
November 2018 INVESTOR PRESENTATION
Slide 2: Forward Looking Statements
FORWARD LOOKING STATEMENTS This presentation contains statements regarding our expectations, beliefs and views about our future financial performance and our business, trends and expectations regarding the markets in which we operate, and our future plans. Those statements constitute “forward-lookin
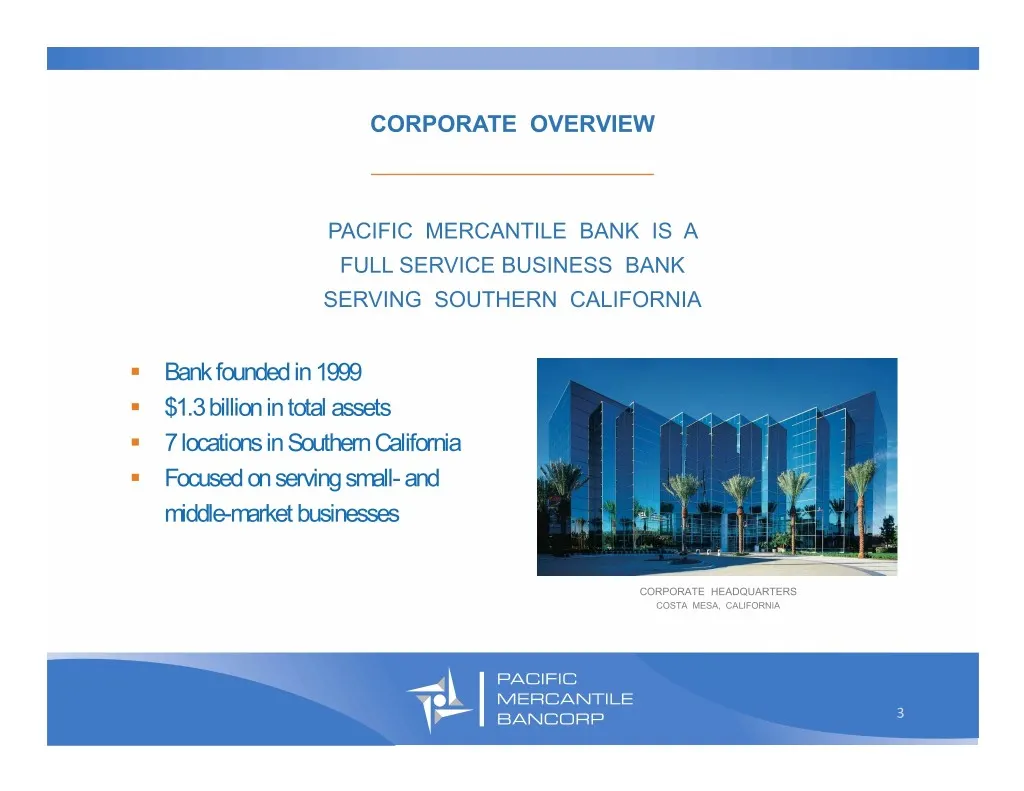
Slide 3: Corporate Overview
CORPORATE OVERVIEW _________________________________ PACIFIC MERCANTILE BANK IS A FULL SERVICE BUSINESS BANK SERVING SOUTHERN CALIFORNIA . Bank founded in 1999 . $1.3 billion in total assets . 7 locations in Southern California . Focused on serving small- and middle-market businesses CORPORATE HEADQ
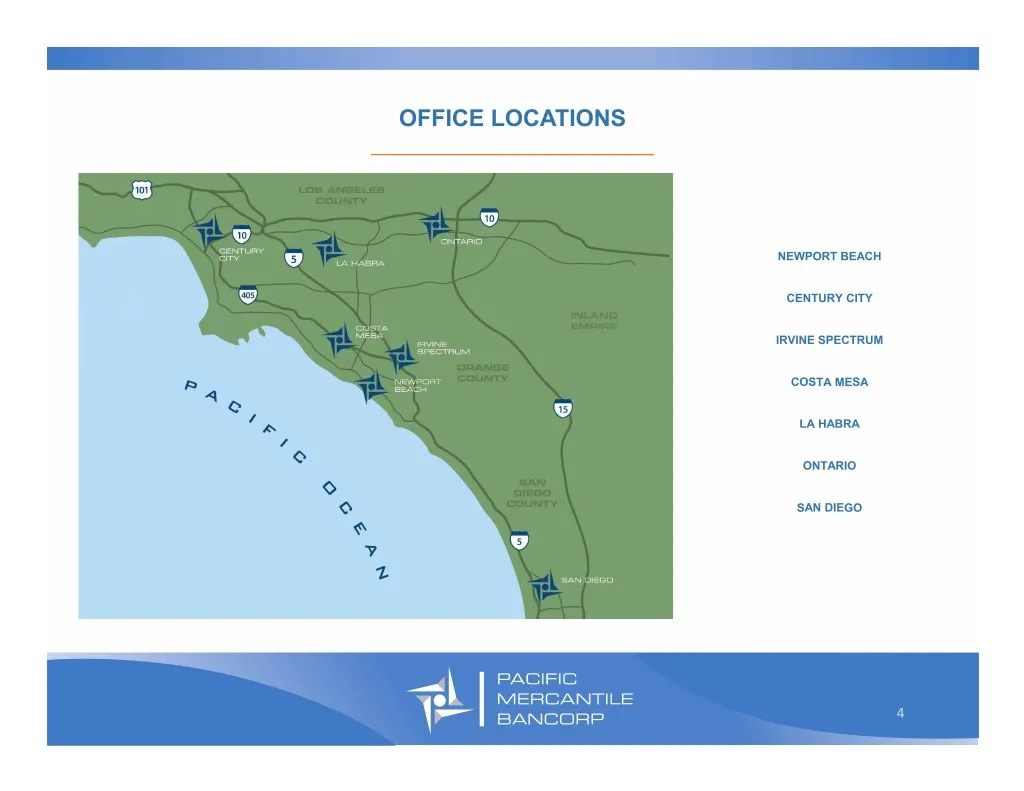
Slide 4: Office Locations
OFFICE LOCATIONS _________________________________ NEWPORT BEACH CENTURY CITY IRVINE SPECTRUM COSTA MESA LA HABRA ONTARIO SAN DIEGO 4
Slide 5: Executive Management Team
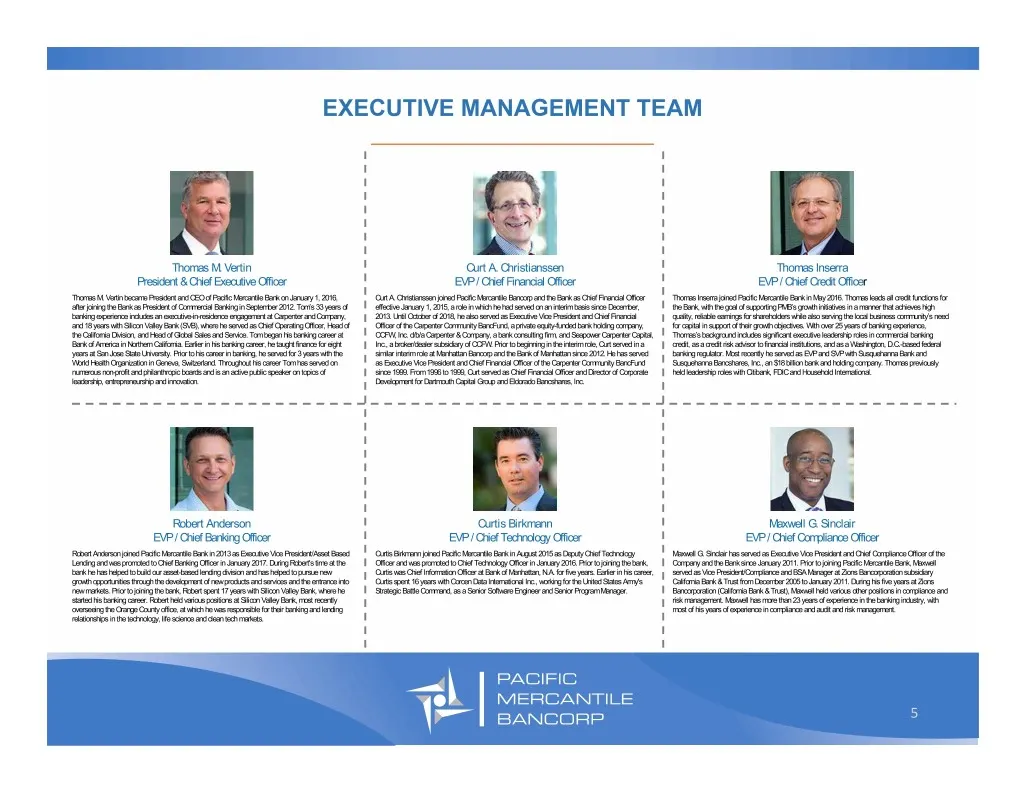
EXECUTIVE MANAGEMENT TEAM _________________________________ Thomas M. Vertin Curt A. Christianssen Thomas Inserra President & Chief Executive Officer EVP / Chief Financial Officer EVP / Chief Credit Officer Thomas M. Vertin became President and CEO of Pacific Mercantile Bank on January 1, 2016, Curt
Slide 6: Board of Directors
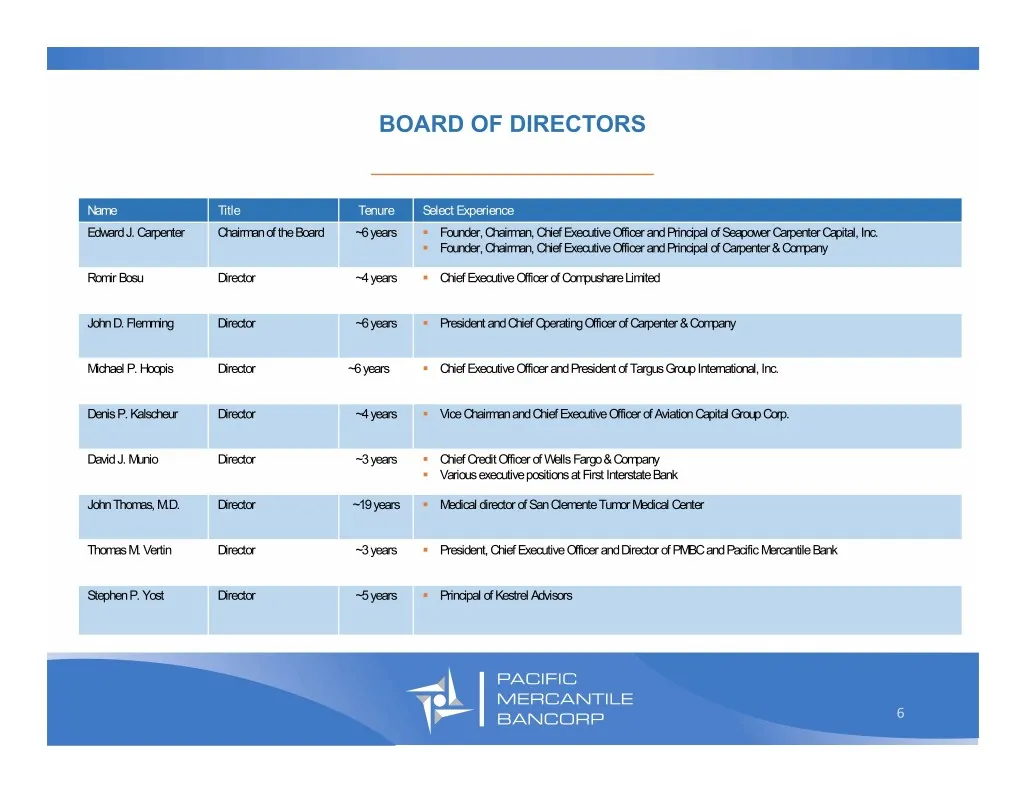
BOARD OF DIRECTORS _________________________________ Name Title Tenure Select Experience Edward J. Carpenter Chairman of the Board ~6 years . Founder, Chairman, Chief Executive Officer and Principal of Seapower Carpenter Capital, Inc. . Founder, Chairman, Chief Executive Officer and Principal of Car
Slide 7: Market Positioning
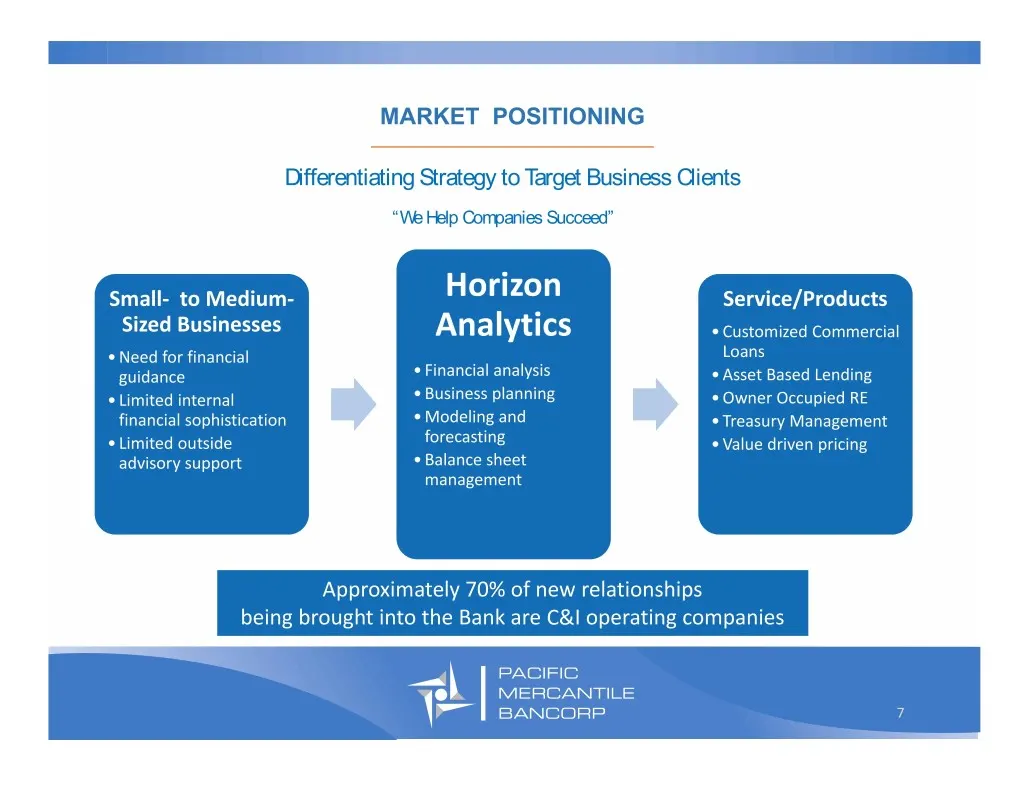
MARKET POSITIONING _________________________________ Differentiating Strategy to Target Business Clients “We Help Companies Succeed” Small‐ to Medium‐ Horizon Service/Products Sized Businesses Analytics • Customized Commercial • Need for financial Loans guidance • Financial analysis • Asset Based Le
Slide 8: Horizon Analytics
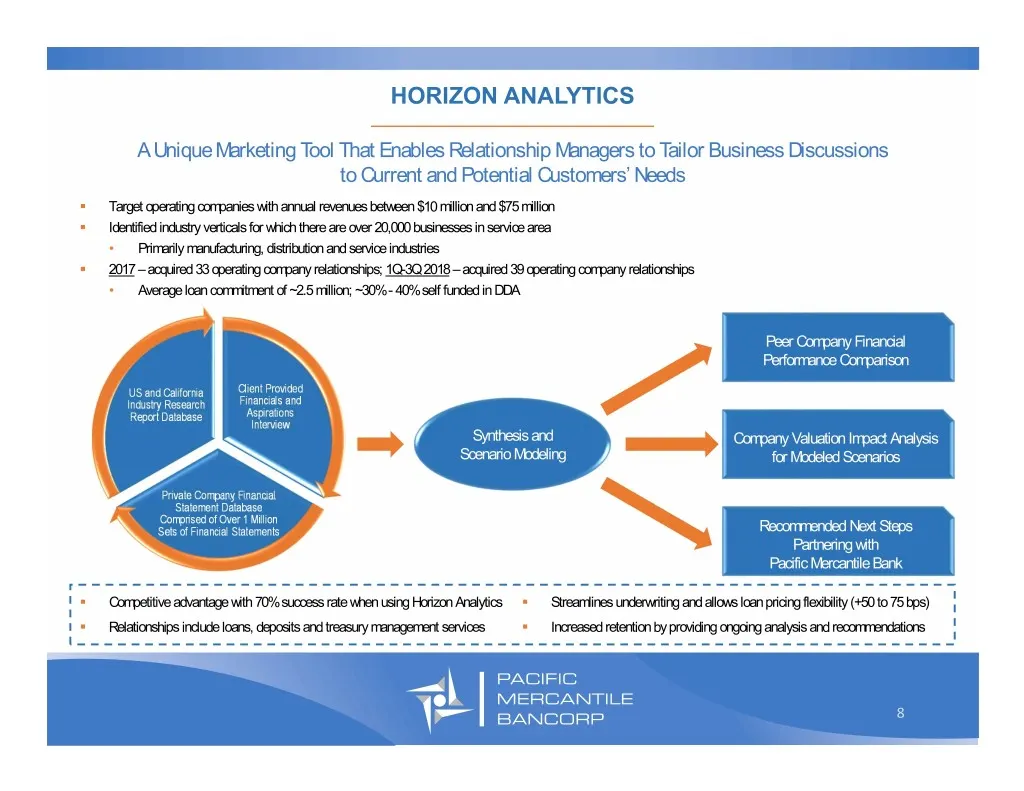
HORIZON ANALYTICS _________________________________ A Unique Marketing Tool That Enables Relationship Managers to Tailor Business Discussions to Current and Potential Customers’ Needs . Target operating companies with annual revenues between $10 million and $75 million . Identified industry vertical
Slide 9: Improving Profitability
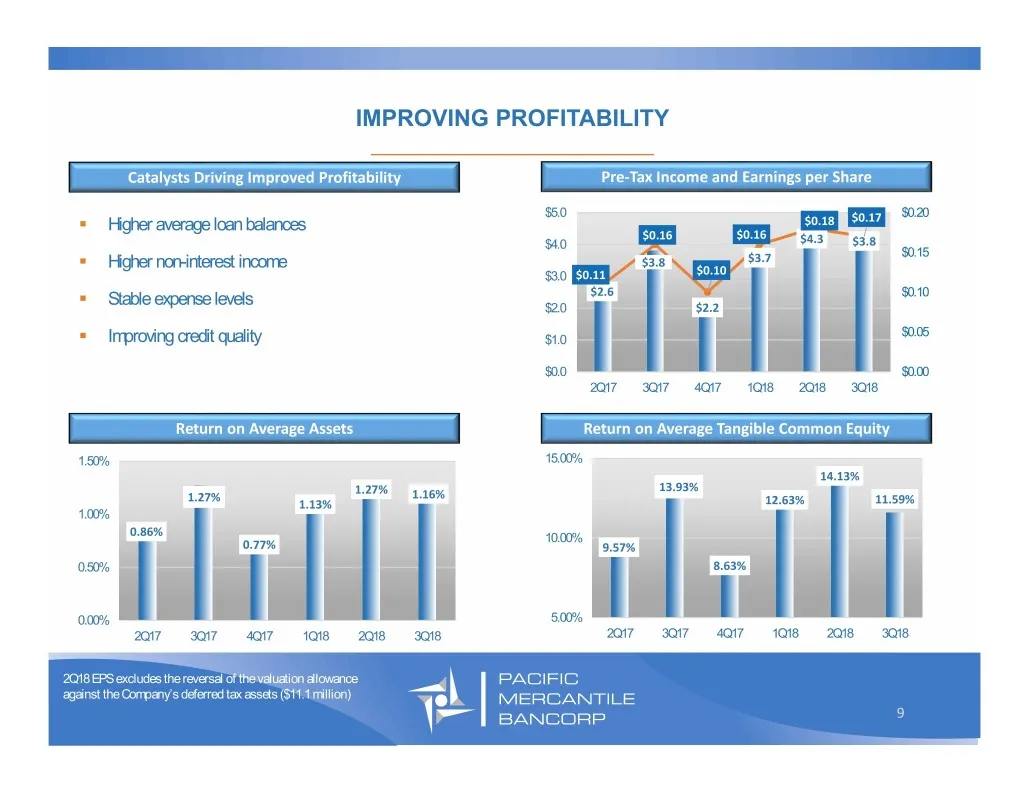
IMPROVING PROFITABILITY _________________________________ Catalysts Driving Improved Profitability Pre‐Tax Income and Earnings per Share $5.0 $0.20 . Higher average loan balances $0.18 $0.17 $0.16 $0.16 $4.0 $4.3 $3.8 $0.15 . Higher non-interest income $3.8 $3.7 $3.0 $0.11 $0.10 . Stable expense lev
Slide 10: Loan Portfolio Focus on Relationship Lending
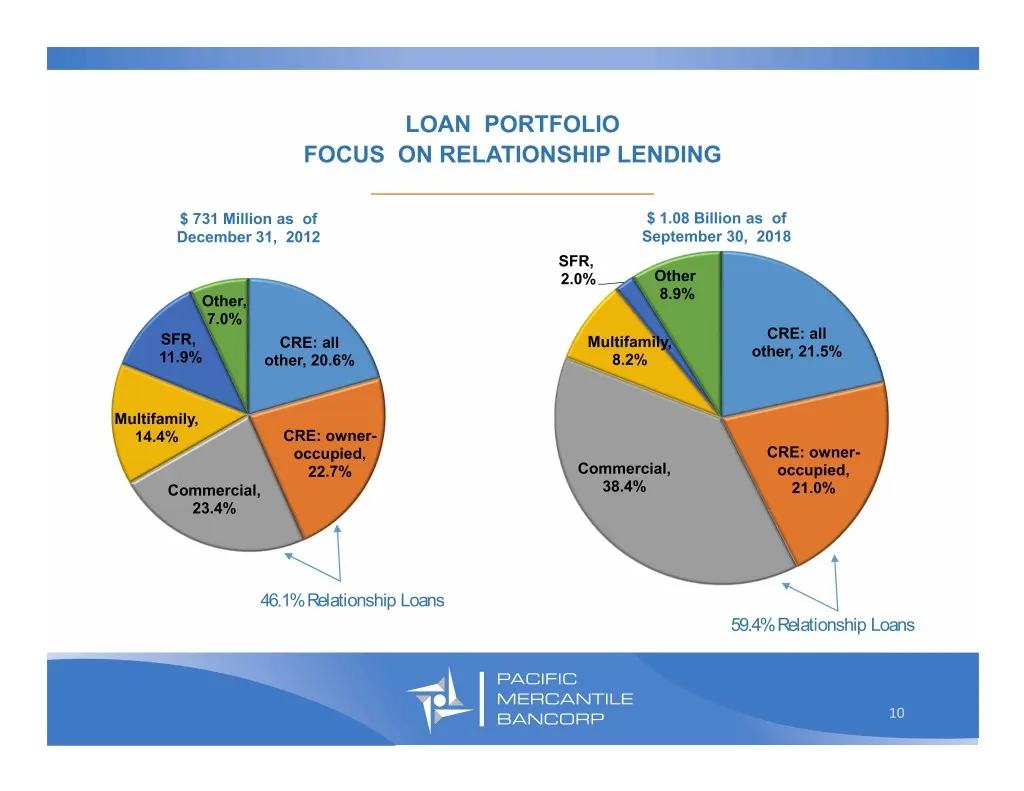
LOAN PORTFOLIO FOCUS ON RELATIONSHIP LENDING _________________________________ $ 731 Million as of $ 1.08 Billion as of December 31, 2012 September 30, 2018 SFR, 2.0% Other Other, 8.9% 7.0% CRE: all SFR, CRE: all Multifamily, other, 21.5% 11.9% other, 20.6% 8.2% Multifamily, 14.4% CRE: owner- occupi
Slide 11: Loan Production Trends
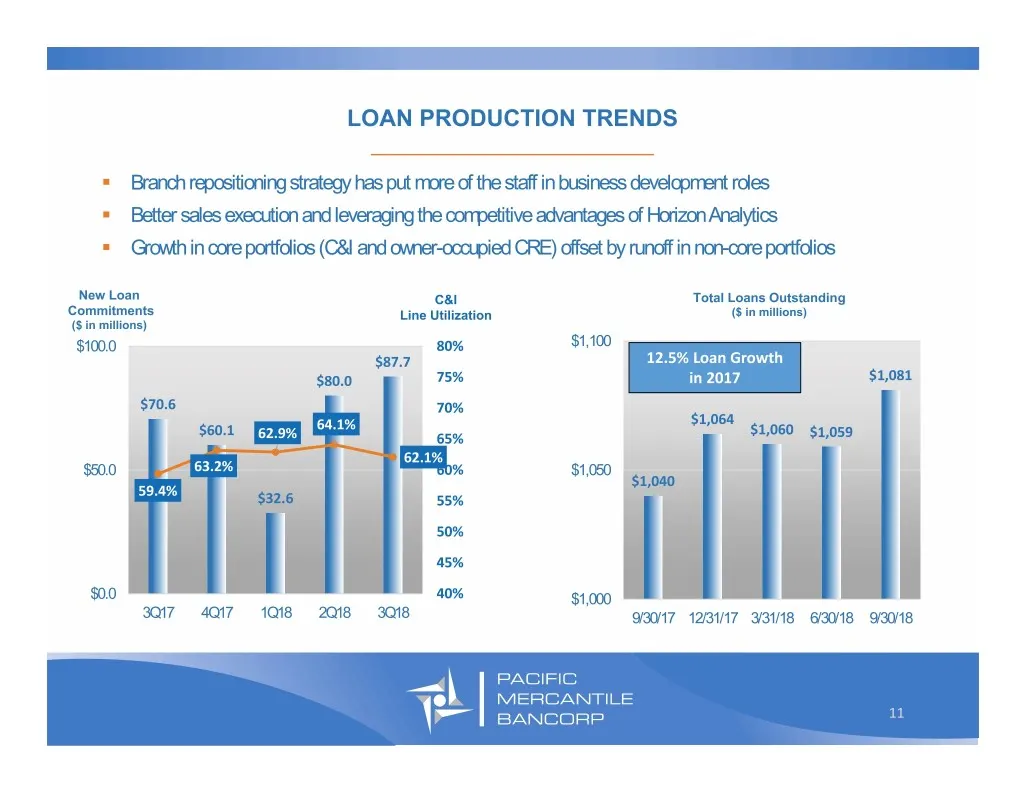
LOAN PRODUCTION TRENDS _________________________________ . Branch repositioning strategy has put more of the staff in business development roles . Better sales execution and leveraging the competitive advantages of Horizon Analytics . Growth in core portfolios (C&I and owner-occupied CRE) offset by
Slide 12: C&I Driving Loan Growth
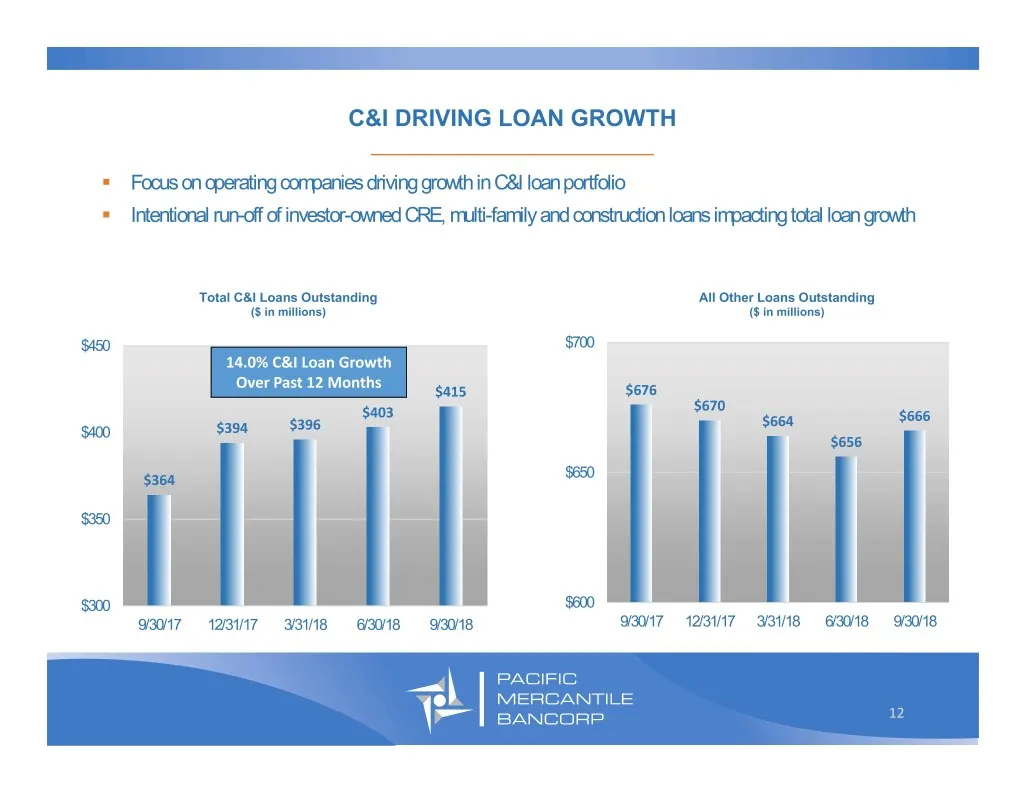
C&I DRIVING LOAN GROWTH _________________________________ . Focus on operating companies driving growth in C&I loan portfolio . Intentional run-off of investor-owned CRE, multi-family and construction loans impacting total loan growth Total C&I Loans Outstanding All Other Loans Outstanding ($ in mil
Slide 13: Loan Repricing Data
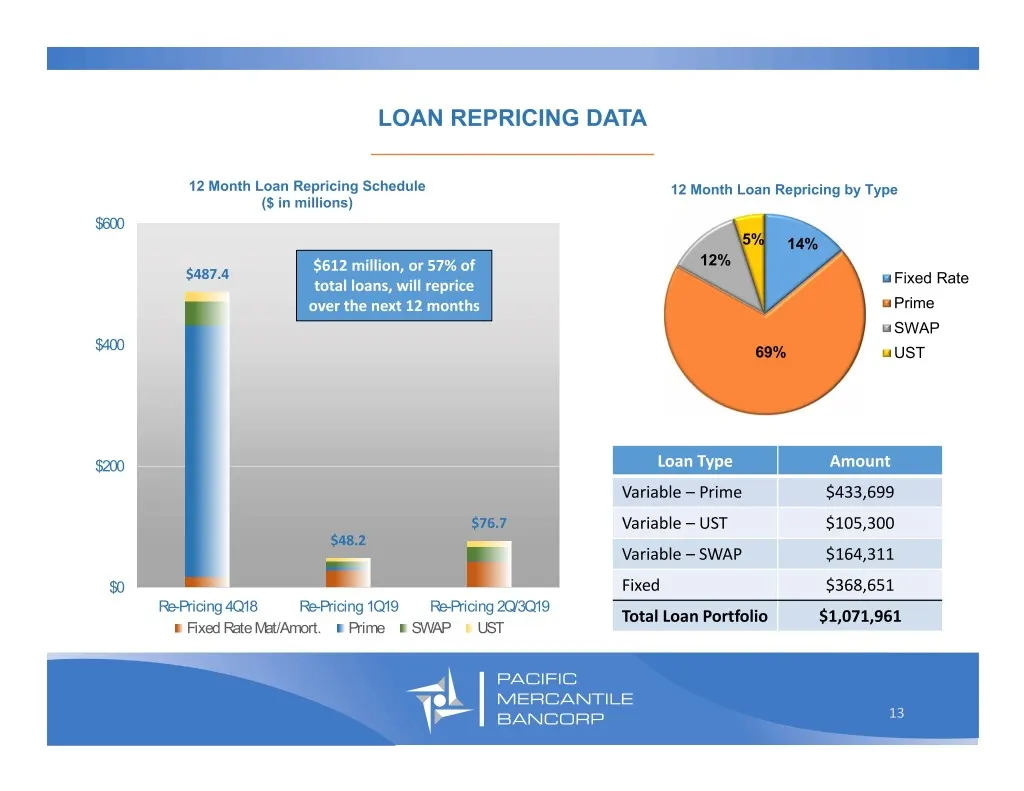
LOAN REPRICING DATA _________________________________ 12 Month Loan Repricing Schedule 12 Month Loan Repricing by Type ($ in millions) $600 5% 14% $612 million, or 57% of 12% $487.4 total loans, will reprice Fixed Rate over the next 12 months Prime SWAP $400 69% UST $200 Loan Type Amount Variable –
Slide 14: Asset Quality
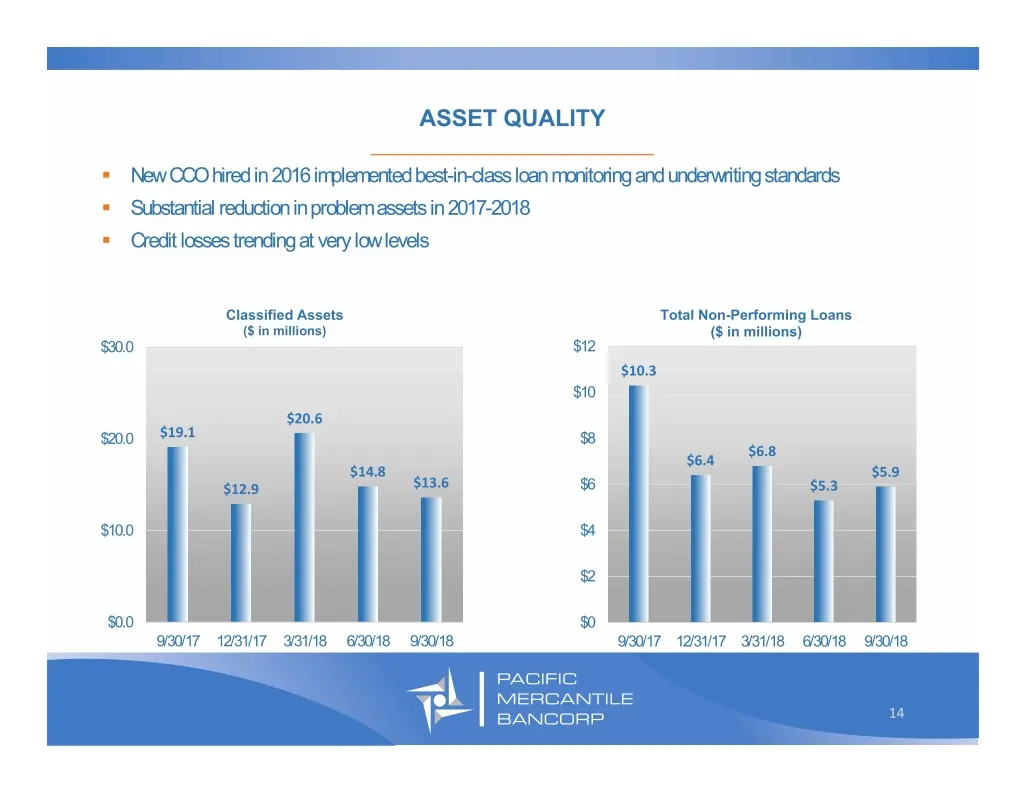
ASSET QUALITY _________________________________ . New CCO hired in 2016 implemented best-in-class loan monitoring and underwriting standards . Substantial reduction in problem assets in 2017-2018 . Credit losses trending at very low levels Classified Assets Total Non-Performing Loans ($ in millions)
Slide 15: Deposit Composition Focused on Core Deposits
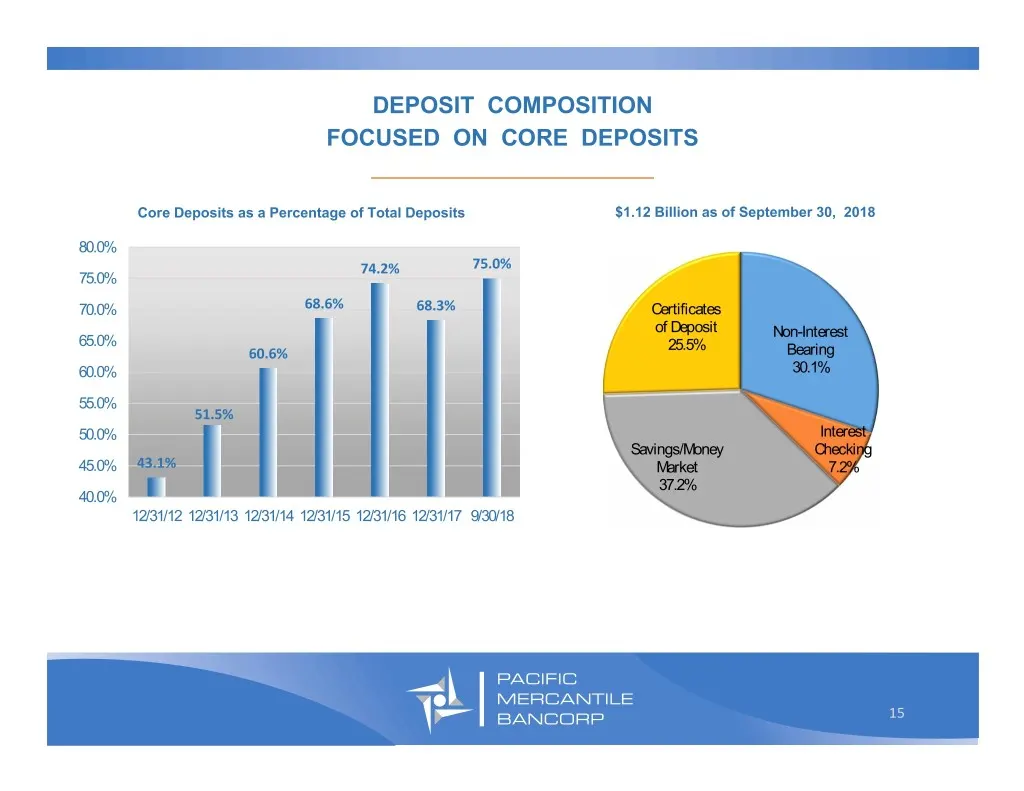
DEPOSIT COMPOSITION FOCUSED ON CORE DEPOSITS _________________________________ Core Deposits as a Percentage of Total Deposits $1.12 Billion as of September 30, 2018 80.0% 74.2% 75.0% 75.0% 70.0% 68.6% 68.3% Certificates of Deposit Non-Interest 65.0% 25.5% 60.6% Bearing 60.0% 30.1% 55.0% 51.5% 50.0%
Slide 16: Improving Funding Profile
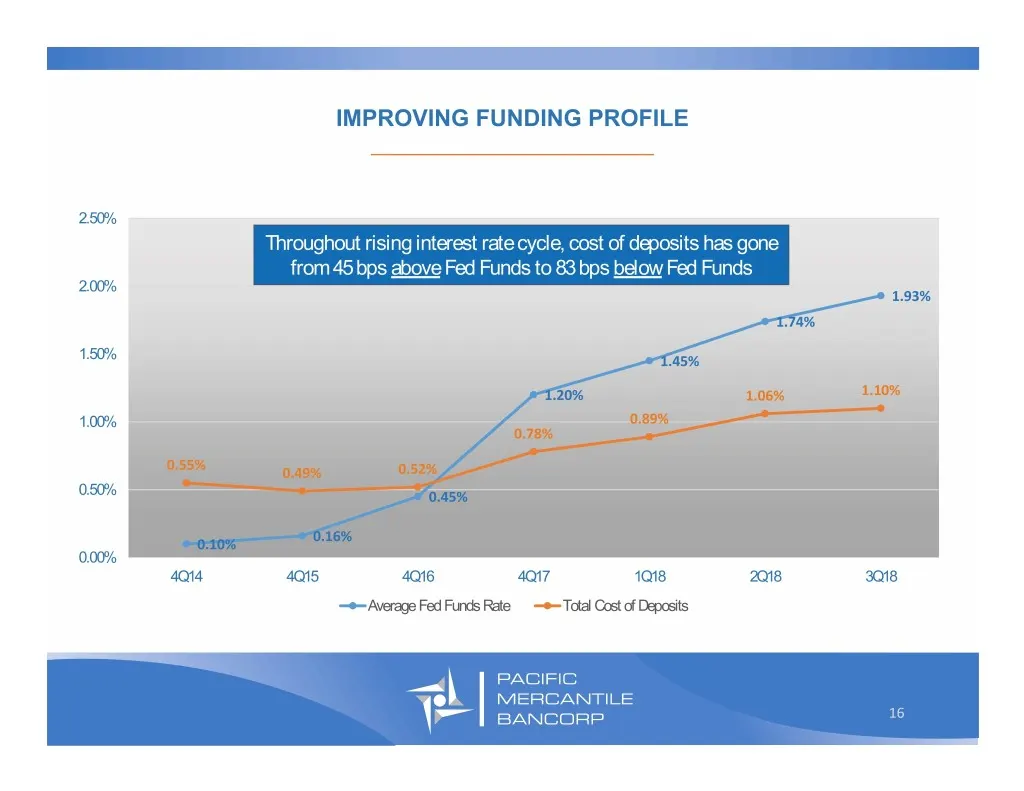
IMPROVING FUNDING PROFILE _________________________________ 2.50% Throughout rising interest rate cycle, cost of deposits has gone from 45 bps above Fed Funds to 83 bps below Fed Funds 2.00% 1.93% 1.74% 1.50% 1.45% 1.20% 1.06% 1.10% 1.00% 0.89% 0.78% 0.55% 0.49% 0.52% 0.50% 0.45% 0.16% 0.10% 0.00% 4
Slide 17: 2018 Deposit Beta Trend
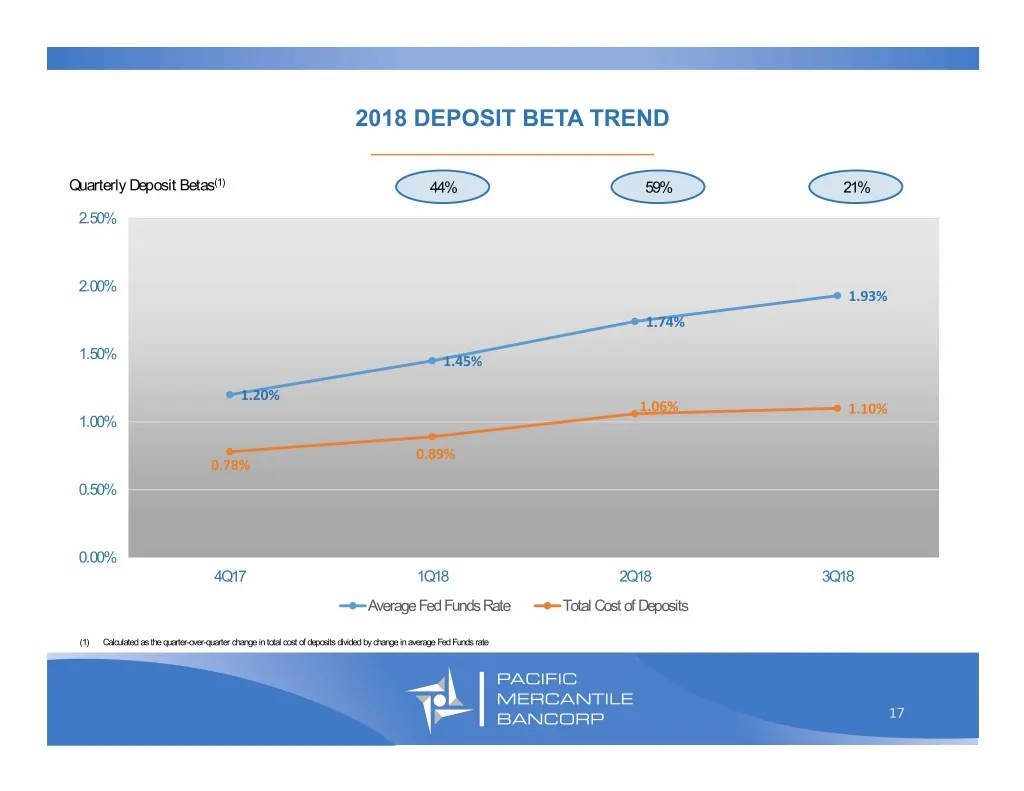
2018 DEPOSIT BETA TREND _________________________________ Quarterly Deposit Betas(1) 44% 59% 21% 2.50% 2.00% 1.93% 1.74% 1.50% 1.45% 1.20% 1.06% 1.10% 1.00% 0.89% 0.78% 0.50% 0.00% 4Q17 1Q18 2Q18 3Q18 Average Fed Funds Rate Total Cost of Deposits (1) Calculated as the quarter-over-quarter change in
Slide 18: Time Deposit Maturity Schedule
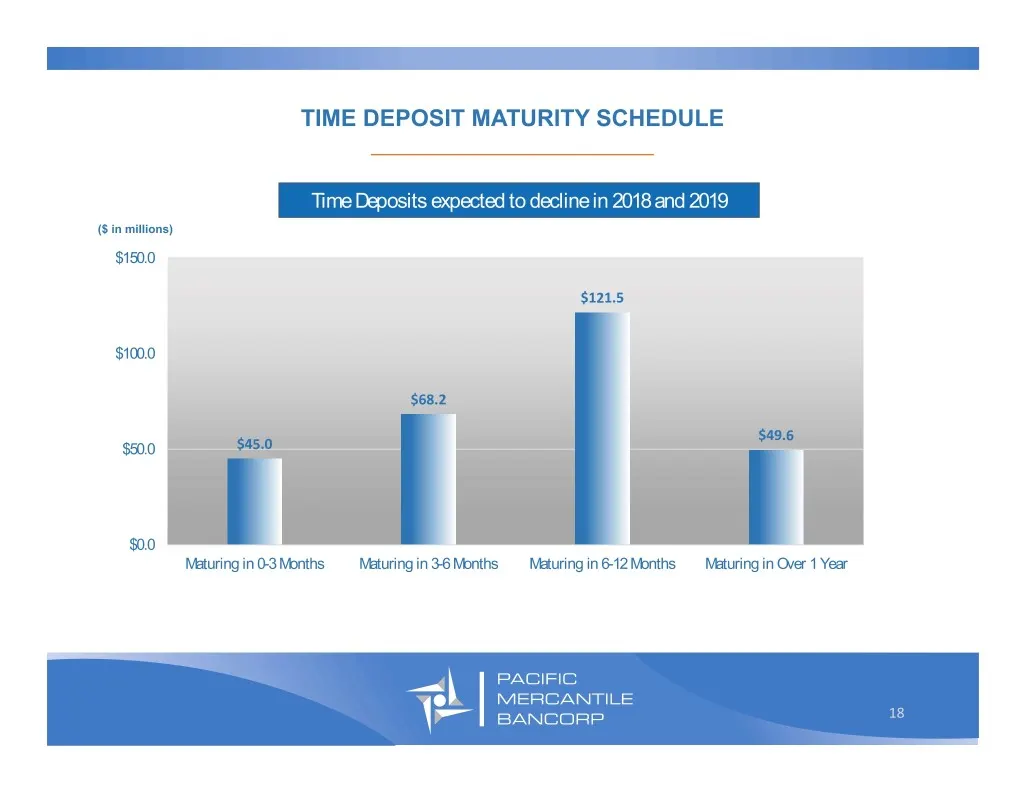
TIME DEPOSIT MATURITY SCHEDULE _________________________________ Time Deposits expected to decline in 2018 and 2019 ($ in millions) $150.0 $121.5 $100.0 $68.2 $49.6 $50.0 $45.0 $0.0 Maturing in 0-3 Months Maturing in 3-6 Months Maturing in 6-12 Months Maturing in Over 1 Year 18
Slide 19: Improving Operating Leverage
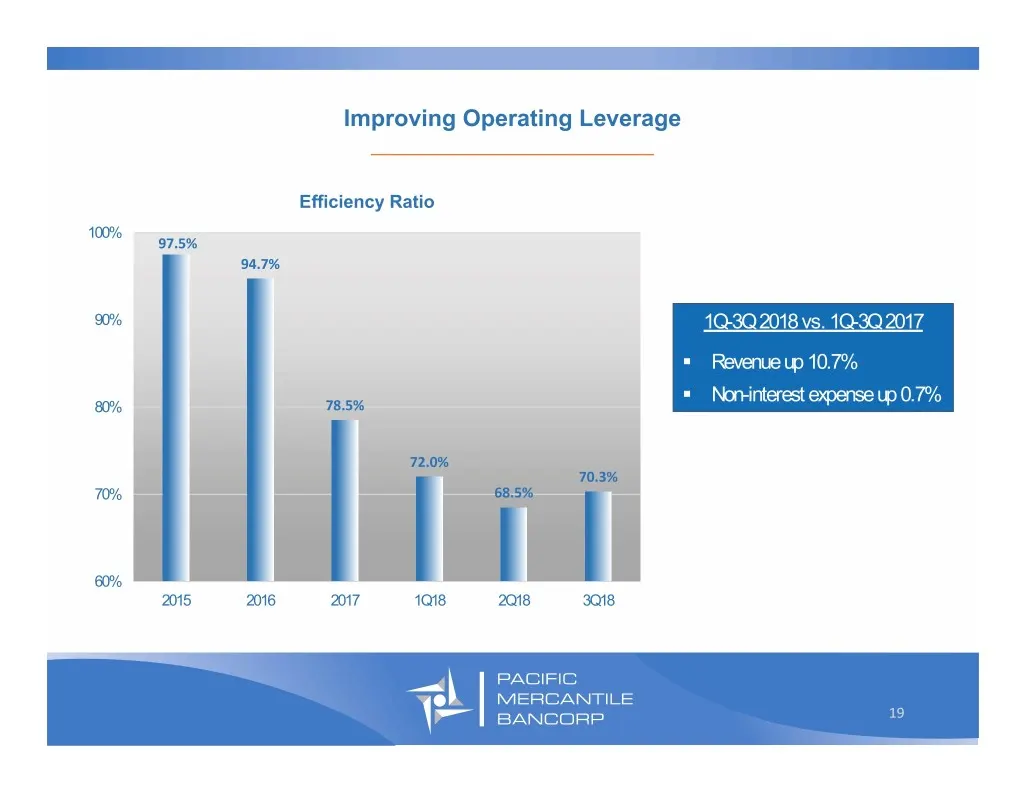
Improving Operating Leverage _________________________________ Efficiency Ratio 100% 97.5% 94.7% 90% 1Q-3Q 2018 vs. 1Q-3Q 2017 . Revenue up 10.7% . Non-interest expense up 0.7% 80% 78.5% 72.0% 70.3% 70% 68.5% 60% 2015 2016 2017 1Q18 2Q18 3Q18 19
Slide 20: Strong Capital Position
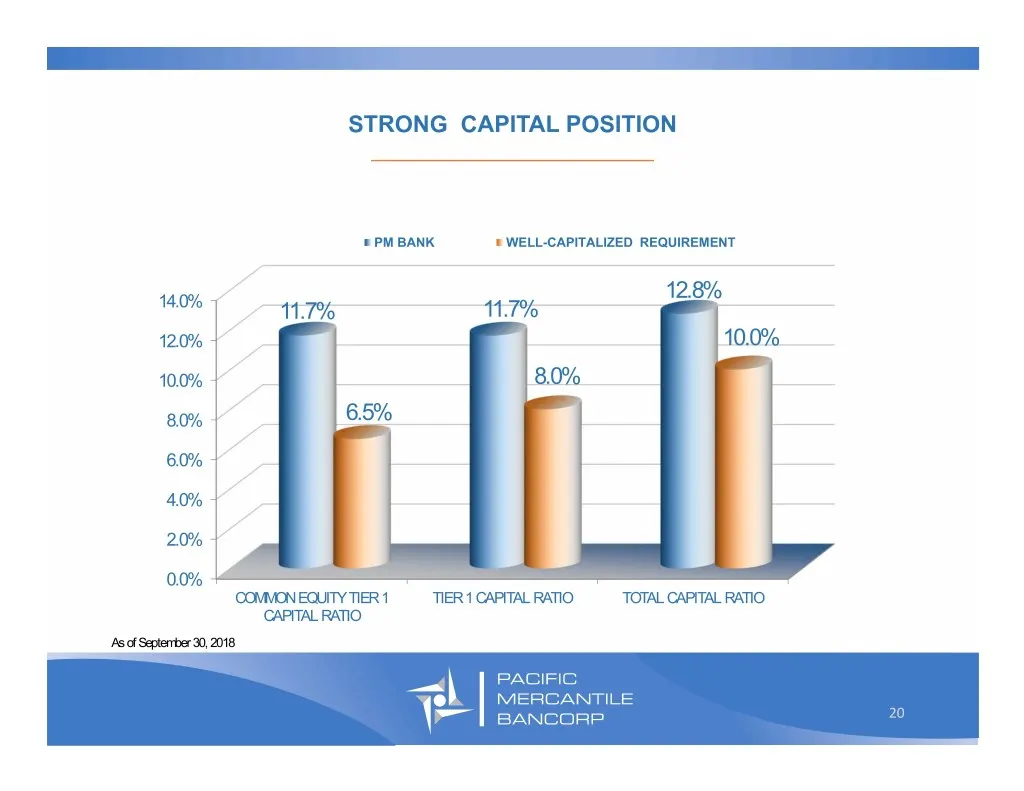
STRONG CAPITAL POSITION _________________________________ PM BANK WELL-CAPITALIZED REQUIREMENT 12.8% 14.0% 11.7% 11.7% 12.0% 10.0% 10.0% 8.0% 8.0% 6.5% 6.0% 4.0% 2.0% 0.0% COMMON EQUITY TIER 1 TIER 1 CAPITAL RATIO TOTAL CAPITAL RATIO CAPITAL RATIO As of September 30, 2018 20
Slide 21: Outlook
OUTLOOK _________________________________ Continued strong commercial loan growth . Runoff from non-core loan portfolios will impact total loan growth Enhancing focus on core deposit gathering . Targeting improvement in deposit mix and reduced cost of funds Increasing net interest margin . Well posi
Slide 22: Investor Relations Contact
Investor Relations: Curt Christianssen (714) 438-2531 Curt.christianssen@pmbank.com 22
Source: SEC EDGAR · 8-K filed Nov 5, 2018
More decks from Pacific Mercantile Bancorp
 Q1 2021 Earnings Presentation18 slides · Apr 26, 2021
 Merger or Acquisition (March 2021)9 slides · Mar 23, 2021
 Q4 2020 Earnings Presentation22 slides · Jan 25, 2021
 Q3 2020 Earnings Presentation23 slides · Nov 2, 2020
 Corporate Update (September 2020)25 slides · Sep 8, 2020
 Corporate Update (August 2020)25 slides · Aug 5, 2020