Vectren — Edison Electric Institute Financial Conference 2017
52 slides from Vectren's conference presentation, Nov 3, 2017
Slide 1: Edison Electric Institute Financial Conference, November 5-8, 2017
November 5-8, 2017 Edison Electric Institute Financial Conference
Slide 2: Management Representatives
Management Representatives Aaron Musgrave Manager, Investor Relations Carl Chapman Chairman, President & CEO Vectren | Investor Presentation | November 2017 2 Susan Hardwick Executive Vice President & CFO Dave Parker Director, Investor Relations
Slide 3: Forward-Looking Statements
Forward-Looking Statements All statements other than statements of historical fact are forward-looking statements made in good faith by the company and are intended to qualify for the safe harbor from liability established by the Private Securities Litigation Reform Act of 1995. Such statements are
Slide 4: Consolidated Q3 2017 Results
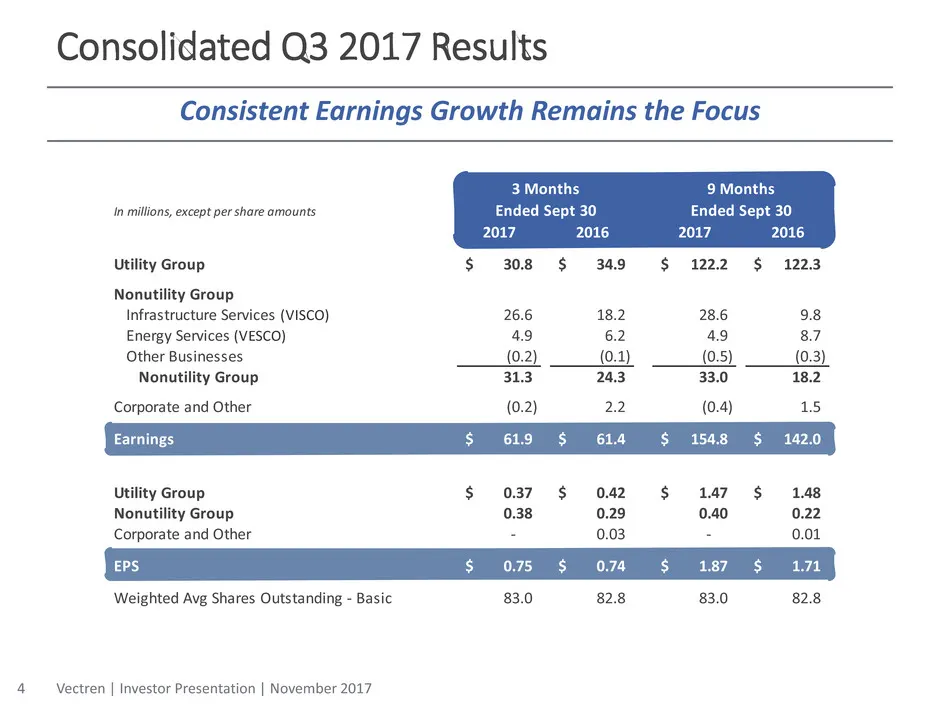
In millions, except per share amounts 2017 2016 2017 2016 Utility Group 30.8$ 34.9$ 122.2$ 122.3$ Nonutility Group Infrastructure Services (VISCO) 26.6 18.2 28.6 9.8 Energy Services (VESCO) 4.9 6.2 4.9 8.7 Other Businesses (0.2) (0.1) (0.5) (0.3) Nonutility Group 31.3 24.3 33.0 18.2 Corporate and Ot
Slide 5: 2017 Guidance Affirmed
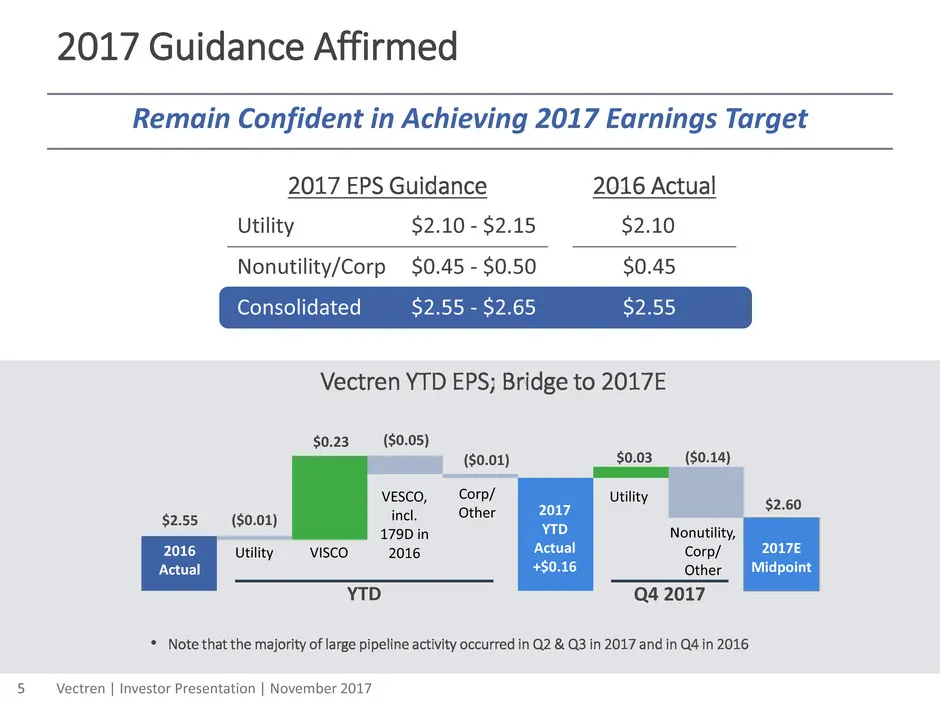
2017 Guidance Affirmed 5 Remain Confident in Achieving 2017 Earnings Target 2017 EPS Guidance 2016 Actual Utility $2.10 - $2.15 $2.10 Nonutility/Corp $0.45 - $0.50 $0.45 Consolidated $2.55 - $2.65 $2.55 Vectren | Investor Presentation | November 2017 VISCO ($0.01) Vectren YTD EPS; Bridge to 2017E $2
Slide 6: Key Drivers of 2017 Guidance Remain Unchanged
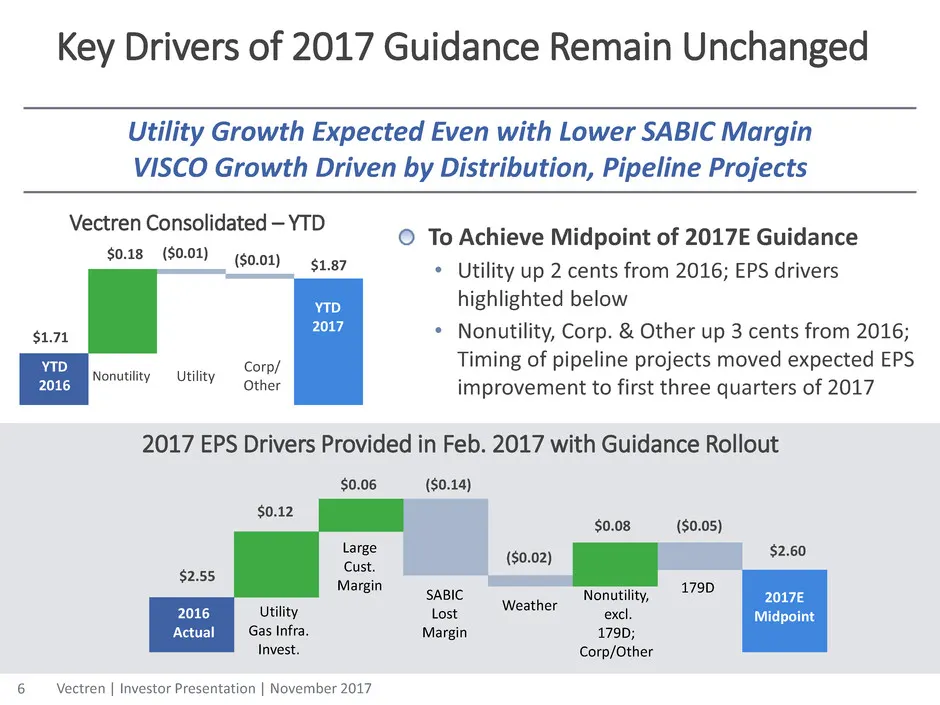
Utility Corp/ Other YTD 2017 Nonutility $1.71 $1.87 ($0.01) $0.18 ($0.01) YTD 2016 Key Drivers of 2017 Guidance Remain Unchanged 6 2016 Actual Vectren | Investor Presentation | November 2017 Utility Growth Expected Even with Lower SABIC Margin VISCO Growth Driven by Distribution, Pipeline Projects 1
Slide 7: Dividend Increased 7.1% in November 2017
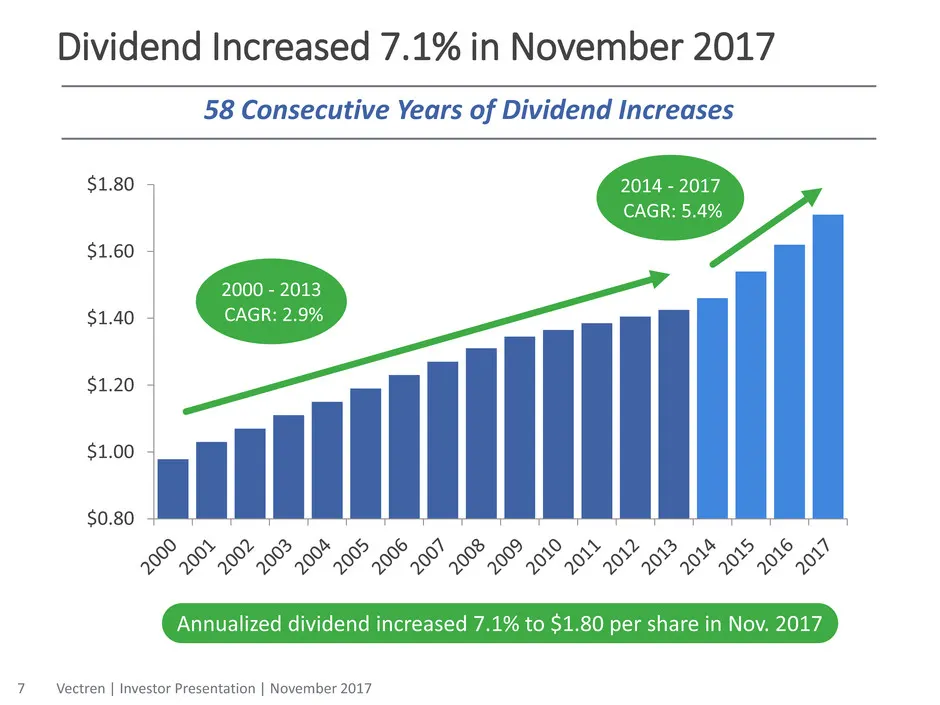
Dividend Increased 7.1% in November 2017 7 $0.80 $1.00 $1.20 $1.40 $1.60 $1.80 2014 - 2017 CAGR: 5.4% 2000 - 2013 CAGR: 2.9% Annualized dividend increased 7.1% to $1.80 per share in Nov. 2017 58 Consecutive Years of Dividend Increases Vectren | Investor Presentation | November 2017
Slide 8: Q3 2017 Results and Highlights
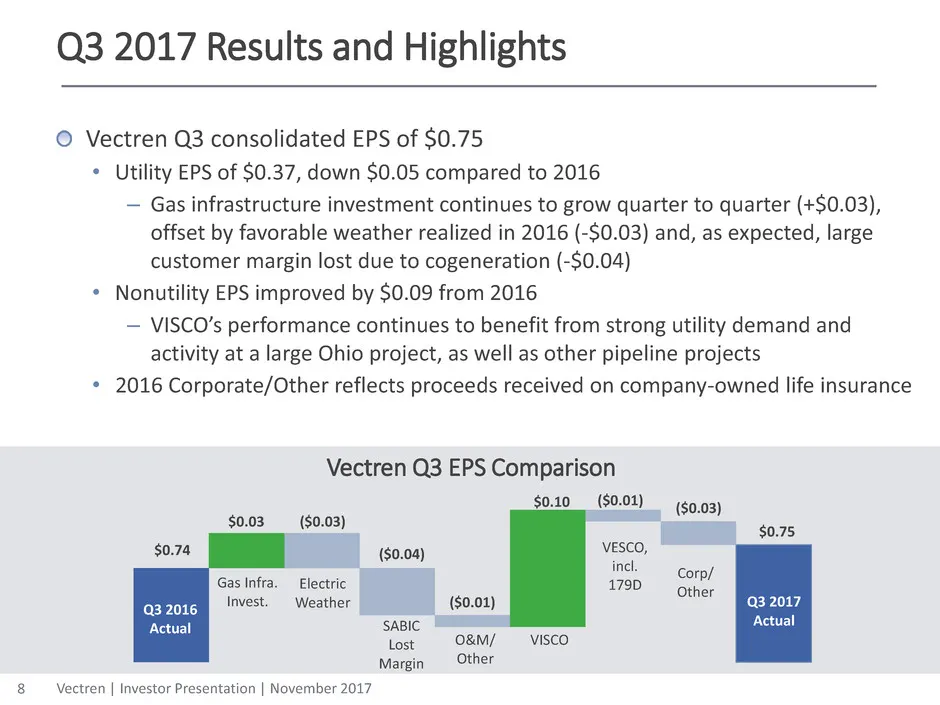
Q3 2017 Results and Highlights 8 VISCO Corp/ Other Vectren Q3 EPS Comparison $0.74 $0.75 $0.03 $0.10 ($0.04) ($0.01) ($0.03) Q3 2016 Actual VESCO, incl. 179D Gas Infra. Invest. SABIC Lost Margin Electric Weather O&M/ Other Q3 2017 Actual ($0.01) Vectren | Investor Presentation | November 2017 ($0.03
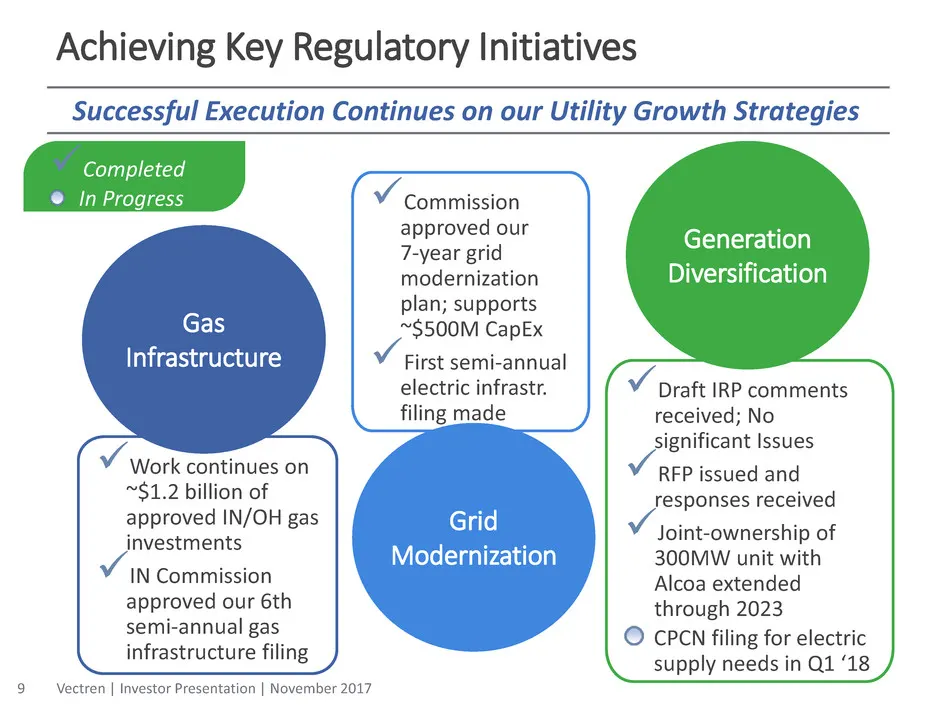
Slide 9: Achieving Key Regulatory Initiatives
Completed In Progress Achieving Key Regulatory Initiatives 9 Successful Execution Continues on our Utility Growth Strategies Vectren | Investor Presentation | November 2017 Draft IRP comments received; No significant Issues RFP issued and responses received Joint-ownership of 300MW unit with Alc
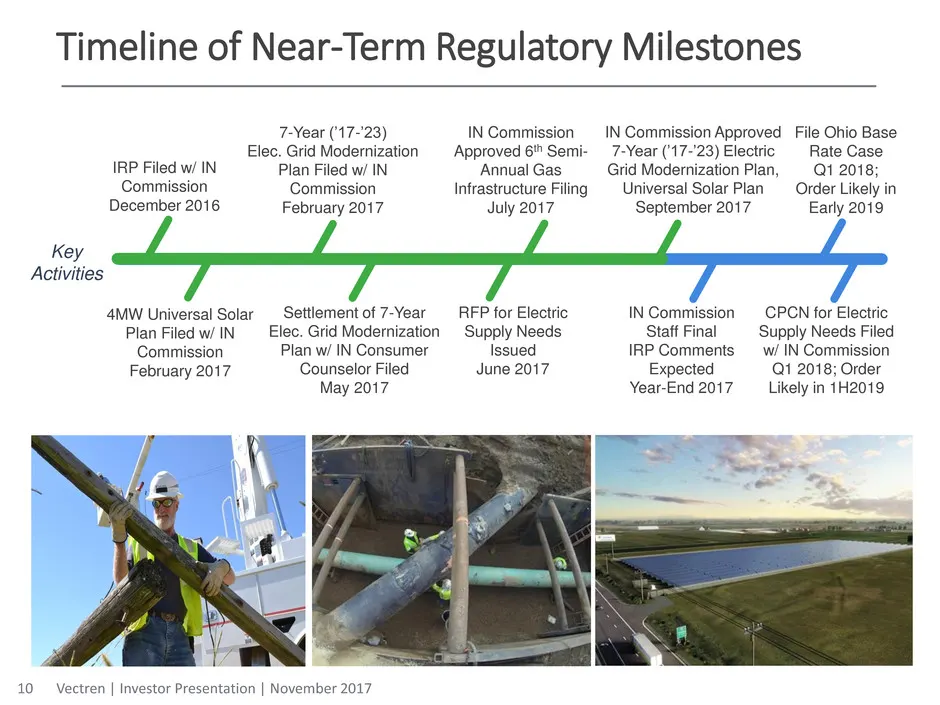
Slide 10: Timeline of Near-Term Regulatory Milestones
Timeline of Near-Term Regulatory Milestones 10 Vectren | Investor Presentation | November 2017 7-Year (’17-’23) Elec. Grid Modernization Plan Filed w/ IN Commission February 2017 Key Activities IN Commission Approved 6th Semi- Annual Gas Infrastructure Filing July 2017 File Ohio Base Rate Case Q1 20
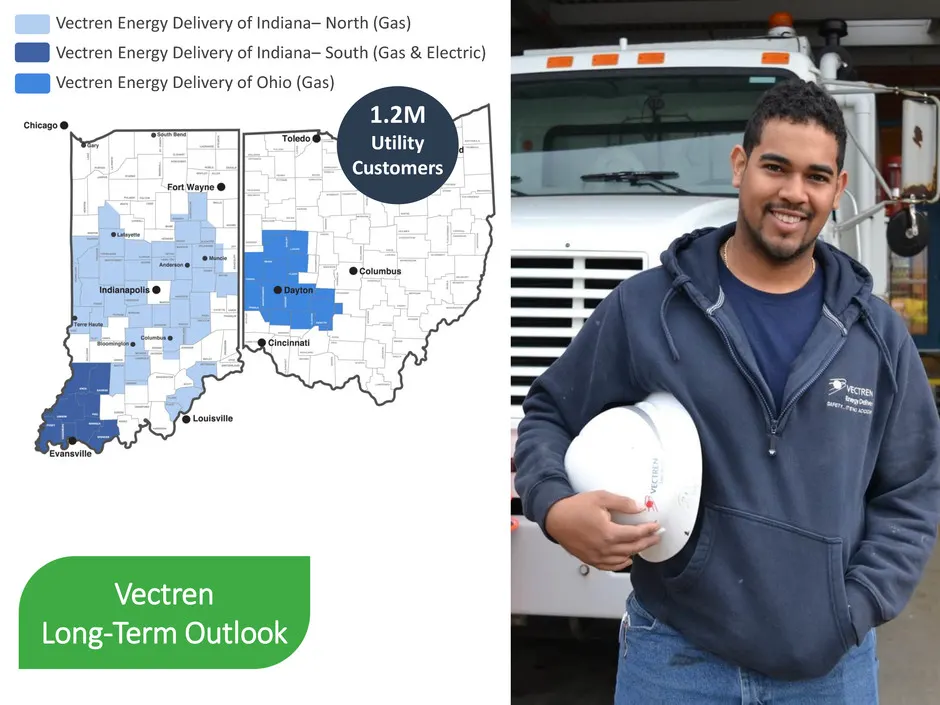
Slide 11: Vectren Long-Term Outlook
Vectren Long-Term Outlook 1.2M Utility Customers Vectren Energy Delivery of Indiana– North (Gas) Vectren Energy Delivery of Indiana– South (Gas & Electric) Vectren Energy Delivery of Ohio (Gas)
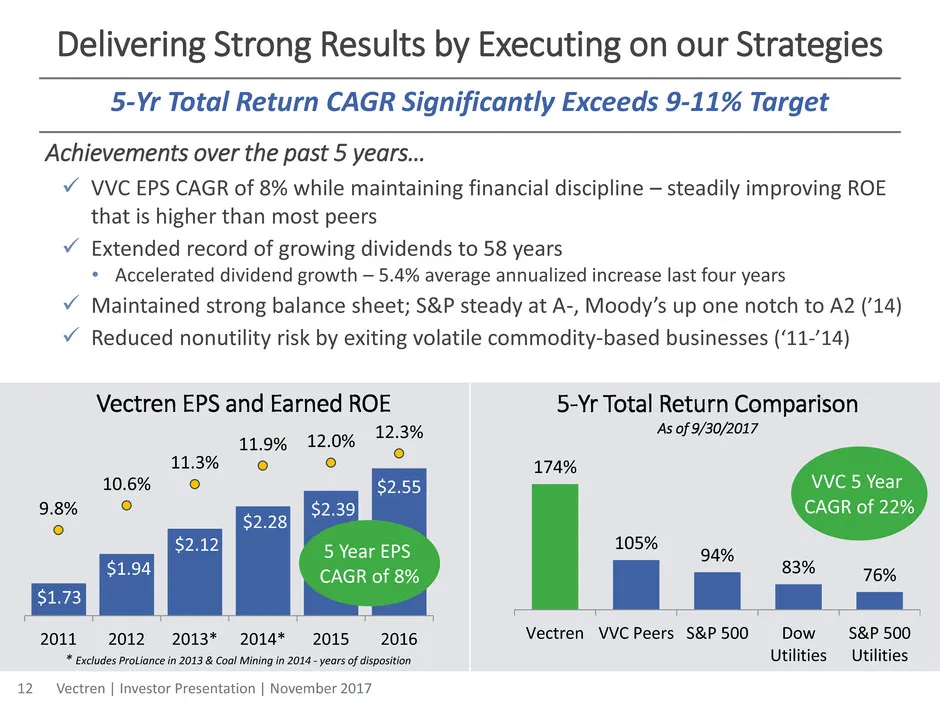
Slide 12: Delivering Strong Results by Executing on our Strategies
Delivering Strong Results by Executing on our Strategies Achievements over the past 5 years… VVC EPS CAGR of 8% while maintaining financial discipline – steadily improving ROE that is higher than most peers Extended record of growing dividends to 58 years • Accelerated dividend growth – 5.4% ave
Slide 13: Disciplined Utility Growth Key To Vectren's Success
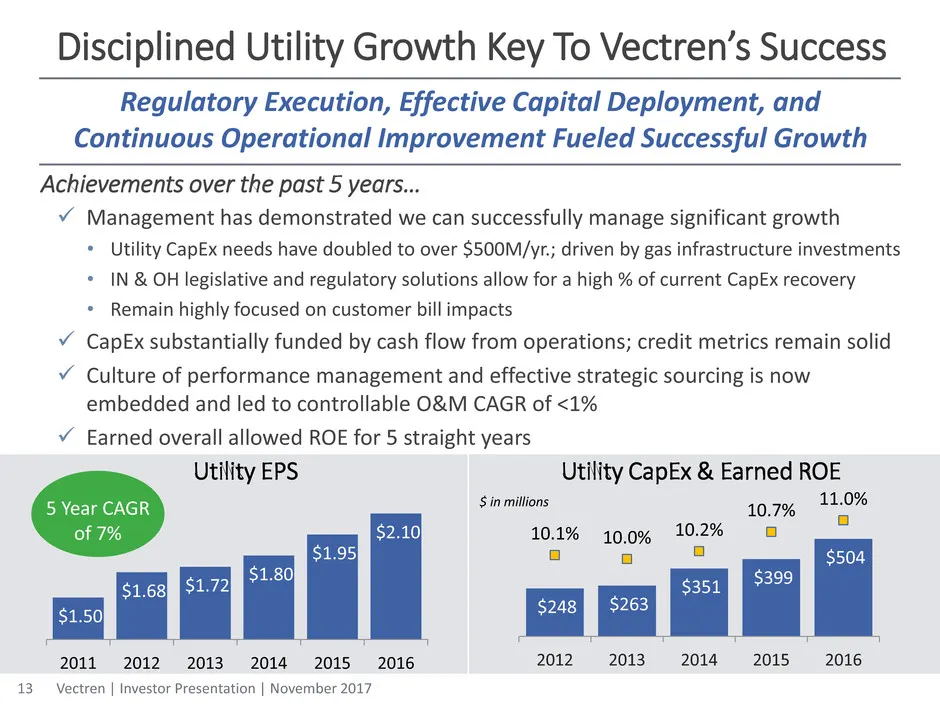
Disciplined Utility Growth Key To Vectren’s Success Management has demonstrated we can successfully manage significant growth • Utility CapEx needs have doubled to over $500M/yr.; driven by gas infrastructure investments • IN & OH legislative and regulatory solutions allow for a high % of current
Slide 14: Long-Term Targets
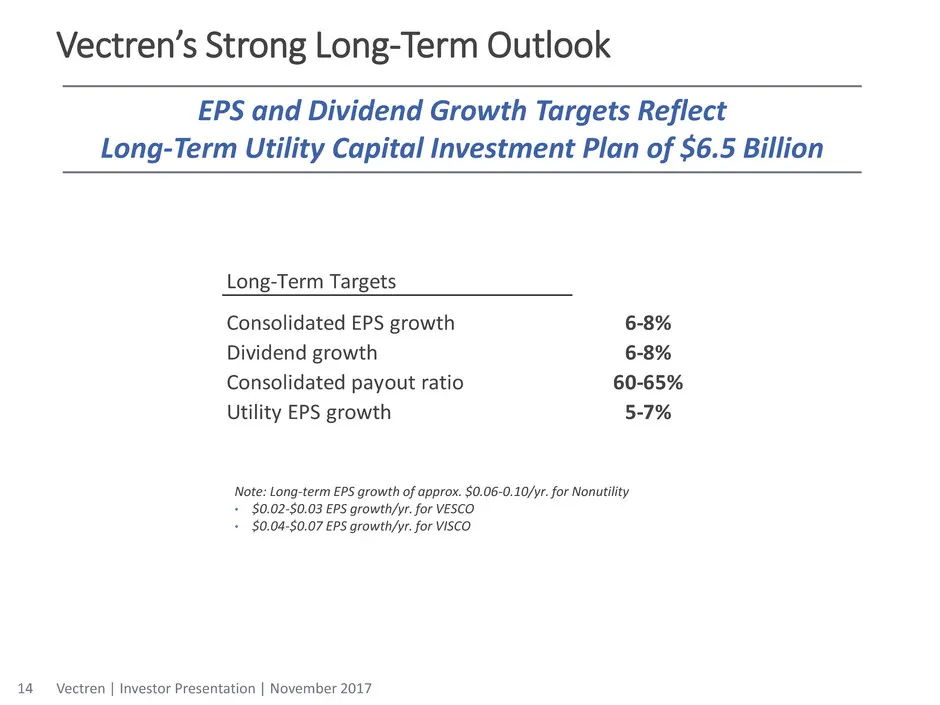
Long-Term Targets Consolidated EPS growth 6-8% Dividend growth 6-8% Consolidated payout ratio 60-65% Utility EPS growth 5-7% Vectren’s Strong Long-Term Outlook Note: Long-term EPS growth of approx. $0.06-0.10/yr. for Nonutility • $0.02-$0.03 EPS growth/yr. for VESCO • $0.04-$0.07 EPS growth/yr. for
Slide 15: Vectren's Strong Long-Term Outlook (cont.)
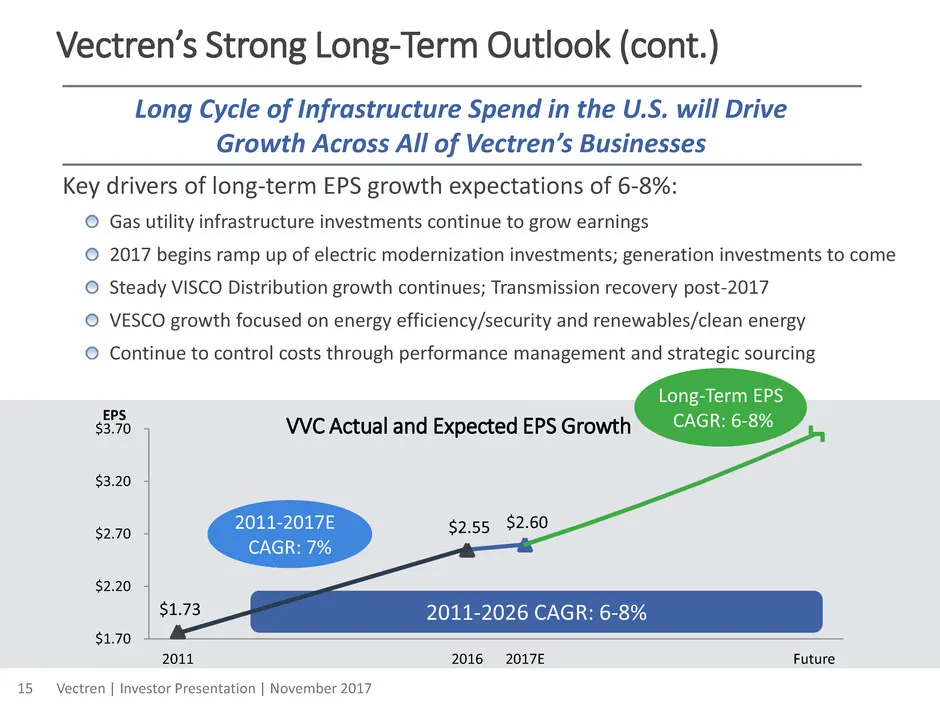
$1.73 $2.55 $2.60 $1.70 $2.20 $2.70 $3.20 $3.70 2011 2016 2017E Future EPS Key drivers of long-term EPS growth expectations of 6-8%: Gas utility infrastructure investments continue to grow earnings 2017 begins ramp up of electric modernization investments; generation investments to come Steady VISCO
Slide 16: Significant Utility CapEx Drives Earnings
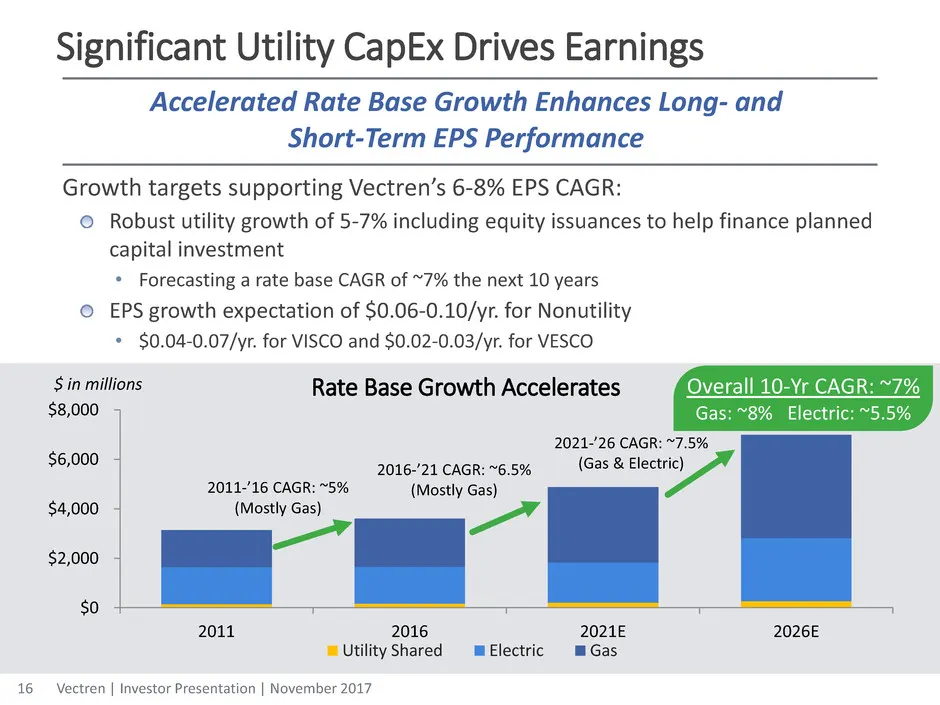
Significant Utility CapEx Drives Earnings Accelerated Rate Base Growth Enhances Long- and Short-Term EPS Performance $0 $2,000 $4,000 $6,000 $8,000 2011 2016 2021E 2026E Utility Shared Electric Gas 2021-’26 CAGR: ~7.5% (Gas & Electric) $ in millions 2016-’21 CAGR: ~6.5% (Mostly Gas) 2011-’16 CAGR: ~
Slide 17: Corporate Tax Reform
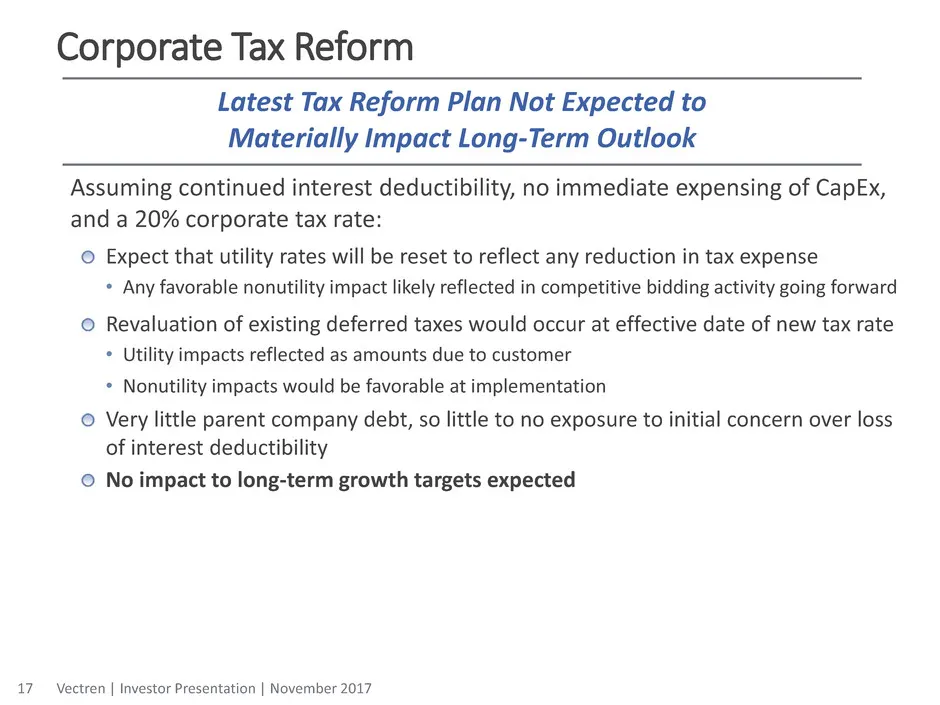
Corporate Tax Reform Assuming continued interest deductibility, no immediate expensing of CapEx, and a 20% corporate tax rate: Expect that utility rates will be reset to reflect any reduction in tax expense • Any favorable nonutility impact likely reflected in competitive bidding activity going forw
Slide 18: Utility Outlook
Utility Outlook
Slide 19: Expected Utility EPS CAGR of 5-7%
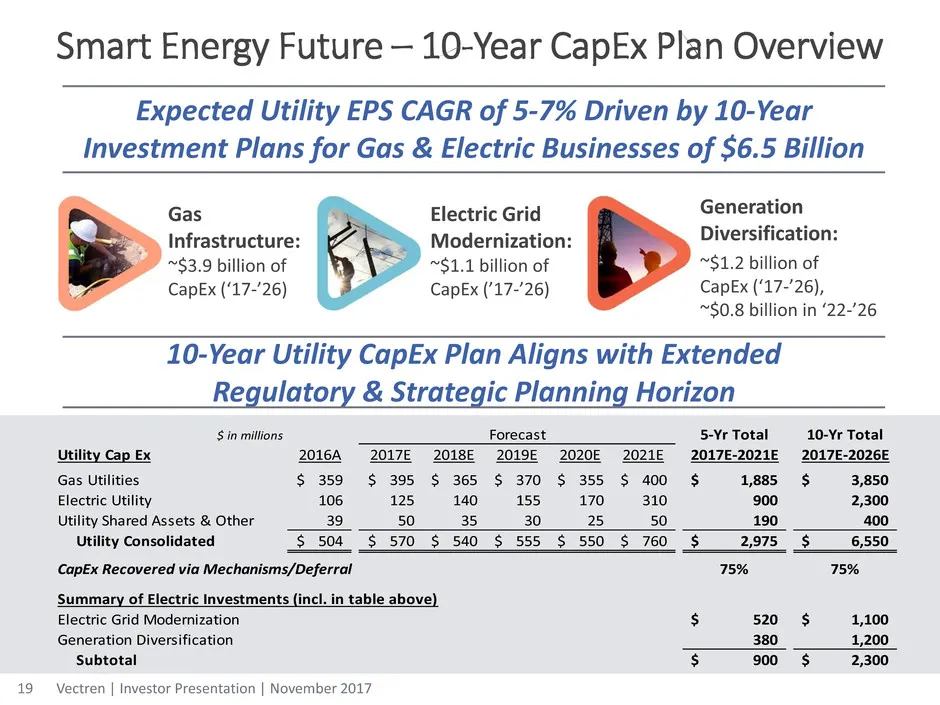
Expected Utility EPS CAGR of 5-7% Driven by 10-Year Investment Plans for Gas & Electric Businesses of $6.5 Billion Generation Diversification: ~$1.2 billion of CapEx (‘17-’26), ~$0.8 billion in ‘22-’26 Gas Infrastructure: ~$3.9 billion of CapEx (‘17-’26) Electric Grid Modernization: ~$1.1 billion of
Slide 20: Financing Utility Investment
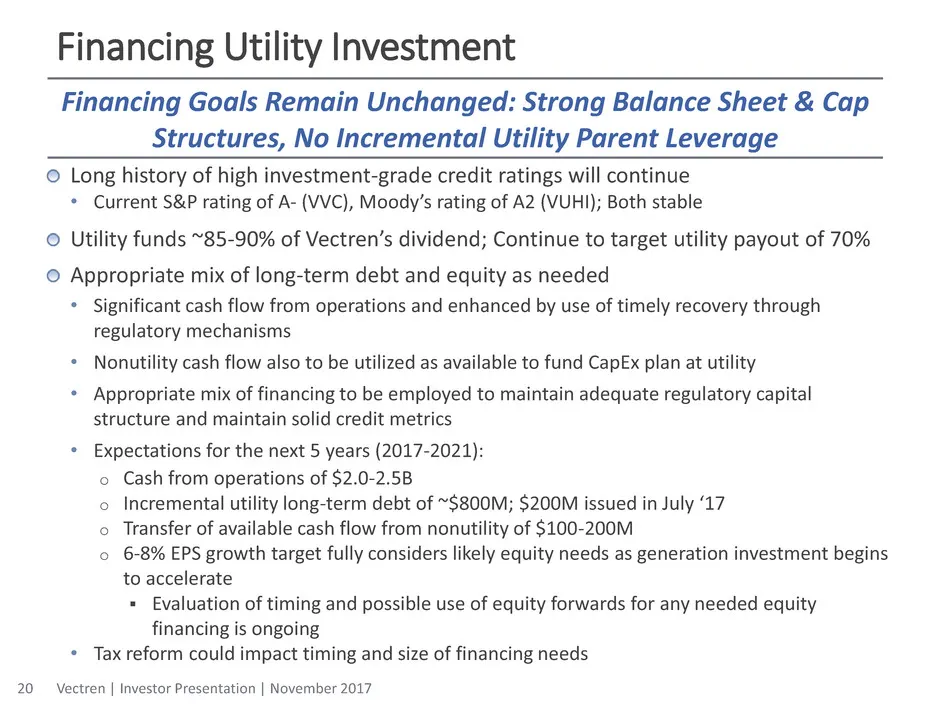
Financing Utility Investment Long history of high investment-grade credit ratings will continue • Current S&P rating of A- (VVC), Moody’s rating of A2 (VUHI); Both stable Utility funds ~85-90% of Vectren’s dividend; Continue to target utility payout of 70% Appropriate mix of long-term debt and equit
Slide 21: Favorable Utility Environments
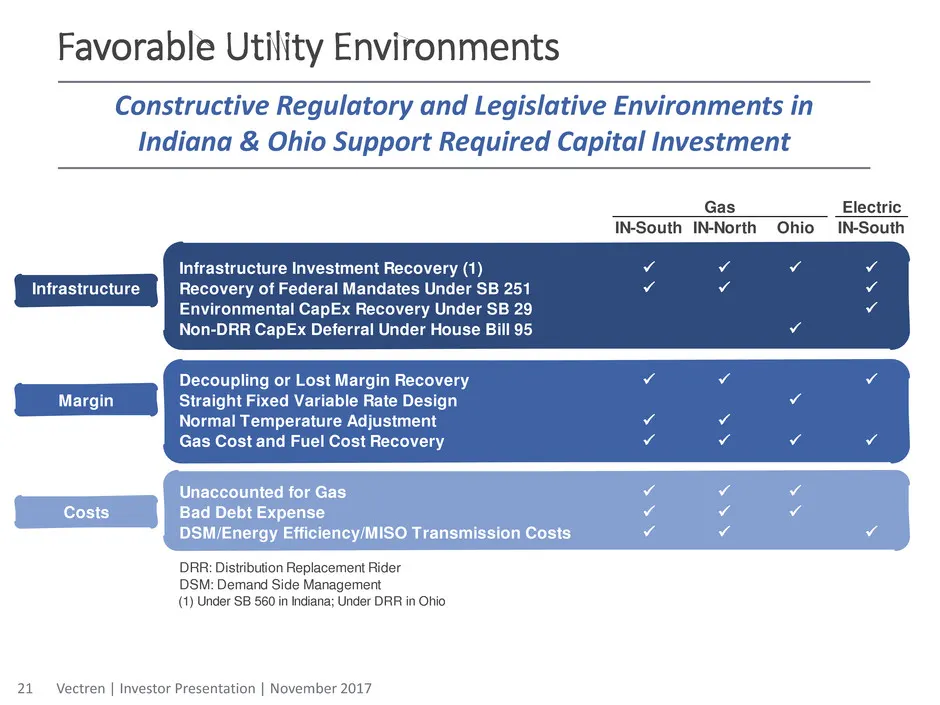
Favorable Utility Environments Constructive Regulatory and Legislative Environments in Indiana & Ohio Support Required Capital Investment Electric IN-South IN-North Ohio IN-South Infrastructure Investment Recovery (1) Infrastructure Recovery of Federal Mandates Under SB 251 Environment
Slide 22: Nonutility Outlook
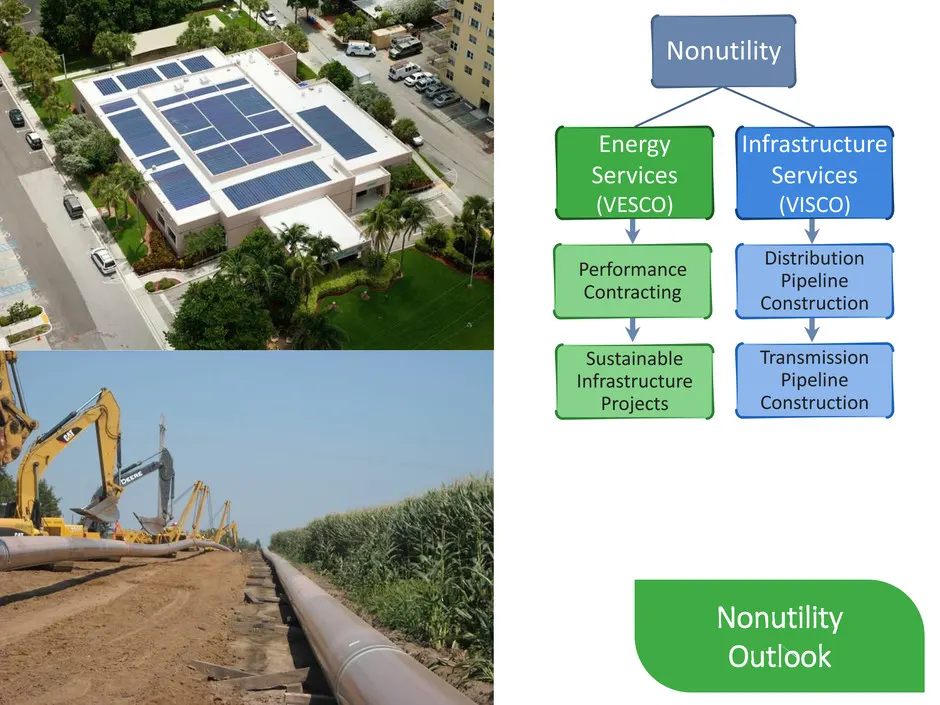
Nonutility Infrastructure Services (VISCO) Performance Contracting Sustainable Infrastructure Projects Energy Services (VESCO) Distribution Pipeline Construction Transmission Pipeline Construction Nonutility Outlook
Slide 23: Q3 2017 Nonutility Results
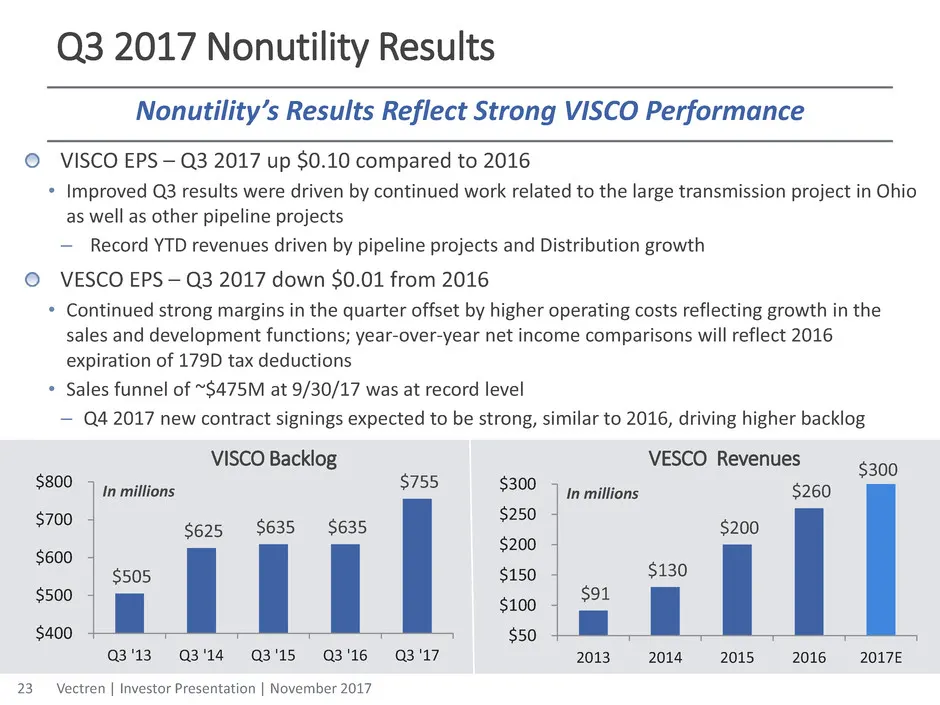
$505 $625 $635 $635 $755 $400 $500 $600 $700 $800 Q3 '13 Q3 '14 Q3 '15 Q3 '16 Q3 '17 In millions $91 $130 $200 $260 $300 $50 $100 $150 $200 $250 $300 2013 2014 2015 2016 2017E In millions Q3 2017 Nonutility Results VISCO EPS – Q3 2017 up $0.10 compared to 2016 • Improved Q3 results were driven by co
Slide 24: VISCO Outlook
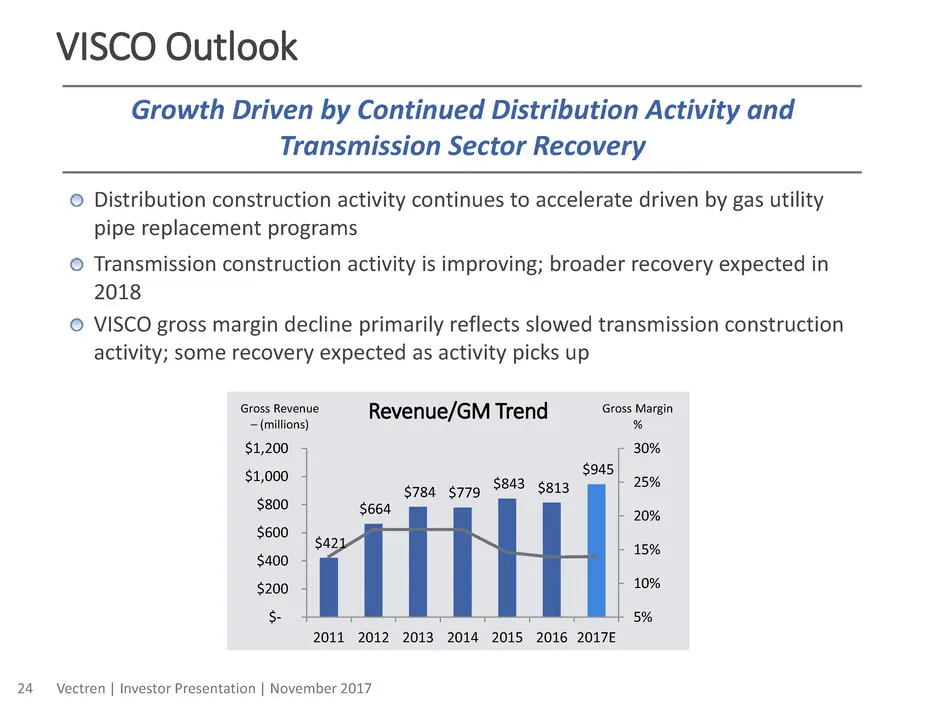
VISCO Outlook Distribution construction activity continues to accelerate driven by gas utility pipe replacement programs Transmission construction activity is improving; broader recovery expected in 2018 VISCO gross margin decline primarily reflects slowed transmission construction activity; some re
Slide 25: VESCO Outlook
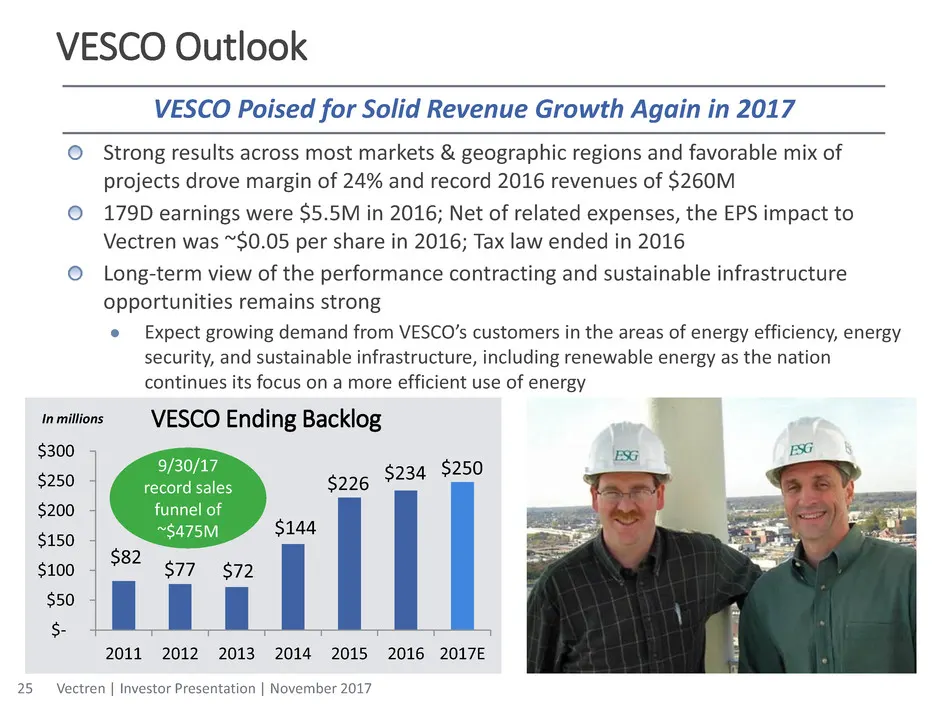
VESCO Outlook Strong results across most markets & geographic regions and favorable mix of projects drove margin of 24% and record 2016 revenues of $260M 179D earnings were $5.5M in 2016; Net of related expenses, the EPS impact to Vectren was ~$0.05 per share in 2016; Tax law ended in 2016 Long-term
Slide 26: Appendix
Appendix
Slide 27: Gas Infrastructure
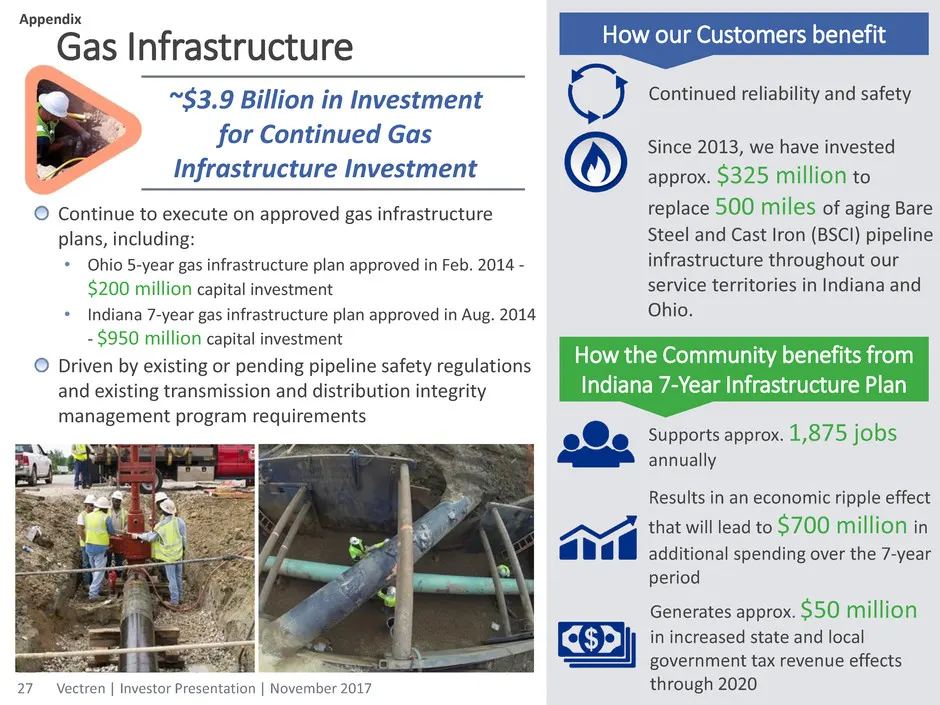
Gas Infrastructure Continue to execute on approved gas infrastructure plans, including: • Ohio 5-year gas infrastructure plan approved in Feb. 2014 - $200 million capital investment • Indiana 7-year gas infrastructure plan approved in Aug. 2014 - $950 million capital investment Driven by existing or
Slide 28: Electric Grid Modernization
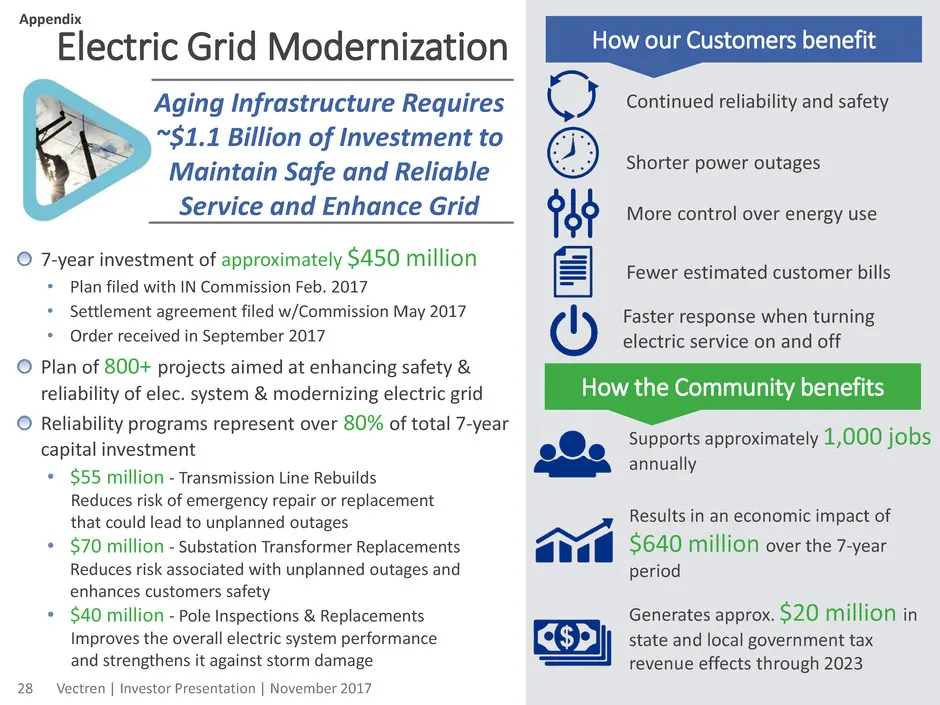
Electric Grid Modernization 7-year investment of approximately $450 million • Plan filed with IN Commission Feb. 2017 • Settlement agreement filed w/Commission May 2017 • Order received in September 2017 Plan of 800+ projects aimed at enhancing safety & reliability of elec. system & modernizing elec
Slide 29: Generation Diversification
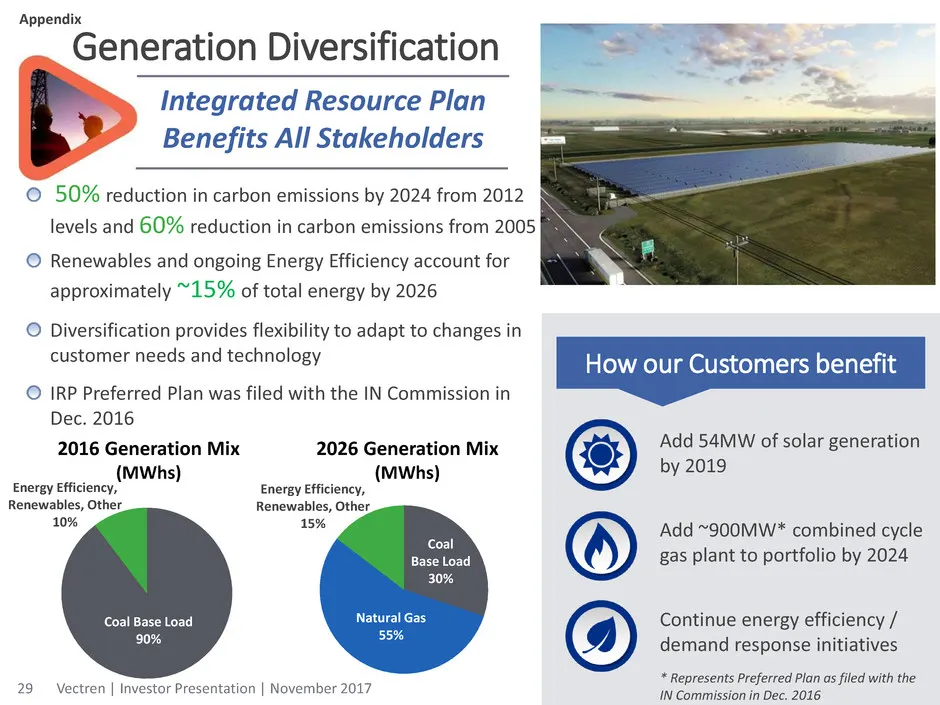
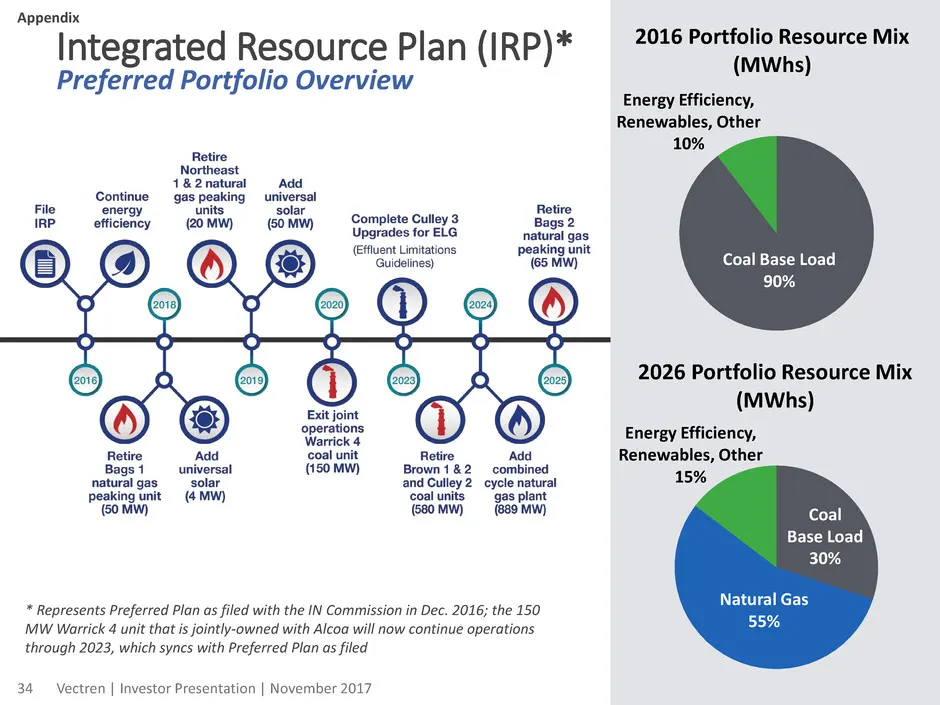
2016 Generation Mix (MWhs) Energy Efficiency, Renewables, Other 10% Coal Base Load 90% 50% reduction in carbon emissions by 2024 from 2012 levels and 60% reduction in carbon emissions from 2005 Renewables and ongoing Energy Efficiency account for approximately ~15% of total energy by 2026 Diversific
Slide 30: Utility Metrics
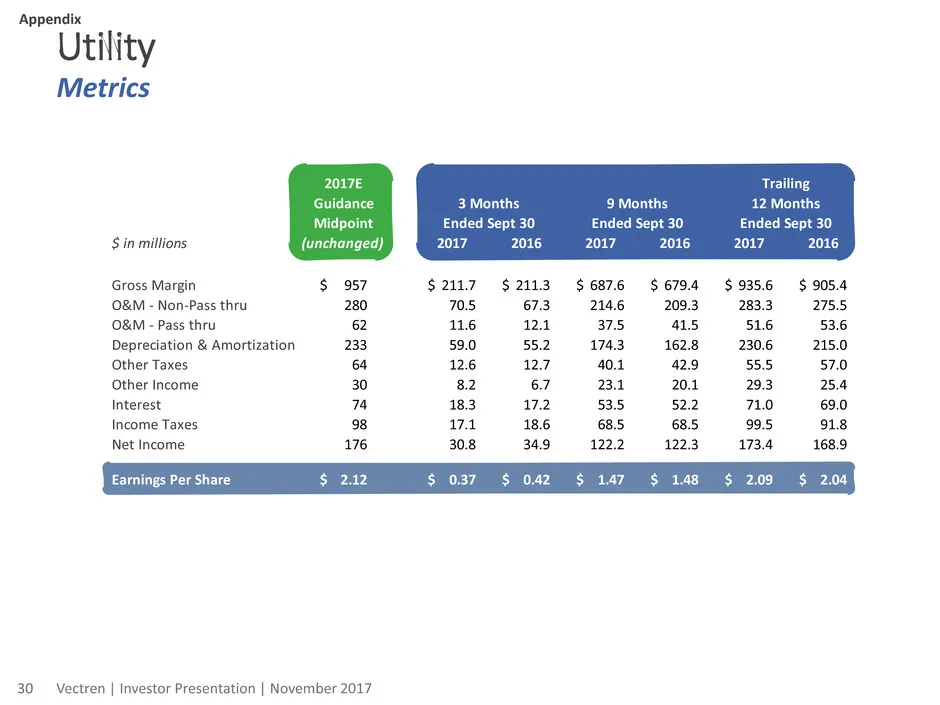
Utility Metrics 30 Appendix 2017E Guidance Midpoint $ in millions (unchanged) 2017 2016 2017 2016 2017 2016 Gross Margin 957$ 211.7$ 211.3$ 687.6$ 679.4$ 935.6$ 905.4$ O&M - Non-Pass thru 280 70.5 67.3 214.6 209.3 283.3 275.5 O&M - Pass thru 62 11.6 12.1 37.5 41.5 51.6 53.6 Depreciation & Amortizati
Slide 31: Utility Regulatory Update
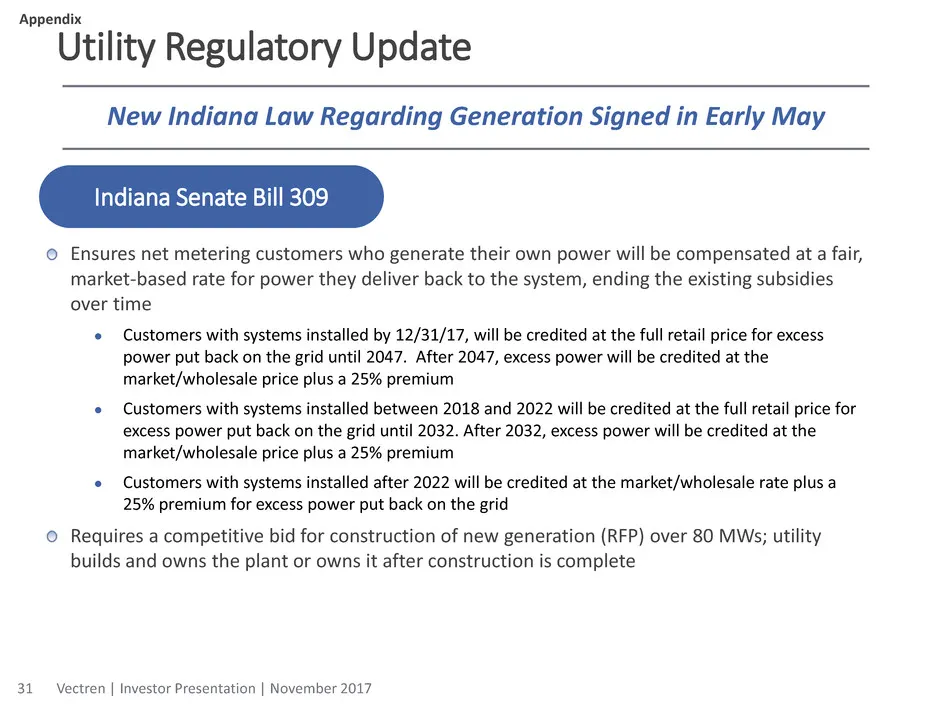
Utility Regulatory Update 31 Ensures net metering customers who generate their own power will be compensated at a fair, market-based rate for power they deliver back to the system, ending the existing subsidies over time ● Customers with systems installed by 12/31/17, will be credited at the full re
Slide 32: Utility Regulatory Update (continued)
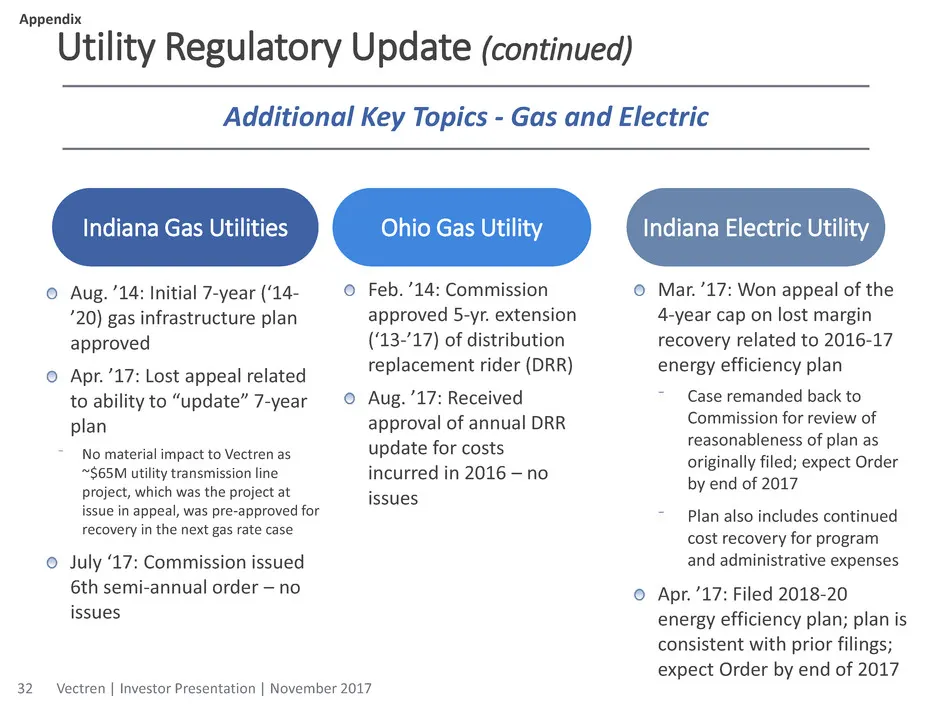
Utility Regulatory Update (continued) 32 Feb. ’14: Commission approved 5-yr. extension (‘13-’17) of distribution replacement rider (DRR) Aug. ’17: Received approval of annual DRR update for costs incurred in 2016 – no issues Aug. ’14: Initial 7-year (‘14- ’20) gas infrastructure plan approved Apr. ’
Slide 33: Anticipated Timing of Near-Term Base Rate Case Activity
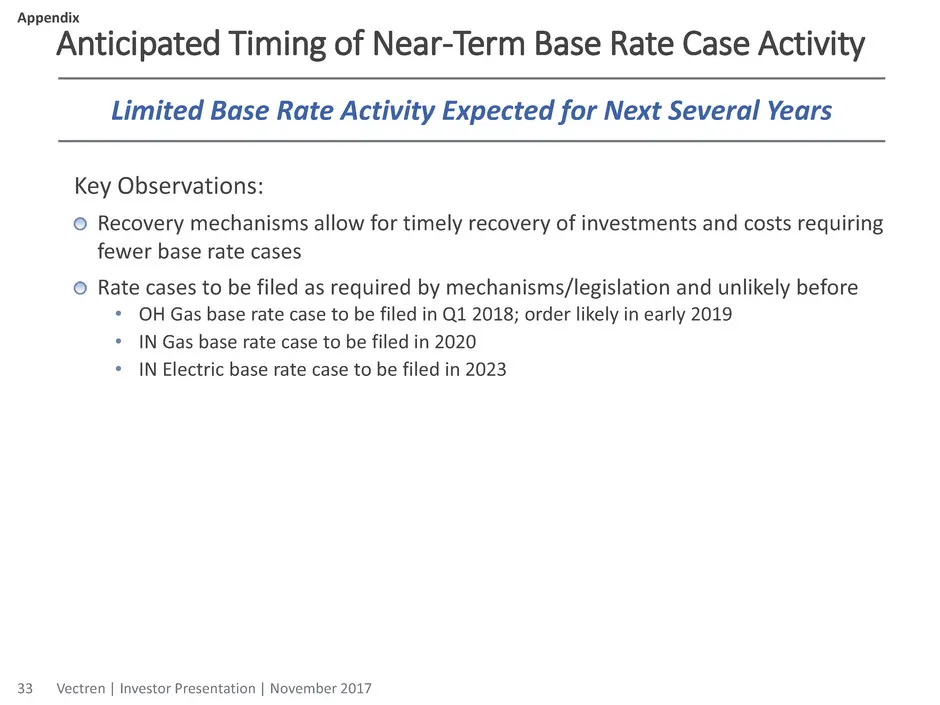
Anticipated Timing of Near-Term Base Rate Case Activity 33 Limited Base Rate Activity Expected for Next Several Years Key Observations: Recovery mechanisms allow for timely recovery of investments and costs requiring fewer base rate cases Rate cases to be filed as required by mechanisms/legislation
Slide 34: Integrated Resource Plan (IRP) Preferred Portfolio Overview
Integrated Resource Plan (IRP)* Preferred Portfolio Overview * Represents Preferred Plan as filed with the IN Commission in Dec. 2016; the 150 MW Warrick 4 unit that is jointly-owned with Alcoa will now continue operations through 2023, which syncs with Preferred Plan as filed 2016 Portfolio Resourc
Slide 35: Utility Business Review Environmental & Sustainability
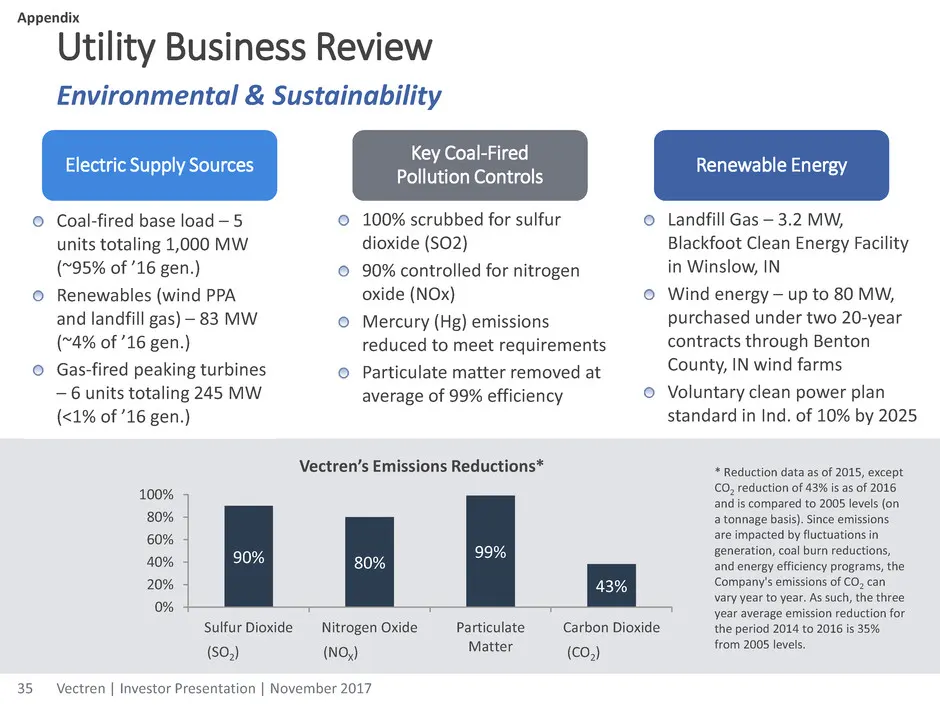
Utility Business Review 35 Environmental & Sustainability Appendix Renewable Energy Key Coal-Fired Pollution Controls Landfill Gas – 3.2 MW, Blackfoot Clean Energy Facility in Winslow, IN Wind energy – up to 80 MW, purchased under two 20-year contracts through Benton County, IN wind farms Voluntary
Slide 36: Coal-Fired Generation Current Portfolio
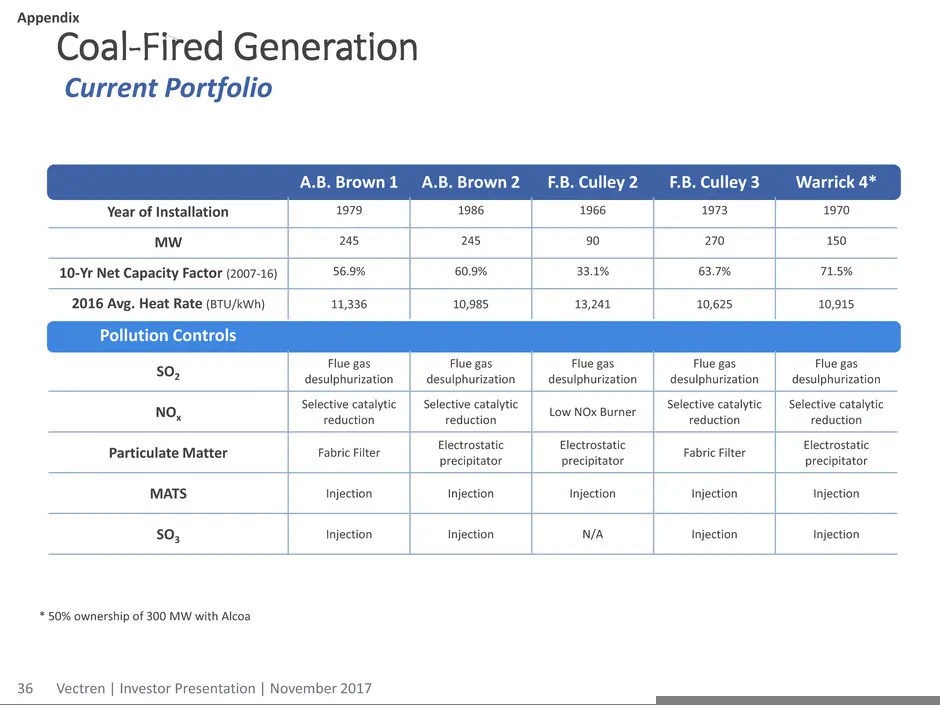
A.B. Brown 1 A.B. Brown 2 F.B. Culley 2 F.B. Culley 3 Warrick 4* Year of Installation 1979 1986 1966 1973 1970 MW 245 245 90 270 150 10-Yr Net Capacity Factor (2007-16) 56.9% 60.9% 33.1% 63.7% 71.5% 2016 Avg. Heat Rate (BTU/kWh) 11,336 10,985 13,241 10,625 10,915 Pollution Controls SO2 Flue gas desu
Slide 37: State Utility Commissioners
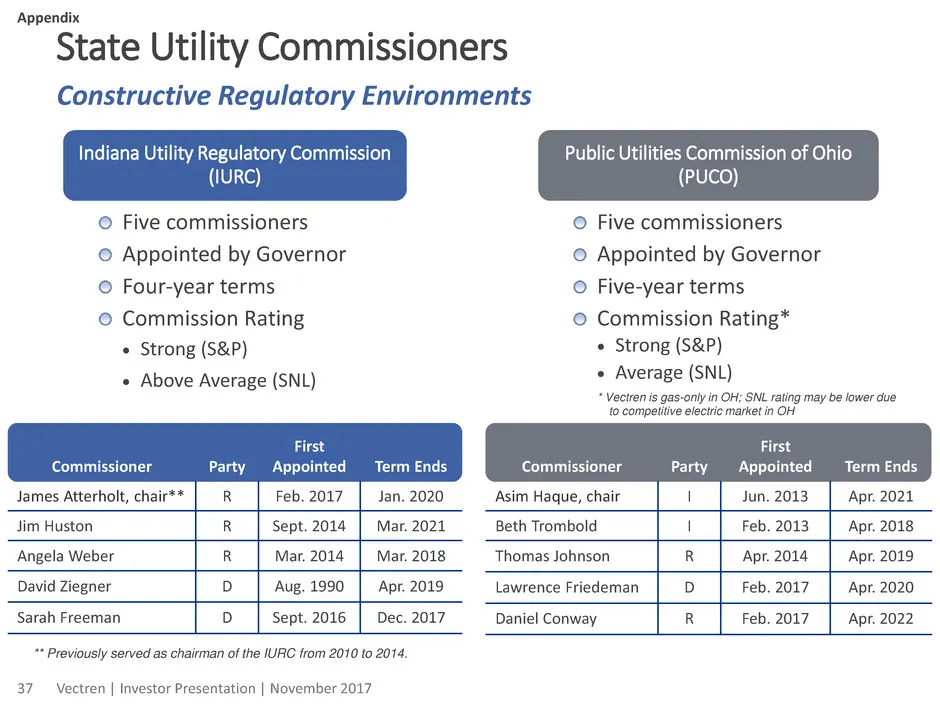
State Utility Commissioners 37 Constructive Regulatory Environments Appendix Indiana Utility Regulatory Commission (IURC) Public Utilities Commission of Ohio (PUCO) Five commissioners Appointed by Governor Four-year terms Commission Rating Strong (S&P) Above Average (SNL) Five commissioners Appo
Slide 38: VISCO Business Profile
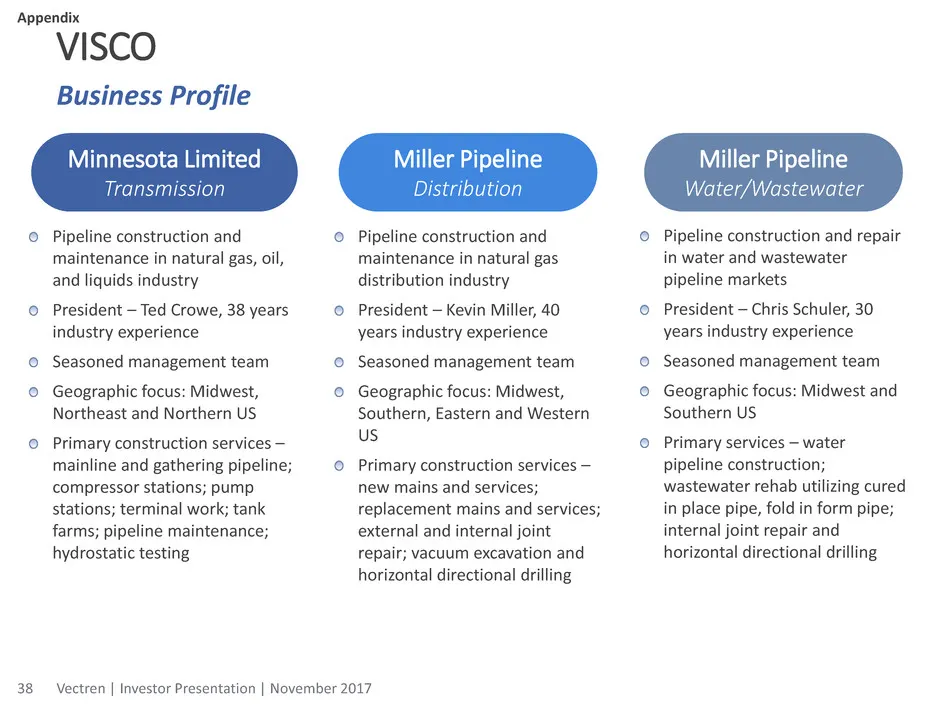
VISCO Pipeline construction and maintenance in natural gas, oil, and liquids industry President – Ted Crowe, 38 years industry experience Seasoned management team Geographic focus: Midwest, Northeast and Northern US Primary construction services – mainline and gathering pipeline; compressor stations
Slide 39: VISCO Distribution Opportunities
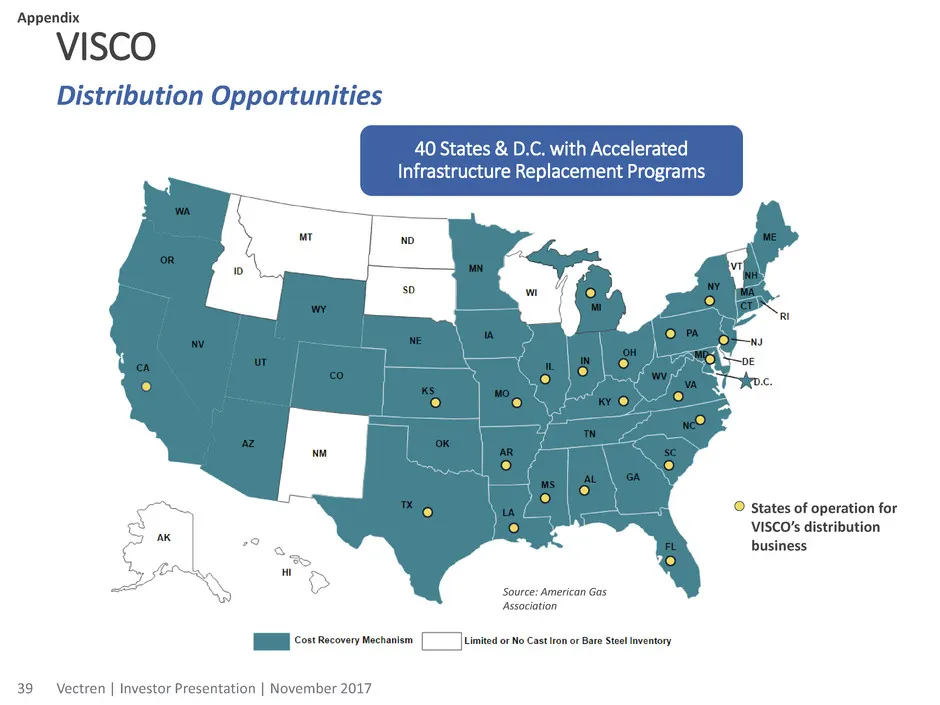
VISCO 39 Distribution Opportunities Appendix States of operation for VISCO’s distribution business Source: American Gas Association 40 States & D.C. with Accelerated Infrastructure Replacement Programs Vectren | Investor Presentation | November 2017
Slide 40: VISCO Long-Term Customer Relationships
VISCO 40 Long-Term Customer Relationships Long-Term Customers Long-term customer relationships are key Relationship with top 10 distribution customers averages 20+ years Reputation for high quality construction work and customer service Shared culture of commitment to safety with our customers Bui
Slide 41: VISCO Competitive Landscape
VISCO 41 Competitive Landscape Competition Consolidation continues in our industry Fragmented market – many small family-owned contractors still servicing geographic territories Market has a preference for larger contractors VISCO has strong brand recognition in the industry VISCO’s seasoned m
Slide 42: Infrastructure Services (VISCO) Metrics
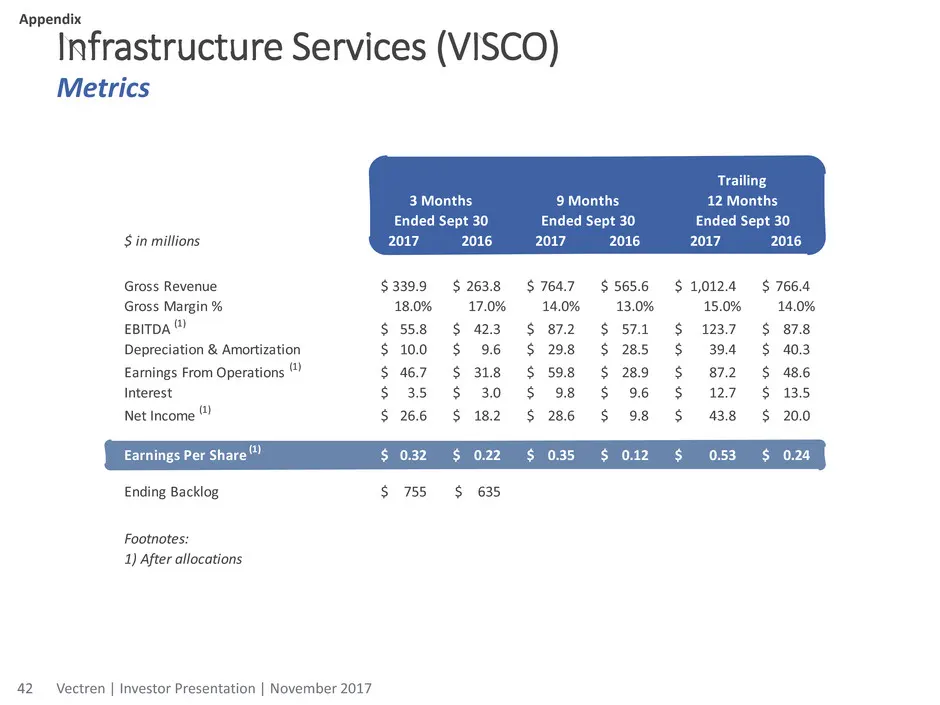
$ in millions 2017 2016 2017 2016 2017 2016 Gross Revenue 339.9$ 263.8$ 764.7$ 565.6$ 1,012.4$ 766.4$ Gross Margin % 18.0% 17.0% 14.0% 13.0% 15.0% 14.0% EBITDA (1) 55.8$ 42.3$ 87.2$ 57.1$ 123.7$ 87.8$ Depreciation & Amortization 10.0$ 9.6$ 29.8$ 28.5$ 39.4$ 40.3$ Earnings From Operations (1) 46.7$ 3
Slide 43: Infrastructure Services (VISCO) Metrics – year look
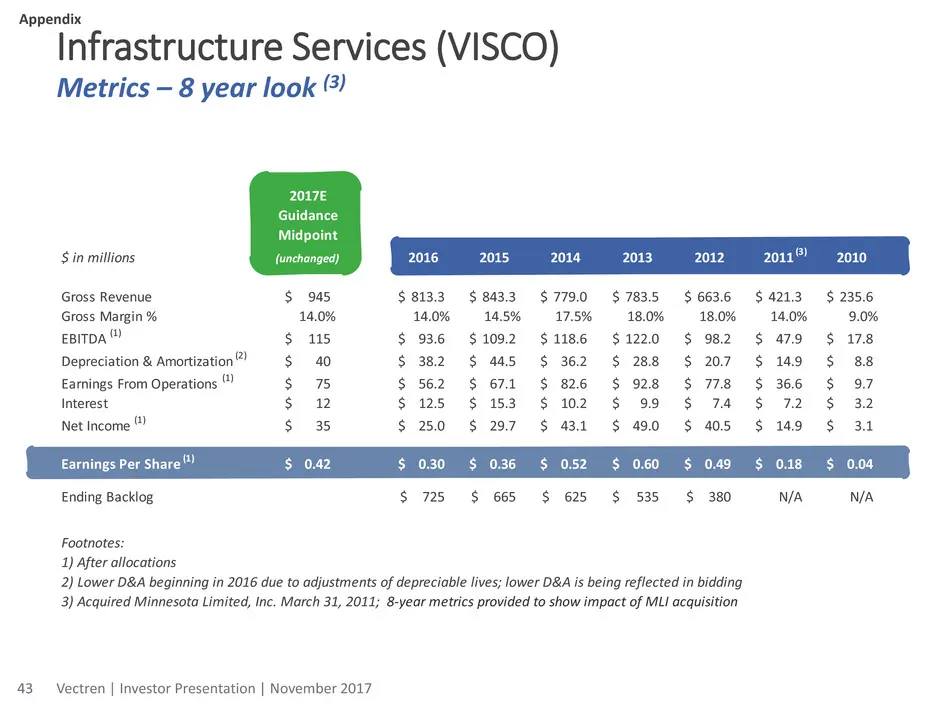
Infrastructure Services (VISCO) Metrics – 8 year look (3) 43 Appendix Vectren | Investor Presentation | November 2017 2017E Guidance Midpoint $ in millions (unchanged) 2016 2015 2014 2013 2012 2011 (3) 2010 Gross Revenue 945$ 813.3$ 843.3$ 779.0$ 783.5$ 663.6$ 421.3$ 235.6$ Gross Margin % 14.0% 14.0
Slide 44: Infrastructure Services Customer Contracts and Backlog
Infrastructure Services (VISCO) General Description of Types of Customer Contracts for Infrastructure Services Infrastructure Services operates primarily under two types of contracts – blanket contracts and bid contracts. Blanket contracts are ones which a customer is not committed to specific vol
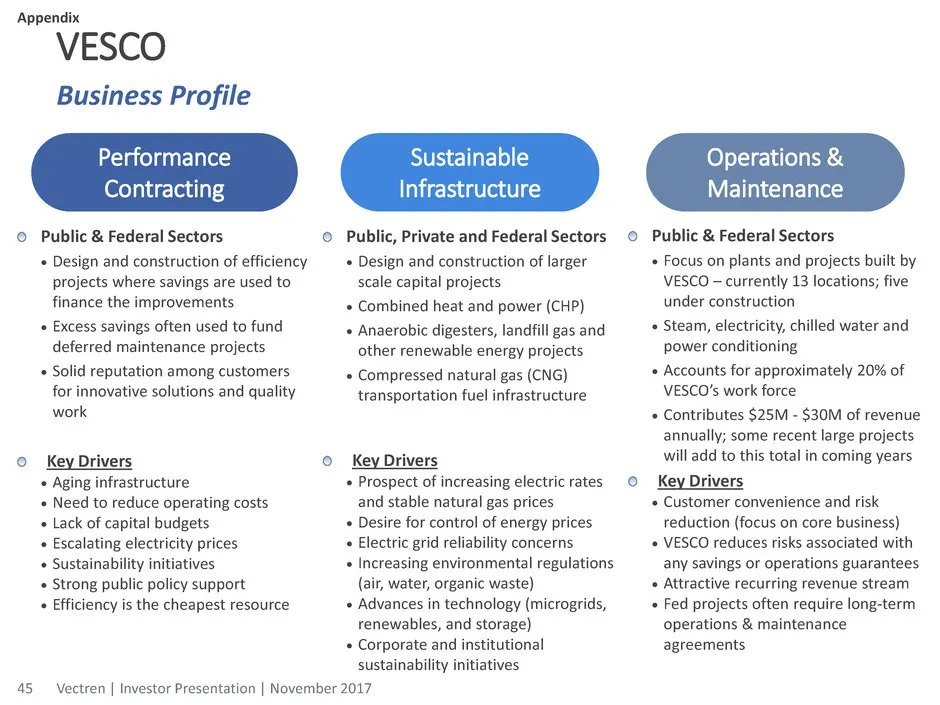
Slide 45: VESCO Public & Federal Sectors
VESCO Public & Federal Sectors Design and construction of efficiency projects where savings are used to finance the improvements Excess savings often used to fund deferred maintenance projects Solid reputation among customers for innovative solutions and quality work Key Drivers Aging infras
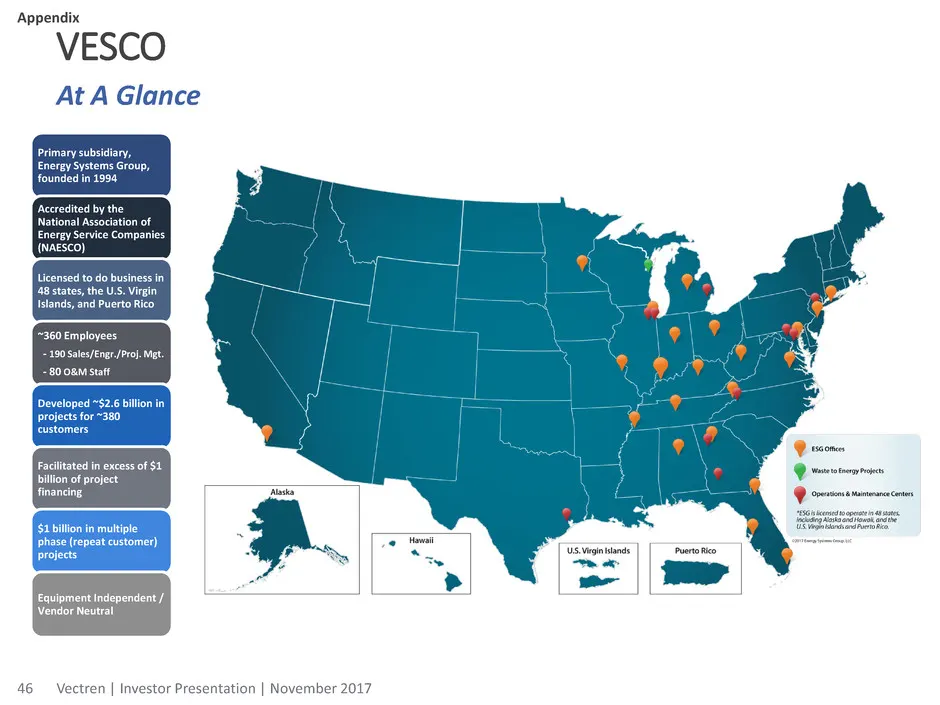
Slide 46: VESCO At A Glance
VESCO 46 At A Glance Primary subsidiary, Energy Systems Group, founded in 1994 Accredited by the National Association of Energy Service Companies (NAESCO) Licensed to do business in 48 states, the U.S. Virgin Islands, and Puerto Rico ~360 Employees - 190 Sales/Engr./Proj. Mgt. - 80 O&M Staff Develop
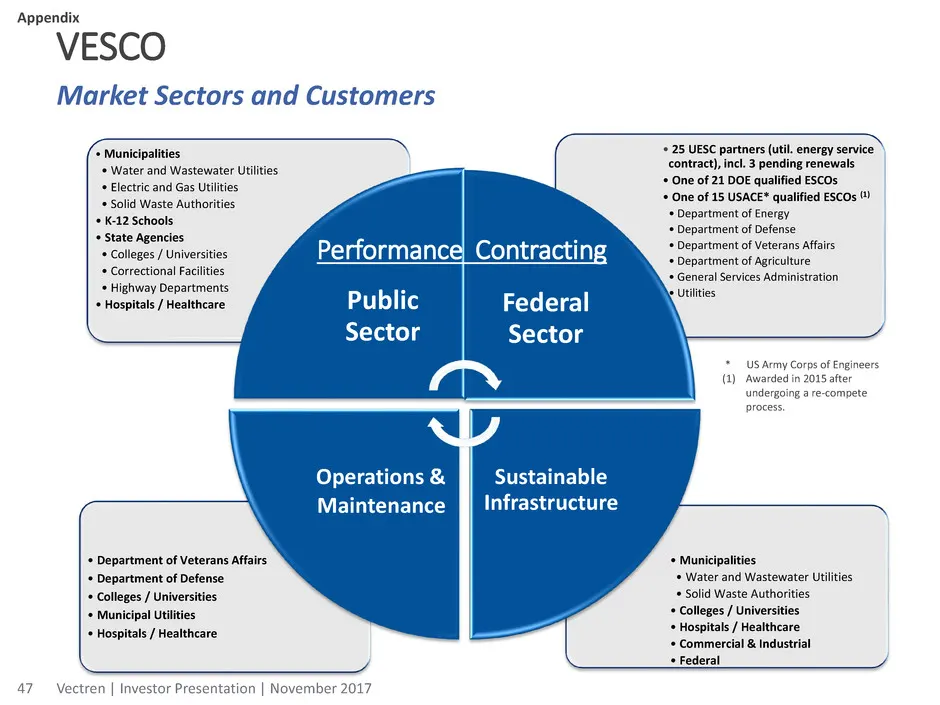
Slide 47: VESCO Market Sectors and Customers
VESCO 47 Market Sectors and Customers Appendix • Municipalities • Water and Wastewater Utilities • Solid Waste Authorities • Colleges / Universities • Hospitals / Healthcare • Commercial & Industrial • Federal • Department of Veterans Affairs • Department of Defense • Colleges / Universities • Munic
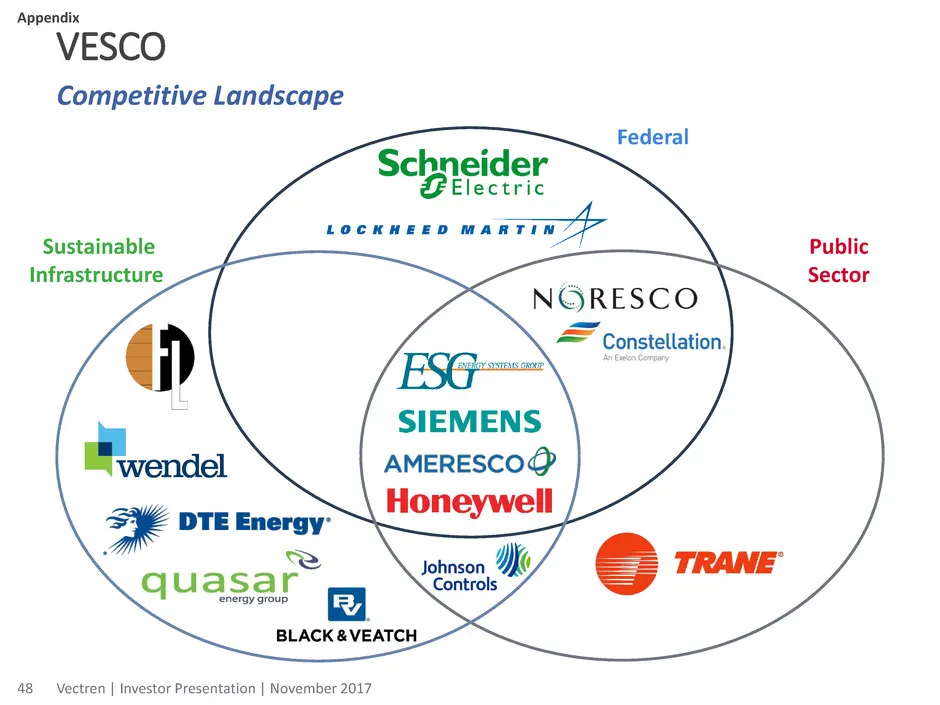
Slide 48: VESCO Competitive Landscape
VESCO 48 Competitive Landscape Sustainable Infrastructure Federal Public Sector Appendix Vectren | Investor Presentation | November 2017
Slide 49: Key VESCO Projects
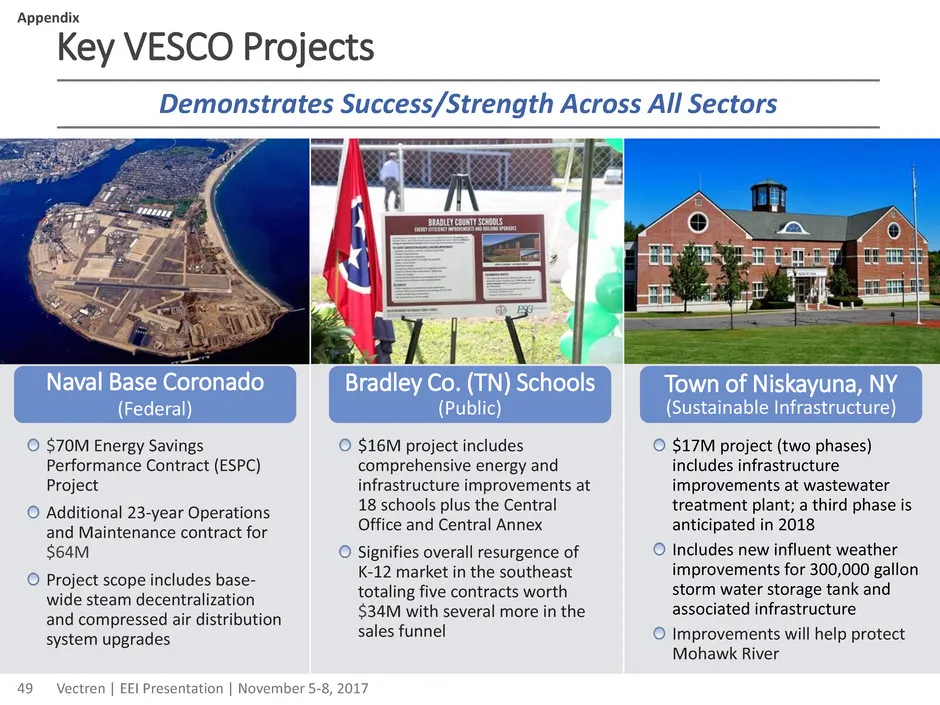
Key VESCO Projects $16M project includes comprehensive energy and infrastructure improvements at 18 schools plus the Central Office and Central Annex Signifies overall resurgence of K-12 market in the southeast totaling five contracts worth $34M with several more in the sales funnel $70M Energy Savi
Slide 50: Energy Services (VESCO) Metrics
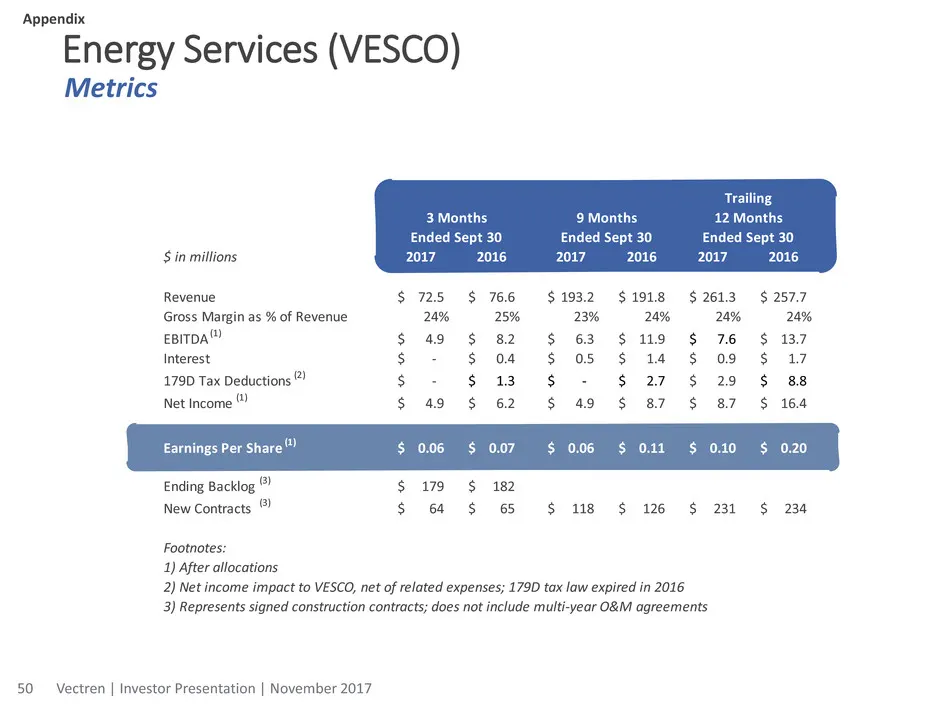
Energy Services (VESCO) 50 Metrics Appendix $ in millions 2017 2016 2017 2016 2017 2016 Revenue 72.5$ 76.6$ 193.2$ 191.8$ 261.3$ 257.7$ Gross Margin as % of Revenue 24% 25% 23% 24% 24% 24% EBITDA (1) 4.9$ 8.2$ 6.3$ 11.9$ 7.6$ 13.7$ Interest -$ 0.4$ 0.5$ 1.4$ 0.9$ 1.7$ 179D Tax Deductions (2) -$ 1.3$
Slide 51: Energy Services (VESCO) Metrics – year look
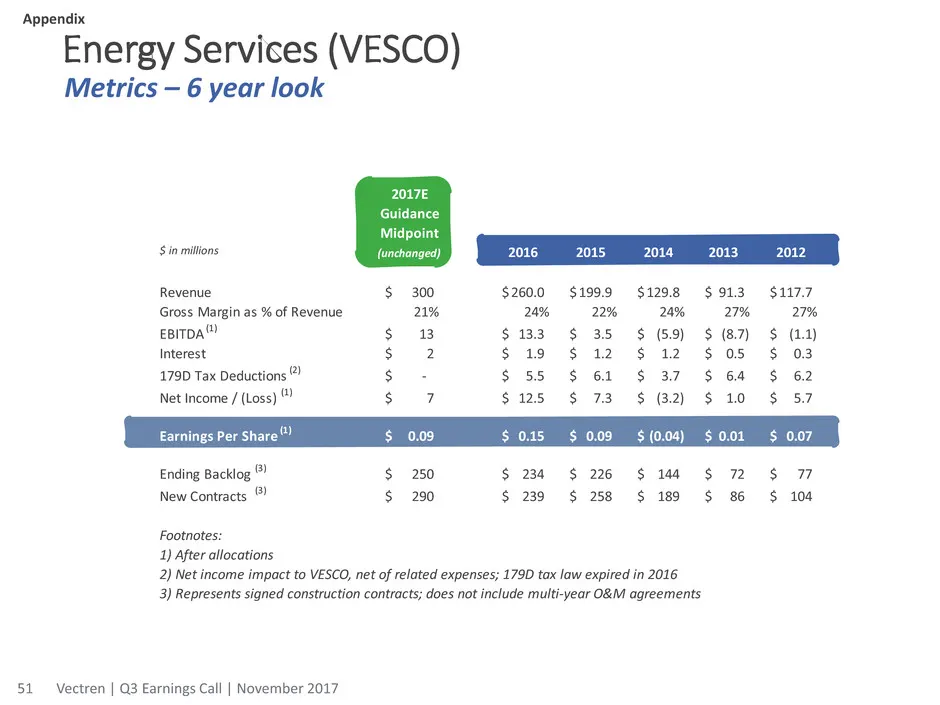
Energy Services (VESCO) 51 Metrics – 6 year look Appendix Vectren | Q3 Earnings Call | November 2017 2017E Guidance Midpoint $ in millions (unchanged) 2016 2015 2014 2013 2012 Revenue 300$ 260.0$ 199.9$ 129.8$ 91.3$ 117.7$ Gross Margin as % of Revenue 21% 24% 22% 24% 27% 27% EBITDA (1) 13$ 13.3$ 3.5
Slide 52: Use of Non-GAAP Performance Measures and Per Share Measures
Use of Non-GAAP Performance Measures and Per Share Measures 52 Appendix Contribution to Vectren's Basic EPS Per share earnings contributions of the Utility Group, Nonutility Group, and Corporate and Other are presented and are non-GAAP measures. Such per share amounts are based on the earnings contr
Source: SEC EDGAR · 8-K filed Nov 3, 2017
More decks from Vectren Corporation
 Edison Electric Institute Financial Conference 201833 slides · Nov 9, 2018
 Q2 2018 Earnings Presentation31 slides · Aug 3, 2018
 Merger or Acquisition (June 2018)18 slides · Jun 12, 2018
 American Gas Association Financial Forum 201855 slides · May 18, 2018
 Q1 2018 Earnings Presentation27 slides · May 4, 2018
 FY2017 Earnings Presentation43 slides · Feb 27, 2018