Clicks Group Limited · JSE:CLS
Clicks — RMB Morgan Stanley Big Five Investor Conference 2010
24 slides from Clicks's conference presentation, 2010
Slide 1: RMB Morgan Stanley Big Five Investor Conference 2010
DAVID KNEALE Chief Executive Officer RMB MORGAN STANLEY BIG FIVE INVESTOR CONFERENCE 2010
Slide 2: Agenda
AGENDA Demographics - driving healthcare spend The political agenda Clicks Group’s healthcare offering Can SA become world class at retail healthcare? 2
Slide 3: Demographics – Increase in Living Standards
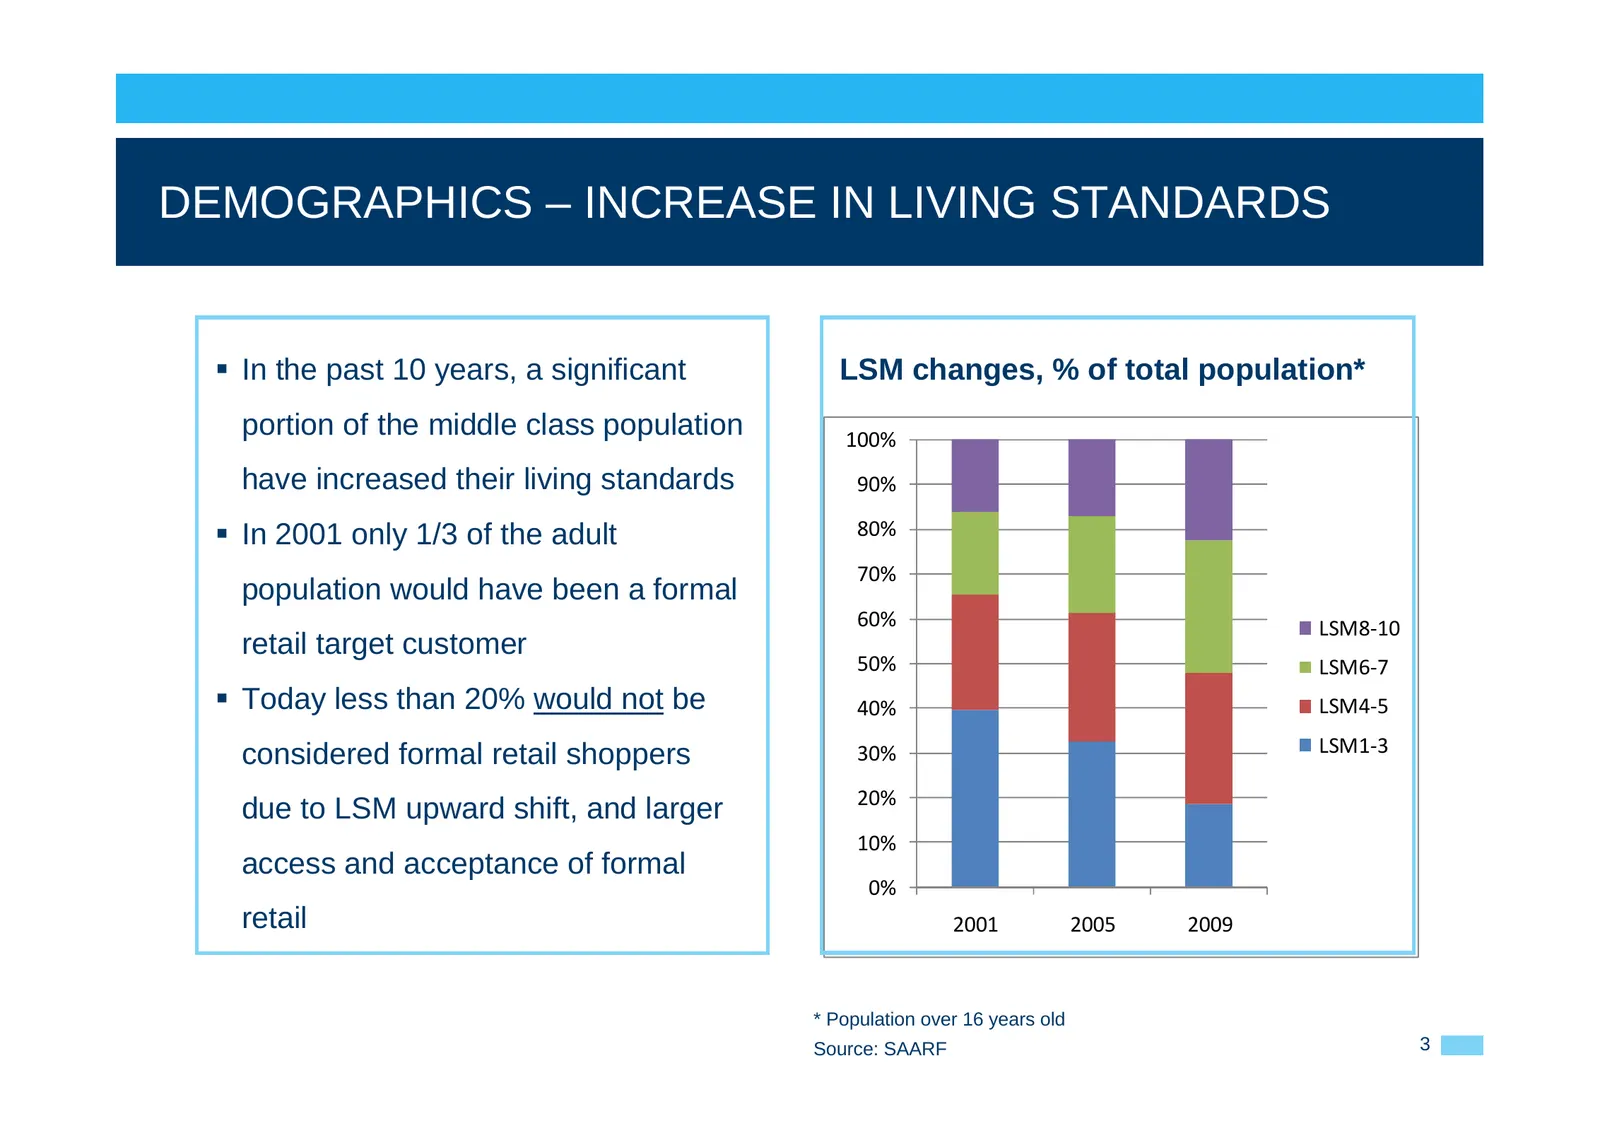
DEMOGRAPHICS – INCREASE IN LIVING STANDARDS In the past 10 years, a significant LSM changes, % of total population* portion of the middle class population 100% have increased their living standards 90% In 2001 only 1/3 of the adult 80% 70% population would have been a formal 60% LSM8‐10 retail t
Slide 4: Demographics – Ageing Population
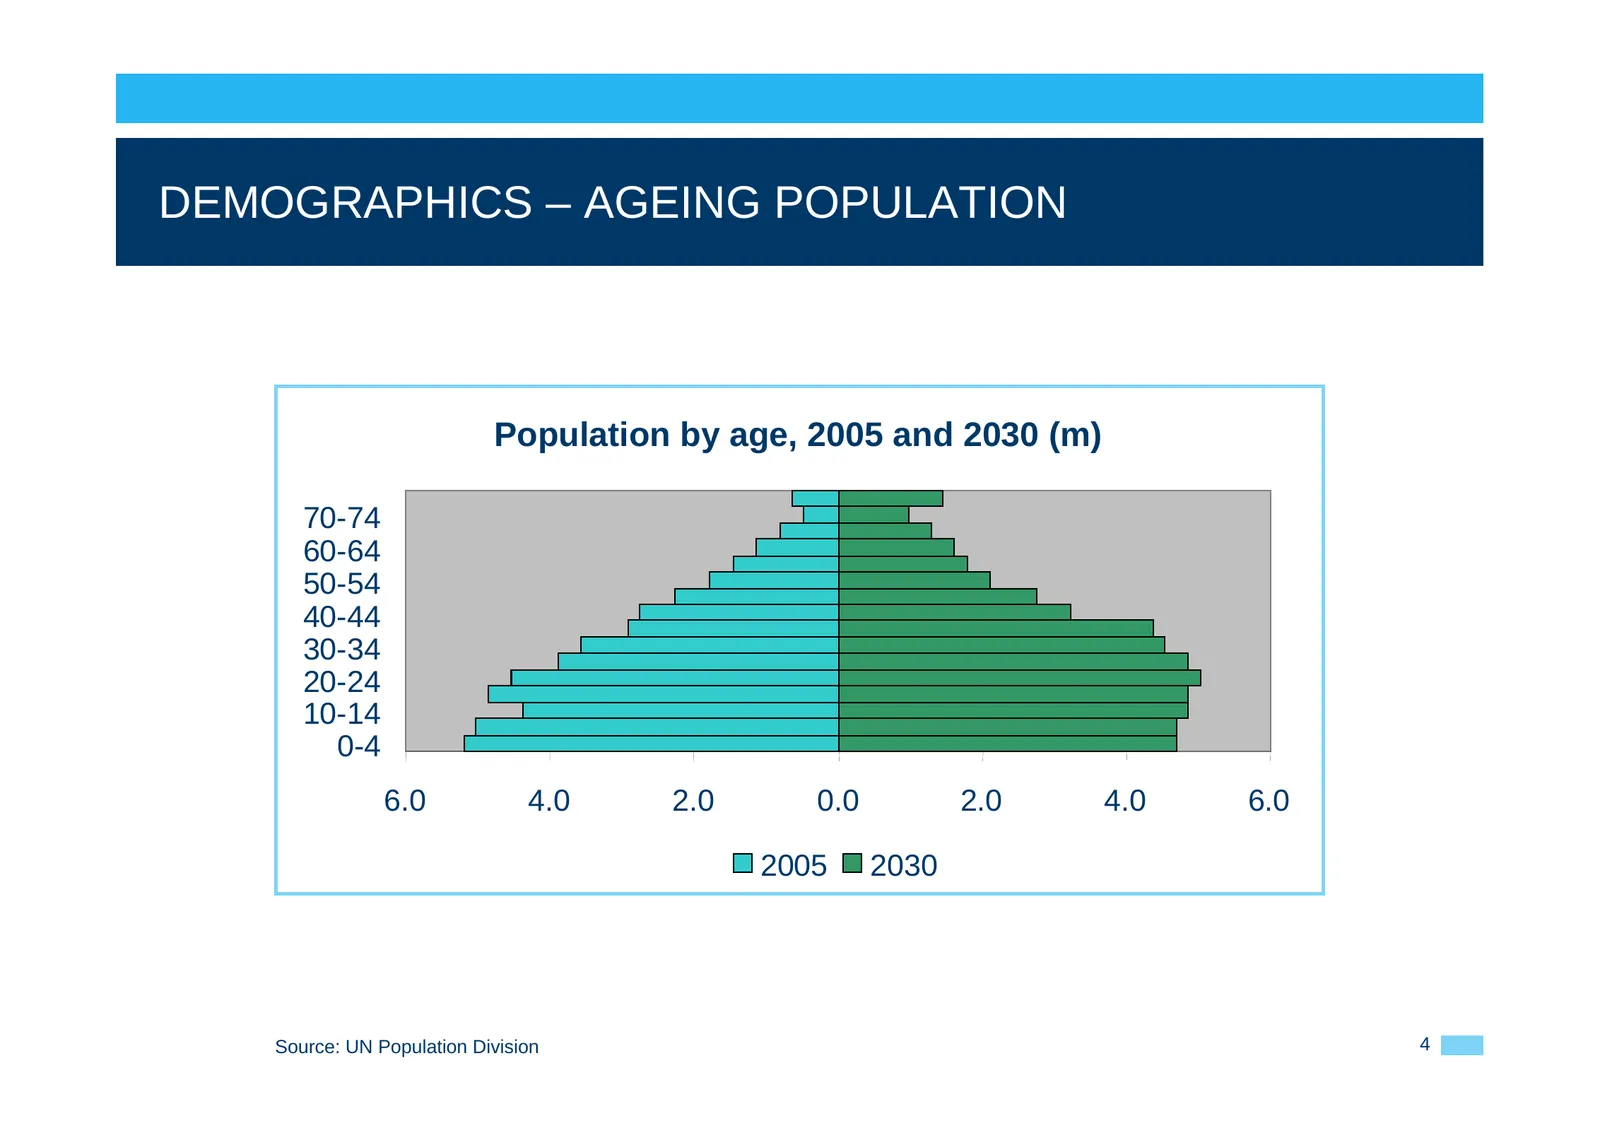
DEMOGRAPHICS – AGEING POPULATION Population by age, 2005 and 2030 (m) 70-74 60-64 50-54 40-44 30-34 20-24 10-14 0-4 6.0 4.0 2.0 0.0 2.0 4.0 6.0 2005 2030 Source: UN Population Division 4
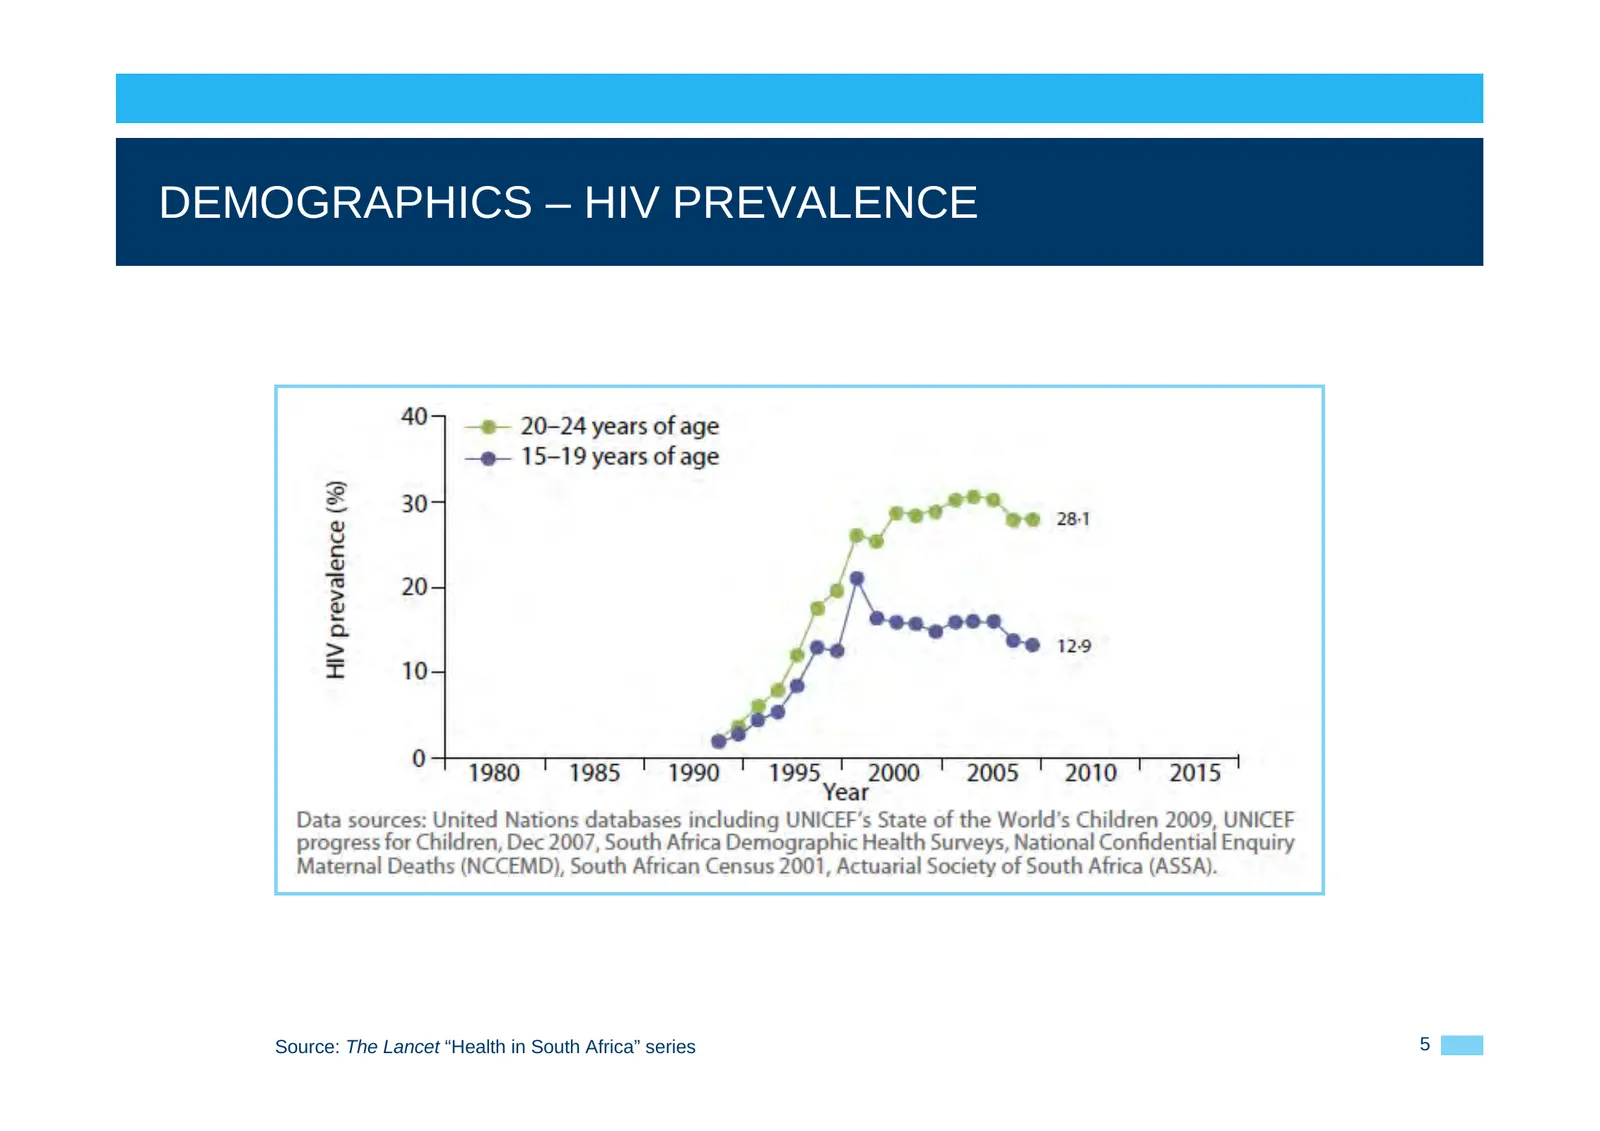
Slide 5: Demographics – HIV Prevalence
DEMOGRAPHICS – HIV PREVALENCE Source: The Lancet “Health in South Africa” series 5
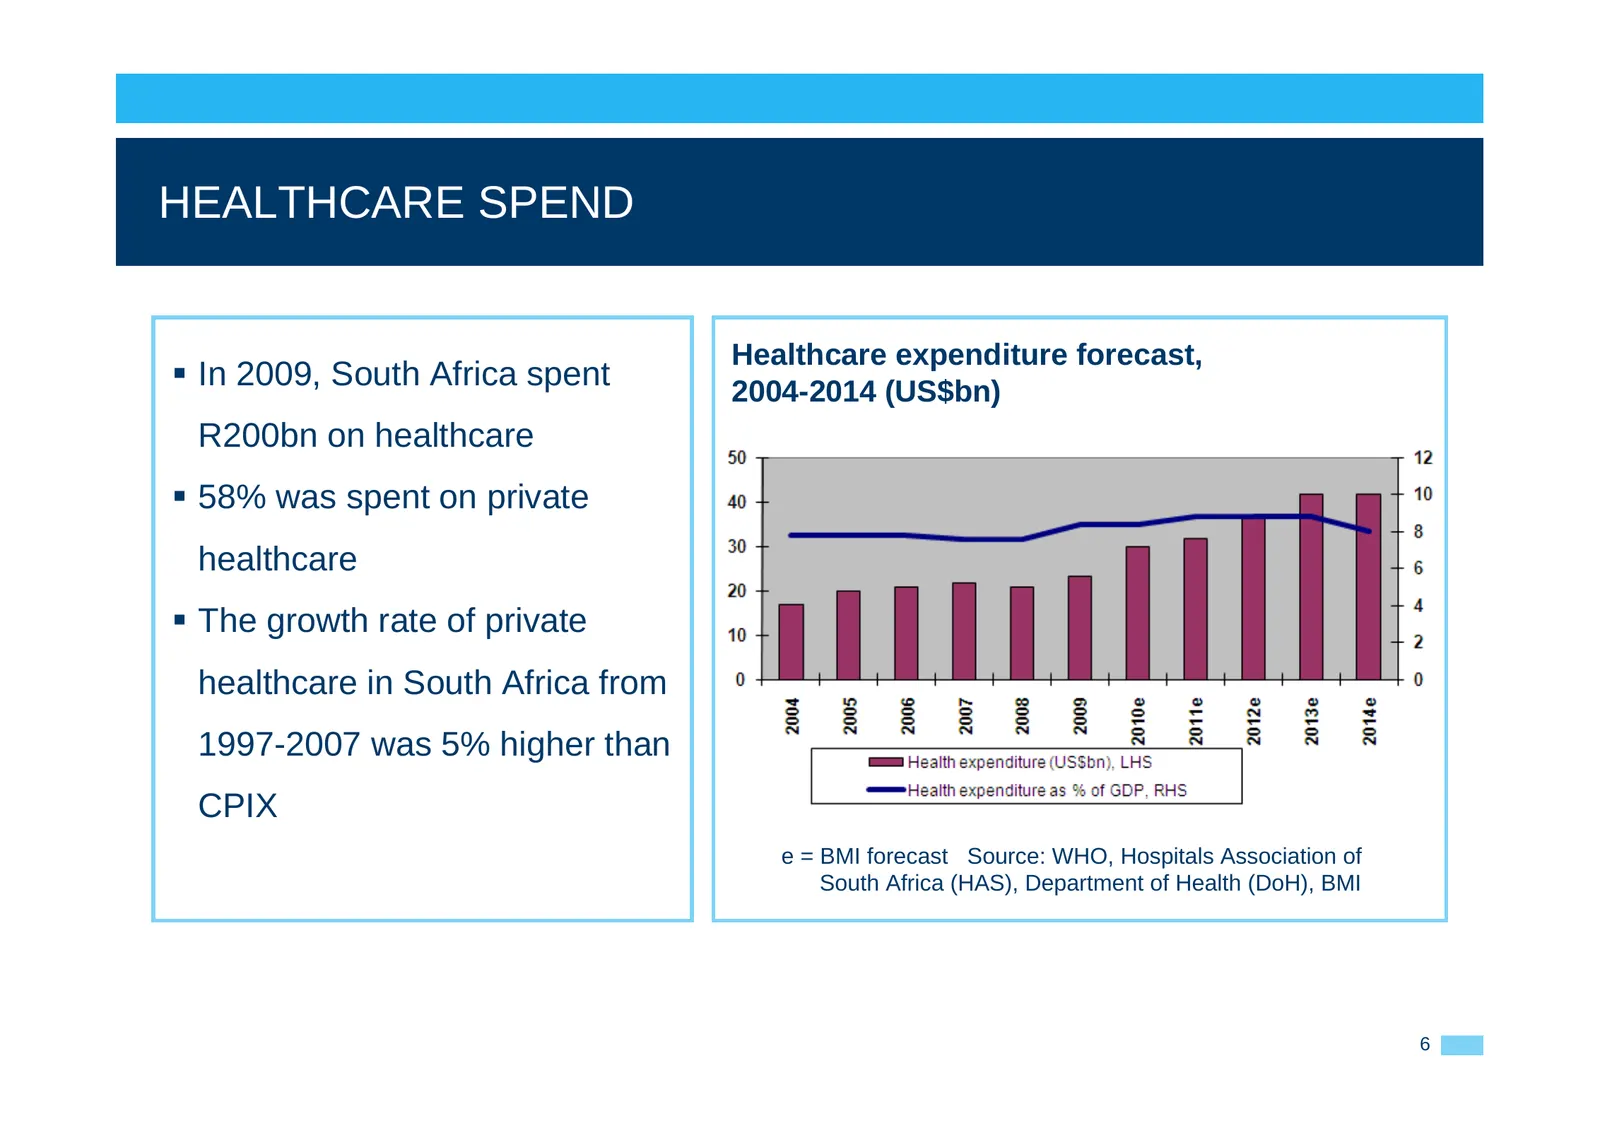
Slide 6: Healthcare Spend
HEALTHCARE SPEND Healthcare expenditure forecast, In 2009, South Africa spent 2004-2014 (US$bn) R200bn on healthcare 58% was spent on private healthcare The growth rate of private healthcare in South Africa from 1997-2007 was 5% higher than CPIX e = BMI forecast Source: WHO, Hospitals Associat
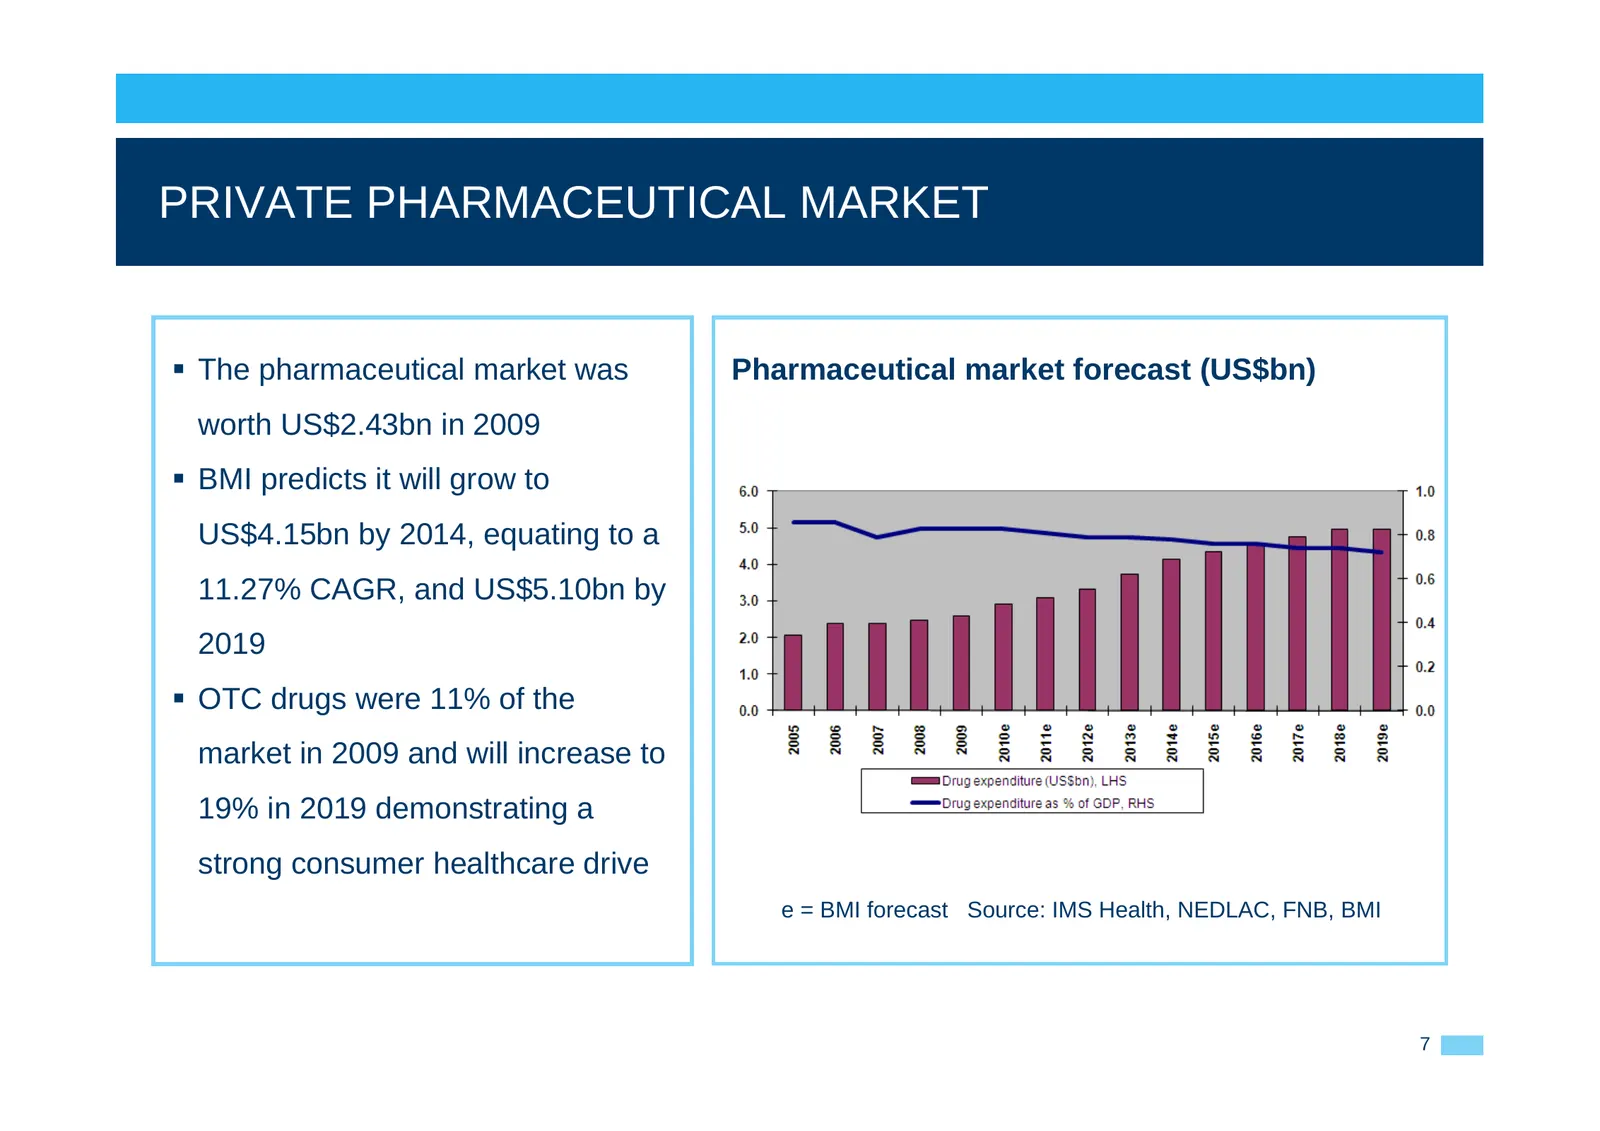
Slide 7: Private Pharmaceutical Market
PRIVATE PHARMACEUTICAL MARKET The pharmaceutical market was Pharmaceutical market forecast (US$bn) worth US$2.43bn in 2009 BMI predicts it will grow to US$4.15bn by 2014, equating to a 11.27% CAGR, and US$5.10bn by 2019 OTC drugs were 11% of the market in 2009 and will increase to 19% in 2019
Slide 8: Agenda
AGENDA Demographics - driving healthcare spend The political agenda Clicks Group’s healthcare offering Can SA become world class at retail healthcare? 8
Slide 9: Healthcare is a National Priority
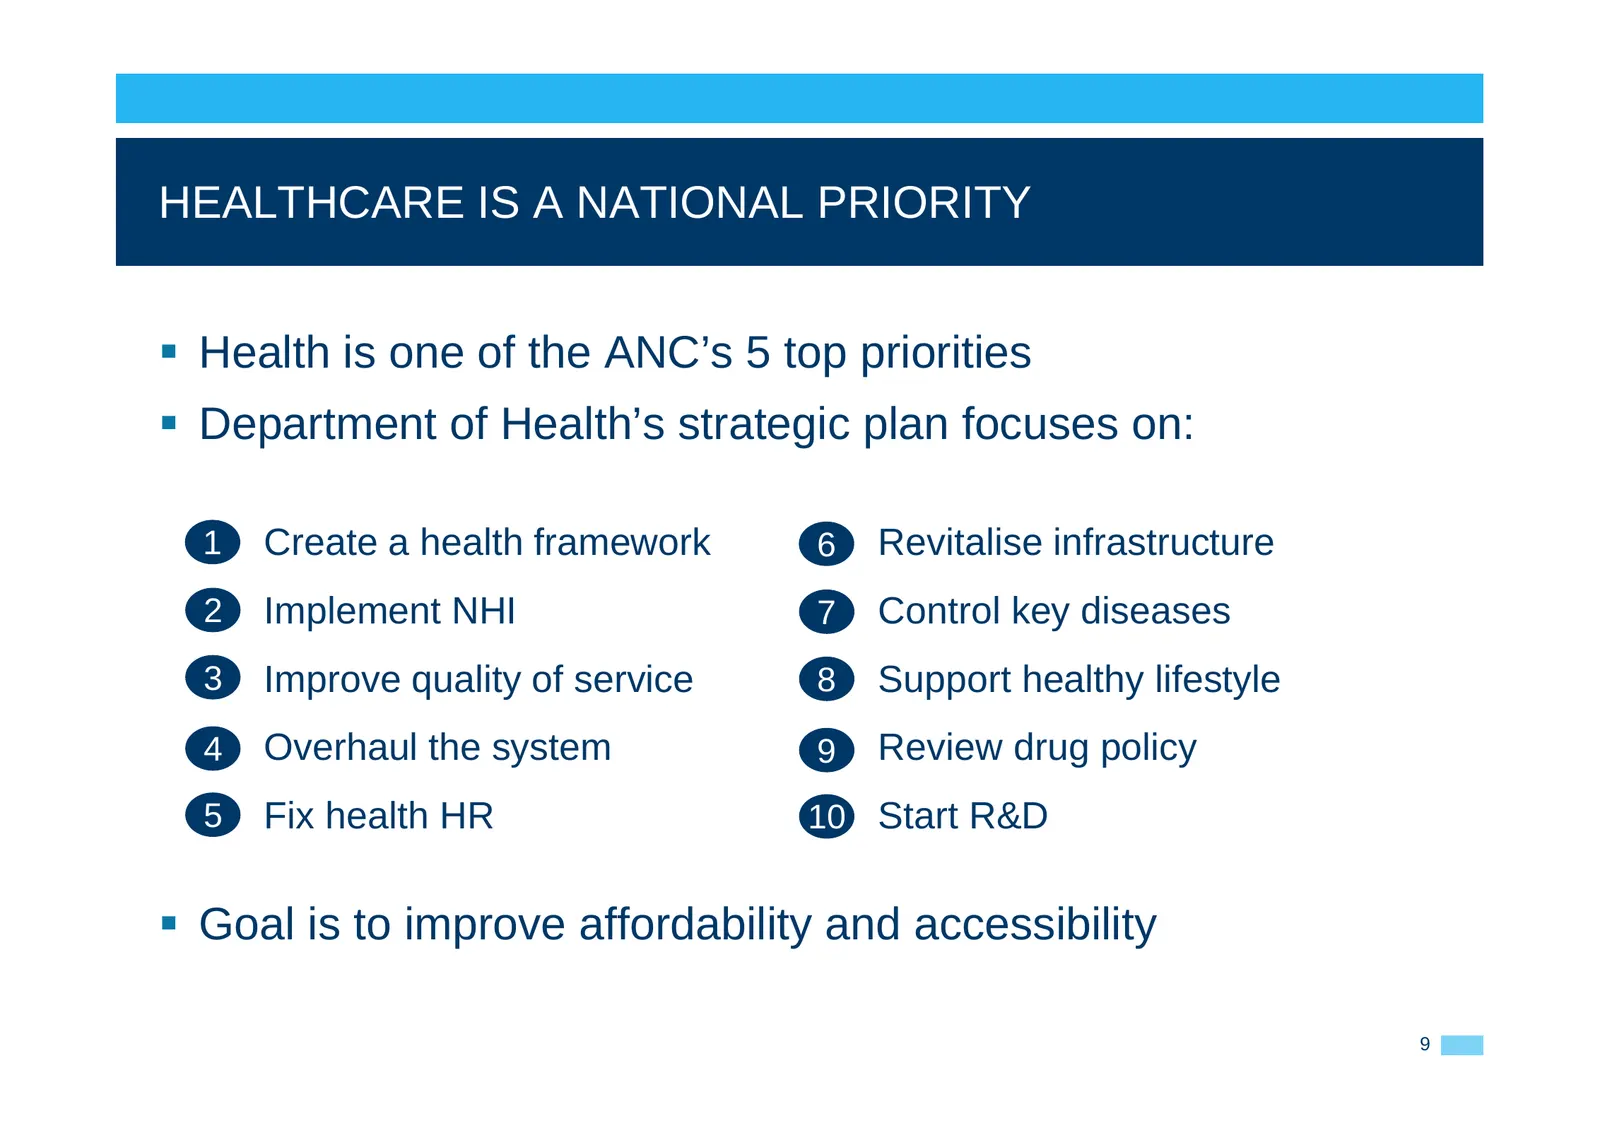
HEALTHCARE IS A NATIONAL PRIORITY Health is one of the ANC’s 5 top priorities Department of Health’s strategic plan focuses on: 1 Create a health framework 6 Revitalise infrastructure 2 Implement NHI 7 Control key diseases 3 Improve quality of service 8 Support healthy lifestyle 4 Overhaul the s
Slide 10: National Health Insurance
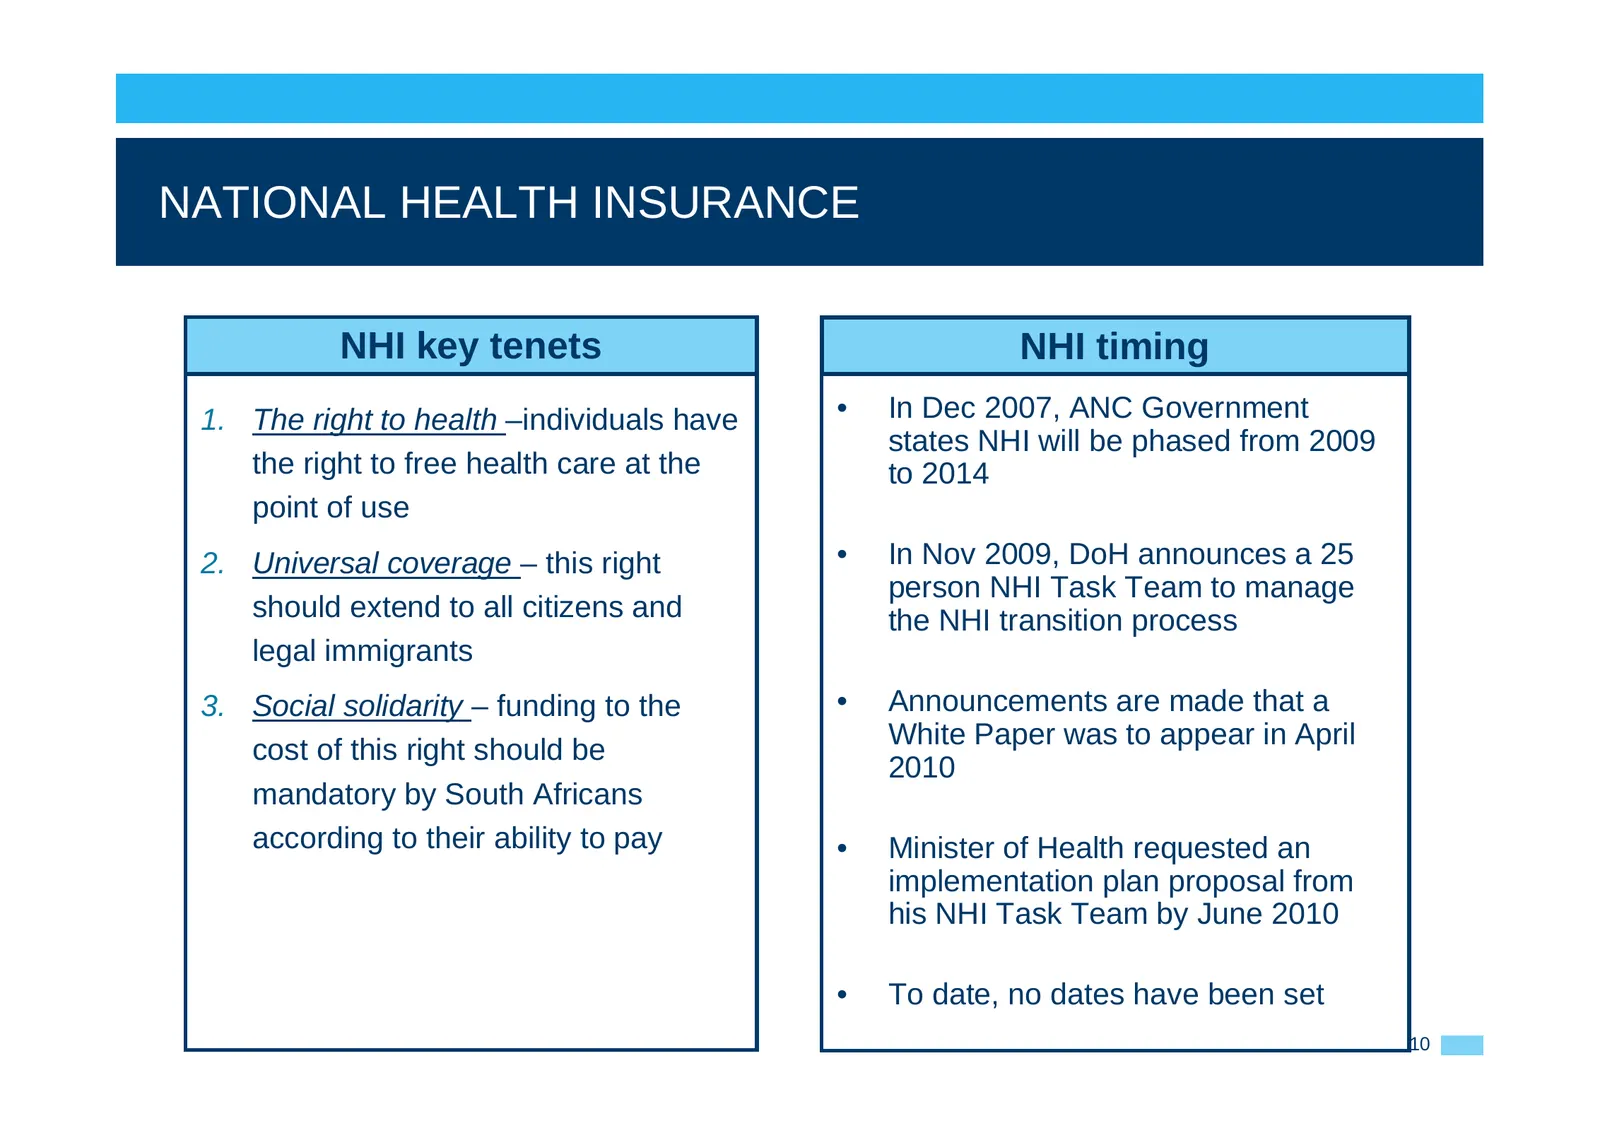
NATIONAL HEALTH INSURANCE NHI key tenets NHI timing 1. The right to health –individuals have • In Dec 2007, ANC Government states NHI will be phased from 2009 the right to free health care at the to 2014 point of use 2. Universal coverage – this right • In Nov 2009, DoH announces a 25 person NHI Tas
Slide 11: Key Health Priorities Shorter-Term
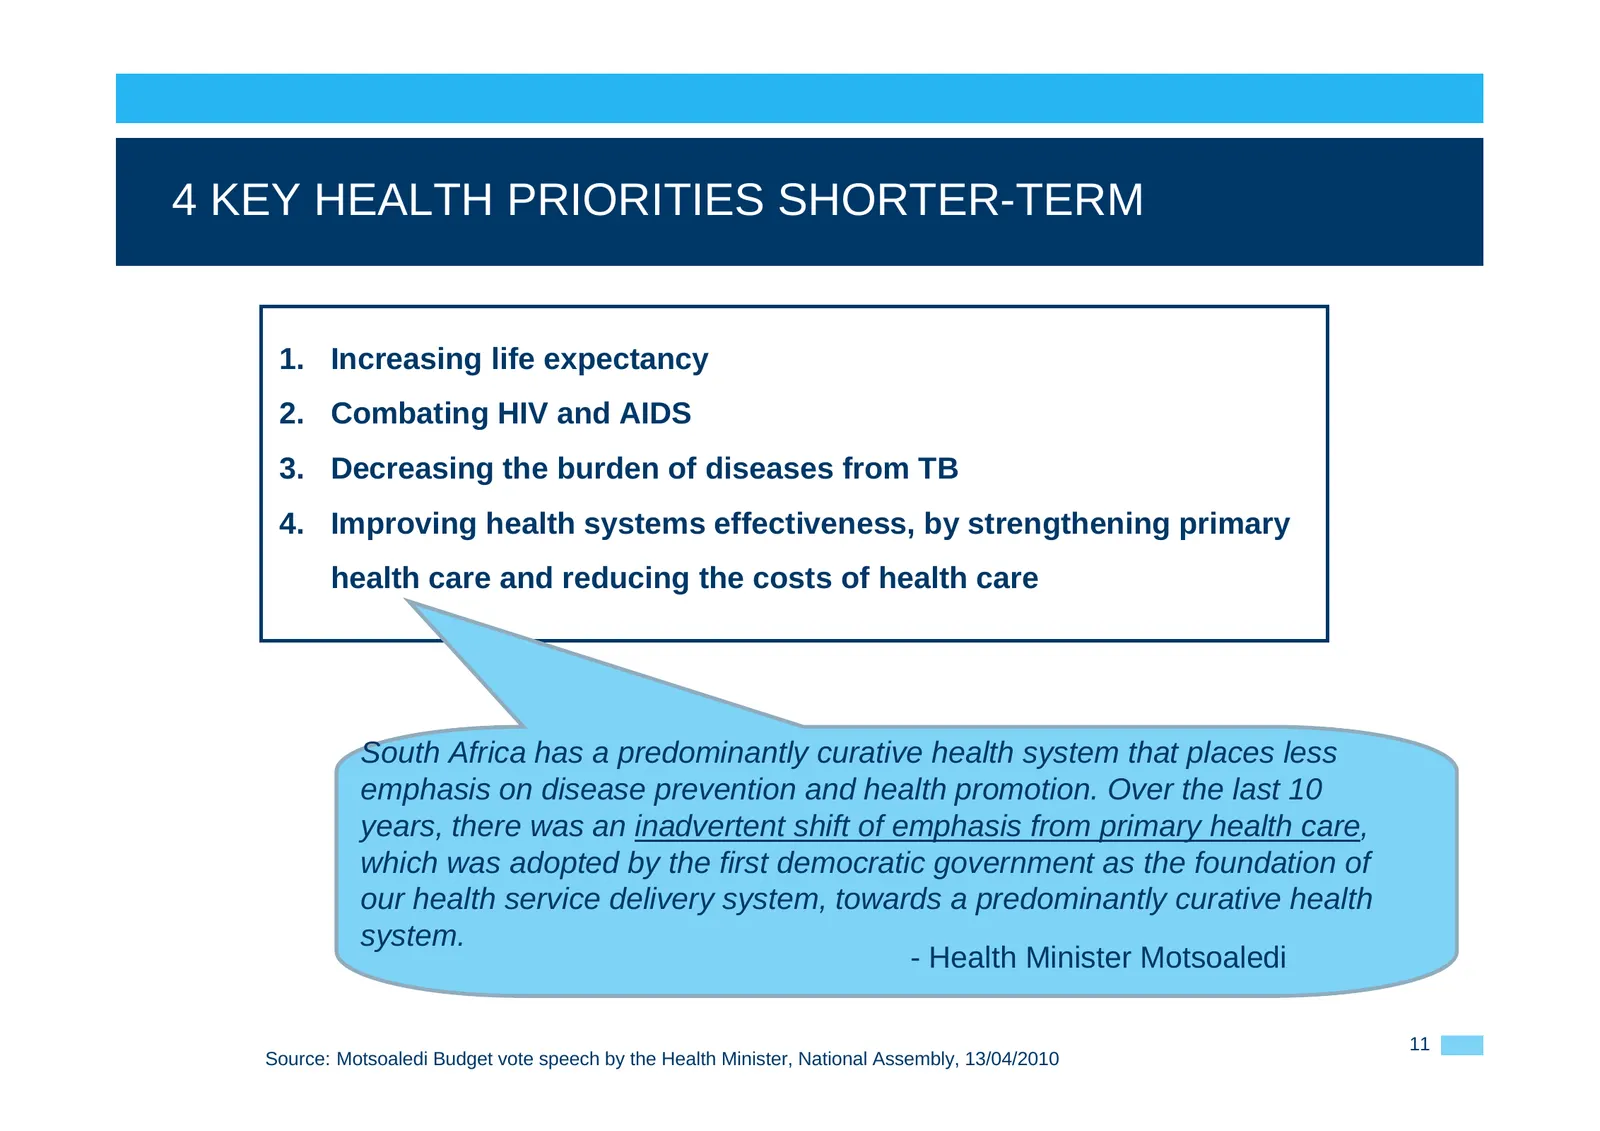
4 KEY HEALTH PRIORITIES SHORTER-TERM 1. Increasing life expectancy 2. Combating HIV and AIDS 3. Decreasing the burden of diseases from TB 4. Improving health systems effectiveness, by strengthening primary health care and reducing the costs of health care South Africa has a predominantly curative he
Slide 12: Agenda
AGENDA Demographics - driving healthcare spend The political agenda Clicks Group’s healthcare offering Can SA become world class at retail healthcare? 12
Slide 13: Clicks Pharmacy
CLICKS PHARMACY 250 pharmacies in 370 stores Target of 500 Clinic built in all pharmacies 12% pharmacy market share at Feb 2010 Target of 30% 1.4m scripts per month 450 pharmacists, 900 professional staff 1.7m ClubCard holders on pharmacy database 13
Slide 14: Clicks Direct Medicines
CLICKS DIRECT MEDICINES Courier pharmacy - national coverage Unique offer to medical aids 2% market share at Feb 2010 500 000 scripts 14
Slide 15: United Pharmaceutical Distributors
UNITED PHARMACEUTICAL DISTRIBUTORS Only national full range pharmaceutical wholesaler 40% share of private wholesale market Link banner buying group – 250 members Operation in Botswana services SADC region Distribution agency capability 15
Slide 16: Our Healthcare Agenda
OUR HEALTHCARE AGENDA Promote pharmacy as the gatekeeper to primary healthcare Wider pharmacist / nurse practitioner prescribing Improve access to self medication Down schedule to international standards Liberalise advertising rules 16
Slide 17: Agenda
AGENDA Demographics - driving healthcare spend The political agenda Clicks Group’s healthcare offering Can SA become world class at retail healthcare? 17
Slide 18: World Class Retail Healthcare
WORLD CLASS RETAIL HEALTHCARE SA has the right combination to create world class retail healthcare 1. A significant ‘health need’ in the country, specifically around primary health care 2. Corporate pharmacy still only 6 years old 3. A growing number of accessible and affordable formalised retail co
Slide 19: Primary healthcare need example: HIV testing
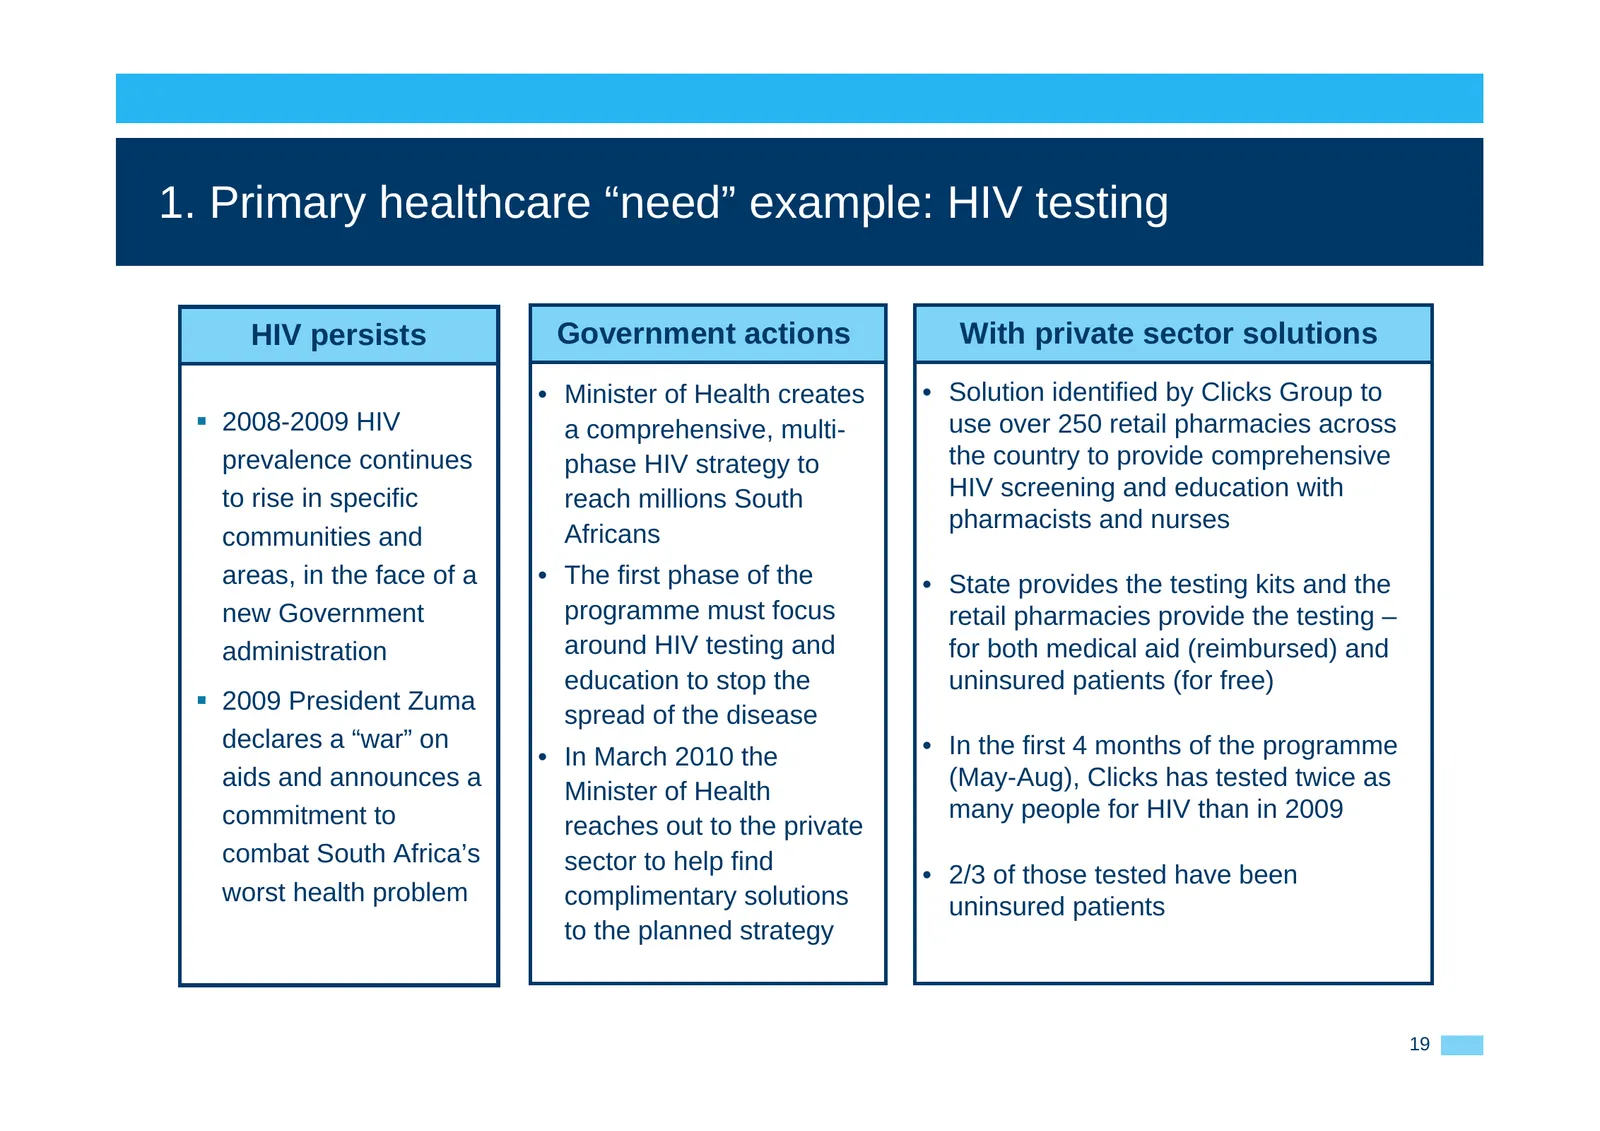
1. Primary healthcare “need” example: HIV testing HIV persists Government actions With private sector solutions • Minister of Health creates • Solution identified by Clicks Group to 2008-2009 HIV a comprehensive, multi- use over 250 retail pharmacies across prevalence continues phase HIV strategy
Slide 20: Primary healthcare need example (continued)
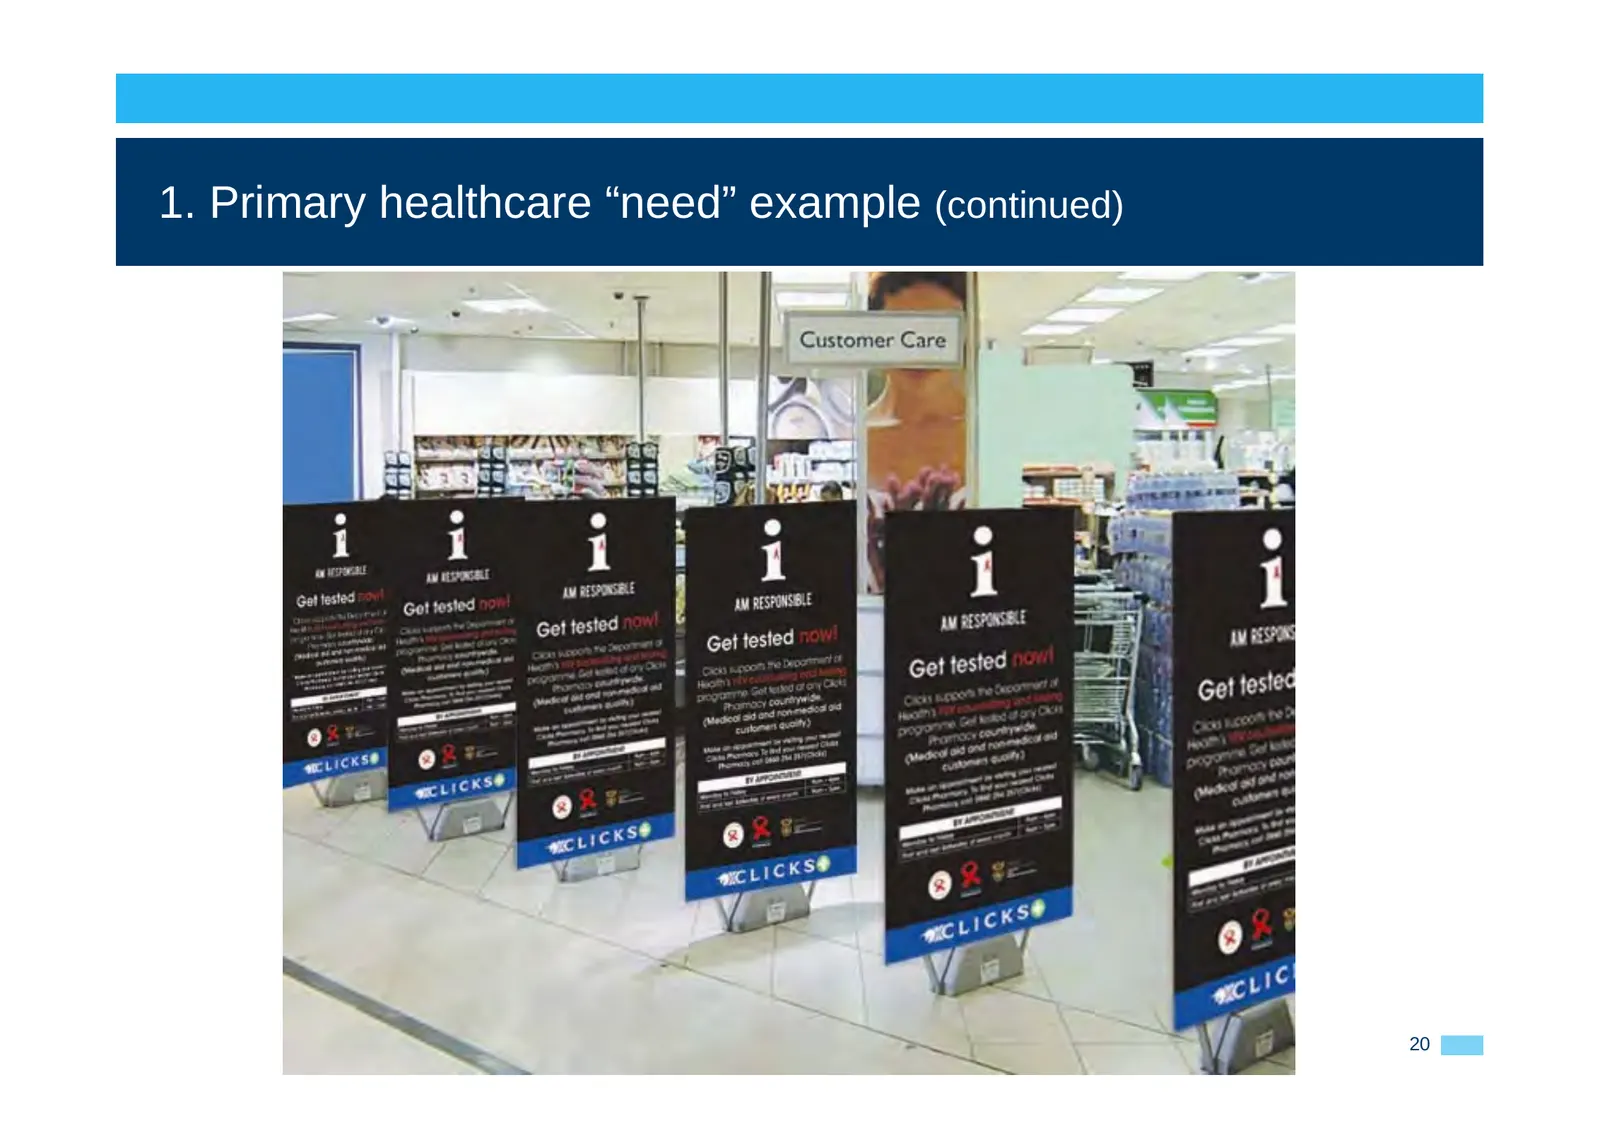
1. Primary healthcare “need” example (continued) 20
Slide 21: Corporate pharmacy still young
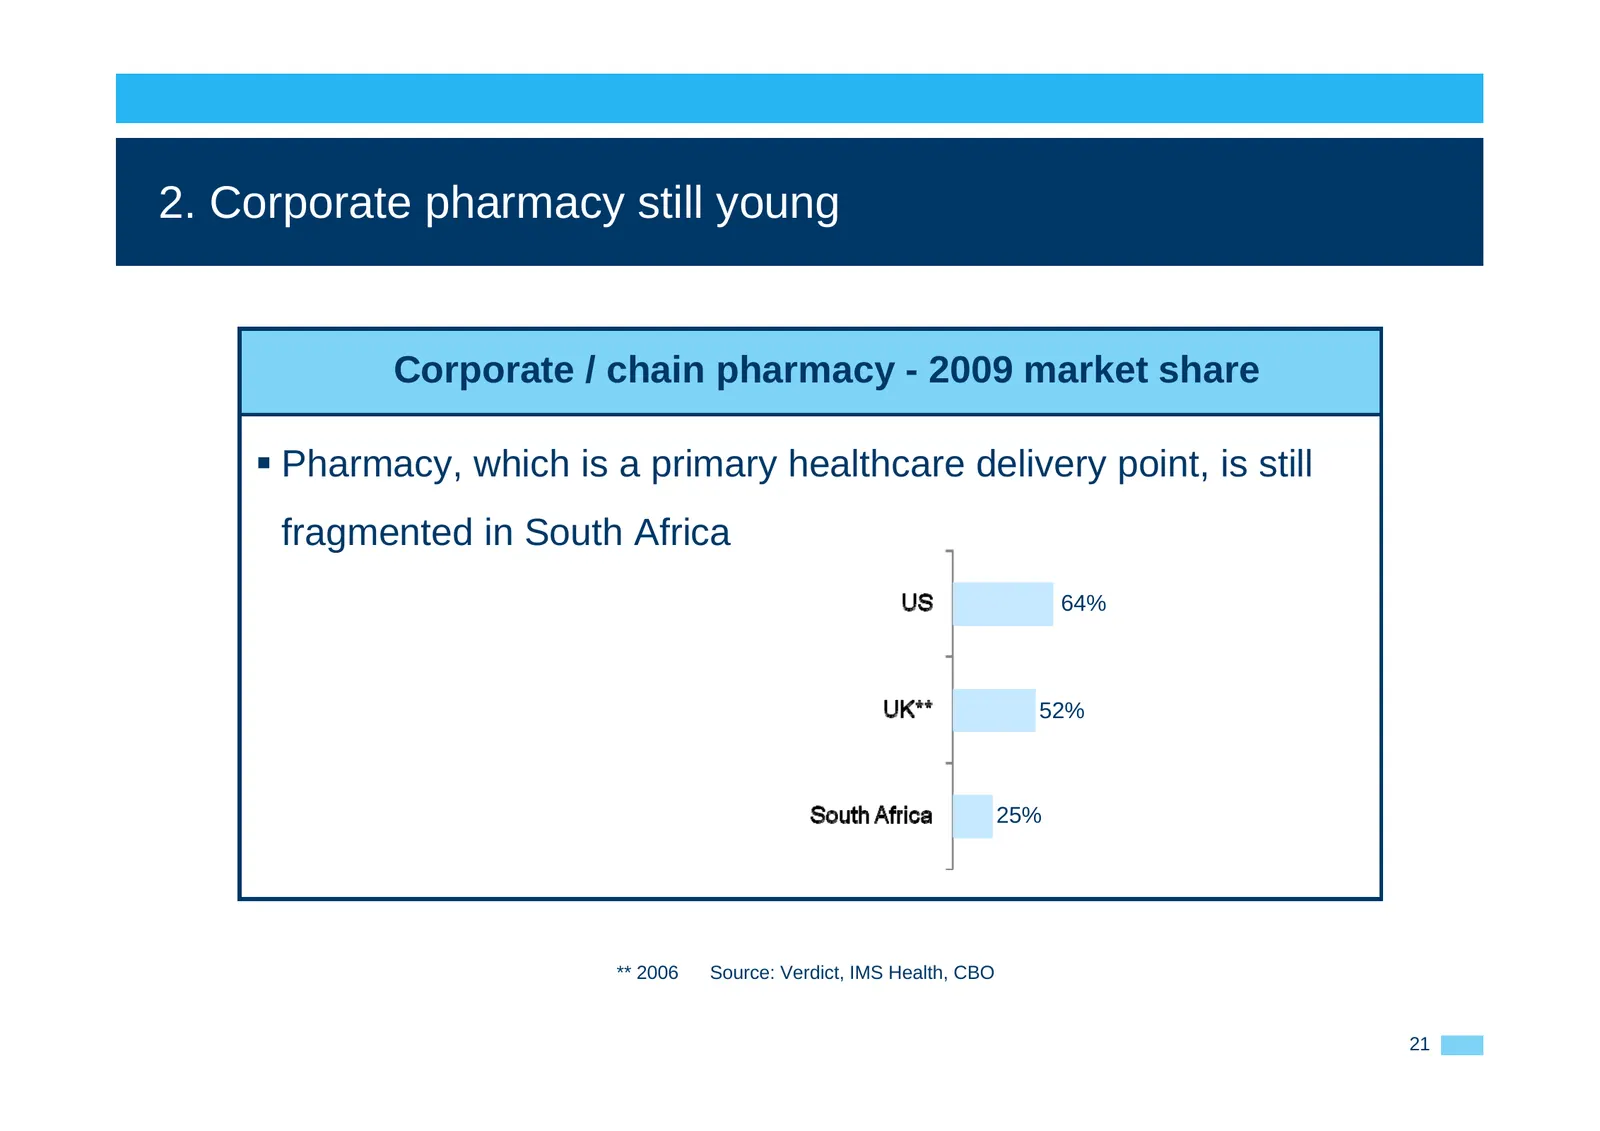
2. Corporate pharmacy still young Corporate / chain pharmacy - 2009 market share Pharmacy, which is a primary healthcare delivery point, is still fragmented in South Africa 64% 52% 25% ** 2006 Source: Verdict, IMS Health, CBO 21
Slide 22: Potential for retail clinic development
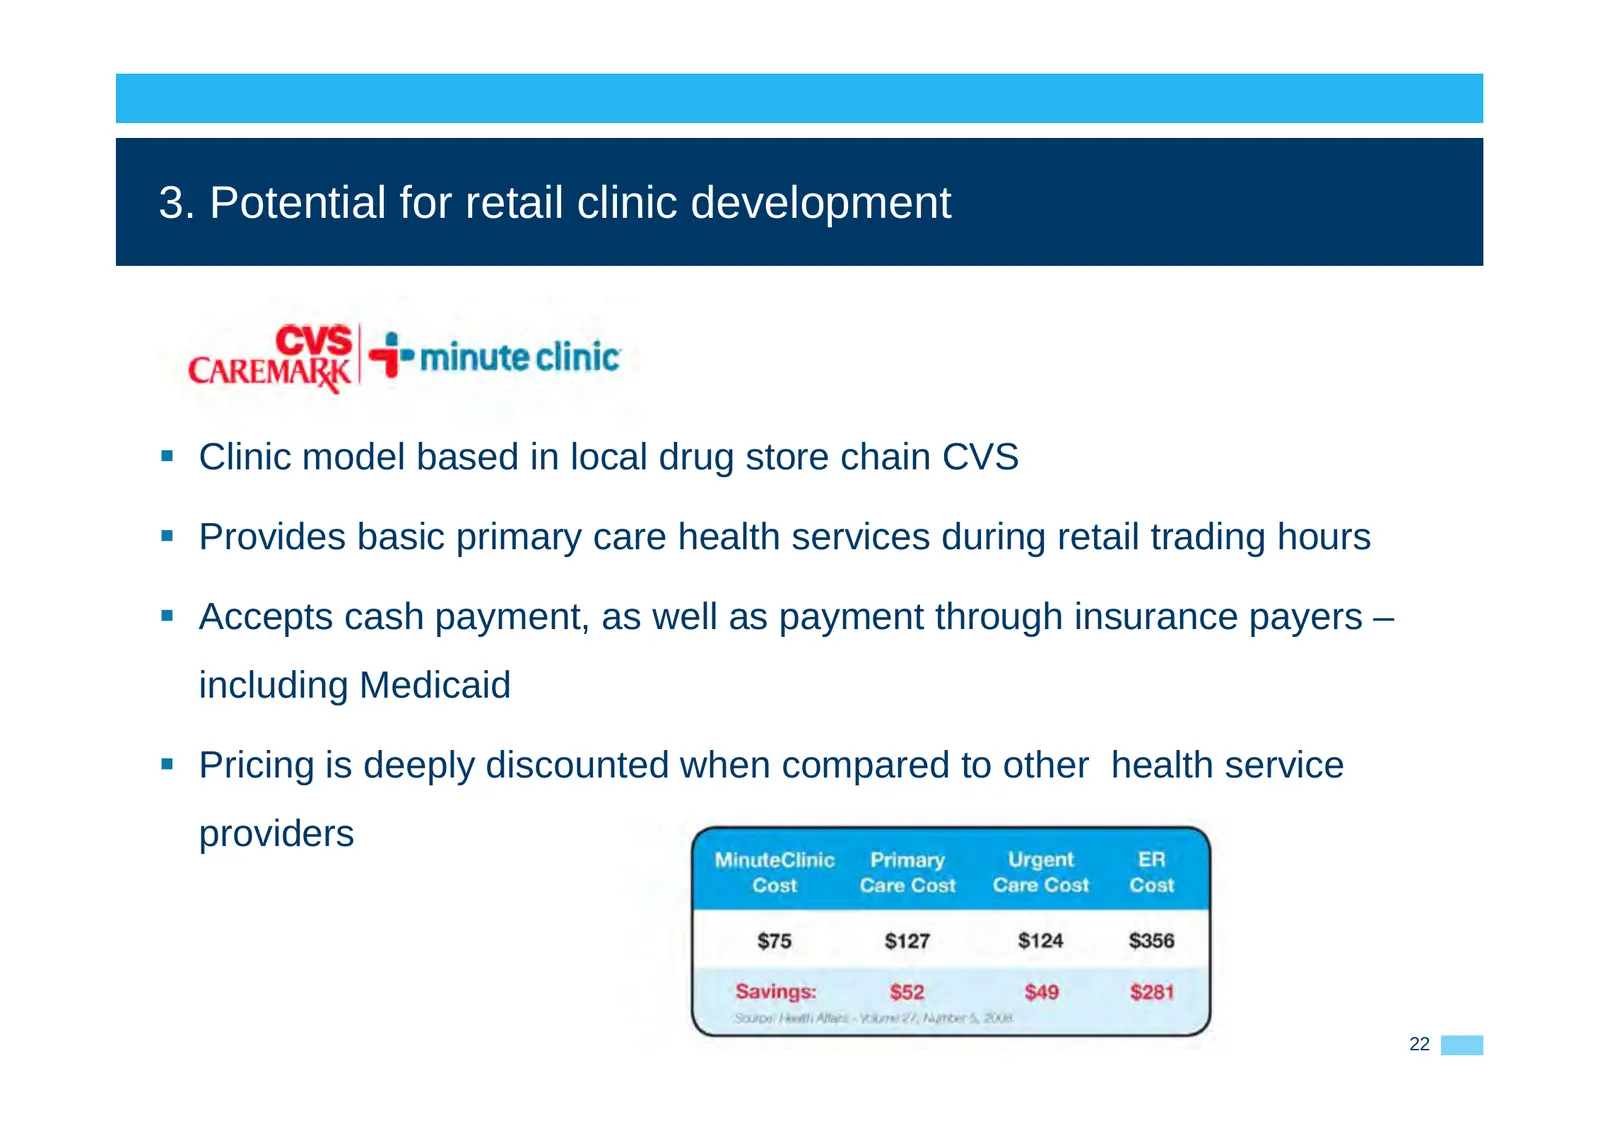
3. Potential for retail clinic development Clinic model based in local drug store chain CVS Provides basic primary care health services during retail trading hours Accepts cash payment, as well as payment through insurance payers – including Medicaid Pricing is deeply discounted when compare
Slide 23: Potential for retail clinic development (continued)
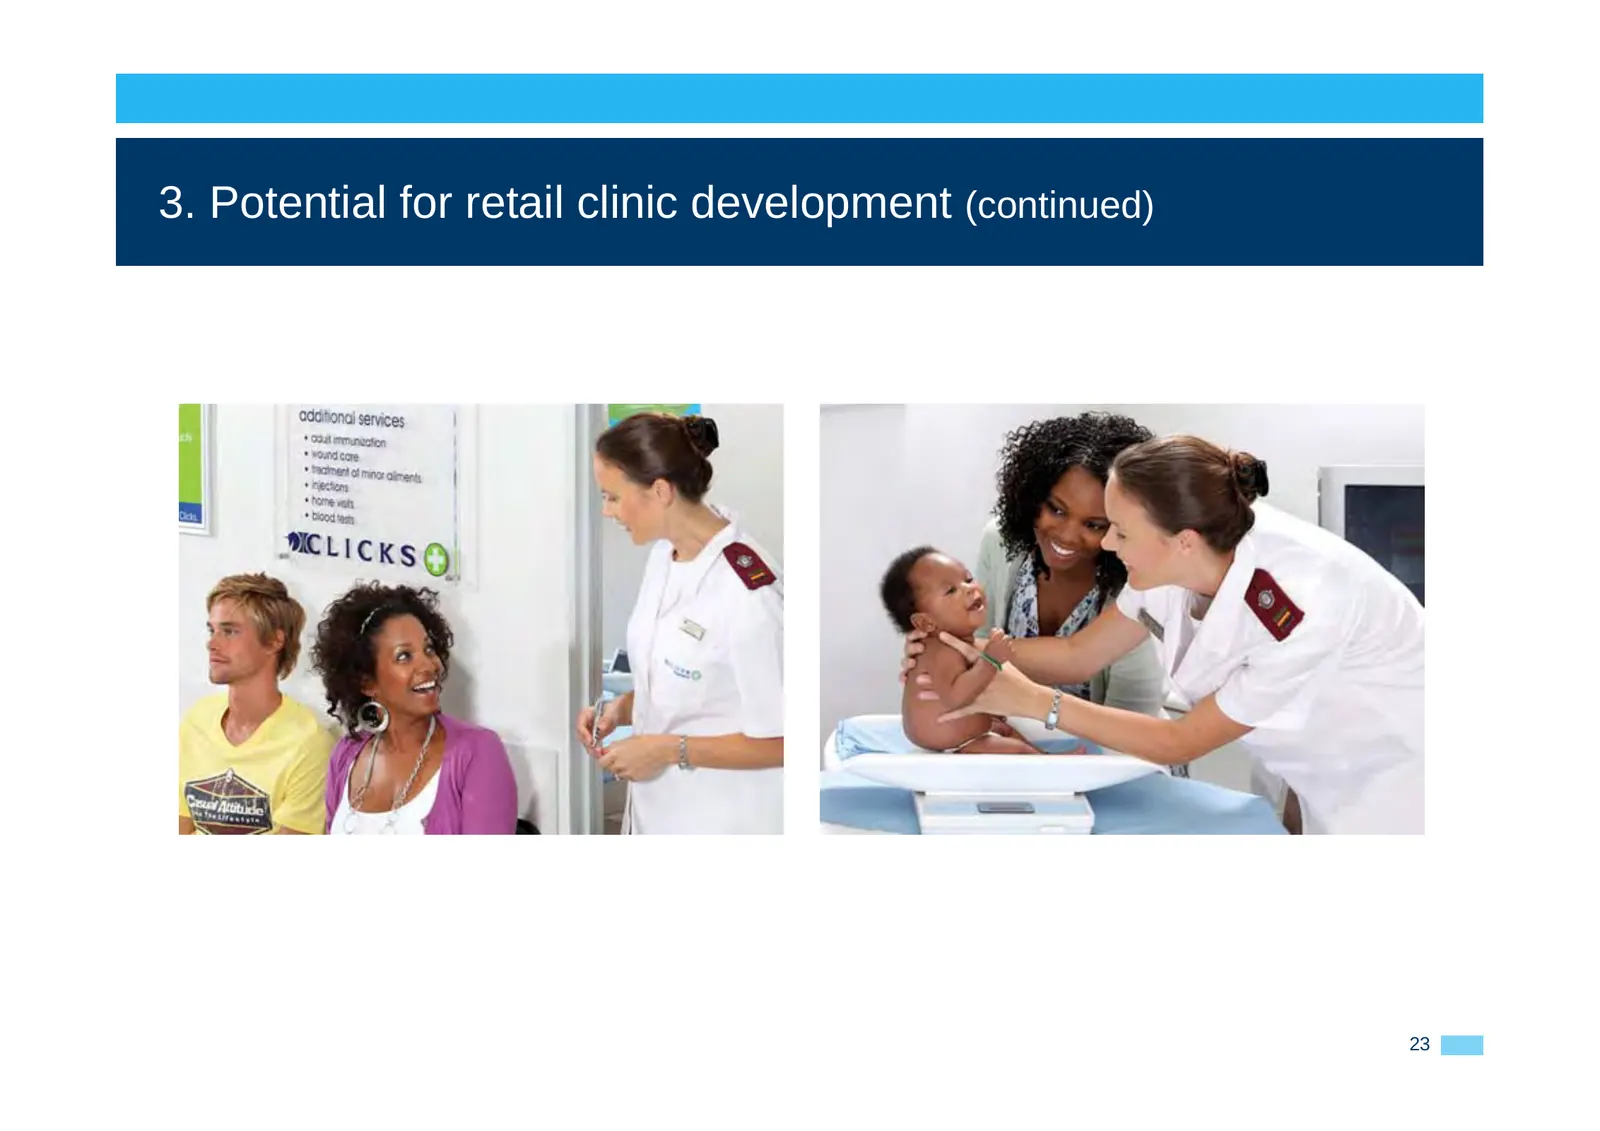
3. Potential for retail clinic development (continued) 23
Slide 24: What will make SA retail healthcare a success?
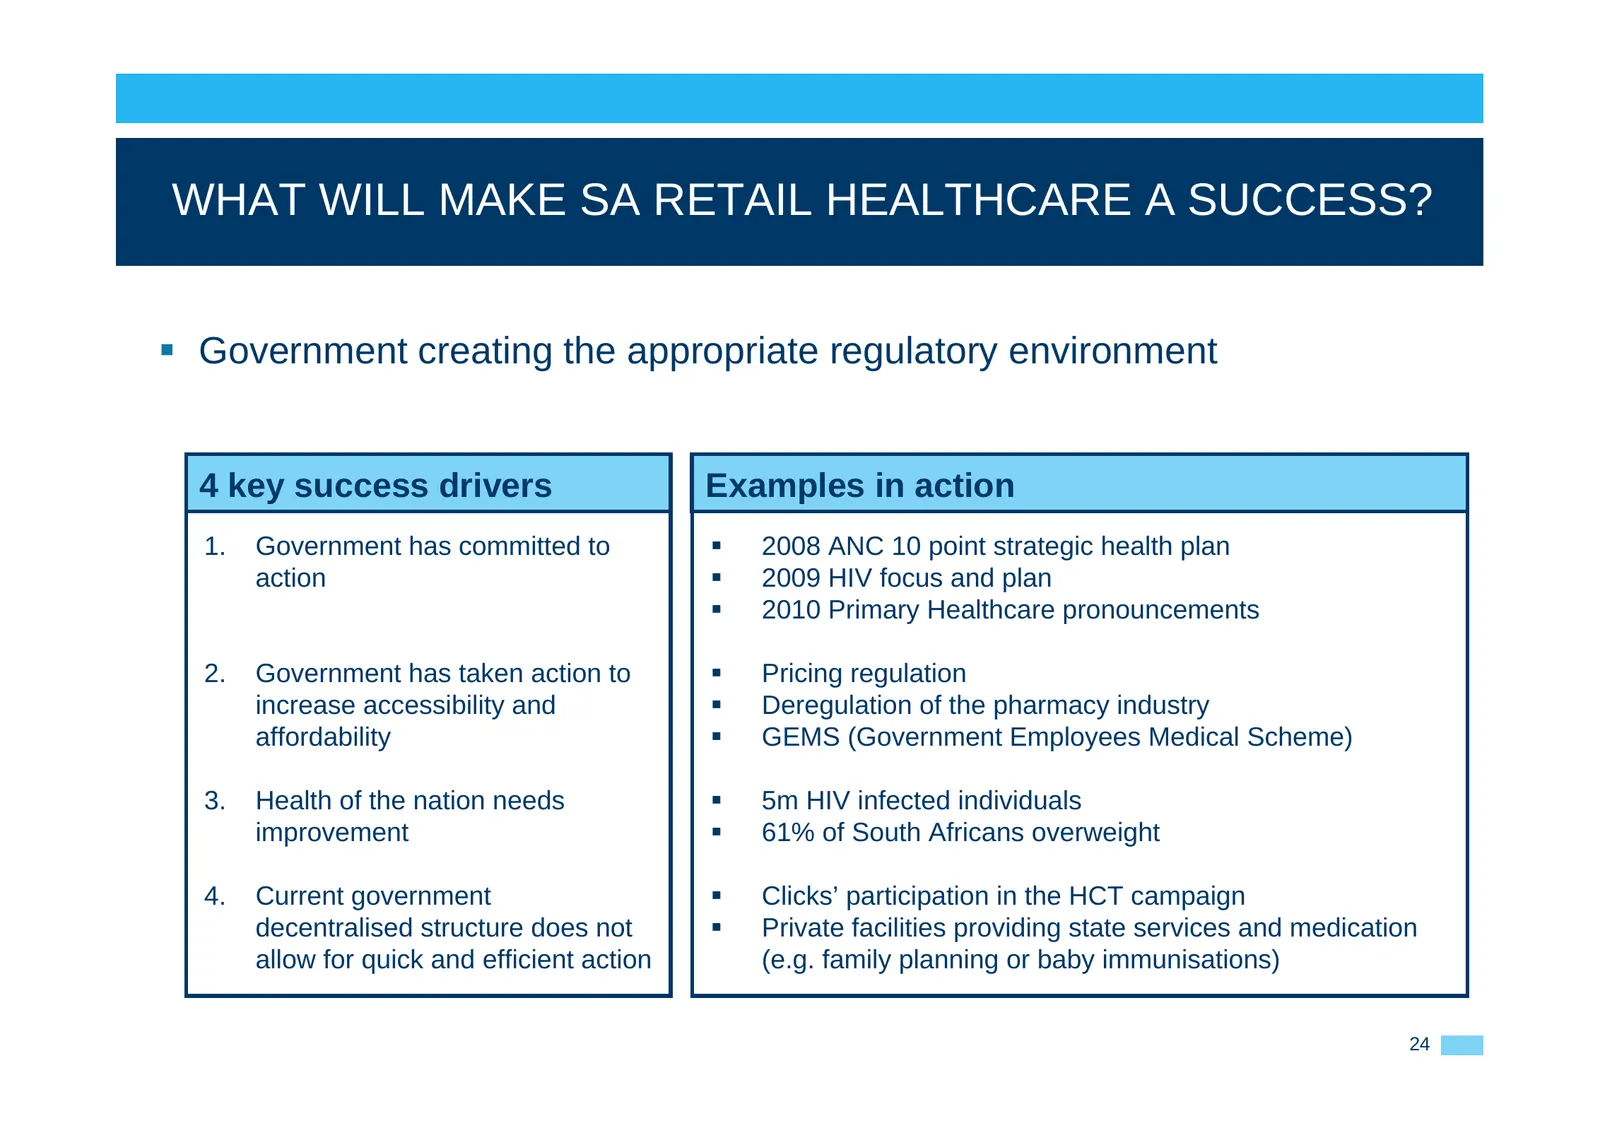
WHAT WILL MAKE SA RETAIL HEALTHCARE A SUCCESS? Government creating the appropriate regulatory environment 4 key success drivers Examples in action 1. Government has committed to 2008 ANC 10 point strategic health plan action 2009 HIV focus and plan 2010 Primary Healthcare pronouncements 2. G
Source: Internet Archive copy of clicksgroup.co.za
More decks from Clicks Group Limited
 FY2026 Earnings Presentation42 slides · October 2026
 FY2026 Earnings Presentation44 slides · October 2026
 Q2 2026 Earnings Presentation29 slides · Apr 23, 2026
 H1 2026 Earnings Presentation36 slides · April 2026
 FY2025 Earnings Presentation40 slides · October 2025
 FY2025 Earnings Presentation35 slides · Aug 31, 2025