HCC Insurance — Conference Presentation (March 2008)
46 slides from HCC Insurance's conference presentation, Mar 19, 2008
Slide 1
Slide 2: About Forward-Looking Statements
ABOUT FORWARD-LOOKING STATEMENTS: This presentation contains certain "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933, and Section 21E of the Securities Exchange Act of 1934, which are intended to be covered by the safe harbors created by those laws. These
Slide 3: Overview
OVERVIEW HCC 5 (r)
Slide 4: Corporate Profile
CORPORATE PROFILE Specialty Insurance since 1974 Based in Houston, Texas with offices across the USA and international offices in Bermuda, Spain, Ireland and the U.K. Diversified operations include both P&C and Life Insurance Companies, Underwriting Agencies and Intermediaries Rated AA (Very Strong)
Slide 5: Corporate Philosophy
CORPORATE PHILOSOPHY Long Term Growth of Shareholders' Equity Capital Preservation Risk Management Diversification of Operations Disciplined Underwriting Cycle Management Conservative Investment Philosophy
Slide 6: Shareholders' Equity
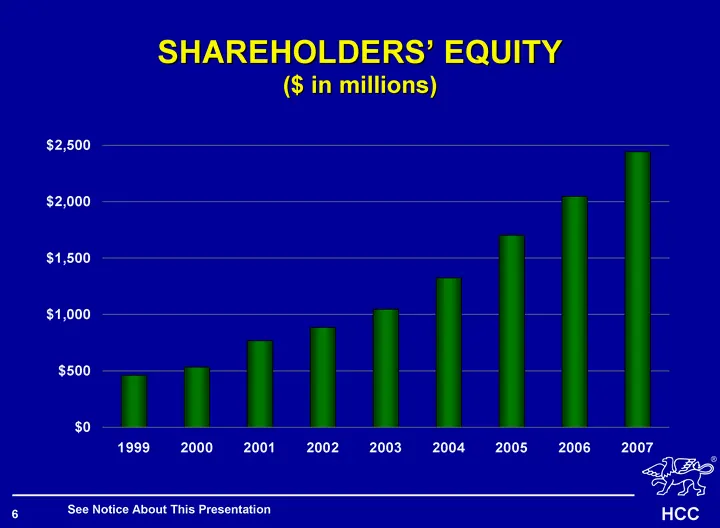
SHAREHOLDERS' EQUITY ($ in millions) See Notice About This Presentation 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 S/E 440430000 458439000 530930000 763453000 882907000 1047000000 1323665000 1700000000 2043000000 2440000000
Slide 7: Growth in Book Value
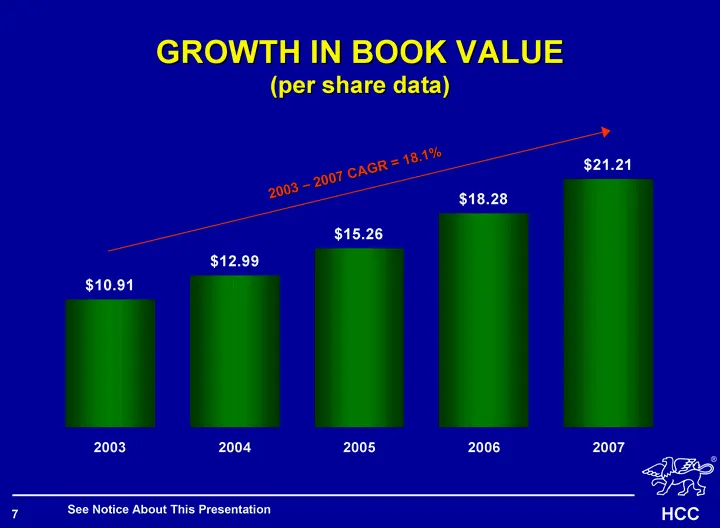
GROWTH IN BOOK VALUE (per share data) See Notice About This Presentation 2003 2004 2005 2006 2007 BV 10.91 12.99 15.26 18.28 21.21 2003 - 2007 CAGR = 18.1%
Slide 8: Operations
OPERATIONS HCC 15 (r)
Slide 9: Lines of Business
LINES OF BUSINESS Diversified Financial Products Group Life, Accident & Health Aviation London Market Other Specialty Lines
Slide 10: Diversified Financial Products
DIVERSIFIED FINANCIAL PRODUCTS Directors' and Officers' Liability Errors and Omissions Surety Credit Employment Practices Liability Financial Products
Slide 11: D&O and E&O Exposure
D&O AND E&O EXPOSURE Wrote approximately $1.4 billion of D&O and E&O premium in 2006 and 2007 combined Majority of the D&O business is written excess, usually with high attachment points Majority of the E&O insurance was for limits of $1 million or less Except for run-off policies, HCC has not writt
Slide 12: D&O and E&O Exposure
D&O AND E&O EXPOSURE Average D&O limit is less than $10 million gross and $8 million net As of December 31, the Company had 18 non-Side A only D&O or E&O claims and seven Side A only claims Of the claims reported, only one was primary with a policy limit of $5 million gross Average policy limit for
Slide 13: Group Life, Accident & Health
GROUP LIFE, ACCIDENT & HEALTH Medical Stop-Loss Specialty Disability Group Life Insurance Medical Excess Insurance Alternative Workers Comp / Occupational Accident Insurance Short Term Medical
Slide 14: Aviation
AVIATION Pleasure and Business Aircraft Owners and Pilots Rotor Wing Aircraft Foreign Commuter Airlines Cargo Operations Military and Law Enforcement Antique and Vintage Aircraft Do not write Major Airlines, Product Manufacturers and Satellites
Slide 15: London Market Account
LONDON MARKET ACCOUNT Energy, Onshore and Offshore Marine Property Accident and Health
Slide 16: Other Specialty Lines
OTHER SPECIALTY LINES Event and Contingency Brown Water Marine U.K. Liability & Commercial Motor Public Entity
Slide 17: HCC Insurance Companies
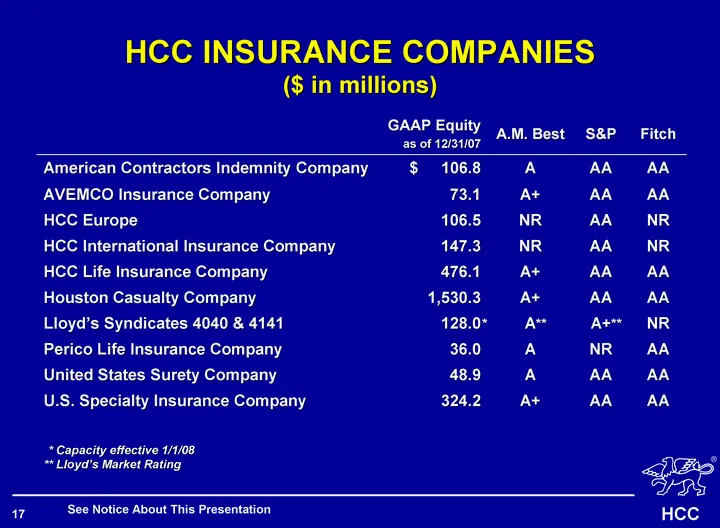
HCC INSURANCE COMPANIES ($ in millions) GAAP Equity as of 12/31/07 GAAP Equity as of 12/31/07 A.M. Best S&P Fitch American Contractors Indemnity Company $ 106.8 A AA AA AVEMCO Insurance Company 73.1 A+ AA AA HCC Europe 106.5 NR AA NR HCC International Insurance Company 147.3 NR AA NR HCC Life Insura
Slide 18: HCC Intermediaries & Underwriting Operations
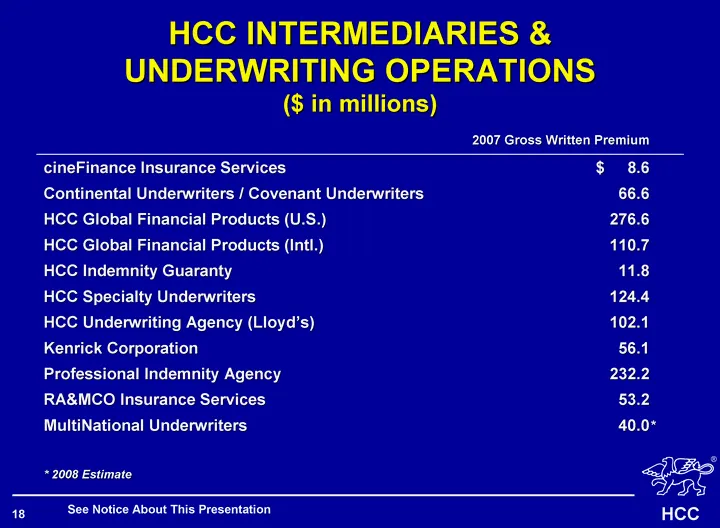
HCC INTERMEDIARIES & UNDERWRITING OPERATIONS ($ in millions) 2007 Gross Written Premium 2007 Gross Written Premium cineFinance Insurance Services cineFinance Insurance Services $ 8.6 Continental Underwriters / Covenant Underwriters Continental Underwriters / Covenant Underwriters 66.6 HCC Global Fin
Slide 19: Financials
FINANCIALS HCC 37 (r)
Slide 20: Strong Balance Sheet
STRONG BALANCE SHEET HCC 39 (r)
Slide 21: Building the Balance Sheet
BUILDING THE BALANCE SHEET OUR STRATEGY Underwriting Profitability Acquisitions Organic Growth Retentions Duration of Loss Reserves Investment Income See Notice About This Presentation
Slide 22: Balance Sheet Strengths
BALANCE SHEET STRENGTHS Low Risk Investment Portfolio High Quality Reinsurers Conservative Loss Reserves Strong Liquidity Low Debt to Total Capital Ratio of 11.7% Shareholders' Equity of $2.4 Billion Assets of $8.1 Billion See Notice About This Presentation
Slide 23: Reinsurance Recoverables
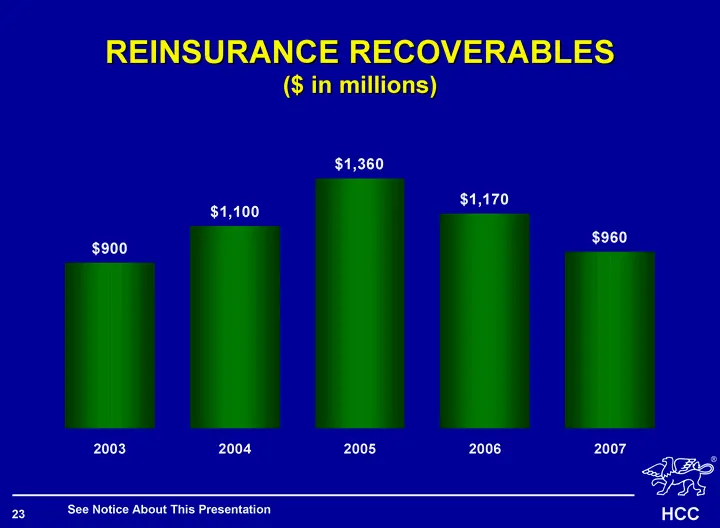
REINSURANCE RECOVERABLES ($ in millions) See Notice About This Presentation 2003 2004 2005 2006 2007 Reinsurance Recoverables 900 1100 1360 1170 960
Slide 24: Net Loss Reserves
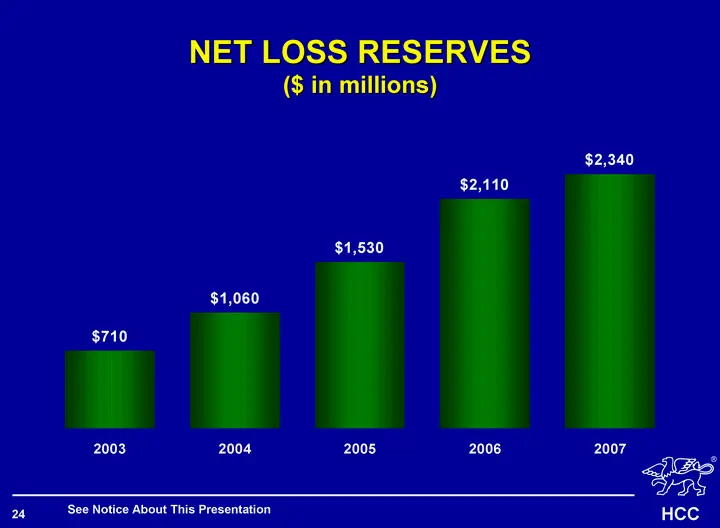
NET LOSS RESERVES ($ in millions) See Notice About This Presentation 2003 2004 2005 2006 2007 Net Loss Reserves 710 1060 1530 2110 2340
Slide 25: Operating Cash Flow
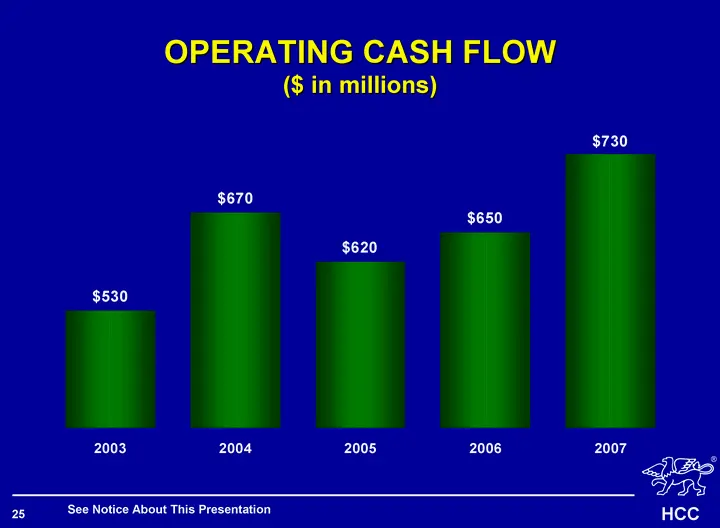
OPERATING CASH FLOW ($ in millions) See Notice About This Presentation 2003 2004 2005 2006 2007 Cash Flow 570 670 620 650 730
Slide 26: Investment Assets
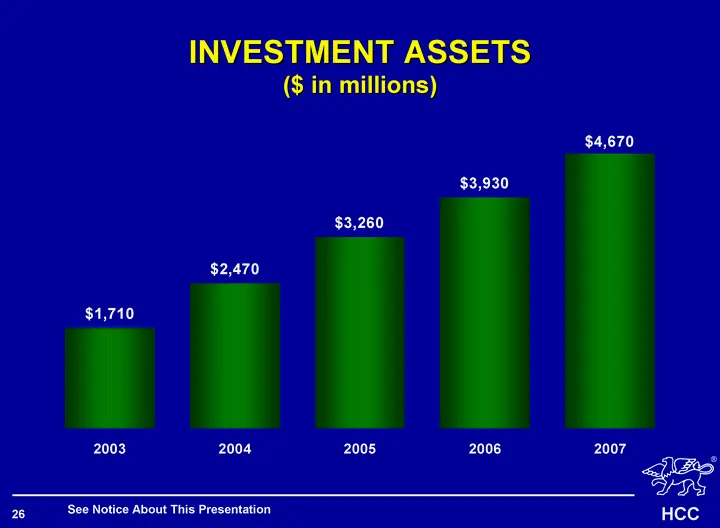
INVESTMENT ASSETS ($ in millions) See Notice About This Presentation 2003 2004 2005 2006 2007 Investment Assets 1710 2470 3260 3930 4670
Slide 27: Conservative Investment Portfolio
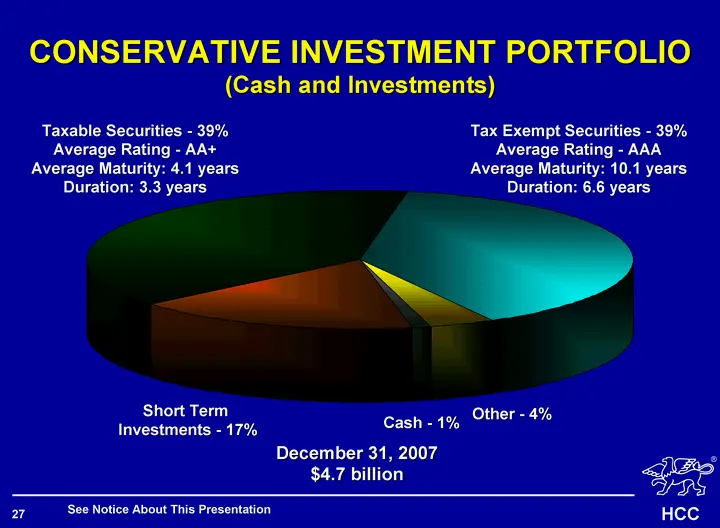
Taxable Securities Tax Exempt Securities Other Cash Short Term Investments 6/30/2007 39 39 4 1 17 CONSERVATIVE INVESTMENT PORTFOLIO (Cash and Investments) See Notice About This Presentation December 31, 2007 $4.7 billion Short Term Investments - 17% Tax Exempt Securities - 39% Average Rating - AAA A
Slide 28: Invested Assets
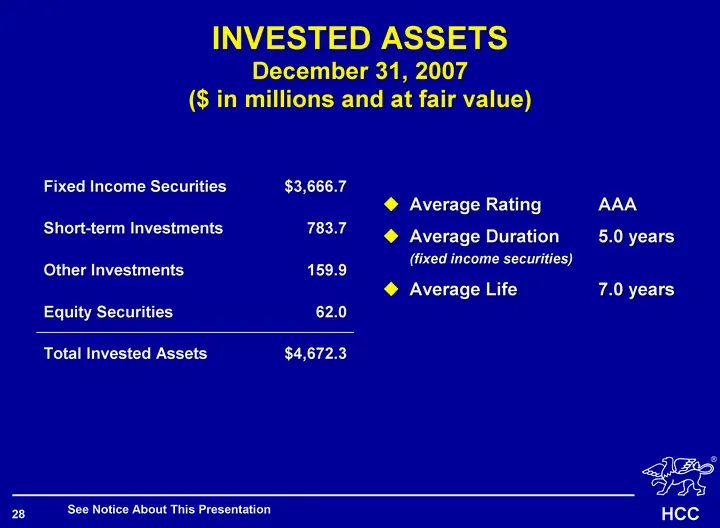
Average Rating AAA Average Duration 5.0 years (fixed income securities) Average Life 7.0 years Fixed Income Securities $3,666.7 Short-term Investments 783.7 Other Investments 159.9 Equity Securities 62.0 Total Invested Assets $4,672.3 See Notice About This Presentation INVESTED ASSETS December 31, 2
Slide 29: Investments Subprime/Credit Market Exposure
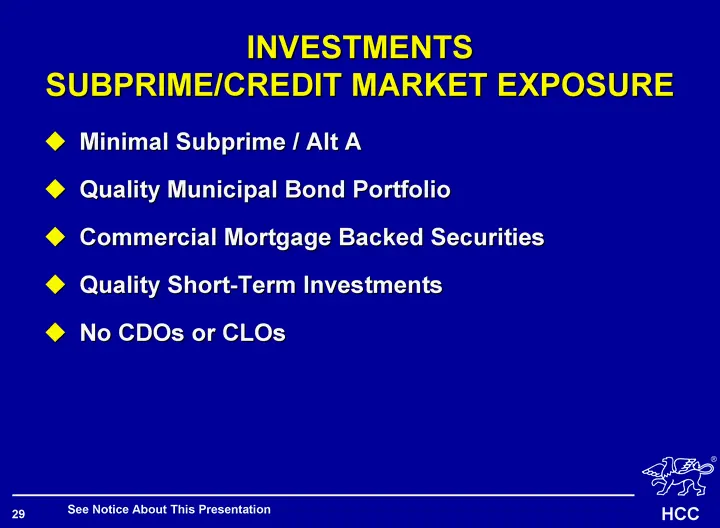
INVESTMENTS SUBPRIME/CREDIT MARKET EXPOSURE Minimal Subprime / Alt A Quality Municipal Bond Portfolio Commercial Mortgage Backed Securities Quality Short-Term Investments No CDOs or CLOs See Notice About This Presentation
Slide 30: Total Assets
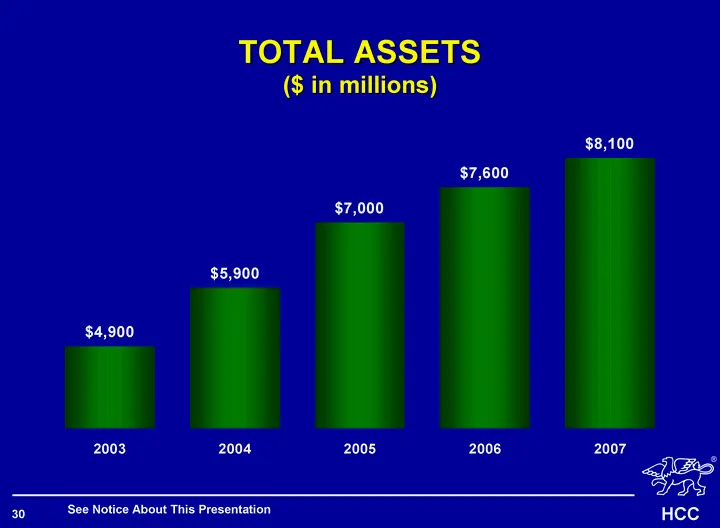
TOTAL ASSETS ($ in millions) See Notice About This Presentation 2003 2004 2005 2006 2007 Total Assets 4900 5900 7000 7600 8100
Slide 31: Shareholders' Equity
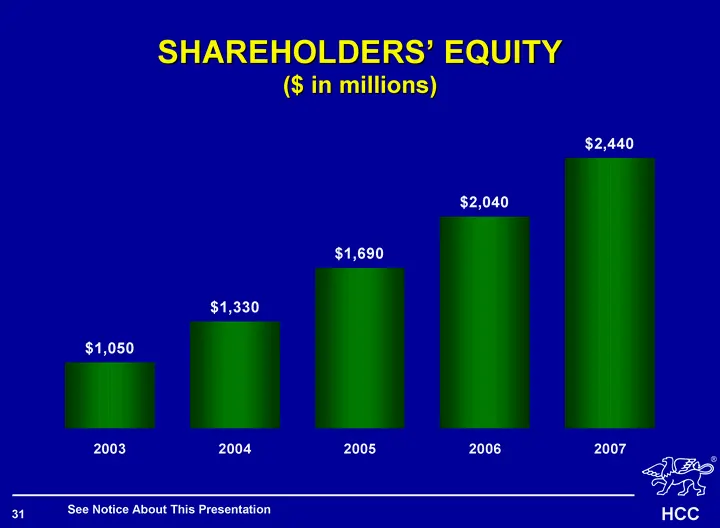
SHAREHOLDERS' EQUITY ($ in millions) See Notice About This Presentation 2003 2004 2005 2006 2007 SE 1050 1330 1690 2040 2440
Slide 32: Income Statement
INCOME STATEMENT HCC 63 (r)
Slide 33: Gross Written Premium
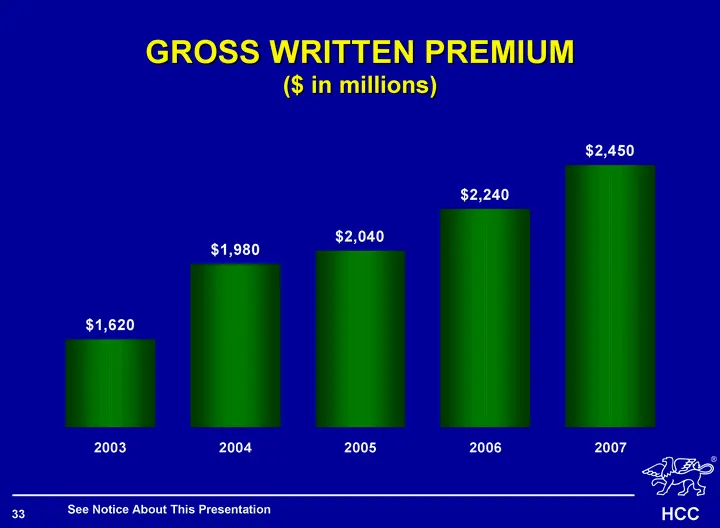
GROSS WRITTEN PREMIUM ($ in millions) 2003 2004 2005 2006 2007 GWP 1620 1980 2040 2240 2450 See Notice About This Presentation
Slide 34: Net Written Premium
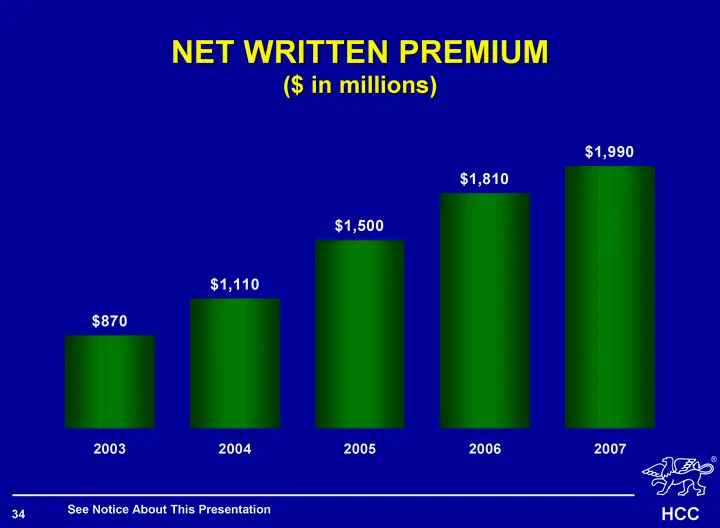
NET WRITTEN PREMIUM ($ in millions) 2003 2004 2005 2006 2007 NWP 870 1110 1500 1810 1990 See Notice About This Presentation
Slide 35: Net Earned Premium
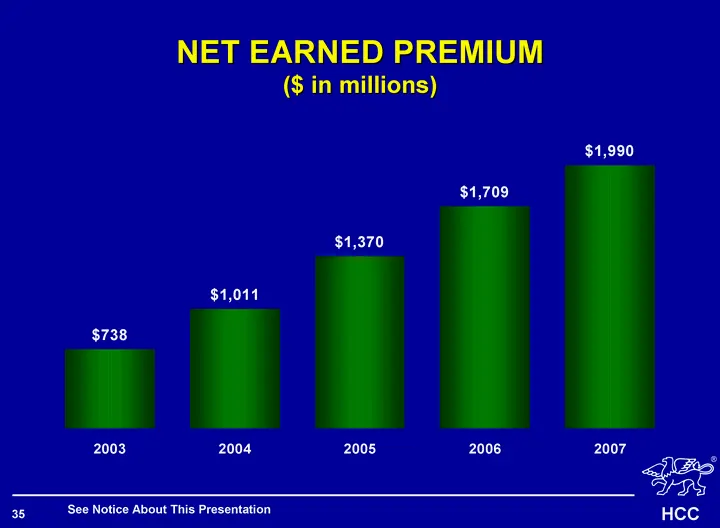
NET EARNED PREMIUM ($ in millions) 2003 2004 2005 2006 2007 NEP 738 1011 1370 1709 1990 See Notice About This Presentation
Slide 36: Fee & Commission Income
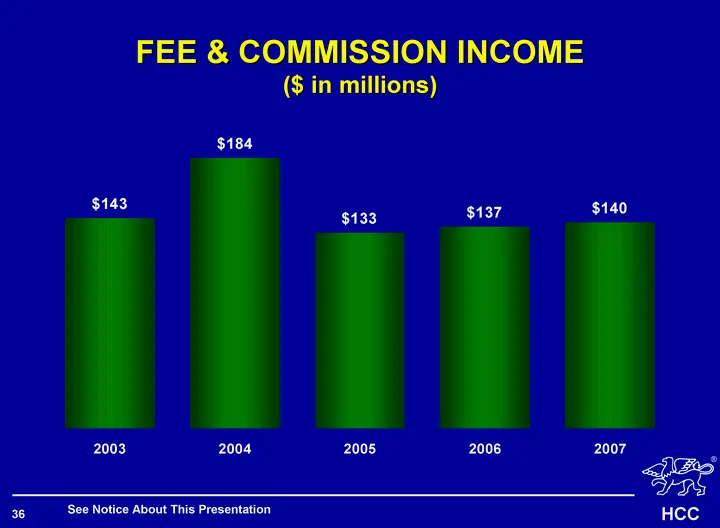
FEE & COMMISSION INCOME ($ in millions) 2003 2004 2005 2006 2007 F&C 143 184 133 137 140 See Notice About This Presentation
Slide 37: Investment Income
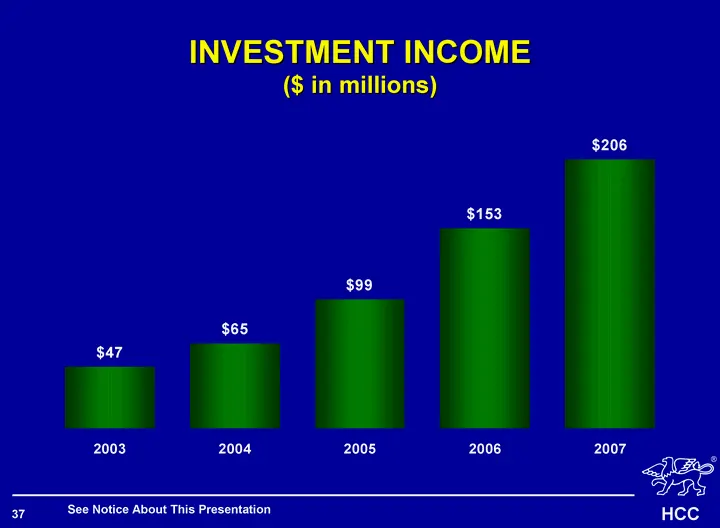
INVESTMENT INCOME ($ in millions) 2003 2004 2005 2006 2007 Investment Income 47 65 99 153 206 See Notice About This Presentation
Slide 38: Total Revenue
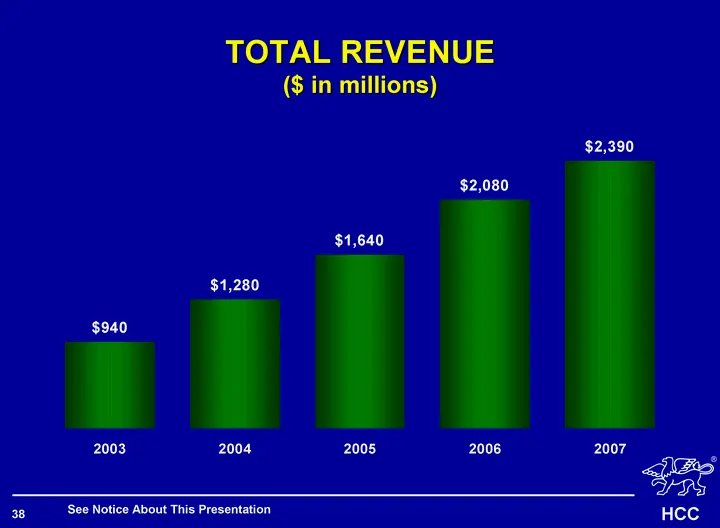
TOTAL REVENUE ($ in millions) 2003 2004 2005 2006 2007 Total Revenur 940 1280 1640 2080 2390 See Notice About This Presentation
Slide 39: Net Earnings
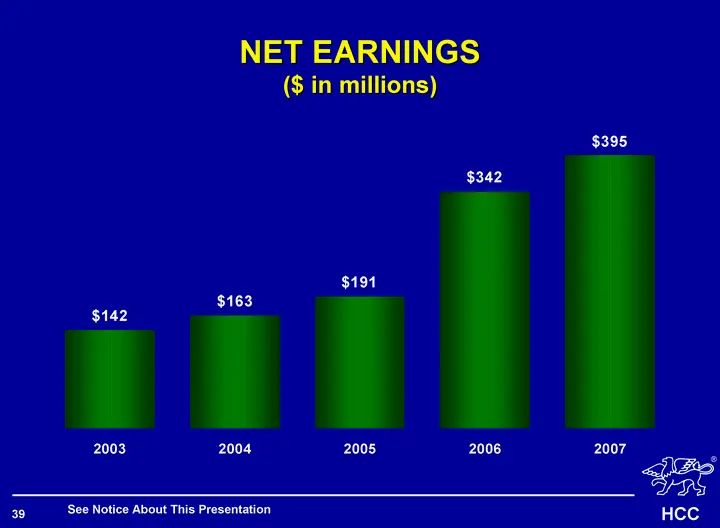
NET EARNINGS ($ in millions) 2003 2004 2005 2006 2007 Net Earnings 142 163 191 342 395 See Notice About This Presentation
Slide 40: Net Earnings per Diluted Share
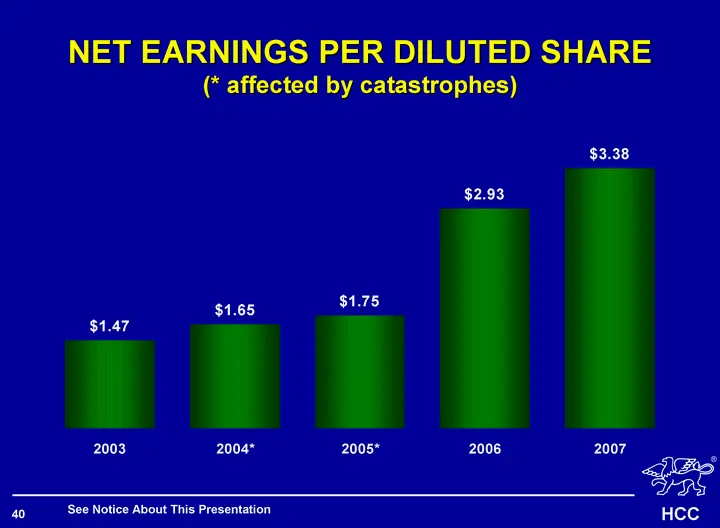
NET EARNINGS PER DILUTED SHARE (* affected by catastrophes) 2003 2004* 2005* 2006 2007 Net Earnings per diluted share 1.47 1.65 1.75 2.93 3.38 See Notice About This Presentation
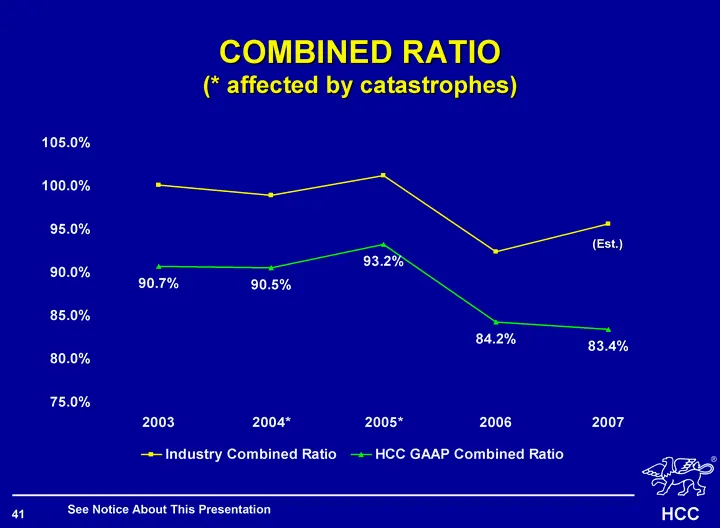
Slide 41: Combined Ratio
2003 2004* 2005* 2006 2007 Peer Group Average** 0.959 0.934 0.91 0.844 0.841 Industry Combined Ratio 1.001 0.989 1.012 0.924 0.956 HCC GAAP Combined Ratio 0.907 0.905 0.932 0.842 0.834 COMBINED RATIO (* affected by catastrophes) See Notice About This Presentation (Est.)
Slide 42: Summary
SUMMARY HCC 83 (r)
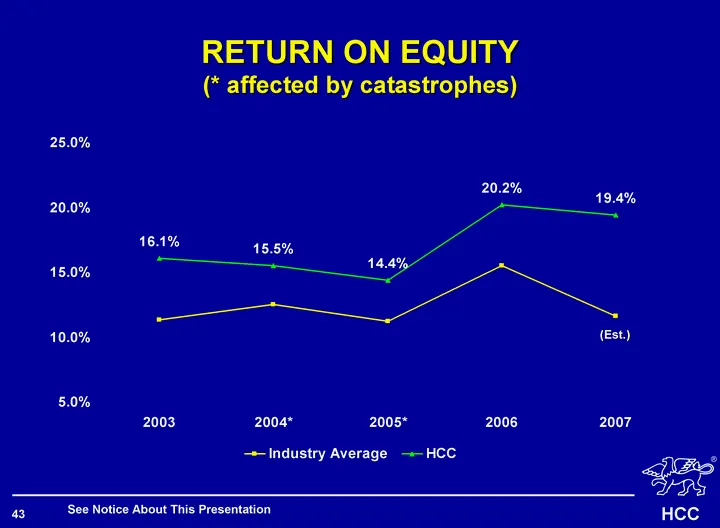
Slide 43: Return on Equity
2003 2004* 2005* 2006 2007 Industry Average 0.113 0.125 0.112 0.155 0.116 HCC Average 0.171 0.171 0.171 0.171 0.171 HCC 0.161 0.155 0.144 0.202 0.194 See Notice About This Presentation RETURN ON EQUITY (* affected by catastrophes) (Est.)
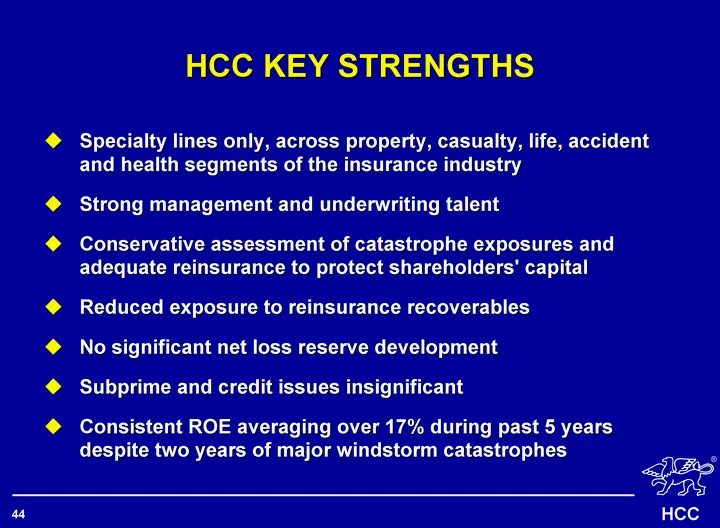
Slide 44: HCC Key Strengths
HCC KEY STRENGTHS Specialty lines only, across property, casualty, life, accident and health segments of the insurance industry Strong management and underwriting talent Conservative assessment of catastrophe exposures and adequate reinsurance to protect shareholders' capital Reduced exposure to rei
Slide 45: About Forward-Looking Statements
ABOUT FORWARD-LOOKING STATEMENTS: This presentation contains certain "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933, and Section 21E of the Securities Exchange Act of 1934, which are intended to be covered by the safe harbors created by those laws. These
Slide 46
Source: SEC EDGAR · 8-K filed Mar 19, 2008
More decks from HCC Insurance Holdings Inc
 Q2 2015 Earnings Presentation31 slides · Aug 14, 2015
 Merger or Acquisition (June 2015)22 slides · Jun 23, 2015
 Merger or Acquisition (June 2015)10 slides · Jun 10, 2015
 Merger or Acquisition (June 2015)30 slides · Jun 10, 2015
 Q1 2015 Earnings Presentation35 slides · May 21, 2015
 36th Annual Raymond James Institutional Investors Conference (February 2015)36 slides · Feb 27, 2015