AGL Resources — Calyon Securities Utility & Energy Merchant Conference 2005
19 slides from AGL Resources's conference presentation, Dec 1, 2005
Slide 1: Delivering On Our Long-Term Value Proposition
Exhibit 99.1 Delivering On Our Long-Term Value Proposition Kevin P. Madden Executive Vice President, External Affairs Andrew W. Evans Senior Vice President and Chief Financial Officer Calyon Securities Utility & Energy Merchant Conference New York, NY December 1, 2005 Ó A
Slide 2: Important Note to Investors: Forward Looking Statements
Important Note to Investors Forward Looking Statements Statements in this presentation that are not historical facts, including statements regarding our estimates, beliefs, expectations, intentions, strategies or projections, may be “forward-looking statements” as defined in the Private Securities L
Slide 3: Important Note to Investors: Non-GAAP Measures
Important Note to Investors Non-GAAP Measures Company management evaluates segment financial performance based on earnings before interest and taxes (EBIT), which includes the effects of corporate expense allocations. EBIT is a non-GAAP (accounting principles generally accepted in the United States
Slide 4: Who We Are
Who We Are … • Largest natural gas distribution company in Southeast and Mid-Atlantic based on number of customers • Market capitalization of $2.7 billion • $6.1 billion in assets • Primarily a regulated business; focused on gas only • Strategic niche player in non-utility businesses: asset manageme
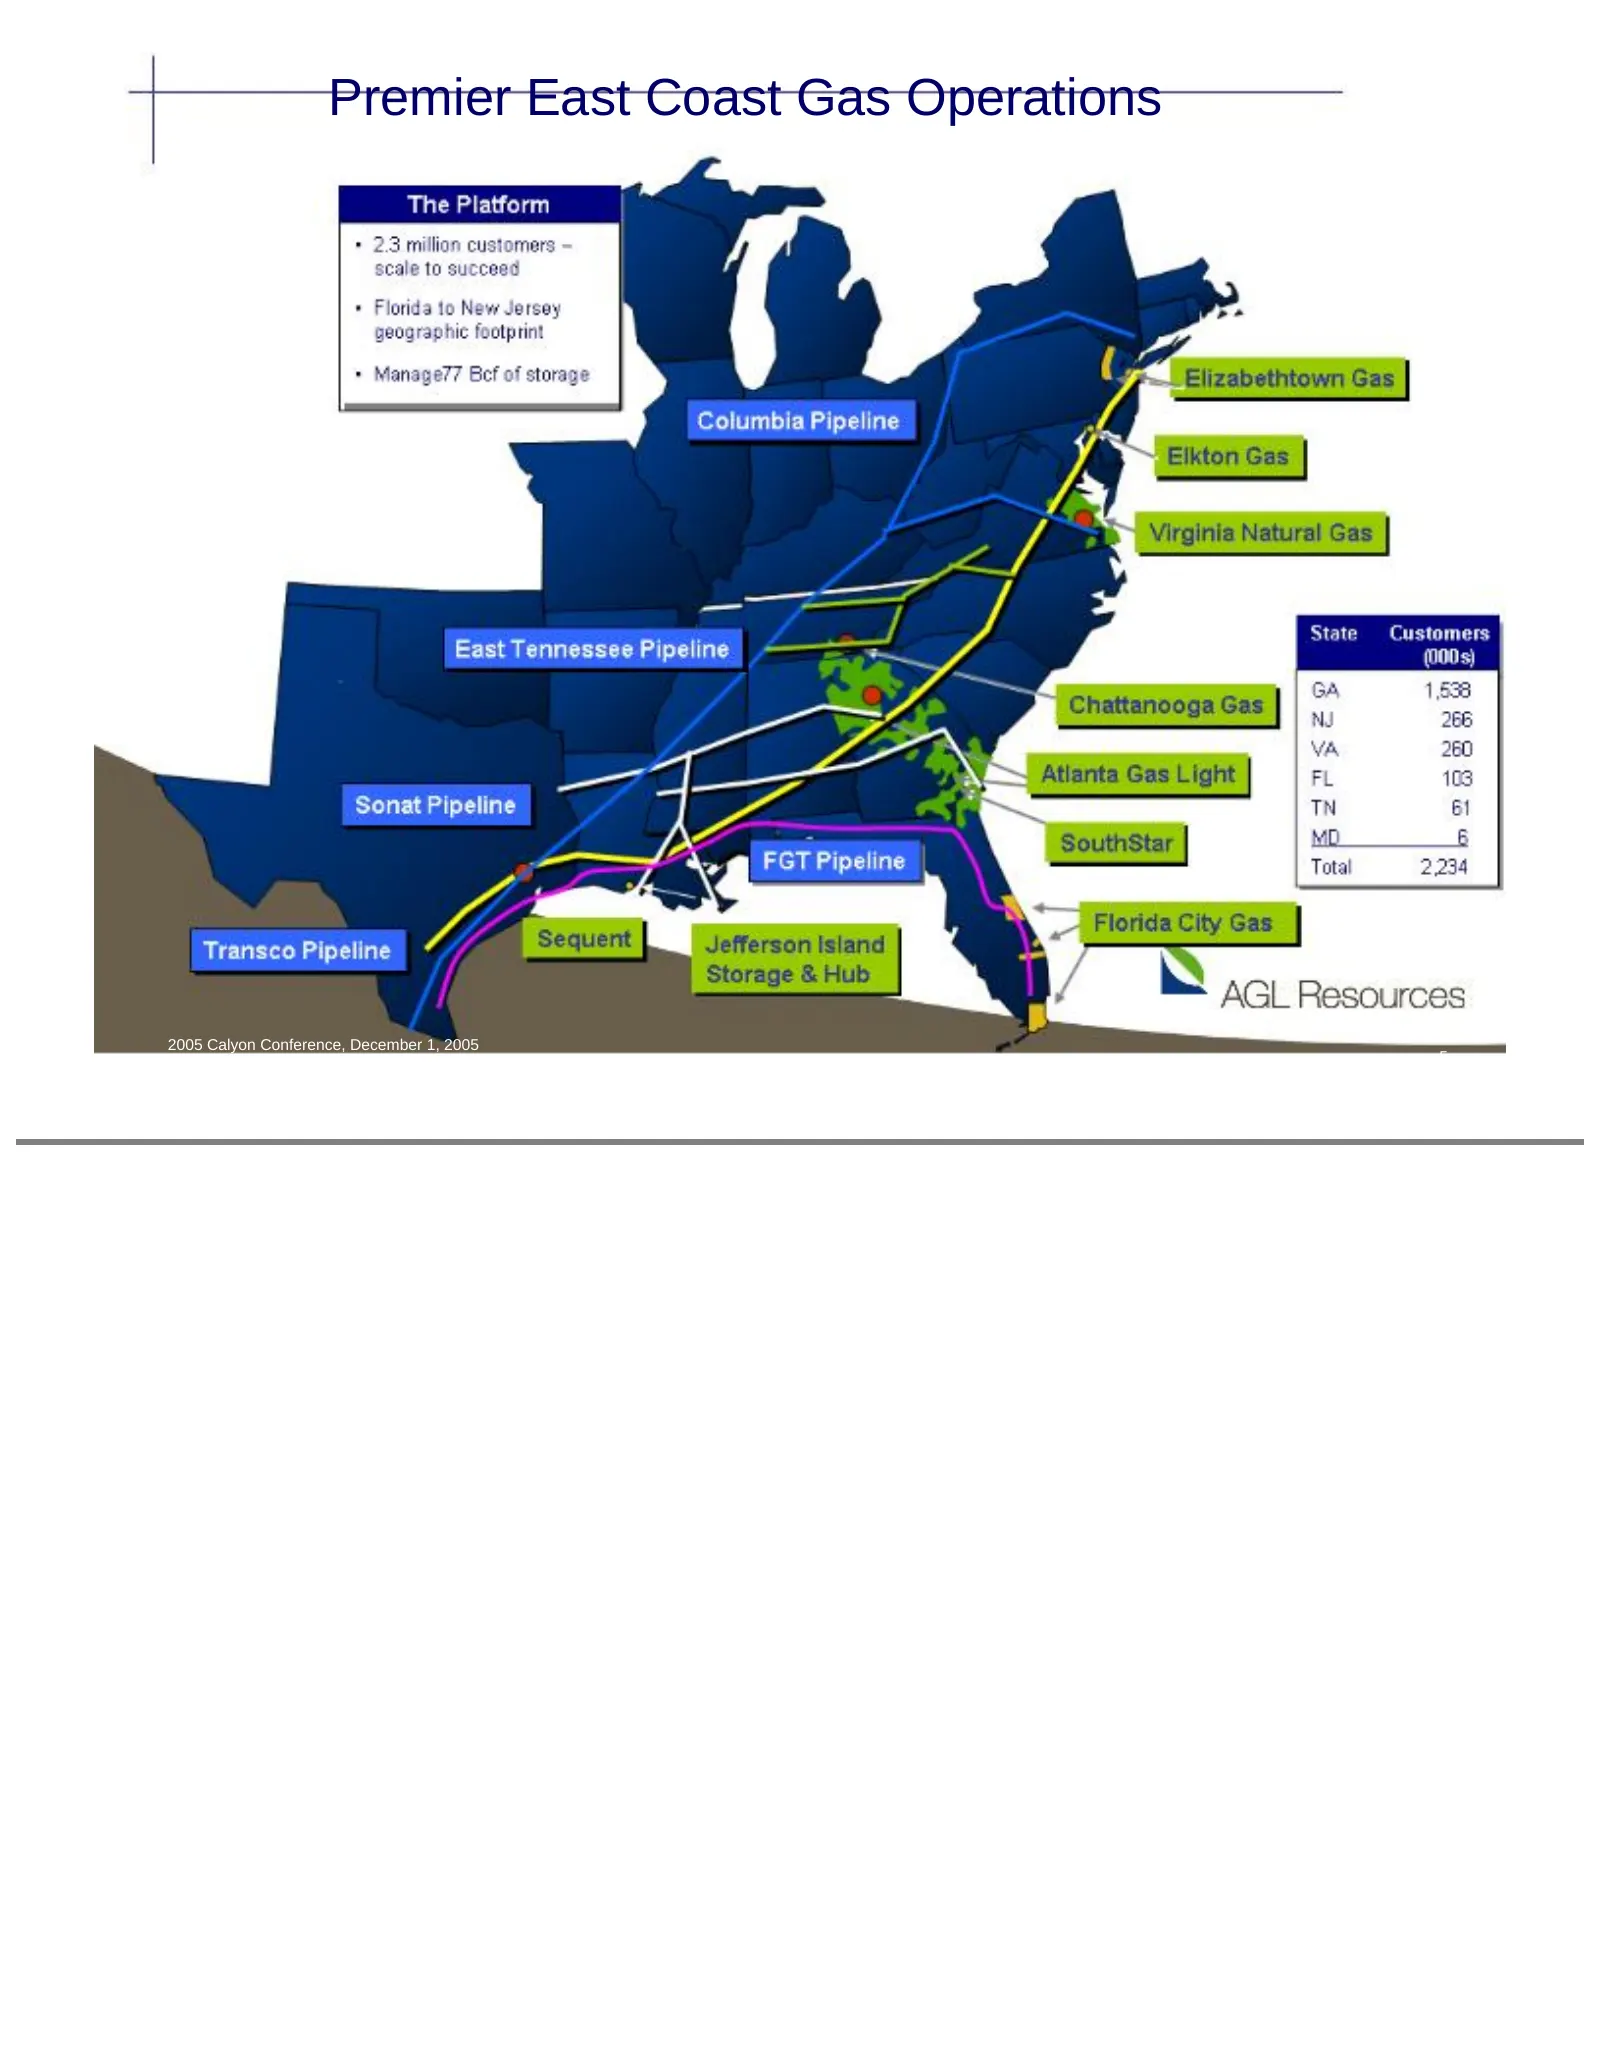
Slide 5: Premier East Coast Gas Operations
Premier East Coast Gas Operations 2005 Calyon Conference, December 1, 2005 5
Slide 6: Regulatory Compact Fosters Annuity-Like Earnings
Regulatory Compact Fosters Annuity-Like Earnings • Stay-outs in Georgia (5 years) and New Jersey (5-year rate freeze with 75% sharing in years 4 and 5) • Straight fixed variable rates in Georgia • Pipeline replacement program (PRP) in Georgia; applied for in New Jersey • Weather normalization progra
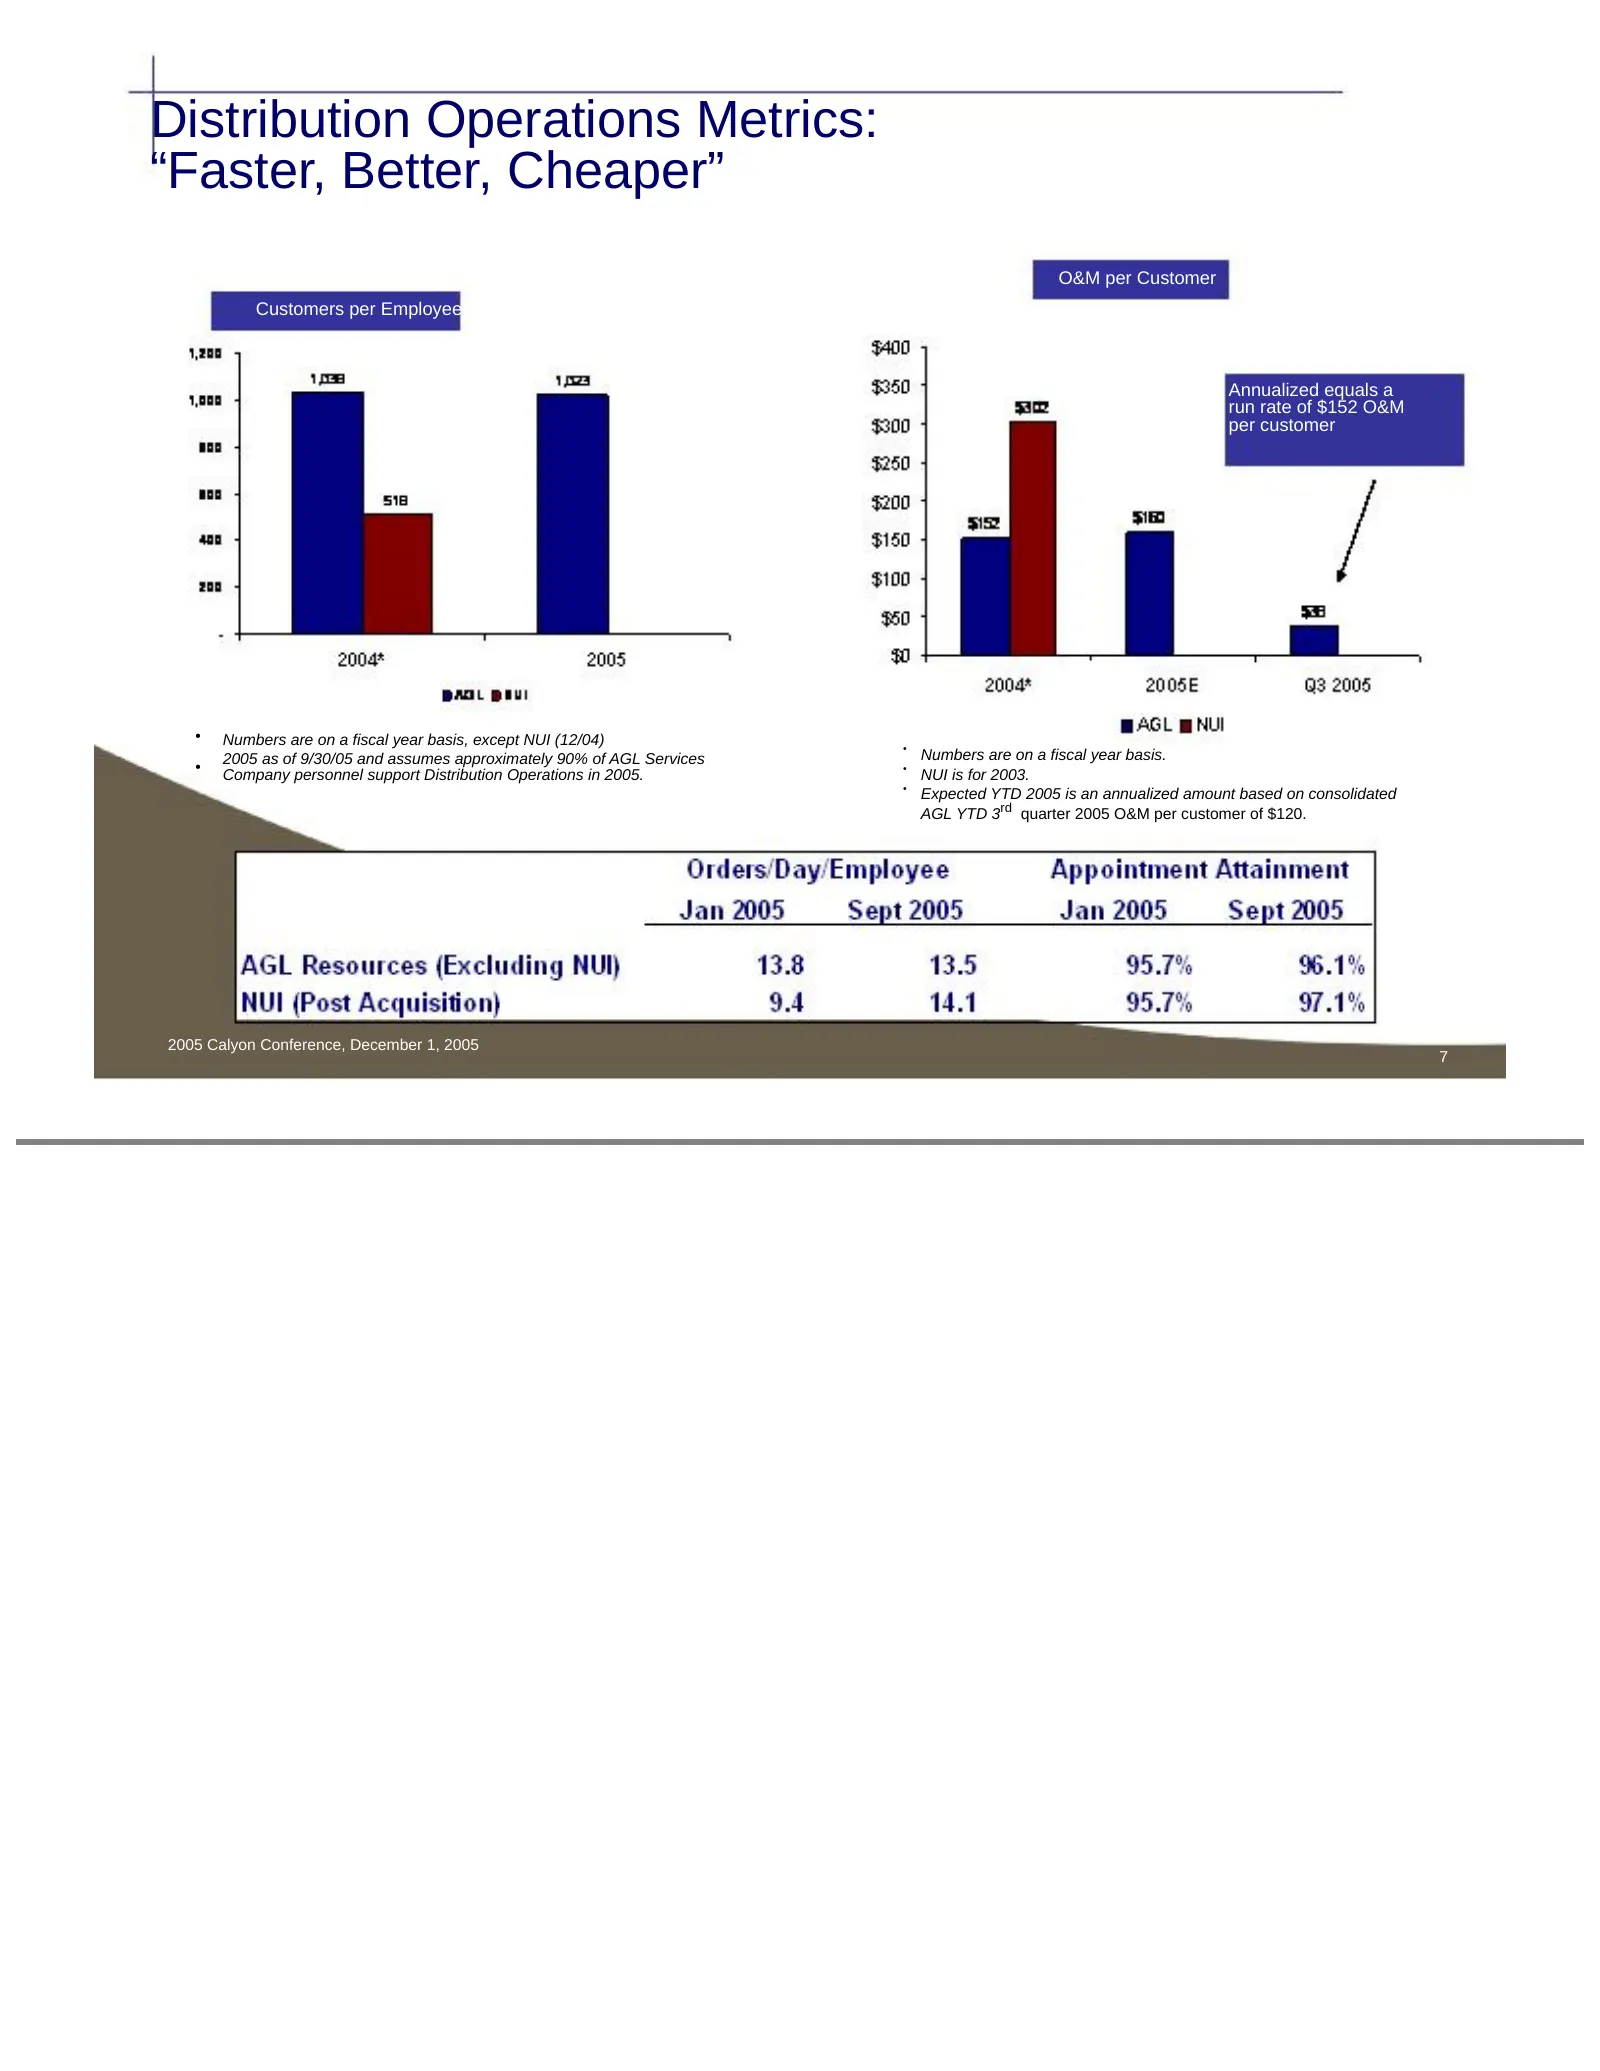
Slide 7: Distribution Operations Metrics: Faster, Better, Cheaper
Distribution Operations Metrics: “Faster, Better, Cheaper” O&M per Customer Customers per Employee Annualized equals a run rate of $152 O&M per customer • Numbers are on a fiscal year basis, except NUI (12/04) • 2005 as of 9/30/05 and assumes approximately 90% of AGL Services Numbers are on a fiscal
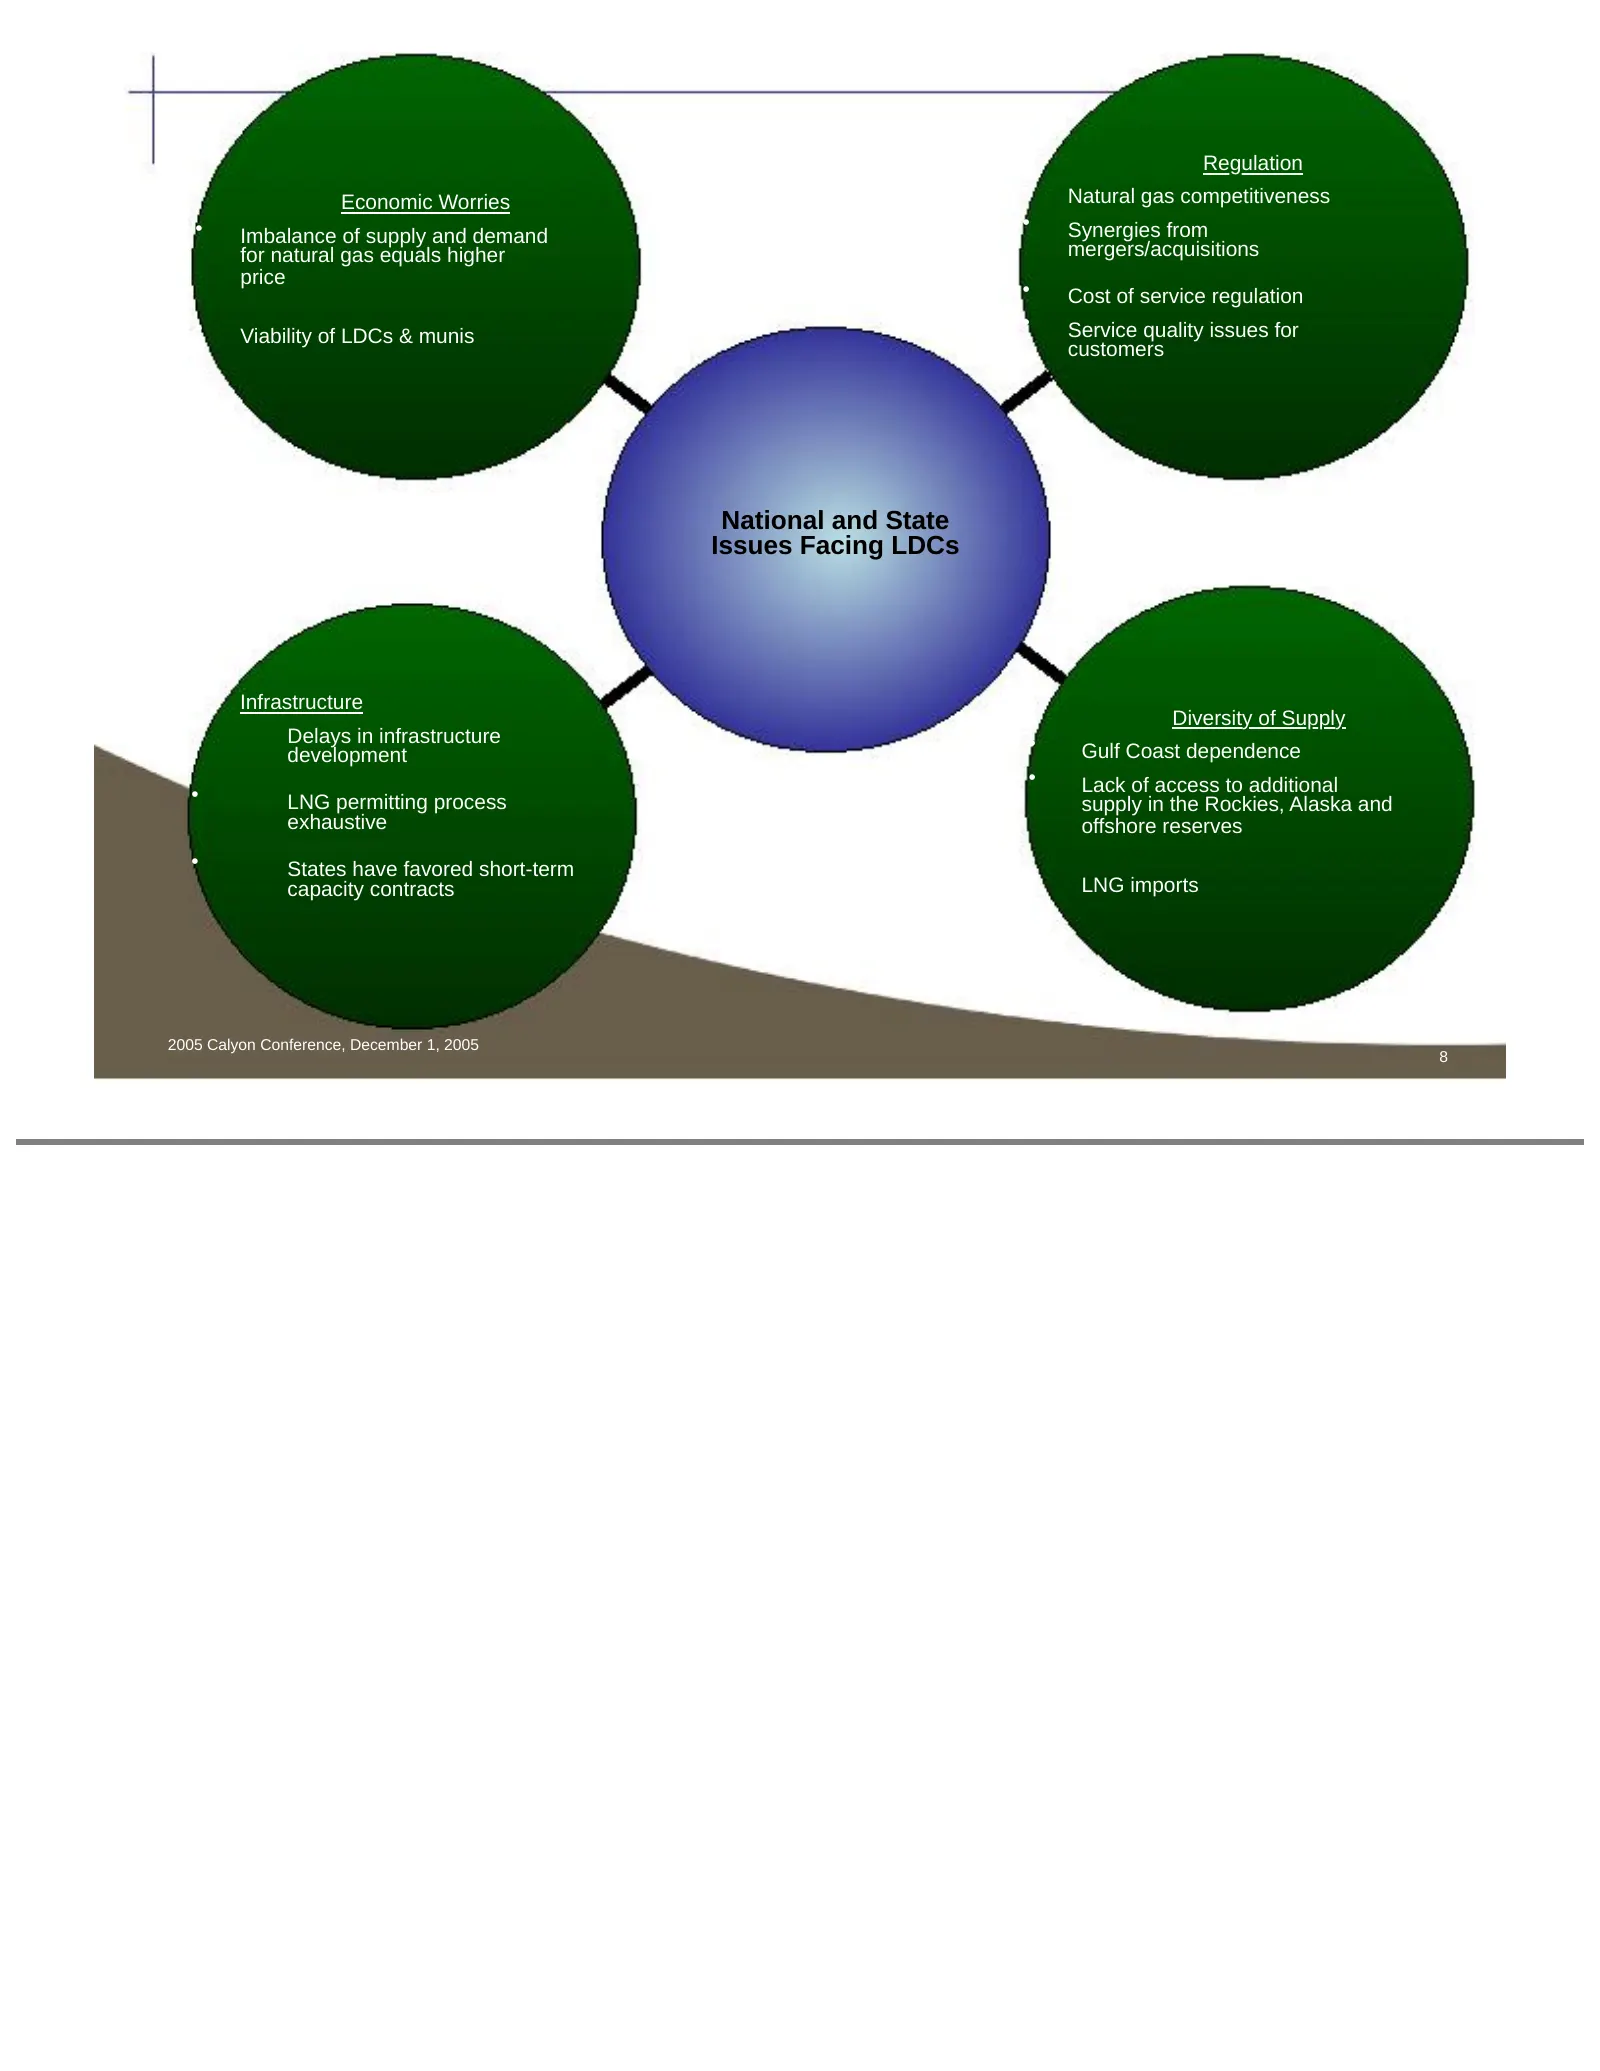
Slide 8: National and State Issues Facing LDCs
Regulation • Natural gas competitiveness Economic Worries • • Synergies from Imbalance of supply and demand for natural gas equals higher mergers/acquisitions price • Cost of service regulation • • Service quality issues for Viability of LDCs & munis customers National and State Issues Facing LDCs I
Slide 9: AGL Resources' Solutions
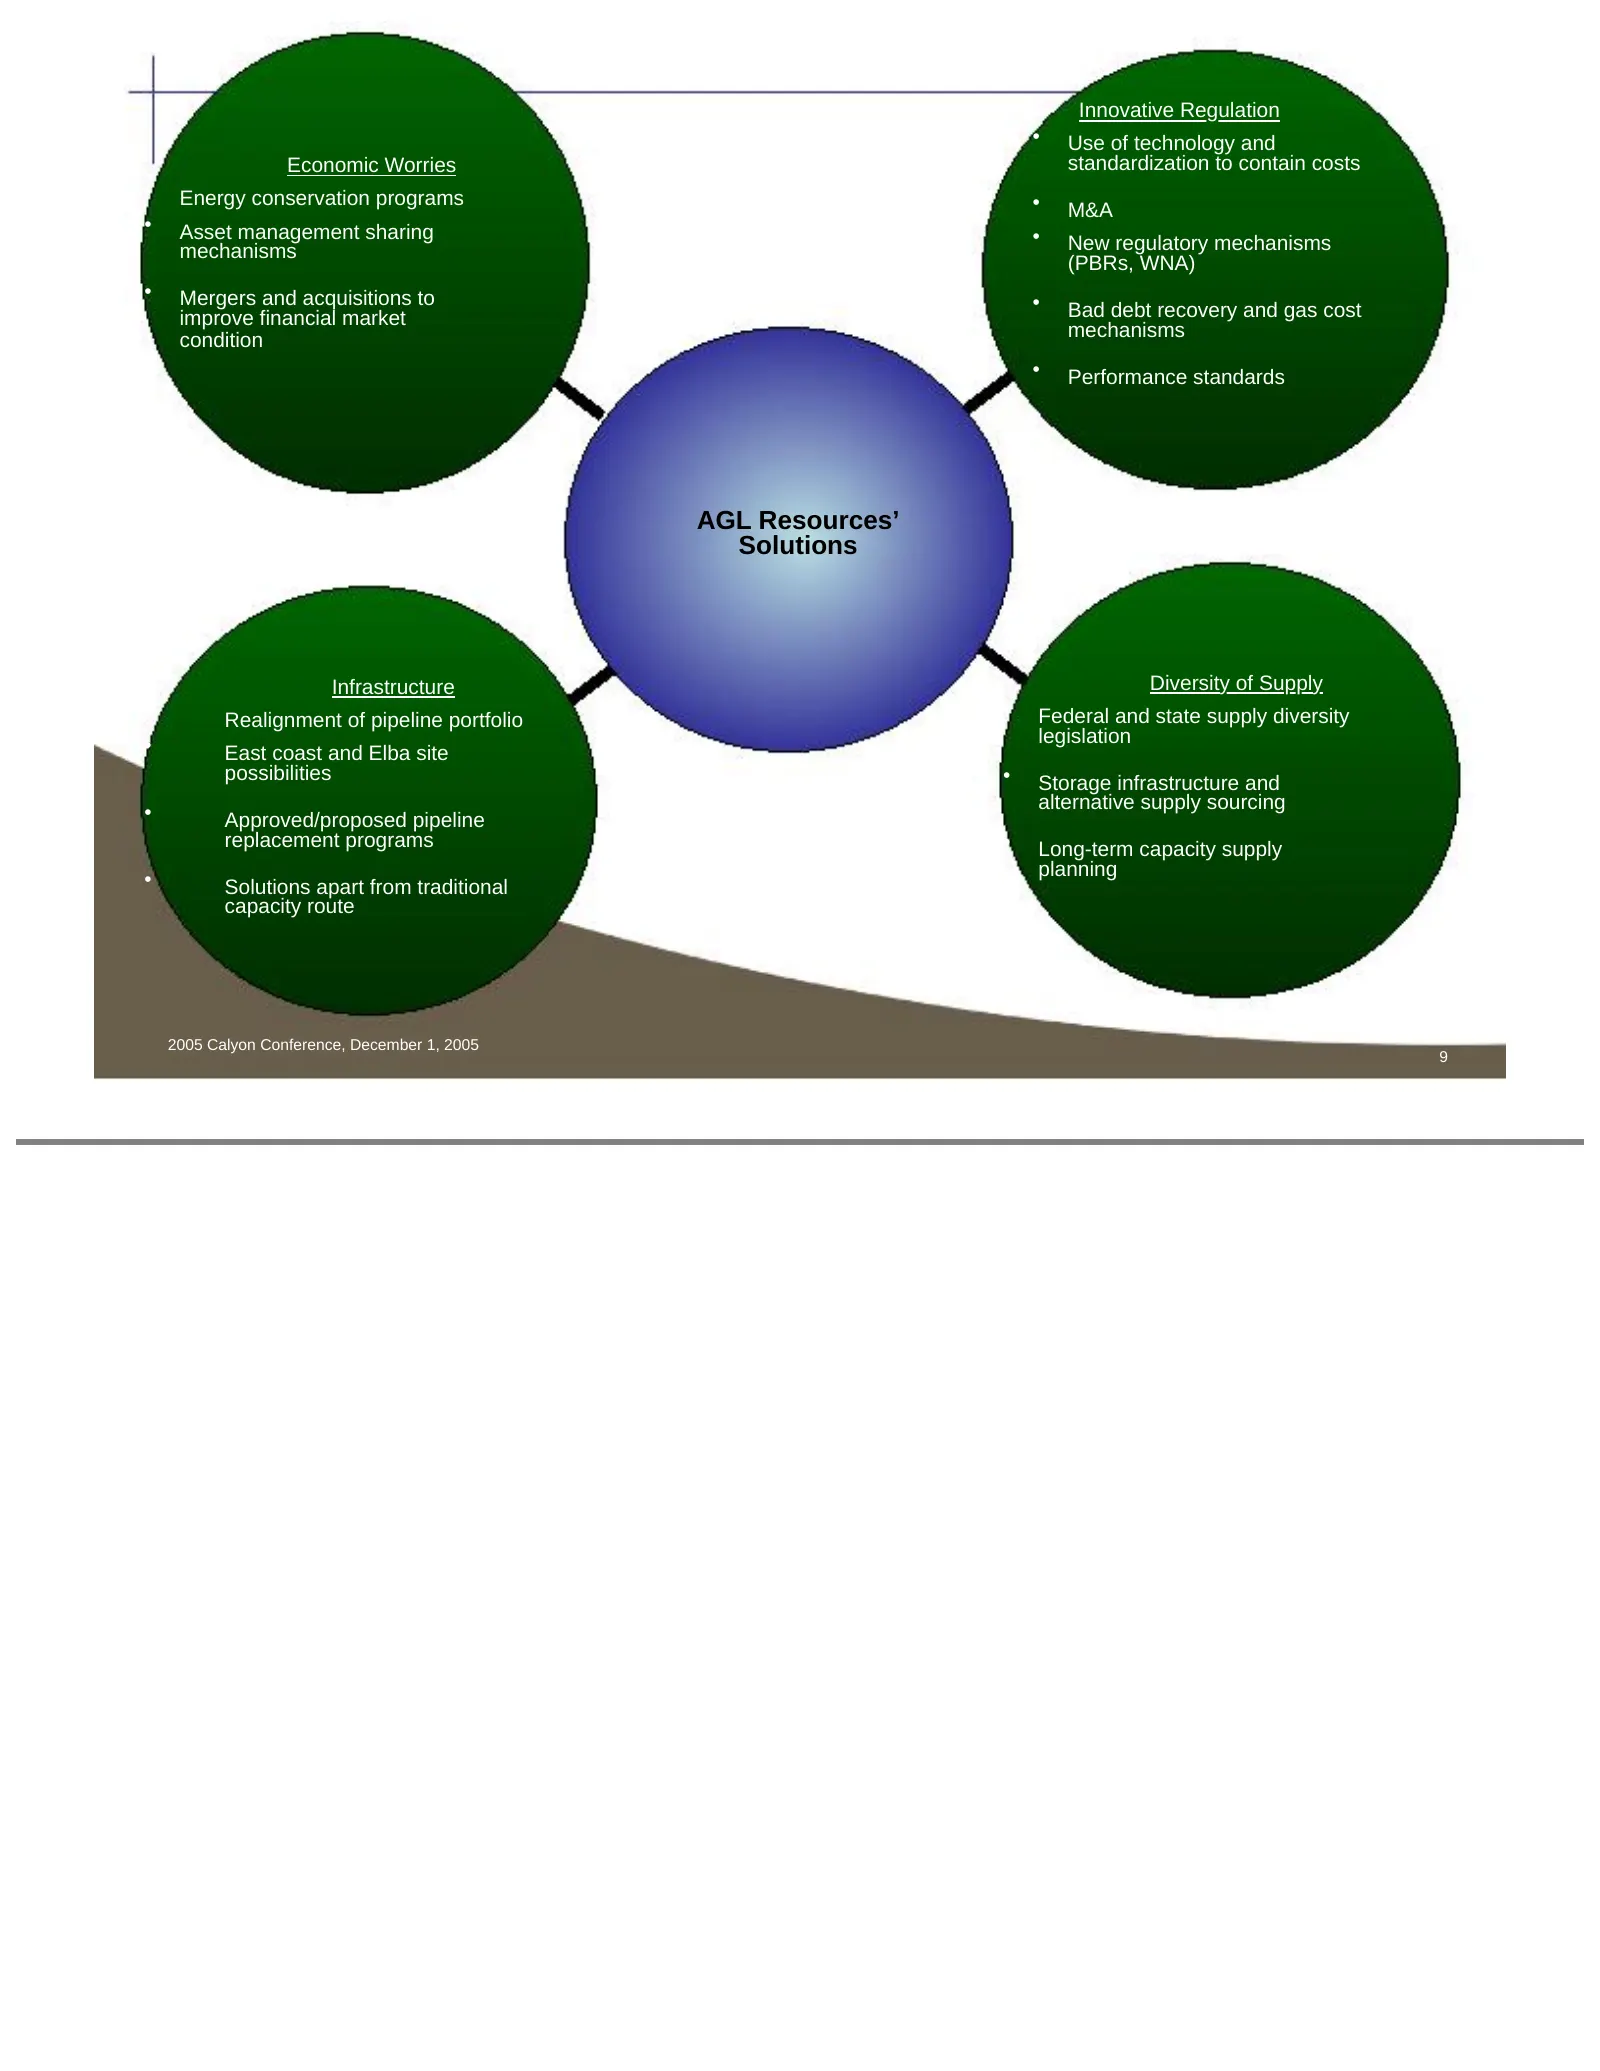
Innovative Regulation • Use of technology and Economic Worries standardization to contain costs • Energy conservation programs • M&A • Asset management sharing • New regulatory mechanisms mechanisms (PBRs, WNA) • Mergers and acquisitions to • Bad debt recovery and gas cost improve financial market c
Slide 10: Delivering On Our Long-Term Value Proposition
Delivering On Our Long-Term Value Proposition Andrew W. Evans Senior Vice President and Chief Financial Officer Calyon Securities Utility & Energy Merchant Conference New York, NY December 1, 2005 Ó A
Slide 11: SouthStar Energy Services (SSE)
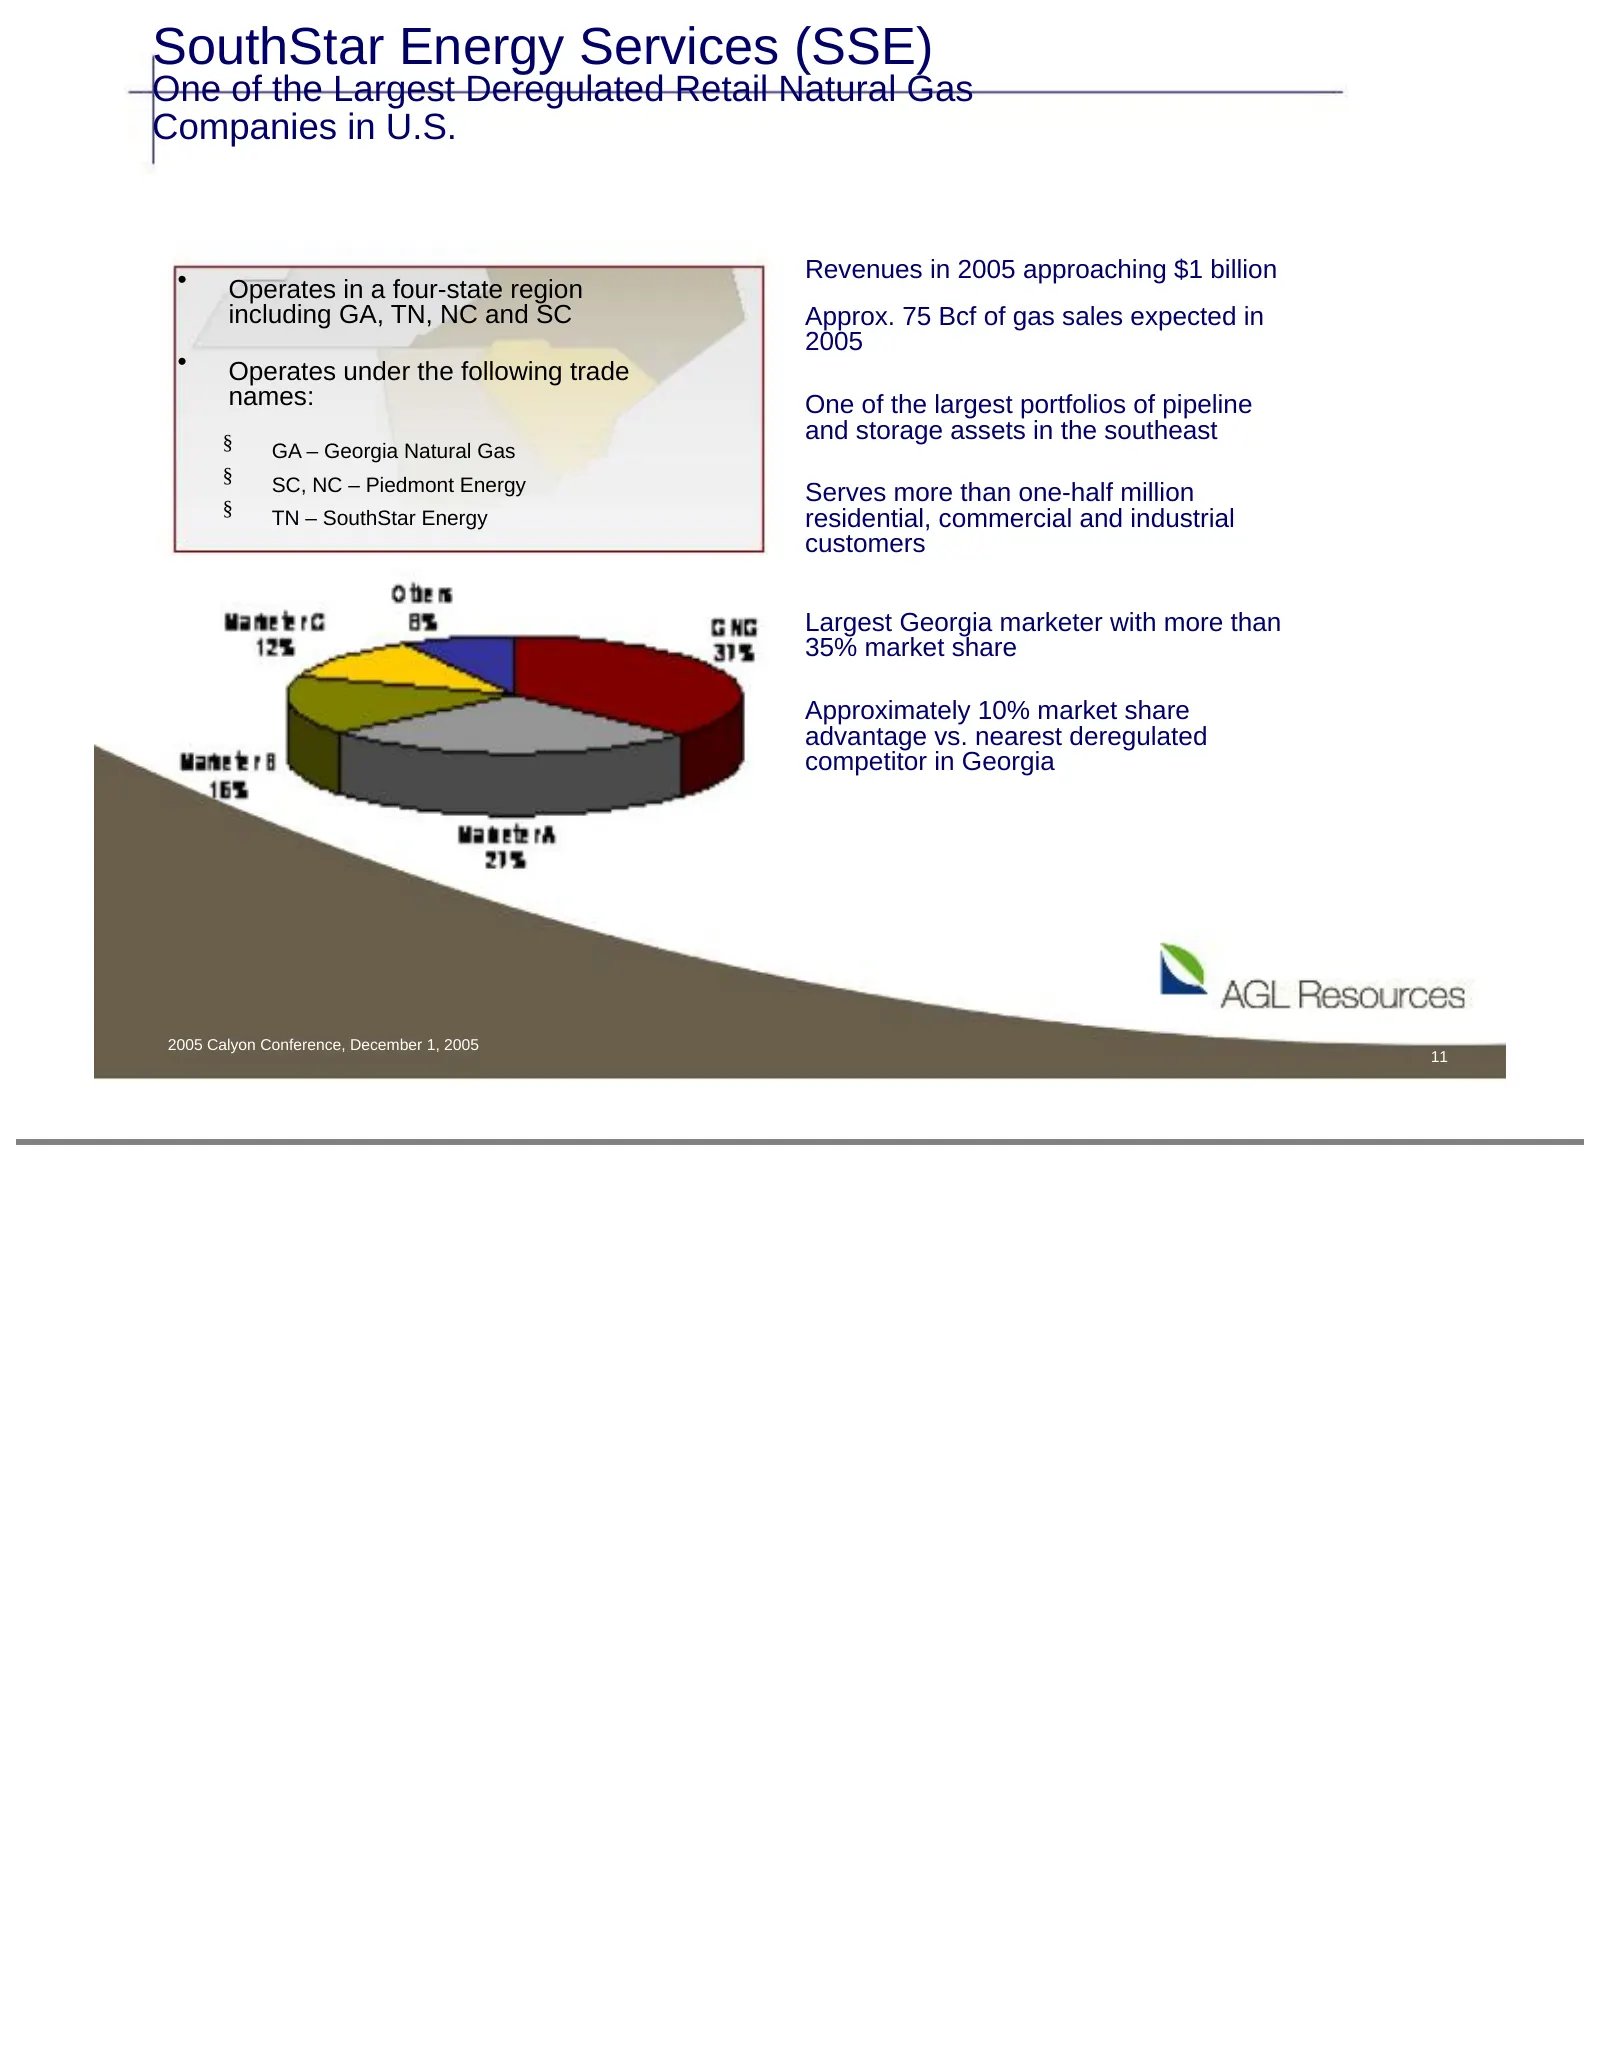
SouthStar Energy Services (SSE) One of the Largest Deregulated Retail Natural Gas Companies in U.S. • Revenues in 2005 approaching $1 billion Operates in a four-state region including GA, TN, NC and SC Approx. 75 Bcf of gas sales expected in 2005 • Operates under the following trade names: One of th
Slide 12: Sequent Energy Management
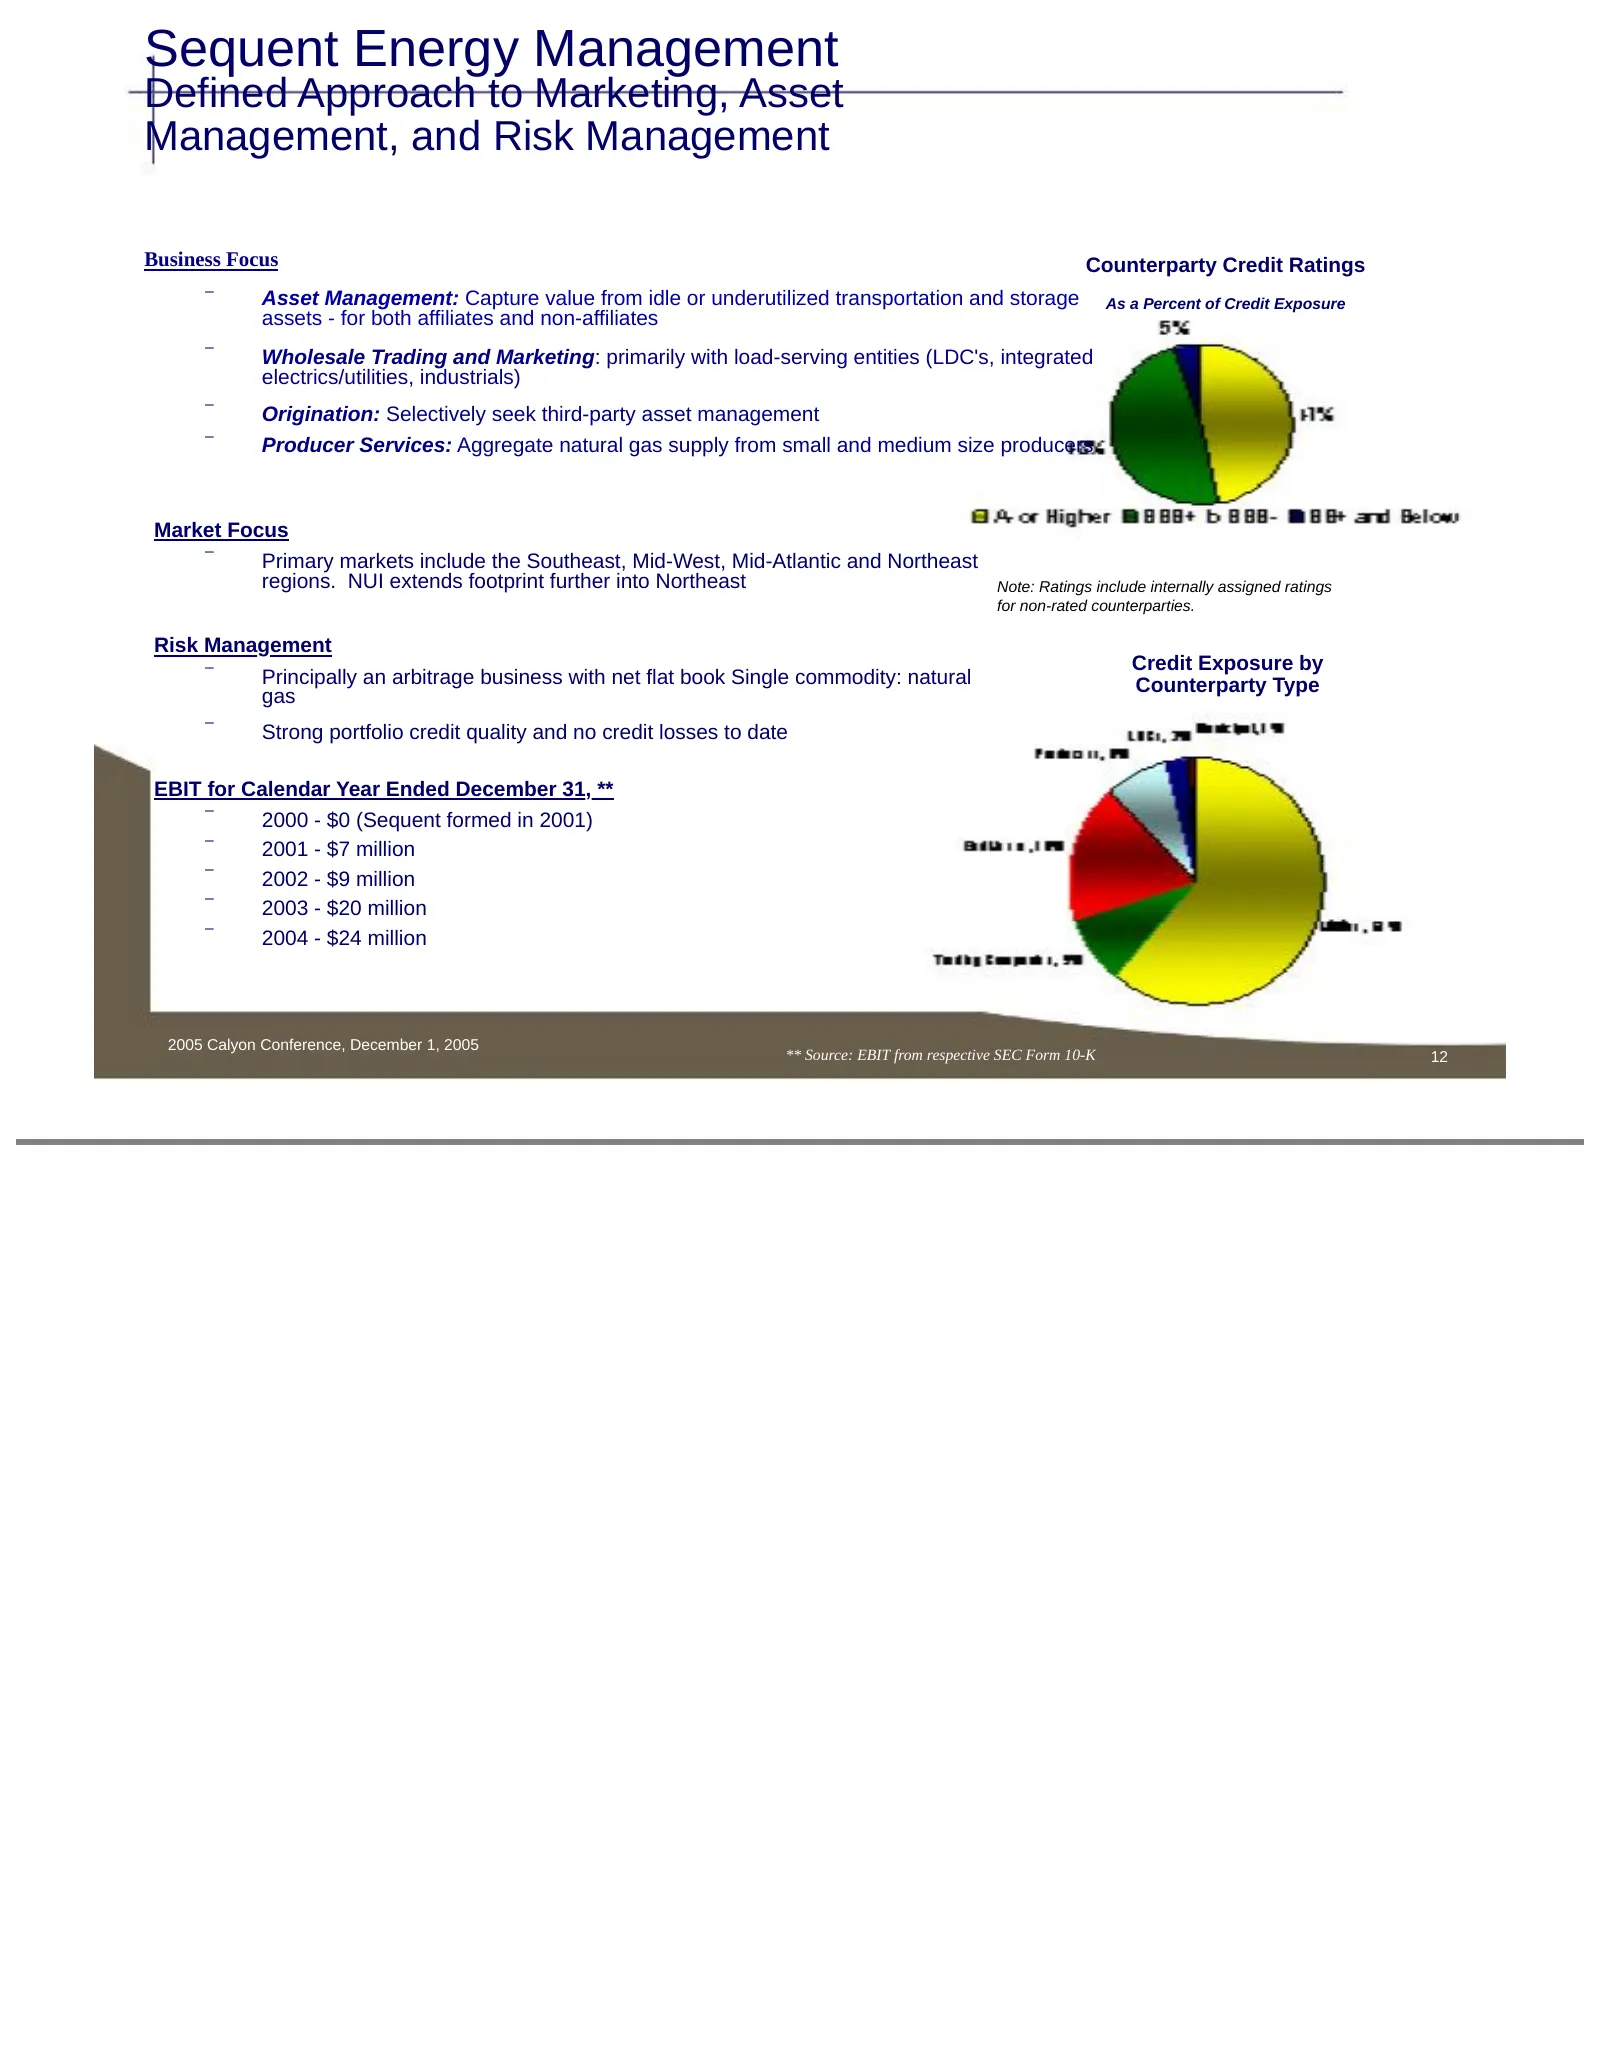
Sequent Energy Management Defined Approach to Marketing, Asset Management, and Risk Management Business Focus Counterparty Credit Ratings – Asset Management: Capture value from idle or underutilized transportation and storage As a Percent of Credit Exposure assets - for both affiliates and non-affil
Slide 13: Strategic Energy Investments
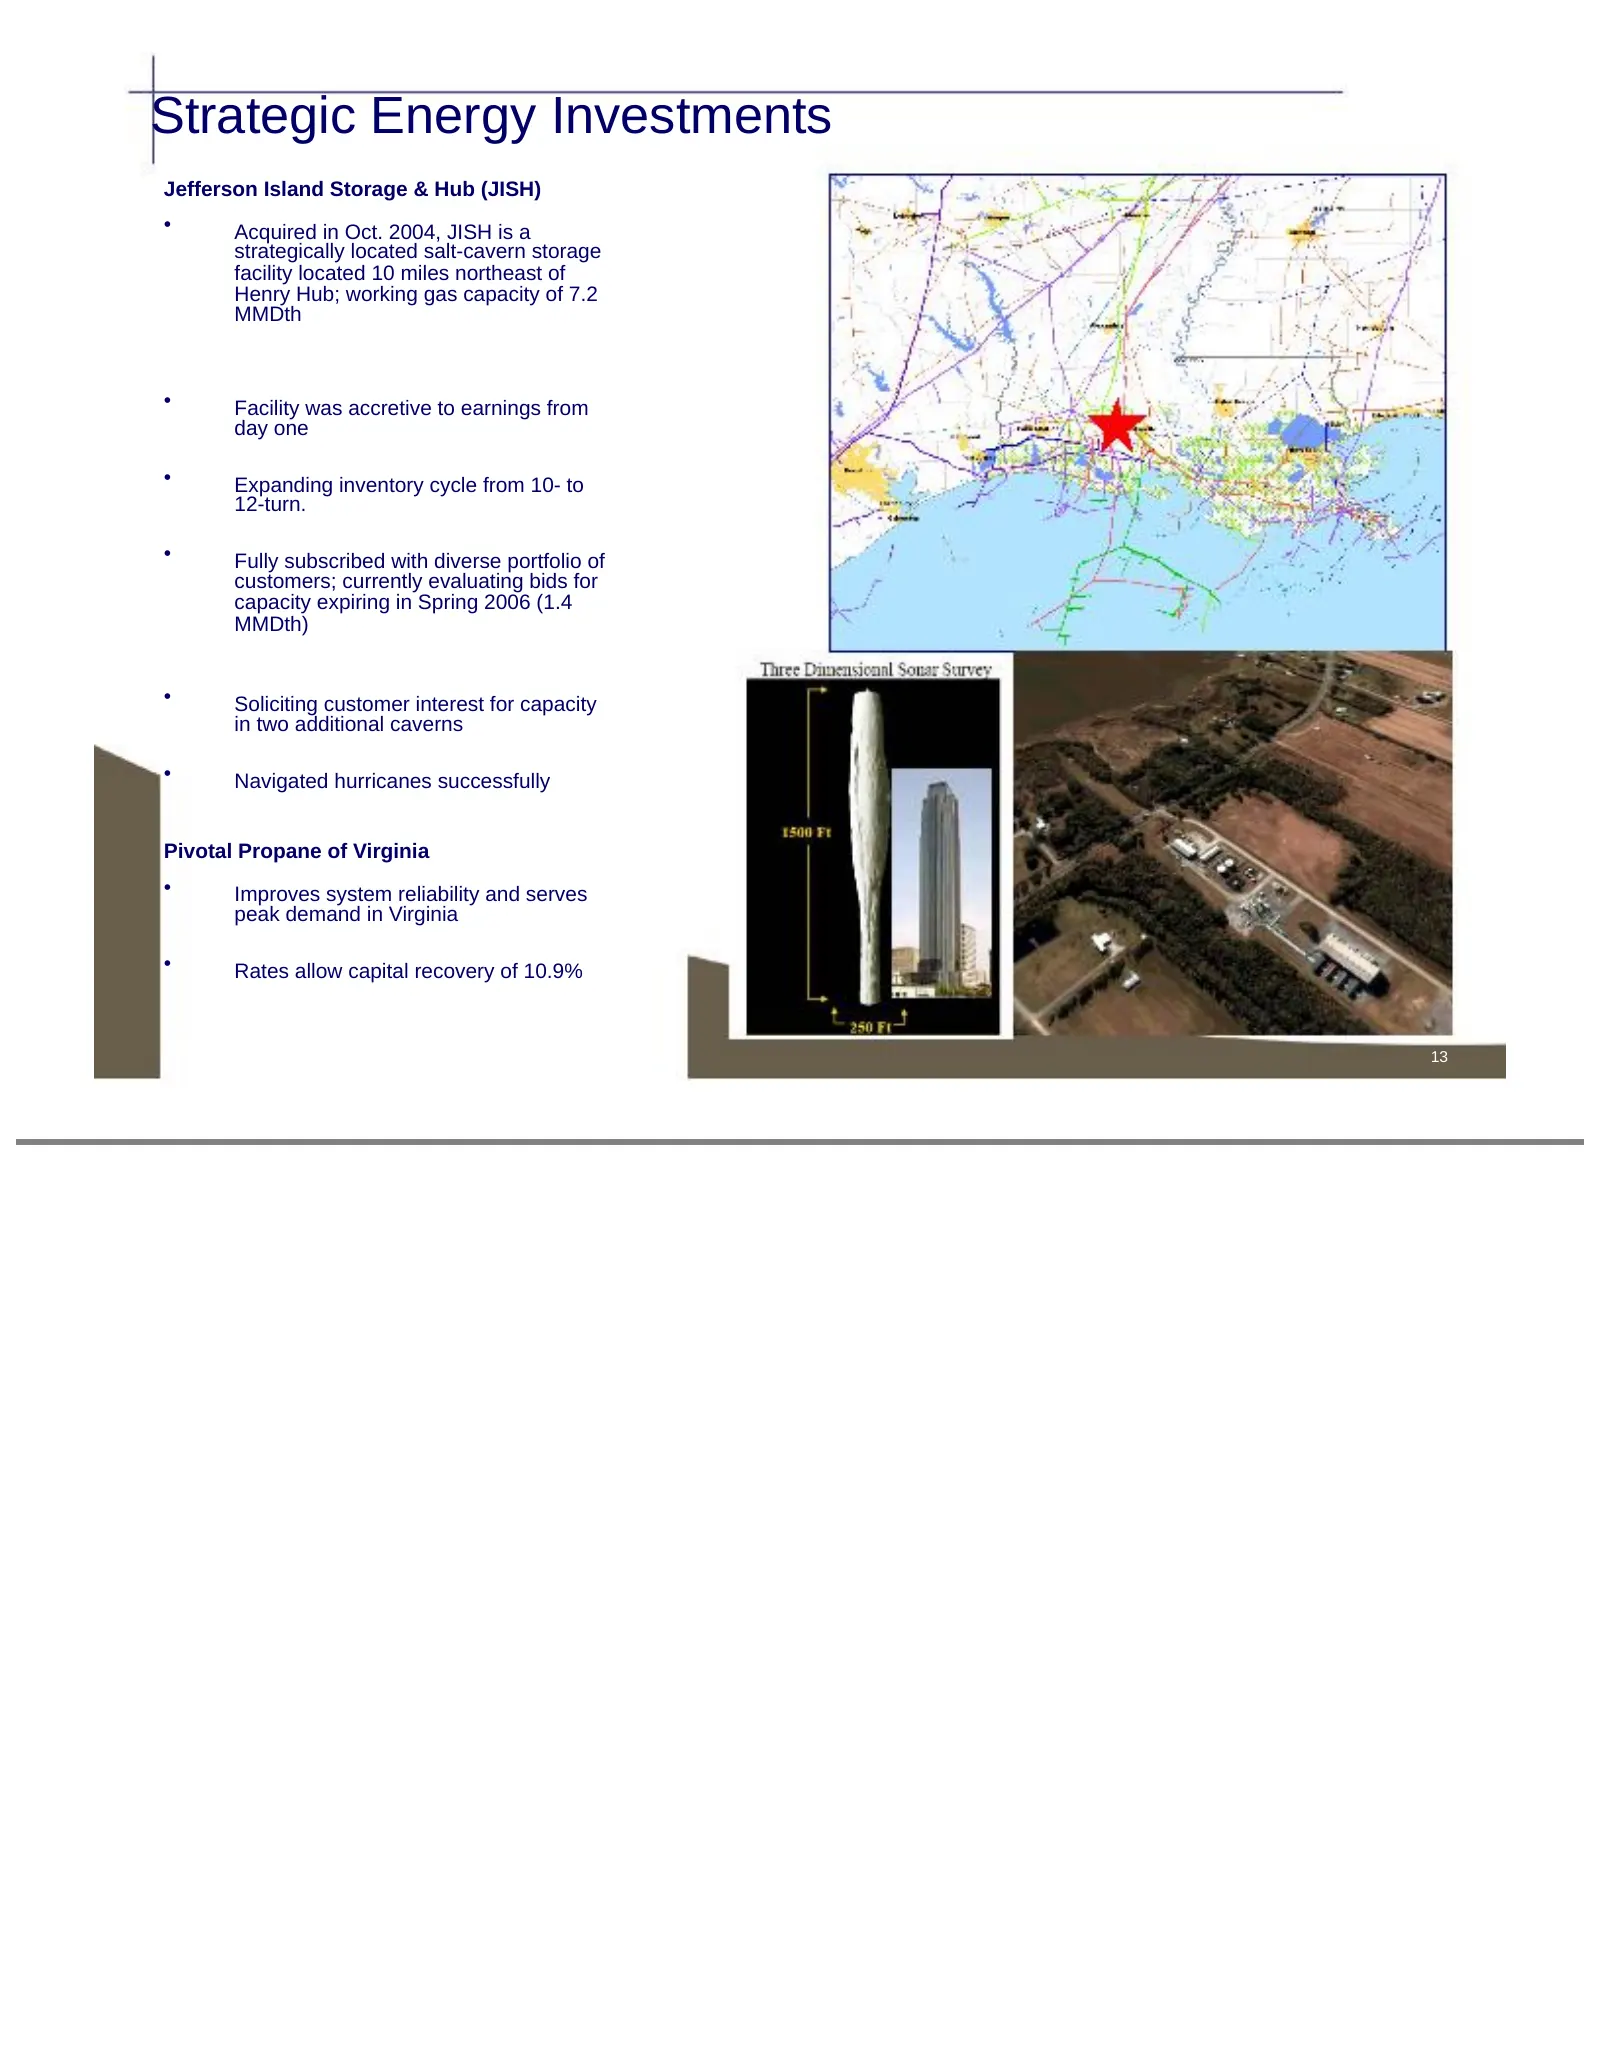
Strategic Energy Investments Jefferson Island Storage & Hub (JISH) • Acquired in Oct. 2004, JISH is a strategically located salt-cavern storage facility located 10 miles northeast of Henry Hub; working gas capacity of 7.2 MMDth • Facility was accretive to earnings from day one • Expanding inventory
Slide 14: Strong Regulated Asset Base and Earnings
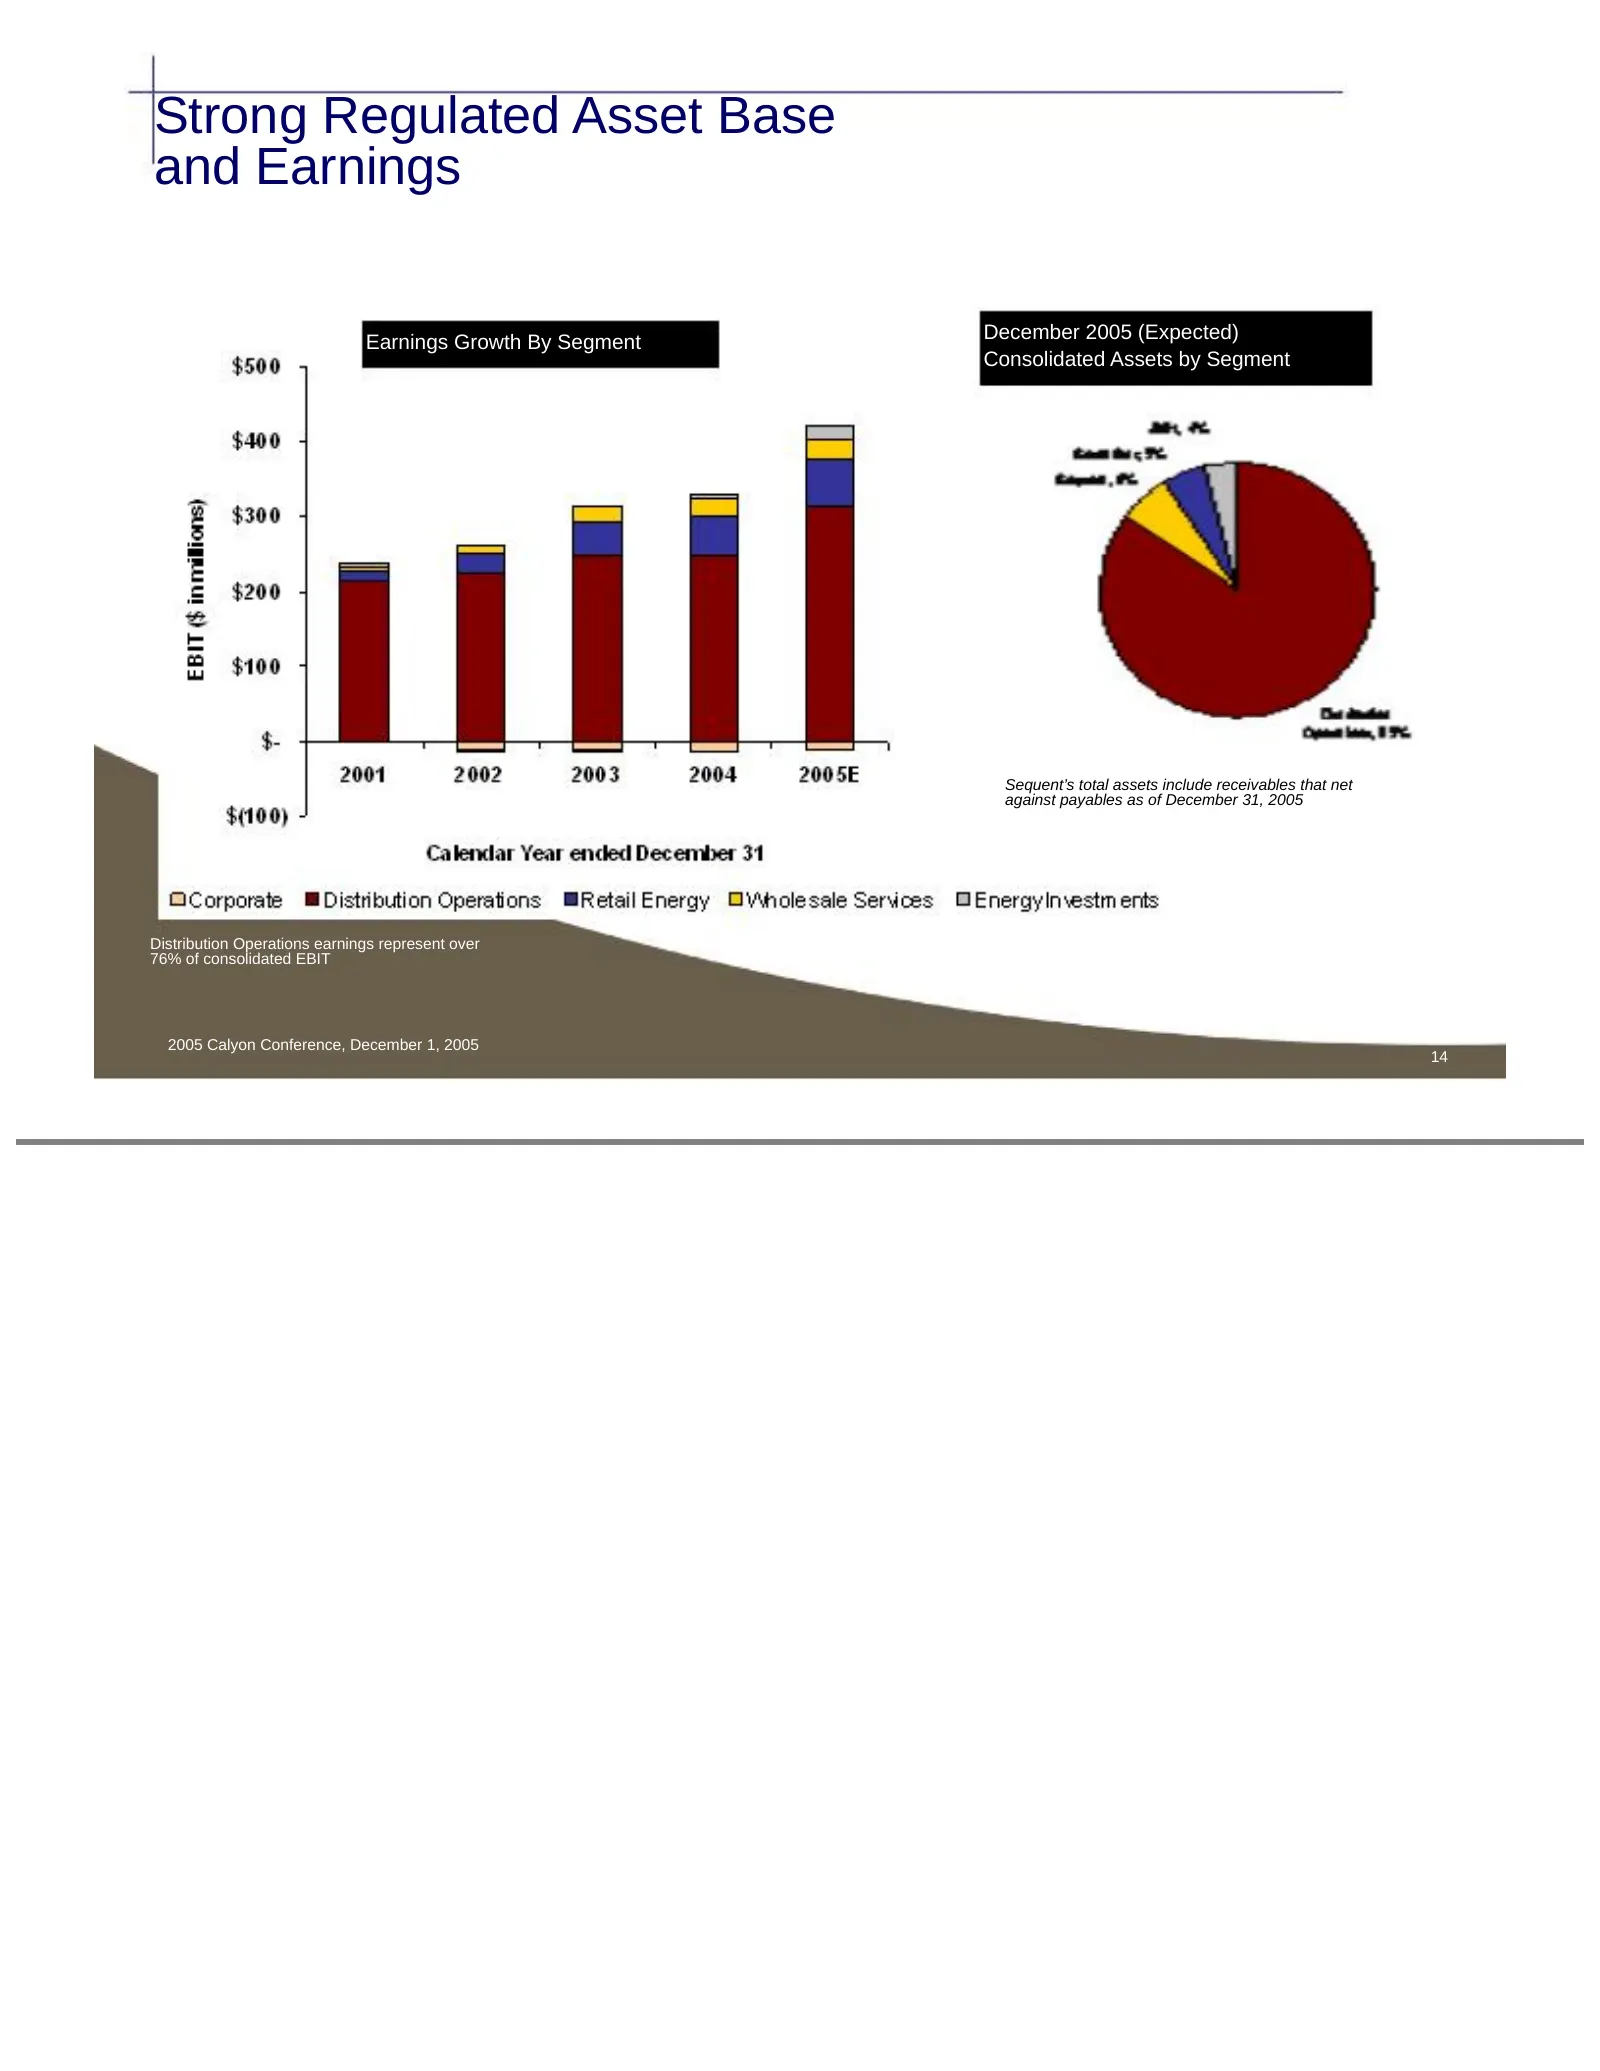
Strong Regulated Asset Base and Earnings Earnings Growth By Segment December 2005 (Expected) Consolidated Assets by Segment Sequent’s total assets include receivables that net against payables as of December 31, 2005 Distribution Operations earnings represent over 76% of consolidated EBIT 2005 Calyo
Slide 15: AGL Resources Core EPS 2000-2006
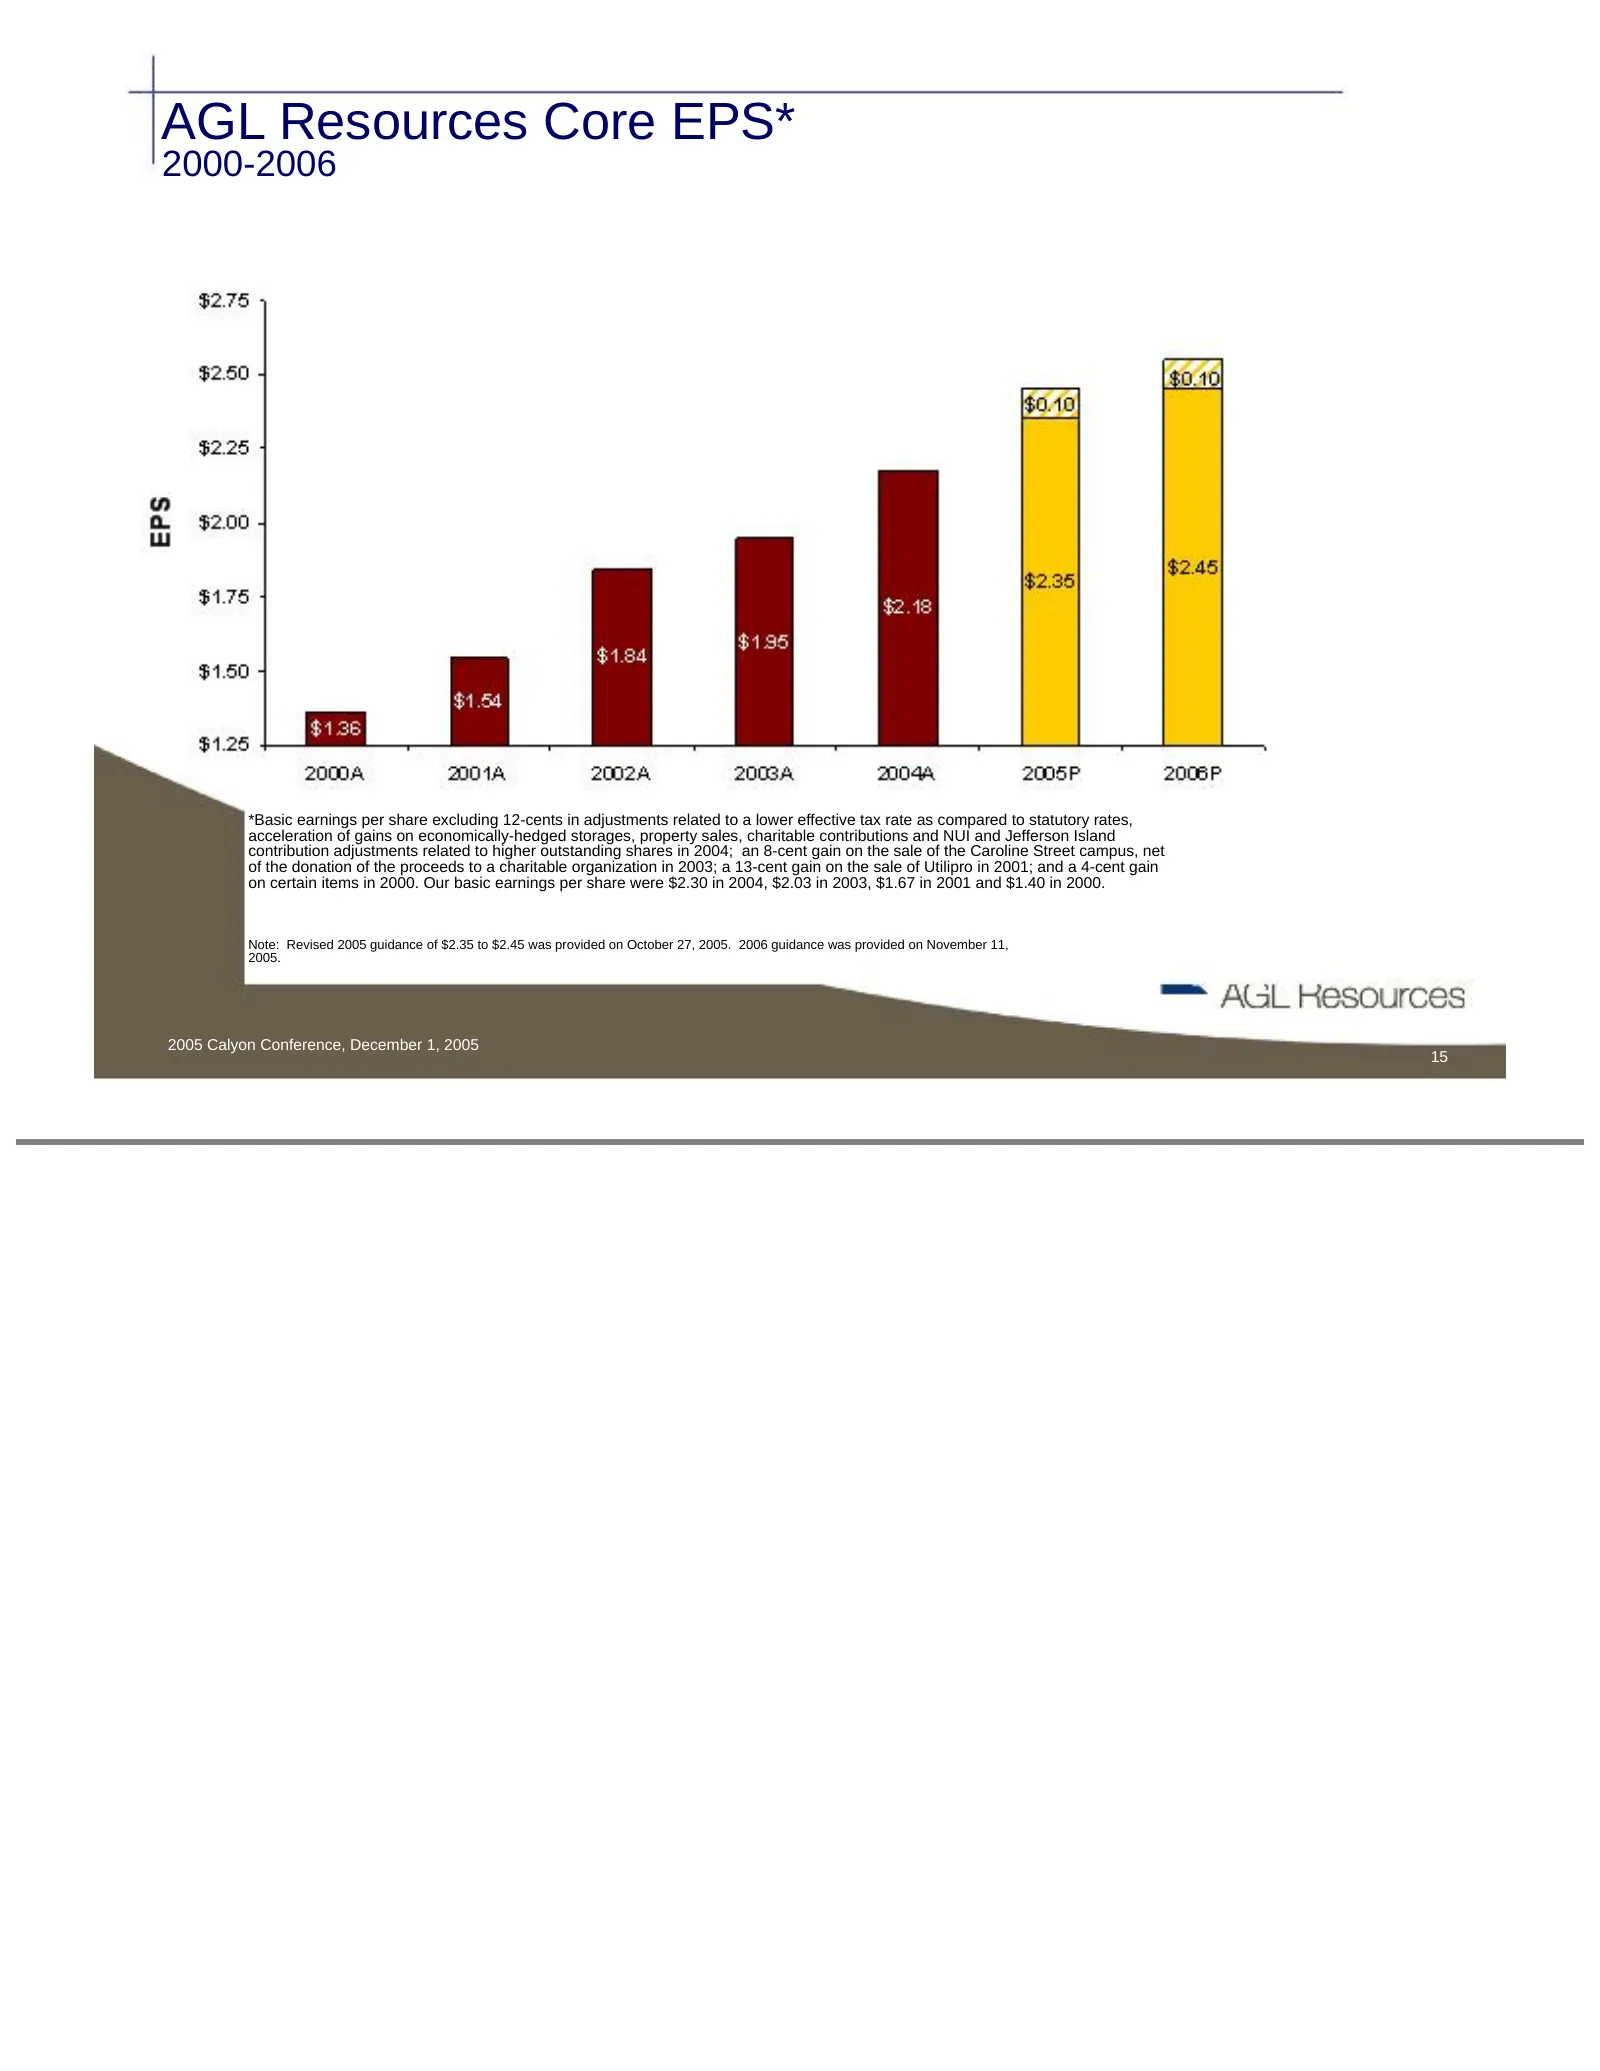
AGL Resources Core EPS* 2000-2006 *Basic earnings per share excluding 12-cents in adjustments related to a lower effective tax rate as compared to statutory rates, acceleration of gains on economically-hedged storages, property sales, charitable contributions and NUI and Jefferson Island contributio
Slide 16: Cash Flow Projections
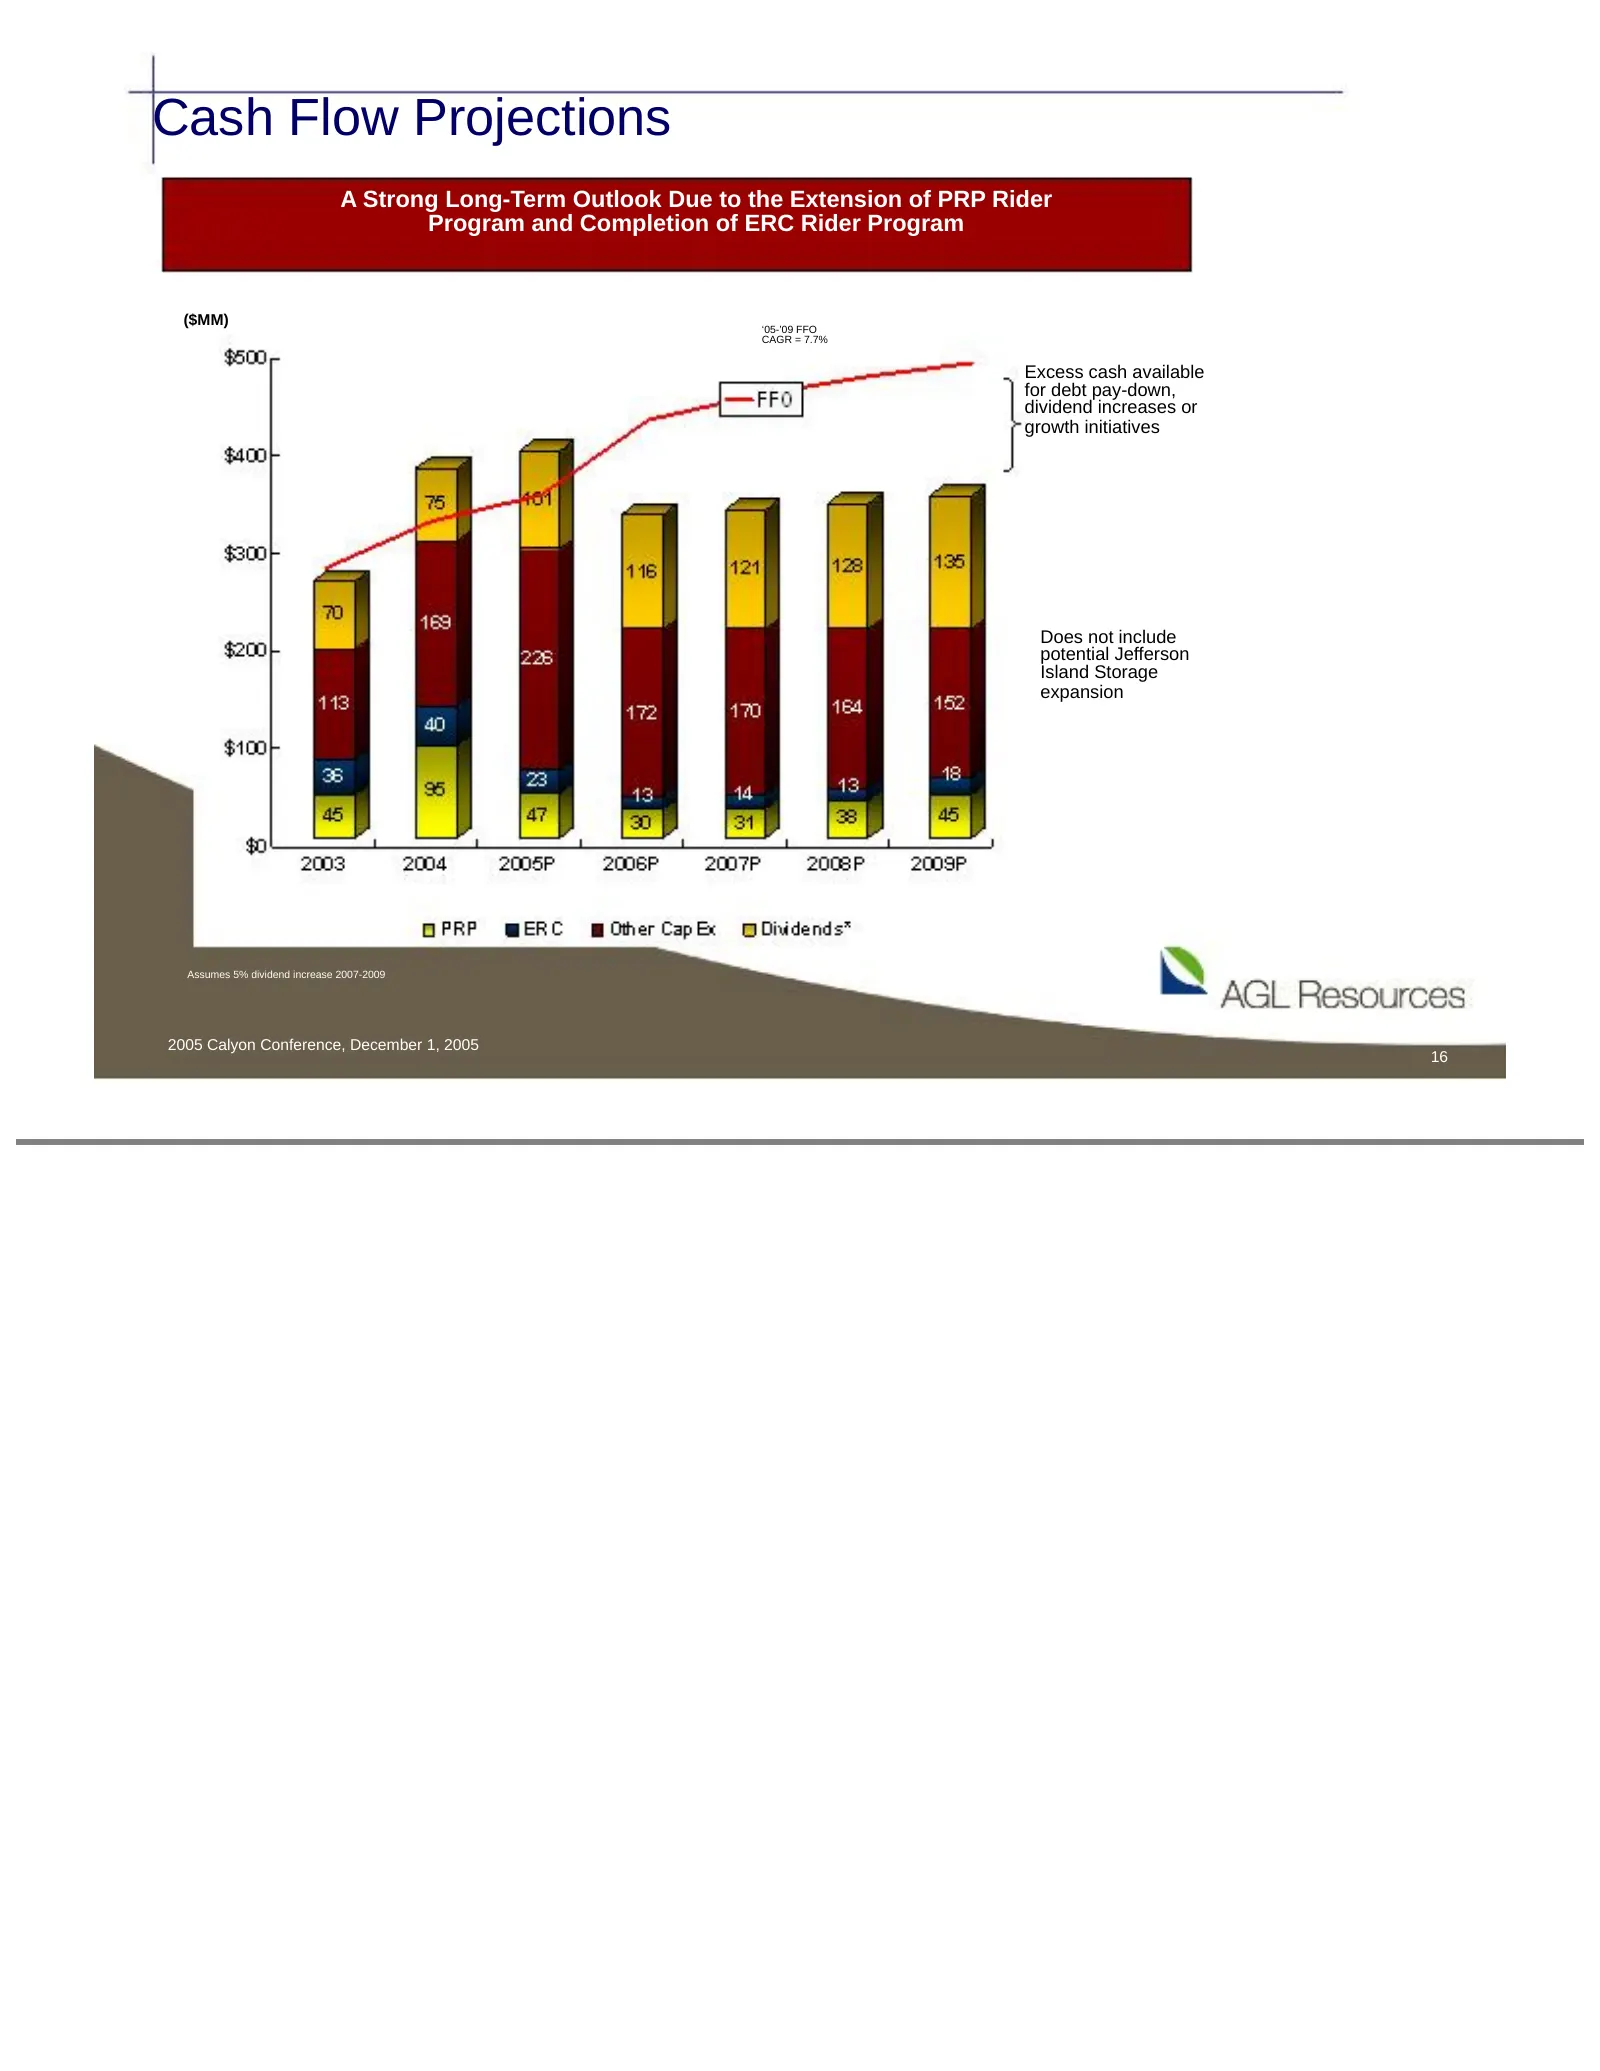
Cash Flow Projections A Strong Long-Term Outlook Due to the Extension of PRP Rider Program and Completion of ERC Rider Program ($MM) ‘05-’09 FFO CAGR = 7.7% Excess cash available for debt pay-down, dividend increases or growth initiatives Does not include potential Jefferson Island Storage expansion
Slide 17: ATG Valuation
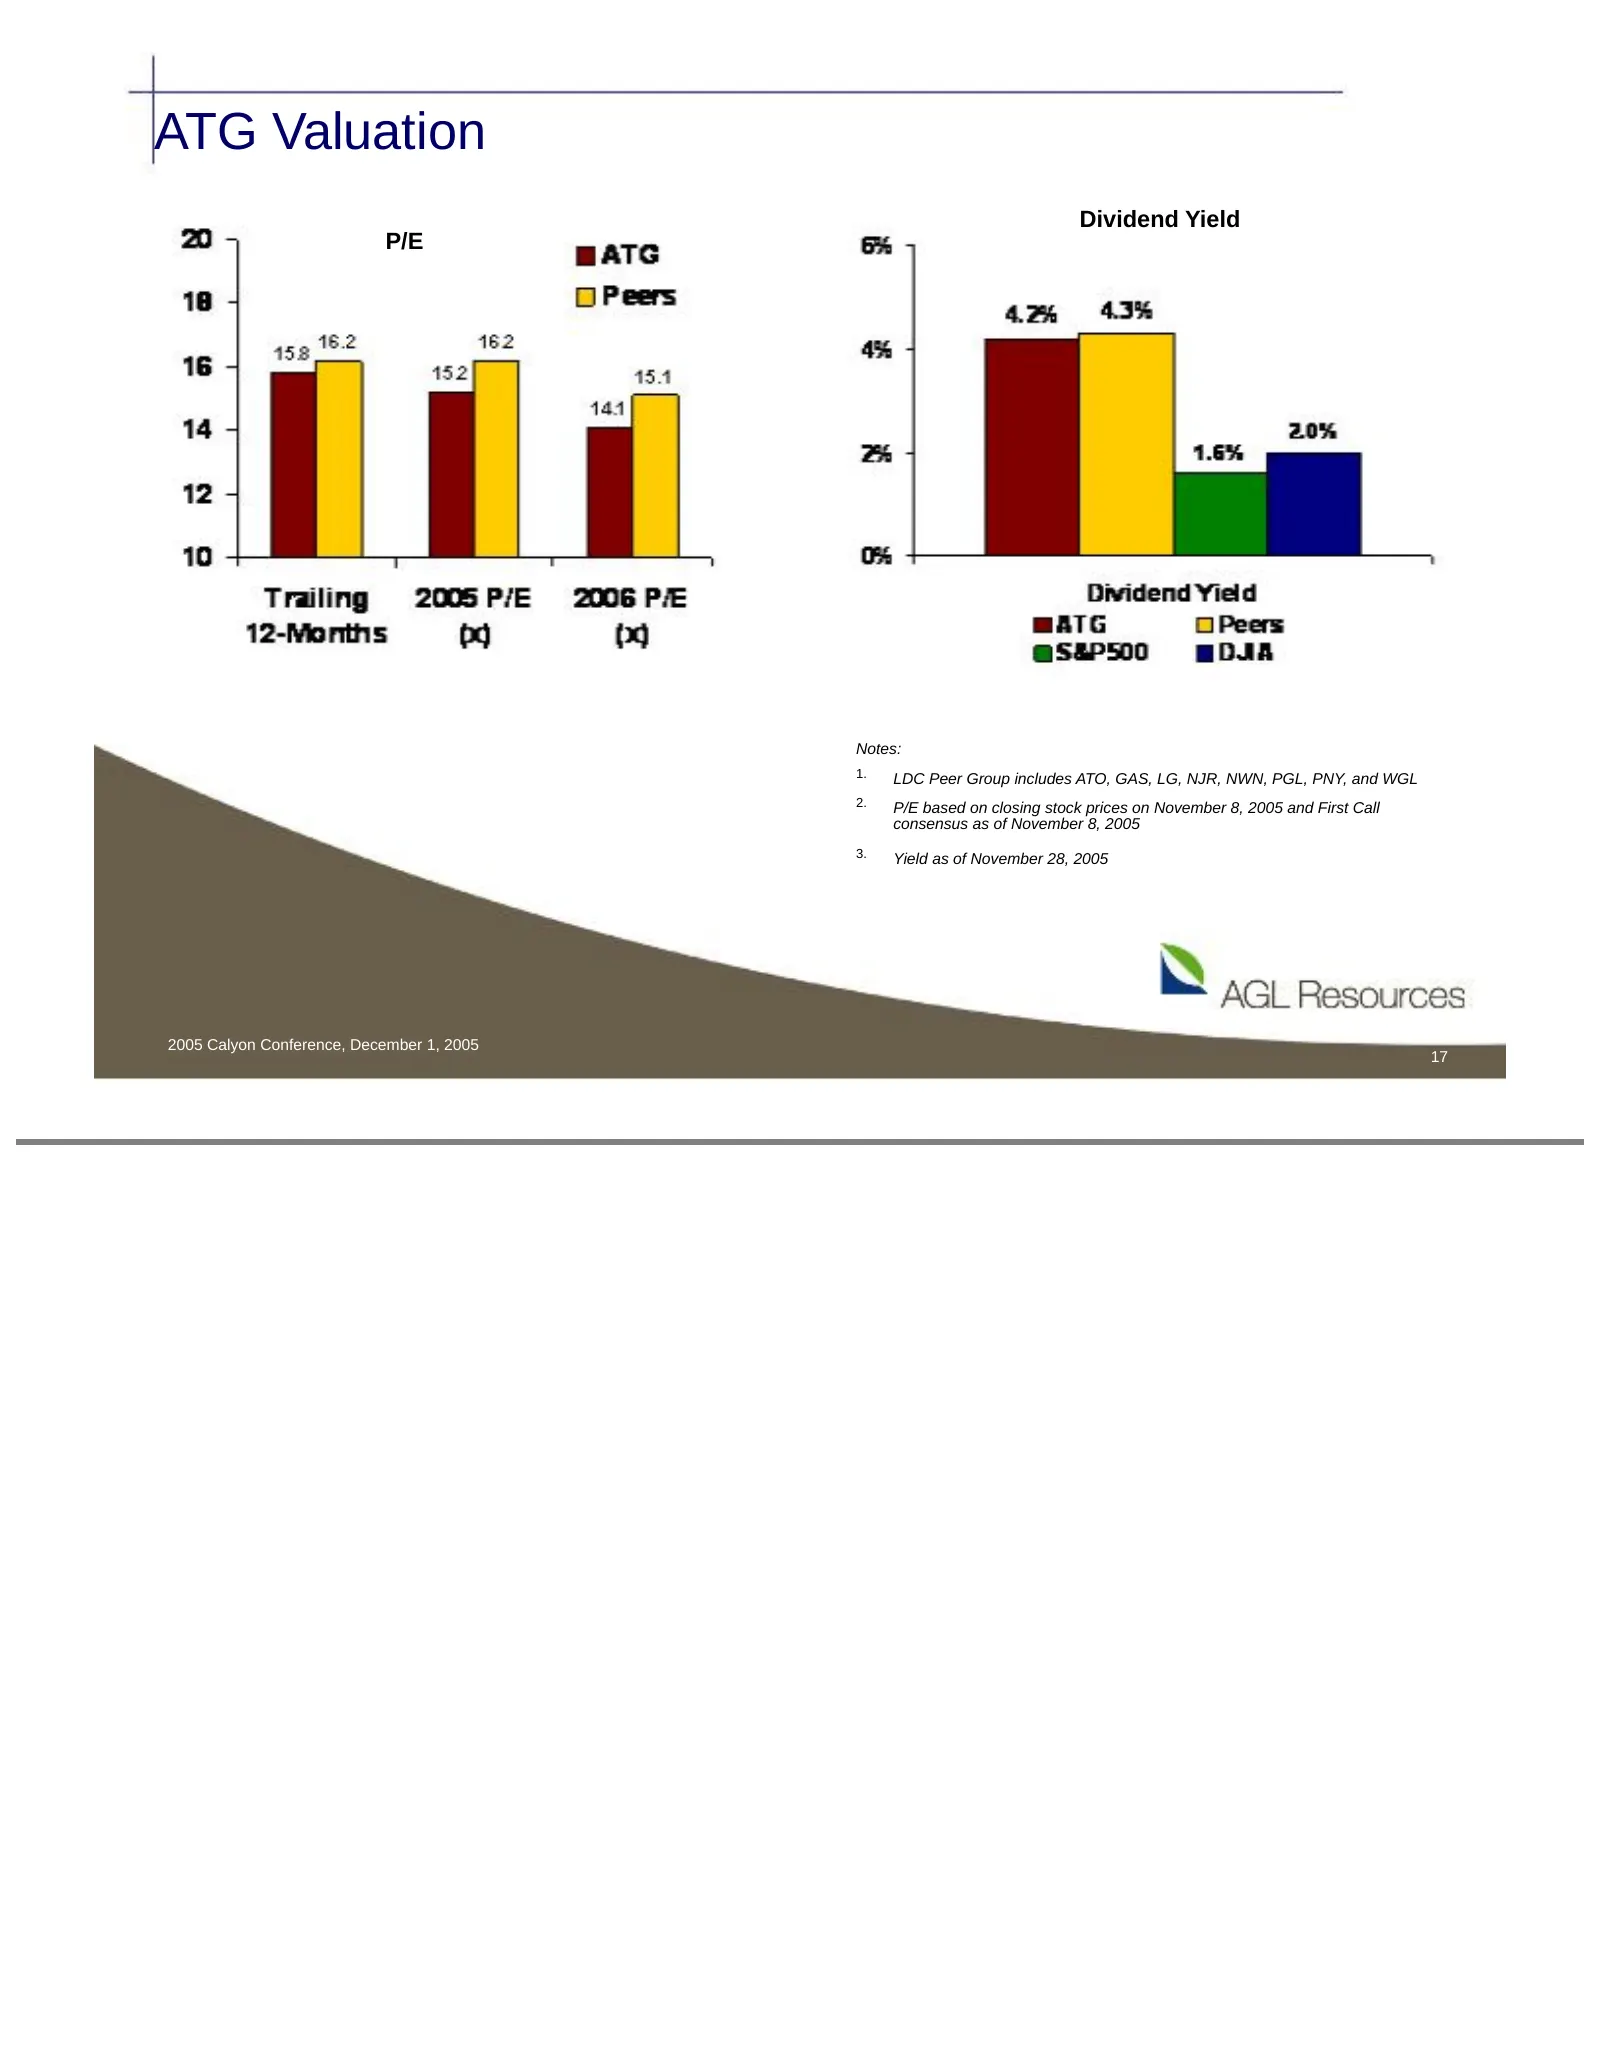
ATG Valuation Dividend Yield P/E Notes: 1. LDC Peer Group includes ATO, GAS, LG, NJR, NWN, PGL, PNY, and WGL 2. P/E based on closing stock prices on November 8, 2005 and First Call consensus as of November 8, 2005 3. Yield as of November 28, 2005 2005 Calyon Conference, December 1, 2005 17
Slide 18: Shareholder Return by Core EPS
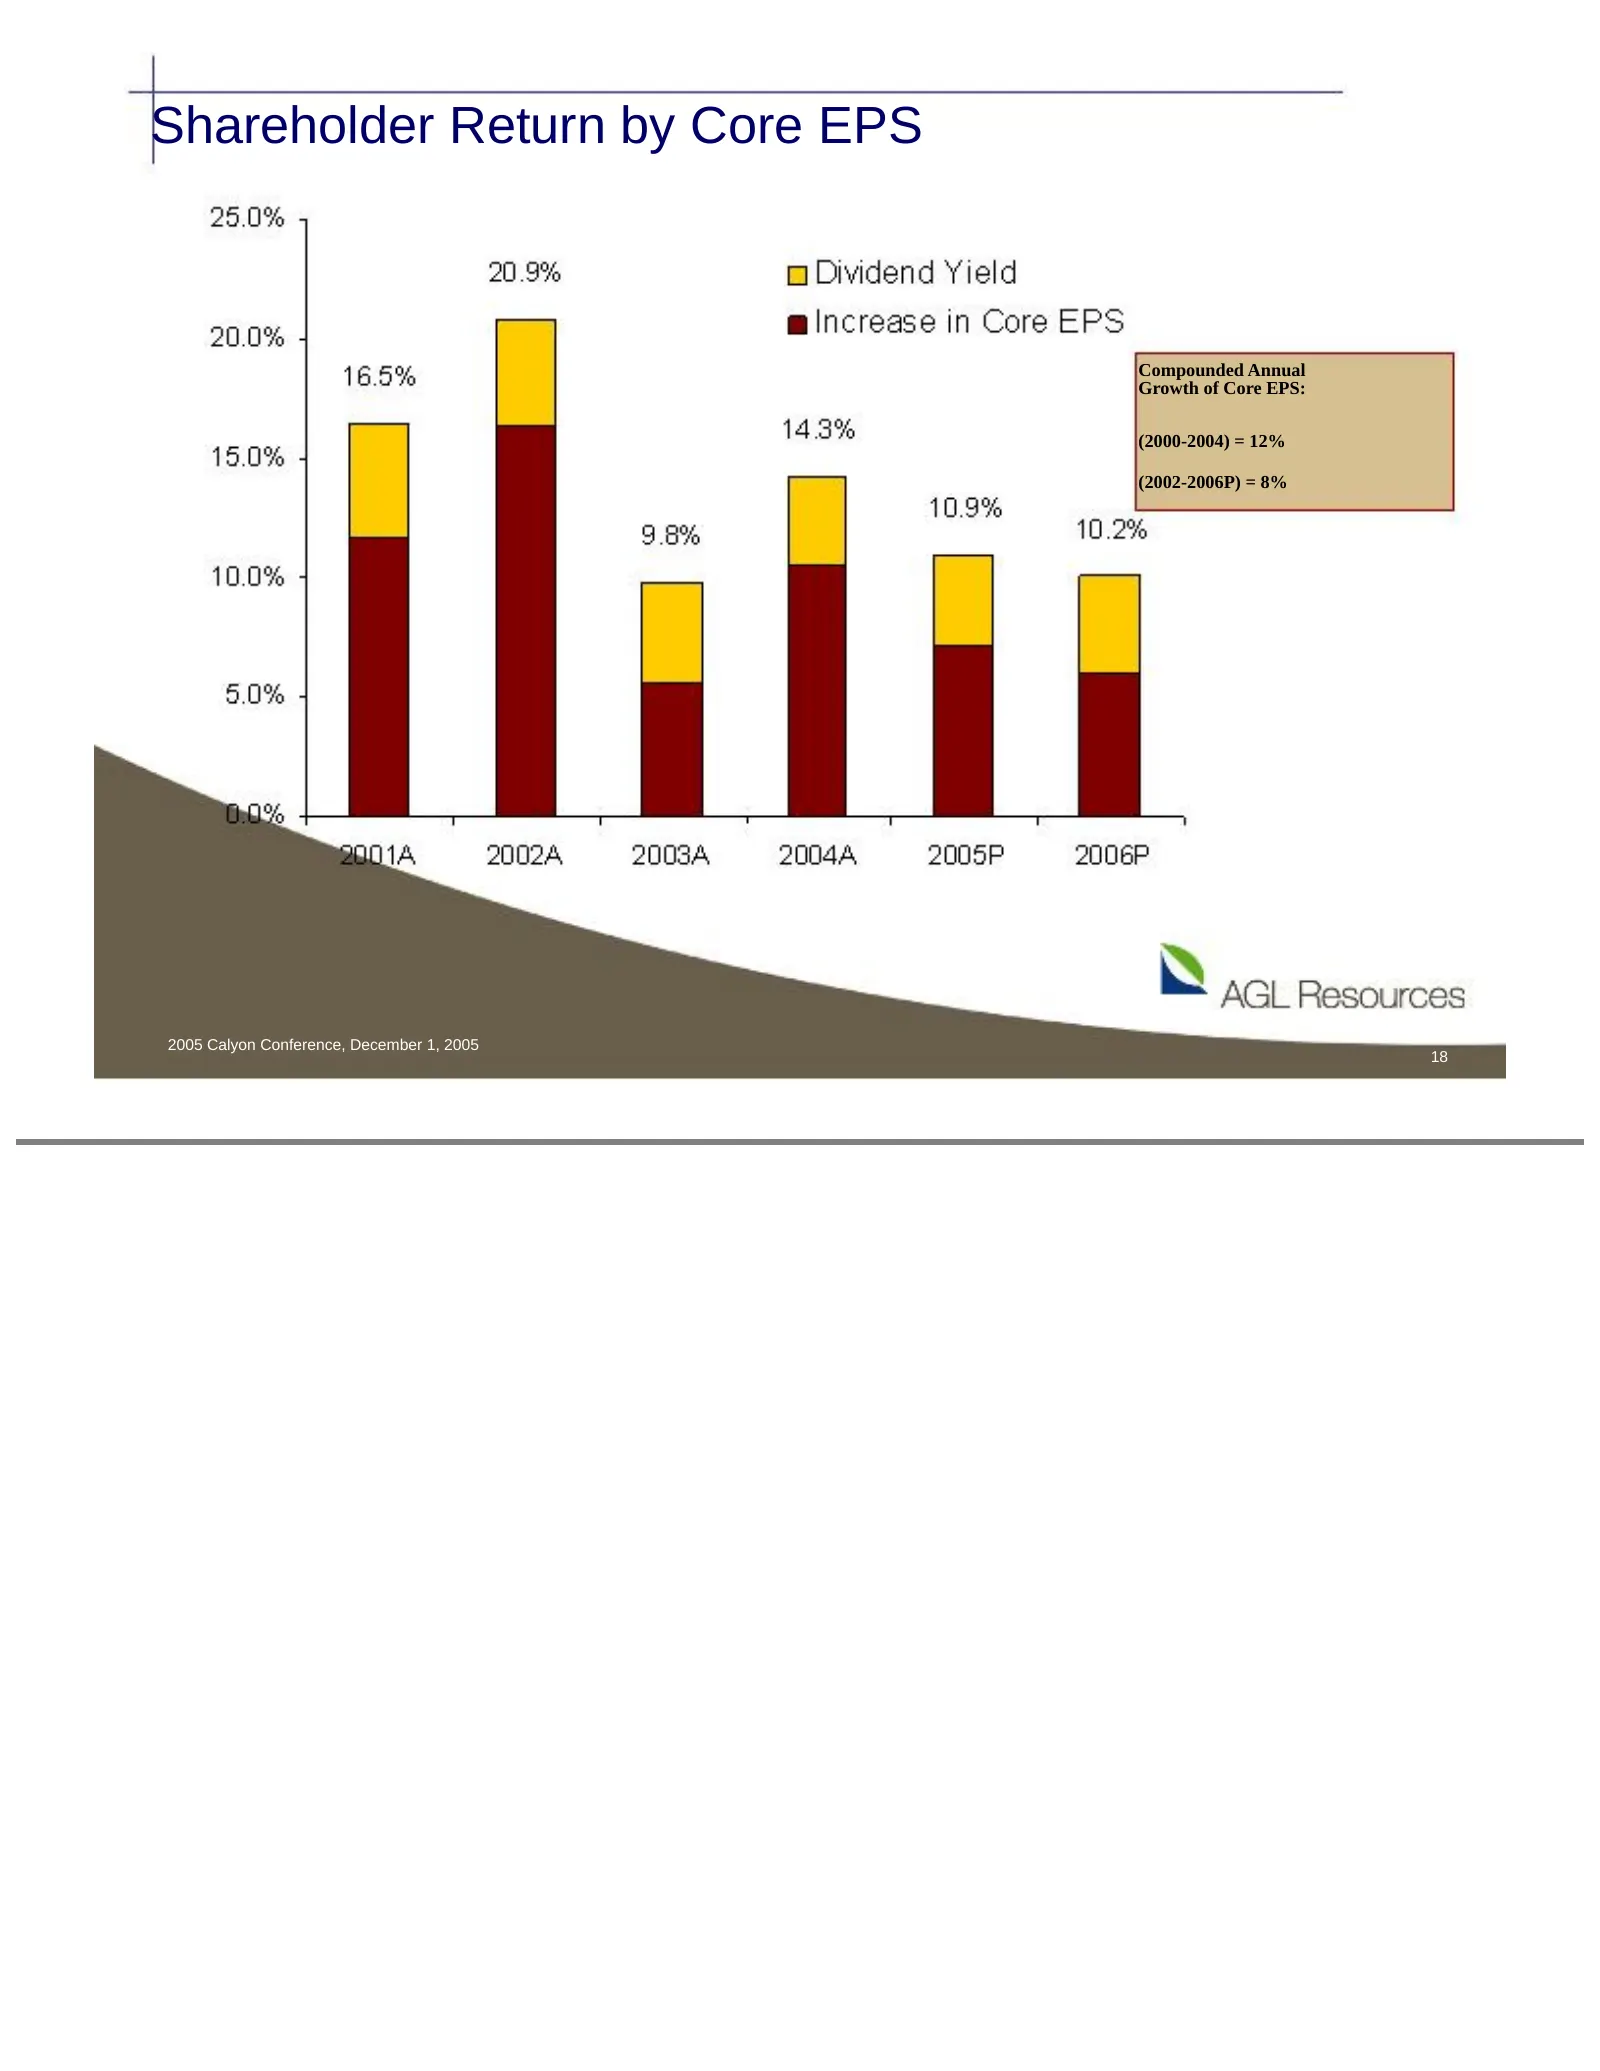
Shareholder Return by Core EPS Compounded Annual Growth of Core EPS: (2000-2004) = 12% (2002-2006P) = 8% 2005 Calyon Conference, December 1, 2005 18
Slide 19
Source: SEC EDGAR · 8-K filed Dec 1, 2005
More decks from AGL Resources Inc
 Merger or Acquisition (August 2015)12 slides · Aug 24, 2015
 Investor Day (March 2015)89 slides · Mar 25, 2015
 Q4 2014 Earnings Presentation26 slides · Feb 12, 2015
 Q3 2014 Earnings Presentation24 slides · Nov 10, 2014
 Q2 2014 Earnings Presentation19 slides · Jul 30, 2014
 Q1 2014 Earnings Presentation19 slides · Apr 29, 2014