Sunrise Senior Living — Sunrise Assisted Living — Investor Presentation (September 2001)
44 slides from Sunrise Senior Living's investor presentation, Sep 6, 2001
Slide 1: Sunrise Assisted Living
Slide 2: Sunrise Assisted Living, Inc. Company Presentation
SUNRISE ASSISTED LIVING, INC. COMPANY PRESENTATION SEPTEMBER 6, 2001
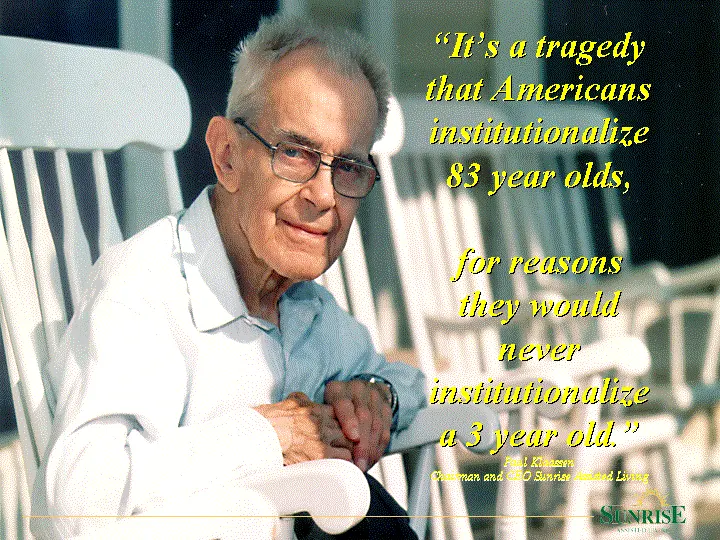
Slide 3
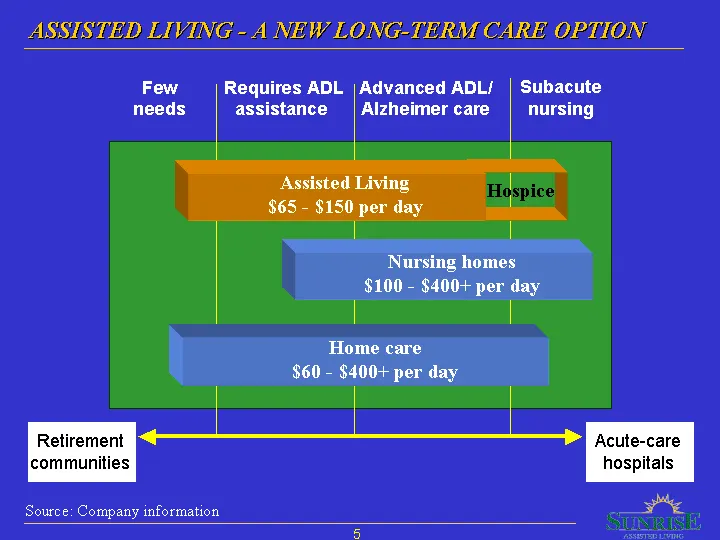
Slide 4: Assisted Living a New Long-Term Care Option
ASSISTED LIVING A NEW LONG-TERM CARE OPTION Few Requires ADL |Advanced ADL/ | Subacute needs assistance | Alzheimer care nursing Nursing homes $100 - $400+ per day Home care $60 - $400+ per day Source: Company information Acute-care hospitals ie
Slide 5: The Sunrise Principles of Service
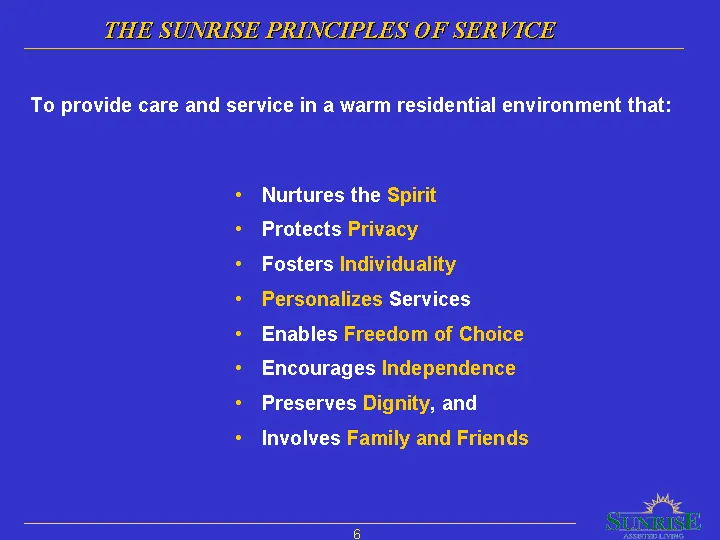
THE SUNRISE PRINCIPLES OF SERVICE To provide care and service in a warm residential environment that: + Nurtures the Spirit + Protects Privacy + Fosters Individuality ° Personalizes Services - Enables Freedom of Choice + Encourages Independence + Preserves Dignity, and + Involves Family and Friends
Slide 6: Sector Demographic Growth
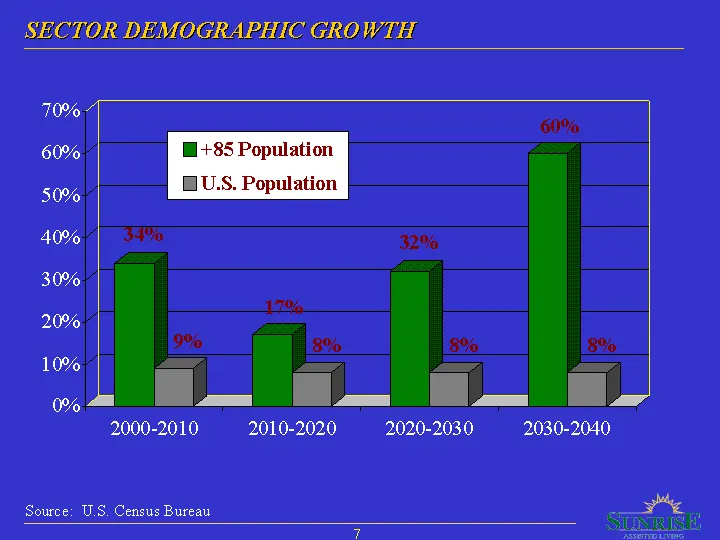
SECTOR DEMOGRAPHIC GROWTH 70% on |—cLVKk 50% 40% 60% 30% 20% 10% 0% 2000-2010 2010-2020 2020-2030 2030-2040 Source: U.S. Census Bureau
Slide 7: Strong Demographic Trends
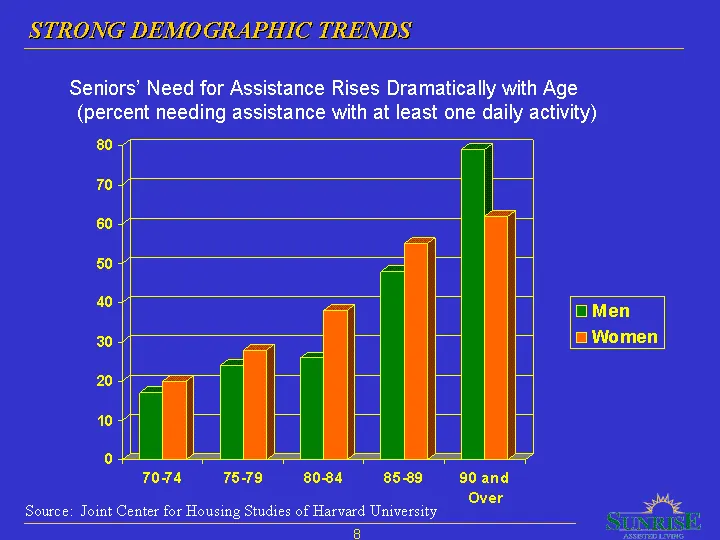
STRONG DEMOGRAPHIC TRENDS, Seniors’ Need for Assistance Rises Dramatically with Age (percent needing assistance with at least one daily activity) 80 70 60 50 “0 OMen Women 30 20 10 C) 70-74 75-79 80-84 85-89 90and Over oe Source: Joint Center for Housing Studies of Harvard University 8
Slide 8: Long-Term Care - $150 Billion Market
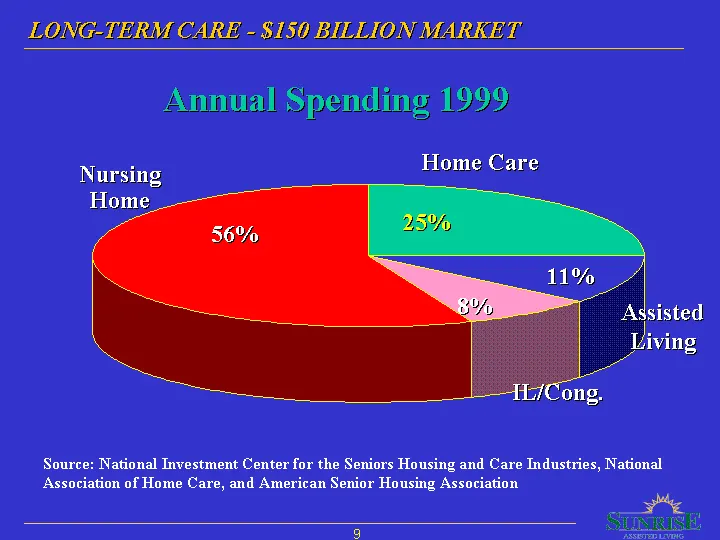
LONG-TERM CARE - $150 BILLION MARKET Annual Spending 1999 Home Care Nursing Home EL sisted iving, L/Cong, Source: National Investment Center for the Seniors Housing and Care Industries, National Association of Home Care, and American Senior Housing Association
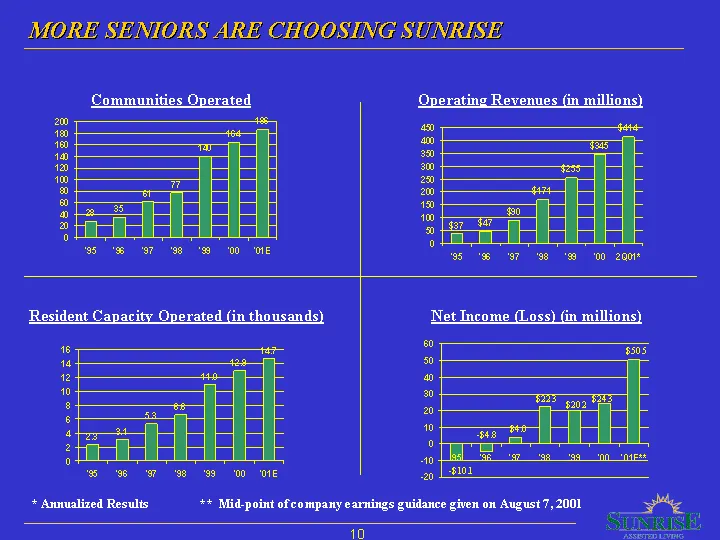
Slide 9: More Seniors Are Choosing Sunrise
MORE SENIORS ARE CHOOSING SUNKISE Communities Operated Operating Revenues (in millions) g a 160 “ as 1 30 % on ie = ao = 200 a io a 3s 10 80 a eee 4 SDT DD Dw 95'S SF SB 0 2001 Resident Capacity Operated (in thousands} Net Income —— os 144 so nef © no 2 e val ia bat ay ” $48 : a a 40 x 6 ew se sw OE
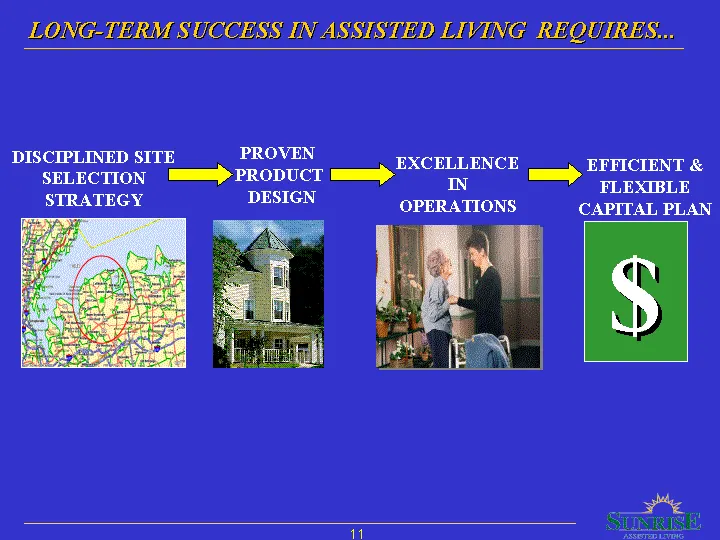
Slide 10: Long-Term Success in Assisted Living Requires...
LONG-TERM SUCCESS IN ASSISTED LIVING REQUIRES... DISCIPLINED SITE PROVEN EXCELLENCE EFFICIENT & SELECTION ==> PRODUCT > as DESIGN FLEXIBLE OPERATIONS
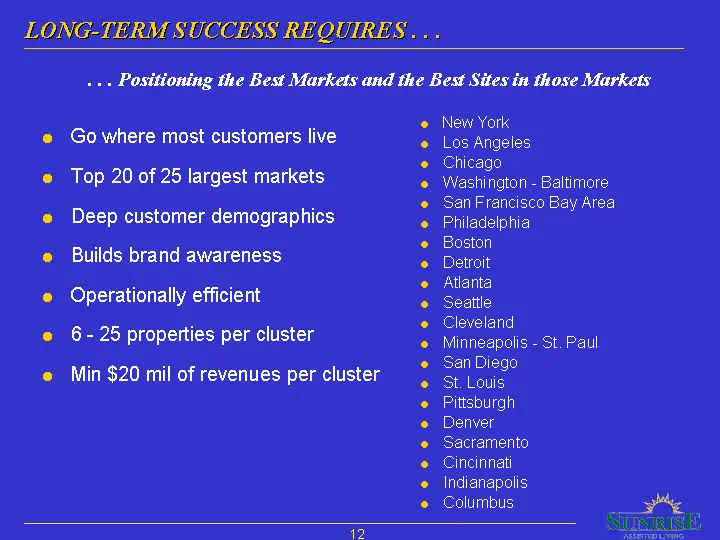
Slide 11: Long-Term Success Requires... Best Markets and Sites
LONG-TERM SUCCESS REQUIRES... ... Positioning the Best Markets and the Best Sites in those Markets New York Los Angeles Chicago Washington - Baltimore San Francisco Bay Area Philadelphia Boston Detroit Atlanta Seattle Cleveland Minneapolis - St. Paul San Diego St. Louis Pittsburgh Denver Sacramento
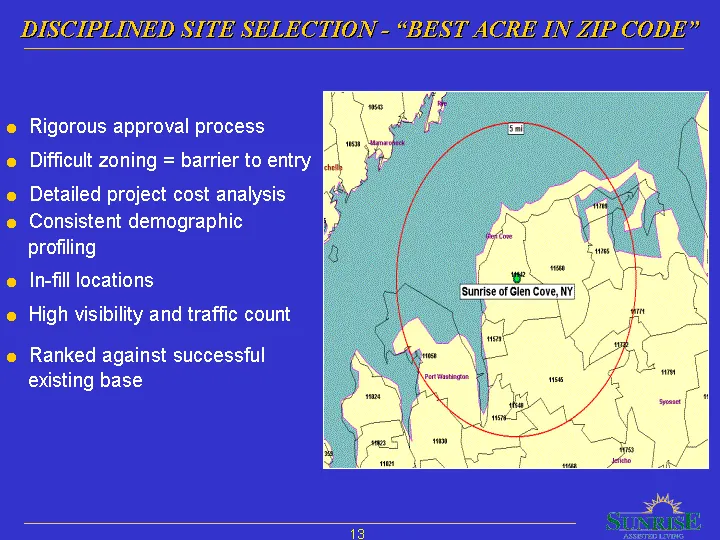
Slide 12: Disciplined Site Selection - Best Acre in Zip Code
DISCIPLINED SITE SELECTION - “BEST ACKE IN ZIP CODE” ie ~__{Suniseofcien cove.ny] ~~! my eae
Slide 13: Development Activity Industry Pipeline
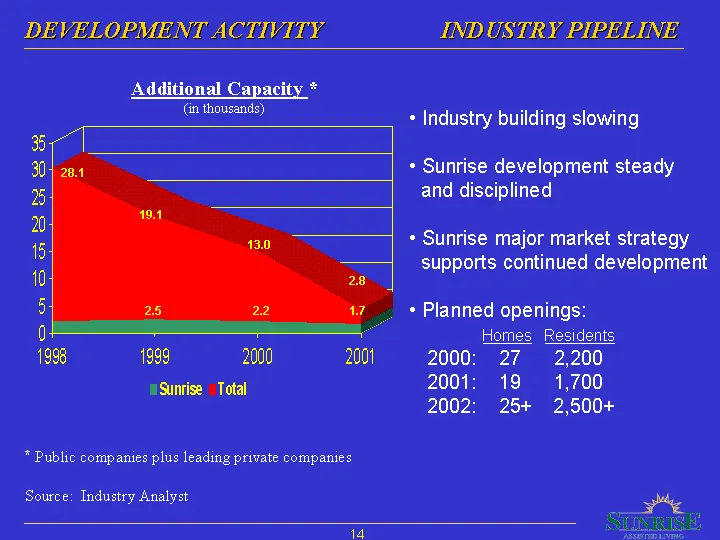
DEVELOPMENT ACTIVITY INDUSTRY PIPELINE Additional Capacity * (in thousands) + Industry building slowing 5) 30 + Sunrise development steady B and disciplined t + Sunrise major market strategy 0 supports continued development 5 + Planned openings: 0 Homes Residents 1998 1999 2000 2001 2000: 27 2,200 1
Slide 14: Development Pipeline
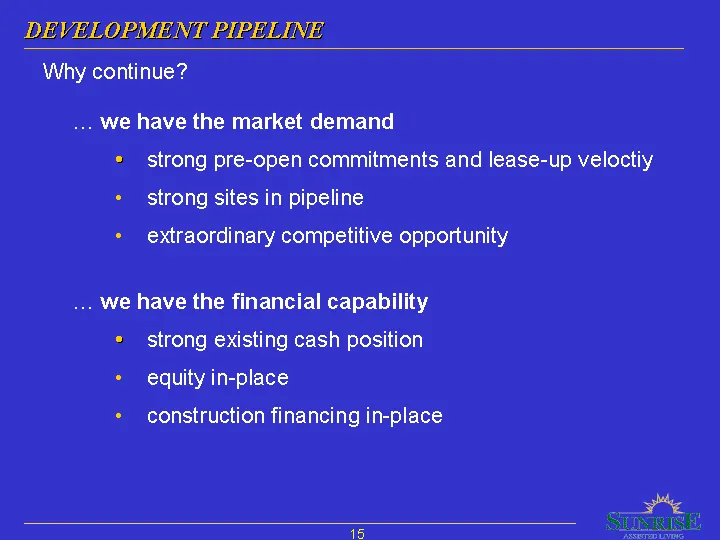
DEVELOPMENT PIPELINE Why continue? ... we have the market demand « strong pre-open commitments and lease-up veloctiy - strong sites in pipeline - extraordinary competitive opportunity ... we have the financial capability « strong existing cash position ° equity in-place * construction financing in-p
Slide 15: Long Term Success Requires... Flexible Proven Model
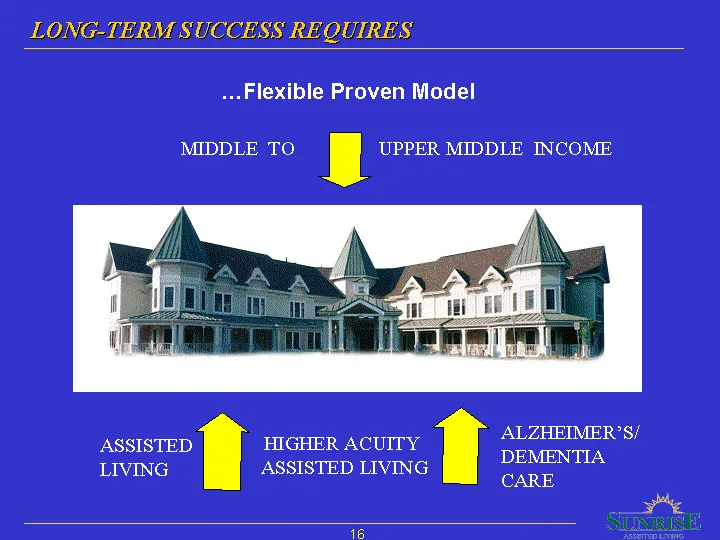
LONG TERM SUCCESS REQUIRES, ...Flexible Proven Model MIDDLE TO i | UPPER MIDDLE INCOME ASSISTED HIGHER ACUITY OMENS sf LIVING ASSISTED LIVING Cone " S mate 16 wal
Slide 16
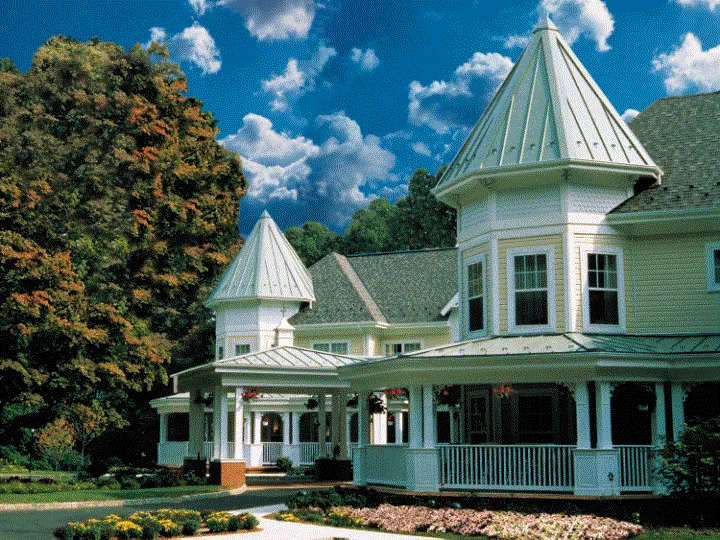
Slide 17
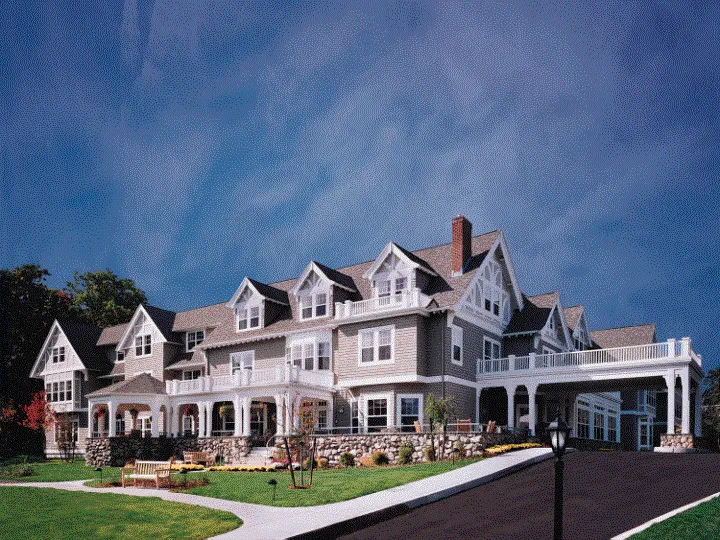
Slide 18
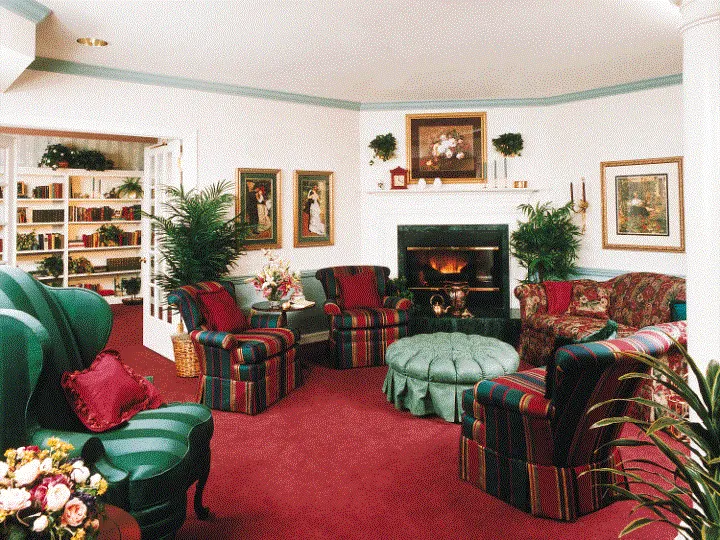
Slide 19
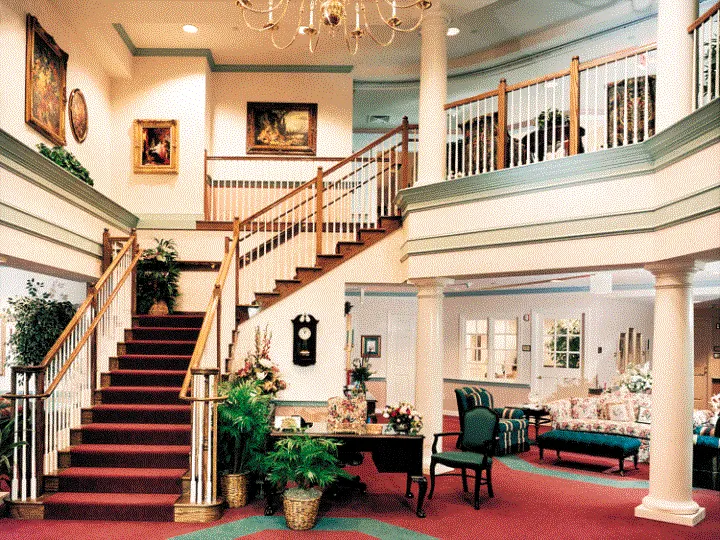
Slide 20
Slide 21
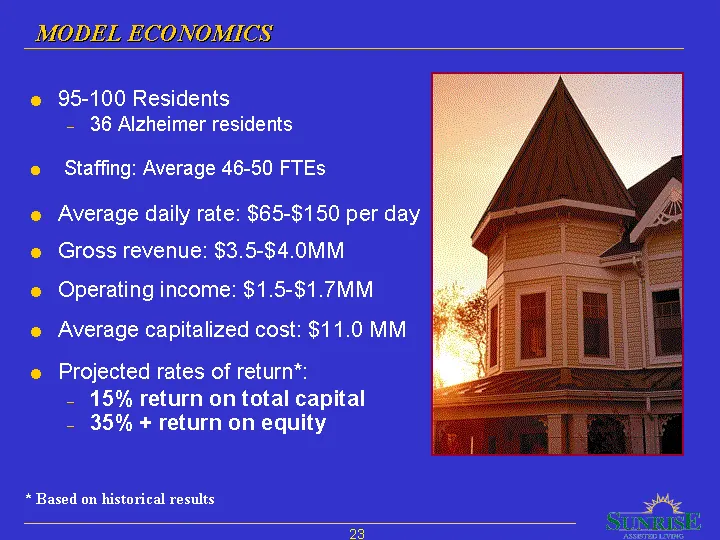
Slide 22: Model Economics
MODEL ECONOMICS, e 95-100 Residents — 36 Alzheimer residents e Staffing: Average 46-50 FTEs e Average daily rate: $65-$150 per day e Gross revenue: $3.5-$4.0MM e Operating income: $1.5-$1.7MM e Average capitalized cost: $11.0 MM e Projected rates of return*: - 15% return on total capital - 35% + ret
Slide 23: Long Term Success Requires... Excellence in Operations
LONG TERM SUCCESS REQUIRES... .«» EXCELLENCE IN OPERATIONS 04
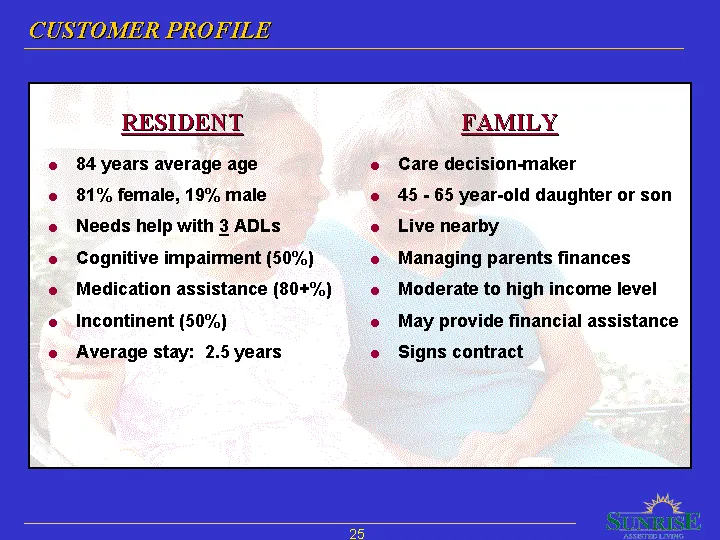
Slide 24: Customer Profile
CUSTOMER PROFILE RESIDENT e 84 years average age e 81% female, 19% male e Needs help with 3 ADLs e Cognitive impairment (50%) e Medication assistance (80+%) e Incontinent (50%) e Average stay: 2.5 years 45 - 65 year-old daughter or son Live nearby Managing parents finances Moderate to high income le
Slide 25: Twenty Years Experience in Resident Care
TWENTY YEARS EXPERIENCE IN RESIDENT CARE e Unique resident care programs - Wellness programs - Medication management - Reminiscence/Alzheimer's care e Training programs - Leadership development - Five star program - Promote from within e Continuous quality improvement - Focus on customer satisfactio
Slide 26: Long Term Success Requires... Efficient & Flexible Capital Plan
LONG TERM SUCCESS REQUIRES... ... EFFICIENT & FLEXIBLE CAPITAL PLAN
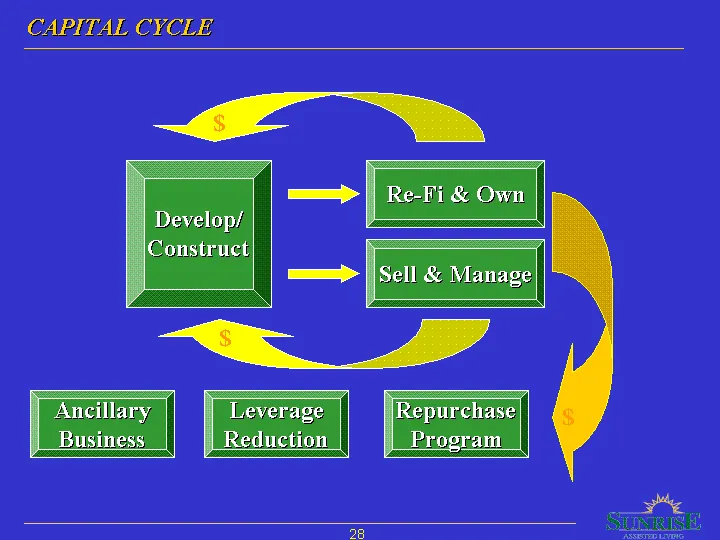
Slide 27: Capital Cycle
CAPITAL CYCLE 98
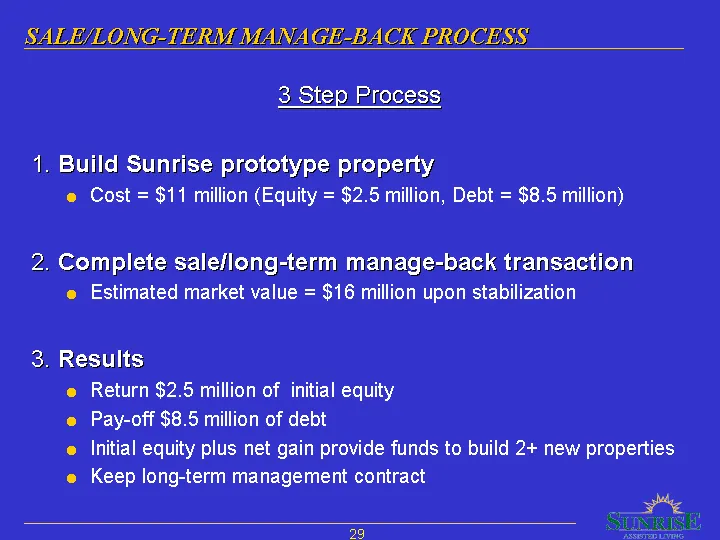
Slide 28: Sale/Long-Term Manage-Back Process: Step Process
SALE/LONG- TERM MANAGE-BACK PROCESS: 3 Step Process 1. Build Sunrise prototype property e Cost = $11 million (Equity = $2.5 million, Debt = $8.5 million) 2, Complete sale/long-term manage-back transaction e Estimated market value = $16 million upon stabilization 3. Results e Return $2.5 million of i
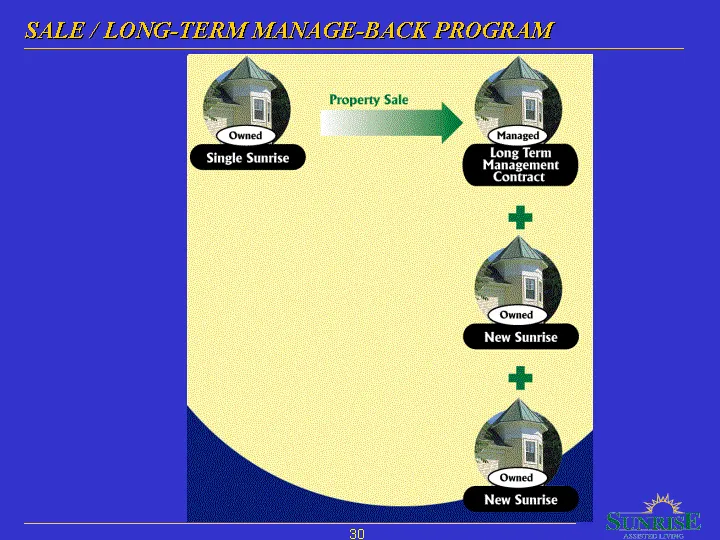
Slide 29: Sale / Long-Term Manage-Back Program
SALE / LONG-TERM MANAGH-BACK PROGRAM Long Term Management Contract Single Sunrise : = New Sunrise Gi) New Sunrise
Slide 30: Sale / Long-Term Manage-Back Program
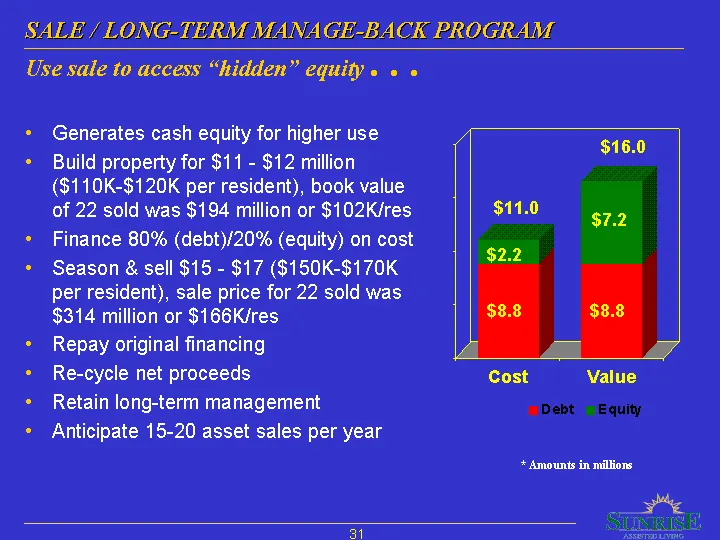
SALE / LONG-TERM MANAGH-BACK PROGRAM Use sale to access “hidden” equity» « « + Generates cash equity for higher use + Build property for $11 - $12 million ($110K-$120K per resident), book value of 22 sold was $194 million or $102K/res + Finance 80% (debt)/20% (equity) on cost + Season & sell $15 - $
Slide 31: Development Cycle - Pain Versus Gain
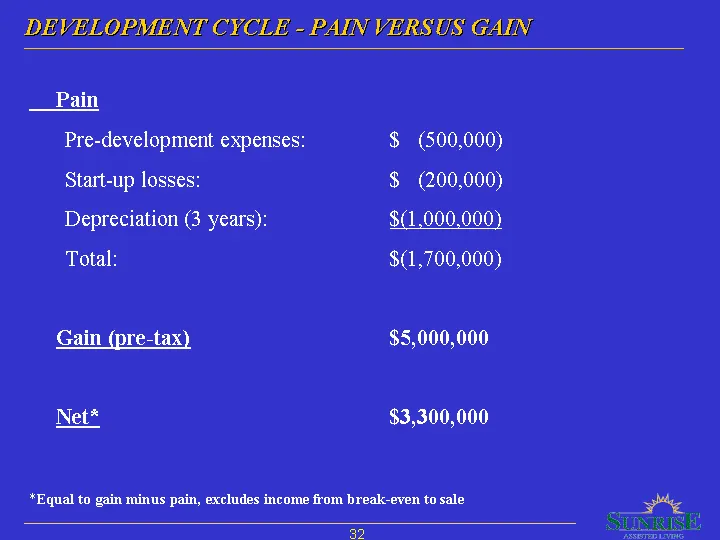
DEVELOPMENT CYCLE - PAIN VERSUS GAIN Pain Pre-development expenses: $ (500,000) Start-up losses: $ (200,000) Depreciation (3 years): $1,000,000 Total: $(1,700,000) Gain (pre-tax) $5,000,000 Net* $3,300,000 *Equal to gain minus pain, excludes income from break-even to sale 90
Slide 32: Sale/Long-Term Manage-Back Summary
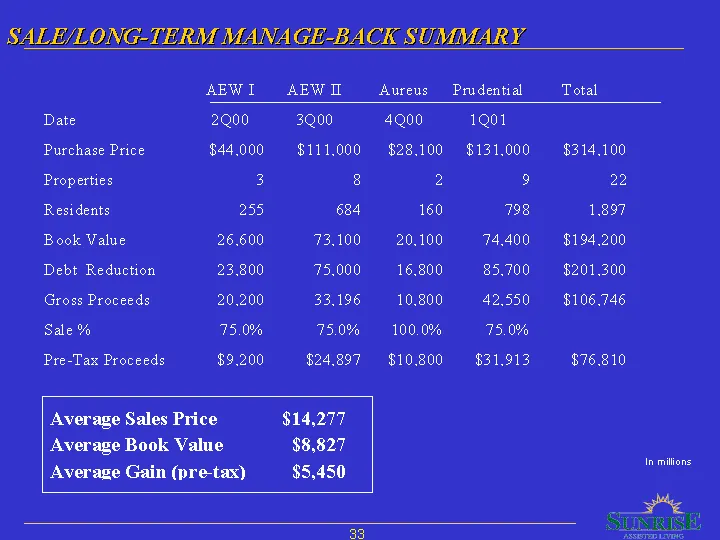
SALE/LONG- TERM MANAGE-BACK SUMMARY AEWI AEWI Aureus Prudential Total Date 2Q00 3Q00 4Q00 1901 Purchase Price $44,000 $111,000 $28,100 $131,000 $314,100 Properties 3 8 2 9 22 Residents 255 684 160 798 1.897 Book Value 26,600 73,100 20,100 74,400 $194,200 Debt Reduction 23,800 75,000 16,800 85,700 $2
Slide 33: Success in Four Key Areas Produces:
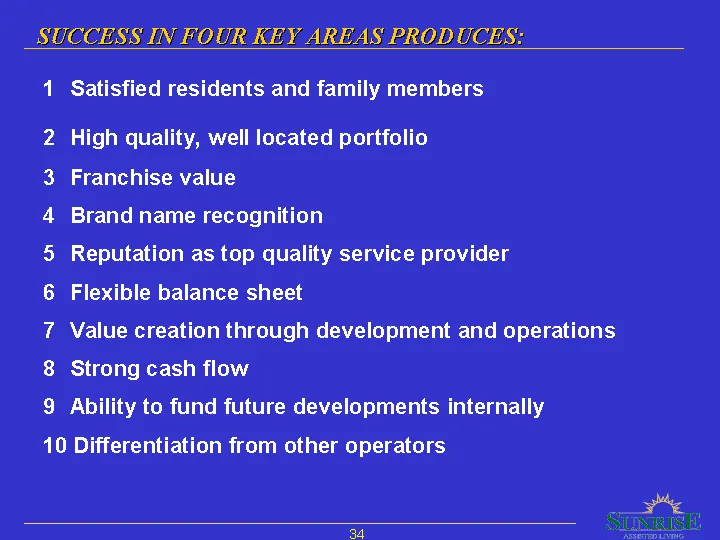
SUCCESS IN FOUR KEY AREAS PRODUCES: = Satisfied residents and family members High quality, well located portfolio Franchise value Brand name recognition Reputation as top quality service provider Flexible balance sheet Value creation through development and operations Strong cash flow Ability to fun
Slide 34: Business Overview - Sunrise Results
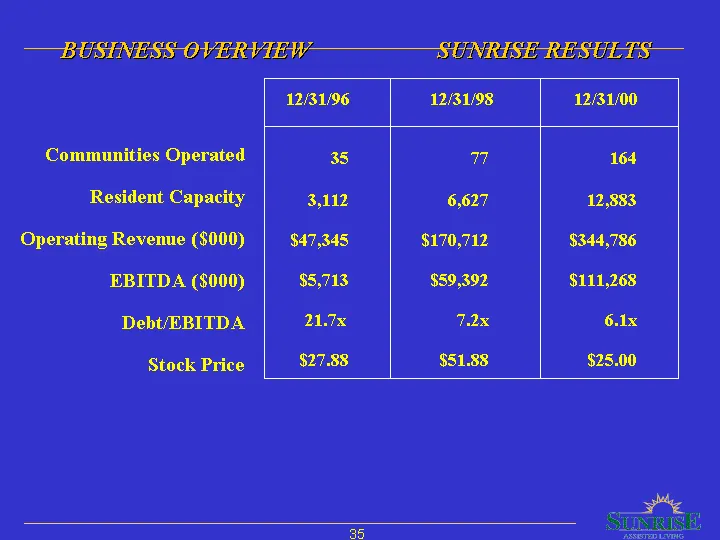
— BUSINESS OVERVIEW —__ SUNRISH RESULTS 12/31/96 12/31/98 12/31/00 Communities Operated 35 7 164 Resident Capacity 3,112 6,627 12,883 Operating Revenue ($000) | $47,345 $170,712 $344,786 EBITDA ($000) $5,713 $59,392 $111,268 Debt(EBITDA 21.7x Tax 6.1x Stock Price $27.88 $51.88 $25.00 95
Slide 35: Sunrise Growth Drivers
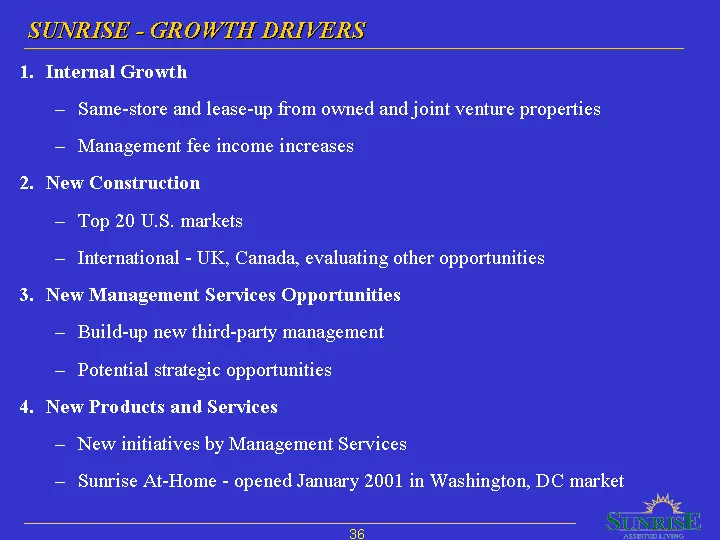
SUNEISH ~GROWIH DRIVERS 1. Internal Growth — Same-store and lease-up from owned and joint venture properties — Management fee income increases 2. New Construction = Top 20 U.S. markets — International - UK, Canada, evaluating other opportunities 3. New Management Services Opportunities — Build-up ne
Slide 36: Sunrise Value Components - Combined Value Estimate
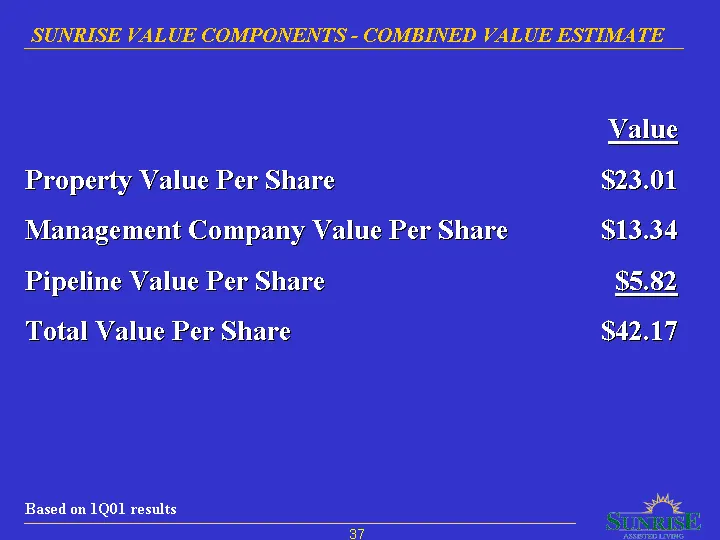
SUNRISE VALUE COMPONENTS - COMBINED VALUE ESTIMATE Value Property Value Per Share $23.01 Management Company Value Per Share $13.34 Pipeline Value Per Share $5.82 Total Value Per Share $42.17 Based on 1Q01 results
Slide 37: Sunrise Value Components - Property Value Estimate
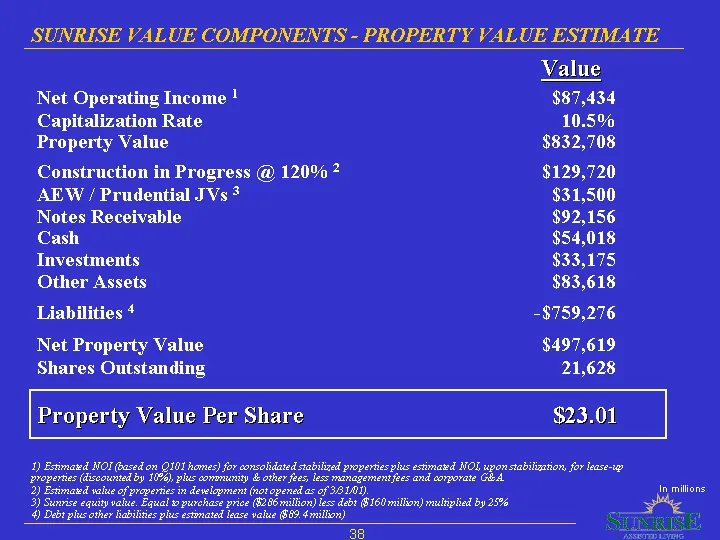
SUNRISE VALUE COMPONENTS - PROPERTY VALUE ESTIMATE Value Net Operating Income ! $87,434 Capitalization Rate 10.5% Property Value $832,708 Construction in Progress @ 120% 2 $129,720 AEW / Prudential JVs * $31,500 Notes Receivable $92,156 Cash $54,018 Investments $33,175 Other Assets $83,618 Liabiliti
Slide 38: Sunrise Value Components - Mgmt Co. Value Estimate
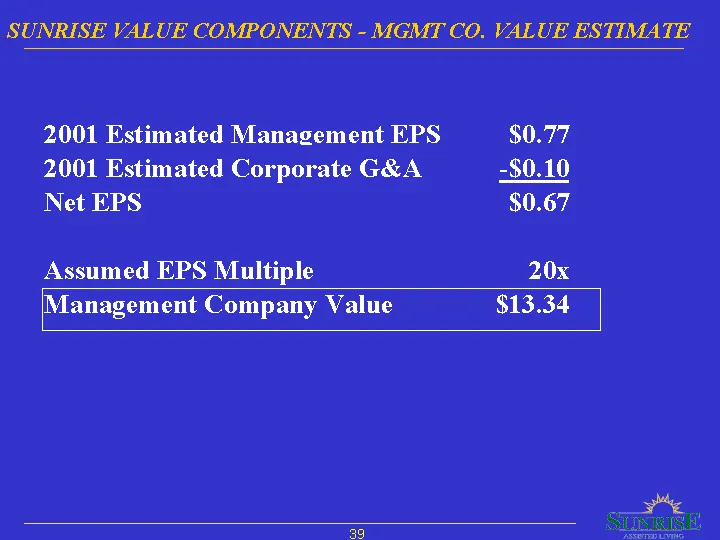
SUNRISE VALUE COMPONENTS - MGMT CO. VALUE ESTIMATE 2001 Estimated Management EPS $0.77 2001 Estimated Corporate G&A -$0.10 Net EPS $0.67 Assumed EPS Multiple 20x |Management Company Value $13.34 39
Slide 39: Sunrise Value Components - Pipeline Value Estimate
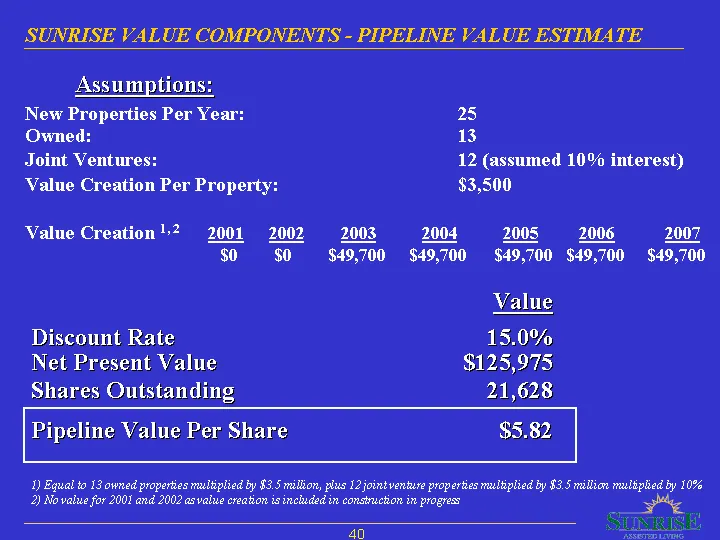
SUNRISE VALUE COMPONENTS - PIPELINE VALUE ESTIMATE Assumptions: New Properties Per Year: 25 Owned: 13 Joint Ventures: 12 (assumed 10% interest) Value Creation Per Property: $3,500 Value Creation? 2001 2002 -2003-«S 2004. «2005-2006 2007 $0 $0 $49,700 $49,700 $49,700 $49,700 $49,700 Value Discount Ra
Slide 40: Sunrise Year 2001 Highlights
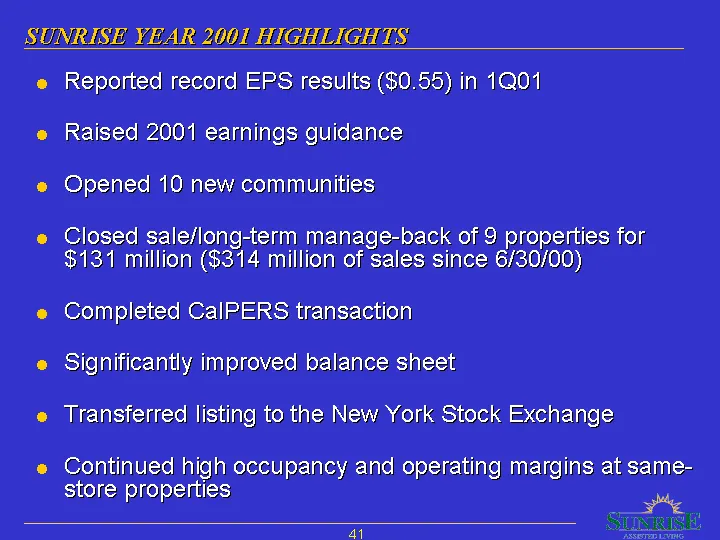
SUNEISH VEAR 2001 HIGHLIGHTS Reported record EPS results ($0155) in 101 Raised 2001 earnings guidance Opened 10 new communities Closed sale/long-term manage-back of 9 properties for $131 million ($314 million of sales since 6/30/00) Completed CalPERS transaction Significantly improved balance sheet
Slide 41: Pricing Power
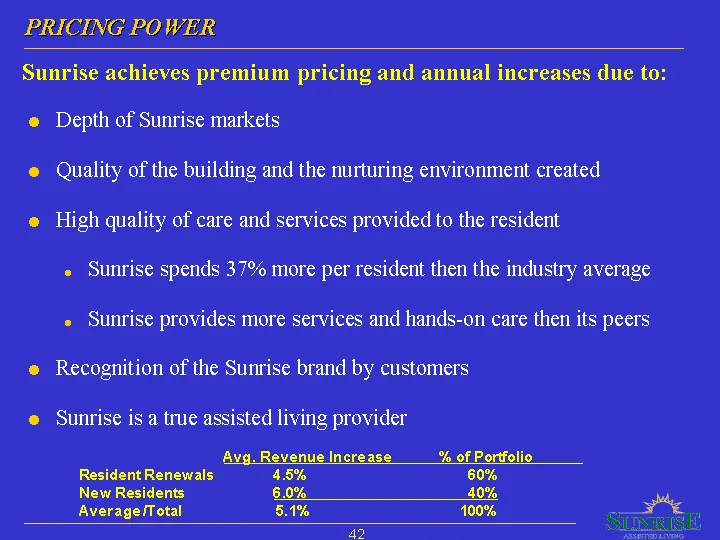
PRICING POWER Sunrise achieves premium pricing and annual increases due to: e Depth of Sunrise markets e Quality of the building and the nurturing environment created e High quality of care and services provided to the resident « Sunrise spends 37% more per resident then the industry average e Sunri
Slide 42: Convertible Notes — $127.6 Million Due June 2002
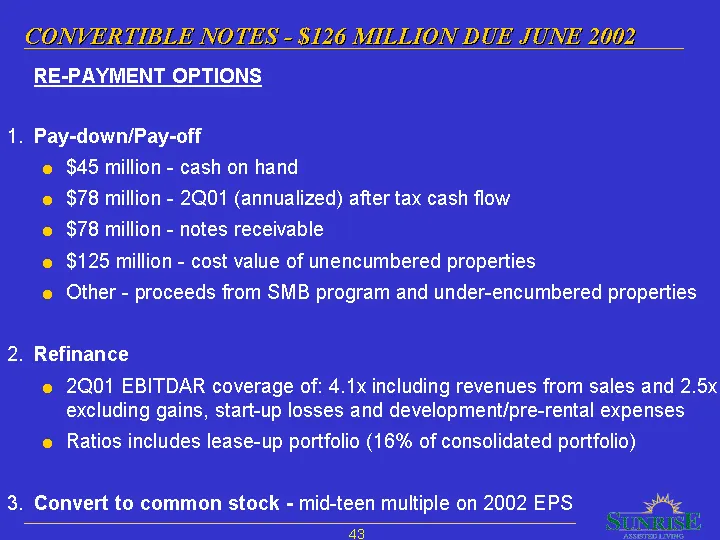
CONVERTIBLE NOTES — $1276 MILLION DUE JUNE 20027 RE-PAYMENT OPTIONS 1. Pay-down/Pay-off e $45 million - cash on hand e $78 million - 2Q01 (annualized) after tax cash flow e $78 million - notes receivable e $125 million - cost value of unencumbered properties e Other - proceeds from SMB program and u
Slide 43: Why SRZ?
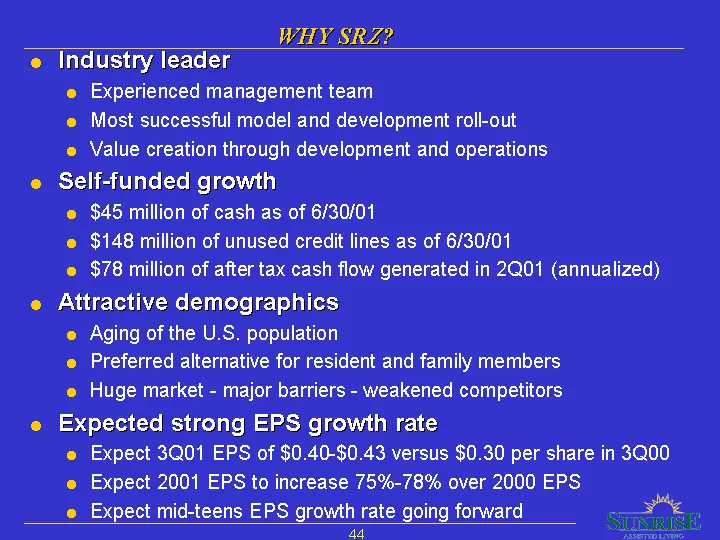
WHY SEZ? Industry leader e Experienced management team e Most successful model and development roll-out e Value creation through development and operations Self-funded growth e $45 million of cash as of 6/30/01 e $148 million of unused credit lines as of 6/30/01 e $78 million of after tax cash flow
Slide 44: Sunrise Assisted Living
F 7\ 9: ame SUNRISE ASSISTED LIVING
Source: SEC EDGAR · 8-K filed Sep 6, 2001
More decks from Sunrise Senior Living
 Merger or Acquisition (August 2012)12 slides · Aug 22, 2012
 Investor Presentation (June 2011)27 slides · Jun 14, 2011
 Investor Presentation (May 2008)38 slides · May 21, 2008
 Investor Presentation (May 2008)38 slides · May 14, 2008
 Lehman Brothers Ninth Annual Healthcare Conference 200642 slides · Mar 8, 2006
 Investor Presentation (May 2005)39 slides · May 18, 2005