Sterling Bancshares — Merger or Acquisition (February 2011)
26 slides from Sterling Bancshares's merger presentation, Feb 22, 2011
Slide 1: Filed by Comerica Incorporated Pursuant to Rule 425
Filed by Comerica Incorporated Pursuant to Rule 425 under the Securities Act of 1933 and deemed filed pursuant to Rule 14a-12 of the Securities Exchange Act of 1934 Subject Company: Sterling Bancshares, Inc. (Commission File No. 1-34768) The following document is filed herewith pursuant to Rule 425
Slide 2: Additional filing information and participants in solicitation
A free copy of the preliminary Proxy Statement/Prospectus, and, when it becomes available, a free copy of the definitive Proxy Statement/Prospectus, as well as other filings containing information about Comerica and Sterling, may be obtained at the SEC’s Internet site (http://www.sec.gov). You will
Slide 3: Sterling Bank All Officer Meeting
Comerica Incorporated Sterling Bank All Officer Meeting February 21, 2011 Pat Faubion President – Texas Market
Slide 4: Safe Harbor Statement; Disclaimer
Safe Harbor Statement; Disclaimer Any statements in this presentation that are not historical facts are forward-looking statements as defined in the Private Securities Litigation Reform Act of 1995. Words such as "anticipates," "believes," "feels," "expects," "estimates," "seeks," "strives," "plans,
Slide 5: Comerica: A Brief Overview
Comerica: A Brief Overview Among the top 25 U.S. bank holding companies Largest U.S. bank with corporate headquarters in Texas $54 billion in assets Founded over 160 years ago Major lines of business include: • Business Bank • Retail Bank • Wealth and Institutional Management Major markets include:
Slide 6: Our Core Businesses
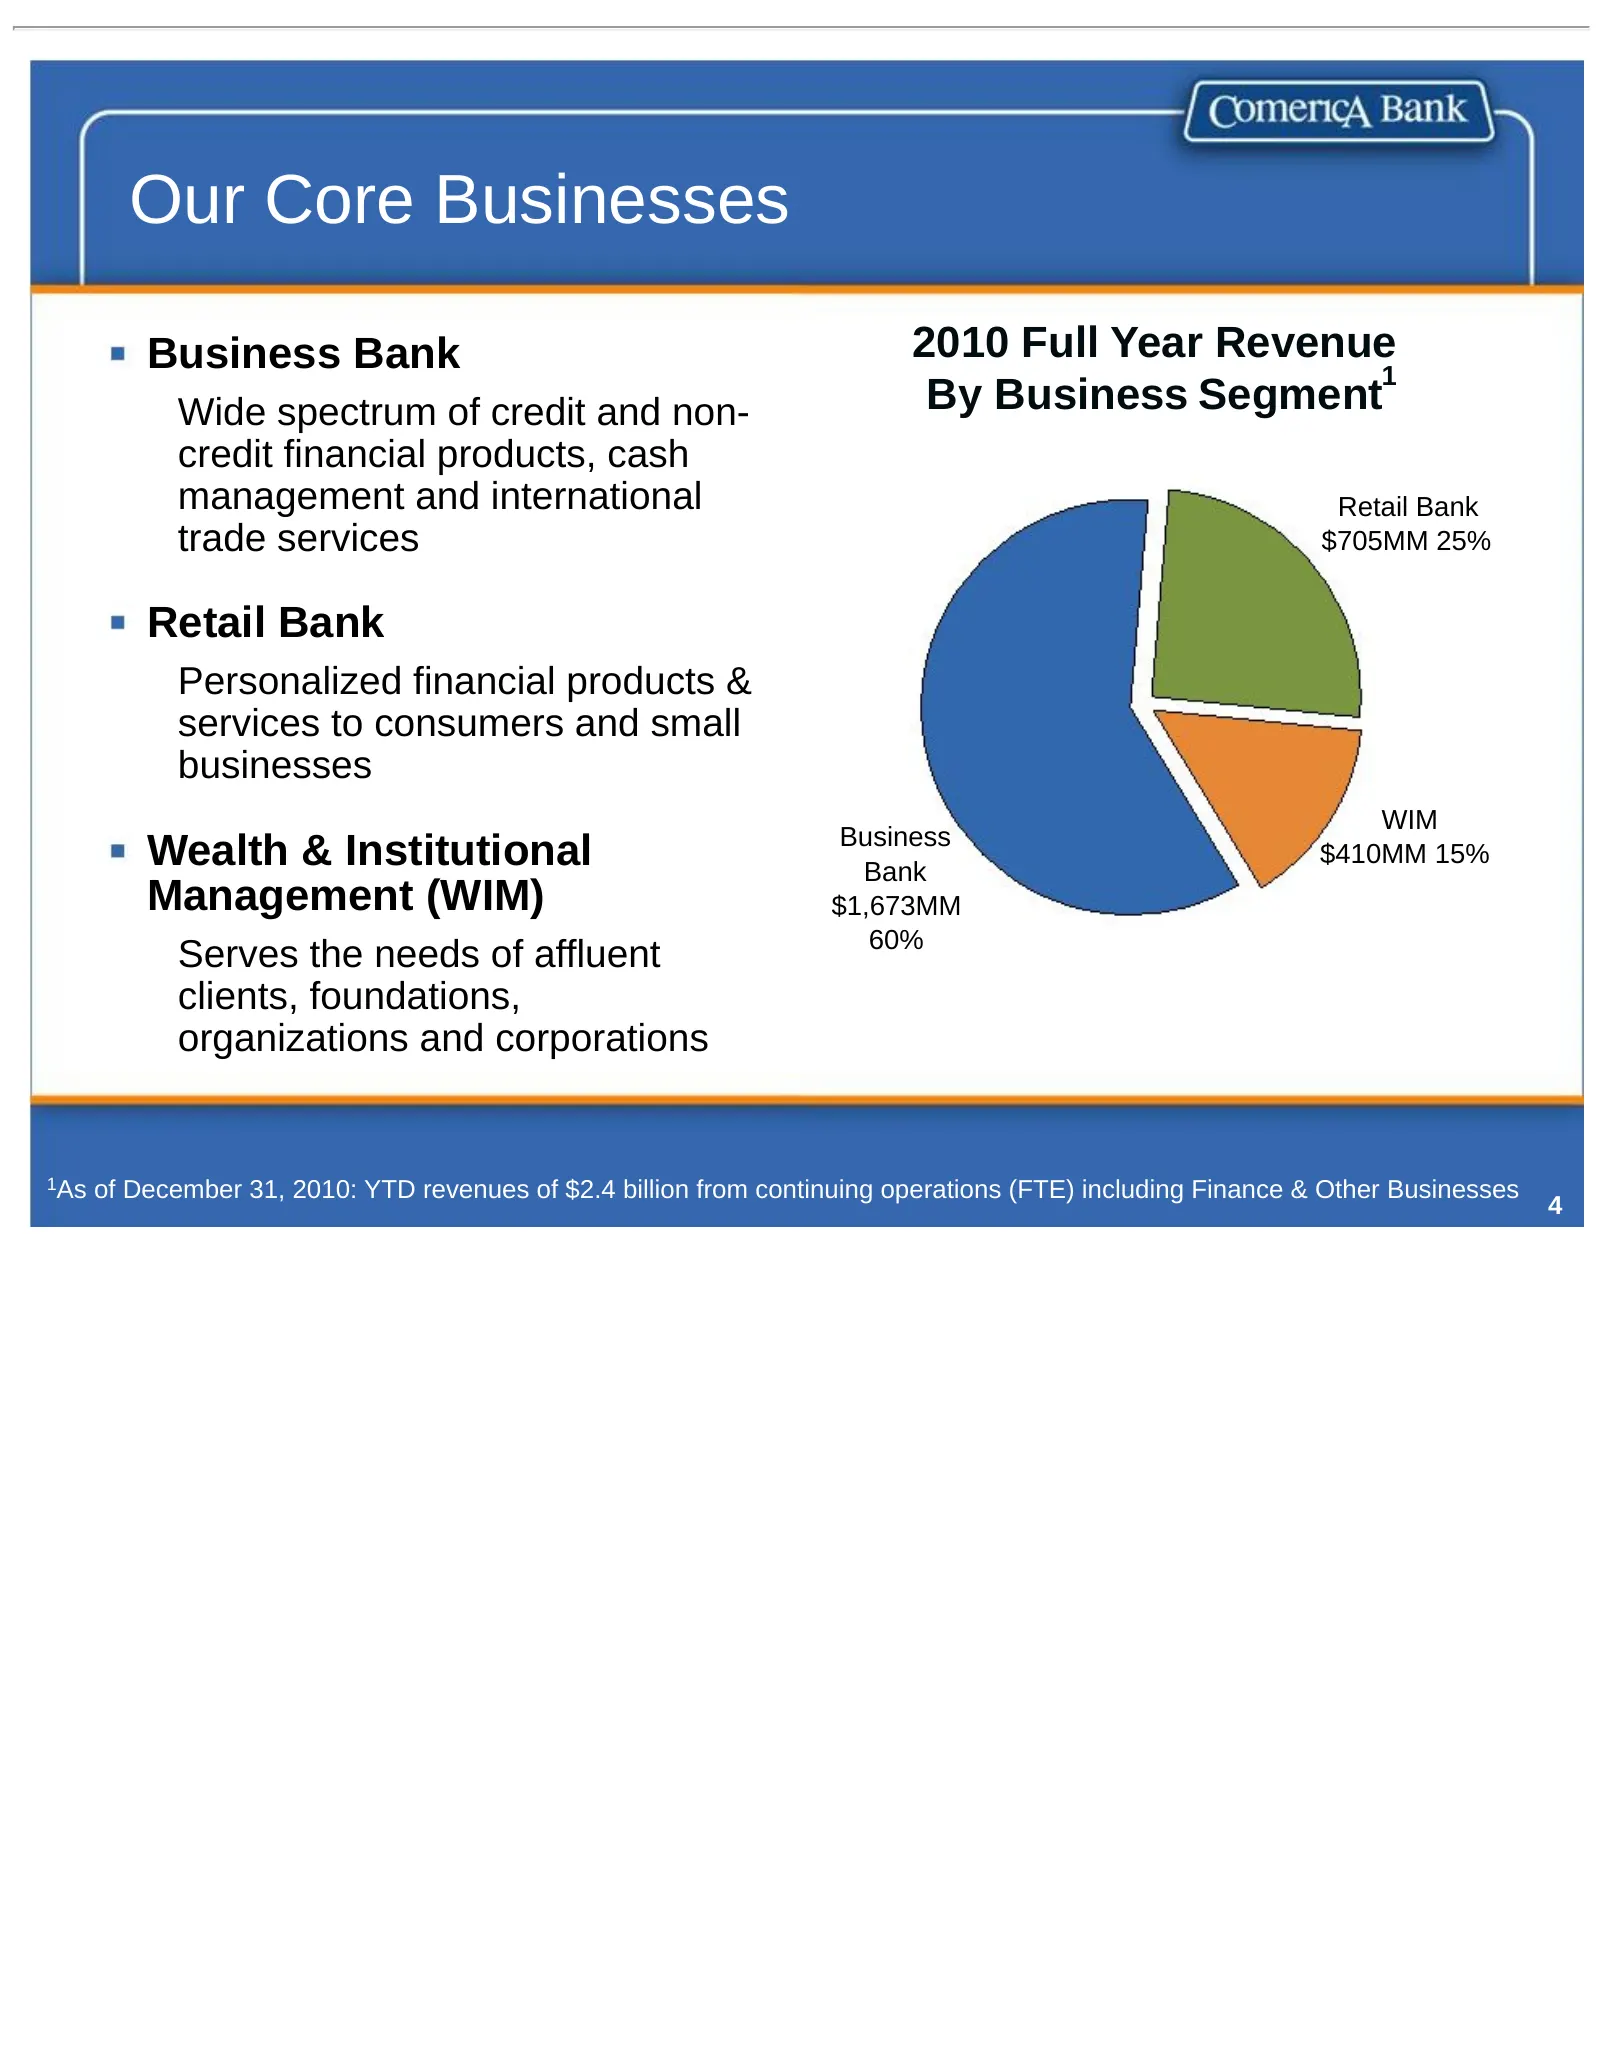
Our Core Businesses Business Bank 2010 Full Year Revenue 1 Wide spectrum of credit and non- By Business Segment credit financial products, cash management and international Retail Bank trade services $705MM 25% Retail Bank Personalized financial products & services to consumers and small businesses
Slide 7: Where We Operate
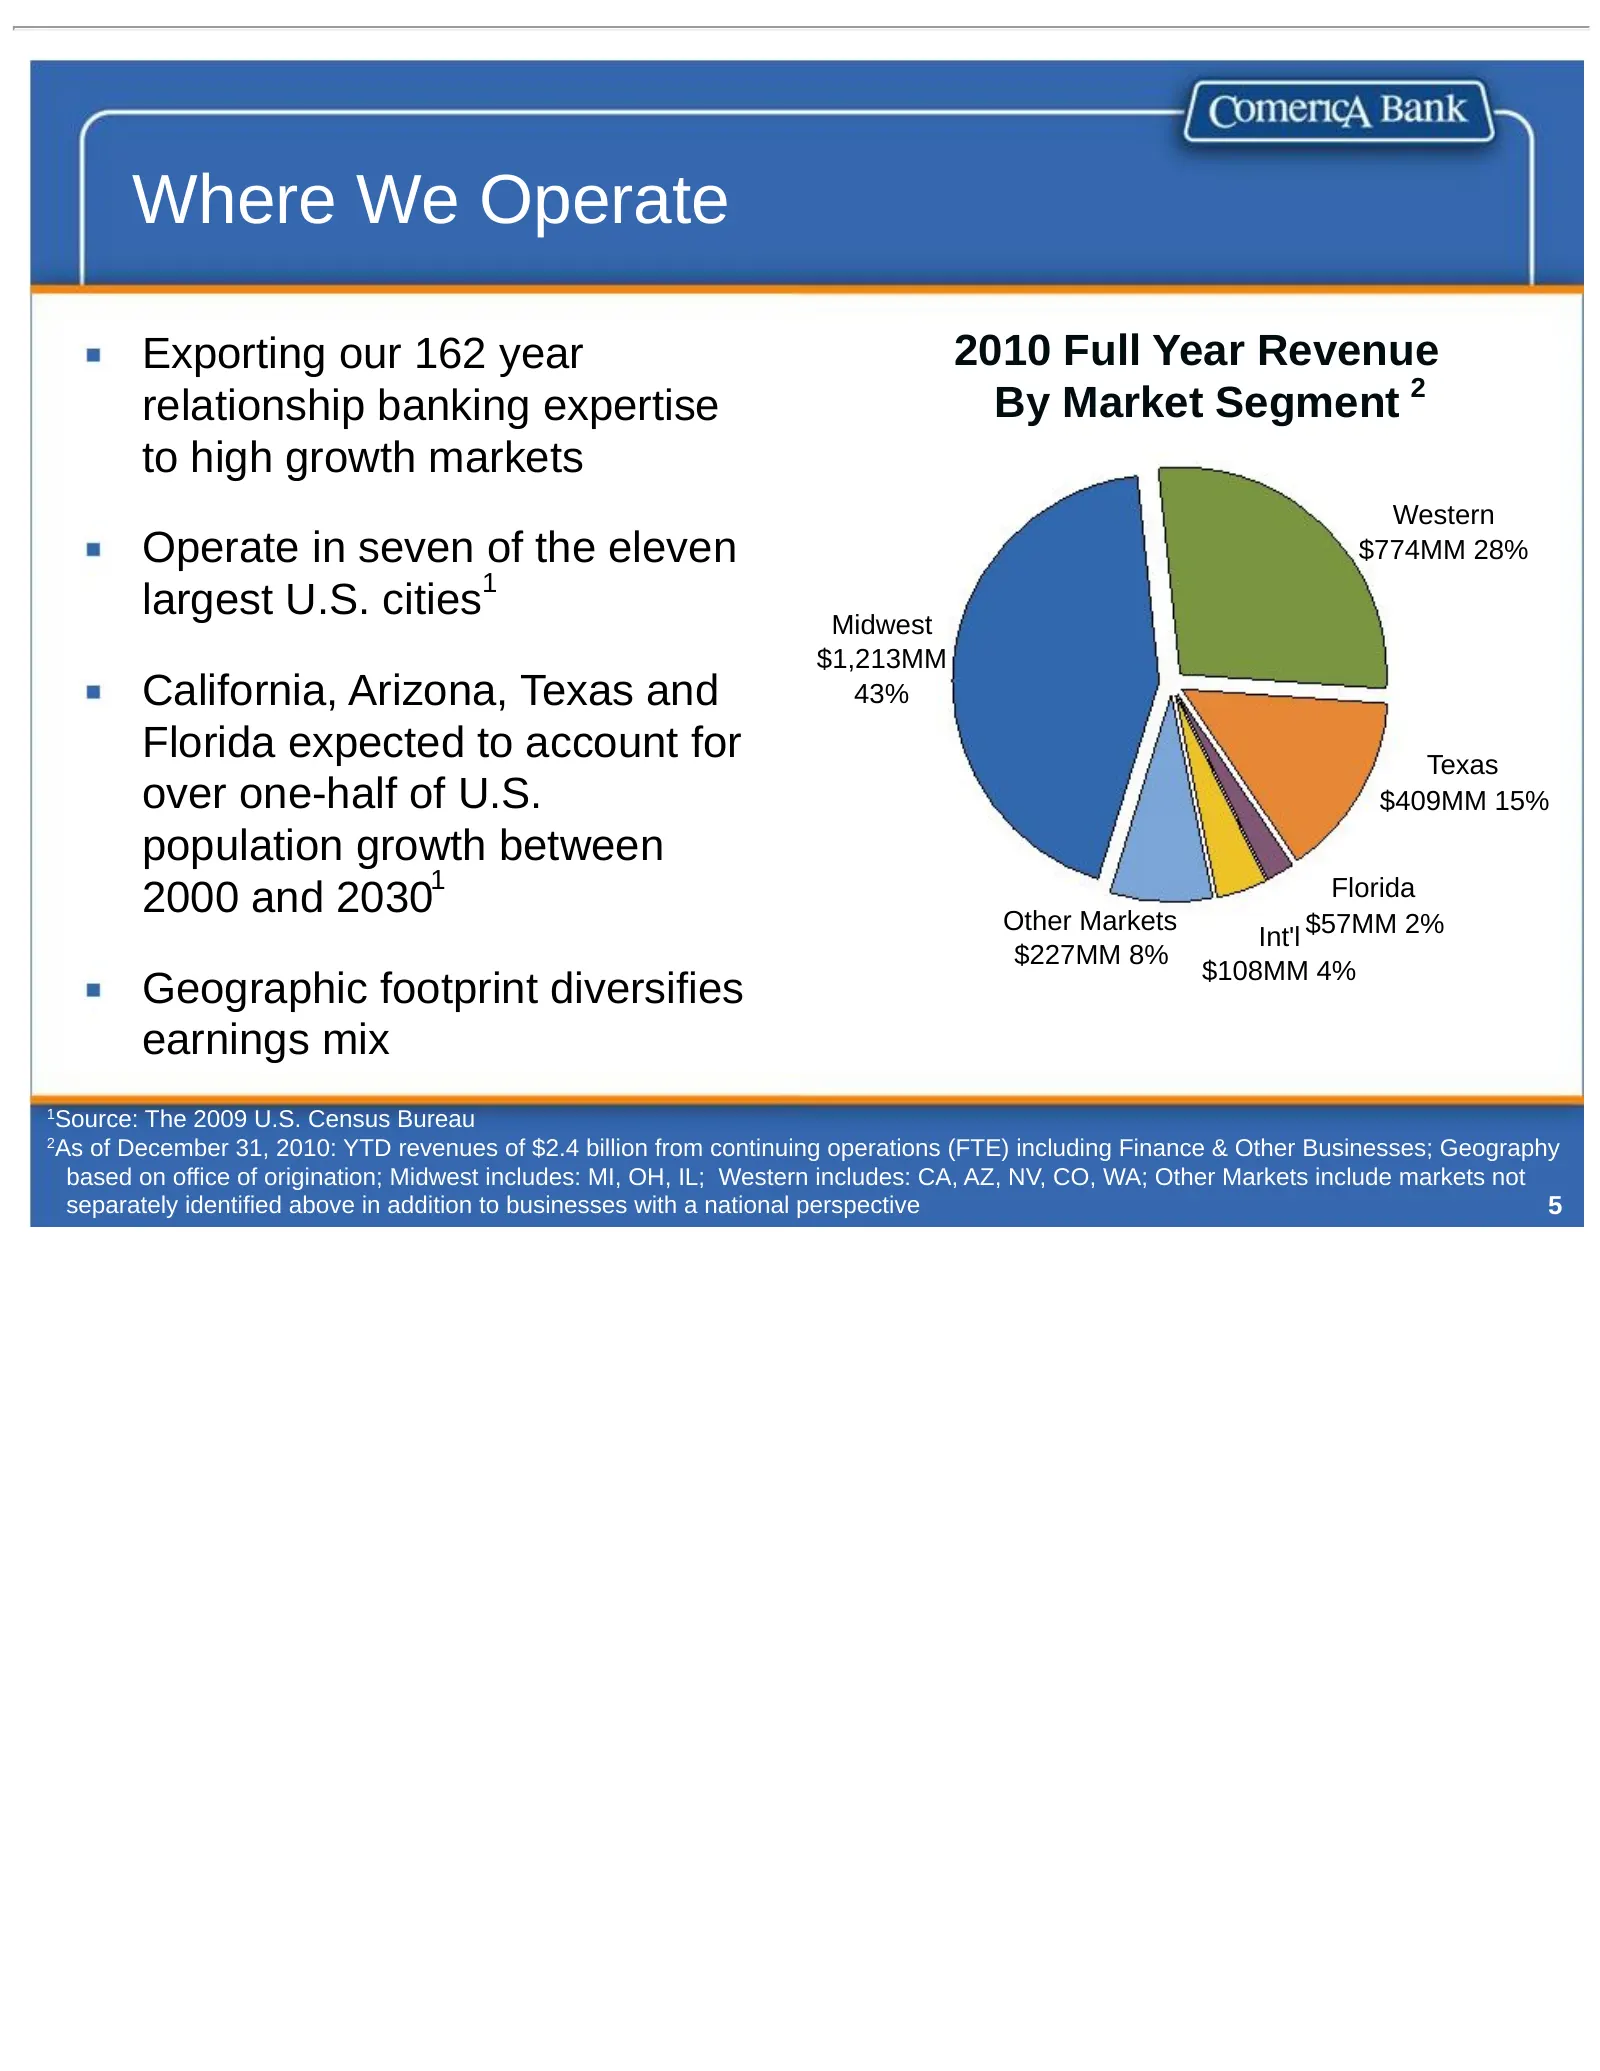
Where We Operate Exporting our 162 year 2010 Full Year Revenue relationship banking expertise By Market Segment 2 to high growth markets Western Operate in seven of the eleven $774MM 28% 1 largest U.S. cities Midwest $1,213MM California, Arizona, Texas and 43% Florida expected to account for Texas o
Slide 8: Texas Market: Prepared for Growth
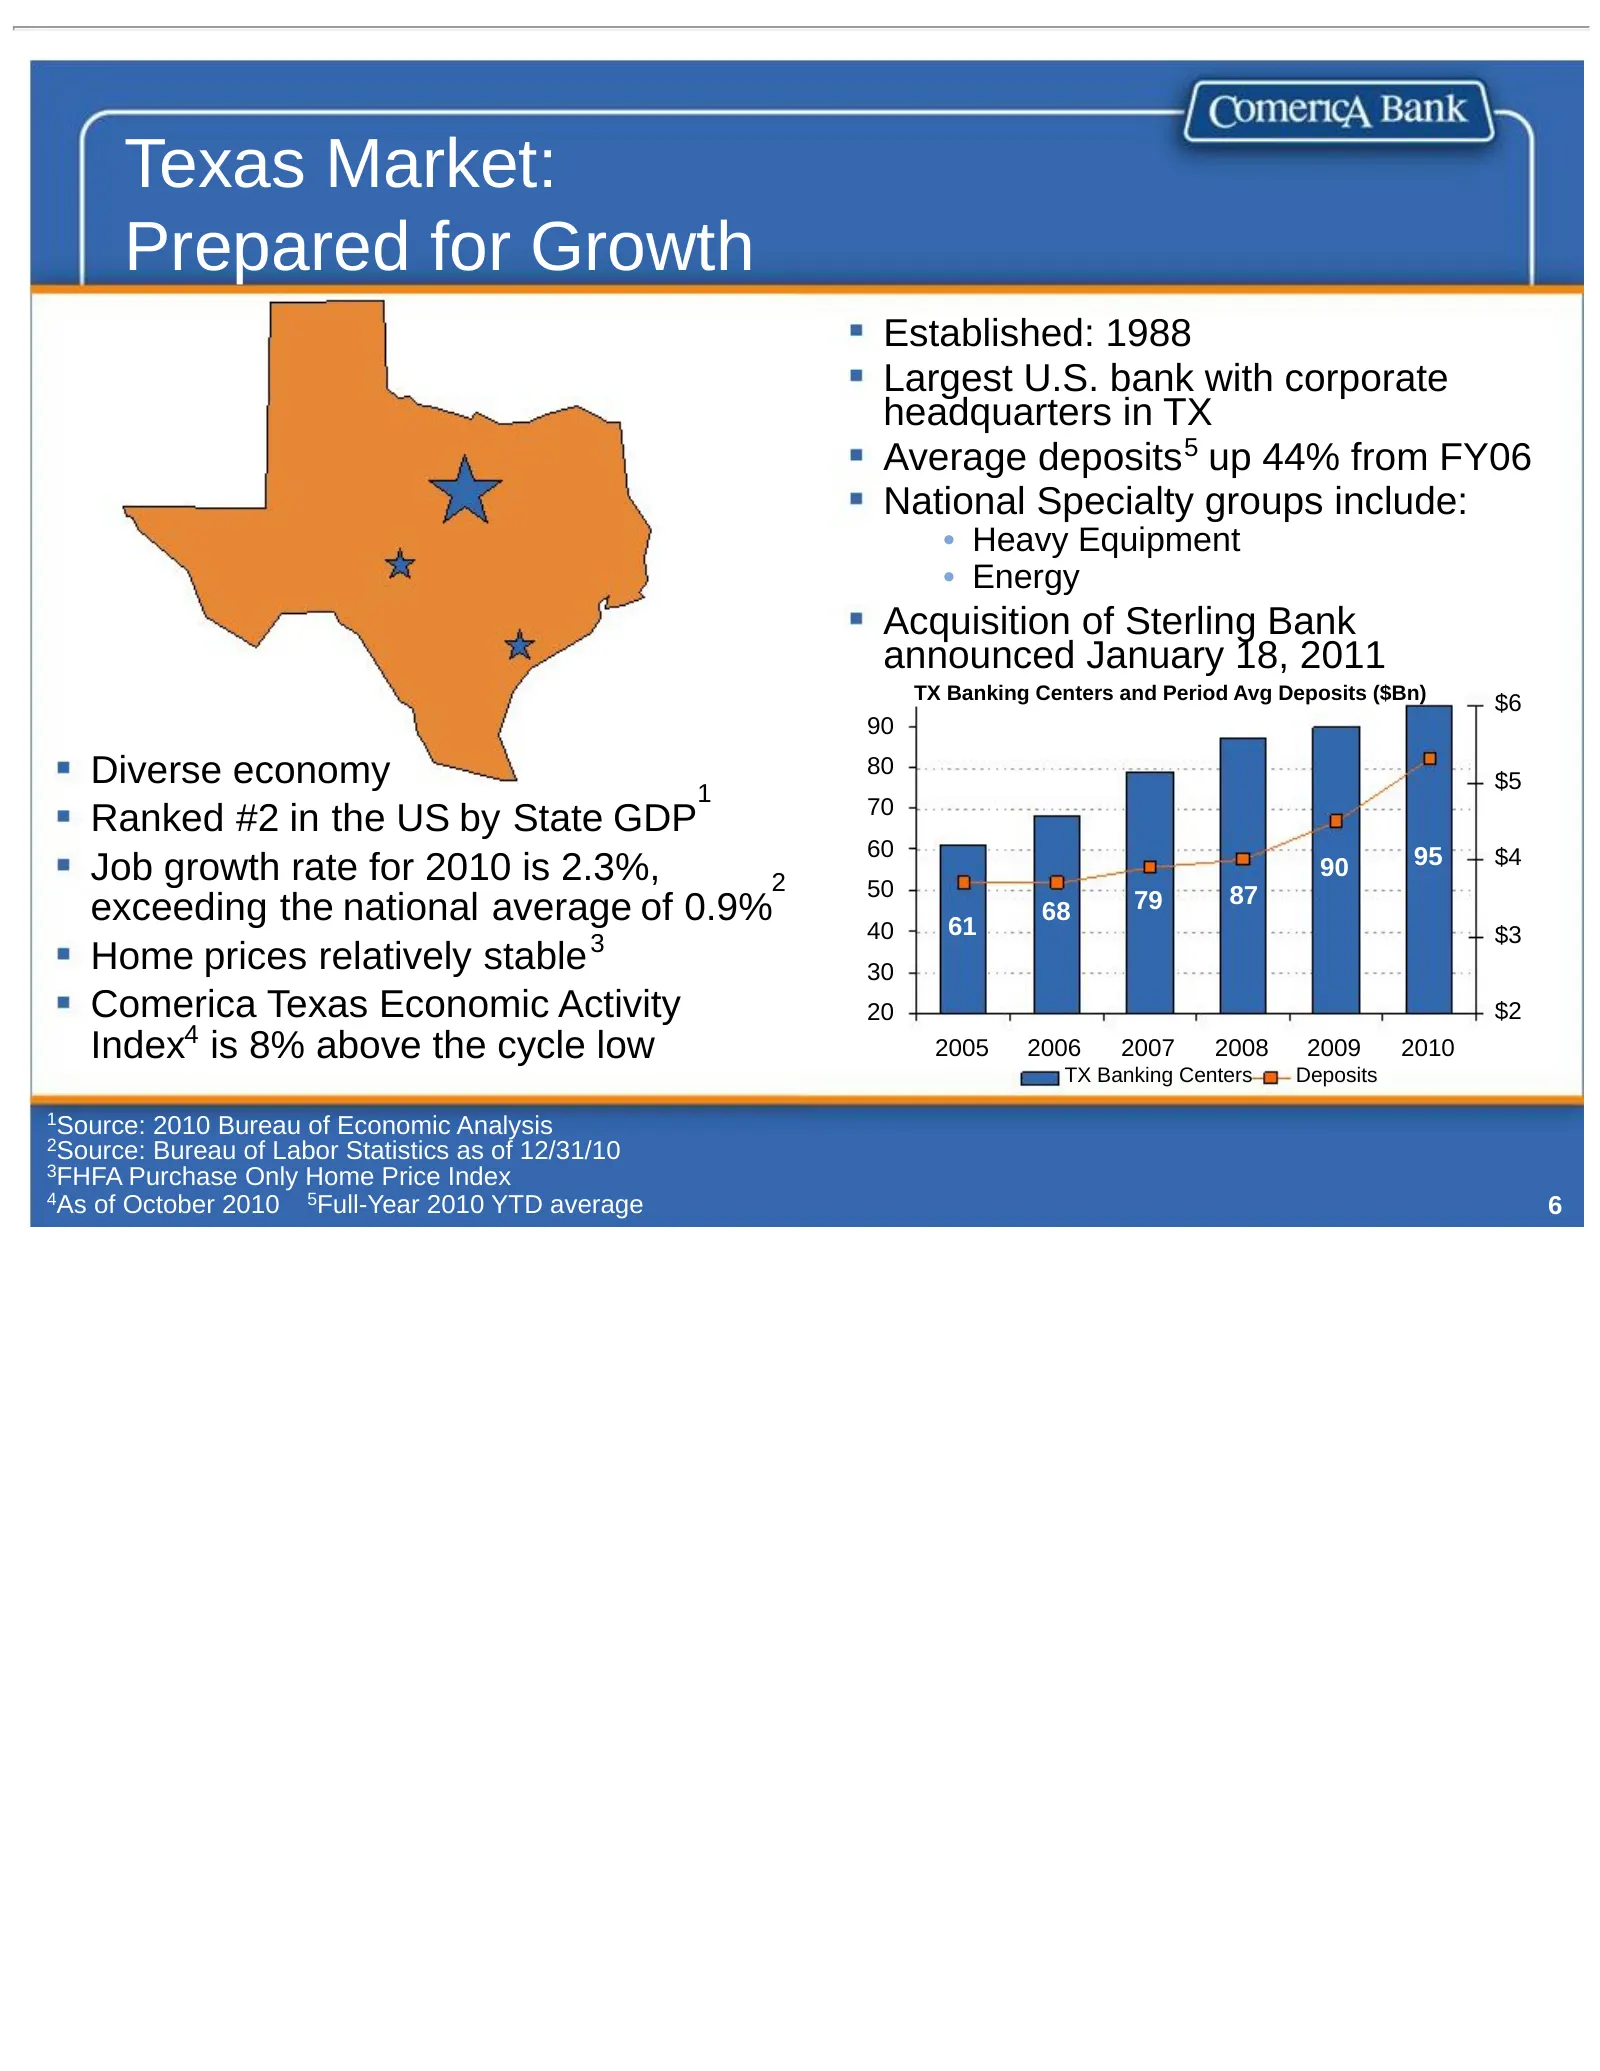
Texas Market: Prepared for Growth Established: 1988 Largest U.S. bank with corporate headquarters in TX Average deposits 5 up 44% from FY06 National Specialty groups include: • Heavy Equipment • Energy Acquisition of Sterling Bank announced January 18, 2011 TX Banking Centers and Period Avg Deposits
Slide 9: Comerica Key Differentiators
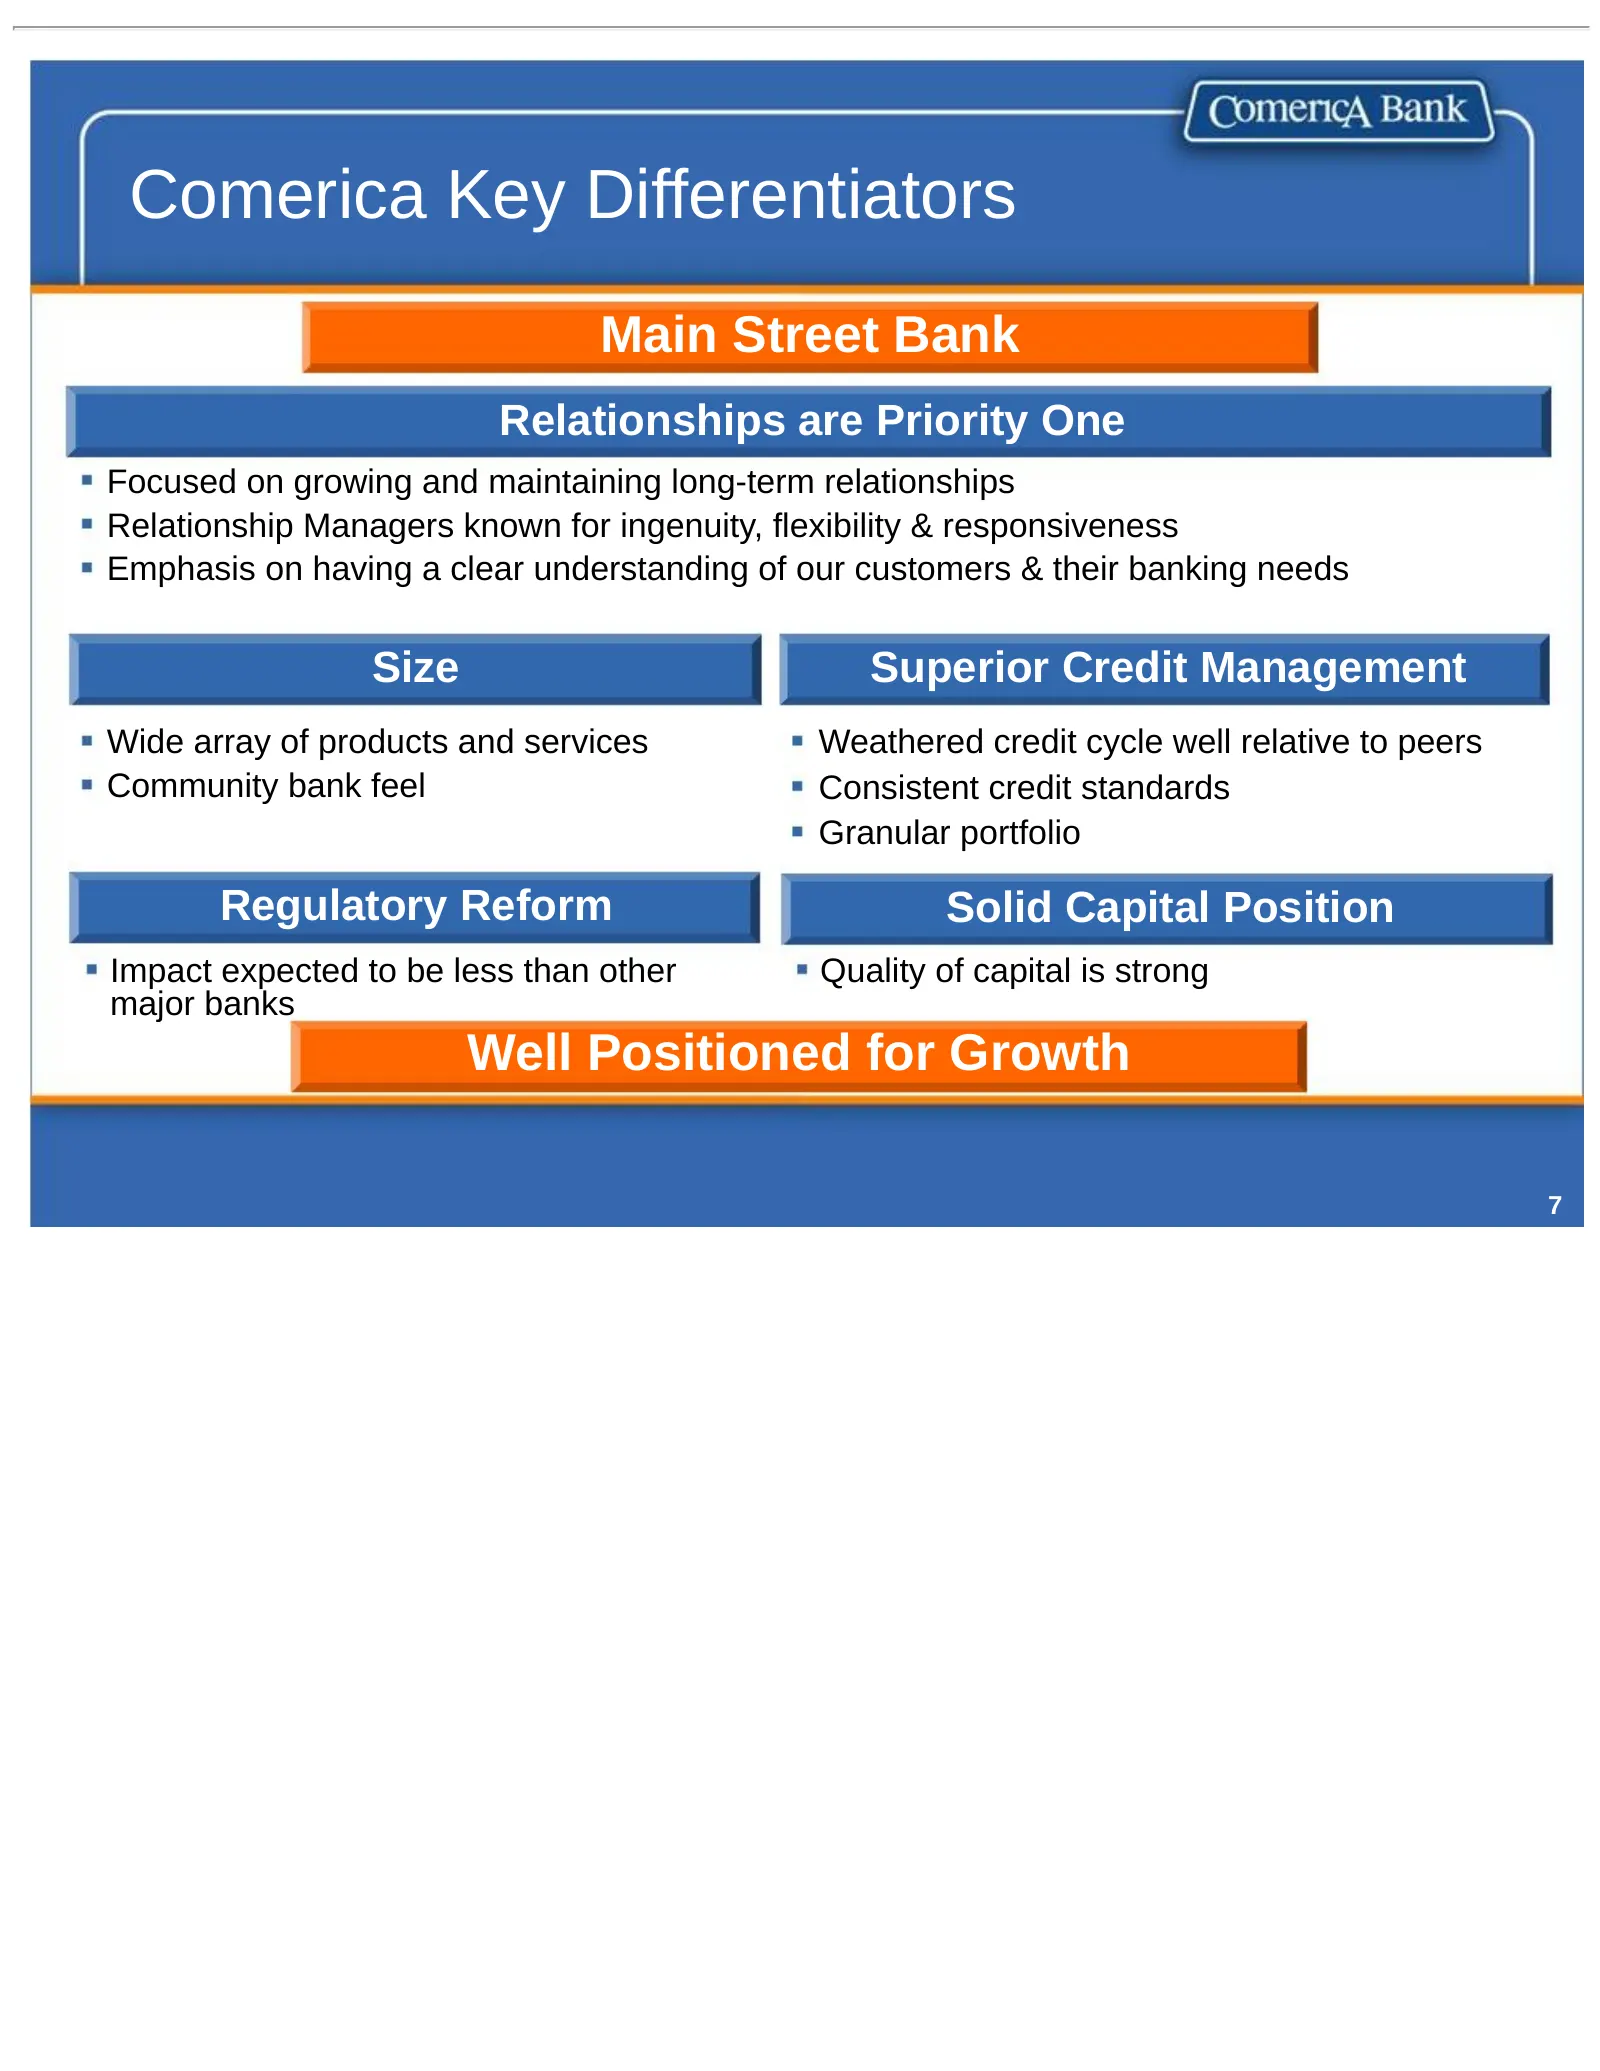
Comerica Key Differentiators Main Street Bank Relationships are Priority One Focused on growing and maintaining long-term relationships Relationship Managers known for ingenuity, flexibility & responsiveness Emphasis on having a clear understanding of our customers & their banking needs Size Superio
Slide 10: Long-term Corporate Strategy
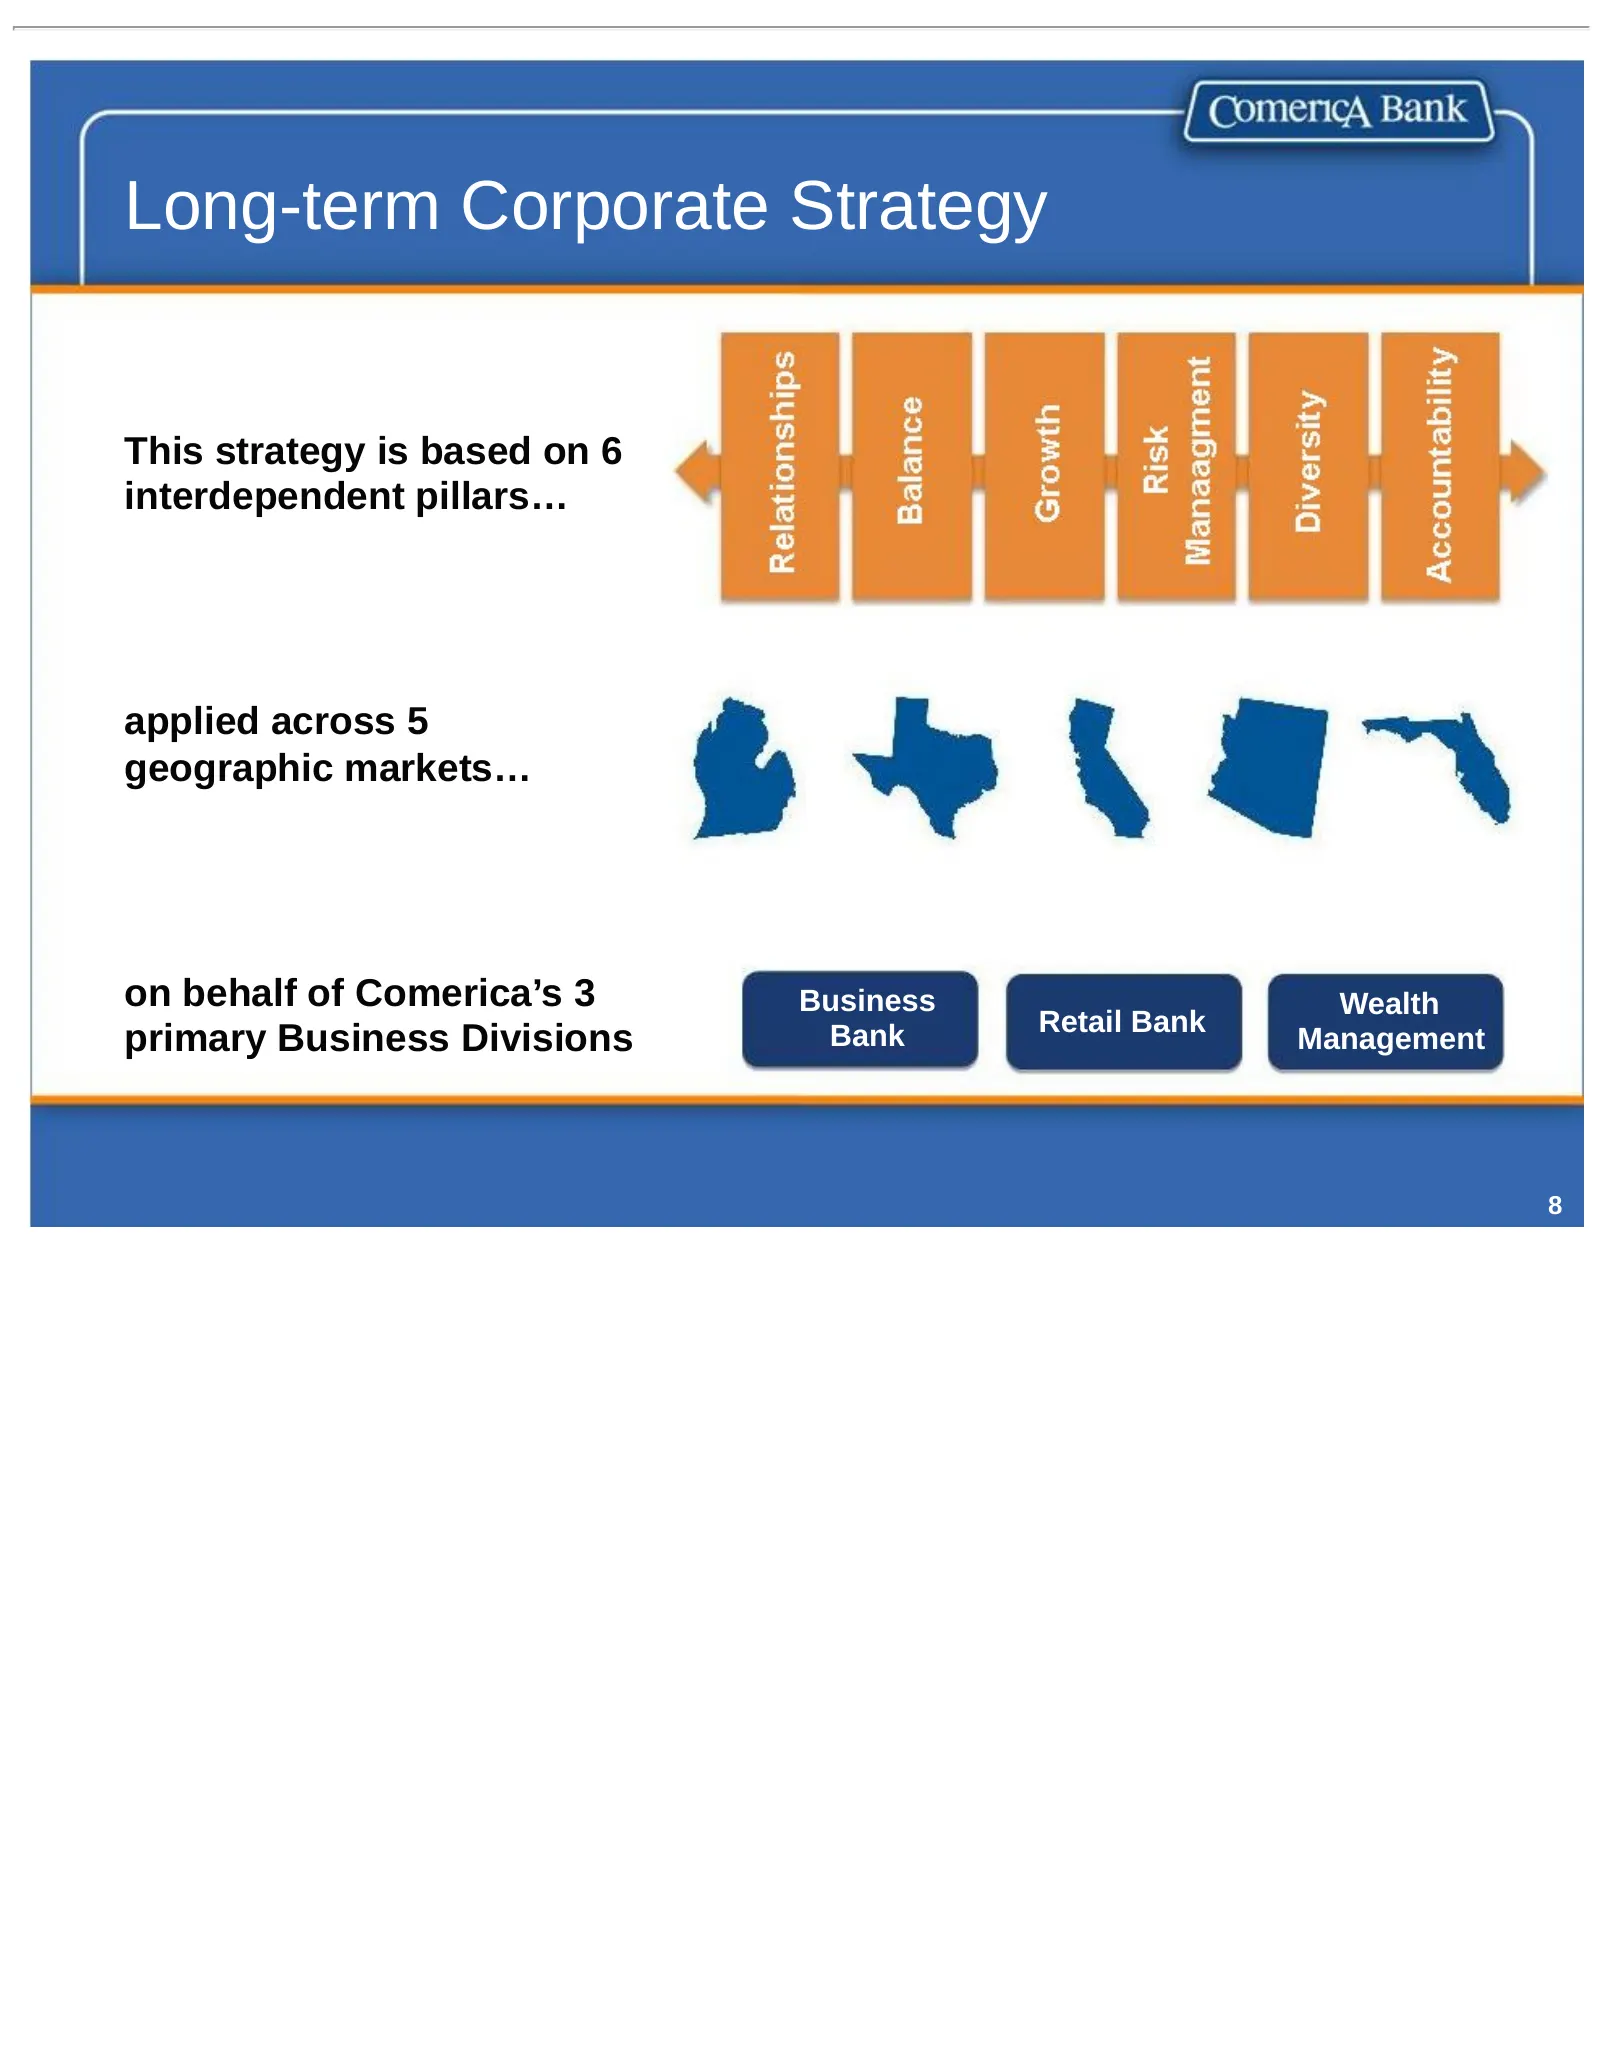
Long-term Corporate Strategy This strategy is based on 6 interdependent pillars… applied across 5 geographic markets… on behalf of Comerica’s 3 Business Wealth Retail Bank primary Business Divisions Bank Management 8
Slide 11: Long-term Corporate Strategy: Relationships and Balance
Long-term Corporate Strategy • Relationships • Client focused, concentrated on growing and maintaining long-term relationships • A platform that leverages our three Lines of Business to cross-sell services • Long-tenured bankers, known for ingenuity, flexibility and responsiveness • Community Bank s
Slide 12: Long-term Corporate Strategy: Growth and Risk Management
Long-term Corporate Strategy • Growth • Measured investments in targeted markets and Lines of Business • Emphasis on Cross-sells across the Lines of Business • Emphasis on importance of deposit base • Risk Management • Maintain a strong, quality capital position • Active credit management • Proactiv
Slide 13: Long-term Corporate Strategy: Diversity and Accountability
Long-term Corporate Strategy • Diversity • Highly recognized by several diversity ranking publications • Focus on internal human capital and external supplier diversity • Accountability • Strategic guidelines for each Line of Business • Monthly financial reporting and forecasting • Focus on employee
Slide 14: Financial Highlights
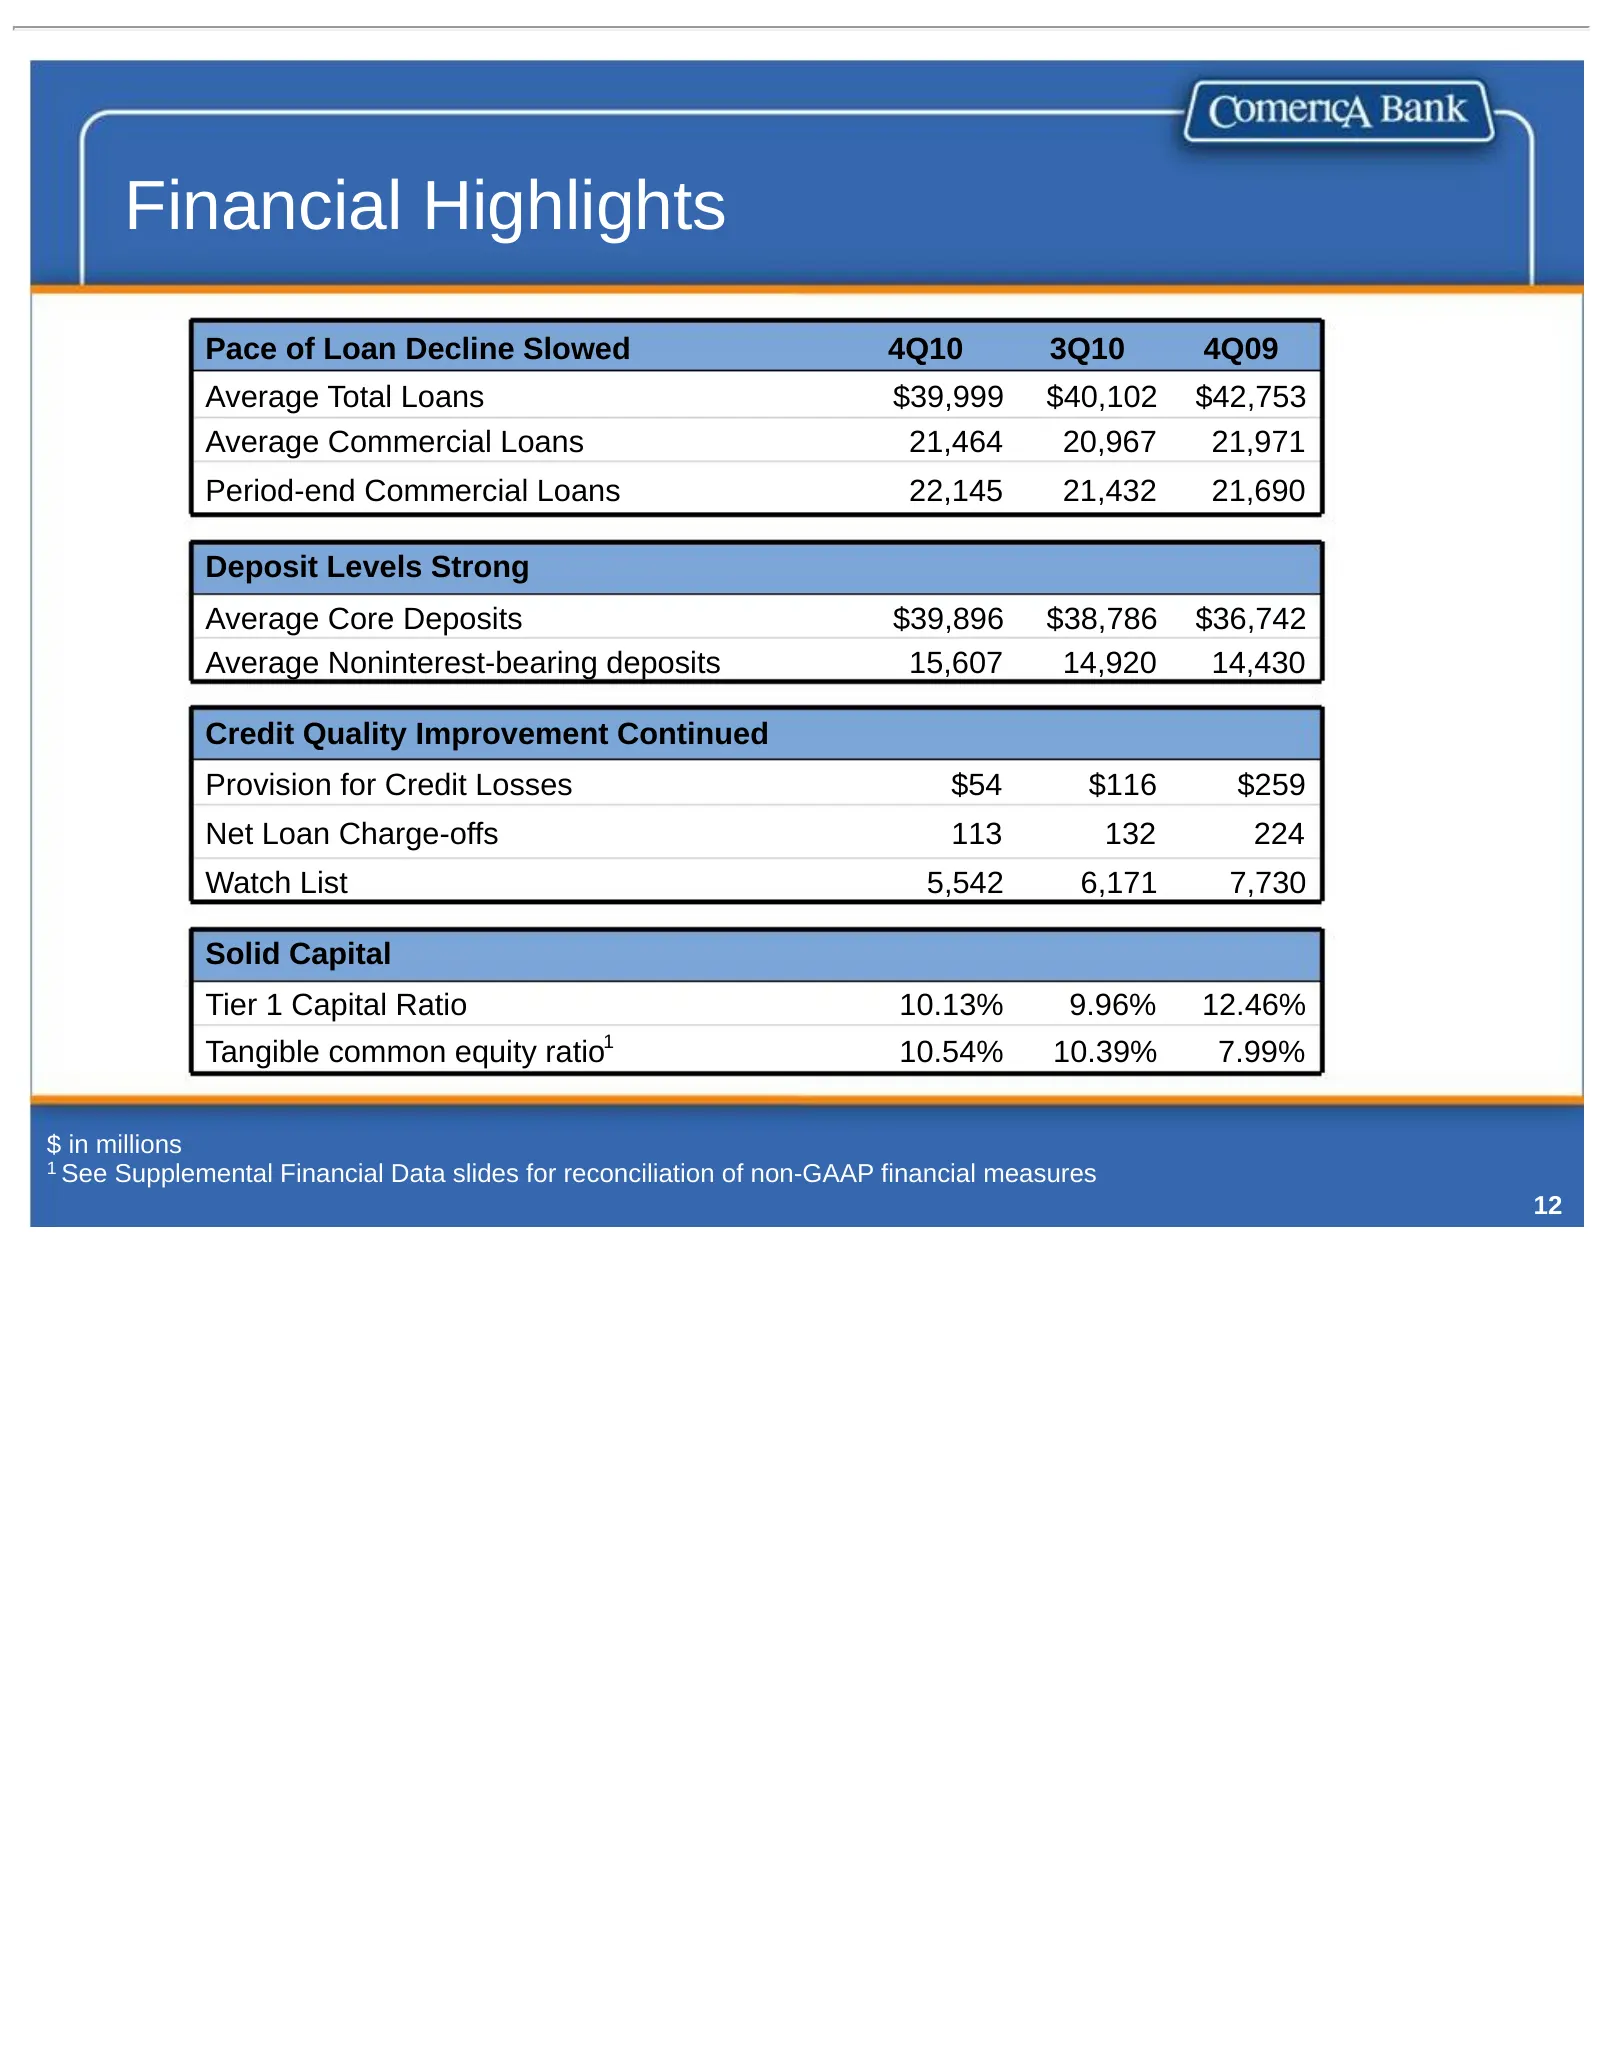
Financial Highlights Pace of Loan Decline Slowed 4Q10 3Q10 4Q09 Average Total Loans $39,999 $40,102 $42,753 Average Commercial Loans 21,464 20,967 21,971 Period-end Commercial Loans 22,145 21,432 21,690 Deposit Levels Strong Average Core Deposits $39,896 $38,786 $36,742 Average Noninterest-bearing d
Slide 15: Credit Quality Positive Trends Continued
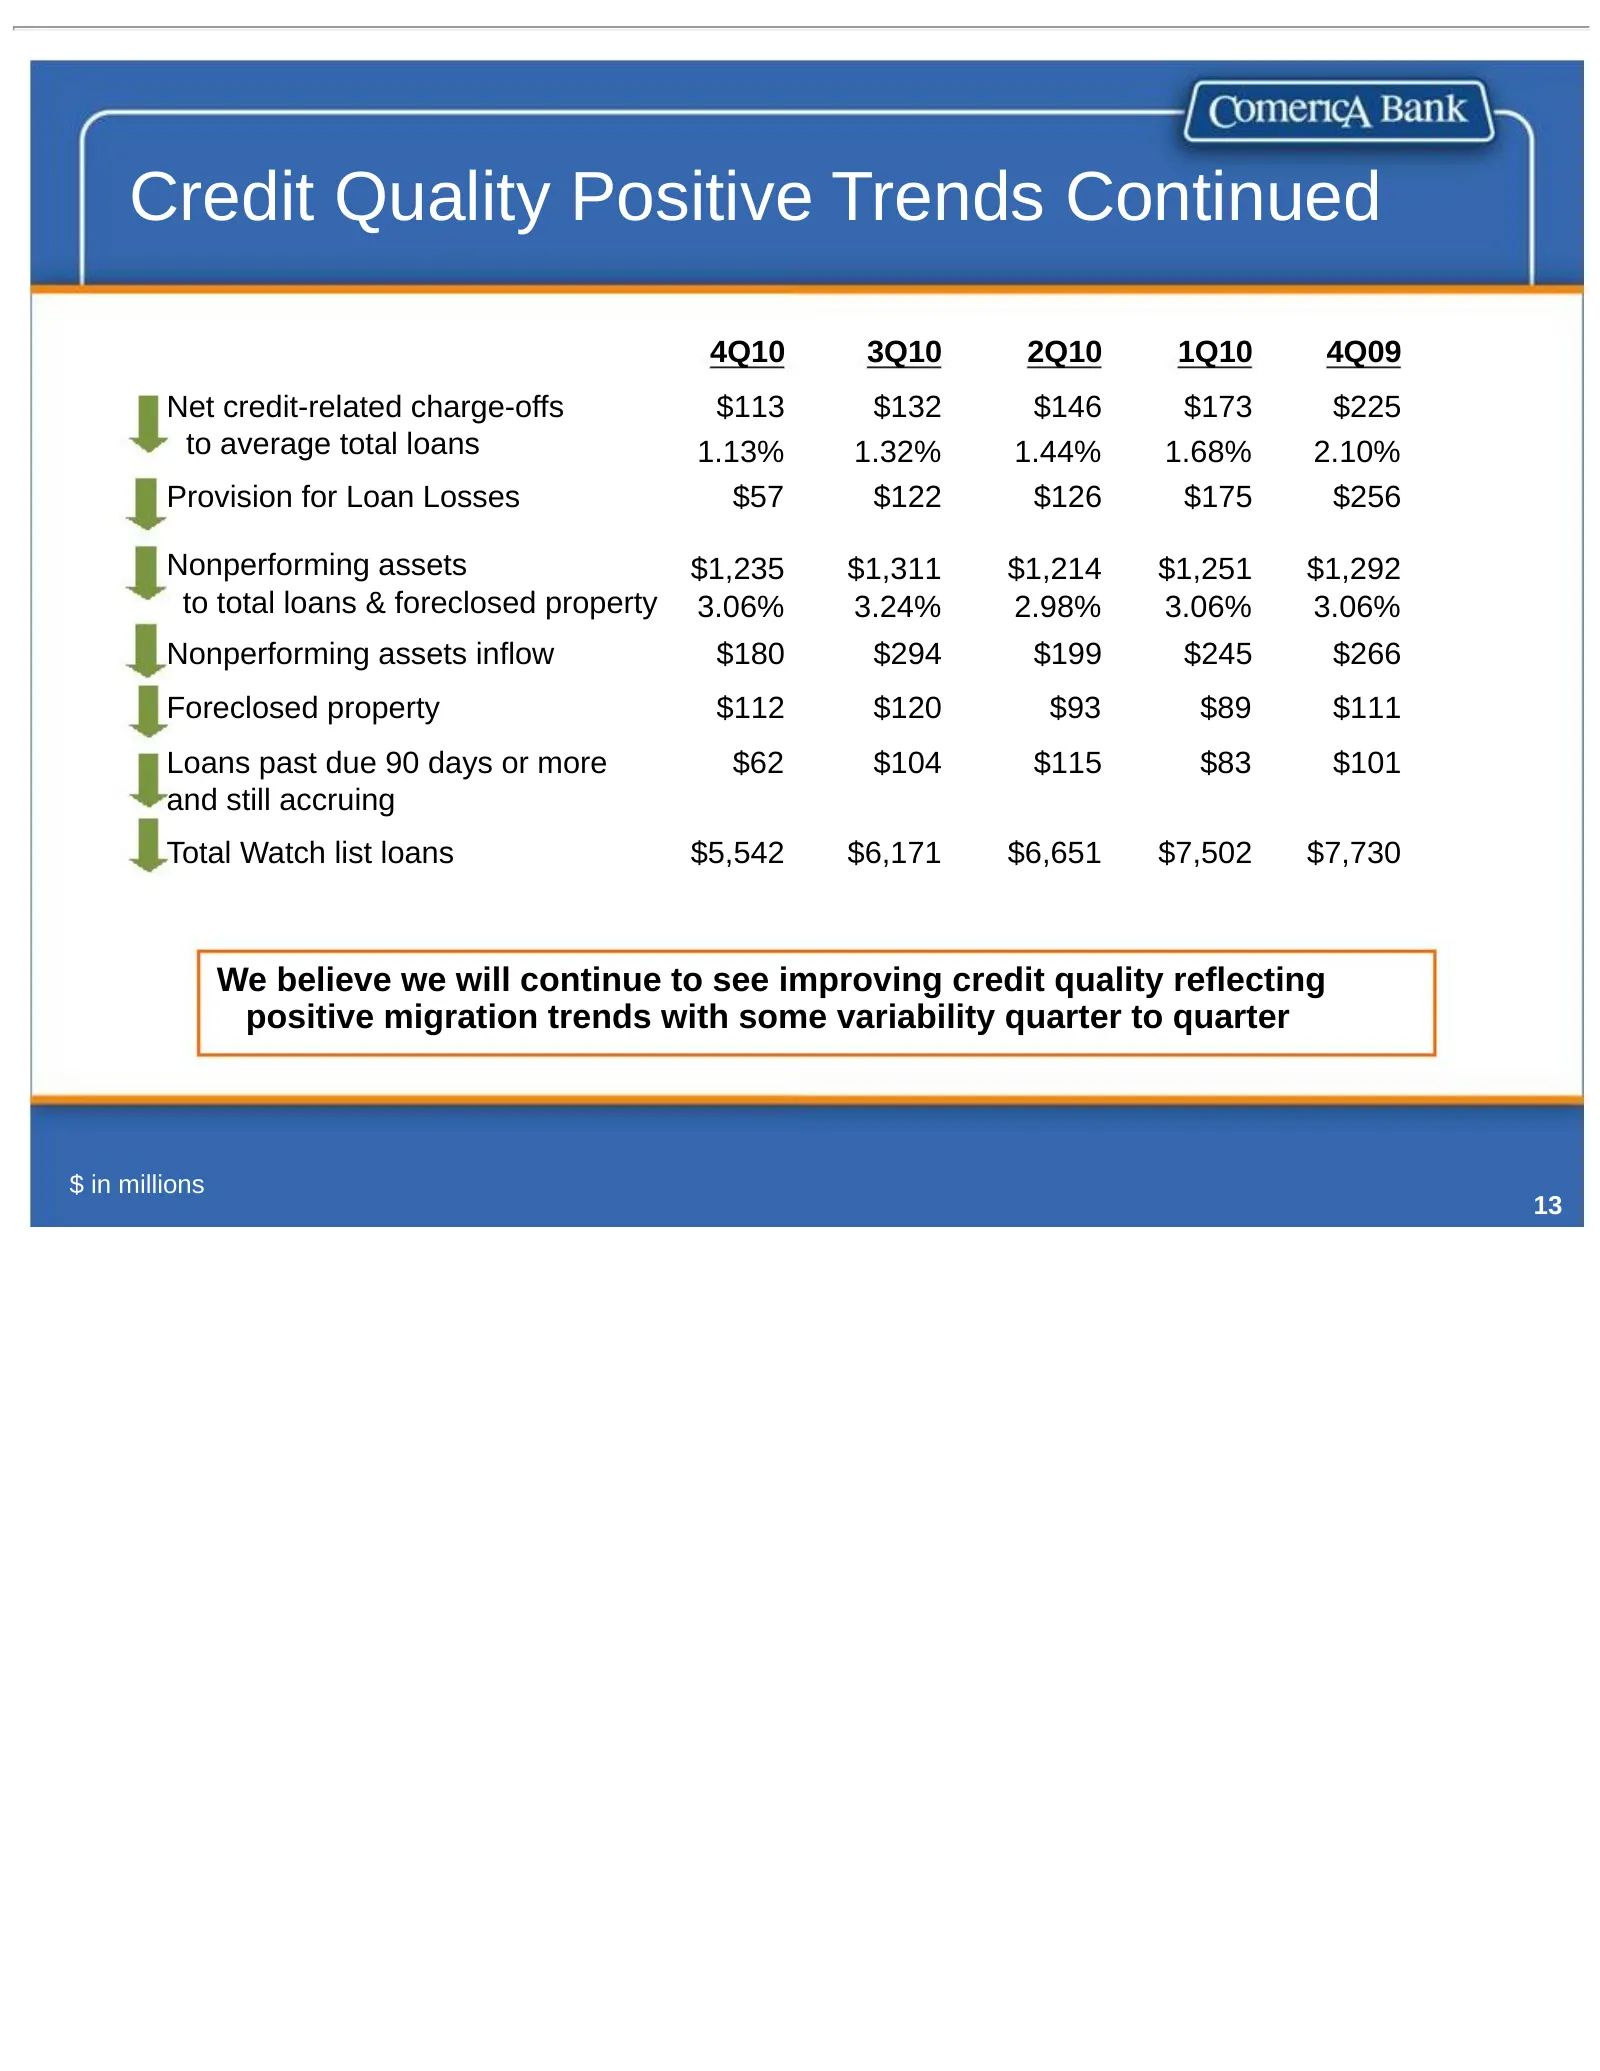
Credit Quality Positive Trends Continued 4Q10 3Q10 2Q10 1Q10 4Q09 Net credit-related charge-offs $113 $132 $146 $173 $225 to average total loans 1.13% 1.32% 1.44% 1.68% 2.10% Provision for Loan Losses $57 $122 $126 $175 $256 Nonperforming assets $1,235 $1,311 $1,214 $1,251 $1,292 to total loans & fo
Slide 16: Credit Quality Positive Trends Continued
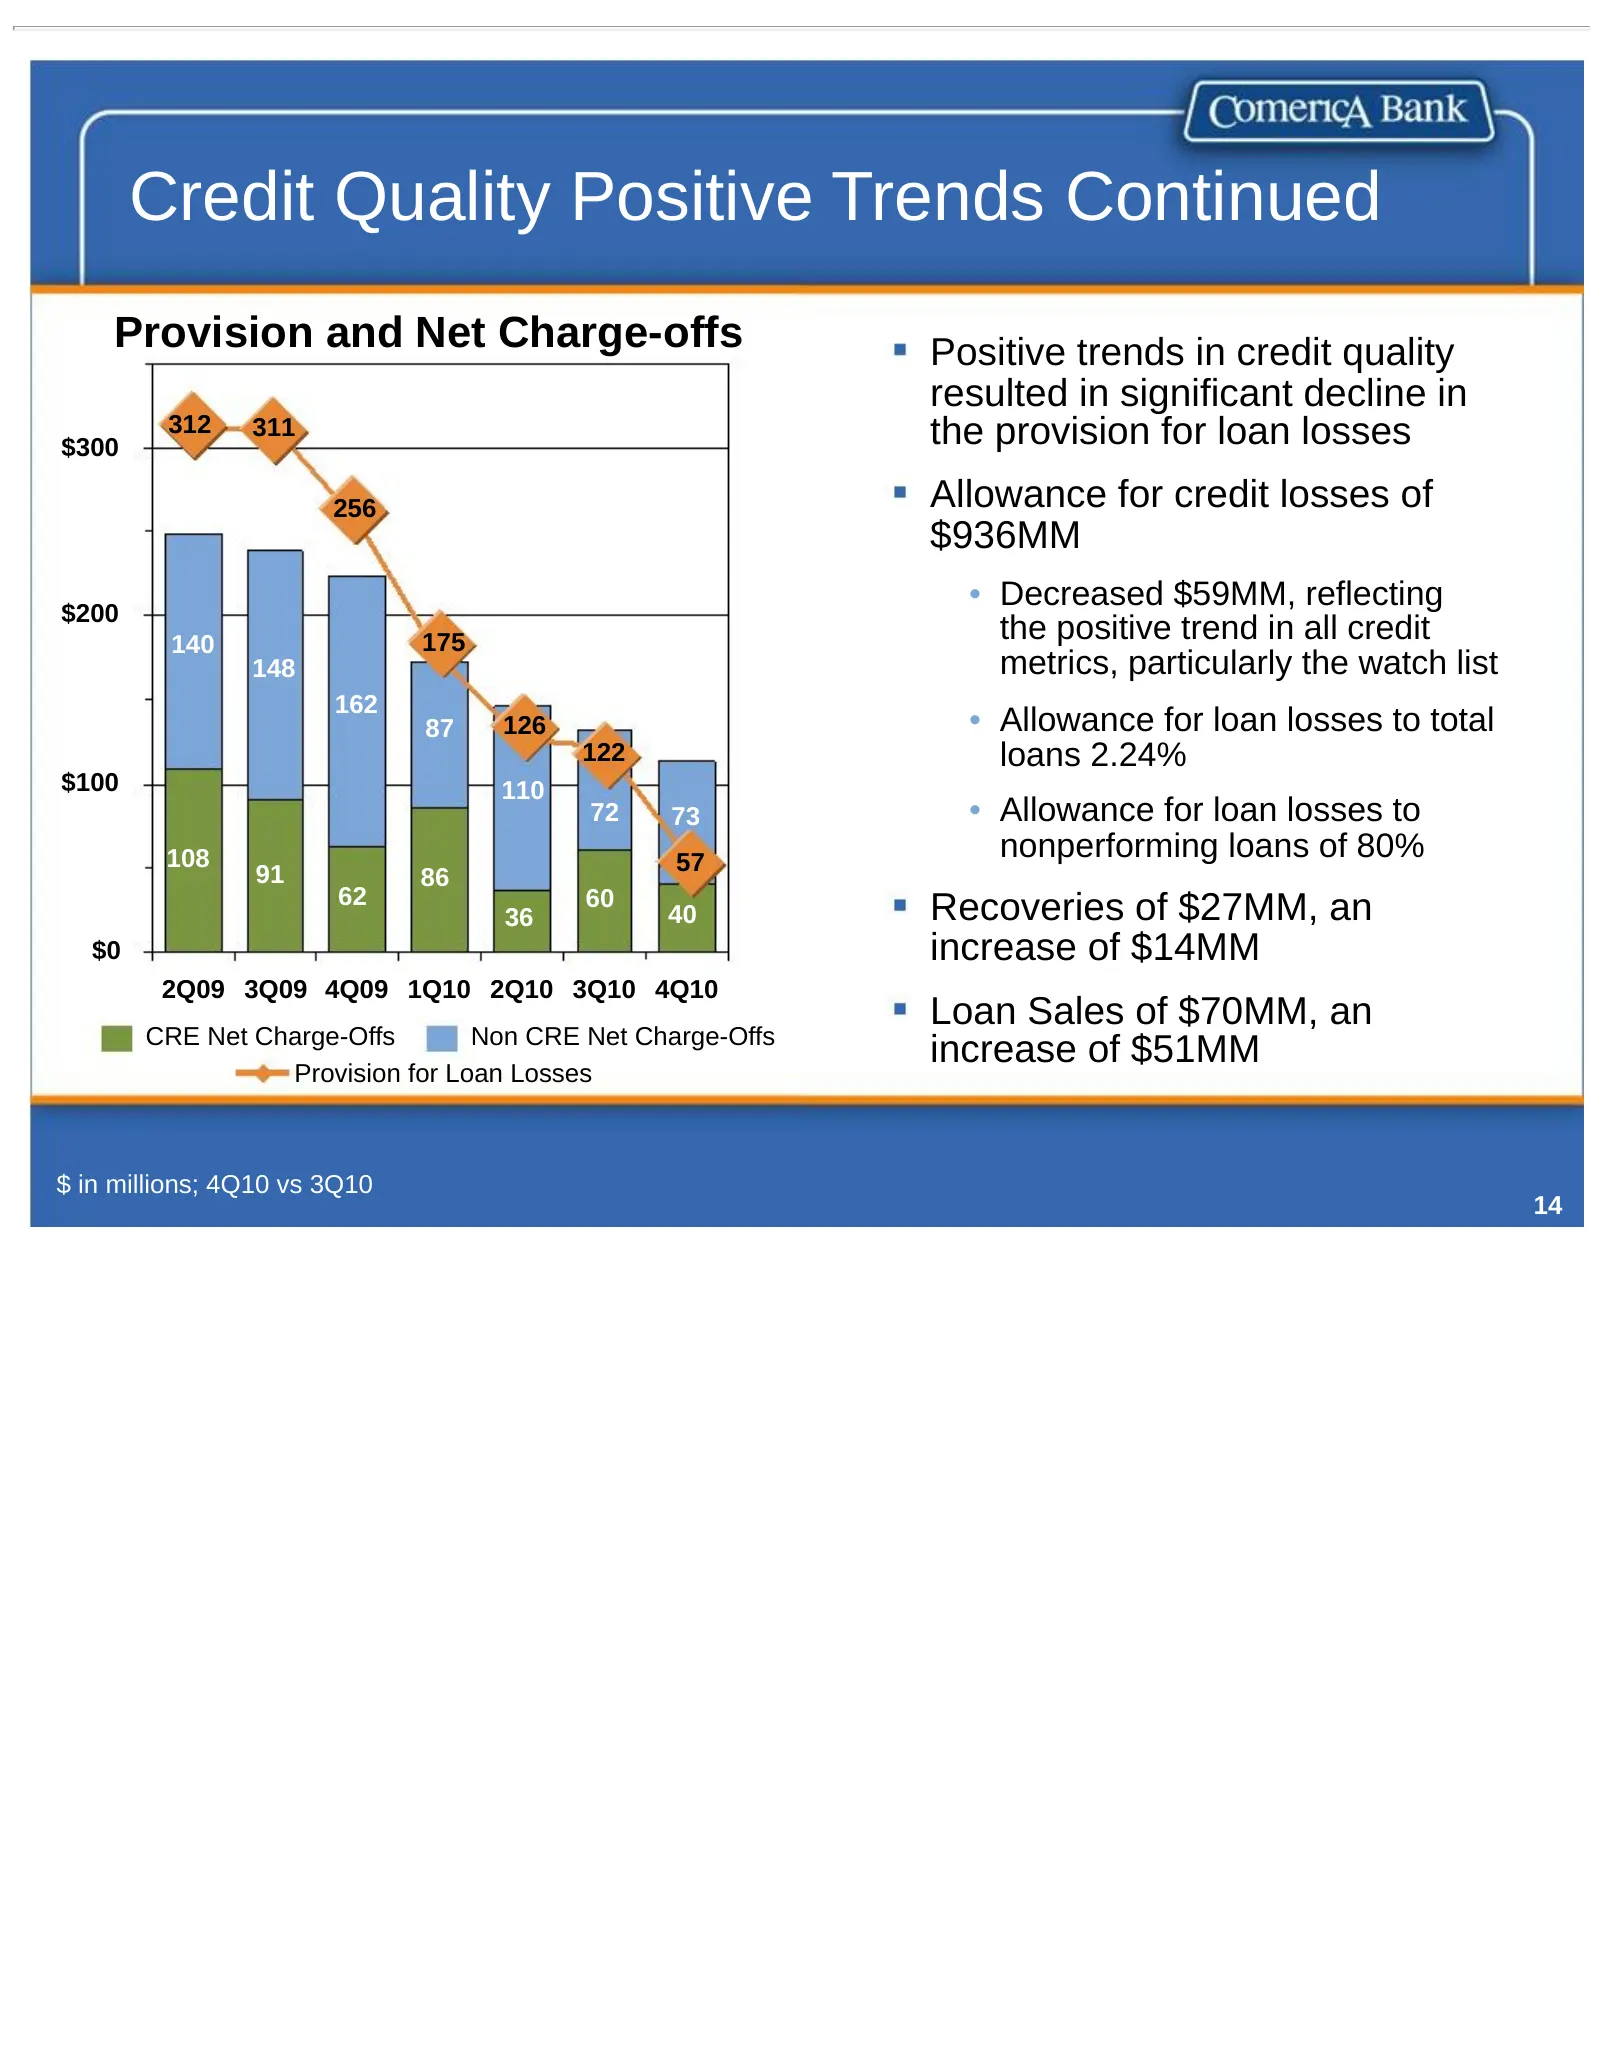
Credit Quality Positive Trends Continued Provision and Net Charge-offs Positive trends in credit quality resulted in significant decline in $300 312 311 the provision for loan losses 256 Allowance for credit losses of $936MM • Decreased $59MM, reflecting $200 140 175 the positive trend in all credit
Slide 17: Credit Quality Ratios vs. Peers
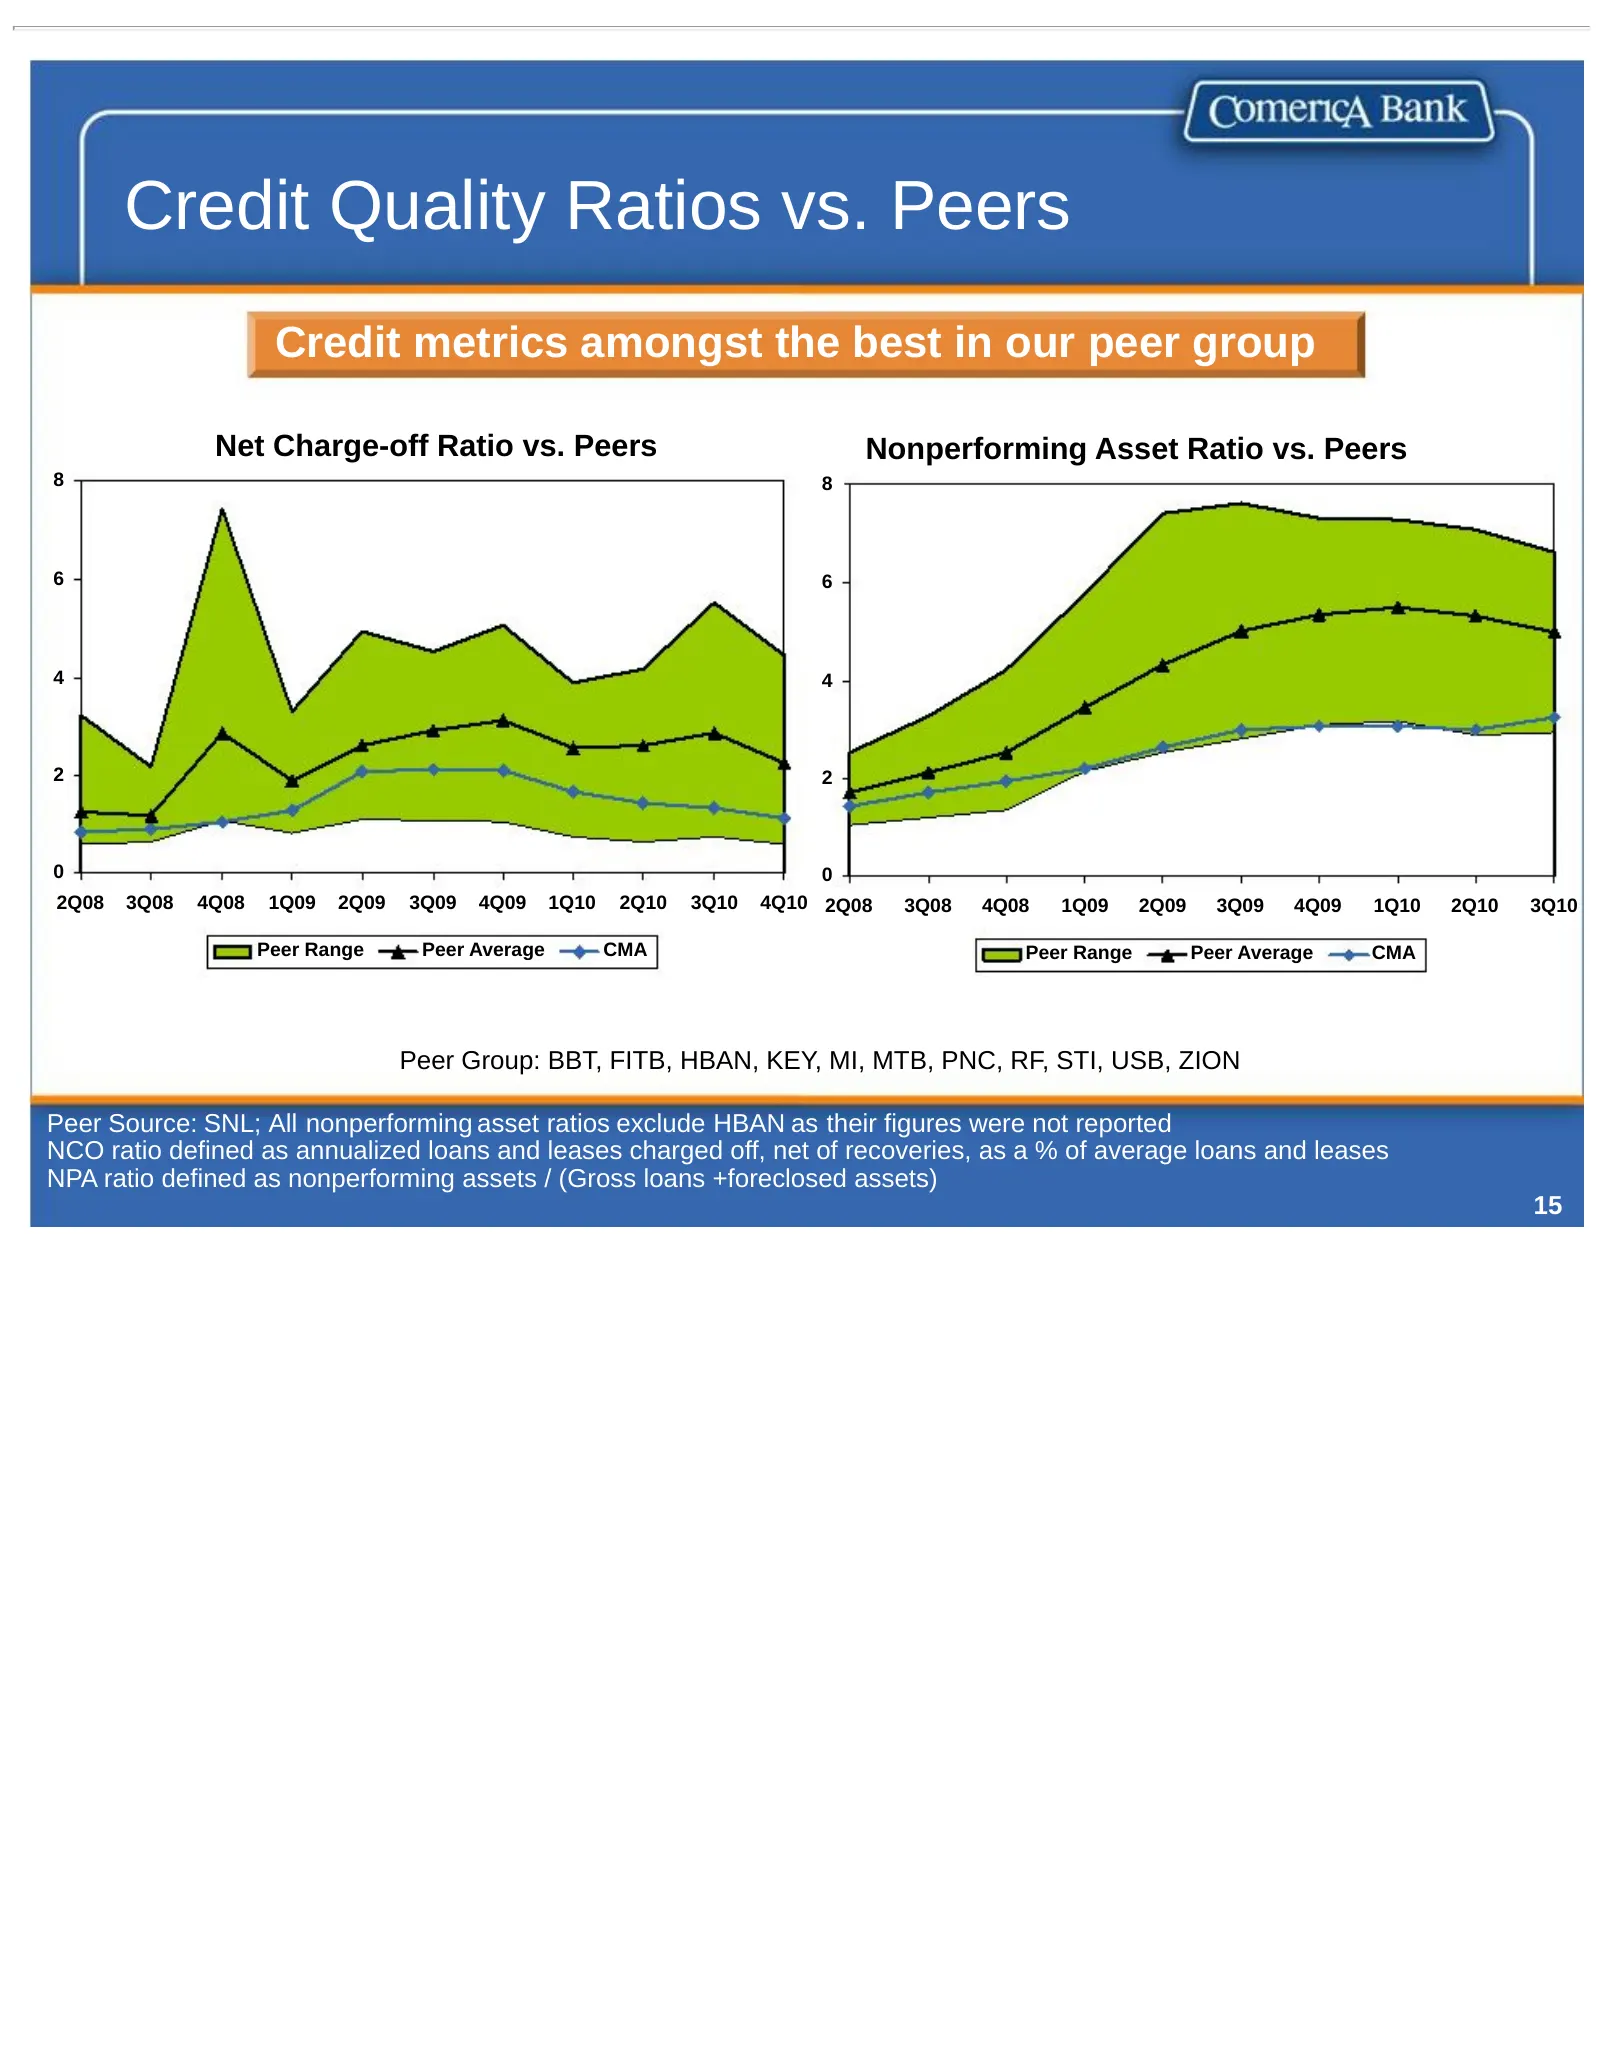
Credit Quality Ratios vs. Peers Credit metrics amongst the best in our peer group Net Charge-off Ratio vs. Peers Nonperforming Asset Ratio vs. Peers 8 8 6 6 4 4 2 2 0 0 2Q08 3Q08 4Q08 1Q09 2Q09 3Q09 4Q09 1Q10 2Q10 3Q10 4Q10 2Q08 3Q08 4Q08 1Q09 2Q09 3Q09 4Q09 1Q10 2Q10 3Q10 Peer Range Peer Average CM
Slide 18: Strong Capital Ratios
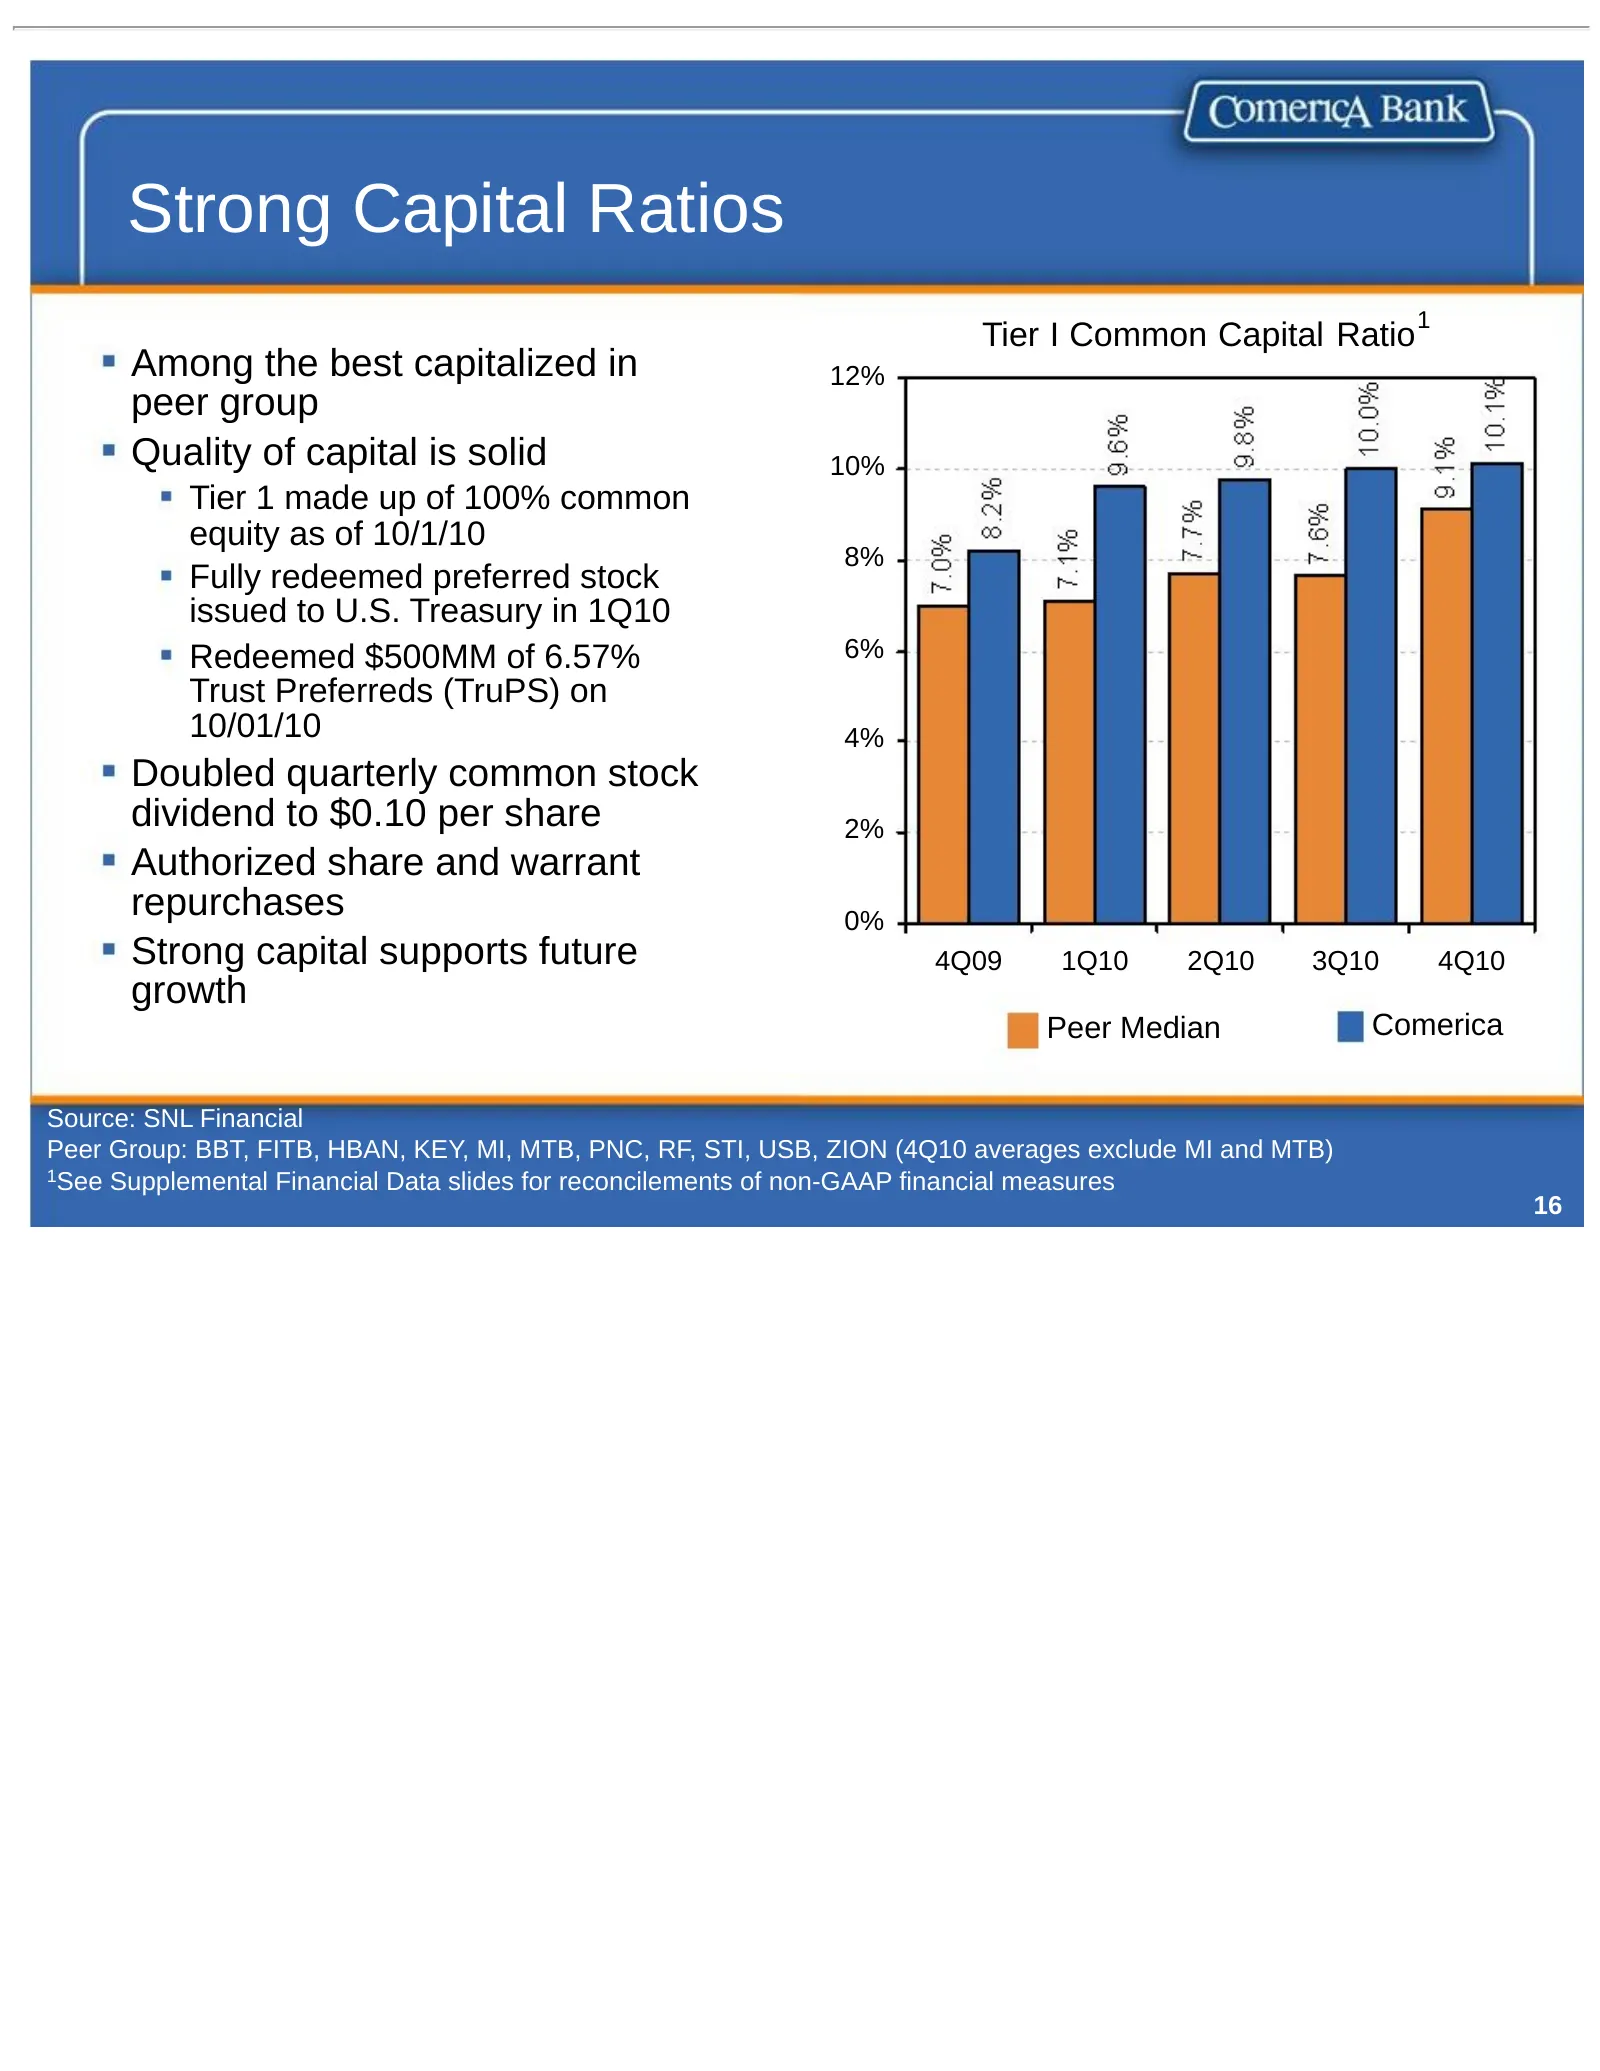
Strong Capital Ratios 1 Tier I Common Capital Ratio Among the best capitalized in 12% peer group Quality of capital is solid 10% Tier 1 made up of 100% common equity as of 10/1/10 8% Fully redeemed preferred stock issued to U.S. Treasury in 1Q10 Redeemed $500MM of 6.57% 6% Trust Preferreds (TruPS) o
Slide 19: Sterling Bank Acquisition – A Unique Opportunity
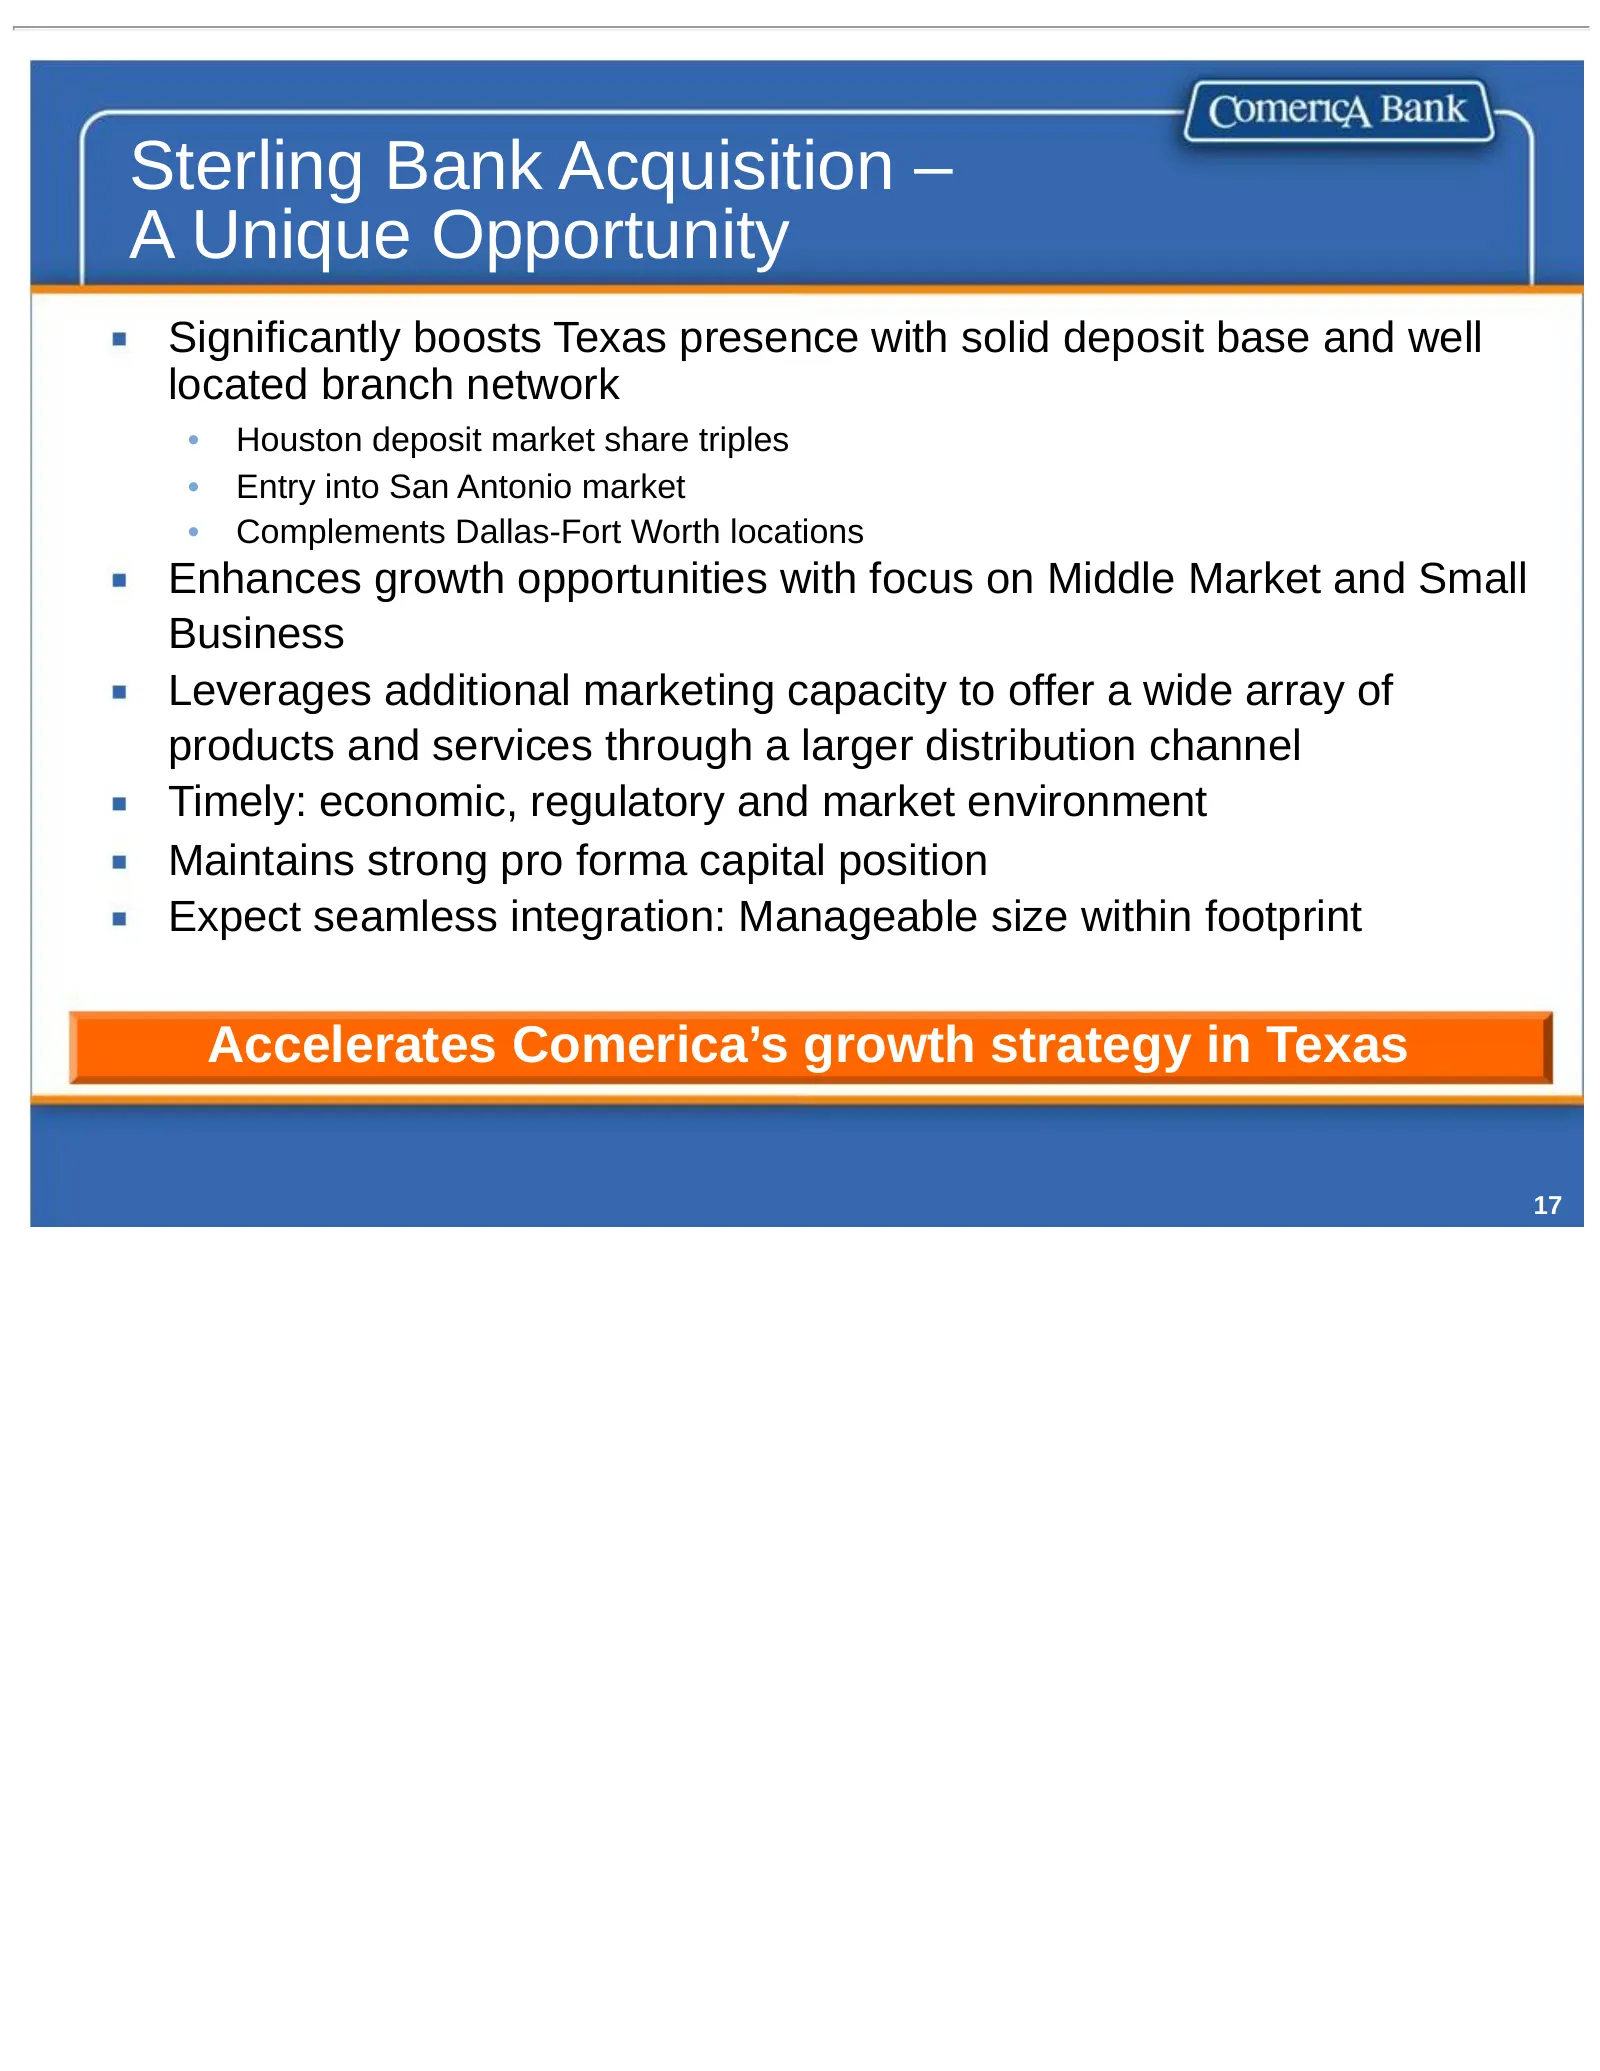
Sterling Bank Acquisition – A Unique Opportunity Significantly boosts Texas presence with solid deposit base and well located branch network • Houston deposit market share triples • Entry into San Antonio market • Complements Dallas-Fort Worth locations Enhances growth opportunities with focus on Mi
Slide 20: Sterling Bank Acquisition – Opportunity to Leverage C&I Expertise
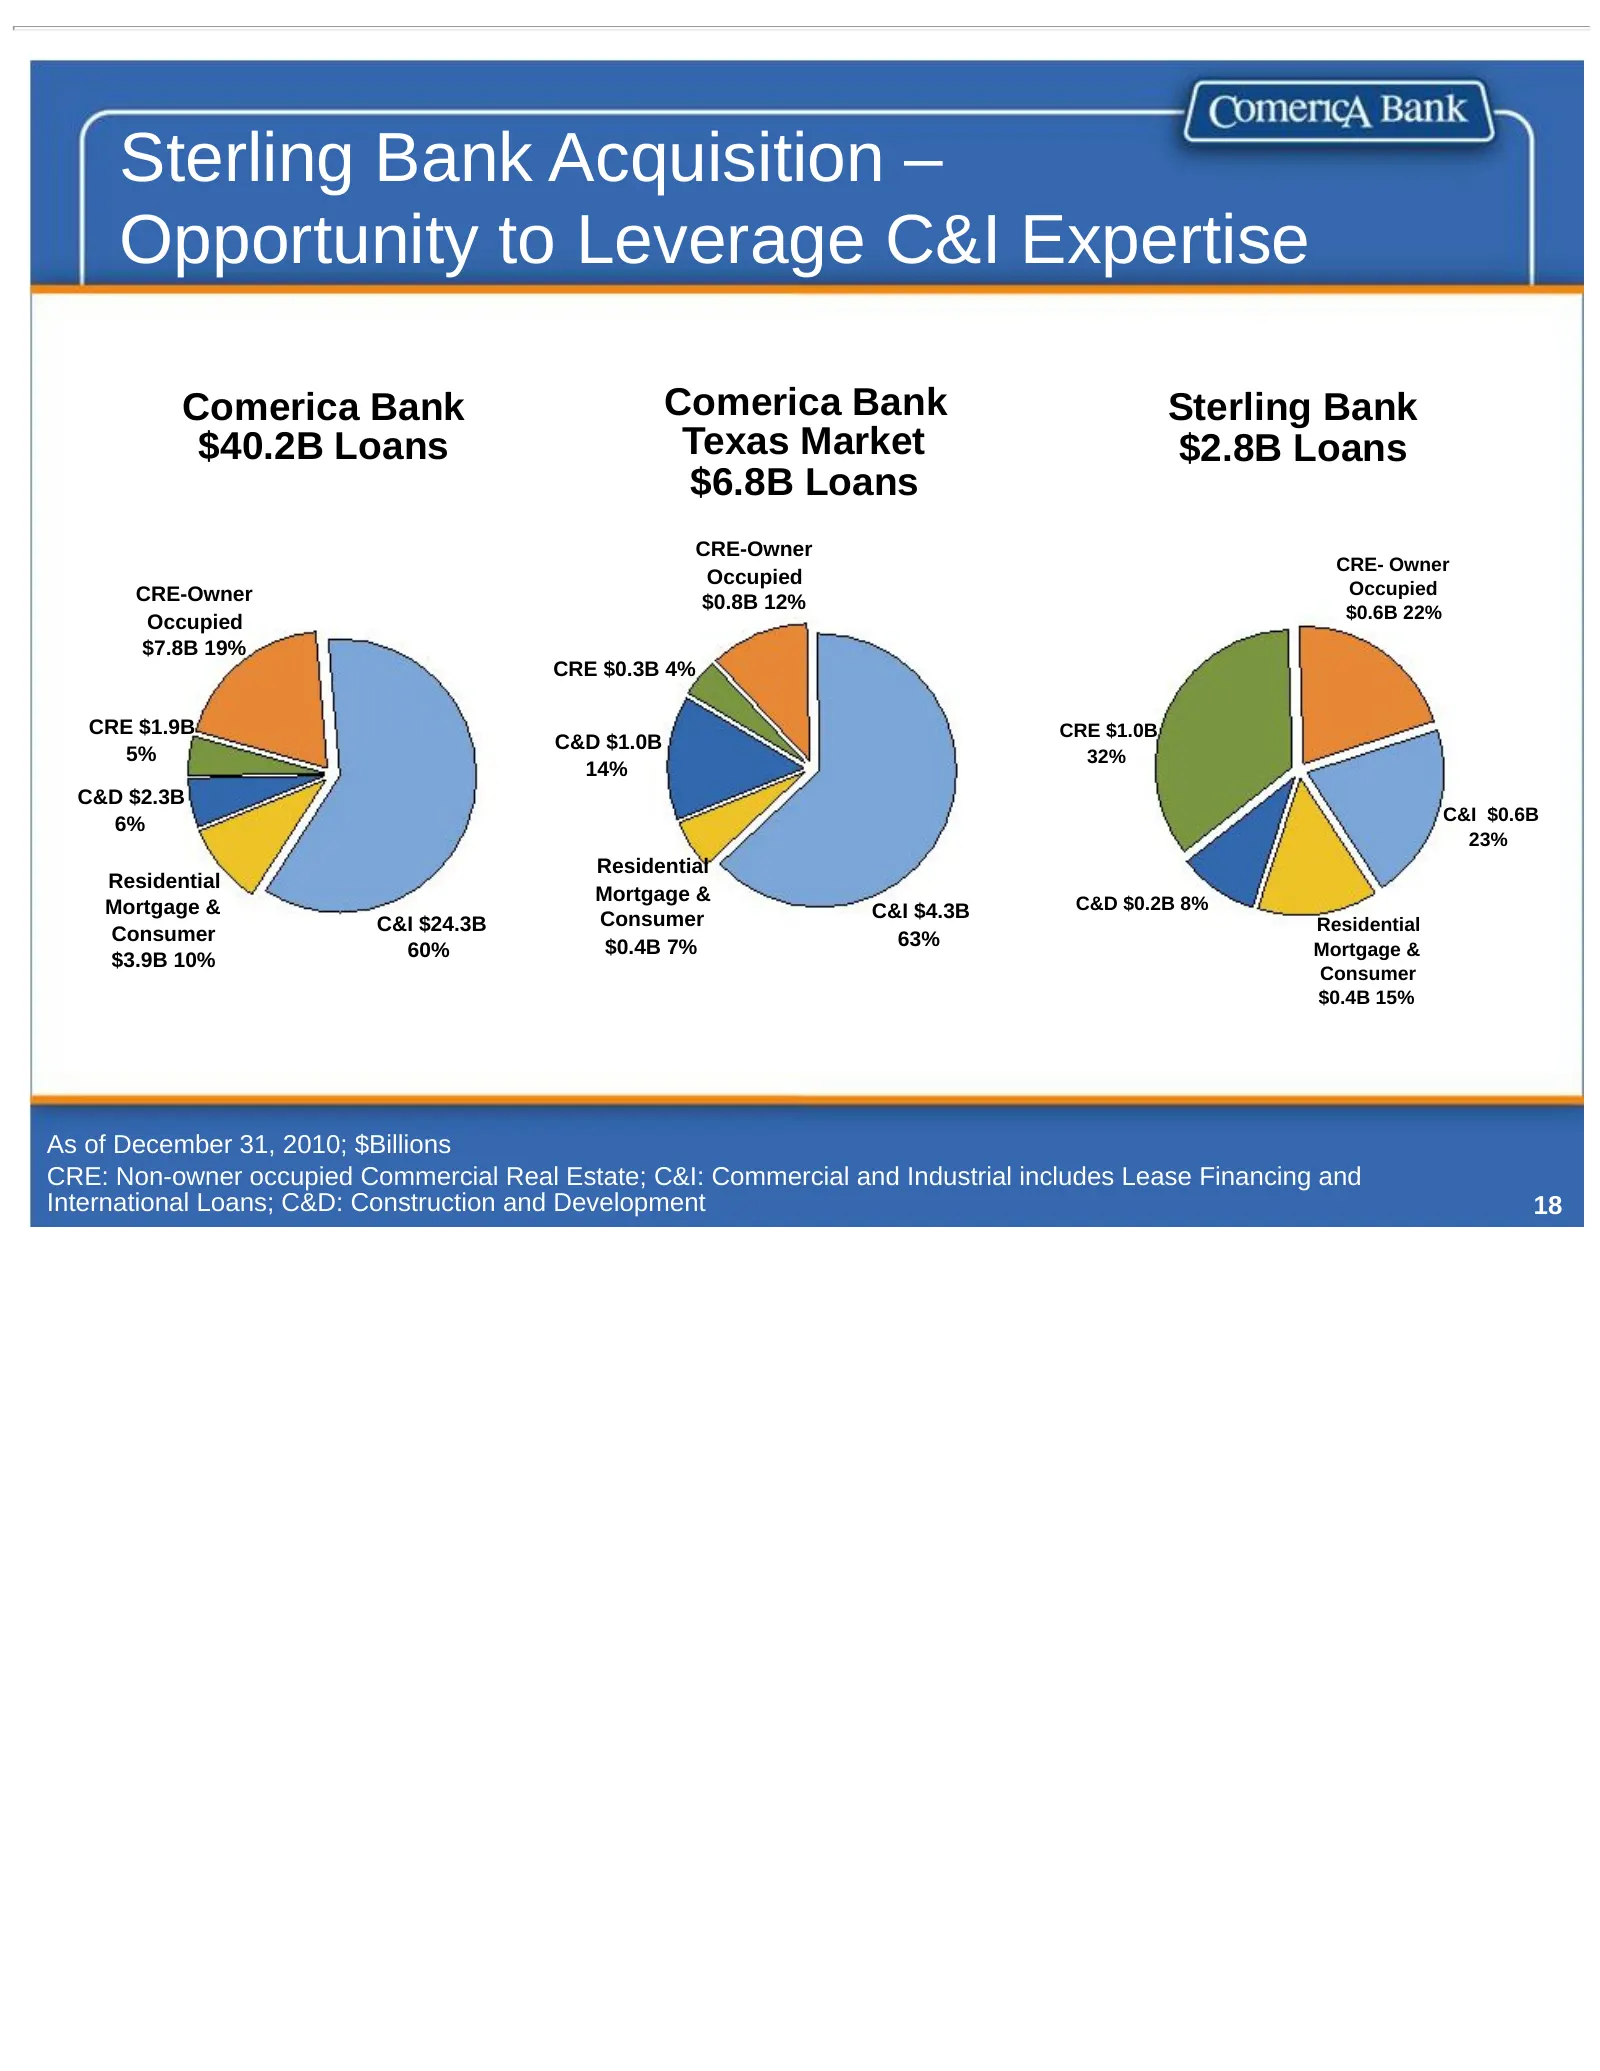
Sterling Bank Acquisition – Opportunity to Leverage C&I Expertise Comerica Bank Comerica Bank Sterling Bank $40.2B Loans Texas Market $2.8B Loans $6.8B Loans CRE-Owner CRE- Owner Occupied CRE-Owner Occupied $0.8B 12% $0.6B 22% Occupied $7.8B 19% CRE $0.3B 4% CRE $1.9B CRE $1.0B C&D $1.0B 5% 32% 14%
Slide 21: Sterling Bank Acquisition – Attractive Deposit Mix
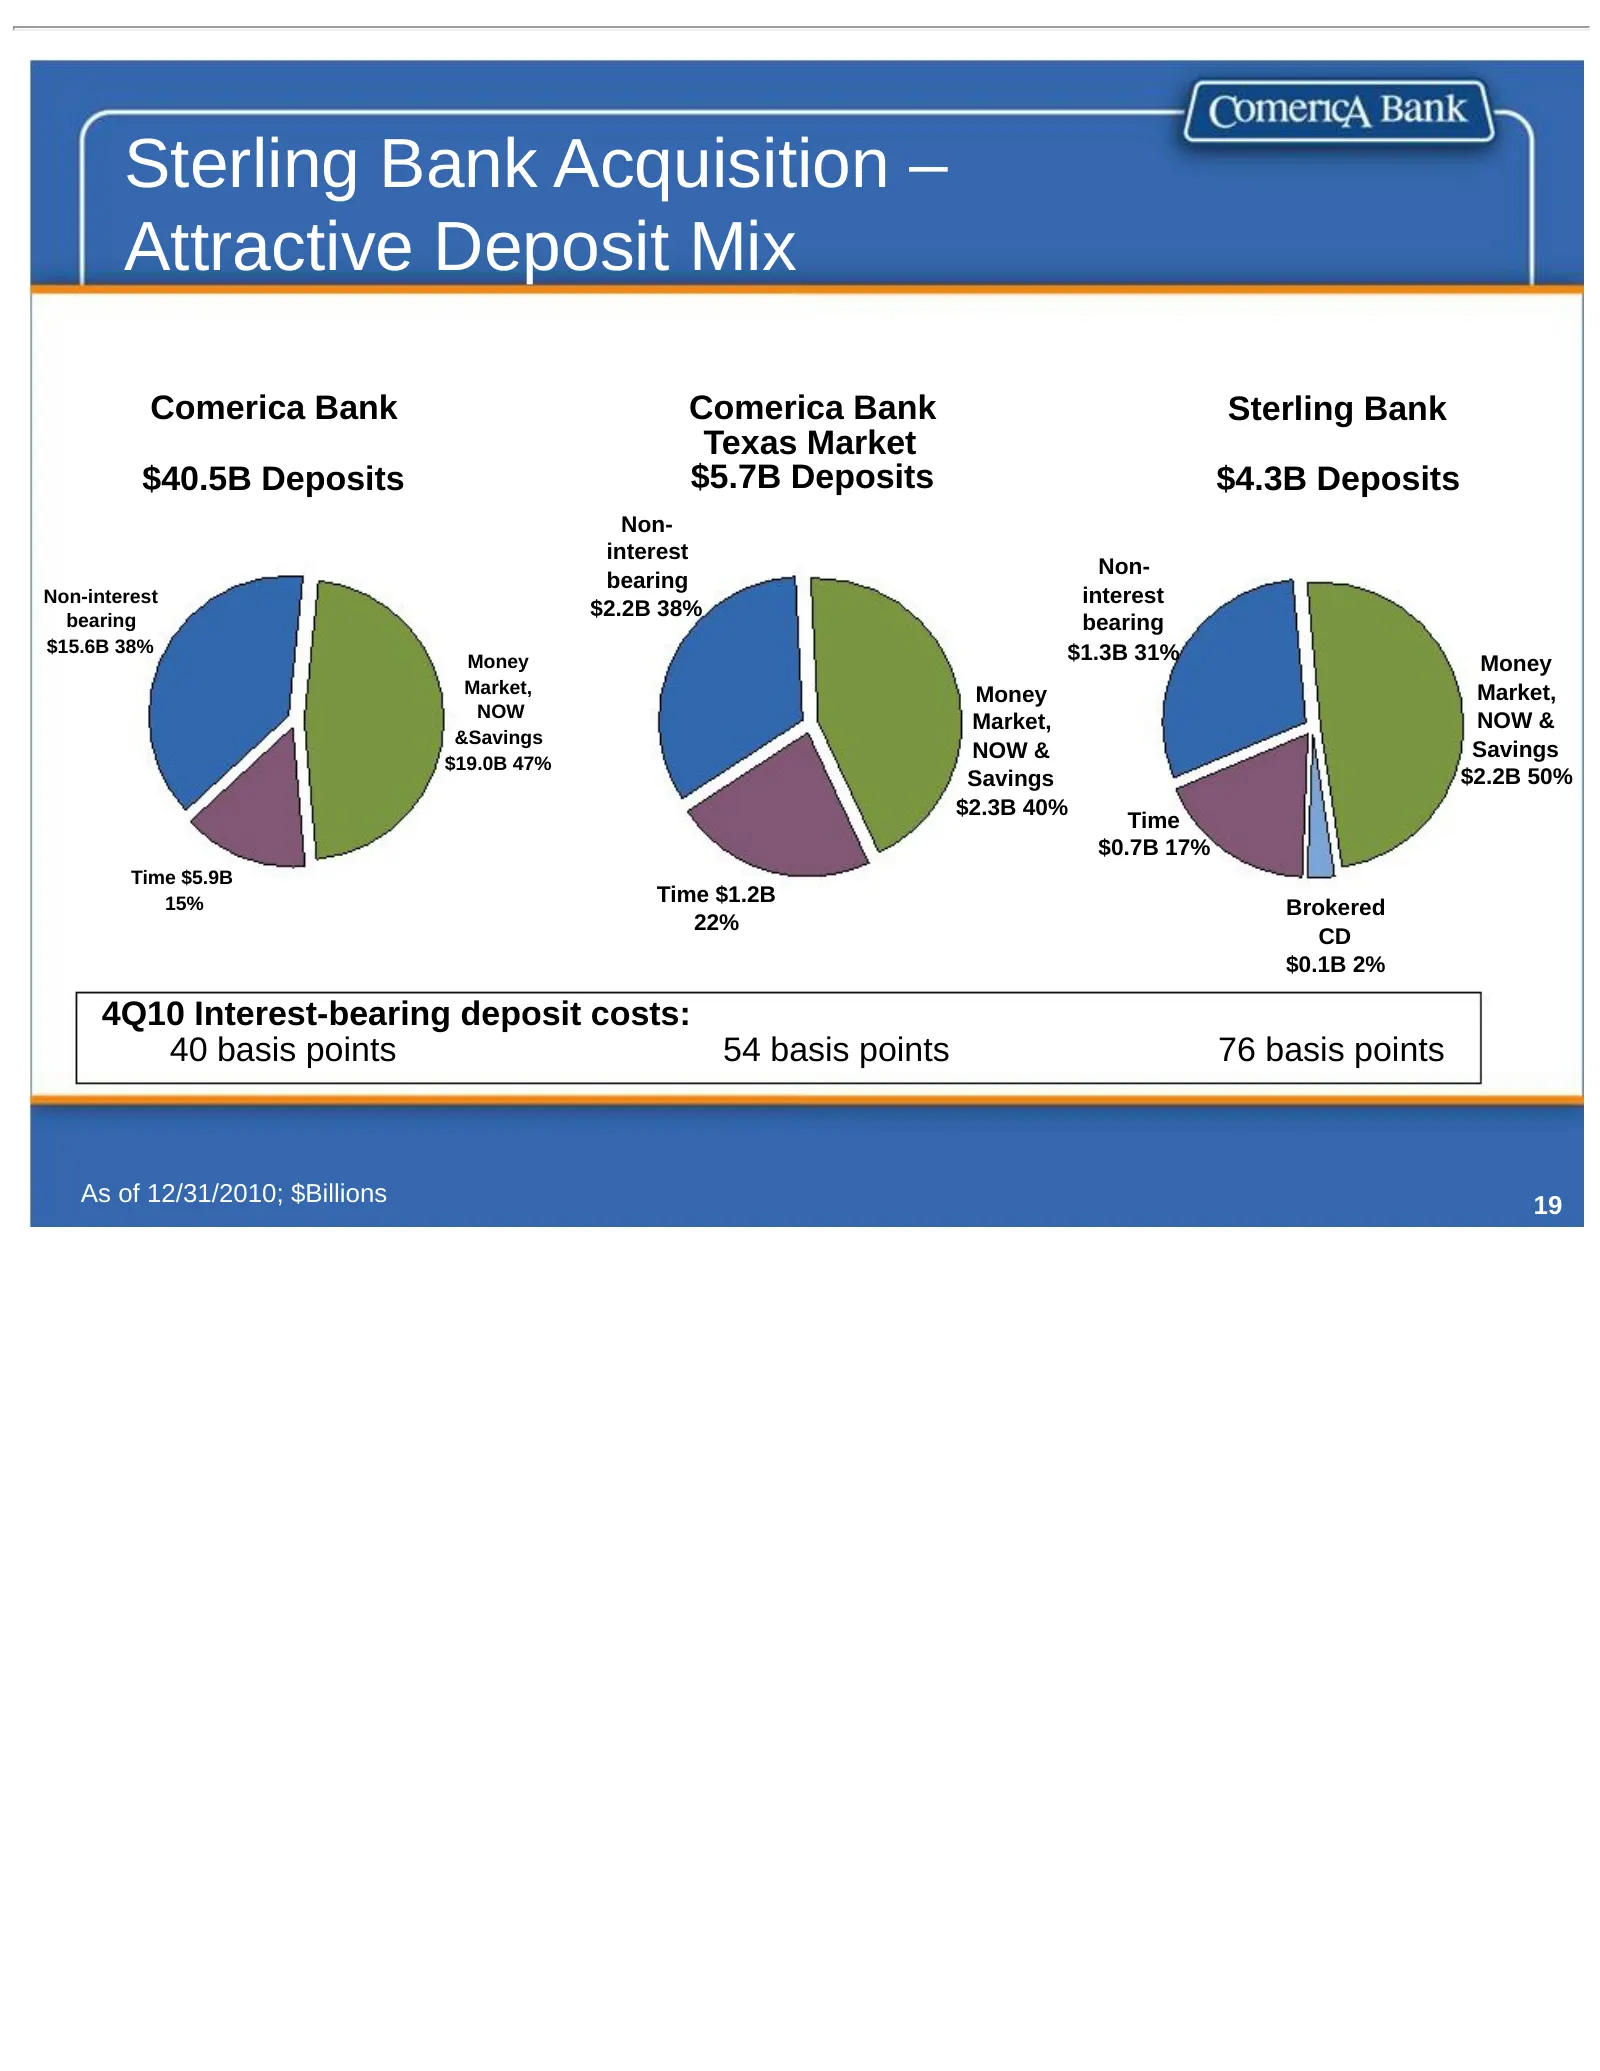
Sterling Bank Acquisition – Attractive Deposit Mix Comerica Bank Comerica Bank Sterling Bank Texas Market $40.5B Deposits $5.7B Deposits $4.3B Deposits Non- interest Non- bearing Non-interest interest bearing $2.2B 38% bearing $15.6B 38% $1.3B 31% Money Money Market, Money Market, NOW NOW & Market,
Slide 22: Sterling Bank Acquisition – Expanding in Attractive Markets
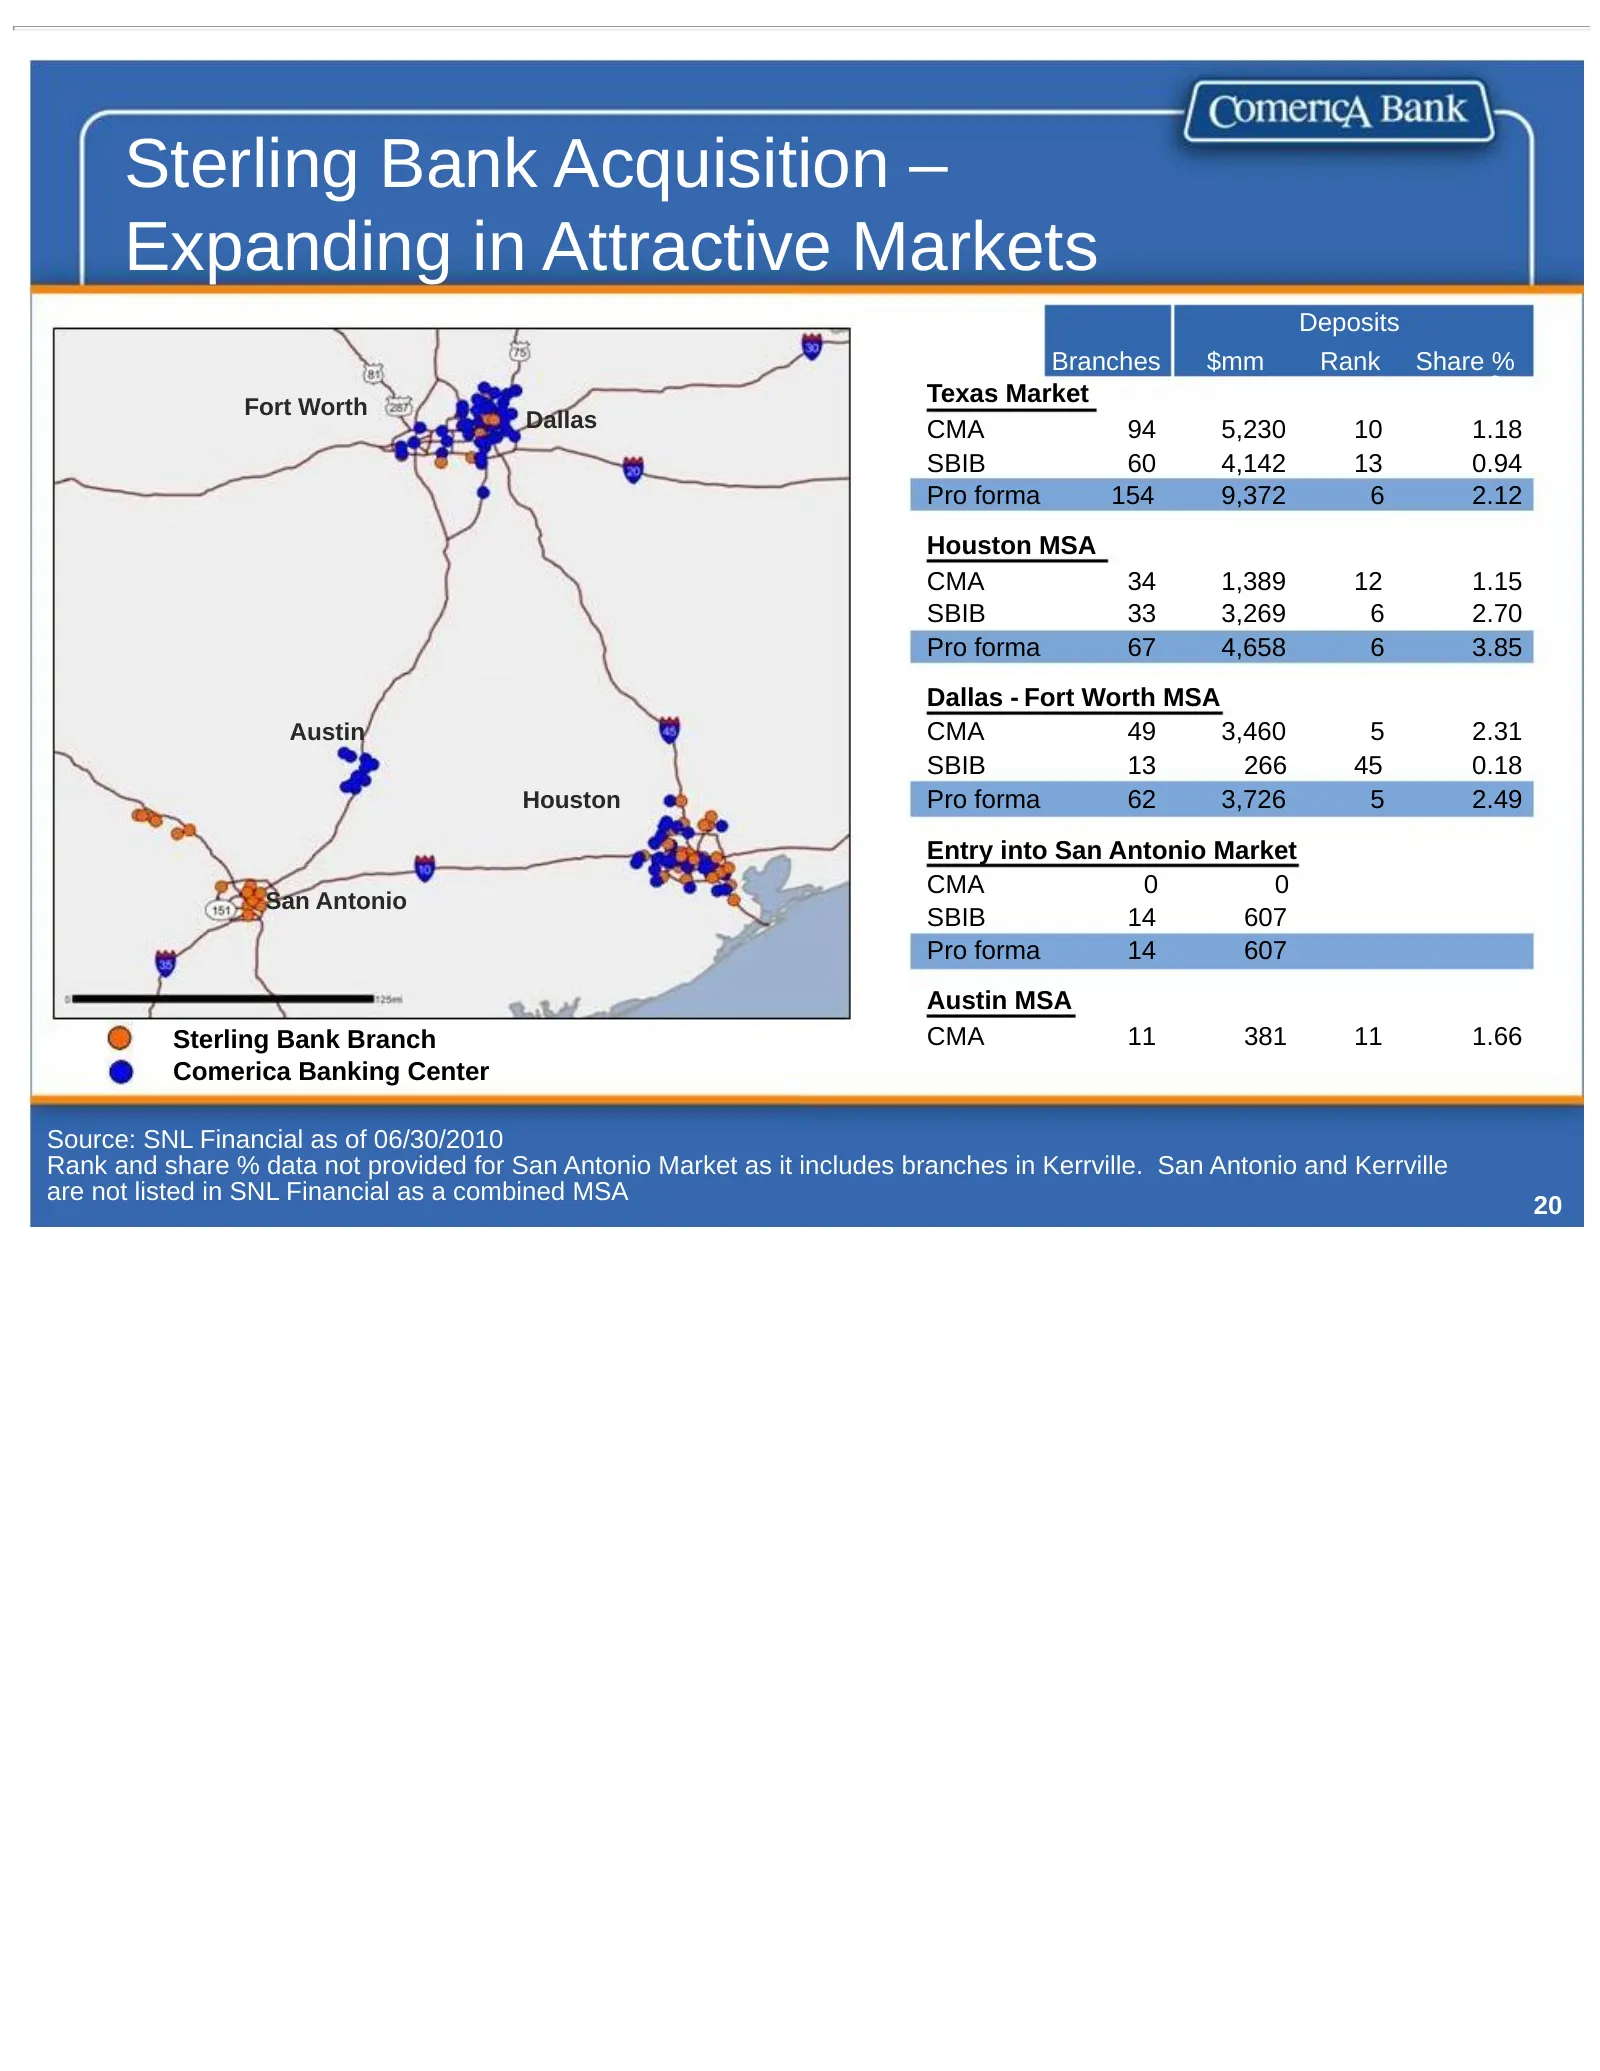
Sterling Bank Acquisition – Expanding in Attractive Markets Deposits Branches $mm Rank Share % 2 Texas Market Fort Worth Dallas CMA 94 5,230 10 1.18 SBIB 60 4,142 13 0.94 Pro forma 154 9,372 6 2.12 Houston MSA CMA 34 1,389 12 1.15 SBIB 33 3,269 6 2.70 Pro forma 67 4,658 6 3.85 Dallas - Fort Worth MS
Slide 23: Sterling Acquisition – Fits Comerica's Main Street Bank Strategy
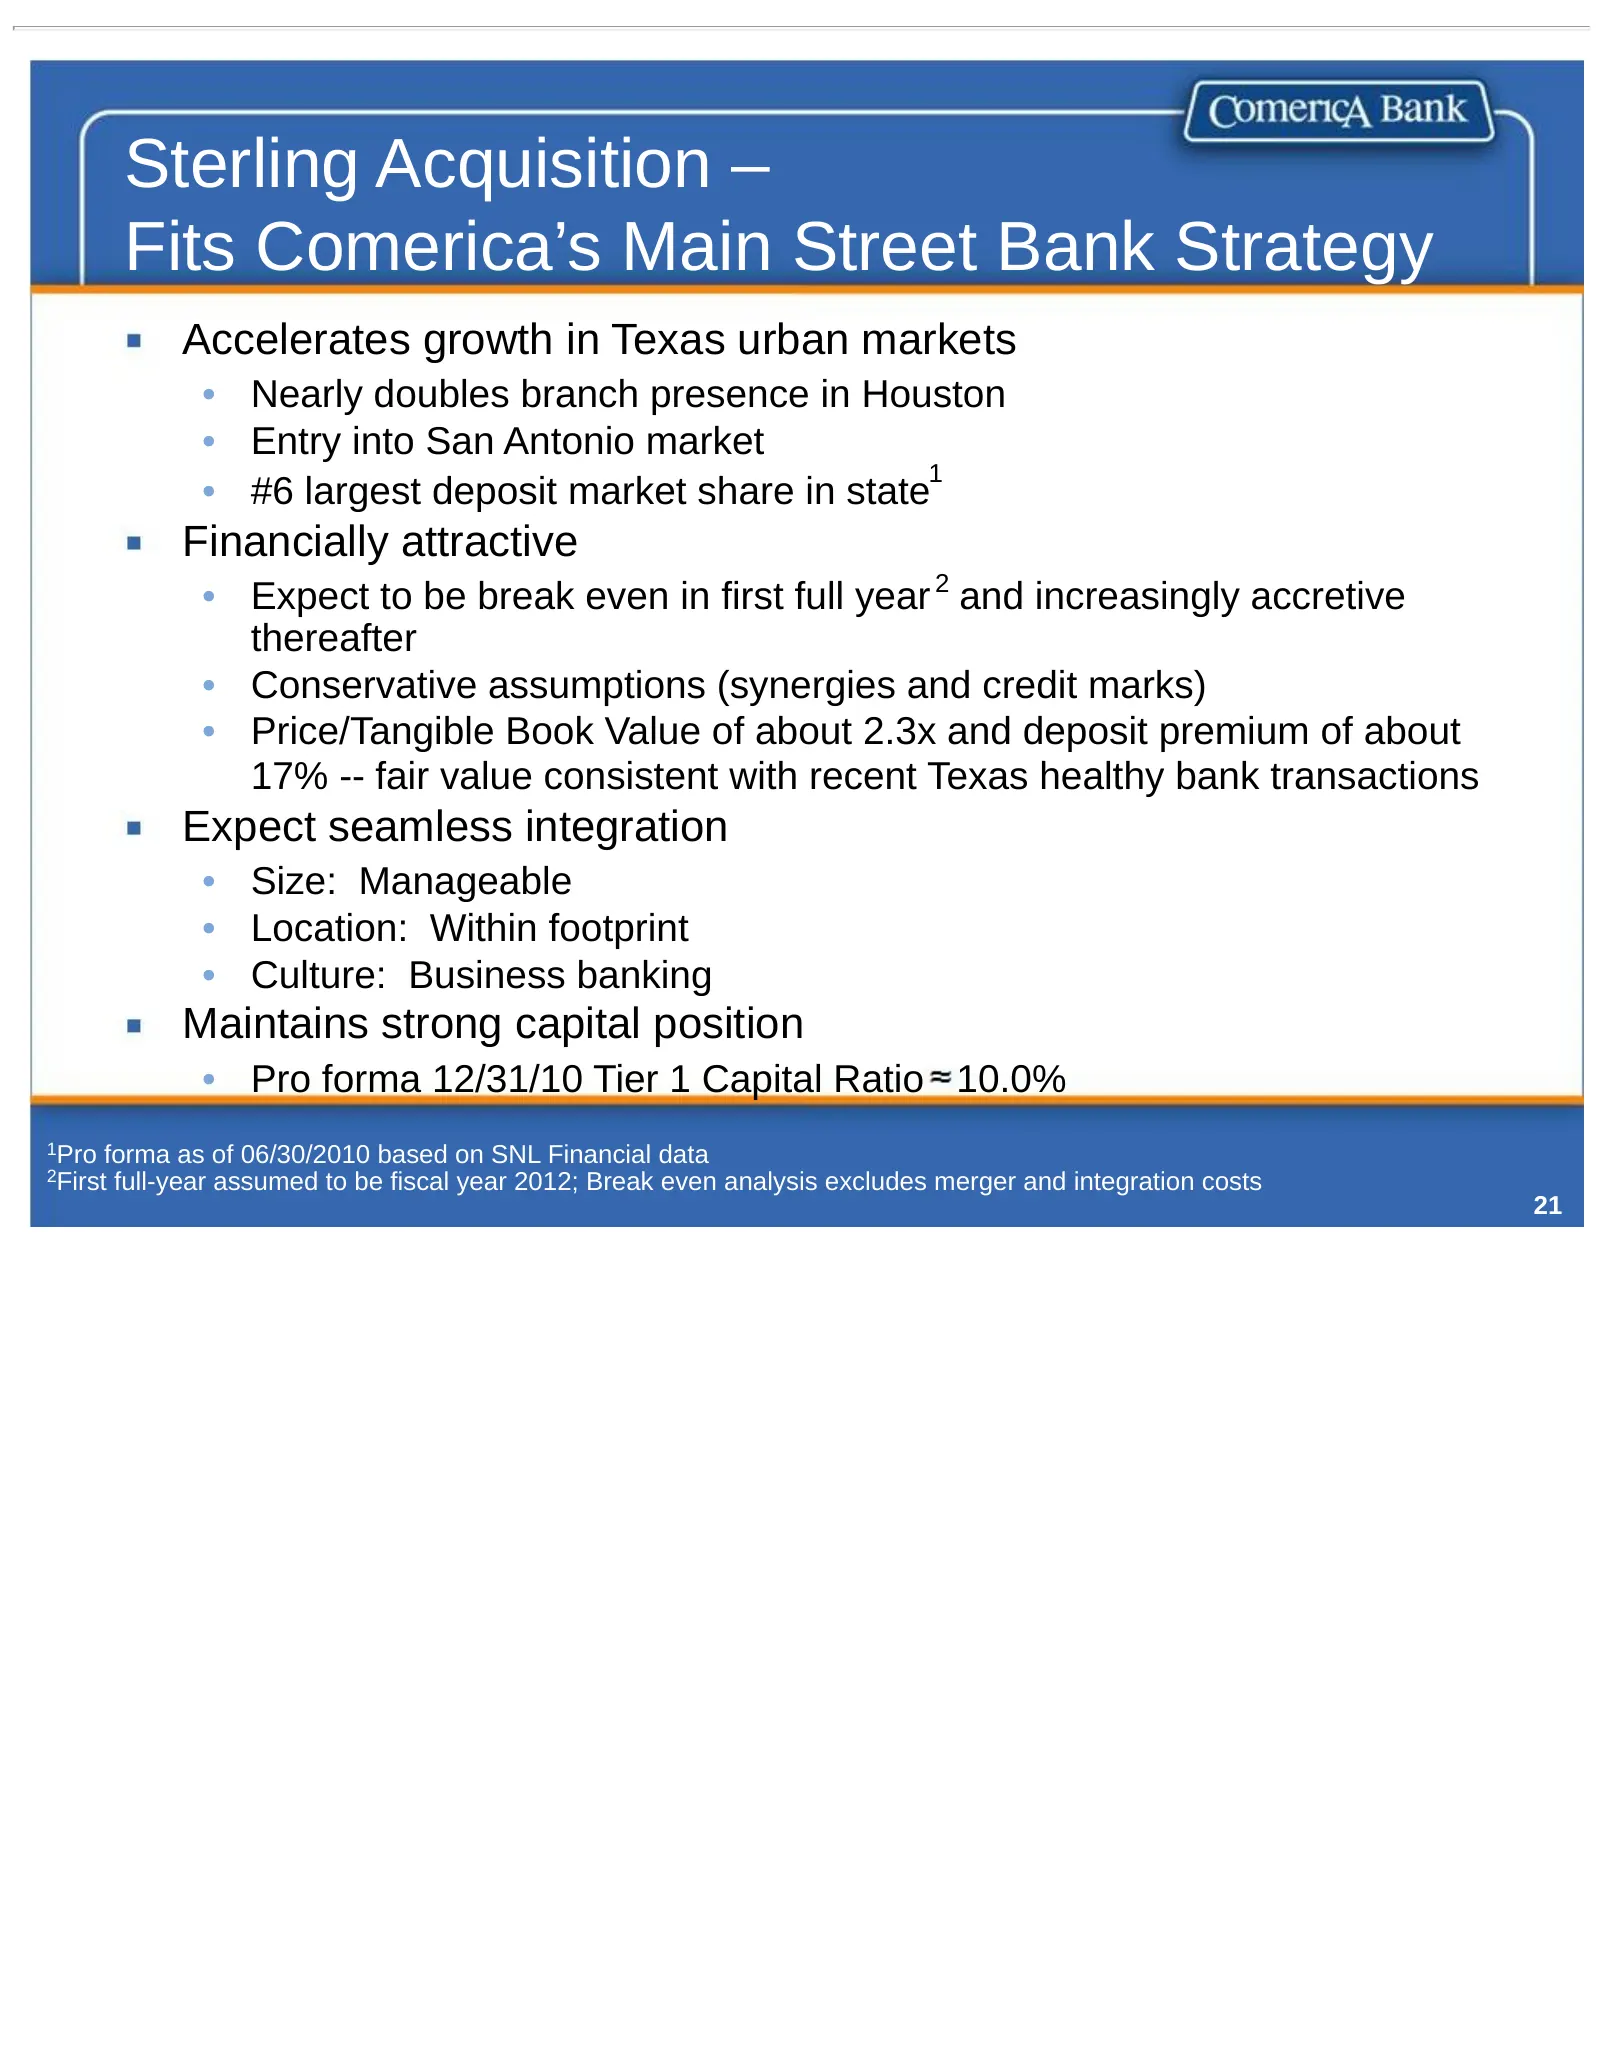
Sterling Acquisition – Fits Comerica’s Main Street Bank Strategy Accelerates growth in Texas urban markets • Nearly doubles branch presence in Houston • Entry into San Antonio market 1 • #6 largest deposit market share in state Financially attractive • Expect to be break even in first full year 2 an
Slide 24: Poised for the Future
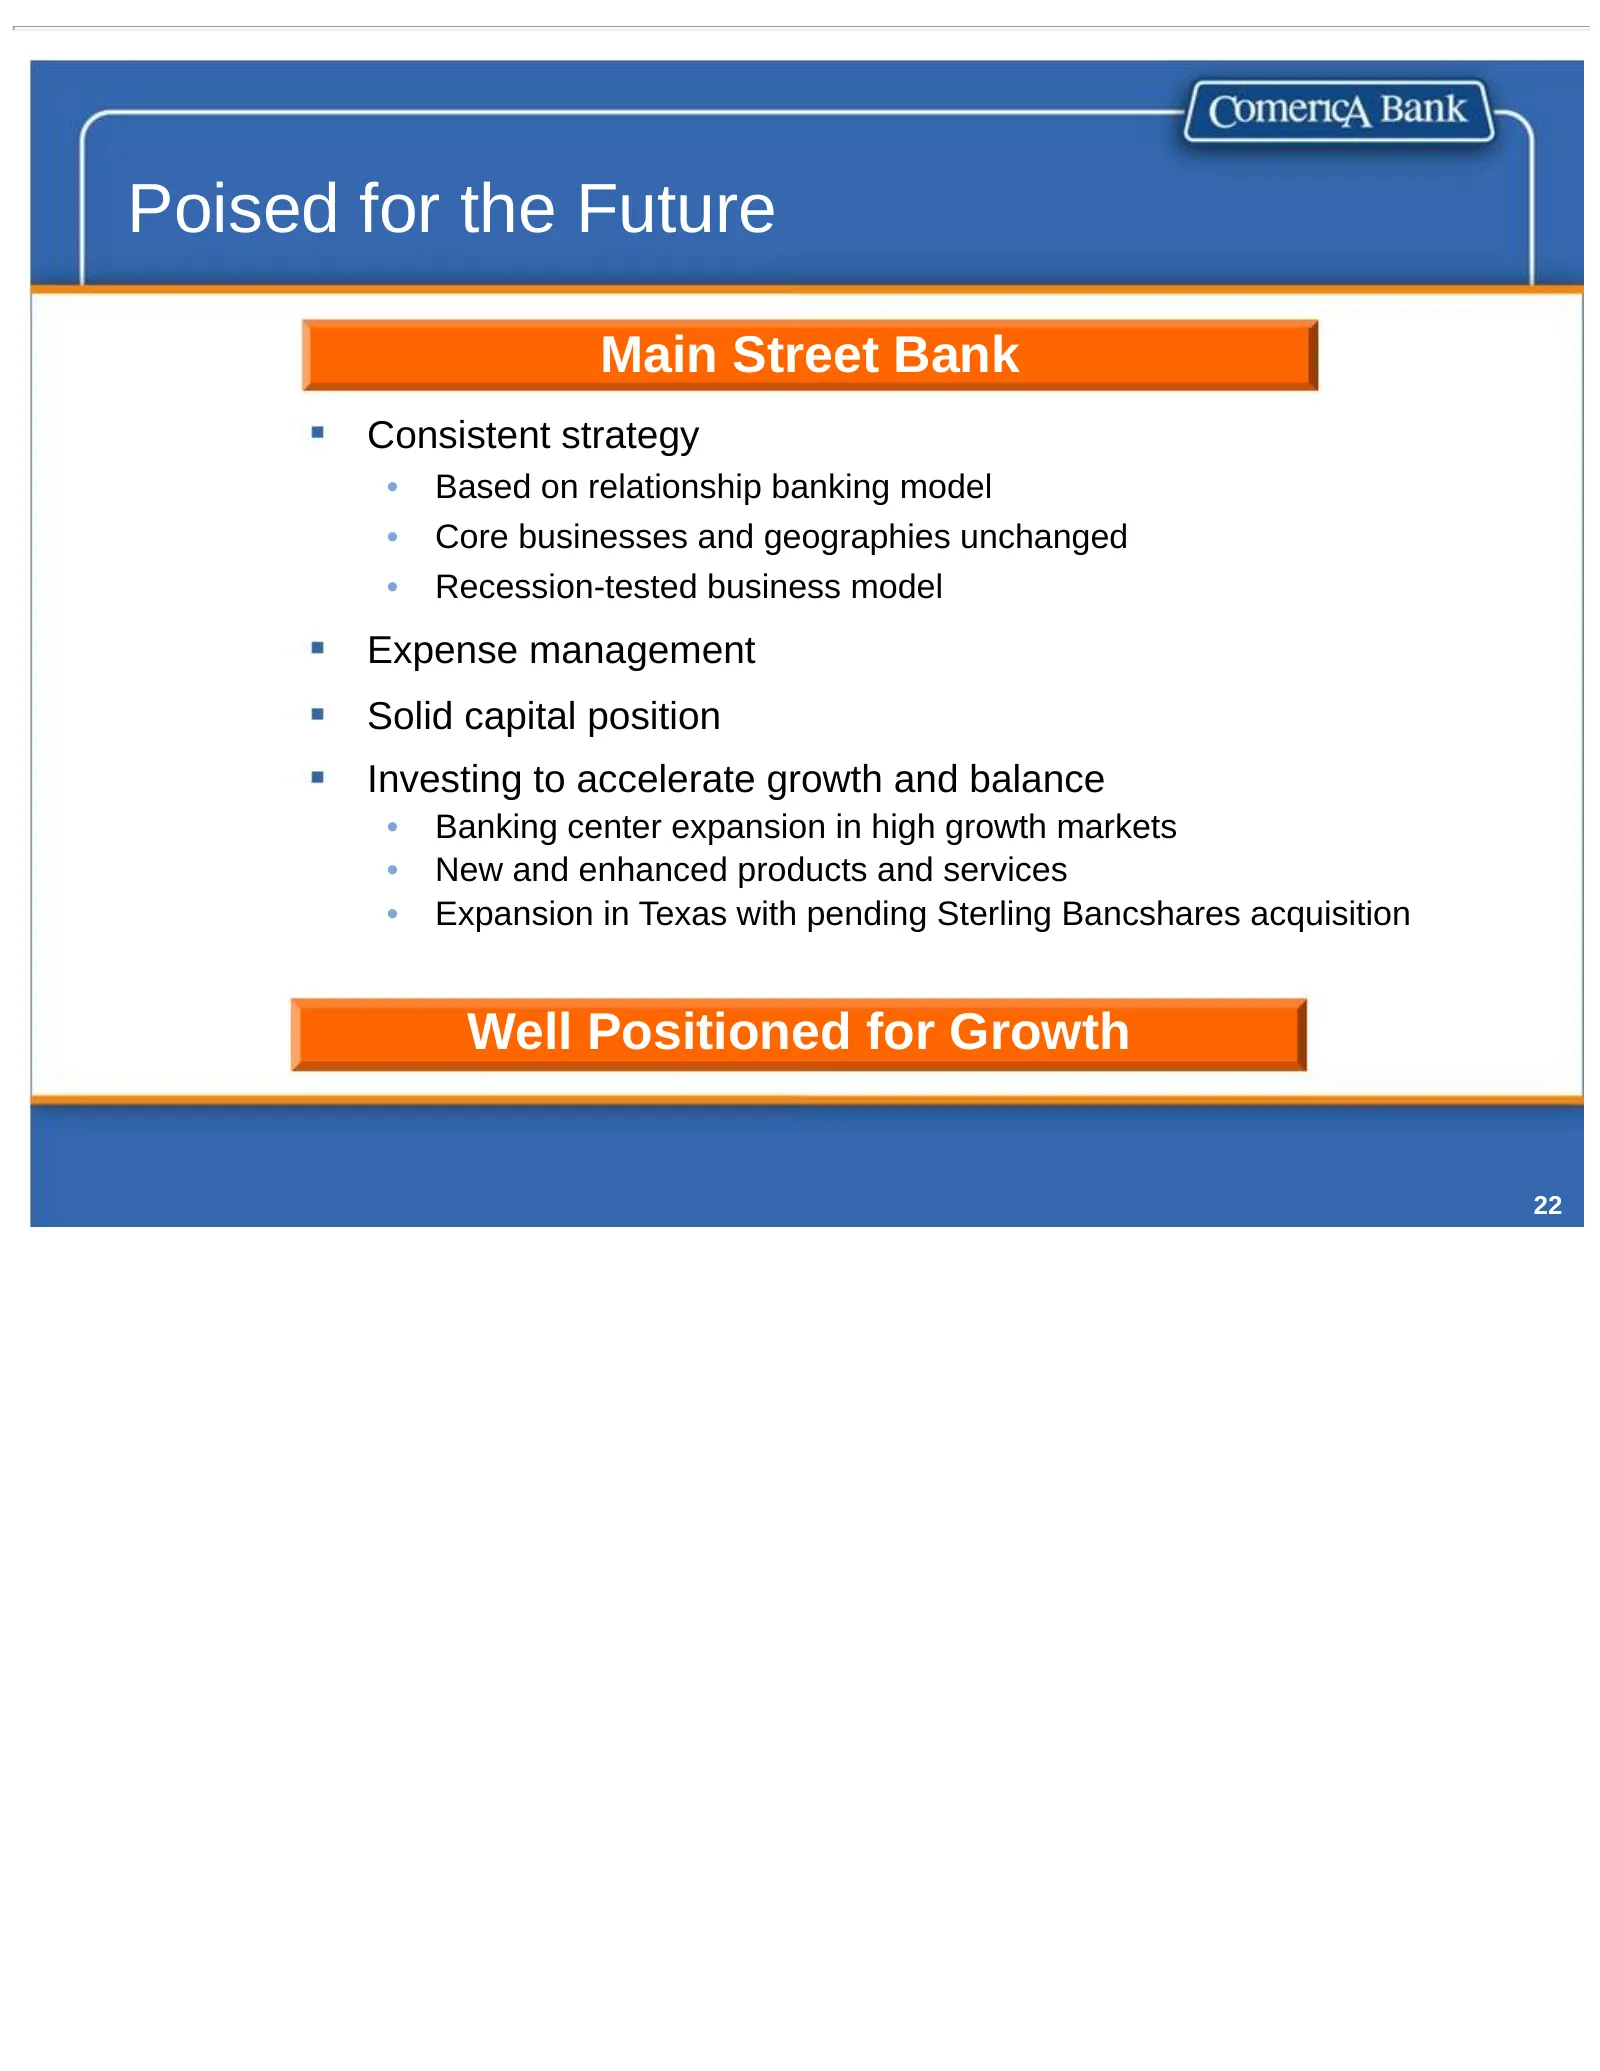
Poised for the Future Main Street Bank Consistent strategy • Based on relationship banking model • Core businesses and geographies unchanged • Recession-tested business model Expense management Solid capital position Investing to accelerate growth and balance • Banking center expansion in high growt
Slide 25: Supplemental Financial Data
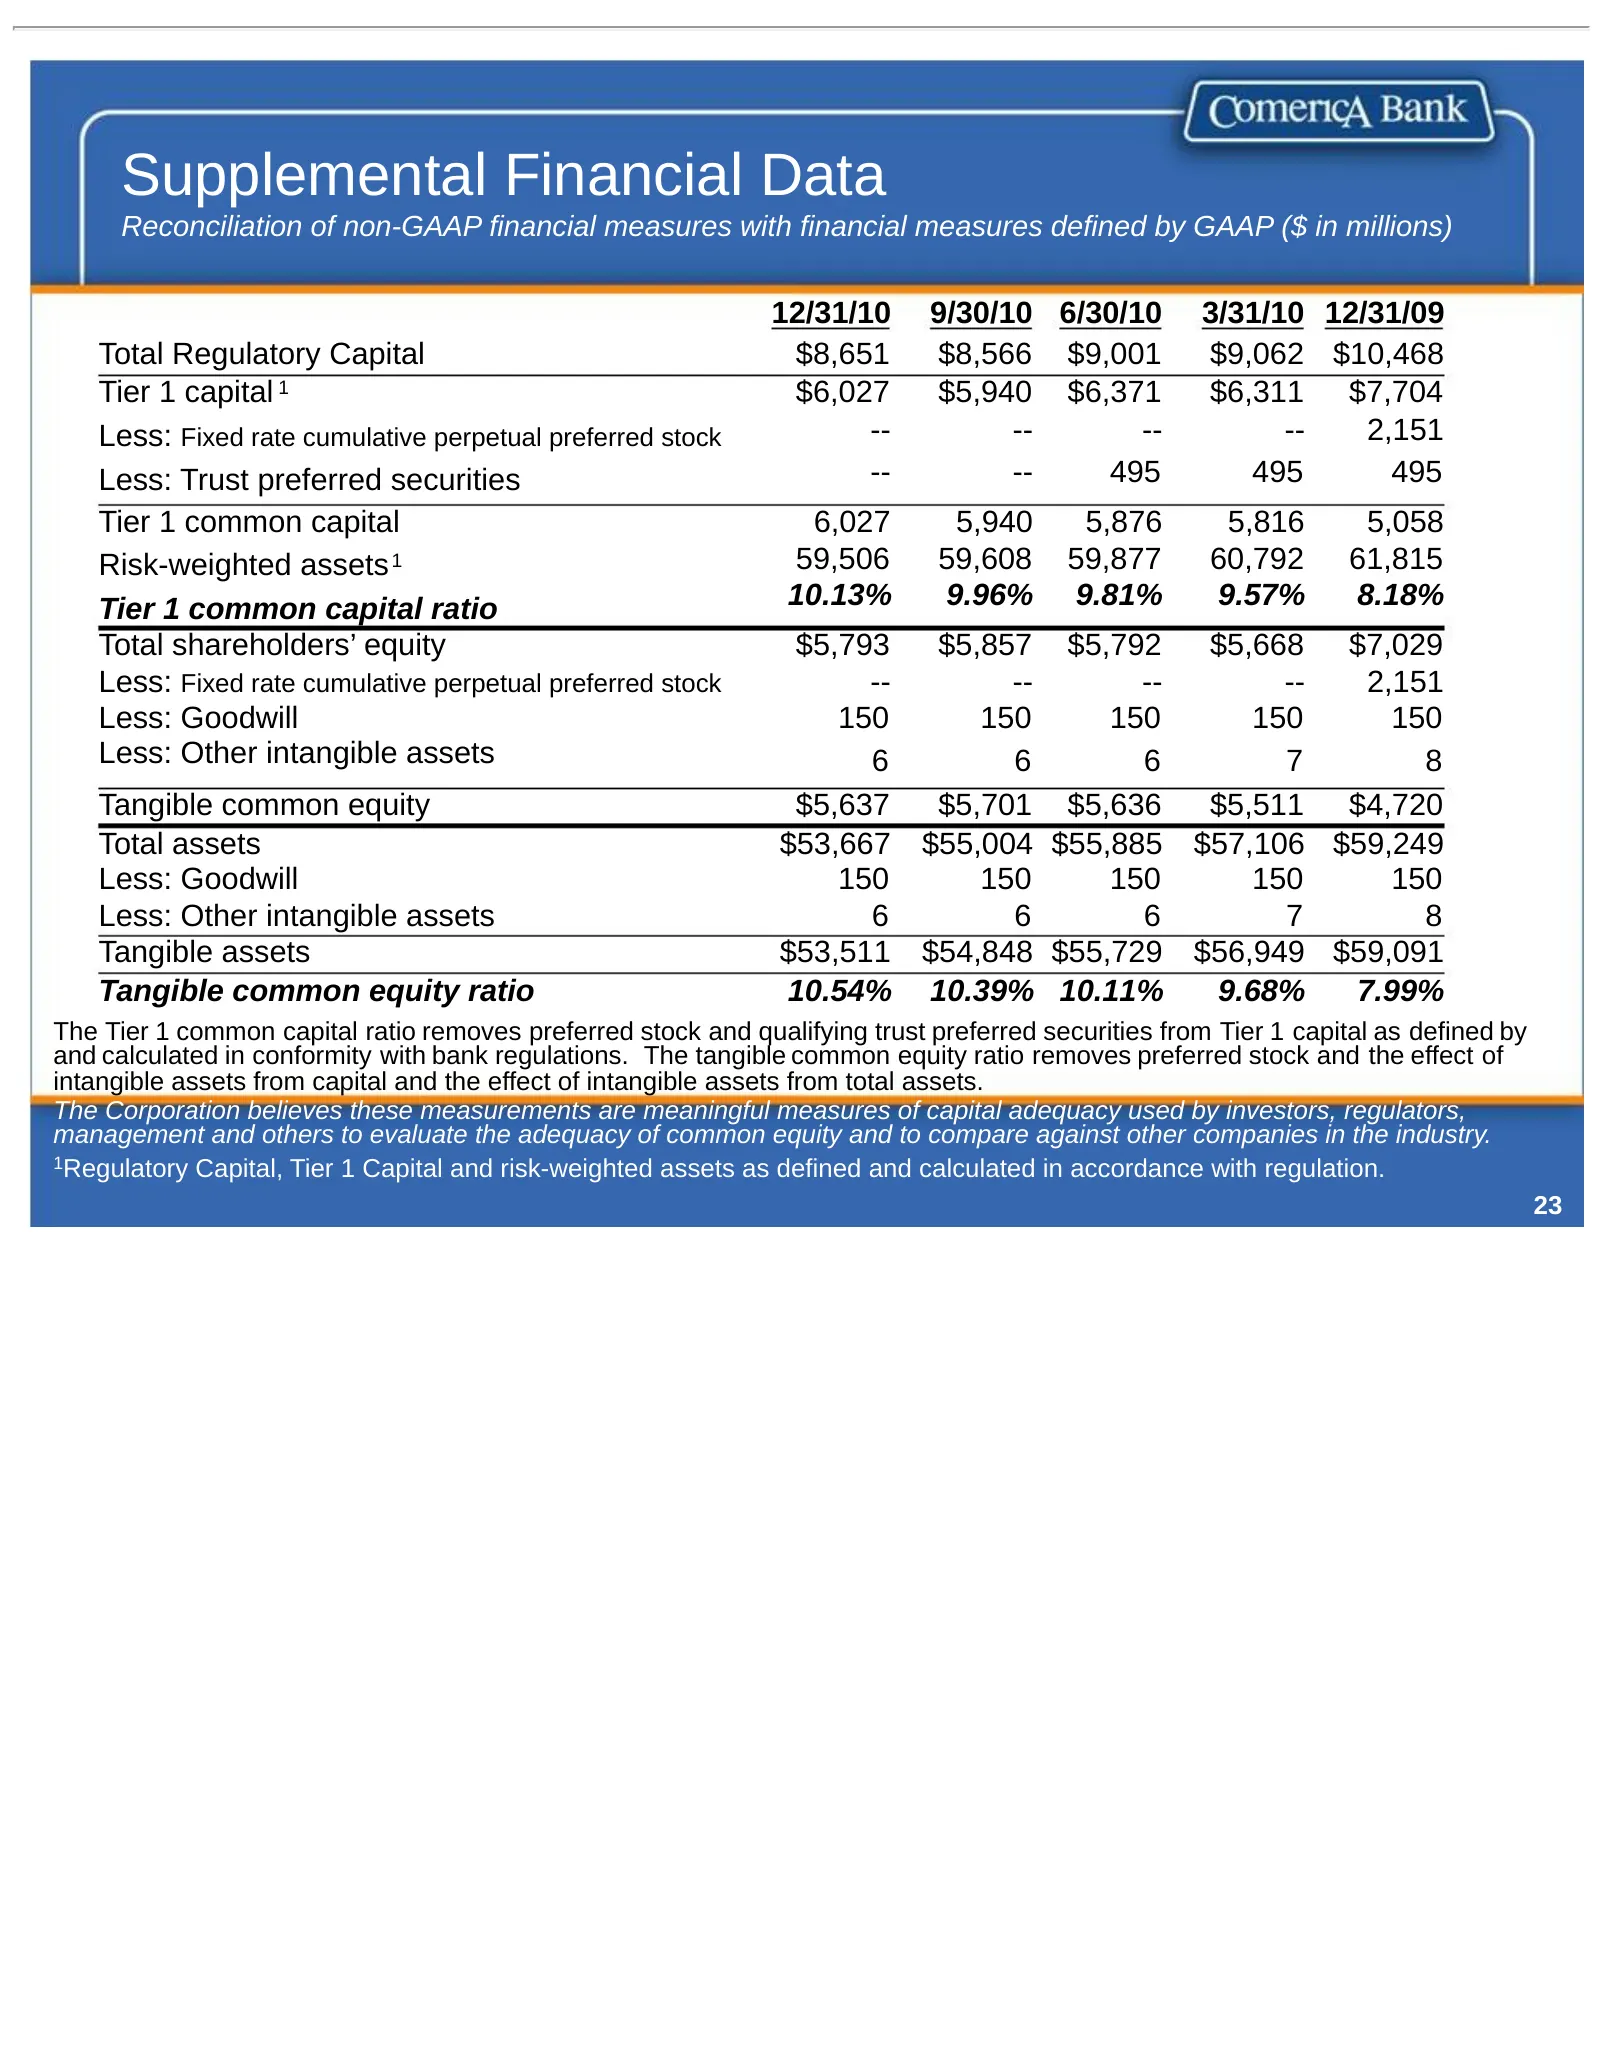
Supplemental Financial Data Reconciliation of non-GAAP financial measures with financial measures defined by GAAP ($ in millions) 12/31/10 9/30/10 6/30/10 3/31/10 12/31/09 Total Regulatory Capital $8,651 $8,566 $9,001 $9,062 $10,468 Tier 1 capital 1 $6,027 $5,940 $6,371 $6,311 $7,704 Less: Fixed rat
Slide 26: Additional Information For Shareholders
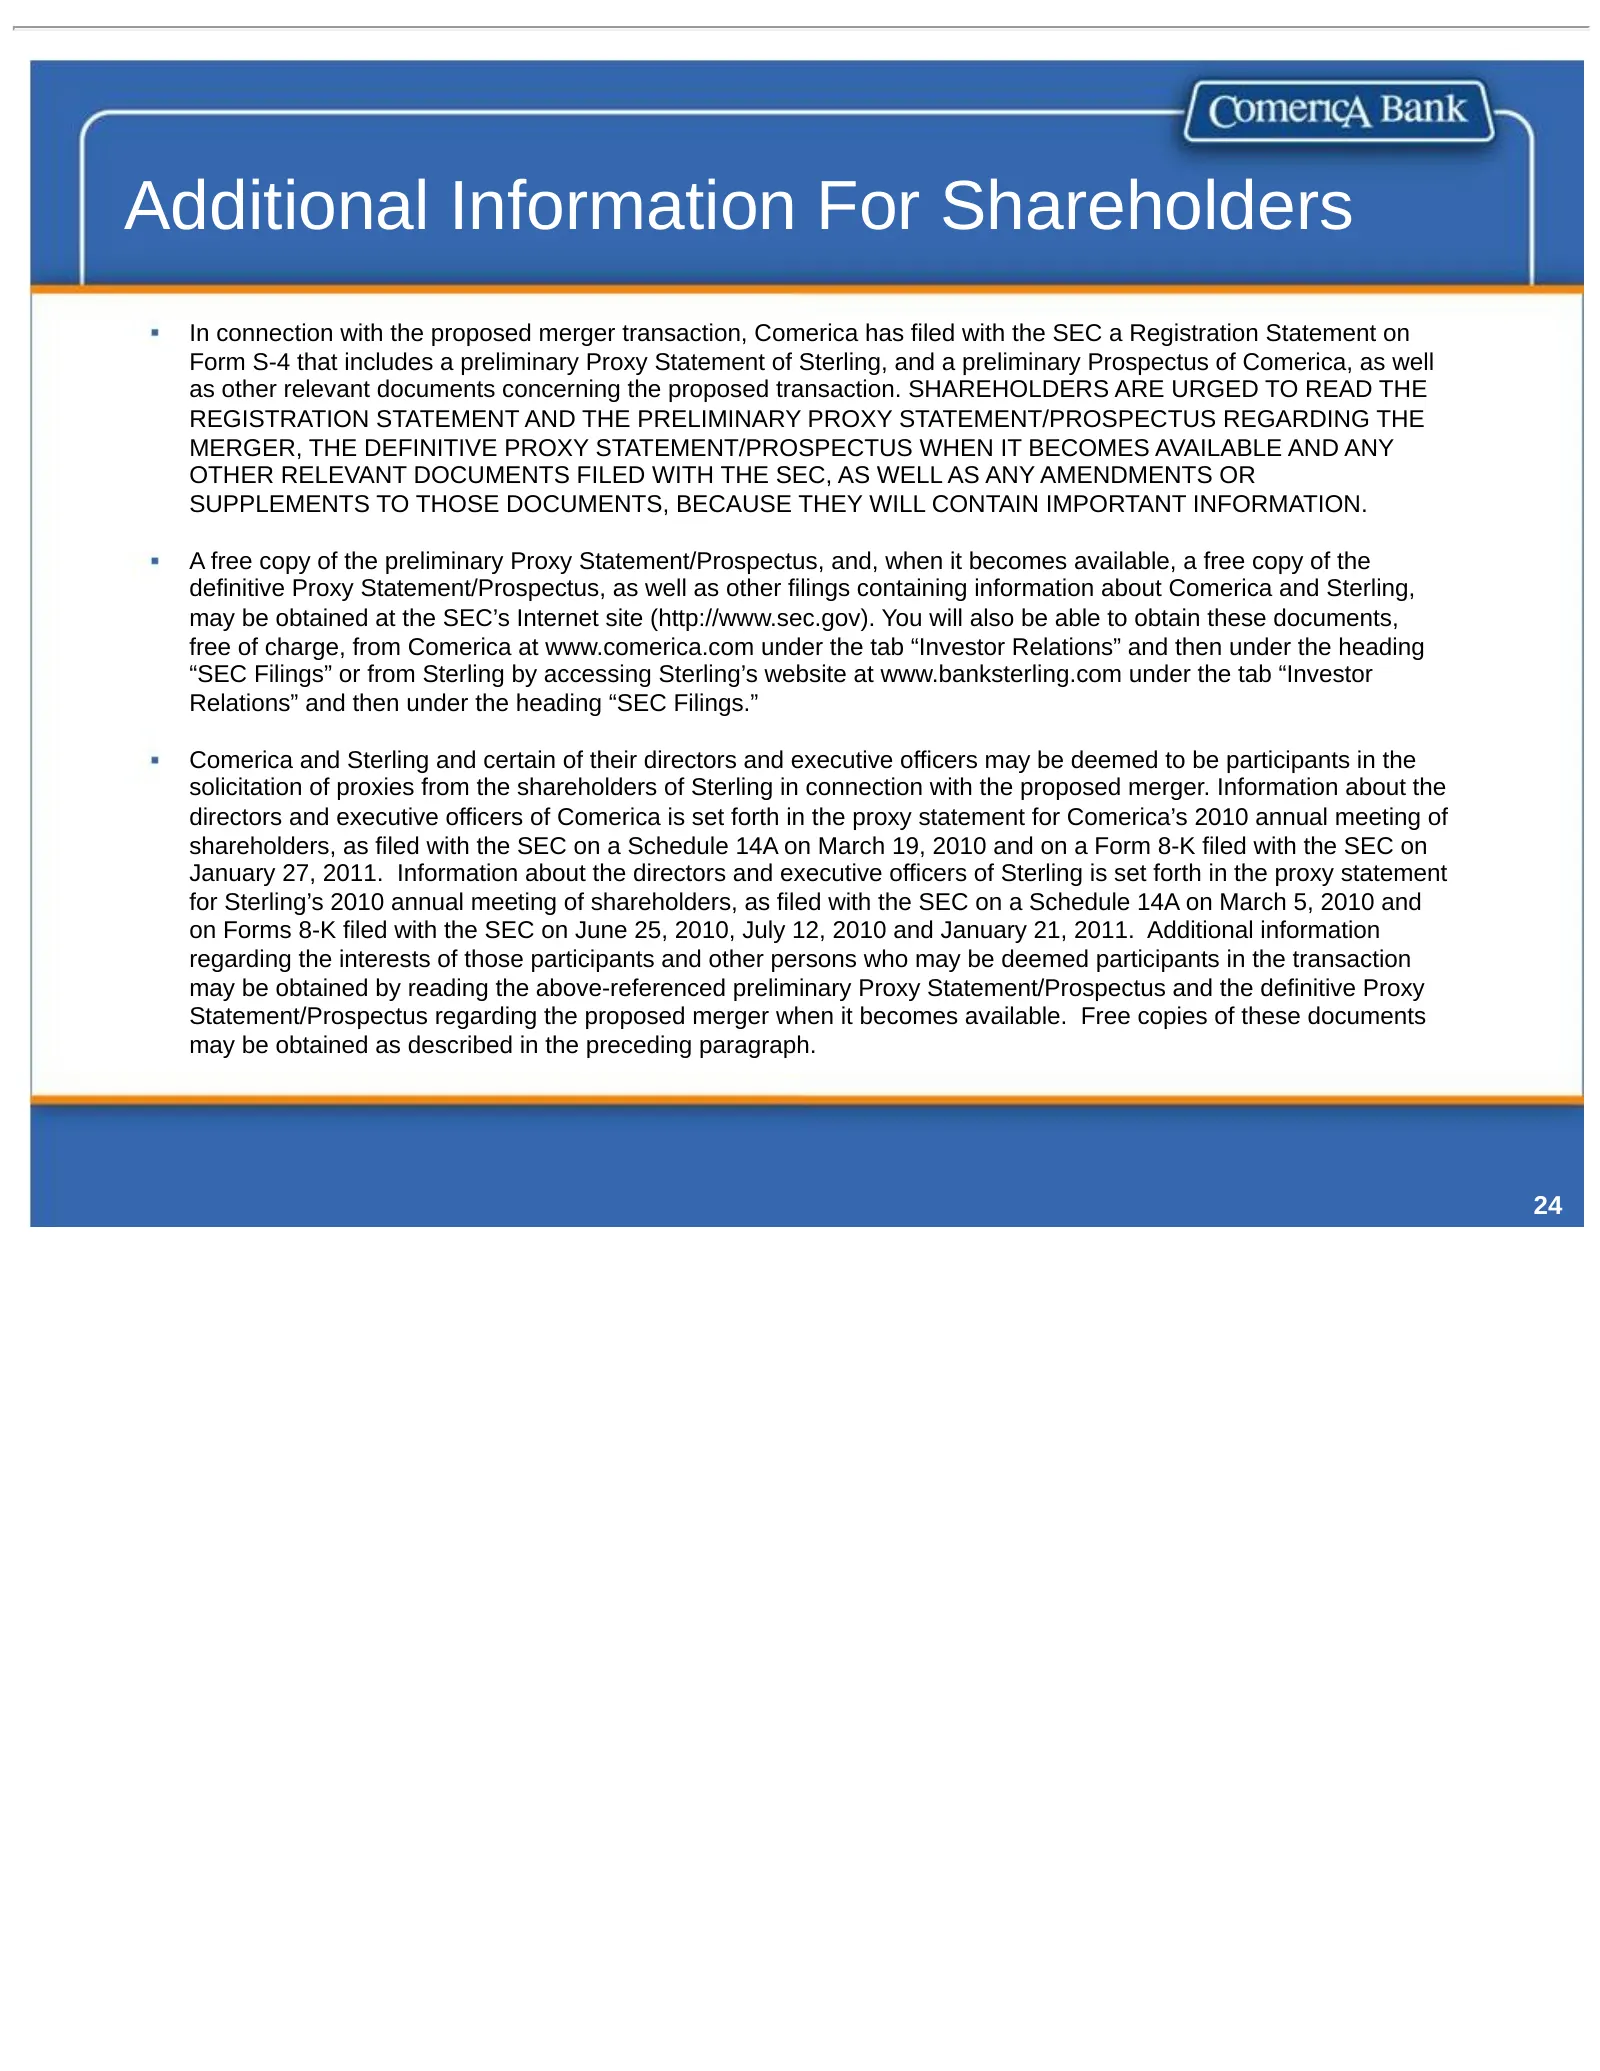
Additional Information For Shareholders In connection with the proposed merger transaction, Comerica has filed with the SEC a Registration Statement on Form S-4 that includes a preliminary Proxy Statement of Sterling, and a preliminary Prospectus of Comerica, as well as other relevant documents conc
Source: SEC EDGAR · 425 filed Feb 22, 2011
More decks from Sterling Bancshares Inc
 Q2 2011 Earnings Presentation40 slides · Jul 19, 2011
 Merger or Acquisition (May 2011)48 slides · May 4, 2011
 Shareholder Meeting (April 2011)40 slides · Apr 26, 2011
 Q1 2011 Earnings Presentation43 slides · Apr 19, 2011
 Merger or Acquisition (February 2011)68 slides · Feb 7, 2011
 Merger or Acquisition (January 2011)22 slides · Jan 18, 2011