Barratt Redrow plc · LSE:BTRW
Barratt Redrow — Barratt Developments — H1 FY2018 Earnings Presentation
56 slides from Barratt Redrow's earnings presentation, Feb 21, 2018
Slide 1: Results Presentation – Half year ended 31 December 2017
RESULTS PRESENTATION Half year ended 31 December 2017 21 February 2018 Madden Gardens, Letchworth Garden City 1
Slide 2: David Thomas, Chief Executive
Weaver View, Winsford David Thomas Chief Executive 2
Slide 3: Summary
SUMMARY Strong financial and operational performance in the first half Robust market fundamentals Operational improvements delivering margin benefits Disciplined volume growth with a focus on addressing supply-side challenges Delivering attractive cash returns Confidence in the business going forwar
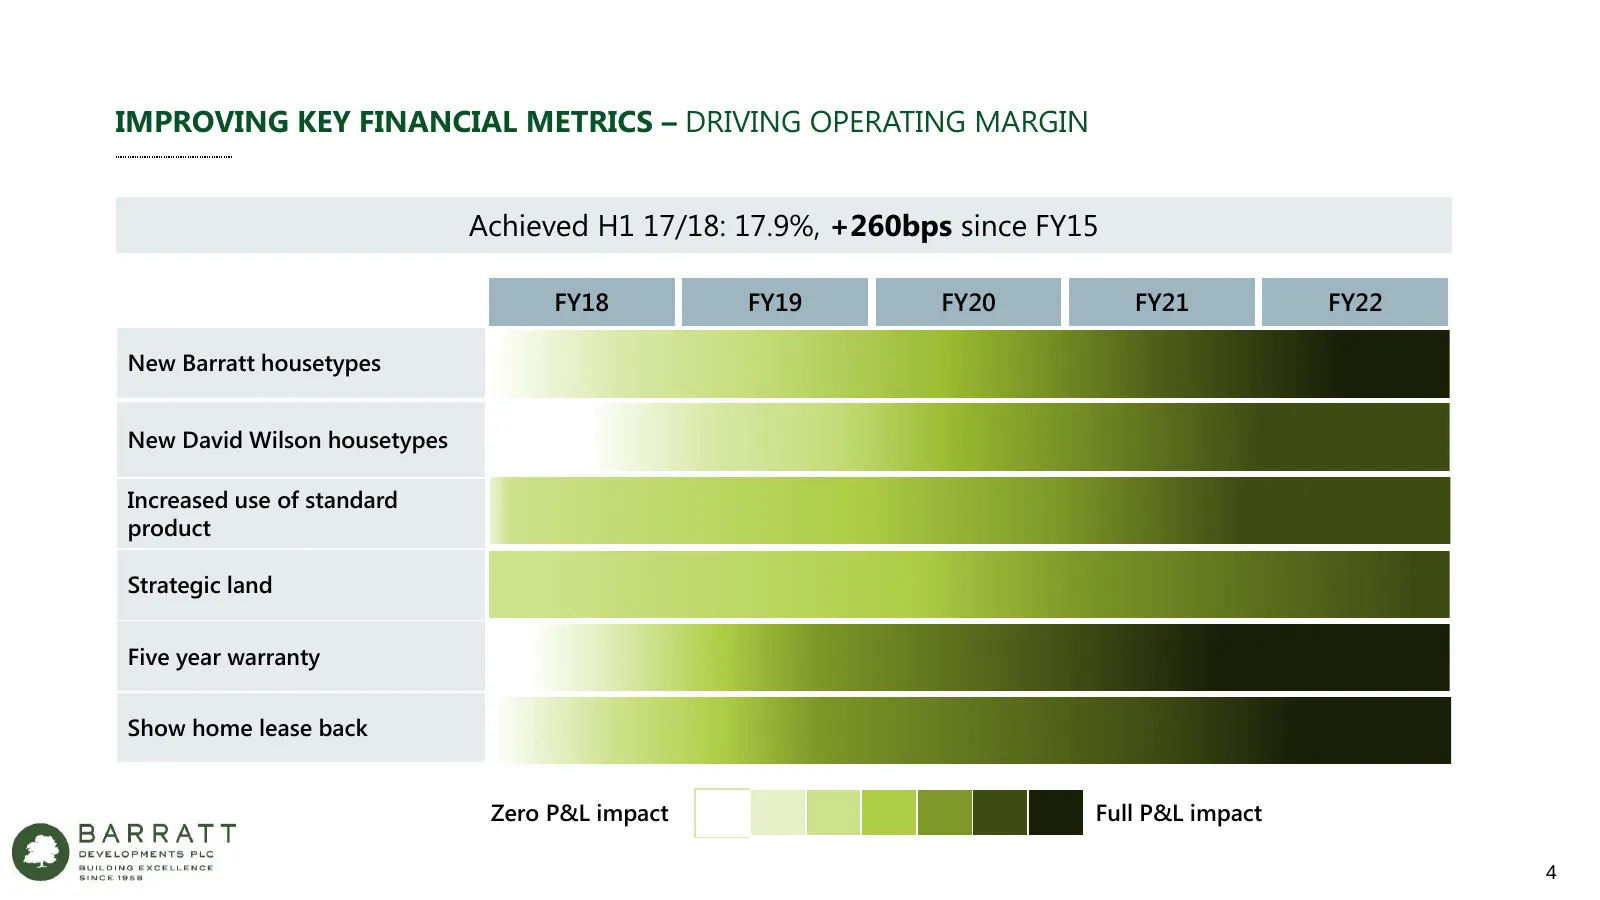
Slide 4: Improving Key Financial Metrics – Driving Operating Margin
IMPROVING KEY FINANCIAL METRICS – DRIVING OPERATING MARGIN Achieved H1 17/18: 17.9%, +260bps since FY15 FY18 FY19 FY20 FY21 FY22 New Barratt housetypes New David Wilson housetypes Increased use of standard product Strategic land Five year warranty Show home lease back Zero P&L impact Full P&L impact
Slide 5: Steven Boyes, Chief Operating Officer
Steven Boyes Chief Operating Officer Saxon Gate, Stamford Bridge 5
Slide 6: Strong Sales Performance
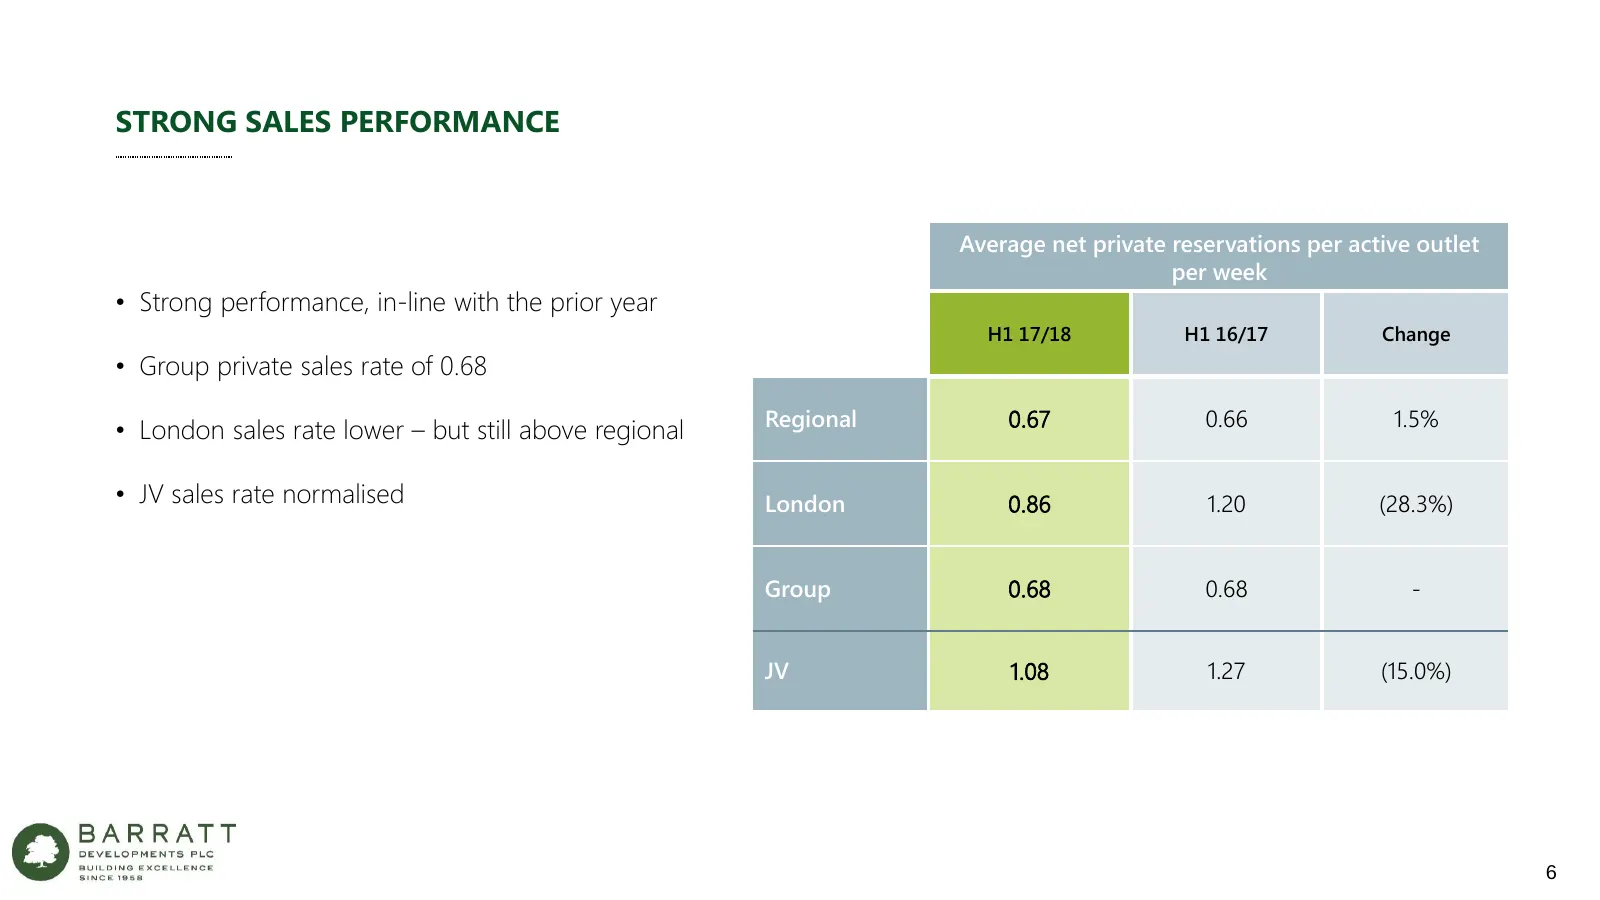
STRONG SALES PERFORMANCE Average net private reservations per active outlet per week • Strong performance, in-line with the prior year H1 17/18 H1 16/17 Change • Group private sales rate of 0.68 Regional 0.67 0.66 1.5% • London sales rate lower – but still above regional • JV sales rate normalised L
Slide 7: Completion Growth
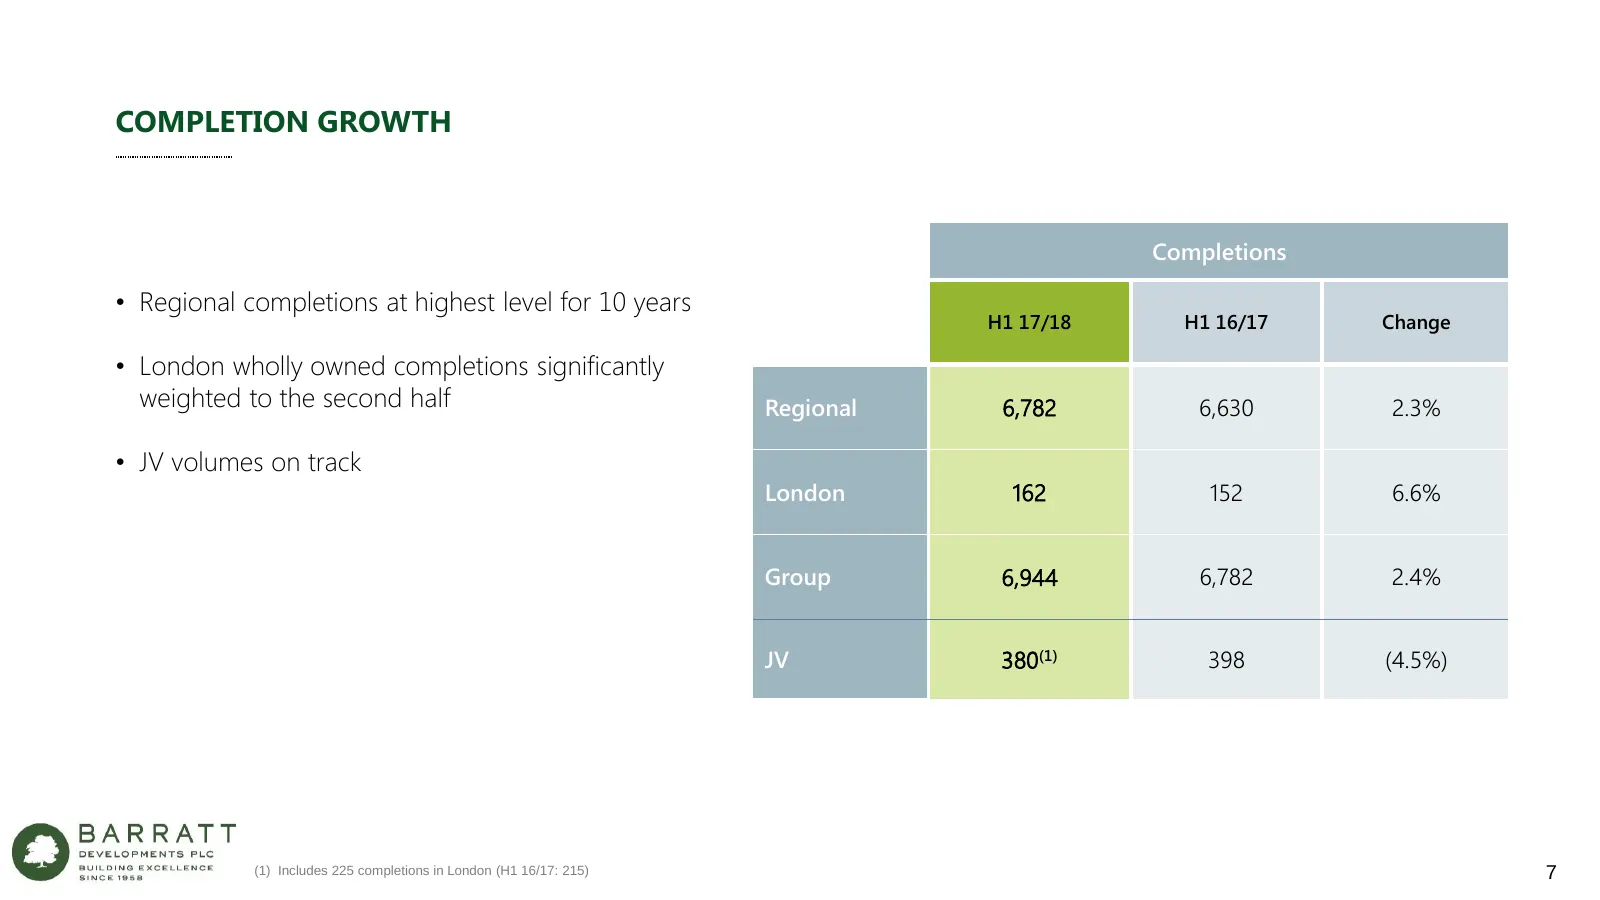
COMPLETION GROWTH Completions • Regional completions at highest level for 10 years H1 17/18 H1 16/17 Change • London wholly owned completions significantly weighted to the second half Regional 6,782 6,630 2.3% • JV volumes on track London 162 152 6.6% Group 6,944 6,782 2.4% JV 380(1) 398 (4.5%) (1)
Slide 8: Completions Analysis – Buyer Type
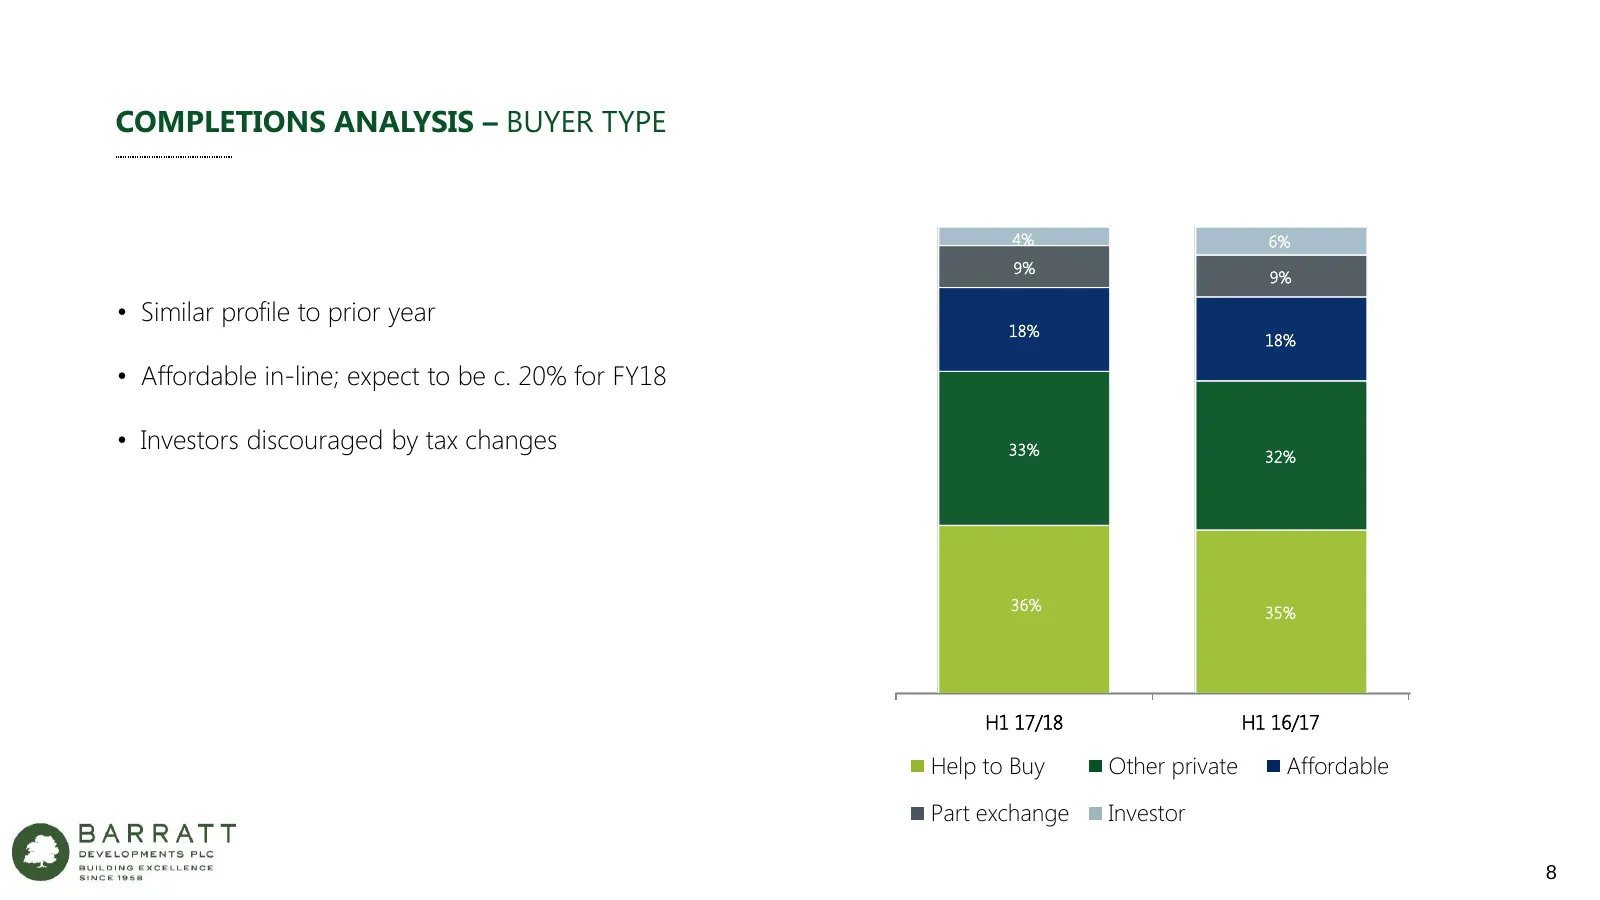
COMPLETIONS ANALYSIS – BUYER TYPE 4% 6% 9% 9% • Similar profile to prior year 18% 18% • Affordable in-line; expect to be c. 20% for FY18 • Investors discouraged by tax changes 33% 32% 36% 35% H1 17/18 H1 16/17 Help to Buy Other private Affordable Part exchange Investor 8
Slide 9: Pricing Trends Remain Positive
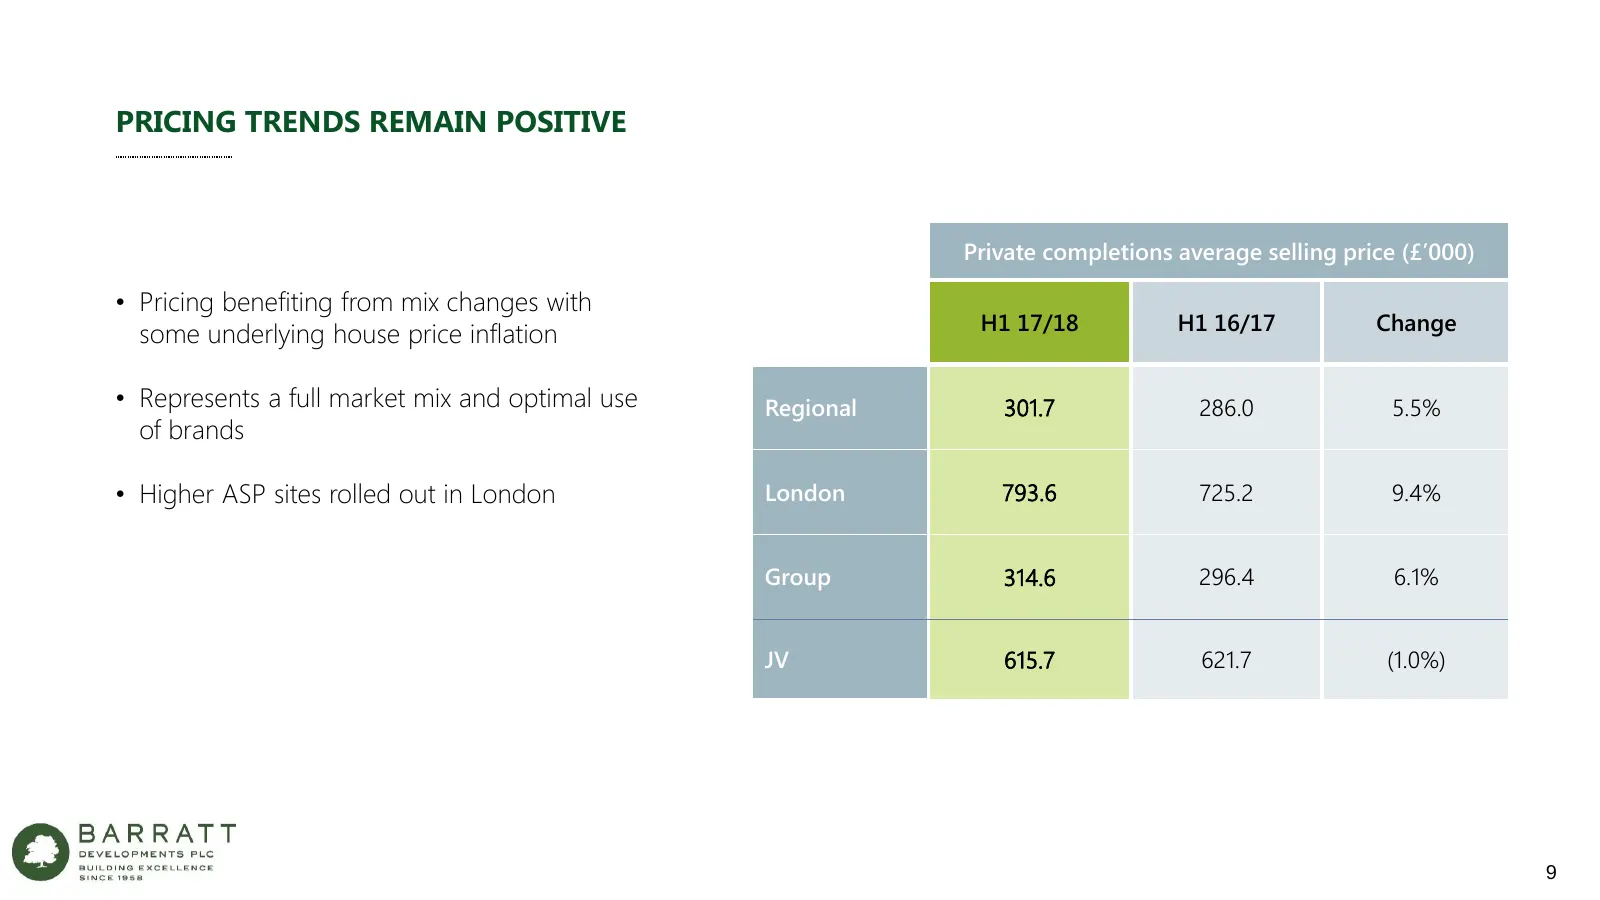
PRICING TRENDS REMAIN POSITIVE Private completions average selling price (£’000) • Pricing benefiting from mix changes with H1 17/18 H1 16/17 Change some underlying house price inflation • Represents a full market mix and optimal use Regional 301.7 286.0 5.5% of brands • Higher ASP sites rolled out
Slide 10: Land Market
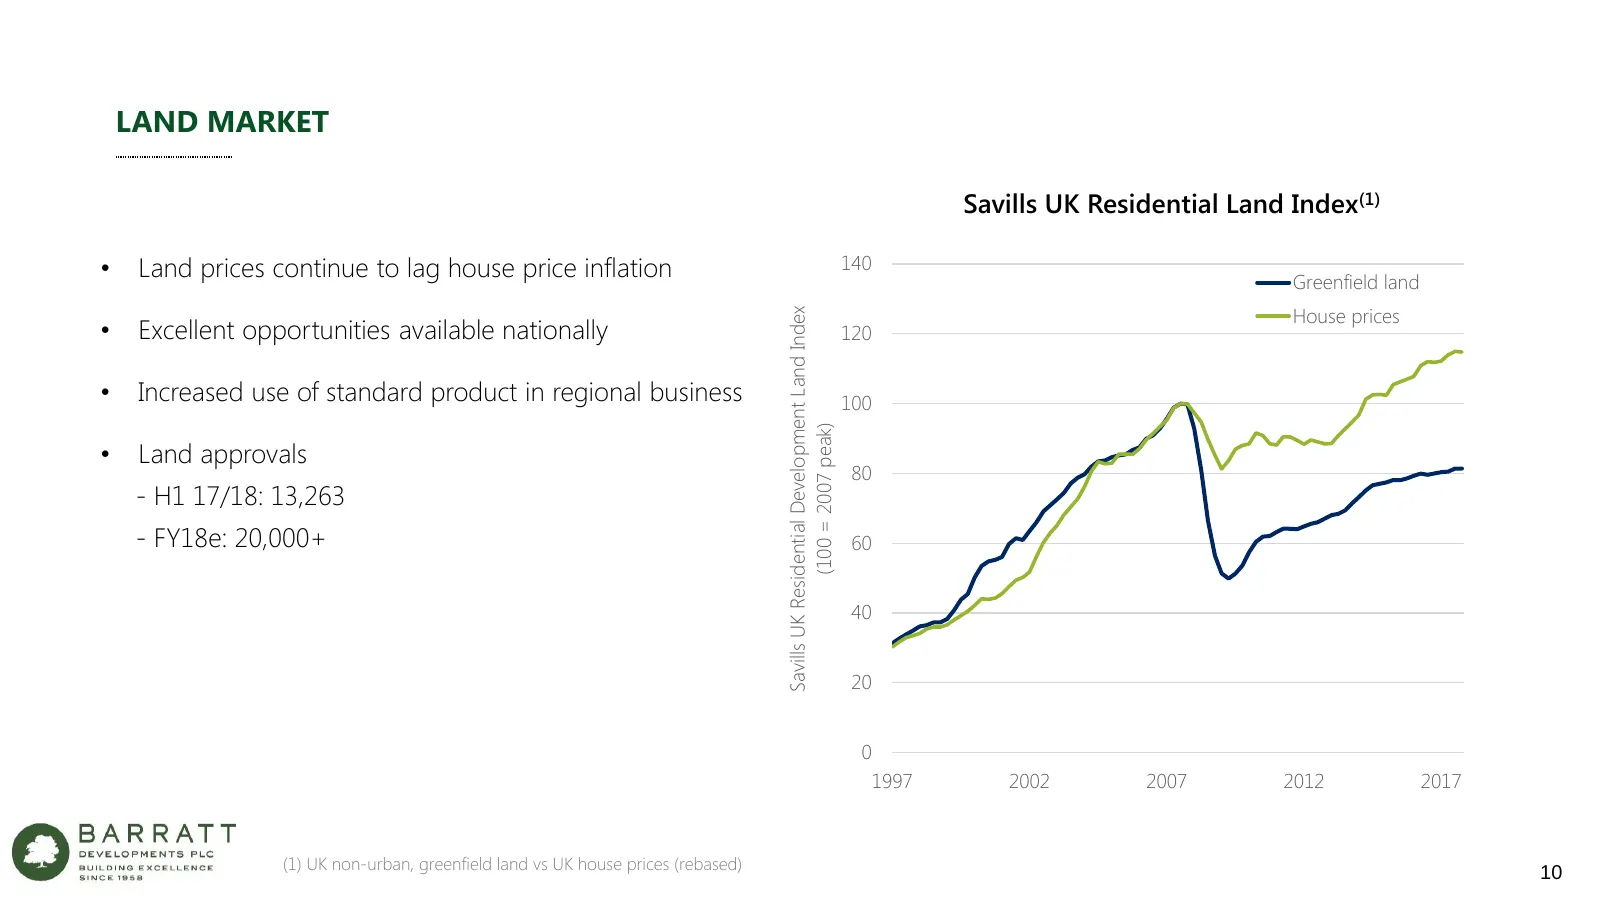
LAND MARKET Savills UK Residential Land Index(1) HOLDING PICTURE – CB • Land prices continue to lag house price inflation 140 Greenfield land SPEAKING TO PHIL BARNES House prices Savills UK Residential Development Land Index • Excellent opportunities available nationally 120 • Increased use of stand
Slide 11: Land Approvals
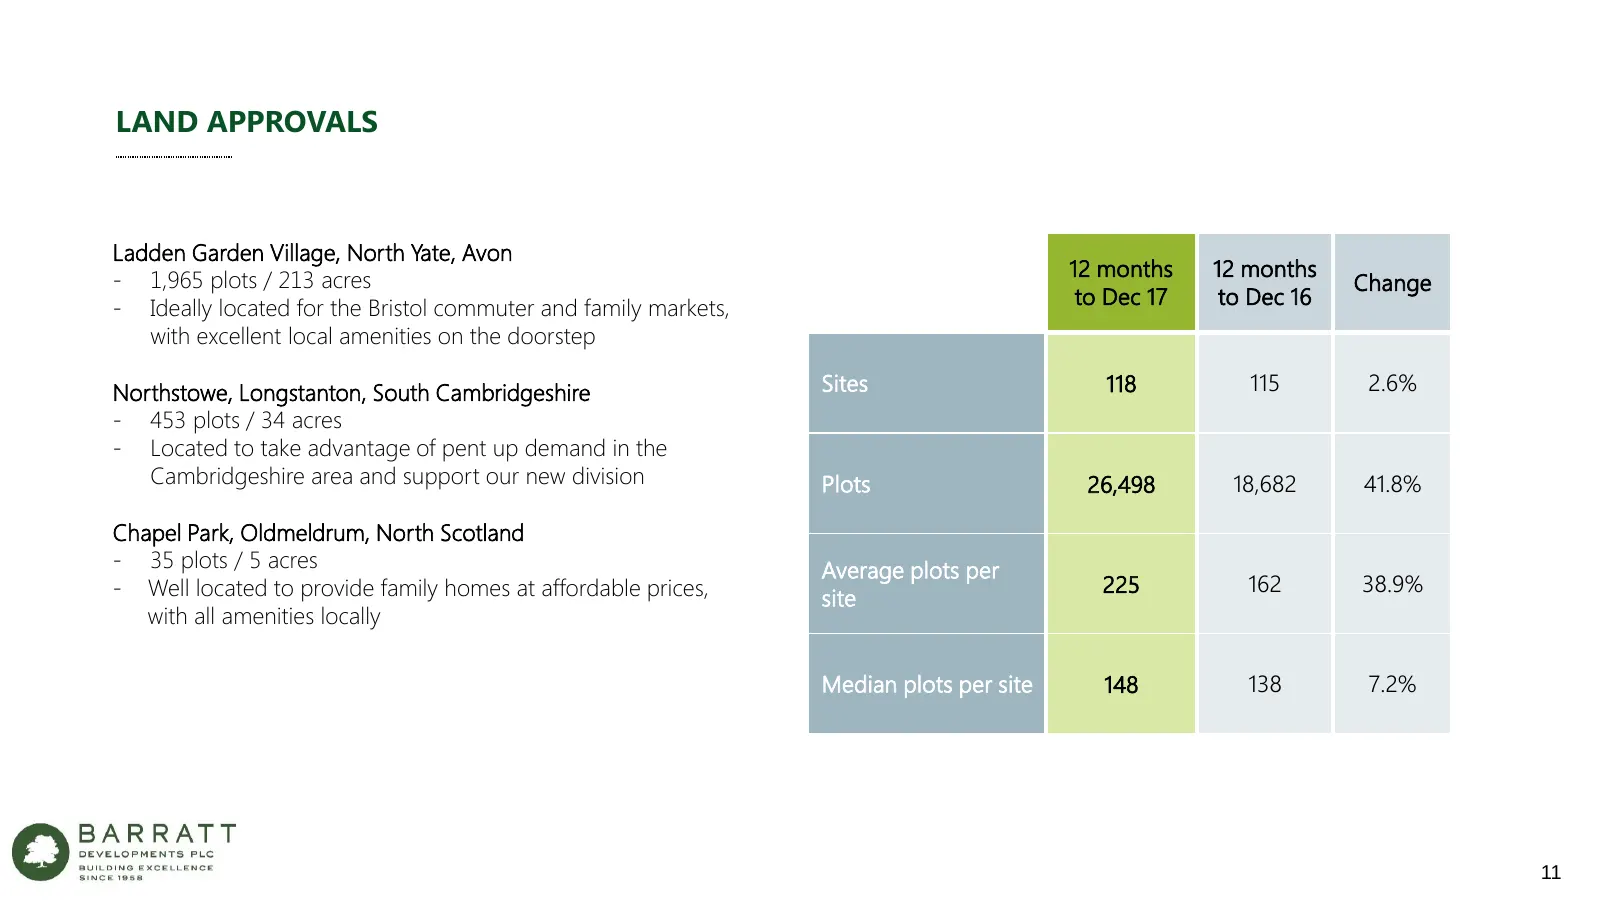
LAND APPROVALS Ladden Garden Village, North Yate, Avon 12 months 12 months - 1,965 plots / 213 acres Change to Dec 17 to Dec 16 - Ideally located for the Bristol commuter and family markets, with excellent local amenities on the doorstep Northstowe, Longstanton, South Cambridgeshire Sites 118 115 2.
Slide 12: Land Bank – National Coverage
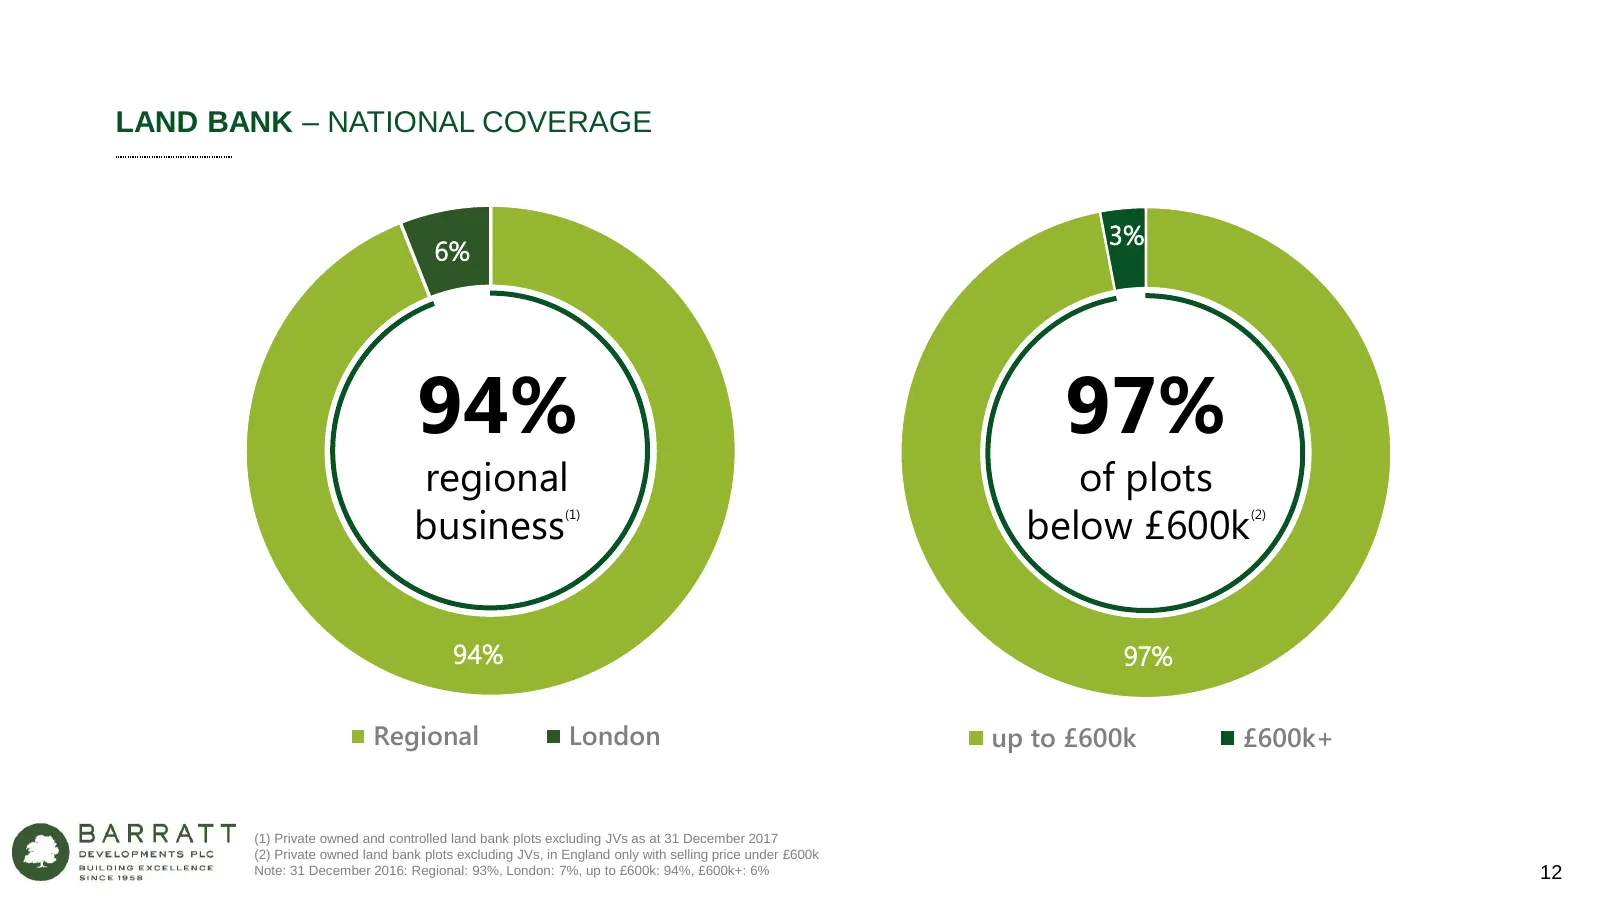
LAND BANK – NATIONAL COVERAGE 3% 6% 94% 97% regional of plots business (1) below £600k (2) 94% 97% Regional London up to £600k £600k+ (1) Private owned and controlled land bank plots excluding JVs as at 31 December 2017 (2) Private owned land bank plots excluding JVs, in England only with selling pr
Slide 13: Land Bank – London
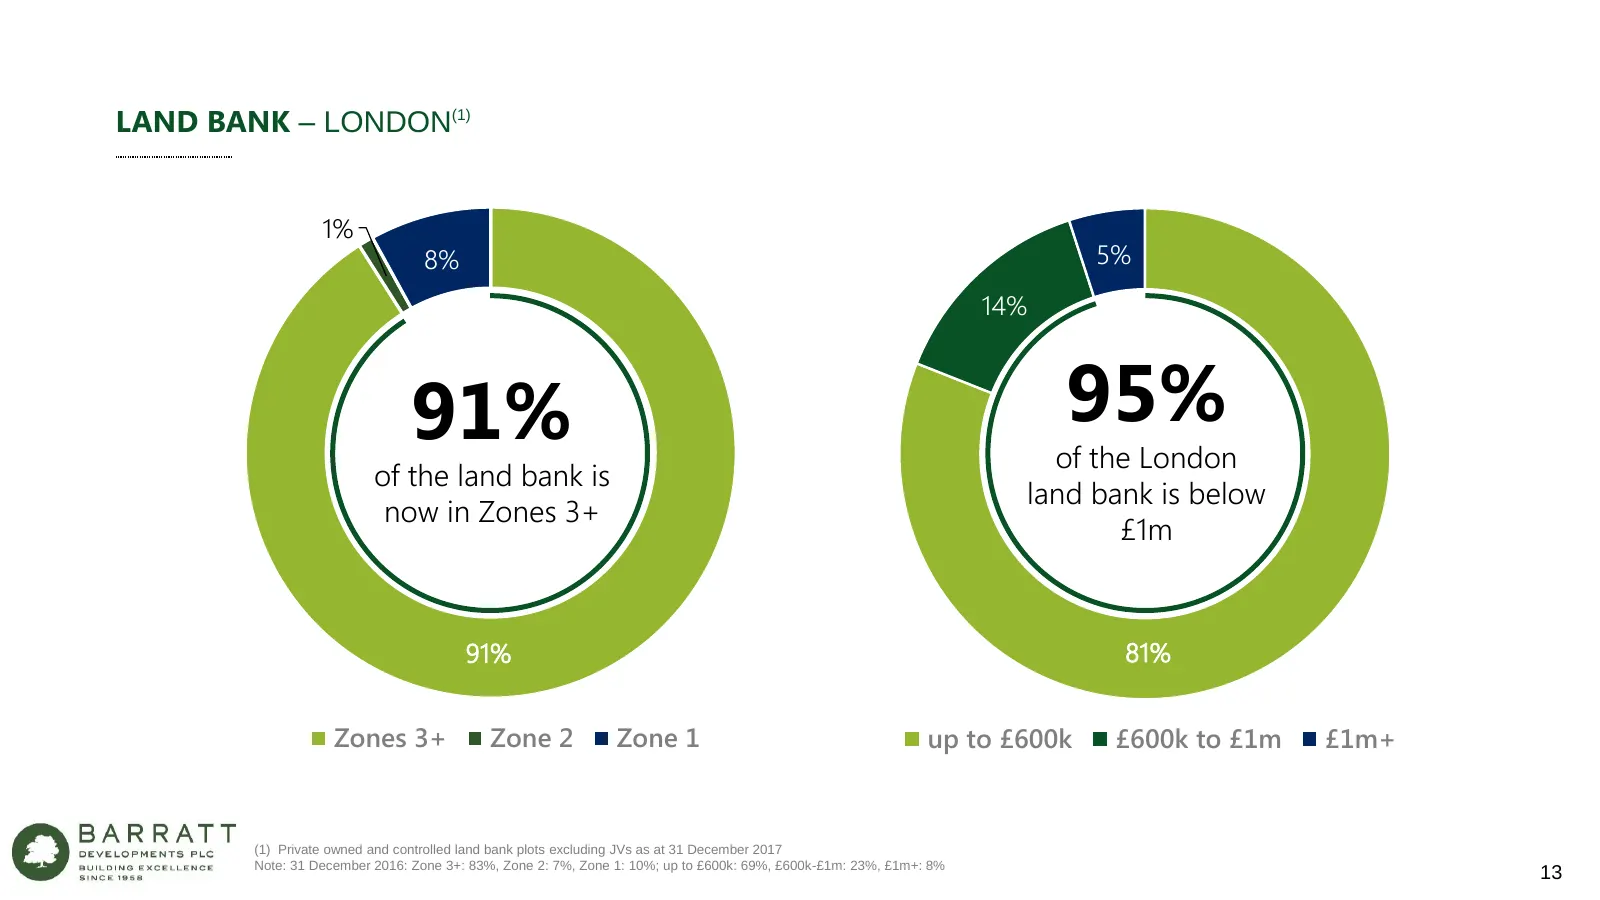
LAND BANK – LONDON(1) 1% 8% 5% 14% 91% 95% of the London of the land bank is land bank is below now in Zones 3+ £1m 91% 81% Zones 3+ Zone 2 Zone 1 up to £600k £600k to £1m £1m+ (1) Private owned and controlled land bank plots excluding JVs as at 31 December 2017 Note: 31 December 2016: Zone 3+: 83%,
Slide 14: Driving Operating Margin – Strategic Land
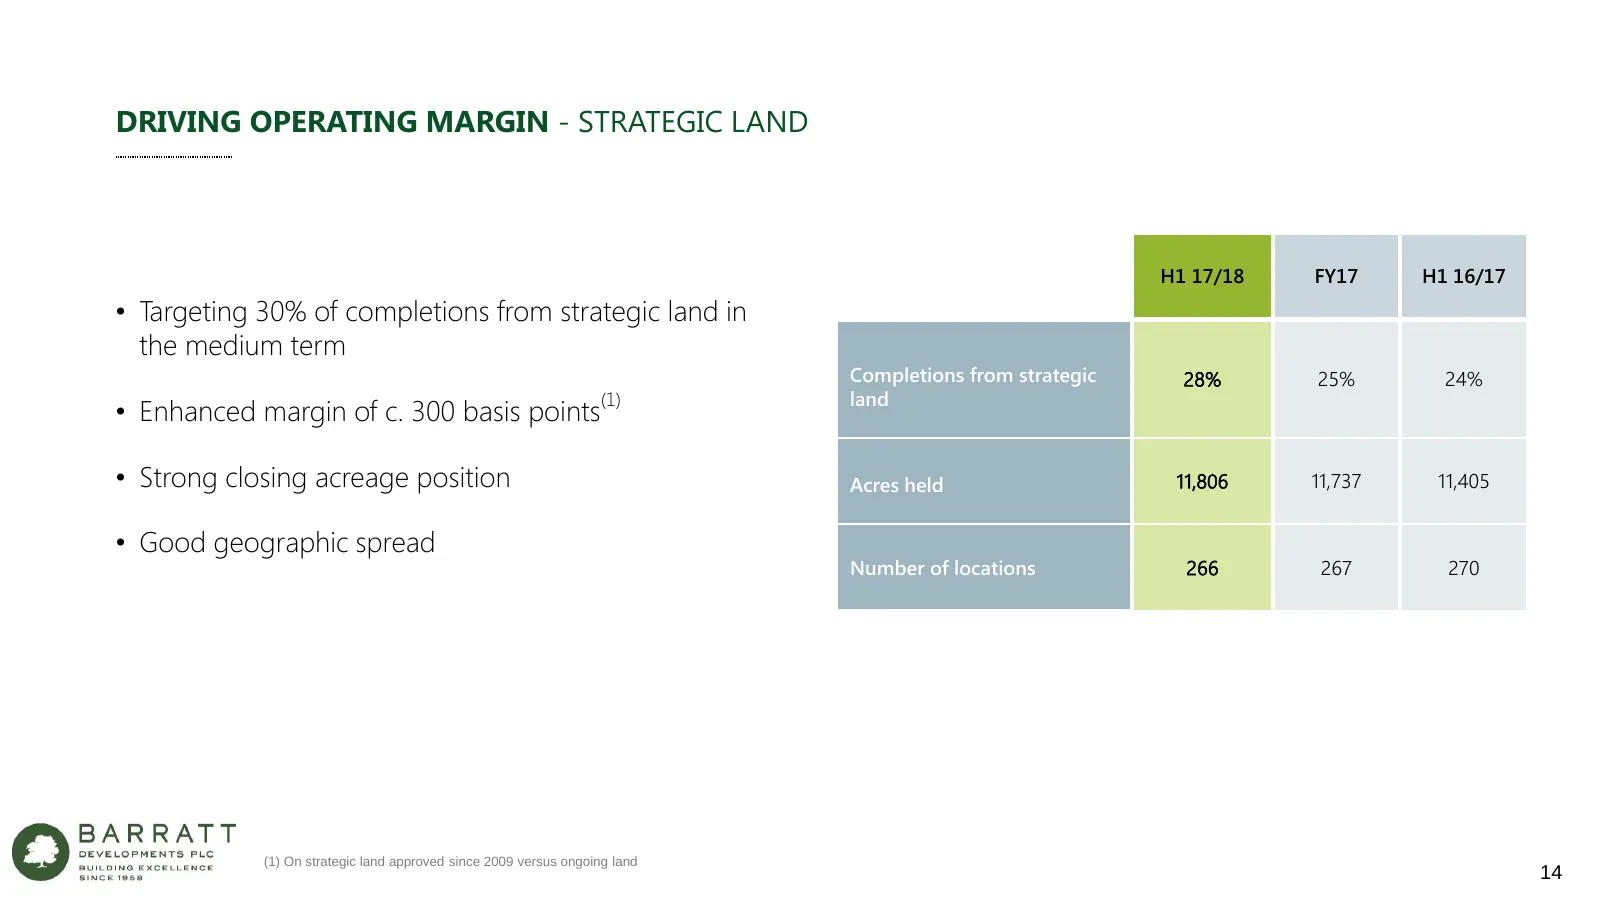
DRIVING OPERATING MARGIN - STRATEGIC LAND H1 17/18 FY17 H1 16/17 • Targeting 30% of completions from strategic land in the medium term Completions from strategic 28% 25% 24% (1) land • Enhanced margin of c. 300 basis points • Strong closing acreage position Acres held 11,806 11,737 11,405 • Good geo
Slide 15: Driving Operating Margin – Product
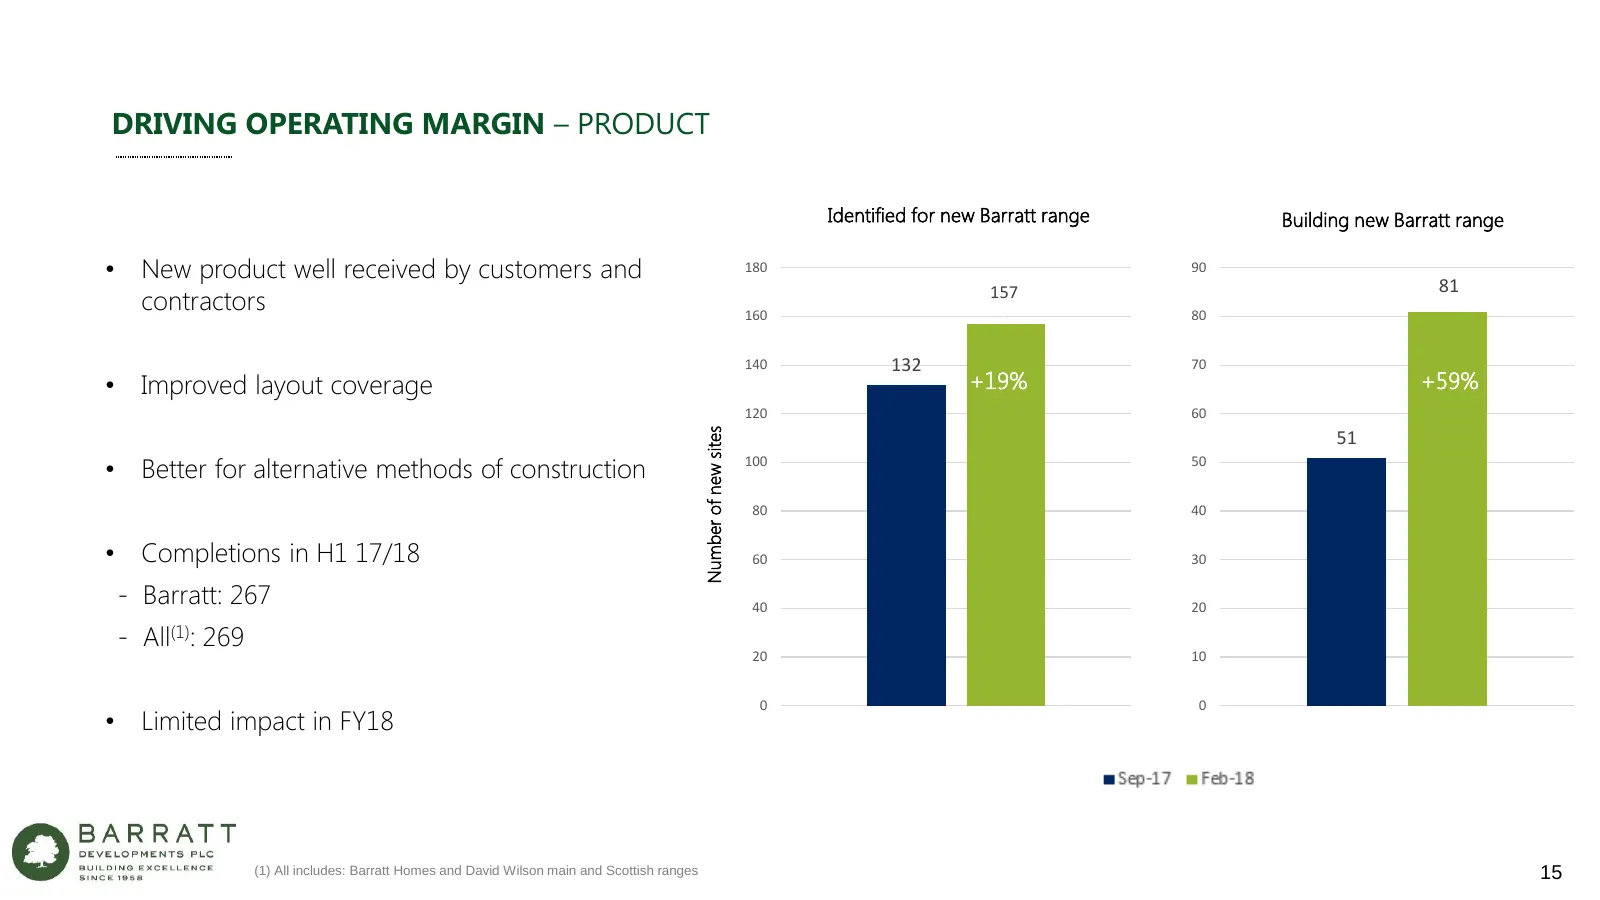
DRIVING OPERATING MARGIN – PRODUCT Identified for new Barratt range Building new Barratt range • New product well received by customers and 180 90 81 contractors 160 157 80 140 132 70 • Improved layout coverage +19% +59% 120 60 Number of new sites 51 • Better for alternative methods of construction
Slide 16: Customer First – We Place Customers at the Heart
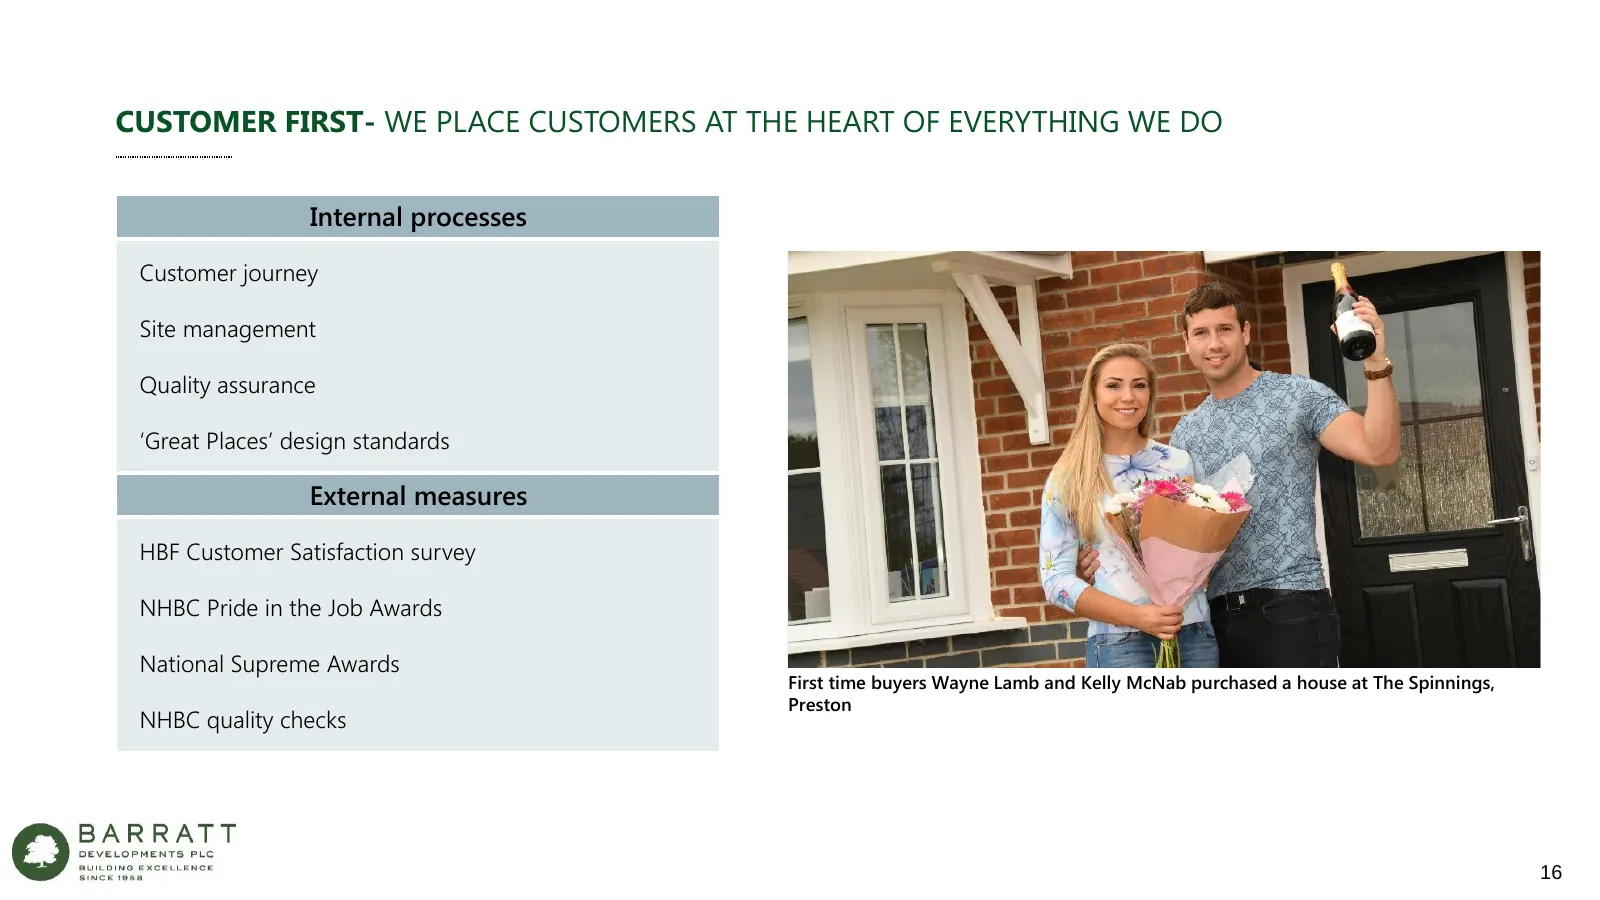
CUSTOMER FIRST- WE PLACE CUSTOMERS AT THE HEART OF EVERYTHING WE DO Internal processes Customer journey Site management Quality assurance ‘Great Places’ design standards External measures HBF Customer Satisfaction survey NHBC Pride in the Job Awards National Supreme Awards First time buyers Wayne La
Slide 17: Customer First – Our Achievements
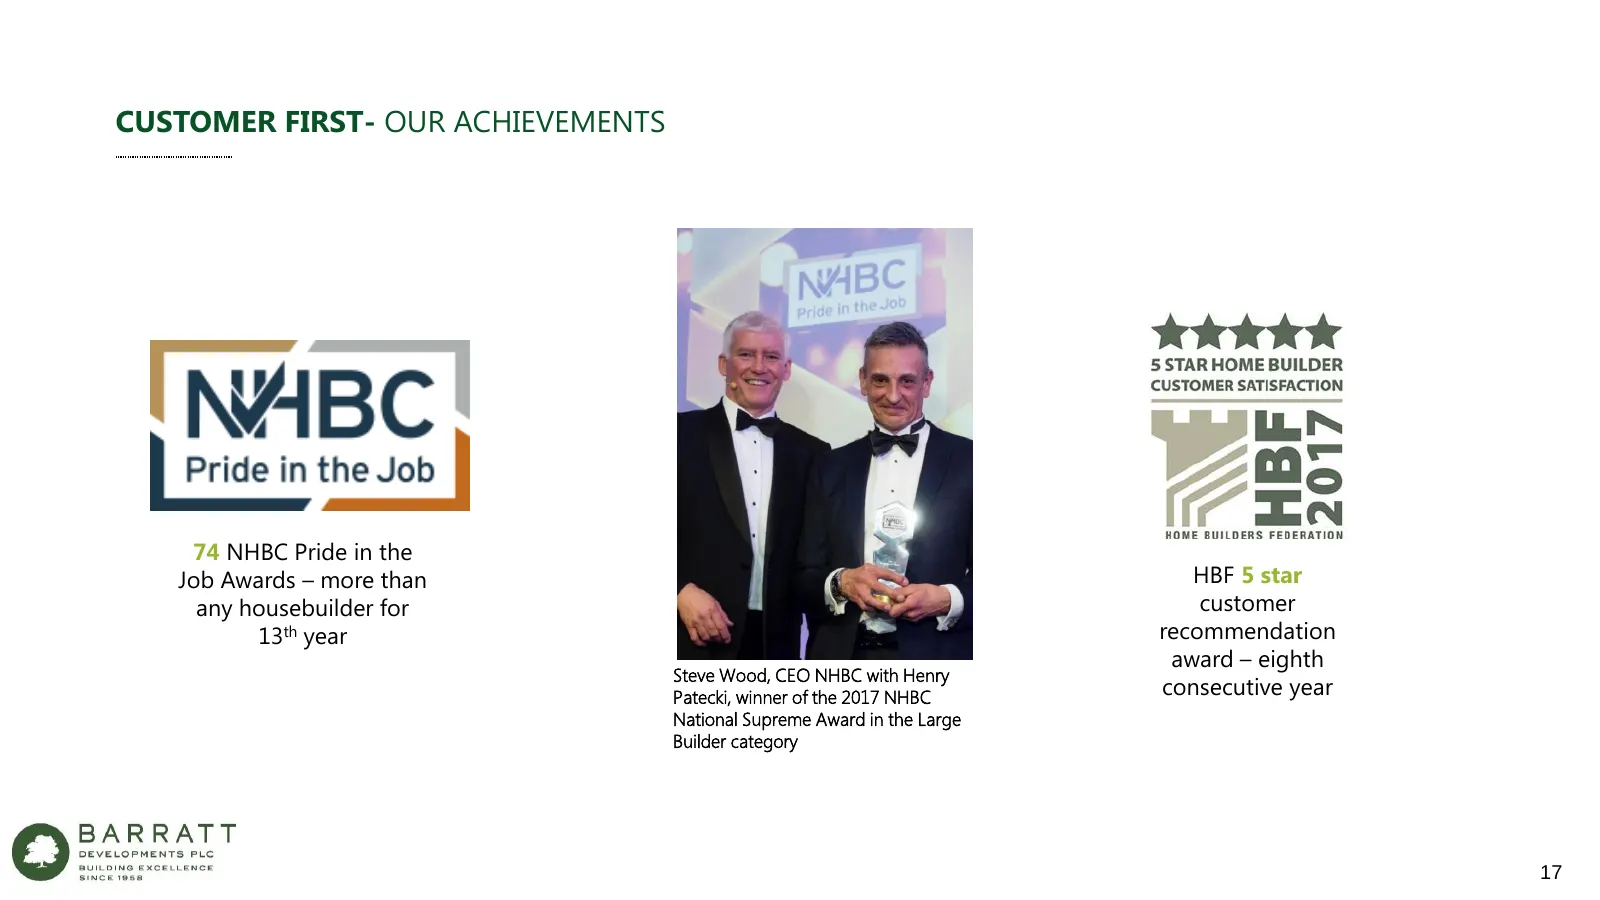
CUSTOMER FIRST- OUR ACHIEVEMENTS 74 NHBC Pride in the Job Awards – more than HBF 5 star any housebuilder for customer 13th year recommendation award – eighth Steve Wood, CEO NHBC with Henry Patecki, winner of the 2017 NHBC consecutive year National Supreme Award in the Large Builder category 17
Slide 18: Managing the Cost Environment
MANAGING THE COST ENVIRONMENT Materials Labour • Modest inflationary pressure • Labour inflation has eased • Some material pressures • Simplifying build e.g. timber, insulation • Increased use of offsite • 100% pricing fixed to June 2018 manufacturing • 1/3rd of pricing fixed for FY19 • Apprenticesh
Slide 19: Strong Performance
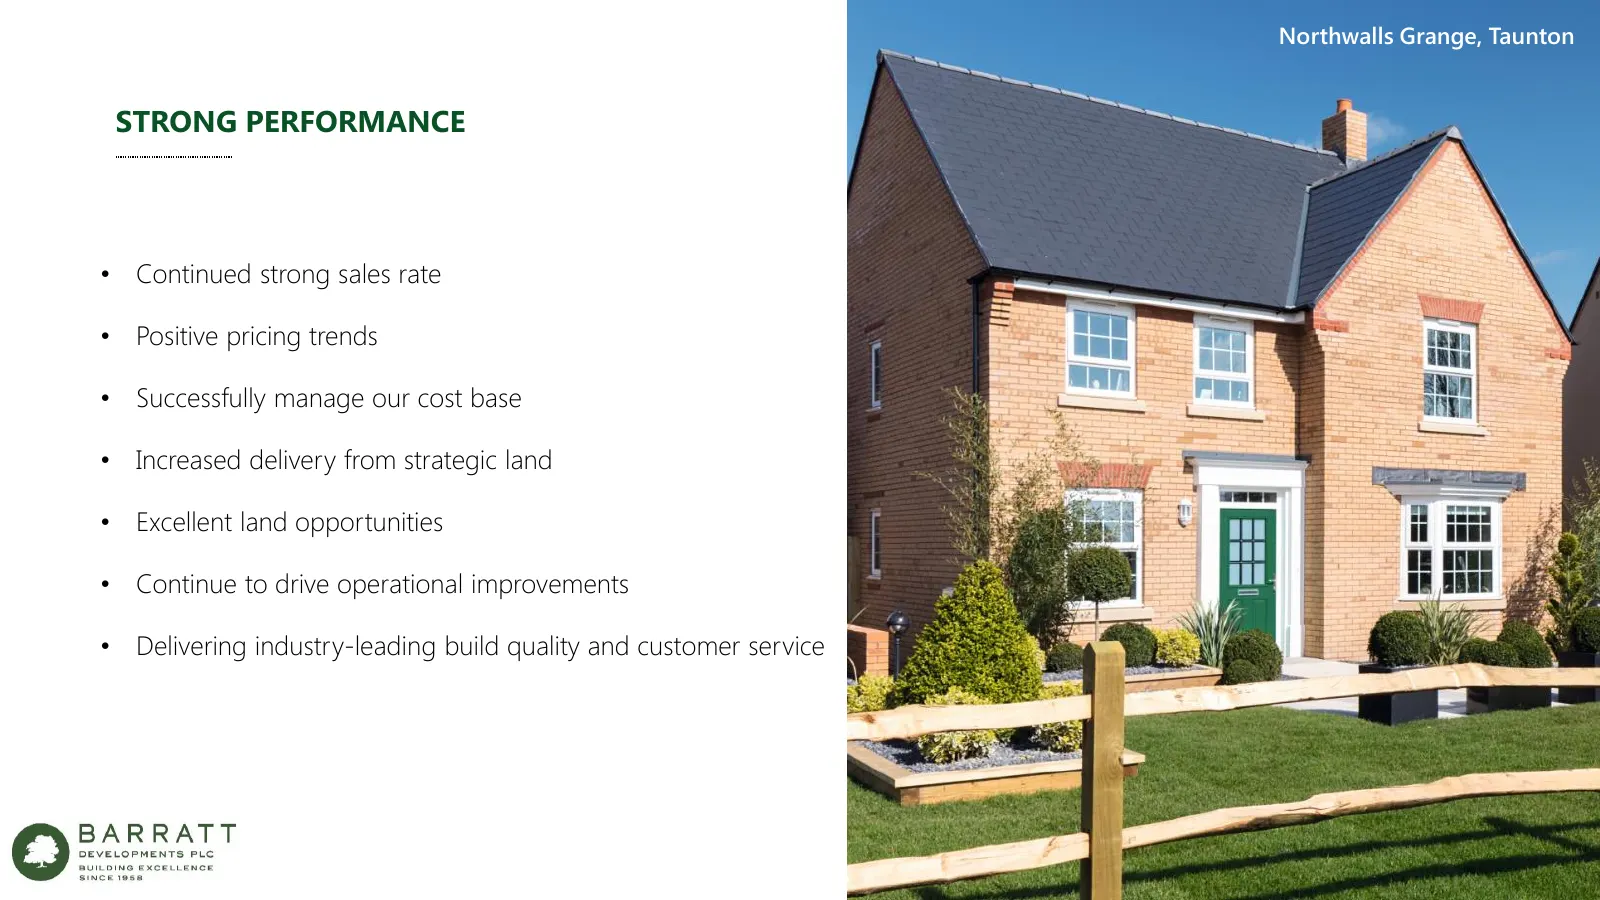
Northwalls Grange, Taunton STRONG PERFORMANCE • Continued strong sales rate • Positive pricing trends • Successfully manage our cost base • Increased delivery from strategic land • Excellent land opportunities • Continue to drive operational improvements • Delivering industry-leading build quality a
Slide 20: Jessica White, Chief Financial Officer
Jessica White Chief Financial Officer Lauder Gardens, Strathaven 20
Slide 21: Key Highlights
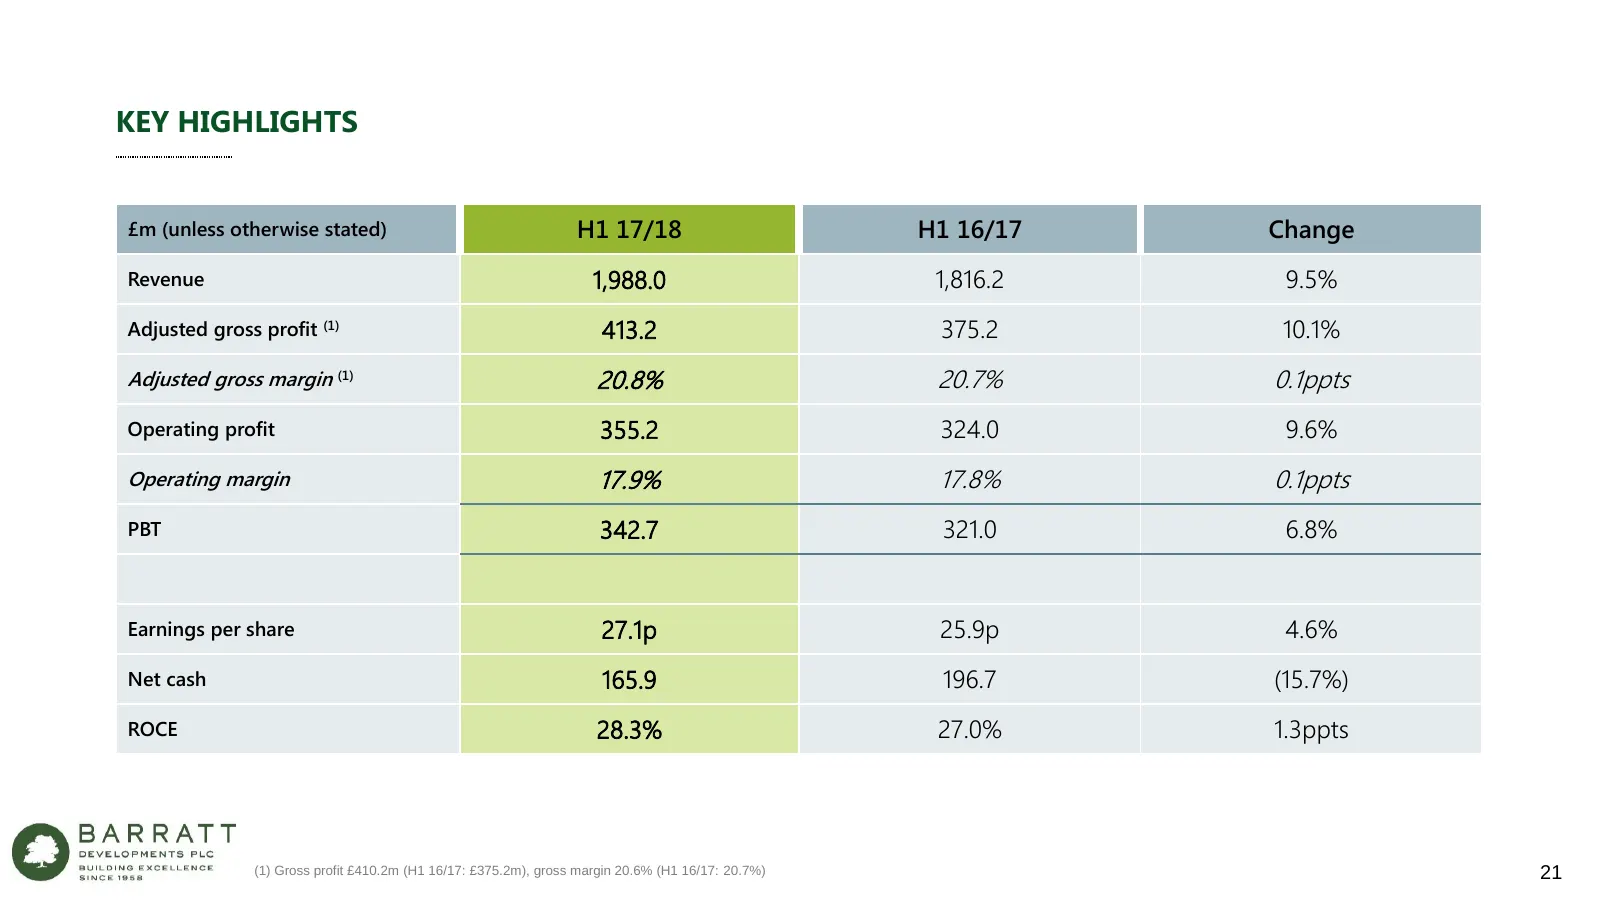
KEY HIGHLIGHTS £m (unless otherwise stated) H1 17/18 H1 16/17 Change Revenue 1,988.0 1,816.2 9.5% Adjusted gross profit (1) 413.2 375.2 10.1% Adjusted gross margin (1) 20.8% 20.7% 0.1ppts Operating profit 355.2 324.0 9.6% Operating margin 17.9% 17.8% 0.1ppts PBT 342.7 321.0 6.8% Earnings per share 2
Slide 22: Revenue Summary
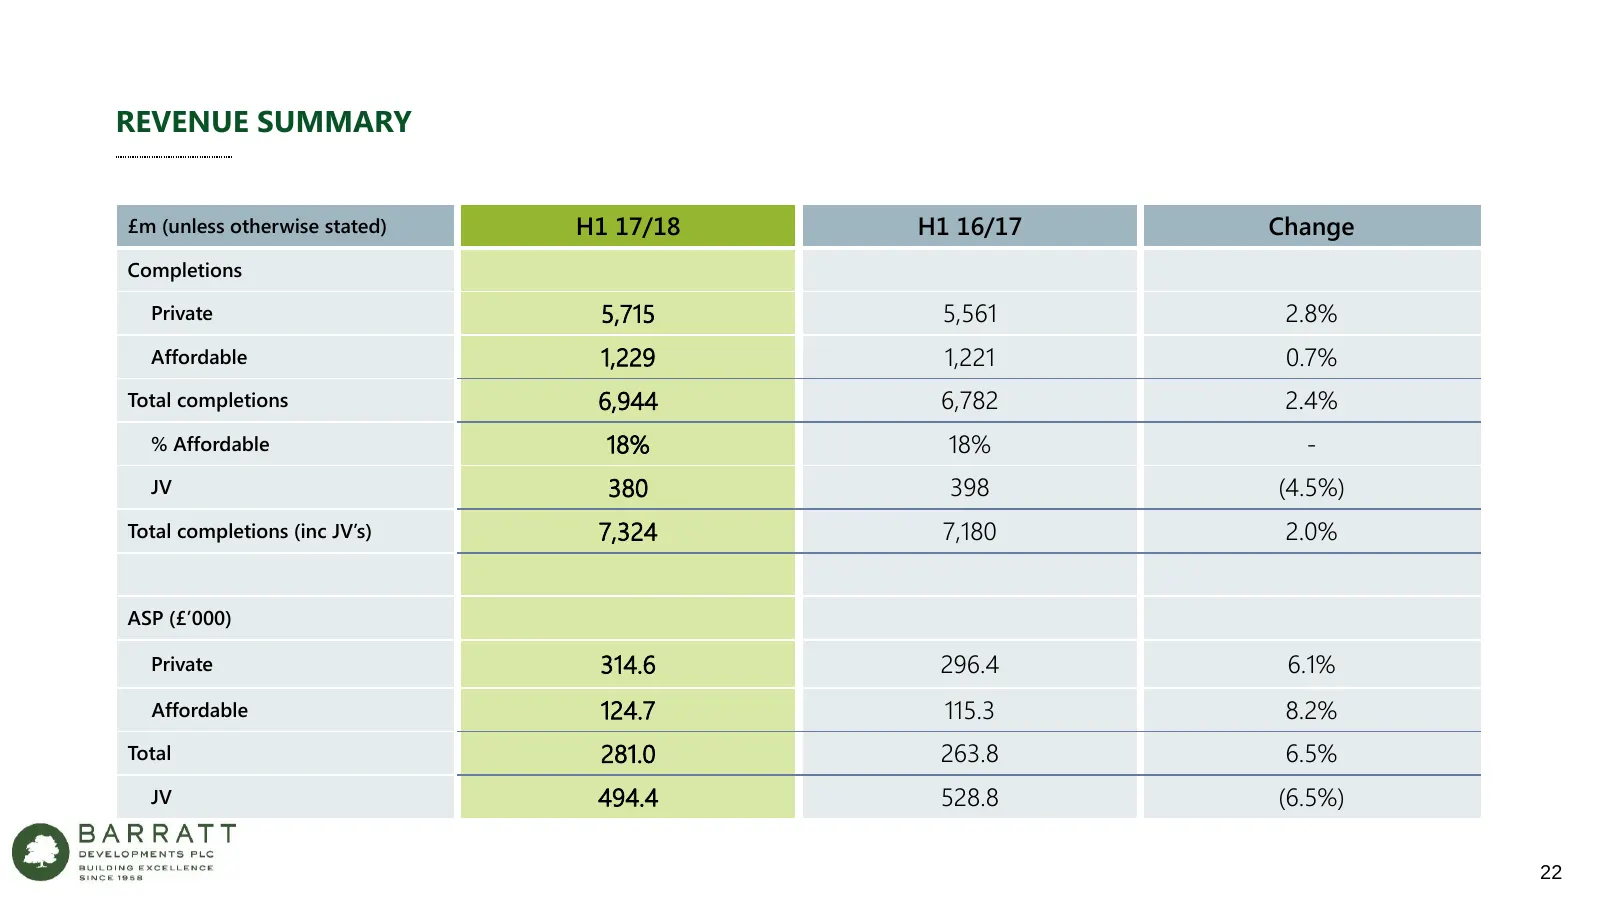
REVENUE SUMMARY £m (unless otherwise stated) H1 17/18 H1 16/17 Change Completions Private 5,715 5,561 2.8% Affordable 1,229 1,221 0.7% Total completions 6,944 6,782 2.4% % Affordable 18% 18% - JV 380 398 (4.5%) Total completions (inc JV’s) 7,324 7,180 2.0% ASP (£’000) Private 314.6 296.4 6.1% Afford
Slide 23: Operating Margin Bridge
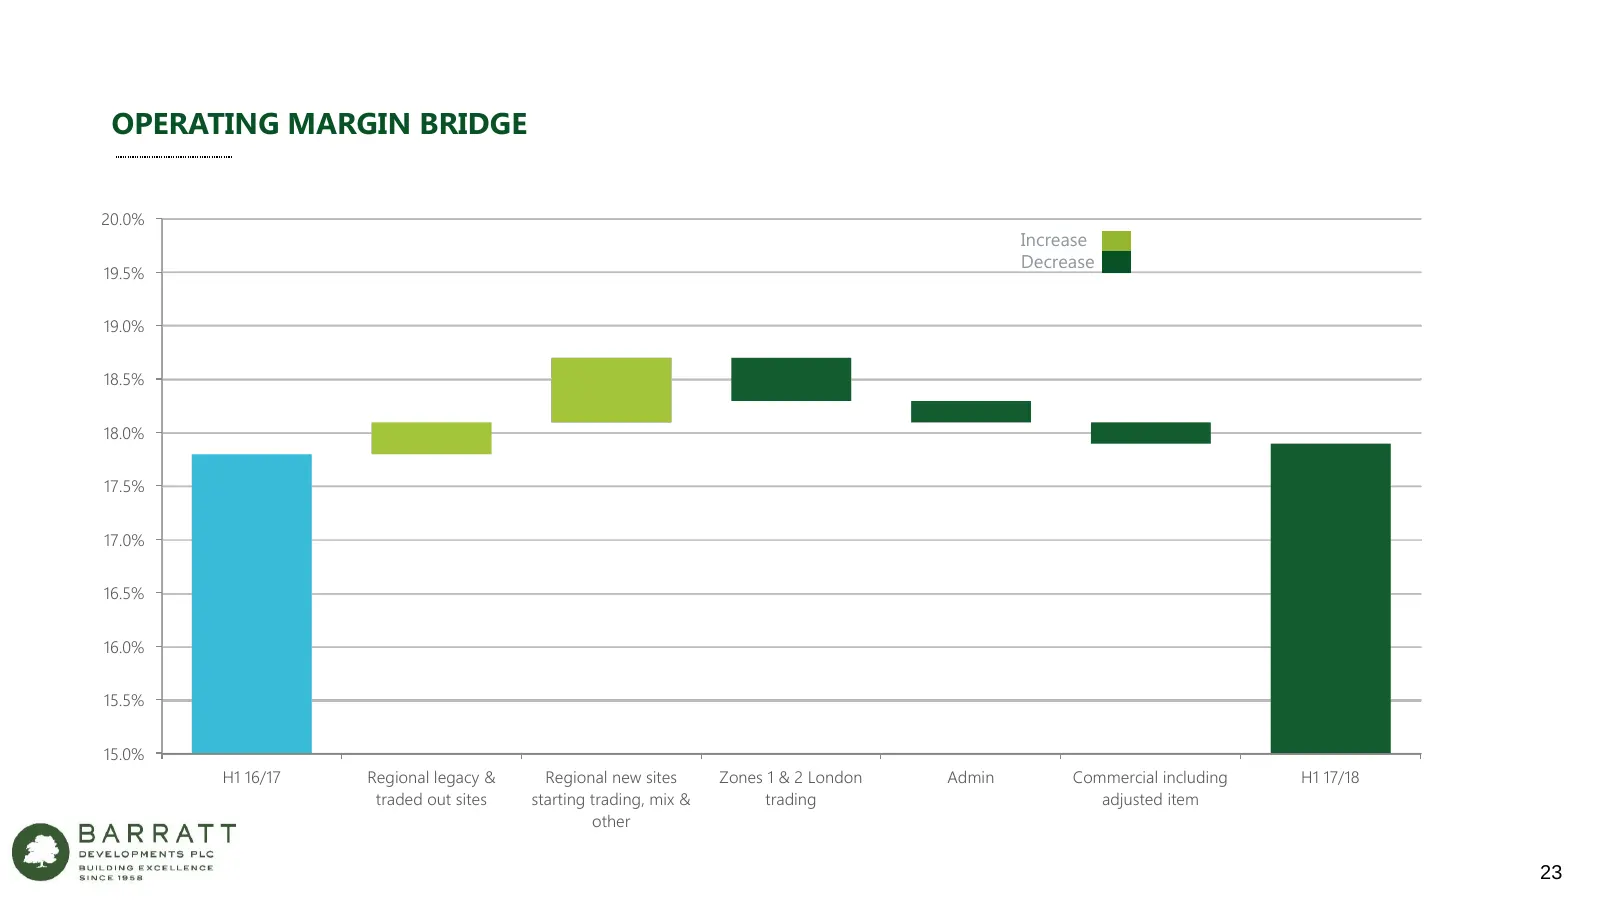
OPERATING MARGIN BRIDGE 20.0% Increase Decrease 19.5% 19.0% 18.5% 18.0% 17.5% 17.0% 16.5% 16.0% 15.5% 15.0% H1 16/17 Regional legacy & Regional new sites Zones 1 & 2 London Admin Commercial including H1 17/18 traded out sites starting trading, mix & trading adjusted item other 23
Slide 24: Balance Sheet
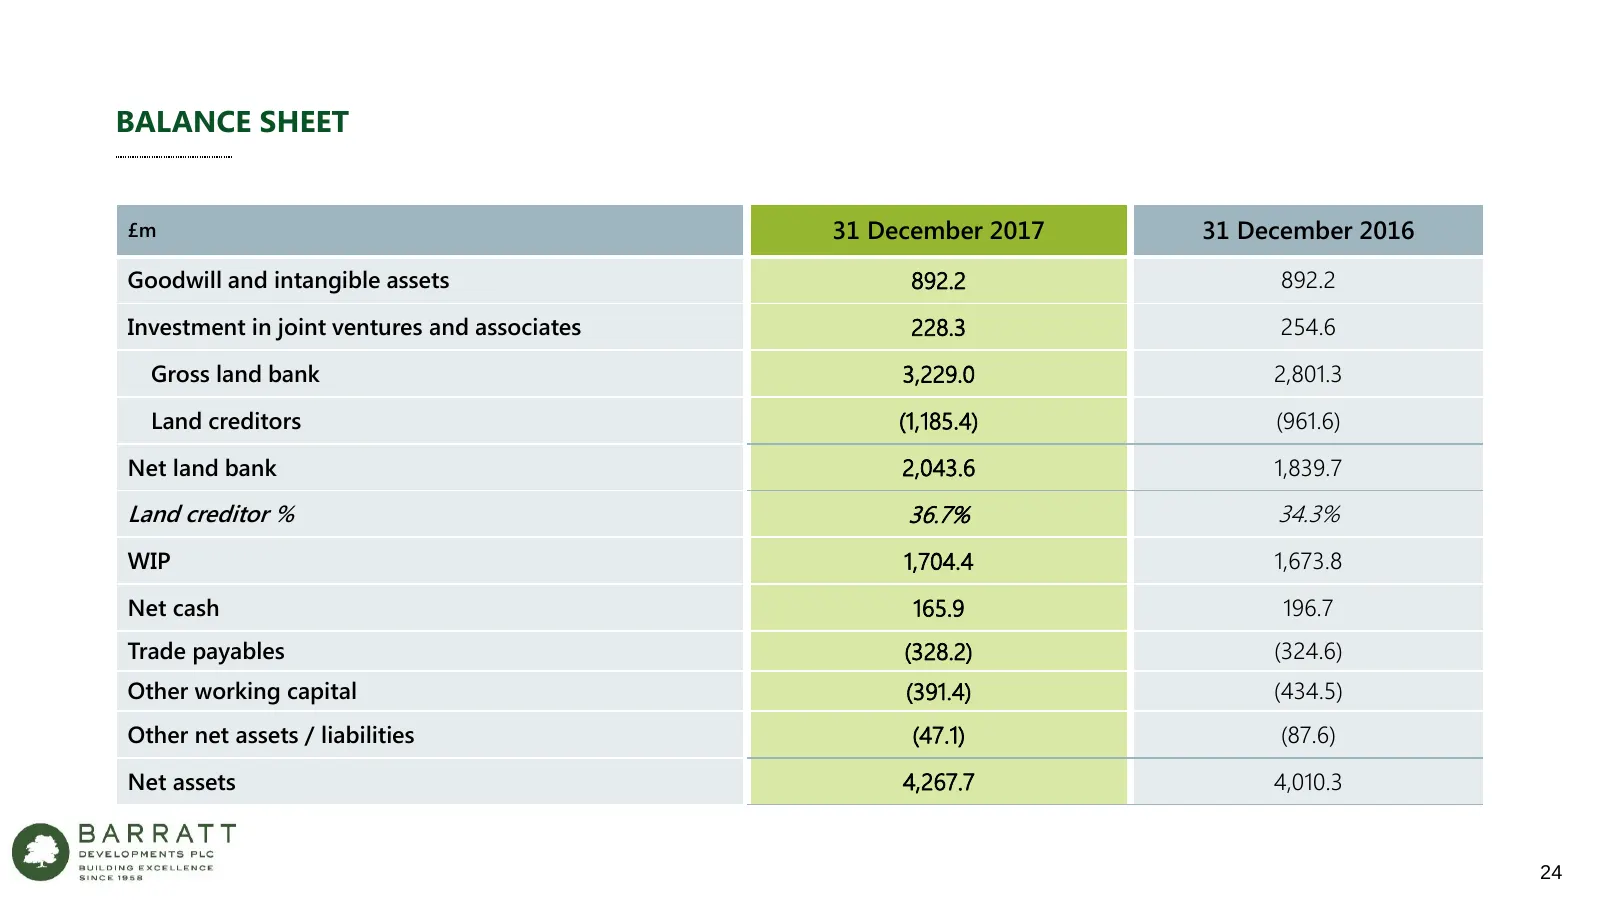
BALANCE SHEET £m 31 December 2017 31 December 2016 Goodwill and intangible assets 892.2 892.2 Investment in joint ventures and associates 228.3 254.6 Gross land bank 3,229.0 2,801.3 Land creditors (1,185.4) (961.6) Net land bank 2,043.6 1,839.7 Land creditor % 36.7% 34.3% WIP 1,704.4 1,673.8 Net cas
Slide 25: Land Bank
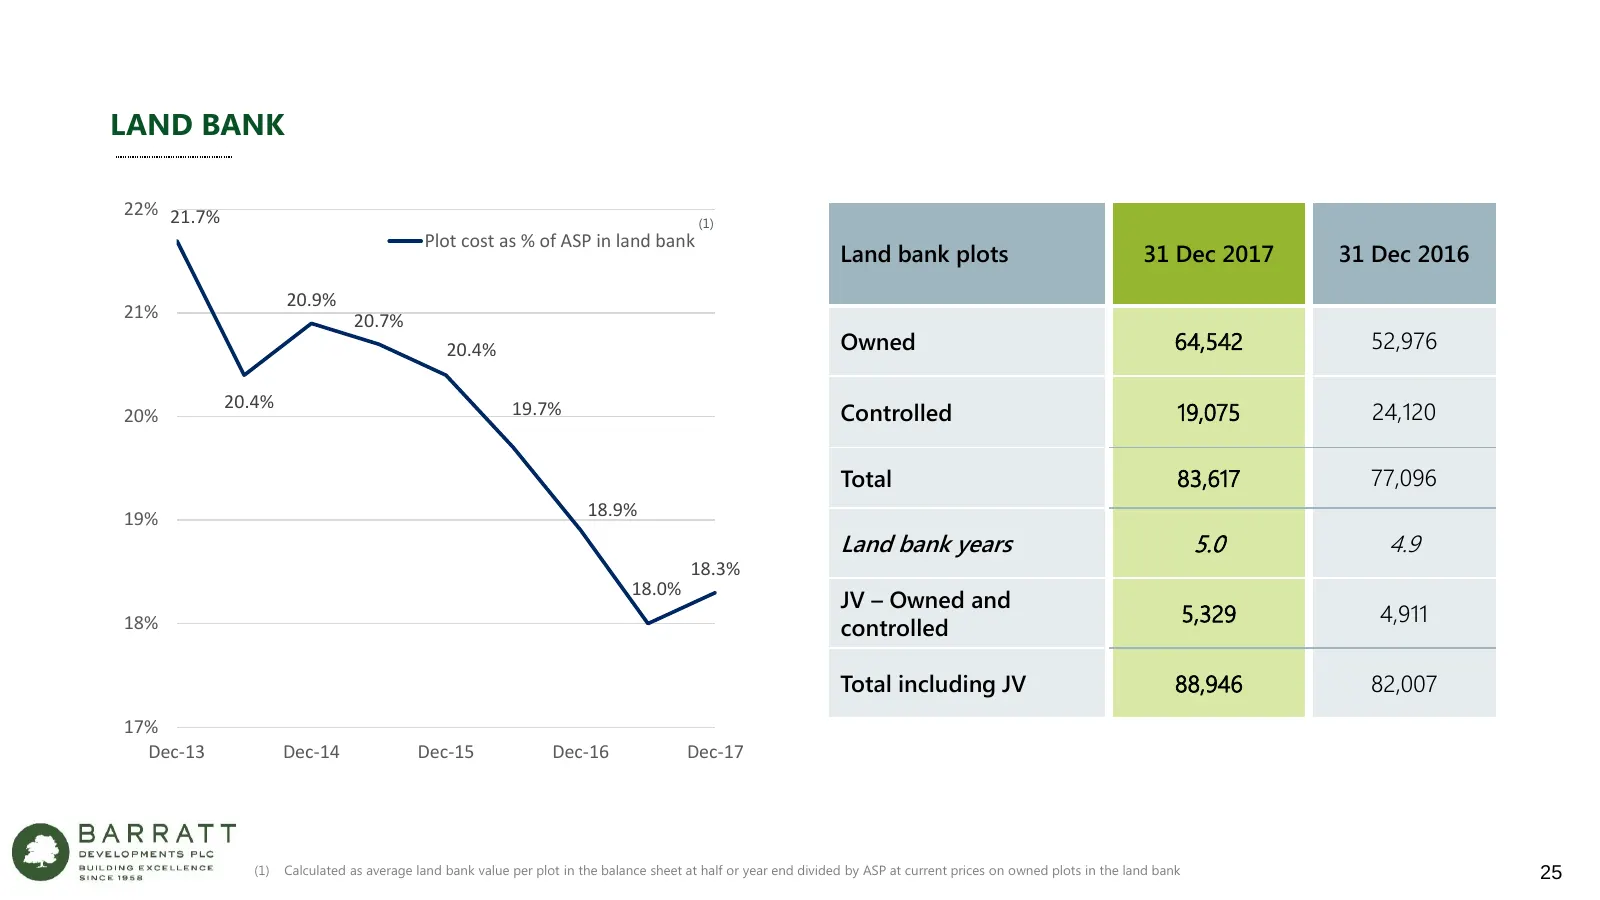
LAND BANK 22% 21.7% (1) Plot cost as % of ASP in land bank Land bank plots 31 Dec 2017 31 Dec 2016 20.9% 21% 20.7% 20.4% Owned 64,542 52,976 20.4% 20% 19.7% Controlled 19,075 24,120 Total 83,617 77,096 19% 18.9% Land bank years 5.0 4.9 18.3% 18.0% JV – Owned and 5,329 4,911 18% controlled Total incl
Slide 26: Work in Progress
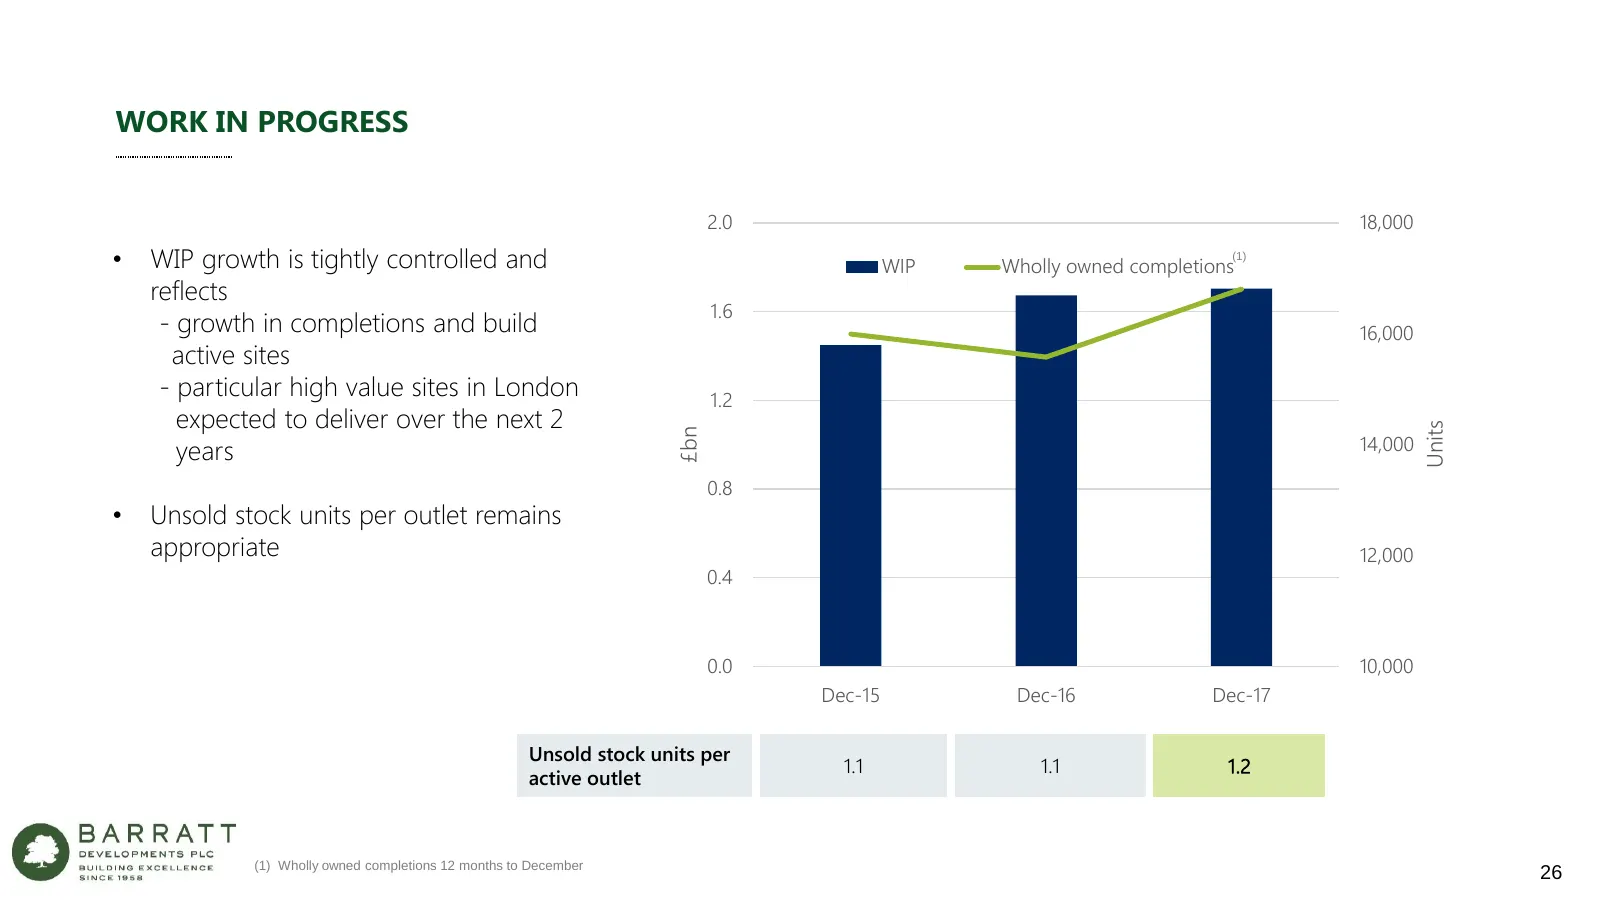
WORK IN PROGRESS 2.0 18,000 • WIP growth is tightly controlled and WIP (1) Wholly owned completions reflects 1.6 - growth in completions and build 16,000 active sites - particular high value sites in London 1.2 expected to deliver over the next 2 Units £bn years 14,000 0.8 • Unsold stock units per o
Slide 27: Legacy Asset Reduction
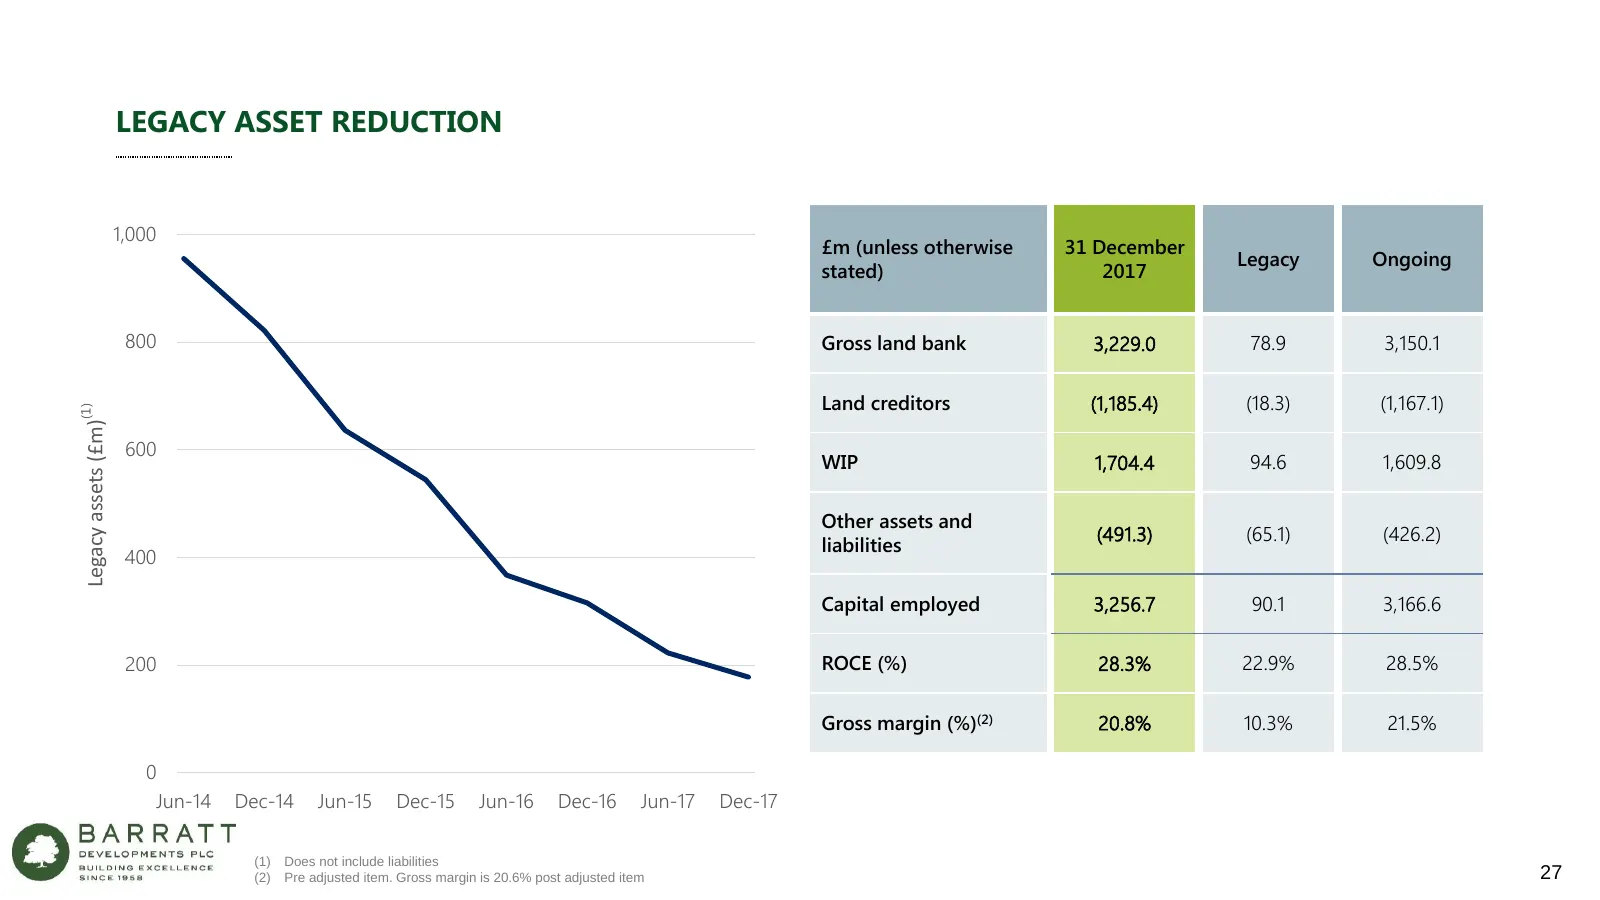
LEGACY ASSET REDUCTION 1,000 £m (unless otherwise 31 December Legacy Ongoing stated) 2017 800 Gross land bank 3,229.0 78.9 3,150.1 Land creditors (1,185.4) (18.3) (1,167.1) (1) Legacy assets (£m) 600 WIP 1,704.4 94.6 1,609.8 Other assets and (491.3) (65.1) (426.2) liabilities 400 Capital employed 3,
Slide 28: Cash Flow
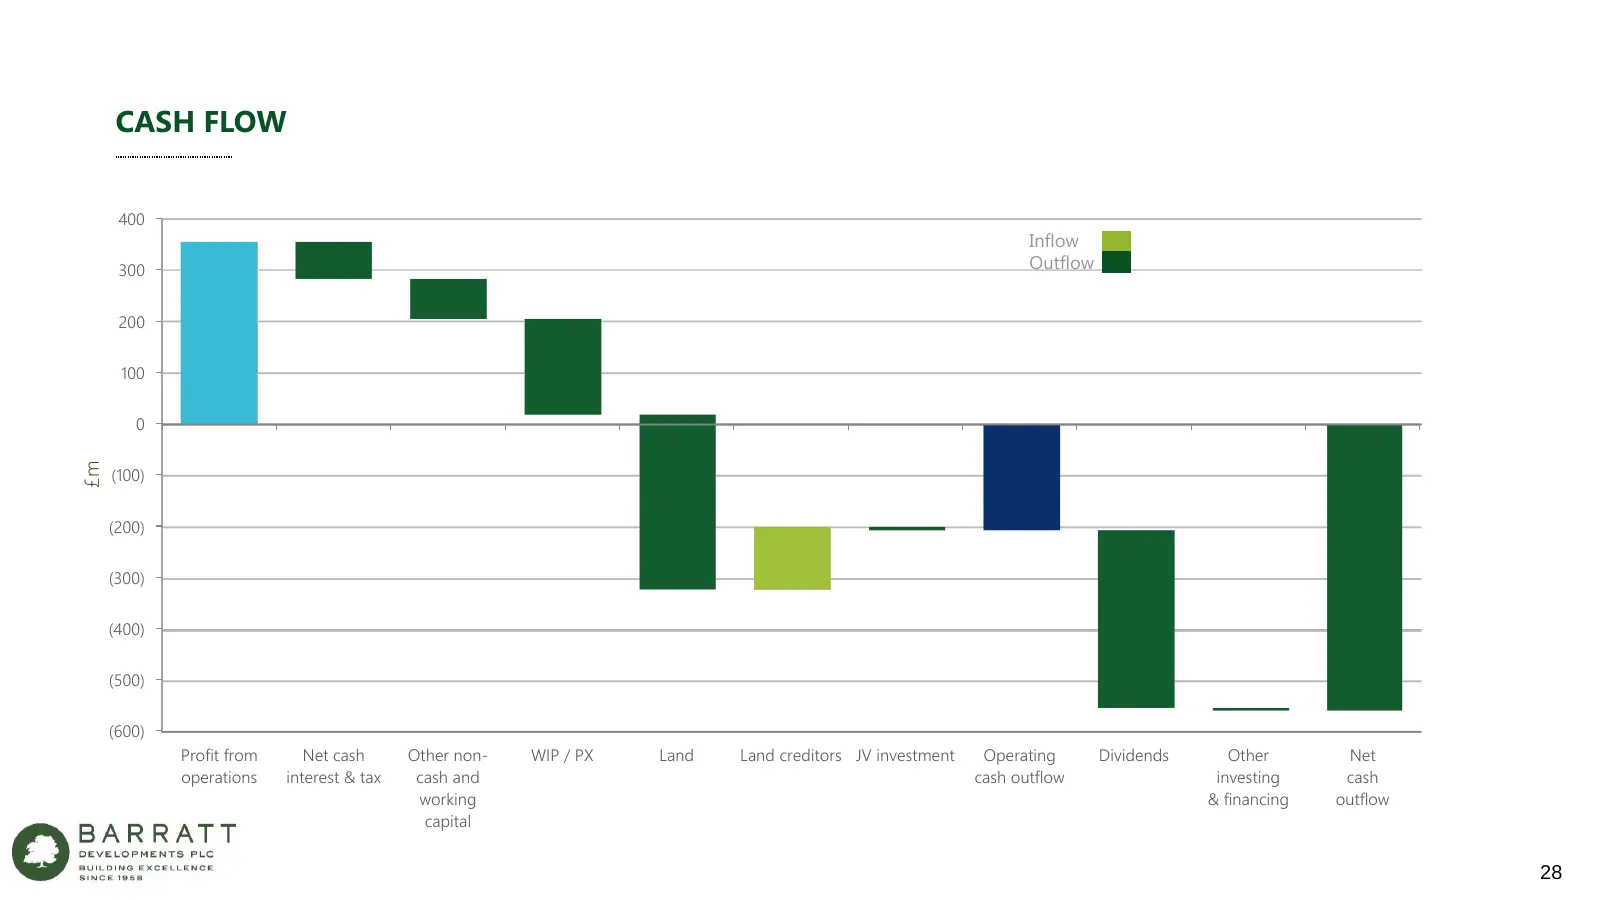
CASH FLOW 400 Inflow 300 Outflow 200 100 0 £m (100) (200) (300) (400) (500) (600) Profit from Net cash Other non- WIP / PX Land Land creditors JV investment Operating Dividends Other Net operations interest & tax cash and cash outflow investing cash working & financing outflow capital 28
Slide 29: Gearing
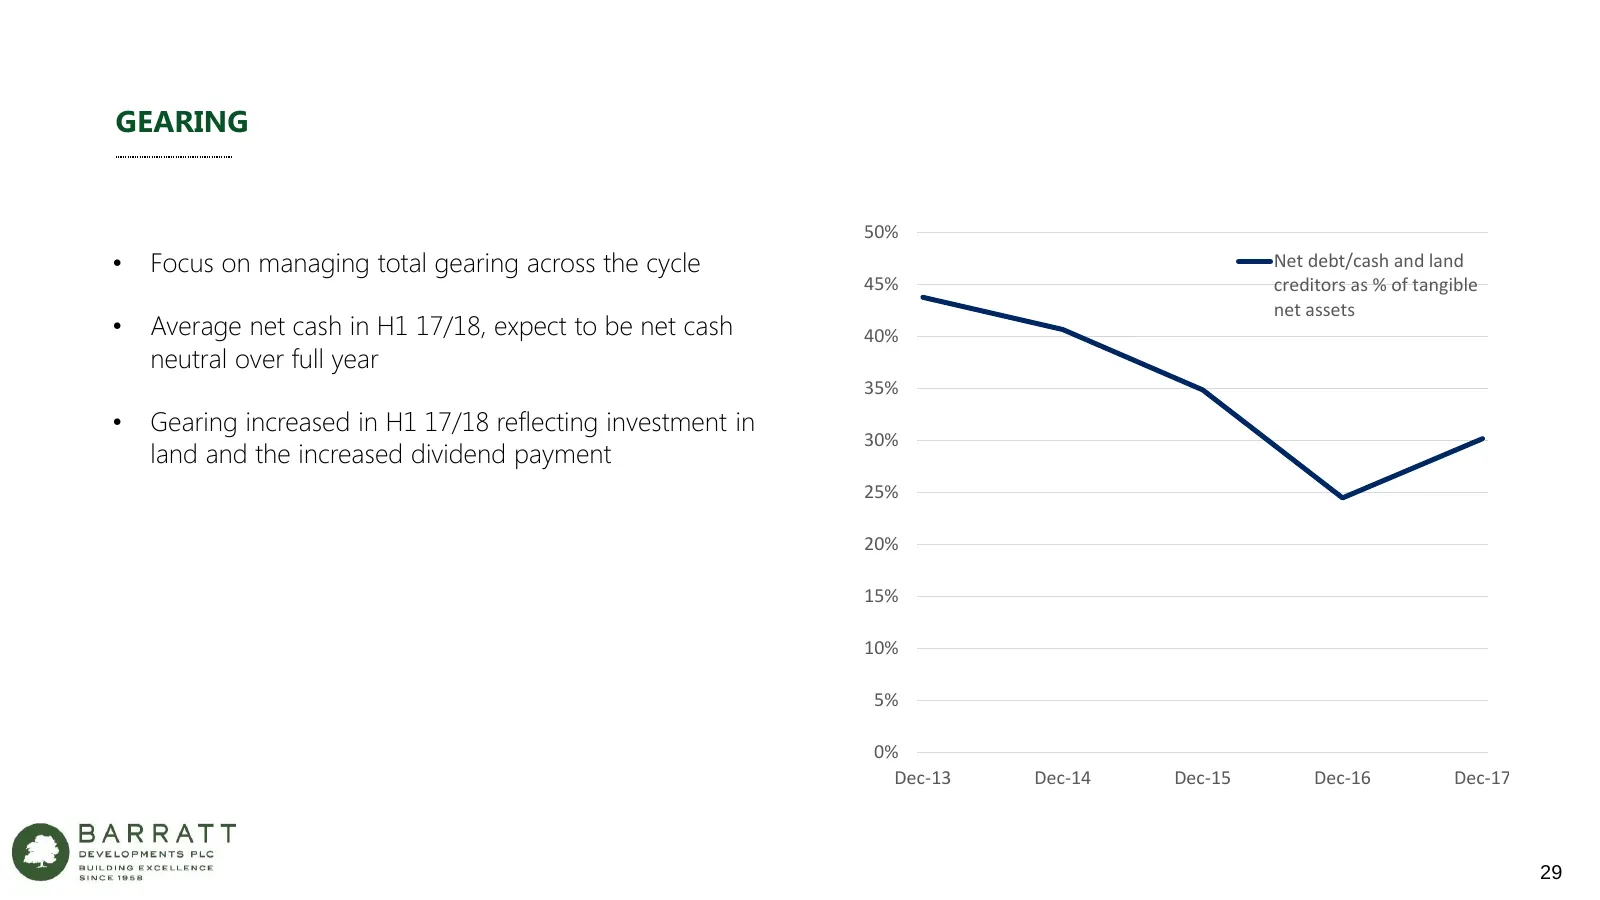
GEARING 50% • Focus on managing total gearing across the cycle Net debt/cash and land 45% creditors as % of tangible net assets • Average net cash in H1 17/18, expect to be net cash 40% neutral over full year 35% • Gearing increased in H1 17/18 reflecting investment in 30% land and the increased div
Slide 30: Guidance for FY18
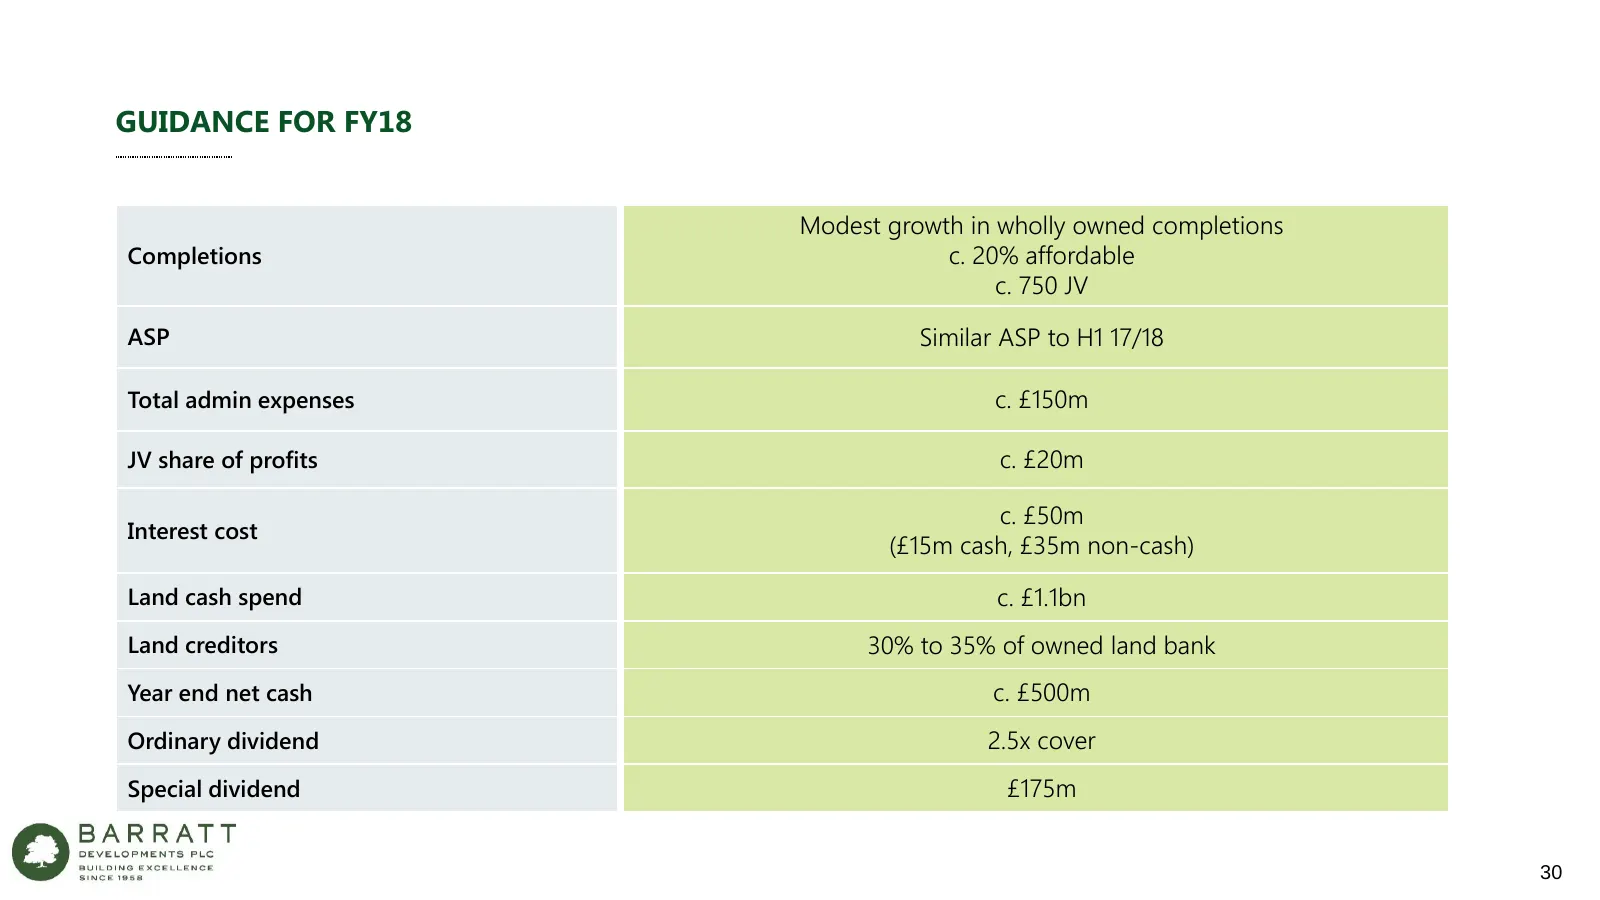
GUIDANCE FOR FY18 Modest growth in wholly owned completions Completions c. 20% affordable c. 750 JV ASP Similar ASP to H1 17/18 Total admin expenses c. £150m JV share of profits c. £20m c. £50m Interest cost (£15m cash, £35m non-cash) Land cash spend c. £1.1bn Land creditors 30% to 35% of owned land
Slide 31: David Thomas, Chief Executive
David Thomas Chief Executive Belle Vue, Doncaster31
Slide 32: Key Differentiators
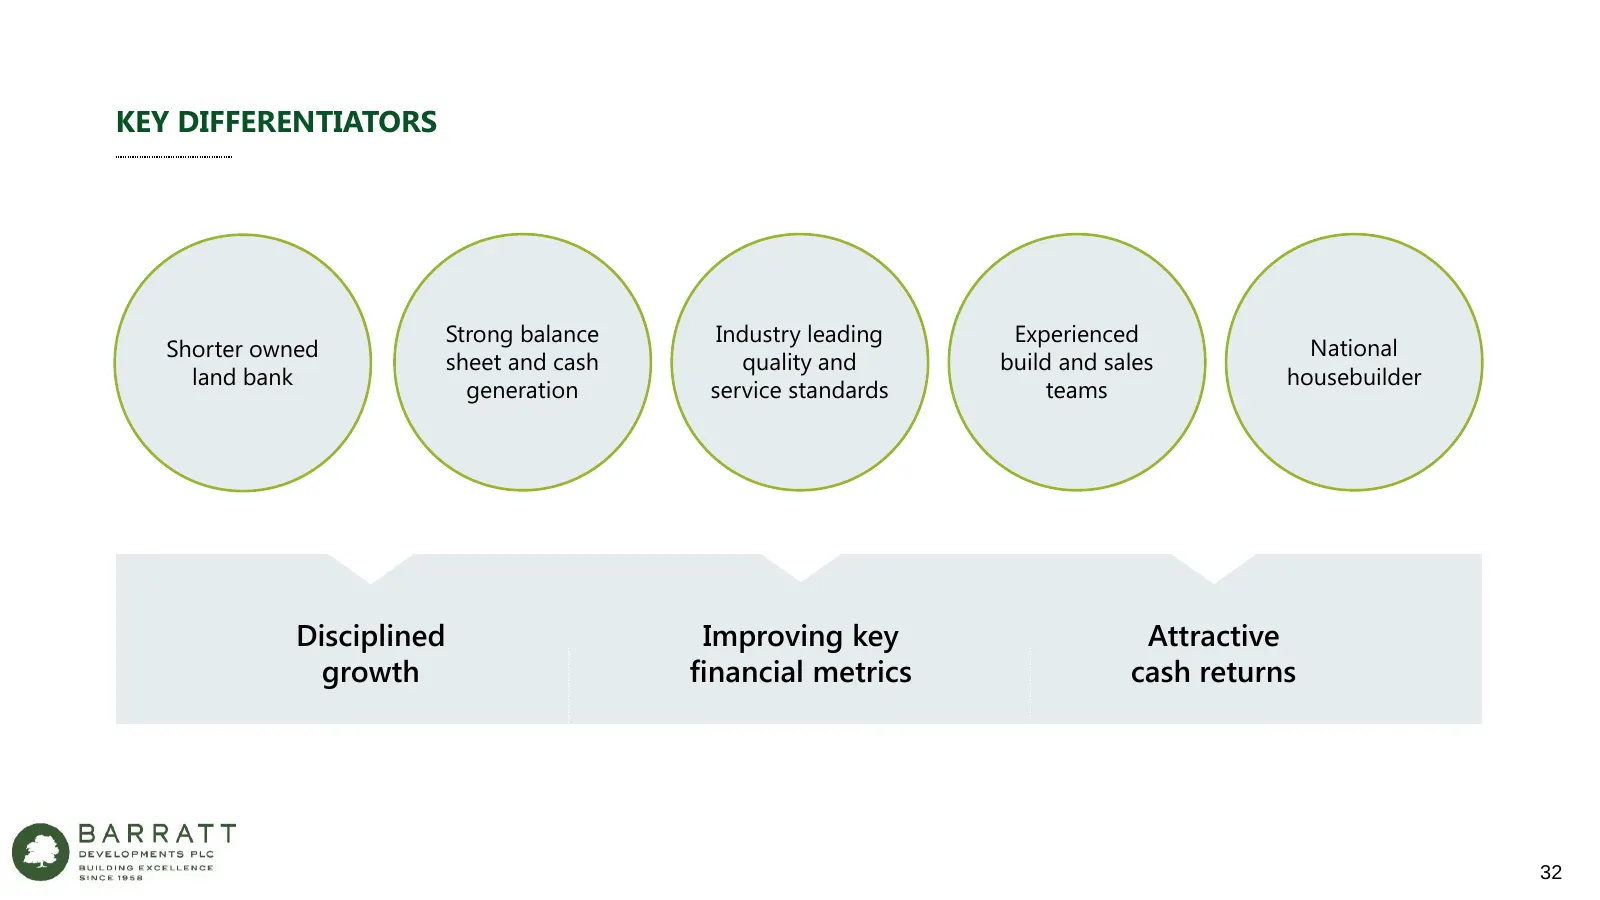
KEY DIFFERENTIATORS Strong balance Industry leading Experienced Shorter owned National sheet and cash quality and build and sales land bank housebuilder generation service standards teams Disciplined Improving key Attractive growth financial metrics cash returns 32
Slide 33: Market Fundamentals Remain Attractive
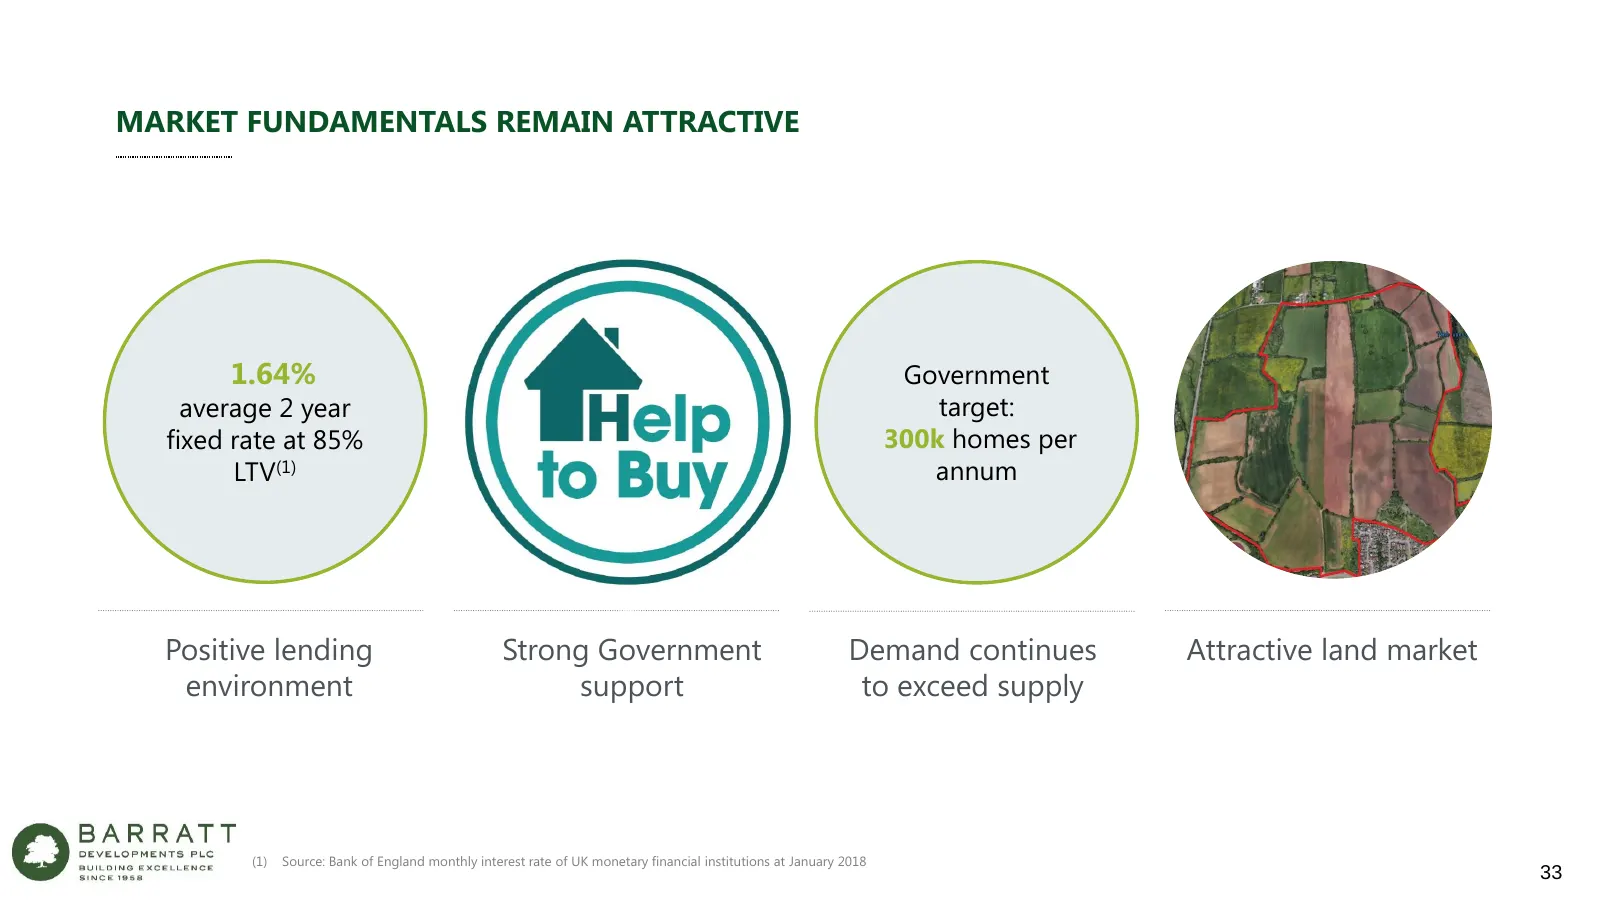
MARKET FUNDAMENTALS REMAIN ATTRACTIVE 1.64% Government average 2 year target: Need new picture fixed rate at 85% 300k homes per LTV(1) annum Positive lending Strong Government Demand continues Attractive land market environment support to exceed supply (1) Source: Bank of England monthly interest ra
Slide 34: Positive Lending Environment
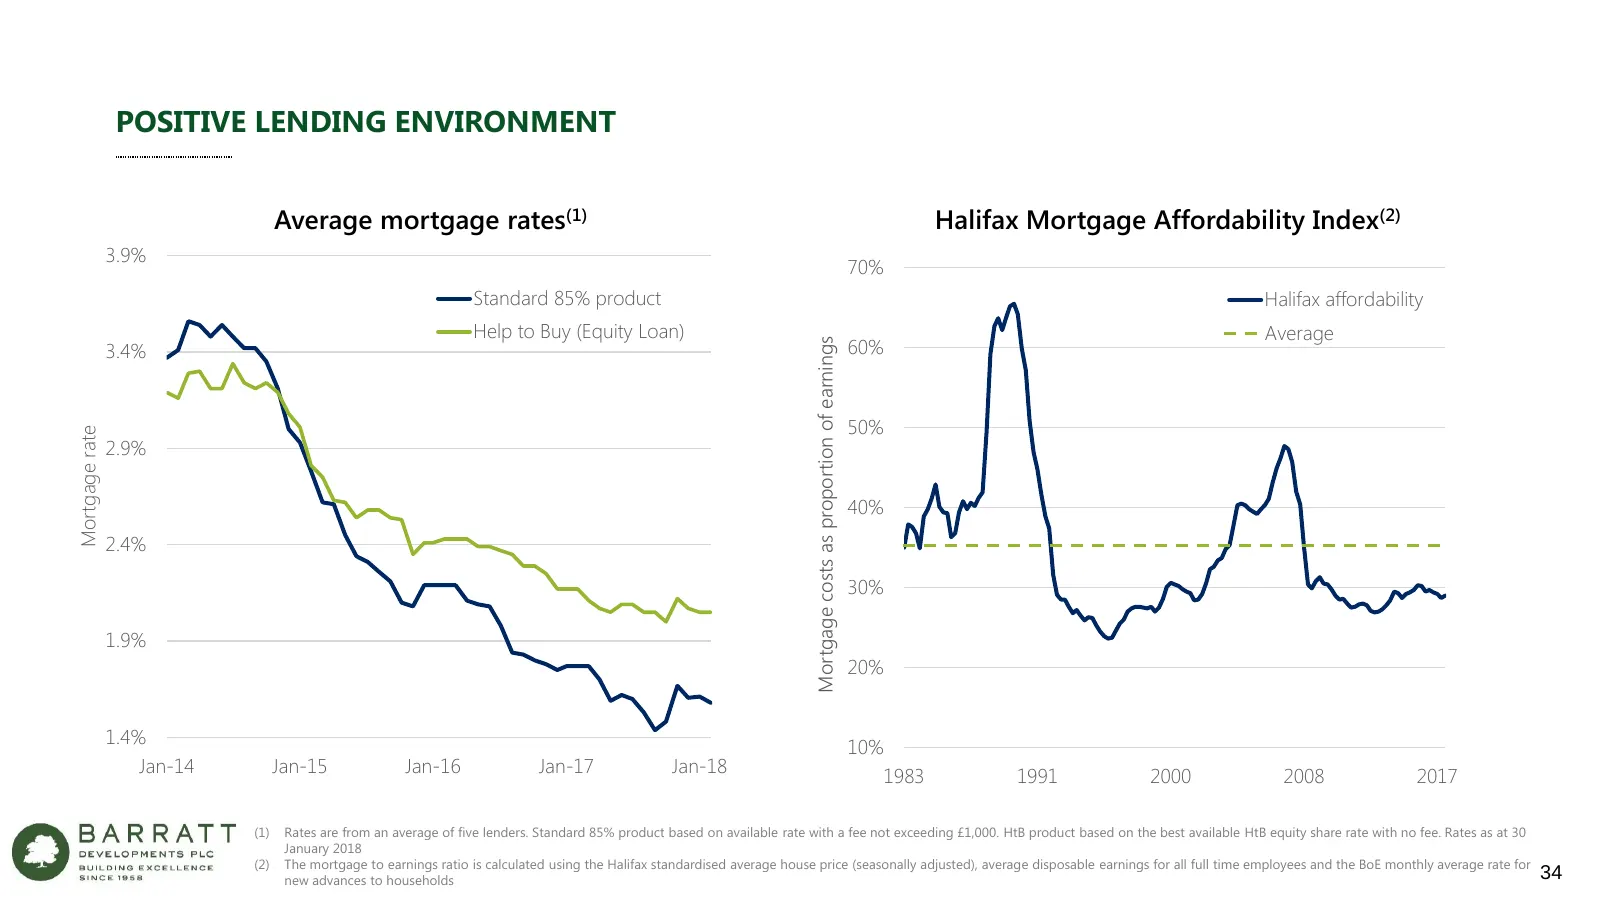
POSITIVE LENDING ENVIRONMENT Average mortgage rates(1) Halifax Mortgage Affordability Index(2) 3.9% 70% Standard 85% product Halifax affordability Help to Buy (Equity Loan) Average 60% Mortgage costs as proportion of earnings 3.4% 50% Mortgage rate 2.9% 40% 2.4% 30% 1.9% 20% 1.4% 10% Jan-14 Jan-15 J
Slide 35: Addressing Market Challenges
ADDRESSING MARKET CHALLENGES Alternative Skills methods of Quality and shortages construction Service 35
Slide 36: Disciplined Growth – Self Help and Supporting the Wider Industry
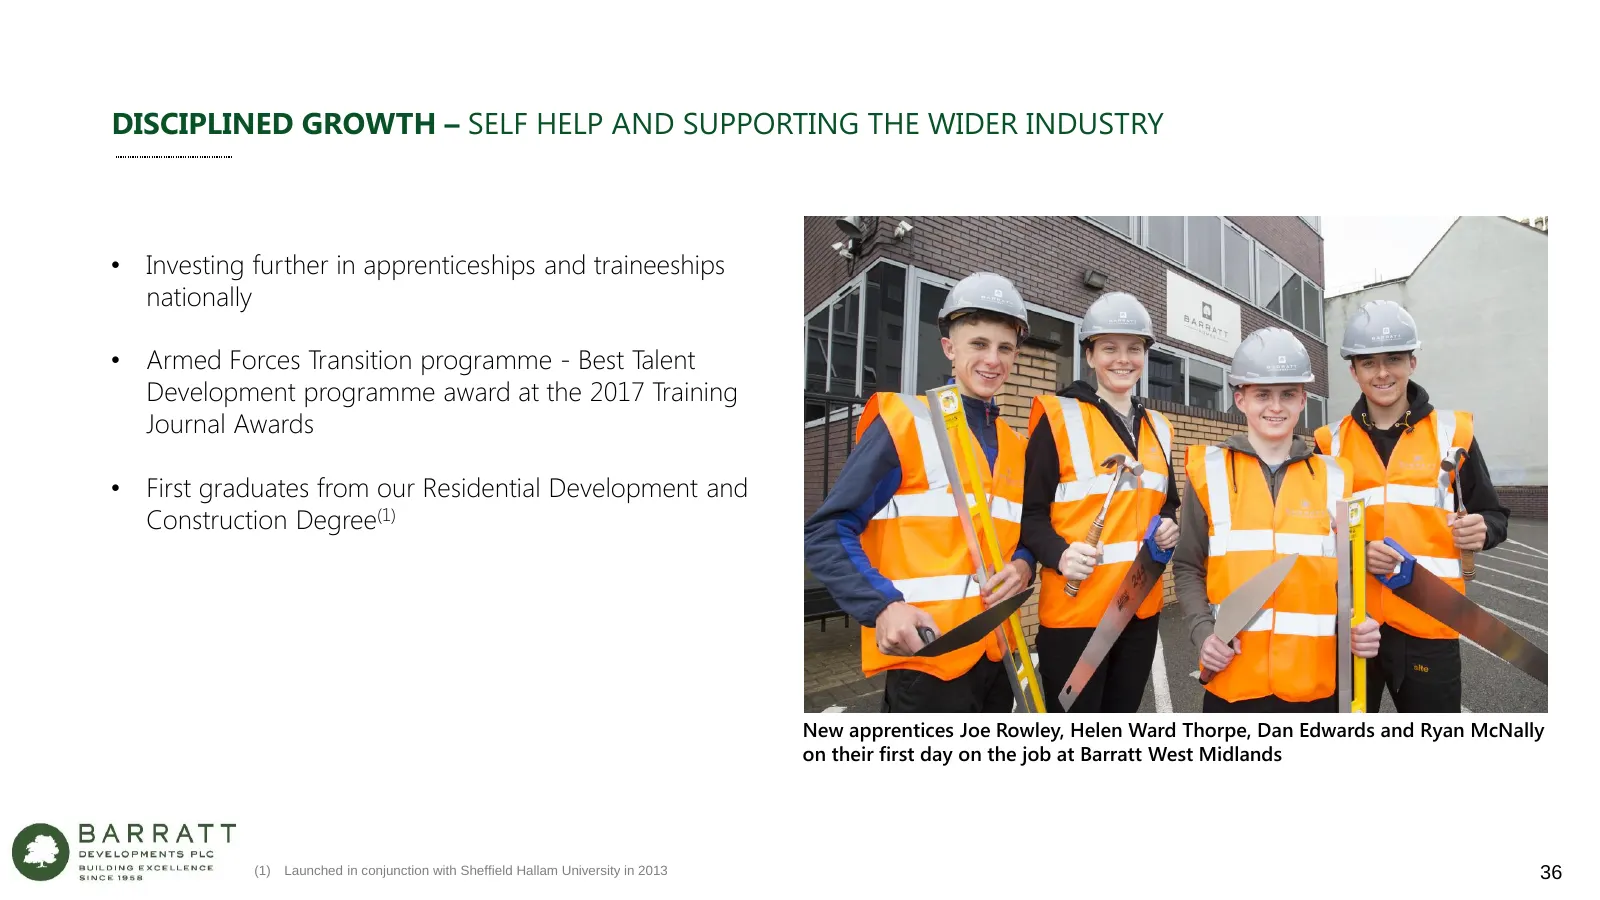
DISCIPLINED GROWTH – SELF HELP AND SUPPORTING THE WIDER INDUSTRY • Investing further in apprenticeships and traineeships nationally • Armed Forces Transition programme - Best Talent Development programme award at the 2017 Training Journal Awards • First graduates from our Residential Development and
Slide 37: Disciplined Growth – Alternative Methods of Construction
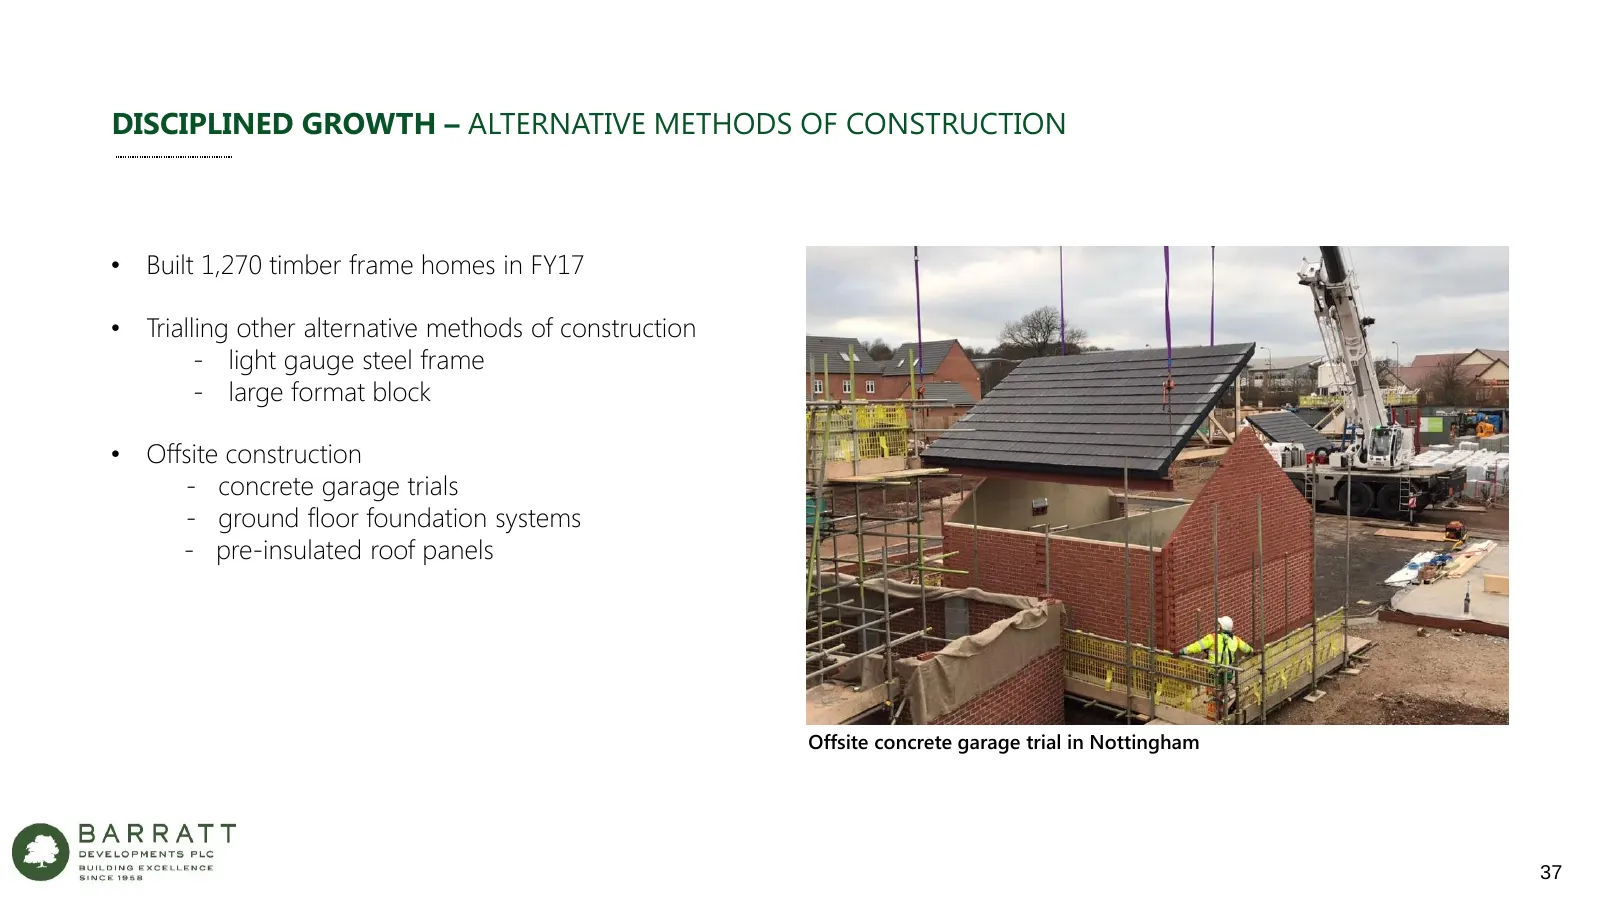
DISCIPLINED GROWTH – ALTERNATIVE METHODS OF CONSTRUCTION • Built 1,270 timber frame homes in FY17 • Trialling other alternative methods of construction - light gauge steel frame - large format block • Offsite construction - concrete garage trials - ground floor foundation systems - pre-insulated roo
Slide 38: Disciplined Growth – Quantity
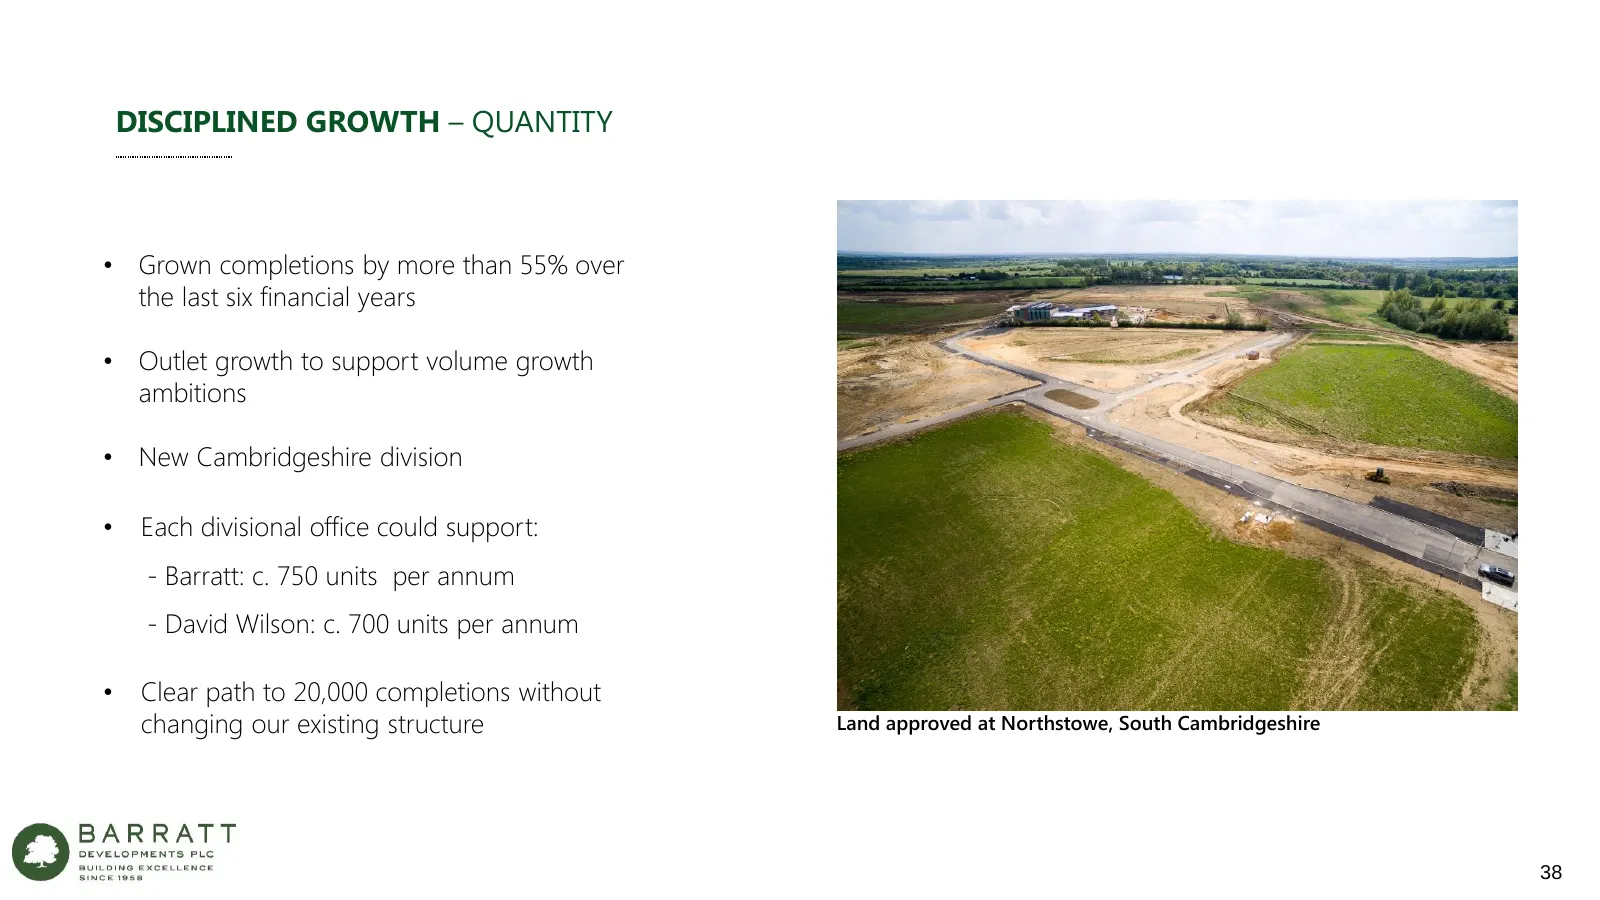
DISCIPLINED GROWTH – QUANTITY • Grown completions by more than 55% over the last six financial years • Outlet growth to support volume growth ambitions • New Cambridgeshire division • Each divisional office could support: - Barratt: c. 750 units per annum - David Wilson: c. 700 units per annum • Cle
Slide 39: Attractive Cash Returns
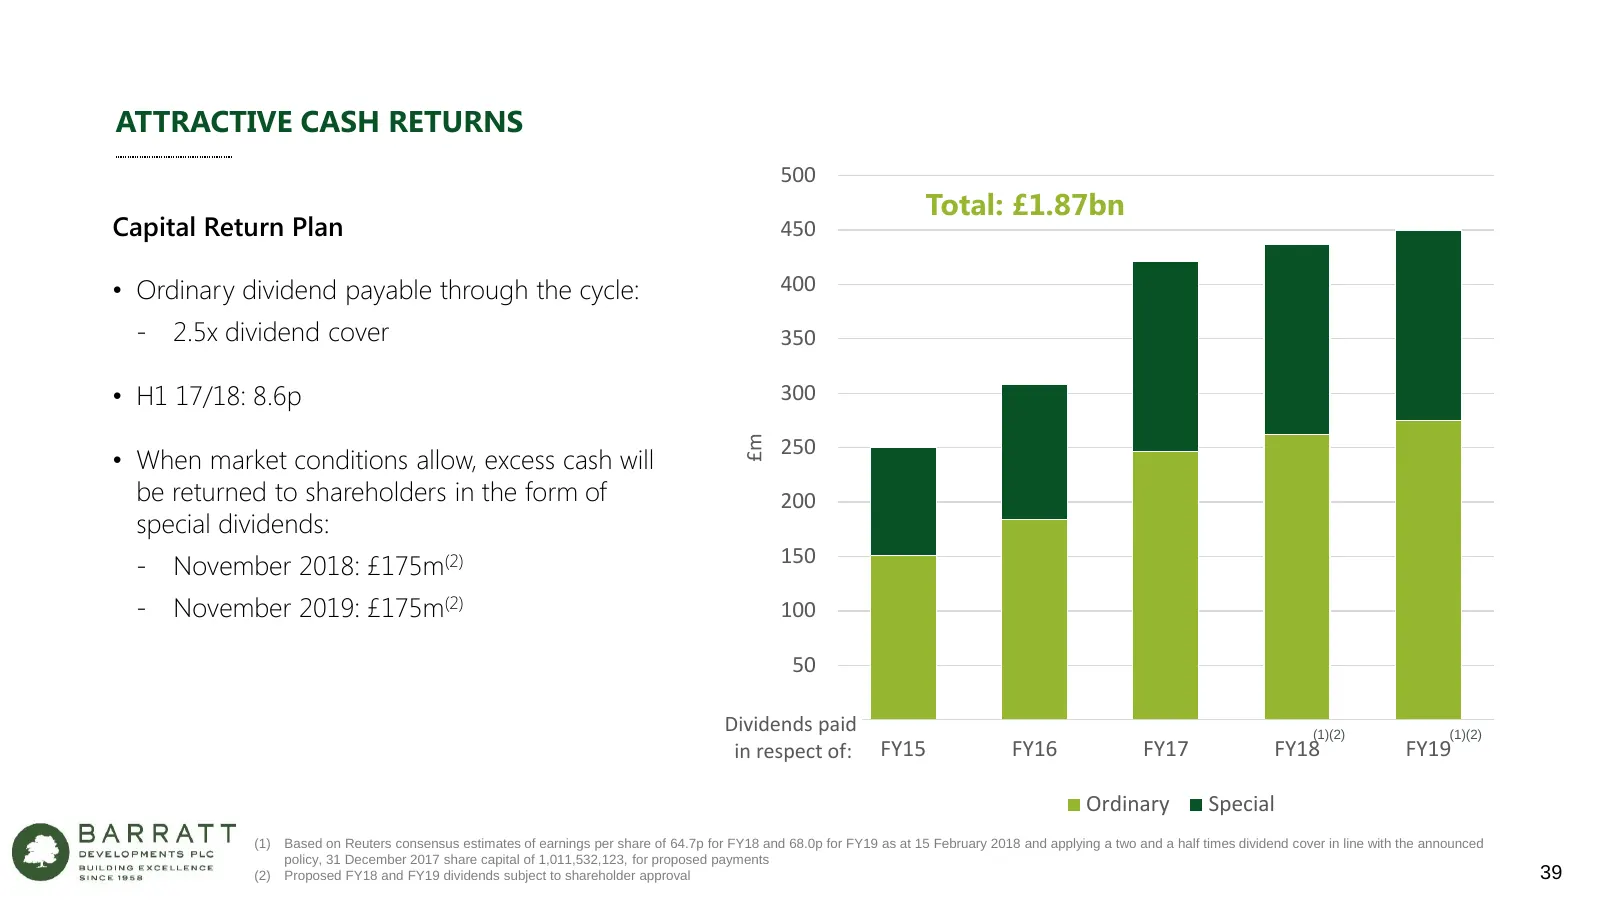
ATTRACTIVE CASH RETURNS 500 Total: £1.87bn Capital Return Plan 450 • Ordinary dividend payable through the cycle: 400 - 2.5x dividend cover 350 • H1 17/18: 8.6p 300 £m 250 • When market conditions allow, excess cash will be returned to shareholders in the form of 200 special dividends: 150 - Novembe
Slide 40: Current Trading – Sales Performance
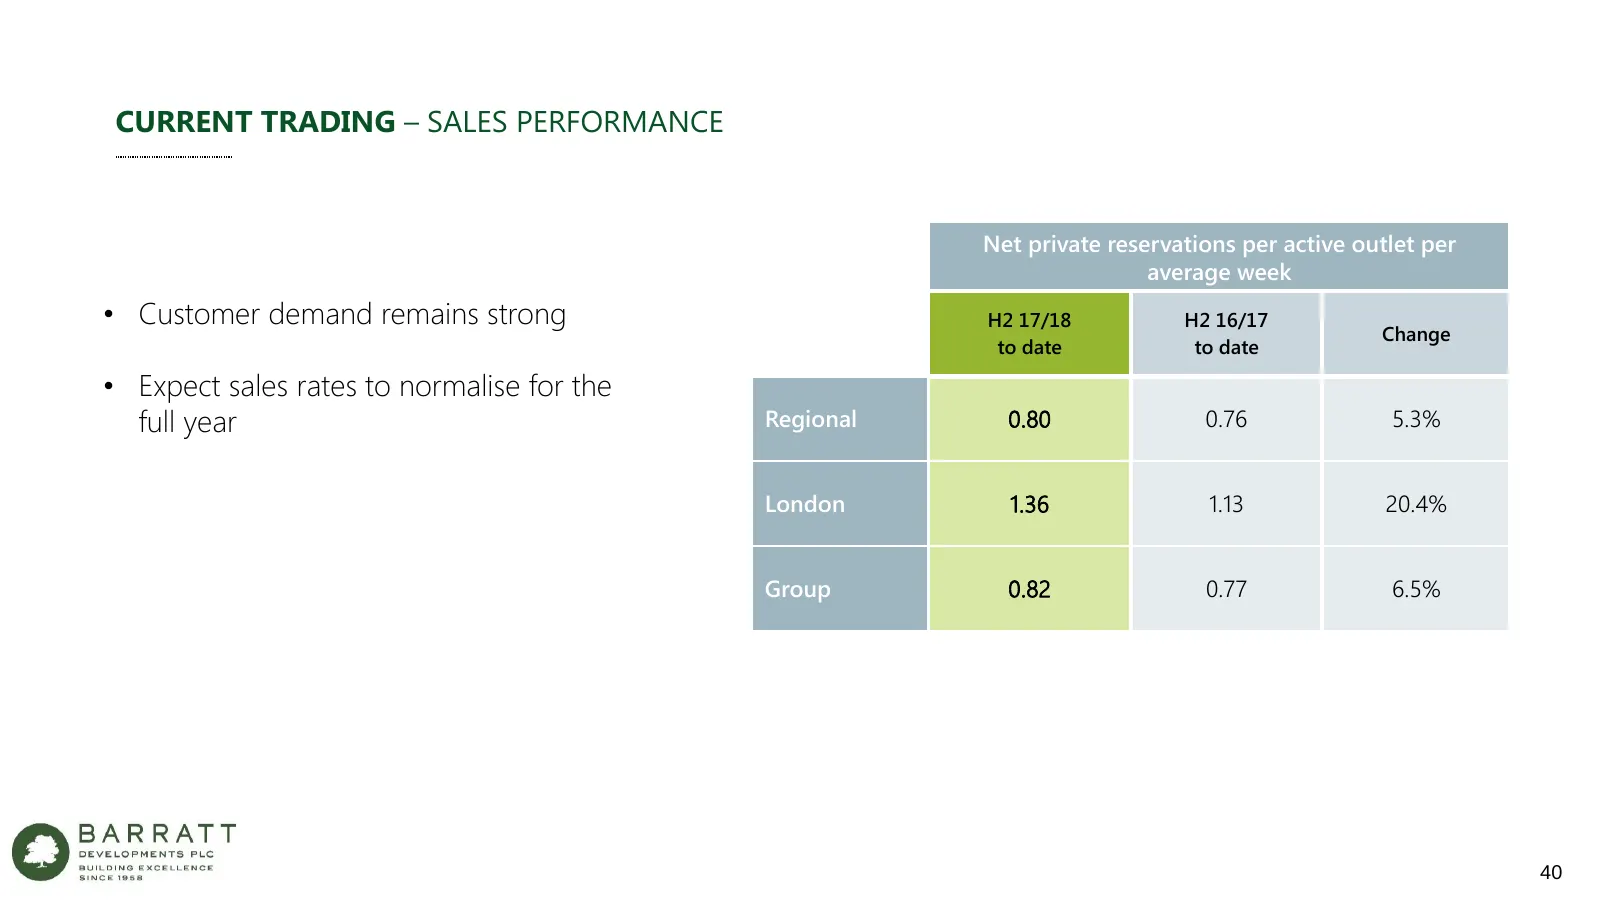
CURRENT TRADING – SALES PERFORMANCE Net private reservations per active outlet per average week • Customer demand remains strong H2 17/18 H2 16/17 Change to date to date • Expect sales rates to normalise for the full year Regional 0.80 0.76 5.3% London 1.36 1.13 20.4% Group 0.82 0.77 6.5% 40
Slide 41: Current Trading – Forward Order Book
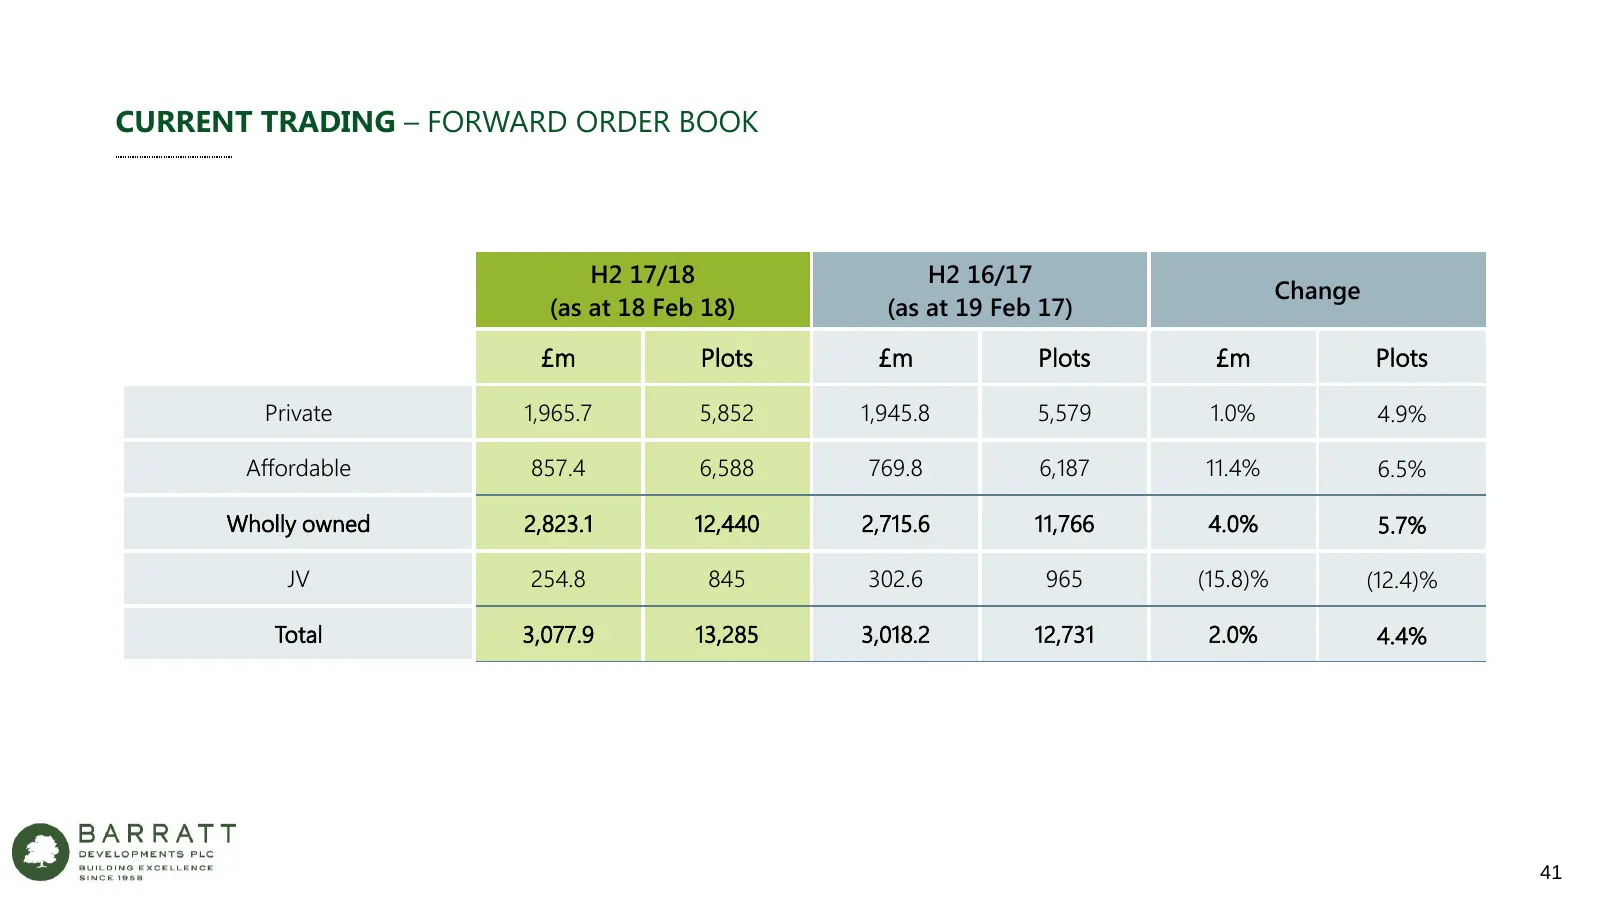
CURRENT TRADING – FORWARD ORDER BOOK H2 17/18 H2 16/17 Change (as at 18 Feb 18) (as at 19 Feb 17) £m Plots £m Plots £m Plots Private 1,965.7 5,852 1,945.8 5,579 1.0% 4.9% Affordable 857.4 6,588 769.8 6,187 11.4% 6.5% Wholly owned 2,823.1 12,440 2,715.6 11,766 4.0% 5.7% JV 254.8 845 302.6 965 (15.8)%
Slide 42: Operating Framework
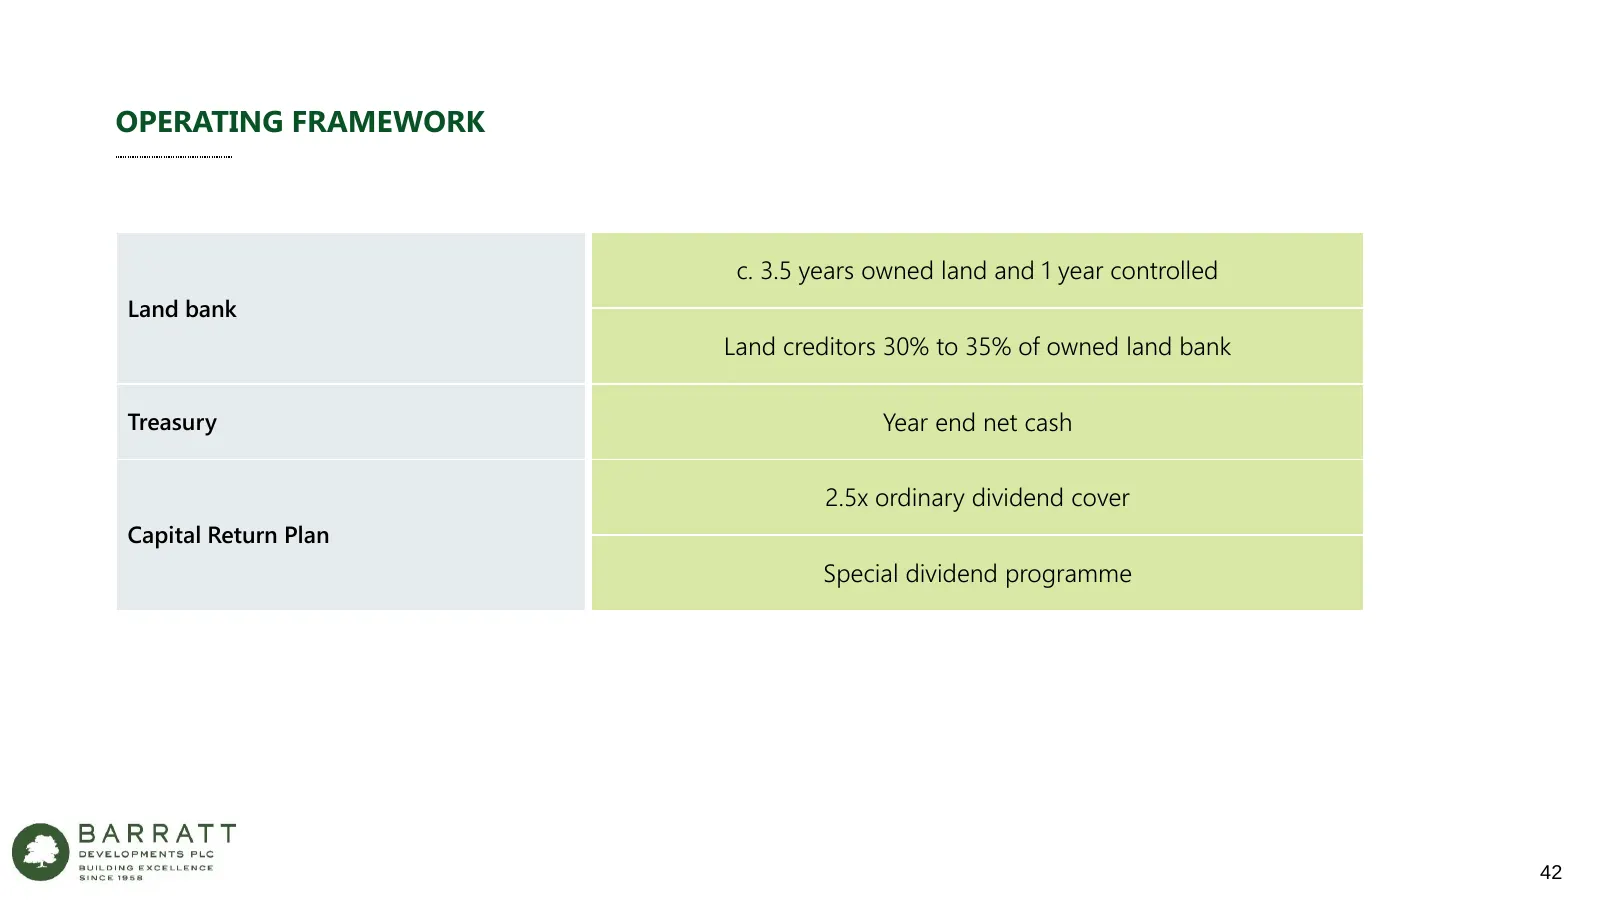
OPERATING FRAMEWORK c. 3.5 years owned land and 1 year controlled Land bank Land creditors 30% to 35% of owned land bank Treasury Year end net cash 2.5x ordinary dividend cover Capital Return Plan Special dividend programme 42
Slide 43: Positive on Outlook
POSITIVE ON OUTLOOK • Clear plan to drive operating margin • Disciplined growth • Clearly defined operating framework • Extended Capital Return Plan • Confidence in the business going forward Pembroke Park, Cirencester 43
Slide 44: Q&A
Q&A Kingsbrook, Aylesbury 44
Slide 45: Appendices – Index
APPENDICES - INDEX Page Definitions 46 P&L 47 Balance sheet - land bank 48 Land creditors - payment profile 49 Completions - product type 50 London land prices 51 Investment in joint ventures and associates 52 Joint venture land bank plots 53 Net interest charge analysis 54 Financing arrangements 55
Slide 46: Definitions
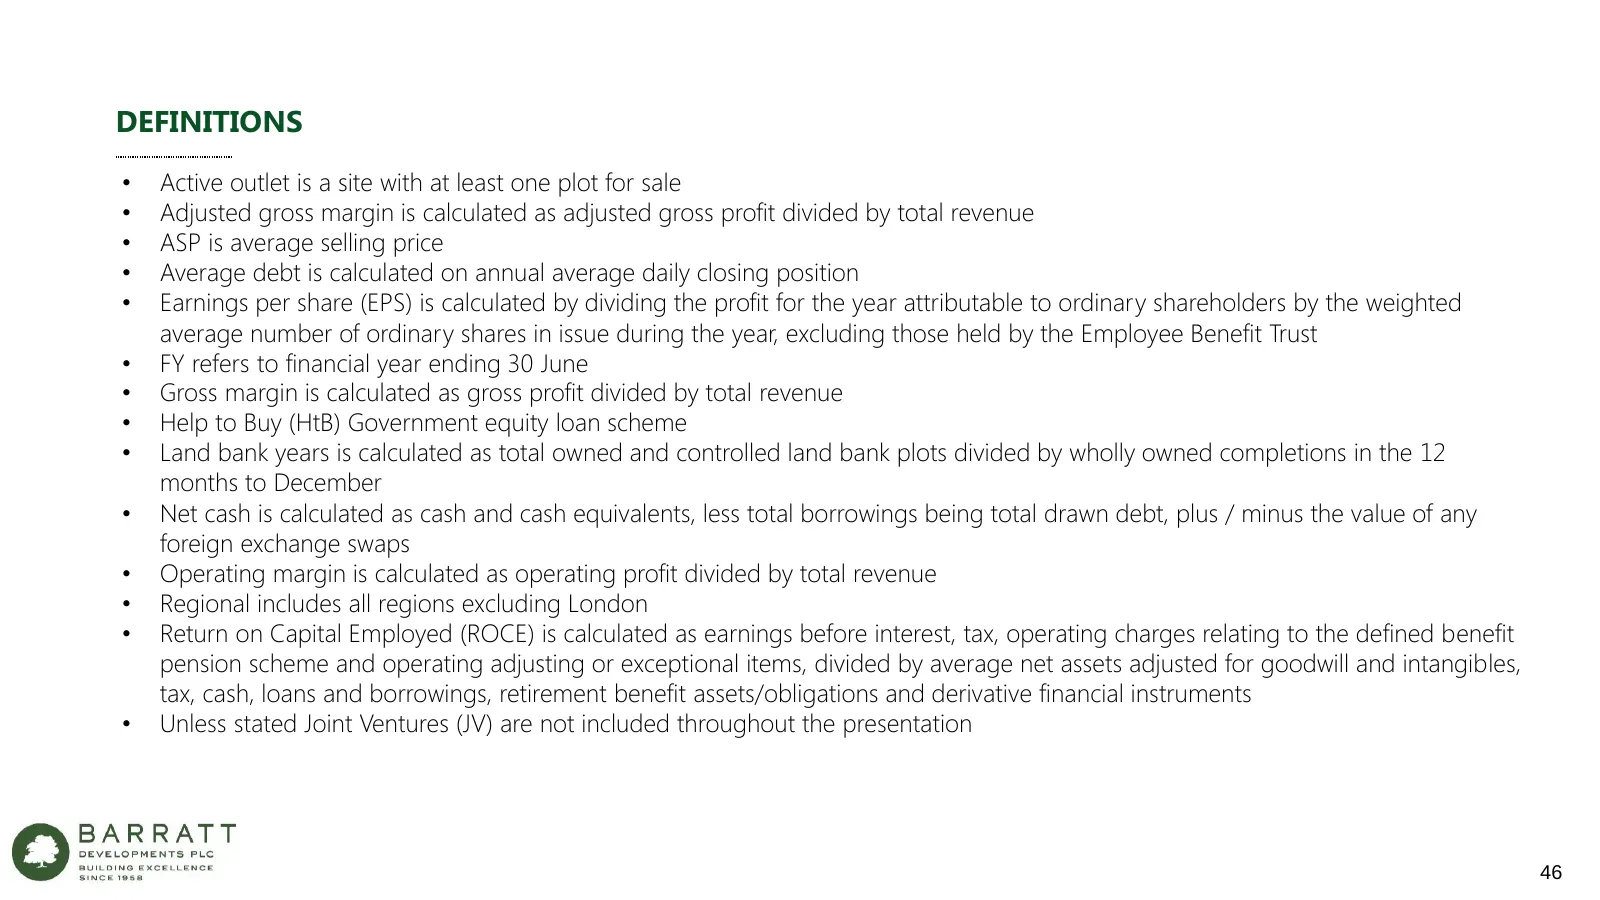
DEFINITIONS • Active outlet is a site with at least one plot for sale • Adjusted gross margin is calculated as adjusted gross profit divided by total revenue • ASP is average selling price • Average debt is calculated on annual average daily closing position • Earnings per share (EPS) is calculated
Slide 47: P&L
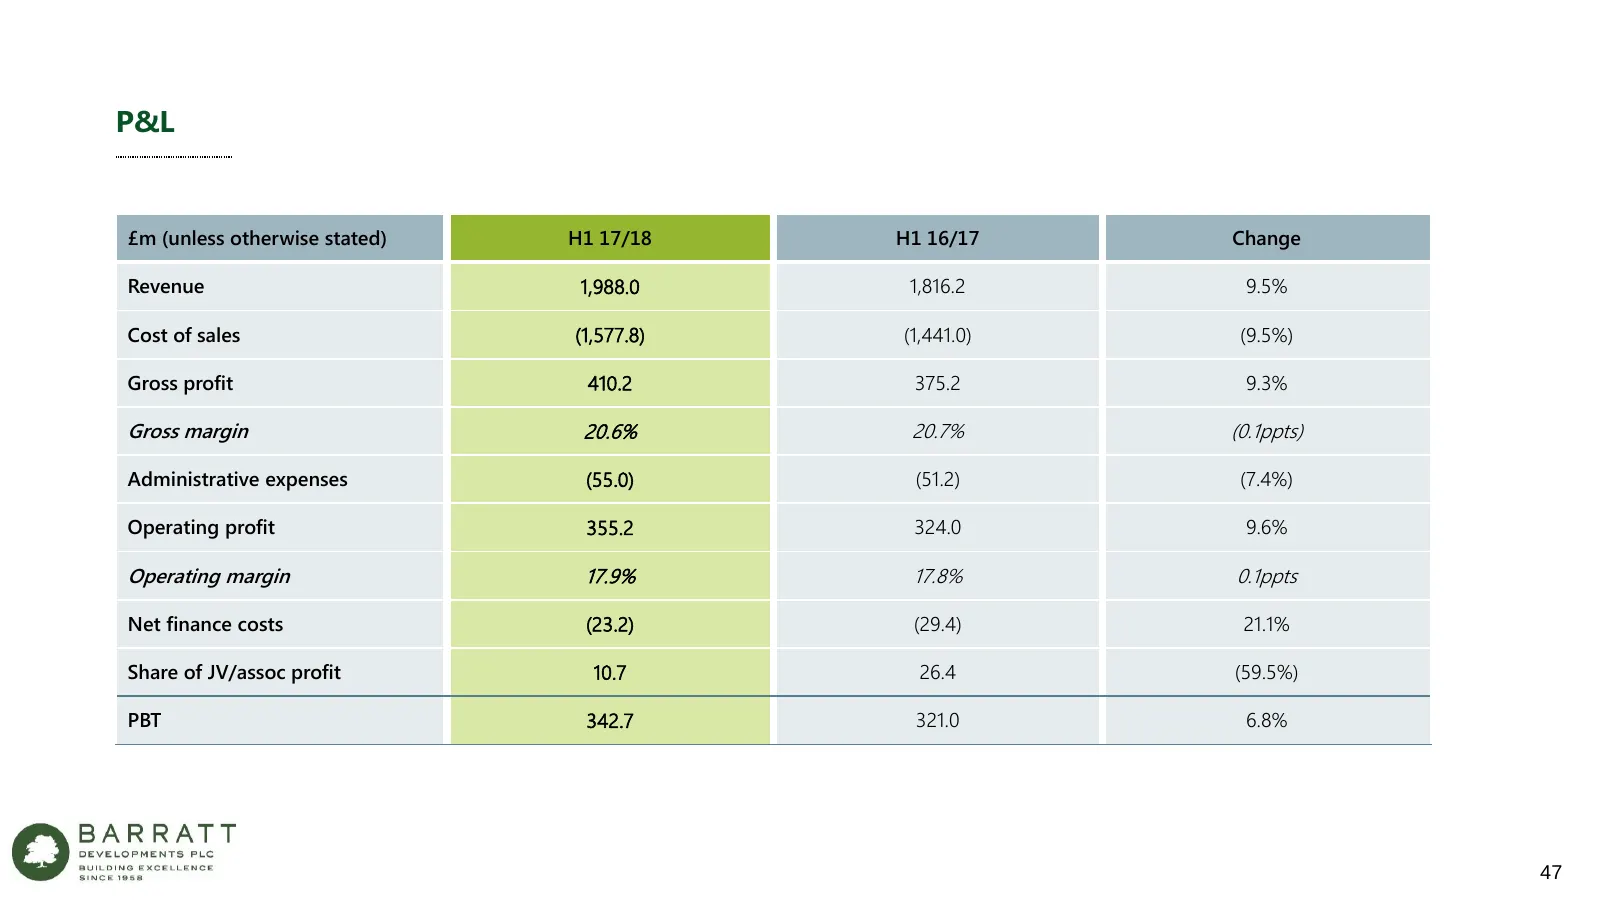
P&L £m (unless otherwise stated) H1 17/18 H1 16/17 Change Revenue 1,988.0 1,816.2 9.5% Cost of sales (1,577.8) (1,441.0) (9.5%) Gross profit 410.2 375.2 9.3% Gross margin 20.6% 20.7% (0.1ppts) Administrative expenses (55.0) (51.2) (7.4%) Operating profit 355.2 324.0 9.6% Operating margin 17.9% 17.8%
Slide 48: Balance Sheet – Land Bank
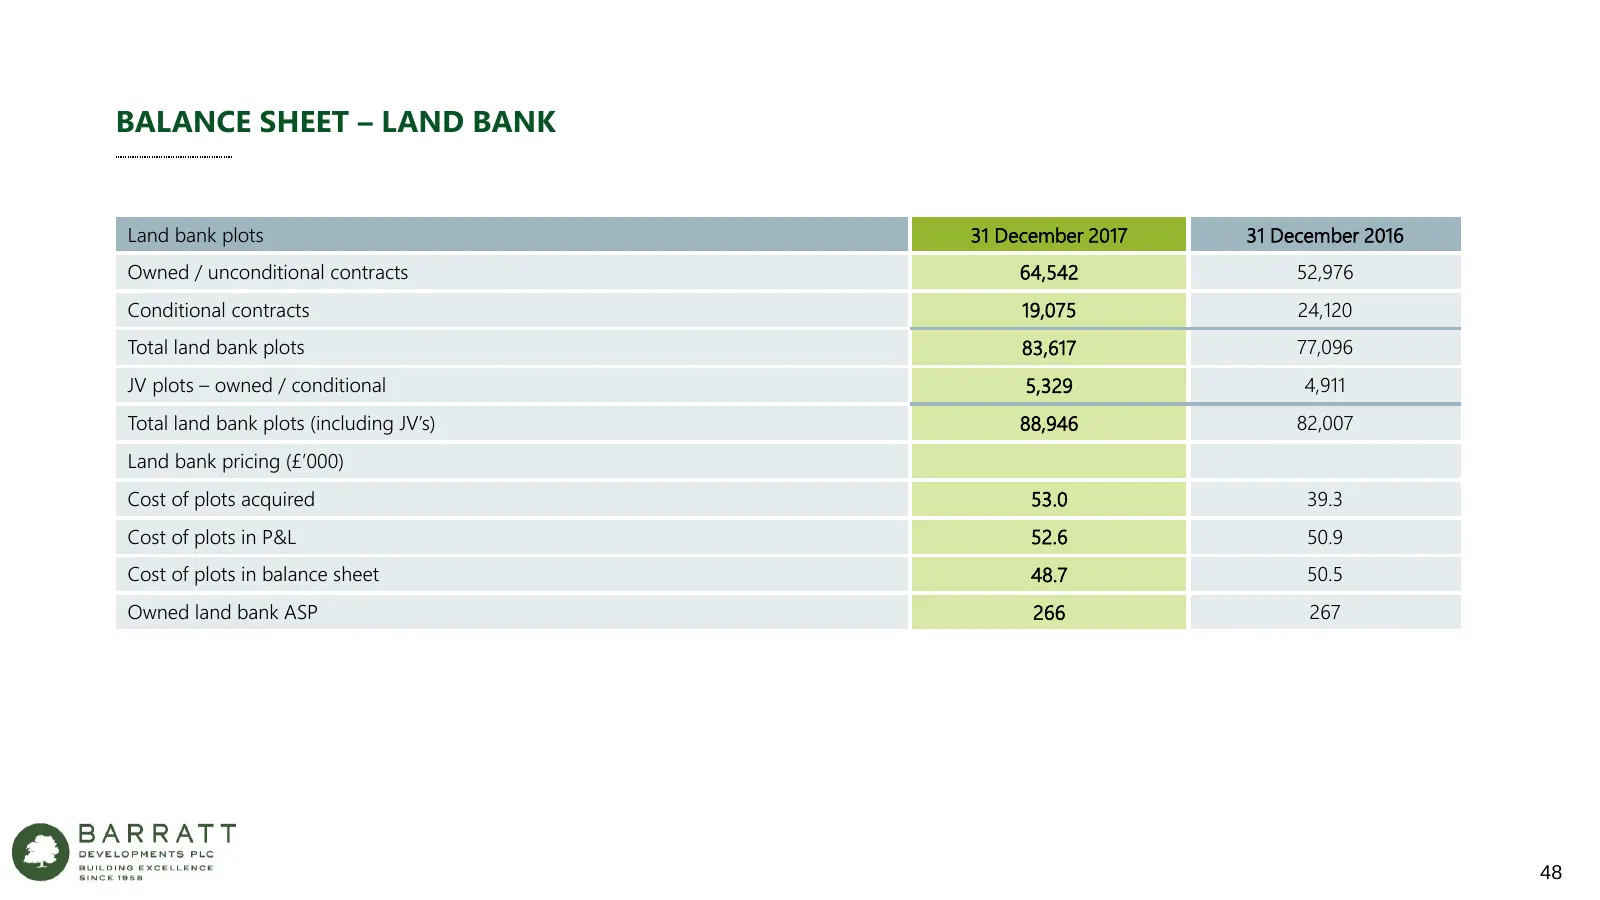
BALANCE SHEET – LAND BANK Land bank plots 31 December 2017 31 December 2016 Owned / unconditional contracts 64,542 52,976 Conditional contracts 19,075 24,120 Total land bank plots 83,617 77,096 JV plots – owned / conditional 5,329 4,911 Total land bank plots (including JV’s) 88,946 82,007 Land bank
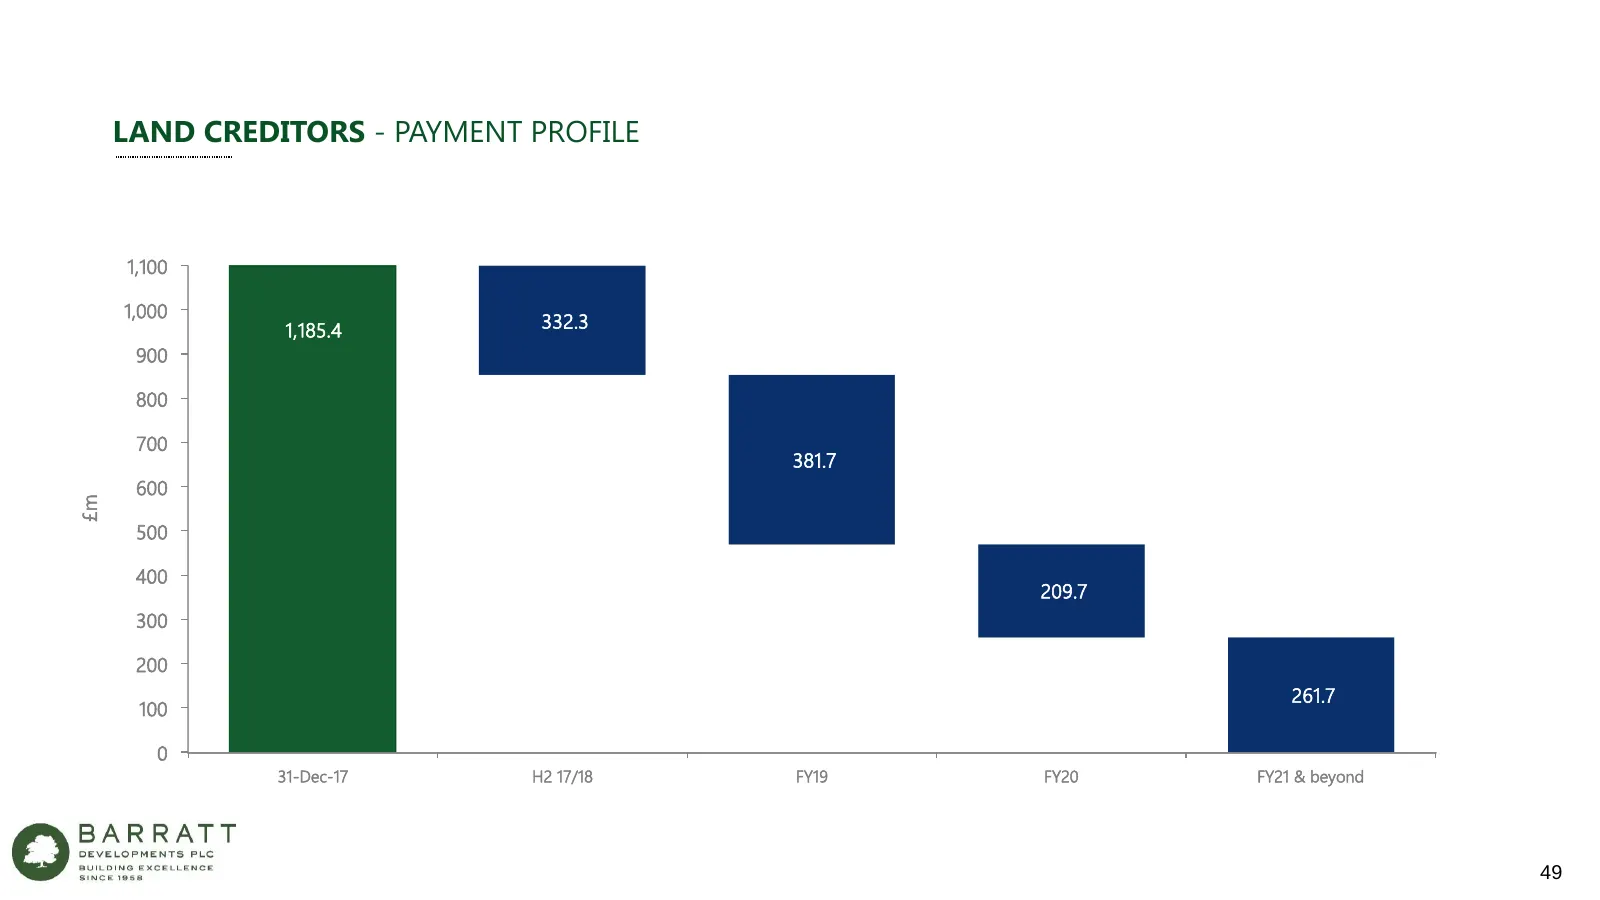
Slide 49: Land Creditors – Payment Profile
LAND CREDITORS - PAYMENT PROFILE 1,100 1,000 1,185.4 332.3 900 800 700 381.7 600 £m 500 400 209.7 300 200 261.7 100 0 31-Dec-17 H2 17/18 FY19 FY20 FY21 & beyond 49
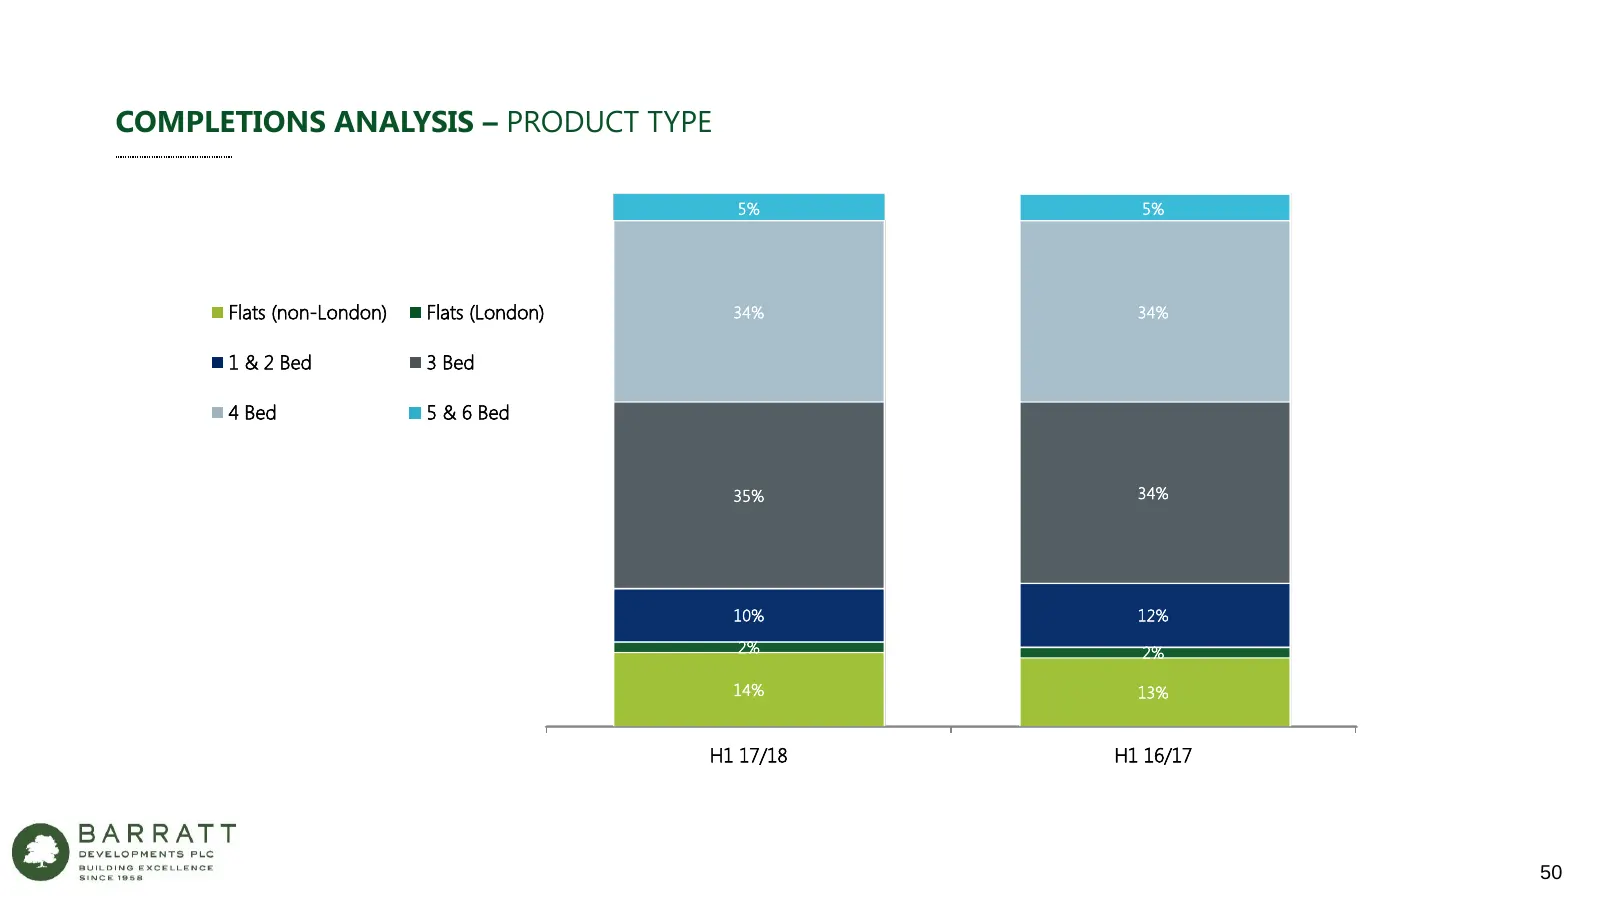
Slide 50: Completions Analysis – Product Type
COMPLETIONS ANALYSIS – PRODUCT TYPE 5% 5% Flats (non-London) Flats (London) 34% 34% 1 & 2 Bed 3 Bed 4 Bed 5 & 6 Bed 35% 34% 10% 12% 2% 2% 14% 13% H1 17/18 H1 16/17 50
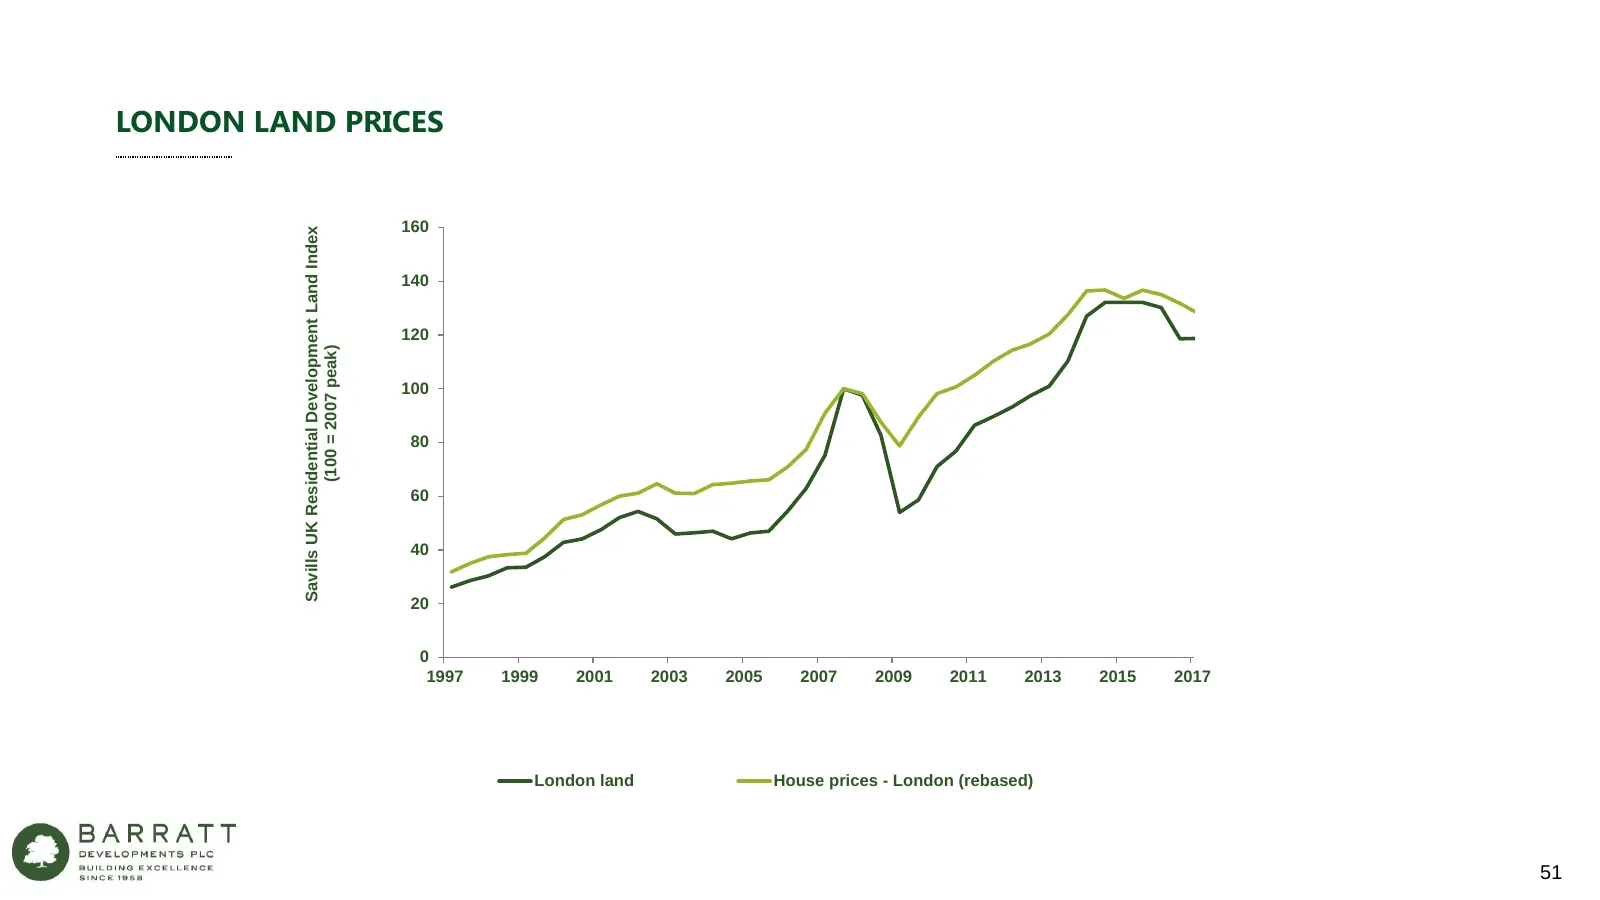
Slide 51: London Land Prices
LONDON LAND PRICES 160 Savills UK Residential Development Land Index 140 (100 = 2007 peak) 120 100 80 60 40 20 0 1997 1999 2001 2003 2005 2007 2009 2011 2013 2015 2017 London land House prices - London (rebased) 51
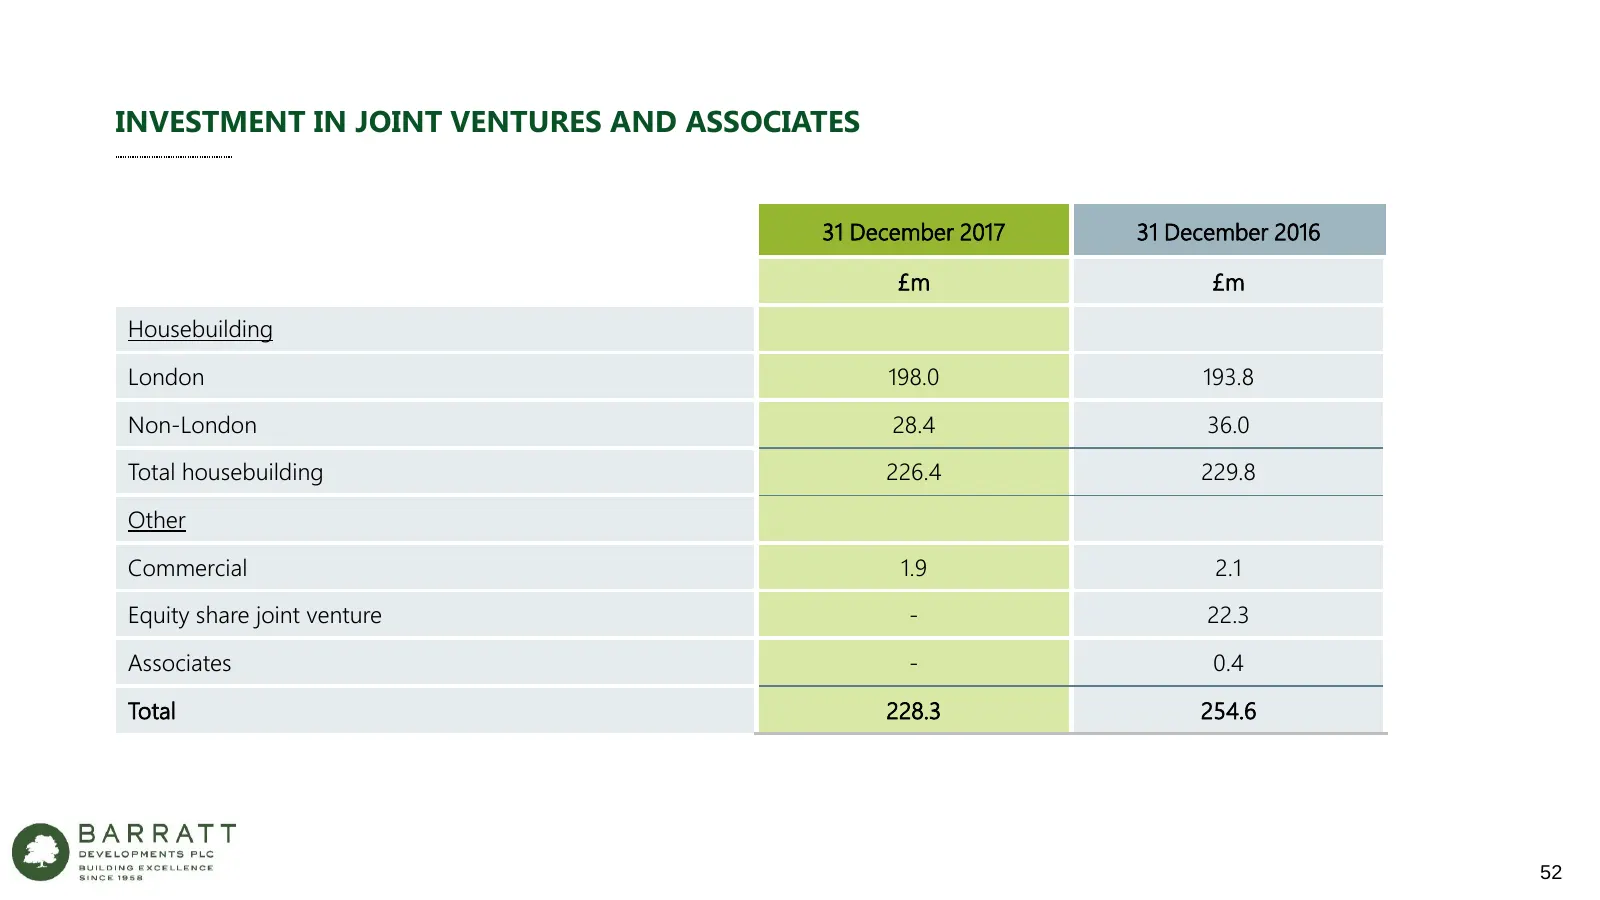
Slide 52: Investment in Joint Ventures and Associates
INVESTMENT IN JOINT VENTURES AND ASSOCIATES 31 December 2017 31 December 2016 £m £m Housebuilding London 198.0 193.8 Non-London 28.4 36.0 Total housebuilding 226.4 229.8 Other Commercial 1.9 2.1 Equity share joint venture - 22.3 Associates - 0.4 Total 228.3 254.6 52
Slide 53: Joint Venture Land Bank Plots
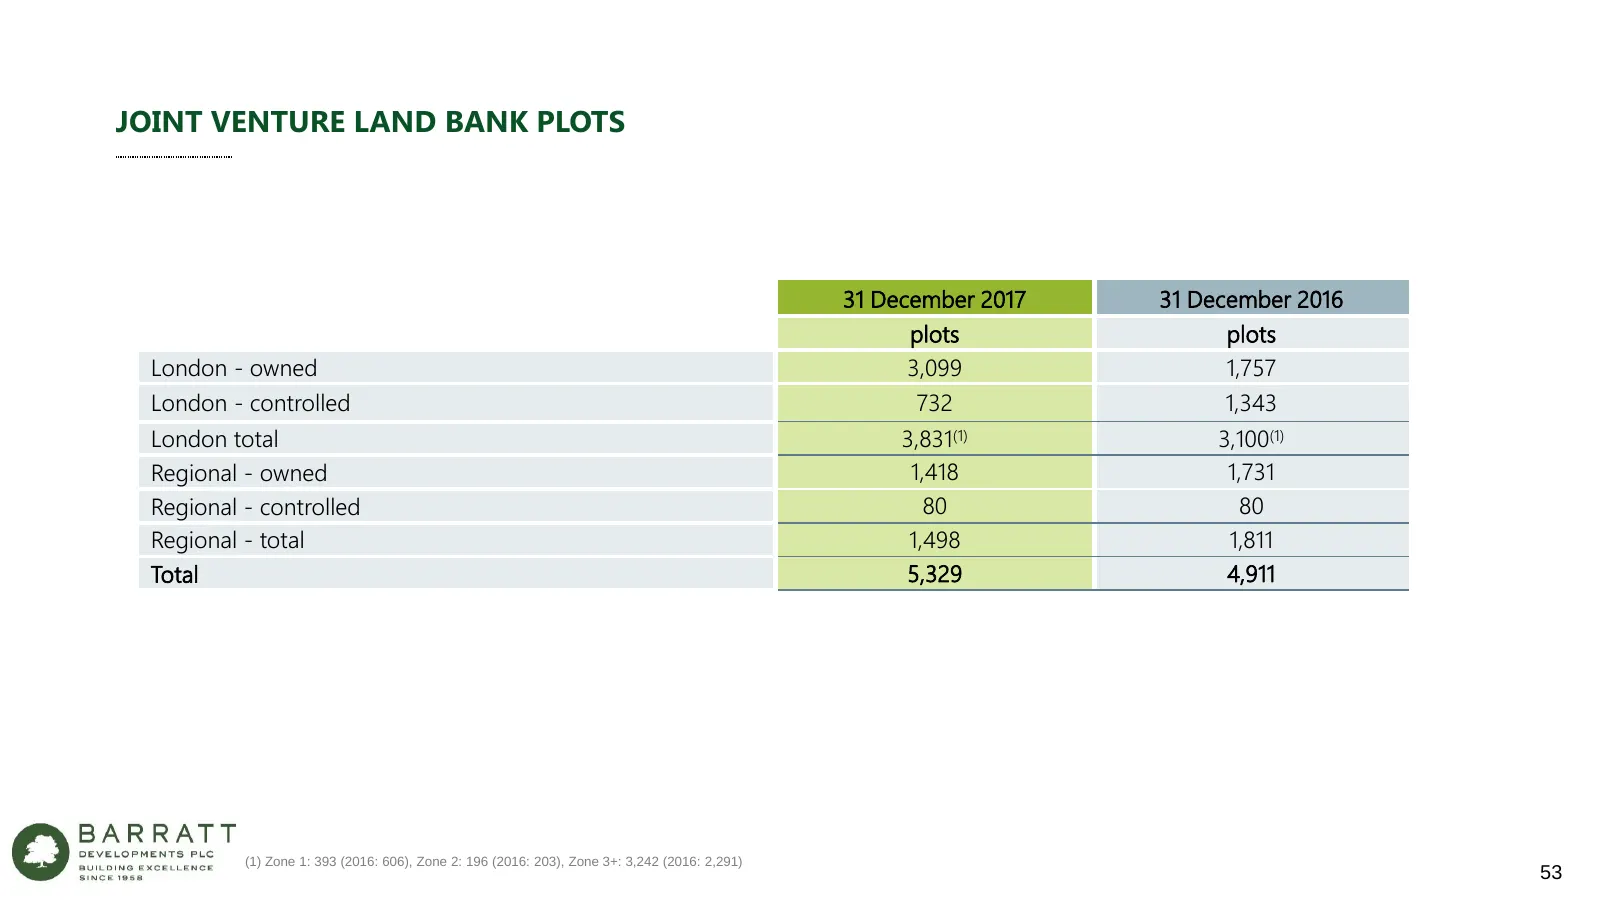
JOINT VENTURE LAND BANK PLOTS 31 December 2017 31 December 2016 plots plots London - owned 3,099 1,757 London - controlled 732 1,343 London total 3,831(1) 3,100(1) Regional - owned 1,418 1,731 Regional - controlled 80 80 Regional - total 1,498 1,811 Total 5,329 4,911 (1) Zone 1: 393 (2016: 606), Zon
Slide 54: Net Interest Charge Analysis
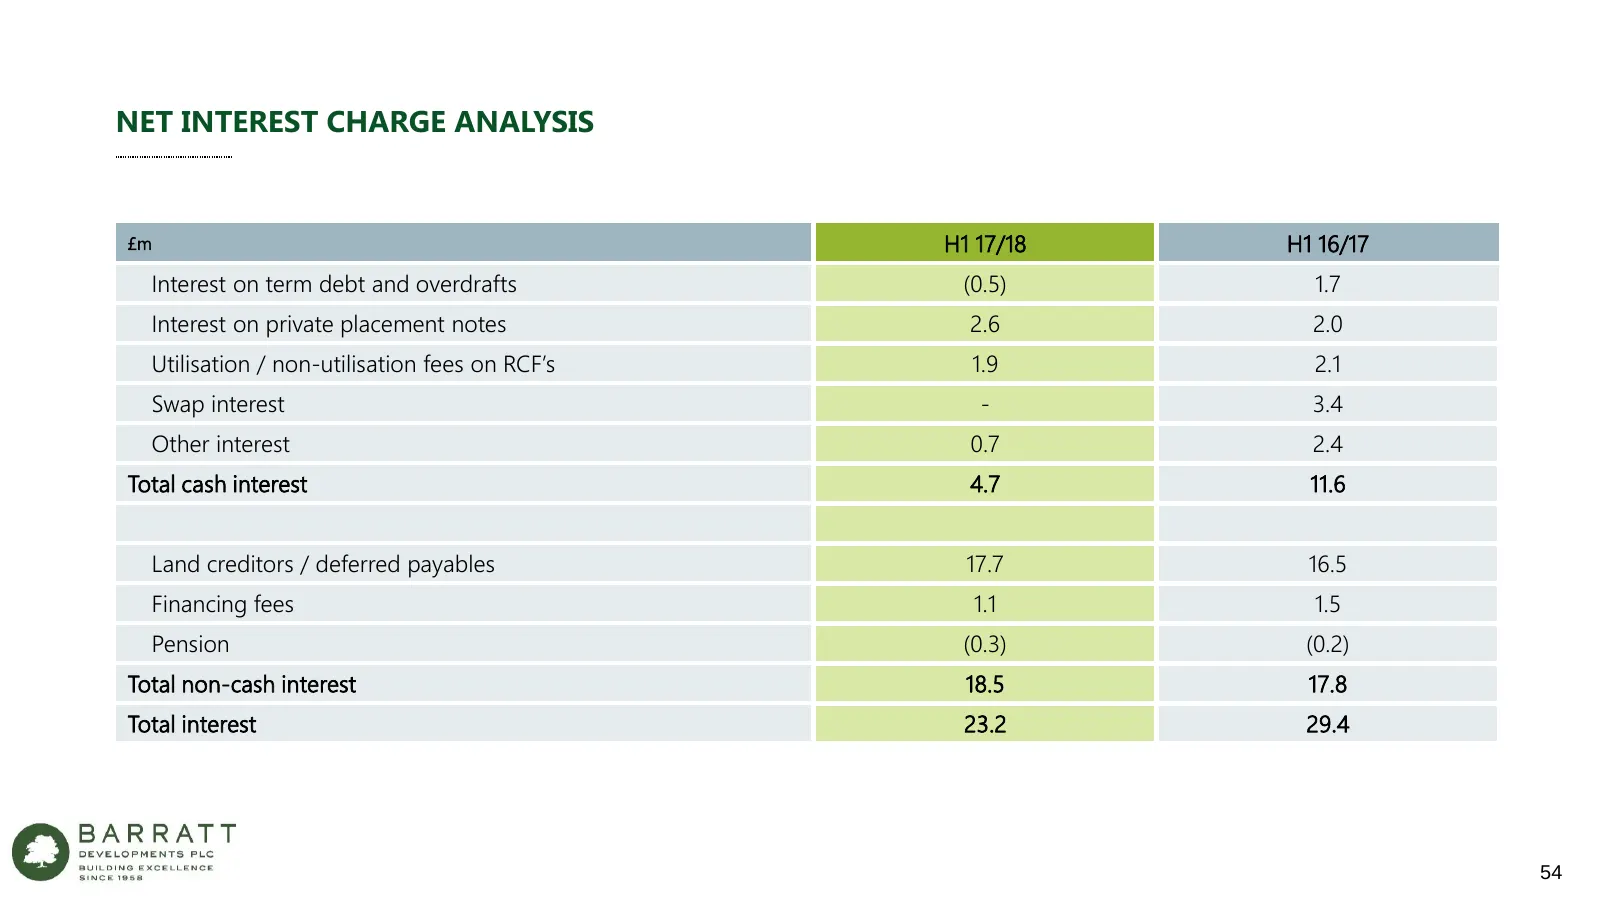
NET INTEREST CHARGE ANALYSIS £m H1 17/18 H1 16/17 Interest on term debt and overdrafts (0.5) 1.7 Interest on private placement notes 2.6 2.0 Utilisation / non-utilisation fees on RCF’s 1.9 2.1 Swap interest - 3.4 Other interest 0.7 2.4 Total cash interest 4.7 11.6 Land creditors / deferred payables
Slide 55: Financing Arrangements
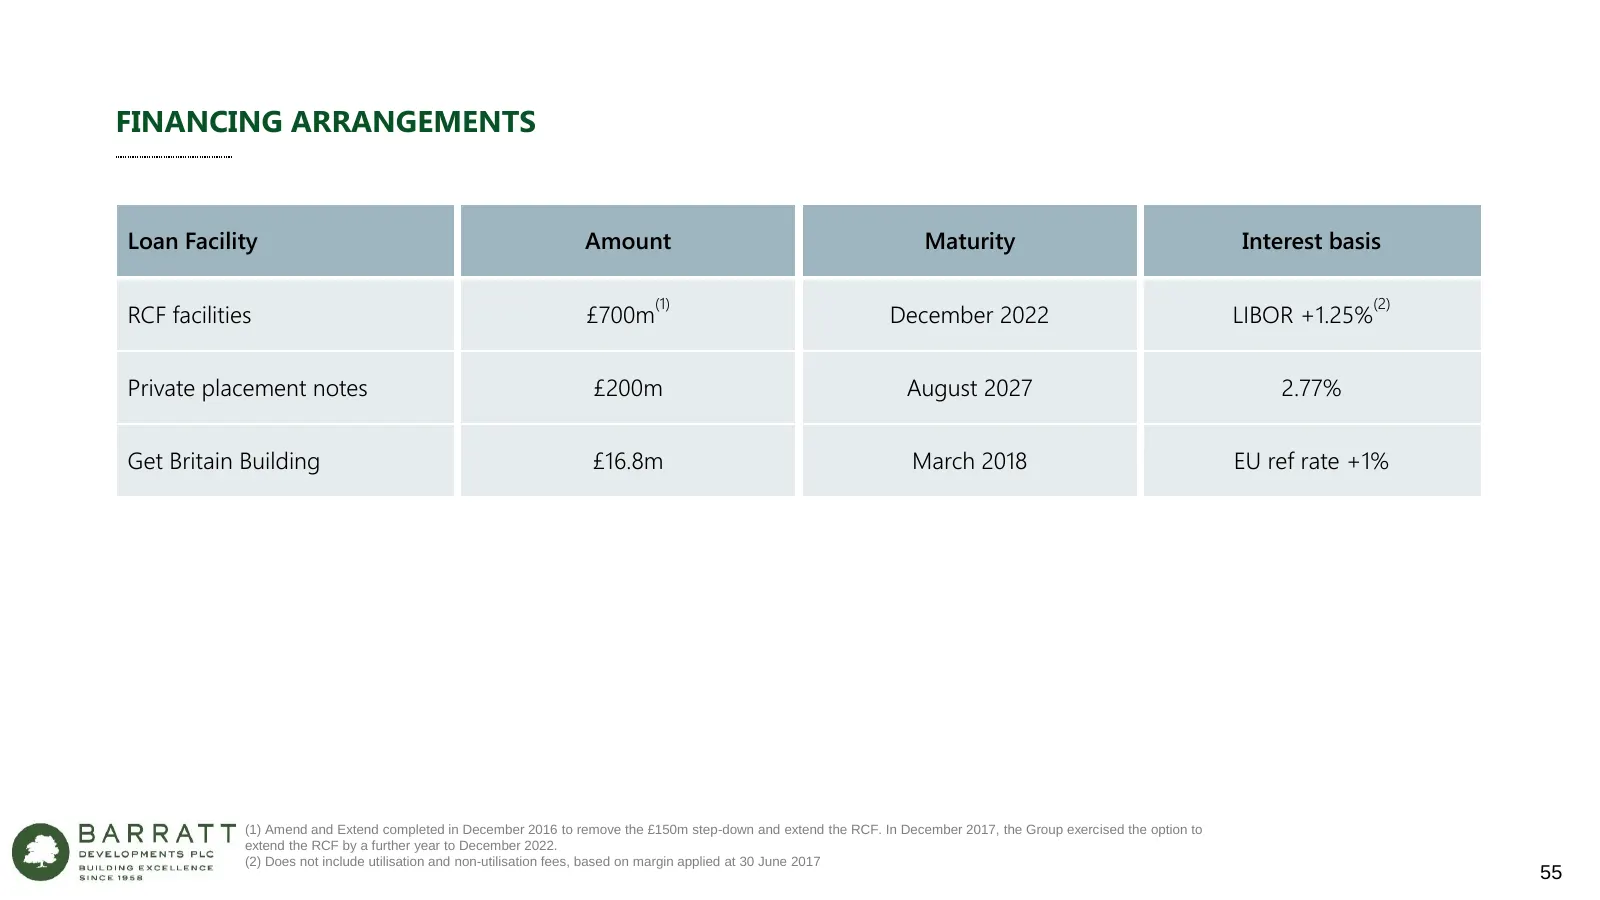
FINANCING ARRANGEMENTS Loan Facility Amount Maturity Interest basis (1) (2) RCF facilities £700m December 2022 LIBOR +1.25% Private placement notes £200m August 2027 2.77% Get Britain Building £16.8m March 2018 EU ref rate +1% (1) Amend and Extend completed in December 2016 to remove the £150m step-
Slide 56: Disclaimer
DISCLAIMER This document has been prepared by Barratt Developments PLC (the “Company”) solely for use at a presentation in connection with the Company‘s Interim Results Announcement in respect of the half year ended 31 December 2017. For the purposes of this notice, the presentation (the “Presentati
Source: Internet Archive copy of barrattdevelopments.co.uk
More decks from Barratt Redrow plc
 FY2026 Earnings Presentation59 slides · Sep 16, 2026
 HY26 Earnings Presentation59 slides · Feb 11, 2026
 FY2025 Earnings Presentation60 slides · Sep 17, 2025
 Corporate Update (May 2025)30 slides · May 1, 2025
 Investor Day (February 2025)40 slides · Feb 12, 2025
 HY25 Earnings Presentation51 slides · Feb 12, 2025