Kingfisher PLC · LSE:KGF
Kingfisher — H1 2011/12 Earnings Presentation
49 slides from Kingfisher's earnings presentation, September 2011
Slide 1: Disclaimer
Disclaimer The following presentation is being made only to, and is only directed at, persons to whom such presentation may lawfully be communicated (‘relevant persons’). Any person who is not a relevant person should not act or rely on this presentation or any of its contents. This presentation doe
Slide 2: Ian Cheshire, Group Chief Executive
Ian Cheshire Group Chief Executive 2
Slide 3: Agenda
Agenda Introduction and summary Ian Cheshire Group CEO Financial review Kevin O’Byrne Group CFO Common range Euan Sutherland CEO, UK & Ireland Questions 3
Slide 4: Summary
Summary • Strong results in difficult times for retailers – Sales +3%*, adjusted PBT +24% • Self-help initiatives driving our performance in all geographies – Particularly strong sales growth in France – Group gross margin +60bps – Costs (SG&A) ratio to sales flat • Good progress with final year of
Slide 5: 'Delivering Value' update
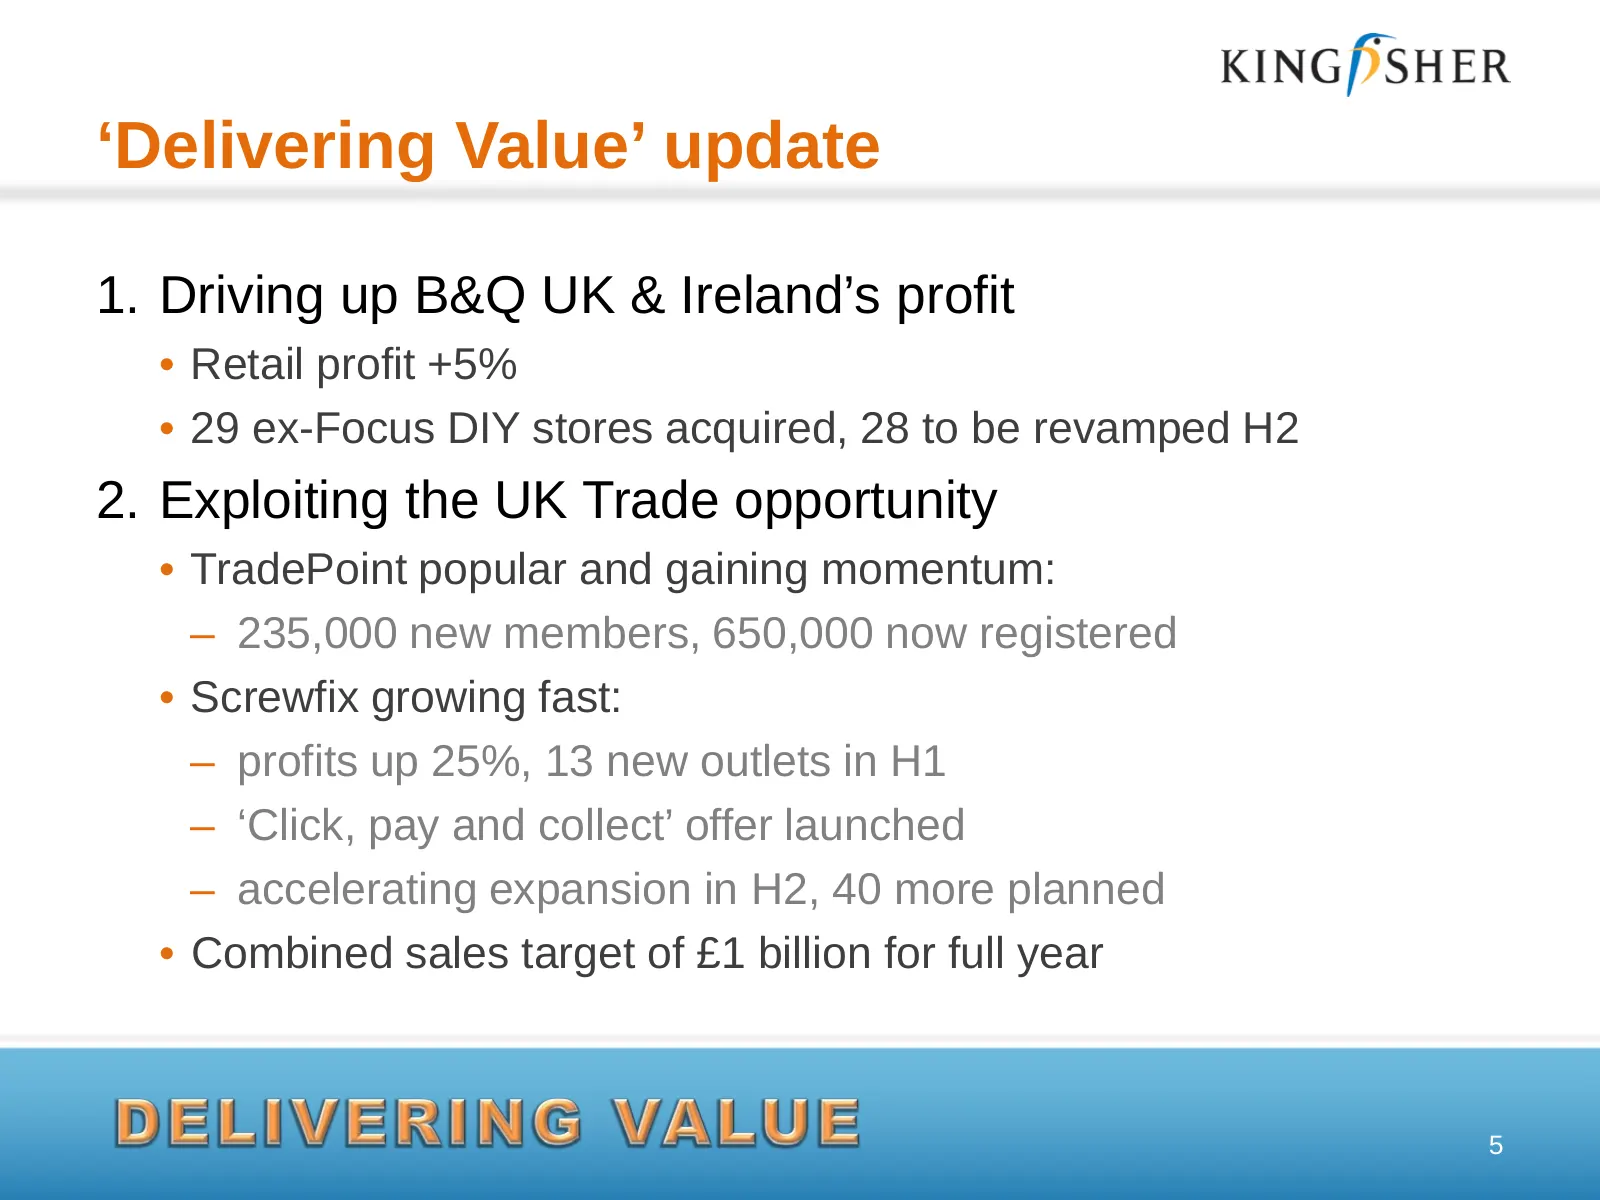
‘Delivering Value’ update 1. Driving up B&Q UK & Ireland’s profit • Retail profit +5% • 29 ex-Focus DIY stores acquired, 28 to be revamped H2 2. Exploiting the UK Trade opportunity • TradePoint popular and gaining momentum: – 235,000 new members, 650,000 now registered • Screwfix growing fast: – pro
Slide 6: 'Delivering Value' update
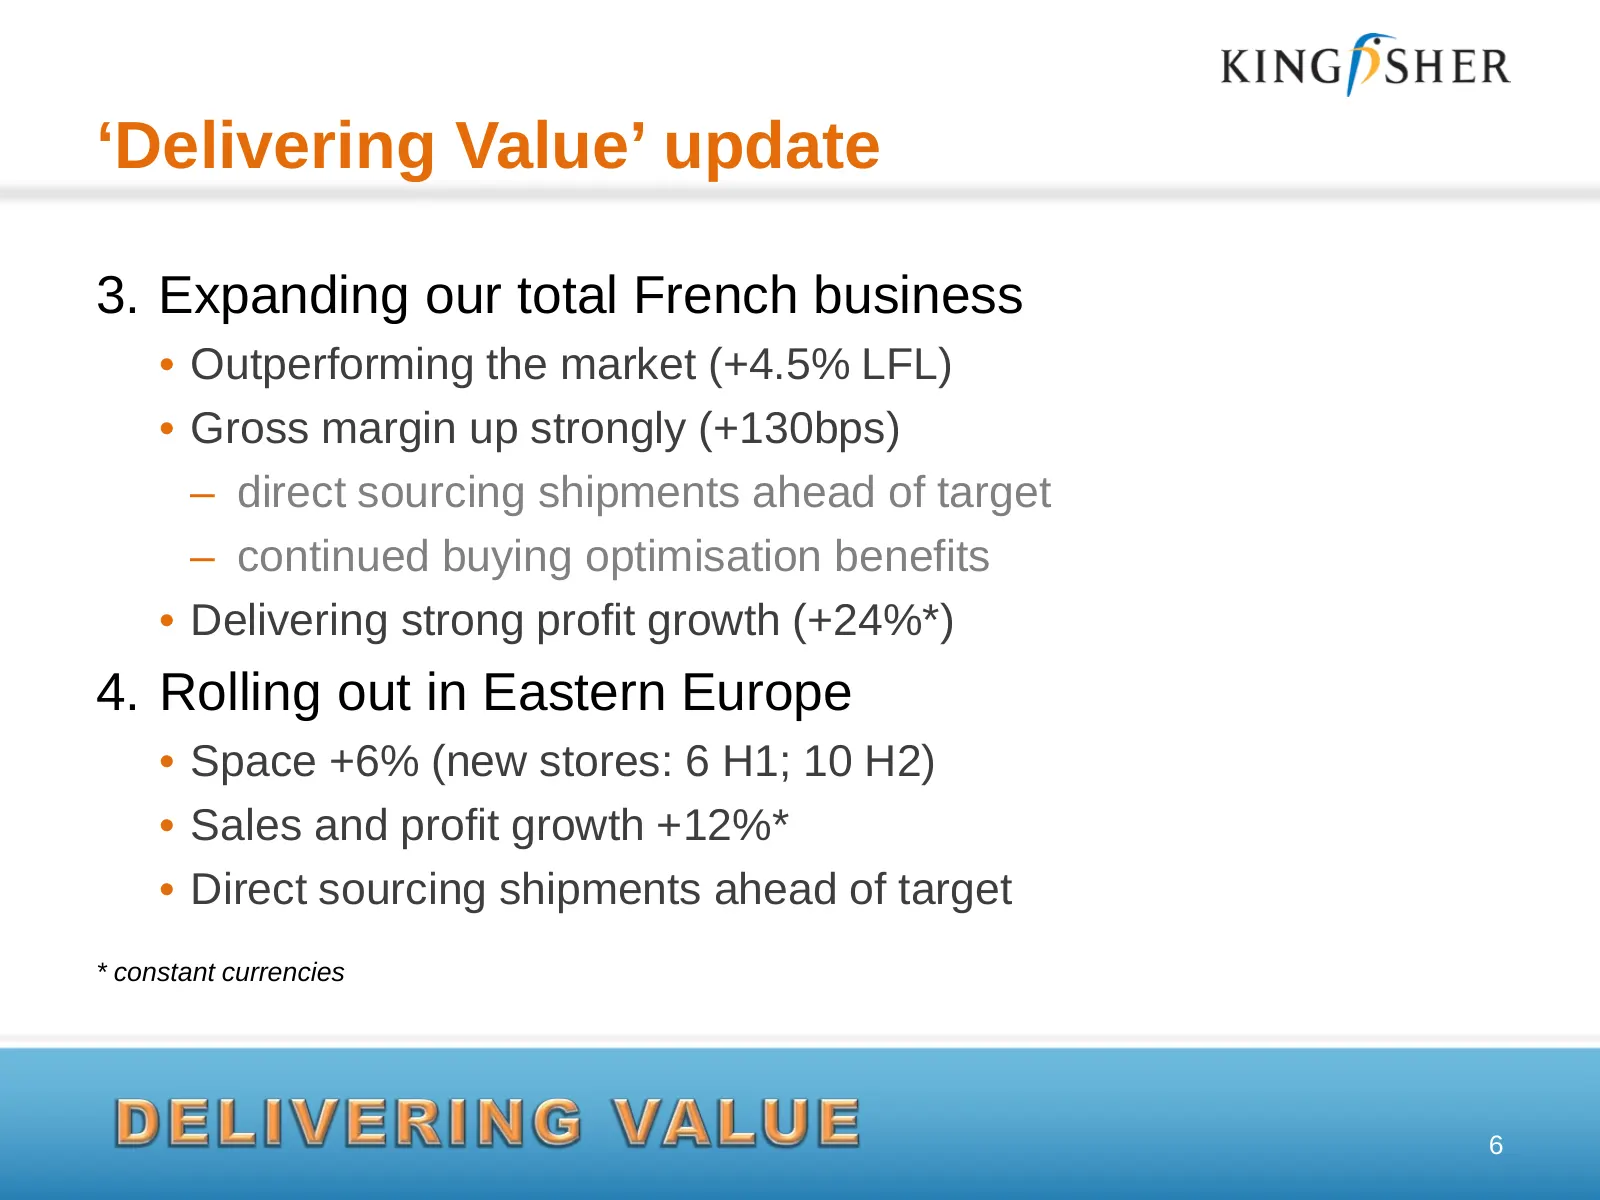
‘Delivering Value’ update 3. Expanding our total French business • Outperforming the market (+4.5% LFL) • Gross margin up strongly (+130bps) – direct sourcing shipments ahead of target – continued buying optimisation benefits • Delivering strong profit growth (+24%*) 4. Rolling out in Eastern Europe
Slide 7: 'Delivering Value' update
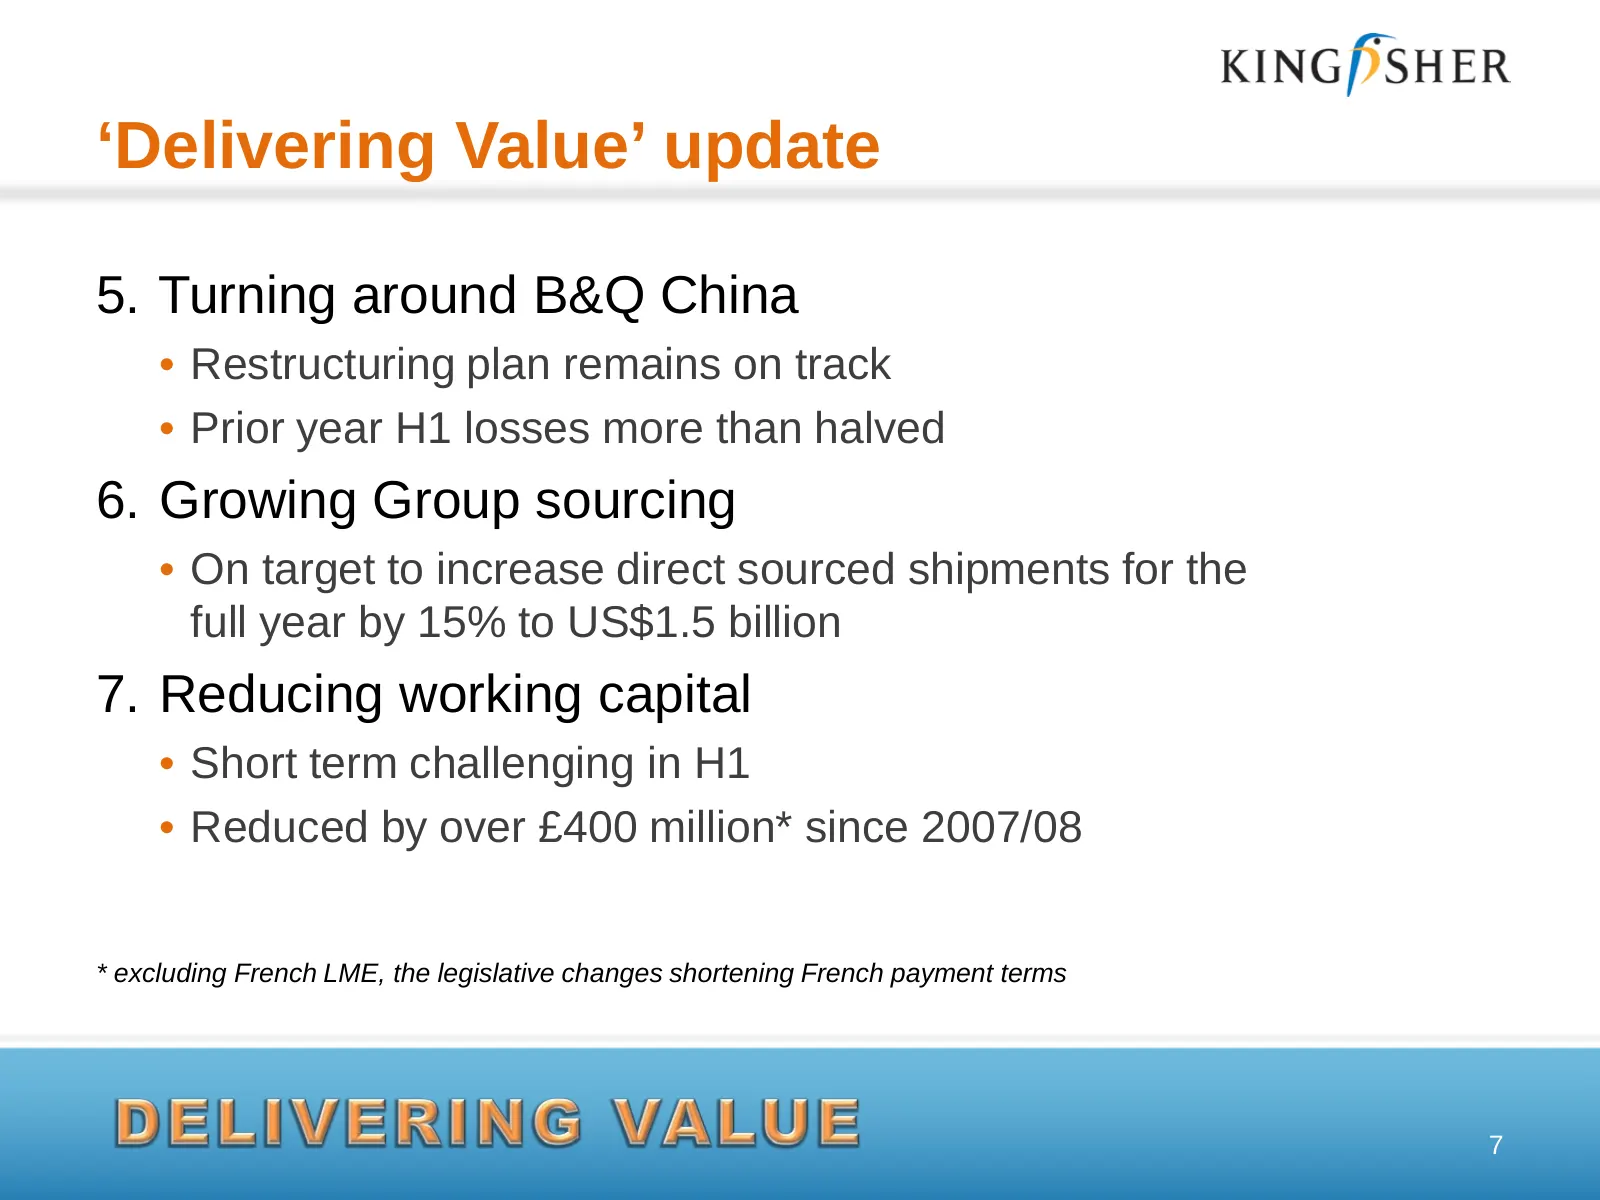
‘Delivering Value’ update 5. Turning around B&Q China • Restructuring plan remains on track • Prior year H1 losses more than halved 6. Growing Group sourcing • On target to increase direct sourced shipments for the full year by 15% to US$1.5 billion 7. Reducing working capital • Short term challengi
Slide 8: 2011/12 – 'stepping up a gear'
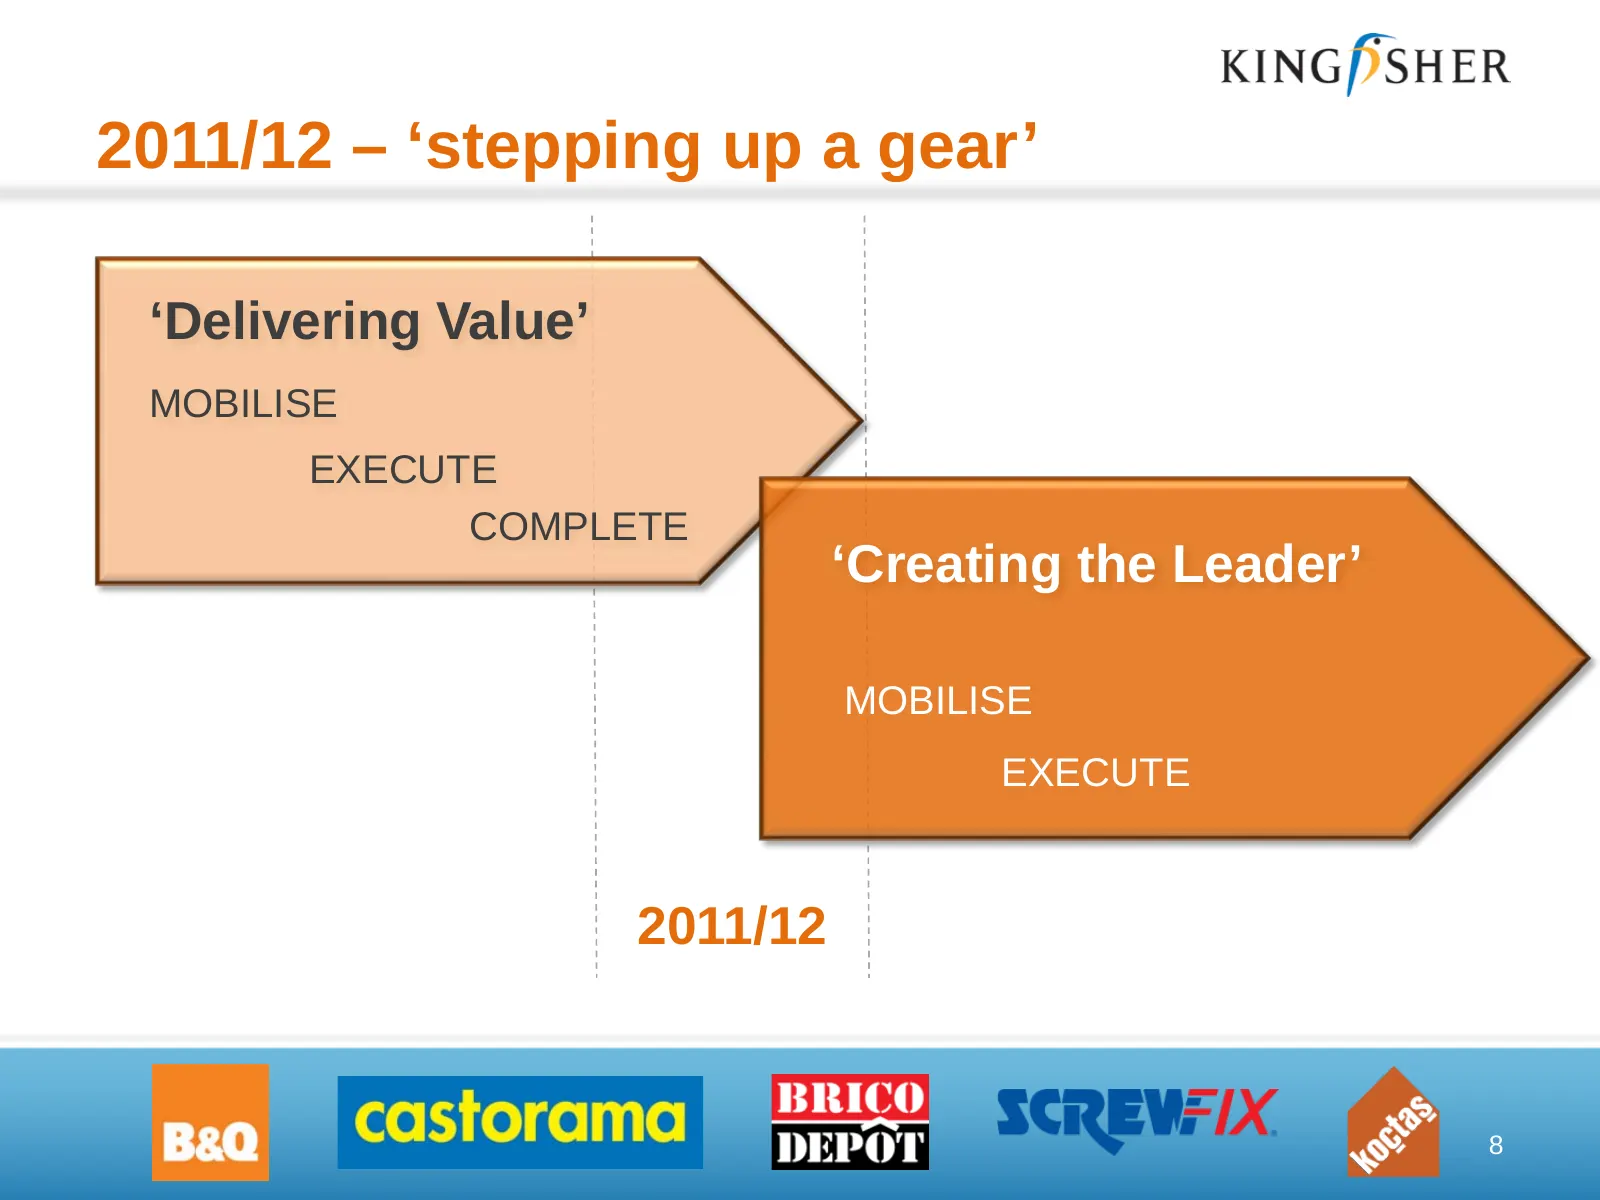
2011/12 – ‘stepping up a gear’ ‘Delivering Value’ MOBILISE EXECUTE COMPLETE ‘Creating the Leader’ MOBILISE EXECUTE 2011/12 8
Slide 9: 'Creating the Leader'
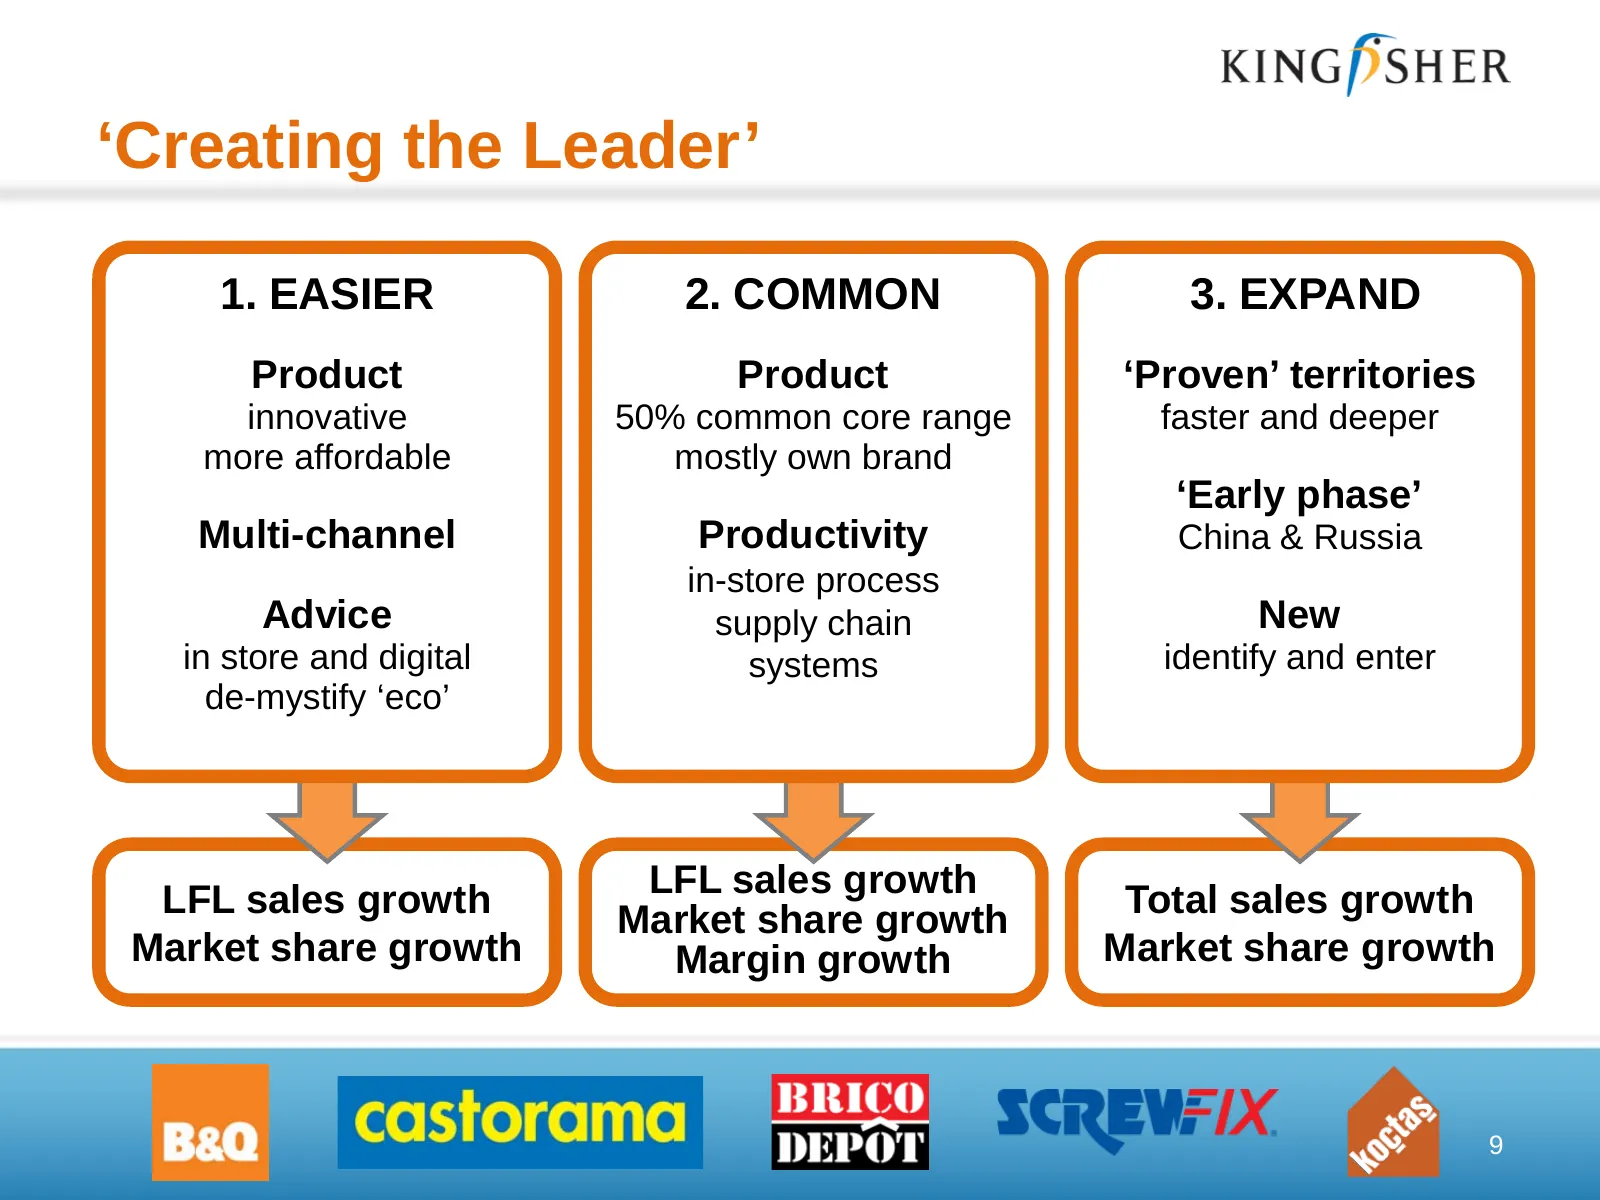
‘Creating the Leader’ 1. EASIER 2. COMMON 3. EXPAND Product Product ‘Proven’ territories innovative 50% common core range faster and deeper more affordable mostly own brand ‘Early phase’ Multi-channel Productivity China & Russia in-store process Advice supply chain New in store and digital systems i
Slide 10: Kevin O'Byrne, Group Finance Director
Kevin O’Byrne Group Finance Director 10
Slide 11: Financial highlights
Financial highlights • Adjusted pre-tax profit £439m, up 24% • Free cash flow of £133m while investing for growth • Proactive use of balance sheet strength • Reported net debt £186m • Interim dividend up 28% in line with stated policy 11
Slide 12: Group sales up 3.0%*
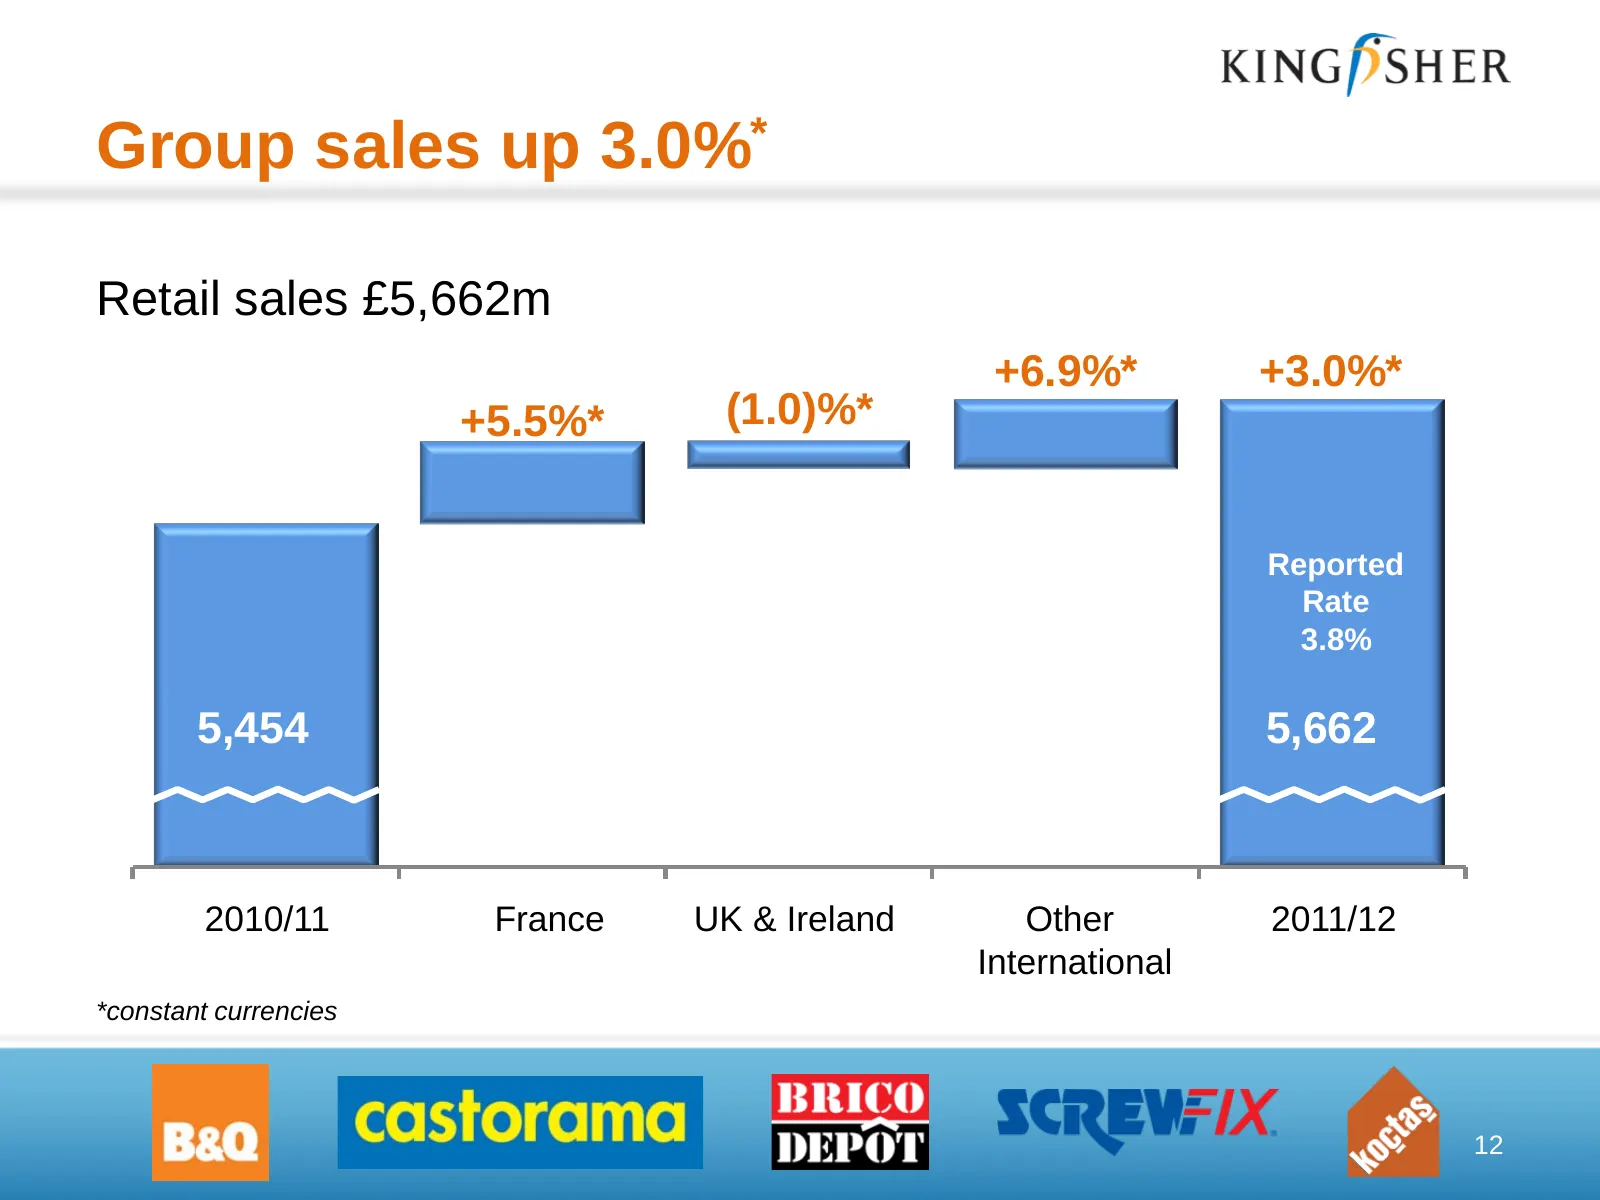
Group sales up 3.0%* Retail sales £5,662m +6.9%* +3.0%* +5.5%* (1.0)%* Reported Rate 3.8% 5,454 5,662 2010/11 France UK & Ireland Other 2011/12 International *constant currencies 12
Slide 13: Group retail profit up 16.5%*
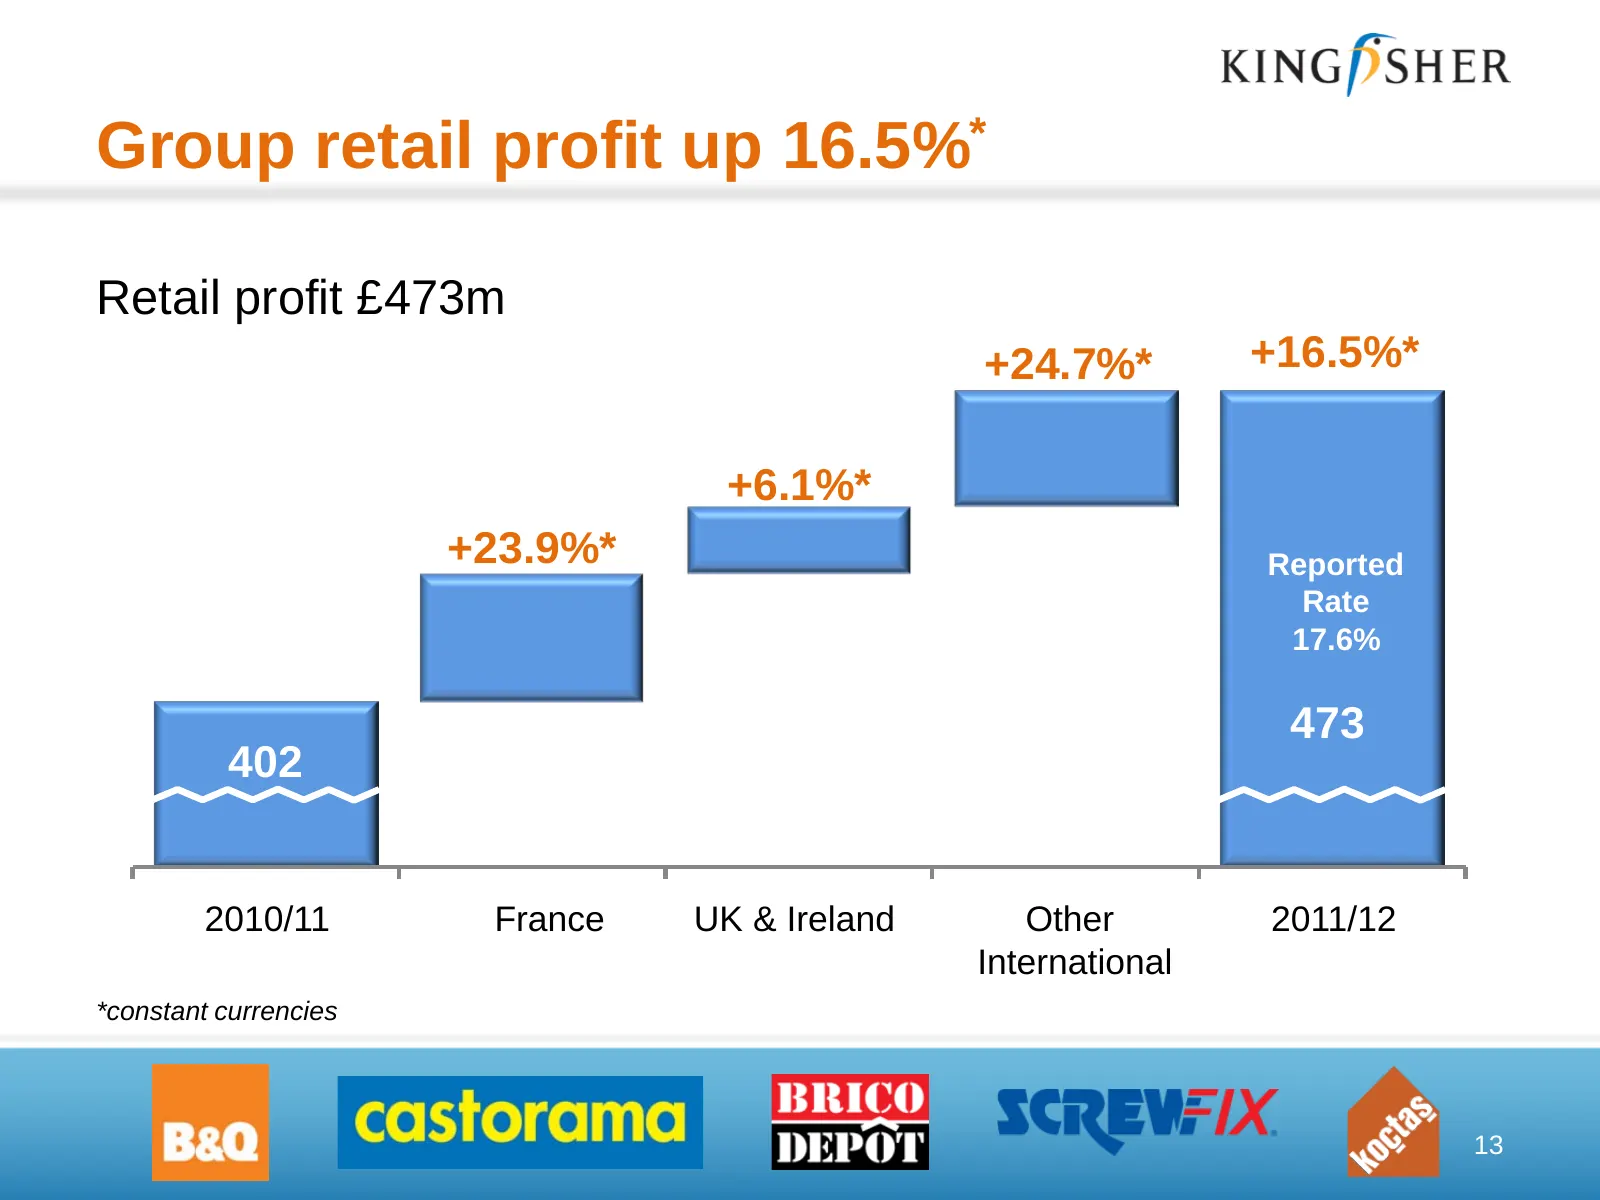
Group retail profit up 16.5%* Retail profit £473m +24.7%* +16.5%* +6.1%* +23.9%* Reported Rate 17.6% 473 402 2010/11 France UK & Ireland Other 2011/12 International *constant currencies 13
Slide 14: Financial highlights
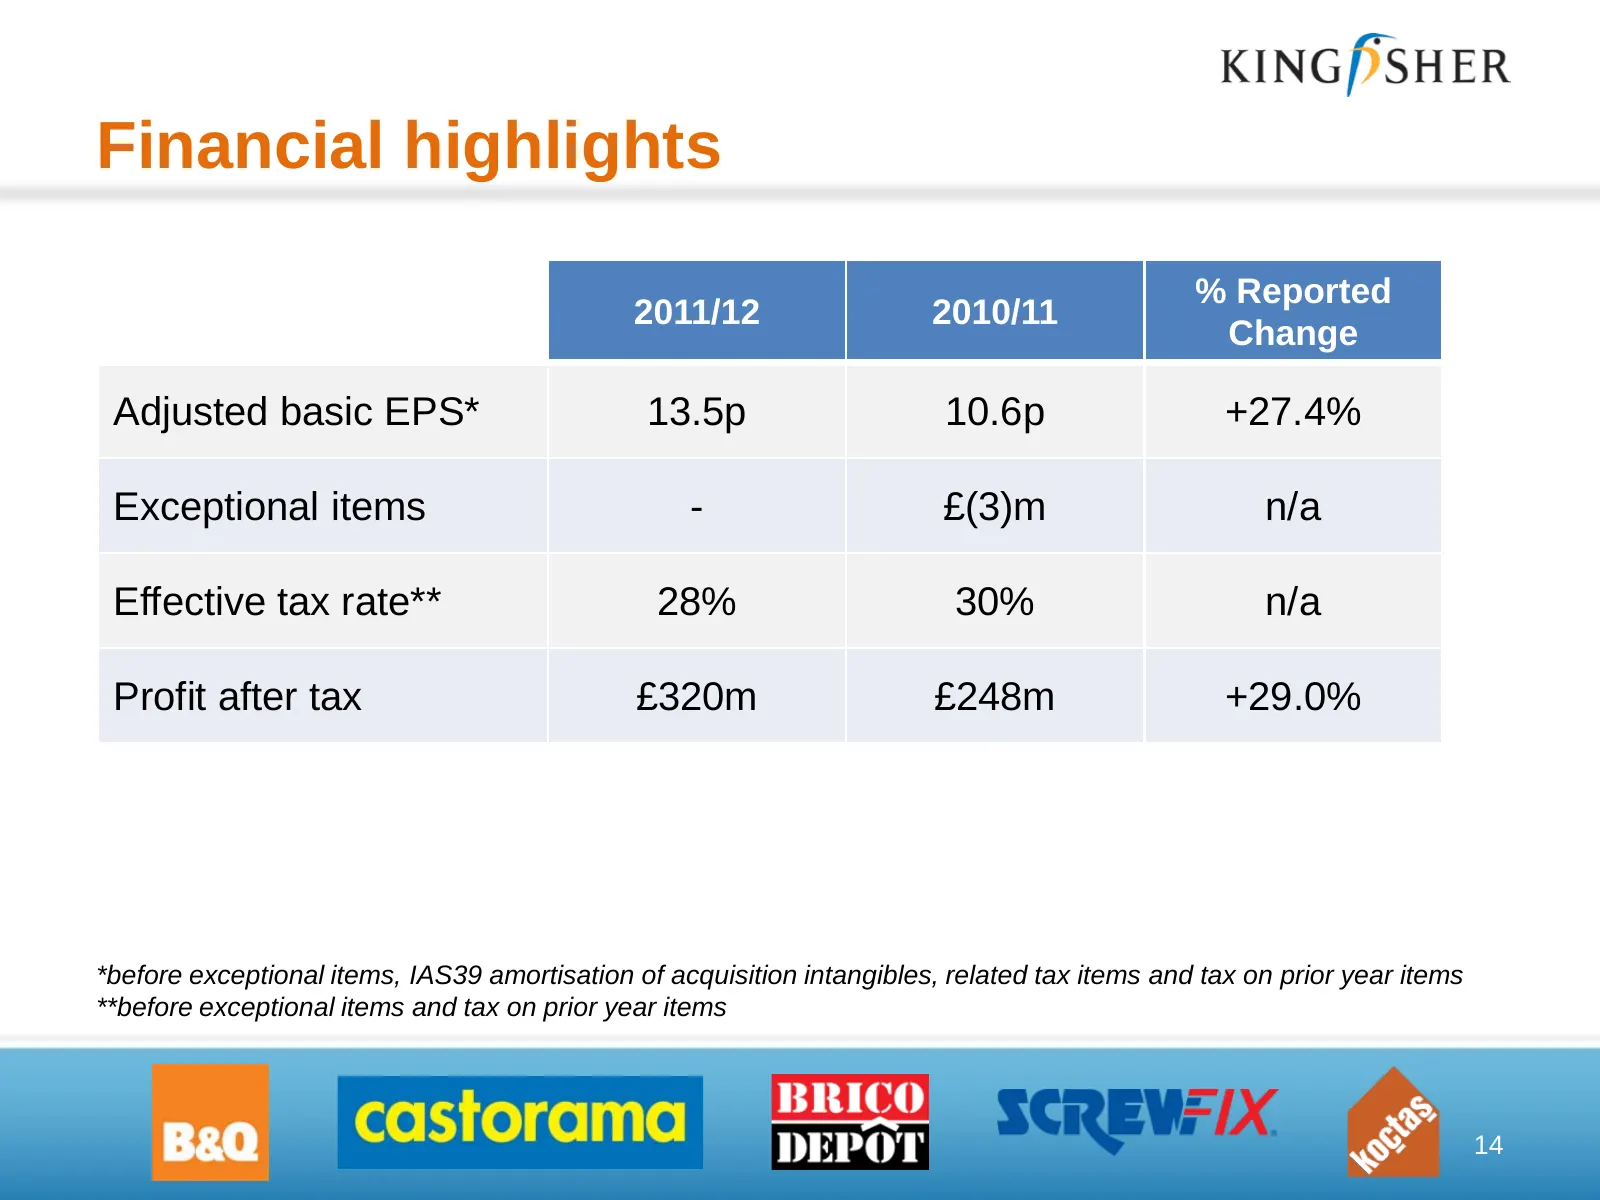
Financial highlights % Reported 2011/12 2010/11 Change Adjusted basic EPS* 13.5p 10.6p +27.4% Exceptional items - £(3)m n/a Effective tax rate** 28% 30% n/a Profit after tax £320m £248m +29.0% *before exceptional items, IAS39 amortisation of acquisition intangibles, related tax items and tax on prio
Slide 15: Free cash flow
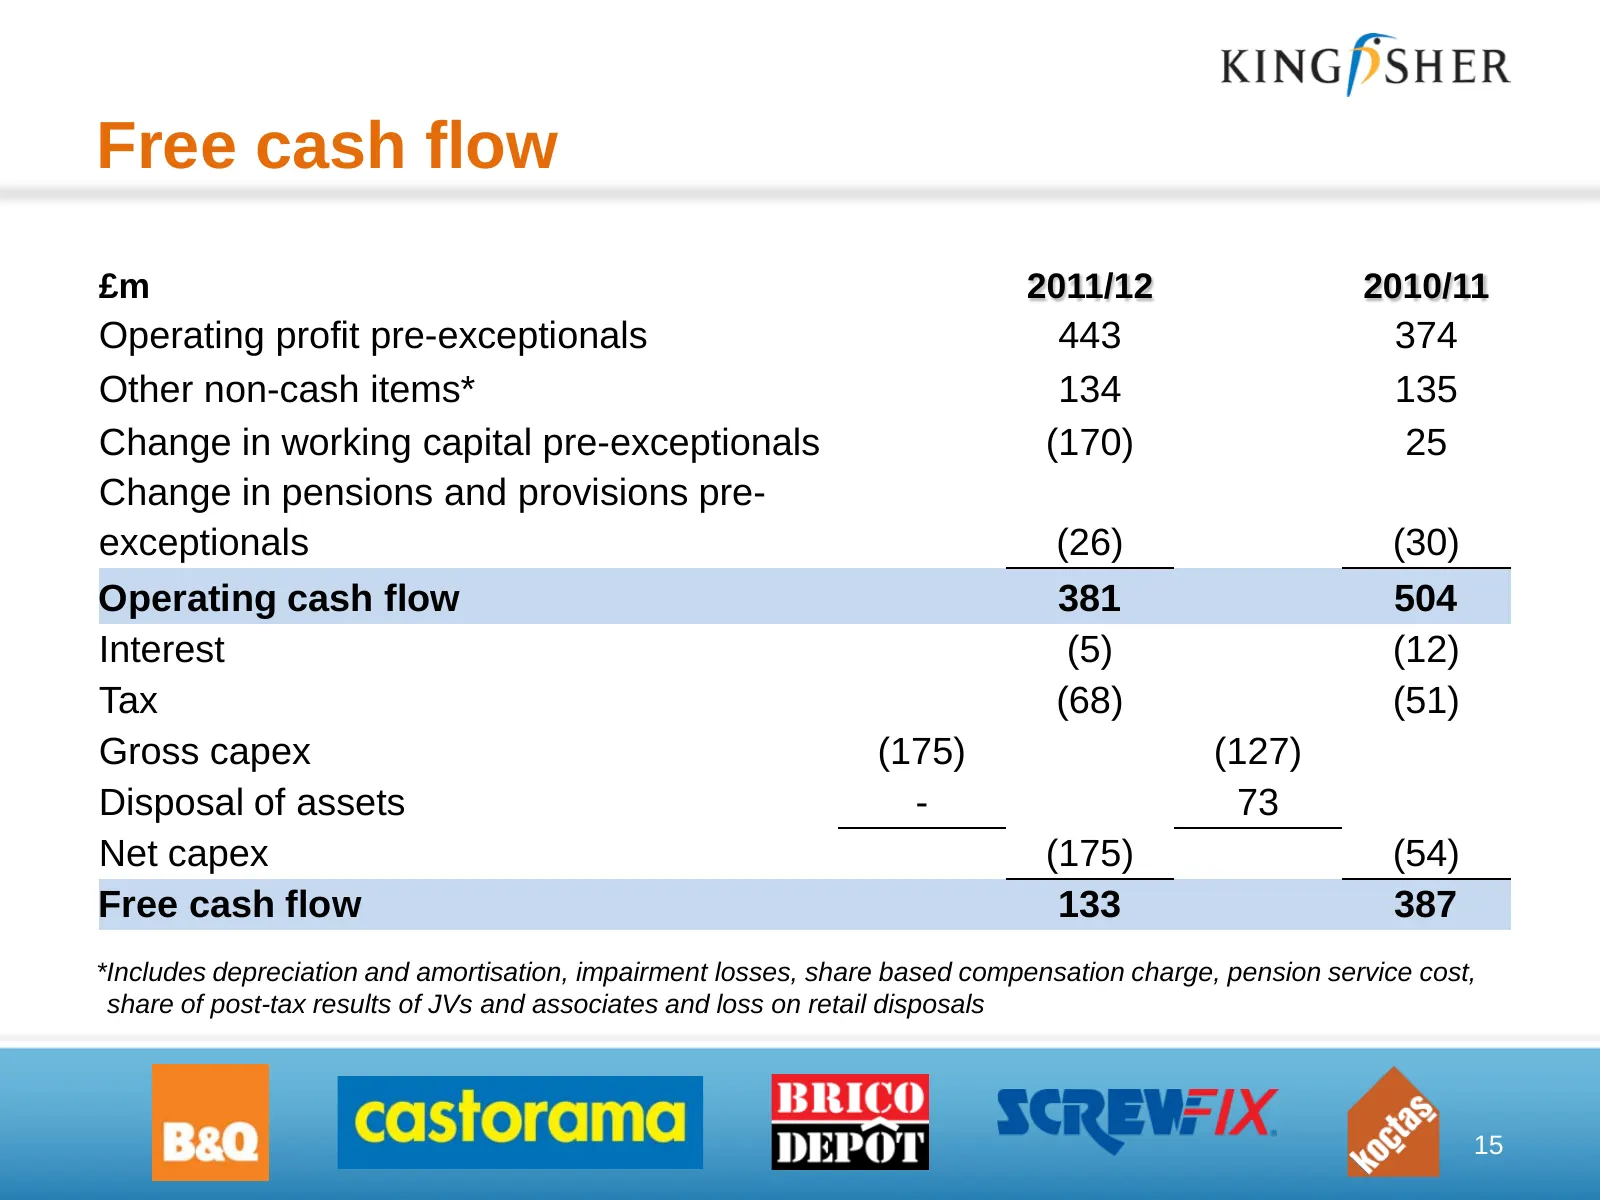
Free cash flow £m 2011/12 2010/11 Operating profit pre-exceptionals 443 374 Other non-cash items* 134 135 Change in working capital pre-exceptionals (170) 25 Change in pensions and provisions pre- exceptionals (26) (30) Operating cash flow 381 504 Interest (5) (12) Tax (68) (51) Gross capex (175) (1
Slide 16: Use of free cashflow
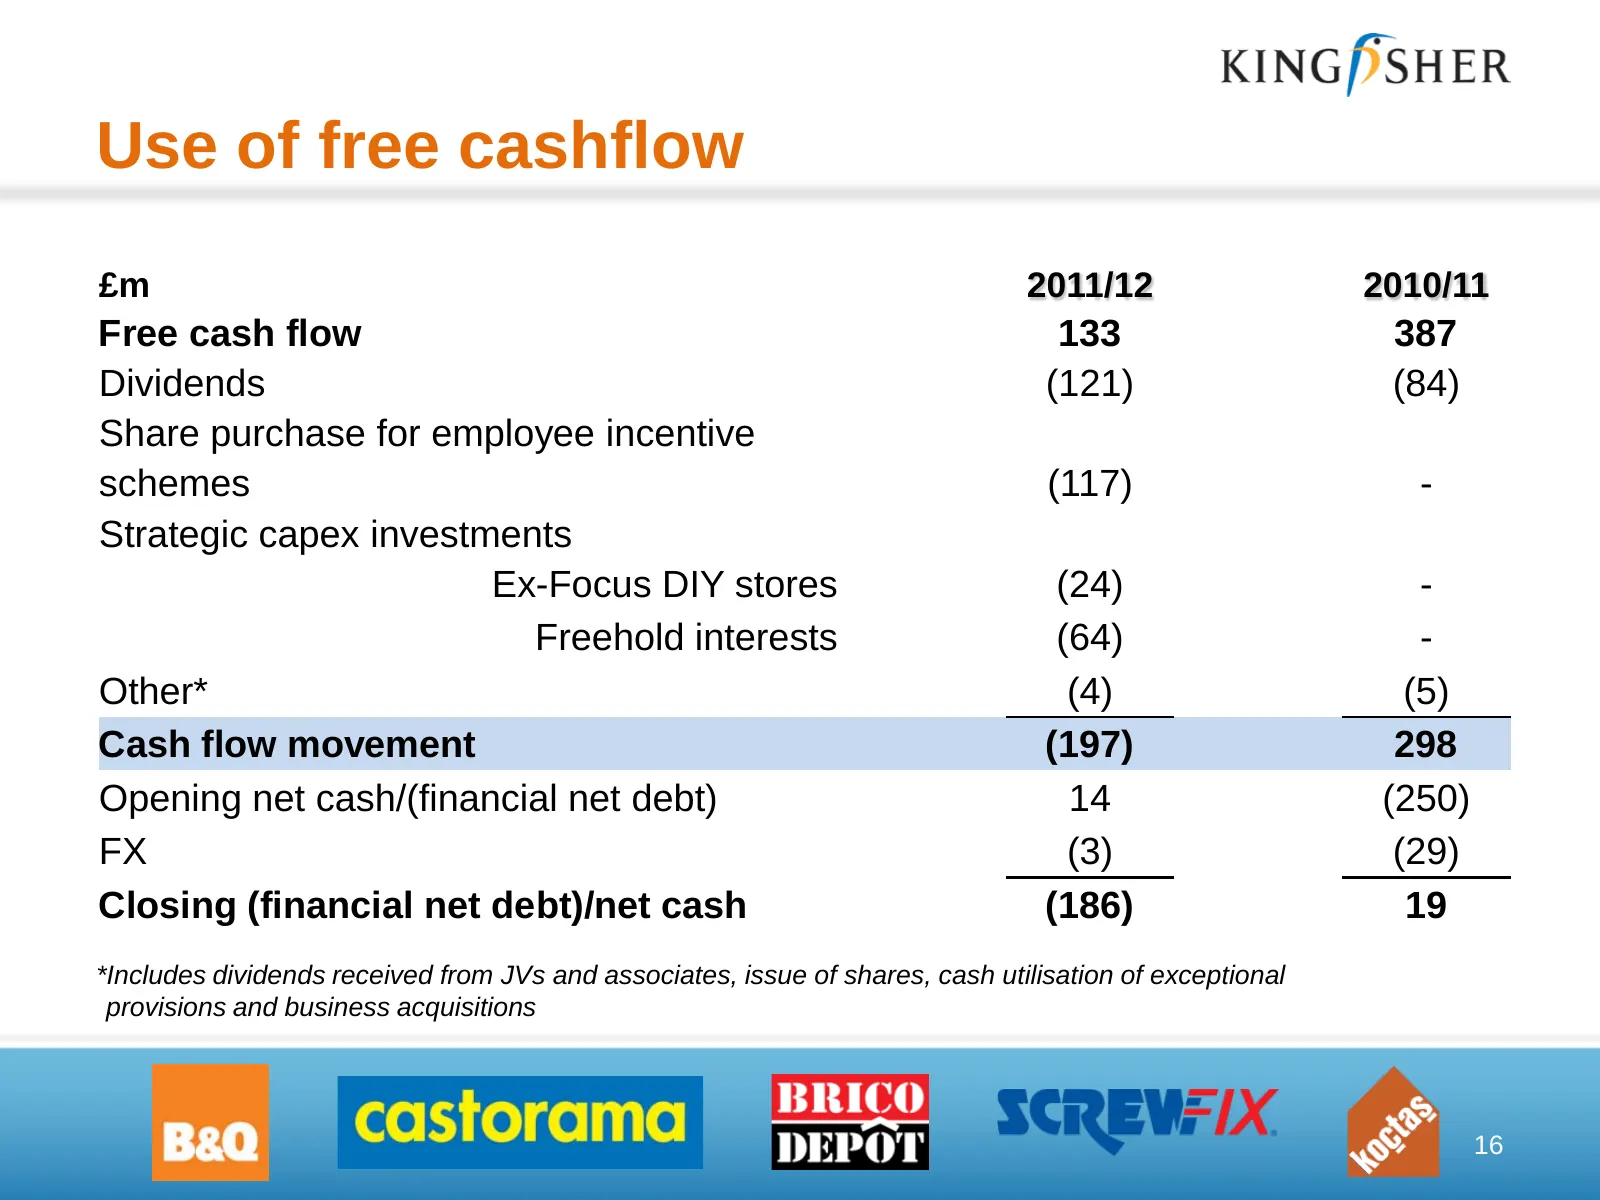
Use of free cashflow £m 2011/12 2010/11 Free cash flow 133 387 Dividends (121) (84) Share purchase for employee incentive schemes (117) - Strategic capex investments Ex-Focus DIY stores (24) - Freehold interests (64) - Other* (4) (5) Cash flow movement (197) 298 Opening net cash/(financial net debt)
Slide 17: Higher growth investment…
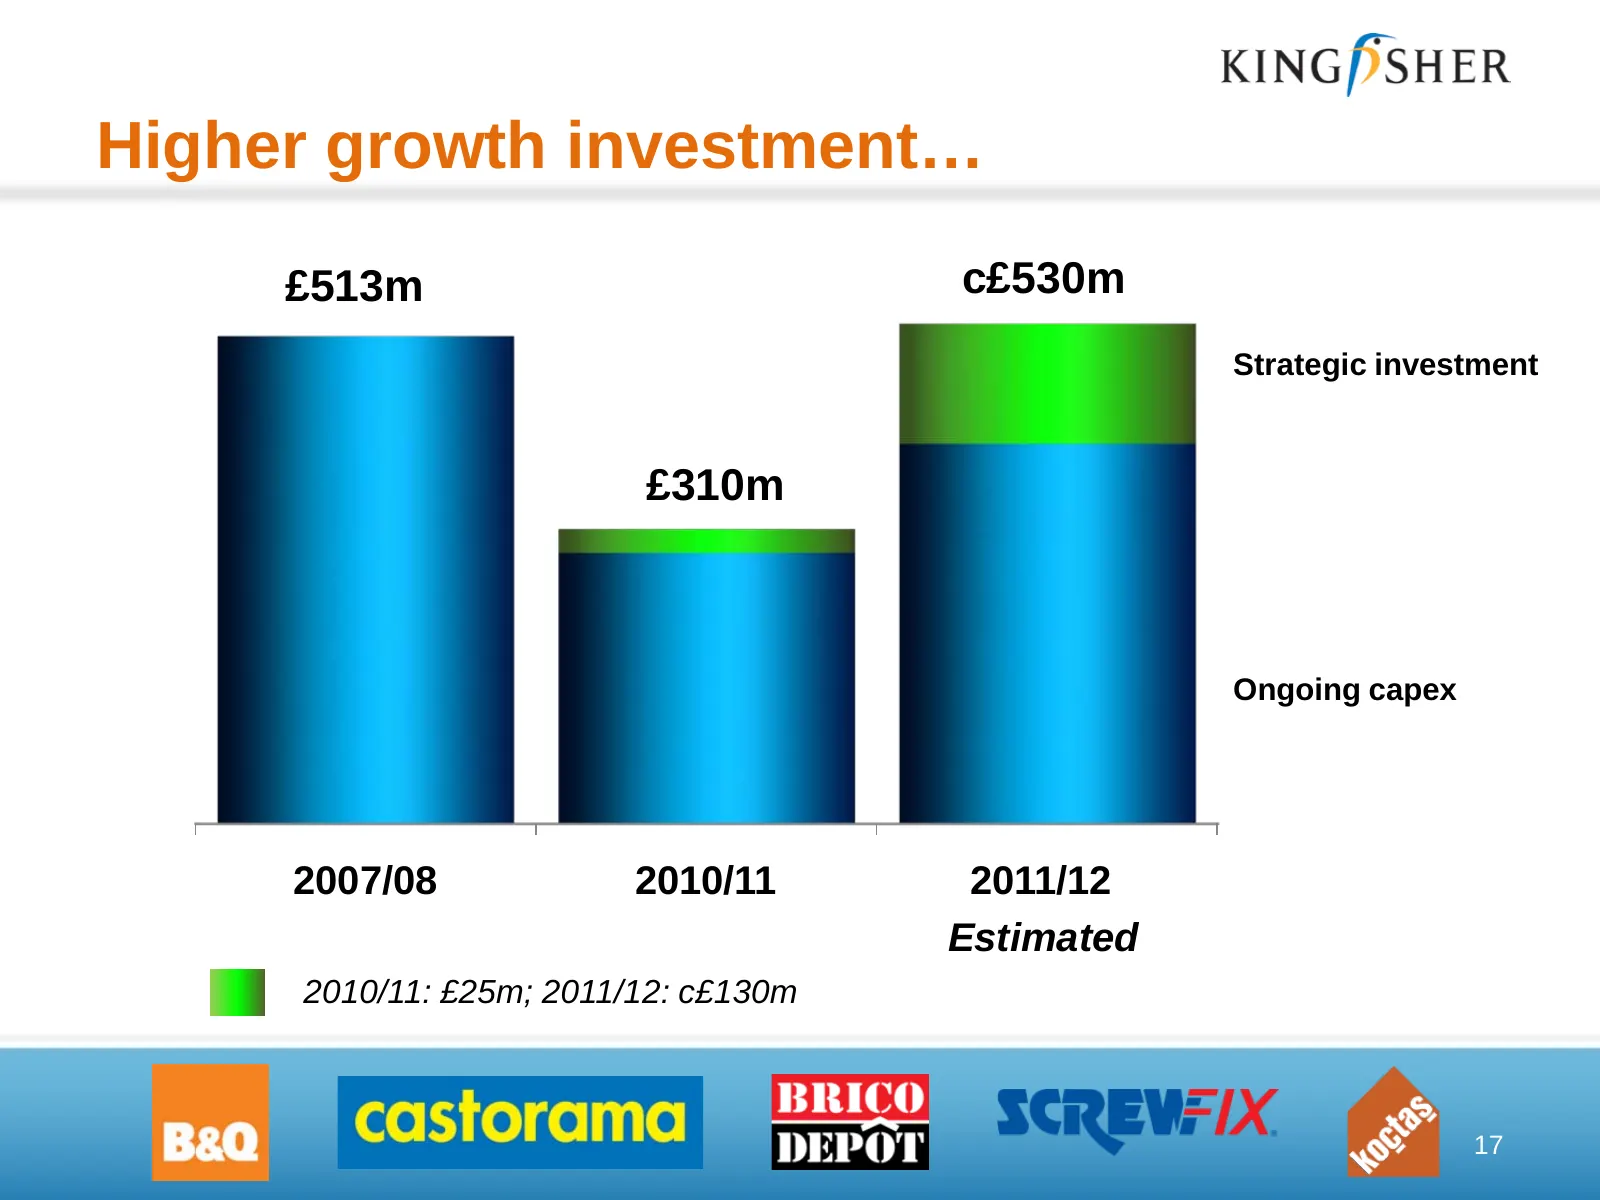
Higher growth investment… £513m c£530m Strategic investment £310m Ongoing capex 2007/08 2010/11 2011/12 Estimated 2010/11: £25m; 2011/12: c£130m 17
Slide 18: Summary
Summary • Profit growth in all divisions • Adjusted basic EPS up 27% • Continued investing in development and growth • Proactive use of balance sheet strength • Dividend growth 18
Slide 19: Euan Sutherland
Euan Sutherland CEO, Kingfisher UK & Ireland, Kingfisher Brands Network 19
Slide 20: Common Range
KING/SHER Common Range BRICO ————— DEPOT
Slide 21: Attractive market
Attractive market • Big and growing – Over 500 million homes, £120 billion market* • Scale advantage – Customer tastes converging across markets – Few known manufacturer brands • Defensible – Customers demand choice and advice – Multi-channel specialist preferable to generalist or digital pure play
Slide 22: A key element of our strategy
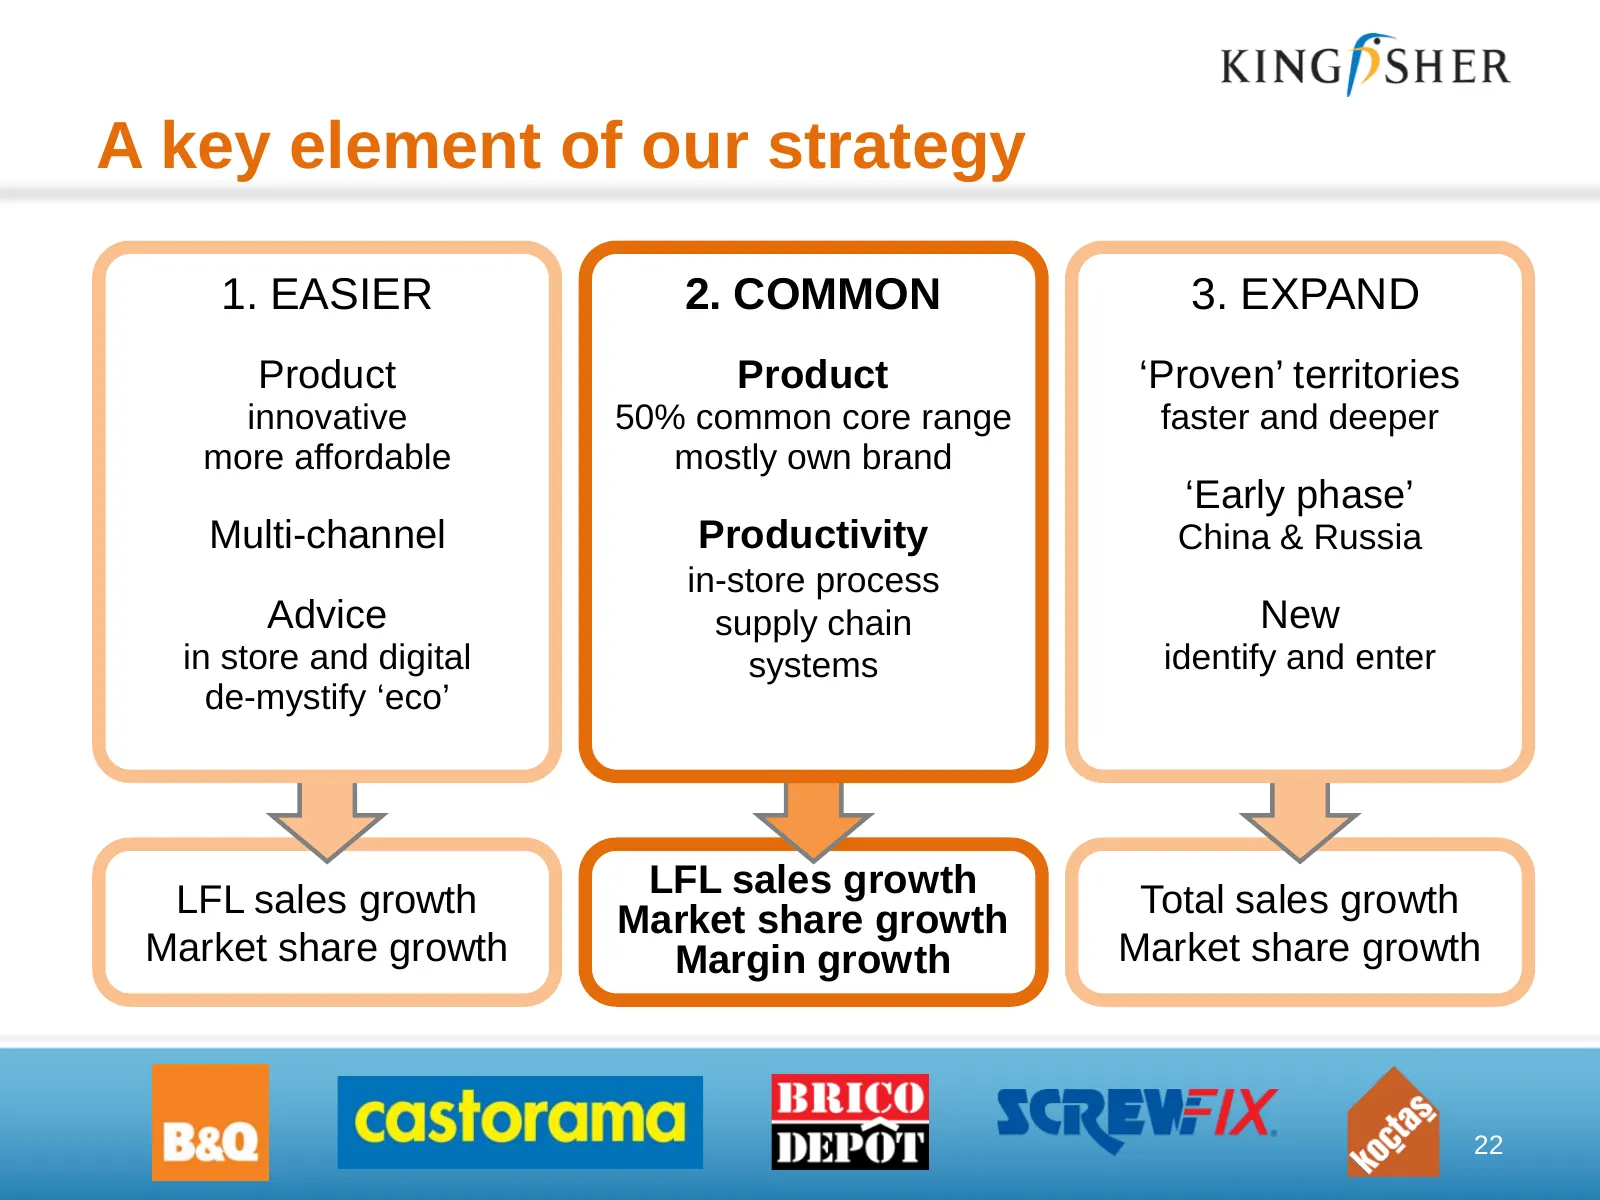
A key element of our strategy 1. EASIER 2. COMMON 3. EXPAND Product Product ‘Proven’ territories innovative 50% common core range faster and deeper more affordable mostly own brand ‘Early phase’ Multi-channel Productivity China & Russia in-store process Advice supply chain New in store and digital s
Slide 23: A best in class common range will drive leadership and performance
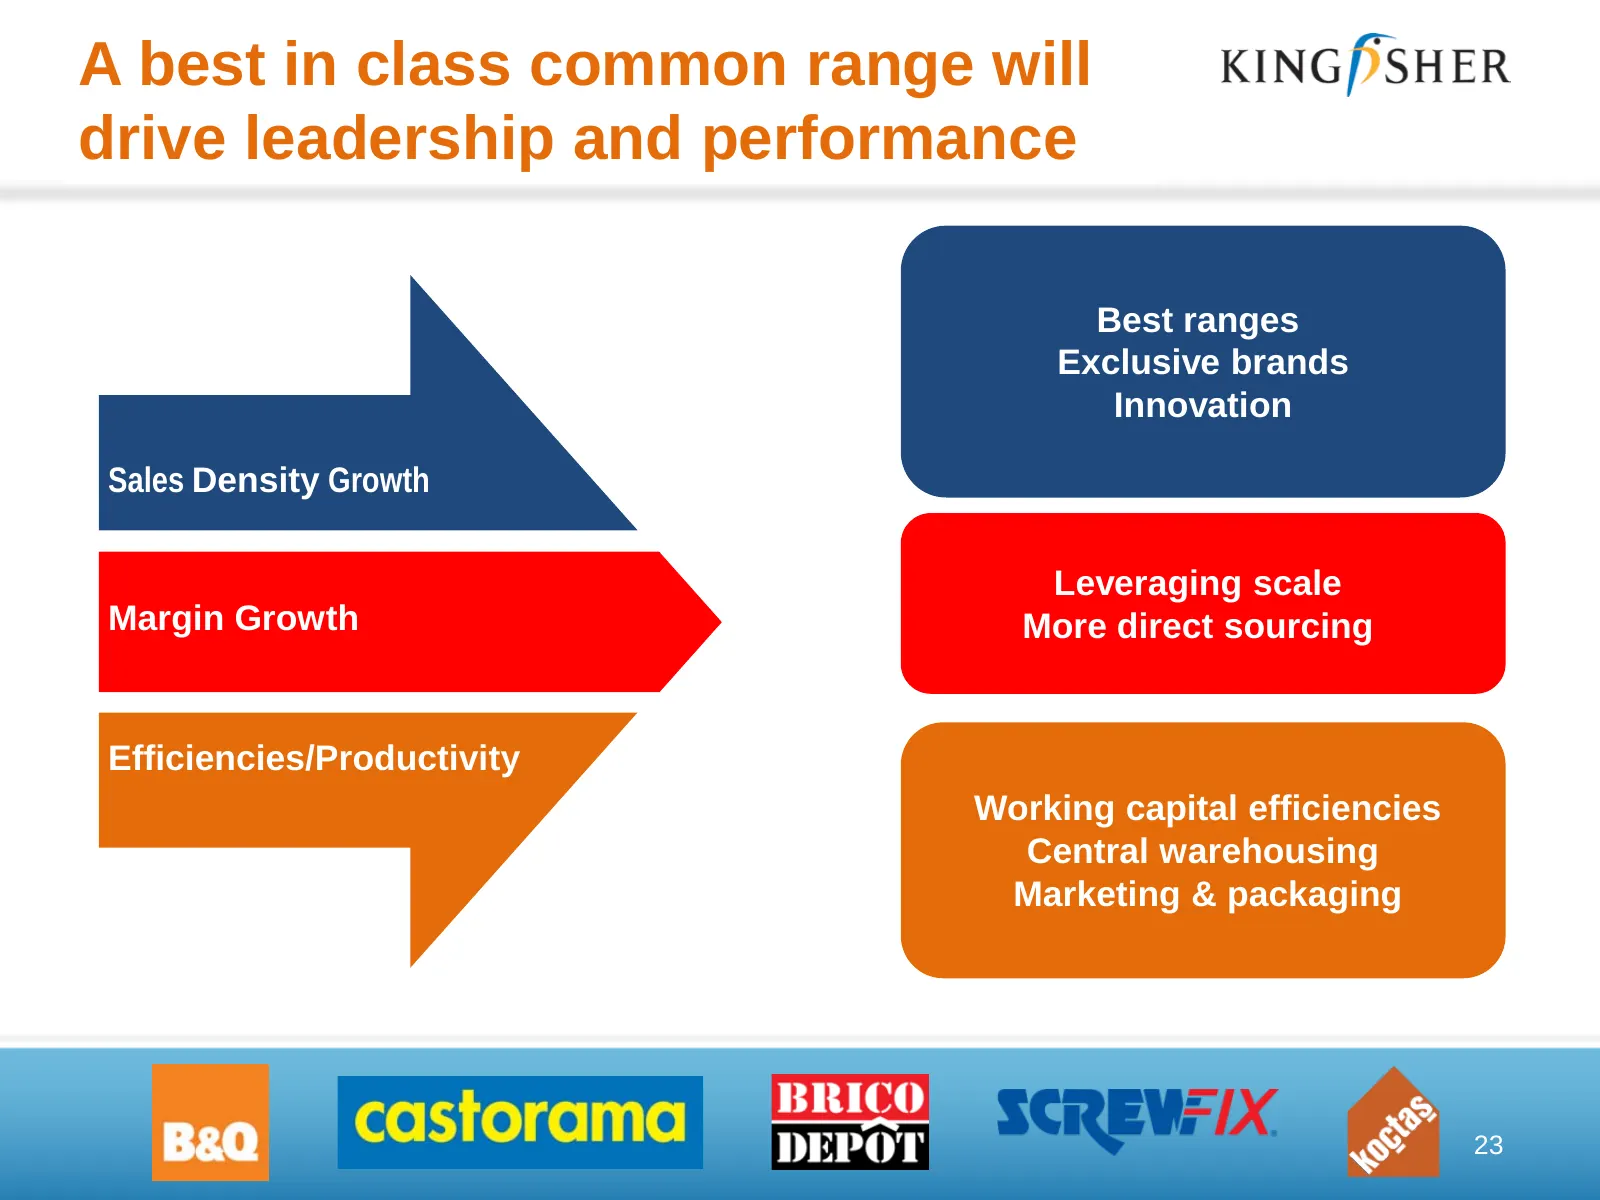
A best in class common range will drive leadership and performance Best ranges Exclusive brands Innovation Sales Density Growth Leveraging scale Margin Growth More direct sourcing Efficiencies/Productivity Working capital efficiencies Central warehousing Marketing & packaging 23
Slide 24: The time is right…
KING/SHER The time ts right... BRICO ————— DEPOT
Slide 25: Common range – key enablers
Common range – key enablers 1. Excellent global sourcing capability 2. New cross-group network approach • not just a central ‘push down’ 3. Group-wide common own branding • newly introduced ‘Superbrands’ 4. In-house innovation 25
Slide 26: Excellent global sourcing capability
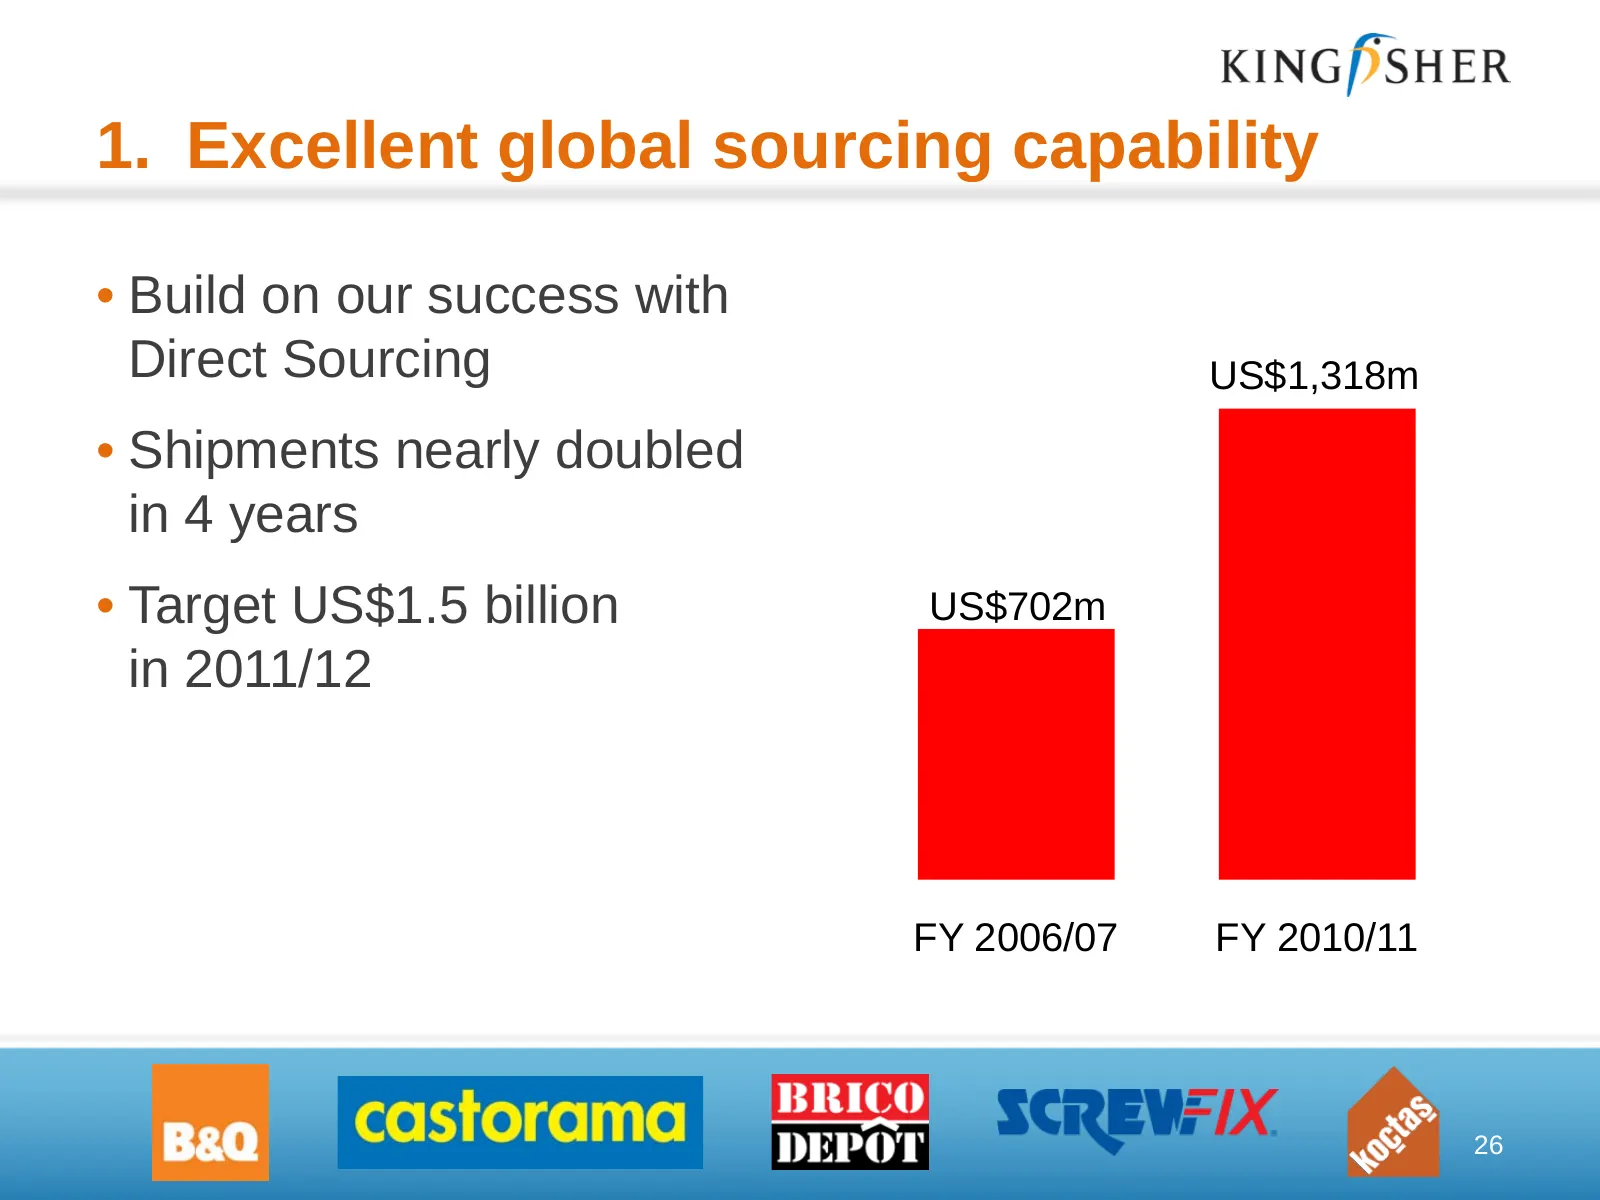
1. Excellent global sourcing capability • Build on our success with Direct Sourcing US$1,318m • Shipments nearly doubled in 4 years • Target US$1.5 billion US$702m in 2011/12 FY 2006/07 FY 2010/11 26
Slide 27: Excellent global sourcing capability: vendors
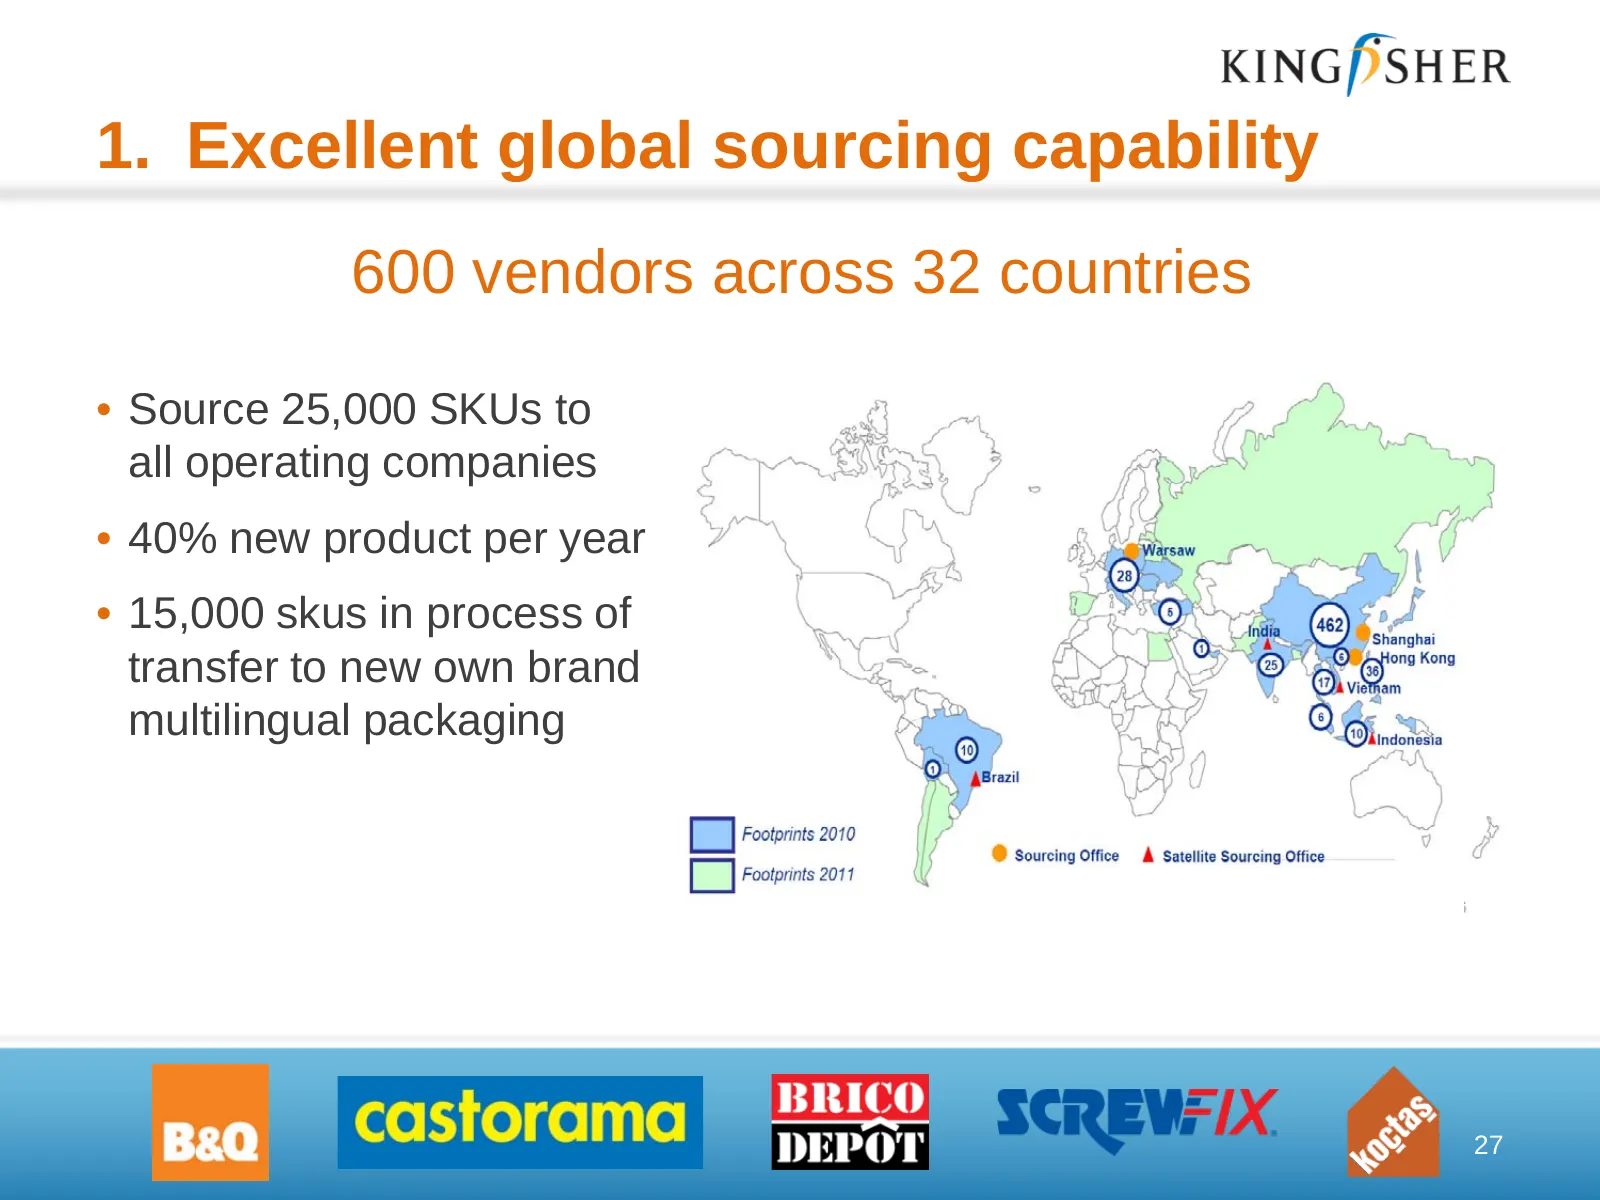
1. Excellent global sourcing capability 600 vendors across 32 countries • Source 25,000 SKUs to all operating companies • 40% new product per year • 15,000 skus in process of transfer to new own brand multilingual packaging 27
Slide 28: Excellent global sourcing capability: printed bamboo
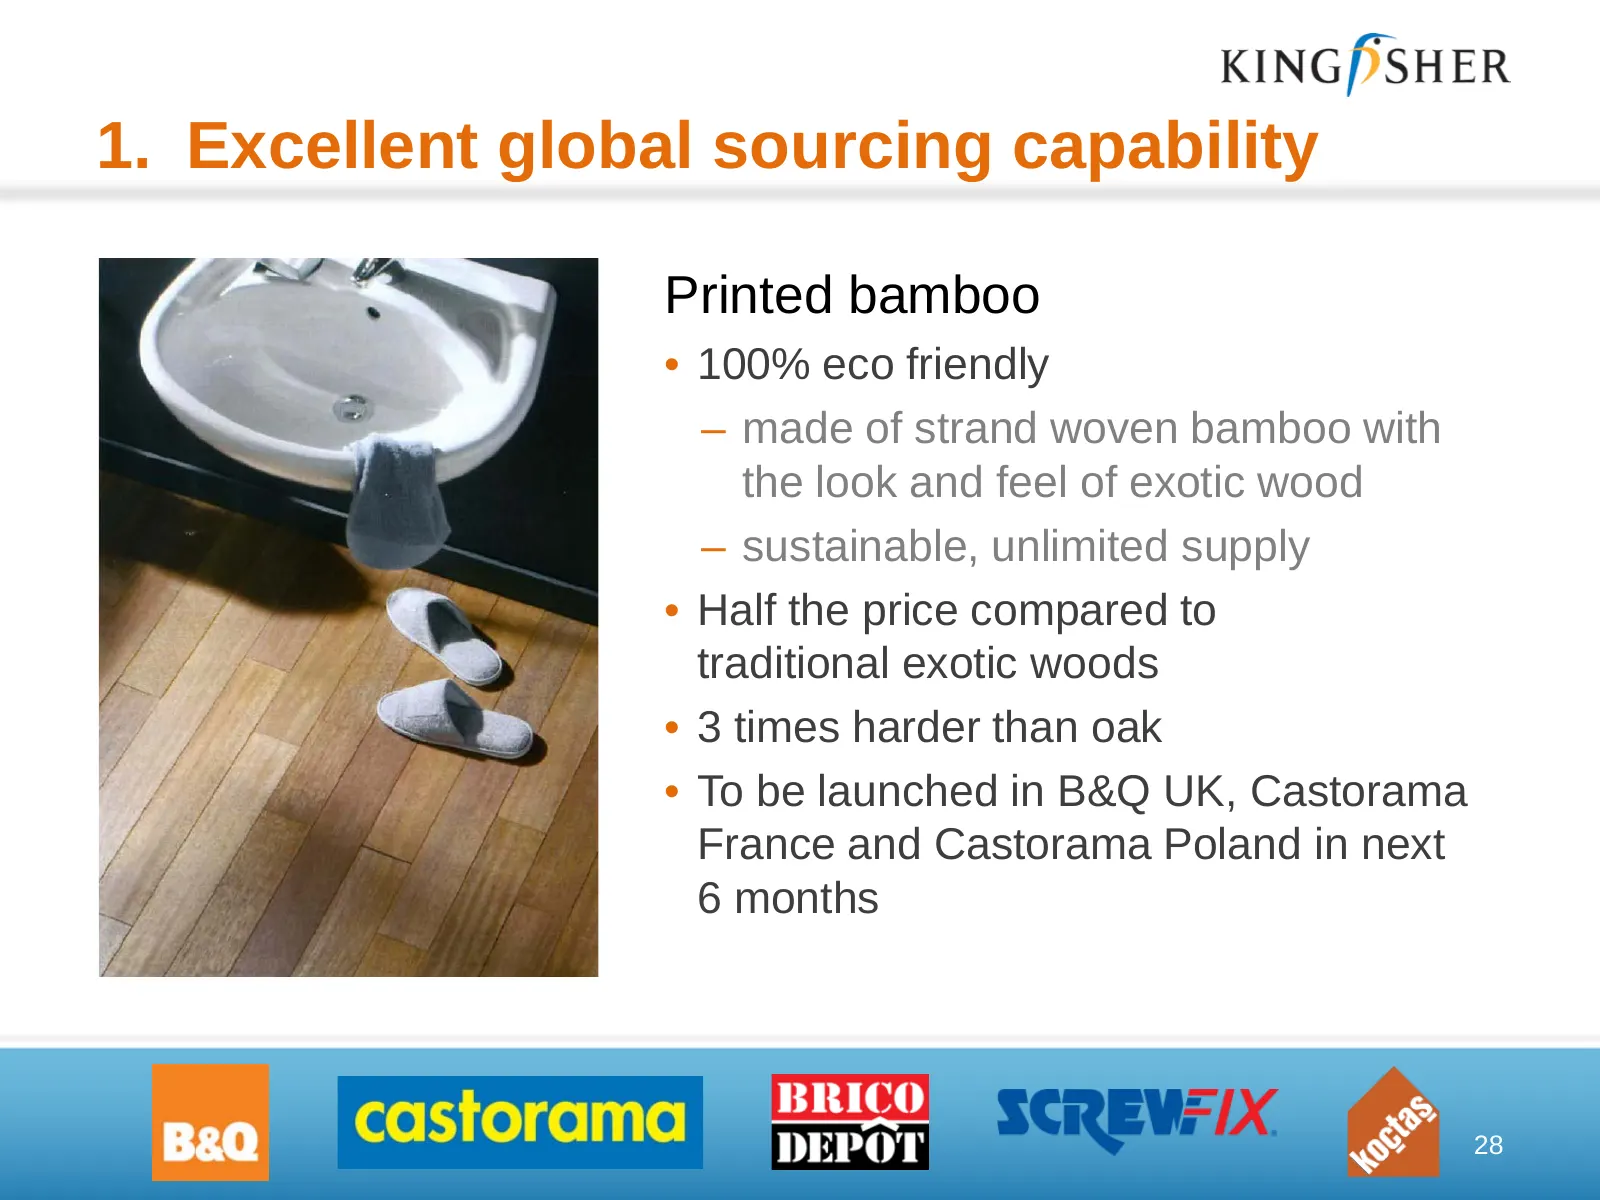
1. Excellent global sourcing capability Printed bamboo • 100% eco friendly – made of strand woven bamboo with the look and feel of exotic wood – sustainable, unlimited supply • Half the price compared to traditional exotic woods • 3 times harder than oak • To be launched in B&Q UK, Castorama France
Slide 29: New cross-group network approach
2. New cross-group network approach Group Executive - clear mandate 29
Slide 30: New cross-group network approach
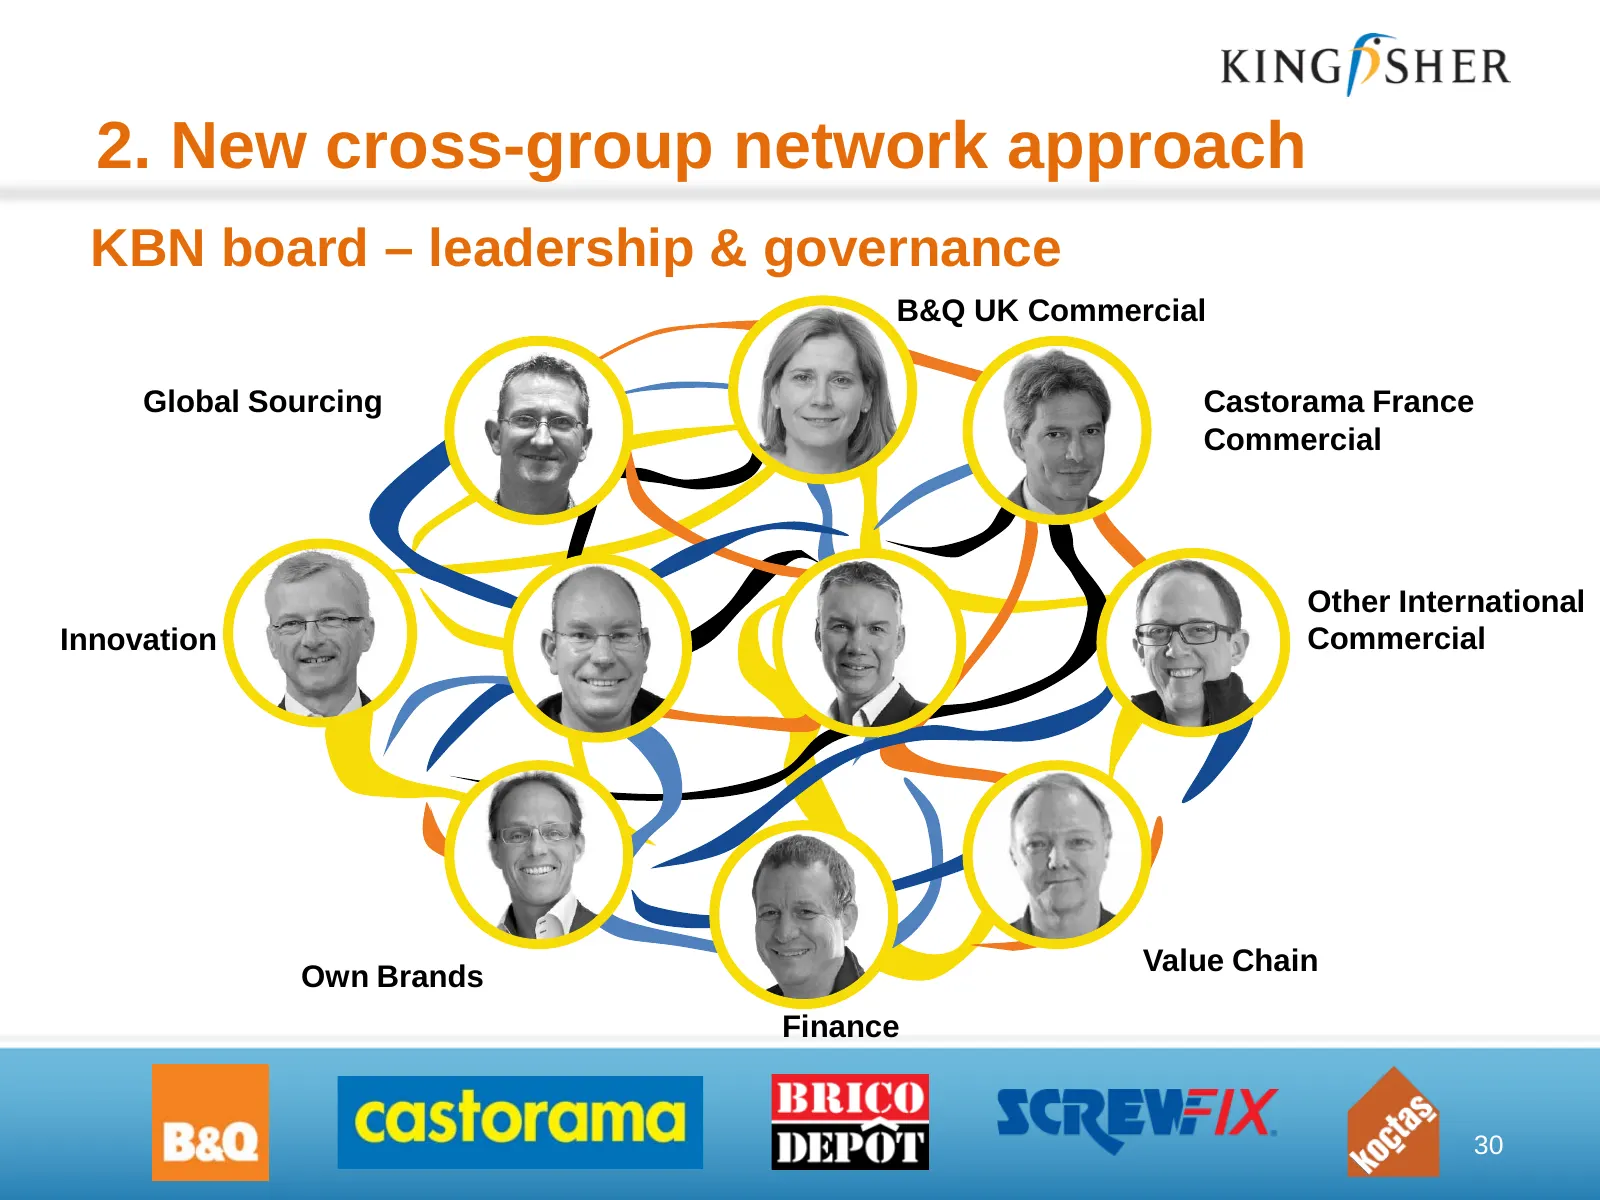
2. New cross-group network approach KBN board – leadership & governance B&Q UK Commercial Global Sourcing Castorama France Commercial Other International Innovation Commercial Value Chain Own Brands Finance 30
Slide 31: New cross-group network approach
2. New cross-group network approach The wider KBN network – making it happen on-shelf 600+ commercial colleagues across the Group 31
Slide 32: New cross-group network approach
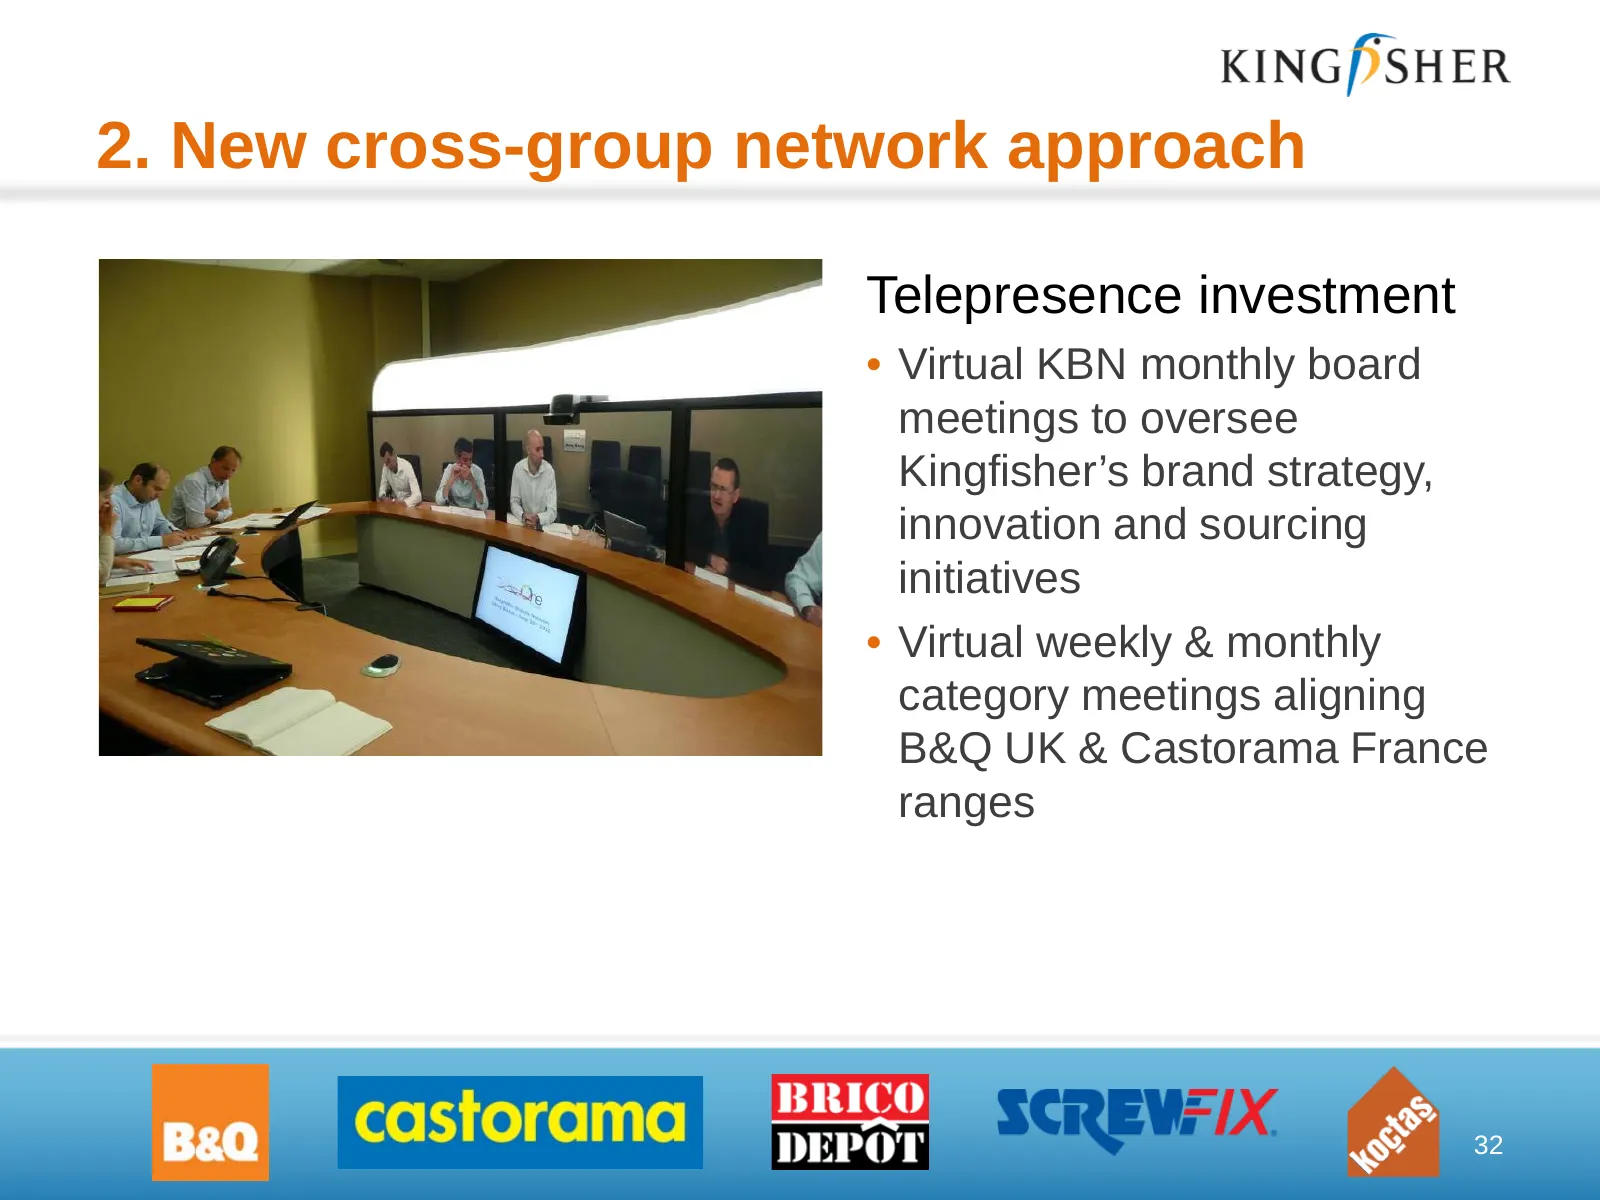
2. New cross-group network approach Telepresence investment • Virtual KBN monthly board meetings to oversee Kingfisher’s brand strategy, innovation and sourcing initiatives • Virtual weekly & monthly category meetings aligning B&Q UK & Castorama France ranges 32
Slide 33: New cross-group network approach
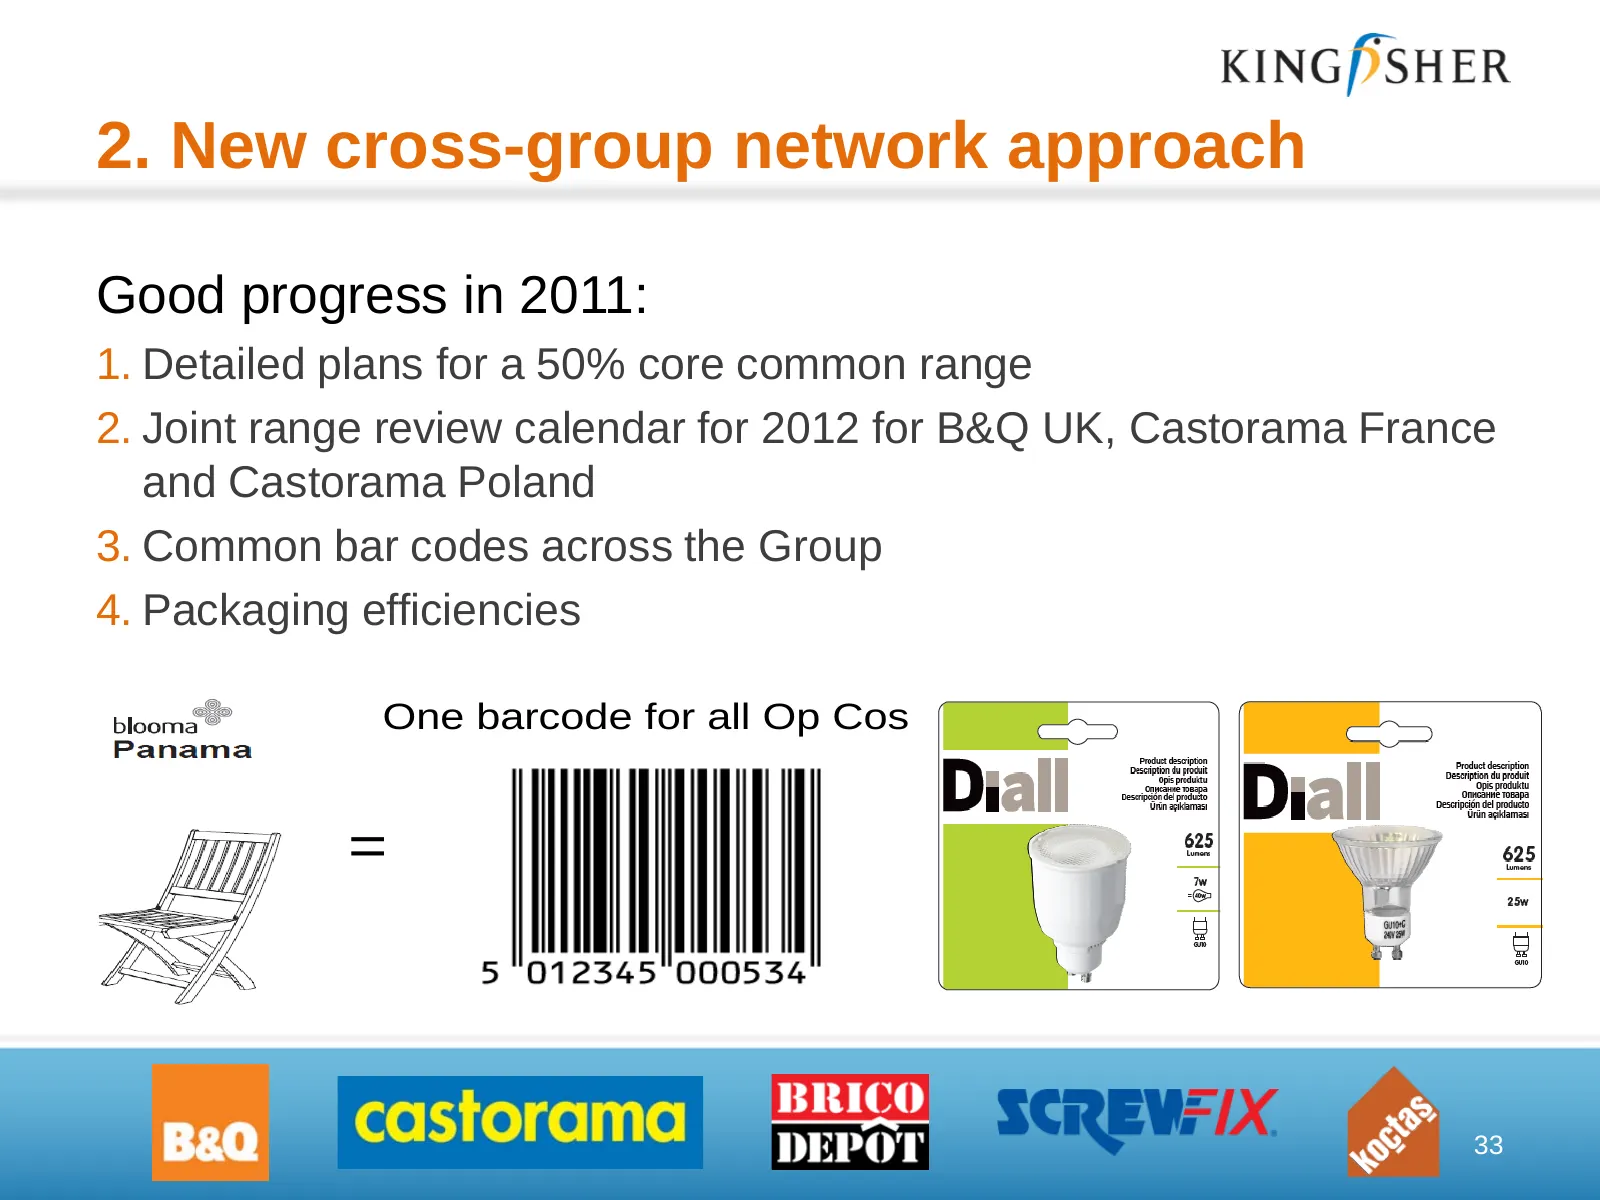
2. New cross-group network approach Good progress in 2011: 1. Detailed plans for a 50% core common range 2. Joint range review calendar for 2012 for B&Q UK, Castorama France and Castorama Poland 3. Common bar codes across the Group 4. Packaging efficiencies One barcode for all Op Cos = 33
Slide 34: Group-wide common own branding
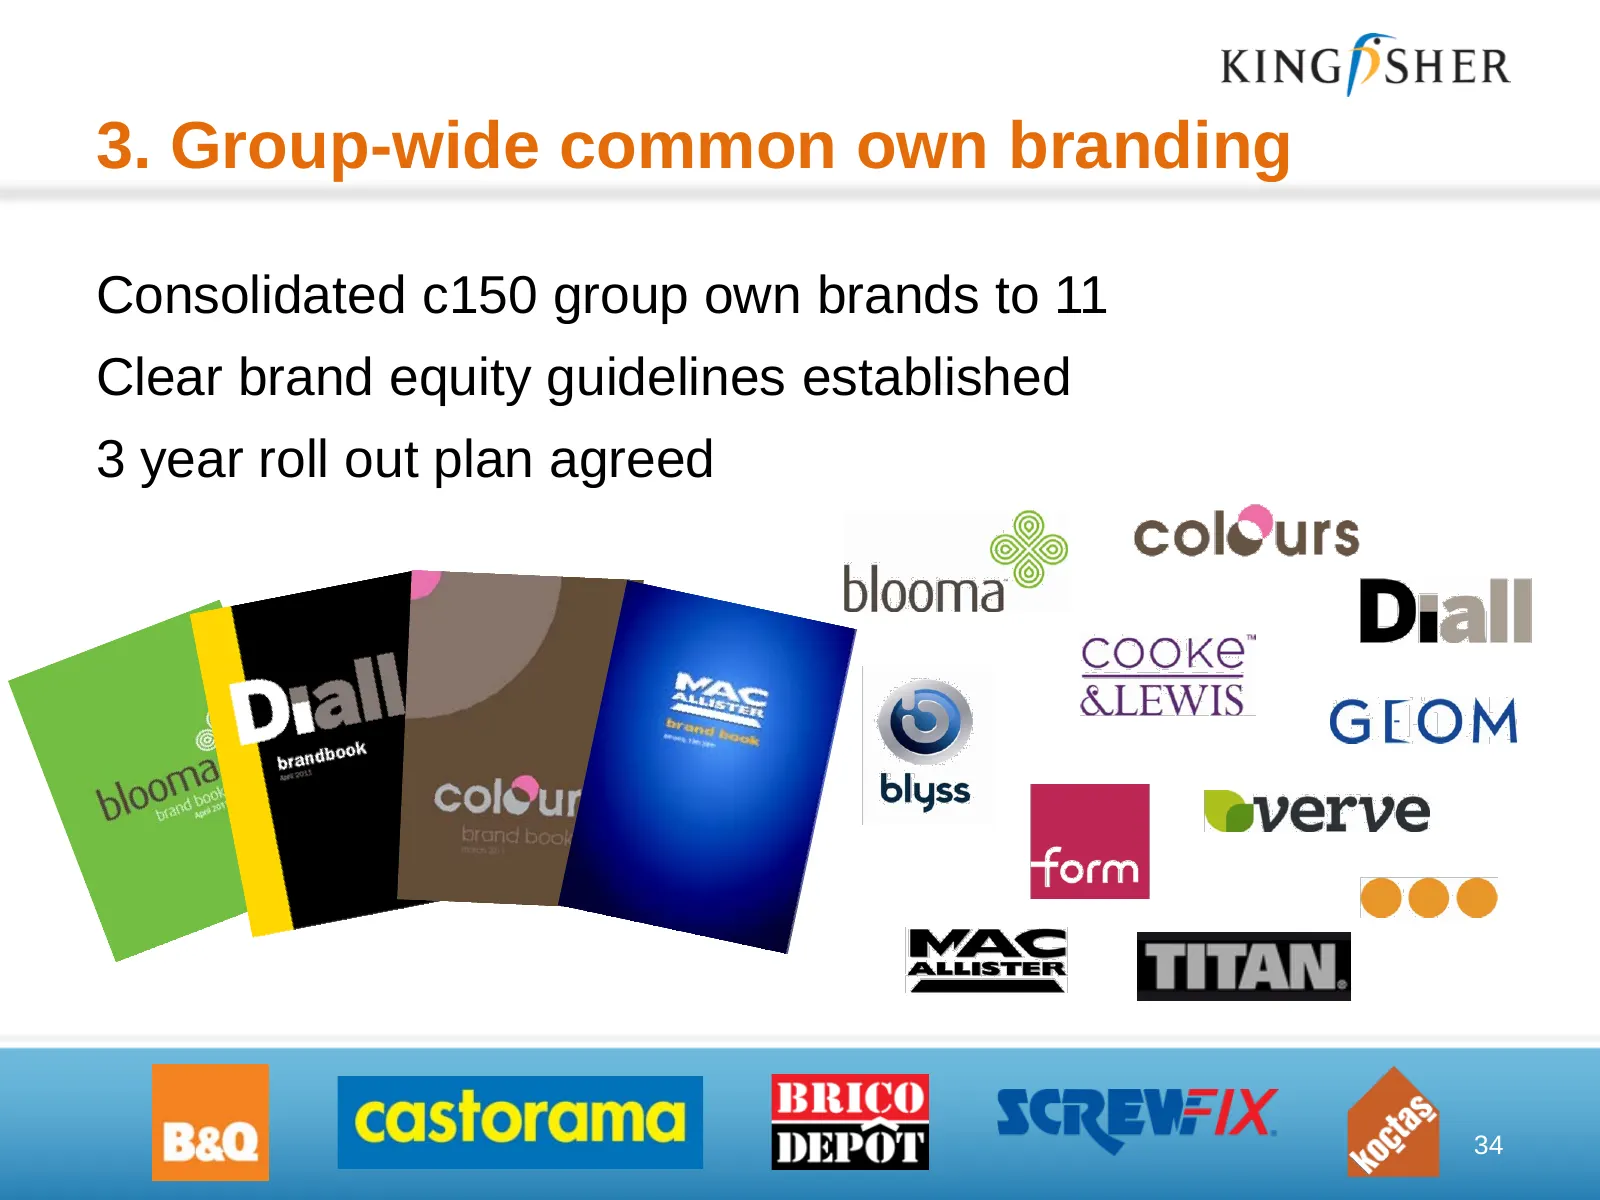
3. Group-wide common own branding Consolidated c150 group own brands to 11 Clear brand equity guidelines established 3 year roll out plan agreed 34
Slide 35: In-house innovation
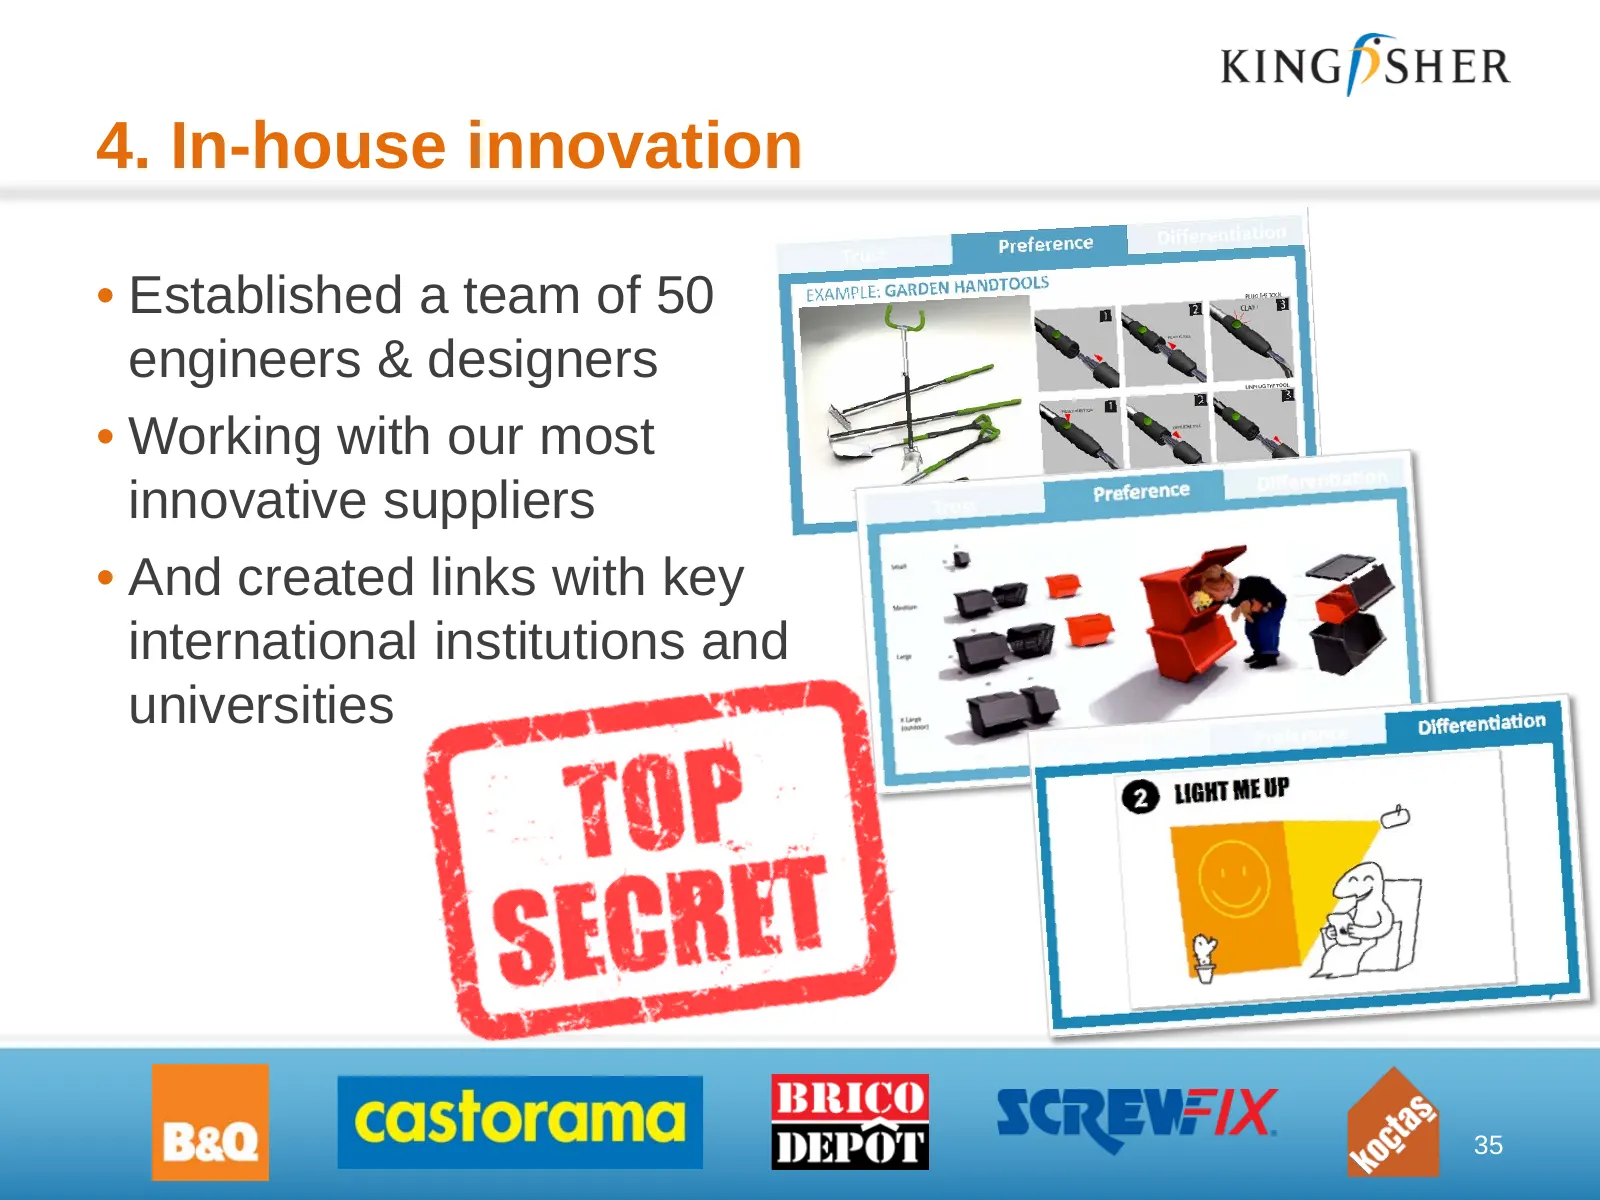
4. In-house innovation • Established a team of 50 engineers & designers • Working with our most innovative suppliers • And created links with key international institutions and universities 35
Slide 36: It's starting to work…
KING/SHER It’s starting to work... BRICO ————— DEPOT
Slide 37: . . . in stores in 2011
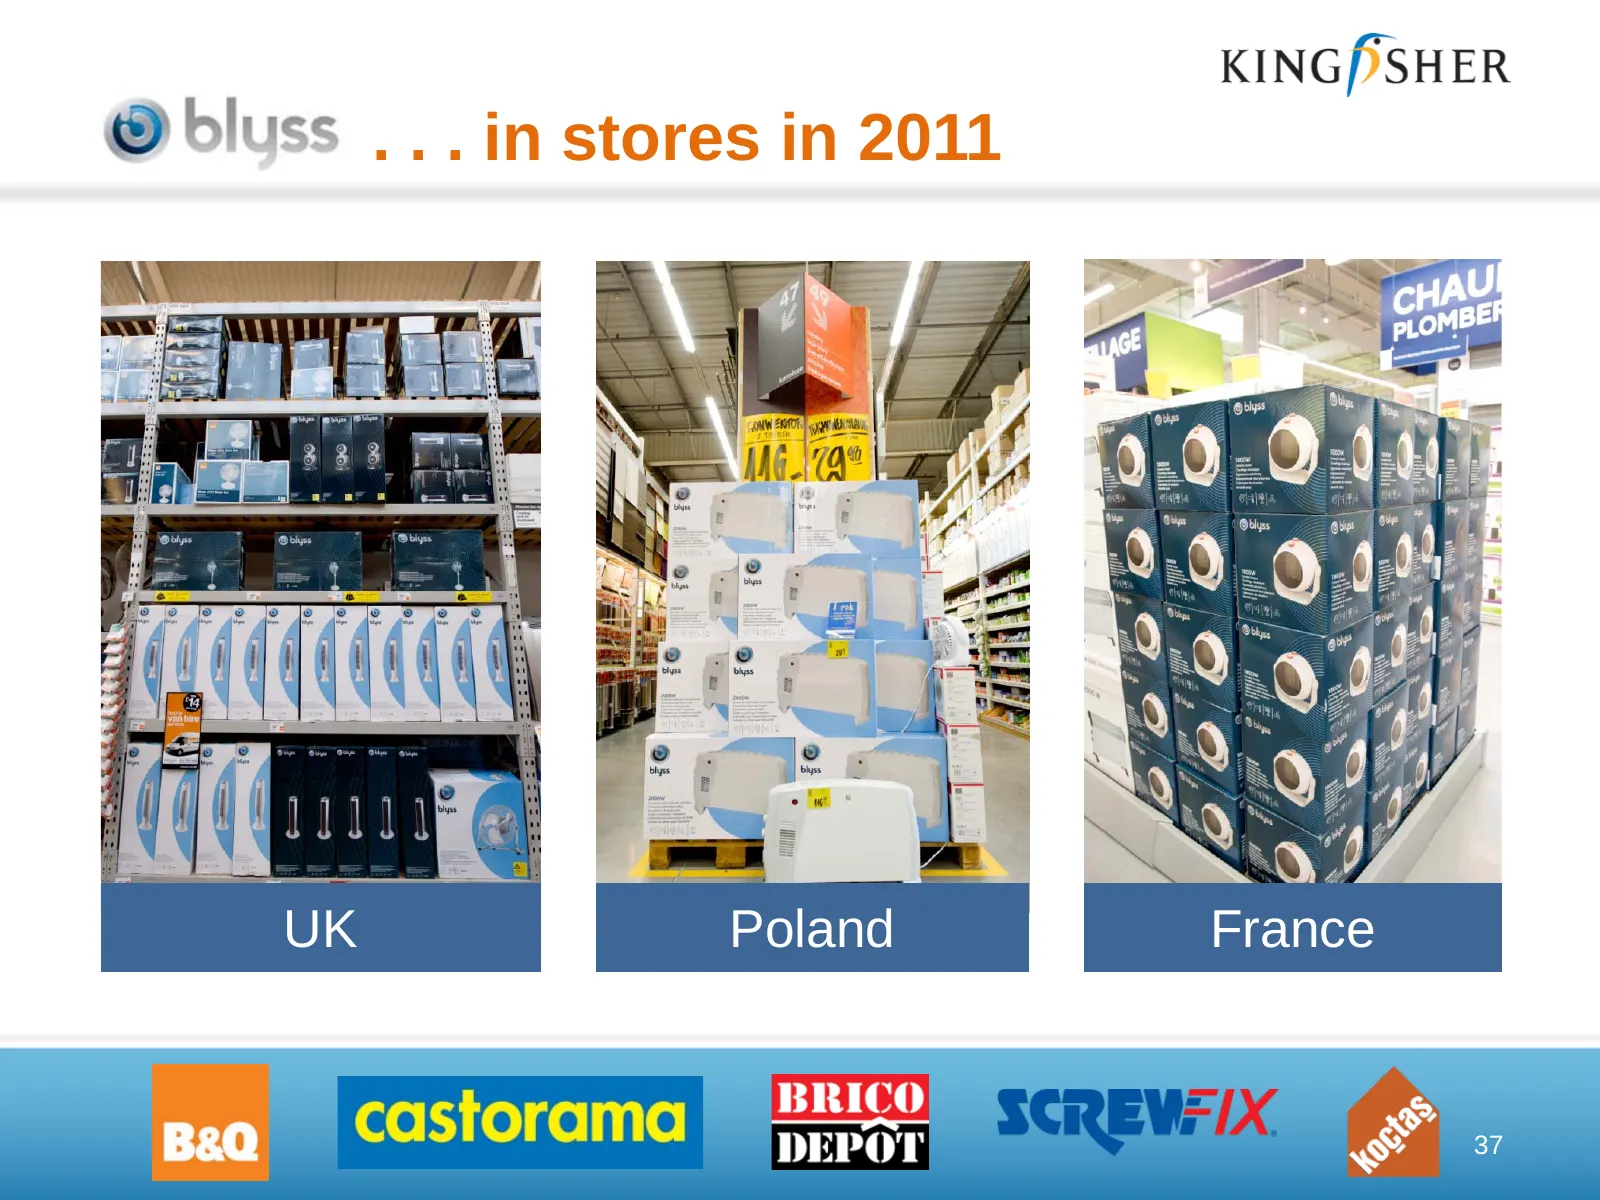
. . . in stores in 2011 UK Poland France 37
Slide 38: . . . in stores in 2011
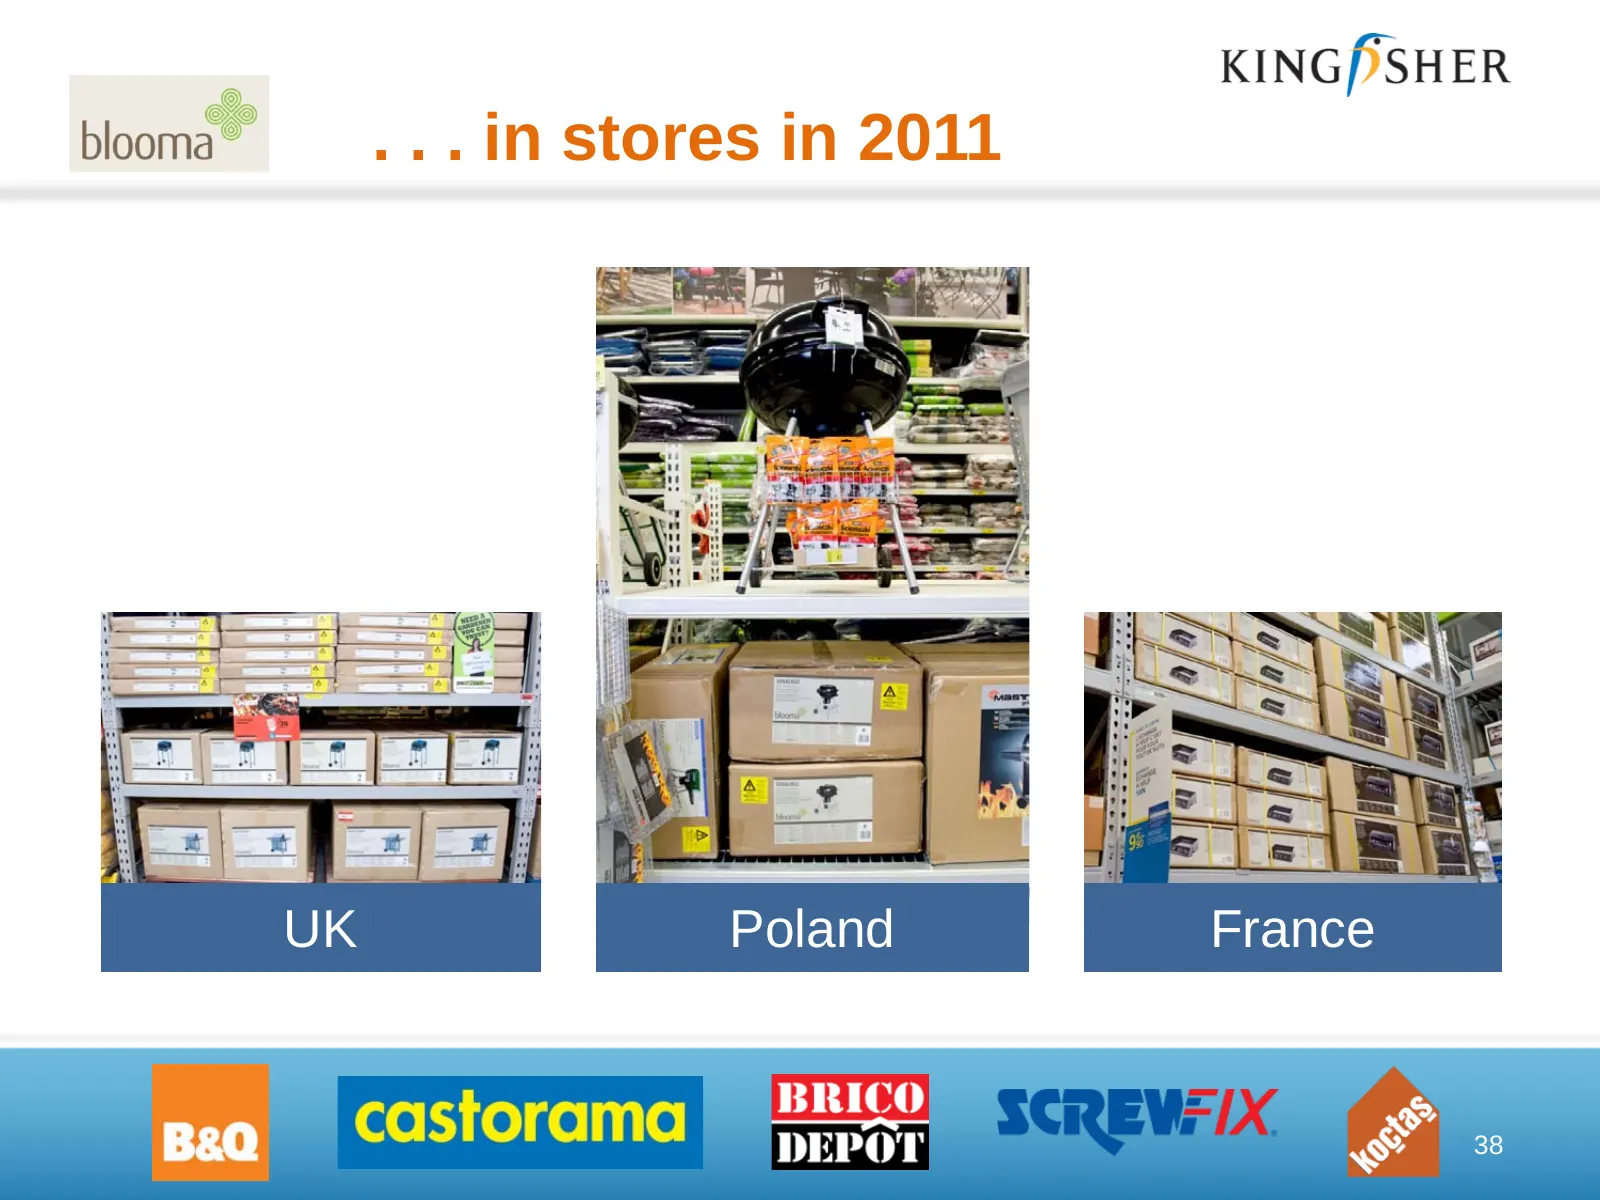
. . . in stores in 2011 UK Poland France 38
Slide 39: . . . in stores in 2011
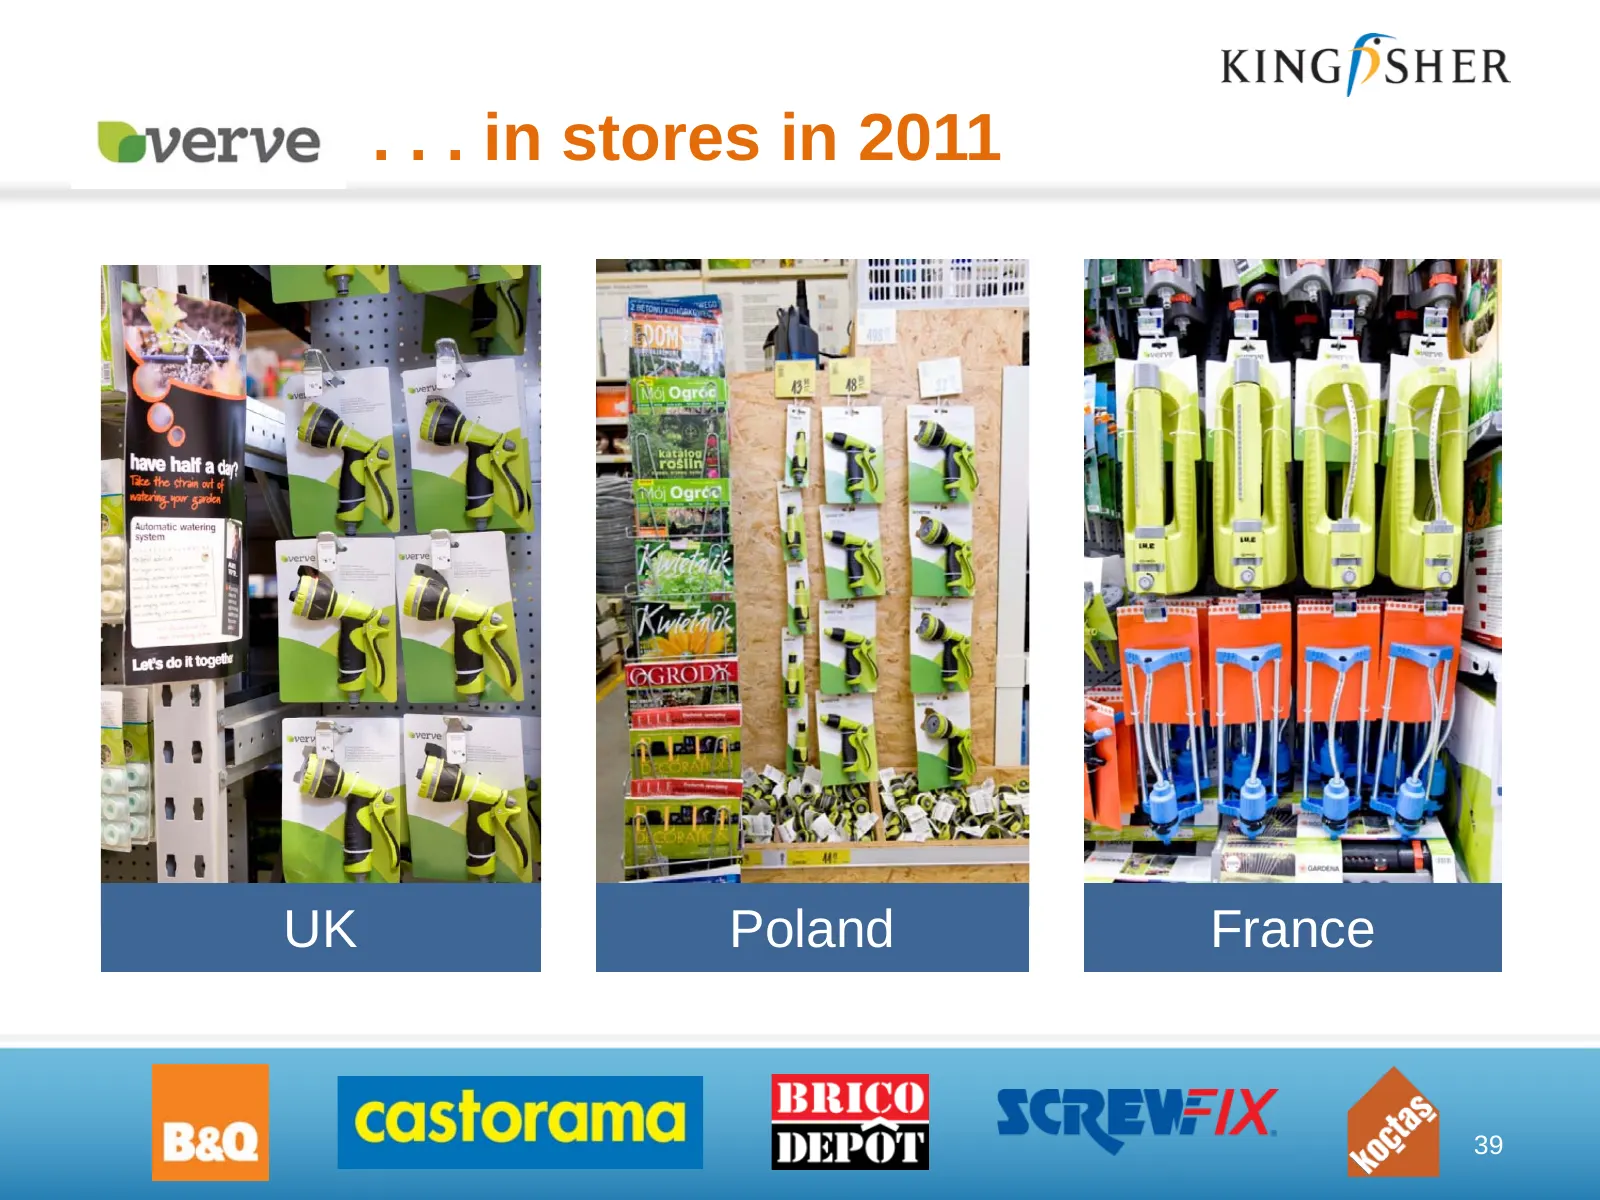
. . . in stores in 2011 UK Poland France 39
Slide 40: . . . in stores in 2011
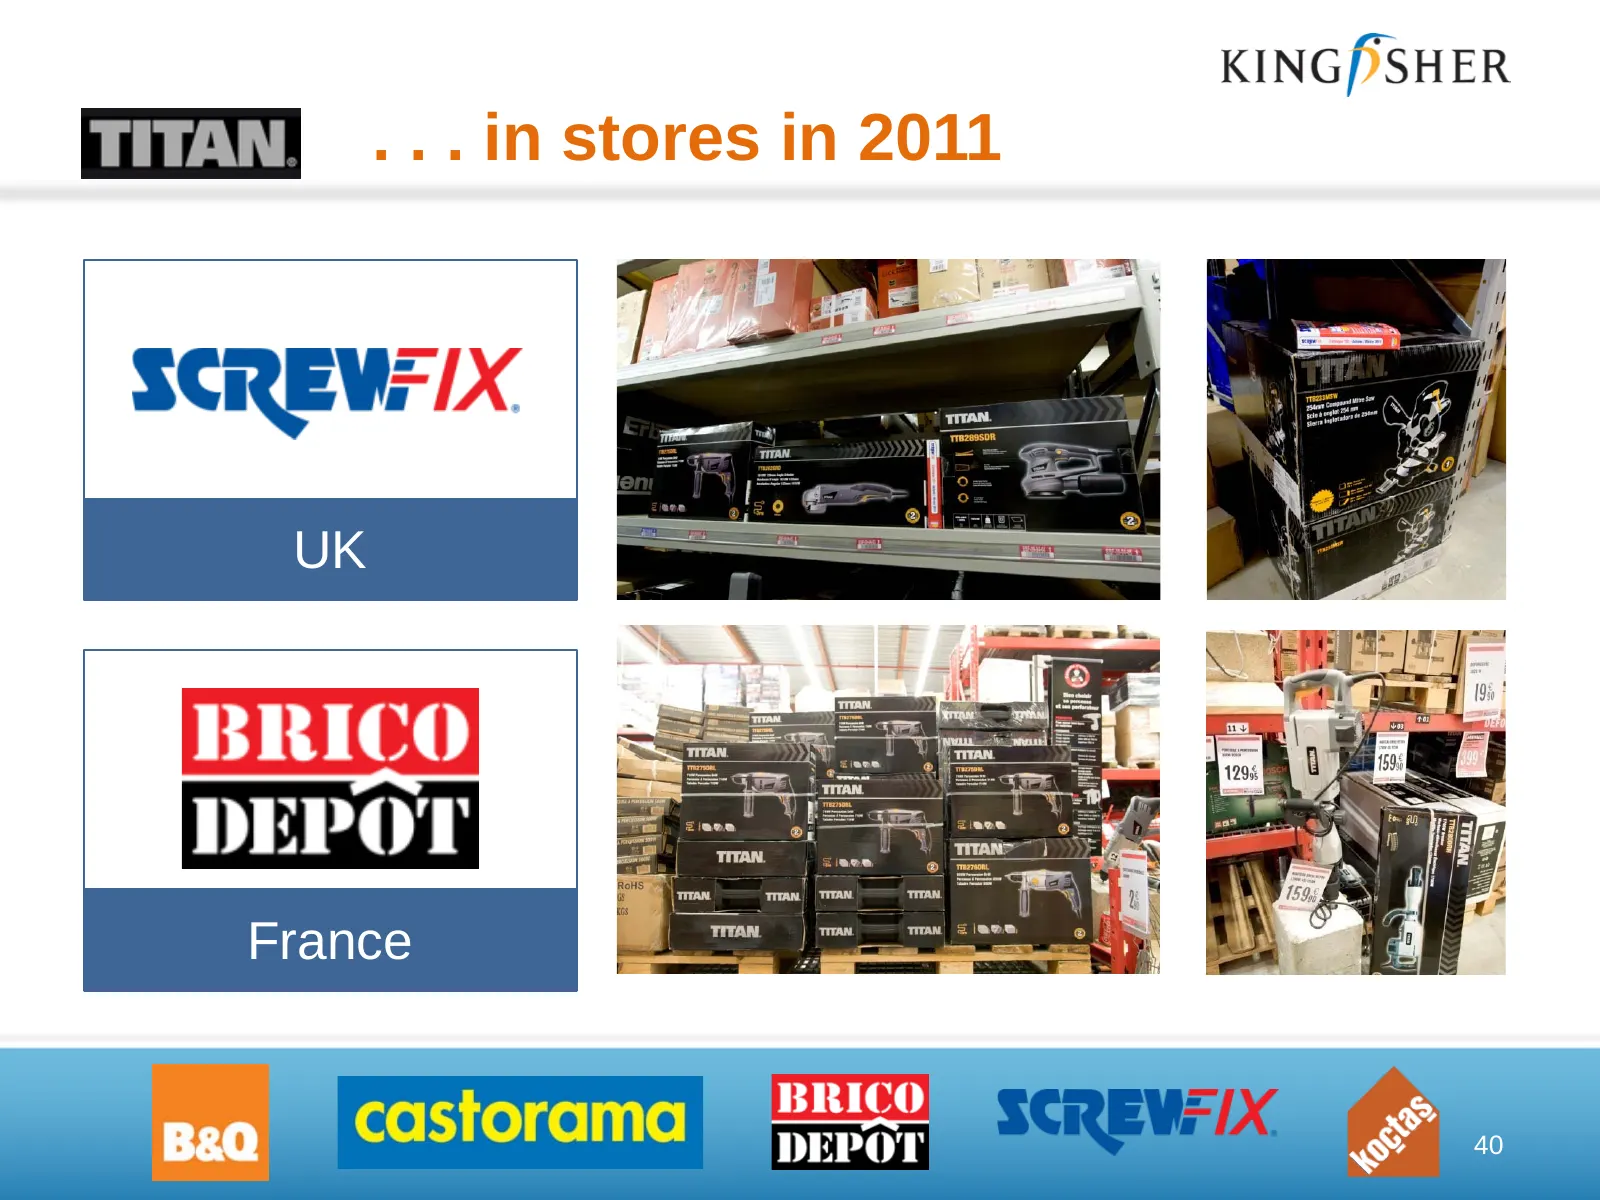
. . . in stores in 2011 UK UK France UK 40
Slide 41: Common range – Summary
Common range – Summary 1. The time is right for a Kingfisher common range 2. Key enablers are in place • excellent global sourcing capability • new cross-group network approach • group-wide common own branding • in-house innovation 3. Encouraging early start 41
Slide 42: Ian Cheshire, Group Chief Executive
Ian Cheshire Group Chief Executive 42
Slide 43: Summary & Outlook
Summary & Outlook • Strong results in difficult times • Self-help driving our performance • Good progress with ‘Delivering Value’ • Transition to next phase ‘Creating the Leader’ well underway • Outlook – not expecting much help from our markets – confident we can continue to outperform 43
Slide 44: Cautionary note regarding forward-looking statements
Cautionary note regarding forward-looking statements This document contains forward-looking statements and is therefore subject to risks, assumptions and uncertainties that could cause actual results to differ materially from those expressed or implied because they relate to future events. These for
Slide 45: Questions
KING/SHER Questions BRICO ————— DEPOT
Slide 46: Appendices
KING/SHER Appendices BRICO ————— DEPOT
Slide 47: Statutory financial reconciliation
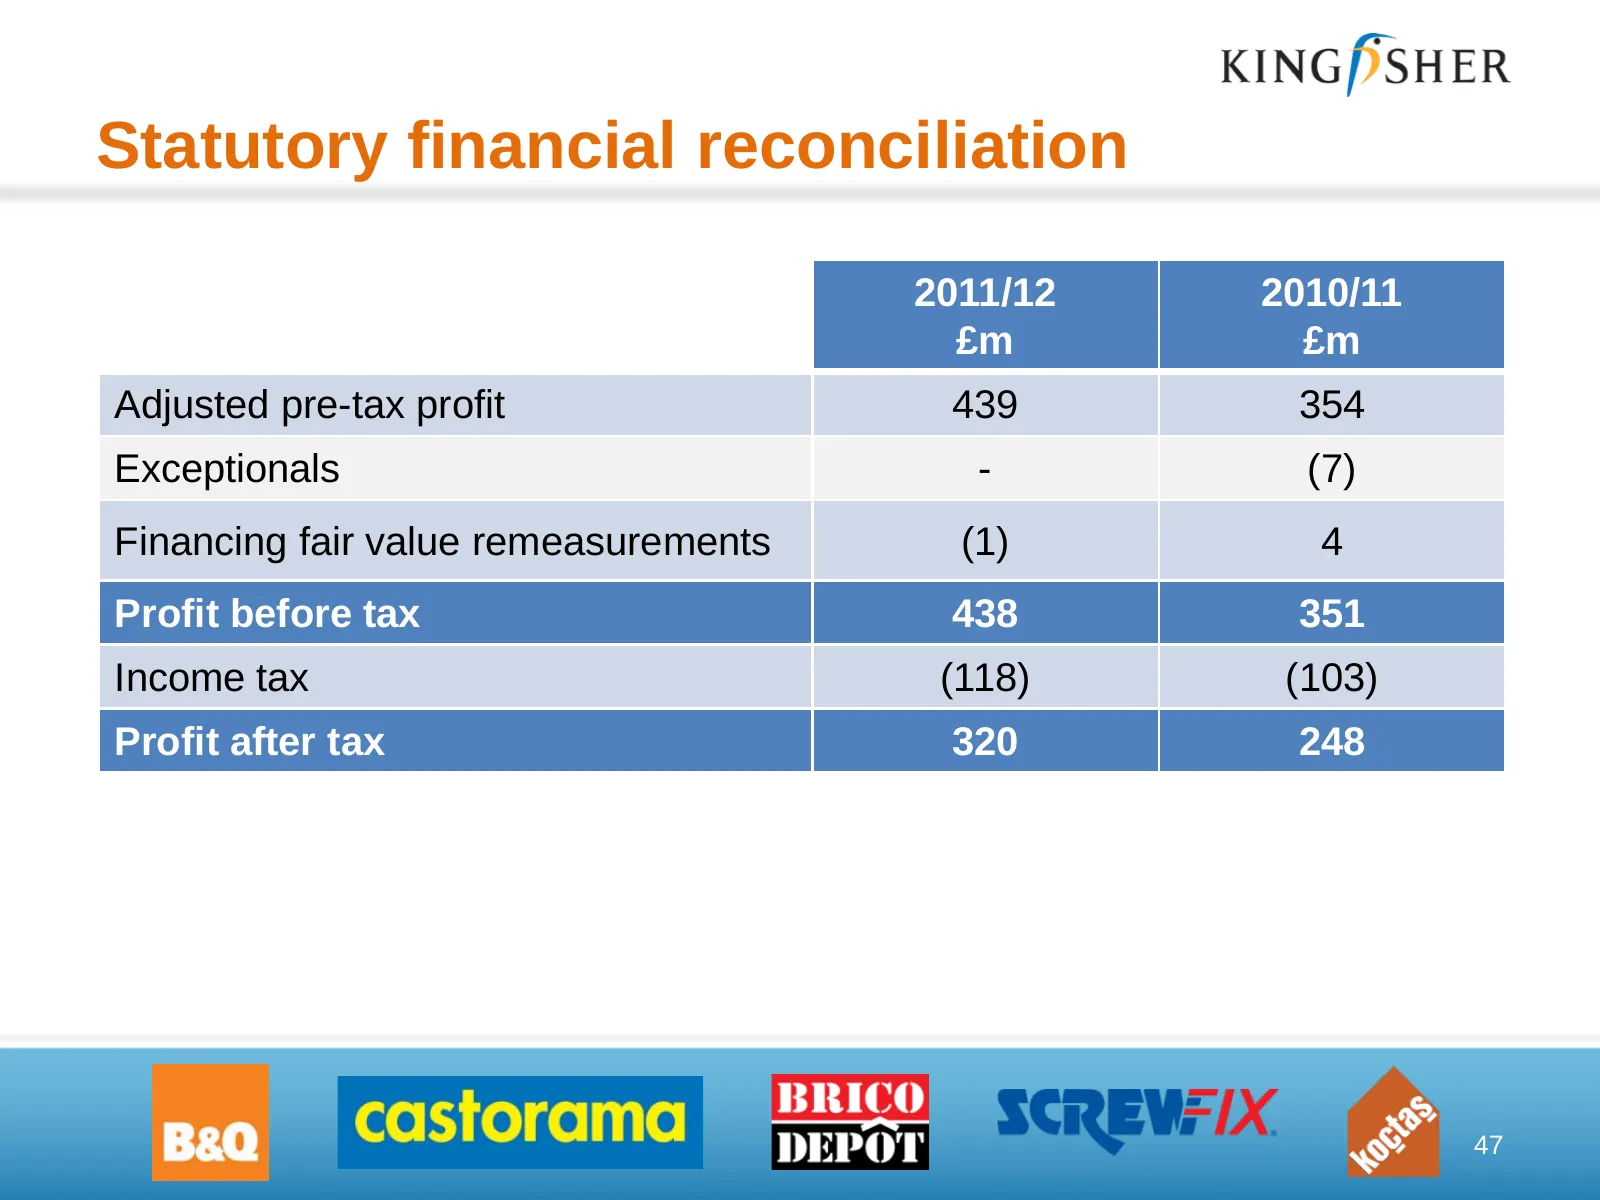
Statutory financial reconciliation 2011/12 2010/11 £m £m Adjusted pre-tax profit 439 354 Exceptionals - (7) Financing fair value remeasurements (1) 4 Profit before tax 438 351 Income tax (118) (103) Profit after tax 320 248 47
Slide 48: Financial timetable 2011/12
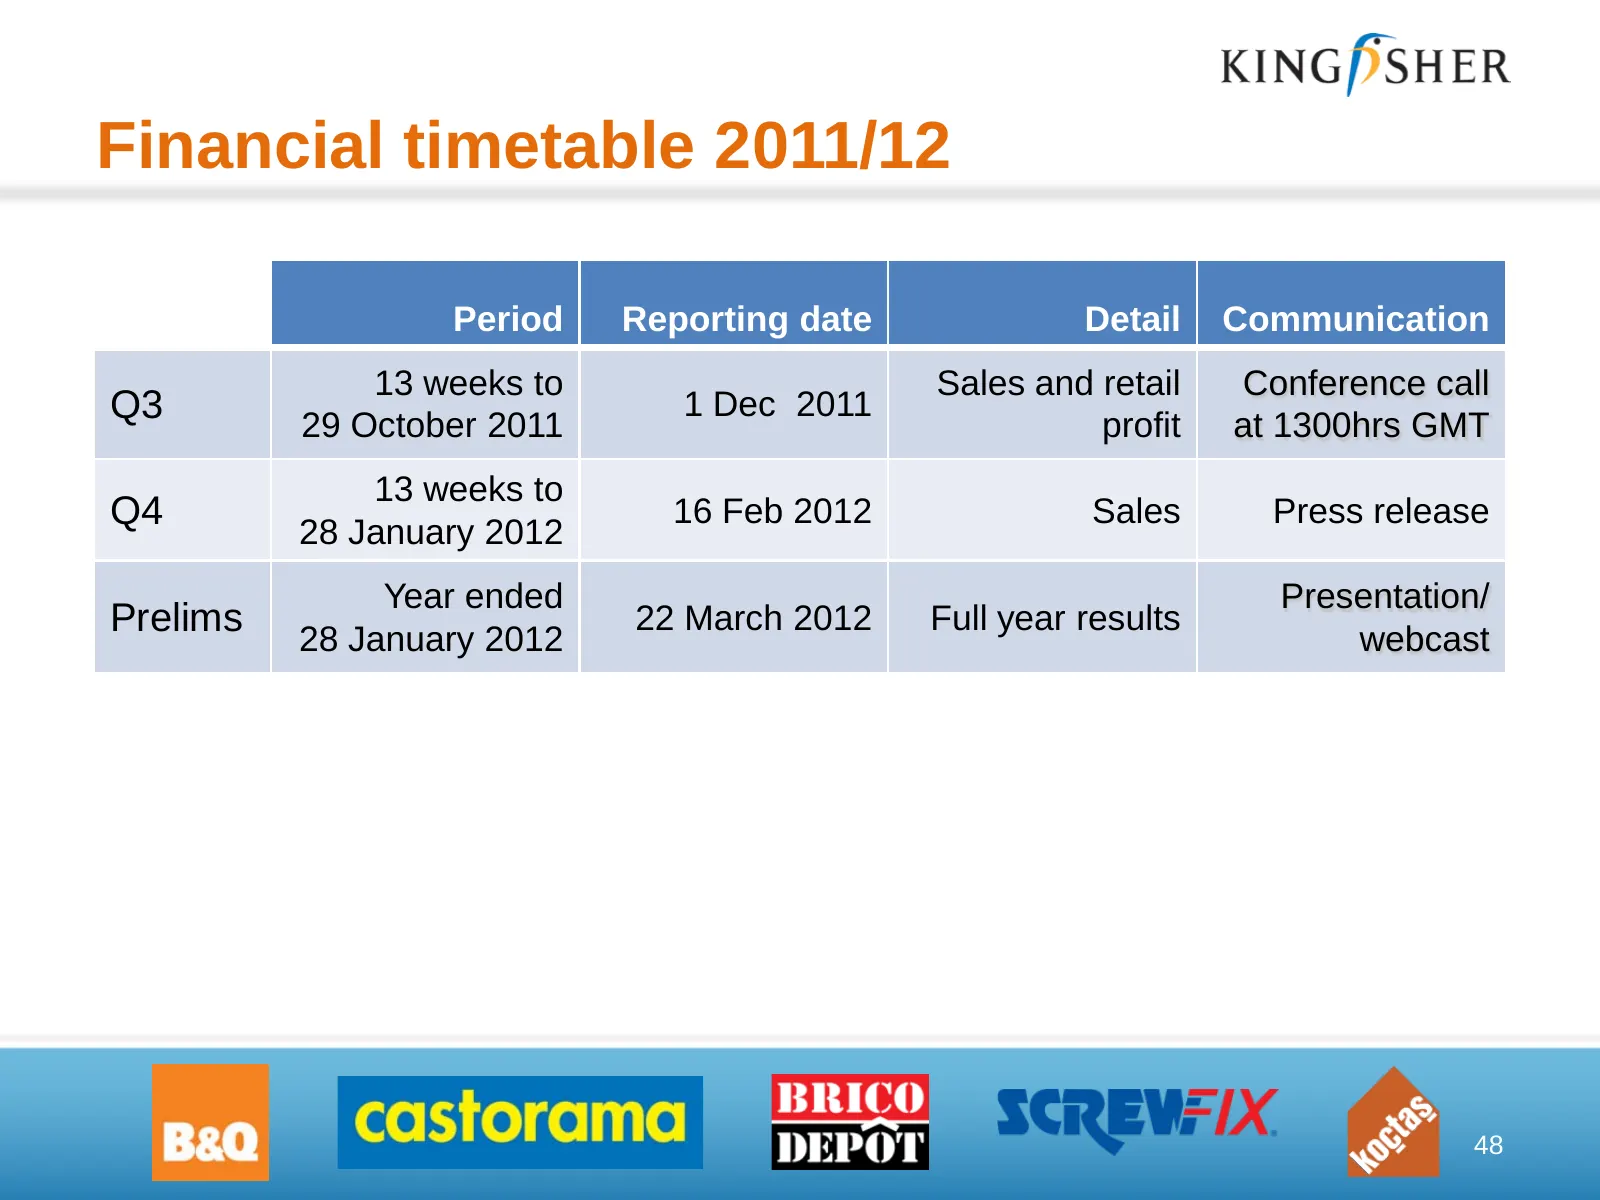
Financial timetable 2011/12 Period Reporting date Detail Communication 13 weeks to Sales and retail Conference call Q3 29 October 2011 1 Dec 2011 profit at 1300hrs GMT 13 weeks to Q4 28 January 2012 16 Feb 2012 Sales Press release Year ended Presentation/ Prelims 28 January 2012 22 March 2012 Full y
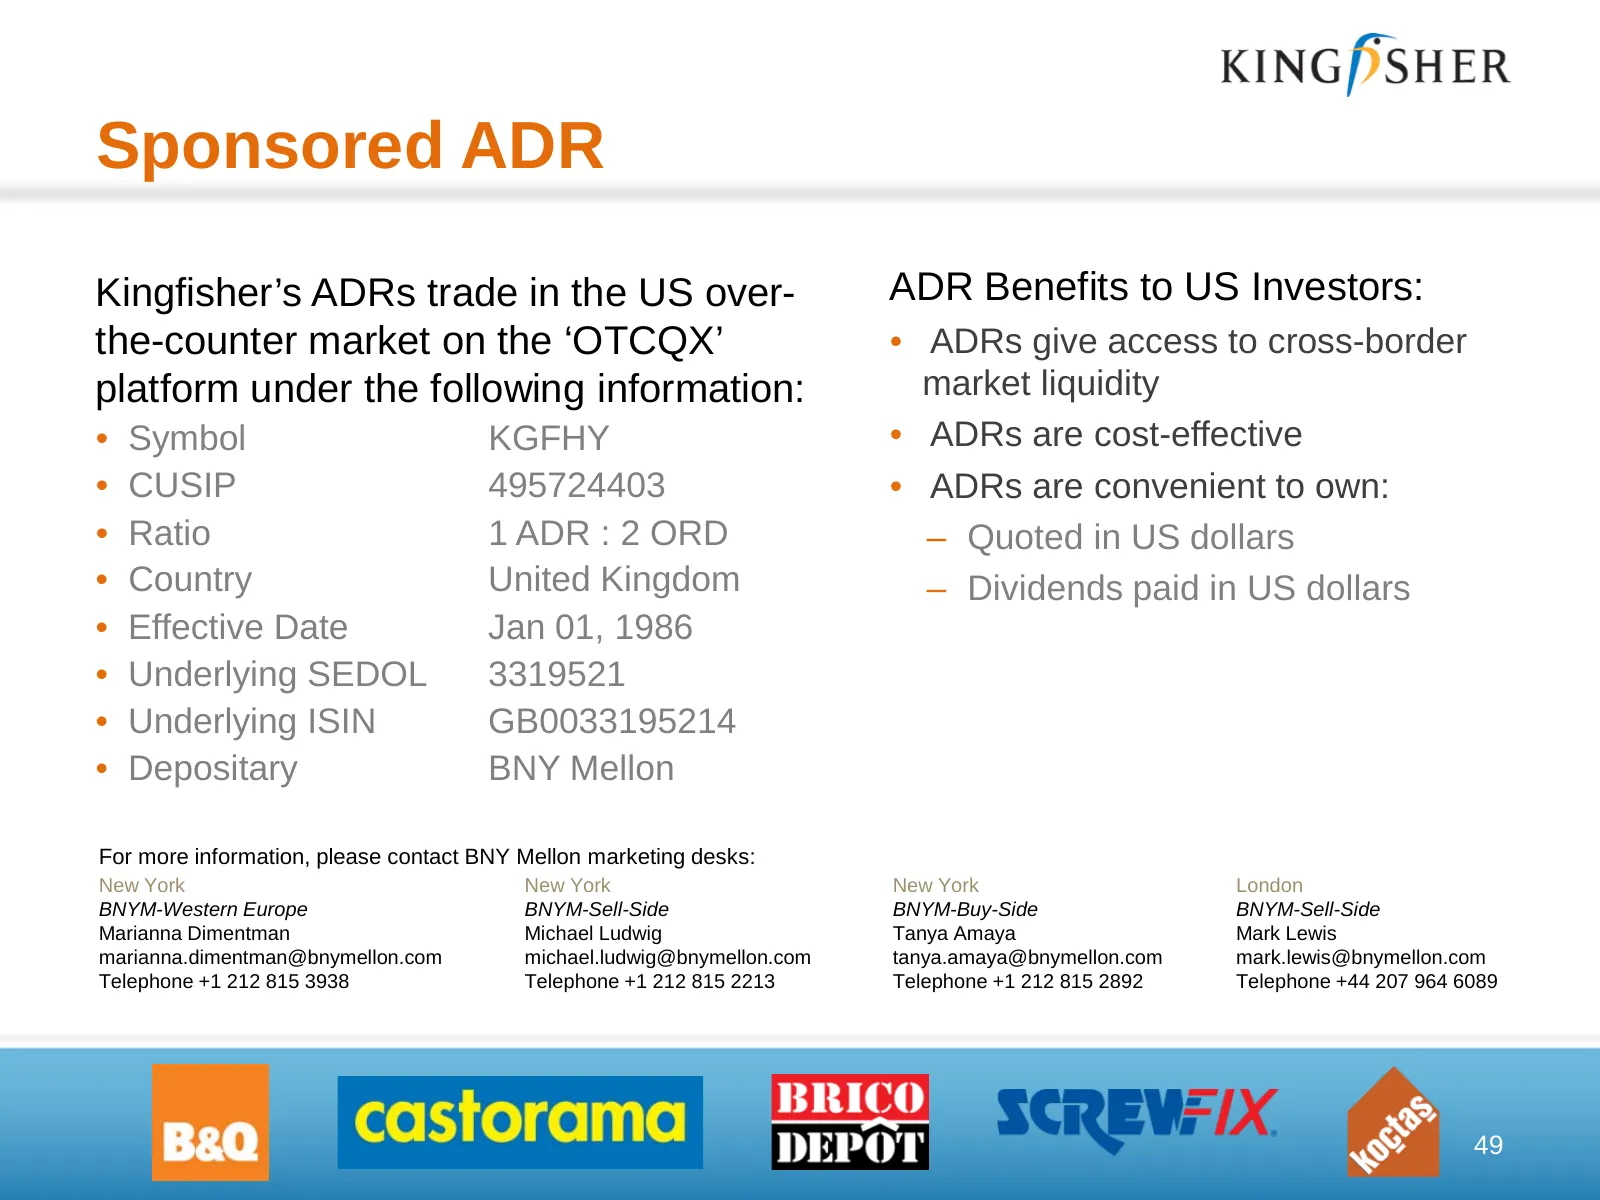
Slide 49: Sponsored ADR
Sponsored ADR Kingfisher’s ADRs trade in the US over- ADR Benefits to US Investors: the-counter market on the ‘OTCQX’ • ADRs give access to cross-border platform under the following information: market liquidity • Symbol KGFHY • ADRs are cost-effective • CUSIP 495724403 • ADRs are convenient to own:
Source: Internet Archive copy of kingfisher.com
More decks from Kingfisher PLC
 H1 2026/27 Earnings Presentation33 slides · Sep 22, 2026
 FY2025/26 Earnings Presentation39 slides · Mar 24, 2026
 H1 2025/26 Earnings Presentation38 slides · Sep 23, 2025
 H1 2025/26 Earnings Presentation6 slides · September 2025
 FY2024/25 Earnings Presentation35 slides · Apr 8, 2025
 FY2024/25 Earnings Presentation40 slides · Mar 25, 2025