VEREIT — American Realty Capital Properties — Merger or Acquisition (October 2013)
25 slides from VEREIT's merger presentation, Oct 7, 2013
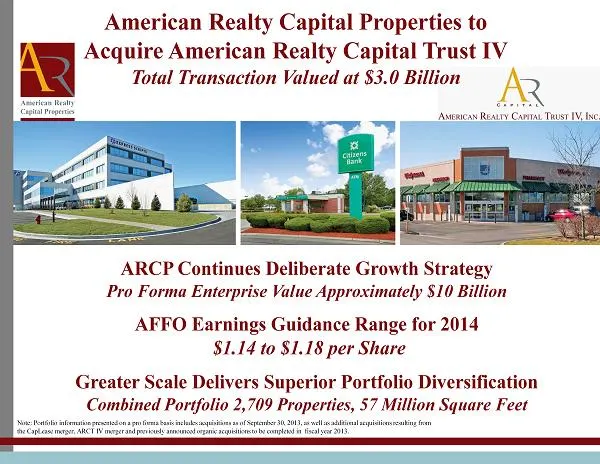
Slide 1: ARCP Continues Deliberate Growth Strategy
February 2013 ARCP Continues Deliberate Growth Strategy Pro Forma Enterprise Value Approximately $10 Billion AFFO Earnings Guidance Range for 2014 $1.14 to $1.18 per Share Greater Scale Delivers Superior Portfolio Diversification Combined Portfolio 2,709 Properties, 57 Million Square Feet American R
Slide 2: Additional Information about the Proposed Transaction and Where to Find It
2 Additional Information about the Proposed Transaction and Where to Find It This communication does not constitute an offer to sell or the solicitation of an offer to buy any securities or a solicitation of any vote or approval. In connection with the proposed transaction, American Realty Capital P
Slide 3: Forward-Looking Statements
3 Forward - Looking Statements Information set forth herein contains “forward - looking statements” (as defined in Section 21E of the Securities Exchange Act of 1934, as amended), which reflect ARCP’s and ARCT IV’s expectations regarding future events. The forward - looking statements involve a numb
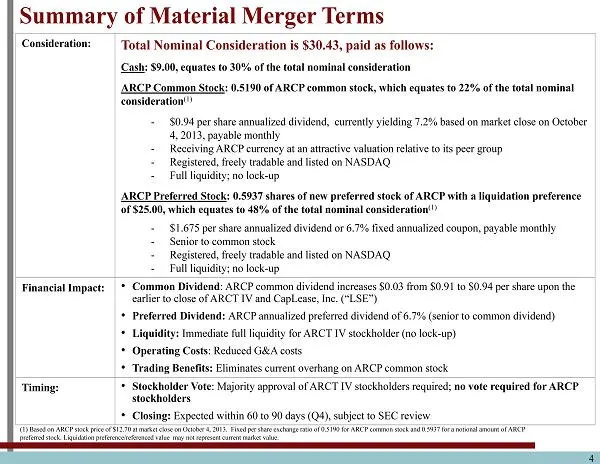
Slide 4: Summary of Material Merger Terms
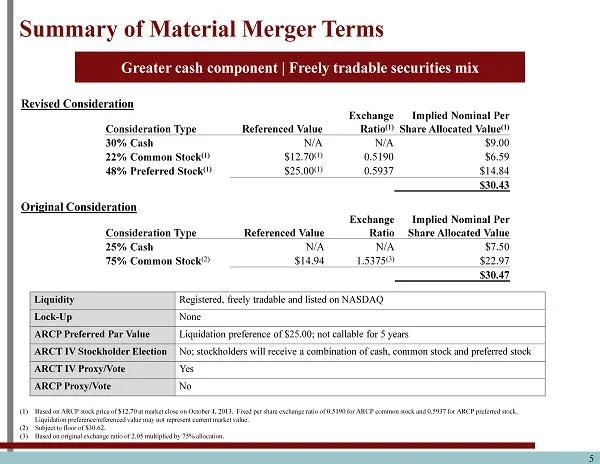
4 Summary of Material Merger Terms Consideration: Total Consideration is $30.43, paid as follows: Cash : $9.00, equates to 30% of the total nominal consideration ARCP Common Stock : 0.5190 of ARCP common stock, which equates to 22% of the total nominal consideration (1) - $0.94 per share annualized
Slide 5: Summary of Material Merger Terms (continued)
5 Summary of Material Merger Terms Liquidity Registered, freely tradable and listed on NASDAQ Lock - Up None ARCP Preferred Par Value Liquidation preference of $25.00; not callable for 5 years ARCT IV Stockholder Election No; stockholders will receive a combination of cash, common stock and preferre
Slide 6: Comparison of Transaction Terms
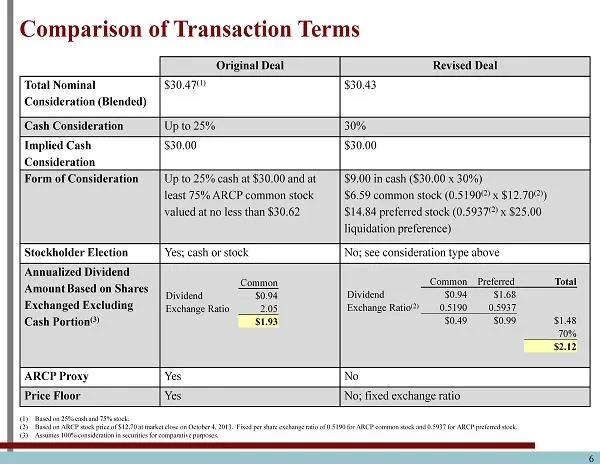
6 Comparison of Transaction Terms Original Deal Revised Deal Total Nominal Consideration (Blended) $30.47 (1) $30.43 Cash Consideration Up to 25% 30% Implied Cash Consideration $30.00 $30.00 Form of Consideration Up to 25% cash at $30.00 and at least 75% ARCP common stock valued at no less than $30.
Slide 7: ARCT IV Stockholder Benefits
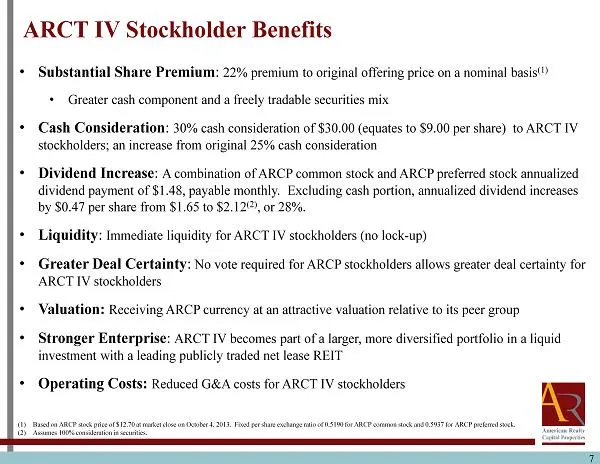
7 ARCT IV Stockholder Benefits • Substantial Share Premium : 22% premium to original offering price on a nominal basis (1) • Greater cash component and a freely tradable securities mix • Cash Consideration : 30% cash consideration of $30.00 (equates to $9.00 per share) to ARCT IV stockholders; an in
Slide 8: ARCP Preferred Equity Terms
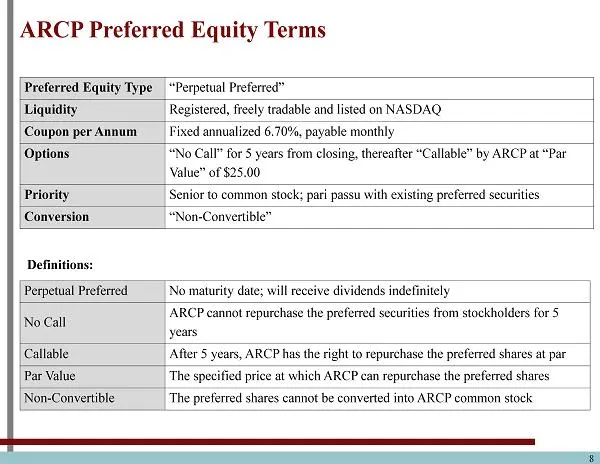
8 ARCP Preferred Equity Terms Preferred Equity Type “Perpetual Preferred” Liquidity Registered, freely tradable and listed on NASDAQ Coupon per Annum Fixed annualized 6.70%, payable monthly Options “No Call” for 5 years from closing, thereafter “Callable” by ARCP at “Par Value” of $25.00 Priority Se
Slide 9: Common Stock vs. Preferred Stock
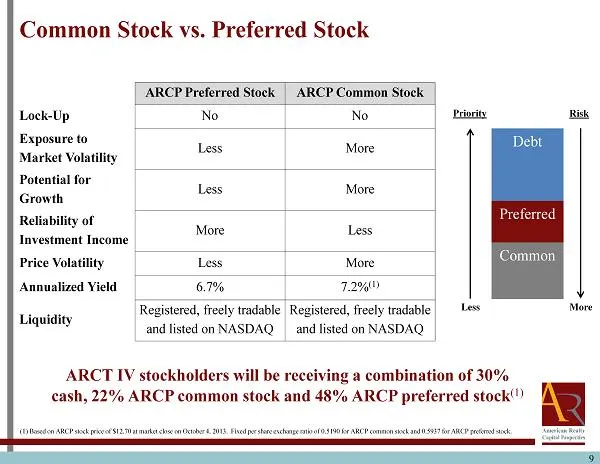
9 Common Stock vs. Preferred Stock ARCP Preferred Stock ARCP Common Stock Lock - Up No No Exposure to Market Volatility Less More Potential for Growth Less More Reliability of Investment Income More Less Price Volatility Less More Annualized Yield 6.7% 7.2% (1) Liquidity Registered, freely tradable
Slide 10: ARCP Unique Strategy and Scale
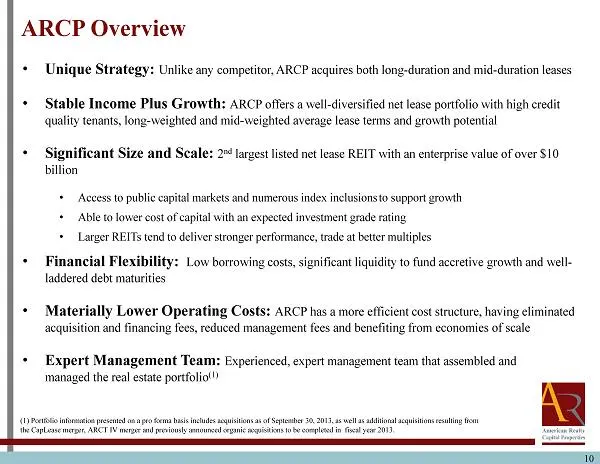
• Unique Strategy: Unlike any competitor, ARCP acquires both long - duration and mid - duration leases • Stable Income Plus Growth: ARCP offers a well - diversified net lease portfolio with high credit quality tenants, long - weighted and mid - weighted average lease terms and growth potential • Sig
Slide 11: Notable Recent ARCP Activity
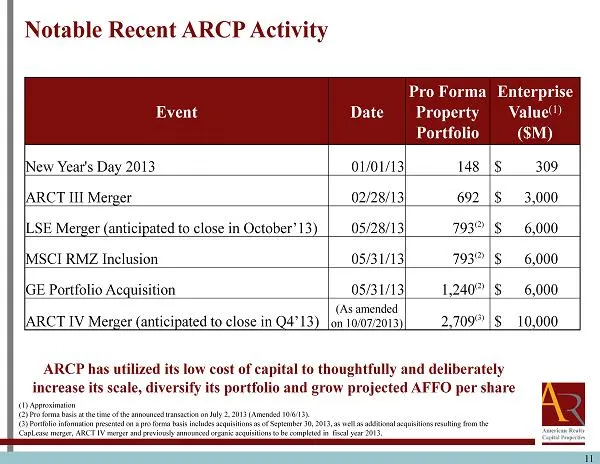
11 Notable Recent ARCP Activity ARCP has utilized its low cost of capital to thoughtfully and deliberately increase its scale, diversify its portfolio and grow projected AFFO per share Event Date Pro Forma Property Portfolio Enterprise Value (1) ($M) New Year's Day 2013 01/01/13 148 $ 309 ARCT III M
Slide 12: ARCP Stockholder Benefits
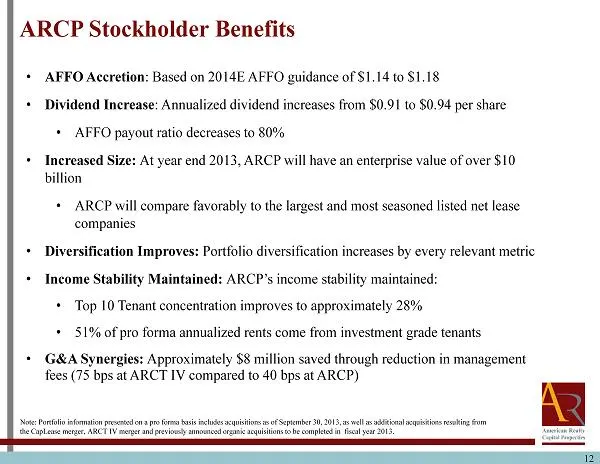
12 ARCP S tockholder Benefits • AFFO Accretion : Based on 2014E AFFO guidance of $1.14 to $ 1.18 • Dividend Increase : Annualized dividend increases from $0.91 to $0.94 per share • AFFO payout ratio decreases to 80% • Increased Size: At year end 2013, ARCP will have an enterprise value of over $10 b
Slide 13: Increase in ARCP's Annualized Dividend
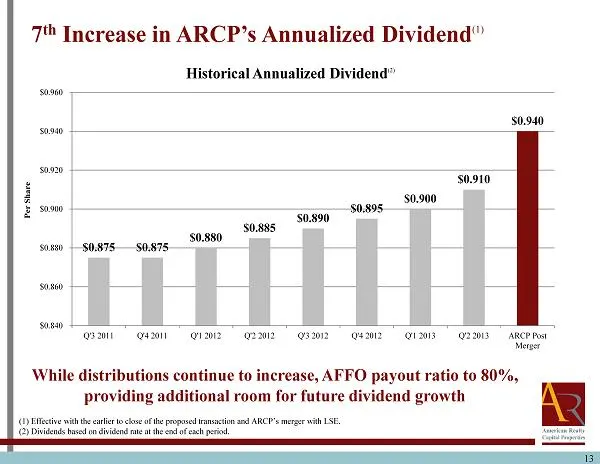
13 7 th Increase in ARCP’s Annualized Dividend (1) (1) Effective with the earlier to close of the proposed transaction and ARCP’s merger with LSE. (2) Dividends based on dividend rate at the end of each period. $0.875 $0.875 $0.880 $0.885 $0.890 $0.895 $0.900 $0.910 $0.940 $0.840 $0.860 $0.880 $0.90
Slide 14: Pro Forma ARCP Top 10 Tenant Concentration
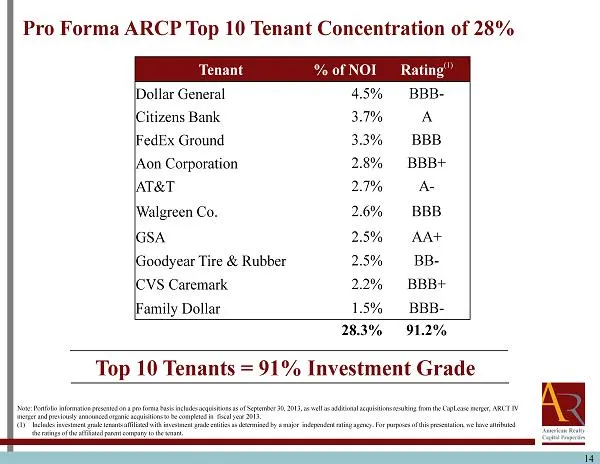
14 Tenant % of NOI Rating (1) Dollar General 4.5% BBB - Citizens Bank 3.7% A FedEx Ground 3.3% BBB Aon Corporation 2.8% BBB + AT&T 2.7% A - Walgreen Co. 2.6% BBB GSA 2.5% AA + Goodyear Tire & Rubber 2.5% BB - CVS Caremark 2.2% BBB + Family Dollar 1.5% BBB - 28.3% 91.2% Top 10 Tenants = 91% Investmen
Slide 15: Only 8.4% Lease Maturities in the Next 3 Years
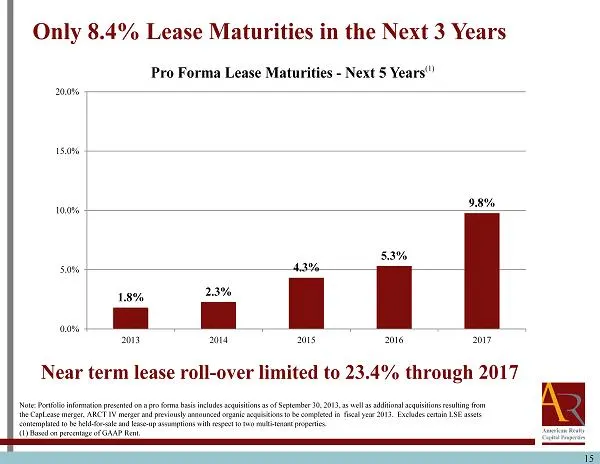
15 15 Note: Portfolio information presented on a pro forma basis includes acquisitions as of September 30, 2013, as well as additional ac qui sitions resulting from the CapLease merger, ARCT IV merger and previously announced organic acquisitions to be completed in fiscal year 2013. Excludes certain
Slide 16: ARCP's Proven Management Team
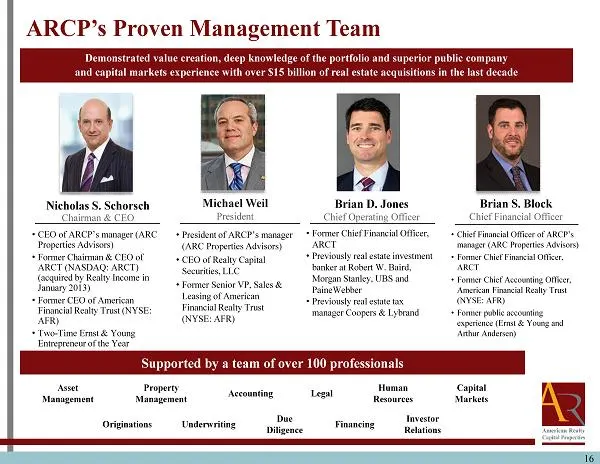
16 ARCP’s Proven Management Team Demonstrated value creation, deep knowledge of the portfolio and superior public company and capital markets experience with over $15 billion of real estate acquisitions in the last decade Supported by a team of over 100 professionals Asset Management Property Manage
Slide 17: American Realty Capital Properties to Become Self-Managed
17 American Realty Capital Properties to Become Self - Managed ARCP announced that its board of directors determined that it’s in the best interests of ARCP and its stockholders to become self - managed following the pending closings of the previously announced acquisitions. Due to the rapid growth
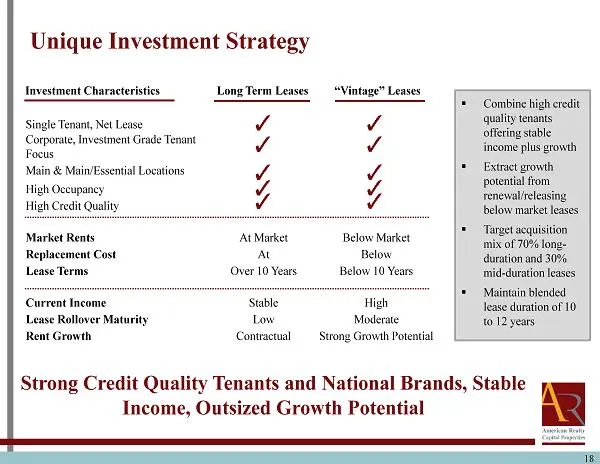
Slide 18: Unique Investment Strategy
18 Unique Investment Strategy Long Term Leases Strong Credit Quality Tenants and National Brands, Stable Income, Outsized Growth Potential Single Tenant, Net Lease Corporate, Investment Grade Tenant Focus Main & Main/Essential Locations High Occupancy High Credit Quality Market Rents At Market Below
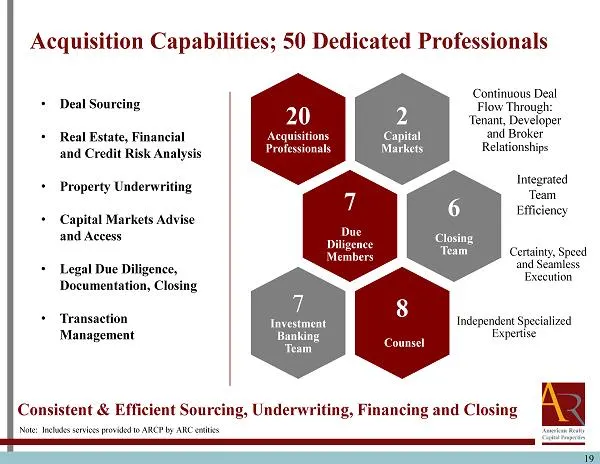
Slide 19: Acquisition Capabilities; Dedicated Professionals
19 Acquisition Capabilities; 50 Dedicated Professionals 2 Capital Markets Continuous Deal Flow Through: Tenant, Developer and Broker Relationsh ips 20 Acquisitions Professionals 7 Due Diligence Members Certainty, Speed and Seamless Execution 6 Closing Team 8 Counsel Independent Specialized Expertise
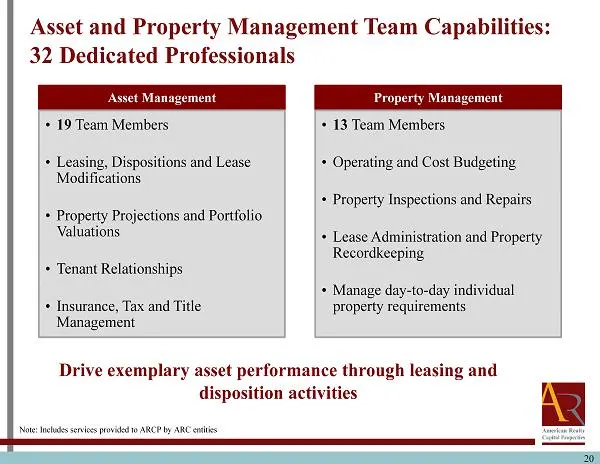
Slide 20: Asset and Property Management Team Capabilities
20 Asset and Property Management Team Capabilities: 32 Dedicated Professionals Asset Management • 19 Team Members • Leasing, Dispositions and Lease Modifications • Property Projections and Portfolio Valuations • Tenant Relationships • Insurance, Tax and Title Management Property Management • 13 Team
Slide 21: ARCP's Management Structure Brings Significant Benefits to Stockholders
21 ARCP’s Management Structure Brings Significant Benefits to S tockholders Scale, Experience and Expertise Generate Better Execution at Lower Cost • Largest U.S. buyer of net lease real estate • Vertically integrated team of 100 real estate professionals • Efficient operational, legal and administr
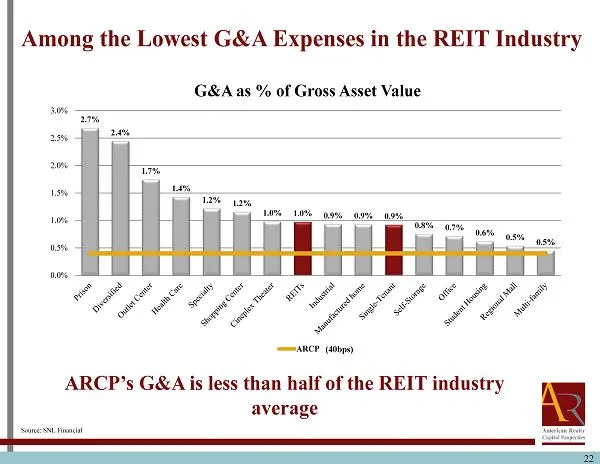
Slide 22: ARCP's G&A is less than half of the REIT industry average
22 ARCP’s G&A is less than half of the REIT industry average Among the Lowest G&A Expenses in the REIT Industry Source: SNL Financial 2.7% 2.4% 1.7% 1.4% 1.2% 1.2% 1.0% 1.0% 0.9% 0.9% 0.9% 0.8% 0.7% 0.6% 0.5% 0.5% 0.0% 0.5% 1.0% 1.5% 2.0% 2.5% 3.0% G&A as % of Gross Asset Value ARCP (3bp) (40bps)
Slide 23: Combined Company Offers Stockholders Significant Benefits
23 Combined Company Offers S tockholders Significant Benefits • Favorable Cost of Capital: Near all - time low interest rates provide favorable acquisition environment • Liquidity and Access to Capital: Increases enterprise value and provides immediate common stock liquidity, access to capital and f
Slide 24: ARCP Offers a Compelling Value Proposition
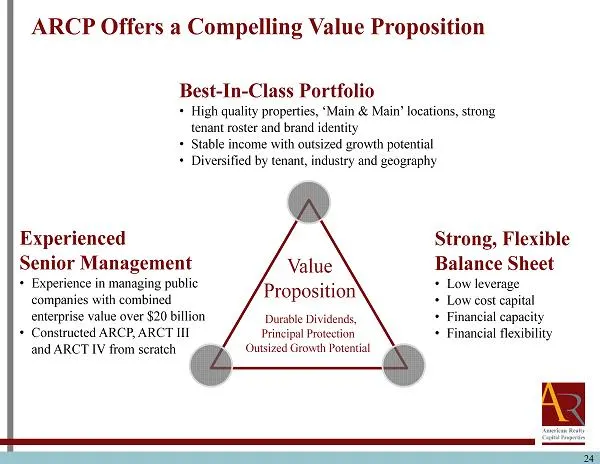
24 ARCP Offers a Compelling Value Proposition Experienced Senior Management • Experience in managing public companies with combined enterprise value over $20 billion • Constructed ARCP, ARCT III and ARCT IV from scratch Best - In - Class Portfolio • High quality properties, ‘Main & Main’ locations,
Slide 25: Funds from Operations and Adjusted Funds from Operations
25 Funds from Operations and Adjusted Funds from Operations ARCP and ARCT IV consider funds from operations (“FFO”) and AFFO, which is FFO as adjusted to exclude acquisition - related fees and expenses, amortization of above - market lease assets and liabilities, amortization of deferred financing c
Source: SEC EDGAR · 425 filed Oct 7, 2013
More decks from VEREIT Inc
 Q3 2021 Earnings Presentation35 slides · Oct 29, 2021
 Q2 2021 Earnings Presentation35 slides · Aug 5, 2021
 Q1 2021 Earnings Presentation35 slides · May 6, 2021
 Merger or Acquisition (April 2021)16 slides · Apr 29, 2021
 Q4 2020 Earnings Presentation44 slides · Feb 24, 2021
 Q1 2021 Earnings Presentation39 slides · 2021