Health Net — Investor Day (February 2012)
74 slides from Health Net's investor day presentation, Feb 16, 2012
Slide 1: Health Net, Inc. 2012 Investor Day
Exhibit 99.1 Health Net, Inc. 2012 Investor Day February 16, 2012
Slide 2: Cautionary Statements
Cautionary Statements Health Net, Inc. and its representatives may from time to time make written and oral forward-looking statements within the meaning of the Private Securities Litigation Reform Act (“PSLRA”) of 1995, including statements in this and other presentations, in press releases, filings
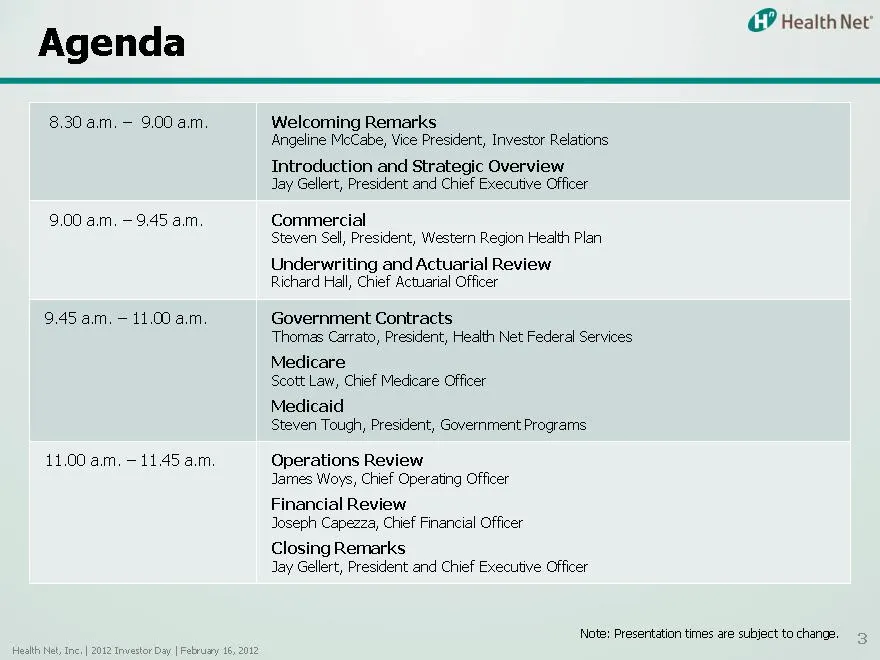
Slide 3: Agenda
Agenda 8.30 a.m. – 9.00 a.m. Welcoming Remarks Angeline McCabe, Vice President, Investor Relations Introduction and Strategic Overview Jay Gellert, President and Chief Executive Officer 9.00 a.m. – 9.45 a.m. Commercial Steven Sell, President, Western Region Health Plan Underwriting and Actuarial Rev
Slide 4: Setting the Stage
Setting the Stage Jay Gellert President and Chief Executive Officer
Slide 5: Today's Agenda
Today’s Agenda • Setting the stage • Three panels – Commercial businesses – Government businesses – Operations and financial review • Summary and outlook
Slide 6: Where We Are
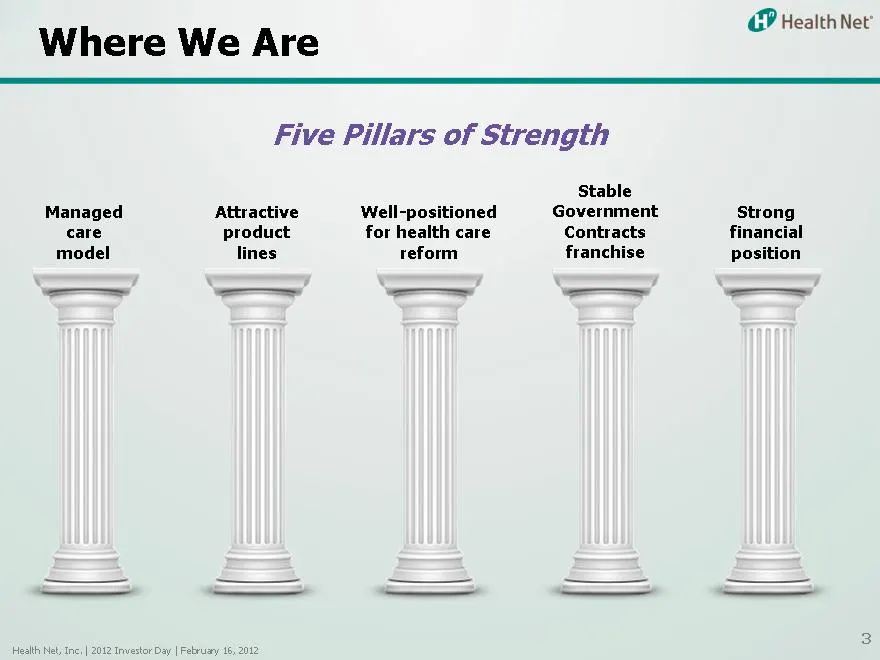
Where We Are Five Pillars of Strength Stable Managed Attractive Well-positioned Government Strong care product for health care Contracts financial model lines reform franchise position
Slide 7: The Environment
The Environment • Economy driving change, focused on cost • Commercial customers need affordable products with adequate coverage • Government customers facing increasing budget pressures • Providers seeking opportunities to transform • Health care reform implementation and timetable still uncertain
Slide 8: The Pace of Change is Intensifying
The Pace of Change is Intensifying • Commercial customers • State efforts • Federal initiatives • Providers and other partners Health Net, Inc. | 2012 Investor Day | February 16, 2012
Slide 9: Our Responses
Our Responses • Tailored network products meeting customer needs for affordable premiums and range of benefits • Deeper involvement with key government customers – California Medicaid – Medicare Advantage / Seniors and Persons with Disabilities (SPD) – New TRICARE contract • Preparing for the future
Slide 10: Today's Agenda
Today’s Agenda • Setting the stage • Three panels – Commercial business – Government businesses – Operations and financial review • Summary and outlook
Slide 11: A Sustainable Commercial Strategy
A Sustainable Commercial Strategy Steve Sell President, Western Region Health Plan
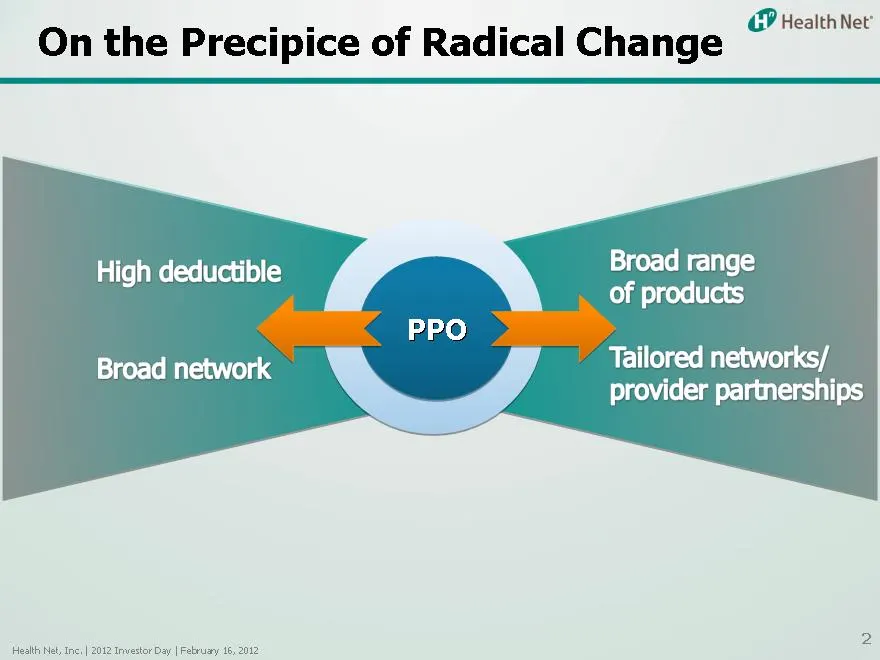
Slide 12: On the Precipice of Radical Change
On the Precipice of Radical Change High deductible Broad network Broad range of products Tailored networks/provider partners PPO
Slide 13: Why the Change?
Why the Change? Economy Buyer choice, comfort with managed care Regulatory reform, standardized products Exchanges Provider transformation
Slide 14: Keys for Development
Keys for Development Competitive markets Organized delivery Prudent purchasers Market sensitive plans with regional differentiation
Slide 15: Positioned for Growth
Positioned for Growth Health Net gaining share in network-model HMO market Tailored network products are the primary growth engine Tailored network products yield stable performance Strategic provider partnerships Cost effective for buyers Gross margin expansion Sustainable commercial strategy
Slide 16: A Growing California HMO Market
A Growing California HMO Market Employer groups choosing value over broad network – 2010 to 2011 • PPO declined from 37 percent to 34 percent • HSA/HDHP stayed flat at 6 percent • HMO grew from 57 percent to 60 percent – 2011 to 2015 forecast • HMO share to grow from 60 percent to 68 percent • Assum
Slide 17: Health Net Gaining
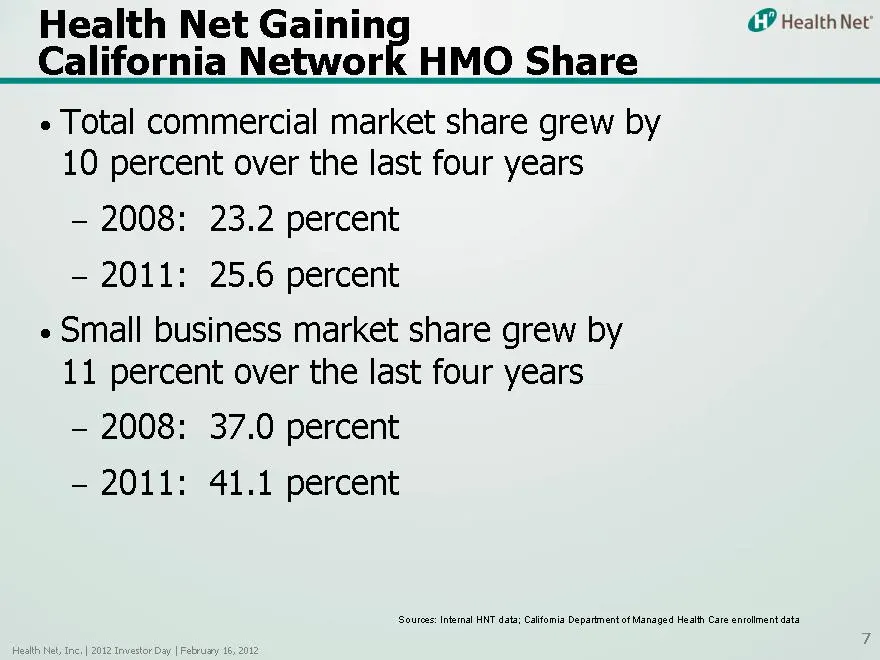
Health Net Gaining California Network HMO Share Total commercial market share grew by 10 percent over the last four years 2008: 23.2 percent 2011: 25.6 percent Small business market share grew by 11 percent over the last four years 2008: 37.0 percent 2011: 41.1 percent Health Net, Inc. | 2012 Invest
Slide 18: Growth in Tailored Networks Products
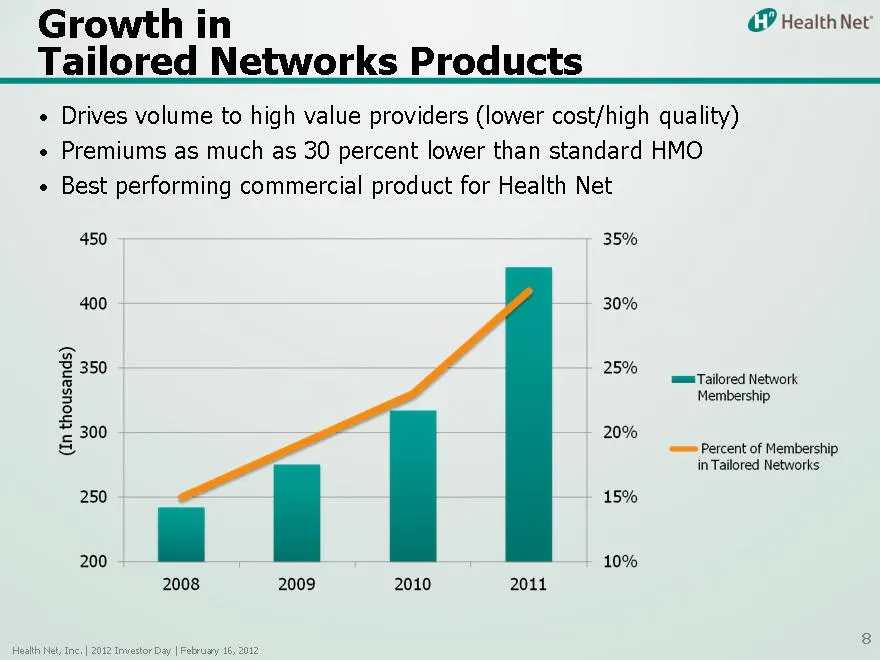
Growth in Tailored Networks Products Drives volume to high value providers (lower cost/high quality) Premiums as much as 30 percent lower than standard HMO Best performing commercial product for Health Net n ds) 350 thousa 300 (In 2008 2009 2010 2011 35% 30% 25% 20% 15% 10% Tailored Network Membersh
Slide 19: Evolution of Tailored Network Products
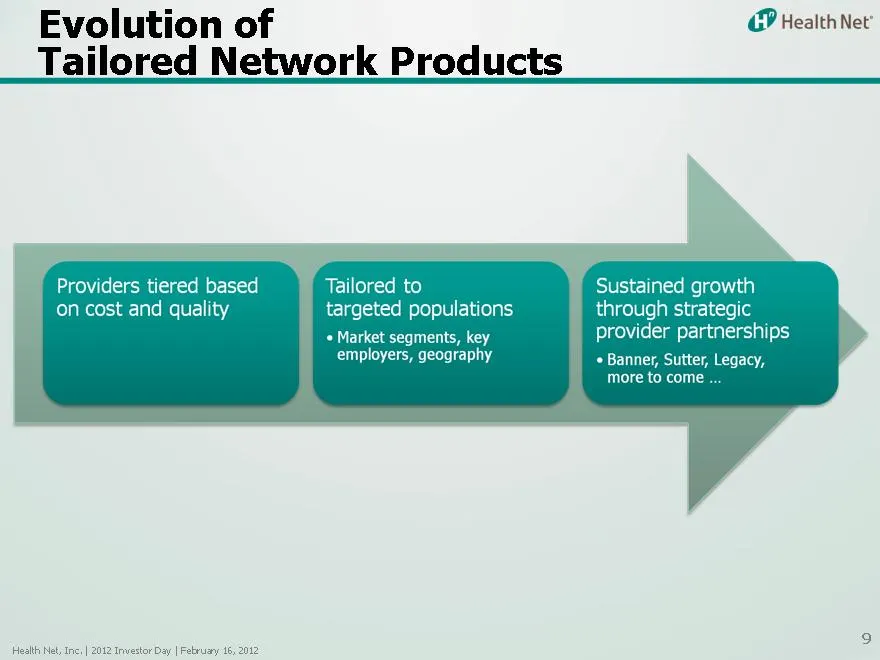
Evolution of Tailored Network Products Providers tiered based on cost and quality Tailored to targeted populations • Market segments, key employers, geography Sustained growth through strategic provider partnerships • Banner, Sutter, Legacy, more to come …
Slide 20: Tailored Network with a Large Employer Group
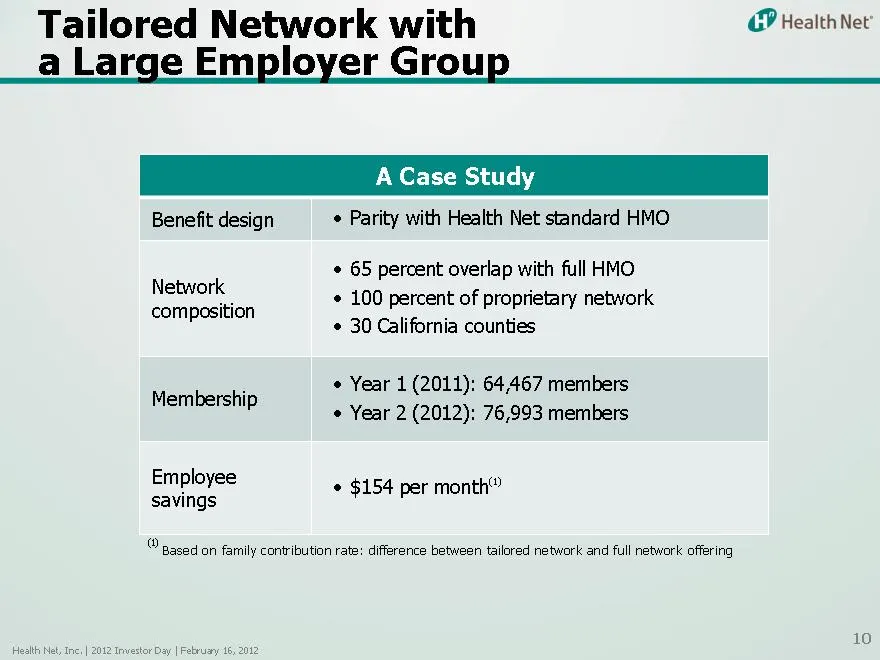
Tailored Network with a Large Employer Group A Case Study Benefit design • Parity with Health Net standard HMO • 65 percent overlap with full HMO Network • 100 percent of proprietary network composition • 30 California counties • Year 1 (2011): 64,467 members Membership • Year 2 (2012): 76,993 membe
Slide 21: Creating Virtual Staff Models
Creating Virtual Staff Models Founded on HNT’s managed care capability Market driven (access, affordability, quality) Service-focused (personal, simple, local) Sustained through provider partnerships
Slide 22: A Sustainable Commercial Strategy
A Sustainable Commercial Strategy Move from PPO to tailored networks and strategic partnerships Alignment with customers and delivery system partners Multiple-year deals Fixed budget vs. fee-for service Shared growth and savings goals Targeted segment, regional and product expansion Continued underw
Slide 23: Underwriting and Actuarial Review
Underwriting and Actuarial Review Richard Hall, FSA, MAAA Chief Actuarial Officer
Slide 24: Driving Commercial Improvement
Driving Commercial Improvement Steady underwriting and pricing discipline HMO historical benefit disadvantage vs. PPO, but offers better value Provider partnerships sharing risk 2012 pricing assumptions and outlook
Slide 25: Underwriting and Pricing Discipline
Underwriting and Pricing Discipline Rigorous analytical process Review membership demographics Identify best gross margin opportunities Perform sensitivity analyses Targeted geographies, segments and products Enhanced sales and underwriting process optimizes profitability and membership Tailored net
Slide 26: Targeted Markets: Mix Matters
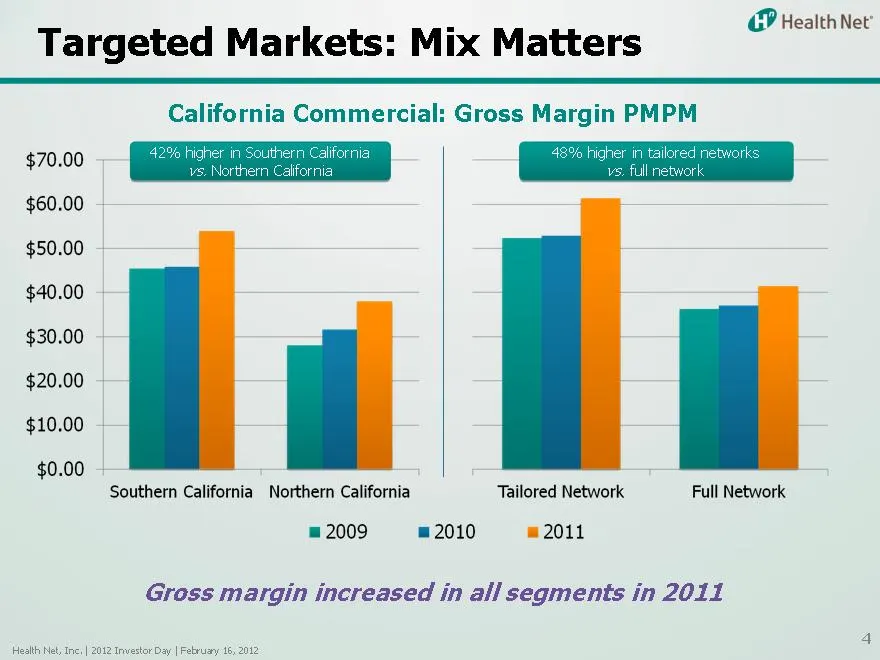
Targeted Markets: Mix Matters California Commercial: Gross Margin PMPM $70.00 $60.00 $50.00 $40.00 $30.00 $20.00 $10.00 $0.00 42% higher in Southern California vs. Northern California Southern California Northern California 48% higher in tailored networks vs. full network Tailored Network Full Netwo
Slide 27: 2011 Results Affirm Strategy
2011 Results Affirm Strategy Targeted pricing improved large group mix – MCR of renewing groups better than cancelled groups by 440 basis points – Retention rates improved 700 basis points Solid small group results – MCR of renewing groups better than cancelled groups by 360 basis points Gross margi
Slide 28: The Premium Differentials: Move to HMO
The Premium Move Differentials: to HMO Traditional HMO vs. PPO – HMO is 40 percent less – Example: Los Angeles County – HMO – $30 copay / $3,000 out-of-pocket (OOP) max – PPO – $30 copay in-network / $500 deductible / $4,000 OOP maximum Tailored network is 10 percent to 50 percent less than traditio
Slide 29: Provider Partnership Value Proposition
Provider Partnership Value Proposition Local presence, people and relationships Proven leading network HMO model Focus on all lines of business Innovative network structure and reimbursement methodologies Experience with providers on wellness, touch points, etc. Providers only want a few partners
Slide 30: 2012 Pricing Assumptions
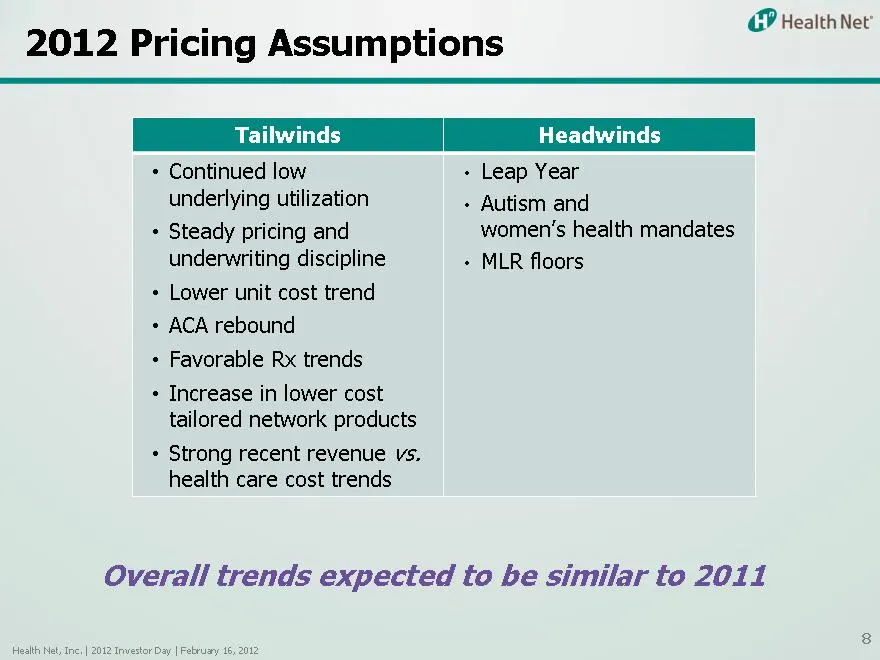
2012 Pricing Assumptions Tailwinds Continued low underlying utilization Steady pricing and underwriting discipline Lower unit cost trend ACA rebound Favorable Rx trends Increase in lower cost tailored network products Strong recent revenue vs. health care cost trends Headwinds Leap Year Autism and w
Slide 31: Beyond 2012
Beyond 2012 Positioned for exchanges and health care reform Significant increase in tailored network partnerships and membership – PPO becomes the old indemnity – Strategic provider partnerships growth just beginning Continued low utilization trend Steady underwriting and pricing discipline Synergy
Slide 32: Government Programs
Government Programs Steve Tough President, Government Programs
Slide 33: Government Programs
Government Programs Government Programs include: – Department of Defense (DoD) • TRICARE • Behavioral health – Department of Veterans Affairs (VA) – Medicare – Medicaid Health Net, Inc. | 2012 Investor Day | February 16, 2012
Slide 34: Current Landscape
Current Landscape Continued economic pressures on state and federal budgets Health care cost containment is essential Military families and veterans have broad needs beyond TRICARE Medicare Advantage opportunities Medicaid poised for growth Diversified government payors
Slide 35: Government Contracts
Government Contracts Tom Carrato President, Health Net Federal Services
Slide 36: Time of Change
Time of Change Historical view of DoD and VA health Impact of budget pressures Role for the private sector Health Net, Inc. | 2012 Investor Day | February 16, 2012
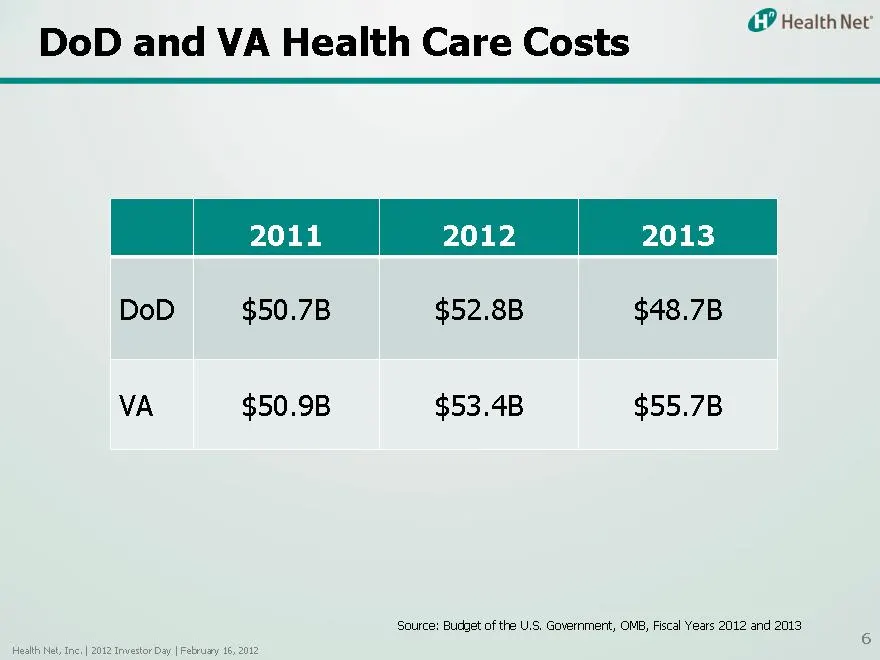
Slide 37: DoD and VA Health Care Costs
DoD and VA Health Care Costs 2011 2012 2013 DoD $50.7B $52.8B $48.7B VA $50.9B $53.4B $55.7B Source: Budget of the U.S. Government, OMB, Fiscal Years 2012 and 2013
Slide 38: Our Strengths
Our Strengths Experienced and trusted partner Diverse service offerings Innovative behavioral health solutions
Slide 39: Where We Are Now
Where We Are Now New TRICARE contract (T-3) successfully implemented Continue with current Military & Family Life Consultant (MFLC) contract Successfully expanded VA “footprint” into a solid and growing business
Slide 40: DoD Growth Opportunities
DoD Growth Opportunities TRICARE – TRICARE Overseas – TRICARE for Life (TFL) Behavioral health needs growing – MFLC proposal being evaluated – Military OneSource RFP to be released shortly Expand MFLC platform – $1.6 billion in funding for support of U.S. Air Force and National Guard
Slide 41: TRICARE for Life
TRICARE for Life Covers over 2 million individuals eligible for Medicare – TRICARE provides Medicare Supplement-like benefits – DoD version of a dual eligibles program Current program is unmanaged Costs increasing and shared by DoD (40 percent) and Centers for Medicare & Medicaid Services (CMS) (60
Slide 42: Veterans Affairs Growth Opportunities
Veterans Affairs Growth Opportunities Rural mental health Outpatient clinics Claims repricing and auditing Patient-Centered Community Care
Slide 43: Summary and Outlook
Summary and Outlook Stable TRICARE performance MFLC performing well Substantial DoD opportunities New VA opportunities
Slide 44: Medicare
Medicare Scott Law Chief Medicare Officer
Slide 45: Medicare Update
Medicare Update Strong return with marketing Initial membership results better than expected – Improved membership retention Bid to achieve gross margin expansion
Slide 46: Medicare 2012
Medicare 2012 Better MCR with renewed enrollment growth Focus on risk adjustment factors Implementing new quality programs and measures Seeking four star ratings across the board 4 stars in Oregon 3.5 stars in California and Arizona
Slide 47: Medicare Advantage Outlook
Medicare Advantage Outlook Anticipate Medicare Advantage (MA) improvement in 2012 – Enrollment growth – Better margins Preparing 2013 bid Planning new markets Apply tailored network strategy to MA
Slide 48: Medicaid
Medicaid Steve Tough President, Government Programs
Slide 49: Medicaid Overview
Medicaid Overview Participate in 12 California counties Largest state health plan in California Strong position with key populations Latinos Seniors and Persons with Disabilities (SPD) beneficiaries
Slide 50: Opportunities for Growth
Opportunities for Growth Increase in Medicaid enrollment expected to continue State of California committed to expand Medicaid managed care Affordable Care Act (ACA) expected to add over 2 million new Medicaid members in California beginning in 2014 State of California 2012 budget proposes: Expand M
Slide 51: Dual-Eligibles Opportunity
Dual-Eligibles Opportunity California has approximately 1.2 million “duals” – 375,000 in Los Angeles County Combined State of California/CMS health care annual spend exceeds $30 billion Demonstration pilot expected to launch January 2013 State plans to utilize current Medicaid infrastructure Califor
Slide 52: Fundamental Reform for Duals
Fundamental Reform for Duals Population management Managed care tools Group model Partnering with other services Systemic reform Cost Quality Built on California success Attractive national model Health Net, Inc. | 2012 Investor Day | February 16, 2012
Slide 53: Why Can California be a Good National Model?
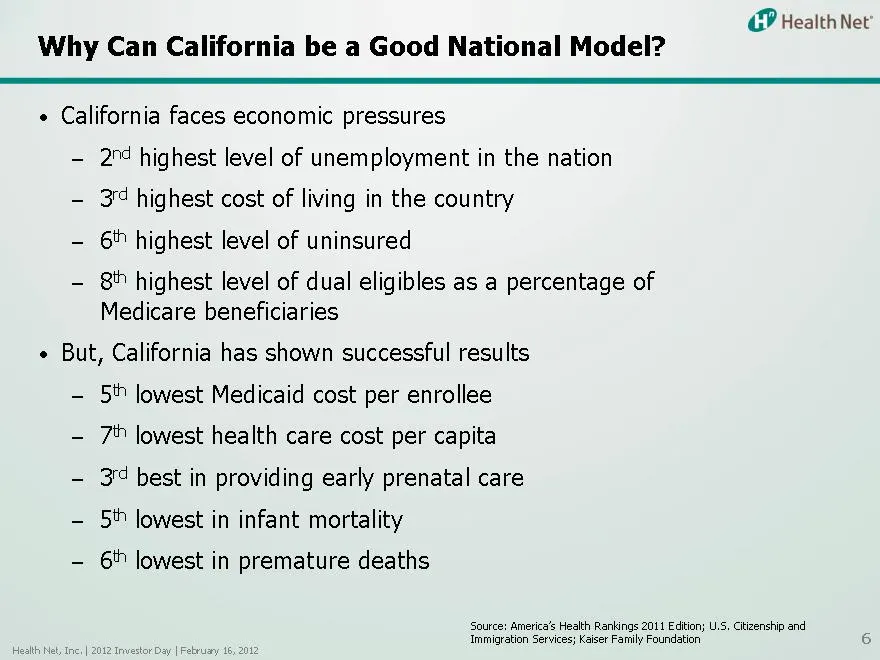
Why Can California be a Good National Model? California faces economic pressures – 2nd highest level of unemployment in the nation – 3rd highest cost of living in the country – 6th highest level of uninsured – 8th highest level of dual eligibles as a percentage of Medicare beneficiaries But, Califor
Slide 54: Key Takeaways
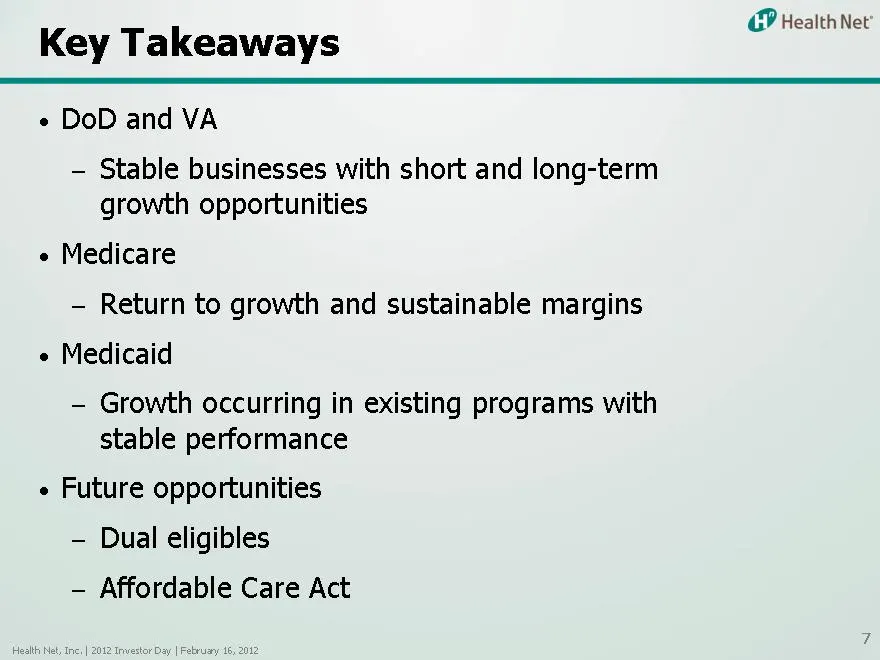
Key Takeaways DoD and VA – Stable businesses with short and long-term growth opportunities Medicare – Return to growth and sustainable margins Medicaid – Growth occurring in existing programs with stable performance Future opportunities – Dual eligibles – Affordable Care Act Health Net, Inc. | 2012
Slide 55: Operations Review: Lower Cost, Strong Results
Operations Review: Lower Cost, Strong Results Jim Woys Chief Operating Officer Health Net, Inc. | 2012 Investor Day | February 16, 2012
Slide 56: G&A Overview
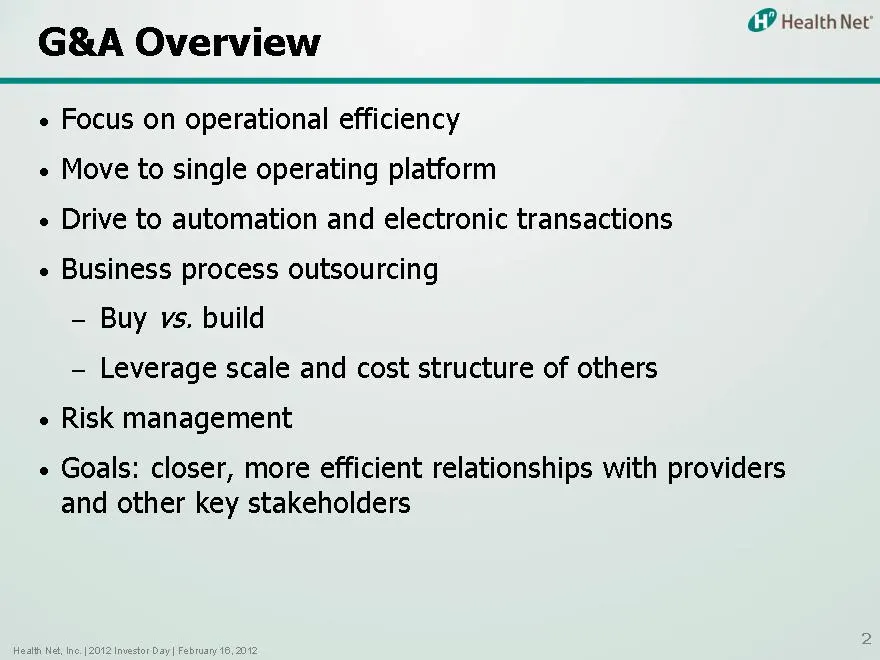
G&A Overview Focus on operational efficiency Move to single operating platform Drive to automation and electronic transactions Business process outsourcing Buy vs. build Leverage scale and cost structure of others Risk management Goals: closer, more efficient relationships with providers and other k
Slide 57: Key Actions to Date
Key Actions to Date Outsourcing – Infrastructure (IBM) – Application (Cognizant) – Business process (Cognizant) System and operational consolidation – Contact center – Company and divisional realignment Performance improvements – Strengthened performance standards – Implemented performance monitorin
Slide 58: Focus on Performance
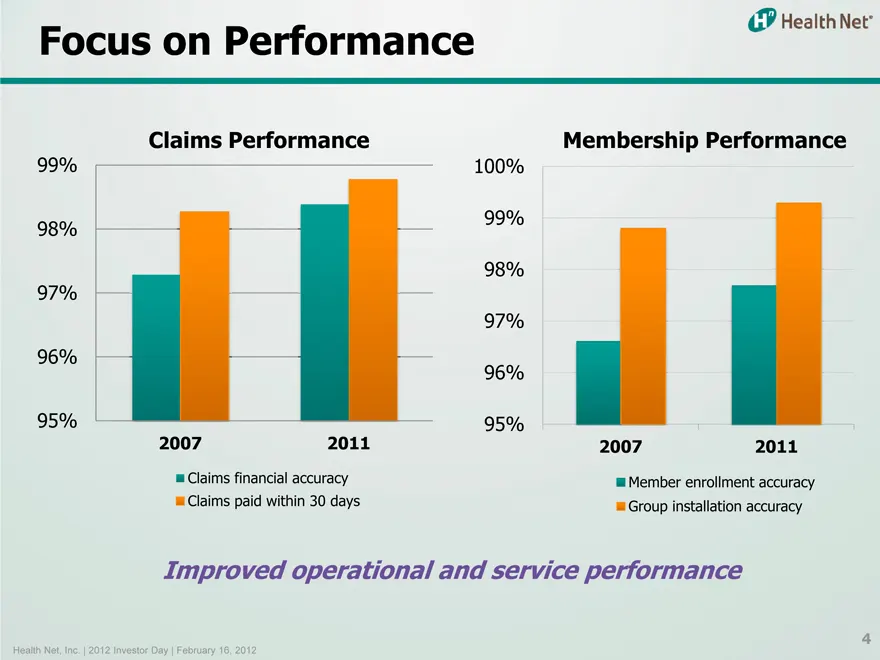
Focus on Performance Claims Performance 99% 98% 97% 96% 95% 2007 2008 Claims financial accuracy Claims paid within 30 days Membership Performance 100% 99% 98% 97% 96% 95% 2007 2008 Member enrollment accuracy Group installation accuracy Improved operational and service performance
Slide 59: Further G&A Improvement
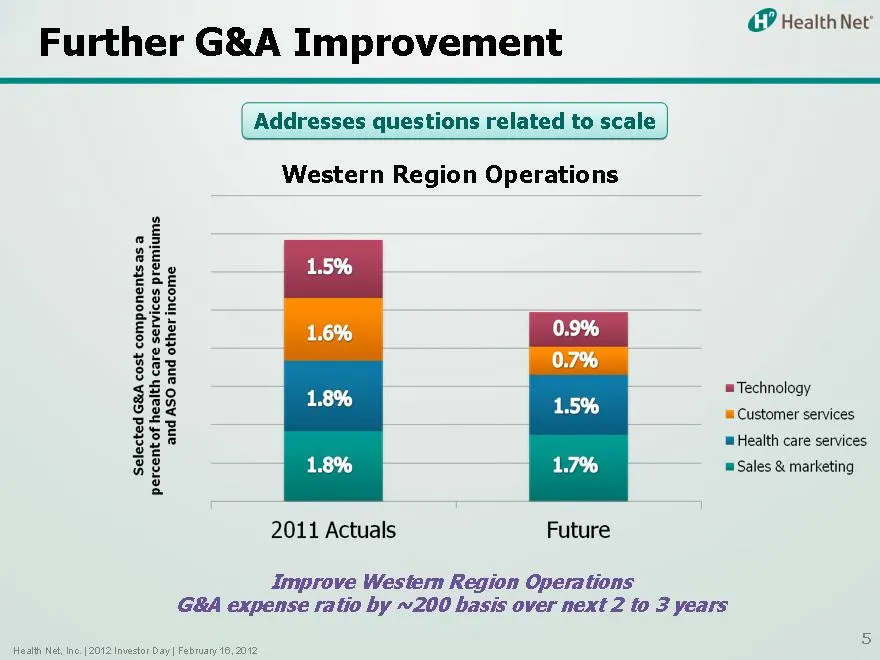
Further G&A Improvement Addresses questions related to scale Western Region Operations Selected G&A cost components as a percent of health care services premiums and ASO and other income 2011 Actuals Future Technology Customer services Health care services Sales & marketing Improve Western Region Op
Slide 60: Next Steps
Next Steps Application, infrastructure and business process outsourcing – Consider incremental strategic outsourcing, especially IT System and operational consolidation – Further rationalize IT platforms – Modernize call center technology and operations Performance improvements – Improved delivery o
Slide 61: Financial Review
Financial Review Joseph Capezza Chief Financial Officer
Slide 62: 2011 Results vs. Original Guidance
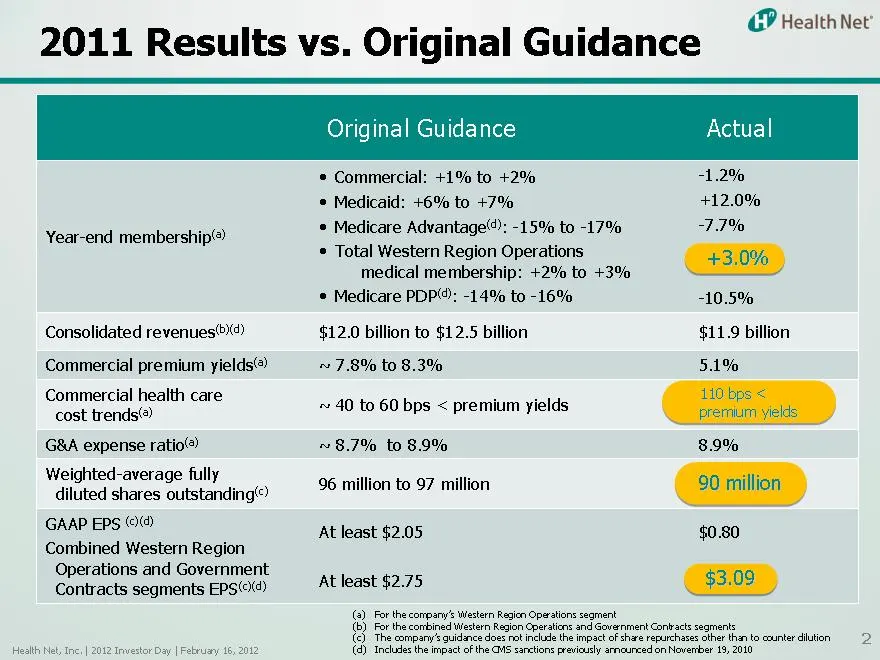
2011 Results vs. Original Guidance Original Guidance Actual • Commercial: +1% to +2% -1.2% • Medicaid: +6% to +7% +12.0% • Medicare Advantage(d): -15% to -17% -7.7% Year-end membership(a) • Total Western Region Operations +3.0% medical membership: +2% to +3% • Medicare PDP(d): -14% to -16% -10.5% Co
Slide 63: Solid 2011 Sets the Stage for 2012
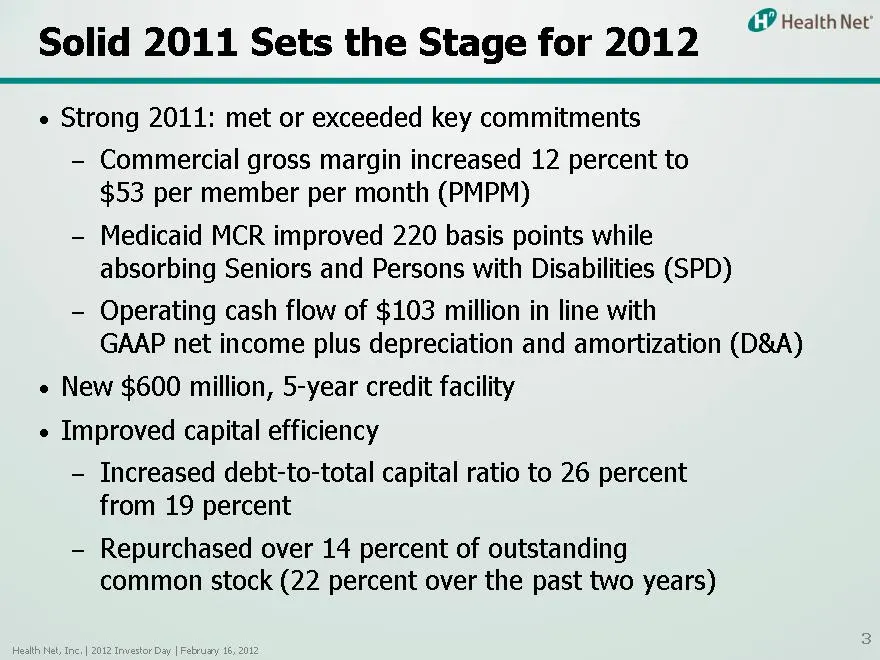
Solid 2011 Sets the Stage for 2012 • Strong 2011: met or exceeded key commitments – Commercial gross margin increased 12 percent to $53 per member per month (PMPM) – Medicaid MCR improved 220 basis points while absorbing Seniors and Persons with Disabilities (SPD) – Operating cash flow of $103 milli
Slide 64: 2012 Earnings Guidance
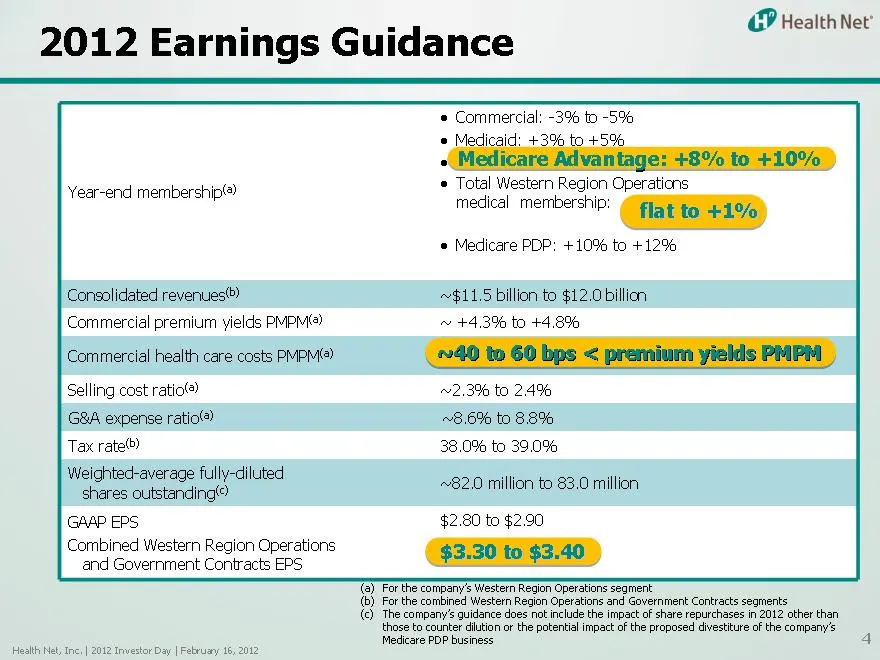
2012 Earnings Guidance • Commercial: -3% to -5% • Medicaid: Medicare +3% Advantage: to +5% +8% to +10% (a) Total Western Region Operations Year-end membership medical membership: flat to +1% • Medicare PDP: +10% to +12% Consolidated revenues(b) ~$11.5 billion to $12.0 billion Commercial premium yiel
Slide 65: Major Drivers of 2012 Earnings
Major Drivers of 2012 Earnings • Significant Medicare improvement – Renewed enrollment growth and continued margin gains – Better MCR with improved risk mix • Continued Medicaid improvement – Stable MCR and membership growth of 3 percent to 5 percent • Expect 10 to 30 basis point improvement in G&A
Slide 66: 2012 Cash Flow from Operations
2012 Cash Flow from Operations • Annualized operating cash flow expected to be equal to GAAP net income plus D&A – Expect approximately $270 million in 2012 • Quarterly reported operating cash flow subject to timing of government payments – Medicare – Medicaid – TRICARE
Slide 67: 2012 Cash at Parent
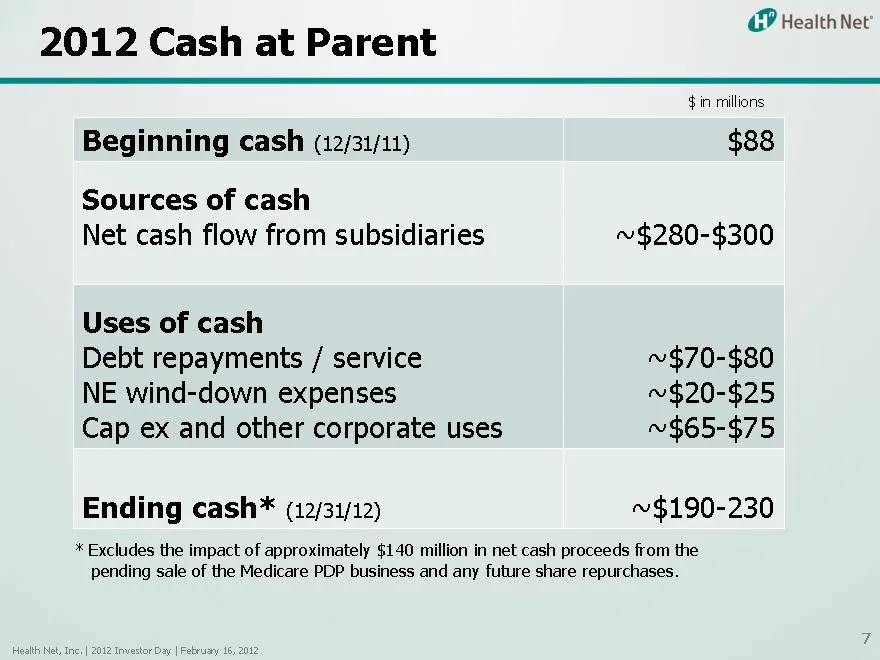
2012 Cash at Parent $ in millions Beginning cash (12/31/11) $88 Sources of cash Net cash flow from subsidiaries ~$280-$300 Uses of cash Debt repayments / service ~$70-$80 NE wind-down expenses ~$20-$25 Cap ex and other corporate uses ~$65-$75 Ending cash* (12/31/12) ~$190-230 * Excludes the impact o
Slide 68: Uses of Cash
Uses of Cash • Organic growth • Share repurchase
Slide 69: Key Takeaways
Key Takeaways • On track for: – Continued Western Region Operations gross margin expansion – Further commercial and Medicare margin improvement – Medicare and Medicaid membership growth – Lower G&A expense ratio – Continued strong cash flow performance – Pending Medicare PDP sale
Slide 70: Summary and Outlook
Summary and Outlook Jay Gellert President and Chief Executive Officer
Slide 71: Today's Agenda
Today’s Agenda • Setting the stage • Three panels – Commercial business – Government businesses – Operations and financial review • Summary and outlook
Slide 72: Building Shareholder Value
Building Shareholder Value • Strategic response to changing environment • Diverse book of businesses a real strength • Several key growth opportunities • Growing operational efficiency • Stable and predictable financial performance • Prudent use of cash
Slide 73: Future Opportunities
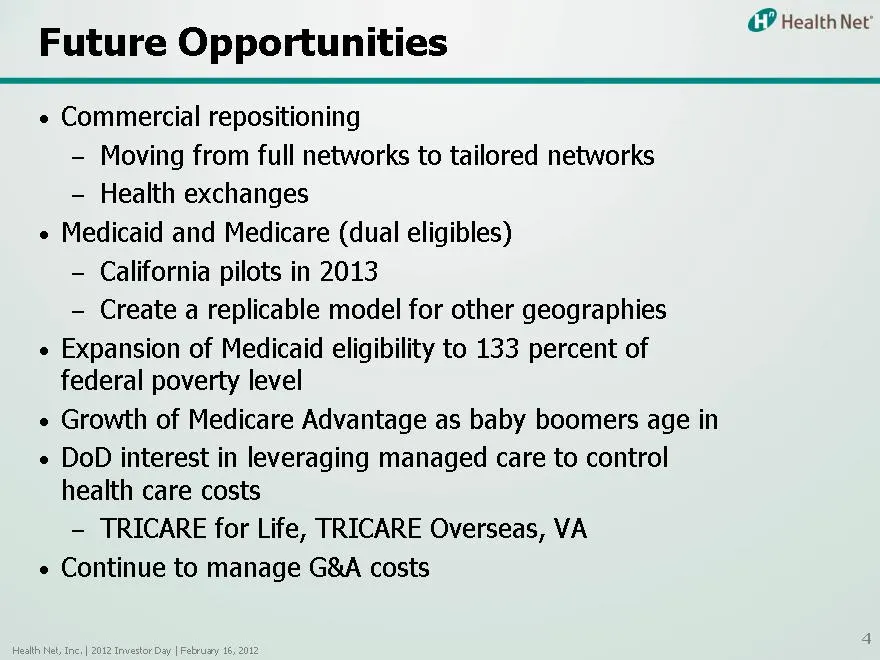
Future Opportunities • Commercial repositioning – Moving from full networks to tailored networks – Health exchanges • Medicaid and Medicare (dual eligibles) – California pilots in 2013 – Create a replicable model for other geographies • Expansion of Medicaid eligibility to 133 percent of federal pov
Slide 74: Health Net Investor Day
=. 2012 HealthNet’ Investor Day
Source: SEC EDGAR · 8-K filed Feb 16, 2012
More decks from Health Net Inc
 Q2 2015 Earnings Presentation25 slides · Sep 23, 2015
 SPAC Merger (July 2015)18 slides · Jul 15, 2015
 SPAC Merger (July 2015)18 slides · Jul 14, 2015
 Merger or Acquisition (July 2015)13 slides · Jul 2, 2015
 30th Annual J.P. Morgan Healthcare Conference (January 2012)13 slides · Jan 9, 2012
 Barclays Capital 2011 Global Healthcare Conference11 slides · Mar 14, 2011