Advanced Life Sciences Holdings Inc
Advanced Life Sciences — Lazard Capital Markets Third Annual Life Sciences Conference 2006
28 slides from Advanced Life Sciences's conference presentation, Nov 28, 2006
Slide 1: Lazard Capital Markets Third Annual Life Sciences Conference
Lazard Capital Markets Third Annual Life Sciences Conference November 28, 2006
Slide 2: Safe Harbor Statement
Safe Harbor Statement This presentation contains forward-looking statements about Advanced Life Sciences Holdings, Inc., including statements regarding the clinical trials and regulatory pathway of cethromycin. Forward-looking statements represent our management’s judgment regarding future events. T
Slide 3: Advanced Life Sciences Overview
Advanced Life Sciences Overview Clinical stage biopharmaceutical company developing innovative drugs to treat life-threatening diseases Focusing on: Infectious diseases Inflammation Oncology
Slide 4: Investment Highlights
Investment Highlights Second generation ketolide antibiotic cethromycin in Phase III The right drug at the right time Designed to overcome emerging resistance Safety & efficacy suggested in over 3,800 patients Pivotal phase III trials in CAP at 200 sites worldwide Market need for alternative ketolid
Slide 5: Clinical Pipeline
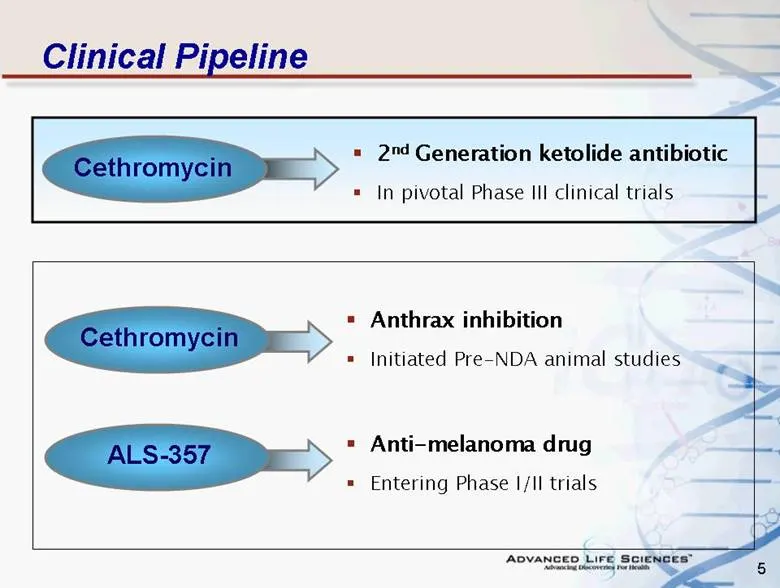
Anti-melanoma drug Entering Phase I/II trials Anthrax inhibition Initiated Pre-NDA animal studies 2 nd Generation ketolide antibiotic In pivotal Phase III clinical trials Clinical Pipeline Cethromycin ALS-357 Cethromycin
Slide 6: Spectrum of RTI Activity
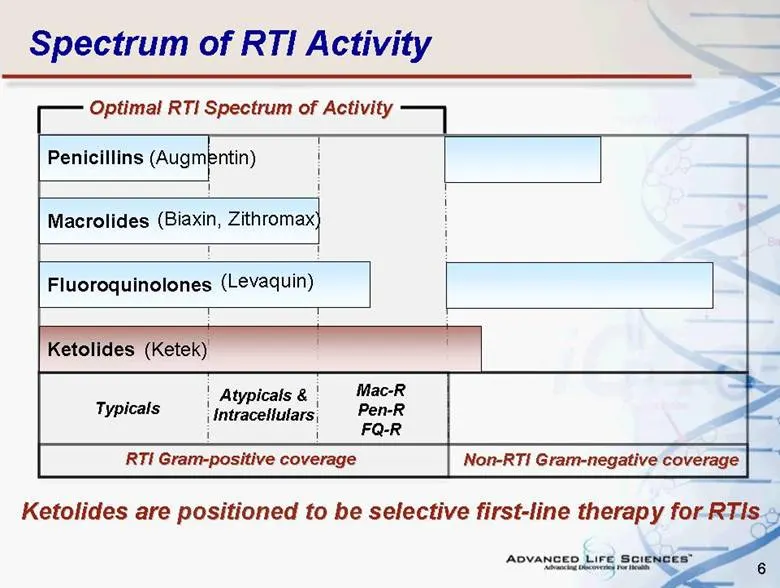
Spectrum of RTI Activity Typicals Atypicals & Intracellulars Mac-R Pen-R FQ-R Ketolides Penicillins (Augmentin) Macrolides Fluoroquinolones Optimal RTI Spectrum of Activity Ketolides are positioned to be selective first-line therapy for RTIs RTI Gram-positive coverage Non-RTI Gram-negative coverage
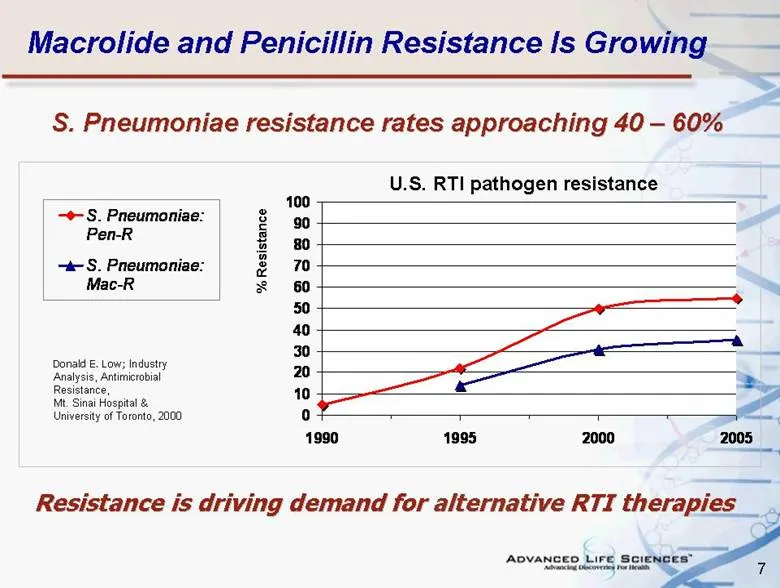
Slide 7: Macrolide and Penicillin Resistance Is Growing
Macrolide and Penicillin Resistance Is Growing Resistance is driving demand for alternative RTI therapies Donald E. Low; Industry Analysis, Antimicrobial Resistance, Mt. Sinai Hospital & University of Toronto, 2000 % Resistance S. Pneumoniae resistance rates approaching 40 – 60% U.S. RTI pathogen re
Slide 8: Need for Products that Overcome Resistance
Need for Products that Overcome Resistance Antibiotic resistance in community acquired RTI is a $5 billion 1 economic burden in the U.S. Cost of hospitalized CAP patients unresponsive to penicillins or macrolides is $15,000 2 per patient vs. $200 office visit with prescription MCOs seek new antibiot
Slide 9: Collateral Damage Rising
Collateral Damage Rising Overuse of fluoroquinolones and cephalosporins have caused Increased incidence of clostridium difficile associated disease (CDAD) Class cross resistance Heavy GI side effects and may lead to decreased use of these drug classes for RTIs Ketolides may offer alternative that do
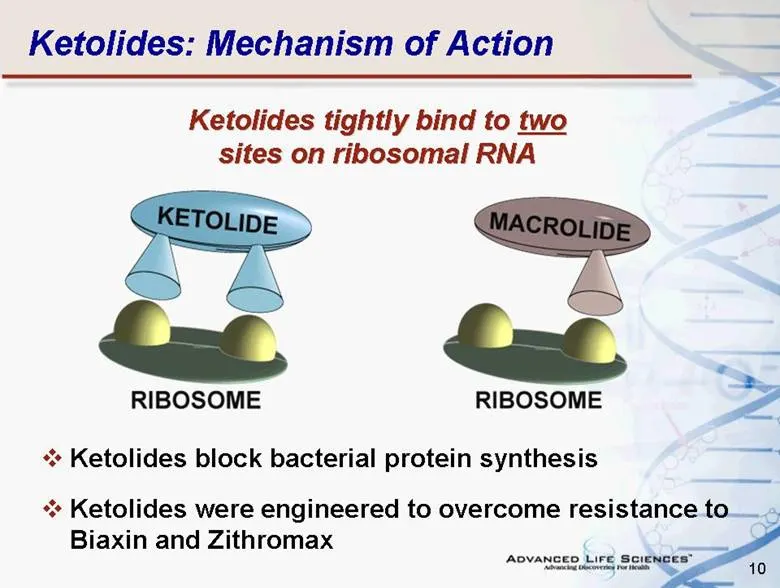
Slide 10: Ketolides block bacterial protein synthesis
Ketolides block bacterial protein synthesis Ketolides were engineered to overcome resistance to Biaxin and Zithromax Ketolides: Mechanism of Action Ketolides tightly bind to two sites on ribosomal RNA
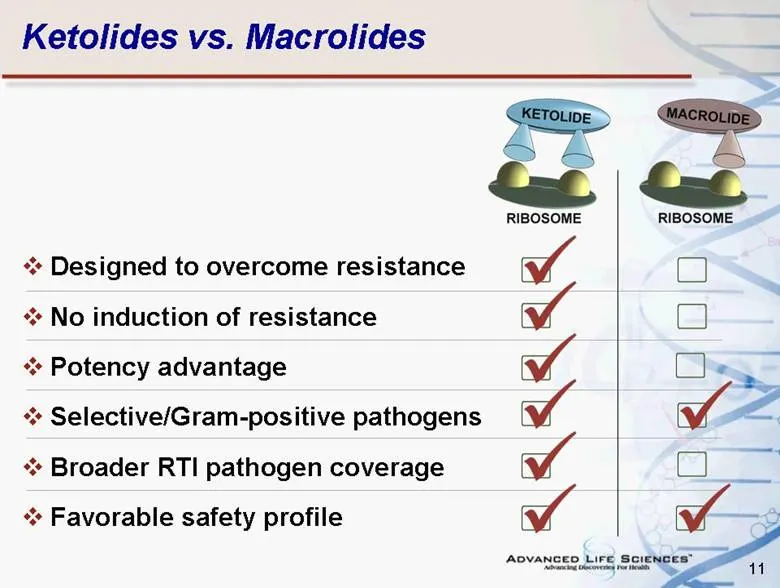
Slide 11: Ketolides vs. Macrolides: Designed to overcome resistance
Designed to overcome resistance No induction of resistance Potency advantage Selective/Gram-positive pathogens Broader RTI pathogen coverage Favorable safety profile Ketolides vs. Macrolides
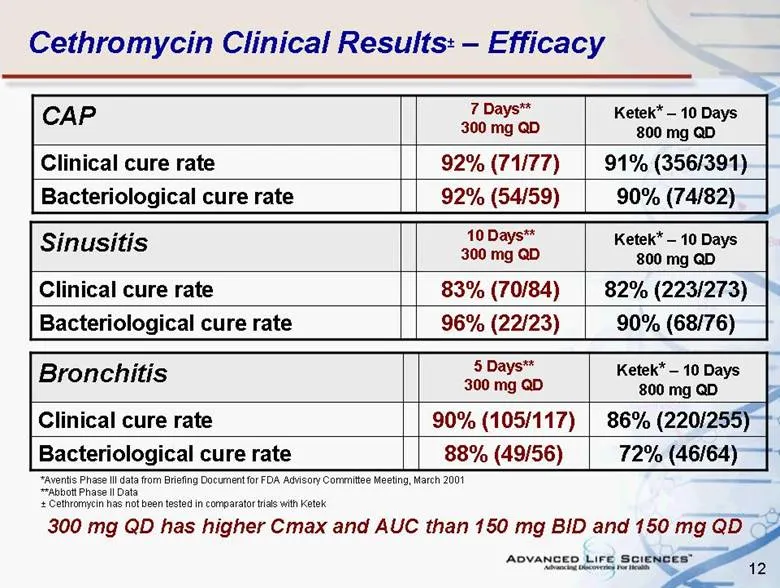
Slide 12: Cethromycin Clinical Results – Efficacy
Cethromycin Clinical Results ± – Efficacy 72% (46/64) 88% (49/56) Bacteriological cure rate 86% (220/255) 90% (105/117) Clinical cure rate Ketek * – 10 Days 800 mg QD 5 Days** 300 mg QD Bronchitis 90% (68/76) 96% (22/23) Bacteriological cure rate 82% (223/273) 83% (70/84) Clinical cure rate Ketek *
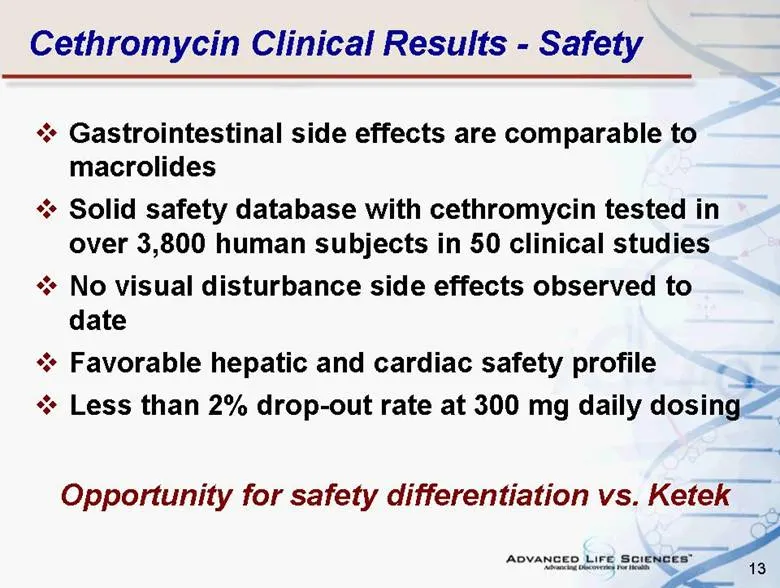
Slide 13: Cethromycin Clinical Results - Safety
Cethromycin Clinical Results - Safety Gastrointestinal side effects are comparable to macrolides Solid safety database with cethromycin tested in over 3,800 human subjects in 50 clinical studies No visual disturbance side effects observed to date Favorable hepatic and cardiac safety profile Less tha
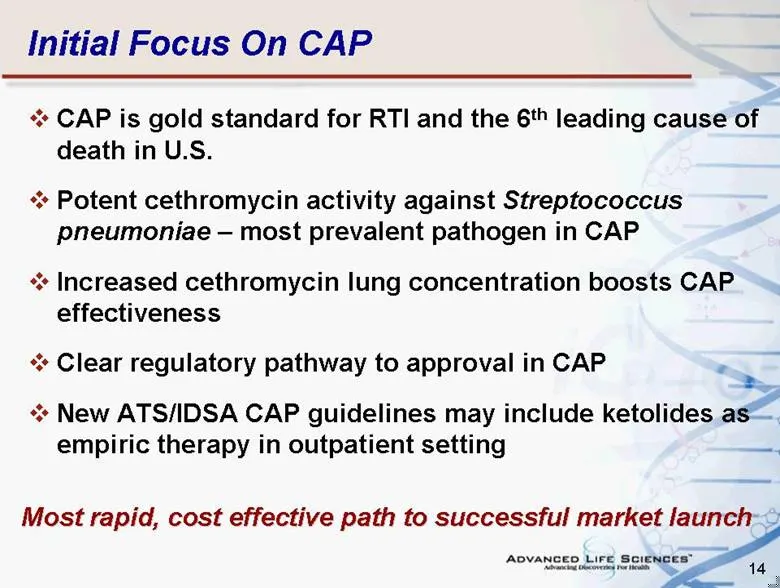
Slide 14: Initial Focus On CAP
Initial Focus On CAP CAP is gold standard for RTI and the 6 th leading cause of death in U.S. Potent cethromycin activity against Streptococcus pneumoniae – most prevalent pathogen in CAP Increased cethromycin lung concentration boosts CAP effectiveness Clear regulatory pathway to approval in CAP Ne
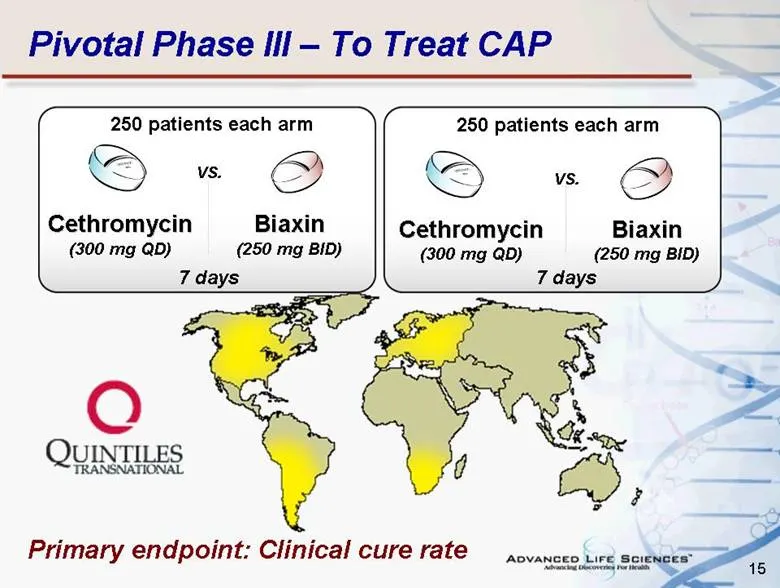
Slide 15: Pivotal Phase III – To Treat CAP
Pivotal Phase III – To Treat CAP Cethromycin (300 mg QD) VS. Biaxin (250 mg BID) Cethromycin (300 mg QD) VS. Biaxin (250 mg BID) Primary endpoint: Clinical cure rate 250 patients each arm 250 patients each arm 7 days 7 days
Slide 16: Phase III Clinical Trial Design
Phase III Clinical Trial Design Powered to demonstrate clinical cure rate non-inferiority endpoint using 95% confidence interval Secondary Endpoint: Bacteriological cure rate Two phase III, double-blind, randomized, global trials with approximately 200 clinical sites worldwide At each site, subjects
Slide 17: Microbiological Evaluations
Microbiological Evaluations Qualified sputum is cultured to identify S. pneumoniae, H. influenzae, M. catarrhalis, L. pneumophila, S. aureus, S. pyogenes Acute and convalescent serology to detect L. pneumophila, M. pneumoniae and C. pneumoniae Urine is assayed for L. pneumophila antigen Trials are d
Slide 18: Phase III Clinical Trial Timeline Update
Phase III Clinical Trial Timeline Update Enrollment is continuing Rigorous trial design and seasonality are titrating the flow of qualified patients Blinded data show promising clinical and bacteriological cure rates and favorable safety profile Changing regulatory landscape in the antibiotic space
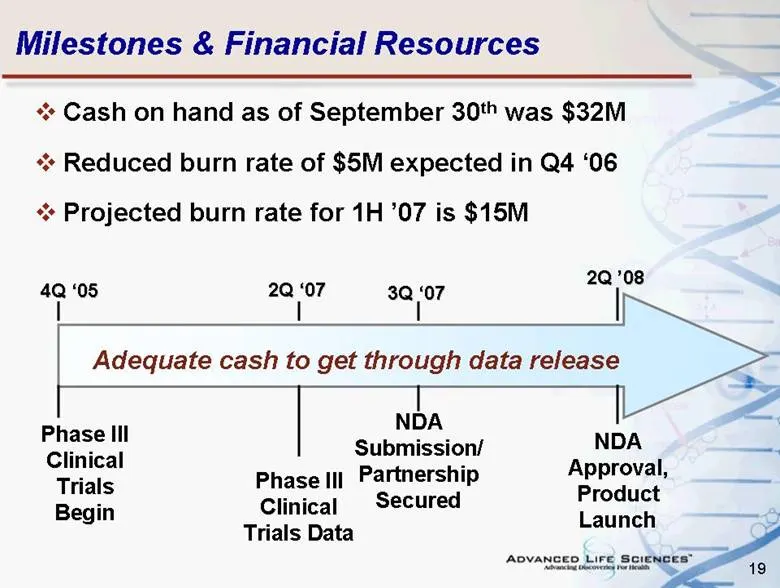
Slide 19: Milestones & Financial Resources
Milestones & Financial Resources 4Q ‘05 2Q ‘07 3Q ‘07 Phase III Clinical Trials Begin Phase III Clinical Trials Data NDA Submission/Partnership Secured 2Q ’08 NDA Approval, Product Launch Cash on hand as of September 30 th was $32M Reduced burn rate of $5M expected in Q4 ‘06 Projected burn rate for
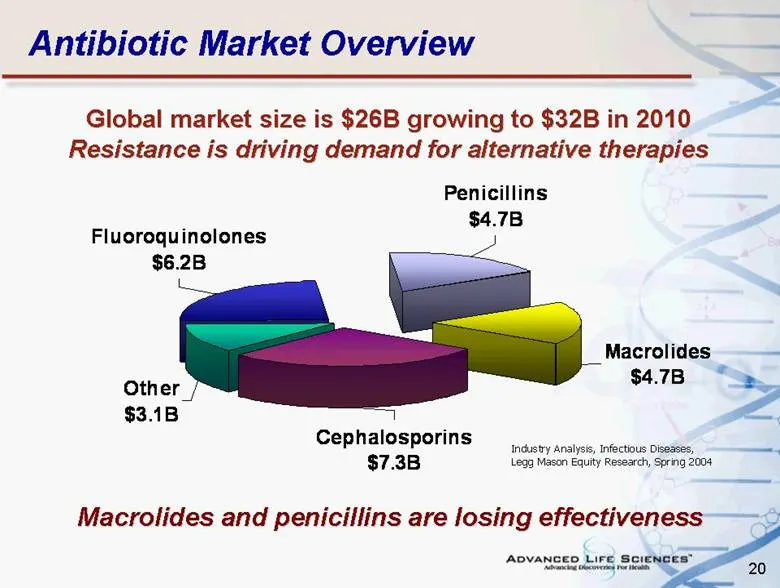
Slide 20: Antibiotic Market Overview
Antibiotic Market Overview Global market size is $26B growing to $32B in 2010 Resistance is driving demand for alternative therapies Industry Analysis, Infectious Diseases, Legg Mason Equity Research, Spring 2004 Macrolides and penicillins are losing effectiveness Macrolides $4.7B Cephalosporins $7.
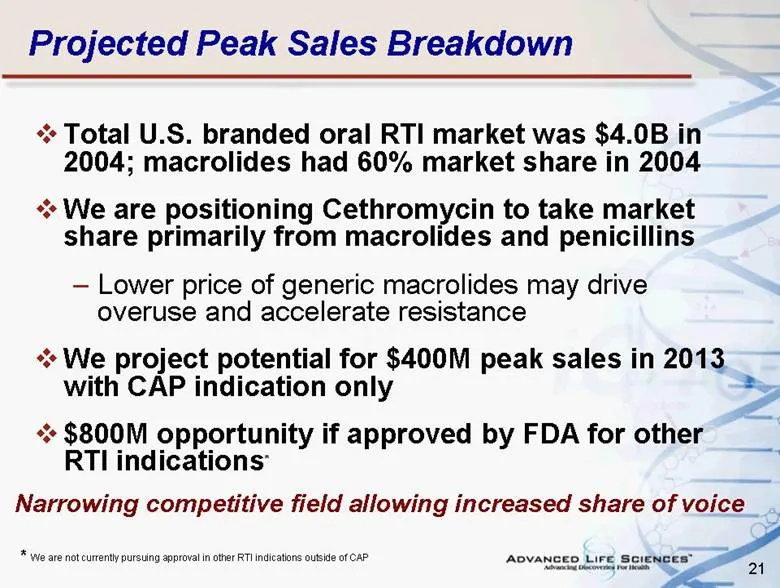
Slide 21: Projected Peak Sales Breakdown
Projected Peak Sales Breakdown Total U.S. branded oral RTI market was $4.0B in 2004; macrolides had 60% market share in 2004 We are positioning Cethromycin to take market share primarily from macrolides and penicillins Lower price of generic macrolides may drive overuse and accelerate resistance We
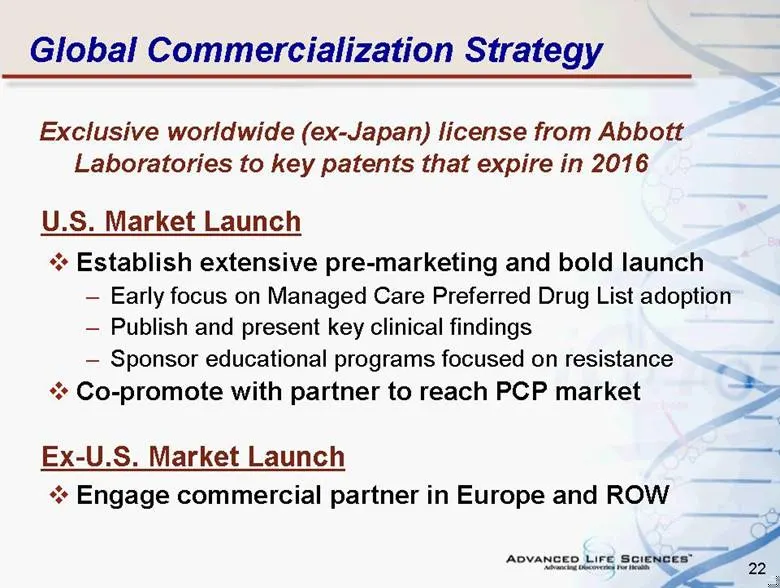
Slide 22: Global Commercialization Strategy
Global Commercialization Strategy Establish extensive pre-marketing and bold launch Early focus on Managed Care Preferred Drug List adoption Publish and present key clinical findings Sponsor educational programs focused on resistance Co-promote with partner to reach PCP market Engage commercial part
Slide 23: Cethromycin Anthrax Inhibition
Cethromycin Anthrax Inhibition Need for novel agents with new mechanisms for bioterrorism protection Collaboration with USAMRIID Cethromycin exhibited superior potency in vitro vs. approved drugs against over 30 anthrax strains In vivo results demonstrated equivalence to Cipro, the current gold stan
Slide 24: Recently Completed Milestones
Recently Completed Milestones Presented clinical data at ICAAC and IDSA in Fall, ‘06 Initiated pre-NDA animal studies for anthrax indication in July, ‘06 Engaged DSM and Cardinal as commercial manufacturing partners in May, ‘06 Completed $36M PIPE equity offering in March, ’06
Slide 25: Senior Management Team
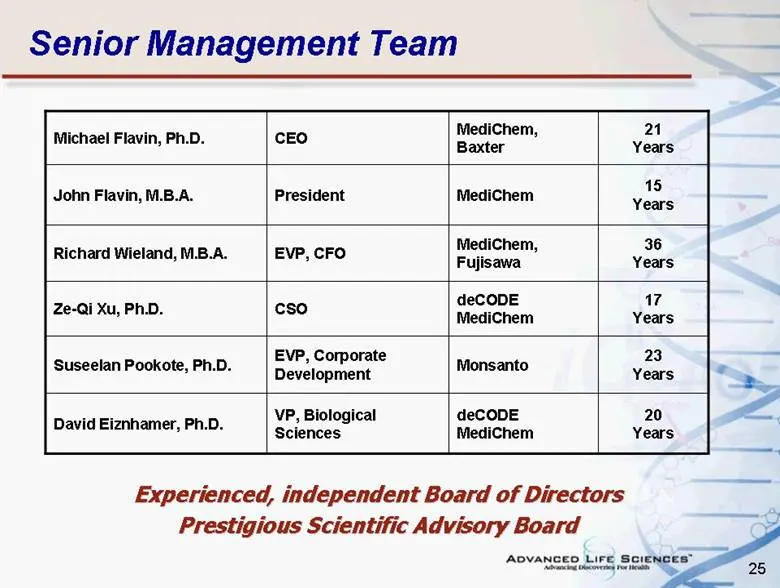
Senior Management Team Experienced, independent Board of Directors Prestigious Scientific Advisory Board 36 Years MediChem, Fujisawa EVP, CFO Richard Wieland, M.B.A. 15 Years MediChem President John Flavin, M.B.A. 20 Years deCODE MediChem VP, Biological Sciences David Eiznhamer, Ph.D. 17 Years deCOD
Slide 26: Financial Summary
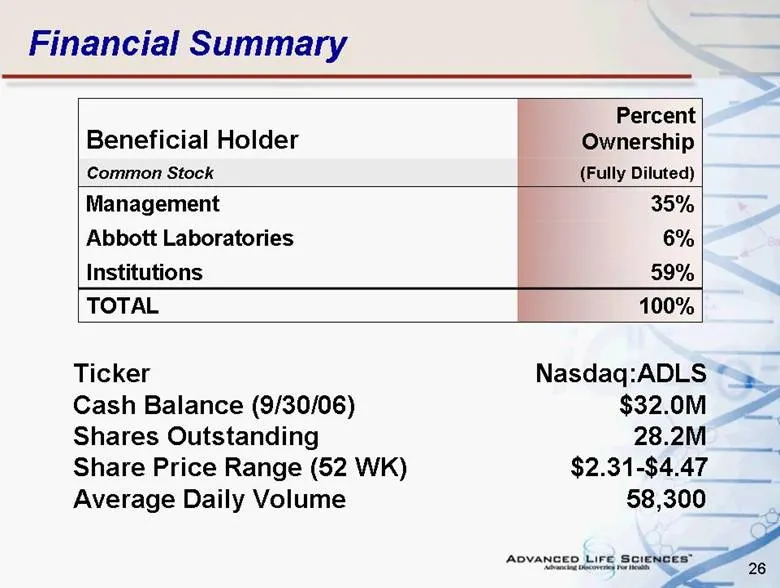
Financial Summary 100% TOTAL 59% Institutions 6% Abbott Laboratories 35% Management (Fully Diluted) Common Stock Percent Ownership Beneficial Holder Ticker Nasdaq:ADLS Cash Balance (9/30/06) $32.0M Shares Outstanding 28.2M Share Price Range (52 WK) $2.31-$4.47 Average Daily Volume 58,300
Slide 27: Investment Highlights
Investment Highlights Second generation ketolide antibiotic cethromycin in Phase III The right drug at the right time Designed to overcome emerging resistance Safety & efficacy suggested in over 3,800 patients Pivotal phase III trials in CAP at 200 sites worldwide Market need for alternative ketolid
Slide 28: Lazard Capital Markets Third Annual Life Sciences Conference
Lazard Capital Markets Third Annual Life Sciences Conference November 28, 2006
Source: SEC EDGAR · 8-K filed Nov 28, 2006