Ditech — Walter Investment Management — Merger or Acquisition (March 2011)
23 slides from Ditech's merger presentation, Mar 28, 2011
Slide 1: Walter Investment Makes Strategic Acquisition of Leading Business Services Company
Investor Presentation Walter Investment Makes Strategic Acquisition of Leading Business Services Company March 28, 2011
Slide 2: Safe Harbor Statement
Safe Harbor Statement Certain statements in this release and in any of Walter Investment Management Corp.'s public documents referred to herein, contain or incorporate by reference "forward-looking" statements as defined in Section 27A of the Securities Act of 1933, as amended, and Section 21E of th
Slide 3: Management Team
Management Team Brian Libman Chief Strategic Officer Charles Cauthen President & COO of WIMC Kim Perez CFO of WIMC Denmar Dixon Vice Chairman & EVP of WIMC Keith Anderson President & CEO of Green Tree Credit Solutions Cheryl Collins CFO of Green Tree Credit Solutions Mark O'Brien Chairman & CEO of W
Slide 4: Strategic Rationale
Green Tree is a premier "asset-light," fee-based business services company providing high-touch, third-party servicing of credit-sensitive consumer loans The two companies are a very solid fit: Similar business models with long, established track records of producing industry leading servicing resul
Slide 5: Transaction Overview
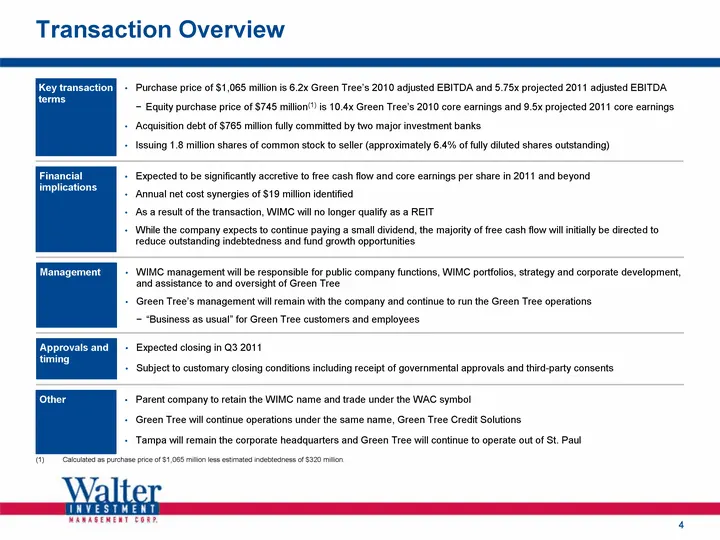
Transaction Overview Key transaction terms Financial implications Management Approvals and timing Purchase price of $1,065 million is 6.2x Green Tree's 2010 adjusted EBITDA and 5.75x projected 2011 adjusted EBITDA Equity purchase price of $745 million(1) is 10.4x Green Tree's 2010 core earnings and
Slide 6: Green Tree Overview
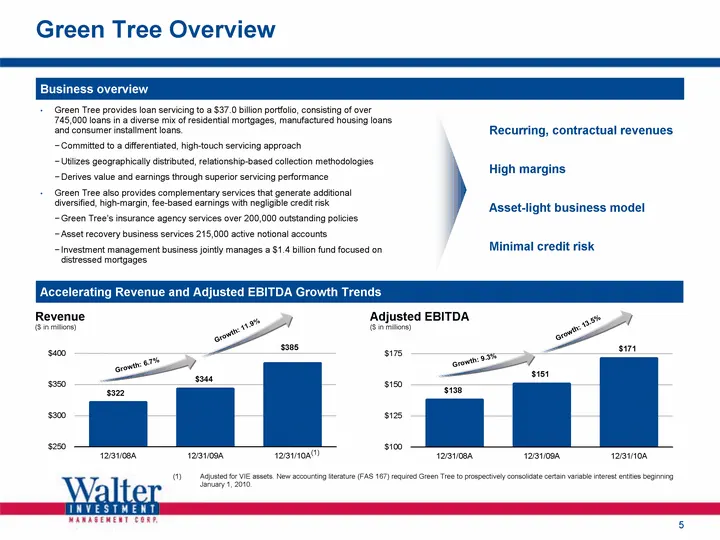
Green Tree Overview Business overview Green Tree provides loan servicing to a $37.0 billion portfolio, consisting of over 745,000 loans in a diverse mix of residential mortgages, manufactured housing loans and consumer installment loans. Committed to a differentiated, high-touch servicing approach U
Slide 7: Green Tree's Complementary Business Lines
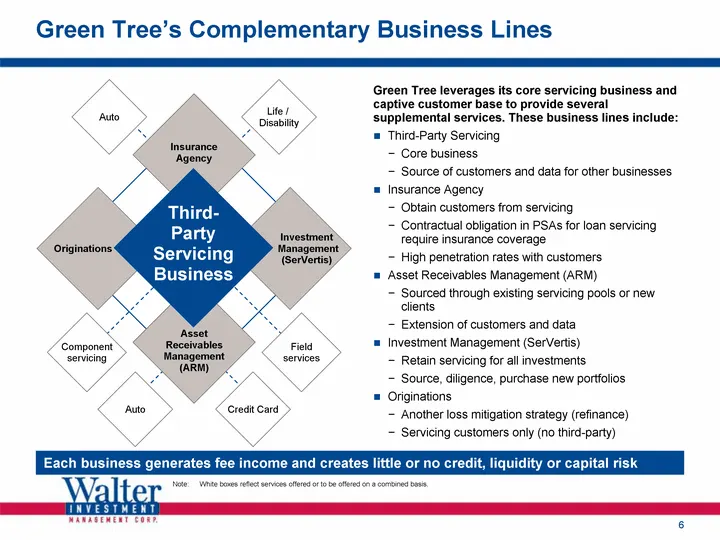
Green Tree's Complementary Business Lines Green Tree leverages its core servicing business and captive customer base to provide several supplemental services. These business lines include: Third-Party Servicing Core business Source of customers and data for other businesses Insurance Agency Obtain c
Slide 8: Diverse Sources of Revenue
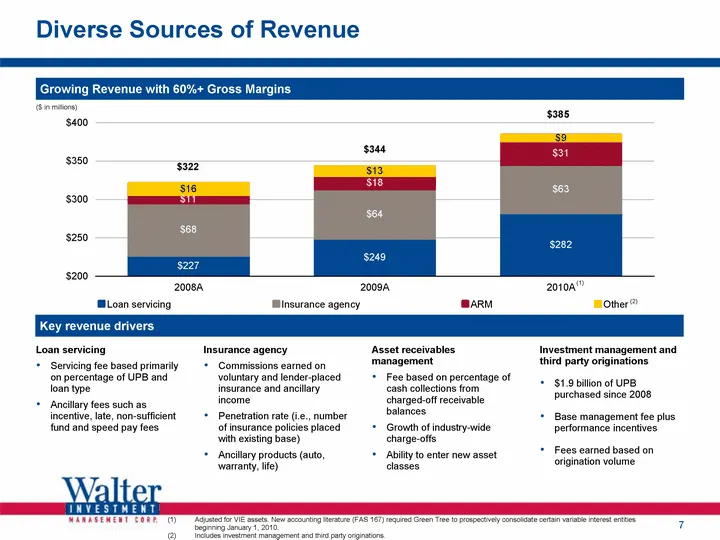
Insurance agency Commissions earned on voluntary and lender-placed insurance and ancillary income Penetration rate (i.e., number of insurance policies placed with existing base) Ancillary products (auto, warranty, life) Asset receivables management Fee based on percentage of cash collections from ch
Slide 9: New Servicing Business Profitability
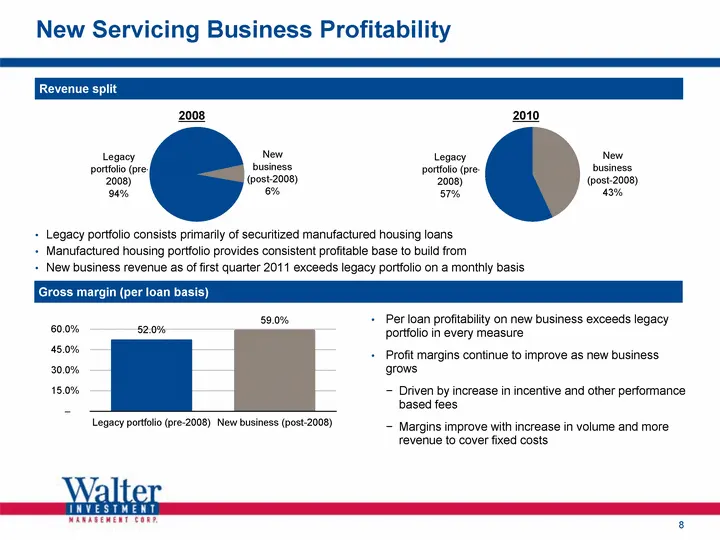
New Servicing Business Profitability Legacy portfolio consists primarily of securitized manufactured housing loans Manufactured housing portfolio provides consistent profitable base to build from New business revenue as of first quarter 2011 exceeds legacy portfolio on a monthly basis Per loan profi
Slide 10: Overview of Sector Trends
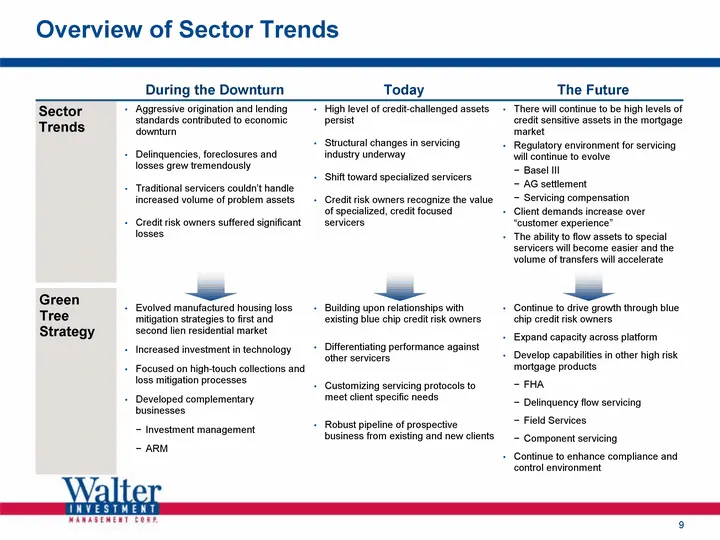
Overview of Sector Trends Sector Trends Green Tree Strategy Aggressive origination and lending standards contributed to economic downturn Delinquencies, foreclosures and losses grew tremendously Traditional servicers couldn't handle increased volume of problem assets Credit risk owners suffered sign
Slide 11: Significant Market Opportunity
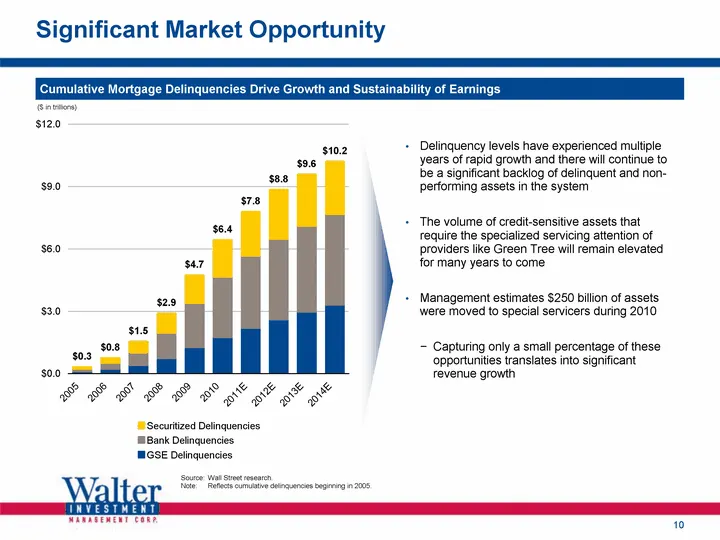
Significant Market Opportunity Cumulative Mortgage Delinquencies Drive Growth and Sustainability of Earnings Source: Wall Street research. Note: Reflects cumulative delinquencies beginning in 2005. ($ in trillions) Delinquency levels have experienced multiple years of rapid growth and there will con
Slide 12: WIMC and Green Tree Excel at Special Servicing
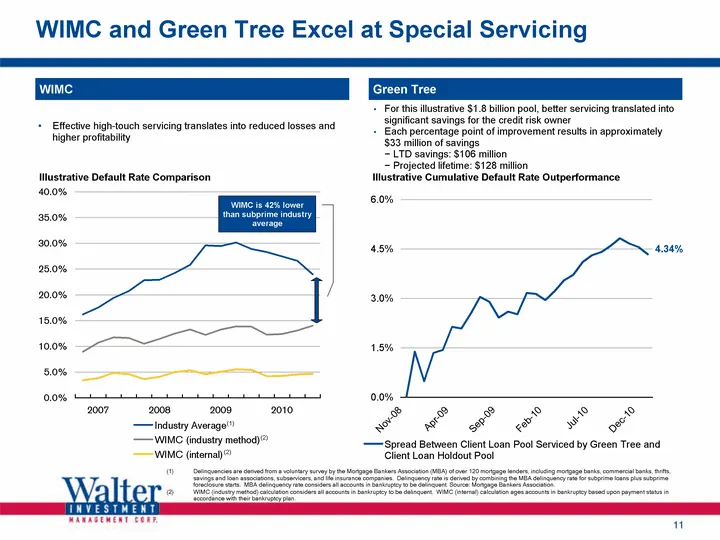
WIMC and Green Tree Excel at Special Servicing (1) Delinquencies are derived from a voluntary survey by the Mortgage Bankers Association (MBA) of over 120 mortgage lenders, including mortgage banks, commercial banks, thrifts, savings and loan associations, subservicers, and life insurance companies.
Slide 13: Best-In-Class Servicing Platform that Maximizes Value of Credit Sensitive Assets
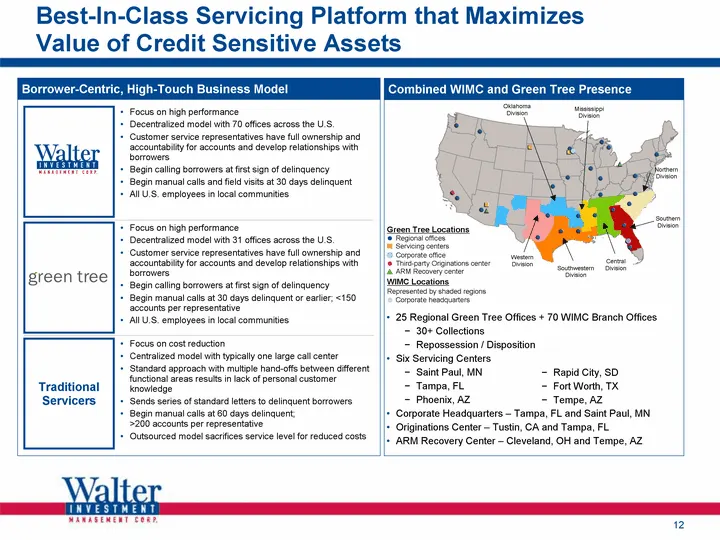
Best-In-Class Servicing Platform that Maximizes Value of Credit Sensitive Assets Borrower-Centric, High-Touch Business Model Combined WIMC and Green Tree Presence Traditional Servicers Focus on high performance Decentralized model with 31 offices across the U.S. Customer service representatives have
Slide 14: Green Tree Has a Proven Track Record of Adding New Business
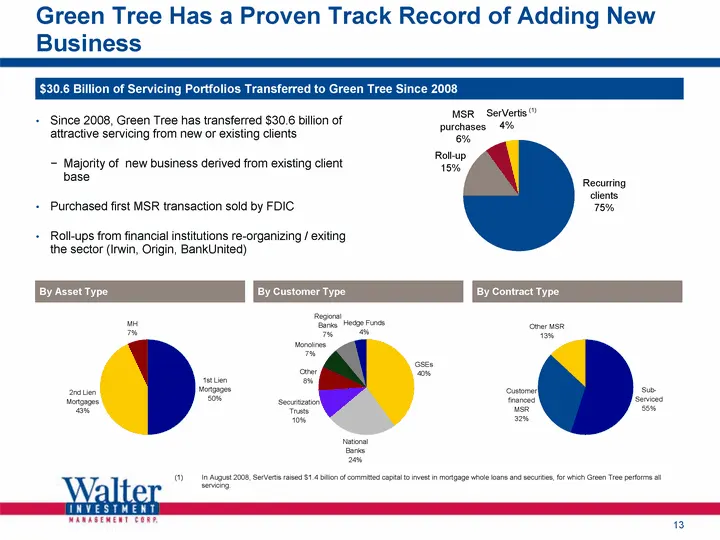
Green Tree Has a Proven Track Record of Adding New Business Since 2008, Green Tree has transferred $30.6 billion of attractive servicing from new or existing clients Majority of new business derived from existing client base Purchased first MSR transaction sold by FDIC Roll-ups from financial instit
Slide 15: Attractive Growth Prospects
Attractive Growth Prospects Fundamental industry shift toward credit-focused servicers Longstanding relationships with diverse, blue chip customer base generating repeat business Heavily invested in proprietary technology built specifically for servicing credit-sensitive customers Strong independent
Slide 16: Significant Synergies
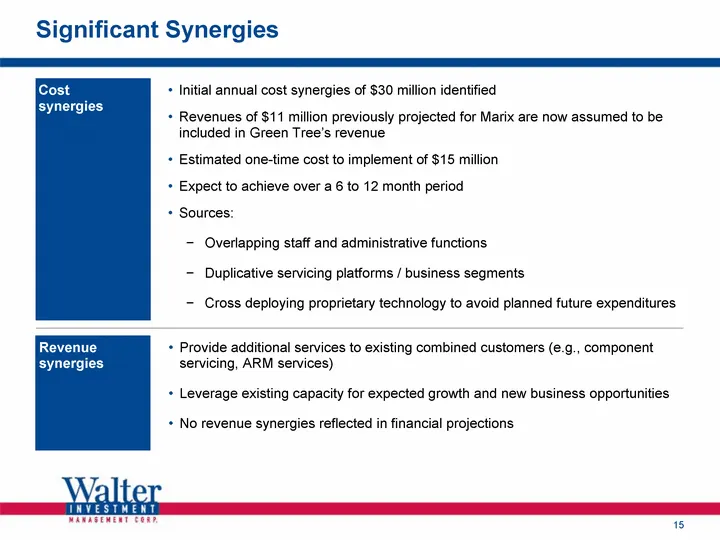
Significant Synergies Cost synergies Revenue synergies Initial annual cost synergies of $30 million identified Revenues of $11 million previously projected for Marix are now assumed to be included in Green Tree's revenue Estimated one-time cost to implement of $15 million Expect to achieve over a 6
Slide 17: Financial Outlook - Run Rate Analysis
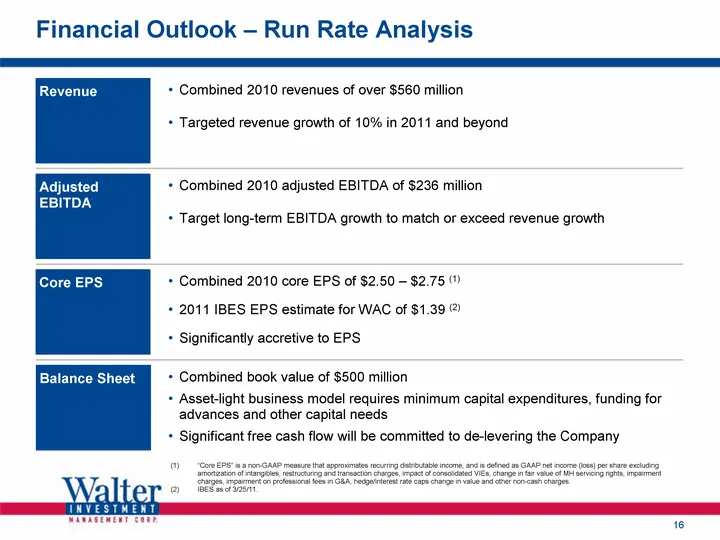
Financial Outlook - Run Rate Analysis (1) "Core EPS" is a non-GAAP measure that approximates recurring distributable income, and is defined as GAAP net income (loss) per share excluding amortization of intangibles, restructuring and transaction charges, impact of consolidated VIEs, change in fair va
Slide 18: Strategic Rationale for the Acquisition of Green Tree
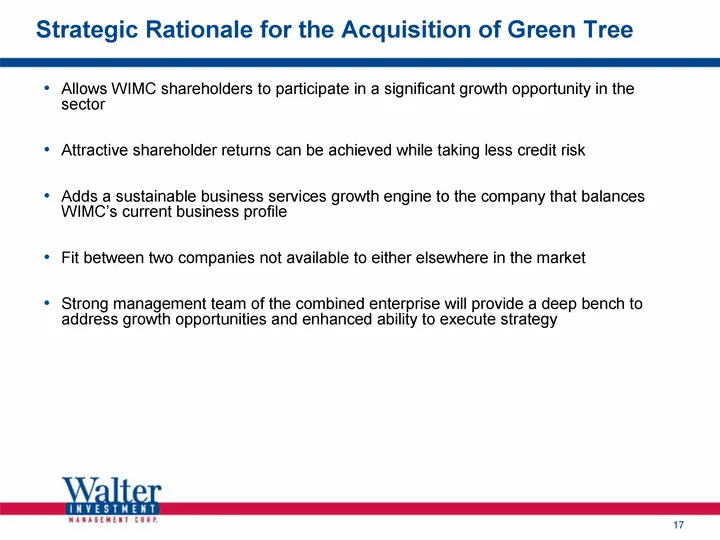
Allows WIMC shareholders to participate in a significant growth opportunity in the sector Attractive shareholder returns can be achieved while taking less credit risk Adds a sustainable business services growth engine to the company that balances WIMC's current business profile Fit between two compa
Slide 19: Appendix
MANAGEMENT CORP. Appendix
Slide 20: Use of Non-GAAP Measures
Use of Non-GAAP Measures Generally Accepted Accounting Principles ("GAAP") is the standard framework of guidelines for financial accounting. It includes the standards, conventions and rules accountants follow in reporting and summarizing transactions, and in the preparation of financial statements.
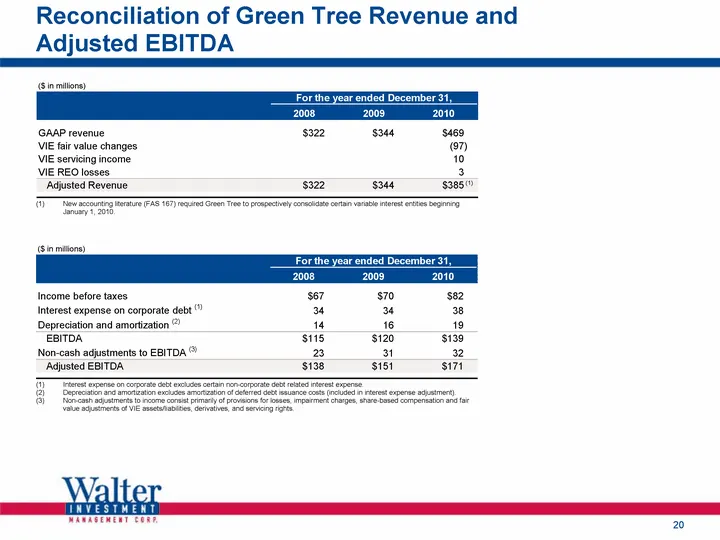
Slide 21: Reconciliation of Green Tree Revenue and Adjusted EBITDA
Reconciliation of Green Tree Revenue and Adjusted EBITDA (1) Interest expense on corporate debt excludes certain non-corporate debt related interest expense. (2) Depreciation and amortization excludes amortization of deferred debt issuance costs (included in interest expense adjustment). (3) Non-cas
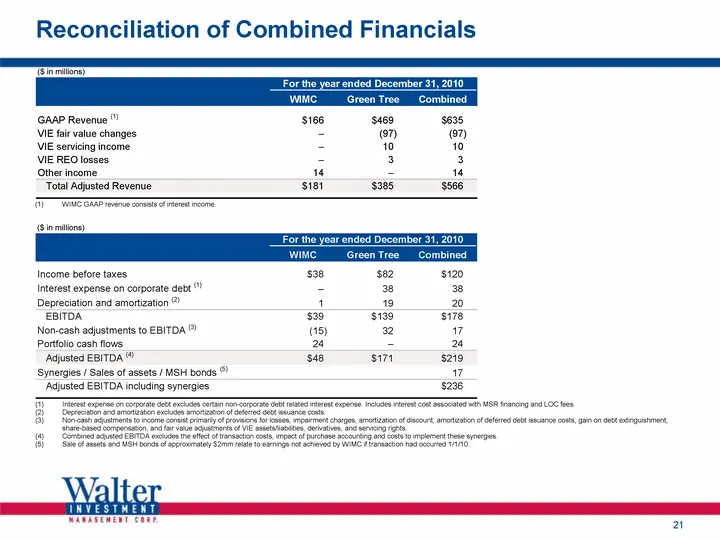
Slide 22: Reconciliation of Combined Financials
Reconciliation of Combined Financials (1) WIMC GAAP revenue consists of interest income. (1) Interest expense on corporate debt excludes certain non-corporate debt related interest expense. Includes interest cost associated with MSR financing and LOC fees. (2) Depreciation and amortization excludes
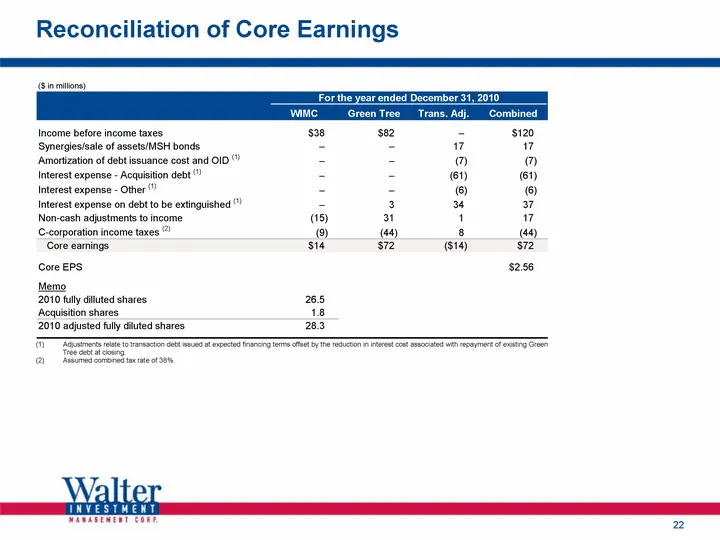
Slide 23: Reconciliation of Core Earnings
Reconciliation of Core Earnings (1) Adjustments relate to transaction debt issued at expected financing terms offset by the reduction in interest cost associated with repayment of existing Green Tree debt at closing. (2) Assumed combined tax rate of 38%.
Source: SEC EDGAR · 8-K filed Mar 28, 2011
More decks from Ditech Holding Corporation
 Presentation (December 2018)27 slides · Dec 14, 2018
 Q2 2018 Earnings Presentation21 slides · Aug 9, 2018
 Q1 2018 Earnings Presentation27 slides · Jun 6, 2018
 Walter Investment Management — Debt Investor Presentation (October 2017)15 slides · Oct 23, 2017
 Walter Investment Management — Debt Investor Presentation (August 2017)35 slides · Aug 1, 2017
 Walter Investment Management — Debt Investor Presentation (August 2017)5 slides · Aug 1, 2017