InterContinental Hotels Group PLC · LSE:IHG
InterContinental Hotels — Investor Day (February 2024)
90 slides from InterContinental Hotels's investor day presentation, Feb 20, 2024
Slide 1: Update on Strategic Priorities
Update on Strategic Priorities 20 February 2024
Slide 2: Cautionary note regarding forward-looking statements
Cautionary note regarding forward-looking statements This presentation may contain projections and forward looking-statements. The words “believe”, “expect”, “anticipate”, “intend” and “plan” and similar expressions identify forward-looking statements. All statements other than statements of histori
Slide 3: Introductory video
Introductory video True Hosp
Slide 4: Elie Maalouf
Elie Maalouf Chief Executive Officer 4
Slide 5: Agenda
Agenda Our industry IHG’s business model, track record and growth algorithm Strategic priorities Regional updates Margin potential, cash generation and capital allocation Conclusions Q&A 5
Slide 6: Leadership Team
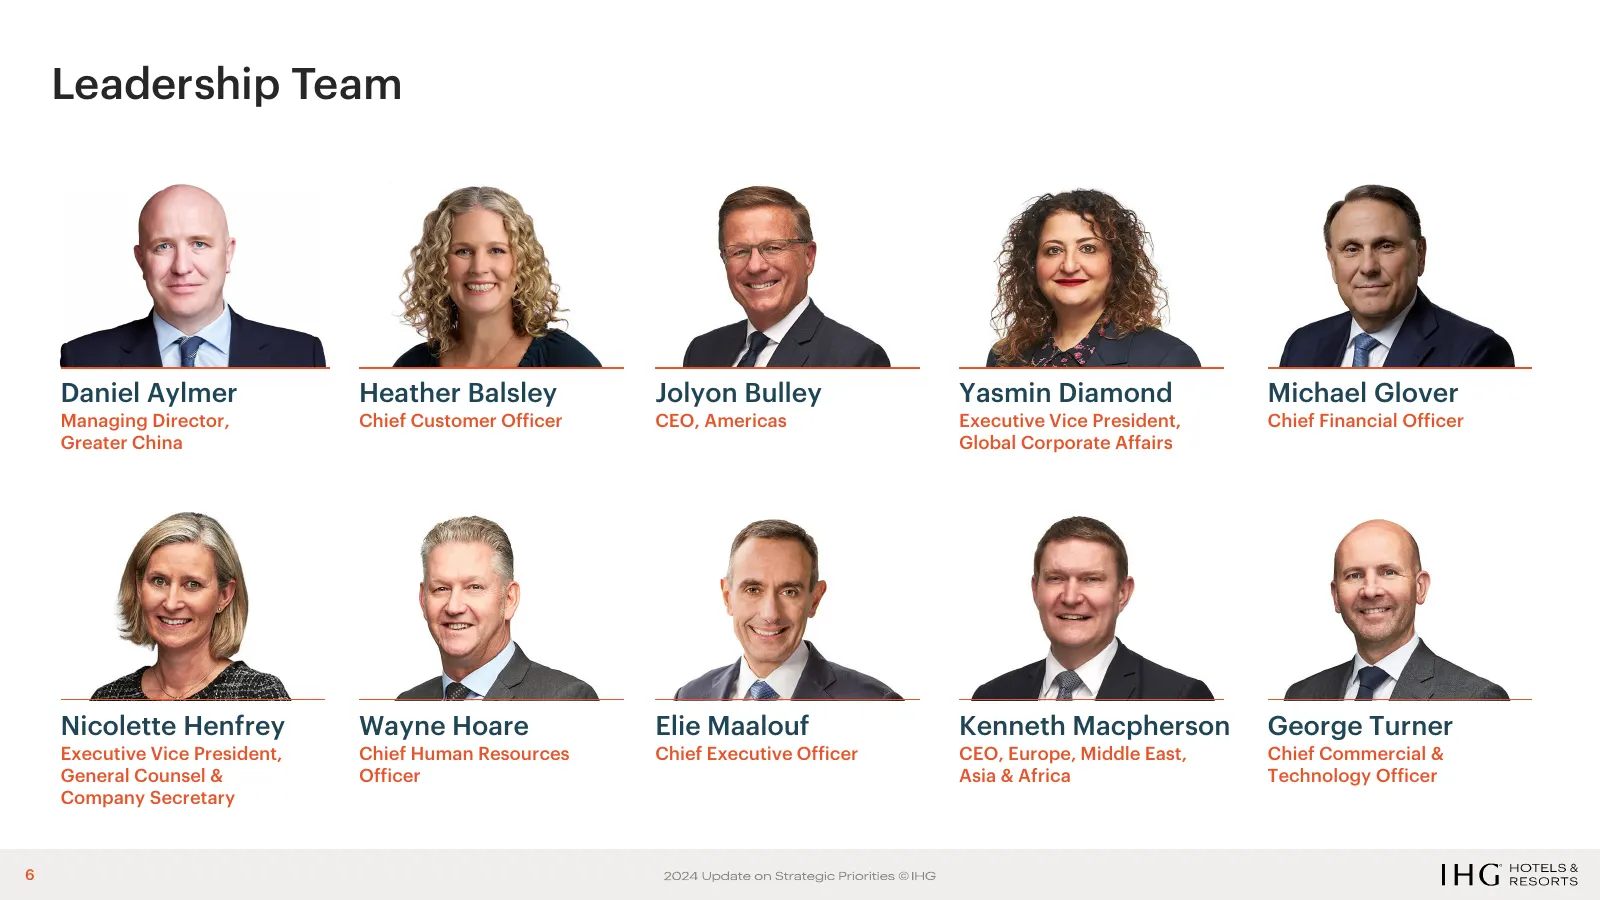
Leadership Team Daniel Aylmer Heather Balsley Jolyon Bulley Yasmin Diamond Michael Glover Managing Director, Chief Customer Officer CEO, Americas Executive Vice President, Chief Financial Officer Greater China Global Corporate Affairs Nicolette Henfrey Wayne Hoare Elie Maalouf Kenneth Macpherson Geo
Slide 7: Our industry
IHG HOTELS & RESORTS Our industry
Slide 8: Attractions of our industry
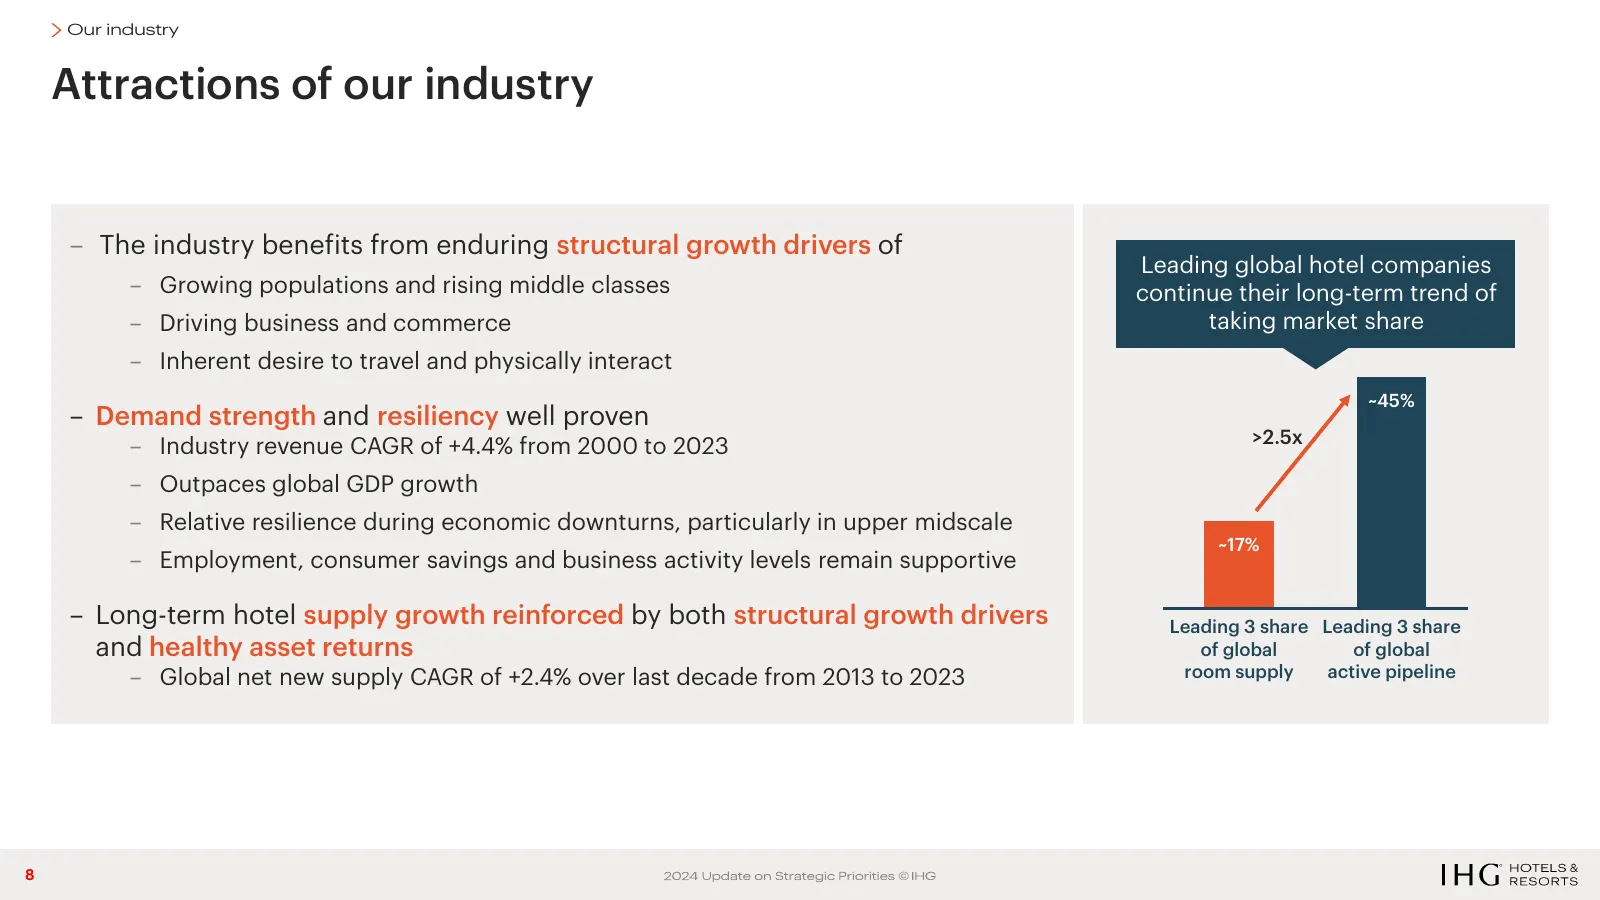
Our industry Attractions of our industry – The industry benefits from enduring structural growth drivers of Leading global hotel companies – Growing populations and rising middle classes continue their long-term trend of – Driving business and commerce taking market share – Inherent desire to travel
Slide 9: Industry growth forecasts
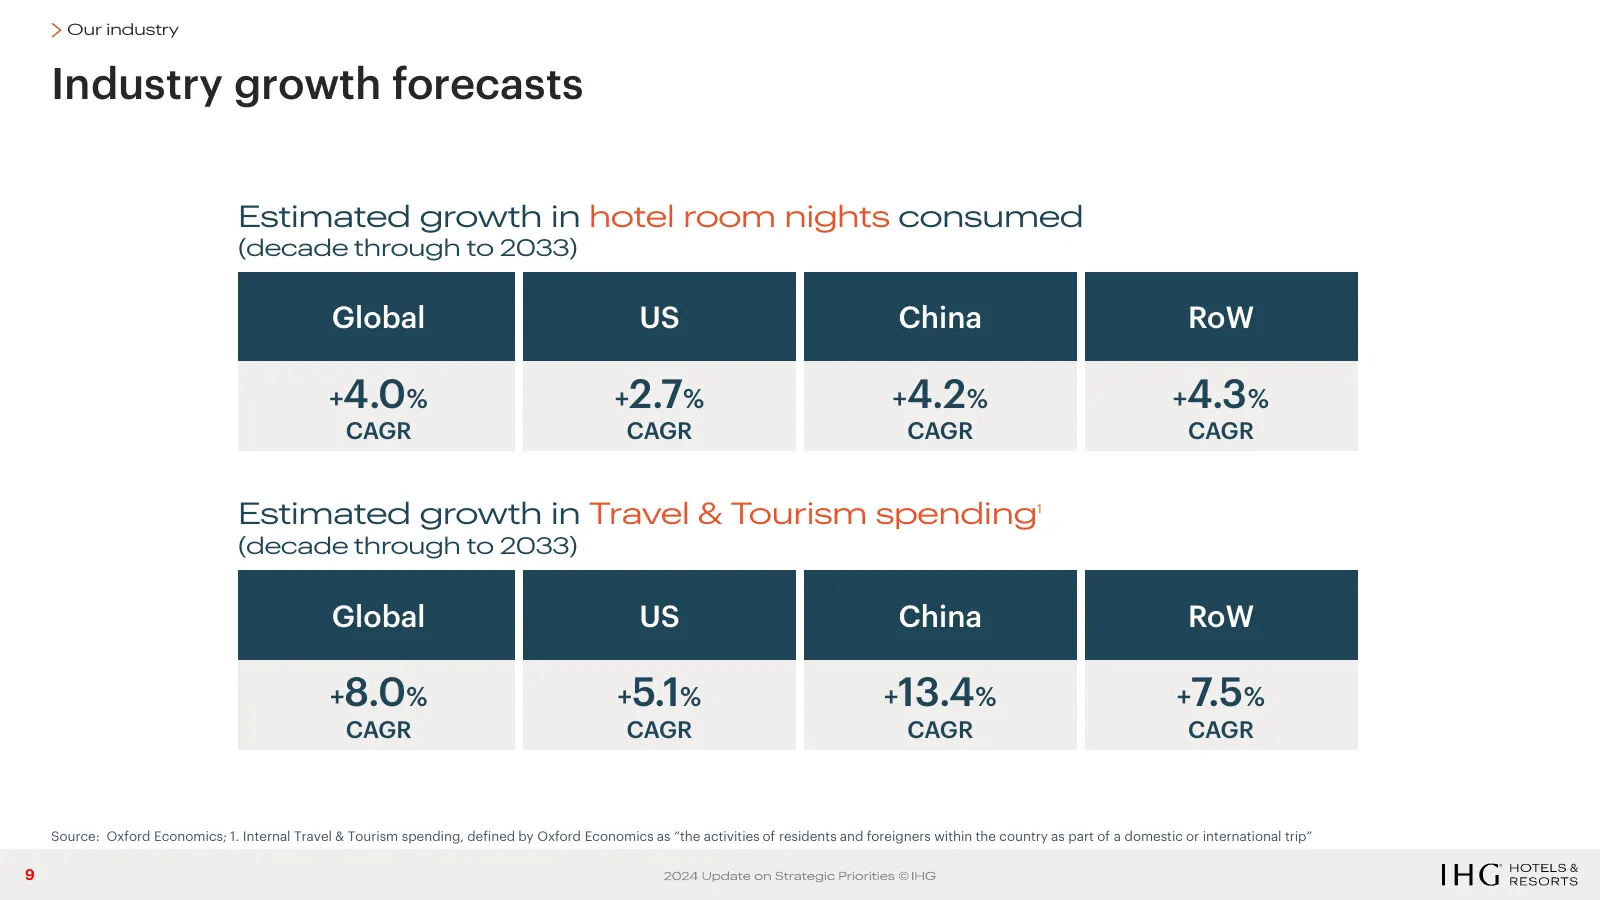
Our industry Industry growth forecasts Estimated growth in hotel room nights consumed (decade through to 2033) Global US China RoW +4.0% +2.7% +4.2% +4.3% CAGR CAGR CAGR CAGR Estimated growth in Travel & Tourism spending1 (decade through to 2033) Global US China RoW +8.0% +5.1% +13.4% +7.5% CAGR CAG
Slide 10: IHG's business model, track record and growth algorithm
IHG’s business model, track record and growth algorithm
Slide 11: IHG's strong business model: sustainable competitive advantage
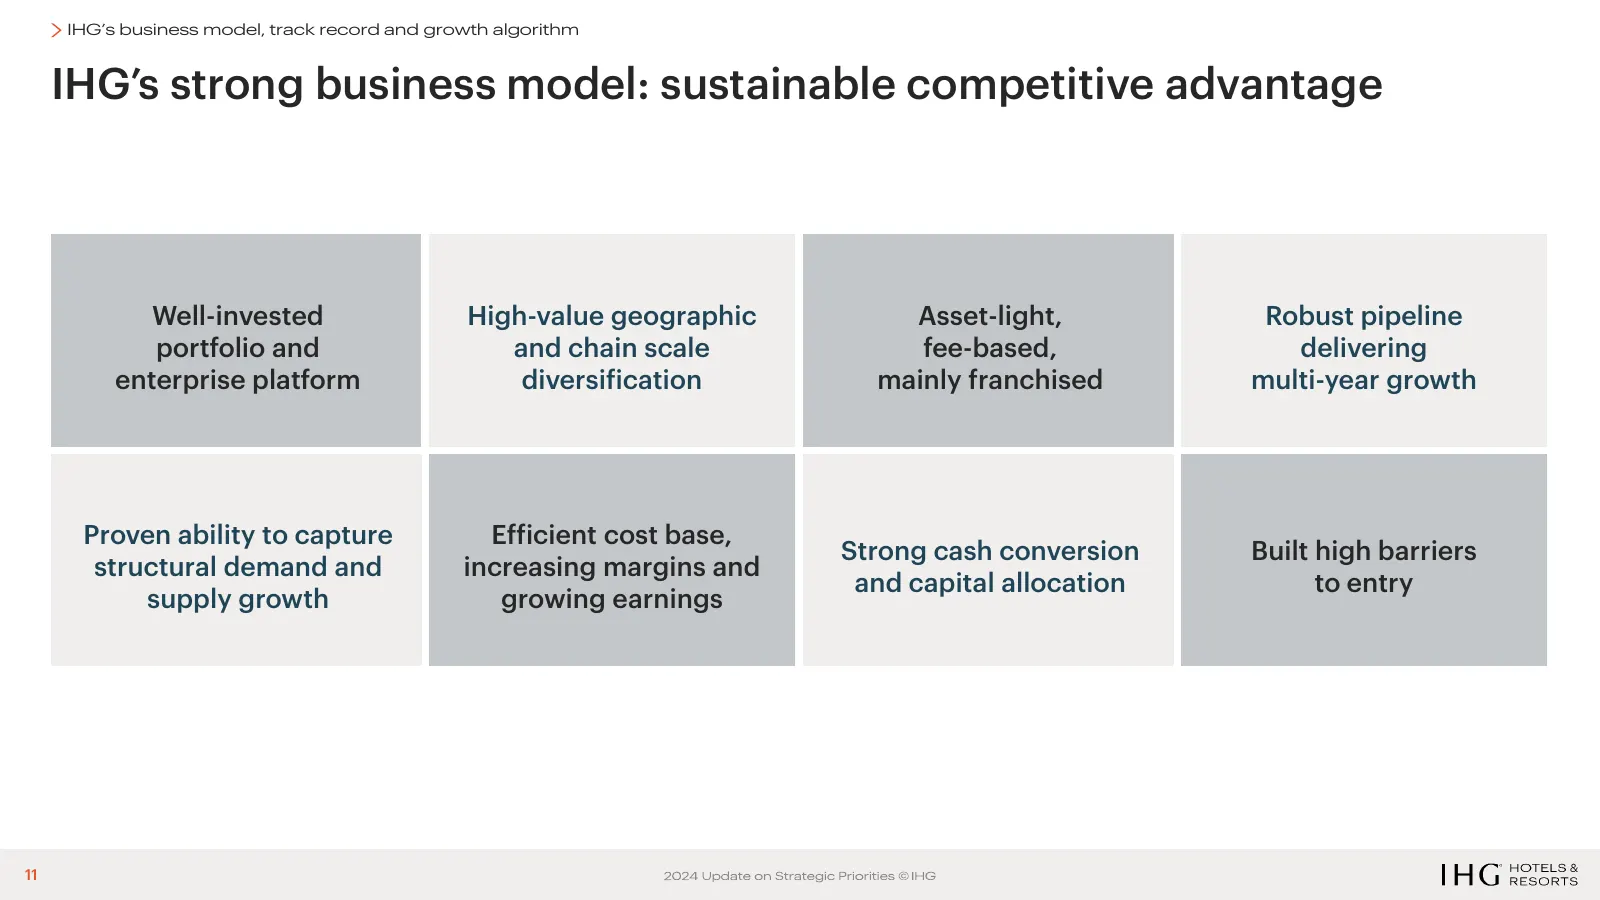
IHG’s business model, track record and growth algorithm IHG’s strong business model: sustainable competitive advantage Well-invested High-value geographic Asset-light, Robust pipeline portfolio and and chain scale fee-based, delivering enterprise platform diversification mainly franchised multi-year
Slide 12: Our strong track record
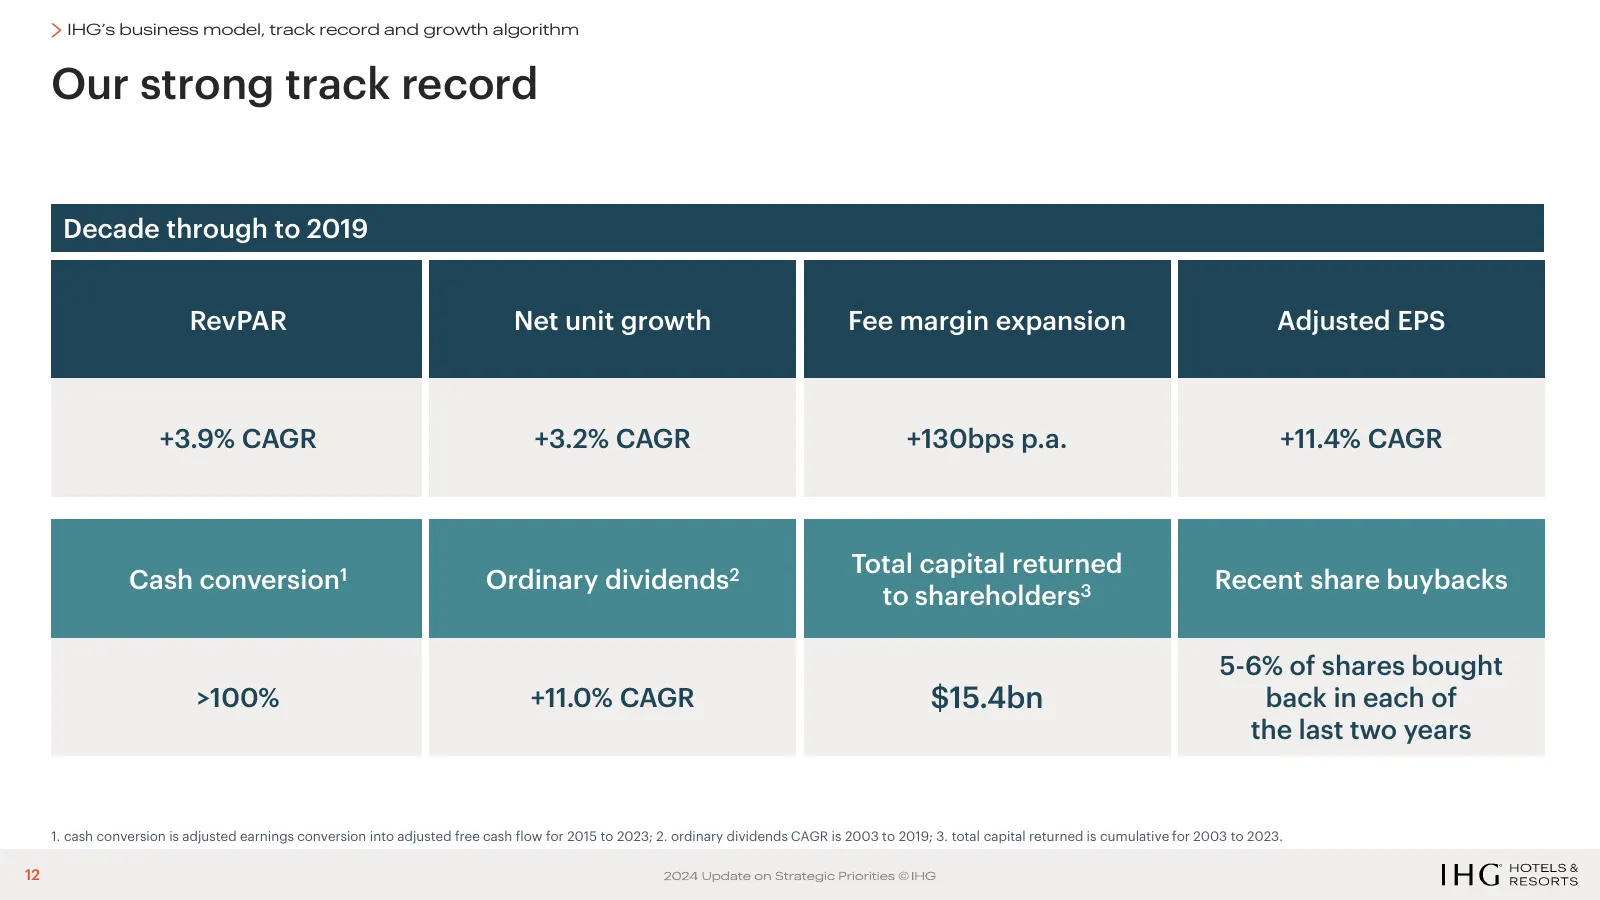
IHG’s business model, track record and growth algorithm Our strong track record Decade through to 2019 RevPAR Net unit growth Fee margin expansion Adjusted EPS +3.9% CAGR +3.2% CAGR +130bps p.a. +11.4% CAGR Total capital returned Cash conversion1 Ordinary dividends2 Recent share buybacks to sharehol
Slide 13: Our outlook: compounding growth and sustainable shareholder value creation
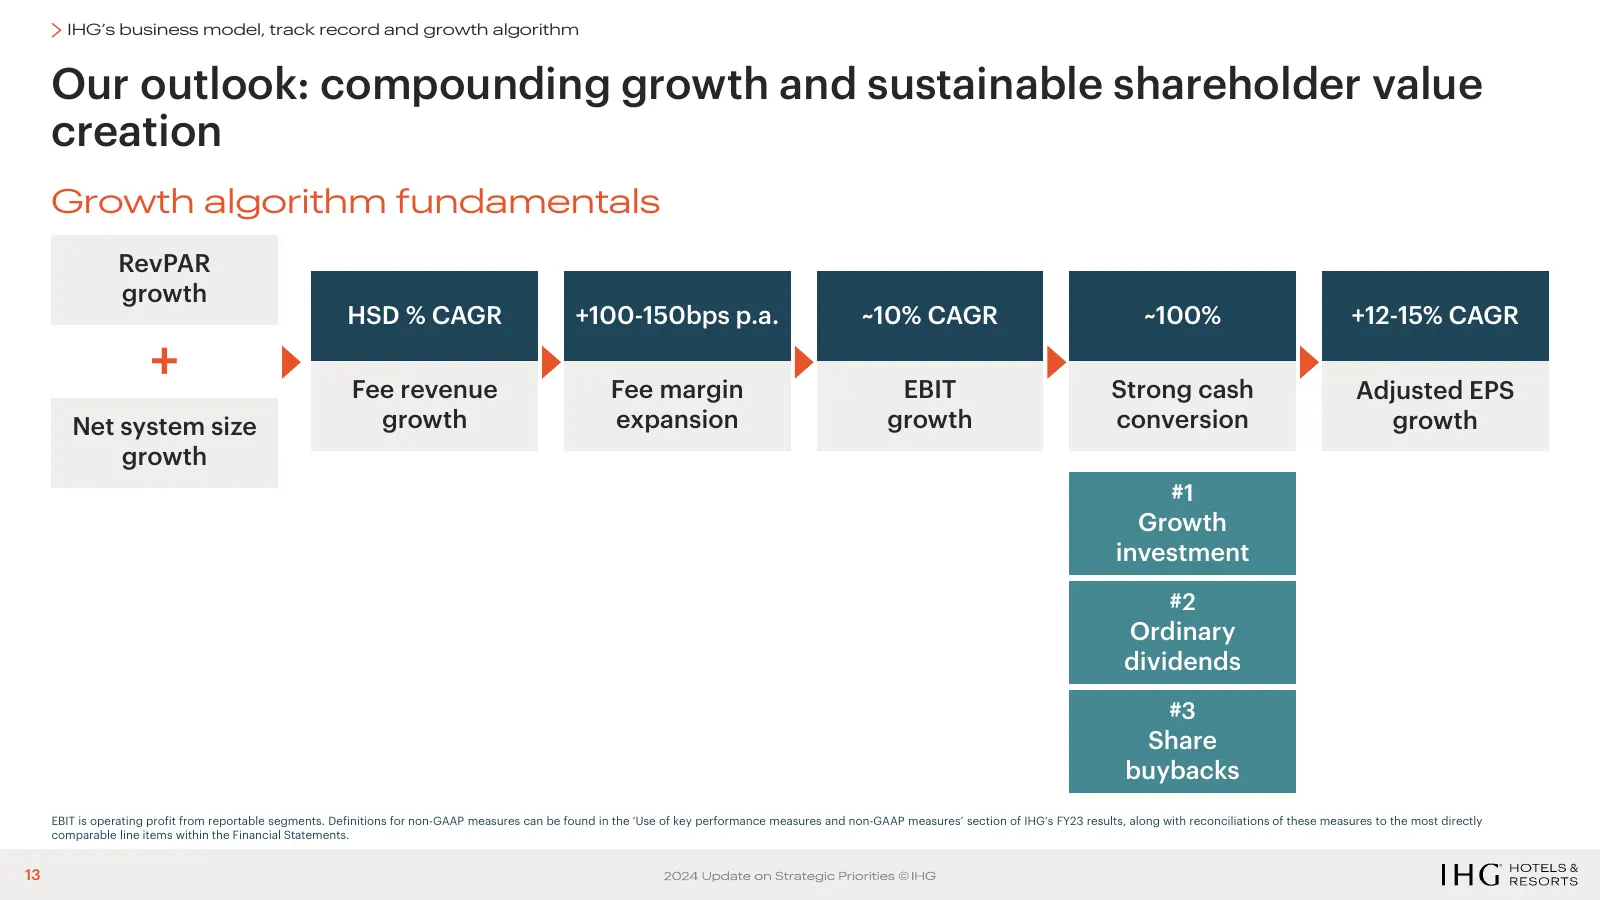
IHG’s business model, track record and growth algorithm Our outlook: compounding growth and sustainable shareholder value creation Growth algorithm fundamentals RevPAR growth HSD % CAGR +100-150bps p.a. ~10% CAGR ~100% +12-15% CAGR + Fee revenue Fee margin EBIT Strong cash Adjusted EPS Net system si
Slide 14: Underpinned by clear purpose, ambition and strategic priorities
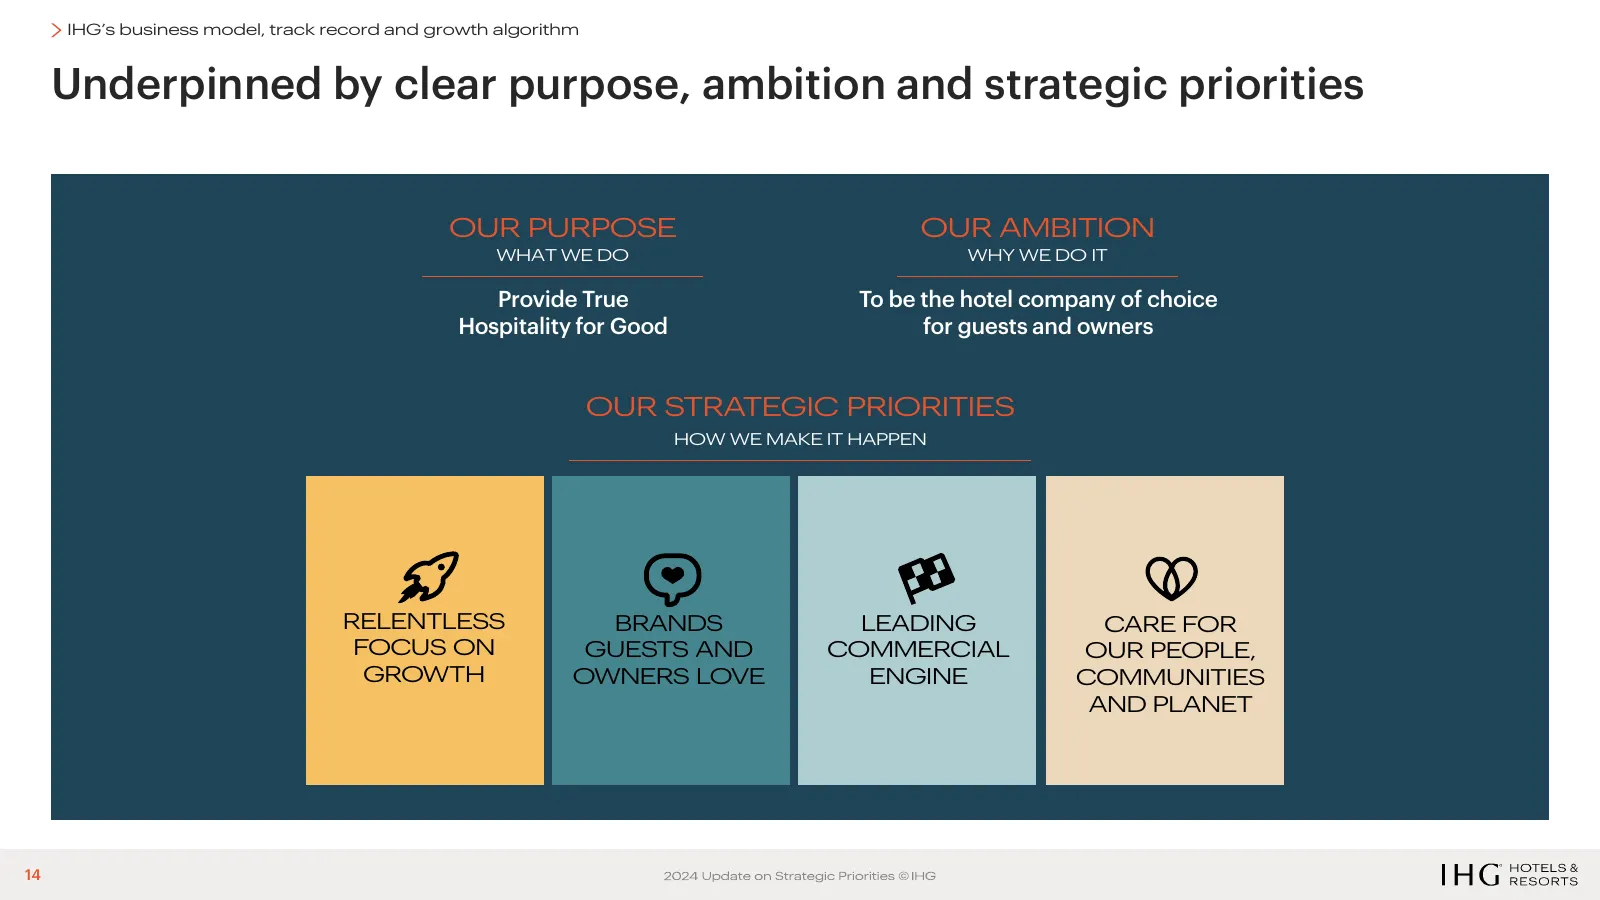
IHG’s business model, track record and growth algorithm Underpinned by clear purpose, ambition and strategic priorities OUR PURPOSE OUR AMBITION WHAT WE DO WHY WE DO IT Provide True To be the hotel company of choice Hospitality for Good for guests and owners OUR STRATEGIC PRIORITIES HOW WE MAKE IT H
Slide 15: Strategic priorities
IHG HOTELS & RESORTS Strategic priorities
Slide 16: Relentless focus on growth
Strategic priorities OUR PILLARS RELENTLESS FOCUS ON GROWTH 16
Slide 17: Asset light, mainly franchised, and geographically diverse
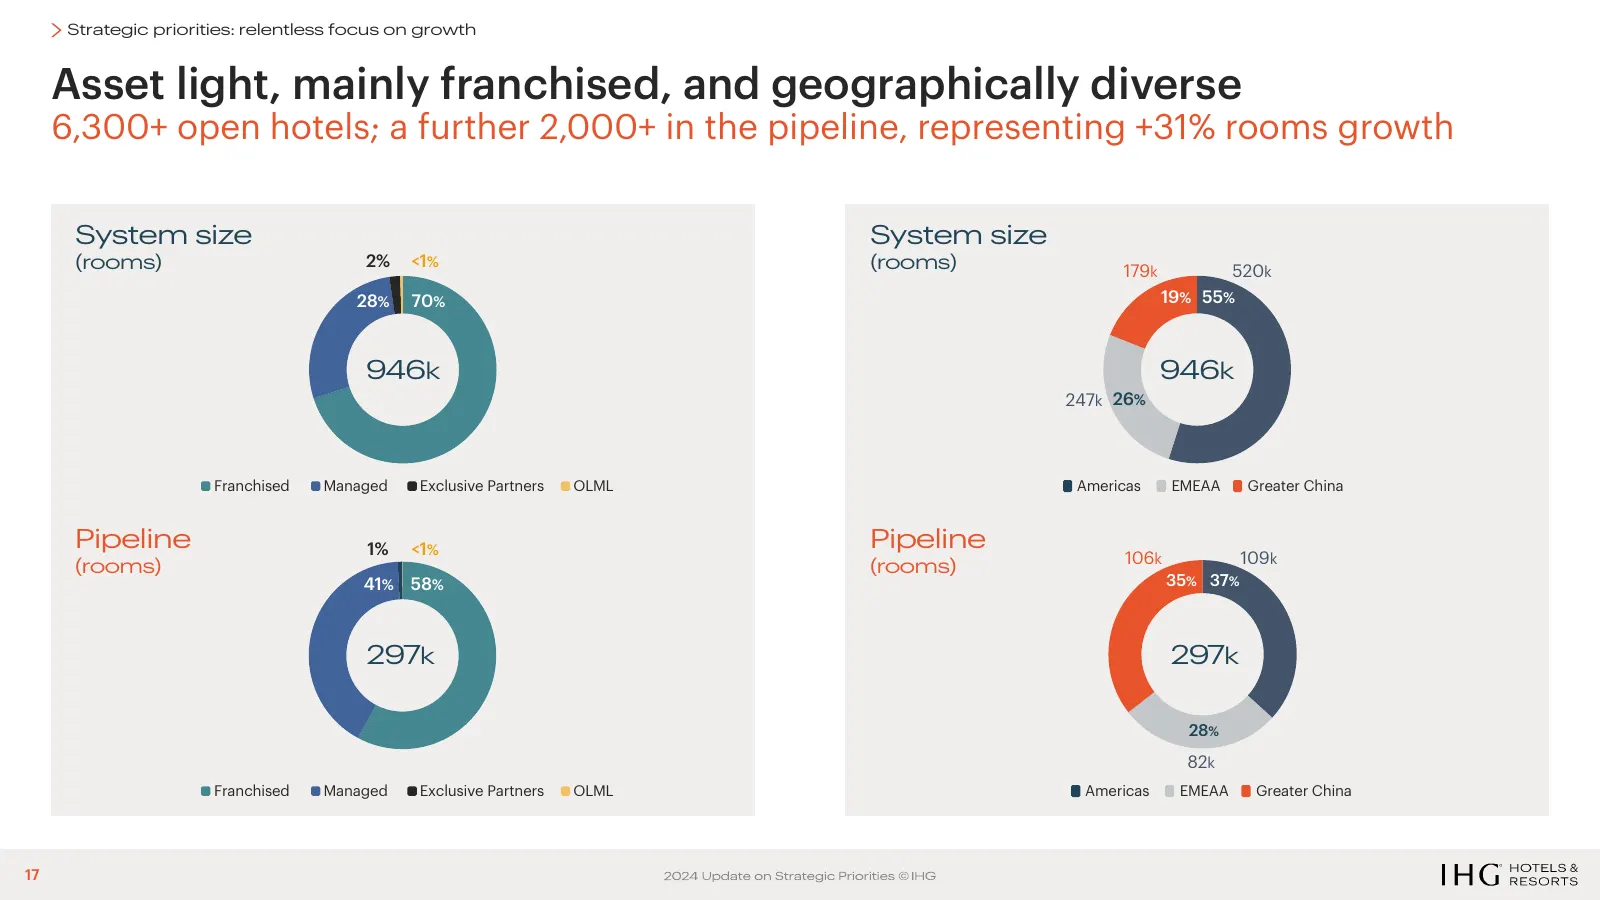
Strategic priorities: relentless focus on growth Asset light, mainly franchised, and geographically diverse 6,300+ open hotels; a further 2,000+ in the pipeline, representing +31% rooms growth System size System size (rooms) 2% <1% (rooms) 179k 520k 28% 70% 19% 55% 946k 946k 247k 26% Franchised Mana
Slide 18: Three regions of scale with notable growth potential
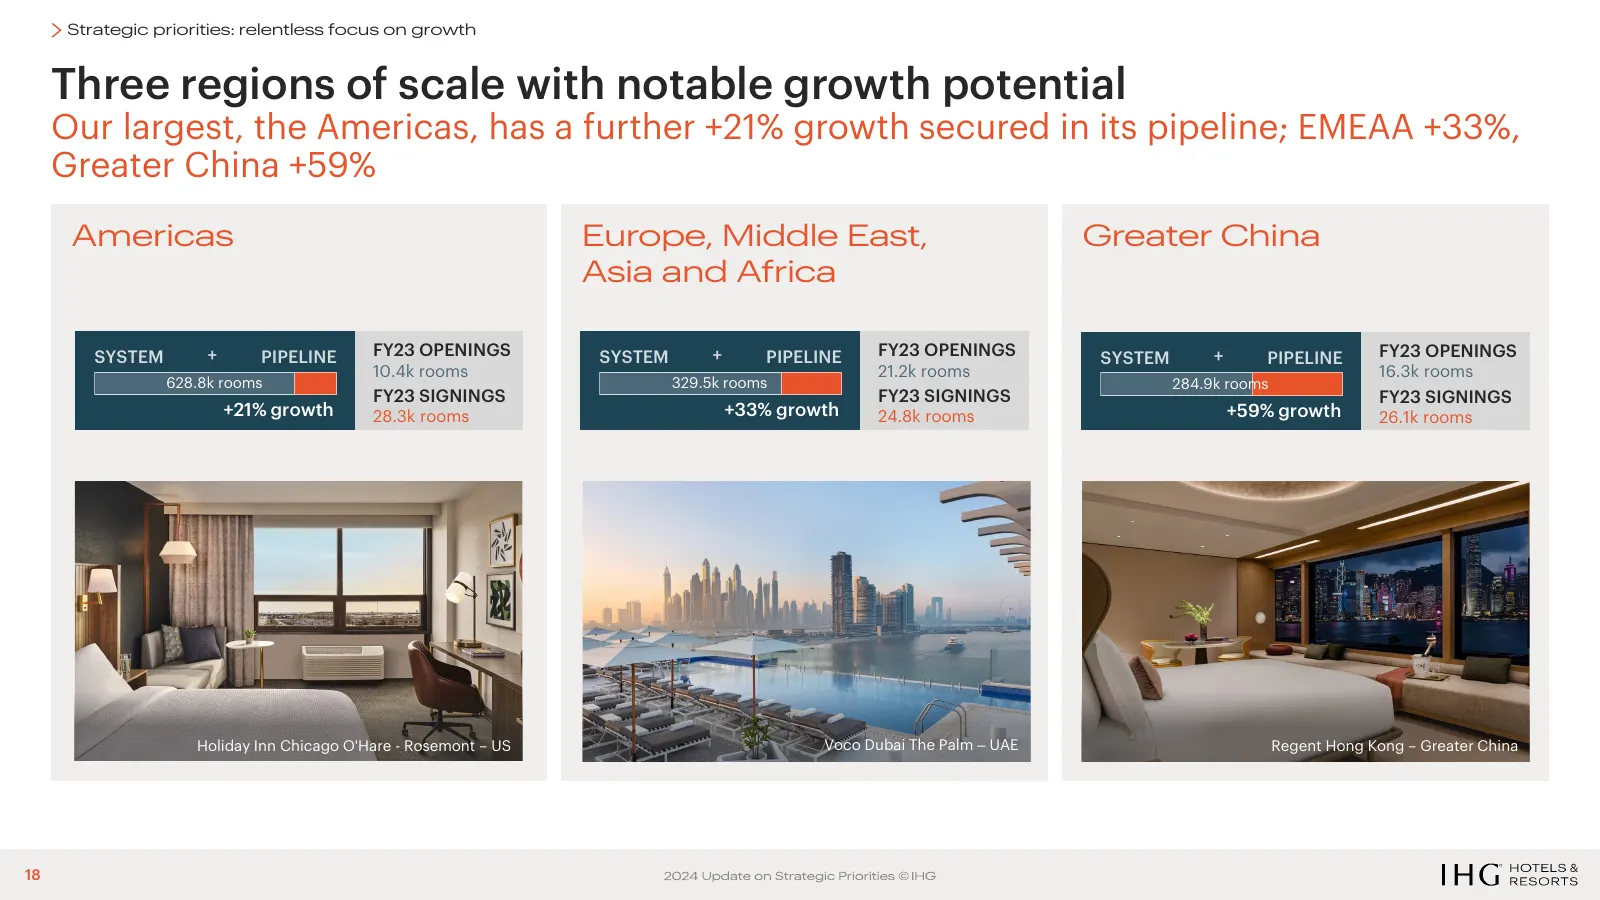
Strategic priorities: relentless focus on growth Three regions of scale with notable growth potential Our largest, the Americas, has a further +21% growth secured in its pipeline; EMEAA +33%, Greater China +59% Americas Europe, Middle East, Greater China Asia and Africa SYSTEM + PIPELINE FY23 OPENIN
Slide 19: Brand portfolio expansion since 2015
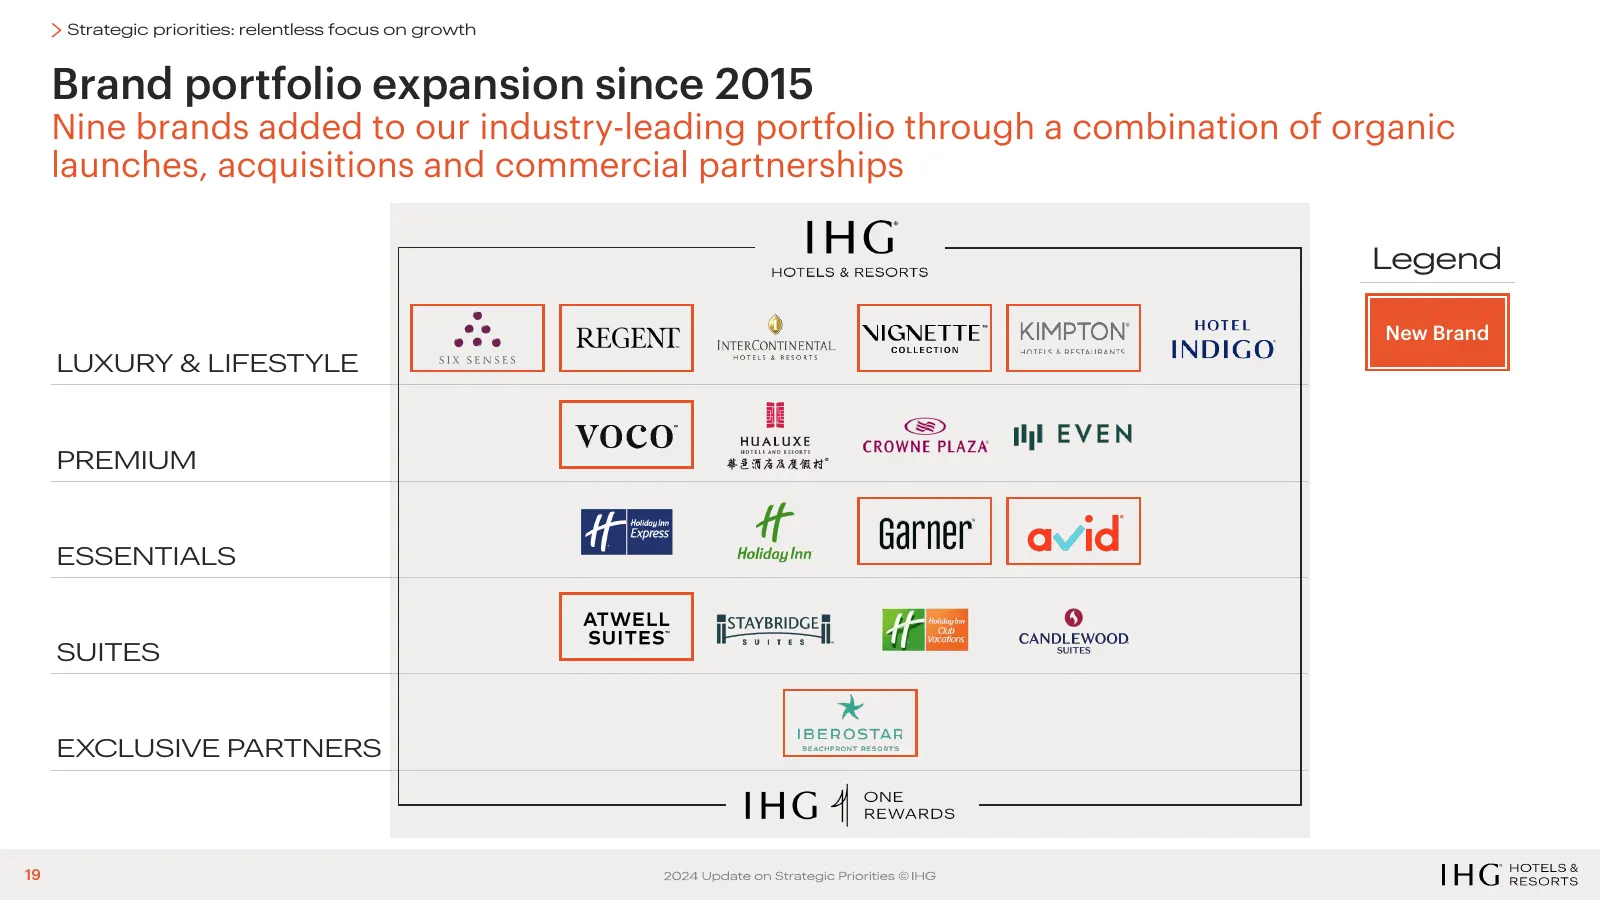
Strategic priorities: relentless focus on growth Brand portfolio expansion since 2015 Nine brands added to our industry-leading portfolio through a combination of organic launches, acquisitions and commercial partnerships Legend New Brand LUXURY & LIFESTYLE PREMIUM ESSENTIALS SUITES EXCLUSIVE PARTNE
Slide 20: Balanced portfolio mix of 19 preferred brands across segments
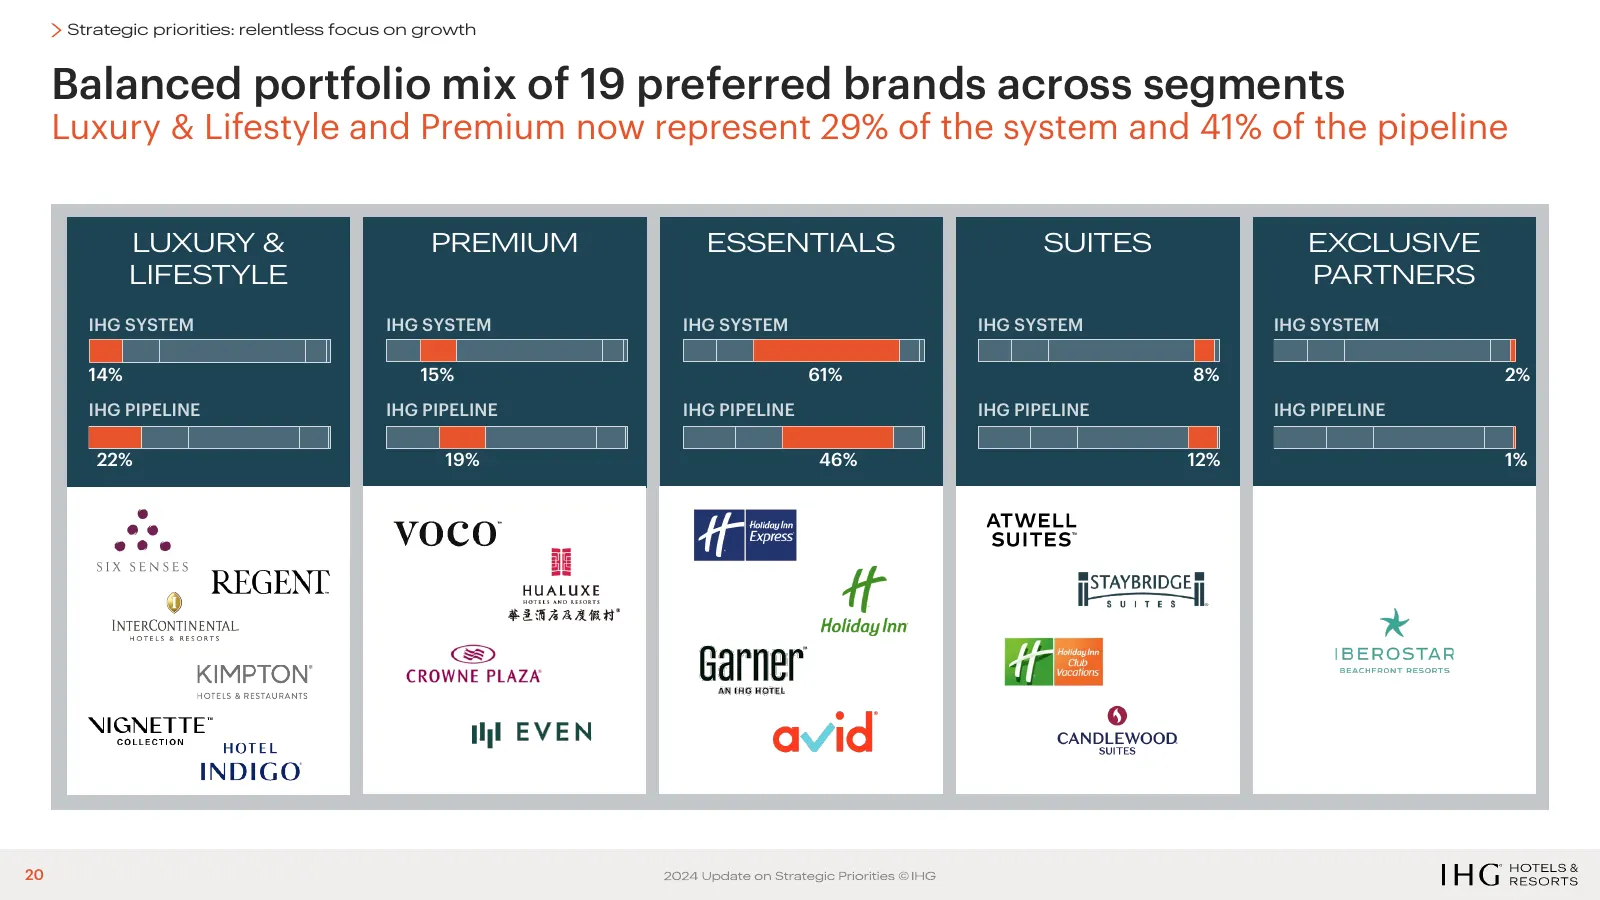
Strategic priorities: relentless focus on growth Balanced portfolio mix of 19 preferred brands across segments Luxury & Lifestyle and Premium now represent 29% of the system and 41% of the pipeline LUXURY & PREMIUM ESSENTIALS SUITES EXCLUSIVE LIFESTYLE PARTNERS IHG SYSTEM IHG SYSTEM IHG SYSTEM IHG S
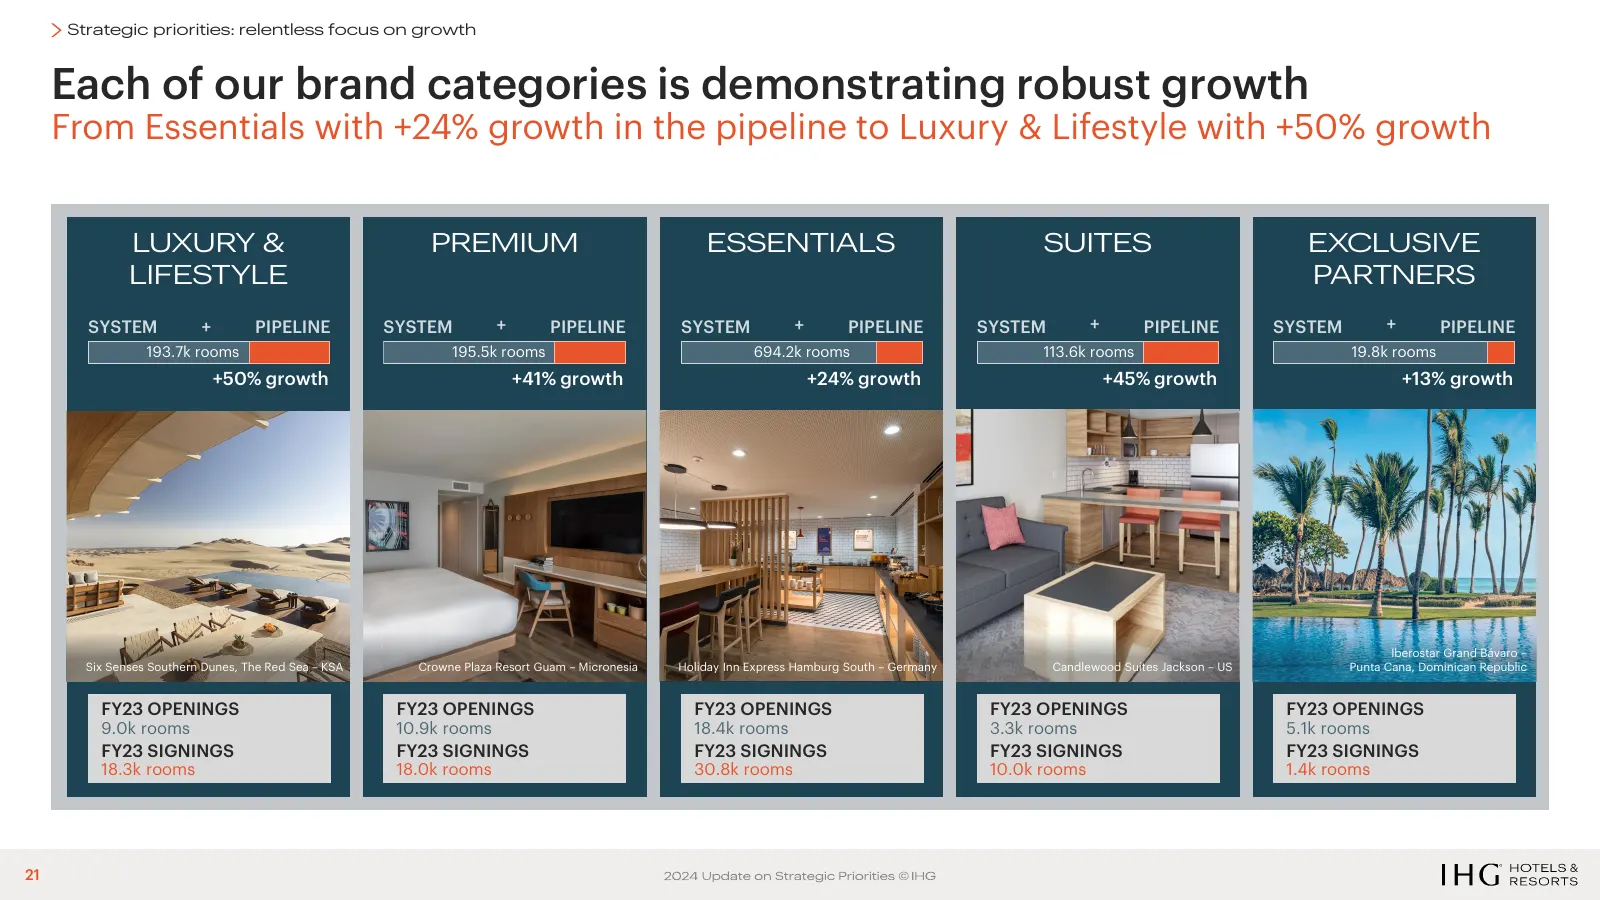
Slide 21: Each of our brand categories is demonstrating robust growth
Strategic priorities: relentless focus on growth Each of our brand categories is demonstrating robust growth From Essentials with +24% growth in the pipeline to Luxury & Lifestyle with +50% growth LUXURY & PREMIUM ESSENTIALS SUITES EXCLUSIVE LIFESTYLE PARTNERS SYSTEM + PIPELINE SYSTEM + PIPELINE SYS
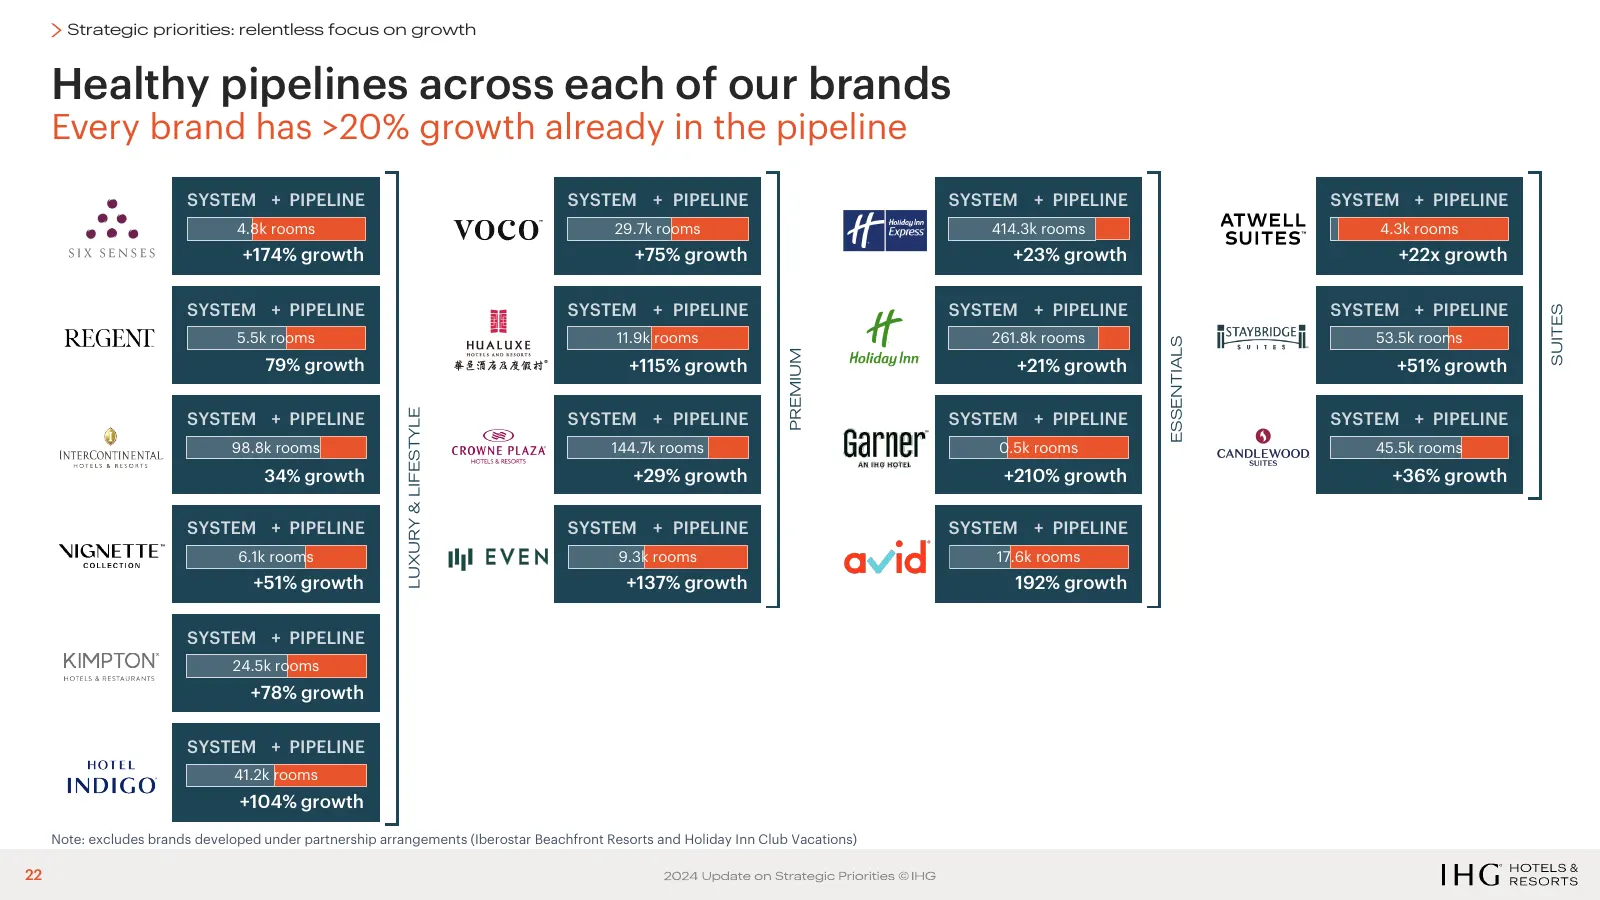
Slide 22: Healthy pipelines across each of our brands
Strategic priorities: relentless focus on growth Healthy pipelines across each of our brands Every brand has >20% growth already in the pipeline SYSTEM + PIPELINE SYSTEM + PIPELINE SYSTEM + PIPELINE SYSTEM + PIPELINE 4.8k rooms 29.7k rooms 414.3k rooms 4.3k rooms +174% growth +75% growth +23% growth
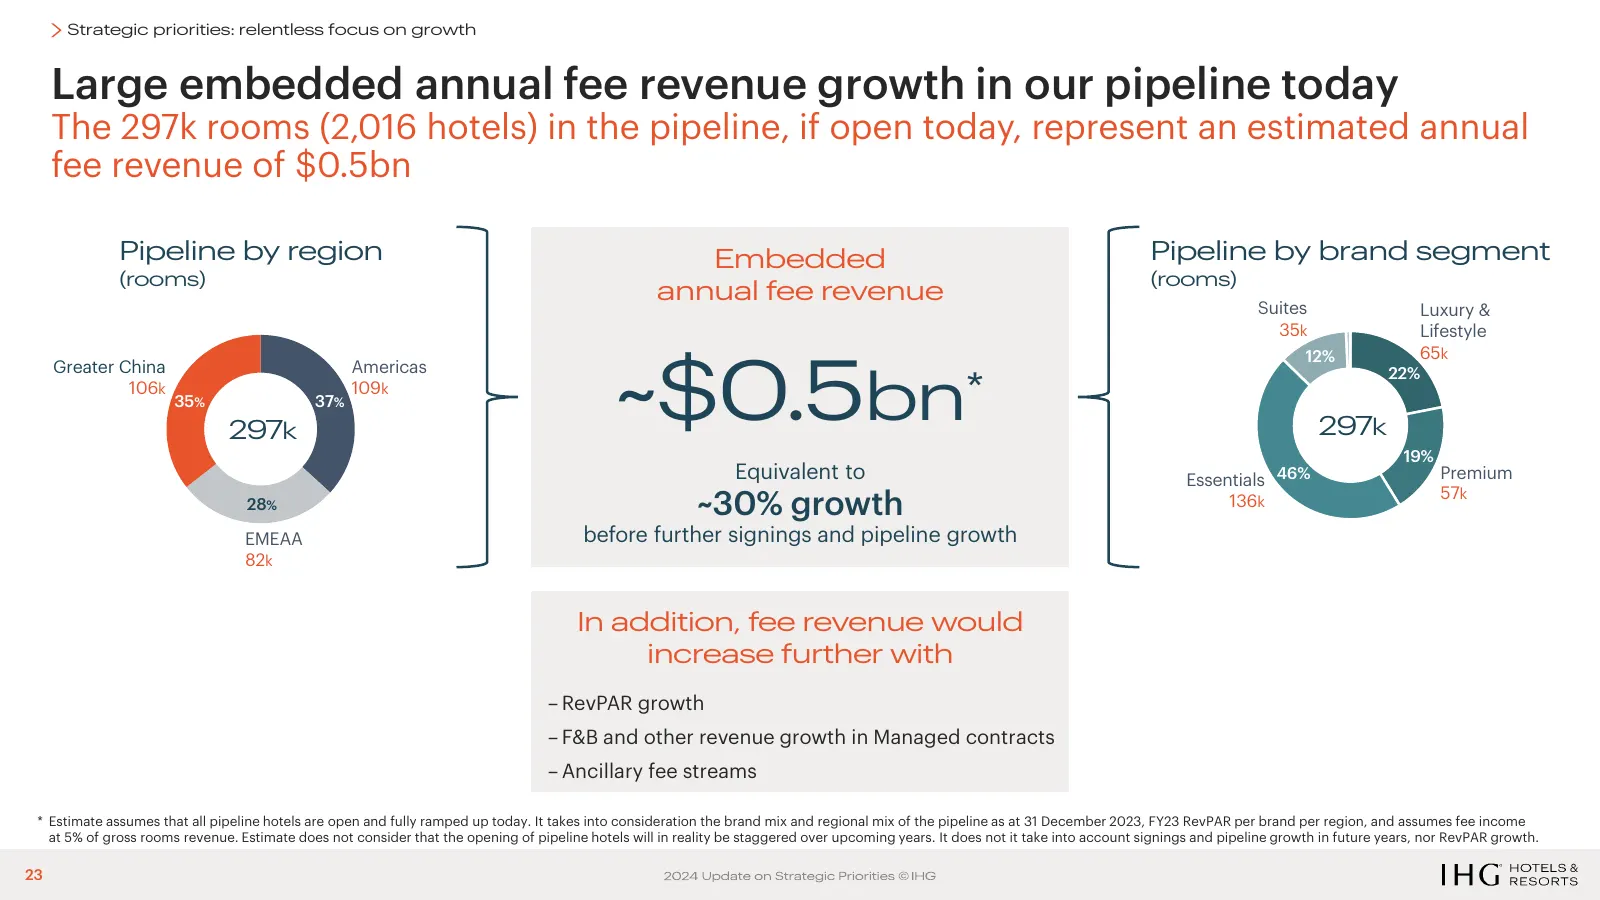
Slide 23: Large embedded annual fee revenue growth in our pipeline today
Strategic priorities: relentless focus on growth Large embedded annual fee revenue growth in our pipeline today The 297k rooms (2,016 hotels) in the pipeline, if open today, represent an estimated annual fee revenue of $0.5bn Pipeline by region Embedded Pipeline by brand segment (rooms) (rooms) annu
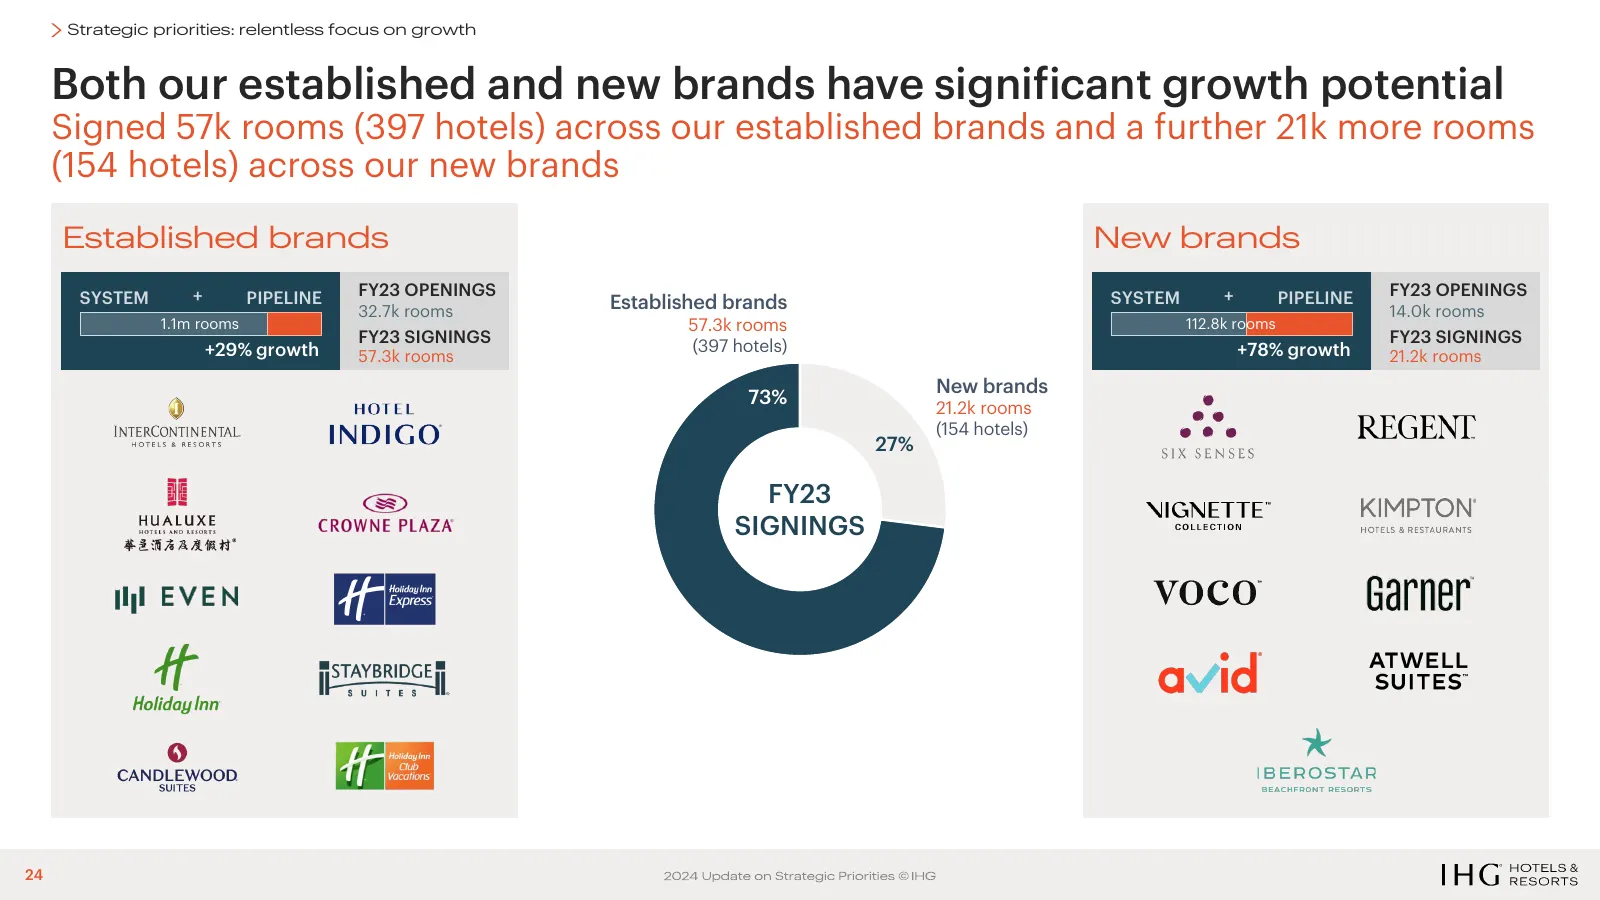
Slide 24: Both our established and new brands have significant growth potential
Strategic priorities: relentless focus on growth Both our established and new brands have significant growth potential Signed 57k rooms (397 hotels) across our established brands and a further 21k more rooms (154 hotels) across our new brands Established brands New brands SYSTEM + PIPELINE FY23 OPEN
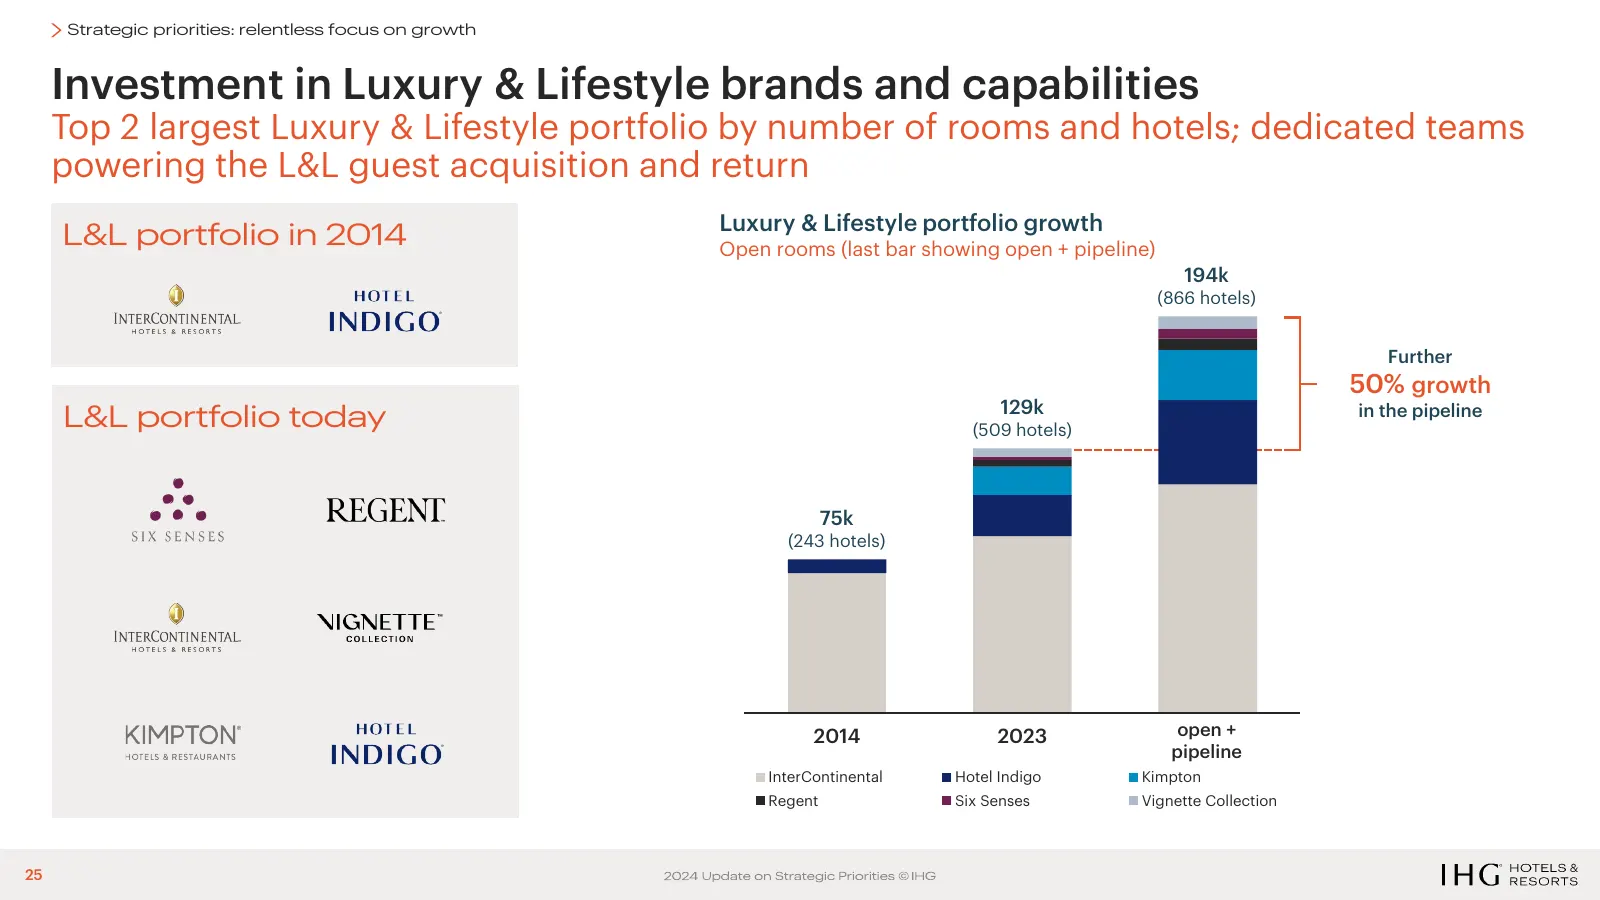
Slide 25: Investment in Luxury & Lifestyle brands and capabilities
Strategic priorities: relentless focus on growth Investment in Luxury & Lifestyle brands and capabilities Top 2 largest Luxury & Lifestyle portfolio by number of rooms and hotels; dedicated teams powering the L&L guest acquisition and return Luxury & Lifestyle portfolio growth L&L portfolio in 2014
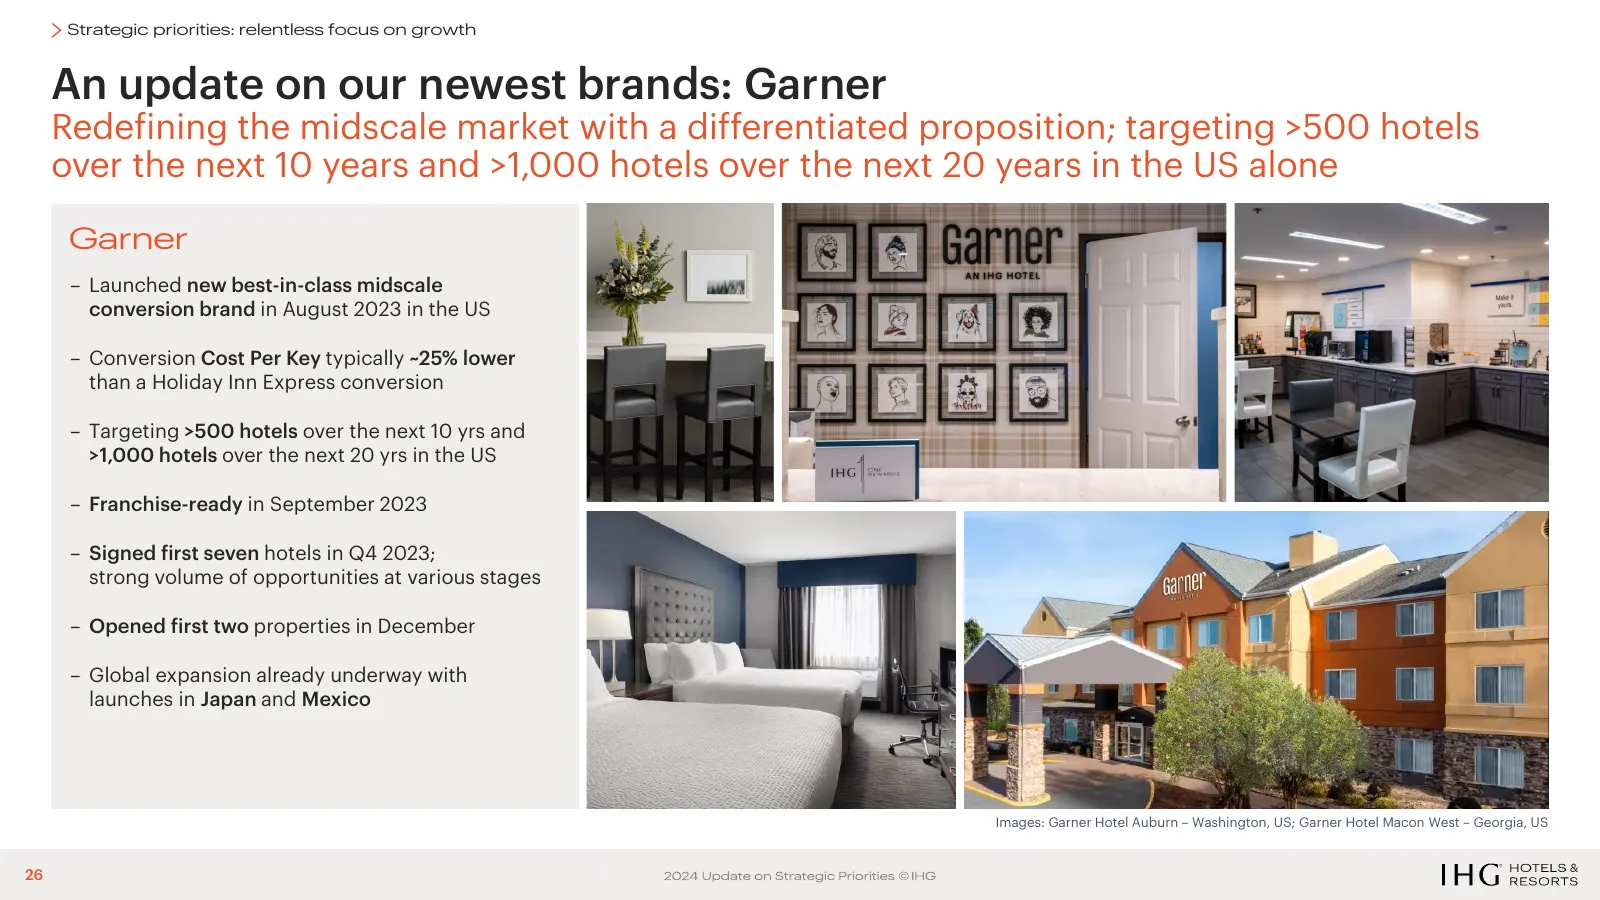
Slide 26: An update on our newest brands: Garner
Strategic priorities: relentless focus on growth An update on our newest brands: Garner Redefining the midscale market with a differentiated proposition; targeting >500 hotels over the next 10 years and >1,000 hotels over the next 20 years in the US alone Garner – Launched new best-in-class midscale
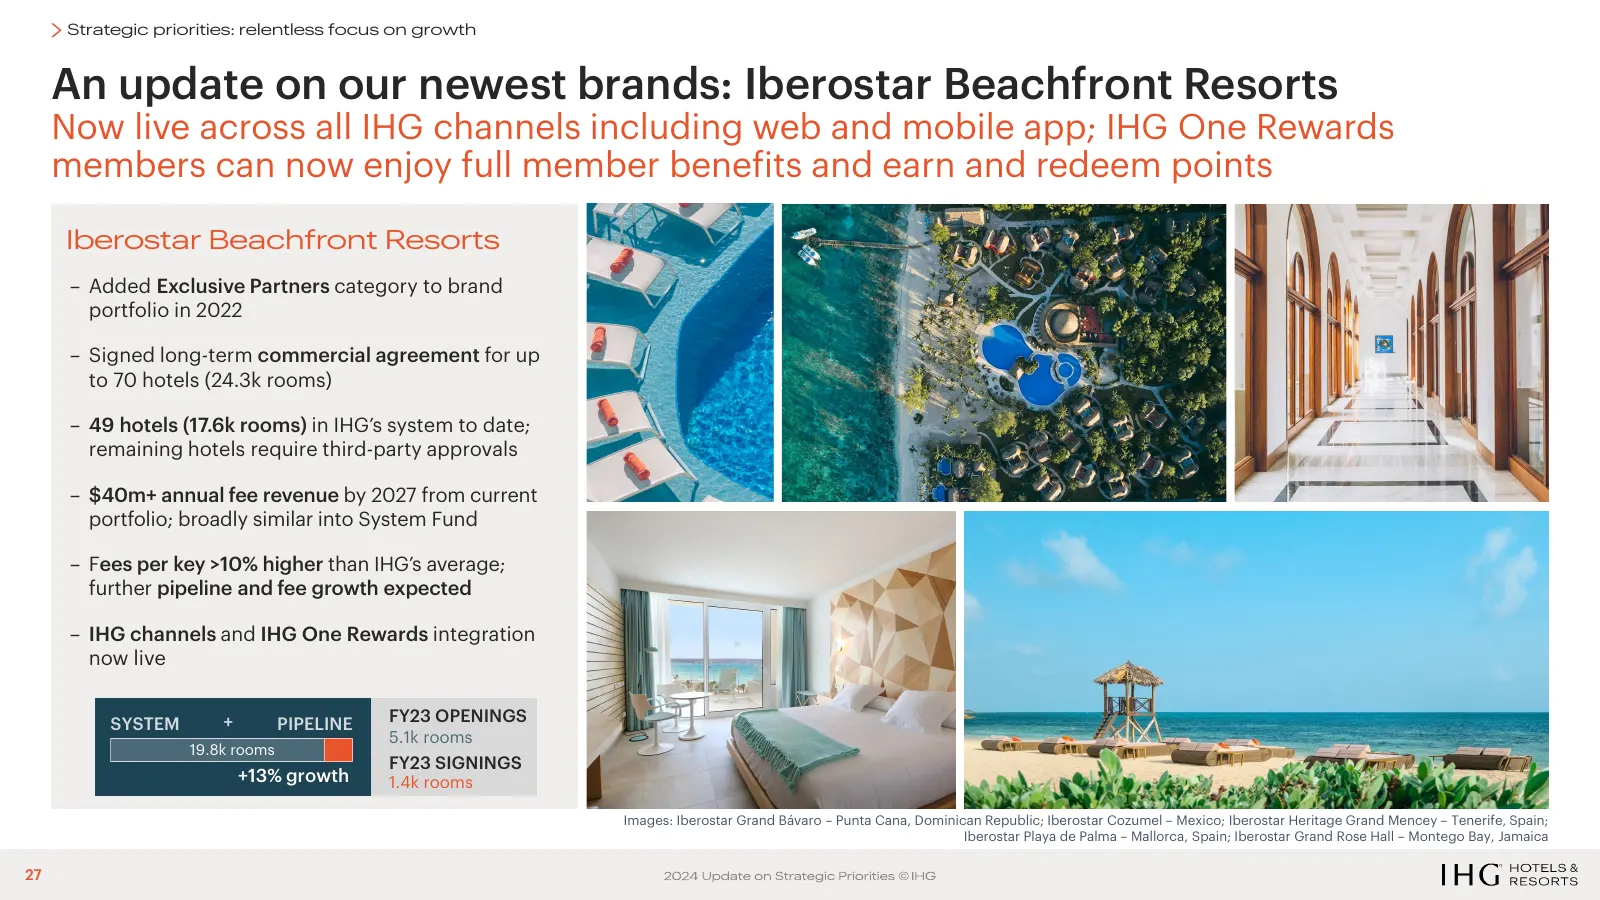
Slide 27: An update on our newest brands: Iberostar Beachfront Resorts
Strategic priorities: relentless focus on growth An update on our newest brands: Iberostar Beachfront Resorts Now live across all IHG channels including web and mobile app; IHG One Rewards members can now enjoy full member benefits and earn and redeem points Iberostar Beachfront Resorts – Added Excl
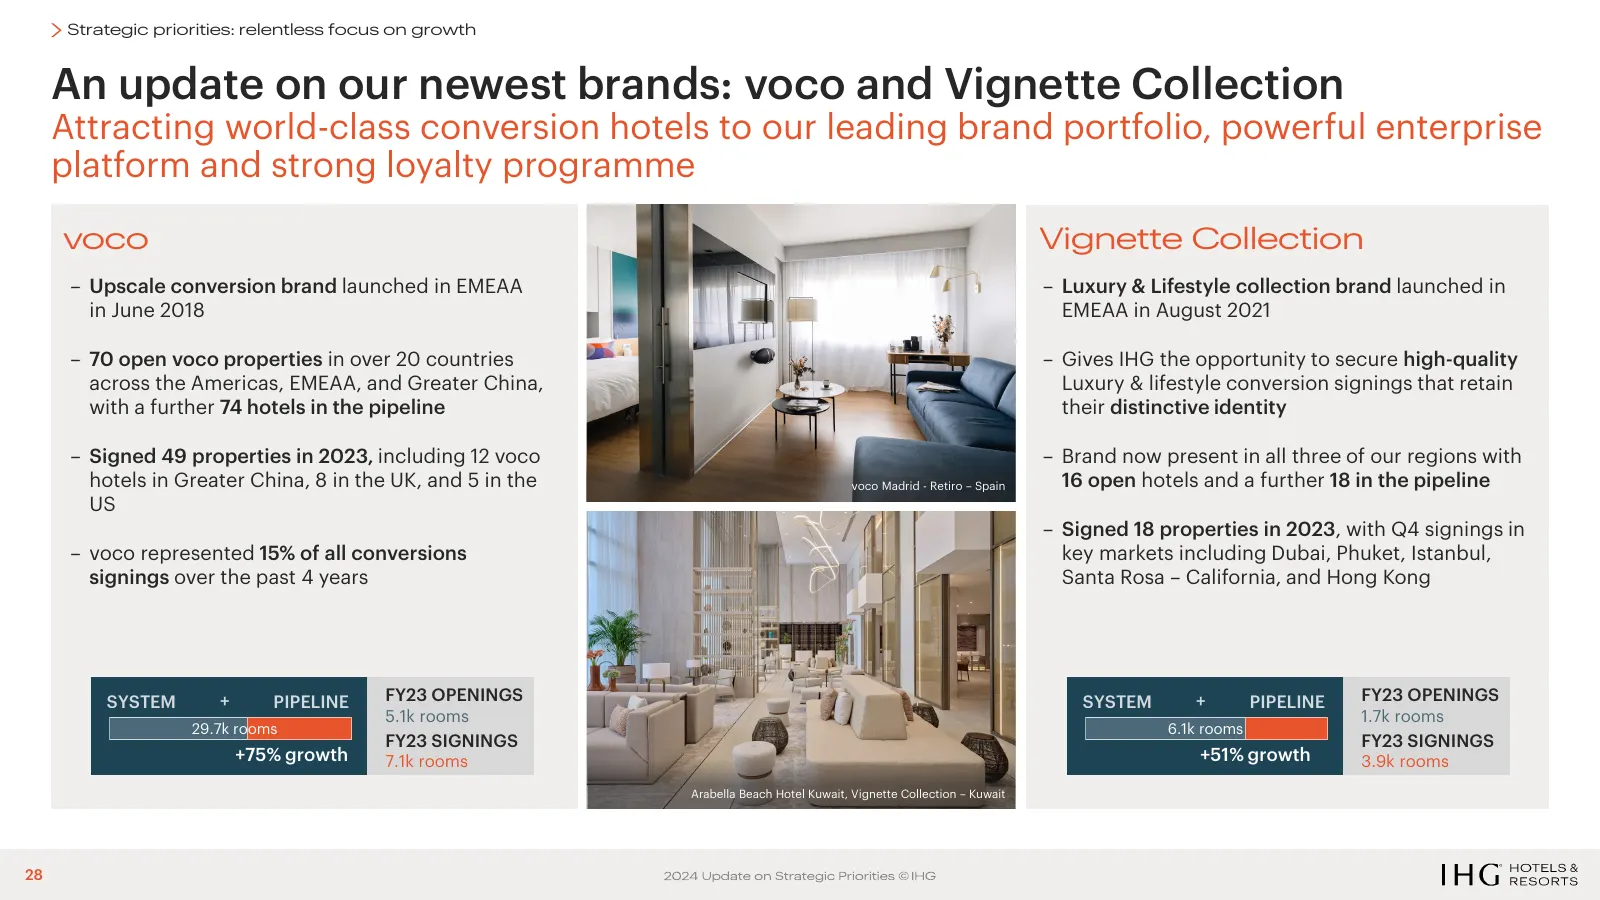
Slide 28: An update on our newest brands: voco and Vignette Collection
Strategic priorities: relentless focus on growth An update on our newest brands: voco and Vignette Collection Attracting world-class conversion hotels to our leading brand portfolio, powerful enterprise platform and strong loyalty programme voco Vignette Collection – Upscale conversion brand launche
Slide 29: Increases in new build as well as conversions signings
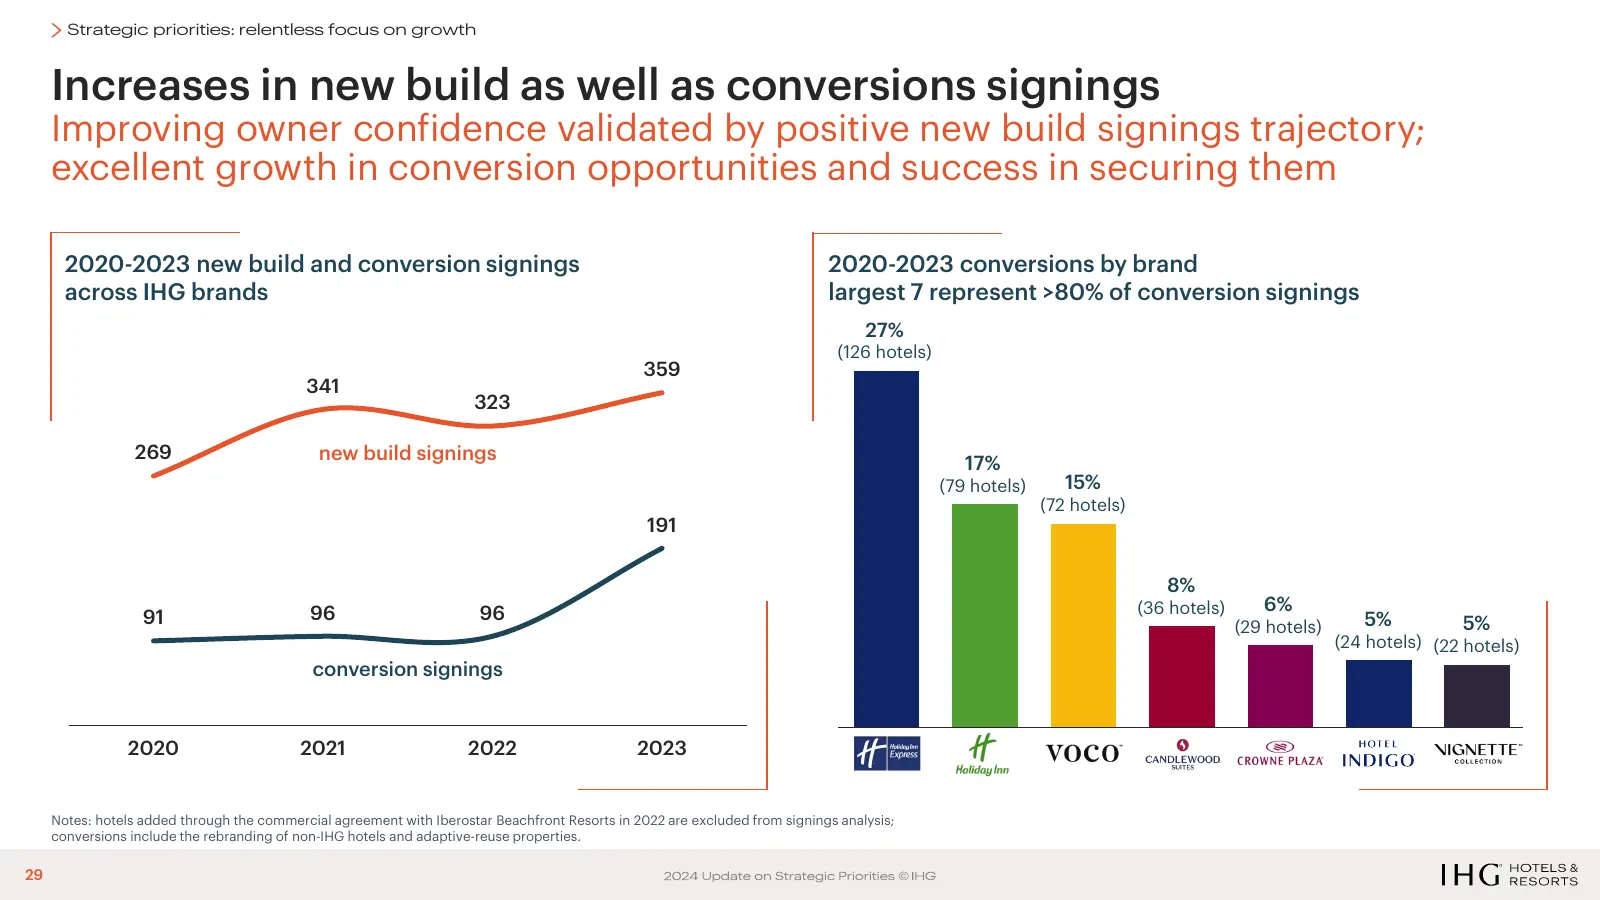
Strategic priorities: relentless focus on growth Increases in new build as well as conversions signings Improving owner confidence validated by positive new build signings trajectory; excellent growth in conversion opportunities and success in securing them 2020-2023 new build and conversion signing
Slide 30: Brands guests and owners love
Strategic priorities OUR PILLARS BRANDS GUESTS AND OWNERS LOVE 30
Slide 31: Strengthening the IHG Hotels & Resorts masterbrand
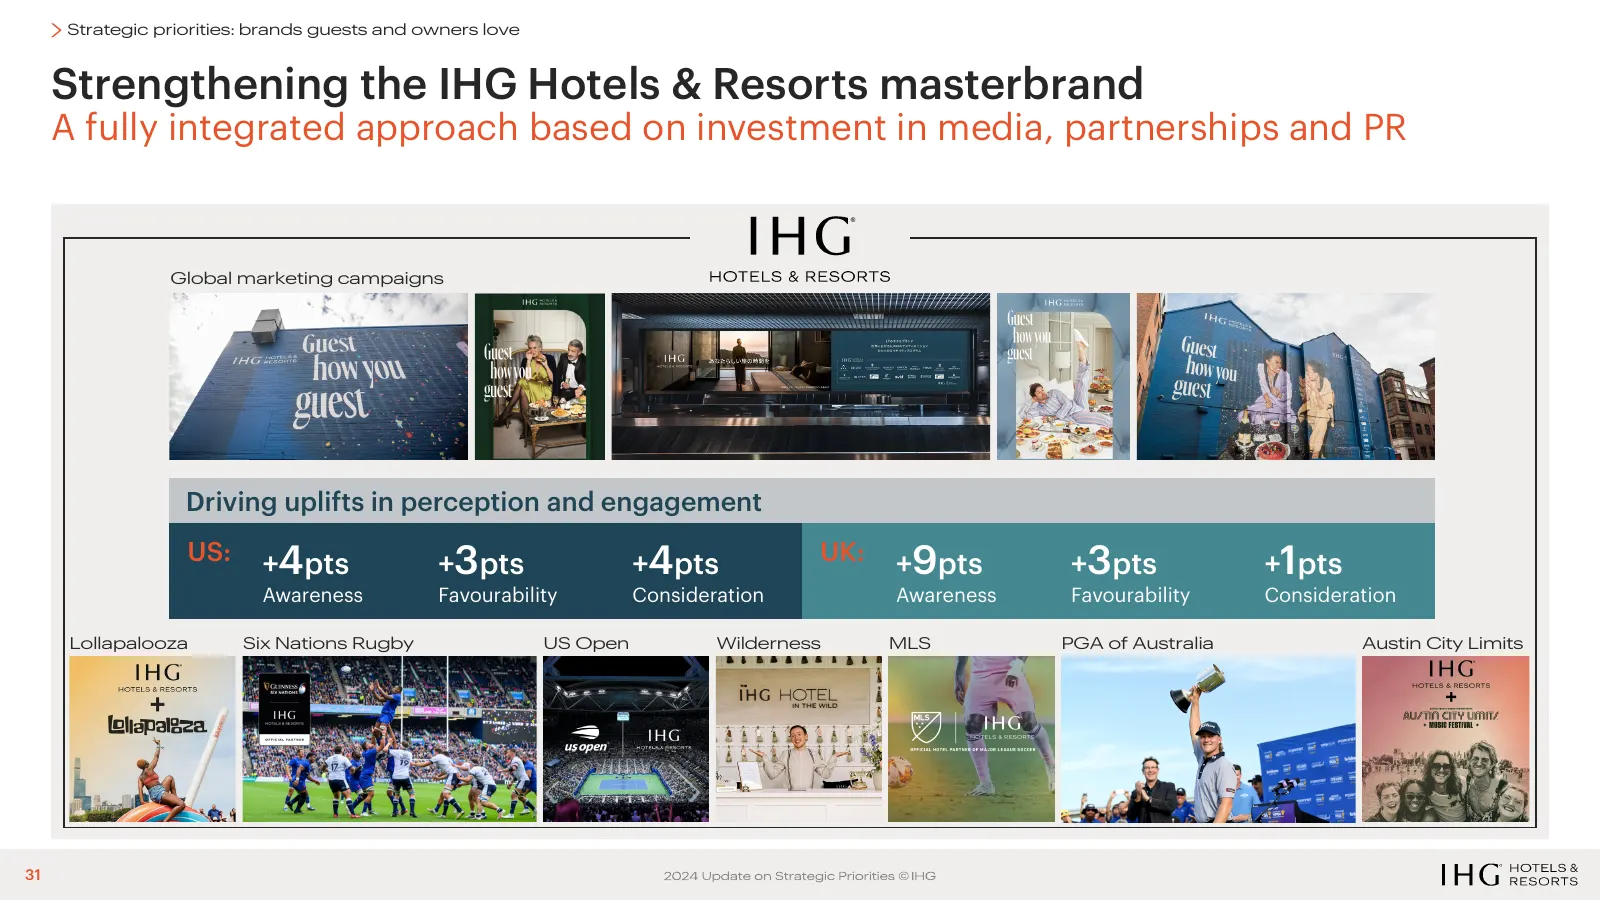
Strategic priorities: brands guests and owners love Strengthening the IHG Hotels & Resorts masterbrand A fully integrated approach based on investment in media, partnerships and PR Global marketing campaigns Driving uplifts in perception and engagement US: +4pts +3pts +4pts UK: +9pts +3pts +1pts Awa
Slide 32: Driving demand to hotels by leveraging advanced analytics
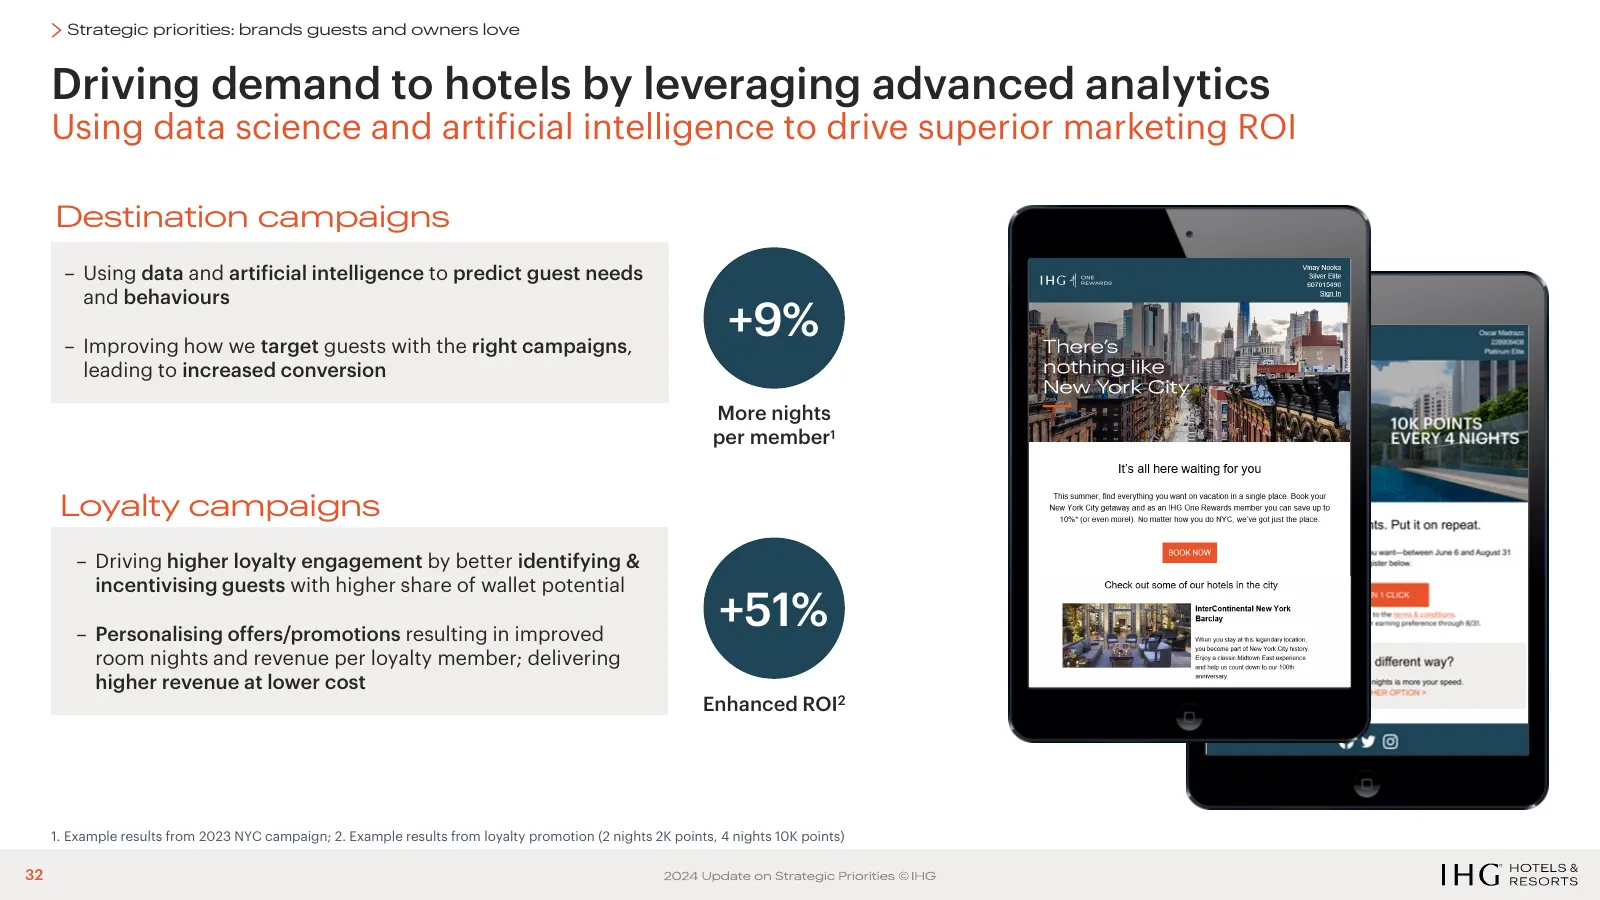
Strategic priorities: brands guests and owners love Driving demand to hotels by leveraging advanced analytics Using data science and artificial intelligence to drive superior marketing ROI Destination campaigns – Using data and artificial intelligence to predict guest needs and behaviours – Improvin
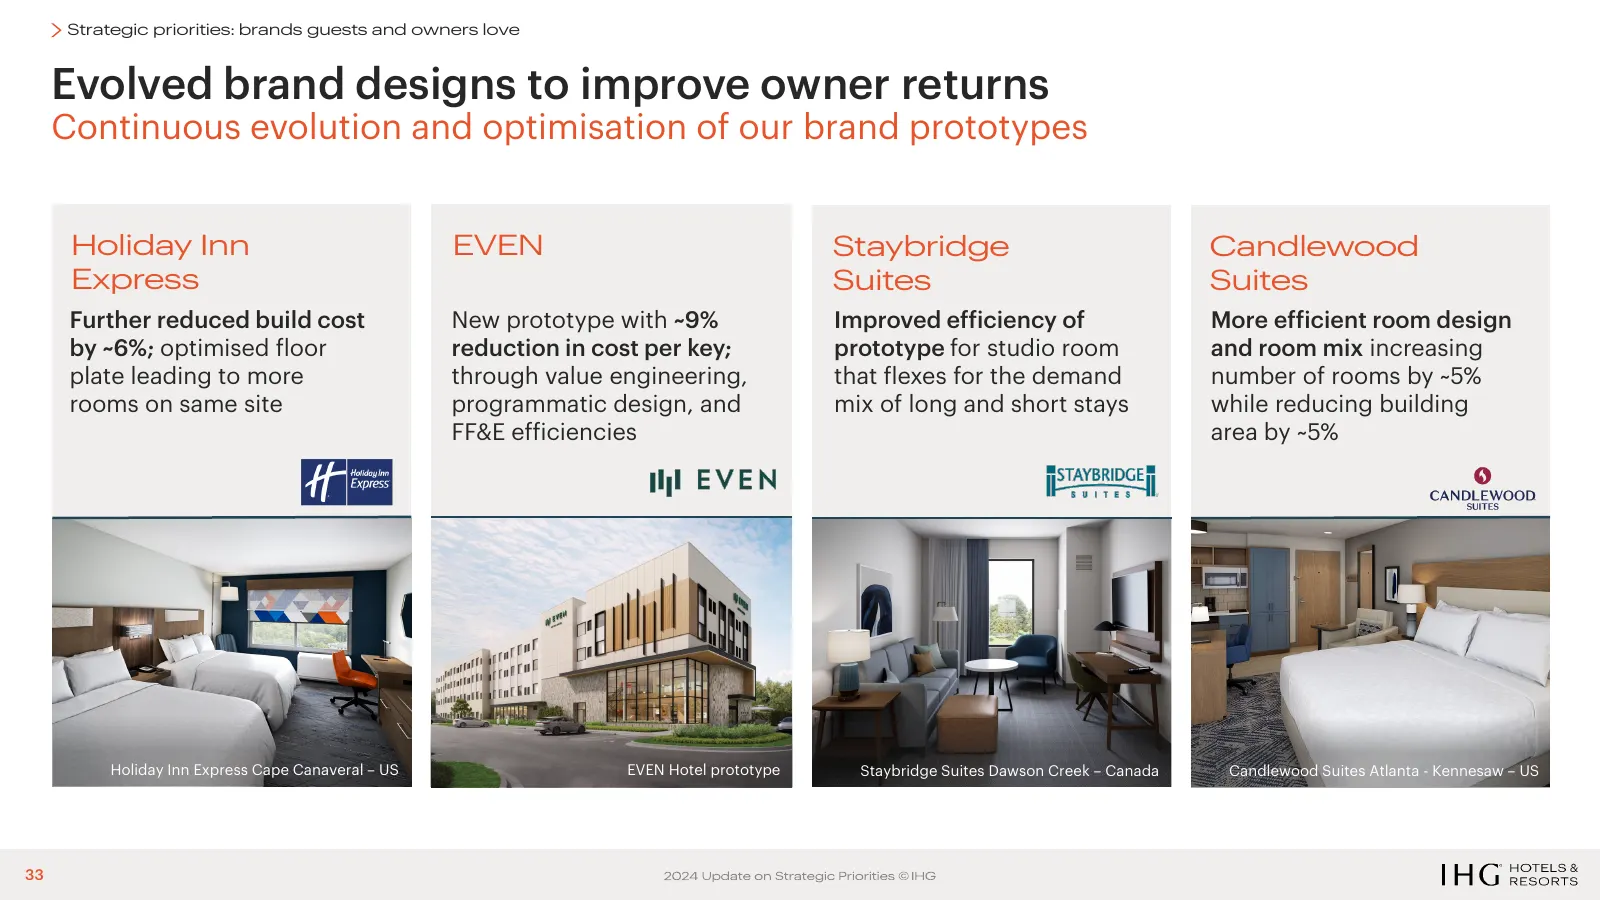
Slide 33: Evolved brand designs to improve owner returns
Strategic priorities: brands guests and owners love Evolved brand designs to improve owner returns Continuous evolution and optimisation of our brand prototypes Holiday Inn EVEN Staybridge Candlewood Express Suites Suites Further reduced build cost New prototype with ~9% Improved efficiency of More
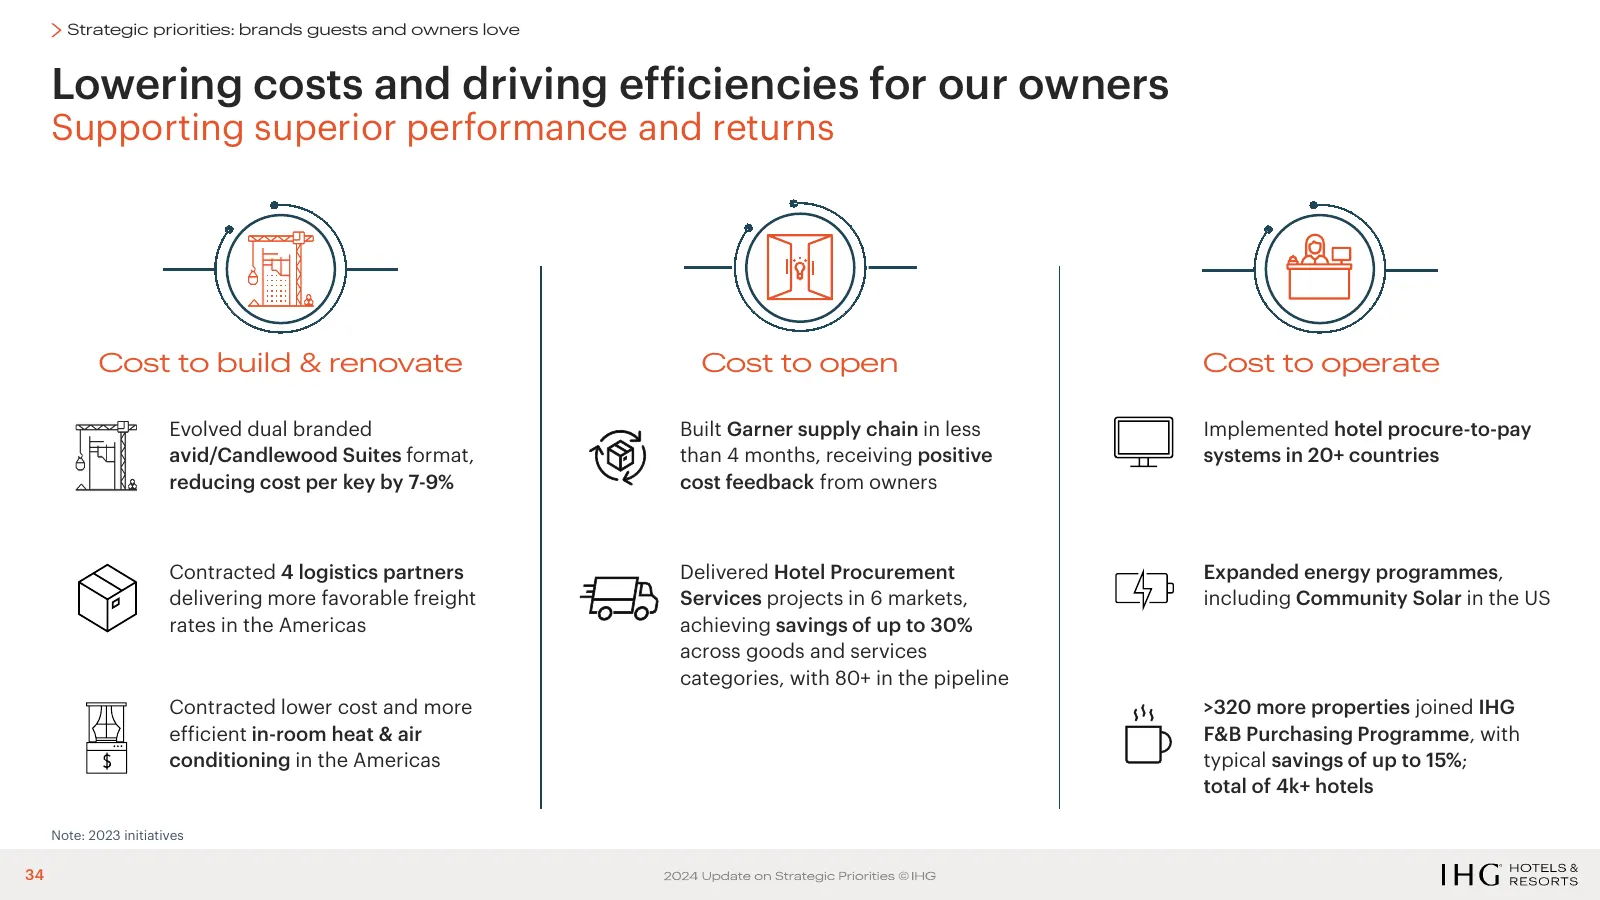
Slide 34: Lowering costs and driving efficiencies for our owners
Strategic priorities: brands guests and owners love Lowering costs and driving efficiencies for our owners Supporting superior performance and returns Cost to build & renovate Cost to open Cost to operate Evolved dual branded Built Garner supply chain in less Implemented hotel procure-to-pay avid/Ca
Slide 35: Leading commercial engine
Strategic priorities OUR PILLARS LEADING COMMERCIAL ENGINE 35
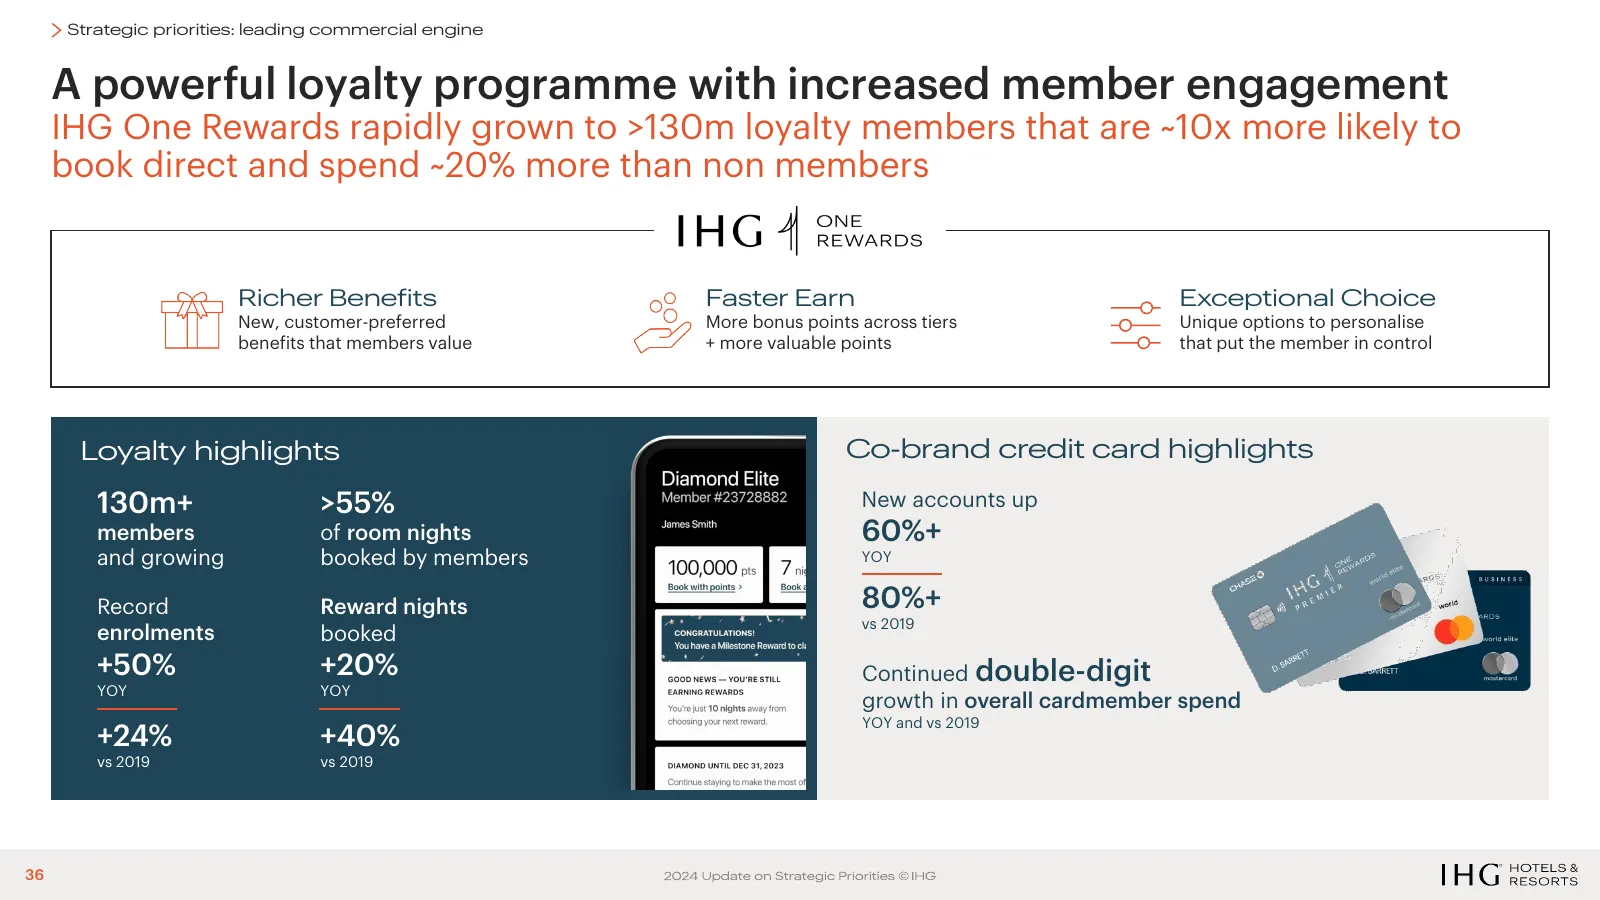
Slide 36: A powerful loyalty programme with increased member engagement
Strategic priorities: leading commercial engine A powerful loyalty programme with increased member engagement IHG One Rewards rapidly grown to >130m loyalty members that are ~10x more likely to book direct and spend ~20% more than non members Richer Benefits Faster Earn Exceptional Choice New, custo
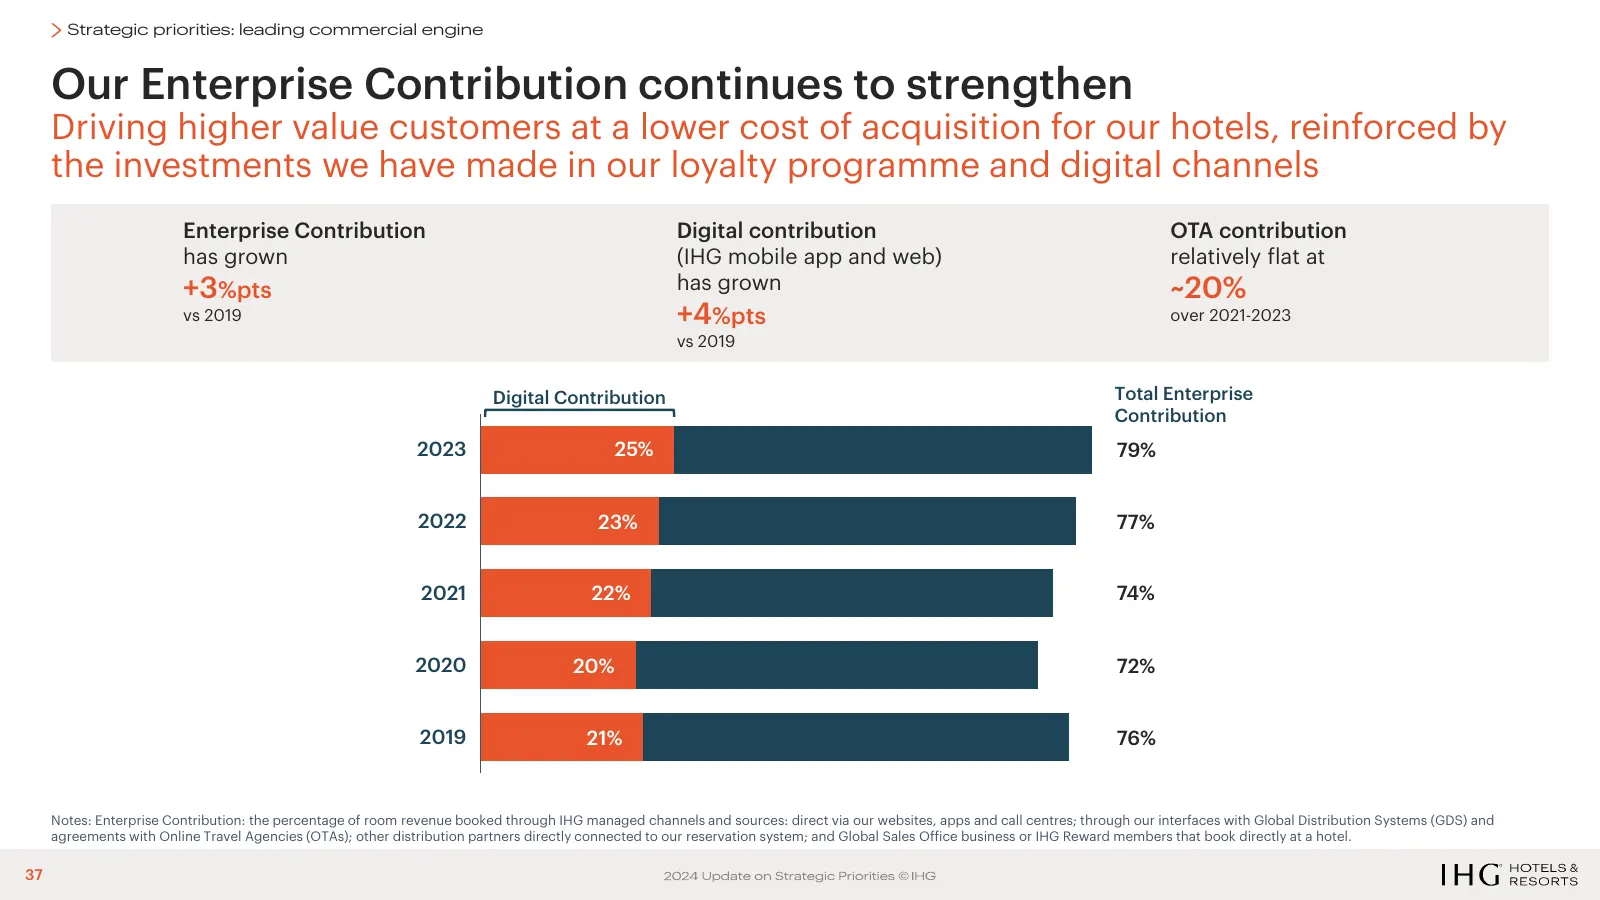
Slide 37: Our Enterprise Contribution continues to strengthen
Strategic priorities: leading commercial engine Our Enterprise Contribution continues to strengthen Driving higher value customers at a lower cost of acquisition for our hotels, reinforced by the investments we have made in our loyalty programme and digital channels Enterprise Contribution Digital c
Slide 38: Innovating our hotel tech stack
Strategic priorities: leading commercial engine Innovating our hotel tech stack Creating a superior value proposition for our owners through best-in-class technology platforms 1 2 3 Guest Reservation Revenue Management Property Management System System System (GRS) (RMS) (PMS) 38
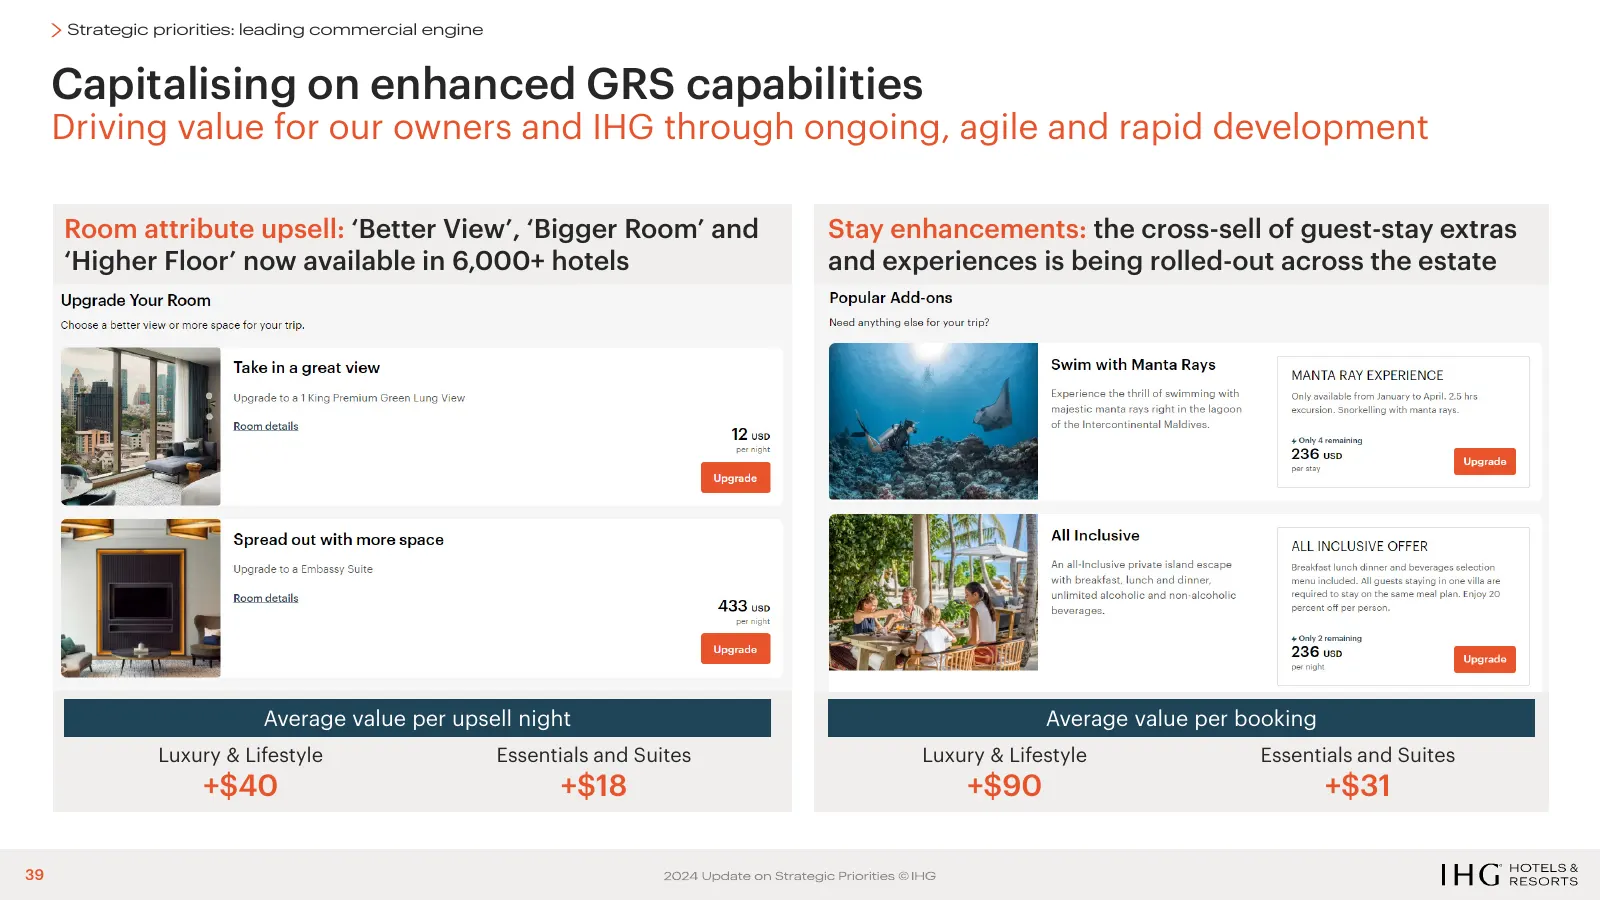
Slide 39: Capitalising on enhanced GRS capabilities
Strategic priorities: leading commercial engine Capitalising on enhanced GRS capabilities Driving value for our owners and IHG through ongoing, agile and rapid development Room attribute upsell: ‘Better View’, ‘Bigger Room’ and Stay enhancements: the cross-sell of guest-stay extras ‘Higher Floor’ no
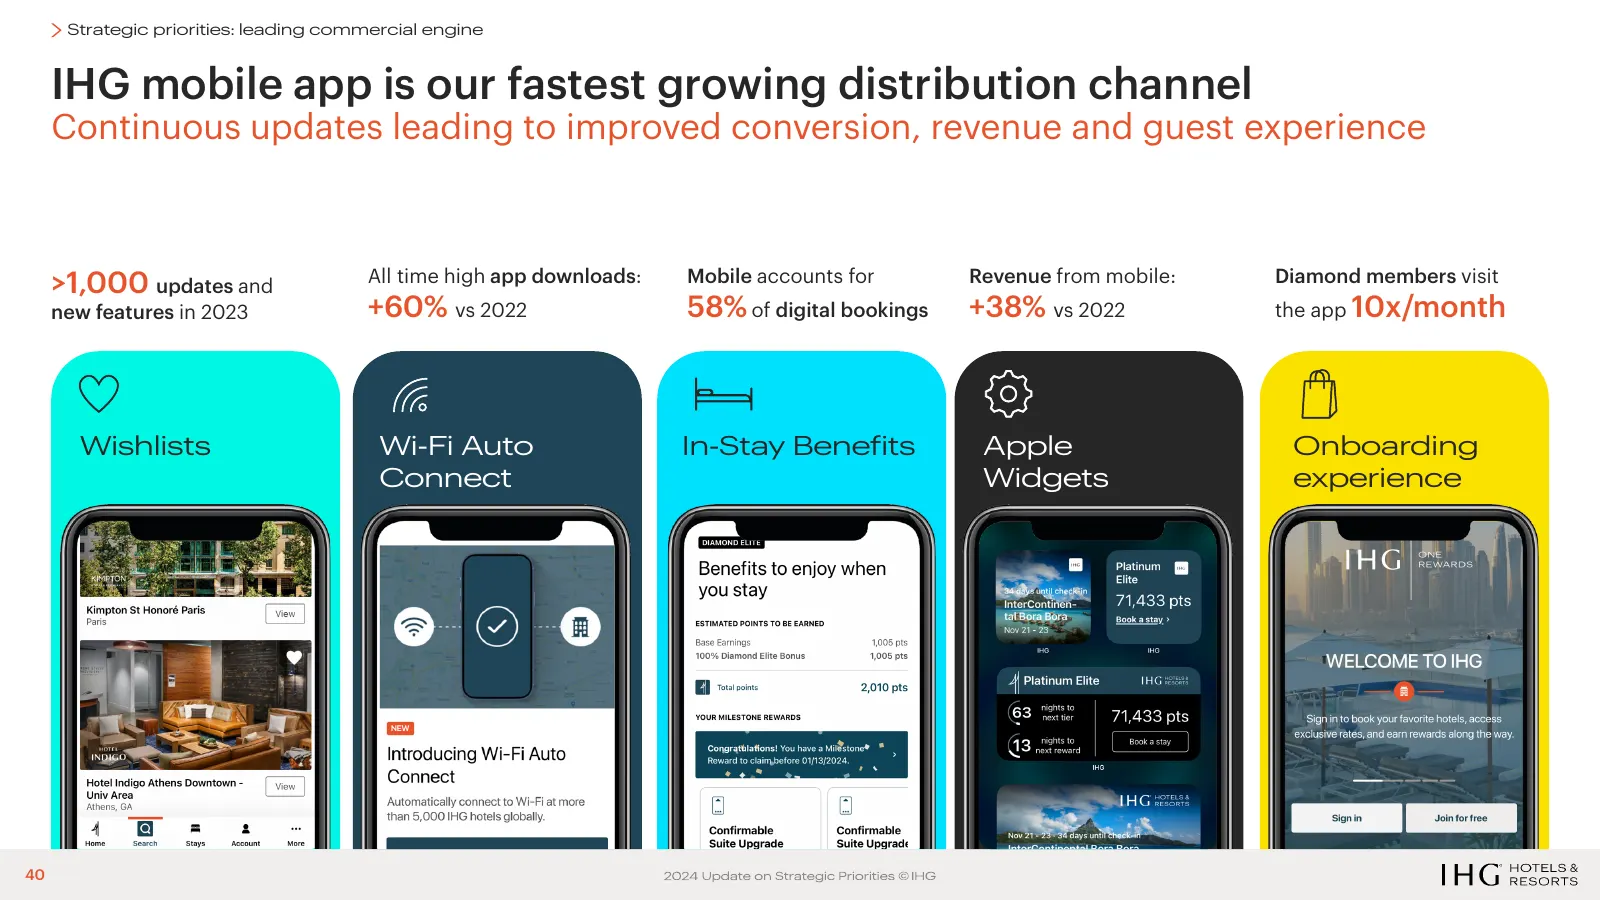
Slide 40: IHG mobile app is our fastest growing distribution channel
Strategic priorities: leading commercial engine IHG mobile app is our fastest growing distribution channel Continuous updates leading to improved conversion, revenue and guest experience >1,000 updates and All time high app downloads: Mobile accounts for Revenue from mobile: Diamond members visit ne
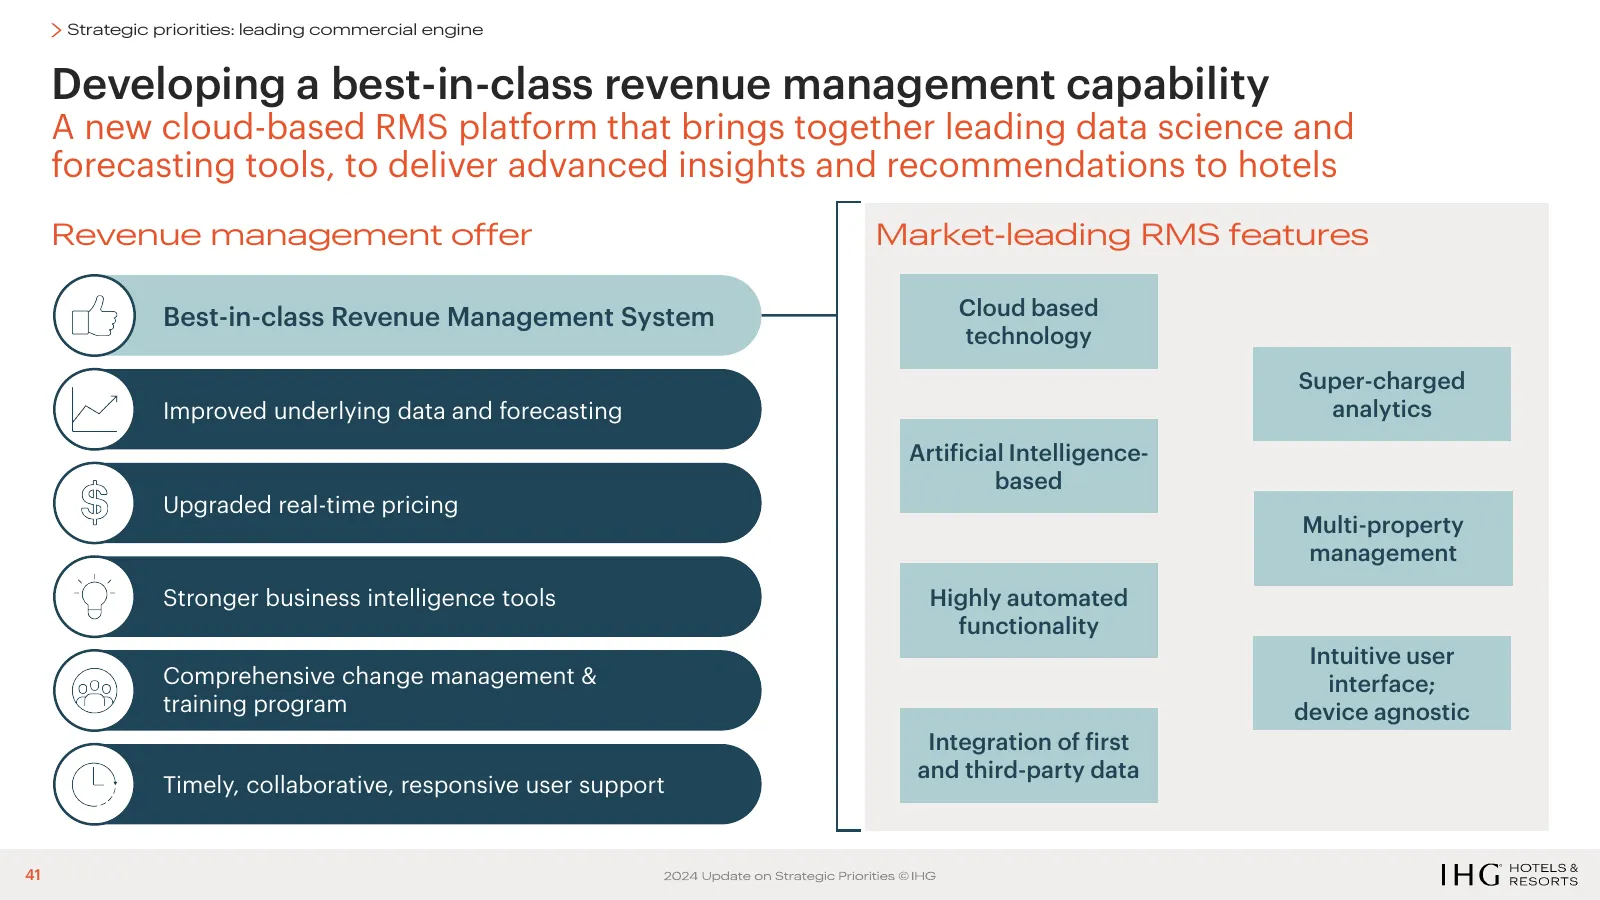
Slide 41: Developing a best-in-class revenue management capability
Strategic priorities: leading commercial engine Developing a best-in-class revenue management capability A new cloud-based RMS platform that brings together leading data science and forecasting tools, to deliver advanced insights and recommendations to hotels Revenue management offer Market-leading
Slide 42: Care for our people, communities and planet
Strategic priorities OUR PILLARS CARE FOR OUR PEOPLE, COMMUNITIES AND PLANET 42
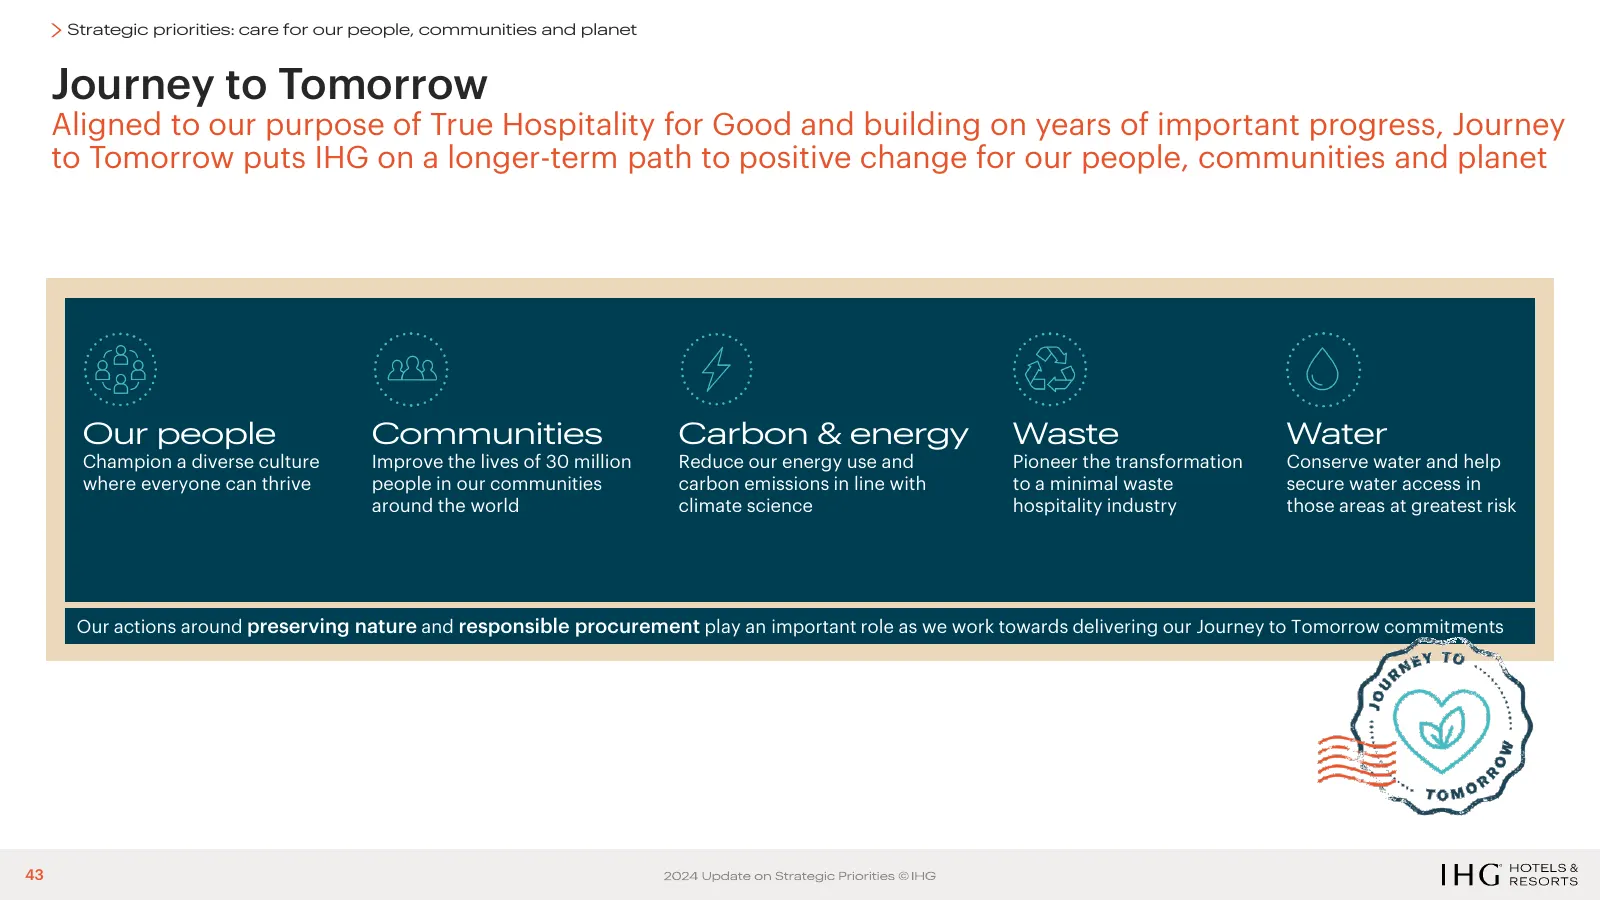
Slide 43: Journey to Tomorrow
Strategic priorities: care for our people, communities and planet Journey to Tomorrow Aligned to our purpose of True Hospitality for Good and building on years of important progress, Journey to Tomorrow puts IHG on a longer-term path to positive change for our people, communities and planet Our peop
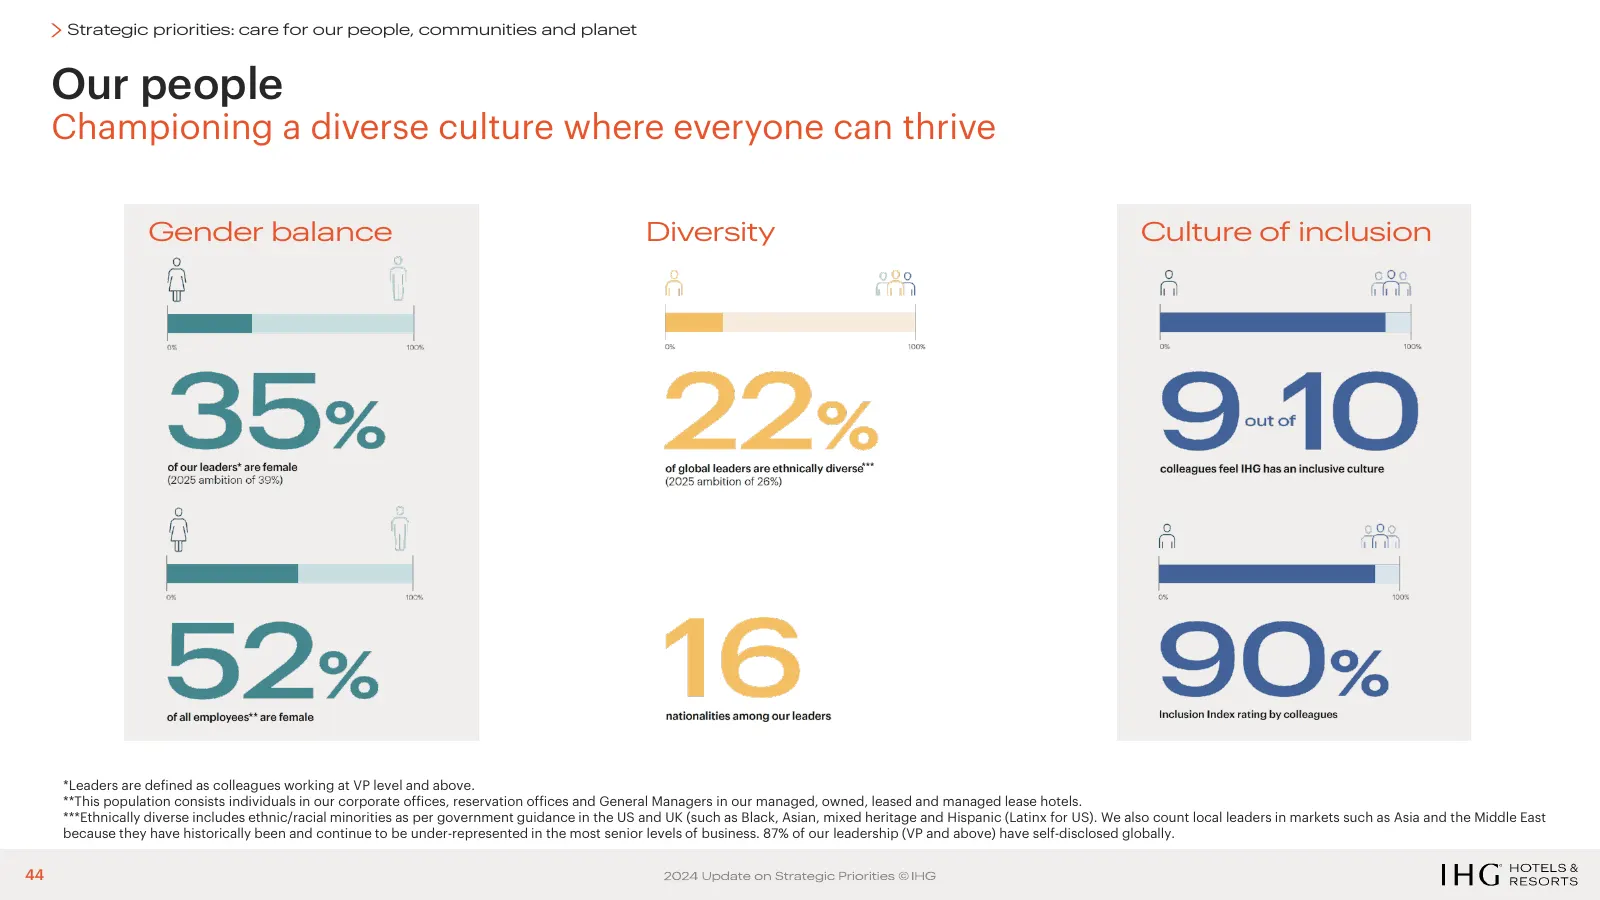
Slide 44: Our people
Strategic priorities: care for our people, communities and planet Our people Championing a diverse culture where everyone can thrive Gender balance Diversity Culture of inclusion *** *Leaders are defined as colleagues working at VP level and above. **This population consists individuals in our corpo
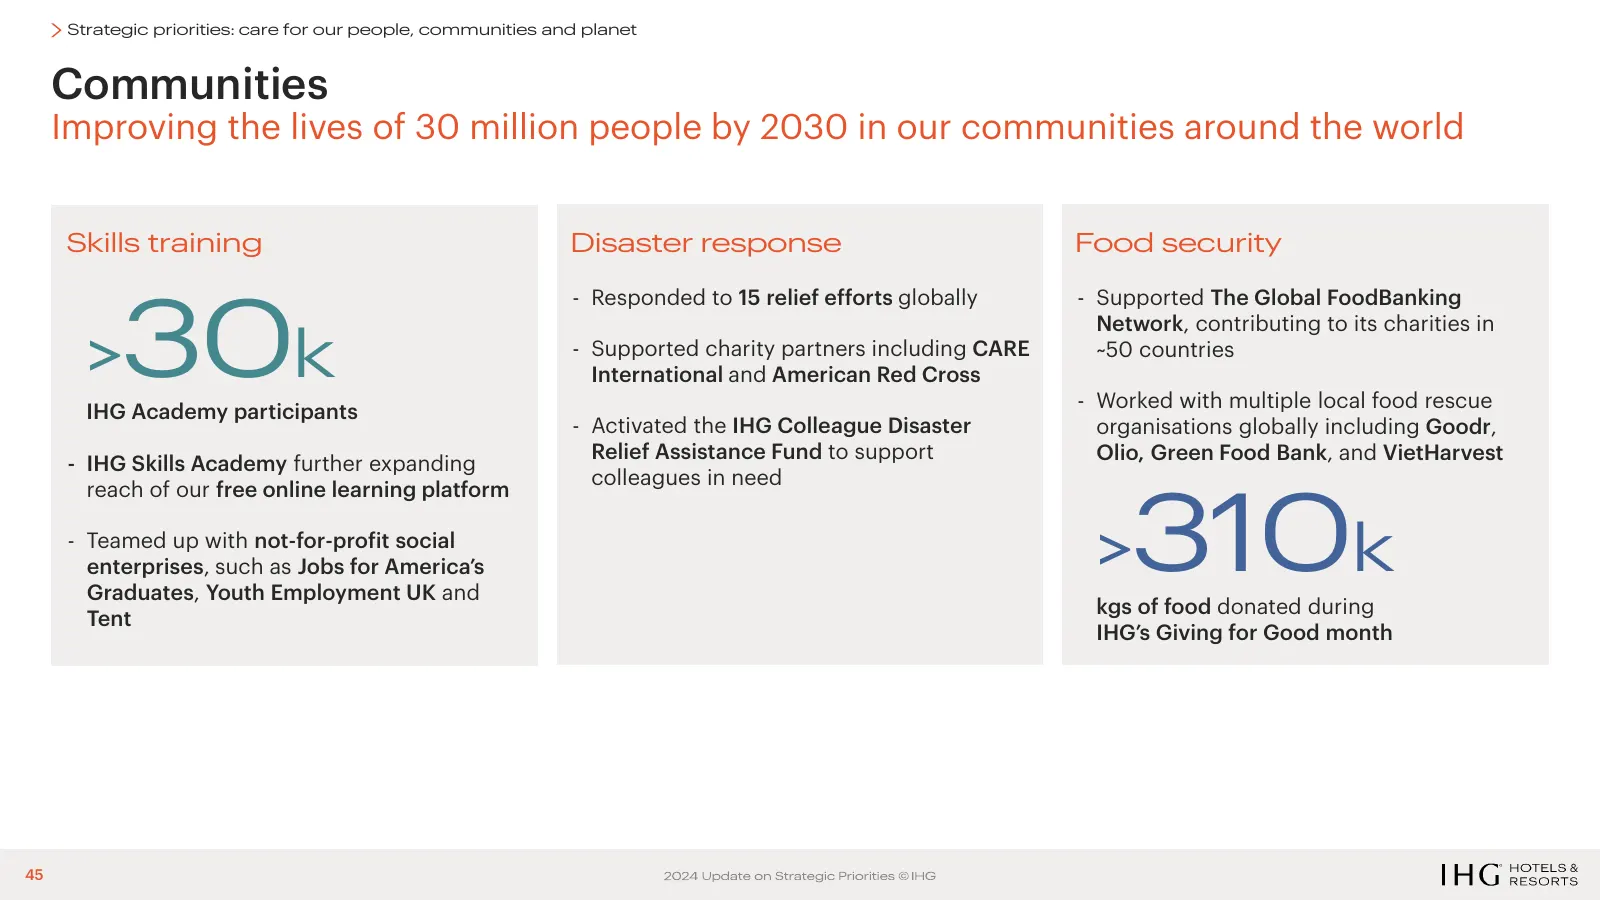
Slide 45: Communities
Strategic priorities: care for our people, communities and planet Communities Improving the lives of 30 million people by 2030 in our communities around the world Skills training Disaster response Food security 30k - Responded to 15 relief efforts globally - Supported The Global FoodBanking > Networ
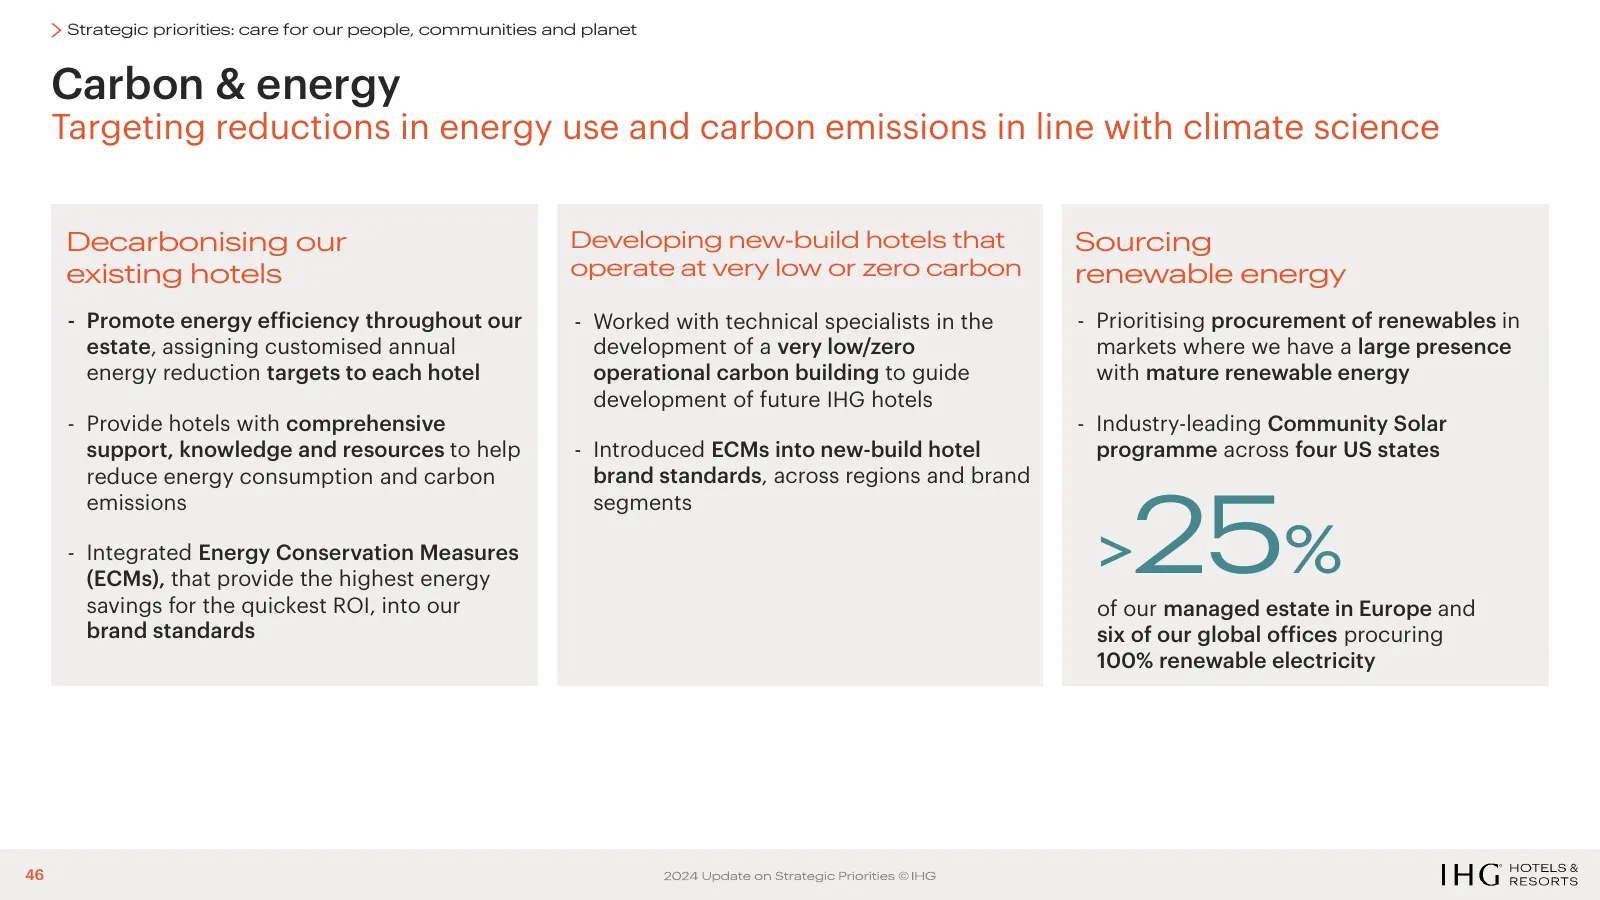
Slide 46: Carbon & energy
Strategic priorities: care for our people, communities and planet Carbon & energy Targeting reductions in energy use and carbon emissions in line with climate science Decarbonising our Developing new-build hotels that Sourcing existing hotels operate at very low or zero carbon renewable energy - Pro
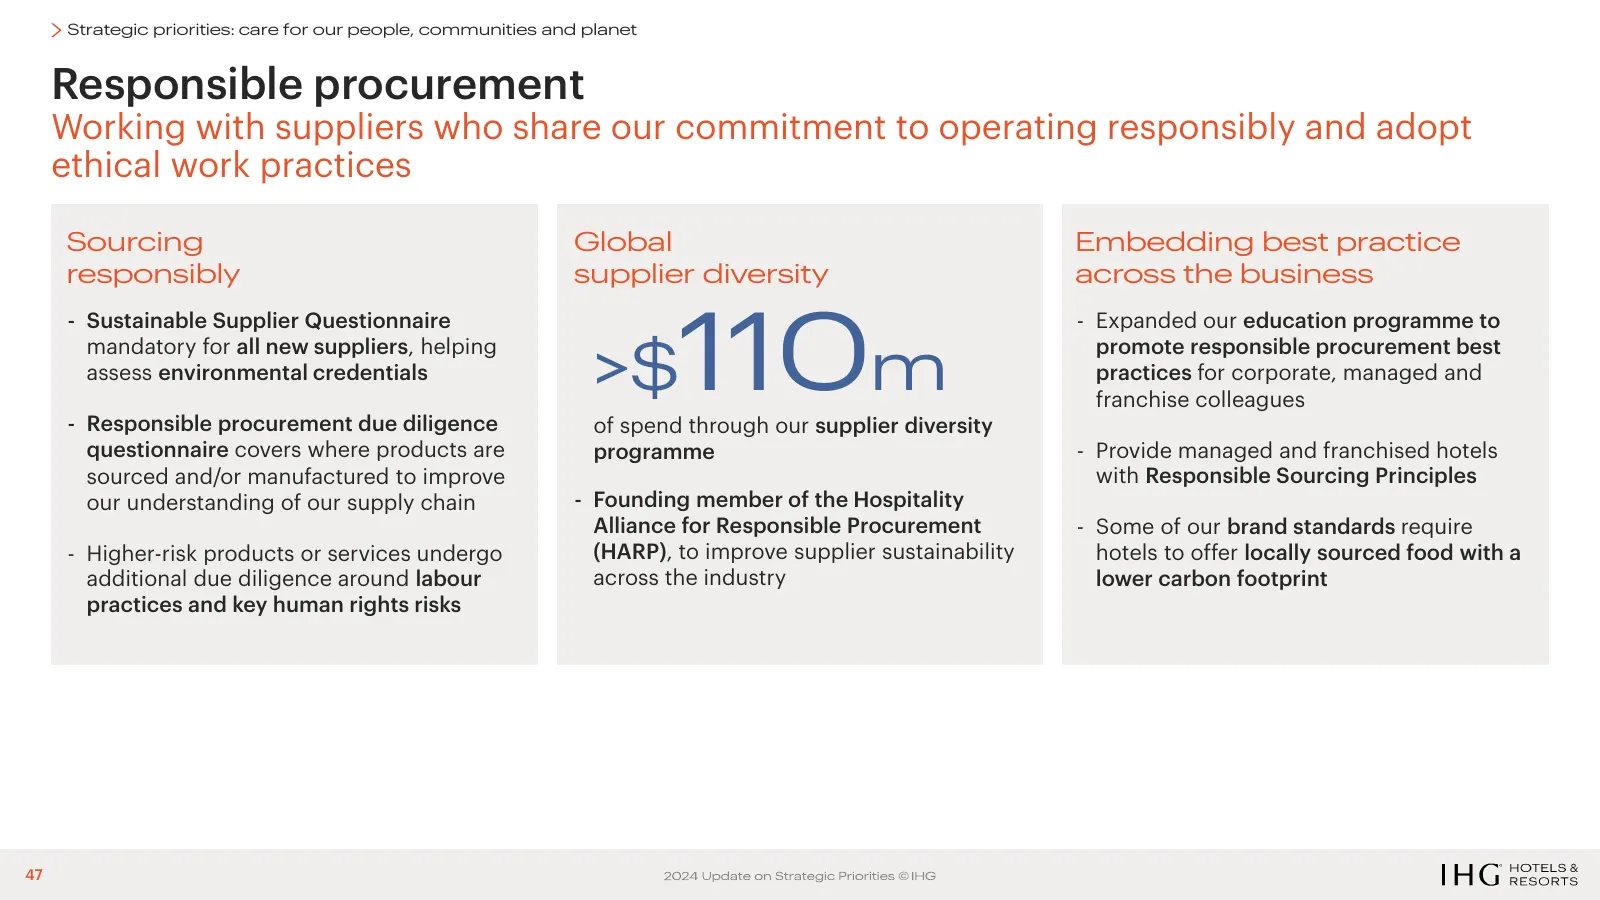
Slide 47: Responsible procurement
Strategic priorities: care for our people, communities and planet Responsible procurement Working with suppliers who share our commitment to operating responsibly and adopt ethical work practices Sourcing Global Embedding best practice responsibly supplier diversity across the business 110m - Sustai
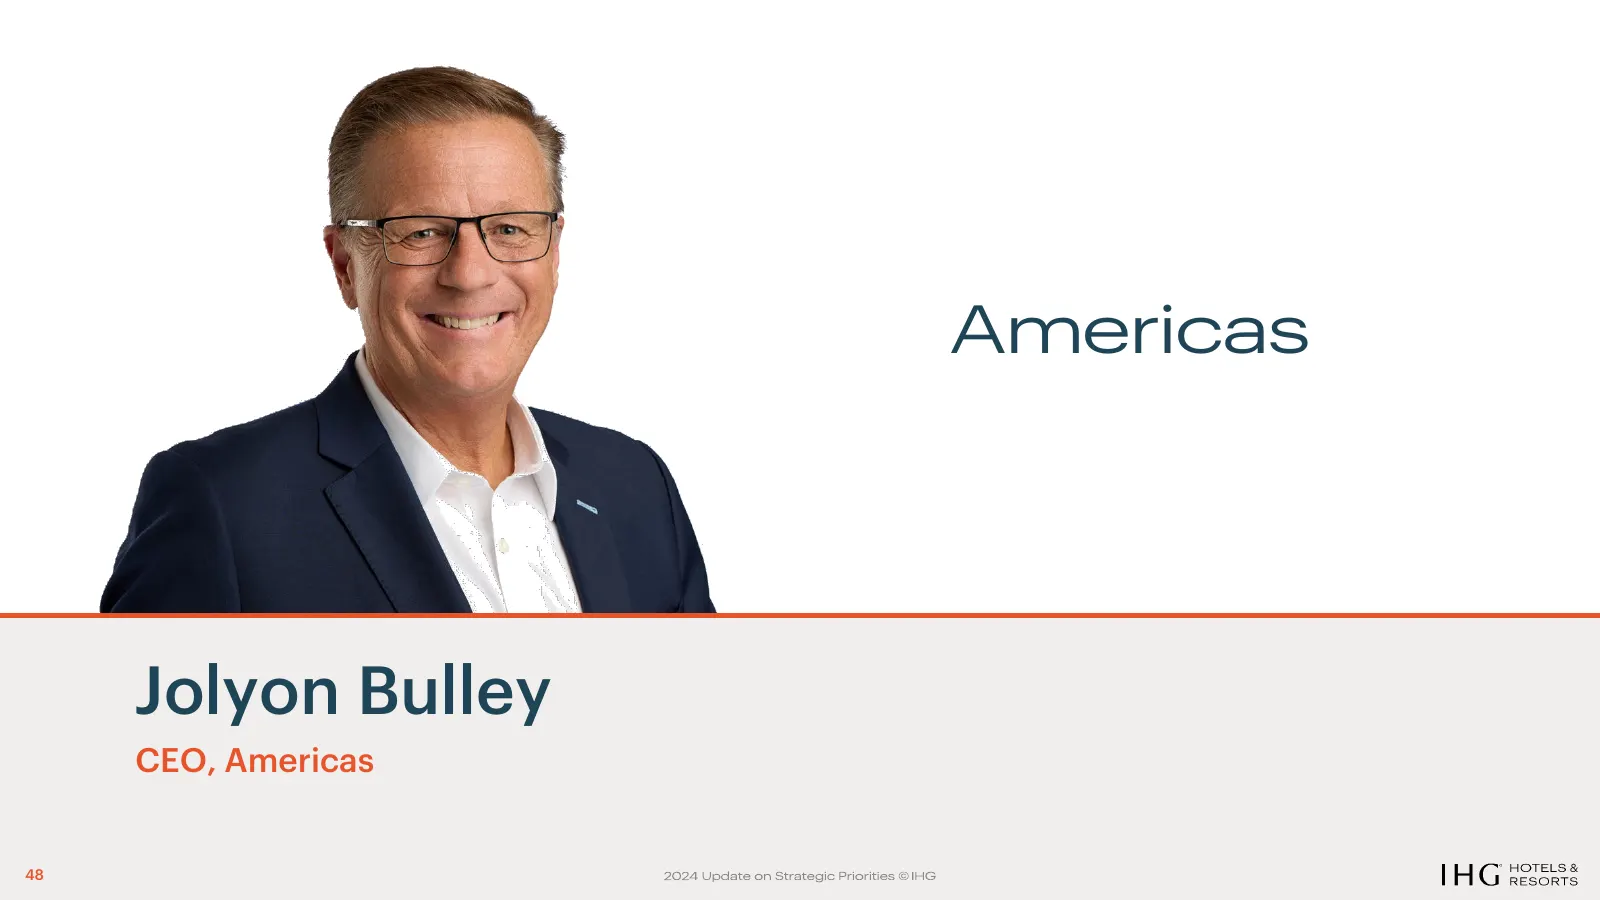
Slide 48: Americas
Americas Jolyon Bulley CEO, Americas 48
Slide 49: Americas: overview
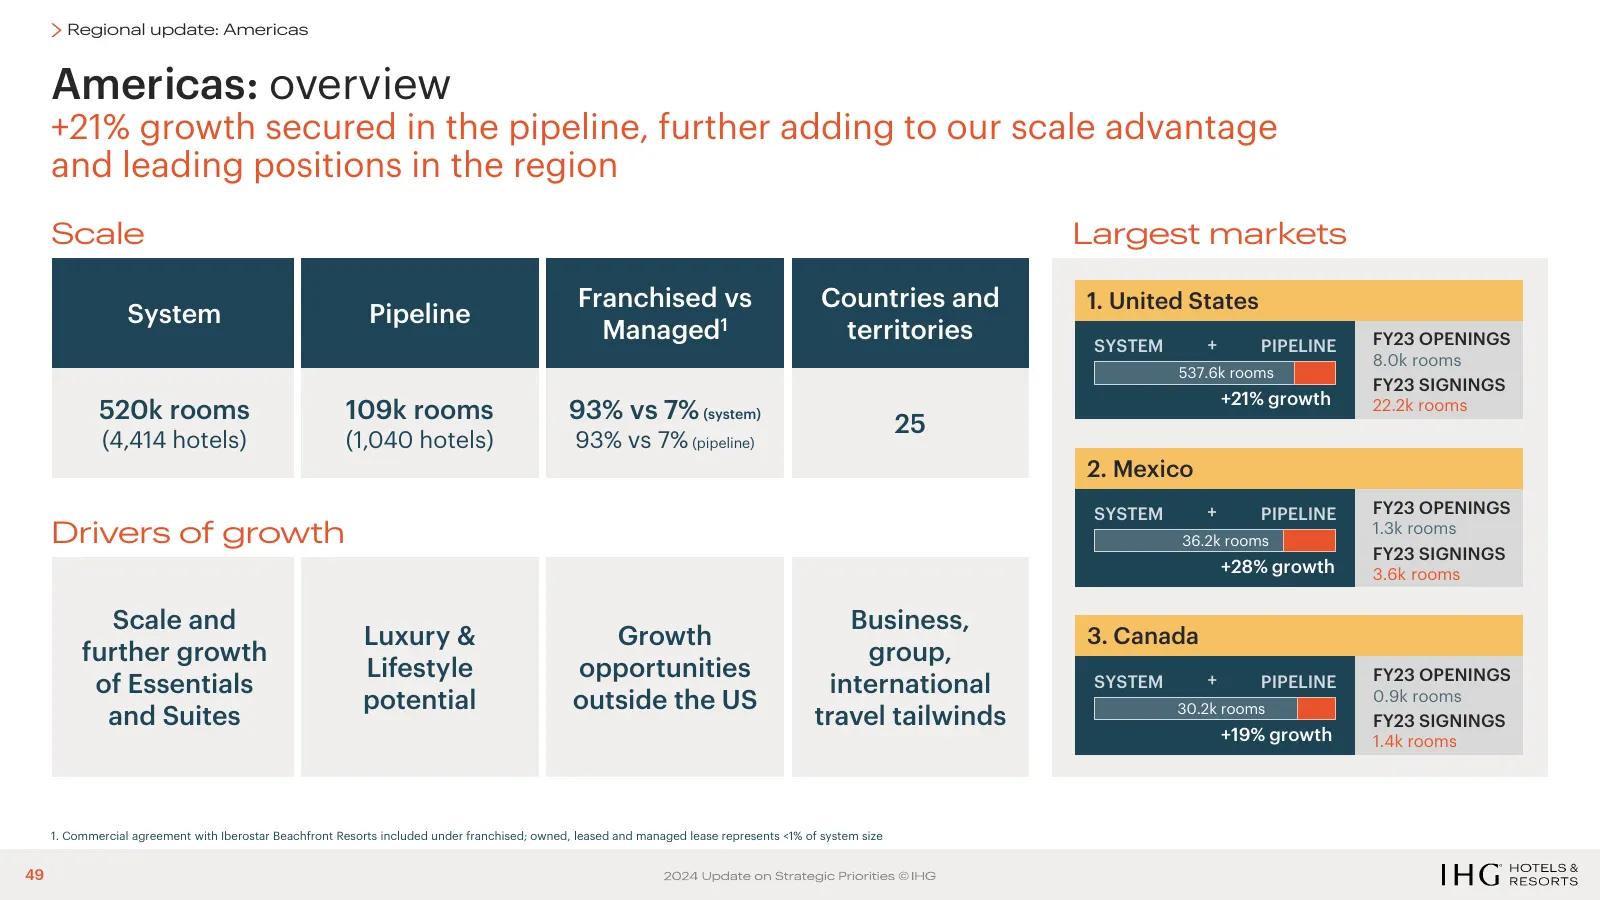
Regional update: Americas Americas: overview +21% growth secured in the pipeline, further adding to our scale advantage and leading positions in the region Scale Largest markets Franchised vs Countries and 1. United States System Pipeline Managed1 territories SYSTEM + PIPELINE FY23 OPENINGS 8.0k roo
Slide 50: Americas: brand portfolio mix
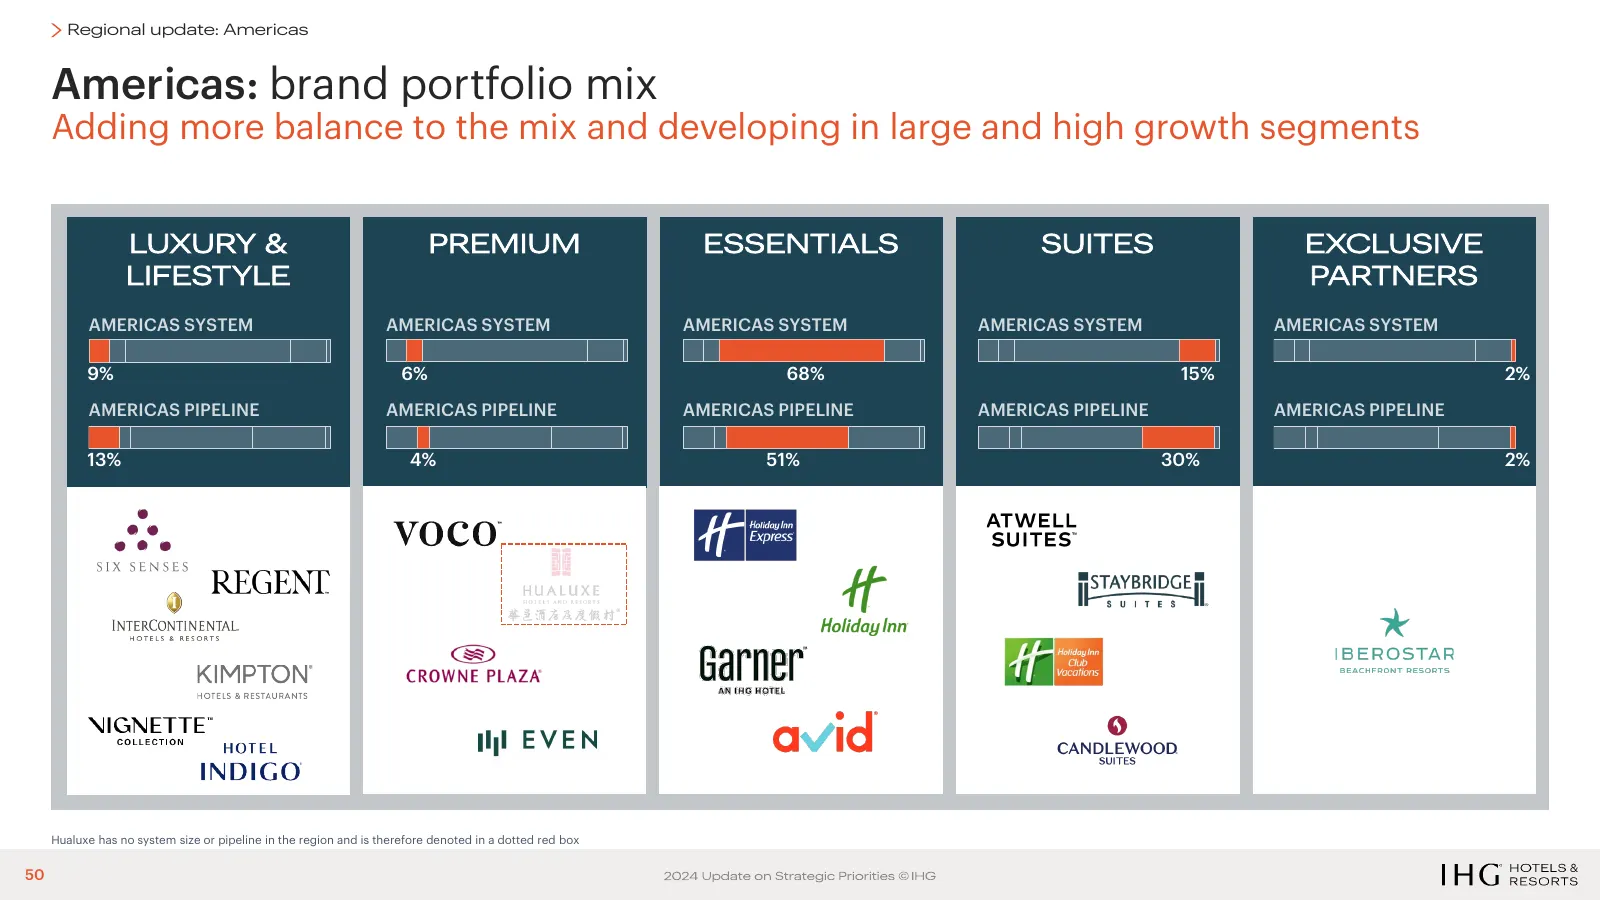
Regional update: Americas Americas: brand portfolio mix Adding more balance to the mix and developing in large and high growth segments LUXURY & PREMIUM ESSENTIALS SUITES EXCLUSIVE LIFESTYLE PARTNERS AMERICAS SYSTEM AMERICAS SYSTEM AMERICAS SYSTEM AMERICAS SYSTEM AMERICAS SYSTEM 9% 6% 68% 15% 2% AME
Slide 51: Americas: continued growth potential in Essentials and Suites
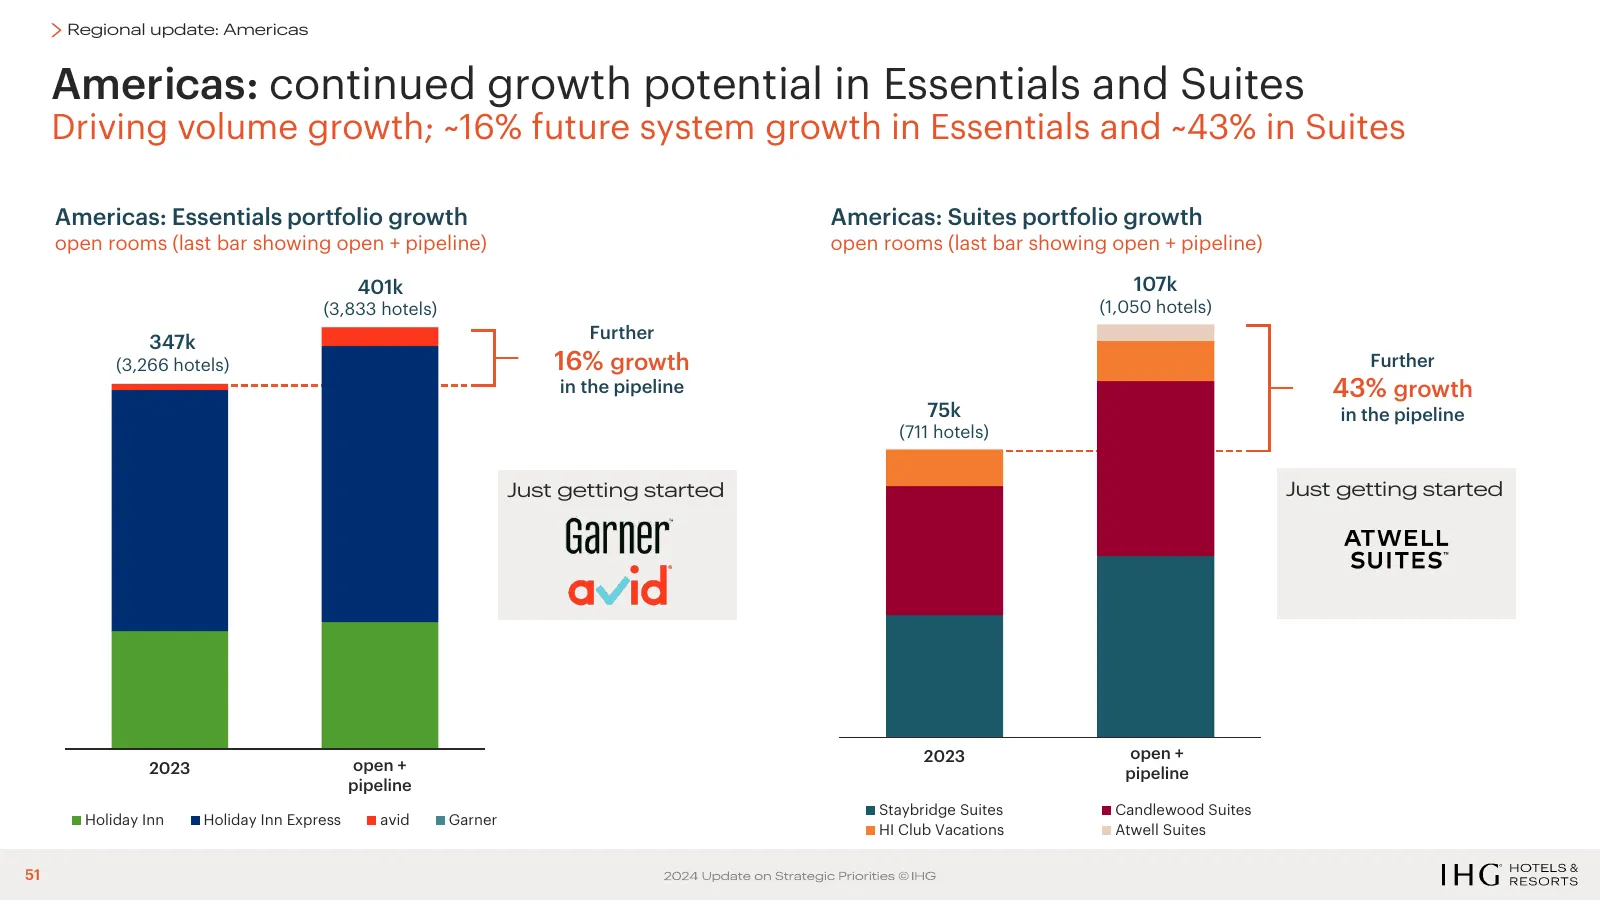
Regional update: Americas Americas: continued growth potential in Essentials and Suites Driving volume growth; ~16% future system growth in Essentials and ~43% in Suites Americas: Essentials portfolio growth Americas: Suites portfolio growth open rooms (last bar showing open + pipeline) open rooms (
Slide 52: Americas: investing in Luxury & Lifestyle
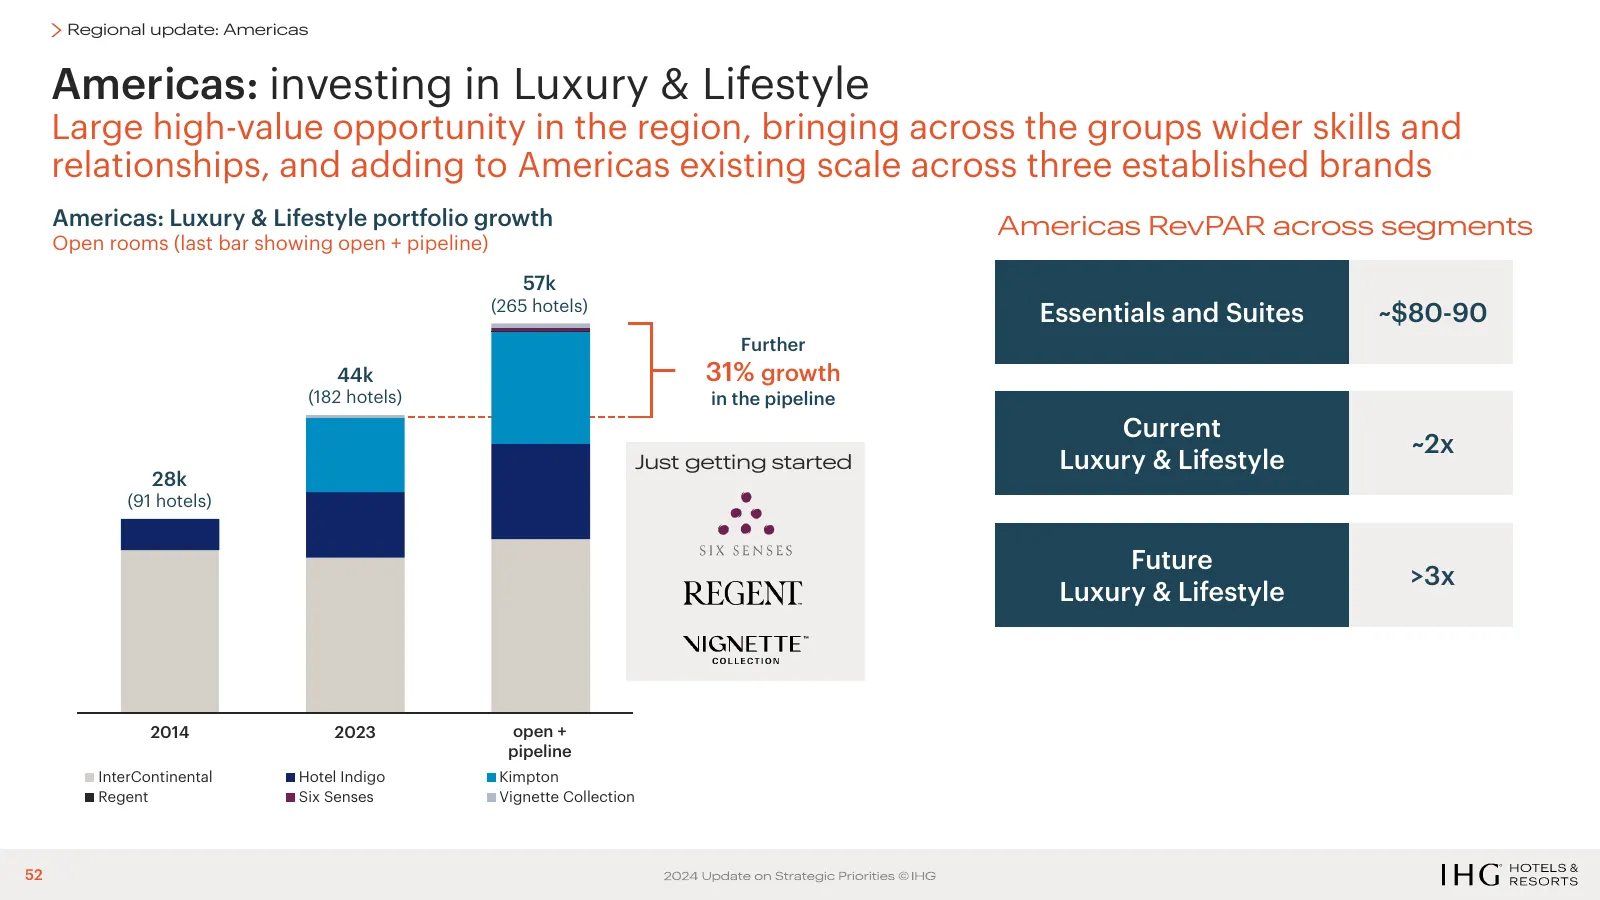
Regional update: Americas Americas: investing in Luxury & Lifestyle Large high-value opportunity in the region, bringing across the groups wider skills and relationships, and adding to Americas existing scale across three established brands Americas: Luxury & Lifestyle portfolio growth Americas RevP
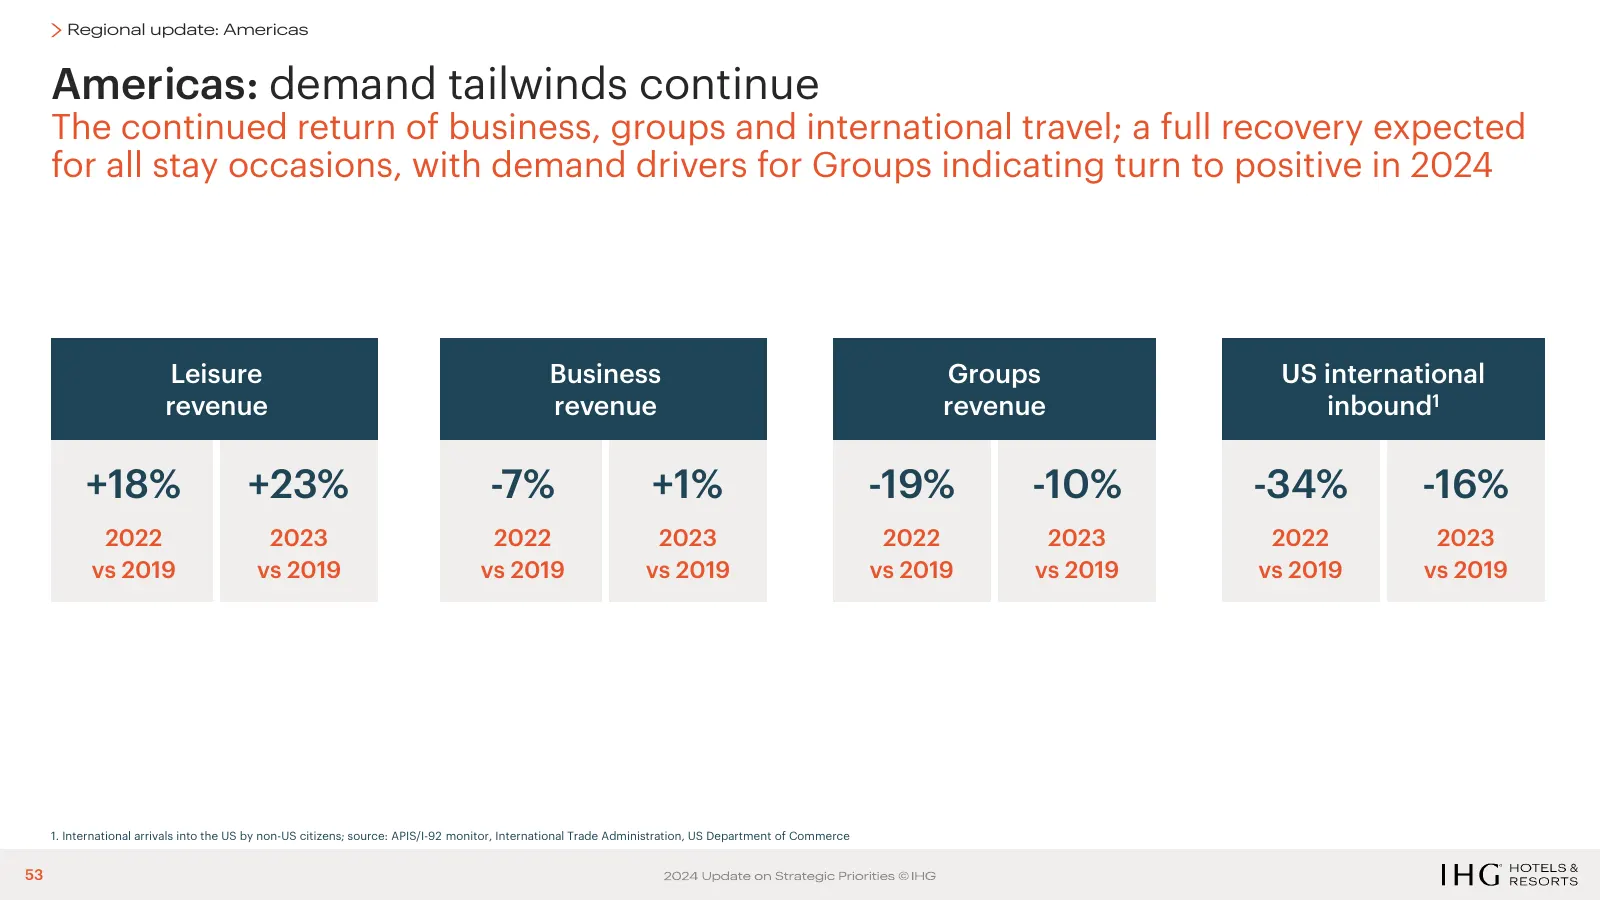
Slide 53: Americas: demand tailwinds continue
Regional update: Americas Americas: demand tailwinds continue The continued return of business, groups and international travel; a full recovery expected for all stay occasions, with demand drivers for Groups indicating turn to positive in 2024 Leisure Business Groups US international revenue revenu
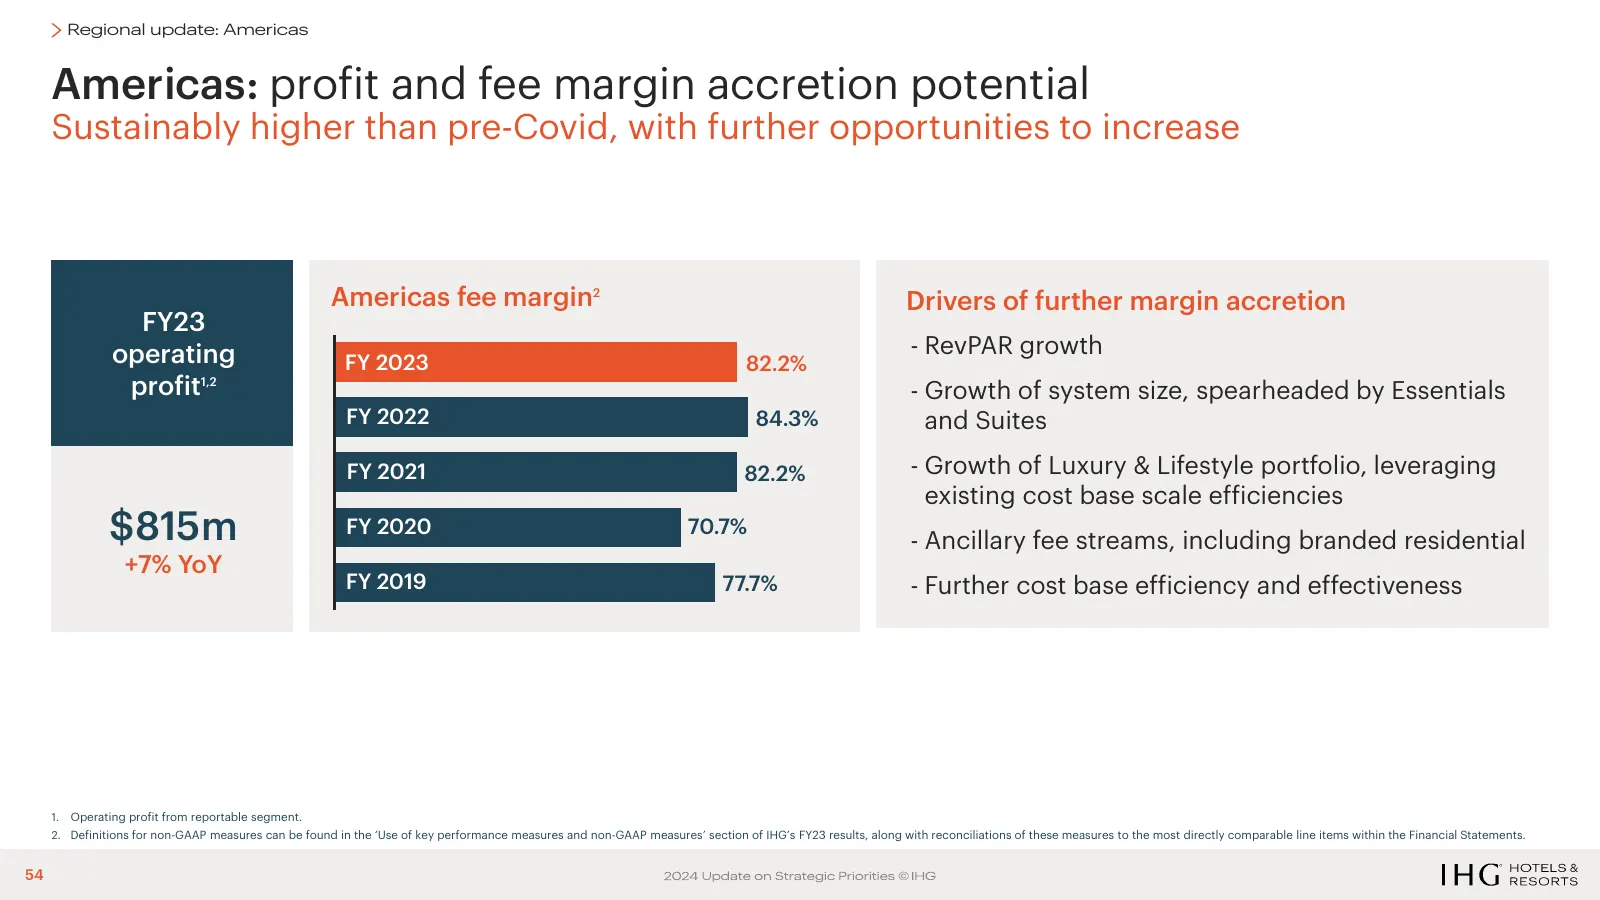
Slide 54: Americas: profit and fee margin accretion potential
Regional update: Americas Americas: profit and fee margin accretion potential Sustainably higher than pre-Covid, with further opportunities to increase Americas fee margin2 Drivers of further margin accretion FY23 operating - RevPAR growth FY 2023 82.2% profit1,2 - Growth of system size, spearheaded
Slide 55: Europe, Middle East, Asia and Africa
Europe, Middle East, Asia and Africa Kenneth Macpherson CEO, Europe, Middle East, Asia and Africa 55
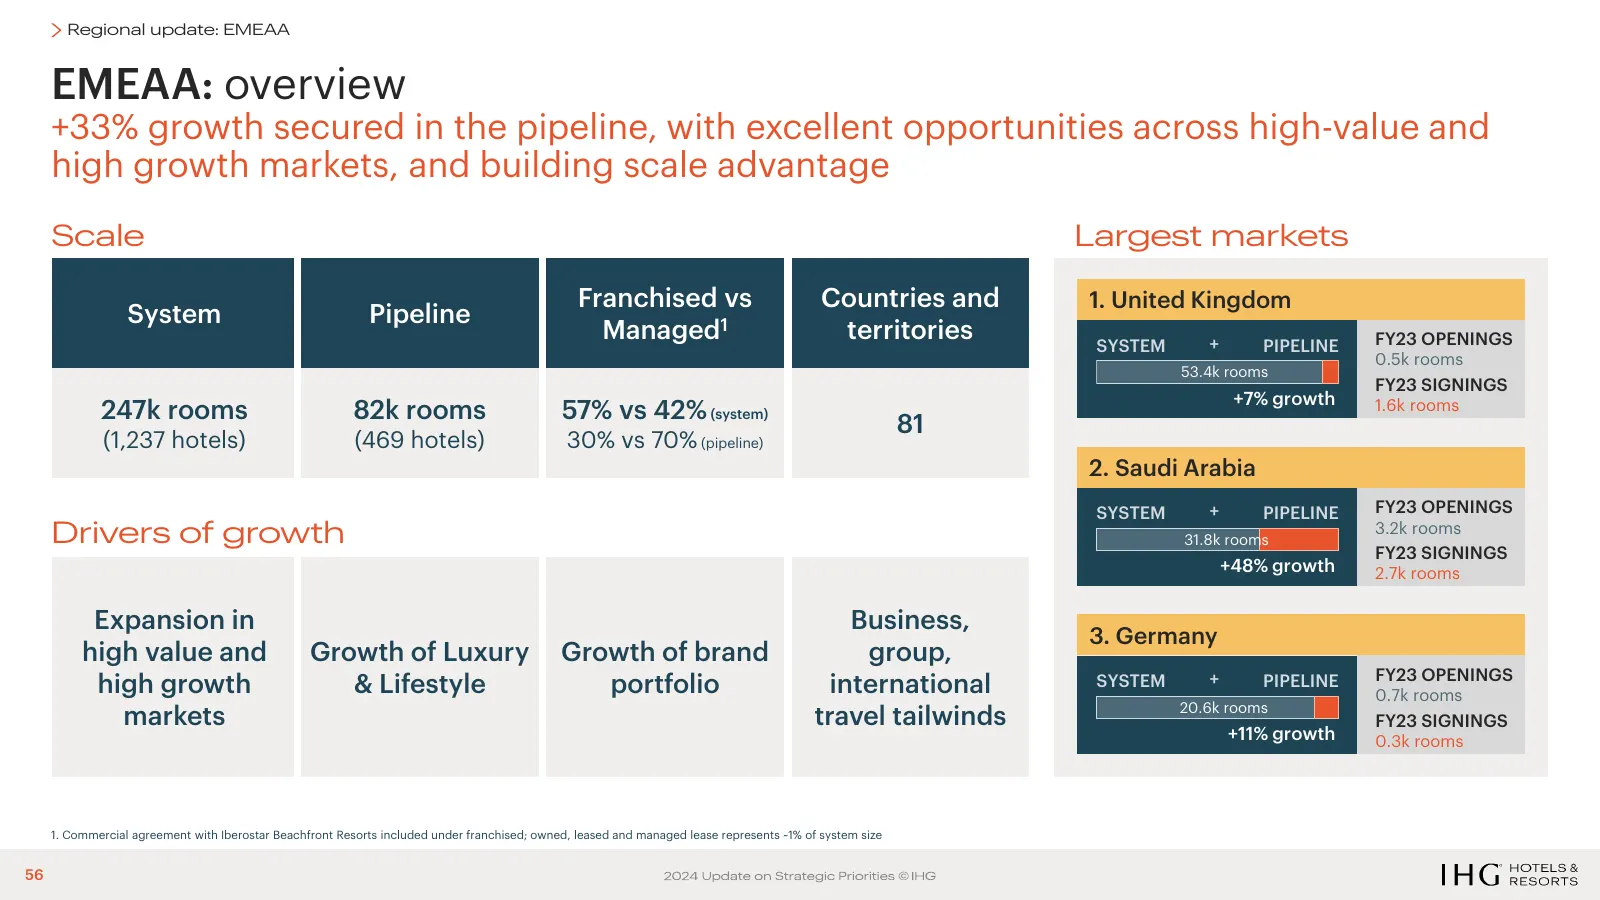
Slide 56: EMEAA: overview
Regional update: EMEAA EMEAA: overview +33% growth secured in the pipeline, with excellent opportunities across high-value and high growth markets, and building scale advantage Scale Largest markets Franchised vs Countries and 1. United Kingdom System Pipeline Managed1 territories SYSTEM + PIPELINE
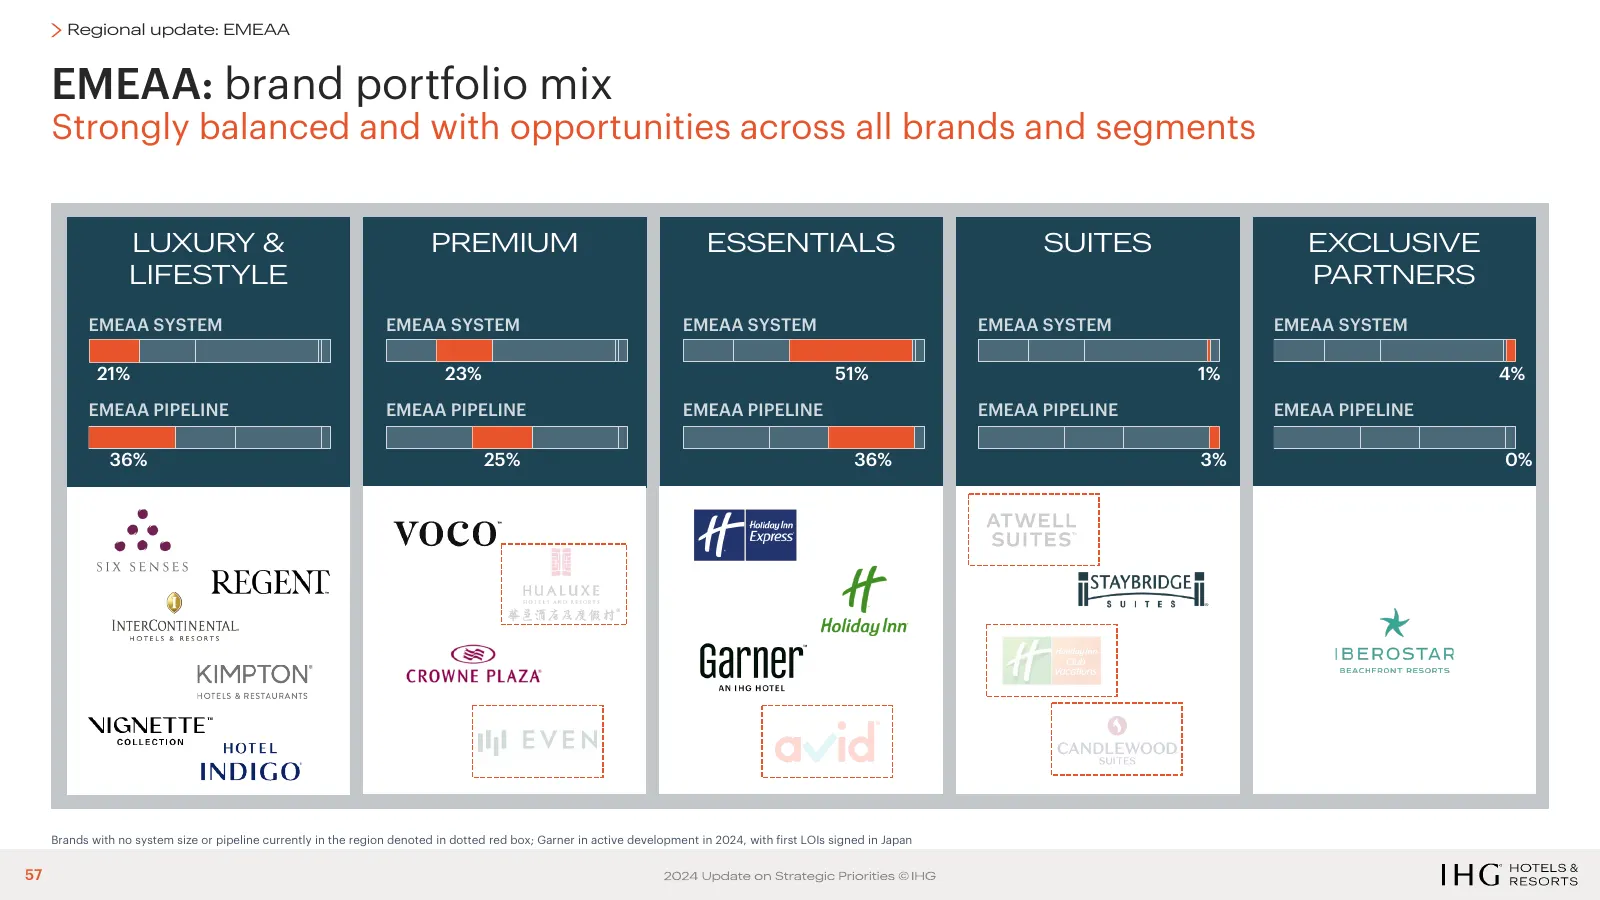
Slide 57: EMEAA: brand portfolio mix
Regional update: EMEAA EMEAA: brand portfolio mix Strongly balanced and with opportunities across all brands and segments LUXURY & PREMIUM ESSENTIALS SUITES EXCLUSIVE LIFESTYLE PARTNERS EMEAA SYSTEM EMEAA SYSTEM EMEAA SYSTEM EMEAA SYSTEM EMEAA SYSTEM 21% 23% 51% 1% 4% EMEAA PIPELINE EMEAA PIPELINE E
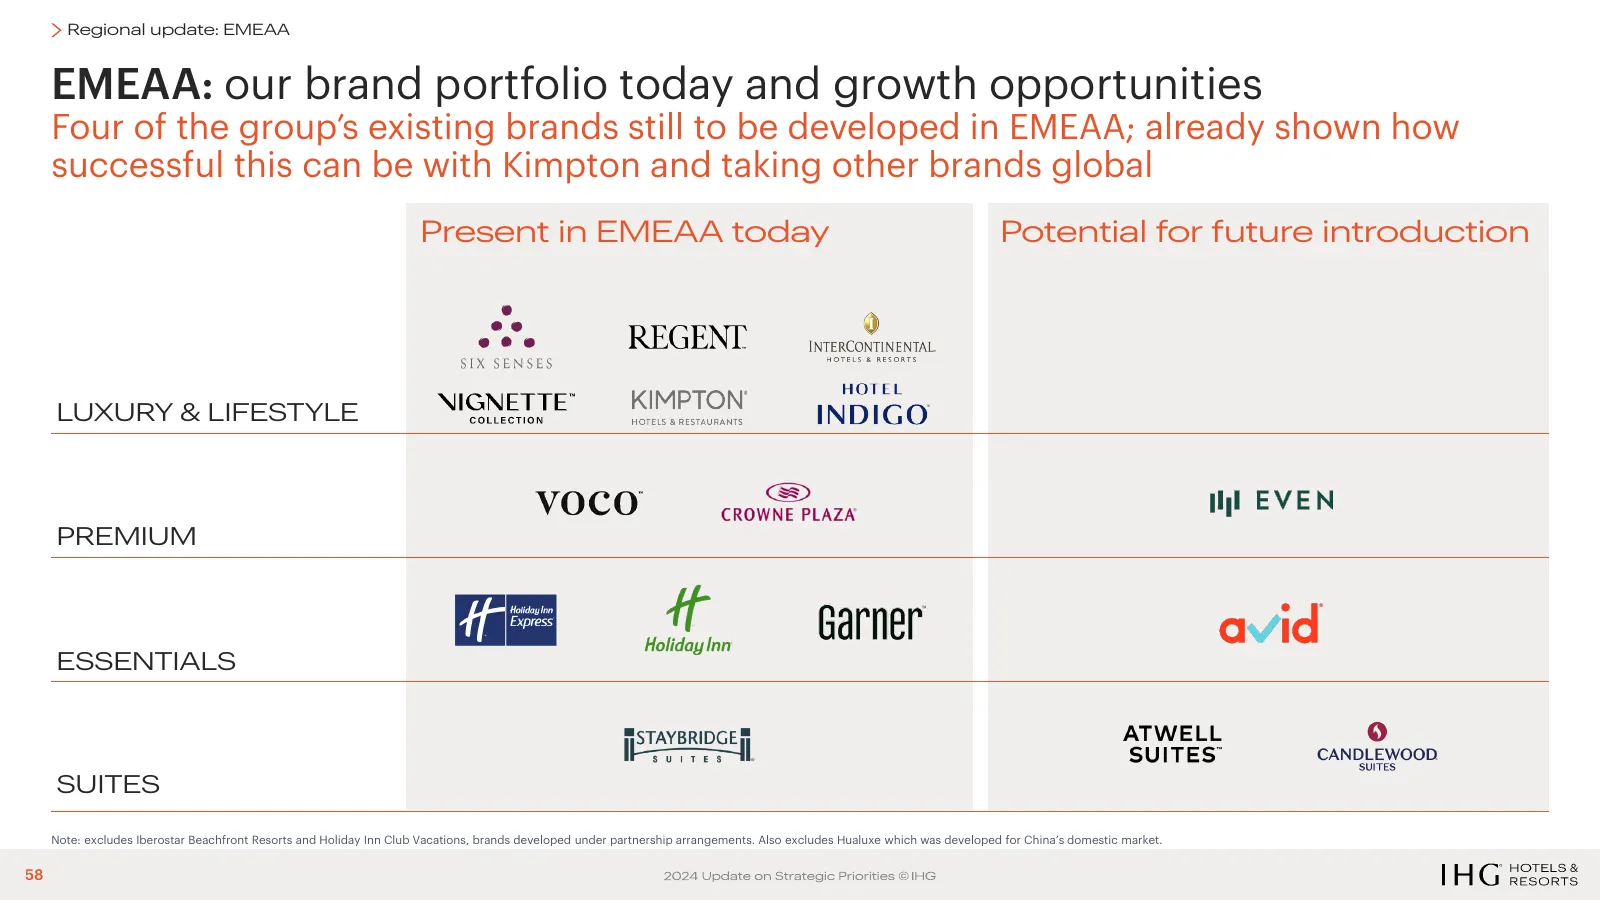
Slide 58: EMEAA: our brand portfolio today and growth opportunities
Regional update: EMEAA EMEAA: our brand portfolio today and growth opportunities Four of the group’s existing brands still to be developed in EMEAA; already shown how successful this can be with Kimpton and taking other brands global Present in EMEAA today Potential for future introduction LUXURY &
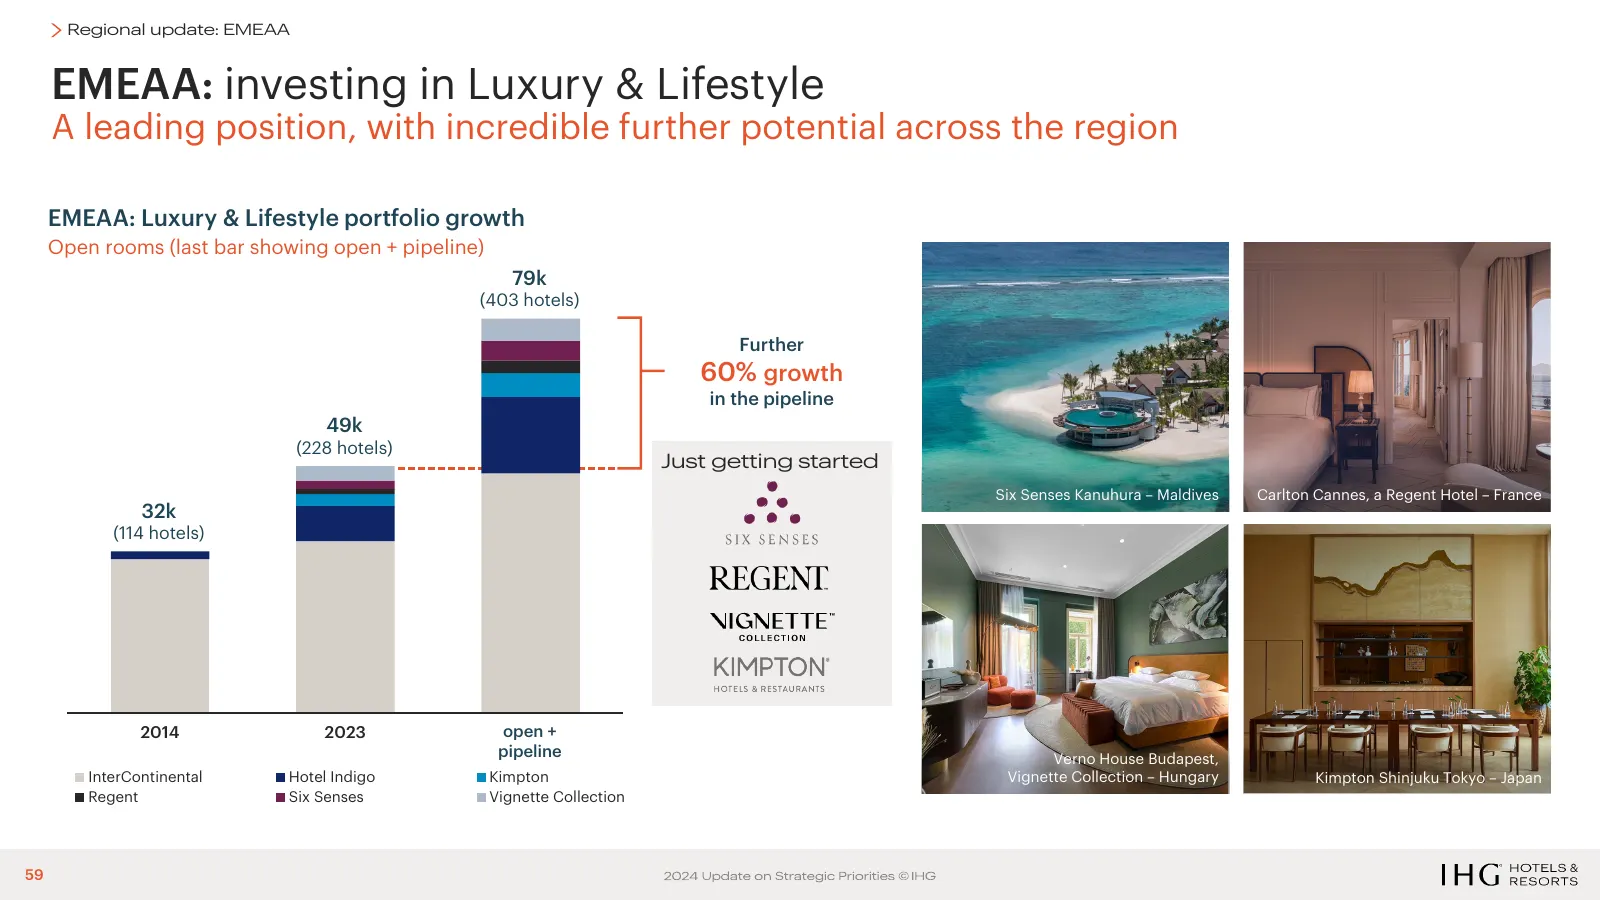
Slide 59: EMEAA: investing in Luxury & Lifestyle
Regional update: EMEAA EMEAA: investing in Luxury & Lifestyle A leading position, with incredible further potential across the region EMEAA: Luxury & Lifestyle portfolio growth Open rooms (last bar showing open + pipeline) 79k (403 hotels) Further 60% growth in the pipeline 49k (228 hotels) Just get
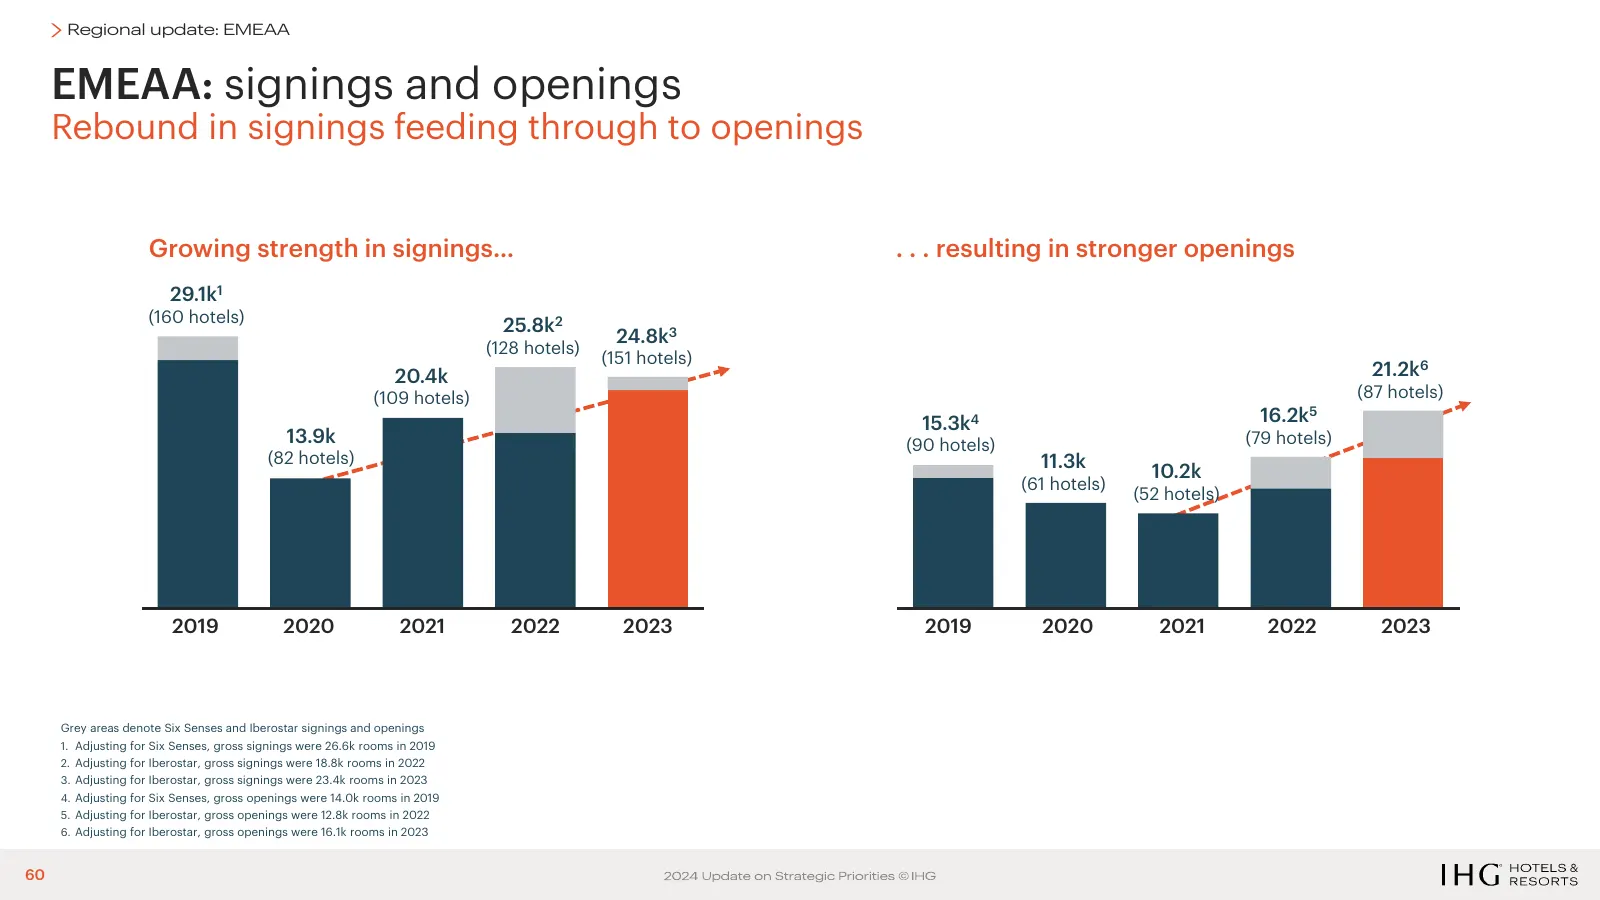
Slide 60: EMEAA: signings and openings
Regional update: EMEAA EMEAA: signings and openings Rebound in signings feeding through to openings Growing strength in signings… . . . resulting in stronger openings 29.1k1 (160 hotels) 25.8k2 24.8k3 (128 hotels) (151 hotels) 20.4k 21.2k6 (109 hotels) (87 hotels) 15.3k4 16.2k5 13.9k (90 hotels) (79
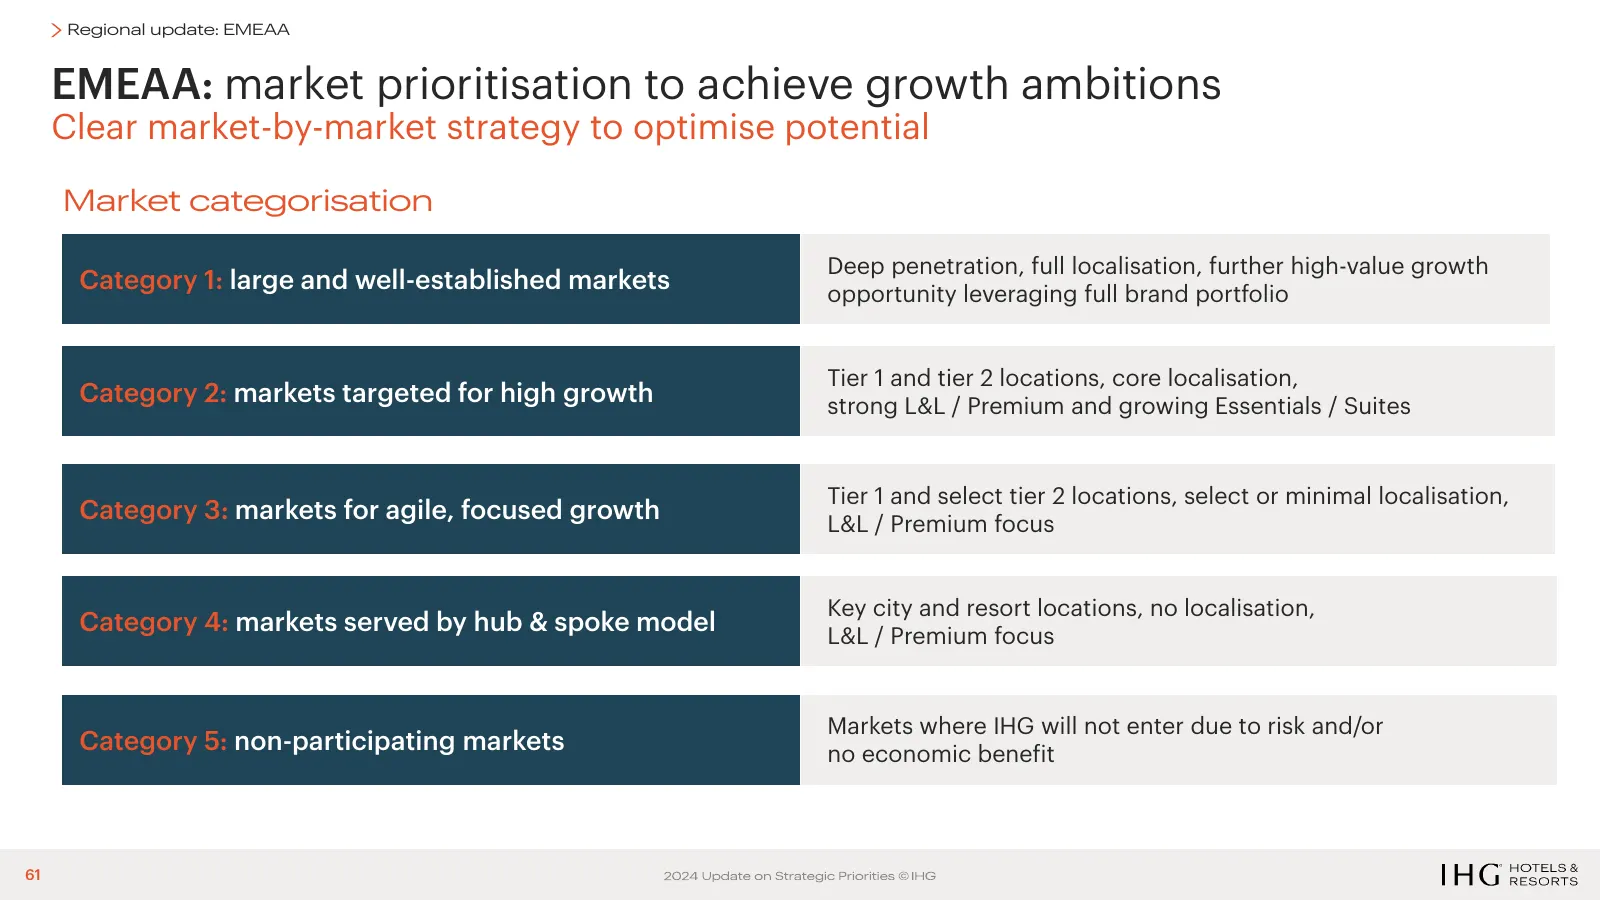
Slide 61: EMEAA: market prioritisation to achieve growth ambitions
Regional update: EMEAA EMEAA: market prioritisation to achieve growth ambitions Clear market-by-market strategy to optimise potential Market categorisation Deep penetration, full localisation, further high-value growth Category 1: large and well-established markets opportunity leveraging full brand
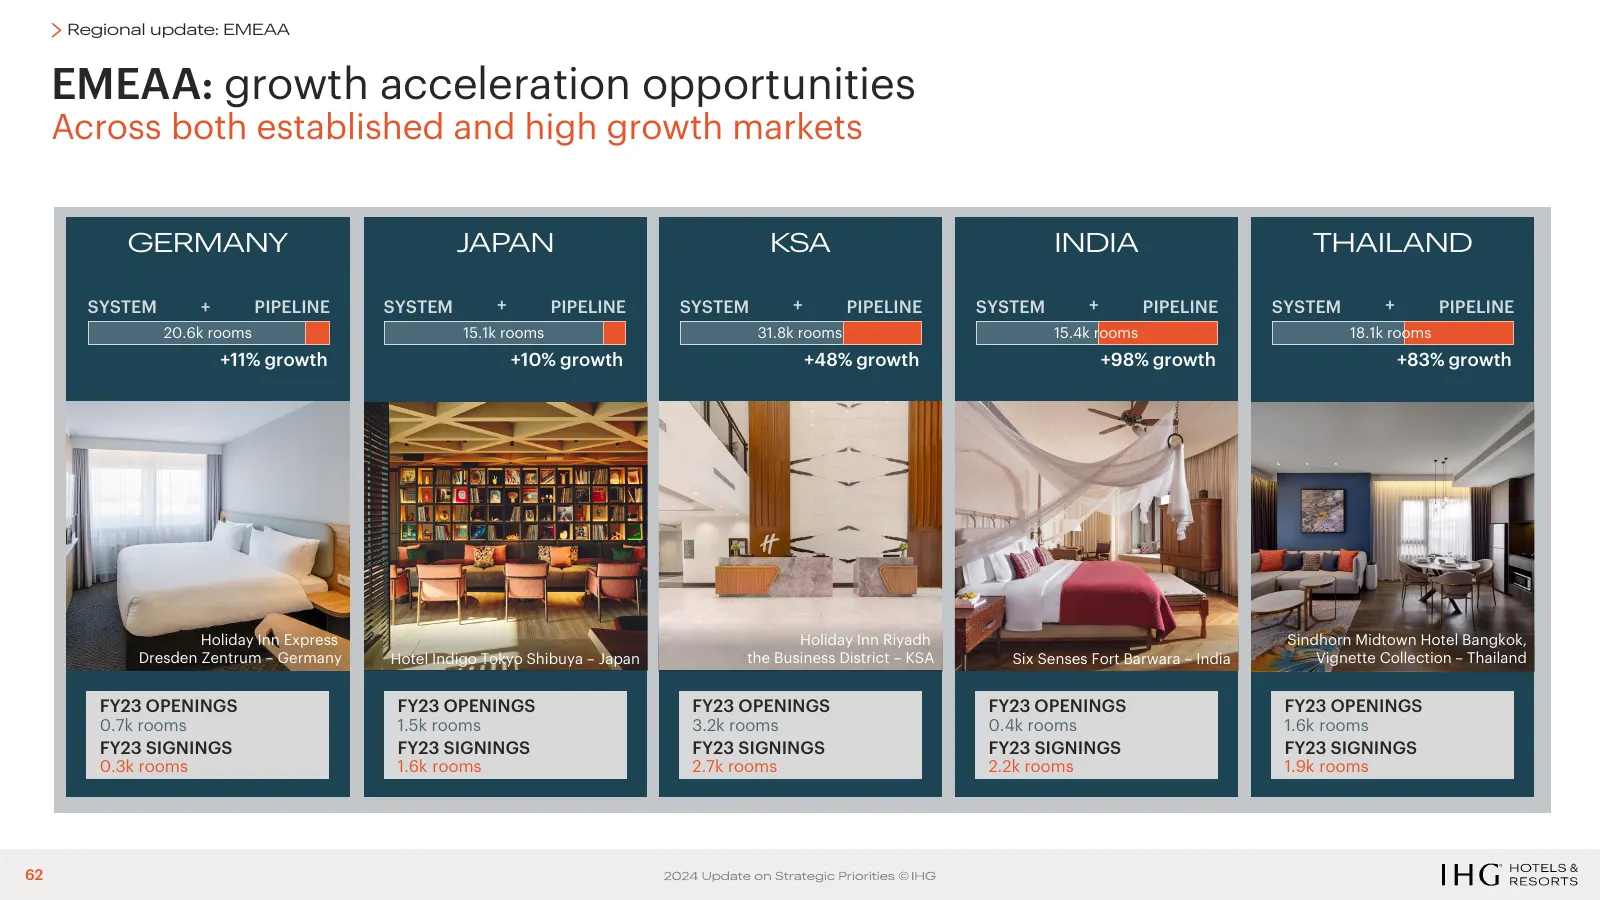
Slide 62: EMEAA: growth acceleration opportunities
Regional update: EMEAA EMEAA: growth acceleration opportunities Across both established and high growth markets GERMANY JAPAN KSA INDIA THAILAND SYSTEM + PIPELINE SYSTEM + PIPELINE SYSTEM + PIPELINE SYSTEM + PIPELINE SYSTEM + PIPELINE 20.6k rooms 15.1k rooms 31.8k rooms 15.4k rooms 18.1k rooms +11%
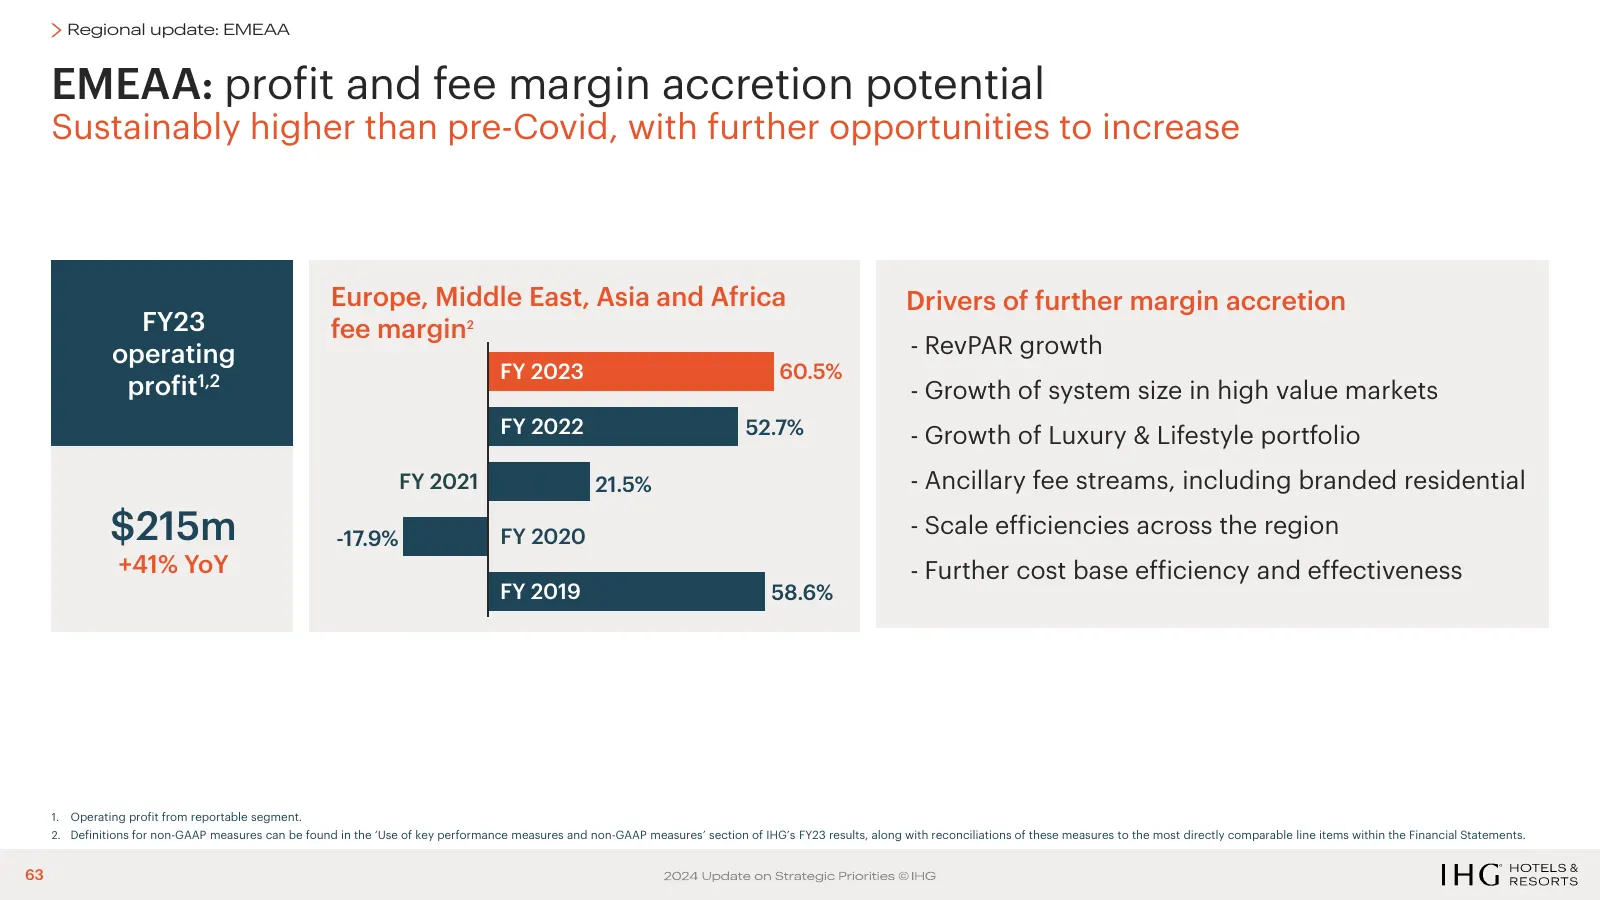
Slide 63: EMEAA: profit and fee margin accretion potential
Regional update: EMEAA EMEAA: profit and fee margin accretion potential Sustainably higher than pre-Covid, with further opportunities to increase Europe, Middle East, Asia and Africa Drivers of further margin accretion FY23 fee margin2 operating - RevPAR growth FY 2023 60.5% profit1,2 - Growth of sy
Slide 64: Greater China
Greater China Daniel Aylmer Managing Director, Greater China 64
Slide 65: Greater China: overview
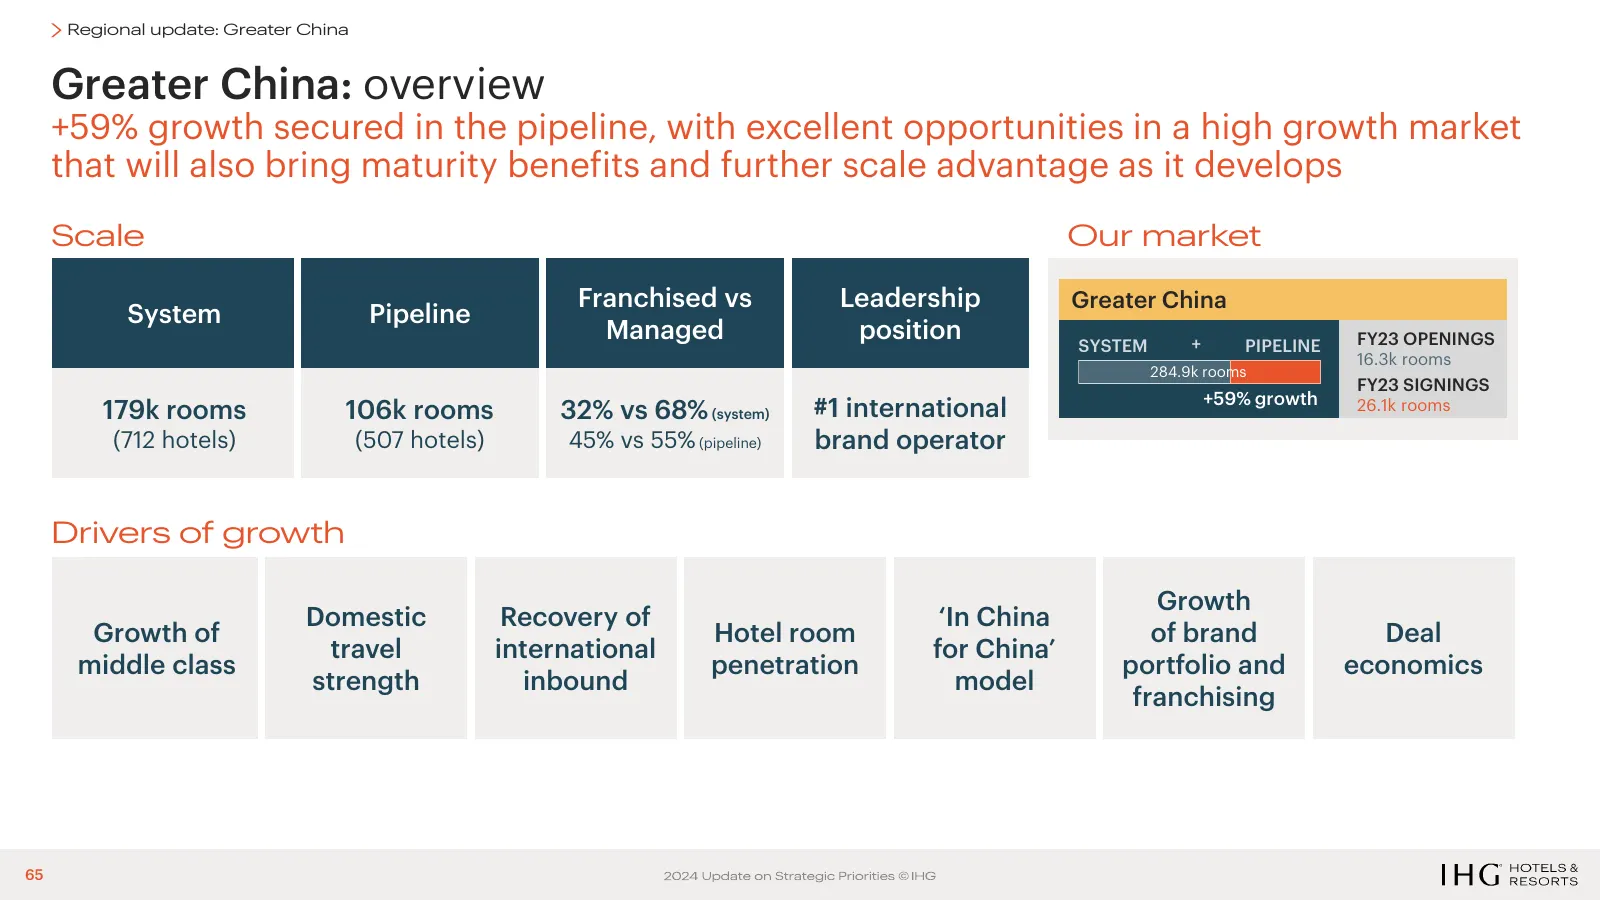
Regional update: Greater China Greater China: overview +59% growth secured in the pipeline, with excellent opportunities in a high growth market that will also bring maturity benefits and further scale advantage as it develops Scale Our market Franchised vs Leadership Greater China System Pipeline M
Slide 66: Greater China: robust growth across key industry drivers
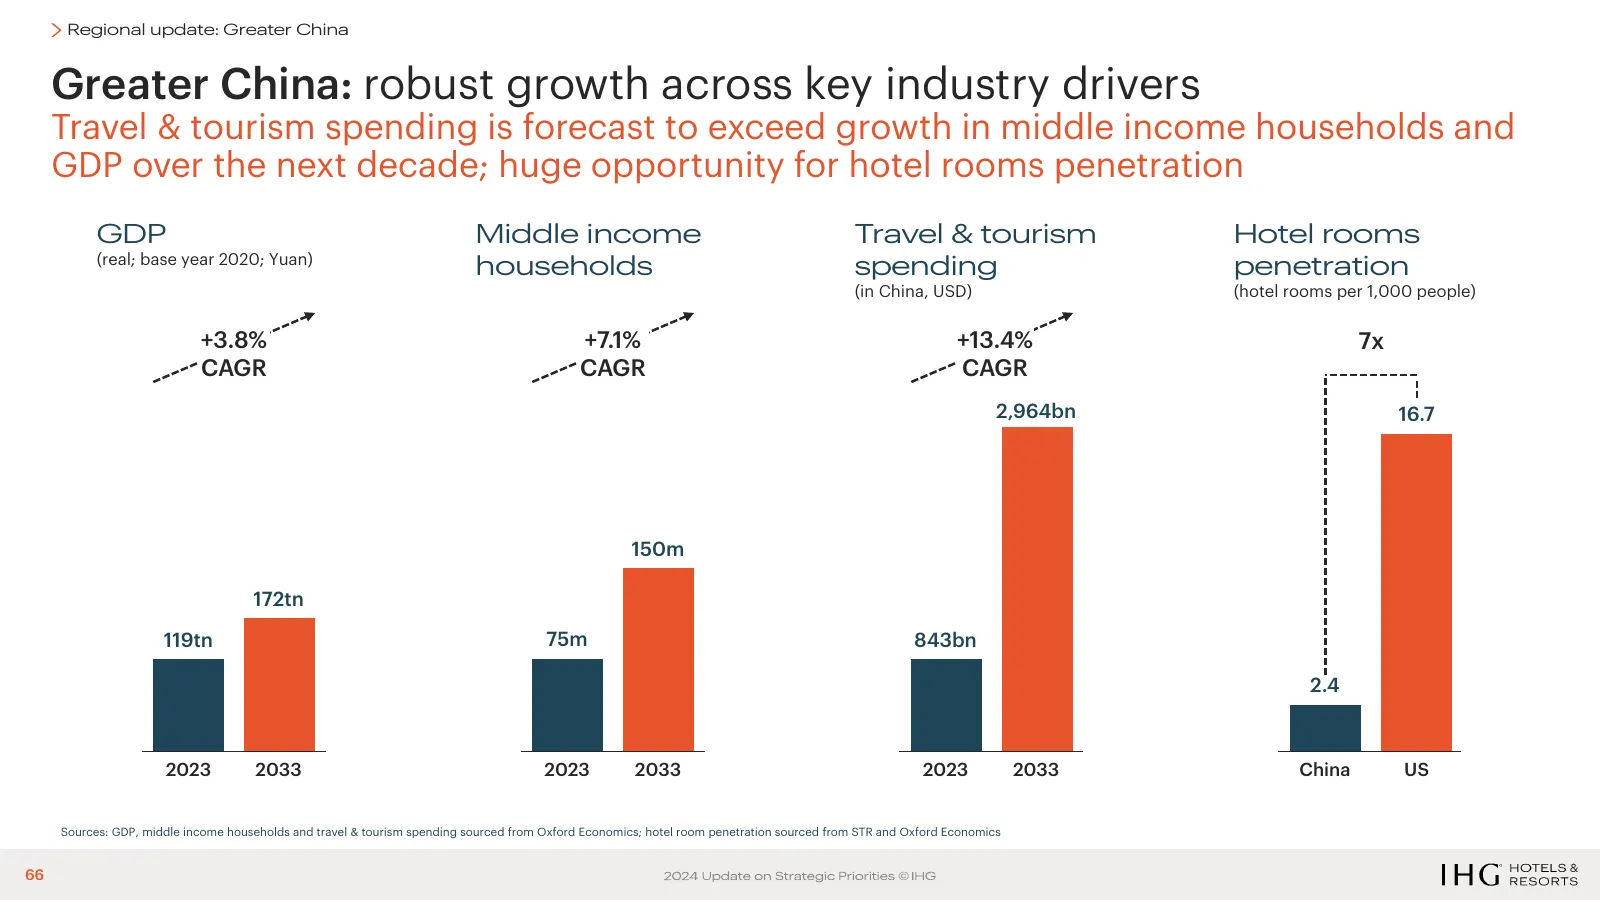
Regional update: Greater China Greater China: robust growth across key industry drivers Travel & tourism spending is forecast to exceed growth in middle income households and GDP over the next decade; huge opportunity for hotel rooms penetration GDP Middle income Travel & tourism Hotel rooms (real;
Slide 67: Greater China: brand portfolio mix
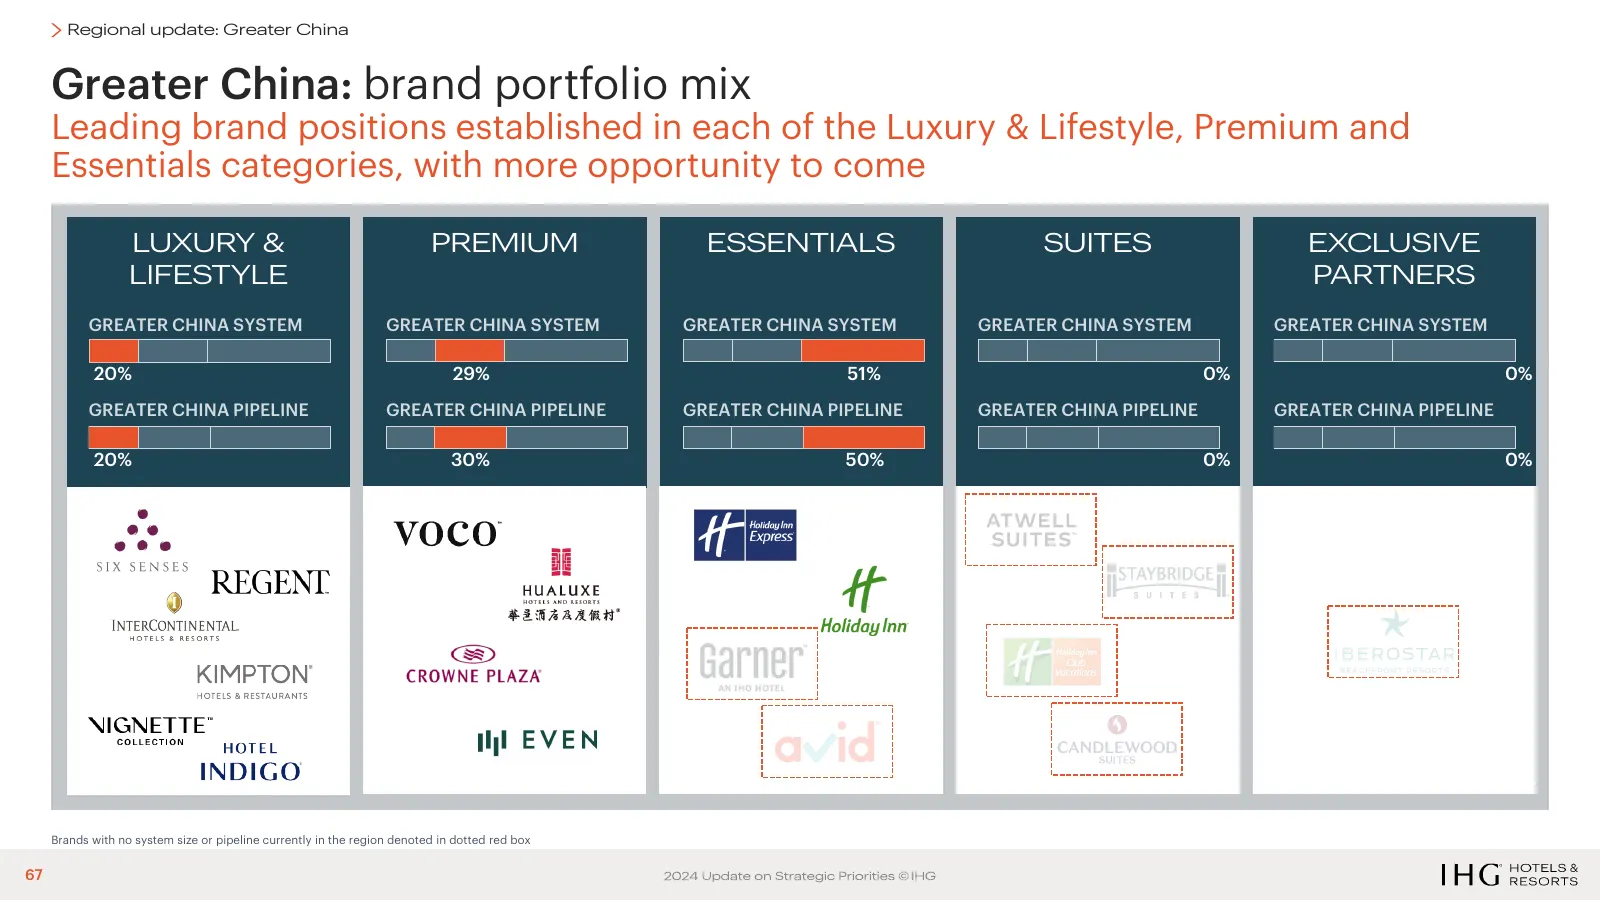
Regional update: Greater China Greater China: brand portfolio mix Leading brand positions established in each of the Luxury & Lifestyle, Premium and Essentials categories, with more opportunity to come LUXURY & PREMIUM ESSENTIALS SUITES EXCLUSIVE LIFESTYLE PARTNERS GREATER CHINA SYSTEM GREATER CHINA
Slide 68: Greater China: our brand portfolio today and growth opportunities
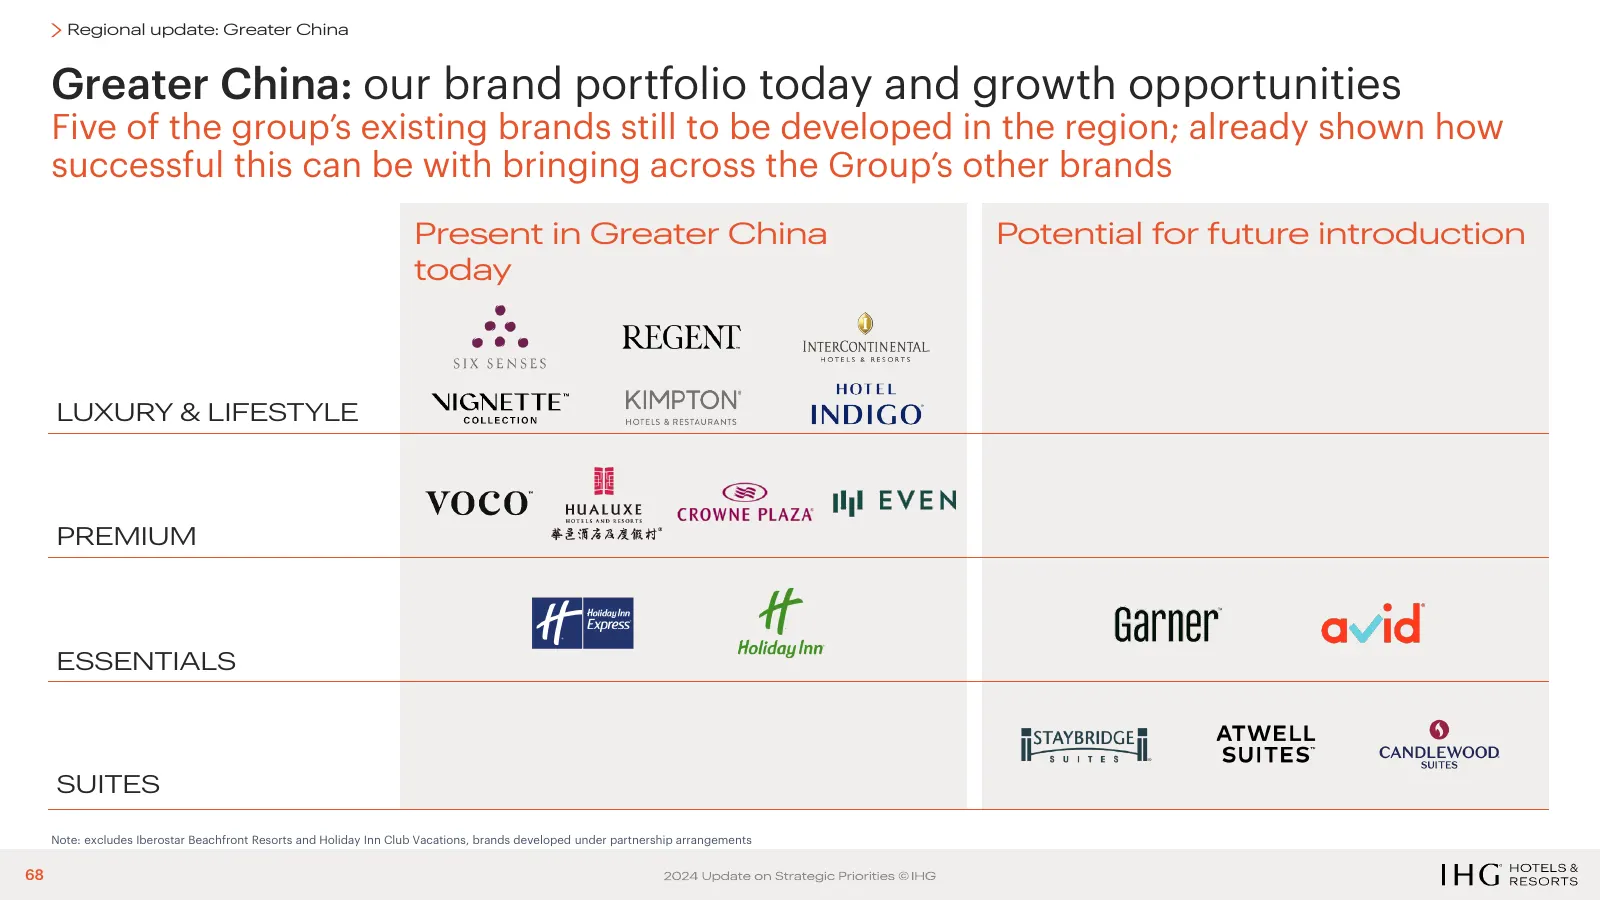
Regional update: Greater China Greater China: our brand portfolio today and growth opportunities Five of the group’s existing brands still to be developed in the region; already shown how successful this can be with bringing across the Group’s other brands Present in Greater China Potential for futu
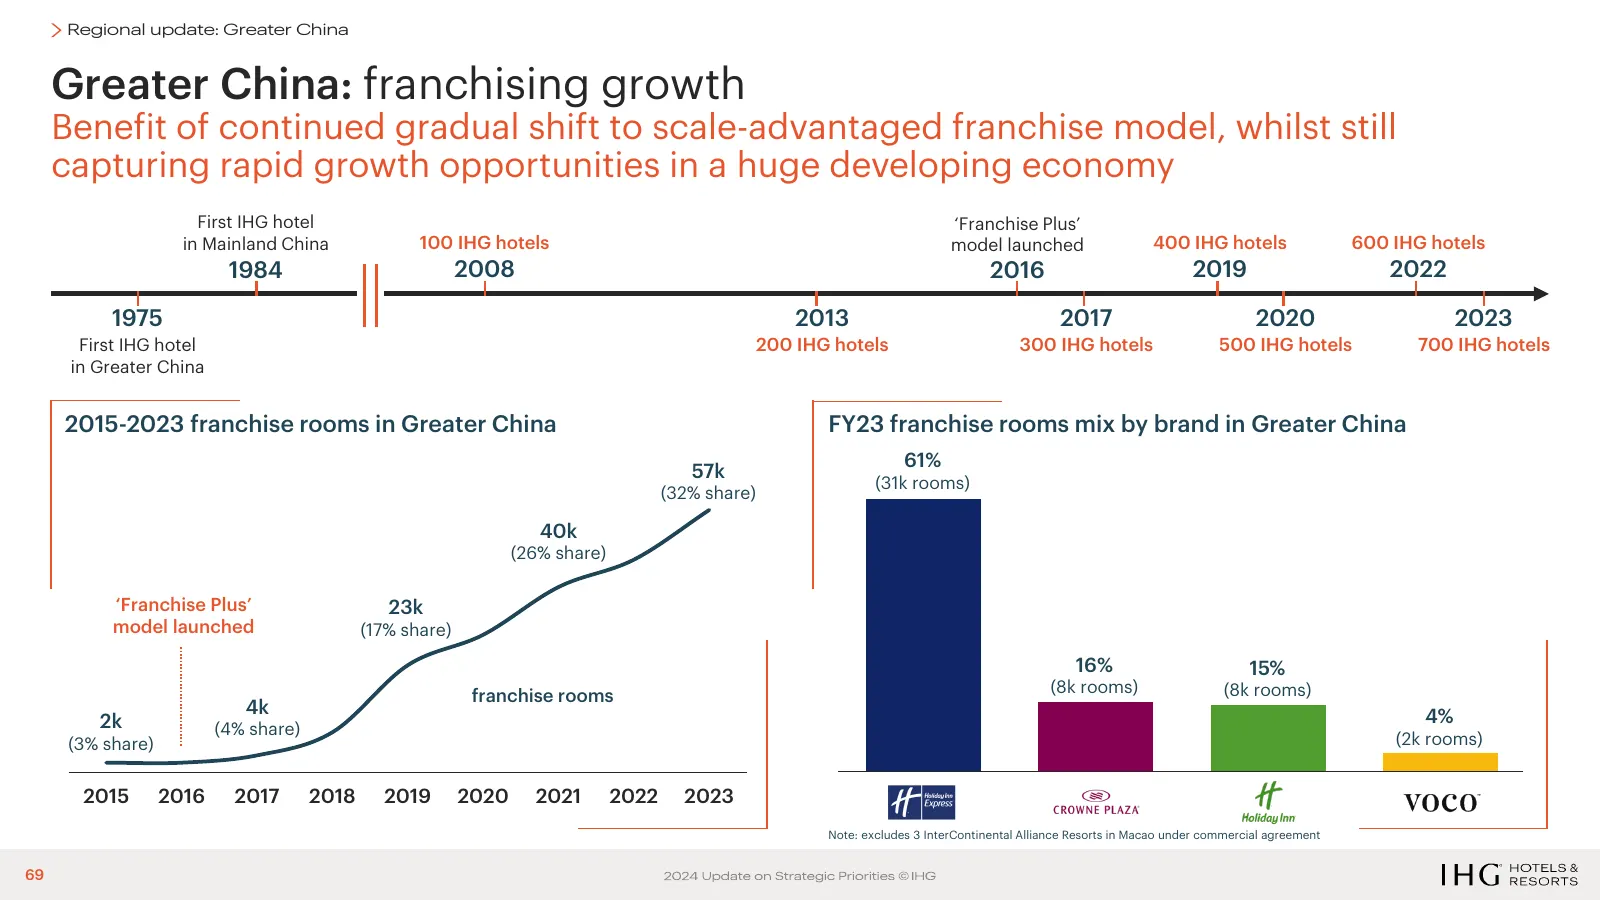
Slide 69: Greater China: franchising growth
Regional update: Greater China Greater China: franchising growth Benefit of continued gradual shift to scale-advantaged franchise model, whilst still capturing rapid growth opportunities in a huge developing economy First IHG hotel ‘Franchise Plus’ in Mainland China 100 IHG hotels model launched 400
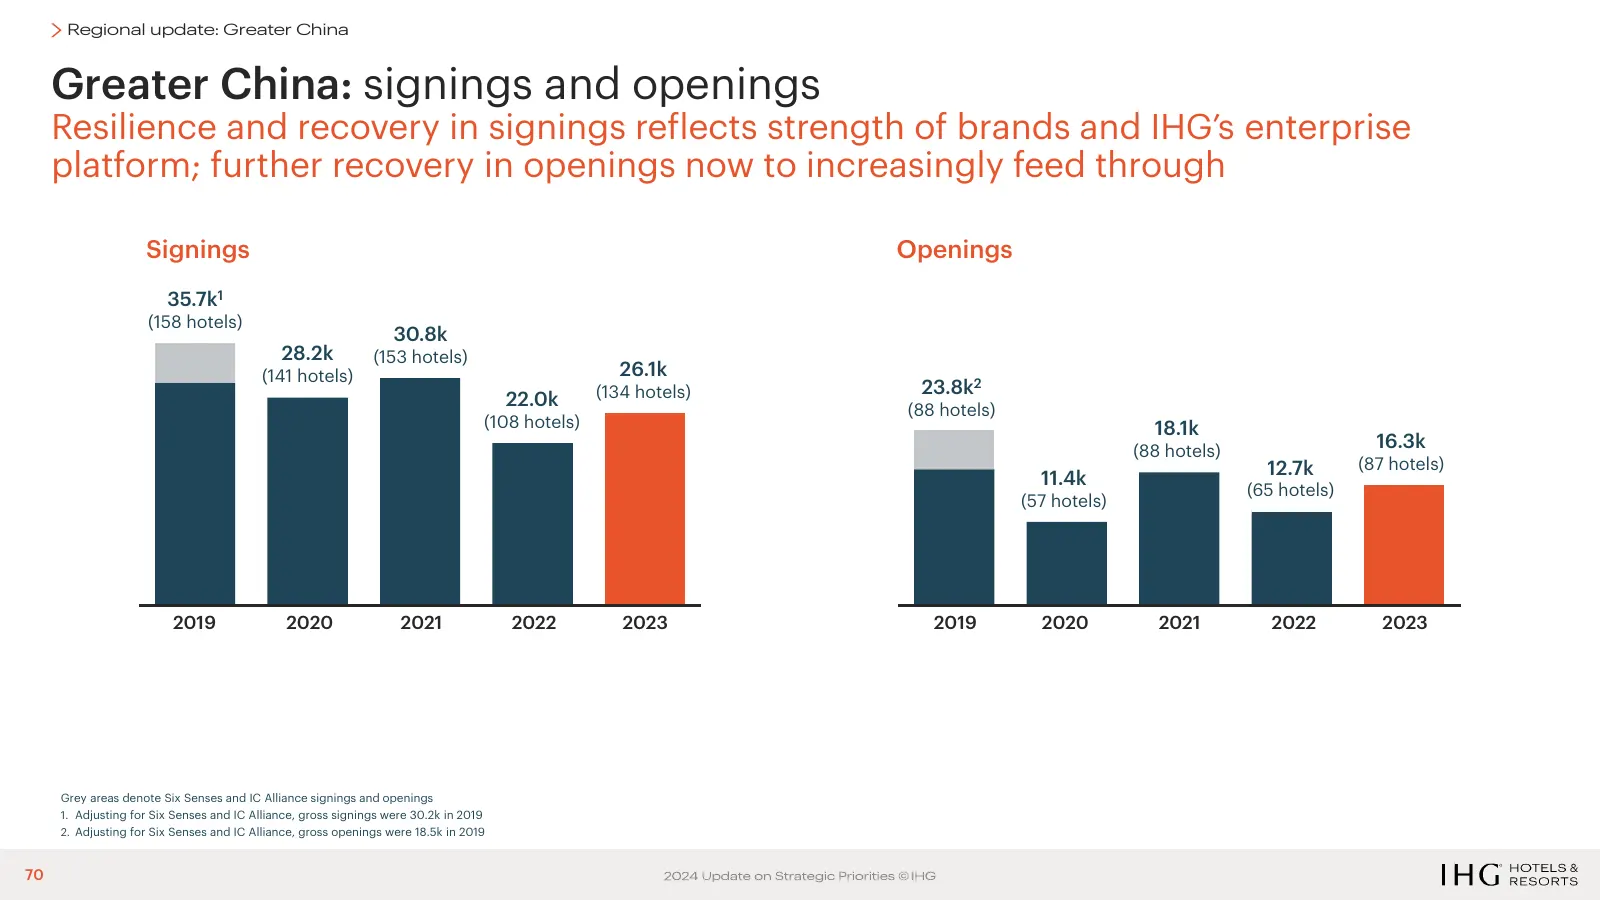
Slide 70: Greater China: signings and openings
Regional update: Greater China Greater China: signings and openings Resilience and recovery in signings reflects strength of brands and IHG’s enterprise platform; further recovery in openings now to increasingly feed through Signings Openings 35.7k1 (158 hotels) 30.8k 28.2k (153 hotels) (141 hotels)
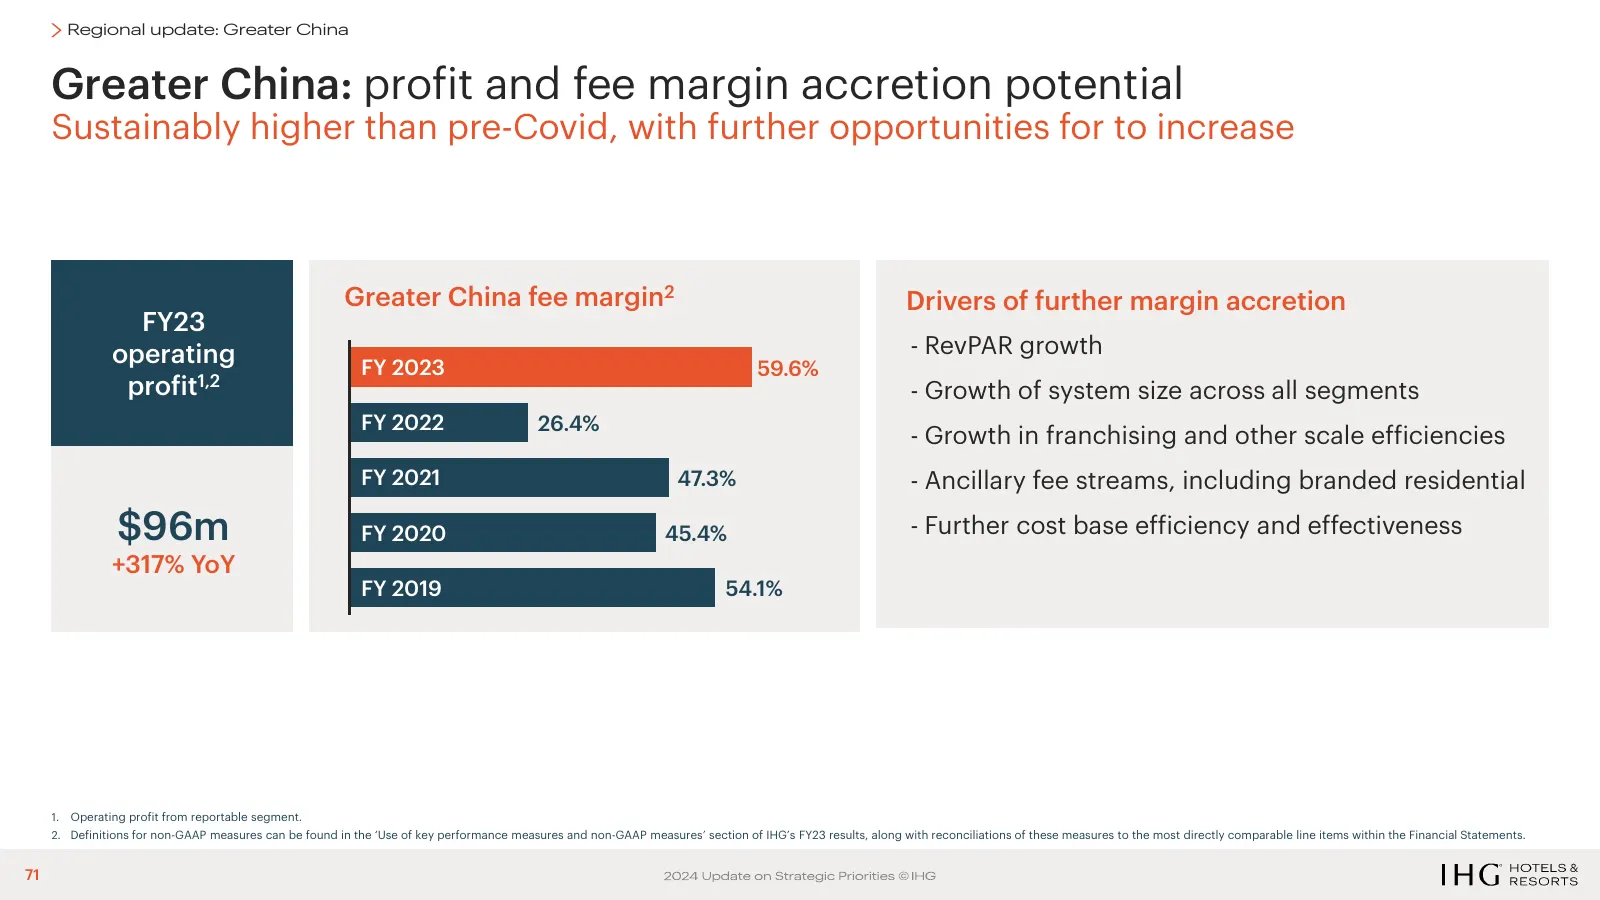
Slide 71: Greater China: profit and fee margin accretion potential
Regional update: Greater China Greater China: profit and fee margin accretion potential Sustainably higher than pre-Covid, with further opportunities for to increase Greater China fee margin2 Drivers of further margin accretion FY23 operating - RevPAR growth FY 2023 59.6% profit1,2 - Growth of syste
Slide 72: Group margin potential, cash generation and capital allocation
Group margin potential, cash generation and capital allocation Michael Glover Chief Financial Officer 72
Slide 73: Strong track record of margin accretion by delivering growth in fee business revenue
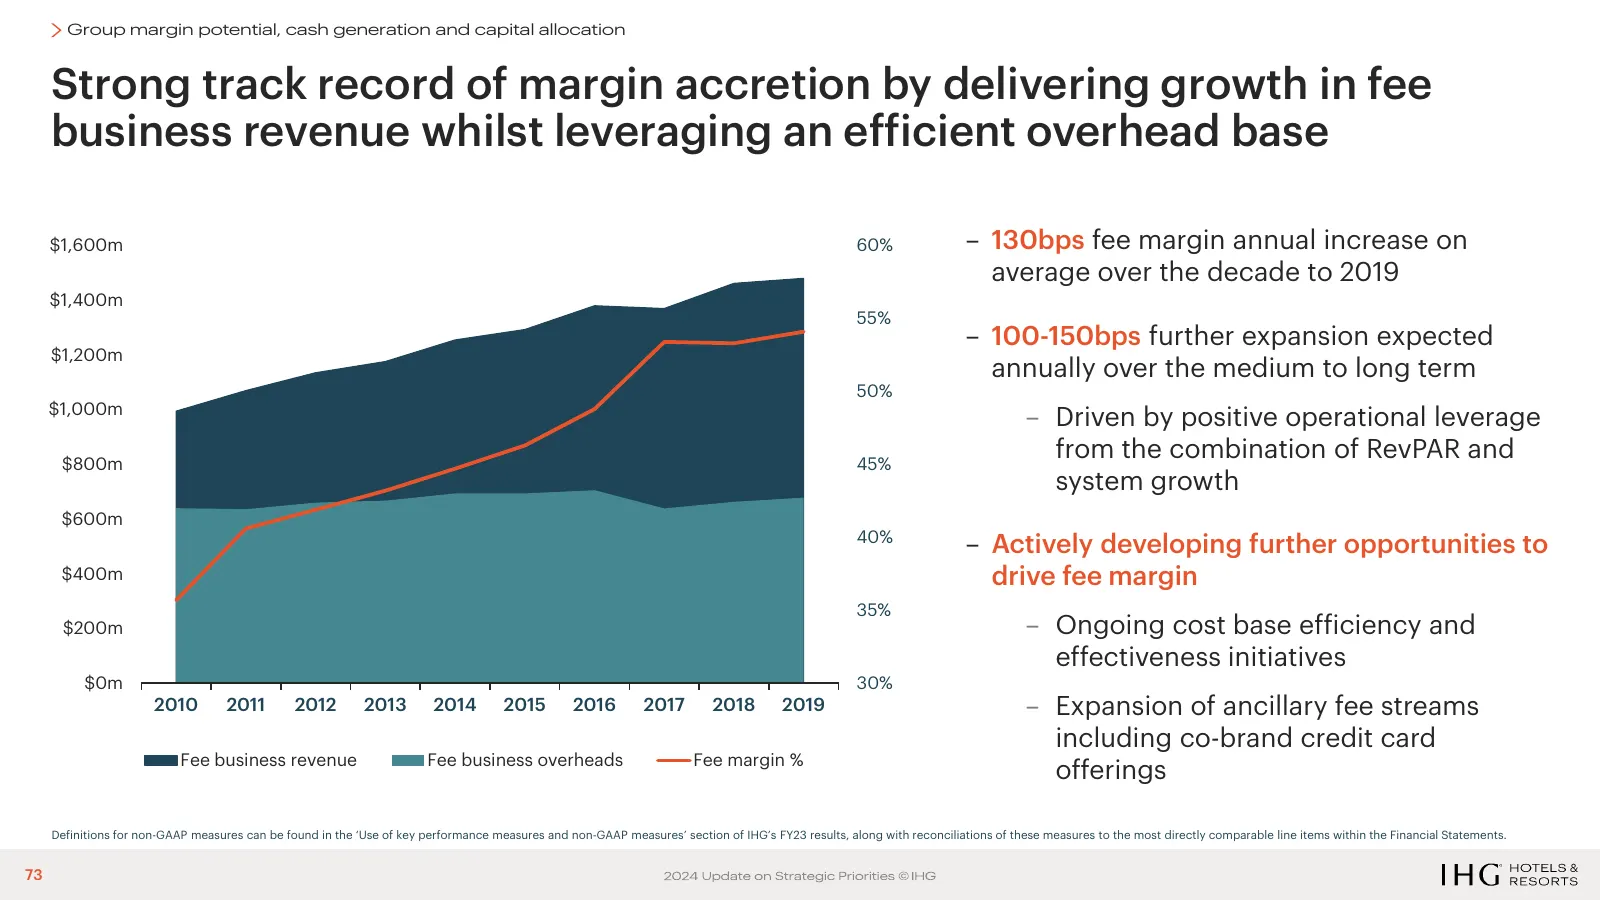
Group margin potential, cash generation and capital allocation Strong track record of margin accretion by delivering growth in fee business revenue whilst leveraging an efficient overhead base $1,600m 60% – 130bps fee margin annual increase on average over the decade to 2019 $1,400m 55% – 100-150bps
Slide 74: IHG typically converts >100% of earnings into free cash
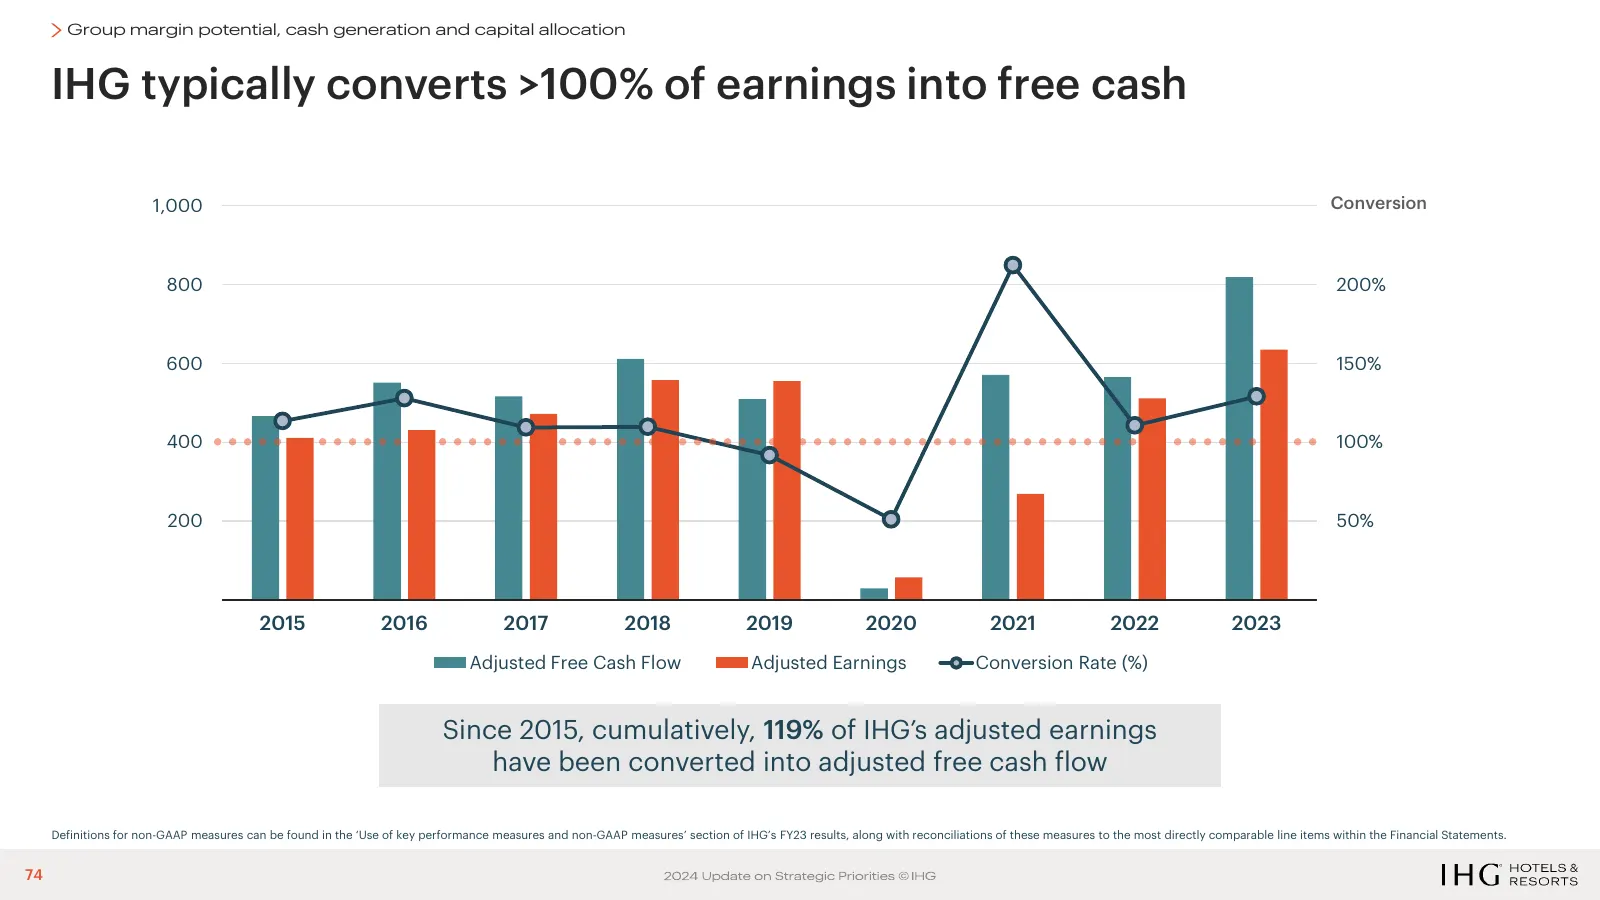
Group margin potential, cash generation and capital allocation IHG typically converts >100% of earnings into free cash 1,000 Conversion 250% 800 200% 600 150% 400 100% 200 50% 0 0% 2015 2016 2017 2018 2019 2020 2021 2022 2023 Adjusted Free Cash Flow Adjusted Earnings Conversion Rate (%) Since 2015,
Slide 75: Continuing our capital allocation approach to routinely return surplus capital
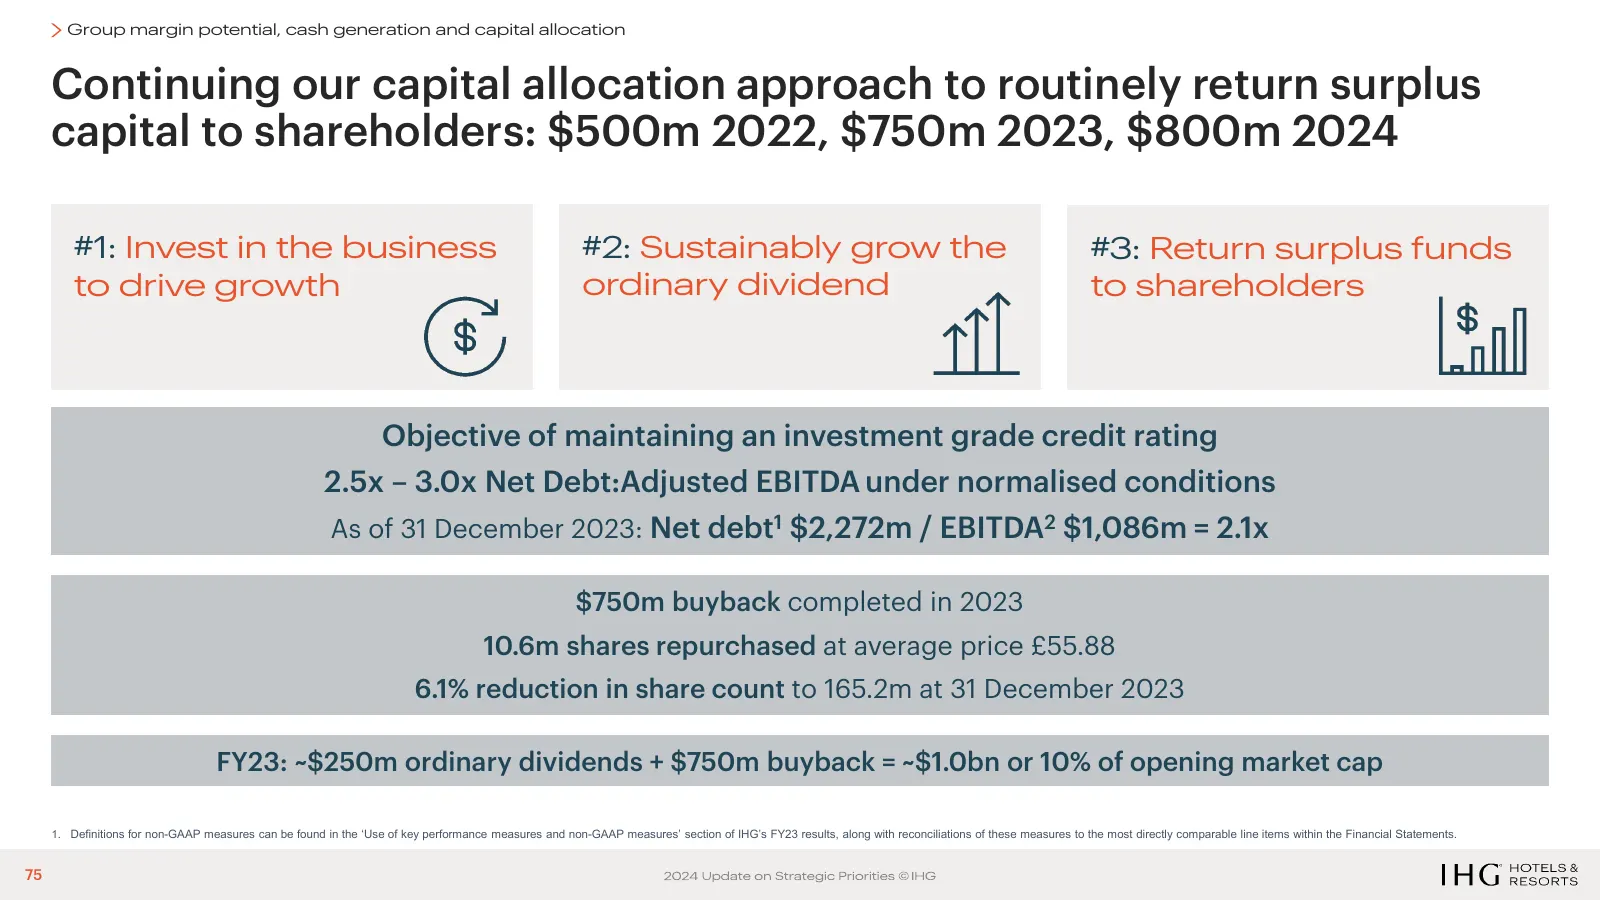
Group margin potential, cash generation and capital allocation Continuing our capital allocation approach to routinely return surplus capital to shareholders: $500m 2022, $750m 2023, $800m 2024 #1: Invest in the business #2: Sustainably grow the #3: Return surplus funds to drive growth ordinary divi
Slide 76: Proven model of investing for growth, sustainably growing the dividend
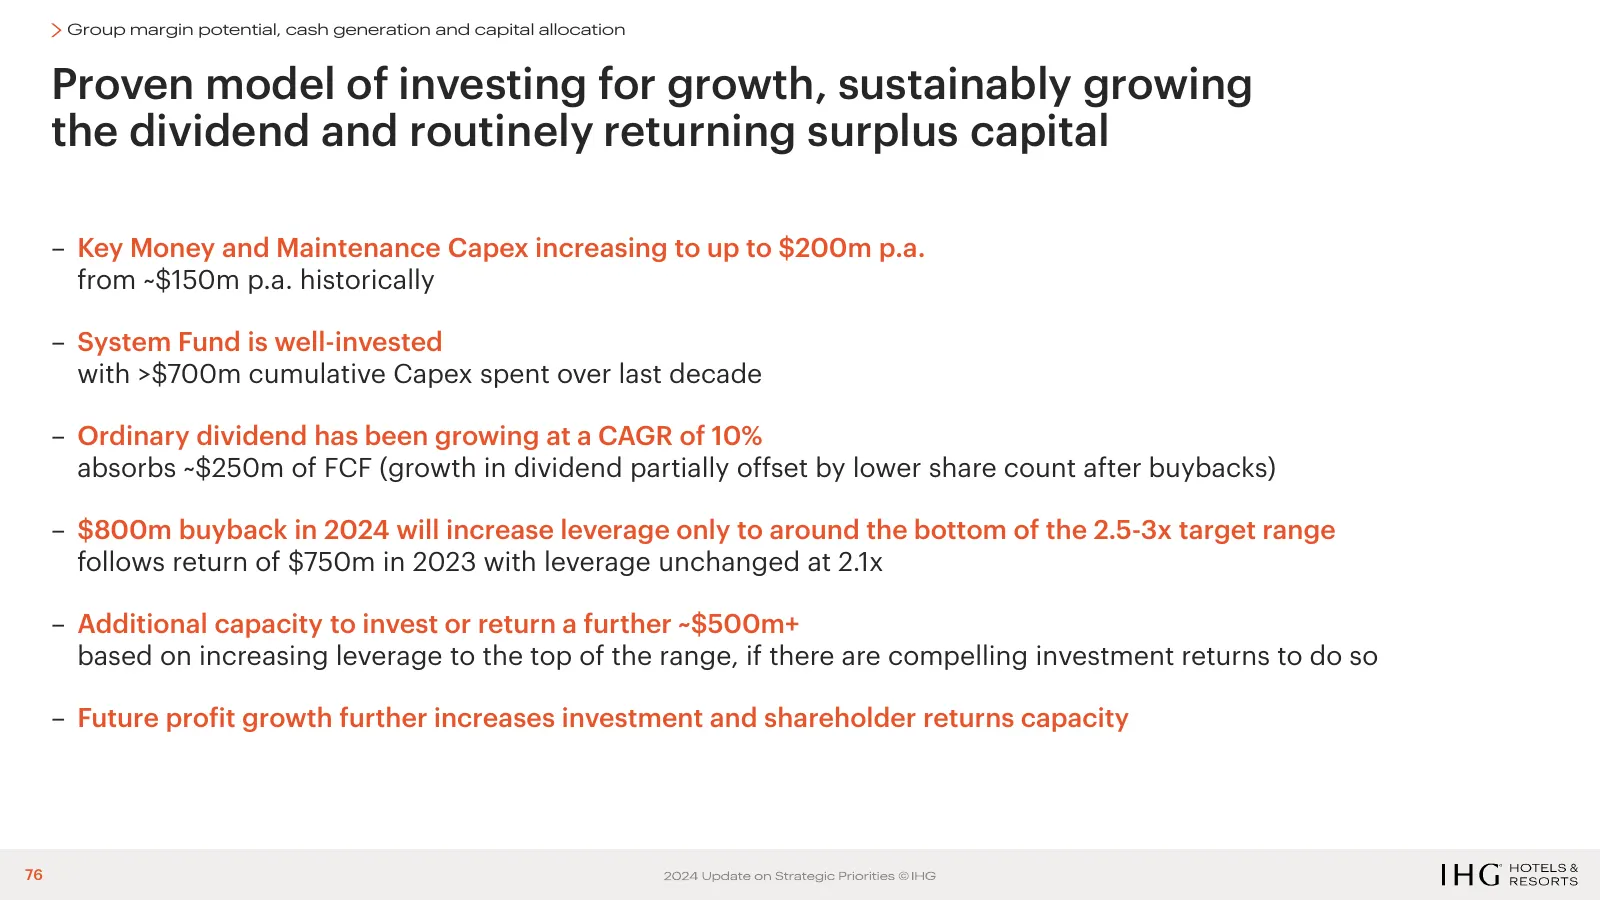
Group margin potential, cash generation and capital allocation Proven model of investing for growth, sustainably growing the dividend and routinely returning surplus capital – Key Money and Maintenance Capex increasing to up to $200m p.a. from ~$150m p.a. historically – System Fund is well-invested
Slide 77: Conclusions
Conclusions Elie Maalouf Chief Executive Officer 77
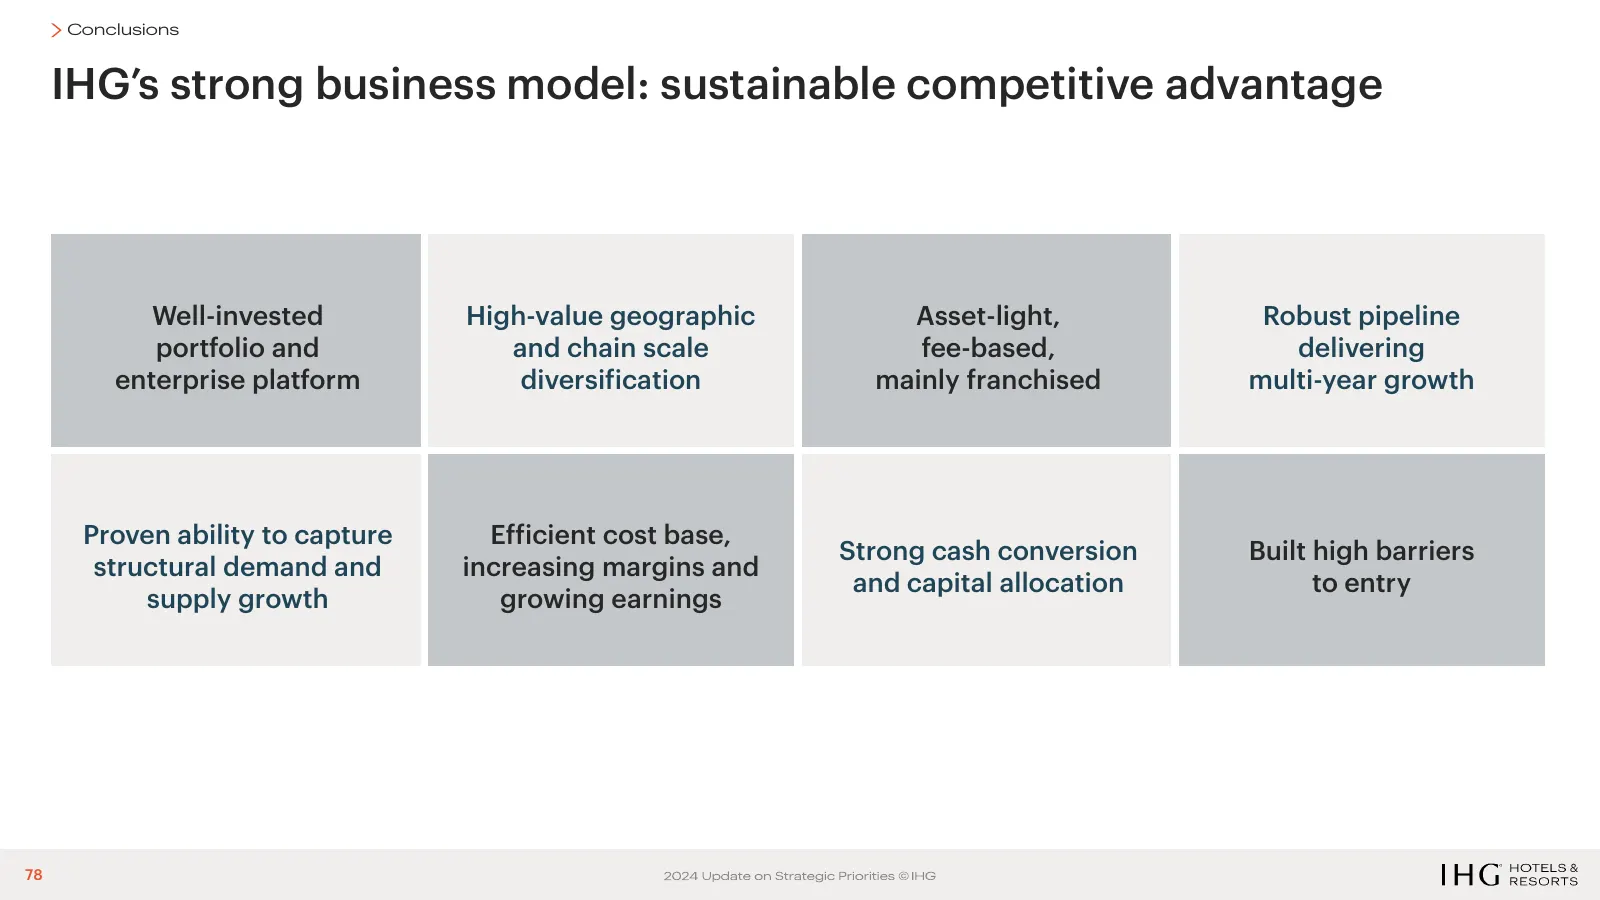
Slide 78: IHG's strong business model: sustainable competitive advantage
Conclusions IHG’s strong business model: sustainable competitive advantage Well-invested High-value geographic Asset-light, Robust pipeline portfolio and and chain scale fee-based, delivering enterprise platform diversification mainly franchised multi-year growth Proven ability to capture Efficient
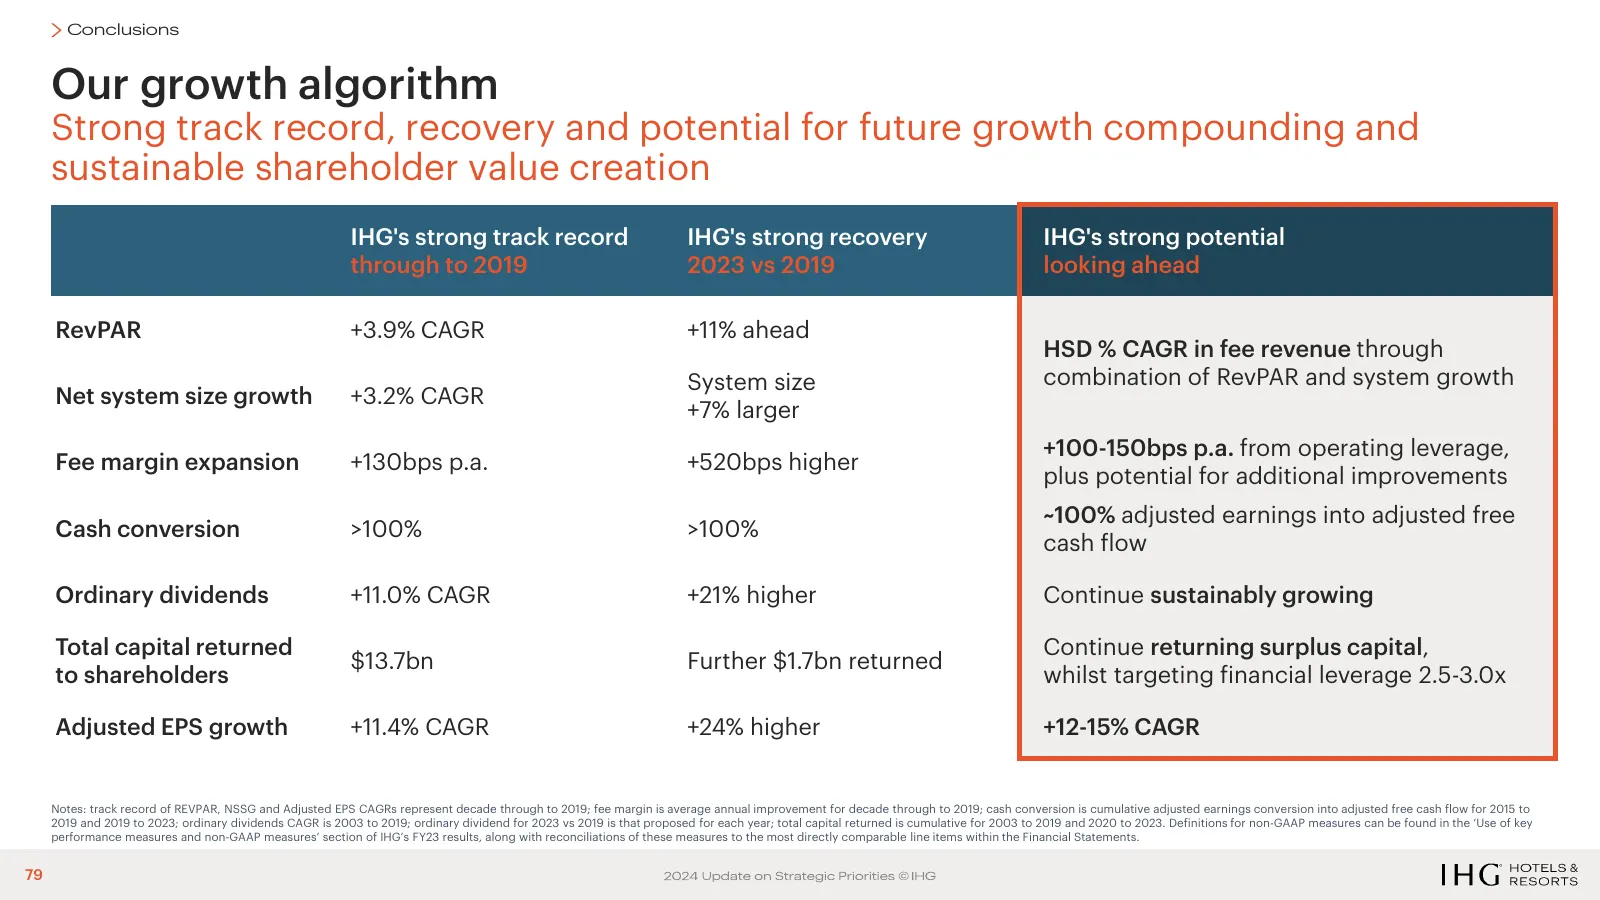
Slide 79: Our growth algorithm
Conclusions Our growth algorithm Strong track record, recovery and potential for future growth compounding and sustainable shareholder value creation IHG's strong track record IHG's strong recovery IHG's strong potential through to 2019 2023 vs 2019 looking ahead RevPAR +3.9% CAGR +11% ahead HSD % C
Slide 80: Q&A
Q&A Analysts and institutional investors wishing to ask questions should use the following dial-in details: UK: 0800 048 7798 US: 800 579 2543 International: (+1) 785 424 1789 Conference ID: IHG; To ask a question, press *1. To withdraw a question, press *2.
Slide 81: Appendices
IHG HOTELS & RESORTS Appendices
Slide 82: Asset light, mainly franchised, and geographically diverse
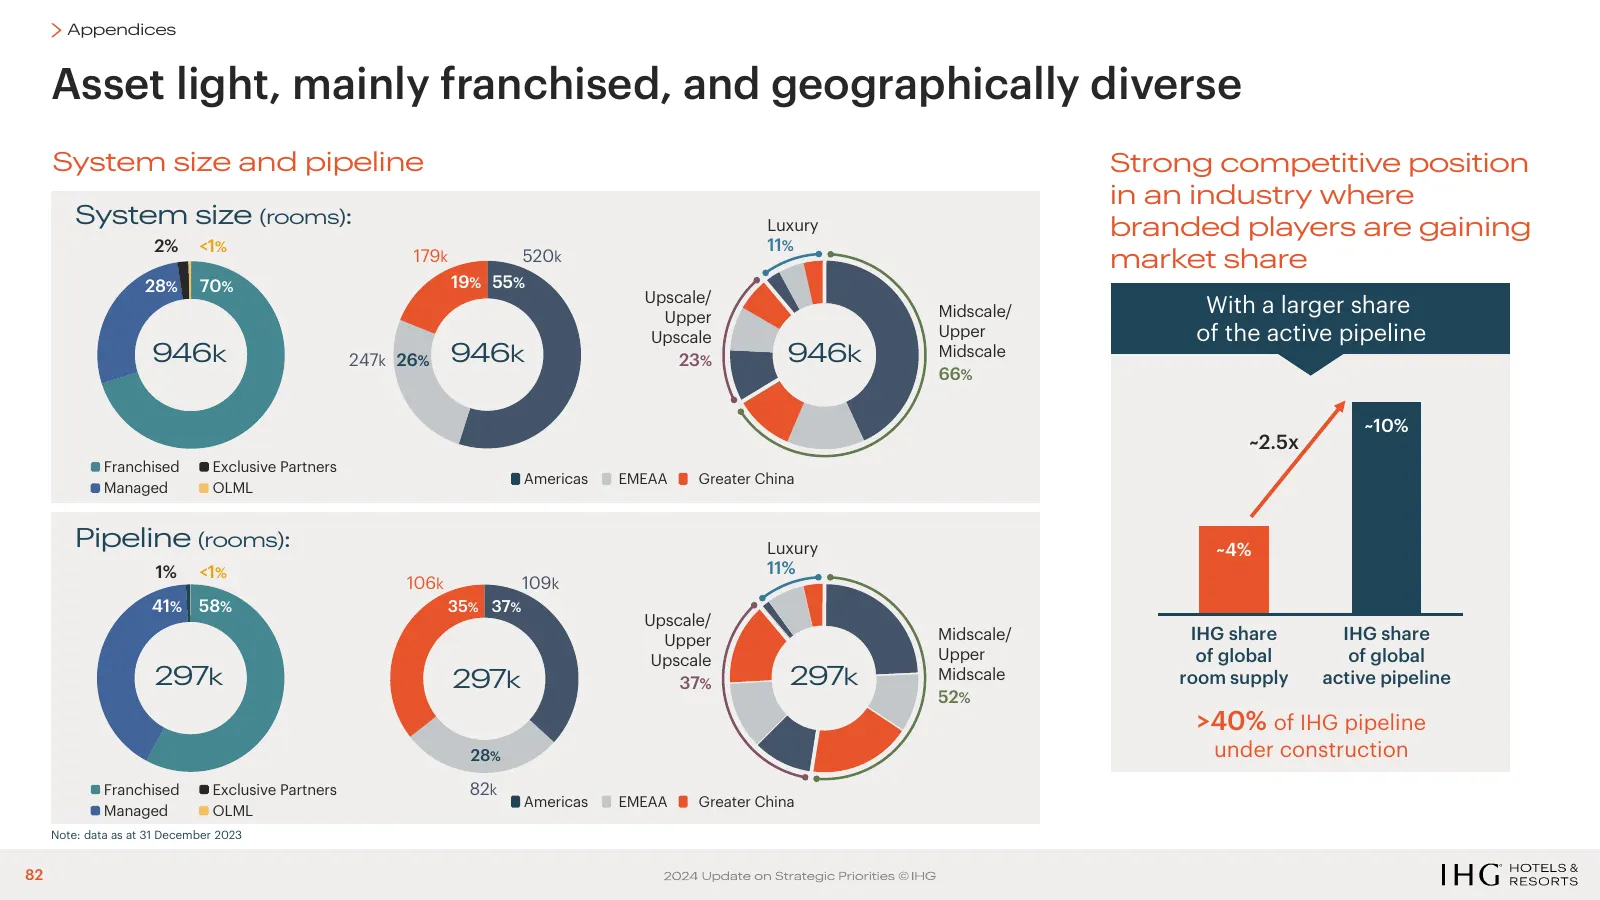
Appendices Asset light, mainly franchised, and geographically diverse System size and pipeline Strong competitive position in an industry where System size (rooms): Luxury branded players are gaining 2% <1% 11% 179k 520k market share 28% 70% 19% 55% Upscale/ Upper Midscale/ With a larger share Upsca
Slide 83: Strong portfolio of 19 preferred brands across chain scales
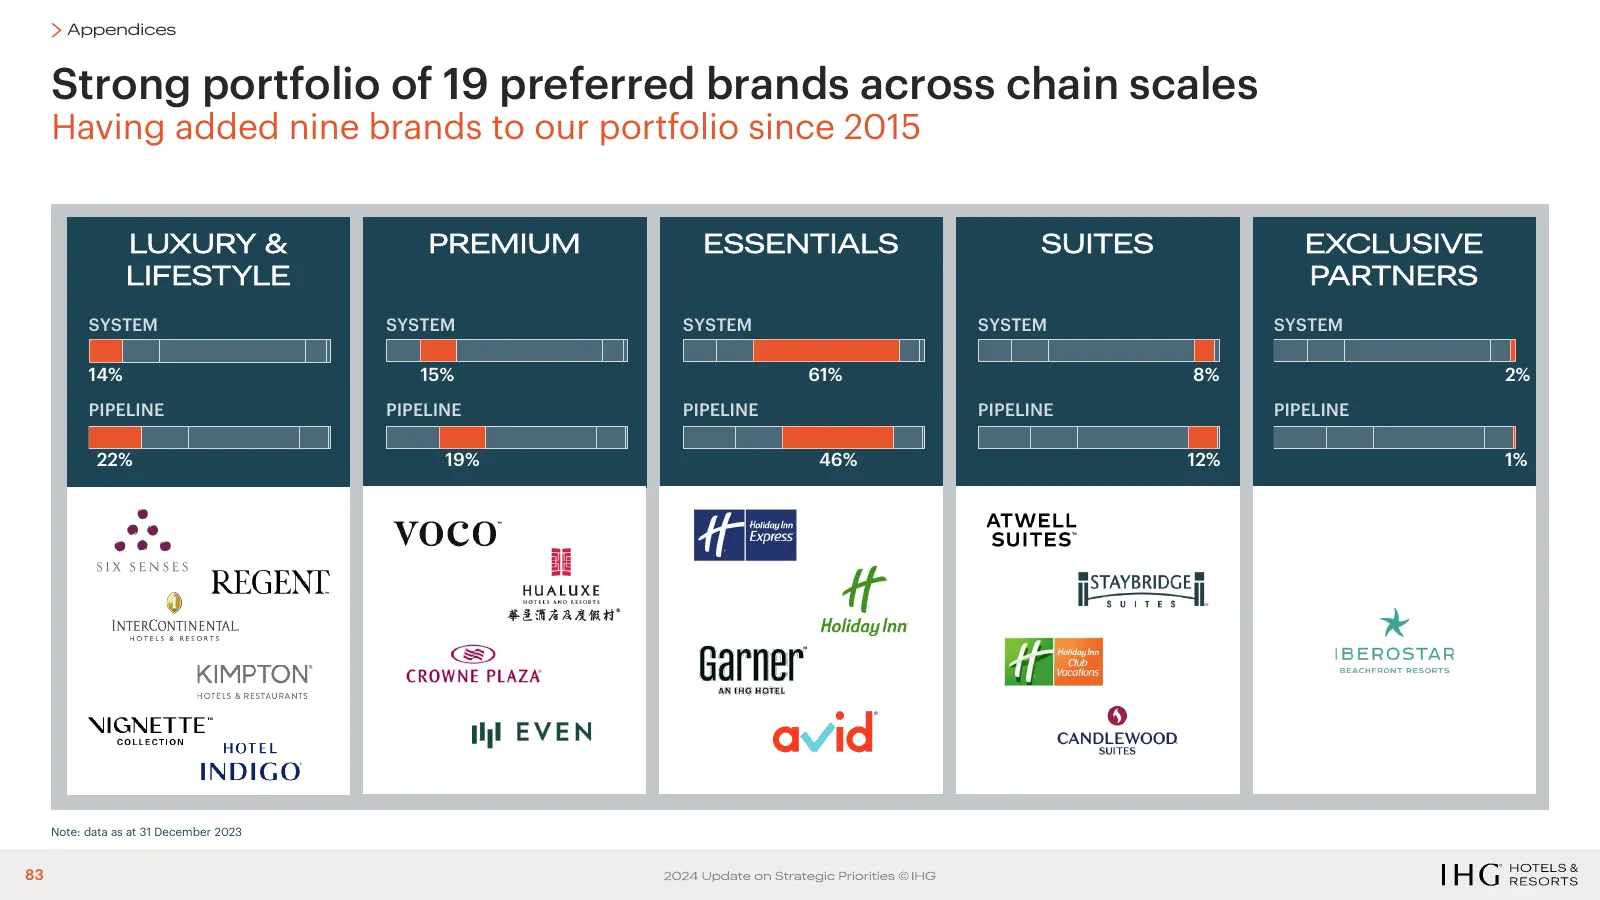
Appendices Strong portfolio of 19 preferred brands across chain scales Having added nine brands to our portfolio since 2015 LUXURY & PREMIUM ESSENTIALS SUITES EXCLUSIVE LIFESTYLE PARTNERS SYSTEM SYSTEM SYSTEM SYSTEM SYSTEM 14% 15% 61% 8% 2% PIPELINE PIPELINE PIPELINE PIPELINE PIPELINE 22% 19% 46% 12
Slide 84: Luxury & Lifestyle
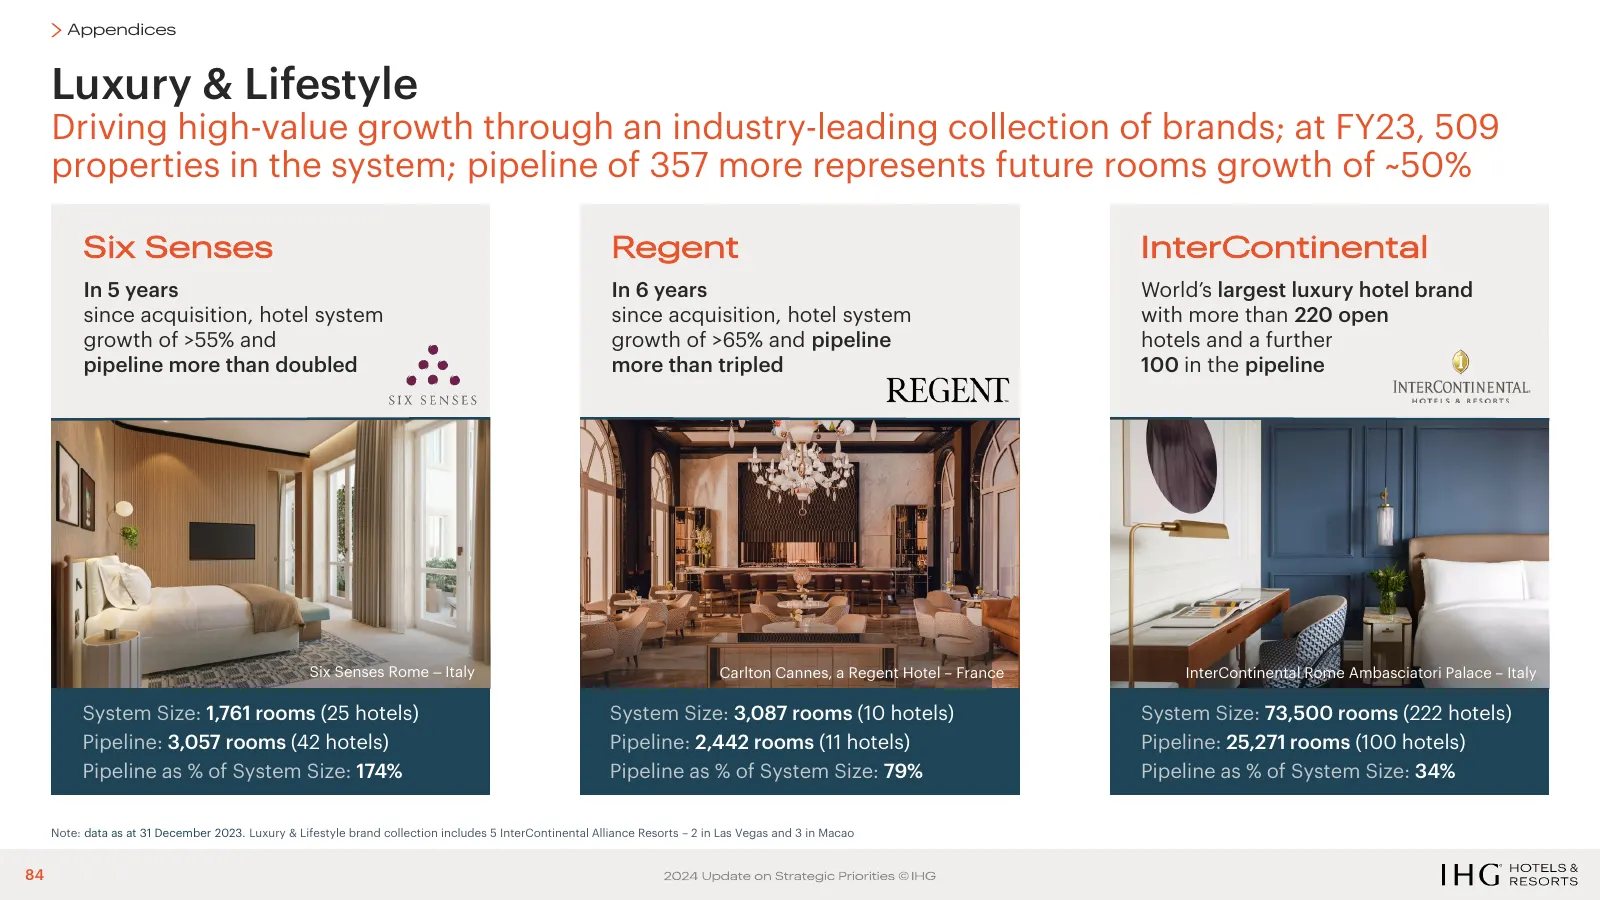
Appendices Luxury & Lifestyle Driving high-value growth through an industry-leading collection of brands; at FY23, 509 properties in the system; pipeline of 357 more represents future rooms growth of ~50% Six Senses Regent InterContinental In 5 years In 6 years World’s largest luxury hotel brand sin
Slide 85: Luxury & Lifestyle
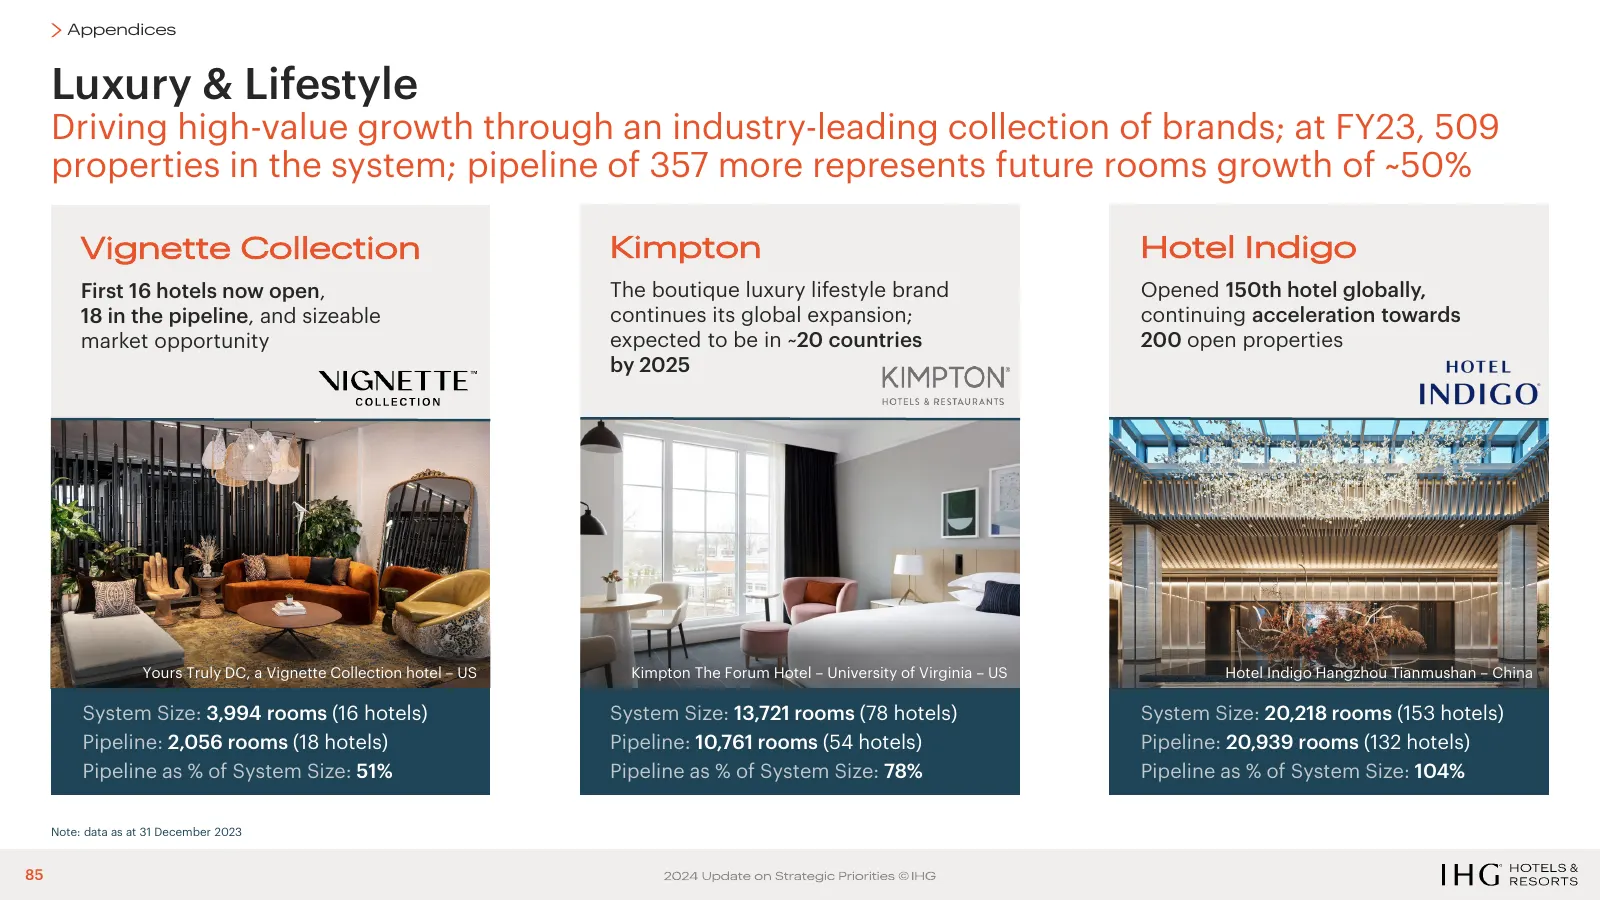
Appendices Luxury & Lifestyle Driving high-value growth through an industry-leading collection of brands; at FY23, 509 properties in the system; pipeline of 357 more represents future rooms growth of ~50% Vignette Collection Kimpton Hotel Indigo First 16 hotels now open, The boutique luxury lifestyl
Slide 86: Premium
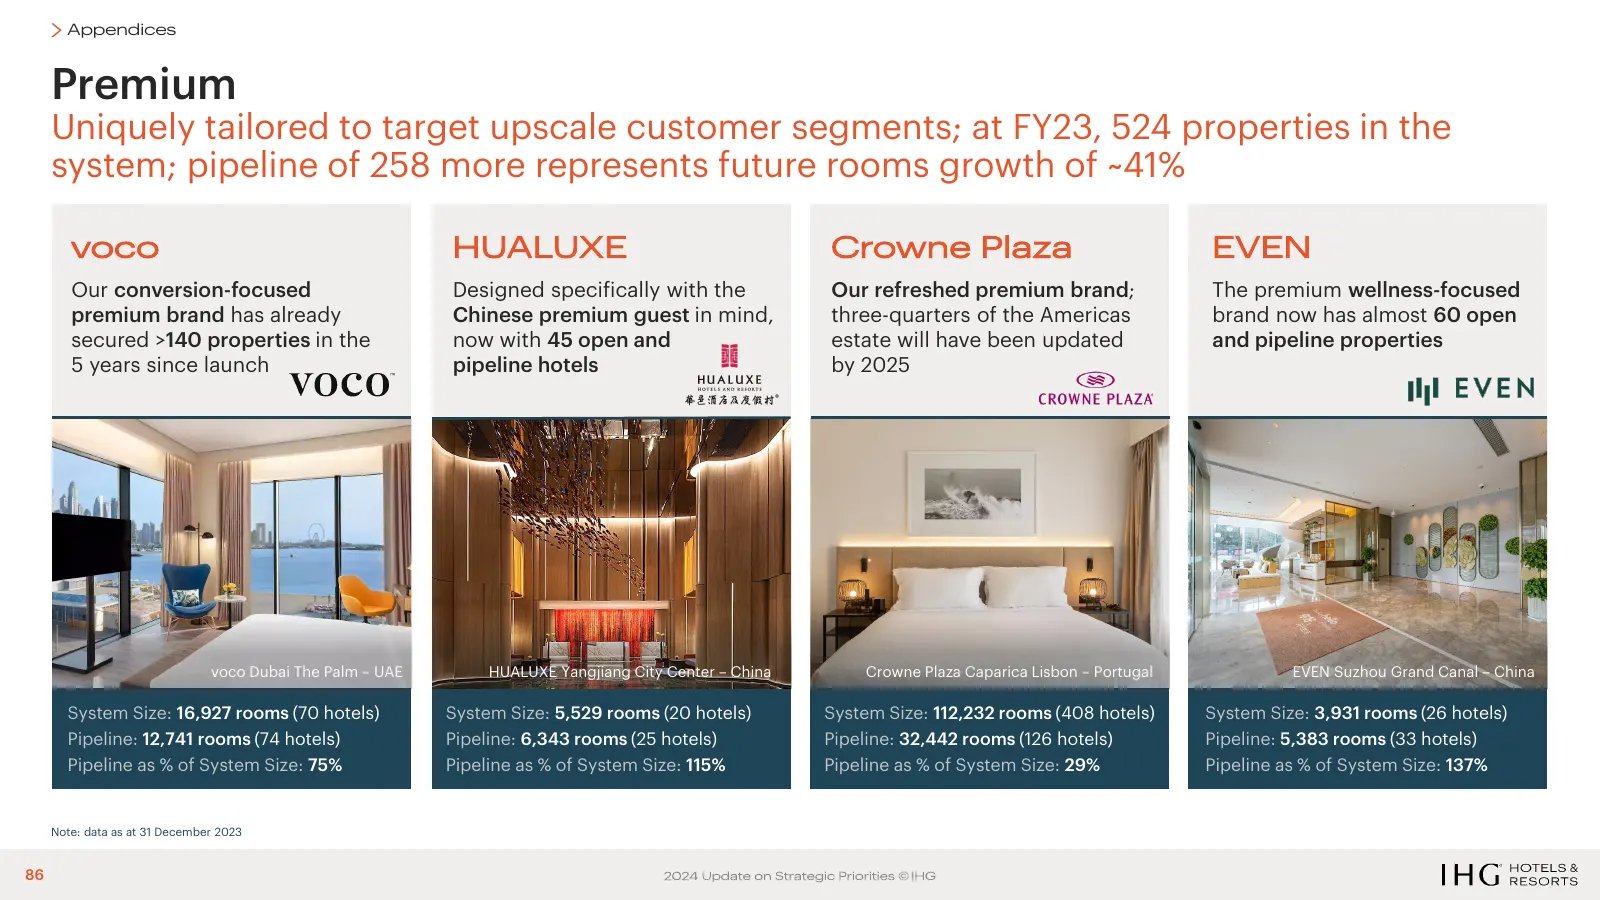
Appendices Premium Uniquely tailored to target upscale customer segments; at FY23, 524 properties in the system; pipeline of 258 more represents future rooms growth of ~41% voco HUALUXE Crowne Plaza EVEN Our conversion-focused Designed specifically with the Our refreshed premium brand; The premium w
Slide 87: Essentials
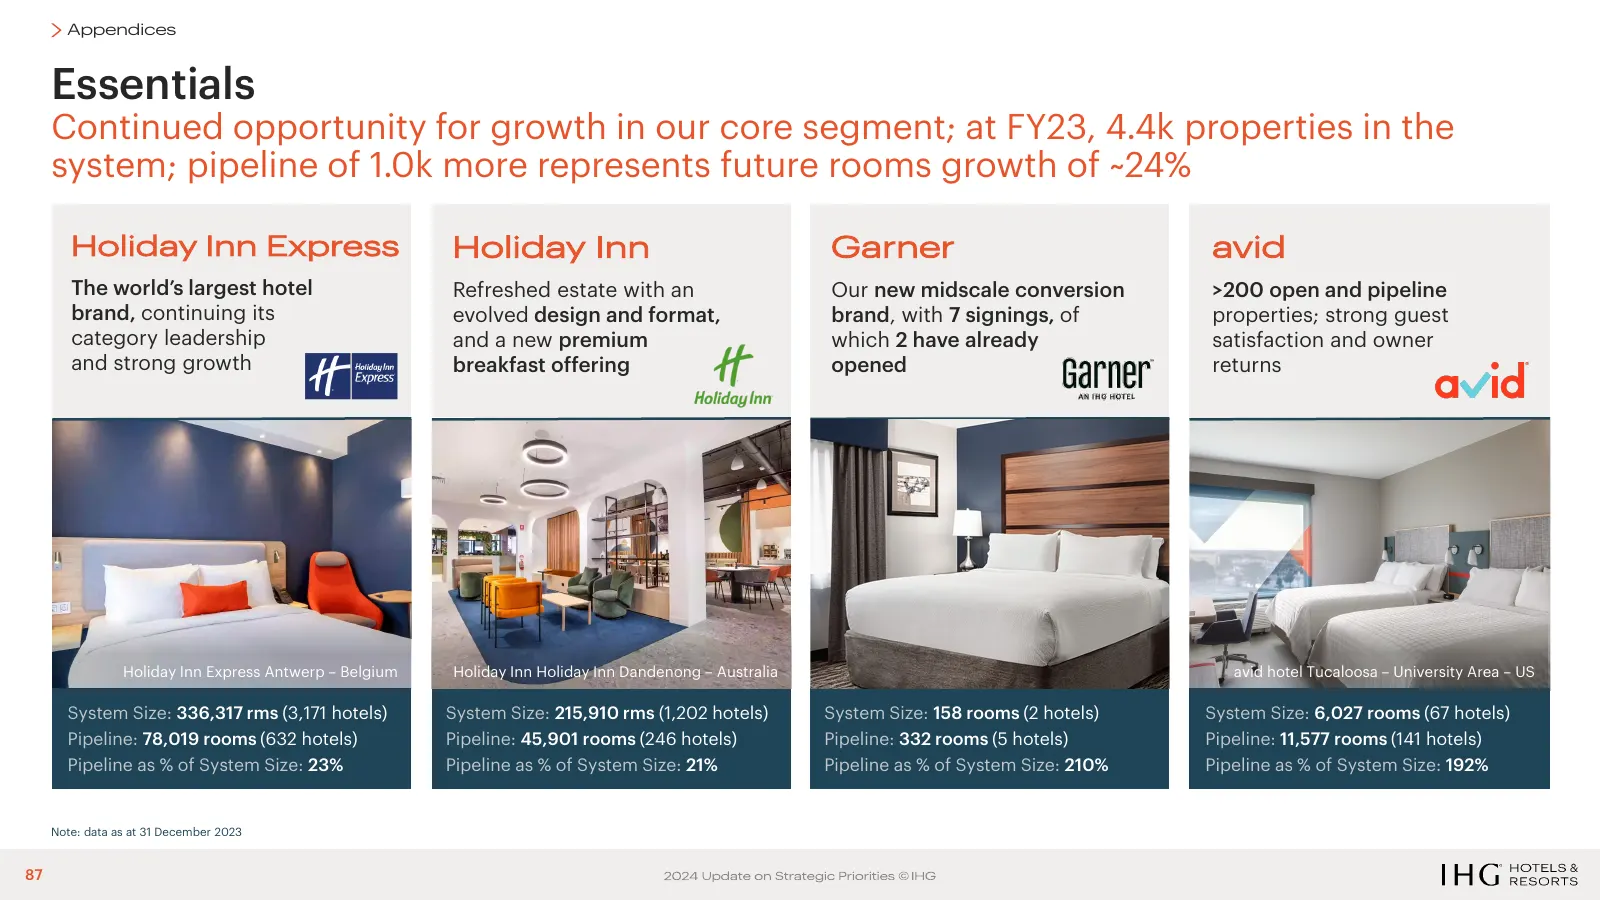
Appendices Essentials Continued opportunity for growth in our core segment; at FY23, 4.4k properties in the system; pipeline of 1.0k more represents future rooms growth of ~24% Holiday Inn Express Holiday Inn Garner avid The world’s largest hotel Refreshed estate with an Our new midscale conversion
Slide 88: Suites
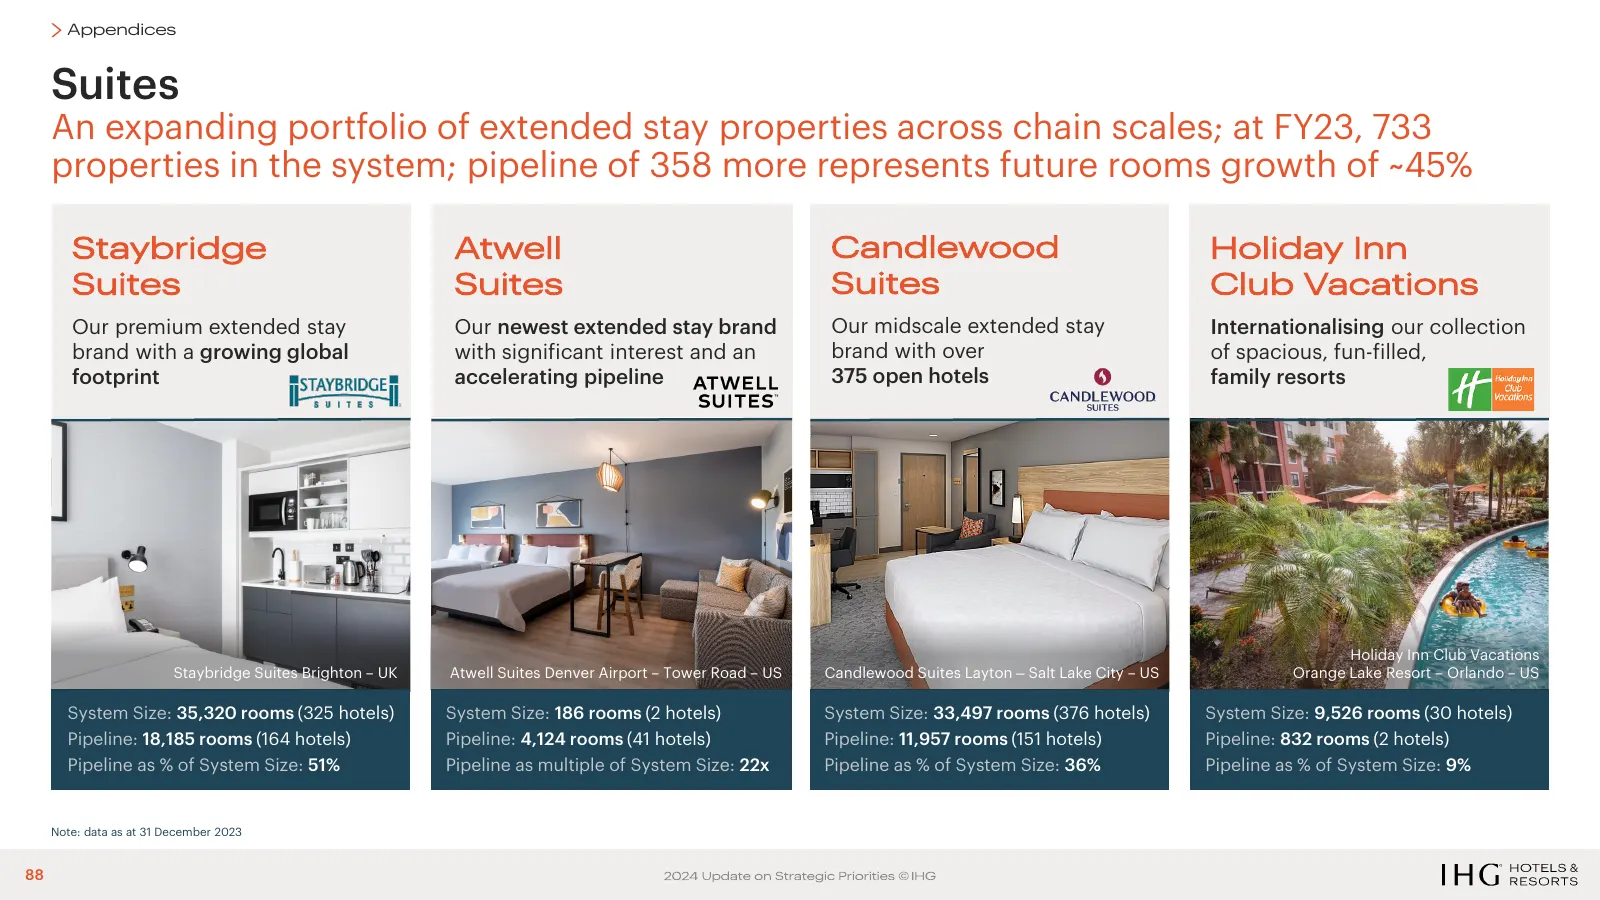
Appendices Suites An expanding portfolio of extended stay properties across chain scales; at FY23, 733 properties in the system; pipeline of 358 more represents future rooms growth of ~45% Staybridge Atwell Candlewood Holiday Inn Suites Suites Suites Club Vacations Our premium extended stay Our newe
Slide 89: Exclusive Partners
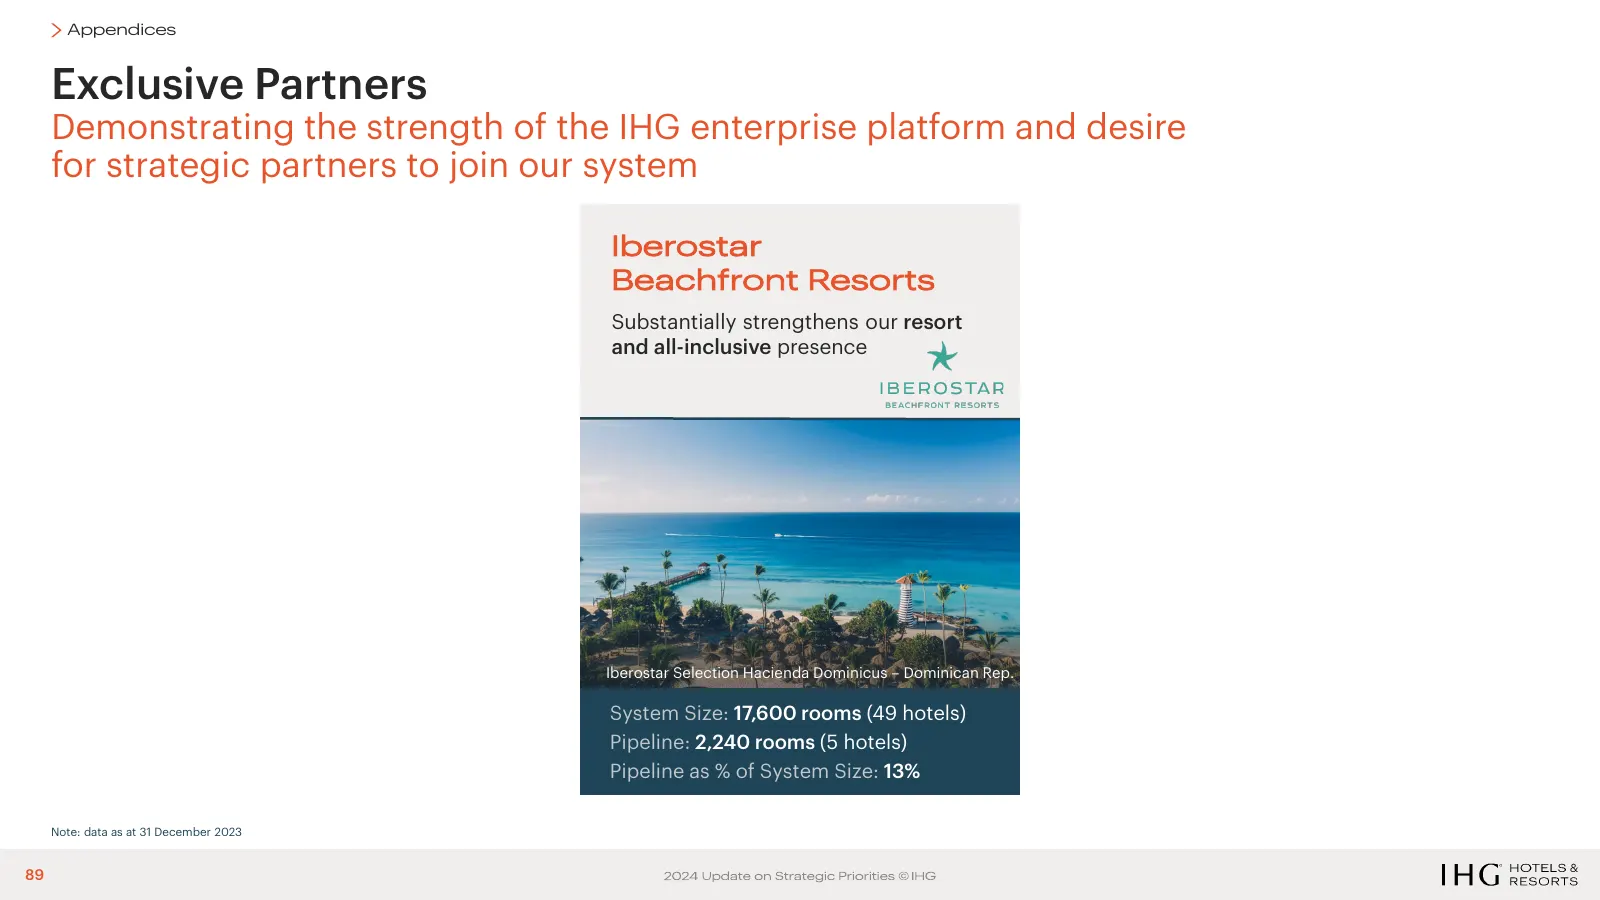
Appendices Exclusive Partners Demonstrating the strength of the IHG enterprise platform and desire for strategic partners to join our system Iberostar Beachfront Resorts Substantially strengthens our resort and all-inclusive presence Iberostar Selection Hacienda Dominicus – Dominican Rep. System Siz
Slide 90: IHG sesorrs
IHG sesorrs e ees REGENT * Il EVEN IBEROSTAR 0 INTERCONTINENTAL 4f Holiday Inn NIGNETTE Garner KIMPTON avid HOTEL INDIGO ATWELL SUITES VOco qISTAYBRIDGER ne | 90 fe) CROWNE PLAZA (5) CANDLEWOOD SUITES REWARDS,
Source: Internet Archive copy of ihgplc.com
More decks from InterContinental Hotels Group PLC
 Investor Presentation (November 2026)82 slides · November 2026
 H1 2026 Earnings Presentation78 slides · Aug 11, 2026
 Investor Presentation (May 2026)94 slides · May 2026
 FY 2025 Earnings Presentation71 slides · Feb 17, 2026
 H1 2025 Earnings Presentation75 slides · Aug 7, 2025
 Investor Presentation (June 2025)132 slides · June 2025