Argo Group International Holdings Ltd
Argo Group International — Investor Presentation (December 2013)
22 slides from Argo Group International's investor presentation, Dec 18, 2013
Slide 1: 3Q 2013 Investor Presentation
3Q 2013 Investor Presentation December 2013
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains "forward-looking statements" which are made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. The forward-looking statements are based on the Company's current expectations and beliefs concerning futu
Slide 3: Argo Group at a Glance
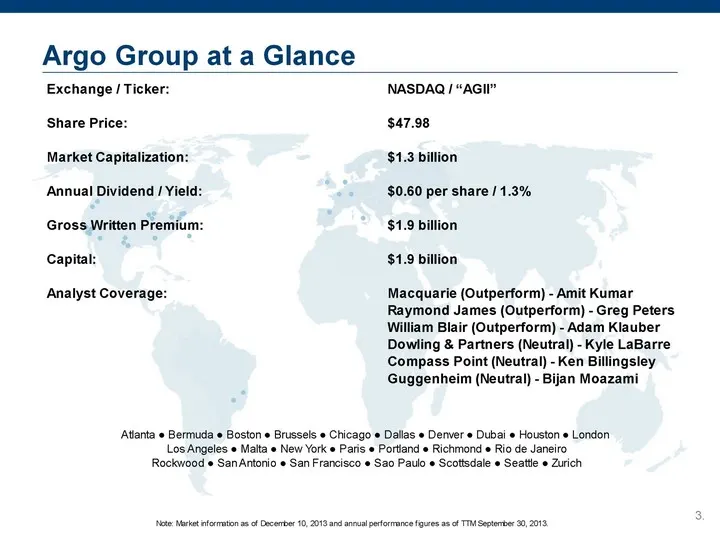
Leen Argo Group at a Glance Exchange / Ticker: NASDAQ /“AGII” Share Price: $47.98 Market Capitalization: $1.3 billion Annual Dividend / Yield: $0.60 per share /1.3% Gross Written Premium: $1.9 billion Capital: $1.9 billion Analyst Coverage: Macquarie (Outperform) - Amit Kumar Raymond James (Outperfo
Slide 4: Strong & Focused Specialty Franchise
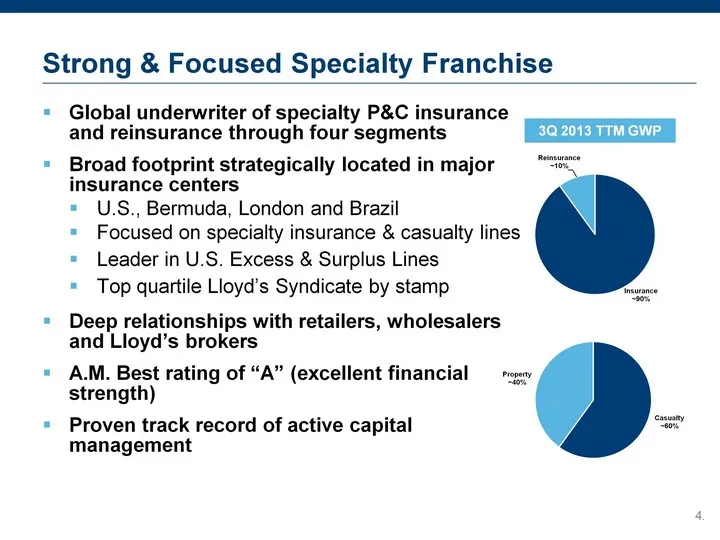
Strong & Focused Specialty Franchise Global underwriter of specialty P&C insurance and reinsurance through four segments Broad footprint strategically located in major insurance centers U.S., Bermuda, London and Brazil Focused on specialty insurance & casualty lines Leader in U.S. Excess & Surplus L
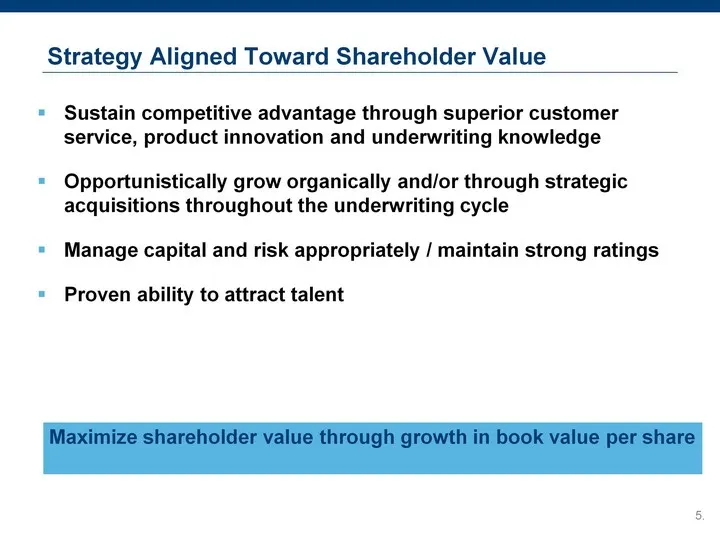
Slide 5: Strategy Aligned Toward Shareholder Value
Maximize shareholder value through growth in book value per share Strategy Aligned Toward Shareholder Value Sustain competitive advantage through superior customer service, product innovation and underwriting knowledge Opportunistically grow organically and/or through strategic acquisitions througho
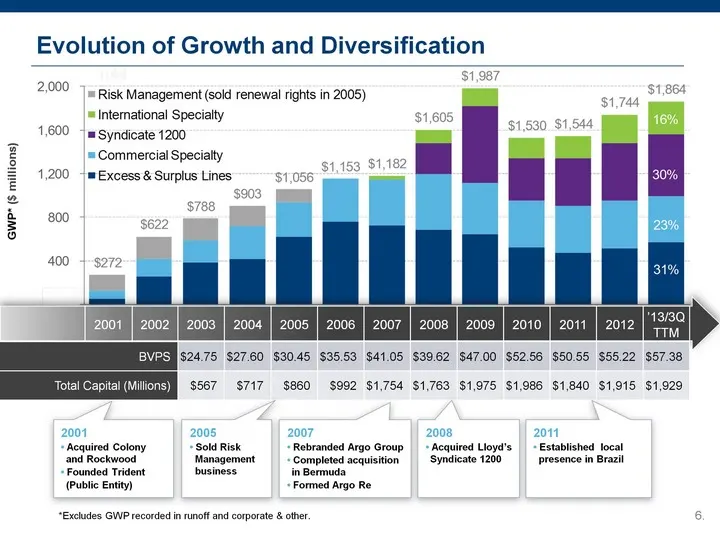
Slide 6: Evolution of Growth and Diversification
Evolution of Growth and Diversification $23.03 $501.1M $30.36 $716.8M $992.0M $54.85 $1,844.7M 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 '13/3QTTM BVPS BVPS BVPS $24.75 $27.60 $30.45 $35.53 $41.05 $39.62 $47.00 $52.56 $50.55 $55.22 $57.38 Total Capital (Millions) Total Capital (Mil
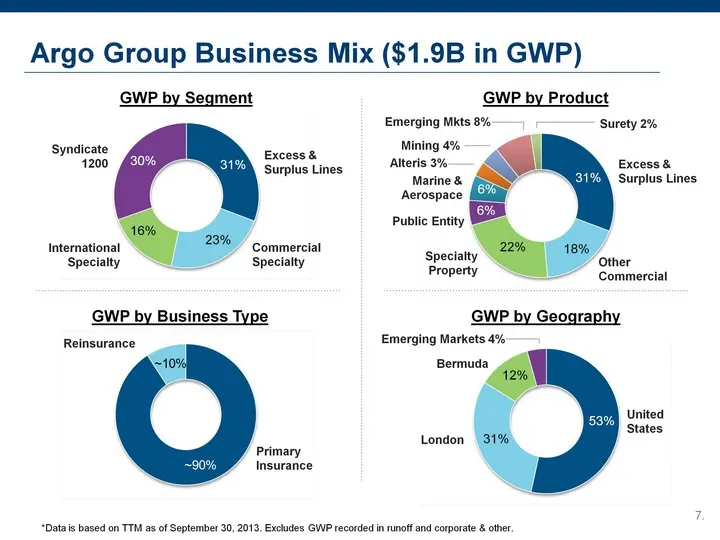
Slide 7: Argo Group Business Mix
Argo Group Business Mix ($1.9B in GWP) 7. GWP by Segment Excess & Surplus Lines Commercial Specialty Syndicate 1200 International Specialty 30% 16% 31% GWP by Product GWP by Geography United States London Bermuda *Data is based on TTM as of September 30, 2013. Excludes GWP recorded in runoff and cor
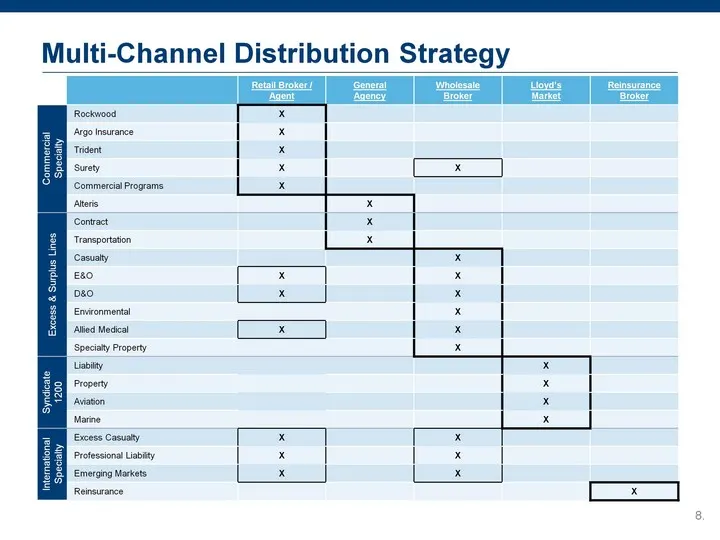
Slide 8: Multi-Channel Distribution Strategy
Multi-Channel Distribution Strategy Retail Broker / Agent General Agency Wholesale Broker Lloyd's Market Reinsurance Broker Commercial Specialty Rockwood X Commercial Specialty Argo Insurance X Commercial Specialty Trident X Commercial Specialty Surety X X Commercial Specialty Commercial Programs X
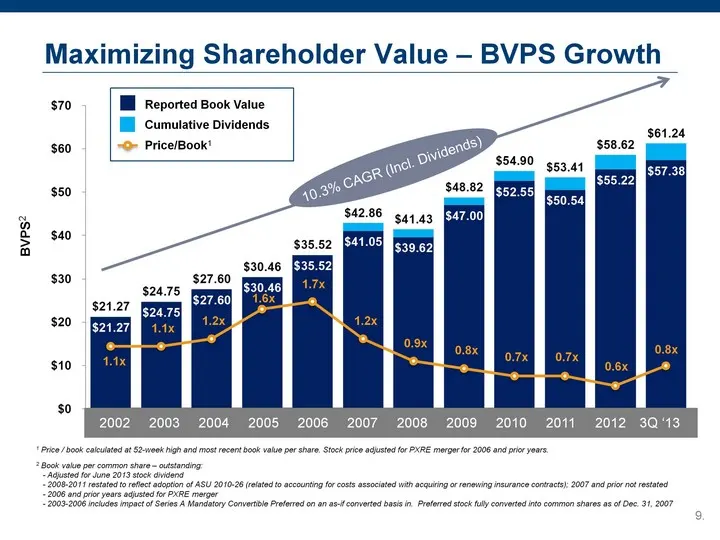
Slide 9: Maximizing Shareholder Value - BVPS Growth
(CHART) Maximizing Shareholder Value - BVPS Growth 1 Price / book calculated at 52-week high and most recent book value per share. Stock price adjusted for PXRE merger for 2006 and prior years. 2 Book value per common share - outstanding: - Adjusted for June 2013 stock dividend - 2008-2011 restated
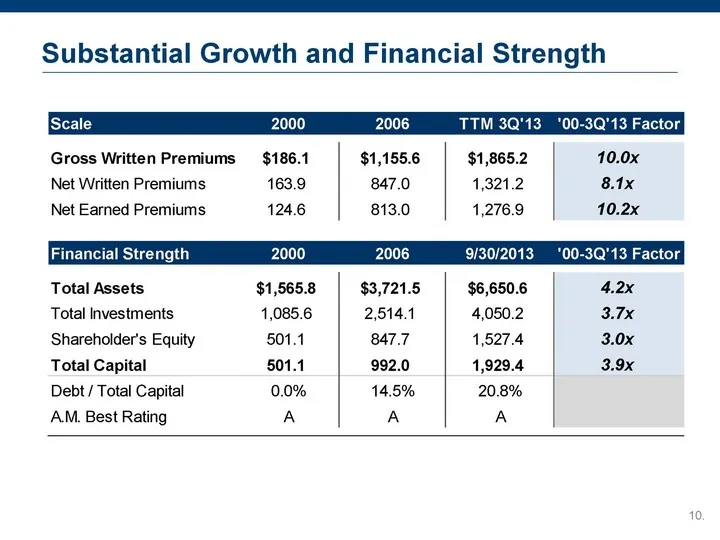
Slide 10: Substantial Growth and Financial Strength
Substantial Growth and Financial Strength
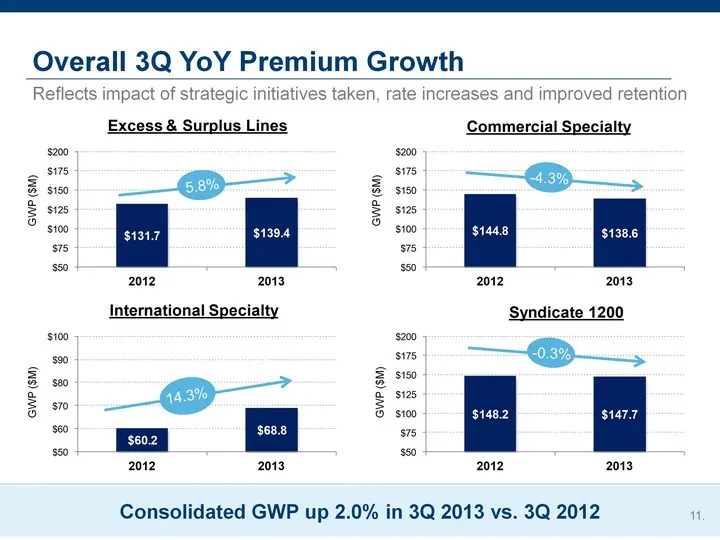
Slide 11: Consolidated GWP up 2.0% in 3Q 2013 vs. 3Q 2012
Consolidated GWP up 2.0% in 3Q 2013 vs. 3Q 2012 Overall 3Q YoY Premium Growth Reflects impact of strategic initiatives taken, rate increases and improved retention GWP ($M) GWP ($M) -4.3% GWP ($M) GWP ($M) 11. 14.3% 5.8% -0.3%
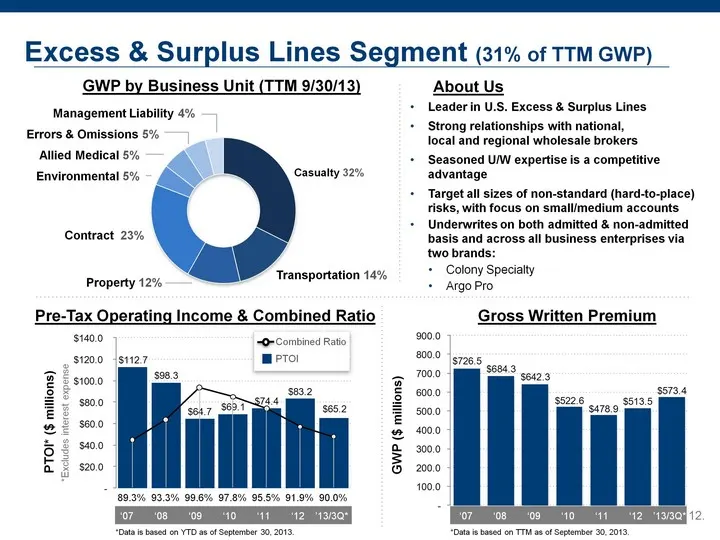
Slide 12: Excess & Surplus Lines: About Us
About Us Leader in U.S. Excess & Surplus Lines Strong relationships with national, local and regional wholesale brokers Seasoned U/W expertise is a competitive advantage Target all sizes of non-standard (hard-to-place) risks, with focus on small/medium accounts Underwrites on both admitted & non-adm
Slide 13: Outperformed E&S Peers in 2012
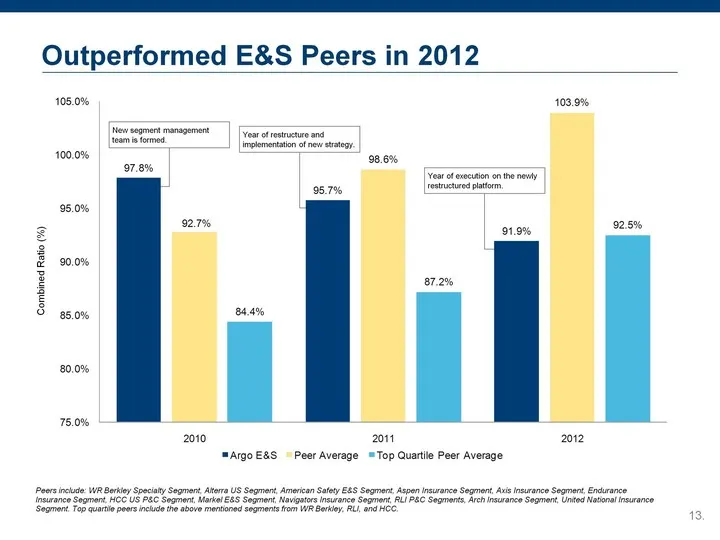
Outperformed E&S Peers in 2012 Peers include: WR Berkley Specialty Segment, Alterra US Segment, American Safety E&S Segment, Aspen Insurance Segment, Axis Insurance Segment, Endurance Insurance Segment, HCC US P&C Segment, Markel E&S Segment, Navigators Insurance Segment, RLI P&C Segments, Arch Insu
Slide 14: Commercial Specialty (23% of GWP)
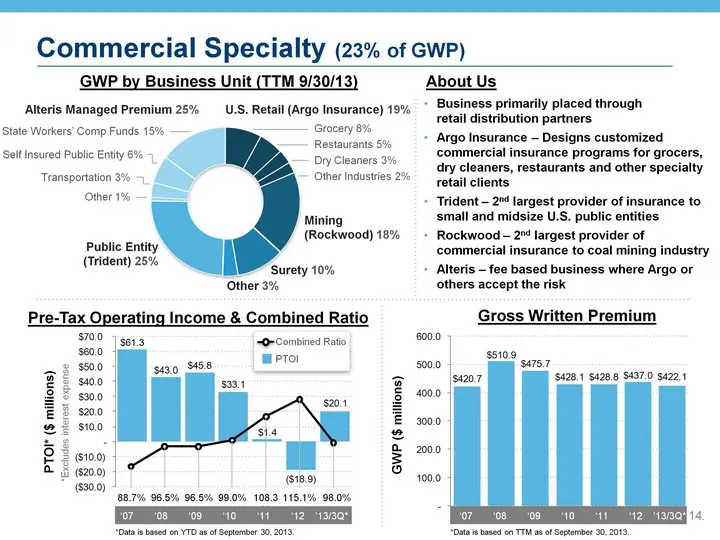
Commercial Specialty (23% of GWP) About Us Business primarily placed through retail distribution partners Argo Insurance - Designs customized commercial insurance programs for grocers, dry cleaners, restaurants and other specialty retail clients Trident - 2nd largest provider of insurance to small a
Slide 15: Syndicate 1200 (30% of GWP)
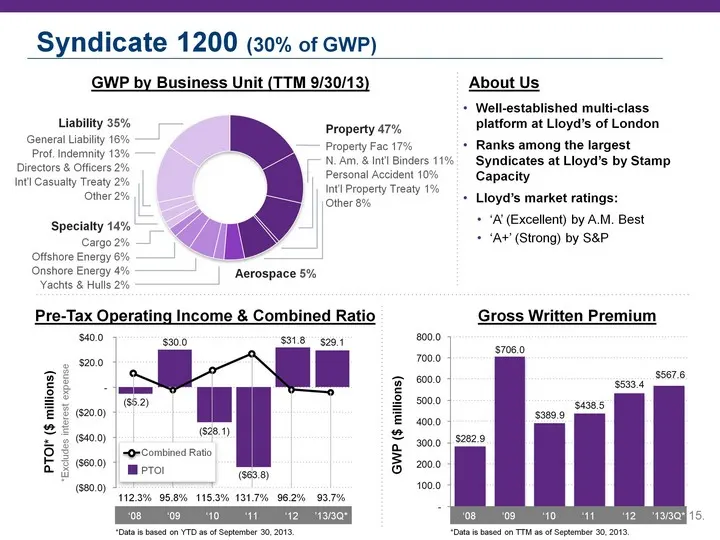
General Liability 16% Prof. Indemnity 13% Directors & Officers 2% Int'l Casualty Treaty 2% Other 2% Syndicate 1200 (30% of GWP) About Us Well-established multi-class platform at Lloyd's of London Ranks among the largest Syndicates at Lloyd's by Stamp Capacity Lloyd's market ratings: 'A' (Excellent)
Slide 16: International Specialty (16% of GWP)
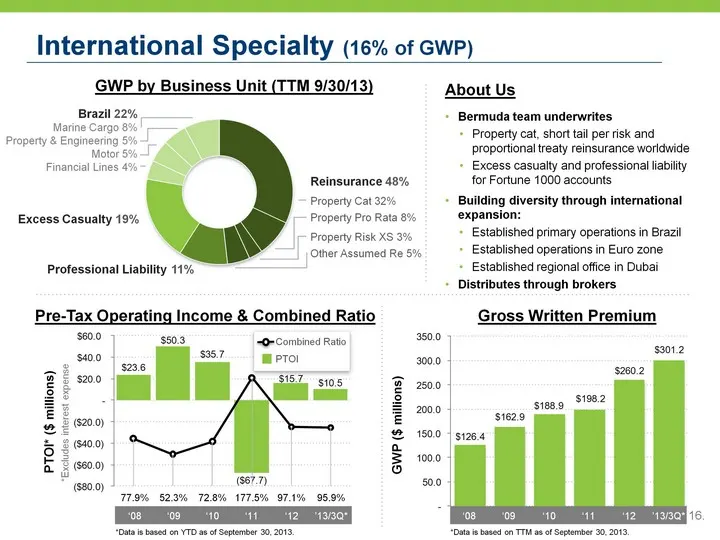
International Specialty (16% of GWP) About Us Bermuda team underwrites Property cat, short tail per risk and proportional treaty reinsurance worldwide Excess casualty and professional liability for Fortune 1000 accounts Building diversity through international expansion: Established primary operatio
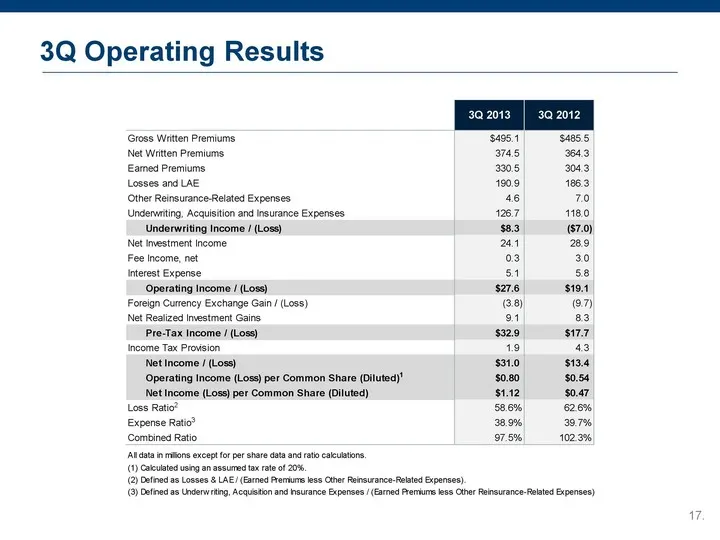
Slide 17: 3Q Operating Results
3Q Operating Results ‘Gross Witten Premiums Ses beets eee est Lom) per Common Share (luted) ‘Atta rons except opr stare ata aa causes (1) Catvates using an assume tax ate of
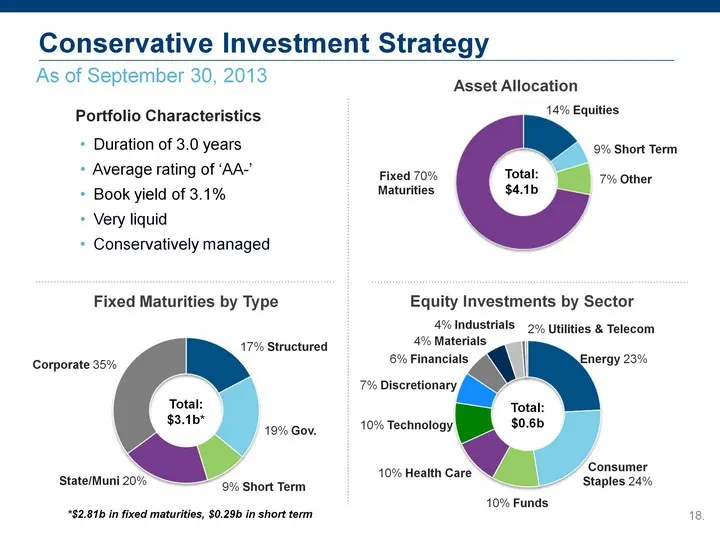
Slide 18: Conservative Investment Strategy
18. As of September 30, 2013 Conservative Investment Strategy 17% 18. Portfolio Characteristics Duration of 3.0 years Average rating of 'AA-' Book yield of 3.1% Very liquid Conservatively managed Total: $4.1b Equity Investments by Sector 10% Health Care Energy 23% 6% Financials 4% Industrials 10% Te
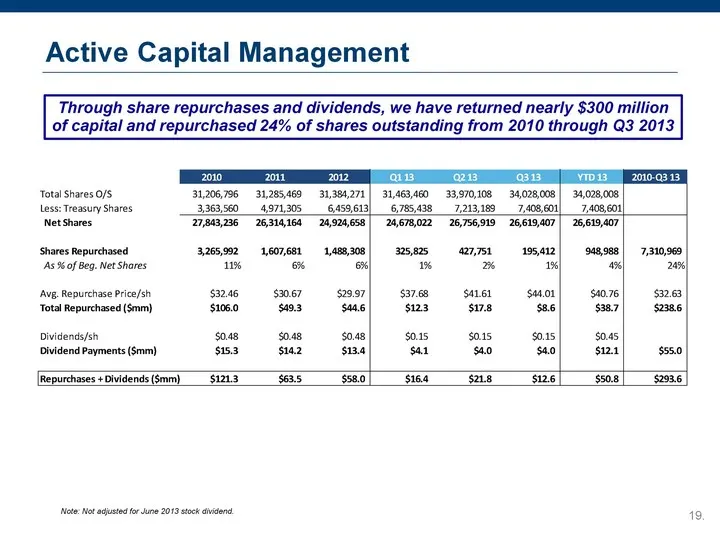
Slide 19: Active Capital Management
Active Capital Management Through share repurchases and dividends, we have returned nearly $300 million of capital and repurchased 24% of shares outstanding from 2010 through Q3 2013 Note: Not adjusted for June 2013 stock dividend.
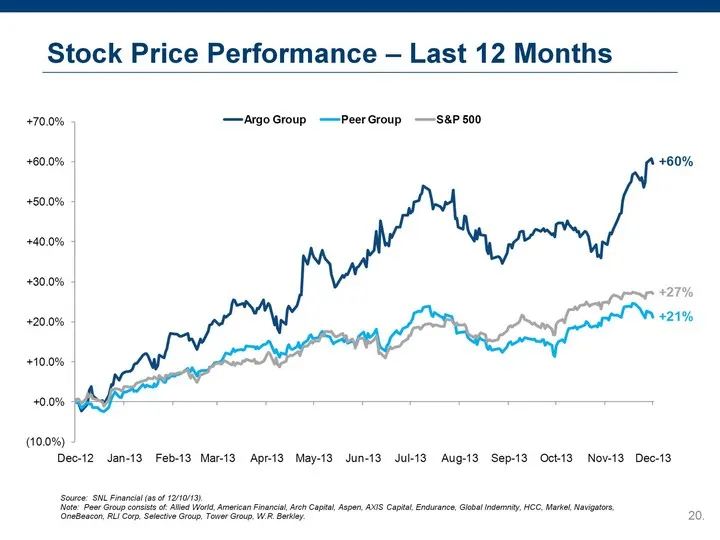
Slide 20: Stock Price Performance
Stock Price Performance - Last 12 Months Source: SNL Financial (as of 12/10/13). Note: Peer Group consists of: Allied World, American Financial, Arch Capital, Aspen, AXIS Capital, Endurance, Global Indemnity, HCC, Markel, Navigators, OneBeacon, RLI Corp, Selective Group, Tower Group, W.R. Berkley.
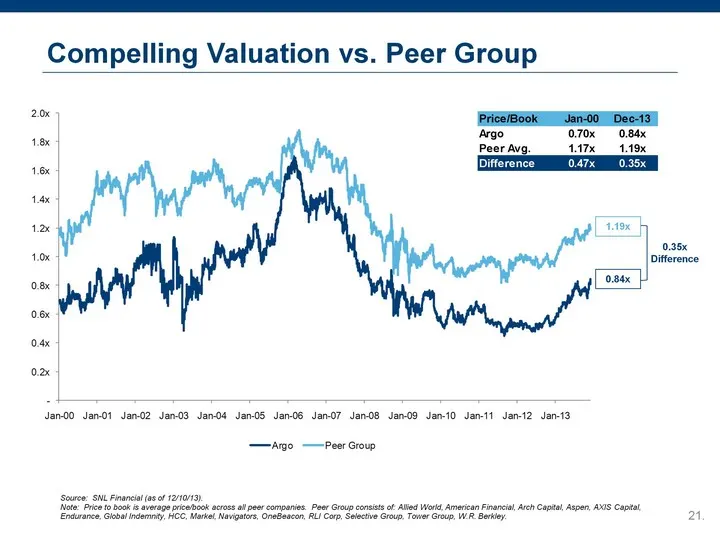
Slide 21: Compelling Valuation vs. Peer Group
Compelling Valuation vs. Peer Group 0.84x 1.19x 0.35x Difference Source: SNL Financial (as of 12/10/13). Note: Price to book is average price/book across all peer companies. Peer Group consists of: Allied World, American Financial, Arch Capital, Aspen, AXIS Capital, Endurance, Global Indemnity, HCC,
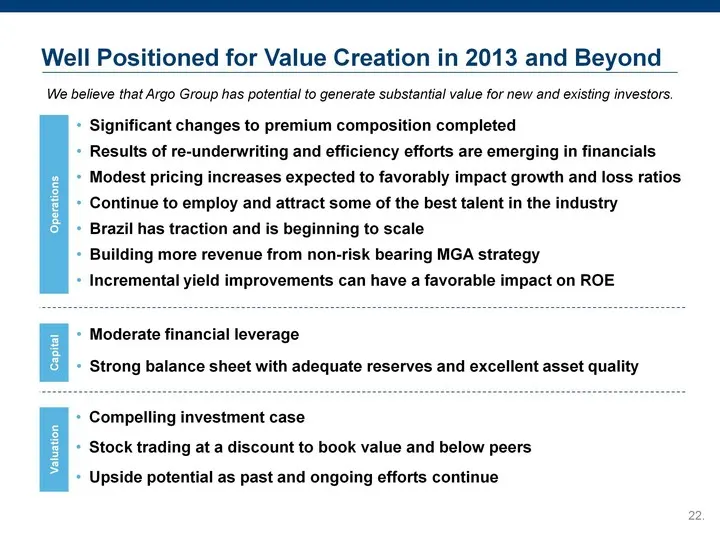
Slide 22: Well Positioned for Value Creation in 2013 and Beyond
Well Positioned for Value Creation in 2013 and Beyond Valuation Compelling investment case Stock trading at a discount to book value and below peers Upside potential as past and ongoing efforts continue We believe that Argo Group has potential to generate substantial value for new and existing inves
Source: SEC EDGAR · 8-K filed Dec 18, 2013
More decks from Argo Group International Holdings Ltd
 Proxy Contest (November 2022)39 slides · Nov 18, 2022
 Corporate Update (September 2022)23 slides · Sep 8, 2022
 Investor Presentation (February 2022)24 slides · Feb 23, 2022
 Q3 2021 Earnings Presentation7 slides · Nov 3, 2021
 Investor Day (March 2021)59 slides · Mar 12, 2021
 Investor Presentation (November 2020)17 slides · Nov 10, 2020