AltaGas Ltd. · TSX:ALA
AltaGas — Investor Day (December 2023)
99 slides from AltaGas's investor day presentation, Dec 5, 2023
Slide 1: Fundamentally Focused: 2023 Investor Day
Fundamentally Focused 2023 Investor Day December 5, 2023
Slide 2: Forward-Looking Information
Forward-Looking Information This presentation contains forward-looking information (forward-looking statements). Words such as "may", "can", "would", "could", "should", "likely", "will", "intend", "contemplate", "plan", "anticipate", "believe", "aim", "seek", "future", "commit", "propose", "contempl
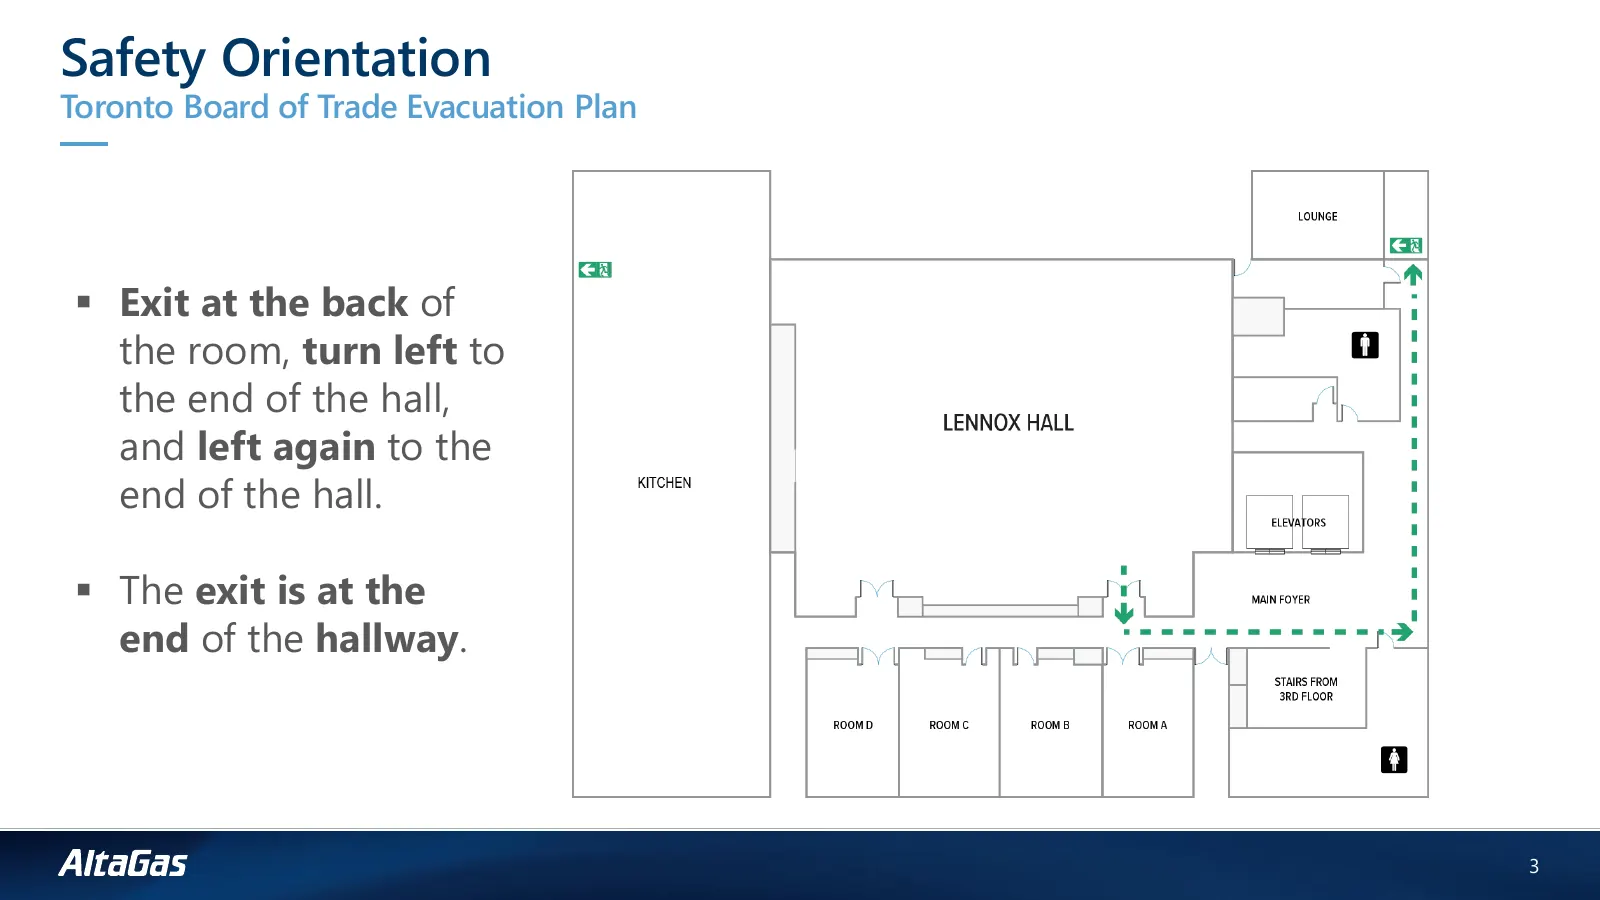
Slide 3: Safety Orientation
Safety Orientation Toronto Board of Trade Evacuation Plan ▪ Exit at the back of the room, turn left to the end of the hall, and left again to the end of the hall. ▪ The exit is at the end of the hallway. 3
Slide 4: Land Acknowledgement
Land Acknowledgement We respectfully acknowledge that we work on the traditional lands of Indigenous Peoples of Canada and the United States, and we are grateful for their stewardship, sharing and celebration of these territories. We value building trusting and enduring relationships with Indigenous
Slide 5: Our Focus Areas
Our Focus Areas 1 2 3 4 The Journey we Key Themes and Advancements since The Road Ahead have Been On Market Fundamentals the Last Investor Day Notes: *See "Forward-looking Information“ 5
Slide 6: Agenda and Speakers
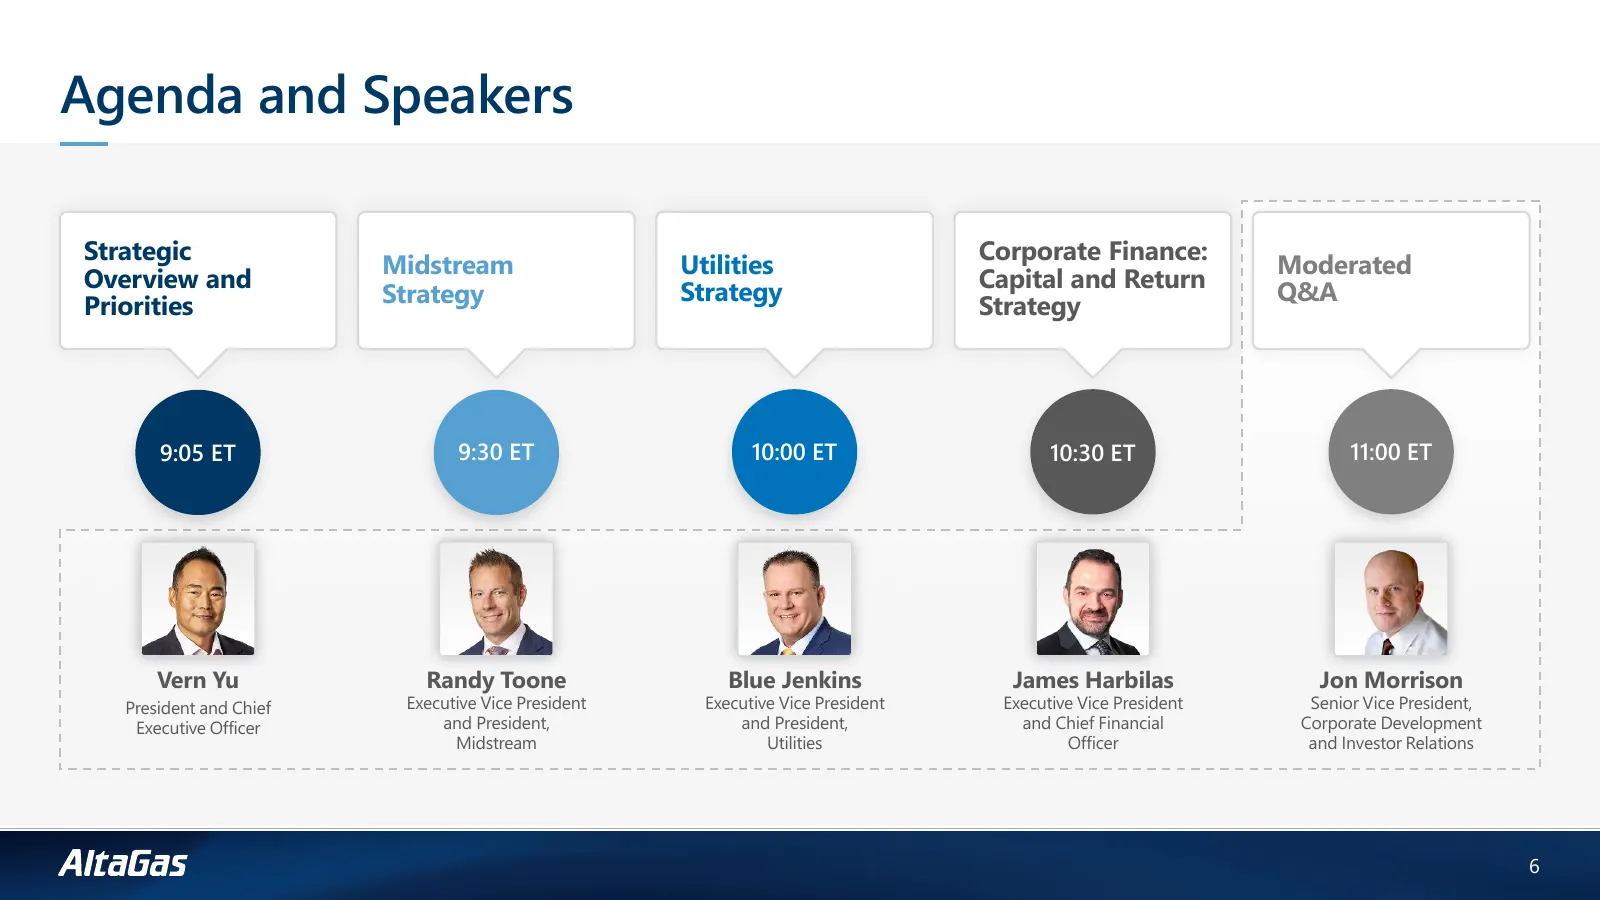
Agenda and Speakers Strategic Corporate Finance: Midstream Utilities Moderated Overview and Capital and Return Strategy Strategy Q&A Priorities Strategy 9:05 ET 9:30 ET 10:00 ET 10:30 ET 11:00 ET Vern Yu Randy Toone Blue Jenkins James Harbilas Jon Morrison President and Chief Executive Vice Presiden
Slide 7: Strategic Overview and Corporate Priorities
Strategic Overview and President and Corporate Chief ExecutivePriorities Officer Vern Yu President and Chief Executive Officer 7
Slide 8: Strategic Priorities
Strategic Priorities 1 Equity Self-funding Model 2 Commercial De-risking 3 Continued De-leveraging 4 Optimize Returns 5 Capital Allocation 8
Slide 9: Energy Outlook
Energy Outlook 9
Slide 10: Energy Security and Affordability
Energy Security and Affordability ▪ Energy security, reliability, and affordability have returned to forefront as the most important themes today. ▪ Energy evolution will continue, but slower than many believe – it will be an evolution not a revolution. ▪ Natural gas and NGLs remain critical for lon
Slide 11: Key Themes Driving our Forward Outlook
Key Themes Driving our Forward Outlook 1 Global Energy Demand Continues to Compound 2 Fundamentals for Natural Gas and NGLs are Robust 3 Gas Utilities Critical for Long-term Energy Delivery 4 Canadian Midstream Set-up is Compelling Notes: *See "Forward-looking Information“ Energy Fundamentals are a
Slide 12: Global Energy Demand Continues to Compound
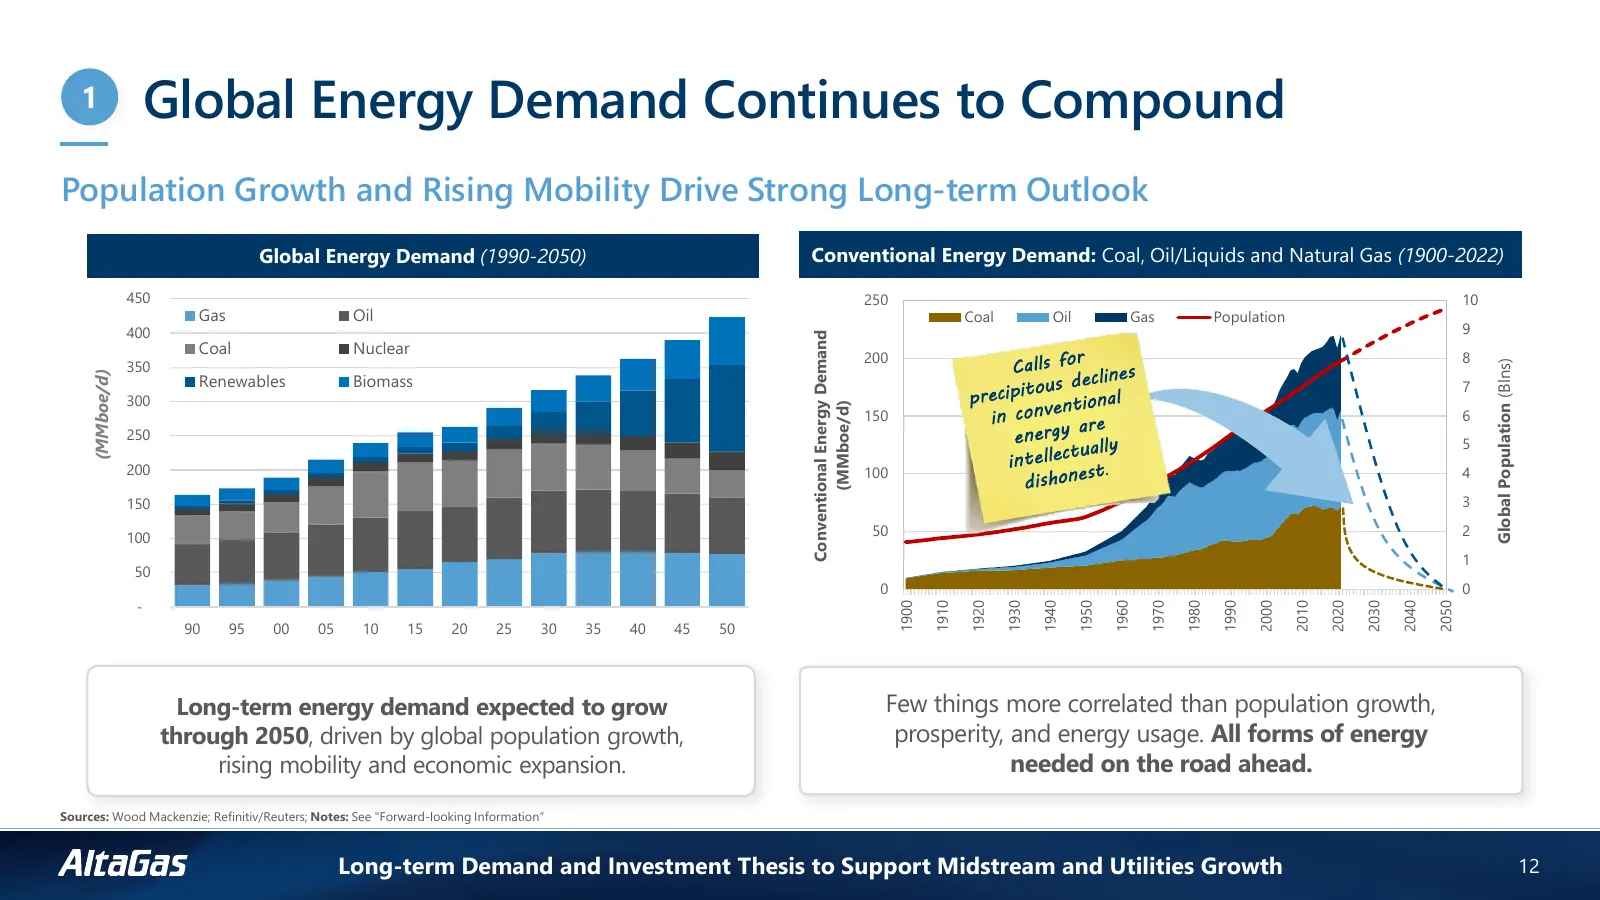
1 Global Energy Demand Continues to Compound Population Growth and Rising Mobility Drive Strong Long-term Outlook Global Energy Demand (1990-2050) Conventional Energy Demand: Coal, Oil/Liquids and Natural Gas (1900-2022) 450 250 10 Gas Oil Coal Oil Gas Population 400 9 Conventional Energy Demand Coa
Slide 13: Fundamentals for Natural Gas and NGLs are Robust
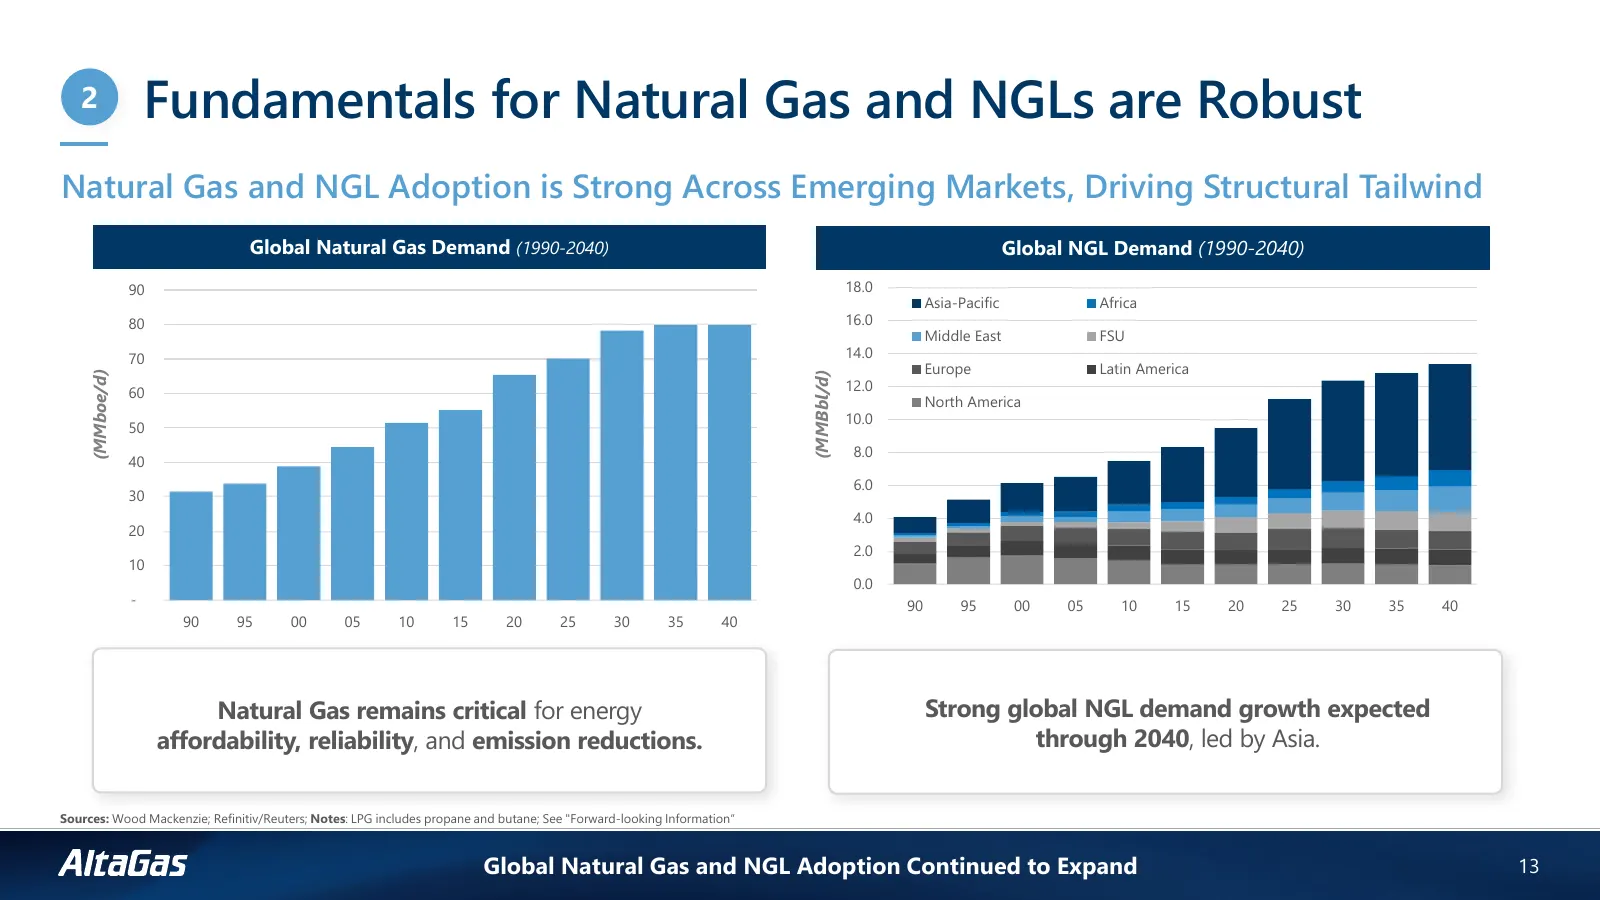
2 Fundamentals for Natural Gas and NGLs are Robust Natural Gas and NGL Adoption is Strong Across Emerging Markets, Driving Structural Tailwind Global Natural Gas Demand (1990-2040) Global NGL Demand (1990-2040) 90 18.0 Asia-Pacific Africa 80 16.0 Middle East FSU 70 14.0 Europe Latin America (MMboe/d
Slide 14: Gas Utilities Critical for Long-term Energy Delivery
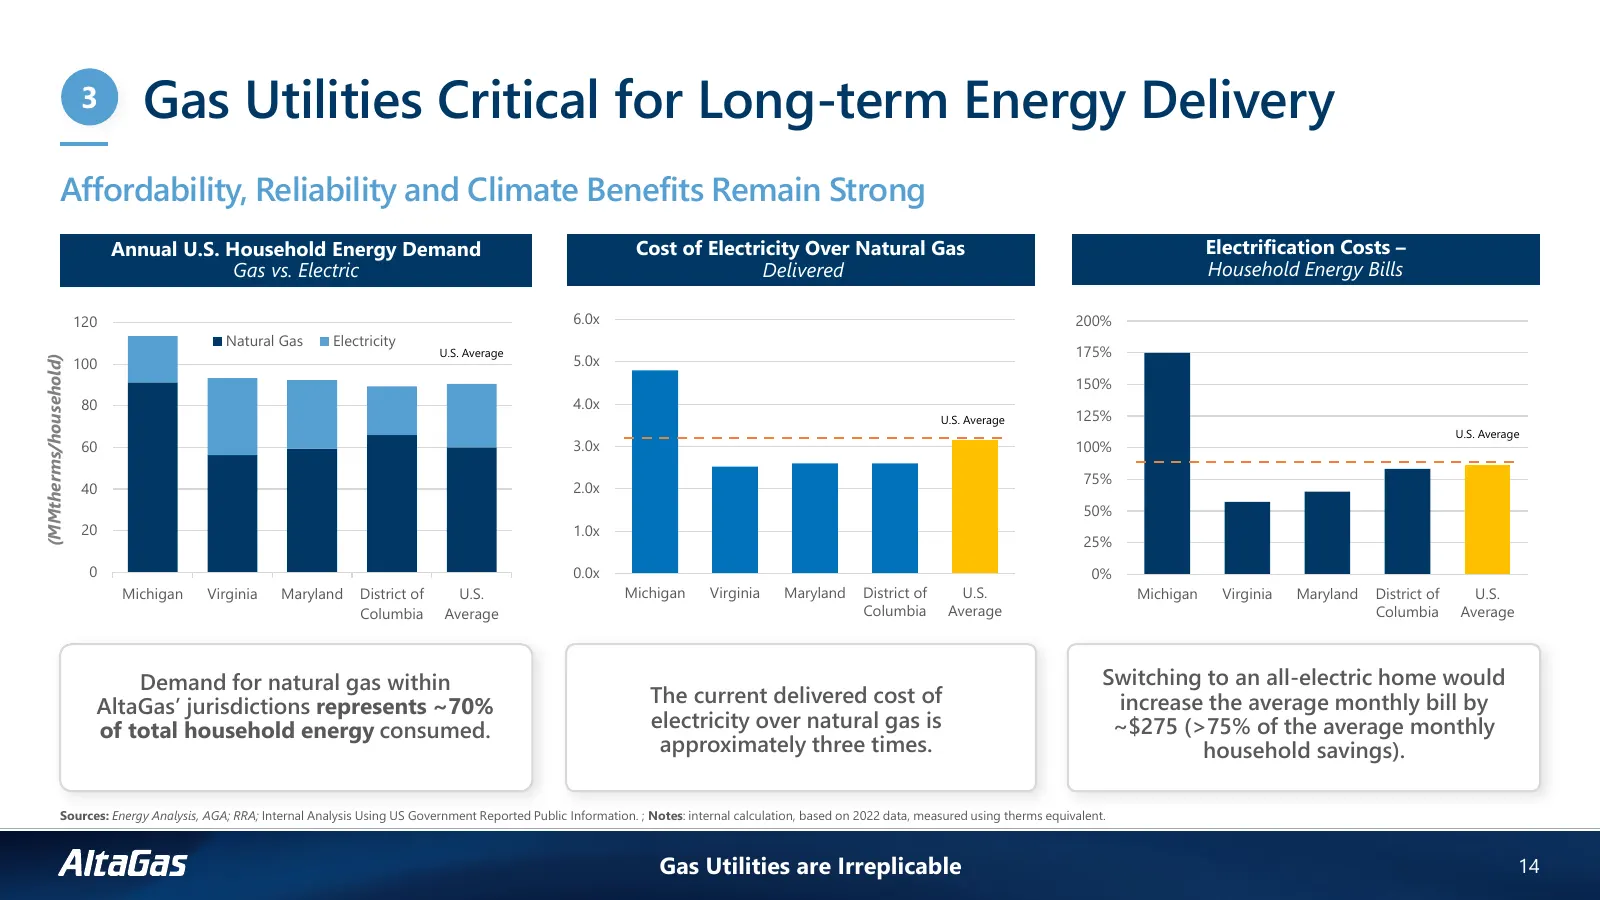
3 Gas Utilities Critical for Long-term Energy Delivery Affordability, Reliability and Climate Benefits Remain Strong Annual U.S. Household Energy Demand Cost of Electricity Over Natural Gas Electrification Costs – Gas vs. Electric Delivered Household Energy Bills 120 6.0x 200% Natural Gas Electricit
Slide 15: Canadian Midstream Set-up is Compelling
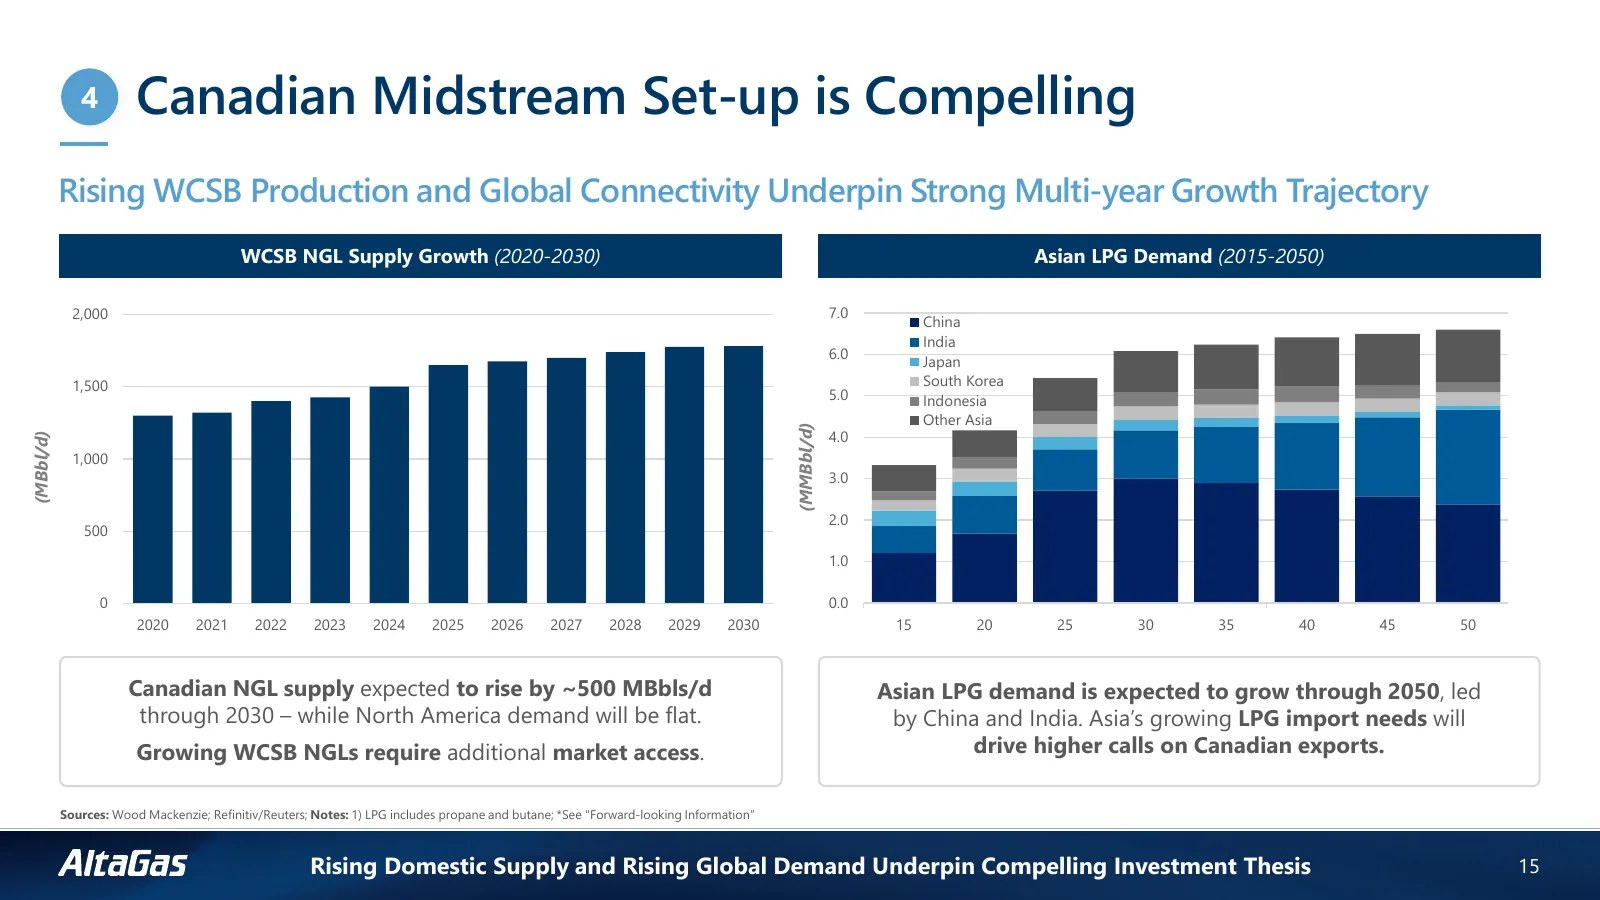
4 Canadian Midstream Set-up is Compelling Rising WCSB Production and Global Connectivity Underpin Strong Multi-year Growth Trajectory WCSB NGL Supply Growth (2020-2030) Asian LPG Demand (2015-2050) 2,000 7.0 China India 6.0 Japan 1,500 South Korea 5.0 Indonesia Other Asia (MMBbl/d) 4.0 (MBbl/d) 1,00
Slide 16: ESG Goals and Performance
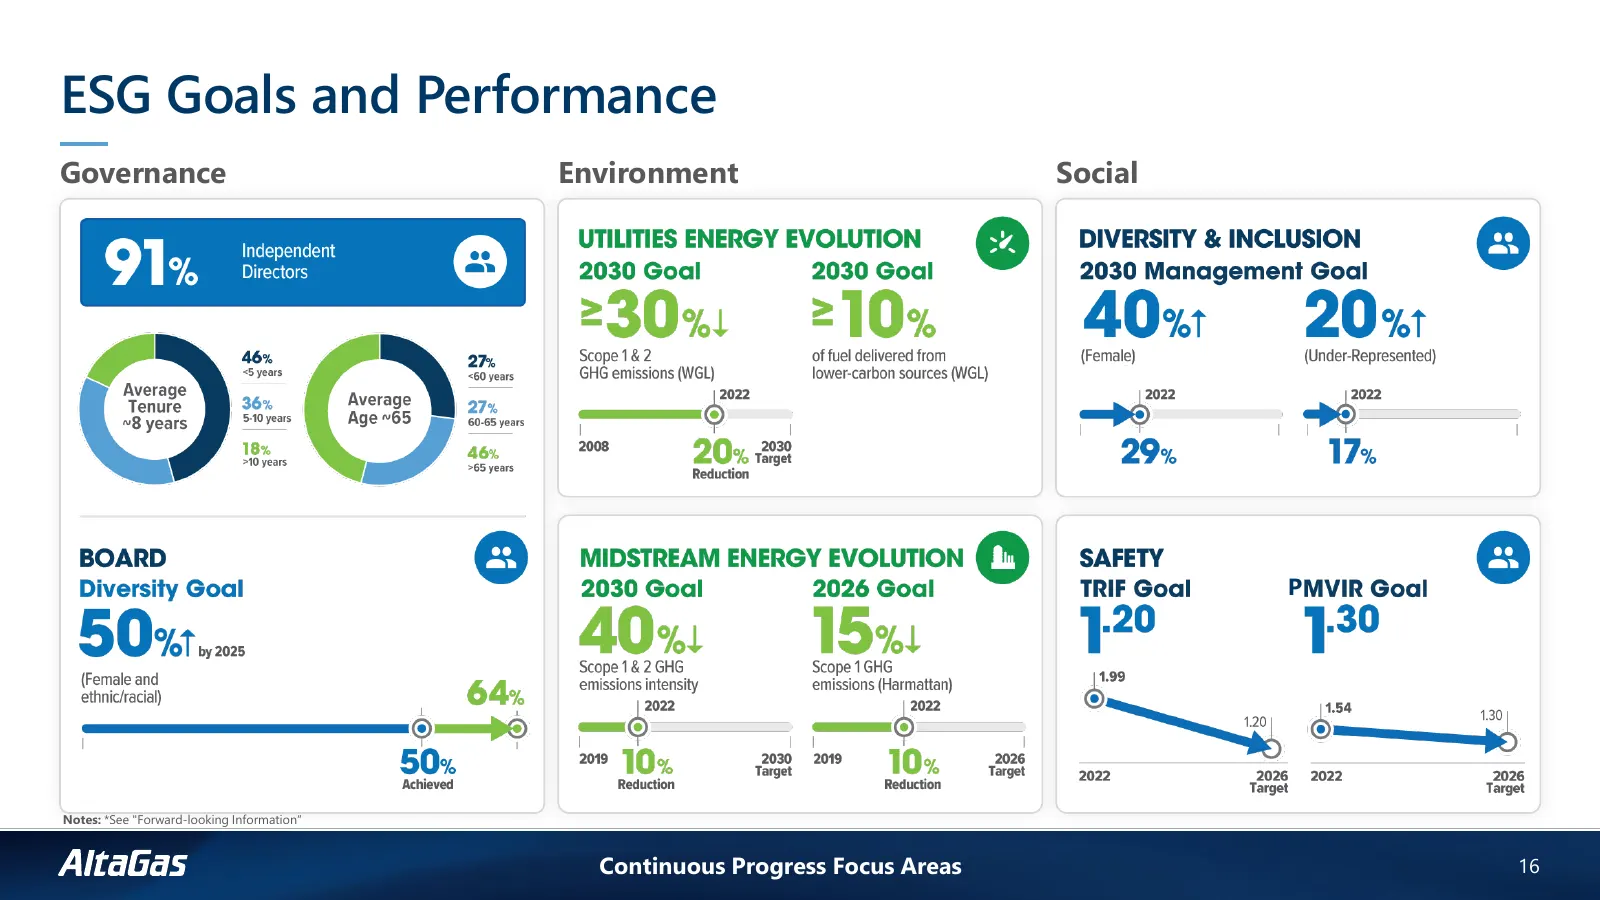
ESG Goals and Performance Governance Environment Social w P Notes: *See "Forward-looking Information“ Continuous Progress Focus Areas 16
Slide 17: The Road Ahead
The Road Ahead AltaGas if ~ =
Slide 18: Our Focus Areas
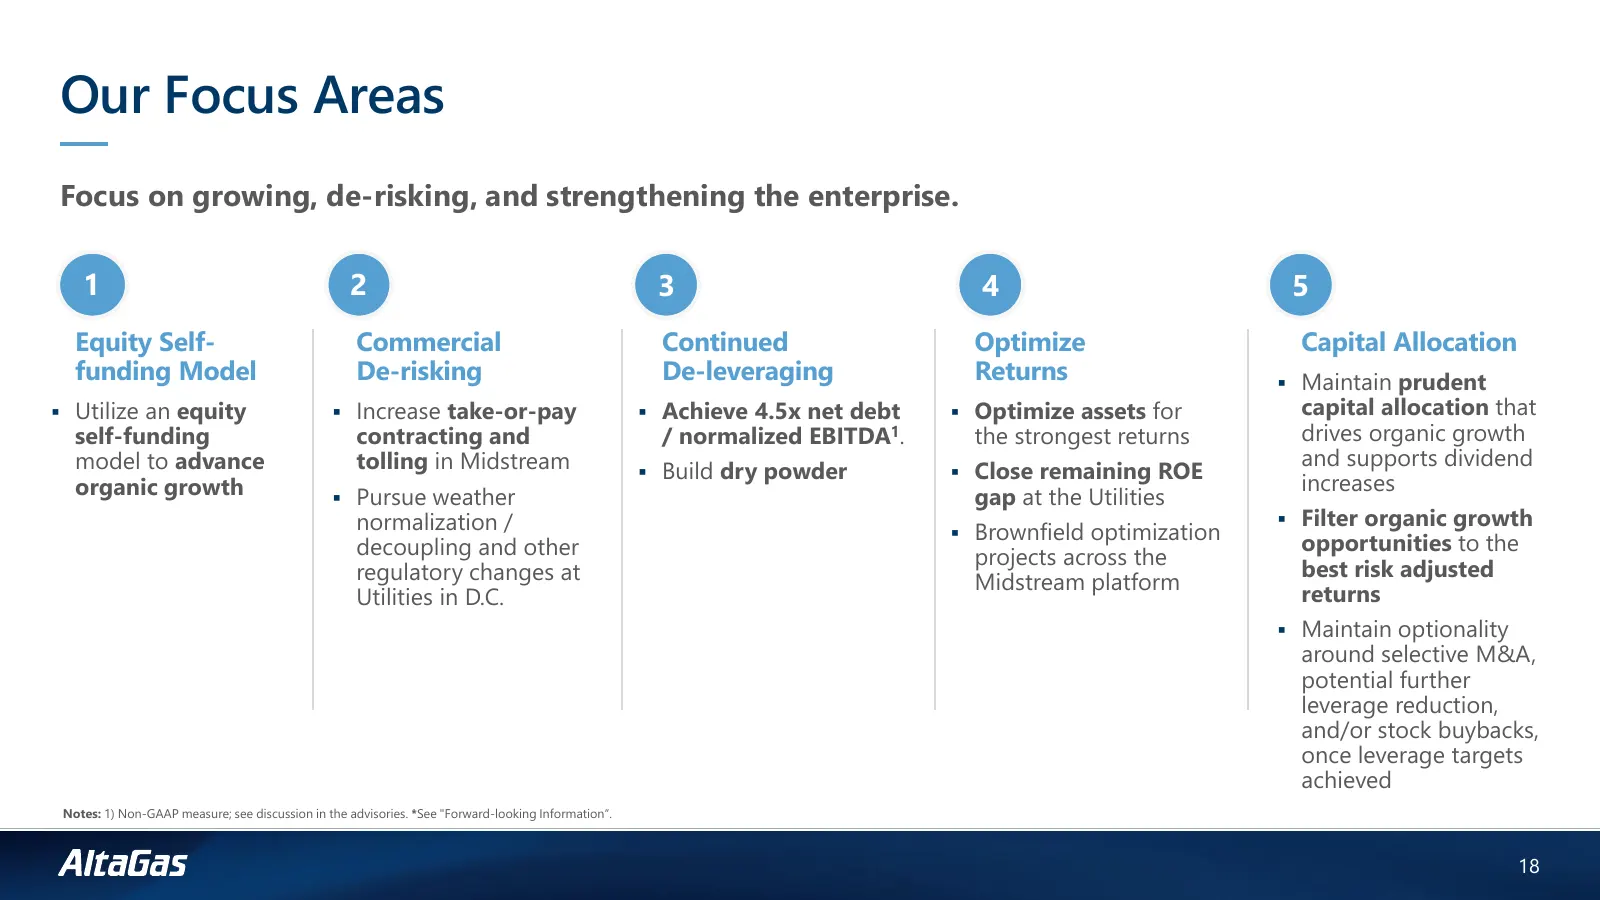
Our Focus Areas Focus on growing, de-risking, and strengthening the enterprise. 1 2 3 4 5 Equity Self- Commercial Continued Optimize Capital Allocation funding Model De-risking De-leveraging Returns ▪ Maintain prudent ▪ Utilize an equity ▪ Increase take-or-pay ▪ Achieve 4.5x net debt ▪ Optimize asse
Slide 19: Delivering on Core Objectives
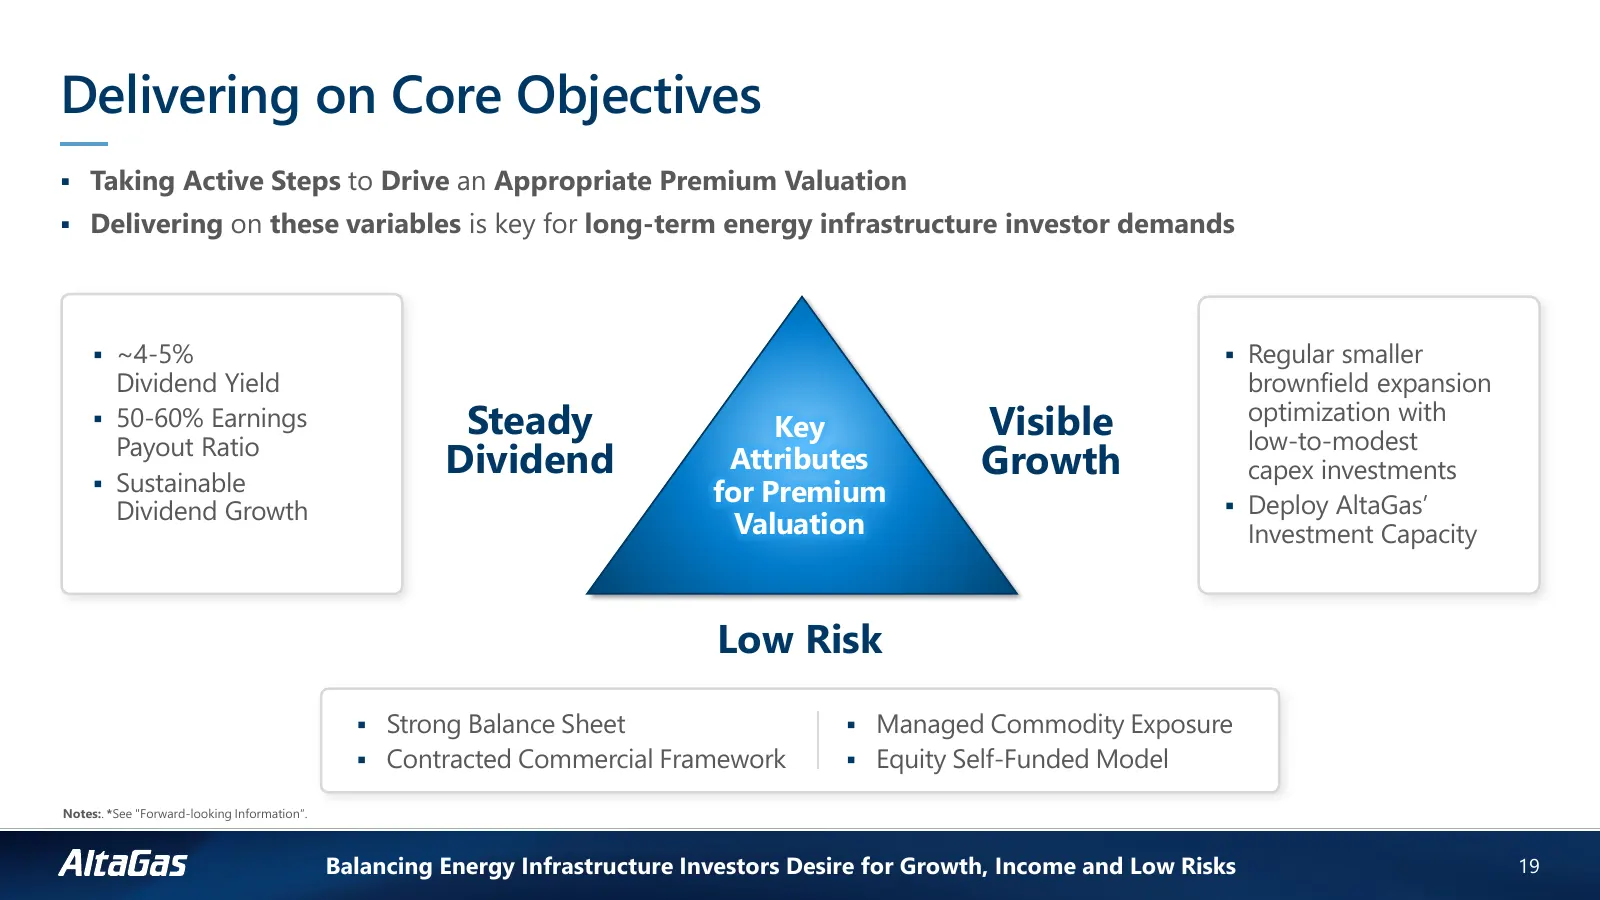
Delivering on Core Objectives ▪ Taking Active Steps to Drive an Appropriate Premium Valuation ▪ Delivering on these variables is key for long-term energy infrastructure investor demands ▪ ~4-5% ▪ Regular smaller Dividend Yield brownfield expansion ▪ 50-60% Earnings Steady Key Visible optimization wi
Slide 20: Midstream Strategic Focus
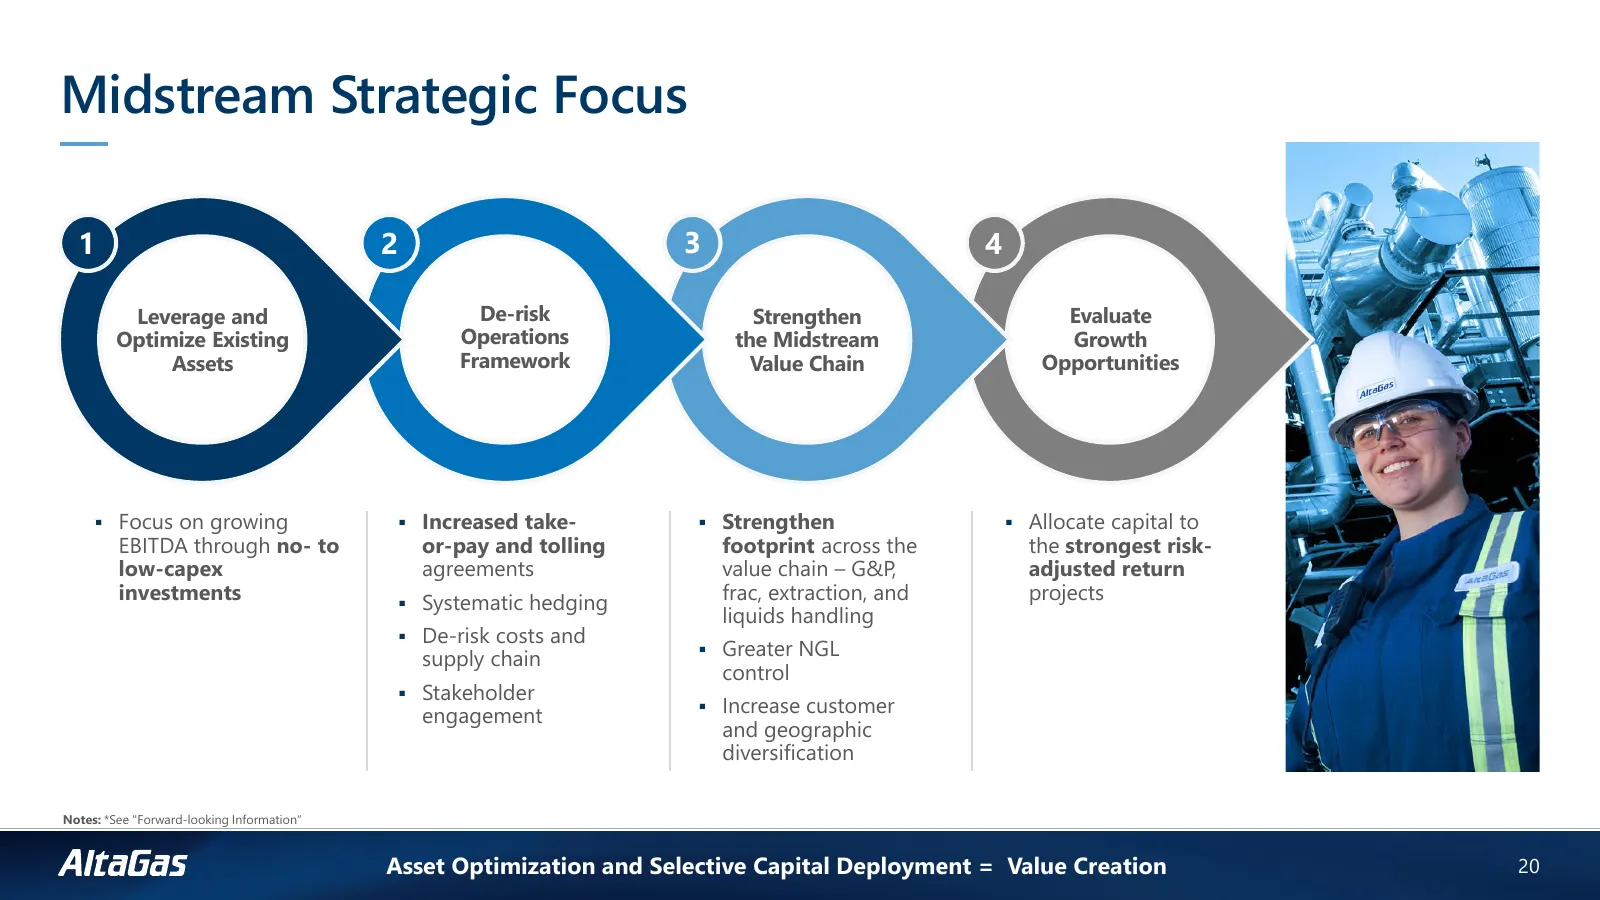
Midstream Strategic Focus 1 2 3 4 Leverage and De-risk Strengthen Evaluate Optimize Existing Operations the Midstream Growth Assets Framework Value Chain Opportunities ▪ Focus on growing ▪ Increased take- ▪ Strengthen ▪ Allocate capital to EBITDA through no- to or-pay and tolling footprint across th
Slide 21: Utilities Strategic Focus
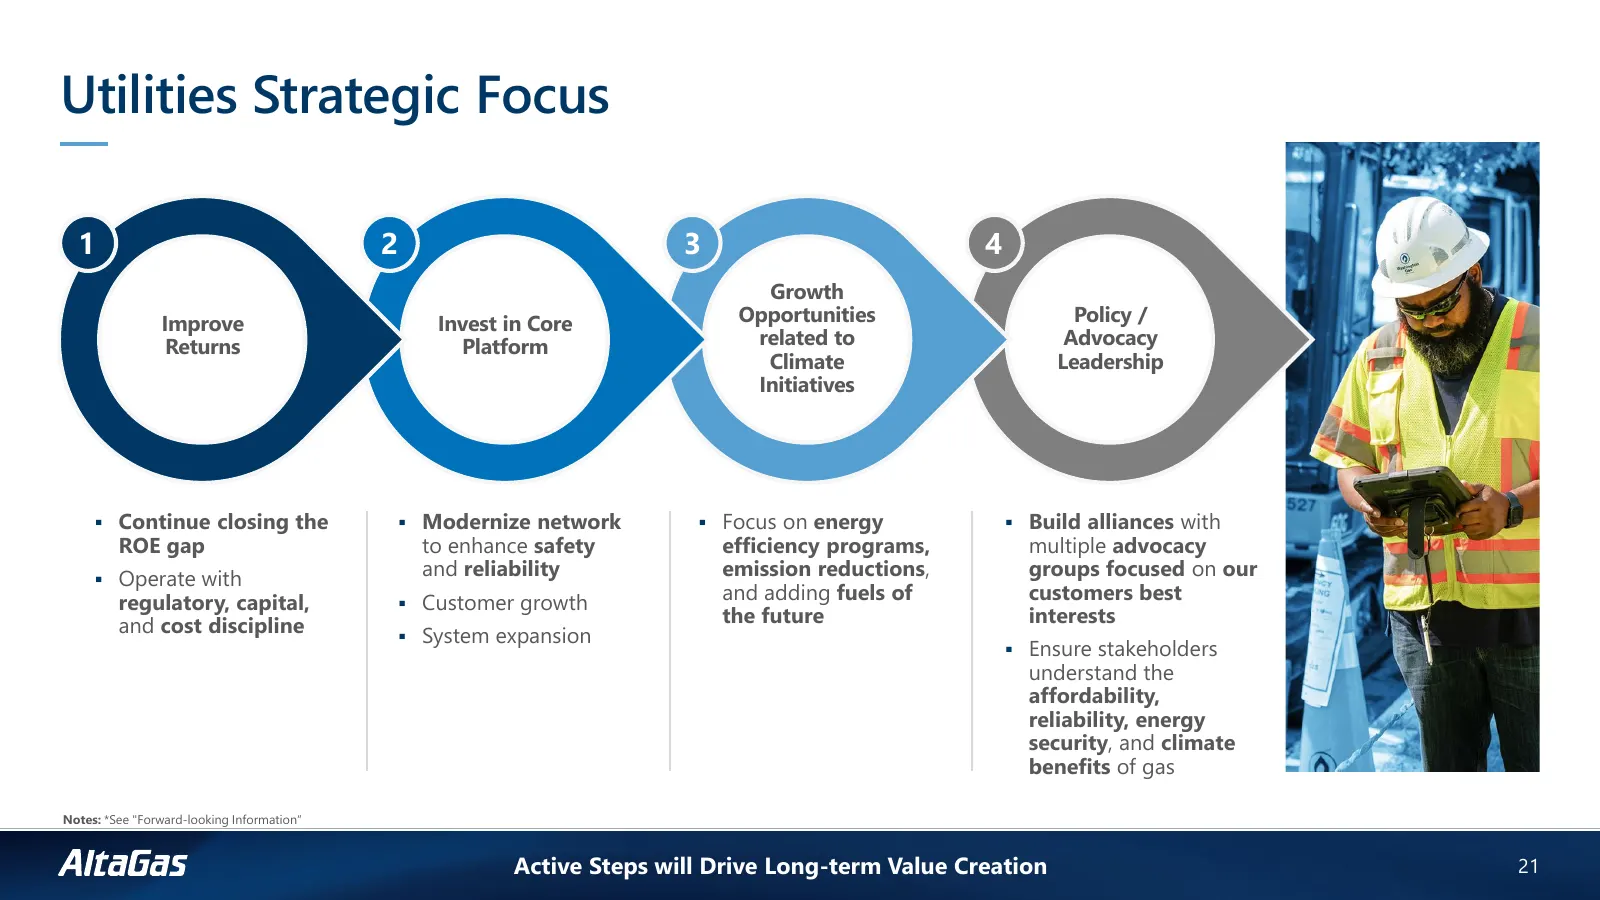
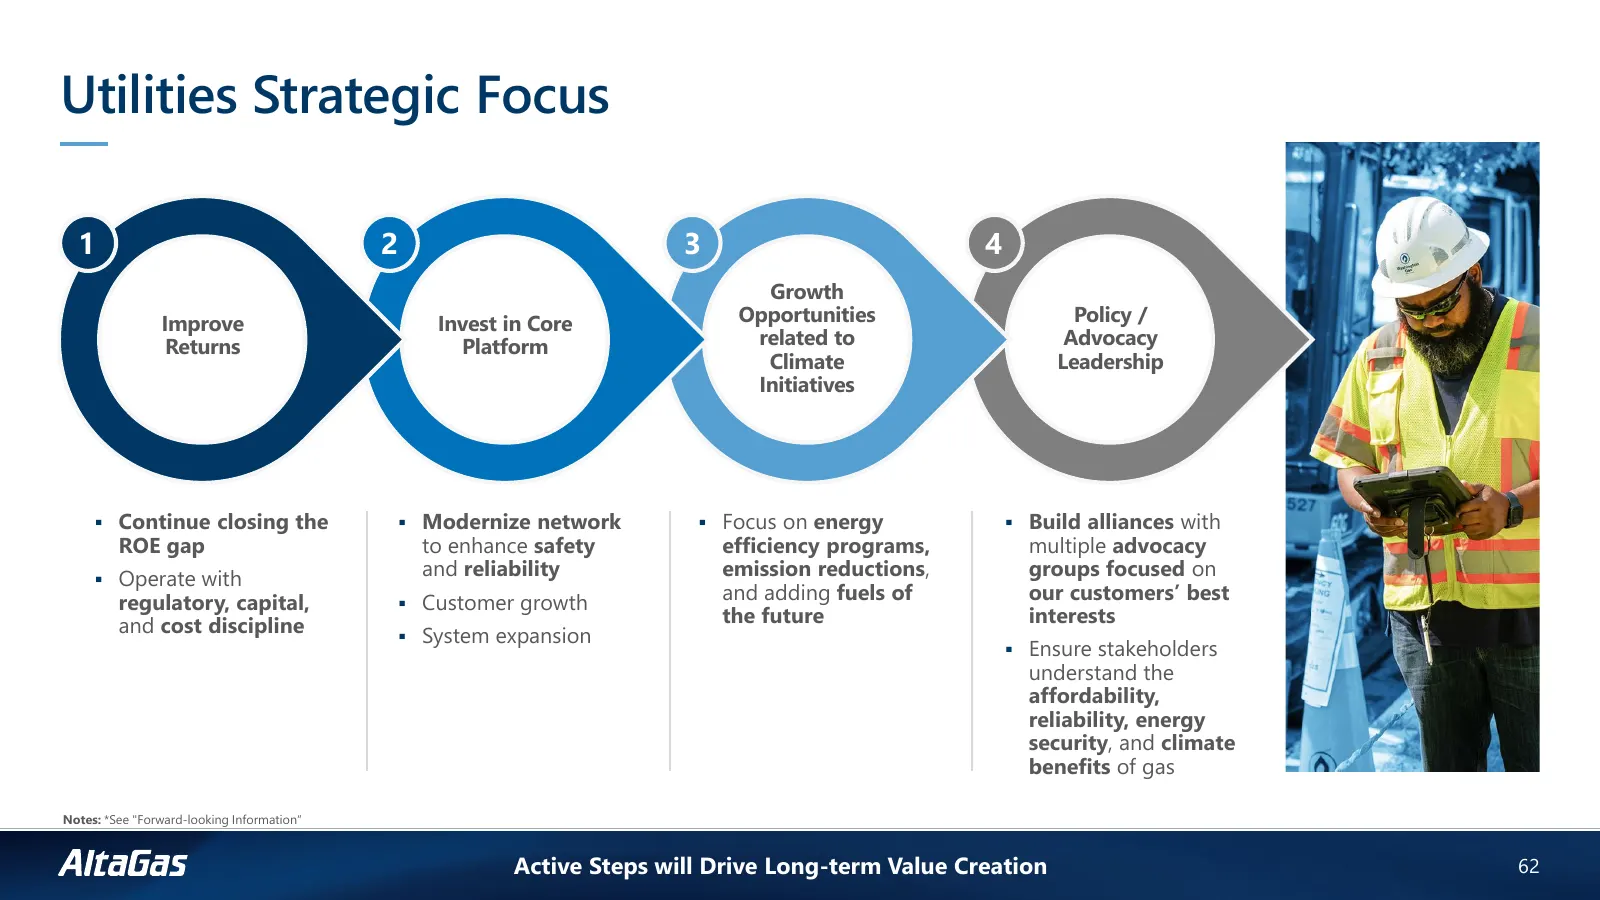
Utilities Strategic Focus 1 2 3 4 Growth Improve Invest in Core Opportunities Policy / Returns Platform related to Advocacy Climate Leadership Initiatives ▪ Continue closing the ▪ Modernize network ▪ Focus on energy ▪ Build alliances with ROE gap to enhance safety efficiency programs, multiple advoc
Slide 22: AltaGas Value Proposition
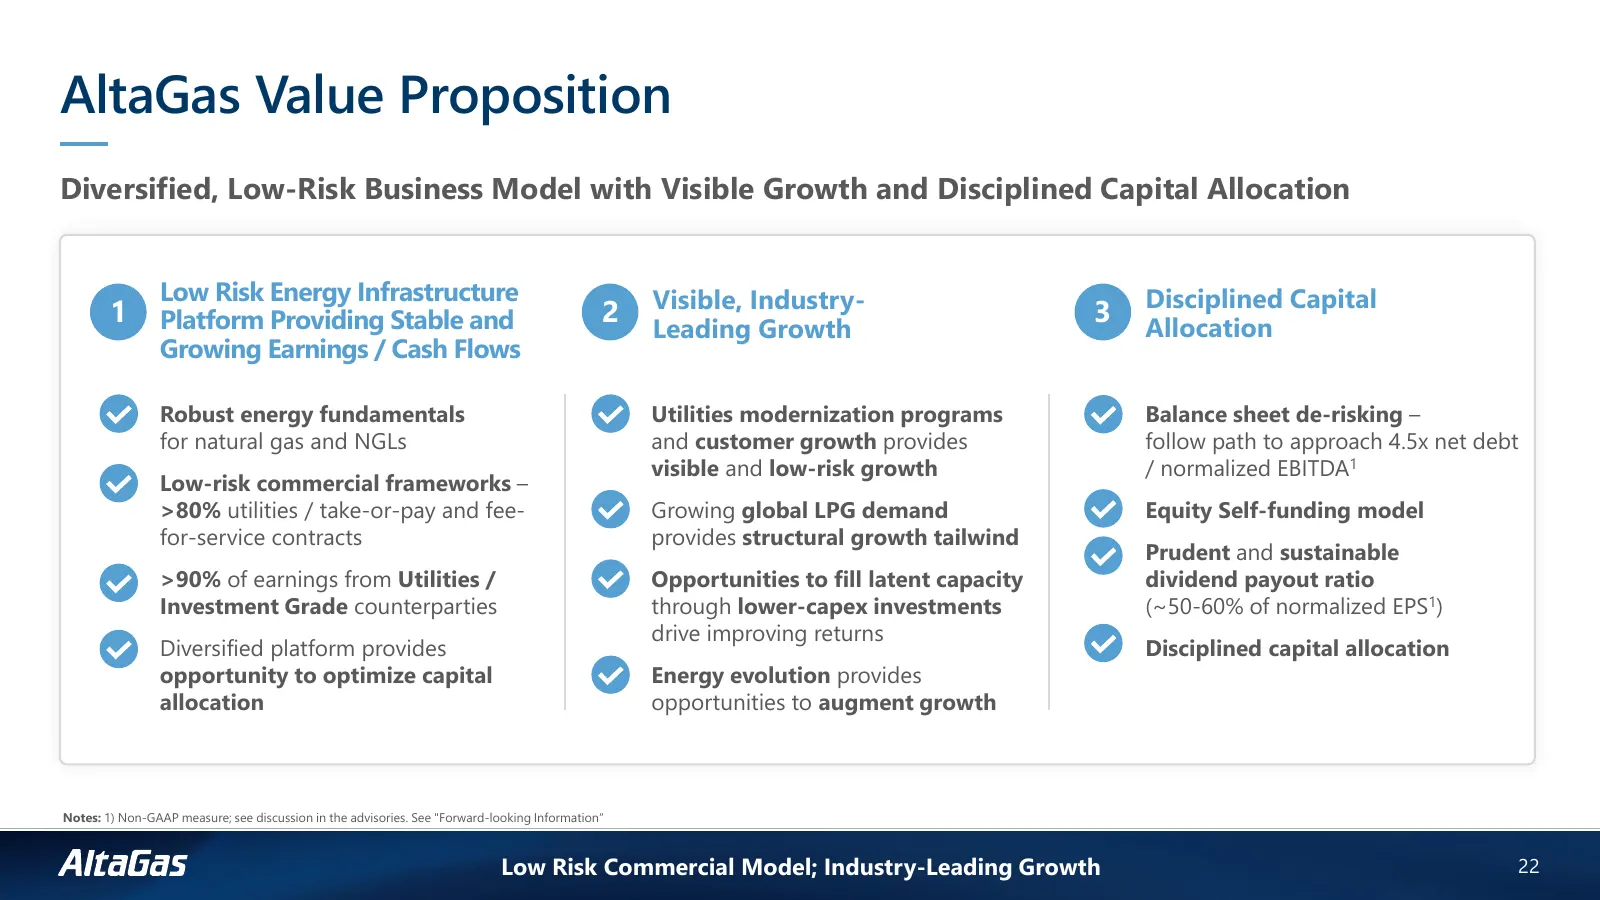
AltaGas Value Proposition Diversified, Low-Risk Business Model with Visible Growth and Disciplined Capital Allocation Low Risk Energy Infrastructure Visible, Industry- Disciplined Capital 1 Platform Providing Stable and 2 3 Leading Growth Allocation Growing Earnings / Cash Flows Robust energy fundam
Slide 23: Midstream Strategy
Midstream Strategy Randy Toone Executive Vice President and President, Midstream 23
Slide 24: Premiere, Globally Connected Midstream Platform
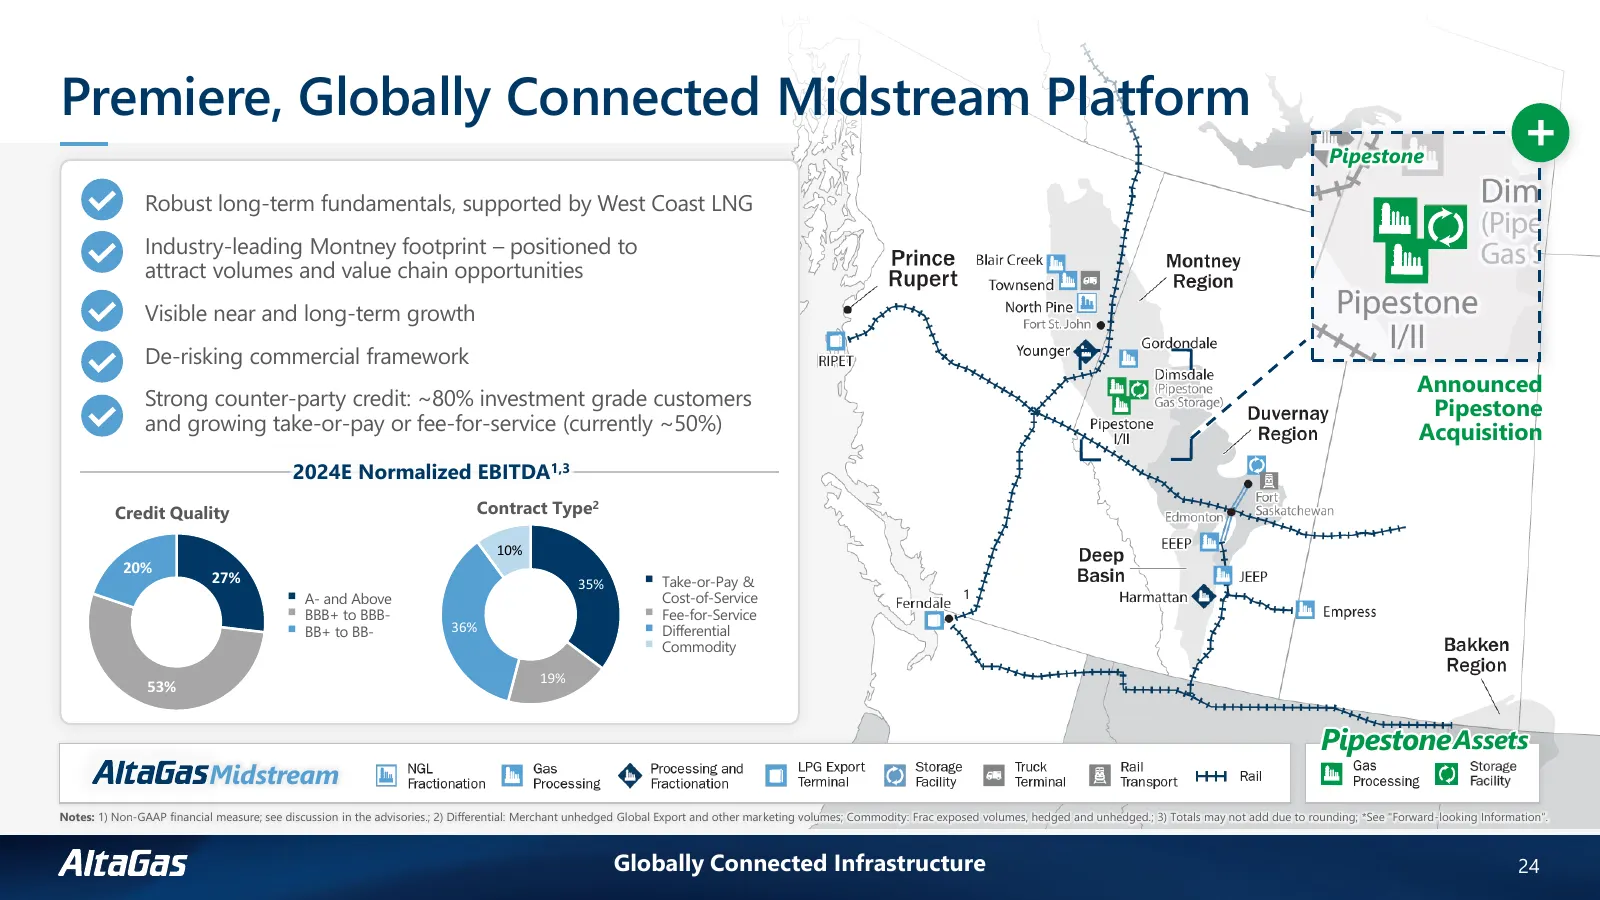
Premiere, Globally Connected Midstream Platform Pipestone + Robust long-term fundamentals, supported by West Coast LNG Industry-leading Montney footprint – positioned to attract volumes and value chain opportunities Visible near and long-term growth De-risking commercial framework Announced Strong c
Slide 25: Key Themes Driving our Forward Outlook
Key Themes Driving our Forward Outlook 1 Canada set to deliver robust natural gas and NGL production growth mid- to- late-decade for LNG exports. 2 Montney will be the key supply resource and require further infrastructure additions. 3 Growing Canadian NGL volumes best served in premiere Asian marke
Slide 26: Updates Since the Last Investor Day – December 2021
Updates Since the Last Investor Day – December 2021 What’s Been Advanced Since the Last Investor Day What Excites Us Moving Forward ▪ Optimized LPG exports – increased export volumes >20% ▪ Global exports growth and connectivity – continued through optimizing operations, logistics, and value chain.
Slide 27: Midstream Macro Outlook
Midstream Macro Outlook 27
Slide 28: Asian LPG Import Demands to Grow ~45% by 2040
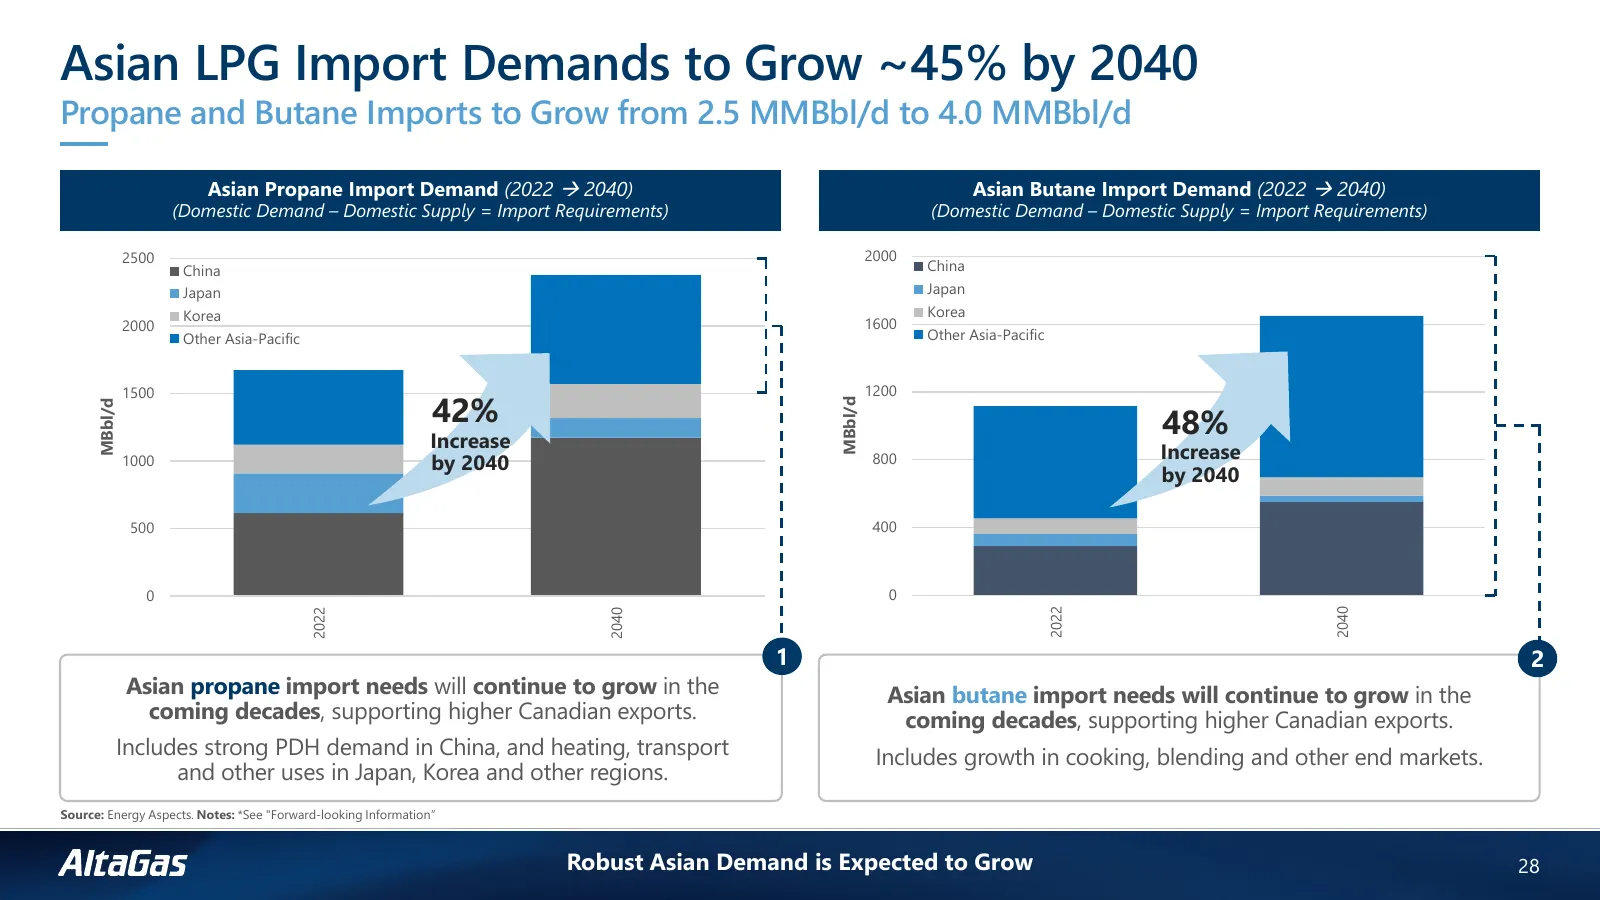
Asian LPG Import Demands to Grow ~45% by 2040 Propane and Butane Imports to Grow from 2.5 MMBbl/d to 4.0 MMBbl/d Asian Propane Import Demand (2022 → 2040) Asian Butane Import Demand (2022 → 2040) (Domestic Demand – Domestic Supply = Import Requirements) (Domestic Demand – Domestic Supply = Import Re
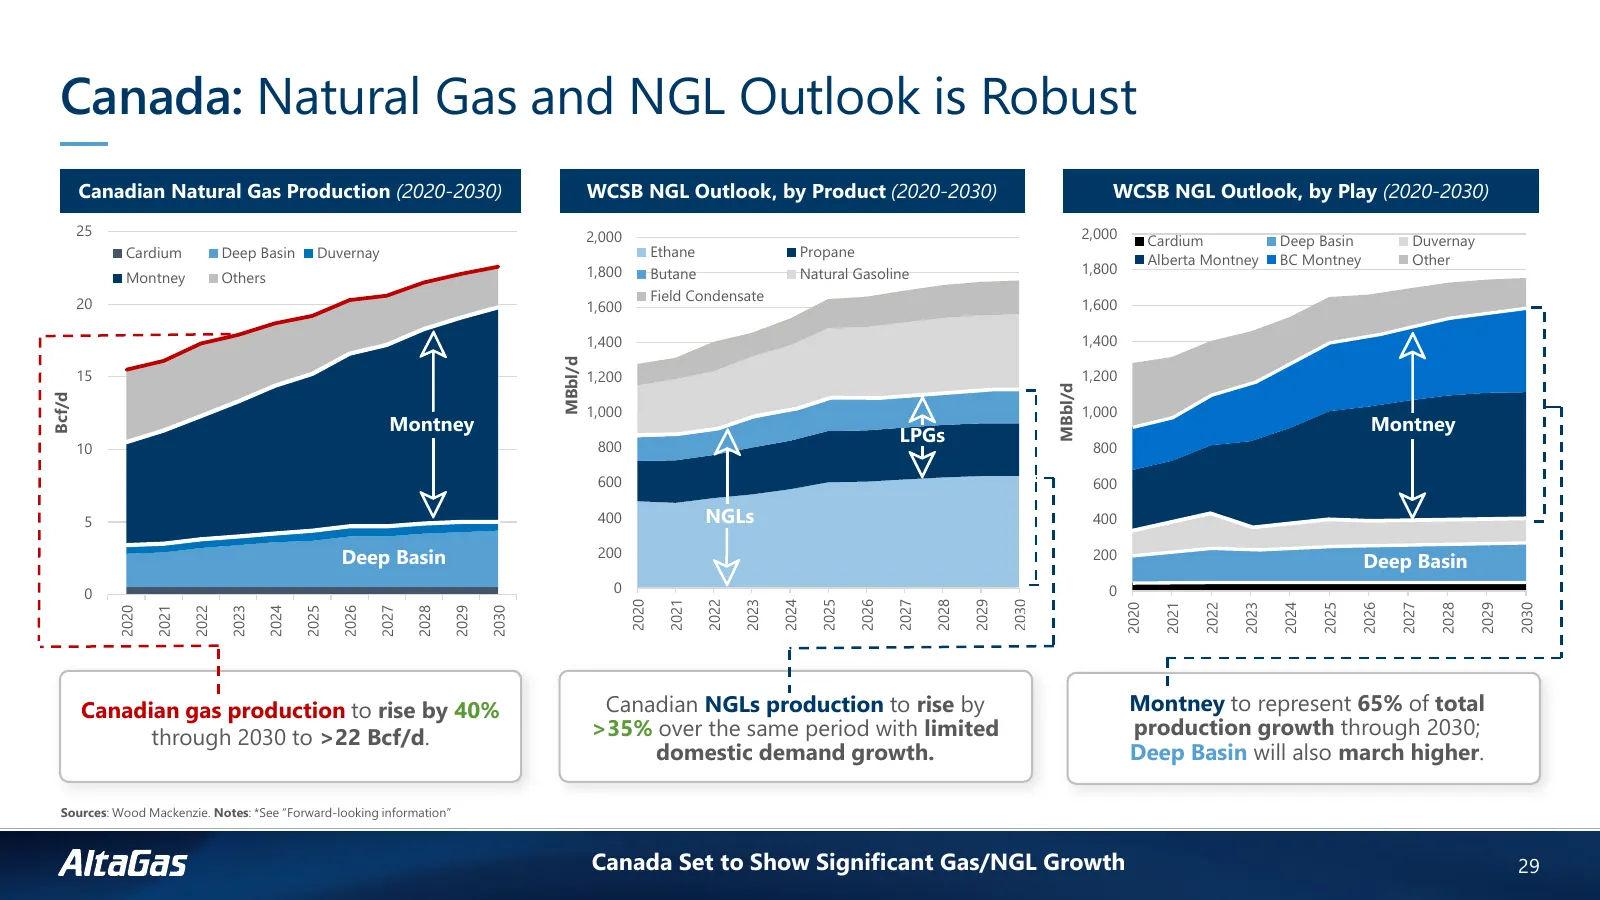
Slide 29: Canada: Natural Gas and NGL Outlook is Robust
Canada: Natural Gas and NGL Outlook is Robust Canadian Natural Gas Production (2020-2030) WCSB NGL Outlook, by Product (2020-2030) WCSB NGL Outlook, by Play (2020-2030) 25 2,000 2,000 Cardium Deep Basin Duvernay Cardium Deep Basin Duvernay Ethane Propane Alberta Montney BC Montney Other 1,800 Butane
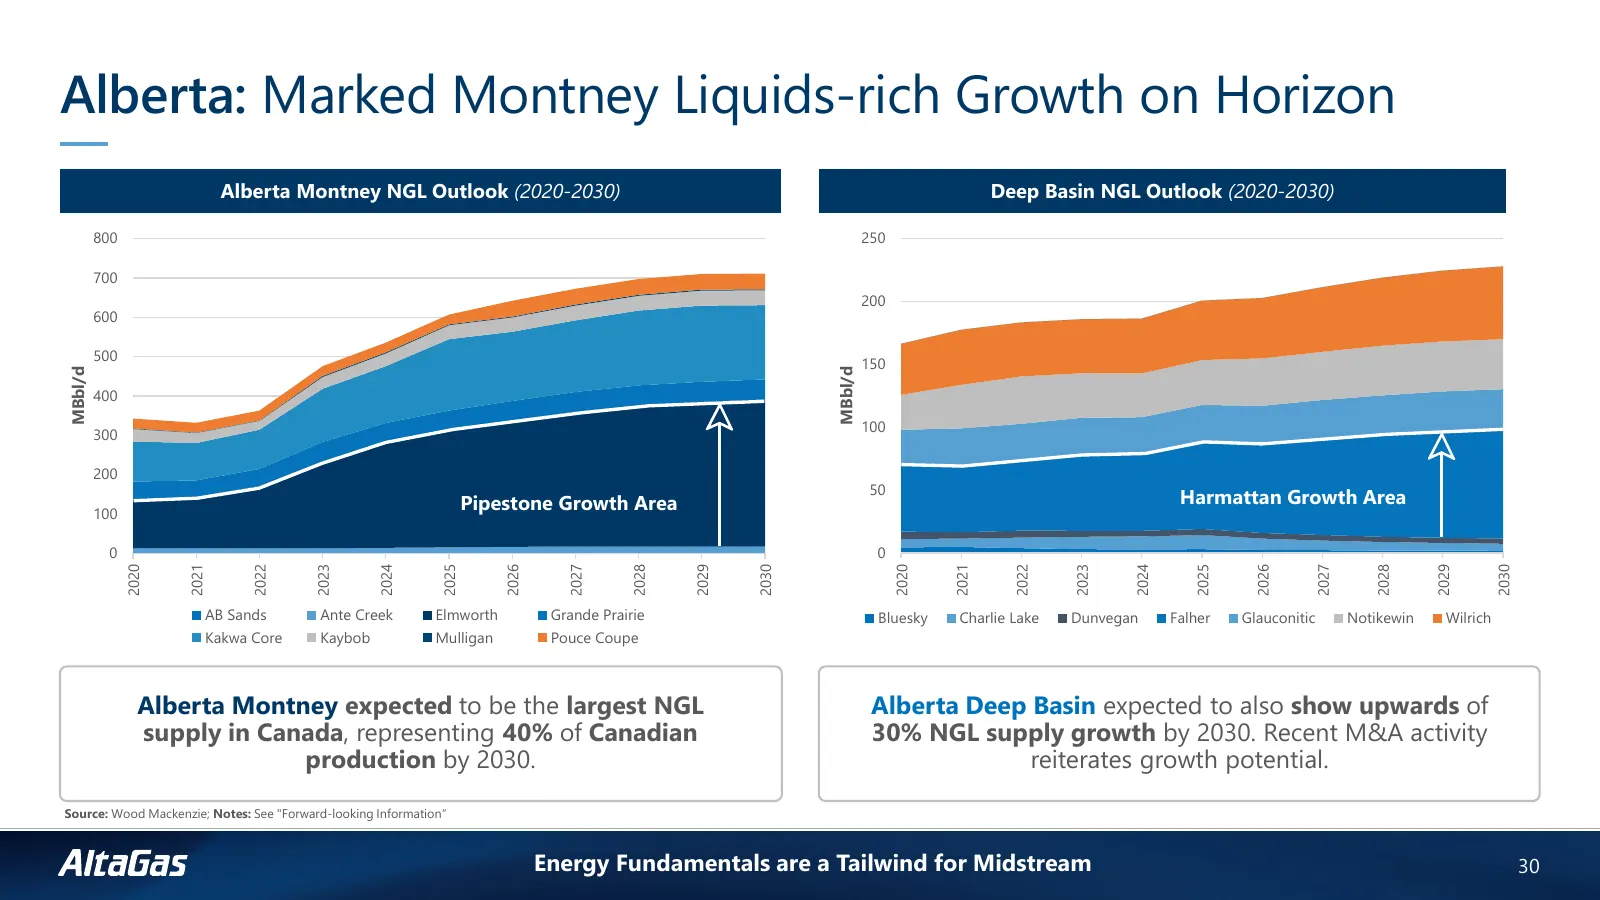
Slide 30: Alberta: Marked Montney Liquids-rich Growth on Horizon
Alberta: Marked Montney Liquids-rich Growth on Horizon Alberta Montney NGL Outlook (2020-2030) Deep Basin NGL Outlook (2020-2030) 800 250 700 200 600 500 150 MBbl/d MBbl/d 400 100 300 200 50 Pipestone Growth Area Harmattan Growth Area 100 0 0 2029 2020 2021 2022 2023 2024 2025 2026 2027 2028 2030 20
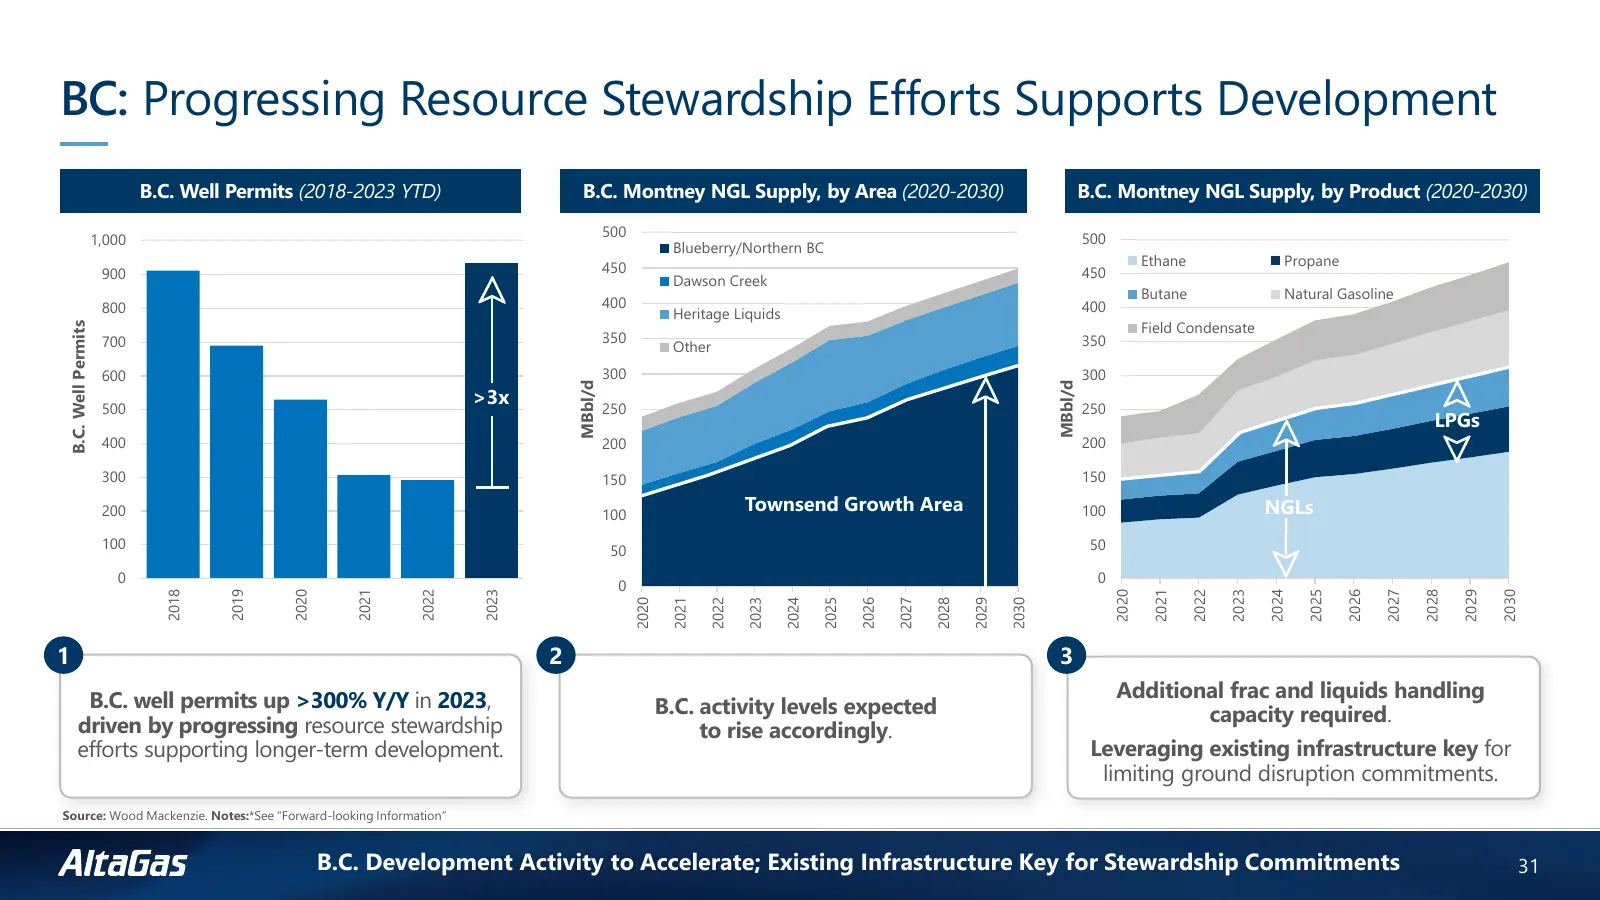
Slide 31: BC: Progressing Resource Stewardship Efforts Supports Development
BC: Progressing Resource Stewardship Efforts Supports Development B.C. Well Permits (2018-2023 YTD) B.C. Montney NGL Supply, by Area (2020-2030) B.C. Montney NGL Supply, by Product (2020-2030) 500 500 1,000 Blueberry/Northern BC 450 Ethane Propane 900 450 Dawson Creek Butane Natural Gasoline 800 400
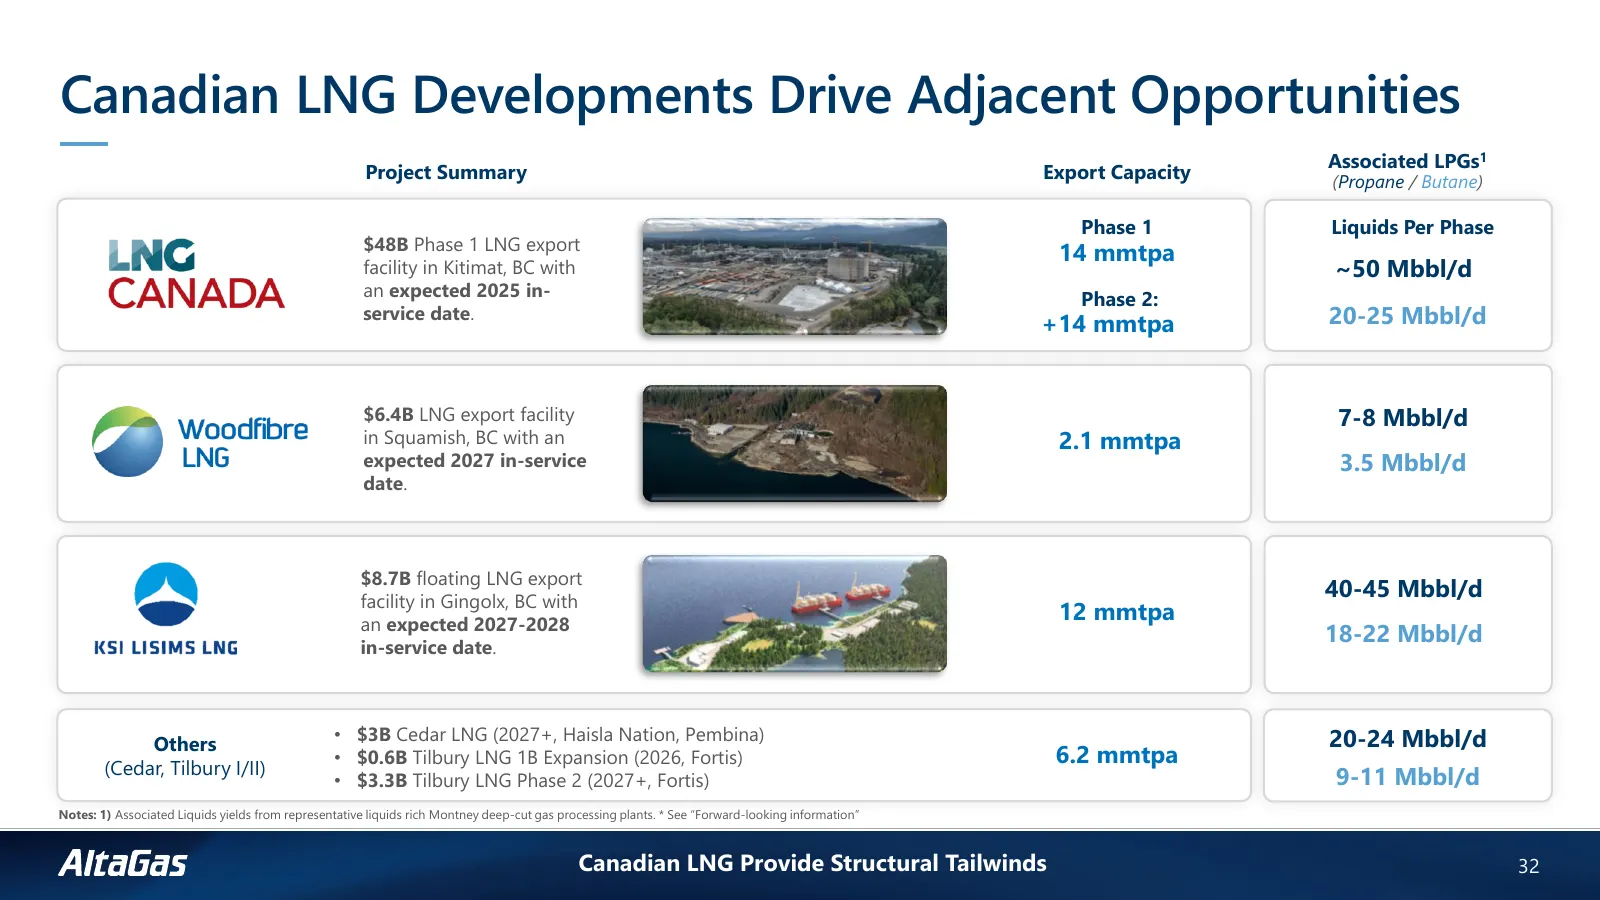
Slide 32: Canadian LNG Developments Drive Adjacent Opportunities
Canadian LNG Developments Drive Adjacent Opportunities Associated LPGs1 Project Summary Export Capacity (Propane / Butane) Phase 1 Liquids Per Phase $48B Phase 1 LNG export 14 mmtpa facility in Kitimat, BC with ~50 Mbbl/d an expected 2025 in- Phase 2: service date. +14 mmtpa 20-25 Mbbl/d $6.4B LNG e
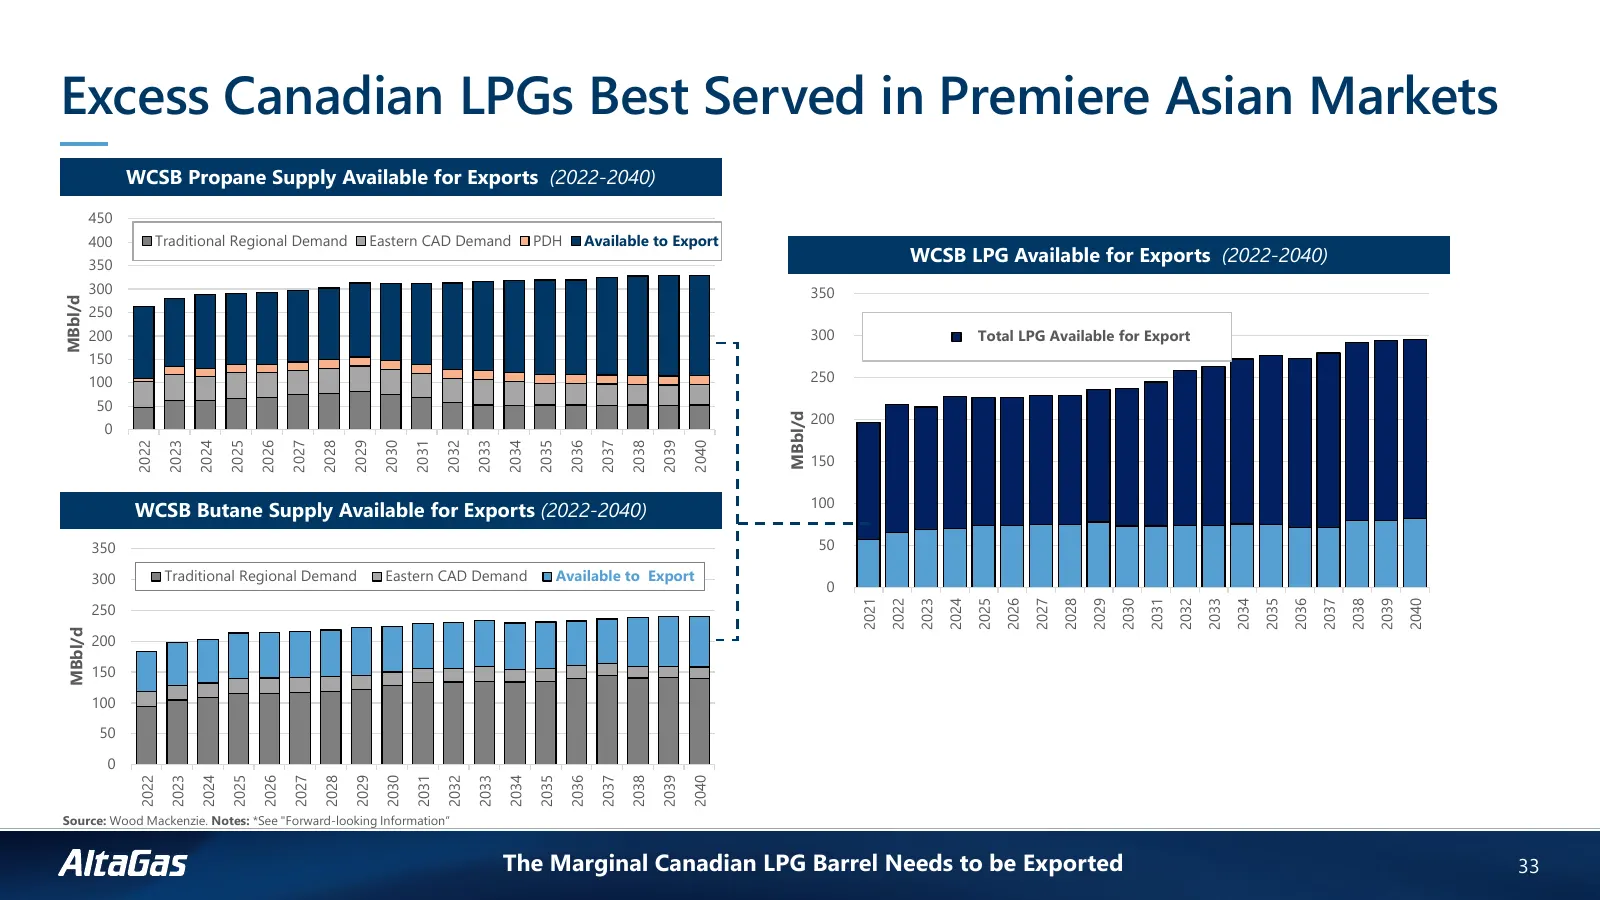
Slide 33: Excess Canadian LPGs Best Served in Premiere Asian Markets
Excess Canadian LPGs Best Served in Premiere Asian Markets WCSB Propane Supply Available for Exports (2022-2040) 450 400 Traditional Regional Demand Eastern CAD Demand PDH Available to Export 350 WCSB LPG Available for Exports (2022-2040) 300 350 MBbl/d 250 200 300 Total LPG Propane Available Availa
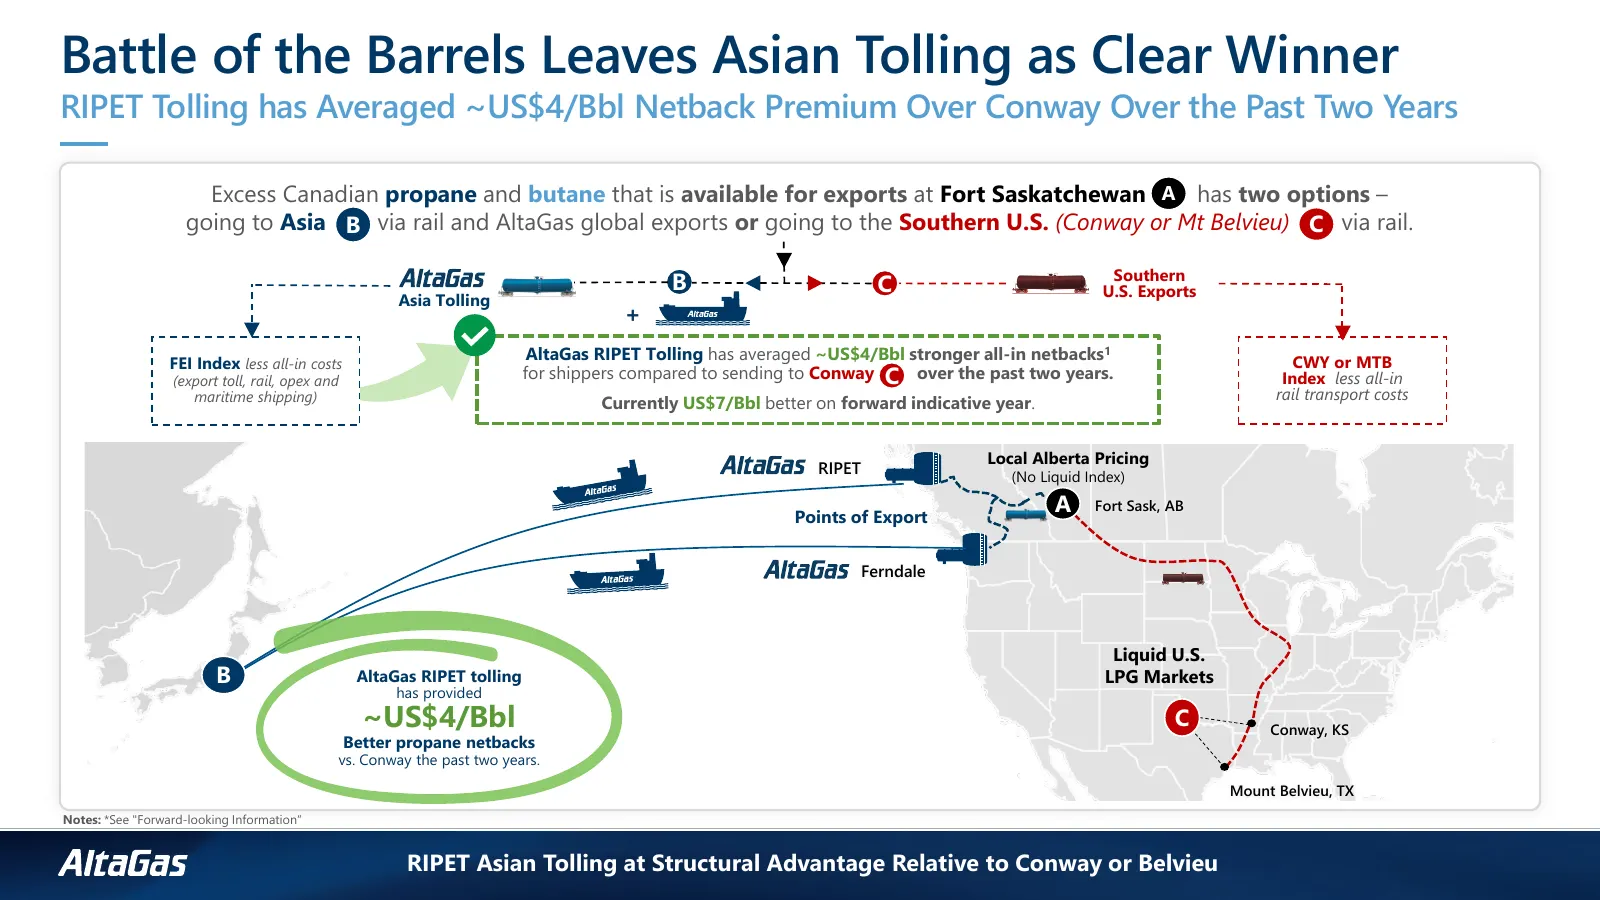
Slide 34: Battle of the Barrels Leaves Asian Tolling as Clear Winner
Battle of the Barrels Leaves Asian Tolling as Clear Winner RIPET Tolling has Averaged ~US$4/Bbl Netback Premium Over Conway Over the Past Two Years Excess Canadian propane and butane that is available for exports at Fort Saskatchewan A has two options – going to Asia B via rail and AltaGas global ex
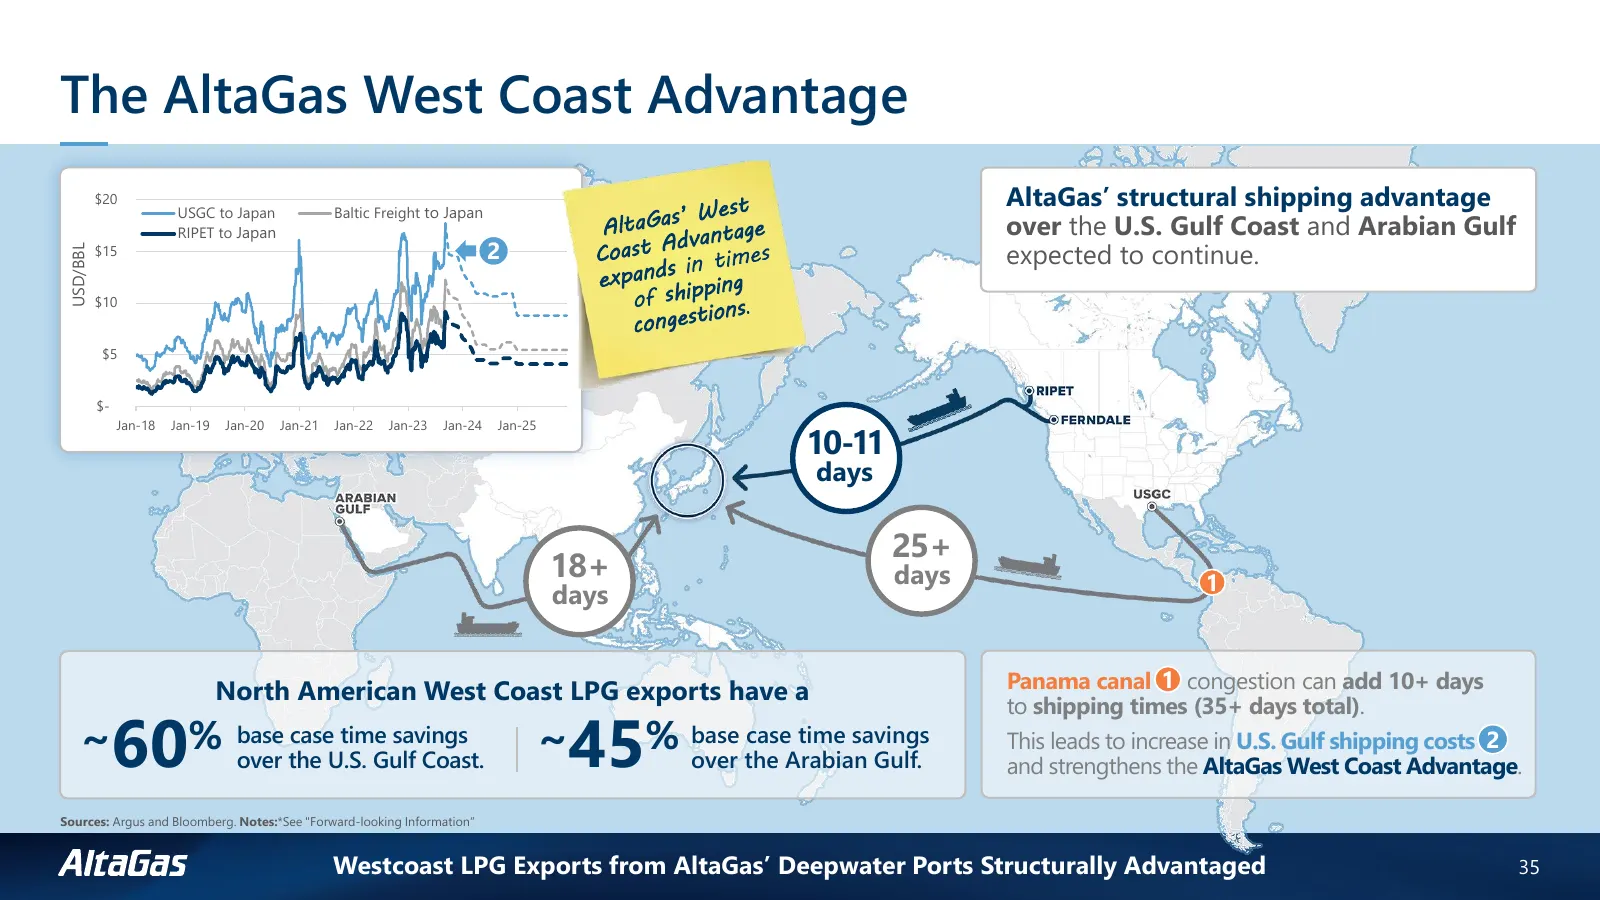
Slide 35: The AltaGas West Coast Advantage
The AltaGas West Coast Advantage $20 USGC to Japan Baltic Freight to Japan AltaGas’ structural shipping advantage RIPET to Japan Chiba over the U.S. Gulf Coast and Arabian Gulf $15 2 expected to continue. USD/BBL $10 $5 $- Jan-18 Jan-19 Jan-20 Jan-21 Jan-22 Jan-23 Jan-24 Jan-25 10-11 days 25+ 18+ da
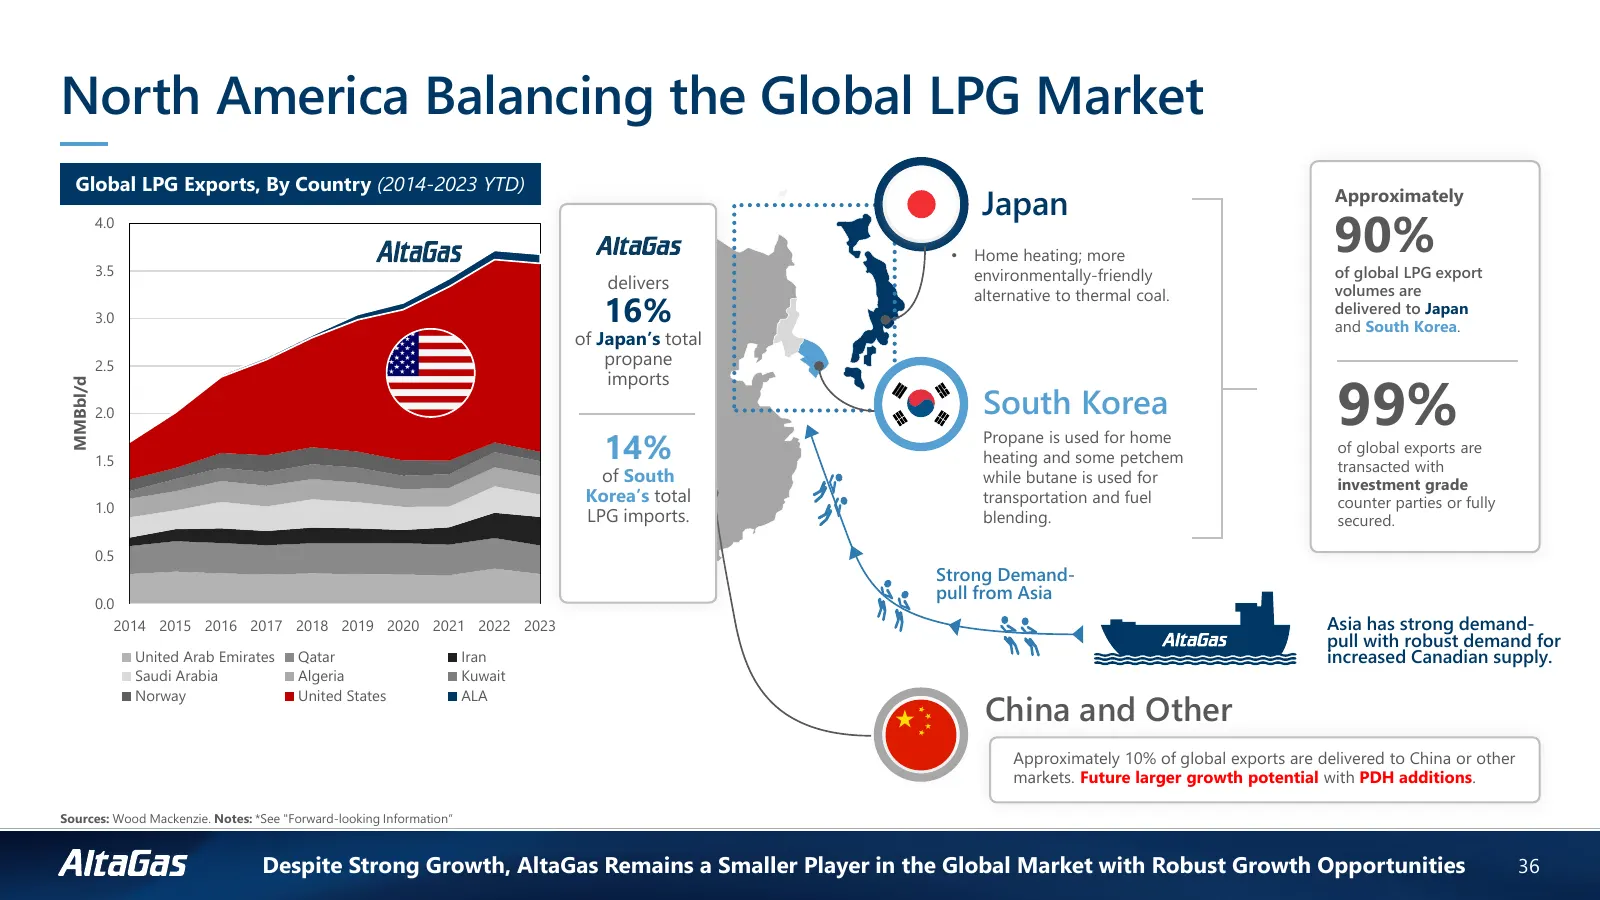
Slide 36: North America Balancing the Global LPG Market
North America Balancing the Global LPG Market Global LPG Exports, By Country (2014-2023 YTD) Japan Approximately 4.0 3.5 • Home heating; more 90% environmentally-friendly of global LPG export delivers volumes are alternative to thermal coal. 3.0 16% delivered to Japan and South Korea. of Japan’s tot
Slide 37: The Panama Problem is Real
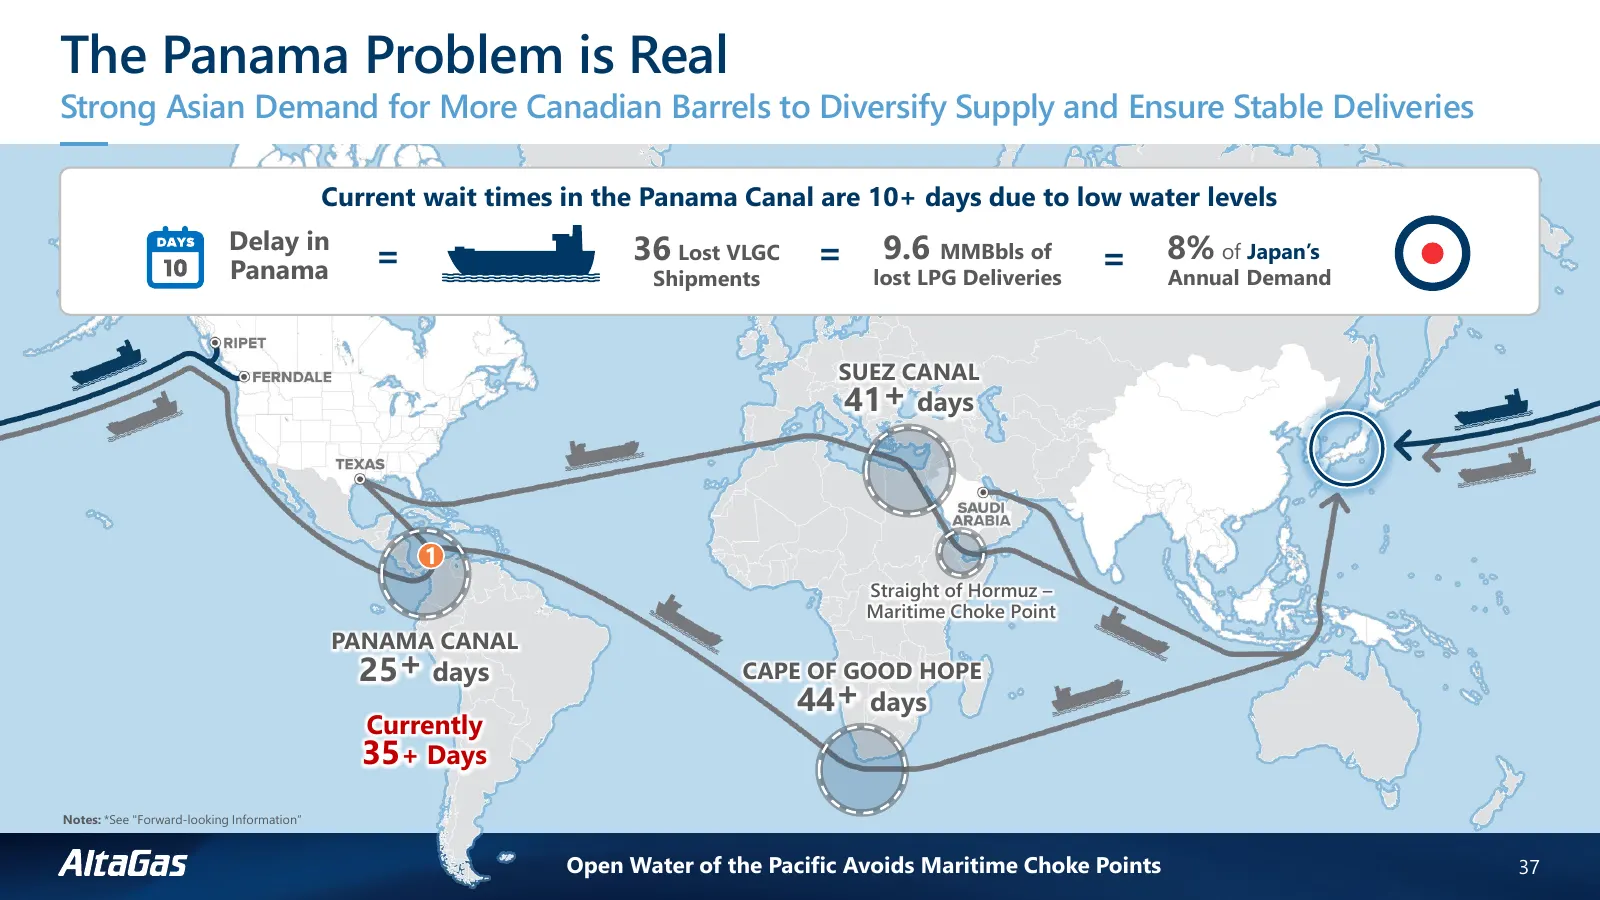
The Panama Problem is Real Strong Asian Demand for More Canadian Barrels to Diversify Supply and Ensure Stable Deliveries Current wait times in the Panama Canal are 10+ days due to low water levels Delay in 36 Lost VLGC 9.6 MMBbls of 8% of Japan’s Panama = = = Shipments lost LPG Deliveries Annual De
Slide 38: The Midstream Road Ahead
The Midstream Road Ahead | AltaGas 38
Slide 39: Midstream Strategic Focus
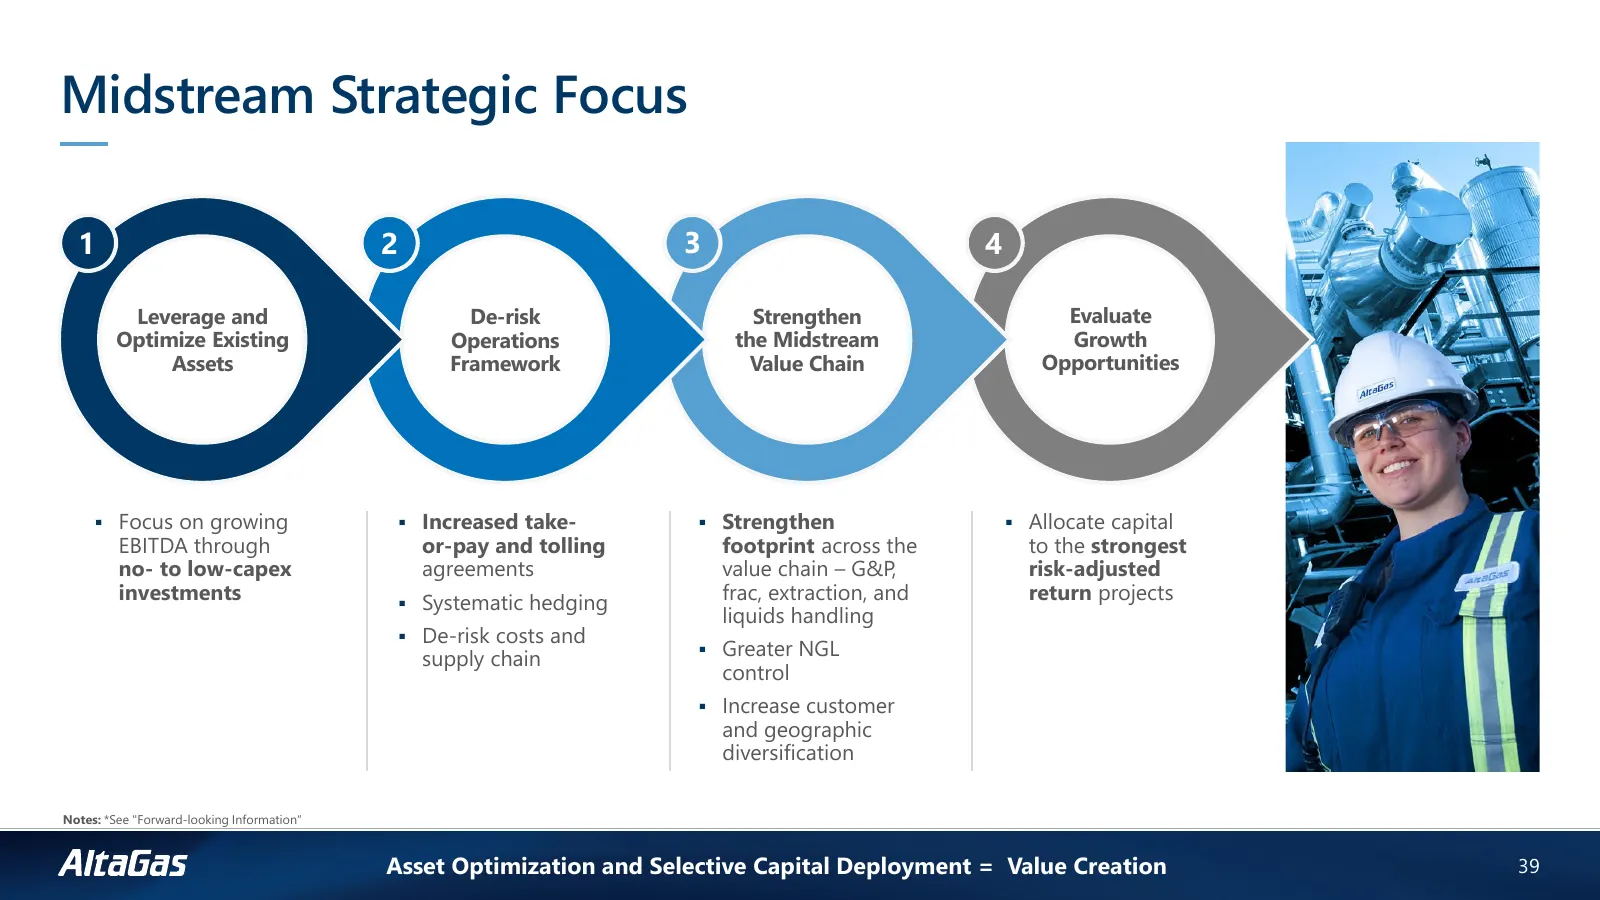
Midstream Strategic Focus 1 2 3 4 Leverage and De-risk Strengthen Evaluate Optimize Existing Operations the Midstream Growth Assets Framework Value Chain Opportunities ▪ Focus on growing ▪ Increased take- ▪ Strengthen ▪ Allocate capital EBITDA through or-pay and tolling footprint across the to the s
Slide 40: Leverage and Optimize Existing Assets
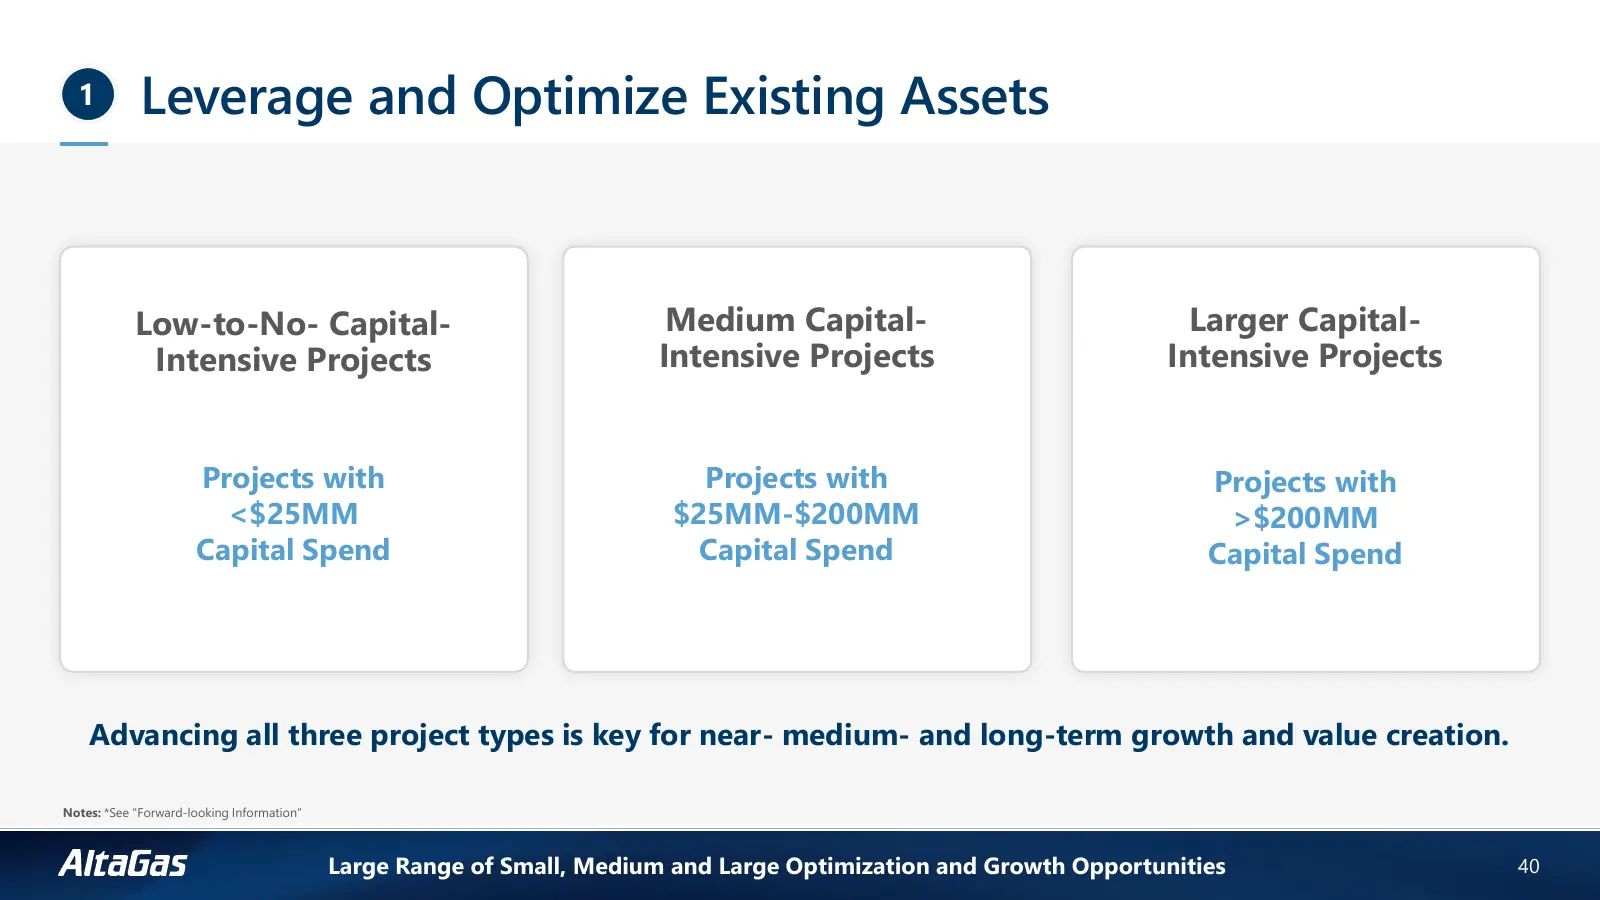
1 Leverage and Optimize Existing Assets Low-to-No- Capital- Medium Capital- Larger Capital- Intensive Projects Intensive Projects Intensive Projects Projects with Projects with Projects with <$25MM $25MM-$200MM >$200MM Capital Spend Capital Spend Capital Spend Advancing all three project types is ke
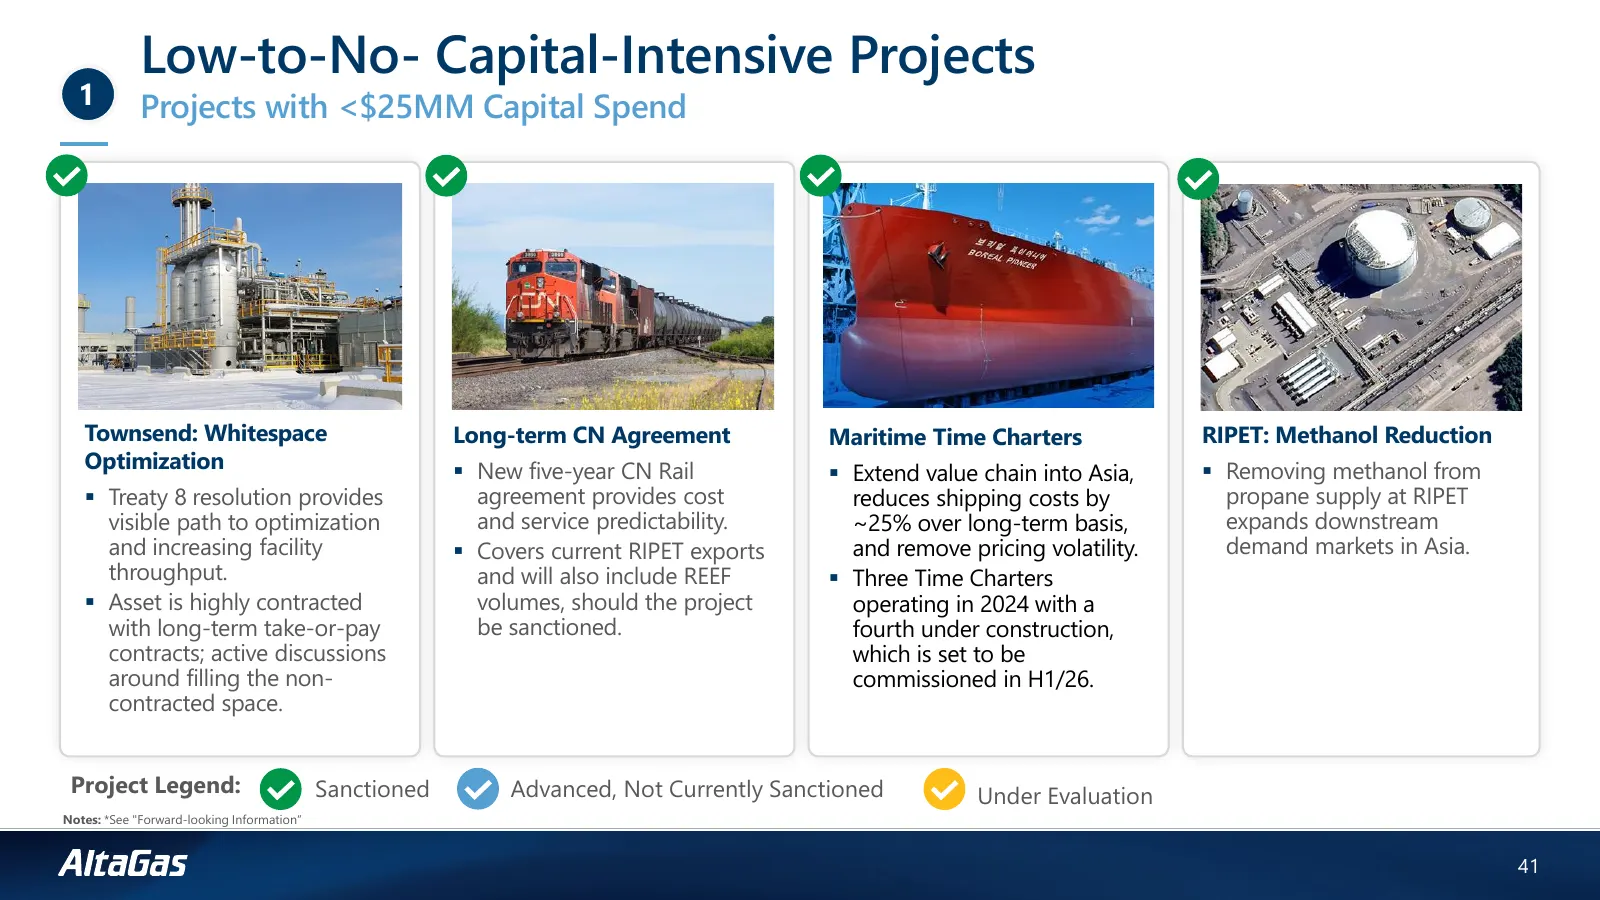
Slide 41: Low-to-No-Capital-Intensive Projects
Low-to-No- Capital-Intensive Projects 1 Projects with <$25MM Capital Spend Townsend: Whitespace Long-term CN Agreement Maritime Time Charters RIPET: Methanol Reduction Optimization ▪ New five-year CN Rail ▪ Extend value chain into Asia, ▪ Removing methanol from ▪ Treaty 8 resolution provides agreeme
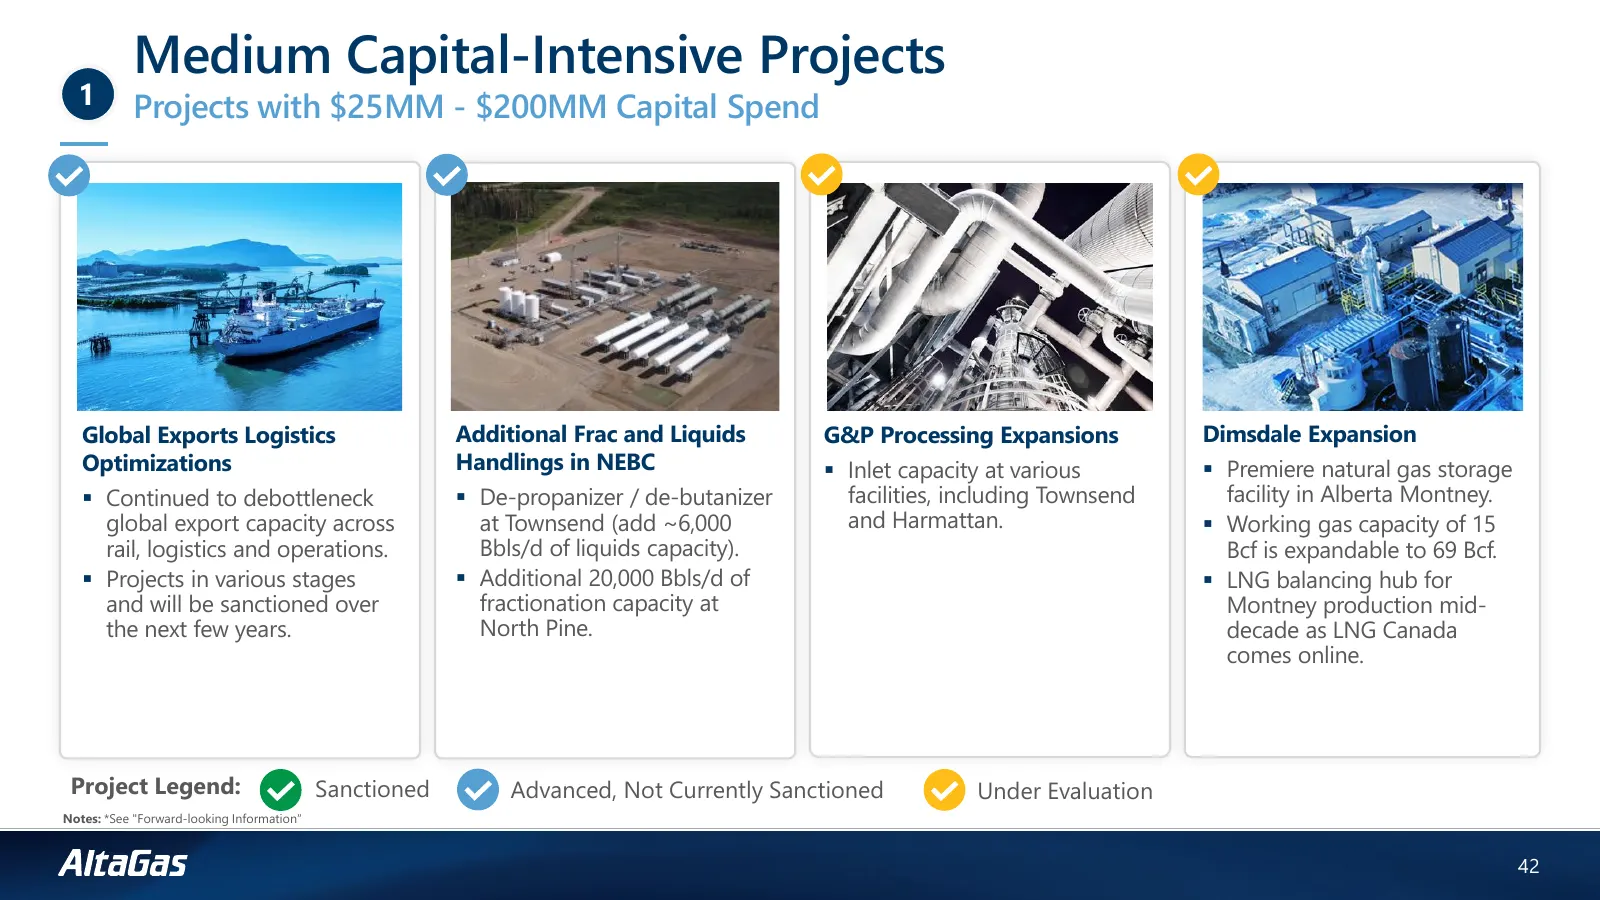
Slide 42: Medium Capital-Intensive Projects
Medium Capital-Intensive Projects 1 Projects with $25MM - $200MM Capital Spend Global Exports Logistics Additional Frac and Liquids G&P Processing Expansions Dimsdale Expansion Optimizations Handlings in NEBC ▪ Inlet capacity at various ▪ Premiere natural gas storage ▪ Continued to debottleneck ▪ De
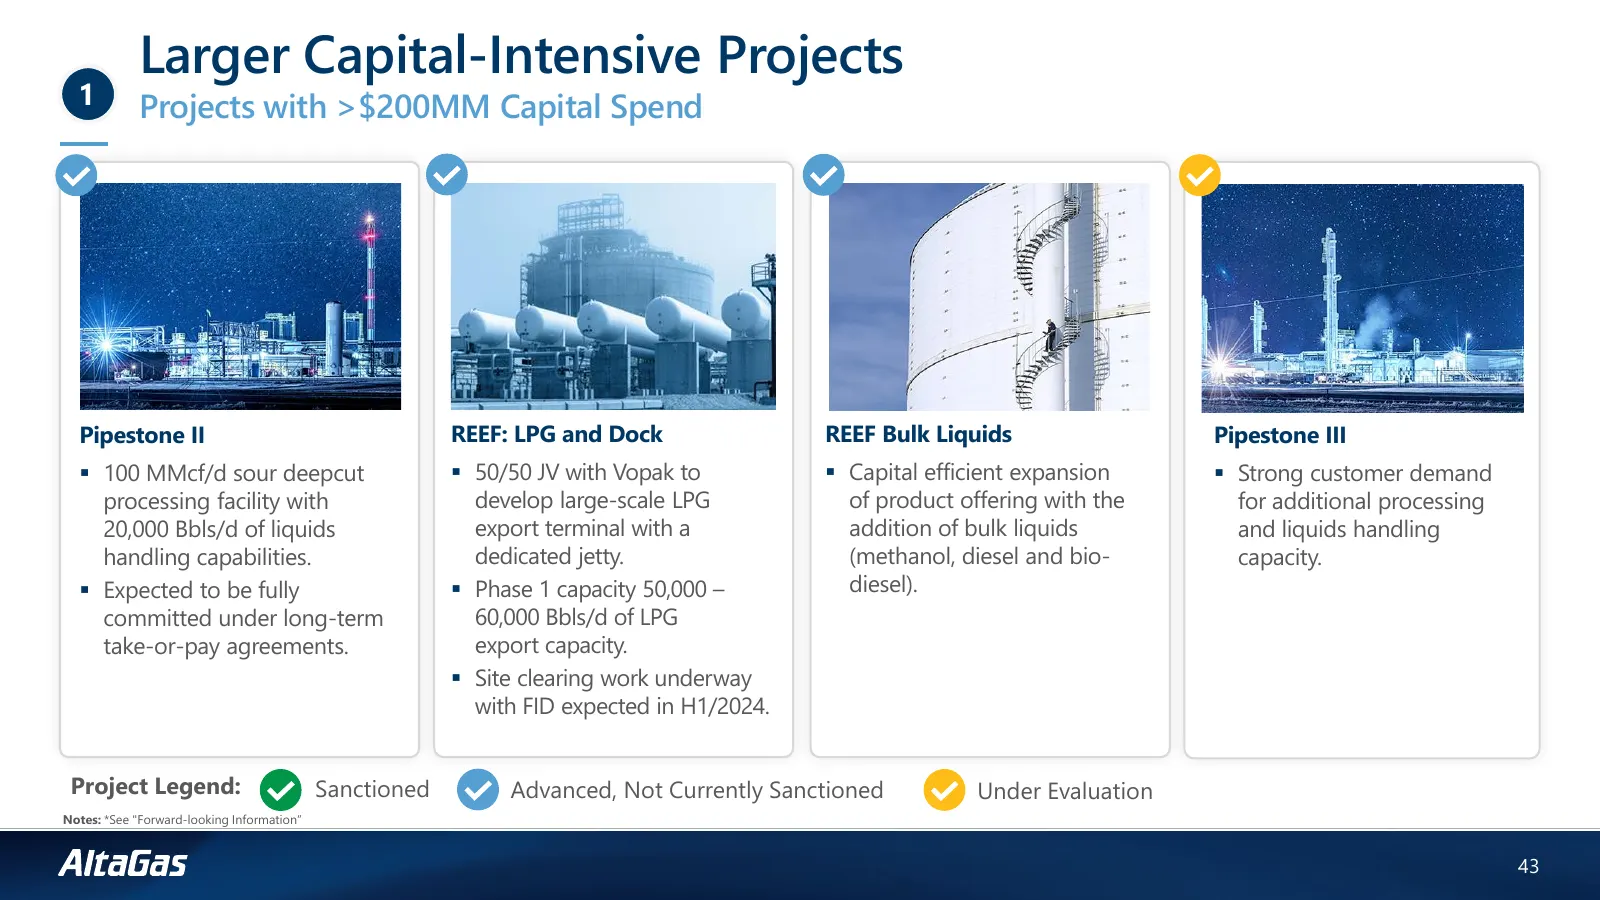
Slide 43: Larger Capital-Intensive Projects
Larger Capital-Intensive Projects 1 Projects with >$200MM Capital Spend Pipestone II REEF: LPG and Dock REEF Bulk Liquids Pipestone III ▪ 100 MMcf/d sour deepcut ▪ 50/50 JV with Vopak to ▪ Capital efficient expansion ▪ Strong customer demand processing facility with develop large-scale LPG of produc
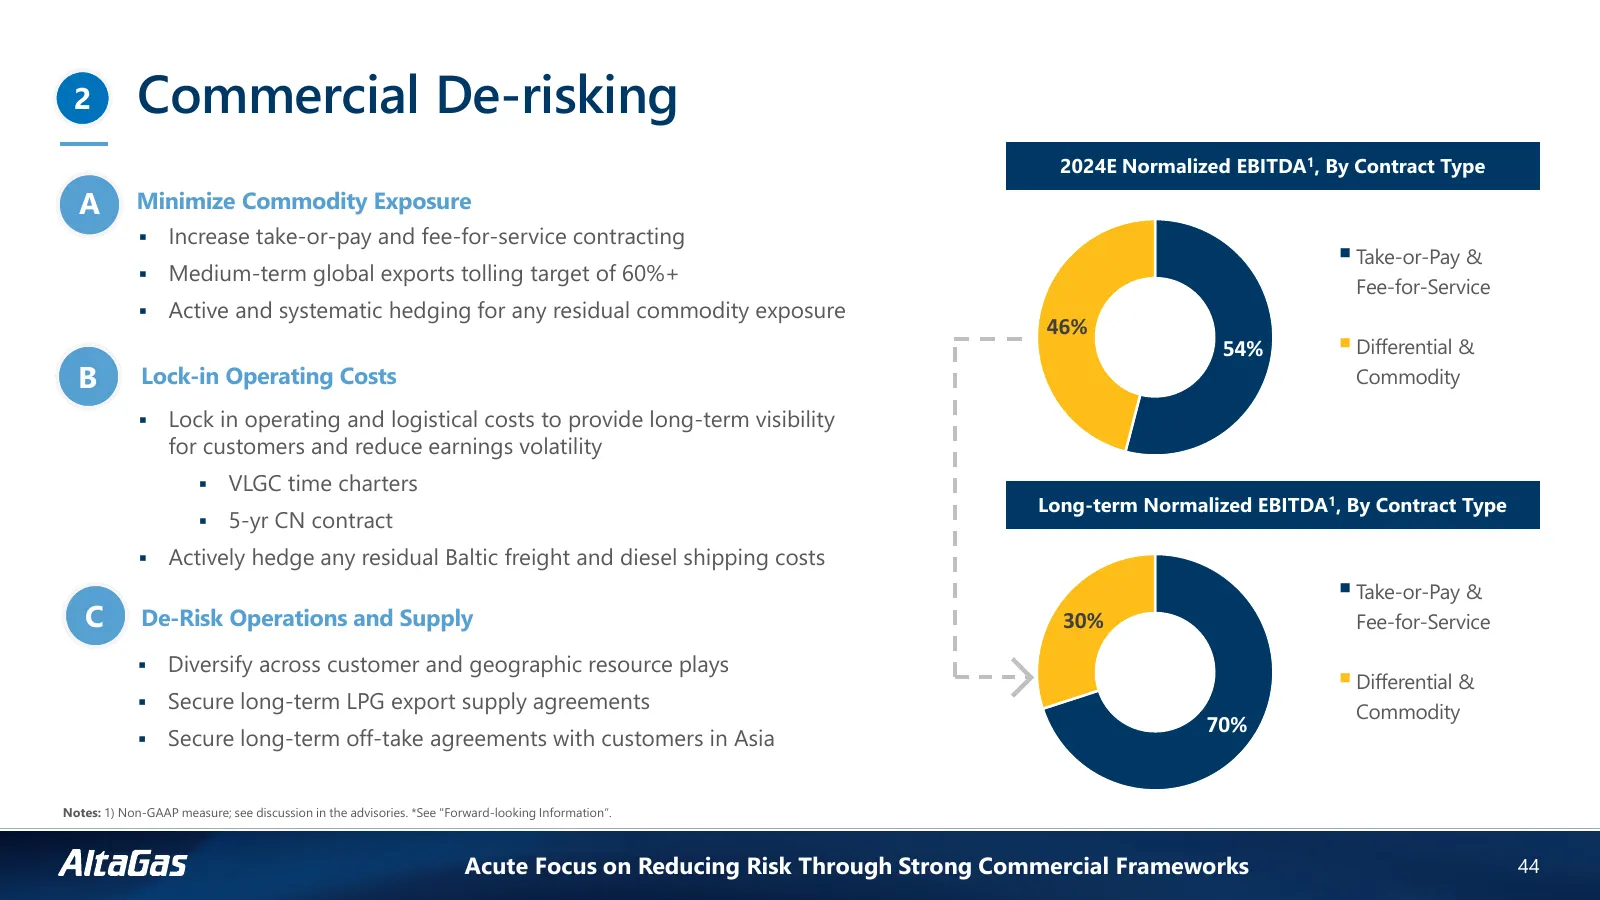
Slide 44: Commercial De-risking
2 Commercial De-risking 2024E Normalized EBITDA1, By Contract Type A Minimize Commodity Exposure ▪ Increase take-or-pay and fee-for-service contracting ▪ Take-or-Pay & ▪ Medium-term global exports tolling target of 60%+ Fee-for-Service ▪ Active and systematic hedging for any residual commodity expos
Slide 45: Global Exports Tolling
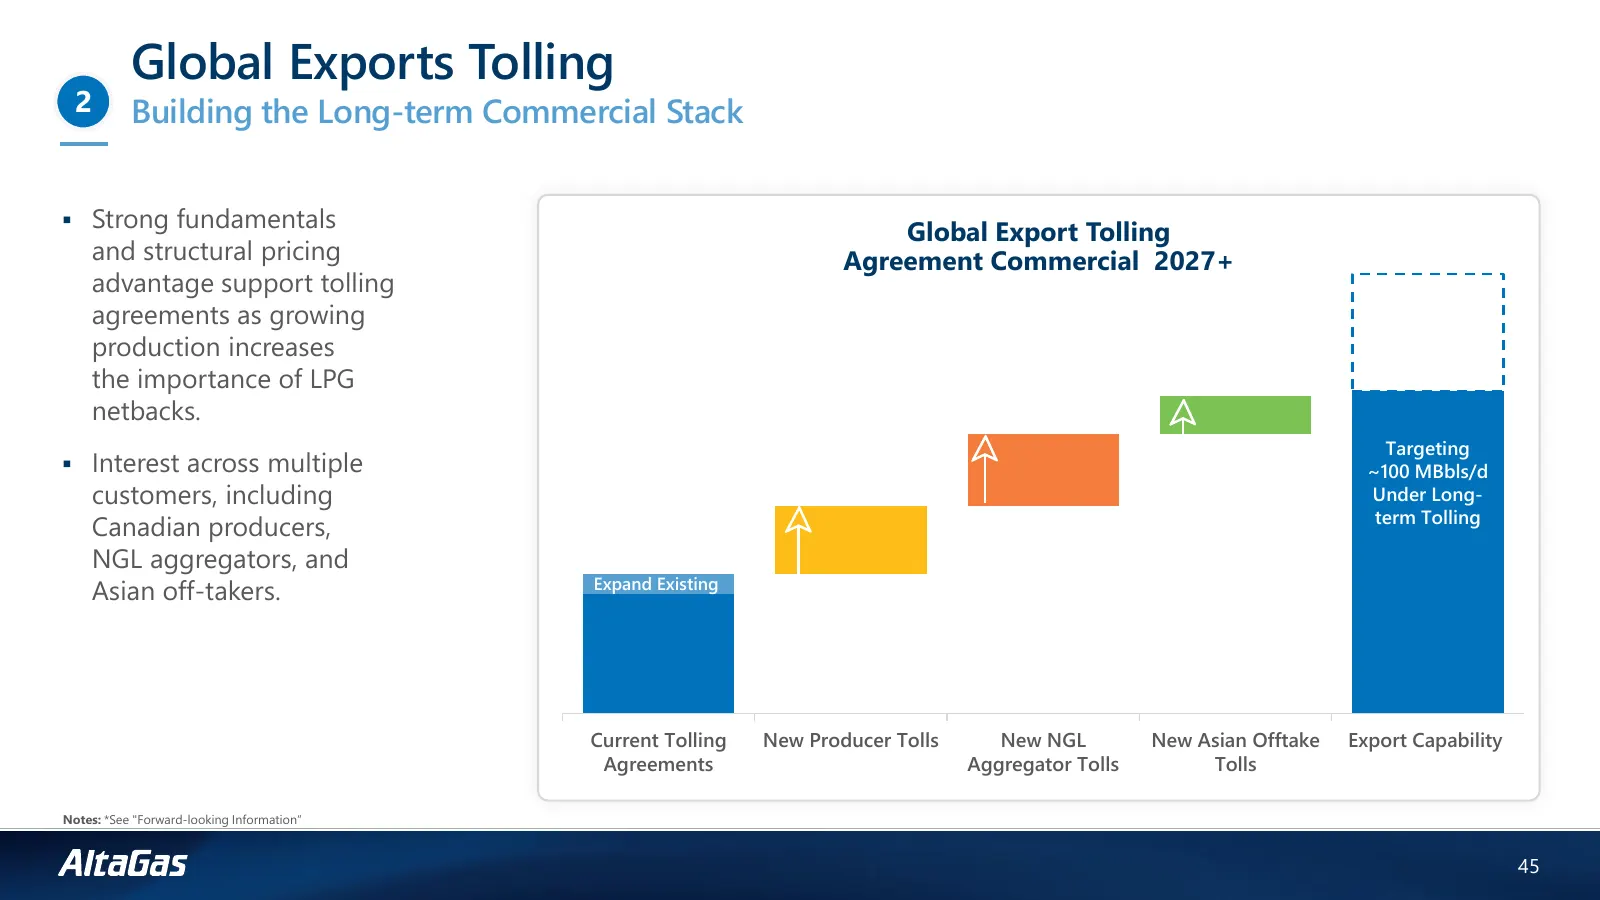
Global Exports Tolling 2 Building the Long-term Commercial Stack ▪ Strong fundamentals Global Export Tolling and structural pricing Agreement Commercial 2027+ advantage support tolling agreements as growing production increases the importance of LPG netbacks. Targeting ▪ Interest across multiple ~10
Slide 46: Strengthening the AltaGas Value Chain
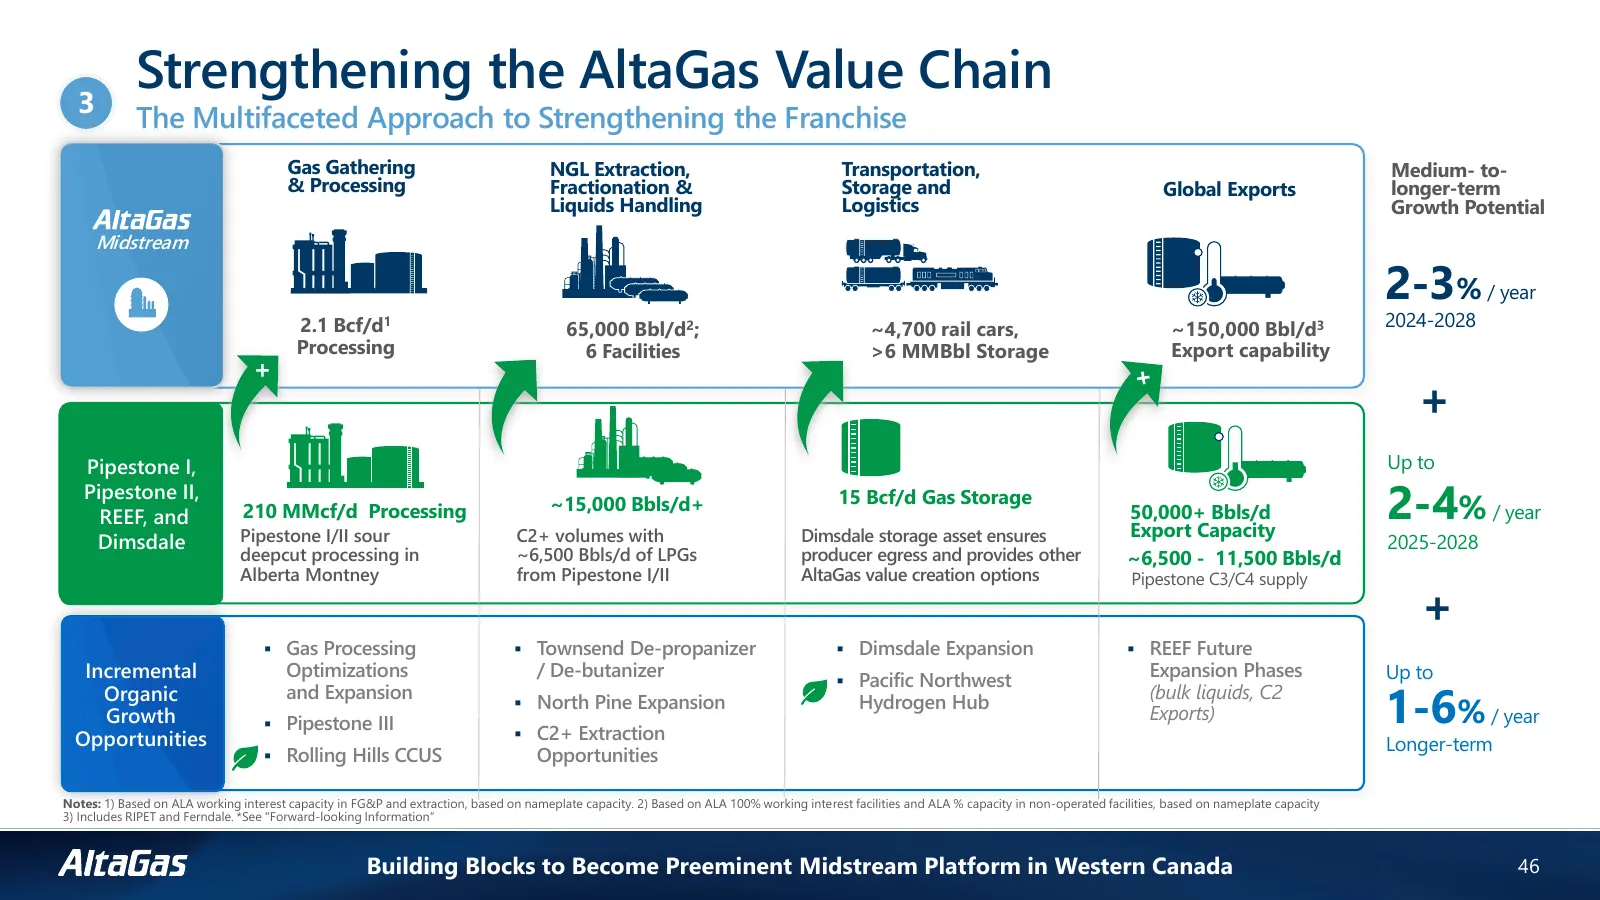
3 Strengthening the AltaGas Value Chain The Multifaceted Approach to Strengthening the Franchise Gas Gathering NGL Extraction, Transportation, Medium- to- & Processing Fractionation & Storage and Global Exports longer-term Liquids Handling Logistics Growth Potential Midstream 2-3% / year 2.1 Bcf/d1
Slide 47: Pipestone Acquisition
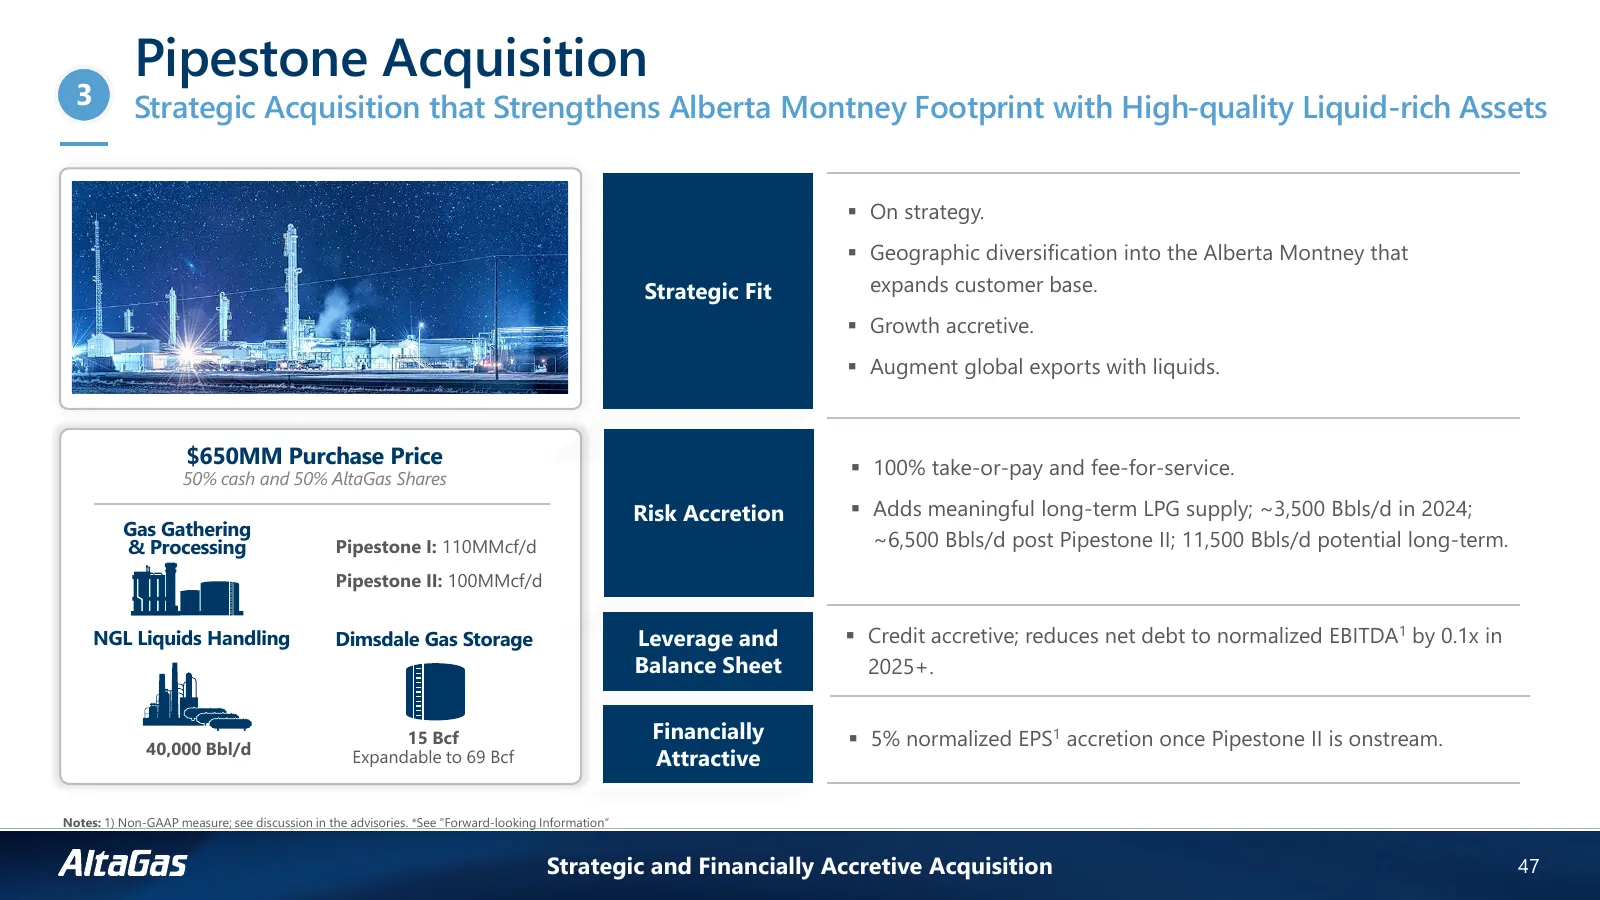
Pipestone Acquisition 3 Strategic Acquisition that Strengthens Alberta Montney Footprint with High-quality Liquid-rich Assets ▪ On strategy. ▪ Geographic diversification into the Alberta Montney that Strategic Fit expands customer base. ▪ Growth accretive. ▪ Augment global exports with liquids. $650
Slide 48: Global Exports Optimization and Growth
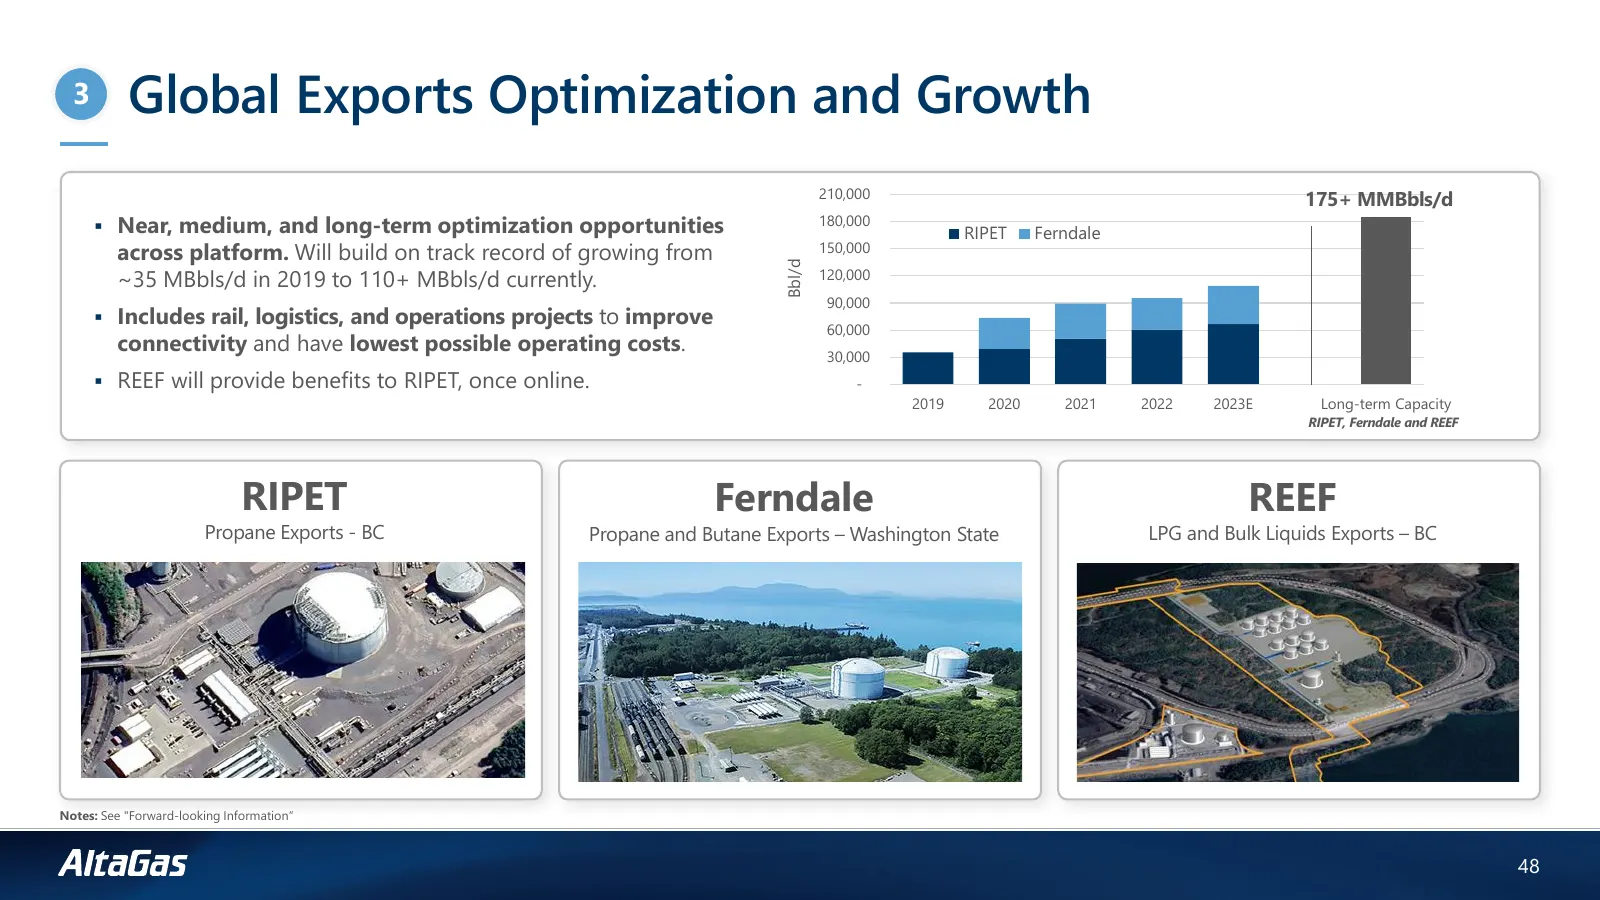
3 Global Exports Optimization and Growth 210,000 175+ MMBbls/d ▪ Near, medium, and long-term optimization opportunities 180,000 RIPET Ferndale across platform. Will build on track record of growing from 150,000 Bbl/d ~35 MBbls/d in 2019 to 110+ MBbls/d currently. 120,000 90,000 ▪ Includes rail, logi
Slide 49: Rolling Hills and Pacific Northwest Hydrogen Hub
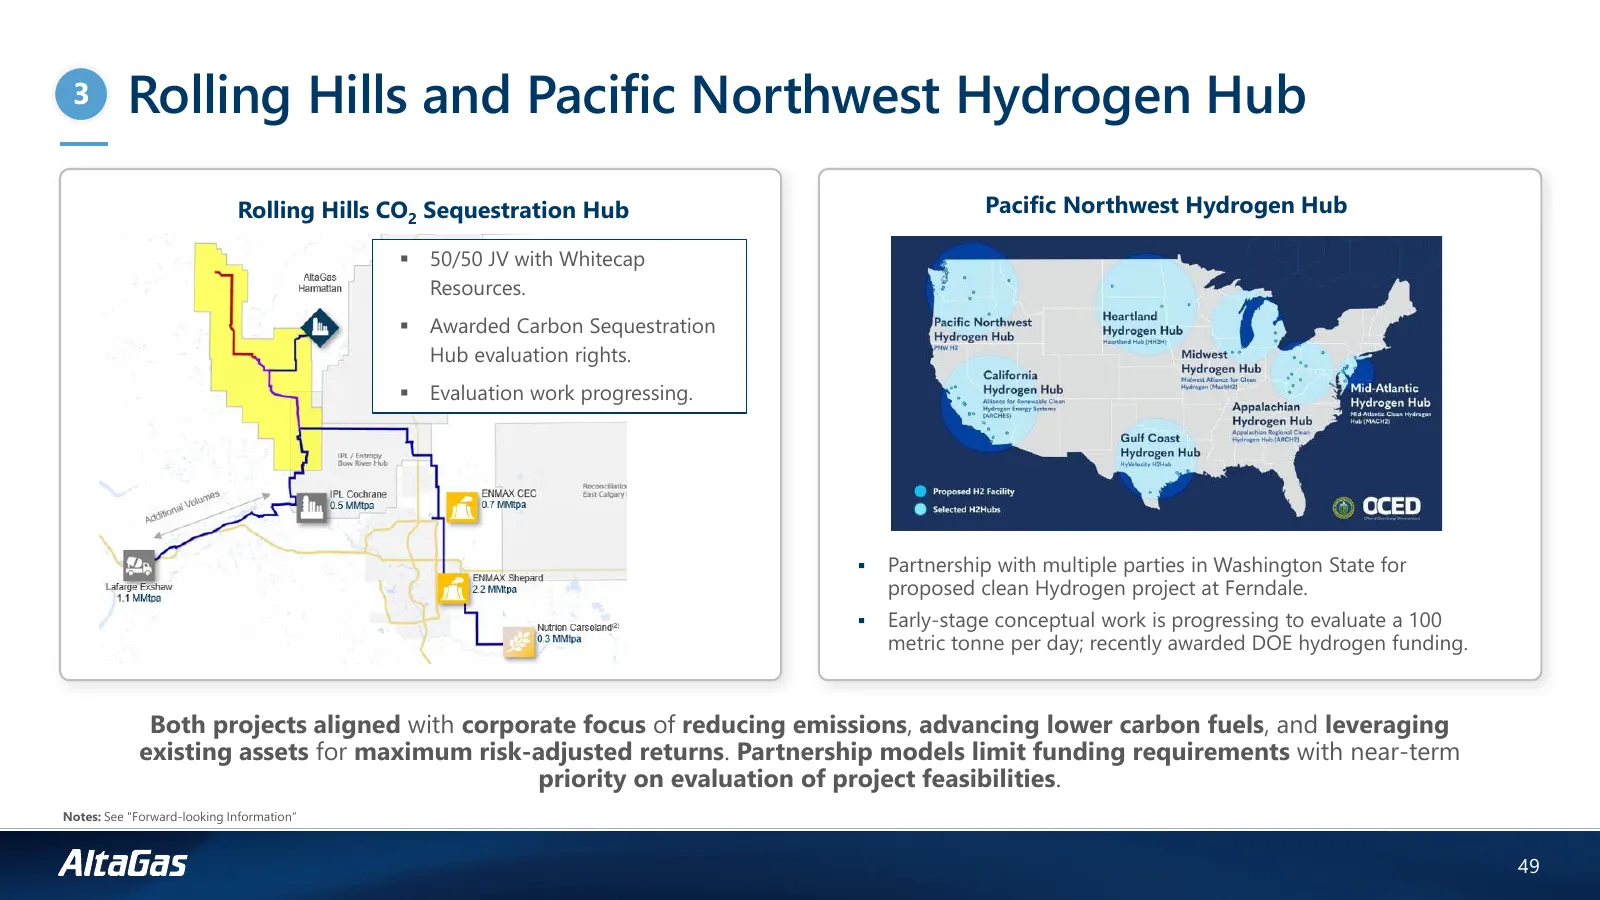
3 Rolling Hills and Pacific Northwest Hydrogen Hub Rolling Hills CO2 Sequestration Hub Pacific Northwest Hydrogen Hub ▪ 50/50 JV with Whitecap Resources. ▪ Awarded Carbon Sequestration Hub evaluation rights. ▪ Evaluation work progressing. ▪ Partnership with multiple parties in Washington State for p
Slide 50: The Midstream Investment Opportunity
The Midstream Investment Opportunity Robustfundamentals, Robust long-term long-term provide fundamentals provide structural growth forstructural growth. the platform. Industry-leading global LPG exports platform provides long-term competitive moat. GlobalMontney Industry-leading LPG export platform
Slide 51: Utilities Strategy
Utilities Strategy Blue Jenkins Executive Vice President and President, Utilities 51
Slide 52: High Growth Rate Regulated Utilities Platform
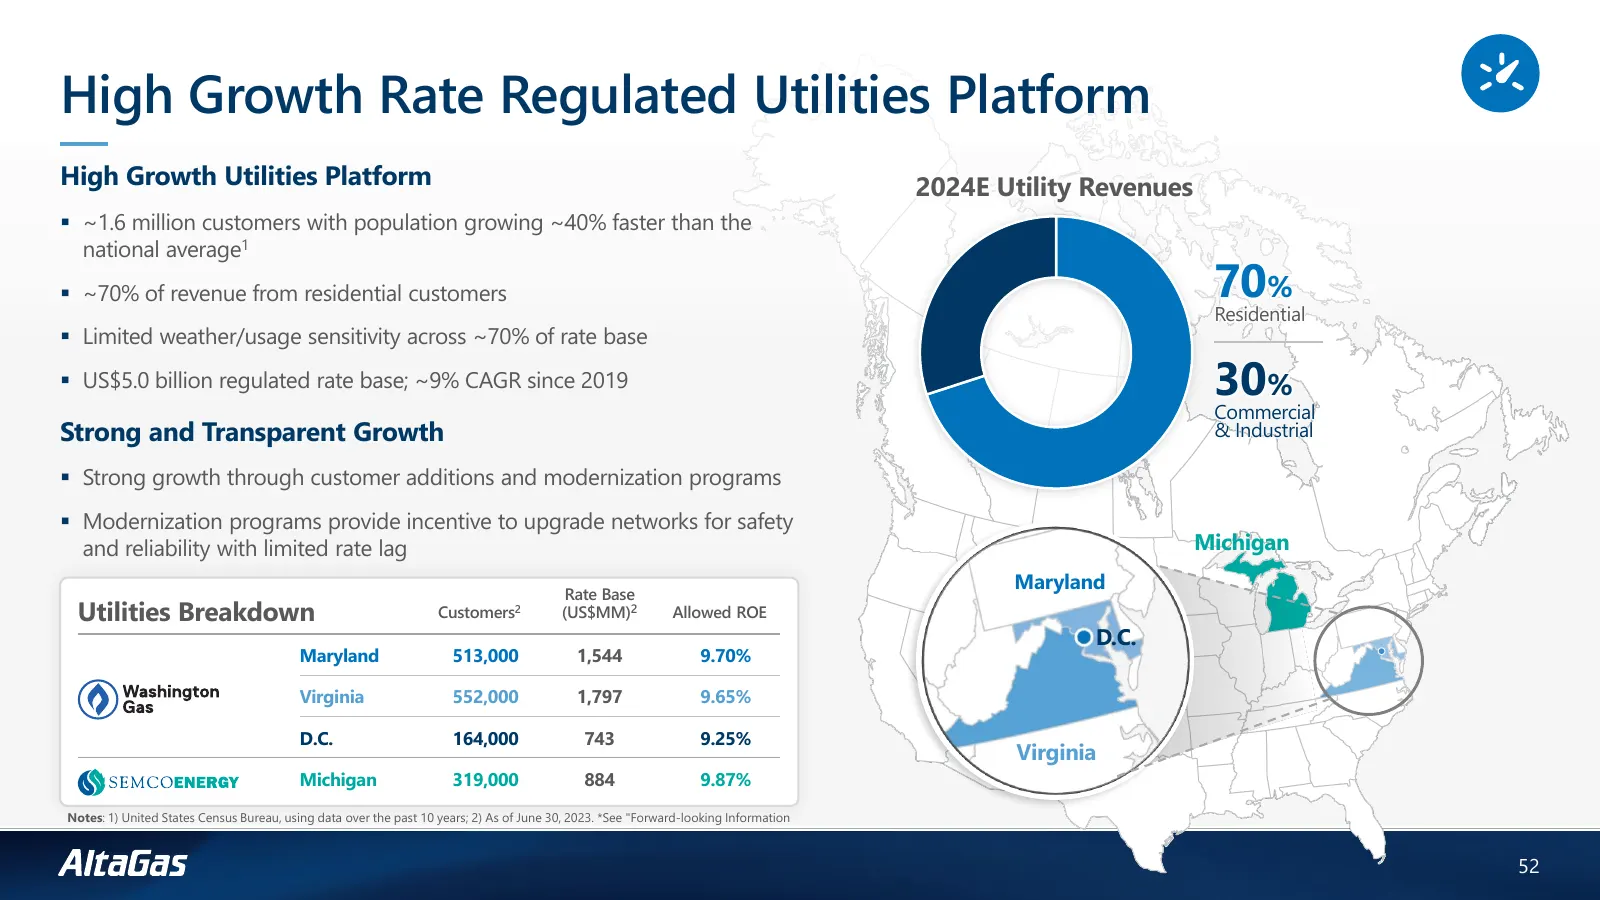
High Growth Rate Regulated Utilities Platform High Growth Utilities Platform 2024E Utility Revenues ▪ ~1.6 million customers with population growing ~40% faster than the national average1 ▪ ~70% of revenue from residential customers 70% Residential ▪ Limited weather/usage sensitivity across ~70% of
Slide 53: Updates Since the Last Investor Day – December 2021
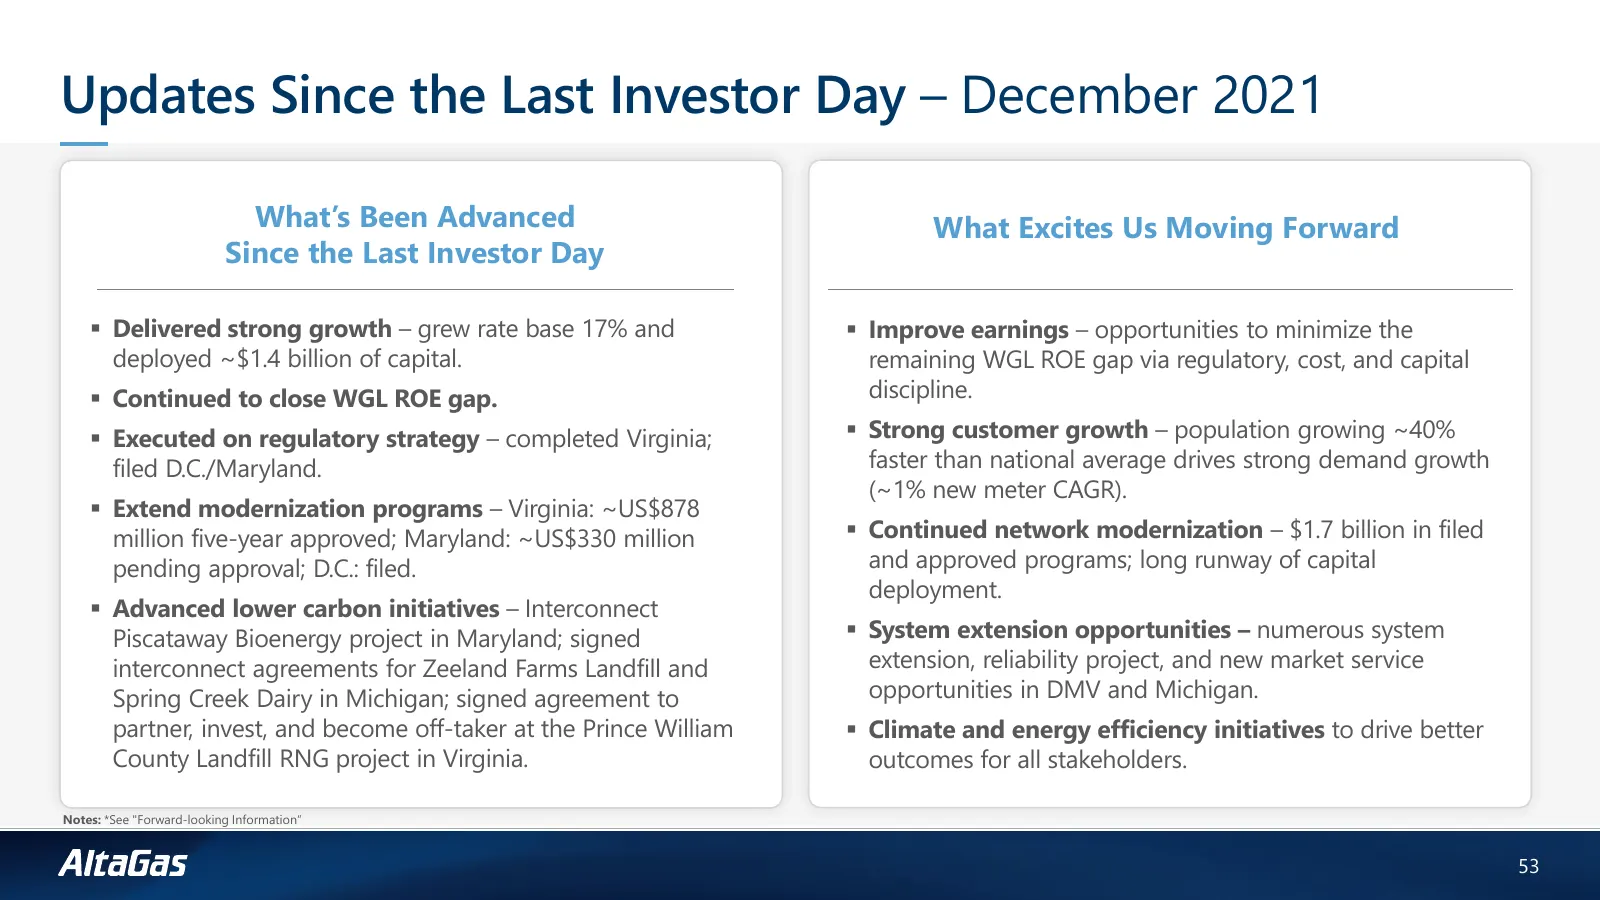
Updates Since the Last Investor Day – December 2021 What’s Been Advanced What Excites Us Moving Forward Since the Last Investor Day ▪ Delivered strong growth – grew rate base 17% and ▪ Improve earnings – opportunities to minimize the deployed ~$1.4 billion of capital. remaining WGL ROE gap via regul
Slide 54: Key Themes Driving our Forward Outlook
Key Themes Driving our Forward Outlook 1 Natural gas will be critical for long-term energy demand 2 Energy security, reliability, and affordability have returned to today’s forefront 3 Electrification is not a panacea – material disadvantages on cost and emissions relative to natural gas 4 AltaGas c
Slide 55: Utilities Macro Outlook
Utilities Macro Outlook 55
Slide 56: Natural Gas Conversion Efficiency Leads the Industry
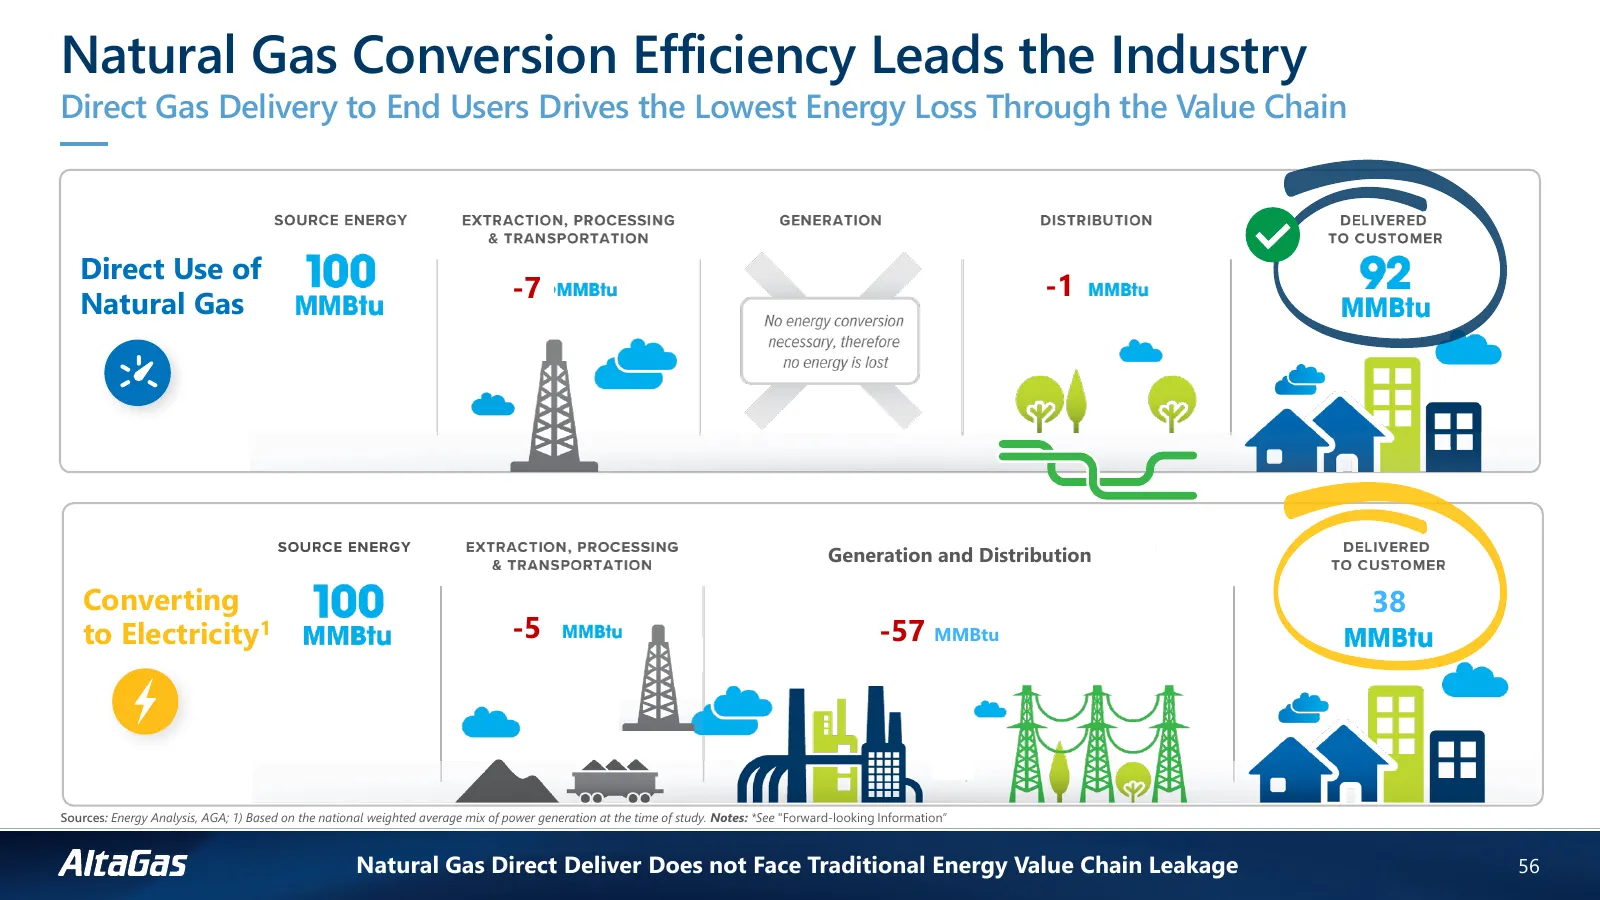
Natural Gas Conversion Efficiency Leads the Industry Direct Gas Delivery to End Users Drives the Lowest Energy Loss Through the Value Chain Direct Use of -7 -1 Natural Gas Generation and Distribution Converting 38 to Electricity1 -5 -57 MMBtu Sources: Energy Analysis, AGA; 1) Based on the national w
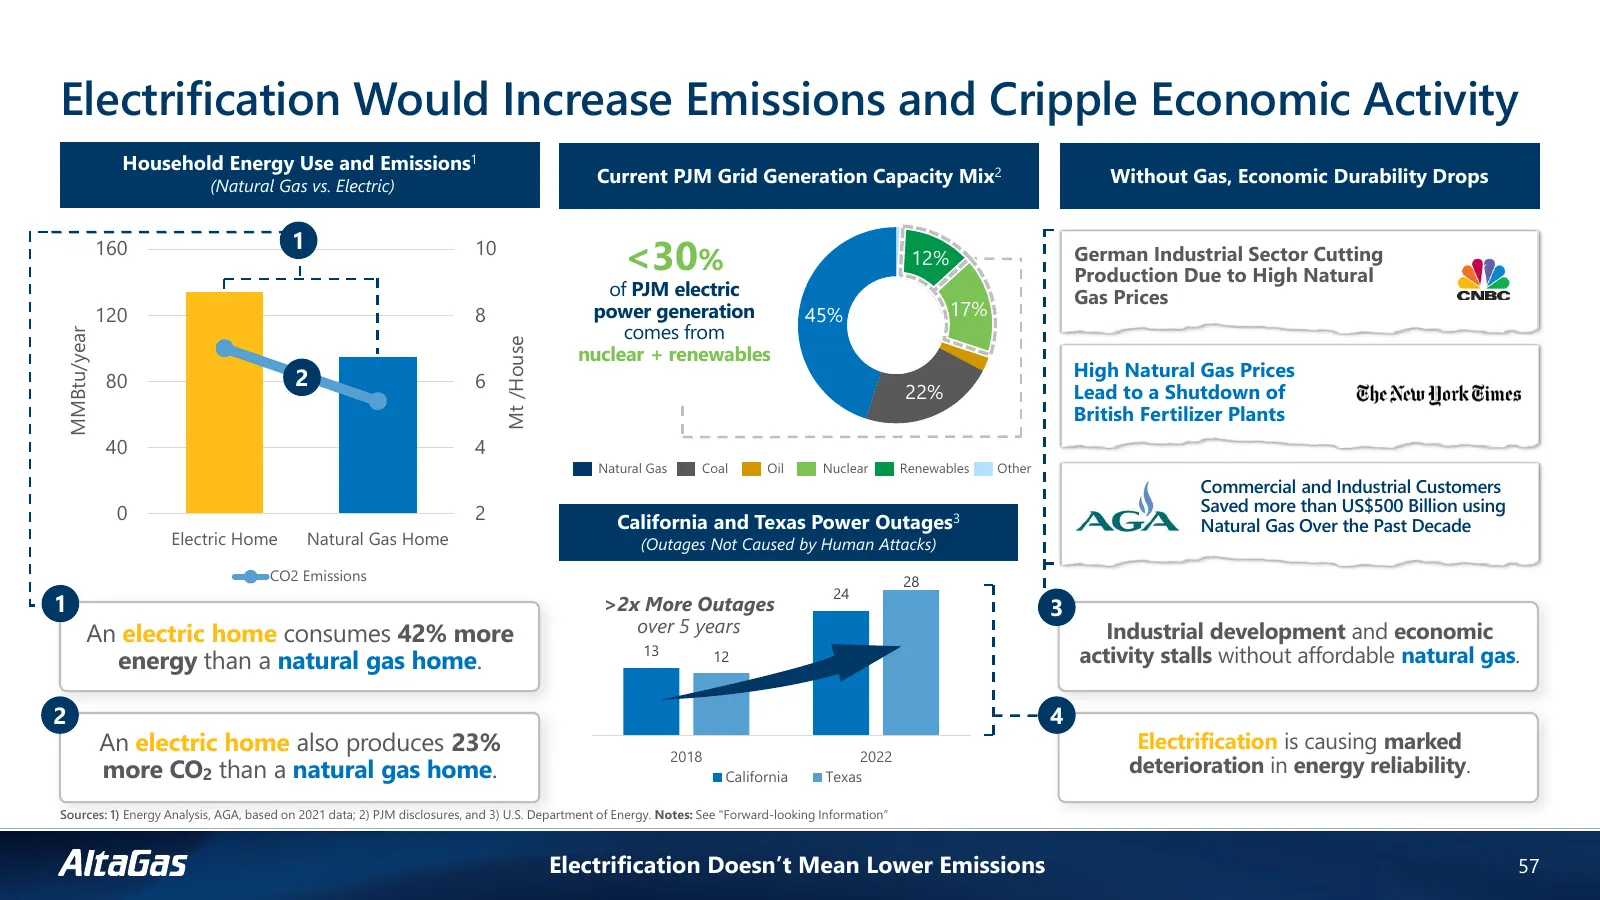
Slide 57: Electrification Would Increase Emissions and Cripple Economic Activity
Electrification Would Increase Emissions and Cripple Economic Activity Household Energy Use and Emissions1 (Natural Gas vs. Electric) Current PJM Grid Generation Capacity Mix2 Without Gas, Economic Durability Drops 1 160 10 <30% 12% German Industrial Sector Cutting Production Due to High Natural of
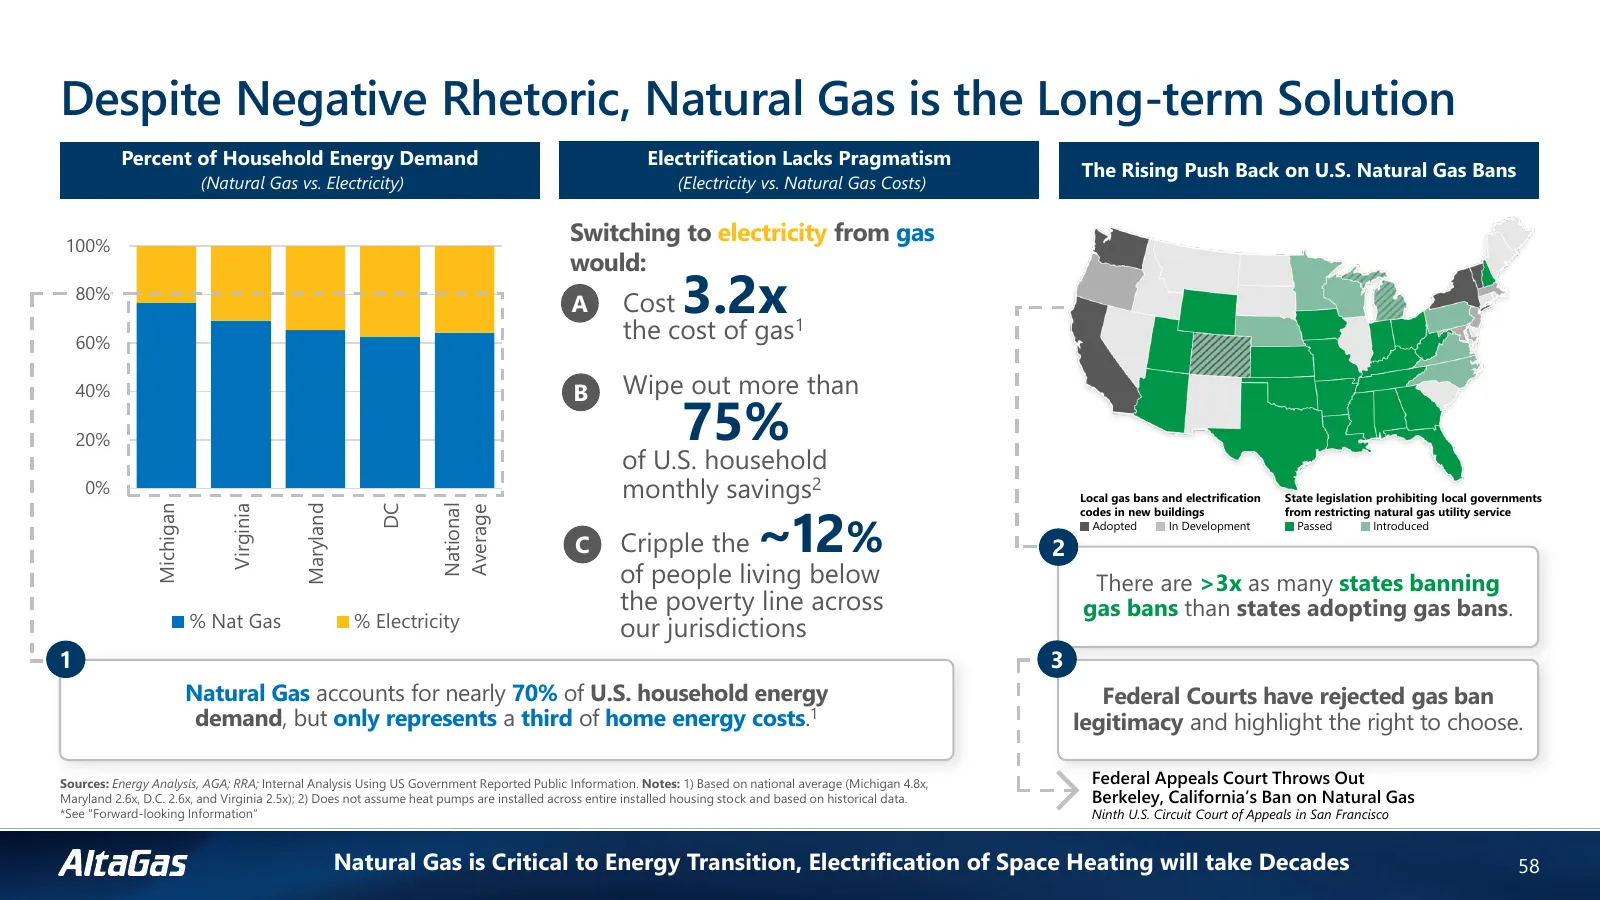
Slide 58: Despite Negative Rhetoric, Natural Gas is the Long-term Solution
Despite Negative Rhetoric, Natural Gas is the Long-term Solution Percent of Household Energy Demand Electrification Lacks Pragmatism The Rising Push Back on U.S. Natural Gas Bans (Natural Gas vs. Electricity) (Electricity vs. Natural Gas Costs) 100% Switching to electricity from gas would: 80% A Cos
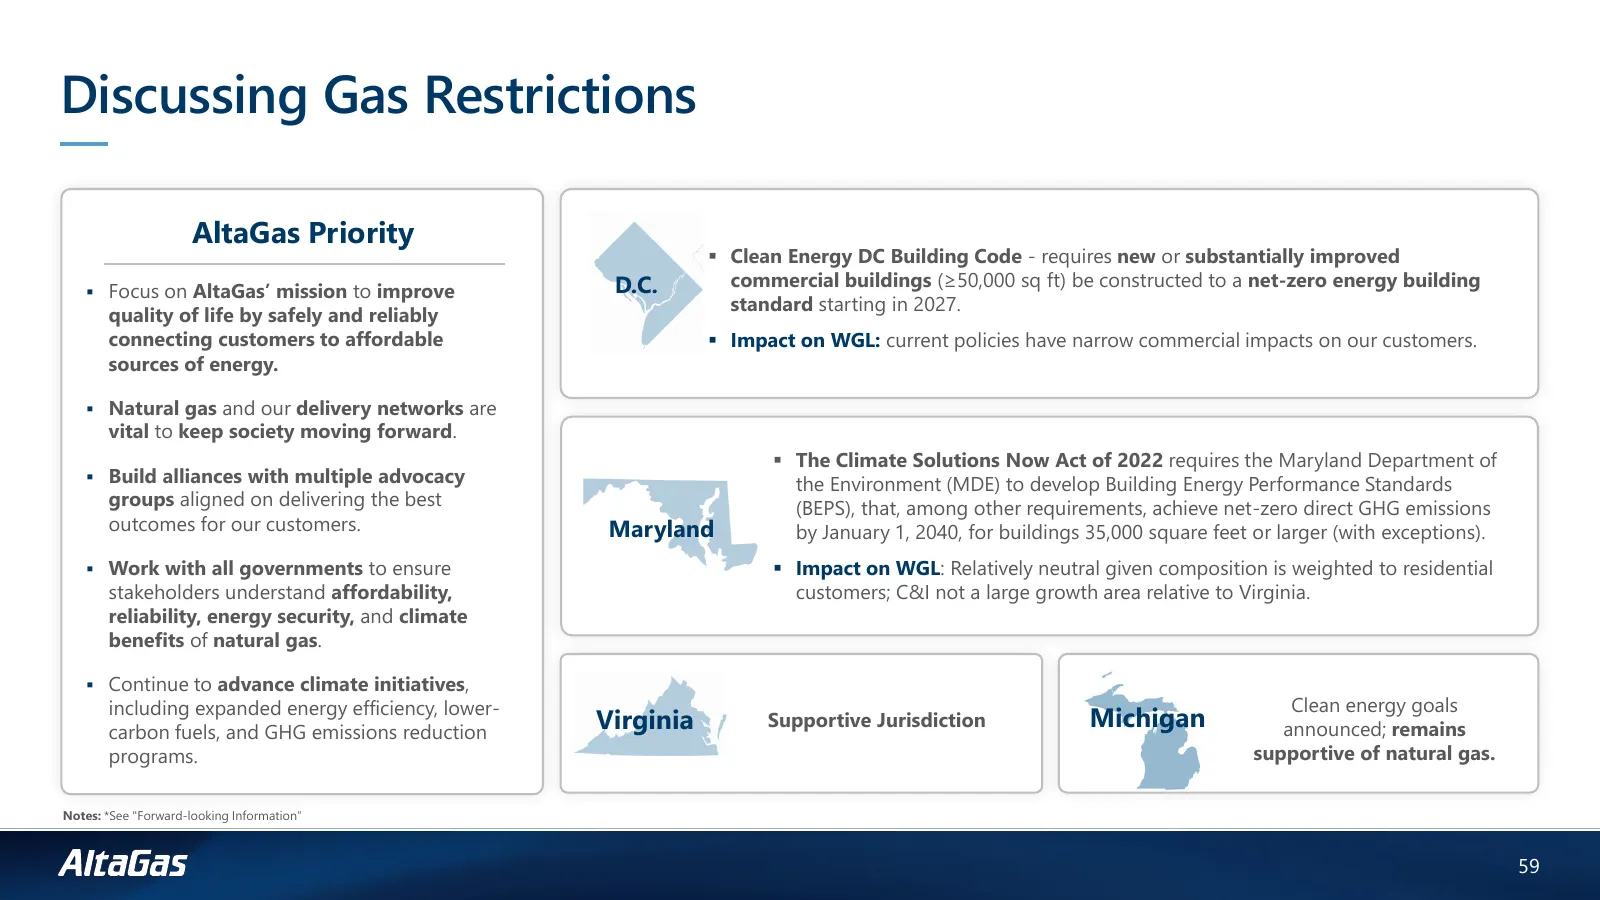
Slide 59: Discussing Gas Restrictions
Discussing Gas Restrictions AltaGas Priority ▪ Clean Energy DC Building Code - requires new or substantially improved D.C. commercial buildings (≥50,000 sq ft) be constructed to a net-zero energy building ▪ Focus on AltaGas’ mission to improve standard starting in 2027. quality of life by safely and
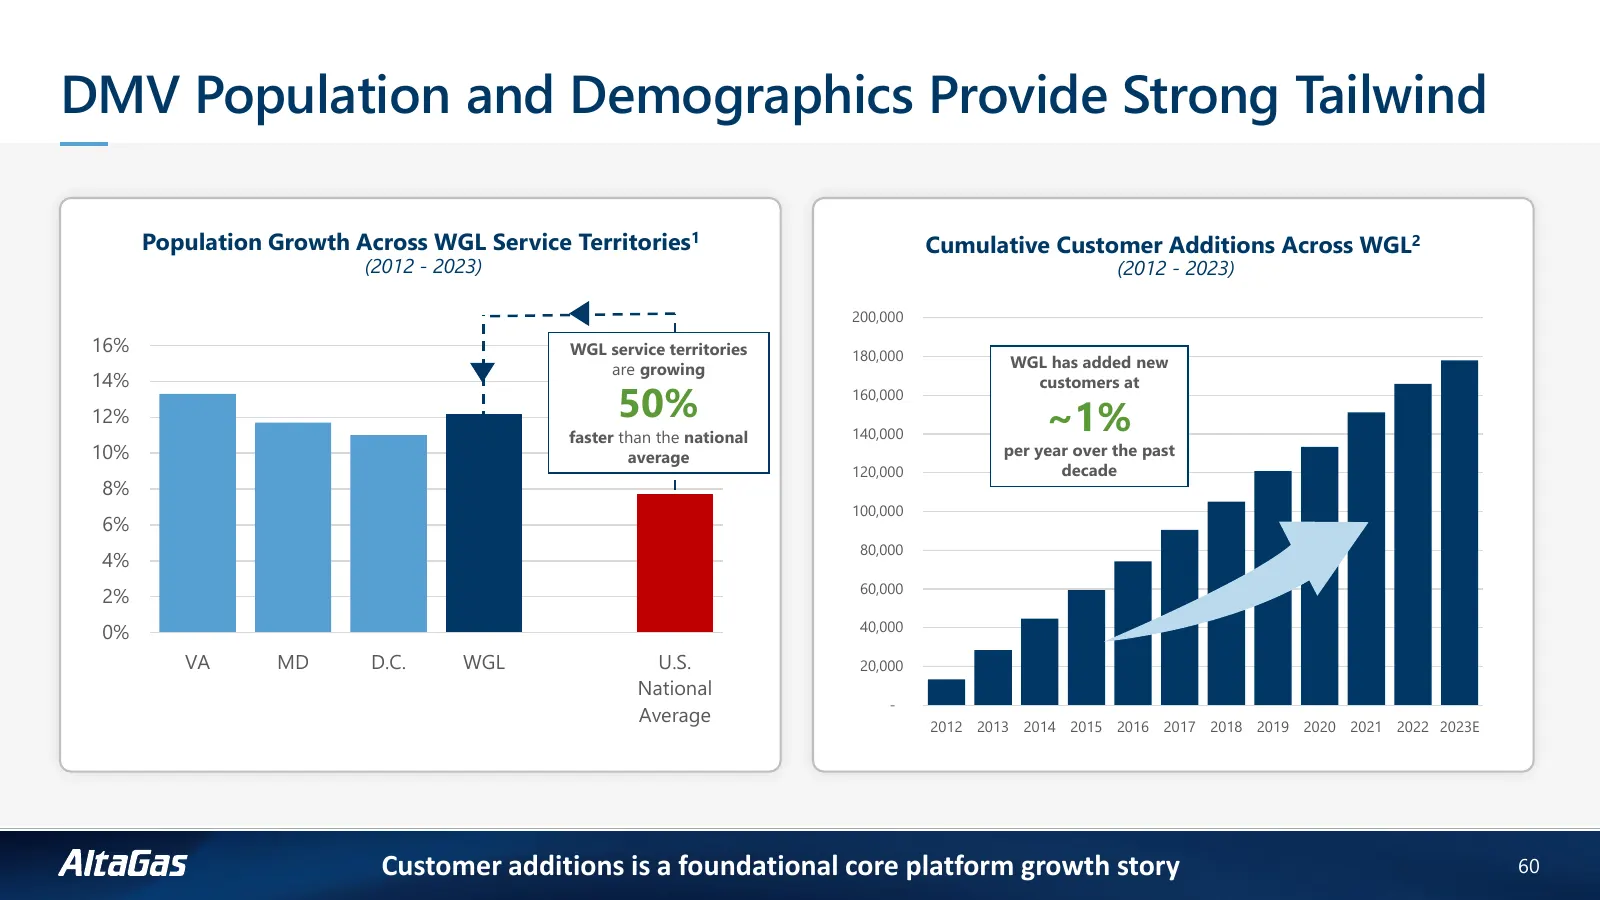
Slide 60: DMV Population and Demographics Provide Strong Tailwind
DMV Population and Demographics Provide Strong Tailwind Population Growth Across WGL Service Territories1 Cumulative Customer Additions Across WGL2 (2012 - 2023) (2012 - 2023) 200,000 16% WGL service territories 180,000 are growing WGL has added new 14% customers at 12% 50% 160,000 ~1% faster than t
Slide 61: The Utilities Road Ahead
AltaGas Road Ahead les The Utili
Slide 62: Utilities Strategic Focus
Utilities Strategic Focus 1 2 3 4 Growth Improve Invest in Core Opportunities Policy / Returns Platform related to Advocacy Climate Leadership Initiatives ▪ Continue closing the ▪ Modernize network ▪ Focus on energy ▪ Build alliances with ROE gap to enhance safety efficiency programs, multiple advoc
Slide 63: Improve Returns at WGL
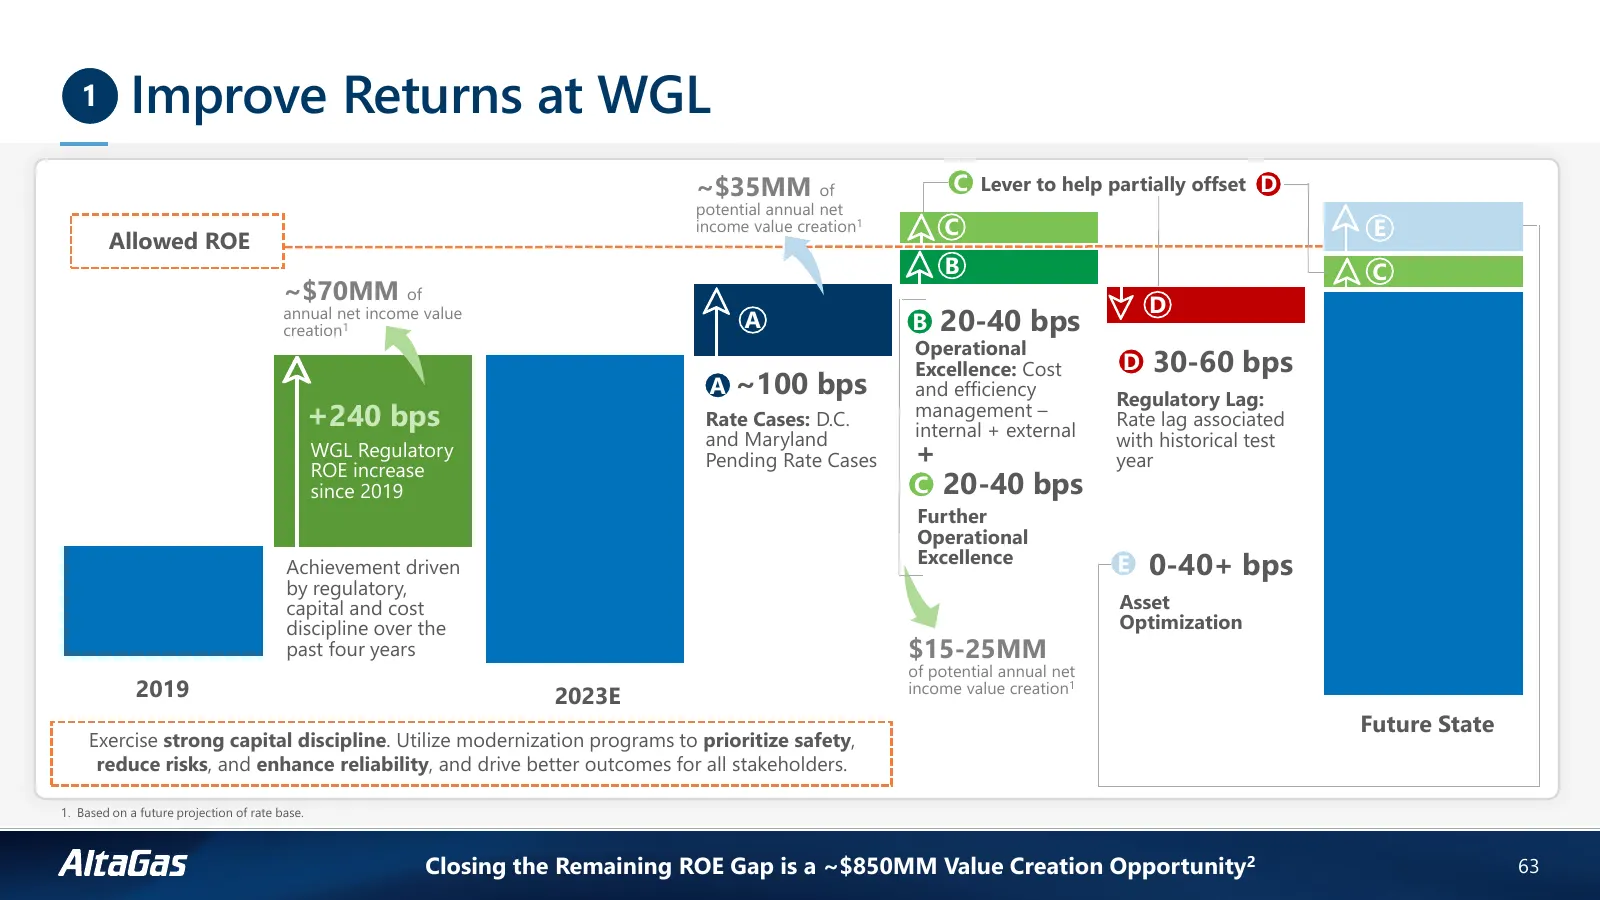
1 Improve Returns at WGL ~$35MM of C Lever to help partially offset D potential annual net income value creation1 C E Allowed ROE B C ~$70MM of D annual net income value creation1 A B 20-40 bps Operational Excellence: Cost D 30-60 bps A ~100 bps and efficiency Regulatory Lag: +240 bps Rate Cases: D.
Slide 64: Address Aging Infrastructure
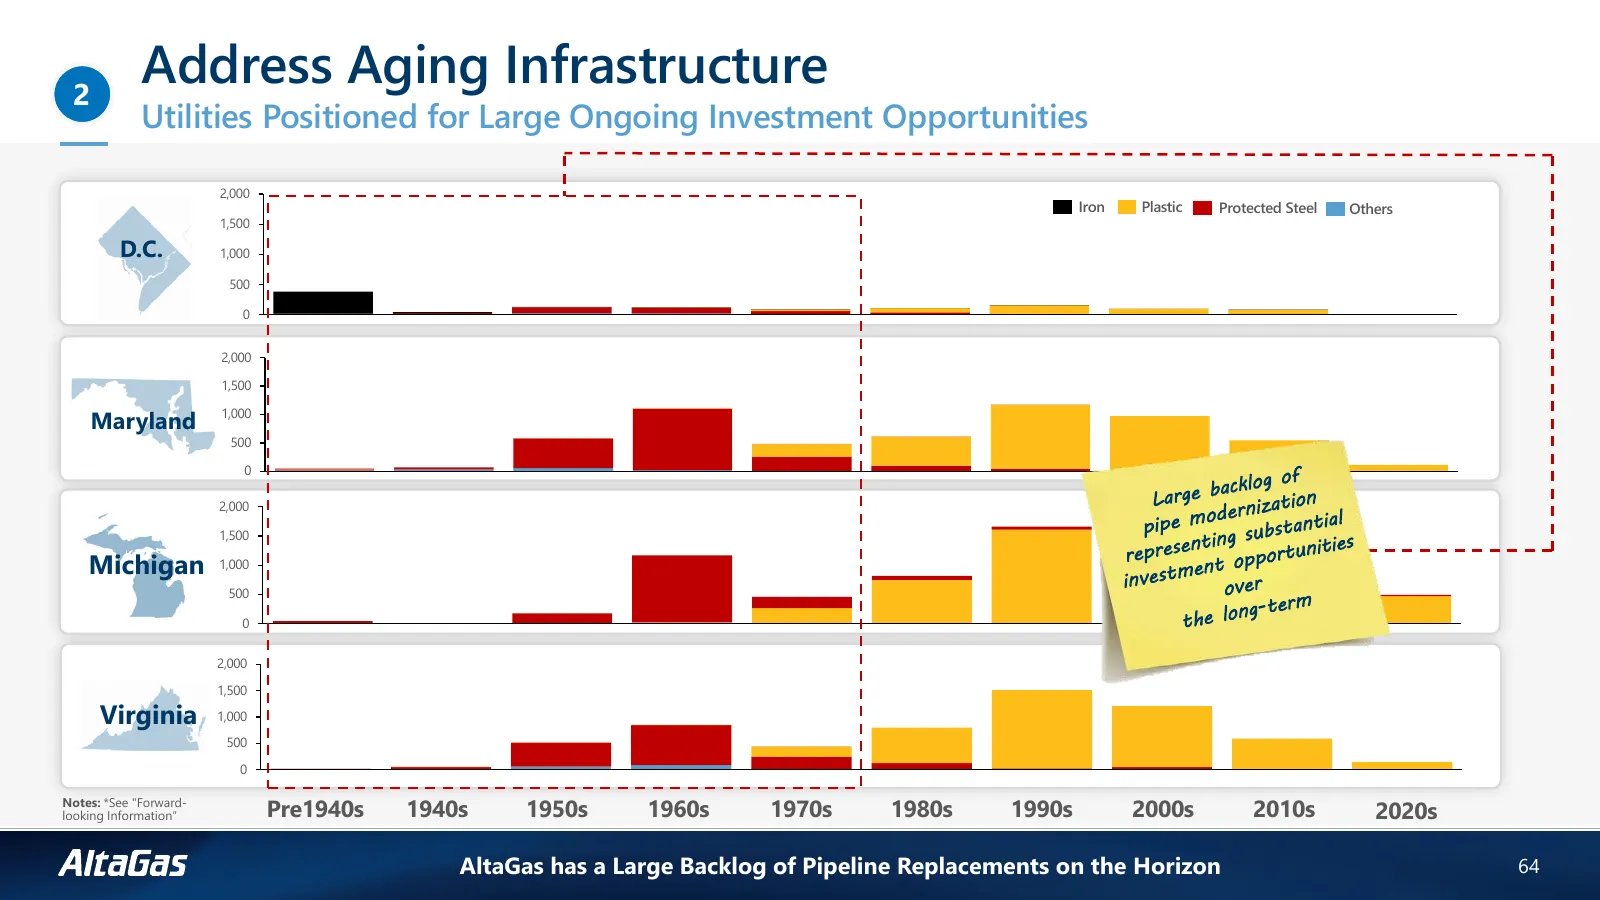
2 Address Aging Infrastructure Utilities Positioned for Large Ongoing Investment Opportunities 2,000 Iron Plastic Protected Steel Others 1,500 D.C. 1,000 500 0 2,000 1,500 Maryland 1,000 500 0 2,000 1,500 Michigan 1,000 500 0 2,000 1,500 Virginia 1,000 500 0 Notes: *See "Forward- looking Information
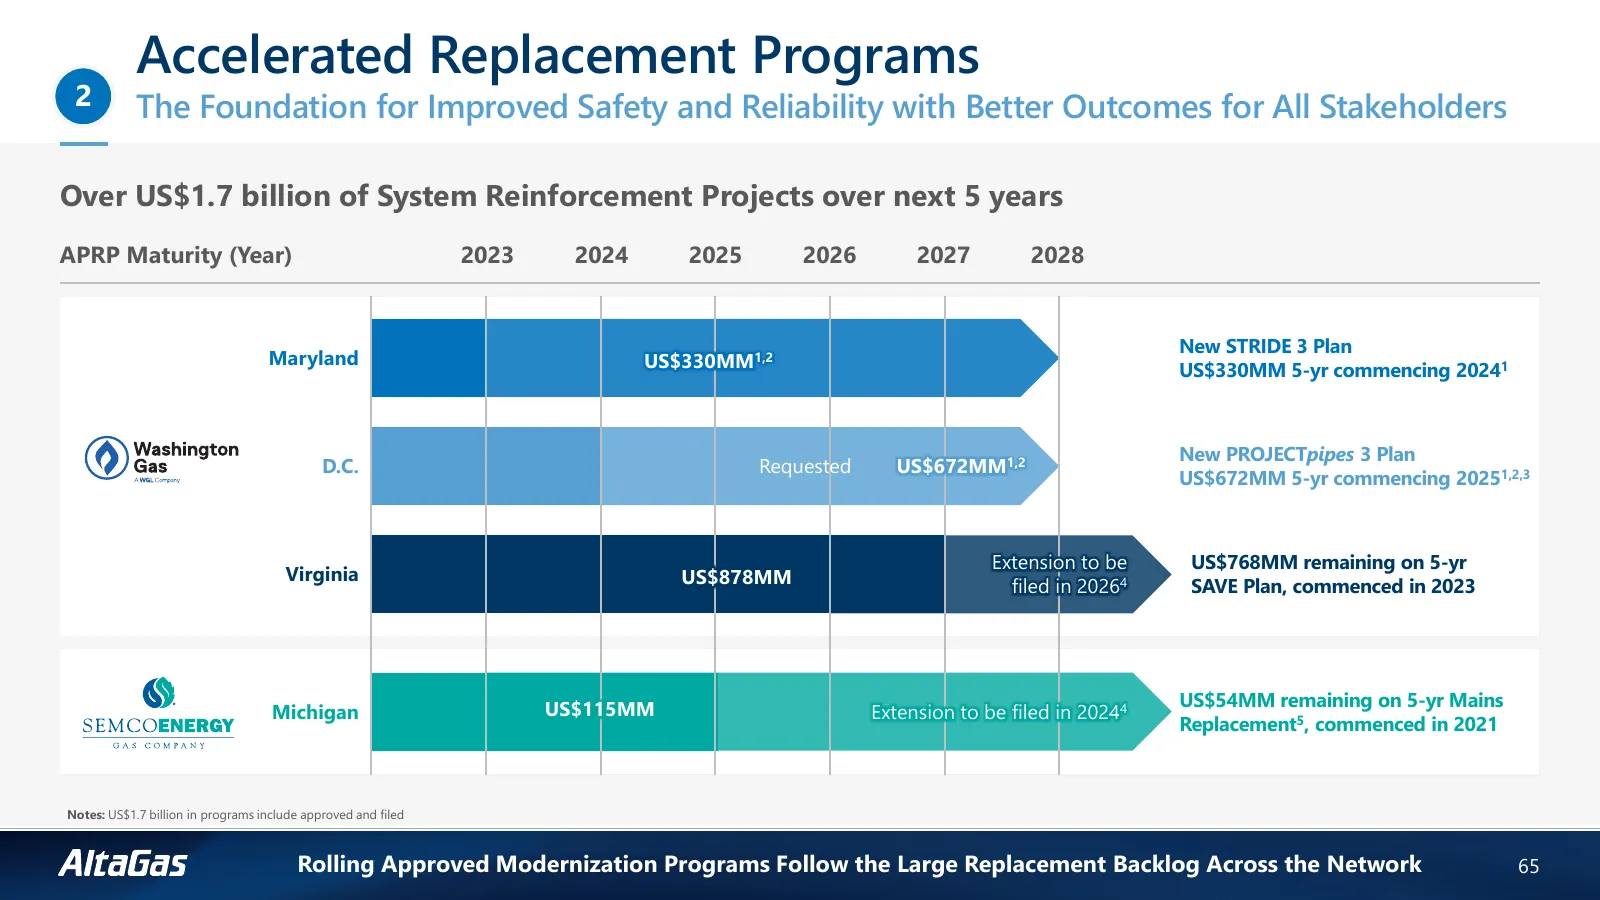
Slide 65: Accelerated Replacement Programs
Accelerated Replacement Programs 2 The Foundation for Improved Safety and Reliability with Better Outcomes for All Stakeholders Over US$1.7 billion of System Reinforcement Projects over next 5 years APRP Maturity (Year) 2023 2024 2025 2026 2027 2028 New STRIDE 3 Plan Maryland US$330MM1,2 US$330MM 5-
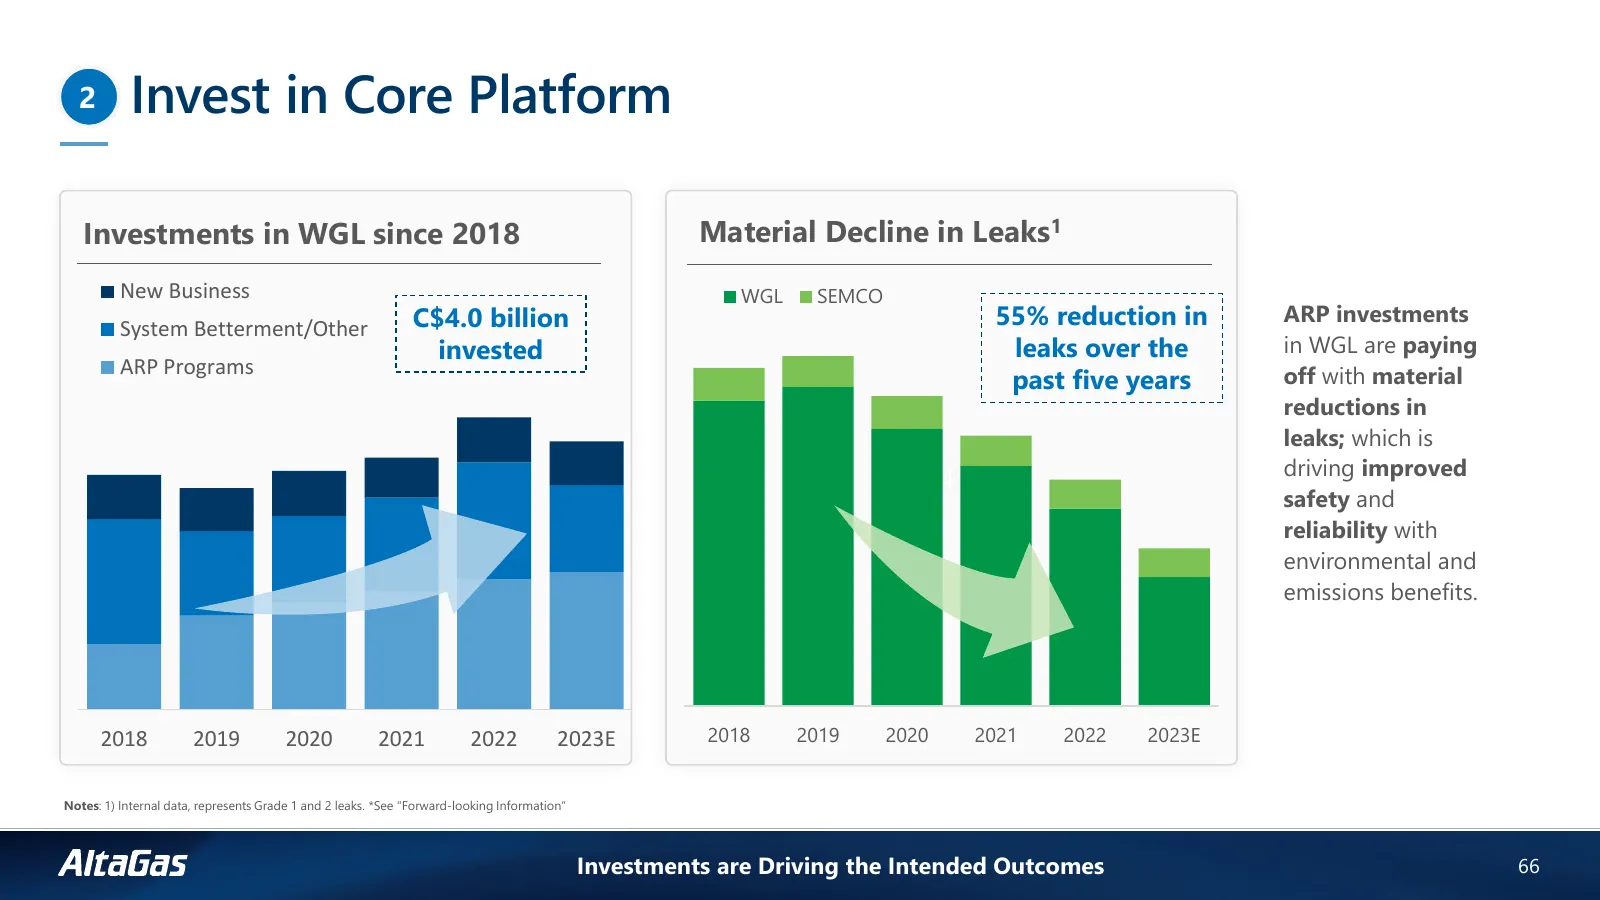
Slide 66: Invest in Core Platform
2 Invest in Core Platform Investments in WGL since 2018 Material Decline in Leaks1 New Business WGL SEMCO System Betterment/Other C$4.0 billion 55% reduction in ARP investments invested leaks over the in WGL are paying ARP Programs off with material past five years reductions in leaks; which is driv
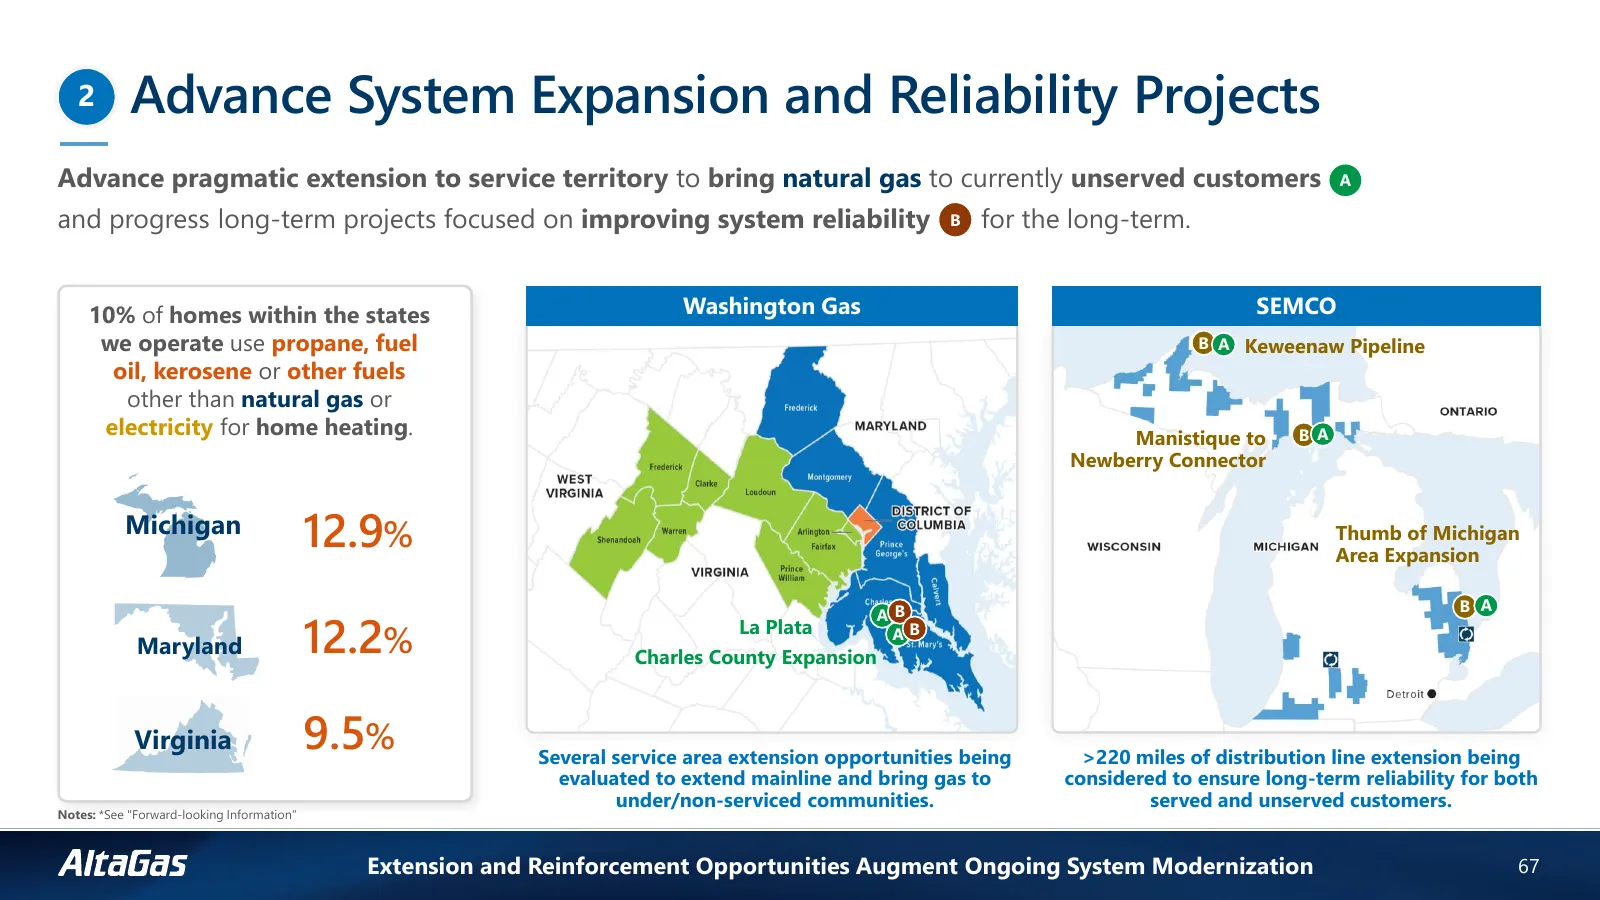
Slide 67: Advance System Expansion and Reliability Projects
2 Advance System Expansion and Reliability Projects Advance pragmatic extension to service territory to bring natural gas to currently unserved customers A and progress long-term projects focused on improving system reliability B for the long-term. 10% of homes within the states Washington Gas SEMCO
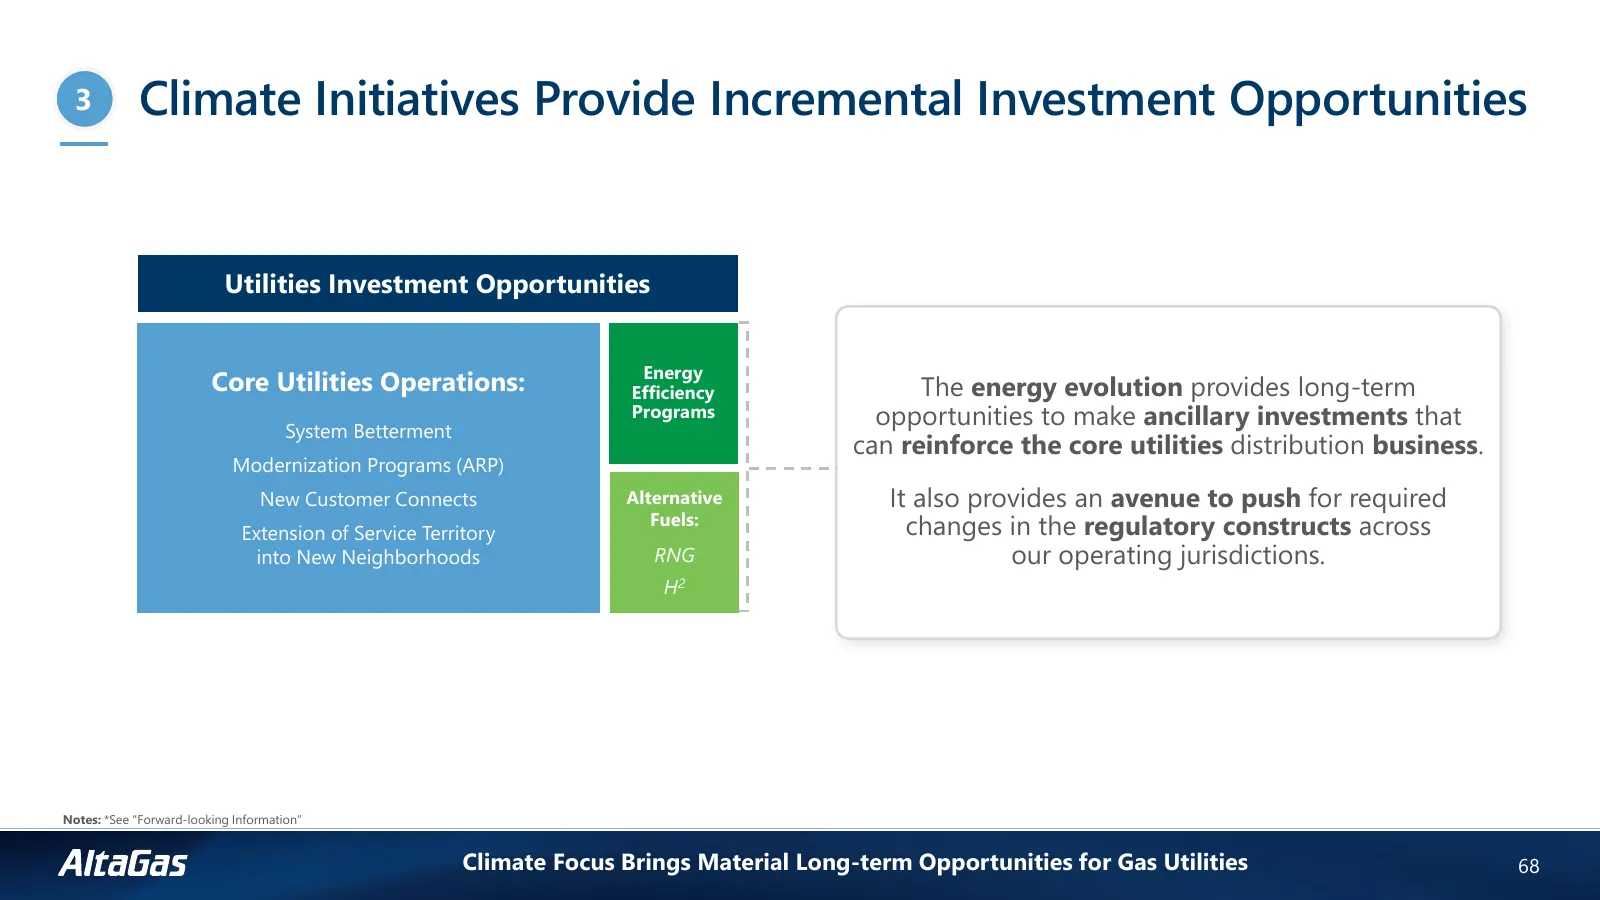
Slide 68: Climate Initiatives Provide Incremental Investment Opportunities
3 Climate Initiatives Provide Incremental Investment Opportunities Utilities Investment Opportunities Energy Core Utilities Operations: Efficiency The energy evolution provides long-term System Betterment Programs opportunities to make ancillary investments that can reinforce the core utilities dist
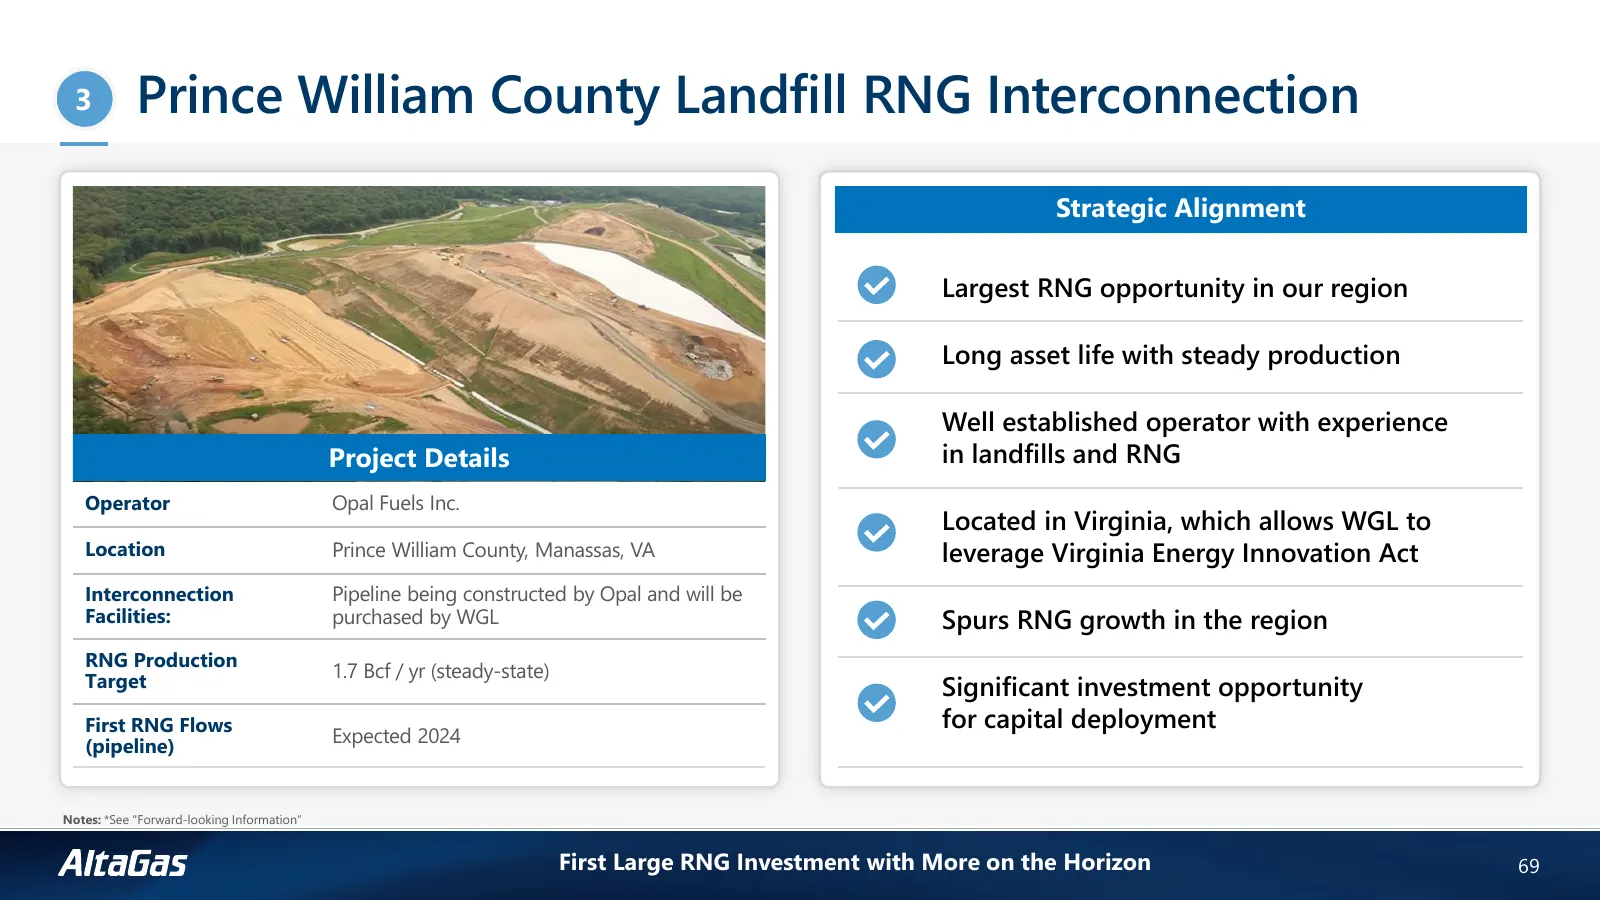
Slide 69: Prince William County Landfill RNG Interconnection
3 Prince William County Landfill RNG Interconnection Strategic Alignment Largest RNG opportunity in our region Long asset life with steady production Well established operator with experience Project Details in landfills and RNG Operator Opal Fuels Inc. Located in Virginia, which allows WGL to Locat
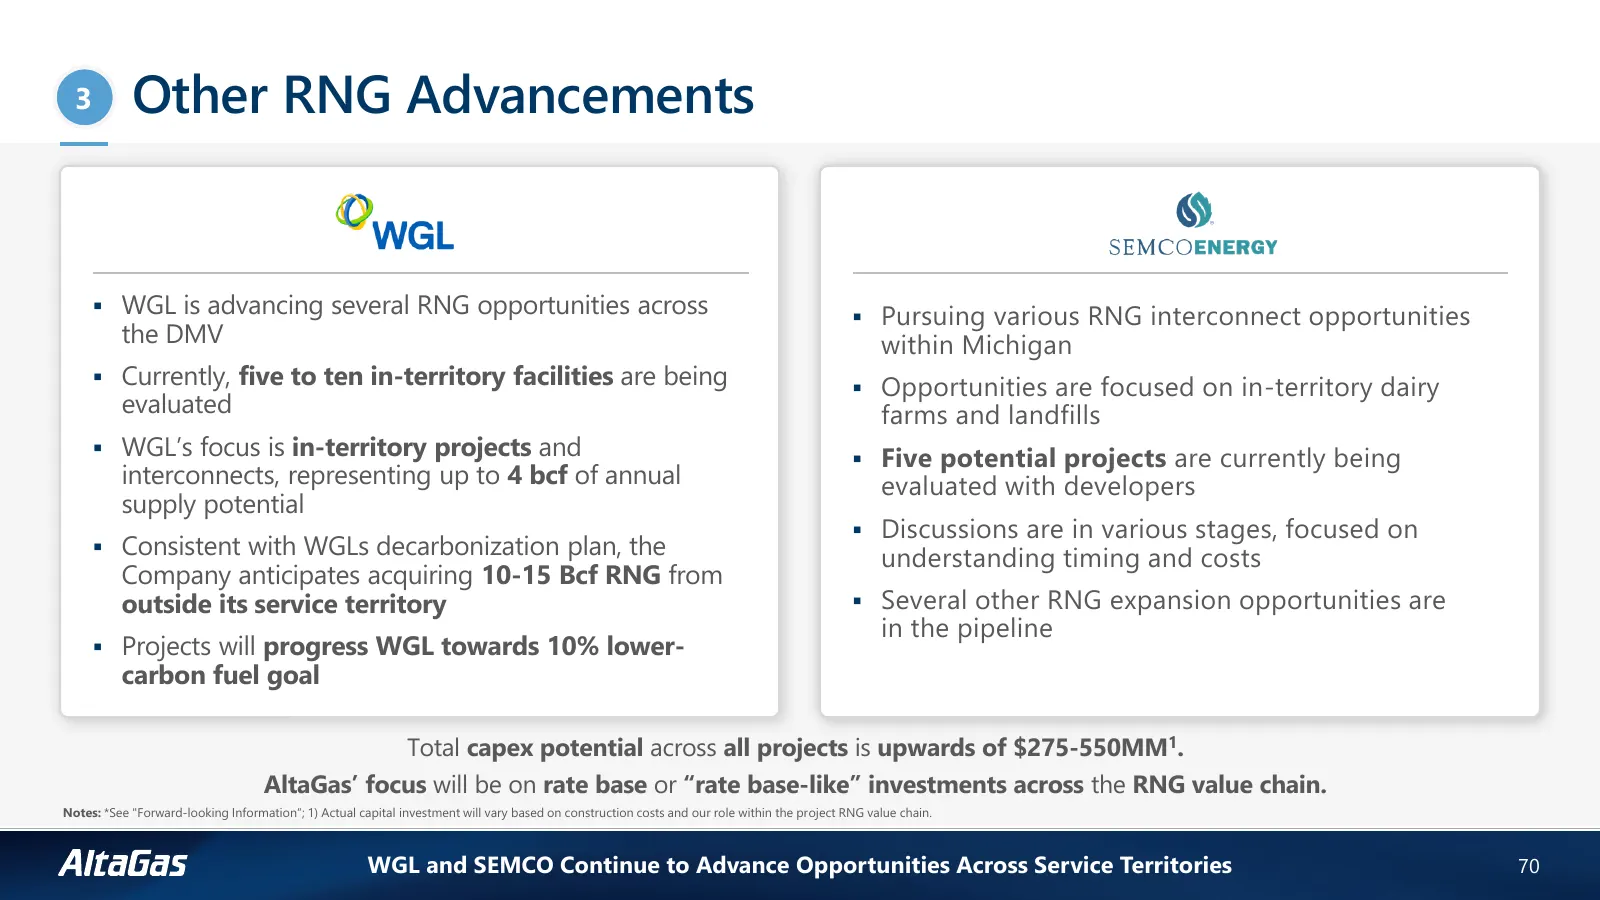
Slide 70: Other RNG Advancements
33 Other RNG Advancements ▪ WGL is advancing several RNG opportunities across ▪ Pursuing various RNG interconnect opportunities the DMV within Michigan ▪ Currently, five to ten in-territory facilities are being ▪ Opportunities are focused on in-territory dairy evaluated farms and landfills ▪ WGL’s f
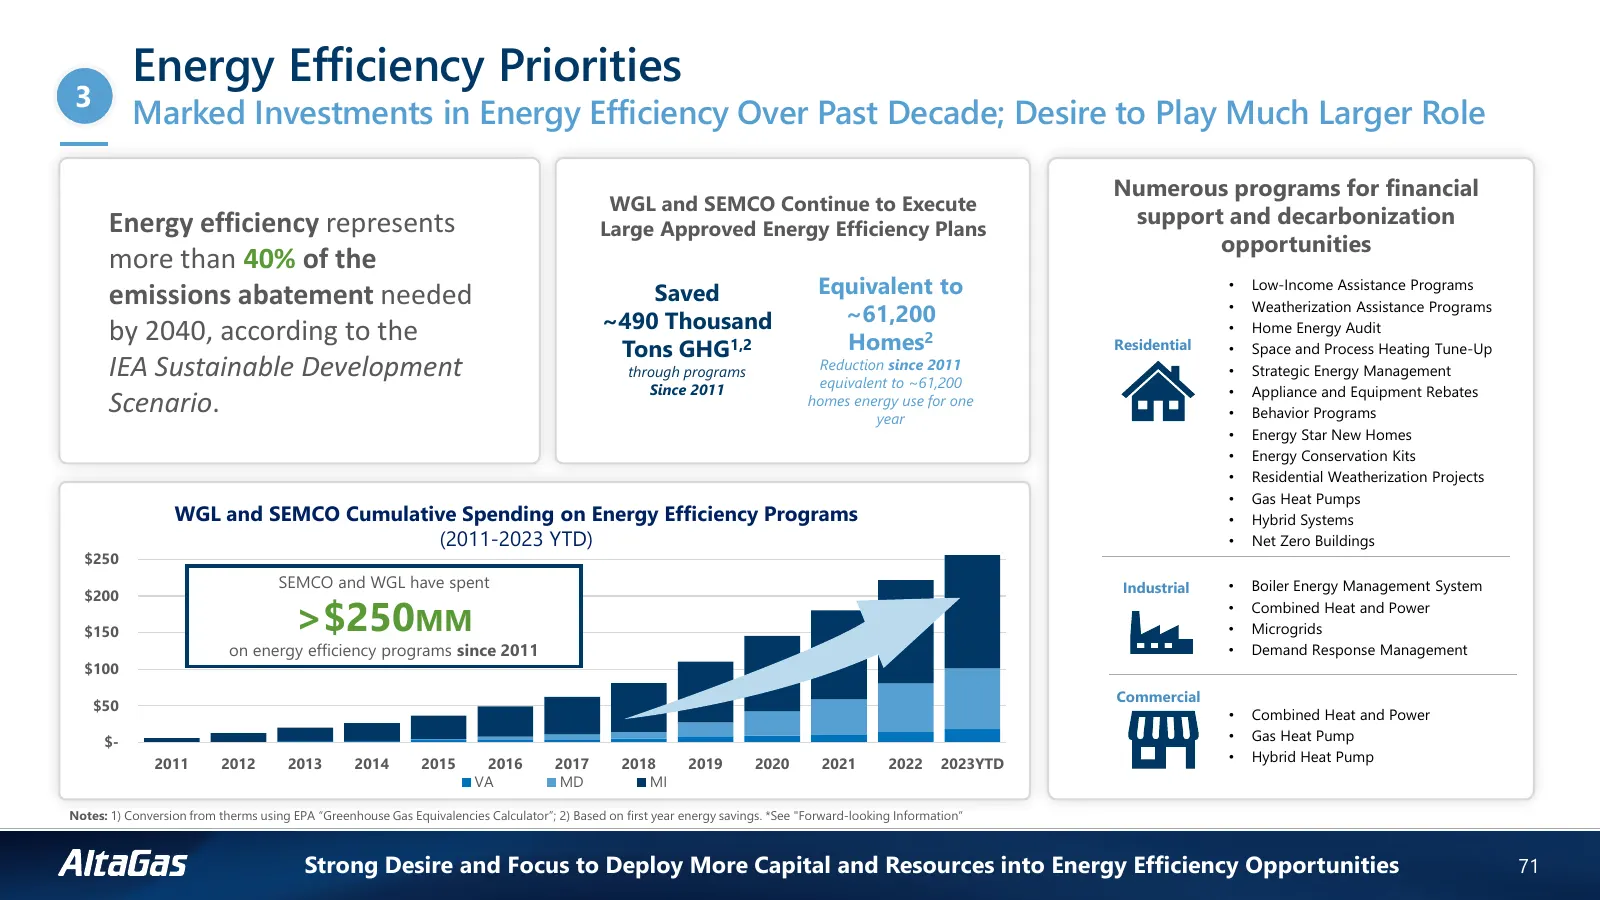
Slide 71: Energy Efficiency Priorities
Energy Efficiency Priorities 3 Marked Investments in Energy Efficiency Over Past Decade; Desire to Play Much Larger Role Numerous programs for financial WGL and SEMCO Continue to Execute Energy efficiency represents Large Approved Energy Efficiency Plans support and decarbonization opportunities mor
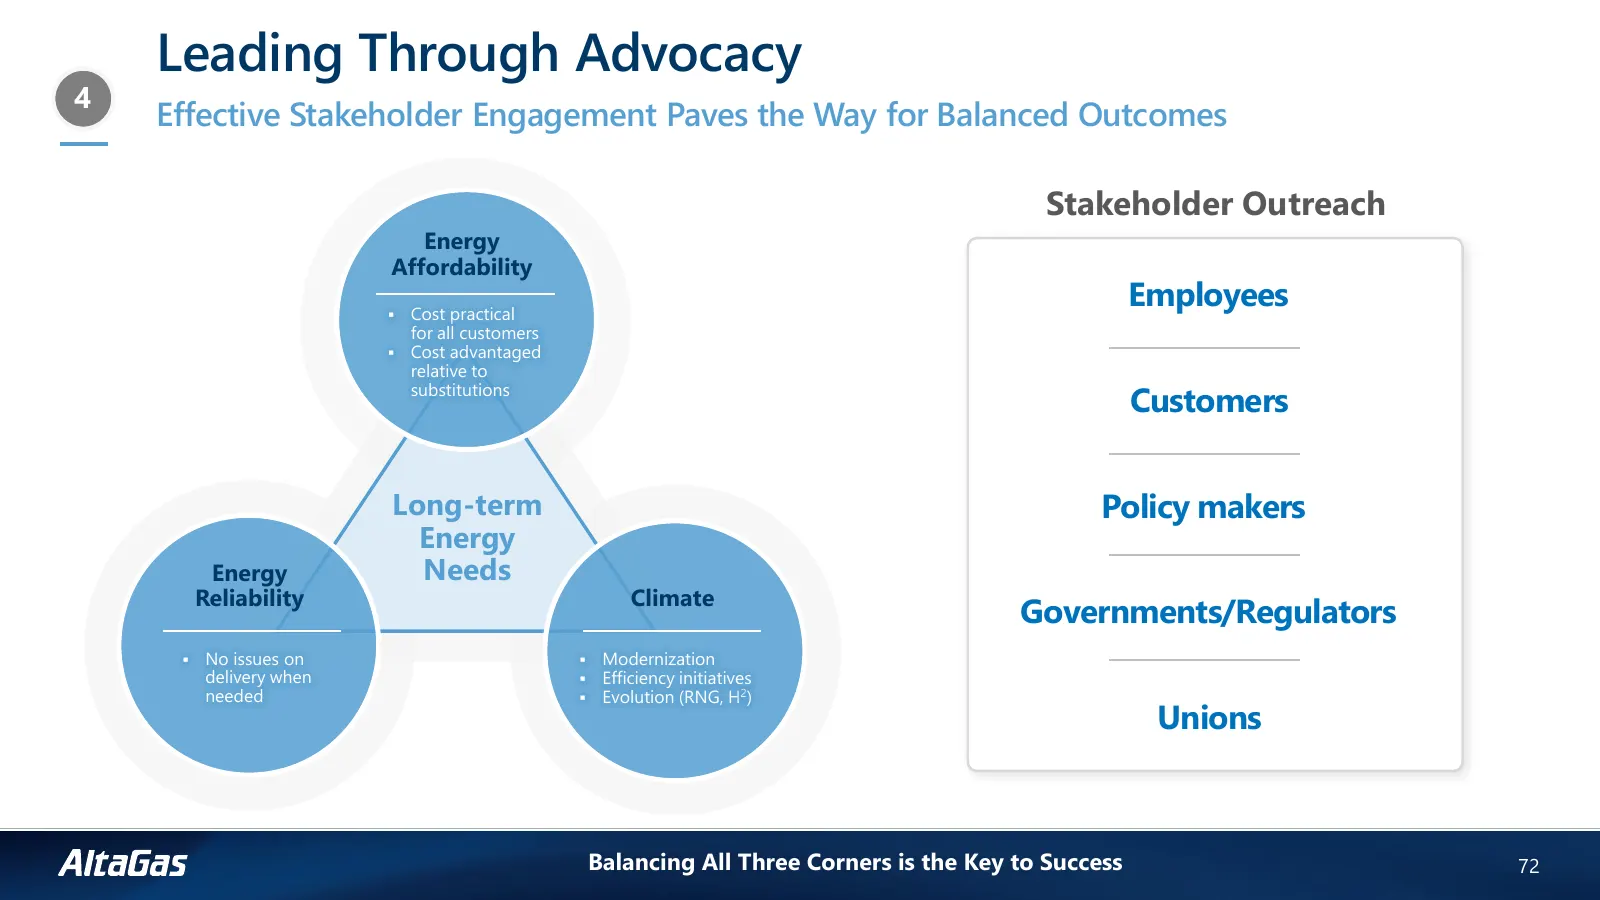
Slide 72: Leading Through Advocacy
Leading Through Advocacy 4 Effective Stakeholder Engagement Paves the Way for Balanced Outcomes Stakeholder Outreach Energy Affordability ▪ Cost practical Employees for all customers ▪ Cost advantaged relative to substitutions Customers Long-term Policy makers Energy Energy Needs Reliability Climate
Slide 73: The Utilities Investment Opportunity
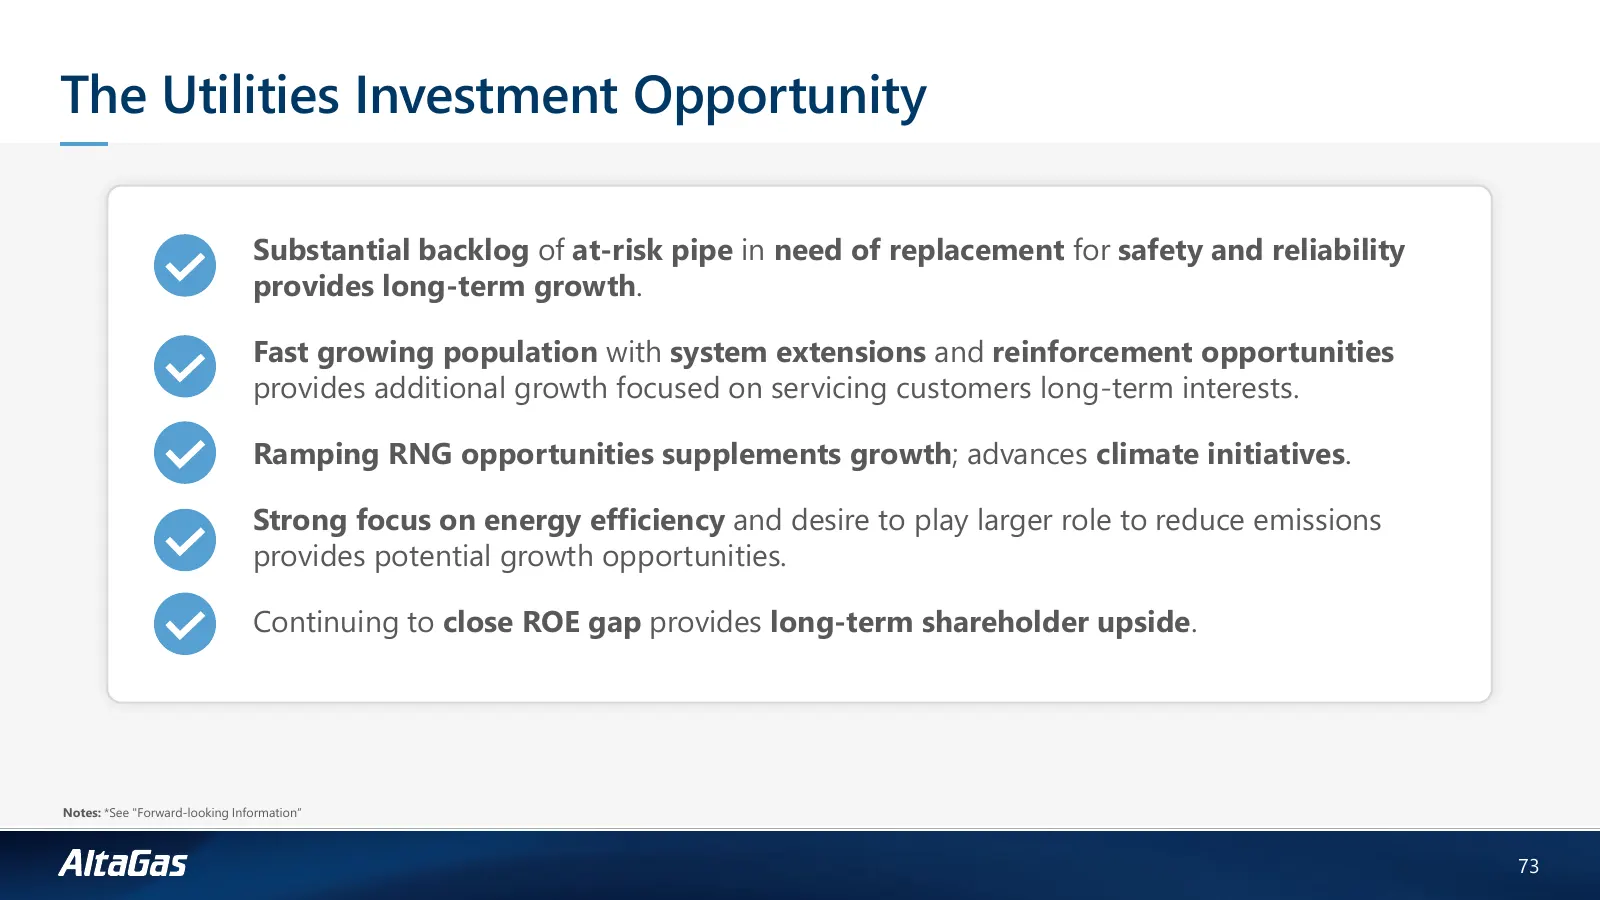
The Utilities Investment Opportunity Substantial backlog of at-risk pipe in need of replacement for safety and reliability providesfundamentals, Robust long-term long-term growth. provide structural growth for the platform. Fast growing Industry-leading population global LPG with system exports plat
Slide 74: Coffee Break
Coffee Break 74
Slide 75: Capital and Returns Strategy
Capital and Returns Strategy James Harbilas Executive Vice President and Chief Financial Officer 75
Slide 76: Updates Since the Last Investor Day – December 2021
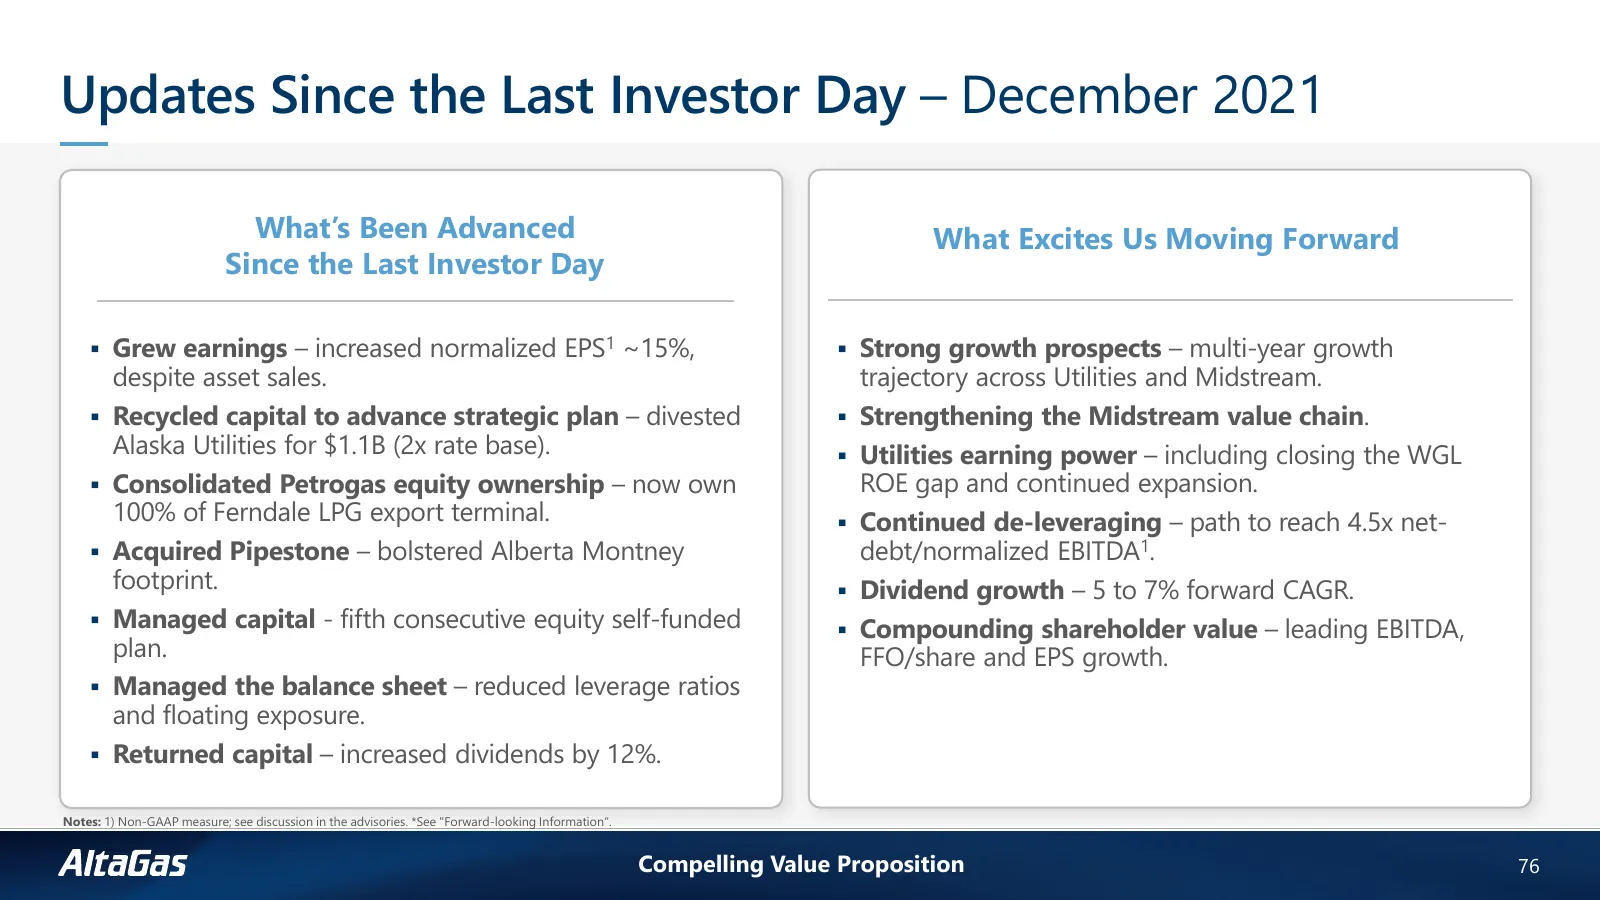
Updates Since the Last Investor Day – December 2021 What’s Been Advanced What Excites Us Moving Forward Since the Last Investor Day ▪ Grew earnings – increased normalized EPS1 ~15%, ▪ Strong growth prospects – multi-year growth despite asset sales. trajectory across Utilities and Midstream. ▪ Recycl
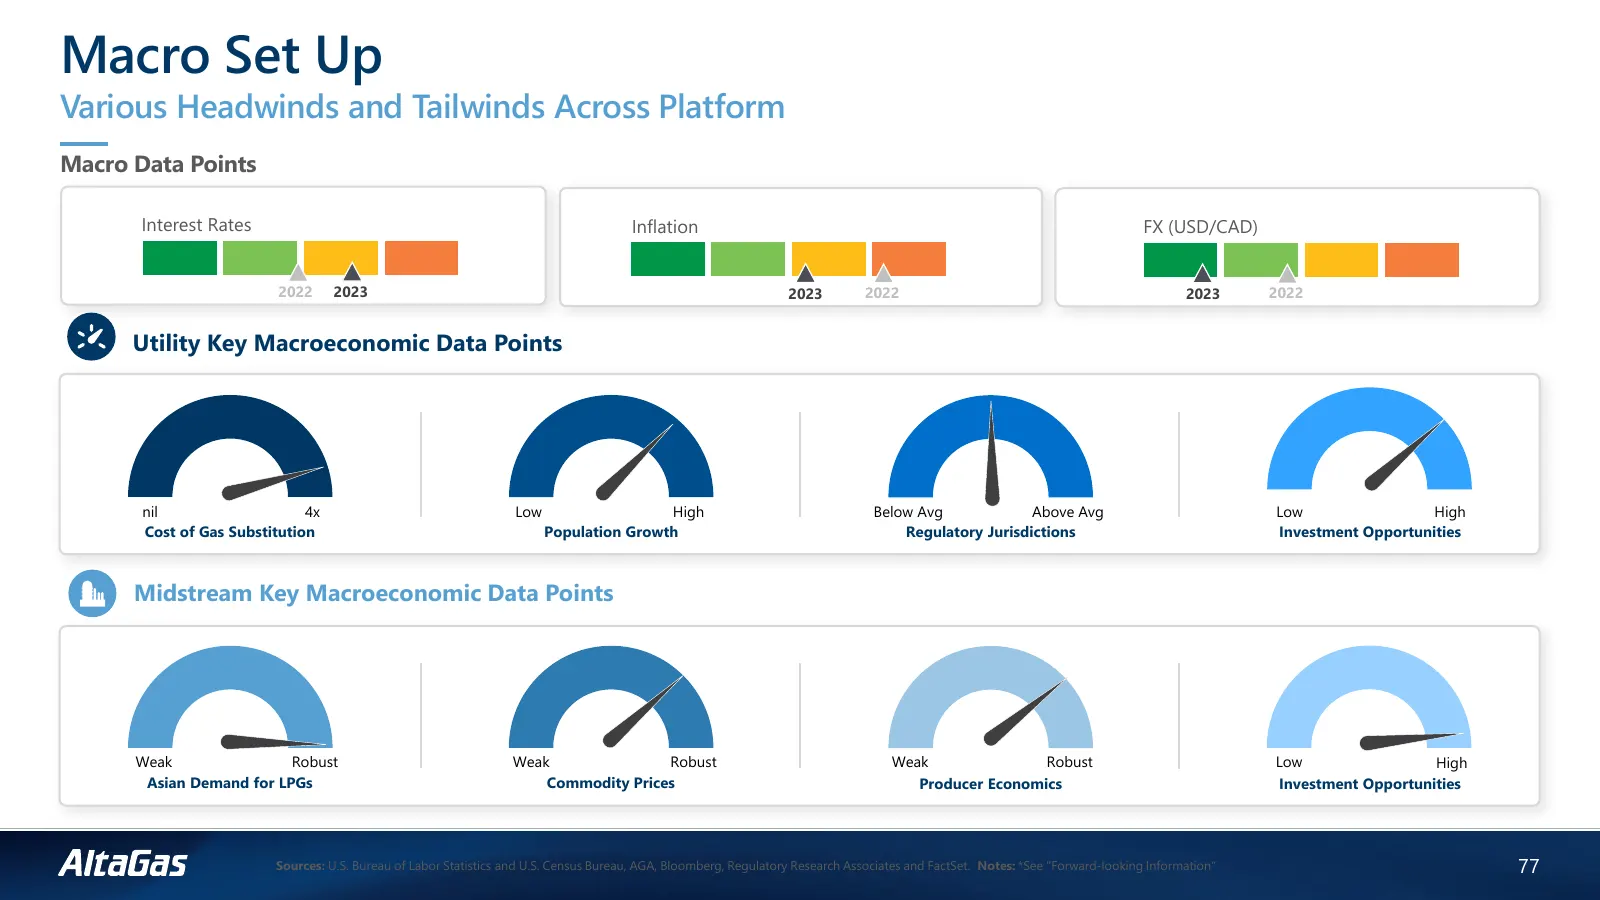
Slide 77: Macro Set Up
Macro Set Up Various Headwinds and Tailwinds Across Platform Macro Data Points Interest Rates Inflation FX (USD/CAD) 2022 2023 2023 2022 2023 2022 Utility Key Macroeconomic Data Points nil 4x Low High Below Avg Above Avg Low High Cost of Gas Substitution Population Growth Regulatory Jurisdictions In
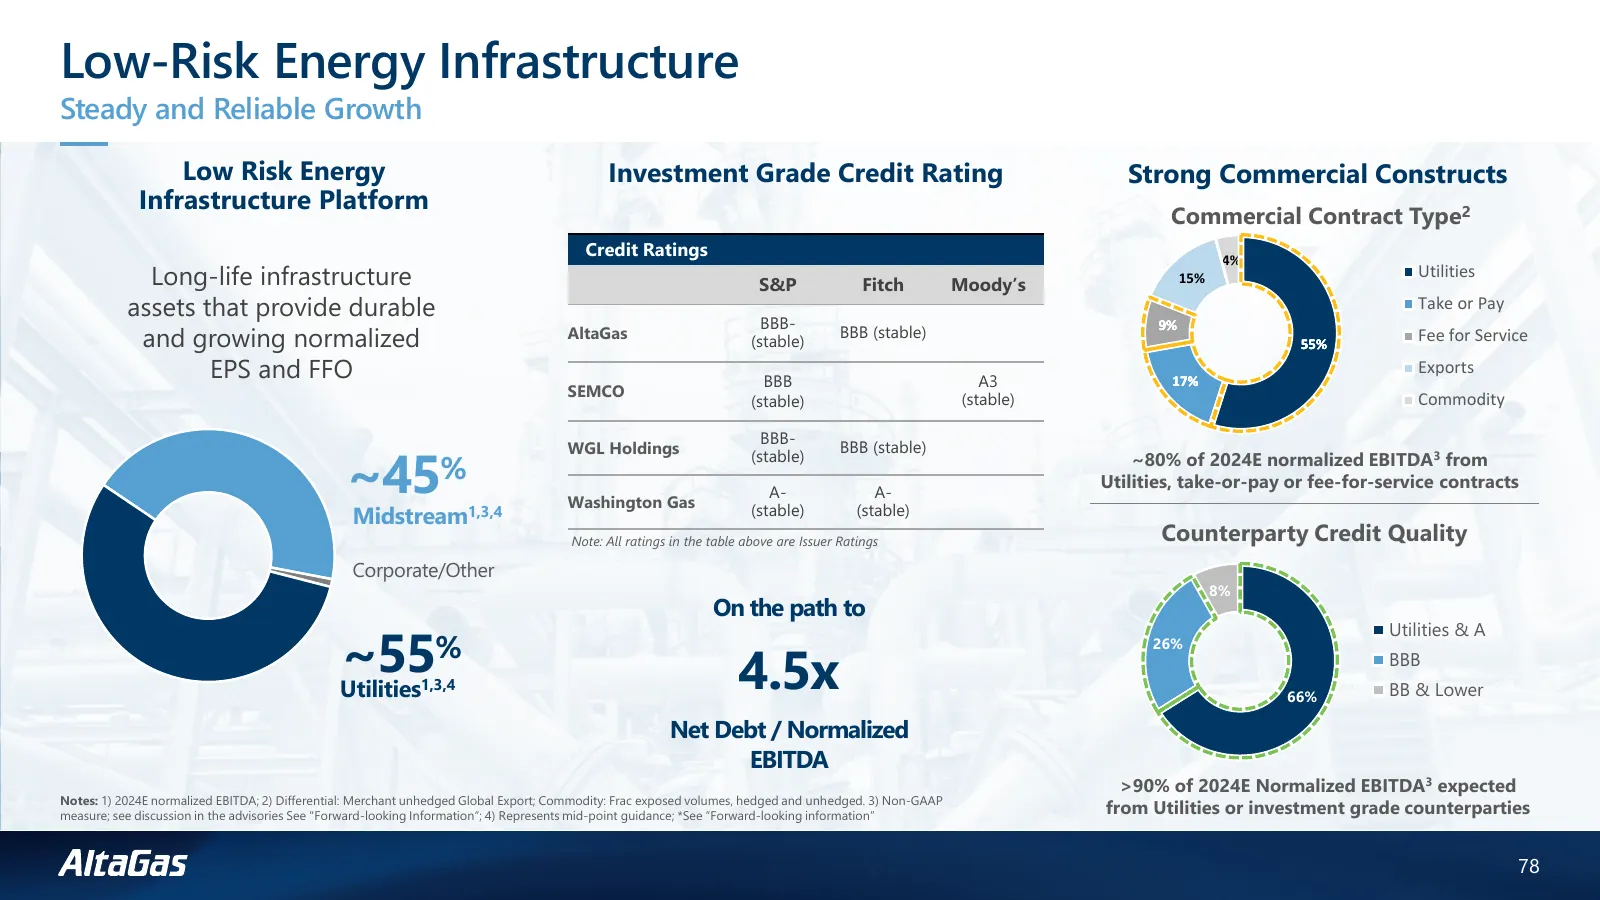
Slide 78: Low-Risk Energy Infrastructure
Low-Risk Energy Infrastructure Steady and Reliable Growth Low Risk Energy Investment Grade Credit Rating Strong Commercial Constructs Infrastructure Platform Commercial Contract Type2 Credit Ratings 4% Long-life infrastructure S&P Fitch Moody’s 15% Utilities assets that provide durable BBB- Take or
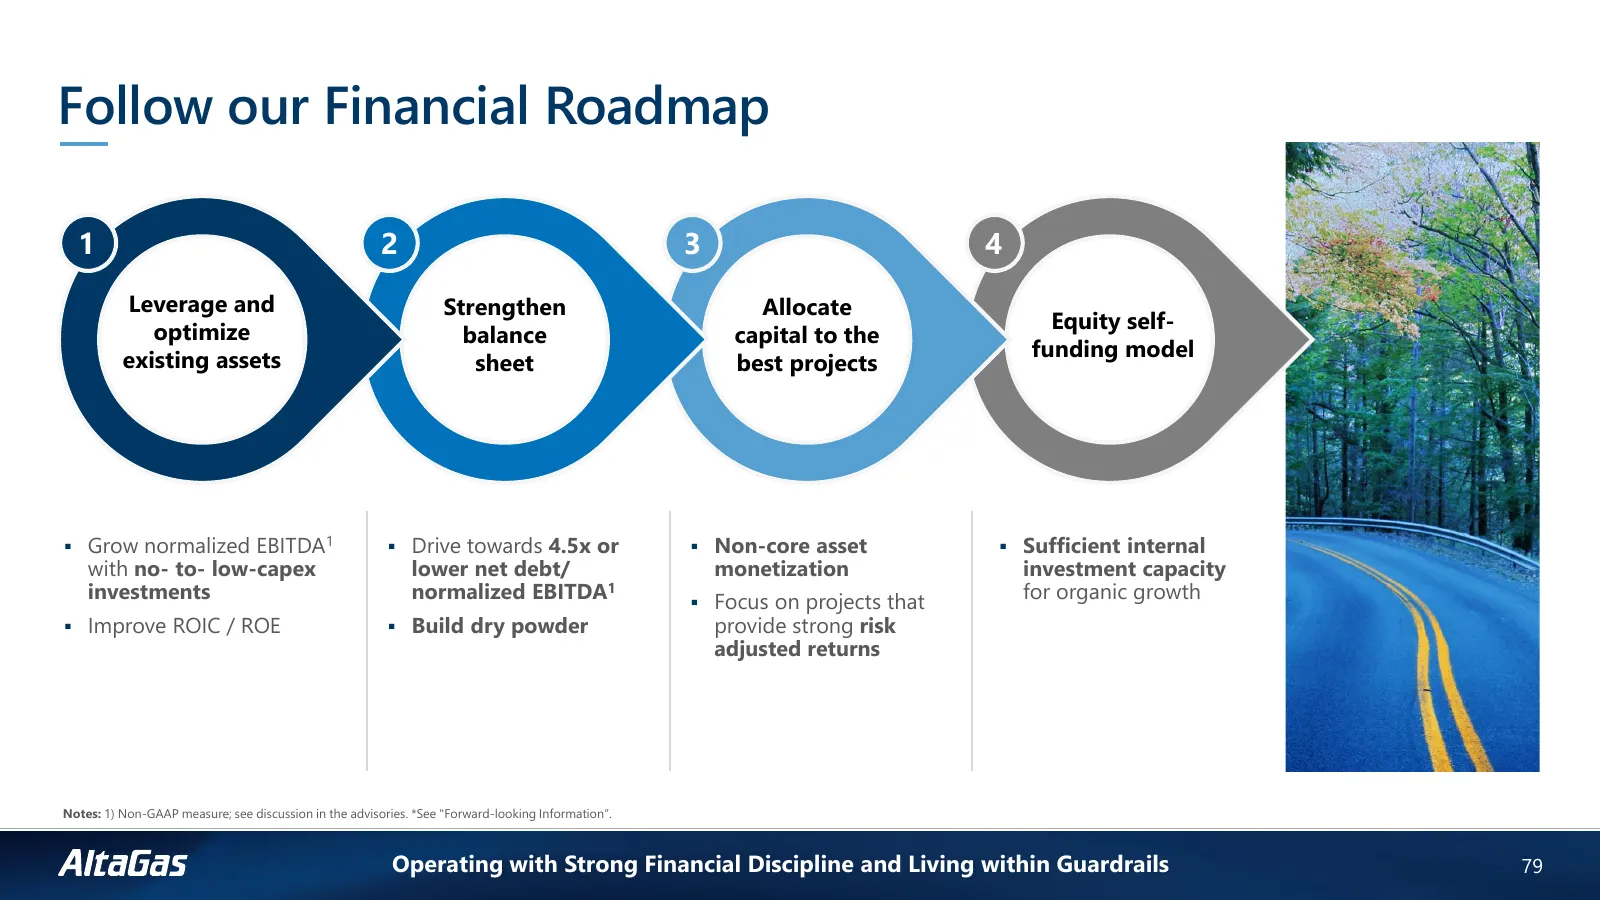
Slide 79: Follow our Financial Roadmap
Follow our Financial Roadmap 1 2 3 4 Leverage and Strengthen Allocate optimize Equity self- balance capital to the existing assets funding model sheet best projects ▪ Grow normalized EBITDA1 ▪ Drive towards 4.5x or ▪ Non-core asset ▪ Sufficient internal with no- to- low-capex lower net debt/ monetiz
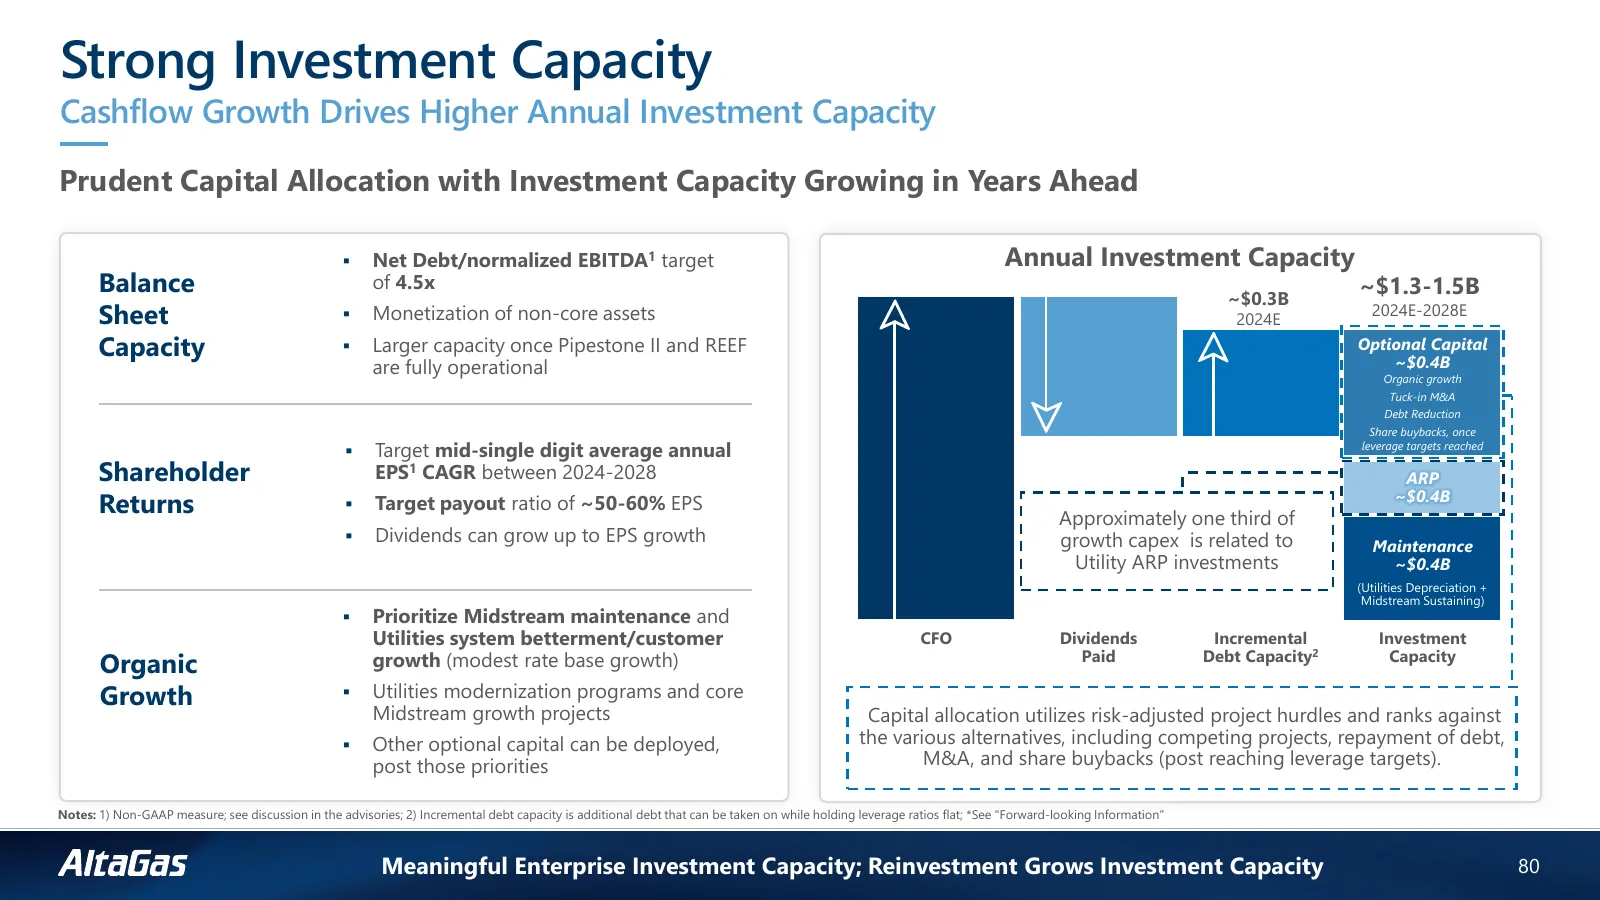
Slide 80: Strong Investment Capacity
Strong Investment Capacity Cashflow Growth Drives Higher Annual Investment Capacity Prudent Capital Allocation with Investment Capacity Growing in Years Ahead ▪ Net Debt/normalized EBITDA1 target Annual Investment Capacity Balance of 4.5x ~$0.3B ~$1.3-1.5B Sheet ▪ Monetization of non-core assets 202
Slide 81: Capital Allocation Framework
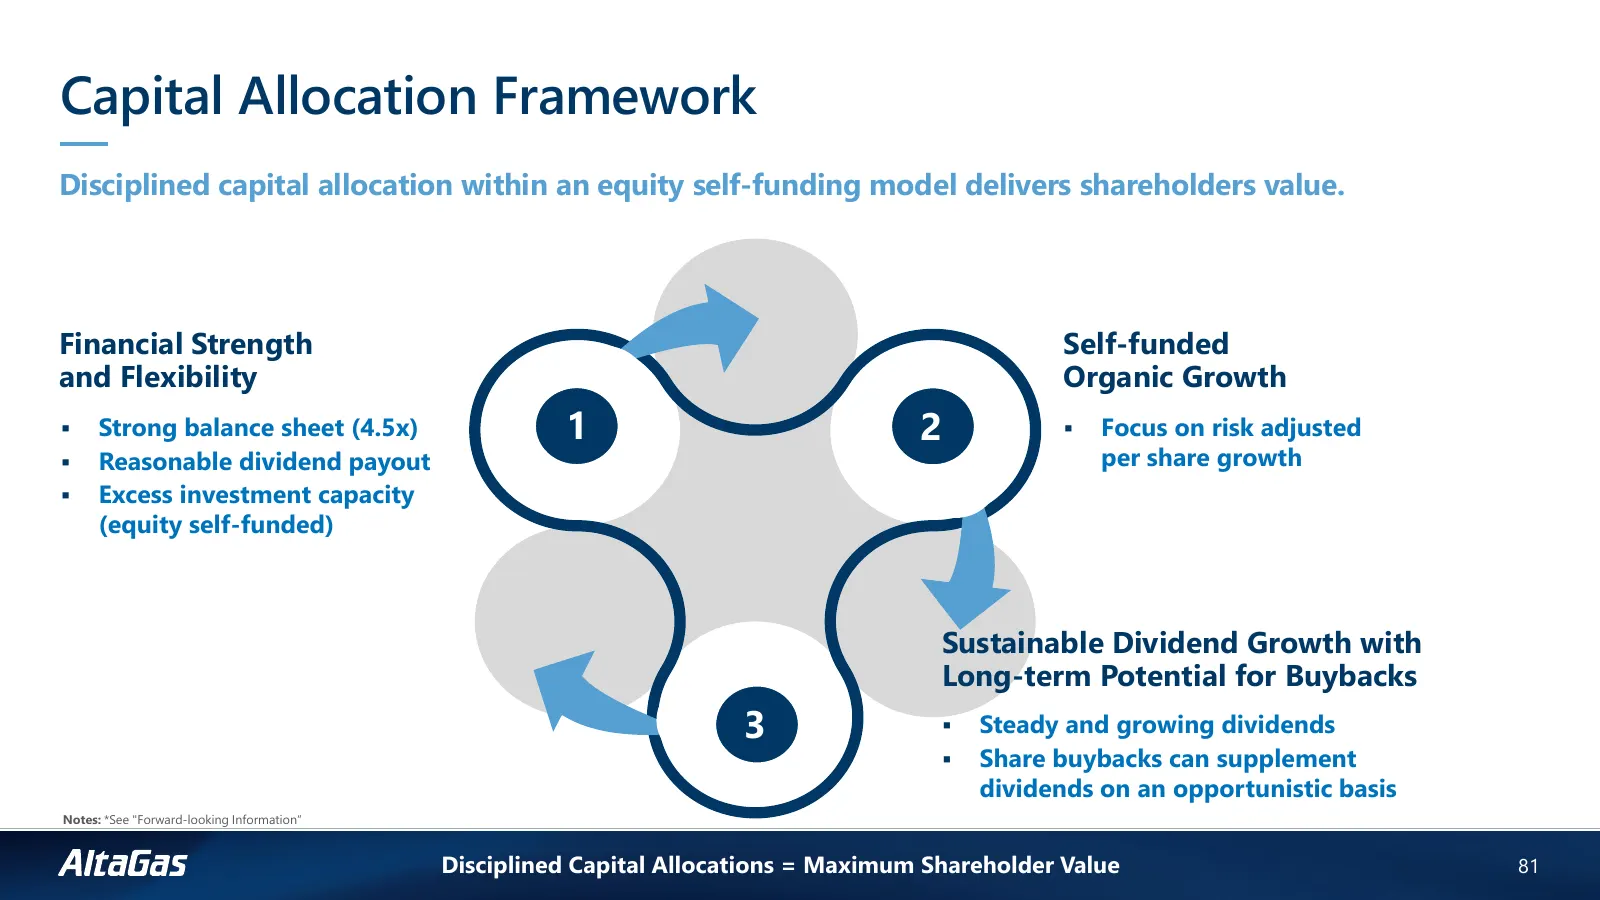
Capital Allocation Framework Disciplined capital allocation within an equity self-funding model delivers shareholders value. Financial Strength Self-funded and Flexibility Organic Growth ▪ Strong balance sheet (4.5x) 1 2 ▪ Focus on risk adjusted ▪ Reasonable dividend payout per share growth ▪ Excess
Slide 82: Balance Sheet is Structured to Weather the Current Environment
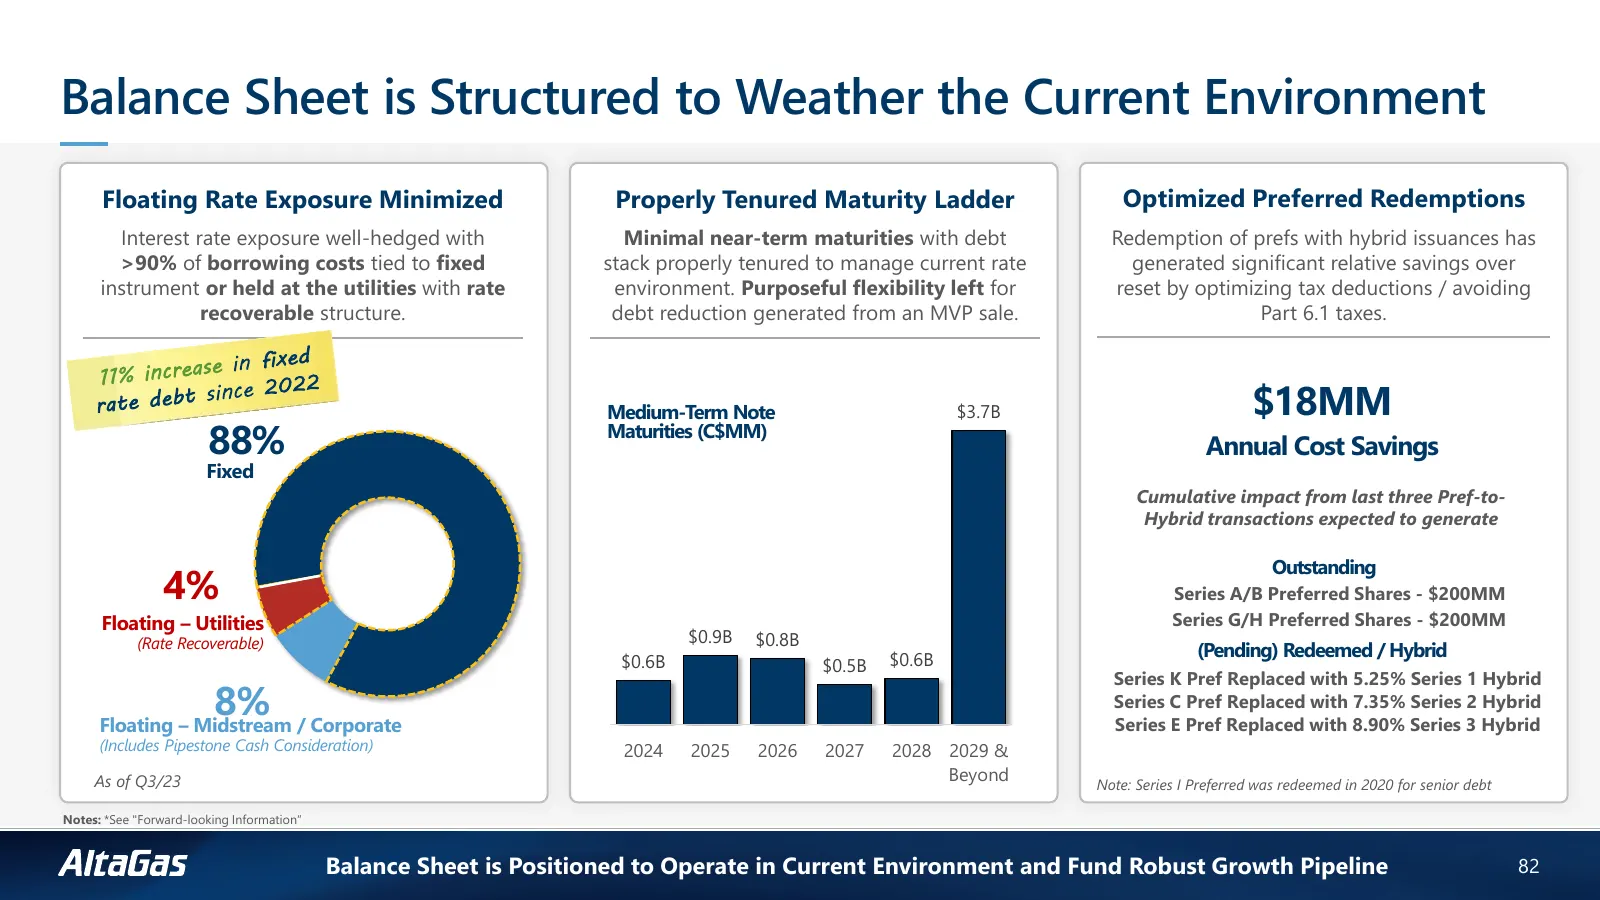
Balance Sheet is Structured to Weather the Current Environment Floating Rate Exposure Minimized Properly Tenured Maturity Ladder Optimized Preferred Redemptions Interest rate exposure well-hedged with Minimal near-term maturities with debt Redemption of prefs with hybrid issuances has >90% of borrow
Slide 83: The Various Paths to Achieving Our Leverage Target
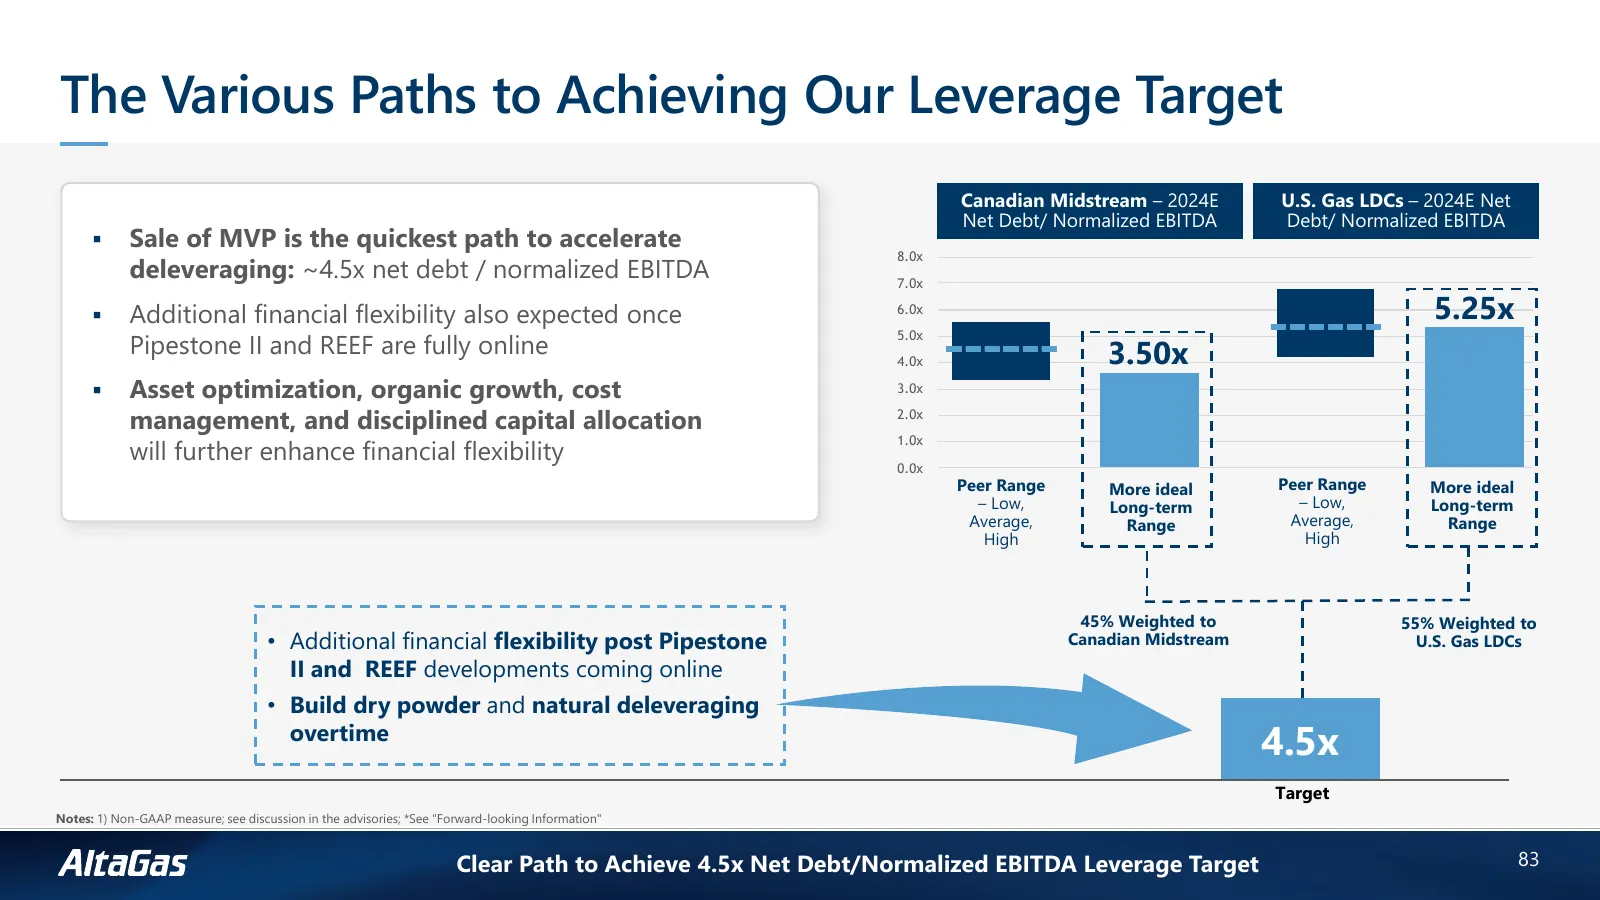
The Various Paths to Achieving Our Leverage Target Canadian Midstream – 2024E U.S. Gas LDCs – 2024E Net Net Debt/ Normalized EBITDA Debt/ Normalized EBITDA ▪ Sale of MVP is the quickest path to accelerate 8.0x deleveraging: ~4.5x net debt / normalized EBITDA 7.0x ▪ Additional financial flexibility a
Slide 84: Live by Specific Investment Criteria
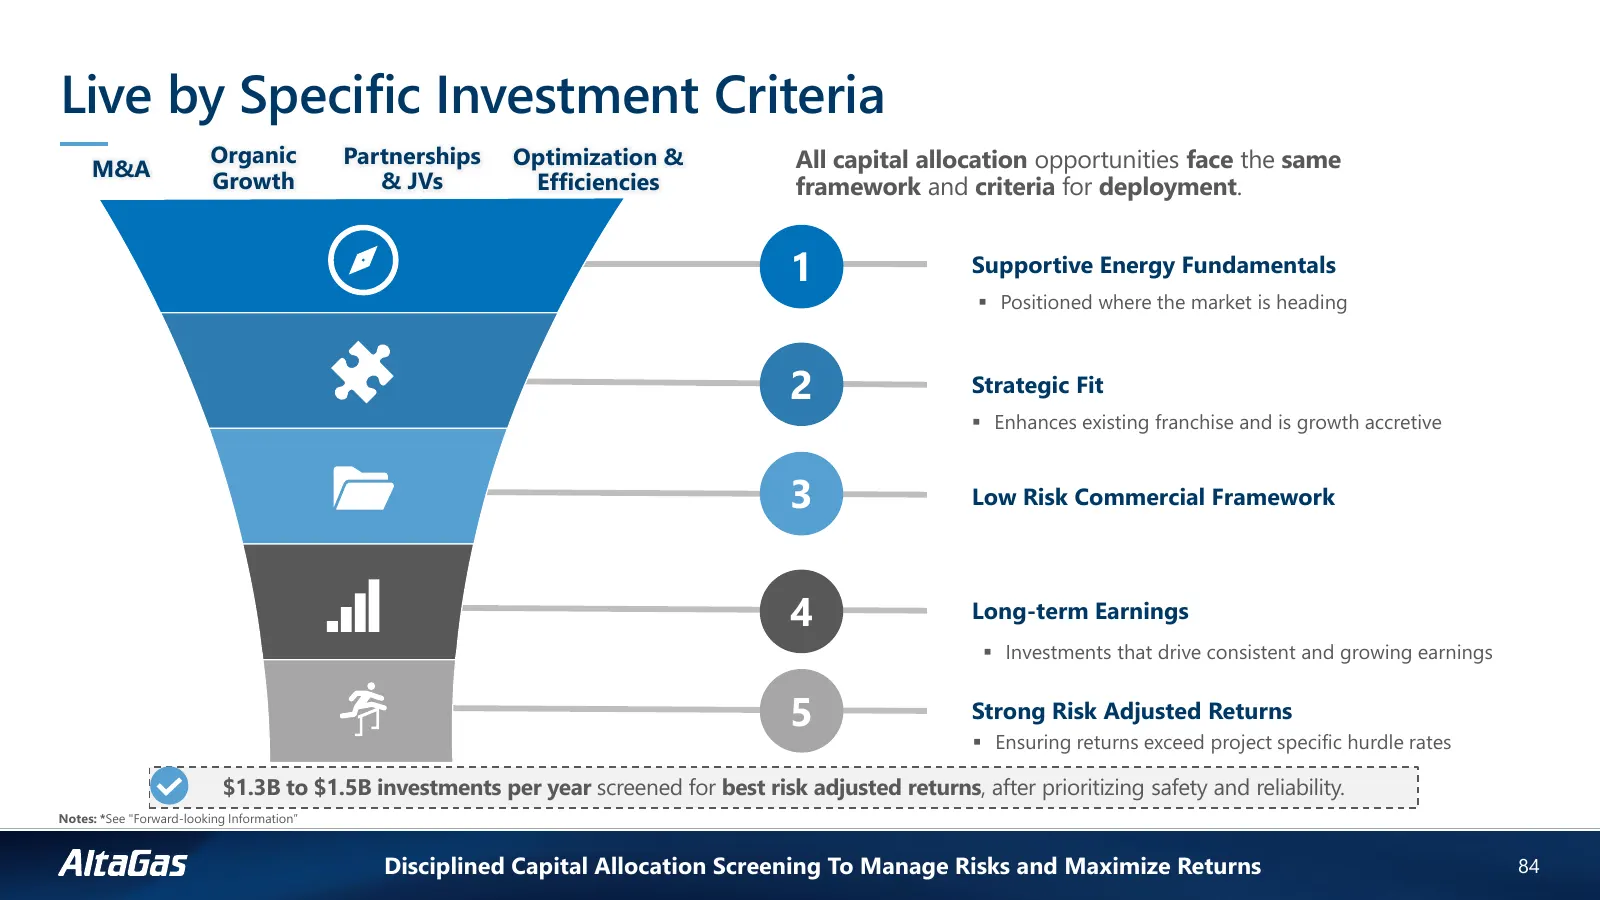
Live by Specific Investment Criteria Organic Partnerships Optimization & All capital allocation opportunities face the same M&A Growth & JVs Efficiencies framework and criteria for deployment. 1 Supportive Energy Fundamentals ▪ Positioned where the market is heading 2 Strategic Fit ▪ Enhances existi
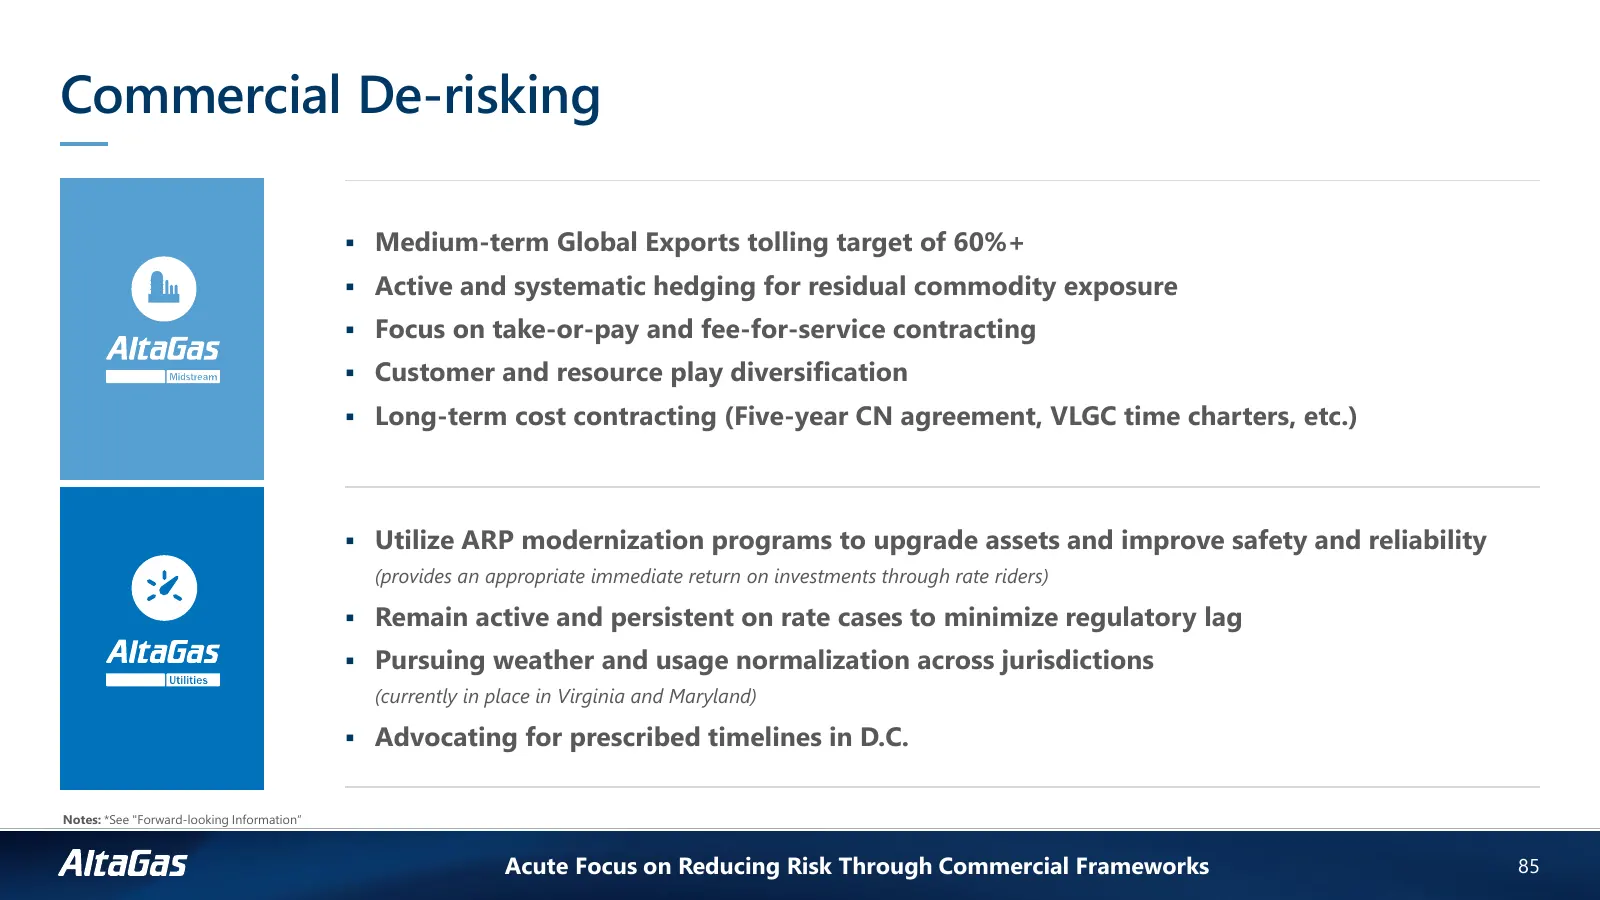
Slide 85: Commercial De-risking
Commercial De-risking ▪ Medium-term Global Exports tolling target of 60%+ ▪ Active and systematic hedging for residual commodity exposure ▪ Focus on take-or-pay and fee-for-service contracting ▪ Customer and resource play diversification ▪ Long-term cost contracting (Five-year CN agreement, VLGC tim
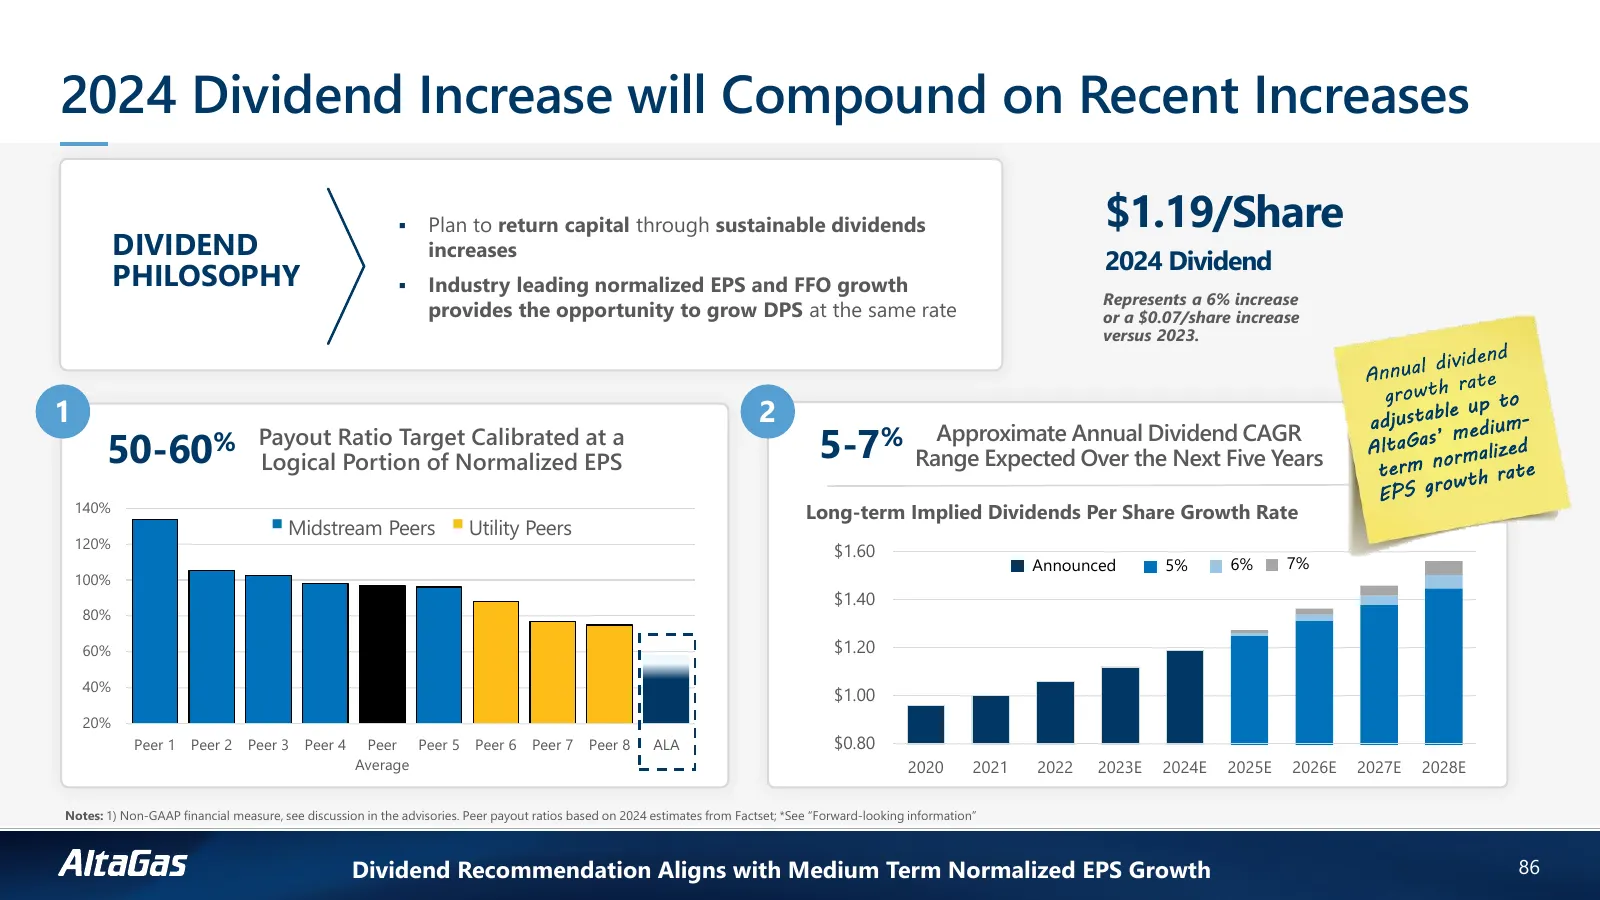
Slide 86: 2024 Dividend Increase will Compound on Recent Increases
2024 Dividend Increase will Compound on Recent Increases ▪ Plan to return capital through sustainable dividends $1.19/Share DIVIDEND increases 2024 Dividend PHILOSOPHY ▪ Industry leading normalized EPS and FFO growth Represents a 6% increase provides the opportunity to grow DPS at the same rate or a
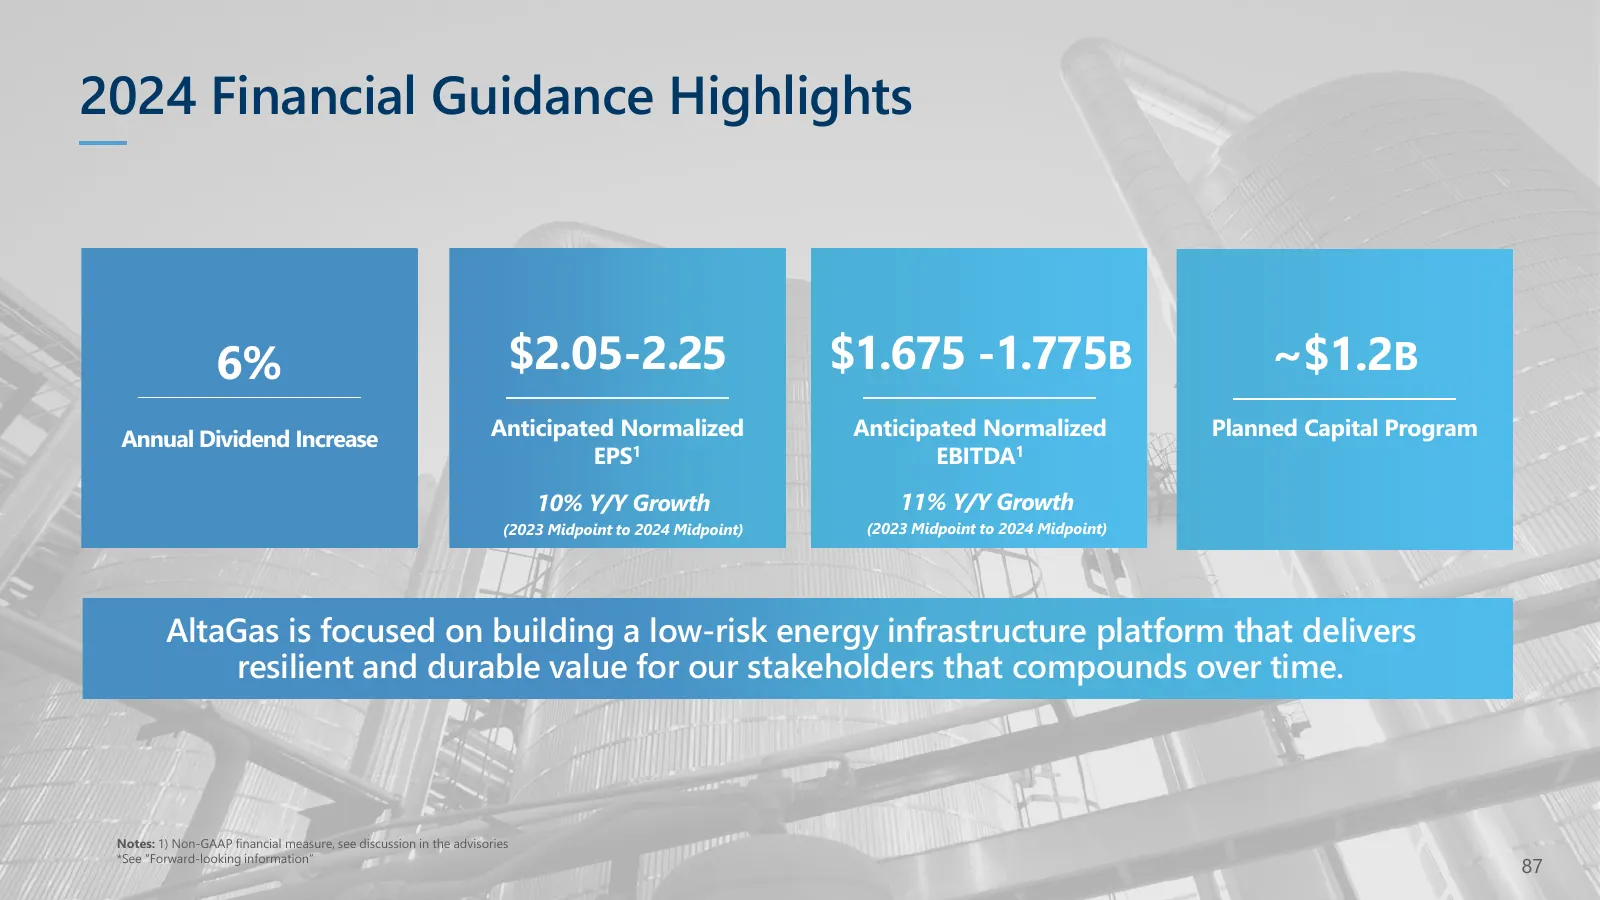
Slide 87: 2024 Financial Guidance Highlights
2024 Financial Guidance Highlights 6% $2.05-2.25 $1.675 -1.775B ~$1.2B Annual Dividend Increase Anticipated Normalized Anticipated Normalized Planned Capital Program EPS1 EBITDA1 10% Y/Y Growth 11% Y/Y Growth (2023 Midpoint to 2024 Midpoint) (2023 Midpoint to 2024 Midpoint) AltaGas is focused on bui
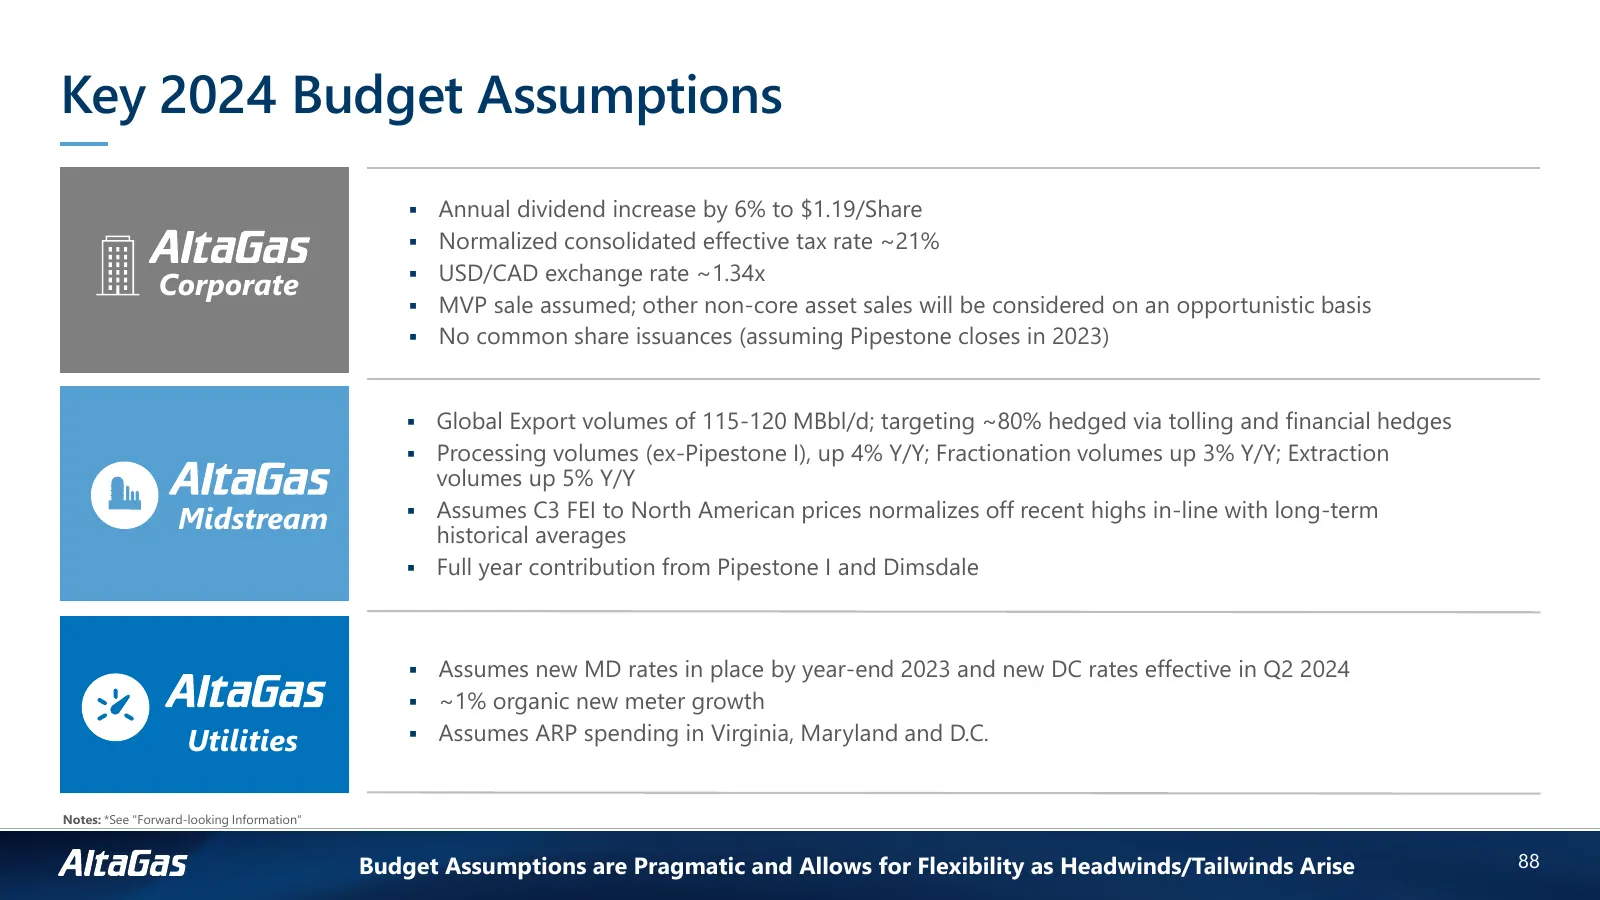
Slide 88: Key 2024 Budget Assumptions
Key 2024 Budget Assumptions ▪ Annual dividend increase by 6% to $1.19/Share ▪ Normalized consolidated effective tax rate ~21% USD/CAD exchange rate ~1.34x Corporate ▪ ▪ MVP sale assumed; other non-core asset sales will be considered on an opportunistic basis ▪ No common share issuances (assuming Pip
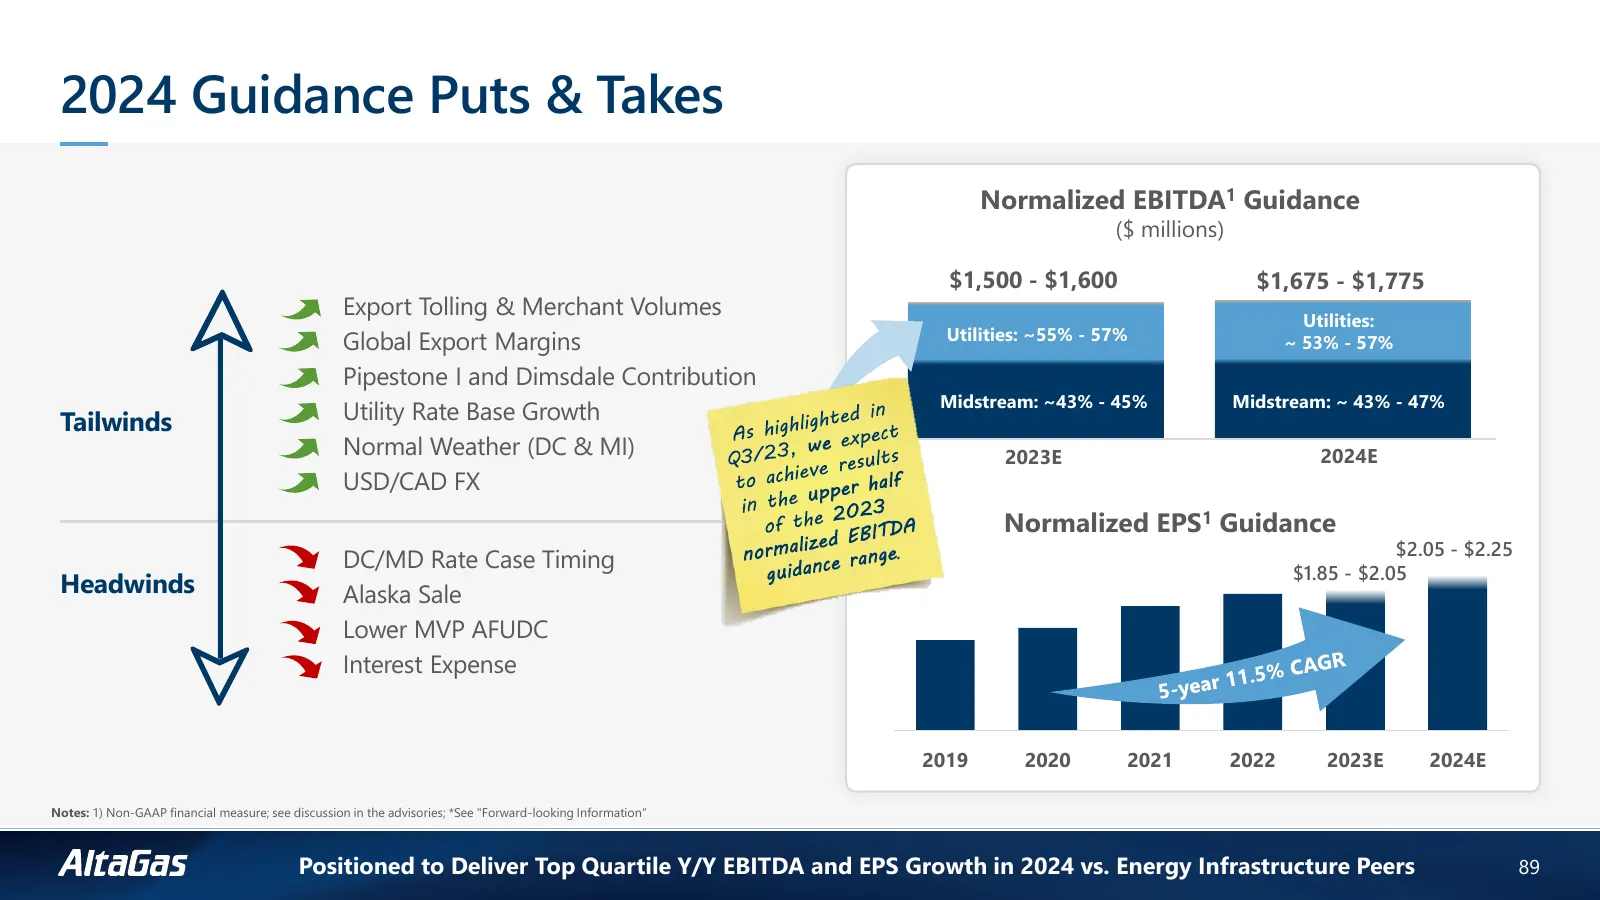
Slide 89: 2024 Guidance Puts & Takes
2024 Guidance Puts & Takes Normalized EBITDA1 Guidance ($ millions) $1,500 - $1,600 $1,675 - $1,775 Export Tolling & Merchant Volumes Utilities: Utilities: ~55% - 57% Global Export Margins ~ 53% - 57% Pipestone I and Dimsdale Contribution Midstream: ~43% - 45% Midstream: ~ 43% - 47% Tailwinds Utilit
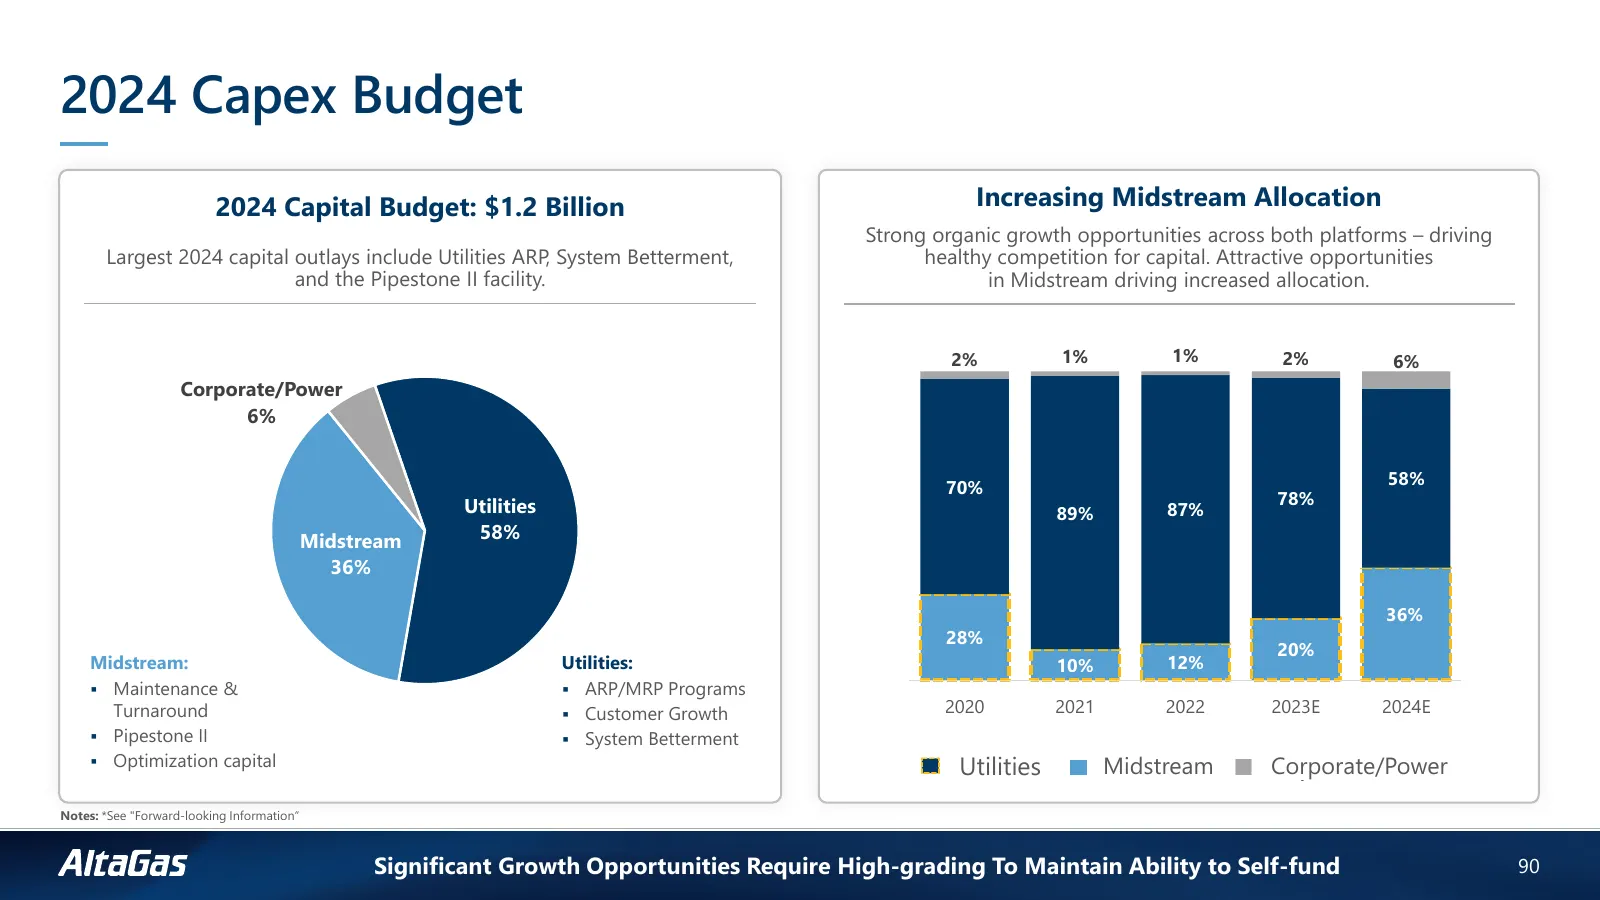
Slide 90: 2024 Capex Budget
2024 Capex Budget 2024 Capital Budget: $1.2 Billion Increasing Midstream Allocation Strong organic growth opportunities across both platforms – driving Largest 2024 capital outlays include Utilities ARP, System Betterment, healthy competition for capital. Attractive opportunities and the Pipestone I
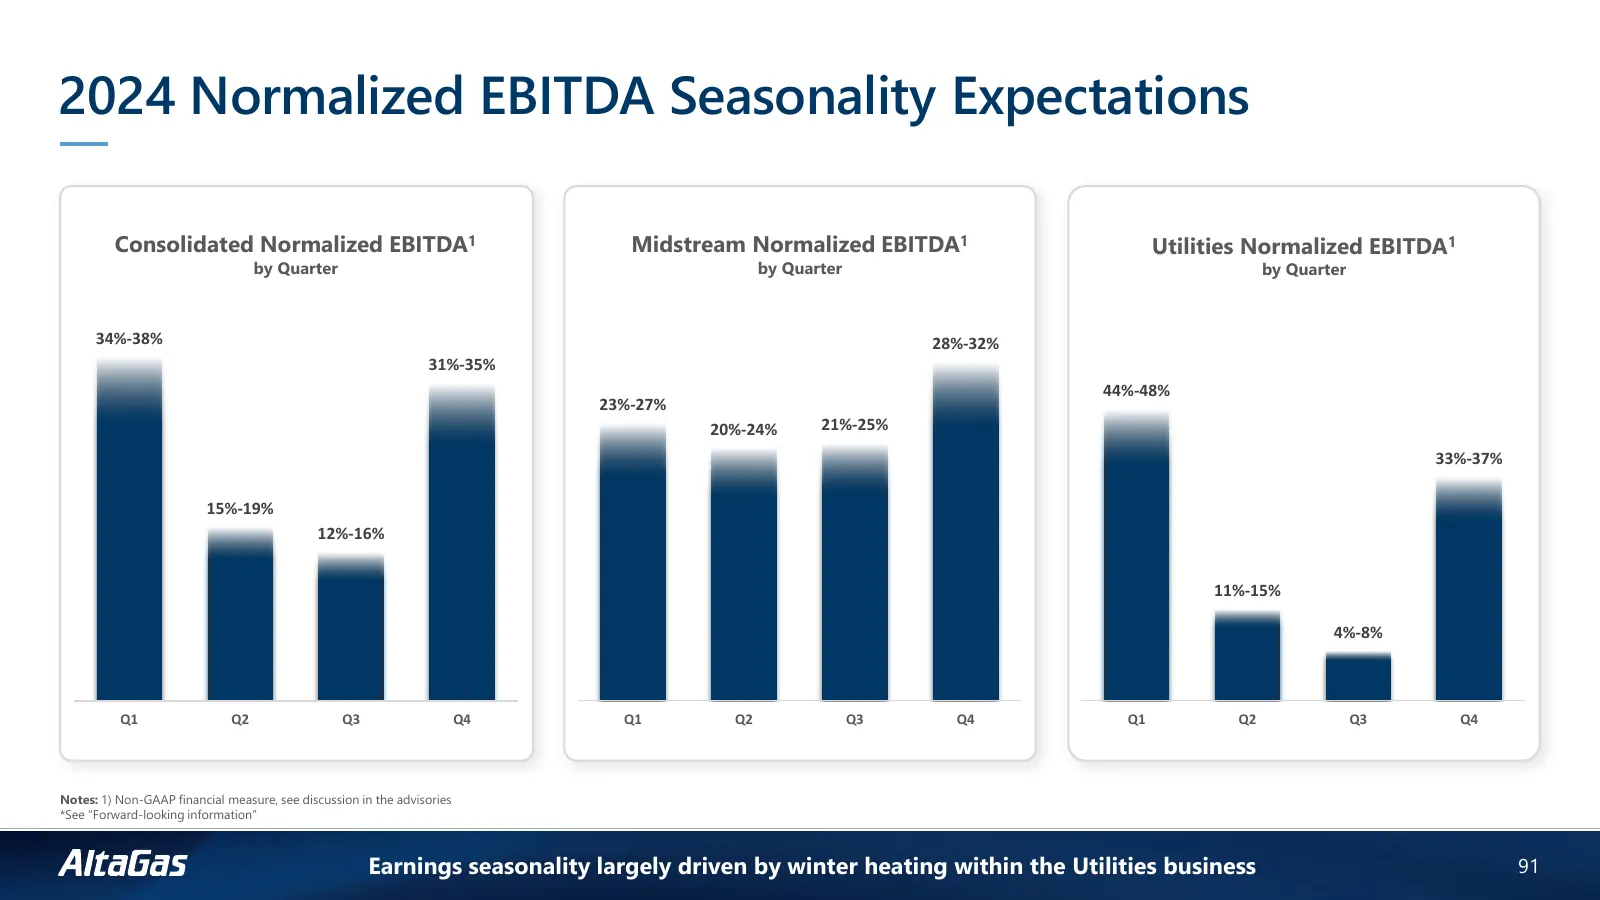
Slide 91: 2024 Normalized EBITDA Seasonality Expectations
2024 Normalized EBITDA Seasonality Expectations Consolidated Normalized EBITDA1 Midstream Normalized EBITDA1 Utilities Normalized EBITDA1 by Quarter by Quarter by Quarter 34%-38% 28%-32% 31%-35% 44%-48% 23%-27% 20%-24% 21%-25% 33%-37% 15%-19% 12%-16% 11%-15% 4%-8% Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4
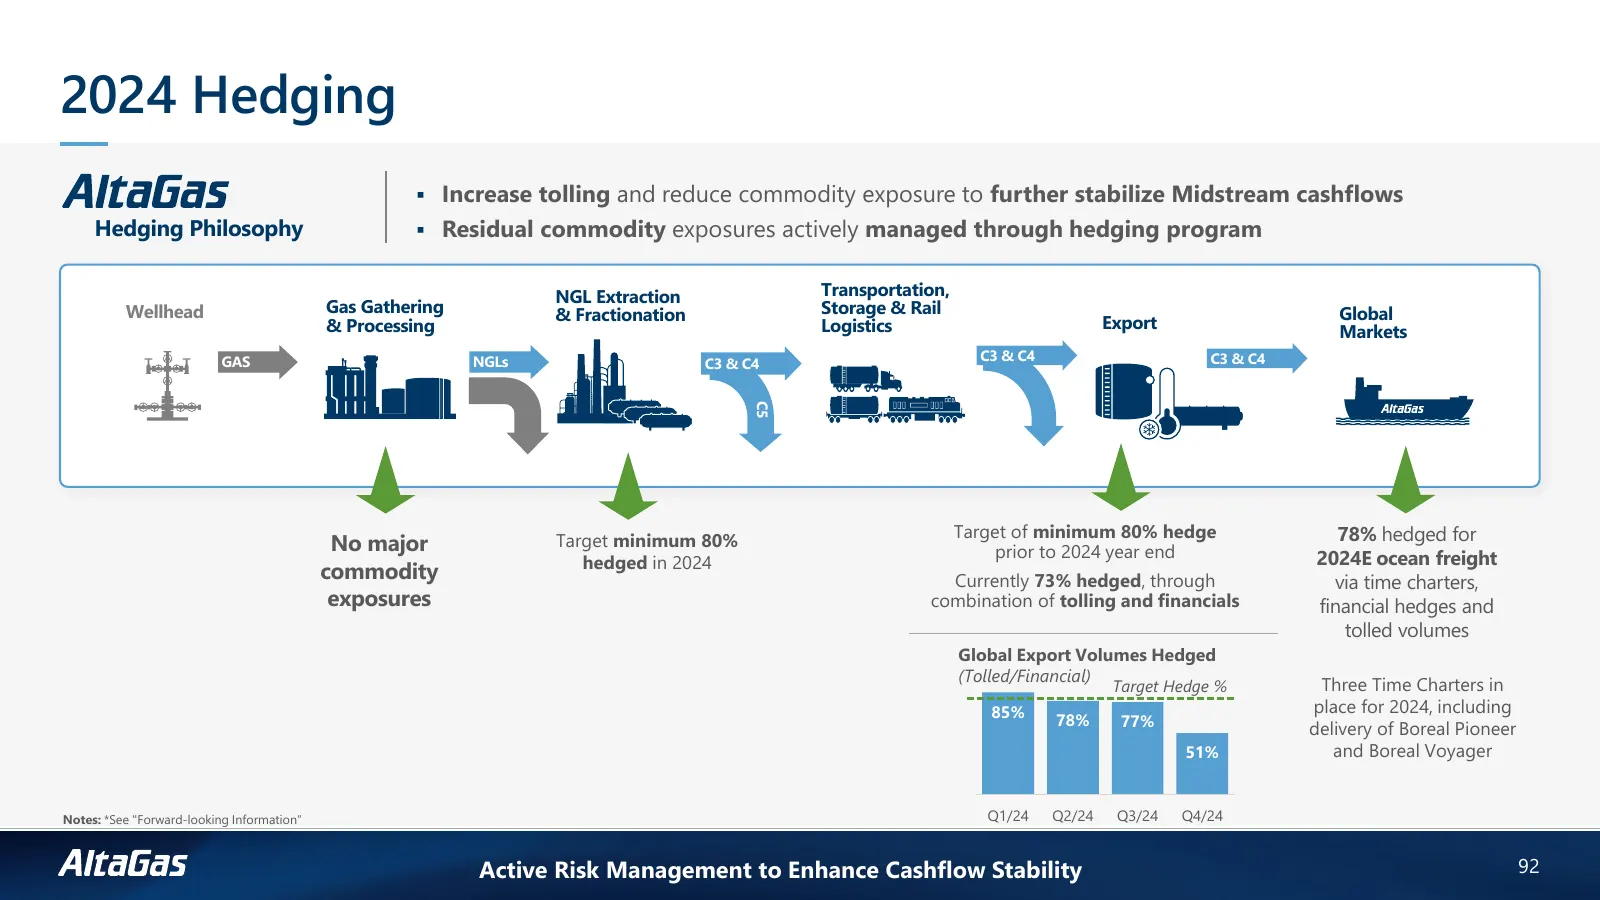
Slide 92: 2024 Hedging
2024 Hedging ▪ Increase tolling and reduce commodity exposure to further stabilize Midstream cashflows Hedging Philosophy ▪ Residual commodity exposures actively managed through hedging program NGL Extraction Transportation, Wellhead Gas Gathering & Fractionation Storage & Rail Global & Processing L
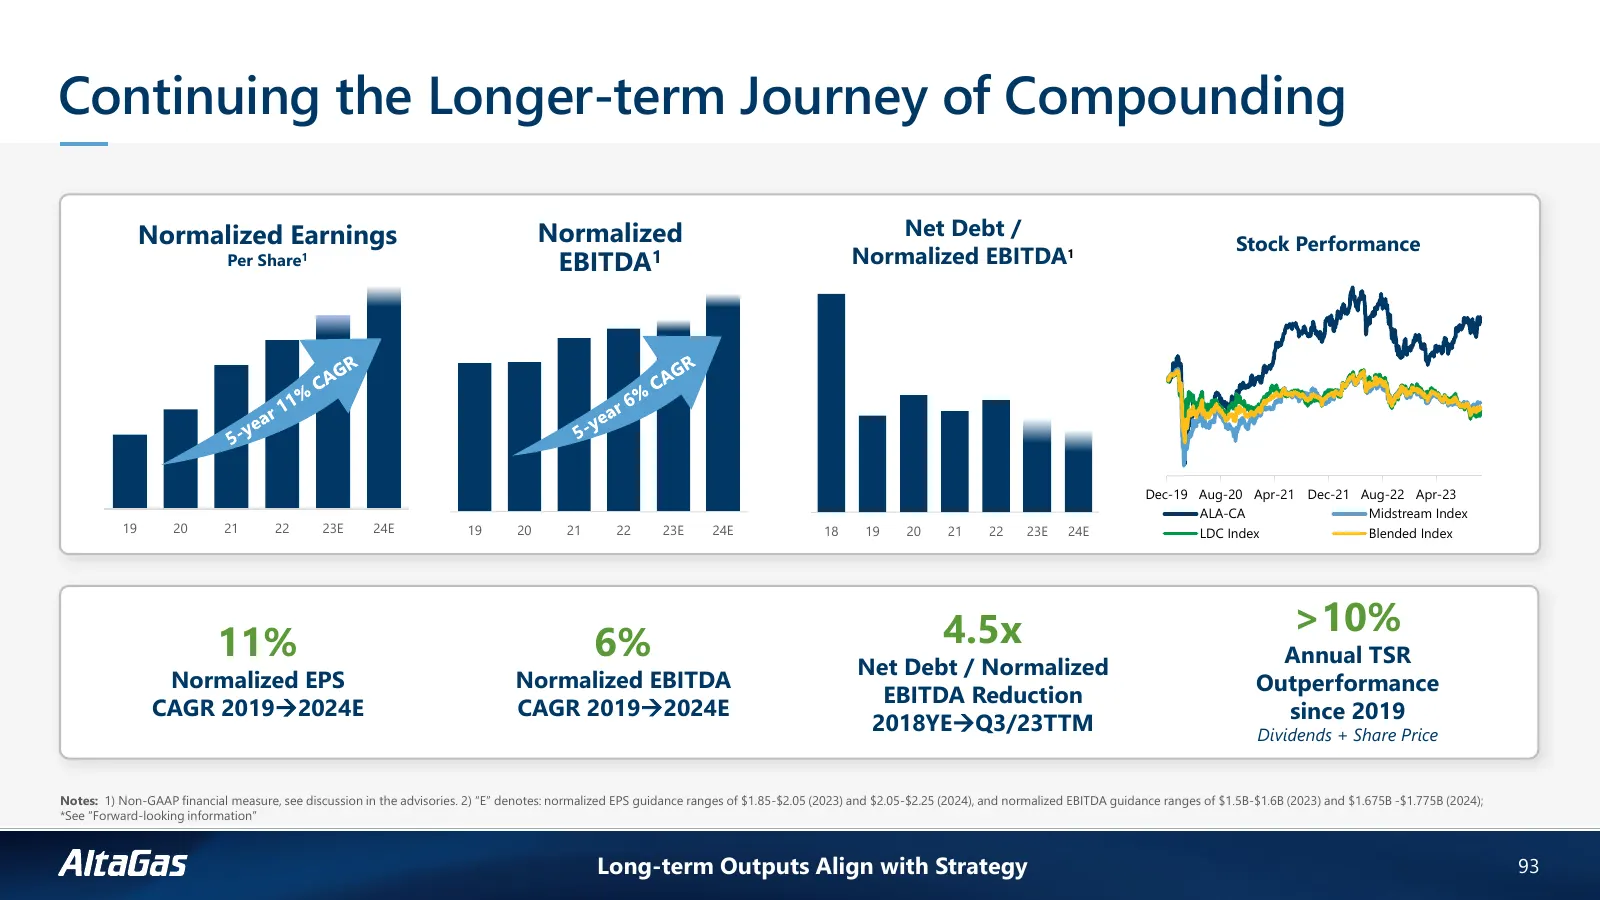
Slide 93: Continuing the Longer-term Journey of Compounding
Continuing the Longer-term Journey of Compounding Normalized Earnings Normalized Net Debt / Stock Performance Per Share1 EBITDA1 Normalized EBITDA1 Dec-19 Aug-20 Apr-21 Dec-21 Aug-22 Apr-23 ALA-CA Midstream Index 19 20 21 22 23E 24E 19 20 21 22 23E 24E 18 19 20 21 22 23E 24E LDC Index Blended Index
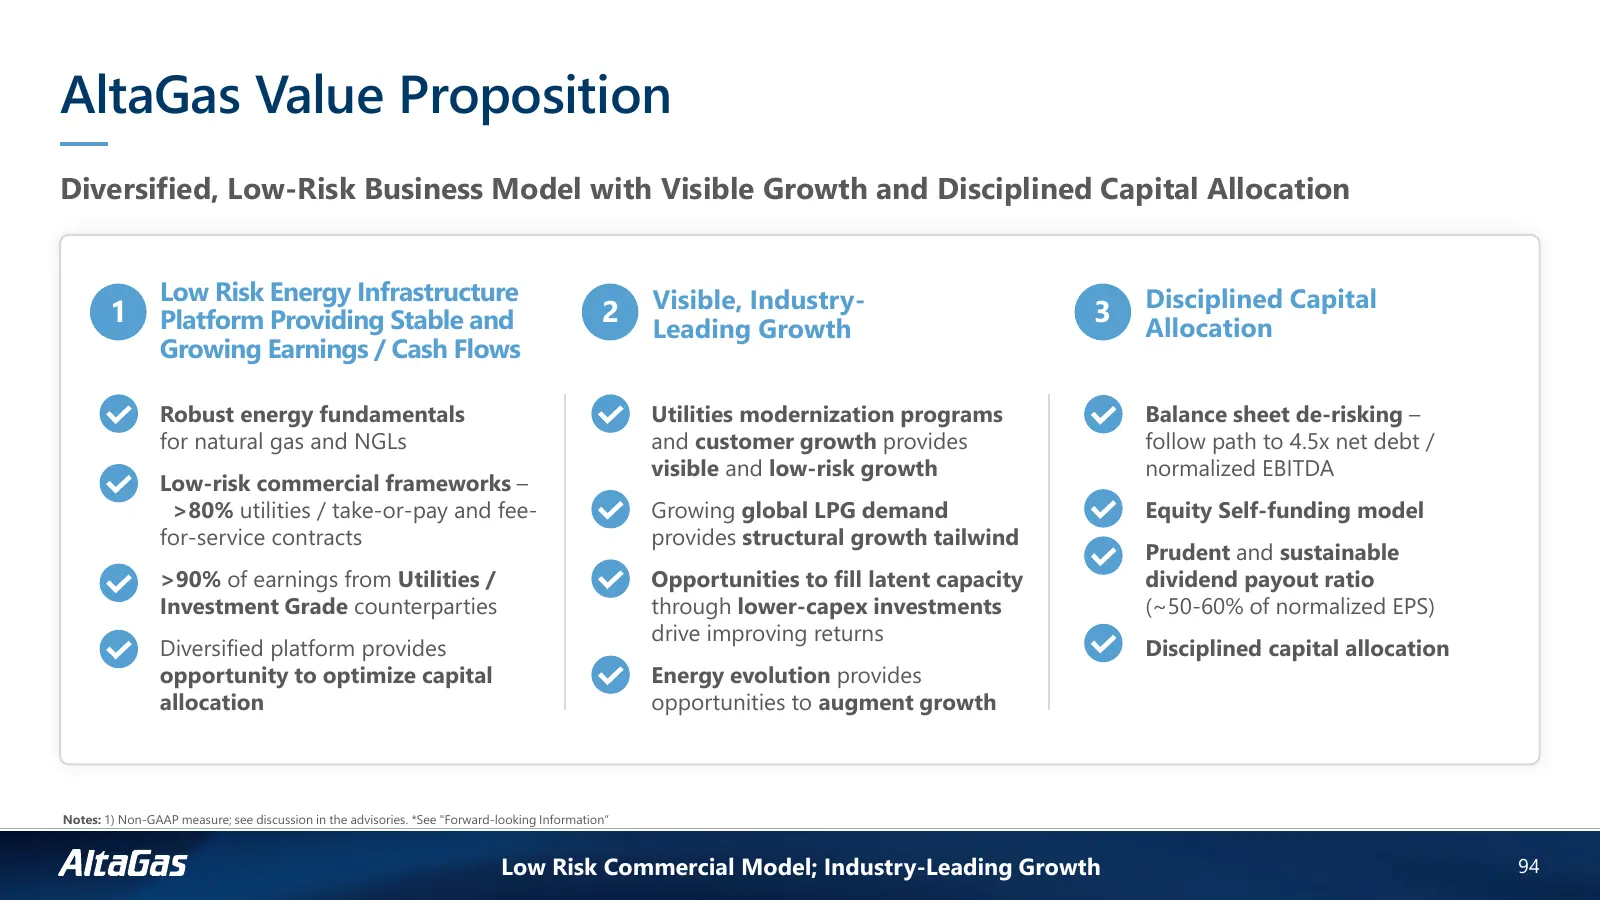
Slide 94: AltaGas Value Proposition
AltaGas Value Proposition Diversified, Low-Risk Business Model with Visible Growth and Disciplined Capital Allocation Low Risk Energy Infrastructure Visible, Industry- Disciplined Capital 1 Platform Providing Stable and 2 3 Leading Growth Allocation Growing Earnings / Cash Flows Robust energy fundam
Slide 95: Q&A
Q&A 95
Slide 96: Thank you for joining
Thank you for joining AltaGas if ~ =
Slide 97: Appendix
Appendix 97
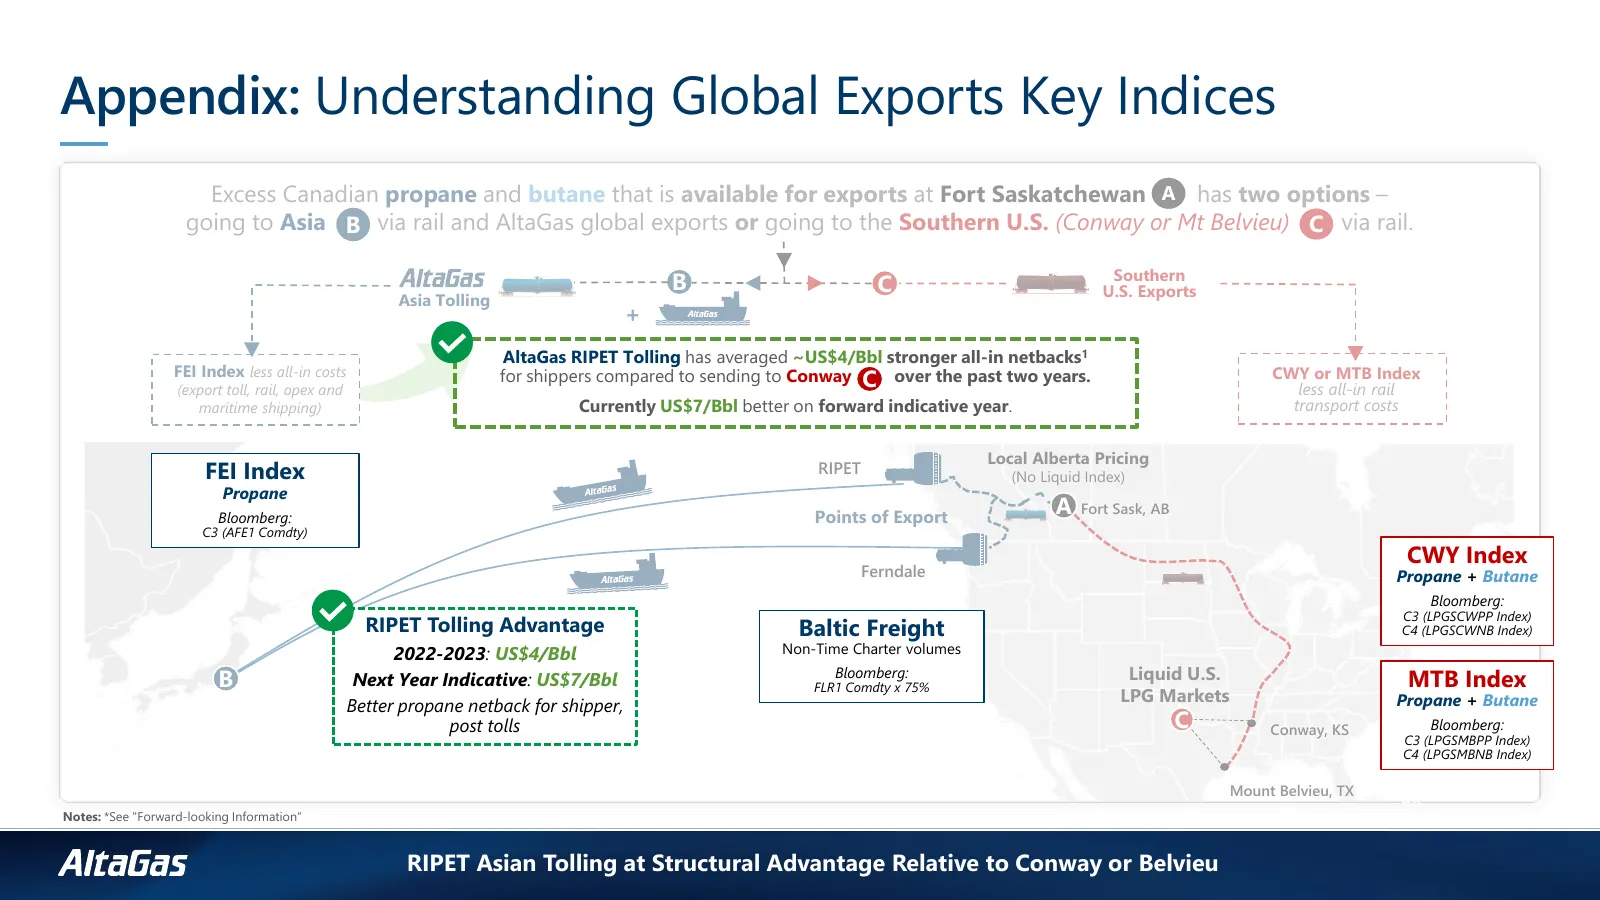
Slide 98: Appendix: Understanding Global Exports Key Indices
Appendix: Understanding Global Exports Key Indices Excess Canadian propane and butane that is available for exports at Fort Saskatchewan A has two options – going to Asia B via rail and AltaGas global exports or going to the Southern U.S. (Conway or Mt Belvieu) C via rail. Southern B C U.S. Exports
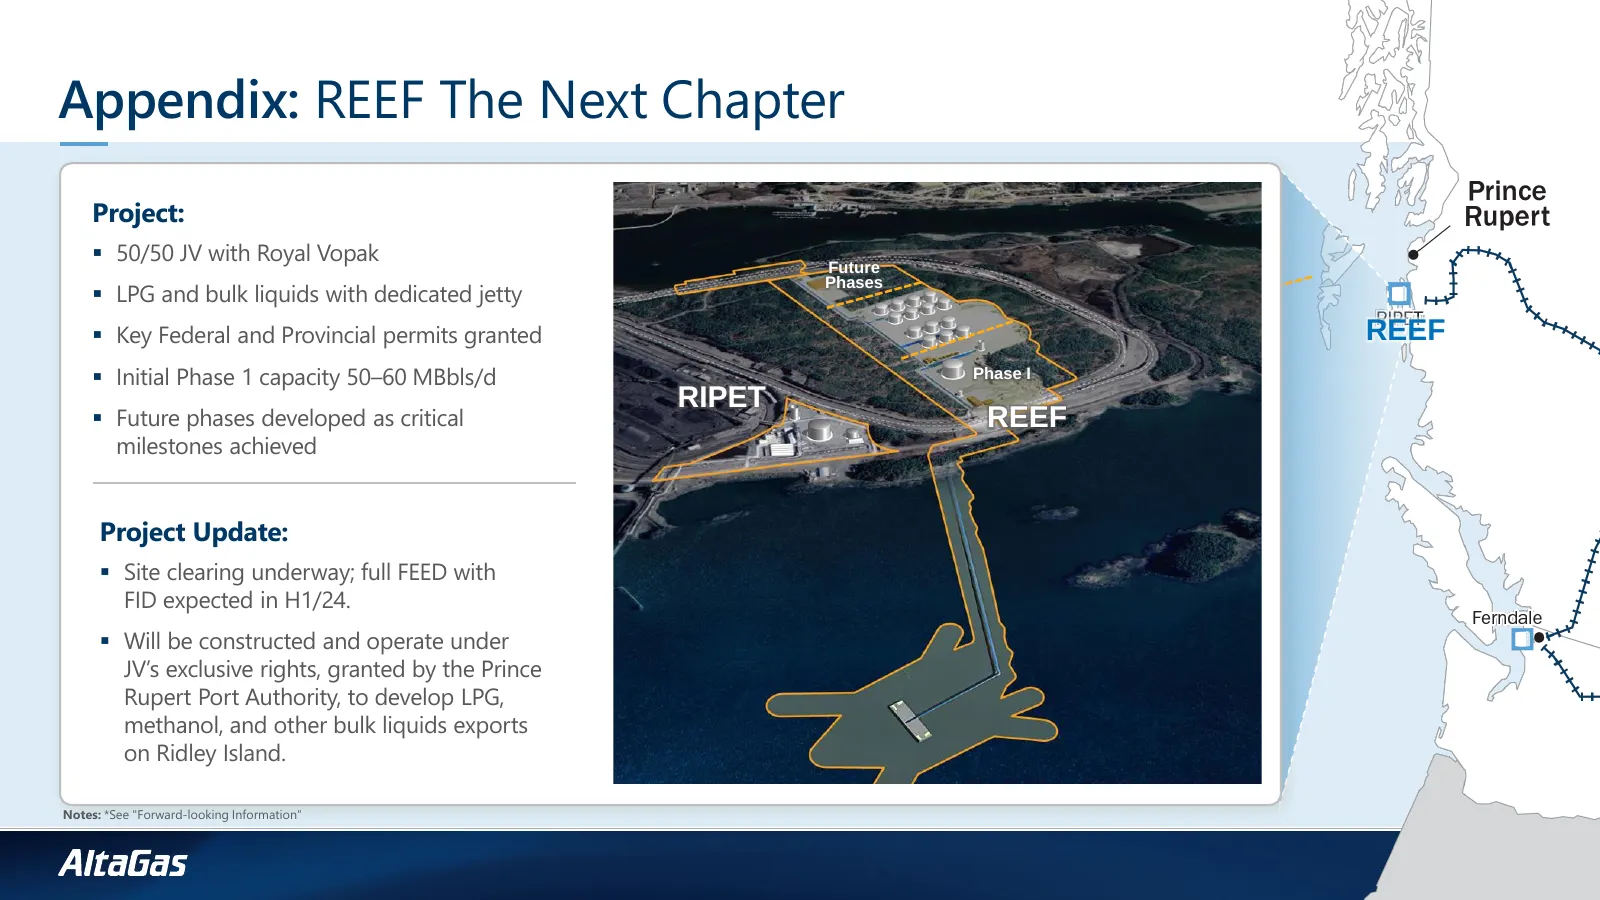
Slide 99: Appendix: REEF The Next Chapter
Appendix: REEF The Next Chapter Project: ▪ 50/50 JV with Royal Vopak Future Future Phases Phases ▪ LPG and bulk liquids with dedicated jetty ▪ Key Federal and Provincial permits granted REEF ▪ Initial Phase 1 capacity 50–60 MBbls/d Phase I I Phase RIPET ▪ Future phases developed as critical RIPET RE
Source: Internet Archive copy of altagas.ca
More decks from AltaGas Ltd.
 Q3 2026 Earnings Presentation23 slides · Oct 29, 2026
 Q2 2026 Earnings Presentation24 slides · Jul 30, 2026
 Investor Presentation (June 2026)58 slides · June 2026
 Investor Presentation (May 2026)61 slides · May 2026
 Q1 2026 Earnings Presentation24 slides · Apr 30, 2026
 Q4 2025 Earnings Presentation30 slides · Mar 6, 2026