Carolina Financial Corporation
Carolina Financial — IPO Roadshow (November 2015)
24 slides from Carolina Financial's IPO roadshow presentation, Nov 30, 2015
Slide 1: Common Stock Offering Investor Presentation
Common Stock Offering Investor Presentation NASDAQ: CARO November 2015 Filed pursuant to Rule 433 Issuer Free Writing Prospectus, Dated November 30, 2015 Relating to the Preliminary Prospectus Dated November 30, 2015 Registration Statement No. 333 - 206676
Slide 2: Disclaimer
2 Disclaimer Certain statements in this presentation contain “forward - looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 , such as statements relating to future plans and expectations, and are thus prospective . Such forward - looking statements include
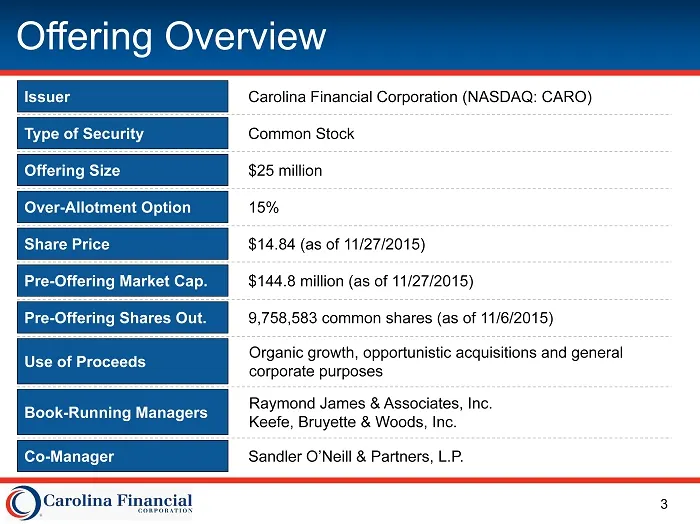
Slide 3: Offering Overview
3 Offering Overview 15% Carolina Financial Corporation (NASDAQ: CARO) Common Stock $25 million $14.84 (as of 11/27/2015) 9,758,583 common shares (as of 11/6/2015) Organic growth, opportunistic acquisitions and general corporate purposes Raymond James & Associates, Inc. Keefe, Bruyette & Woods, Inc.
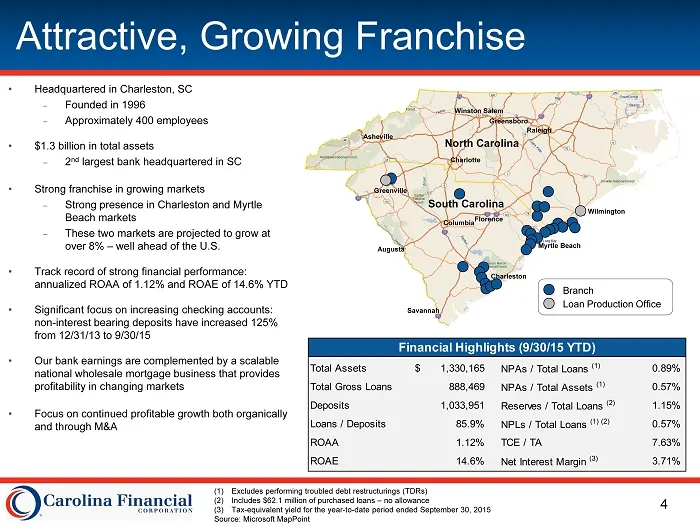
Slide 4: Financial Highlights and Attractive, Growing Franchise
4 Financial Highlights (9/30/15 YTD) Total Assets 1,330,165$ NPAs / Total Loans (1) 0.89% Total Gross Loans 888,469 NPAs / Total Assets (1) 0.57% Deposits 1,033,951 Reserves / Total Loans (2) 1.15% Loans / Deposits 85.9% NPLs / Total Loans (1) (2) 0.57% ROAA 1.12% TCE / TA 7.63% ROAE 14.6% Net Inter
Slide 5: Strong Culture and Company Goals
5 Strong Culture and Company Goals Safety and Soundness Profitability Growth Vision: To Be THE Trusted Community Bank of Choice Mission: Values: Guiding Principles: Leadership Integrity Communication Quality Offering competitive community banking products and superior service experiences for our cus
Slide 6: Seasoned Executive Management Team
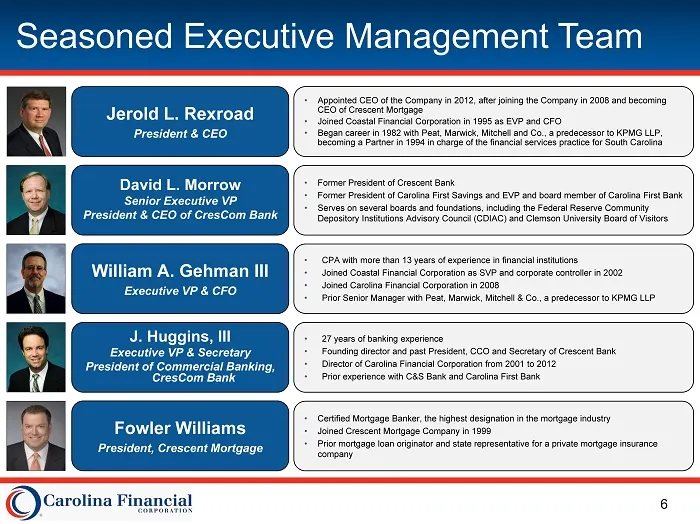
6 William A. Gehman III Executive VP & CFO • CPA with more than 13 years of experience in financial institutions • Joined Coastal Financial Corporation as SVP and corporate controller in 2002 • Joined Carolina Financial Corporation in 2008 • Prior Senior Manager with Peat, Marwick, Mitchell & Co., a
Slide 7: History of Growth
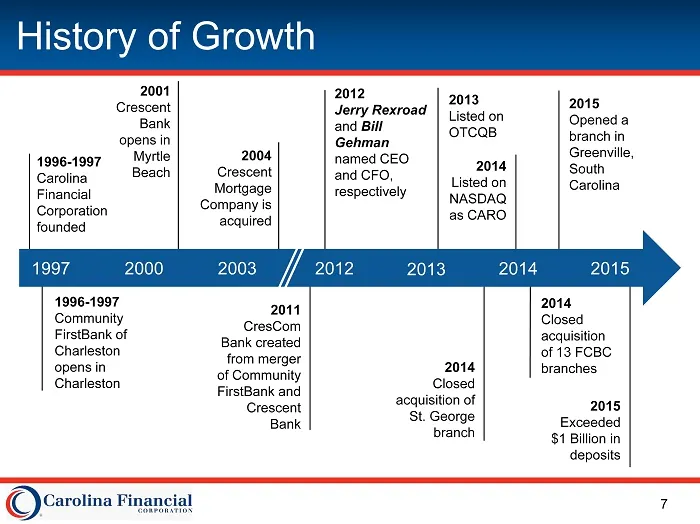
7 History of Growth 1997 2000 2015 2003 1996 - 1997 Carolina Financial Corporation founded 2011 CresCom Bank created from merger of Community FirstBank and Crescent Bank 2014 Closed acquisition of 13 FCBC branches 2004 Crescent Mortgage Company is acquired 2012 Jerry Rexroad and Bill Gehman named CE
Slide 8: Executing on Strategic Plan
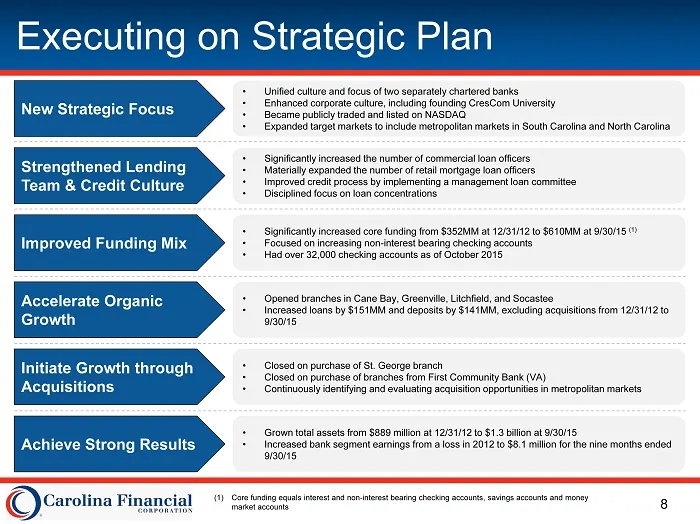
8 Executing on Strategic Plan • Unified culture and focus of two separately chartered banks • Enhanced corporate culture, including founding CresCom University • Became publicly traded and listed on NASDAQ • Expanded target markets to include metropolitan markets in South Carolina and North Carolina
Slide 9: Attractive, Growing Markets
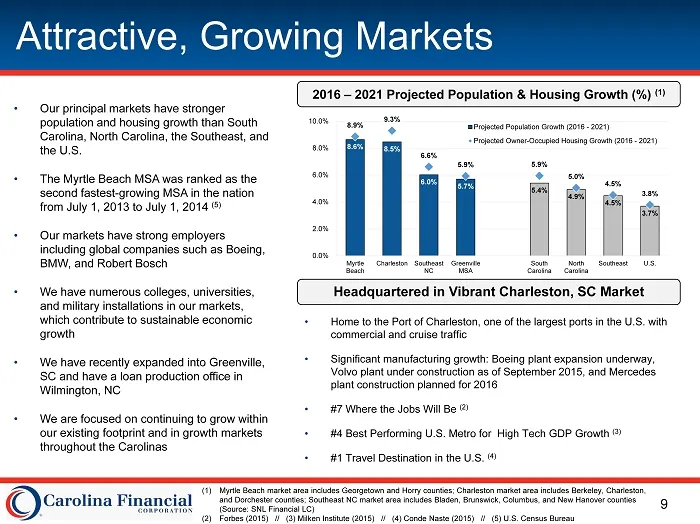
9 Attractive, Growing Markets (1) Myrtle Beach market area includes Georgetown and Horry counties; Charleston market area includes Berkeley, Charleston, and Dorchester counties; Southeast NC market area includes Bladen, Brunswick, Columbus, and New Hanover counties (Source: SNL Financial LC) (2) For
Slide 10: Carolina Financial Investment Rationale
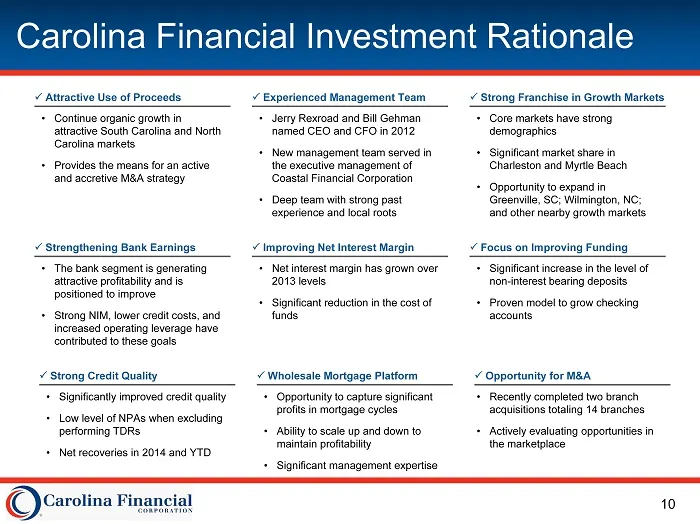
10 Carolina Financial Investment Rationale Wholesale Mortgage Platform • Opportunity to capture significant profits in mortgage cycles • Ability to scale up and down to maintain profitability • Significant management expertise Strong Credit Quality • Significantly improved credit quality • Low l
Slide 11: Strengthening Commercial Banking Platform
Strengthening Commercial Banking Platform
Slide 12: Strong Balance Sheet Growth
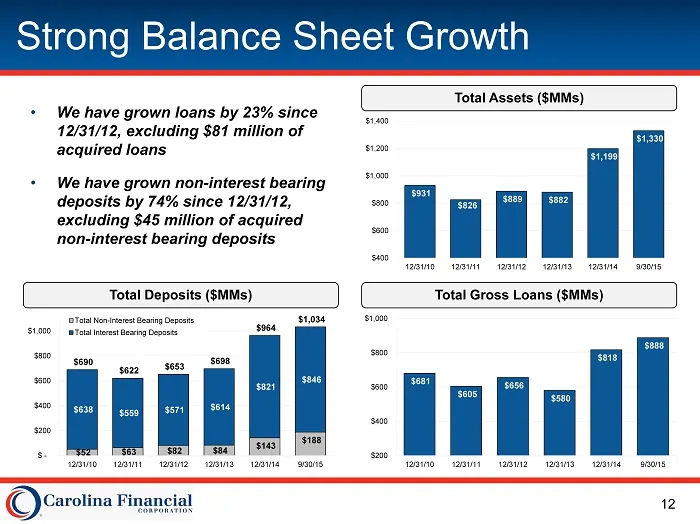
12 Strong Balance Sheet Growth • We have grown loans by 2 3% since 12/31/12, excluding $81 million of acquired loans • We have grown non - interest bearing deposits by 74% since 12/31/12, excluding $45 million of acquired non - interest bearing deposits Total Deposits ($MMs) Total Gross Loans ($MMs)
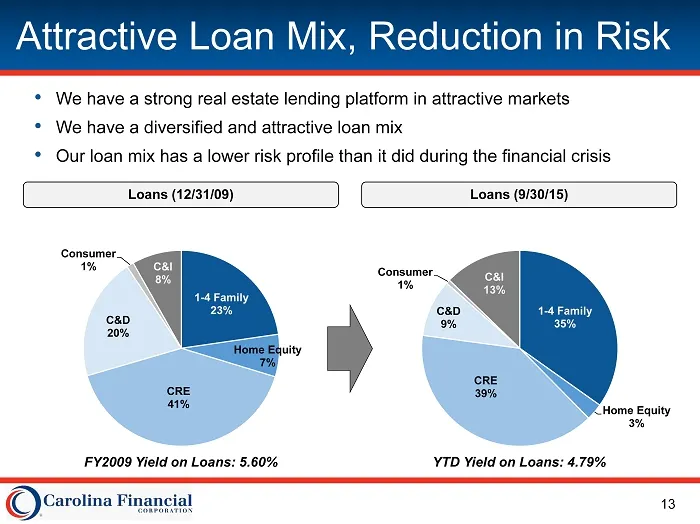
Slide 13: Attractive Loan Mix, Reduction in Risk
13 Attractive Loan Mix, Reduction in Risk Loans (12/31/09) Loans (9/30/15) 1 - 4 Family 35% Home Equity 3% CRE 39% C&D 9% Consumer 1% C&I 13% • We have a strong real estate lending platform in attractive markets • We have a diversified and attractive loan mix • Our loan mix has a lower risk profile
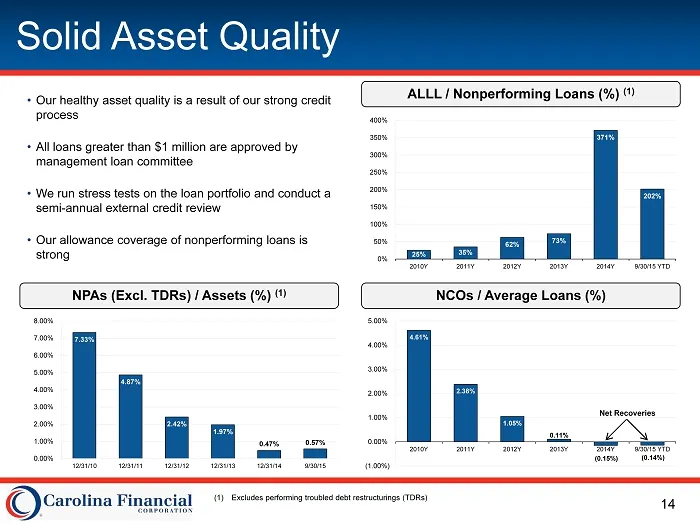
Slide 14: Solid Asset Quality
14 Solid Asset Quality ALLL / Nonperforming Loans (%) (1) • Our healthy asset quality is a result of our strong credit process • All loans greater than $1 million are approved by management loan committee • We run stress tests on the loan portfolio and conduct a semi - annual external credit review
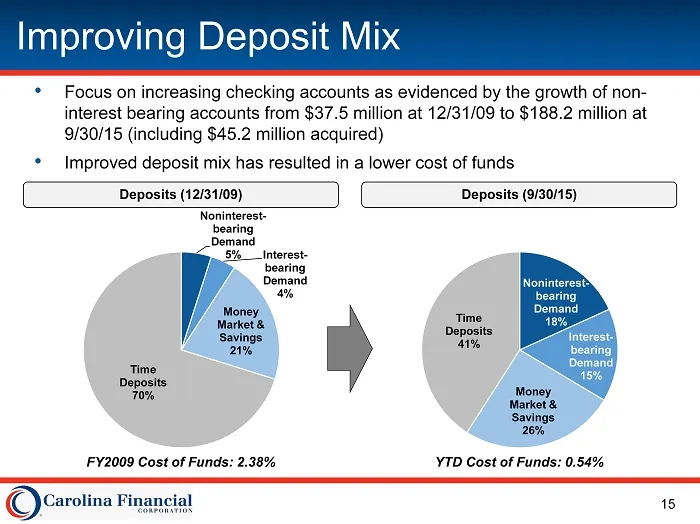
Slide 15: Improving Deposit Mix
15 Improving Deposit Mix Deposits (12/31/09) Deposits (9/30/15) Noninterest - bearing Demand 18% Interest - bearing Demand 15% Money Market & Savings 26% Time Deposits 41% • Focus on increasing checking accounts as evidenced by the growth of non - interest bearing accounts from $37.5 million at 12/3
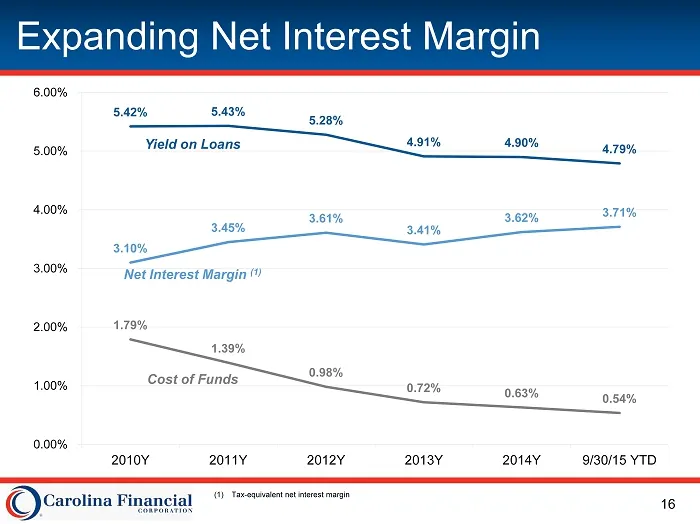
Slide 16: Expanding Net Interest Margin
16 Expanding Net Interest Margin 5.42% 5.43% 5.28% 4.91% 4.90% 4.79% 3.10% 3.45% 3.61% 3.41% 3.62% 3.71% 1.79% 1.39% 0.98% 0.72% 0.63% 0.54% 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% 2010Y 2011Y 2012Y 2013Y 2014Y 9/30/15 YTD Yield on Loans Net Interest Margin (1) Cost of Funds (1) Tax - equivalent n
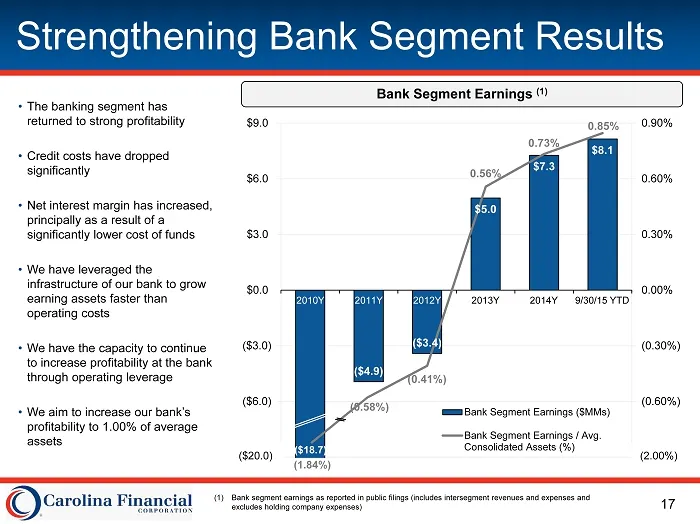
Slide 17: Strengthening Bank Segment Results
17 ($4.9) ($3.4) $5.0 $7.3 $8.1 (0.58%) (0.41%) 0.56% 0.73% 0.85% (0.90%) (0.60%) (0.30%) 0.00% 0.30% 0.60% 0.90% ($9.0) ($6.0) ($3.0) $0.0 $3.0 $6.0 $9.0 Bank Segment Earnings ($MMs) Bank Segment Earnings / Avg. Consolidated Assets (%) Strengthening Bank Segment Results Bank Segment Earnings (1) •
Slide 18: Attractive Wholesale Mortgage Platform
18 Attractive Wholesale Mortgage Platform
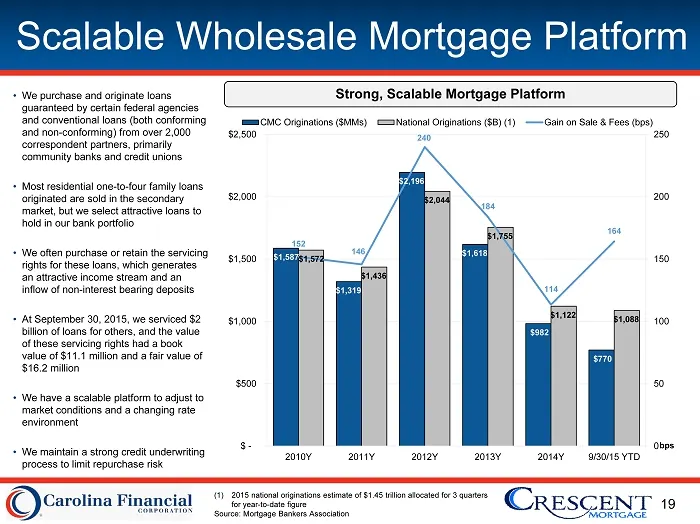
Slide 19: Scalable Wholesale Mortgage Platform
19 Scalable Wholesale Mortgage Platform $1,587 $1,319 $2,196 $1,618 $982 $770 $1,572 $1,436 $2,044 $1,755 $1,122 $1,088 152 146 240 184 114 164 0 50 100 150 200 250 $ - $500 $1,000 $1,500 $2,000 $2,500 2010Y 2011Y 2012Y 2013Y 2014Y 9/30/15 YTD bps CMC Originations ($MMs) National Originations ($B) (
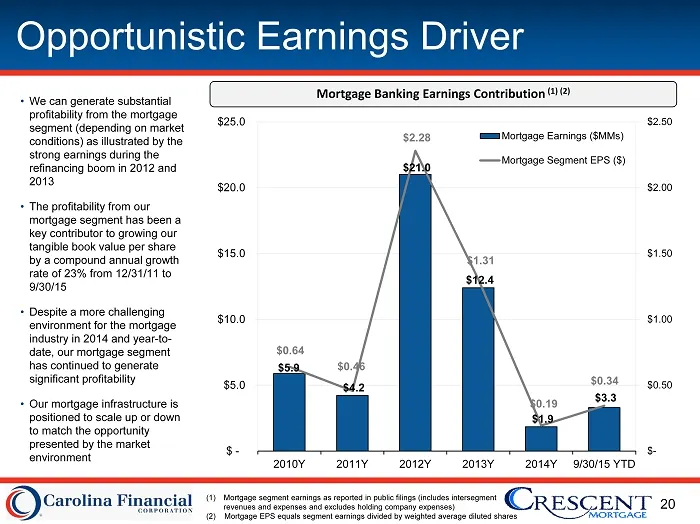
Slide 20: Opportunistic Earnings Driver
20 Opportunistic Earnings Driver • We can generate substantial profitability from the mortgage segment (depending on market conditions) as illustrated by the strong earnings during the refinancing boom in 2012 and 2013 • The profitability from our mortgage segment has been a key contributor to growi
Slide 21: Strategic Opportunity
Strategic Opportunity O Carolina Financial ‘CORPORATION
Slide 22: Focus on Shareholder Results
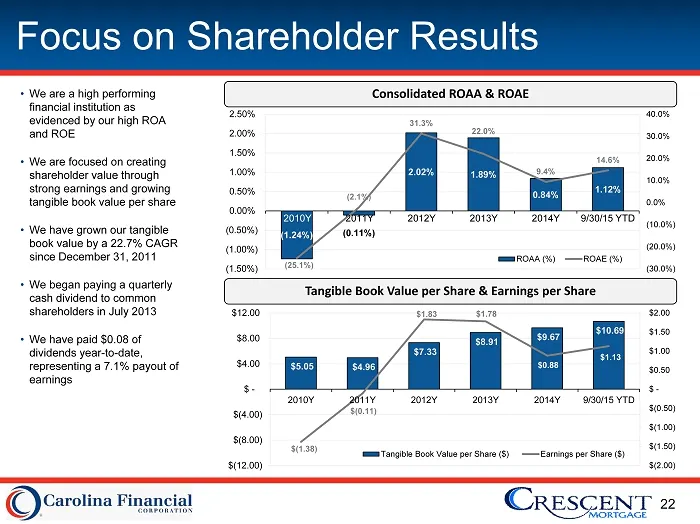
22 Focus on Shareholder Results • We are a high performing financial institution as evidenced by our high ROA and ROE • We are focused on creating shareholder value through strong earnings and growing tangible book value per share • We have grown our tangible book value by a 22.7% CAGR since Decembe
Slide 23: Attractive Organic and Strategic Growth
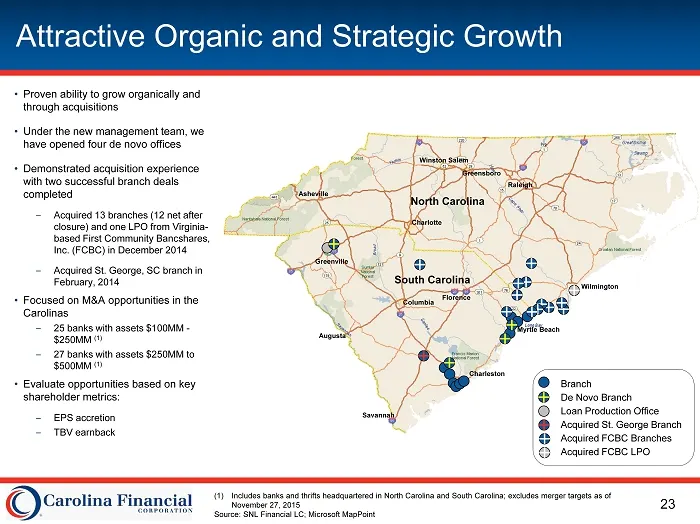
23 Attractive Organic and Strategic Growth • Proven ability to grow organically and through acquisitions • Under the new management team, we have opened four de novo offices • Demonstrated acquisition experience with two successful branch deals completed – Acquired 13 branches (12 net after closure)
Slide 24: Investment Considerations
24 Investment Considerations x Focus on increasing shareholder value as evidenced by 23% compound annual growth in TBV per share from 12/31/11 to 9/30/2015 x Scarcity value – large foothold in the high growth Charleston and Myrtle Beach markets x Strong markets to support continued growth x Experien
Source: SEC EDGAR · FWP filed Nov 30, 2015
More decks from Carolina Financial Corporation
 Q4 2019 Earnings Presentation19 slides · Jan 29, 2020
 Merger or Acquisition (November 2019)13 slides · Nov 18, 2019
 Q3 2019 Earnings Presentation15 slides · Oct 24, 2019
 Q2 2019 Earnings Presentation18 slides · Jul 25, 2019
 Q1 2019 Earnings Presentation15 slides · Apr 24, 2019
 Q4 2018 Earnings Presentation13 slides · Jan 24, 2019