Holly Energy Partners LP — UBS Leveraged Finance Conference 2005
30 slides from Holly Energy Partners LP's conference presentation, May 12, 2005
Slide 1: Holly Energy Partners, L.P. UBS Leveraged Finance Conference
Holly Energy Partners, L.P. UBS Leveraged Finance Conference May 12, 2005
Slide 2: Agenda
HEP background / History of Holly Corporation Holly Corporation assets HEP Assets HEP's first acquisition - Alon USA assets HEP growth / safety / stability HEP financials
Slide 3: Safe Harbor Disclosure
Safe Harbor Disclosure Statements made during the course of this presentation that are not historical facts are "forward-looking statements" within the meaning of the U.S. Private Securities Litigation Reform Act of 1995. Forward-looking statements are inherently uncertain and necessarily involve ri
Slide 4: Senior notes issued to finance Alon USA asset acquisition
On February 28, 2005, Holly Energy Partners issued $150 million of senior notes due 2015 to finance the acquisition of logistic assets from Alon USA Holly Energy anticipates additional debt and equity offerings to fund its future acquisition path.
Slide 5: HEP's formation - Holly Corporation as sponsor
HEP's formation -- Holly Corporation as sponsor Holly Corporation (NYSE: HOC) entered refining business in 1969 Acquired refinery in Artesia, NM-expanded capacity 3 times since purchase Acquired refinery in Great Falls, MT in 1982 Acquired refinery in Woods Cross, UT in 2003
Slide 6: Holly Corporation refineries and key statistics
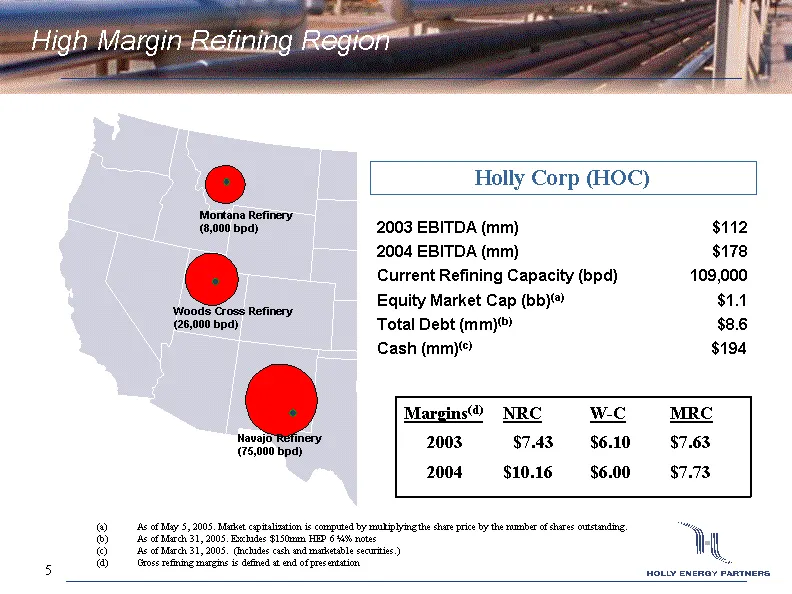
Woods Cross Refinery (26,000 bpd) Montana Refinery (8,000 bpd) High Margin Refining Region Margins(d) NRC W-C MRC 2003 $7.43 $6.10 $7.63 2004 $10.16 $6.00 $7.73 2003 EBITDA (mm) $112 2004 EBITDA (mm) $178 Current Refining Capacity (bpd) 109,000 Equity Market Cap (bb)(a) $1.1 Total Debt (mm)(b) $8.6
Slide 7: HEP's formation - logistic assets valuation
HEP's formation -- Holly Corporation as sponsor Holly has acquired and/or built extensive storage, terminalling and pipeline distribution network to support refining operations Inherent problem with refiners: Pipeline and terminal assets (Logistic assets) which are imbedded in refining operations te
Slide 8: HEP's formation - unlocking logistic asset values
HEP's formation -- Holly Corporation as sponsor Late 1990's: Began to explore ways to unlock logistic assets values Sale of logistic assets to 3rd party 'problematic' because of refining reliance to deliver feedstocks and move products to market Early 2000: Began to explore Master Limited Partnershi
Slide 9: Holly Energy Partners IPO
HEP's formation -- Holly Corporation as sponsor Holly Energy Partners (NYSE: HEP) IPO Brought to market by Goldman Sachs, UBS, Lehman Bros., A.G Edwards & Raymond James 7 millions common units sold at $22.25 (current price: $43) $100 million credit facility created, led by Union Bank of California (
Slide 10: MLP Investment Space
MLP Investment Space Two 'requirements' in the MLP investment space: Pay 'healthy' distribution Grow distribution through asset growth
Slide 11: MLP Investment Space - Yield Profile
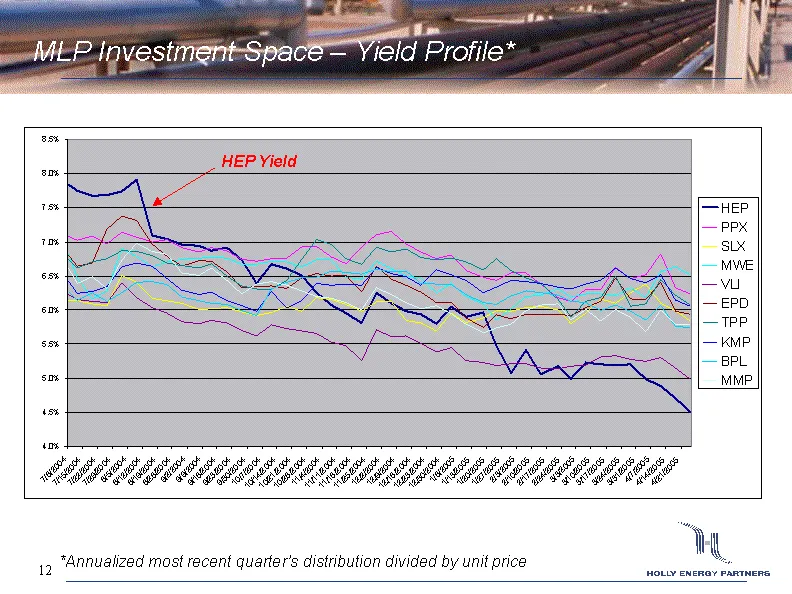
MLP Investment Space - Yield Profile* HEP Yield *Annualized most recent quarter's distribution divided by unit price
Slide 12: Existing Products Pipelines
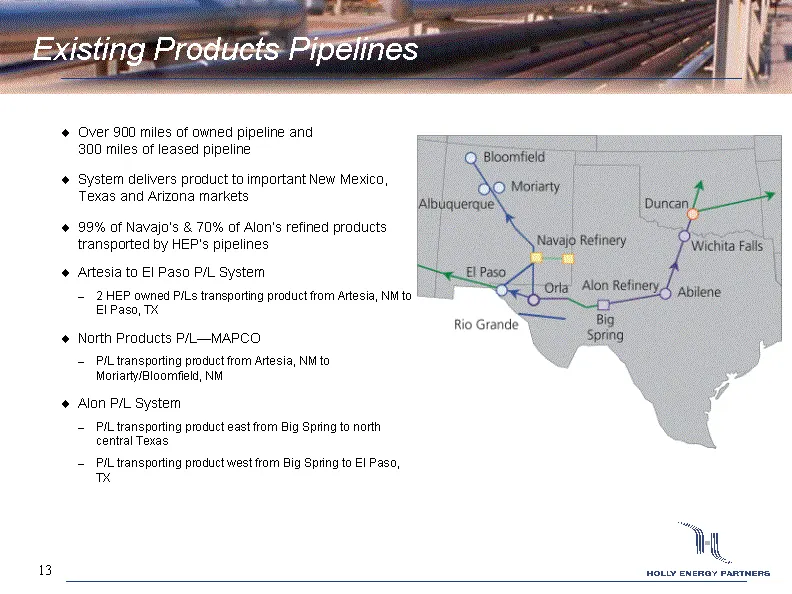
Existing Products Pipelines Over 900 miles of owned pipeline and 300 miles of leased pipeline System delivers product to important New Mexico, Texas and Arizona markets 99% of Navajo's & 70% of Alon's refined products transported by HEP's pipelines Artesia to El Paso P/L System 2 HEP owned P/Ls tran
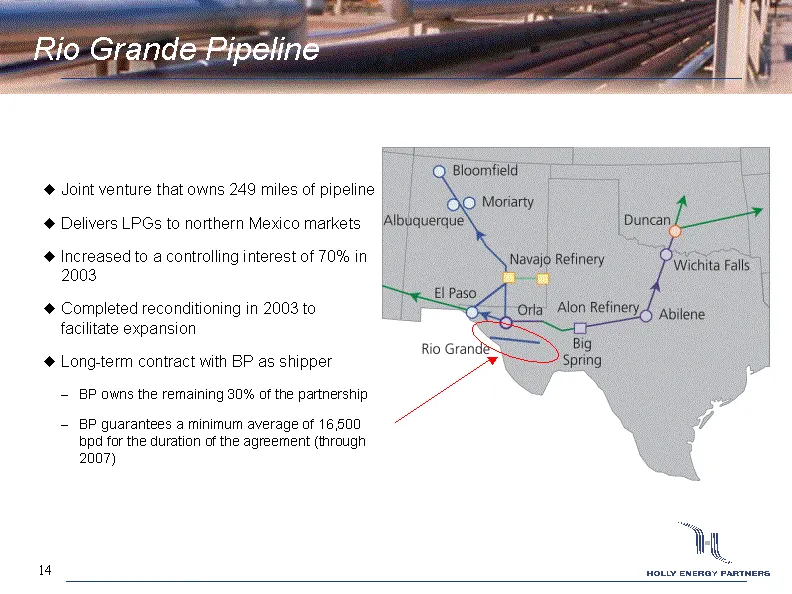
Slide 13: Rio Grande Pipeline
Rio Grande Pipeline Joint venture that owns 249 miles of pipeline Delivers LPGs to northern Mexico markets Increased to a controlling interest of 70% in 2003 Completed reconditioning in 2003 to facilitate expansion Long-term contract with BP as shipper BP owns the remaining 30% of the partnership BP
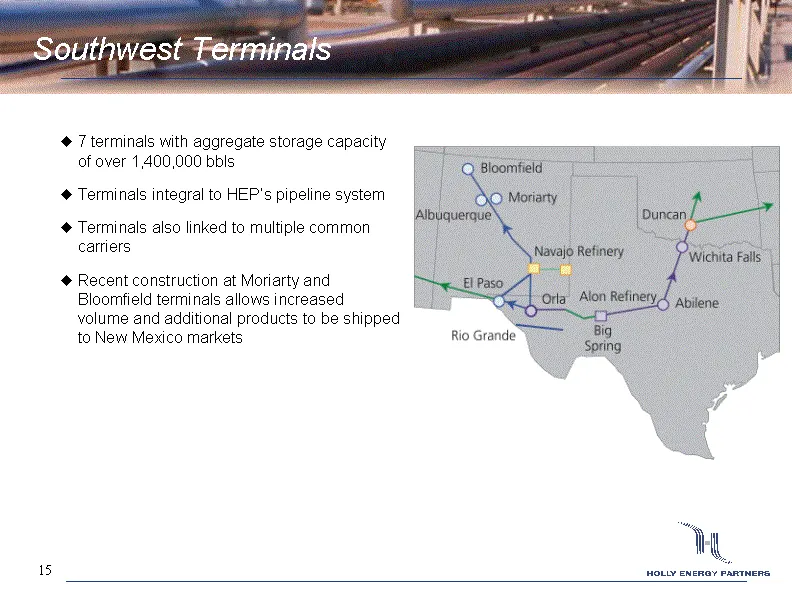
Slide 14: Southwest Terminals
Southwest Terminals 7 terminals with aggregate storage capacity of over 1,400,000 bbls Terminals integral to HEP's pipeline system Terminals also linked to multiple common carriers Recent construction at Moriarty and Bloomfield terminals allows increased volume and additional products to be shipped
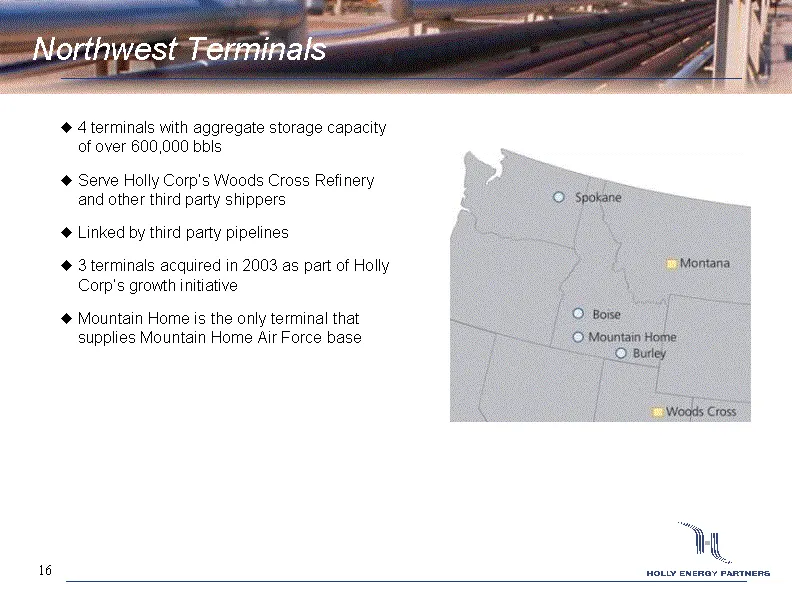
Slide 15: Northwest Terminals
Northwest Terminals 4 terminals with aggregate storage capacity of over 600,000 bbls Serve Holly Corp's Woods Cross Refinery and other third party shippers Linked by third party pipelines 3 terminals acquired in 2003 as part of Holly Corp's growth initiative Mountain Home is the only terminal that s
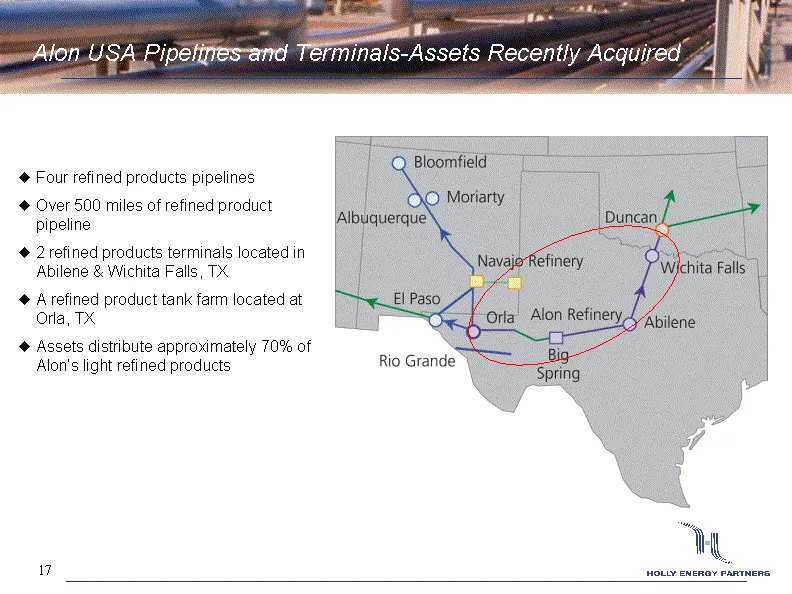
Slide 16: Alon USA Pipelines and Terminals - Assets Recently Acquired
Alon USA Pipelines and Terminals-Assets Recently Acquired Four refined products pipelines Over 500 miles of refined product pipeline 2 refined products terminals located in Abilene & Wichita Falls, TX A refined product tank farm located at Orla, TX Assets distribute approximately 70% of Alon's light
Slide 17: HEP's Acquisition of Alon USA Pipelines & Terminals
HEP's Acquisition of Alon USA Pipelines & Terminals To finance this acquisition: HEP issued 937,500 subordinated units to Alon Issued $150 million, 6 1/4% Senior Notes, due 2015
Slide 18: Stable Cash Flows
Stable Cash Flows 94% of HEP's revenues comes from long-term contracts 15-year agreements with Holly Corp & Alon USA (on newly acquired Alon assets) Minimum revenue commitment of $35.4 million from Holly Corp Alon USA has leased 20,000 bpd of capacity in the "8-12-8" pipeline from Orla to El Paso, T
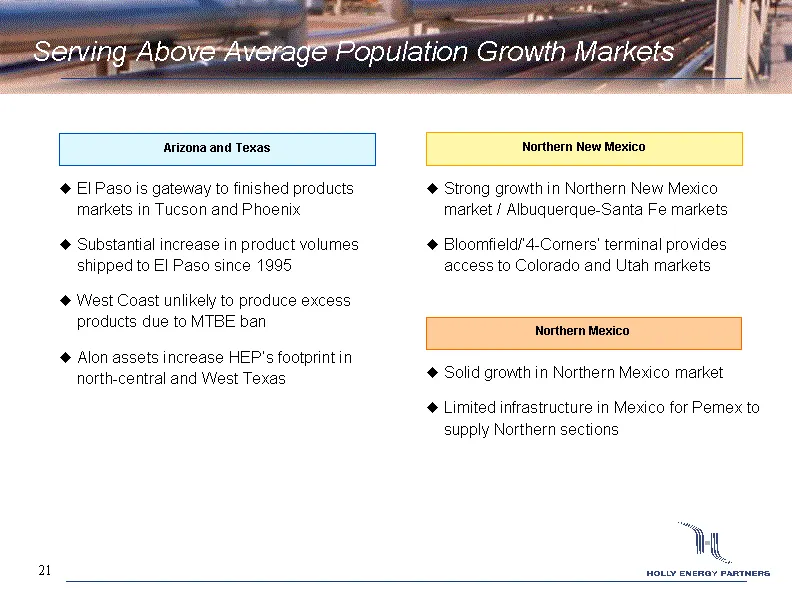
Slide 19: Serving Above Average Population Growth Markets
Serving Above Average Population Growth Markets Arizona and Texas El Paso is gateway to finished products markets in Tucson and Phoenix Substantial increase in product volumes shipped to El Paso since 1995 West Coast unlikely to produce excess products due to MTBE ban Alon assets increase HEP's foot
Slide 20: Senior Unsecured Notes
Senior Unsecured Notes Issuers: Holly Energy Partners, L.P. & Holly Energy Finance Corp Underwriters: UBS (book-runner) Banc of America and Goldman (co-managers) Issue Size: $150 million Pricing Date: February 11, 2005 Maturity: March 1, 2015 (10 years) Coupon: 6-1/4% (215 bp over 10-yr Treasuries)
Slide 21: Senior Unsecured Notes - Redemption terms
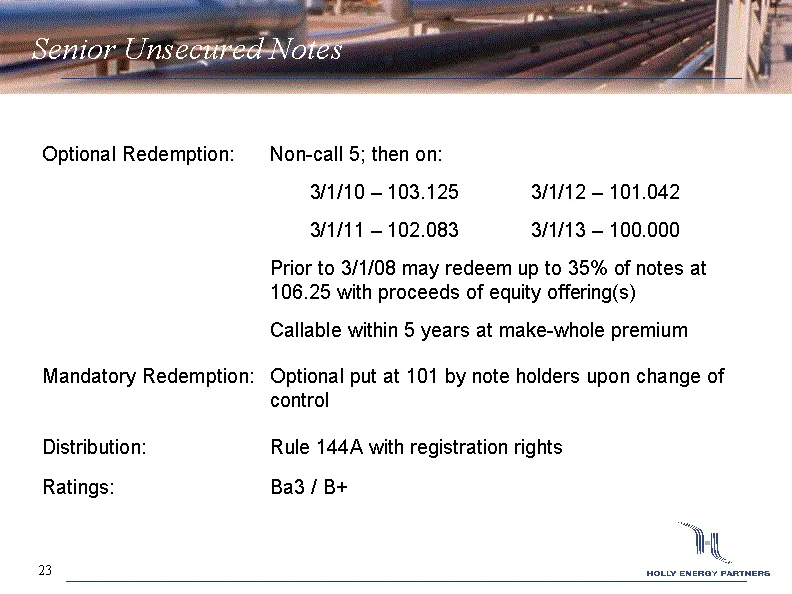
Senior Unsecured Notes Optional Redemption: Non-call 5; then on: 3/1/10 - 103.125 3/1/12 - 101.042 3/1/11 - 102.083 3/1/13 - 100.000 Prior to 3/1/08 may redeem up to 35% of notes at 106.25 with proceeds of equity offering(s) Callable within 5 years at make-whole premium Mandatory Redemption: Optiona
Slide 22: Interest Rate Swap
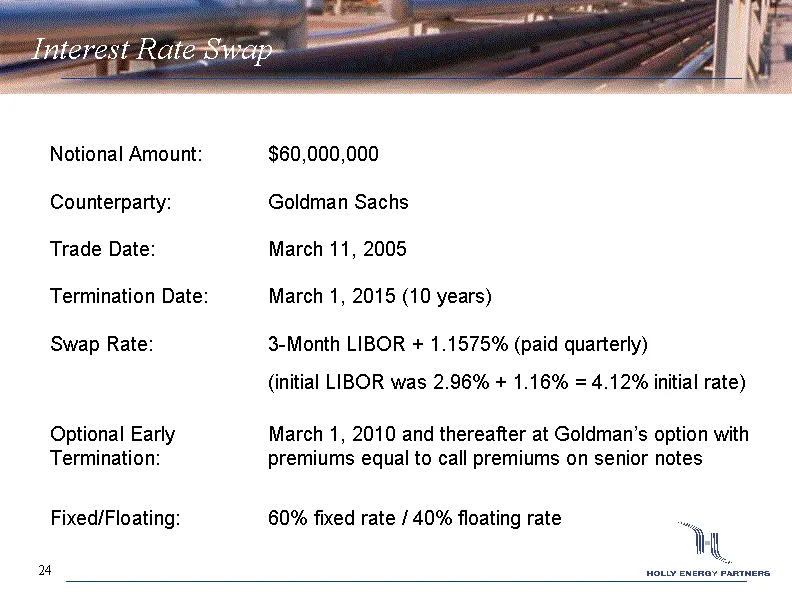
Interest Rate Swap Notional Amount: $60,000,000 Counterparty: Goldman Sachs Trade Date: March 11, 2005 Termination Date: March 1, 2015 (10 years) Swap Rate: 3-Month LIBOR + 1.1575% (paid quarterly) (initial LIBOR was 2.96% + 1.16% = 4.12% initial rate) Optional Early Termination: March 1, 2010 and t
Slide 23: Moody's Rating and Restrictions
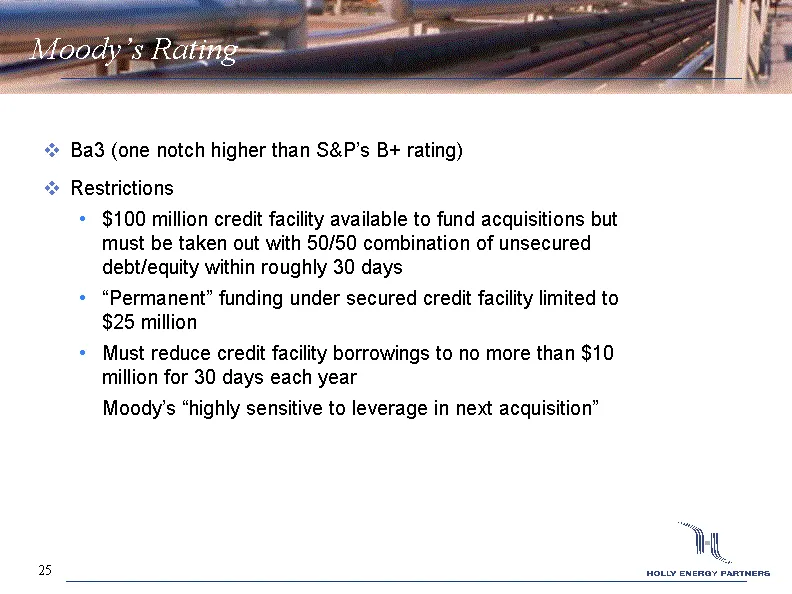
Moody's Rating Ba3 (one notch higher than S&P's B+ rating) Restrictions $100 million credit facility available to fund acquisitions but must be taken out with 50/50 combination of unsecured debt/equity within roughly 30 days "Permanent" funding under secured credit facility limited to $25 million Mu
Slide 24: HEP Consolidated Statement Of Income
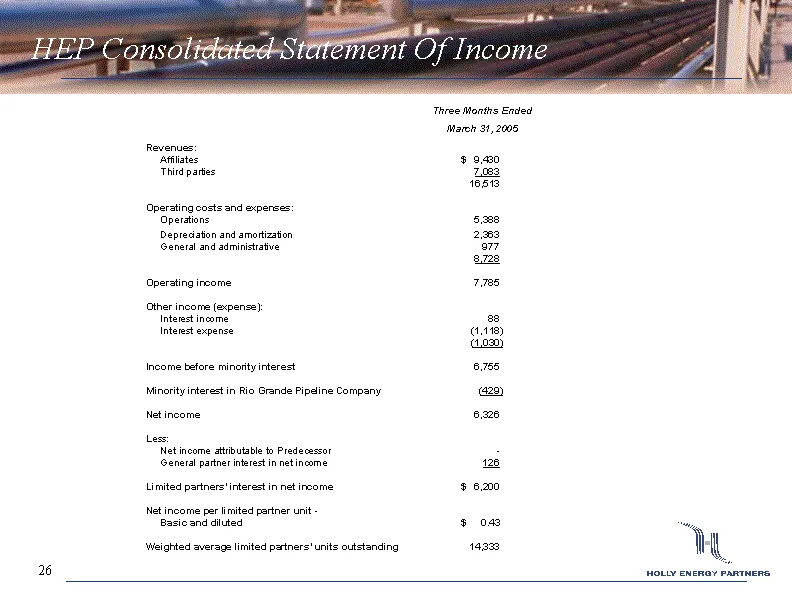
HEP Consolidated Statement Of Income Revenues: Affiliates $ 9,430 Third parties 7,083 16,513 Operating costs and expenses: Operations 5,388 Depreciation and amortization 2,363 General and administrative 977 8,728 Operating income 7,785 Other income (expense): Interest income 88 Interest expense (1,1
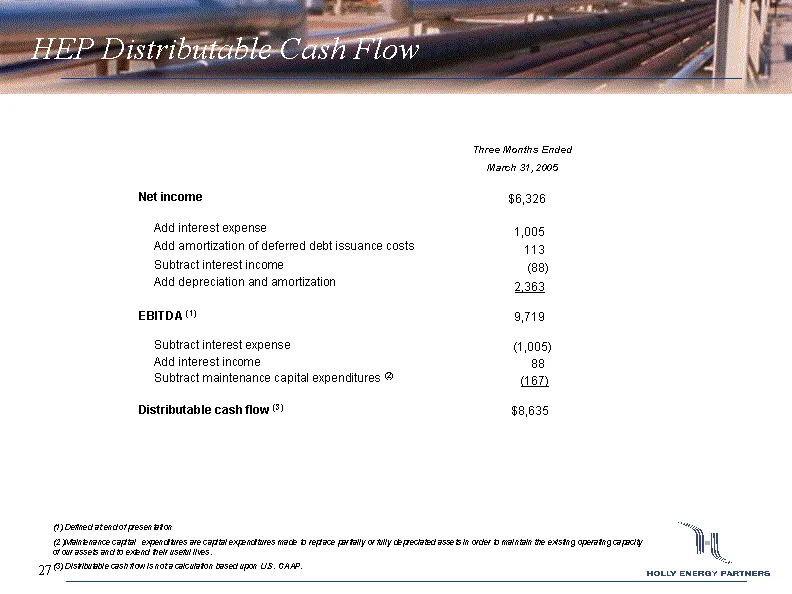
Slide 25: HEP Distributable Cash Flow
HEP Distributable Cash Flow Net income $6,326 Add interest expense 1,005 Add amortization of deferred debt issuance costs 113 Subtract interest income (88) Add depreciation and amortization 2,363 EBITDA (1) 9,719 Subtract interest expense (1,005) Add interest income 88 Subtract maintenance capital e
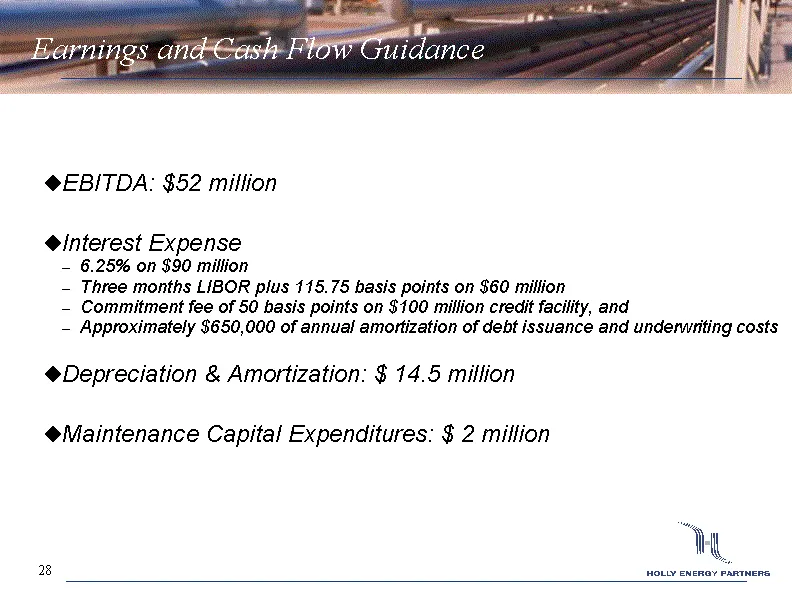
Slide 26: Earnings and Cash Flow Guidance
Earnings and Cash Flow Guidance EBITDA: $52 million Interest Expense 6.25% on $90 million Three months LIBOR plus 115.75 basis points on $60 million Commitment fee of 50 basis points on $100 million credit facility, and Approximately $650,000 of annual amortization of debt issuance and underwriting
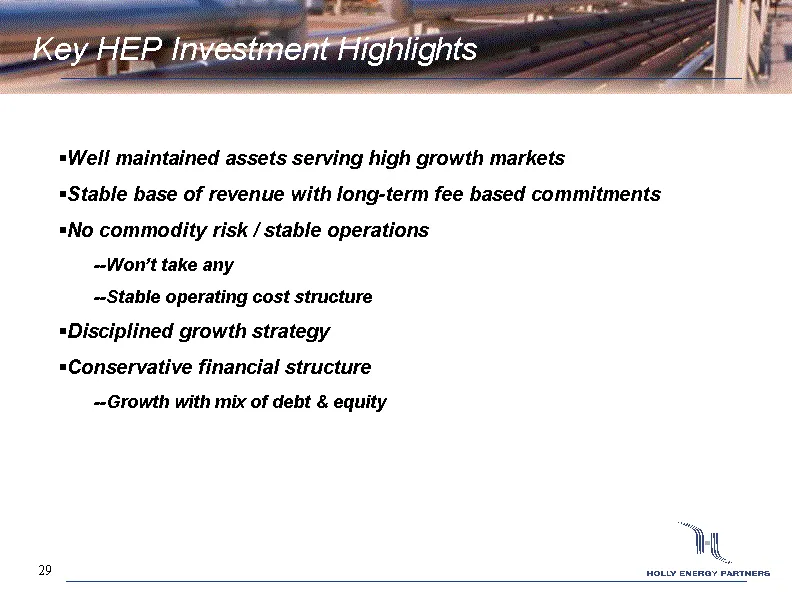
Slide 27: Key HEP Investment Highlights
Key HEP Investment Highlights Well maintained assets serving high growth markets Stable base of revenue with long-term fee based commitments No commodity risk / stable operations - --Won't take any - --Stable operating cost structure Disciplined growth strategy Conservative financial structure - --G
Slide 28: Question period from audience
Holly Energy Partners, L.P. (HEP) Question period from audience Holly Energy Partners, L.P. 100 Crescent Court, Suite 1600 Dallas, Texas 75201 (214) 871-3555
Slide 29: Definitions
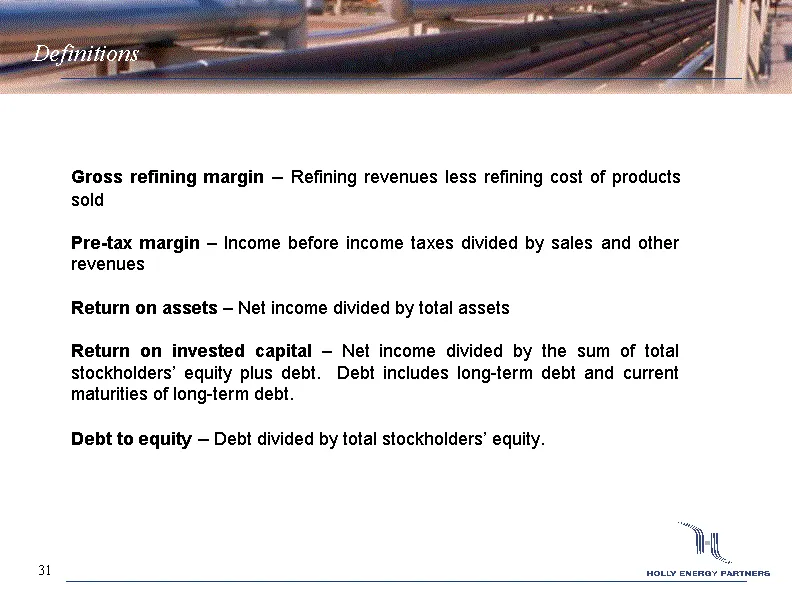
Definitions Gross refining margin - Refining revenues less refining cost of products sold Pre-tax margin - Income before income taxes divided by sales and other revenues Return on assets - Net income divided by total assets Return on invested capital - Net income divided by the sum of total stockhol
Slide 30: Definitions - Holly Corporation EBITDA 2004 & 2003
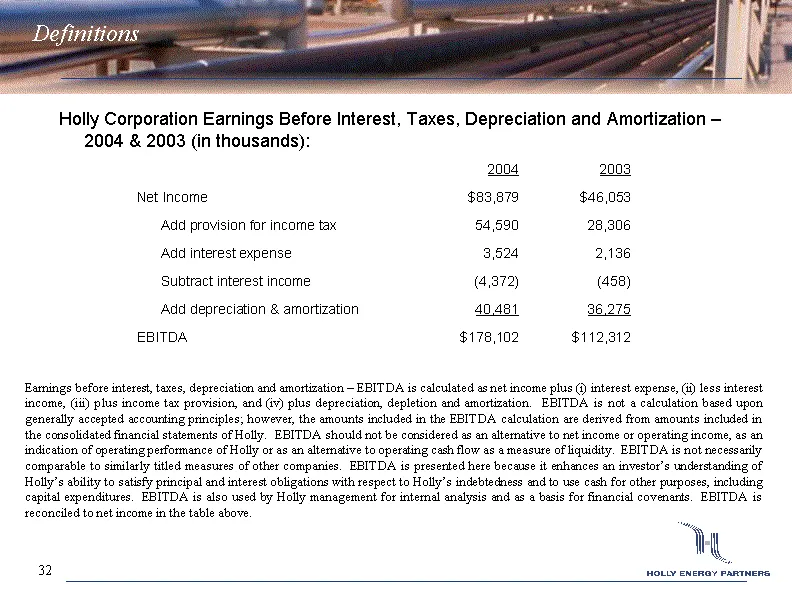
Definitions Holly Corporation Earnings Before Interest, Taxes, Depreciation and Amortization - 2004 & 2003 (in thousands): 2004 2003 Net Income $83,879 $46,053 Add provision for income tax 54,590 28,306 Add interest expense 3,524 2,136 Subtract interest income (4,372) (458) Add depreciation & amorti
Source: SEC EDGAR · 8-K filed May 12, 2005
More decks from Holly Energy Partners LP
 Investor Presentation (March 2023)20 slides · Mar 2, 2023
 Investor Presentation (August 2022)24 slides · Aug 16, 2022
 Investor Presentation (May 2022)23 slides · May 17, 2022
 Investor Presentation (March 2022)12 slides · Mar 22, 2022
 Investor Presentation (March 2022)18 slides · Mar 1, 2022
 Investor Presentation (December 2021)18 slides · Dec 9, 2021