Magnetite Mines Ltd. · ASX:MGT
Magnetite Mines — Shareholder Meeting (November 2015)
16 slides from Magnetite Mines's shareholder meeting presentation, Nov 26, 2015
Slide 1: Magnetite Mines Limited - AGM Presentation - 2015
1 Magnetite Mines Limited - AGM Presentation - 2015
Slide 2: Iron Ore Insights - AGM
GORDON TOLL - 26 November 2015 - Adelaide Iron Ore Insights - AGM 2 Magnetite Mines Limited - AGM Presentation - 2015
Slide 3: Disclaimer and Competent Persons Statement
DISCLAIMER AND COMPETANT PERSONS STATEMENT 3 Magnetite Mines Limited - AGM Presentation - 2015
Slide 4: Lodestone Group
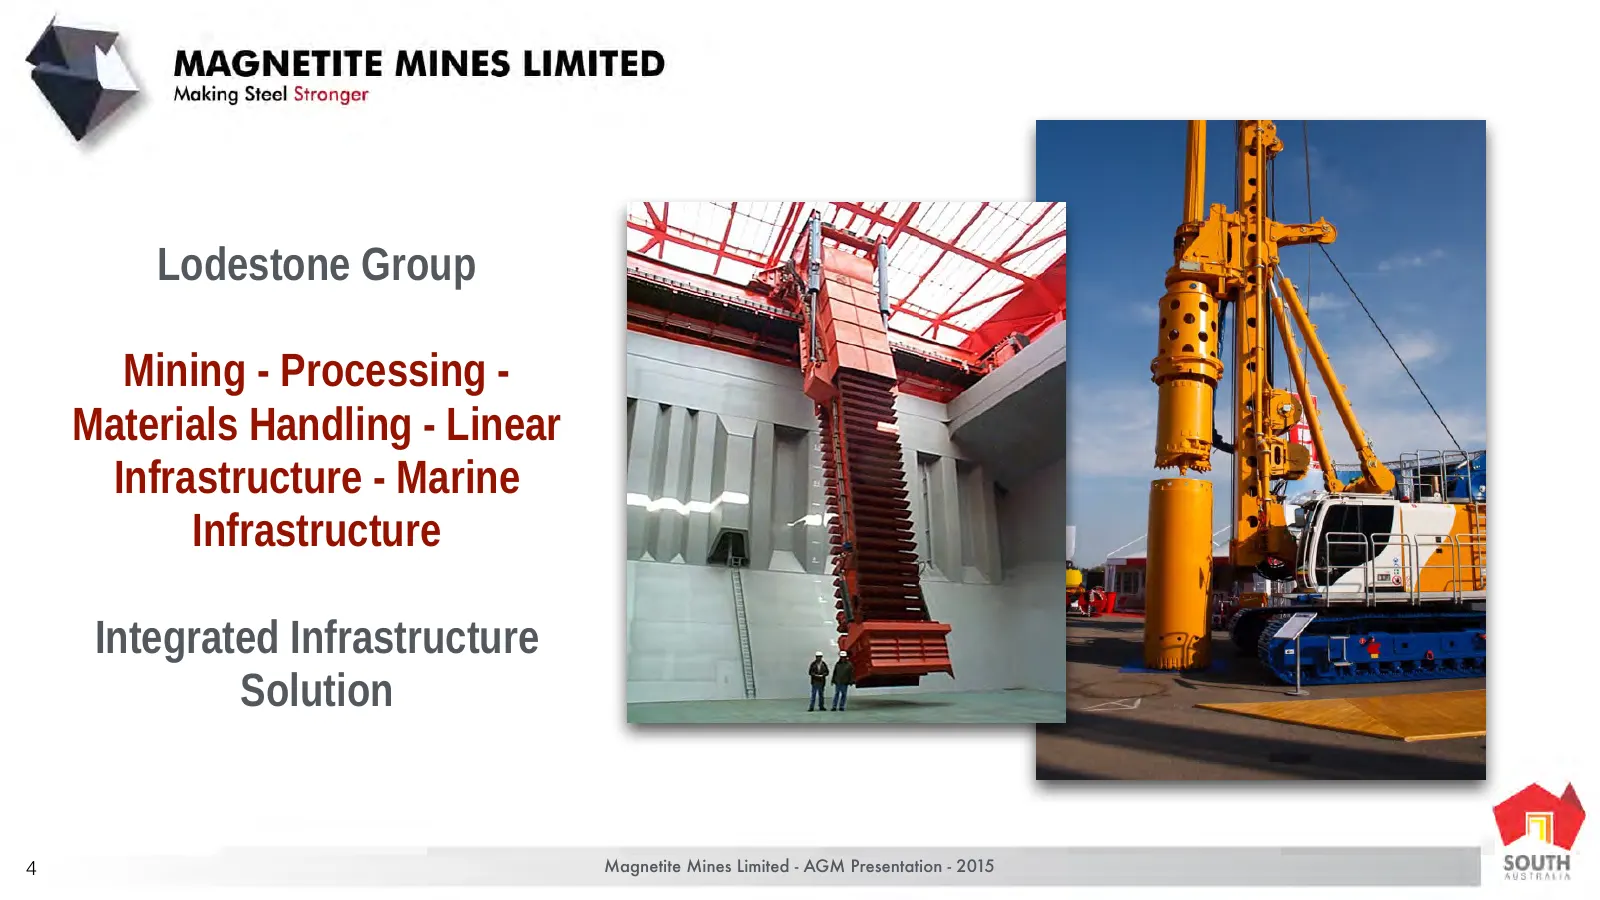
Lodestone Group Mining - Processing - Materials Handling - Linear Infrastructure - Marine Infrastructure Integrated Infrastructure Solution 4 Magnetite Mines Limited - AGM Presentation - 2015
Slide 5: Lodestone: In-depth knowledge of iron ore and steel industries
Lodestone In-depth knowledge of iron ore and steel industries 5 Magnetite Mines Limited - AGM Presentation - 2015
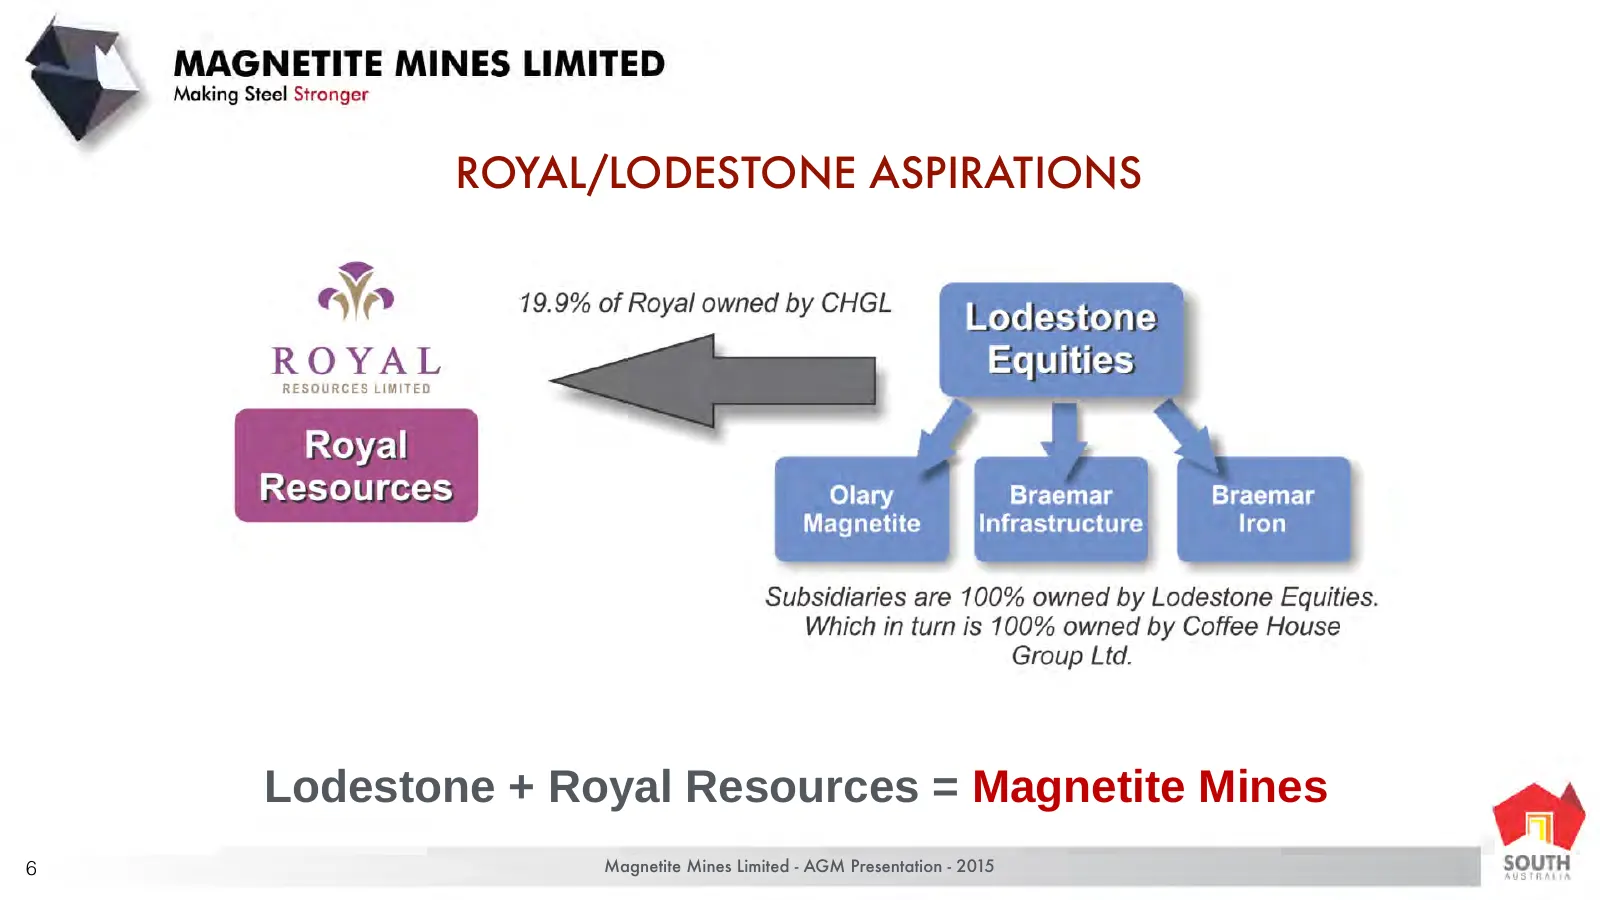
Slide 6: Royal/Lodestone Aspirations
ROYAL/LODESTONE ASPIRATIONS Lodestone + Royal Resources = Magnetite Mines 6 Magnetite Mines Limited - AGM Presentation - 2015
Slide 7: Some Simple Facts
SOME SIMPLE FACTS FACT ONE: There is probably no better and more encouraging regulatory jurisdiction anywhere in the world, than exists in South Australia, for developing a major iron ore project. FACT TWO: To Lodestone’s knowledge, the Mawson Iron Province of South Australia is the largest potentia
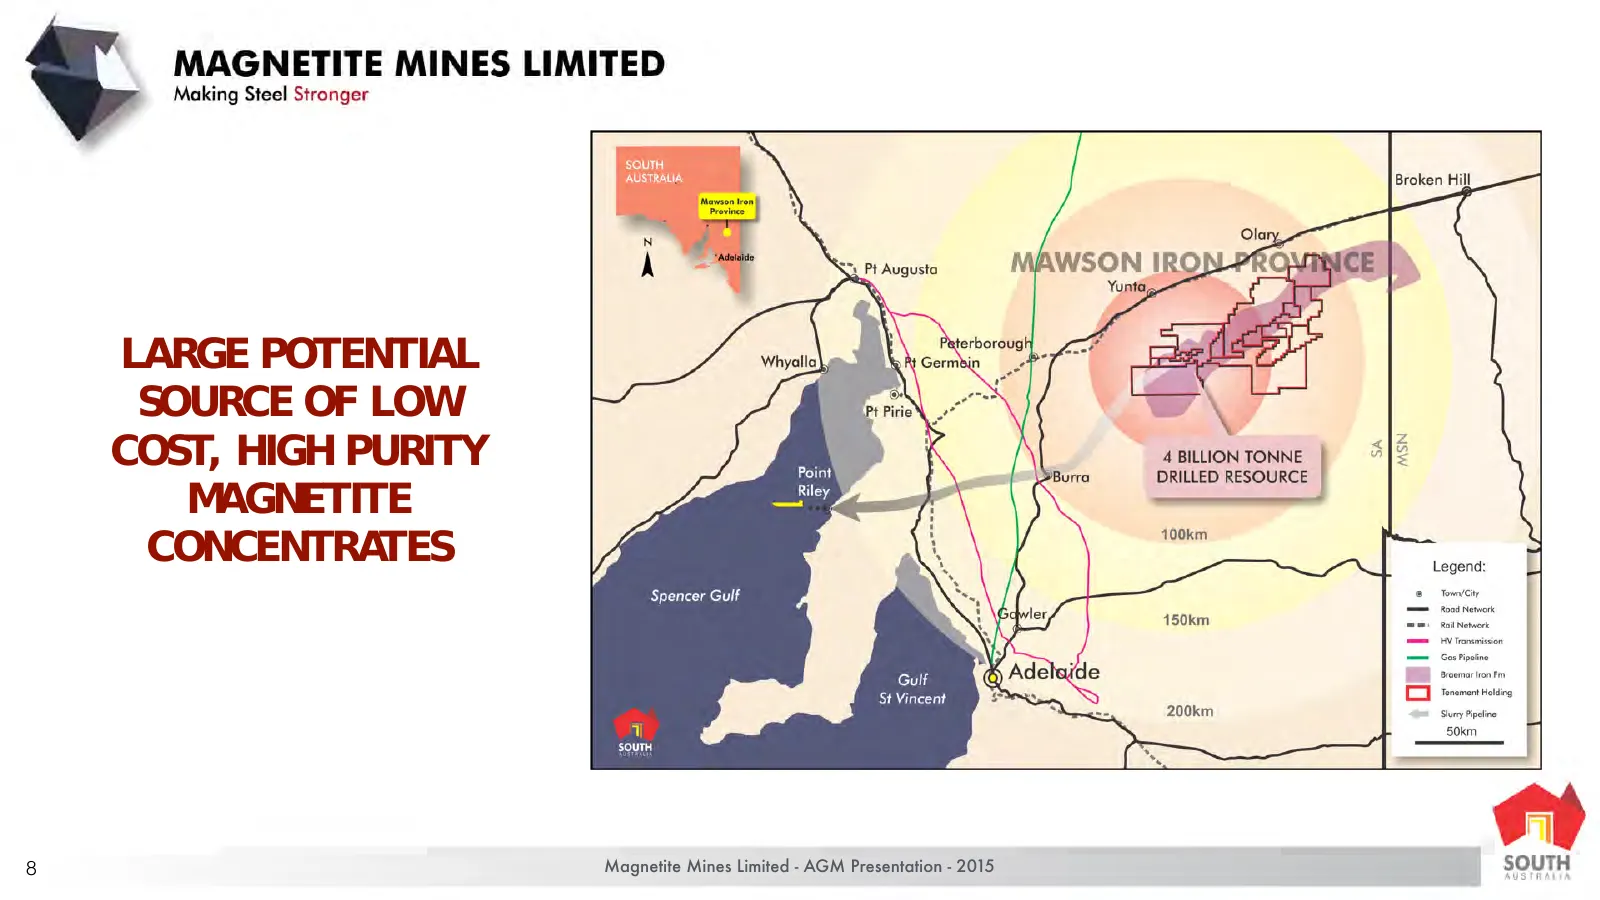
Slide 8: Large Potential Source of Low Cost, High Purity Magnetite Concentrates
LARGE POTENTIAL SOURCE OF LOW COST, HIGH PURITY MAGNETITE CONCENTRATES 8 Magnetite Mines Limited - AGM Presentation - 2015
Slide 9: Demographics Drive Demand
DEMOGRAPHICS DRIVE DEMAND •Global demand for steel and iron ore will continue to grow. •Recent iron ore prices provide little insight for longer-term prices •In last century, steel production increased from 60 million tpy to 1,600 million tpy •Largest increases were the in 35 years after WW2 and the
Slide 10: Urbanisation and Industrialisation
URBANISATION AND INDUSTRIALISATION •Chinese urbanisation & industrialisation drove high metals demand of past 15 years •In 2010, GLOBAL urban population exceeded rural population for the first time •The UN projects two thirds of the world’s population will be urbanised by 2030 •Urbanisation requires
Slide 11: Inevitable Consequences I
INEVITABLE CONSEQUENCES I •Future economic growth will be heavily concentrated in emerging markets •India, Brazil and Indonesia will join China in the ten largest economies •South Korea, Mexico and Turkey are likely to rank in the top 15 •There will be up to 3 billion more middle-class consumers by
Slide 12: Inevitable Consequences II
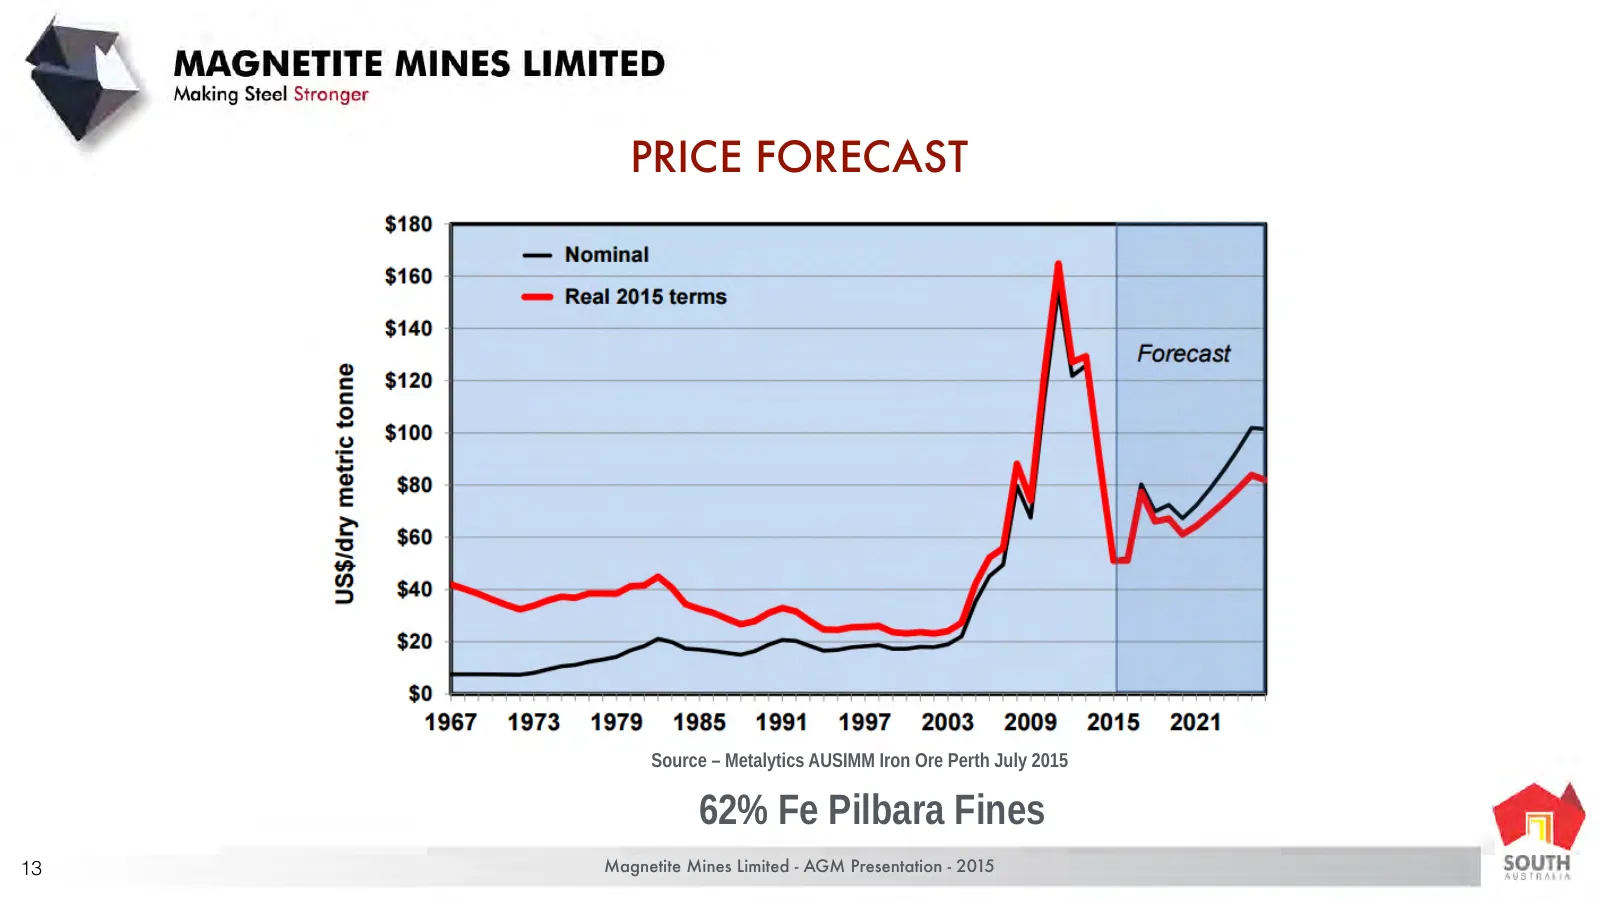
INEVITABLE CONSEQUENCES II •Iron ore will continue to be the main source of iron units in steel making globally •The volume of seaborne traded iron ore more than trebled in the last 15 years •Cycle peak prices of US$180 per tonne were not sustainable •Similarly prices sub-$55 per tonne are not susta
Slide 13: Price Forecast: 62% Fe Pilbara Fines
PRICE FORECAST Source – Metalytics AUSIMM Iron Ore Perth July 2015 62% Fe Pilbara Fines 13 Magnetite Mines Limited - AGM Presentation - 2015
Slide 14: Inevitable Consequences III
INEVITABLE CONSEQUENCES III •Future iron ore mines need to produce high iron, low impurity, low cost iron units •Sintering processes now allow high volume use of high quality concentrates •Current producers in the Pilbara and Minas Gerais will not be able to replace depleting resources of high quali
Slide 15: Heavy Duty Steel Re-Bar - The Work Horse of Urbanisation
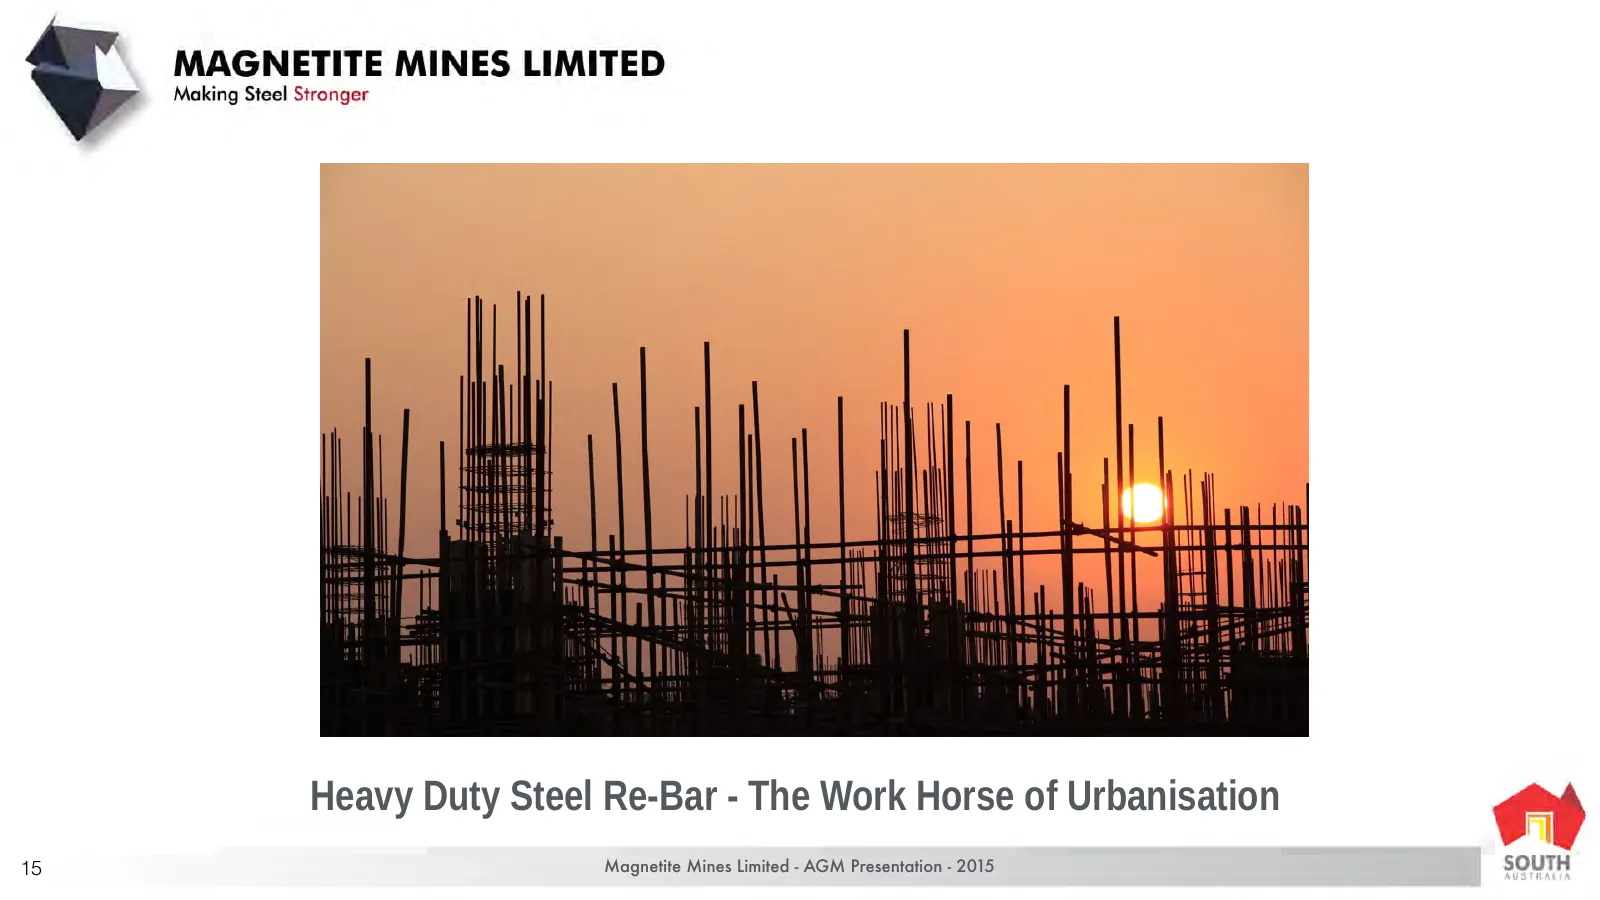
Heavy Duty Steel Re-Bar - The Work Horse of Urbanisation 15 Magnetite Mines Limited - AGM Presentation - 2015
Slide 16: Magnetite Mines Limited - AGM Presentation - 2015
16 Magnetite Mines Limited - AGM Presentation - 2015
Source: Internet Archive copy of magnetitemines.com
More decks from Magnetite Mines Ltd.
 Investor Presentation (September 2026)41 slides · September 2026
 Investor Presentation (March 2026)22 slides · Mar 10, 2026
 Shareholder Meeting (November 2025)18 slides · Nov 26, 2025
 Investor Presentation (August 2025)22 slides · Aug 8, 2025
 TACTIC Conference 202516 slides · Jul 30, 2025
 The Australian Green Iron & Steel Forum 202519 slides · Mar 26, 2025