Ucb S.A. · EURONEXT:UCB
Ucb — H1 2009 Earnings Presentation
45 slides from Ucb's earnings presentation, Jul 31, 2009
Slide 1: Delivering to become the next generation biopharma leader
Delivering to become the next generation biopharma leader 2009 Half-Year Financial Results Amye, living with rheumatoid arthritis 31 July 2009
Slide 2: Disclaimer and safe harbour
Disclaimer and safe harbour 2 the next generation biopharma leader 31 July 2009 Forward-looking statements: This presentation includes “forward-looking statements” relating to UCB and Schwarz Pharma that are subject to known and unknown risks and uncertainties, many of which are outside of UCB’s and
Slide 3: UCB
UCB 3 the next generation biopharma leader 31 July 2009 Vision • To become the next generation biopharmaceutical leader • To provide breakthrough innovation for patients suffering from severe diseases Therapeutic focus • Central nervous system (CNS) • Immunology Foundation • UCB = UCB Pharma + Cellt
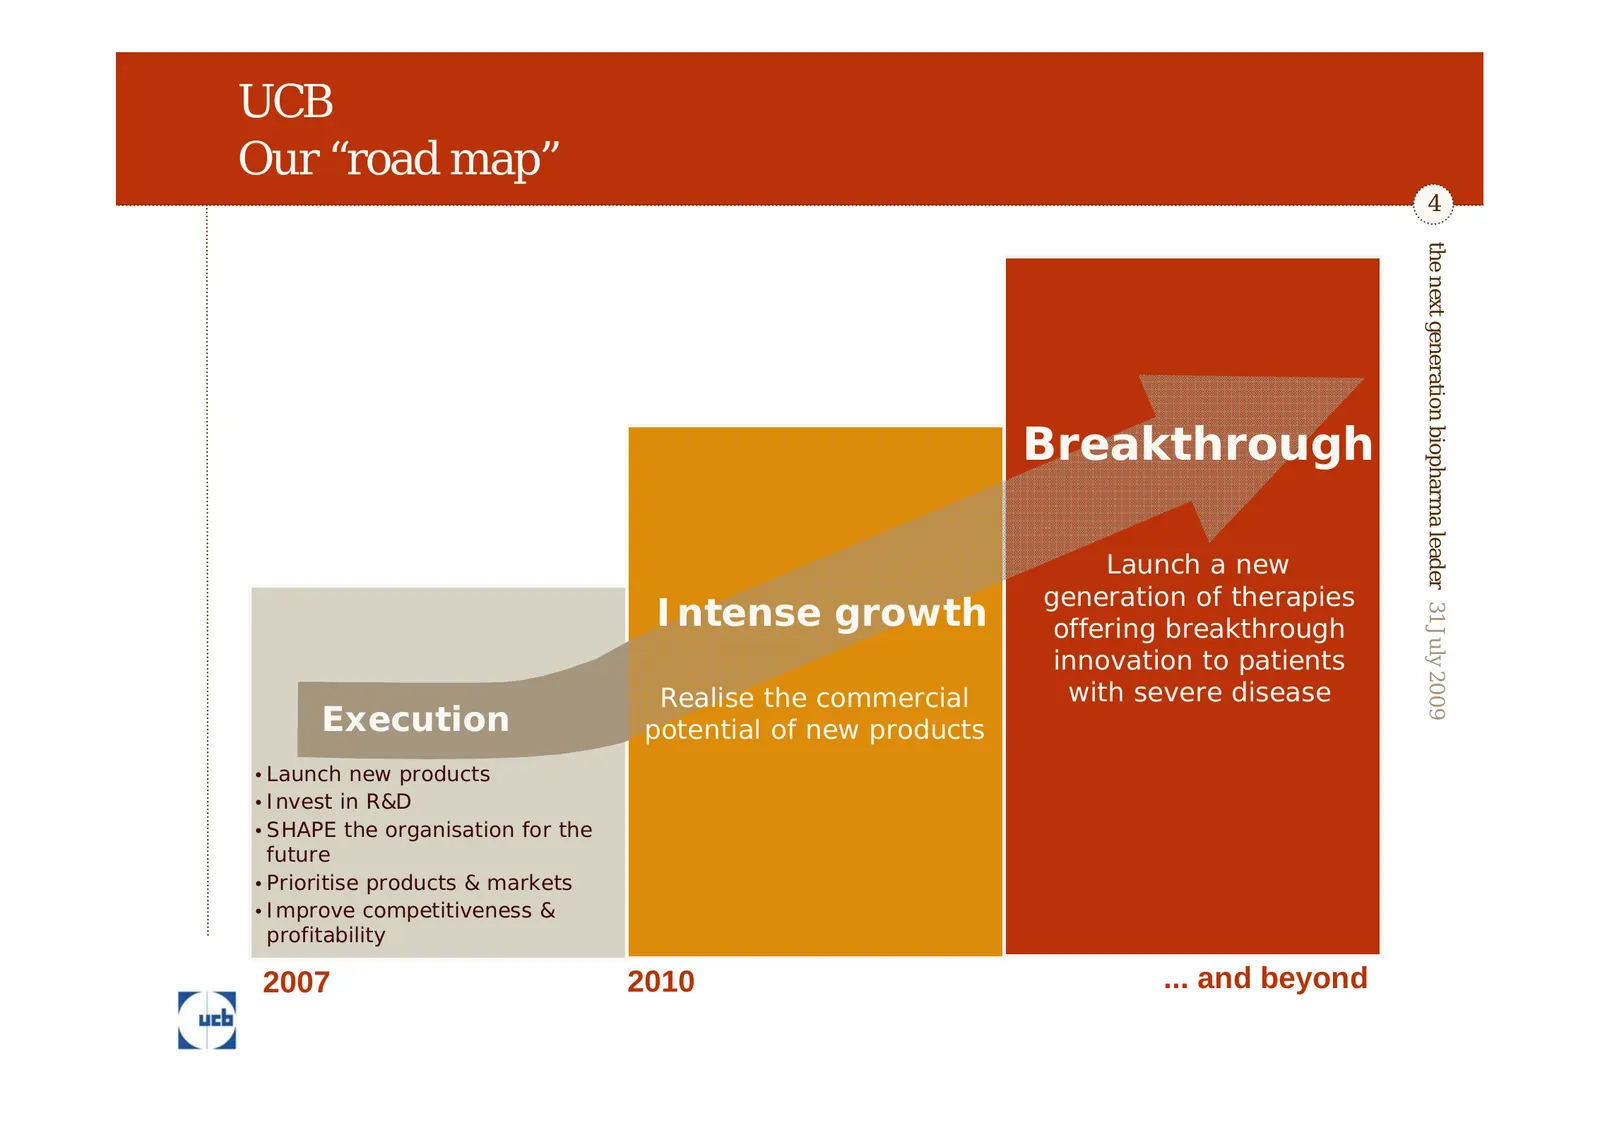
Slide 4: Our road map
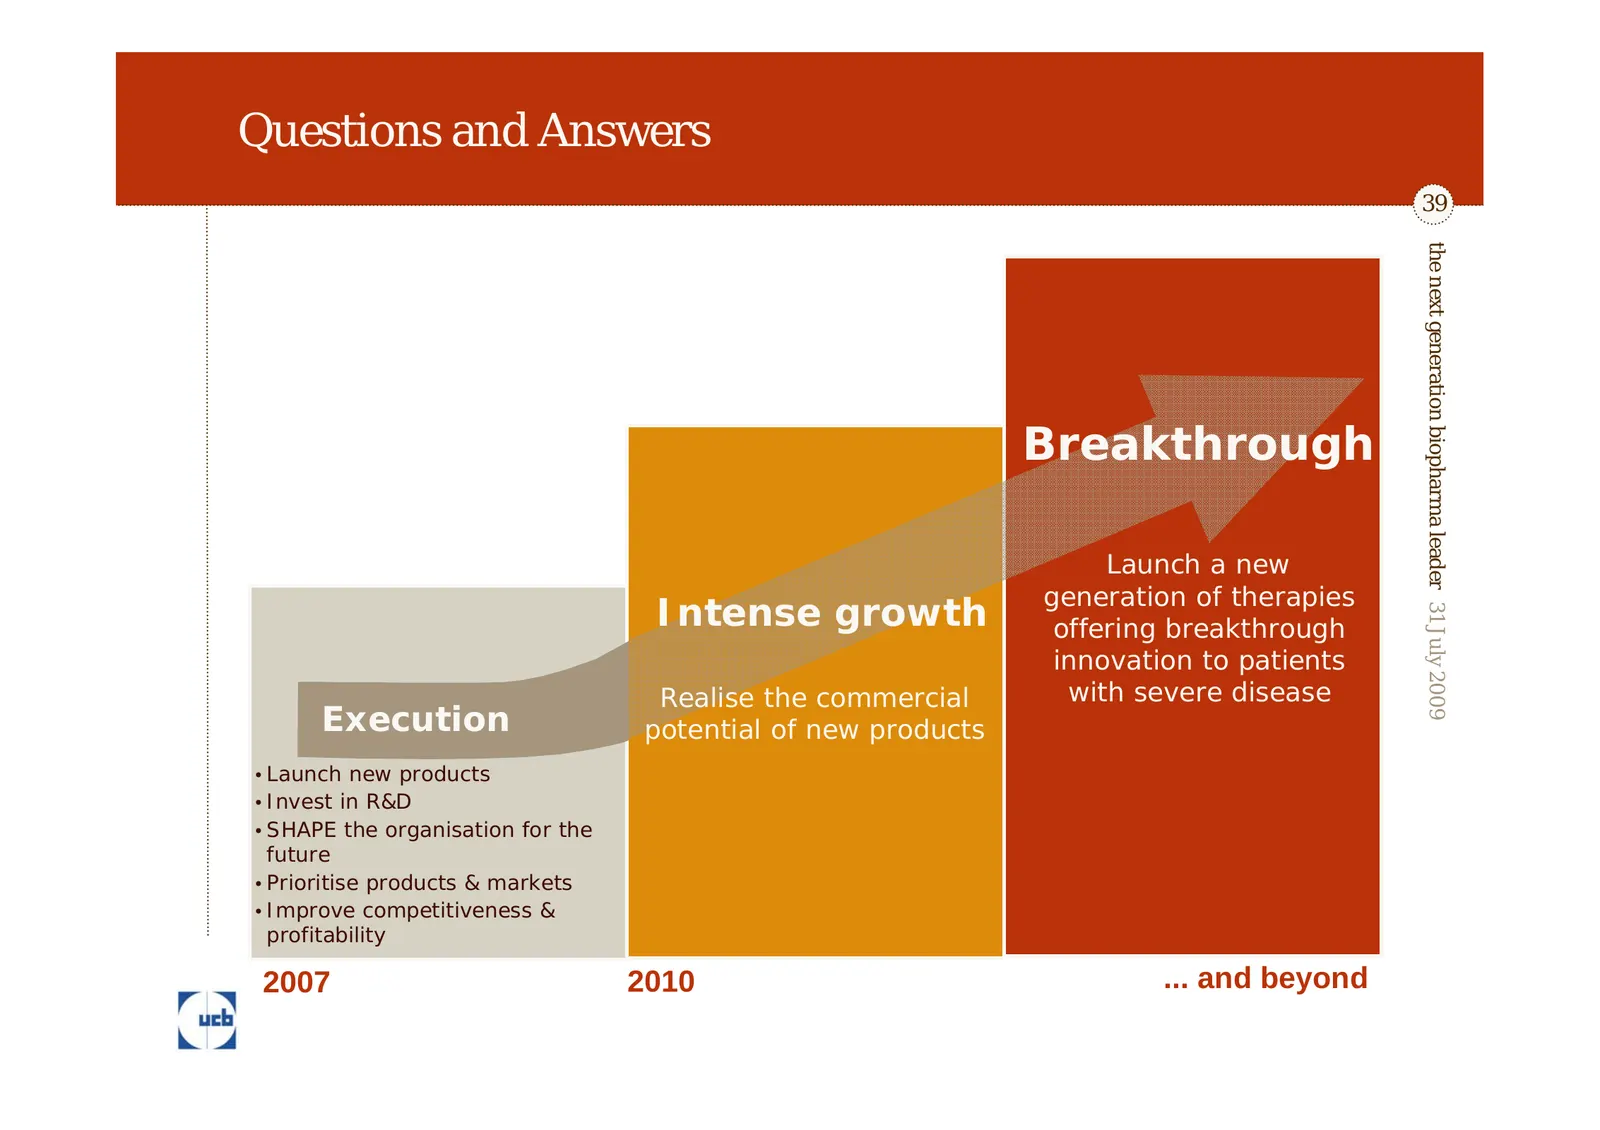
UCB Our “road map” 4 the next generation biopharma leader 31 July 2009 Breakthrough Launch a new generation of therapies Intense growth offering breakthrough innovation to patients Realise the commercial with severe disease Execution potential of new products • Launch new products • Invest in R&D •
Slide 5: Agenda
Agenda 5 the next generation biopharma leader 31 July 2009 Progress so far • Roch Doliveux, CEO Financial performance • Detlef Thielgen, CFO Drug development • Iris Loew-Friedrich, CMO Conclusion • Roch Doliveux, CEO
Slide 6: H1 2009 Delivery and execution
H1 2009 Delivery and execution 6 the next generation biopharma leader 31 July 2009 UCB is progressing to become the next generation biopharma leader • Major regulatory milestones achieved • 3+1 product launches in the last 4 months • UCB enters the next stage of its transformation 2009 revenue and R
Slide 7: Net sales of major and new products
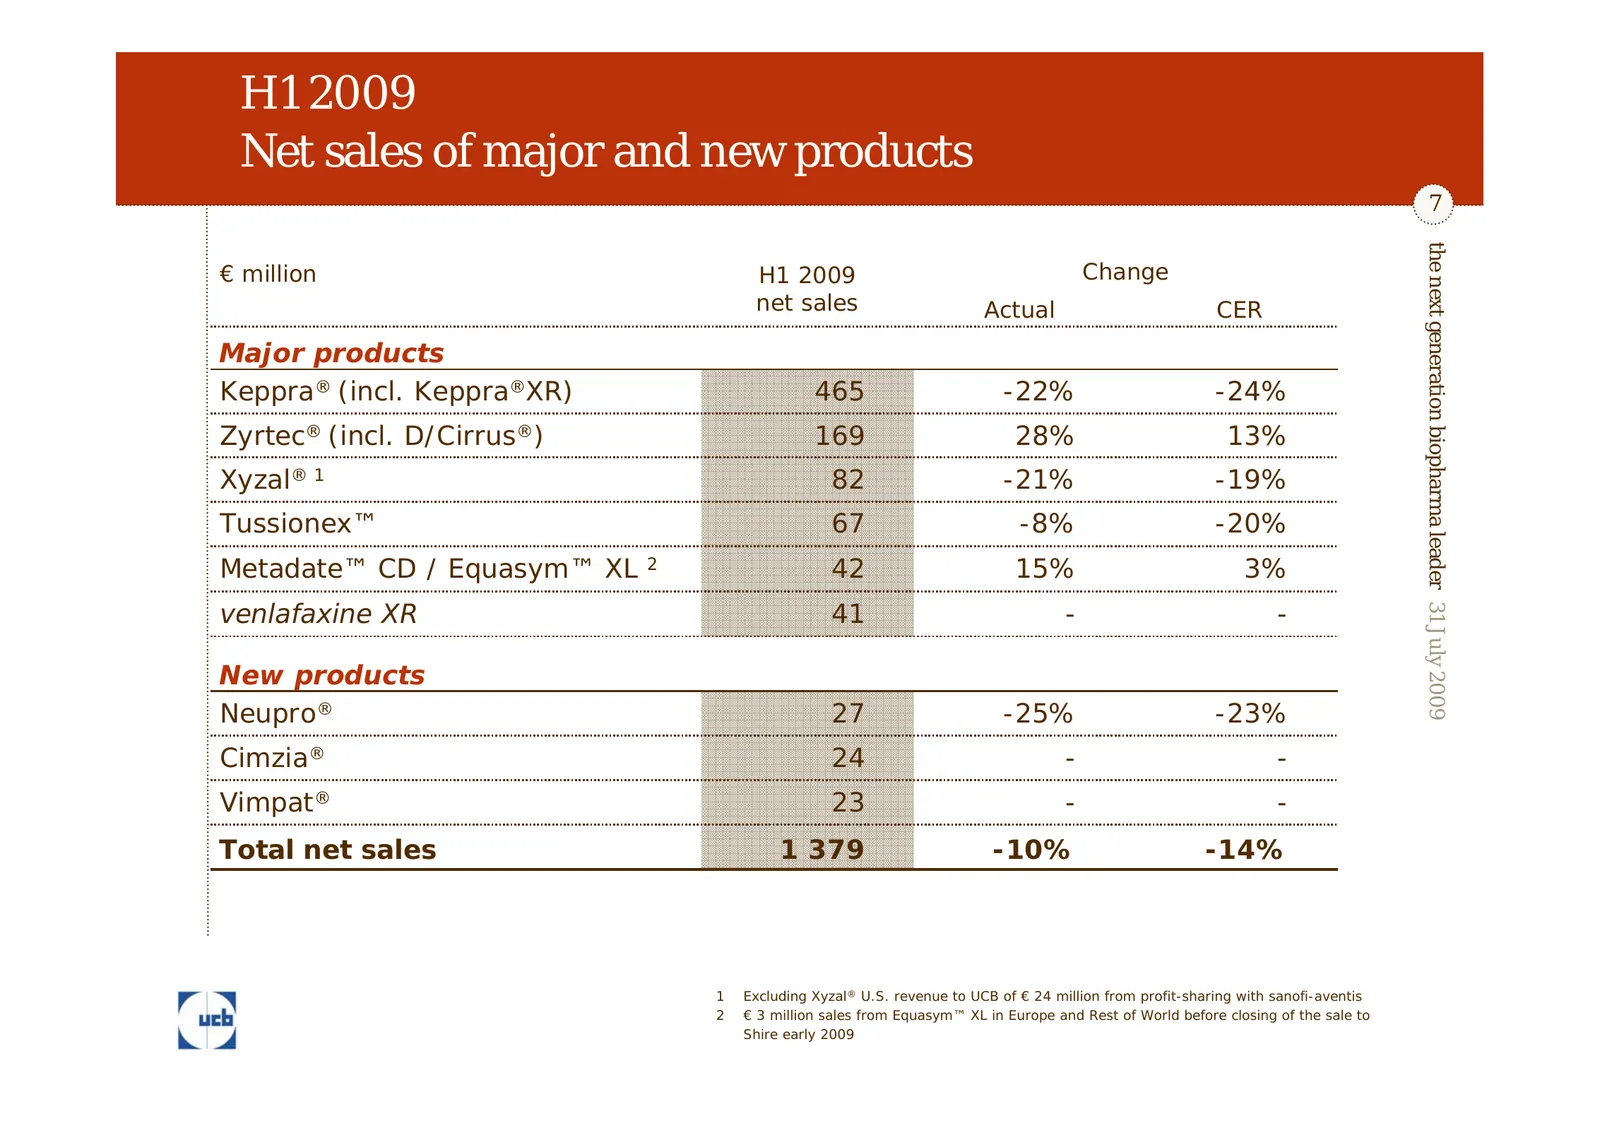
H1 2009 Net sales of major and new products 7 the next generation biopharma leader 31 July 2009 € million H1 2009 Change net sales Actual CER Major products Keppra® (incl. Keppra®XR) 465 -22% -24% Zyrtec® (incl. D/Cirrus®) 169 28% 13% Xyzal® 1 82 -21% -19% Tussionex™ 67 -8% -20% Metadate™ CD / Equas
Slide 8: Keppra franchise
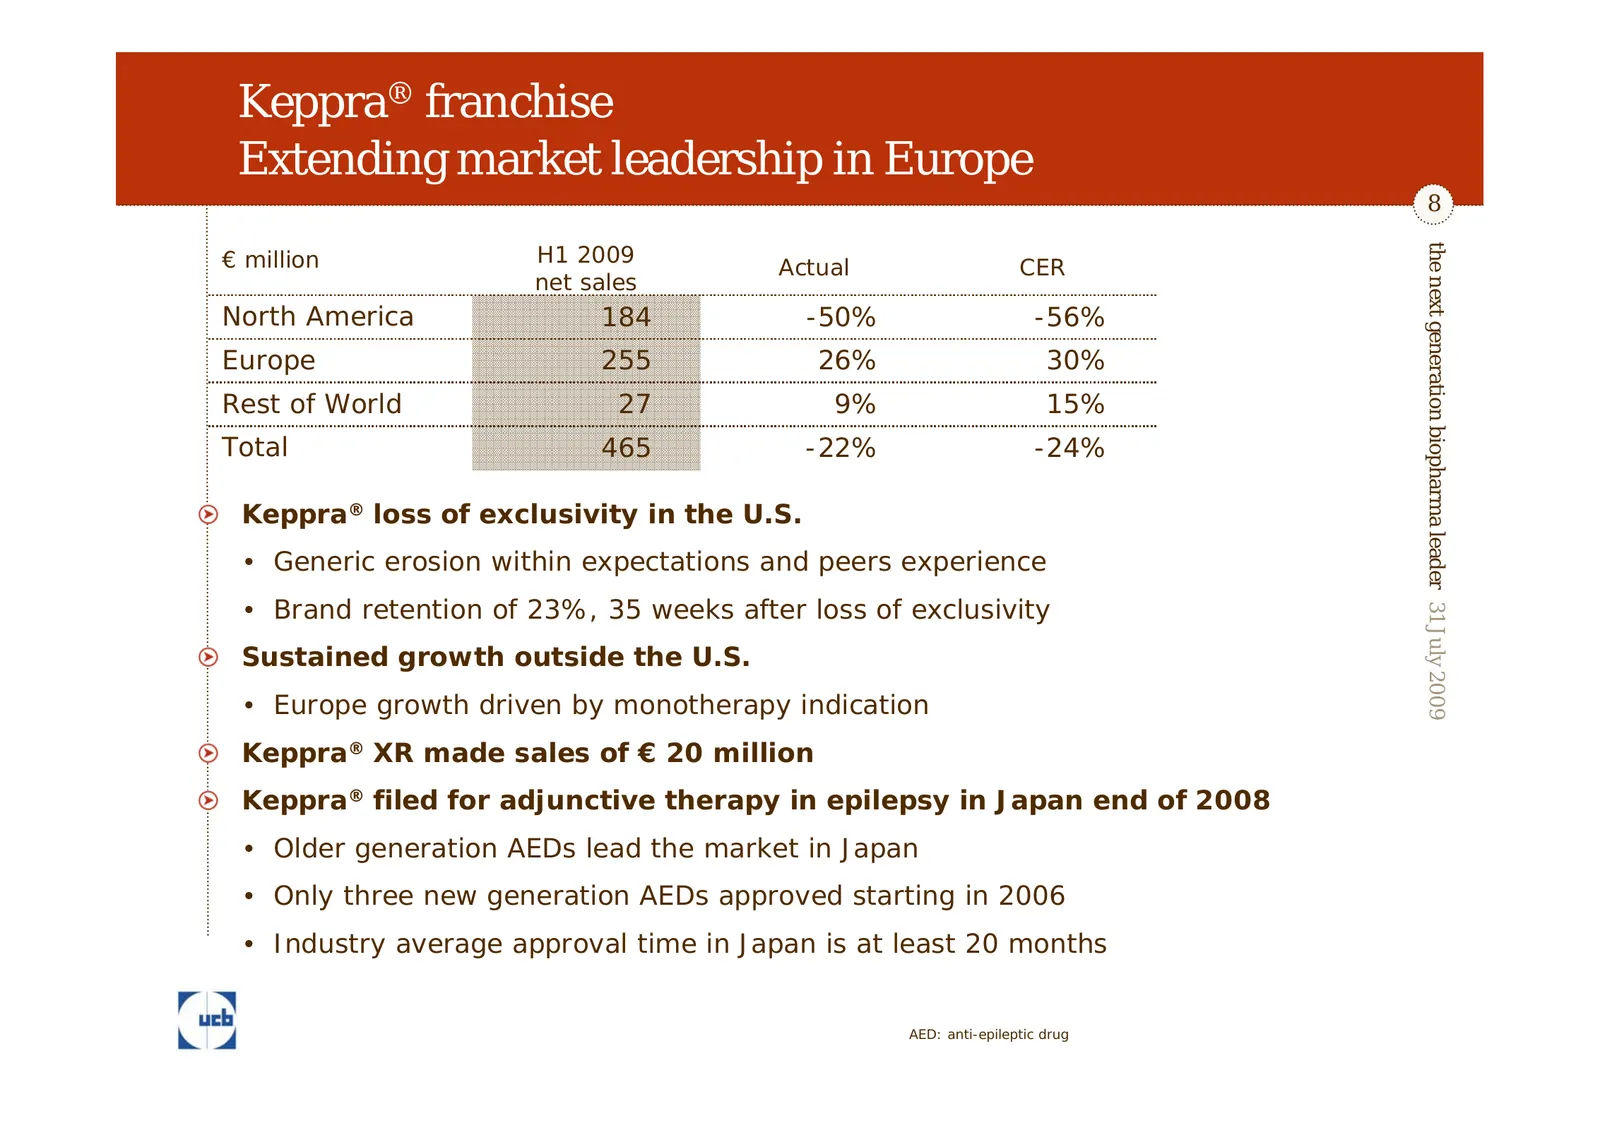
Keppra® franchise Extending market leadership in Europe 8 H1 2009 the next generation biopharma leader 31 July 2009 € million Actual CER net sales North America 184 -50% -56% Europe 255 26% 30% Rest of World 27 9% 15% Total 465 -22% -24% Keppra® loss of exclusivity in the U.S. • Generic erosion with
Slide 9: Welcome back to Neupro in Europe
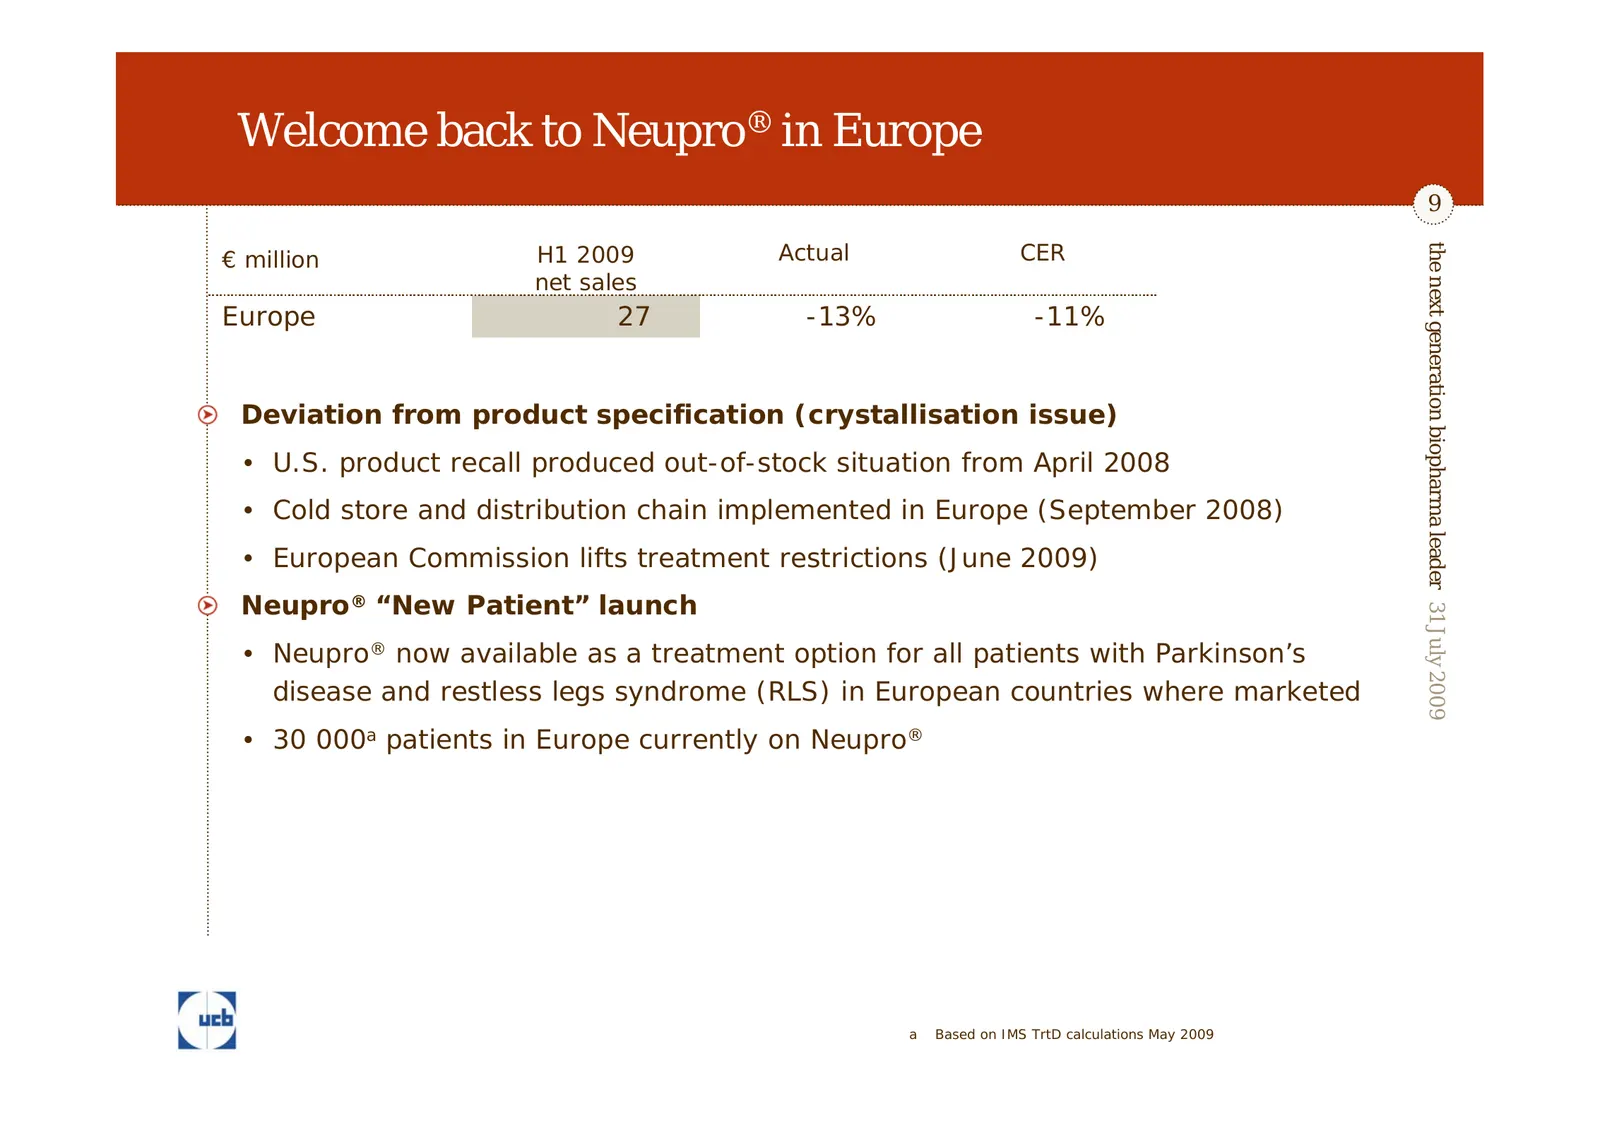
Welcome back to Neupro® in Europe 9 H1 2009 Actual CER the next generation biopharma leader 31 July 2009 € million net sales Europe 27 -13% -11% Deviation from product specification (crystallisation issue) • U.S. product recall produced out-of-stock situation from April 2008 • Cold store and distrib
Slide 10: Product launches in four months
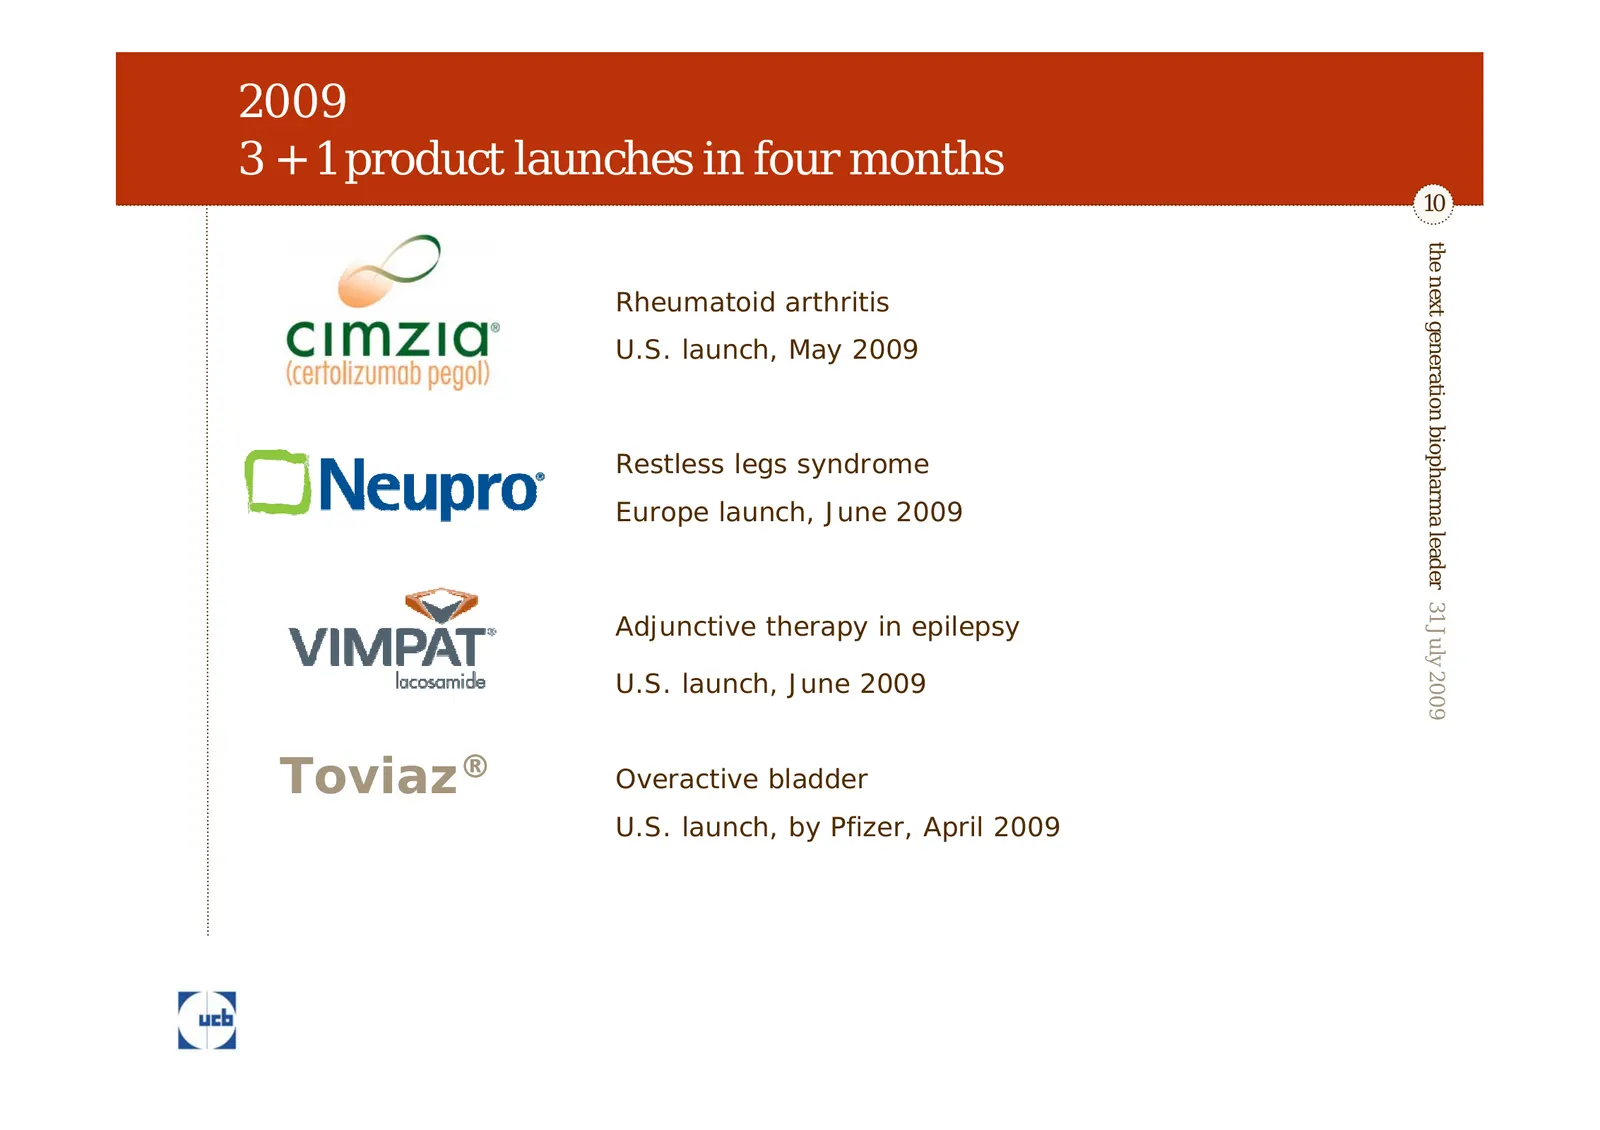
2009 3 + 1 product launches in four months 10 the next generation biopharma leader 31 July 2009 Rheumatoid arthritis U.S. launch, May 2009 Restless legs syndrome Europe launch, June 2009 Adjunctive therapy in epilepsy U.S. launch, June 2009 Toviaz® Overactive bladder U.S. launch, by Pfizer, April 20
Slide 11: Cimzia: Patient-centricity…
the next generation biopharma leader 31 July 2009 11 Cimzia® : Patient-centricity…
Slide 12: Led to intelligent innovation as first result of partnership
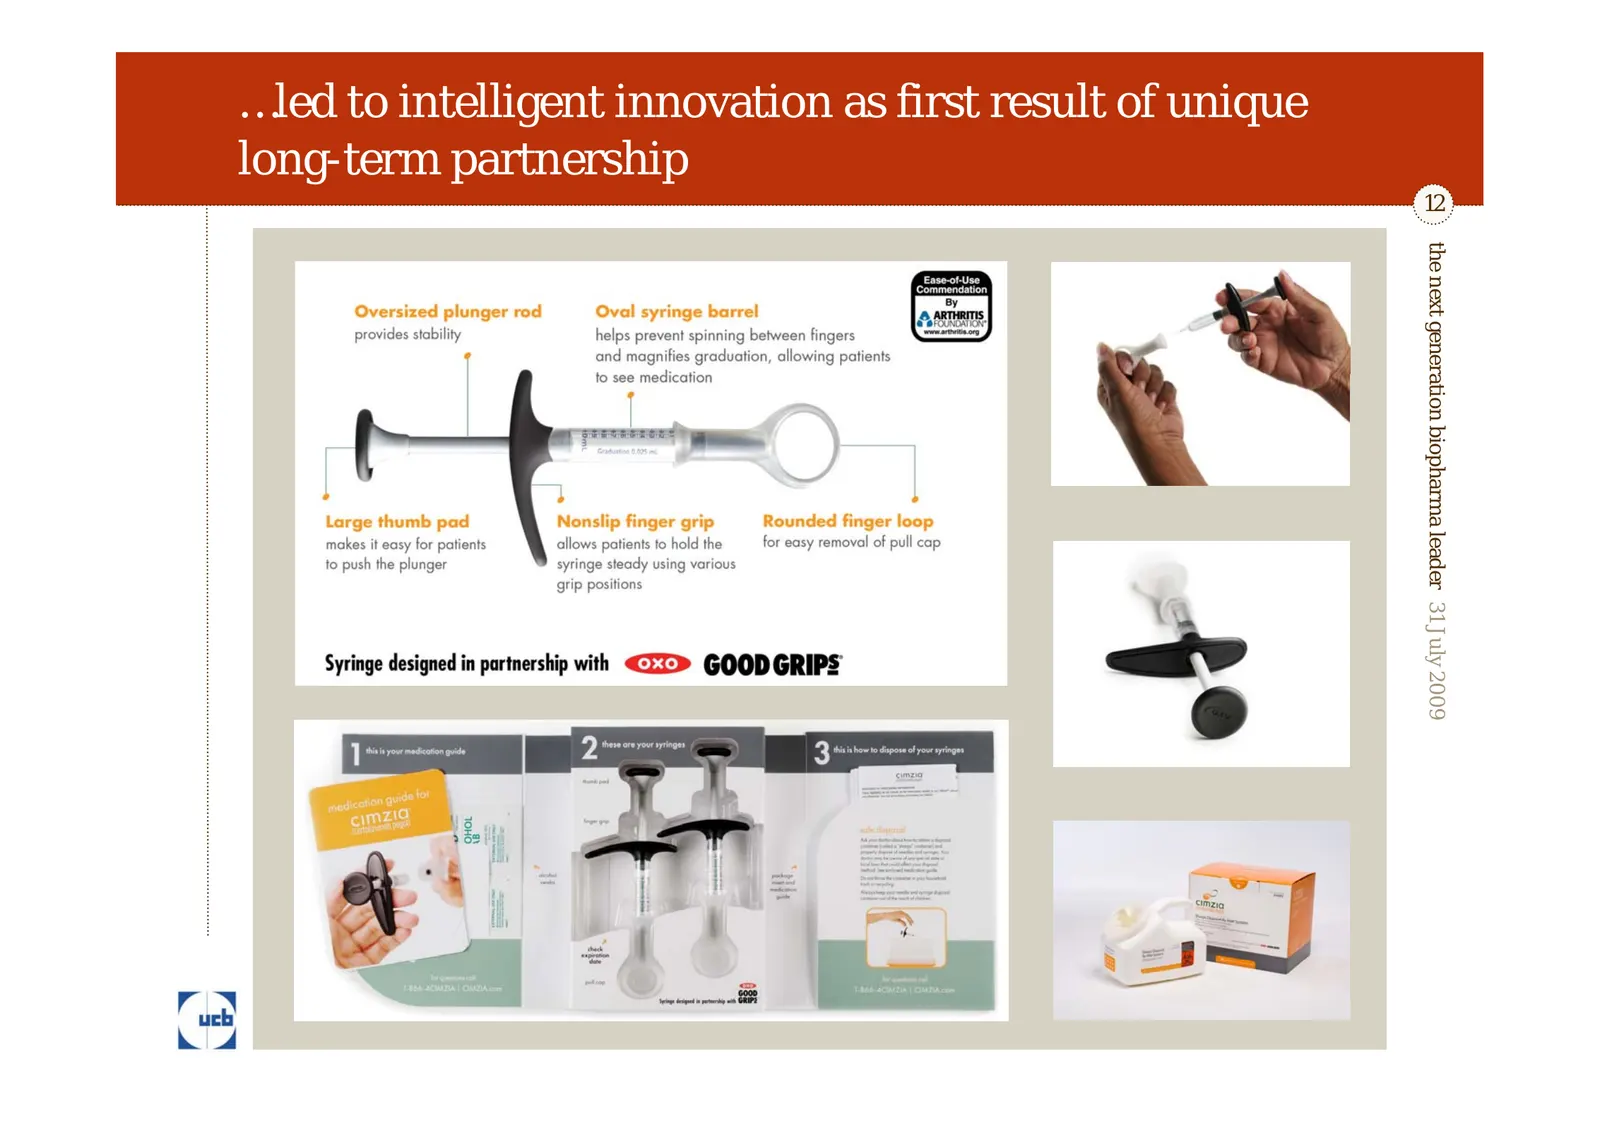
…led to intelligent innovation as first result of unique long-term partnership 12 the next generation biopharma leader 31 July 2009
Slide 13: Cimzia roll-out in U.S.
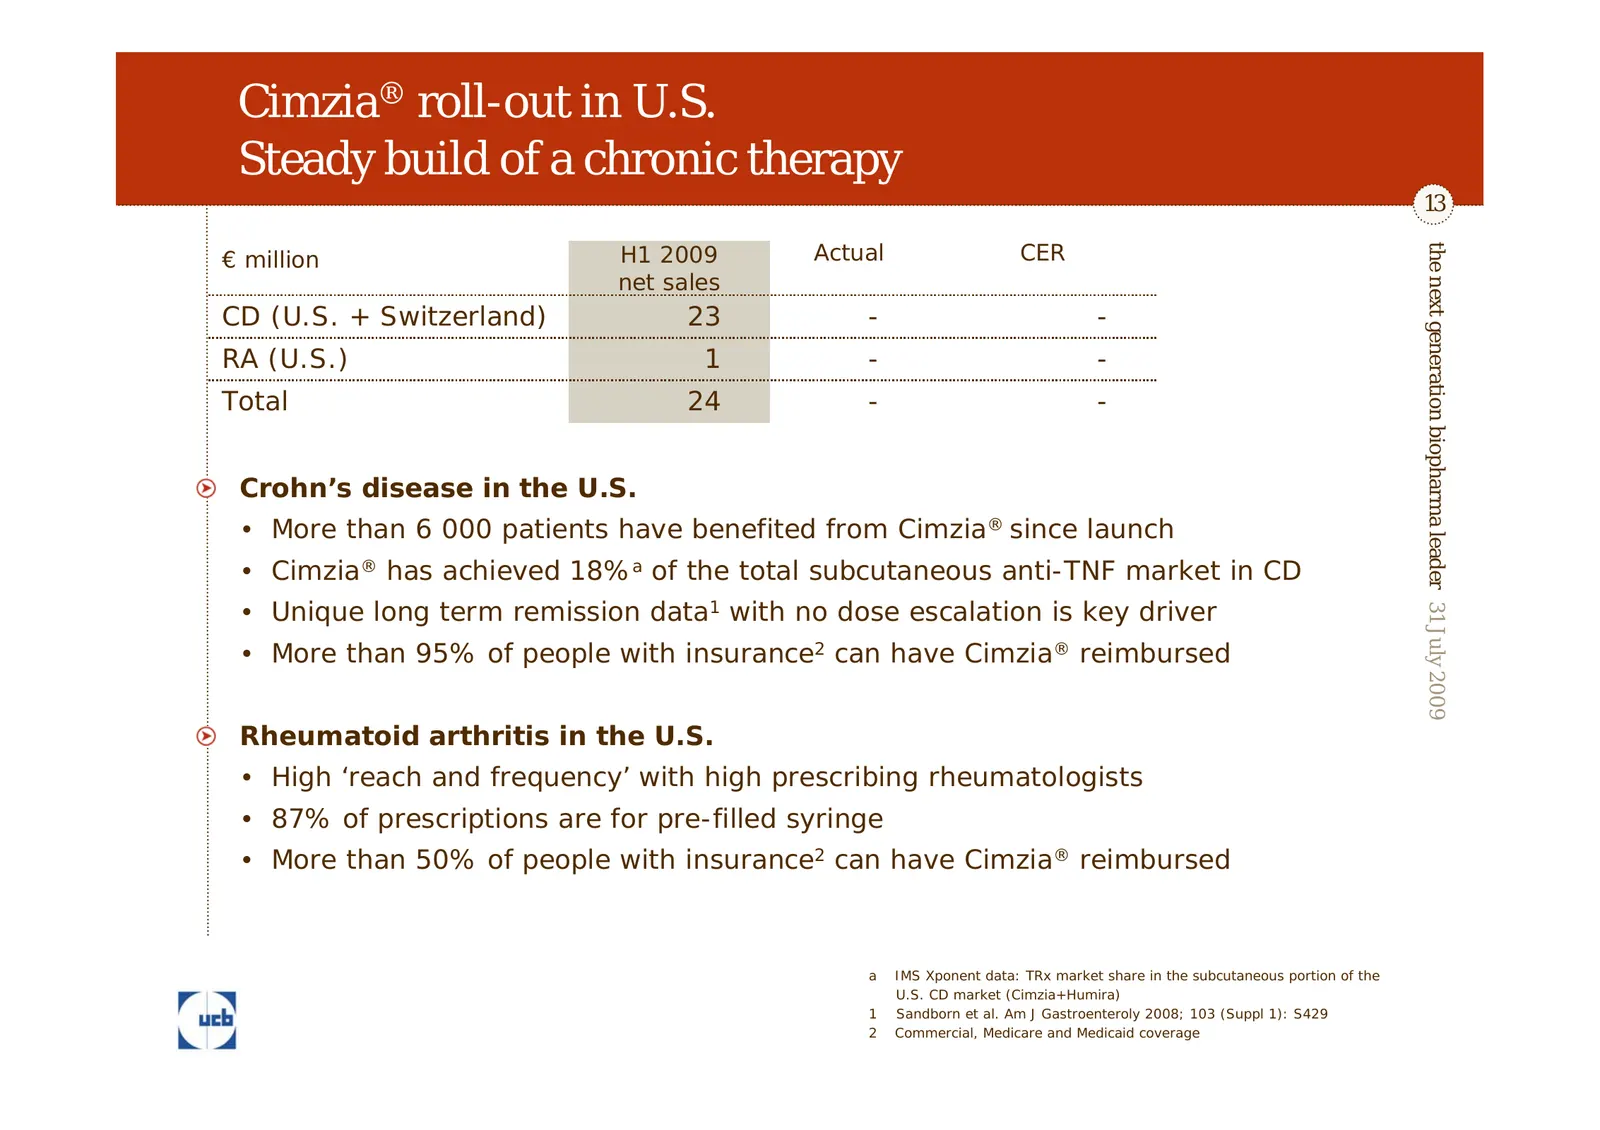
Cimzia® roll-out in U.S. Steady build of a chronic therapy 13 H1 2009 Actual CER the next generation biopharma leader 31 July 2009 € million net sales CD (U.S. + Switzerland) 23 - - RA (U.S.) 1 - - Total 24 - - Crohn’s disease in the U.S. • More than 6 000 patients have benefited from Cimzia® since
Slide 14: Cimzia in rheumatoid arthritis in U.S.
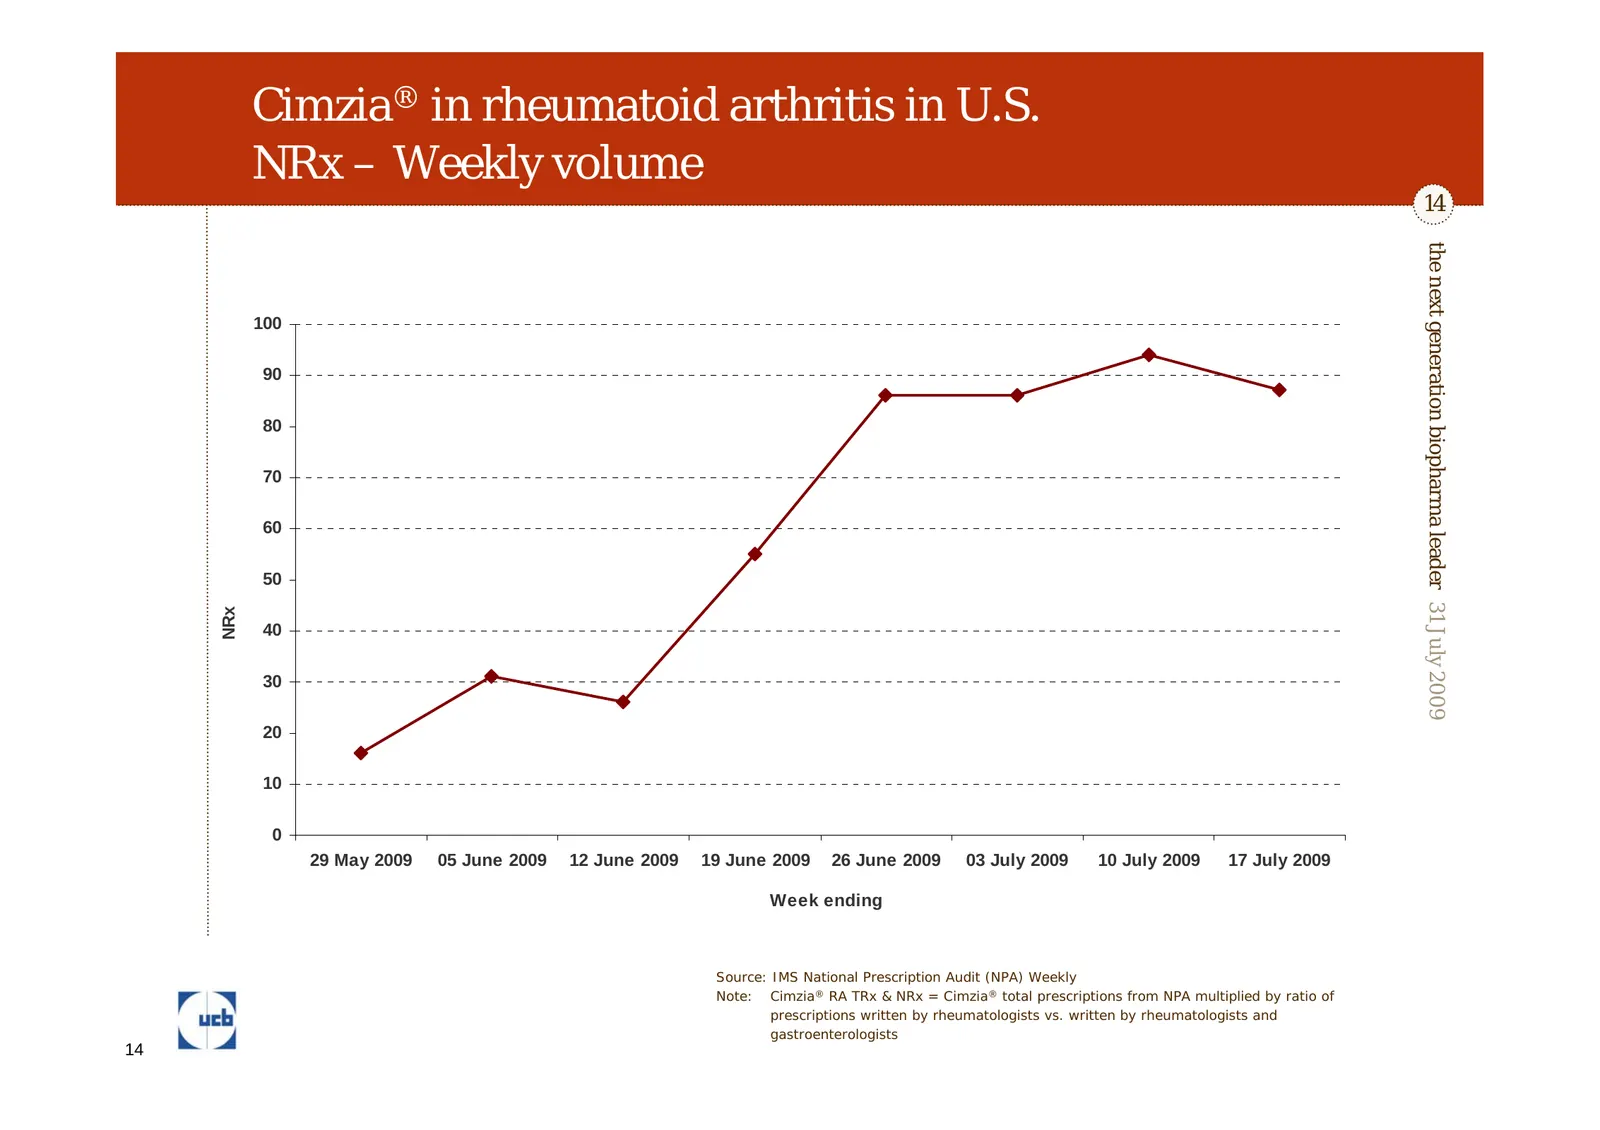
Cimzia® in rheumatoid arthritis in U.S. NRx – Weekly volume 14 the next generation biopharma leader 31 July 2009 100 90 80 70 60 50 NRx 40 30 20 10 0 29 May 2009 05 June 2009 12 June 2009 19 June 2009 26 June 2009 03 July 2009 10 July 2009 17 July 2009 Week ending Source: IMS National Prescription A
Slide 15: Cimzia in Crohn's disease
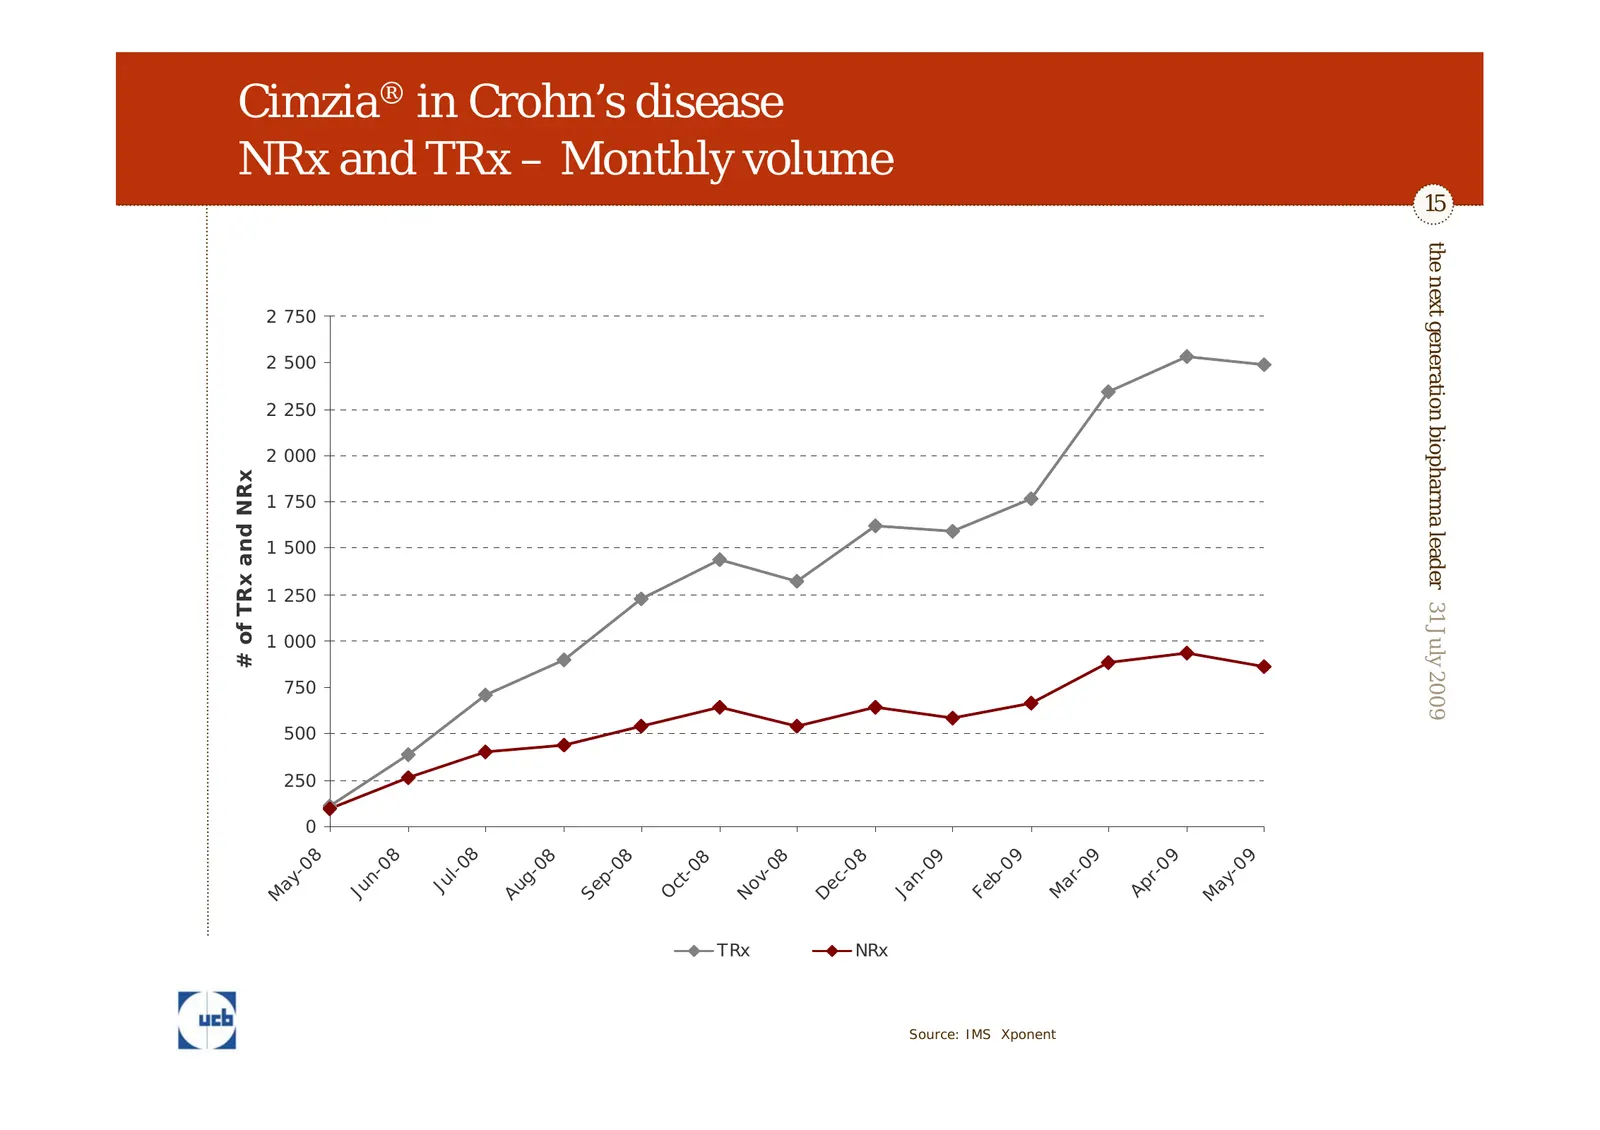
Cimzia® in Crohn’s disease NRx and TRx – Monthly volume 15 the next generation biopharma leader 31 July 2009 2 750 2 500 2 250 2 000 # of TRx and NRx 1 750 1 500 1 250 1 000 750 500 250 0 08 8 09 8 9 9 9 08 08 8 8 09 8 -0 -0 0 -0 -0 0 -0 -0 l- r- g- p- n- n- b- ar ov ay ay ec ct Ju Ap Au Fe Ju Se Ja
Slide 16: Vimpat in epilepsy
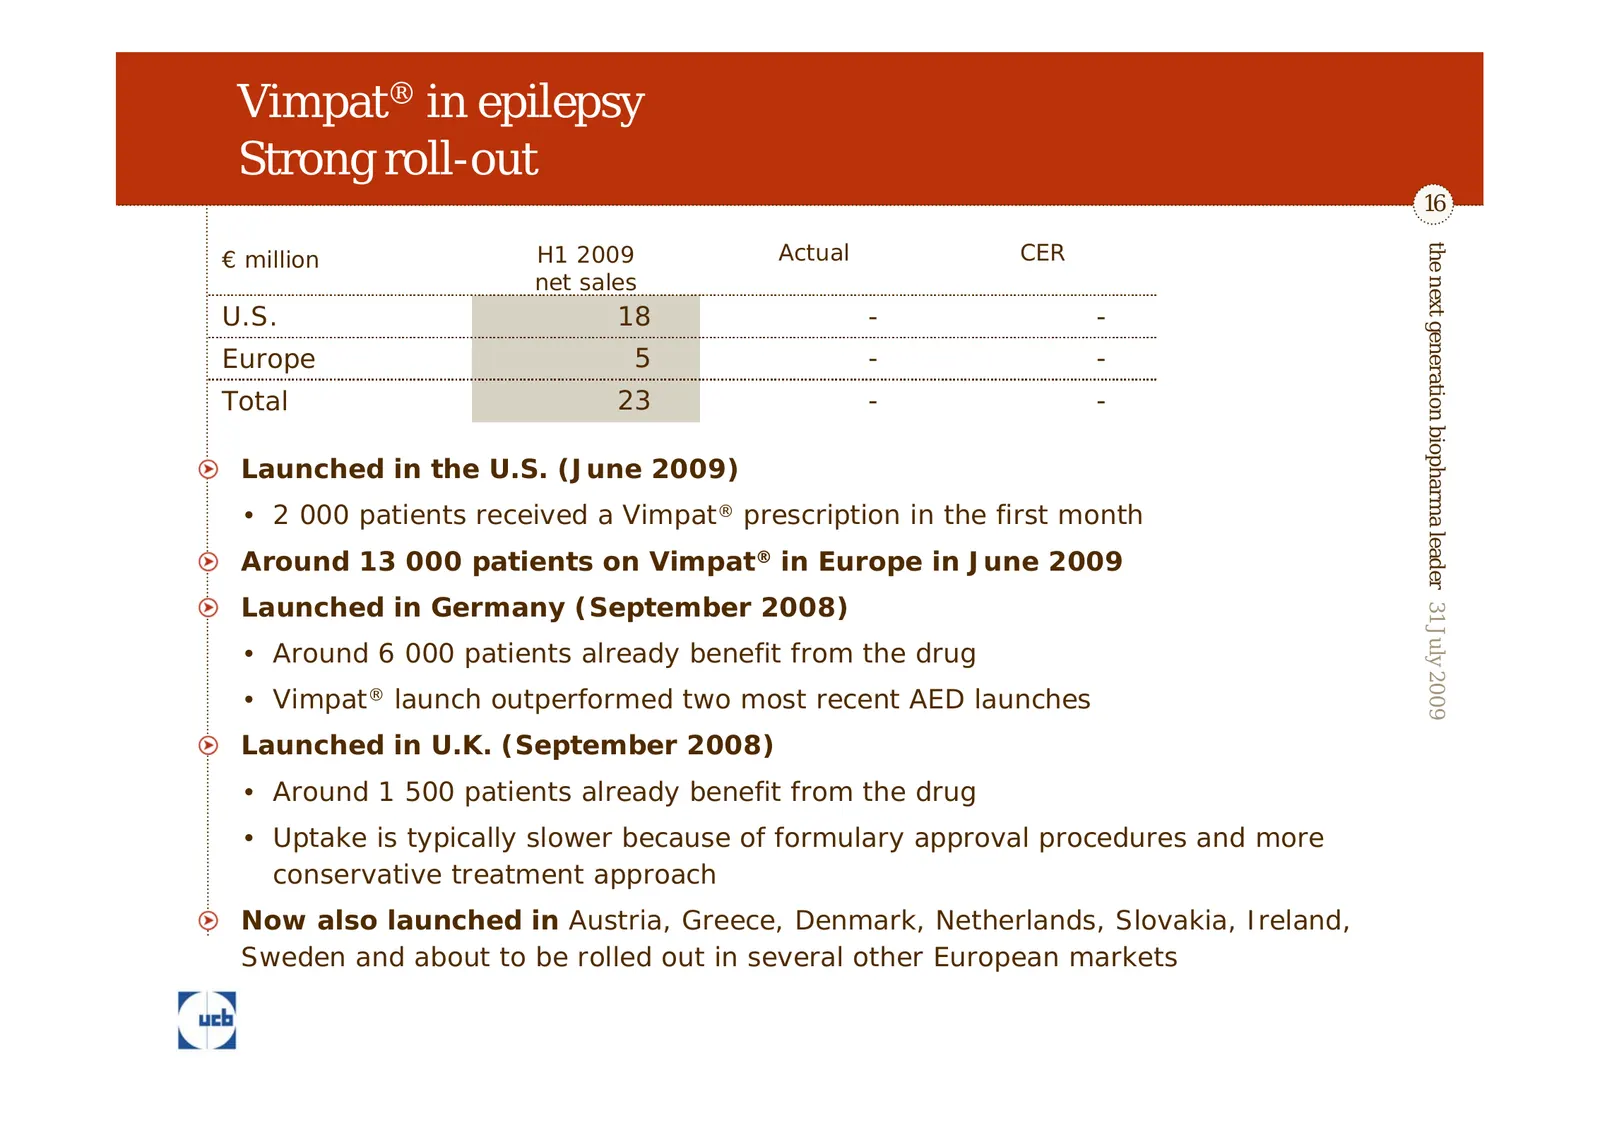
Vimpat® in epilepsy Strong roll-out 16 H1 2009 Actual CER the next generation biopharma leader 31 July 2009 € million net sales U.S. 18 - - Europe 5 - - Total 23 - - Launched in the U.S. (June 2009) • 2 000 patients received a Vimpat® prescription in the first month Around 13 000 patients on Vimpat®
Slide 17: Vimpat in Germany
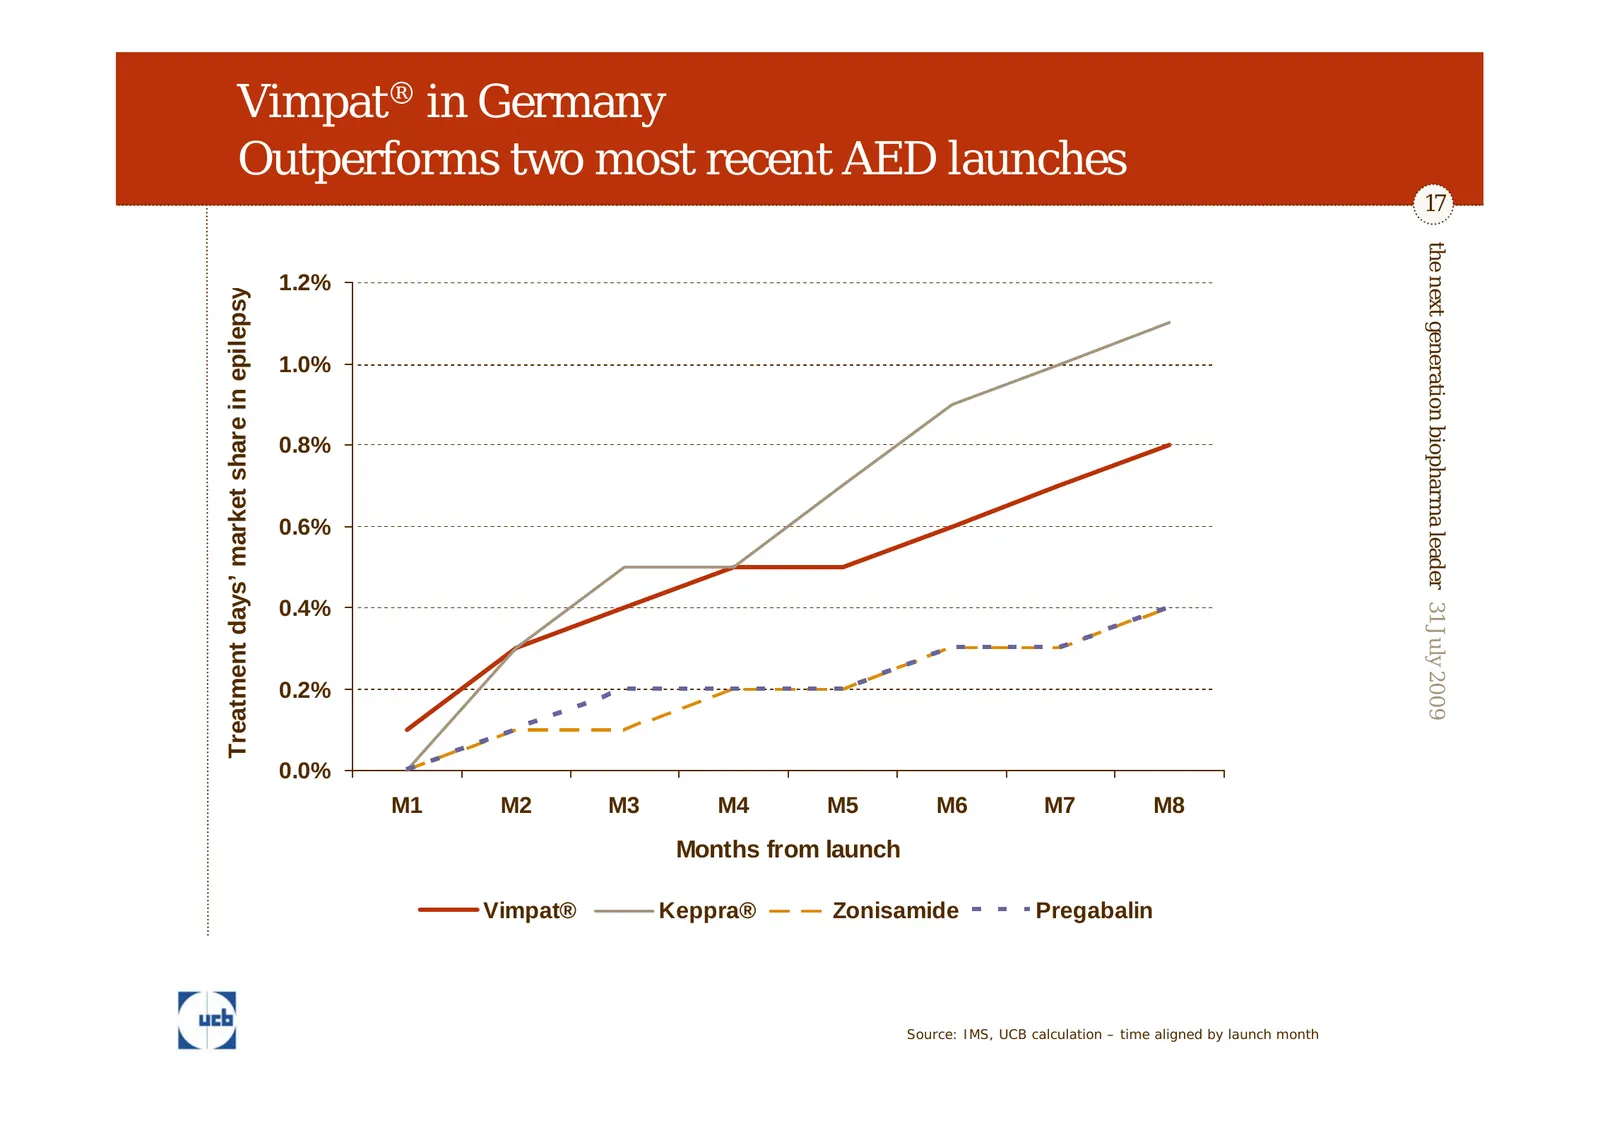
Vimpat® in Germany Outperforms two most recent AED launches 17 the next generation biopharma leader 31 July 2009 1.2% Treatment days’ market share in epilepsy 1.0% 0.8% 0.6% 0.4% 0.2% 0.0% M1 M2 M3 M4 M5 M6 M7 M8 Months from launch Vimpat® Keppra® Zonisamide Pregabalin Source: IMS, UCB calculation –
Slide 18: Vimpat in the U.S.
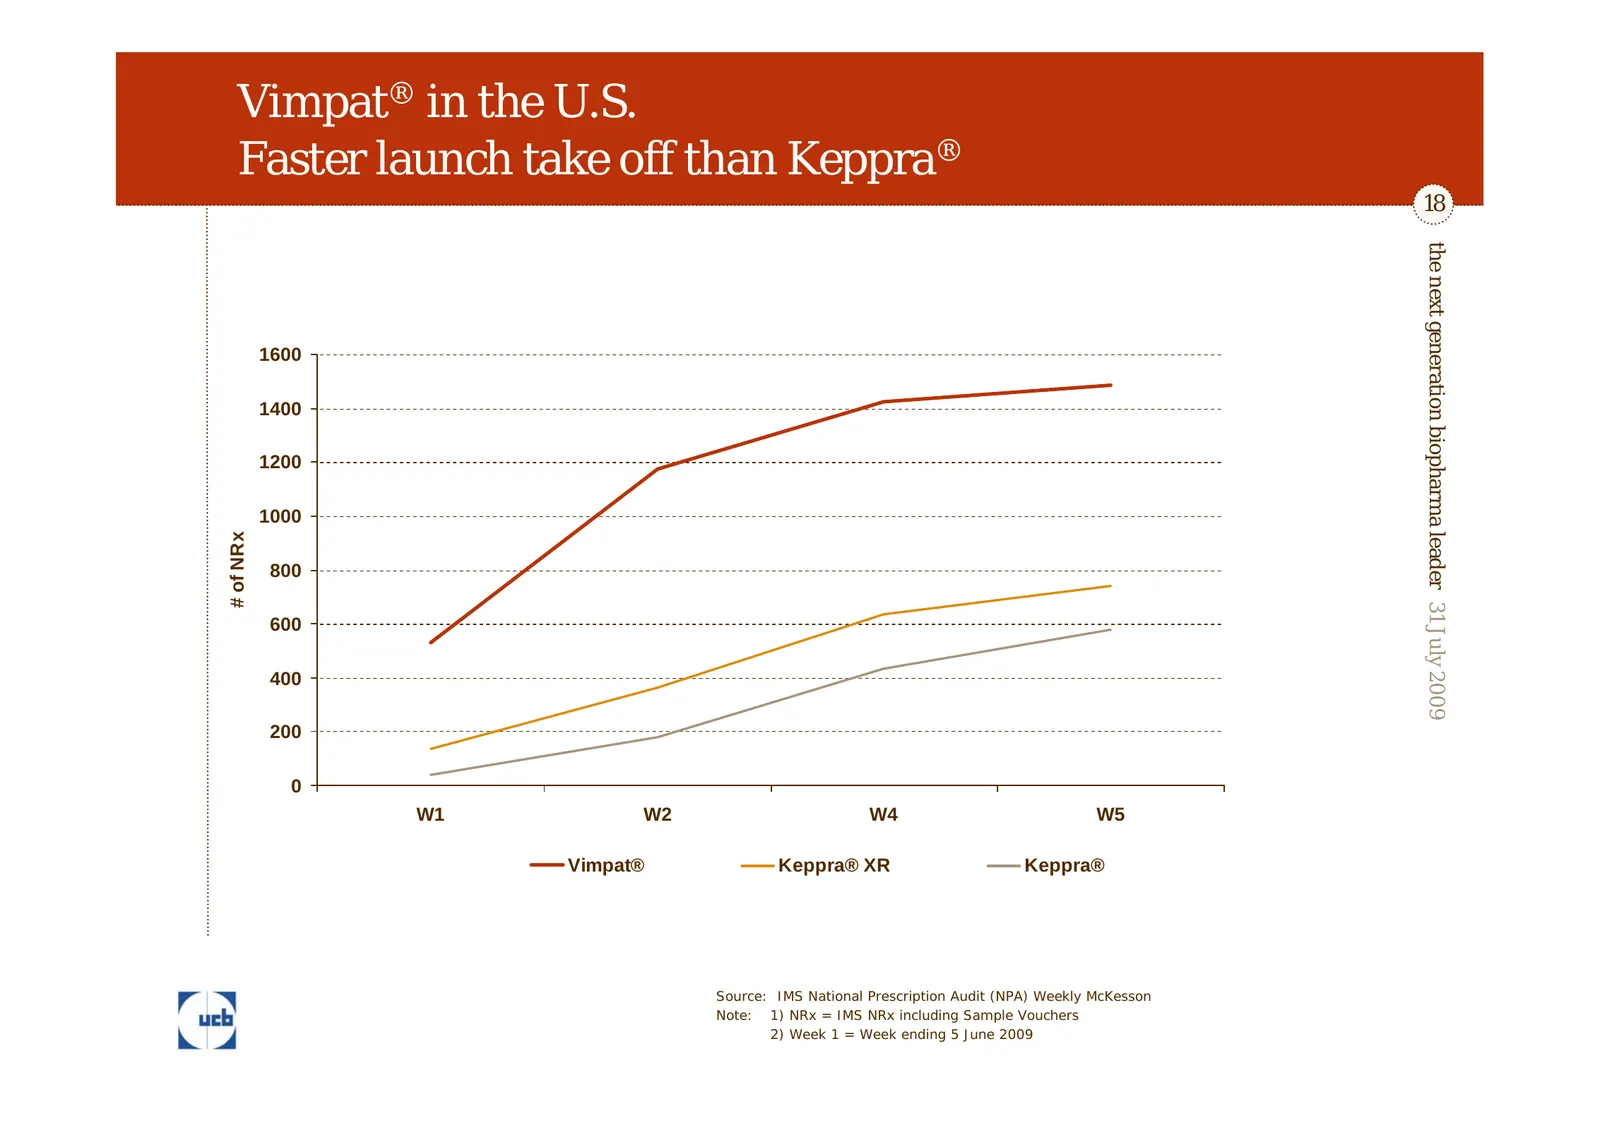
Vimpat® in the U.S. Faster launch take off than Keppra® 18 the next generation biopharma leader 31 July 2009 1600 1400 1200 1000 # of NRx 800 600 400 200 0 W1 W2 W4 W5 Vimpat® Keppra® XR Keppra® Source: IMS National Prescription Audit (NPA) Weekly McKesson Note: 1) NRx = IMS NRx including Sample Vou
Slide 19: H1 2009 financial performance
19 the next generation biopharma leader 31 July 2009 H1 2009 financial performance Detlef Thielgen, CFO
Slide 20: H1 2009 Financial highlights
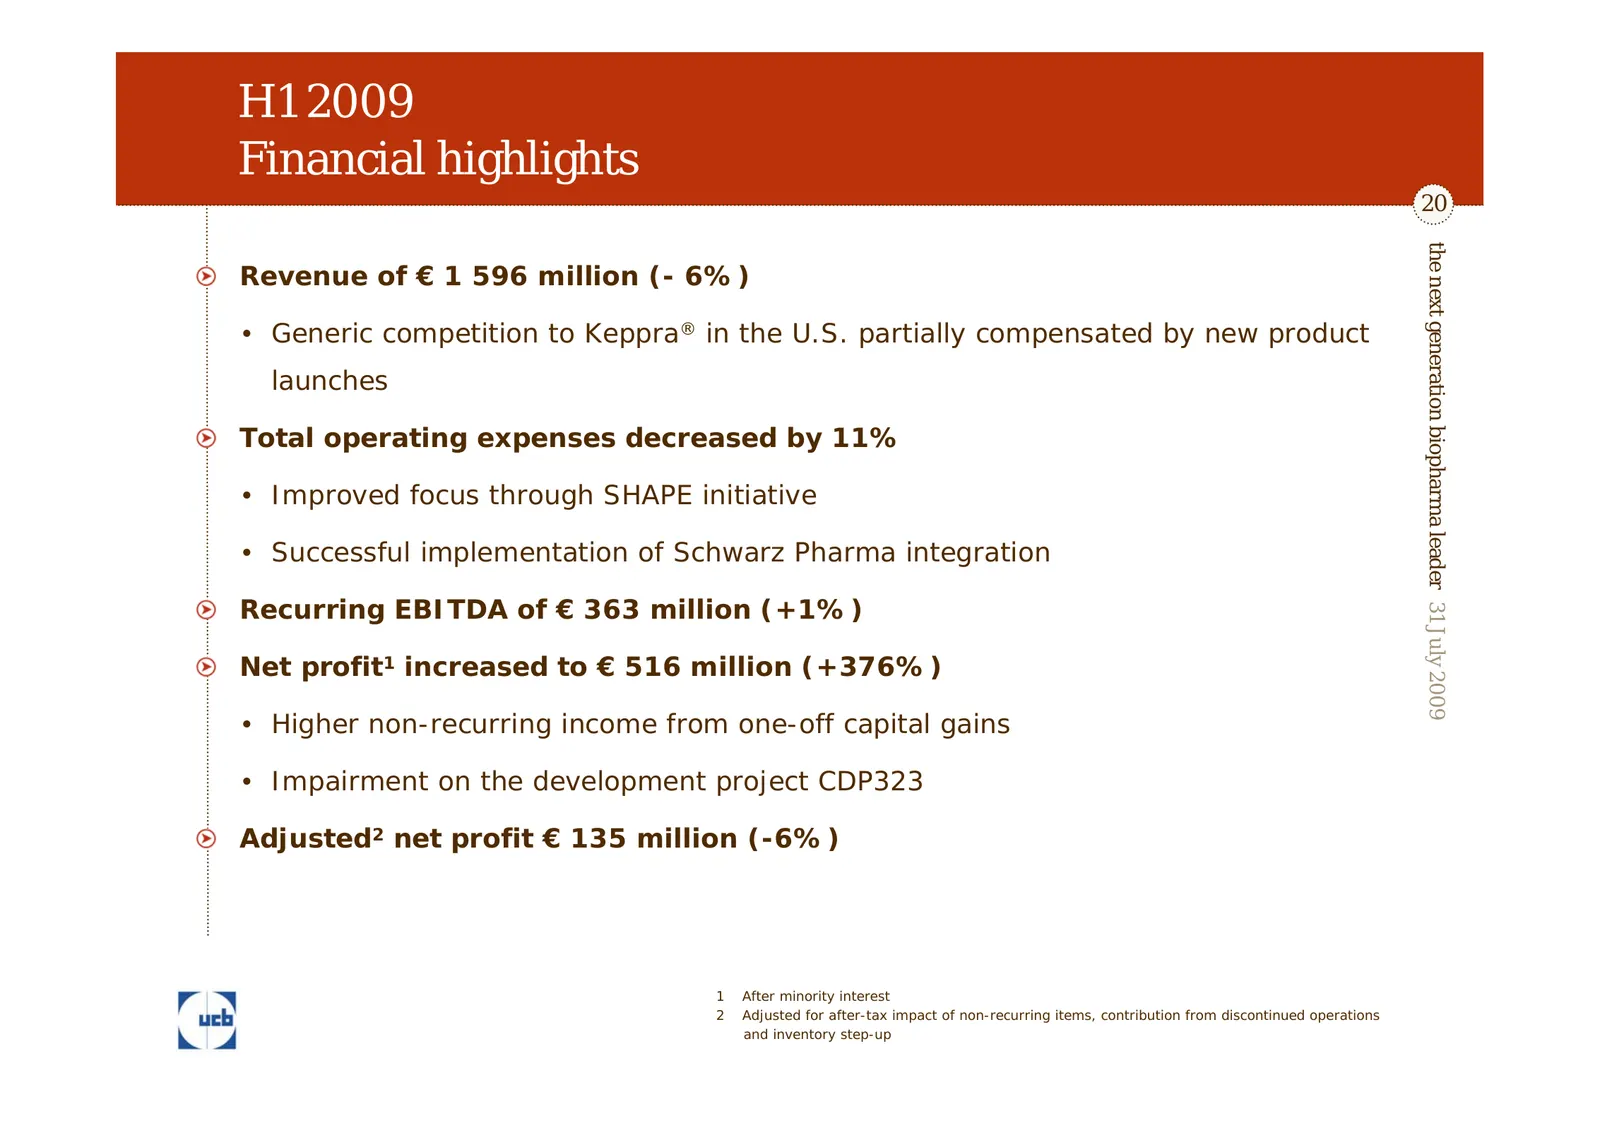
H1 2009 Financial highlights 20 the next generation biopharma leader 31 July 2009 Revenue of € 1 596 million (- 6%) • Generic competition to Keppra® in the U.S. partially compensated by new product launches Total operating expenses decreased by 11% • Improved focus through SHAPE initiative • Success
Slide 21: Recurring EBITDA
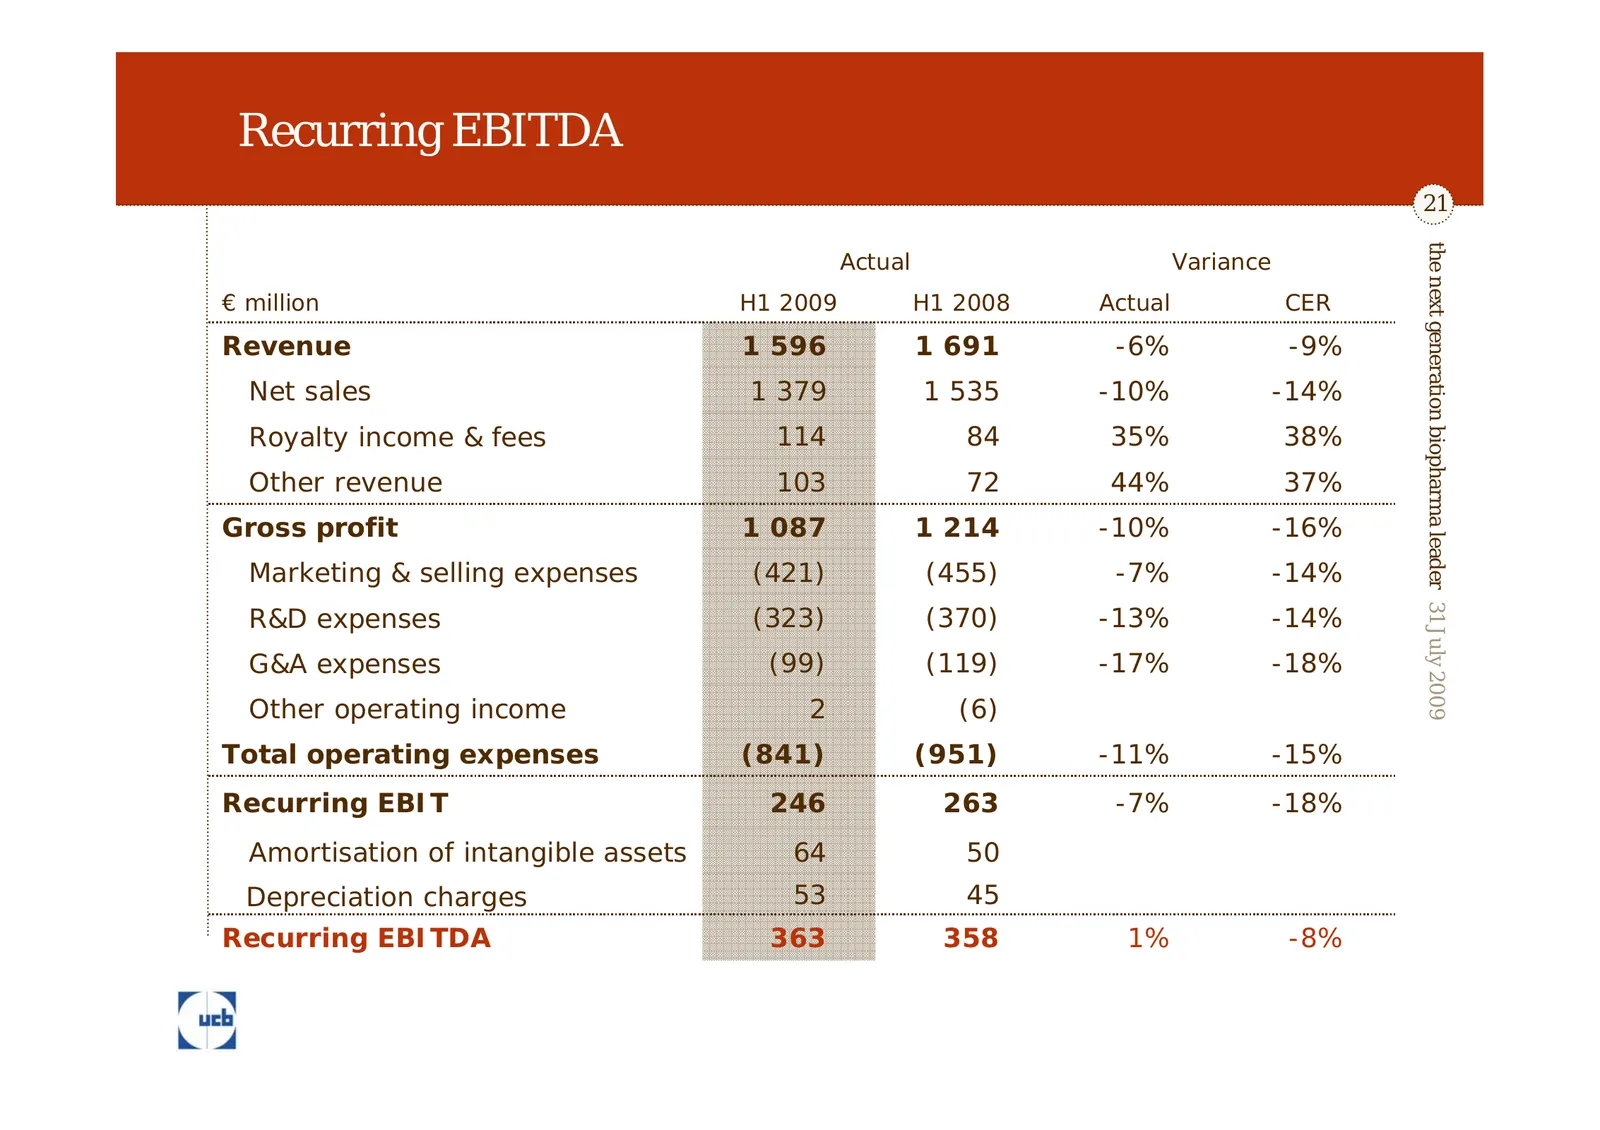
Recurring EBITDA 21 the next generation biopharma leader 31 July 2009 Actual Variance € million H1 2009 H1 2008 Actual CER Revenue 1 596 1 691 -6% -9% Net sales 1 379 1 535 -10% -14% Royalty income & fees 114 84 35% 38% Other revenue 103 72 44% 37% Gross profit 1 087 1 214 -10% -16% Marketing & sell
Slide 22: Net profit
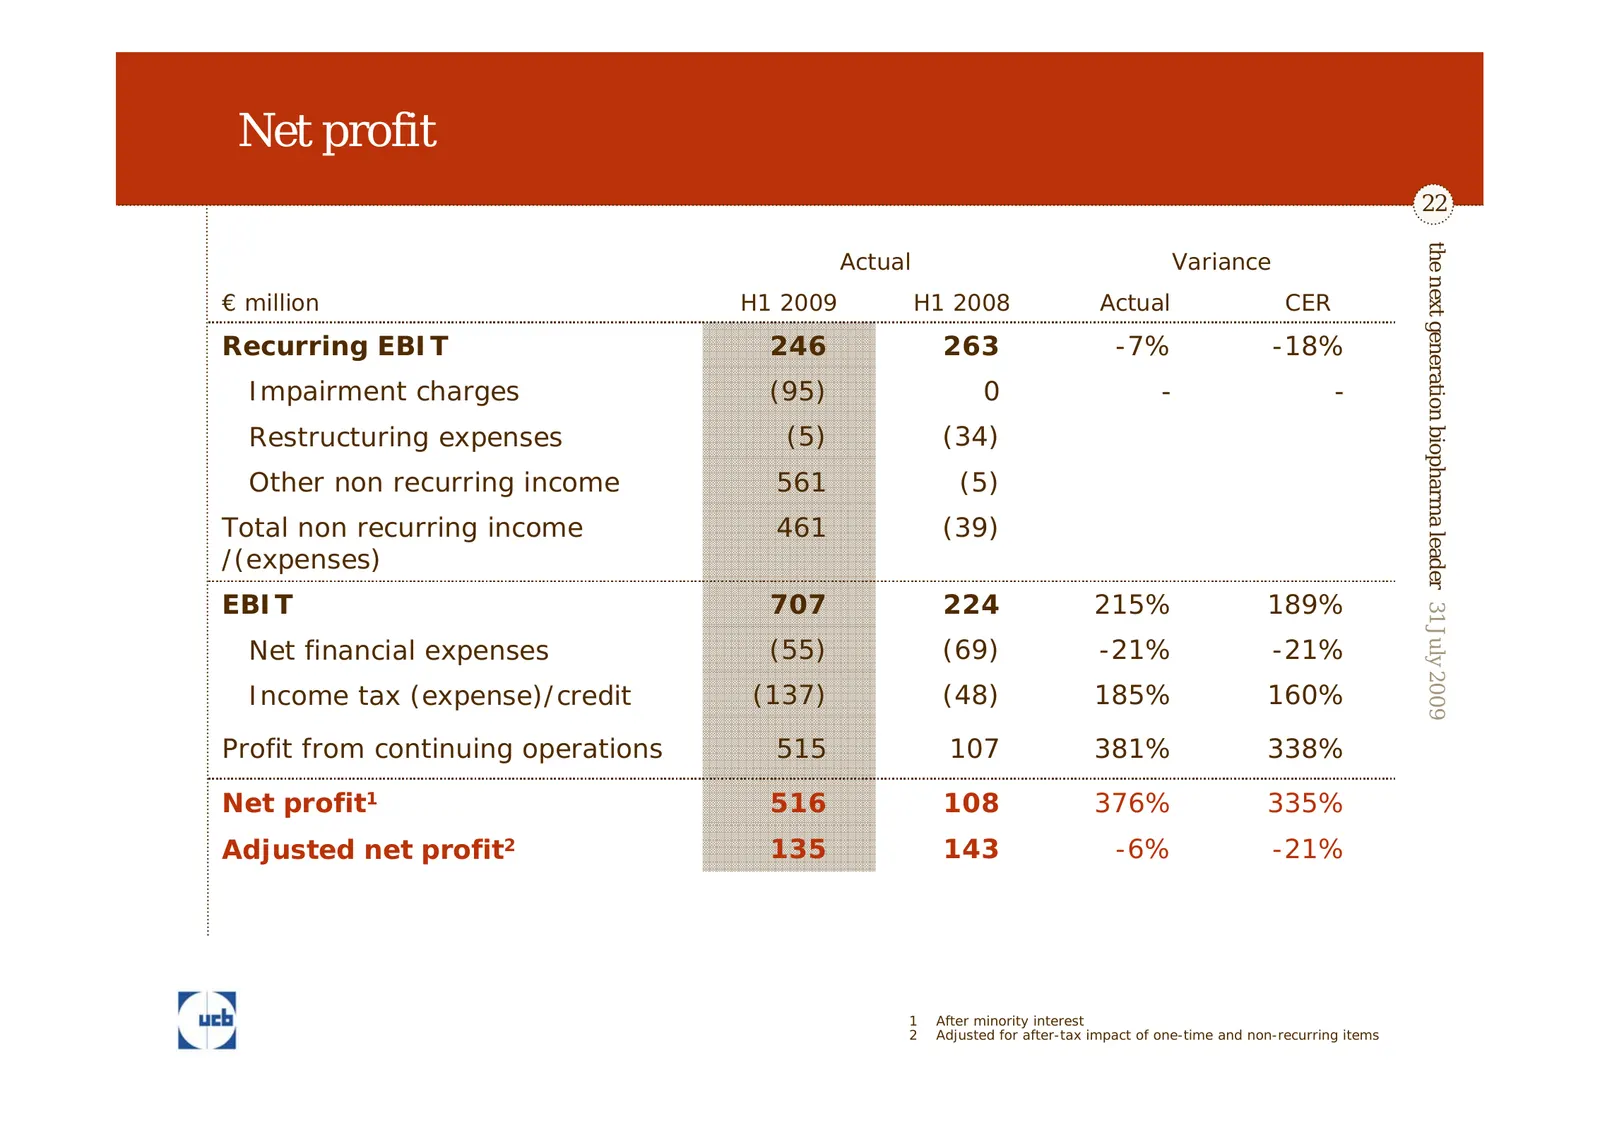
Net profit 22 the next generation biopharma leader 31 July 2009 Actual Variance € million H1 2009 H1 2008 Actual CER Recurring EBIT 246 263 -7% -18% Impairment charges (95) 0 - - Restructuring expenses (5) (34) Other non recurring income 561 (5) Total non recurring income 461 (39) /(expenses) EBIT 7
Slide 23: Balance sheet
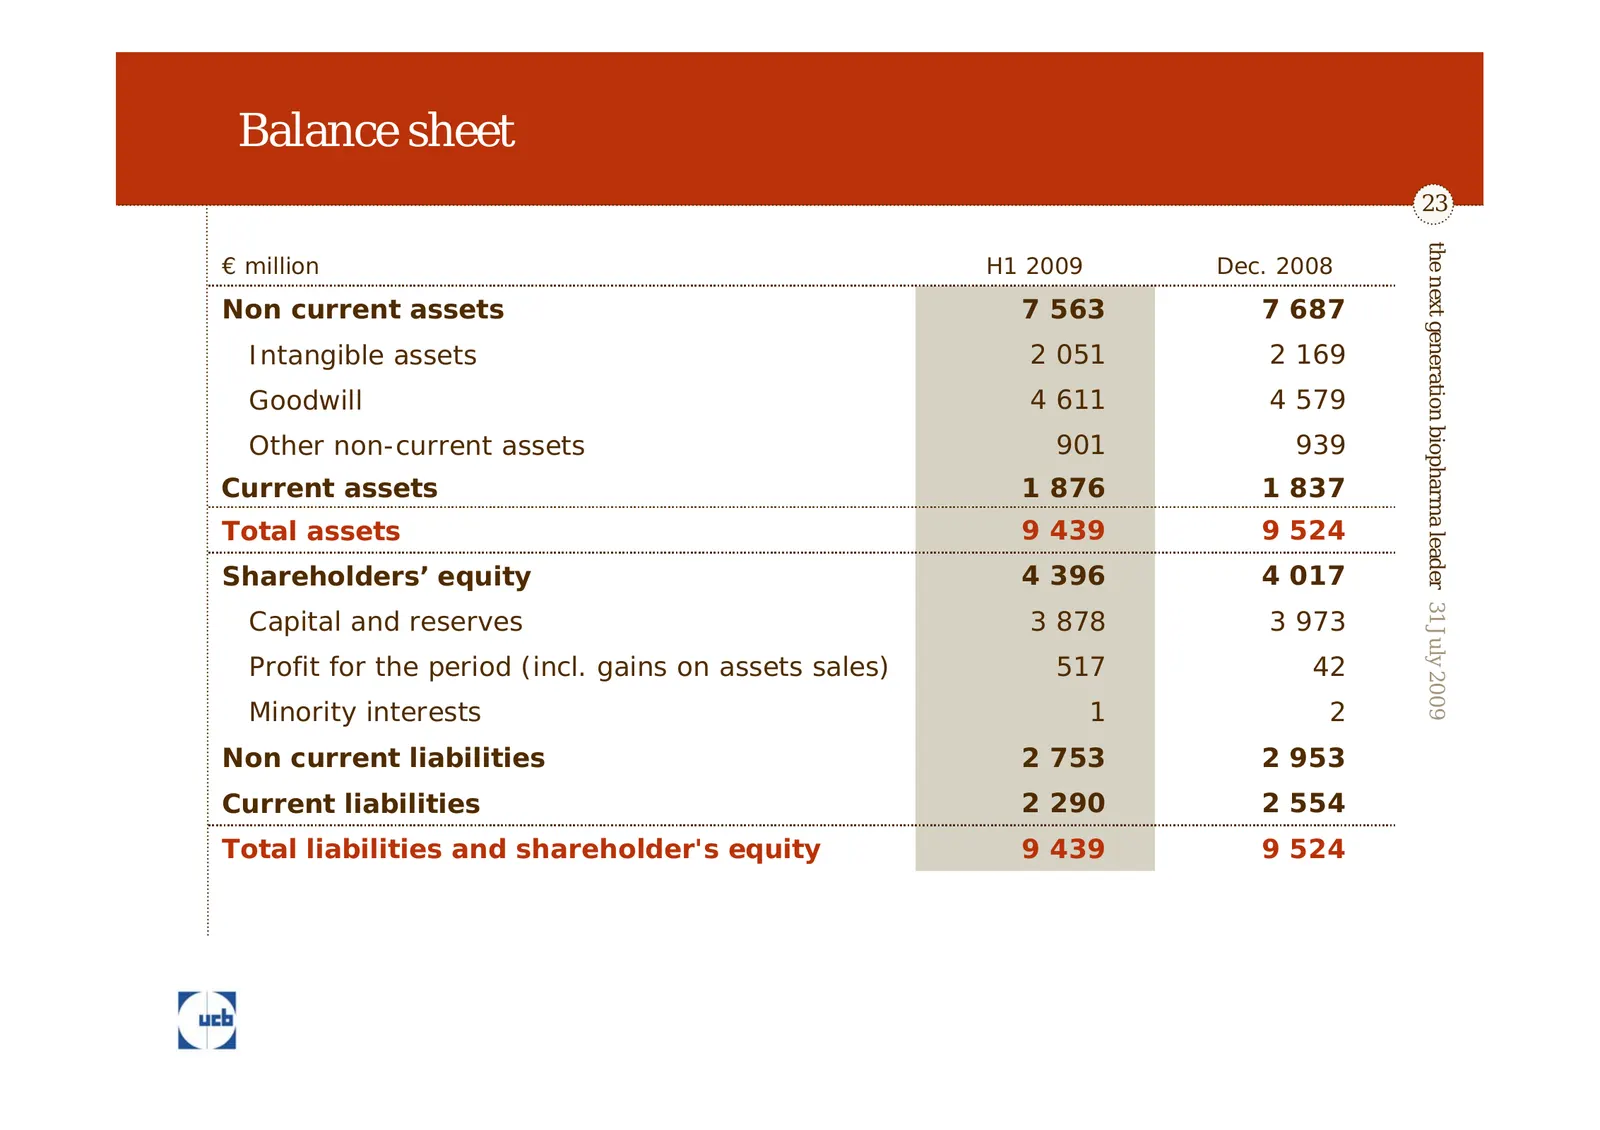
Balance sheet 23 the next generation biopharma leader 31 July 2009 € million H1 2009 Dec. 2008 Non current assets 7 563 7 687 Intangible assets 2 051 2 169 Goodwill 4 611 4 579 Other non-current assets 901 939 Current assets 1 876 1 837 Total assets 9 439 9 524 Shareholders’ equity 4 396 4 017 Capit
Slide 24: Cash flow
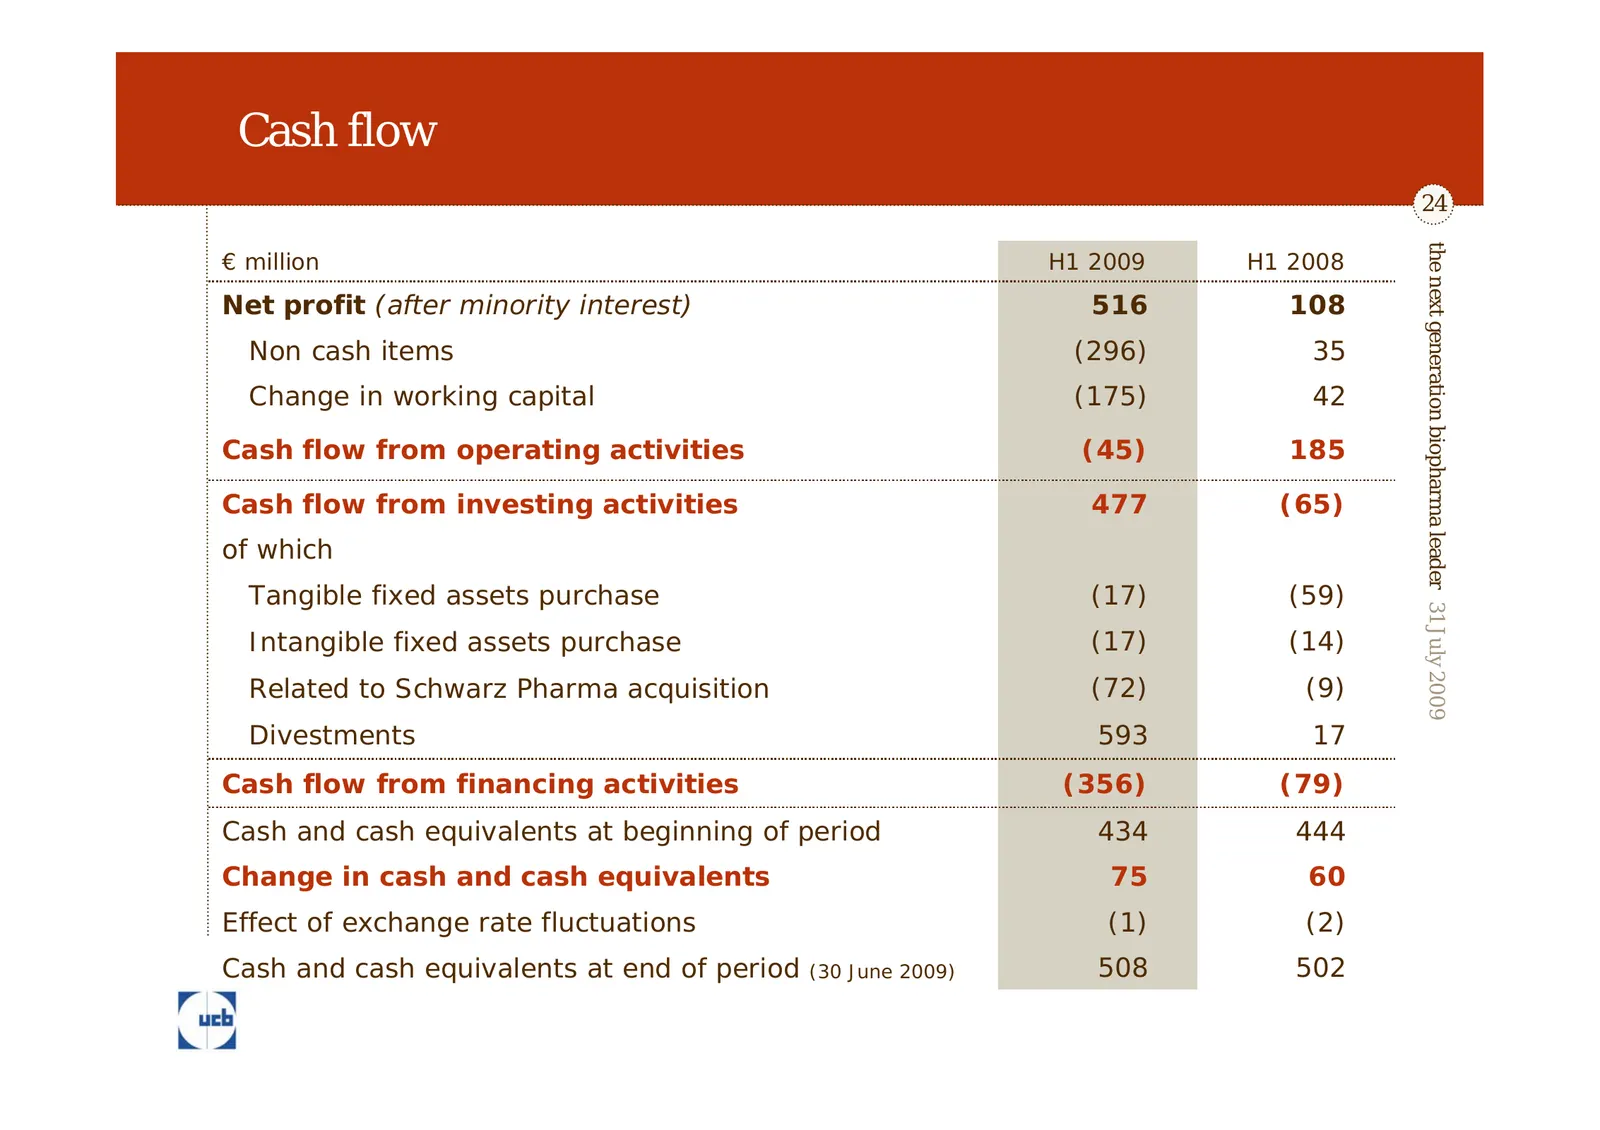
Cash flow 24 the next generation biopharma leader 31 July 2009 € million H1 2009 H1 2008 Net profit (after minority interest) 516 108 Non cash items (296) 35 Change in working capital (175) 42 Cash flow from operating activities (45) 185 Cash flow from investing activities 477 (65) of which Tangible
Slide 25: 2009 financial outlook
2009 financial outlook UCB on track to deliver its financial guidance 25 the next generation biopharma leader 31 July 2009 Revenue expected to reach between € 3.1 - 3.3 billion • Full generic competition to Keppra® in the U.S for the whole year • Partially compensated by newly launched products Recu
Slide 26: Development
26 the next generation biopharma leader 31 July 2009 Development Iris Loew-Friedrich, Chief Medical Officer Executive Vice-President Global Projects and Development
Slide 27: Drug Development Process
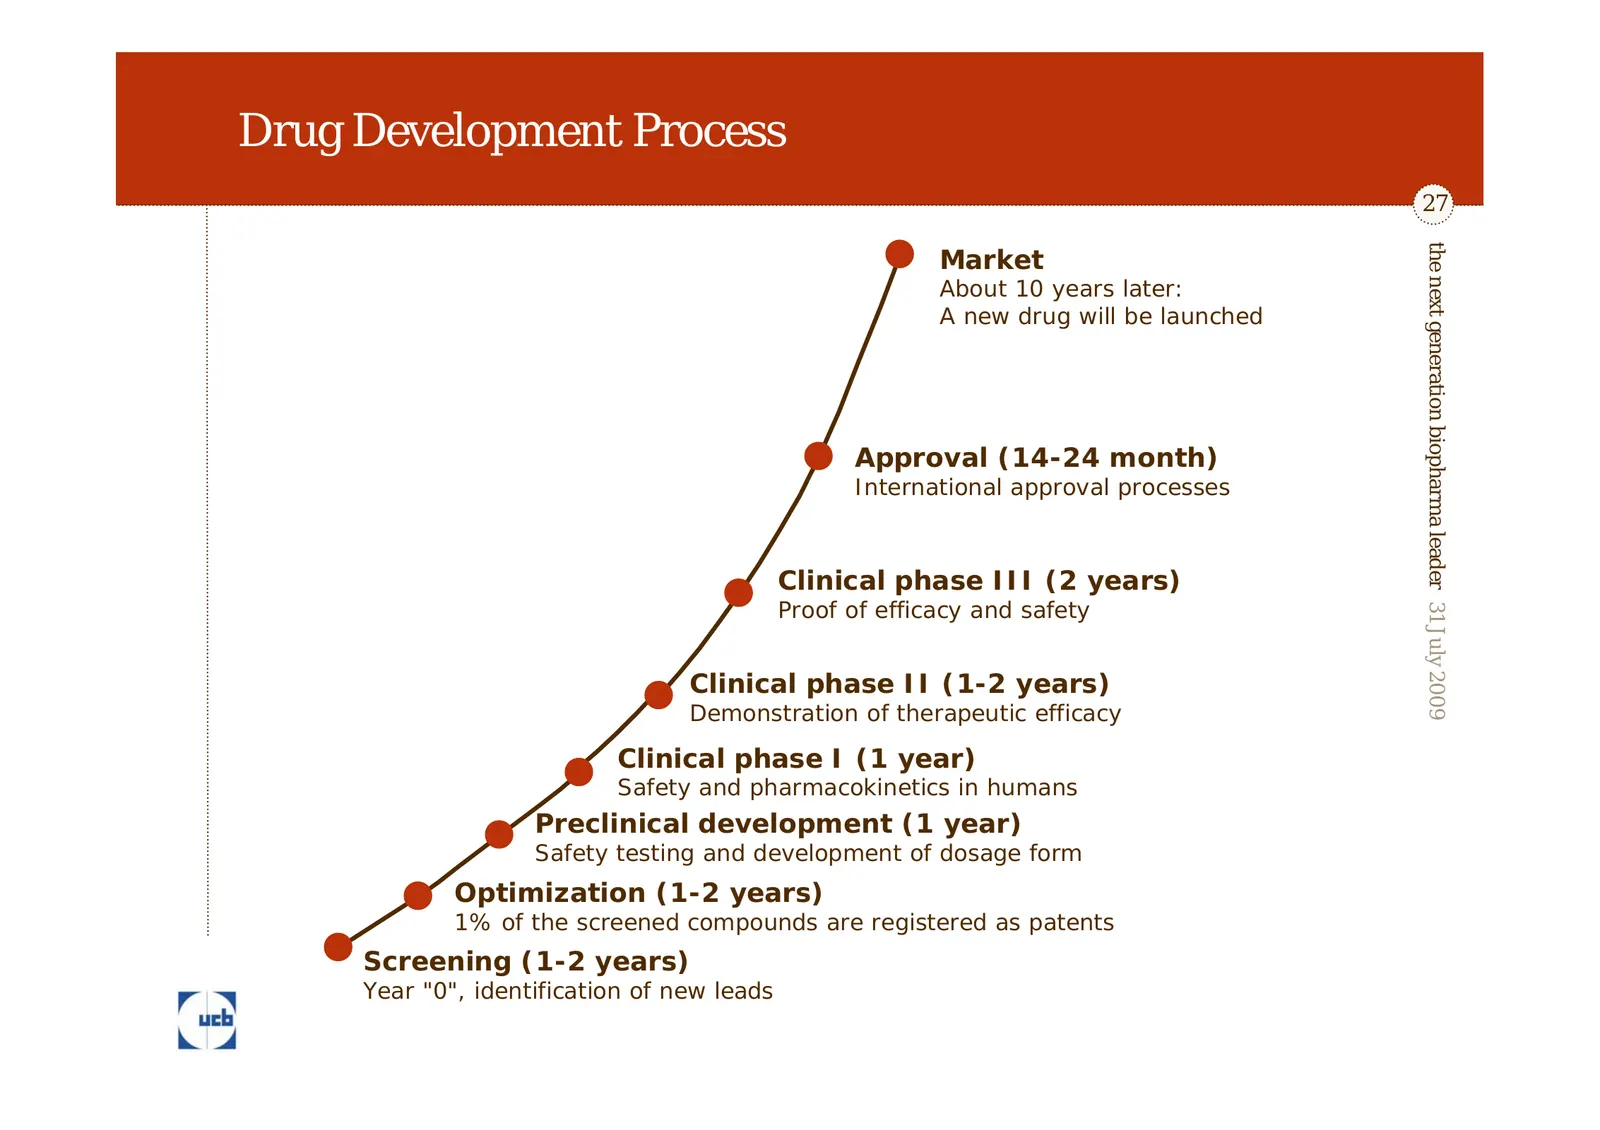
Drug Development Process 27 the next generation biopharma leader 31 July 2009 Market About 10 years later: A new drug will be launched Approval (14-24 month) International approval processes Clinical phase III (2 years) Proof of efficacy and safety Clinical phase II (1-2 years) Demonstration of ther
Slide 28: Update on clinical development
Update on clinical development 28 the next generation biopharma leader 31 July 2009 Vimpat® in DNP: path forward still to be confirmed by regulatory authorities • New Phase III trial design • UCB decision expected in H2 2009 Brivaracetam in epilepsy: further analysis of Phase III studies ongoing • R
Slide 29: Epilepsy: Distribution of seizure types
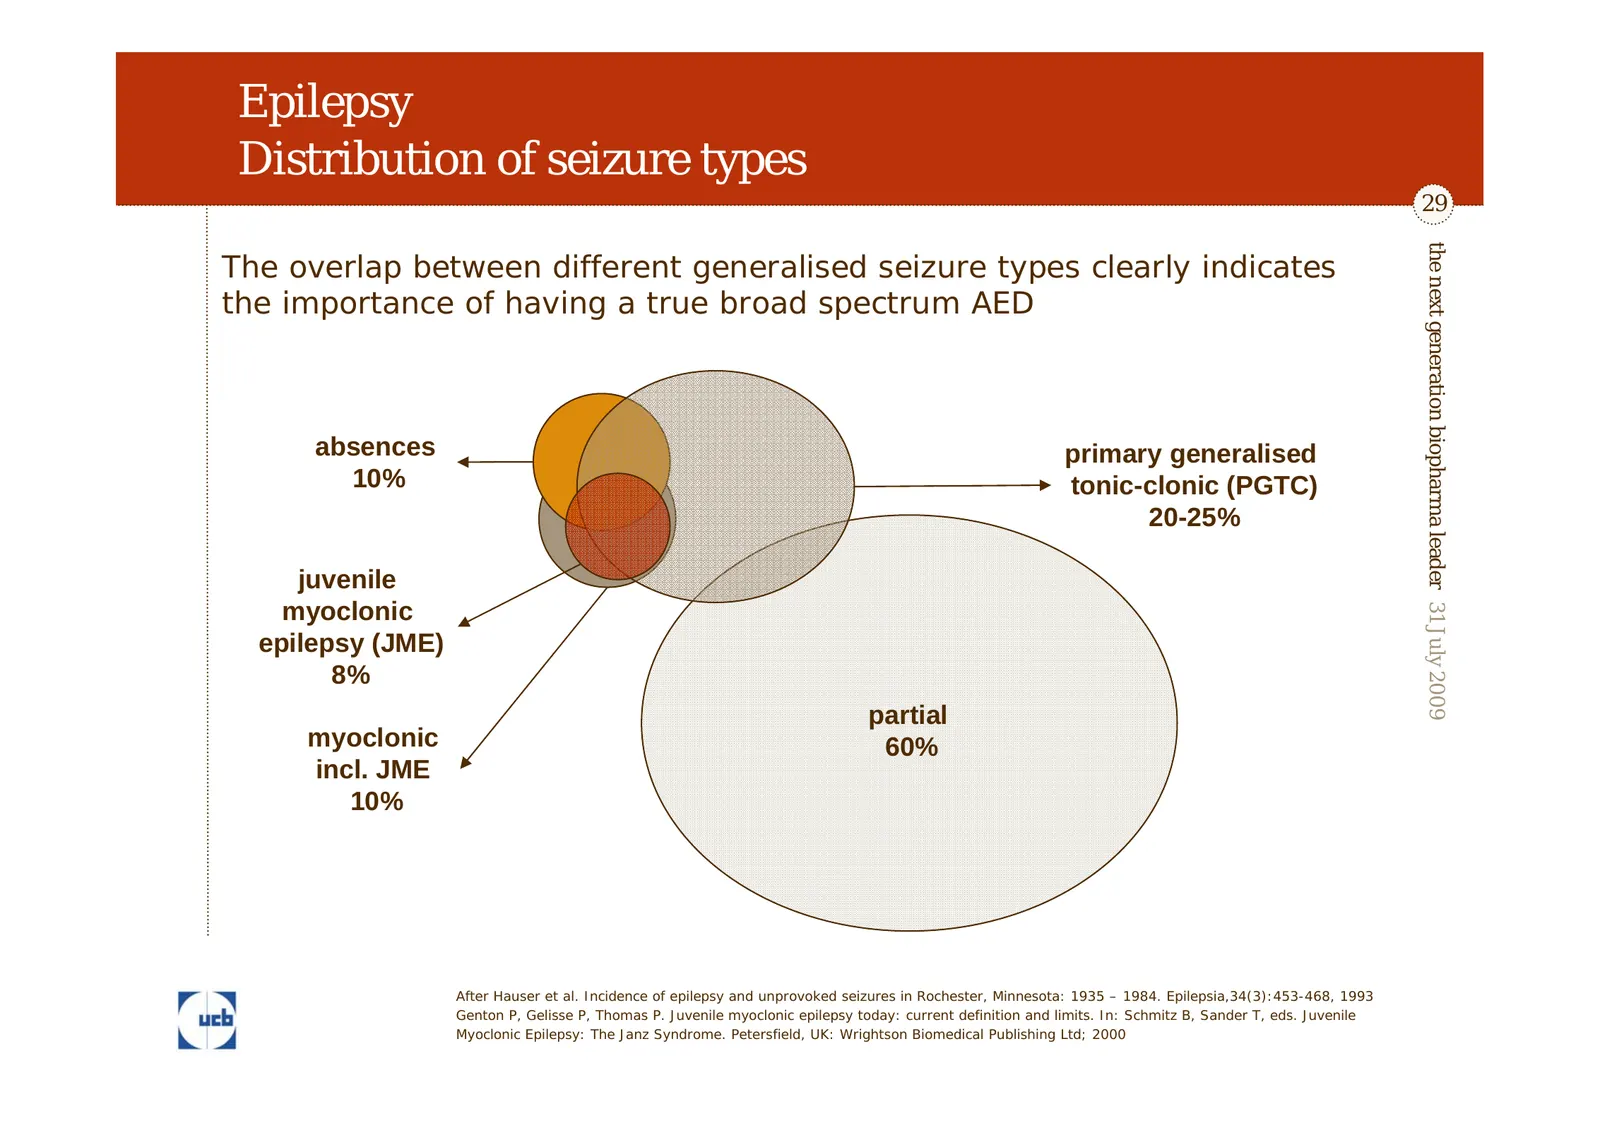
Epilepsy Distribution of seizure types 29 the next generation biopharma leader 31 July 2009 The overlap between different generalised seizure types clearly indicates the importance of having a true broad spectrum AED absences primary generalised 10% tonic-clonic (PGTC) 20-25% juvenile myoclonic epil
Slide 30: Vimpat: Increasing patient access
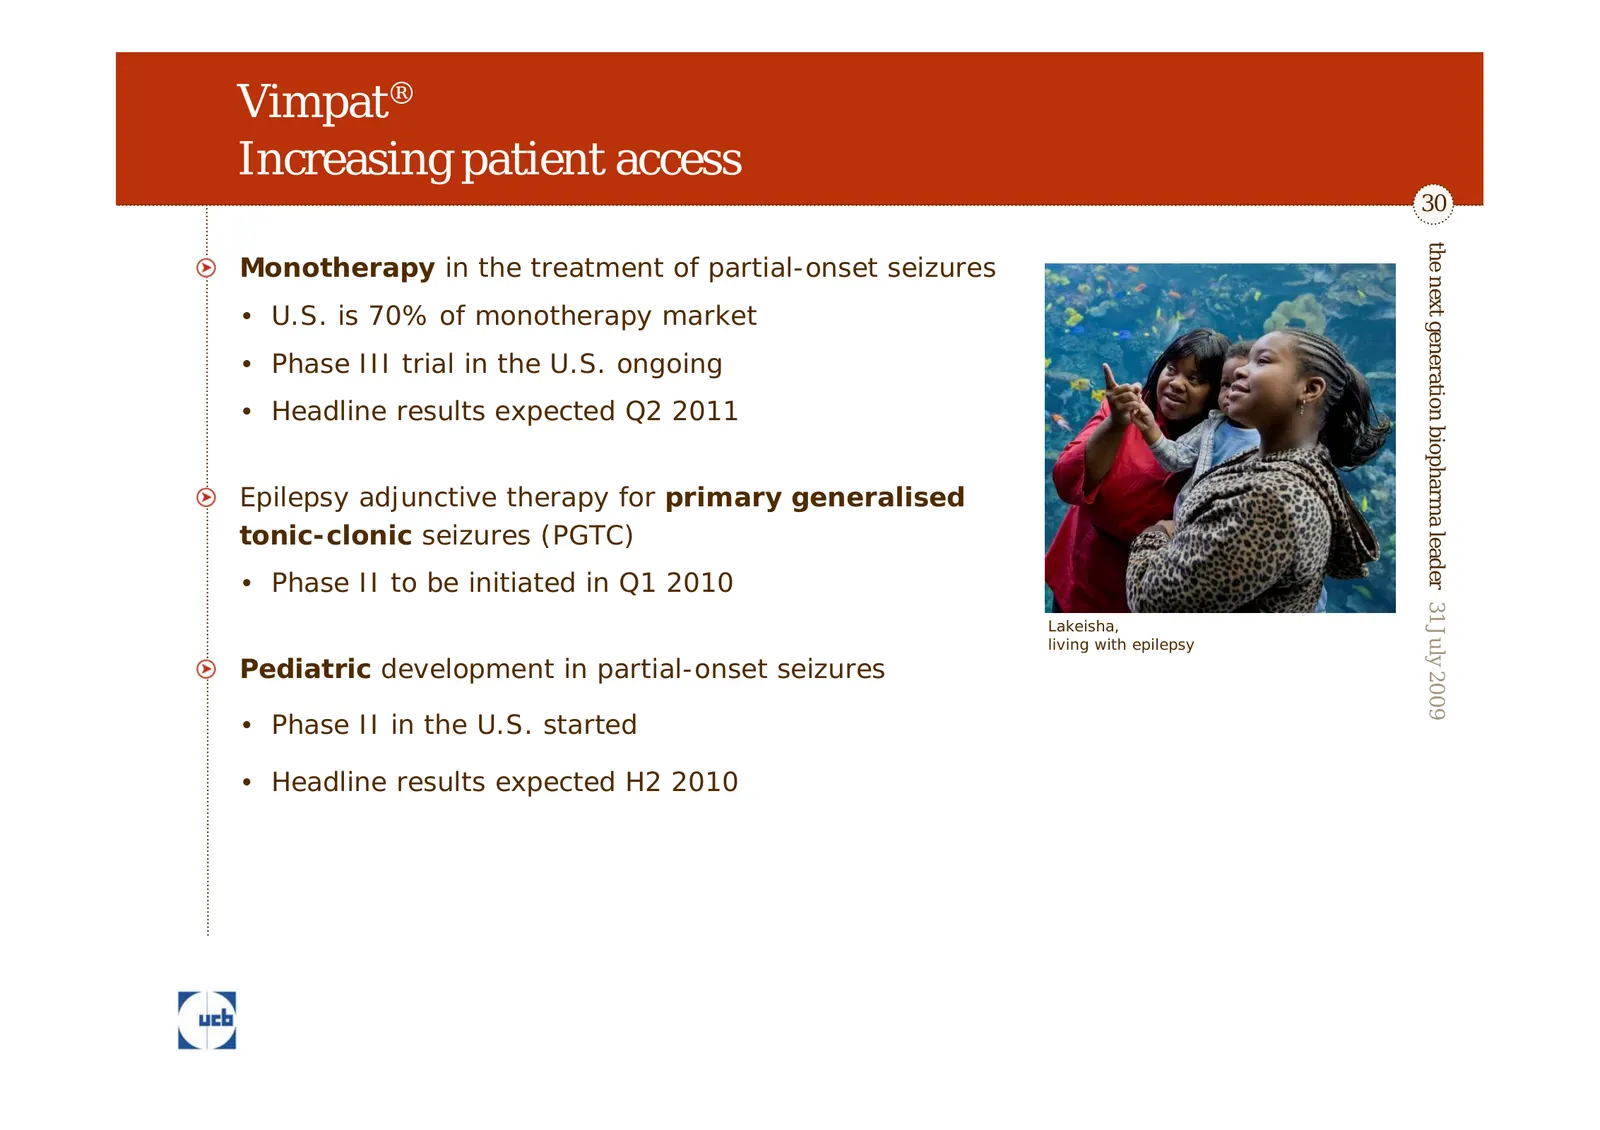
Vimpat® Increasing patient access 30 the next generation biopharma leader 31 July 2009 Monotherapy in the treatment of partial-onset seizures • U.S. is 70% of monotherapy market • Phase III trial in the U.S. ongoing • Headline results expected Q2 2011 Epilepsy adjunctive therapy for primary generali
Slide 31: Neupro: Working to make it available in the U.S.
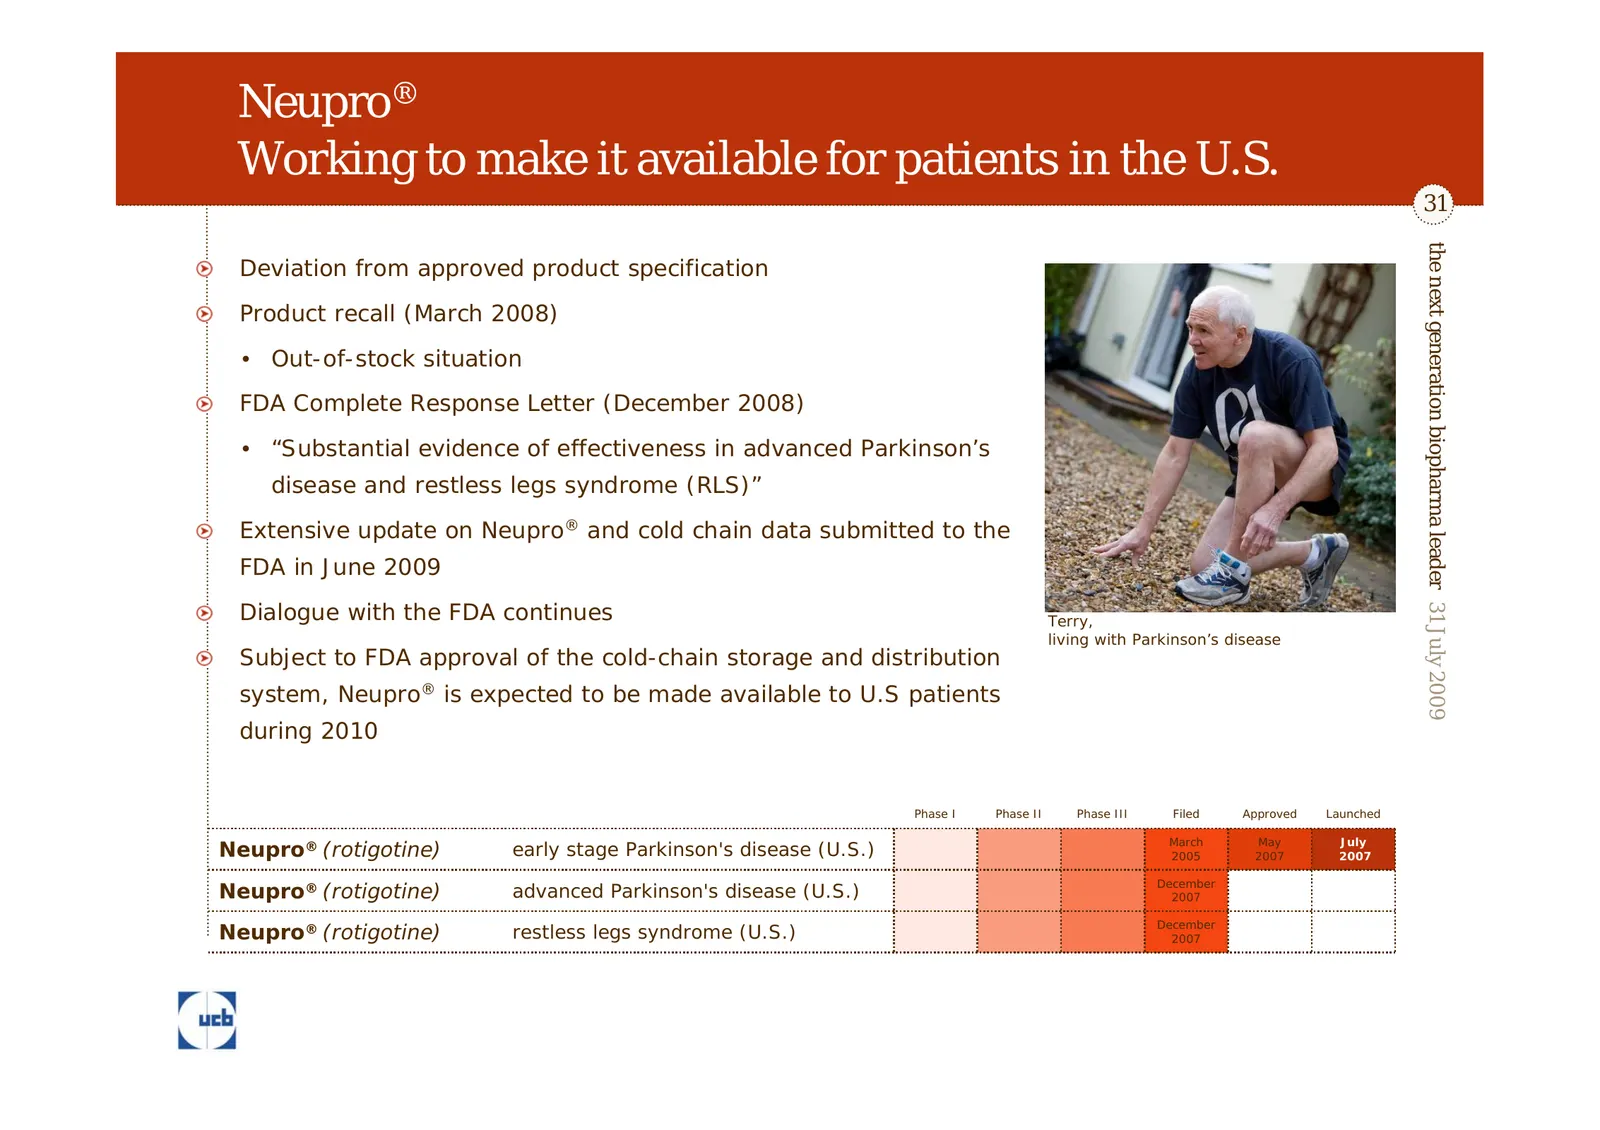
Neupro® Working to make it available for patients in the U.S. 31 the next generation biopharma leader 31 July 2009 Deviation from approved product specification Product recall (March 2008) R A • Out-of-stock situation om en w fr FDA Complete Response Letter (December 2008) ti Ne t pa dd • “Substanti
Slide 32: Cimzia: Increasing patient access
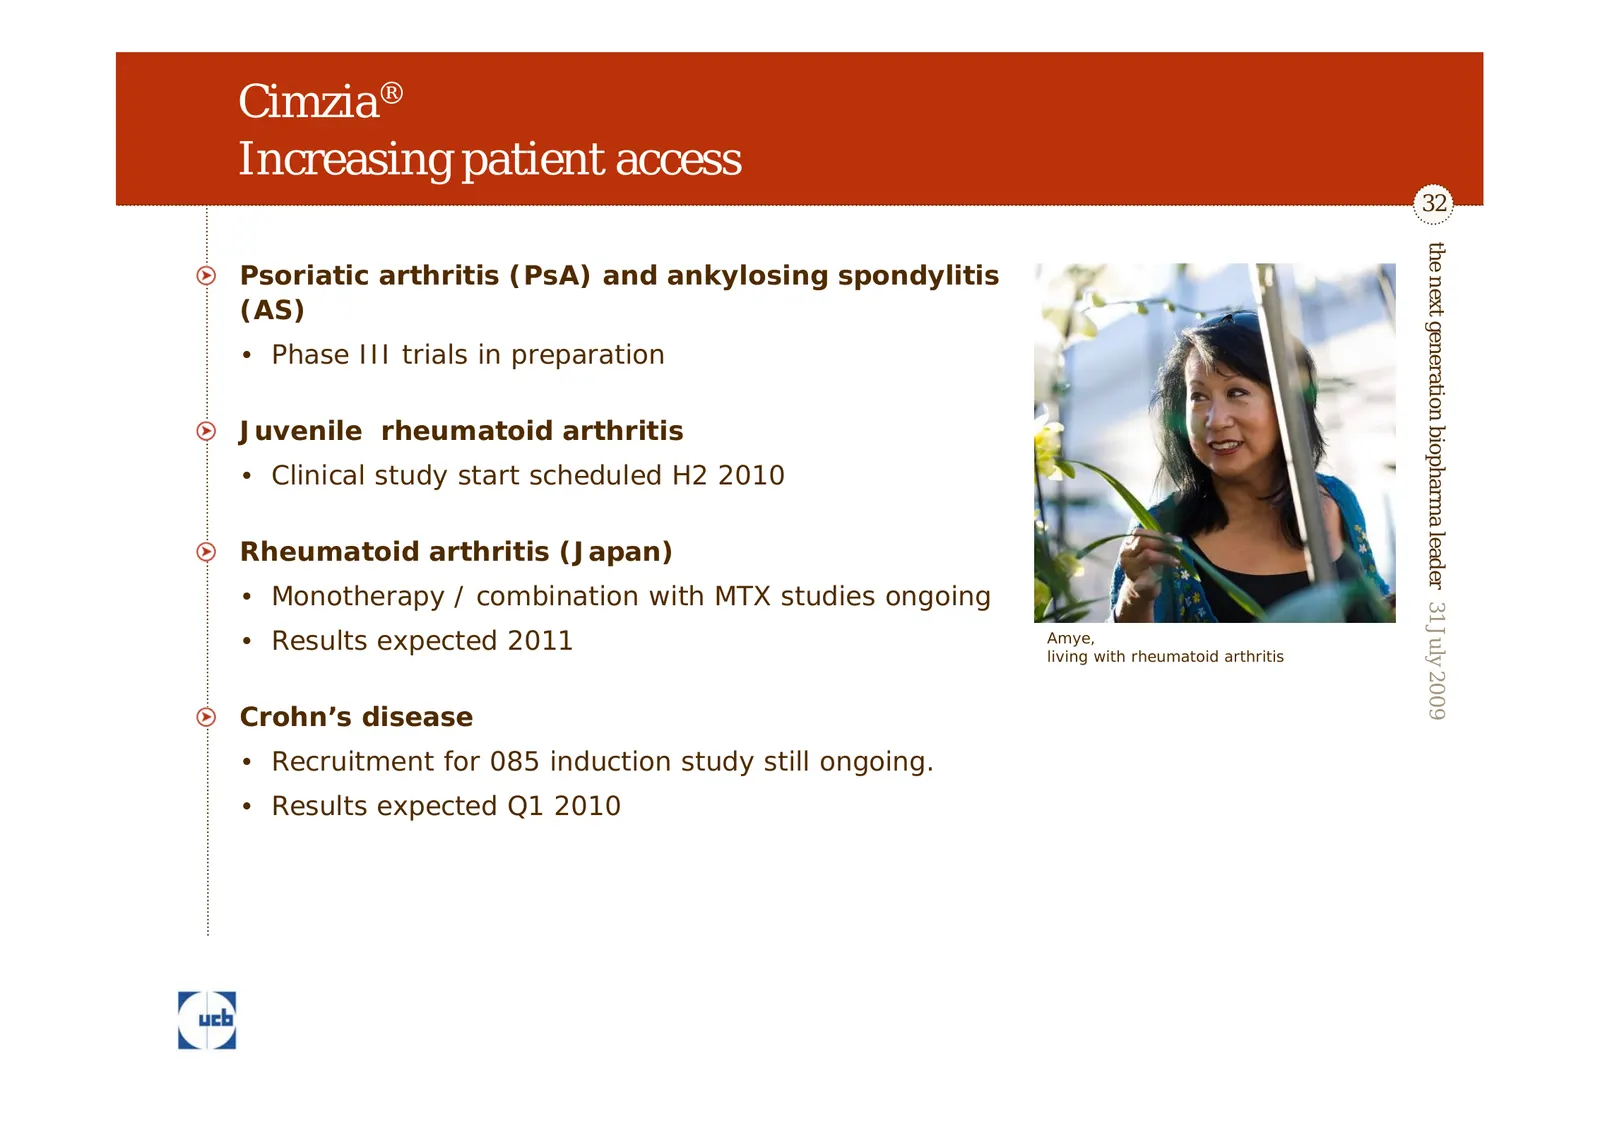
Cimzia® Increasing patient access 32 the next generation biopharma leader 31 July 2009 Psoriatic arthritis (PsA) and ankylosing spondylitis (AS) • Phase III trials in preparation Juvenile rheumatoid arthritis • Clinical study start scheduled H2 2010 Rheumatoid arthritis (Japan) • Monotherapy / combi
Slide 33: CDP7851 in bone loss disorders
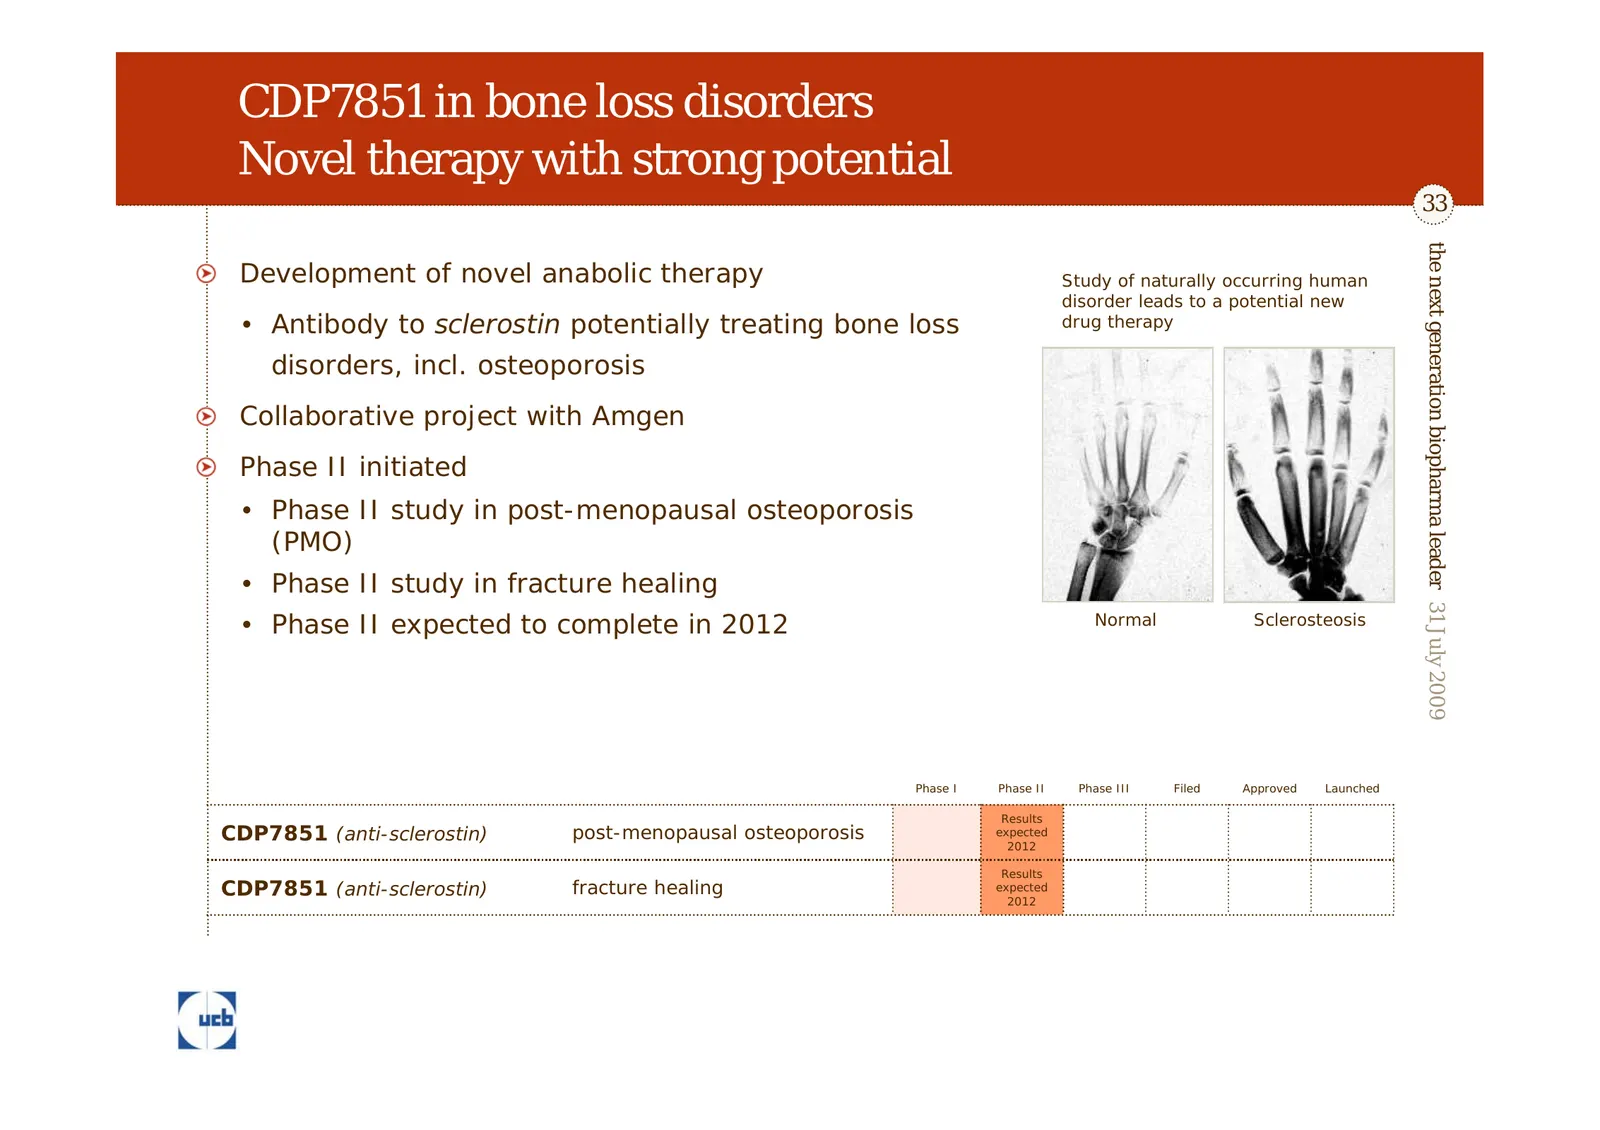
CDP7851 in bone loss disorders Novel therapy with strong potential 33 the next generation biopharma leader 31 July 2009 Development of novel anabolic therapy Study of naturally occurring human disorder leads to a potential new • Antibody to sclerostin potentially treating bone loss drug therapy diso
Slide 34: Development pipeline
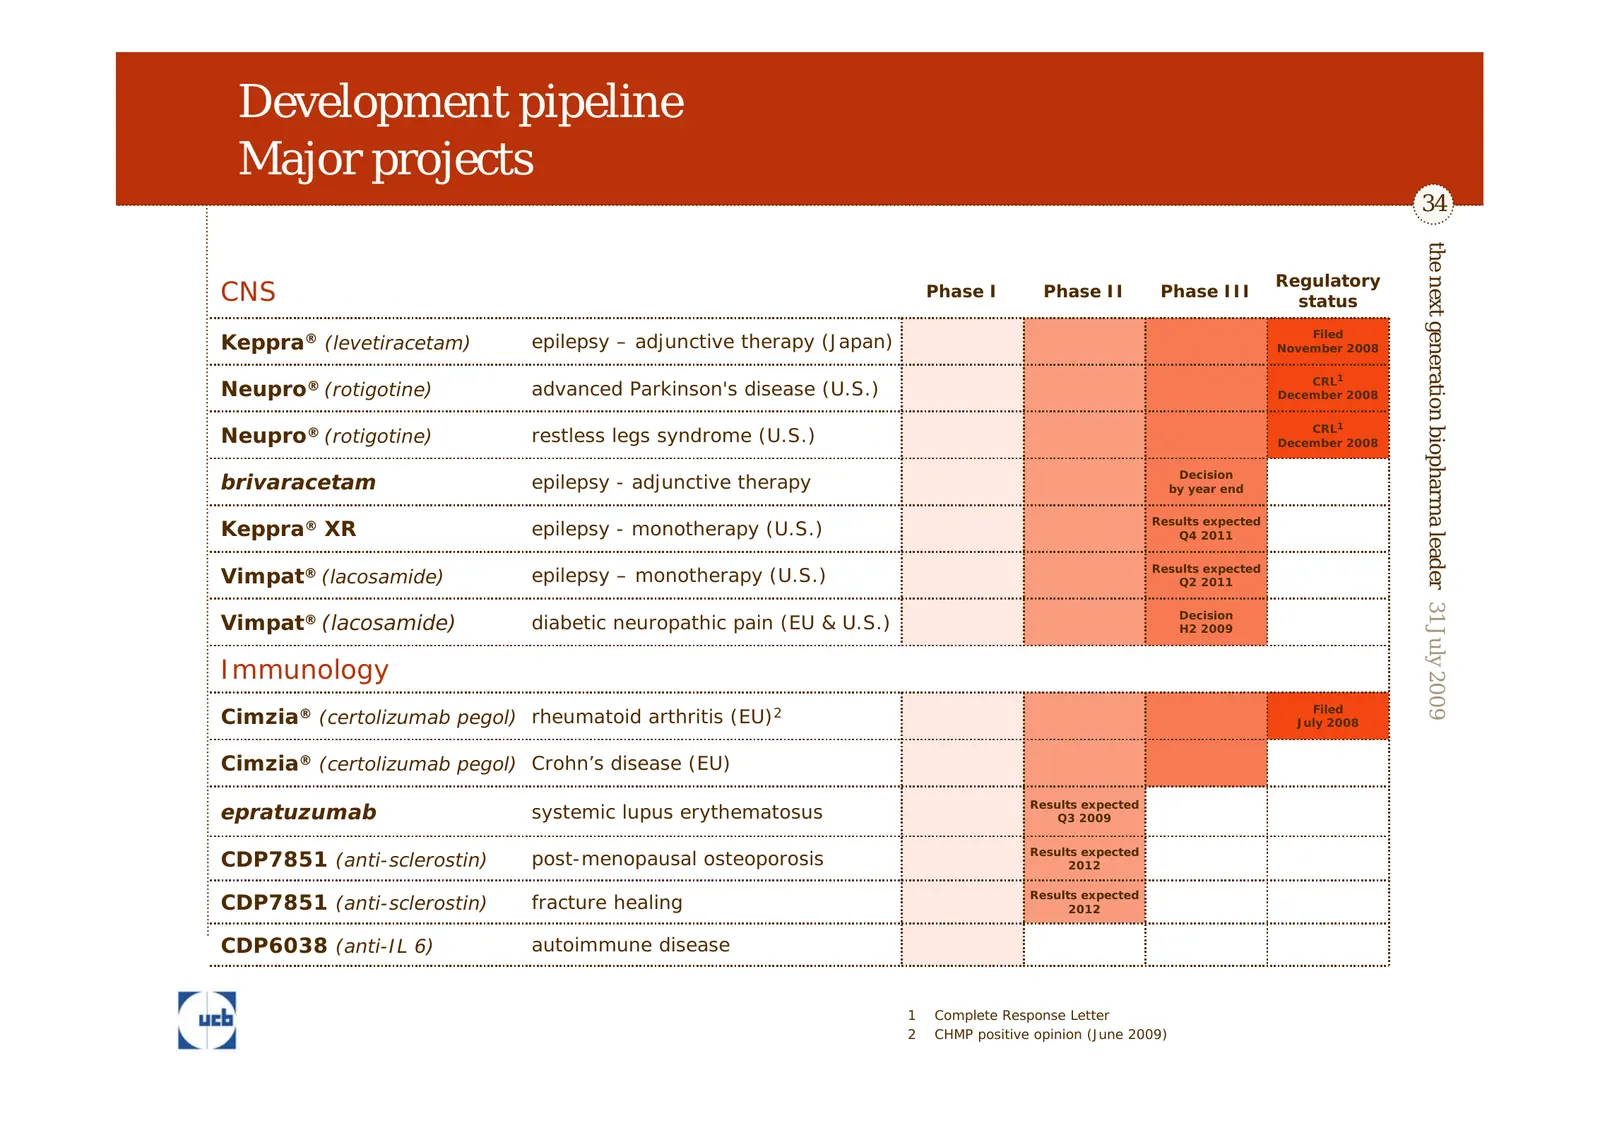
Development pipeline Major projects 34 the next generation biopharma leader 31 July 2009 Regulatory CNS Phase I Phase II Phase III status Filed Keppra® (levetiracetam) epilepsy – adjunctive therapy (Japan) November 2008 CRL1 Neupro® (rotigotine) advanced Parkinson's disease (U.S.) December 2008 CRL1
Slide 35: Conclusion
the next generation biopharma leader 31 July 2009 35 Roch Doliveux, Conclusion CEO
Slide 36: H1 2009 Highlights
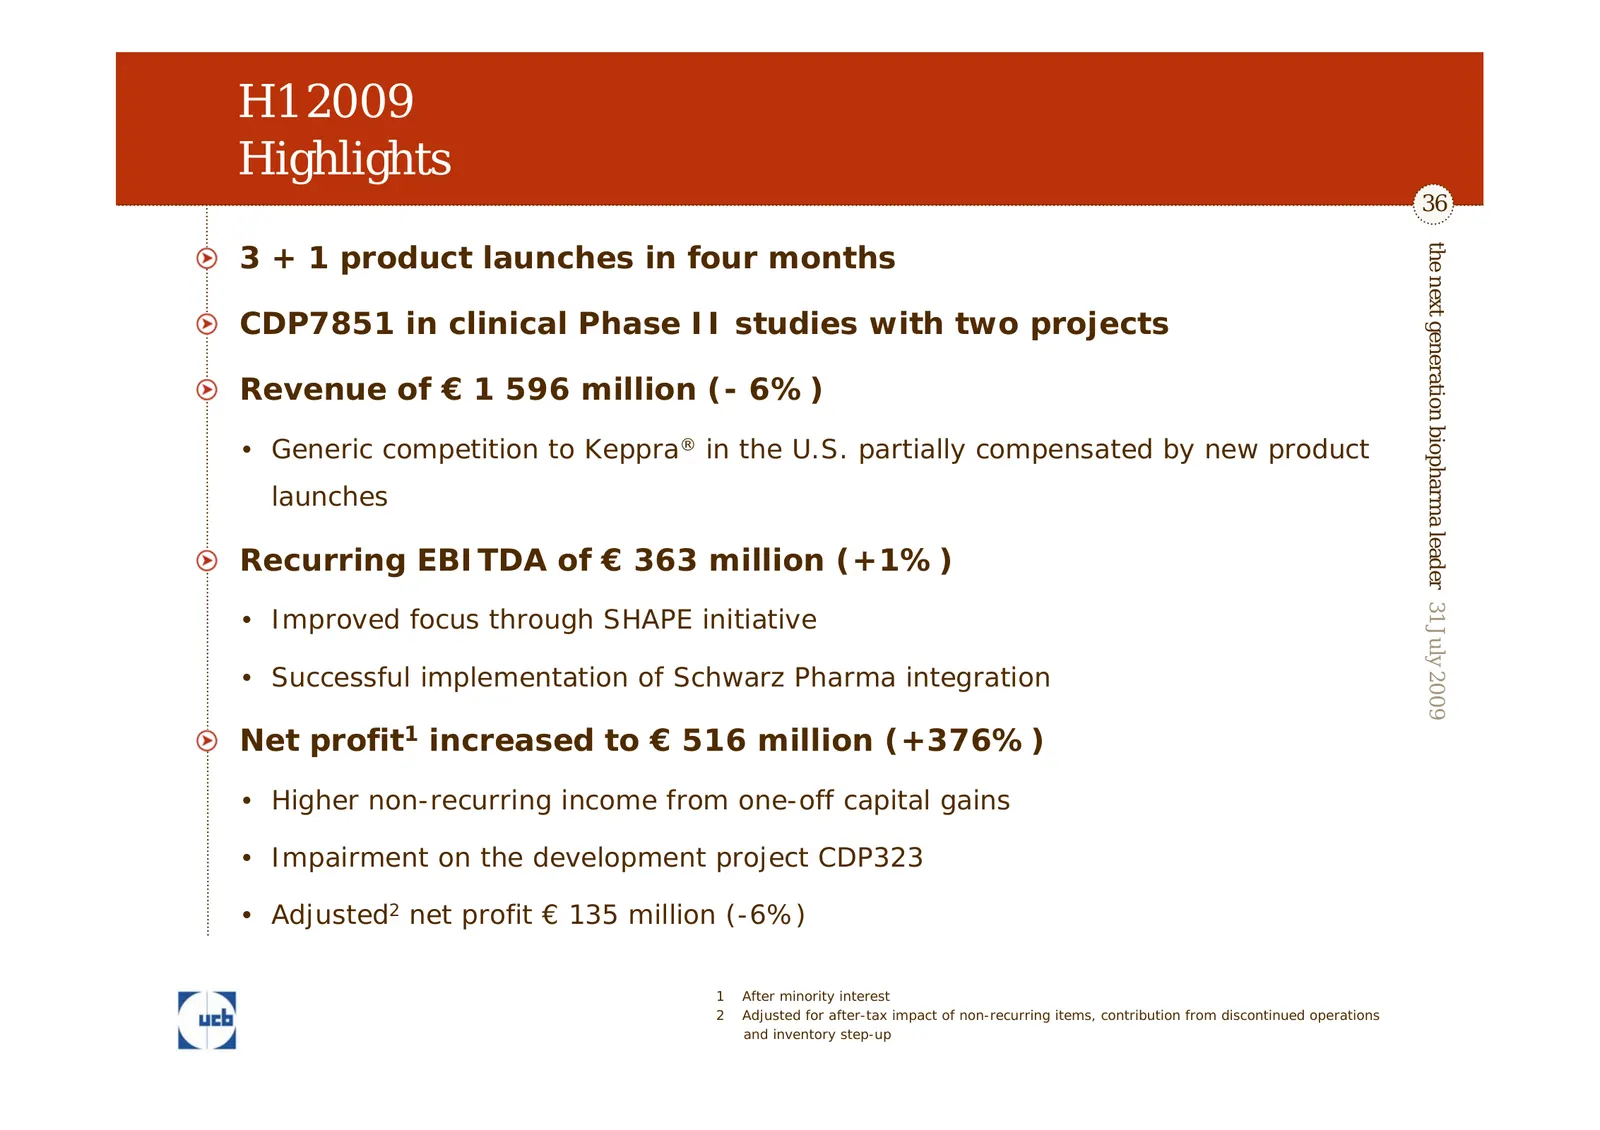
H1 2009 Highlights 36 3 + 1 product launches in four months the next generation biopharma leader 31 July 2009 CDP7851 in clinical Phase II studies with two projects Revenue of € 1 596 million (- 6%) • Generic competition to Keppra® in the U.S. partially compensated by new product launches Recurring
Slide 37: Transformation & focus
Transformation & focus 37 the next generation biopharma leader 31 July 2009 New right-sized organisation in place • Workforce reduced by 19% vs. August 2008 Resources being focused on core markets and products • Non strategic emerging markets sold to GSK • Equasym® sold to Shire and Somatostatine-UC
Slide 38: UCB priorities for 2009
UCB priorities for 2009 38 the next generation biopharma leader 31 July 2009 Successfully launch Cimzia®, Vimpat®, Neupro® Continue delivery of late stage pipeline Transformation & Focus (SHAPE): • Maximize core assets, optimise non-core assets • Fully implement new organisational and geographical f
Slide 39: Questions and Answers
Questions and Answers 39 the next generation biopharma leader 31 July 2009 Breakthrough Launch a new generation of therapies Intense growth offering breakthrough innovation to patients Realise the commercial with severe disease Execution potential of new products • Launch new products • Invest in R&
Slide 40: Appendix
the next generation biopharma leader 31 July 2009 40 Appendix
Slide 41: Regulatory and development delivery
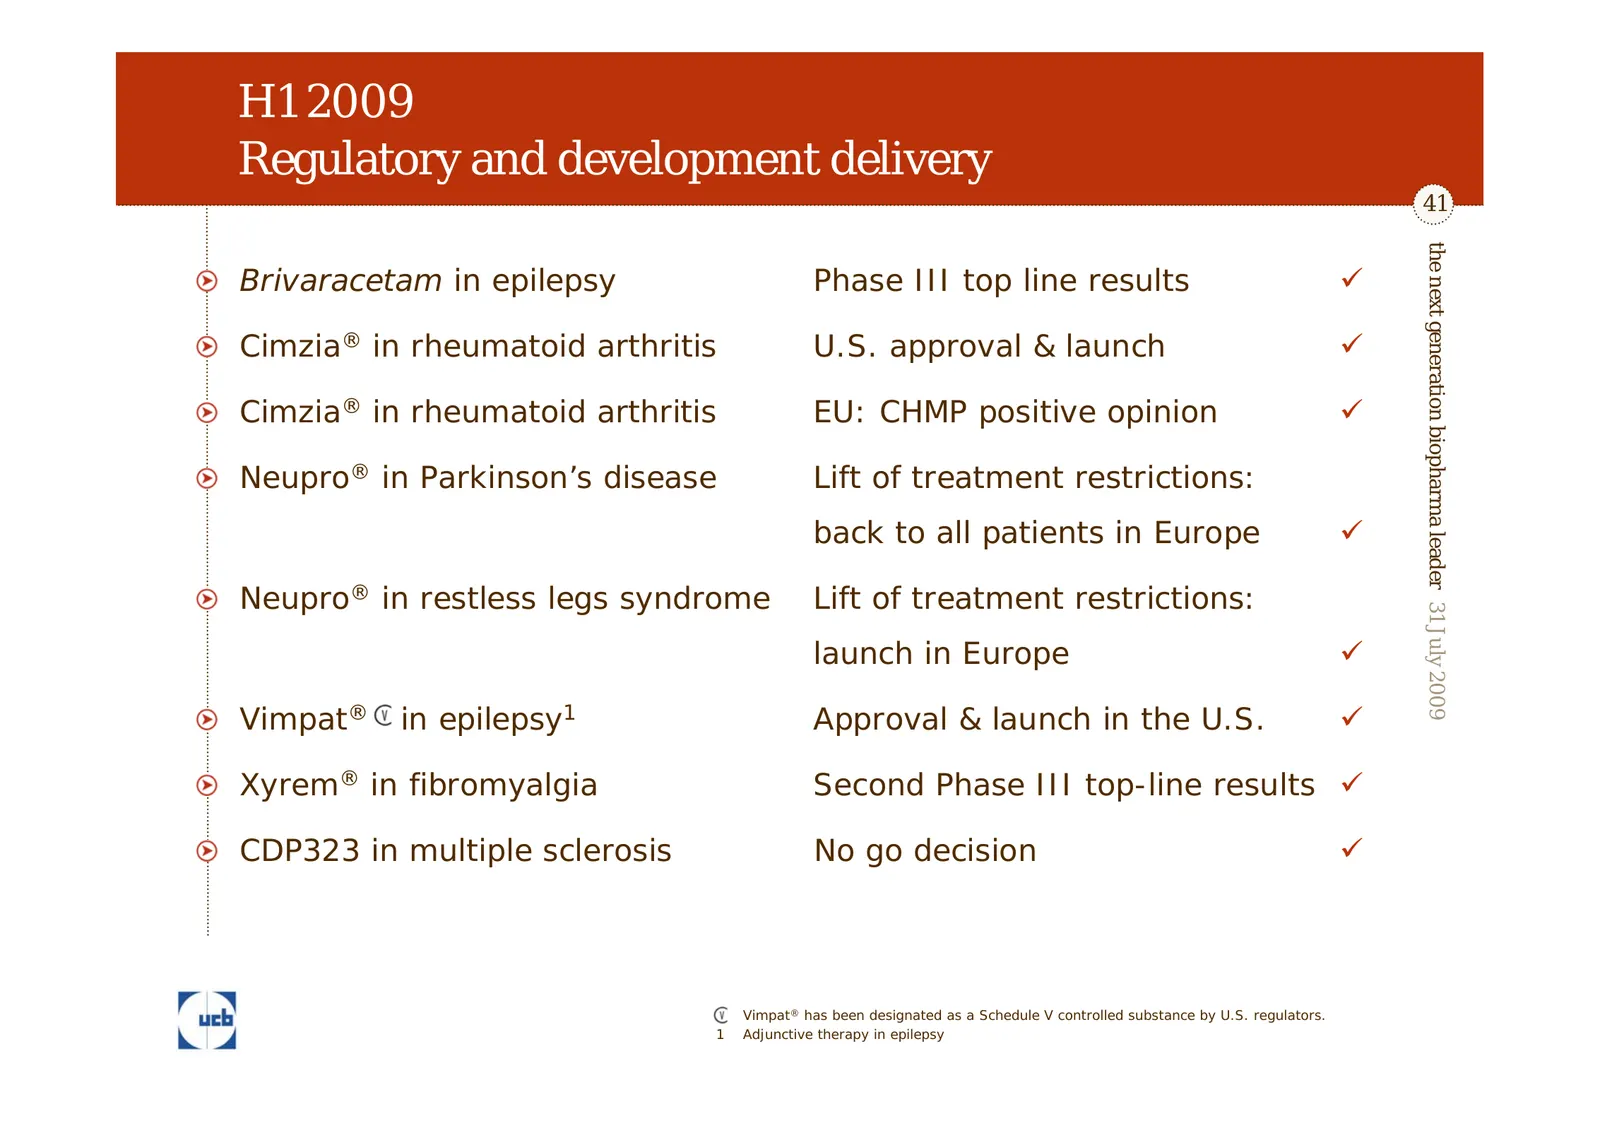
H1 2009 Regulatory and development delivery 41 the next generation biopharma leader 31 July 2009 Brivaracetam in epilepsy Phase III top line results 9 Cimzia® in rheumatoid arthritis U.S. approval & launch 9 Cimzia® in rheumatoid arthritis EU: CHMP positive opinion 9 Neupro® in Parkinson’s disease L
Slide 42: Income statement
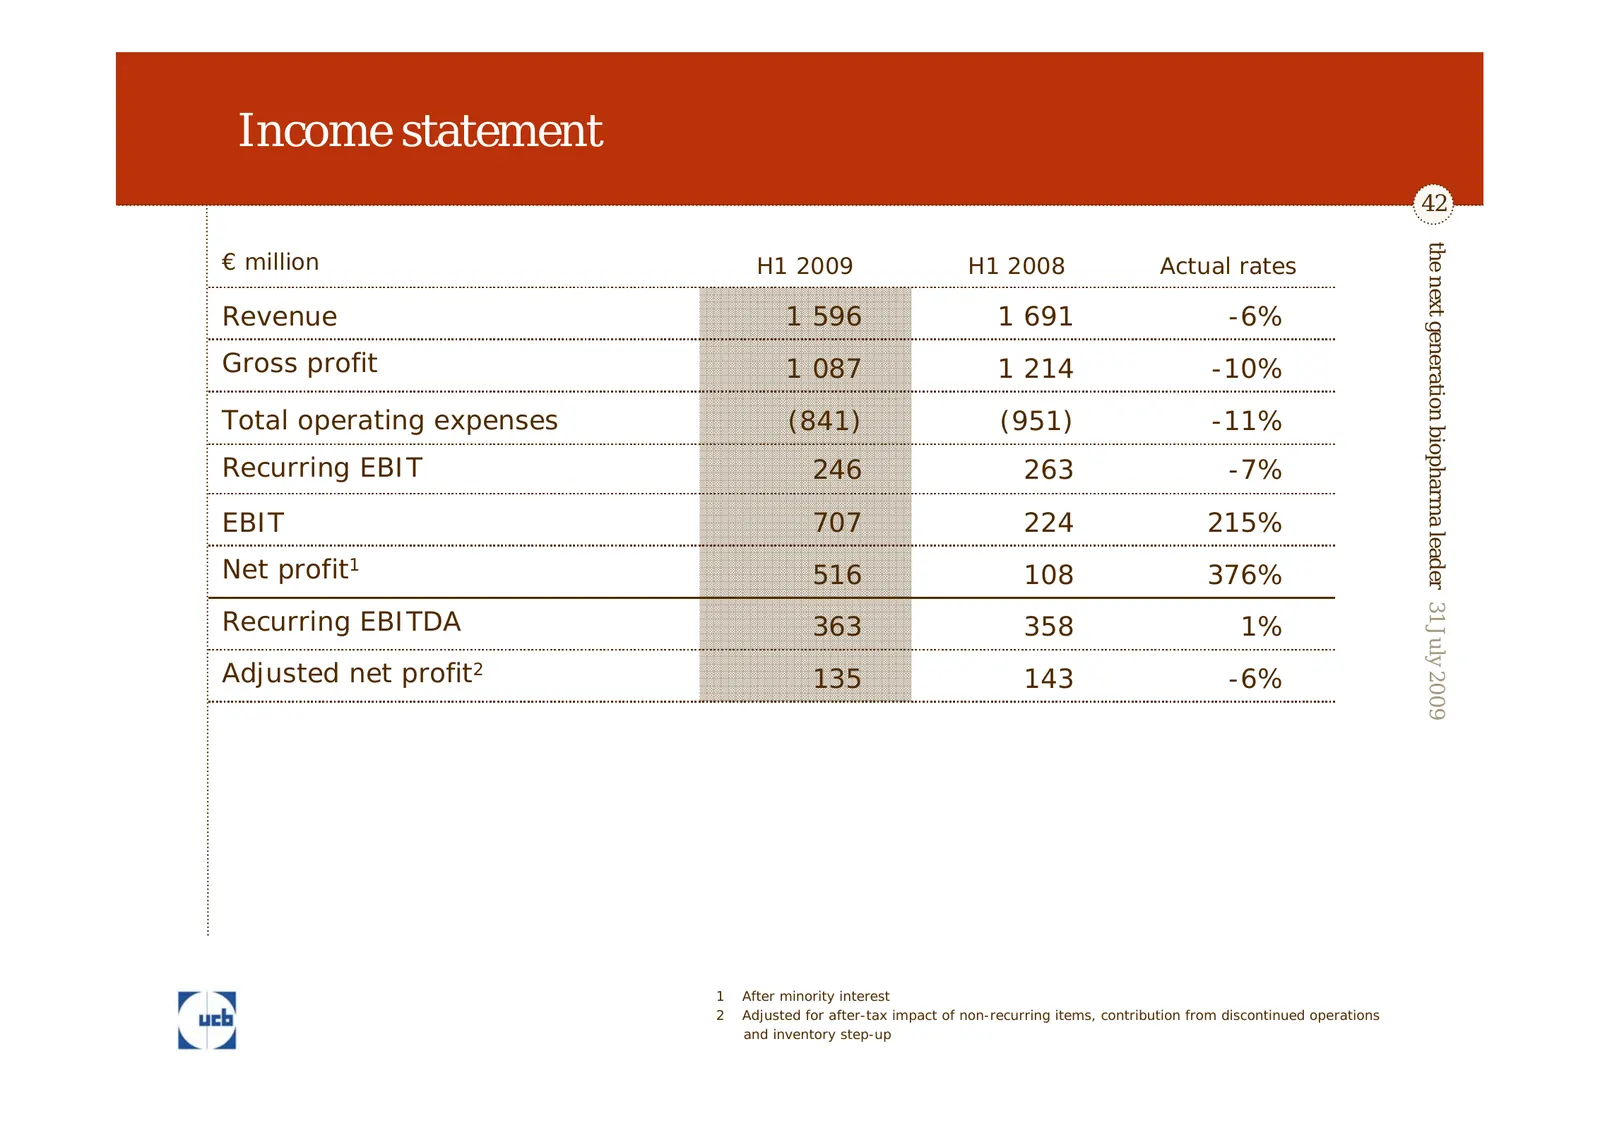
Income statement 42 the next generation biopharma leader 31 July 2009 € million H1 2009 H1 2008 Actual rates Revenue 1 596 1 691 -6% Gross profit 1 087 1 214 -10% Total operating expenses (841) (951) -11% Recurring EBIT 246 263 -7% EBIT 707 224 215% Net profit1 516 108 376% Recurring EBITDA 363 358
Slide 43: Net sales by geography
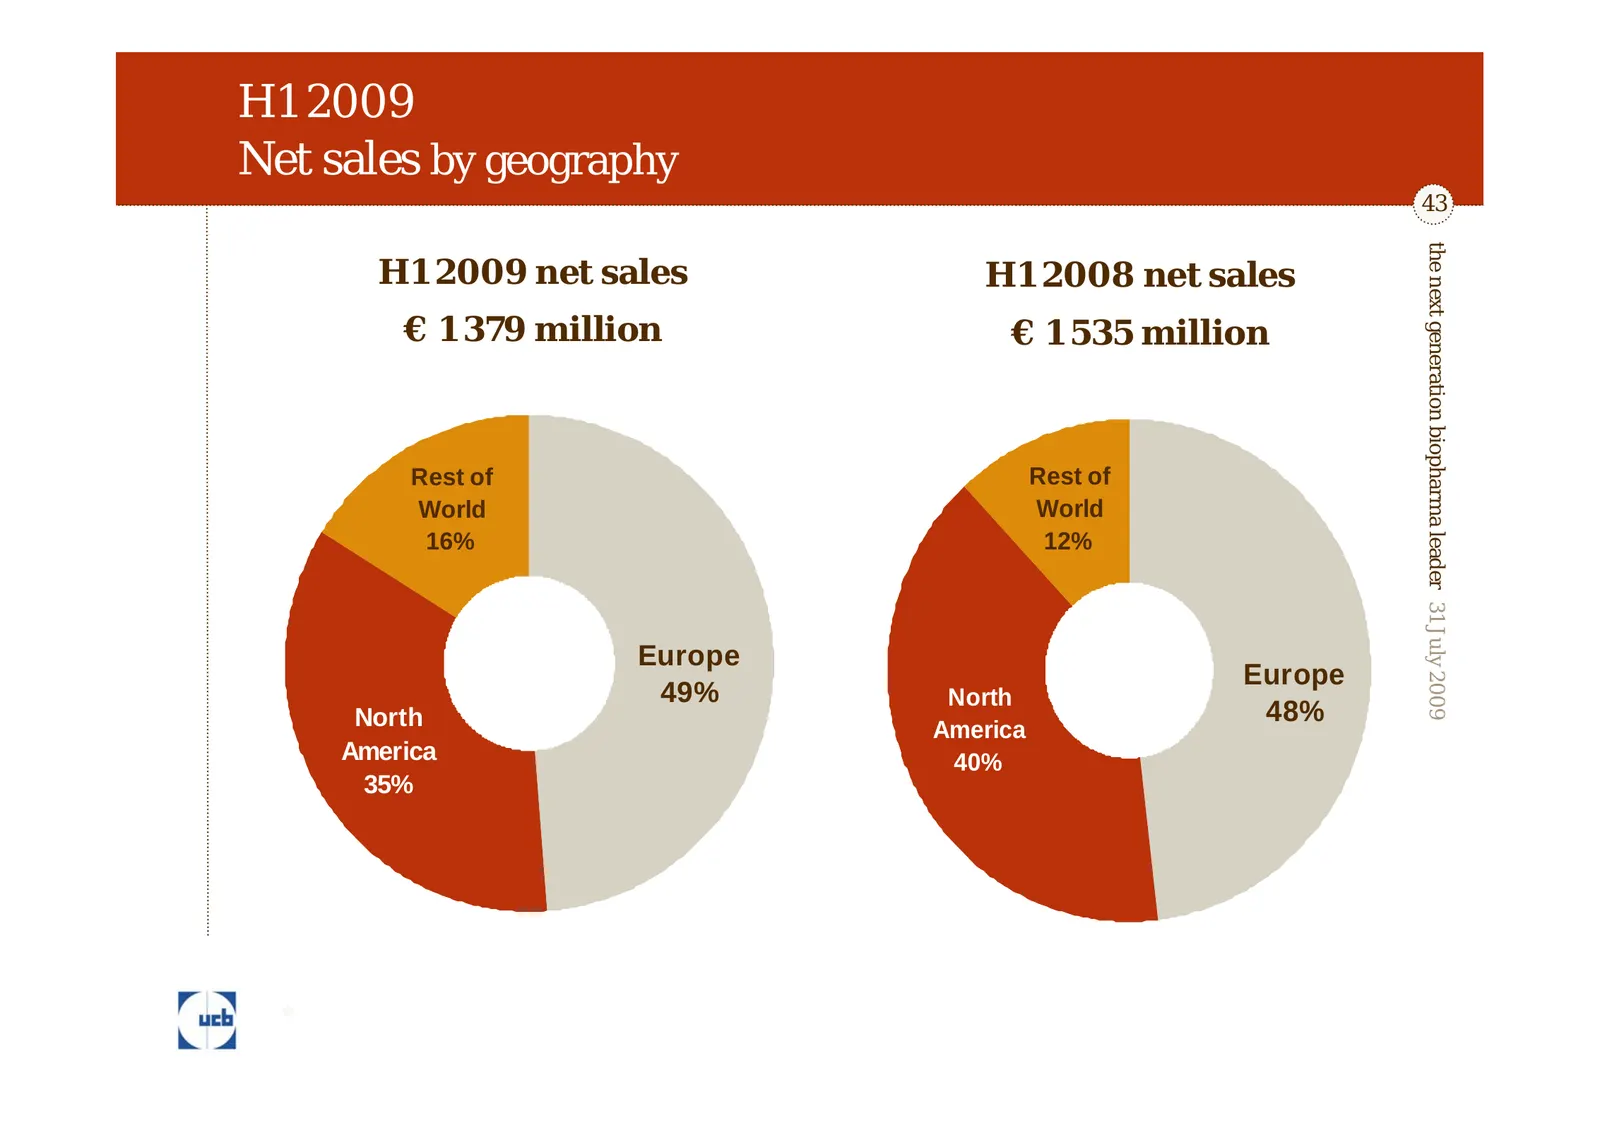
H1 2009 Net sales by geography 43 the next generation biopharma leader 31 July 2009 H1 2009 net sales H1 2008 net sales € 1 379 million € 1 535 million Rest of Rest of World World 16% 12% Europe Europe 49% North North 48% America America 40% 35% *
Slide 44: Net sales by therapy area
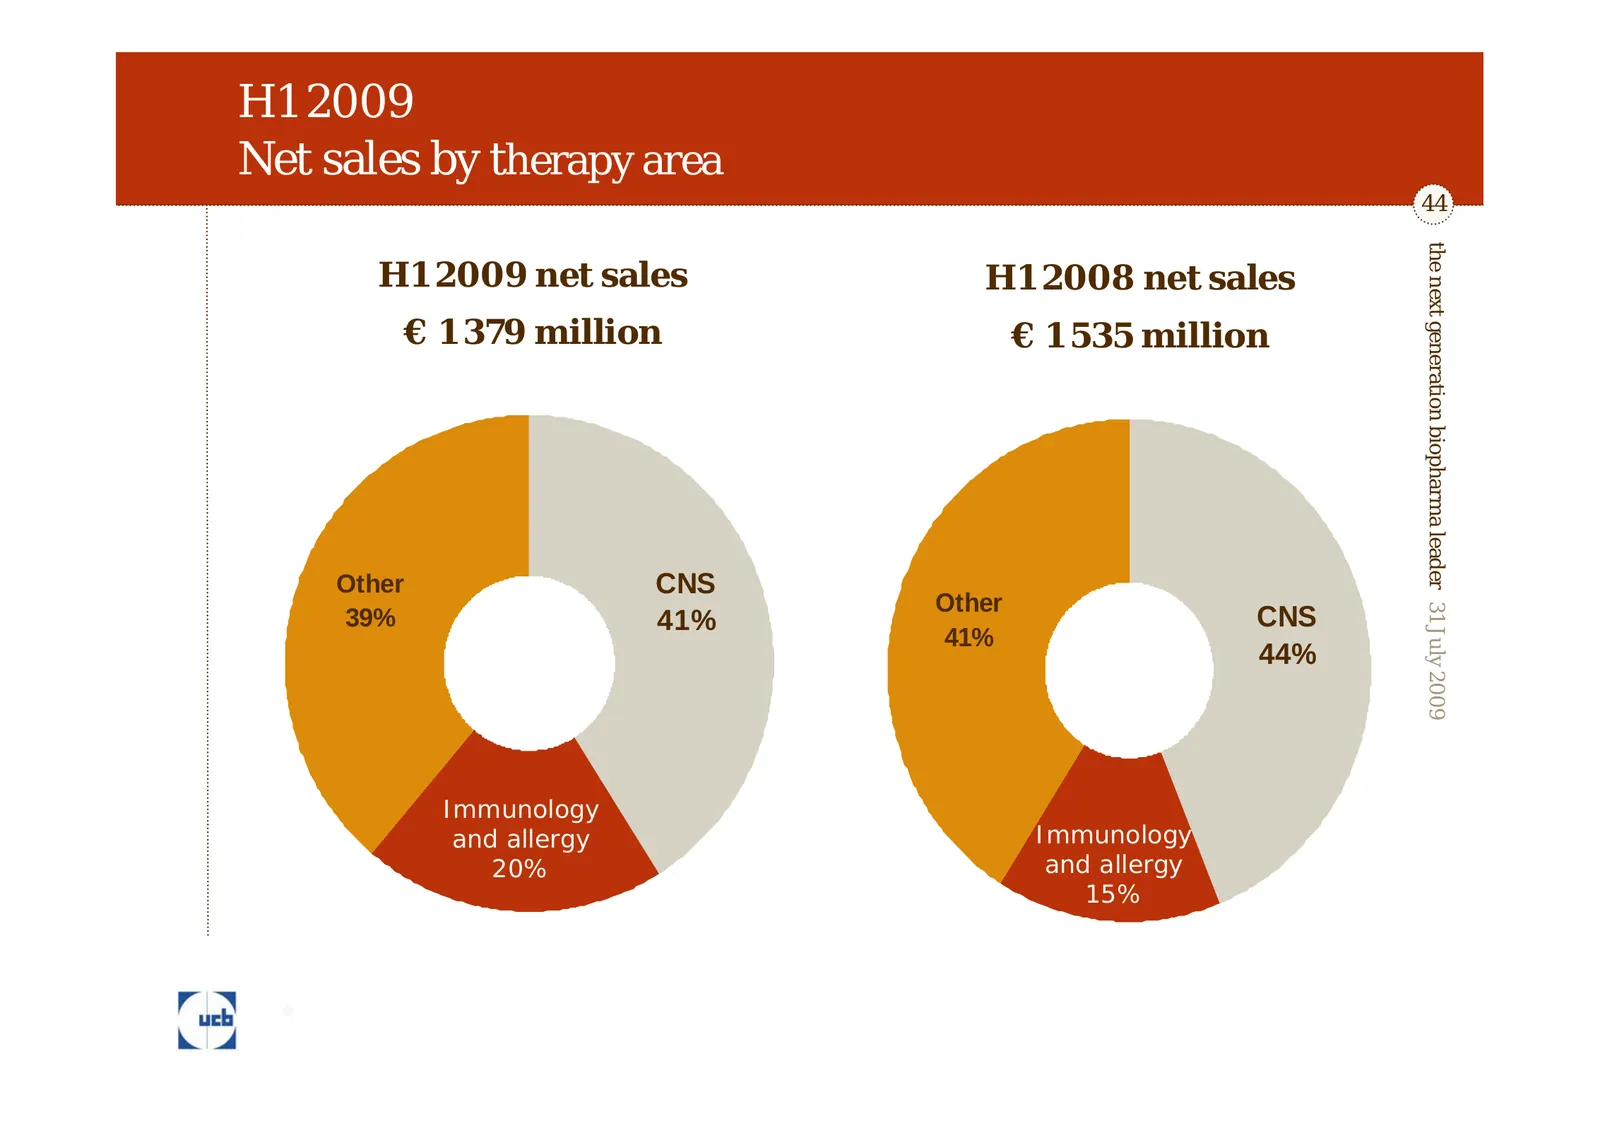
H1 2009 Net sales by therapy area 44 the next generation biopharma leader 31 July 2009 H1 2009 net sales H1 2008 net sales € 1 379 million € 1 535 million Other CNS Other 39% 41% CNS 41% 44% Immunology and allergy Immunology 20% and allergy 15% *
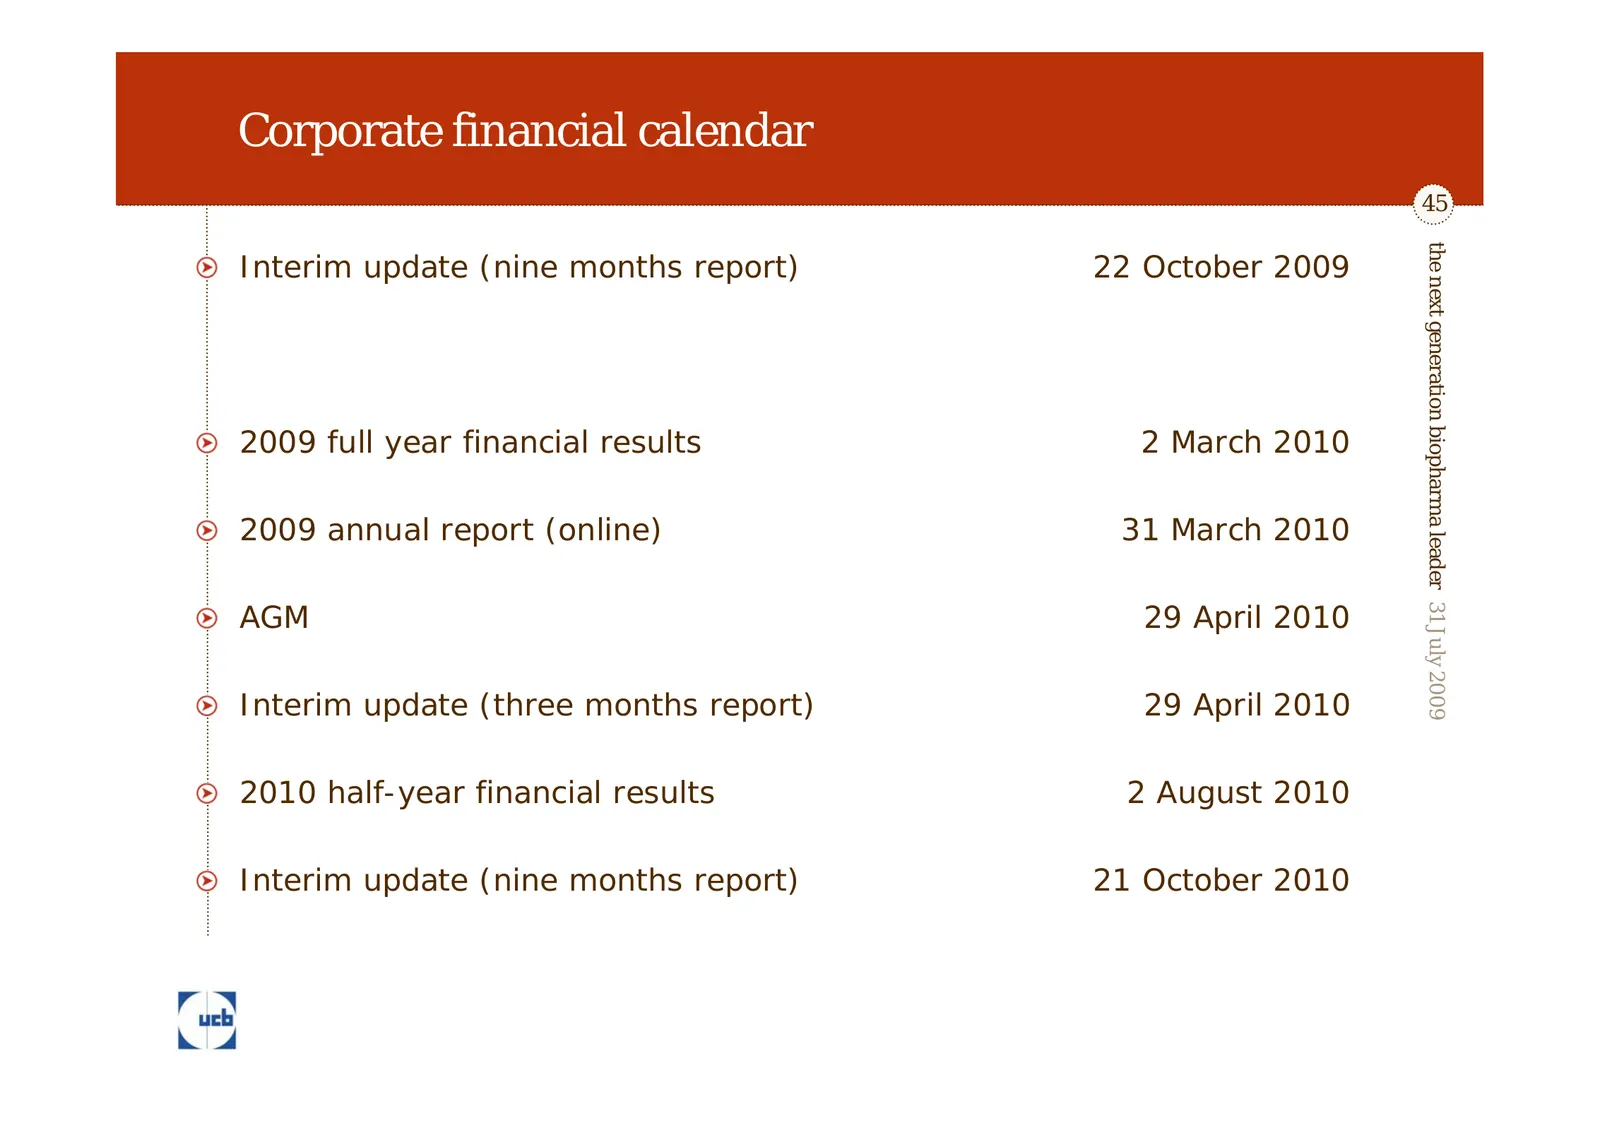
Slide 45: Corporate financial calendar
Corporate financial calendar 45 the next generation biopharma leader 31 July 2009 Interim update (nine months report) 22 October 2009 2009 full year financial results 2 March 2010 2009 annual report (online) 31 March 2010 AGM 29 April 2010 Interim update (three months report) 29 April 2010 2010 half
Source: Internet Archive copy of ucb.com
More decks from Ucb S.A.
 H1 2026 Earnings Presentation22 slides · Jul 30, 2026
 FY2025 Earnings Presentation22 slides · Feb 26, 2026
 44th Annual J.P. Morgan Healthcare Conference 202616 slides · Jan 14, 2026
 H1 2025 Earnings Presentation21 slides · Jul 31, 2025
 FY2024 Earnings Presentation18 slides · Feb 27, 2025
 43rd Annual J.P. Morgan Healthcare Conference (January 2025)13 slides · Jan 15, 2025