M&G PLC · LSE:MNG
M&G — Investor Presentation
61 slides from M&G's investor presentation
Slide 1: Techy Tuesday Tax Tools: Extracting Profits and Annual Allowance
Techy Tuesday Tax Tools Extracting Profits and Annual Allowance The information that follows is based on our understanding of current taxation, legislation and HM Revenue & Customs practice all of which are liable to change without notice. This is just for UK advisers – it’s not for use with clients
Slide 2: Important Information
Important Information This content is based on our understanding of current taxation, legislation and HM Revenue & Customs practice all of which are liable to change without notice. The impact of any taxation (and any tax reliefs) depends on individual circumstances. Where content includes case stud
Slide 3: Learning Objectives
Learning Objectives By the end of this session you will be able to: Demonstrate the Understand the inputs required for theory for using the using the Extracting Extracting Company Profits Company Profits and Annual and Annual Allowance tools Allowance tools
Slide 4: Profit Extraction
Profit Extraction Salary, dividend or pension? This is just for UK advisers – it’s not for use with clients
Slide 5: Your business is your pension?
Your business is your pension?
Slide 6: Spot the difference
Spot the difference “….my retirement is sorted out, I heard about this unlisted company no-one has heard of and bought up the shares with my SIPP, it’ll definitely do well enough to cover my retirement and it’s not too risky…..” No-one, ever, probably “…..my business is my pension….” Lots of people,
Slide 7: Corporation Tax (wef April 2023)
Corporation Tax (wef April 2023)
Slide 8: Corporation Tax changes
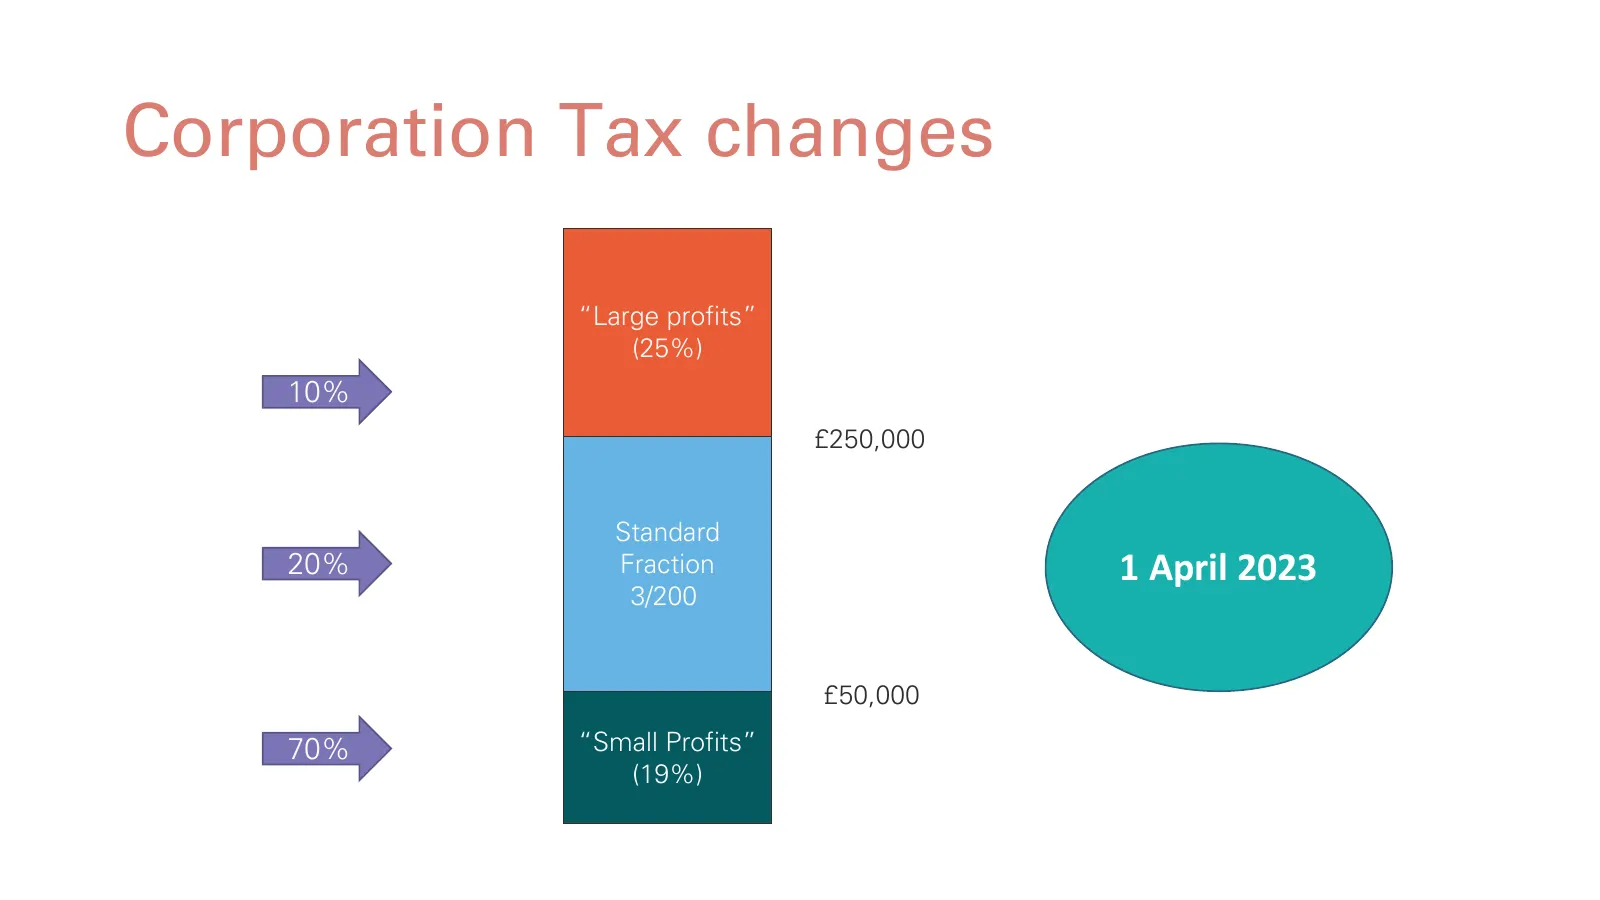
Corporation Tax changes “Large profits” (25%) 10% £250,000 Standard 20% Fraction 1 April 2023 3/200 £50,000 70% “Small Profits” (19%)
Slide 9: Calculating corporation tax
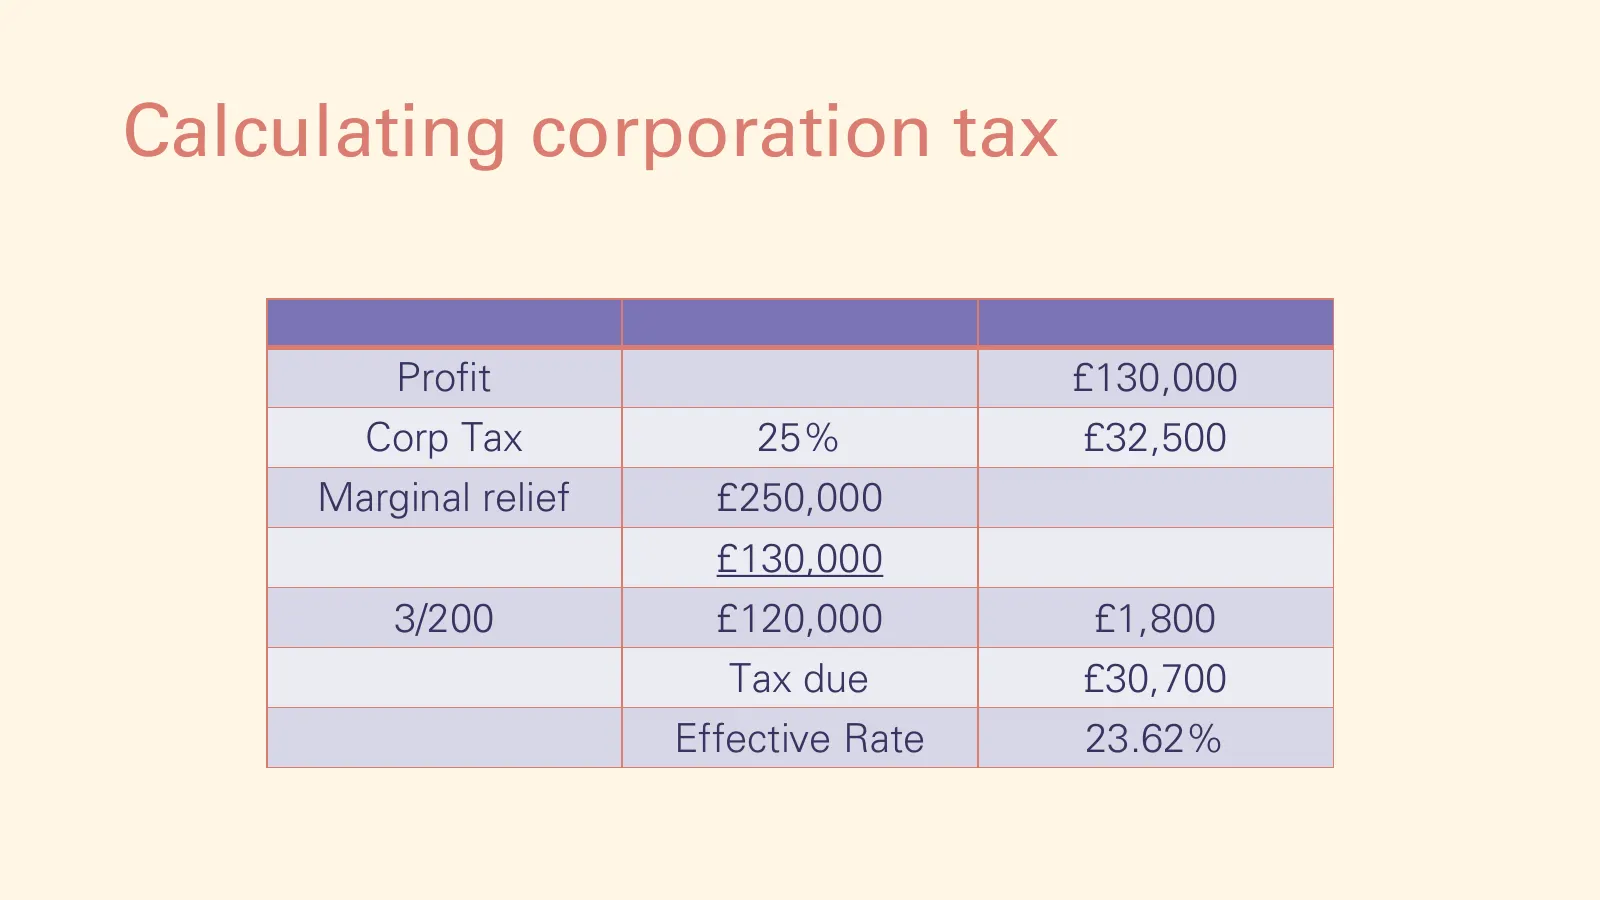
Calculating corporation tax Profit £130,000 Corp Tax 25% £32,500 Marginal relief £250,000 £130,000 3/200 £120,000 £1,800 Tax due £30,700 Effective Rate 23.62%
Slide 10: Effective rates
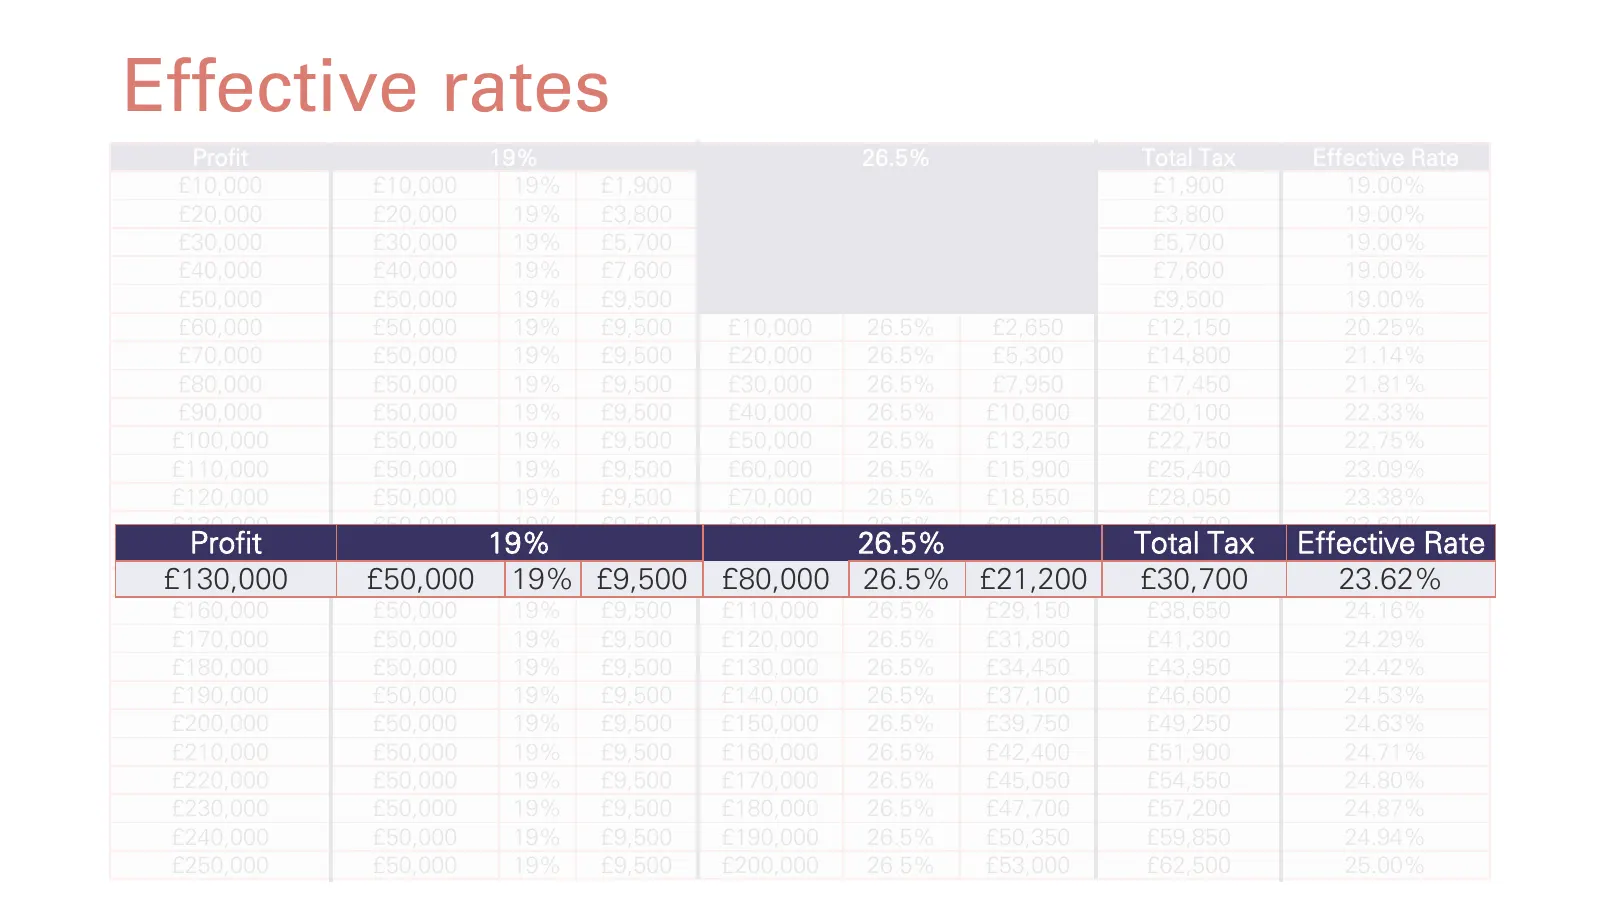
Effective rates Profit 19% 26.5% Total Tax Effective Rate £10,000 £10,000 19% £1,900 £1,900 19.00% £20,000 £20,000 19% £3,800 £3,800 19.00% £30,000 £30,000 19% £5,700 £5,700 19.00% £40,000 £40,000 19% £7,600 £7,600 19.00% £50,000 £50,000 19% £9,500 £9,500 19.00% £60,000 £50,000 19% £9,500 £10,000 26
Slide 11: Tax Relief
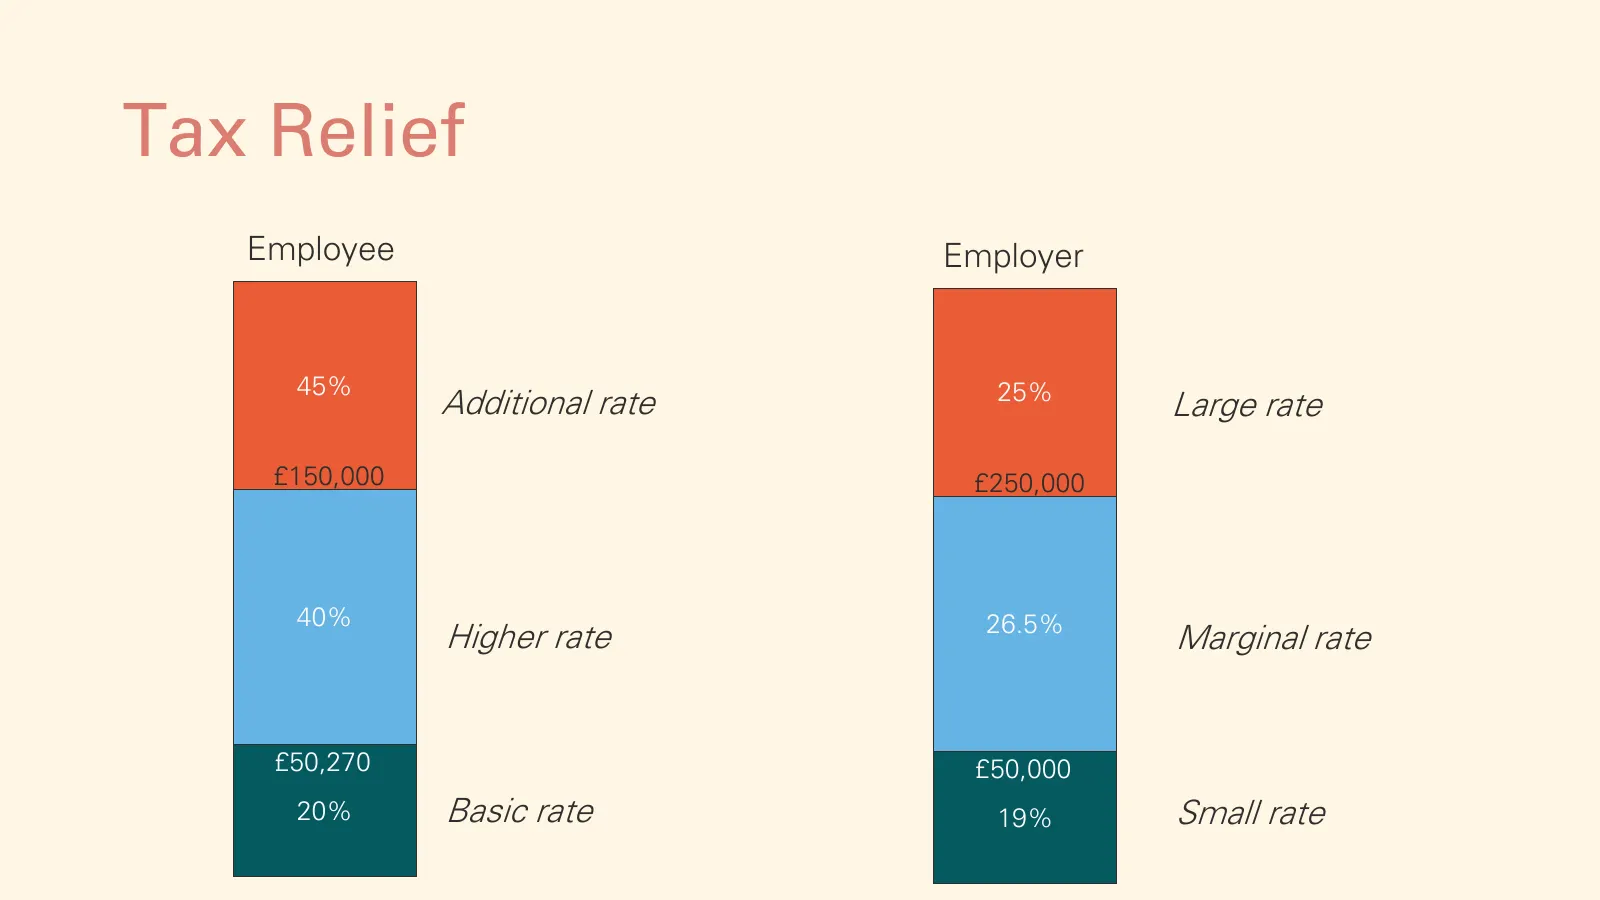
Tax Relief Employee Employer 45% 25% Additional rate Large rate £150,000 £250,000 40% 26.5% Higher rate Marginal rate £50,270 £50,000 20% Basic rate 19% Small rate
Slide 12: Employer tax relief
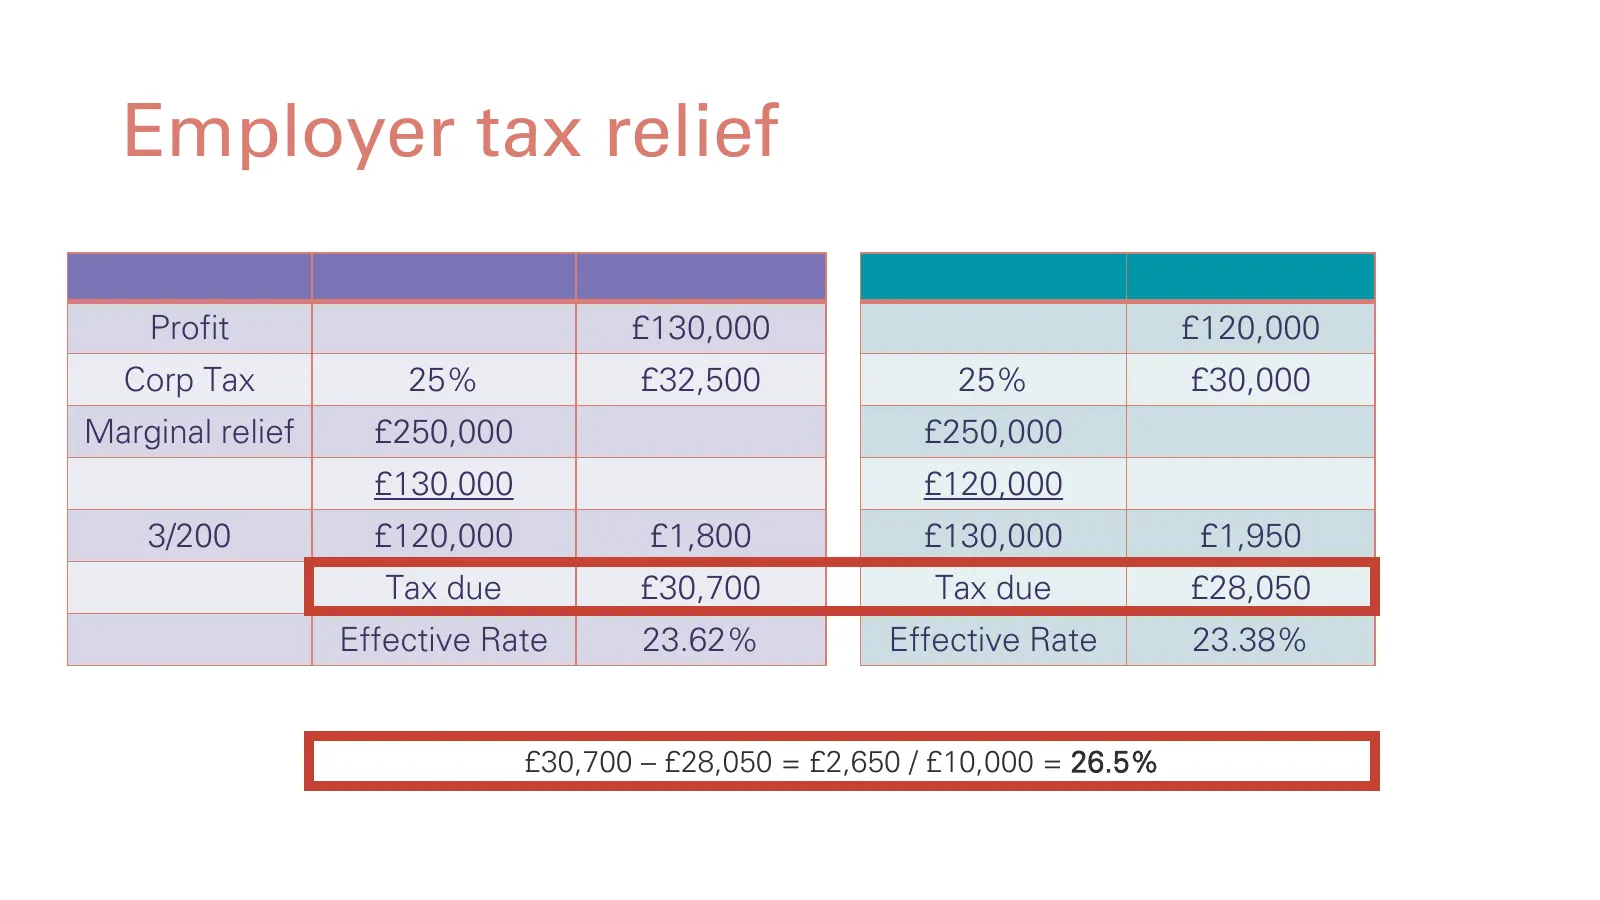
Employer tax relief Profit £130,000 £120,000 Corp Tax 25% £32,500 25% £30,000 Marginal relief £250,000 £250,000 £130,000 £120,000 3/200 £120,000 £1,800 £130,000 £1,950 Tax due £30,700 Tax due £28,050 Effective Rate 23.62% Effective Rate 23.38% £30,700 – £28,050 = £2,650 / £10,000 = 26.5%
Slide 13: Wholly and Exclusively
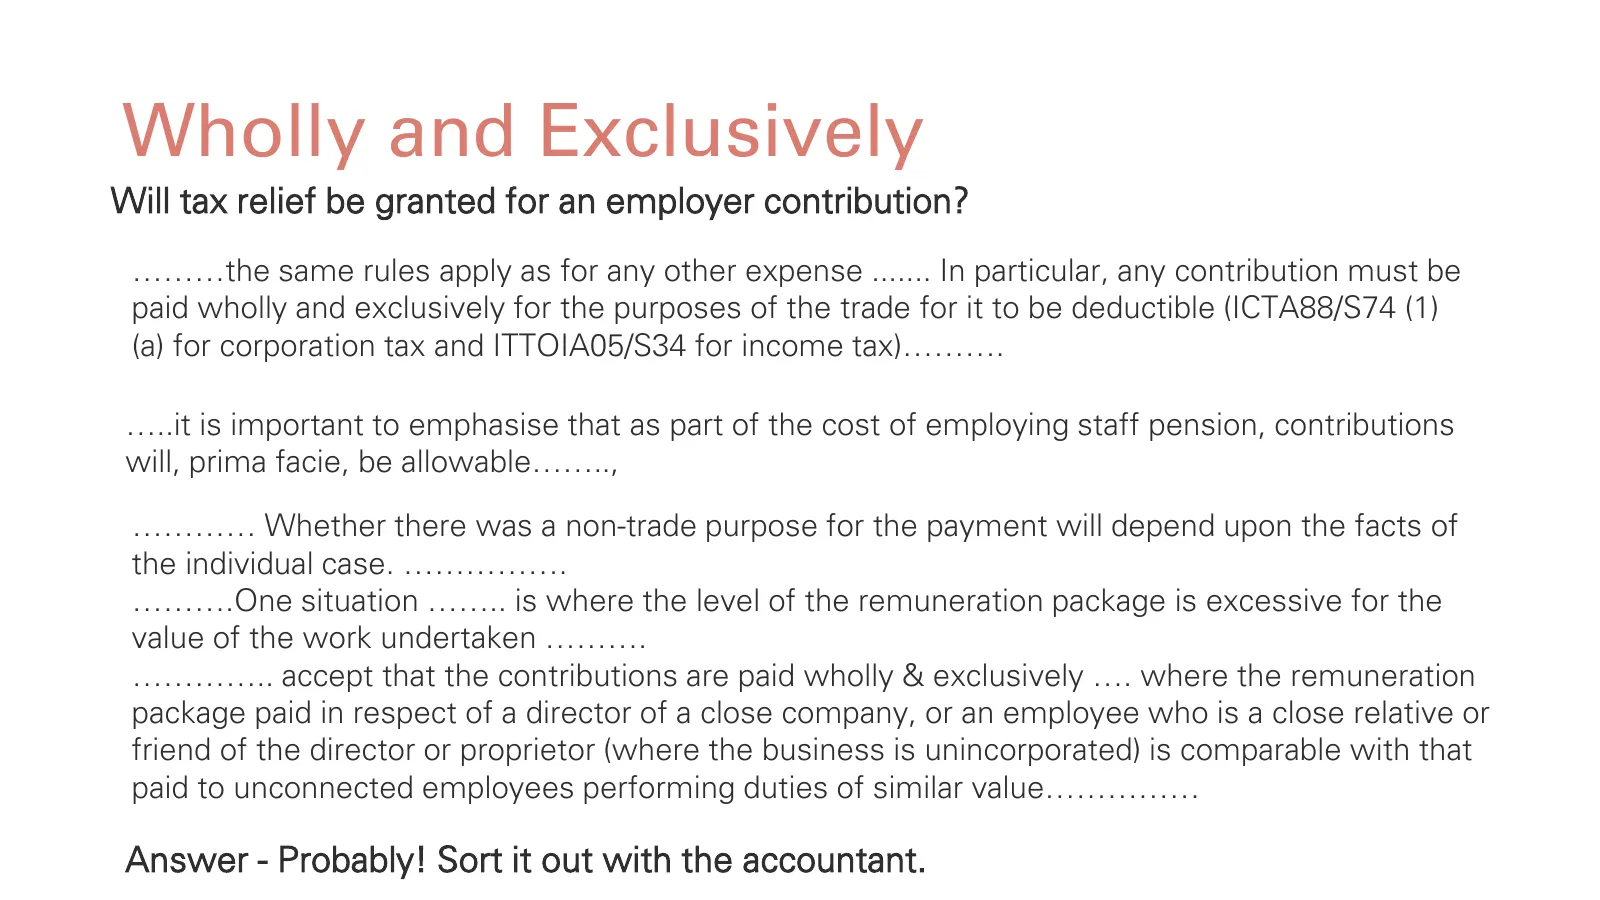
Wholly and Exclusively Will tax relief be granted for an employer contribution? ………the same rules apply as for any other expense ....... In particular, any contribution must be paid wholly and exclusively for the purposes of the trade for it to be deductible (ICTA88/S74 (1) (a) for corporation tax a
Slide 14: Employer contribution: the years
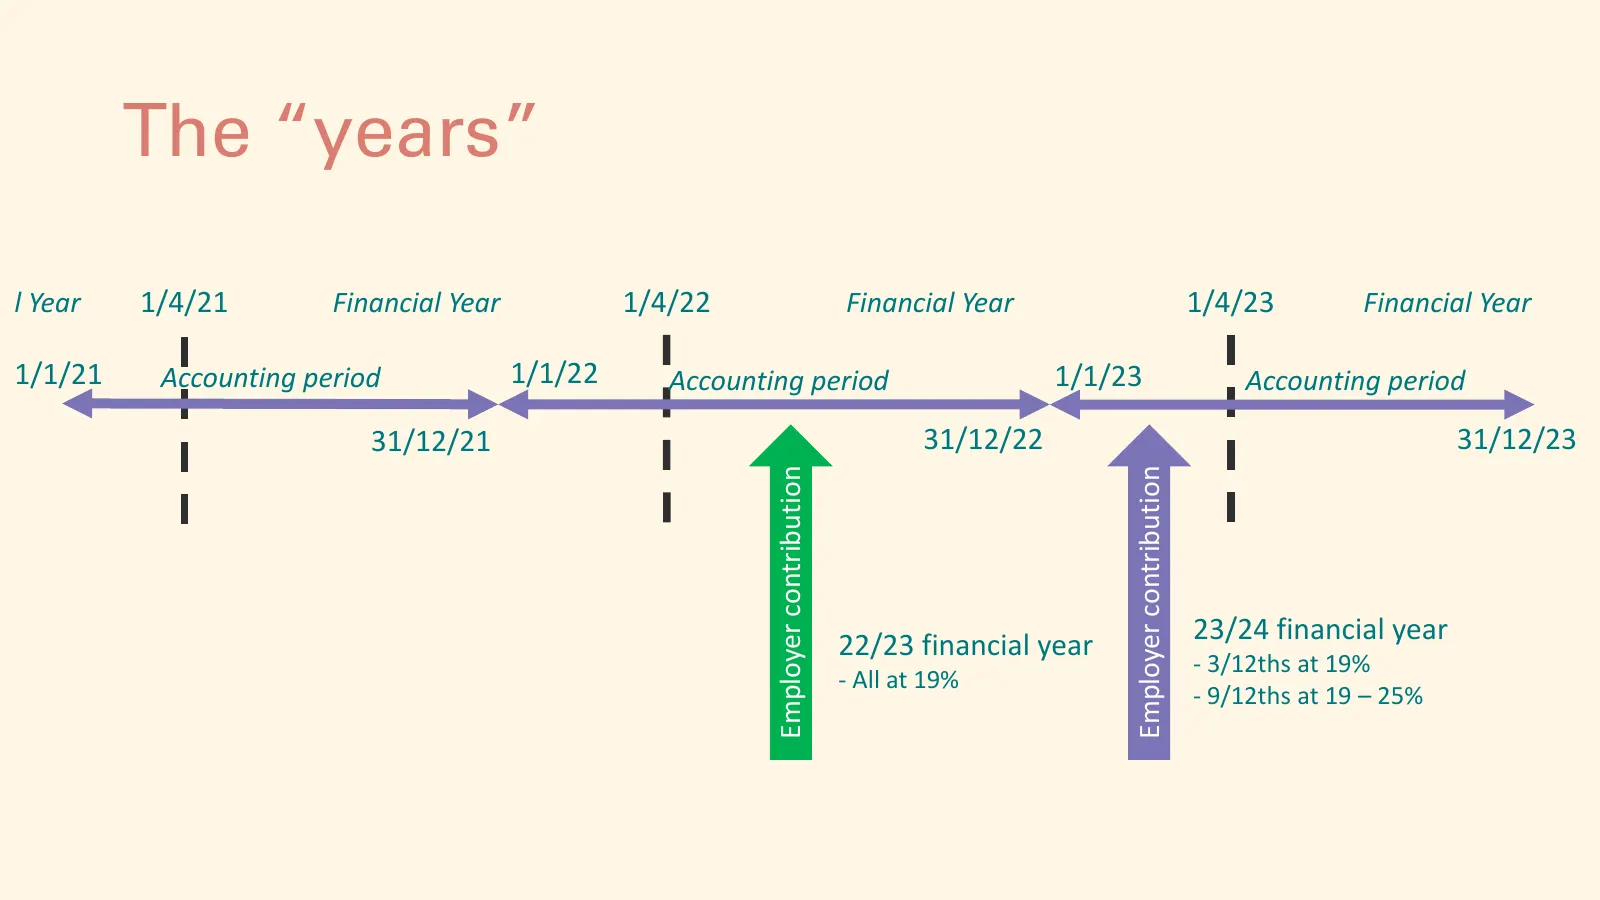
The “years” l Year 1/4/21 Financial Year 1/4/22 Financial Year 1/4/23 Financial Year 1/1/21 Accounting period 1/1/22 Accounting period 1/1/23 Accounting period 31/12/21 31/12/22 31/12/23 Employer contribution Employer contribution 23/24 financial year 22/23 financial year - 3/12ths at 19% - All at 1
Slide 15: Dividends
Dividends
Slide 16: Dividend Tax Allowance 2023/24
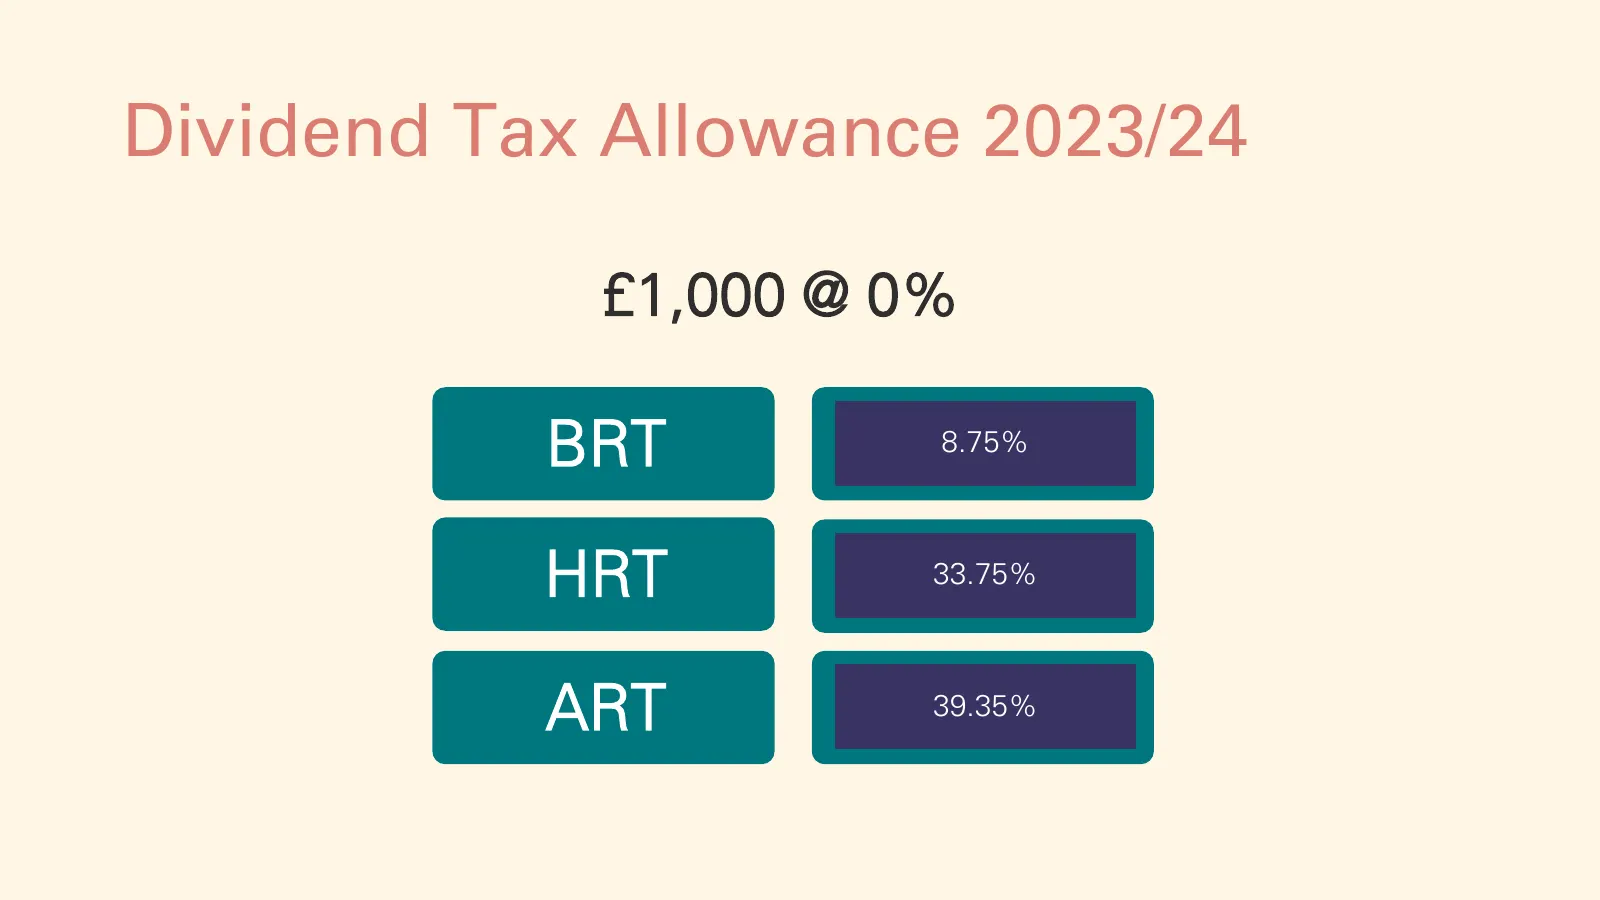
Dividend Tax Allowance 2023/24 £1,000 @ 0% BRT 8.75% HRT 33.75% ART 39.35%
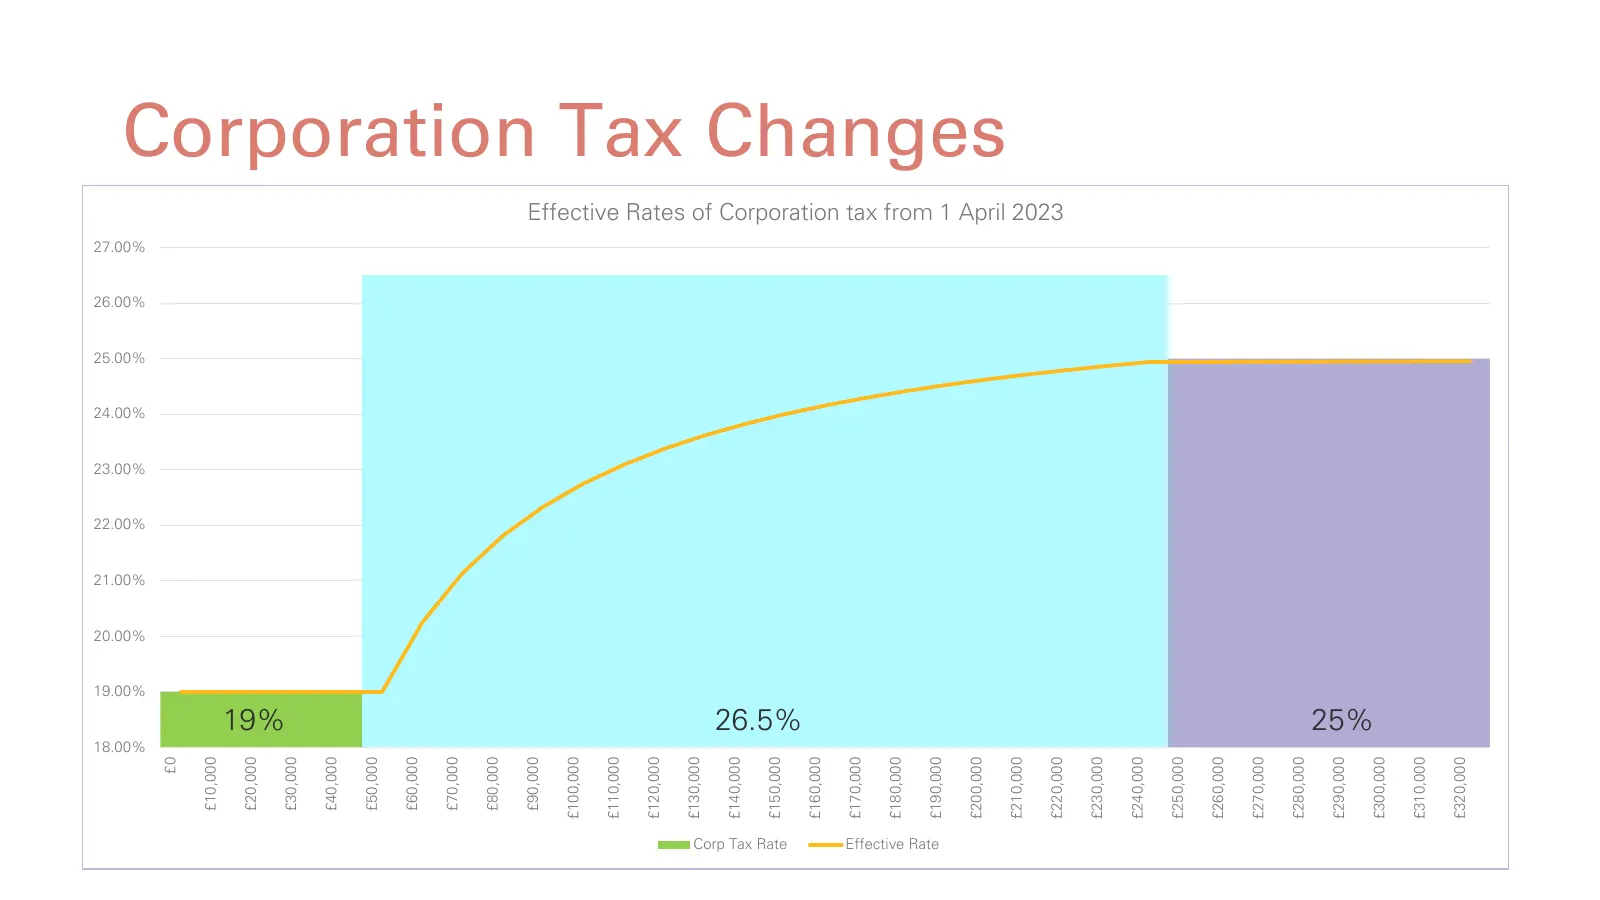
Slide 17: Corporation Tax Changes
18.00% 19.00% 20.00% 21.00% 22.00% 23.00% 25.00% 26.00% 27.00% 24.00% £0 £10,000 £20,000 19% £30,000 £40,000 £50,000 £60,000 £70,000 £80,000 £90,000 £100,000 £110,000 £120,000 £130,000 £140,000 £150,000 Corp Tax Rate 26.5% £160,000 £170,000 £180,000 Effective Rate £190,000 £200,000 Corporation Tax C
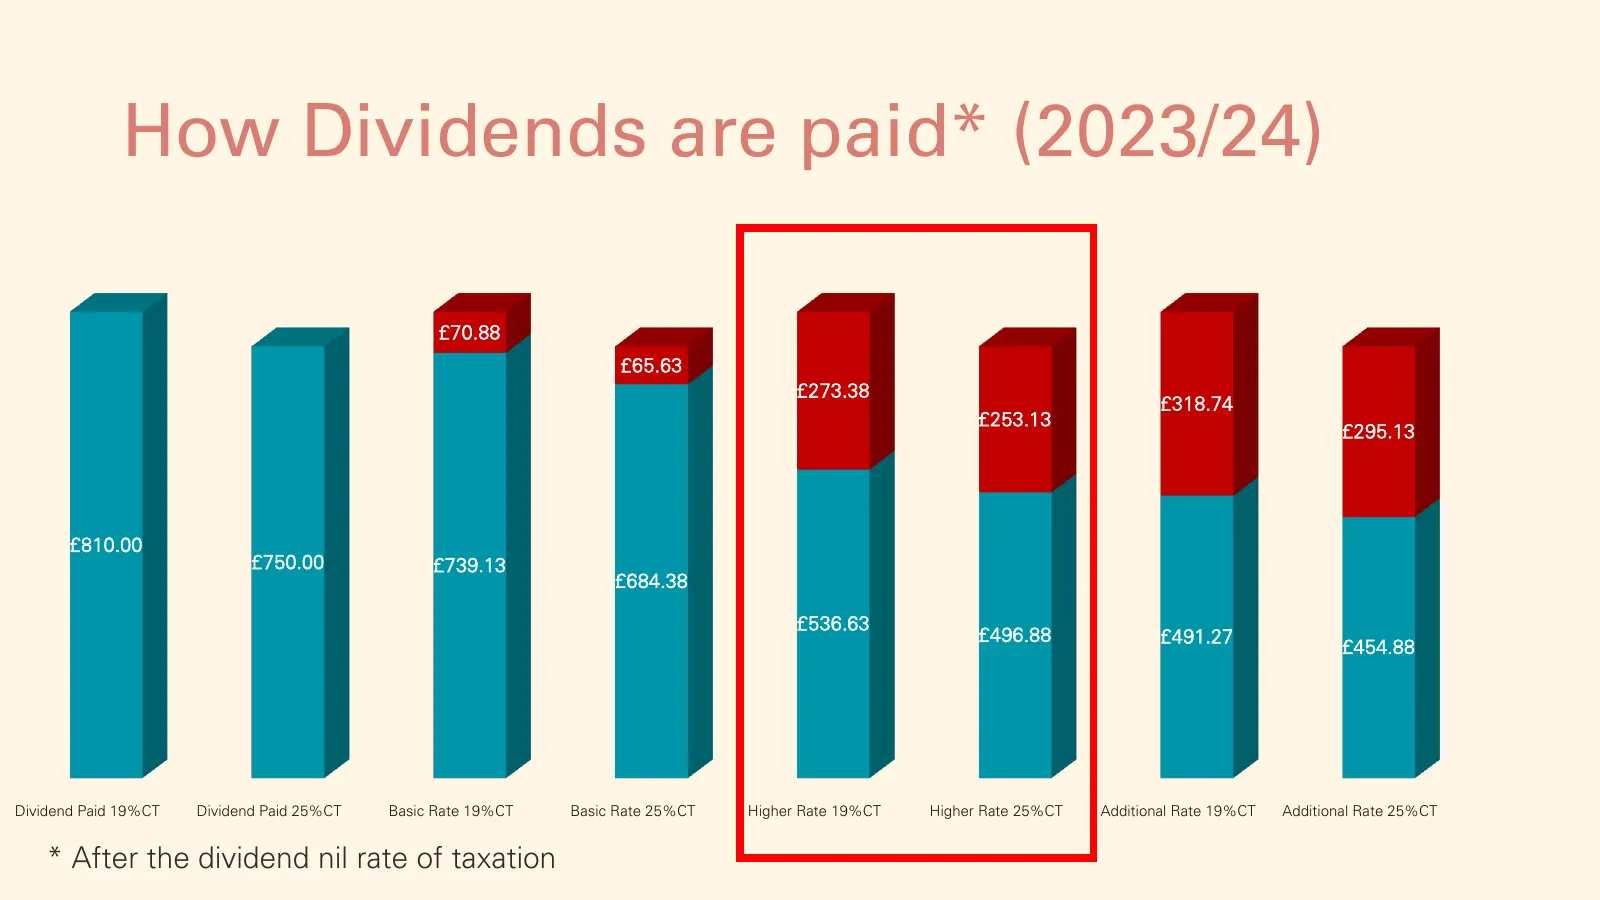
Slide 18: How Dividends are paid (2023/24)
How Dividends are paid* (2023/24) £70.88 £65.63 £273.38 £318.74 £253.13 £295.13 £810.00 £750.00 £739.13 £684.38 £536.63 £496.88 £491.27 £454.88 Dividend Paid 19%CT Dividend Paid 25%CT Basic Rate 19%CT Basic Rate 25%CT Higher Rate 19%CT Higher Rate 25%CT Additional Rate 19%CT Additional Rate 25%CT *
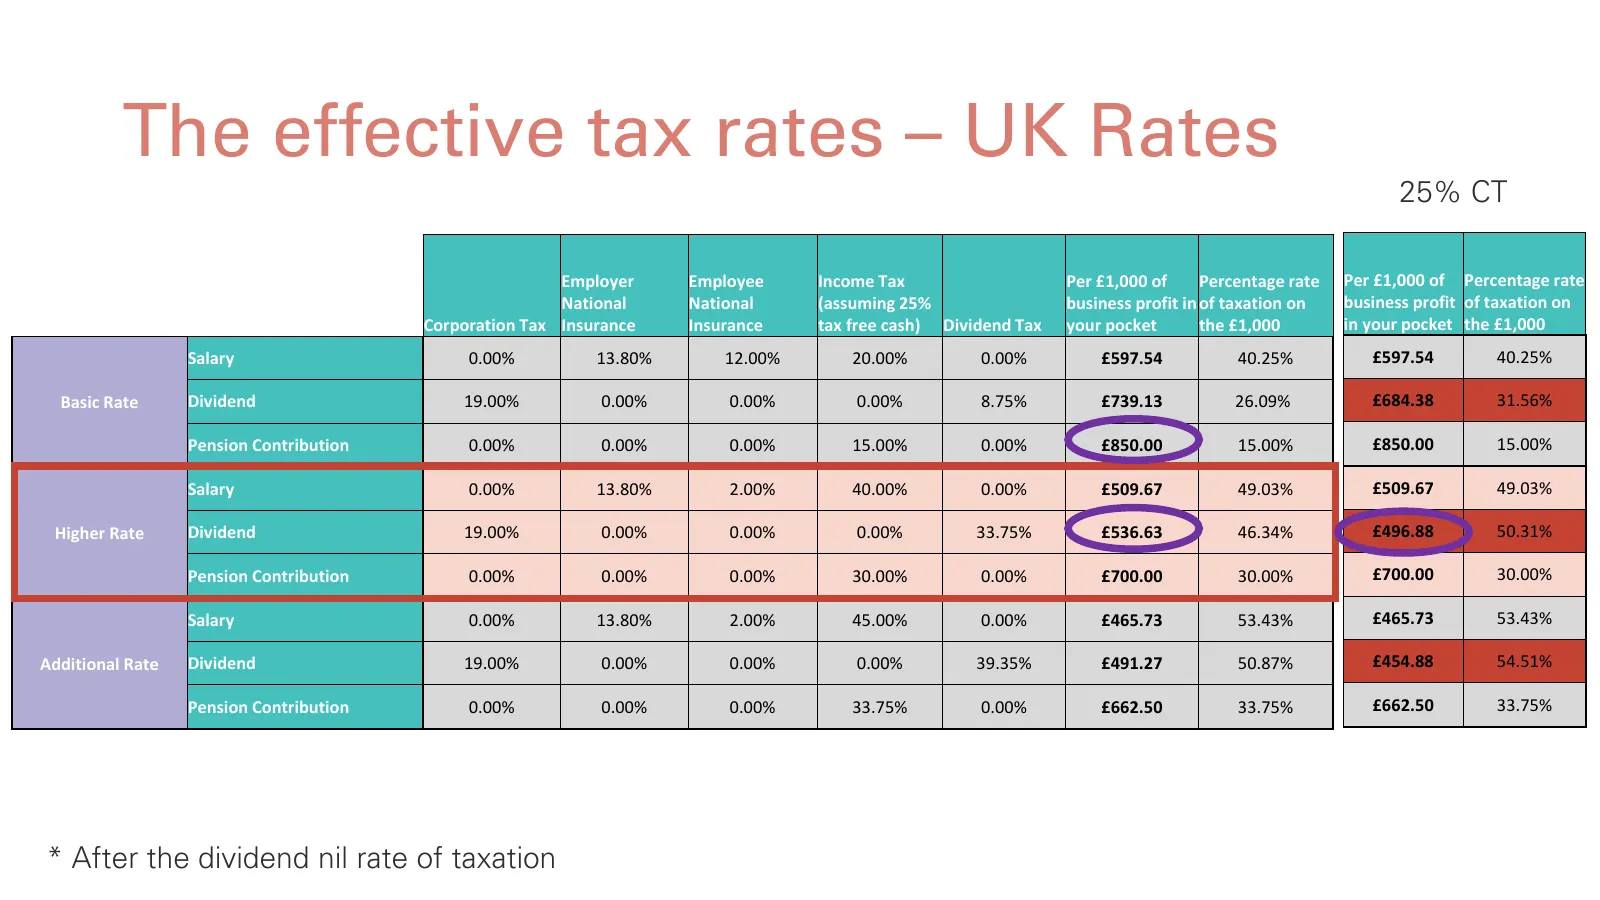
Slide 19: The effective tax rates – UK Rates
The effective tax rates – UK Rates 25% CT Employer Employee Income Tax Per £1,000 of Percentage rate Per £1,000 of Percentage rate National National (assuming 25% business profit in of taxation on business profit of taxation on Corporation Tax Insurance Insurance tax free cash) Dividend Tax your poc
Slide 20: Cash problem? Eroding value or surplus
Cash problem? Eroding value Surplus or not funding Earmarked retirement? Liquidity
Slide 21: Mary
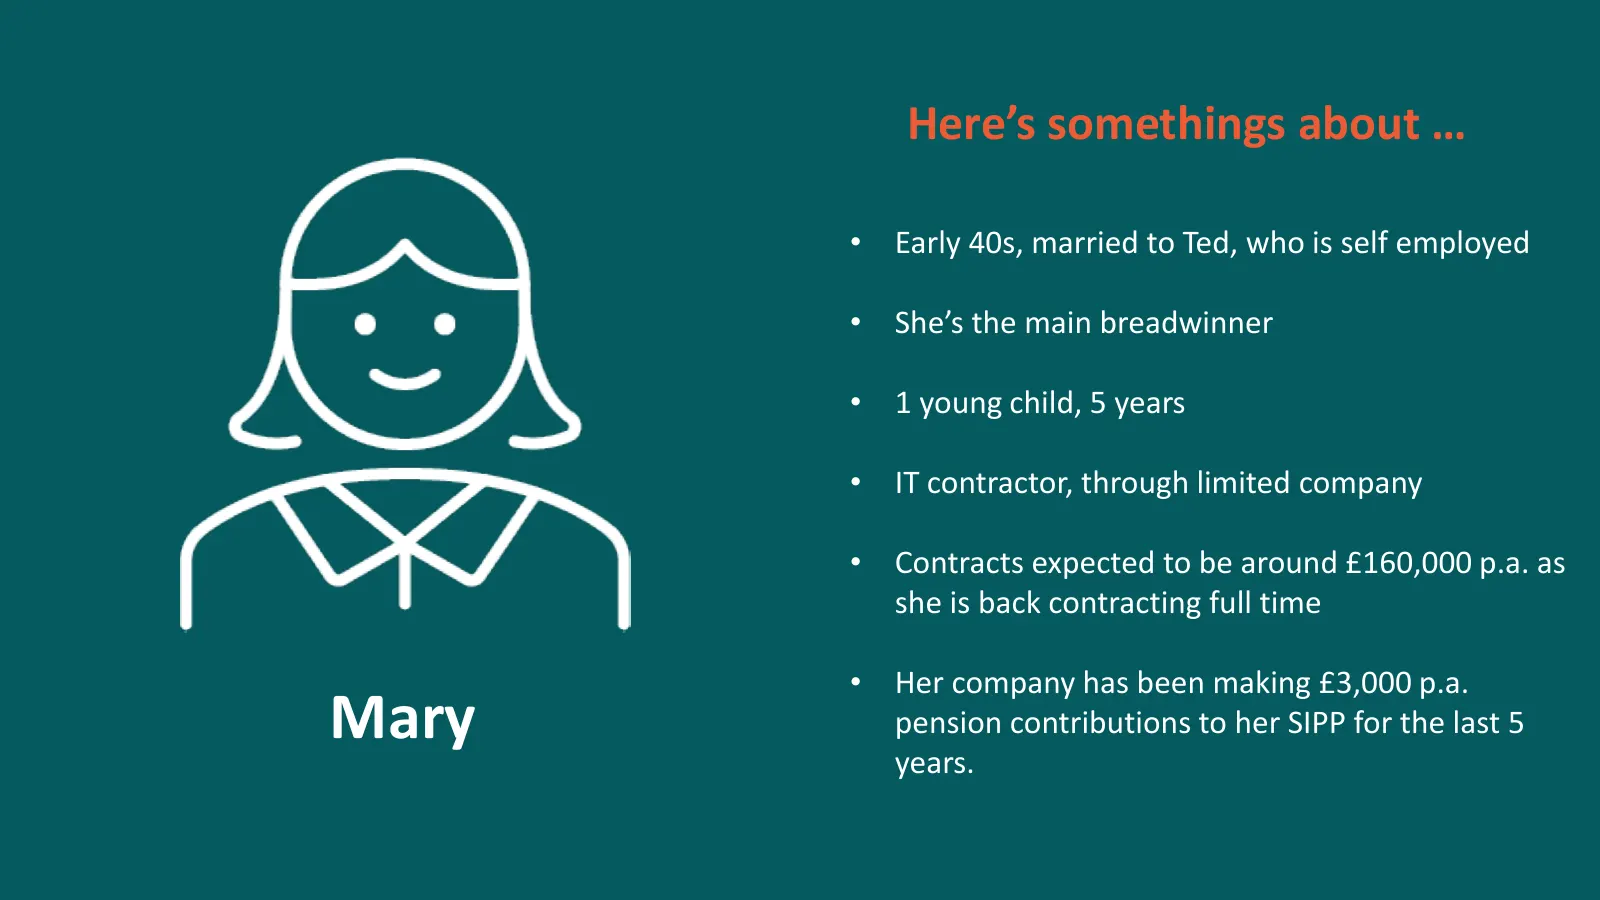
Here’s somethings about … • Early 40s, married to Ted, who is self employed • She’s the main breadwinner • 1 young child, 5 years • IT contractor, through limited company • Contracts expected to be around £160,000 p.a. as she is back contracting full time • Her company has been making £3,000 p.a. Ma
Slide 22: How much AA in 2023/24 – carry forward
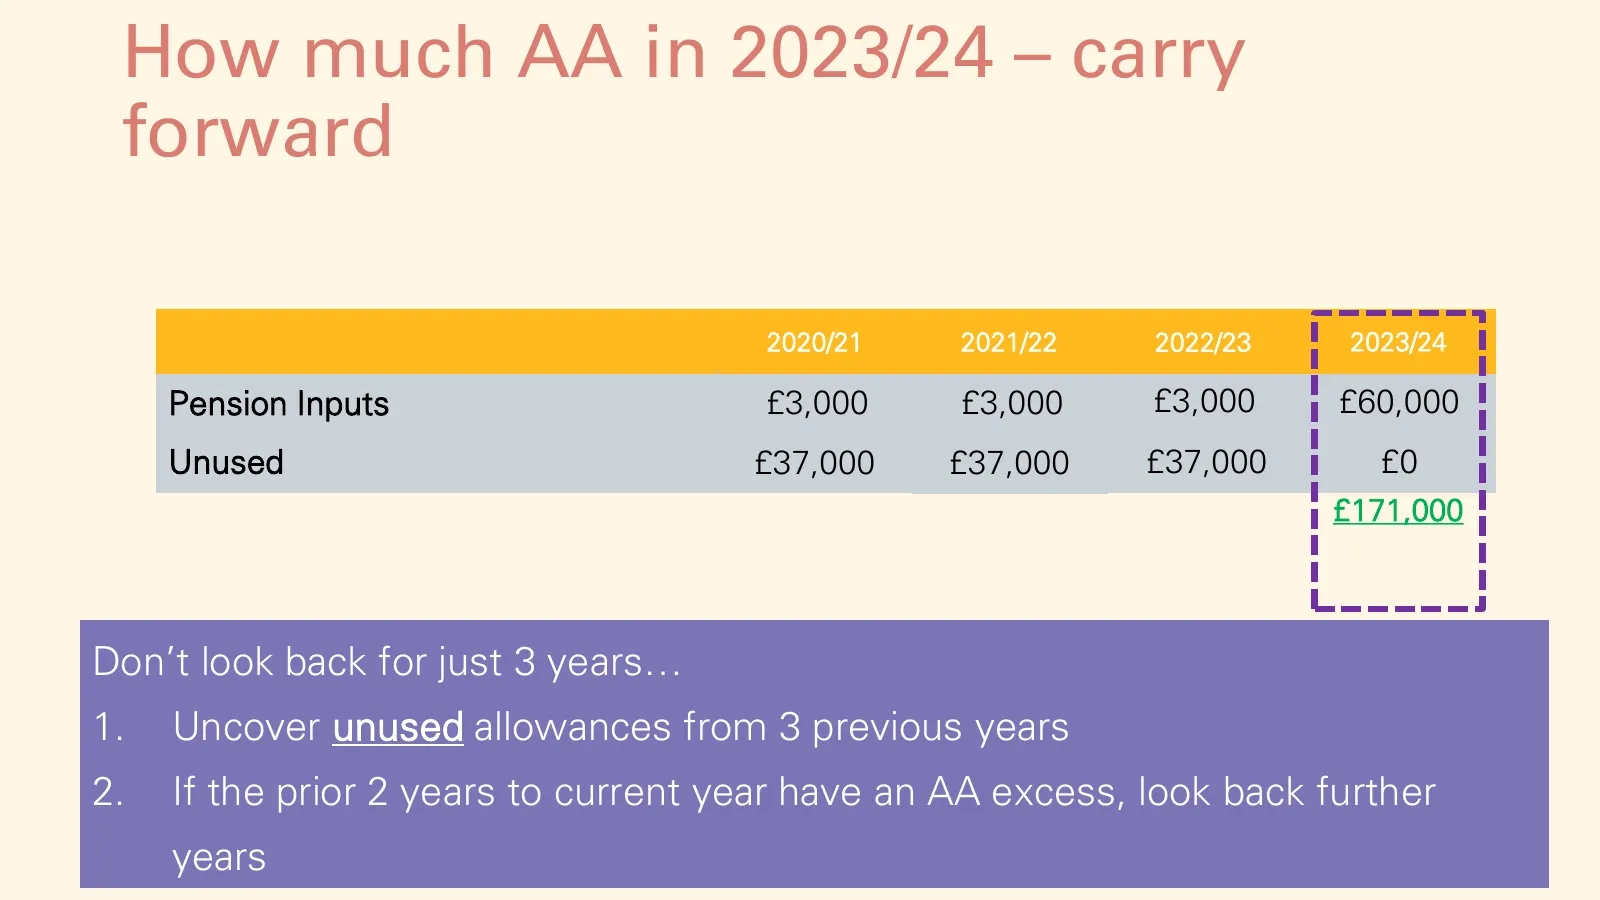
How much AA in 2023/24 – carry forward 2020/21 2021/22 2022/23 2023/24 Pension Inputs £3,000 £3,000 £3,000 £60,000 Unused £37,000 £37,000 £37,000 £0 £171,000 Don’t look back for just 3 years… 1. Uncover unused allowances from 3 previous years 2. If the prior 2 years to current year have an AA excess
Slide 23: £160,000 - Decisions, decisions
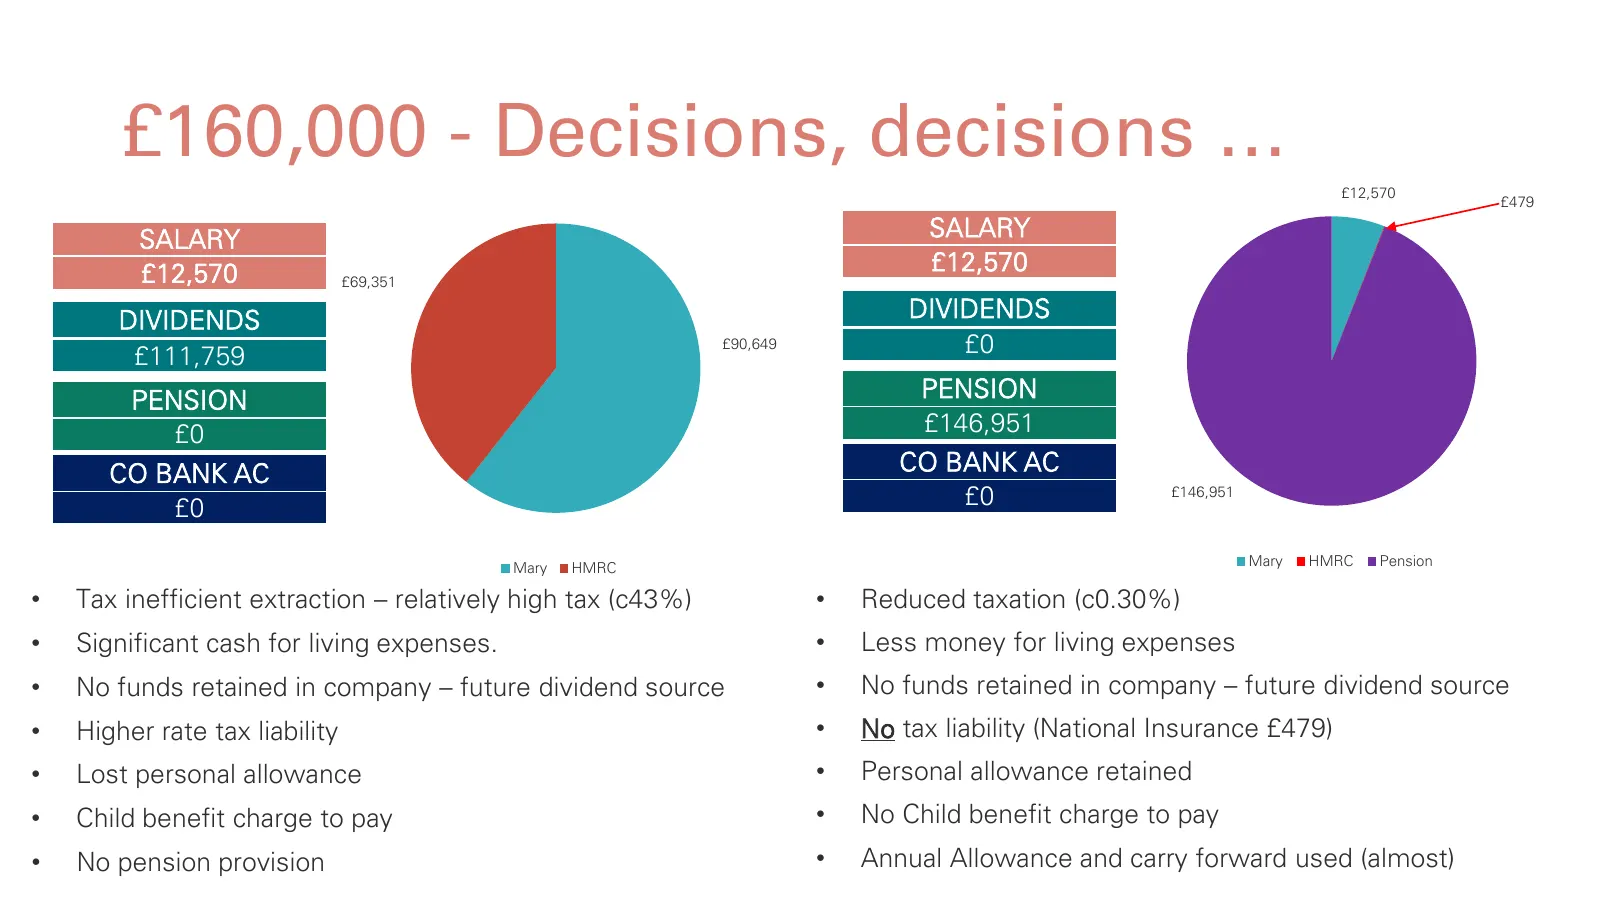
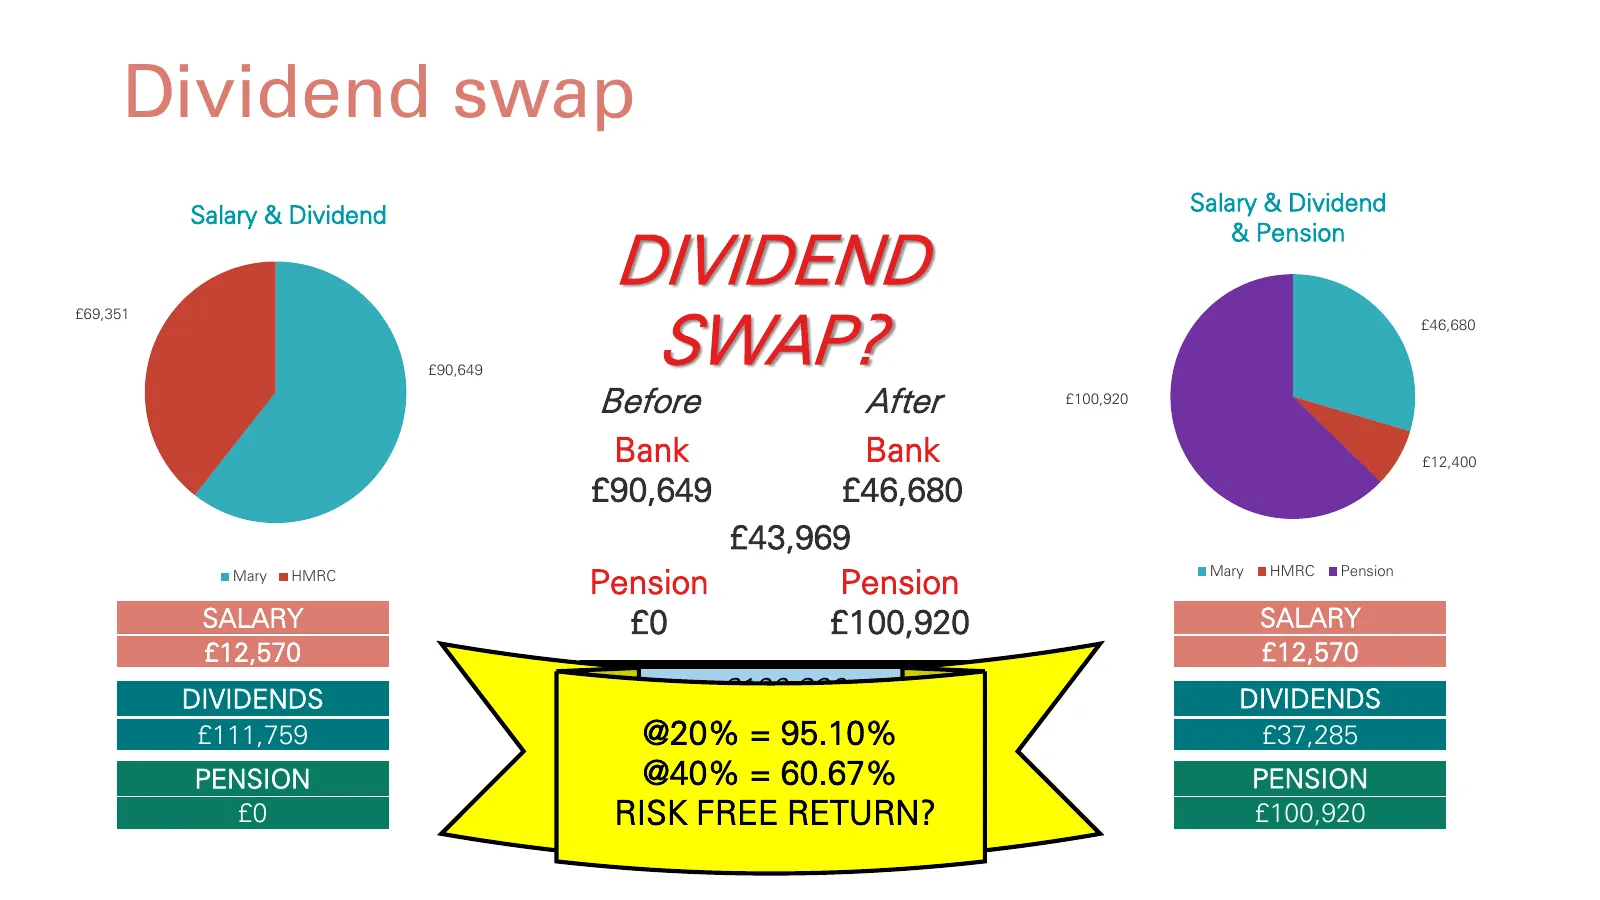
£160,000 - Decisions, decisions … £12,570 £479 SALARY SALARY £12,570 £12,570 £69,351 DIVIDENDS DIVIDENDS £111,759 £90,649 £0 PENSION PENSION £0 £146,951 CO BANK AC CO BANK AC £0 £0 £146,951 Mary HMRC Mary HMRC Pension • Tax inefficient extraction – relatively high tax (c43%) • Reduced taxation (c0.3
Slide 24: How about take what you need?
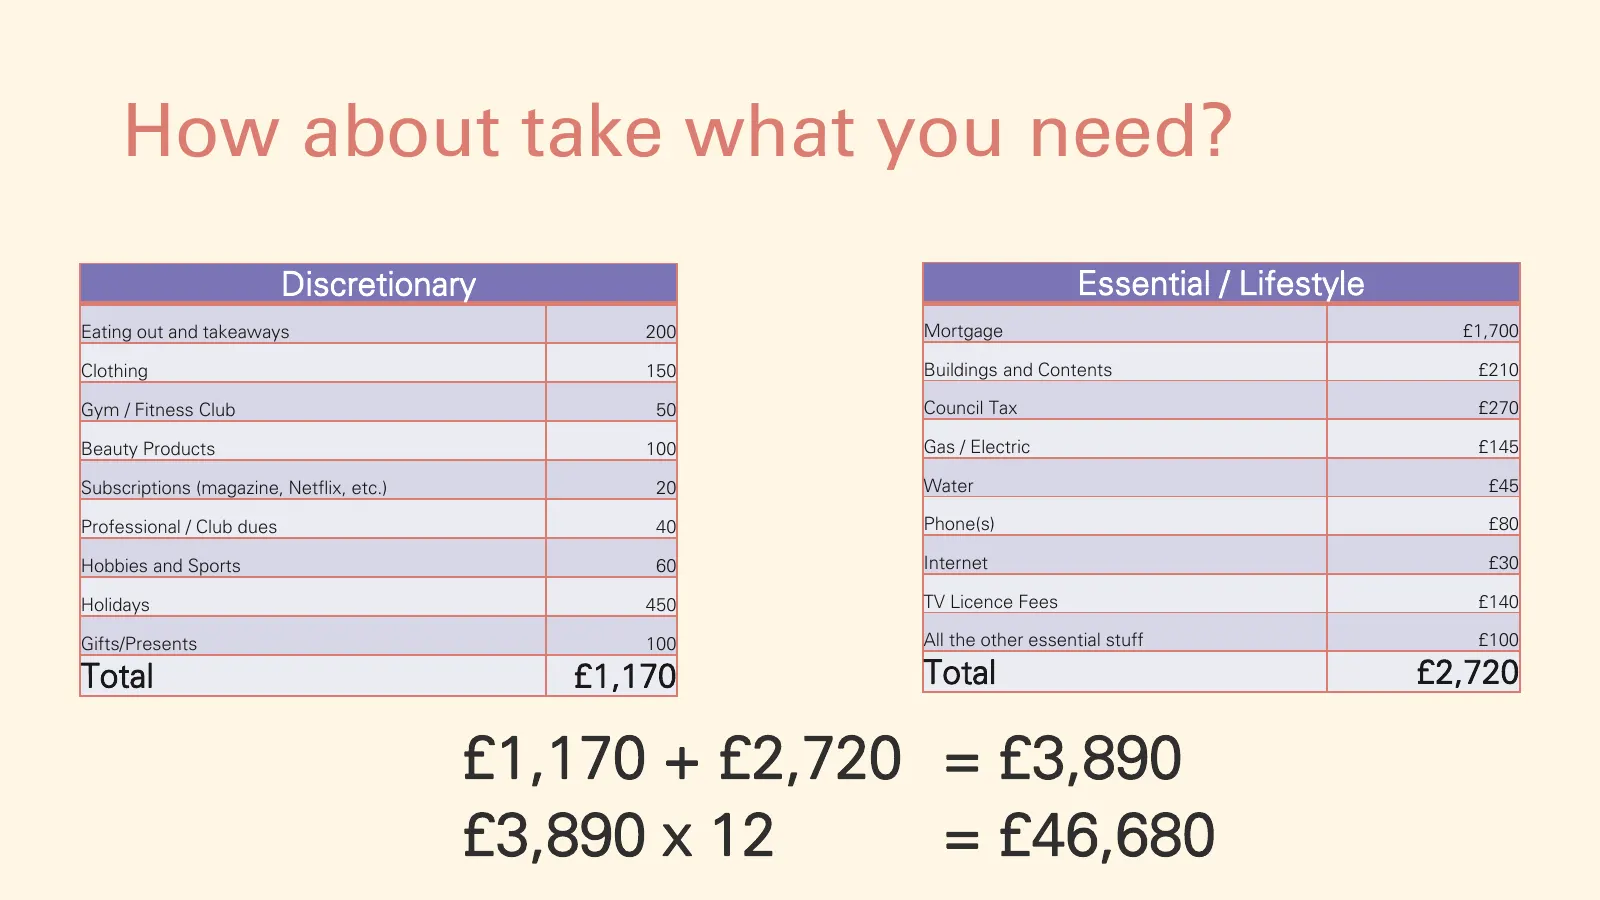
How about take what you need? Discretionary Essential / Lifestyle Eating out and takeaways 200 Mortgage £1,700 Clothing 150 Buildings and Contents £210 Gym / Fitness Club 50 Council Tax £270 Beauty Products 100 Gas / Electric £145 Subscriptions (magazine, Netflix, etc.) 20 Water £45 Professional / C
Slide 25: Dividend swap
Dividend swap Salary & Dividend Salary & Dividend DIVIDEND & Pension SWAP? £69,351 £46,680 £90,649 Before After £100,920 Bank Bank £12,400 £90,649 £46,680 £43,969 Pension Pension Mary HMRC Mary HMRC Pension SALARY £0 £100,920 SALARY £12,570 £12,570 DIVIDENDS £100,920 DIVIDENDS £111,759 @ 20%==95.10%
Slide 26: An easier way to do this
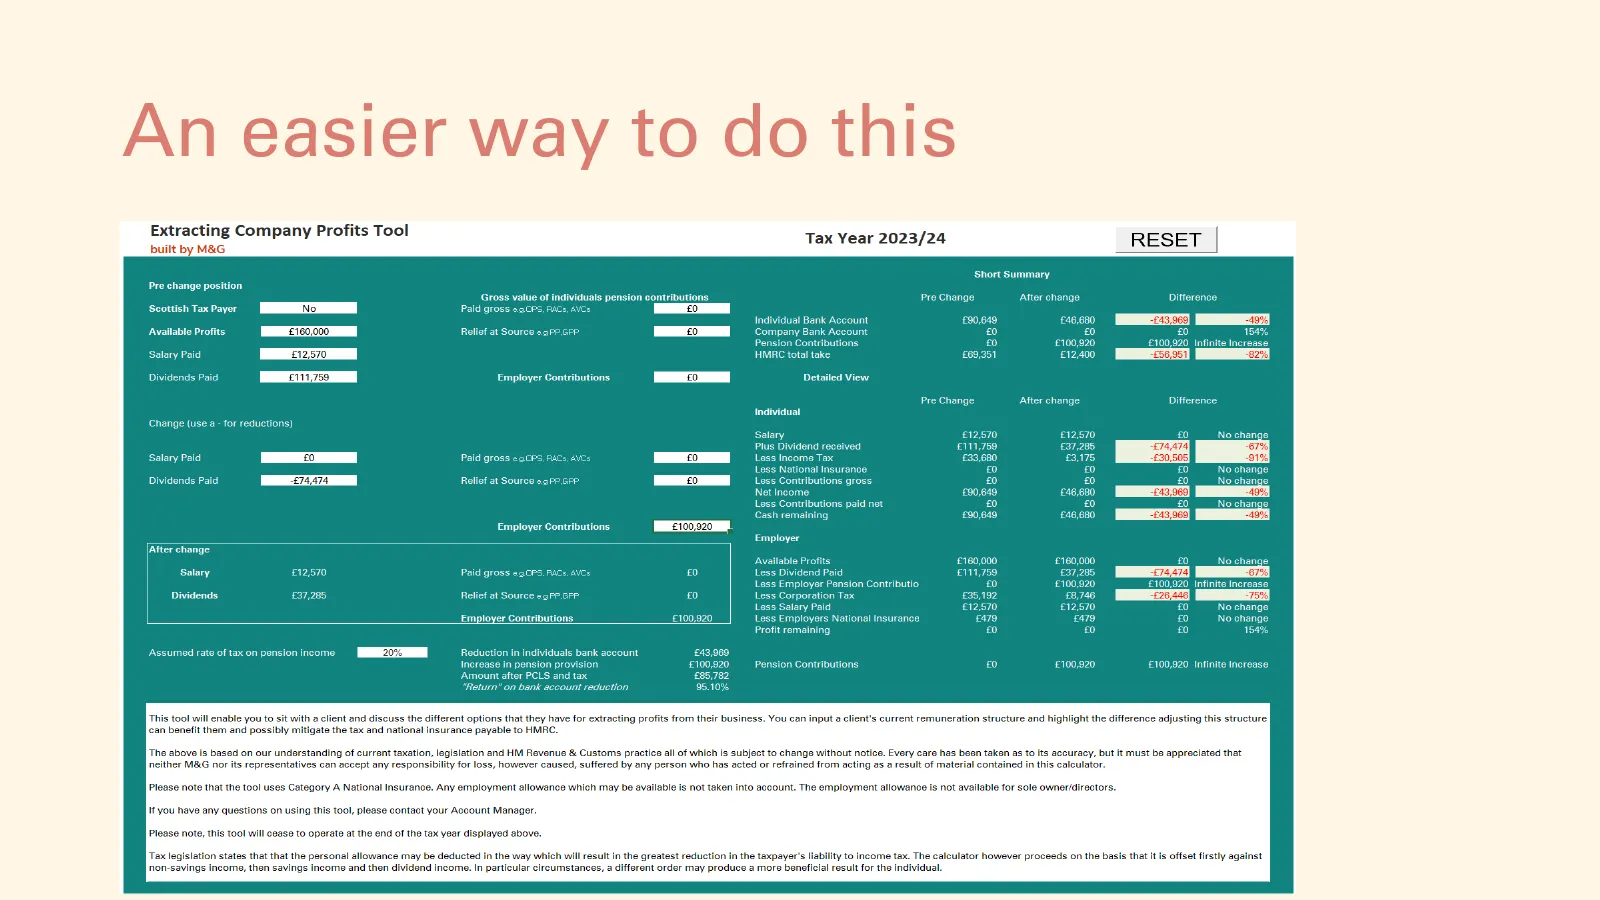
Extracting Company Profits Tool Pre change positio Scottish Tax Payer ‘Available Profits Salary Paid Salary Paid Dividends Pals Assumed rato of ta a "£160,000 £12570 Pald gross Employer Contributions Reduction in individuals Bank soeount £43,000, 782 Tax Year 2023/24 Company Bank Account HMRC total
Slide 27: Plan B (and beyond)
Plan B (and beyond) “Business is my pension” b) Can’t sell when you want? c) Can’t get what you want? d) Usually tax free on death (BPR 100%/50%) e) Creditor risk? f) Entrepreneurs relief (risk of retained profits) (now called Business Asset Disposal Relief) g) Would you advise a client to invest no
Slide 28: LETS GO LIVE.
LETS GO LIVE.
Slide 29: Annual Allowance
Annual Allowance Pension inputs and the taper This is just for UK advisers – it’s not for use with clients
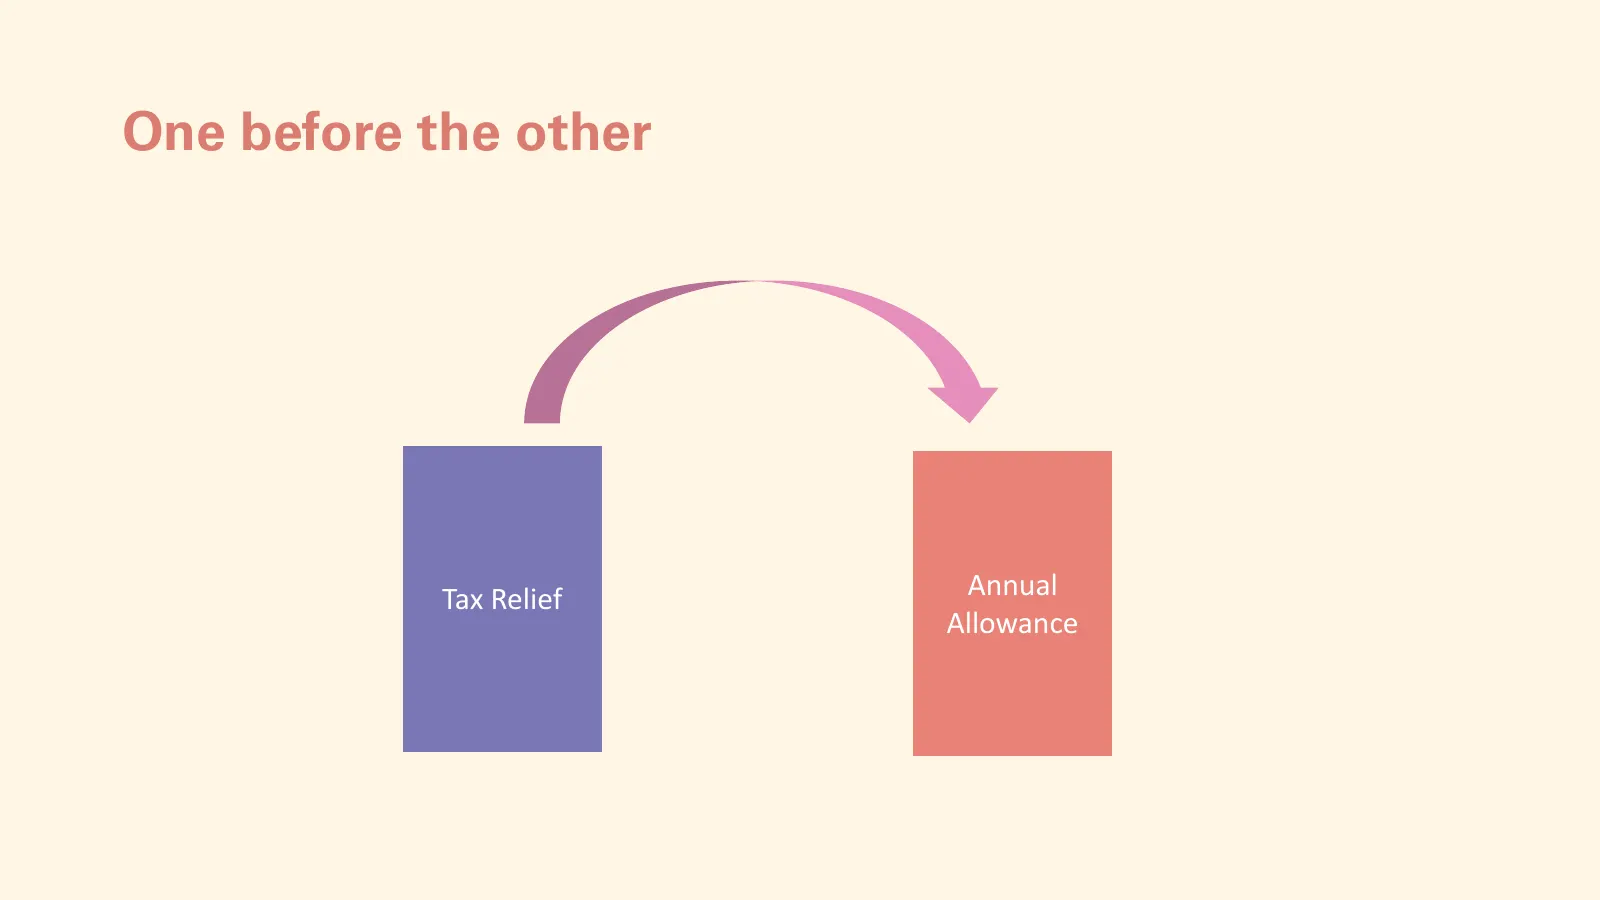
Slide 30: One before the other
One before the other Tax Relief Annual Allowance
Slide 31: Annual Allowance: The three options
Annual Allowance The three options
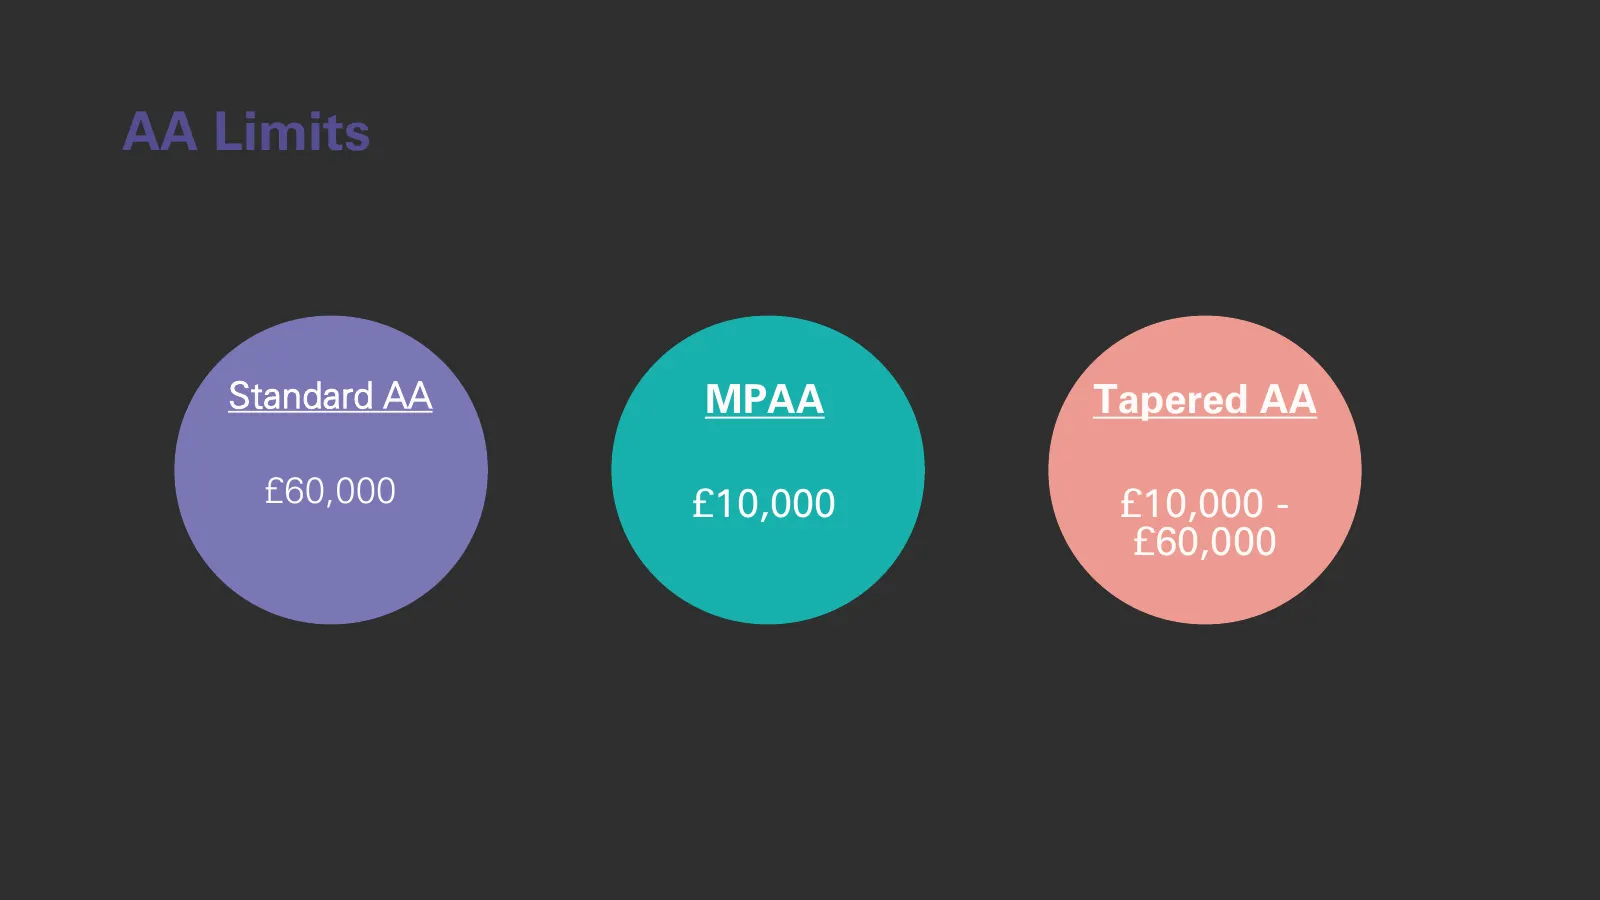
Slide 32: AA Limits
AA Limits Standard AA MPAA Tapered AA £60,000 £10,000 £10,000 - £60,000
Slide 33: Calculating Pension Input Amounts
Calculating Pension Input Amounts
Slide 34: Money Purchase Inputs
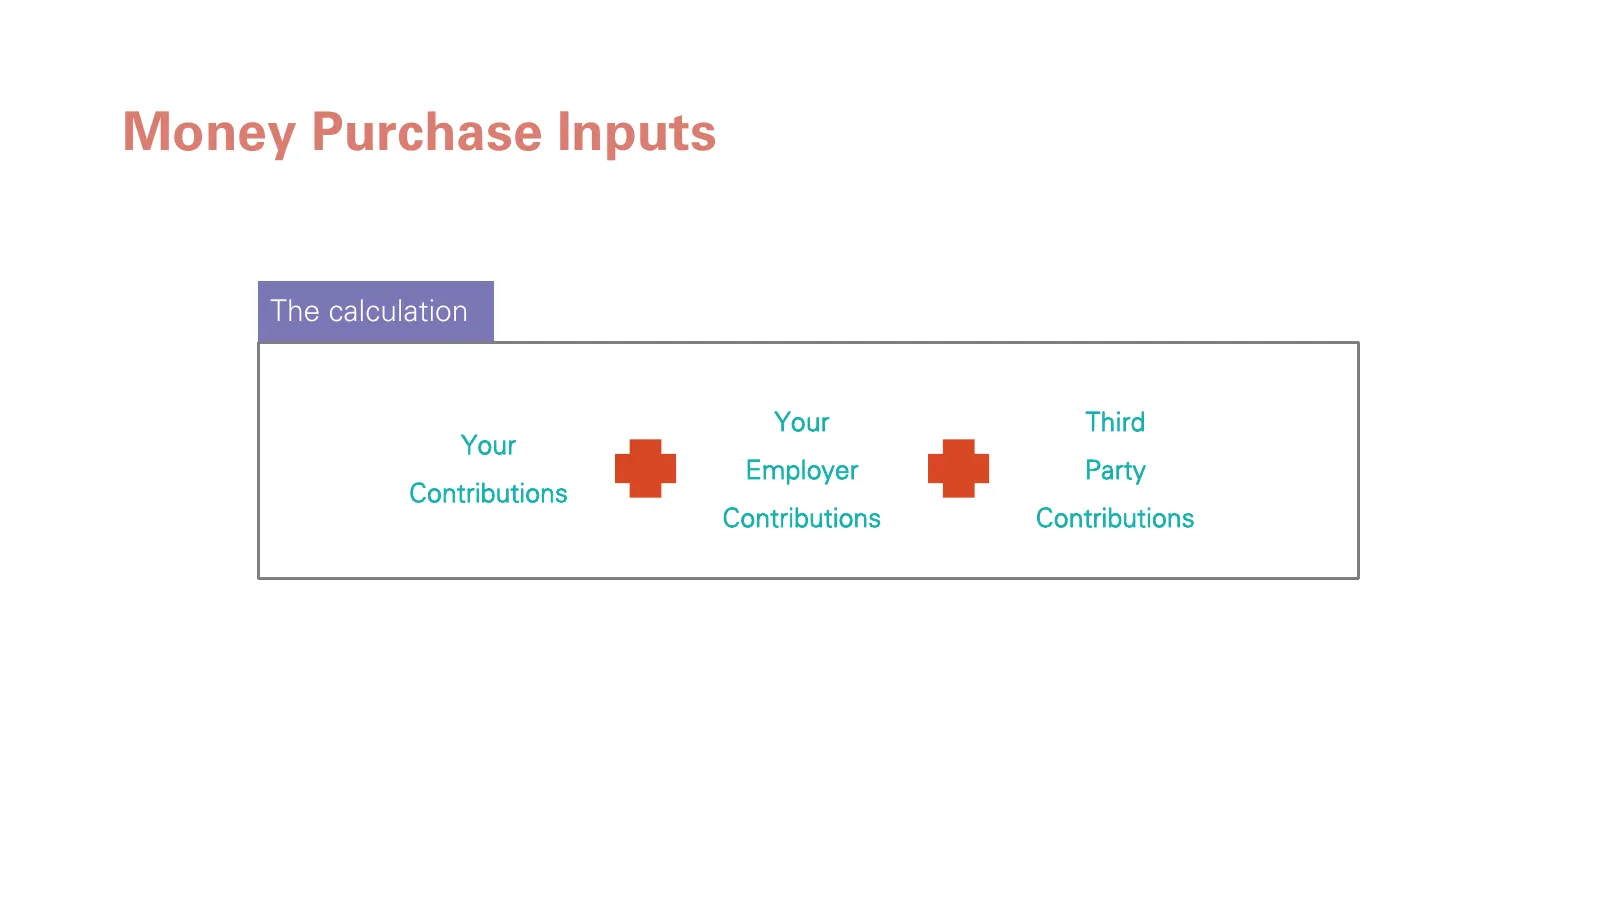
Money Purchase Inputs The calculation Your Third Your Employer Party Contributions Contributions Contributions
Slide 35: DB Inputs
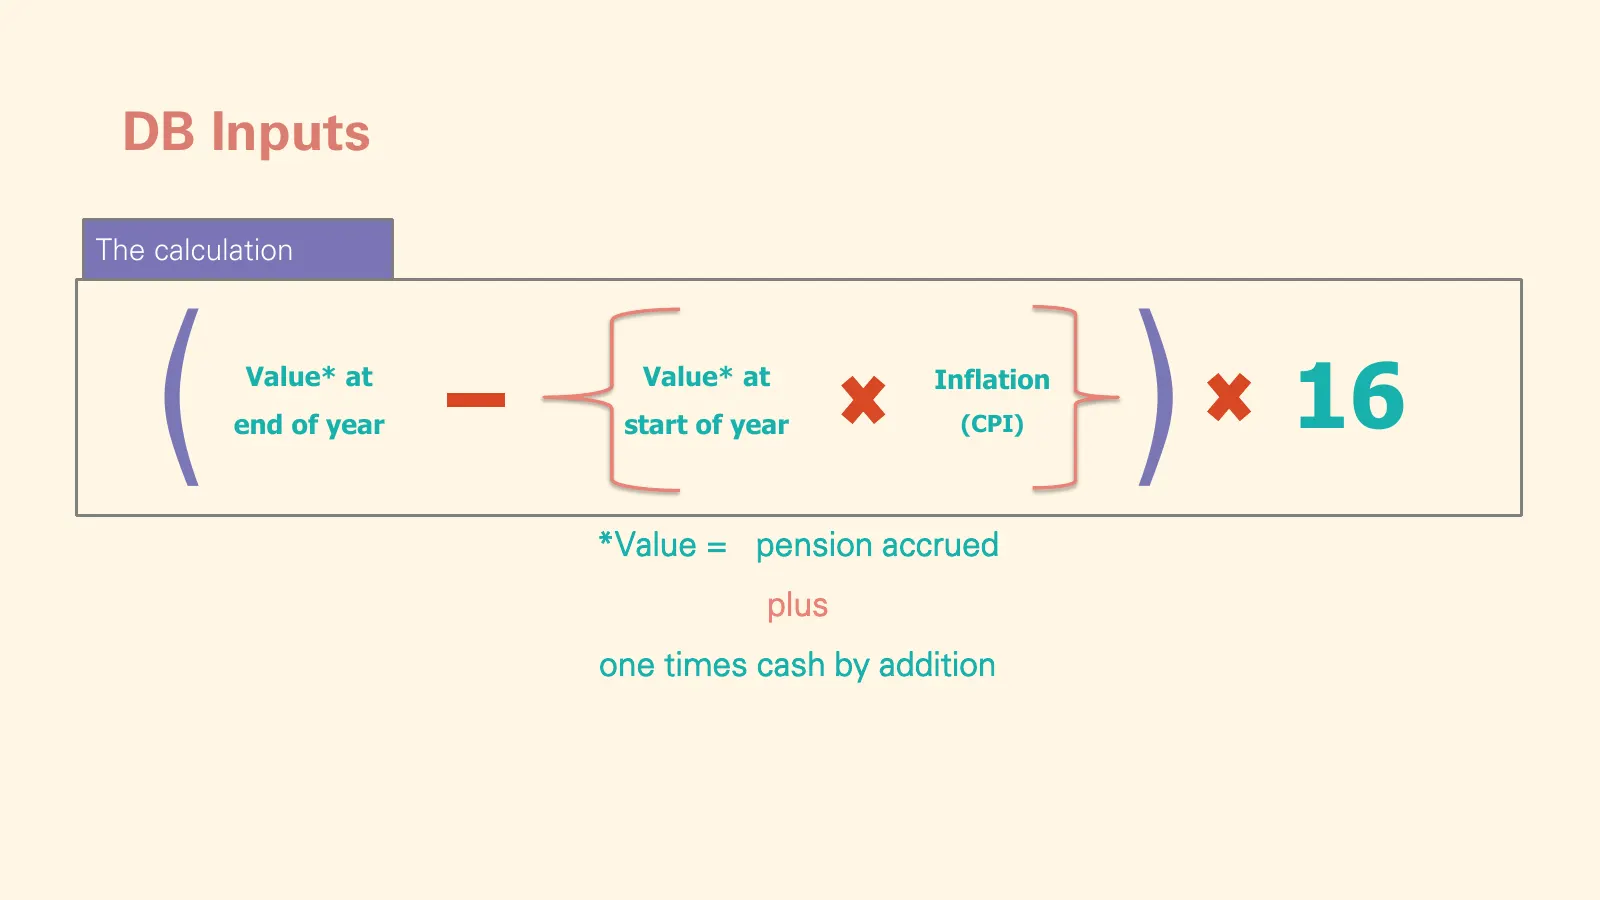
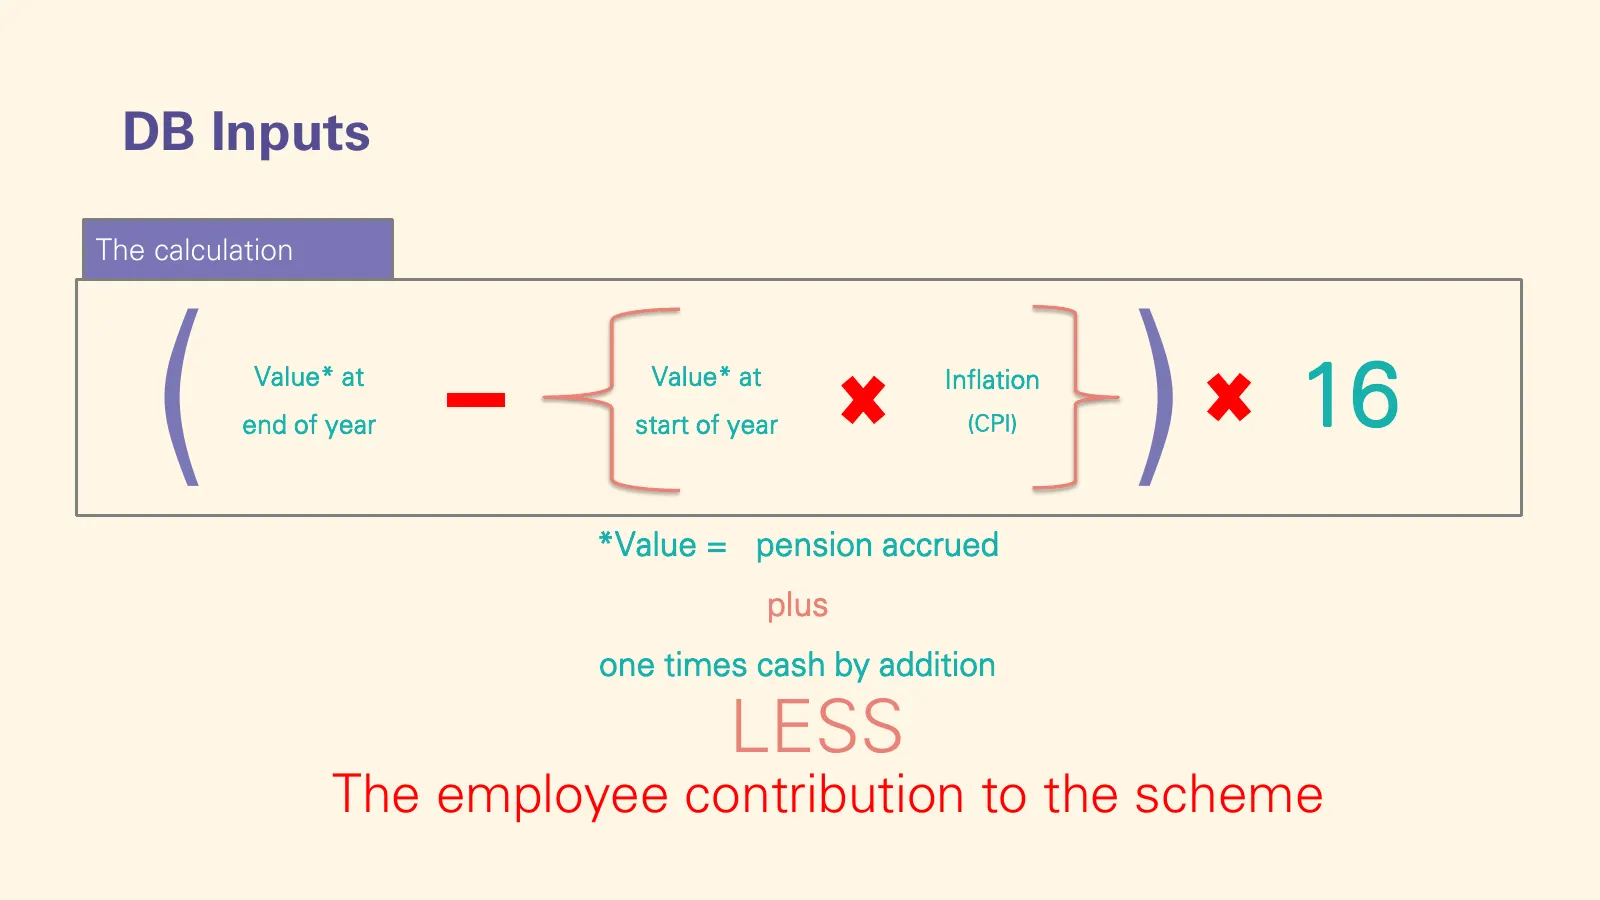
DB Inputs The calculation ( Value* at end of year Value* at start of year Inflation (CPI) *Value = pension accrued ) 16 plus one times cash by addition
Slide 36: Carry Forward Provisions
Carry Forward Provisions
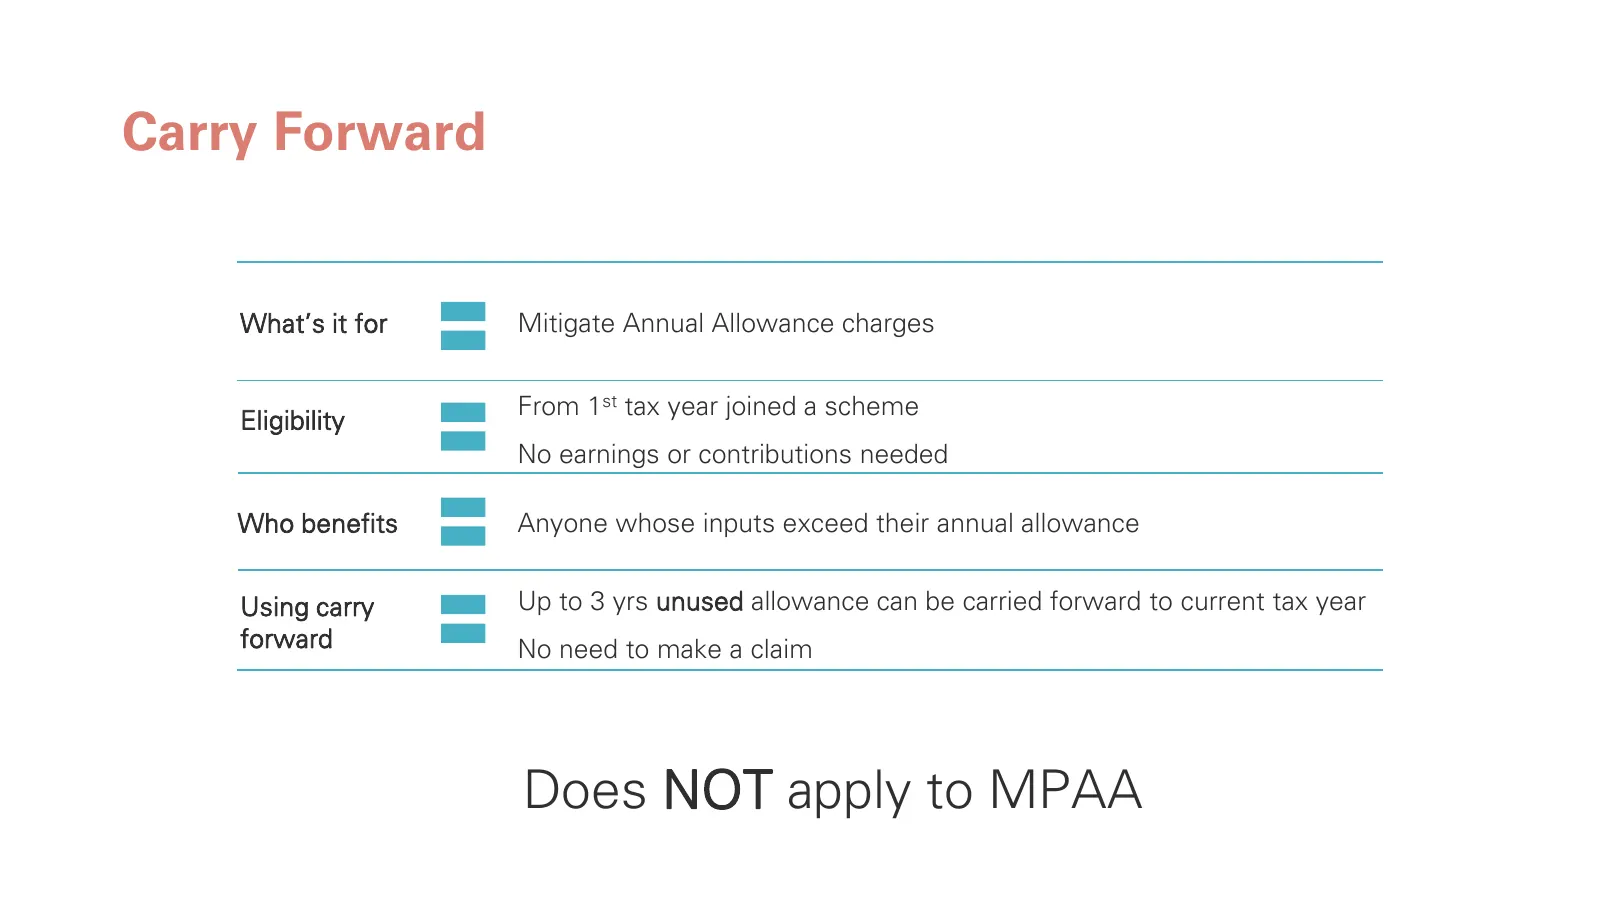
Slide 37: Carry Forward Does NOT apply to MPAA
Carry Forward What’s it for Mitigate Annual Allowance charges From 1st tax year joined a scheme Eligibility No earnings or contributions needed Who benefits Anyone whose inputs exceed their annual allowance Using carry Up to 3 yrs unused allowance can be carried forward to current tax year forward N
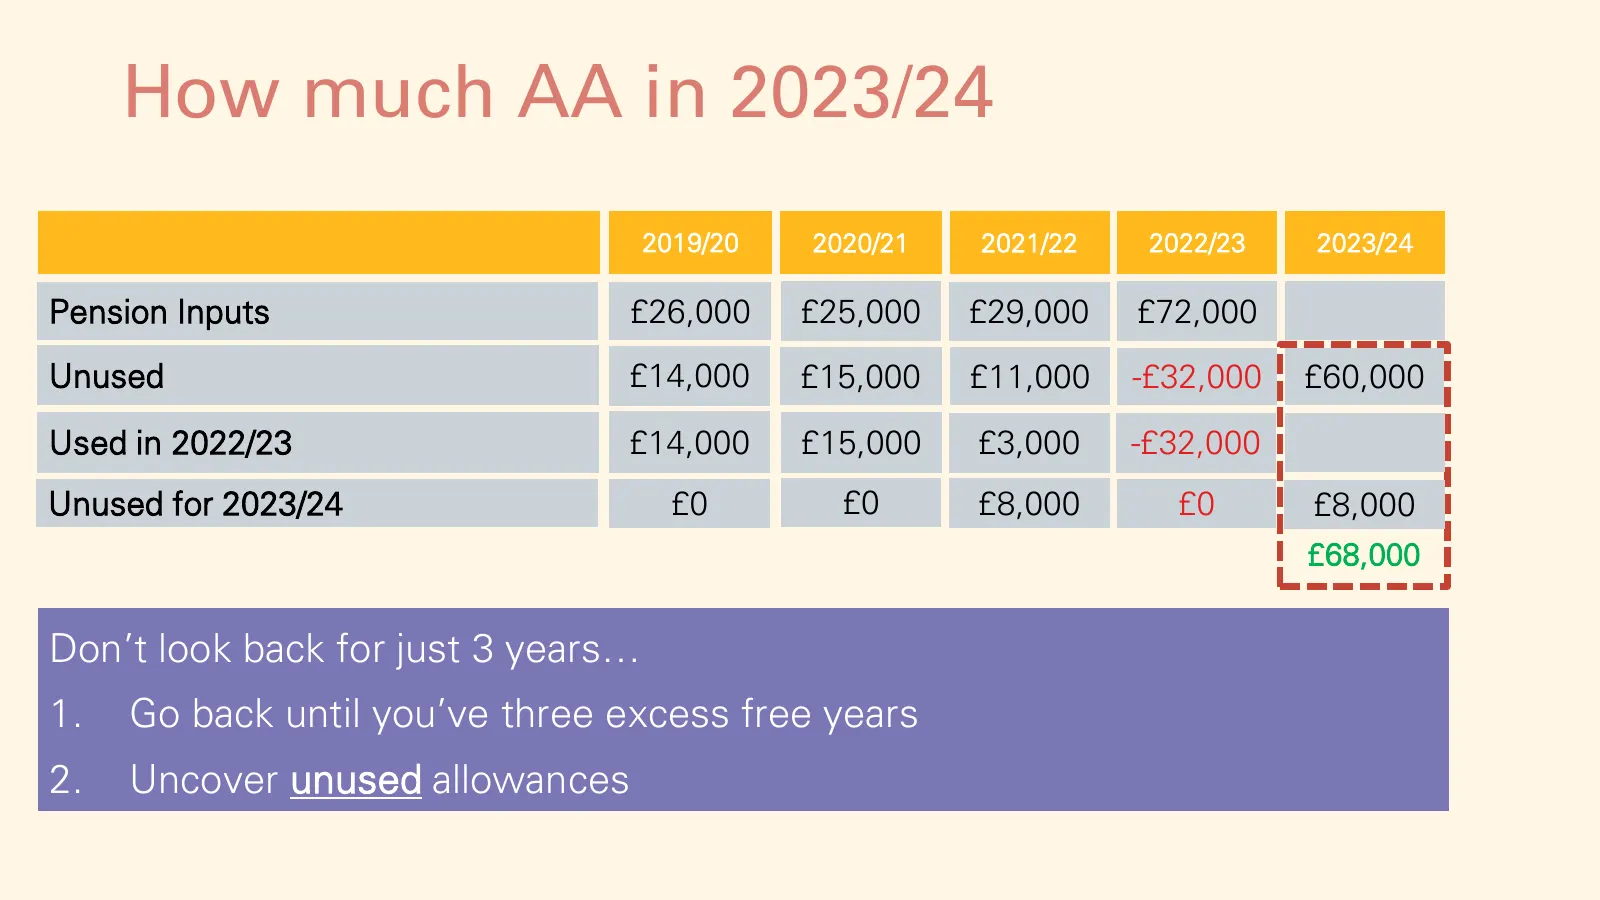
Slide 38: How much AA in 2023/24
How much AA in 2023/24 2019/20 2020/21 2021/22 2022/23 2023/24 Pension Inputs £26,000 £25,000 £29,000 £72,000 Unused £14,000 £15,000 £11,000 -£32,000 £60,000 Used in 2022/23 £14,000 £15,000 £3,000 -£32,000 Unused for 2023/24 £0 £0 £8,000 £0 £8,000 £68,000 Don’t look back for just 3 years… 1. Go back
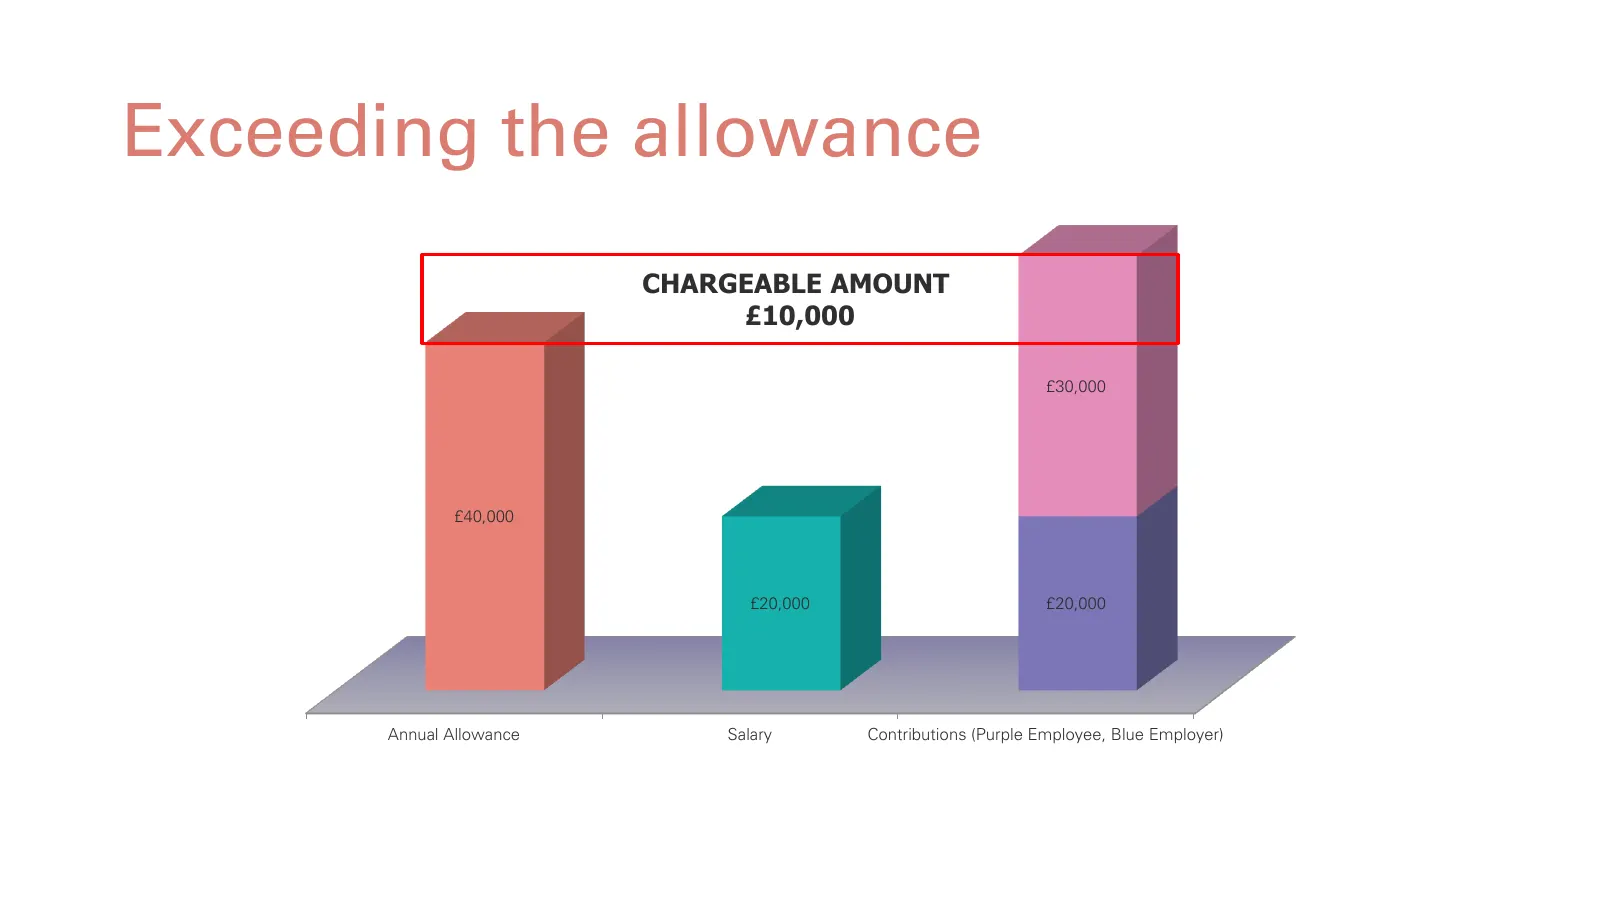
Slide 39: Exceeding the allowance
Exceeding the allowance CHARGEABLE AMOUNT £10,000 £30,000 £40,000 £20,000 £20,000 Annual Allowance Salary Contributions (Purple Employee, Blue Employer)
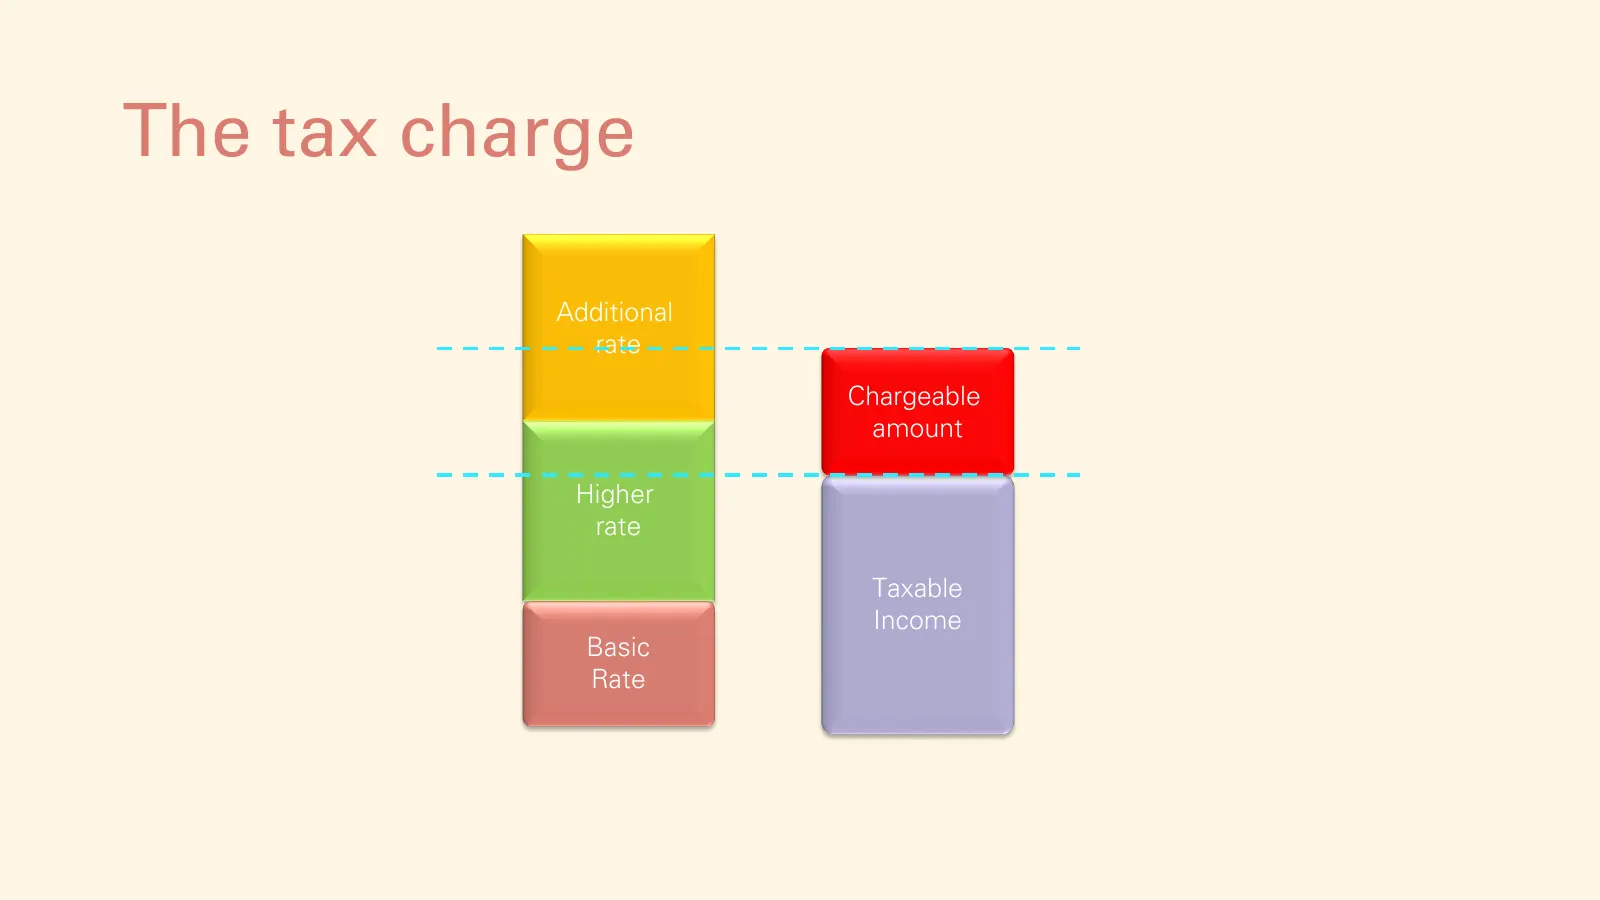
Slide 40: The tax charge
The tax charge Additional rate Chargeable amount Higher rate Taxable Income Basic Rate
Slide 41: Tapered Annual Allowance
Tapered Annual Allowance
Slide 42: Threshold Income & Adjusted Income
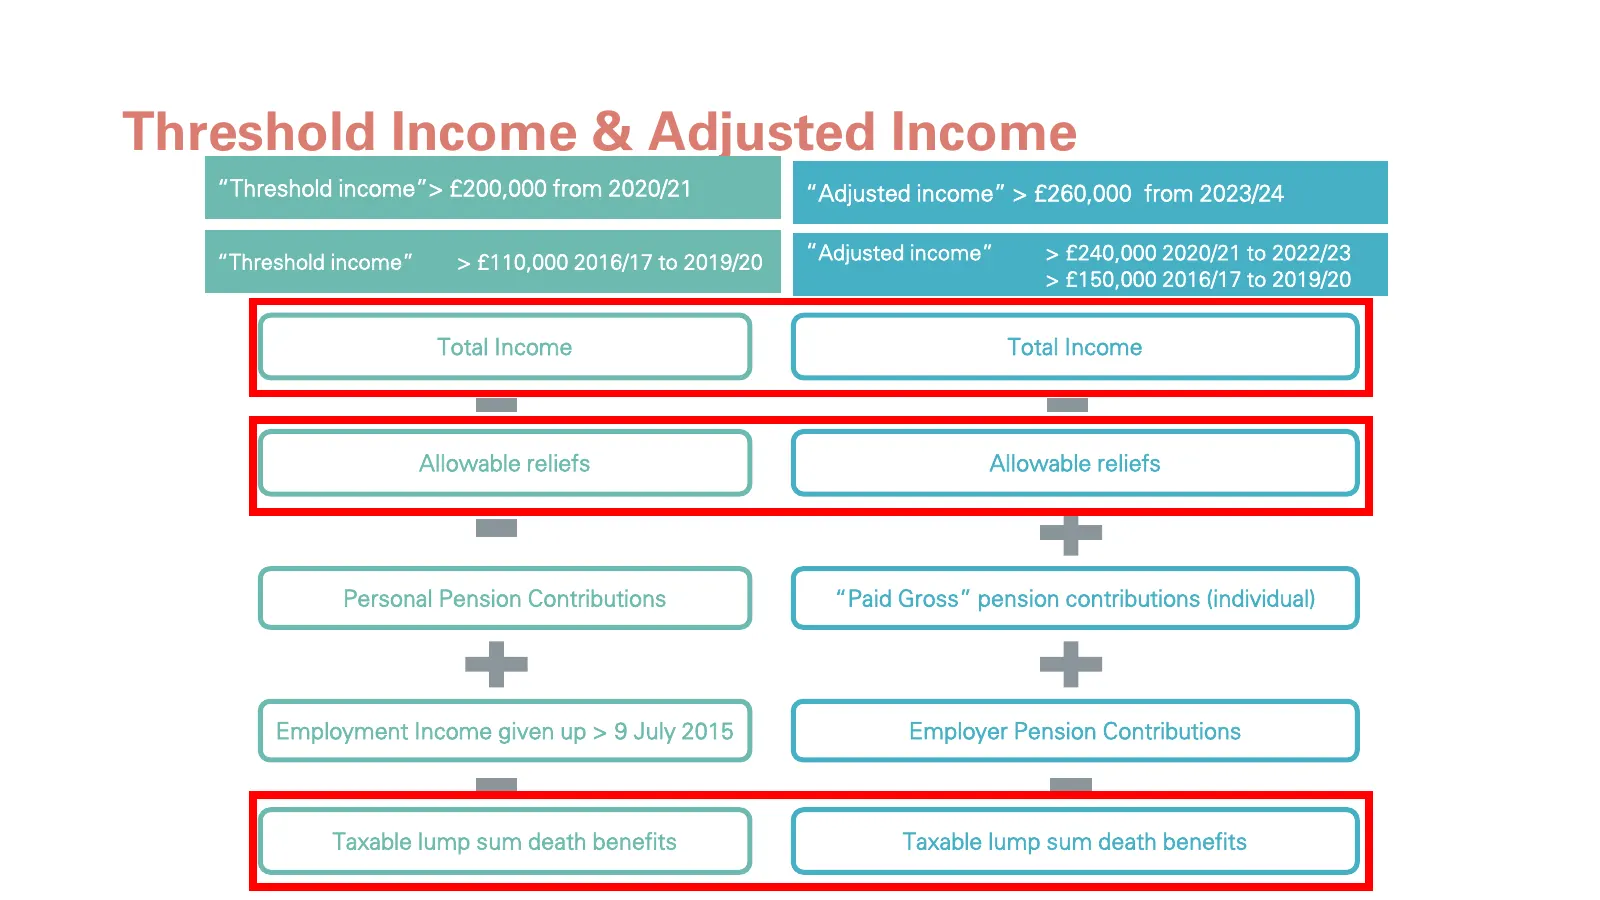
Threshold Income & Adjusted Income “Threshold income”> £200,000 from 2020/21 “Adjusted income” > £260,000 from 2023/24 “Threshold income” > £110,000 2016/17 to 2019/20 “Adjusted income” > £240,000 2020/21 to 2022/23 > £150,000 2016/17 to 2019/20 Total Income Total Income Allowable reliefs Allowable
Slide 43: What’s included in Total Income?
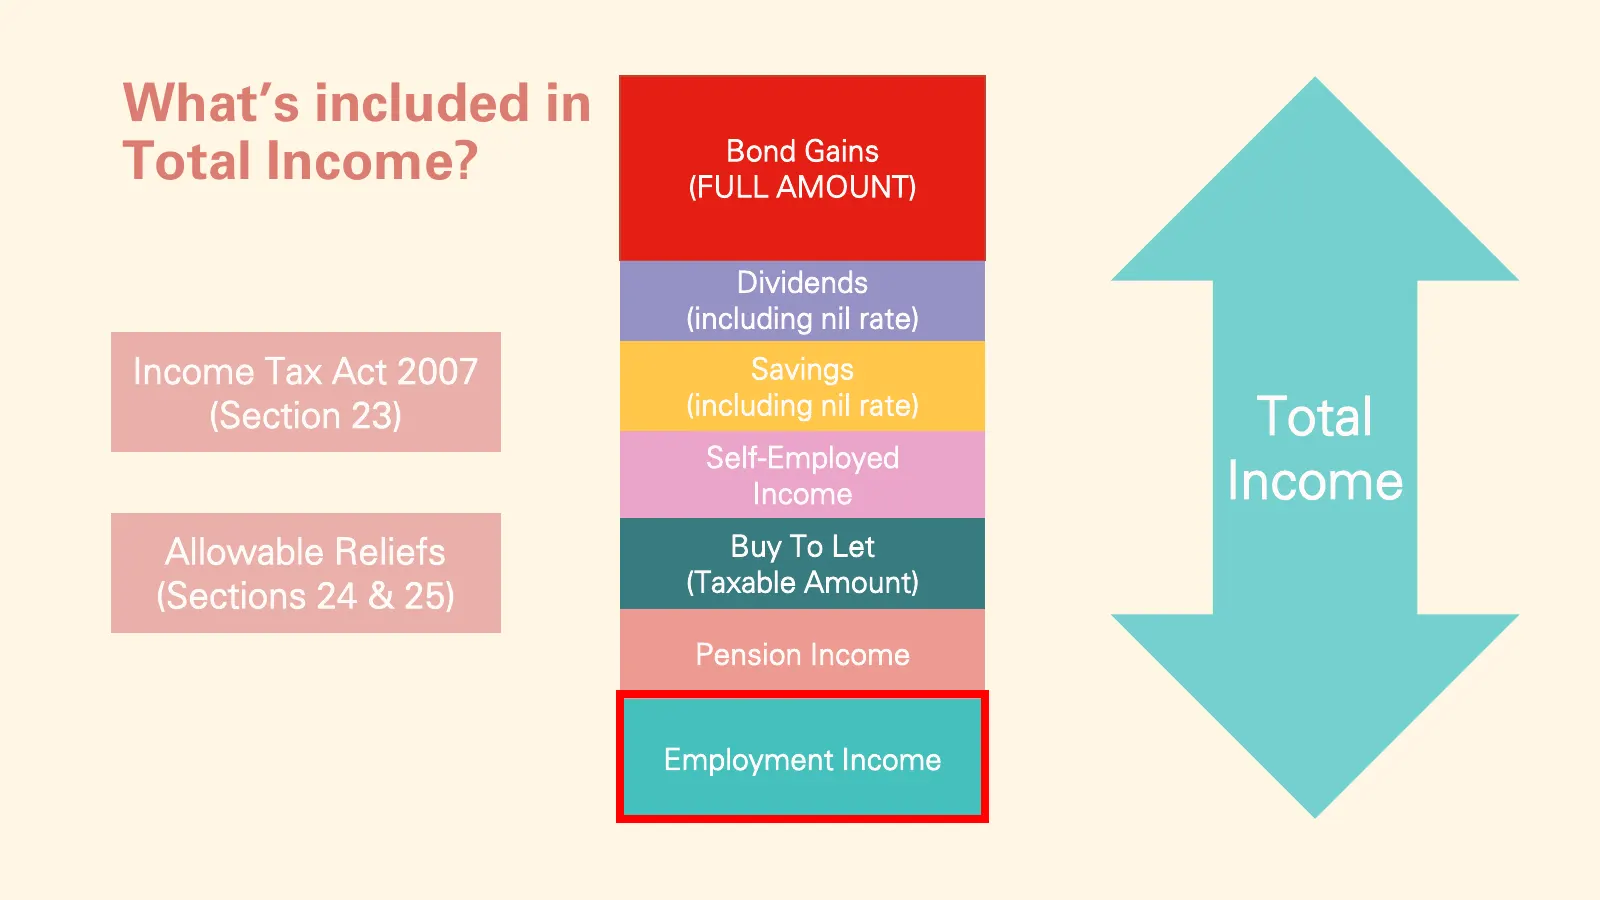
What’s included in Total Income? Bond Gains (FULL AMOUNT) Dividends (including nil rate) Income Tax Act 2007 Savings (Section 23) (including nil rate) Total Self-Employed Income Income Allowable Reliefs Buy To Let (Taxable Amount) (Sections 24 & 25) Pension Income Employment Income
Slide 44: So what do we use?
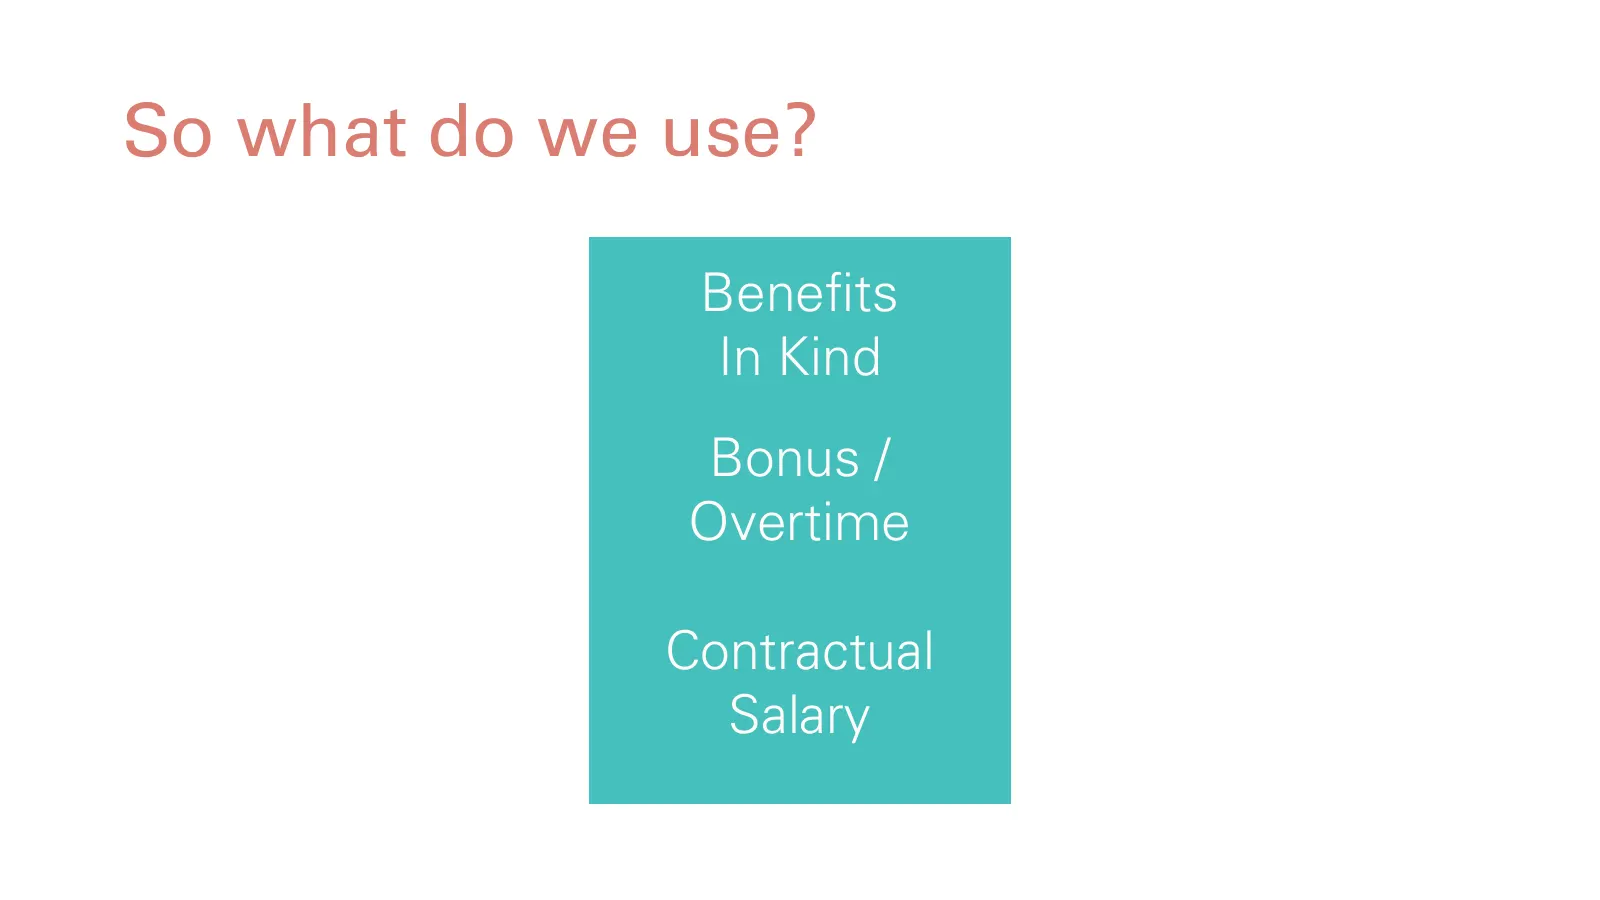
So what do we use? Benefits In Kind Bonus / Overtime Contractual Salary
Slide 45: So what do we use?
So what do we use? Benefits In Kind Bonus / Overtime Contractual Salary
Slide 46: So what do we use?
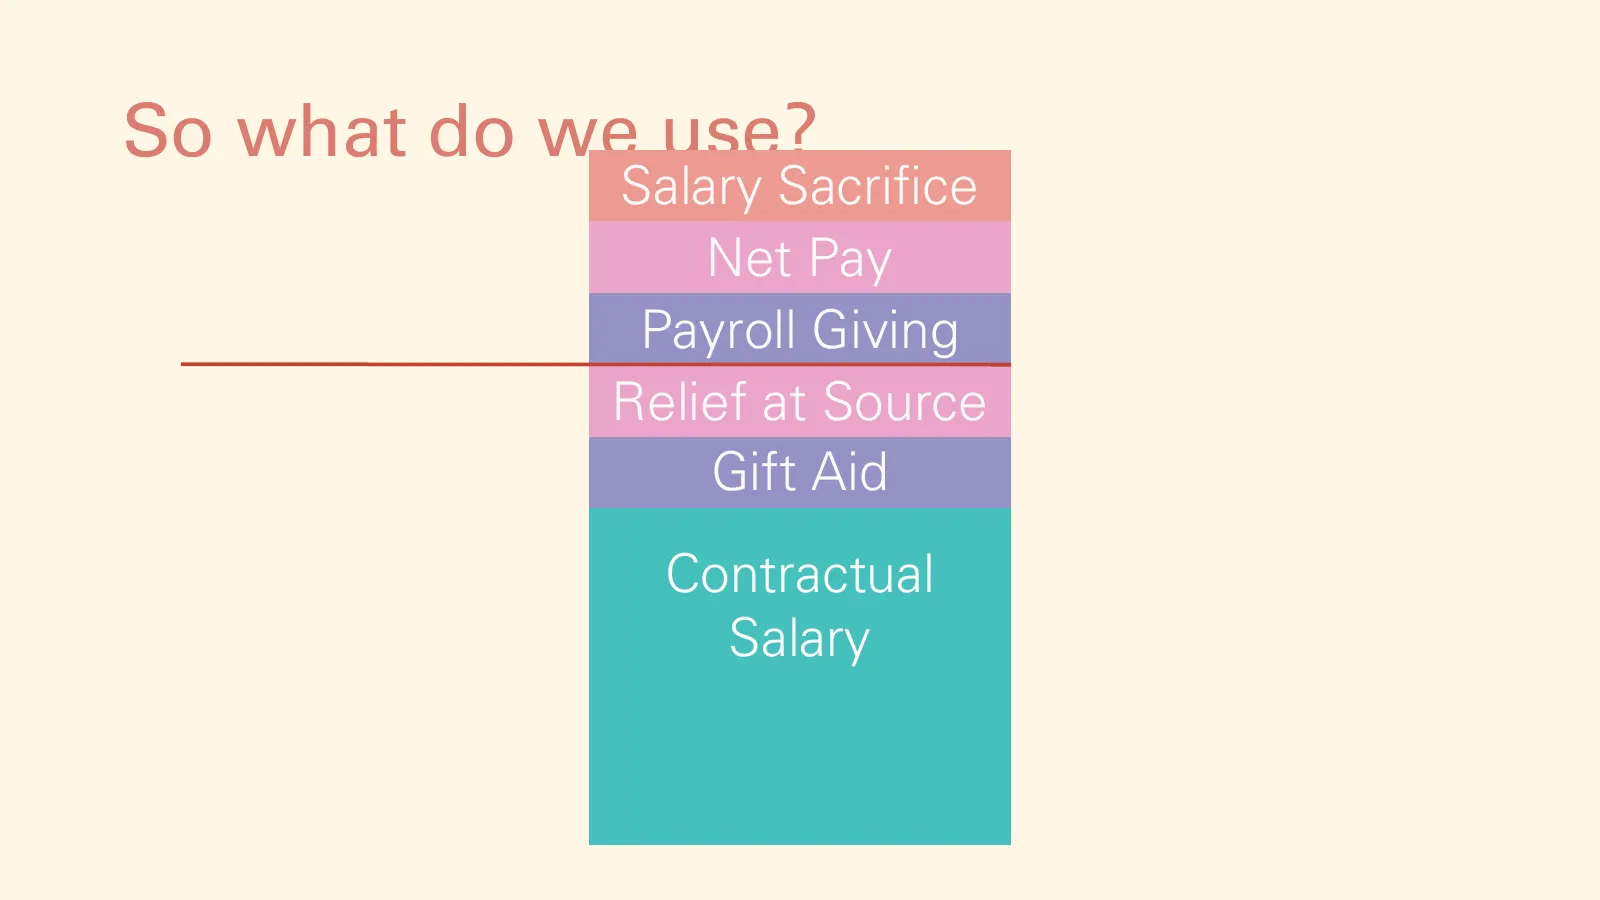
So what do we use? Salary Sacrifice Net Pay Payroll Giving Relief at Source Gift Aid Contractual Salary
Slide 47: What figure do you use for employer contributions?
What figure do you use for employer contributions?
Slide 48: Money Purchase Inputs
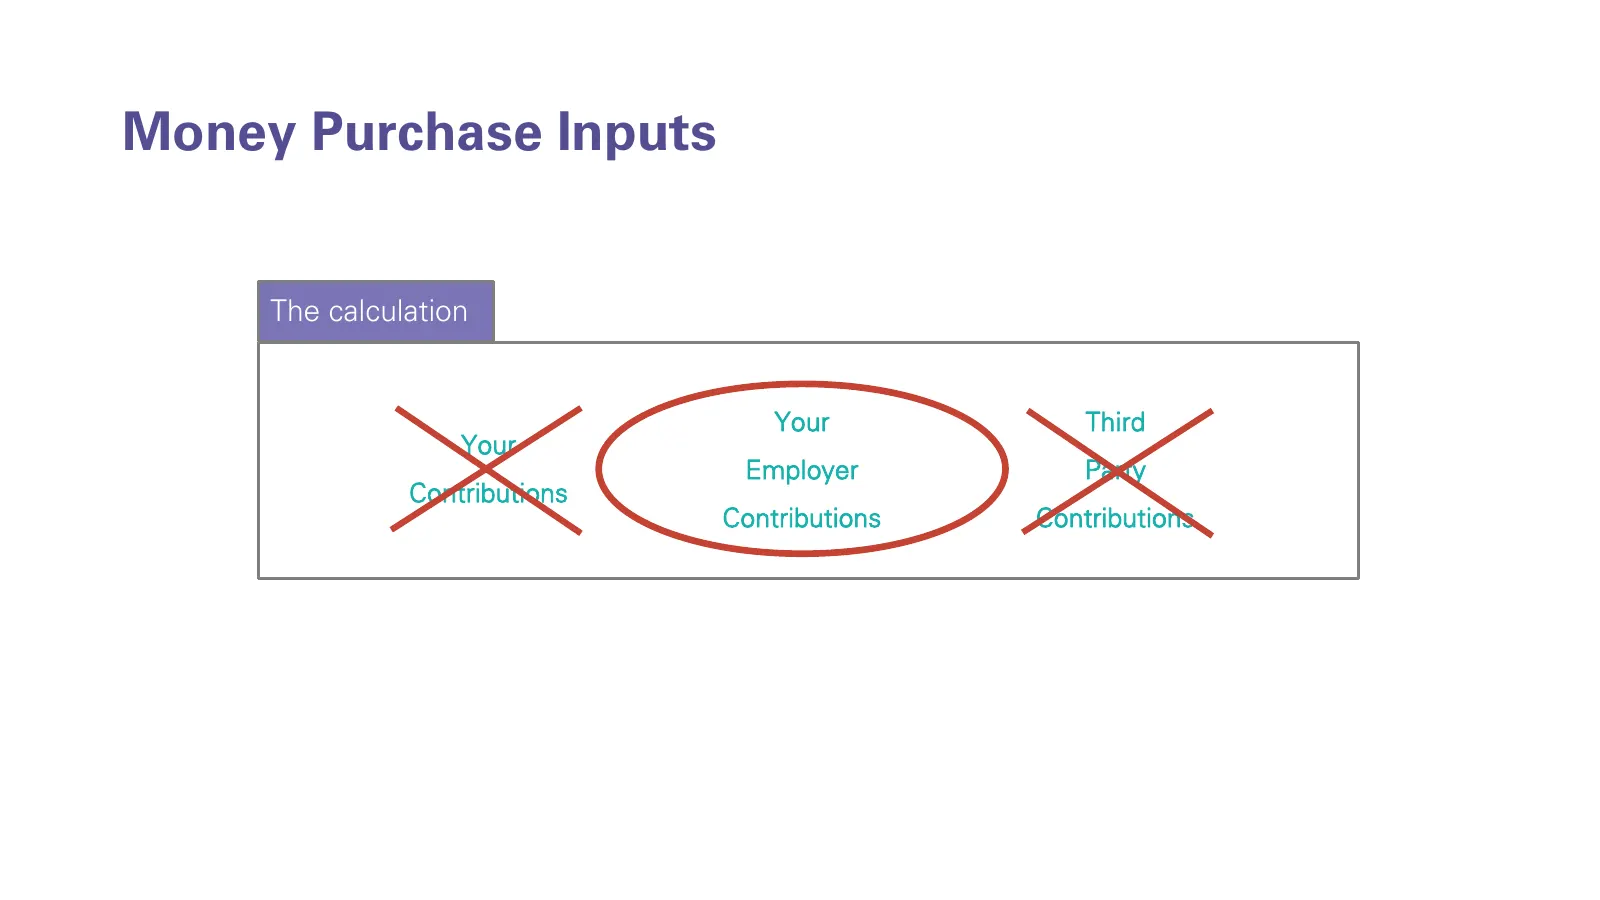
Money Purchase Inputs The calculation Your Third Your Employer Party Contributions Contributions Contributions
Slide 49: DB Inputs
DB Inputs The calculation ( Value* at end of year Value* at start of year Inflation *Value = pension accrued (CPI) ) 16 plus one times cash by addition LESS The employee contribution to the scheme
Slide 50: The Easy Way: Tapered Annual Allowance Calculator
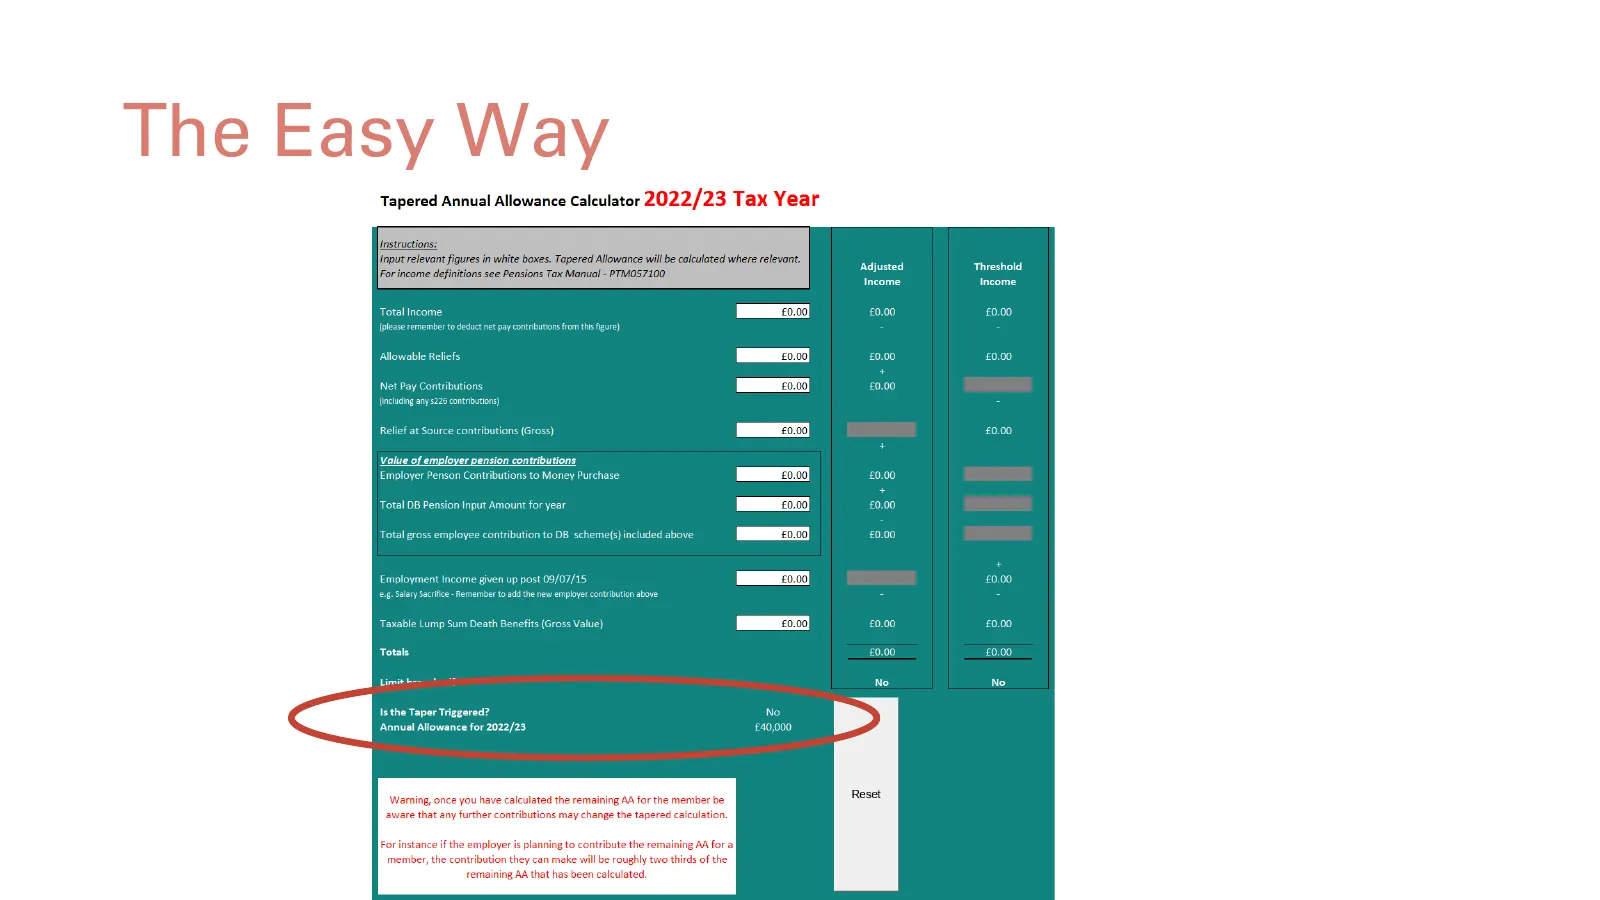
Tapered Annual Allowance Calculator instructions: input relevant figures in white boxes. Topered Allowance will be calculated where relevont. For income definitions see Pensions Tax Manuel - PTMO57100 a Threshold Income Income Total Income 0.00 £0.00 Allowabl £0.00 £0.00 Net Pay Contribution 0.00 (e
Slide 51: Planning
Planning
Slide 52: Case study: Peter
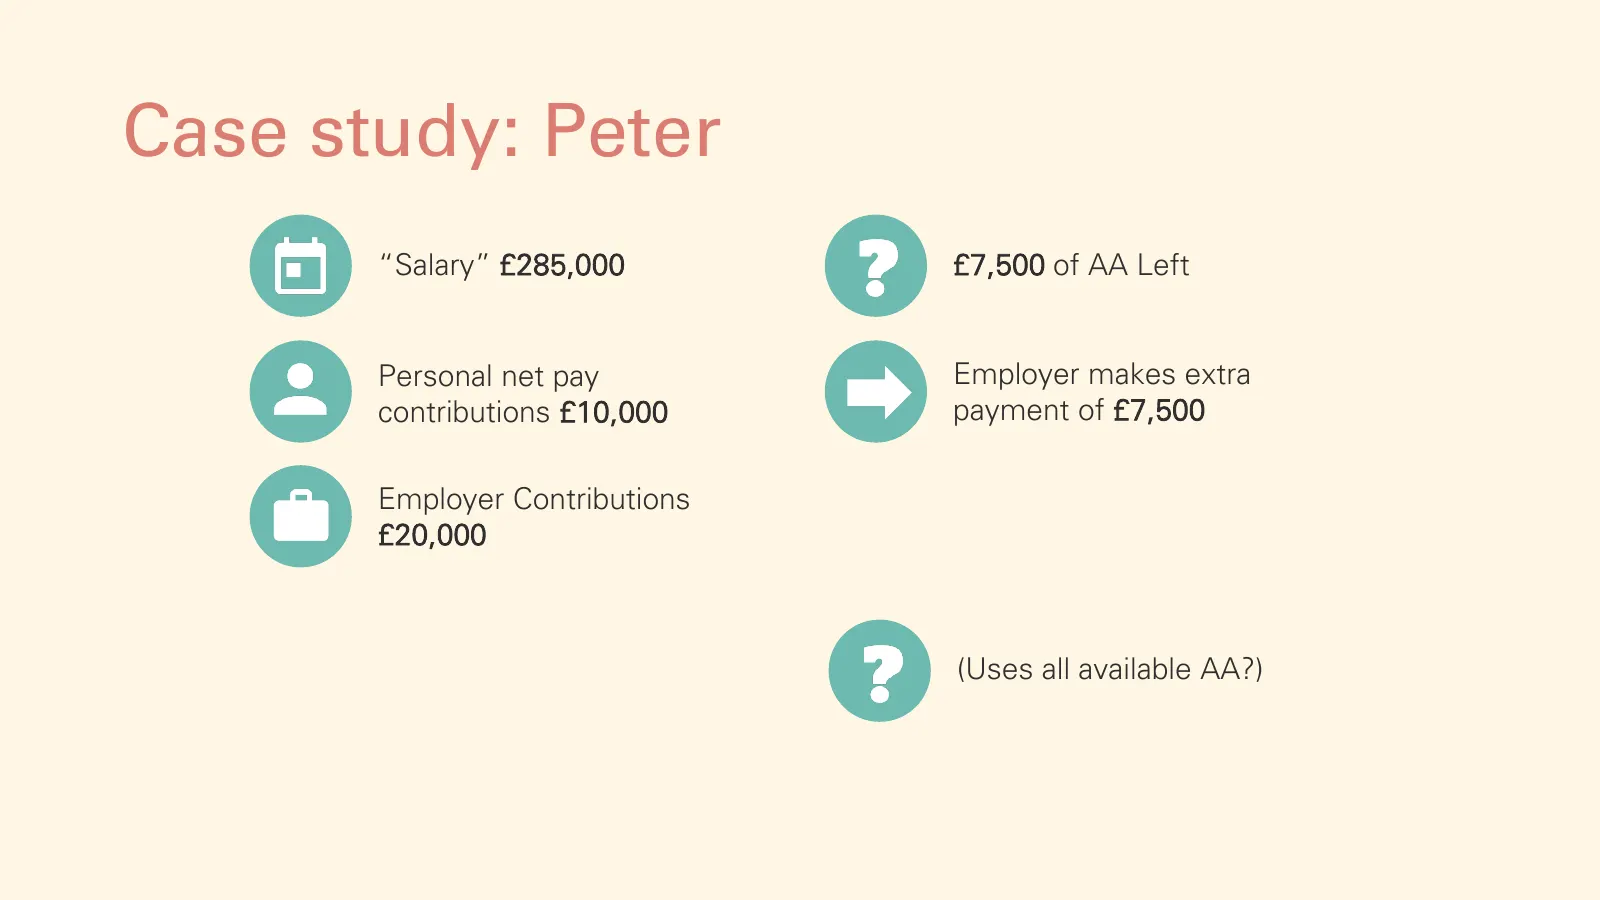
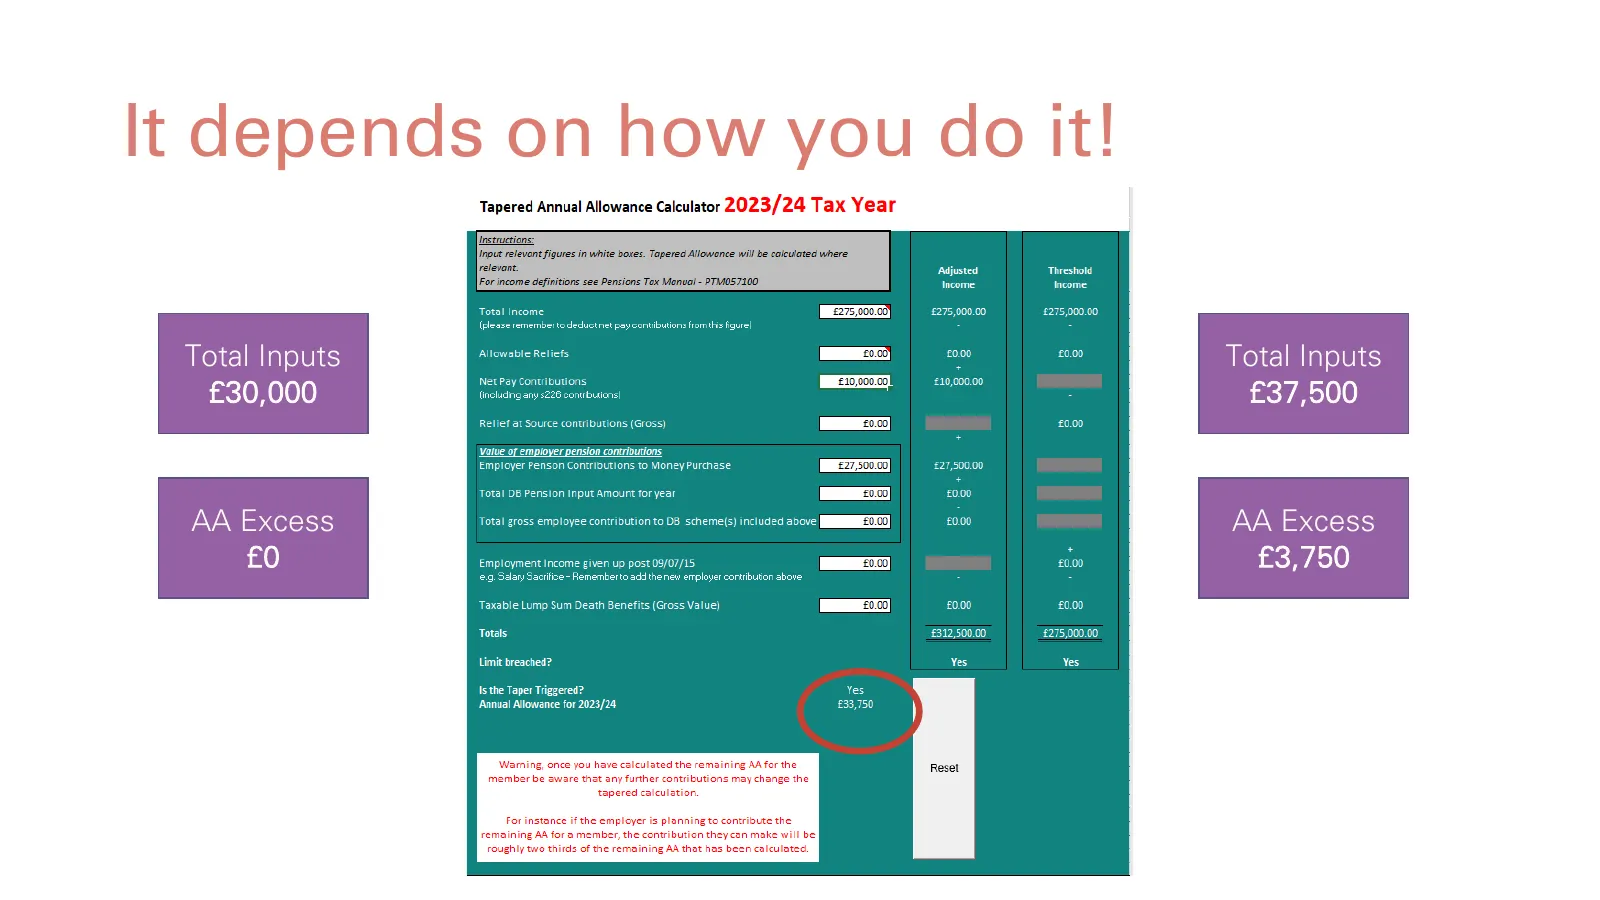
Case study: Peter “Salary” £285,000 £7,500 of AA Left Personal net pay Employer makes extra contributions £10,000 payment of £7,500 Employer Contributions £20,000 (Uses all available AA?)
Slide 53: It depends on how you do it!
It depends on how you do it! Total Inputs Total Inputs £30,000 £37,500 AA Excess AA Excess £0 £3,750
Slide 54: Case Study: Peter
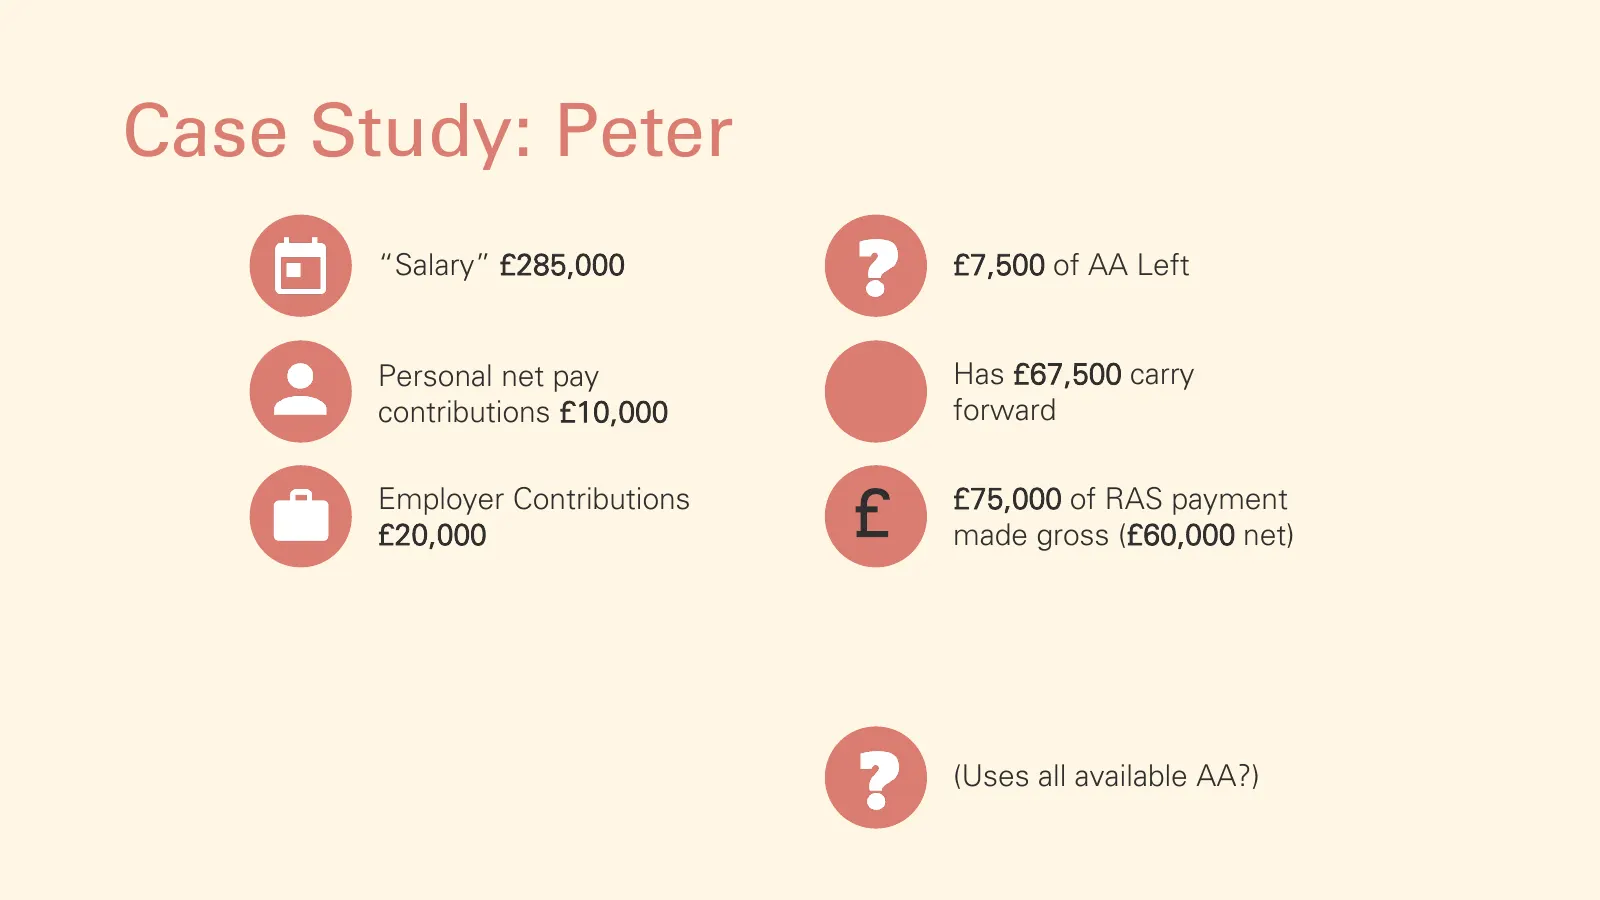
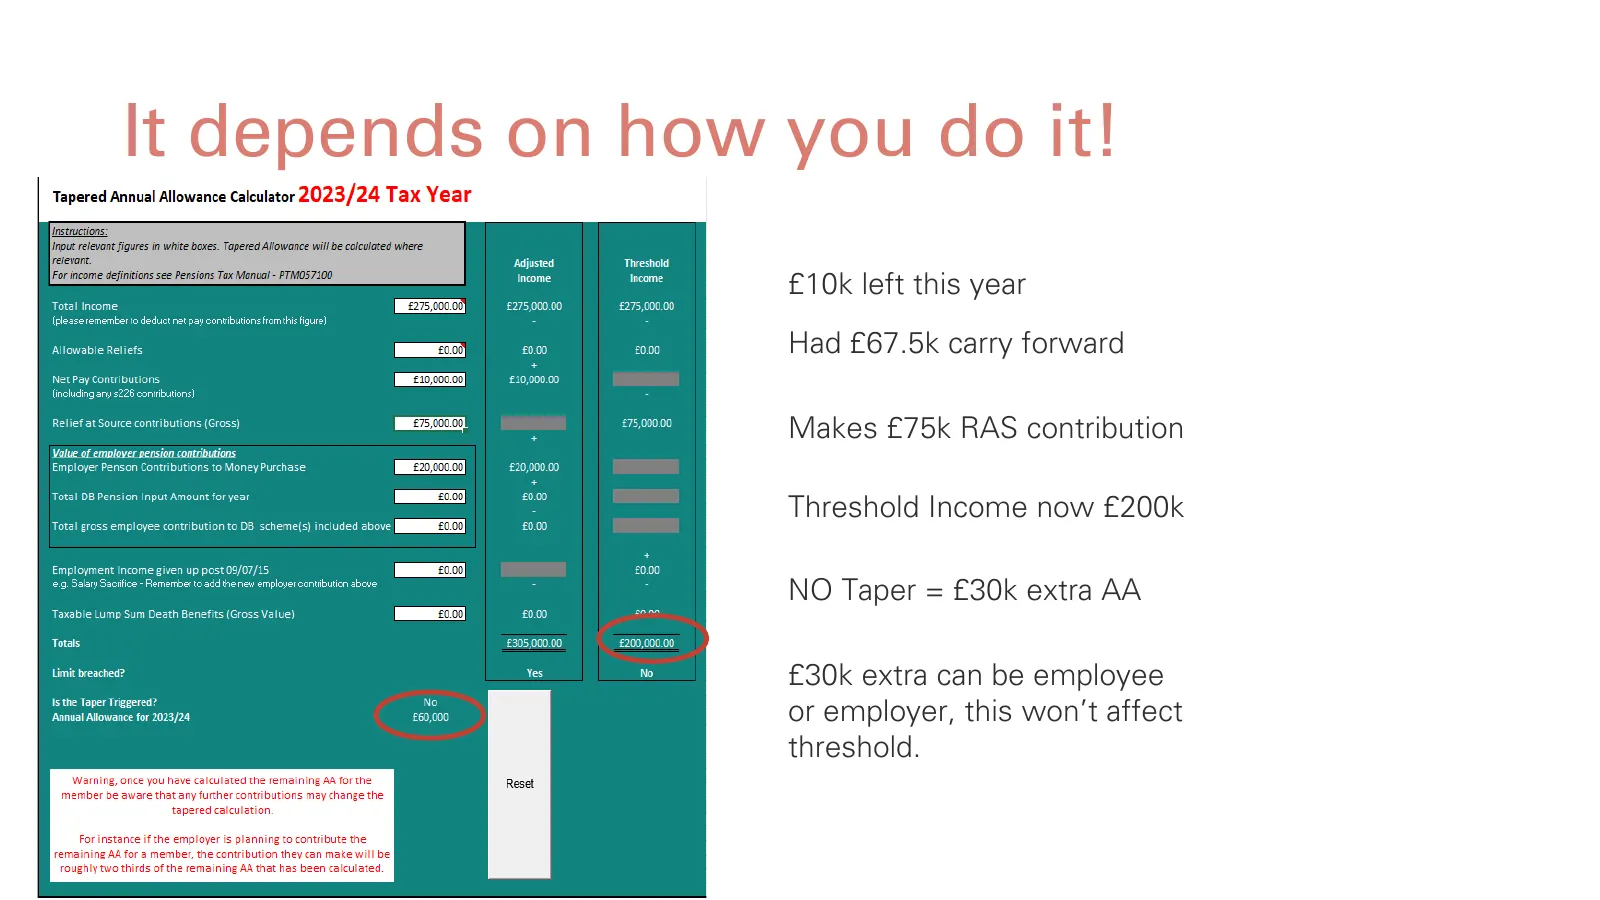
Case Study: Peter “Salary” £285,000 £7,500 of AA Left Personal net pay Has £67,500 carry contributions £10,000 forward Employer Contributions £20,000 £ £75,000 of RAS payment made gross (£60,000 net) (Uses all available AA?)
Slide 55: It depends on how you do it!
It depends on how you do it! £10k left this year Had £67.5k carry forward Makes £75k RAS contribution Threshold Income now £200k NO Taper = £30k extra AA £30k extra can be employee or employer, this won’t affect threshold.
Slide 56: If only there was an easy way to do this…
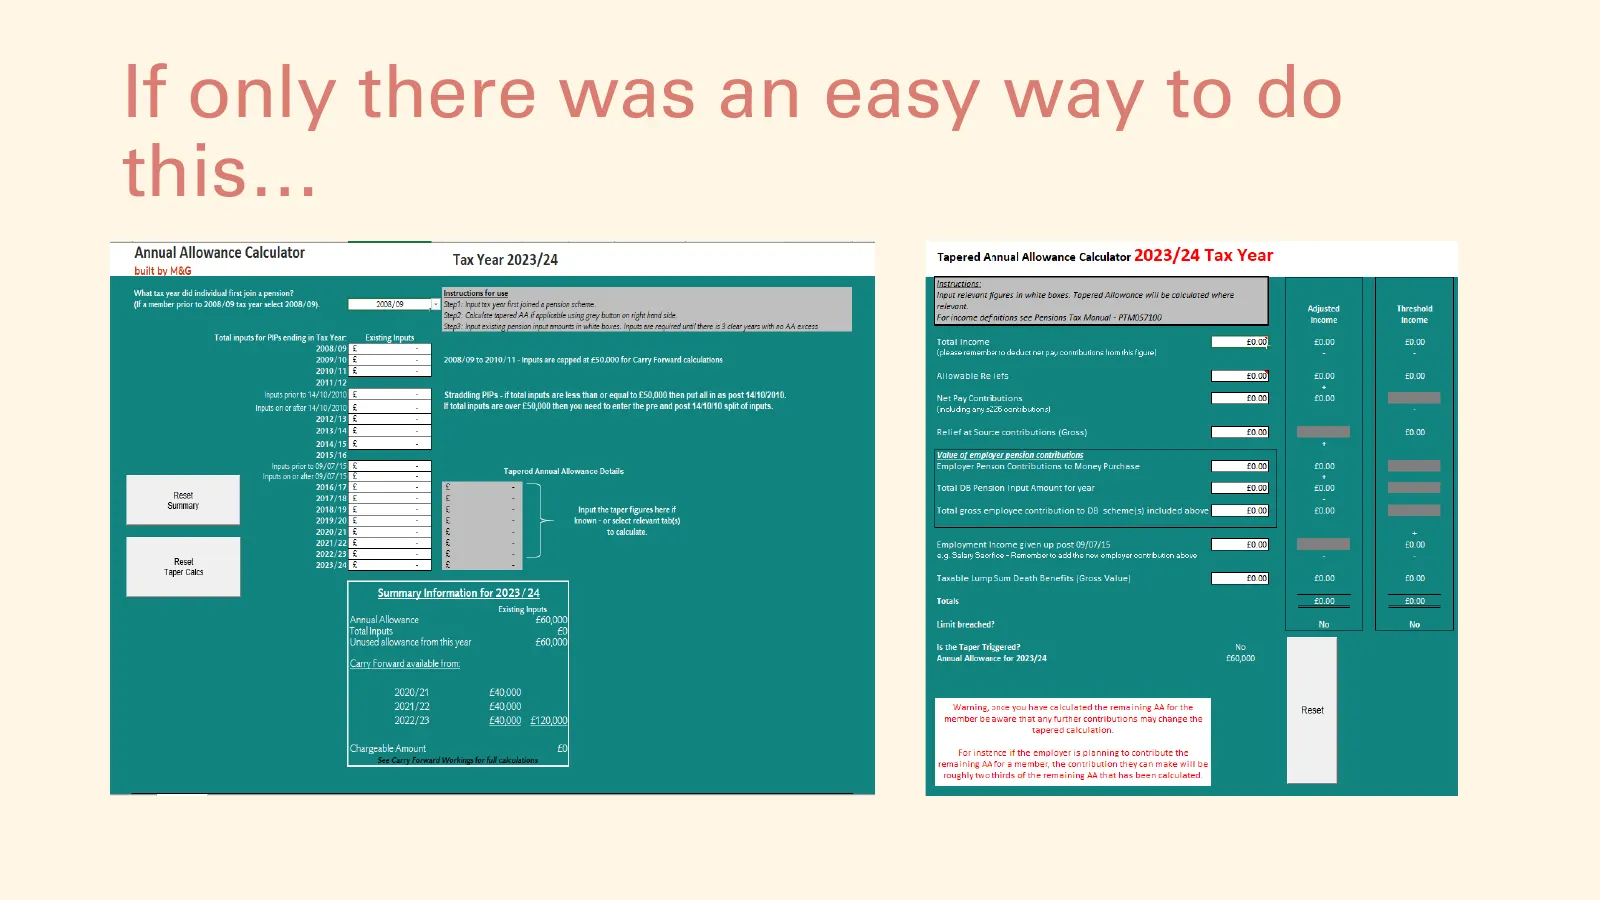
If only there was an easy way to do this…
Slide 57: LETS GO LIVE.
LETS GO LIVE.
Slide 58: Learning Objectives
Learning Objectives By the end of this session you will be able to: Demonstrate the Understand the inputs required for theory for using the using the Extracting Extracting Company Profits Company Profits and Annual and Annual Allowance tools Allowance tools
Slide 59: Support
Support Articles Videos Tools & Ask the Techs Calculators
Slide 60: Thanks for your time
Thanks for your time Get in touch with your usual contact if you need further help.
Slide 61: M&G plc company information
M&G plc is a company incorporated and with its principal place of business in England, and its affiliated companies constitute a leading savings and investments business. M&G plc is the direct parent company of The Prudential Assurance Company Limited. The Prudential Assurance Company Limited is not
Source: company website
More decks from M&G PLC
 Q2 2026 Earnings Presentation54 slides · Sep 2, 2026
 M&G Wealth — M&G MPS Webinar (May 2026)24 slides · May 2026
 FY2025 Earnings Presentation59 slides · Mar 12, 2026
 H1 2025 Earnings Presentation51 slides · Sep 3, 2025
 Investor Presentation (August 2025)58 slides · August 2025
 Merger or Acquisition (May 2025)9 slides · May 30, 2025