Durr AG · XETR:DUE
Durr — H1 2012 Earnings Presentation
22 slides from Durr's earnings presentation, Aug 1, 2012
Slide 1: Conference Call: Results January - June 2012 Dürr Group
Conference Call Results January - June 2012 Dürr Group Ralf W. Dieter, CEO Ralph Heuwing, CFO Bietigheim-Bissingen, August 1, 2012 www.durr.com -1-
Slide 2: Disclaimer
Disclaimer This presentation has been prepared independently by Dürr AG (“Dürr”). The presentation contains statements which address such key issues as Dürr´s strategy, future financial results, market positions and product development. Such statements should be carefully considered, and it should b
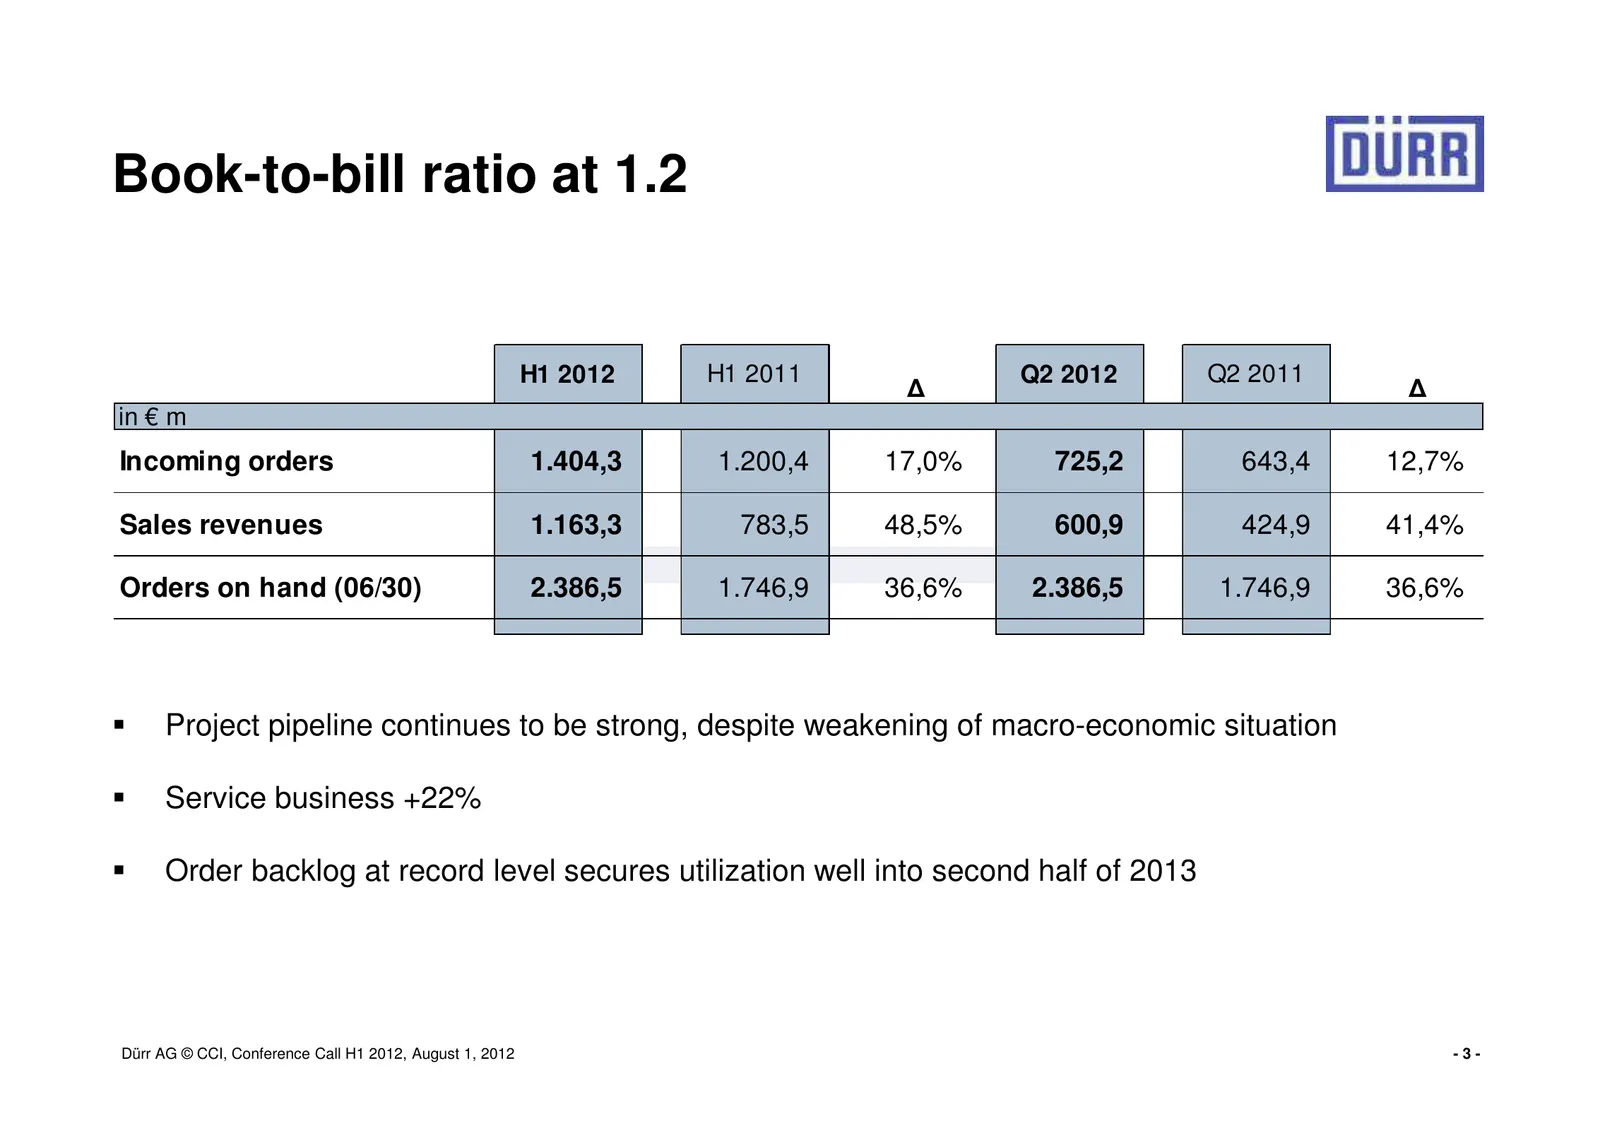
Slide 3: Book-to-bill ratio at 1.2
Book-to-bill ratio at 1.2 H1 2012 H1 2011 Q2 2012 Q2 2011 ∆ ∆ in € m Incoming orders 1.404,3 1.200,4 17,0% 725,2 643,4 12,7% Sales revenues 1.163,3 783,5 48,5% 600,9 424,9 41,4% Orders on hand (06/30) 2.386,5 1.746,9 36,6% 2.386,5 1.746,9 36,6% Project pipeline continues to be strong, despite weaken
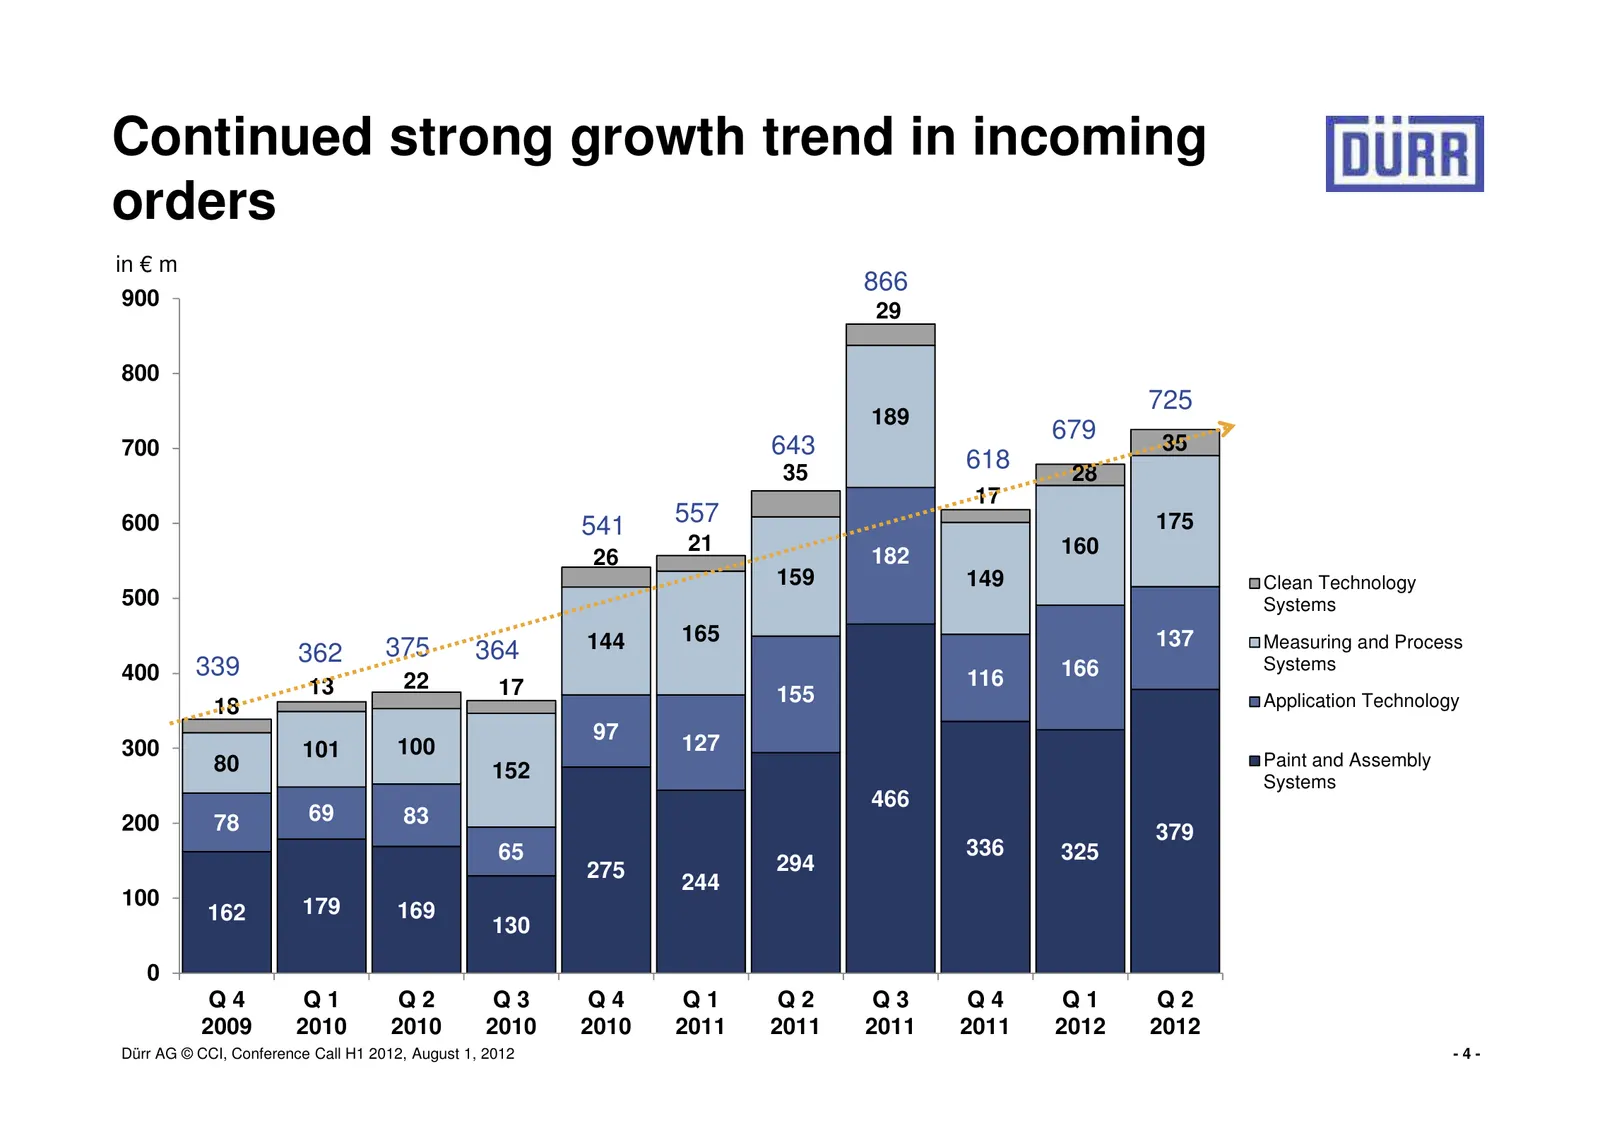
Slide 4: Continued strong growth trend in incoming orders
Continued strong growth trend in incoming orders in € m 866 900 29 800 725 189 679 35 700 643 35 618 28 17 600 541 557 175 21 160 26 182 159 149 Clean Technology 500 Systems 144 165 137 Measuring and Process 362 375 364 400 339 116 166 Systems 13 22 17 155 Application Technology 18 97 300 101 100 12
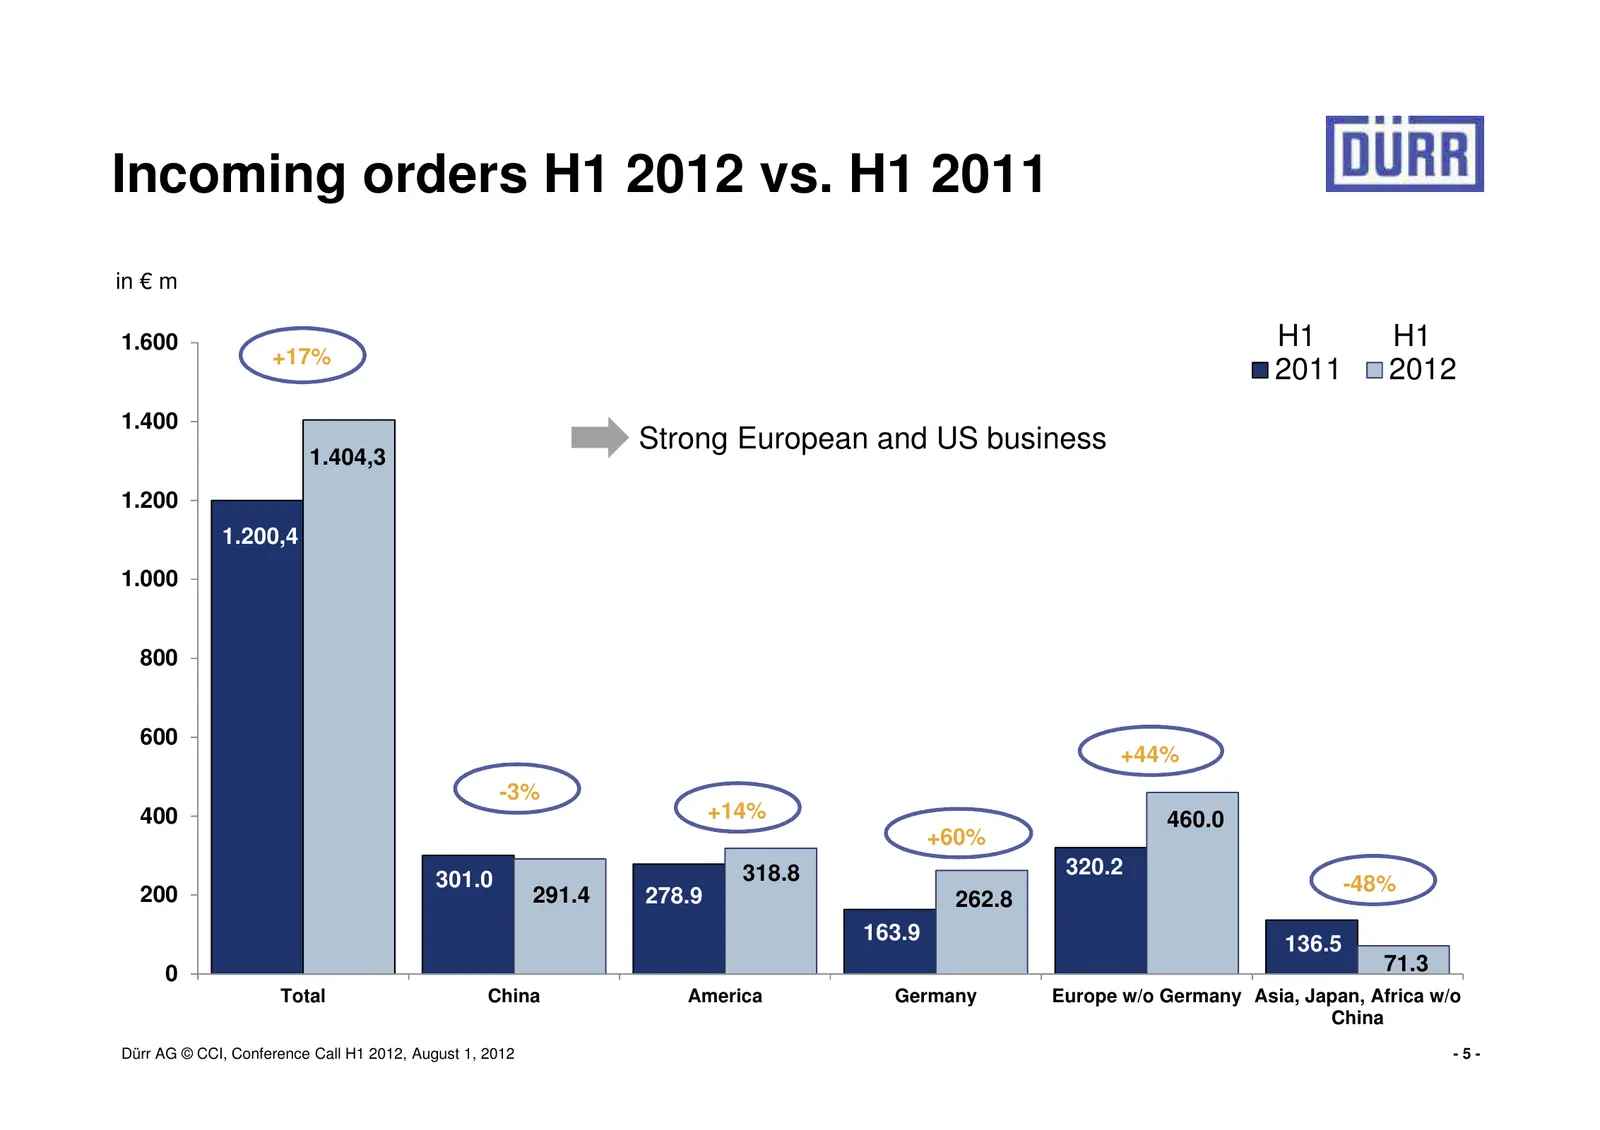
Slide 5: Incoming orders H1 2012 vs. H1 2011
Incoming orders H1 2012 vs. H1 2011 in € m 1.600 H1 H1 +17% 2011 2012 1.400 Strong European and US business 1.404,3 1.200 1.200,4 1.000 800 600 +44% -3% 400 +14% 460.0 +60% 318.8 320.2 301.0 -48% 200 291.4 278.9 262.8 163.9 136.5 0 71.3 Total China America Germany Europe w/o Germany Asia, Japan, Afr
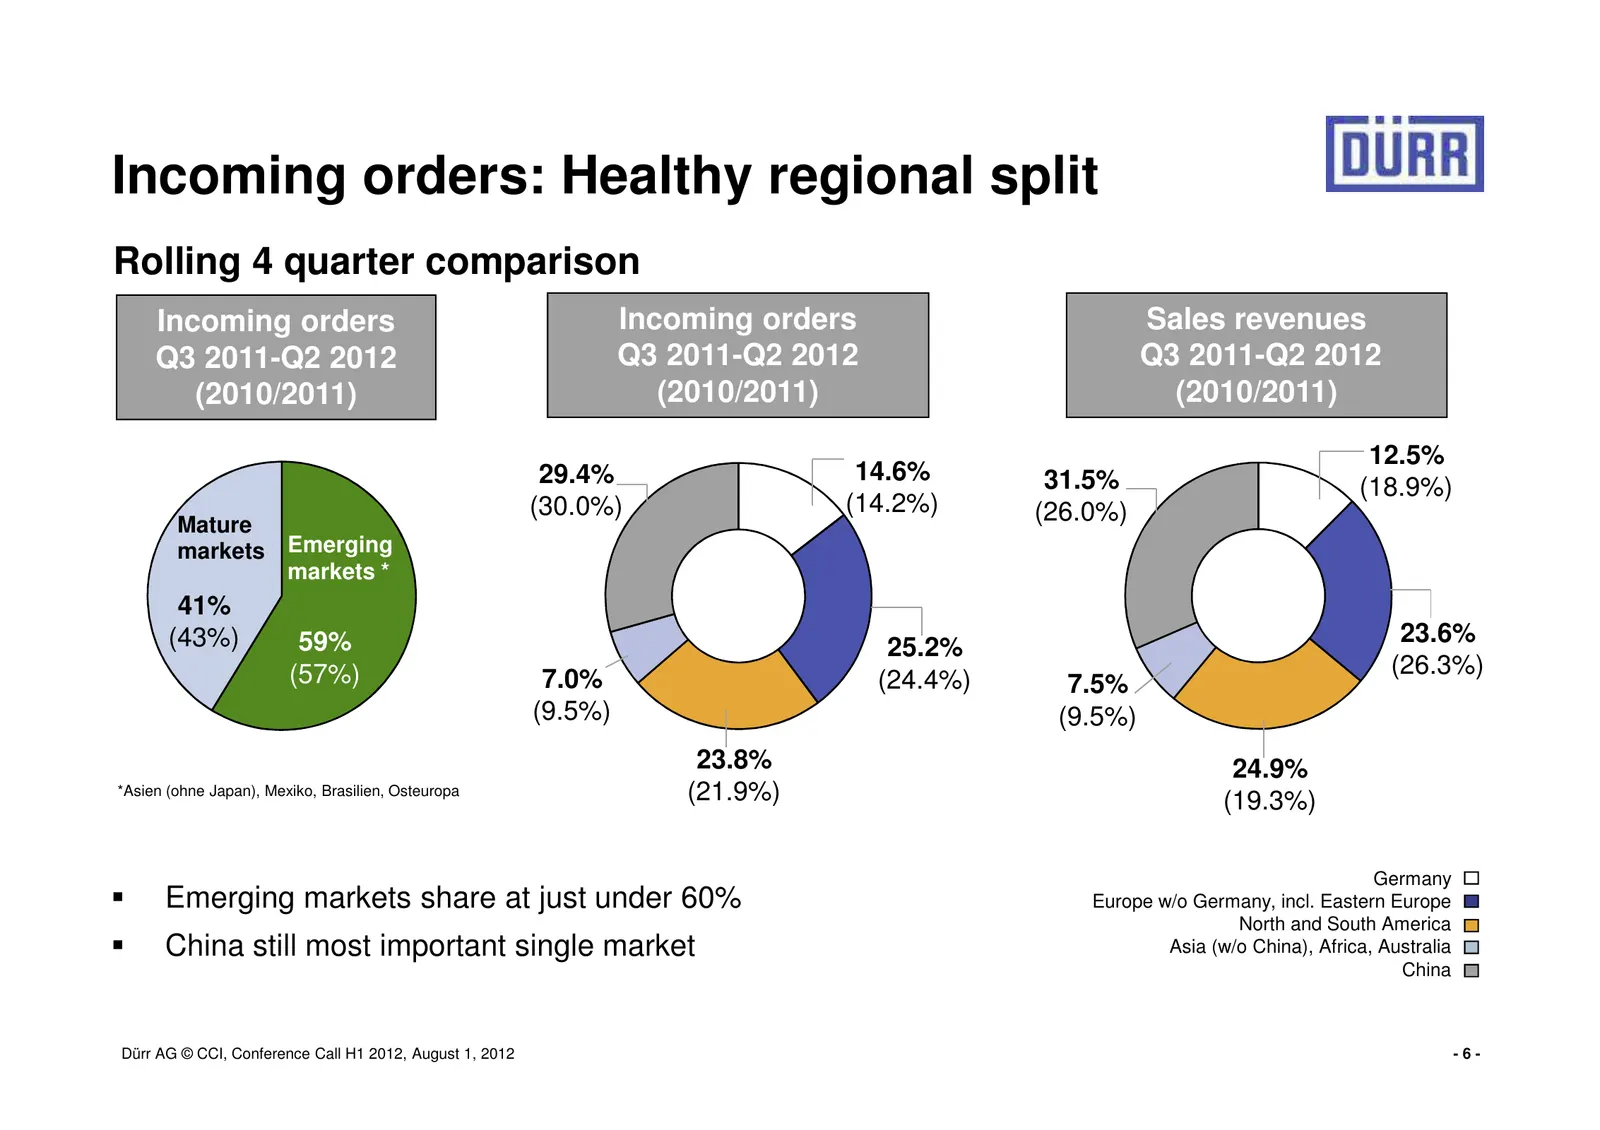
Slide 6: Incoming orders: Healthy regional split
Incoming orders: Healthy regional split Rolling 4 quarter comparison Incoming orders Incoming orders Sales revenues Q3 2011-Q2 2012 Q3 2011-Q2 2012 Q3 2011-Q2 2012 (2010/2011) (2010/2011) (2010/2011) 12.5% 29.4% 14.6% 31.5% (18.9%) (30.0%) (14.2%) (26.0%) Mature markets Emerging markets * 41% (43%)
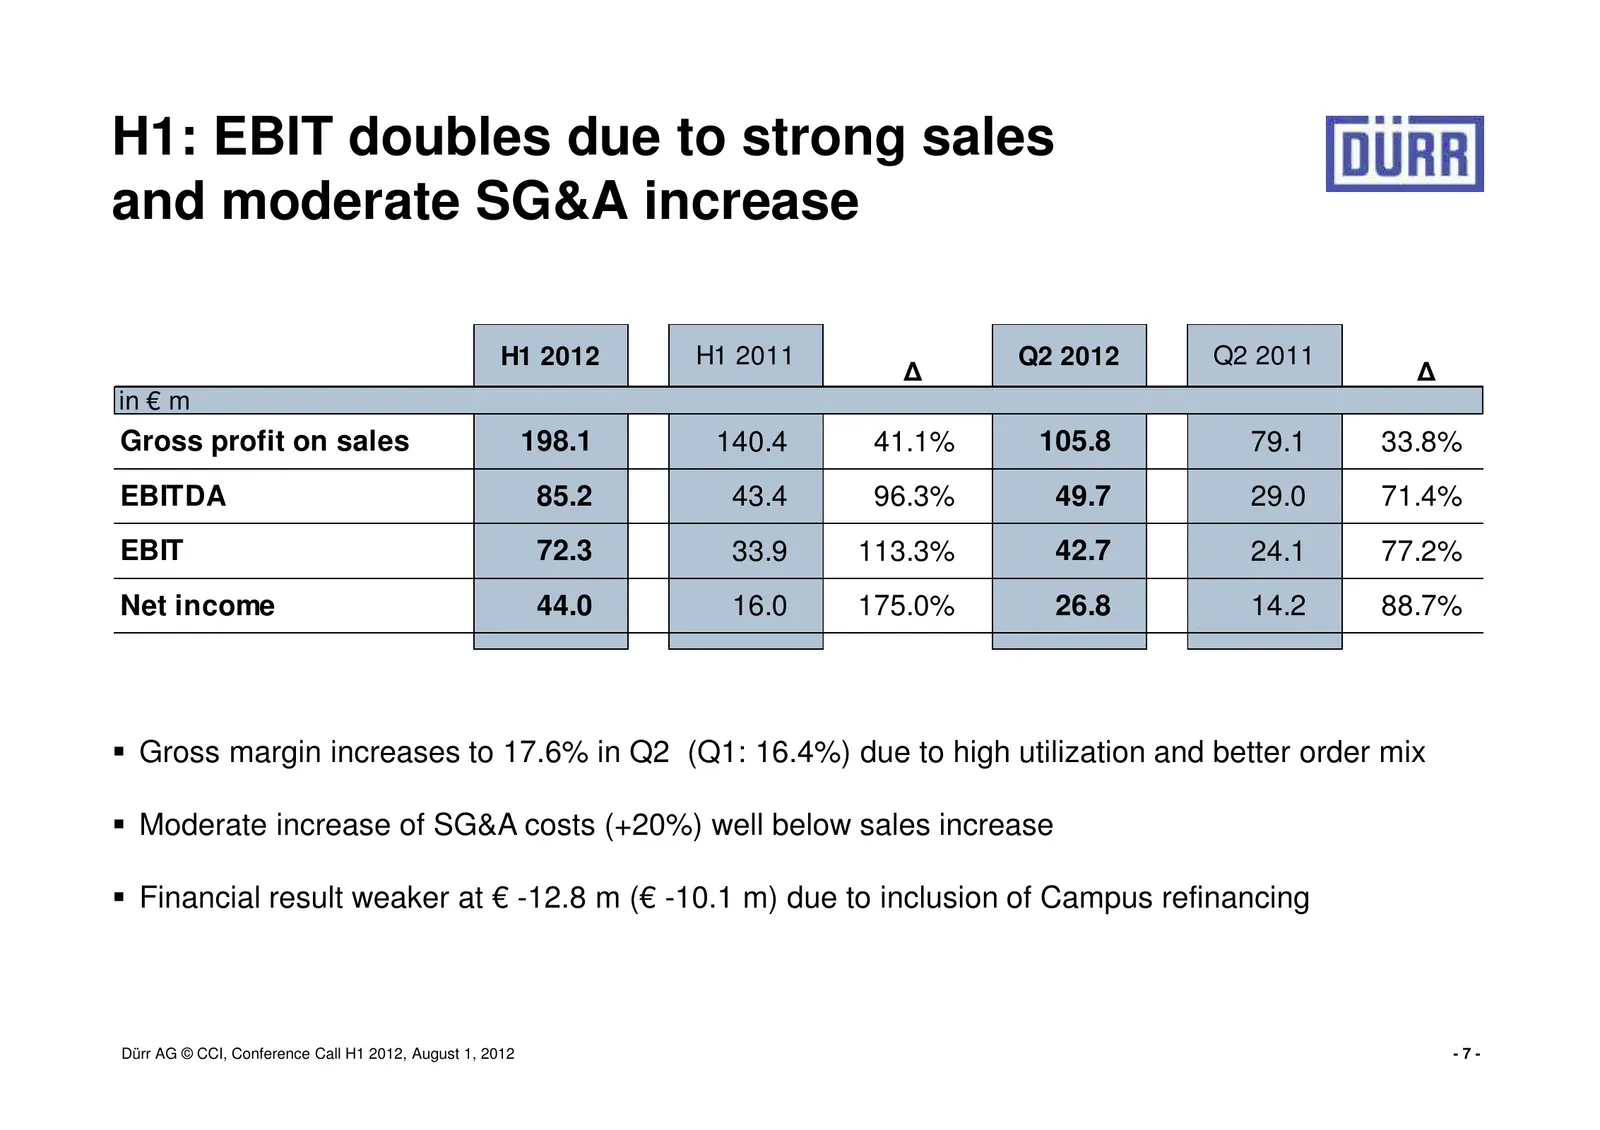
Slide 7: H1: EBIT doubles due to strong sales and moderate SG&A increase
H1: EBIT doubles due to strong sales and moderate SG&A increase H1 2012 H1 2011 Q2 2012 Q2 2011 ∆ ∆ in € m Gross profit on sales 198.1 140.4 41.1% 105.8 79.1 33.8% EBITDA 85.2 43.4 96.3% 49.7 29.0 71.4% EBIT 72.3 33.9 113.3% 42.7 24.1 77.2% Net income 44.0 16.0 175.0% 26.8 14.2 88.7% Gross margin in
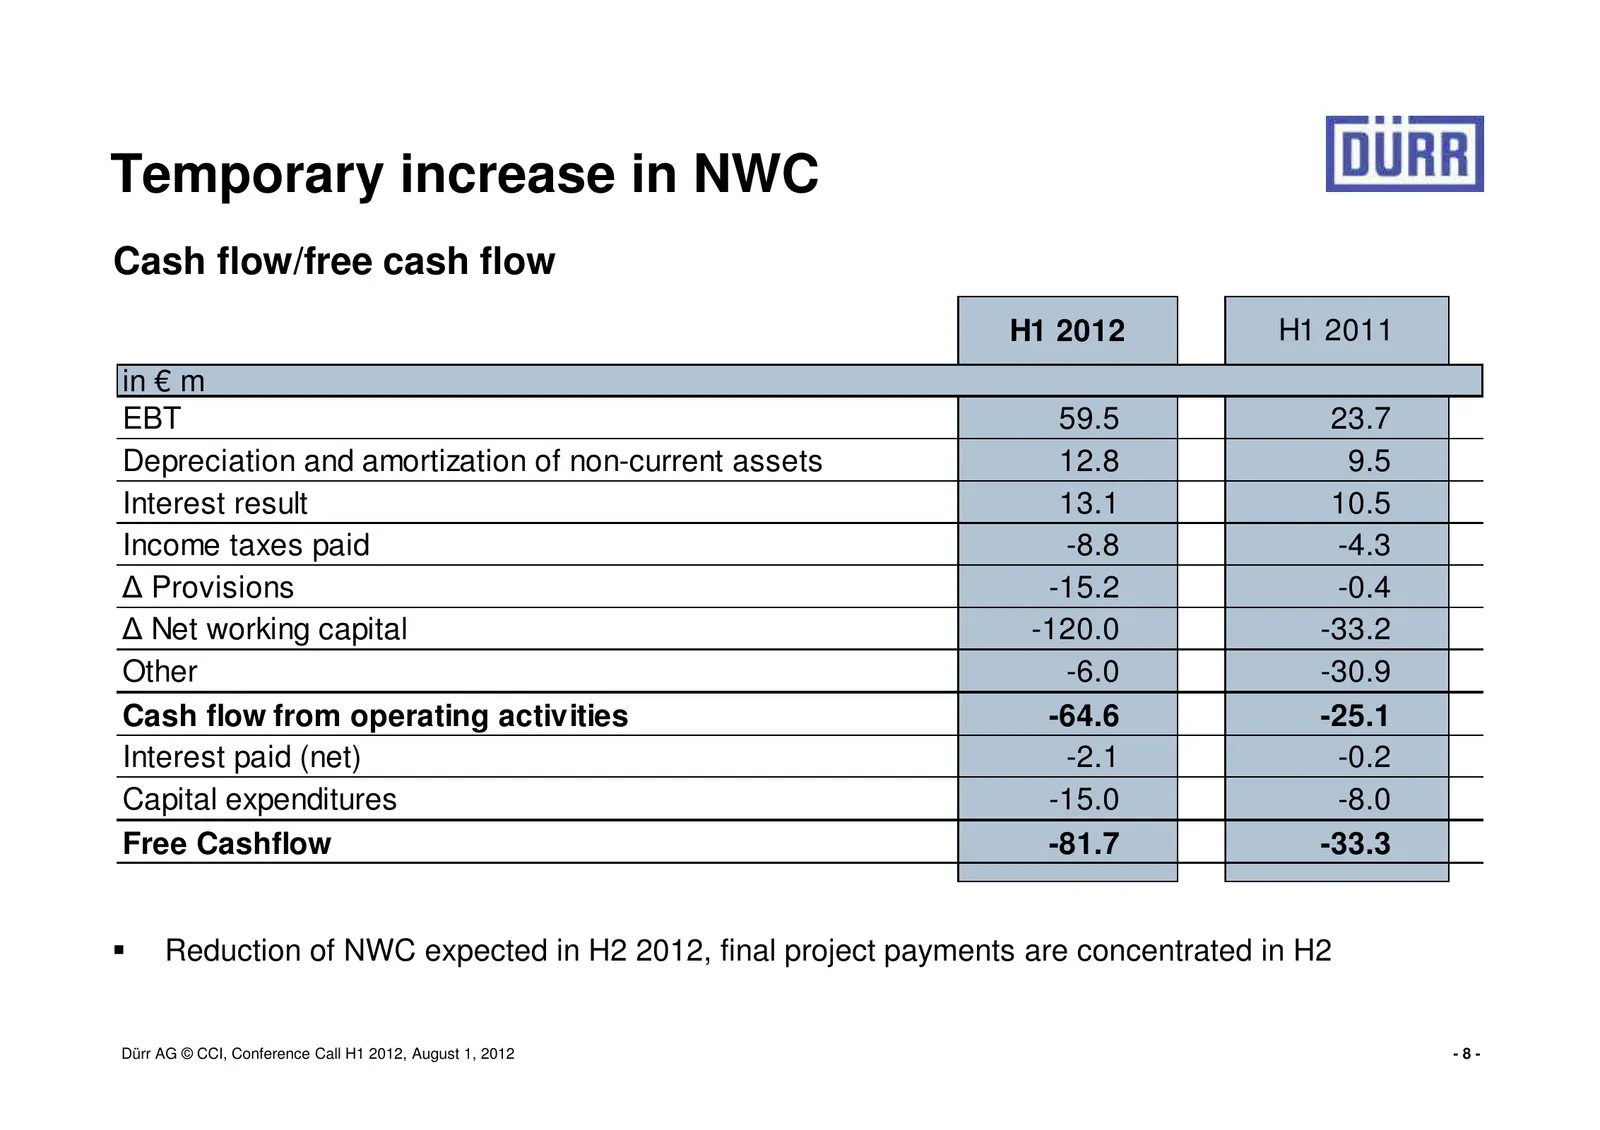
Slide 8: Temporary increase in NWC
Temporary increase in NWC Cash flow/free cash flow H1 2012 H1 2011 in € m EBT 59.5 23.7 Depreciation and amortization of non-current assets 12.8 9.5 Interest result 13.1 10.5 Income taxes paid -8.8 -4.3 ∆ Provisions -15.2 -0.4 ∆ Net working capital -120.0 -33.2 Other -6.0 -30.9 Cash flow from operat
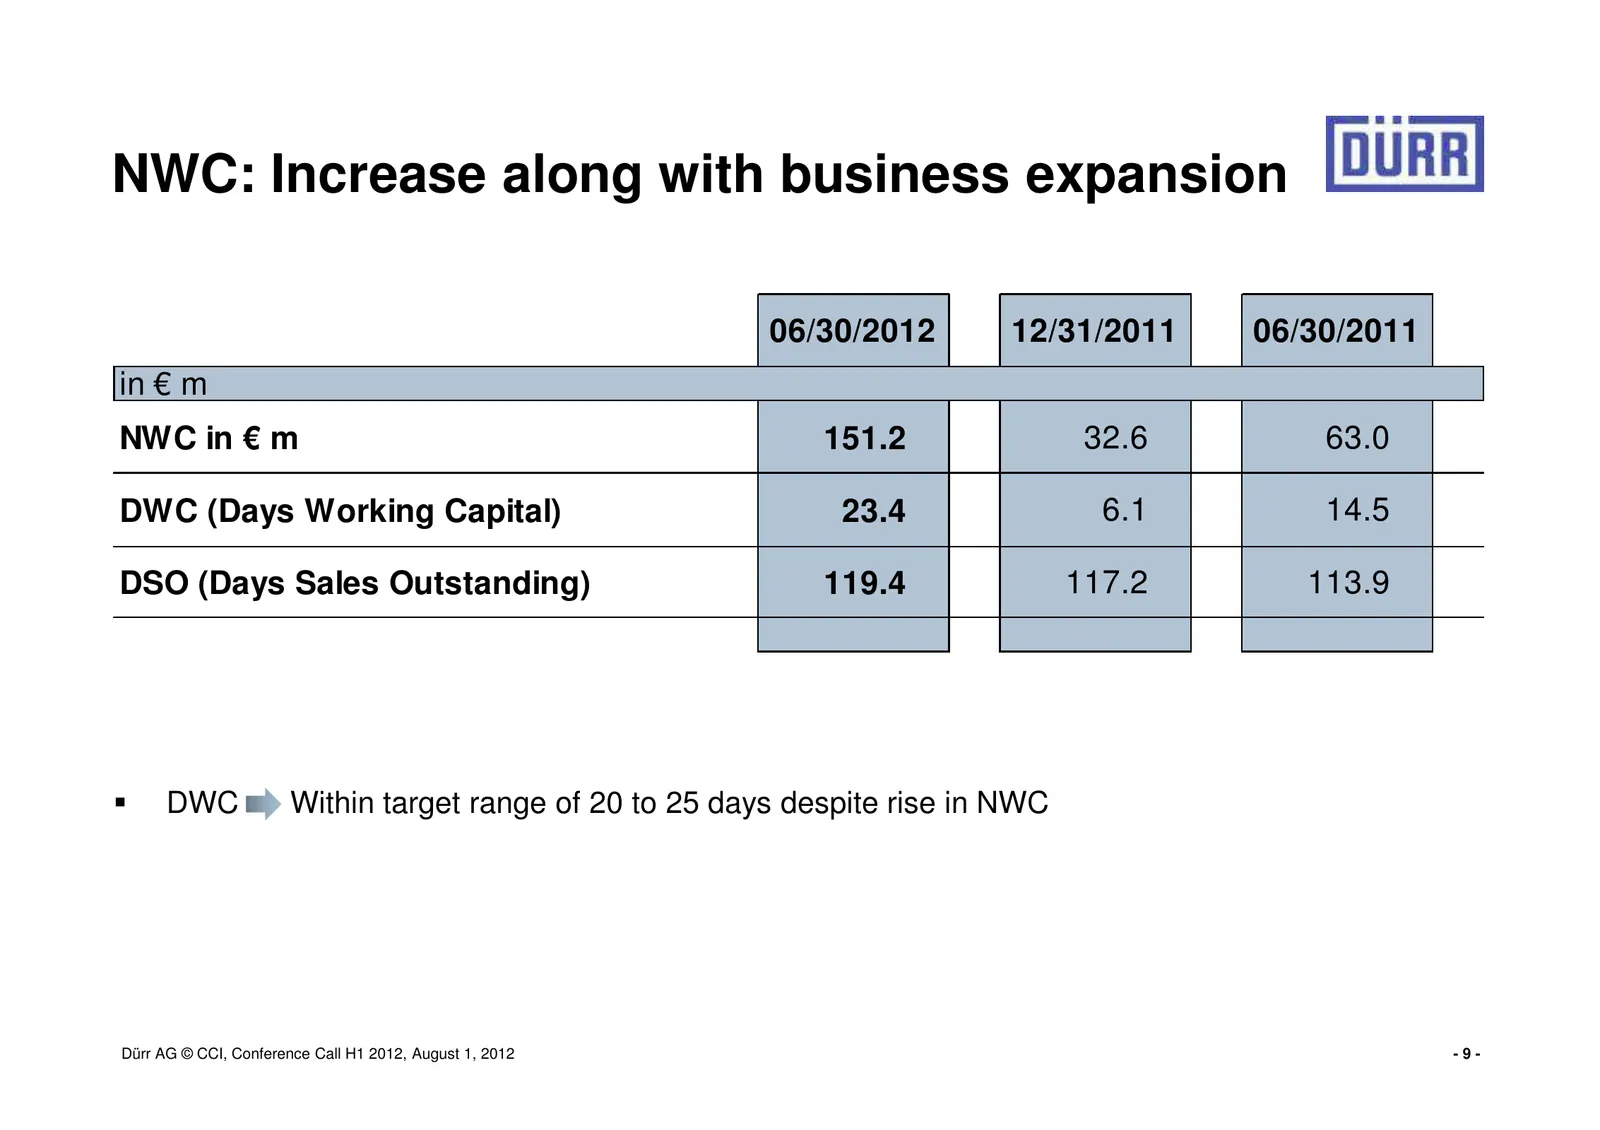
Slide 9: NWC: Increase along with business expansion
NWC: Increase along with business expansion 06/30/2012 12/31/2011 06/30/2011 in € m NWC in € m 151.2 32.6 63.0 DWC (Days Working Capital) 23.4 6.1 14.5 DSO (Days Sales Outstanding) 119.4 117.2 113.9 DWC Within target range of 20 to 25 days despite rise in NWC Dürr AG © CCI, Conference Call H1 2012,
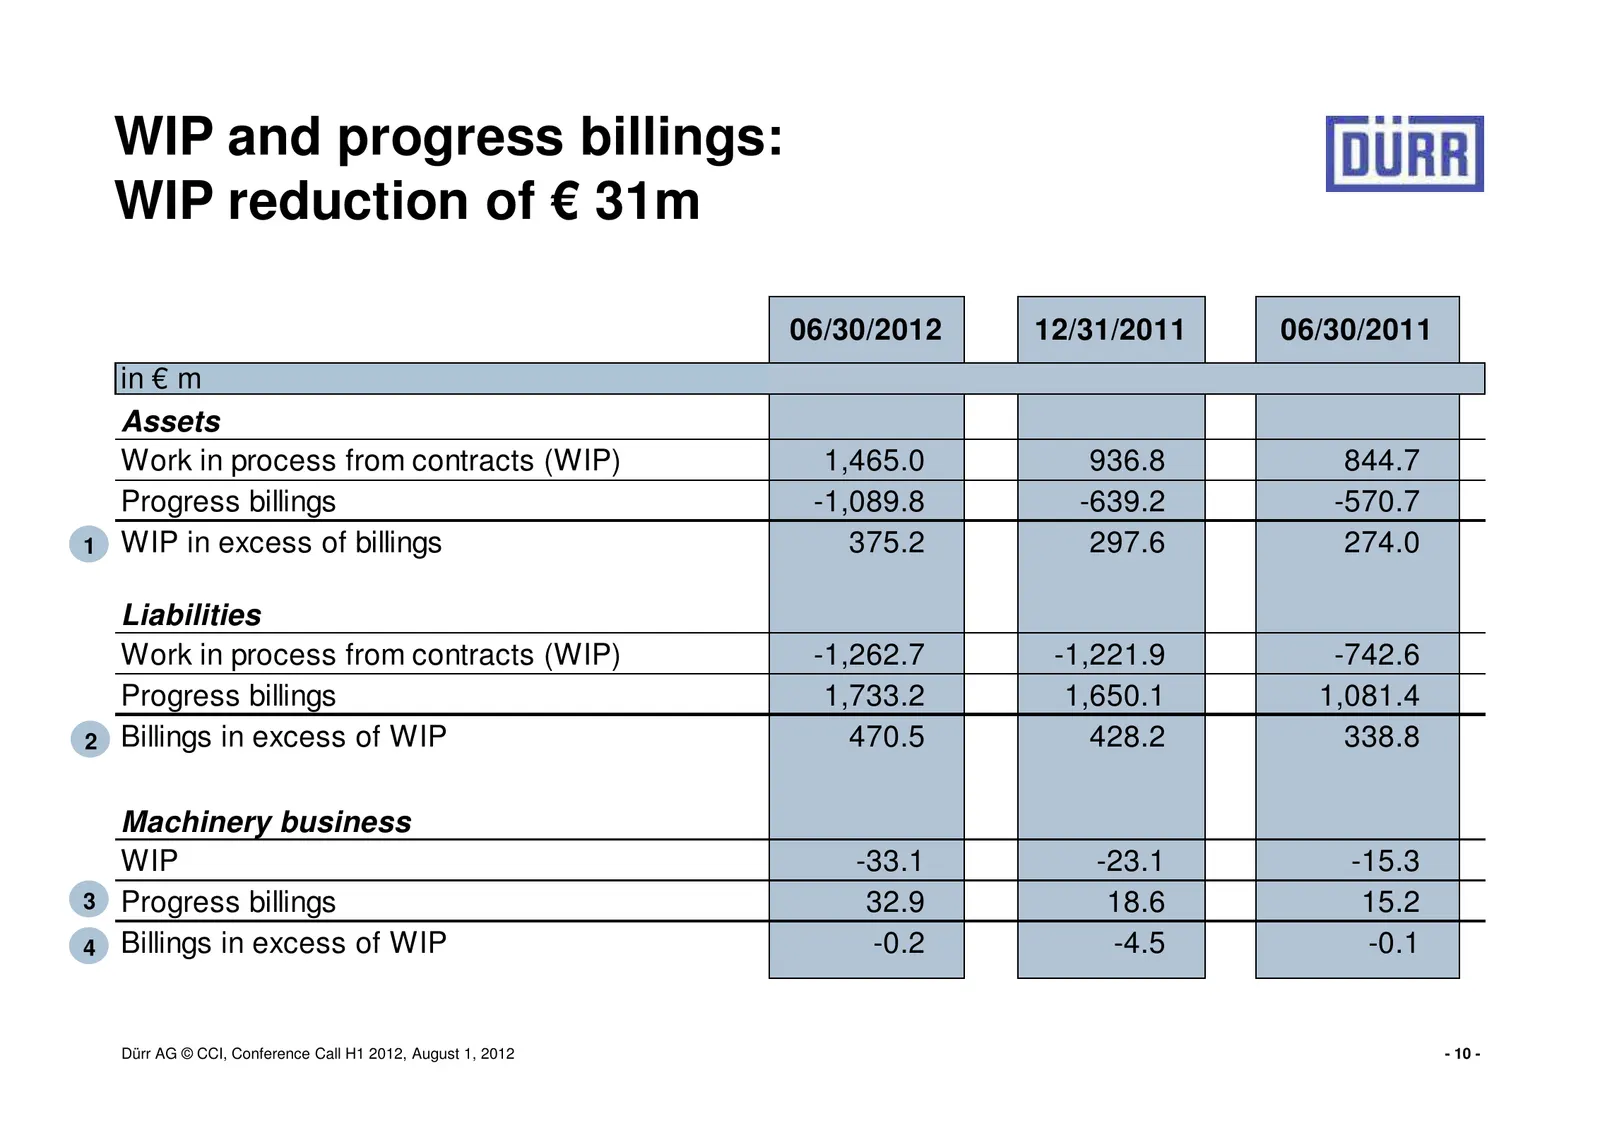
Slide 10: WIP and progress billings: WIP reduction of € 31m
WIP and progress billings: WIP reduction of € 31m 06/30/2012 12/31/2011 06/30/2011 in € m Assets Work in process from contracts (WIP) 1,465.0 936.8 844.7 Progress billings -1,089.8 -639.2 -570.7 1 WIP in excess of billings 375.2 297.6 274.0 Liabilities Work in process from contracts (WIP) -1,262.7 -
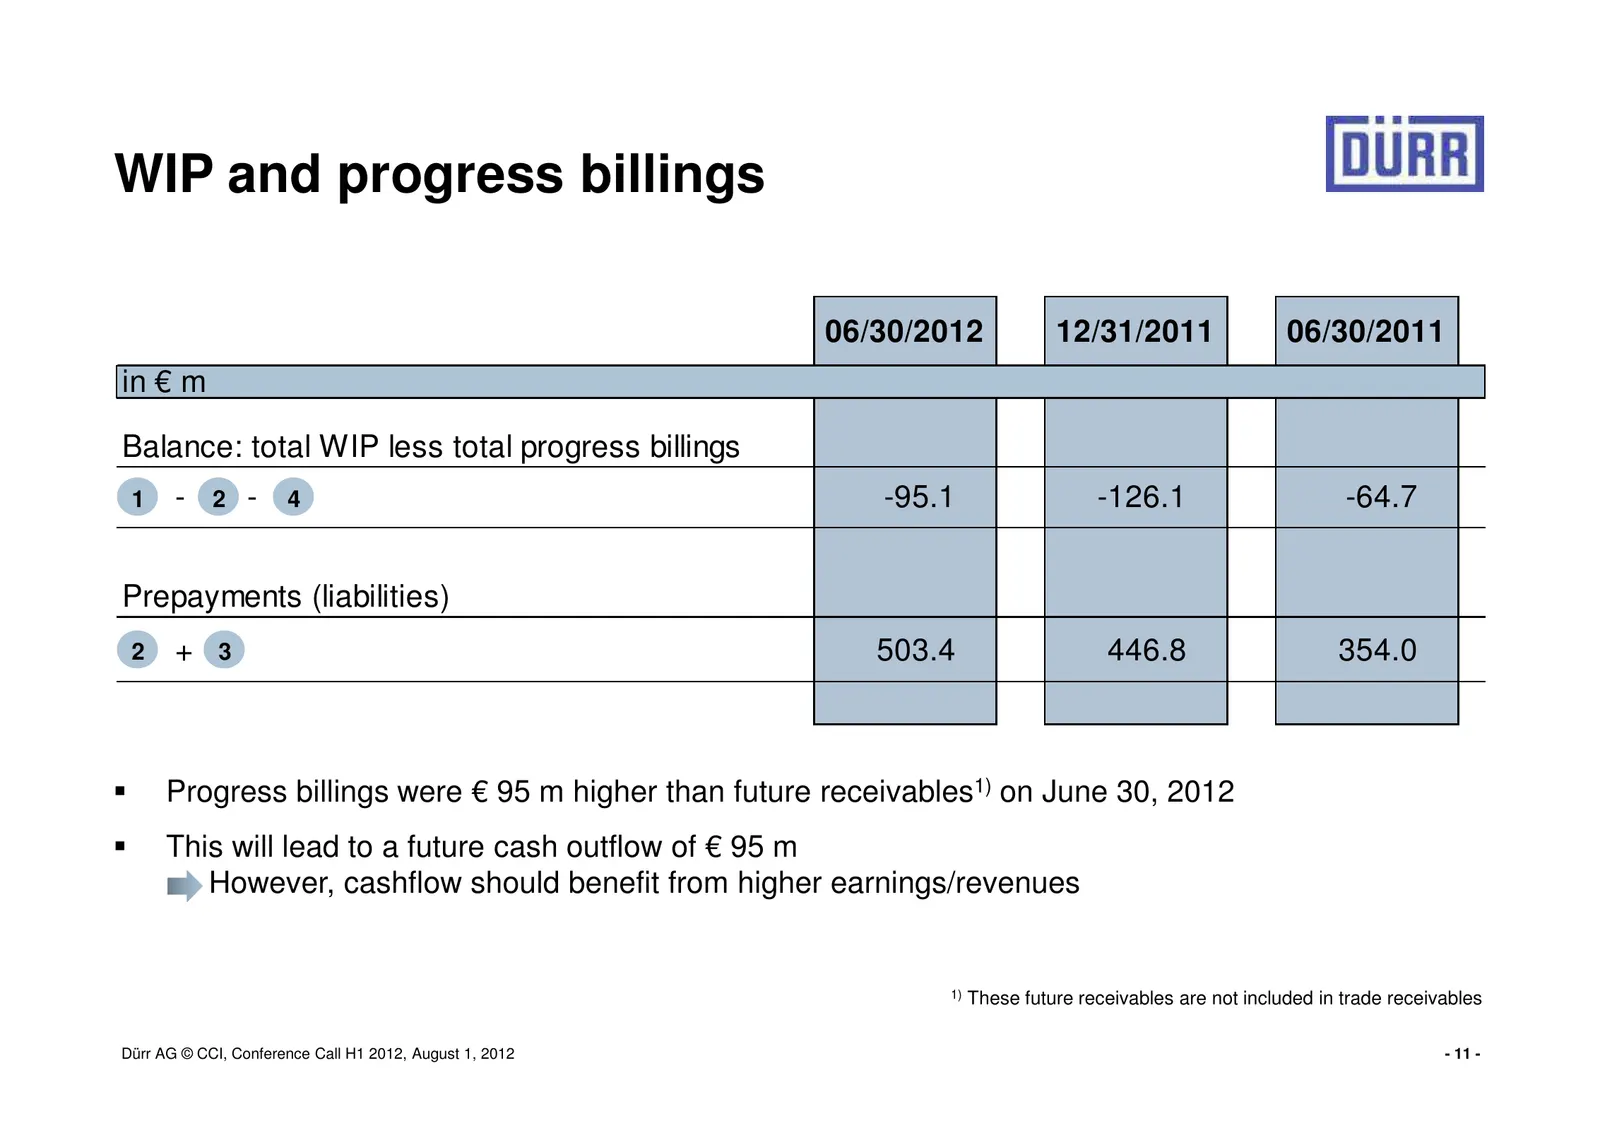
Slide 11: WIP and progress billings
WIP and progress billings 06/30/2012 12/31/2011 06/30/2011 in € m Balance: total WIP less total progress billings 1 - 2 - 4 -95.1 -126.1 -64.7 Prepayments (liabilities) 2 + 3 503.4 446.8 354.0 Progress billings were € 95 m higher than future receivables1) on June 30, 2012 This will lead to a future
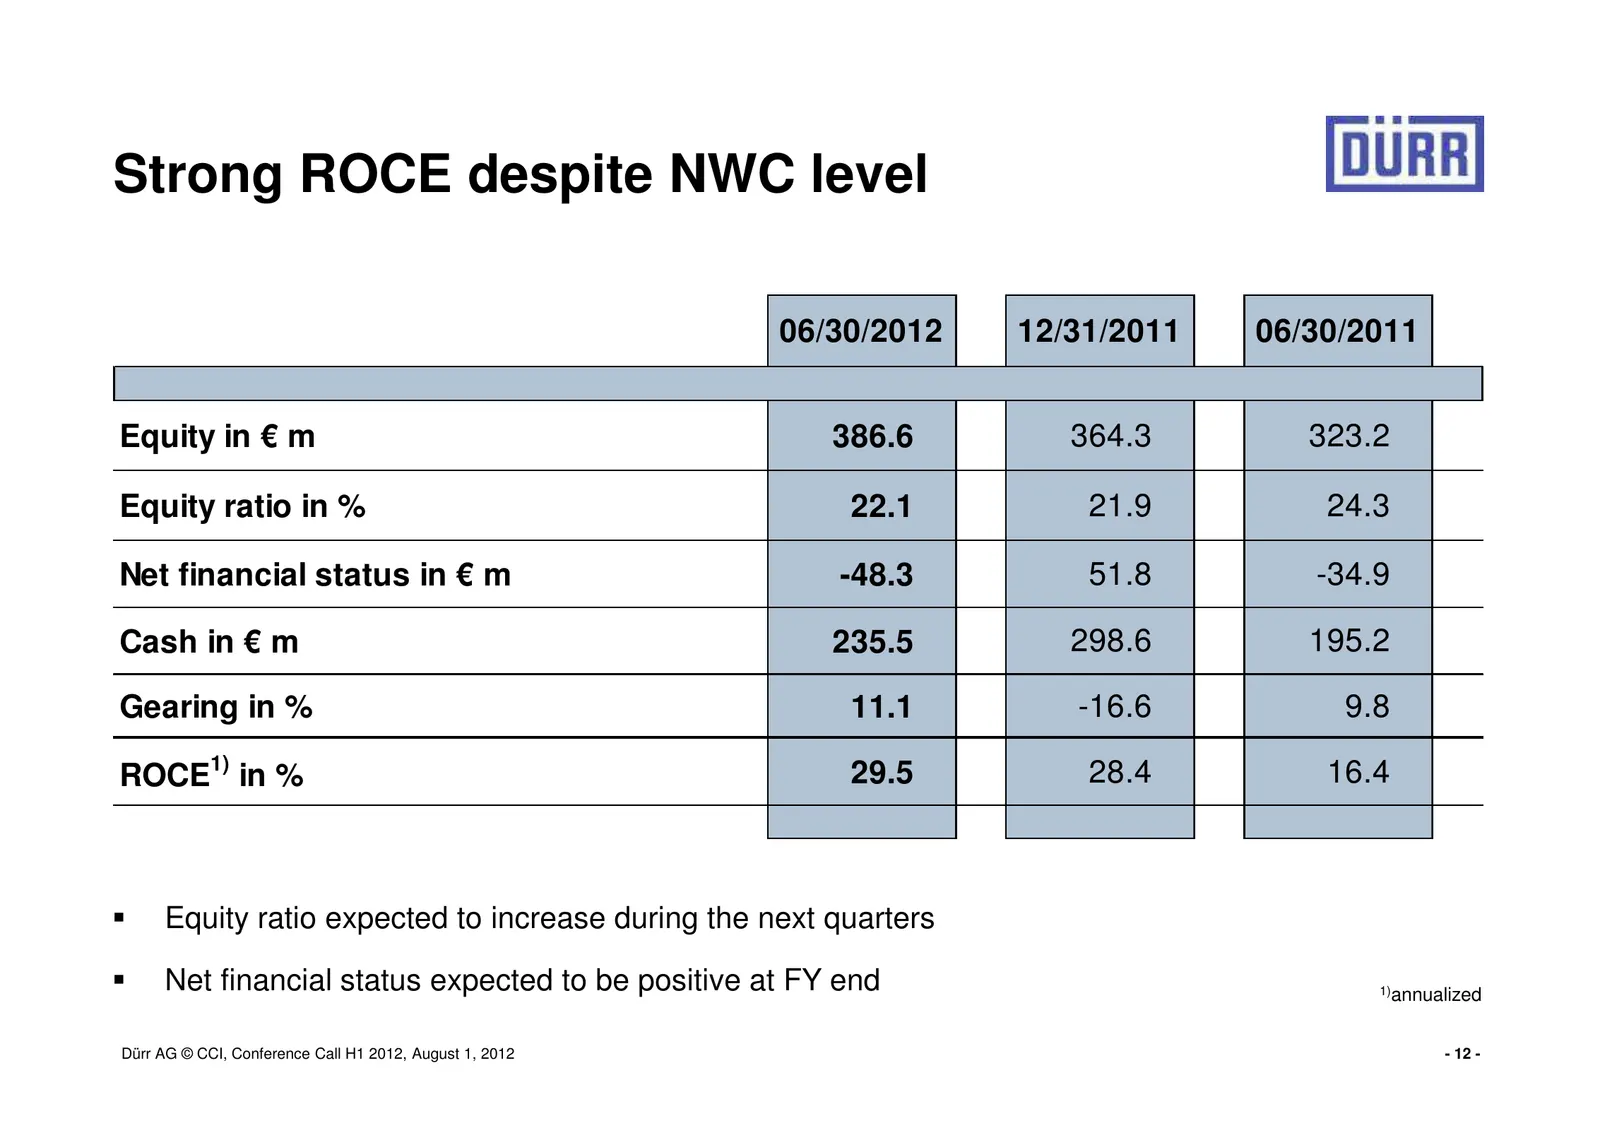
Slide 12: Strong ROCE despite NWC level
Strong ROCE despite NWC level 06/30/2012 12/31/2011 06/30/2011 Equity in € m 386.6 364.3 323.2 Equity ratio in % 22.1 21.9 24.3 Net financial status in € m -48.3 51.8 -34.9 Cash in € m 235.5 298.6 195.2 Gearing in % 11.1 -16.6 9.8 ROCE1) in % 29.5 28.4 16.4 Equity ratio expected to increase during t
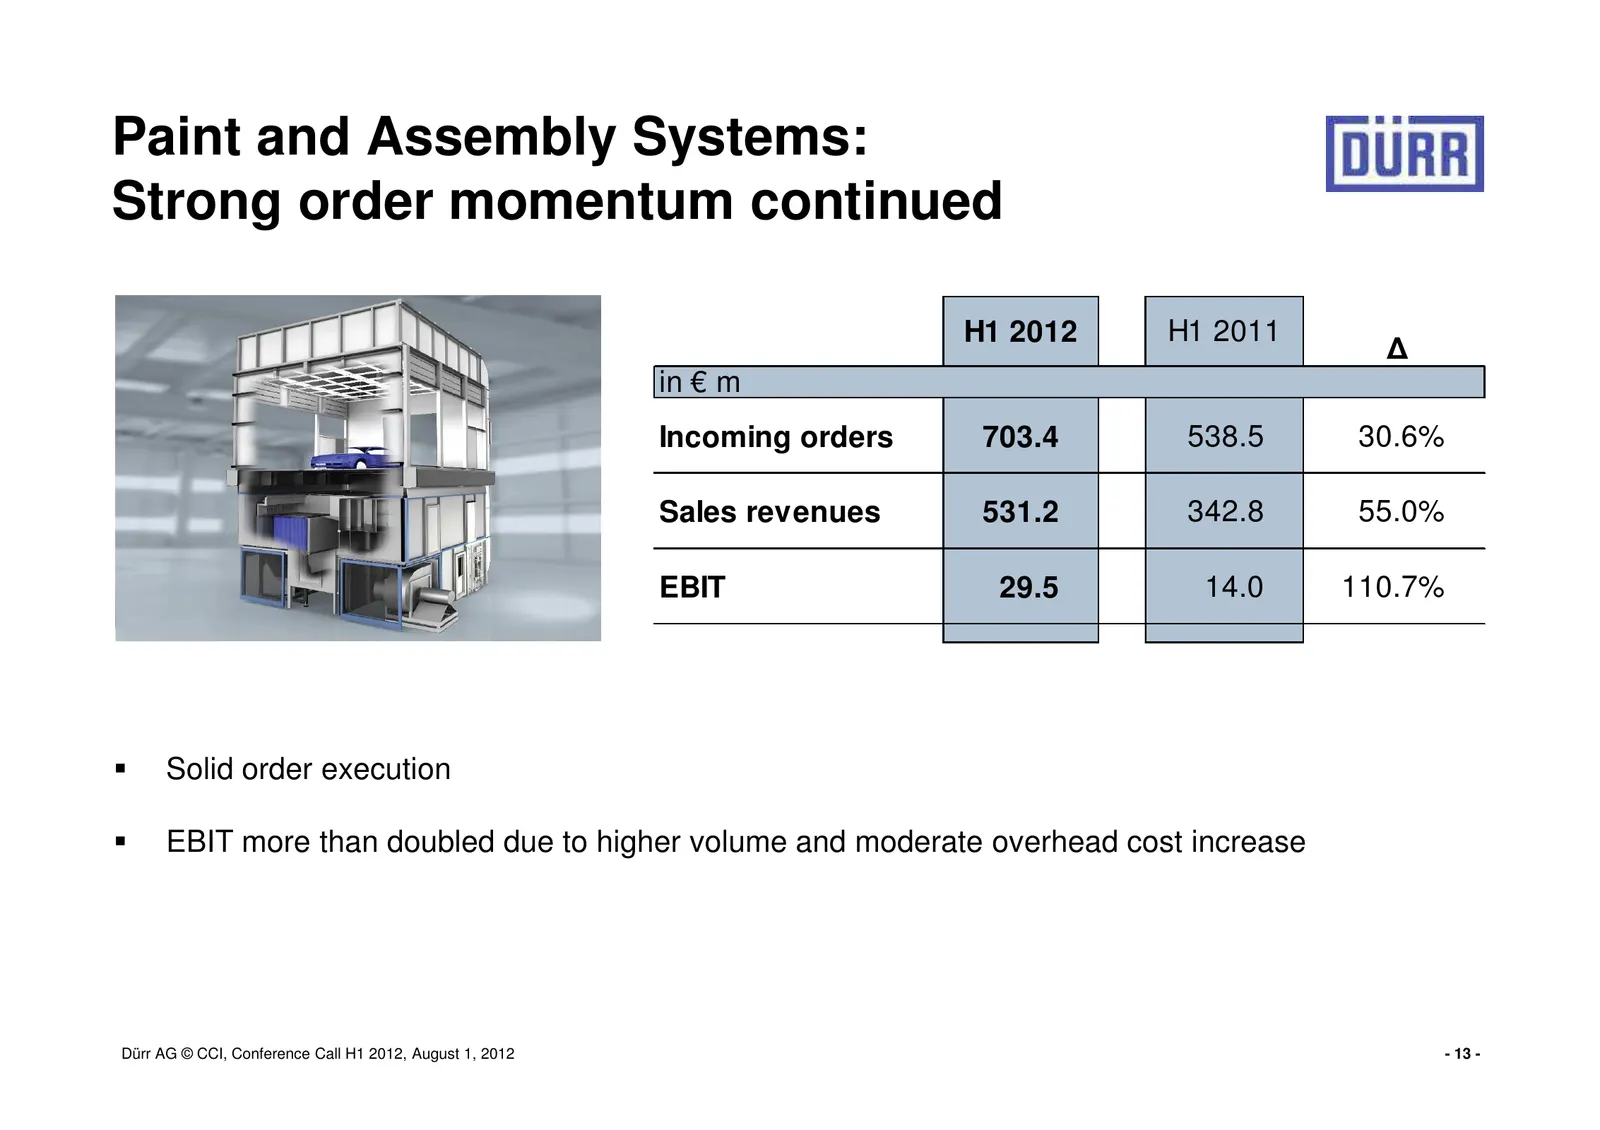
Slide 13: Paint and Assembly Systems: Strong order momentum continued
Paint and Assembly Systems: Strong order momentum continued H1 2012 H1 2011 ∆ in € m Incoming orders 703.4 538.5 30.6% Sales revenues 531.2 342.8 55.0% EBIT 29.5 14.0 110.7% Solid order execution EBIT more than doubled due to higher volume and moderate overhead cost increase Dürr AG © CCI, Conferenc
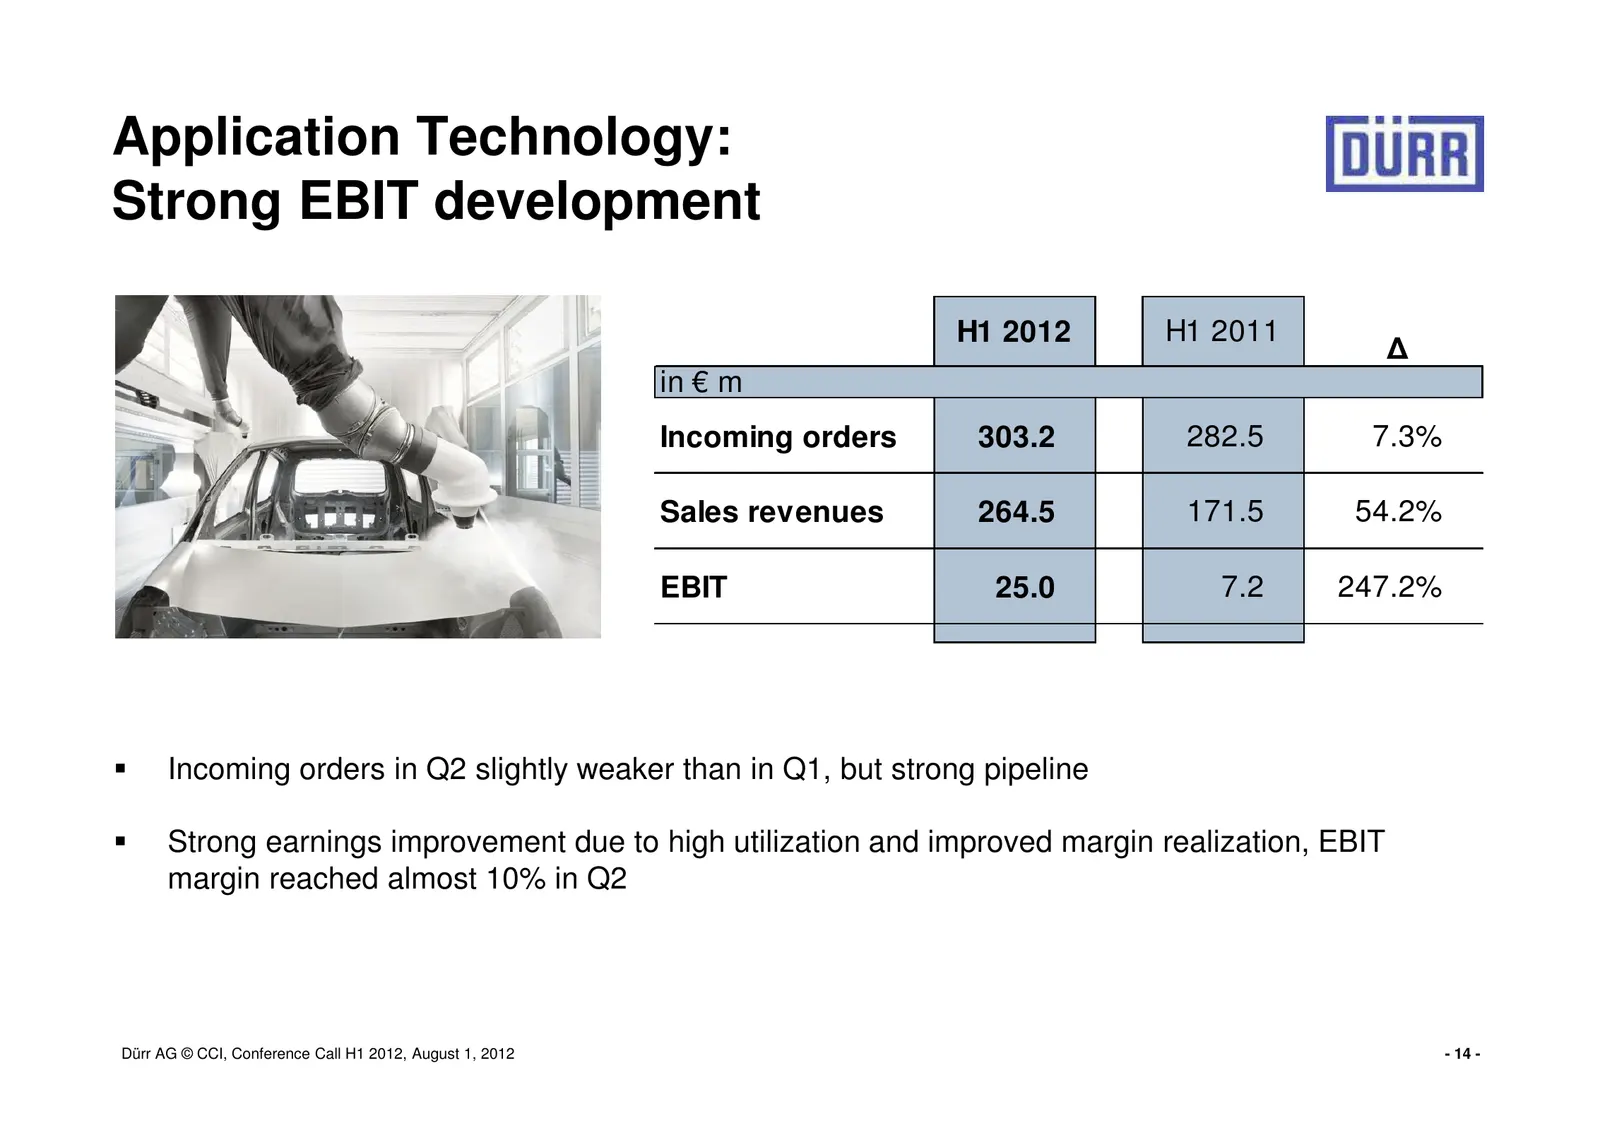
Slide 14: Application Technology: Strong EBIT development
Application Technology: Strong EBIT development H1 2012 H1 2011 ∆ in € m Incoming orders 303.2 282.5 7.3% Sales revenues 264.5 171.5 54.2% EBIT 25.0 7.2 247.2% Incoming orders in Q2 slightly weaker than in Q1, but strong pipeline Strong earnings improvement due to high utilization and improved margi
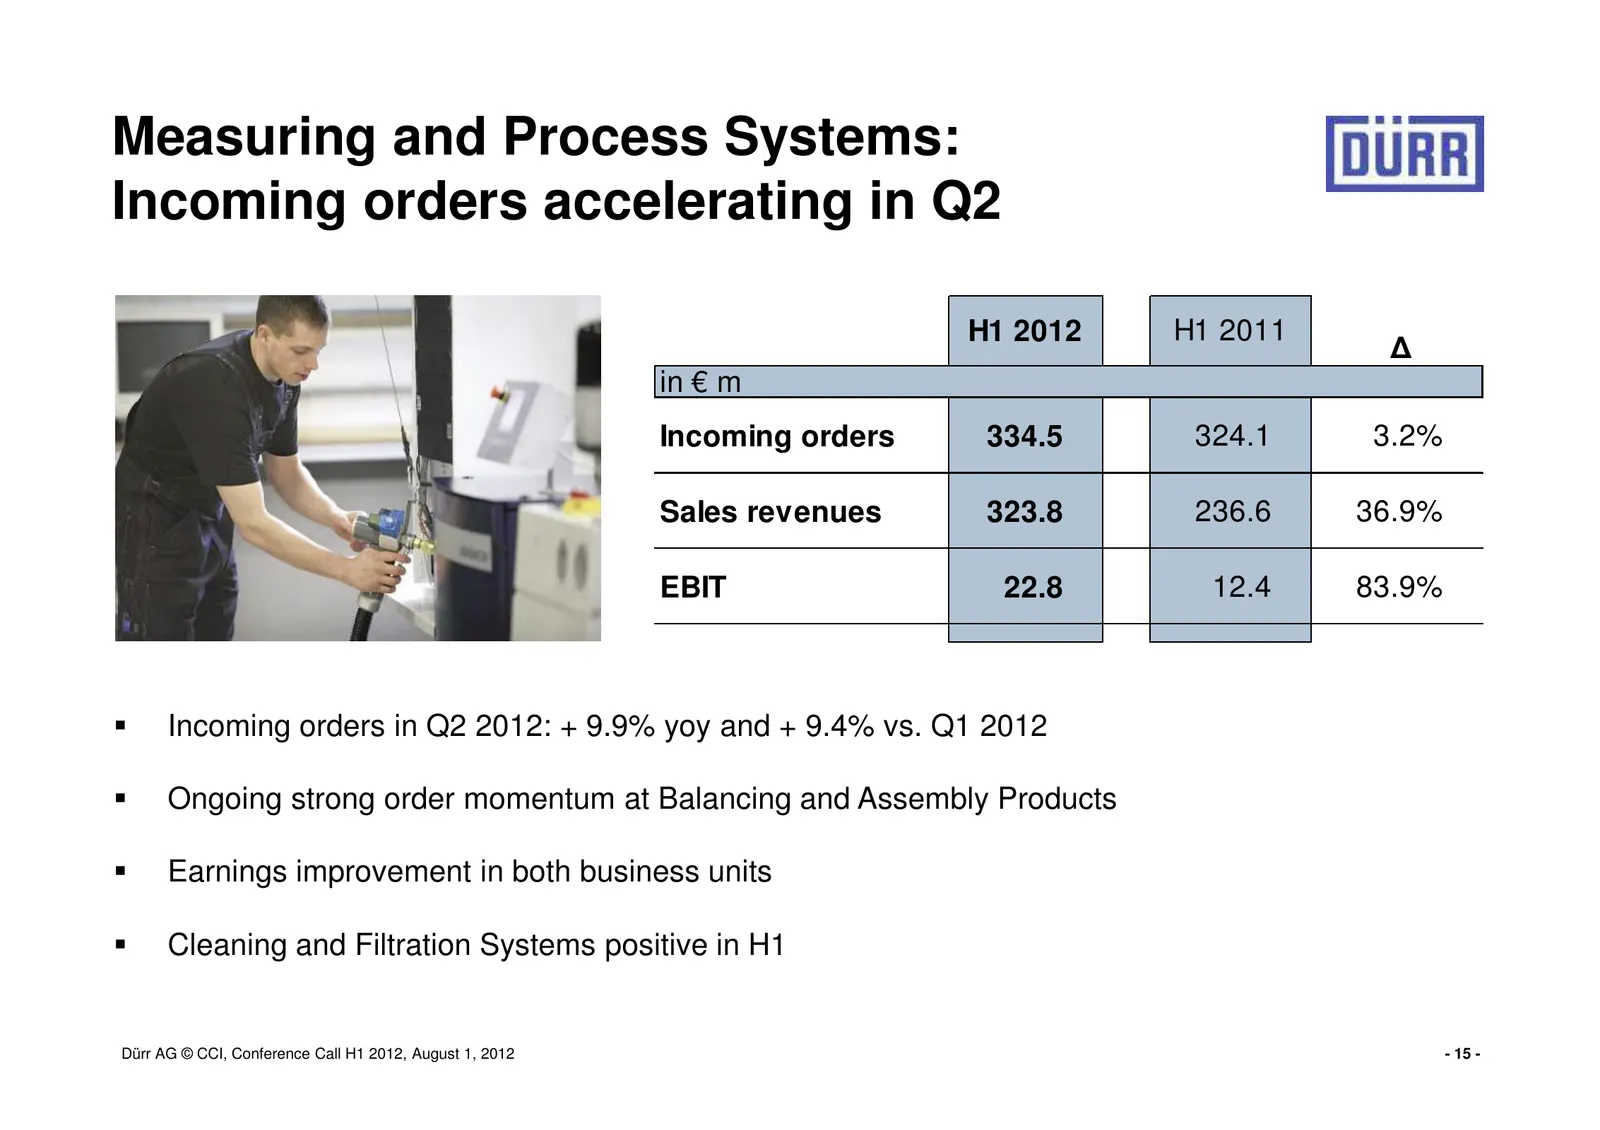
Slide 15: Measuring and Process Systems: Incoming orders accelerating in Q2
Measuring and Process Systems: Incoming orders accelerating in Q2 H1 2012 H1 2011 ∆ in € m Incoming orders 334.5 324.1 3.2% Sales revenues 323.8 236.6 36.9% EBIT 22.8 12.4 83.9% Incoming orders in Q2 2012: + 9.9% yoy and + 9.4% vs. Q1 2012 Ongoing strong order momentum at Balancing and Assembly Prod
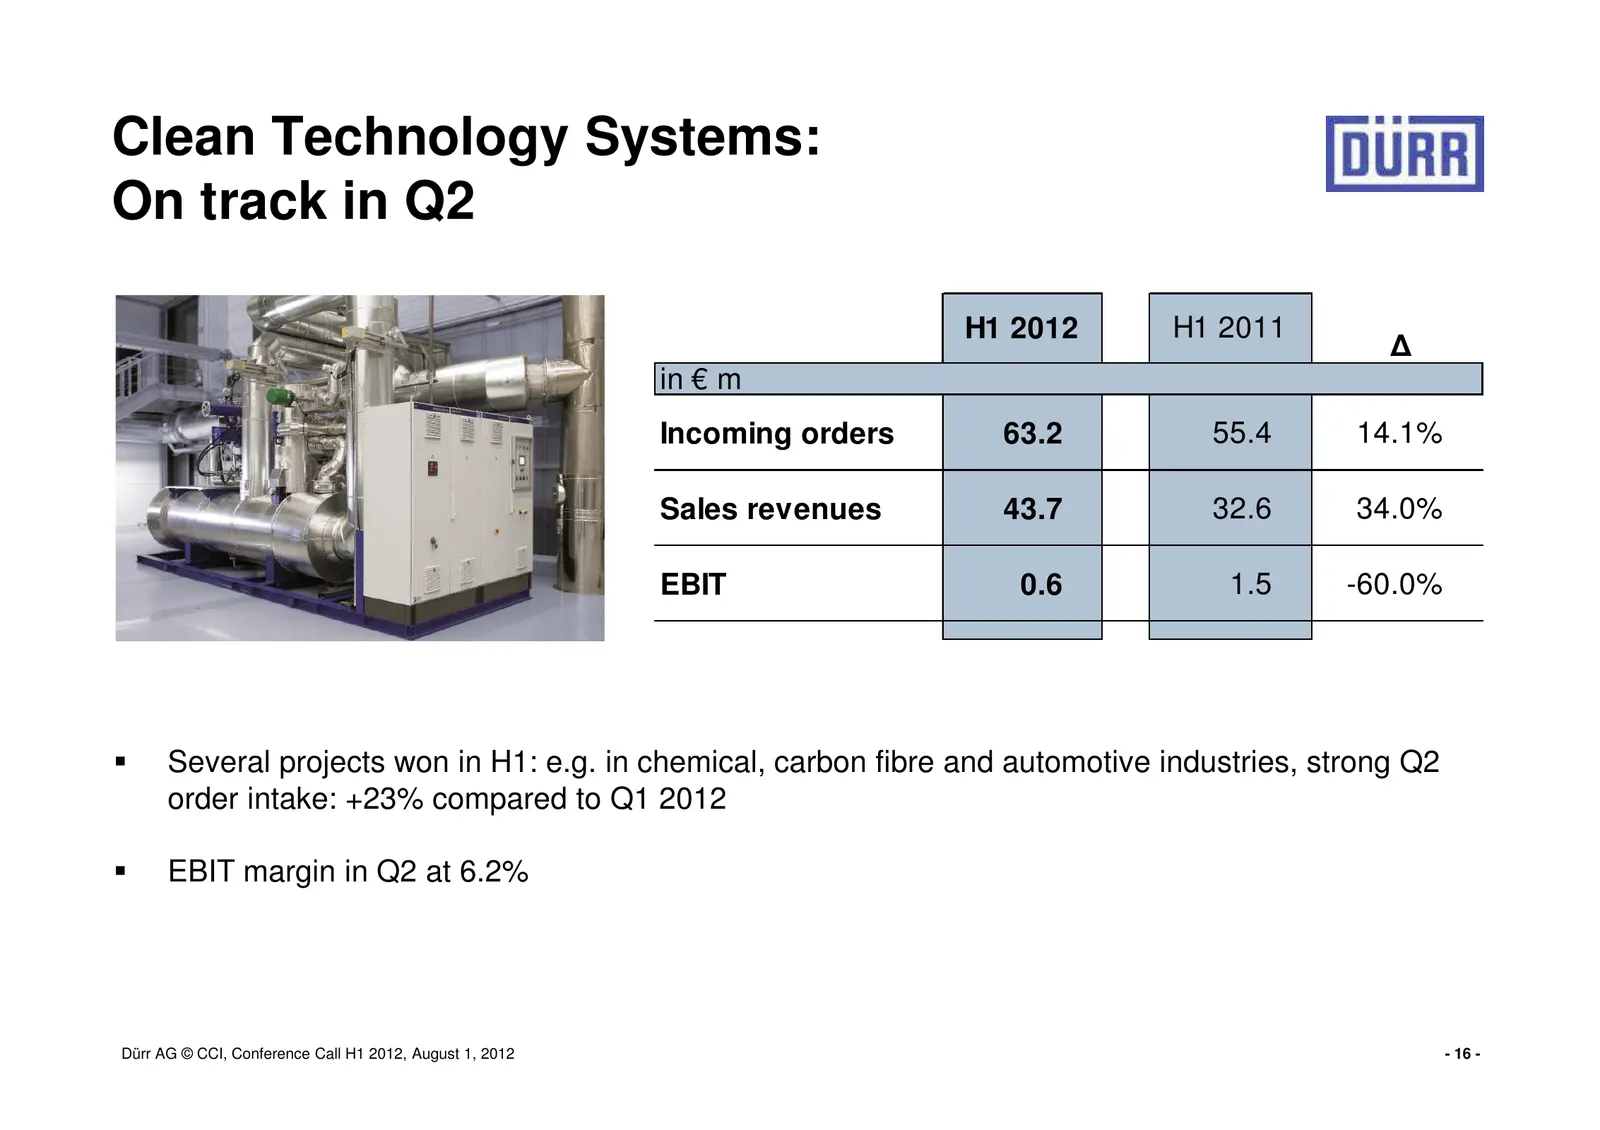
Slide 16: Clean Technology Systems: On track in Q2
Clean Technology Systems: On track in Q2 H1 2012 H1 2011 ∆ in € m Incoming orders 63.2 55.4 14.1% Sales revenues 43.7 32.6 34.0% EBIT 0.6 1.5 -60.0% Several projects won in H1: e.g. in chemical, carbon fibre and automotive industries, strong Q2 order intake: +23% compared to Q1 2012 EBIT margin in Q
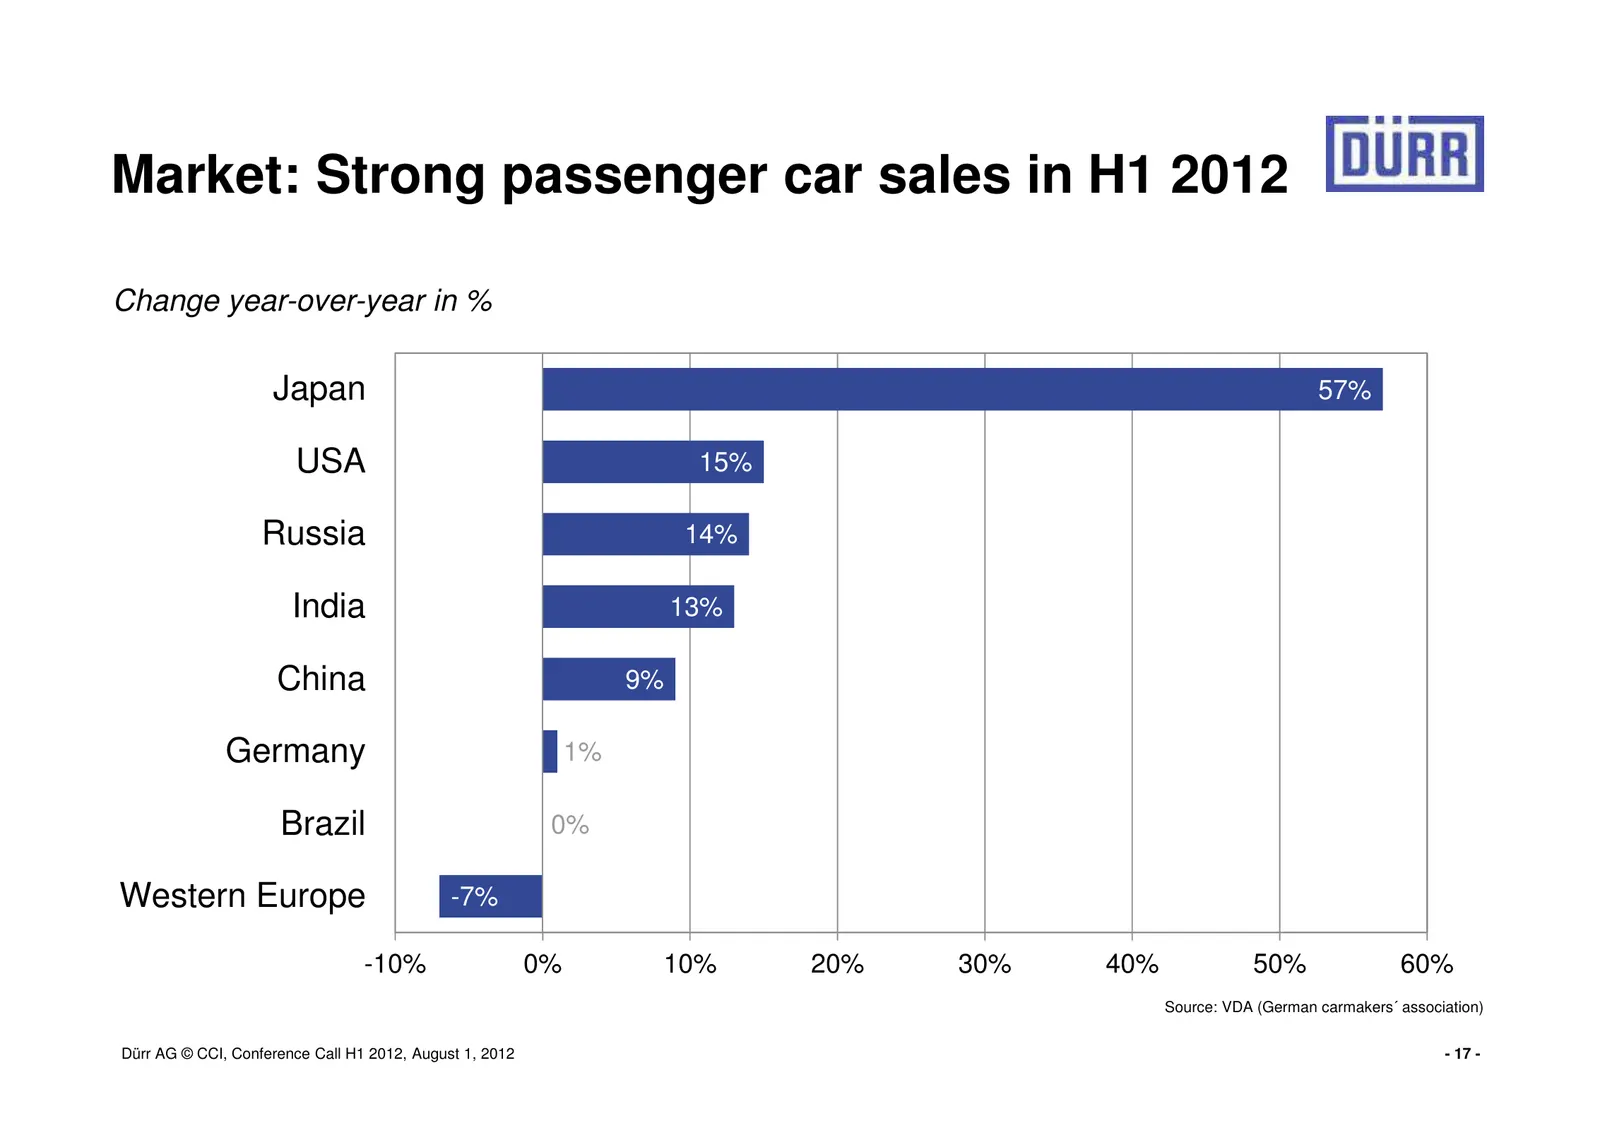
Slide 17: Market: Strong passenger car sales in H1 2012
Market: Strong passenger car sales in H1 2012 Change year-over-year in % Japan 57% USA 15% Russia 14% India 13% China 9% Germany 1% Brazil 0% Western Europe -7% -10% 0% 10% 20% 30% 40% 50% 60% Source: VDA (German carmakers´ association) Dürr AG © CCI, Conference Call H1 2012, August 1, 2012 - 17 -
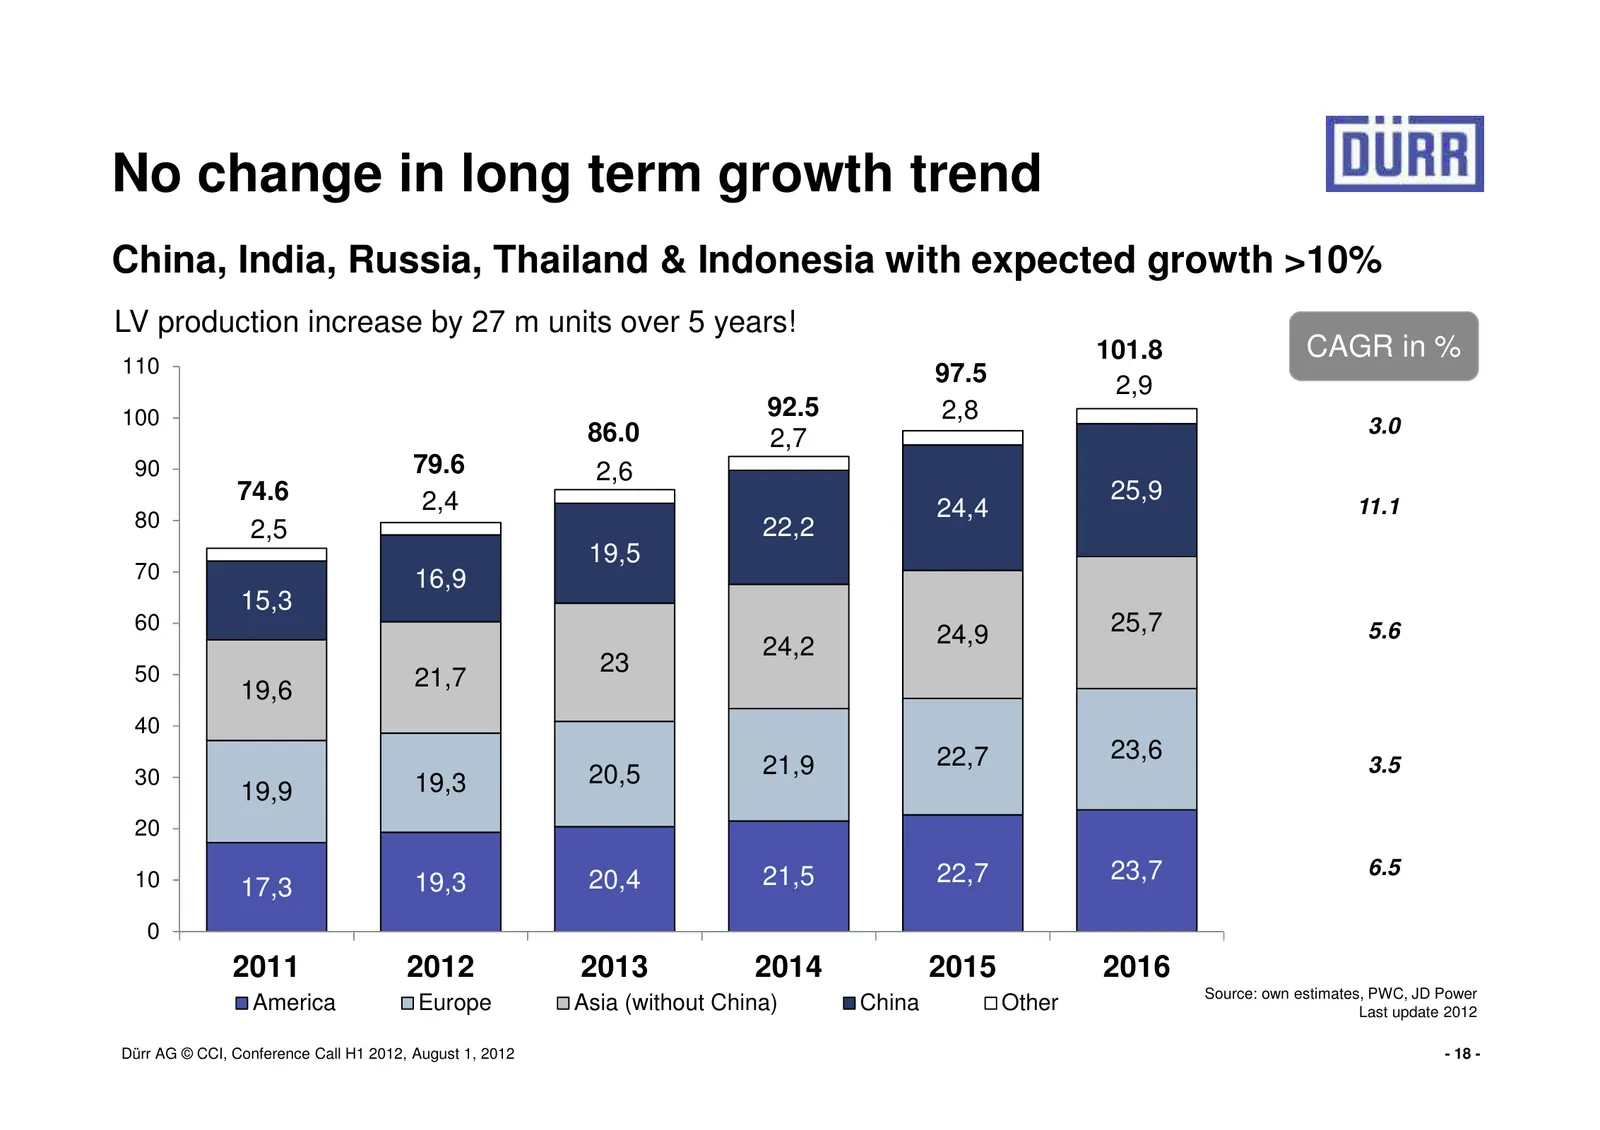
Slide 18: No change in long term growth trend
No change in long term growth trend China, India, Russia, Thailand & Indonesia with expected growth >10% LV production increase by 27 m units over 5 years! 101.8 CAGR in % 110 97.5 2,9 100 92.5 2,8 86.0 3.0 2,7 90 79.6 2,6 74.6 2,4 25,9 80 24,4 11.1 2,5 22,2 19,5 70 16,9 15,3 60 24,9 25,7 5.6 24,2 5
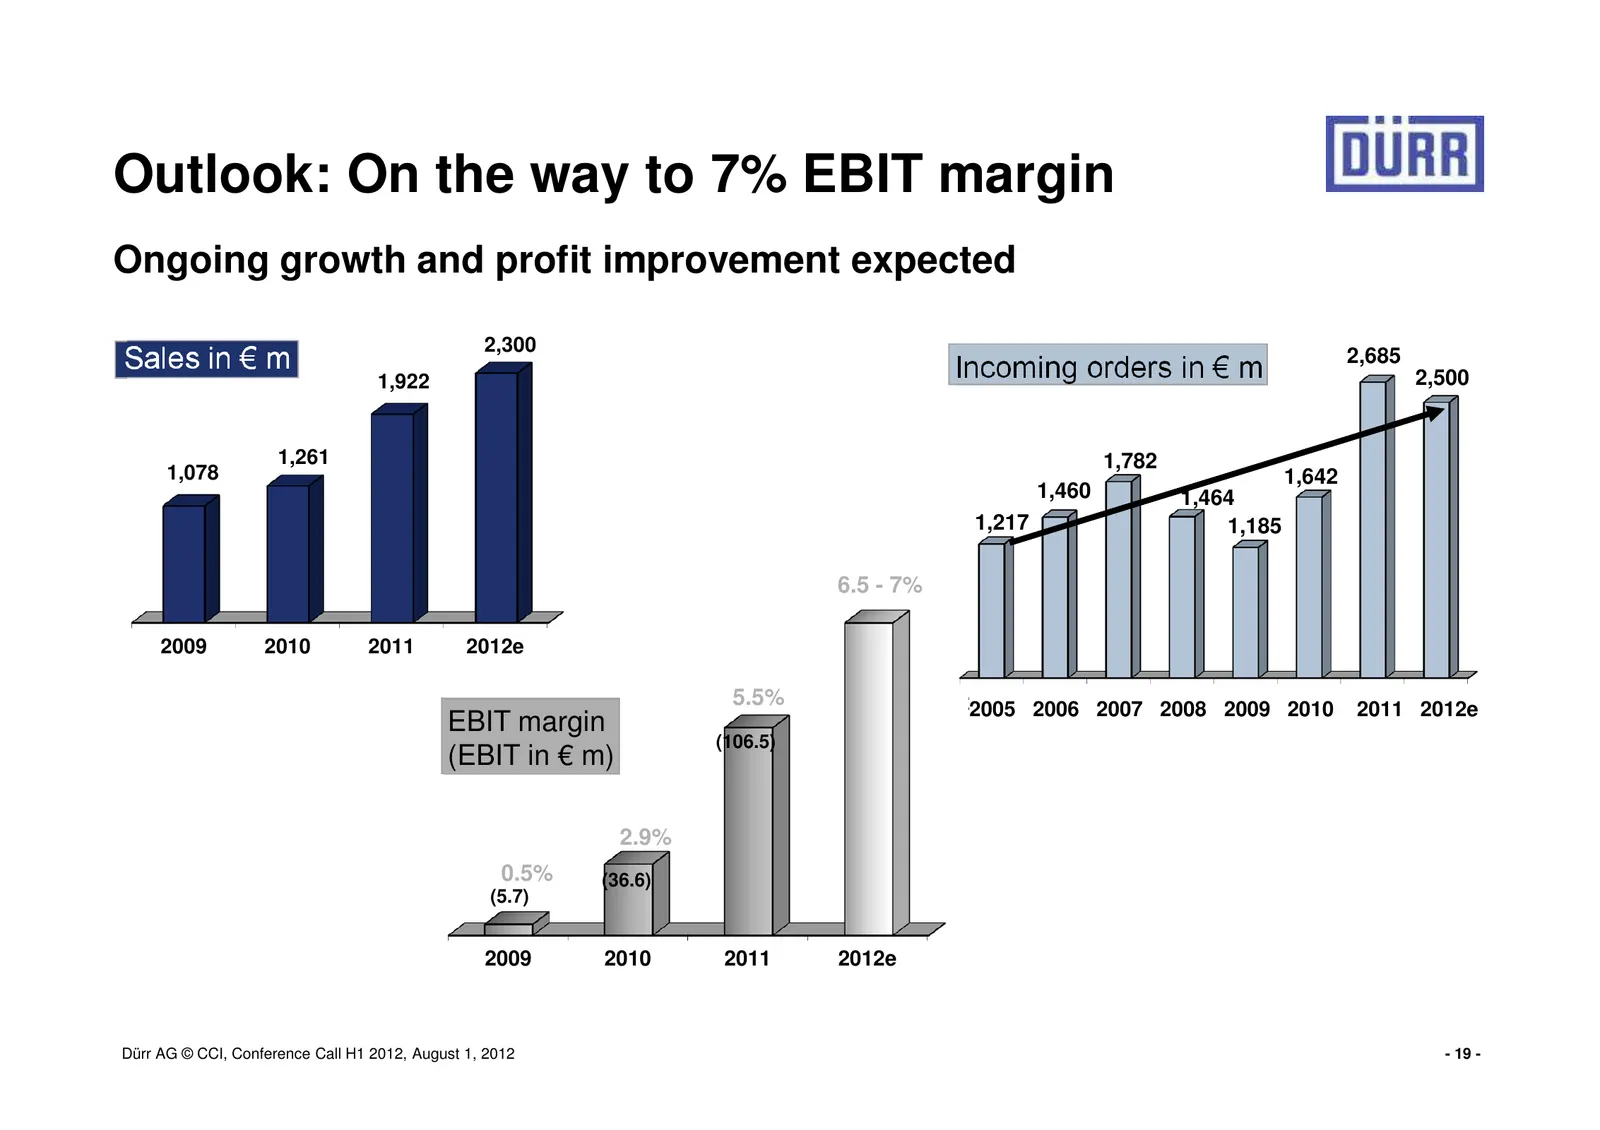
Slide 19: Outlook: On the way to 7% EBIT margin
Outlook: On the way to 7% EBIT margin Ongoing growth and profit improvement expected 2,300 Sales in € m Incoming orders in € m 2,685 1,922 2,500 1,261 1,782 1,078 1,642 1,460 1,464 1,217 1,185 6.5 - 7% 2009 2010 2011 2012e 5.5% 2005 2005 2006 2007 2007 2008 2009 2009 2010 2011 2011 2012e EBIT margin
Slide 20: Summary
Summary H1 better than expected, incoming orders in Q2 above Q1 and Q2 2011, EBIT margin already at 7.1% in Q2 Positive long term market outlook (PwC), despite current macro-economic slowdown Solid project execution Positive 2012 outlook supported by order backlog, incoming orders and pipeline. Marg
Slide 21: Financial calendar
Financial calendar 09/25/2012 Baader Conference, Munich 09/26/2012 Berenberg & Goldman Conference, Munich 11/06/2012 Interim report for the first nine months of 2012 Analyst conference 11/13-14/2012 UBS Conference, London 12/4-7/2012 Berenberg Conference, London Contact: Dürr Aktiengesellschaft Günt
Slide 22: Conference Call: Results January - June 2012 Dürr Group
Conference Call Results January - June 2012 Dürr Group Ralf W. Dieter, CEO Ralph Heuwing, CFO Bietigheim-Bissingen, August 1, 2012 www.durr.com - 22 -
Source: Internet Archive copy of durr.com
More decks from Durr AG
 Q3 2026 Earnings Presentation33 slides · Nov 12, 2026
 Q2 2026 Earnings Presentation39 slides · Aug 6, 2026
 Q1 2026 Earnings Presentation35 slides · May 12, 2026
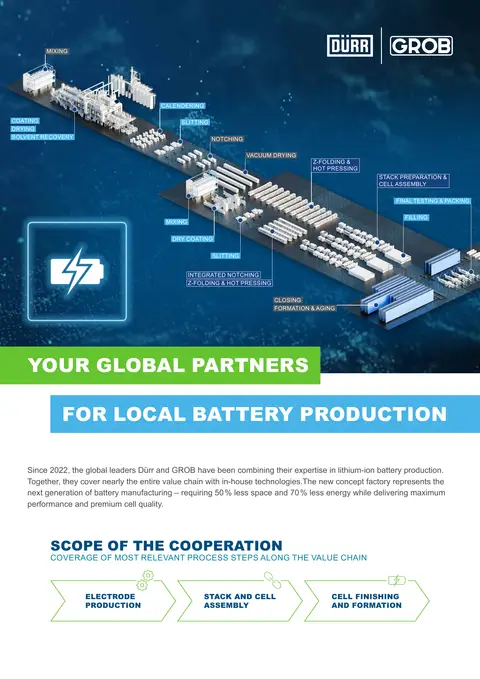 Fact Sheet (2025)2 slides · Dec 2, 2025
 Q3 2025 Earnings Presentation46 slides · Nov 13, 2025
 Q2 2025 Earnings Presentation31 slides · Jul 24, 2025