Sappi Limited · JSE:SAP
Sappi — Q1 FY2024 Earnings Presentation
46 slides from Sappi's earnings presentation, Feb 7, 2024
Slide 1: Q1 FY24 financial results
Steve Binnie Chief Executive Officer, Sappi Limited 07 February 2024 Q1 FY24 financial results 1
Slide 2: Forward-looking statements and Regulation G disclosure
Forward-looking statements and Regulation G disclosure Forward-looking statements Certain statements in this release that are neither reported financial results nor other historical information are forward-looking statements, including but not limited to statements that are predictions of or indicat
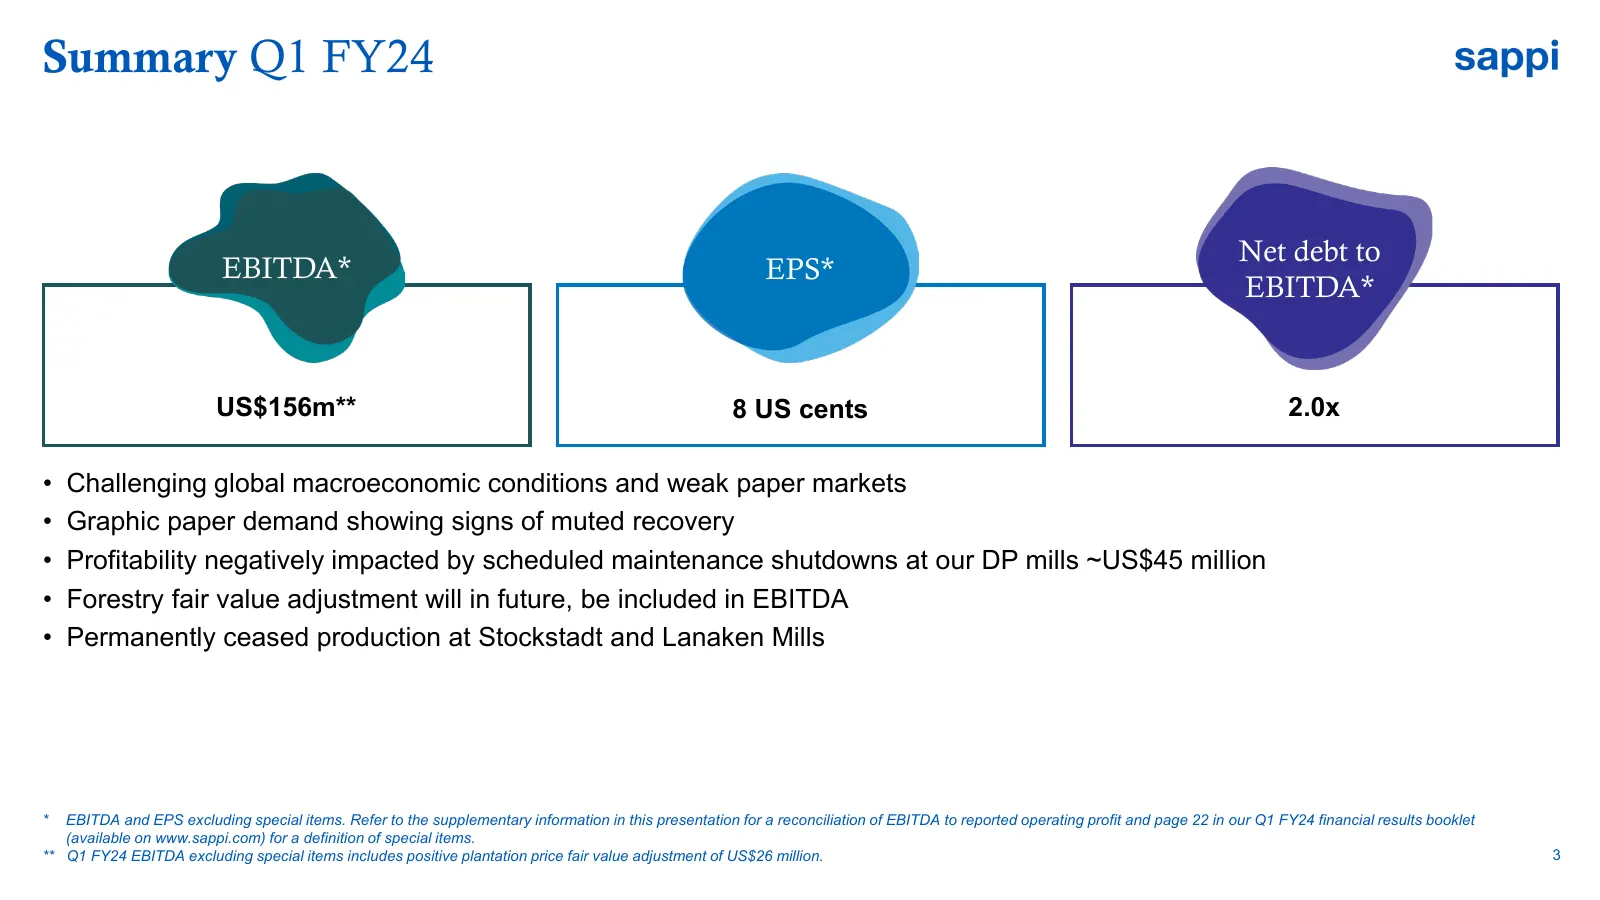
Slide 3: Summary Q1 FY24
Summary Q1 FY24 Net debt to EBITDA* EPS* EBITDA* US$156m** 8 US cents 2.0x • Challenging global macroeconomic conditions and weak paper markets • Graphic paper demand showing signs of muted recovery • Profitability negatively impacted by scheduled maintenance shutdowns at our DP mills ~US$45 million
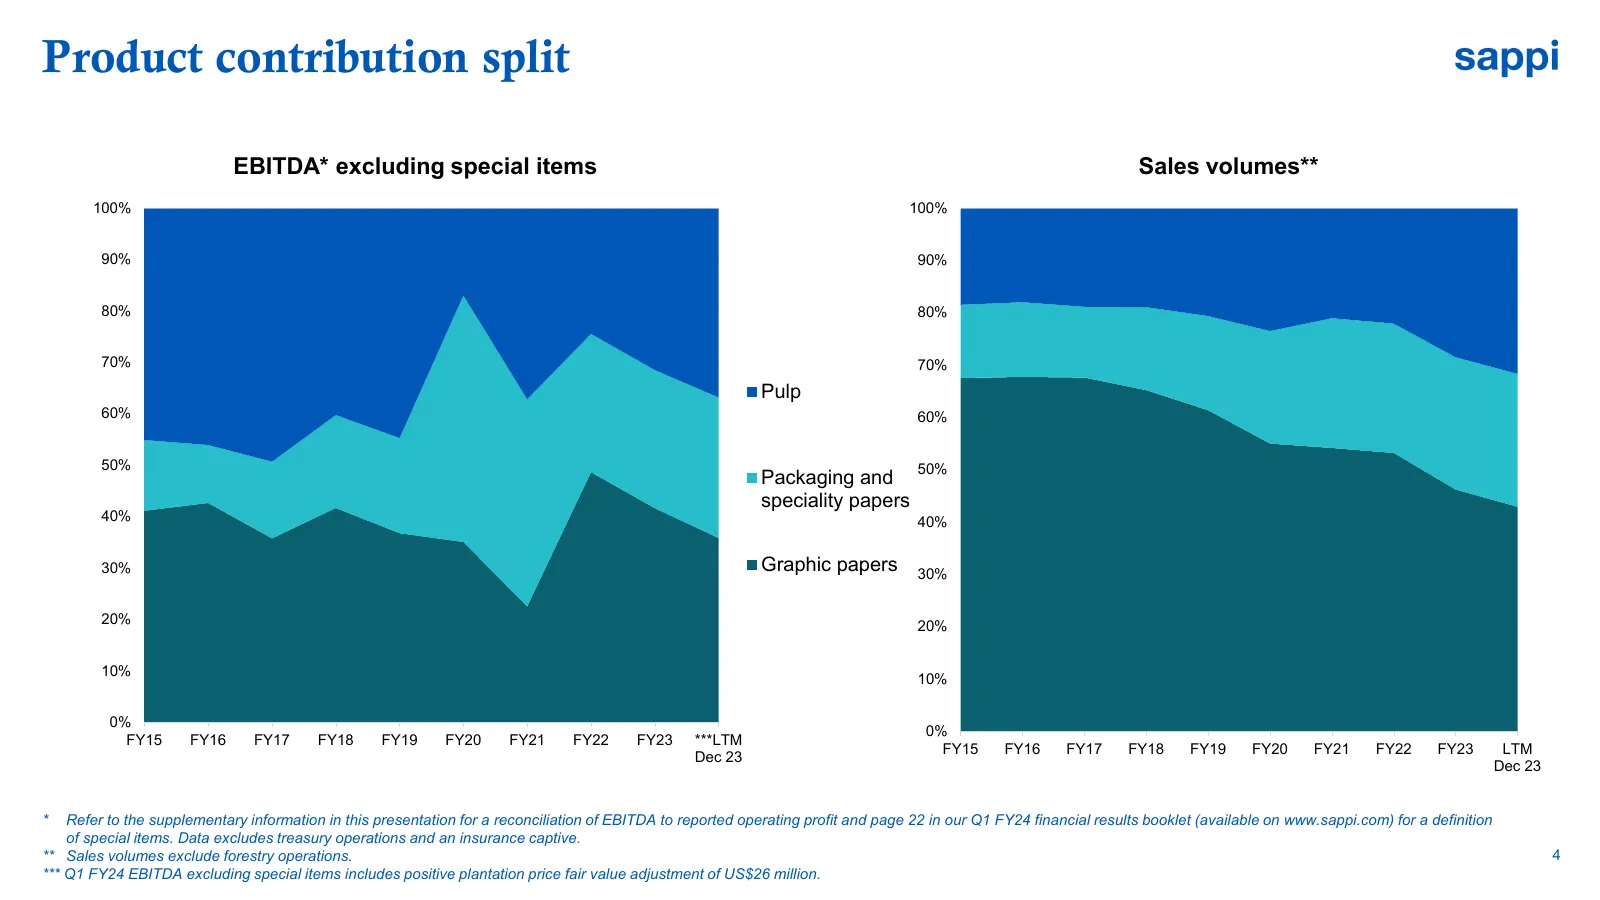
Slide 4: Product contribution split
Product contribution split EBITDA* excluding special items Sales volumes** 100% 100% 90% 90% 80% 80% 70% 70% Pulp 60% 60% 50% Packaging and 50% speciality papers 40% 40% 30% Graphic papers 30% 20% 20% 10% 10% 0% 0% FY15 FY16 FY17 FY18 FY19 FY20 FY21 FY22 FY23 ***LTM FY15 FY16 FY17 FY18 FY19 FY20 FY2
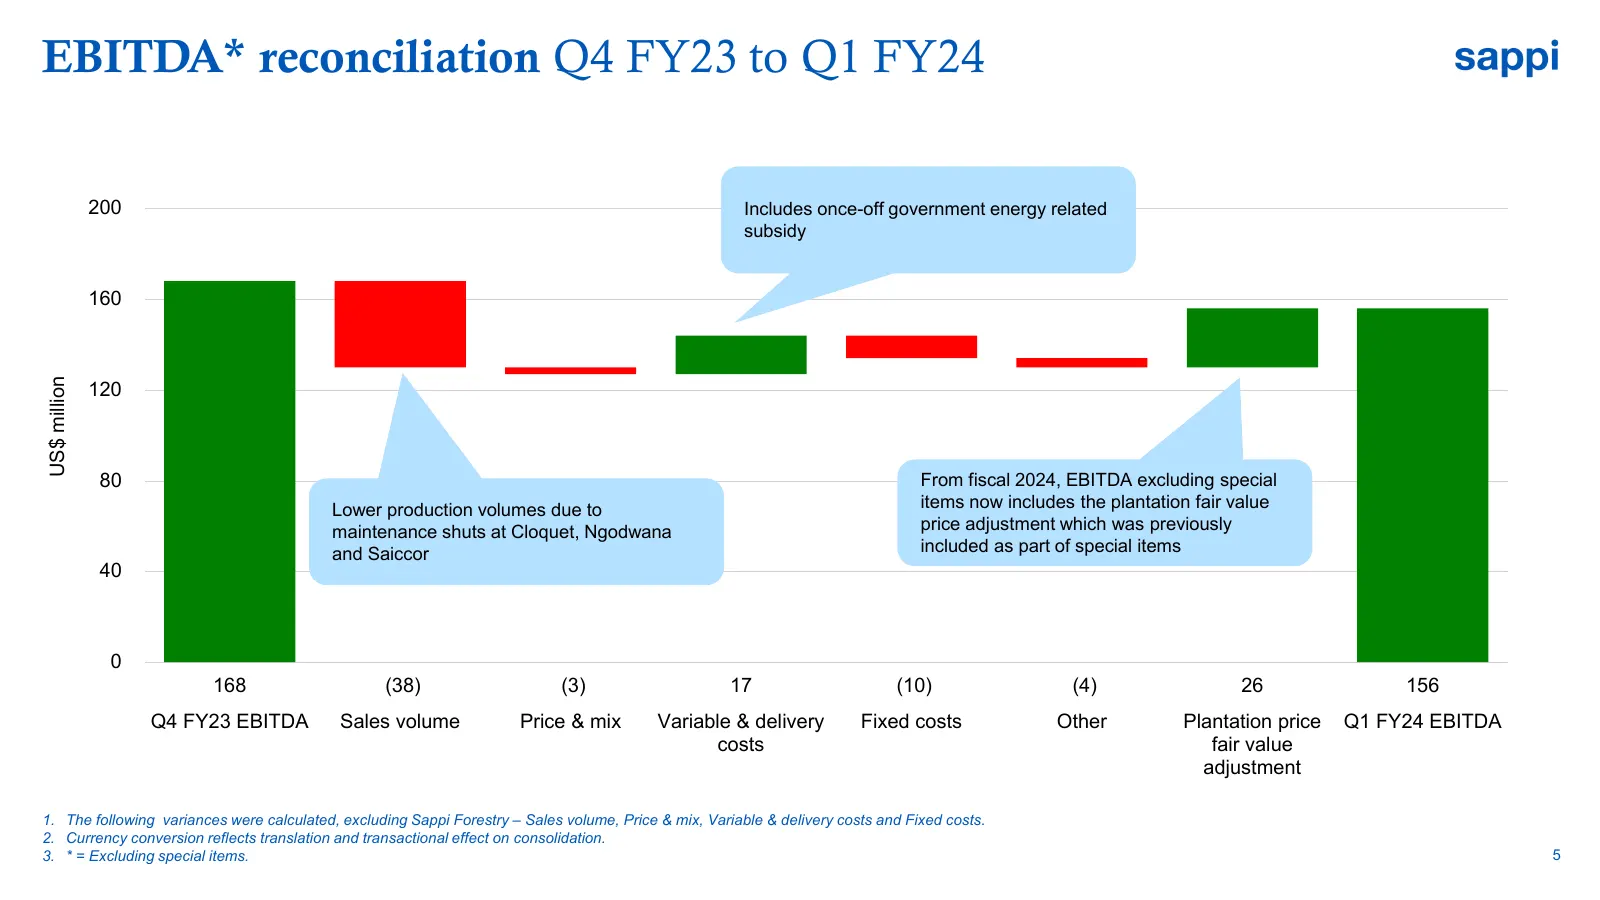
Slide 5: EBITDA reconciliation Q4 FY23 to Q1 FY24
EBITDA* reconciliation Q4 FY23 to Q1 FY24 200 Includes once-off government energy related subsidy 160 120 US$ million 80 From fiscal 2024, EBITDA excluding special Lower production volumes due to items now includes the plantation fair value maintenance shuts at Cloquet, Ngodwana price adjustment whi
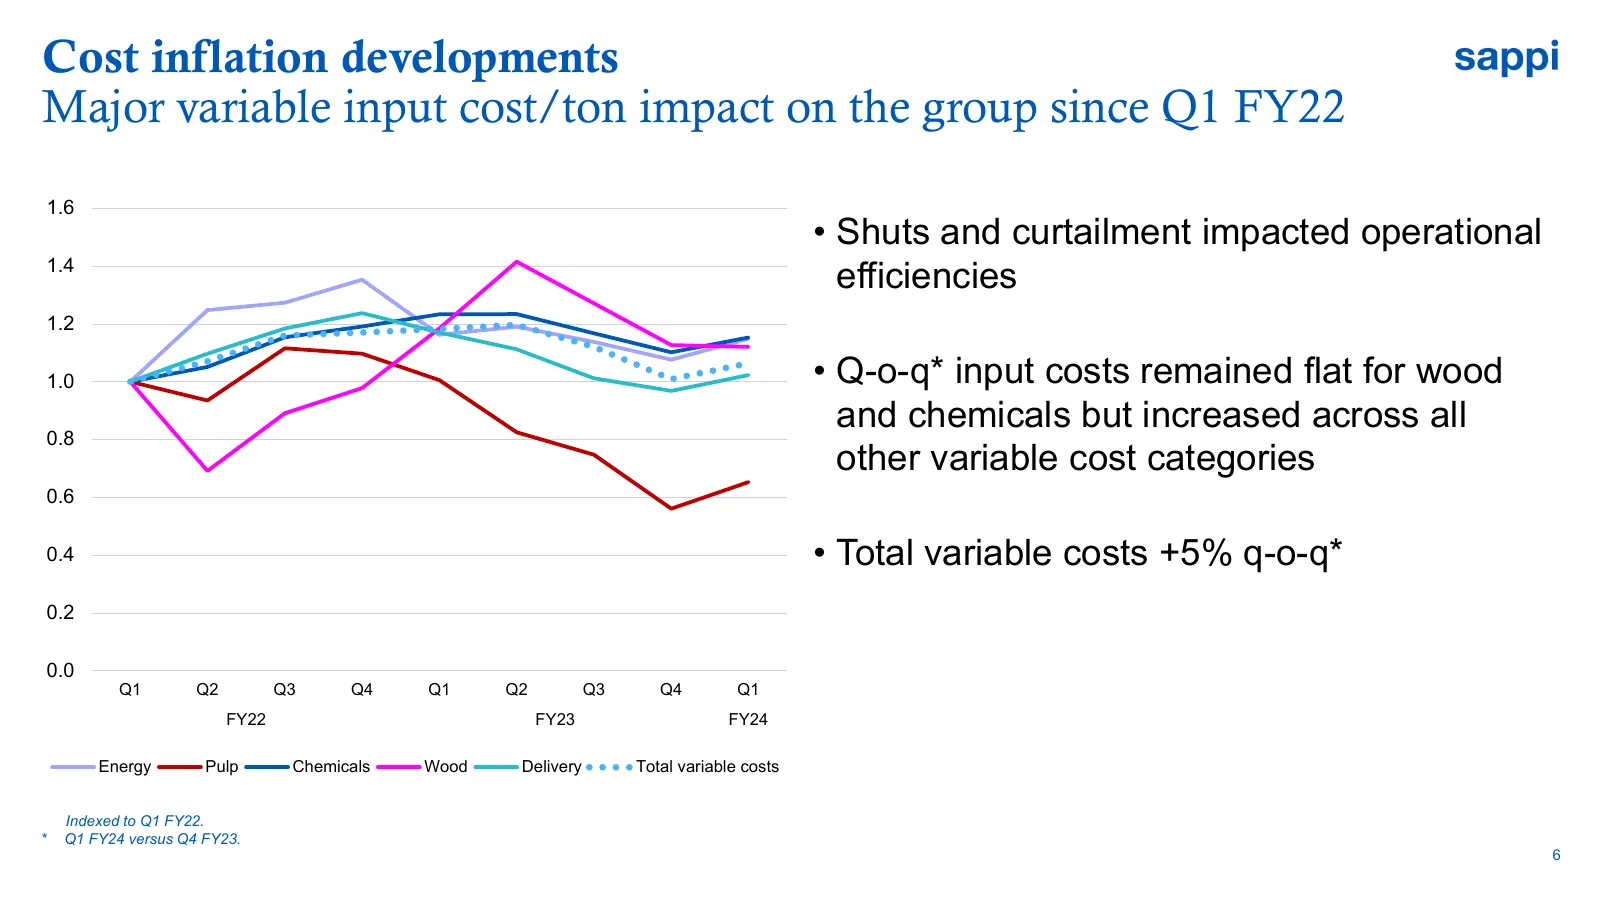
Slide 6: Cost inflation developments
Cost inflation developments Major variable input cost/ton impact on the group since Q1 FY22 1.6 • Shuts and curtailment impacted operational 1.4 efficiencies 1.2 1.0 • Q-o-q* input costs remained flat for wood and chemicals but increased across all 0.8 other variable cost categories 0.6 0.4 • Total
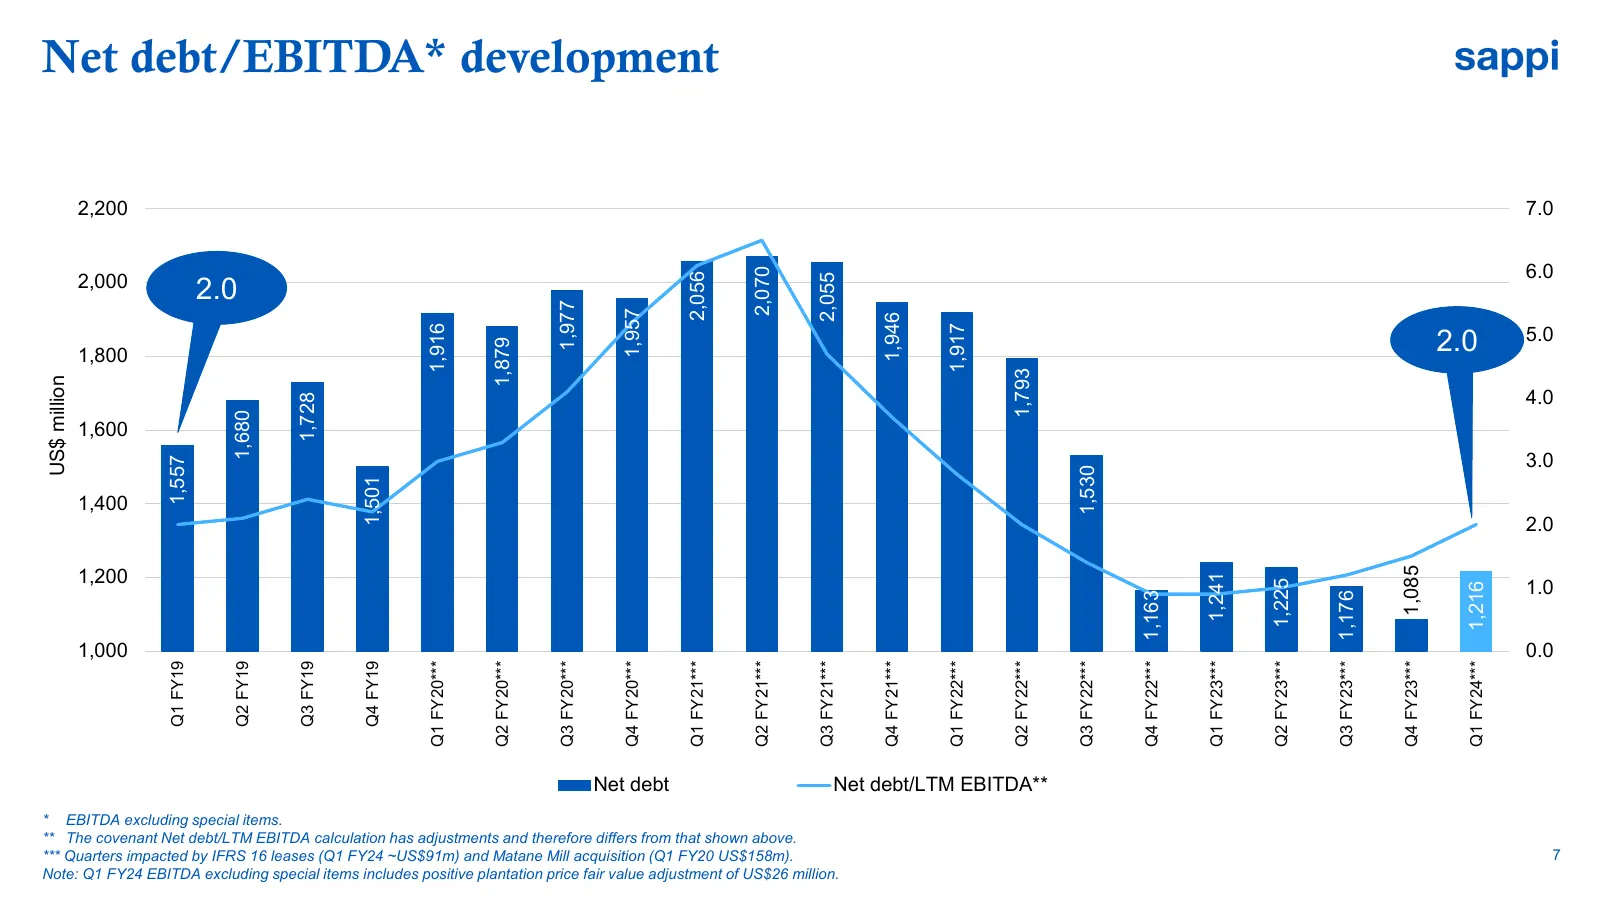
Slide 7: Net debt/EBITDA development
Net debt/EBITDA* development 2,200 7.0 6.0 2,070 2,000 2.0 2,056 2,055 1,977 1,957 1,946 2.0 5.0 1,917 1,916 1,879 1,800 1,793 US$ million 4.0 1,728 1,680 1,600 3.0 1,557 1,530 1,501 1,400 2.0 1,200 1,085 1,241 1.0 1,225 1,216 1,163 1,176 1,000 0.0 Q1 FY19 Q2 FY19 Q3 FY19 Q4 FY19 Q1 FY20*** Q2 FY20*
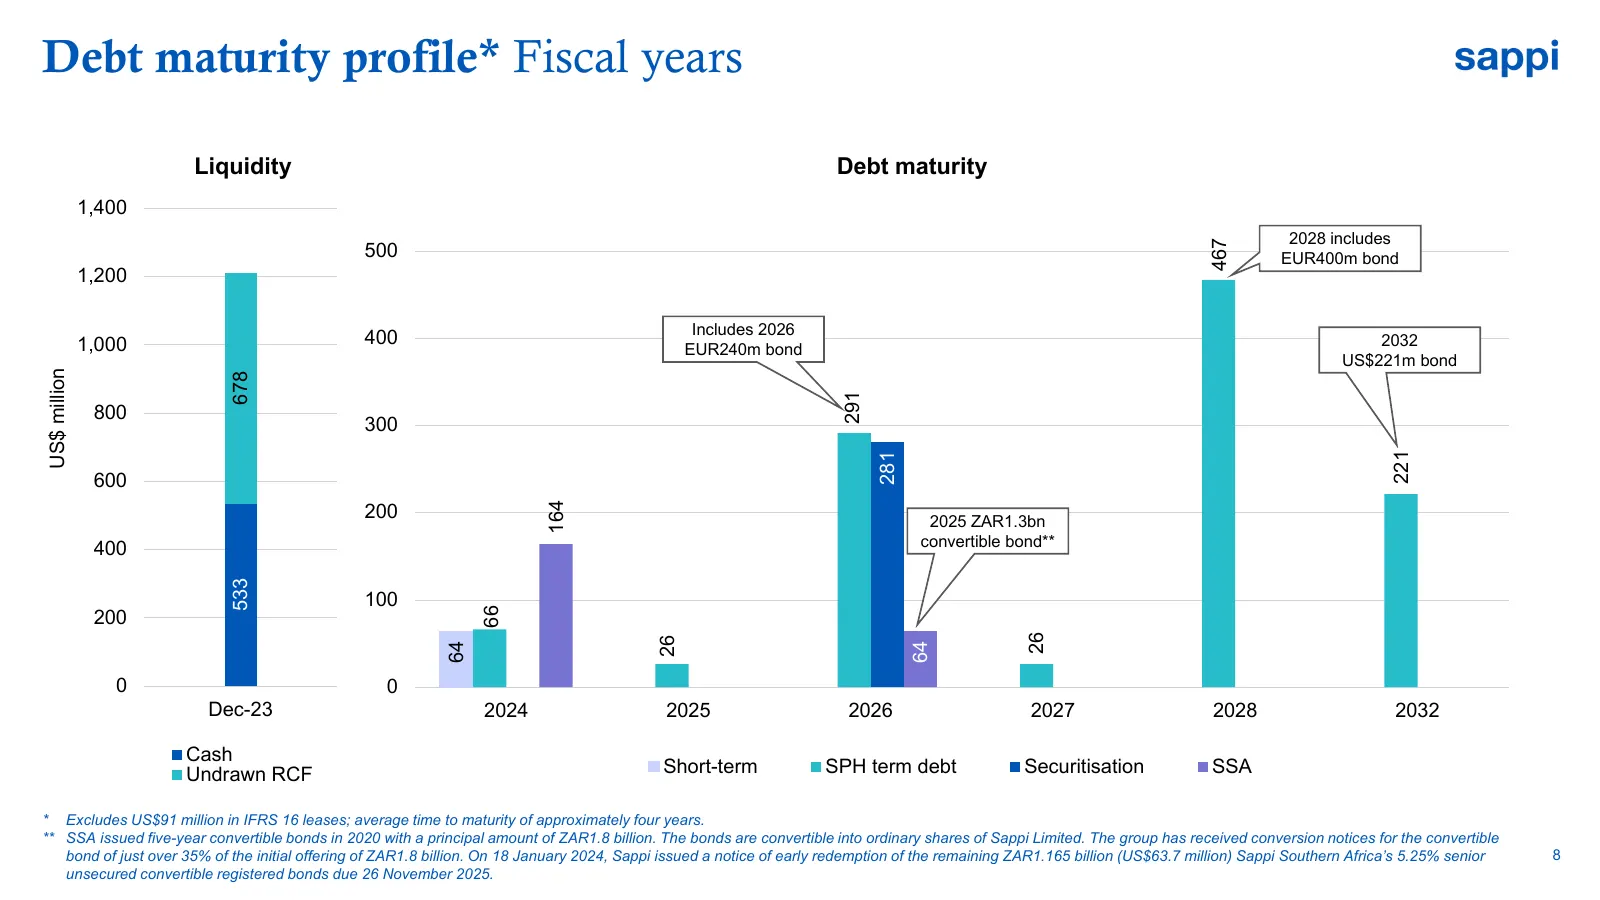
Slide 8: Debt maturity profile
Debt maturity profile* Fiscal years Liquidity Debt maturity 1,400 2028 includes 500 467 EUR400m bond 1,200 Includes 2026 1,000 400 2032 EUR240m bond US$221m bond US$ million 678 291 800 300 221 281 600 200 164 2025 ZAR1.3bn convertible bond** 400 533 100 200 66 26 26 64 64 0 0 Dec-23 2024 2025 2026
Slide 9: Cash flow and capex
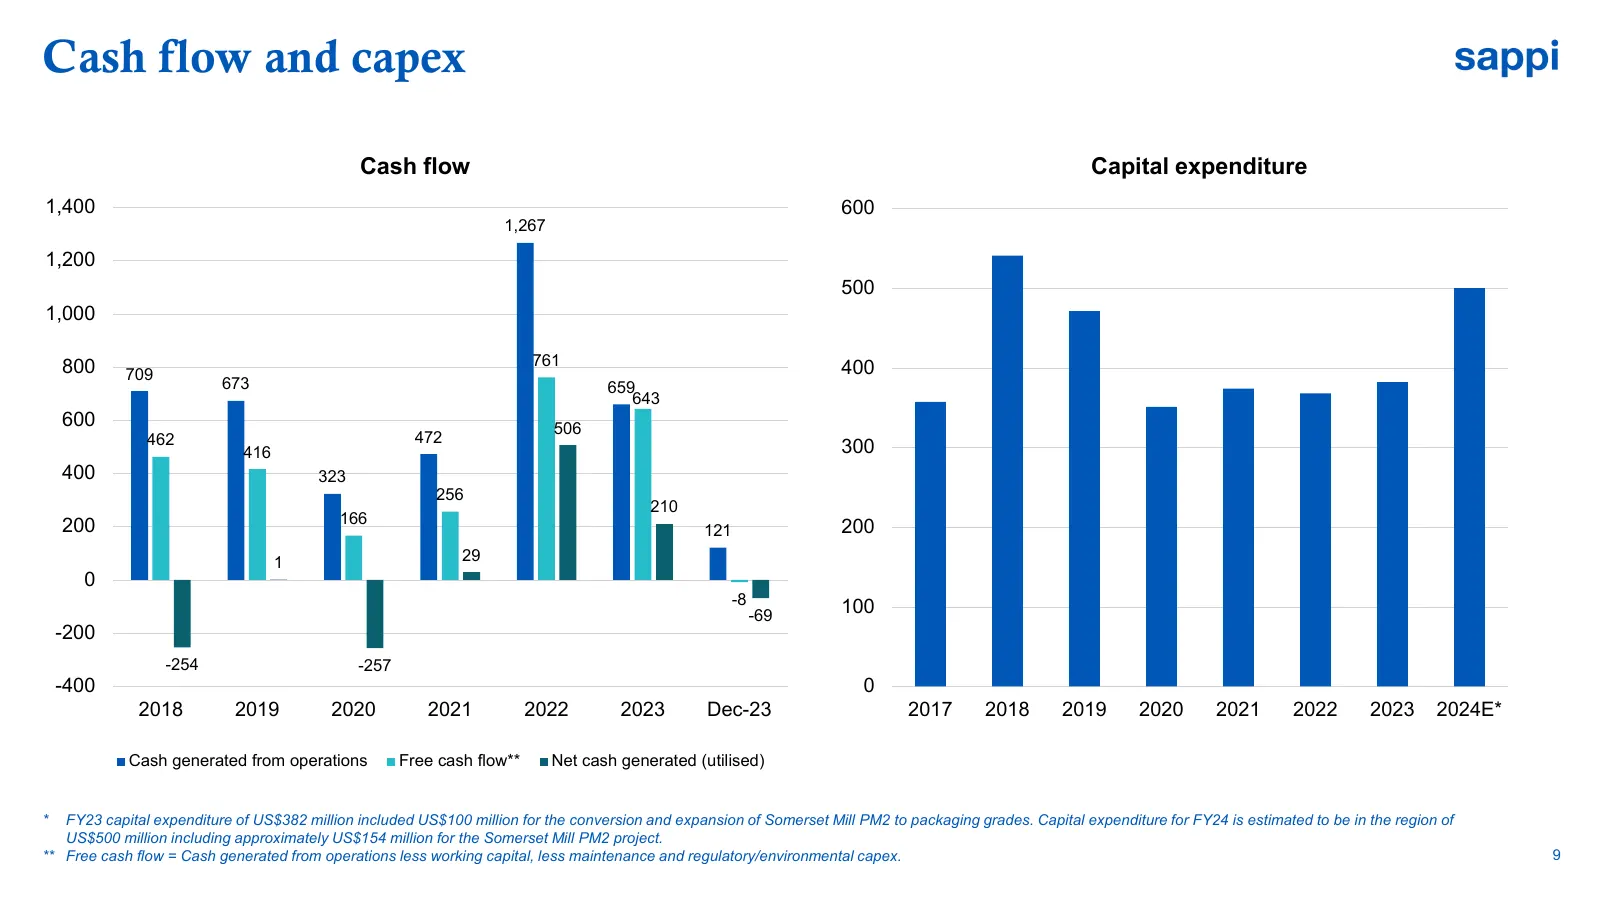
Cash flow and capex Cash flow Capital expenditure 1,400 600 1,267 1,200 500 1,000 800 761 400 709 673 659 643 600 506 462 472 416 300 400 323 256 210 166 200 121 200 1 29 0 -8 100 -69 -200 -254 -257 -400 0 2018 2019 2020 2021 2022 2023 Dec-23 2017 2018 2019 2020 2021 2022 2023 2024E* Cash generated
Slide 10: Disciplined capital allocation
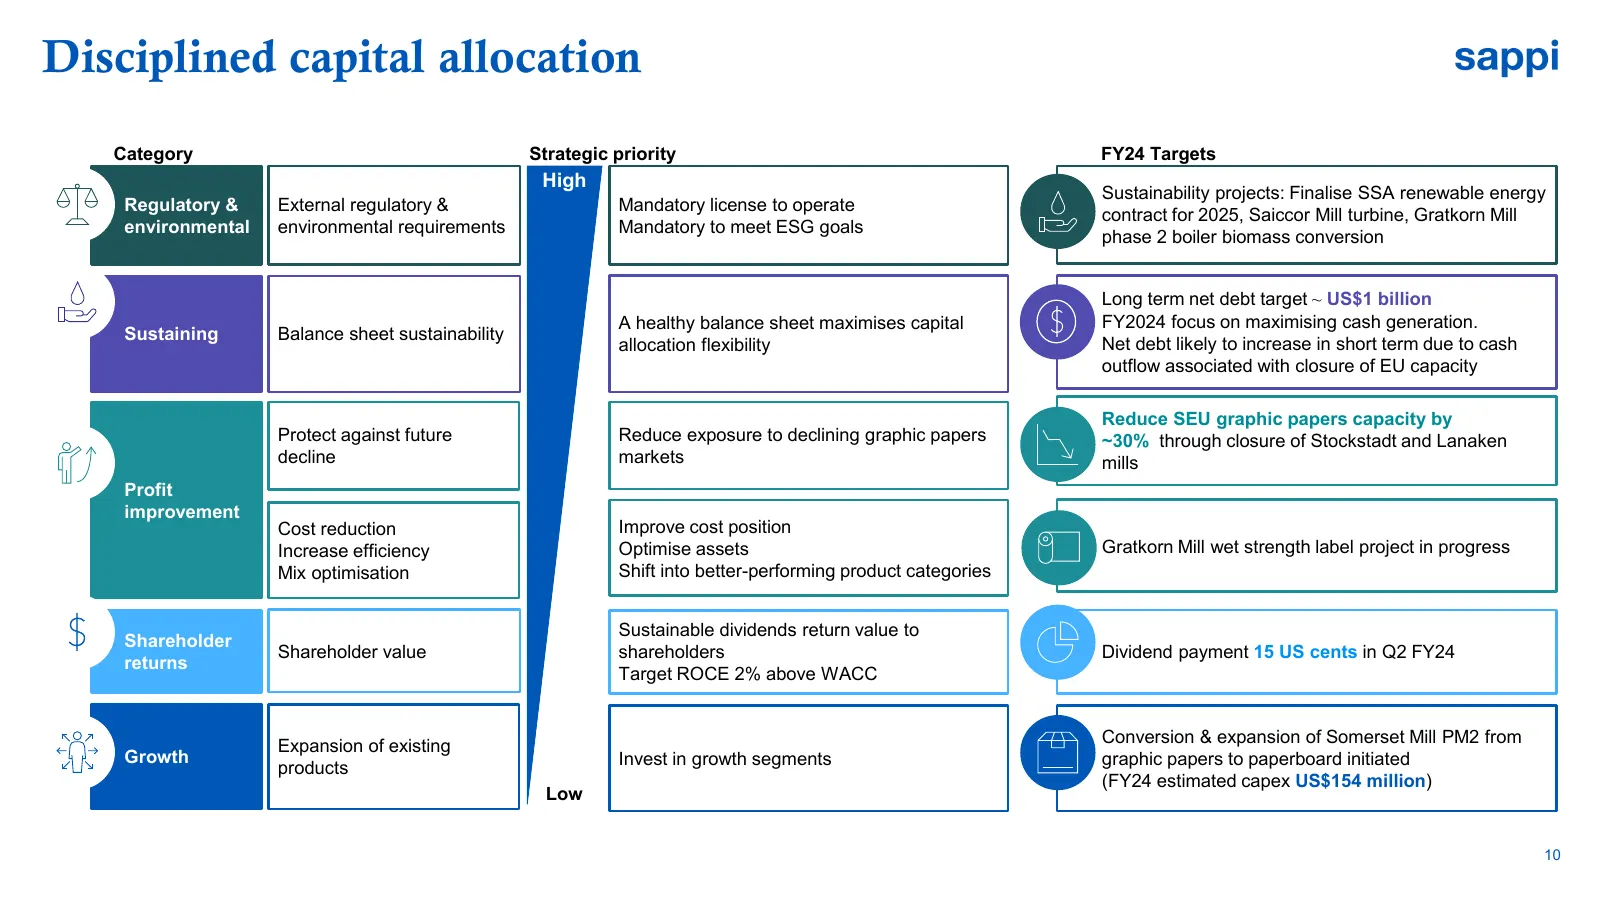
Disciplined capital allocation Category Strategic priority FY24 Targets High Sustainability projects: Finalise SSA renewable energy Regulatory & External regulatory & Mandatory license to operate contract for 2025, Saiccor Mill turbine, Gratkorn Mill environmental environmental requirements Mandator
Slide 11: Segmental overview
sappi Segmental overview
Slide 12: Dissolving pulp summary Q1 FY24
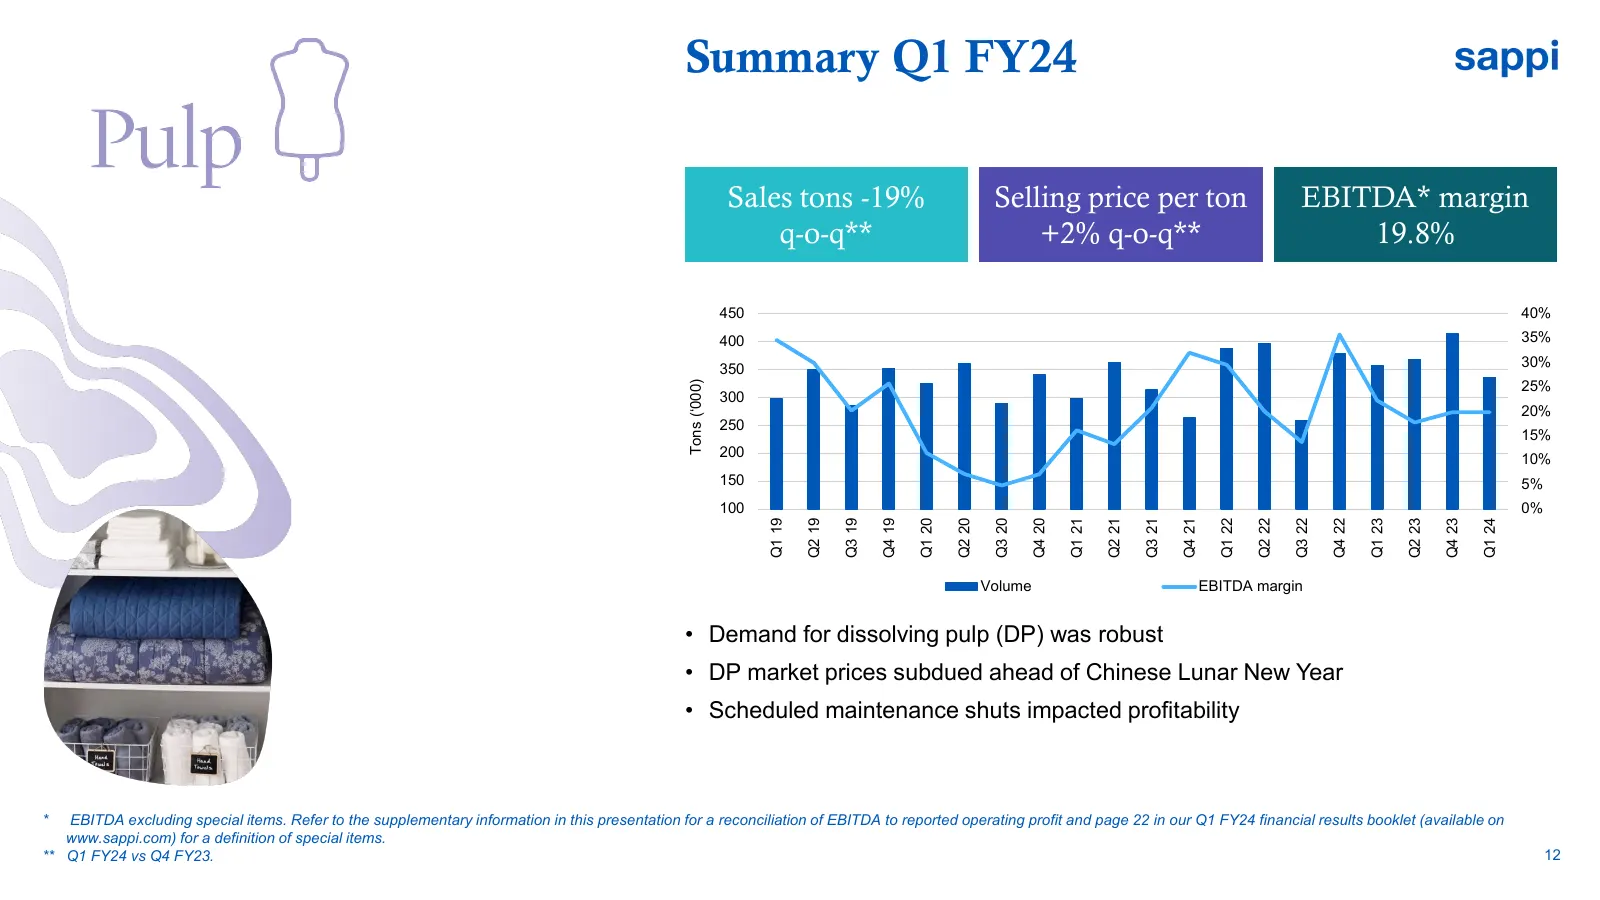
Summary Q1 FY24 Sales tons -19% Selling price per ton EBITDA* margin q-o-q** +2% q-o-q** 19.8% 450 40% 400 35% 350 30% 25% Tons (‘000) 300 20% 250 15% 200 10% 150 5% 100 0% Q1 19 Q2 19 Q3 19 Q4 19 Q1 20 Q2 20 Q3 20 Q4 20 Q1 21 Q2 21 Q3 21 Q4 21 Q1 22 Q2 22 Q3 22 Q4 22 Q1 23 Q2 23 Q4 23 Q1 24 Volume
Slide 13: Packaging and speciality papers
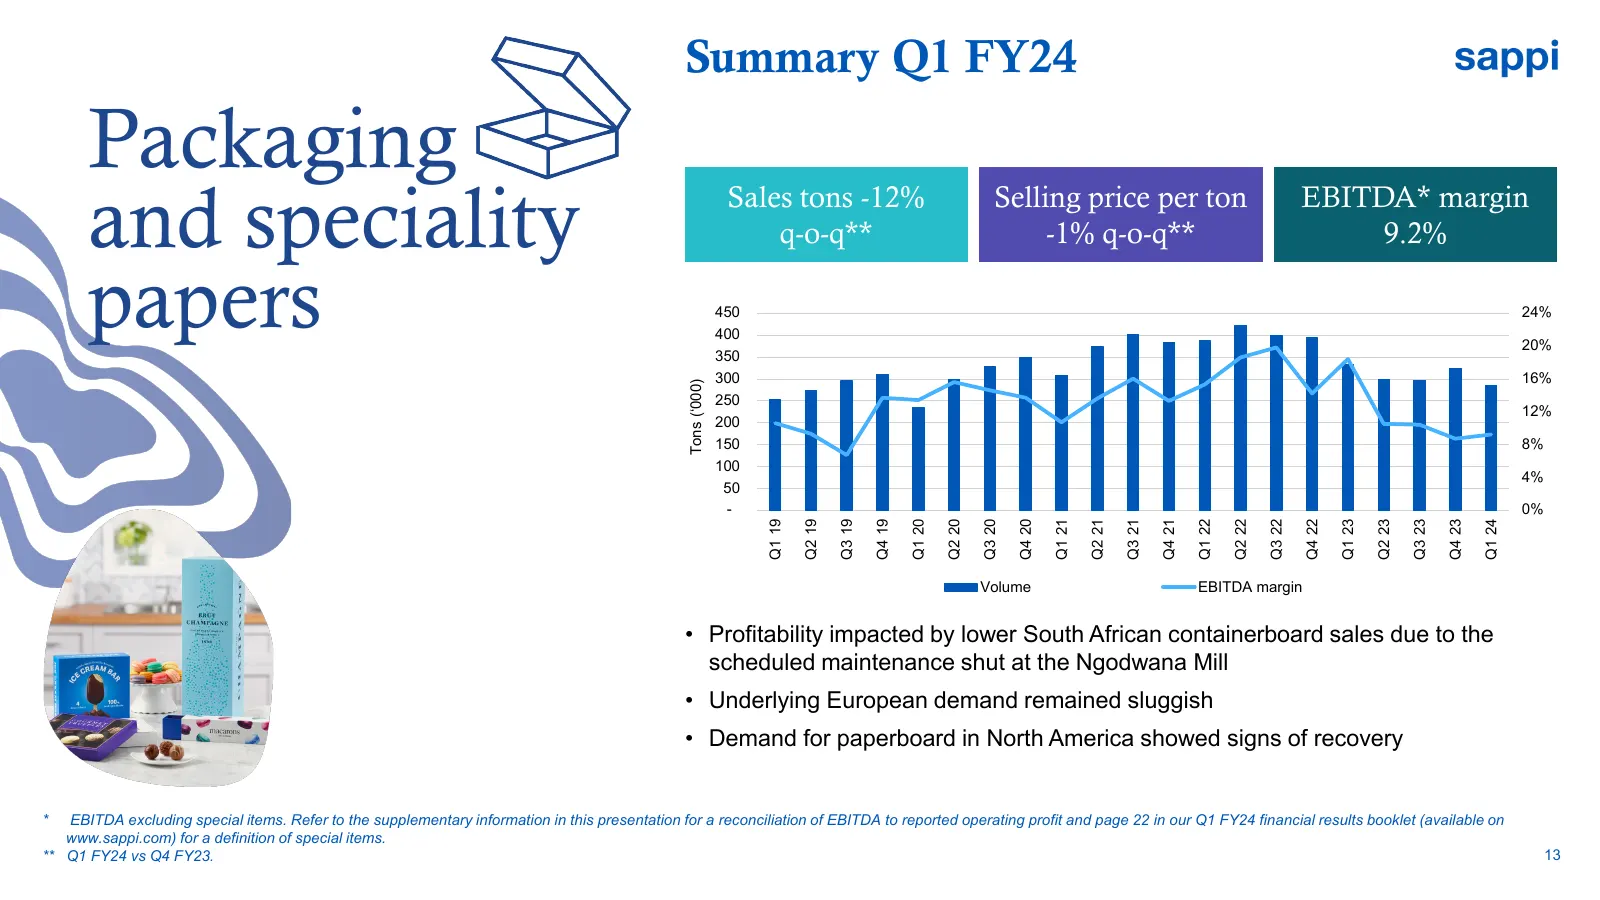
Summary Q1 FY24 Packaging and speciality Sales tons -12% q-o-q** Selling price per ton -1% q-o-q** EBITDA* margin 9.2% papers 450 400 350 24% 20% 300 16% Tons (‘000) 250 12% 200 150 8% 100 4% 50 - 0% Q1 19 Q2 19 Q3 19 Q4 19 Q1 20 Q2 20 Q3 20 Q4 20 Q1 21 Q2 21 Q3 21 Q4 21 Q1 22 Q2 22 Q3 22 Q4 22 Q1 2
Slide 14: Graphic papers summary Q1 FY24
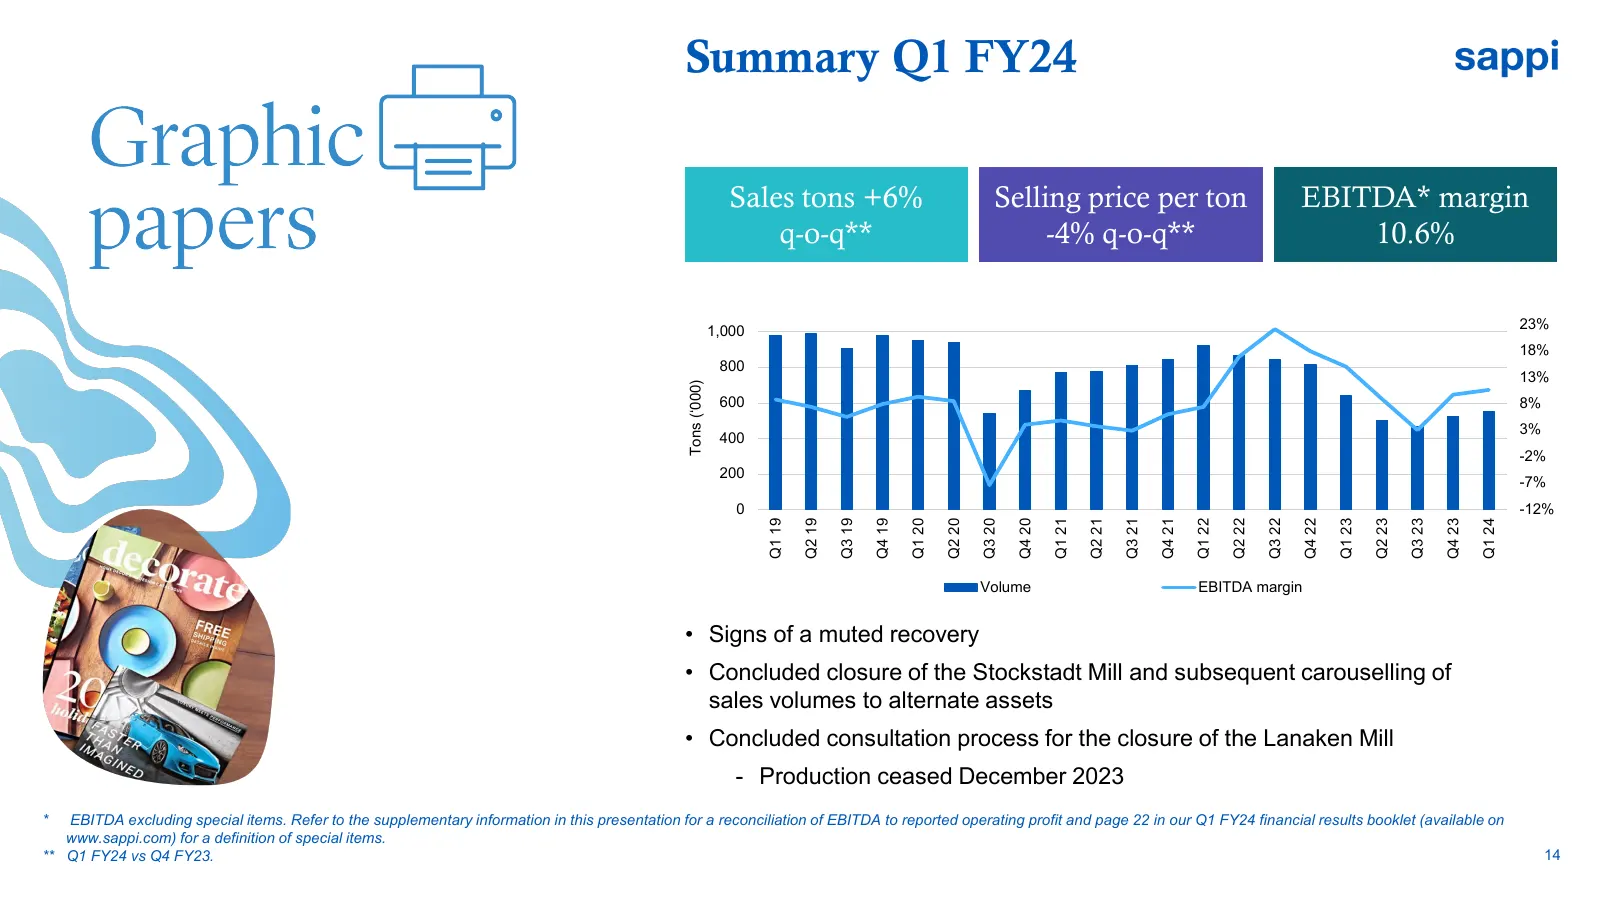
Summary Q1 FY24 Sales tons +6% Selling price per ton EBITDA* margin q-o-q** -4% q-o-q** 10.6% 1,000 23% 18% 800 13% Tons (‘000) 600 8% 3% 400 -2% 200 -7% 0 -12% Q1 19 Q2 19 Q3 19 Q4 19 Q1 20 Q2 20 Q3 20 Q4 20 Q1 21 Q2 21 Q3 21 Q4 21 Q1 22 Q2 22 Q3 22 Q4 22 Q1 23 Q2 23 Q3 23 Q4 23 Q1 24 Volume EBITDA
Slide 15: Regional segments Summary Q1 FY24
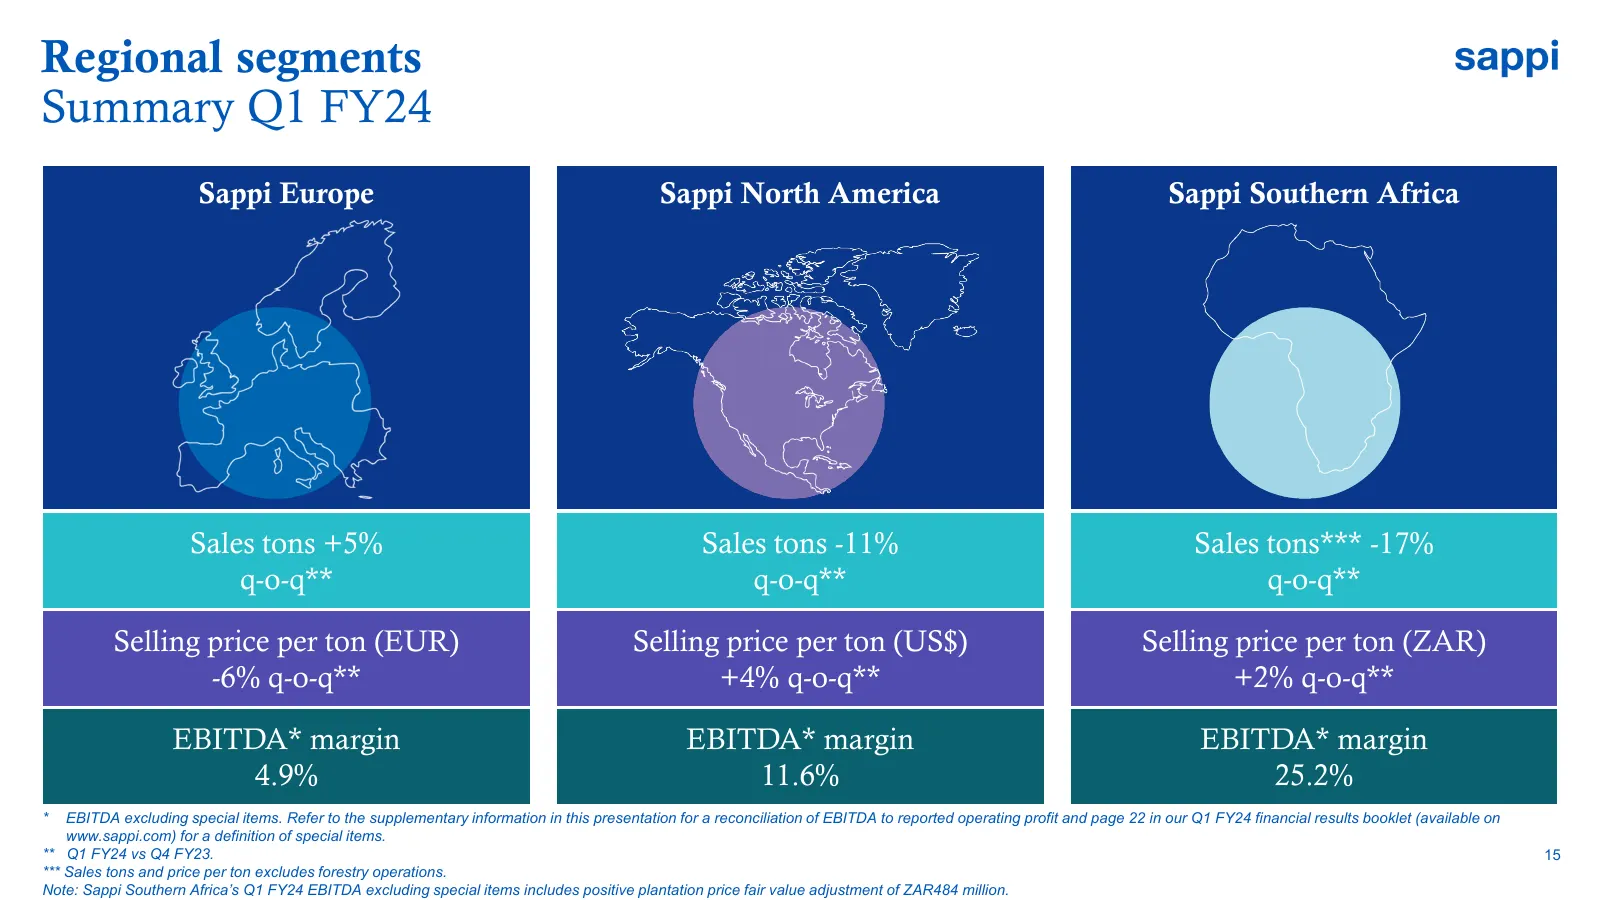
Regional segments Summary Q1 FY24 Sappi Europe Sappi North America Sappi Southern Africa Sales tons +5% Sales tons -11% Sales tons*** -17% q-o-q** q-o-q** q-o-q** Selling price per ton (EUR) Selling price per ton (US$) Selling price per ton (ZAR) -6% q-o-q** +4% q-o-q** +2% q-o-q** EBITDA* margin EB
Slide 16: Regional segments continued
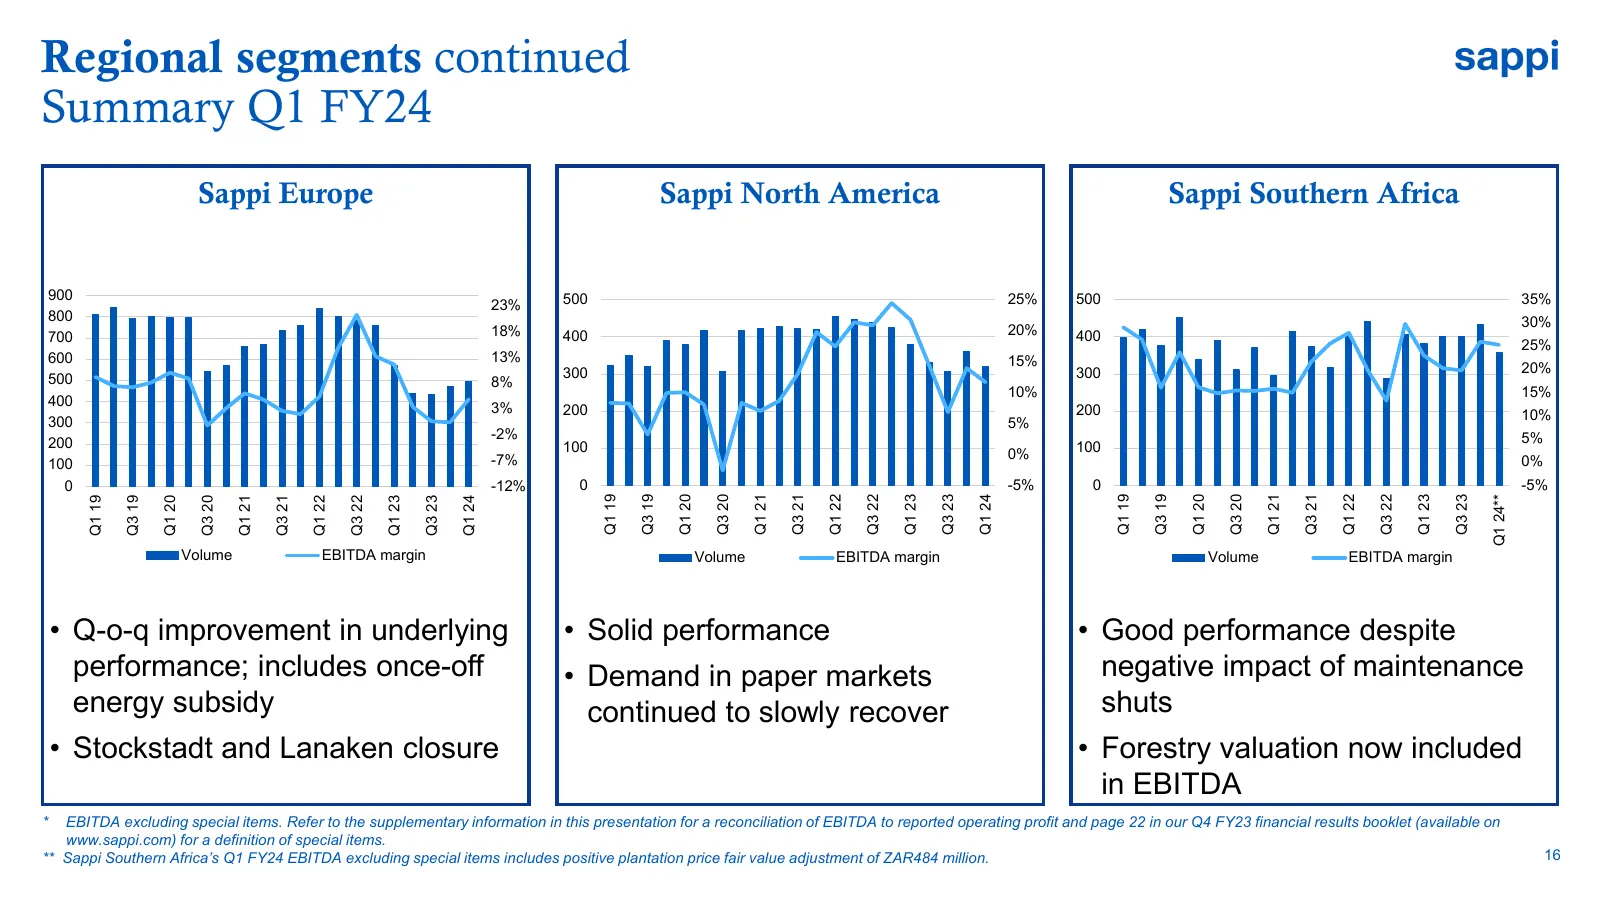
Regional segments continued Summary Q1 FY24 Sappi Europe Sappi North America Sappi Southern Africa 900 500 25% 500 35% 23% 800 30% 700 18% 400 20% 400 25% 600 13% 15% 300 300 20% 500 8% 10% 15% 400 3% 200 200 10% 300 5% -2% 5% 200 100 100 -7% 0% 100 0% 0 -12% 0 -5% 0 -5% Q1 19 Q3 19 Q1 20 Q3 20 Q1 2
Slide 17: Our business strategy
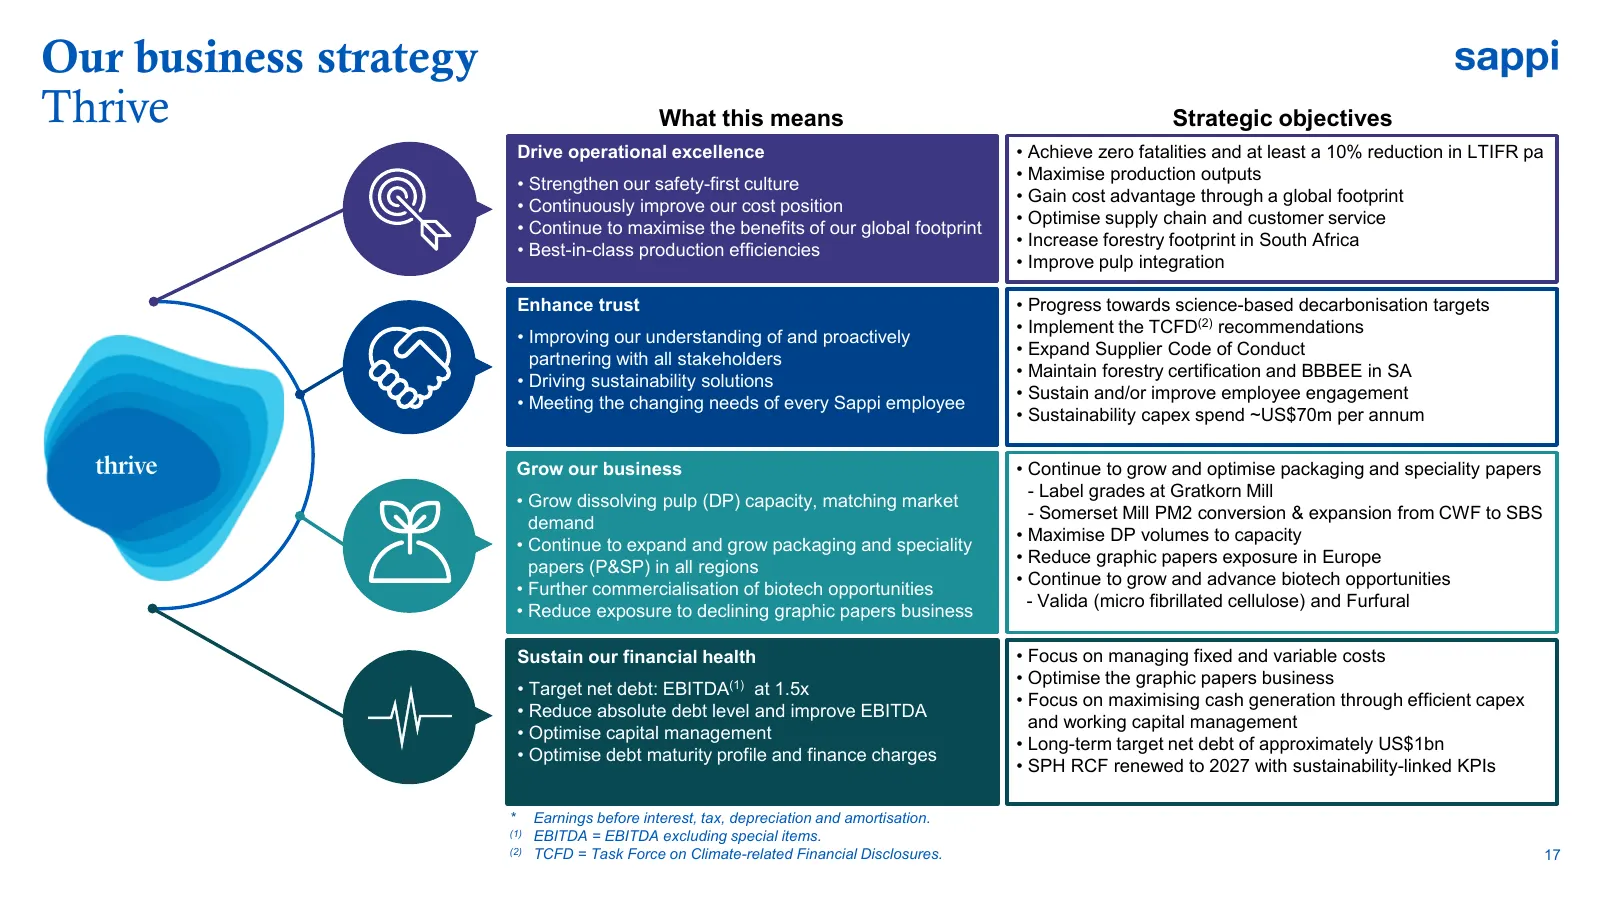
Our business strategy Thrive What this means Strategic objectives Drive operational excellence • Achieve zero fatalities and at least a 10% reduction in LTIFR pa • Maximise production outputs • Strengthen our safety-first culture • Gain cost advantage through a global footprint • Continuously improv
Slide 18: ESG - Continuously rethinking what we do and how we do it
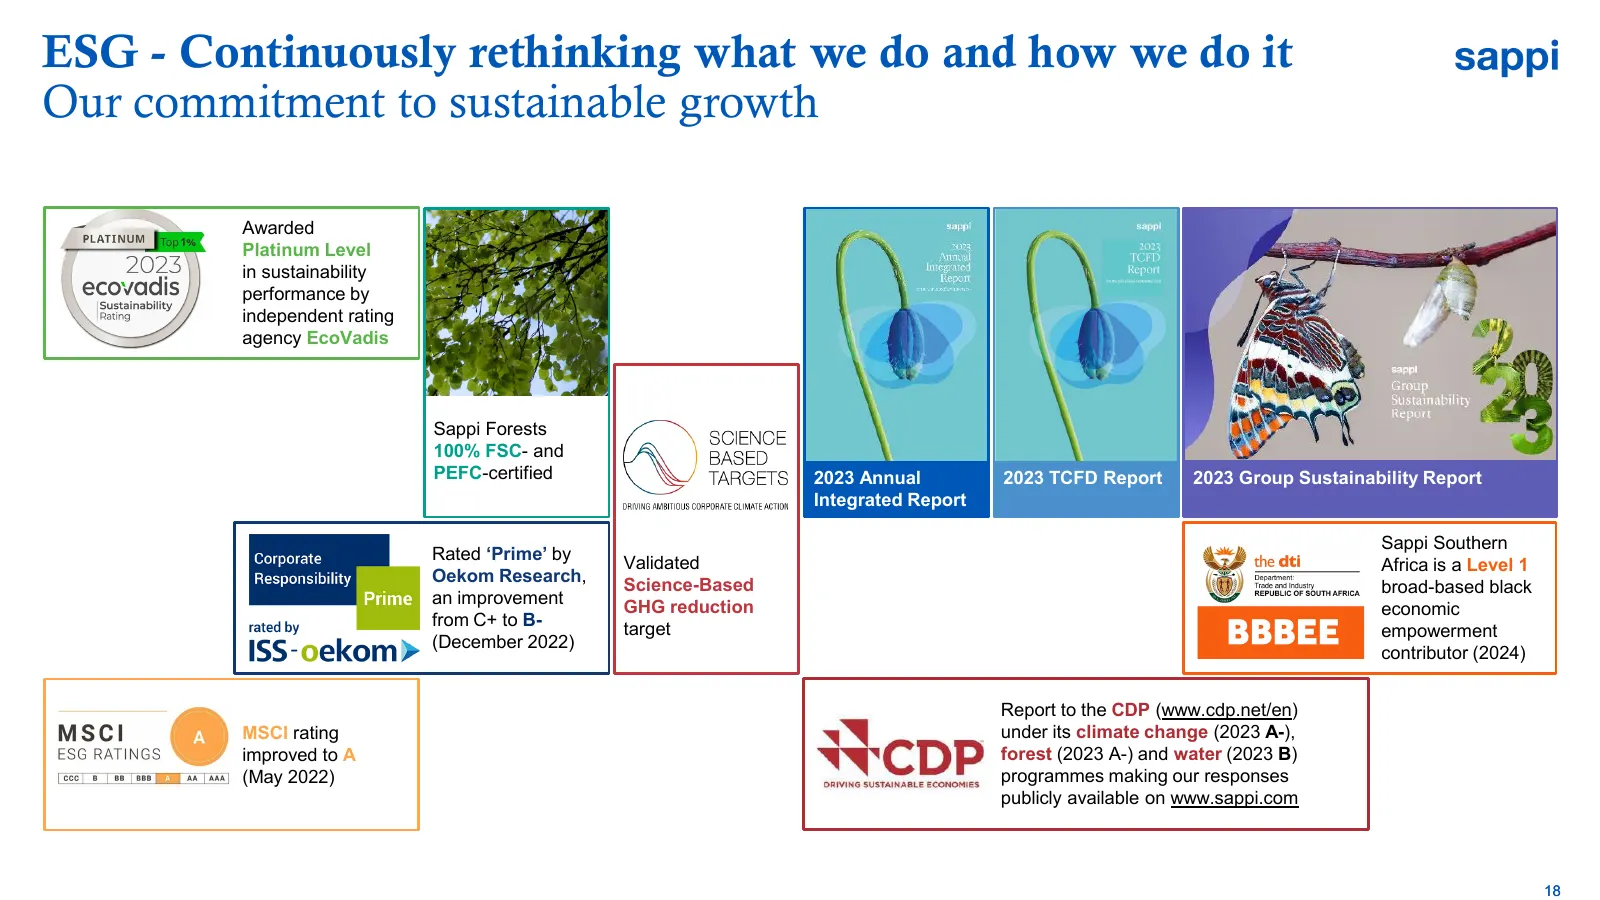
ESG - Continuously rethinking what we do and how we do it Our commitment to sustainable growth Awarded Platinum Level in sustainability performance by independent rating agency EcoVadis Sappi Forests 100% FSC- and PEFC-certified 2023 Annual 2023 TCFD Report 2023 Group Sustainability Report Integrate
Slide 19: Outlook
Outlook 19
Slide 20: Outlook
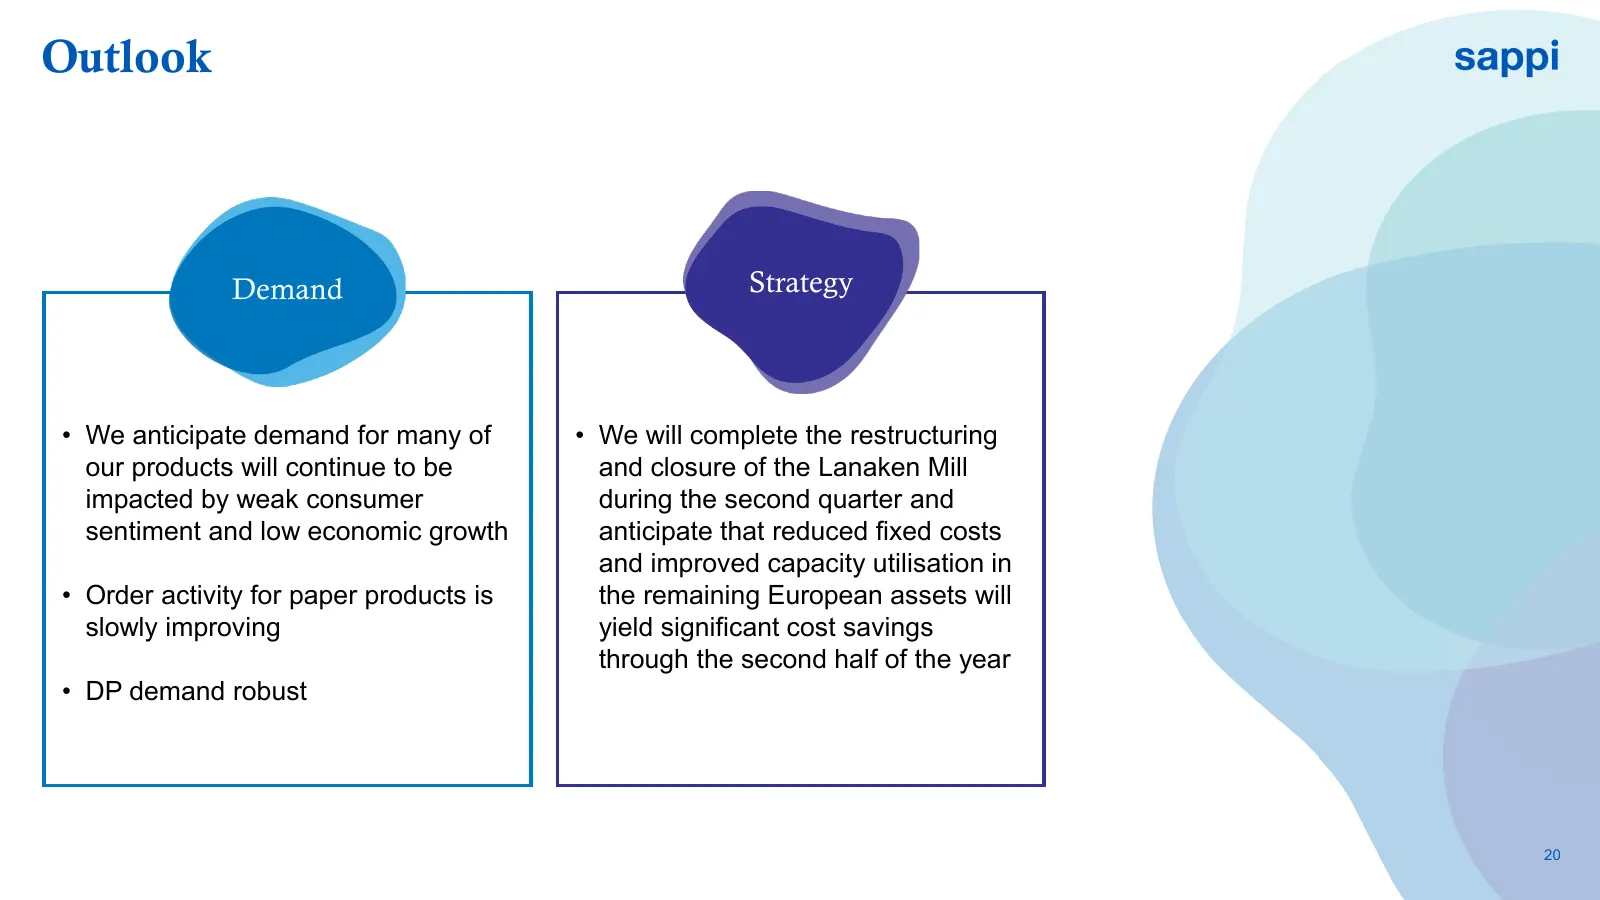
Outlook Demand Strategy • We anticipate demand for many of • We will complete the restructuring our products will continue to be and closure of the Lanaken Mill impacted by weak consumer during the second quarter and sentiment and low economic growth anticipate that reduced fixed costs and improved
Slide 21: Outlook continued
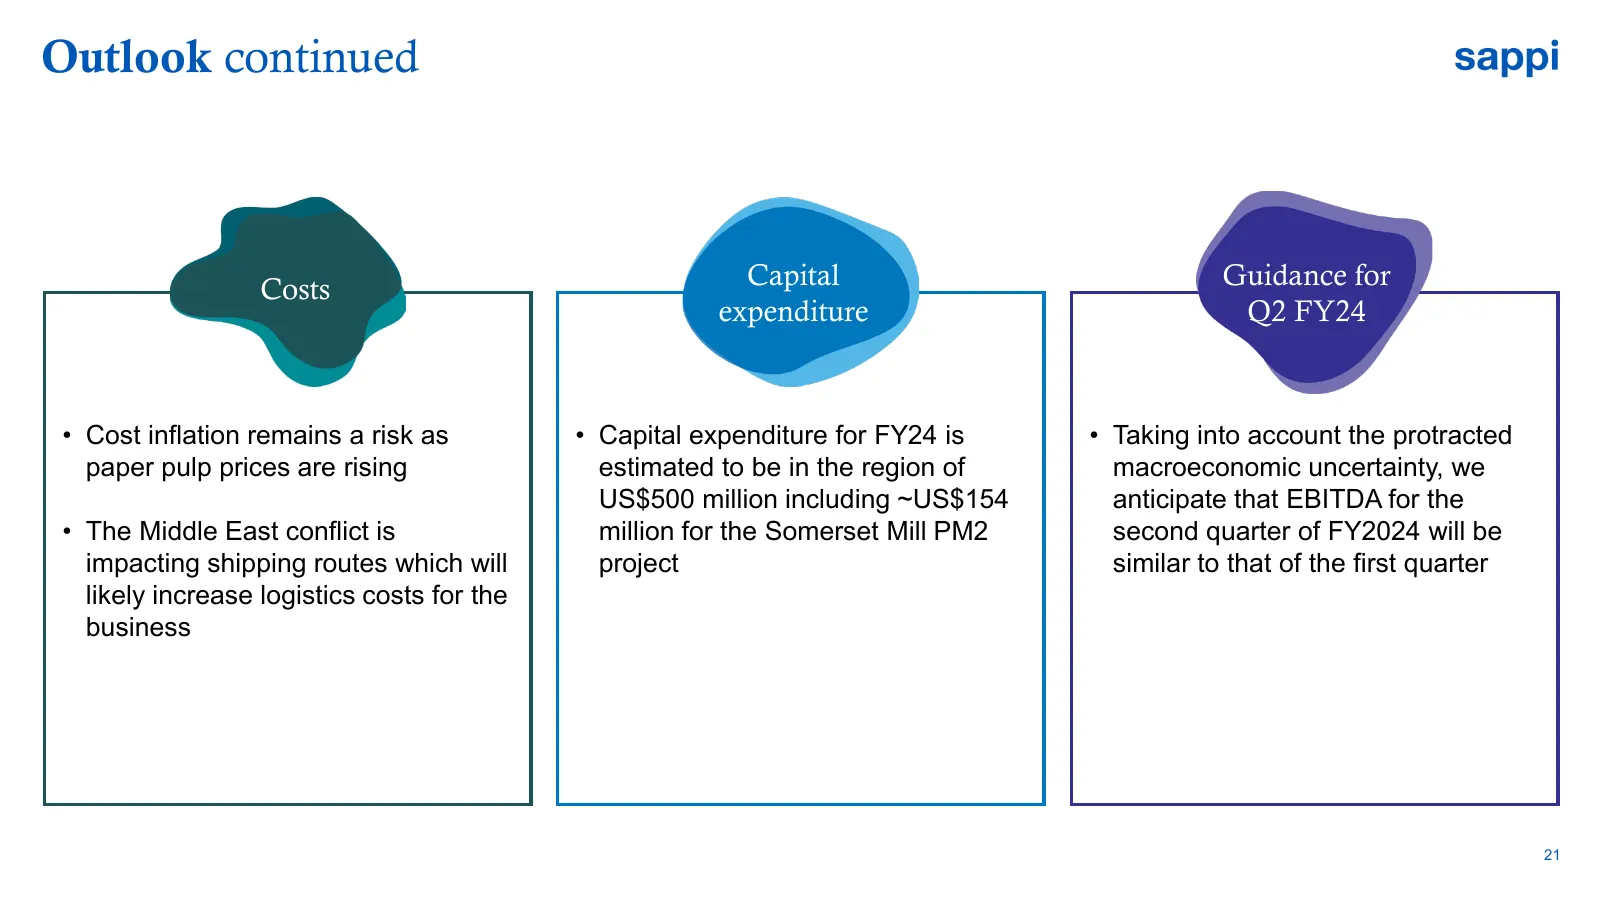
Outlook continued Costs Capital Guidance for expenditure Q2 FY24 • Cost inflation remains a risk as • Capital expenditure for FY24 is • Taking into account the protracted paper pulp prices are rising estimated to be in the region of macroeconomic uncertainty, we US$500 million including ~US$154 anti
Slide 22: Thank you
sappi Thank you
Slide 23: Supplementary information
Supplementary information 23
Slide 24: EBITDA and operating profit
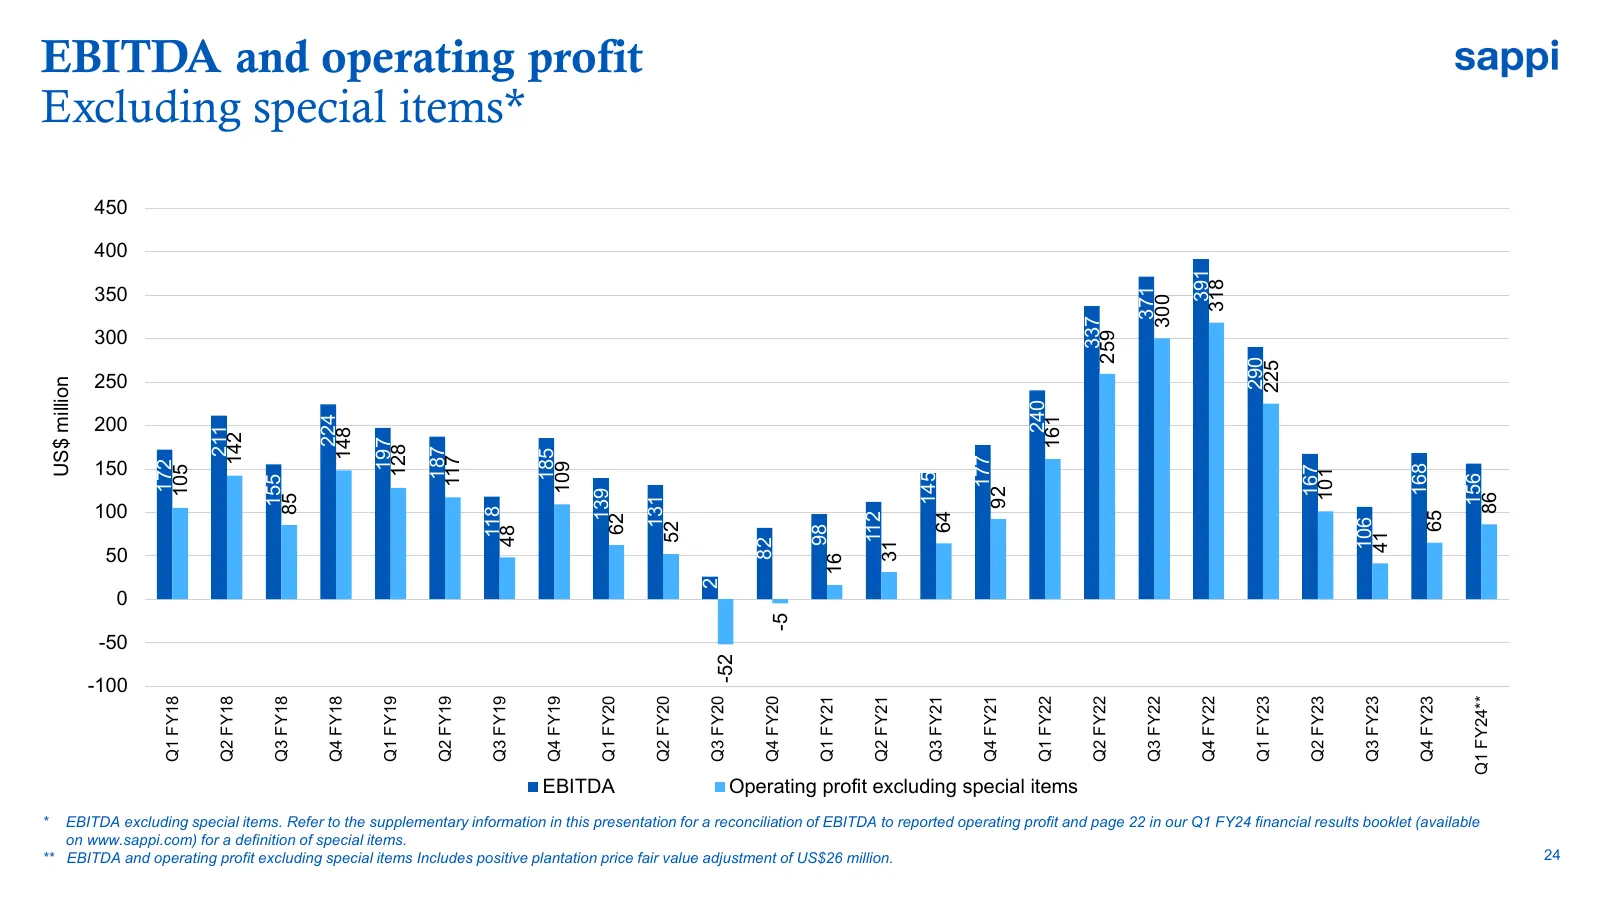
EBITDA and operating profit Excluding special items* 450 400 391 318 350 371 300 337 300 259 290 225 250 US$ million 240 200 224 161 211 148 142 197 128 187 185 150 177 117 172 109 168 167 105 101 145 156 155 92 139 86 85 131 100 118 65 64 112 62 106 52 98 48 41 82 31 50 16 26 0 -5 -50 -52 -100 Q1 F
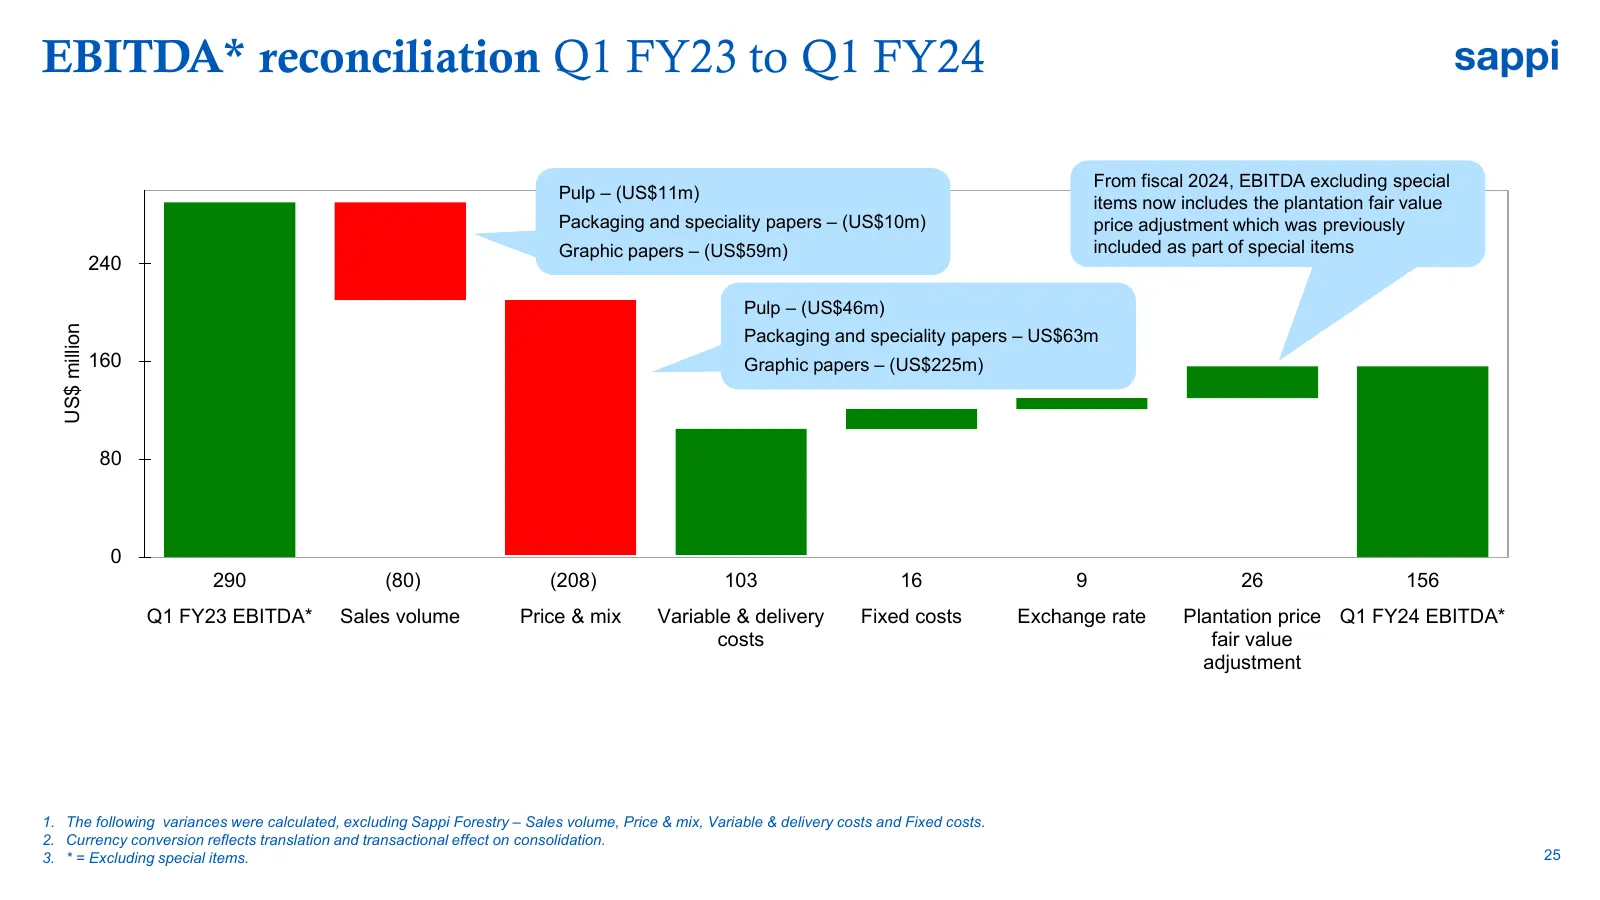
Slide 25: EBITDA reconciliation Q1 FY23 to Q1 FY24
EBITDA* reconciliation Q1 FY23 to Q1 FY24 From fiscal 2024, EBITDA excluding special Pulp – (US$11m) items now includes the plantation fair value Packaging and speciality papers – (US$10m) price adjustment which was previously Graphic papers – (US$59m) included as part of special items 240 Pulp – (U
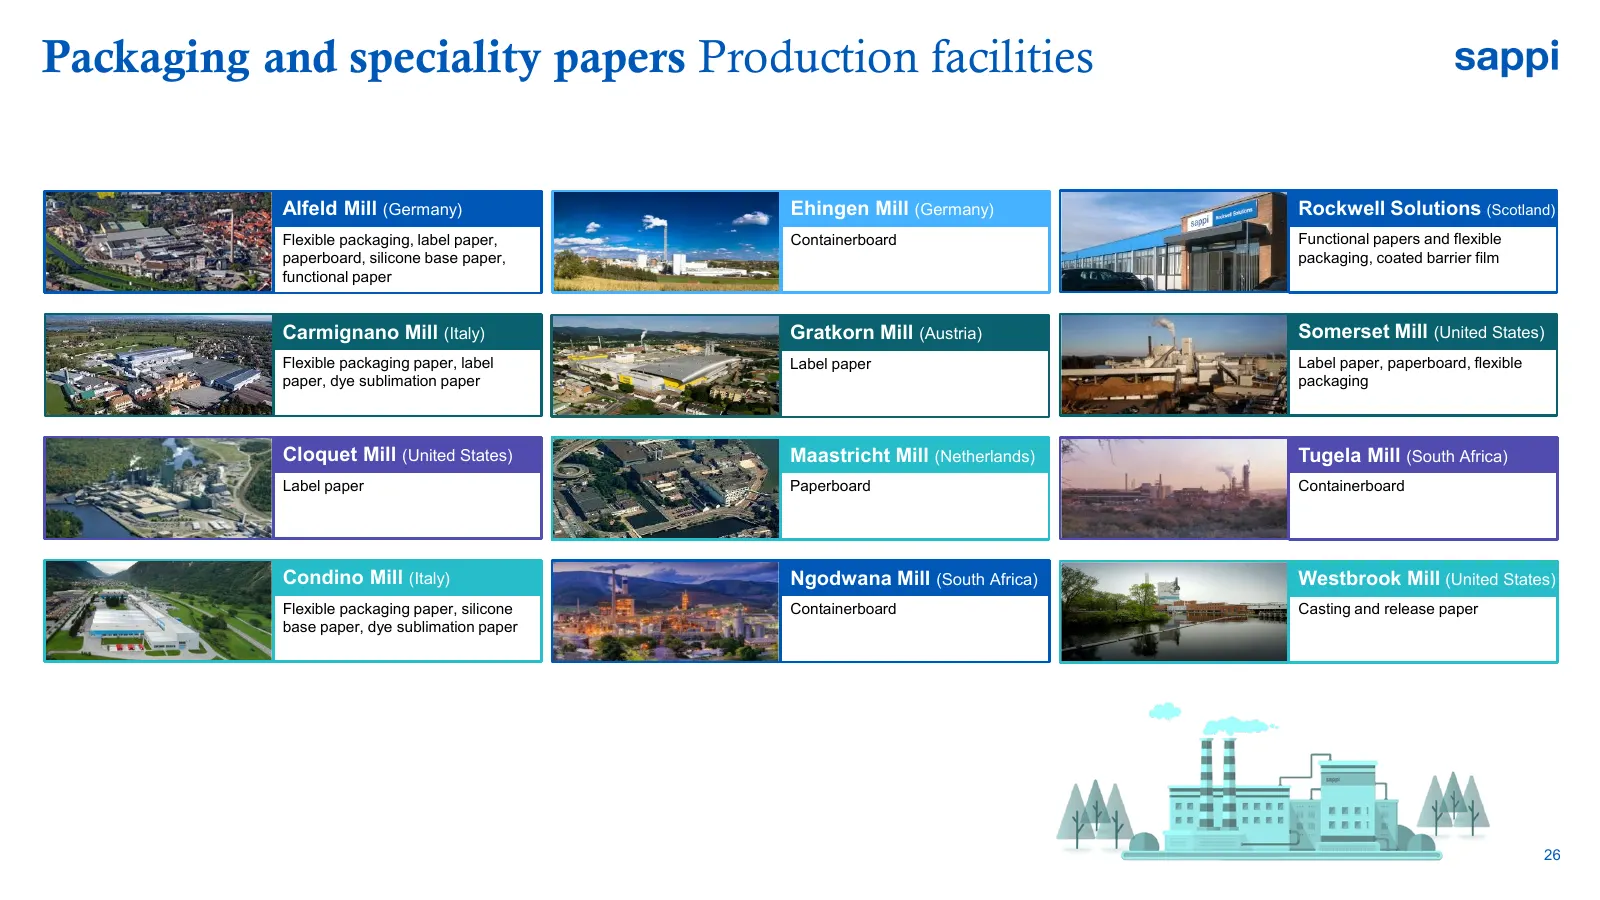
Slide 26: Packaging and speciality papers Production facilities
Packaging and speciality papers Production facilities Alfeld Mill (Germany) Ehingen Mill (Germany) Rockwell Solutions (Scotland) Flexible packaging, label paper, Containerboard Functional papers and flexible paperboard, silicone base paper, packaging, coated barrier film functional paper Carmignano
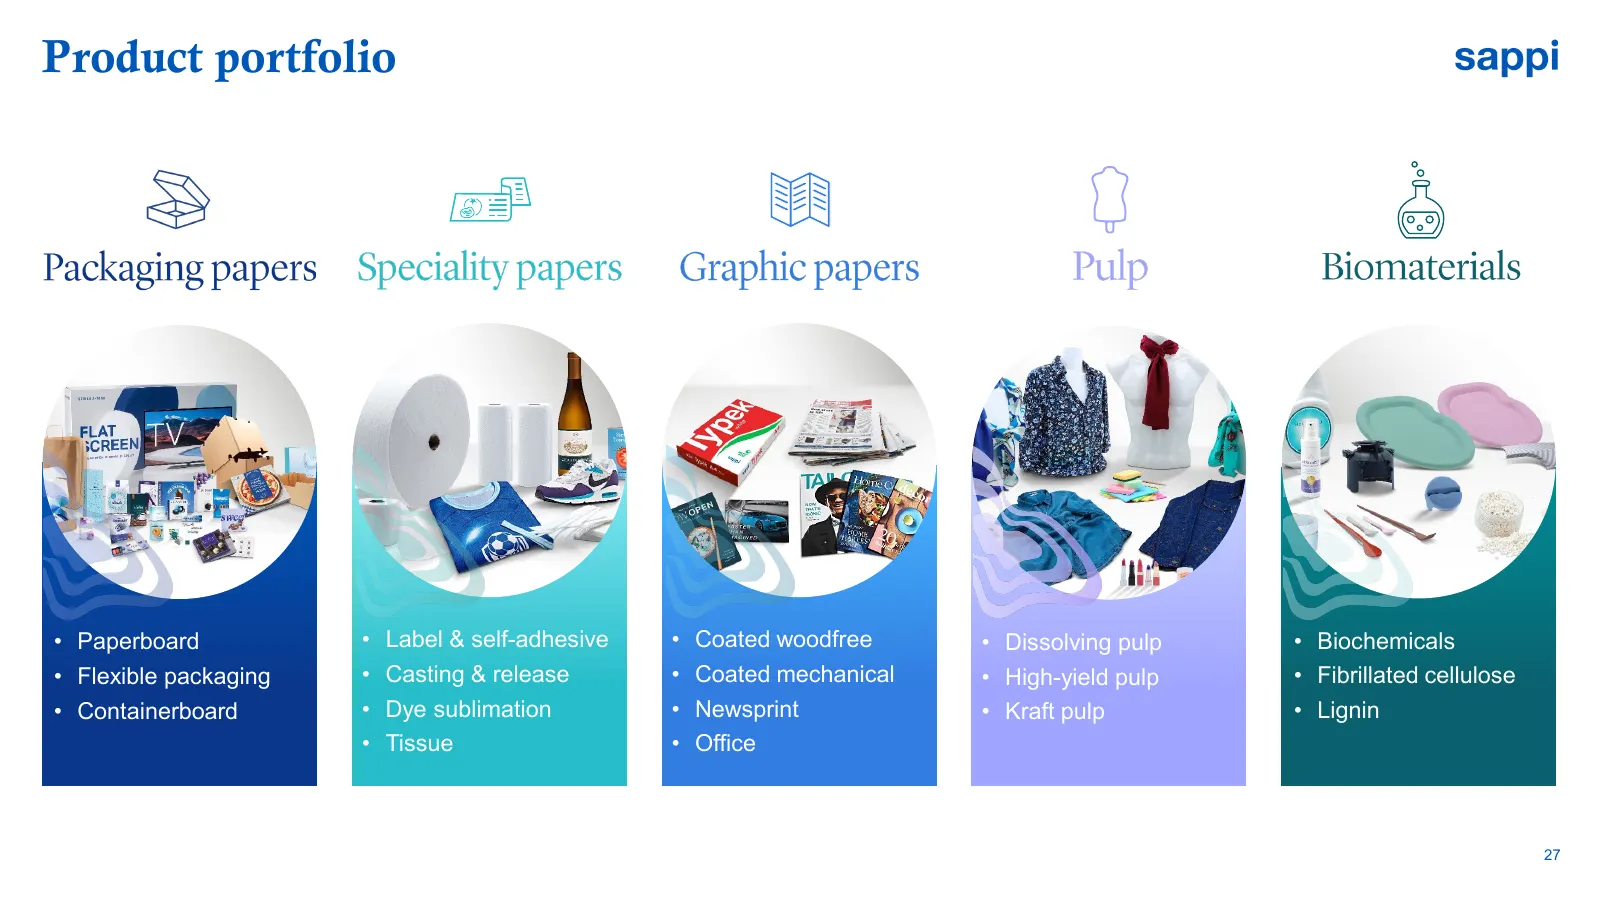
Slide 27: Product portfolio
Product portfolio • Paperboard • Label & self-adhesive • Coated woodfree • Dissolving pulp • Biochemicals • Flexible packaging • Casting & release • Coated mechanical • High-yield pulp • Fibrillated cellulose • Containerboard • Dye sublimation • Newsprint • Kraft pulp • Lignin • Tissue • Office 27
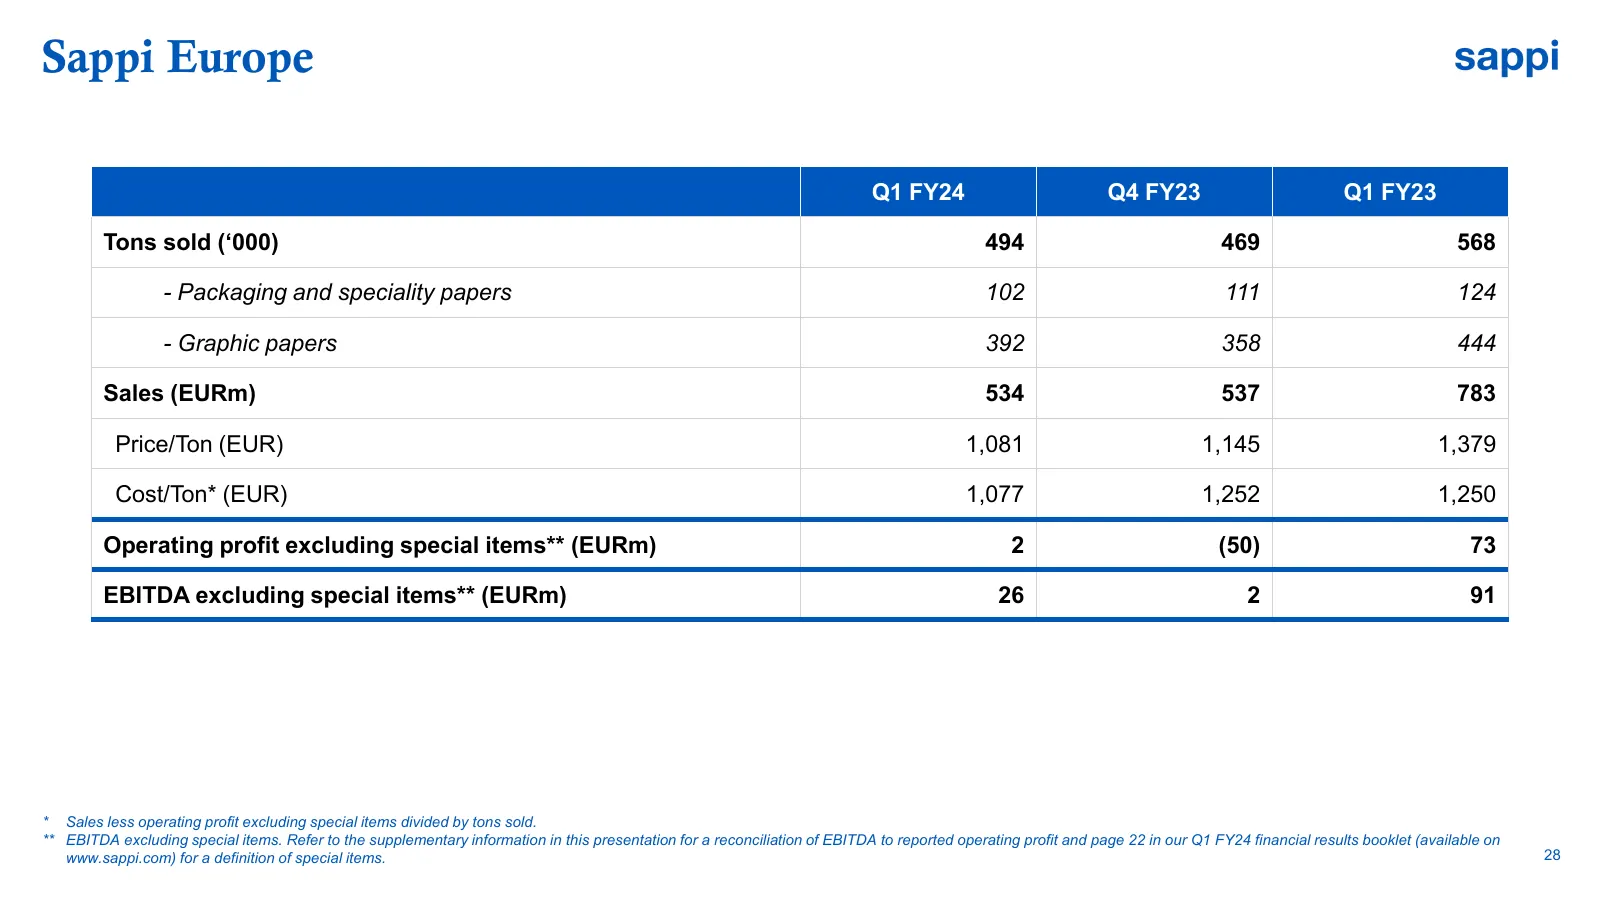
Slide 28: Sappi Europe
Sappi Europe Q1 FY24 Q4 FY23 Q1 FY23 Tons sold (‘000) 494 469 568 - Packaging and speciality papers 102 111 124 - Graphic papers 392 358 444 Sales (EURm) 534 537 783 Price/Ton (EUR) 1,081 1,145 1,379 Cost/Ton* (EUR) 1,077 1,252 1,250 Operating profit excluding special items** (EURm) 2 (50) 73 EBITDA
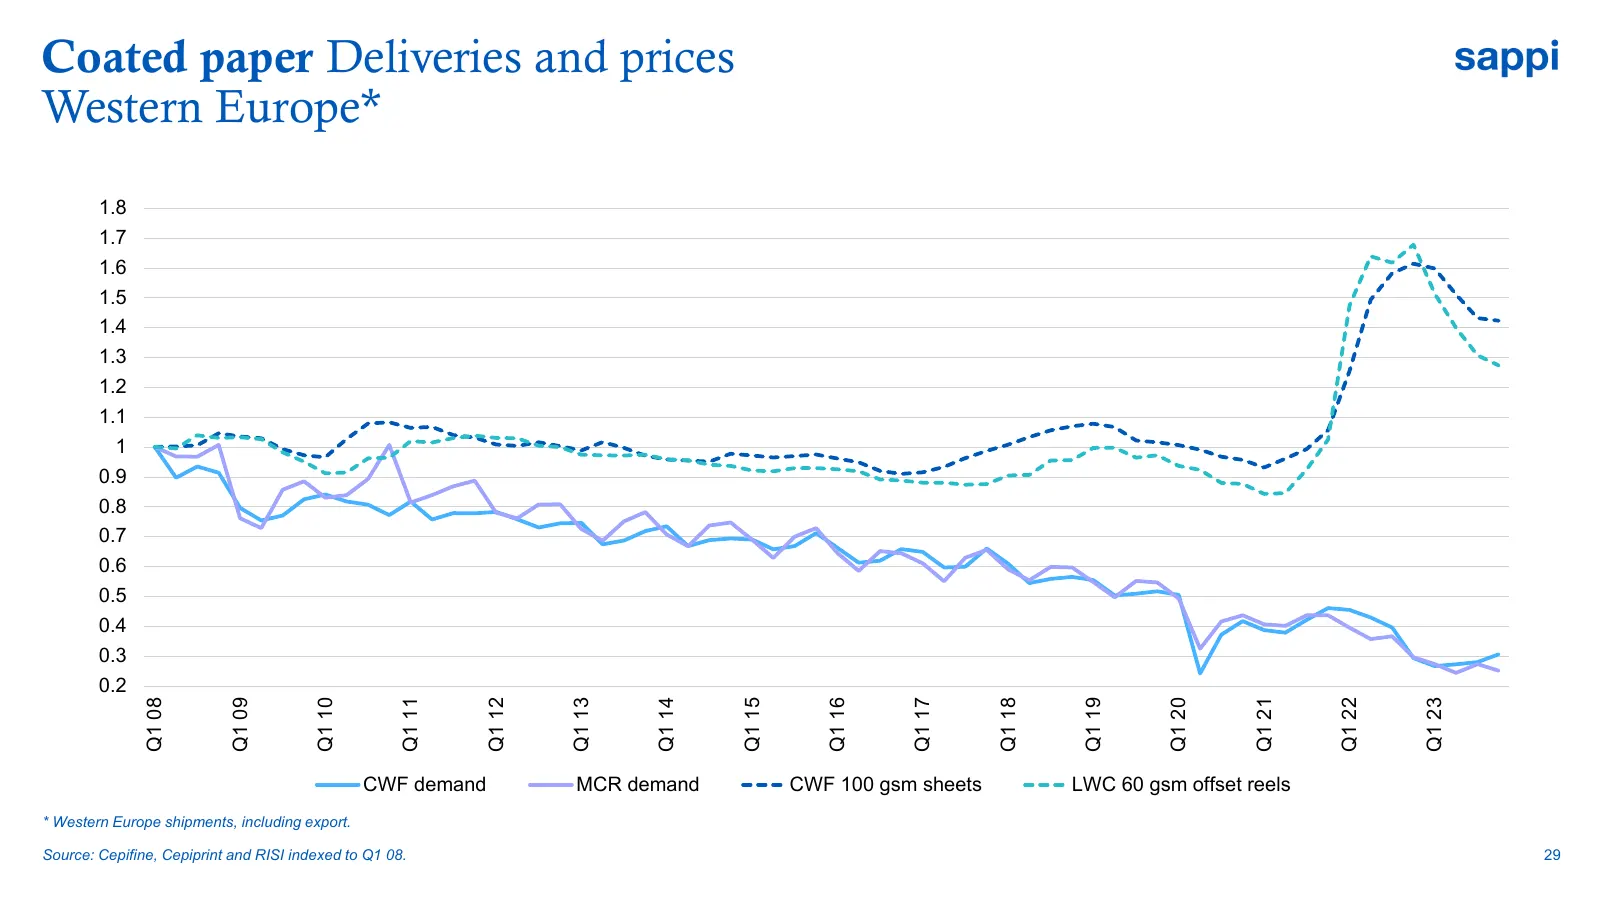
Slide 29: Coated paper Deliveries and prices Western Europe
Coated paper Deliveries and prices Western Europe* 1.8 1.7 1.6 1.5 1.4 1.3 1.2 1.1 1 0.9 0.8 0.7 0.6 0.5 0.4 0.3 0.2 Q1 08 Q1 09 Q1 10 Q1 11 Q1 12 Q1 13 Q1 14 Q1 15 Q1 16 Q1 17 Q1 18 Q1 19 Q1 20 Q1 21 Q1 22 Q1 23 CWF demand MCR demand CWF 100 gsm sheets LWC 60 gsm offset reels * Western Europe shipm
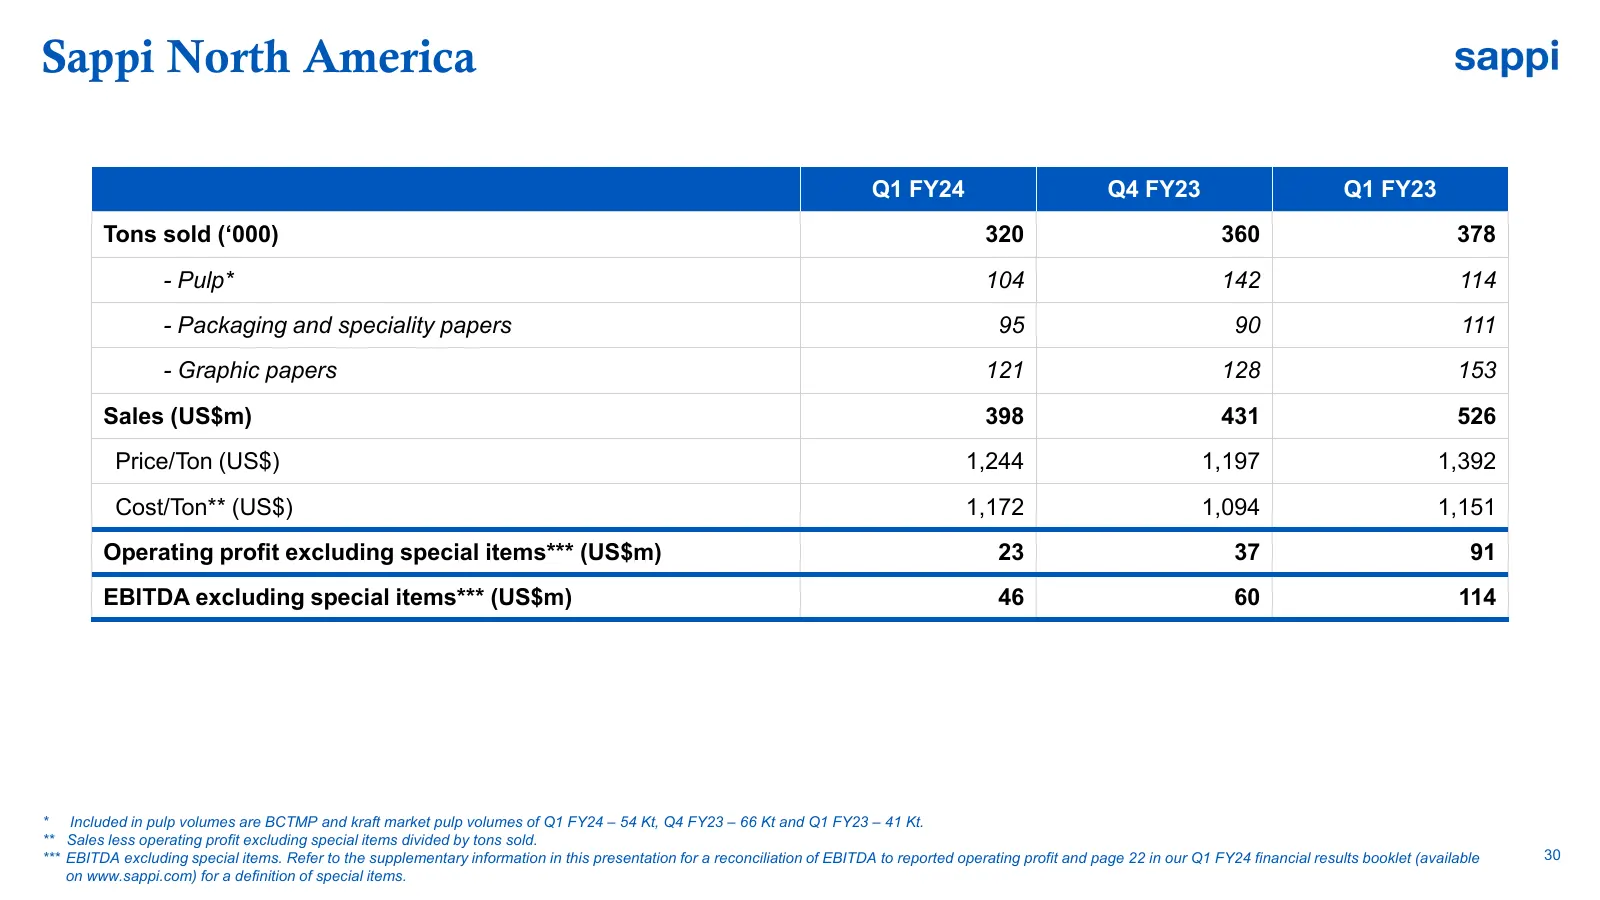
Slide 30: Sappi North America
Sappi North America Q1 FY24 Q4 FY23 Q1 FY23 Tons sold (‘000) 320 360 378 - Pulp* 104 142 114 - Packaging and speciality papers 95 90 111 - Graphic papers 121 128 153 Sales (US$m) 398 431 526 Price/Ton (US$) 1,244 1,197 1,392 Cost/Ton** (US$) 1,172 1,094 1,151 Operating profit excluding special items
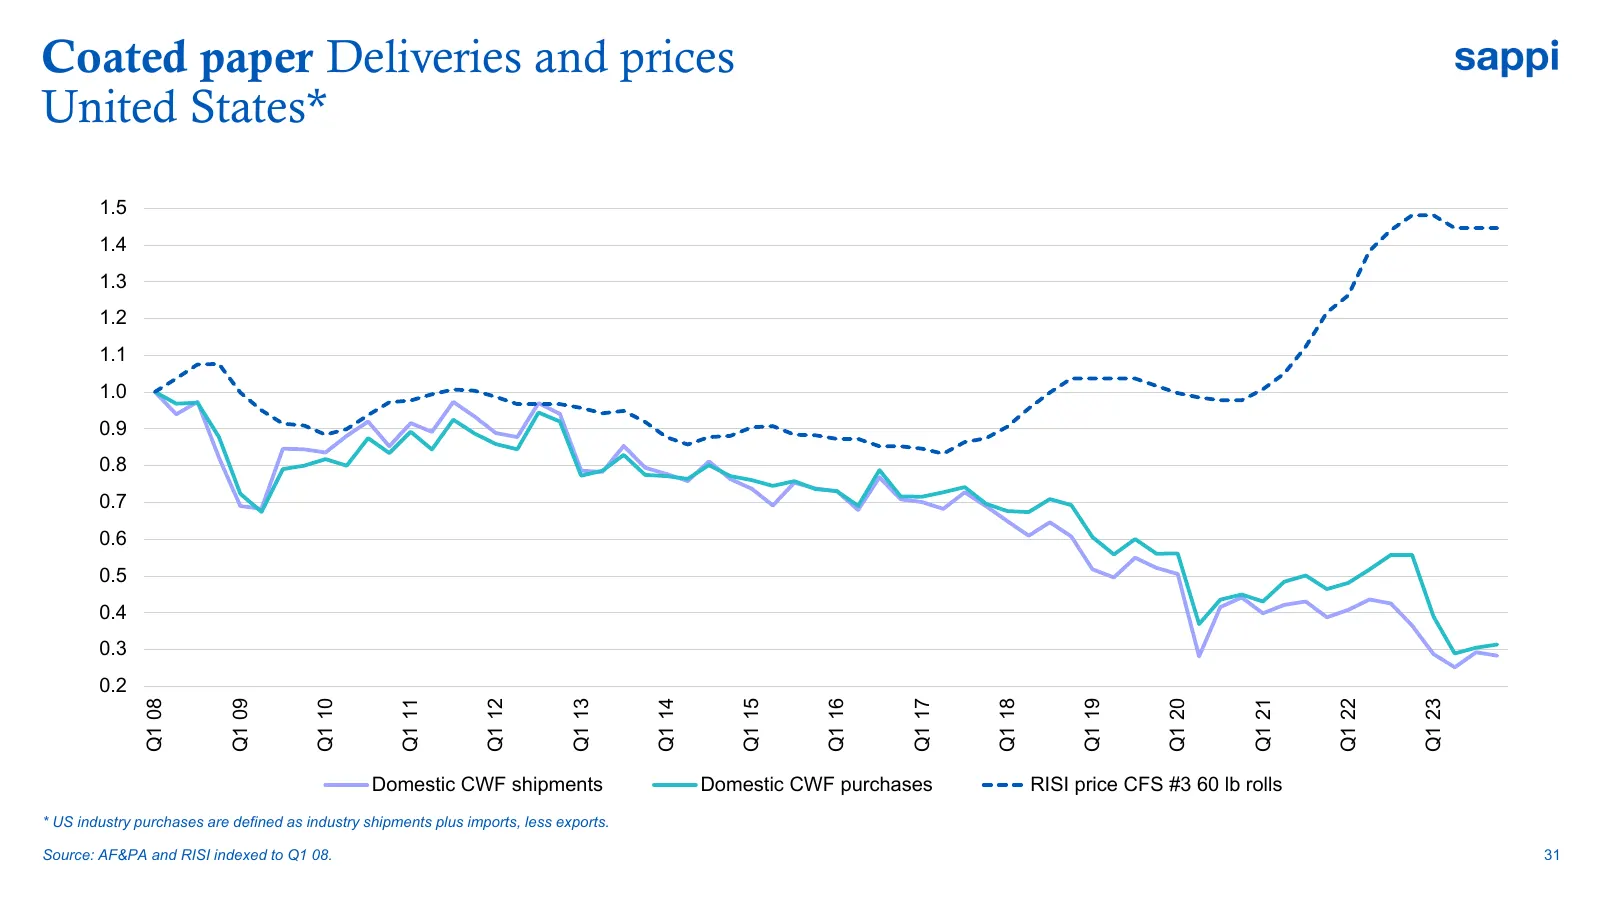
Slide 31: Coated paper Deliveries and prices United States
Coated paper Deliveries and prices United States* 1.5 1.4 1.3 1.2 1.1 1.0 0.9 0.8 0.7 0.6 0.5 0.4 0.3 0.2 Q1 08 Q1 09 Q1 10 Q1 11 Q1 12 Q1 13 Q1 14 Q1 15 Q1 16 Q1 17 Q1 18 Q1 19 Q1 20 Q1 21 Q1 22 Q1 23 Domestic CWF shipments Domestic CWF purchases RISI price CFS #3 60 lb rolls * US industry purchase
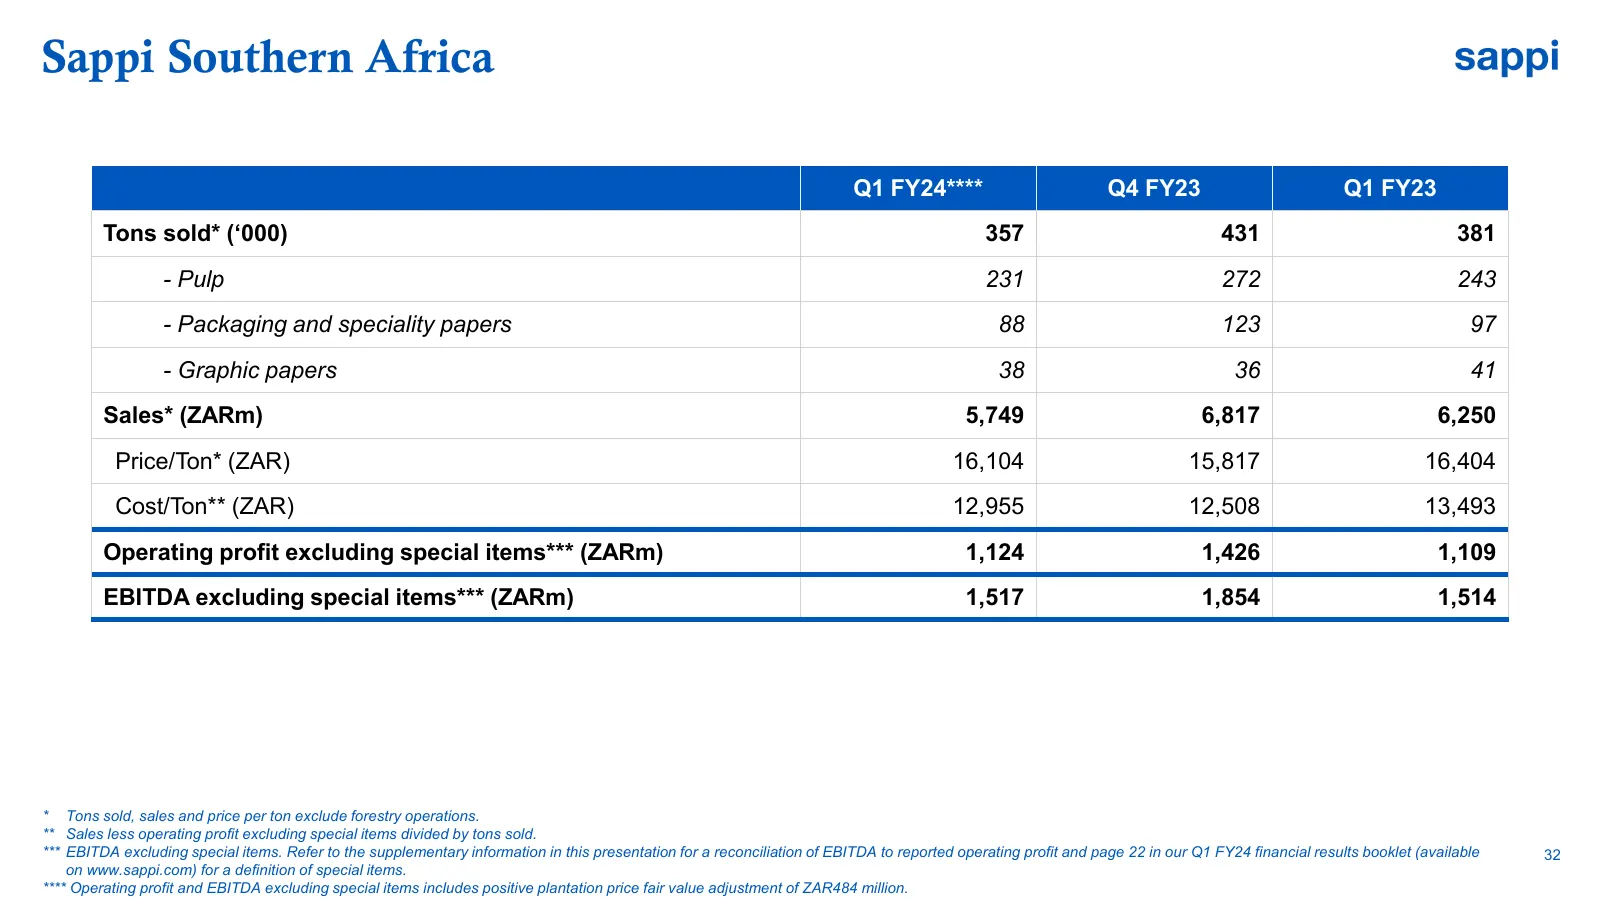
Slide 32: Sappi Southern Africa
Sappi Southern Africa Q1 FY24**** Q4 FY23 Q1 FY23 Tons sold* (‘000) 357 431 381 - Pulp 231 272 243 - Packaging and speciality papers 88 123 97 - Graphic papers 38 36 41 Sales* (ZARm) 5,749 6,817 6,250 Price/Ton* (ZAR) 16,104 15,817 16,404 Cost/Ton** (ZAR) 12,955 12,508 13,493 Operating profit exclud
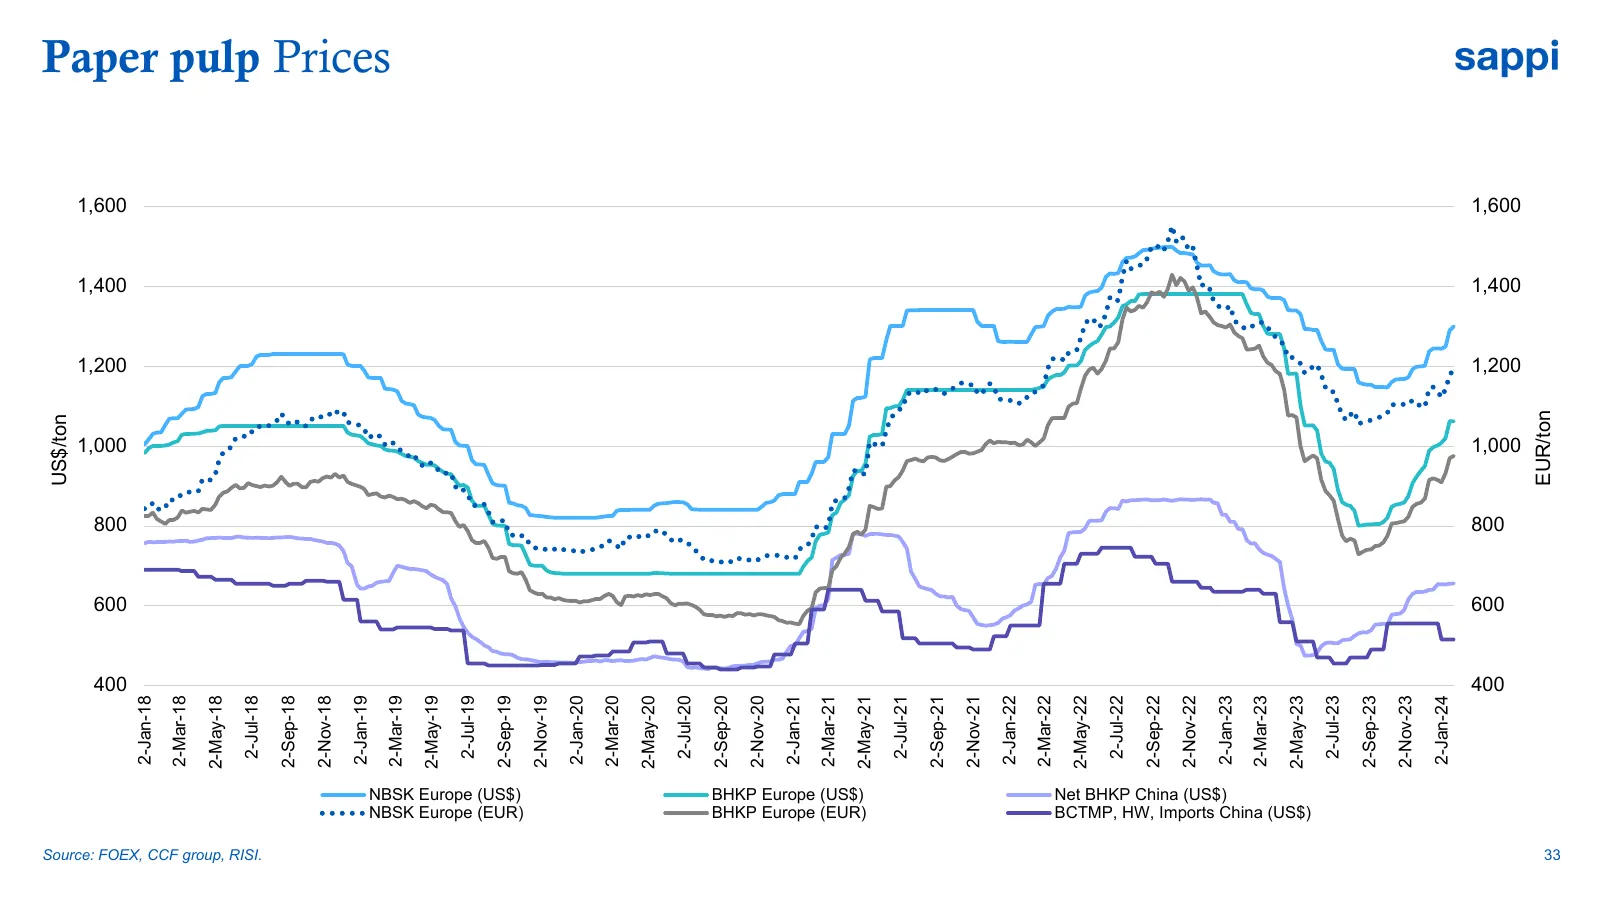
Slide 33: Paper pulp prices
US$/ton 1,000 1,200 1,400 1,600 400 600 800 2-Jan-18 2-Mar-18 2-May-18 Source: FOEX, CCF group, RISI. 2-Jul-18 2-Sep-18 2-Nov-18 2-Jan-19 Paper pulp Prices 2-Mar-19 2-May-19 2-Jul-19 2-Sep-19 NBSK Europe (US$) NBSK Europe (EUR) 2-Nov-19 2-Jan-20 2-Mar-20 2-May-20 2-Jul-20 2-Sep-20 2-Nov-20 2-Jan-21
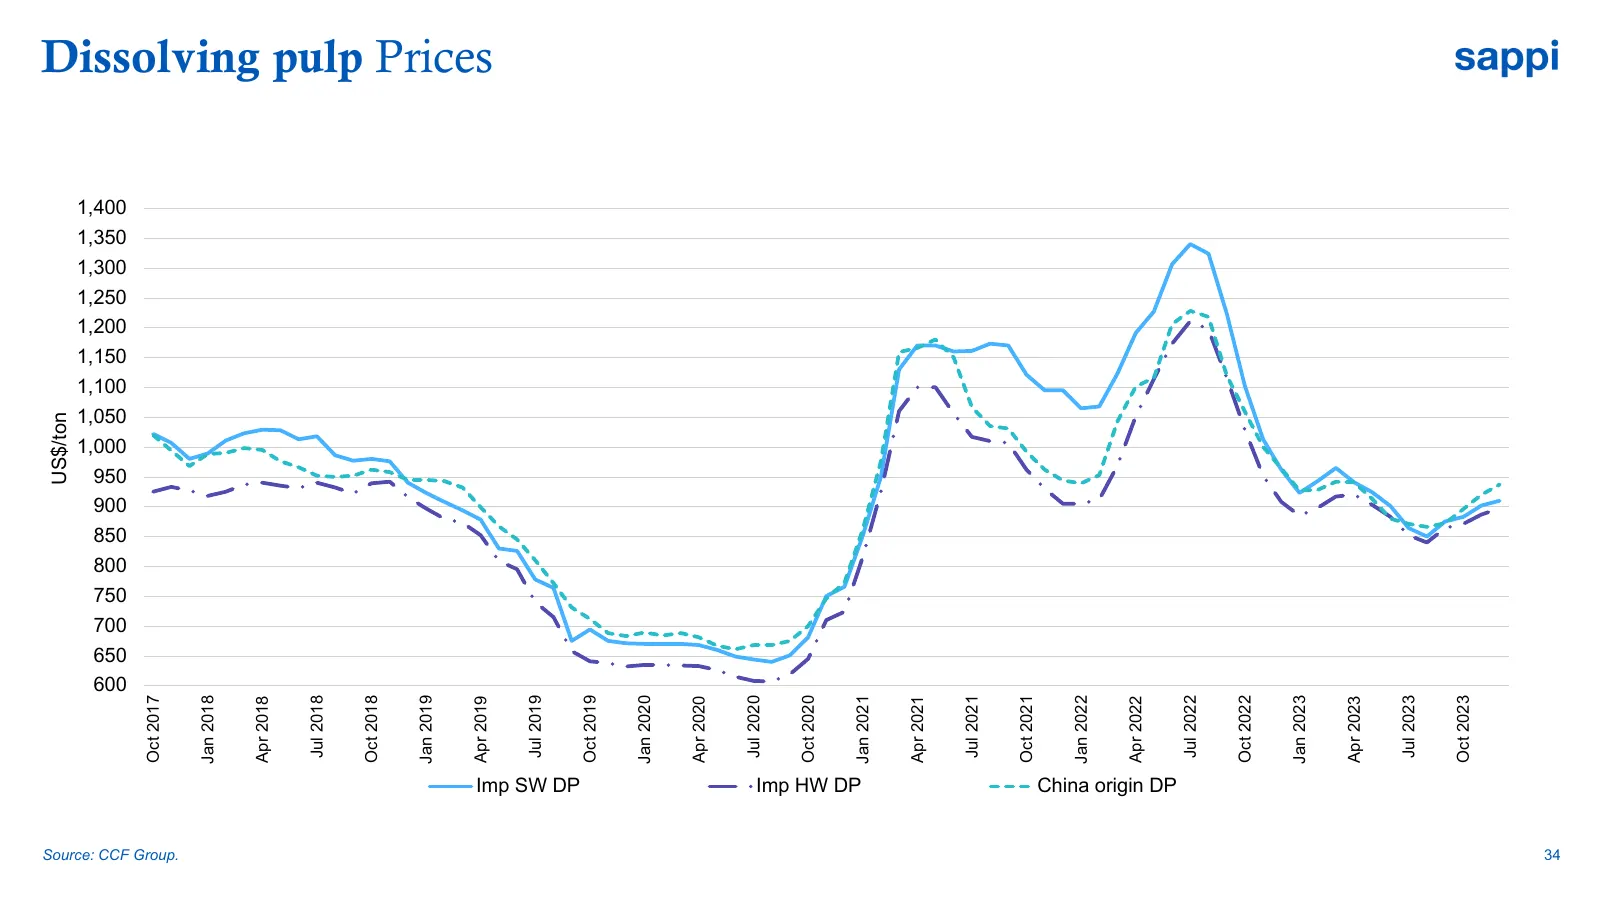
Slide 34: Dissolving pulp prices
US$/ton 1,000 1,050 1,100 1,150 1,200 1,250 1,300 1,350 1,400 600 650 700 750 800 850 900 950 Oct 2017 Source: CCF Group. Jan 2018 Apr 2018 Jul 2018 Oct 2018 Jan 2019 Apr 2019 Dissolving pulp Prices Jul 2019 Imp SW DP Oct 2019 Jan 2020 Apr 2020 Jul 2020 Oct 2020 Imp HW DP Jan 2021 Apr 2021 Jul 2021
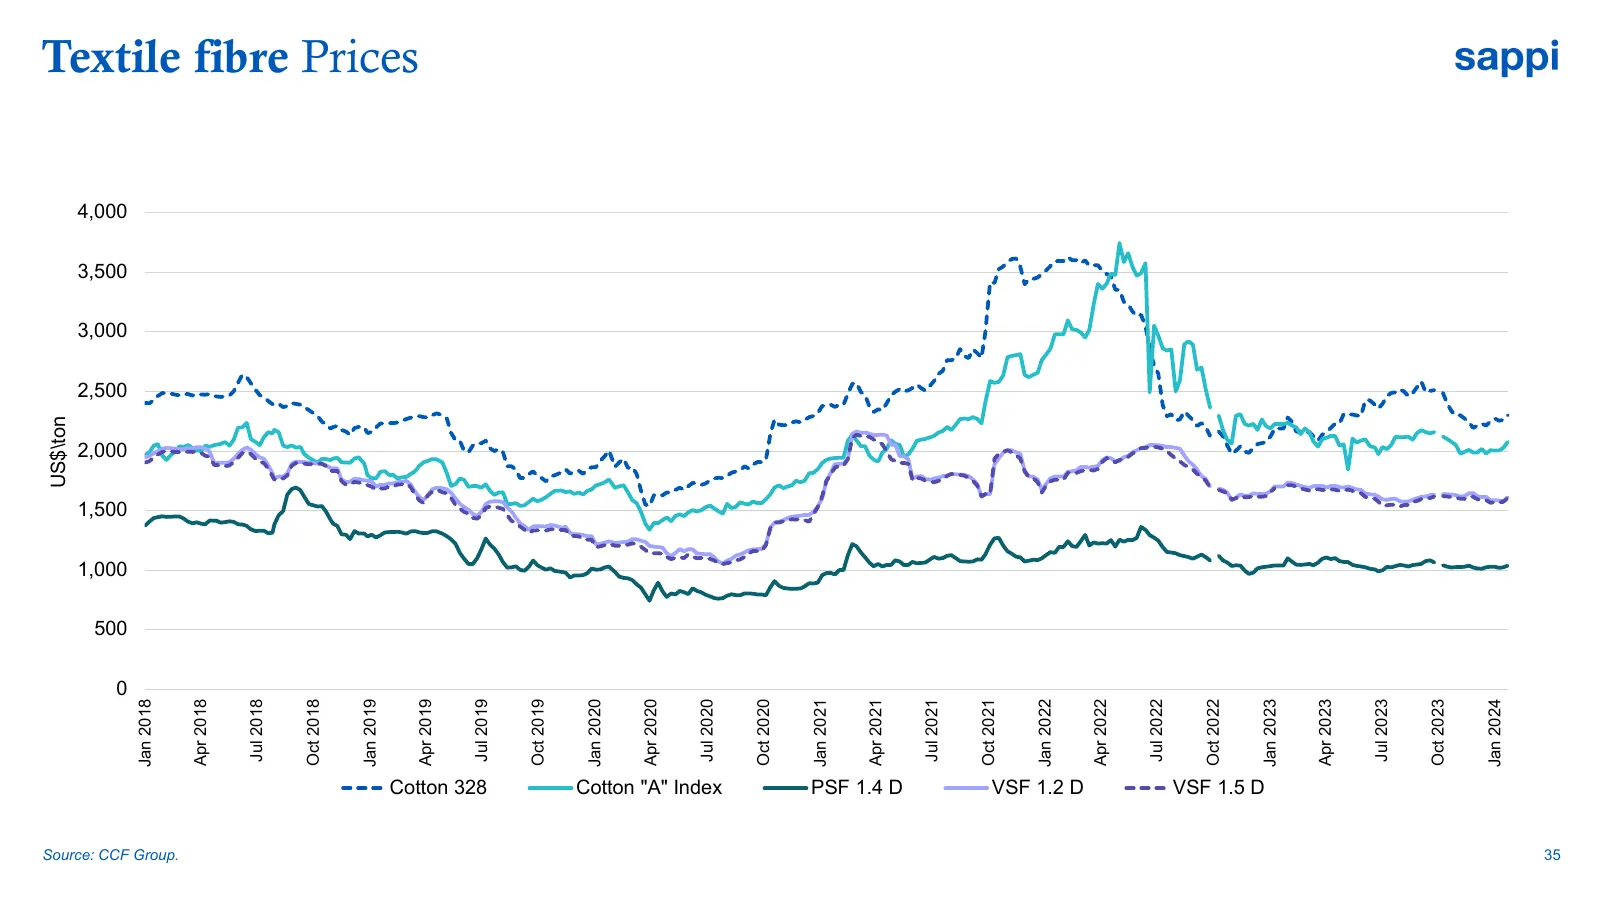
Slide 35: Textile fibre prices
US$\ton 1,000 1,500 2,000 2,500 3,000 3,500 4,000 0 500 Jan 2018 Source: CCF Group. Apr 2018 Jul 2018 Oct 2018 Jan 2019 Textile fibre Prices Apr 2019 Cotton 328 Jul 2019 Oct 2019 Jan 2020 Apr 2020 Jul 2020 Cotton "A" Index Oct 2020 Jan 2021 Apr 2021 PSF 1.4 D Jul 2021 Oct 2021 Jan 2022 VSF 1.2 D Apr
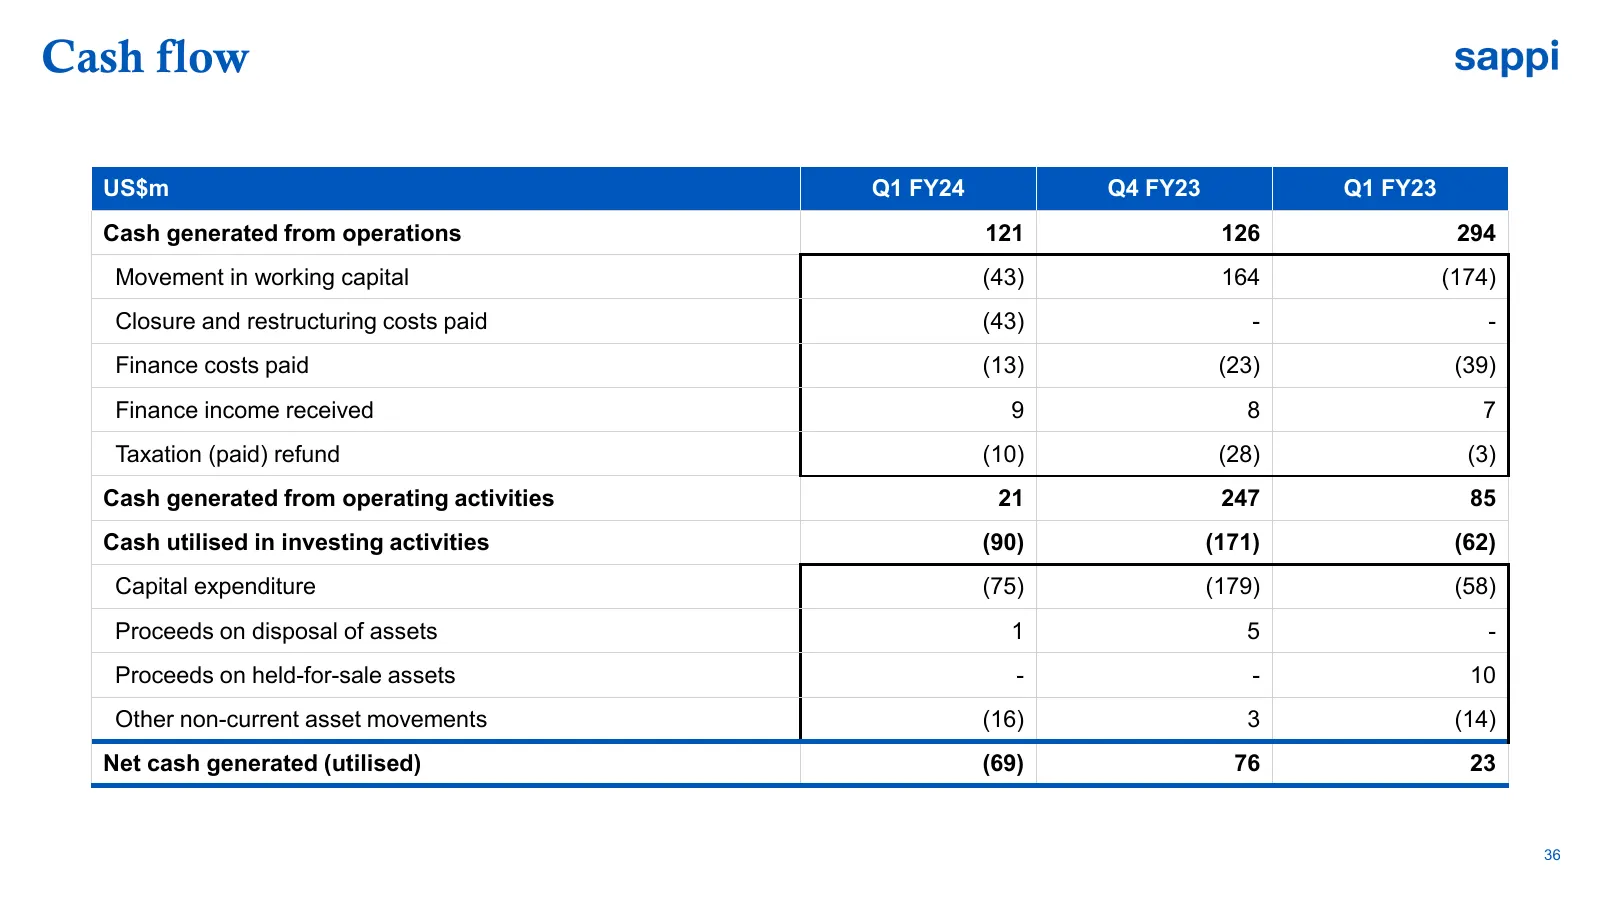
Slide 36: Cash flow
Cash flow US$m Q1 FY24 Q4 FY23 Q1 FY23 Cash generated from operations 121 126 294 Movement in working capital (43) 164 (174) Closure and restructuring costs paid (43) - - Finance costs paid (13) (23) (39) Finance income received 9 8 7 Taxation (paid) refund (10) (28) (3) Cash generated from operatin
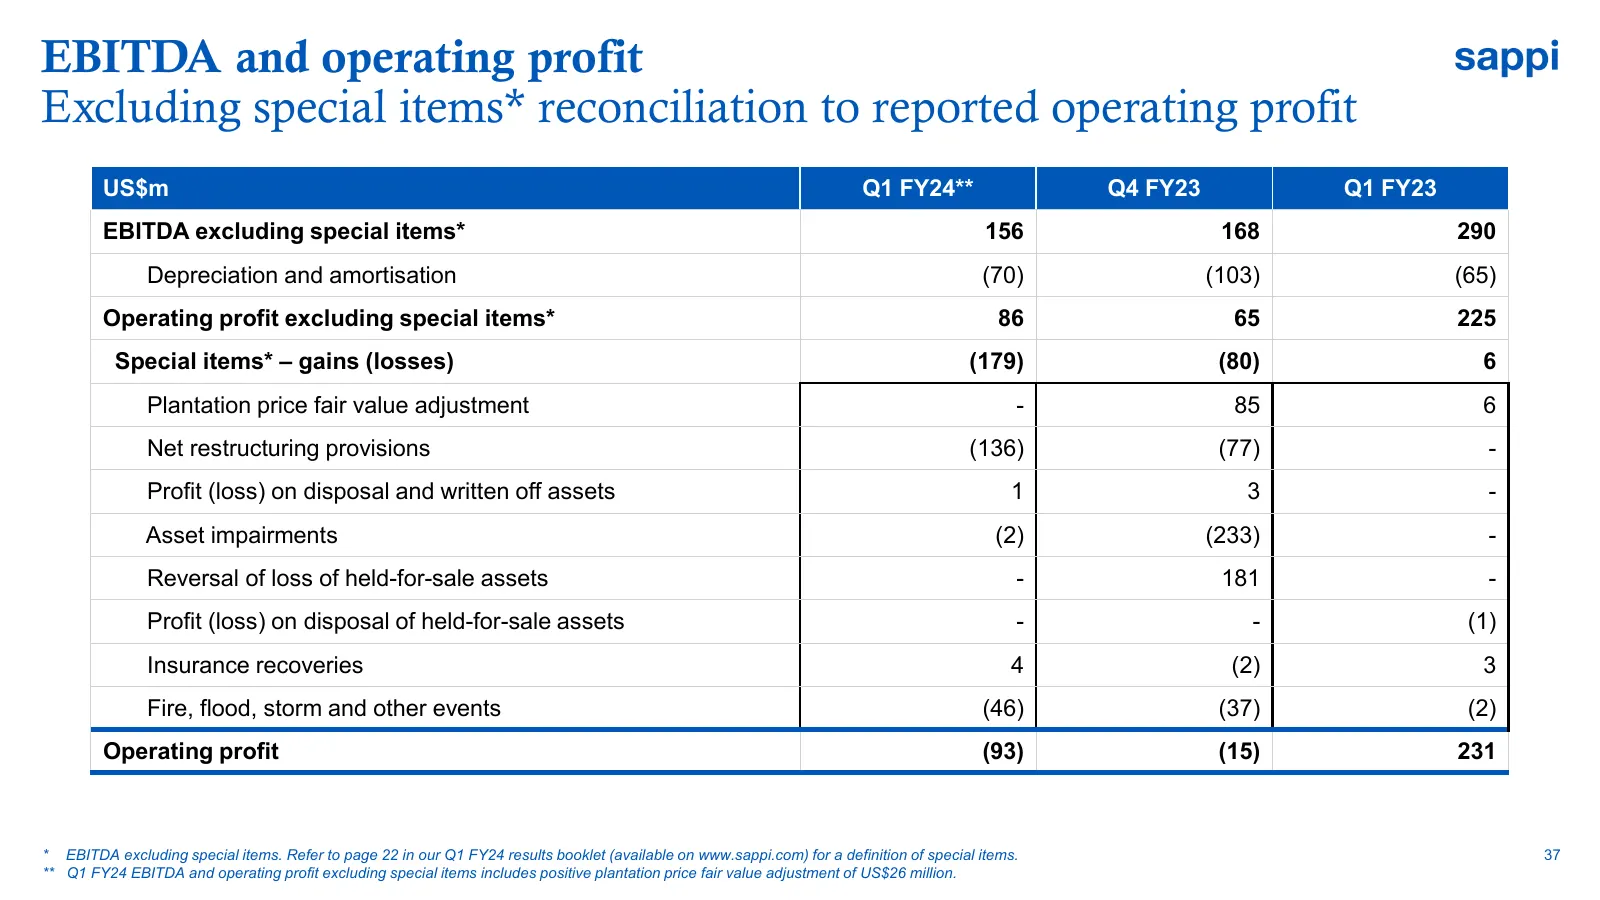
Slide 37: EBITDA and operating profit reconciliation to reported operating profit
EBITDA and operating profit Excluding special items* reconciliation to reported operating profit US$m Q1 FY24** Q4 FY23 Q1 FY23 EBITDA excluding special items* 156 168 290 Depreciation and amortisation (70) (103) (65) Operating profit excluding special items* 86 65 225 Special items* – gains (losses
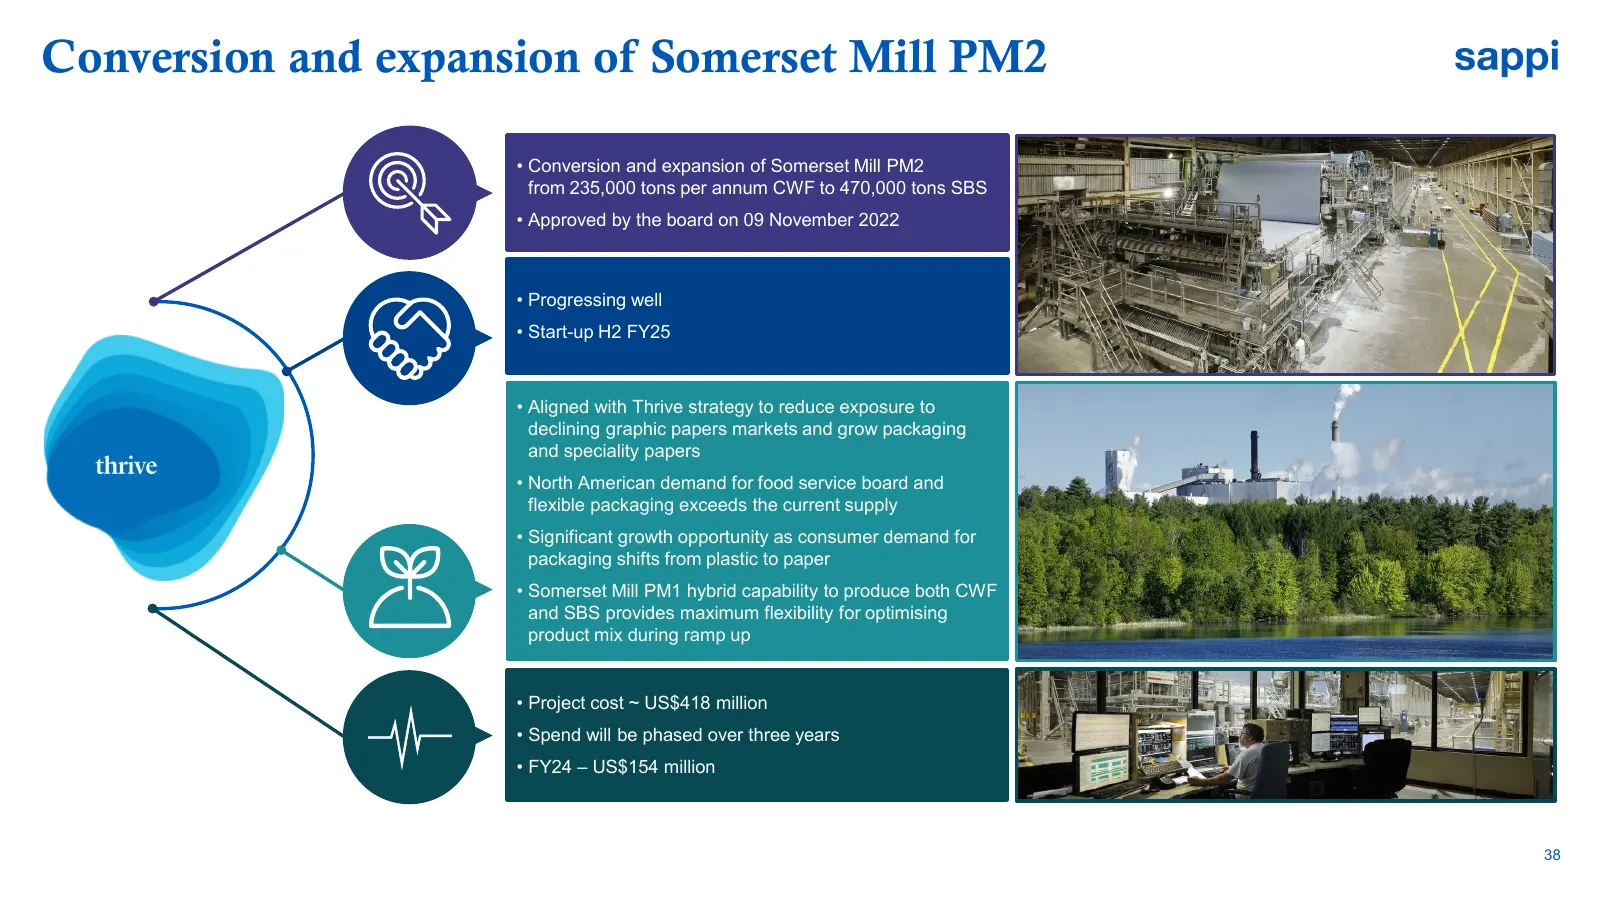
Slide 38: Conversion and expansion of Somerset Mill PM2
Conversion and expansion of Somerset Mill PM2 • Conversion and expansion of Somerset Mill PM2 from 235,000 tons per annum CWF to 470,000 tons SBS • Approved by the board on 09 November 2022 • Progressing well • Start-up H2 FY25 • Aligned with Thrive strategy to reduce exposure to declining graphic p
Slide 39: Sustainability is at the core of our business and work culture
Who we are Sustainability is at the core of our business and work culture. Every solution we create supports our goal to make everyday products more sustainable. We know that the long-term sustainability of our business will only be ensured by delivering sustained value for our stakeholders. We will
Slide 40: Our approved science-based targets
Our approved science-based targets Our commitment • Reduce Scope 1 and Scope 2 GHG emissions by 41.5% per ton of product by 2030 from a 2019 base year.* • 44% of our suppliers by spend will have science-based targets by 2026. * The target boundary includes biogenic emissions and removals from bioene
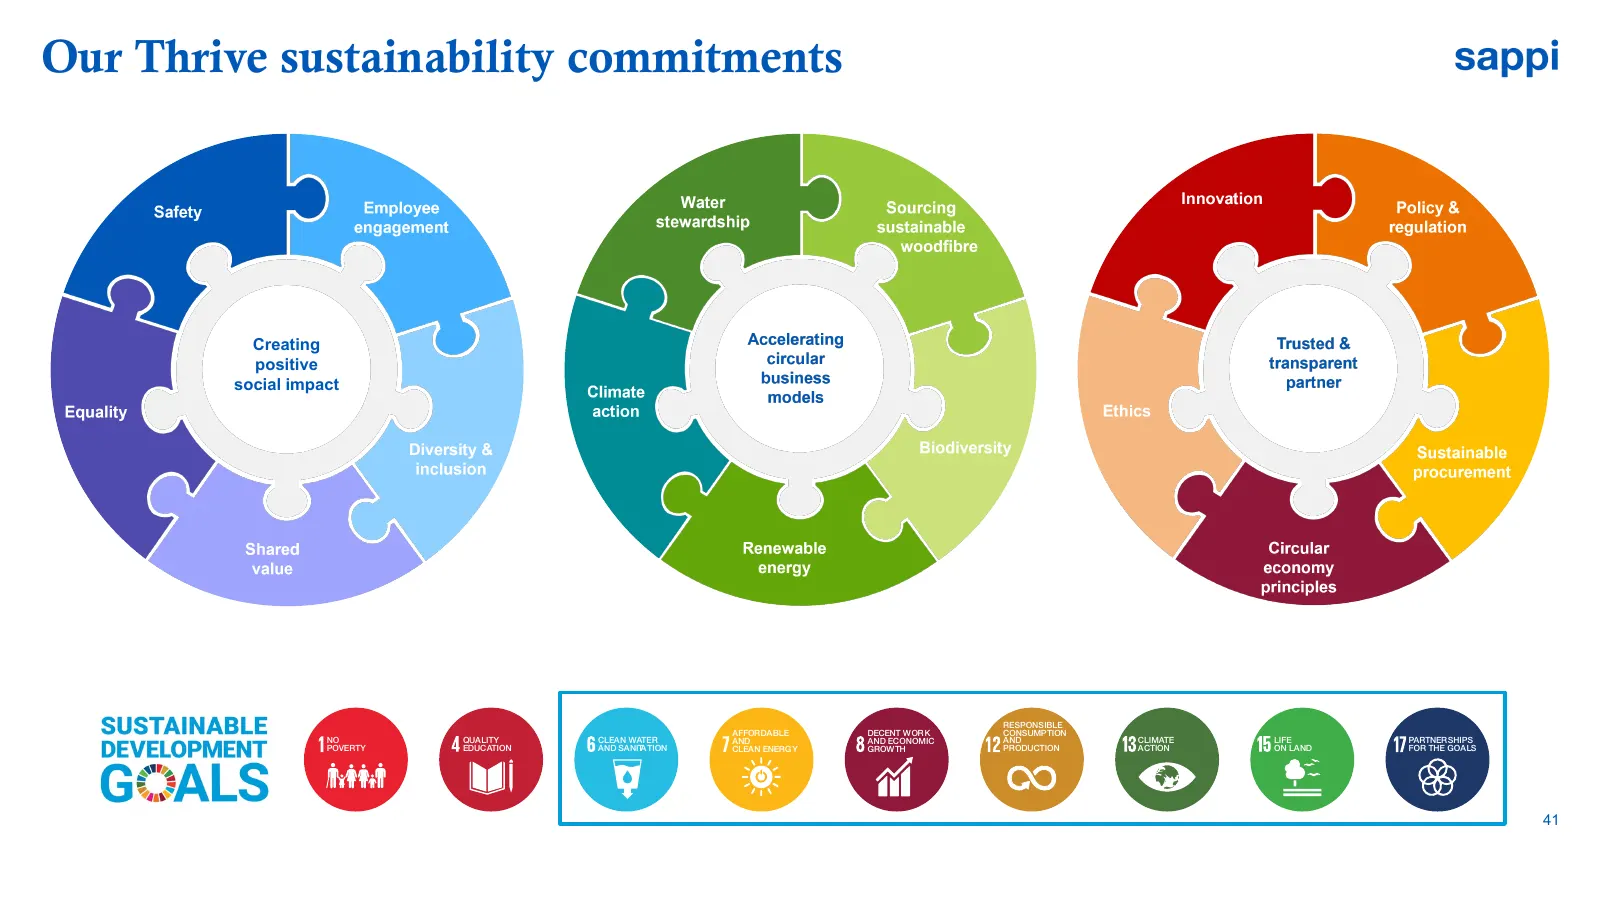
Slide 41: Our Thrive sustainability commitments
Our Thrive sustainability commitments Creating positive social impact RESPONSIBLE AFFORDABLE DECENT WOR K CONSUMPTION NO QUALITY CLEAN WATER AND AND ECONOMIC AND CLIMATE LIFE PARTNERSHIPS POVERTY EDUCATION AND SANITA TION CLEAN ENERGY GROWTH PRODUCTION ACTION ON LAND FOR THE GOALS 41
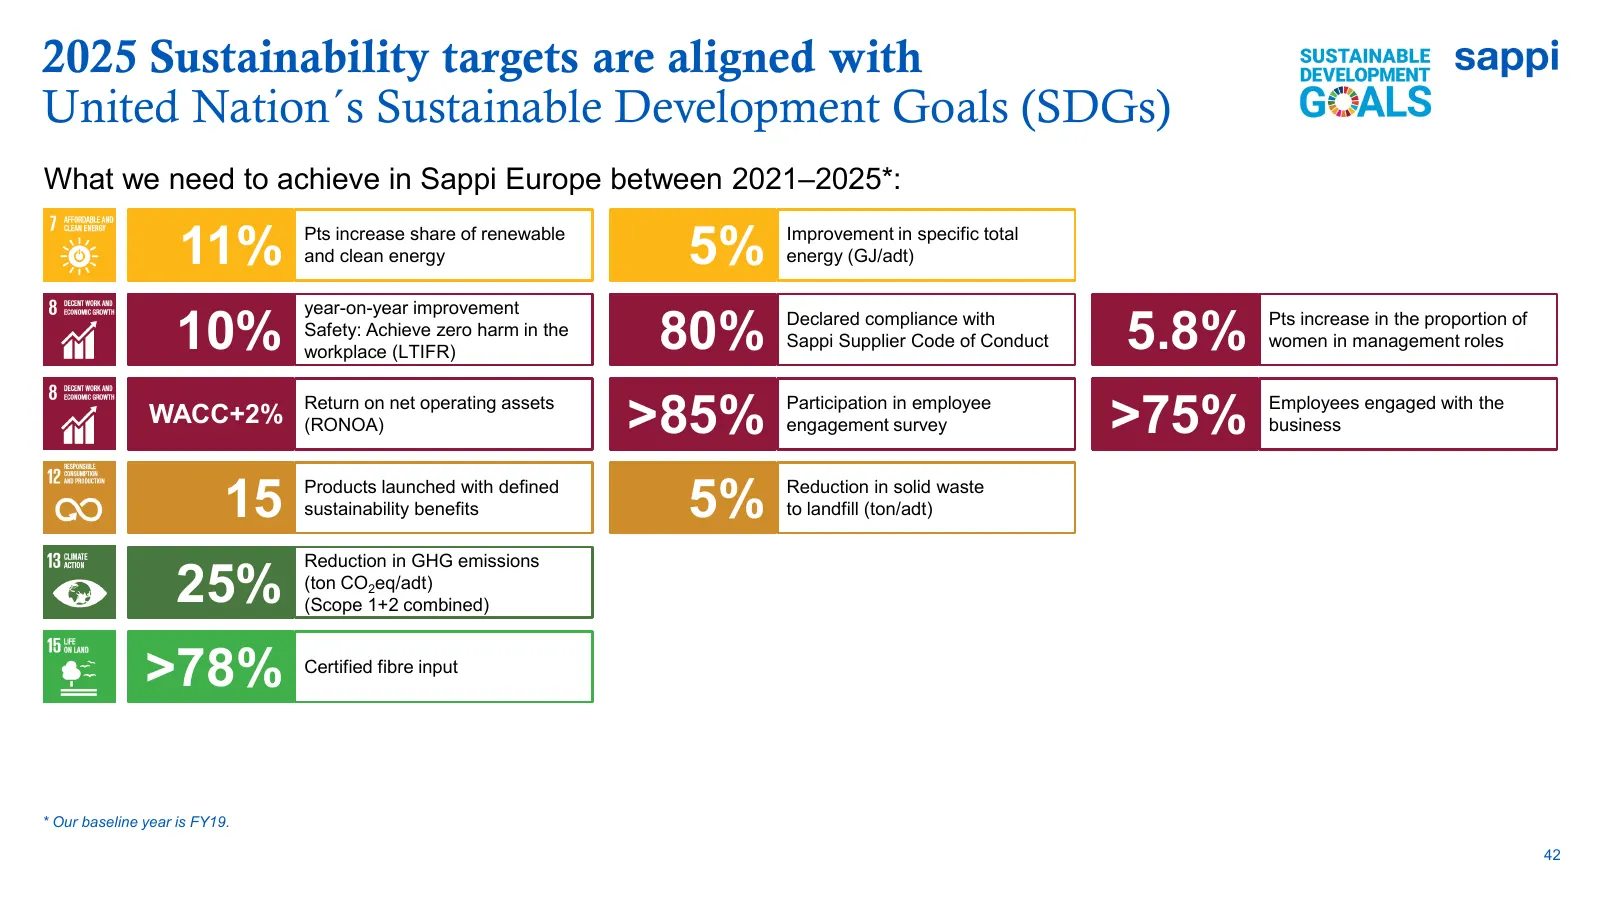
Slide 42: 2025 Sustainability targets - Sappi Europe
2025 Sustainability targets are aligned with United Nation´s Sustainable Development Goals (SDGs) What we need to achieve in Sappi Europe between 2021–2025*: 11% Pts increase share of renewable and clean energy 5% Improvement in specific total energy (GJ/adt) 10% 80% 5.8% year-on-year improvement De
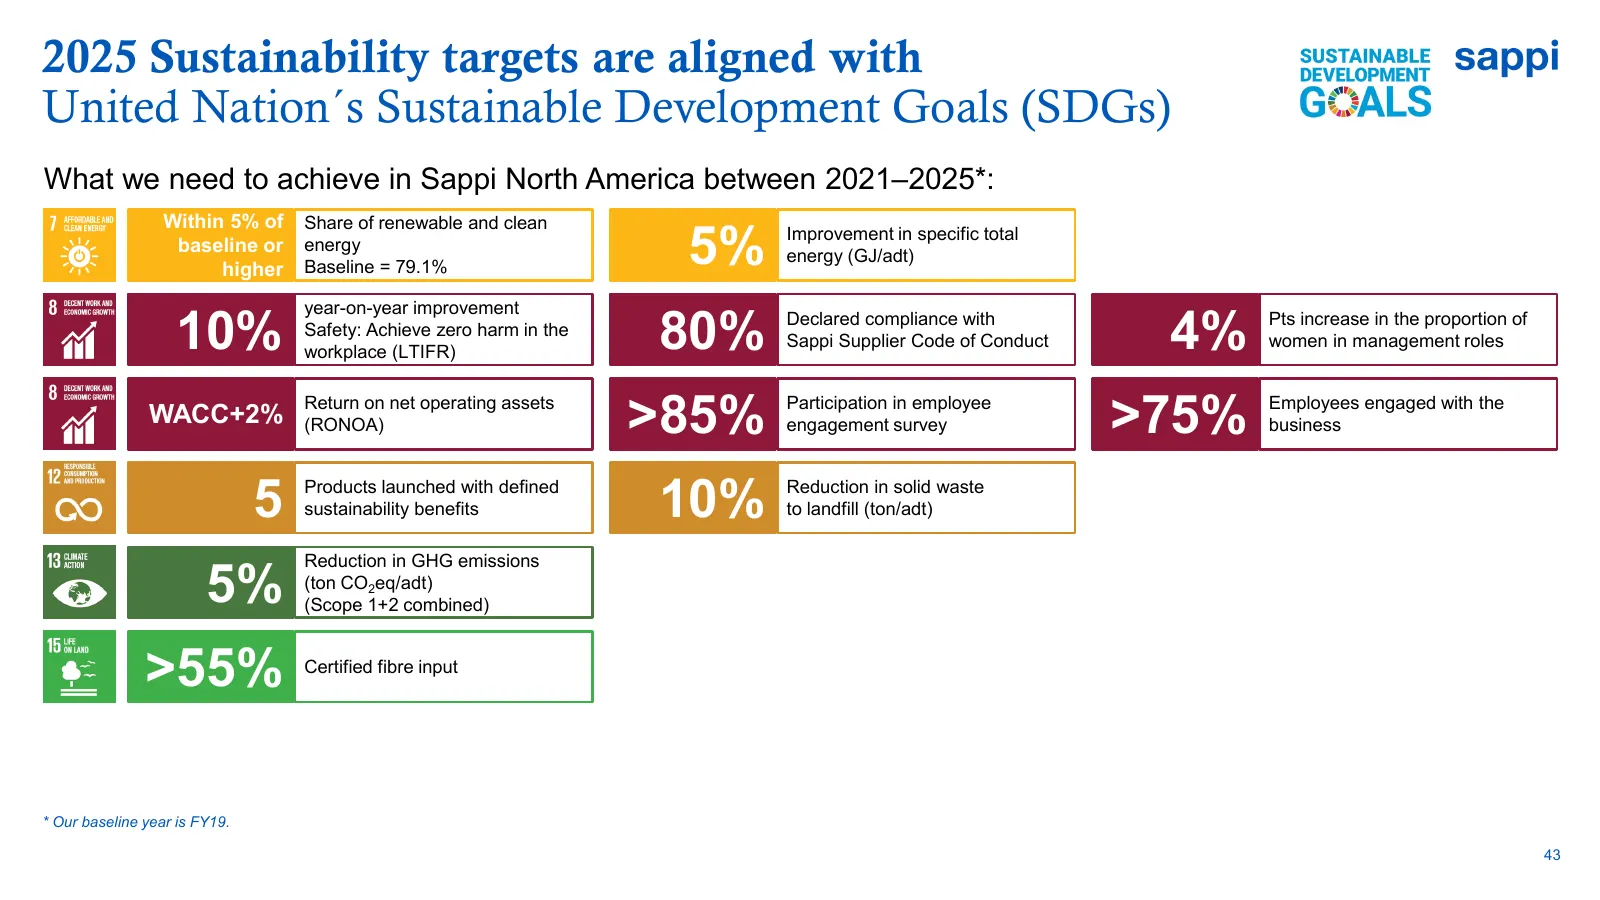
Slide 43: 2025 Sustainability targets - Sappi North America
2025 Sustainability targets are aligned with United Nation´s Sustainable Development Goals (SDGs) What we need to achieve in Sappi North America between 2021–2025*: Within 5% of 5% Share of renewable and clean Improvement in specific total baseline or energy energy (GJ/adt) higher Baseline = 79.1% 1
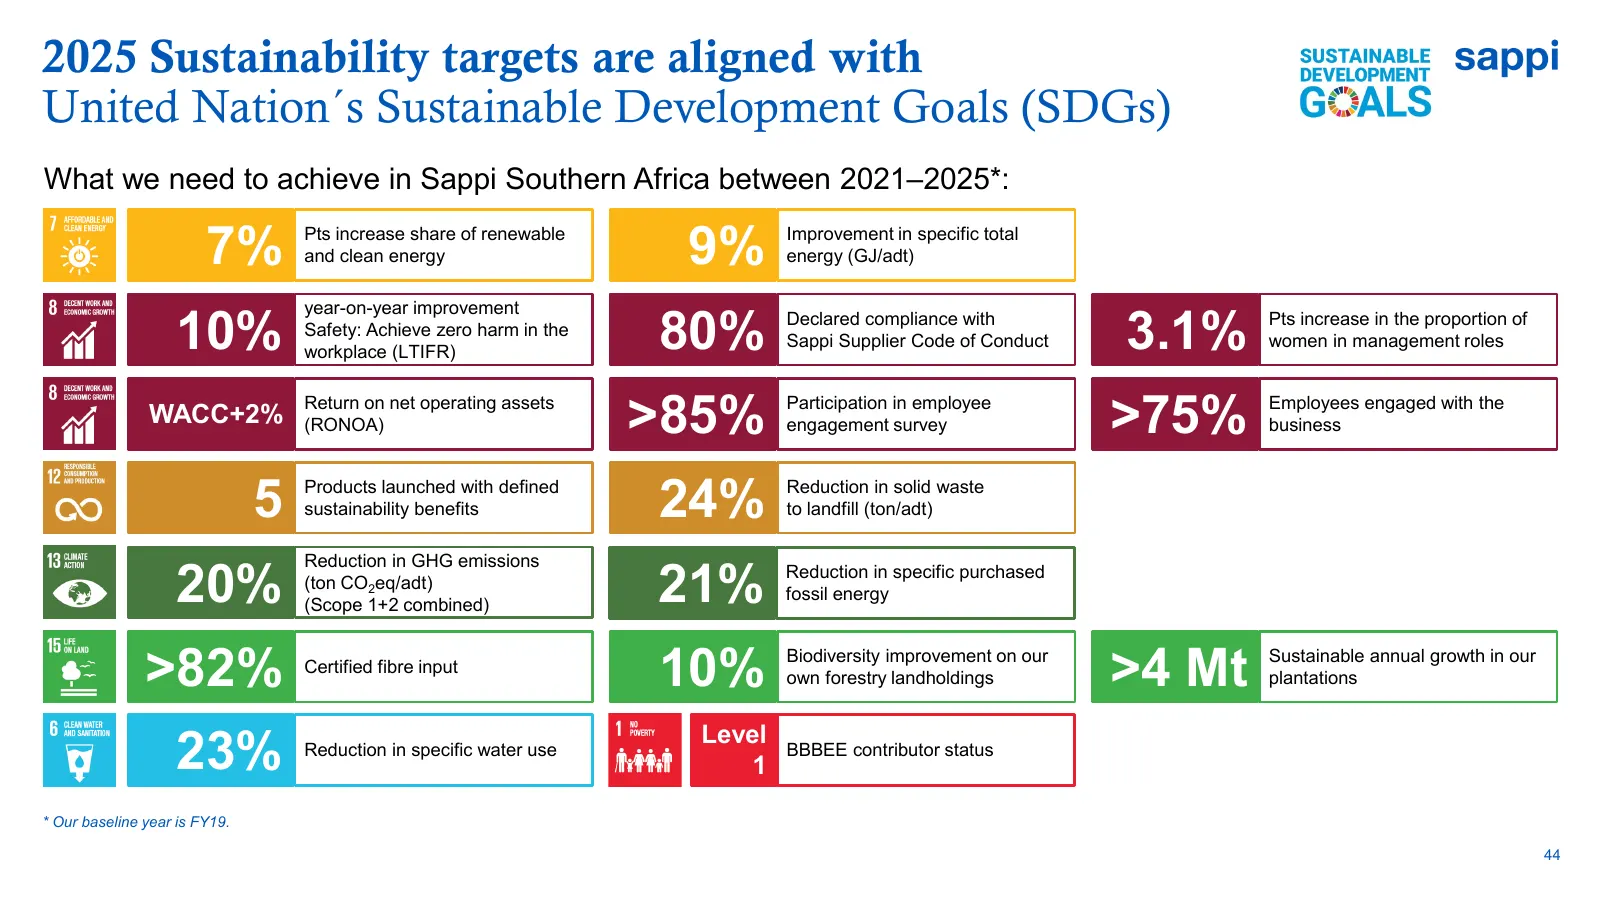
Slide 44: 2025 Sustainability targets - Sappi Southern Africa
2025 Sustainability targets are aligned with United Nation´s Sustainable Development Goals (SDGs) What we need to achieve in Sappi Southern Africa between 2021–2025*: 7% Pts increase share of renewable and clean energy 9% Improvement in specific total energy (GJ/adt) 10% 80% 3.1% year-on-year improv
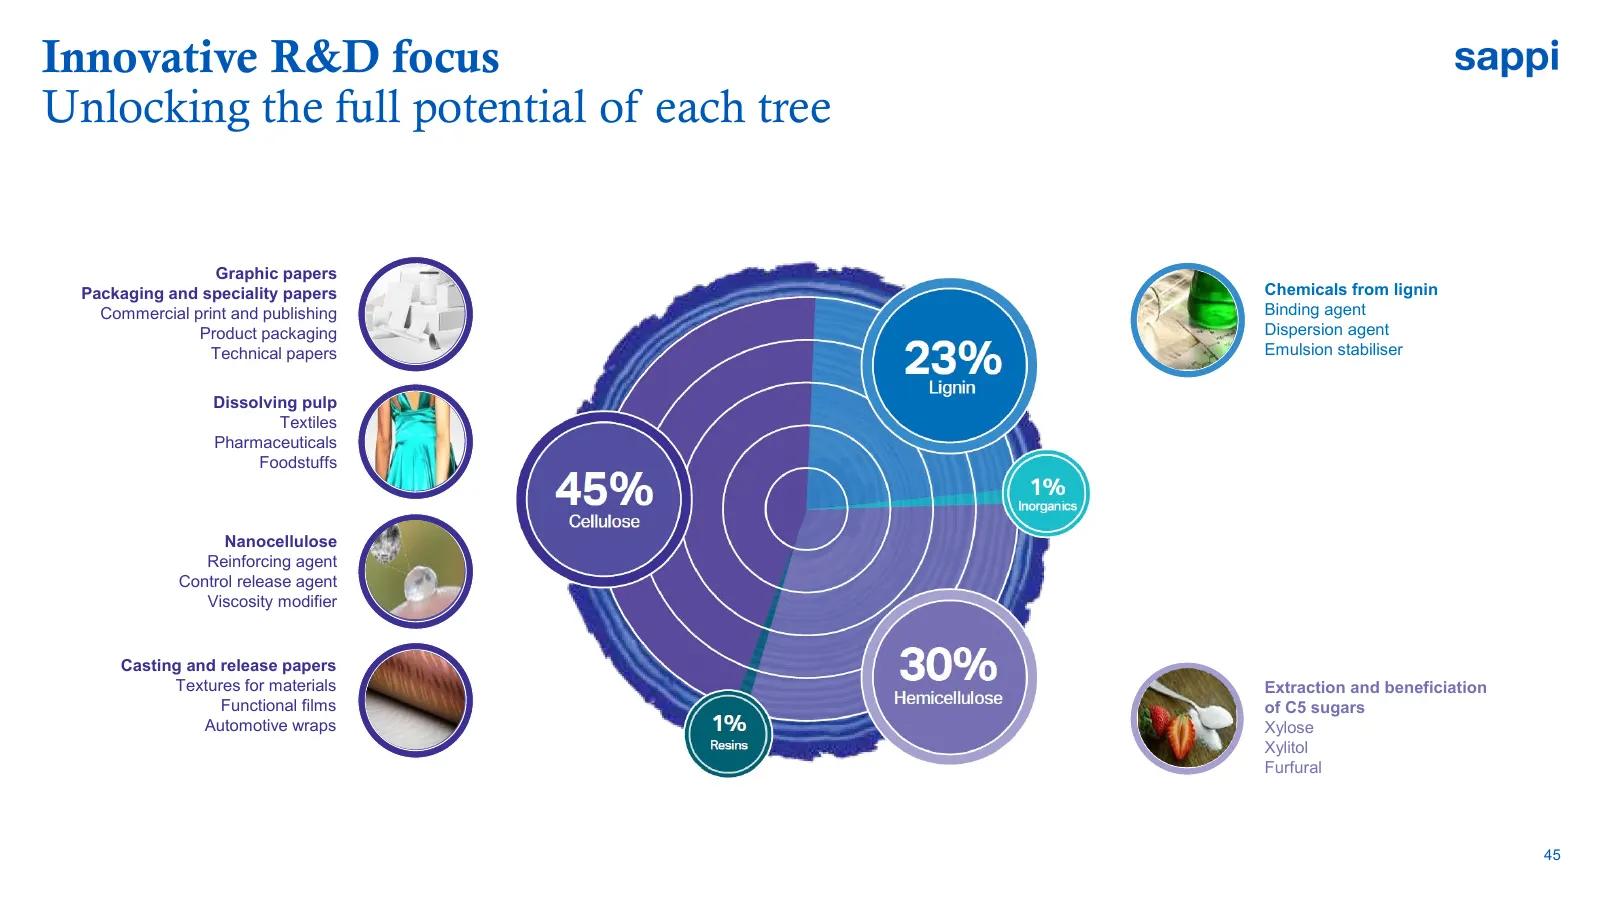
Slide 45: Innovative R&D focus: Unlocking the full potential of each tree
Innovative R&D focus Unlocking the full potential of each tree Graphic papers Packaging and speciality papers Chemicals from lignin Commercial print and publishing Binding agent Product packaging Dispersion agent Technical papers Emulsion stabiliser Dissolving pulp Textiles Pharmaceuticals Foodstuff
Slide 46: Thank you
sappi Thank you
Source: company website
More decks from Sappi Limited
 Q3 FY26 Earnings Presentation47 slides · Aug 6, 2026
 Q2 2026 Earnings Presentation44 slides · May 7, 2026
 Q1 2026 Earnings Presentation43 slides · Feb 4, 2026
 Merger or Acquisition (December 2025)16 slides · Dec 4, 2025
 Q4 2025 Earnings Presentation61 slides · Nov 6, 2025
 Q3 FY25 Earnings Presentation59 slides · Aug 7, 2025