Magnetite Mines Ltd. · ASX:MGT
Magnetite Mines — Royal Resources — Investor Presentation (June 2014)
30 slides from Magnetite Mines's investor presentation, June 2014
Slide 1: A Low Cost Premium Iron Ore Project in South Australia
A Low Cost Premium Iron Ore Project in South Australia Phil Crabb, Executive Chairman and Dr Gavin England, Project Manager June 2014
Slide 2: Disclaimer and Competent Person’s Statement
Disclaimer and Competent Person’s Statement This presentation has been prepared by Royal Resources Limited (ABN 34 108 102 432) (“Royal”) based on information available to it. No representation or warranty, express or implied, is made as to the fairness, accuracy, completeness or correctness of the
Slide 3: Razorback Premium Iron Project – South Australia
Razorback Premium Iron Project – South Australia NPV of $2.7 Billion IRR of 39% 67% Magnetite Iron Concentrate 2.7 Billion Tonne of Resource PFS complete, independently reviewed 3
Slide 4: Presentation Agenda
Presentation Agenda Investment Case Corporate Overview The Razorback Project Project Financials Summary 4
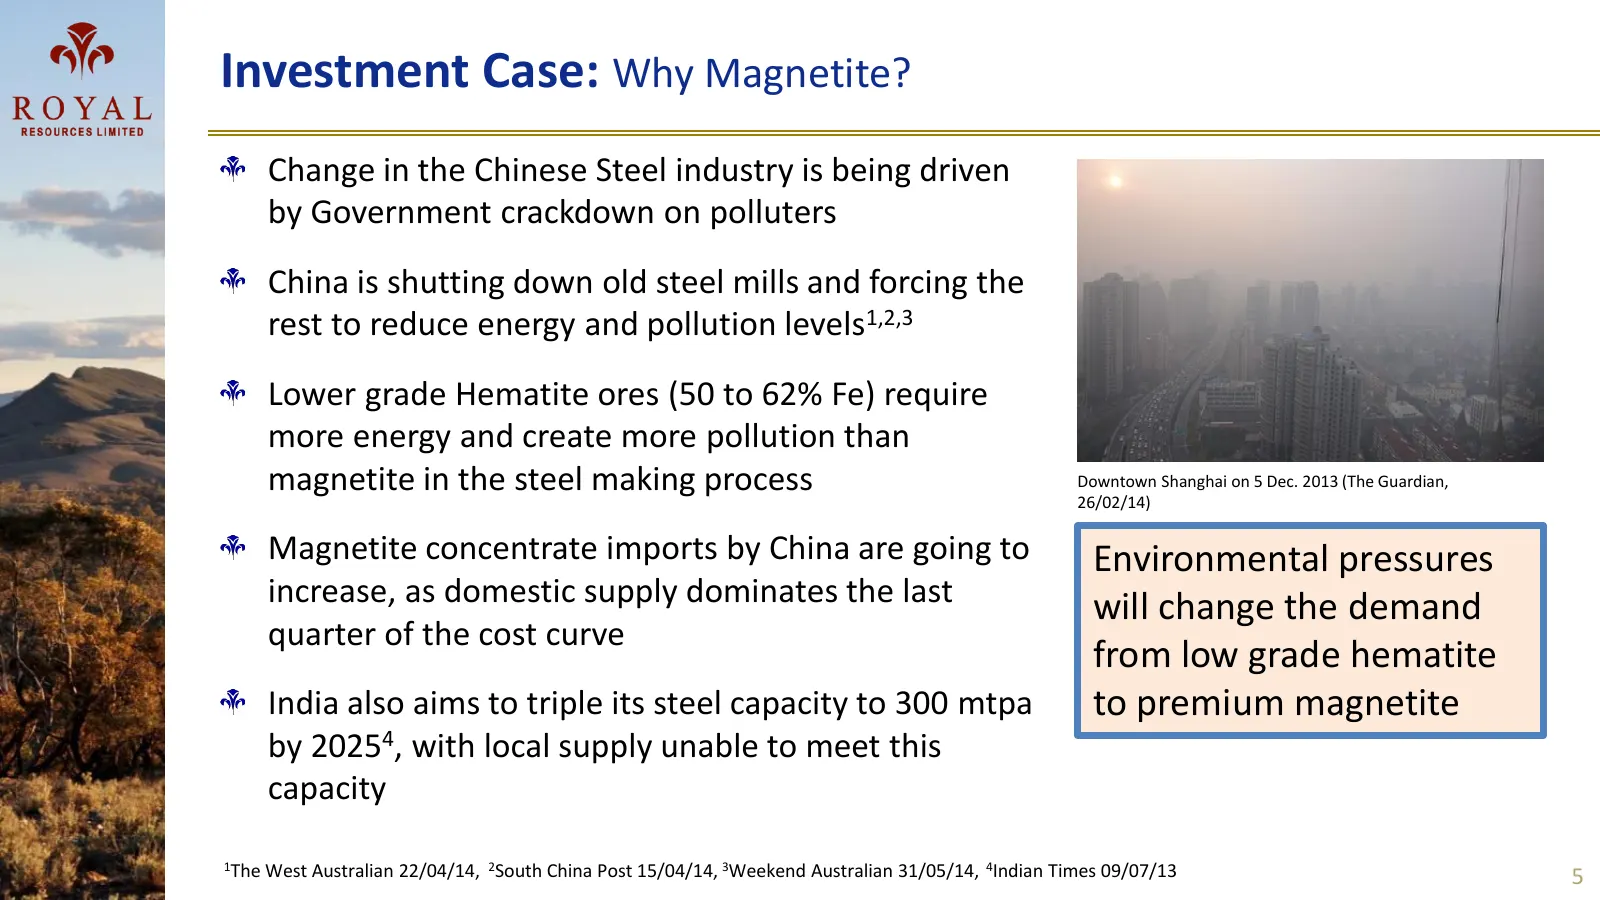
Slide 5: Investment Case: Why Magnetite?
Investment Case: Why Magnetite? Change in the Chinese Steel industry is being driven by Government crackdown on polluters China is shutting down old steel mills and forcing the rest to reduce energy and pollution levels1,2,3 Lower grade Hematite ores (50 to 62% Fe) require more energy and create mor
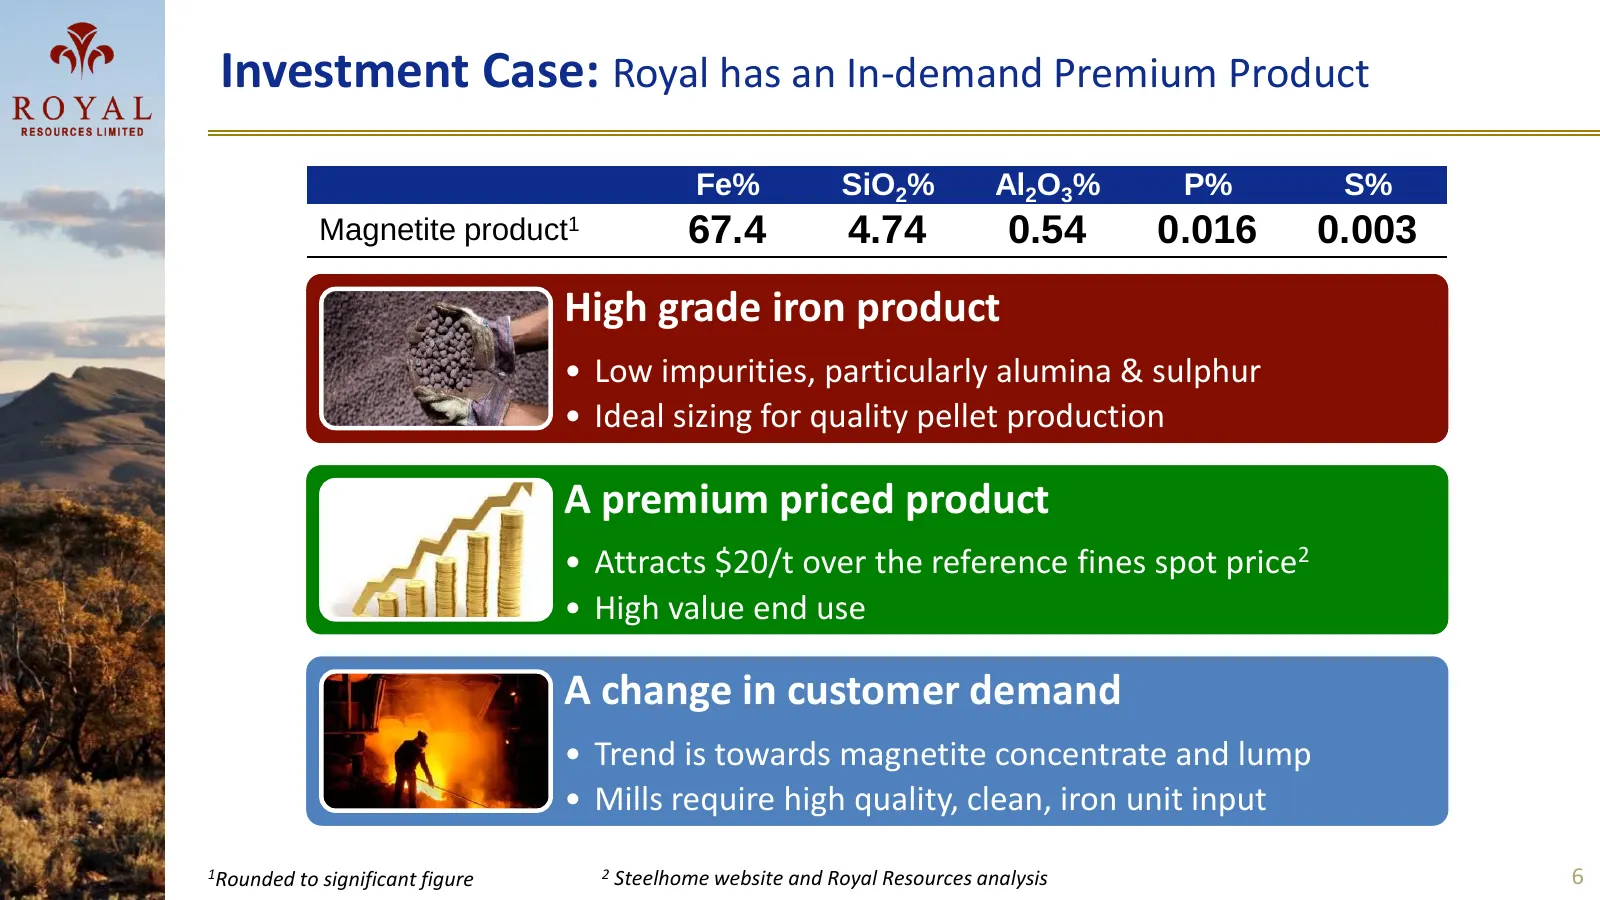
Slide 6: Investment Case: Royal has an In-demand Premium Product
Investment Case: Royal has an In-demand Premium Product Fe% SiO2% Al2O3% P% S% Magnetite product1 67.4 4.74 0.54 0.016 0.003 High grade iron product • Low impurities, particularly alumina & sulphur • Ideal sizing for quality pellet production A premium priced product • Attracts $20/t over the refere
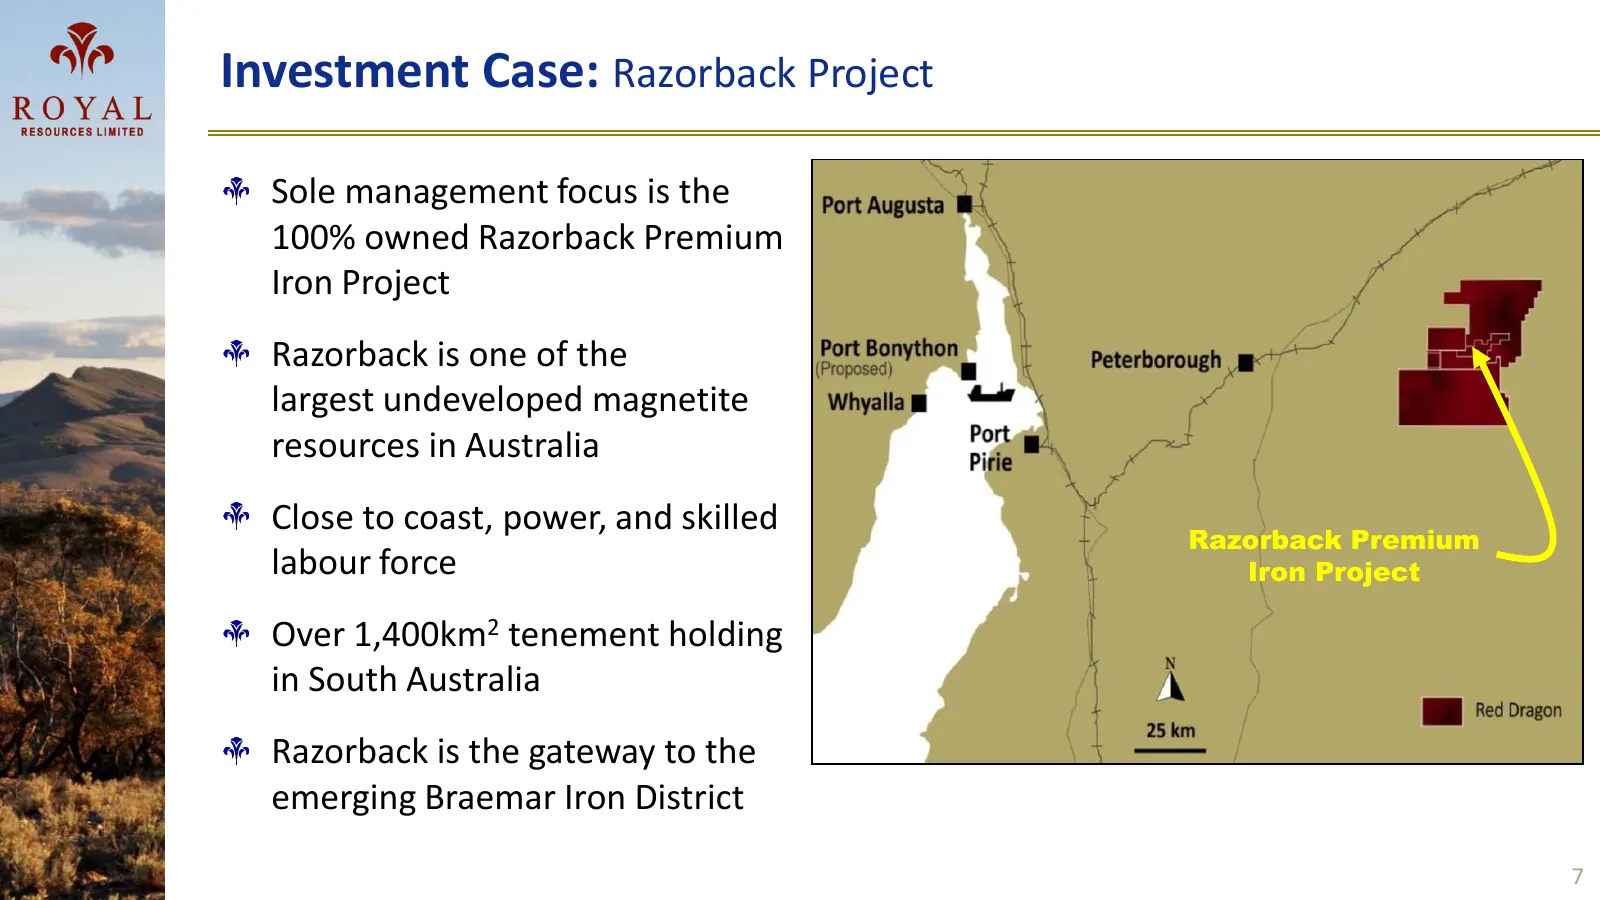
Slide 7: Investment Case: Razorback Project
Investment Case: Razorback Project Sole management focus is the 100% owned Razorback Premium Iron Project Razorback is one of the largest undeveloped magnetite resources in Australia Close to coast, power, and skilled Razorback Premium labour force Iron Project Over 1,400km2 tenement holding in Sout
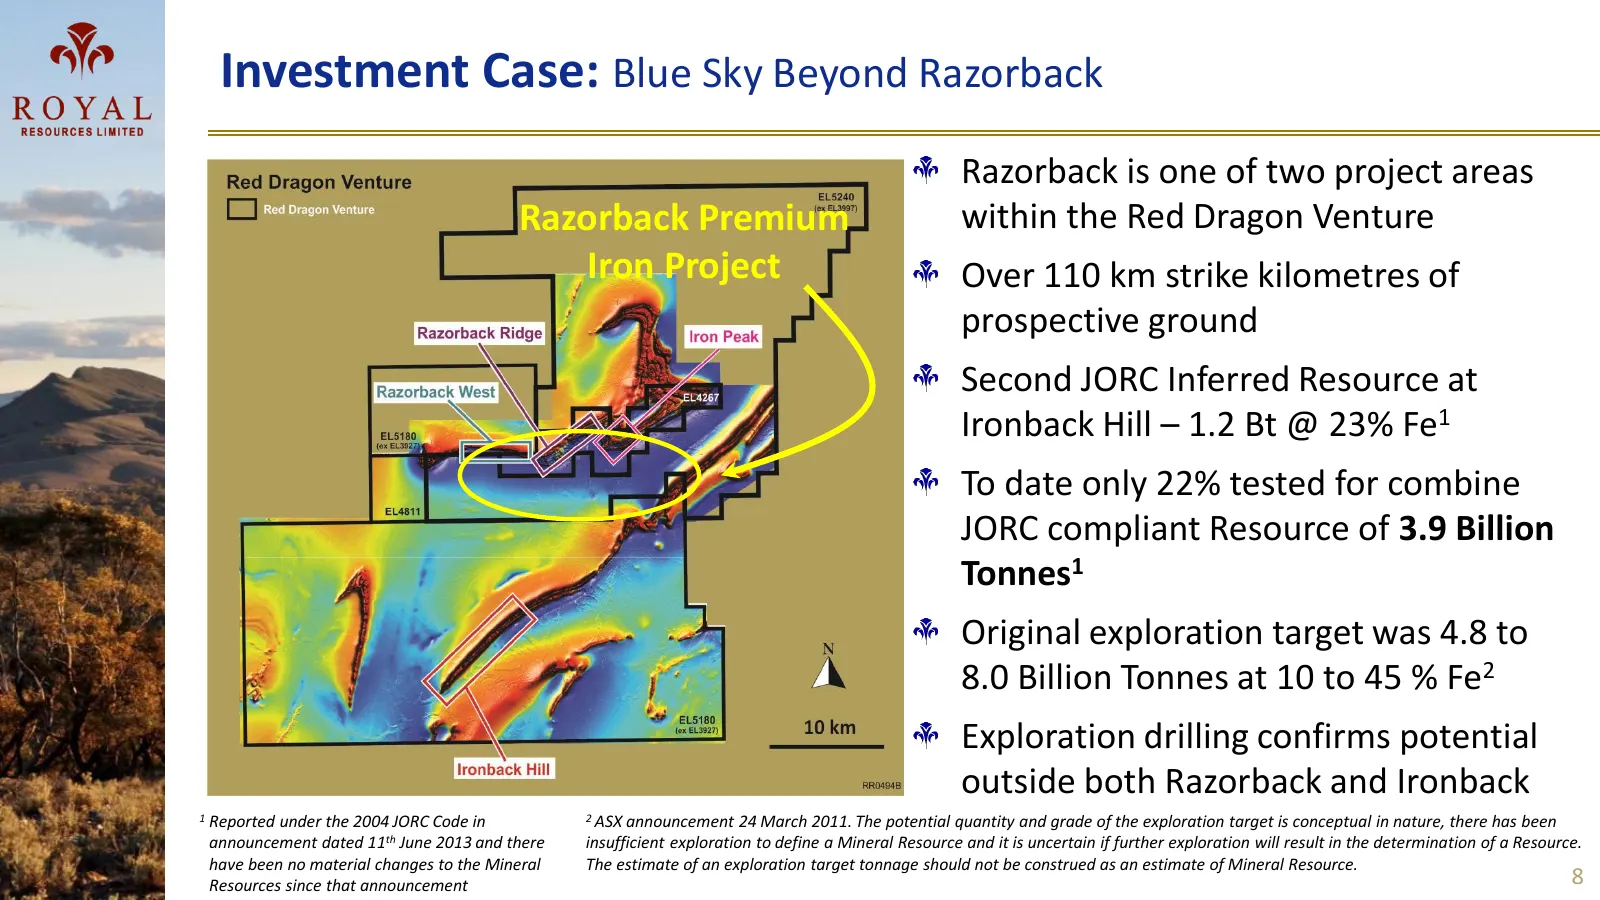
Slide 8: Investment Case: Blue Sky Beyond Razorback
Investment Case: Blue Sky Beyond Razorback Razorback is one of two project areas Razorback Premium within the Red Dragon Venture Iron Project Over 110 km strike kilometres of prospective ground Second JORC Inferred Resource at Ironback Hill – 1.2 Bt @ 23% Fe1 To date only 22% tested for combine JORC
Slide 9: Presentation Agenda
Presentation Agenda Investment Case Corporate Overview The Razorback Project Project Financials Summary 9
Slide 10: Corporate Overview: Royal Resources
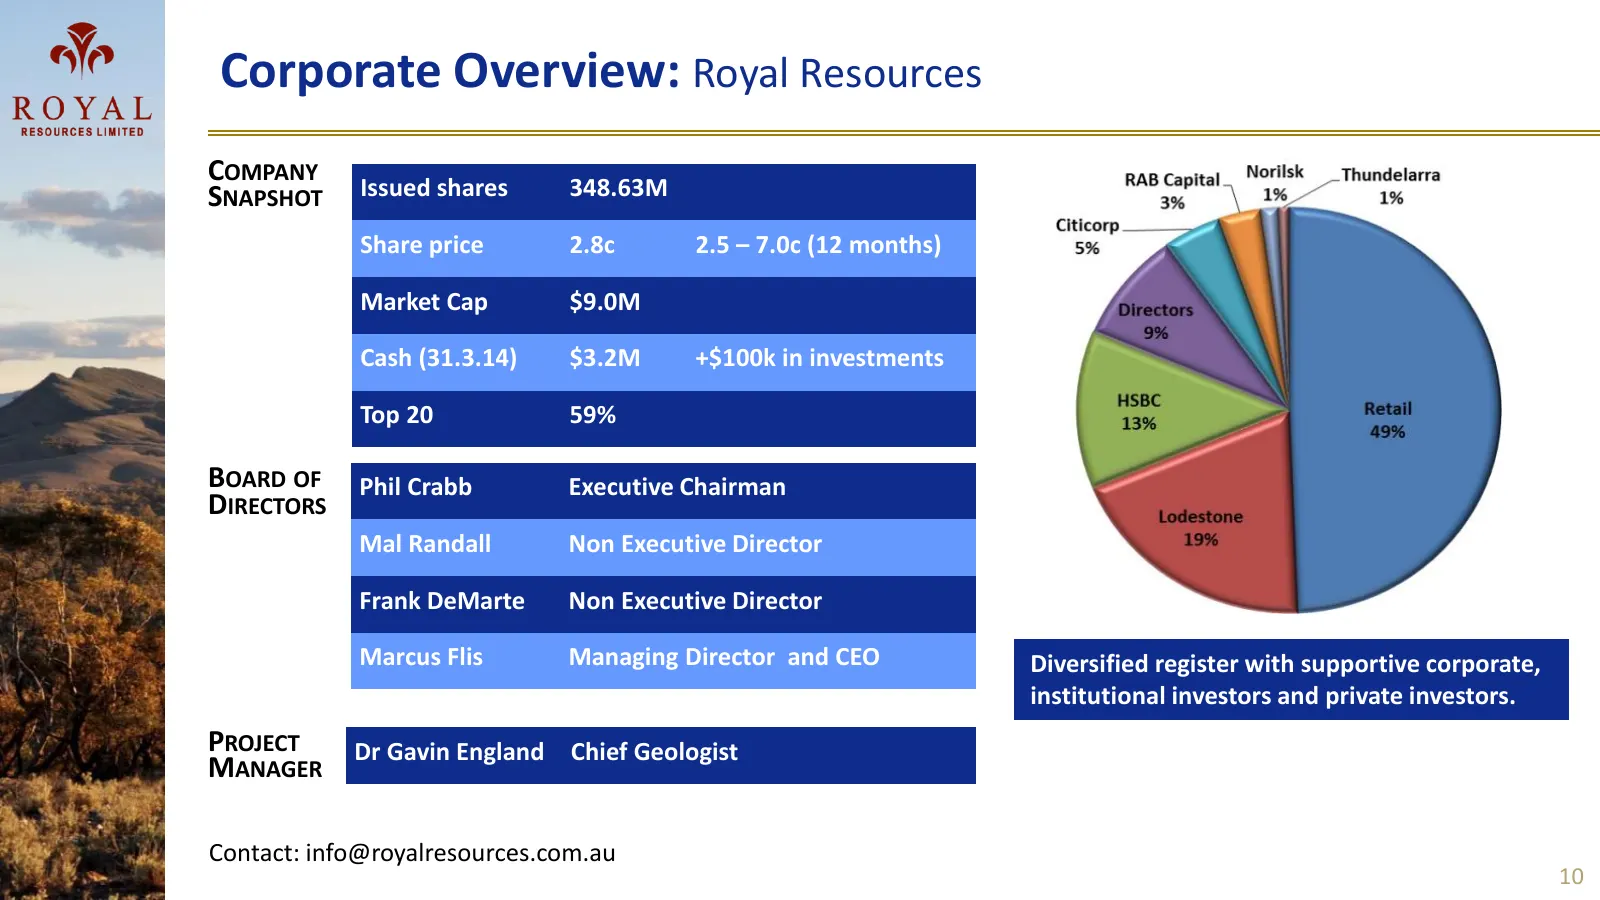
Corporate Overview: Royal Resources COMPANY SNAPSHOT Issued shares 348.63M Share price 2.8c 2.5 – 7.0c (12 months) Market Cap $9.0M Cash (31.3.14) $3.2M +$100k in investments Top 20 59% BOARD OF Phil Crabb Executive Chairman DIRECTORS Mal Randall Non Executive Director Frank DeMarte Non Executive Di
Slide 11: Corporate Overview: Investment Highlights
Corporate Overview: Investment Highlights Razorback has one of the lowest capital intensive magnetite projects in Australia An impressive NVP of $2.7 Billion and IRR of 39% MoU with major shareholder Gordon Toll’s Braemar Infrastructure to provide all transport and infrastructure, heavily reducing t
Slide 12: Royal Resources
Royal Resources Investment Case Corporate Overview The Razorback Project Project Financials Summary 12
Slide 13: Razorback Project: Magnetite Deposit Geology
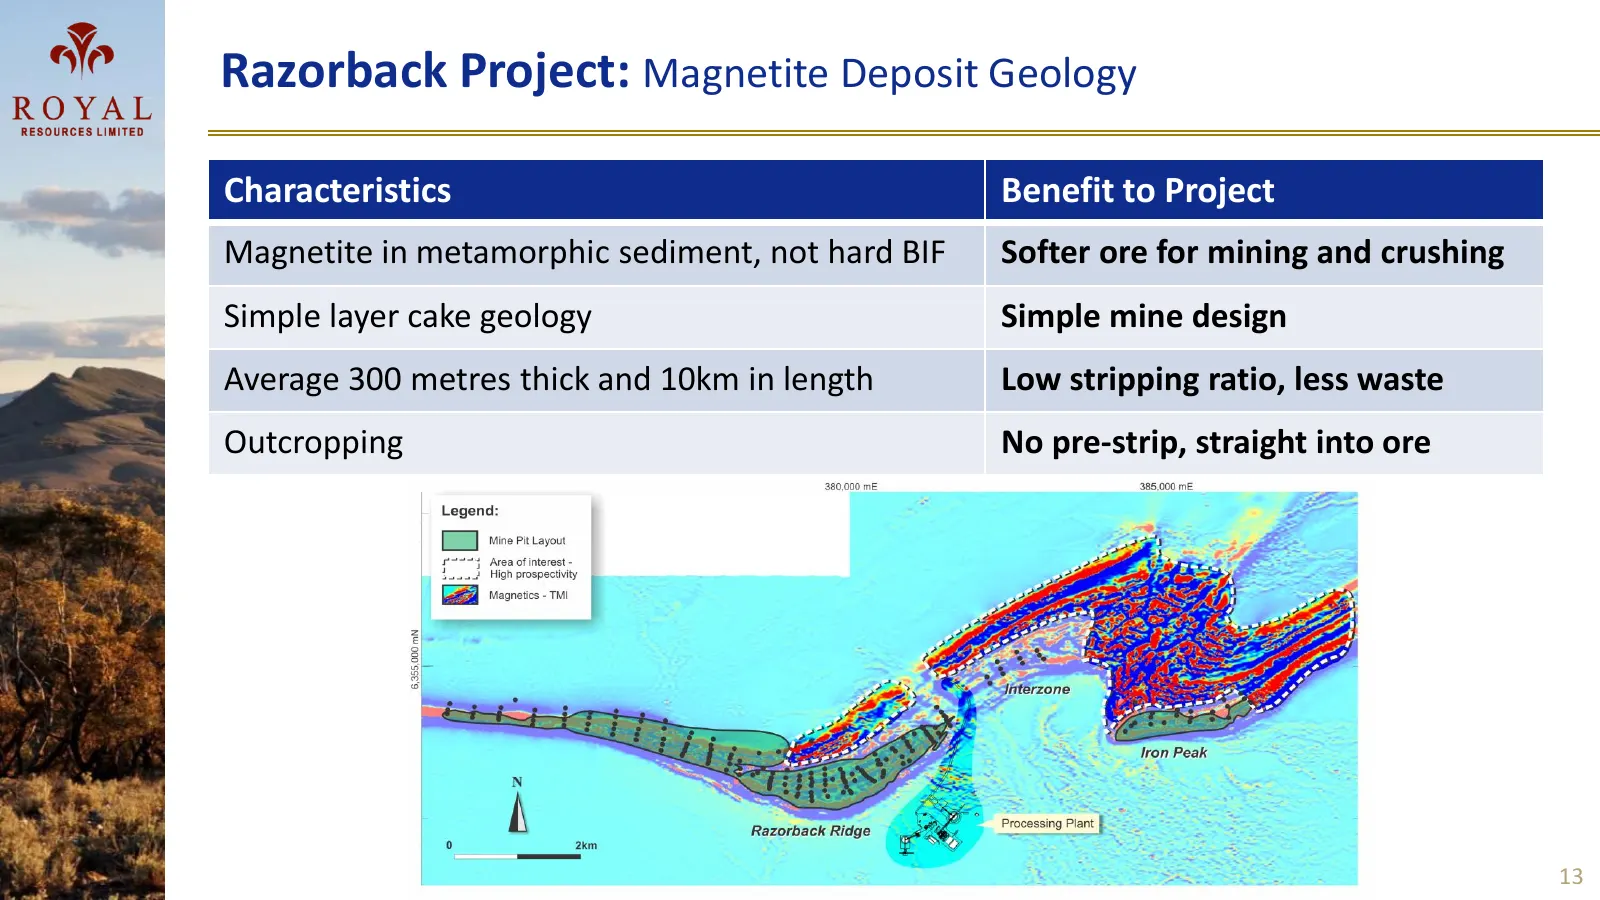
Razorback Project: Magnetite Deposit Geology Characteristics Benefit to Project Magnetite in metamorphic sediment, not hard BIF Softer ore for mining and crushing Simple layer cake geology Simple mine design Average 300 metres thick and 10km in length Low stripping ratio, less waste Outcropping No p
Slide 14: Razorback Project: Resource Profile
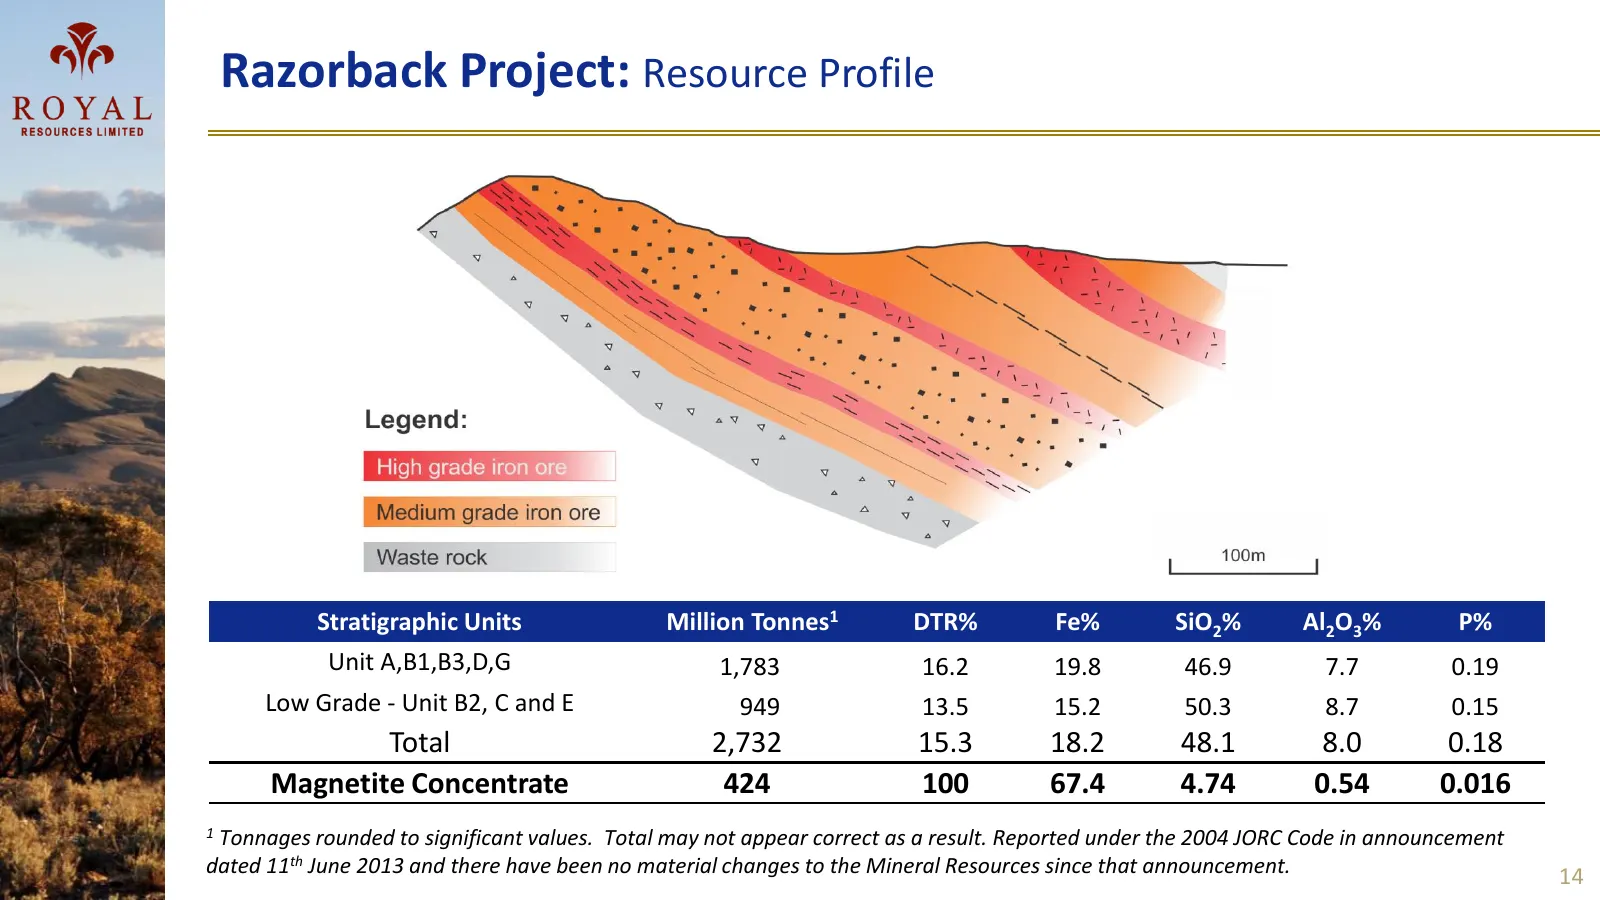
Razorback Project: Resource Profile Stratigraphic Units Million Tonnes1 DTR% Fe% SiO2% Al2O3% P% Unit A,B1,B3,D,G 1,783 16.2 19.8 46.9 7.7 0.19 Low Grade - Unit B2, C and E 949 13.5 15.2 50.3 8.7 0.15 Total 2,732 15.3 18.2 48.1 8.0 0.18 Magnetite Concentrate 424 100 67.4 4.74 0.54 0.016 1 Tonnages r
Slide 15: Razorback Project: Progress achieved to date
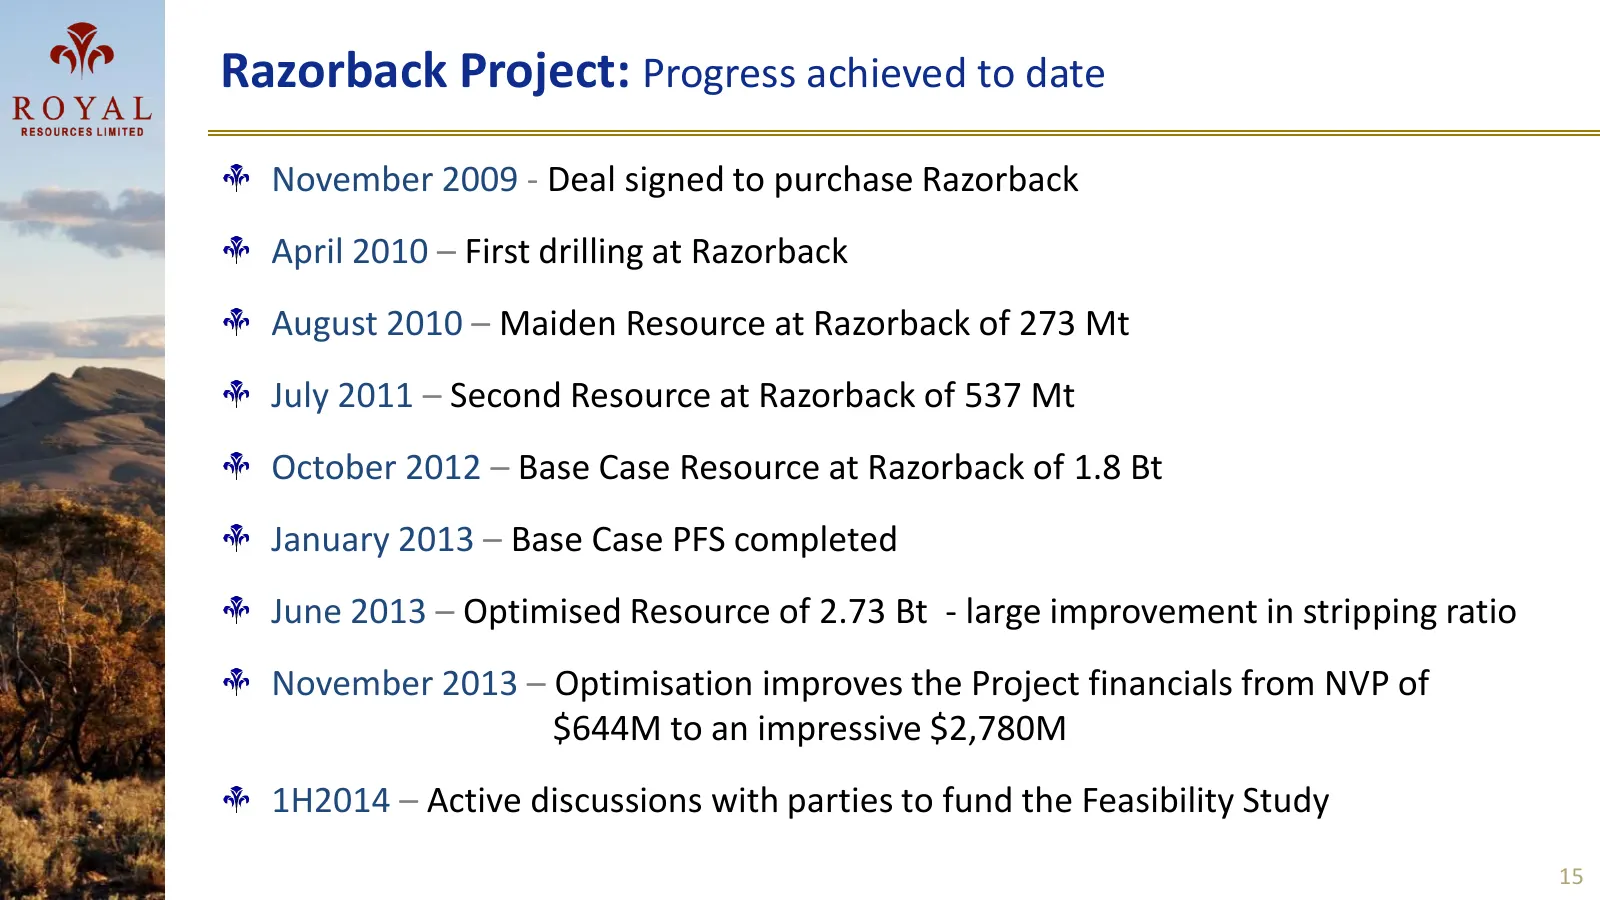
Razorback Project: Progress achieved to date November 2009 - Deal signed to purchase Razorback April 2010 – First drilling at Razorback August 2010 – Maiden Resource at Razorback of 273 Mt July 2011 – Second Resource at Razorback of 537 Mt October 2012 – Base Case Resource at Razorback of 1.8 Bt Jan
Slide 16: Razorback Project: Aggressive pathway to production
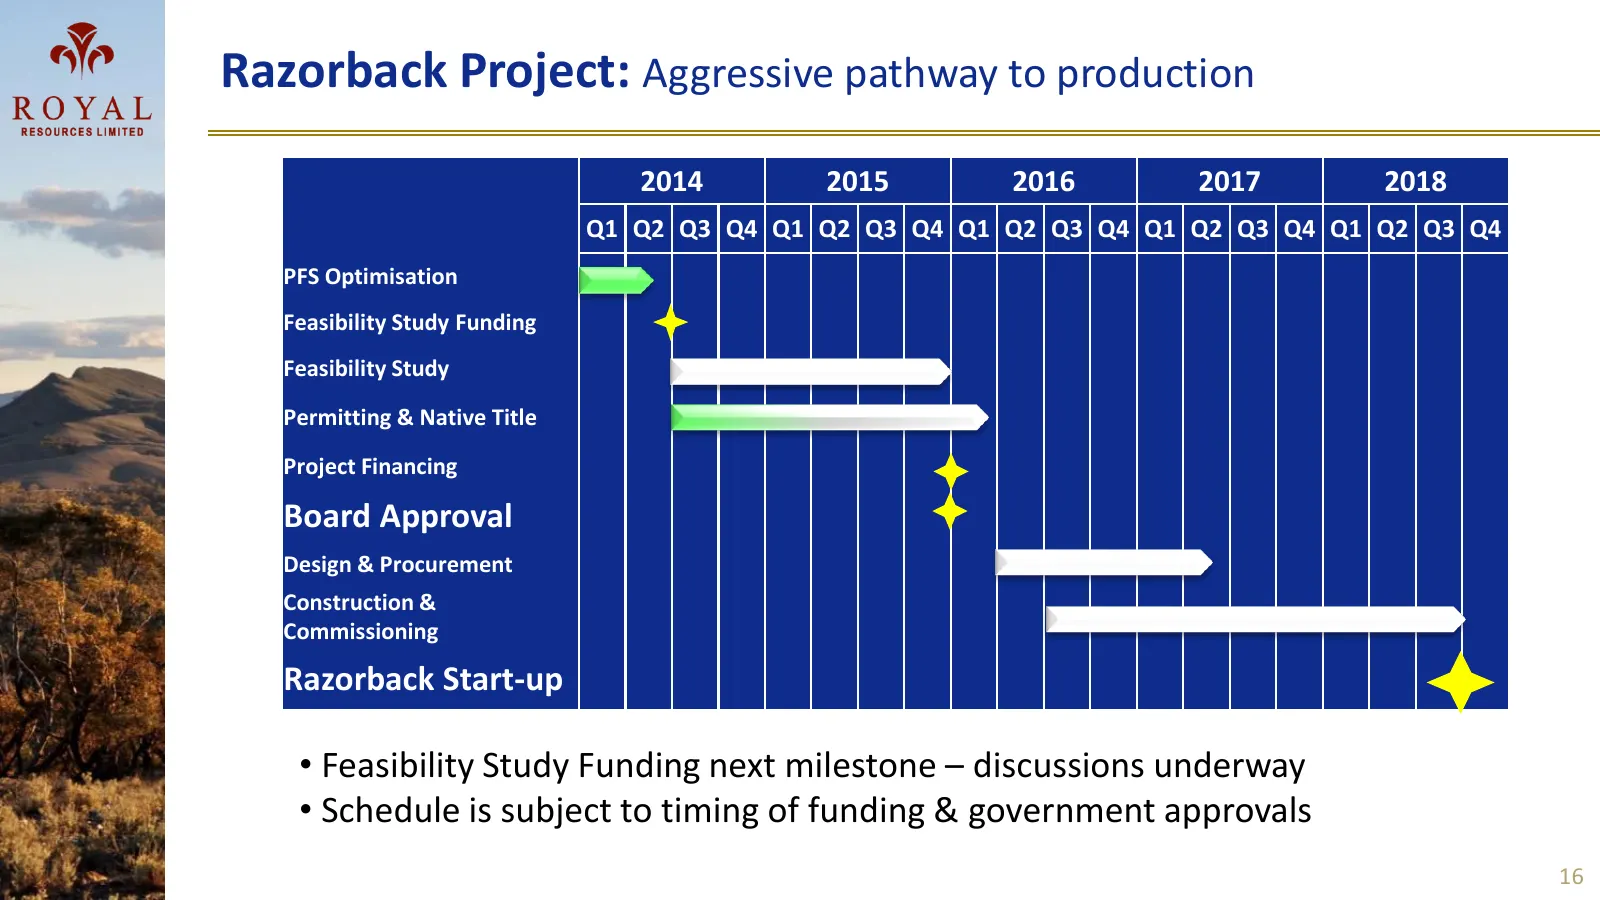
Razorback Project: Aggressive pathway to production 2014 2015 2016 2017 2018 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 PFS Optimisation Feasibility Study Funding Feasibility Study Permitting & Native Title Project Financing Board Approval Design & Procurement Construction & Commiss
Slide 17: Razorback Project: Business Case for New Generation Mine
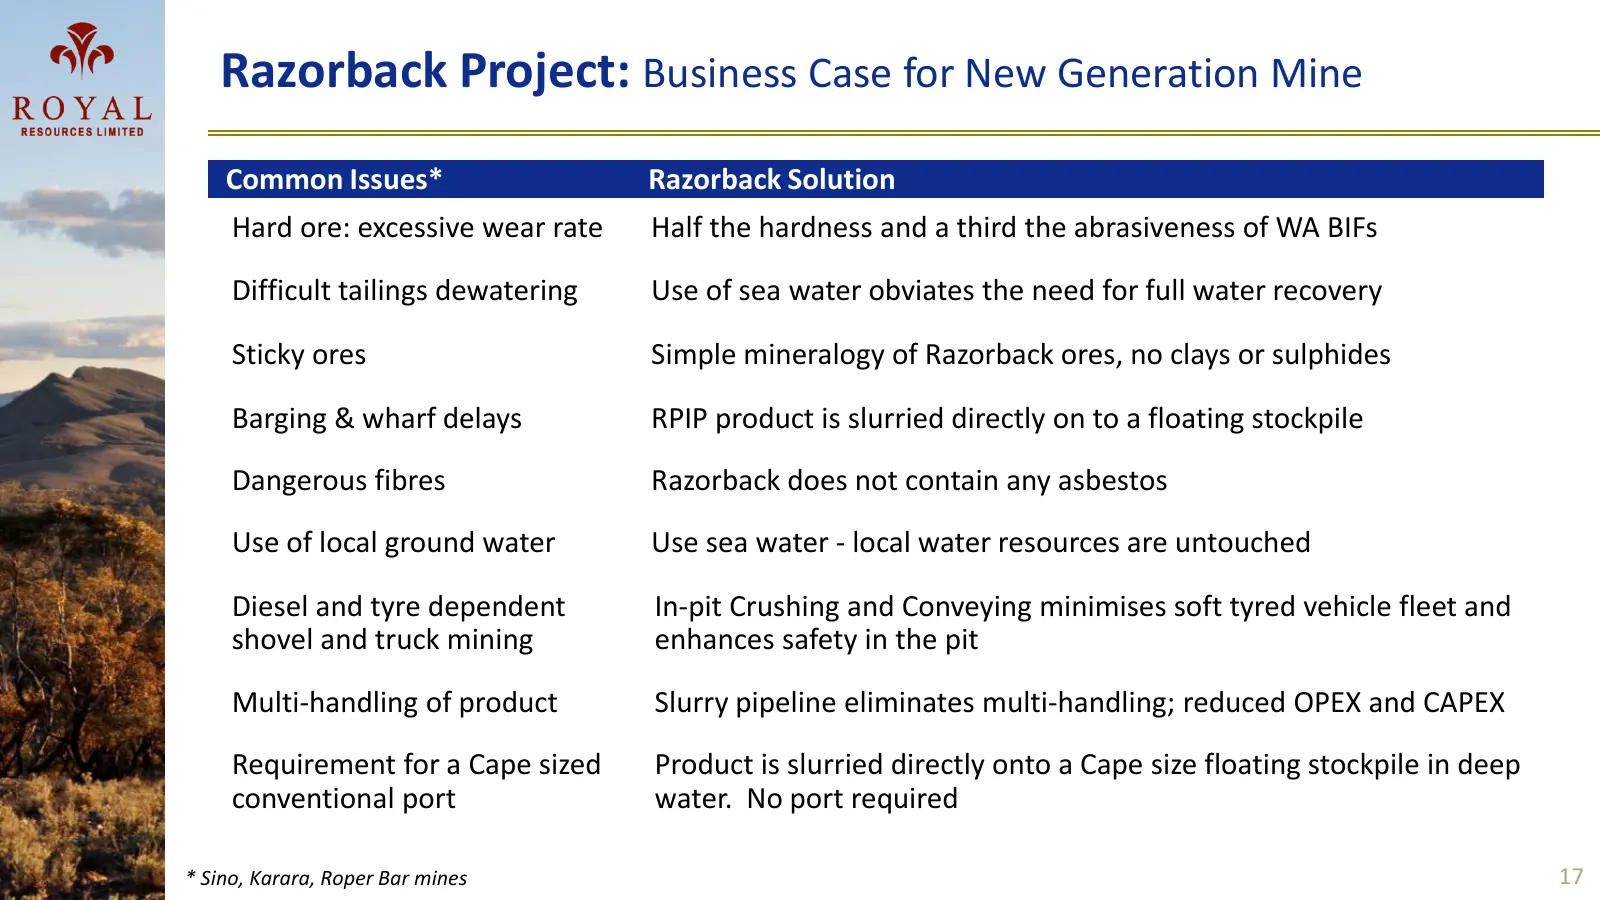
Razorback Project: Business Case for New Generation Mine Common Issues* Razorback Solution Hard ore: excessive wear rate Half the hardness and a third the abrasiveness of WA BIFs Difficult tailings dewatering Use of sea water obviates the need for full water recovery Sticky ores Simple mineralogy of
Slide 18: Razorback Project: Open Pit Design with Conventional Processing
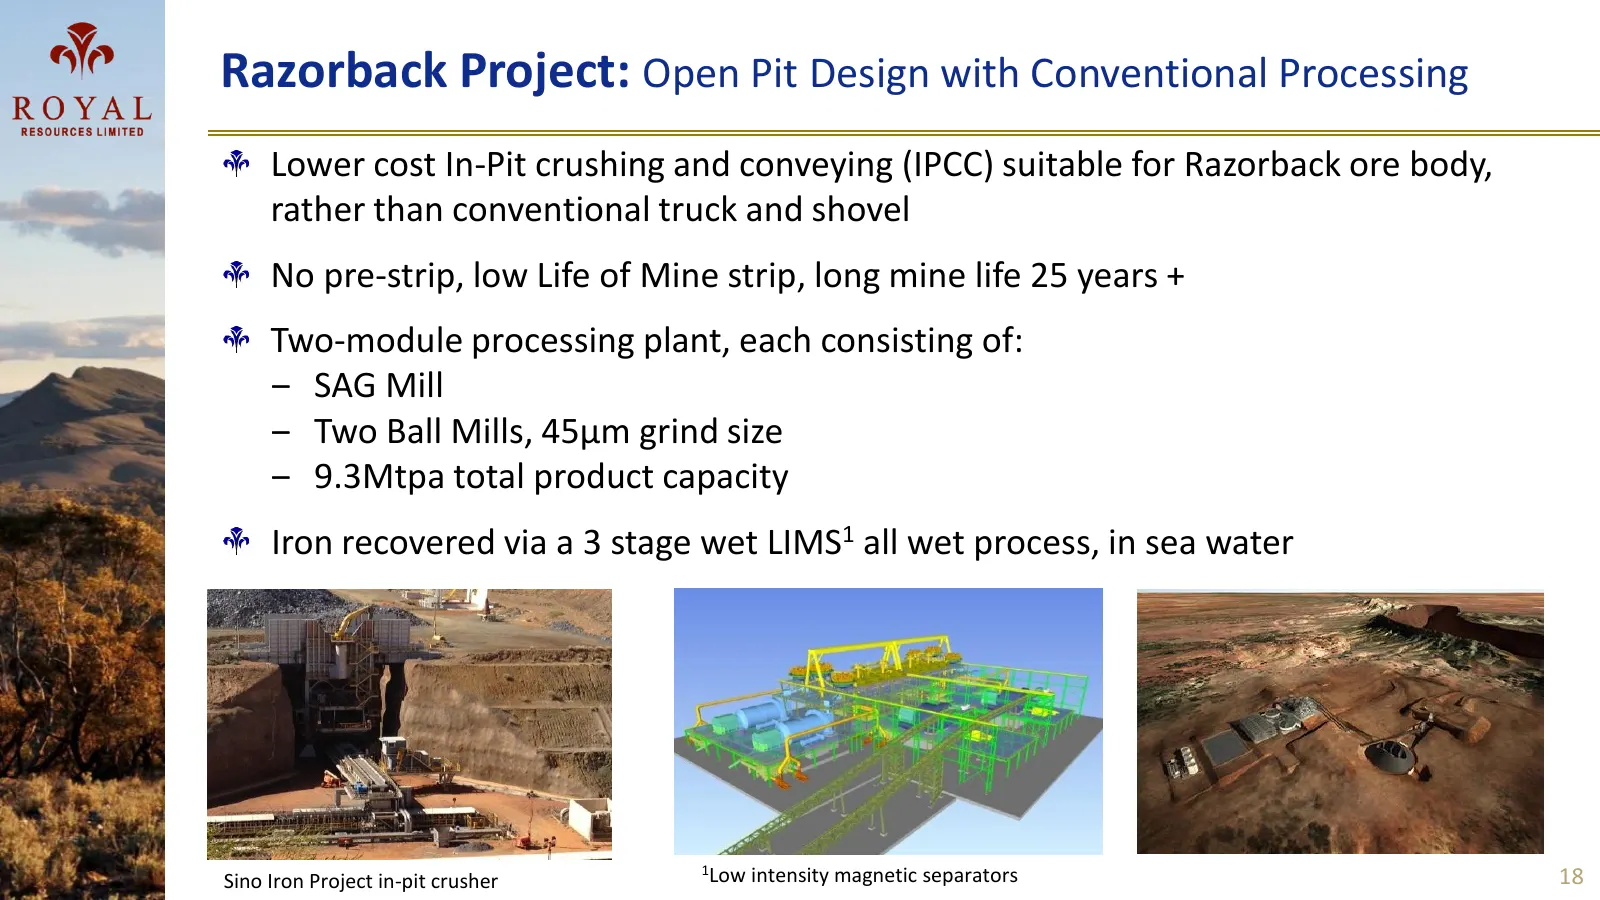
Razorback Project: Open Pit Design with Conventional Processing Lower cost In-Pit crushing and conveying (IPCC) suitable for Razorback ore body, rather than conventional truck and shovel No pre-strip, low Life of Mine strip, long mine life 25 years + Two-module processing plant, each consisting of:
Slide 19: Razorback Project: Integrated Mine to Ship Infrastructure
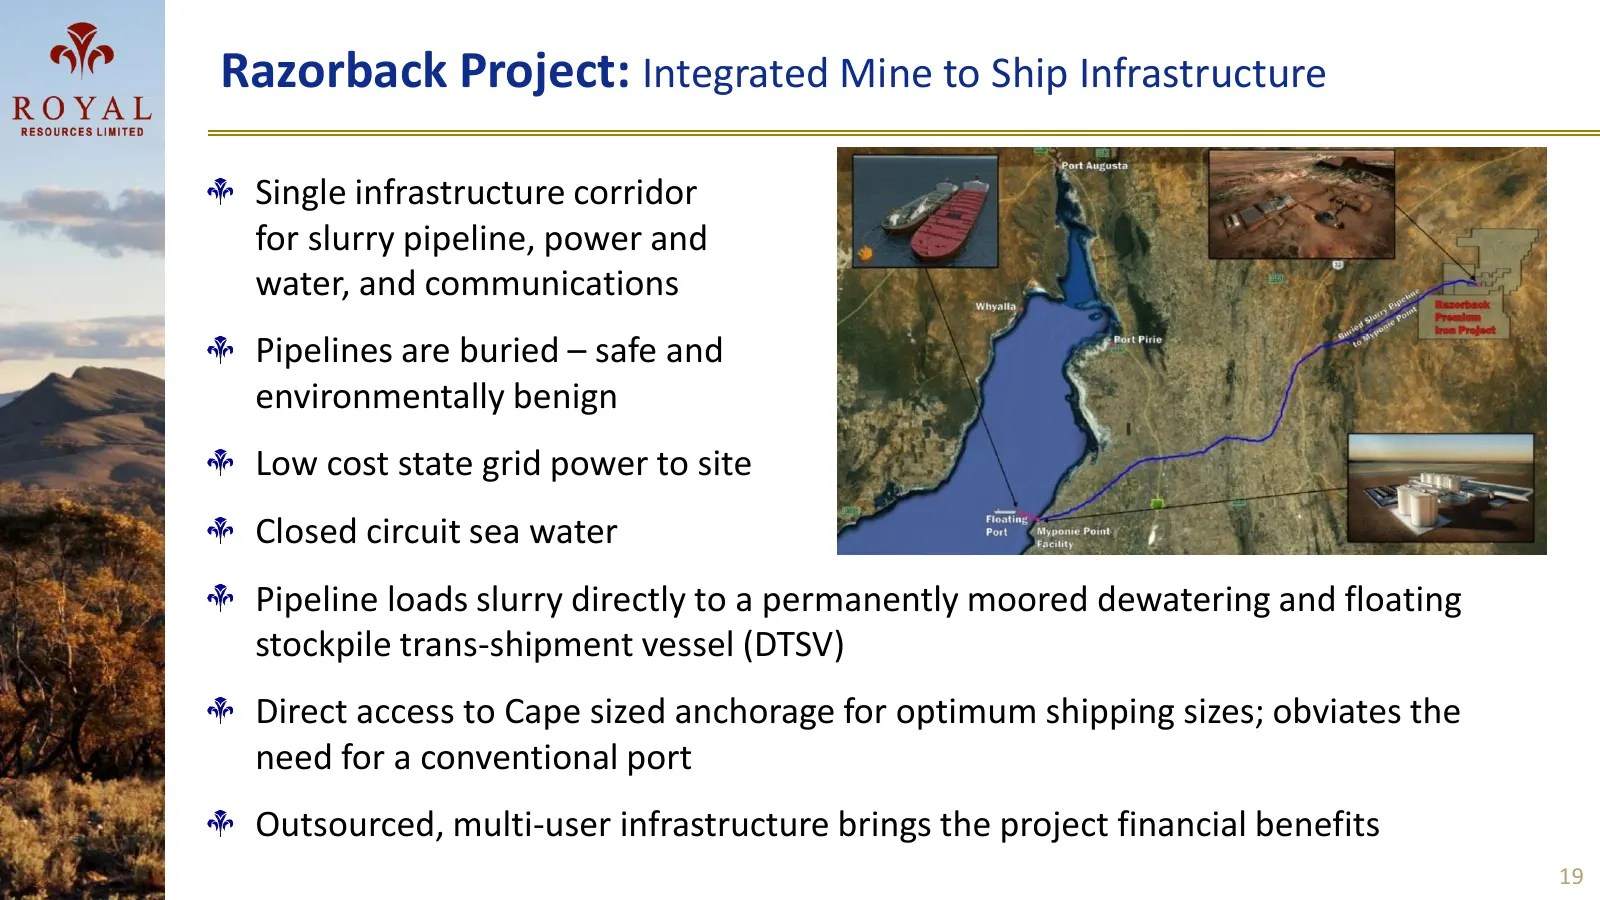
Razorback Project: Integrated Mine to Ship Infrastructure Single infrastructure corridor for slurry pipeline, power and water, and communications Pipelines are buried – safe and environmentally benign Low cost state grid power to site Closed circuit sea water Pipeline loads slurry directly to a perm
Slide 20: Royal Resources
Royal Resources Investment Case Corporate Overview The Razorback Project Project Financials Summary 20
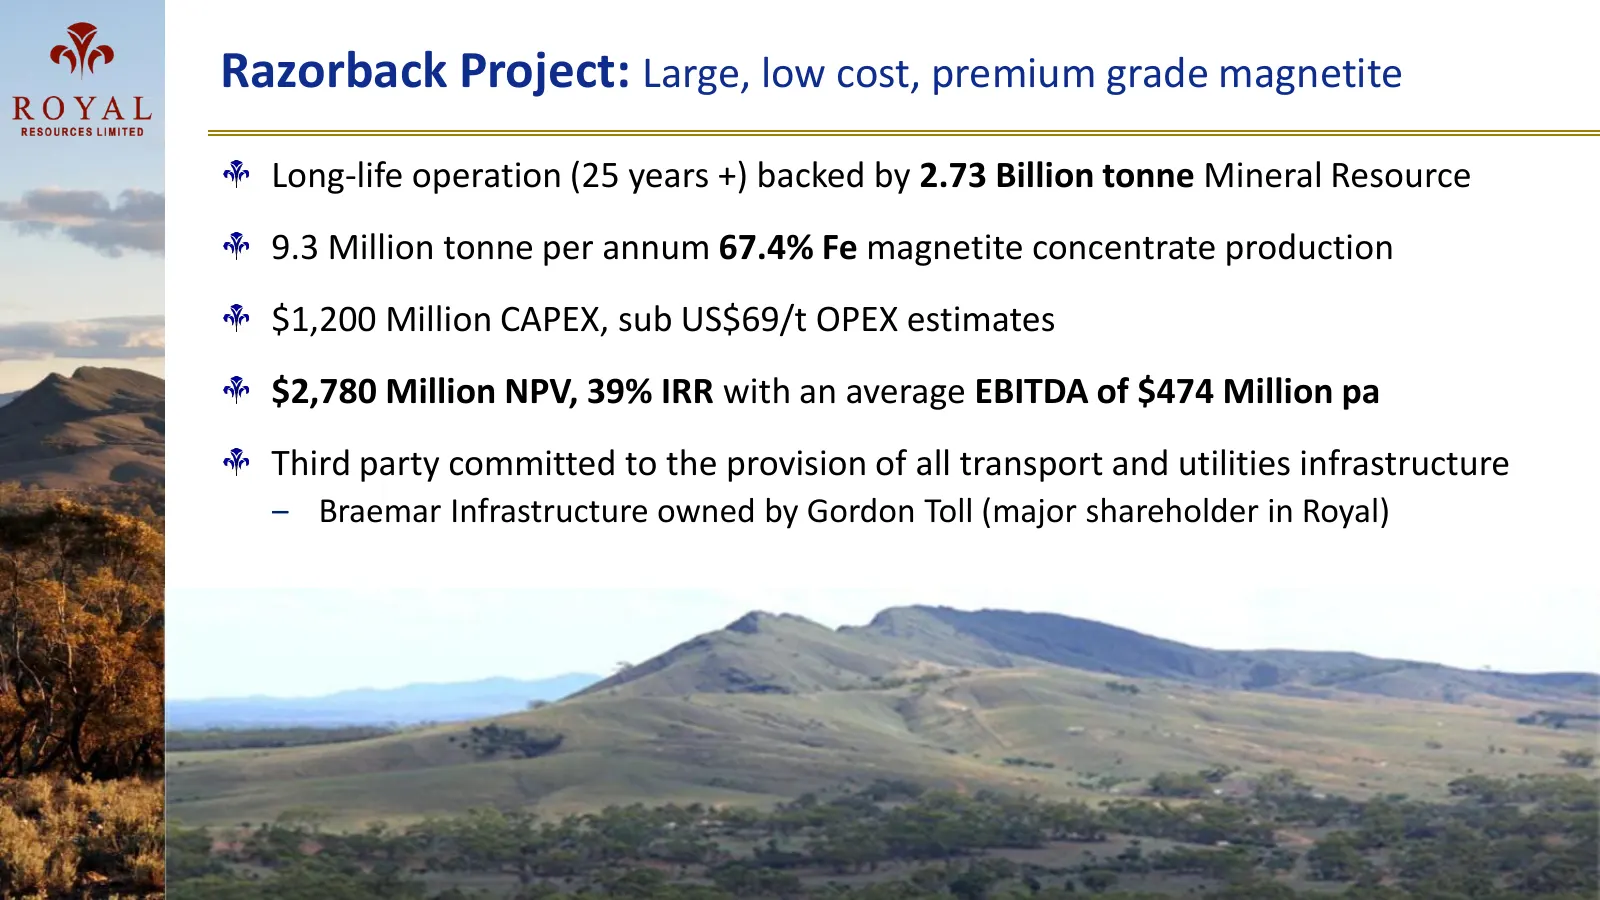
Slide 21: Razorback Project: Large, low cost, premium grade magnetite
Razorback Project: Large, low cost, premium grade magnetite Long-life operation (25 years +) backed by 2.73 Billion tonne Mineral Resource 9.3 Million tonne per annum 67.4% Fe magnetite concentrate production $1,200 Million CAPEX, sub US$69/t OPEX estimates $2,780 Million NPV, 39% IRR with an averag
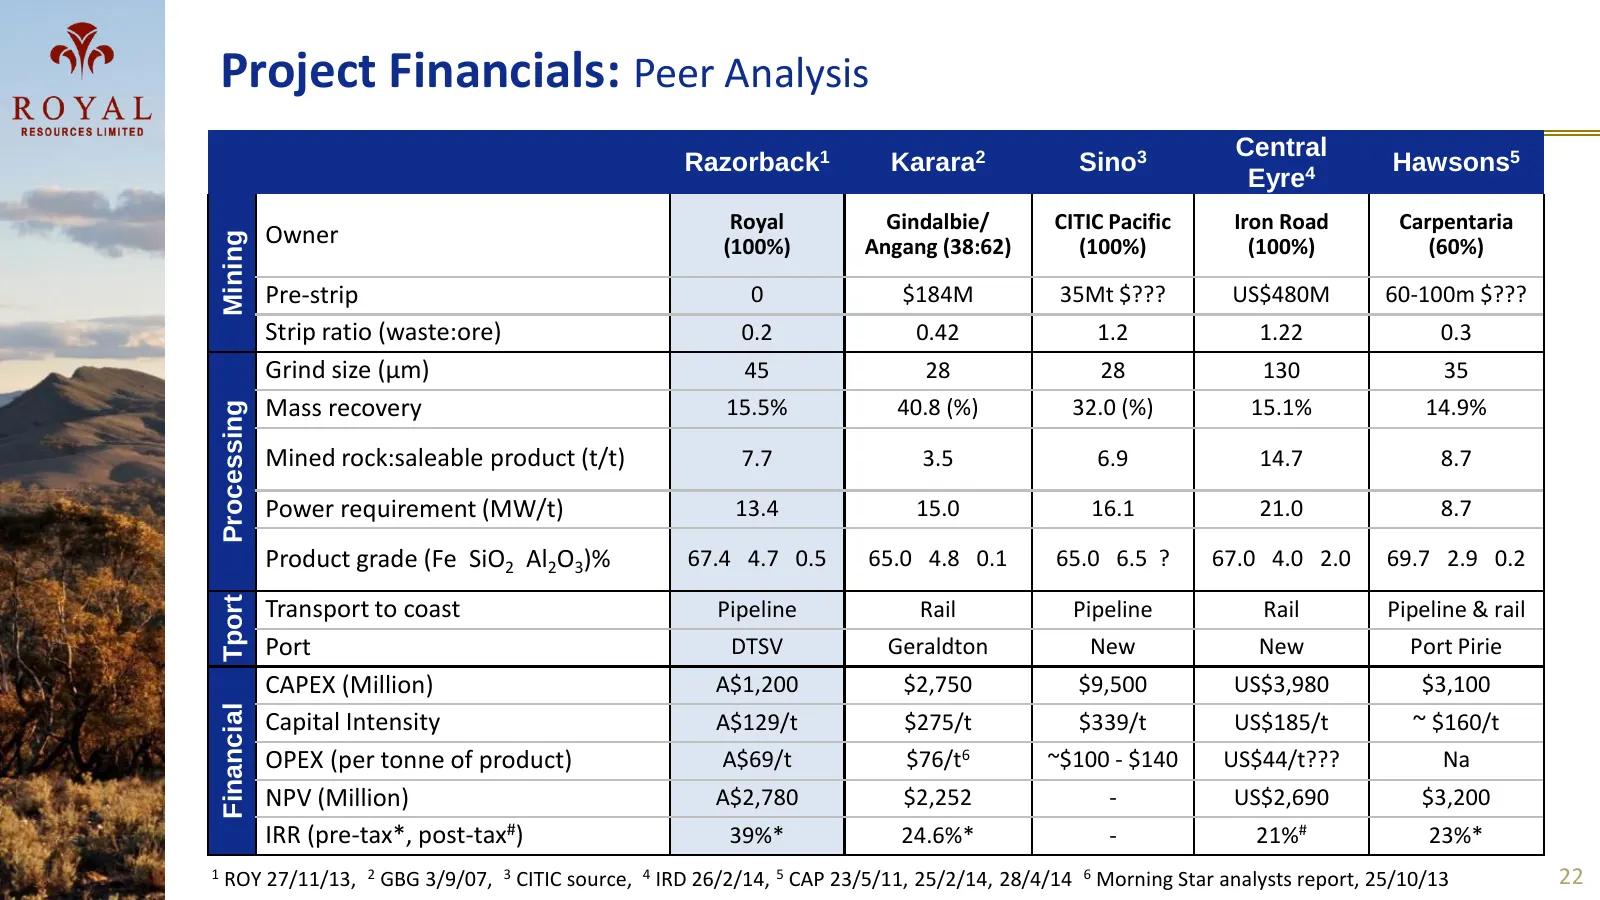
Slide 22: Project Financials: Peer Analysis
Project Financials: Peer Analysis Central Razorback1 Karara2 Sino3 Hawsons5 Eyre4 Royal Gindalbie/ CITIC Pacific Iron Road Carpentaria Mining Owner (100%) Angang (38:62) (100%) (100%) (60%) Pre-strip 0 $184M 35Mt $??? US$480M 60-100m $??? Strip ratio (waste:ore) 0.2 0.42 1.2 1.22 0.3 Grind size (µm)
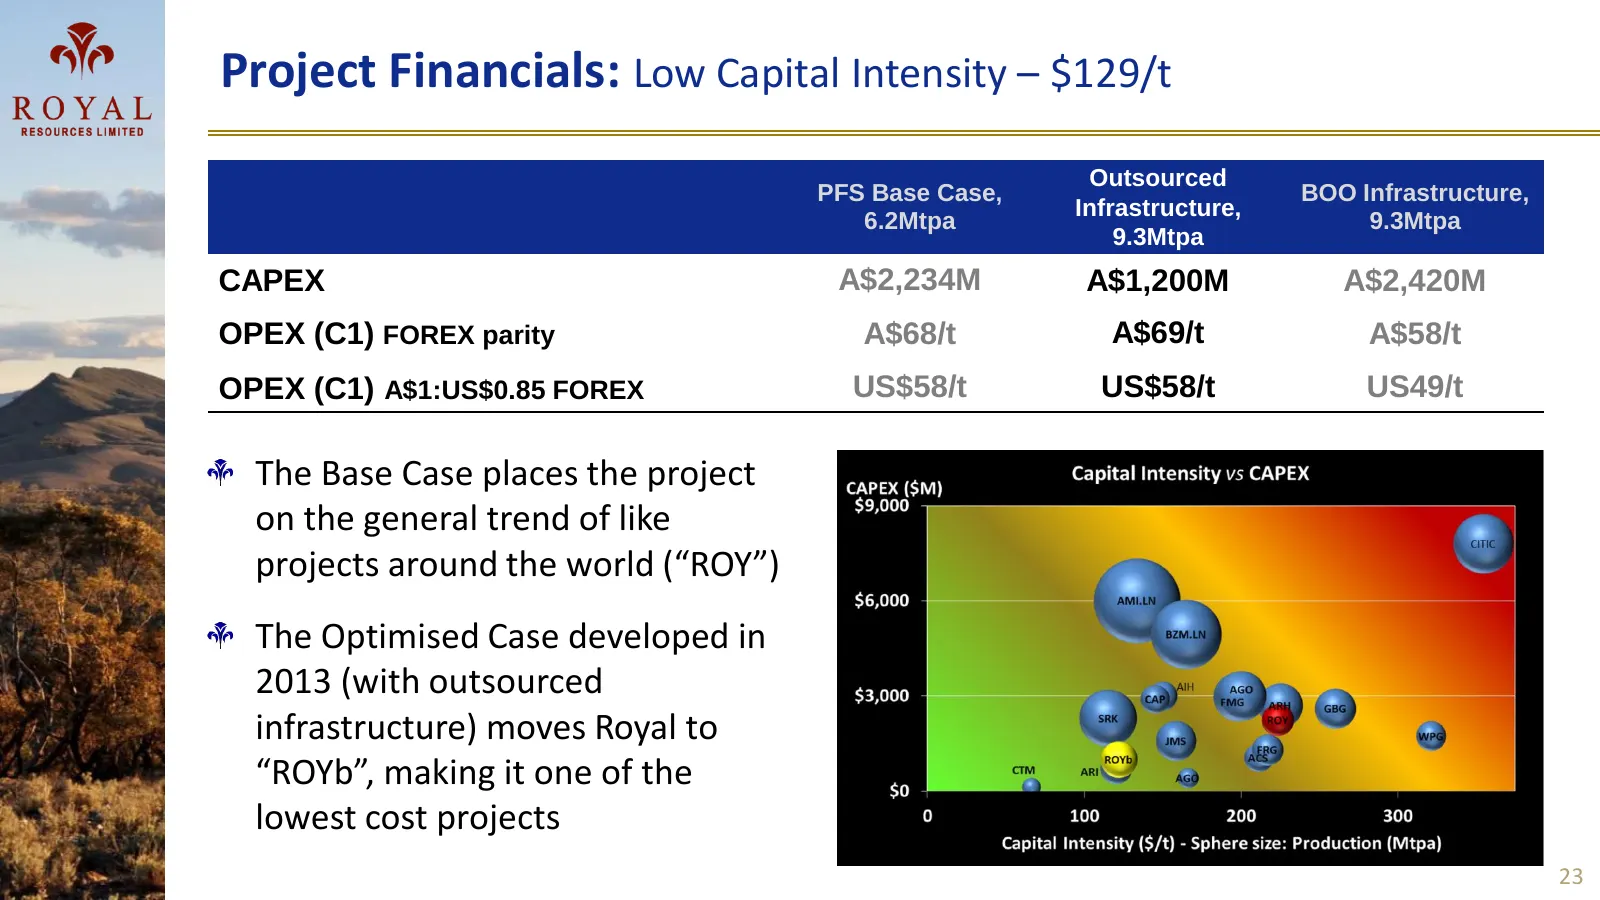
Slide 23: Project Financials: Low Capital Intensity – $129/t
Project Financials: Low Capital Intensity – $129/t Outsourced PFS Base Case, BOO Infrastructure, Infrastructure, 6.2Mtpa 9.3Mtpa 9.3Mtpa CAPEX A$2,234M A$1,200M A$2,420M OPEX (C1) FOREX parity A$68/t A$69/t A$58/t OPEX (C1) A$1:US$0.85 FOREX US$58/t US$58/t US49/t The Base Case places the project on
Slide 24: Royal Resources
Royal Resources Investment Case Corporate Overview The Razorback Project Project Financials Summary 24
Slide 25: Summary: Investment Credentials
Summary: Investment Credentials Razorback has one of the lowest capital intensive magnetite projects in Australia An impressive NVP of $2.7 Billion and IRR of 39% MoU with major shareholder Gordon Toll’s Braemar Infrastructure to provide all transport and infrastructure, heavily reducing the CAPEX R
Slide 26: Appendix: Board and Management
Appendix: Board and Management Philip Crabb: Mr Crabb is a fellow of the Australasian Institute of Mining and Metallurgy and a member of the Institute of Executive Chairman Executive Chairman Company Directors. Mr Crabb has been actively engaged in mineral exploration and mining activities for the p
Slide 27: Appendix: Board and Management
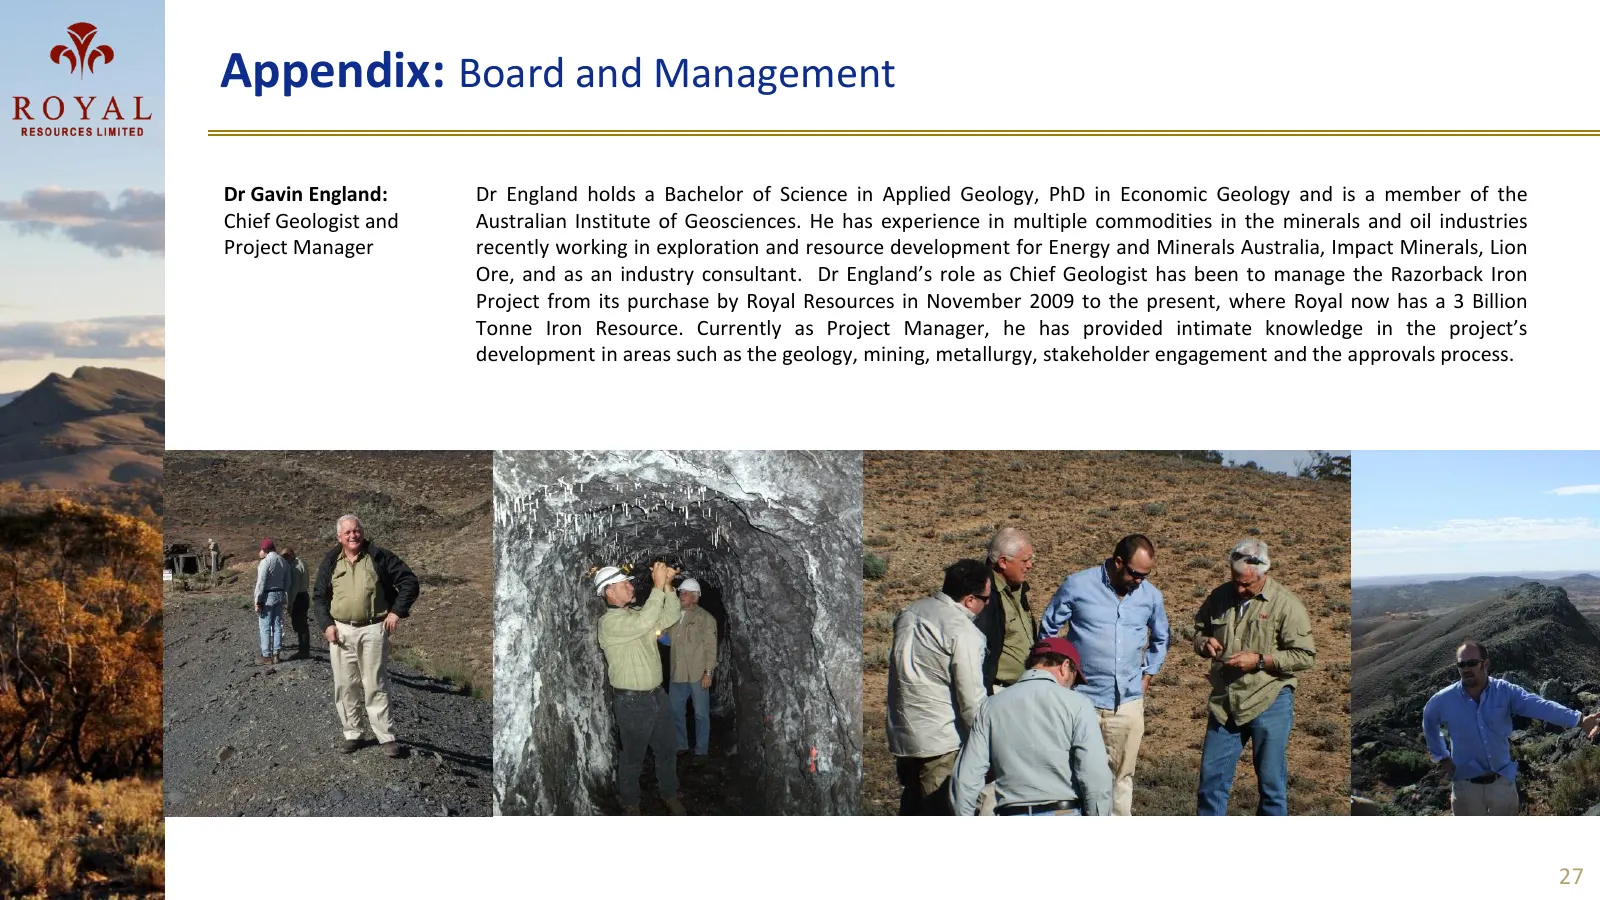
Appendix: Board and Management Dr Gavin England: Dr England holds a Bachelor of Science in Applied Geology, PhD in Economic Geology and is a member of the Chief Geologist and Australian Institute of Geosciences. He has experience in multiple commodities in the minerals and oil industries Project Man
Slide 28: Appendix: A Supply Constraint, Not Oversupply, more likely
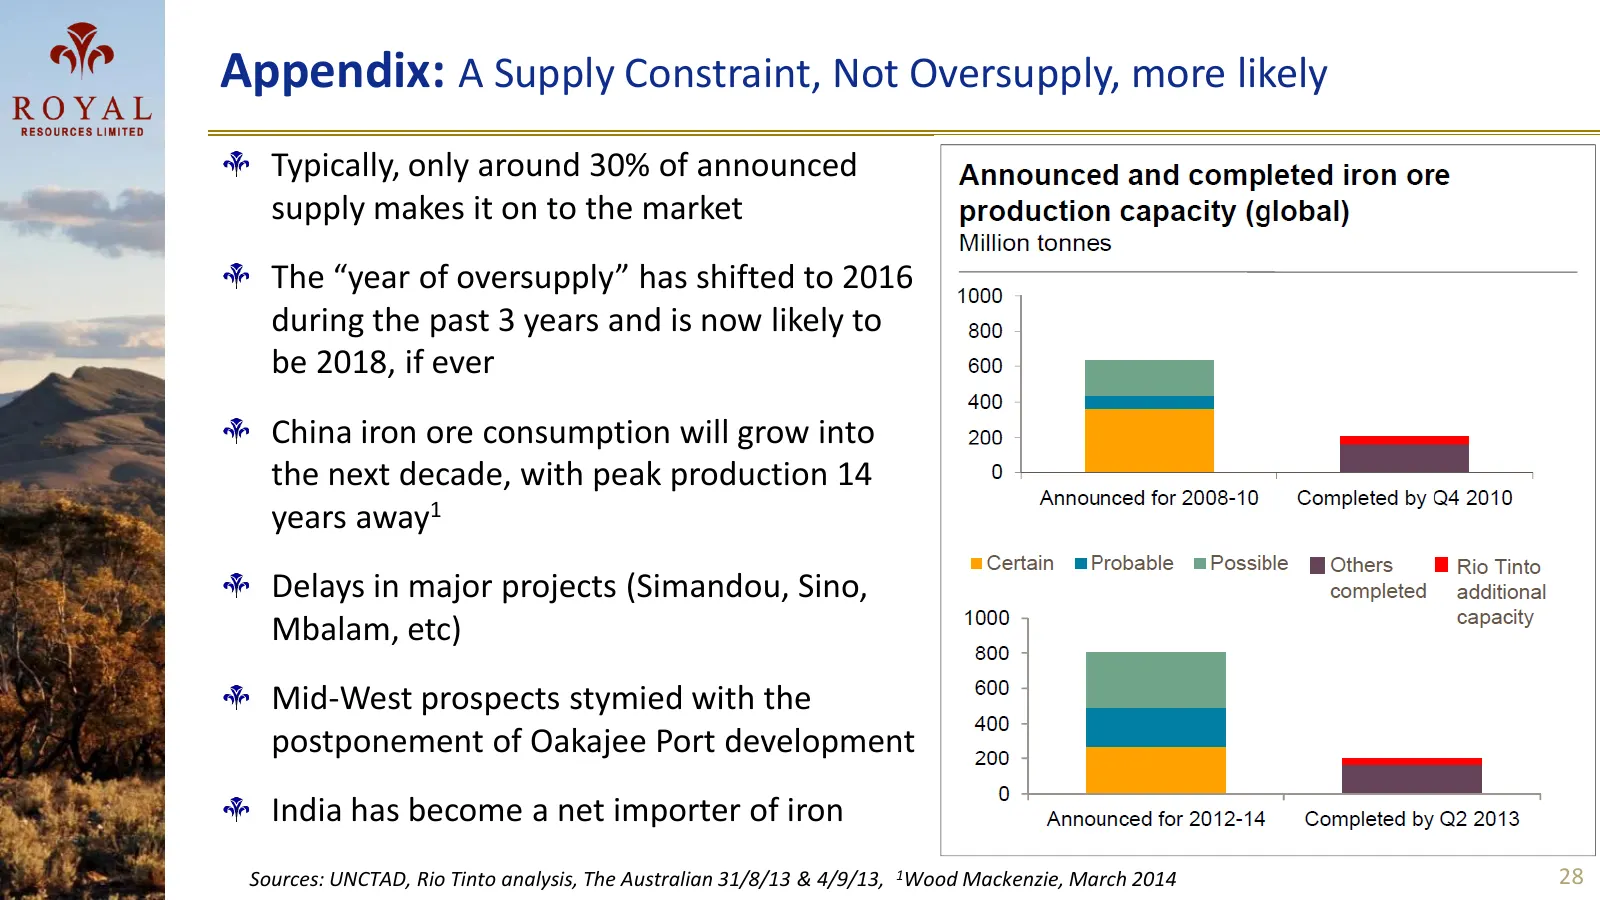
Appendix: A Supply Constraint, Not Oversupply, more likely Typically, only around 30% of announced supply makes it on to the market The “year of oversupply” has shifted to 2016 during the past 3 years and is now likely to be 2018, if ever China iron ore consumption will grow into the next decade, wi
Slide 29: Appendix: A Price Above US$110/t for the Longer Term?
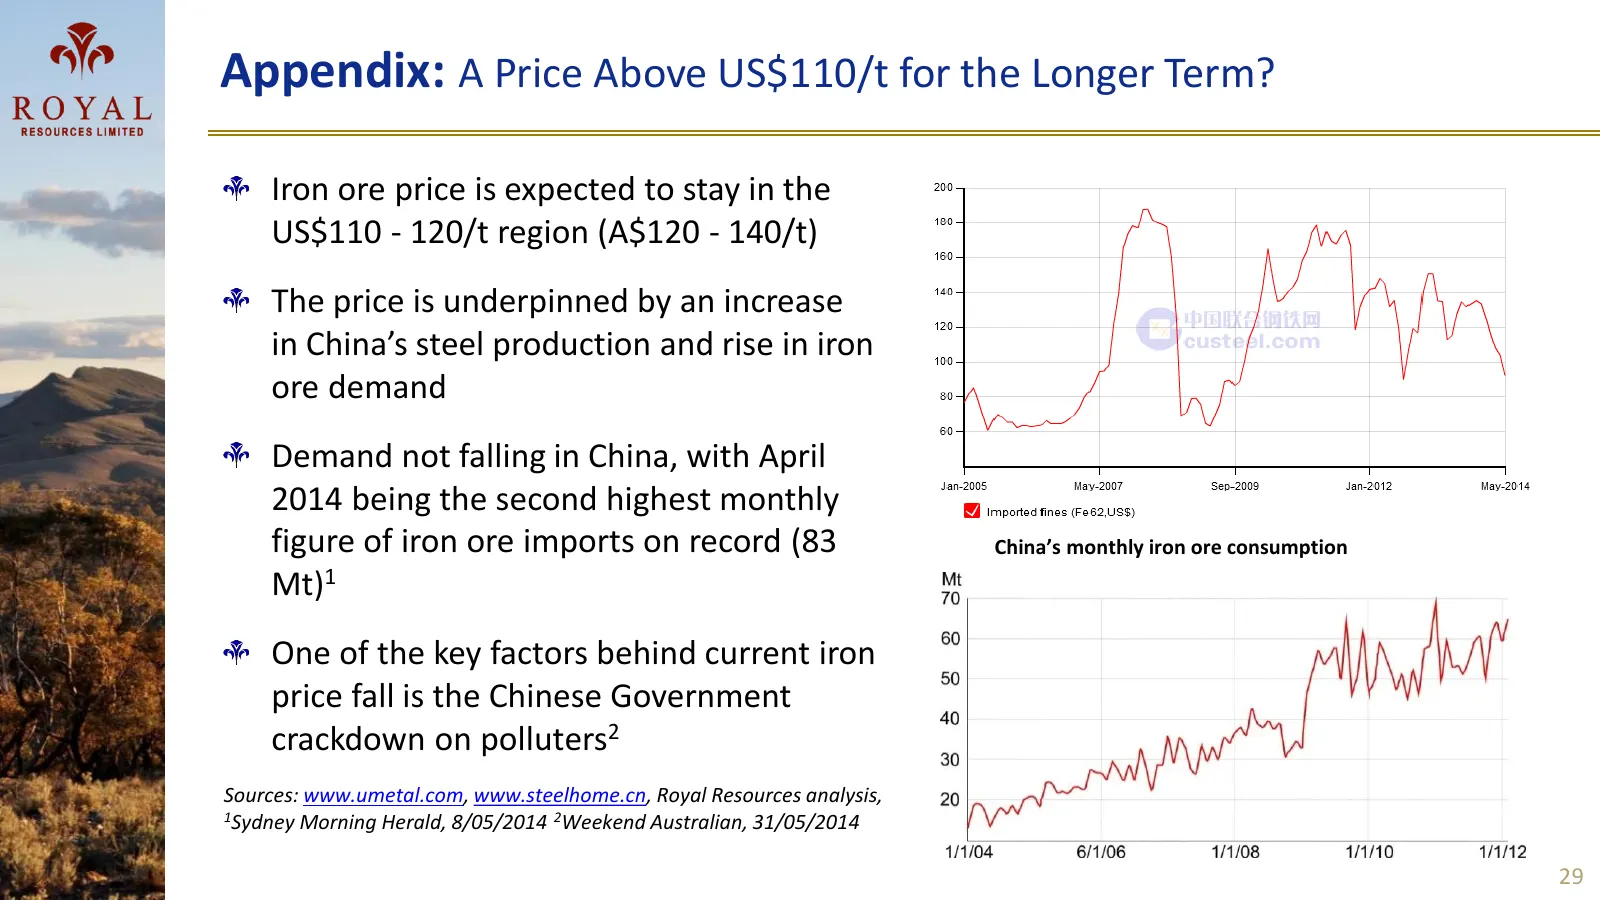
Appendix: A Price Above US$110/t for the Longer Term? Iron ore price is expected to stay in the US$110 - 120/t region (A$120 - 140/t) The price is underpinned by an increase in China’s steel production and rise in iron ore demand Demand not falling in China, with April 2014 being the second highest
Slide 30: Appendix: A Premium Product attracting a Premium price
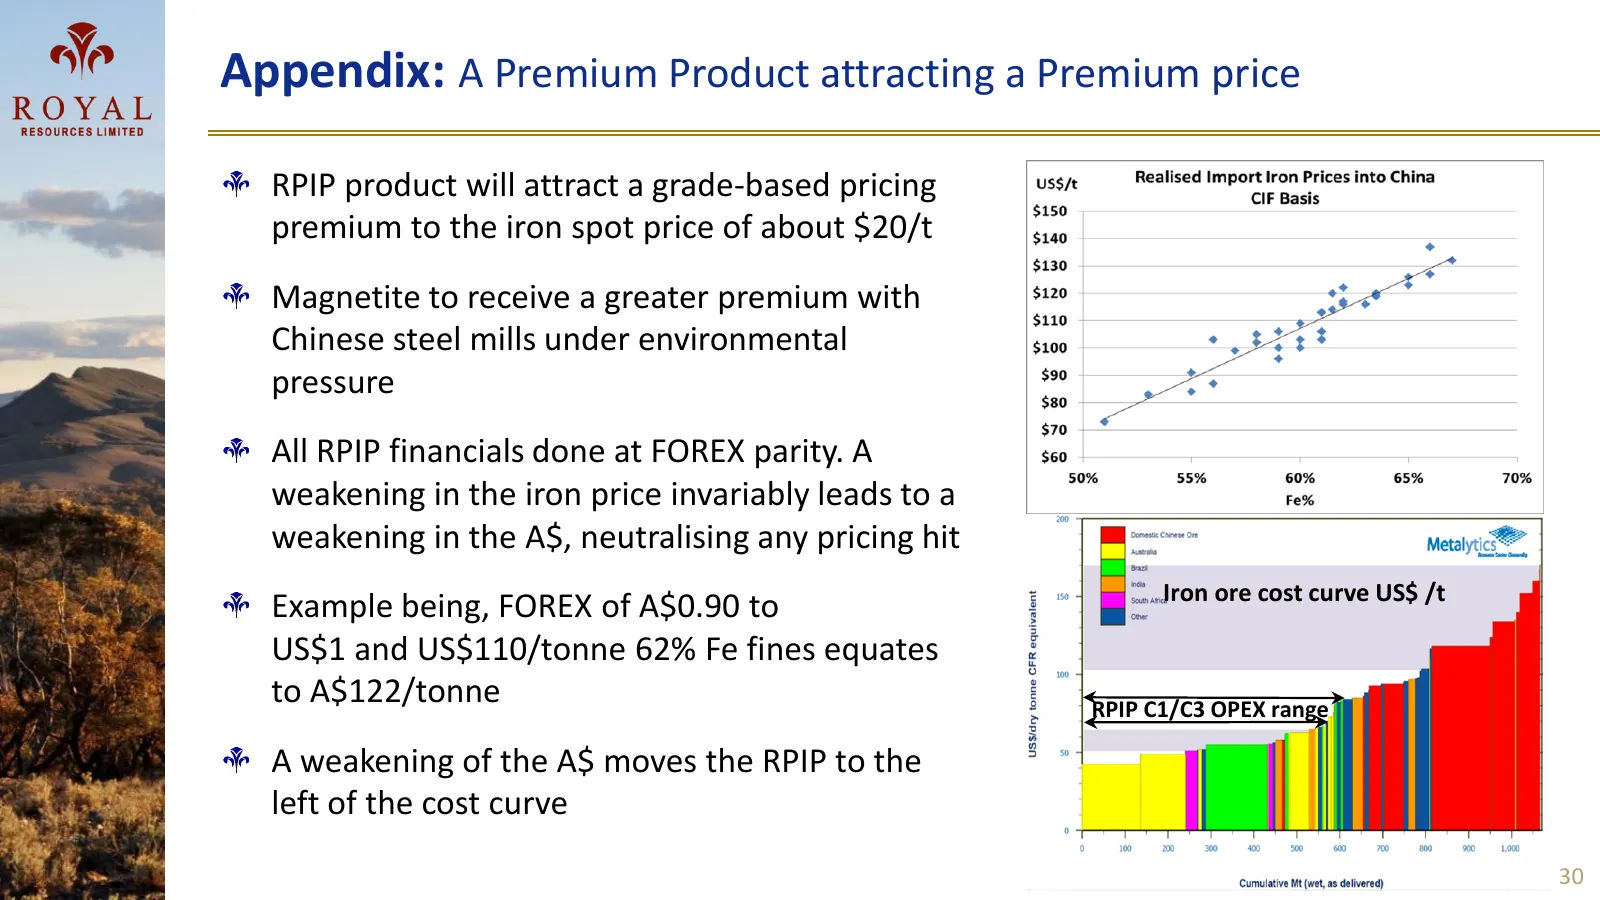
Appendix: A Premium Product attracting a Premium price RPIP product will attract a grade-based pricing premium to the iron spot price of about $20/t Magnetite to receive a greater premium with Chinese steel mills under environmental pressure All RPIP financials done at FOREX parity. A weakening in t
Source: Internet Archive copy of magnetitemines.com
More decks from Magnetite Mines Ltd.
 Investor Presentation (September 2026)41 slides · September 2026
 Investor Presentation (March 2026)22 slides · Mar 10, 2026
 Shareholder Meeting (November 2025)18 slides · Nov 26, 2025
 Investor Presentation (August 2025)22 slides · Aug 8, 2025
 TACTIC Conference 202516 slides · Jul 30, 2025
 The Australian Green Iron & Steel Forum 202519 slides · Mar 26, 2025